 filings.tools
Cover and table of contents
131K characters. Original on sec.gov · Markdown
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
| ☑ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the fiscal year ended December 31, 2019
OR
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the transition period from _____ to _____
Commission File Number: 001-34991
TARGA RESOURCES CORP.
(Exact name of registrant as specified in its charter)
| Delaware | 20-3701075 | |
|---|---|---|
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) | |
| 811 Louisiana Street, Suite 2100, Houston, Texas | 77002 | |
| (Address of principal executive offices) | (Zip Code) |
(713) 584-1000
(Registrant’s telephone number, including area code)
Securities registered pursuant to section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||
|---|---|---|---|---|
| Common Stock | TRGP | New York Stock Exchange |
Securities registered pursuant to section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☑ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐ No ☑
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☑ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☑ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | ☑ | Accelerated filer | ☐ | |
| Non-accelerated filer | ☐ | Smaller reporting company | ☐ | |
| Emerging growth company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes ☐ No ☑
The aggregate market value of the common stock held by non-affiliates of the registrant was approximately $8,974.0 million on June 28, 2019, based on $39.26 per share, the closing price of the common stock as reported on the New York Stock Exchange (NYSE) on such date.
As of February 17, 2020, there were 233,046,042 shares of the registrant’s common stock, $0.001 par value, outstanding.
DOCUMENTS INCORPORATED BY REFERENCE
None
TABLE OF CONTENTS
CAUTIONARY STATEMENT ABOUT FORWARD-LOOKING STATEMENTS
Targa Resources Corp.’s (together with its subsidiaries, including Targa Resources Partners LP (the “Partnership” or “TRP”), “we,” “us,” “our,” “Targa,” “TRC,” or the “Company”) reports, filings and other public announcements may from time to time contain statements that do not directly or exclusively relate to historical facts. Such statements are “forward-looking statements.” You can typically identify forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, by the use of forward-looking statements, such as “may,” “could,” “project,” “believe,” “anticipate,” “expect,” “estimate,” “potential,” “plan,” “forecast” and other similar words.
All statements that are not statements of historical facts, including statements regarding our future financial position, business strategy, budgets, projected costs and plans and objectives of management for future operations, are forward-looking statements.
These forward-looking statements reflect our intentions, plans, expectations, assumptions and beliefs about future events and are subject to risks, uncertainties and other factors, many of which are outside our control. Important factors that could cause actual results to differ materially from the expectations expressed or implied in the forward-looking statements include known and unknown risks. Known risks and uncertainties include, but are not limited to, the following risks and uncertainties:
| • | the level and success of crude oil and natural gas drilling around our assets, our success in connecting natural gas supplies to our gathering and processing systems, oil supplies to our gathering systems and natural gas liquid supplies to our logistics and transportation facilities and our success in connecting our facilities to transportation services and markets; |
|---|
| • | the timing and extent of changes in natural gas, natural gas liquids, crude oil and other commodity prices, interest rates and demand for our services; |
|---|
| • | our ability to access the capital markets, which will depend on general market conditions, the credit ratings for the Partnership’s and our debt obligations, and demand for our common equity and the Partnership’s senior notes; |
|---|
| • | the amount of collateral required to be posted from time to time in our transactions; |
|---|
| • | our success in risk management activities, including the use of derivative instruments to hedge commodity price risks; |
|---|
| • | the level of creditworthiness of counterparties to various transactions with us; |
|---|
| • | changes in laws and regulations, particularly with regard to taxes, safety and protection of the environment; |
|---|
| • | weather and other natural phenomena; |
|---|
| • | industry changes, including the impact of consolidations and changes in competition; |
|---|
| • | our ability to timely obtain and maintain necessary licenses, permits and other approvals; |
|---|
| • | our ability to grow through internal growth projects or acquisitions and the successful integration and future performance of such assets; |
|---|
| • | general economic, market and business conditions; and |
|---|
| • | the risks described elsewhere in “Item 1A. Risk Factors” in this Annual Report and our reports and registration statements filed from time to time with the United States Securities and Exchange Commission (“SEC”). |
|---|
Although we believe that the assumptions underlying our forward-looking statements are reasonable, any of the assumptions could be inaccurate, and, therefore, we cannot assure you that the forward-looking statements included in this Annual Report will prove to be accurate. Some of these and other risks and uncertainties that could cause actual results to differ materially from such forward-looking statements are more fully described in “Item 1A. Risk Factors” in this Annual Report. Except as may be required by applicable law, we undertake no obligation to publicly update or advise of any change in any forward-looking statement, whether as a result of new information, future events or otherwise.
As generally used in the energy industry and in this Annual Report, the identified terms have the following meanings:
| Bbl | Barrels (equal to 42 U.S. gallons) | |
|---|---|---|
| BBtu | Billion British thermal units | |
| Bcf | Billion cubic feet | |
| Btu | British thermal units, a measure of heating value | |
| /d | Per day | |
| GAAP | Accounting principles generally accepted in the United States of America | |
| gal | U.S. gallons | |
| LIBOR | London Interbank Offered Rate | |
| LPG | Liquefied petroleum gas | |
| MBbl | Thousand barrels | |
| MMBbl | Million barrels | |
| MMBtu | Million British thermal units | |
| MMcf | Million cubic feet | |
| MMgal | Million U.S. gallons | |
| NGL(s) | Natural gas liquid(s) | |
| NYMEX | New York Mercantile Exchange | |
| NYSE | New York Stock Exchange | |
| SCOOP | South Central Oklahoma Oil Province | |
| STACK | Sooner Trend, Anadarko, Canadian and Kingfisher | |
| VLGC | Very large gas carrier |
PART I
Item 1. Business.
Overview
Targa Resources Corp. (NYSE: TRGP) is a publicly traded Delaware corporation formed in October 2005. Targa is a leading provider of midstream services and is one of the largest independent midstream energy companies in North America. We own, operate, acquire, and develop a diversified portfolio of complementary domestic midstream energy assets.
The following should be read in conjunction with our audited consolidated financial statements and the notes thereto. We have prepared our accompanying consolidated financial statements under GAAP and the rules and regulations of the SEC. Our accounting records are maintained in U.S. dollars and all references to dollars in this report are to U.S. dollars, except where stated otherwise. Our consolidated financial statements include our accounts and those of our majority-owned and/or controlled subsidiaries, and all significant intercompany items have been eliminated in consolidation. The address of our principal executive offices is 811 Louisiana Street, Suite 2100, Houston, Texas 77002, and our telephone number at this address is (713) 584-1000.
Our Operations
We are engaged primarily in the business of:
| • | gathering, compressing, treating, processing, transporting and selling natural gas; |
|---|
| • | transporting, storing, fractionating, treating, and selling NGLs and NGL products, including services to LPG exporters; and |
|---|
| • | gathering, storing, terminaling and selling crude oil. |
|---|
To provide these services, we operate in two primary segments: (i) Gathering and Processing, and (ii) Logistics and Transportation (also referred to as the Downstream Business).
In the fourth quarter of 2019, we made the following changes to the presentation of our reportable segments:
| • | Renamed the Logistics and Marketing segment as “Logistics and Transportation.” The updated name better describes the business composition and activity of the segment given the recent completion of our common carrier Grand Prix Pipeline (“Grand Prix”) that transports NGLs to our fractionation assets in Mont Belvieu. The change in naming convention did not impact previously reported results for the segment. This segment is also referred to as the Downstream Business. |
|---|
| • | Due to changes in how our executive team evaluates segment performance, results of commodity derivative activities related to our equity volume hedges that are designated as accounting hedges are now reported in the Gathering and Processing segment. These hedge activities were previously reported in Other. Our prior period segment information has been updated to reflect the change. There was no impact to our Consolidated Statements of Operations. |
|---|
Our Gathering and Processing segment includes assets used in the gathering of natural gas produced from oil and gas wells and processing this raw natural gas into merchantable natural gas by extracting NGLs and removing impurities; and assets used for crude oil gathering and terminaling. The Gathering and Processing segment's assets are located in the Permian Basin of West Texas and Southeast New Mexico (including the Midland, Central and Delaware Basins); the Eagle Ford Shale in South Texas; the Barnett Shale in North Texas; the Anadarko, Ardmore, and Arkoma Basins in Oklahoma (including the SCOOP and STACK) and South Central Kansas; the Williston Basin in North Dakota (including the Bakken and Three Forks plays); and the onshore and near offshore regions of the Louisiana Gulf Coast and the Gulf of Mexico.
Our Logistics and Transportation segment includes the activities and assets necessary to convert mixed NGLs into NGL products and also includes other assets and value-added services such as transporting, storing, fractionating, terminaling, and marketing of NGLs and NGL products, including services to LPG exporters and certain natural gas supply and marketing activities in support of our other businesses. The Logistics and Transportation segment also includes Grand Prix, as well as our equity interest in Gulf Coast Express Pipeline LLC (“GCX”), a natural gas pipeline transporting volumes from West Texas to the Gulf Coast. Grand Prix integrates our gathering and processing positions in the Permian Basin, Southern Oklahoma and North Texas with our downstream facilities in Mont Belvieu, Texas. The associated assets, including these pipelines, are generally connected to and supplied in part by our Gathering and Processing segment and, except for the pipelines and smaller terminals, are located predominantly in Mont Belvieu and Galena Park, Texas, and in Lake Charles, Louisiana.
Acquisitions and Organic Growth Projects
Since 2010, the year of our initial public offering, we have expanded our midstream services footprint substantially. The expansion of our business has been fueled by a combination of third-party acquisitions and major organic growth investments in our businesses. Third-party acquisitions included our 2012 acquisition of Saddle Butte Pipeline LLC’s crude oil pipeline and terminal system and natural gas gathering and processing operations in North Dakota (referred to by us as “Badlands”), our 2015 acquisition of Atlas Pipeline Partners L.P. (“APL,” renamed by us as Targa Pipeline Partners LP or “TPL”), and our 2017 acquisition of gas gathering and processing and crude oil gathering assets in the Permian Basin (referred to by us as the “Permian Acquisition”). As a result of these transactions, we acquired natural gas gathering, processing and treating assets in West Texas, South Texas, North Texas, Oklahoma and North Dakota, as well as crude oil gathering and terminal assets in North Dakota and West Texas.
We also continue to invest capital in our businesses to enhance our competitive advantage as an integrated midstream services provider. We have invested approximately $8.4 billion in growth capital expenditures since 2015, including approximately $2.6 billion in 2019 (approximately $2.3 billion of net growth capital). These expansion investments are distributed across our businesses, with 52% to Gathering and Processing and 48% related to Logistics and Transportation. We expect to continue to invest in both large and small organic growth projects in 2020 and currently estimate that we will invest approximately $1.2 to $1.3 billion in net organic growth capital expenditures in 2020.
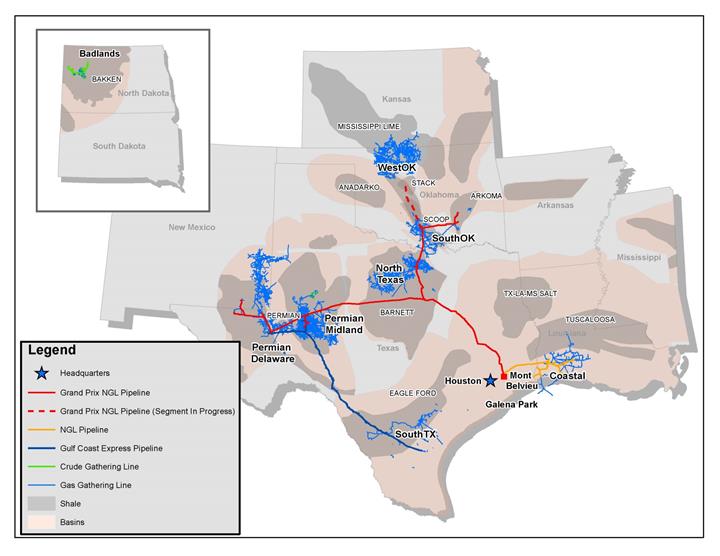
The map below highlights our more significant assets:
Recent Developments
Gathering and Processing Segment Expansion
Permian Midland Processing Expansions
In response to increasing production and to meet the infrastructure needs of producers, we have recently completed construction of or are constructing three new 250 MMcf/d cryogenic natural gas processing plants in the Midland Basin. The first plant, the Hopson Plant, began operations in the second quarter of 2019. The second plant, the Pembrook Plant, began operations in the third quarter of 2019. In August 2019, we announced the Gateway Plant, which is expected to begin operations in the fourth quarter of 2020.
Permian Delaware Processing Expansions
In March 2018, we announced that we entered into long-term fee-based agreements with an investment grade energy company for natural gas gathering and processing services in the Delaware Basin and for downstream transportation, fractionation and other related services. The agreements are underpinned by the customer's dedication of significant acreage within a large, well-defined area in the Delaware Basin. We constructed approximately 220 miles of 12- to 24-inch high-pressure rich gas gathering pipelines across the Delaware Basin that are operational. We have recently completed construction of or are currently constructing two new 250 MMcf/d cryogenic natural gas processing plants in the Delaware Basin. The first plant, the Falcon Plant, began operations late in the third quarter of 2019. The second plant, the Peregrine Plant, is expected to begin operations in the second quarter of 2020. We will provide NGL transportation services on Grand Prix and fractionation services at our Mont Belvieu complex for a majority of the NGLs from the Falcon and Peregrine Plants.
Badlands
In January 2018, we announced the formation of a 50/50 joint venture with Hess Midstream Partners LP under which Targa would construct and operate a new 200 MMcf/d natural gas processing plant (“LM4 Plant”) at Targa’s existing Little Missouri facility. The LM4 Plant began operations in the third quarter of 2019.
Logistics and Transportation Segment Expansion
Grand Prix NGL Pipeline
In the third quarter of 2019, we began full service into Mont Belvieu on Grand Prix, our new common carrier NGL pipeline that transports NGLs from the Permian Basin, North Texas, and Southern Oklahoma to our fractionation and storage complex in the NGL market hub at Mont Belvieu, Texas. The pipeline is comprised of three primary segments:
| • | Permian Basin Segment – Connects our Gathering and Processing positions (as well as third-party positions) throughout the Delaware and Midland Basins to North Texas. The capacity of the 24-inch diameter pipeline segment from the Permian Basin is approximately 300 MBbl/d, expandable to 550 MBbl/d. |
|---|
| • | Southern Oklahoma Extension – Connects our SouthOK and North Texas Gathering and Processing positions (as well as third-party positions) to our North Texas to Mont Belvieu Segment. The extension varies in capacity based on telescoping pipe size. |
|---|
| • | North Texas to Mont Belvieu Segment – The Permian Basin Segment and Southern Oklahoma Extension connect to a 30-inch diameter pipeline segment in North Texas, which connects Permian, North Texas and Oklahoma volumes to Mont Belvieu. The North Texas to Mont Belvieu Segment has a capacity of approximately 450 MBbl/d, expandable to 950 MBbl/d. |
|---|
In February 2019, we announced an additional extension:
| • | Central Oklahoma Extension – Extends from Southern Oklahoma to the STACK region of Central Oklahoma where it will connect with The Williams Companies, Inc. (“Williams”) Bluestem Pipeline, linking the Conway, Kansas, and Mont Belvieu, Texas, NGL markets. In connection with this project, Williams has committed significant volumes to us that we will transport on Grand Prix and fractionate at our Mont Belvieu facilities. The Central Oklahoma Extension is expected to be completed in the first quarter of 2021. |
|---|
Grand Prix Pipeline LLC (“Grand Prix Joint Venture”), a consolidated subsidiary of which Targa owns a 56% interest, owns the portion of Grand Prix extending from the Permian Basin to Mont Belvieu, Texas. Volumes flowing on the pipeline from the Permian Basin to Mont Belvieu, Texas, accrue to the Grand Prix Joint Venture, while the volumes flowing from North Texas and Oklahoma to Mont Belvieu accrue solely to Targa’s benefit.
Fractionation Expansion
In February 2018, we announced plans to construct a new 100 MBbl/d fractionation train (“Train 6”) in Mont Belvieu, Texas, which began operations in the second quarter of 2019. Targa Train 6 LLC (“Train 6 JV”), a joint venture between Targa and Stonepeak Infrastructure Partners (“Stonepeak”), owns a 100% interest in the fractionation train. Certain fractionation-related infrastructure for Train 6, such as storage caverns and brine handling, were funded and are owned 100% by Targa.
In November 2018, we announced plans to construct two new 110 MBbl/d fractionation trains in Mont Belvieu, Texas (“Train 7 and Train 8”), which are expected to begin operations by the end of the first quarter of 2020 and the end of the third quarter of 2020, respectively. In January 2019, Williams committed to Targa significant volumes which Targa will transport on Grand Prix and fractionate at Targa’s Mont Belvieu facilities (including Train 7). Williams was also granted an option to purchase a 20% equity interest in the fractionation train, which was originally wholly owned by Targa. Williams exercised its initial option and executed a joint venture agreement with us in the second quarter of 2019. Certain fractionation-related infrastructure for Train 7, such as storage caverns and brine handling, will be funded and owned 100% by Targa.
LPG Export Expansion
In February 2019, we announced plans to further expand our LPG export capabilities of propane and butanes at our Galena Park Marine Terminal by increasing refrigeration capacity and associated load rates. With the additional infrastructure, our effective export capacity will increase to up to 15 MMBbl per month, depending upon the mix of propane and butane demand, vessel size and availability of supply, among other factors. The expansion is expected to be fully completed in the third quarter of 2020.
Gulf Coast Express Pipeline
In December 2017, we entered into definitive joint venture agreements to form GCX with Kinder Morgan Texas Pipeline LLC (“KMTP”) and DCP Midstream Partners, LP (“DCP”) for the purpose of developing the Gulf Coast Express Pipeline (“GCX Pipeline”), a natural gas pipeline from the Waha hub, including direct connections to the tailgate of many of our Midland Basin processing facilities, to Agua Dulce in South Texas. The pipeline provides an outlet for increased natural gas production from the Permian Basin to growing markets along the Texas Gulf Coast. Targa GCX Pipeline LLC (“GCX DevCo JV”), a joint venture between us and Stonepeak, and DCP each own a 25% interest, KMTP owns a 34% interest, and Altus Midstream Company owns the remaining 16% interest in GCX. KMTP serves as the operator of GCX Pipeline. We have committed significant volumes to GCX Pipeline. In addition, Pioneer Natural Resources Company, a joint owner in our WestTX Permian Basin assets, also committed volumes to GCX Pipeline. GCX Pipeline is designed to transport up to 1.98 Bcf/d of natural gas and commenced operations late in the third quarter of 2019.
Badlands Interest Sale
In April 2019, we closed on the sale of a 45% interest in Targa Badlands LLC (“Targa Badlands”), the entity that holds substantially all of the assets previously wholly owned by Targa in North Dakota, to funds managed by GSO Capital Partners and Blackstone Tactical Opportunities (collectively, “Blackstone”) for $1.6 billion in cash. We used the net cash proceeds to repay debt and for general corporate purposes, including funding our growth capital program. We continue to be the operator of Targa Badlands and hold majority governance rights. Future growth capital of Targa Badlands is expected to be funded on a pro rata ownership basis. Targa Badlands pays a minimum quarterly distribution (“MQD”) to Blackstone and Targa, with Blackstone having a priority right on such MQDs. Additionally, Blackstone’s capital contributions would have a liquidation preference upon a sale of Targa Badlands. Targa Badlands is a discrete entity and the assets and credit of Targa Badlands are not available to satisfy the debts and other obligations of Targa or its other subsidiaries.
Asset Sales
We continue to evaluate and execute asset sales to reduce leverage and focus on our core operations. During 2019, we closed on the sale of an equity-method investment for $73.8 million. In November 2019, we executed agreements to sell our crude gathering and storage business in the Permian Delaware for approximately $134 million. The sale closed early in the first quarter of 2020.
We have also engaged Jefferies LLC to evaluate the potential divestiture of our crude gathering business in the Permian Midland, which includes crude gathering and storage assets. The sale process is ongoing, and the potential divestiture is predicated on third party valuations adequately capturing our forward growth expectations for the assets. No assurance can be made that a sale will be consummated.
Financing Activities
In January 2019, the Partnership issued $750.0 million of 6½% Senior Notes due July 2027 and $750.0 million of 6⅞% Senior Notes due January 2029, resulting in total net proceeds of $1,486.6 million. The net proceeds from the issuance were used to redeem in full the Partnership’s 4⅛% Senior Notes due 2019, at par value plus accrued interest through the redemption date, with the remainder used for general partnership purposes, which included repayment of borrowings under the Partnership’s credit facilities.
Our universal shelf registration statement on Form S-3 filed in May 2016 expired in May 2019. Accordingly, in May 2019, we filed with the SEC a universal shelf registration statement on Form S-3 that registers the issuance and sale of certain debt and equity securities from time to time in one or more offerings (the “May 2019 Shelf”). The May 2019 Shelf will expire in May 2022.
In November 2019, the Partnership issued $1.0 billion aggregate principal amount of 5½% Senior Notes due March 2030, resulting in net proceeds of $990.8 million. The net proceeds from the issuance were used to repay borrowings under its credit facilities and for general partnership purposes.
On December 6, 2019, we amended the Partnership’s accounts receivable securitization facility (the “Securitization Facility”) to extend the facility through a termination date of December 4, 2020.
Corporation Tax Matters
The Internal Revenue Service (“IRS”) notified us on April 3, 2019, that it will examine Targa’s federal income tax returns (Form 1120) for 2014, 2015 and 2016. We are fully cooperating with the IRS in the audit process and do not anticipate material changes in prior year taxable income.
Organization Structure
The diagram below shows our corporate structure as of February 17, 2020:
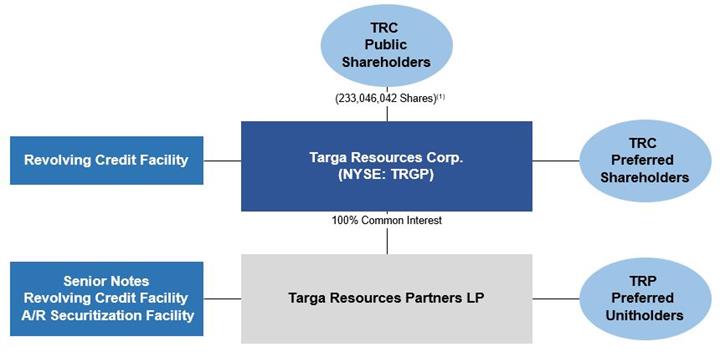
| (1) | Common shares outstanding as of February 17, 2020. |
|---|
Growth Drivers
We believe that our near-term growth will be driven by organic projects being placed into service, as well as the level of producer activity in the basins where our gathering and processing infrastructure is located and the level of demand for services provided by our logistics and transportation assets. We believe our assets are not easily replicated, are located in many attractive and active areas of exploration and production activity and are near key markets and logistics centers. Grand Prix integrates our gathering and processing positions in the Permian Basin, Southern Oklahoma and North Texas with our downstream facilities in Mont Belvieu, Texas and further increases our competitive capabilities to provide reliable, integrated midstream services to customers. Over the longer term, we expect our growth will continue to be driven by our integrated midstream service offering and the strong position of our quality assets which will benefit from production from shale plays and by the deployment of shale exploration and production technologies in both liquids-rich natural gas and crude oil resource plays that will also provide additional opportunities for our Downstream Business. We expect that organic growth and third-party acquisitions will continue to be a part of our growth strategy.
Attractive Asset Positions
We believe that our positioning in some of the most attractive basins will allow us to capture increased natural gas supplies for gathering and processing, increased NGLs for transportation and fractionation and increased crude oil supplies for gathering and terminaling. Producers continue to focus drilling activity on their most attractive acreage, especially in the Permian Basin where we have a large and well positioned interconnected footprint and are benefiting from rig activity in and around our systems.
The development of shale and unconventional resource plays has resulted in increasing NGL supplies that continue to generate demand for our transportation services on Grand Prix, fractionation services at the Mont Belvieu market hub and for LPG export services at our Galena Park Marine Terminal on the Houston Ship Channel. Since 2010, in response to increasing demand, we added 378 MBbl/d of additional fractionation capacity with the additions of Cedar Bayou Fractionator (“CBF”) Trains 3, 4, and 5, and Train 6, and have additional capacity of 220 MBbl/d under construction. We believe that the higher volumes of fractionated NGLs will also result in increased demand for other related fee-based services provided by our logistics and transportation assets. Continued demand for fractionation capacity is expected to lead to other future growth opportunities.
As domestic producers have focused their drilling in crude oil and liquids-rich areas, new gas processing facilities are being built to accommodate liquids-rich gas, which contributes to the increasing supply of NGLs produced domestically. As drilling in these areas continues, the supply of NGLs requiring transportation and fractionation to market hubs is expected to continue to grow. As the supply of NGLs increases, our integrated Mont Belvieu and Galena Park Marine Terminal assets allow us to provide the raw product, fractionation, storage, interconnected terminaling, refrigeration and ship loading capabilities to support exports by third-party customers. Grand Prix transports volumes from the Permian Basin and our North Texas and southern Oklahoma systems to our fractionation and storage complex in the NGL market hub at Mont Belvieu further enhancing the integration of our gathering and processing assets with our logistics and transportation assets. Grand Prix positions us to offer an integrated midstream service across the NGL value chain to our customers by linking supply to key markets.
Drilling and production activity from liquids-rich natural gas shale plays and similar crude oil resource plays
We are actively pursuing natural gas gathering and processing and NGL transportation and fractionation opportunities associated with liquids-rich natural gas from shale and other resource plays and are also actively pursuing crude gathering and natural gas gathering and processing and NGL transportation and fractionation opportunities from active crude oil resource plays. We believe that our leadership position in the Downstream Business, which includes our transportation, fractionation and export services, provides us with a competitive advantage relative to other midstream companies without these capabilities.
Organic growth and third-party acquisitions
We have a demonstrated track record of completing organic growth and third-party acquisitions. Since 2015, we have executed on approximately $8.4 billion of growth capital projects and approximately $6.0 billion in third-party acquisitions. We expect to continue to grow both organically and through third-party acquisitions.
Competitive Strengths and Strategies
We believe that we are well positioned to execute our business strategies due to the following competitive strengths:
Strategically located gathering and processing asset base
Our gathering and processing businesses are strategically located in attractive oil and gas producing basins and are well positioned within each of those basins. Activity in the shale resource plays underlying our gathering assets is driven by the economics of oil, condensate, gas and NGL production from the particular reservoirs in each play. Activity levels for most of our gathering and processing assets are driven by commodity prices, primarily crude oil prices. If drilling and production activities in these areas continue, the volumes of natural gas and crude oil available to our gathering and processing systems will likely increase.
Leading fractionation, LPG export and NGL infrastructure position
We are one of the largest fractionators of NGLs in the Gulf Coast. Our fractionation assets are primarily located in Mont Belvieu, Texas, and to a lesser extent Lake Charles, Louisiana, which are key market centers for NGLs. Our logistics operations at Mont Belvieu, the major U.S. hub of NGL infrastructure, include connections to a number of mixed NGL (“mixed NGLs” or “Y-grade”) supply pipelines, storage, interconnection and takeaway pipelines and other transportation infrastructure. Our logistics assets, including fractionation facilities, storage wells, low ethane propane de-ethanizer, and our Galena Park Marine Terminal and related pipeline systems and interconnects, are also located near and connected to key consumers of NGL products including the petrochemical and industrial markets. Grand Prix is one of the Y-grade supply pipelines that connects the very active Permian Basin to Mont Belvieu. The location and interconnectivity of these assets are not easily replicated, and we have additional capability to expand their capacity. We have extensive experience in operating these assets and developing, permitting and constructing new midstream assets.
Comprehensive package of midstream services
We provide a comprehensive package of services to natural gas and crude oil producers. These services are essential to gather, process, treat and transport wellhead gas to meet pipeline standards; extract, transport and fractionate NGLs for sale into petrochemical, industrial, commercial and export markets; and gather crude. We believe that our ability to offer these integrated services provides us with an advantage in competing for new supplies because we can provide substantially all of the services that producers, marketers and others require for moving natural gas, NGLs and crude oil from wellhead to market on a cost-effective basis. Both Grand Prix and the GCX Pipeline further enhance our position to offer an integrated midstream service across the NGL and natural gas value chain by linking supply to key markets. Additionally, we believe that the significant investment we have made to construct and acquire assets in key strategic positions and the expertise we have in operating such assets make us well-positioned to remain a leading provider of comprehensive services in the midstream sector.
High quality and efficient assets
Our gathering and processing systems and logistics and transportation assets consist of high-quality, well-maintained facilities, resulting in low-cost, efficient operations. Advanced technologies have been implemented for processing plants (primarily cryogenic units utilizing centralized control systems), measurement systems (essentially all electronic and electronically linked to a central data-base) and operations and maintenance management systems to manage work orders and implement preventative maintenance schedules (computerized maintenance management systems). These applications have allowed proactive management of our operations resulting in lower costs and minimal downtime. We have established a reputation in the midstream industry as a reliable and cost-effective supplier of services to our customers and have a track record of safe, efficient, and reliable operation of our facilities. We will continue to pursue new contracts, cost efficiencies and operating improvements of our assets. Such improvements in the past have included new production and acreage commitments, reducing fuel gas and flare volumes and improving facility capacity and NGL recoveries. We will also continue to optimize existing plant assets to improve and maximize capacity and throughput.
In addition to routine annual maintenance expenses, our maintenance capital expenditures have averaged approximately $126 million per year over the last three years. We believe that our assets are well-maintained and we are focused on continuing to operate our existing assets, and operating our new assets, in a prudent, safe and cost-effective manner.
Large, diverse business mix with favorable contracts and increasing fee-based business
We maintain gas gathering and processing positions in strategic oil and gas producing areas across multiple basins and provide these and other services under attractive contract terms to a diverse mix of producers across our areas of operation. Consequently, we are not dependent on any one oil and gas basin or counterparty. Our Logistics and Transportation assets are typically located near key market hubs and near most of our NGL customers. They also serve must-run portions of the natural gas and natural gas liquids value chain, are primarily fee-based and have a diverse mix of customers.
Our contract portfolio has attractive rate and term characteristics including a significant fee-based component, especially in our Downstream Business. Our expected continued growth of the fee-based Downstream Business may result in increasing fee-based cash flow. The Permian Acquisition resulted in increased fee-based cash flow as the entities acquired have primarily fee-based gathering and processing contracts. Additionally, the long-term agreements with the investment grade energy company in the Delaware Basin for natural gas gathering and processing services and logistics and transportation services is fee-based. We also have an initiative underway to reduce our commodity price exposure across our gathering and processing business by amending contracts or entering into new contracts with primarily fee-based components and/or protections.
Financial flexibility
We have historically maintained sufficient liquidity and have funded our growth investments with a mix of equity, debt, asset sales and joint ventures over time in order to manage our leverage ratio. Disciplined management of liquidity, leverage and commodity price volatility allow us to be flexible in our long-term growth strategy and enable us to pursue strategic acquisitions and large growth projects.
Experienced and long-term focused management team
Our current executive management team possesses breadth and depth of experience working in the midstream energy business. Many members of our executive management team have been with us since the company was formed in 2005, managed many of our businesses prior to acquisition by Targa, or joined shortly thereafter. Other officers and key employees have significant experience in the industry and with our assets and businesses.
Attractive cash flow characteristics
We believe that our strategy, combined with our high-quality asset portfolio, allows us to generate attractive cash flows. Geographic, business and customer diversity enhances our cash flow profile. Our Gathering and Processing segment contract mix has increasing components of fee-based margin driven by: (i) fees added to percent-of-proceeds contracts for natural gas treating and compression, (ii) new/amended contracts with a combination of percent-of-proceeds and fee-based components, including fee floors, and (iii) essentially fully fee-based crude oil gathering and gas gathering and processing contracts. Contracts in our Coastal Gathering and Processing segment are primarily hybrid contracts (percent-of-liquids with a fee floor) or percent-of-liquids contracts (whereby we receive an agreed upon percentage of the actual proceeds of the NGLs). Contracts in the Downstream Business are predominately fee-based (based on volumes and contracted rates), with a large take-or-pay component. Our contract mix, along with our commodity hedging program, serves to mitigate the impact of commodity price movements on cash flow.
We have hedged the commodity price risk associated with a portion of our expected natural gas, NGL and condensate equity volumes, future commodity purchases and sales, and transportation basis risk by entering into financially settled derivative transactions. These transactions include swaps, futures, purchased puts (or floors) and costless collars. The primary purpose of our commodity risk management activities is to hedge our exposure to price risk and to mitigate the impact of fluctuations in commodity prices on cash flow. We have intentionally tailored our hedges to approximate specific NGL products and to approximate our actual NGL and residue natural gas delivery points. Although the degree of hedging will vary, we intend to continue to manage some of our exposure to commodity prices by entering into similar hedge transactions. We also monitor and manage our inventory levels with a view to mitigate losses related to downward price exposure.
Asset base well-positioned for organic growth
We believe that our asset platform and strategic locations allow us to maintain and potentially grow our volumes and related cash flows as our supply areas benefit from continued exploration and development over time. Technology advances have resulted in increased domestic oil and liquids-rich gas drilling and production activity. The location of our assets provides us with access to natural gas and crude oil supplies and proximity to end-user markets and liquid market hubs while positioning us to capitalize on drilling and production activity in those areas. We believe that as global supply and demand for natural gas, crude oil and NGLs, and services for each grows over the long term, our infrastructure will increase in value as such infrastructure takes on increasing importance in meeting that growing supply and demand.
While we have set forth our strategies and competitive strengths above, our business involves numerous risks and uncertainties which may prevent us from executing our strategies. These risks include the adverse impact of changes in natural gas, NGL and condensate/crude oil prices, the supply of or demand for these commodities, and our inability to access sufficient additional production to replace natural declines in production. For a more complete description of the risks associated with an investment in us, see “Item 1A. Risk Factors.”
Our Business Operations
Our operations are reported in two segments: (i) Gathering and Processing, and (ii) Logistics and Transportation (also referred to as the Downstream Business).
Gathering and Processing Segment
Our Gathering and Processing segment consists of gathering, compressing, dehydrating, treating, conditioning, processing, and marketing natural gas and gathering crude oil. The gathering of natural gas consists of aggregating natural gas produced from various wells through varying diameter gathering lines to processing plants. Natural gas has a widely varying composition depending on the field, the formation and the reservoir from which it is produced. The processing of natural gas consists of the extraction of imbedded NGLs and the removal of water vapor and other contaminants to form (i) a stream of marketable natural gas, commonly referred to as residue gas, and (ii) a stream of mixed NGLs. Once processed, the residue gas is transported to markets through pipelines that are owned by third parties and the GCX Pipeline. End-users of residue gas include large commercial and industrial customers, as well as natural gas and electric utilities serving individual consumers. We sell our residue gas either directly to such end-users or to marketers into intrastate or interstate pipelines, which are typically located in close proximity or with ready access to our facilities. The gathering of crude oil consists of aggregating crude oil production primarily through gathering pipeline systems, which deliver crude oil to a combination of other pipelines, rail and truck.
We continually seek new supplies of natural gas and crude oil, both to offset the natural decline in production from connected wells and to increase throughput volumes. We obtain additional natural gas and crude oil supply in our operating areas by contracting for production from new wells or by capturing existing production currently gathered by others. Competition for new natural gas and crude oil supplies is based primarily on location of assets, commercial terms including pre-existing contracts, service levels and access to markets. The commercial terms of natural gas gathering and processing arrangements and crude oil gathering are driven, in part, by capital costs, which are impacted by the proximity of systems to the supply source and by operating costs, which are impacted by operational efficiencies, facility design and economies of scale.
The Gathering and Processing segment's assets are located in the Permian Basin of West Texas and Southeast New Mexico (including the Midland, Central and Delaware Basins); the Eagle Ford Shale in South Texas; the Barnett Shale in North Texas; the Anadarko, Ardmore, and Arkoma Basins in Oklahoma (including the SCOOP and STACK) and South Central Kansas; the Williston Basin in North Dakota (including the Bakken and Three Forks plays) and in the onshore and near offshore regions of the Louisiana Gulf Coast and the Gulf of Mexico.
The natural gas processed in this segment is supplied through our gathering systems which, in aggregate, consist of approximately 28,900 miles of natural gas pipelines and include 46 owned and operated processing plants. During 2019, we processed an average of 4,438.2 MMcf/d of natural gas and produced an average of 505.4 MBbl/d of NGLs. In addition to our natural gas gathering and processing, the Badlands operations include a crude oil gathering system and four terminals with crude oil operational storage capacity of 205 MBbl, and our Permian operations include a crude oil gathering system and two terminals with crude oil operational storage capacity of 20 MBbl. In January 2020, we closed on the sale of our crude gathering and storage business in the Permian Delaware, see “—Recent Developments—Asset Sales” above. During 2019, we gathered an aggregate average of 255.9 MBbl/d of crude oil in the Badlands and Permian.
The Gathering and Processing segment’s operations consist of Permian Midland, Permian Delaware, SouthTX, North Texas, SouthOK, WestOK, Coastal and Badlands each as described below:
Permian Midland
The Permian Midland system consists of approximately 6,600 miles of natural gas gathering pipelines and fourteen processing plants with an aggregate nameplate capacity of 2,129 MMcf/d, all located within the Permian Basin in West Texas. Ten of these plants and 4,800 miles of gathering pipelines belong to a joint venture (“WestTX”), in which we have an approximate 72.8% ownership. Pioneer, a major producer in the Permian Basin, owns the remaining interest in the WestTX system.
In addition, we are constructing the Gateway Plant, a new 250 MMcf/d cryogenic natural gas processing plant included as part of WestTX in the Midland Basin. The Gateway Plant is expected to begin operations in the fourth quarter of 2020.
Permian Delaware
The Permian Delaware system consists of approximately 5,900 miles of natural gas gathering pipelines and eight processing plants with an aggregate capacity of 1,050 MMcf/d, all within the Delaware Basin in West Texas and Southeastern New Mexico. One additional plant, the 250 MMcf/d Peregrine Plant, is currently being constructed and expected to be completed in the second quarter of 2020.
The Permian Midland and Permian Delaware systems are interconnected and volumes may flow from one system to the other providing increased operational flexibility and redundancy.
SouthTX
The South Texas system contains approximately 900 miles of high-pressure and low-pressure gathering and transmission pipelines and three natural gas processing plants in the Eagle Ford Shale. The South Texas system processes natural gas through the Silver Oak I, Silver Oak II and Raptor gas processing plants. The Silver Oak I and II Plants (the “Silver Oak Plants”) are each 200 MMcf/d cryogenic plants. The Raptor Plant is a 260 MMcf/d cryogenic plant.
We participate in two joint ventures in South Texas with a subsidiary of Southcross Energy Partners LLC, which consist of our 75% share in T2 LaSalle Gathering Company LLC (“T2 LaSalle”) and our 50% share in T2 Eagle Ford Gathering Company LLC (“T2 Eagle Ford”). T2 LaSalle owns approximately 60 miles of high-pressure gathering pipeline and T2 Eagle Ford owns approximately 120 miles of high-pressure gathering pipelines. Together, these two pipelines gather and transport gas to the Silver Oak Plants. T2 Eagle Ford also owns the residue gas delivery pipelines downstream of the Silver Oak Plants. On April 1, 2019, we assumed the operatorship of T2 LaSalle and T2 Eagle Ford.
We also participate in a third joint venture in South Texas, which is with Sanchez Midstream. We own a 50% interest in the Carnero Joint Venture (“Carnero”) and Sanchez Midstream owns the remaining 50% interest. Carnero owns and Targa operates the Silver Oak II Plant, the Raptor Plant and approximately 45 miles of high-pressure gathering pipeline located in La Salle, Dimmitt and Webb Counties, Texas which connects Sanchez Energy’s Catarina Ranch gathering system and Comanche Ranch acreage to the Raptor Plant.
North Texas
North Texas includes two interconnected gathering systems in the Fort Worth Basin, Chico and Shackelford, and includes gas from the Barnett Shale and Marble Falls plays. The systems consist of approximately 4,700 miles of pipelines gathering wellhead natural gas.
The Chico gathering system gathers natural gas for the Chico and Longhorn plants. The Chico Plant has an aggregate processing capacity of 265 MMcf/d and an integrated fractionation capacity of 15 MBbl/d. The Longhorn Plant has processing capacity of 200 MMcf/d. The Shackelford gathering system gathers wellhead natural gas largely for the Shackelford Plant, which has processing capacity of 13 MMcf/d. Natural gas gathered from the northern and eastern portions of the Shackelford gathering system is typically transported to the Chico Plant for processing.
SouthOK
The SouthOK gathering system is located in the Ardmore and Anadarko Basins and includes the Golden Trend, SCOOP, and Woodford Shale areas of southern Oklahoma. The gathering system has approximately 2,300 miles of pipelines.
The SouthOK system includes six separate operational processing plants with a total nameplate capacity of 710 MMcf/d, including: the Coalgate, Stonewall, Hickory Hills and Tupelo facilities, which are owned by our Centrahoma Joint Venture, and our wholly-owned Velma and Velma V-60 plants. We have a 60% ownership interest in Centrahoma. The remaining 40% ownership interest in Centrahoma is held by MPLX LP (“MPLX”).
WestOK
The WestOK gathering system is located in north central Oklahoma and southern Kansas’ Anadarko Basin and includes the Woodford shale and the STACK. The gathering system expands into 13 counties with approximately 6,600 miles of natural gas gathering pipelines.
The WestOK system has a total nameplate capacity of 458 MMcf/d with three separate cryogenic natural gas processing plants located at the Waynoka I and II and Chester facilities, and one refrigeration plant at the Chaney Dell facility.
Coastal
Our Coastal assets, located in and offshore South Louisiana, gather and process natural gas produced from shallow-water central and western Gulf of Mexico natural gas wells and from deep shelf and deep-water Gulf of Mexico production via connections to third-party pipelines or through pipelines owned by us. Coastal consists of approximately 3,295 MMcf/d of natural gas processing capacity, 11 MBbl/d of integrated fractionation capacity, 980 miles of onshore gathering system pipelines, and 170 miles of offshore gathering system pipelines. The processing plants are comprised of five wholly-owned and operated plants, one partially owned and operated plant, and two partially owned plants which are non-operated. Toca, a partially owned, non-operated plant, was shut down in January 2019 and has been excluded from the preceding statistics. Our Coastal plants have access to markets across the U.S. through the interstate natural gas pipelines to which they are interconnected. The industry continues to rationalize gas processing capacity along the western Louisiana Gulf Coast with most of the producer volumes going to more efficient plants, such as our Barracuda, Lowry and Gillis plants.
Badlands
The Badlands operations are located in the Bakken and Three Forks Shale plays of the Williston Basin in North Dakota and include approximately 510 miles of crude oil gathering pipelines, 120 MBbl of operational crude oil storage capacity at the Johnsons Corner Terminal, 30 MBbl of operational crude oil storage capacity at the Alexander Terminal, 30 MBbl of operational crude oil storage at New Town and 25 MBbl of operational crude oil storage at Stanley. The Badlands assets also include approximately 280 miles of natural gas gathering pipelines and the Little Missouri I-III natural gas processing plants, which have a gross processing capacity of approximately 90 MMcf/d. Additionally, Targa operates the 200 MMcf/d Little Missouri 4 plant (“LM4 Plant”), in which Targa Badlands and Hess Midstream Partners LP each own a 50% interest, which was completed in the third quarter of 2019.
In April 2019, we closed on the sale of a 45% interest in Targa Badlands to Blackstone. Targa continues to be the operator of Badlands and holds majority governance rights.
The following table lists the Gathering and Processing segment’s processing plants and related volumes for the year ended December 31, 2019:
| Facility | Process Type (1) | Operated /Non-Operated | % Owned | Location | Gross Processing Capacity (MMcf/d) (2) | Gross Plant Natural Gas Inlet Throughput Volume (MMcf/d) (3) (4) (5) | Gross NGL Production (MBbl/d) (3) (4) (5) | |||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Permian Midland | ||||||||||||||||||
| Consolidator (6) | Cryo | Operated | 72.8 | Reagan County, TX | 150.0 | |||||||||||||
| Midkiff (6) | Cryo | Operated | 72.8 | Reagan County, TX | 80.0 | |||||||||||||
| Driver (6) | Cryo | Operated | 72.8 | Midland County, TX | 200.0 | |||||||||||||
| Benedum (6) | Cryo | Operated | 72.8 | Upton County, TX | 45.0 | |||||||||||||
| Edward (6) | Cryo | Operated | 72.8 | Upton County, TX | 200.0 | |||||||||||||
| Buffalo (6) | Cryo | Operated | 72.8 | Martin County, TX | 200.0 | |||||||||||||
| Joyce (6) | Cryo | Operated | 72.8 | Upton County, TX | 200.0 | |||||||||||||
| Johnson (6) | Cryo | Operated | 72.8 | Midland County, TX | 200.0 | |||||||||||||
| Hopson (6) | Cryo | Operated | 72.8 | Midland County, TX | 250.0 | |||||||||||||
| Pembrook (6) | Cryo | Operated | 72.8 | Upton County, TX | 250.0 | |||||||||||||
| Mertzon | Cryo | Operated | 100.0 | Irion County, TX | 52.0 | |||||||||||||
| Sterling | Cryo | Operated | 100.0 | Sterling County, TX | 92.0 | |||||||||||||
| Tarzan | Cryo | Operated | 100.0 | Martin County, TX | 10.0 | |||||||||||||
| High Plains | Cryo | Operated | 100.0 | Midland County, TX | 200.0 | |||||||||||||
| Area Total | 2,129.0 | 1,489.1 | 209.1 | |||||||||||||||
| Permian Delaware | ||||||||||||||||||
| Sand Hills | Cryo | Operated | 100.0 | Crane County, TX | 165.0 | |||||||||||||
| Loving | Cryo | Operated | 100.0 | Loving County, TX | 70.0 | |||||||||||||
| Oahu | Cryo | Operated | 100.0 | Pecos County, TX | 60.0 | |||||||||||||
| Wildcat | Cryo | Operated | 100.0 | Winkler County, TX | 250.0 | |||||||||||||
| Falcon | Cryo | Operated | 100.0 | Culberson County, TX | 250.0 | |||||||||||||
| Saunders (7) | Cryo | Operated | 100.0 | Lea County, NM | 60.0 | |||||||||||||
| Eunice (7) | Cryo | Operated | 100.0 | Lea County, NM | 110.0 | |||||||||||||
| Monument (7) (16) | Cryo | Operated | 100.0 | Lea County, NM | 85.0 | |||||||||||||
| Area Total | 1,050.0 | 599.7 | 78.6 | |||||||||||||||
| SouthTX | ||||||||||||||||||
| Silver Oak I | Cryo | Operated | 100.0 | Bee County, TX | 200.0 | |||||||||||||
| Silver Oak II | Cryo | Operated | 50.0 | Bee County, TX | 200.0 | |||||||||||||
| Raptor | Cryo | Operated | 50.0 | La Salle County, TX | 260.0 | |||||||||||||
| Area Total | 660.0 | 321.2 | 41.6 | |||||||||||||||
| North Texas | ||||||||||||||||||
| Chico (8) | Cryo | Operated | 100.0 | Wise County, TX | 265.0 | |||||||||||||
| Shackelford | Cryo | Operated | 100.0 | Shackelford County, TX | 13.0 | |||||||||||||
| Longhorn | Cryo | Operated | 100.0 | Wise County, TX | 200.0 | |||||||||||||
| Area Total | 478.0 | 226.9 | 26.8 | |||||||||||||||
| SouthOK (9) | ||||||||||||||||||
| Coalgate | Cryo | Operated | 60.0 | Coal County, OK | 80.0 | |||||||||||||
| Stonewall | Cryo | Operated | 60.0 | Coal County, OK | 200.0 | |||||||||||||
| Tupelo | Cryo | Operated | 60.0 | Coal County, OK | 120.0 | |||||||||||||
| Hickory Hills | Cryo | Operated | 60.0 | Hughes County, OK | 150.0 | |||||||||||||
| Velma | Cryo | Operated | 100.0 | Stephens County, OK | 100.0 | |||||||||||||
| Velma V-60 | Cryo | Operated | 100.0 | Stephens County, OK | 60.0 | |||||||||||||
| Area Total | 710.0 | 606.1 | 67.1 | |||||||||||||||
| WestOK (9) | ||||||||||||||||||
| Waynoka I | Cryo | Operated | 100.0 | Woods County, OK | 200.0 | |||||||||||||
| Waynoka II | Cryo | Operated | 100.0 | Woods County, OK | 200.0 | |||||||||||||
| Chaney Dell (10) | RA | Operated | 100.0 | Major County, OK | 30.0 | |||||||||||||
| Chester (10) | Cryo | Operated | 100.0 | Woodward County, OK | 28.0 | |||||||||||||
| Area Total | 458.0 | 330.2 | 21.6 | |||||||||||||||
| Coastal (11) | ||||||||||||||||||
| Gillis (12) | Cryo | Operated | 100.0 | Calcasieu Parish, LA | 180.0 | |||||||||||||
| Acadia (10) | Cryo | Operated | 100.0 | Acadia Parish, LA | 80.0 | |||||||||||||
| Big Lake (13) | Cryo | Operated | 100.0 | Calcasieu Parish, LA | 180.0 | |||||||||||||
| VESCO | Cryo | Operated | 76.8 | Plaquemines Parish, LA | 750.0 | |||||||||||||
| Barracuda | Cryo | Operated | 100.0 | Cameron Parish, LA | 190.0 | |||||||||||||
| Lowry (14) | Cryo | Operated | 100.0 | Cameron Parish, LA | 265.0 | |||||||||||||
| Terrebone (15) | RA | Non-operated | 8.4 | Terrebonne Parish, LA | 950.0 | |||||||||||||
| Toca (17) | Cryo/RA | Non-operated | 12.6 | St. Bernard Parish, LA | 1,150.0 | |||||||||||||
| Sea Robin | Cryo | Non-operated | 0.9 | Vermillion Parish, LA | 700.0 | |||||||||||||
| Area Total | 4,445.0 | 748.3 | 46.8 | |||||||||||||||
| Badlands | ||||||||||||||||||
| Little Missouri I-III (18) | Cryo/RA | Operated | 55.0 | McKenzie County, ND | 90.0 | |||||||||||||
| Little Missouri IV | RA | Operated | 27.5 | McKenzie County, ND | 200.0 | |||||||||||||
| Area Total | 290.0 | 116.7 | 13.8 | |||||||||||||||
| Segment System Total | 10,220.0 | 4,438.2 | 505.4 |
| (1) | Cryo – Cryogenic Processing; RA – Refrigerated Absorption Processing. |
|---|
| (2) | Gross processing capacity represents 100% of ownership interests and may differ from nameplate processing capacity due to multiple factors including items such as compression limitations, and quality and composition of the gas being processed. |
|---|
| (3) | Plant natural gas inlet represents the volume of natural gas passing through the meter located at the inlet of the natural gas processing plant, except for Badlands which represents the total wellhead gathered volume. |
|---|
| (4) | Plant natural gas inlet and NGL production volumes represent 100% of ownership interests for our consolidated VESCO joint venture, Silver Oak II, Raptor, Coalgate, Stonewall, Tupelo, and Hickory Hills plants and our ownership share of volumes for other partially owned plants that we proportionately consolidate based on our ownership interest which may be adjustable subject to an annual redetermination based on our proportionate share of plant production. |
|---|
| (5) | Per day Gross Plant Natural Gas Inlet and NGL Production statistics for plants listed above are based on the number of calendar days during 2019. |
|---|
| (6) | Gross plant natural gas inlet throughput volumes and gross NGL production volumes for WestTX are presented on a pro-rata net basis representing our undivided ownership interest in WestTX, which we proportionately consolidate in our financial statements. |
|---|
| (7) | Includes throughput other than plant inlet, primarily from compressor stations. |
|---|
| (8) | The Chico plant has fractionation capacity of approximately 15 MBbl/d. |
|---|
| (9) | Certain processing facilities in these business units are capable of processing more than their nameplate capacity and when capacity is exceeded the facilities will off-load volumes to other processors, as needed. The gross plant natural gas inlet throughput volume includes these off-loaded volumes. |
|---|
| (10) | Plant is idle. |
|---|
| (11) | Coastal also includes two offshore gathering systems which have a combined length of approximately 200 miles. |
|---|
| (12) | The Gillis plant has fractionation capacity of approximately 11 MBbl/d. |
|---|
| (13) | Plant is available and operates subject to market conditions. |
|---|
| (14) | Plant restarted operation in March 2019. |
|---|
| (15) | Plant is anticipated to shutdown on March 31, 2020. |
|---|
| (16) | The Monument plant has fractionation capacity of approximately 1.8 MBbl/d. |
|---|
| (17) | The Toca plant was shut down in January 2019, but has been retained in this table to include its volumes for 2019. |
|---|
| (18) | Little Missouri Trains I and II are refrigeration plants and Little Missouri Train III is a Cryo plant. |
|---|
Logistics and Transportation Segment
Our Logistics and Transportation segment is also referred to as our Downstream Business. Our Downstream Business includes the activities and assets necessary to transport and convert mixed NGLs into NGL products and also includes other assets and value-added services described below. The Logistics and Transportation segment includes Grand Prix, as well as our equity interest in GCX. The associated assets, including these pipelines, are generally connected to and supplied in part by our Gathering and Processing segment and, except for the pipelines and smaller terminals, are located predominantly in Mont Belvieu and Galena Park, Texas, and in Lake Charles, Louisiana. Our fractionation, pipeline transportation, storage and terminaling businesses include approximately 2,000 miles of company-owned pipelines to transport mixed NGLs and specification products.
The Logistics and Transportation segment also transports, distributes and markets NGLs via terminals and transportation assets across the U.S. We own or commercially manage terminal facilities in a number of states, including Texas, Oklahoma, Louisiana, Arizona, California, Florida, Alabama, Mississippi, Tennessee, Kentucky and New Jersey. The geographic diversity of our assets provides direct access to many NGL customers as well as markets via trucks, barges, ships, rail cars and open-access regulated NGL pipelines owned by third parties.
Additional description of the Logistics and Transportation segment assets and business activities associated with Pipelines, Fractionation, NGL Storage and Terminaling, Petroleum Logistics, NGL Distribution and Marketing, Wholesale Domestic Marketing, Refinery Services, Commercial Transportation and Natural Gas Marketing follows below.
Pipelines
Our primary pipeline assets are Grand Prix and our equity interest in GCX.
Grand Prix connects our gathering and processing positions throughout the Permian Basin, North Texas, and Southern Oklahoma (as well as third-party positions) to our fractionation and storage complex in the NGL market hub at Mont Belvieu, Texas. Grand Prix transports NGLs from the Permian Basin on a 24-inch diameter pipeline with a capacity of 300 MMBbl/d, expandable to 550 MMBbl/d, and from North Texas and Southern Oklahoma via pipeline of varying capacity, which both connect to a 30-inch diameter segment into Mont Belvieu. The final segment has a 450 MMBbl/d capacity, which is expandable to 950 MMBbl/d. We own a 56% interest in the Permian and Mont Belvieu segments of Grand Prix through the Grand Prix Joint Venture. Volumes flowing on the pipeline from the Permian Basin to Mont Belvieu accrue to the Grand Prix Joint Venture, while the volumes flowing from North Texas and Oklahoma to Mont Belvieu accrue solely to Targa’s benefit.
GCX Pipeline transports natural gas from the Waha hub in West Texas to Agua Dulce in South Texas and has a capacity of 1.98 Bcf/d. GCX DevCo JV, of which we own a 20% interest, owns a 25% interest in GCX Pipeline, which is operated by KMTP.
Additionally, through our 50% ownership interest in Cayenne Pipeline, LLC, we operate the Cayenne pipeline, which transports mixed NGLs from VESCO in Venice, Louisiana, to an interconnection with a third-party NGL pipeline in Toca, Louisiana.
Fractionation
After being extracted in the field, mixed NGLs are typically transported to a centralized facility for fractionation where the mixed NGLs are separated into discrete NGL products: ethane, ethane-propane mix, propane, normal butane, iso-butane and natural gasoline.
Contracts for our NGL fractionation services are fee-based arrangements. These fees are subject to adjustment for changes in certain fractionation expenses, including energy costs. The operating results of our NGL fractionation business are dependent upon the volume of mixed NGLs fractionated, the level of fractionation fees charged and product gains/losses from fractionation.
We believe that sufficient volumes of mixed NGLs will be available for fractionation in commercially viable quantities for the foreseeable future due to historical increases in NGL production from shale plays and other shale-technology-driven resource plays in areas of the U.S. that include Texas, New Mexico, Oklahoma and the Rockies and certain other basins accessed by pipelines to Mont Belvieu, as well as from conventional production of NGLs in areas such as the Permian Basin, Mid-Continent, East Texas, South Louisiana and shelf and deep-water Gulf of Mexico. Hydrocarbon dew point specifications implemented by individual natural gas pipelines and the Policy Statement on Provisions Governing Natural Gas Quality and Interchangeability in Interstate Natural Gas Pipeline Company Tariffs enacted in 2006 by the Federal Energy Regulatory Commission (“FERC”) should result in volumes of mixed NGLs being available for fractionation because natural gas requires processing or conditioning to meet pipeline quality specifications. These requirements establish a base volume of mixed NGLs during periods when it might be otherwise uneconomical to process certain sources of natural gas. Furthermore, significant volumes of mixed NGLs are contractually committed to our NGL fractionation facilities.
Although competition for NGL fractionation services is primarily based on the fractionation fee, the ability of an NGL fractionator to obtain mixed NGLs and distribute NGL products is also an important competitive factor. This ability is a function of the existence of storage infrastructure and supply and market connectivity necessary to conduct such operations. We believe that the location, scope and capability of our logistics assets, including our transportation and distribution systems, give us access to both substantial sources of mixed NGLs and a large number of end-use markets.
Our fractionation assets include ownership interests in three stand-alone fractionation facilities that are located on the Gulf Coast, two of which we operate at Mont Belvieu, Texas and at Lake Charles, Louisiana. We have an equity investment in the third fractionation facility, Gulf Coast Fractionators LP (“GCF”), also located at Mont Belvieu. In addition to the three stand-alone facilities included in the Logistics and Transportation segment, we also own fractionation assets at Chico, Monument and Gillis included in our Gathering and Processing segment.
Five of the six existing fractionation trains at the Mont Belvieu facility representing a gross capacity of 493.0 MBbl/d are part of our 88%-owned Cedar Bayou Fractionators. A 100 MBbl/d fractionation train, Train 6, began operations in the second quarter of 2019. Train 6 JV, a joint venture between Targa and Stonepeak, owns 100% interest in the fractionation train. Certain fractionation-related infrastructure for Train 6, such as storage caverns and brine handling, were funded and are owned 100% by Targa.
Two additional fractionation trains, which are currently under construction at the Mont Belvieu facility, are not part of CBF or the Train 6 JV. The additional fractionation trains are being fully integrated with our existing Gulf Coast NGL storage, terminaling and delivery infrastructure, which includes an extensive network of connections to key petrochemical and industrial customers as well as our LPG export terminal at Galena Park on the Houston Ship Channel. The additional fractionation trains are: (1) the 110 MBbl/d Train 7, a joint venture with Williams, which is expected to begin operations by the end of the first quarter 2020 and (2) the 110 MBbl/d Train 8, which is expected to begin operations by the end of the third quarter 2020.
We also have a natural gasoline hydrotreater at Mont Belvieu, Texas that removes sulfur from natural gasoline, allowing customers to meet stringent fuel content standards. The facility has a capacity of 35 MBbl/d and is supported by long-term fee-based contracts that have certain guaranteed volume commitments and/or provisions for deficiency payments.
The following table details the Logistics and Transportation segment’s fractionation and treating facilities:
| Facility | % Owned | Gross Capacity (MBbl/d) (1) | Gross Throughput 2019 (MBbl/d) | |||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Operated Facilities: | ||||||||||||
| Lake Charles Fractionator (Lake Charles, LA) (2) | 100.0 | 55.0 | 4.6 | |||||||||
| Train 6 Fractionator (Mont Belvieu, TX) (3) | 20.0 | 100.0 | 73.5 | |||||||||
| Cedar Bayou Fractionators (Mont Belvieu, TX) (4) | 88.0 | 493.0 | 430.8 | |||||||||
| Targa LSNG Hydrotreater (Mont Belvieu, TX) | 100.0 | 35.0 | 35.8 | |||||||||
| Non-operated Facilities: | ||||||||||||
| Gulf Coast Fractionator (Mont Belvieu, TX) | 38.8 | 125.0 | 125.4 |
| (1) | Actual fractionation capacities may vary due to the Y-grade composition of the gas being processed and does not contemplate ethane rejection. |
|---|
| (2) | Lake Charles Fractionator runs in a mode of ethane/propane splitting for a local petrochemical customer and is configured to handle raw product. |
|---|
| (3) | Train 6 began operations in the second quarter of 2019. |
|---|
| (4) | Gross capacity represents 100% of the volume. Capacity includes 40 MBbl/d of additional back-end butane/gasoline fractionation capacity. |
|---|
NGL Storage and Terminaling
In general, our NGL storage assets provide warehousing of mixed NGLs, NGL products and petrochemical products in underground wells, which allows for the injection and withdrawal of such products at various times in order to meet supply and demand cycles. Similarly, our terminaling operations provide the inbound/outbound logistics and warehousing of mixed NGLs, NGL products and petrochemical products in above-ground storage tanks. Our NGL underground storage and terminaling facilities serve single markets, such as propane, as well as multiple products and markets. For example, the Mont Belvieu and Galena Park facilities have extensive pipeline connections for mixed NGL supply and delivery of component NGLs, including Grand Prix. In addition, some of our facilities are connected to marine, rail and truck loading and unloading facilities that provide services and products to our customers. We provide long and short-term storage and terminaling services and throughput capability to third-party customers for a fee.
Across the Logistics and Transportation segment, we own 34 storage wells at our facilities with a gross NGL storage capacity of approximately 72 MMBbl, and operate 6 non-owned wells, the usage of which may be limited by brine handling capacity, which is utilized to displace NGLs from storage.
We operate our storage and terminaling facilities to support our key fractionation facilities at Mont Belvieu and Lake Charles for receipt of mixed NGLs and storage of fractionated NGLs to service the petrochemical, refinery, export and heating customers/markets as well as our wholesale domestic terminals that focus on logistics to service the heating market customer base. Our international export assets include our facilities at both Mont Belvieu and the Galena Park Marine Terminal near Houston, Texas, which have the capability to load propane, butane and international grade low ethane propane. The facilities currently have the capacity to export approximately 10 MMBbl per month of propane and/or butane. We have the capability to load VLGC vessels, alongside small and medium sized export vessels. We continue to experience demand growth for U.S.-based NGLs (both propane and butane) for export into international markets and are in the process of enhancing our loading capabilities.
The following table details the Logistics and Transportation segment’s NGL storage and terminaling facilities:
| Facility | % Owned | Location | Description | Throughput for 2019 (MMgal) | Number of Operational Wells | Gross Storage Capacity (MMBbl) | ||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Galena Park Marine Terminal (1) | 100 | Harris County, TX | NGL import/export terminal | 5,162.8 | N/A | 0.8 | ||||||||
| Mont Belvieu Terminal & Storage | 100 | Chambers County, TX | Transport and storage terminal | 21,860.0 | 22 | (2) | 50.8 | |||||||
| Hackberry Terminal & Storage | 100 | Cameron Parish, LA | Storage terminal | 1,623.0 | 12 | (3) | 20.9 | |||||||
| Patriot | 100 | Harris County, TX | Dock and land for expansion (Not in service) | N/A | N/A | N/A |
| (1) | Volumes reflect total import and export across the dock/terminal and may include volumes that have also been handled at the Mont Belvieu Terminal. |
|---|
| (2) | Excludes six non-owned wells which we operate on behalf of Chevron Phillips Chemical Company LLC and one additional non-owned well that is being prepared for operations. One additional well has been drilled and is being prepared for operations. One additional well is permitted. |
|---|
| (3) | Five of 12 owned wells leased to Citgo Petroleum Corporation under long-term leases. |
|---|
Petroleum Logistics
Our Petroleum Logistics business owns and operates a storage and terminaling facility in Channelview, Texas, including a 35,000 Bbl/d nameplate capacity crude oil and condensate splitter (the “Channelview Splitter”). This facility serves the refined petroleum products, crude oil, LPG, and petrochemicals markets. The Channelview storage and terminaling facility’s throughput for the year ended December 31, 2019, was 219.7 MMgal and the gross storage capacity was 0.6 MMBbl. The Channelview Splitter splits crude oil and condensate into its various components, including naphtha, distillate, gas oil, kerosene/jet fuel and liquefied petroleum gas and has segregated storage for the crude and condensate and each of the components.
NGL Distribution and Marketing
We market our own NGL production and also purchase component NGL products from other NGL producers and marketers for resale. Additionally, we also purchase product for resale in our Logistics and Transportation segment, including exports. During the year ended December 31, 2019, our distribution and marketing services business sold an average of 651.0 MBbl/d of NGLs.
We generally purchase mixed NGLs at a monthly pricing index less applicable fractionation, transportation and marketing fees and resell these component products to petrochemical manufacturers, refineries and other marketing and retail companies. This is primarily a physical settlement business in which we earn margins from purchasing and selling NGL products from customers under contract. We also earn margins by purchasing and reselling NGL products in the spot and forward physical markets. To effectively serve our distribution and marketing customers, we contract for and use many of the assets included in our Logistics and Transportation segment.
Wholesale Domestic Marketing
Our wholesale domestic propane marketing operations primarily sell propane and related logistics services to major multi-state retailers, independent retailers and other end-users. Our propane supply primarily originates from both our refinery/gas supply contracts and our other owned or managed logistics and transportation assets. We sell propane at a fixed posted price or at a market index basis at the time of delivery and in some circumstances, we earn margin on a netback basis.
The wholesale domestic propane marketing business is significantly impacted by seasonal and weather-driven demand, particularly in the winter, which can impact the price and volume of propane sold in the markets we serve.
Refinery Services
In our refinery services business, we typically provide NGL balancing services through contractual arrangements with refiners to purchase and/or market propane and to supply butanes. We use our commercial transportation assets (discussed below) and contract for and use the storage, transportation and distribution assets included in our Logistics and Transportation segment to assist refinery customers in managing their NGL product demand and production schedules. This includes both feedstocks consumed in refinery processes and the excess NGLs produced by other refining processes. Under typical netback purchase contracts, we generally retain a portion of the resale price of NGL sales or receive a fixed minimum fee per gallon on products sold. Under netback sales contracts, fees are earned for locating and supplying NGL feedstocks to the refineries based on a percentage of the cost to obtain such supply or a minimum fee per gallon.
Key factors impacting the results of our refinery services business include production volumes, prices of propane and butanes, as well as our ability to perform receipt, delivery and transportation services in order to meet refinery demand.
Commercial Transportation
Our NGL transportation and distribution infrastructure includes a wide range of assets supporting both third-party customers and the delivery requirements of our marketing and asset management business. We provide fee-based transportation services to refineries and petrochemical companies throughout the Gulf Coast area. Our assets are also deployed to serve our wholesale domestic distribution terminals, fractionation facilities, underground storage facilities and pipeline injection terminals. These distribution assets provide a variety of ways to transport products to and from our customers.
Our transportation assets, as of December 31, 2019, include approximately 698 railcars that we lease and manage, approximately 138 leased and managed transport tractors and 2 company-owned pressurized NGL barges.
The following table details the Logistics and Transportation segment’s raw NGL, propane and butane terminaling facilities:
| Facility | % Owned | Location | Description | Throughput for 2019 (MMgal) (1) | Usable Storage Capacity (MMgal) | |||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Calvert City Terminal | 100 | Marshall County, KY | Propane terminal | 11.3 | 0.1 | |||||||||
| Greenville Terminal | 100 | Washington County, MS | Marine propane terminal | 23.7 | 1.5 | |||||||||
| Port Everglades Terminal | 100 | Broward County, FL | Marine propane terminal | 17.3 | 1.6 | |||||||||
| Tyler Terminal | 100 | Smith County, TX | Propane terminal | 14.5 | 0.2 | |||||||||
| Abilene Transport (2) | 100 | Taylor County, TX | Raw NGL transport terminal | 15.7 | 0.1 | |||||||||
| Bridgeport Transport (2) | 100 | Jack County, TX | Raw NGL transport terminal | 116.0 | 0.1 | |||||||||
| Gladewater Transport (2) | 100 | Gregg County, TX | Raw NGL transport terminal | 3.6 | 0.3 | |||||||||
| Chattanooga Terminal | 100 | Hamilton County, TN | Propane terminal | 16.8 | 0.9 | |||||||||
| Sparta Terminal | 100 | Sparta County, NJ | Propane terminal | 13.5 | 0.2 | |||||||||
| Hattiesburg Terminal (3) | 50 | Forrest County, MS | Propane terminal | 352.8 | 179.8 | |||||||||
| Winona Terminal | 100 | Flagstaff County, AZ | Propane terminal | 12.2 | 0.3 | |||||||||
| Jacksonville Transload (4) | 100 | Duval County, FL | Butane transload | 1.6 | — | |||||||||
| Fort Lauderdale Transload (4) | 100 | Broward County, FL | Butane transload | 1.8 | — | |||||||||
| Eagle Lake Transload (4) | 100 | Polk County, FL | Butane/propane transload | 4.6 | — |
| (1) | Throughputs include volumes related to exchange agreements and third-party storage agreements. |
|---|
| (2) | Volumes reflect total transport and injection volumes. |
|---|
| (3) | Throughput volume reflects 100% of the facility capacity. |
|---|
| (4) | Rail-to-truck transload equipment. |
|---|
Natural Gas Marketing
We also market natural gas available to us from the Gathering and Processing segment, purchase and resell natural gas in selected U.S. markets and manage the scheduling and logistics for these activities.
Seasonality
Overall, parts of our business are impacted by seasonality. Our downstream marketing business can be significantly impacted by seasonal and weather-driven demand, which can impact the price and volume of product sold in the markets we serve, as well as the level of inventory we hold in order to meet anticipated demand. See further discussion of the extent to which our business is affected by seasonality in “Item 1A. Risk Factors.”
Operational Risks and Insurance
We are subject to all risks inherent in the midstream natural gas, NGLs and crude oil businesses. These risks include, but are not limited to, explosions, fires, mechanical failure, terrorist attacks, product spillage, weather, nature and inadequate maintenance of rights of way. These risks could result in damage to or destruction of operating assets and other property, or could result in personal injury, loss of life or environmental pollution, as well as curtailment or suspension of operations at the affected facility. We maintain, on behalf of ourselves and our subsidiaries, including the Partnership, general public liability, property, boiler and machinery and business interruption insurance in amounts that we consider to be appropriate for such risks. Such insurance is subject to deductibles that we consider reasonable and not excessive given the current insurance market environment.
The occurrence of a significant loss that is not insured, fully insured or indemnified against, or the failure of a party to meet its indemnification obligations, could materially and adversely affect our operations and financial condition. While we currently maintain levels and types of insurance that we believe to be prudent under current insurance industry market conditions, our inability to secure these levels and types of insurance in the future could negatively impact our business operations and financial stability, particularly if an uninsured loss were to occur. No assurance can be given that we will be able to maintain these levels of insurance in the future at rates considered commercially reasonable, particularly named windstorm coverage and contingent business interruption coverage for our onshore operations.
Competition
We face strong competition in acquiring new natural gas or crude oil supplies. Competition for natural gas and crude oil supplies is primarily based on the location of gathering and processing facilities, pricing arrangements, reputation, efficiency, flexibility, treating capabilities (as applicable), reliability and access to end-use markets or liquid marketing hubs. Competitors to our gathering and processing operations include other natural gas gatherers and processors, such as major interstate and intrastate pipeline companies, master limited partnerships and oil and gas producers. Our major competitors for natural gas supplies in our current operating regions include DCP, Enable Midstream Partners, L.P., Energy Transfer Equity, L.P. (“Energy Transfer”), Enlink Midstream Partners LP, Enterprise Products Partners L.P. (“Enterprise”), Kinder Morgan, Inc. (“Kinder Morgan”), MPLX, ONEOK, Inc. (“ONEOK”), WTG Gas Processing, L.P. and several other pipeline companies. Our competitors for crude oil gathering services in North Dakota include Crestwood Equity Partners LP, Kinder Morgan, MPLX and Summit Midstream Partners, LLC. Our competitors may have greater financial resources than we possess.
We also compete for NGL supplies for Grand Prix. Competition for NGL supplies is primarily based on the location of gathering and processing facilities and their connectivity to NGL pipeline takeaway options, access to end-use markets or liquid marketing hubs, pricing and contractual arrangements, reputation, efficiency, flexibility, and reliability. Competitors to our NGL pipeline include other midstream providers with NGL transportation capabilities, such as major interstate and intrastate pipeline companies, master limited partnerships and midstream natural gas and NGL companies. Our major competitors for NGL supplies in our current operating regions include DCP, Energy Transfer, Enterprise and ONEOK.
Additionally, we face competition for mixed NGLs supplies at our fractionation facilities. Our competitors include large oil, natural gas and petrochemical companies. The fractionators in which we own an interest in the Mont Belvieu region compete for volumes of mixed NGLs with other fractionators also located at Mont Belvieu, Texas. Among the primary competitors are Enterprise, LoneStar NGL LLC (“LoneStar”) and ONEOK. In addition, certain producers fractionate mixed NGLs for their own account in captive facilities. The Mont Belvieu fractionators also compete on a more limited basis with fractionators in Conway, Kansas and a number of decentralized, smaller fractionation facilities in Texas, Louisiana and New Mexico. Our other fractionation facilities compete for mixed NGLs with the fractionators at Mont Belvieu as well as other fractionation facilities located in Louisiana. Our customers who are significant producers of mixed NGLs and NGL products or consumers of NGL products may develop their own fractionation facilities in lieu of using our services. Our primary competitors in providing export services to our customers are Enterprise, LoneStar and Phillips 66.
We also compete for NGL products to market through our Logistics and Transportation segment. Our competitors include major oil and gas producers who market NGL products for their own account and for others. Additionally, we compete with several other NGL marketing companies, including BP p.l.c., DCP, Energy Transfer, Enterprise and ONEOK.
Regulation of Operations
Regulation of pipeline gathering and transportation services, natural gas, NGL and crude oil sales, and transportation of natural gas, NGLs and crude oil may affect certain aspects of our business and the market for our products and services.
Gathering Pipeline Regulation
Our natural gas gathering operations are typically subject to ratable take and common purchaser statutes in the states in which we operate. The common purchaser statutes generally require gathering pipelines to purchase or take without undue discrimination as to source of supply or producer. These statutes are designed to prohibit discrimination in favor of one producer over another or one source of supply over another. The regulations under these statutes can have the effect of imposing some restrictions on our ability as an owner of gathering facilities to decide with whom we contract to gather natural gas. The states in which we operate have adopted complaint-based regulation of natural gas gathering activities, which allows natural gas producers and shippers to file complaints with state regulators in an effort to resolve grievances relating to gathering access and rate discrimination. The rates we charge for gathering are deemed just and reasonable unless challenged in a complaint. We cannot predict whether such a complaint will be filed against us in the future. Failure to comply with state regulations can result in the imposition of administrative, civil and criminal penalties.
Section 1(b) of the Natural Gas Act of 1938 (“NGA”) exempts natural gas gathering facilities from regulation as a natural gas company by FERC under the NGA. We believe that the natural gas pipelines in our gathering systems, including the gas gathering systems that are part of the Badlands and of the Pelican and Seahawk gathering systems, meet the traditional tests FERC has used to establish a pipeline’s status as a gatherer not subject to regulation as a natural gas company. However, to the extent our gathering systems buy and sell natural gas, such gatherers, in their capacity as buyers and sellers of natural gas, are now subject to Order No. 704. See “—Regulation of Operations—FERC Market Transparency Rules.”
Natural Gas Processing
Our natural gas gathering and processing operations are not presently subject to FERC regulation. However, since May 2009, we have been required to report to FERC information regarding natural gas sale and purchase transactions for some of our operations depending on the volume of natural gas transacted during the prior calendar year. See “—Regulation of Operations—FERC Market Transparency Rules.” There can be no assurance that our processing operations will continue to be exempt from other FERC regulation in the future.
Sales of Natural Gas, NGLs and Crude Oil
The price at which we buy and sell natural gas, NGLs and crude oil is currently not subject to federal rate regulation and, for the most part, is not subject to state rate regulation. However, with regard to our physical purchases and sales of these energy commodities and any related hedging activities that we undertake, we are required to observe anti-market manipulation laws and related regulations enforced by FERC and/or the Commodities Futures Trading Commission (“CFTC”). See “—Regulation of Operations—EP Act of 2005.” Since May 2009, we have been required to report to FERC information regarding natural gas sale and purchase transactions for some of our operations depending on the volume of natural gas transacted during the prior calendar year. See “—Regulation of Operations—FERC Market Transparency Rules.” Should we violate the anti-market manipulation laws and regulations, we could also be subject to related third-party damage claims by, among others, market participants, sellers, royalty owners and taxing authorities.
Interstate Natural Gas
We own (in conjunction with Pioneer) and operate the Driver Residue Pipeline, a gas transmission pipeline extending from our Driver processing plant in West Texas just over ten miles to points of interconnection with intrastate and interstate natural gas transmission pipelines. We have obtained a waiver from FERC of the requirements pertaining to the filing of an initial rate for service, the filing of a tariff and compliance with specified accounting and reporting requirements for the Driver Residue Pipeline. As such, the Driver Residue Pipeline is not currently subject to conventional rate regulation; to requirements FERC imposes on “open access” interstate natural gas pipelines; to the obligation to file and maintain a tariff; or to the obligation to conform to certain business practices and to file certain reports. If, however, we receive a bona fide request for firm service on the Driver Residue Pipeline from a third party, FERC would reexamine the waivers it has granted us and would require us to file for authorization to offer “open access” transportation under its regulations, which would impose additional costs upon us.
Interstate Liquids
Targa NGL Pipeline Company LLC (“Targa NGL”) has interstate NGL pipelines that are considered common carrier pipelines subject to regulation by FERC under the Interstate Commerce Act (the “ICA”). More specifically, Targa NGL owns an eight-inch diameter pipeline, a 20-inch diameter pipeline, and a 12-inch diameter pipeline that run between Mont Belvieu, Texas, and Galena Park, Texas. Each of these pipelines is regulated under the ICA and is part of an extensive mixed NGL and purity NGL pipeline receipt and delivery system that provides services to domestic and foreign import and export customers.
Additionally, in 2019, Targa NGL began operating portions of Grand Prix that transports NGLs from Oklahoma to Mont Belvieu, Texas. On July 27, 2018, Targa NGL submitted a petition for declaratory order to FERC on a proposed rate structure and terms of service for such portions of Grand Prix. The Commission granted Targa NGL’s petition for declaratory order subject to certain conditions on March 11, 2019. Targa NGL requested rehearing on April 10, 2019, which is pending at FERC.
Additionally, Grand Prix entered full service during the third quarter of 2019, providing transportation for mixed NGLs from the Permian Basin, including points in New Mexico, to Mont Belvieu, Texas.
The ICA requires that we maintain tariffs on file with FERC for each of these pipelines described above. Those tariffs set forth the rates we charge for providing transportation services as well as the rules and regulations governing these services. The ICA requires, among other things, that rates on interstate common carrier pipelines be “just and reasonable” and non-discriminatory.
Targa NGL also owns a twenty-inch diameter pipeline that runs between Mont Belvieu, Texas, and Galena Park, Texas and a twelve-inch diameter pipeline that runs between Mont Belvieu, Texas and Lake Charles, Louisiana, each of which transport NGLs and that have qualified for a waiver of applicable FERC regulatory requirements under the ICA based on current circumstances. Additionally, the crude oil pipeline system that is part of the Badlands assets also qualifies for such a waiver.
All such waivers are subject to revocation, however, should a particular pipeline’s circumstances change. FERC could, either at the request of other entities or on its own initiative, assert that some or all of these pipelines no longer qualify for a waiver. In the event that FERC were to determine that one more of these pipelines no longer qualified for waiver, we would likely be required to file a tariff with FERC for the applicable pipeline(s) and delivery point(s), provide a cost justification for the transportation charge, and
provide service to all potential shippers without undue discrimination.
Many existing pipelines, including Grand Prix and some of Targa NGL’s pipelines, may utilize the FERC oil pipeline indexing rate methodology which, as currently in effect, allows common carriers to change their rates within prescribed ceiling levels that are tied to changes in the Producer Price Index. FERC’s indexing methodology is subject to review every five years. On March 15, 2018, FERC issued a Revised Policy Statement on Treatment of Income Taxes (“Revised Policy Statement”) stating, among other things, that with respect to oil and refined products pipelines subject to FERC jurisdiction, the impacts of the Revised Policy Statement and the Tax Cuts and Jobs Act of 2017 on the costs of FERC-regulated oil and NGL pipelines will be reflected in FERC’s next five-year review of the oil pipeline index, which will generate the index level to be effective July 1, 2021. FERC’s establishment of a just and reasonable rate, including the determination of the appropriate oil pipeline index, is based on many components, and tax-related changes will affect two such components, the allowance for income taxes and the amount for accumulated deferred income taxes, while other pipeline costs also will continue to affect FERC’s determination of the appropriate pipeline index. Accordingly, depending on FERC’s application of its indexing rate methodology for the next five-year term of index rates, the Revised Policy Statement and tax effects related to the Tax Cuts and Jobs Act of 2017 may impact our revenues associated with any transportation services we may provide pursuant to cost-of-service based rates in the future, including indexed rates.
Tribal Lands
Our intrastate natural gas pipelines in North Dakota are subject to the various regulations of the State of North Dakota. In addition, various federal agencies within the U.S. Department of the Interior, particularly the federal Bureau of Land Management (“BLM”), Office of Natural Resources Revenue (formerly the Minerals Management Service) and the Bureau of Indian Affairs, as well as the Three Affiliated Tribes, promulgate and enforce regulations pertaining to operations on the Fort Berthold Indian Reservation. Please see “Other State and Local Regulation of Operations” below.
Intrastate Natural Gas
Though our natural gas intrastate pipelines are not subject to regulation by FERC as natural gas companies under the NGA, our intrastate pipelines may be subject to certain FERC-imposed reporting requirements depending on the volume of natural gas purchased or sold in a given year. See “—Regulation of Operations—FERC Market Transparency Rules.”
Our intrastate pipelines located in Texas are regulated by the Railroad Commission of Texas (the “RRC”). Our Texas intrastate pipeline, Targa Intrastate Pipeline LLC (“Targa Intrastate”), owns the intrastate pipeline that transports natural gas from our Shackelford processing plant to an interconnect with Atmos Pipeline-Texas that in turn delivers gas to the West Texas Utilities Company’s Paint Creek Power Station. Targa Intrastate also owns a 1.65-mile, ten-inch diameter intrastate pipeline that transports natural gas from a third-party gathering system into the Chico system in Denton County, Texas. Targa Intrastate is a gas utility subject to regulation by the RRC and has a tariff on file with such agency. Our other Texas intrastate pipeline, Targa Gas Pipeline LLC, owns a multi-county intrastate pipeline that transports gas in Crane, Ector, Midland, and Upton Counties, Texas, as well as some lines in North Texas. Targa Gas Pipeline LLC is a gas utility subject to regulation by the RRC and has a tariff on file with such agency.
Our Louisiana intrastate pipeline, Targa Louisiana Intrastate LLC, owns an approximately 60-mile intrastate pipeline system that receives all of the natural gas it transports within or at the boundary of the State of Louisiana. Because all such gas ultimately is consumed within Louisiana, and since the pipeline’s rates and terms of service are subject to regulation by the Office of Conservation of the Louisiana Department of Natural Resources (“DNR”), the pipeline qualifies as a Hinshaw pipeline under Section 1(c) of the NGA and thus is exempt from most FERC regulation.
We have an ownership interest of 50% of the capacity in a 50-mile long intrastate natural gas transmission pipeline, which extends from the tailgate of three natural gas processing plants located near Pettus, Texas to interconnections with existing intrastate and interstate natural gas pipelines near Refugio, Texas. The capacity is held by our subsidiary, TPL SouthTex Transmission Company LP (“TPL SouthTex Transmission”), which is entitled to transport natural gas through its capacity on behalf of third parties to both intrastate and interstate markets. Because the jointly owned pipeline system was initially interconnected only with intrastate markets, each of the capacity holders qualified as an “intrastate pipeline” within the meaning of the Natural Gas Policy Act of 1978 (“NGPA”) and therefore is able to provide transportation of natural gas to interstate markets under Section 311 of the NGPA. Under Sections 311 and 601 of the NGPA, an intrastate pipeline may transport natural gas in interstate commerce without becoming subject to FERC regulation as a “natural-gas company” under the NGA. Transportation of natural gas under authority of Section 311 must be filed with FERC and must be shown to be “fair and equitable.” TPL SouthTex Transmission has a Statement of Operating Conditions on file with FERC. TPL SouthTex Transmission has existing rates applicable to NGPA Section 311 service. The GCX Pipeline, which went into service in late third quarter 2019, transports natural gas from the Permian and Midland Basin to markets on the Texas Gulf Coast. GCX is subject to regulation by the RRC and under Section 311 of the NGPA and, on October 25, 2019, petitioned for rate approval, requesting an effective date of September 25, 2019.
We also operate natural gas pipelines that extend from the tailgate of our processing plants to interconnections with both intrastate and interstate natural gas pipelines. Although these “plant tailgate” pipelines may operate at transmission pressure levels and may transport “pipeline quality” natural gas, we believe they are generally exempt from FERC’s jurisdiction under the Natural Gas Act under FERC’s “stub” line exemption. However, Targa Midland Gas Pipeline LLC (“Targa Midland”) operates our Tarzan plant residue gas pipeline, which provides NGPA Section 311 service and falls outside of the “stub” line exemption. Targa Midland maintains a Statement of Operating Conditions on file with FERC.
FERC issued Order No. 849 on July 18, 2018, which became effective September 13, 2018, establishing new regulations that, among other things, require pipelines providing NGPA Section 311 service to file a new rate election for its interstate rates if the intrastate pipeline’s rates on file with the state regulatory agency are reduced to reflect the reduced income tax rates adopted in the Tax Cuts and Jobs Act. If an NGPA Section 311 pipeline’s interstate service rates are established pursuant to a rate filing with FERC, the pipeline is exempt from filing a new rate election if FERC has approved the interstate rates after December 22, 2017, or the pipeline has a pending rate petition at FERC on the effective date of the reduced intrastate rates. Any such petitions may reduce the rates we are permitted to charge for NGPA Section 311 service.
Texas and Louisiana have adopted complaint-based regulation of intrastate natural gas transportation activities, which allows natural gas producers and shippers to file complaints with state regulators in an effort to resolve grievances relating to pipeline access and rate discrimination. The rates we charge for intrastate transportation are deemed just and reasonable unless challenged in a complaint. We cannot predict whether such a complaint will be filed against us in the future. Failure to comply with state regulations can result in the imposition of administrative, civil and criminal penalties.
Intrastate Liquids
Our intrastate NGL pipelines in Texas transport mixed and purity NGL streams between Targa’s Mont Belvieu and Galena Park, Texas facilities. Grand Prix went into service during the third quarter of 2019, and provides transportation of mixed NGLs from the Permian Basin to Mont Belvieu, Texas. Further, we operate crude gathering pipelines in the Permian Basin. With respect to intrastate movements, these pipelines are not subject to FERC regulation, but are subject to rate regulation by the RRC. They are also subject to U.S. Department of Transportation (“DOT”) safety regulations.
Our intrastate NGL pipelines in Louisiana gather mixed NGLs streams that we own from processing plants in Louisiana and deliver such streams to the Gillis and Lake Charles fractionators in Lake Charles, Louisiana. We deliver mixed and purity NGL streams out of our fractionator to and from Targa-owned storage, to other third-party facilities and pipelines in Louisiana. Additionally, through our 50% ownership interest in Cayenne Pipeline, LLC, we operate the Cayenne pipeline, which transports mixed NGLs from the Venice gas plant in Venice, Louisiana, to an interconnection with a third-party NGL pipeline in Toca, Louisiana. These pipelines are not subject to FERC regulation or rate regulation by the DNR, but are subject to DOT safety regulations. On May 9, 2019, the Louisiana Public Service Commission (“LPSC”) approved applications to register certain pipelines of Cayenne Pipeline, LLC and Targa Downstream LLC in accordance with the LPSC 2015 General Order, Docket No. R-33390.
Other Federal Laws and Regulations Affecting Our Industry
EP Act of 2005
The EP Act of 2005 is a comprehensive compilation of tax incentives, authorized appropriations for grants and guaranteed loans, and significant changes to the statutory policy that affects all segments of the energy industry. Among other matters, the EP Act of 2005 amends the NGA to add an anti-market manipulation provision which makes it unlawful for any entity to engage in prohibited behavior to be prescribed by FERC, and furthermore provides FERC with additional civil penalty authority. The EP Act of 2005 provides FERC with the power to assess civil penalties of up to approximately $1.29 million per violation per day, adjusted annually for inflation, for violations of the NGA and approximately $1.29 million per violation per day, adjusted annually for inflation, for violations of the NGPA. The civil penalty provisions are applicable to entities that engage in the sale of natural gas for resale in interstate commerce. In 2006, FERC issued Order No. 670 to implement the anti-market manipulation provision of the EP Act of 2005. Order No. 670 does not apply to activities that relate only to intrastate or other non-jurisdictional sales or gathering, but does apply to activities of gas pipelines and storage companies that provide interstate services, as well as otherwise non-jurisdictional entities to the extent the activities are conducted “in connection with” gas sales, purchases or transportation subject to FERC jurisdiction, which includes the annual reporting requirements under a final rule on the annual natural gas transaction reporting requirements, as amended by subsequent orders on rehearing (Order No. 704), and the quarterly reporting requirement under Order No. 735. The anti-market manipulation rule and enhanced civil penalty authority reflect an expansion of FERC’s NGA enforcement authority.
FERC Market Transparency Rules
Beginning in 2007, FERC has issued a number of rules intended to provide for greater marketing transparency in the natural gas industry, including Order Nos. 704, 720, and 735. Under Order No. 704, wholesale buyers and sellers of more than 2.2 Bcf of physical natural gas in the previous calendar year, including interstate and intrastate natural gas pipelines, natural gas gatherers, natural gas processors and natural gas marketers, are now required to report, on May 1 of each year, aggregate volumes of natural gas purchased or sold at wholesale in the prior calendar year to the extent such transactions utilize, contribute to, or may contribute to the formation of price indices.
Under Order No. 720, certain non-interstate pipelines delivering, on an annual basis, more than an average of 50 million MMBtu of gas over the previous three calendar years, are required to post on a daily basis certain information regarding the pipeline’s capacity and scheduled flows for each receipt and delivery point that has a design capacity equal to or greater than 15,000 MMBtu/d and interstate pipelines are required to post information regarding the provision of no-notice service. In October 2011, Order No. 720 as clarified was vacated by the Court of Appeals for the Fifth Circuit. We take the position that, at this time, all of our entities are exempt from Order No. 720 as currently effective.
Under Order No. 735, intrastate pipelines providing transportation services under Section 311 of the NGPA and Hinshaw pipelines operating under Section 1(c) of the NGA are required to report on a quarterly basis more detailed transportation and storage transaction information, including: rates charged by the pipeline under each contract; receipt and delivery points and zones or segments covered by each contract; the quantity of natural gas the shipper is entitled to transport, store, or deliver; the duration of the contract; and whether there is an affiliate relationship between the pipeline and the shipper. Order No. 735 also extends FERC’s periodic review of the rates charged by the subject pipelines from three years to five years. On rehearing, FERC reaffirmed Order No. 735 with some modifications. As currently written, this rule does not apply to our Hinshaw pipelines.
Additional proposals and proceedings that might affect the natural gas industry are pending before Congress, FERC and the courts. We cannot predict the ultimate impact of these or the above regulatory changes to our natural gas operations. We do not believe that we would be affected by any such FERC action materially differently than other midstream natural gas companies with whom we compete.
Other State and Local Regulation of Operations
Our business activities are subject to various state and local laws and regulations, as well as orders of regulatory bodies pursuant thereto, governing a wide variety of matters, including operations, marketing, production, pricing, community right-to-know, protection of the environment, safety, marine traffic and other matters. In addition, the Three Affiliated Tribes promulgate and enforce regulations pertaining to operations on the Fort Berthold Indian Reservation, on which we operate a significant portion of our Badlands gathering and processing assets. The Three Affiliated Tribes is a sovereign nation having the right to enforce certain laws and regulations independent from federal, state and local statutes and regulations. For additional information regarding the potential impact of federal, state, tribal or local regulatory measures on our business, see “Risk Factors—Risks Related to Our Business.”
Environmental and Occupational Health and Safety Matters
Our business operations are subject to numerous environmental and occupational health and safety laws and regulations that may be imposed at the federal, regional, state, tribal and local levels. The activities that we conduct in connection with (i) gathering, compressing, treating, processing, transporting and selling natural gas; (ii) storing, fractionating, treating, transporting and selling NGLs and NGL products, including services to LPG exporters; (iii) gathering, storing, terminaling and selling crude oil; and (iv) storing, terminaling and selling refined petroleum products are subject to or may become subject to stringent environmental regulation. We have implemented programs and policies designed to monitor and pursue operation of our pipelines, plants and other facilities in a manner consistent with existing environmental and occupational health and safety laws and regulations, and have incurred and will continue to incur operating and capital expenditures, some of which may be material, to comply with these laws and regulations. Historically, our environmental compliance costs have not had a material adverse effect on our results of operations; however, there can be no assurance that such costs will not be material in the future or that such future compliance will not have a material adverse effect on our business and operational results.
The more significant of these existing environmental and occupational health and safety laws and regulations include the following U.S. legal standards, as amended from time to time:
| • | the Clean Air Act ("CAA"), which restricts the emission of air pollutants from many sources and imposes various pre-construction, operational, monitoring and reporting requirements, and that the EPA has relied upon as authority for adopting climate change regulatory initiatives relating to greenhouse gas ("GHG") emissions; |
|---|
| • | the Federal Water Pollution Control Act, also known as the Clean Water Act, which regulates discharges of pollutants to state and federal waters and establishes the extent to which waterways are subject to federal jurisdiction and rulemaking as protected waters of the United States; |
|---|
| • | the Comprehensive Environmental Response, Compensation and Liability Act of 1980 ("CERCLA"), which imposes liability on generators, transporters, and arrangers of hazardous substances at sites where hazardous substance releases have occurred or are threatening to occur; |
|---|
| • | the Resource Conservation and Recovery Act ("RCRA"), which governs the generation, treatment, storage, transport, and disposal of solid wastes, including hazardous wastes; |
|---|
| • | the Oil Pollution Act of 1990, which subjects owners and operators of onshore facilities, pipelines and other facilities, as well as lessees or permittees of areas in which offshore facilities are located, that are the site of an oil spill in waters of the United States, to liability for removal costs and damages; |
|---|
| • | the Safe Drinking Water Act, which ensures the quality of the nation’s public drinking water through adoption of drinking water standards and controlling the injection of waste fluids into below-ground formations that may adversely affect drinking water sources; |
|---|
| • | the Endangered Species Act, which restricts activities that may affect federally identified endangered and threatened species or their habitats through the implementation of operating restrictions or a temporary, seasonal, or permanent ban in affected areas; |
|---|
| • | the National Environmental Policy Act (NEPA), which requires federal agencies to evaluate major agency actions having the potential to impact the environment and that may require the preparation of environmental assessments and more detailed environmental impact statements that may be made available for public review and comment; and |
|---|
| • | the Occupational Safety and Health Act, which establishes workplace standards for the protection of the health and safety of employees, including the implementation of hazard communications programs designed to inform employees about hazardous substances in the workplace, potential harmful effects of these substances, and appropriate control measures. |
|---|
These environmental and occupational health and safety laws and regulations generally restrict the level of substances generated as a result of our operations that may be emitted to ambient air, discharged to surface water, and disposed or released to surface and below-ground soils and ground water. Additionally, there exist tribal, state and local jurisdictions in the United States where we operate that also have, or are developing or considering developing, similar environmental and occupational health and safety laws and regulations governing many of these same types of activities. Any failure by us to comply with these laws and regulations may result in the assessment of sanctions, including administrative, civil, and criminal penalties; the imposition of investigatory, remedial, and corrective action obligations or the incurrence of capital expenditures; the occurrence of restrictions, delays or cancellations in the permitting, development or expansion of projects; and the issuance of injunctions restricting or prohibiting some or all of our activities
in a particular area. Certain environmental laws also provide for citizen suits, which allow environmental organizations to act in place of the government and sue operators for alleged violations of environmental law. The ultimate financial impact arising from environmental laws and regulations is neither clearly known nor determinable as existing standards are subject to change and new standards continue to evolve.
We own, lease, or operate numerous properties that have been used for crude oil and natural gas midstream services for many years. Additionally, some of our properties have been operated by third parties or by previous owners or operators whose treatment and disposal of hazardous substances, wastes, or petroleum hydrocarbons was not under our control. Under environmental laws such as CERCLA and RCRA, we could incur strict joint and several liability for remediating hydrocarbons, hazardous substances or wastes disposed of or released by us or prior owners or operators. We also could incur costs related to the clean-up of third-party sites to which we sent regulated substances for disposal or to which we sent equipment for cleaning, and for damages to natural resources or other claims related to releases of regulated substances at or from such third-party sites.
Over time, the trend in environmental and occupational health and safety regulation is to typically place more restrictions and limitations on activities that may adversely affect the environment or expose workers to injury and thus, any changes in environmental or occupational health and safety laws and regulations or reinterpretation of enforcement policies that may arise in the future and result in more stringent or costly waste management or disposal, pollution control, remediation or occupational health and safety-related requirements could have a material adverse effect on our business, results of operations and financial position. We may not have insurance or be fully covered by insurance against all environmental and occupational health and safety risks, and we may be unable to pass on increased compliance costs arising out of such risks to our customers. We review regulatory and environmental issues as they pertain to us and we consider regulatory and environmental issues as part of our general risk management approach. For more information on environmental and occupational health and safety matters, see the following Risk Factors under Part I, Item 1A of this Form 10-K: “Our operations are subject to environmental laws and regulations and a failure to comply or an accidental release into the environment may cause us to incur significant costs and liabilities,” “We could incur significant costs in complying with stringent occupational safety and health requirements,” “Laws and regulations regarding hydraulic fracturing could result in restrictions, delays or cancellations in drilling and completing new oil and natural gas wells by our customers, which could adversely impact our revenues by decreasing the volumes of natural gas, NGLs or crude oil through our facilities and reducing the utilization of our assets,” and “Our and our customers’ operations are subject to a series of risks arising out of the threat of climate change (including legislation or regulation to address climate change) that could result in increased operating costs, limit the areas in which oil and natural gas production may occur, and reduce demand for the products and services we provide.”
Pipeline Safety Matters
Many of our natural gas, NGL and crude oil pipelines are subject to regulation by the federal Pipeline and Hazardous Materials Safety Administration (“PHMSA”), an agency of the DOT, under the Natural Gas Pipeline Safety Act of 1968, as amended (“NGPSA”), with respect to natural gas, and the Hazardous Liquids Pipeline Safety Act of 1979, as amended (“HLPSA”), with respect to crude oil, NGLs and condensates. The NGPSA and HLPSA govern the design, installation, testing, construction, operation, replacement and management of natural gas, crude oil, NGL and condensate pipeline facilities. Pursuant to these acts, PHMSA has promulgated regulations governing, among other things, pipeline design, maximum operating pressures, pipeline patrols and leak surveys, public awareness, operation and maintenance procedures, operator qualification, minimum depth requirements and emergency procedures, as well as other matters intended to ensure adequate protection for the public and to prevent accidents and failures. Additionally, PHMSA has promulgated regulations requiring pipeline operators to develop and implement integrity management programs to comprehensively evaluate certain relatively higher risk areas, known as high consequence areas (“HCAs”) and moderate consequence areas (“MCAs”) along pipelines and take additional safety measures to protect people and property in these areas. The HCAs for natural gas pipelines are predicated on high-population areas (which, for natural gas transmission pipelines, may include Class 3 and Class 4 areas) whereas HCAs for crude oil, NGL and condensate pipelines is based on high-population areas, certain drinking water sources and unusually sensitive ecological areas. An MCA is attributable to natural gas pipelines and is based on high-population areas as well as certain principal, high-capacity roadways, though it does not meet the definition of a natural gas pipeline HCA. Various states have also adopted regulations, similar to existing PHMSA regulations for, and may have established agencies analogous to PHMSA to regulate, intrastate gathering and transmission lines. Historically, our pipeline safety compliance costs have not had a material adverse effect on our results of operations; however, there can be no assurance that such costs will not be material in the future or that such future compliance will not have a material adverse effect on our business, financial condition or results of operations. See Risk Factors “We may incur significant costs and liabilities resulting from performance of pipeline integrity programs and related repairs” and “Federal and state legislative and regulatory initiatives relating to pipeline safety that require the use of new or more stringent safety controls or result in more stringent enforcement of applicable legal requirements could subject us to increased capital costs, operational delays and costs of operation” under Item 1A of this Form 10-K for further discussion on pipeline safety standards, including integrity management requirements.
Title to Properties and Rights of Way
Our real property falls into two categories: (1) parcels that we own in fee and (2) parcels in which our interest derives from leases, easements, rights of way, permits or licenses from landowners or governmental authorities permitting the use of such land for our operations. Portions of the land on which our plants and other major facilities are located are owned by us in fee title and we believe that we have satisfactory title to these lands. The remainder of the land on which our plant sites and major facilities are located are held by us pursuant to ground leases between us, as lessee, and the fee owner of the lands, as lessors. We and our predecessors have leased these lands for many years without any material challenge known to us relating to the title to the land upon which the assets are located, and we believe that we have satisfactory leasehold estates to such lands. We have no knowledge of any challenge to the underlying fee title of any material lease, easement, rights of way, permit, lease or license, and we believe that we have satisfactory title to all of our material leases, easements, rights of way, permits, leases and licenses.
Employees
Through a wholly-owned subsidiary of ours, we employ approximately 2,680 people who primarily support our operations. None of those employees are covered by collective bargaining agreements. We consider our employee relations to be good.
Financial Information by Reportable Segment
See “Segment Information” included under Note 28 of the “Consolidated Financial Statements” for a presentation of financial results by reportable segment and see “Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations– By Reportable Segment” for a discussion of our financial results by segment.
Available Information
We make certain filings with the SEC, including our Annual Report on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, and all amendments and exhibits to those reports. We make such filings available free of charge through our website, http://www.targaresources.com, as soon as reasonably practicable after they are filed with the SEC. Our press releases and recent analyst presentations are also available on our website. The SEC also maintains an internet website at http://www.sec.gov that contains reports, proxy and information statements and other information regarding issuers, including us, that file electronically with the SEC. The information contained on the websites referenced in this Annual Report on Form 10-K is not incorporated herein by reference.