 filings.tools
Item 1. Business
43K characters. Original on sec.gov · Markdown
Item 1. Business
OVERVIEW
Visa is a global payments technology company that enables fast, secure and reliable electronic payments across more than 200 countries and territories. We facilitate global commerce through the transfer of value and information among a global network of consumers, merchants, financial institutions, businesses, strategic partners, and government entities. Our advanced transaction processing network, VisaNet, enables authorization, clearing, and settlement of payment transactions and allows us to provide our financial institution and merchant clients with a wide range of products, platforms, and value-added services.
Our mission is to connect the world through the most innovative, reliable, and secure payment network – enabling individuals, businesses, and economies to thrive. To deliver on this mission, we are focused on seven strategic pillars:

Our focus, expertise, and assets have enabled Visa to become one of the world’s largest retail electronic payments networks based on payments volume and number of transactions.
Visa Network
Visa connects millions of consumers and businesses every day through the power of our network.
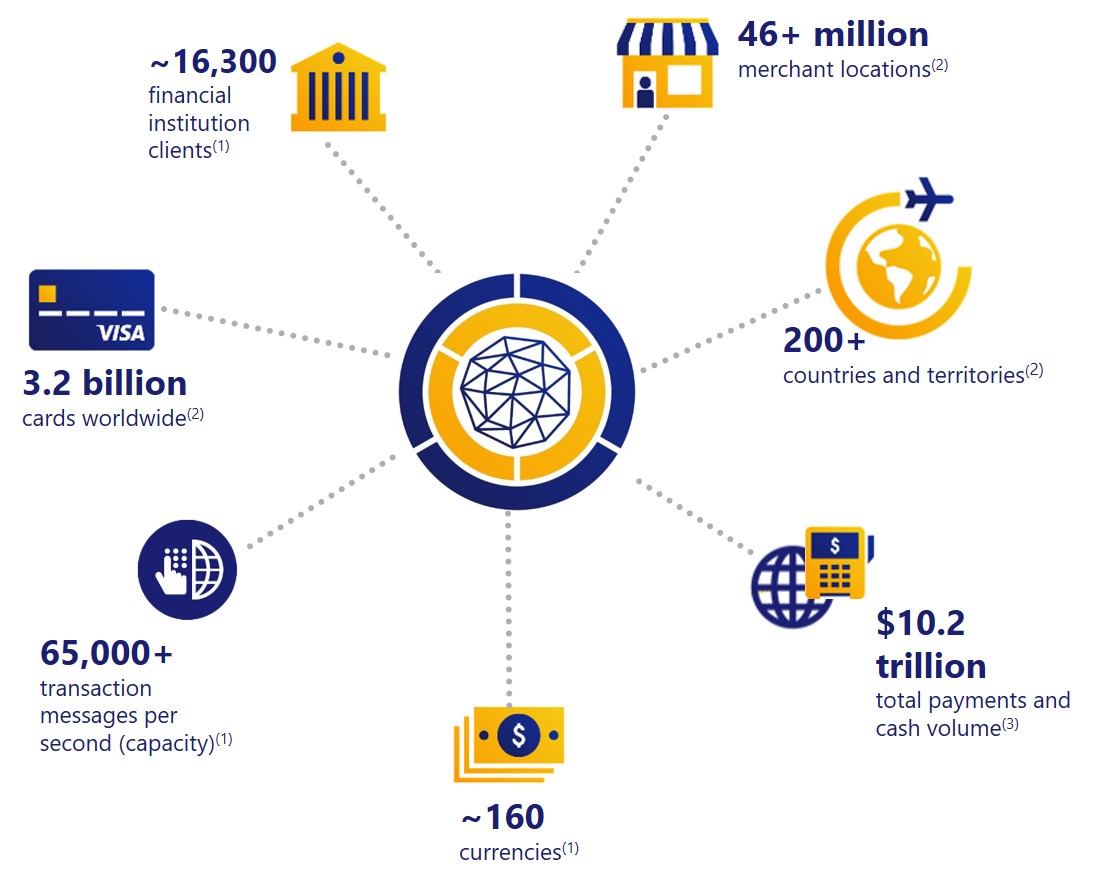
| (1) | As of September 30, 2017 |
| (2) | As of June 30, 2017 |
| (3) | Transacted on our payment products for the 12 months ended June 30, 2017 |
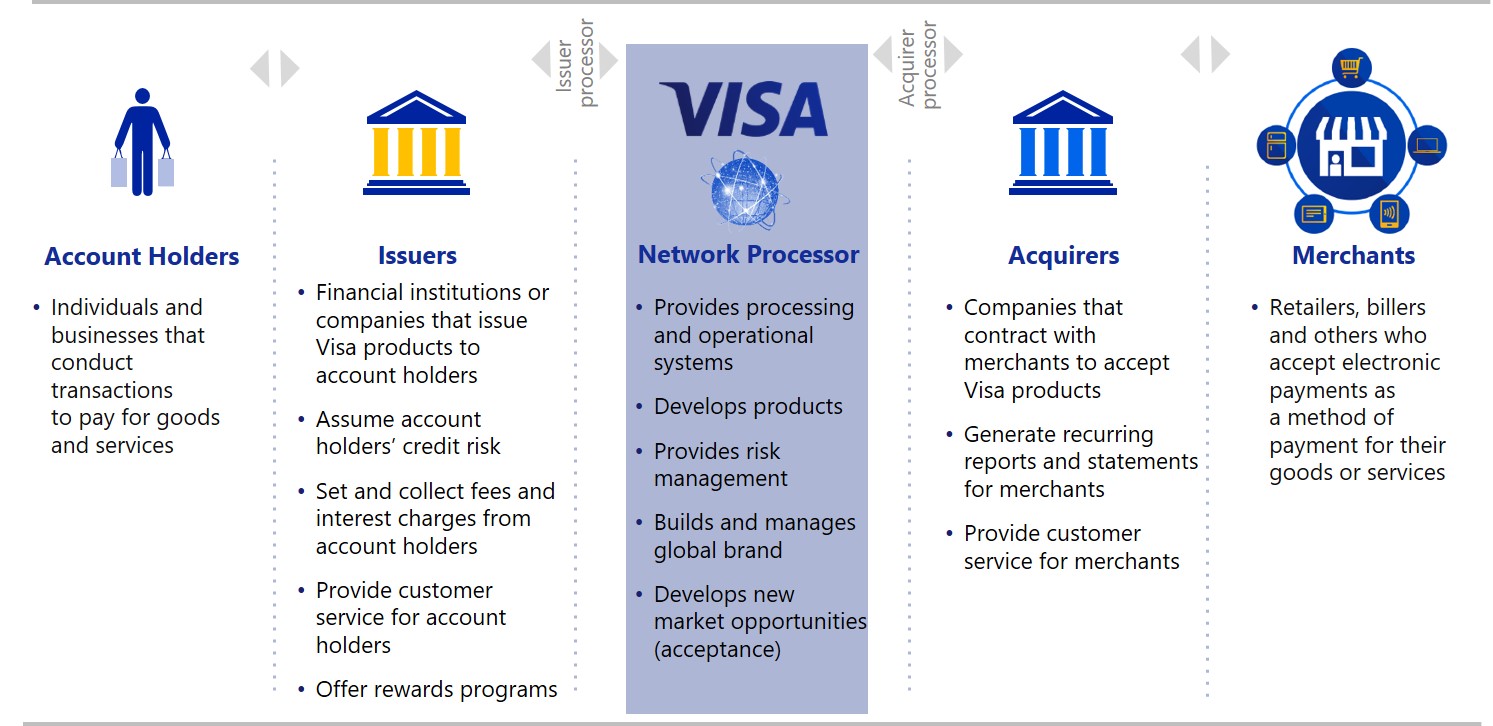
Visa operates in a four party model, which includes card issuing financial institutions, acquirers, and merchants. We are not a bank and do not issue cards, extend credit, or set rates and fees for account holders on Visa products. Generally, our financial institution clients are responsible for managing account holder and merchant relationships.
Visa does not earn revenues from, or bear credit risk with respect to, interest or fees paid by account holders on Visa products. Interchange reimbursement fees represent a transfer of value between the financial institutions participating in our open-loop payments network. We administer the collection and remittance of interchange reimbursement fees through the settlement process, but we generally do not receive any revenue related to interchange reimbursement fees. In addition, we do not receive as revenue the fees that merchants are charged directly for acceptance by their acquirers.
Visa Brand
The Visa brand is one of the world's most recognized, trusted, and valuable brands. Anchored on the notion that Visa is "everywhere you want to be," the brand stands for acceptance, security, convenience, speed, and reliability. In recognition of its strength among clients and consumers, the Visa brand is ranked highly in a number of widely recognized brand studies, including BrandZ Top 100 Most Valuable Global Brands Study, Forbes World’s Most Valuable Brands, Interbrand's Best Global Brands, and YouGov Brand Index. Our brand strength helps us to deliver added value to financial institutions, merchants, and other clients through compelling brand expressions, expanded products and services, and innovative marketing efforts.
Payment Security
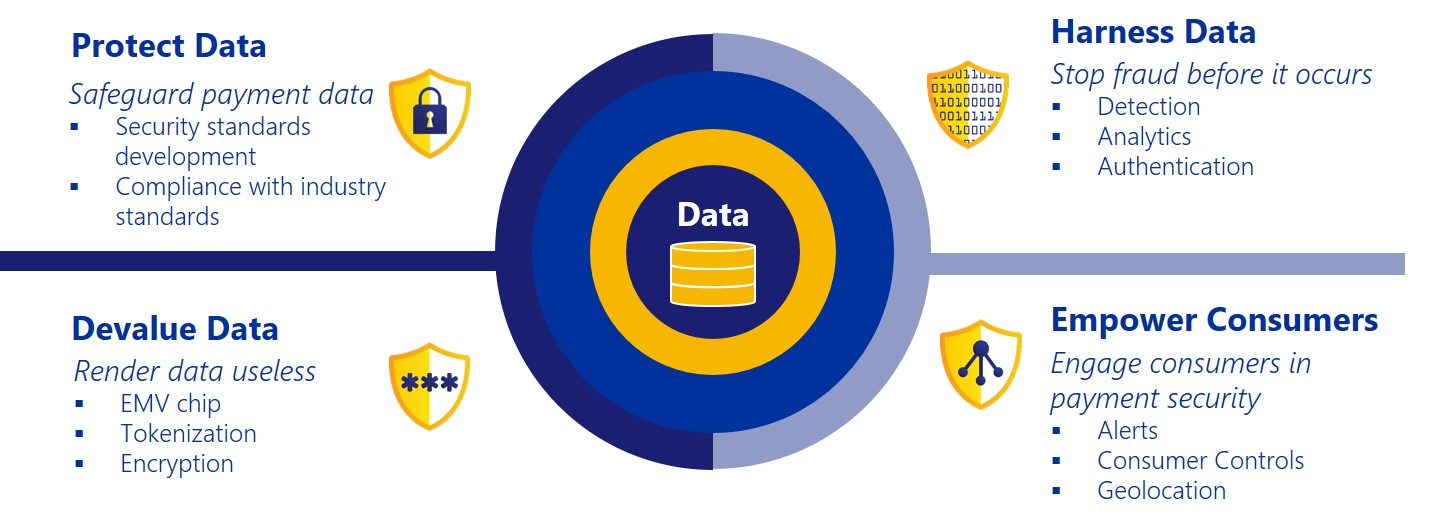
Visa has focused its investments, partnerships, and expertise to enhance the security of our network, and to enable consumers and businesses to pay and be paid with confidence. As payments methods evolve, we are focused on four primary areas:
| • | Protecting payment data with a payments architecture that complies with industry standards; |
| • | Rendering the use of sensitive payment data useless by deploying technologies such as the EMV chip and tokenization; |
| • | Using predictive analytics, intelligence, and insights to identify and prevent fraud before it happens; and |
| • | Empowering consumers to actively protect their own financial information and transactions. |
Fiscal 2017 Key Statistics (including Visa Europe)(1)

| (1) | Figures and period-over-period percentages reflect the inclusion of Visa Europe for the full year of fiscal 2017. We acquired Visa Europe on June 21, 2016. |
| (2) | Please see Item 7—Management's Discussion and Analysis of Financial Condition and Results of Operations for a reconciliation of our adjusted financial results. |
| (3) | For the 12 months ended June 30, 2017, upon which fiscal 2017 service revenues are based. |
KEY INITIATIVES
Visa Europe Integration
In fiscal 2017, we made significant progress on integrating Visa Europe into the broader Visa group following our completion of the acquisition in June 2016. We streamlined and integrated our European functions with the global Visa organization and bolstered the European leadership team. We invested in launching a suite of digital products, including Visa Checkout and Visa Commerce Network, and entered into new strategic partnerships, including Klarna and Paypal, to spur innovation and drive usage and acceptance. We made significant progress in our multi-year effort to harmonize our respective technology systems and prepare for European client migrations onto VisaNet beginning in fiscal 2018. Along with our new innovation center in London, we believe these efforts will help bring more enhanced capabilities as well as provide greater scale and additional levels of cybersecurity for our European clients. In addition, we made significant progress in entering into new commercial agreements with our European clients to transition the business from the prior association business model to a for-profit model. These new commercial arrangements have led to an increase in client incentives as we have replaced the rebates in effect under the prior model.
Technology Transformation
Visa is primarily a technology company. In fiscal 2015, we embarked on a multi-year journey to transform our use of technology. We have increased our technology employee footprint by more than 2,000 globally over the past three years, including nearly 1,000 new college graduates, replacing a significant percentage of our contractor and vendor spend. We are making steady progress on our technology strategic roadmap, resulting in enhanced services in the payments ecosystem and positive impacts to our infrastructure. Since the launch of Visa’s Developer Platform (VDP) in fiscal 2016, we have made our application program interfaces (APIs) available to our developers, clients, and partners. VDP offers them access to Visa technology, services, and tools, and provides safe testing environments for the development of new digital payments and commerce solutions. We added new services to enable clients to develop support for tokenized transactions and create new and innovative solutions in mobile, ecommerce, and digital face-to-face transactions.
Cybersecurity remains a top focus, and in fiscal 2016 we launched our Threat Intelligence Fusion Platform, a cyber command and control center that provides integrated cybersecurity operations to further protect our data and assets. In fiscal 2017, we continued to embed security earlier in the software development lifecycle to further strengthen our security posture. New open technologies have been added systematically to our infrastructure and platform components. We continue to bolster the resiliency of our infrastructure and application services to provide high availability of our client services.
How We Work with Partners – Innovation Centers, Visa Developer Program, Certifications, and Startups
To drive new solutions in the payments space and accelerate the proliferation of safe and fast digital payments, we opened a new innovation center in London in fiscal 2017. Our innovation centers foster collaboration with our financial institution clients, merchants, partners, and developers across the regions to spur the creation of the next generation of payments and commerce applications and solutions. By providing access to Visa capabilities through an open network of APIs, the Visa Developer Platform allows global partners to transform ideas into new digital commerce experiences. Visa’s Everywhere Initiative is an innovation program in over 40 countries designed to generate and harness ideas within the start-up community to solve business problems, influence Visa's product development, and support Visa's clients. Visa makes minority investments in companies around the world that we believe will further our vision and strategic objectives, support deeper engagement with key partners, and expand access to payment solutions worldwide. In addition, through the Visa Ready certification program, we provide the structure that allows partners to introduce devices, software, and solutions that can securely initiate or accept Visa payments.
PRODUCTS & SERVICES
Core Products
Debit: Debit cards are issued by financial institutions to allow consumers and small businesses to purchase goods and services using funds held in their demand deposit accounts. Debit cards enable cardholders to transact – in person, online, or via mobile – without needing cash or checks and without accessing a line of credit. Visa provides a strong brand; the network infrastructure and processing; acceptance; product features and support; risk tools and services; and industry expertise to help issuers optimize their debit offerings.
Credit: Credit cards are issued by financial institutions to allow consumers and businesses to access credit to pay for goods and services. Visa does not extend credit; however, we provide combinations of card benefits, including technology, authorization, fraud tools, and brand support that financial institutions use to support and enable their credit products. We also partner with our clients on product design, consumer segmentation, and consumer experience design to help financial institutions better deliver products and services that match their consumers’ needs.
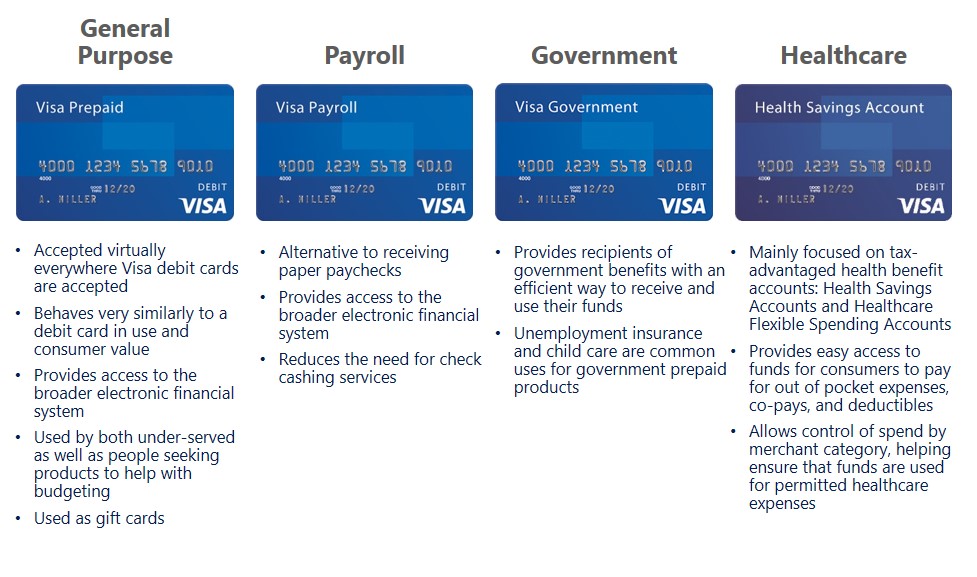
Prepaid: Prepaid products draw from a designated balance funded by individuals, corporations, or governments. Prepaid cards address many consumer-use cases and needs including, general purpose reloadable, payroll, government and corporate disbursements, healthcare, gift, and travel. Prepaid cards also play an important part in financial inclusion, bringing payment solutions to those with limited or no access to traditional banking products.
Commercial: We offer a portfolio of commercial payment solutions including corporate (travel) cards, purchasing cards, virtual accounts, and disbursement accounts covering all major industry segments. The commercial category is a portfolio of solutions designed to bring efficiency, controls, and automation to commercial and government payment processes ranging from employee travel to fully integrated, invoice-based payables. Beyond payment processing, we provide comprehensive data management solutions, consulting and analytics support, and integration capabilities. We support financial institutions, partners in the accounts payable space, and technology companies as they build and expand their commercial payment platforms.
Global ATM: The Visa/PLUS Global ATM network provides account holders with convenient cash access in more than 200 countries and territories worldwide through issuing and acquiring partnerships with both financial institutions and independent ATM operators.
Processing Infrastructure
VisaNet authorizes, clears, and settles transactions processed by Visa, excluding transactions within Europe, which are routed through different software and hardware platforms in the United Kingdom (UK) to perform authorization, clearing, and settlement in Europe. VisaNet consists of multiple synchronized processing centers that are linked by a global telecommunications network and engineered for minimal downtime and uninterrupted connectivity. We are in the process of integrating Visa Europe's processing systems with VisaNet. Until that process is completed, we will continue to maintain the current authorization, clearing, and settlement systems in Europe while ensuring interoperability between such systems and VisaNet.
VisaNet provides secure and reliable payments around the world and is capable of handling more than 65,000 transaction messages a second. VisaNet is built on a centralized architecture, which allows us to analyze each authorization we process in real time and provide value-added processing services such as risk scoring and tokenization. It provides the infrastructure for delivering innovation and other payment system enhancements for domestic payment systems and cross-border international transactions globally. In fiscal 2017, Visa processed over 111.2 billion payment and cash disbursement authorization transactions globally.
A typical Visa transaction begins when an account holder presents his or her Visa product to a merchant as payment for goods or services. The transaction is then sent to the merchant's acquirer and routed to an issuer for an authorization decision. The transaction is either approved or declined and routed back to the acquirer and merchant usually in a matter of seconds.
Transaction Processing Services
Our core transaction processing services involve the routing of payment information and related data to facilitate the authorization, clearing, and settlement of transactions between our issuers and acquirers. Our processing services also address the varied needs of other participants in the evolving payments ecosystem, through such offerings as our merchant gateway and Visa Debit Processing Services (DPS) for issuer processing. Merchant gateway services, provided through CyberSource, enable merchants to accept, process, and reconcile payments, manage fraud and safeguard payment security online and at the physical point of sale. CyberSource additionally enables acquirers and other partners to offer these services to their merchants. Visa DPS provides comprehensive issuer processing services for participating issuers of Visa debit, prepaid, and ATM products. Value-added offerings by Visa DPS to issuer clients include: fraud and risk services, data analytics, marketing campaign management, mobile and digital solutions, back office tools and services, card fulfillment and management, network gateway services, call centers, and web hosting solutions. These and other services support our issuers and acquirers and their use of our products, and promote the growth and security of our payments network.
Digital Products
Visa Checkout: Visa Checkout offers consumers an expedited and secure payment experience for online and mobile transactions wherever Visa Checkout is offered. Visa Checkout helps merchants attain higher rates of completed purchases from their consumers, a particularly important feature as digital commerce shifts from desktop devices to mobile devices, where shoppers have been less likely to complete purchases from their shopping carts. At the end of fiscal 2017, Visa Checkout had over 25 million consumer accounts in 26 countries, seven languages and over 1,600 financial institution partners participating, amounting to $3.8 billion in transaction dollars. More than 350,000 merchants, including some of the largest global retailers, accept Visa Checkout. In fiscal 2017, our product enhancement focus was making Visa Checkout more convenient for consumers to sign in and sign up by enabling biometric sign in. We also successfully piloted a stay-signed-in feature that verifies account holders on their device, allowing a consumer to checkout in as little as two clicks.
Visa Direct: Visa Direct is Visa’s real-time “push” payments platform that allows businesses, governments, and consumers to use the Visa network to transfer funds from an originating account to another via a debit, prepaid, or credit card number. This platform enables faster payments solutions for a range of new use cases, including person-to-person (P2P), disbursements, bill pay, and micro merchant payments. At the end of fiscal 2017, there were over 1 billion Visa debit, prepaid, and credit cards enabled for real-time receipt of funds, providing global scale and reach for partners. Issuers, acquirers, processors, and merchants are able to leverage our existing network connections to build new services, capabilities, and solutions. We have partnered with Adyen, Braintree, Hyperwallet, Ingo Money, OnDeck, PayPal, Stripe and Vantiv to incorporate Visa Direct into their payment solutions. Additionally, in emerging markets, push payments enable mobile applications to allow consumers to use their mobile device to “push” money to a business account via a QR code for payment of goods and services. Visa’s scan-and-pay functionality enables low-cost, low-barrier alternatives for promoting digital payment acceptance for small merchants. Visa has successfully launched merchant-presented QR technology that utilizes Visa Direct in India, Kenya, and Nigeria, and is continuing to work on developing common standards for QR code payments to ensure global interoperability, which is key to the growth of the push payments ecosystem. Work is currently underway to launch QR technology with Visa Direct in 12 additional markets over the next year.
Visa Token Service: The Visa Token Service replaces the card account numbers from the transaction with a token. Tokenization helps to protect consumer financial information and lessen the risk of stolen card credentials, particularly when information regarding a financial instrument is stored on a device, such as a mobile phone or wearable, or is stored on file at an ecommerce merchant. In fiscal 2017, we expanded Visa Token Service to 29 markets and are actively engaged in tokenizing accounts. We also enabled wearables providers FitBit and Garmin to embed Visa tokens in their devices. Finally, we announced a new program to drive acceleration into Internet-of-Things (IoT) payments. Visa Ready for IoT allows certified third-party service providers such as Gemalto, Giesecke & Devrient, FitPay, Infosys, PriNum, and Inside Secure to connect directly to our token service and become Token Service Providers (TSPs). These TSPs will be able to provide a range of services to support Visa tokens for issuers and token requestors, including new account provisioning and life cycle management. By expanding access to the Visa Token Service to new partners, we expect Visa issuers and other partners to be able to more quickly and easily offer secure digital payment services across a wide range of solutions.
Merchant Products
Visa has a suite of products and services to help merchants reduce their payment fraud and improve their customer engagement. Visa Advertising Solutions, Visa Commerce Network, and CyberSource’s product offerings are examples of Visa’s continued investment to deliver industry-leading products and capabilities to our merchant partners.
Visa Advertising Solutions is a service that allows merchants to better target and track the efficacy of their digital campaigns. Visa partners with strategic advertising technology companies to help deliver targeting and measurement capabilities using aggregated and de-identified spend insights. Visa Commerce Network uses Visa’s global payments network to enable merchants to promote relevant offers to acquire new customers, drive loyalty, and increase sales. For example, Uber and Visa Commerce Network have partnered to introduce Visa Local Offers, a card-linked offer program that rewards enrolled U.S. Visa account holders for shopping at thousands of featured merchants in the United States. Uber credits are awarded to the riders’ Uber accounts automatically on qualifying purchases – eliminating the need for coupons or promo codes.
The CyberSource platform enables merchants to manage online, mobile, and in-person payments. CyberSource offers solution packages tailored for merchants, acquirers, and technology partners. CyberSource offers a secure, integrated commerce solution that gives businesses the flexibility to select the ecommerce or point-of-sale platform, financial partner, and hardware of their choice. CyberSource enables businesses to accept payments from over 200 countries and territories across the world through its acquirer and processor connections and its Token Management Service provides a 360 degree view of customer purchases across all sales channels. The CyberSource Decision Manager fraud management service helps businesses minimize fraud losses, maximize revenue, and control costs. The solution combines advanced machine learning methods, a flexible rules engine, and insights derived from billions of CyberSource and Visa transactions. CyberSource's small business solutions are represented by the Authorize.Net brand in North America and the United Kingdom. CyberSource and Authorize.Net capabilities are offered through Visa and our partners.
Risk Products & Payment Security Initiatives
We continue to develop our suite of risk products and services to help clients minimize risk and enable secure commerce. Visa Risk Manager is a decision-making solution that helps issuers improve loss prevention and profitability through enhanced risk evaluation capabilities. Products like Visa Advanced Authorization evaluate the risk associated with every participating VisaNet transaction. In addition to reducing fraud, clients can increase approval rates by utilizing Visa's risk products that provide more insightful, real-time information and accept transactions that were once deemed too risky. For example, Mobile Location Confirmation, a service that enhances Visa Advanced Authorization by adding geolocation intelligence in real time, informs issuers if their participating account holder’s mobile phone is near a purchase location. This new data improves the issuer’s ability to make more informed decisions. Another tool that issuers can utilize across their entire card portfolio is Transaction Controls, which allows account holders to place restrictions on their enrolled cards that define when, where, and how those cards can be used to better manage account spending and security.
We have also extended our fraud prediction capabilities to merchants via Visa Transaction Advisor, which provides real-time analytics and identifies suspicious transactions that require additional verification before the transaction is processed. Visa's use of 3-D Secure technology is designed to make digital transactions safer by using risk-based authorization in real-time. Additionally, in fiscal 2017, Visa acquired CardinalCommerce, an industry leader in digital payment authentication. The acquisition enables Visa to help reduce fraud and support digital commerce.
Beyond our risk products and services, we continue to work with the Payment Card Industry Security Standards Council, EMVCo, and other industry standards organizations to develop and support standards for payment data security, EMV chip payment technology, tokenization, and 3-D Secure 2.0. We also partner with clients, merchants, governments, and law enforcement agencies to help identify fraud and share information about security best practices, threat intelligence, and legal and regulatory developments.
OTHER BUSINESS DEVELOPMENTS
Visa Foundation. In fiscal 2017, we established the Visa Foundation, a nonprofit public benefit corporation, aimed at enabling economic opportunity for the underserved, with a particular focus on helping low-income micro and small enterprises thrive. In February 2017, the foundation was funded with a contribution of 2.2 million shares of Visa class A common stock to advance these goals.
Capital Structure. In September 2017, we issued $2.5 billion of senior notes with maturities ranging between 5 and 30 years. Subsequent to our fiscal year-end, in October 2017, we used the majority of the proceeds from this new debt to redeem the $1.75 billion of senior notes scheduled to mature in December 2017.
INTELLECTUAL PROPERTY
We own and manage the Visa brand, which stands for acceptance, security, convenience, speed, and reliability. Our portfolio of trademarks, in particular our family of Visa marks, our PLUS mark, and our Dove design mark, are important to our business. We give our clients access to these assets through agreements with our issuers and acquirers, which authorize the use of our trademarks in connection with their participation in our payments network. We also own a number of patents, patent applications, and other intellectual property relating to payment solutions, transaction processing, security systems, and other matters. We rely on a combination of patent, trademark, copyright, and trade secret laws in the United States and other jurisdictions, as well as confidentiality procedures and contractual provisions, to protect our proprietary technology.
NET OPERATING REVENUES
Our gross revenues are principally comprised of service revenues, data processing revenues, international transaction revenues, and other revenues. Net operating revenues are gross revenues reduced by costs incurred under client incentive arrangements. We have one reportable segment, Payment Services.
Revenue Details

COMPETITION
The global payments industry continues to undergo dynamic change. Existing and emerging competitors compete with Visa's network and payment solutions for consumers and for participation by financial institutions and merchants. Technology and innovation are shifting consumer habits and driving growth opportunities in ecommerce, mobile payments, block chain technology, and digital currencies. These advances are enabling new entrants, many of which depart from traditional network payment models. In certain countries, the evolving regulatory landscape is changing how we compete, creating local networks, or enabling processing competition.
We compete against all forms of payment. This includes paper-based payments, primarily cash and checks, and all forms of electronic payments. Our electronic payment competitors principally include:
Global or Multi-Regional Networks, which typically offer a range of branded, general purpose card payment products that can be used at millions of merchant locations around the world. Examples include MasterCard, American Express, Discover, JCB, and UnionPay. These competitors may be more concentrated in specific geographic regions, such as JCB in Japan and Discover in the United States, or have a leading position in certain countries. For example, UnionPay operates the sole domestic acceptance mark in China and is expanding into other global markets. See Item 1A—Risk Factors—Regulatory Risks—Government-imposed restrictions on payment systems may prevent us from competing against providers in certain countries, including significant markets such as China and Russia. Based on available data, Visa is one of the largest retail electronic funds transfer networks used throughout the world. The following chart compares our network with these network competitors for calendar year 2016(1):

| (1) | UnionPay, which operates primarily within the Chinese domestic market, is not included in this table as Visa currently does not compete in that market under local law. Although we are uncertain how UnionPay reports certain volumes, reportedly its numbers could approach or exceed some of those listed in this chart. |
| (2) | The data presented are provided by our financial institution clients, inclusive of Europe for the second half of calendar year 2016. Previously submitted information may be updated and all data are subject to review by Visa. |
| (3) | MasterCard, American Express, JCB and Discover/Diners Club data sourced from The Nilson Report issue 1109 (May 2017). Includes all consumer and commercial credit, debit and prepaid cards. Some figures are estimates and currency figures are in U.S. dollars. MasterCard excludes Maestro and Cirrus figures. American Express includes figures for third-party issuers. Discover figures consist of U.S. data only and include third-party issuers. JCB figures include third-party issuers and other payment-related products. |
Local and regional networks, that operate in many countries, often with the support of government influence or mandate. In some cases, they are owned by financial institutions. These networks typically focus on debit payment products, have functionality or their brand marks present with the Visa brand on the card or payment device, and may have strong local acceptance, and recognizable brands. Examples include STAR, NYCE, and Pulse in the United States, Interac in Canada, EFTPOS in Australia and Mir in Russia.
Alternate Payment Providers, which often have a primary focus of enabling payments through ecommerce and mobile channels, but which are expanding or may expand their offerings to the physical point of sale. These companies may process payments using in-house account transfers between parties, electronic funds transfer networks like the Automated Clearing House (ACH), or global or local networks like Visa. In some cases, these entities are both a partner and a competitor to Visa. Examples of alternate payment providers include PayPal, Alipay, and WeChat. Alipay and WeChat Pay are among the fastest growing mobile payment providers in the world and may pose a competitive challenge to Visa and other international networks outside of China.
Other Electronic Payments Networks like the ACH in the United States are often regulated by local governments. Historically focused on interbank transfers, many are adding capabilities that may make them more competitive for retail payments. MasterCard acquired VocaLink Holdings Limited in 2016, which provides faster payments technology that competes with our Visa Direct offering. We also compete with closed-loop payment systems, emerging payments networks like Zelle, wire transfers, and electronic benefit transfers.
Payment Processors, which we compete with for the processing of Visa transactions or which may benefit from mandates requiring them to handle processing under local regulation. For example, as a result of regulation in Europe under the Interchange Fee Regulation (IFR), we may face competition from other networks, processors, and other third-parties who could process Visa transactions directly with issuers and acquirers.
We also face increasingly intense competitive pressure on the prices we charge our financial institution clients. We believe our fundamental value proposition of acceptance, security, convenience, speed, and reliability offers us a key competitive advantage. We succeed in part because we understand the needs of the individual markets in which we operate and partner with local financial institutions, merchants, governments, non-governmental organizations, and business organizations to provide tailored solutions. We believe Visa is well-positioned competitively, due to our global brand, our broad set of Visa-branded payment products, and our proven track record of processing payment transactions securely and reliably through VisaNet.
SEASONALITY
We generally do not experience any pronounced seasonality in our business. No individual quarter of fiscal 2017 or fiscal 2016 accounted for more than 30% of our operating revenues in those years.
WORKING CAPITAL
Payments settlement due to and from our financial institution clients can represent a substantial daily working capital requirement. Most U.S. dollar settlements are settled within the same day and do not result in a receivable or payable balance, while settlement in currencies other than the U.S. dollar generally remain outstanding for one to two business days, which is consistent with industry practice for such transactions.
FINANCIAL INFORMATION ABOUT GEOGRAPHIC AREAS
For more information on the concentration of our operating revenues and other financial information, see Note 12—Enterprise-wide Disclosures and Concentration of Business to our consolidated financial statements included in Item 8—Financial Statements and Supplementary Data of this report.
GOVERNMENT REGULATION
As a global payments technology company, we are subject to complex and evolving global regulations in the various jurisdictions in which our products and services are used. The most significant government regulations that impact our business are discussed below. For further discussion of how global regulations may impact our business, see Item 1A—Risk Factors—Regulatory Risks.
Supervisory Oversight of the Payments Industry. Visa is subject to financial sector oversight and regulation in substantially all of the jurisdictions in which we operate. In the United States, for example, the Federal Financial Institutions Examination Council (FFIEC) has supervisory oversight over Visa under applicable federal banking laws and policies as a technology service provider to U.S. financial institutions. The federal banking agencies comprising the FFIEC are the Federal Reserve Board, the Comptroller of the Currency, the Federal Deposit Insurance Corporation, the National Credit Union Administration, and the Consumer Financial Protection Bureau (CFPB). Visa also may be separately examined by the CFPB as a service provider to the banks that issue Visa-branded consumer credit and debit card products. Central banks in other countries, including Russia, Ukraine, Hong Kong and the United Kingdom (as discussed below), have recognized or designated Visa, for purposes of various degrees of financial stability regulation, as a retail payment system. Visa is also subject to oversight by banking and financial sector authorities in other jurisdictions, such as Brazil, Mexico, Uruguay and Colombia.
Government-imposed Market Participation and Restrictions. Certain governments, including China, Russia, Indonesia, and India, have taken actions to advantage domestic payments systems and/or certain issuers, payments networks, or processors, including by imposing regulations that favor domestic providers, impose local ownership requirements on processors, or mandate domestic processing be done entirely in that country.
Interchange Rates and Fees. An increasing number of jurisdictions around the world regulate or influence debit and credit interchange reimbursement rates in their regions. For example, the Dodd-Frank Wall Street Reform and Consumer Act (Dodd-Frank Act) in the United States limits interchange reimbursement rates for certain debit card transactions, the European Union's (EU) IFR limits interchange rates in Europe (as discussed below) and the Reserve Bank of Australia regulates average permissible levels of interchange.
Network Exclusivity and Routing. In the United States, the Dodd-Frank Act limits network exclusivity and preferred routing arrangements for the debit and prepaid market segments. Other jurisdictions impose similar limitations, such as the IFR’s prohibition on restrictions that prevent multiple payment brands or functionality on the same card.
No-surcharge Rules. We have historically enforced rules that prohibit merchants from charging higher prices to consumers who pay using Visa products instead of other means. However, merchants’ ability to surcharge varies by geographic market as well as Visa product type, and continues to be impacted by litigation, regulation, and legislation.
Privacy and Data Protection. Aspects of our operations or business are subject to privacy, data use and data security regulations, which impact the way we use and handle data, operate our products and services, and even impact our ability to offer a product or service. In addition, regulators are proposing new laws or regulations which could require Visa to adopt certain cybersecurity and data handling practices. In many jurisdictions consumers must be notified in the event of a data breach, and such notification requirements continue to increase in scope and cost. The changing privacy laws in the United States, Europe and elsewhere, including the adoption by the European Union of the General Data Protection Regulation, which will become effective in May 2018, create new individual privacy rights and impose increased obligations on companies handling personal data.
Anti-corruption, Anti-money Laundering, Anti-terrorism, and Sanctions. We are subject to anti-corruption laws and regulations, including the U.S. Foreign Corrupt Practices Act (FCPA), the UK Bribery Act, and other laws that generally prohibit the making or offering of improper payments to foreign government officials and political figures for the purpose of obtaining or retaining business or to gain an unfair business advantage. We are also subject to anti-money laundering and anti-terrorist financing laws and regulations, including the U.S. Bank Secrecy Act and the USA PATRIOT Act. In addition, we are subject to economic and trade sanctions programs administered by the Office of Foreign Assets Control (OFAC) in the United States. Therefore, we do not permit financial institutions or other entities that are domiciled in countries or territories subject to comprehensive OFAC trade sanctions (currently, Cuba, Iran, North Korea, Syria, and Crimea), or that are included on OFAC's list of Specially Designated Nationals and Blocked Persons, to issue or acquire Visa-branded cards or engage in transactions using our services.
Internet Transactions. Many jurisdictions have adopted regulations that require payments system participants to monitor, identify, filter, restrict, or take other actions with regard to certain types of payment transactions on the Internet, such as gambling and the purchase of cigarettes or alcohol.
Additional Regulatory Developments. Various regulatory agencies also continue to examine a wide variety of other issues, including mobile payment transactions, tokenization, access rights for non-financial institutions, money transfer, identity theft, account management guidelines, disclosure rules, security, and marketing that could affect our financial institution clients and us.
European Regulations and Supervisory Oversight. In addition, following the Visa Europe acquisition in June 2016, we are subject to complex and evolving regulation of our business in the European Economic Area. Visa Europe has been designated as a Recognized Payment System in the United Kingdom, bringing it within the scope of the Bank of England’s oversight and subject to various requirements, including on issues such as governance and risk management designed to maintain the stability of the UK financial system. Visa Europe is also subject to the Eurosystem’s oversight, whose main focus is on the functioning of card payments, as well as the security, operational reliability, and business continuity of the schemes and their payment instruments. Furthermore, Visa Europe is regulated by the United Kingdom’s Payment Systems Regulator (PSR), which has wide ranging powers and authority to review our business practices, systems, rules and fees with respect to promoting competition and innovation in the United Kingdom, and ensuring payments meet account holder needs. It also is the regulator responsible for monitoring Visa Europe's compliance with the IFR in the United Kingdom. The IFR regulates interchange rates within Europe, requires Visa Europe to separate its payment card scheme activities from processing activities for accounting, organization, and decision making purposes within the European Union and imposes limitations on network exclusivity and routing. National competent authorities in other EU markets and the European
Central Bank itself have the ability not only to monitor Visa's compliance with the IFR but also to impose their own oversight regimes.
There are other regulations in the European Union that impact our business, as discussed above, including, privacy and data protection, anti-bribery, anti-money laundering, anti-terrorism and sanctions. Other recent regulatory changes in Europe such as the PSD2 require, among other things, that our financial institution clients provide certain customer account access rights to emerging non-financial institution players.
AVAILABLE INFORMATION
We are subject to the reporting requirements of the Securities Exchange Act of 1934, as amended (Exchange Act) and its rules and regulations. The Exchange Act requires us to file periodic reports, proxy statements and other information with the U.S. Securities and Exchange Commission (SEC). Copies of these reports, proxy statements and other information can be viewed at http://www.sec.gov. Our corporate website is accessible at http://corporate.visa.com. We make available, free of charge, on our investor relations website at http://investor.visa.com our annual reports on Form 10-K, our quarterly reports on Form 10-Q, our current reports on Form 8-K and any amendments to those reports as soon as reasonably practicable after they are electronically filed with, or furnished to, the SEC. We also may include supplemental financial information on our investor relations website at http://investor.visa.com and may use this website as a means of disclosing material, non-public information and for complying with our disclosure obligations under Regulation FD. Accordingly, investors should monitor such portions of our investor relations website, in addition to following SEC filings and publicly available conference calls. The information contained on, or accessible through, our corporate website, including the information contained on our investor relations website, is not incorporated by reference into this report or any other report filed with, or furnished to, the SEC.
Previous: Cover and table of contents · Next: Item 1A. Risk Factors