 filings.tools
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
106K characters. Original on sec.gov · Markdown
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
EXECUTIVE SUMMARY
FINANCIAL SUMMARY FOR 2017 (compared to 2016)
| § | Total revenues increased $297.6 million, or 8%, to $3,890.3 million |
|---|
| § | Gross profit decreased $0.3 million to $1,000.6 million |
|---|
| § | Aggregates segment sales increased $134.3 million, or 5%, to $3,096.1 million |
|---|
| § | Aggregates segment freight-adjusted revenues increased $98.5 million, or 4%, to $2,392.7 million |
|---|
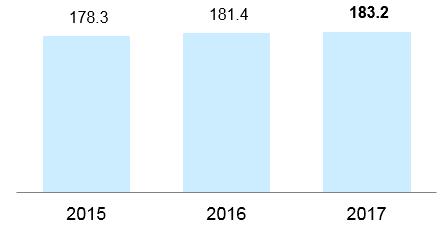
| § | Shipments increased 1%, or 1.8 million tons, to 183.2 million tons |
|---|
| § | Freight-adjusted sales price increased 3%, or $0.41 per ton |
|---|
| § | Segment gross profit decreased $13.1 million, or 2%, to $860.0 million |
|---|
| § | Segment gross profit margin was 27.8%, compared to 29.5% |
|---|
| § | Asphalt, Concrete and Calcium segment gross profit increased $12.8 million, or 10%, to $140.5 million, collectively |
|---|
| § | Selling, administrative and general (SAG) expenses increased 3% to $323.9 million and decreased 0.45 percentage points (45 basis points) as a percentage of total revenues |
|---|
| § | Operating earnings decreased $32.5 million, or 5%, to $647.1 million |
|---|
| § | Earnings from continuing operations were $593.4 million, or $4.40 per diluted share, compared to $422.4 million, or $3.11 per diluted share |
|---|
| § | Discrete items in 2017 include: |
|---|
| § | $297.0 million of net tax benefits (including $268.2 million related to the Tax Cuts and Jobs Act (TCJA) and a $28.8 million partial release of a net operating loss (NOL) carryforward valuation allowance) |
|---|
| § | pretax interest charges of $153.1 million related to the July and December debt purchases ($148.0 million) and carried interest on the March debt issuance ($5.1 million) |
|---|
| § | pretax gains of $10.5 million for the sale of real estate and businesses |
|---|
| § | pretax charges of $4.3 million for property donation |
|---|
| § | pretax charges of $18.1 million for divested operations |
|---|
| § | pretax charges of $6.7 million for one-time employee bonuses |
|---|
| § | pretax charges of $3.1 million associated with business development, net of an asset purchase agreement termination fee |
|---|
| § | pretax charges of $1.9 million for restructuring |
|---|
| § | Discrete items in 2016 include: |
|---|
| § | $11.3 million of tax benefits |
|---|
| § | pretax gains of $16.2 million on the sale of real estate |
|---|
| § | pretax gains of $11.0 million for business interruption claims |
|---|
| § | pretax charges of $16.9 million for divested operations |
|---|
| § | pretax losses of $10.5 million from asset impairment |
|---|
| § | Net earnings were $601.2 million, an increase of $181.7 million, or 43% |
|---|
| § | Adjusted EBITDA was $981.9 million, an increase of $15.9 million, or 2% |
|---|
| § | Returned capital to shareholders via dividends ($132.3 million versus $106.3 million) and share repurchases ($60.3 million versus $161.5 million) |
|---|
2017 results were negatively impacted by unusually harsh weather: severe flooding in California during the first quarter; extreme rainfall in core Southeastern markets (Alabama, Florida, Georgia, Louisiana and Mississippi) during the second quarter; and hurricanes (Harvey and Irma)/tropical storm (Nate) conditions across our Florida, Georgia, Gulf Coast, North Carolina, South Carolina and coastal Texas markets during the third quarter; and their lingering effects on costs into the fourth quarter.
| Part II | 28 |
We closed the acquisition of Aggregates USA on December 29, 2017 for $616 million (net of $287 million immediately disposed and including $6 million of liabilities assumed). This transaction complements and expands our service offerings in Georgia, South Carolina and Florida with 3 granite quarries and 16 rail distribution yards. The integration is proceeding as planned. Although full synergy capture will require at least 18 to 24 months, we still expect this acquisition to be accretive to 2018 earnings ($50 million of EBITDA).
For the full year, capital expenditures were $464.2 million. This amount included $296.5 million of core operating and maintenance capital investments to improve or replace existing property, plant & equipment, in line with expectations. In addition, we invested $167.7 million in internal growth projects to secure new aggregates reserves, develop new production sites, enhance our distribution capabilities and support the targeted growth of our asphalt and concrete operations.
At the end of the fourth quarter, total debt was $2,854.9 million and cash and cash equivalents was $141.6 million. In 2017, we early retired $1,087.4 million of notes due in 2021 and 2018 for $1,228.2 million. One-time interest charges related to these early debt retirements were $148.0 million. In December, we also entered into a 6-month $350.0 million term loan that we refinanced on a long-term basis in February 2018.
Our record safety performance in 2017 reinforces our confidence that our core operating disciplines remain strong.
2017 ACQUISITIONS
We continue to pursue opportunities for value-creating acquisitions, swaps and greenfield investments. We completed a number of important bolt-on acquisitions, making attractive additions to our coast-to-coast footprint in states ranging from Georgia to California and up to Illinois and Virginia. Of particular note was the acquisition of Aggregates USA, which added approximately 460 million tons of proven and probable reserves to our leading reserve base and further strengthened our best-in-class distribution network, adding 16 new rail distribution yards in our Florida, Georgia and South Carolina markets.
We will continue to make disciplined investments in organic and acquisition-led growth, while continuing to emphasize capital returns and cost control. We are completely focused on actions that improve returns to our shareholders. We seek continuous, compounding improvement, generating big results through small actions. Our capital allocation priorities remain unchanged:
| § | deploying operating capital to sustain our franchise |
|---|
| § | maintaining the financial strength and flexibility needed through the cycle |
|---|
| § | strategic growth through mergers and acquisitions and internal development |
|---|
| § | returning excess cash to shareholders through a healthy mix of sustainable dividend growth and stock repurchases |
|---|
For a detailed discussion of our acquisitions and divestitures, see Note 19 “Acquisitions and Divestitures” in Item 8 “Financial Statements and Supplementary Data.”
Estimated impact of tax reform
While the full impact of the TCJA continues to be assessed, we expect our earnings and cash flows will benefit meaningfully going forward. On a net basis, and leaving all other factors unchanged, our total effective tax rate should decline from approximately 28% to 20%.
We continue to evaluate other aspects of the TCJA including immediate deductibility of certain qualified capital spending. We expect core capital spending (necessary to support an increased level of shipments and further improve production costs and operating efficiencies) of approximately $250 million. We also plan for over $350 million in internal growth capital expenditures during 2018, including the development of strategic quarry sites in California and Texas. At this time, we do not know how much of this $600 million of capital spending will qualify for immediate deductibility.
| Part II | 29 |
MARKET DEVELOPMENTS AND OUTLOOK
We expect strong earnings growth in 2018. Leading indicators, such as the pre-construction pipeline and construction starts in our markets, as well as our own order backlogs, point toward growth. Private demand continues to grow and public demand is strengthening after relative weakness in 2016 and part of 2017. These positive trends provide greater visibility into demand and indicate the continuation of a favorable pricing environment. Recent acquisitions are performing well and should make meaningful contributions to our earnings growth in 2018 and beyond.
Private demand in Vulcan-served markets continues to recover, and public demand appears to be firming up after a disappointing 2017. The pricing climate for our materials remains positive, supported by solid demand visibility, rising diesel prices, rising cement prices, and expanding contractor margins. For 2018 we expect same-store aggregates shipment growth of 4% to 6% and aggregates pricing growth of 3% to 5%, albeit with significant variability across individual markets.
We also expect our margin performance to return to its longer-term trend of continuous, compounding improvements. Weather-related cost pressures faced in 2017 are not anticipated, and rising diesel and distribution costs should flow-through to pricing, although with a lag. Tax reform and the acquisition of Aggregates USA will also support growth in earnings and in cash flow.
Management expectations for 2018 include:
| § | Same-store aggregates shipments growth of 4% to 6% |
|---|
| § | Inclusive of Aggregates USA operations (~7 million tons), total aggregates shipments in the range of 200 million tons |
|---|
| § | Same-store aggregates freight-adjusted price increase of 3% to 5% |
|---|
| § | High single-digit gross profit growth in Asphalt, Concrete and Calcium segments, collectively |
|---|
| § | SAG expenses of approximately $335 million, including $5 million related to Aggregates USA |
|---|
| § | Net Earnings of $585 to $635 million |
|---|
| § | Adjusted EBITDA of $1.150 to $1.250 billion, including $50 million from Aggregates USA |
|---|
| § | Interest expense of approximately $125 million, excluding charges associated with refinancing activities |
|---|
| § | Depreciation, depletion, accretion and amortization expense of approximately $340 million |
|---|
| § | An effective tax rate of approximately 20% |
|---|
| § | Earnings from continuing operations of $4.00 to $4.65 per diluted share |
|---|
The ultimate level and quarterly timing of shipments in 2018 will depend in part on the pace of starts and construction activity for larger, publicly-funded projects. However, we have better visibility than we did one year ago. We expect pricing to improve throughout the year, partly in response to rising diesel costs and other inflationary trends. With a return to approximately 5% same-store shipment growth, we anticipate a return to the incremental flow-through rates achieved earlier in the recovery cycle.
| Part II | 30 |
COMPETITIVE ADVANTAGES
Zoning and permitting regulations have made it increasingly difficult to expand existing quarries or to develop new quarries. Such regulations, while curtailing expansion, also increase the value of our reserves. The competitive advantages of our aggregates focused business strategy include:
STRATEGICALLY LOCATED COAST-TO-COAST ASSETS
| § | largest aggregates supplier in the U.S. with diversified regional exposure |
|---|
| § | reserves are primarily located in high-growth markets that require large amounts of aggregates to meet local demand |
|---|
| § | complementary asphalt and concrete businesses in select markets |
|---|
BETTER SALES AND SERVICE
| § | empowered local leadership teams with intimate knowledge of local markets, leveraged with the strength and knowledge of the largest aggregates supplier in the U.S. |
|---|
| § | extensive and advantaged logistics network (as shown on map on page 8) |
|---|
| § | benefits of scale in operations, procurement and administrative support |
|---|
POSITIONED TO CAPITALIZE ON MARKET RECOVERY
| § | 79% of U.S. population growth from 2018 to 2028 is projected to occur in Vulcan served states |
|---|
| § | currently operating at well below full capacity and extremely well positioned to further leverage fixed costs to sales as we move forward |
|---|
| § | effective post-mining land management to generate significant additional value |
|---|
OUR COMMITMENTS
We crush rocks for a living, but at its core, this is a relationship business. We are deeply committed to our customers and our people, and deeply embedded in our communities. Over our more than six decades as a public company, we have built a strong, resilient and vital business on this foundation of doing things the right way.
Our commitment to customers — We have the capabilities to fulfill our customers’ needs on large, complex jobs with unmatched performance and service and we aim to be the supplier of choice for smaller contractors. With all of our customers, we strive to maintain and improve our relationships, to provide outstanding value and service for a fair price by being a solution provider rather than simply an aggregates provider.
Our commitment to our employees — We work hard to ensure our employees’ safety and health, in a positive environment where each person can thrive. We are completely focused on the things that we can control, and it is here that our people continue to make all the difference: increasing unit profitability, delivering incremental earnings and improving our world-class aggregates franchise every day.
Our commitment to our communities — Our people contribute to the cities, towns and neighborhoods where they live and work, in big ways and in small; from disaster relief to the support of education and a wide variety of other social causes and programs. At Vulcan, this means a great deal more than just financial support. Our people throughout the United States, and in Mexico, are generously volunteering their time, talent and energy to improve the world around them.
Our commitment to the environment — We take a long-term approach that bears in mind the demands of the present and the needs of the future. As we continue to build on our legacy, we do so with a clear view of our responsibility to future generations.
Our commitment to our shareholders — We work hard every day to generate returns that exceed market averages. We are good stewards, with responsible operating and capital project expenditures, to achieve a healthy return on our shareholders’ investment in us. We will continue to strive to be the market leader, winning on margin performance, consistent strength of execution and pricing performance; earning a superior return on the very significant capital invested in our business.
| Part II | 31 |
RECONCILIATION OF NON-GAAP FINANCIAL MEASURES
Gross profit margin excluding freight and delivery revenues is not a Generally Accepted Accounting Principle (GAAP) measure. We present this metric as it is consistent with the basis by which we review our operating results. Likewise, we believe that this presentation is consistent with our competitors and consistent with the basis by which investors analyze our operating results considering that freight and delivery services represent pass-through activities. Reconciliation of this metric to its nearest GAAP measure is presented below:
GROSS PROFIT MARGIN IN ACCORDANCE WITH GAAP
| dollars in millions | 2017 | 2016 | 2015 | |||||||
| Gross profit | $ 1,000.6 | $ 1,000.8 | $ 857.5 | |||||||
| Total revenues | $ 3,890.3 | $ 3,592.7 | $ 3,422.2 | |||||||
| Gross profit margin | 25.7% | 27.9% | 25.1% |
GROSS PROFIT MARGIN EXCLUDING FREIGHT AND DELIVERY REVENUES
| dollars in millions | 2017 | 2016 | 2015 | |||||||
| Gross profit | $ 1,000.6 | $ 1,000.8 | $ 857.5 | |||||||
| Total revenues | $ 3,890.3 | $ 3,592.7 | $ 3,422.2 | |||||||
| Freight and delivery revenues 1 | 528.9 | 536.0 | 538.1 | |||||||
| Total revenues excluding freight and delivery revenues | $ 3,361.4 | $ 3,056.7 | $ 2,884.1 | |||||||
| Gross profit margin excluding freight and delivery revenues | 29.8% | 32.7% | 29.7% |
| 1 | Includes freight to remote distribution sites. |
SAME-STORE
We have provided certain information on a same-store basis. When discussing our financial results in comparison to prior periods, we may exclude the operating results of recently acquired/divested businesses that do not have comparable results in the periods being discussed. These recently acquired/divested businesses are disclosed in Note 19 “Acquisitions and Divestitures” in Item 8 “Financial Statements and Supplementary Data.” This approach allows us to evaluate the performance of our operations on a comparable basis. We believe that measuring performance on a same-store basis is useful to investors because it enables evaluation of how our operations are performing period over period without the effects of acquisition and divestiture activity. Our same-store information may not be comparable to similar measures used by other entities.
| Part II | 32 |
Aggregates segment gross profit margin as a percentage of freight-adjusted revenues is not a GAAP measure. We present this metric as it is consistent with the basis by which we review our operating results. We believe that this presentation is consistent with our competitors and meaningful to our investors as it excludes freight, delivery and transportation revenues, which are pass-through activities. It also excludes immaterial other revenues related to services, such as landfill tipping fees, that are derived from our aggregates business. Incremental gross profit as a percentage of freight-adjusted revenues represents the year-over-year change in gross profit divided by the year-over-year change in freight-adjusted revenues. Reconciliations of these metrics to their nearest GAAP measures are presented below:
AGGREGATES SEGMENT GROSS PROFIT MARGIN IN ACCORDANCE WITH GAAP
| dollars in millions | 2017 | 2016 | 2015 | |||||||
| Aggregates segment | ||||||||||
| Gross profit | $ 860.0 | $ 873.1 | $ 755.7 | |||||||
| Segment sales | $ 3,096.1 | $ 2,961.8 | $ 2,777.8 | |||||||
| Gross profit margin | 27.8% | 29.5% | 27.2% | |||||||
| Incremental gross profit margin | n/a | 63.8% |
AGGREGATES SEGMENT GROSS PROFIT AS A PERCENTAGE OF FREIGHT-ADJUSTED REVENUES
| dollars in millions | 2017 | 2016 | 2015 | |||||||
| Aggregates segment | ||||||||||
| Gross profit | $ 860.0 | $ 873.1 | $ 755.7 | |||||||
| Segment sales | $ 3,096.1 | $ 2,961.8 | $ 2,777.8 | |||||||
| Less | ||||||||||
| Freight, delivery and transportation revenues 1 | 670.7 | 651.9 | 644.7 | |||||||
| Other revenues | 32.7 | 15.7 | 20.6 | |||||||
| Freight-adjusted revenues | $ 2,392.7 | $ 2,294.2 | $ 2,112.5 | |||||||
| Gross profit as a percentage of | ||||||||||
| freight-adjusted revenues | 35.9% | 38.1% | 35.8% | |||||||
| Incremental gross profit as a percentage of | ||||||||||
| freight-adjusted revenues | n/a | 64.6% |
| 1 | At the segment level, freight, delivery and transportation revenues include intersegment freight & delivery revenues, which are eliminated at the consolidated level. |
| Part II | 33 |
GAAP does not define "cash gross profit" and it should not be considered as an alternative to earnings measures defined by GAAP. We present this metric for the convenience of investment professionals who use such metrics in their analyses and for shareholders who need to understand the metrics we use to assess performance. We and the investment community use this metric to assess the operating performance of our business. Additionally, we present this metric as we believe that it closely correlates to long-term shareholder value. We do not use this metric as a measure to allocate resources. Aggregates segment cash gross profit per ton is computed by dividing Aggregates segment cash gross profit by tons shipped. Reconciliation of this metric to its nearest GAAP measure is presented below:
CASH GROSS PROFIT
| in millions, except per ton data | 2017 | 2016 | 2015 | |||||||
| Aggregates segment | ||||||||||
| Gross profit | $ 860.0 | $ 873.1 | $ 755.7 | |||||||
| Depreciation, depletion, accretion and amortization | 245.2 | 236.5 | 228.5 | |||||||
| Aggregates segment cash gross profit | $ 1,105.2 | $ 1,109.6 | $ 984.2 | |||||||
| Unit shipments - tons | 183.2 | 181.4 | 178.3 | |||||||
| Aggregates segment cash gross profit per ton | $ 6.03 | $ 6.12 | $ 5.52 | |||||||
| Asphalt segment | ||||||||||
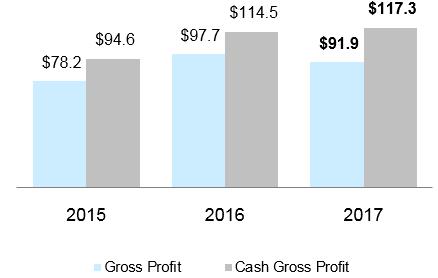
| Gross profit | $ 91.9 | $ 97.7 | $ 78.2 | |||||||
| Depreciation, depletion, accretion and amortization | 25.4 | 16.8 | 16.4 | |||||||
| Asphalt segment cash gross profit | $ 117.3 | $ 114.5 | $ 94.6 | |||||||
| Concrete segment | ||||||||||
| Gross profit | $ 46.1 | $ 26.5 | $ 20.2 | |||||||
| Depreciation, depletion, accretion and amortization | 13.8 | 12.1 | 11.4 | |||||||
| Concrete segment cash gross profit | $ 59.9 | $ 38.6 | $ 31.6 | |||||||
| Calcium segment | ||||||||||
| Gross profit | $ 2.5 | $ 3.5 | $ 3.5 | |||||||
| Depreciation, depletion, accretion and amortization | 0.7 | 0.8 | 0.7 | |||||||
| Calcium segment cash gross profit | $ 3.2 | $ 4.3 | $ 4.2 |
| Part II | 34 |
GAAP does not define "Earnings Before Interest, Taxes, Depreciation and Amortization” (EBITDA) and it should not be considered as an alternative to earnings measures defined by GAAP. We present this metric for the convenience of investment professionals who use such metrics in their analyses and for shareholders who need to understand the metrics we use to assess performance. We use this metric to assess the operating performance of our business and as a basis for strategic planning and forecasting as we believe that it closely correlates to long-term shareholder value. We do not use this metric as a measure to allocate resources. We adjust EBITDA for certain items to provide a more consistent comparison of earnings performance from period to period. Reconciliation of this metric to its nearest GAAP measure is presented below:
EBITDA AND ADJUSTED EBITDA
| in millions | 2017 | 2016 | 2015 | |||||||
| Net earnings | $ 601.2 | $ 419.5 | $ 221.2 | |||||||
| Income tax expense (benefit) | (232.1) | 124.9 | 94.9 | |||||||
| Interest expense, net of interest income | 291.1 | 133.3 | 220.3 | |||||||
| (Earnings) loss on discontinued operations, net of tax | (7.8) | 2.9 | 11.7 | |||||||
| EBIT | 652.4 | 680.6 | 548.1 | |||||||
| Depreciation, depletion, accretion and amortization | 306.0 | 284.9 | 274.8 | |||||||
| EBITDA | $ 958.4 | $ 965.5 | $ 822.9 | |||||||
| Gain on sale of real estate and businesses 1 | $ (10.5) | $ (16.2) | $ (6.3) | |||||||
| Property donation | 4.3 | 0.0 | 0.0 | |||||||
| Business interruption claims recovery, net of incentives | 0.0 | (11.0) | 0.0 | |||||||
| Charges associated with divested operations | 18.1 | 16.9 | 7.1 | |||||||
| Business development, net of termination fee 2 | 3.1 | 0.0 | 1.0 | |||||||
| One-time employee bonuses | 6.7 | 0.0 | 0.0 | |||||||
| Asset impairment | 0.0 | 10.5 | 5.2 | |||||||
| Restructuring charges | 1.9 | 0.3 | 5.0 | |||||||
| Adjusted EBITDA | $ 981.9 | $ 966.0 | $ 834.9 | |||||||
| Depreciation, depletion, accretion and amortization | 306.0 | 284.9 | 274.8 | |||||||
| Adjusted EBIT | $ 675.9 | $ 681.1 | $ 560.1 |
| 1 | The 2016 amount includes a $4.3 million gain (reflected within Other operating income, net) for plant relocation reimbursement. |
| 2 | Includes only non-routine business development charges. |
2018 PROJECTED EBITDA
The following reconciliation to the mid-point of the range of 2018 Projected EBITDA excludes adjustments for charges associated with divested operations, asset impairment and other unusual gains and losses. Due to the difficulty of forecasting the timing or amount of items that have not yet occurred, are out of our control, or cannot be reasonably predicted, we are unable to estimate the significance of this unavailable information.
| 2018 Projected | ||||
| in millions | Mid-point | |||
| Net earnings | $ 585 | |||
| Income tax expense | 150 | |||
| Interest expense, net of interest income | 125 | |||
| Discontinued operations, net of tax | 0 | |||
| Depreciation, depletion, accretion and amortization | 340 | |||
| Projected EBITDA | $ 1,200 |
| Part II | 35 |
RESULTS OF OPERATIONS
Total revenues include sales of product to customers, net of any discounts and taxes, and freight and delivery revenues billed to customers. Related freight and delivery costs are included in cost of revenues. This presentation is consistent with the basis on which we review our consolidated results of operations. We discuss separately our discontinued operations, which consists of our former Chemicals business.
The following table highlights significant components of our consolidated operating results including EBITDA and Adjusted EBITDA.
CONSOLIDATED OPERATING RESULT HIGHLIGHTS
| For the years ended December 31 | 2017 | 2016 | 2015 | |||||||
| in millions, except per share data | ||||||||||
| Total revenues | $ 3,890.3 | $ 3,592.7 | $ 3,422.2 | |||||||
| Cost of revenues | 2,889.7 | 2,591.9 | 2,564.7 | |||||||
| Gross profit | $ 1,000.6 | $ 1,000.8 | $ 857.5 | |||||||
| Selling, administrative and general expenses | $ 323.9 | $ 315.0 | $ 286.8 | |||||||
| Operating earnings | $ 647.1 | $ 679.6 | $ 549.8 | |||||||
| Interest expense | $ 295.5 | $ 134.1 | $ 220.6 | |||||||
| Earnings from continuing operations | ||||||||||
| before income taxes | $ 361.3 | $ 547.3 | $ 327.9 | |||||||
| Earnings from continuing operations | $ 593.4 | $ 422.4 | $ 232.9 | |||||||
| Earnings (loss) on discontinued operations, net of income taxes | 7.8 | (2.9) | (11.7) | |||||||
| Net earnings | $ 601.2 | $ 419.5 | $ 221.2 | |||||||
| Basic earnings (loss) per share | ||||||||||
| Continuing operations | $ 4.48 | $ 3.17 | $ 1.75 | |||||||
| Discontinued operations | 0.06 | (0.02) | (0.09) | |||||||
| Basic net earnings per share | $ 4.54 | $ 3.15 | $ 1.66 | |||||||
| Diluted earnings (loss) per share | ||||||||||
| Continuing operations | $ 4.40 | $ 3.11 | $ 1.72 | |||||||
| Discontinued operations | 0.06 | (0.02) | (0.08) | |||||||
| Diluted net earnings per share | $ 4.46 | $ 3.09 | $ 1.64 | |||||||
| EBITDA | $ 958.4 | $ 965.5 | $ 822.9 | |||||||
| Adjusted EBITDA | $ 981.9 | $ 966.0 | $ 834.9 |
| Part II | 36 |
Net earnings for 2017 were $601.2 million ($4.46 per diluted share) compared to $419.5 million ($3.09 per diluted share) in 2016 and $221.2 million ($1.64 per diluted share) in 2015. Each year's results were impacted by discrete items, as follows:
Net earnings for 2017 include:
| § | $297.0 million of net tax benefits (TCJA — $268.2 million and partial release of the Alabama NOL carryforward valuation allowance — $28.8 million) |
|---|
| § | pretax gains of $10.5 million related to the sale of real estate and businesses |
|---|
| § | pretax charges of $4.3 million for property donation |
|---|
| § | pretax charges of $18.1 million associated with divested operations |
|---|
| § | pretax charges of $6.7 million for one-time employee bonuses |
|---|
| § | pretax charges of $3.1 million associated with business development, net of an asset purchase agreement termination fee |
|---|
| § | pretax charges of $1.9 million for restructuring |
|---|
| § | a pretax loss on debt purchases of $148.0 million presented as a component of interest expense (see Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data”) |
|---|
Net earnings for 2016 include:
| § | $11.3 million of tax benefits (utilization of foreign tax credits — $6.5 million, and partial release of the Alabama NOL carryforward valuation allowance — $4.8 million) |
|---|
| § | pretax gains of $16.2 million related to the sale of real estate |
|---|
| § | pretax gains of $11.0 million for business interruption claims (net of incentives) |
|---|
| § | pretax charges of $16.9 million associated with divested operations |
|---|
| § | pretax losses of $10.5 million from asset impairment |
|---|
Net earnings for 2015 include:
| § | $1.8 million of net tax charges (foreign tax credit carryforward impairment — $6.5 million, and partial release of the Alabama NOL carryforward valuation allowance — $4.7 million) |
|---|
| § | pretax gains of $6.3 million related to the sale of real estate and businesses |
|---|
| § | pretax charges of $7.1 million associated with divested operations |
|---|
| § | pretax losses of $5.2 million from asset impairment |
|---|
| § | pretax charges of $5.0 million for restructuring |
|---|
| § | a pretax loss on debt purchases of $67.1 million presented as a component of interest expense (see Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data”) |
|---|
EARNINGS FROM CONTINUING OPERATIONS BEFORE INCOME TAXES
Year-over-year changes in earnings from continuing operations before income taxes are summarized below:
| in millions | |||||||
| 2015 | $ 327.9 | 2016 | $ 547.3 | ||||
| Higher (lower) aggregates gross profit | 117.5 | (13.1) | |||||
| Higher (lower) asphalt gross profit | 19.5 | (5.7) | |||||
| Higher concrete gross profit | 6.4 | 19.6 | |||||
| Higher (lower) calcium gross profit | 0.0 | (1.0) | |||||
| Higher selling, administrative and general expenses | (28.1) | (8.9) | |||||
| Higher gain on sale of property, plant & equipment and businesses | 5.5 | 2.4 | |||||
| Lower (higher) restructuring charges | 4.7 | (1.6) | |||||
| Lower (higher) interest expense | 86.5 | (161.4) | |||||
| All other | 7.4 | (16.3) | |||||
| 2016 | $ 547.3 | 2017 | $ 361.3 |
| Part II | 37 |
OPERATING RESULTS BY SEGMENT
We present our results of operations by segment at the gross profit level. We have four operating (and reportable) segments organized around our principal product lines: (1) Aggregates, (2) Asphalt, (3) Concrete and (4) Calcium. Management reviews earnings for the product line reporting segments principally at the gross profit level.
- AGGREGATES
Our year-over-year aggregates shipments:
| § | increased 1% in 2017 |
|---|
| § | increased 2% in 2016 |
|---|
| § | increased 10% in 2015 |
|---|
Through the first nine months of 2017, shipments were down 1% due to extreme weather — severe flooding, winds and wildfires in California; hurricanes/tropical storms in our Texas and Southeastern markets. Shipment trends rebounded in the fourth quarter as drier weather allowed for some catch-up on deferred work. Fourth quarter shipments improved markedly year-over-year in California and across the Southeast, with most markets experiencing double-digit gains. We expect the shipment growth seen in the fourth quarter to continue into 2018. Private demand in Vulcan-served markets continues to recover, and public demand appears to be firming up after a disappointing 2017.
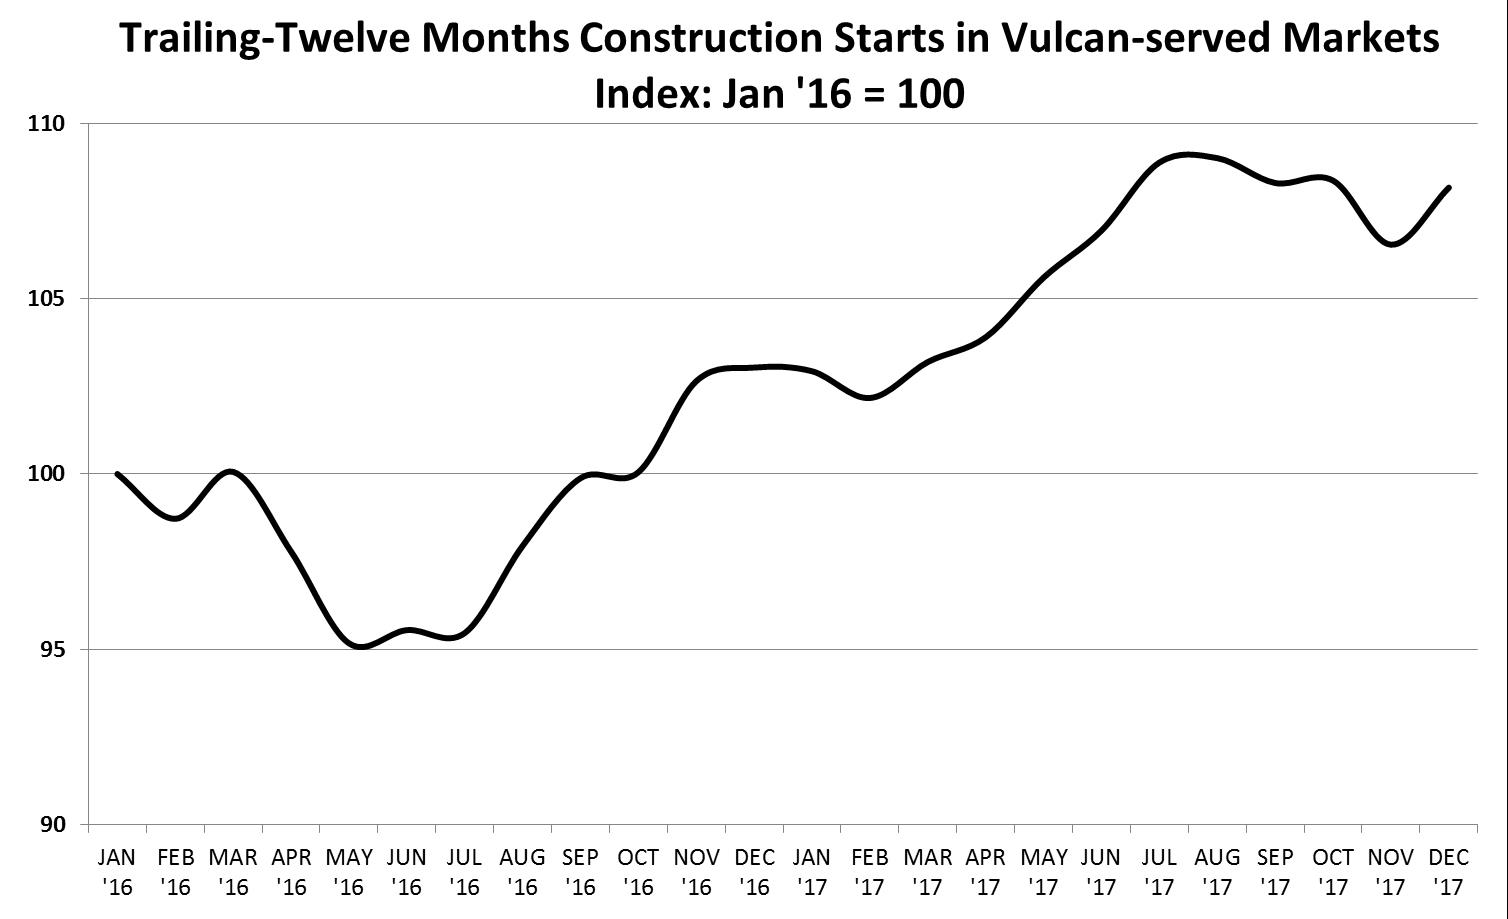
Source: Dodge Data & Analytics
Our year-over-year freight-adjusted selling price1 for aggregates:
| § | increased 3% in 2017 |
|---|
| § | increased 7% in 2016 |
|---|
| § | increased 7% in 2015 |
|---|
| 1 | We routinely arrange the delivery of our aggregates to the customer. Additionally, we incur transportation costs to move aggregates from the production site to remote distribution sites. These costs are passed on to our customers in the aggregates price. We remove these pass-through freight and transportation revenues (and any other aggregates-derived revenues, such as landfill tipping fees) from the freight-adjusted selling price for aggregates. See the Reconciliation of Non-GAAP Financial Measures within this Item 7 for a reconciliation of freight-adjusted revenues. |
| Part II | 38 |
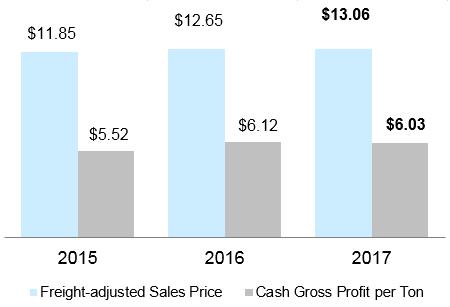
Pricing increased 3%, or $0.41 per ton, despite negative geographic and product mix impacts. Excluding mix impact, aggregates price increased 4%. Pricing remained particularly strong in California (up 7%) and Georgia (up 9%) supported by strong visibility to continued demand recovery. Texas experienced relative pricing weakness as storms negatively impacted not only total demand but also the mix of work. The pricing climate for aggregates remains positive, supported by solid demand visibility and expanding contractor margins.
| AGGREGATES SEGMENT SALES AND FREIGHT-ADJUSTED REVENUES | AGGREGATES GROSS PROFIT AND CASH GROSS PROFIT |
| in millions | in millions |
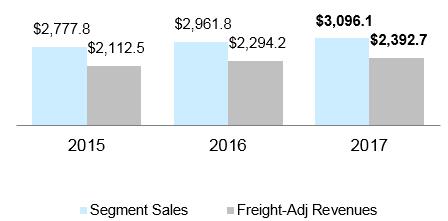 | 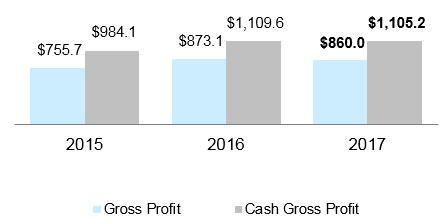 |
| AGGREGATES UNIT SHIPMENTS | AGGREGATES SELLING PRICE AND CASH GROSS PROFIT PER TON | ||
| tons, in millions | Freight-adjusted average sales price per ton 2 | ||
 |  | ||
| 2 | Freight-adjusted sales price is calculated as freight-adjusted revenues divided by aggregates unit shipments |
Aggregates segment gross profit decreased $13.1 million (2%). Unit gross profit decreased 2%, to $4.69 per ton, while unit cash gross profit decreased 1% to $6.03 per ton. These results were lower than 2016 due in large part to the aforementioned weather events which, while difficult to quantify, negatively impacted segment gross profit. Additionally, a 22% increase in the unit cost of diesel fuel, costs related to the transition to two new, more efficient ships to transport aggregates from our quarry in Mexico and certain expenses related to acquired operations negatively impacted segment gross profit in comparison to 2016.
| Part II | 39 |
- ASPHALT
Our year-over-year asphalt mix shipments:
| § | increased 11% in 2017 1 |
|---|
| § | increased 3% in 2016 |
|---|
| § | increased 30% in 2015 2 |
|---|
| 1 | The 11% increase in asphalt mix shipments in 2017 was largely attributable to a January 2017 acquisition of asphalt mix operations and a construction paving business in Tennessee. |
| 2 | The 30% increase in asphalt mix shipments in 2015 was largely attributable to the January 2015 swap of our concrete operations in California for asphalt mix operations, primarily in Arizona. |
Asphalt shipments were 10.4 million tons in total and 9.4 million tons on a same-store basis. Same-store shipments increased 1% versus the prior year, as volumes in Arizona and New Mexico accounted for the year-over-year increase. Asphalt segment gross profit decreased 6% to $91.9 million. A 10% increase in liquid asphalt unit cost negatively affected materials margins by $14.2 million.
| ASPHALT SEGMENT SALES | ASPHALT GROSS PROFIT AND CASH GROSS PROFIT |
| in millions | in millions |
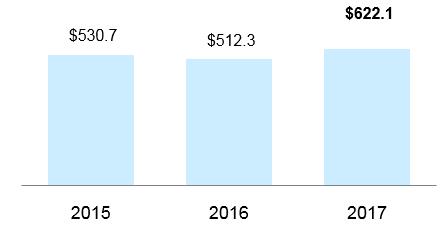 |  |
| Part II | 40 |
- CONCRETE
Our year-over-year ready-mixed concrete shipments:
| § | increased 19% in 2017 1 |
|---|
| § | increased 7% in 2016 |
|---|
| § | decreased 25% in 2015 2 |
|---|
| 1 | Of the 19% increase in ready-mixed concrete shipments in 2017, 9% was attributable to a March 2017 acquisition of ready-mixed concrete facilities in California. |
| 2 | The 25% decrease in ready-mixed concrete shipments in 2015 was largely attributable to the aforementioned January 2015 swap of our concrete operations in California. |
Concrete segment gross profit increased 74% and gross profit margin increased three percentage points (300 basis points) versus the prior year driven by increased shipments and improved materials margins. Shipments increased 19% versus the prior year. On a same-store basis, shipments increased 9%. Materials margins per cubic yard improved 3% versus the prior year.
| CONCRETE SEGMENT SALES | CONCRETE GROSS PROFIT AND CASH GROSS PROFIT |
| in millions | in millions |
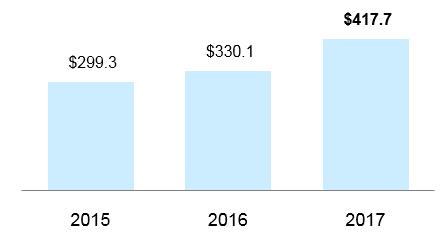 | 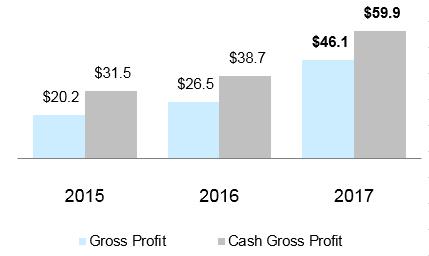 |
- CALCIUM
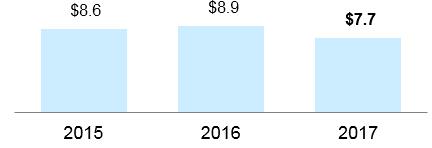
Our Calcium segment volumes and sales were negatively impacted by the aforementioned hurricanes and tropical storm resulting in a $1.0 million decrease in segment gross profit.
| CALCIUM SEGMENT SALES | CALCIUM GROSS PROFIT AND CASH GROSS PROFIT |
| in millions | in millions |
 | 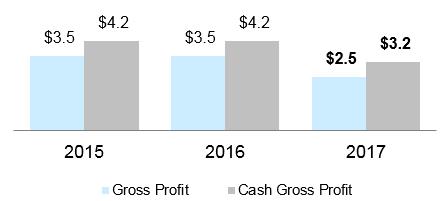 |
In total, the 2017 gross profit contributions from our three non-aggregates (Asphalt, Concrete and Calcium) segments was $140.5 million, a 10% increase over 2016, and a 38% increase over 2015.
| Part II | 41 |
SELLING, ADMINISTRATIVE AND GENERAL EXPENSES
in millions
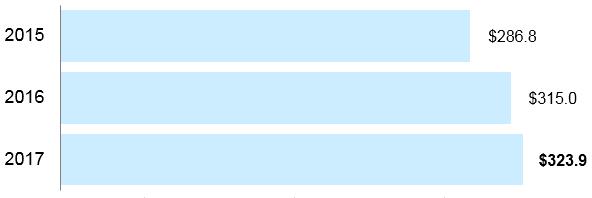
As a percentage of total revenues, SAG expense was:
| § | 8.3% in 2017 — decreased 0.45 percentage points (45 basis points) |
|---|
| § | 8.8% in 2016 — increased 0.4 percentage points (40 basis points) |
|---|
| § | 8.4% in 2015 — decreased 0.7 percentage points (70 basis points) |
|---|
Our comparative total company employment levels at year end:
| § | increased 15% in 2017 |
|---|
| § | increased 4% in 2016 |
|---|
| § | increased 4% in 2015 |
|---|
We work continuously to improve our organizational support of operations and create a more scalable and efficient overhead structure. Subsequently, in January 2018, we reorganized several of our staff functions for the purpose of more effectively and efficiently supporting long-term growth and margin improvement.
GAIN ON SALE OF PROPERTY, PLANT & EQUIPMENT AND BUSINESSES
in millions
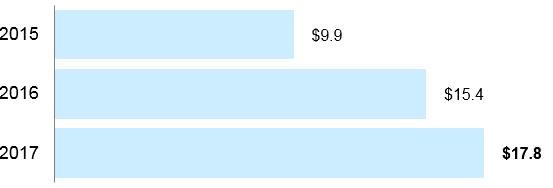
The 2017 gain on sale of property, plant & equipment and businesses of $17.8 million includes $8.0 million of pretax gain from a swap of ready-mixed concrete operations for an asphalt operation (all in Arizona) and $2.5 million of pretax gain related to a property donation. The 2016 gain includes $11.9 million of pretax gain from surplus land sales in Virginia and California. The 2015 gain includes a $5.9 million pretax gain from the previously mentioned asset exchange (we exited the ready-mixed concrete business in California and added thirteen asphalt plant locations, primarily in Arizona). See Note 19 "Acquisitions and Divestitures" in Item 8 "Financial Statements and Supplementary Data."
| Part II | 42 |
OTHER OPERATING EXPENSE, NET
Other operating expense, which has an approximate run-rate of $16.0 million a year (exclusive of discrete items), is composed of various operating items not specifically presented in the accompanying Consolidated Statements of Comprehensive Income. The total other operating expense, net and significant items included in the total were:
| § | $47.4 million in 2017 — includes discrete items as follows: |
|---|
| § | $3.1 million of business development charges, net of a termination fee. These net charges were composed of $11.1 million of non-routine business development charges partially offset by an $8.0 million credit related to an asset purchase agreement termination fee |
|---|
| § | $18.1 million of charges associated with divested operations including $16.6 million of environmental liability accruals related to the Hewitt Landfill matter (see Note 12 to the consolidated financial statements) |
|---|
| § | $6.7 million of one-time cash bonuses for non-incentive employees ($1,000 per employee) |
|---|
| § | $4.3 million of charges related to a property donation |
|---|
| § | $1.9 million of managerial restructuring charges |
|---|
| § | $21.7 million in 2016 — includes discrete items as follows: |
|---|
| § | $16.9 million of charges associated with divested operations, including charges associated with office space no longer needed and vacated ($5.2 million), the write-off of a prepaid royalty asset resulting from a change in long-term mining plans ($3.6 million), a property litigation settlement ($1.9 million), a pension withdrawal settlement revision ($1.5 million), and environmental liability accruals associated with previously divested properties ($4.5 million) |
|---|
| § | $10.5 million of impairment charges related to the termination of a nonstrategic aggregates site lease we no longer intended to develop ($9.6 million) and wrote off nonrecoverable project costs related to two Aggregates segment capital projects that we no longer intend to complete ($0.9 million) |
|---|
| § | $11.7 million gain referable to the settlement of business interruption claims related to the 2010 Gulf Coast oil spill |
|---|
| § | $4.3 million gain referable to a plant relocation |
|---|
| § | $30.8 million in 2015 — includes discrete items as follows: |
|---|
| § | $7.1 million of charges associated with divested operations, including severance ($1.4 million) and environmental liability accruals associated with previously divested properties ($5.7 million) |
|---|
| § | $5.2 million of impairment charges related to our decision not to renew an Aggregates segment lease on a California land parcel |
|---|
| § | $5.0 million of restructuring charges related to changes to our executive management team and a new divisional organization structure |
|---|
| Part II | 43 |
INTEREST EXPENSE
in millions
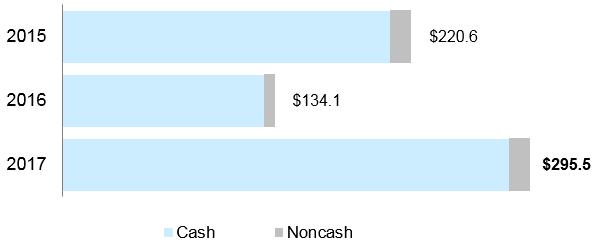
Interest expense was $295.5 million in 2017 compared to $134.1 million in 2016. The higher interest expense resulted from the $148.0 million of charges related to the 2017 debt purchases coupled with $5.1 million of carried interest on debt issued in March. Interest expense in 2016 decreased $86.5 million from 2015, as interest expense for 2015 included charges for debt purchases of $67.1 million. See Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data” for additional discussion.
INCOME TAXES
Our income tax expense (benefit) from continuing operations for the years ended December 31 is shown below:
| dollars in millions | 2017 | 2016 | 2015 | |||||||
| Earnings from continuing operations | ||||||||||
| before income taxes | $ 361.3 | $ 547.3 | $ 327.9 | |||||||
| Income tax expense (benefit) | $ (232.1) | $ 124.9 | $ 94.9 | |||||||
| Effective tax rate | -64.2% | 22.8% | 29.0% |
The $357.0 million decrease in our 2017 income tax expense is primarily due to the year-over-year reduction in our earnings from continuing operations plus $330.4 million of tax benefits (remeasurement of our deferred tax assets and liabilities at the new 21% federal corporate income tax rate — $301.6 million and the partial release of the Alabama NOL carryforward valuation allowance — $28.8 million), partially offset by $21.1 million of lost tax benefits associated with tax deductions accelerated into 2017 (e.g., lost U.S. production deduction) and a $12.3 million tax expense for the one-time Deemed Repatriation Transition Tax (see Note 9 “ Income Taxes” in Item 8 Financial Statements and Supplementary Data”).
The $30.0 million increase in our 2016 income tax expense is primarily related to the year-over-year improvement in our earnings from continuing operations partially offset by $36.1 million of tax benefits (utilization of foreign tax credits — $6.5 million, partial release of the Alabama NOL carryforward valuation allowance — $4.8 million, and excess tax benefits related to share-based compensation — $24.8 million). The excess tax benefit from share-based compensation resulted from our early adoption of ASU 2016-09 (see Note 1 “Significant Accounting Policies” in Item 8 “Financial Statements and Supplementary Data” under the caption Share-based Compensation). The 2016 reduction in the effective tax rate was due primarily to higher benefits from the statutory depletion deduction (related to higher aggregates sales) and the early adoption of ASU 2016-09.
A reconciliation of the federal statutory rate of 35% to our effective tax rates for 2017, 2016 and 2015 is presented in Note 9 “Income Taxes” in Item 8 “Financial Statements and Supplementary Data.”
| Part II | 44 |
DISCONTINUED OPERATIONS
Pretax earnings (loss) from discontinued operations were:
| § | $13.0 million in 2017 |
|---|
| § | $(4.9) million in 2016 |
|---|
| § | $(19.3) million in 2015 |
|---|
The $13.0 million, $(4.9) million and $(19.3) million pretax earnings (loss) from discontinued operations for 2017, 2016 and 2015, respectively, resulted primarily from general and product liability costs, including legal defense costs and environmental remediation costs associated with our former Chemicals business. The 2017 results also include insurance recoveries from previously incurred general liability costs. For additional information about discontinued operations, see Note 2 "Discontinued Operations" in Item 8 "Financial Statements and Supplementary Data."
LIQUIDITY AND FINANCIAL RESOURCES
Our primary sources of liquidity are cash provided by our operating activities and a substantial, committed bank line of credit. Additional sources of capital include access to the capital markets, the sale of surplus real estate, and dispositions of nonstrategic operating assets. We believe these financial resources are sufficient to fund our business requirements for 2018, including:
| § | cash contractual obligations |
|---|
| § | capital expenditures |
|---|
| § | debt service obligations |
|---|
| § | dividend payments |
|---|
| § | potential share repurchases |
|---|
| § | potential acquisitions |
|---|
Our balanced approach to capital deployment remains unchanged. We intend to balance reinvestment in our business, growth through acquisitions and return of capital to shareholders, while sustaining financial strength and flexibility. In 2017 and 2016, we returned $132.3 and $106.3 million, respectively, in cash to shareholders through our dividends and $60.3 million and $161.5 million, respectively, through share repurchases.
We actively manage our capital structure and resources in order to minimize the cost of capital while properly managing financial risk. We seek to meet these objectives by adhering to the following principles:
| § | maintain substantial bank line of credit borrowing capacity |
|---|
| § | proactively manage our debt maturity schedule such that repayment/refinancing risk in any single year is low |
|---|
| § | maintain an appropriate balance of fixed-rate and floating-rate debt |
|---|
| § | minimize financial and other covenants that limit our operating and financial flexibility |
|---|
CASH
Included in our December 31, 2017 cash and cash equivalents and restricted cash balances of $146.6 million is $54.4 million of cash held at our foreign subsidiaries. All of this $54.4 million of cash relates to earnings that are indefinitely reinvested offshore. Use of this cash is currently limited to our foreign operations.
| Part II | 45 |
CASH FROM OPERATING ACTIVITIES
in millions
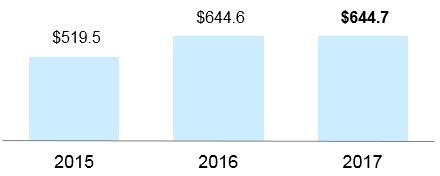
Net cash provided by operating activities is derived primarily from net earnings before noncash deductions for depreciation, depletion, accretion and amortization.
| in millions | 2017 | 2016 | 2015 | |||||||
| Net earnings | $ 601.2 | $ 419.5 | $ 221.2 | |||||||
| Depreciation, depletion, accretion | ||||||||||
| and amortization (DDA&A) | 306.0 | 284.9 | 274.8 | |||||||
| Net earnings before noncash deductions for DDA&A | $ 907.2 | $ 704.4 | $ 496.0 | |||||||
| Net gain on sale of property, plant & | ||||||||||
| equipment and businesses | (17.8) | (15.4) | (9.9) | |||||||
| Contributions to pension plans | (20.0) | (9.6) | (14.0) | |||||||
| Cost of debt purchase | 140.8 | 0.0 | 67.1 | |||||||
| Other operating cash flows, net 1 | (365.5) | (34.8) | (19.7) | |||||||
| Net cash provided by operating activities | $ 644.7 | $ 644.6 | $ 519.5 |
| 1 | Primarily reflects changes to working capital balances. The increase from 2016 to 2017 reflects a $301.6 million reduction of our net deferred income liabilities as a result of the TCJA. |
2017 versus 2016 — Net cash provided by operating activities was $644.7 million during 2017 and $644.6 during 2016. Although net earnings increased by $181.7 million compared to 2016, 2017 earnings included discrete deferred tax benefits of $301.6 million referable to the TCJA (see Note 9 “Income Taxes” in Item 8 “Financial Statements and Supplementary Data”) partially offset by cost of debt purchases of $140.8 million (see Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data”). Cash paid for debt purchases is presented as a component of financing activities.
2016 versus 2015 — Net cash provided by operating activities was $644.6 million during 2016, a $125.1 million increase compared to 2015. This increase was primarily attributable to the $198.3 million increase in net earnings, $67.1 million of which was due to the 2015 charges associated with debt purchases (see Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data”). Cash paid for this debt purchase is presented as a component of financing activities. Additionally, upon our 2016 early adoption of ASU 2016-09 (see Note 1 “Significant Accounting Policies” in Item 8 “Financial Statements and Supplementary Data” under the caption Share-based Compensation), gross excess tax benefits for 2016 of $28.0 million are classified as operating cash flows. Conversely, gross excess tax benefits of $18.4 million for 2015 are classified as financing cash flows.
| Part II | 46 |
CASH FROM INVESTING ACTIVITIES
in millions
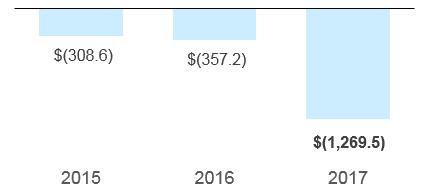
2017 versus 2016 — Net cash used for investing activities was $1,269.5 million during 2017, a $912.3 million increase compared to 2016. We invested $459.6 million in our existing operations in 2017, a $109.4 million increase compared to 2016. Of this $459.6 million, $167.7 million was invested in internal growth projects to secure new aggregates reserves, develop new production sites, enhance our distribution capabilities and support the targeted growth of our asphalt and concrete operations. Additionally, during 2017, we acquired several businesses for $822.4 million of cash consideration (excluding the assets immediately divested in the Aggregates USA acquisition for $287.3 million) as described in Note 19 “Acquisitions and Divestitures” in Item 8 “Financial Statements and Supplementary Data.” During 2016, we expanded our aggregates distribution capabilities in Georgia and completed two strategic bolt-on acquisitions in New Mexico and Texas for $32.5 million of cash consideration.
2016 versus 2015 — Net cash used for investing activities was $357.2 million during 2016, a $48.6 million increase compared to 2015. We invested $350.1 million in our existing operations in 2016, a $60.9 million increase compared to 2015. Of this $350.1 million, $99.2 million was invested in shipping capacity enhancements, new site developments and other growth opportunities. As noted above, acquisitions during 2016 totaled $32.5 million in cash consideration. Comparatively, acquisitions during 2015 totaled $27.2 million in cash consideration (see Note 19 “Acquisitions and Divestitures” in Item 8 “Financial Statements and Supplementary Data”).
CASH FROM FINANCING ACTIVITIES
in millions
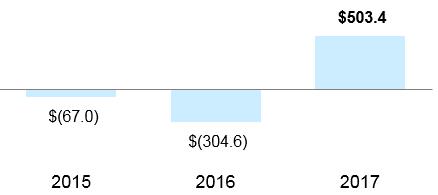
2017 VERSUS 2016 — Net cash provided by financing activities in 2017 was $503.4 million, an increase of $808.0 million compared with the cash used during 2016. This increase was primarily attributable to the 2017 debt issuances (as described in the section below) which provided net proceeds of $2,184.7 million partially offset by the repayment of our $235.0 million line of credit and the early retirement of notes due in 2018 and 2021 for a total cost of $1,228.2 million ($1,087.4 million principal and $140.8 million cost of debt purchase). Additionally, we increased dividends to our shareholders by $26.0 million ($1.00 per share compared to $0.80 per share). Share repurchases decreased by $101.2 million (510,283 shares @ $118.18 per share compared to 1,426,659 shares @ $113.18 per share).
2016 VERSUS 2015 — Net cash used for financing activities in 2016 was $304.6 million, an increase of $237.6 million from 2015. This increase was primarily attributable to a $193.1 million increase in return of capital to our shareholders via increased dividends ($0.80 per share compared to $0.40 per share) and share repurchases (1,426,659 shares @ $113.18 per share compared to 228,000 shares @ $94.19 per share). Additionally, there were no proceeds from the exercise of employee stock options in 2016 (compared to $73.0 million in 2015) as only stock-only stock appreciation rights (SOSARs) remained outstanding at the beginning of the year. Finally, we early adopted ASU 2016-09 in 2016 resulting in gross excess tax benefits of $28.0 million classified as operating cash flows rather than financing cash flows.
| Part II | 47 |
DEBT
Certain debt measures as of December 31 are outlined below:
| dollars in millions | 2017 | 2016 | ||||||||
| Debt | ||||||||||
| Current maturities of long-term debt | $ 41.4 | $ 0.1 | ||||||||
| Short-term debt | 0.0 | 0.0 | ||||||||
| Long-term debt 1 | 2,813.5 | 1,982.8 | ||||||||
| Total debt | $ 2,854.9 | $ 1,982.9 | ||||||||
| Capital | ||||||||||
| Total debt | $ 2,854.9 | $ 1,982.9 | ||||||||
| Equity | 4,968.9 | 4,572.5 | ||||||||
| Total capital | $ 7,823.8 | $ 6,555.4 | ||||||||
| Total Debt as a Percentage of Total Capital | 36.5% | 30.2% | ||||||||
| Weighted-average Effective Interest Rates | ||||||||||
| Line of credit 2 | 1.25% | 1.25% | ||||||||
| Term debt | 4.26% | 7.52% | ||||||||
| Fixed versus Floating Interest Rate Debt | ||||||||||
| Fixed-rate debt | 61.8% | 88.3% | ||||||||
| Floating-rate debt | 38.2% | 11.7% |
| 1 | Includes borrowing under our line of credit for which we have the intent and ability to extend repayment beyond twelve months, as follows: December 31, 2017 — $250.0 million and December 31, 2016 — $235.0 million. The December 31, 2017 long-term debt also includes a $350.0 million unsecured term loan due 2018 which was subsequently refinanced in February 2018. |
| 2 | Reflects the margin above LIBOR for LIBOR-based borrowings; we also paid upfront fees that are amortized to interest expense and pay fees for unused borrowing capacity and standby letters of credit. |
LINE OF CREDIT
Covenants, borrowings, cost ranges and other details are described in Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data.” As of December 31, 2017, we were in compliance with the line of credit covenants and the credit margin for the London Interbank Offered Rate (LIBOR) borrowings was 1.25%, the credit margin for base rate borrowings was 0.25%, and the commitment fee for the unused portion was 0.15%.
As of December 31, 2017, our available borrowing capacity under the line of credit was $456.8 million. Utilization of the borrowing capacity was as follows:
| § | $250.0 million was borrowed |
|---|
| § | $43.2 million was used to provide support for outstanding standby letters of credit |
|---|
TERM DEBT
All of our $2,631.5 million of term debt is unsecured. $2,031.3 million of such debt is governed by two essentially identical indentures that contain customary investment-grade type covenants. The primary covenant in both indentures limits the amount of secured debt we may incur without ratably securing such debt. $600.0 million of such debt is governed, as described below, largely by the same credit agreement that governs our line of credit. As of December 31, 2017, we were in compliance with all term debt covenants.
In December 2017, we early retired via tender offer, $564.9 million of the 7.50% notes due 2021 at a cost of $662.6 million including a premium of $96.2 million and transaction costs of $1.6 million. Additionally, we recognized net noncash expense of $4.2 million with the acceleration of deferred debt issuance costs. Subsequently, in January 2018 we early retired via redemption the remaining $35.1 million of the 7.50% notes due 2021 at a cost of $40.7 million including a premium of $5.6 million.
| Part II | 48 |
Also in December 2017, we entered into a 6-month $350.0 million unsecured term loan with one of the banks that provides our line of credit. Borrowings bear interest at LIBOR plus 1.25%, and may be prepaid any time without penalty. This term loan incorporates by reference the representations, covenants and events of default contained in the credit agreement for the line of credit. As such, it is subject to the same affirmative, negative and financial covenants.
The December 2017 early debt retirement and acquisition of Aggregates USA were funded by a combination of cash on hand, our line of credit and the new 6-month unsecured term loan.
In June 2017, we issued $1,000.0 million of debt composed of three issuances as follows: (1) $700.0 million of 4.50% senior notes due June 2047, (2) $50.0 million of 3.90% senior notes due April 2027 (these notes are a further issuance of, and form a single series with, the 3.90% notes issued in March 2017), and (3) $250.0 million of floating-rate senior notes due June 2020. These issuances resulted in proceeds of $989.5 million (net of original issue discounts/premiums, underwriter fees and other transaction costs). The proceeds were used to partially finance an acquisition and to early retire the notes due in 2018 ($272.5 million @ 7.00% and $250.0 million @ 10.375%). This early retirement was completed in July at a cost of $565.6 million (including a $43.0 million premium) and $3.0 million of noncash expense associated with the acceleration of unamortized discounts, deferred debt issuance costs and deferred interest rate derivative settlement losses.
As a result of these 2017 early debt retirements described above, we recognized $139.2 million of premiums, $1.6 million of transaction costs and $7.2 million of net noncash expense associated with the acceleration of unamortized discounts, deferred debt issuance costs and deferred interest rate derivative settlement losses. The combined charge of $148.0 million was a component of interest expense for the year ended December 31, 2017.
In June 2017, we drew the full $250.0 million on the unsecured delayed draw term loan entered into in December 2016. These funds were used to repay the $235.0 million borrowed on our line of credit and for general corporate purposes. Borrowings bear interest in the same manner as the line of credit. The term loan principal will be repaid quarterly beginning March 2018 as follows: quarters 5 – 8 @ $1.6 million/quarter; 9 – 12 @ $3.1 million/quarter; 13 – 19 @ $4.7 million/quarter and $198.4 million for quarter 20 (December 2021). The term loan may be prepaid at any time without penalty. It is provided by the same group of banks that provides our line of credit, and is governed by the same credit agreement as the line of credit. As such, it is subject to the same affirmative, negative, and financial covenants.
In March 2017, we issued $350.0 million of 3.90% senior notes due April 2027 for proceeds of $345.5 million (net of original issue discounts, underwriter fees and other transaction costs). The proceeds were used for general corporate purposes. This series of notes now totals $400.0 million due to the additional $50.0 million of notes issued in June (as described above).
In March, April and August of 2015, we completed the refinancing of $485.1 million principal amount of debt as described in Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data.” And, in December 2015 we refinanced at maturity the $150.0 million of 10.125% notes via borrowing on our line of credit. These refinancing actions had the following benefits, among others: (1) eliminated $621.1 million of debt maturities in 2015 – 2018, (2) extended the weighted-average life of our debt portfolio, and (3) lowered our weighted-average interest rate.
The 2015 refinancing actions resulted in charges totaling $67.1 million. Such charges are detailed in Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data” and are presented in the accompanying Consolidated Statement of Comprehensive Income as a component of interest expense for the year ended December 31, 2015.
| Part II | 49 |
DEBT PAYMENTS AND MATURITIES
There were no significant scheduled debt payments during 2017 and 2016. Scheduled debt payments during 2015 included $150.0 million in December to retire the 10.125% notes (which were refinanced via long-term borrowings on our line of credit). Additionally, we refinanced $485.1 million of debt in 2015 as described in Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data.”
As of December 31, 2017, maturities for the next four quarters and maturities (excluding borrowings on the line of credit) for the next five years are due as follows:
| 2018 | Debt | |||||
| in millions | Debt Maturities | in millions | Maturities | |||
| First quarter 2018 | $ 36.6 | 2018 | $ 391.4 | |||
| Second quarter 2018 | 351.6 | 2019 | 12.5 | |||
| Third quarter 2018 | 1.6 | 2020 | 268.8 | |||
| Fourth quarter 2018 | 1.6 | 2021 | 218.5 | |||
| 2022 | 0.1 |
As previously noted, in January 2018, we early retired via redemption the remaining $35.1 million of the 7.50% notes due 2021 (reflected in the $36.6 million first quarter maturities above). Additionally, in February 2018, we refinanced the $350.0 unsecured term loan due second quarter 2018 by issuing $350.0 million of 30-year 4.70% notes due 2048.
DEBT RATINGS
Our debt ratings and outlooks as of December 31, 2017 are as follows:
| Rating/Outlook | Date | Description | ||||||||
| Senior Unsecured Term Debt 1 | ||||||||||
| Fitch | BBB-/stable | 2/20/2018 | rating/outlook affirmed | |||||||
| Moody's | Baa3/stable | 2/20/2018 | rating/outlook affirmed | |||||||
| Standard & Poor's | BBB/stable | 2/20/2018 | rating/outlook affirmed |
| 1 | Not all of our long-term debt is rated. |
| Part II | 50 |
EQUITY
Our common stock issuances and purchases are as follows:
| in thousands | 2017 | 2016 | 2015 | |||||||
| Common stock shares at January 1, | ||||||||||
| issued and outstanding | 132,339 | 133,172 | 131,907 | |||||||
| Common Stock Issuances | ||||||||||
| Share-based compensation plans | 495 | 594 | 1,493 | |||||||
| Common Stock Purchases | ||||||||||
| Purchased and retired | (510) | (1,427) | (228) | |||||||
| Common stock shares at December 31, | ||||||||||
| issued and outstanding | 132,324 | 132,339 | 133,172 |
On February 10, 2006, our Board of Directors authorized us to purchase up to 10,000,000 shares of our common stock. On February 10, 2017, there were 1,756,757 shares remaining under this authorization and our Board of Directors authorized us to purchase an additional 8,243,243 shares to refresh the number of shares we are authorized to purchase to 10,000,000. As of December 31, 2017, there were 9,489,717 shares remaining under the authorization. Depending upon market, business, legal and other conditions, we may purchase shares from time to time through the open market (including plans designed to comply with Rule 10b5-1 of the Securities Exchange Act of 1934) and/or privately negotiated transactions. The authorization has no time limit, does not obligate us to purchase any specific number of shares, and may be suspended or discontinued at any time.
Our common stock purchases (all of which were open market purchases) are detailed below:
| in thousands, except average cost | 2017 | 2016 | 2015 | |||||||
| Shares Purchased and Retired | ||||||||||
| Number | 510 | 1,427 | 228 | |||||||
| Cost 1 | $ 60,303 | $ 161,463 | $ 21,475 | |||||||
| Average cost per share 1 | $ 118.18 | $ 113.18 | $ 94.19 |
| 1 | Excludes commissions of $0.02 per share. |
There were no shares held in treasury as of December 31, 2017, 2016 and 2015.
OFF-BALANCE SHEET ARRANGEMENTS
We have no off-balance sheet arrangements, such as financing or unconsolidated variable interest entities, that either have or are reasonably likely to have a current or future material effect on our:
| § | results of operations and financial position |
|---|
| § | capital expenditures |
|---|
| § | liquidity and capital resources |
|---|
| Part II | 51 |
STANDBY LETTERS OF CREDIT
For a discussion of our standby letters of credit see Note 6 "Debt" in Item 8 "Financial Statements and Supplementary Data."
CASH CONTRACTUAL OBLIGATIONS
We expect core capital spending (excluding growth) of $250.0 million during 2018. Excluding future cash requirements for capital expenditures and immaterial or contingent contracts, our obligations to make future contractual payments as of December 31, 2017 are summarized in the table below:
| Note | Payments Due by Year | |||||||||||||
| in millions | Reference | 2018 | 2019-2020 | 2021-2022 | Thereafter | Total | ||||||||
| Cash Contractual Obligations | ||||||||||||||
| Bank line of credit 1 | ||||||||||||||
| Principal payments | Note 6 | $ 0.0 | $ 0.0 | $ 250.0 | $ 0.0 | $ 250.0 | ||||||||
| Interest payments and fees 2 | Note 6 | 8.9 | 20.0 | 10.0 | 0.0 | 38.9 | ||||||||
| Term debt | ||||||||||||||
| Principal payments | Note 6 | 391.4 | 281.3 | 218.6 | 1,740.2 | 2,631.5 | ||||||||
| Interest payments | Note 6 | 102.4 | 193.3 | 172.3 | 1,144.5 | 1,612.5 | ||||||||
| Operating leases | Note 7 | 36.4 | 64.9 | 48.2 | 106.3 | 255.8 | ||||||||
| Mineral royalties | Note 12 | 22.5 | 34.0 | 22.7 | 132.2 | 211.4 | ||||||||
| Unconditional purchase obligations | ||||||||||||||
| Capital | Note 12 | 134.5 | 0.0 | 0.0 | 0.0 | 134.5 | ||||||||
| Noncapital 3 | Note 12 | 10.4 | 15.1 | 3.6 | 3.0 | 32.1 | ||||||||
| Benefit plans 4 | Note 10 | 11.7 | 36.9 | 32.0 | 78.4 | 159.0 | ||||||||
| Total cash contractual obligations 5, 6 | $ 718.2 | $ 645.5 | $ 757.4 | $ 3,204.6 | $ 5,325.7 |
| 1 | Bank line of credit represents borrowings under our unsecured $750.0 million line of credit that expires December 2021. |
| 2 | Includes fees for unused borrowing capacity, and fees for standby letters of credit. The figures for all years assume that the amount of unused borrowing capacity and the amount of standby letters of credit do not change from December 31, 2017, and borrowing costs reflect a rising LIBOR. |
| 3 | Noncapital unconditional purchase obligations relate primarily to transportation and electricity contracts. |
| 4 | Payments in "Thereafter" column for benefit plans are for the years 2023-2027. |
| 5 | The above table excludes discounted asset retirement obligations in the amount of $218.1 million at December 31, 2017, the majority of which have an estimated settlement date beyond 2022 (see Note 17 "Asset Retirement Obligations" in Item 8 "Financial Statements and Supplementary Data"). |
| 6 | The above table excludes liabilities for unrecognized tax benefits in the amount of $11.6 million at December 31, 2017, as we cannot make a reasonably reliable estimate of the amount and period of related future payment of these uncertain tax positions (for more details, see Note 9 "Income Taxes" in Item 8 "Financial Statements and Supplementary Data"). |
| Part II | 52 |
CRITICAL ACCOUNTING POLICIES
We follow certain significant accounting policies when preparing our consolidated financial statements. A summary of these policies is included in Note 1 "Summary of Significant Accounting Policies" in Item 8 "Financial Statements and Supplementary Data."
We prepare these financial statements to conform with accounting principles generally accepted in the United States of America. These principles require us to make estimates and judgments that affect reported amounts of assets, liabilities, revenues and expenses, and the related disclosures of contingent assets and contingent liabilities at the date of the financial statements. We base our estimates on historical experience, current conditions and various other assumptions we believe reasonable under existing circumstances and evaluate these estimates and judgments on an ongoing basis. The results of these estimates form the basis for our judgments about the carrying values of assets and liabilities as well as identifying and assessing the accounting treatment with respect to commitments and contingencies. Our actual results may materially differ from these estimates.
We believe the following critical accounting policies require the most significant judgments and estimates used in the preparation of our consolidated financial statements:
| 1. | Goodwill impairment |
|---|
| 2. | Impairment of long-lived assets excluding goodwill |
|---|
| 3. | Business combinations and purchase price allocation |
|---|
| 4. | Pension and other postretirement benefits |
|---|
| 5. | Environmental compliance costs |
|---|
| 6. | Claims and litigation including self-insurance |
|---|
| 7. | Income taxes |
|---|
- GOODWILL IMPAIRMENT
Goodwill represents the excess of the cost of net assets acquired in business combinations over the fair value of the identifiable tangible and intangible assets acquired and liabilities assumed in a business combination. Goodwill impairment exists when the fair value of a reporting unit is less than its carrying amount. Goodwill is tested for impairment on an annual basis or more frequently whenever events or changes in circumstances would more likely than not reduce the fair value of a reporting unit below its carrying amount. The impairment evaluation is a critical accounting policy because goodwill is material to our total assets (as of December 31, 2017, goodwill represents 33% of total assets) and the evaluation involves the use of significant estimates, assumptions and judgment.
HOW WE TEST GOODWILL FOR IMPAIRMENT
Goodwill is tested for impairment at the reporting unit level, one level below our operating segments. We have identified 17 reporting units (of which 9 carry goodwill) based primarily on geographic location. We have the option of either assessing qualitative factors to determine whether it is more likely than not that the carrying value of our reporting units exceeds their respective fair value or proceeding directly to a quantitative test. We elected to perform the quantitative impairment test for all years presented.
The quantitative impairment test compares the fair value of a reporting unit to its carrying value, including goodwill. If the fair value exceeds its carrying value, the goodwill of the reporting unit is not considered impaired. However, if the carrying value of a reporting unit exceeds its fair value, we recognize an impairment loss equal to that excess.
HOW WE DETERMINE CARRYING VALUE AND FAIR VALUE
First, we determine the carrying value of each reporting unit by assigning assets and liabilities, including goodwill, to those units as of the measurement date. Then, we estimate the fair values of the reporting units using both an income approach (which involves discounting estimated future cash flows) and a market approach (which involves the application of revenue and EBITDA multiples of comparable companies). We consider market factors when determining the assumptions and estimates used in our valuation models. Finally, to assess the reasonableness of the reporting unit fair values, we compare the total of the reporting unit fair values to our market capitalization.
| Part II | 53 |
OUR FAIR VALUE ASSUMPTIONS
We base our fair value estimates on market participant assumptions we believe to be reasonable at the time, but such assumptions are subject to inherent uncertainty and actual results may differ. Changes in key assumptions or management judgment with respect to a reporting unit or its prospects may result from a change in market conditions, market trends, interest rates or other factors outside of our control, or underperformance relative to historical or projected operating results. These conditions could result in a significantly different estimate of the fair value of our reporting units, which could result in an impairment charge in the future.
The significant assumptions in our discounted cash flow models include our estimate of future profitability, capital requirements and the discount rate. The profitability estimates used in the models were derived from internal operating budgets and forecasts for long-term demand and pricing in our industry. Estimated capital requirements reflect replacement capital estimated on a per ton basis and if applicable, acquisition capital necessary to support growth estimated in the models. The discount rate was derived using a capital asset pricing model.
RESULTS OF OUR IMPAIRMENT TESTS
The results of our annual impairment tests for:
| § | November 1, 2017 indicated that the fair values of all reporting units with goodwill substantially exceeded (in excess of 100%) their carrying values |
|---|
| § | November 1, 2016 indicated that the fair values of all reporting units with goodwill substantially exceeded (in excess of 100%) their carrying values |
|---|
| § | November 1, 2015 indicated that the fair values of all reporting units with goodwill substantially exceeded (in excess of 100%) their carrying values |
|---|
For additional information about goodwill, see Note 18 "Goodwill and Intangible Assets" in Item 8 "Financial Statements and Supplementary Data."
- IMPAIRMENT OF LONG-LIVED ASSETS EXCLUDING GOODWILL
We evaluate the carrying value of long-lived assets, including intangible assets subject to amortization, when events and circumstances indicate that the carrying value may not be recoverable. The impairment evaluation is a critical accounting policy because long-lived assets are material to our total assets (as of December 31, 2017, net property, plant & equipment represents 41% of total assets, while net other intangible assets represents 11% of total assets) and the evaluation involves the use of significant estimates, assumptions and judgment. The carrying value of long-lived assets is considered impaired when the estimated undiscounted cash flows from such assets are less than their carrying value. In that event, we recognize a loss equal to the amount by which the carrying value exceeds the fair value.
Fair value is estimated primarily by using a discounted cash flow methodology that requires considerable judgment and assumptions. Our estimate of net future cash flows is based on historical experience and assumptions of future trends, which may be different from actual results. We periodically review the appropriateness of the estimated useful lives of our long-lived assets.
We test long-lived assets for impairment at the lowest level for which identifiable cash flows are largely independent of the cash flows of other assets. As a result, our long-lived asset impairment test is at a significantly lower level than the level at which we test goodwill for impairment. In markets where we do not produce downstream products (e.g., asphalt mix and ready-mixed concrete), the lowest level of largely independent identifiable cash flows is at the individual aggregates operation or a group of aggregates operations collectively serving a local market. Conversely, in vertically integrated markets, the cash flows of our downstream and upstream businesses are not largely independently identifiable as the selling price of the upstream products (aggregates) impacts the profitability of the downstream business.
During 2017, we recorded no loss on impairment of long-lived assets. During 2016, we recorded a $10.5 million impairment loss resulting from the termination of a nonstrategic aggregates lease and the write off of nonrecoverable project costs related to two Aggregates segment capital projects that we no longer intend to complete. During 2015, we recorded a $5.2 million impairment loss resulting from exiting a lease for an Aggregates segment site.
| Part II | 54 |
We maintain certain long-lived assets that are not currently being used in our operations. These assets totaled $415.7 million at December 31, 2017, representing an 11% increase from December 31, 2016. Of the total $415.7 million, approximately 50% relates to real estate held for future development and expansion of our operations. In addition, approximately 25% is comprised of real estate (principally former mining sites) pending development as commercial or residential real estate, reservoirs or landfills. The remaining 25% is composed of aggregates, asphalt and concrete operating assets idled temporarily as a result of a decline in demand for our products. We anticipate moving idled assets back into operation as demand recovers. We evaluate the useful lives and the recoverability of these assets whenever events or changes in circumstances indicate that carrying amounts may not be recoverable.
For additional information about long-lived assets and intangible assets, see Note 4 "Property, Plant & Equipment" and Note 18 "Goodwill and Intangible Assets" in Item 8 "Financial Statements and Supplementary Data."
- BUSINESS COMBINATIONS AND PURCHASE PRICE ALLOCATION
Our strategic long-term plans include potential investments in value-added acquisitions of related or similar businesses. When an acquisition is completed, our consolidated statements of comprehensive income includes the operating results of the acquired business starting from the date of acquisition, which is the date that control is obtained.
HOW WE DETERMINE AND ALLOCATE THE PURCHASE PRICE
The purchase price is determined based on the fair value of consideration transferred to and liabilities assumed from the seller as of the date of acquisition. We allocate the purchase price to the fair values of the tangible and identifiable intangible assets acquired and liabilities assumed as of at the date of acquisition. Goodwill is recorded for the excess of the purchase price over the net of the fair value of the identifiable assets acquired and liabilities assumed. The purchase price allocation is a critical accounting policy because the estimation of fair values of acquired assets and assumed liabilities is judgmental and requires various assumptions. Additionally, the amounts assigned to depreciable and amortizable assets compared to amounts assigned to goodwill, which is not amortized, can significantly affect our results of operations.
Fair value is the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction, and therefore represents an exit price. A fair value measurement assumes the highest and best use of the asset by market participants. The fair value hierarchy prioritizes the inputs to valuation techniques used to measure fair value into three broad levels as described below:
Level 1: Quoted prices in active markets for identical assets or liabilities Level 2: Inputs that are derived principally from or corroborated by observable market data Level 3: Inputs that are unobservable and significant to the overall fair value measurement
Level 1 fair values are used to value investments in publicly-traded entities and assumed obligations for publicly-traded long-term debt.
Level 2 fair values are typically used to value acquired machinery and equipment, land, buildings, and assumed liabilities for asset retirement obligations, environmental remediation and compliance obligations. Additionally, Level 2 fair values are typically used to value assumed contracts at other-than-market rates.
Level 3 fair values are used to value acquired mineral reserves as well as leased mineral interests (referred to in our financial statements as contractual rights in place) and other identifiable intangible assets. We determine the fair values of owned mineral reserves and leased mineral interests using a lost profits approach and/or an excess earnings approach. These valuation techniques require management to estimate future cash flows. The estimate of future cash flows is based on available historical information and future expectations and assumptions determined by management, but is inherently uncertain. Key assumptions in estimating future cash flows include sales price, shipment volumes, production costs and capital needs. The present value of the projected net cash flows represents the fair value assigned to mineral reserves and mineral interests. The discount rate is a significant assumption used in the valuation model and is based on the required rate of return that a hypothetical market participant would require if purchasing the acquired business, with an adjustment for the risk of these assets not generating the projected cash flows.
| Part II | 55 |
Other identifiable intangible assets may include, but are not limited to noncompetition agreements and favorable/unfavorable lease agreements. The fair values of these assets are typically determined by an excess earnings method, a replacement cost method or a market approach.
MEASUREMENT PERIOD ADJUSTMENTS
We may adjust the amounts recognized in an acquisition during a measurement period after the acquisition date. Any such adjustments are the result of subsequently obtaining additional information that existed at the acquisition date regarding the assets acquired or the liabilities assumed. Measurement period adjustments are generally recorded as increases or decreases to goodwill, if any, recognized in the transaction. The cumulative impact of measurement period adjustments on depreciation, amortization and other income statement items are recognized in the period the adjustment is determined. The measurement period ends once we have obtained all necessary information that existed as of the acquisition date, but does not extend beyond one year from the date of acquisition. Any adjustments to assets acquired or liabilities assumed beyond the measurement period are recorded through earnings.
- PENSION AND OTHER POSTRETIREMENT BENEFITS
Accounting for pension and postretirement benefits requires that we make significant assumptions about the valuation of benefit obligations and the performance of plan assets. Each year we review the following primary assumptions:
| § | DISCOUNT RATES — The discount rate used in calculating the present value of projected benefit payments and the discount rates used to measure service cost and interest cost |
|---|
| § | EXPECTED RETURN ON PLAN ASSETS — The expected future return on plan assets reduces the recorded net benefit costs |
|---|
| § | RATE OF COMPENSATION INCREASE — Annual pay increases after 2015 will not increase our pension plan obligations as a result of a 2013 plan amendment |
|---|
| § | RATE OF INCREASE IN THE PER CAPITA COST OF COVERED HEALTHCARE BENEFITS — Future increases in the per capita cost after 2015 will not increase our postretirement medical benefits obligation as a result of a 2012 plan amendment to cap medical coverage cost at the 2015 level |
|---|
HOW WE SET OUR ASSUMPTIONS
The effective discount rate is the weighted-average of the spot rates for each cash flow on the yield curve for high-quality bonds as of the measurement date. At December 31, 2017, the discount rates for our various plans ranged from 3.24% to 3.79% (December 31, 2016 ranged from 3.43% to 4.41%).
In estimating the expected return on plan assets, we consider past performance and long-term future return expectations for the types of investments held by the plan as well as the expected long-term allocation of plan assets to these investments. At December 31, 2017, the expected return on plan assets remained at 7.00%.
Changes to the assumptions listed above would have an impact on the projected benefit obligations and the annual net benefit cost. The following table reflects the favorable and unfavorable outcomes associated with a change in certain assumptions:
| (Favorable) Unfavorable | |||||||||||
| 0.5 Percentage Point Increase | 0.5 Percentage Point Decrease | ||||||||||
| Inc (Dec) in | Inc (Dec) in | Inc (Dec) in | Inc (Dec) in | ||||||||
| in millions | Benefit Obligation | Annual Benefit Cost | Benefit Obligation | Annual Benefit Cost | |||||||
| Actuarial Assumptions | |||||||||||
| Discount rates | |||||||||||
| Pension | $ (63.9) | $ (1.3) | $ 70.8 | $ 1.4 | |||||||
| Other postretirement benefits | (1.3) | 0.0 | 1.3 | 0.0 | |||||||
| Expected return on plan assets | not applicable | (4.3) | not applicable | 4.3 |
| Part II | 56 |
As of the December 31, 2017 measurement date, the fair value of our pension plan assets increased from $749.5 million for the prior year-end to $840.9 million due to investment gains and $10.6 million of contributions to the qualified pension plans.
We use a full yield curve approach to estimate the service and interest cost, applying the specific spot rates along the yield curve to the relevant projected cash flows. The weighted-average discount rates used to measure service and interest costs for 2017 were 4.63% and 3.63%, respectively, for our pension plans and 3.96% and 2.89%, respectively, for our other postretirement plans. The weighted-average discount rates used to measure service and interest costs for 2016 were 4.68% and 3.79%, respectively, for our pension plans and 3.77% and 2.81%, respectively, for our other postretirement plans.
During 2018, we expect to recognize net pension credit of $(5.5) million and net postretirement credit of $(3.1) million compared to expense of $3.2 million and credit of $(3.4) million, respectively, in 2017. The reductions in cost recognition are primarily due to strong asset returns during 2017 and anticipated discretionary contributions to the pension plans.
We do not anticipate contributions to the funded pension plans will be required during 2018; however, we do anticipate making discretionary contributions of $100.0 million. We currently do not anticipate that the funded status of any of our plans will fall below statutory thresholds requiring accelerated funding or constraints on benefit levels or plan administration.
For additional information about pension and other postretirement benefits, see Note 10 "Benefit Plans" in Item 8 "Financial Statements and Supplementary Data."
- ENVIRONMENTAL COMPLIANCE COSTS
Our environmental compliance costs include the cost of ongoing monitoring programs, the cost of remediation efforts and other similar costs. Our accounting policy for environmental compliance costs is a critical accounting policy because it involves the use of significant estimates and assumptions and requires considerable management judgment.
HOW WE ACCOUNT FOR ENVIRONMENTAL COSTS
To account for environmental costs, we:
| § | expense or capitalize environmental costs consistent with our capitalization policy |
|---|
| § | expense costs for an existing condition caused by past operations that do not contribute to future revenues |
|---|
| § | accrue costs for environmental assessment and remediation efforts when we determine that a liability is probable and we can reasonably estimate the cost |
|---|
At the early stages of a remediation effort, environmental remediation liabilities are not easily quantified due to the uncertainties of various factors. The range of an estimated remediation liability is defined and redefined as events in the remediation effort occur, but generally liabilities are recognized no later than completion of the remedial feasibility study. When we can estimate a range of probable loss, we accrue the most likely amount. If no amount in the range of probable loss is considered most likely, the minimum loss in the range is accrued. As of December 31, 2017, the difference between the amount accrued and the maximum loss in the range for all sites for which a range can be reasonably estimated was $3.1 million — this amount does not represent our maximum exposure to loss for all environmental remediation obligations as it excludes those sites for which a range of loss cannot be reasonably estimated at this time. Our environmental remediation obligations are recorded on an undiscounted basis.
Accrual amounts may be based on technical cost estimations or the professional judgment of experienced environmental managers. Our Safety, Health and Environmental Affairs Management Committee routinely reviews cost estimates and key assumptions in response to new information, such as the kinds and quantities of hazardous substances, available technologies and changes to the parties participating in the remediation efforts. However, a number of factors, including adverse agency rulings and unanticipated conditions as remediation efforts progress, may cause actual results to differ materially from accrued costs.
For additional information about environmental compliance costs, see Note 8 "Accrued Environmental Remediation Costs" in Item 8 "Financial Statements and Supplementary Data."
| Part II | 57 |
- CLAIMS AND LITIGATION INCLUDING SELF-INSURANCE
We are involved with claims and litigation, including items covered under our self-insurance program. We are self-insured for losses related to workers' compensation up to $2.0 million per occurrence and automotive and general/product liability up to $3.0 million per occurrence. We have excess coverage on a per occurrence basis beyond these retention levels.
Under our self-insurance program, we aggregate certain claims and litigation costs that are reasonably predictable based on our historical loss experience and accrue losses, including future legal defense costs, based on actuarial studies. Certain claims and litigation costs, due to their unique nature, are not included in our actuarial studies. For matters not included in our actuarial studies, legal defense costs are accrued when incurred.
Our accounting policy for claims and litigation including self-insurance is a critical accounting policy because it involves the use of significant estimates and assumptions and requires considerable management judgment.
HOW WE ASSESS THE PROBABILITY OF LOSS
We use both internal and outside legal counsel to assess the probability of loss, and establish an accrual when the claims and litigation represent a probable loss and the cost can be reasonably estimated. Significant judgment is used in determining the timing and amount of the accruals for probable losses, and the actual liability could differ materially from the accrued amounts.
For additional information about claims and litigation including self-insurance, see Note 1 "Summary of Significant Accounting Policies" in Item 8 "Financial Statements and Supplementary Data" under the caption Claims and Litigation Including Self-insurance.
- INCOME TAXES
VALUATION OF OUR DEFERRED TAX ASSETS
We file federal, state and foreign income tax returns and account for the current and deferred tax effects of such returns using the asset and liability method. We recognize deferred tax assets and liabilities (which reflect our best assessment of the future taxes we will pay) based on the differences between the book basis and tax basis of assets and liabilities. Deferred tax assets represent items to be used as a tax deduction or credit in future tax returns while deferred tax liabilities represent items that will result in additional tax in future tax returns.
Significant judgments and estimates are required in determining our deferred tax assets and liabilities. These estimates are updated throughout the year to consider income tax return filings, our geographic mix of earnings, legislative changes and other relevant items. We are required to account for the effects of changes in income tax rates on deferred tax balances in the period in which the legislation is enacted. Refer to Note 9 “Income Taxes” in Item 8 “Financial Statements and Supplementary Data” for a discussion of the impact of the Tax Cuts and Jobs Act enacted in December 2017.
Each quarter we analyze the likelihood that our deferred tax assets will be realized. Realization of the deferred tax assets ultimately depends on the existence of sufficient taxable income of the appropriate character in either the carryback or carryforward period. A valuation allowance is recorded if, based on the weight of all available positive and negative evidence, it is more likely than not (a likelihood of more than 50%) that some portion, or all, of a deferred tax asset will not be realized. A summary of our deferred tax assets is included in Note 9 “Income Taxes” in Item 8 “Financial Statements and Supplementary Data.”
| Part II | 58 |
LIABILITY FOR UNRECOGNIZED TAX BENEFITS
We recognize a tax benefit associated with a tax position when we judge it is more likely than not that the position will be sustained based upon the technical merits of the position. For a tax position that meets the more likely than not recognition threshold, we measure the income tax benefit as the largest amount that we judge to have a greater than 50% likelihood of being realized. A liability is established for the unrecognized portion of any tax position. Our liability for unrecognized tax benefits is adjusted periodically due to changing circumstances, such as the progress of tax audits, case law developments and new or emerging legislation.
The years open to tax examinations vary by jurisdiction. While it is often difficult to predict the final outcome or the timing of resolution of any particular tax matter, we believe our liability for unrecognized tax benefits is appropriate.
We consider a tax position to be resolved at the earlier of the issue being “effectively settled,” settlement of an examination, or the expiration of the statute of limitations. Upon resolution of a tax position, any liability for unrecognized tax benefits will be released.
Our liability for unrecognized tax benefits is generally presented as noncurrent. However, if we anticipate paying cash within one year to settle an uncertain tax position, the liability is presented as current. We classify interest and penalties associated with our liability for unrecognized tax benefits as income tax expense.
NEW ACCOUNTING STANDARDS
For a discussion of accounting standards recently adopted or pending adoption and the effect such accounting changes will have on our results of operations, financial position or liquidity, see Note 1 "Summary of Significant Accounting Policies" in Item 8 "Financial Statements and Supplementary Data" under the caption New Accounting Standards.
FORWARD-LOOKING STATEMENTS
The foregoing discussion and analysis, as well as certain information contained elsewhere in this Annual Report, contain "forward-looking statements" within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, and are intended to be covered by the safe harbor created thereby. See the discussion in Safe Harbor Statement under the Private Securities Litigation Reform Act of 1995 in Part I, above.
| Part II | 59 |
Previous: Item 6. SELECTED FINANCIAL DATA · Next: Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK