 filings.tools
Vulcan Materials (VMC) 10-K risk factor changes: FY2023 vs FY2022
The 2023-12-31 10-K against the 2022-12-31 one, compared heading by heading and sentence by sentence.
Item 1A18 rewritten4 added6 removed82 unchanged
All filing items1,360 rewritten490 added554 removed2,807 unchanged
Sentence counts leave out repeated page headers and footers. 11 of those lines differ and are listed apart under each item.
Summary
counted, not written
- Item 1A headings could not be compared: only 0 carried over between the two years, which usually means one filing was read wrongly, so none is reported as new or removed.
- Sentence by sentence, 490 added, 554 removed, 1,360 rewritten and 2,807 unchanged across 22 items that differ.
- Not counted above: 11 repeated page header or footer lines also differ. They are listed apart under each item.
- New this year: Item 1C. cybersecurity; Item 6. [reserved].
Sentences by item
24 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2023; struck-through words were in FY2022. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. RISK FACTORS
18 rewritten, 4 added, 6 removed, 82 unchanged
A downturn in Vulcan-served markets, particularly in our top revenue-generating markets, could have a material adverse effect on our business, financial [removed: condition,] [added: condition] and results of operations.
In [removed: 2022,] [added: 2023,] voters in local jurisdictions in [added: Arizona,] California, [removed: Florida,] Georgia, [added: New Mexico,] North Carolina, South [removed: Carolina, Texas] [added: Carolina] and [removed: Virginia,] [added: Texas,] among others, approved bond and revenue-raising measures to provide additional resources for transportation projects.
In November 2021, the federal Infrastructure Investment and Jobs Act (IIJA), which included a [removed: five year] [added: five-year] road, bridge and public transportation program reauthorization at record levels, was signed into law.
[removed: We are subject to various risks arising from our international business operations and relationships —] We are [added: also] subject to both the risks of conducting international business and the requirements of the Foreign Corrupt Practices Act of 1977 (the FCPA) associated with our aggregates production facilities including those located in British Columbia, Canada; Puerto Cortés, Honduras; and Quintana Roo, Mexico.
Recently, the Mexican government has taken actions that adversely affect our property and operations in [removed: that country,] [added: Mexico,] including arbitrary shutdown orders to immediately cease underwater quarrying and extraction operations.
We continue to vigorously pursue all lawful avenues available to us in order to protect our rights, under both Mexican and international [removed: law and intend to resume normal operations in Mexico as soon as permitted.][added: law.]
Our aggregates operations are subject to the risks of open pit and underground mining [removed: –] [added: —] Aggregates mining involves risks such as pit wall failures, pillar or ceiling collapse, flooding, and seismic events related to geologic conditions and our mining activities.
A deterioration in our credit ratings and/or the state of the capital markets could negatively impact the cost and/or availability of financing — We currently have approximately [removed: $4.0] [added: $3.9] billion of debt with maturities between [removed: 2023] [added: 2024] and 2048.
Our effective tax rate is subject to change — Factors that may increase our future effective tax rate include, but are not limited to: governmental authorities increasing statutory income tax rates or eliminating deductions [added: (particularly the depletion deduction)] or credits; the mix of jurisdictions in which our earnings are [removed: taxed;] [added: taxed and the mix of earnings from depletable versus non-depletable businesses;] changes in the valuation of our deferred tax assets and liabilities; the effect our stock price has with regard to excess tax benefits from share-based compensation; adjustments to estimated taxes upon finalization of various income tax returns; the resolution of issues arising from income tax audits with various tax authorities; and the interpretation of income tax laws and/or administrative practices.
Expectations relating to environmental, social and governance [removed: (ESG)] considerations [added: and related reporting obligations] expose us to potential liabilities, increased costs, reputational [removed: harm,] [added: harm] and other adverse effects on our [removed: business —] [added: business —] Many governments, regulators, investors, employees, customers and other stakeholders are increasingly focused on [removed: ESG] [added: environmental, social and governance] considerations relating to businesses, including climate change and greenhouse gas emissions, human and civil rights, and diversity, equity and inclusion.
In addition, we make statements about our [removed: ESG] [added: sustainability] goals and initiatives through our [removed: ESG] [added: sustainability] report, our other non-financial reports, information provided on our website, press releases and other communications.
Responding to these [removed: ESG] [added: environmental, social and governance] considerations and implementing these goals and initiatives involves risks and uncertainties, requires investments, and depends in part on third-party performance or data that is outside our control.
We cannot guarantee that we will achieve our announced [removed: ESG] [added: sustainability] goals and initiatives.
Any failure, or perceived failure, by us to achieve our goals, further our initiatives, adhere to our public statements, comply with [added: related] federal, state or international [removed: ESG] laws and regulations, or meet evolving and varied stakeholder expectations and standards could result in legal and regulatory proceedings against us.
We may incur material costs and losses as a result of claims that our products do not meet regulatory requirements or contractual specifications [removed: —] [added: —] Our operations involve providing products that must meet building code or other regulatory requirements and contractual specifications for durability, stress-level capacity, weight-bearing capacity and other characteristics.
We are dependent on information technology systems (our own and those of our service providers such as Amazon Web Services), and these systems contain [removed: confidential or sensitive] [added: non-public] data about our business, employees, [removed: suppliers,] [added: suppliers] and customers — The protection of our information technology systems and the data contained therein is critical to us.
[removed: We have a dedicated information security team that executes our information security program and routinely tests the security of our applications, networks, databases, etc.] The loss of use of information technology systems (whether ours or our service providers), regardless of the cause, would disrupt our business operations.
The failure to keep secure the confidential and sensitive data about our business, employees, suppliers and customers, regardless of the reason for such failure, could expose us, our employees, suppliers and/or our customers to the misuse of such data and could [removed: result in reputational harm] [added: damage our reputation, cause us to incur significant liability] and [added: have a material adverse effect on our business,] financial [removed: liability.][added: condition and results of operations.]
We are subject to various risks arising from our international business operations and relationships — We are subject to risks associated with potential disruption caused by changes in domestic or global political, economic and diplomatic developments, including war, civil and political unrest, illnesses declared as a public health emergency (including viral pandemics such as COVID-19), terrorism, expropriation and local labor conditions.
We have a dedicated information security team that executes our information security program and routinely tests the security of our applications, networks, databases, etc. While we have security measures and technology in place designed to protect proprietary or classified information about our business, employees, suppliers and customers, there can be no assurance that our efforts will prevent all threats to our information technology systems (or those of our service providers).
In addition, the rapid evolution and increased adoption of artificial intelligence technologies may intensify our cybersecurity risks.
Because the techniques used to obtain unauthorized access or sabotage information technology systems change frequently, become more sophisticated and generally are not identified until they are launched against a target, we may be unable to anticipate these techniques or implement adequate preventative measures.
Our business is exposed to the risks associated with a pandemic, epidemic or other public health emergency, such as the coronavirus (COVID-19) pandemic — The COVID-19 pandemic caused governments and businesses around the world to implement strict measures to help control the spread of the virus.
The vast majority, if not all, of these measures are no longer in place in the United States.
While our industry was deemed essential in every state in which we operate and we continued to operate across our footprint when such measures were in place, our operations, supply chain, customers, and transportation networks were negatively impacted by such measures (including our own) and the health of our employees.
The progression of COVID-19 (which remains highly uncertain) or another pandemic may result in future measures taken by governments and/or businesses (including our own) that could negatively impact our business.
The Audit Committee, which has oversight responsibility for our information security program, is briefed on such program at least twice annually, and our Chief Financial Officer is briefed on such program at least quarterly.
Additionally, weather events, such as hurricanes and tornadoes, can negatively impact our distribution network.
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
358 rewritten, 120 added, 140 removed, 624 unchanged
The following generally includes a comparison of our results of operations and liquidity and capital resources for [removed: 2022] [added: 2023] and [removed: 2021.][added: 2022.]
For the discussion of changes from [removed: 2020 to] 2021 [added: to 2022] and other financial information related to [removed: 2020,] [added: 2021,] refer to Part II, Item 7.
Management’s Discussion and Analysis of Financial Condition and Results of Operations, of our Form 10-K for the year ended December 31, [removed: 2021] [added: 2022] filed with the Securities and Exchange Commission on February [removed: 25, 2022.][added: 24, 2023.]
FINANCIAL SUMMARY FOR [removed: 2022] [added: 2023] (compared to [removed: 2021)][added: 2022)]
Total revenues increased [removed: $1,763.0] [added: $466.7] million, or [removed: 32%,] [added: 6%,] to [removed: $7,315.2] [added: $7,781.9] million
Gross profit increased [removed: $184.3] [added: $390.9] million, or [removed: 13%,] [added: 25%,] to [removed: $1,557.7] [added: $1,948.5] million
Selling, administrative and general (SAG) expenses increased [removed: 23%] [added: 5%] to [removed: $515.1 million and decreased 0.5 percentage point (50 basis points)] [added: $542.8 million, unchanged] as a percentage of total revenues
Earnings attributable to Vulcan from continuing operations were [removed: $4.45] [added: $7.06] per diluted share, compared to [removed: $5.05] [added: $4.45] per diluted share
Adjusted earnings attributable to Vulcan from continuing operations were [removed: $5.11] [added: $7.00] per diluted share, compared to [removed: $5.04] [added: $5.11] per diluted share
Net earnings attributable to Vulcan were [removed: $575.6] [added: $933.2] million, [removed: a decrease] [added: an increase] of [removed: $95.2] [added: $357.6] million, or [removed: 14%][added: 62%]
Adjusted EBITDA was [removed: $1,625.6] [added: $2,011.3] million, an increase of [removed: $174.3] [added: $385.7] million, or [removed: 12%][added: 24%]
Aggregates segment sales increased [removed: $927.8] [added: $637.1] million, or [removed: 21%,] [added: 12%,] to [removed: $5,272.8] [added: $5,909.9] million
Aggregates segment freight-adjusted revenues increased [removed: $561.3] [added: $577.1] million, or [removed: 17%,] [added: 15%,] to [removed: $3,875.2] [added: $4,452.3] million
Freight-adjusted sales price increased [removed: 10.3%,] [added: 15.9%,] or [removed: $1.53] [added: $2.60] per ton to [removed: $16.40][added: $19.00]
Aggregates segment gross profit increased [removed: $112.8] [added: $325.1] million, or [removed: 9%,] [added: 23%,] to [removed: $1,408.5] [added: $1,733.6] million
Unit profitability (as measured by gross profit per ton) increased [removed: 3%] [added: 24%] to [removed: $5.96] [added: $7.40] per ton
Asphalt, Concrete and Calcium segment sales [removed: increased $1,040.4] [added: decreased $192.9] million, or [removed: 67%,] [added: 7%,] to [removed: $2,591.9] [added: $2,399.0] million, collectively
Asphalt, Concrete and Calcium segment gross profit increased [removed: $71.5] [added: $65.7] million, or [removed: 92%,] [added: 44%,] to [removed: $149.2] [added: $214.9] million, collectively
Returned capital to shareholders via dividends of [removed: $212.6] [added: $228.4] million [removed: @ $1.60] [added: at $1.72] per share versus [removed: $196.4] [added: $212.6] million [removed: @ $1.48] [added: at $1.60] per share
At year-end [removed: 2022,] [added: 2023,] total debt to Adjusted EBITDA was [removed: 2.4x (2.3x] [added: 1.9x, or 1.5x] on a net debt [removed: basis).][added: basis, reflecting $949.2 million of cash on hand.]
Adjusted EBITDA, Aggregates segment freight-adjusted revenues, [removed: net] [added: cash gross profit per ton,] debt to Adjusted EBITDA and Return on invested capital are non-GAAP measures.
Through economic cycles we intend to balance reinvestment in our business, growth through [removed: acquisitions,] [added: acquisitions] and [added: internal growth projects, and] return of capital to shareholders while maintaining financial strength and flexibility evidenced by our strong balance sheet and investment-grade credit ratings.
2.Growth Capital (including [removed: greenfields] [added: acquisitions] and [removed: acquisitions)][added: greenfields)]
During [removed: 2022,] [added: 2023,] we invested [removed: $380.1] [added: $424.5] million [added: in capital expenditures] to replace or improve existing property, plant & equipment.
Our second priority is to grow our franchise through [added: business acquisitions and] internal growth [removed: projects and business acquisitions.][added: projects.]
During [removed: 2022,] [added: 2023,] we invested [removed: $232.5] [added: $200.8] million in internal growth projects to secure new aggregates reserves, develop new production and/or distribution sites, enhance our distribution capabilities and support the targeted growth of our asphalt and concrete operations.
For business acquisitions, we tend to look for bolt-on acquisitions which are [removed: easy] [added: easier] to integrate and will pursue large business combinations that are the right fit and the right price.
We [removed: look at a lot of] [added: evaluate many] potential acquisitions and only make offers on a few.
During [removed: 2022,] [added: 2023,] we paid a dividend per share of [removed: $1.60] [added: $1.72] and paid total dividends of [removed: $212.6] [added: $228.4] million.
Our expectations for [removed: 2023] [added: 2024] include:
Continued [removed: acceleration] [added: improvement] in Aggregates segment cash gross profit per ton [removed: improvement ($7.83] [added: ($9.46] in [removed: 2022)][added: 2023)]
Total shipments [removed: down 2%] [added: flat] to [removed: 6% (236.3] [added: down 4% (234.3] million tons in [removed: 2022)][added: 2023)]
[removed: High-single] [added: Mid-single] digit increase in freight-adjusted [added: unit] cash cost (freight-adjusted price less segment cash gross profit per ton; [removed: $8.57] [added: $9.54] in [removed: 2022)][added: 2023)]
Interest expense of approximately [removed: $195] [added: $155] million
An effective tax rate of [removed: approximately] 22% [added: to 23%]
Net earnings attributable to Vulcan of [removed: between $715] [added: $1,070] million [removed: and $835] [added: to $1,190] million
Adjusted EBITDA [removed: of] between [removed: $1,725] [added: $2,150] million and [removed: $1,875] [added: $2,300] million
Additionally, we expect to spend [removed: $600] [added: $625] million to [removed: $650] [added: $675] million on capital expenditures, including growth projects.
[removed: 7%] [added: 27%] improvement in Aggregates gross profit per ton since [removed: 2020][added: 2021]
[removed: 10%] [added: 27%] improvement in Aggregates cash gross profit per ton since [removed: 2020][added: 2021]
Operating earnings increased $476.0 million, or 50%, to $1,427.4 million
Shipments decreased 1%, or 2.0 million tons, to 234.3 million tons
Returned capital to shareholders via share repurchases of $200.0 million at $204.52 average price per share compared to none in the prior year
2023 was an exceptional year for our company.
We generated $933.2 million in net earnings attributable to Vulcan (a 62% increase over the prior year), produced $2,011.3 million in Adjusted EBITDA (a 24% increase over the prior year), expanded EBITDA margin by 360 basis points and generated $1,536.8 million of operating cash flow that can be reinvested in our business.
Our industry leading aggregates gross profit per ton was $7.40 for the full year (a 24% improvement), and cash gross profit per ton was $9.46 per ton for the full year (a 21% improvement), with both metrics increasing each quarter on a year-over-year basis.
Six consecutive years of unit profitability improvement during a continuously shifting macro backdrop demonstrates the durability of our uniquely positioned aggregates-led business.
We carry momentum into 2024, and our focus is the same – compounding unit margins through all parts of the cycle and creating value for our shareholders through improving returns on capital.
Return on invested capital improved 280 basis points to 16.3% through a combination of solid operating earnings and disciplined capital management.
We did not complete any business acquisitions in 2023.
However, during the last 10 years, we have completed almost 40 acquisitions, including more than 70 aggregates quarries and sales yards in our top 10 revenue states.
We deployed an additional $203.6 million of capital for opportunistic land purchases of strategic reserves in California, North Carolina and Texas.
During 2023, we returned $200.0 million to our shareholders through share repurchases.
We are well positioned to deliver another year of earnings growth and strong cash generation in 2024.
The pricing environment remains positive, and we expect pricing momentum and operational execution will lead to attractive expansion in aggregates unit profitability, regardless of the macro demand environment.
Freight-adjusted price improvement of 10% to 12% ($19.00 in 2023)
Total Asphalt, Concrete and Calcium segment cash gross profit of approximately $275 million ($323 million in 2023, which included approximately 4 million cubic yards from concrete operations divested in late 2023)
Relative contribution of approximately 70% from the Asphalt segment and 30% from the Concrete segment
Selling, Administrative and General expenses of $550 million to $560 million ($543 million in 2023)
In 2019, we set a target of $9 of cash gross profit per ton on volumes of 230 to 240 million tons, which we exceeded in 2023.
Our durable growth strategy gives us confidence that we will deliver more value to our shareholders on every ton of aggregates we sell.
Our new target: achieve $11 to $12 cash gross profit per ton when we reach 260 to 270 million tons.
| | *Cash gross profit per ton is a non-GAAP measure. See the definitions and reconciliations within this Item 7 under the caption Reconciliation of Non-GAAP Financial Measures.* |
*Production and sales are currently halted at our Calica operations in Mexico.
We also manage our land with biodiversity in mind.
| EBITDA 1 | | | $ 2,025.4 | | | $ 1,517.9 | | | $ 1,480.5 | |
| Tons | | | 234.3 | | | 236.3 | | | 222.9 | |
| Tons | | | 13.4 | | | 12.2 | | | 11.4 | |
| Cubic yards | | | 7.5 | | | 10.5 | | | 5.6 | |
pretax net gain of $67.1 million related to the sale of excess real estate and businesses
pretax loss on discontinued operations of $14.7 million
$12.9 million of tax charges related to a valuation allowance against Calica deferred tax assets, including net operating loss (NOL) carryforwards
pretax loss on discontinued operations of $25.2 million
| | *2022* | $ 788.1 | | | 2023 | $ 1,245.1 | |
decreased 1% in 2023
Aggregates shipments decreased 1%, reflecting weakness in residential demand partially offset by healthy industrial project activity in certain Southeastern markets.
increased 15.9% in 2023
The pricing environment remained positive in 2023 with all markets realizing year-over-year improvement.
Freight-adjusted pricing increased 15.9% versus the prior year to $19.00.
Aggregates segment gross profit increased 23% to $1,733.6 million (or $7.40 per ton), and gross profit margin expanded 260 basis points.
Operating earnings decreased $59.4 million, or 6%, to $951.4 million
Shipments increased 6%, or 13.5 million tons, to 236.3 million tons
Our aggregates-led business delivered solid results in 2022 as our teams executed well in a challenging macro-environment.
We continued to improve our aggregates unit profitability and demonstrate the resiliency of our business.
While net earnings attributable to Vulcan were down 14%, our relentless focus on our operating disciplines coupled with nimble pricing actions to overcome inflationary pressures led to a 12% increase in our full year Adjusted EBITDA.
We carry solid pricing momentum into 2023 and are focused on our operating disciplines to manage costs and improve efficiencies.
By controlling what we can control, we expect to deliver another year of earnings growth.
We remain committed to our stated long-term target leverage range of 2.0x to 2.5x total debt to Adjusted EBITDA.
Return on invested capital was 13.5% and we remain committed to driving further improvement through solid operating earnings growth coupled with disciplined capital management.
During August 2021, we closed on one such large business combination (U.S. Concrete) for $1,634.5 million.
We closed four business acquisitions during 2022 for total consideration of $594.6 million.
During 2022, we made no share repurchases.
Most leading indicators of demand remain healthy in the near term, and we carry strong pricing momentum into 2023.
Overall shipments will be dependent upon the depth and duration of the decline in residential construction activity, the timing of highway starts converting to aggregates shipments and the impact of rising interest rates on private nonresidential construction activity as the year progresses.
We are encouraged by the strength in leading indicators that support growth in public construction activity, particularly highways, and we are well positioned to benefit in geographic markets where the need is greatest.
On the private side, slowing single-family construction activity has outweighed continued growth in multi-family, leading to overall declines in residential demand.
Nonresidential demand remains at healthy levels and continues to benefit from manufacturing and other heavy industrial projects.
As always, we are focused on the things we can control, and our execution on our operating and commercial disciplines will lead to further improvement in our aggregates unit profitability and earnings growth in 2023.
Freight-adjusted price growth of 11% to 13% ($16.40 per ton in 2022)
Total Asphalt, Concrete and Calcium segment cash gross profit collectively in line with 2022 ($268 million in 2022)
Asphalt segment improvement driven by low-single digit growth in volume and price.
The price and cost inflection achieved in the second half of 2022 should lead to continued margin improvement in 2023.
We expect the Asphalt segment to contribute approximately 40% to 50% of non-aggregates cash gross profit
Concrete segment same-store volumes (we divested approximately 2 million cubic yards in 2022) expected to decline mid-single digit due to slowing residential construction activity.
Price growth should offset the higher cost for raw materials.
We expect the Concrete segment to contribute approximately 50% to 60% of non-aggregates cash gross profit
SAG expenses of $515 million to $530 million
Mexico Update
On May 5, 2022, Mexican government officials presented employees at our Calica operations in Quintana Roo, Mexico, with arbitrary shut down orders to immediately cease underwater quarrying and extraction operations.
On May 8, 2022, we filed an application in our North American Free Trade Agreement (NAFTA) arbitration seeking permission to file an ancillary claim in connection with this latest shutdown of our remaining Mexico operations.
On July 11, 2022, the NAFTA arbitration tribunal granted our application.
The ancillary claim will be addressed as part of the pending arbitration, and it is expected that the NAFTA arbitration tribunal will issue a decision no earlier than 2024.
Our environmental stewardship commitment is designed to protect plant and animal species and habitats, as well as the air we breathe, the water we use and the planet we all share.
In addition, we provided over 220 scholarships to students nationwide and emphasized diversity, equity and inclusion in our community outreach and contributions.
| EBITDA 1 | | | $ 1,543.1 | | | $ 1,484.9 | | | $ 1,275.0 | |
| Tons (thousands) | | | 236,345 | | | 222,863 | | | 208,295 | |
| Tons (thousands) | | | 12,156 | | | 11,392 | | | 11,835 | |
| Cubic yards (thousands) | | | 10,534 | | | 5,616 | | | 2,951 | |
| Calcium | | | | | | | | | | |
| Tons (thousands) | | | 228 | | | 246 | | | 282 | |
An excerpt. Shown here: 40 of 358 rewritten, 40 of 120 added and 40 of 140 removed. The counts are complete. For every sentence, read Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS in the FY2023 filing and the FY2022 filing.
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
3 rewritten, 5 added, 0 removed, 16 unchanged
In addition to floating-rate borrowings, we at times use interest rate swaps to manage the mix of fixed-rate and floating-rate [removed: debt and to mitigate the risk of higher interest rates.][added: debt.]
At December 31, [removed: 2022,] [added: 2023,] the estimated fair value of our long-term debt including current maturities was [removed: $3,672.3] [added: $3,798.5] million compared to a face value of [removed: $3,941.9] [added: $3,941.5] million.
The effect of a decline in interest rates of one percentage point would increase the fair value of our debt by approximately [removed: $232.4] [added: $247.0] million.
In March 2023, we issued $550.0 million of 5.80% fixed-rate debt maturing in March 2026.
Concurrently, we entered into fixed-to-floating interest rate swap agreements designated as fair value hedges in the amount of $550.0 million.
Under these swap agreements, we receive a fixed interest rate of 5.80% (matches the fixed rate we pay on the $550.0 million of debt) and pay daily compound SOFR plus 0.241%.
The changes in the fair value of these swaps designated as fair value hedges are recorded in interest expense consistent with the change in fair value of the hedged fixed-rate debt.
At December 31, 2023, we recognized a net liability of $0.3 million equal to the fair value of this swap and a corresponding decrease in the fair value of the hedged fixed-rate debt.
Item 1. BUSINESS
100 rewritten, 62 added, 63 removed, 316 unchanged
Vulcan Materials Company operates primarily in the U.S. and is the nation’s largest supplier of construction aggregates (primarily crushed stone, sand and gravel) and a major producer of [removed: aggregates-based construction materials, including] [added: aggregates-intensive downstream products such as] asphalt mix and ready-mixed concrete.
As of December 31, [removed: 2022,] [added: 2023,] we had [removed: 404] [added: 397] active aggregates facilities as shown below.
][added: 10](https://www.sec.gov/Archives/edgar/data/1396009/000139600924000006/vmc-20231231x10kg002.jpg)]
[removed: *For] [added: For] additional [removed: information regarding our Calica operations in Mexico,] [added: information,] see Note 12 “Commitments and Contingencies” in Item 8 “Financial Statements and Supplementary Data.”*
[removed: While aggregates is our focus and primary business, as of December 31, 2022,] [added: Additionally,] we further [removed: served] [added: serve] our customers through our [removed: 71] [added: 66] asphalt facilities and [removed: 142] [added: 63] concrete facilities located in Alabama, Arizona, California, Maryland, New Mexico, [removed: Oklahoma,] Tennessee, Texas, Virginia, the U.S. Virgin Islands and Washington D.C.
Our strategy and competitive advantage are based on our strength in [removed: aggregates,] [added: aggregates] which are used in most types of construction and in the production of asphalt mix and ready-mixed concrete.
Our strategy for long-term value creation is built on: (1) an aggregates\-focused business, (2) [removed: a disciplined approach to growth management and capital allocation, (3) a focus] [added: an emphasis] on [removed: continuous compounding improvement in profitability, (4)] [added: durable growth, (3)] a holistic approach to land management, and [removed: (5)] [added: (4)] our commitment to safety, health and the environment.
][added: 39](https://www.sec.gov/Archives/edgar/data/1396009/000139600924000006/vmc-20231231x10kg003.jpg)]
Our [removed: 404] [added: 397] active aggregates facilities as of December 31, [removed: 2022] [added: 2023] provide opportunities to share and scale best practices across our operations and to procure equipment (fixed and mobile), parts, supplies and services in an efficient and cost-effective manner, both regionally and nationally.
Additionally, we are able to [removed: share best practices across the organization and] leverage our size for administrative support, customer service, accounting, procurement, technical support and engineering.
[removed: growth management:] Demand for our products is dependent on construction activity and correlates positively with changes in [removed: population growth, household formation] [added: population, employment] and [removed: employment.][added: household formations.]
During the next decade [removed: (2022] [added: (2023] - [removed: 2032),] [added: 2033),] Woods & Poole Economics projects that [removed: 75%] [added: 76%] of the U.S. population growth, [removed: 74%] [added: 75%] of household [removed: formation] [added: formations] and [removed: 73%] [added: 74%] of new jobs will occur in Vulcan-served states.
Our coast-to-coast footprint serves [removed: 20] [added: 35] of the top [removed: 25] [added: 50] highest-growth metropolitan statistical areas in [removed: 22] [added: 23] states plus Washington D.C. The close proximity of our aggregates reserves and our production facilities to this projected population growth creates many opportunities to invest capital in high-return projects.
][added: 31](https://www.sec.gov/Archives/edgar/data/1396009/000139600924000006/vmc-20231231x10kg004.jpg)]
*Source: Woods & Poole Economics, Complete Economic and Demographic Data Source (CEDDS) [removed: 2022*][added: 2023*]
Our top ten revenue producing states accounted for [removed: 84%] [added: 88%] of our [removed: 2022] [added: 2023] revenues while our top five accounted for [removed: 62%.][added: 65%.]
| | VULCAN’S TOP TEN REVENUE PRODUCING STATES IN [removed: 2022] [added: 2023] | | | | | | | | | | | |
While an aggregates-focused business, we selectively make investments in downstream [added: asphalt and concrete] products that drive local market profitability.
Our downstream businesses [removed: (asphalt and concrete)] use internally\-produced aggregates almost exclusively when available in the market from a Vulcan aggregates operation.
Through our 2021 acquisition of U.S. Concrete, we entered the New Jersey, New York, [removed: Oklahoma,] Pennsylvania and U.S. Virgin Islands concrete markets and expanded our California, Texas and Washington D.C. concrete markets.
[removed: We] [added: To optimize our asset portfolio consistent with our aggregates-focused business model, we] subsequently exited the New Jersey, New York and Pennsylvania concrete markets in [removed: 2022.][added: 2022 and exited the Texas concrete market in 2023.]
[removed: While] Adjusted EBITDA increased [removed: 12%] [added: 24%] in [removed: 2022] [added: 2023] (net earnings attributable to Vulcan [removed: decreased 14% in 2022),] [added: increased 62%), while] invested capital [added: only] increased by [removed: 18%, primarily as a result of acquisitions.][added: 2%.]
[added: | *1* | *ROIC and Adjusted EBITDA are] Non-GAAP financial [added: measures. Non-GAAP financial] measures are defined and reconciled within Item 7 “Management’s Discussion and Analysis of Financial Condition and Results of Operations” under the caption “Reconciliation of Non-GAAP Financial [removed: Measures.”][added: Measures.”* | |]
[removed: We provide] [added: Our] logistics systems [removed: that give us] [added: produce] real-time information including [removed: on-site,] [added: on-site and] mobile visibility to orders, deliveries and digital shipping records.
[removed: 4.] [added: 3.] LAND MANAGEMENT
With [removed: more than 240,000] [added: approximately 300,000] acres in our land portfolio, a long-term holistic approach to preserving land and water is integral to sustaining our success.
We are putting land to use before we mine by creating opportunities [removed: for agriculture] [added: such as agricultural use] and timber development.
Because of the evolving needs of our communities, we listen to and collaborate with our neighbors to prepare the land for its highest and best [removed: use after mining is complete.][added: use.]
Our [removed: work] [added: engagement] with state, regional and local governments to develop solutions [added: like this] today will benefit future generations.
[removed: 5.] [added: 4.] SAFETY, HEALTH AND THE ENVIRONMENT
A strategy for sustainable, long-term value creation must include doing right by [removed: your] [added: our] employees, [removed: your] [added: our] neighbors and the environment in which [removed: you] [added: we] operate.
The Safety, Health and Environmental Affairs Committee of our Board of Directors, along with the full Board, has oversight responsibility for our [removed: environmental, safety and] [added: safety,] health [added: and environmental] programs and results.
In [removed: 2022,] [added: 2023,] we [removed: achieved] [added: experienced] an overall Mine Safety and Health Administration (MSHA) safety performance of [removed: 1.00] [added: 1.2] injuries per 200,000 employee hours worked, which is [removed: both industry-leading and considered world-class.][added: well below the 2022 industry average of 1.8 injuries.]
Our charitable foundation alone has provided nearly [removed: $66] [added: $70] million in support over the past 20 years to essential charitable, civic and educational organizations that strengthen and enrich our communities.
The actions of our [removed: Grandin Sand Plant facility] [added: Fort Myers team] in Florida [removed: over the last two years] are a prime example of our commitment to community relations.
Our [removed: reforestation] [added: solar generation] efforts at our [removed: Calica quarry] [added: San Emidio Quarry] in [removed: Mexico] [added: California] provide another example of our commitment to environmental stewardship.
The sources of these materials are [removed: highway and] [added: highway,] infrastructure [removed: projects] and other demolition projects where concrete structures or asphalt paving is being removed.
During [removed: 2022,] [added: 2023,] we reused [removed: 1.7] [added: 2.0] million tons of RAP and recycled [removed: 2.1] [added: 1.9] million tons of concrete.
As of December 31, [removed: 2022,] [added: 2023,] we had [removed: 404] [added: 397] active aggregates facilities, [removed: 71] [added: 66] asphalt facilities, [removed: 142] [added: 63] concrete facilities and 1 calcium facility.
Our [removed: 2022] [added: 2023] total revenues and gross profit by segment are illustrated as follows (Calcium revenues and gross profit were less than one percent):
*Production and sales are currently halted at our Calica operations in Mexico.
| | 2. | California | | | | 7. | | Arizona | | | | |
| | 3. | Georgia | | | | 8. | | Alabama | | | | |
Aggregates are an essential product with high barriers to entry, limited substitutes and very favorable pricing characteristics.
While aggregates is our focus and primary business, we also offer aggregates-intensive downstream asphalt and concrete products in select markets where these products enhance our aggregates-driven returns.
2. DURABLE GROWTH
Our durable growth comes from organic growth in our existing business as well as inorganic growth through mergers and acquisitions supplemented with greenfield developments.
Together, this three-pronged approach enables us to enhance our core and expand our reach.
The result is an ability to grow our aggregates unit profitability throughout the cycle.
ENHANCING OUR CORE: We drive organic growth and differentiate ourselves from other aggregates producers through our strategic disciplines, the Vulcan Way of Selling (Commercial Excellence & Logistics Innovation) and the Vulcan Way of Operating (Operational Excellence & Strategic Sourcing).
The Vulcan Way of Selling uses technology, innovation and analytics to win work and capture value.
Custom, proprietary technology gives us real-time, forward looking insight into all our end markets.
Coaching and development of our people, along with clear performance metrics and accountability, drive sales execution.
The Vulcan Way of Operating is the combination of tools, processes and approaches used by our teams to drive value in our operations every day.
By focusing on consistent execution, production efficiency and controlling costs, we provide the highest quality material and the best service to our customers.
Expanding on these strategic disciplines:
We are dedicated to continuous improvement of our safety programs through ongoing internal inspections, regulatory audits and sharing of best practices.
As a result of these strategic disciplines, from 2021 to 2023, aggregates gross profit per ton has increased from $5.81 to $7.40 (an increase of 27%), and aggregates cash gross profit per ton has increased from $7.43 to $9.46 (an increase of 27%).
EXPANDING OUR REACH: We also drive growth by expanding our reach through mergers and acquisitions and by pursuing greenfield development in anticipation of future growth.
Our disciplined approach focuses on aggregates, aims to achieve a number one or number two position in the markets we serve and strategically pursues downstream asphalt and concrete businesses complementary to our aggregates position in select markets.
From 2021 to 2023, we invested $2,233.1 million in acquisitions as outlined in Note 19 “Acquisitions and Divestitures” in Item 8 “Financial Statements and Supplementary Data.” During the last 10 years, we have completed almost 40 acquisitions, including more than 70 aggregates quarries and sales yards in our top 10 revenue states.
Our annual Return on Invested Capital (ROIC) increased 2.8 percentage points (280 basis points) in 2023 as a result of solid operating earnings growth and disciplined capital management.
In 2023, we sold excess real estate in Virginia for net proceeds of $66.1 million resulting in a pretax gain of $65.7 million and real estate associated with a former recycled concrete facility in Illinois for net proceeds of $16.5 million resulting in a pretax gain of $15.2 million.
Many of our operations not only meet regulatory requirements for reclamation planning at the end of a quarry’s life but they also use a proactive approach to conservation and engagement while the quarries are in operation.
For example, we originally purchased land in Polk County, Florida, with the intention of building a quarry.
However, after an extensive review of the environmental impacts to sensitive species, our environmental team collaborated with various governmental agencies to identify an alternative beneficial use for the land.
The property became the Tiger Creek Conservation Bank.
Beginning in 2022, this property now serves as a protected habitat for endangered or sensitive species.
Designation as a conservation bank allows us to generate revenue by selling mitigation credits for third party impacts to endangered or sensitive species or to utilize those credits for our impacts.
In the wake of Hurricane Ian, which struck Florida’s west coast in September 2022, among those affected were many of our own employees; yet the same employees set aside their own hardships and reported to the facility just hours after the storm.
We produced and delivered more than 145,000 tons of essential construction materials, with the support of more than 60 employees and 100 truck drivers, for the repair of the Sanibel Causeway, which enabled its reopening 10 days ahead of schedule.
We currently maintain 39 WHC certified sites containing wildlife enhancement programs.
We converted 10 acres of our quarry into a solar facility which is projected to generate more than four million kilowatt-hours of clean renewable energy annually, enough to provide approximately 70% of the quarry’s annual electricity needs.
This facility supports our goals to source renewable energy, reducing the carbon intensity of our products and improving energy resiliency.
Location and transportation of reserves: Aggregates have a high weight-to-price ratio that makes transportation expensive relative to the cost of the material.
In most cases, aggregates are produced near where they are used so that the transportation cost does not exceed the product cost.
Through September 30, 2023, states have committed highway and bridge formula funds to support over 31,000 new projects.
This is in addition to over 29,000 new projects supported in FFY 2022.
The proceeds from these divestitures are available to be redeployed into our aggregates-led franchise.
Heidelberg Materials AG
Aggregates are used in virtually all types of public and private construction, practically no substitutes for quality aggregates exist, and significant barriers to entry exist in most markets.
*Source: 2021 reported financial information and Company estimates.
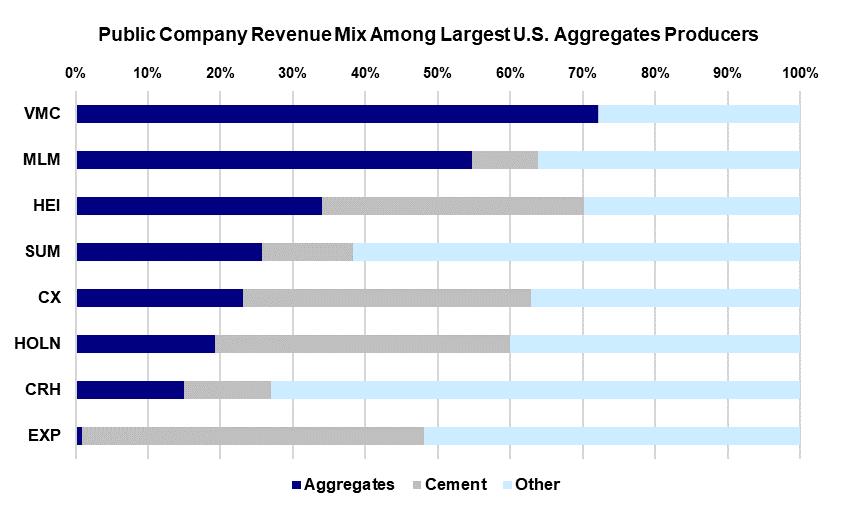
VMC includes U.S. Concrete revenues subsequent to the August 2021 acquisition.*
2.
Growth management AND CAPITAL ALLOCATION
| | 2. | California | | | | 7. | | Alabama | | | | |
| | 3. | Georgia | | | | 8. | | Arizona | | | | |
capital allocation: Our long-term capital allocation strategy is focused on the following priorities:
Operating Capital (maintain and grow the value of our franchise)
Growth Capital (including greenfields and acquisitions)
Dividend Growth (with a keen focus on sustainability)
Return Excess Cash to Shareholders (primarily via share repurchases)
During 2022, we reinvested $612.6 million into core operating & maintenance capital and internal growth capital, in addition to $451.3 million and $362.2 million reinvested in 2021 and 2020, respectively.
These investments are fundamental actions that sustain and strengthen the business.
They improve the longer-term efficiency, capacity and flexibility of our production, and they support our strong commitment to superior customer service.
From 2020 to 2022, we invested $2,307.4 million in acquisitions as outlined in Note 19 “Acquisitions and Divestitures” in Item 8 “Financial Statements and Supplementary Data.”
Our annual Return on Invested Capital (ROIC) decreased 0.7 percentage points (70 basis points) in 2022.
We remain committed to driving improvement in our ROIC through solid operating earnings growth coupled with disciplined capital management.
ROIC and Adjusted EBITDA are Non-GAAP financial measures.
3. compounding improvement in profitability
Our focus on the Vulcan Way of Selling (Commercial Excellence & Logistics Innovation) and the Vulcan Way of Operating (Operational Excellence & Strategic Sourcing) has made us one of the most profitable public companies in the industry (as measured by aggregates gross profit per ton).
We manage the Vulcan Way of Selling & Operating locally and align our talent and incentives accordingly.
Our knowledgeable and experienced workforce and our flexible production capabilities allow us to manage operational and overhead costs aggressively.
As a result, from 2020 to 2022, aggregates gross profit per ton has improved from $5.57 to $5.96 (an increase of 7%), and aggregates cash gross profit per ton has improved from $7.11 to $7.83 (an increase of 10%).
For example, in 2021 we partnered with the city of Atlanta to convert our Bellwood Quarry into a reservoir.
This reservoir will serve as an emergency water supply for Atlanta, holding more than 2 billion gallons of water from the Chattahoochee River.
This amount is enough backup water supply to last between 30 and 90 days — a significant improvement from the city’s previous reserve of three to five days.
We are proud to have worked with the city of Atlanta to provide an extremely valuable asset that protects and serves local communities.
This aggregates operation provided support to federal, state and local government clients to help rebuild from Hurricane Irma and Hurricane Matthew along the Florida coast.
We worked with the Army Corps of Engineers, the Federal Emergency Management Agency and county officials to support the reconstruction of beaches to improve public usability and protection from future storm events.
We focus on our environmental stewardship programs with the same intensity that we bring to our health and safety initiatives.
Since then, we have received accreditation for 40 quarry sites containing wildlife enhancement programs.
Since we began closely recording data about our reforestation efforts, we have planted an average of 2,885 trees per hectare, significantly more than the 500 recommended by the National Forestry Commission.
Over a nearly 20-year time span, we have planted approximately 80,000 trees.
We also maintain nearly 30% of our land as protected forest and as a natural forest conservation area, which contains three Mayan archaeological sites and four cenotes (underground natural pools historically used for sacred Mayan ceremonies).
Location and transportation of reserves: Aggregates have a high weight-to-value ratio and, in most cases, must be produced near where they are used; if not, transportation can cost more than the materials, rendering them uncompetitive compared to locally produced materials.
We also ship railroad ballast to eleven additional states and supply direct shipments to Hawaii.
*Source: Company estimates*
This approval rate was higher than the historical average.
The FFY 2023 spending package also enables states and localities to use funds from the American Rescue Plan Act of 2021, a COVID-19 relief package for infrastructure projects, including highways, roads and bridges.
An excerpt. Shown here: 40 of 100 rewritten, 40 of 62 added and 40 of 63 removed. The counts are complete. For every sentence, read Item 1. BUSINESS in the FY2023 filing and the FY2022 filing.
Item 3. LEGAL PROCEEDINGS
1 rewritten, 0 added, 0 removed, 6 unchanged
We were not subject to any penalties in [removed: 2022] [added: 2023] for failure to disclose transactions identified by the Internal Revenue Service as abusive under Internal Revenue Code Section 6707A.
Cover and table of contents
19 rewritten, 6 added, 1 removed, 114 unchanged
| þ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 For the Fiscal Year Ended December 31, [removed: 2022] [added: 2023] OR | |
| Aggregate market value of voting and non-voting common stock held by non-affiliates as of June 30, [removed: 2022:] [added: 2023:] | [removed: $18,855,378,169] [added: $29,892,023,372] |
| Number of shares of common stock, $1.00 par value, outstanding as of February [removed: 14, 2023:] [added: 13, 2024:] | [removed: 132,974,340] [added: 132,227,110] |
| Portions of the registrant’s annual proxy statement for the annual meeting of its shareholders to be held on May [removed: 12, 2023,] [added: 10, 2024] are incorporated by reference into Part III of this Annual Report on Form 10-K. | |
| VULCAN MATERIALS COMPANY ANNUAL REPORT ON FORM 10-k fISCAL YEAR ENDED DECEMBER 31, [removed: 2022] [added: 2023] CONTENTs | | | |
| | 2 | [Properties](#PartI_Item2) | [removed: 27] [added: 28] |
| | 9 | [Changes in and Disagreements with Accountants on Accounting and Financial Disclosure](#PartII_Item9) | [removed: 131] [added: 129] |
| | 9A | [Controls and Procedures](#PartII_Item9A) | [removed: 131] [added: 129] |
| | 9B | [Other Information](#PartII_Item9B) | [removed: 133] [added: 131] |
| | 9C | [Disclosure Regarding Foreign Jurisdictions that Prevent Inspections](#PartII_Item9C) | [removed: 133] [added: 131] |
| III | 10 | [Directors, Executive Officers and Corporate Governance](#PartIII_Item10) | [removed: 134] [added: 132] |
| | 11 | [Executive Compensation](#PartIII_Item11) | [removed: 134] [added: 132] |
| | 12 | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters](#PartIII_Item12) | [removed: 134] [added: 132] |
| | 13 | [Certain Relationships and Related Transactions, and Director Independence](#PartIII_Item13) | [removed: 134] [added: 132] |
| | 14 | [Principal [removed: Accounting] [added: Accountant] Fees and Services](#PartIII_Item14) | [removed: 134] [added: 132] |
| IV | 15 | [Exhibits and Financial Statement Schedules](#PartIV_Item15) | [removed: 135] [added: 133] |
| | 16 | [Form 10-K Summary](#PartIV_Item16) | [removed: 139] [added: 137] |
a pandemic, epidemic or other public health [removed: emergency, such as the COVID-19 outbreak][added: emergency]
We are the company we are today thanks to the positive actions of our [removed: nearly 12,000] employees.

| --- | --- | --- |
| | 1C | [Cybersecurity](#PartI_Item1C) | 26 |
| | 6 | \[[Reserved](#PartII_Item6)\] | 37 |
| | — | [Signatures](#Signatures) | 138 |
domestic and global political, economic or diplomatic developments
| | — | [Signatures](#Signatures) | 140 |
Item 1B. UNRESOLVED STAFF COMMENTS
0 rewritten, 0 added, 2 removed, 2 unchanged
| | |
| --- | --- |
Page headers and footers: 1 line differs, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
| Part I | 26 |
Item 1C. cybersecurity
0 rewritten, 39 added, 0 removed, 0 unchanged
New section this year
cybersecurity
We have a cross-departmental approach to addressing cybersecurity risk, including input from employees and our Board of Directors (the "Board").
The Board, Audit Committee, senior management and our Risk Management Committee (a taskforce led by senior corporate officers that draws on the subject matter expertise of senior managers from various functional departments and from line operations management) devote significant resources to cybersecurity and risk management processes to adapt to the changing cybersecurity landscape and respond to emerging threats in a timely and effective manner.
Our cybersecurity risk management program leverages the National Institute of Standards and Technology (NIST) framework, which organizes cybersecurity risks into five categories: identify, protect, detect, respond and recover.
We regularly assess the threat landscape and take a holistic view of cybersecurity risks, with a layered cybersecurity strategy based on prevention, detection and mitigation.
Key enterprise-level cybersecurity risks are incorporated into the Risk Management Committee’s framework and are assessed throughout the year.
In addition, we have a set of Company-wide policies and procedures concerning cybersecurity matters, which include an IT Security Policy and Cyber Incident Response Plan, as well as other policies that directly or indirectly relate to cybersecurity, non-public information and the use of the internet, social media, email, and wireless devices.
These policies go through an internal review process and are approved by appropriate members of management.
Our Chief Information Officer is responsible for developing and implementing our information security program and reporting on cybersecurity matters to the Board.
Our Chief Information Officer has served in this role since April 2022 and has 28 years of experience in Information Technology.
He earned a bachelor’s degree in Computer Science and a master’s degree in Information Technology.
We view cybersecurity as a shared responsibility, and we periodically perform simulations and tabletop exercises at a management level and incorporate external resources and advisors as needed.
All employees with computer access are asked to complete cybersecurity training at least once per year and have access to more frequent cybersecurity trainings through online trainings.
We also require employees in certain roles to complete additional role-based, specialized cybersecurity trainings.
We have continued to expand investments in IT security, including additional end-user training, using layered defenses, identifying and protecting critical assets, strengthening monitoring and alerting, and engaging experts.
We regularly test defenses by performing simulations and drills at both a technical level (including through penetration tests) and by reviewing our operational policies and procedures with third-party experts.
At the management level, our IT cybersecurity team regularly monitors cybersecurity threats and alerts and meets to discuss threat levels, trends and remediation.
The team regularly collects data on risk areas and conducts an annual risk assessment.
Further, we conduct periodic external penetration tests and maturity testing to assess our processes and procedures and the threat landscape.
These tests and assessments are useful tools for maintaining a robust cybersecurity program to protect our investors, customers, employees and vendors.
In addition to assessing our own cybersecurity preparedness, we also consider and evaluate cybersecurity risks associated with use of third-party service providers.
Our Internal Audit team conducts an annual review of critical third-party hosted applications with a specific focus on any sensitive data shared with third parties.
User access reviews of critical hosted applications are required at least annually, and System and Organization Controls (SOC) 1 or SOC 2 reports provided by the vendors are reviewed annually.
If a third-party vendor is not able to provide a SOC 1 or SOC 2 report, we take additional steps to assess their cybersecurity preparedness and assess our relationship on that basis.
Our assessment of risks associated with use of third-party providers is part of our overall cybersecurity risk management framework.
| | |
| --- | --- |
The Audit Committee and the full Board actively participate in discussions with management and among themselves regarding cybersecurity risks.
The Audit Committee performs an annual review of our cybersecurity program, which includes discussion of management’s actions to identify and detect threats, as well as planned actions in the event of a response or recovery situation.
The Audit Committee’s annual review also includes review of recent enhancements to the Company’s defenses and management’s progress on its cybersecurity strategic roadmap.
In addition, the Board receives semi-annual updates from the Chief Information Officer.
Further, at least annually, the Board receives updates on the Company’s Crisis Management Guide, which includes, among other things, the Cybersecurity Incident Response Plan.
To aid the Board with its cybersecurity and data privacy oversight responsibilities, the Board periodically hosts experts for presentations on these topics.
For example, the Board has hosted an expert to discuss developments in the cybersecurity threat landscape and to review our performance at our most recent tabletop exercise.
We face a number of cybersecurity risks in connection with our business.
Although such risks have not materially affected us, our business strategy, results of operations or financial condition, to date, we have, from time to time, experienced threats to and breaches of our data and systems, including malware and computer virus attacks.
For more information about the cybersecurity risks we face, see the risk factor entitled “We are dependent on information technology systems (our own and those of our service providers such as Amazon Web Services), and these systems contain non-public data about our business, employees, suppliers and customers” in Item 1A “Risk Factors.”
| | |
| --- | --- |
Page headers and footers: 2 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
| Part I | 26 |
| Part I | 27 |
Item 2. PROPERTIES
47 rewritten, 28 added, 70 removed, 120 unchanged
We principally serve markets in [removed: twenty-two] [added: 23] states, the U.S. Virgin Islands, Washington D.C., and the local markets surrounding our operations in Freeport, Bahamas; British Columbia, Canada; Puerto Cortés, Honduras and Quintana Roo, [removed: Mexico.][added: Mexico (see the NAFTA Arbitration section in Note 12 “Commitments and Contingencies” in Item 8 “Financial Statements and Supplementary Data”).]
The following map illustrates the location of our [removed: 234] [added: 235] aggregates production stage properties and [removed: 78] [added: 80] development stage properties.
Our [removed: 36] [added: 34] aggregates exploration stage properties are excluded from this map.
][added: 41](https://www.sec.gov/Archives/edgar/data/1396009/000139600924000006/vmc-20231231x10kg016.jpg)]
[removed: *For] [added: For] additional [removed: information regarding our Calica operations in Mexico,] [added: information,] see Note 12 “Commitments and Contingencies” in Item 8 “Financial Statements and Supplementary Data.”*
As of December 31, [removed: 2022,] [added: 2023,] we directly operated substantially all of our aggregates production facilities.
Our [removed: 2022] [added: 2023] measured, indicated and inferred aggregates resources are based on an initial assessment using an average sales price assumption ranging from approximately [removed: $6.00] [added: $12.00] to [removed: $24.00] [added: $23.00] per ton depending on the location/market.
The table below presents, by division, [removed: the tons of measured, indicated and inferred aggregates resources and the percentage] [added: details] of [added: our] aggregates resources [removed: by commodity] as of December 31, [removed: 2022.][added: 2023.]
| [removed: | | |] *(millions of tons)* | | | | | | | | [removed: *Percentage by Commodity*] | | | | | [added: | | | |]
| [removed: *Division* *1*] | | [removed: |] *Measured (M)* | | *Indicated (I)* | | *Total [removed: (M) + (I)*] [added: (M)+(I)*] | | [removed: *Inferred*] [added: *Measured (M)*] | | [removed: Stone 2] [added: *Indicated (I)*] | | [added: *Total (M)+(I)*] | [removed: Gravel] | [added: Total (M)+(I)] | [added: | *Inferred* |]
| International | | [added: 0.0] | [removed: *0.0*] | [added: 61.1] | [removed: *61.1*] | [added: 61.1] | [removed: *61.1*] | [added: 0.0] | [removed: *0.0*] | [added: 0.0] | [removed: *0.4%*] | [added: 0.0] | | [removed: *0.0%*] [added: 61.1] | | [added: 0.0 |]
| *1* | *The divisions are defined by states/countries as follows:* *Central Division* — *Illinois, Kentucky and Tennessee* *East Division* — *North Carolina, South Carolina and North/Central Georgia* *International Division* — *Puerto Cortés (Honduras) and* *Quintana Roo (Mexico)* [removed: *Mountain West Division* — *Arizona and New Mexico*] *Northeast Division* — *Delaware, Maryland, New Jersey, New York, Pennsylvania, Virginia and Washington D.C.* *South Division* — *Florida (excluding panhandle), South Georgia, Freeport (Bahamas) and the U.S. Virgin Islands* *Southern Gulf Coast Division* — *Alabama, Arkansas, Florida Panhandle, Louisiana and Mississippi* *Southwest Division* — *Oklahoma and Texas* *Western Division* — [removed: *California] [added: *Arizona,* *California, New Mexico] and British Columbia (Canada)* | |
Our [removed: 2022] [added: 2023] proven and probable aggregates reserves were estimated by internal experts (i.e. geologists or engineers).
The economic viability of our reserves were determined using average aggregates prices ranging from approximately [removed: $6.00] [added: $12.00] to [removed: $24.00] [added: $23.00] per ton depending on the location/market.
| [removed: | | |] *(millions of tons)* | | | | | | | [removed: *Percentage by Commodity Type*] | | | | | [added: | | | | | |]
| [removed: *Division* *1*] | | [added: *Stone* *2*] | [removed: *Proven*] | | | | | [added: *Sand & Gravel*] | | [removed: *Stone* *3*] | | | [removed: *Gravel*] | | [added: | |]
| Southern Gulf Coast | | | [removed: 1,705.3] [added: 26] | | | [added: 0] | | | [added: 26] | [removed: 14.7%] | | [added: 21] | [removed: 0.0%] | | [added: 2 | | | 49 | |]
| [removed: *Division* *1*] | | | [removed: *Probable*] [added: *Stone* *3*] | | | | | | [added: *Sand & Gravel*] | [removed: *Stone* *3*] | | | [removed: *Gravel*] | | [added: | | |]
| International [added: 5] | | | [added: 472.8 | |] 0.0 | | [added: 472.8] | | [added: 0.0] | | [added: 0.0] | [removed: 0.0%] | [added: 0.0] | | [removed: 0.0%] [added: 472.8] | | [added: 4.0 |]
| *2* | *Production totals for the two prior years were as follows: [removed: 2021] [added: 2022] – [removed: 222.8] [added: 235.0] million tons and [removed: 2020] [added: 2021] – [removed: 203.1] [added: 222.8] million tons.* | |
| *4* | *Includes a maximum of [removed: 285.7] [added: 269.9] million tons of reserves encumbered by volumetric production payments as defined in Note 2 “Revenues” in Item 8 “Financial Statements and Supplementary Data.”* | |
Of the 15.6 billion tons of estimated proven and probable aggregates reserves reported at the end of [removed: 2022, 13.2] [added: 2023, 12.9] billion tons or [removed: 85%] [added: 82%] are located on production stage [removed: properties] [added: properties,] and [removed: 2.4] [added: 2.7] billion tons or [removed: 15%] [added: 18%] are located on development stage properties.
Of the 15.6 billion tons of aggregates reserves at December 31, [removed: 2022, 9.2] [added: 2023, 9.6] billion tons or [removed: 59%] [added: 61%] are located on owned land and [removed: 6.4] [added: 6.0] billion tons or [removed: 41%] [added: 39%] are located on leased land.
Our land portfolio consists of [removed: more than 240,000] [added: approximately 300,000] acres.
The table below presents, by division, the count of active aggregates facilities as of December 31, [removed: 2022] [added: 2023] and the types of facilities operated.
| | | | *Production Stage Mining Properties* *1* | | | | | | | | | [removed: Sales] [added: *Sales*] | | | *Recycled* | | | *Total* | |
| Central | | | [removed: 48] [added: 46] | | | [removed: 3] [added: 4] | | | [removed: 51] [added: 50] | | | 4 | | | [removed: 10] [added: 8] | | | [removed: 65] [added: 62] | |
| East | | | [removed: 51] [added: 52] | | | 0 | | | [removed: 51] [added: 52] | | | 8 | | | [removed: 7] [added: 5] | | | [removed: 66] [added: 65] | |
| International [removed: 3] | | | [removed: 2] [added: 1] | | | 0 | | | [removed: 2] [added: 1] | | | 0 | | | 0 | | | [removed: 2] [added: 1] | |
| Northeast | | | 17 | | | 6 | | | 23 | | | [removed: 26] [added: 24] | | | [removed: 13] [added: 12] | | | [removed: 62] [added: 59] | |
| South | | | [removed: 12] [added: 14] | | | 8 | | | [removed: 20] [added: 22] | | | [removed: 19] [added: 21] | | | 1 | | | [removed: 40] [added: 44] | |
| Southwest | | | [removed: 17] [added: 16] | | | 14 | | | [removed: 31] [added: 30] | | | [removed: 23] [added: 25] | | | 1 | | | [removed: 55] [added: 56] | |
| Western | | | [removed: 10] [added: 13] | | | [removed: 9] [added: 18] | | | [removed: 19] [added: 31] | | | [removed: 4] [added: 5] | | | [removed: 15] [added: 19] | | | [removed: 38] [added: 55] | |
| *1* | *The facility counts above only include mining properties with production in the current year [removed: (excludes for] [added: (for] example, [added: excludes] mining properties with sales from existing stockpiles with no current year production).* | |
As of December 31, [removed: 2022,] [added: 2023,] we operated a number of facilities producing asphalt mix, ready-mixed concrete and calcium in several of our divisions as reflected in the table below:
| Central | | | | | | | | | | | | | | | [removed: 10] [added: 11] | | | 0 | | | 0 | |
| International | | | | | | | | | | | | | | | 0 | | | [removed: 2] [added: 0] | | | 0 | |
| Northeast | | | | | | | | | | | | | | | 0 | | | [removed: 38] [added: 36] | | | 0 | |
| South | | | | | | | | | | | | | | | 0 | | | [removed: 0] [added: 1] | | | 1 | |
| Southwest | | | | | | | | | | | | | | | [removed: 15] [added: 14] | | | [removed: 74] [added: 0] | | | 0 | |
*Production and sales are currently halted at our Calica operations in Mexico.
| | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | |
| *Division* *1* | | *Resources* | | *Resources* | | *Resources* | | *Resources* | | *Resources* | | *Resources* | | Resources | | *Resources* |
| Central | | 615.8 | | 1,167.3 | | 1,783.1 | | 8.8 | | 4.6 | | 13.4 | | 1,796.5 | | 580.7 |
| East | | 2,594.4 | | 747.0 | | 3,341.4 | | 0.0 | | 0.0 | | 0.0 | | 3,341.4 | | 295.3 |
| Northeast | | 835.5 | | 15.9 | | 851.4 | | 41.2 | | 0.0 | | 41.2 | | 892.6 | | 19.2 |
| South | | 558.7 | | 526.3 | | 1,085.0 | | 22.2 | | 52.4 | | 74.6 | | 1,159.6 | | 384.4 |
| Southern Gulf Coast | | 635.2 | | 108.3 | | 743.5 | | 42.0 | | 0.0 | | 42.0 | | 785.5 | | 218.4 |
| Southwest | | 478.5 | | 39.0 | | 517.5 | | 93.1 | | 57.5 | | 150.6 | | 668.1 | | 500.0 |
| Western | | 449.8 | | 873.6 | | 1,323.4 | | 220.3 | | 897.6 | | 1,117.9 | | 2,441.3 | | 901.0 |
| Total | | 6,167.9 | | 3,538.5 | | 9,706.4 | | 427.6 | | 1,012.1 | | 1,439.7 | | 11,146.1 | | 2,899.0 |
The table below presents, by division, details of our aggregates reserves and production as of December 31, 2023.
| | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | |
| | | | *Proven* | | *Probable* | | *Total* | | *Proven* | | *Probable* | | *Total* | | Total | | *2023* *2* |
| *Division* *1* | | | *Reserves* | | *Reserves* | | *Reserves* | | *Reserves* | | *Reserves* | | *Reserves* | | Reserves | | *Production* |
| Central | | | 1,971.9 | | 1,056.6 | | 3,028.5 | | 7.5 | | 5.0 | | 12.5 | | 3,041.0 | | 35.1 |
| East 4 | | | 2,839.6 | | 993.8 | | 3,833.4 | | 0.0 | | 0.0 | | 0.0 | | 3,833.4 | | 50.1 |
| Northeast | | | 1,370.8 | | 503.5 | | 1,874.3 | | 60.7 | | 37.2 | | 97.9 | | 1,972.2 | | 26.1 |
| South | | | 802.9 | | 389.2 | | 1,192.1 | | 180.0 | | 27.3 | | 207.3 | | 1,399.4 | | 29.8 |
| Southern Gulf Coast | | | 1,679.0 | | 58.1 | | 1,737.1 | | 0.0 | | 0.0 | | 0.0 | | 1,737.1 | | 26.4 |
| Southwest | | | 1,183.2 | | 105.0 | | 1,288.2 | | 151.9 | | 0.0 | | 151.9 | | 1,440.1 | | 31.1 |
| Western | | | 754.7 | | 171.7 | | 926.4 | | 414.9 | | 399.5 | | 814.4 | | 1,740.8 | | 33.4 |
| Total | | | 11,074.9 | | 3,277.9 | | 14,352.8 | | 815.0 | | 469.0 | | 1,284.0 | | 15,636.8 | | 236.0 |
| Total | | | 185 | | | 50 | | | 235 | | | 108 | | | 48 | | | 391 | |
| | |
| --- | --- |
| | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | |
| | | | *Aggregates Resources* | | | | | | | | | | | Sand & | |
| Central | | | *581.3* | | *1,167.5* | | *1,748.8* | | *529.5* | | *16.4%* | | | *0.1%* | |
| East | | | *2,685.7* | | *757.9* | | *3,443.6* | | *295.3* | | *27.1%* | | | *0.0%* | |
| Mountain West | | | *31.5* | | *0.4* | | *31.9* | | *26.7* | | *0.0%* | | | *0.4%* | |
| Northeast | | | *947.4* | | *16.0* | | *963.4* | | *19.2* | | *6.7%* | | | *0.4%* | |
| South | | | *581.0* | | *578.7* | | *1,159.7* | | *382.8* | | *10.1%* | | | *1.1%* | |
| Southern Gulf Coast | | | *690.0* | | *108.3* | | *798.3* | | *218.4* | | *7.1%* | | | *0.3%* | |
| Southwest | | | *568.1* | | *97.3* | | *665.4* | | *500.0* | | *7.4%* | | | *1.1%* | |
| Western | | | *521.6* | | *1,751.9* | | *2,273.5* | | *666.6* | | *12.1%* | | | *9.3%* | |
| Total | | | 6,606.6 | | 4,539.1 | | 11,145.7 | | 2,638.5 | | 87.3% | | | 12.7% | |
The tables below present by reserve classification — proven, probable and total proven & probable — and by division, the tons of aggregates reserves as of December 31, 2022 and the percentages by commodity type.
The third (proven & probable) table also notes the 2022 production.
| | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | |
| | | | *Aggregates Reserves* | | | | | | | | | | *Sand &* | |
| Central | | | 1,965.8 | | | | | | | 16.8% | | | 0.1% | |
| East 4 | | | 2,688.4 | | | | | | | 23.1% | | | 0.0% | |
| International 5 | | | 476.8 | | | | | | | 4.1% | | | 0.0% | |
| Mountain West | | | 257.6 | | | | | | | 0.7% | | | 1.5% | |
| Northeast | | | 1,380.4 | | | | | | | 11.4% | | | 0.5% | |
| South | | | 1,007.8 | | | | | | | 7.1% | | | 1.5% | |
| Southwest | | | 1,348.7 | | | | | | | 10.2% | | | 1.4% | |
| Western | | | 795.4 | | | | | | | 4.0% | | | 2.9% | |
| Total Proven Reserves | | | 11,626.2 | | | | | | | 92.1% | | | 7.9% | |
| | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | |
| | | | *(millions of tons)* | | | | | | | *Percentage by Commodity Type* | | | | |
| | | | *Aggregates Reserves* | | | | | | | | | | *Sand &* | |
| Central | | | 1,067.5 | | | | | | | 26.7% | | | 0.1% | |
| East 4 | | | 1,098.5 | | | | | | | 27.6% | | | 0.0% | |
| Mountain West | | | 66.2 | | | | | | | 0.5% | | | 1.1% | |
| Northeast | | | 439.1 | | | | | | | 10.1% | | | 1.0% | |
| South | | | 427.8 | | | | | | | 10.0% | | | 0.7% | |
An excerpt. Shown here: 40 of 47 rewritten, all 28 added and 40 of 70 removed. The counts are complete. For every sentence, read Item 2. PROPERTIES in the FY2023 filing and the FY2022 filing.
Page headers and footers: 1 line differs, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
| Part I | 27 |
Item 4. MINE SAFETY DISCLOSURES
14 rewritten, 5 added, 9 removed, 53 unchanged
The names, positions and ages, as of February 20, [removed: 2023,] [added: 2024,] of our executive officers are as follows:
| J. Thomas Hill | [removed: Chairman, President] [added: Chairman] and Chief Executive Officer | [removed: 63] [added: 64] |
| Mary Andrews Carlisle | Senior Vice President and Chief Financial Officer | [removed: 42] [added: 43] |
| Stanley G. Bass | Chief Strategy Officer | [removed: 61] [added: 62] |
| [removed: Thompson S. Baker II] [added: Ronnie A. Pruitt] | Chief Operating Officer | [removed: 64] [added: 53] |
| Darren L. Hicks | Senior Vice President and Chief Human Resources Officer | [removed: 53] [added: 54] |
| David P. Clement | Senior Vice President, [removed: East Division,] Operations [removed: Support and] [added: Support,] Procurement | [removed: 62] [added: 63] |
| Denson N. Franklin III | Senior Vice President, General Counsel and Secretary | [removed: 59] [added: 60] |
| Jerry F. Perkins Jr. | Senior Vice President, [removed: Southern Gulf Coast and Central Divisions,] [added: Business Development,] Commercial [removed: Excellence] [added: Excellence, Land,] | [removed: 53] [added: 54] |
[removed: | Ronnie A. Pruitt |] [added: He previously served as] Senior Vice [removed: President,] [added: President of the] Southwest and Western [removed: Divisions | 52 |][added: Divisions.]
| Randy L. Pigg | Vice President, Controller and Principal Accounting Officer | [removed: 50] [added: 51] |
Baker II was [removed: appointed] [added: elected President effective September 2023 after serving as] Chief Operating Officer [removed: effective] [added: since] May 2019.
Clement is Senior Vice President of [removed: the East Division,] Operations Support and Procurement.
Prior to that, he served in a number of positions with Vulcan, including [removed: Manager] [added: Manager,] Financial Research & Reporting and Finance Director of the Central Region.
| Thompson S. Baker II | President | 65 |
| | Logistics | |
He served as President through September 2023.
Pruitt was appointed Chief Operating Officer effective September 2023.
Perkins Jr. is Senior Vice President of Business Development, Commercial Excellence, Land and Logistics.
| Jason P. Teter | Senior Vice President, Mountain West, Northeast and South Divisions | 48 |
Perkins Jr. is Senior Vice President of the Central and Southern Gulf Coast Divisions as well as Commercial Excellence.
Pruitt is Senior Vice President of the Southwest and Western Divisions.
Jason P.
Teter is Senior Vice President of the Mountain West, Northeast and South Divisions.
Prior to his current position, he was Senior Vice President of the Mideast and Southeast Divisions.
He joined Vulcan in 2013 as Vice President of Business Development.
He previously served as Vice President of Finance, President of the Southeast Division and President of the Southern Gulf Coast Division.
Before joining Vulcan, he spent ten years in various finance, business development and general management positions with Lafarge North America.
Item 5. MARKET FOR REGISTRANT'S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
9 rewritten, 9 added, 12 removed, 5 unchanged
As of February [removed: 14, 2023,] [added: 13, 2024,] the number of shareholders of record was [removed: 2,158.][added: 2,058.]
Purchases of our equity securities during the quarter ended December 31, [removed: 2022] [added: 2023] are summarized below:
| | | | | | [removed: | |] *Total [removed: Number* |] [added: Number of*] | | [removed: *Maximum*] [added: *Maximum Number*] | |
| | *Total* | | | | [removed: | | *Purchased as* |] [added: *Shares Purchased*] | | [removed: *Shares that] [added: *of Shares That] May* | |
| | *Number of* | | [removed: |] *Average* | | [removed: | *Part] [added: *As Part] of Publicly* | | [removed: |] *Yet Be Purchased* | |
| | *Shares* | | [removed: |] *Price Paid* | | [removed: |] *Announced Plans* | | [removed: |] *Under the Plans* | |
| *Period* | *Purchased* | | [removed: |] *Per Share* | | [removed: |] *or Programs* | | [removed: |] *or Programs* *1* | |
| *1* | [removed: *In* *February 2017,] [added: *In February 2017,] our Board of Directors authorized us to [removed: purchase* *up] [added: purchase up] to 10,000,000 shares of our common [removed: stock.* *As] [added: stock. As] of December 31, [removed: 2022,] [added: 2023,] there [removed: were* *8,064,851* *shares] [added: were 7,087,260 shares] remaining under [removed: this* *authorization.] [added: this authorization.] Depending upon market, business, legal and other conditions, we [removed: may purchase shares* *from] [added: may purchase shares from] time to time [removed: through* *the* *open market* *(including* *plans] [added: through the open market (including plans] designed to comply with Rule 10b5-1 of the Securities Exchange Act of [removed: 1934)] [added: 1934)] and/or [removed: through* *privately] [added: through privately] negotiated [removed: transactions.* *The] [added: transactions. The] authorization has no time limit, does not obligate us to purchase any specific number of [removed: shares,] [added: shares] and may be suspended or discontinued at any time.* | [removed: |]
We did not have any unregistered sales of equity securities during the fourth quarter of [removed: 2022.][added: 2023.]
| | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | |
| | | | | | | | | |
| 2023 | | | | | | | | |
| Oct 1 - Oct 31 | 253,123 | | $ 197.40 | | 253,123 | | 7,570,365 | |
| Nov 1 - Nov 30 | 483,105 | | $ 207.11 | | 483,105 | | 7,087,260 | |
| Dec 1 - Dec 31 | 0 | | $ 0.00 | | 0 | | 7,087,260 | |
| Total | 736,228 | | $ 203.77 | | 736,228 | | | |
| | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | |
| | | | | | | | *of Shares* | | | *Number of* | |
| 2022 | | | | | | | | | | | |
| Oct 1 - Oct 31 | 0 | | | $ 0.00 | | | 0 | | | 8,064,851 | |
| Nov 1 - Nov 30 | 0 | | | $ 0.00 | | | 0 | | | 8,064,851 | |
| Dec 1 - Dec 31 | 0 | | | $ 0.00 | | | 0 | | | 8,064,851 | |
| Total | 0 | | | $ 0.00 | | | 0 | | | | |
| | | |
| --- | --- | --- |
| | |
Page headers and footers: 1 line differs, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
| Part II | 37 |
Item 6. [reserved]
0 rewritten, 4 added, 0 removed, 0 unchanged
New section this year
\[reserved\]
| | |
| --- | --- |
| | |
Page headers and footers: 1 line differs, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
| Part II | 37 |
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
720 rewritten, 184 added, 238 removed, 1,353 unchanged
We have audited the accompanying consolidated balance sheets of Vulcan Materials Company and subsidiaries (the “Company”) as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] the related consolidated statements of comprehensive income, equity, and cash flows, for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] and the related notes (collectively referred to as the “financial statements”).
In our opinion, the financial statements present fairly, in all material respects, the financial position of the Company as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] in conformity with accounting principles generally accepted in the United States of America.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company's internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on [removed: the] criteria established in *Internal Control* *—* *Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission and our report dated February [removed: 24, 2023] [added: 22, 2024] expressed an unqualified opinion on the Company's internal control over financial reporting.
Critical Audit [removed: Matters][added: Matter]
The critical audit [removed: matters] [added: matter] communicated below [removed: are matters] [added: is a matter] arising from the current-period audit of the financial statements that [removed: were] [added: was] communicated or required to be communicated to the audit committee and that (1) [removed: relate] [added: relates] to accounts or disclosures that are material to the financial statements and (2) involved our especially challenging, subjective, or complex judgments.
The communication of critical audit matters does not alter in any way our opinion on the financial statements, taken as a whole, and we are not, by communicating the critical audit [removed: matters] [added: matter] below, providing [added: a] separate [removed: opinions] [added: opinion] on the critical audit [removed: matters] [added: matter] or on the accounts or disclosures to which [removed: they relate.][added: it relates.]
Specific to the Hewitt Landfill Environmental Matter, management is engaged in groundwater testing, certain remedial procedures and ongoing dialogue with [removed: federal and local agencies such as] the Environmental Protection Agency (EPA), Los Angeles Regional Water Quality Control Board [removed: (RWQCB) and the] [added: (RWQCB),] Los Angeles Department of Water and Power [removed: (LADWP) as well as other interested parties.][added: (LADWP), and Honeywell.]
The testing and dialogue is related to the Company’s [removed: potential] contribution to soil, soil vapor and/or groundwater contamination in the former Hewitt Landfill in Los Angeles and the potential contribution of the Hewitt Landfill to groundwater contamination in the North Hollywood Operable Unit (NHOU) of the San Fernando Valley Superfund Site.
The groundwater treatment system for the Hewitt Landfill on-site remediation is fully [removed: operational] [added: operational,] and the [removed: incurred and] anticipated costs have been fully accrued for based on facts and circumstances known to the Company at this time.
| | [removed: 2022] [added: 2023] | | | [removed: *2021*] [added: *2022*] | | | [removed: *2020*] [added: *2021*] | |
| Total revenues | $ [removed: 7,315.2] [added: 7,781.9] | | | $ [removed: 5,552.2] [added: 7,315.2] | | | $ [removed: 4,856.8] [added: 5,552.2] | |
| Cost of revenues | [removed: 5,757.5] [added: (5,833.4)] | | | [removed: 4,178.8] [added: (5,757.5)] | | | [removed: 3,575.3] [added: (4,178.8)] | |
| Gross profit | [removed: 1,557.7] [added: 1,948.5] | | | [removed: 1,373.4] [added: 1,557.7] | | | [removed: 1,281.5] [added: 1,373.4] | |
| Selling, administrative and general expenses | [removed: 515.1] [added: (542.8)] | | | [removed: 417.6] [added: (515.1)] | | | [removed: 359.8] [added: (417.6)] | |
| Gain on sale of property, plant & equipment and businesses | [removed: 10.7] [added: 76.4] | | | [removed: 120.1] [added: 10.7] | | | [removed: 4.0] [added: 120.1] | |
| Loss on impairments | [removed: (67.9)] [added: (28.3)] | | | [removed: (4.6)] [added: (67.9)] | | | [removed: 0.0] [added: (4.6)] | |
| Other operating expense, net | [removed: (34.0)] [added: (26.4)] | | | [removed: (60.5)] [added: (34.0)] | | | [removed: (30.0)] [added: (60.5)] | |
| Operating earnings | [removed: 951.4] [added: 1,427.4] | | | [removed: 1,010.8] [added: 951.4] | | | [removed: 895.7] [added: 1,010.8] | |
| Other nonoperating income (expense), net | [removed: 5.1] [added: (2.7)] | | | [removed: 10.7] [added: 5.1] | | | [removed: (17.5)] [added: 10.7] | |
| Interest income | [removed: 0.8] [added: 16.5] | | | [removed: 1.6] [added: 0.8] | | | 1.6 | |
| Interest expense | [removed: 169.2] [added: (196.1)] | | | [removed: 149.3] [added: (169.2)] | | | [removed: 136.0] [added: (149.3)] | |
| Earnings from continuing operations before income taxes | [removed: 788.1] [added: 1,245.1] | | | [removed: 873.8] [added: 788.1] | | | [removed: 743.8] [added: 873.8] | |
| Income tax [removed: expense] [added: (expense) benefit] | | | | | | | | |
| Current | [removed: 133.4] [added: (343.6)] | | | [removed: 133.5] [added: (133.4)] | | | [removed: 93.9] [added: (133.5)] | |
| Deferred | [removed: 59.6] [added: 44.2] | | | [removed: 66.6] [added: (59.6)] | | | [removed: 61.9] [added: (66.6)] | |
| Total income tax expense | [removed: 193.0] [added: (299.4)] | | | [removed: 200.1] [added: (193.0)] | | | [removed: 155.8] [added: (200.1)] | |
| Earnings from continuing operations | [removed: 595.1] [added: 945.7] | | | [removed: 673.7] [added: 595.1] | | | [removed: 588.0] [added: 673.7] | |
| Loss on discontinued operations, net of tax | [removed: (18.6)] [added: (10.8)] | | | [removed: (3.3)] [added: (18.6)] | | | [removed: (3.5)] [added: (3.3)] | |
| Net earnings | [removed: 576.5] [added: 934.9] | | | [removed: 670.4] [added: 576.5] | | | [removed: 584.5] [added: 670.4] | |
| (Earnings) loss attributable to noncontrolling interest | [removed: (0.9)] [added: (1.7)] | | | [removed: 0.4] [added: (0.9)] | | | [removed: 0.0] [added: 0.4] | |
| Net earnings attributable to Vulcan | $ [removed: 575.6] [added: 933.2] | | | $ [removed: 670.8] [added: 575.6] | | | $ [removed: 584.5] [added: 670.8] | |
| Amortization of prior cash flow hedge loss | [removed: 1.5] [added: 1.6] | | | 1.5 | | | [removed: 1.7] [added: 1.5] | |
| Adjustment for funded status of benefit plans | [removed: (6.5)] [added: 4.2] | | | [removed: 13.4] [added: (6.5)] | | | [removed: 6.4] [added: 13.4] | |
| Amortization of actuarial loss and prior service cost for benefit plans | [removed: 3.0] [added: 5.1] | | | [removed: 13.7] [added: 3.0] | | | [removed: 23.0] [added: 13.7] | |
| Other comprehensive income (loss) | [removed: (2.0)] [added: 10.9] | | | [removed: 28.6] [added: (2.0)] | | | [removed: 16.4] [added: 28.6] | |
| Comprehensive income | [removed: 574.5] [added: 945.8] | | | [removed: 699.0] [added: 574.5] | | | [removed: 600.9] [added: 699.0] | |
| Comprehensive (earnings) loss attributable to noncontrolling interest | [removed: (0.9)] [added: (1.7)] | | | [removed: 0.4] [added: (0.9)] | | | [removed: 0.0] [added: 0.4] | |
| Comprehensive income attributable to Vulcan | $ [removed: 573.6] [added: 944.1] | | | $ [removed: 699.4] [added: 573.6] | | | $ [removed: 600.9] [added: 699.4] | |
| Continuing operations | $ [removed: 4.47] [added: 7.10] | | | $ [removed: 5.08] [added: 4.47] | | | $ [removed: 4.44] [added: 5.08] | |
| Discontinued operations | [removed: (0.14)] [added: (0.08)] | | | [removed: (0.03)] [added: (0.14)] | | | (0.03) | |
February 22, 2024
| | 2023 | | | *2022* | |
| Other assets | 27.8 | | | (92.3) | | | (44.0) | |
| Distribution to noncontrolling interest | (0.8) | | | 0.0 | | | 0.0 | |
| common stock | (1.0) | | (1.0) | | | 0.0 | | (201.5) | | 0.0 | | | (202.5) | | 0.0 | | (202.5) | |
| Distribution to noncontrolling | | | | | | | | | | | | | | | | | | |
| interest | 0.0 | | 0.0 | | | 0.0 | | 0.0 | | 0.0 | | | 0.0 | | (0.8) | | (0.8) | |
| Balances at December 31, 2023 | 132.1 | | $ 132.1 | | | $ 2,880.1 | | $ 4,615.0 | | $ (143.8) | | | $ 7,483.4 | | $ 24.5 | | $ 7,507.9 | |
For additional information about business combinations, see Note 19.
Allowances for credit losses were $13.6 million and $10.9 million at December 31, 2023 and 2022, respectively.
| Interest rate swaps | | | $ (0.3) | | | $ 0.0 | |
During the third quarter of 2023, net assets held for sale (our concrete operations in Texas) with a carrying value of $513.3 million were written down to their estimated fair value (less cost to sell) of $485.0 million, resulting in an impairment loss of $28.3 million; these net assets were subsequently sold during the fourth quarter resulting in additional loss on sale of $13.8 million.
As previously noted, during the third quarter of 2023, we recorded a $28.3 million loss on impairment of long-lived assets related to the fourth quarter sale of concrete operations in Texas.
See Note 19 for divestiture information and Note 18 for a related goodwill impairment charge in 2022.
| Discount rate | 4.56% | | | 4.20% | |
| 2024 | $ 48.9 | |
| 2025 | 32.2 | |
| 2026 | 20.8 | |
| 2027 | 11.0 | |
| 2028 | 5.5 | |
| SOSARs 1 | | $ 1.2 | | | 1.2 | |
In November 2023, the Financial Accounting Standards Board (FASB) issued Accounting Standards Update (ASU) 2023-07, “Segment Reporting – Improvements to Reportable Segment Disclosures,” which requires enhanced disclosures related to significant segment expenses and a description of how the chief operating decision maker utilizes segment operating profit or loss to assess segment performance.
The new standard is effective for fiscal years beginning after December 15, 2023 and is to be applied retrospectively.
We are assessing the effect of this ASU on our consolidated financial statements and related disclosures.
In December 2023, the FASB issued ASU 2023-09, “Income Taxes – Improvements to Income Tax Disclosures,” which requires disclosure of specific categories and disaggregation of information in the rate reconciliation table and expands disclosures related to income taxes paid.
The new standard is effective for fiscal years beginning after December 15, 2024 and is to be applied prospectively.
We are assessing the effect of this ASU on our consolidated financial statements and related disclosures.
| East | $ 1,665.2 | | | $ 201.4 | | | $ 363.0 | | | $ 0.0 | | | $ 2,229.6 | |
| Gulf Coast | 3,324.8 | | | 231.6 | | | 539.8 | | | 9.0 | | | 4,105.2 | |
| West | 919.9 | | | 707.7 | | | 346.5 | | | 0.0 | | | 1,974.1 | |
| Segment sales | $ 5,909.9 | | | $ 1,140.7 | | | $ 1,249.3 | | | $ 9.0 | | | $ 8,308.9 | |
| Total revenues | $ 5,382.9 | | | $ 1,140.7 | | | $ 1,249.3 | | | $ 9.0 | | | $ 7,781.9 | |
The effect of the LIFO liquidation on our results was as follows:
2023 — decrease cost of revenues by $3.6 million and increase net earnings by $2.7 million
In March 2023, we issued $550.0 million of 5.80% fixed-rate debt maturing in March 2026.
Concurrently, we entered into fixed-to-floating interest rate swap agreements designated as fair value hedges in the amount of $550.0 million.
Under these swap agreements, we receive a fixed interest rate of 5.80% (matches the fixed rate we pay on the $550.0 million of debt) and pay daily compound Secured Overnight Financing Rate (SOFR) plus 0.241%.
The changes in the fair value of these swaps designated as fair value hedges are recorded in interest expense and are perfectly offset by changes in the fair value of the related debt also recorded in interest expense.
These swaps are recognized at fair value in the accompanying Consolidated Balance Sheets at December 31 as follows:
| | | | | | *Fair Value* *1* | | | | |
| | |
| | |
Goodwill Valuation — Concrete Reporting Units — Refer to Notes 1 and 18 to the consolidated financial statements
*Critical Audit Matter Description*
The Company’s evaluation of goodwill for impairment involves the comparison of the fair value of each reporting unit to its carrying value.
The Company determines the fair value of its reporting units using both an income approach (which involves discounted estimated future cash flows) and a market approach (which involves the application of revenue and earnings before interest, taxes, depreciation, and amortization (EBITDA) multiples for comparable companies).
The goodwill balance was $3,689.6 million as of December 31, 2022, of which $267.7 million was allocated to concrete reporting units.
The fair value exceeded the carrying value for each reporting unit as of the measurement date and, therefore, no impairment was recognized.
We identified goodwill for certain concrete reporting units as a critical audit matter because of the significant estimates and assumptions management makes to estimate the fair value and the sensitivity of the fair value of each to selected revenue and EBITDA multiples and discount rates.
This required a high degree of auditor judgment and an increased extent of effort, including the need to involve our fair value specialists, when performing audit procedures to evaluate the reasonableness of management’s estimates: specifically, assumptions related to the selection of revenue and EBITDA multiples and the discount rates.
*How the Critical Audit Matter Was Addressed in the Audit*
Our audit procedures related to the selection of revenue and EBITDA multiples and the discount rates for the concrete reporting units included the following, among others:
We tested the effectiveness of controls over management’s goodwill impairment evaluation, including those over the determination of the fair value of the concrete reporting units, such as controls related to management’s selection of revenue and EBITDA multiples and the discount rates.
With the assistance of our fair value specialists, we performed the following:
Evaluated the discount rates, including testing the underlying source information and the mathematical accuracy of the calculations, and developing a range of independent estimates and comparing those to the discount rates selected by management.
Evaluated the revenue and EBITDA multiples, including testing the underlying source information and mathematical accuracy of the calculations, and comparing the multiples selected by management to its guideline companies and comparable sale transactions, to the extent applicable.
February 24, 2023
| Deferred loss on cash flow hedge | 0.0 | | | 0.0 | | | (14.7) | |
| | | | | | |
| --- | --- | --- | --- | --- | --- |
| | | | | | |
| Customers, less allowance for credit losses | | | | | |
| 2022 — $10.9; 2021 — $10.3 | 845.6 | | | 783.2 | |
| Other | 199.7 | | | 55.5 | |
| Deferred tax expense | 57.7 | | | 66.8 | | | 62.0 | |
| Prepaid expenses | 9.5 | | | (14.2) | | | 2.6 | |
| Other assets | (101.8) | | | (29.8) | | | (14.4) | |
| Settlements of interest rate derivatives | 0.0 | | | 0.0 | | | (19.9) | |
| Balances at December 31, 2019 | 132.4 | | $ 132.4 | | | $ 2,791.3 | | $ 2,895.9 | | $ (197.7) | | | $ 5,621.9 | | $ 0.0 | | $ 5,621.9 | |
| common stock | (0.2) | | (0.2) | | | 0.0 | | (25.9) | | 0.0 | | | (26.1) | | 0.0 | | (26.1) | |
Year-over-year comparisons are significantly impacted by our August 2021 acquisition of U.S. Concrete (see Note 19).
This includes conditions resulting from the impacts of the current conflict between Russia and Ukraine, as construction activity continues to be impacted by cost inflation and capacity constraints (including supply chain bottlenecks, labor shortages and transportation availability).
The results of our annual impairment tests performed as of November 1, 2021 and 2020 indicated that the fair values of all reporting units with goodwill substantially exceeded (in excess of 100%) their carrying values.
The results of our annual impairment test performed as of November 1, 2022 indicated that the fair values of all reporting units with goodwill exceeded their carrying values by approximately 10% to greater than 100%.
The reporting units with the smallest excess of fair value versus carrying value include concrete operations acquired with U.S. Concrete in August 2021.
| | | | | | |
| --- | --- | --- | --- | --- | --- |
| | | | | | |
| Discount rate | 4.20% | | | 1.10% | |
| 2023 | $ 55.2 | |
An excerpt. Shown here: 40 of 720 rewritten, 40 of 184 added and 40 of 238 removed. The counts are complete. For every sentence, read Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA in the FY2023 filing and the FY2022 filing.
Page headers and footers: 2 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
| Part II | 129 |
| Part II | 130 |
Item 9A. CONTROLS AND PROCEDURES
14 rewritten, 4 added, 4 removed, 32 unchanged
Our Chief Executive Officer and Chief Financial Officer, with the participation of other management officials, evaluated the effectiveness of the design and operation of the disclosure controls and procedures as of December 31, [removed: 2022.][added: 2023.]
Based upon that evaluation, our Chief Executive Officer and Chief Financial Officer concluded that our disclosure controls and procedures were effective as of December 31, [removed: 2022.][added: 2023.]
We [removed: are in] [added: completed] the [removed: process] [added: implementation] of [removed: replacing] our [removed: legacy] quote to [removed: cash] [added: invoice] software system for our ready-mixed concrete [removed: operations.][added: operations in the fourth quarter of 2023.]
No other changes were made during the fourth quarter of [removed: 2022] [added: 2023] to our internal controls over financial reporting, nor have there been other factors that materially affect these controls.
Based on this evaluation, management concluded that our internal control over financial reporting was effective as of December 31, [removed: 2022.][added: 2023.]
Deloitte & Touche LLP, an independent registered public accounting firm, as auditors of our consolidated financial statements, has issued an attestation report on the effectiveness of our internal control over financial reporting as of December 31, [removed: 2022.][added: 2023.]
[removed: LIMITATIONS OF] [added: INHERENT LIMITATIONS ON] EFFECTIVENESS OF [removed: CONTROLS AND PROCEDURES][added: CONTROLS]
[removed: In designing and evaluating our disclosure controls and procedures, management recognizes that any controls and procedures,] [added: A control system,] no matter how well designed and operated, can provide only [removed: reasonable] [added: reasonable, not absolute,] assurance [removed: of achieving] [added: that] the [removed: desired] control [removed: objectives.][added: system’s objectives will be met.]
[removed: In addition, the] [added: The] design of [removed: disclosure controls and procedures] [added: a control system] must reflect the fact that there are resource [removed: constraints] [added: constraints,] and [removed: that management is required to apply its judgment in evaluating] the benefits of [removed: possible] controls [removed: and procedures] [added: must be considered] relative to their costs.
To the shareholders and [added: the] Board of Directors of Vulcan Materials Company:
We have audited the internal control over financial reporting of Vulcan Materials Company and subsidiaries (the “Company”) as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in *Internal Control* — *Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in *Internal Control* — *Integrated Framework (2013)* issued by COSO.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated financial statements as of and for the year ended December 31, [removed: 2022,] [added: 2023,] of the Company and our report dated February [removed: 24, 2023,] [added: 22, 2024,] expressed an unqualified opinion on those financial statements.
Because of [removed: the] [added: its] inherent limitations, internal control over financial reporting may not prevent or detect misstatements.
In addition, we are in the process of replacing our quote to invoice system for our aggregates and asphalt operations and expect the full implementation of this system to be completed by the fourth quarter of 2024.
Management does not expect that our disclosure controls and procedures or our internal controls over financial reporting will prevent or detect all errors and all fraud.
Further, because of the inherent limitations in all control systems, no evaluation of controls can provide absolute assurance that misstatements due to error or fraud will not occur or that all control issues and instances of fraud, if any, have been detected.
| February 22, 2024 |
We expect the full implementation of this system to be completed in the fourth quarter of 2023.
On August 26, 2021, we completed our acquisition of U.S. Concrete, which operated under its own set of systems and internal controls.
We completed the process of integrating U.S. Concrete processes to our internal control over financial reporting environment in the fourth quarter of 2022.
| February 24, 2023 |
Page headers and footers: 2 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
| Part II | [removed: 131] [added: 129] |
| Part II | [removed: 132] [added: 130] |
Item 9B. OTHER INFORMATION
0 rewritten, 15 added, 1 removed, 1 unchanged
SECURITIES TRADING PLANS OF SECTION 16 OFFICERS AND DIRECTORS
During the three months ended December 31, 2023, certain of our Section 16 officers and directors listed below adopted trading arrangements for the sale of shares of our common stock as follows:
| | | | | | | |
| --- | --- | --- | --- | --- | --- | --- |
| | | | | | | |
| | | *Trading Arrangement* | | | | *Number* |
| | | *Rule* | *Non-Rule* | | *Expiration* | *of Shares* |
| *Name and Title* | *Action* | *10b5-1* *1* | *10b5-1* *2* | *Date* | *of Plan* | *to be Sold* *3* |
| Denson N. Franklin III, Senior Vice President, General Counsel and Secretary | Adoption | X | | December 13, 2023 | Earlier of when all shares under plan are sold and December 31, 2024 | 3,200 |
| | | | | | | |
| | |
| --- | --- |
| *1* | *Intended to satisfy the affirmative defense conditions of Rule 10b5-1(c).* |
| *2* | *Not intended to satisfy the affirmative defense conditions of Rule 10b5-1(c).* |
| *3* | *The actual number of shares of our common stock to be sold may vary as a result of shares withheld for payment of taxes.* |
None.
Item 9C. DISCLOSURE REGARDING FOREIGN JURISDICTIONS THAT PREVENT INSPECTIONS
0 rewritten, 0 added, 0 removed, 6 unchanged
Page headers and footers: 1 line differs, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
| Part II | [removed: 133] [added: 131] |
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
2 rewritten, 0 added, 0 removed, 2 unchanged
On or about March [removed: 27, 2023,] [added: 25, 2024,] we expect to file a definitive proxy statement with the Securities and Exchange Commission pursuant to Regulation 14A (our [removed: “2023] [added: “2024] Proxy Statement”).
The information under the headings “Proposal 1 - Election of Directors,” “Corporate Governance – Policies,” “Corporate Governance – Director Nomination Process,” “Corporate Governance – Committees of the Board of Directors” and “Delinquent Section 16(a) Reports” (to the extent reported therein) included in our [removed: 2023] [added: 2024] Proxy Statement is incorporated herein by reference.
Item 11. EXECUTIVE COMPENSATION
1 rewritten, 0 added, 0 removed, 1 unchanged
The information under the headings “Compensation Discussion and Analysis,” “Director Compensation,” “Executive Compensation,” “Corporate Governance – Compensation Committee Interlocks and Insider Participation,” and “Compensation Committee Report” included in our [removed: 2023] [added: 2024] Proxy Statement is incorporated herein by reference.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED
1 rewritten, 0 added, 0 removed, 2 unchanged
The information under the headings “Security Ownership of Certain Beneficial Owners and Management,” and “Equity Compensation Plans” included in our [removed: 2023] [added: 2024] Proxy Statement is incorporated herein by reference.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
1 rewritten, 0 added, 0 removed, 1 unchanged
The information under the headings “Corporate Governance – Director Independence,” and “Corporate Governance – Transactions with Related Persons” included in our [removed: 2023] [added: 2024] Proxy Statement is incorporated herein by reference.
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
3 rewritten, 0 added, 0 removed, 4 unchanged
PRINCIPAL [removed: ACCOUNTING] [added: ACCOUNTANT] FEES AND SERVICES
The information under the heading “Independent Registered Public Accounting Firm” included in our [removed: 2023] [added: 2024] Proxy Statement is incorporated herein by reference.
| Part III | [removed: 134] [added: 132] |
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
43 rewritten, 3 added, 6 removed, 46 unchanged
| | Report of Independent Registered Public Accounting Firm (PCAOB ID 34) | 74 – [removed: 76] [added: 75] | |
| | Consolidated Statements of Comprehensive Income | [removed: 77] [added: 76] | |
| | Consolidated Balance Sheets | [removed: 78] [added: 77] | |
| | Consolidated Statements of Cash Flows | [removed: 79] [added: 78] | |
| | Consolidated Statements of Equity | [removed: 80] [added: 79] | |
| | Notes to Consolidated Financial Statements | [removed: 81] [added: 80] – [removed: 130] [added: 128] | |
| Exhibit [removed: 4(k)] [added: 4(l)] | | Indenture, dated as of May 1, 1991, by and between Legacy Vulcan Corp. (formerly Vulcan Materials Company) and First Trust of New York (as successor trustee to Morgan Guaranty Trust Company of New York) filed as Exhibit 4 to the Form S-3 on May 2, 1991 (Registration No. 33-40284) 1 | | |
| Exhibit [removed: 4(l)] [added: 4(m)] | | [Supplemental Indenture No. 1, dated as of November 16, 2007, among the Company, Legacy Vulcan Corp. and The Bank of New York, as Trustee, filed as Exhibit 4.1 to the Company’s Current Report on Form 8-K filed on November 21, 2007 1](http://www.sec.gov/Archives/edgar/data/1396009/000095012307015875/y427068kexv4w1.htm) | | |
| Exhibit [removed: 4(m)] [added: 4(n)] | | [Supplemental Indenture No. 2, dated as of June 30, 2015, between Legacy Vulcan, LLC and The Bank of New York Mellon Trust Company, N.A., as Trustee, filed as Exhibit 4(a) to the Company’s Quarterly Report on Form 10-Q filed on August 5, 2015 1](http://www.sec.gov/Archives/edgar/data/1396009/000139600915000030/vmc-20150630ex4a14b97ea.htm) | | |
| Exhibit [removed: 4(n)] [added: 4(o)] | | [Indenture, dated as of February 23, 2018, between Vulcan Materials Company and Regions Bank, as Trustee, filed as Exhibit 4.1 to the Company’s Current Report on Form 8-K filed on February 26, 2018 1](http://www.sec.gov/Archives/edgar/data/1396009/000119312518057209/d539453dex41.htm) | | |
| Exhibit [removed: 4(o)] [added: 4(p)] | | [Description of [removed: Securities](https://www.sec.gov/Archives/edgar/data/1396009/000139600923000007/vmc-20221231xex4_o.htm)] [added: Securities, filed as Exhibit 4(o) to the Company’s Annual Report on Form 10-K filed on February 24, 2023 1](https://www.sec.gov/Archives/edgar/data/1396009/000139600923000007/vmc-20221231xex4_o.htm)] | | |
| Exhibit [removed: 10(b)] [added: 10(e)] | | [removed: [Credit] [added: [Fourth Amendment to Credit] Agreement, dated [removed: June 30, 2021,] [added: as of August 8, 2022,] among Vulcan Materials Company, Truist Bank, as Administrative Agent, and the Lenders and other parties named therein, filed as Exhibit 10.1 to the Company’s Current Report on Form 8-K filed on [removed: July 1, 2021 1](http://www.sec.gov/Archives/edgar/data/1396009/000119312521206349/d72908dex101.htm)] [added: August 9, 2022 1](http://www.sec.gov/Archives/edgar/data/1396009/000119312522215212/d711767dex101.htm)] | | |
| Exhibit [removed: 10(c)] [added: 10(b)] | | [First Amendment to Credit Agreement, dated June 30, 2021, among Vulcan Materials Company, Truist Bank, as Administrative Agent, and the Lenders and other parties named therein, filed as Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q filed on August 5, 2021 1](http://www.sec.gov/Archives/edgar/data/1396009/000139600921000044/vmc-20210630xex10_2.htm) | | |
| Exhibit [removed: 10(d)] [added: 10(c)] | | [removed: [First] [added: [Second] Amendment to Credit Agreement, dated August 16, 2021, by and between Vulcan Materials Company and Truist Bank, as Administrative Agent, filed as Exhibit [removed: 10.1] [added: 10.2] to the Company’s Quarterly Report on Form 10-Q filed on November 5, 2021 [removed: 1](http://www.sec.gov/Archives/edgar/data/1396009/000139600921000050/vmc-20210930xex10_1.htm)] [added: 1](http://www.sec.gov/Archives/edgar/data/1396009/000139600921000050/vmc-20210930xex10_2.htm)] | | |
| Exhibit [removed: 10(e)] [added: 10(d)] | | [removed: [Second] [added: [Third] Amendment to Credit Agreement, dated [removed: August 16, 2021,] [added: March 18, 2022,] by and between Vulcan Materials Company and Truist Bank, as Administrative Agent, filed as Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q filed on [removed: November] [added: May] 5, [removed: 2021 1](http://www.sec.gov/Archives/edgar/data/1396009/000139600921000050/vmc-20210930xex10_2.htm)] [added: 2022 1](http://www.sec.gov/ix?doc=/Archives/edgar/data/0001396009/000139600922000017/vmc-20220331xex10_2.htm)] | | |
| Exhibit [removed: 10(i)] [added: 10(f)] | | [Unfunded Supplemental Benefit Plan for Salaried Employees, as amended, filed as Exhibit 10.4 to the Company’s Current Report on Form 8-K filed on December 17, 2008 1](http://www.sec.gov/Archives/edgar/data/1396009/000095014408009390/g17056exv10w4.htm),2 | | |
| Exhibit [removed: 10(j)] [added: 10(g)] | | [Amendment No. 1 to the Unfunded Supplemental Benefit Plan for Salaried Employees filed as Exhibit 10.1 to the Company’s Current Report on Form 8-K on January 7, 2014 1](https://www.sec.gov/Archives/edgar/data/1396009/000114420414000953/v364833_ex10-1.htm),2 | | |
| Exhibit [removed: 10(k)] [added: 10(h)] | | [Deferred Compensation Plan for Directors Who Are Not Employees of the Company, as amended, filed as Exhibit 10.5 to the Company’s Current Report on Form 8-K filed on December 17, 2008 1](http://www.sec.gov/Archives/edgar/data/1396009/000095014408009390/g17056exv10w5.htm),2 | | |
| Exhibit [removed: 10(l)] [added: 10(i)] | | [Executive Deferred Compensation Plan, as amended, filed as Exhibit 10.1 to the Company's Current Report on Form 8-K filed on December 17, 2008 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000095014408009390/g17056exv10w1.htm) | | |
| Exhibit [removed: 10(m)] [added: 10(j)] | | [Form of Change of Control Employment Agreement dated January 1, 2016, filed as Exhibit 10.1 to the Company's Current Report on Form 8-K filed on January 7, 2016 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000114420416074571/v428515_ex10-1.htm) | | |
| Exhibit [removed: 10(n)] [added: 10(k)] | | [Vulcan Materials Company Change of Control Severance Plan for Senior Officers, effective January 1, 2016, filed as Exhibit 10(m) to the Company’s Annual Report on Form 10-K filed on February 25, 2016 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600916000044/vmc-20151231ex10ma03dee.htm) | | |
| Exhibit [removed: 10(o)] [added: 10(l)] | | [Executive Incentive Plan of the Company, as amended, filed as Exhibit 10.2 to the Company's Current Report on Form 8-K filed on December 17, 2008 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000095014408009390/g17056exv10w2.htm) | | |
| Exhibit [removed: 10(p)] [added: 10(m)] | | [Vulcan Materials Company 2016 Omnibus Long-Term Incentive Plan, filed as Exhibit 99 to the Company’s Registration Statement on Form S-8 (File No. 333-211349) filed on May 13, 2016 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000119312516590099/d155821dex99.htm) | | |
| Exhibit [removed: 10(q)] [added: 10(n)] | | [Form of Non-Employee Director Deferred Stock Unit Agreement under the Vulcan Materials Company 2016 Omnibus Long-Term Incentive Plan, filed as Exhibit 10(y) to the Company’s Quarterly Report on Form 10-Q filed on August 3, 2016 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600916000071/vmc-20160630xex10_y.htm) | | |
| Exhibit [removed: 10(r)] [added: 10(o)] | | [Form of Stock-Only Stock Appreciation Rights Award Agreement under the Vulcan Materials Company 2016 Omnibus Long-Term Incentive Plan, filed as Exhibit 10(z) to the Company’s Quarterly Report on Form 10-Q filed on August 3, 2016 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600916000071/vmc-20160630xex10_z.htm) | | |
| Exhibit [removed: 10(s)] [added: 10(p)] | | [Form of Restricted Stock Unit Award Agreement under the Vulcan Materials Company 2016 Omnibus Long-Term Incentive Plan, filed as Exhibit 10(aa) to the Company’s Quarterly Report on Form 10-Q filed on August 3, 2016 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600916000071/vmc-20160630xex10_aa.htm) | | |
| Exhibit [removed: 10(t)] [added: 10(q)] | | [Form of Performance Share Unit Award Agreement under the Vulcan Materials Company 2016 Omnibus Long-Term Incentive Plan, filed as Exhibit 10(bb) to the Company’s Quarterly Report on Form 10-Q filed on August 3, 2016 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600916000071/vmc-20160630xex10_bb.htm) | | |
| Exhibit [removed: 10(u)] [added: 4(k)] | | [removed: [Offer Letter,] [added: [Tenth Supplemental Indenture,] dated as of [removed: June 19, 2018, by and] [added: March 3, 2023,] between [removed: Suzanne H. Wood and] Vulcan Materials [removed: Company,] [added: Company and Regions Bank as Trustee,] filed as Exhibit [removed: 10.2] [added: 4.1] to the Company’s Current [removed: report] [added: Report] on Form 8-K filed on [removed: July 10, 2018 1, 2](http://www.sec.gov/Archives/edgar/data/1396009/000089882218000048/offerletter.htm)] [added: March 3, 2023 1](http://www.sec.gov/Archives/edgar/data/1396009/000119312523060087/d477082dex41.htm)] | | |
| Exhibit [removed: 10(v)] [added: 10(r)] | | [Form of Performance Share Unit Award Agreement (2019) under the Vulcan Materials Company 2016 Omnibus Long-Term Incentive Plan, filed as Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q filed on May 3, 2019 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600919000033/vmc-20190331xex10_1.htm) | | |
| Exhibit [removed: 10(w)] [added: 10(s)] | | [Form of Performance Share Unit Award Agreement (2020) under the Vulcan Materials Company 2016 Omnibus Long-Term Incentive Plan, filed as Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q filed on May 6, 2020 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600920000015/vmc-20200331xex10_1.htm) | | |
| Exhibit [removed: 10(x)] [added: 10(t)] | | [Form of Stock-Only Appreciation Rights Award Agreement (2020) under the Vulcan Materials Company 2016 Omnibus Long-Term Incentive Plan, filed as Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q filed on May 6, 2020 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600920000015/vmc-20200331xex10_2.htm) | | |
| Exhibit [removed: 10(y)] [added: 10(u)] | | [Form of Restricted Stock Unit Award Agreement (2020) under the Vulcan Materials Company 2016 Omnibus Long-Term Incentive Plan, filed as Exhibit 10.3 to the Company’s Quarterly Report on Form 10-Q filed on May 6, 2020 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600920000015/vmc-20200331xex10_3.htm) | | |
| Exhibit [removed: 10(z)] [added: 10(v)] | | [Form of Non-Employee Director Restricted Stock Unit Award Agreement under the Vulcan Materials Company 2016 Omnibus Long-Term Incentive Plan filed as Exhibit 10.3 to the Company’s Quarterly Report on Form 10-Q filed on August 5, 2020 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600920000040/vmc-20200630xex10_3.htm) | | |
| Exhibit 21 | | [List of the Company's material subsidiaries as of December 31, [removed: 202](https://www.sec.gov/Archives/edgar/data/1396009/000139600923000007/vmc-20221231xex21.htm)2] [added: 202](https://www.sec.gov/Archives/edgar/data/1396009/000139600924000006/vmc-20231231xex21.htm)3] | | |
| Exhibit 23 | | [Consent of Deloitte & Touche LLP, Independent Registered Public Accounting [removed: Firm](https://www.sec.gov/Archives/edgar/data/1396009/000139600923000007/vmc-20221231xex23.htm)] [added: Firm](https://www.sec.gov/Archives/edgar/data/1396009/000139600924000006/vmc-20231231xex23.htm)] | | |
| Exhibit 24 | | [Powers of [removed: Attorney](https://www.sec.gov/Archives/edgar/data/1396009/000139600923000007/vmc-20221231xex24.htm)] [added: Attorney](https://www.sec.gov/Archives/edgar/data/1396009/000139600924000006/vmc-20231231xex24.htm)] | | |
| Exhibit 31(a) | | [Certification of Chief Executive Officer pursuant to Section 302 of the Sarbanes-Oxley Act of [removed: 2002](https://www.sec.gov/Archives/edgar/data/1396009/000139600923000007/vmc-20221231xex31.htm)] [added: 2002](https://www.sec.gov/Archives/edgar/data/1396009/000139600924000006/vmc-20231231xex31.htm)] | | |
| Exhibit 31(b) | | [Certification of Chief Financial Officer pursuant to Section 302 of the Sarbanes-Oxley Act of [removed: 2002](https://www.sec.gov/Archives/edgar/data/1396009/000139600923000007/vmc-20221231xex31.htm)] [added: 2002](https://www.sec.gov/Archives/edgar/data/1396009/000139600924000006/vmc-20231231xex31.htm)] | | |
| Exhibit 32(a) | | [Certification of Chief Executive Officer pursuant to Section 906 of the Sarbanes-Oxley Act of [removed: 2002](https://www.sec.gov/Archives/edgar/data/1396009/000139600923000007/vmc-20221231xex32.htm)] [added: 2002](https://www.sec.gov/Archives/edgar/data/1396009/000139600924000006/vmc-20231231xex32.htm)] | | |
| Exhibit 32(b) | | [Certification of Chief Financial Officer pursuant to Section 906 of the Sarbanes-Oxley Act of [removed: 2002](https://www.sec.gov/Archives/edgar/data/1396009/000139600923000007/vmc-20221231xex32.htm)] [added: 2002](https://www.sec.gov/Archives/edgar/data/1396009/000139600924000006/vmc-20231231xex32.htm)] | | |
| Part IV | 133 |
| Part IV | 134 |
| Exhibit 97 | | [Clawback Policy](https://www.sec.gov/Archives/edgar/data/1396009/000139600924000006/vmc-20231231xex97.htm) | | |
| Exhibit 10(f) | | [Second Amendment to Credit Agreement, dated March 18, 2022, by and between Vulcan Materials Company and Truist Bank, as Administrative Agent, filed as Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q filed on May 5, 2022 1](http://www.sec.gov/ix?doc=/Archives/edgar/data/0001396009/000139600922000017/vmc-20220331xex10_1.htm) | | |
| Exhibit 10(g) | | [Third Amendment to Credit Agreement, dated March 18, 2022, by and between Vulcan Materials Company and Truist Bank, as Administrative Agent, filed as Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q filed on May 5, 2022 1](http://www.sec.gov/ix?doc=/Archives/edgar/data/0001396009/000139600922000017/vmc-20220331xex10_2.htm) | | |
| Exhibit 10(h) | | [Fourth Amendment to Credit Agreement, dated as of August 8, 2022, among Vulcan Materials Company, Truist Bank, as Administrative Agent, and the Lenders and other parties named therein, filed as Exhibit 10.1 to the Company’s Current Report on Form 8-K filed on August 9, 2022 1](http://www.sec.gov/Archives/edgar/data/1396009/000119312522215212/d711767dex101.htm) | | |
| Part IV | 137 |
| Exhibit 10(aa) | | [Independent Contractor Consulting Agreement, dated August 31, 2022, between the Company and Suzanne H. Wood, filed as Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q filed on November 3, 2022 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600922000049/vmc-20220930xex10_2.htm) | | |
| Part IV | 138 |
An excerpt. Shown here: 40 of 43 rewritten, all 3 added and all 6 removed. The counts are complete. For every sentence, read Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES in the FY2023 filing and the FY2022 filing.
Item 16. FORM 10-K SUMMARY
6 rewritten, 2 added, 2 removed, 19 unchanged
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized on February [removed: 24, 2023.][added: 22, 2024.]
| | ] [added: 1](https://www.sec.gov/Archives/edgar/data/1396009/000139600924000006/vmc-20231231x10kg039.jpg)] J. Thomas Hill [removed: Chairman, President] [added: Chairman] and Chief Executive Officer |
| ] [added: 3](https://www.sec.gov/Archives/edgar/data/1396009/000139600924000006/vmc-20231231x10kg040.jpg)] J. Thomas Hill | [removed: Chairman, President] [added: Chairman] and Chief Executive Officer (Principal Executive Officer) | February [removed: 24, 2023] [added: 22, 2024] |
| ] [added: 24](https://www.sec.gov/Archives/edgar/data/1396009/000139600924000006/vmc-20231231x10kg041.jpg)] Mary Andrews Carlisle | Senior Vice President and Chief Financial Officer (Principal Financial Officer) | February [removed: 24, 2023] [added: 22, 2024] |
| ] [added: 38](https://www.sec.gov/Archives/edgar/data/1396009/000139600924000006/vmc-20231231x10kg042.jpg)] Randy L. Pigg | Vice President, Controller (Principal Accounting Officer) | February [removed: 24, 2023] [added: 22, 2024] |
| ] [added: 22](https://www.sec.gov/Archives/edgar/data/1396009/000139600924000006/vmc-20231231x10kg043.jpg)] Denson N. Franklin III Attorney-in-Fact | | February [removed: 24, 2023] [added: 22, 2024] |
| Part IV | 137 |
| Part IV | 138 |
| Part IV | 139 |
| Part IV | 140 |