 filings.tools
Vivmark Residential 10-Q 2022-09-30
Filed 2022-10-28. 8 sections, 212K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
Table of Contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-Q
| ☒ | QUARTERLY REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 For the quarterly period ended September 30, 2022 |
OR
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 For the transition period from to |
Commission File Number: 1-12252 (Equity Residential)
Commission File Number: 0-24920 (ERP Operating Limited Partnership)
EQUITY RESIDENTIAL
ERP OPERATING LIMITED PARTNERSHIP
(Exact name of registrant as specified in its charter)
| Maryland (Equity Residential) | 13-3675988 (Equity Residential) | |
| Illinois (ERP Operating Limited Partnership) | 36-3894853 (ERP Operating Limited Partnership) | |
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) | |
| Two North Riverside Plaza**,** Chicago**,** Illinois 60606 | (312) 474-1300 | |
| (Address of principal executive offices) (Zip Code) | (Registrant’s telephone number, including area code) |
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||
| Common Shares of Beneficial Interest, $0.01 Par Value (Equity Residential) | EQR | New York Stock Exchange | ||
| 7.57% Notes due August 15, 2026 (ERP Operating Limited Partnership) | N/A | New York Stock Exchange |
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days.
| Equity Residential Yes ☒ No ☐ | ERP Operating Limited Partnership Yes ☒ No ☐ |
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files).
| Equity Residential Yes ☒ No ☐ | ERP Operating Limited Partnership Yes ☒ No ☐ |
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
Equity Residential:
| Large accelerated filer | ☒ | Accelerated filer | ☐ | |||
| Non-accelerated filer | ☐ | Smaller reporting company | ☐ | |||
| Emerging growth company | ☐ |
l
ERP Operating Limited Partnership:
| Large accelerated filer | ☐ | Accelerated filer | ☐ | |||
| Non-accelerated filer | ☒ | Smaller reporting company | ☐ | |||
| Emerging growth company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act.
| Equity Residential ☐ | ERP Operating Limited Partnership ☐ |
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act).
| Equity Residential Yes ☐ No ☒ | ERP Operating Limited Partnership Yes ☐ No ☒ |
The number of EQR Common Shares of Beneficial Interest, $0.01 par value, outstanding on October 21, 2022 was 377,918,920.
Table of Contents
EXPLANATORY NOTE
This report combines the reports on Form 10-Q for the quarterly period ended September 30, 2022 of Equity Residential and ERP Operating Limited Partnership. Unless stated otherwise or the context otherwise requires, references to “EQR” mean Equity Residential, a Maryland real estate investment trust (“REIT”), and references to “ERPOP” mean ERP Operating Limited Partnership, an Illinois limited partnership. References to the “Company,” “we,” “us” or “our” mean collectively EQR, ERPOP and those entities/subsidiaries owned or controlled by EQR and/or ERPOP. References to the “Operating Partnership” mean collectively ERPOP and those entities/subsidiaries owned or controlled by ERPOP. The following chart illustrates the Company’s and the Operating Partnership’s corporate structure:
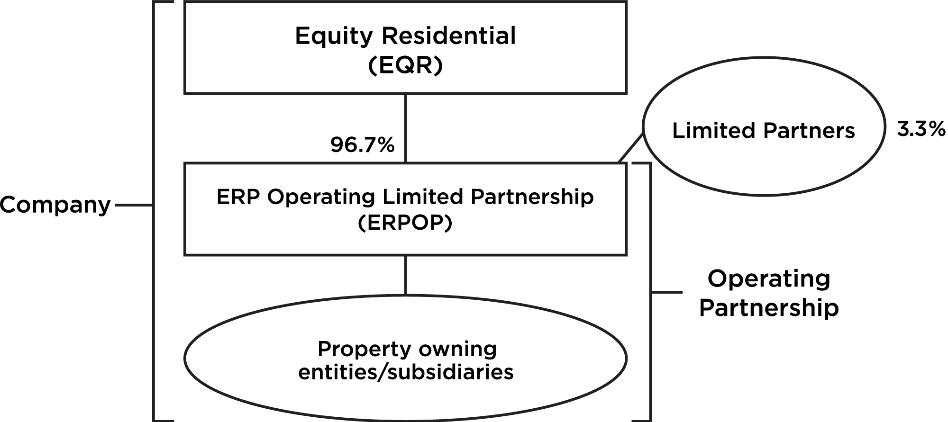
EQR is the general partner of, and as of September 30, 2022 owned an approximate 96.7% ownership interest in, ERPOP. The remaining 3.3% interest is owned by limited partners. As the sole general partner of ERPOP, EQR has exclusive control of ERPOP’s day-to-day management. Management operates the Company and the Operating Partnership as one business. The management of EQR consists of the same members as the management of ERPOP.
The Company is structured as an umbrella partnership REIT (“UPREIT”) and EQR contributes all net proceeds from its various equity offerings to ERPOP. In return for those contributions, EQR receives a number of OP Units (see definition below) in ERPOP equal to the number of Common Shares it has issued in the equity offering. The Company may acquire properties in transactions that include the issuance of OP Units as consideration for the acquired properties. Such transactions may, in certain circumstances, enable the sellers to defer in whole or in part, the recognition of taxable income or gain that might otherwise result from the sales. This is one of the reasons why the Company is structured in the manner shown above. Based on the terms of ERPOP’s partnership agreement, OP Units can be exchanged with Common Shares on a one-for-one basis because the Company maintains a one-for-one relationship between the OP Units of ERPOP issued to EQR and the outstanding Common Shares.
The Company believes that combining the reports on Form 10-Q of EQR and ERPOP into this single report provides the following benefits:
-
enhances investors’ understanding of the Company and the Operating Partnership by enabling investors to view the business as a whole in the same manner as management views and operates the business;
-
eliminates duplicative disclosure and provides a more streamlined and readable presentation since a substantial portion of the disclosure applies to both the Company and the Operating Partnership; and
-
creates time and cost efficiencies through the preparation of one combined report instead of two separate reports.
Table of Contents
The Company believes it is important to understand the few differences between EQR and ERPOP in the context of how EQR and ERPOP operate as a consolidated company. All of the Company’s property ownership, development and related business operations are conducted through the Operating Partnership and EQR has no material assets or liabilities other than its investment in ERPOP. EQR’s primary function is acting as the general partner of ERPOP. EQR also issues equity from time to time, the net proceeds of which it is obligated to contribute to ERPOP. EQR
Showing the first 8K of 150K characters. Open the full section
Item 2. Management’s Discussion and Analysis of Financial Condition and Results of Operations
For further information including definitions for capitalized terms not defined herein, refer to the consolidated financial statements and footnotes thereto included in the Company’s and the Operating Partnership’s Annual Report on Form 10-K for the year ended December 31, 2021. In addition, please refer to the Definitions section below for various capitalized terms not immediately defined in this Item 2, Management’s Discussion and Analysis of Financial Condition and Results of Operations.
Forward-Looking Statements
Forward-looking statements are intended to be made pursuant to the safe harbor provisions of the Private Securities Litigation Reform Act of 1995. These statements are based on current expectations, estimates, projections and assumptions made by management. While the Company’s management believes the assumptions underlying its forward-looking statements are reasonable, such information is inherently subject to uncertainties and may involve certain risks, which could cause actual results, performance or achievements of the Company to differ materially from anticipated future results, performance or achievements expressed or implied by such forward-looking statements. Many of these uncertainties and risks are difficult to predict and beyond management’s control, such as the current novel coronavirus (“COVID-19”) pandemic. Additional factors that might cause such differences are discussed in Part I of the Company’s and the Operating Partnership’s Annual Report on Form 10-K for the year ended December 31, 2021, particularly those under Item 1A, Risk Factors. Forward-looking statements and related uncertainties are also included in the Notes to Consolidated Financial Statements in this report*.* Forward-looking statements are not guarantees of future performance, results or events. The forward-looking statements contained herein are made as of the date hereof and the Company undertakes no obligation to update or supplement these forward-looking statements.
Overview
Equity Residential (“EQR”) is committed to creating communities where people thrive. The Company, a member of the S&P 500, is focused on the acquisition, development and management of residential properties located in and around dynamic cities that attract affluent long-term renters. ERP Operating Limited Partnership (“ERPOP”) is focused on conducting the multifamily property business of EQR. EQR is a Maryland real estate investment trust (“REIT”) formed in March 1993 and ERPOP is an Illinois limited partnership formed in May 1993. References to the “Company,” “we,” “us” or “our” mean collectively EQR, ERPOP and those entities/subsidiaries owned or controlled by EQR and/or ERPOP. References to the “Operating Partnership” mean collectively ERPOP and those entities/subsidiaries owned or controlled by ERPOP.
EQR is the general partner of, and as of September 30, 2022 owned an approximate 96.7% ownership interest in, ERPOP. All of the Company’s property ownership, development and related business operations are conducted through the Operating Partnership and EQR has no material assets or liabilities other than its investment in ERPOP. EQR issues equity from time to time, the net proceeds of which it is obligated to contribute to ERPOP, but does not have any indebtedness as all debt is incurred by the Operating Partnership. The Operating Partnership holds substantially all of the assets of the Company, including the Company’s ownership interests in its joint ventures. The Operating Partnership conducts the operations of the business and is structured as a partnership with no publicly traded equity.
The Company’s corporate headquarters is located in Chicago, Illinois and the Company also operates regional property management offices in most of its markets.
Table of Contents
Available Information
You may access our Annual Report on Form 10-K, our Quarterly Reports on Form 10-Q, our Current Reports on Form 8-K, our proxy statements and any amendments to any of those reports/statements we file with or furnish to the Securities and Exchange Commission (“SEC”) free of charge on our website, www.equityapartments.com. These reports/statements are made available on our website as soon as reasonably practicable after we file them with or furnish them to the SEC. The information contained on our website, including any information referred to in this report as being available on our website, is not a part of or incorporated into this report.
Business Objectives and Operating and Investing Strategies
The Company’s and the Operating Partnership’s overall business objectives and operating and investing strategies have not changed from the information included in the Company’s and the Operating Partnership’s Annual Report on Form 10-K for the year ended December 31, 2021.
Results of Operations
2022 Transactions
In conjunction with our business objectives and operating and investing strategies, the following table provides a rollforward of the transactions that occurred during the nine months ended September 30, 2022:
Portfolio Rollforward
($ in thousands)
| Properties | Apartment Units | Purchase Price | Acquisition Cap Rate | |||||||||||||
| 12/31/2021 | 310 | 80,407 | ||||||||||||||
| Acquisitions: | ||||||||||||||||
| Consolidated Rental Properties | 1 | 172 | $ | 113,000 | 3.5 | % | ||||||||||
| Unconsolidated Land Parcels (1) | — | — | $ | 56,886 | ||||||||||||
| Sales Price | Disposition Yield | |||||||||||||||
| Dispositions: | ||||||||||||||||
| Consolidated Rental Properties | (3 | ) | (945 | ) | $ | (746,150 | ) | (3.4 | %) | |||||||
| Configuration Changes | — | (40 | ) | |||||||||||||
| 9/30/2022 | 308 | 79,594 |
(1)
The purchase price listed represents the total consideration for the closing of the respective joint ventures.
Acquisitions
The consolidated property acquired during the nine months ended September 30, 2022 was located in San Diego, CA; and
During the nine months ended September 30, 2022, the Company acquired its joint venture partner’s 25% interest in a 432-unit apartment property in Chevy Chase, MD for $32.2 million, and the property is now wholly owned.
Dispositions
The consolidated properties disposed of during the nine months ended September 30, 2022 were located in New York City (2) and Washington, D.C. and the sales generated an Unlevered IRR of 5.3%.
Table of Contents
Developments
The Company commenced construction on one consolidated and three unconsolidated apartment properties during the nine months ended September 30, 2022, located in Santa Clara, CA, Fort Worth, TX, Frisco, TX and Dallas, TX, consisting of 1,278 apartment units in the aggregate totaling approximately $417.7 million of expected development costs;
The Company stabilized one consolidated apartment property during the nine months ended September 30, 2022, located in Bethesda, MD, consisting of 154 apartment units totaling approximately $73.0 million of development costs; and
The Company spent approximately $155.6 million during the nine months ended September 30, 2022, primarily for consolidated and unconsolidated development projects.
Investments in Unconsolidated Entities
The Company entered into two separate unconsolidated joint ventures during the nine months ended September 30, 2022 for the purpose of developing vacant land parcels in Frisco, TX and Wakefield, MA. The Company’s total investment in these two joint ventures is approximately $63.2 million as of September 30, 2022. One of the projects is related to the Company’s joint venture development program with Toll Brothers, Inc. (“Toll”), which commenced construction during the first quarter of 2022 prior to our entrance into the joint venture.
See Notes 4, 6 and 14 in the Notes to Consolidated Financial Statements for additional discussion regarding the Company’s real estate investments and investments in partially owned entities.
Future Outlook
The Company assumes consolidated rental acquisitions of approximately $113.0 million and consolidated rental dispositions of approximately $746.0 million during the year ending December 31, 2022. Given current uncertainty in the transaction environment, the Company’s acquisition and disposition assumptions reflect no additional activities beyond one land parcel sale for $5.5 million currently under contract and scheduled to close in the fourth quarter of 2022; and
We currently anticipate spending approximately $200.0 million on development costs during the year ending December 31, 2022, primarily for consolidated and unconsolidated properties currently under construction (amount only includes our share of development costs).
The above 2022 assumptions are based on current expectations and are forward-looking.
Comparison of the nine months and quarter ended September 30, 2022 to the nine months and quarter ended September 30, 2021
The following table presents a reconciliation of diluted earnings per share/unit for the nine months and quarter ended September 30, 2022 as compared to the same period in 2021:
| Nine Months Ended September 30 | Quarter Ended September 30 | |||||||
| Diluted earnings per share/unit for period ended 2021 | $ | 2.14 | $ | 1.15 | ||||
| Property NOI | 0.49 | 0.17 | ||||||
| Interest expense | (0.03 | ) | — | |||||
| Corporate overhead (1) | (0.03 | ) | (0.01 | ) | ||||
| Net gain/loss on property sales | (0.73 | ) | (0.43 | ) | ||||
| Non-operating asset gains/losses | (0.06 | ) | — | |||||
| Depreciation expense | (0.13 | ) | — | |||||
| Other | (0.02 | ) | (0.02 | ) | ||||
| Diluted earnings per share/unit for period ended 2022 | $ | 1.63 | $ | 0.86 |
(1)
Corporate overhead includes property management and general and administrative expenses.
The Company’s primary financial measure for evaluating each of its apartment communities is net operating income (“NOI”). NOI represents rental income less direct property operating expenses (including real estate taxes and insurance). The Company believes that NOI is helpful to investors as a supplemental measure of its operating performance because it is a direct measure of the actual operating results of the Company’s apartment properties.
Table of Contents
The following tables present reconciliations of operating income per the consolidated statements of operations to NOI, along with rental income, operating expenses and NOI per the consolidated statements of operations allocated between same store and non-same store results (amounts in thousands):
| Nine Months Ended September 30, | ||||||||||||||||
| 2022 | 2021 | $ Change | % Change | |||||||||||||
| Operating income | $ | 873,683 | $ | 1,033,958 | $ | (160,275 | ) | (15.5 | )% | |||||||
| Adjustments: | ||||||||||||||||
| Property management | 83,035 | 74,357 | 8,678 | 11.7 | % | |||||||||||
| General and administrative | 47,033 | 43,102 | 3,931 | 9.1 | % | |||||||||||
| Depreciation | 667,896 | 616,032 | 51,864 | 8.4 | % | |||||||||||
| Net (gain) loss on sales of real estate properties | (304,346 | ) | (587,623 | ) | 283,277 | (48.2 | )% | |||||||||
| Total NOI | $ | 1,367,301 | $ | 1,179,826 | $ | 187,475 | 15.9 | % | ||||||||
| Rental income: | ||||||||||||||||
| Same store | $ | 1,882,181 | $ | 1,694,503 | $ | 187,678 | 11.1 | % | ||||||||
| Non-same store/other | 153,296 | 124,364 | 28,932 | 23.3 | % | |||||||||||
| Total rental income | 2,035,477 | 1,818,867 | 216,610 | 11.9 | % | |||||||||||
| Operating expenses: | ||||||||||||||||
| Same store | 600,987 | 583,471 | 17,516 | 3.0 | % | |||||||||||
| Non-same store/other | 67,189 | 55,570 | 11,619 | 20.9 | % | |||||||||||
| Total operating expenses | 668,176 | 639,041 | 29,135 | 4.6 | % | |||||||||||
| NOI: | ||||||||||||||||
| Same store | 1,281,194 | 1,111,032 | 170,162 | 15.3 | % | |||||||||||
| Non-same store/other | 86,107 | 68,794 | 17,313 | 25.2 | % | |||||||||||
| Total NOI | $ | 1,367,301 | $ | 1,179,826 | $ | 187,475 | 15.9 | % |
Note: See Note 13 in the Notes to Consolidated Financial Statements for detail by reportable segment/market. Non-same store/other NOI results consist primarily of properties acquired in calendar years 2021 and 2022, operations from the Company’s development properties and operations prior to disposition from 2021 and 2022 sold properties.
The increase in same store rental income is primarily driven by strong Physical Occupancy and continued growth in pricing.
The increase in same store operating expenses is due primarily to:
Utilities – An $11.0 million increase primarily from gas and electric due to higher commodity prices;
Repairs and maintenance – A $6.8 million increase primarily driven by volume and timing of maintenance and repairs along with increases in minimum wage on contracted services; and
On-site payroll – A $4.5 million decrease due to improved sales and service staff utilization from various technology initiatives and higher than usual staffing vacancies during the current period.
The increase in non-same store/other NOI is due primarily to a positive impact of higher NOI from properties acquired during 2021 and 2022 of $45.2 million and higher NOI from development properties in lease-up of $14.6 million, partially offset by a negative impact of lost NOI from 2021 and 2022 dispositions of $41.1 million and a negative impact of $1.2 million in lower NOI from one former master-leased property and two properties that have been removed from same store while undergoing major renovations.
The increase in consolidated total NOI is primarily a result of the Company’s higher NOI from same store properties, largely due to improvement in same store revenues as noted above. Operating expense growth remains modest due to a combination of continued success in managing controllable expenses and modest growth in real estate tax expense (increased by only $1.2 million), leading to 15.3% same store NOI growth for the nine months ended September 30, 2022 as compared to the prior year period.
See the Same Store Results section below for additional discussion of those results.
Property management expenses include off-site expenses associated with the self-management of the Company’s properties as well as management fees paid to any third-party management companies. These expenses increased approximately $8.7 million or 11.7% and approximately $2.0 million or 8.2% for the nine months and quarter ended September 30, 2022, respectively, as compared to the prior year periods. These increases are primarily attributable to increases in payroll-related costs, training/conference costs, temporary help/contractors costs, travel costs and employment expenses, partially offset by decreases in legal and professional fees.
General and administrative expenses, which includes corporate operating expenses, increased approximately $3.9 million or 9.1% and approximately $0.3 million or 2.5% for the nine months and quarter ended September 30, 2022, respectively, as compared to the prior year periods, primarily due to increases in payroll-related costs, legal and professional fees and training/conference costs.
Table of Contents
Depreciation expense, which includes depreciation on non-real estate assets, increased approximately $51.9 million or 8.4% for the nine months ended September 30, 2022, as compared to the prior year period, primarily as a result of additional depreciation expense on properties acquired in 2021 and 2022 and development properties placed in service during 2021, partially offset by lower depreciation from properties sold in 2021 and 2022. Depreciation expense decreased approximately $1.3 million or 0.6% for the quarter ended September 30, 2022 as compared to the prior year period, primarily as a result of lower depreciation from properties sold in the fourth quarter of 2021 and 2022 and in-place leases for 2021 acquisitions being fully depreciated as of December 31, 2021, partially offset by additional depreciation expense on properties acquired in 2022 and development properties placed in service during 2021.
Net gain on sales of real estate properties decreased approximately $283.3 million or 48.2% and approximately $167.4 million or 46.0% for the nine months and quarter ended September 30, 2022, respectively, as compared to the prior year periods, primarily as a result of a lower sales volume with the sale of three consolidated apartment properties in 2022 as compared to the sale of ten consolidated apartment properties in the same period in 2021.
Interest and other income decreased approximately $20.4 million or 80.8% and approximately $0.3 million or 26.0% for the nine months and quarter ended September 30, 2022, respectively, as compared to the prior year periods. These decreases are primarily due to a gain of $23.6 million on the sale of various investment securities that occurred during 2021 but not during 2022, partially offset by increases in litigation settlement proceeds that occurred during 2022 but not during 2021.
Other expenses decreased approximately $1.7 million or 15.7% for the nine months ended September 30, 2022 as compared to the prior year period, primarily due to a decline in construction defect and litigation reserves recorded between 2022 and 2021, partially offset by increases in advocacy contributions and demolition/abatement costs. Other expenses increased approximately $0.3 million or 8.7% for the quarter ended September 30, 2022 as compared to the prior year period, primarily due to increases in advocacy contributions and demolition/abatement costs, partially offset by construction defect and litigation reserves that occurred during 2021 but not during 2022.
Interest expense, including amortization of deferred financing costs, increased approximately $14.6 million or 7.0% and approximately $4.3 million or 6.2% for the nine months and quarter ended September 30, 2022, respectively, as compared to the prior year periods. These increases are primarily due to higher overall interest rates and lower capitalized interest. The effective interest cost on all indebtedness, excluding debt extinguishment costs/prepayment penalties, for the nine months ended September 30, 2022 was 3.67% as compared to 3.51% for the prior year period, and for the quarter ended September 30, 2022 was 3.67% as compared to 3.46% for the prior year period. The Company capitalized interest of approximately $4.2 million and $12.4 million during the nine months ended September 30, 2022 and 2021, respectively, and $1.9 million and $4.2 million during the quarters ended September 30, 2022 and 2021, respectively.
Same Store Results
Properties that the Company owned and were stabilized for all of both of the nine months ended September 30, 2022 and 2021 (the “Nine-Month 2022 Same Store Properties”), which represented 72,869 apartment units, drove the Company’s results of operations. Properties are considered “stabilized” when they have achieved 90% occupancy for three consecutive months. Properties are included in same store when they are stabilized for all of the current and comparable periods presented.
The following table provides comparative total same store results and statistics for the Nine-Month 2022 Same Store Properties:
September YTD 2022 vs. September YTD 2021
Same Store Results/Statistics Including 72,869 Same Store Apartment Units
$ in thousands (except for Average Rental Rate)
| September YTD 2022 | September YTD 2021 | ||||||||||||||||||||||||||||
| Residential | % Change | Non- Residential | % Change | Total | % Change | Residential | Non- Residential | Total | |||||||||||||||||||||
| Revenues | $ | 1,813,450 | 11.2 | % | $ | 68,731 | 8.1 | % | $ | 1,882,181 | 11.1 | % | Revenues | $ | 1,630,928 | $ | 63,575 | $ | 1,694,503 | ||||||||||
| Expenses | $ | 583,185 | 3.0 | % | $ | 17,802 | 3.1 | % | $ | 600,987 | 3.0 | % | Expenses | $ | 566,210 | $ | 17,261 | $ | 583,471 | ||||||||||
| NOI | $ | 1,230,265 | 15.5 | % | $ | 50,929 | 10.0 | % | $ | 1,281,194 | 15.3 | % | NOI | $ | 1,064,718 | $ | 46,314 | $ | 1,111,032 | ||||||||||
| Average Rental Rate | $ | 2,866 | 10.5 | % | Average Rental Rate | $ | 2,594 | ||||||||||||||||||||||
| Physical Occupancy | 96.5 | % | 0.6 | % | Physical Occupancy | 95.9 | % | ||||||||||||||||||||||
| Turnover | 33.6 | % | (1.6 | %) | Turnover | 35.2 | % |
Note: Same store revenues for all leases are reflected on a straight-line basis in accordance with GAAP for the current and comparable periods.
Table of Contents
The following table provides results and statistics related to our Residential same store operations for the nine months ended September 30, 2022 and 2021:
September YTD 2022 vs. September YTD 2021
Same Store Residential Results/Statistics by Market
| Increase (Decrease) from Prior Year | ||||||||||||||||||||||||||||||||
| Markets/Metro Areas | Apartment Units | Sept. YTD 22 % of Actual NOI | Sept. YTD 22 Average Rental Rate | Sept. YTD 22 Weighted Average Physical Occupancy % | Sept. YTD 22 Turnover | Average Rental Rate | Physical Occupancy | Turnover | ||||||||||||||||||||||||
| Los Angeles | 14,662 | 20.0 | % | $ | 2,725 | 96.9 | % | 28.3 | % | 11.4 | % | 0.2 | % | (3.8 | %) | |||||||||||||||||
| Orange County | 4,028 | 5.8 | % | 2,591 | 97.1 | % | 25.8 | % | 13.6 | % | (0.6 | %) | (1.4 | %) | ||||||||||||||||||
| San Diego | 2,706 | 4.1 | % | 2,737 | 97.0 | % | 29.3 | % | 11.9 | % | (0.7 | %) | (5.2 | %) | ||||||||||||||||||
| Subtotal – Southern California | 21,396 | 29.9 | % | 2,701 | 97.0 | % | 28.0 | % | 11.8 | % | 0.0 | % | (3.5 | %) | ||||||||||||||||||
| San Francisco | 11,366 | 17.6 | % | 3,127 | 96.3 | % | 32.1 | % | 8.0 | % | 1.6 | % | (5.2 | %) | ||||||||||||||||||
| Washington, D.C. | 14,186 | 16.2 | % | 2,432 | 96.9 | % | 33.8 | % | 4.7 | % | 0.6 | % | (2.5 | %) | ||||||||||||||||||
| New York | 8,536 | 13.1 | % | 3,964 | 97.0 | % | 34.9 | % | 15.8 | % | 2.7 | % | 3.9 | % | ||||||||||||||||||
| Seattle | 9,331 | 11.4 | % | 2,472 | 95.1 | % | 41.9 | % | 10.7 | % | (0.7 | %) | 2.5 | % | ||||||||||||||||||
| Boston | 6,430 | 9.9 | % | 3,165 | 96.2 | % | 37.3 | % | 10.9 | % | 0.5 | % | (0.4 | %) | ||||||||||||||||||
| Denver | 1,624 | 1.9 | % | 2,275 | 96.9 | % | 48.4 | % | 12.0 | % | 0.2 | % | 2.5 | % | ||||||||||||||||||
| Total | 72,869 | 100.0 | % | $ | 2,866 | 96.5 | % | 33.6 | % | 10.5 | % | 0.6 | % | (1.6 | %) |
Note: The above table reflects Residential same store results only. Residential operations account for approximately 96.3% of total revenues for the nine months ended September 30, 2022.
Despite geopolitical and economic uncertainties, demand to live in our apartment communities remained healthy, which our financial results reflected, as we continued to capture the gap between in-place rent levels and market rent levels. Demand for our apartments continues to support strong Physical Occupancy with pricing that is largely in-line with expectations, including modest use of Leasing Concessions. Key operating drivers for this performance during 2022 include:
Pricing – Pricing (net of Leasing Concessions) in 2022 has been the strongest in the Company’s history, driven by continued improvement across the portfolio, especially in New York. After this unprecedented 2022 growth, pricing began to moderate in late August 2022, which is typical, with slightly greater than anticipated price sensitivity in Seattle and San Francisco as of late. The use of Leasing Concessions has also declined significantly from its peak in February 2021.
Physical Occupancy – Physical Occupancy of 96.5% for the nine months ended September 30, 2022 remained strong, exceeding 2021 levels and contributing to growth in Same Store Residential Revenues.
Percentage of Residents Renewing and Turnover – We continue to see a high Percentage of Residents Renewing in our portfolio, which we believe reflects both the strength of demand and quality of our product. The Percentage of Residents Renewing has been strong at 53.8% for the third quarter of 2022. Turnover remains low at 33.6% for the nine months ended September 30, 2022, reflecting a healthy and consistent trend of historically high resident retention.
In addition to these stronger fundamentals, bad debt, net has moderated during the nine months ended September 30, 2022 with improvement in resident collections primarily driven by receipt of governmental rental assistance payments on behalf of our residents.
Transaction activity has slowed as buyers and sellers adjust their expectations to a volatile economic climate and rising interest rates. While this type of environment can be challenging, the Company has traditionally found investment opportunities during periods of market dislocation as our ability to move quickly and our relatively low cost of capital creates flexibility that can provide us a competitive advantage.
Long-term, we expect elevated single family home ownership costs, positive household formation trends and the overall deficit in housing across the country to buffer the impact on our business from potential economic weakness. We also see our affluent resident base as being more resilient to rising inflation due to higher levels of disposable income and lower relative rent-to-income ratios.
Table of Contents
Liquidity and Capital Resources
With approximately $2.3 billion in readily available liquidity, a strong balance sheet, limited near-term maturities, very strong credit metrics and ample access to capital markets, the Company believes it is well positioned to meet its future obligations and opportunities. See further discussion below and Note 14 in the Notes to Consolidated Financial Statements for discussion of events, if any, subsequent to September 30, 2022.
Statements of Cash Flows
The following table sets forth our sources and uses of cash flows for the nine months ended September 30, 2022 and 2021 (amounts in thousands):
| Nine Months Ended September 30, | ||||||||
| 2022 | 2021 | |||||||
| Cash flow provided by (used for): | ||||||||
| Operating activities | $ | 1,120,228 | $ | 978,213 | ||||
| Investing activities | $ | 243,336 | $ | (309,589 | ) | |||
| Financing activities | $ | (1,602,333 | ) | $ | (541,603 | ) |
The following provides information regarding the Company’s cash flows from operating, investing and financing activities for the nine months ended September 30, 2022.
Operating Activities
Our operating cash flows are primarily impacted by NOI and its components, such as Average Rental Rates, Physical Occupancy levels and operating expenses related to our properties. Cash provided by operating activities for the nine months ended September 30, 2022 as compared to the prior year period, increased by approximately $142.0 million as a direct result of the NOI and other changes discussed above in Results of Operations.
Investing Activities
Our investing cash flows are primarily impacted by our transaction activity (acquisitions/dispositions), development spend, capital expenditures and unconsolidated joint venture activity. For the nine months ended September 30, 2022, key drivers were:
Acquired one consolidated rental property for approximately $113.0 million in cash;
Disposed of three consolidated rental properties, receiving net proceeds of approximately $720.3 million;
Invested $81.9 million primarily in development projects;
Invested $141.7 million in capital expenditures to real estate; and
Invested $136.5 million primarily in unconsolidated development joint venture entities as well as unconsolidated investments in real estate technology funds/companies for various technology initiatives.
Financing Activities
Our financing cash flows primarily relate to our borrowing activity (debt proceeds or repayment), distributions/dividends to shareholders and other Common Share activity. For the nine months ended September 30, 2022, key drivers were:
Obtained $37.4 million in variable rate construction mortgage debt that is non-recourse to the Company;
Repaid $264.1 million of mortgage loans (inclusive of scheduled principal repayments);
Repaid $500.0 million of unsecured notes by using disposition proceeds;
Acquired our joint venture partner’s 25% interest in an apartment property for $32.2 million;
Issued Common Shares related to share option exercises and ESPP purchases and received net proceeds of $24.3 million, which were contributed to the capital of the Operating Partnership in exchange for additional OP Units (on a one-for-one Common Share per OP Unit basis); and
Paid dividends/distributions on Common Shares, Preferred Shares, Units (including OP Units and restricted units) and noncontrolling interests in partially owned properties totaling approximately $740.0 million.
Table of Contents
Short-Term Liquidity and Cash Proceeds
The Company generally expects to meet its short-term liquidity requirements, including capital expenditures related to maintaining its existing properties and scheduled unsecured note and mortgage note repayments, through its working capital, net cash provided by operating activities and borrowings under the Company’s revolving credit facility and commercial paper program. Currently, the Company considers its cash provided by operating activities to be adequate to meet operating requirements and payments of distributions.
The following table presents the Company’s balances for cash and cash equivalents, restricted deposits and the available borrowing capacity on its revolving credit facility as of September 30, 2022 and December 31, 2021 (amounts in thousands):
| September 30, 2022 | December 31, 2021 | |||||||
| Cash and cash equivalents | $ | 44,788 | $ | 123,832 | ||||
| Restricted deposits | $ | 76,679 | $ | 236,404 | ||||
| Unsecured revolving credit facility availability | $ | 2,306,537 | $ | 2,181,372 |
Credit Facility and Commercial Paper Program
The Company has a $2.5 billion unsecured revolving credit facility maturing November 1, 2024. The Company has the ability to increase available borrowings by an additional $750.0 million by adding lenders to the facility, obtaining the agreement of existing lenders to increase their commitments or incurring one or more term loans. The interest rate on advances under the facility will generally be the London Interbank Offered Rate (“LIBOR”) plus a spread (currently 0.775%), or based on bids received from the lending group, and the Company pays an annual facility fee (currently 0.125%). Both the spread and the facility fee are dependent on the Company’s senior unsecured credit rating.
The unsecured revolving credit agreement contains provisions that establish a process for entering into an amendment to replace LIBOR under certain circumstances, such as the anticipated phase-out of LIBOR.
The Company may borrow up to a maximum of $1.0 billion under its commercial paper program subject to market conditions. The notes will be sold under customary terms in the United States commercial paper note market and will rank pari passu with all of the Company’s other unsecured senior indebtedness.
The Company limits its utilization of the revolving credit facility in order to maintain liquidity to support its $1.0 billion commercial paper program along with certain other obligations. The following table presents the availability on the Company’s unsecured revolving credit facility as of October 21, 2022 (amounts in thousands):
| October 21, 2022 | ||||
| Unsecured revolving credit facility commitment | $ | 2,500,000 | ||
| Commercial paper balance outstanding | (145,000 | ) | ||
| Unsecured revolving credit facility balance outstanding | — | |||
| Other restricted amounts | (3,463 | ) | ||
| Unsecured revolving credit facility availability | $ | 2,351,537 |
Dividend Policy
The Company declared a dividend/distribution for the first, second and third quarters of 2022 of $0.625 per share/unit in each quarter, an annualized increase of 3.7% over the amount paid in 2021. All future dividends/distributions remain subject to the discretion of the Company’s Board of Trustees.
Total dividends/distributions paid in October 2022 amounted to $242.7 million (excluding distributions on Partially Owned Properties), which consisted of certain distributions declared during the quarter ended September 30, 2022.
Table of Contents
Long-Term Financing and Capital Needs
The Company expects to meet its long-term liquidity requirements, such as lump sum unsecured note and mortgage debt maturities, property acquisitions and financing of development activities, through the issuance of secured and unsecured debt and equity securities (including additional OP Units), proceeds received from the disposition of certain properties and joint ventures, along with cash generated from operations after all distributions. The Company has a significant number of unencumbered properties available to secure additional mortgage borrowings should unsecured capital be unavailable or the cost of alternative sources of capital be too high. The value of and cash flow from these unencumbered properties are in excess of the requirements the Company must maintain in order to comply with covenants under its unsecured notes and line of credit. Of the $28.0 billion in investment in real estate on the Company’s balance sheet at September 30, 2022, $24.3 billion or 87.0% was unencumbered. However, there can be no assurances that these sources of capital will be available to the Company in the future on acceptable terms or otherwise.
EQR issues equity and guarantees certain debt of the Operating Partnership from time to time. EQR does not have any indebtedness as all debt is incurred by the Operating Partnership. The Company settled all of its outstanding forward sales agreements under its At-The-Market (“ATM”) share offering program subsequent to September 30, 2022. See Note 14 in the Notes to Consolidated Financial Statements for additional discussion.
The Company’s total debt summary schedule as of September 30, 2022 is as follows:
Debt Summary as of September 30, 2022
($ in thousands)
| Debt Balances | % of Total | |||||||
| Secured | $ | 1,967,827 | 26.2 | % | ||||
| Unsecured | 5,530,364 | 73.8 | % | |||||
| Total | $ | 7,498,191 | 100.0 | % | ||||
| Fixed Rate Debt: | ||||||||
| Secured – Conventional | $ | 1,634,342 | 21.8 | % | ||||
| Unsecured – Public | 5,340,807 | 71.2 | % | |||||
| Fixed Rate Debt | 6,975,149 | 93.0 | % | |||||
| Floating Rate Debt: | ||||||||
| Secured – Conventional | 97,611 | 1.3 | % | |||||
| Secured – Tax Exempt | 235,874 | 3.1 | % | |||||
| Unsecured – Revolving Credit Facility | — | — | ||||||
| Unsecured – Commercial Paper Program | 189,557 | 2.6 | % | |||||
| Floating Rate Debt | 523,042 | 7.0 | % | |||||
| Total | $ | 7,498,191 | 100.0 | % |
The Company’s long-term financing and capital needs and sources have not changed materially from the information included in the Company's and the Operating Partnership's Annual Report on Form 10-K for the year ended December 31, 2021.
Definitions
The definition of certain terms described above or below are as follows:
Acquisition Cap Rate – NOI that the Company anticipates receiving in the next 12 months (or the year two or three stabilized NOI for properties that are in lease-up at acquisition) less an estimate of property management costs/management fees allocated to the project (generally ranging from 2.0% to 4.0% of revenues depending on the size and income streams of the asset) and less an estimate for in-the-unit replacement capital expenditures (generally ranging from $100-$450 per apartment unit depending on the age and condition of the asset) divided by the gross purchase price of the asset. The weighted average Acquisition Cap Rate for acquired properties is weighted based on the projected NOI streams and the relative purchase price for each respective property.
Average Rental Rate – Total Residential rental revenues reflected on a straight-line basis in accordance with GAAP divided by the weighted average occupied apartment units for the reporting period presented.
Table of Contents
Disposition Yield – NOI that the Company anticipates giving up in the next 12 months less an estimate of property management costs/management fees allocated to the project (generally ranging from 2.0% to 4.0% of revenues depending on the size and income streams of the asset) and less an estimate for in-the-unit replacement capital expenditures (generally ranging from $100-$450 per apartment unit depending on the age and condition of the asset) divided by the gross sales price of the asset. The weighted average Disposition Yield for sold properties is weighted based on the projected NOI streams and the relative sales price for each respective property.
Leasing Concessions – Reflects upfront discounts on both new move-in and renewal leases on a straight-line basis.
Non-Residential – Consists of revenues and expenses from retail and public parking garage operations.
Non-Same Store Properties – For annual comparisons, primarily includes all properties acquired during 2021 and 2022, plus any properties in lease-up and not stabilized as of January 1, 2021.
Percentage of Residents Renewing – Leases renewed expressed as a percentage of total renewal offers extended during the reporting period.
Physical Occupancy – The weighted average occupied apartment units for the reporting period divided by the average of total apartment units available for rent for the reporting period.
Residential – Consists of multifamily apartment revenues and expenses.
Same Store Properties – For annual comparisons, primarily includes all properties acquired or completed that are stabilized prior to January 1, 2021, less properties subsequently sold. Properties are included in Same Store when they are stabilized for all of the current and comparable periods presented.
Same Store Residential Revenues – Revenues from our same store properties presented on a GAAP basis which reflects the impact of Leasing Concessions on a straight-line basis.
Turnover – Total Residential move-outs (including inter-property and intra-property transfers) divided by total Residential apartment units.
Unlevered Internal Rate of Return (“IRR”) – The Unlevered IRR on sold properties is the compound annual rate of return calculated by the Company based on the timing and amount of: (i) the gross purchase price of the property plus any direct acquisition costs incurred by the Company; (ii) total revenues earned during the Company’s ownership period; (iii) total direct property operating expenses (including real estate taxes and insurance) incurred during the Company’s ownership period; (iv) capital expenditures incurred during the Company’s ownership period; and (v) the gross sales price of the property net of selling costs.
Critical Accounting Policies and Estimates
The Company’s and the Operating Partnership’s critical accounting policies and estimates have not changed from the information included in the Company’s and the Operating Partnership’s Annual Report on Form 10-K for the year ended December 31, 2021.
Table of Contents
Funds From Operations and Normalized Funds From Operations
The following is the Company’s and the Operating Partnership’s reconciliation of net income to FFO available to Common Shares and Units / Units and Normalized FFO available to Common Shares and Units / Units for the nine months and quarters ended September 30, 2022 and 2021:
Funds From Operations and Normalized Funds From Operations
(Amounts in thousands)
| Nine Months Ended September 30, | Quarter Ended September 30, | |||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||
| Net income | $ | 641,641 | $ | 835,736 | $ | 335,165 | $ | 447,332 | ||||||||
| Net (income) loss attributable to Noncontrolling Interests – Partially Owned Properties | (2,726 | ) | (1,957 | ) | (1,143 | ) | (534 | ) | ||||||||
| Preferred/preference distributions | (2,318 | ) | (2,318 | ) | (773 | ) | (773 | ) | ||||||||
| Net income available to Common Shares and Units / Units | 636,597 | 831,461 | 333,249 | 446,025 | ||||||||||||
| Adjustments: | ||||||||||||||||
| Depreciation | 667,896 | 616,032 | 214,129 | 215,397 | ||||||||||||
| Depreciation – Non-real estate additions | (3,189 | ) | (3,228 | ) | (1,075 | ) | (1,052 | ) | ||||||||
| Depreciation – Partially Owned Properties | (2,097 | ) | (2,676 | ) | (543 | ) | (994 | ) | ||||||||
| Depreciation – Unconsolidated Properties | 1,897 | 1,867 | 657 | 634 | ||||||||||||
| Net (gain) loss on sales of unconsolidated entities - operating assets | (9 | ) | (4 | ) | — | — | ||||||||||
| Net (gain) loss on sales of real estate properties | (304,346 | ) | (587,623 | ) | (196,551 | ) | (363,928 | ) | ||||||||
| FFO available to Common Shares and Units / Units (1) (3) (4) | 996,749 | 855,829 | 349,866 | 296,082 | ||||||||||||
| Adjustments: | ||||||||||||||||
| Impairment – non-operating assets | — | — | — | — | ||||||||||||
| Write-off of pursuit costs | 3,296 | 3,557 | 781 | 910 | ||||||||||||
| Debt extinguishment and preferred share redemption (gains) losses | 4,316 | 264 | 3,847 | — | ||||||||||||
| Non-operating asset (gains) losses | (1,174 | ) | (23,014 | ) | 156 | 294 | ||||||||||
| Other miscellaneous items | 1,832 | 4,520 | 2,017 | 1,179 | ||||||||||||
| Normalized FFO available to Common Shares and Units / Units (2) (3) (4) | $ | 1,005,019 | $ | 841,156 | $ | 356,667 | $ | 298,465 | ||||||||
| FFO (1) (3) | $ | 999,067 | $ | 858,147 | $ | 350,639 | $ | 296,855 | ||||||||
| Preferred/preference distributions | (2,318 | ) | (2,318 | ) | (773 | ) | (773 | ) | ||||||||
| FFO available to Common Shares and Units / Units (1) (3) (4) | $ | 996,749 | $ | 855,829 | $ | 349,866 | $ | 296,082 | ||||||||
| Normalized FFO (2) (3) | $ | 1,007,337 | $ | 843,474 | $ | 357,440 | $ | 299,238 | ||||||||
| Preferred/preference distributions | (2,318 | ) | (2,318 | ) | (773 | ) | (773 | ) | ||||||||
| Normalized FFO available to Common Shares and Units / Units (2) (3) (4) | $ | 1,005,019 | $ | 841,156 | $ | 356,667 | $ | 298,465 |
(1)
The National Association of Real Estate Investment Trusts (“Nareit”) defines funds from operations (“FFO”) (December 2018 White Paper) as net income (computed in accordance with accounting principles generally accepted in the United States (“GAAP”)), excluding gains or losses from sales and impairment write-downs of depreciable real estate and land when connected to the main business of a REIT, impairment write-downs of investments in entities when the impairment is directly attributable to decreases in the value of depreciable real estate held by the entity and depreciation and amortization related to real estate. Adjustments for partially owned consolidated and unconsolidated partnerships and joint ventures are calculated to reflect funds from operations on the same basis.
(2)
Normalized funds from operations (“Normalized FFO”) begins with FFO and excludes:
-
the impact of any expenses relating to non-operating asset impairment;
-
pursuit cost write-offs;
-
gains and losses from early debt extinguishment and preferred share redemptions;
-
gains and losses from non-operating assets; and
-
other miscellaneous items.
Table of Contents
(3)
The Company believes that FFO and FFO available to Common Shares and Units / Units are helpful to investors as supplemental measures of the operating performance of a real estate company, because they are recognized measures of performance by the real estate industry and by excluding gains or losses from sales and impairment write-downs of depreciable real estate and excluding depreciation related to real estate (which can vary among owners of identical assets in similar condition based on historical cost accounting and useful life estimates), FFO and FFO available to Common Shares and Units / Units can help compare the operating performance of a company’s real estate between periods or as compared to different companies. The Company also believes that Normalized FFO and Normalized FFO available to Common Shares and Units / Units are helpful to investors as supplemental measures of the operating performance of a real estate company because they allow investors to compare the Company’s operating performance to its performance in prior reporting periods and to the operating performance of other real estate companies without the effect of items that by their nature are not comparable from period to period and tend to obscure the Company’s actual operating results. FFO, FFO available to Common Shares and Units / Units, Normalized FFO and Normalized FFO available to Common Shares and Units / Units do not represent net income, net income available to Common Shares / Units or net cash flows from operating activities in accordance with GAAP. Therefore, FFO, FFO available to Common Shares and Units / Units, Normalized FFO and Normalized FFO available to Common Shares and Units / Units should not be exclusively considered as alternatives to net income, net income available to Common Shares / Units or net cash flows from operating activities as determined by GAAP or as a measure of liquidity. The Company’s calculation of FFO, FFO available to Common Shares and Units / Units, Normalized FFO and Normalized FFO available to Common Shares and Units / Units may differ from other real estate companies due to, among other items, variations in cost capitalization policies for capital expenditures and, accordingly, may not be comparable to such other real estate companies.
(4)
FFO available to Common Shares and Units / Units and Normalized FFO available to Common Shares and Units / Units are calculated on a basis consistent with net income available to Common Shares / Units and reflects adjustments to net income for preferred distributions and premiums on redemption of preferred shares/preference units in accordance with GAAP. The equity positions of various individuals and entities that contributed their properties to the Operating Partnership in exchange for OP Units are collectively referred to as the “Noncontrolling Interests – Operating Partnership”. Subject to certain restrictions, the Noncontrolling Interests – Operating Partnership may exchange their OP Units for Common Shares on a one-for-one basis.
Item 3. Quantitative and Qualitative Disclosures About Market Risk
The Company’s and the Operating Partnership’s market risk has not changed materially from the amounts and information reported in Part II, Item 7A, Quantitative and Qualitative Disclosures About Market Risk, to the Company’s and the Operating Partnership’s Annual Report on Form 10-K for the year ended December 31, 2021.
Item 4. Controls and Procedures
Equity Residential
(a)
Evaluation of Disclosure Controls and Procedures:
Effective as of September 30, 2022, the Company carried out an evaluation, under the supervision and with the participation of the Company’s management, including the Chief Executive Officer and Chief Financial Officer, of the effectiveness of the Company’s disclosure controls and procedures pursuant to Exchange Act Rules 13a-15 and 15d-15. Based on that evaluation, the Chief Executive Officer and Chief Financial Officer concluded that the disclosure controls and procedures are effective to ensure that information required to be disclosed by the Company in its Exchange Act filings is recorded, processed, summarized and reported within the time periods specified in the SEC’s rules and forms.
(b)
Changes in Internal Control over Financial Reporting:
There were no changes to the internal control over financial reporting of the Company identified in connection with the Company’s evaluation referred to above that occurred during the third quarter of 2022 that have materially affected, or are reasonably likely to materially affect, the Company’s internal control over financial reporting.
ERP Operating Limited Partnership
(a)
Evaluation of Disclosure Controls and Procedures:
Effective as of September 30, 2022, the Operating Partnership carried out an evaluation, under the supervision and with the participation of the Operating Partnership’s management, including the Chief Executive Officer and Chief Financial Officer of EQR, of the effectiveness of the Operating Partnership’s disclosure controls and procedures pursuant to Exchange Act Rules 13a-15 and 15d-15. Based on that evaluation, the Chief Executive Officer and Chief Financial Officer concluded that the disclosure controls and procedures are effective to ensure that information required to be disclosed by the Operating Partnership in its Exchange Act filings is recorded, processed, summarized and reported within the time periods specified in the SEC’s rules and forms.
Table of Contents
(b)
Changes in Internal Control over Financial Reporting:
There were no changes to the internal control over financial reporting of the Operating Partnership identified in connection with the Operating Partnership’s evaluation referred to above that occurred during the third quarter of 2022 that have materially affected, or are reasonably likely to materially affect, the Operating Partnership’s internal control over financial reporting.
PART II. OTHER INFORMATION
Item 1. Legal Proceedings
As of September 30, 2022, the Company does not believe there is any litigation pending or threatened against it that, individually or in the aggregate, may reasonably be expected to have a material adverse effect on the Company.
Item 1A. Risk Factors
There have been no material changes to the risk factors that were discussed in Part I, Item 1A of the Company’s and the Operating Partnership’s Annual Report on Form 10-K for the year ended December 31, 2021.
Item 2. Unregistered Sales of Equi****ty Securities and Use of Proceeds
During the quarter ended September 30, 2022, EQR issued 6,572 Common Shares in exchange for 6,572 OP Units held by various limited partners of ERPOP. OP Units are generally exchangeable into Common Shares on a one-for-one basis or, at the option of ERPOP, the cash equivalent thereof, at any time one year after the date of issuance. These shares were either registered under the Securities Act of 1933, as amended (the “Securities Act”), or issued in reliance on an exemption from registration under Section 4(a)(2) of the Securities Act and the rules and regulations promulgated thereunder, as these were transactions by an issuer not involving a public offering. In light of the manner of the sale and information obtained by EQR from the limited partners in connection with these transactions, EQR believes it may rely on these exemptions.
Item 3. Defaults Up****on Senior Securities
None.
Item 4. Mine Saf****ety Disclosures
Not applicable.
Item 5. Other Information
None.
Item 6. Exhibits – See the Exhibit Index.
Table of Contents
EXHIBI****T INDEX
The exhibits listed below are filed as part of this report. References to exhibits or other filings under the caption “Location” indicate that the exhibit or other filing has been filed, that the indexed exhibit and the exhibit referred to are the same and that the exhibit referred to is incorporated by reference. The Commission file numbers for our Exchange Act filings referenced below are 1-12252 (Equity Residential) and 0-24920 (ERP Operating Limited Partnership).
Table of Contents
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, each registrant has duly caused this report to be signed on its behalf by the undersigned thereunto duly authorized.
| EQUITY RESIDENTIAL | ||||
| Date: | October 28, 2022 | By: | /s/ Robert A. Garechana | |
| Robert A. Garechana | ||||
| Executive Vice President and Chief Financial Officer | ||||
| (Principal Financial Officer) | ||||
| Date: | October 28, 2022 | By: | /s/ Ian S. Kaufman | |
| Ian S. Kaufman | ||||
| Senior Vice President and Chief Accounting Officer | ||||
| (Principal Accounting Officer) |
| ERP OPERATING LIMITED PARTNERSHIP BY: EQUITY RESIDENTIAL ITS GENERAL PARTNER | ||||
| Date: | October 28, 2022 | By: | /s/ Robert A. Garechana | |
| Robert A. Garechana | ||||
| Executive Vice President and Chief Financial Officer | ||||
| (Principal Financial Officer) | ||||
| Date: | October 28, 2022 | By: | /s/ Ian S. Kaufman | |
| Ian S. Kaufman | ||||
| Senior Vice President and Chief Accounting Officer | ||||
| (Principal Accounting Officer) |