 filings.tools
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
95K characters. Original on sec.gov · Markdown
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
| --- | --- |
The Company’s common stock is registered under the Exchange Act, and is listed on the New York Stock Exchange under the symbol “WAT”. As of February 16, 2018, the Company had 92 common stockholders of record. The Company has not declared or paid any dividends on its common stock in its past three fiscal years. The Company has not made any sales of unregistered equity securities in the years ended December 31, 2017, 2016 or 2015.
Securities Authorized for Issuance under Equity Compensation Plans
Equity compensation plan information is incorporated by reference from Part III, Item 12, Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters, of this document and should be considered an integral part of this Item 5.
Table of Contents
Stock Price Performance Graph
The following performance graph and related information shall not be deemed to be “soliciting material” or to be “filed” with the SEC, nor shall such information be incorporated by reference into any future filing under the Securities Act of 1933, as amended, or the Exchange Act, except to the extent that the Company specifically incorporates it by reference into such filing.
The following graph compares the cumulative total return on $100 invested as of December 31, 2012 (the last day of public trading of the Company’s common stock in fiscal year 2012) through December 31, 2017 (the last day of public trading of the common stock in fiscal year 2017) in the Company’s common stock, the NYSE Market Index, the SIC Code 3826 Index, the S&P 500 Index and the S&P Health Care Index. The return of the indices is calculated assuming reinvestment of dividends during the period presented. The Company has not paid any dividends since its IPO. The stock price performance shown on the graph below is not necessarily indicative of future price performance.
COMPARISON OF CUMULATIVE TOTAL RETURN SINCE DECEMBER 31, 2012
AMONG WATERS CORPORATION, NYSE MARKET INDEX, SIC CODE 3826 INDEX –
LABORATORY ANALYTICAL INSTRUMENTS, S&P 500 INDEX
AND S&P HEALTH CARE INDEX
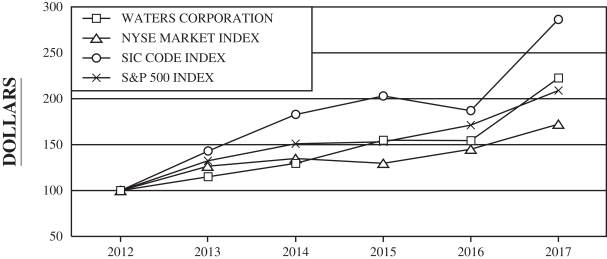
| 2012 | 2013 | 2014 | 2015 | 2016 | 2017 | |||||||||||||||||||
| WATERS CORPORATION | $ | 100.00 | $ | 114.78 | $ | 129.38 | $ | 154.48 | $ | 154.26 | $ | 221.75 | ||||||||||||
| NYSE MARKET INDEX | $ | 100.00 | $ | 126.28 | $ | 134.81 | $ | 129.29 | $ | 144.73 | $ | 171.83 | ||||||||||||
| SIC CODE INDEX | $ | 100.00 | $ | 142.80 | $ | 182.12 | $ | 202.31 | $ | 186.41 | $ | 285.16 | ||||||||||||
| S&P 500 INDEX | $ | 100.00 | $ | 132.39 | $ | 150.51 | $ | 152.59 | $ | 170.84 | $ | 208.14 |
Table of Contents
Market for Registrant’s Common Equity
The quarterly range of high and low sales prices for the Company’s common stock as reported by the New York Stock Exchange is as follows:
| Price Range | ||||||||
| For the Quarter Ended | High | Low | ||||||
| April 2, 2016 | $ | 133.60 | $ | 112.00 | ||||
| July 2, 2016 | $ | 143.73 | $ | 128.90 | ||||
| October 1, 2016 | $ | 162.53 | $ | 140.76 | ||||
| December 31, 2016 | $ | 160.00 | $ | 133.35 | ||||
| April 1, 2017 | $ | 158.81 | $ | 134.68 | ||||
| July 1, 2017 | $ | 187.65 | $ | 154.15 | ||||
| September 30, 2017 | $ | 190.39 | $ | 171.32 | ||||
| December 31, 2017 | $ | 201.95 | $ | 179.27 |
Purchases of Equity Securities by the Issuer
The following table provides information about purchases by the Company during the three months ended December 31, 2017 of equity securities registered by the Company under the Exchange Act (in thousands, except per share data):
| Period | Total Number of Shares Purchased (1) | Average Price Paid per Share | Total Number of Shares Purchased as Part of Publicly Announced Programs (2) | Maximum Dollar Value of Shares that May Yet Be Purchased Under the Programs (2) | ||||||||||||
| October 1 to October 28, 2017 | — | $ | — | — | $ | 885,182 | ||||||||||
| October 28 to November 25, 2017 | 260 | $ | 196.20 | 260 | $ | 834,170 | ||||||||||
| November 26 to December 31, 2017 | 182 | $ | 196.65 | 171 | $ | 800,462 | ||||||||||
| Total | 442 | $ | 196.39 | 431 | $ | 800,462 | ||||||||||
| (1) | The Company repurchased $10 million of common stock related to the vesting of restricted stock units during 2017. |
|---|
| (2) | In May 2017, the Company’s Board of Directors authorized the repurchase of up to $1 billion of its outstanding common stock in open market transactions over a three-year period. |
|---|
Table of Contents
| Item 6: Selected | Financial Data |
|---|
The following table sets forth selected historical consolidated financial and operating data for the periods indicated. The statement of operations and balance sheet data is derived from financial statements for the years 2017, 2016, 2015, 2014 and 2013. The Company’s financial statements as of December 31, 2017 and 2016, and for each of the three years in the period ended December 31, 2017 are included in Item 8, Financial Statements and Supplementary Data, in Part II of this Form 10-K.
| In thousands, except per share and employees data | 2017 | 2016 | 2015 | 2014 | 2013 | |||||||||||||||
| STATEMENT OF OPERATIONS DATA: | ||||||||||||||||||||
| Net sales | $ | 2,309,078 | $ | 2,167,423 | $ | 2,042,332 | $ | 1,989,344 | $ | 1,904,218 | ||||||||||
| Income from operations before income taxes | $ | 641,097 | $ | 600,114 | $ | 541,919 | $ | 490,740 | $ | 490,105 | ||||||||||
| Net income* | $ | 20,311 | $ | 521,503 | $ | 469,053 | $ | 431,620 | $ | 450,003 | ||||||||||
| Net income per basic common share* | $ | 0.25 | $ | 6.46 | $ | 5.70 | $ | 5.12 | $ | 5.27 | ||||||||||
| Weighted-average number of basic common shares | 79,793 | 80,786 | 82,336 | 84,358 | 85,426 | |||||||||||||||
| Net income per diluted common share* | $ | 0.25 | $ | 6.41 | $ | 5.65 | $ | 5.07 | $ | 5.20 | ||||||||||
| Weighted-average number of diluted common shares and equivalents | 80,604 | 81,417 | 83,087 | 85,151 | 86,546 | |||||||||||||||
| BALANCE SHEET AND OTHER DATA: | ||||||||||||||||||||
| Cash, cash equivalents and investments | $ | 3,393,701 | $ | 2,813,032 | $ | 2,399,263 | $ | 2,055,388 | $ | 1,803,670 | ||||||||||
| Working capital, including current maturities of debt** | $ | 3,663,977 | $ | 3,115,124 | $ | 2,649,457 | $ | 2,236,558 | $ | 2,038,100 | ||||||||||
| Total assets** | $ | 5,324,354 | $ | 4,662,059 | $ | 4,268,677 | $ | 3,874,690 | $ | 3,580,106 | ||||||||||
| Long-term debt** | $ | 1,897,501 | $ | 1,701,966 | $ | 1,493,027 | $ | 1,237,463 | $ | 1,188,162 | ||||||||||
| Stockholders’ equity | $ | 2,233,788 | $ | 2,301,949 | $ | 2,058,851 | $ | 1,894,666 | $ | 1,763,173 | ||||||||||
| Employees | 7,020 | 6,899 | 6,594 | 6,161 | 5,965 |
| * | The provision for income taxes for 2017 includes a $550 million estimate for the impact of the enactment of the 2017 Tax Act, which was signed into law on December 22, 2017. The $550 million income tax provision reduced net income per share by $6.82. The $550 million income tax provision primarily consists of an estimated Transition Tax as well as estimated income tax provisions for state and withholding taxes and a provision associated with the remeasurement of the Company’s deferred tax assets and liabilities from 35% to the new U.S. corporate income tax rate of 21%. |
|---|
The Company adopted new accounting guidance related to stock-based compensation in 2017. The new accounting guidance requires the excess tax benefits or deficiencies related to stock-based compensation to be reflected in the consolidated statements of operations as a component of the provision for income taxes, whereas they were previously recognized in equity. This aspect of the new accounting guidance was required to be adopted on a prospective basis for the statement of operations and retroactive restatement is not permitted. In 2017, the Company recognized an excess tax benefit, which decreased income tax expense by $20 million and added $0.24 to net income per diluted share.
| ** | In 2015, the Company adopted new accounting guidance related to the presentation of debt issuance costs and deferred income taxes, both standards have been applied above retrospectively. Certain debt issuance costs have been reclassified from intangible assets and are presented as a direct deduction from the carrying value of the associated debt. Current deferred tax assets and liabilities have been reclassified as non-current deferred tax assets and liabilities. |
|---|
Table of Contents
| Item 7: Management’s | Discussion and Analysis of Financial Condition and Results of Operations |
|---|
Business and Financial Overview
The Company has two operating segments: Waters® and TA®. Waters products and services primarily consist of high performance liquid chromatography (“HPLC”), ultra performance liquid chromatography (“UPLC®” and together with HPLC, referred to as “LC”), mass spectrometry (“MS”) and precision chemistry consumable products and related services. TA products and services primarily consist of thermal analysis, rheometry and calorimetry instrument systems and service sales. The Company’s products are used by pharmaceutical, biochemical, industrial, nutritional safety, environmental, academic and governmental customers. These customers use the Company’s products to detect, identify, monitor and measure the chemical, physical and biological composition of materials and to predict the suitability and stability of fine chemicals, pharmaceuticals, water, polymers, metals and viscous liquids in various industrial, consumer goods and healthcare products.
The Company’s operating results are as follows for the years ended December 31, 2017, 2016 and 2015 (dollars in thousands, except per share data):
| Year Ended December 31, | % change | |||||||||||||||||||
| 2017 | 2016 | 2015 | 2017 vs. 2016 | 2016 vs. 2015 | ||||||||||||||||
| Revenues: | ||||||||||||||||||||
| Product sales | $ | 1,552,349 | $ | 1,460,296 | $ | 1,385,256 | 6 | % | 5 | % | ||||||||||
| Service sales | 756,729 | 707,127 | 657,076 | 7 | % | 8 | % | |||||||||||||
| Total net sales | 2,309,078 | 2,167,423 | 2,042,332 | 7 | % | 6 | % | |||||||||||||
| Costs and operating expenses: | ||||||||||||||||||||
| Cost of sales | 947,067 | 891,453 | 842,672 | 6 | % | 6 | % | |||||||||||||
| Selling and administrative expenses | 544,703 | 513,031 | 495,747 | 6 | % | 3 | % | |||||||||||||
| Research and development expenses | 132,593 | 125,187 | 118,545 | 6 | % | 6 | % | |||||||||||||
| Litigation provisions | 11,114 | 3,524 | 3,939 | 215 | % | (11 | %) | |||||||||||||
| Purchased intangibles amortization | 6,743 | 9,889 | 10,123 | (32 | %) | (2 | %) | |||||||||||||
| Acquired in-process research and development | 5,000 | — | 3,855 | — | (100 | %) | ||||||||||||||
| Operating income | 661,858 | 624,339 | 567,451 | 6 | % | 10 | % | |||||||||||||
| Operating income as a % of sales | 28.7 | % | 28.8 | % | 27.8 | % | ||||||||||||||
| Interest expense, net | (20,761 | ) | (24,225 | ) | (25,532 | ) | (14 | %) | (5 | %) | ||||||||||
| Income before income taxes | 641,097 | 600,114 | 541,919 | 7 | % | 11 | % | |||||||||||||
| Provision for income taxes | 620,786 | 78,611 | 72,866 | 690 | % | 8 | % | |||||||||||||
| Net income | $ | 20,311 | $ | 521,503 | $ | 469,053 | (96 | %) | 11 | % | ||||||||||
| Net income per diluted common share | $ | 0.25 | $ | 6.41 | $ | 5.65 | (96 | %) | 13 | % |
In 2017, the Company’s sales increased 7% as compared to 2016. This growth was balanced across all customer and product classes. Instrument system sales increased 6% and 4% in 2017 and 2016, respectively. The increased demand for instrument system sales in 2017 was balanced across our LC-MS and TA instrument systems, while the increase in 2016 was primarily due to LC-MS instrument systems. Recurring revenues (combined sales of precision chemistry consumables and services) increased 7% and 8% in 2017 and 2016, respectively, as a result of a larger installed base of customers and higher billing demand for service sales.
Geographically, the Company experienced 10% sales growth in both Europe and Asia in 2017, while sales in the Americas was flat in 2017 as compared to the previous year. The Americas’ sales growth was negatively impacted by natural disasters in the U.S., Mexico and Puerto Rico, as well as weaker customer sentiment in the first half of 2017. Europe’s sales growth can be primarily attributed to the increase in customer demand from the improvement in the European economy as well as the effect of foreign currency translation, which added 2% to
Table of Contents
sales growth in 2017. Asia’s sales growth was a result of the double-digit sales growth in China and India on strong demand for our products and services in those countries and in spite of lower customer demand in India in the second half of 2017 resulting from the implementation of the new Goods and Services Tax system.
In 2016, the Company’s sales grew 6% as compared to 2015, with strong sales in our pharmaceutical and industrial markets, including balance across all product classes. The effect of foreign currency translation increased sales by 1% in 2017 and decreased sales by 1% in 2016 across all products and services. Recent acquisitions had a minimal impact on sales growth in both 2017 and 2016.
Sales to pharmaceutical customers grew 7% and 9% in 2017 and 2016, respectively. These increases were driven by the increasing need for global access to prescription drugs and the testing of newer and more complex biologic drugs. Geographically, the growth within our pharmaceutical market in 2017 was driven by double-digit growth in China, India and Europe, while sales growth in 2016 was driven by double-digit growth in China and Japan.
Combined sales to industrial customers, which includes materials characterization, food, environmental and fine chemical markets, grew 4% and 6% in 2017 and 2016, respectively. The growth in both 2017 and 2016 was driven by recent product introductions and rising global regulatory standards in both food and materials markets. Geographically, industrial market sales growth was highest in China and India in 2017, with modest growth in other regions offset by flat sales in the Americas. In 2016, industrial market sales growth was highest in Europe, followed by Asia and offset by weakness in the U.S.
Combined sales to governmental and academic customers increased 8% in 2017 and decreased 4% in 2016. The increase in sales to governmental and academic customers in 2017 was broad-based across all geographies, with double-digit growth in Europe and the Americas. The decreases in 2016 were a result of these institutions reducing their spending on the Company’s products. In 2016, combined sales to governmental and academic customers grew in China and India but declined in all other regions. Sales to governmental and academic customers are highly dependent on when institutions receive funding to purchase our instrument systems and, as such, sales growth rates can vary significantly from period to period.
Operating income was $662 million in 2017, an increase of 6% as compared to 2016. This increase was primarily a result of the effect of higher sales volume achieved in 2017 being somewhat offset by the impact of $13 million of severance costs primarily associated with the closure of a facility in Germany and costs associated with providing U.S. employees with an early retirement transition incentive; an $11 million litigation settlement provision and related costs and a $5 million charge relating to a milestone payment for the licensing of certain intellectual property relating to mass spectrometry technologies yet to be commercialized. The change in operating income in 2017 as compared with 2016 was also impacted by $4 million of expense in 2017 related to the acceleration of certain stock awards as compared to $7 million of similar expense in 2016. Operating income increased 10% in 2016 as compared to 2015 as a result of higher sales volumes achieved in 2016 and the positive impact of foreign currency translation on our U.K. manufacturing and research and development costs as a result of the significantly weaker British Pound.
The provision for income taxes for 2017 includes a $550 million estimate for the impact of the enactment of the legislation informally referred to as the Tax Cuts and Jobs Act (the “2017 Tax Act”), which was signed into law on December 22, 2017. The 2017 Tax Act changed the U.S. tax system to a territorial system, including base broadening measures requiring the taxation of the Company’s historical unremitted foreign earnings through a deemed repatriation, which resulted in a $550 million income tax provision that reduced net income per share by $6.82 for the twelve months ended December 31, 2017, as well as eliminating or reducing certain domestic deductions and credits and limiting the deductibility of interest expense and executive compensation. The $550 million income tax provision primarily consists of an estimated Transition Toll Tax (“Transition Tax”) of $490 million, as well as estimated income tax provisions for state and withholding taxes of $40 million and a $20 million provision associated with the remeasurement of the Company’s deferred tax assets and liabilities
Table of Contents
from 35% to the new U.S. corporate income tax rate of 21%. The Transition Tax will be paid over an eight-year period, starting in 2018, and will not accrue interest. As a result of the 2017 Tax Act, the Company was able to gain access to its cash and investment balances held outside the U.S. in a tax efficient manner that can be used for any general corporate purposes in the U.S. Going forward, the Company estimates that its effective income tax rate will increase approximately one to three percentage points in the future. The final impact of the 2017 Tax Act may differ from these estimates due to, among other things, changes in interpretations, analysis and assumptions made by the Company, additional guidance that may be issued by the U.S. Department of the Treasury, and tax planning actions that the Company may undertake.
In the first quarter of 2017, the Company adopted a new accounting standard that requires the excess tax benefit or deficiency on stock-based compensation to be included in the statement of operations as a component of the provision for income taxes, whereas previously it was recognized in equity. As a result, the Company recorded a tax benefit on stock-based compensation in 2017 that decreased income tax expense by $20 million and added $0.24 to net income per diluted share, respectively. Additionally, this standard required the Company to present the tax benefit in the consolidated statements of cash flows as an operating activity, whereas in the past this tax benefit was reflected as a financing activity. All prior periods presented in the cash flow have been adjusted accordingly.
The Company generated $698 million, $643 million and $573 million of net cash flows from operations in 2017, 2016 and 2015, respectively. The increases in operating cash flow in each year were primarily a result of the increase in sales and operating income. Beginning in 2018, and for the next four years, the Company is required to make annual U.S. federal tax payments of approximately $40 million to tax authorities in connection with the estimated $550 million 2017 Tax Act liabilities. The remaining 60% of this liability is required to be paid over a three-year period beginning in 2023. Also as a result of the 2017 Tax Act, the Company is expecting to make $40 million in state and withholding tax payments during 2018.
Cash flows used in investing activities included capital expenditures related to property, plant, equipment and software capitalization of $85 million, $95 million and $100 million in 2017, 2016 and 2015, respectively. In 2017, the Company made a $7 million payment for an investment in a developer of analytical system solutions used to make measurements, predict stability and accelerate product discovery in the routine analytic, process monitoring and quality control release processes for life science and biopharmaceutical markets. In addition, the Company made a milestone payment of $5 million in 2017 to acquire and license intellectual property. In September 2016, the Company acquired Rubotherm GmbH for approximately $6 million in cash. In February 2018, the Company’s Board of Directors approved expanding its precision chemistry consumable manufacturing operations. The Company anticipates spending an estimated $215 million to build and equip this new state-of-the-art manufacturing facility, which will be paid for with existing cash and investments and the Company does not expect to issue any debt in relation to this expansion.
In November 2017, the Company entered into a new credit agreement (the “2017 Credit Agreement”) that provides for a $1.5 billion revolving facility and a $300 million term loan. The revolving facility and term loan both mature on November 30, 2022 and require no scheduled prepayments before that date. The Company used $1.3 billion of the proceeds from the 2017 Credit Agreement to repay the outstanding amounts under the Company’s existing multi-borrower credit agreement dated June 2013 (the “2013 Credit Agreement”), which was terminated early without penalty. In May 2017, the Company’s Board of Directors authorized the Company to repurchase up to $1 billion of its outstanding common stock over a three-year period. During 2017, 2016 and 2015, the Company repurchased $323 million, $318 million and $327 million of the Company’s outstanding common stock, respectively, under authorized share repurchase programs. The Company believes that it has the financial flexibility to fund these share repurchases given current cash and investment levels and debt borrowing capacity, as well as to invest in research, technology and business acquisitions to further grow the Company’s sales and profits, especially now that the 2017 Tax Act provides the Company with access to its offshore cash at much lower income tax rates. As a result, the Company currently anticipates using $1 billion of cash repatriated into the U.S. to reduce debt and repurchase common stock shares on the open market during 2018.
Table of Contents
Results of Operations
Sales by Geography
Geographic sales information is presented below for the years ended December 31, 2017, 2016 and 2015 (in thousands):
| Year Ended December 31, | % change | |||||||||||||||||||
| 2017 | 2016 | 2015 | 2017 vs. 2016 | 2016 vs. 2015 | ||||||||||||||||
| Net Sales: | ||||||||||||||||||||
| United States | $ | 669,274 | $ | 665,280 | $ | 656,361 | 1 | % | 1 | % | ||||||||||
| Europe | 636,472 | 577,257 | 555,886 | 10 | % | 4 | % | |||||||||||||
| Asia: | ||||||||||||||||||||
| China | 387,059 | 331,354 | 278,600 | 17 | % | 19 | % | |||||||||||||
| Japan | 167,258 | 167,977 | 145,184 | — | 16 | % | ||||||||||||||
| Asia Other | 308,300 | 283,653 | 272,179 | 9 | % | 4 | % | |||||||||||||
| Total Asia | 862,617 | 782,984 | 695,963 | 10 | % | 13 | % | |||||||||||||
| Other | 140,715 | 141,902 | 134,122 | (1 | %) | 6 | % | |||||||||||||
| Total net sales | $ | 2,309,078 | $ | 2,167,423 | $ | 2,042,332 | 7 | % | 6 | % | ||||||||||
In 2017, the sales growth in Asia was driven by double-digit increases in China’s sales across all product and customer classes. The increase in Asia Other in 2017 was driven by strong sales in India across all product and customer classes. Japan’s sales in 2017 were flat as the effect of foreign currency decreased sales by 3%. Japan’s sales in 2017 were driven by recurring revenue sales to governmental and academic customers. Europe’s sales in 2017 were balanced across all product lines and driven by sales to pharmaceutical, governmental and academic customers. Sales growth in the U.S. in 2017 was driven by TA instrument system sales and recurring revenues. In 2017, sales to the rest of the world were impacted by a decrease in demand from industrial customers resulting from recent natural disasters.
In 2016, sales growth in the U.S. was driven by increases in recurring revenues, which were offset by declines in instrument systems sales. U.S. sales increased to pharmaceutical customers but declined to non-pharmaceutical end-markets. Europe’s sales in 2016 were also driven by recurring revenues and primarily due to increases to pharmaceutical and industrial customers. China achieved strong sales growth in all product and customer classes in 2016, with double-digit growth in LC-MS instrument systems and precision chemistry consumables as well as double-digit growth to pharmaceutical customers. Japan’s increase in sales in 2016 was largely driven by the benefit of foreign currency translation, which increased sales by 12%. The increase in sales in the rest of Asia in 2016 was driven by LC-MS instrument systems and precision chemistry consumables sales to pharmaceutical and industrial customers. Sales to the rest of Asia decreased 6% due to the negative effect of foreign currency translation. Sales in the rest of the world in 2016 were broad-based across all product classes as sales increased to industrial customers but declined across all other customer classes.
Table of Contents
Waters Products and Services Net Sales
Net sales for Waters products and services are as follows for the years ended December 31, 2017, 2016 and 2015 (in thousands):
| Year Ended December 31, | % change | |||||||||||||||||||||||||||||||
| 2017 | % of Total | 2016 | % of Total | 2015 | % of Total | 2017 vs. 2016 | 2016 vs. 2015 | |||||||||||||||||||||||||
| Waters instrument systems | $ | 988,750 | 48 | % | $ | 943,218 | 49 | % | $ | 895,626 | 50 | % | 5 | % | 5 | % | ||||||||||||||||
| Chemistry consumables | 372,157 | 18 | % | 345,413 | 18 | % | 317,941 | 17 | % | 8 | % | 9 | % | |||||||||||||||||||
| Total Waters product sales | 1,360,907 | 66 | % | 1,288,631 | 67 | % | 1,213,567 | 67 | % | 6 | % | 6 | % | |||||||||||||||||||
| Waters service | 686,656 | 34 | % | 639,432 | 33 | % | 593,301 | 33 | % | 7 | % | 8 | % | |||||||||||||||||||
| Total Waters net sales | $ | 2,047,563 | 100 | % | $ | 1,928,063 | 100 | % | $ | 1,806,868 | 100 | % | 6 | % | 7 | % | ||||||||||||||||
The increase in Waters instrument system sales (LC and MS technology-based) in both 2017 and 2016 is primarily attributable to higher sales of LC-MS systems that incorporate the Company’s tandem quadrupole technologies. Precision chemistry consumables sales increased in both 2017 and 2016 on the uptake in columns and application-specific testing kits. Waters service sales in both 2017 and 2016 benefited from increased sales of service plans and higher service demand billings to a higher installed base of customers. The effect of foreign currency translation had a minimal impact on Waters sales in both 2017 and 2016.
In 2017, Waters sales increased 10% in both Europe and Asia and were flat in the Americas. Waters sales increased 16% in China and were broad-based across all product and customer classes. Waters sales in Japan decreased 1%, primarily due to foreign currency translation, which decreased sales by 3%. Waters sales in the rest of Asia increased 8% and were driven by recurring revenues across all customer classes.
In 2016, Waters sales increased 2% in the U.S., 4% in Europe, 14% in Asia and 5% in the rest of the world. Waters sales increased 21% in China and were broad-based across all product and customer classes. Waters sales in Japan increased 15%, primarily due to the benefit of foreign currency translation, which increased sales by 12%. Waters sales in the rest of Asia increased 6% and were driven by product sales to pharmaceutical and industrial customers, offset by weakness within governmental and academic markets.
TA Product and Services Net Sales
Net sales for TA products and services are as follows for the years ended December 31, 2017, 2016 and 2015 (in thousands):
| Year Ended December 31, | % change | |||||||||||||||||||||||||||||||
| 2017 | % of Total | 2016 | % of Total | 2015 | % of Total | 2017 vs. 2016 | 2016 vs. 2015 | |||||||||||||||||||||||||
| TA instrument systems | $ | 191,442 | 73 | % | $ | 171,665 | 72 | % | $ | 171,689 | 73 | % | 12 | % | — | |||||||||||||||||
| TA service | 70,073 | 27 | % | 67,695 | 28 | % | 63,775 | 27 | % | 4 | % | 6 | % | |||||||||||||||||||
| Total TA net sales | $ | 261,515 | 100 | % | $ | 239,360 | 100 | % | $ | 235,464 | 100 | % | 9 | % | 2 | % | ||||||||||||||||
TA instrument system sales rebounded across all major product categories after a flat sales growth in 2016. In 2017, TA instrument system sales grew from thermal instrument systems, which were fueled by continued acceptance of the recently introduced Discovery product line. In addition, TA’s rheology instrument systems saw strong performance across the entire range of products in the portfolio, driven by the Discovery Hybrid Rheometer and Rubber Rheometer instrument systems. TA service sales increased in both 2017 and 2016 due to sales of service plans and billings to a higher installed base of customers. The effect of foreign currency translation and recent acquisitions had a minimal impact on TA’s sales in both 2017 and 2016.
Table of Contents
In 2017, TA sales increased 14% in Asia, 11% in Europe and 5% in the Americas. TA achieved double-digit sales growth in Asia, with the exception of Japan, where a 5% sales growth included a 2% negative impact of foreign currency translation. TA sales in the U.S. in 2017 increased 8%, while the rest of the Americas declined after strong sales in the prior year. In 2016, TA sales increased 2% in both the Americas and Asia and increased 1% in Europe. TA sales were flat in the U.S. in 2016 but TA achieved a double-digit increase in the rest of the Americas. TA’s sales in Japan in 2016 increased 19%, with a 10% increase due to the benefit of foreign currency translation.
Cost of Sales
The increase in cost of sales for both 2017 and 2016 were consistent with the increase in sales volumes. The effect of foreign currency translation had a minimal impact on cost of sales in 2017. In 2016, cost of sales included the benefit of a weaker British pound, which reduced the Company’s U.K. manufacturing costs when translated into U.S. dollars.
Cost of sales are affected by many factors, including, but not limited to, foreign currency translation, product mix, product costs of instrument systems and amortization of software platforms. At current foreign currency exchange rates, the Company expects that the impact of foreign currency translation may increase sales and still negatively impact gross profit during 2018, as the foreign currency translation benefit expected on Euro and Japanese yen sales would be somewhat mitigated by the unfavorable effect of a stronger British pound on the Company’s U.K. manufacturing costs.
Selling and Administrative Expenses
Selling and administrative expenses increased 6% in 2017 and increased 3% in 2016. Selling and administrative expenses in both 2017 and 2016 were impacted by headcount additions and higher merit compensation costs, as well as $4 million and $7 million, respectively, of stock compensation expense related to the modification of certain stock awards upon the retirement of senior executives. In 2017, the Company incurred $13 million of severance costs in connection with the closure of a facility in Germany and an early retirement transition incentive program. Severance-related costs in 2016 and 2015 were $3 million and $3 million, respectively, in connection with a reduction in workforce. The effect of foreign currency translation increased selling and administrative expenses by 3% in 2017 and lowered these expenses by 2% in 2016.
As a percentage of net sales, selling and administrative expenses were 23.6%, 23.7% and 24.3% for 2017, 2016 and 2015, respectively.
Research and Development Expenses
Research and development expenses increased 6% in both 2017 and 2016. Research and development expenses in both 2017 and 2016 were impacted by additional headcount, merit compensation and costs associated with new products and the development of new technology initiatives. In addition, the effect of foreign currency translation reduced research and development expenses by 4% and 7% in 2017 and 2016, respectively, primarily due to the weakening of the British pound on the Company’s U.K.-based research and development expenses. In 2016, research and development expenses also included a benefit of $2 million from a government grant.
Acquired In-Process Research and Development
During 2017 and 2015, the Company incurred charges of $5 million and $4 million, respectively, for acquired in-process research and development related to milestone payments associated with a licensing arrangement for certain intellectual property relating to mass spectrometry technologies yet to be commercialized and for which there was no future alternative use as of the acquisition date. These licensing arrangements are significantly related to new, biologically-focused applications, as well as other applications, and require the Company to make additional future payments of up to $7 million if certain milestones are achieved, as well as royalties on future net sales. These future payments may be significant and occur over multiple years.
Table of Contents
Litigation Provision
In 2017, the Company incurred a $11 million litigation provision related to the issuance of a verdict in a German patent litigation case. In addition, the Company recorded $4 million of litigation settlement provisions and related costs in both 2016 and 2015.
Interest Expense, Net
The decreases in net interest expense in 2017 and 2016 were primarily attributable to higher income earned on increased cash, cash equivalents and investment balances.
Provision for Income Taxes
The four principal jurisdictions in which the Company manufactures are the U.S., Ireland, the U.K. and Singapore, where the marginal effective tax rates were approximately 37.5%, 12.5%, 19.25% and 0%, respectively, as of December 31, 2017. The Company has a contractual tax rate in Singapore of 0% on qualifying activities in Singapore through March 2021, based upon the achievement of certain contractual milestones, which the Company expects to continue to meet. The current statutory tax rate in Singapore is 17%. The effect of applying the contractual tax rate rather than the statutory tax rate to income from qualifying activities in Singapore increased the Company’s net income in 2017, 2016 and 2015 by $25 million, $23 million and $20 million, respectively and increased the Company’s net income per diluted share by $0.31, $0.29 and $0.25, respectively.
The Company’s effective tax rate is influenced by many significant factors, including, but not limited to, the wide range of income tax rates in jurisdictions in which the Company operates; sales volumes and profit levels in each tax jurisdiction; changes in tax laws, tax rates and policies; the outcome of various ongoing tax audit examinations; and the impact of foreign currency transactions and translation. As a result of variability in these factors, the Company’s effective tax rates in the future may not be similar to the effective tax rates for the current or prior years.
The Company’s effective tax rates were 96.8%, 13.1% and 13.4% in 2017, 2016 and 2015, respectively. The provision for income taxes for 2017 includes a $550 million estimate for the impact of the enactment of the 2017 Tax Act. Excluding the $550 million income tax expense for the 2017 Tax Act, the effective tax rate in 2017 would have been 11.0% and this effective income tax rate includes a $20 million or (3.1 percentage point) reduction in the income tax expense as a result of the adoption of new accounting guidance related to stock-based compensation. See Note 2 for further information regarding the adoption of this standard.
The 2017 Tax Act changed the U.S. tax system to a territorial system, including base broadening measures requiring the taxation of the Company’s historical unremitted foreign earnings through a deemed repatriation, which resulted in a $550 million income tax provision that reduced net income per share by $6.82 for the twelve months ended December 31, 2017, as well as eliminating or reducing certain domestic deductions and credits and limiting the deductibility of interest expense and executive compensation. The $550 million income tax provision primarily consists of an estimated Transition Tax of $490 million, as well as estimated income tax provisions for state and withholding taxes of $40 million and a $20 million provision associated with the remeasurement of the Company’s deferred tax assets and liabilities from 35% to the new U.S. corporate income tax rate of 21%. The Transition Tax will be paid over an eight-year period, starting in 2018, and will not accrue interest. The final impact of the 2017 Tax Act may differ from these estimates due to, among other things, changes in interpretations, analysis and assumptions made by the Company, additional guidance that may be issued by the U.S. Department of the Treasury, and tax planning actions that the Company may undertake.
The income tax provision for 2016 included a $3 million tax benefit related to a release of a valuation allowance on certain net operating loss carryforwards. In 2015, the income tax provision included a $3 million tax benefit related to the completion of tax audit examinations. The remaining differences between effective tax rates can primarily be attributed to differences in the proportionate amounts of pre-tax income recognized in jurisdictions with different effective tax rates.
Table of Contents
Liquidity and Capital Resources
Condensed Consolidated Statements of Cash Flows (in thousands):
| Year Ended December 31, | ||||||||||||
| 2017 | 2016 | 2015 | ||||||||||
| Net income | $ | 20,311 | $ | 521,503 | $ | 469,053 | ||||||
| Depreciation and amortization | 106,002 | 96,449 | 89,987 | |||||||||
| Stock-based compensation | 39,436 | 40,998 | 33,368 | |||||||||
| Deferred income taxes | 45,510 | 1,204 | 6,581 | |||||||||
| Excess tax benefit related to stock option plans | — | 13,844 | 12,955 | |||||||||
| Gain on sale of assets | — | (1,500 | ) | (1,377 | ) | |||||||
| In-process research and development and other non-cash charges | 5,000 | — | 4,638 | |||||||||
| Change in accounts receivable | (24,013 | ) | (31,721 | ) | (49,888 | ) | ||||||
| Change in inventories | 731 | (20,147 | ) | (19,967 | ) | |||||||
| Change in accounts payable and other current liabilities | 3,175 | 6,842 | 27,451 | |||||||||
| Change in deferred revenue and customer advances | 10,386 | 9,974 | 16,172 | |||||||||
| Effect of the 2017 Tax Act | 530,383 | — | — | |||||||||
| Other changes | (39,281 | ) | 5,474 | (15,725 | ) | |||||||
| Net cash provided by operating activities | 697,640 | 642,920 | 573,248 | |||||||||
| Net cash used in investing activities | (535,752 | ) | (487,918 | ) | (399,739 | ) | ||||||
| Net cash used in financing activities | (63,869 | ) | (115,701 | ) | (82,549 | ) | ||||||
| Effect of exchange rate changes on cash and cash equivalents | 38,669 | (21,335 | ) | (25,472 | ) | |||||||
| Increase in cash and cash equivalents | $ | 136,688 | $ | 17,966 | $ | 65,488 | ||||||
Cash Flow from Operating Activities
Net cash provided by operating activities was $698 million, $643 million and $573 million in 2017, 2016 and 2015, respectively. The changes within net cash provided by operating activities include the following significant changes in the sources and uses of net cash provided by operating activities, aside from the changes in net income:
| • | The changes in accounts receivable were primarily attributable to timing of payments made by customers and timing of sales. Days sales outstanding was 71 days at December 31, 2017, 2016 and 2015. |
|---|
| • | The changes in inventory were primarily attributable to anticipated annual increases in sales volumes, as well as new product launches. |
|---|
| • | The changes in accounts payable and other current liabilities were a result of timing of payments to vendors, as well as income tax expenses related to the 2017 Tax Act which are expected to be settled in the next twelve months. |
|---|
| • | Net cash provided from deferred revenue and customer advances results from annual increases in new service contracts as a higher installed base of customers renew annual service contracts. |
|---|
| • | Other changes were attributable to variation in the timing of various provisions, expenditures, prepaid income taxes and accruals in other current assets, other assets, other liabilities, and income tax expenses related to the 2017 Tax Act. |
|---|
| • | In addition, as a result of the adoption of a new accounting standard related to stock-based compensation, the Company reclassified $14 million and $13 million of excess tax benefits related to stock-based compensation in 2016 and 2015, respectively, from cash flows from financing activities to cash flows from operating activities. |
|---|
Table of Contents
Cash Used in Investing Activities
Net cash used in investing activities totaled $536 million, $488 million and $400 million in 2017, 2016 and 2015, respectively. Additions to fixed assets and capitalized software were $85 million, $95 million and $100 million in 2017, 2016 and 2015, respectively. In February 2018, the Company’s Board of Directors approved expanding its chemistry synthesis operations. The Company anticipates spending an estimated $215 million to build and equip this new state-of-the-art manufacturing facility, which will be paid for with existing cash and investments. The Company does not expect to issue any debt in relation to this expansion.
During 2017, 2016 and 2015, the Company purchased $3.0 billion, $2.4 billion and $2.0 billion of investments, respectively, while $2.5 billion, $2.0 billion and $1.7 billion of investments matured, respectively.
During 2017, the Company made a $7 million payment for an investment in a developer of analytical system solutions used to make measurements, predict stability and accelerate product discovery in the routine analytic, process monitoring and quality control release processes for life science and biopharmaceutical markets. During 2017 and 2015, the Company made payments of $5 million and $3 million, respectively, to acquire and license intellectual property relating to mass spectrometry technologies yet to be commercialized. Business acquisitions, net of cash acquired, were $6 million and $23 million during 2016 and 2015, respectively. There were no business acquisitions in 2017. In 2016, the Company sold an equity investment for $4 million and, in 2015, the Company received $5 million cash from the sale of a building in the U.K.
Cash Used in Financing Activities
In November 2017, the Company entered into the 2017 Credit Agreement, which provides for a $1.5 billion revolving facility and a $300 million term loan. The revolving facility and term loan both mature on November 30, 2022 and require no scheduled prepayments before that date. The Company used $1.3 billion of the proceeds from the 2017 Credit Agreement to repay the outstanding amounts under the 2013 Credit Agreement, which was terminated early without penalty. The Company plans to use future proceeds from the revolving facility for general corporate purposes.
The interest rates applicable to the 2017 Credit Agreement are, at the Company’s option, equal to either the alternate base rate (which is a rate per annum equal to the greatest of (a) the prime rate in effect on such day, (b) the Federal Reserve Bank of New York Rate on such day plus 1/2 of 1% per annum and (c) the adjusted LIBO rate on such day (or if such day is not a business day, the immediately preceding business day) for a deposit in U.S. dollars with a maturity of one month plus 1% per annum) or the applicable 1, 2, 3 or 6 month adjusted LIBO rate or EURIBO rate for Euro-denominated loans, in each case, plus an interest rate margin based upon the Company’s leverage ratio, which can range between 0 and 12.5 basis points for alternate base rate loans and between 80 and 112.5 basis points for LIBO rate or EURIBO rate loans. The facility fee on the 2017 Credit Agreement ranges between 7.5 and 25 basis points per annum, based on the leverage ratio, of the amount of the revolving facility commitments and the outstanding term loan. The 2017 Credit Agreement requires that the Company comply with an interest coverage ratio test of not less than 3.50:1 as of the end of any fiscal quarter for any period of four consecutive fiscal quarters and a leverage ratio test of not more than 3.50:1 as of the end of any fiscal quarter. In addition, the 2017 Credit Agreement includes negative covenants, affirmative covenants, representations and warranties and events of default that are customary for investment grade credit facilities.
Interest on the Company’s fixed rate senior unsecured notes is payable semi-annually each year. Interest on the floating rate senior unsecured notes is payable quarterly. The Company may prepay all or some of the senior unsecured notes at any time in an amount not less than 10% of the aggregate principal amount outstanding, plus the applicable make-whole amount or prepayment premium for Series H and J senior unsecured notes. In the event of a change in control of the Company (as defined in the note purchase agreement), the Company may be required to prepay the senior unsecured notes at a price equal to 100% of the principal amount thereof, plus
Table of Contents
accrued and unpaid interest. These senior unsecured notes require that the Company comply with an interest coverage ratio test of not less than 3.50:1 for any period of four consecutive fiscal quarters and a leverage ratio test of not more than 3.50:1 as of the end of any fiscal quarter. In addition, these senior unsecured notes include customary negative covenants, affirmative covenants, representations and warranties and events of default.
During 2017, 2016 and 2015, the Company’s net debt borrowings increased by $170 million, $160 million and $205 million, respectively. As of December 31, 2017, the Company had a total of $2 billion in outstanding debt, which consisted of $700 million in outstanding senior unsecured notes, $300 million borrowed under a term loan and $1 billion borrowed under a revolving credit facility, with both the term loan and revolving credit facilities under the 2017 Credit Agreement. As of December 31, 2017, the Company had a total amount available to borrow under the 2017 Credit Agreement of $498 million after outstanding letters of credit. As of December 31, 2017, the Company was in compliance with all debt covenants.
In May 2017, the Company’s Board of Directors authorized the Company to repurchase up to $1 billion of its outstanding common stock over a three-year period. During 2017, 2016 and 2015, the Company repurchased 1.8 million, 2.3 million and 2.6 million shares of the Company’s outstanding common stock at a cost of $323 million, $318 million and $327 million, respectively, under the May 2017 authorization and other previously announced programs. As of 2017, the Company had purchased an aggregate of 5.5 million shares at a cost of $750 million under the May 2014 authorization, which is now completed. At December 31, 2017, the Company had a total of $800 million in remaining authorized capacity for future repurchases under the May 2017 authorization. In addition, the Company repurchased $10 million, $8 million and $7 million of common stock related to the vesting of restricted stock units during the years ended December 31, 2017, 2016 and 2015, respectively. As a result of the deemed repatriation of the Company’s offshore cash from the 2017 Tax Act, the Company currently anticipates deploying approximately $1 billion of cash to reduce debt and repurchase the Company’s common stock shares on the open market during 2018.
The Company received $98 million, $62 million and $52 million of proceeds from the exercise of stock options and the purchase of shares pursuant to the Company’s employee stock purchase plan in 2017, 2016 and 2015, respectively.
The Company had cash, cash equivalents and investments of $3,394 million as of December 31, 2017. The majority of the Company’s cash, cash equivalents and investments are generated from foreign operations, with $3,326 million held by foreign subsidiaries at December 31, 2017, of which $304 million was held in currencies other than U.S. dollars. The Company believes it has sufficient levels of cash flow and access to its existing cash, cash equivalents and investments to fund operations and capital expenditures, service debt interest, finance potential acquisitions and continue the authorized stock repurchase program in the U.S. These cash requirements are managed by the Company’s cash flow from operations, its existing cash, cash equivalents and investments, and the use of the Company’s revolving credit facility.
Management believes, as of the date of this report, that its financial position, along with expected future cash flows from earnings based on historical trends and the ability to raise funds from external sources and the borrowing capacity from existing, committed credit facilities, will be sufficient to service debt and fund working capital and capital spending requirements, authorized share repurchase amounts and potential acquisitions for at least the next twelve months. Other than the Company gaining tax efficient access to its offshore cash, cash equivalents and investments as a result of the 2017 Tax Act, there have been no recent significant changes to the Company’s financial position, nor are there any anticipated changes, to warrant a material adjustment related to indefinitely reinvested foreign earnings.
Table of Contents
Contractual Obligations and Commercial Commitments
The following is a summary of the Company’s known contractual obligations as of December 31, 2017 (in thousands):
| Payments Due by Year (1) | ||||||||||||||||||||||||||||||||
| Total | 2018 | 2019 | 2020 | 2021 | 2022 | 2023 | After 2023 | |||||||||||||||||||||||||
| Notes payable and debt | $ | 100,273 | $ | 100,273 | $ | — | $ | — | $ | — | $ | — | $ | — | $ | — | ||||||||||||||||
| Interest on senior unsecured notes | 112,307 | 22,523 | 21,852 | 17,268 | 13,580 | 11,467 | 10,489 | 15,128 | ||||||||||||||||||||||||
| Long-term debt(2) | 1,900,000 | — | — | 100,000 | 150,000 | 1,300,000 | 50,000 | 300,000 | ||||||||||||||||||||||||
| 2017 Tax Act liability | 530,383 | 80,000 | 40,000 | 40,000 | 40,000 | 40,000 | 74,000 | 216,383 | ||||||||||||||||||||||||
| Operating leases | 89,682 | 23,168 | 18,228 | 14,122 | 8,652 | 6,220 | 5,285 | 14,007 | ||||||||||||||||||||||||
| Total | $ | 2,732,645 | $ | 225,964 | $ | 80,080 | $ | 171,390 | $ | 212,232 | $ | 1,357,687 | $ | 139,774 | $ | 545,518 | ||||||||||||||||
| (1) | Does not include normal purchases made in the ordinary course of business and uncertain tax positions discussed below. |
|---|
| (2) | The interest rates applicable to the 2017 Credit Agreement are, at the Company’s option, equal to either the alternate base rate (which is a rate per annum equal to the greatest of (a) the prime rate in effect on such day, (b) the Federal Reserve Bank of New York Rate on such day plus 1/2 of 1% per annum and (c) the adjusted LIBO rate on such day (or if such day is not a business day, the immediately preceding business day) for a deposit in U.S. dollars with a maturity of one month plus 1% per annum) or the applicable 1, 2, 3 or 6 month adjusted LIBO rate or EURIBO rate for Euro-denominated loans, in each case, plus an interest rate margin based upon the Company’s leverage ratio, which can range between 0 and 12.5 basis points for alternate base rate loans and between 80 and 112.5 basis points for LIBO rate or EURIBO rate loans. The facility fee on the 2017 Credit Agreement ranges between 7.5 and 25 basis points per annum, based on the leverage ratio, of the amount of the revolving facility commitments and the outstanding term loan. The 2017 Credit Agreement requires that the Company comply with an interest coverage ratio test of not less than 3.50:1 as of the end of any fiscal quarter for any period of four consecutive fiscal quarters and a leverage ratio test of not more than 3.50:1 as of the end of any fiscal quarter. In addition, the 2017 Credit Agreement includes negative covenants, affirmative covenants, representations and warranties and events of default that are customary for investment grade credit facilities. As of December 31, 2017, the Company was in compliance with all such covenants. |
|---|
The following is a summary of the Company’s known commercial commitments as of December 31, 2017 (in thousands):
| Amount of Commitments Expiration Per Period | ||||||||||||||||||||||||||||||||
| Total | 2018 | 2019 | 2020 | 2021 | 2022 | 2023 | After 2023 | |||||||||||||||||||||||||
| Letters of credit | $ | 1,733 | $ | 1,733 | $ | — | $ | — | $ | — | $ | — | $ | — | $ | — |
From time to time, the Company and its subsidiaries are involved in various litigation matters arising in the ordinary course of business. The Company believes it has meritorious arguments in its current litigation matters and believes any outcome, either individually or in the aggregate, will not be material to the Company’s financial position or results of operations.
The Company has long-term liabilities for deferred employee compensation, including pension and supplemental executive retirement plans. The payments related to the supplemental retirement plan are not included above since they are dependent upon when the employee retires or leaves the Company and whether the employee elects lump-sum or annuity payments. During fiscal year 2018, the Company expects to contribute approximately $4 million to $10 million to the Company’s defined benefit plans.
Table of Contents
The Company has contingent consideration for an earnout pertaining to the Medimass acquisition. The earnout payments are not included above since they are dependent upon many factors that cannot be predicted with any certainty. The estimated fair value of the contingent consideration as of December 31, 2017 is $3 million.
The Company licenses certain technology and software from third parties. Future minimum license fees payable under existing license agreements as of December 31, 2017 are immaterial. The Company enters into licensing arrangements with third parties that require future milestone or royalty payments contingent upon future events. Upon the achievement of certain milestones in existing agreements, the Company could make additional future payments of up to $7 million, as well as royalties on future net sales. It is not possible to predict with reasonable certainty whether these milestones will be achieved or the timing for achievement. As a result, these potential payments are not included in the table above.
The Company accounts for its uncertain tax return reporting positions in accordance with the accounting standards for income taxes, which require financial statement reporting of the expected future tax consequences of uncertain tax reporting positions on the presumption that all concerned tax authorities possess full knowledge of those tax reporting positions, as well as all of the pertinent facts and circumstances, but prohibit any discounting of unrecognized tax benefits associated with those reporting positions for the time value of money. The Company classified interest and penalties related to unrecognized tax benefits as a component of the provision for income taxes. If all of the Company’s unrecognized tax benefits accrued as of December 31, 2017 were to become recognizable in the future, the Company would record a total reduction of approximately $6 million in its income tax provision.
With limited exceptions, the Company is no longer subject to tax audit examinations in significant jurisdictions for the years ended on or before December 31, 2012. However, carryforward tax attributes that were generated in years beginning on or before January 1, 2013 may still be adjusted upon examination by tax authorities if the attributes are utilized. The Company continuously monitors the lapsing of statutes of limitations on potential tax assessments for related changes in the measurement of unrecognized tax benefits, related net interest and penalties, and deferred tax assets and liabilities.
During the year ended December 31, 2016, the Company concluded tax audit disputes outside the U.S. that, in part, related to matters for which the Company had recorded net uncertain tax benefits. The resolution of these tax disputes resulted in a $1 million reduction in the measurement of its unrecognized tax benefits for the year ended December 31, 2016.
During the year ended December 31, 2015, the Company concluded U.S. tax audit disputes that, in part, related to matters for which the Company had recorded net uncertain tax benefits. The resolution of these tax disputes resulted in a $2 million reduction in the measurement of its unrecognized tax benefits and a $2 million decrease in its provision for income taxes for the year ended December 31, 2015.
As of December 31, 2017, the Company expects to record additional reductions in the measurement of its unrecognized tax benefits and related net interest and penalties of approximately $1 million within the next twelve months due to potential tax audit settlements and the lapsing of statutes of limitations on potential tax assessments. The Company does not expect to record any other material reductions in the measurement of its unrecognized tax benefits within the next twelve months.
The Company has not paid any dividends and has no plans, at this time, to pay any dividends in the future.
Off-Balance Sheet Arrangements
The Company has not created, and is not party to, any special-purpose or off-balance sheet entities for the purpose of raising capital, incurring debt or operating parts of its business that are not consolidated (to the extent
Table of Contents
of the Company’s ownership interest therein) into the consolidated financial statements. The Company has not entered into any transactions with unconsolidated entities whereby it has subordinated retained interests, derivative instruments or other contingent arrangements that expose the Company to material continuing risks, contingent liabilities or any other obligation under a variable interest in an unconsolidated entity that provides financing, liquidity, market risk or credit risk support to the Company.
The Company enters into standard indemnification agreements in its ordinary course of business. Pursuant to these agreements, the Company indemnifies, holds harmless and agrees to reimburse the indemnified party for losses suffered or incurred by the indemnified party, generally the Company’s business partners or customers, in connection with patent, copyright or other intellectual property infringement claims by any third party with respect to its current products, as well as claims relating to property damage or personal injury resulting from the performance of services by the Company or its subcontractors. The maximum potential amount of future payments the Company could be required to make under these indemnification agreements is unlimited. Historically, the Company’s costs to defend lawsuits or settle claims relating to such indemnity agreements have been minimal and management accordingly believes the estimated fair value of these agreements is immaterial.
Critical Accounting Policies and Estimates
Summary
The preparation of consolidated financial statements requires the Company to make estimates and judgments that affect the reported amounts of assets, liabilities, revenues and expenses, and related disclosure of contingent liabilities. Critical accounting policies are those that are central to the presentation of the Company’s financial condition and results of operations that require management to make estimates about matters that are highly uncertain and that would have a material impact on the Company’s results of operations given changes in the estimate that are reasonably likely to occur from period to period or use of different estimates that reasonably could have been used in the current period. On an ongoing basis, the Company evaluates its policies and estimates. The Company bases its estimates on historical experience and on various other assumptions that are believed to be reasonable under the circumstances, the results of which form the basis for making judgments about the carrying values of assets and liabilities that are not readily apparent from other sources. Actual amounts may differ from these estimates under different assumptions or conditions. There are other items within the Company’s consolidated financial statements that require estimation, but are not deemed critical as defined above. Changes in estimates used in these and other items could potentially have a material impact on the Company’s consolidated financial statements.
Revenue Recognition
Sales of products and services are generally recorded based on product shipment and performance of service, respectively. The Company’s deferred revenue on the consolidated balance sheets consists of the obligation on instrument service contracts and customer payments received in advance, prior to shipment of the instrument. At December 31, 2017, the Company had current and long-term deferred revenue liabilities of $167 million and $26 million, respectively. Revenue is recognized when all of the following revenue recognition criteria are met: persuasive evidence of an arrangement exists; delivery or performance has occurred; the vendor’s fee is fixed or determinable; collectibility is reasonably assured and, if applicable, upon acceptance when acceptance criteria with contractual cash holdback are specified. Shipping and handling costs are included in cost of sales, net of amounts invoiced to the customer per the order.
Product shipments, including those for demonstration or evaluation, and service contracts are not recorded as revenue until a valid purchase order or master agreement is received, specifying fixed terms and prices. The Company generally recognizes product revenue when legal title has transferred and risk of loss passes to the customer. The Company generally structures its sales arrangements as shipping point or international equivalent and, accordingly, recognizes revenue upon shipment. In some cases, destination-based shipping terms are included in sales arrangements, in which cases revenue is generally recognized when the products arrive at the customer site.
Table of Contents
The Company’s method of revenue recognition for certain products requiring installation is accounted for in accordance with multiple-element revenue recognition accounting standards. With respect to the installation obligations, the larger of the contractual cash holdback or the best estimate of selling price of the installation service is deferred when the product is shipped and revenue is recognized as a multiple-element arrangement when installation is complete. The Company determines the best estimate of selling price of installation based upon a number of factors, including hourly service billing rates and estimated installation hours.
Instrument service contracts are typically billed at the beginning of the maintenance period. The amount of the service contract is amortized ratably to revenue over the instrument maintenance period. There are no deferred costs associated with the service contract, as the cost of the service is recorded when the service is performed. No revenue is recognized until all revenue recognition criteria have been met.
Sales of standalone software are accounted for in accordance with the accounting standards for software revenue recognition. The Company’s software arrangements typically include software licenses and maintenance contracts. Software license revenue is recognized when persuasive evidence of an arrangement exists, delivery has occurred, the fee is fixed or determinable, collection is probable, and there are no significant post-delivery obligations remaining. The revenue associated with the software maintenance contract is recognized ratably over the maintenance term. Unspecified rights to software upgrades are typically sold as part of the maintenance contract on a when-and-if-available basis. The Company uses the residual method to allocate software revenue when a transaction includes multiple elements and vendor specific objective evidence of fair value of undelivered elements exists. Under the residual method, the fair value of the undelivered element (maintenance) is deferred and the remaining portion of the arrangement fee is allocated to the delivered element (software license) and recognized as revenue.
Returns and customer credits are infrequent and are recorded as a reduction to sales. Rights of return are not included in sales arrangements. Revenue associated with products that contain specific customer acceptance criteria is not recognized before the customer acceptance criteria are satisfied. Discounts from list prices are recorded as a reduction to sales.
Loss Provisions on Accounts Receivable and Inventory
The Company maintains allowances for doubtful accounts for estimated losses resulting from the inability of its customers to make required payments. If the financial condition of the Company’s customers were to deteriorate, resulting in an impairment of their ability to make payments, additional allowances may be required. The Company does not request collateral from its customers, but collectibility is enhanced through the use of credit card payments and letters of credit. The Company assesses collectibility based on a number of factors, including, but not limited to, past transaction history with the customer, the credit-worthiness of the customer, industry trends and the macro-economic environment. Historically, the Company has not experienced significant bad debt losses. Sales returns and allowances are estimates of future product returns related to current period revenue. Material differences may result in the amount and timing of revenue for any period if management made different judgments or utilized different estimates for sales returns and allowances for doubtful accounts. The Company’s accounts receivable balance at December 31, 2017 was $534 million, net of allowances for doubtful accounts and sales returns of $9 million.
The Company values all of its inventories at the lower of cost or net realizable value on a first-in, first-out basis (“FIFO”). The Company estimates revisions to its inventory valuations based on technical obsolescence, historical demand, projections of future demand, including that in the Company’s current backlog of orders, and industry and market conditions. If actual future demand or market conditions are less favorable than those projected by management, additional write-downs may be required. The Company’s inventory balance at December 31, 2017 was recorded at its net realizable value of $270 million, which is net of write-downs of $23 million.
Table of Contents
Long-Lived Assets, Intangible Assets and Goodwill
The Company assesses the impairment of identifiable intangibles, long-lived assets and goodwill whenever events or changes in circumstances indicate that the carrying value may not be recoverable. Factors the Company considers important which could trigger impairment include, but are not limited to, the following:
| • | significant underperformance relative to historical or projected future operating results, particularly as it pertains to capitalized software and patent costs; |
|---|
| • | significant negative industry or economic trends, competitive products and technologies; and |
|---|
| • | significant changes or developments in strategic technological collaborations or legal matters which affect the Company’s capitalized patents, purchased technology, trademarks and intellectual properties, such as licenses. |
|---|
When the Company determines that the carrying value of an individual intangible asset, long-lived asset or goodwill may not be recoverable based upon the existence of one or more of the above indicators, an estimate of undiscounted future cash flows produced by that intangible asset, long-lived asset or goodwill, including its eventual residual value, is compared to the carrying value to determine whether impairment exists. In the event that such cash flows are not expected to be sufficient to recover the carrying amount of the asset, the asset is written-down to its estimated fair value. Net intangible assets, long-lived assets and goodwill amounted to $228 million, $349 million and $360 million, respectively, as of December 31, 2017.
The Company performs annual impairment reviews of its goodwill on January 1 of each year. For goodwill impairment review purposes, the Company has two reporting units: Waters and TA. The Company currently does not expect to record an impairment charge in the foreseeable future; however, there can be no assurance that, at the time future reviews are completed, a material impairment charge will not be recorded. The factors that could cause a material goodwill impairment charge in the future include, but are not limited to, the following:
| • | significant decline in the Company’s projected revenue, earnings or cash flows; |
|---|
| • | significant adverse change in legal factors or business climate; |
|---|
| • | significant decline in the Company’s stock price or the stock price of comparable companies; |
|---|
| • | adverse action or assessment by a regulator; and |
|---|
| • | unanticipated competition. |
|---|
Income Taxes
As part of the process of preparing the consolidated financial statements, the Company is required to estimate its income taxes in each of the jurisdictions in which it operates. In addition, as a result of the timing of the new 2017 Tax Act in the U.S., the Company has had to make reasonable estimates on certain amounts related to the deemed repatriation of foreign earnings based on the existing interpretations of the U.S. Department of the Treasury and state and local governments. These processes involve the Company estimating its actual current tax exposure, taking into account the amount, timing and character of taxable income, tax deductions and credits and assessing changes in tax laws, regulations, agreements, treaties and any new interpretations on the taxation of the deemed repatriation of foreign earnings. Differing treatment of items for tax and accounting purposes, such as depreciation, amortization and inventory reserves, result in deferred tax assets and liabilities, which are included within the consolidated balance sheets. In the event that actual results differ from these estimates, or the Company adjusts these estimates in future periods, such changes could materially impact the Company’s financial position and results of operations.
The accounting standards for income taxes require that a company continually evaluate the necessity of establishing or changing a valuation allowance for deferred tax assets depending on whether it is more likely than not that the actual benefit of those assets will be realized in future periods.
Table of Contents
Uncertain Tax Positions
The Company accounts for its uncertain tax return reporting positions in accordance with the accounting standards for income taxes, which require financial statement reporting of the expected future tax consequences of uncertain tax reporting positions on the presumption that all concerned tax authorities possess full knowledge of those tax reporting positions, as well as all of the pertinent facts and circumstances, but prohibit any discounting of unrecognized tax benefits associated with those reporting positions for the time value of money. The Company classified interest and penalties related to unrecognized tax benefits as a component of the provision for income taxes. At December 31, 2017, the Company had unrecognized tax benefits of $7 million.
The Company has been granted a 0% contractual tax rate in Singapore that requires the achievement of certain operational and financial milestones that the Company expects to meet, to the extent not already achieved, by December 31, 2020 and maintain through at least March 31, 2021. As part of the Company’s determination of uncertain tax positions, the Company regularly assesses its progress against these operational and financial milestone targets to determine whether the milestones can be reasonably achieved. These milestones were negotiated with the Singaporean tax authorities and established based on the Company’s historical financial performance; the anticipated customer end-market demand, particularly in certain regions in the world, and the Company’s anticipated future operating plans. These assessments require significant judgments and estimates about the Company’s ability to meet the milestone targets for the following types of objectives: reaching and maintaining annual revenue and business spending targets; meeting capital expenditures targets; attaining and sustaining employment targets; and establishing a local research and development and service center. The Company regularly monitors its actual and forecasted sales and operating results against these milestones and the Company makes the determination as to whether the future forecasted financial results are most likely to be achieved. These milestones are very similar in nature to the previous Singaporean tax holiday contractual agreements that the Company successfully completed. These milestones are not required to be met until December 21, 2020, at the earliest, which gives the Company sufficient time to make any necessary adjustments to its operating plans to achieve the milestones.
Currently, the Company has determined that it is more likely than not to realize the contractual tax rate in Singapore of 0% and has not recognized an uncertain tax benefit in its balance sheet related to the achievement of the contractual milestones in Singapore. However, these milestones can be significantly influenced by the business climate in Singapore and the Company’s overall financial performance and, in the event that the Company determines that the milestone targets are not expected to be met, the Company would no longer be able to record a tax benefit at a 0% contractual tax rate on income earned in Singapore from and after the April 1, 2016 start date of the contract period. At such time, the Company would record an income tax charge on the affected Singapore income earned back to April 1, 2016 at the Singapore statutory tax rate(s) (currently 17%), with a corresponding income tax liability recorded on the balance sheet. For the year ended 2017, the effect of applying the contractual tax rate rather than the statutory tax rate to income from qualifying activities in Singapore increased the Company’s net income and net income per diluted share by $25 million and $0.31, respectively.
On December 22, 2017, the U.S. enacted the 2017 Tax Act, which changed the U.S. tax system to a territorial tax system, including base broadening measures on non-U.S. earnings, whereby foreign earnings are effectively deemed to be repatriated to the U.S., as well as reducing or eliminating certain domestic deductions and credits and limiting the deductibility of interest expense and executive compensation. Included in the 2017 Tax Act is a Transition Tax, which is a one-time, mandatory deemed repatriation tax on the accumulated foreign earnings that have not been previously taxed. Earnings in the form of cash and cash equivalents will be taxed at a rate of 15.5% and all other earnings will be taxed at a rate of 8.0%. As a result, the Company’s historical unremitted foreign earnings were deemed repatriated in 2017 and the Company incurred a $550 million estimated tax provision, which primarily consisted of an estimated Transition Tax, as well as estimated income tax provisions for state and withholding taxes and a provision associated with the remeasurement of the Company’s deferred tax assets and liabilities from 35% to the new U.S. corporate income tax rate of 21%. The Transition Tax will be paid over an eight-year period, starting in 2018, and will not accrue interest. The final
Table of Contents
impact of the 2017 Tax Act may differ from these estimates, due to, among other things, changes in interpretations, analysis and assumptions made by the Company, additional guidance that may be issued by the U.S. Department of the Treasury and tax planning actions that the Company may undertake.
In accordance with guidance in SEC Staff Accounting Bulletin No. 118, the final determination of the Transition Tax and the remeasurement of our deferred assets and liabilities will be completed as additional information becomes available, but no later than one year from the date of enactment of the 2017 Tax Act.
Warranty
Product warranties are recorded at the time revenue is recognized for certain product shipments. While the Company engages in extensive product quality programs and processes, including actively monitoring and evaluating the quality of its component suppliers, the Company’s warranty obligation is affected by product failure rates, material usage and service delivery costs incurred in correcting a product failure. Should actual product failure rates, material usage or service delivery costs differ from the Company’s previous estimates, revisions to the estimated warranty liability would be required. At December 31, 2017, the Company’s warranty liability was $13 million.
Litigation
As described in Item 3, Legal Proceedings, of Part I of this Form 10-K, the Company is a party to various pending litigation matters. With respect to each pending claim, management determines whether it can reasonably estimate whether a loss is probable and, if so, the probable range of that loss. If and when management has determined, with respect to a particular claim, both that a loss is probable and that it can reasonably estimate the range of that loss, the Company records a charge equal to either its best estimate of that loss or the lowest amount in that probable range of loss. The Company will disclose additional exposures when the range of loss is subject to considerable uncertainty.
Pension and Other Retirement Benefits
Assumptions used in determining projected benefit obligations and the fair values of plan assets for the Company’s pension plans and other retirement benefits are evaluated periodically by management. Changes in assumptions are based on relevant Company data. Critical assumptions, such as the discount rate used to measure the benefit obligations and the expected long-term rate of return on plan assets, are evaluated and updated annually. The Company has assumed that the weighted-average expected long-term rate of return on plan assets will be 6.53% for its U.S. benefit plans and 2.64% for its non-U.S. benefit plans.
At the end of each year, the Company determines the discount rate that reflects the current rate at which the pension liabilities could be effectively settled. The Company utilized Milliman’s Bond Matching model to determine the discount rate for its U.S. benefit plans. The Company determined the discount rate for its non-U.S. benefit plans based on the analysis of the Mercer Pension Discount Curve for high quality investments as of December 31, 2017 that best matched the timing of the plan’s future cash flows for the period to maturity of the pension benefits. Once the interest rates were determined, the plan’s cash flow was discounted at the spot interest rate back to the measurement date. At December 31, 2017, the Company determined the weighted-average discount rate to be 3.94% for the U.S. benefit plans and 1.79% for the non-U.S. benefits plans.
A one-quarter percentage point increase in the assumed long-term rate of return would decrease the Company’s net periodic benefit cost for the Waters Retirement Plan by less than $1 million. A one-quarter percentage point increase in the discount rate would decrease the Company’s net periodic benefit cost for the Waters Retirement Plan by less than $1 million.
Stock-based Compensation
The accounting standards for stock-based compensation require that all share-based payments to employees be recognized in the statements of operations based on their fair values. The Company has used the Black-Scholes
Table of Contents
option pricing model and Monte Carlo simulation model to determine the fair value of its stock option awards and performance stock unit awards, respectively. Under the fair-value recognition provisions of this statement, share-based compensation cost is measured at the grant date based on the value of the award and is recognized as expense over the vesting period. Determining the fair value of share-based awards at the grant date requires judgment, including estimating stock price volatility and employee stock option exercise behaviors. If actual results differ significantly from these estimates, stock-based compensation expense and the Company’s results of operations could be materially impacted. As stock-based compensation expense recognized in the consolidated statements of operations is based on awards that ultimately are expected to vest, the amount of the expense has been reduced for estimated forfeitures. These accounting standards require forfeitures to be estimated at the time of grant and revised, if necessary, in subsequent periods if actual forfeitures differ from those estimates. Forfeitures are estimated based on historical experience. If factors change and the Company employs different assumptions in the application of these accounting standards, the compensation expense that the Company records in future periods may differ significantly from what the Company has recorded in the current period. The Company recognizes the expense using the straight-line attribution method.
As of December 31, 2017, unrecognized compensation costs and related weighted-average lives over which the costs will be amortized were as follows (in millions):
| Unrecognized Compensation Costs | Weighted-Average Life in Years | |||||||
| Stock options | $ | 43 | 3.5 | |||||
| Restricted stock units | 34 | 3.0 | ||||||
| Performance stock units | 10 | 2.5 | ||||||
| Restricted stock | — | — | ||||||
| Total | $ | 87 | 3.2 | |||||
Business Combinations and Asset Acquisitions
The Company accounts for business acquisitions under the accounting standards for business combinations. The results of each acquisition are included in the Company’s consolidated results as of the acquisition date and the purchase price of an acquisition is allocated to tangible and intangible assets and assumed liabilities based on their estimated fair values. Any excess of the fair value consideration transferred over the estimated fair values of the net assets acquired is recognized as goodwill. Acquired in-process research and development (“IPR&D”) included in a business combination is capitalized as an indefinite-lived intangible asset. Development costs incurred after the acquisition are expensed as incurred and acquired IPR&D is tested for impairment annually until completion of the acquired programs. Upon commercialization, this indefinite-lived intangible asset is then accounted for as a finite-lived intangible asset and amortized on a straight-line basis over its estimated useful life, subject to periodic impairment reviews. If the research and development project is abandoned, the indefinite-lived asset is charged to expense. Legal costs, due diligence costs, business valuation costs and all other business acquisition costs are expensed when incurred.
The Company also acquires intellectual property through licensing arrangements. These arrangements often require upfront payments and may include additional milestone or royalty payments, contingent upon certain future events. IPR&D acquired in an asset acquisition (as opposed to a business combination) is expensed immediately unless there is an alternative future use. Subsequent payments made for the achievement of milestones are evaluated to determine whether they have an alternative future use or should be expensed. Payments made to third parties subsequent to commercialization are capitalized and amortized over the remaining useful life of the related asset, and are classified as intangible assets.
Contingent Consideration
In addition to the initial cash consideration paid to acquire Medimass, the Company is obligated to make additional earnout payments based on a royalty due on future sales of products containing the REIMS
Table of Contents
technology. In accordance with the accounting standards for business combinations, the Company determines the fair value of the liability for contingent consideration at each reporting date using a probability-weighted discounted cash flow model. Subsequent changes in the fair value of the contingent consideration liability are recorded in the results of operations. The fair value of the contingent consideration liability associated with future earnout payments is based on several factors, including estimated future results and a discount rate reflective of the Company’s creditworthiness. A change in any of these unobservable inputs can significantly change the fair value of the contingent consideration. Although there is no contractual limit, total future undiscounted contingent consideration payments were estimated to be $3 million as of December 31, 2017, based on the Company’s best estimate, as the earnout is based on future sales of certain products through 2034.
Recent Accounting Standard Changes and Developments
Information regarding recent accounting standard changes and developments is incorporated by reference from Part II, Item 8, Financial Statements and Supplementary Data, of this document and should be considered an integral part of this Item 7. See Note 2 in the Notes to the Consolidated Financial Statements for recently adopted and issued accounting standards.
Previous: Item 4. Mine Safety Disclosures · Next: Item 7A. Quantitative and Qualitative Disclosures About Market Risk