 filings.tools
W. R. Berkley (WRB) 10-K risk factor changes: FY2023 vs FY2020
The 2023-12-31 10-K against the 2022-12-31 one, compared heading by heading and sentence by sentence.
Item 1A60 rewritten10 added14 removed257 unchanged
All filing items1,298 rewritten615 added522 removed2,374 unchanged
Summary
counted, not written
- Item 1A lists 28 risk factor headings: 0 new, 3 reworded and 25 unchanged since FY2020. 0 headings from FY2020 no longer appear.
- Sentence by sentence, 615 added, 522 removed, 1,298 rewritten and 2,374 unchanged across 18 items that differ.
- New this year: Item 1C. CYBERSECURITY.
New Item 1A headings (0)
No risk factor heading in this filing is absent from FY2020.
Removed Item 1A headings (0)
Every FY2020 risk factor heading is still here, word for word or reworded.
Reworded Item 1A headings (3)
- The COVID-19 pandemic
[removed: has previously]materially and adversely affected our results of operations, and, whether as a result of COVID-19's long-term effects, or new or emerging variants, or other potential pandemics, may further materially and adversely affect our results of operations, financial position and liquidity in the future. - We may not find suitable
[removed: acquisition candidates or]new insurance ventures and [added: acquisition candidates and] even if we do, we may not successfully[removed: integrate any][added: invest in] such[removed: acquired companies][added: ventures] or successfully[removed: invest in][added: integrate any] such[removed: ventures.][added: acquired companies.] - If
[removed: we experience difficulties with]our information technology, telecommunications or other computer[removed: systems,][added: systems become unavailable or unreliable,] our ability to conduct our business could be negatively or severely impacted.
A heading is new when no FY2020 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
23 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2023; struck-through words were in FY2020. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. RISK FACTORS
60 rewritten, 10 added, 14 removed, 257 unchanged
[removed: We] [added: At times, we] have faced significant competition in our business as a result of existing insurers seeking to gain or maintain market share as well as new entrants and capital providers.
Recently, premium rates have increased for most lines of business, while they have decreased in others, most notably workers' [removed: compensation.][added: compensation and certain professional liability lines of business.]
Recently, insurance prices have generally increased for most lines of business, excluding workers' [removed: compensation.][added: compensation and certain professional liability lines of business.]
Despite [removed: rising] [added: higher] interest rates, current price levels for certain lines of business may remain below the prices required for us to achieve our long-term return objectives.
Our gross reserves for losses and loss expenses were approximately [removed: $17.0] [added: $18.7] billion as of December 31, [removed: 2022.][added: 2023.]
[removed: These estimates, which generally involve actuarial projections, are based on management's assessment of facts and circumstances then known, as] well as estimates of future trends in claims severity and frequency, inflation, judicial theories of liability, reinsurance coverage, legislative changes and other factors, including the actions of third parties, which are beyond our control.
For example, catastrophe losses net of reinsurance recoveries, including COVID-19 related losses, were [removed: $212 million in 2022, $202 million in 2021, and $340] [added: $195] million in [removed: 2020.][added: 2023, $212]
The COVID-19 pandemic [removed: has previously] materially and adversely affected our results of operations, and, whether as a result of COVID-19's long-term effects, or new or emerging variants, or other potential pandemics, may further materially and adversely affect our results of operations, financial position and liquidity in the future.
The [removed: ongoing] COVID-19 pandemic, including the related impact on the U.S. and global economies, materially and adversely affected our results of operations.
The [removed: pandemic and its] [added: pandemic's] impact on our business may continue, and potentially even worsen, whether as a result of COVID-19's long-term effects, or new or emerging variants, or even other potential pandemics.
We cannot predict the magnitude or duration of such impact, particularly given the uncertainties associated with [removed: COVID-19, including regarding the U.S. and global economies and the recovery from its devastating economic and] [added: COVID-19 or] other [removed: effects.][added: potential pandemics.]
The ultimate impact of COVID-19 [added: or other potential pandemics] on our results of operations, financial position and liquidity is not yet known, but includes the following:
Legislative and regulatory initiatives in response to COVID-19 or other similar [added: future] pandemics may adversely affect us, particularly in our workers’ compensation and property coverages businesses.
[added: For] example, our business may be subject to, certain initiatives, including, but not limited to: legislative and regulatory action that seeks to retroactively mandate coverage for losses that our insurance policies would not otherwise cover and which were not priced to cover; legislative and regulatory action providing for shifting presumptions with respect to the burdens of proof for “essential” workers on workers’ compensation coverages and varying definitions of “essential” workers; actions prohibiting us from cancelling insurance policies in accordance with our policy terms or non-renewing policies at their natural expiration; and/or orders to provide premium refunds, grant extended grace periods for premium payments, and provide extended time to pay past due premiums.
As of December 31, [removed: 2022,] [added: 2023,] we recorded approximately [removed: $341] [added: $384] million for COVID-19-related losses.
As the effects of COVID-19 [added: or future pandemics] on industry practices and economic, legal, judicial, social and other environmental conditions occur, unexpected and unintended issues related to claims and coverages may emerge.
There may be uncertainty surrounding the availability of reinsurance coverage for [removed: COVID-19-related] losses [added: related to COVID-19 or any future pandemics] as our reinsurers may dispute the applicability of reinsurance to such losses (including the application of reinsurance reinstatements) and, as a result, our reinsurers may refuse to pay reinsurance recoverables related thereto or they may not pay them on a timely basis.
[added: Legal Proceedings."] In addition, we may be unable to renew our current reinsurance coverages or obtain appropriate new reinsurance covers with respect to certain exposures under our policies, including [removed: COVID-19-related exposures,] [added: exposures related to COVID-19 or any future pandemics,] and therefore our net exposures could increase, or if we are unwilling to bear such increase in net exposure, we may reduce our level of underwriting commitments.
Consequently, any reduced economic activity relating to [removed: COVID-19 or other] potential pandemics is likely to decrease demand for our insurance products and services and negatively impact our premium volumes (and, in certain cases, may result in return of premiums due to a decrease in exposures).
[removed: Further disruptions] [added: Disruptions] in global financial markets due to [removed: the continuing impact of COVID-19 or] future pandemics could cause us to incur [removed: additional] unrealized and/or realized investment losses, including impairments in our fixed maturity portfolio and other investments.
[removed: Over the past several] [added: In recent] years, changing weather patterns and climatic conditions, such as global warming, appear to have contributed to the unpredictability, frequency and severity of natural disasters and created additional uncertainty as to future [added: trends and exposures.]
There is a [removed: growing] scientific consensus that global warming and other climate change are altering the frequency, severity and peril characteristics of catastrophic weather events, such as hurricanes, windstorms, floods and other natural disasters.
Based on our [removed: 2022] [added: 2023] earned premiums, our aggregate deductible under TRIPRA during [removed: 2023] [added: 2024] is approximately [removed: $1,310] [added: $1,464] million.
Because of the uncertainties set forth above, additional liabilities may arise for amounts in excess of the current loss [removed: reserves.]
The Dodd-Frank Act established the [removed: Financial Stability Oversight Council (“FSOC”),] [added: FSOC,] which is authorized to recommend that certain systemically significant non-bank financial companies, including insurance companies, be regulated by the Board of Governors of the Federal Reserve.
The Dodd-Frank Act also established a [removed: Federal Insurance Office (“FIO”)] [added: FIO] which is authorized to study, monitor and report to Congress on the U.S. insurance industry and the significance of global reinsurance to the U.S. insurance market.
[removed: The] [added: For instance, in New York, the NYDFS’s] circular [removed: letter] [added: letter, which applies to our insurance subsidiaries licensed in New York,] states that [removed: the NYDFS expects these] [added: regulated] insurers [added: are expected] to integrate financial risks related to climate change into their governance frameworks, risk management processes, business strategies and scenario analysis, and develop their approach to climate-related financial disclosure.
In addition, the FIO is assessing how the insurance sector may help mitigate [removed: climate-related] [added: climate- related] risks and achieve national climate-related [removed: goals.][added: goals, and it released a report in June 2023 urging insurance regulators to adopt climate-related risk monitoring guidance.]
State regulation is the primary form of regulation of insurance and reinsurance in the United States, although Congress has considered various proposals regarding federal regulation of insurance, in addition to the changes brought about by the [removed: Dodd-Frank Act, such as proposals for the creation of an optional federal charter for insurance companies.]
In addition, the current U.S. administration and the volatile political environment [removed: may increase] [added: (including, in particular,] the [added: upcoming U.S. presidential election in November 2024) increases the] chance of other federal legislative and regulatory changes that could affect us in ways we cannot predict.
However, the two regimes, and their respective requirements, are [removed: likely to diverge in the near future] [added: diverging] due to both the EU’s review of Solvency II described above and [removed: HM Treasury’s publication of a finalized package of] [added: the recently adopted] reforms to the U.K.’s domestic prudential regime [removed: on November 17, 2022] (please see “International Regulation” above for more information).
If we do not have the requisite licenses and approvals or do not comply with applicable regulatory requirements, the insurance regulatory authorities [added: could preclude or temporarily suspend us from carrying on some or all of our activities or monetarily penalize us.]
Changes in the value of the U.S. dollar relative to other currencies [added: have had and] could [added: in the future] have an adverse effect on our results of operations and financial condition.
As of December 31, [removed: 2022,] [added: 2023,] the amount due from our reinsurers was approximately [removed: $3,188] [added: $3,535] million, including amounts due from state funds and industry pools where it was intended that we would bear no risk.
For example our policyholders, independent agents or brokers may not pay a part of or the full amount of premiums owed to us [added: or our brokers or other third party claim administrators may not deliver amounts owed on claims under our insurance and reinsurance contracts for which we have provided funds.]
If conditions in the financial markets and the general economy are unfavorable, which may result from disruptions, uncertainty or volatility in the capital and credit markets, we may be unable to access debt or equity capital on acceptable terms if needed, which could have a negative impact on our ability to invest in our insurance company subsidiaries and/or to take advantage of opportunities to expand our business, such as [removed: possible acquisitions and] the creation of new [removed: ventures,] [added: ventures] and [added: possible acquisitions, and] inhibit our ability to refinance our existing indebtedness if we desire to do so, on terms acceptable to us.
We may not find suitable [removed: acquisition candidates or] new insurance ventures and [added: acquisition candidates and] even if we do, we may not successfully [removed: integrate any] [added: invest in] such [removed: acquired companies] [added: ventures] or successfully [removed: invest in] [added: integrate any] such [removed: ventures.][added: acquired companies.]
As part of our present strategy, we continue to evaluate [removed: possible acquisition transactions and] the [added: possible] start-up of complementary businesses [added: and acquisition transactions] on an ongoing basis, and at any given time we may be engaged in discussions with respect to possible [removed: acquisitions and] new [removed: ventures.][added: ventures and acquisitions.]
We cannot assure you that we will be able to identify suitable [removed: acquisition targets or] insurance [removed: ventures,] [added: ventures or acquisition targets,] that such transactions will be financed and completed on acceptable terms or that our future [removed: acquisitions or] start-up ventures [added: or acquisitions] will be successful.
Our financial results could be adversely affected by acquired businesses not performing as projected, unforeseen liabilities, routine and unanticipated transaction-related charges, diversion of management time and resources to acquisition integration challenges or growth strategies, loss of key employees, challenges in integrating information technology systems of acquired companies with our own, amortization of expenses related to intangibles, charges [added: for impairment of long-term assets or goodwill and indemnification.]
These estimates, which generally involve actuarial projections, are based on management's assessment of facts and circumstances then known, as
million in 2022, and $202 million in 2021.
On December 22, 2023, one of the
Company’s subsidiaries filed a lawsuit against certain reinsurers to recover in excess of $90 million in respect of certain losses paid to its policyholders under certain event cancellation and related insurance policies.
See, "Item 3.
reserves.
- privacy, data protection, and cybersecurity;
Dodd-Frank Act, such as proposals for the creation of an optional federal charter for insurance companies.
As described in “International Regulation” above, the EU is performing a review of Solvency II and various regulatory reforms are expected to be introduced during 2024, which EU member states will implement in their domestic regulation.
vendors and other third parties.
For
This may continue for an indefinite period, with the magnitude of the impact impossible to predict.
In addition, as we continue to evaluate the effects of COVID-19 on the insurance coverages we currently offer, our appetite for providing certain coverages in various jurisdictions may change, which could further negatively impact our premium volumes.
Any such reduction in our premiums would likely cause our expense ratio to rise.
trends and exposures.
For instance, in New York, the NYDFS issued a circular letter in September 2020 that applies to both New York domestic and foreign authorized insurers, such as our insurance subsidiaries licensed in New York.
Implementation of Solvency II in EU member states occurred on January 1, 2016, and as the Solvency II regime evolves over time, we may be required to utilize a significant amount of resources to ensure compliance.
In particular, the European Commission has undertaken a review of Solvency II and on September 22, 2021, published a package of proposed legislative reforms for amending the existing regulatory framework.
The European Council published its agreed position on the European Commission’s proposed reforms in June 2022, and it is now discussing this proposed legislation with the European Parliament.
could preclude or temporarily suspend us from carrying on some or all of our activities or monetarily penalize us.
or our brokers or other third party claim administrators may not deliver amounts owed on claims under our insurance and reinsurance contracts for which we have provided funds.
for impairment of long-term assets or goodwill and indemnification.
corporate income tax rate.
losses.
An excerpt. Shown here: 40 of 60 rewritten, all 10 added and all 14 removed. The counts are complete. For every sentence, read Item 1A. RISK FACTORS in the FY2023 filing and the FY2020 filing.
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
212 rewritten, 108 added, 109 removed, 385 unchanged
While providing our business units with certain operating autonomy, our structure allows us to capitalize on the benefits of economies of scale through centralized capital, investment, reinsurance, enterprise risk management, and actuarial, financial and corporate [removed: legal staff] [added: compliance] support.
[removed: On] [added: In] March [removed: 7,] 2022, the Company sold a real estate investment consisting of an office building located in London for £718 million.
The ultimate impact of COVID-19 on the [removed: economy and the] Company’s results of operations, financial position and liquidity is not within the Company’s control and remains unclear due to, among other factors, its ongoing impact and uncertainty in connection with its claims, reserves and reinsurance recoverables.
For lines with short reporting lags, which include [removed: commercial automobile,] [added: auto,] primary workers’ compensation, other liability (claims-made) and property business, the key assumption is the loss emergence pattern used to project ultimate loss estimates from known losses paid or reported to date.
The following table reflects the impact of changes (which could be favorable or unfavorable) in frequency and severity, relative to our assumptions, on our loss estimate for claims occurring in [removed: 2022:][added: 2023:]
Our net reserves for losses and loss expenses of approximately [removed: $14.2] [added: $15.7] billion as of December 31, [removed: 2022] [added: 2023] relate to multiple accident years.
Approximately [removed: $3.0] [added: $3.1] billion, or [removed: 21%,] [added: 20%,] of the Company’s net loss reserves as of December 31, [removed: 2022] [added: 2023] relate to the Reinsurance & Monoline Excess segment.
Following is a summary of the Company’s reserves for losses and loss expenses by business segment as of December 31, [removed: 2022] [added: 2023] and [removed: 2021:][added: 2022:]
| (In thousands) | | | [added: 2023 | | | | | |] 2022 | | | | | | 2021 | | | [added: | | | | | |]
| Insurance | | | $ | [removed: 11,233,924] [added: 12,518,591] | | | | | $ | [removed: 10,060,420] [added: 11,233,924] | |
| Reinsurance & Monoline Excess | | | [removed: 3,014,955] [added: 3,143,229] | | | | | | [removed: 2,787,942] [added: 3,014,955] | | |
| Net reserves for losses and loss expenses | | | [removed: 14,248,879] [added: 15,661,820] | | | | | | [removed: 12,848,362] [added: 14,248,879] | | |
| Ceded reserves for losses and loss expenses | | | [removed: 2,762,344] [added: 3,077,832] | | | | | | [removed: 2,542,526] [added: 2,762,344] | | |
| Gross reserves for losses and loss expenses | | | $ | [removed: 17,011,223] [added: 18,739,652] | | | | | $ | [removed: 15,390,888] [added: 17,011,223] | |
Following is a summary of the Company’s net reserves for losses and loss expenses by major line of business as of December 31, [removed: 2022] [added: 2023] and [removed: 2021:][added: 2022:]
| [removed: Commercial automobile] [added: Auto] | | | 629,149 | | | | | | 528,398 | | | | | | 1,157,547 | | |
(1)Reserves for excess and assumed workers’ compensation business are net of an aggregate net discount of [removed: $416] [added: $390] million and [removed: $452] [added: $416] million as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] respectively.
(2)Short-tail lines include commercial multi-peril (non-liability), inland marine, accident and health, fidelity and surety, boiler and [removed: machinery] [added: machinery, high net worth homeowners] and other lines.
| (In thousands) | | | [removed: 2022] [added: 2023] | | | | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2020] [added: 2021] | | | | | | | | |
| Increase in prior year loss reserves | | | $ | [removed: (54,511)] [added: (29,681)] | | | | | $ | [removed: (863)] [added: (54,511)] | | | | | $ | [removed: (627)] [added: (863)] | | | | | | | |
| Increase in prior year earned premiums | | | [removed: 18,106] [added: 10,782] | | | | | | [removed: 7,510] [added: 18,106] | | | | | | [removed: 16,807] [added: 7,510] | | | | | | | | |
| Net (unfavorable) favorable prior year development | | | $ | [removed: (36,405)] [added: (18,899)] | | | | | $ | [removed: 6,647] [added: (36,405)] | | | | | $ | [removed: 16,180] [added: 6,647] | | | | | | | |
The COVID-19 global pandemic has impacted, and may further impact, the Company’s [removed: results through its effect on claim frequency and severity.][added: loss costs.]
[removed: The] [added: Accordingly, the] ultimate net impact of COVID-19 on the [removed: Company] [added: Company's reserves] remains uncertain.
As of December 31, [removed: 2022,] [added: 2023,] the Company had recognized losses for COVID-19-related claims activity, net of reinsurance, of approximately [removed: $341] [added: $384] million, of which [removed: $290] [added: $326] million relates to the Insurance segment and [removed: $51] [added: $58] million relates to the Reinsurance & Monoline Excess segment.
Such [removed: $341] [added: $384] million of COVID-19-related losses included [removed: $337] [added: $381] million of reported losses and [removed: $4] [added: $3] million of IBNR.
For the year ended December 31, [removed: 2022,] [added: 2023,] the Company recognized current accident year losses for COVID-19-related claims activity, net of reinsurance, of approximately [removed: $5] [added: $1] million, [added: all] of which [removed: $3 million] relates to the Insurance [removed: segment and $2 million relates to the Reinsurance & Monoline Excess] segment.
[added: The Company experienced lower] reported claim frequency in these lines of business during 2020 and 2021 relative to historical averages, and continued to experience lower reported incurred losses relative to its expectations for these accident years as they developed during 2022.
Due to the [removed: ongoing] uncertainty regarding the ultimate impacts of the pandemic on accident years 2020 and 2021 incurred losses, the Company [removed: has been] [added: was] cautious in reacting to these lower trends in setting and updating its loss ratio estimates for these years.
The unfavorable development on the 2015 through 2019 accident years was concentrated in the general liability and professional liability, including medical professional, lines of business, as well as [removed: commercial] auto liability.
The favorable development on the 2020 accident year was largely concentrated in the [removed: commercial] auto liability and other liability lines of business, including commercial multi-peril liability.
The adverse development on the 2016 through 2019 accident years is concentrated largely in the other liability line of business, including commercial multi-peril liability, but is also seen to a lesser extent in [removed: commercial] auto liability.
[removed: Favorable] [added: Unfavorable] prior year development (net of additional and return premiums) was [removed: $16] [added: $19] million in [removed: 2020.][added: 2023.]
Insurance [removed: -] [added: –] Reserves for the Insurance segment developed [removed: favorably] [added: unfavorably] by $24 million in [removed: 2020] [added: 2023] (net of additional and return premiums).
Reinsurance & Monoline Excess – Reserves for the Reinsurance & Monoline Excess segment developed [removed: unfavorably] [added: favorably] by [removed: $8] [added: $5] million in [removed: 2020.][added: 2023 (net of additional and return premiums).]
The [removed: unfavorable] [added: overall favorable prior year] development [removed: in] [added: for] the segment was driven [added: mainly] by [removed: non-proportional assumed liability business written] [added: favorable development] in [removed: both the U.S. and U.K., and was partially] [added: excess workers’ compensation, substantially] offset by [removed: favorable] [added: unfavorable] development [removed: on] [added: in the non-proportional reinsurance assumed liability and] excess [removed: workers’ compensation] [added: general liability (including umbrella) lines of] business.
The amount of workers’ compensation reserves that were discounted was [removed: $1,267] [added: $1,352] million and [removed: $1,387] [added: $1,464] million at December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] respectively.
The aggregate net discount for those reserves, after reflecting the effects of ceded reinsurance, was [removed: $416] [added: $390] million and [removed: $452] [added: $416] million at December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] respectively.
At December 31, [removed: 2022,] [added: 2023,] discount rates by year ranged from 0.7% to 6.5%, with a weighted average discount rate of 3.4%.
Substantially all discounted workers’ compensation reserves (97% of total discounted reserves at December 31, [removed: 2022)] [added: 2023)] are excess workers’ compensation reserves.
In June 2023, the Company completed a sale of the property and casualty insurance services division of Breckenridge IS, Inc. and recognized a pre-tax net realized gain on investment of $89 million.
| 1% | | | $ | 126,867 | | | | | $ | 381,863 | | | | | $ | 700,608 | |
| 5% | | | 381,863 | | | | | | 646,957 | | | | | | 978,326 | | |
| 10% | | | 700,608 | | | | | | 978,326 | | | | | | 1,325,474 | | |
| December 31, 2023 | | | | | | | | | | | | | | | | | |
| Other liability | | | $ | 1,927,701 | | | | | $ | 4,561,410 | | | | | $ | 6,489,111 | |
| Workers’ compensation (1) | | | 1,019,445 | | | | | | 790,944 | | | | | | 1,810,389 | | |
| Professional liability | | | 527,555 | | | | | | 1,438,102 | | | | | | 1,965,657 | | |
| Auto | | | 722,963 | | | | | | 734,832 | | | | | | 1,457,795 | | |
| Short-tail lines (2) | | | 377,278 | | | | | | 418,361 | | | | | | 795,639 | | |
| Total Insurance | | | 4,574,942 | | | | | | 7,943,649 | | | | | | 12,518,591 | | |
| Reinsurance & Monoline Excess (1) (3) | | | 1,579,069 | | | | | | 1,564,160 | | | | | | 3,143,229 | | |
| Total | | | $ | 6,154,011 | | | | | $ | 9,507,809 | | | | | $ | 15,661,820 | |
The unfavorable development for the segment was concentrated in the early part of the year, with reserve development being flat overall during the second half of 2023.
A key driver of the unfavorable development early in 2023 was property catastrophe losses related to 2022 events which were still being adjusted and settled during the early part of 2023.
In particular, losses related to U.S. winter storms which occurred during the month of December 2022 were a significant contributor to the development, as information gathering and evaluation of many of these claims were still ongoing into the new year.
In addition to the property prior year development discussed above, during 2023 the Insurance segment also experienced adverse prior year development on casualty lines of business for the 2016 through 2019 accident years, which was offset by favorable prior year development on casualty lines of business for the 2020 through 2022 accident years.
The unfavorable development on the 2016 through 2019 accident years was concentrated in the general liability and commercial auto liability lines of business.
The development, which particularly impacted business attaching excess of primary policy limits, was driven by a larger than expected number of large losses reported.
The favorable prior year development on casualty lines for the 2020 through 2022 accident years in the Insurance segment was concentrated in the professional liability, workers’ compensation, and general liability lines of business.
Due to elevated uncertainty regarding incurred loss frequency and severity as a result of ongoing social inflation and the impacts of the COVID-19 pandemic, the Company set its initial loss ratios for the 2020 through 2022 accident years prudently, and largely maintained these estimates through the end of each respective accident year.
The reported loss experience to date for these lines of business for the 2020 through 2022 accident years has been significantly better than was expected, and the Company has begun to react to this favorable emergence as the accident years mature beyond the age of twelve months.
It should also be noted that commercial auto liability experienced adverse prior year development for the 2020 through 2022 accident years, which partially offset the favorable development discussed above; the adverse development was driven by a larger than expected number of large losses reported.
The favorable excess workers’ compensation development was driven by continued lower claim frequency and reported losses
relative to our expectations, and to favorable claim settlements.
The favorable development was spread across many prior accident years.
The unfavorable development for non-proportional reinsurance assumed liability and excess general liability was associated primarily with our U.S. assumed reinsurance business, and related to accounts reinsuring excess and umbrella business and construction projects.
The adverse development was concentrated mainly in accident years 2017 through 2020.
The Company believes social inflation is contributing to an increase in the frequency of large losses for these accident years.
Social inflation can include higher settlement demands from plaintiffs, use of tactics such as litigation funding by the plaintiffs’ bar, negative public sentiment towards large businesses and corporations, and erosion of tort reforms, among others.
The
| Foreign government | | | 33 | | | | | | $ | 102,689 | | | | | $ | 107,301 | |
| Corporate | | | 16 | | | | | | 21,424 | | | | | | 1,928 | | |
| Mortgage-backed securities | | | 15 | | | | | | 4,393 | | | | | | 185 | | |
| Total | | | 74 | | | | | | $ | 151,533 | | | | | $ | 116,031 | |
adjustments to such inputs and the volatility of such inputs over time.
| Independent pricing services | | | $ | 19,589,441 | | | | | 97.3 | | % |
| Observable data | | | 450,356 | | | | | | 2.3 | | |
| Total | | | $ | 20,124,936 | | | | | 100.0 | | % |
| (In thousands) | | | 2023 | | | | | | 2022 | | |
On February 25, 2022, the Company announced that its Board of Directors approved a 3-for-2 common stock split which was paid in the form of a stock dividend to holders of record as of March 9, 2022.
The additional shares were issued on March 23, 2022.
Shares outstanding and per share amounts in this Form 10-K reflect such 3-for-2 common stock split.
The COVID-19 pandemic, including the related impact on the U.S. and global economies, continued to adversely affect our results of operations.
At the same time, COVID-19 has led to reduced loss frequency in certain lines of business (which partially returned to pre-pandemic levels as many economies and legal systems have reopened).
| 1% | | | $ | 116,072 | | | | | $ | 349,370 | | | | | $ | 640,993 | |
| 5% | | | 349,370 | | | | | | 591,908 | | | | | | 895,081 | | |
| 10% | | | 640,993 | | | | | | 895,081 | | | | | | 1,212,690 | | |
| December 31, 2021 | | | | | | | | | | | | | | | | | |
| Other liability | | | $ | 1,724,907 | | | | | $ | 3,319,665 | | | | | $ | 5,044,572 | |
| Workers’ compensation (1) | | | 1,016,014 | | | | | | 903,448 | | | | | | 1,919,462 | | |
| Professional liability | | | 468,680 | | | | | | 1,019,344 | | | | | | 1,488,024 | | |
| Commercial automobile | | | 504,821 | | | | | | 424,382 | | | | | | 929,203 | | |
| Short-tail lines (2) | | | 322,917 | | | | | | 356,242 | | | | | | 679,159 | | |
| Total Insurance | | | 4,037,339 | | | | | | 6,023,081 | | | | | | 10,060,420 | | |
| Reinsurance & Monoline Excess (1) (3) | | | 1,475,623 | | | | | | 1,312,319 | | | | | | 2,787,942 | | |
| Total | | | $ | 5,512,962 | | | | | $ | 7,335,400 | | | | | $ | 12,848,362 | |
Loss cost trends have been impacted and may be further impacted by COVID-19-related claims in certain lines of business.
Losses incurred from COVID-19-related claims have been offset, to a certain extent, by lower claim frequency in certain lines of our businesses; however, as the economy and legal systems have reopened, the benefit of lower claim frequency has partially abated.
New variants of the COVID-19 virus continue to create risks with respect to loss costs and the potential for renewed impact of the other effects of COVID-19 associated with economic conditions, inflation, and social distancing and work from home rules.
Most of the COVID-19-related claims reported to the Company to date involve certain short-tailed lines of business, including contingency and event cancellation, business interruption, and film production delay.
The Company has also received COVID-19-related claims for longer-tailed casualty lines of business such as workers’ compensation and other liability; however, the estimated incurred loss impact for these reported claims are not material at this time.
Given the continuing uncertainty regarding the pandemic's pervasiveness, the future impact that the pandemic may have on claim frequency and severity remains uncertain at this time.
The Company has estimated the potential COVID-19 impact to its contingency and event cancellation, workers’ compensation, and other lines of business under a number of possible scenarios; however, due to COVID-19’s continued evolving impact, there remains uncertainty around the Company’s COVID-19 reserves.
In addition, should the pandemic continue or worsen as a result of new COVID-19 variants or otherwise, governments in the jurisdictions where we operate may impose restrictions, including lockdowns, as well as renew their efforts to expand policy coverage terms beyond the policy’s intended coverage.
Accordingly, losses arising from these actions, and the other factors described above, could exceed the Company’s reserves established for those related policies.
The Company experienced lower
Continuing the pattern seen in recent years, the overall favorable development in 2020 resulted from more significant favorable development on workers’ compensation business, which was partially offset by unfavorable development on professional liability, including excess professional liability
For workers’ compensation, the favorable development was spread across almost all prior accident years, including prior to 2011, but was most significant in accident years 2016 through 2019.
The favorable workers’ compensation development reflects a continuation of the benign loss cost trends experienced during recent years, particularly the favorable claim frequency trends (i.e., number of reported claims per unit of exposure).
The long term trend of declining workers’ compensation frequency can be attributable to improved workplace safety.
Loss severity trends were also aided by our continued investment in claims handling initiatives such as medical case management services and vendor savings through usage of preferred provider networks and pharmacy benefit managers.
Reported workers’ compensation losses in 2020 continued to be below our expectations at most of our businesses, and were below the assumptions underlying our initial loss ratio picks and our previous reserve estimates for most prior accident years.
For professional liability business, unfavorable development was driven mainly by large losses reported in the directors and officers (“D&O”), lawyers professional and excess hospital professional liability lines of business.
For these lines of business, we continue to see an increase in the number of large losses reported and a lengthening of the reporting “tail” beyond historical levels.
We believe a contributing cause is rising social inflation in the form of, for example, higher jury awards on cases that go to trial, and the corresponding higher demands from plaintiffs and higher values required to reach settlement on cases that do not go to trial.
The unfavorable development for professional liability affected mainly accident years 2016 through 2018.
The unfavorable non-proportional assumed liability development was concentrated in accident years 2014 through 2018, and related primarily to accounts insuring construction projects and professional liability exposures.
| Foreign government | | | 36 | | | | | | $ | 119,332 | | | | | $ | 73,900 | |
| Corporate | | | 10 | | | | | | 39,347 | | | | | | 4,649 | | |
An excerpt. Shown here: 40 of 212 rewritten, 40 of 108 added and 40 of 109 removed. The counts are complete. For every sentence, read Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS in the FY2023 filing and the FY2020 filing.
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
7 rewritten, 13 added, 13 removed, 24 unchanged
The Company attempts to manage its interest rate risk by maintaining an appropriate relationship between the effective duration of the investment portfolio and the [removed: approximate duration] [added: average number] of [added: years held for] its liabilities (i.e., policy claims and debt obligations).
The effective duration for the fixed maturity portfolio (including cash and cash equivalents) was 2.4 years at both December 31, [removed: 2022] [added: 2023] and [removed: 2021.][added: 2022.]
The following table outlines the groups of fixed maturity securities and their effective duration at December 31, [removed: 2022:][added: 2023:]
| U.S. government and government agencies | | | 3.1 | | | | | | [removed: 892,258] [added: 1,716,731] | | |
| Cash and cash equivalents | | | 0.0 | | | | | | [removed: 1,449,346] [added: 1,363,195] | | |
The estimated fair value at specified levels at December 31, [removed: 2022] [added: 2023] would be as follows:
| 300 basis point rise | | | $ | [removed: 17,931,180] [added: 20,180,450] | | | | | $ | [removed: (1,297,772)] [added: (1,562,536)] | |
| Mortgage-backed securities | | | 3.9 | | | | | | $ | 2,269,430 | |
| State and municipal | | | 3.2 | | | | | | 2,688,058 | | |
| Foreign government | | | 2.7 | | | | | | 1,666,229 | | |
| Corporate | | | 2.5 | | | | | | 7,654,059 | | |
| Loans receivable | | | 1.4 | | | | | | 198,244 | | |
| Asset-backed securities | | | 1.1 | | | | | | 4,187,040 | | |
| Total | | | 2.4 | | | | | | $ | 21,742,986 | |
| 200 basis point rise | | | 20,691,790 | | | | | | (1,051,196) | | |
| 100 basis point rise | | | 21,215,431 | | | | | | (527,555) | | |
| Base scenario | | | 21,742,986 | | | | | | — | | |
| 100 basis point decline | | | 22,265,903 | | | | | | 522,917 | | |
| 200 basis point decline | | | 22,780,386 | | | | | | 1,037,400 | | |
| 300 basis point decline | | | 23,286,292 | | | | | | 1,543,306 | | |
| Mortgage-backed securities | | | 4.5 | | | | | | $ | 1,669,056 | |
| State and municipal | | | 3.3 | | | | | | 2,942,025 | | |
| Corporate | | | 2.7 | | | | | | 6,703,992 | | |
| Foreign government | | | 2.2 | | | | | | 1,401,522 | | |
| Loans receivable | | | 1.3 | | | | | | 187,981 | | |
| Asset-backed securities | | | 0.9 | | | | | | 3,982,773 | | |
| Total | | | 2.4 | | | | | | $ | 19,228,953 | |
| 200 basis point rise | | | 18,344,941 | | | | | | (884,011) | | |
| 100 basis point rise | | | 18,778,053 | | | | | | (450,899) | | |
| Base scenario | | | 19,228,952 | | | | | | — | | |
| 100 basis point decline | | | 19,692,291 | | | | | | 463,339 | | |
| 200 basis point decline | | | 20,161,330 | | | | | | 932,378 | | |
| 300 basis point decline | | | 20,632,243 | | | | | | 1,403,291 | | |
Item 1. BUSINESS
201 rewritten, 59 added, 34 removed, 438 unchanged
- Insurance - Our Insurance [removed: business] [added: businesses] underwrite predominantly commercial insurance business, including excess and surplus lines, admitted lines and specialty personal lines throughout the United States, as well as insurance business in Asia, Australia, Canada, Continental Europe, Mexico, Scandinavia, South America and the United Kingdom.
Of our [removed: 59] [added: 60] businesses, [removed: 52] [added: 53] have been organized and developed internally and seven have been added through acquisition.
| (In thousands) | | | [removed: 2022] [added: 2023] | | | | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2020] [added: 2021] | | | | | | | | | | | | | | | | | | | | |
| Insurance | | | $ | [removed: 8,784,146] [added: 9,657,121] | | | | | $ | [removed: 7,743,814] [added: 8,784,146] | | | | | $ | [removed: 6,347,101] [added: 7,743,814] | | | | | | | | | | | | | | | | | | | |
| Reinsurance & Monoline Excess | | | [removed: 1,219,924] [added: 1,297,346] | | | | | | [removed: 1,119,053] [added: 1,219,924] | | | | | | [removed: 915,336] [added: 1,119,053] | | | | | | | | | | | | | | | | | | | | |
| Total | | | $ | [removed: 10,004,070] [added: 10,954,467] | | | | | $ | [removed: 8,862,867] [added: 10,004,070] | | | | | $ | [removed: 7,262,437] [added: 8,862,867] | | | | | | | | | | | | | | | | | | | |
| Insurance | | | [removed: 87.8] [added: 88.2] | | % | | | | [removed: 87.4] [added: 87.8] | | % | | | | 87.4 | | % | | | | | | | | | | | | | | | | | | |
| Reinsurance & Monoline Excess | | | [removed: 12.2] [added: 11.8] | | | | | | [removed: 12.6] [added: 12.2] | | | | | | 12.6 | | | | | | | | | | | | | | | | | | | | |
Our twenty-three insurance company subsidiaries rated by Standard & Poor's (“S&P”) have financial strength ratings of A+ (the [removed: seventh] [added: fifth] highest rating out of twenty-seven possible ratings).
Lines of business underwritten by our excess and surplus lines businesses include premises operations, [removed: commercial automobile,] [added: auto,] property, products liability, general liability and professional liability lines.
Its product lines include general liability, [removed: liquor] [added: excess] liability and some property and inland marine coverage.
*Berkley E&S Solutions* provides general liability excess and surplus lines coverages for mid-market U.S. companies with generally hard-to-place, specialized risks that involve moderate to high degrees of hazard and require tailored terms, [added: primarily] utilizing self-insurance retentions.
*Berkley Enterprise Risk Solutions* provides custom workers' compensation programs to [removed: large, motivated] [added: large] employers operating in a broad range of industries.
*Berkley Financial Specialists* serves the insurance needs of companies [added: predominantly] in the financial services [removed: sector and beyond.][added: sector.]
Its products are distributed by a select group of independent retail [removed: agents.][added: agents and wholesale brokers.]
*Berkley Latinoamérica* provides property, casualty, [removed: automobile,] [added: auto,] surety, group life and workers' compensation products and services in its operating territories of Argentina, Brazil, the Caribbean, Colombia, Mexico and Uruguay.
*Berkley One* provides a customizable suite of personal lines insurance solutions including home, condo/co-op, auto, [removed: liability] [added: fine art] and [removed: collectibles.][added: collectibles, liability, collector vehicle and recreational marine.]
*Berkley Program Specialists* is a program management [removed: company] [added: business] offering both admitted and non-admitted insurance support on a nationwide basis for commercial casualty and property program administrators with specialized insurance expertise.
Its book is built around blocks of homogeneous [removed: business, or programs, allowing for efficient processes, effective oversight of existing programs] [added: business] and [removed: sound implementation of new] programs.
Products include general liability, [removed: automobile] [added: auto] liability, law enforcement liability, public officials and educator's legal liability, employment practices liability, incidental medical, property and crime.
*Berkley Surety* provides a full spectrum of surety bonds for construction, environmental and commercial surety accounts in the U.S. and Canada, through an independent agency and broker platform across [removed: 20] [added: 19] field locations.
*Continental Western Group* is a Midwest regional property and casualty insurance operation [removed: based in Des Moines, Iowa,] providing underwriting and risk management services to a broad array of regional businesses in thirteen Midwest states.
| | | | [removed: 2022] [added: 2023] | | | | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2020] [added: 2021] | | | | | | | | | | | | | | | | | | | | |
| Acadia Insurance | | | [removed: 5.2%] [added: 5.3%] | | | | | | [removed: 5.5%] [added: 5.2%] | | | | | | [removed: 6.0%] [added: 5.5%] | | | | | | | | | | | | | | | | | | | | |
| Admiral Insurance | | | [removed: 6.2] [added: 7.0] | | | | | | [removed: 5.9] [added: 6.2] | | | | | | [removed: 5.6] [added: 5.9] | | | | | | | | | | | | | | | | | | | | |
| Berkley Accident and Health | | | [removed: 5.1] [added: 5.3] | | | | | | [removed: 5.0] [added: 5.1] | | | | | | [removed: 5.2] [added: 5.0] | | | | | | | | | | | | | | | | | | | | |
| Berkley Agribusiness | | | 0.8 | | | | | | 0.8 | | | | | | [removed: 1.2] [added: 0.8] | | | | | | | | | | | | | | | | | | | | |
| Berkley Alliance Managers | | | [removed: 2.7] [added: 2.3] | | | | | | [removed: 2.8] [added: 2.7] | | | | | | 2.8 | | | | | | | | | | | | | | | | | | | | |
| Berkley Aspire | | | [removed: 0.9] [added: 1.2] | | | | | | [removed: 0.7] [added: 0.9] | | | | | | [removed: 0.5] [added: 0.7] | | | | | | | | | | | | | | | | | | | | |
| Berkley Asset Protection | | | [removed: 1.0] [added: 0.9] | | | | | | [removed: 0.8] [added: 1.0] | | | | | | 0.8 | | | | | | | | | | | | | | | | | | | | |
| Berkley Canada | | | [removed: 1.2] [added: 1.0] | | | | | | 1.2 | | | | | | [removed: 1.1] [added: 1.2] | | | | | | | | | | | | | | | | | | | | |
| Berkley Construction Solutions | | | [removed: 0.4] [added: 0.6] | | | | | | [removed: —] [added: 0.4] | | | | | | — | | | | | | | | | | | | | | | | | | | | |
| Berkley Custom Insurance | | | [removed: 3.1] [added: 2.9] | | | | | | [removed: 3.2] [added: 3.1] | | | | | | [removed: 3.5] [added: 3.2] | | | | | | | | | | | | | | | | | | | | |
| Berkley Cyber Risk Solutions | | | [removed: 0.9] [added: 0.8] | | | | | | [removed: 0.8] [added: 0.9] | | | | | | [removed: 0.5] [added: 0.8] | | | | | | | | | | | | | | | | | | | | |
| Berkley E&S Solutions | | | [removed: —] [added: 0.1] | | | | | | — | | | | | | — | | | | | | | | | | | | | | | | | | | | |
| Berkley Enterprise Risk Solutions | | | [removed: —] [added: 0.1] | | | | | | — | | | | | | — | | | | | | | | | | | | | | | | | | | | |
| Berkley Entertainment | | | [removed: 1.8] [added: 1.7] | | | | | | 1.8 | | | | | | [removed: 2.1] [added: 1.8] | | | | | | | | | | | | | | | | | | | | |
| Berkley Environmental | | | [removed: 5.6] [added: 6.6] | | | | | | [removed: 5.2] [added: 5.6] | | | | | | [removed: 5.4] [added: 5.2] | | | | | | | | | | | | | | | | | | | | |
| Berkley Financial Specialists | | | 0.6 | | | | | | 0.6 | | | | | | [removed: 0.8] [added: 0.6] | | | | | | | | | | | | | | | | | | | | |
| Berkley Fire & Marine | | | [removed: 0.7] [added: 0.9] | | | | | | [removed: 0.8] [added: 0.7] | | | | | | 0.8 | | | | | | | | | | | | | | | | | | | | |
Our Insurance businesses underwrite predominantly commercial and specialty personal lines insurance business primarily throughout the United States.
Many units offer coverage globally, while others specialize in specific international markets.
The Insurance businesses focus on the following general areas:
*Berkley Specialty Excess* provides excess and surplus lines coverages for hard-to-place risks involved in moderate to high degrees of hazard.
It focuses on highly specialized risk exposures within specific industry verticals such as the environmental and energy industries.
Its predominate focus is on providing excess insurance; however, in some cases it provides highly specialized environmental primary products tailored to the individual risk.
Products are distributed through a minimal number of insurance brokers and agents that specialize in these industry verticals.
*Berkley Technology Underwriters* provides technology error & omission (TE&O) and first party cyber coverage along with traditional package, umbrella and worker's compensation products.
TE&O and cyber products provide industry specialization for both domestic and foreign technology, government contracting, telecommunications, digital media, manufacturing and private equity firms.
*Verus Specialty Insurance* offers tailored casualty, professional liability, and garage coverages, specializing in the excess and surplus lines market.
It primarily serves the construction, manufacturing, garage service and professional sectors through a selective wholesale broker network.
| Berkley Specialty Excess | | | 0.2 | | | | | | — | | | | | | — | | | | | | | | | | | | | | | | | | | | |
| | | | 2023 | | | | | | 2022 | | | | | | 2021 | | | | | | | | | | | | | | | | | | | | |
| | | | 2023 | | | | | | 2022 | | | | | | 2021 | | | | | | | | | | | | | | | | | | | | |
| | | | 2023 | | | | | | 2022 | | | | | | 2021 | | | | | | | | | | | | | | | | | | | | |
| | | | 2023 | | | | | | 2022 | | | | | | 2021 | | | | | | | | | | | | | | | | | | | | |
| | | | 2023 | | | | | | 2022 | | | | | | 2021 | | | | | | | | | | | | | | | | | | | | |
| | | | 2023 | | | | | | 2022 | | | | | | 2021 | | | | | | | | | | | | | | | | | | | | |
| (In thousands) | | | 2023 | | | | | | 2022 | | | | | | 2021 | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | |
| Ceded reserves | | | 3,077,832 | | |
We have received notice from Delaware, our lead state insurance regulator, that we may be considered an IAIG.
In the event that we are deemed to be an IAIG, we would be subject to international oversight coordinated by the Delaware Department of Insurance.
The amendments take effect in phases that began in 2023 and continue through 2025.
An increasing number of U.S. states have adopted, or are considering legislation similar to the CCPA.
Additionally, the NAIC is working on a new Insurance Consumer Privacy Protections Model Law to
reflect the extensive innovations in communications and technology since the adoption of the prior model laws.
*Innovation and Technology*.
As a result of increased innovation and use of technology in the insurance sector, the NAIC and insurance regulators have been focusing on the use of “big data” techniques, such as artificial intelligence, machine learning and automated decision-making.
In December 2023, the NAIC adopted the Model Bulletin on the Use of Artificial Intelligence Systems by Insurers (the “AI Bulletin”).
The AI Bulletin may be adopted and issued by state regulators to licensed insurers.
In addition to affirming that the use of artificial intelligence must comply with existing state law, the AI Bulletin sets forth regulators’ expectations on how insurers will develop, acquire and use artificial intelligence technologies.
In 2024, the NAIC plans to form a new task force to create a regulatory framework for the oversight of insurers’ use of third-party data and models.
The NAIC and state insurance regulators are also focused on addressing unfair discrimination by insurers in the use of consumer data and technology, and certain states have passed laws or are considering action targeting unfair discrimination practices.
For example, in 2021 Colorado enacted a law that prohibits insurers from using external consumer data and information sources (“ECDIS”), as well as algorithms or predictive models that use ECDIS, in a way that unfairly discriminates based on race, color, national or ethnic origin, religion, sex, sexual orientation, disability, gender identity or gender expression.
In August 2023, Colorado adopted regulations requiring life insurers to adopt a governance and risk management framework for the use of artificial intelligence, machine learning and other technologies that utilize “external consumer data.” It is expected that Colorado will also adopt governance and testing regulations for other lines of insurance, in accordance with the requirements of its 2021 law.
We cannot predict whether states will adopt the AI Bulletin, or what, if any, changes to laws or regulations may be enacted with regard to “big data” or artificial intelligence technologies.
Likewise, several states (or underwriting
In 2022, the NAIC adopted a new standard for insurance companies to report their climate-related risks as part of its annual Climate Risk Disclosure Survey, which applies to insurers that meet the reporting threshold of $100 million in U.S. direct premium and are licensed in one of the participating jurisdictions.
Our U.S.-based businesses predominantly underwrite commercial insurance business primarily throughout the United States, although many units offer coverage globally, focusing on the following general areas:
*Berkley Technology Underwriters* provides a broad range of first and third-party insurance programs for technology exposures and technology industries on both a local and global basis.
*Verus Specialty Insurance* offers general liability, professional liability and property coverages for small to mid-sized commercial risks in the excess and surplus lines insurance market through a select group of appointed wholesale brokers.
| Cumulative effect adjustment resulting from changes in accounting principles (1) | | | — | | | | | | — | | | | | | 5,927 | | | | | | | | |
| Restated net reserves at beginning of period | | | 12,848,362 | | | | | | 11,620,393 | | | | | | 10,703,925 | | | | | | | | |
(1)The cumulative effect adjustment resulting from changes in accounting principles relates to the allowance for expected credit losses on reinsurance recoverables that commenced on January 1, 2020 due to the adoption of ASU 2016-13.
| Ceded reserves | | | 2,762,344 | | |
Federal lawmakers also discussed the possibility of a public-private partnership, and there appears to have been a broadly held and bipartisan consensus that pandemic risk is generally uninsurable absent some kind of publicly-funded backstop.
While these state and federal proposals have not meaningfully progressed, there remains a risk that they might be revived, or that future variants of COVID-19 or concerns about the possibility of a future pandemic might prompt similar legislative and regulatory proposals.
The annual filing requirement will become effective once the states have adopted the NAIC holding company amendments.
This annual filing requirement became effective in Delaware, our lead state insurance regulator, on February 7, 2022.
Additionally, the Federal Trade Commission amended the “Standards for Safeguarding Customer Information Rules (otherwise known as the “Safeguards Rule”) in 2021 to require covered financial institutions to implement certain data security measures and practices in their information security programs.
Many of the requirements of the amended Safeguards Rule are similar to New York's cybersecurity regulation and the Cybersecurity Model Law, but there are some differences that may impose increased operational burdens and compliance costs.
The amended Safeguards Rule will become effective in June 2023.
The CPRA amends the CCPA by imposing additional limitations and obligations with respect to covered businesses’ use and sharing of certain personal data.
Other states have considered – and some states have adopted - similar proposals.
For instance, Virginia enacted a data privacy law in 2021 that became effective in January 2023.
Additionally, Colorado, Connecticut and Utah have enacted data privacy laws that will come into effect later in 2023.
These laws establish in those states many of the same data privacy and security requirements as other existing laws, such as the CCPA.
In addition, some states require insurers to
The NAIC’s goal is to address climate-related risks through three areas of insurance regulation: financial risk analysis; insurance market availability and affordability; and consumer education and outreach.
The EU Covered Agreement addresses three areas of prudential supervision: reinsurance, group supervision and the exchange of information between the U.S. and EU.
The EU Covered Agreement establishes group supervision practices that apply only to U.S. and EU insurance groups operating in both territories.
For instance, the EU Covered Agreement states that, provided the U.S. has adopted group supervision including worldwide group governance, solvency, capital and reporting, U.S.-headquartered insurance groups with operations in the EU will be supervised at the worldwide level only by U.S. insurance regulators, thereby precluding EU insurance supervisors from exercising solvency and capital requirements over the worldwide operations of those insurers.
The FIO plans to publish an update to its preemption report during 2023.
The FIO also can recommend that the FSOC designate an insurer as an entity posing risks to the United States’ financial stability in the event of the insurer’s material financial distress or failure, i.e., a “systemically important financial institution” or a “non-bank SIFI.” An insurer so designated by the FSOC will be subject to Federal Reserve supervision and
heightened prudential standards.
The FSOC changed its process for designating non-bank SIFIs, effective in January 2020, by adopting an activities-based approach and moving away from the entities-based approach.
However, the two regimes are likely to diverge in the near future.
The U.K. has undertaken a review of Solvency II and of the regulatory regime applicable to U.K. authorized insurers and reinsurers.
These reforms will be reflected in new U.K. legislation and regulation.
The European Council published its agreed position on the European Commission’s proposed reforms in June 2022, which it is currently negotiating with the European Parliament, although the full extent of the changes will only be known once the package of legislative reforms is finalized.
in May 2018.
adversely impact our business and profitability.
An excerpt. Shown here: 40 of 201 rewritten, 40 of 59 added and all 34 removed. The counts are complete. For every sentence, read Item 1. BUSINESS in the FY2023 filing and the FY2020 filing.
Item 3. LEGAL PROCEEDINGS
0 rewritten, 3 added, 0 removed, 2 unchanged
On December 22, 2023, one of the Company’s subsidiaries filed a lawsuit against certain reinsurers to recover in excess of $90 million in respect of certain losses paid to its policyholders under certain event cancellation and related insurance policies.
The Company believes its claims against the reinsurers are meritorious and expects a positive resolution to its lawsuit.
While an adverse outcome is possible, the Company believes that the outcome, in any case, will not be material to the Company’s financial condition.
Cover and table of contents
34 rewritten, 6 added, 1 removed, 116 unchanged
For the fiscal year ended December 31, [removed: 2022][added: 2023]
The aggregate market value of the registrant's common stock held by non-affiliates as of June 30, [removed: 2022,] [added: 2023,] the last business day of the registrant’s most recently completed second fiscal quarter, was [removed: $14,340,165,170.][added: $12,125,876,386.]
Number of shares of common stock, $.20 par value, outstanding as of February 15, [removed: 2023: 263,446,321][added: 2024: 256,548,669]
Portions of the Company’s definitive proxy statement, which will be filed with the Securities and Exchange Commission within 120 days after December 31, [removed: 2022,] [added: 2023,] are incorporated herein by reference in Part III.
| [SAFE HARBOR [removed: STATEMENT](#i35d9cb1974e34186ad62b3eebe1a5e07_10)] [added: STATEMENT](#ic13c8039c28646a096934b3ce547e717_10)] | | | | | | | | | | | |
| ITEM | | | 1. | | | [removed: [BUSINESS](#i35d9cb1974e34186ad62b3eebe1a5e07_16)] [added: [BUSINESS](#ic13c8039c28646a096934b3ce547e717_16)] | | | [removed: [6](#i35d9cb1974e34186ad62b3eebe1a5e07_16)] [added: [7](#ic13c8039c28646a096934b3ce547e717_16)] | | |
| ITEM | | | 1A. | | | [RISK [removed: FACTORS](#i35d9cb1974e34186ad62b3eebe1a5e07_19)] [added: FACTORS](#ic13c8039c28646a096934b3ce547e717_19)] | | | [removed: [25](#i35d9cb1974e34186ad62b3eebe1a5e07_19)] [added: [27](#ic13c8039c28646a096934b3ce547e717_19)] | | |
| ITEM | | | 1B. | | | [UNRESOLVED STAFF [removed: COMMENTS](#i35d9cb1974e34186ad62b3eebe1a5e07_22)] [added: COMMENTS](#ic13c8039c28646a096934b3ce547e717_22)] | | | [removed: [36](#i35d9cb1974e34186ad62b3eebe1a5e07_22)] [added: [39](#ic13c8039c28646a096934b3ce547e717_22)] | | |
| ITEM | | | 2. | | | [removed: [PROPERTIES](#i35d9cb1974e34186ad62b3eebe1a5e07_25)] [added: [PROPERTIES](#ic13c8039c28646a096934b3ce547e717_25)] | | | [removed: [36](#i35d9cb1974e34186ad62b3eebe1a5e07_25)] [added: [40](#ic13c8039c28646a096934b3ce547e717_25)] | | |
| ITEM | | | 3. | | | [LEGAL [removed: PROCEEDINGS](#i35d9cb1974e34186ad62b3eebe1a5e07_28)] [added: PROCEEDINGS](#ic13c8039c28646a096934b3ce547e717_28)] | | | [removed: [36](#i35d9cb1974e34186ad62b3eebe1a5e07_28)] [added: [40](#ic13c8039c28646a096934b3ce547e717_28)] | | |
| ITEM | | | 4. | | | [MINE SAFETY [removed: DISCLOSURES](#i35d9cb1974e34186ad62b3eebe1a5e07_31)] [added: DISCLOSURES](#ic13c8039c28646a096934b3ce547e717_31)] | | | [removed: [36](#i35d9cb1974e34186ad62b3eebe1a5e07_31)] [added: [40](#ic13c8039c28646a096934b3ce547e717_31)] | | |
| ITEM | | | 5. | | | [MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY [removed: SECURITIES](#i35d9cb1974e34186ad62b3eebe1a5e07_37)] [added: SECURITIES](#ic13c8039c28646a096934b3ce547e717_37)] | | | [removed: [37](#i35d9cb1974e34186ad62b3eebe1a5e07_37)] [added: [41](#ic13c8039c28646a096934b3ce547e717_37)] | | |
| ITEM | | | 7. | | | [MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF [removed: OPERATIONS](#i35d9cb1974e34186ad62b3eebe1a5e07_40)] [added: OPERATIONS](#ic13c8039c28646a096934b3ce547e717_40)] | | | [removed: [39](#i35d9cb1974e34186ad62b3eebe1a5e07_40)] [added: [43](#ic13c8039c28646a096934b3ce547e717_40)] | | |
| ITEM | | | 7A. | | | [QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET [removed: RISK](#i35d9cb1974e34186ad62b3eebe1a5e07_58)] [added: RISK](#ic13c8039c28646a096934b3ce547e717_58)] | | | [removed: [60](#i35d9cb1974e34186ad62b3eebe1a5e07_58)] [added: [62](#ic13c8039c28646a096934b3ce547e717_58)] | | |
| ITEM | | | 8. | | | [FINANCIAL STATEMENTS AND SUPPLEMENTARY [removed: DATA](#i35d9cb1974e34186ad62b3eebe1a5e07_61)] [added: DATA](#ic13c8039c28646a096934b3ce547e717_61)] | | | [removed: [61](#i35d9cb1974e34186ad62b3eebe1a5e07_61)] [added: [63](#ic13c8039c28646a096934b3ce547e717_61)] | | |
| ITEM | | | 9. | | | [CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL [removed: DISCLOSURE](#i35d9cb1974e34186ad62b3eebe1a5e07_163)] [added: DISCLOSURE](#ic13c8039c28646a096934b3ce547e717_166)] | | | [removed: [113](#i35d9cb1974e34186ad62b3eebe1a5e07_163)] [added: [113](#ic13c8039c28646a096934b3ce547e717_166)] | | |
| ITEM | | | 9A. | | | [CONTROLS AND [removed: PROCEDURES](#i35d9cb1974e34186ad62b3eebe1a5e07_166)] [added: PROCEDURES](#ic13c8039c28646a096934b3ce547e717_169)] | | | [removed: [113](#i35d9cb1974e34186ad62b3eebe1a5e07_166)] [added: [113](#ic13c8039c28646a096934b3ce547e717_169)] | | |
| ITEM | | | 9B. | | | [OTHER [removed: INFORMATION](#i35d9cb1974e34186ad62b3eebe1a5e07_169)] [added: INFORMATION](#ic13c8039c28646a096934b3ce547e717_172)] | | | [removed: [115](#i35d9cb1974e34186ad62b3eebe1a5e07_169)] [added: [115](#ic13c8039c28646a096934b3ce547e717_172)] | | |
| ITEM | | | 9C. | | | [DISCLOSURE REGARDING FOREIGN JURISDICTIONS THAT PREVENT [removed: INSPECTIONS](#i35d9cb1974e34186ad62b3eebe1a5e07_172)] [added: INSPECTIONS](#ic13c8039c28646a096934b3ce547e717_175)] | | | [removed: [115](#i35d9cb1974e34186ad62b3eebe1a5e07_172)] [added: [115](#ic13c8039c28646a096934b3ce547e717_175)] | | |
| ITEM | | | 10. | | | [DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE [removed: GOVERNANCE](#i35d9cb1974e34186ad62b3eebe1a5e07_178)] [added: GOVERNANCE](#ic13c8039c28646a096934b3ce547e717_181)] | | | [removed: [116](#i35d9cb1974e34186ad62b3eebe1a5e07_178)] [added: [116](#ic13c8039c28646a096934b3ce547e717_181)] | | |
| ITEM | | | 11. | | | [EXECUTIVE [removed: COMPENSATION](#i35d9cb1974e34186ad62b3eebe1a5e07_181)] [added: COMPENSATION](#ic13c8039c28646a096934b3ce547e717_184)] | | | [removed: [116](#i35d9cb1974e34186ad62b3eebe1a5e07_181)] [added: [116](#ic13c8039c28646a096934b3ce547e717_184)] | | |
| ITEM | | | 12. | | | [SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER [removed: MATTERS](#i35d9cb1974e34186ad62b3eebe1a5e07_184)] [added: MATTERS](#ic13c8039c28646a096934b3ce547e717_187)] | | | [removed: [116](#i35d9cb1974e34186ad62b3eebe1a5e07_184)] [added: [116](#ic13c8039c28646a096934b3ce547e717_187)] | | |
| ITEM | | | 13. | | | [CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR [removed: INDEPENDENCE](#i35d9cb1974e34186ad62b3eebe1a5e07_187)] [added: INDEPENDENCE](#ic13c8039c28646a096934b3ce547e717_190)] | | | [removed: [116](#i35d9cb1974e34186ad62b3eebe1a5e07_187)] [added: [116](#ic13c8039c28646a096934b3ce547e717_190)] | | |
| ITEM | | | 14. | | | [PRINCIPAL ACCOUNTANT FEES AND [removed: SERVICES](#i35d9cb1974e34186ad62b3eebe1a5e07_190)] [added: SERVICES](#ic13c8039c28646a096934b3ce547e717_193)] | | | [removed: [116](#i35d9cb1974e34186ad62b3eebe1a5e07_190)] [added: [116](#ic13c8039c28646a096934b3ce547e717_193)] | | |
| ITEM | | | 15. | | | [EXHIBITS AND FINANCIAL STATEMENT [removed: SCHEDULES](#i35d9cb1974e34186ad62b3eebe1a5e07_196)] [added: SCHEDULES](#ic13c8039c28646a096934b3ce547e717_199)] | | | [removed: [117](#i35d9cb1974e34186ad62b3eebe1a5e07_196)] [added: [117](#ic13c8039c28646a096934b3ce547e717_199)] | | |
| ITEM | | | 16. | | | [FORM 10-K [removed: SUMMARY](#i35d9cb1974e34186ad62b3eebe1a5e07_7)] [added: SUMMARY](#ic13c8039c28646a096934b3ce547e717_7)] | | | [removed: [121](#i35d9cb1974e34186ad62b3eebe1a5e07_205)] [added: [121](#ic13c8039c28646a096934b3ce547e717_208)] | | |
| EX-21 | | | | | | [LIST OF COMPANIES AND [removed: SUBSIDIARIES](https://www.sec.gov/Archives/edgar/data/11544/000001154423000004/wrb1231202210-kex21.htm)] [added: SUBSIDIARIES](https://www.sec.gov/Archives/edgar/data/11544/000001154424000005/wrb1231202310-kex21.htm)] | | | | | |
| EX-23 | | | | | | [CONSENT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING [removed: FIRM](https://www.sec.gov/Archives/edgar/data/11544/000001154423000004/wrb1231202210-kex23.htm)] [added: FIRM](https://www.sec.gov/Archives/edgar/data/11544/000001154424000005/wrb1231202310-kex23.htm)] | | | | | |
| EX-31.1 | | | | | | [CERTIFICATION OF THE CHIEF EXECUTIVE OFFICER PURSUANT TO RULE 13a-14(a) [removed: /15d-14(a)](https://www.sec.gov/Archives/edgar/data/11544/000001154423000004/wrb1231202210-kex311.htm)] [added: /15d-14(a)](https://www.sec.gov/Archives/edgar/data/11544/000001154424000005/wrb1231202310-kex311.htm)] | | | | | |
| EX-31.2 | | | | | | [CERTIFICATION OF THE CHIEF FINANCIAL OFFICER PURSUANT TO RULE 13a-14(a) [removed: /15d-14(a)](https://www.sec.gov/Archives/edgar/data/11544/000001154423000004/wrb1231202210-kex312.htm)] [added: /15d-14(a)](https://www.sec.gov/Archives/edgar/data/11544/000001154424000005/wrb1231202310-kex312.htm)] | | | | | |
| EX-32.1 | | | | | | [CERTIFICATION OF THE CHIEF EXECUTIVE OFFICER AND CHIEF FINANCIAL OFFICER PURSUANT TO 18 U.S.C. SECTION 1350, AS ADOPTED PURSUANT TO SECTION 906 OF THE SARBANES-OXLEY ACT OF [removed: 2002](https://www.sec.gov/Archives/edgar/data/11544/000001154423000004/wrb1231202210-kex321.htm)] [added: 2002](https://www.sec.gov/Archives/edgar/data/11544/000001154424000005/wrb1231202310-kex321.htm)] | | | | | |
Any forward-looking statements contained in this report including statements related to our outlook for the industry and for our performance for the year [removed: 2023] [added: 2024] and beyond, are based upon our historical performance and on current plans, estimates and expectations.
- the ongoing effects of the COVID-19 [removed: pandemic;][added: pandemic or other potential pandemics;]
These risks and uncertainties could cause our actual results for the year [removed: 2023] [added: 2024] and beyond to differ materially from those expressed in any forward-looking statement we make.
| ITEM | | | 1C. | | | [CYBERSECURITY](#ic13c8039c28646a096934b3ce547e717_1881) | | | [39](#ic13c8039c28646a096934b3ce547e717_1881) | | |
| | | | | | | | | | | | |
| EX-10.12 | | | | | | [FORM OF 2023 PERFORMANCE-BASED RESTRICTED STOCK UNIT AGREEMENT UNDER THE W. R. BERKLEY CORPORATION 2018 STOCK INCENTIVE PLAN](https://www.sec.gov/Archives/edgar/data/11544/000001154424000005/wrb1231202310-kex1012.htm) | | | | | |
| EX-97 | | | | | | [W. R. BERKLEY CORPORATION CLAWBACK POLICY](https://www.sec.gov/Archives/edgar/data/11544/000001154424000005/wrb1231202310-kex97.htm) | | | | | |
| | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| EX-4.1 | | | | | | [DESCRIPTION OF REGISTRANT’S SECURITIES REGISTERED PURSUANT TO SECTION 12 OF THE SECURITIES EXCHANGE ACT OF 1934](https://www.sec.gov/Archives/edgar/data/11544/000001154423000004/wrb1231202210-kex41.htm) | | | | | |
Item 1C. CYBERSECURITY
0 rewritten, 22 added, 0 removed, 0 unchanged
New section this year
Cybersecurity Strategy and Risk Management Program
The Company has a documented information security program (the Program) to identify, assess, monitor and manage potential cybersecurity threats and incidents.
The Program is designed to protect the confidentiality, integrity and availability of our information systems and assets that store, process, or transmit information.
The Program is modeled on the global standard for risk assessment, International Organization for Standardization 27001, and is guided by the six domains of cybersecurity established by the National Institute of Standards and Technology Cybersecurity Framework (i.e., govern, identify, protect, detect, respond, and recovery).
The Program seeks to adhere to applicable U.S. and international laws and regulations, including New York State’s cybersecurity regulation applicable to financial services institutions authorized by the New York State Department of Financial Services.
The Program’s security and risk policies and standards, implemented by either the Company or third party assessors or consultants, include:
–information security management tools, such as firewalls, intrusion prevention and detection systems, anti-malware functionality, and access privilege controls;
–vulnerability management, including penetration and control testing and vulnerability scans of information systems;
–incident monitoring, breach notification and escalation, including disaster recovery and incident response plans and resources;
–risk based assessment of third party service providers; and
–annual cybersecurity awareness training for employees and contractors.
The Company has not identified any cybersecurity incidents that have materially affected or are reasonably likely to materially affect the Company, including its business strategy, results of operations, or financial condition, for the period covered by this annual report.
For a discussion regarding risks associated with cybersecurity threats, see Risk Factors – Risks Relating to Our Business – “If our information technology, telecommunications or other computer systems become unavailable or unreliable, our ability to conduct our business could be negatively or severely impacted” and “Failure to maintain the security of information technology systems and confidential data may expose us to liability.”
Board Oversight, Governance and Risk Management
The entire Board of Directors has oversight of risks from cybersecurity threats and receives periodic updates on such risks from the Company’s management, including from the Company’s President and CEO and its Vice President, Chief Information Security Officer (CISO).
Our CISO is principally responsible for assessing and managing all aspects of the Program, including the Company’s Regional Information Security Officers (RISOs), third-party consultants, development of industry trends and control testing and tracking by risk level.
Our CISO meets periodically with senior executives, including the Company’s President and Chief Executive Officer, to discuss the Company’s cybersecurity strategy, and its monitoring, prevention, detection, mitigation, and remediation of cybersecurity risks.
Regular reporting on the Program is also provided to the Company’s Enterprise Risk Management Committee, which is comprised of the President and CEO, Senior Vice President – Enterprise Risk Management, Executive Vice President – Investments, Executive Vice President – Chief Financial Officer, Executive Vice President – Secretary, and the Of Counsel and Assistant Secretary.
Collectively, the CISO and RISOs, along with their teams, in collaboration with the technology and business owners, implement the Program.
Legal, Compliance, and Internal Audit functions also assess the Program’s adherence to regulatory requirements and internal controls.
In the event of a potentially material cybersecurity incident, the Company’s incident response plans establish escalation protocols for relevant IT leaders and functional leaders within Enterprise Risk Management, Legal, Compliance and Internal Audit to engage management as appropriate.
Our CISO has over 25 years of information security experience and is licensed as a Certified Information Systems Security Professional.
Item 2. PROPERTIES
3 rewritten, 0 added, 0 removed, 1 unchanged
At December 31, [removed: 2022,] [added: 2023,] the Company had aggregate office space of [removed: 4,295,165] [added: 4,333,225] square feet, of which [removed: 1,048,136] [added: 1,042,156] were owned and [removed: 3,247,029] [added: 3,291,069] were leased.
Rental expense for the Company's operations was approximately [removed: $43,383,000, $44,051,000] [added: $44,256,000, $43,383,000] and [removed: $44,291,000] [added: $44,051,000] for [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020,] [added: 2021,] respectively.
Future minimum lease payments, without provision for sublease income, are [removed: $32,282,796] [added: $50,222,000] in [removed: 2023, $33,528,105] [added: 2024, $41,249,000] in [removed: 2024] [added: 2025] and [removed: $599,371,375] [added: $166,192,000] thereafter.
Item 5. MARKET FOR THE REGISTRANT'S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
9 rewritten, 6 added, 6 removed, 8 unchanged
In [removed: 2022,] [added: 2023,] the Board declared regular quarterly cash dividends of [removed: $0.09] [added: $0.10] per share in the first [removed: quarter,] [added: quarter] and [removed: $0.10] [added: $0.11] per share in each of the remaining three quarters, [removed: and] [added: as well as] special dividends of $0.50 per share in the [removed: second quarter.][added: first, third, and fourth quarters, for a total of $501 million in aggregate dividends in 2023.]
The approximate number of record holders of the common stock on February 15, [removed: 2023] [added: 2024] was [removed: 323.][added: 327.]
*Assumes initial investment of $100 on January 1, [removed: 2017,] [added: 2018,] with dividends reinvested.*
[removed: 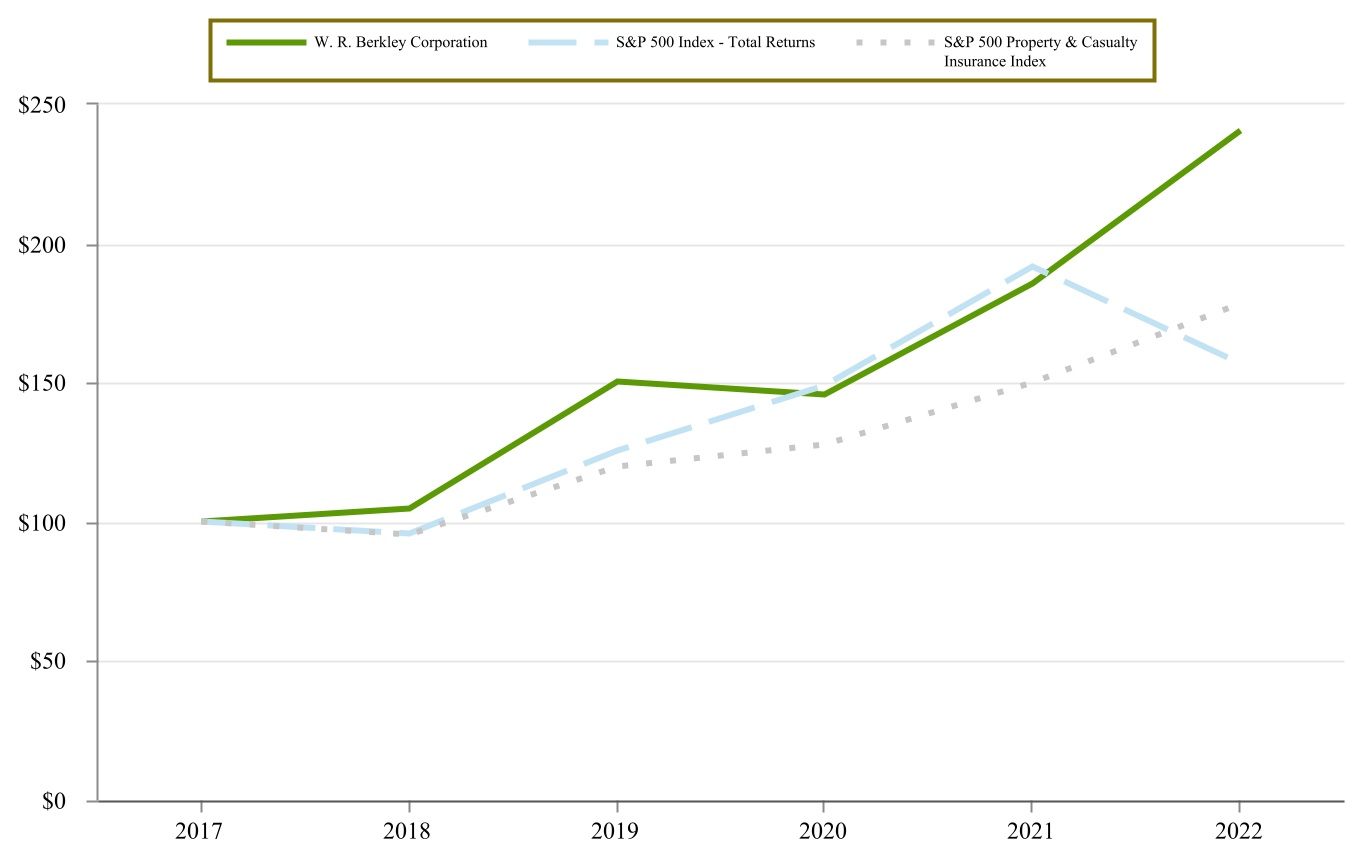][added: ]
As of December 31, [removed: 2022,] [added: 2023,] the S&P 500® Property and Casualty Insurance Index consists of [added: The] Allstate Corporation, Arch Capital Group Ltd. (added Nov.
2022), [removed: Chubb, Ltd.,] [added: Chubb Limited,] Cincinnati Financial Corporation, [added: The Hartford Financial Services Group, Inc., Loews Corporation (CNA), The] Progressive Corporation, The Travelers Companies, Inc., and W. R. Berkley Corporation (added Dec.
| | | | | | | [removed: 2017 | | |] 2018 | | | 2019 | | | 2020 | | | 2021 | | | 2022 | | | [added: 2023 | | |]
| S&P 500 Property and Casualty Insurance Index | | | Cum $ | | | 100.00 | | | [removed: 95.31] [added: 125.87] | | | [removed: 119.97] [added: 133.84] | | | [removed: 127.56] [added: 157.28] | | | [removed: 149.90] [added: 187.04] | | | [removed: 178.27] [added: 207.20] | | |
Set forth below is a summary of the shares repurchased by the Company during the fourth quarter of [removed: 2022] [added: 2023] and the remaining number of shares authorized for purchase by the Company during such period.
The common stock of the Company is traded on the New York Stock Exchange under the symbol “WRB”.
| W. R. Berkley Corporation | | | Cum $ | | | 100.00 | | | 143.83 | | | 139.30 | | | 177.37 | | | 237.46 | | | 238.04 | | |
| S&P 500 Index - Total Returns | | | Cum $ | | | 100.00 | | | 131.48 | | | 155.64 | | | 200.28 | | | 163.89 | | | 207.05 | | |
| October 2023 | | | 371,497 | | | | | | $ | 63.75 | | | | | 371,497 | | | | | | 14,430,487 | | |
| November 2023 | | | — | | | | | | — | | | | | | — | | | | | | 14,430,487 | | |
| December 2023 | | | 1,189,204 | | | | | | 69.75 | | | | | | 1,189,204 | | | | | | 13,241,283 | | |
Subject to availability, the Board currently expects to continue such regular quarterly cash dividends.
| W. R. Berkley Corporation | | | Cum $ | | | 100.00 | | | 104.61 | | | 150.46 | | | 145.72 | | | 185.56 | | | 240.56 | | |
| S&P 500 Index - Total Returns | | | Cum $ | | | 100.00 | | | 95.61 | | | 125.70 | | | 148.81 | | | 191.48 | | | 156.69 | | |
| October 2022 | | | 325,596 | | | | | | $ | 69.22 | | | | | 325,596 | | | | | | 14,568,100 | | |
| November 2022 | | | 938,494 | | | | | | 69.29 | | | | | | 938,494 | | | | | | 13,629,606 | | |
| December 2022 | | | — | | | | | | — | | | | | | — | | | | | | 13,629,606 | | |
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
627 rewritten, 355 added, 326 removed, 859 unchanged
We have audited the accompanying consolidated balance sheets of W. R. Berkley Corporation and subsidiaries (the Company) as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] the related consolidated statements of income, comprehensive income, stockholders’ equity, and cash flows for each of the years in the three‑year period ended December 31, [removed: 2022,] [added: 2023,] and the related notes and financial statement schedules II to VI (collectively, the consolidated financial statements).
In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] and the results of its operations and its cash flows for each of the years in the three-year period ended December 31, [removed: 2022,] [added: 2023,] in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company’s internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in *Internal Control - Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission, and our report dated February [removed: 24, 2023] [added: 23, 2024] expressed an unqualified opinion on the effectiveness of the Company’s internal control over financial reporting.
As discussed in Notes 1 and [removed: 14] [added: 13] to the consolidated financial statements, the Company estimates the reserves for losses and loss expenses (reserves) using a variety of actuarial techniques and methods.
The reserves as of December 31, [removed: 2022] [added: 2023] were [removed: $17.0] [added: $18.7] billion.
[removed: We] [added: With the assistance of actuarial professionals, when appropriate, we] evaluated the design and tested the operating effectiveness of certain internal controls over the Company’s reserving process.
- examining the Company’s actuarial methodologies for compliance with Actuarial Standards of [removed: Practice;][added: Practice]
- evaluating the Company’s ability to discount certain reserves by comparing the expected payout pattern of claims paid to actual claims [removed: paid;][added: paid]
- evaluating the Company’s actuarial point estimate by performing independent actuarial analyses for certain of the larger, more complex [removed: businesses;][added: businesses]
- evaluating the Company’s actuarial point estimate by examining the Company actuaries’ process, and key assumptions for certain of the remaining [removed: businesses;][added: businesses]
- developing an independent range of reserves based on actuarial methodologies and assumptions and comparing to the Company’s recorded [removed: reserves;][added: reserves]
| (In thousands, except per share data) | | | [removed: 2022] [added: 2023] | | | | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2020] [added: 2021] | | |
| Net premiums written | | | $ | [removed: 10,004,070] [added: 10,954,467] | | | | | $ | [removed: 8,862,867] [added: 10,004,070] | | | | | $ | [removed: 7,262,437] [added: 8,862,867] | |
| Change in net unearned premiums | | | [removed: (442,641)] [added: (553,780)] | | | | | | [removed: (756,836)] [added: (442,641)] | | | | | | [removed: (331,594)] [added: (756,836)] | | |
| Net premiums earned | | | [removed: 9,561,429] [added: 10,400,687] | | | | | | [removed: 8,106,031] [added: 9,561,429] | | | | | | [removed: 6,930,843] [added: 8,106,031] | | |
| Net investment income | | | [removed: 779,185] [added: 1,052,835] | | | | | | [removed: 671,618] [added: 779,185] | | | | | | [removed: 583,821] [added: 671,618] | | |
| Net realized and unrealized gains on investments | | | [removed: 217,311] [added: 47,540] | | | | | | [removed: 106,958] [added: 217,311] | | | | | | [removed: 73,514] [added: 106,958] | | |
| Change in allowance for expected credit losses on investments | | | [removed: (14,914)] [added: (498)] | | | | | | [removed: (16,326)] [added: (14,914)] | | | | | | [removed: 29,486] [added: (16,326)] | | |
| Net investment gains | | | [removed: 202,397] [added: 47,042] | | | | | | [removed: 90,632] [added: 202,397] | | | | | | [removed: 103,000] [added: 90,632] | | |
| Revenues from non-insurance businesses | | | [removed: 509,548] [added: 535,508] | | | | | | [removed: 489,151] [added: 509,548] | | | | | | [removed: 389,888] [added: 489,151] | | |
| Insurance service fees | | | [removed: 110,544] [added: 106,485] | | | | | | [removed: 93,857] [added: 110,544] | | | | | | [removed: 88,777] [added: 93,857] | | |
| Other income | | | [removed: 3,396] [added: 381] | | | | | | [removed: 4,177] [added: 3,396] | | | | | | [removed: 2,596] [added: 4,177] | | |
| Total revenues | | | [removed: 11,166,499] [added: 12,142,938] | | | | | | [removed: 9,455,466] [added: 11,166,499] | | | | | | [removed: 8,098,925] [added: 9,455,466] | | |
| Losses and loss expenses | | | [removed: 5,861,750] [added: 6,372,142] | | | | | | [removed: 4,953,960] [added: 5,861,750] | | | | | | [removed: 4,468,706] [added: 4,953,960] | | |
| Other operating costs and expenses | | | [removed: 2,961,505] [added: 3,363,936] | | | | | | [removed: 2,599,270] [added: 2,961,505] | | | | | | [removed: 2,390,392] [added: 2,599,270] | | |
| Expenses from non-insurance businesses | | | [removed: 493,189] [added: 524,998] | | | | | | [removed: 472,151] [added: 493,189] | | | | | | [removed: 384,488] [added: 472,151] | | |
| Interest expense | | | [removed: 130,374] [added: 127,459] | | | | | | [removed: 147,180] [added: 130,374] | | | | | | [removed: 150,537] [added: 147,180] | | |
| Total operating costs and expenses | | | [removed: 9,446,818] [added: 10,388,535] | | | | | | [removed: 8,172,561] [added: 9,446,818] | | | | | | [removed: 7,394,123] [added: 8,172,561] | | |
| Income before income taxes | | | [removed: 1,719,681] [added: 1,754,403] | | | | | | [removed: 1,282,905] [added: 1,719,681] | | | | | | [removed: 704,802] [added: 1,282,905] | | |
| Income tax expense | | | [removed: (334,727)] [added: (370,557)] | | | | | | [removed: (251,890)] [added: (334,727)] | | | | | | [removed: (171,817)] [added: (251,890)] | | |
| Net income before noncontrolling interests | | | [removed: 1,384,954] [added: 1,383,846] | | | | | | [removed: 1,031,015] [added: $] | [added: 1,384,954] | | | | | [removed: 532,985] [added: 1,031,015] | | |
| Noncontrolling interests | | | [removed: (3,892)] [added: (2,487)] | | | | | | [removed: (8,525)] [added: (3,892)] | | | | | | [removed: (2,315)] [added: (8,525)] | | |
| Net income to common stockholders | | | $ | [removed: 1,381,062] [added: 1,381,359] | | | | | $ | [removed: 1,022,490] [added: 1,381,062] | | | | | $ | [removed: 530,670] [added: 1,022,490] | |
| Basic | | | $ | [removed: 4.99] [added: 5.10] | | | | | $ | [removed: 3.69] [added: 4.99] | | | | | $ | [removed: 1.89] [added: 3.69] | |
| Diluted | | | $ | [removed: 4.94] [added: 5.05] | | | | | $ | [removed: 3.66] [added: 4.94] | | | | | $ | [removed: 1.87] [added: 3.66] | |
| (In thousands) | | | [removed: 2022] [added: 2023] | | | | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2020] [added: 2021] | | |
| Net income before noncontrolling interests | | | $ | [removed: 1,384,954] [added: 1,383,846] | | | | | $ | [removed: 1,031,015] [added: 1,384,954] | | | | | $ | [removed: 532,985] [added: 1,031,015] | |
| Other comprehensive [removed: (loss) gain.:] [added: gain (loss):] | | | | | | | | | | | | | | | | | |
| Change in unrealized translation adjustments | | | [removed: 1,179] [added: 32,192] | | | | | | [removed: (20,969)] [added: 1,179] | | | | | | [removed: 29,927] [added: (20,969)] | | |
| Change in unrealized investment [removed: (losses) gains,] [added: gains (losses),] net of taxes | | | [removed: (983,803)] [added: 306,553] | | | | | | [removed: (198,812)] [added: (983,803)] | | | | | | [removed: 140,250] [added: (198,812)] | | |
February 23, 2024
| Stock exercised/vested | | | | | | | | | | | | | | | | | | | | | 10,381 | | | | | | 9,787 | | | | | | 13,775 | | |
| Other | | | | | | | | | | | | | | | | | | | | | (4,922) | | | | | | — | | | | | | — | | |
| Net income to common stockholders | | | $ | 1,381,359 | | | | | $ | 1,381,062 | | | | | $ | 1,022,490 | |
corresponding credit or charge to interest income or expense.
| Beginning of period | | | $ | (892,905) | | | | | $ | (371,676) | | | | | | | | | | | $ | (1,264,581) | |
| Other comprehensive income before reclassifications | | | 252,782 | | | | | | 32,192 | | | | | | | | | | | | 284,974 | | |
| Other comprehensive income | | | 306,553 | | | | | | 32,192 | | | | | | | | | | | | 338,745 | | |
| Ending balance | | | $ | (586,354) | | | | | $ | (339,484) | | | | | | | | | | | $ | (925,838) | |
| Pre-tax | | | $ | 392,903 | | | | | $ | 32,192 | | | | | | | | | | | $ | 425,095 | |
| Other comprehensive income | | | $ | 306,553 | | | | | $ | 32,192 | | | | | | | | | | | $ | 338,745 | |
| December 31, 2023 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| State and municipal | | | $ | 50,547 | | | | | $ | (43) | | | | | $ | 3,132 | | | | | $ | — | | | | | $ | 53,636 | | | | | $ | 50,504 | | | | | | | |
| Residential mortgage-backed | | | 2,868 | | | | | | — | | | | | | 107 | | | | | | — | | | | | | 2,975 | | | | | | 2,868 | | | | | | | | |
| Total held to maturity | | | 53,415 | | | | | | (43) | | | | | | 3,239 | | | | | | — | | | | | | 56,611 | | | | | | 53,372 | | | | | | | | |
| U.S. government and government agency | | | 1,762,997 | | | | | | — | | | | | | 11,403 | | | | | | (57,669) | | | | | | 1,716,731 | | | | | | 1,716,731 | | | | | | | | |
| Special revenue | | | 1,682,550 | | | | | | — | | | | | | 5,651 | | | | | | (82,006) | | | | | | 1,606,195 | | | | | | 1,606,195 | | | | | | | | |
| State general obligation | | | 394,429 | | | | | | — | | | | | | 3,550 | | | | | | (16,405) | | | | | | 381,574 | | | | | | 381,574 | | | | | | | | |
| Pre-refunded | | | 103,029 | | | | | | — | | | | | | 1,634 | | | | | | (185) | | | | | | 104,478 | | | | | | 104,478 | | | | | | | | |
| Corporate backed | | | 166,873 | | | | | | (757) | | | | | | 696 | | | | | | (11,973) | | | | | | 154,839 | | | | | | 154,839 | | | | | | | | |
| Local general obligation | | | 396,041 | | | | | | — | | | | | | 3,188 | | | | | | (11,893) | | | | | | 387,336 | | | | | | 387,336 | | | | | | | | |
| Total state and municipal | | | 2,742,922 | | | | | | (757) | | | | | | 14,719 | | | | | | (122,462) | | | | | | 2,634,422 | | | | | | 2,634,422 | | | | | | | | |
| Residential | | | 1,773,206 | | | | | | — | | | | | | 12,780 | | | | | | (163,844) | | | | | | 1,622,142 | | | | | | 1,622,142 | | | | | | | | |
| Commercial | | | 657,157 | | | | | | (158) | | | | | | 626 | | | | | | (13,312) | | | | | | 644,313 | | | | | | 644,313 | | | | | | | | |
| Total mortgage-backed securities | | | 2,430,363 | | | | | | (158) | | | | | | 13,406 | | | | | | (177,156) | | | | | | 2,266,455 | | | | | | 2,266,455 | | | | | | | | |
| Asset-backed securities | | | 4,252,883 | | | | | | (1,164) | | | | | | 8,527 | | | | | | (73,206) | | | | | | 4,187,040 | | | | | | 4,187,040 | | | | | | | | |
| Industrial | | | 3,679,219 | | | | | | (40) | | | | | | 24,312 | | | | | | (143,936) | | | | | | 3,559,555 | | | | | | 3,559,555 | | | | | | | | |
| Financial | | | 2,838,220 | | | | | | (4,986) | | | | | | 14,681 | | | | | | (68,681) | | | | | | 2,779,234 | | | | | | 2,779,234 | | | | | | | | |
| Utilities | | | 701,865 | | | | | | — | | | | | | 6,471 | | | | | | (23,412) | | | | | | 684,924 | | | | | | 684,924 | | | | | | | | |
| Other | | | 635,975 | | | | | | — | | | | | | 1,605 | | | | | | (7,234) | | | | | | 630,346 | | | | | | 630,346 | | | | | | | | |
| Total corporate | | | 7,855,279 | | | | | | (5,026) | | | | | | 47,069 | | | | | | (243,263) | | | | | | 7,654,059 | | | | | | 7,654,059 | | | | | | | | |
| Foreign government | | | 1,817,386 | | | | | | (29,603) | | | | | | 15,865 | | | | | | (137,419) | | | | | | 1,666,229 | | | | | | 1,666,229 | | | | | | | | |
| Total available for sale | | | 20,861,830 | | | | | | (36,708) | | | | | | 110,989 | | | | | | (811,175) | | | | | | 20,124,936 | | | | | | 20,124,936 | | | | | | | | |
| Total investments in fixed maturity securities | | | $ | 20,915,245 | | | | | $ | (36,751) | | | | | $ | 114,228 | | | | | $ | (811,175) | | | | | $ | 20,181,547 | | | | | $ | 20,178,308 | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | 2023 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | 2022 | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Due in one year or less | | | $ | 1,937,329 | | | | | $ | 1,860,397 | |
| Due after ten years | | | 2,568,038 | | | | | | 2,463,851 | | |
February 24, 2023
| Trading account payable to brokers and clearing organizations | | | — | | | | | | 53,636 | | |
| Change in controlling financial interest of a subsidiary | | | | | | | | | | | | | | | | | | | | | — | | | | | | — | | | | | | (53,635) | | |
| Cumulative effect adjustment resulting from changes in accounting principles | | | | | | | | | | | | | | | | | | | | | — | | | | | | — | | | | | | (30,514) | | |
| Cumulative effect adjustment resulting from changes in accounting principles | | | | | | | | | | | | | | | | | | | | | — | | | | | | — | | | | | | 24,952 | | |
| Stock exercised/vested | | | | | | | | | | | | | | | | | | | | | 9,428 | | | | | | 13,264 | | | | | | 13,917 | | |
| Stock issued | | | | | | | | | | | | | | | | | | | | | 359 | | | | | | 511 | | | | | | 726 | | |
| Cash and cash equivalents at beginning of year | | | 1,568,843 | | | | | | 2,372,366 | | | | | | 1,023,710 | | |
Shares outstanding and per share amounts have been adjusted to reflect the 3-for-2 common stock split effected on March 23, 2022.
For the years ended December 31, 2021 and 2020, the Company did not correct these line items as the effects were not material and had no impact on the total amount of investing activities.
Commissions for insurance brokerage are generally recognized when the underlying insurance policy is effective.
hold to maturity are classified as held to maturity and reported at amortized cost.
term assumptions linearly over 5 years beyond the forecast period.
(2) Acquisitions
In March 2022, the Company acquired an 80.0% ownership interest for $51.1 million in a company engaged in residential and commercial textiles.
The fair value of the assets acquired and liabilities assumed have been estimated based on a third party valuation.
The following table summarizes the estimated fair value of net assets acquired and liabilities assumed for the business combination completed in 2022:
| | | | | | |
| --- | --- | --- | --- | --- | --- |
| Cash and cash equivalents | | | $ | 1,564 | |
| Real estate, furniture and equipment | | | 6,000 | | |
| Intangible assets | | | 25,600 | | |
| Goodwill | | | 15,857 | | |
| Other assets | | | 20,349 | | |
| Total assets acquired | | | 69,370 | | |
| Other liabilities assumed | | | (12,420) | | |
| Noncontrolling interest | | | (5,814) | | |
| Net assets acquired | | | $ | 51,136 | |
| Beginning of period | | | $ | 289,714 | | | | | $ | (351,886) | | | | | | | | | | | $ | (62,172) | |
| Other comprehensive loss before reclassifications | | | (222,359) | | | | | | (20,969) | | | | | | | | | | | | (243,328) | | |
| Other comprehensive loss | | | (198,812) | | | | | | (20,969) | | | | | | | | | | | | (219,781) | | |
| Ending balance | | | $ | 90,900 | | | | | $ | (372,855) | | | | | | | | | | | $ | (281,955) | |
| Pre-tax | | | $ | (254,939) | | | | | $ | (20,969) | | | | | | | | | | | $ | (275,908) | |
| Other comprehensive loss | | | $ | (198,812) | | | | | $ | (20,969) | | | | | | | | | | | $ | (219,781) | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| December 31, 2021 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| State and municipal | | | $ | 69,539 | | | | | $ | (387) | | | | | $ | 10,813 | | | | | $ | — | | | | | $ | 79,965 | | | | | $ | 69,152 | |
| Residential mortgage-backed | | | 4,829 | | | | | | — | | | | | | 632 | | | | | | — | | | | | | 5,461 | | | | | | 4,829 | | |
| Total held to maturity | | | 74,368 | | | | | | (387) | | | | | | 11,445 | | | | | | — | | | | | | 85,426 | | | | | | 73,981 | | |
An excerpt. Shown here: 40 of 627 rewritten, 40 of 355 added and 40 of 326 removed. The counts are complete. For every sentence, read Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA in the FY2023 filing and the FY2020 filing.
Item 9A. CONTROLS AND PROCEDURES
5 rewritten, 1 added, 1 removed, 29 unchanged
During the quarter ended December 31, [removed: 2022,] [added: 2023,] there have been no changes in our internal controls over financial reporting that have materially affected, or are reasonably likely to materially affect, our internal controls over financial reporting.
Based on our evaluation under the framework in Internal Control - Integrated Framework, our management concluded that our internal control over financial reporting was effective as of December 31, [removed: 2022.][added: 2023.]
We have audited W. R. Berkley Corporation and subsidiaries’ (the Company) internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in *Internal Control - Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission.
In our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in *Internal Control - Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated balance sheets of the Company as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] the related consolidated statements of income, comprehensive income, stockholders’ equity, and cash flows for each of the years in the three-year period ended December 31, [removed: 2022,] [added: 2023,] and the related notes and financial statement schedules II to VI (collectively, the consolidated financial statements), and our report dated February [removed: 24, 2023] [added: 23, 2024] expressed an unqualified opinion on those consolidated financial statements.
February 23, 2024
February 24, 2023
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
1 rewritten, 0 added, 0 removed, 0 unchanged
Reference is made to the registrant's definitive proxy statement, which will be filed with the Securities and Exchange Commission within 120 days after December 31, [removed: 2022,] [added: 2023,] and which is incorporated herein by reference.
Item 11. EXECUTIVE COMPENSATION
1 rewritten, 0 added, 0 removed, 0 unchanged
Reference is made to the registrant's definitive proxy statement, which will be filed with the Securities and Exchange Commission within 120 days after December 31, [removed: 2022,] [added: 2023,] and which is incorporated herein by reference.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
1 rewritten, 3 added, 0 removed, 4 unchanged
Reference is made to the registrant's definitive proxy statement, which will be filed with the Securities and Exchange Commission within 120 days after December 31, [removed: 2022,] [added: 2023,] and which is incorporated herein by reference.
Reference is made to the registrant's definitive proxy statement, which will be filed with the Securities and Exchange Commission within 120 days after December 31, 2023, and which is incorporated herein by reference.
Reference is made to the registrant's definitive proxy statement, which will be filed with the Securities and Exchange Commission within 120 days after December 31, 2023, and which is incorporated herein by reference.
Reference is made to the registrant's definitive proxy statement, which will be filed with the Securities and Exchange Commission within 120 days after December 31, 2023, and which is incorporated herein by reference.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
1 rewritten, 0 added, 0 removed, 0 unchanged
Reference is made to the registrant's definitive proxy statement, which will be filed with the Securities and Exchange Commission within 120 days after December 31, [removed: 2022,] [added: 2023,] and which is incorporated herein by reference.
Item 14. PRINCIPAL ACCOUNTING FEES AND SERVICES
1 rewritten, 0 added, 0 removed, 2 unchanged
Reference is made to the registrant's definitive proxy statement, which will be filed with the Securities and Exchange Commission within 120 days after December 31, [removed: 2022,] [added: 2023,] and which is incorporated herein by reference.
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
28 rewritten, 6 added, 1 removed, 101 unchanged
| | | | [Schedule II — Condensed Financial Information of [removed: Registrant](#i35d9cb1974e34186ad62b3eebe1a5e07_211)] [added: Registrant](#ic13c8039c28646a096934b3ce547e717_214)] | | | [removed: [124](#i35d9cb1974e34186ad62b3eebe1a5e07_211)] [added: [123](#ic13c8039c28646a096934b3ce547e717_214)] | | |
| | | | [Schedule III — Supplementary Insurance [removed: Information](#i35d9cb1974e34186ad62b3eebe1a5e07_214)] [added: Information](#ic13c8039c28646a096934b3ce547e717_217)] | | | [removed: [128](#i35d9cb1974e34186ad62b3eebe1a5e07_214)] [added: [127](#ic13c8039c28646a096934b3ce547e717_217)] | | |
| | | | [Schedule V — Valuation and Qualifying [removed: Accounts](#i35d9cb1974e34186ad62b3eebe1a5e07_220)] [added: Accounts](#ic13c8039c28646a096934b3ce547e717_223)] | | | [removed: [130](#i35d9cb1974e34186ad62b3eebe1a5e07_220)] [added: [129](#ic13c8039c28646a096934b3ce547e717_223)] | | |
| | | | [Schedule VI — Supplementary Information Concerning Property — Casualty Insurance [removed: Operations](#i35d9cb1974e34186ad62b3eebe1a5e07_223)] [added: Operations](#ic13c8039c28646a096934b3ce547e717_226)] | | | [removed: [131](#i35d9cb1974e34186ad62b3eebe1a5e07_223)] [added: [130](#ic13c8039c28646a096934b3ce547e717_226)] | | |
| [removed: ([3.6](http://www.sec.gov/Archives/edgar/data/11544/000089914015000593/b3-2.htm))] [added: ([3.6](https://www.sec.gov/Archives/edgar/data/11544/000089914023000449/w022423b.htm))] | | | Amended and Restated By-Laws [added: of the Company] (incorporated by reference to Exhibit [removed: 3 (ii)] [added: 3.2] of the Company’s Current Report on Form 8-K (File No. 1-15202) filed with the Commission on [removed: August 5, 2015).] [added: March 1, 2023).] | | |
| ([4.1](https://www.sec.gov/Archives/edgar/data/11544/000001154423000004/wrb1231202210-kex41.htm)) | | | Description of Registrant’s Securities Registered Pursuant to Section 12 of the Securities Exchange Act of [removed: 1934.] [added: 1934 (incorporated by reference to Exhibit 4.1 of the Company’s Annual Report on Form 10-K (File No. 1-15202) filed with the Commission on February 24, 2023).] | | |
| [removed: [(4.](https://www.sec.gov/Archives/edgar/data/0000011544/000119312521082861/d130286dex42.htm)[7](https://www.sec.gov/Archives/edgar/data/0000011544/000119312521082861/d130286dex42.htm)[)](https://www.sec.gov/Archives/edgar/data/0000011544/000119312521082861/d130286dex42.htm)] [added: [(4.7)](https://www.sec.gov/Archives/edgar/data/0000011544/000119312521082861/d130286dex42.htm)] | | | Second Supplemental Indenture, dated as of March 16, 2021, between the Company and The Bank of New York Mellon, as Trustee, relating to $400,000,000 principal amount of the Company’s 3.550% Senior Notes due 2052, including the form of the Notes as Exhibit A (incorporated by reference to Exhibit 4.2 of the Company’s Current Report on Form 8-K (File No. 1-15202) filed with the Commission on March 16, 2021). | | |
| [removed: [(4.](https://www.sec.gov/Archives/edgar/data/0000011544/000119312521273619/d225177dex42.htm)[8](https://www.sec.gov/Archives/edgar/data/0000011544/000119312521273619/d225177dex42.htm)[)](https://www.sec.gov/Archives/edgar/data/0000011544/000119312521273619/d225177dex42.htm)] [added: [(4.8)](https://www.sec.gov/Archives/edgar/data/0000011544/000119312521273619/d225177dex42.htm)] | | | Third Supplemental Indenture, dated as of September 15, 2021, between the Company and The Bank of New York Mellon, as Trustee, relating to $350,000,000 principal amount of the Company’s 3.150% Senior Notes due 2061, including the form of the Notes as Exhibit A (incorporated by reference to Exhibit 4.2 of the Company’s Current Report on Form 8-K (File No. 1-15202) filed with the Commission on September 15, 2021). | | |
| [removed: [(4.](https://www.sec.gov/Archives/edgar/data/11544/000119312518095381/d542041dex41.htm)[9](https://www.sec.gov/Archives/edgar/data/11544/000119312518095381/d542041dex41.htm)[)](https://www.sec.gov/Archives/edgar/data/11544/000119312518095381/d542041dex41.htm)] [added: [(4.9)](https://www.sec.gov/Archives/edgar/data/11544/000119312518095381/d542041dex41.htm)] | | | Subordinated Indenture, dated as of March 26, 2018, between the Company and The Bank of New York Mellon, as Trustee (incorporated by reference to Exhibit 4.1 of the Company’s Current Report on Form 8-K (File No. 1-15202) filed with the Commission on March 26, 2018). | | |
| [removed: [(4.1](https://www.sec.gov/Archives/edgar/data/11544/000119312518095381/d542041dex42.htm)[0](https://www.sec.gov/Archives/edgar/data/11544/000119312518095381/d542041dex42.htm)[)](https://www.sec.gov/Archives/edgar/data/11544/000119312518095381/d542041dex42.htm)] [added: [(4.10)](https://www.sec.gov/Archives/edgar/data/11544/000119312518095381/d542041dex42.htm)] | | | First Supplemental Indenture, dated as of March 26, 2018, between the Company and The Bank of New York Mellon, as Trustee, relating to $185,000,000 principal amount of the Company’s 5.700% Subordinated Debentures due 2058, including the form of the Securities as Exhibit A (incorporated by reference to Exhibit 4.2 of the Company’s Current Report on Form 8-K (File No. 1-15202) filed with the Commission on March 26, 2018). | | |
| [removed: [(4.1](https://www.sec.gov/Archives/edgar/data/11544/000119312519315039/d797169dex42.htm)[1](https://www.sec.gov/Archives/edgar/data/11544/000119312519315039/d797169dex42.htm)[)](https://www.sec.gov/Archives/edgar/data/11544/000119312519315039/d797169dex42.htm)] [added: [(4.11)](https://www.sec.gov/Archives/edgar/data/11544/000119312519315039/d797169dex42.htm)] | | | Second Supplemental Indenture, dated as of December 16, 2019, between the Company and the Bank of New York Mellon, as Trustee, relating to $300,000,000 principal amount of the Company's 5.100% Subordinated Debentures due 2059, including the form of the Securities as Exhibit A (incorporated by reference to Exhibit 4.2 of the Company's Current Report on Form 8-K (File No. 1-15202) filed with the Commission on December 16, 2019). | | |
| [removed: ([4.1](http://www.sec.gov/Archives/edgar/data/11544/000119312520249826/d70744dex42.htm)[2](http://www.sec.gov/Archives/edgar/data/11544/000119312520249826/d70744dex42.htm)[)](http://www.sec.gov/Archives/edgar/data/11544/000119312520249826/d70744dex42.htm)] [added: ([4.12)](http://www.sec.gov/Archives/edgar/data/11544/000119312520249826/d70744dex42.htm)] | | | Third Supplemental Indenture, dated as of September 21, 2020, between the Company and The Bank of New York Mellon, as Trustee, relating to $250,000,000 principal amount of the Company’s 4.250% Subordinated Debentures due 2060, including the form of the Securities as Exhibit A (incorporated by reference to Exhibit 4.2 of the Company’s Current Report on Form 8-K (File No. 1-15202) filed with the Commission on September 21, 2020). | | |
| [removed: [(4.1](https://www.sec.gov/Archives/edgar/data/11544/000119312521035890/d17400dex42.htm)[3](https://www.sec.gov/Archives/edgar/data/11544/000119312521035890/d17400dex42.htm)[)](https://www.sec.gov/Archives/edgar/data/11544/000119312521035890/d17400dex42.htm)] [added: [(4.13)](https://www.sec.gov/Archives/edgar/data/11544/000119312521035890/d17400dex42.htm)] | | | Fourth Supplemental Indenture, dated as of February 10, 2021, between the Company and The Bank of New York Mellon, as Trustee, relating to $300,000,000 principal amount of the Company’s 4.125% Subordinated Debentures due 2061, including the form of the Securities as Exhibit A (incorporated by reference to Exhibit 4.2 of the Company’s Current Report on Form 8-K (File No. 1-15202) filed with the Commission on February 10, 2021). | | |
| [removed: ([10.1](http://www.sec.gov/Archives/edgar/data/11544/000095012307016856/y44975exv10w1.htm)2)] [added: ([10.1](http://www.sec.gov/Archives/edgar/data/11544/000095012307016856/y44975exv10w1.htm)3)] | | | W. R. Berkley Corporation Deferred Compensation Plan for Officers as amended and restated effective December 1, 2021 (incorporated by reference to Exhibit 10.1 of the Company’s Current Report on Form 8-K (File No. 1-15202) filed with the Commission on November 12, 2021). | | |
| [removed: [(10.1](https://www.sec.gov/Archives/edgar/data/11544/000095012307016856/y44975exv10w2.htm)[3](https://www.sec.gov/Archives/edgar/data/11544/000095012307016856/y44975exv10w2.htm)[)](https://www.sec.gov/Archives/edgar/data/11544/000095012307016856/y44975exv10w2.htm)] [added: [(10.1](https://www.sec.gov/Archives/edgar/data/11544/000095012307016856/y44975exv10w2.htm)[4](https://www.sec.gov/Archives/edgar/data/11544/000095012307016856/y44975exv10w2.htm)[)](https://www.sec.gov/Archives/edgar/data/11544/000095012307016856/y44975exv10w2.htm)] | | | W. R. Berkley Corporation Deferred Compensation Plan for Directors as amended and restated effective December 1, 2021 (incorporated by reference to Exhibit 10.2 of the Company’s Current Report on Form 8-K (File No. 1-15202) filed with the Commission on November 12, 2021). | | |
| [removed: [(10.1](https://www.sec.gov/Archives/edgar/data/11544/000089914019000260/b28130813b.htm)[4](https://www.sec.gov/Archives/edgar/data/11544/000089914019000260/b28130813b.htm)[)](https://www.sec.gov/Archives/edgar/data/11544/000089914019000260/b28130813b.htm)] [added: [(10.1](https://www.sec.gov/Archives/edgar/data/11544/000089914019000260/b28130813b.htm)[5](https://www.sec.gov/Archives/edgar/data/11544/000089914019000260/b28130813b.htm)[)](https://www.sec.gov/Archives/edgar/data/11544/000089914019000260/b28130813b.htm)] | | | W. R. Berkley Corporation Amended and Restated Annual Incentive Compensation Plan (incorporated by reference to Exhibit 10.1 of the Company's Current Report on Form 8-K (File No. 1-15202) filed with the Commission on February 25, 2019). | | |
| [removed: [(10.1](https://www.sec.gov/Archives/edgar/data/11544/000089914019000260/b28130813c.htm)[5](https://www.sec.gov/Archives/edgar/data/11544/000089914019000260/b28130813c.htm)[)](https://www.sec.gov/Archives/edgar/data/11544/000089914019000260/b28130813c.htm)] [added: [(10.1](https://www.sec.gov/Archives/edgar/data/11544/000089914019000260/b28130813c.htm)[6](https://www.sec.gov/Archives/edgar/data/11544/000089914019000260/b28130813c.htm)[)](https://www.sec.gov/Archives/edgar/data/11544/000089914019000260/b28130813c.htm)] | | | W. R. Berkley Corporation 2019 Long-Term Incentive Plan (incorporated by reference to Exhibit 10.2 of the Company's current Report on Form 8-K (File No. 1-15202) filed with the Commission on February 25, 2019). | | |
| [removed: [(10.1](https://www.sec.gov/Archives/edgar/data/11544/000089914019000260/b28130813e.htm)[6](https://www.sec.gov/Archives/edgar/data/11544/000089914019000260/b28130813e.htm)[)](https://www.sec.gov/Archives/edgar/data/11544/000089914019000260/b28130813e.htm)] [added: [(10.](https://www.sec.gov/Archives/edgar/data/11544/000089914019000260/b28130813e.htm)[17](https://www.sec.gov/Archives/edgar/data/11544/000089914019000260/b28130813e.htm)[)](https://www.sec.gov/Archives/edgar/data/11544/000089914019000260/b28130813e.htm)] | | | Form of [removed: 2019] [added: 2020] Performance Unit Award Agreement under the W. R. Berkley Corporation 2019 Long-Term Incentive Plan (incorporated by reference to Exhibit [removed: 10.3] [added: 10.1] of the Company’s [removed: Current] [added: Quarterly] Report on Form [removed: 8-K] [added: 10-Q] (File No. 1-15202) filed with the Commission on [removed: February 25, 2019).] [added: August 3, 2020).] | | |
| [removed: [(10.1](https://www.sec.gov/Archives/edgar/data/11544/000001154420000087/wrb630202010-qex101.htm)[7](https://www.sec.gov/Archives/edgar/data/11544/000001154420000087/wrb630202010-qex101.htm)[)](https://www.sec.gov/Archives/edgar/data/11544/000001154420000087/wrb630202010-qex101.htm)] [added: [(10.1](https://www.sec.gov/Archives/edgar/data/11544/000001154420000087/wrb630202010-qex101.htm)[8](https://www.sec.gov/Archives/edgar/data/11544/000001154420000087/wrb630202010-qex101.htm)[)](https://www.sec.gov/Archives/edgar/data/11544/000001154420000087/wrb630202010-qex101.htm)] | | | Form of [removed: 2020] [added: 2021] Performance Unit Award Agreement under the W. R. Berkley Corporation 2019 Long-Term Incentive Plan (incorporated by reference to Exhibit 10.1 of the Company’s Quarterly Report on Form 10-Q (File No. 1-15202) filed with the Commission on [removed: August 3, 2020).] [added: November 4, 2021).] | | |
| [removed: [(10.1](https://www.sec.gov/Archives/edgar/data/0000011544/000001154421000078/wrb930202110-qex101.htm)[8](https://www.sec.gov/Archives/edgar/data/0000011544/000001154421000078/wrb930202110-qex101.htm)[)](https://www.sec.gov/Archives/edgar/data/0000011544/000001154421000078/wrb930202110-qex101.htm)] [added: [(10.1](https://www.sec.gov/Archives/edgar/data/0000011544/000001154421000078/wrb930202110-qex101.htm)[9](https://www.sec.gov/Archives/edgar/data/0000011544/000001154421000078/wrb930202110-qex101.htm)[)](https://www.sec.gov/Archives/edgar/data/0000011544/000001154421000078/wrb930202110-qex101.htm)] | | | Form of [removed: 2021] [added: 2022] Performance Unit Award Agreement under the W. R. Berkley Corporation 2019 Long-Term Incentive Plan (incorporated by reference to Exhibit 10.1 of the Company’s Quarterly Report on Form 10-Q (File No. 1-15202) filed with the Commission on [removed: November 4, 2021).] [added: May 3, 2022).] | | |
| [removed: (10.19)] [added: (10.20)] | | | Form of [removed: 2022] [added: 2023] Performance Unit Award Agreement under the W. R. Berkley Corporation 2019 Long-Term Incentive Plan (incorporated by reference to Exhibit 10.1 of the Company’s Quarterly Report on Form 10-Q (File No. 1-15202) filed with the Commission on May [removed: 3, 2022).] [added: 4, 2023).] | | |
| [removed: [(10.20)](https://www.sec.gov/Archives/edgar/data/11544/000119312515138266/d910510ddef14a.htm)] [added: [(10.2](https://www.sec.gov/Archives/edgar/data/11544/000119312515138266/d910510ddef14a.htm)[1](https://www.sec.gov/Archives/edgar/data/11544/000119312515138266/d910510ddef14a.htm)[)](https://www.sec.gov/Archives/edgar/data/11544/000119312515138266/d910510ddef14a.htm)] | | | W. R. Berkley Corporation 2009 Directors Stock Plan (incorporated by reference to Annex B of the Company’s 2021 Proxy Statement (File No. 1-15202) filed with the Commission on April 27, 2021). | | |
| [removed: [(10.21)](https://www.sec.gov/Archives/edgar/data/11544/000001154412000021/wrb12312011ex10-14serp.htm)] [added: [(10.2](https://www.sec.gov/Archives/edgar/data/11544/000001154412000021/wrb12312011ex10-14serp.htm)[2](https://www.sec.gov/Archives/edgar/data/11544/000001154412000021/wrb12312011ex10-14serp.htm)[)](https://www.sec.gov/Archives/edgar/data/11544/000001154412000021/wrb12312011ex10-14serp.htm)] | | | Supplemental Benefits Agreement between William R. Berkley and the Company as amended and restated as of December 21, 2011 (incorporated by reference to Exhibit 10.14 of the Company's Annual Report on Form 10-K (File No. 1-15202) filed with the Commission on February 28, 2012). | | |
| [removed: ([21](https://www.sec.gov/Archives/edgar/data/11544/000001154423000004/wrb1231202210-kex21.htm))] [added: ([21](https://www.sec.gov/Archives/edgar/data/11544/000001154424000005/wrb1231202310-kex21.htm))] | | | List of the Company’s subsidiaries. | | |
| [removed: ([23](https://www.sec.gov/Archives/edgar/data/11544/000001154423000004/wrb1231202210-kex23.htm))] [added: ([23](https://www.sec.gov/Archives/edgar/data/11544/000001154424000005/wrb1231202310-kex23.htm))] | | | Consent of Independent Registered Public Accounting Firm. | | |
| [removed: ([31.1](https://www.sec.gov/Archives/edgar/data/11544/000001154423000004/wrb1231202210-kex311.htm))] [added: ([31.1](https://www.sec.gov/Archives/edgar/data/11544/000001154424000005/wrb1231202310-kex311.htm))] | | | Certification of the Chief Executive Officer pursuant to Rule 13a-14(a)/ 15d-14(a). | | |
| [removed: ([31.2](https://www.sec.gov/Archives/edgar/data/11544/000001154423000004/wrb1231202210-kex312.htm))] [added: ([31.2](https://www.sec.gov/Archives/edgar/data/11544/000001154424000005/wrb1231202310-kex312.htm))] | | | Certification of the Chief Financial Officer pursuant to Rule 13a-14(a)/ 15d-14(a). | | |
| [removed: ([32.1](https://www.sec.gov/Archives/edgar/data/11544/000001154423000004/wrb1231202210-kex321.htm))] [added: ([32.1](https://www.sec.gov/Archives/edgar/data/11544/000001154424000005/wrb1231202310-kex321.htm))] | | | Certification of the Chief Executive Officer and Chief Financial Officer pursuant to 18 U.S.C. Section 1350, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of 2002. | | |
| | | | [Schedule IV — Reinsurance](#ic13c8039c28646a096934b3ce547e717_220) | | | [128](#ic13c8039c28646a096934b3ce547e717_220) | | |
| [(10.12)](https://www.sec.gov/Archives/edgar/data/11544/000001154424000005/wrb1231202310-kex1012.htm) | | | Form of 2023 Performance-Based Restricted Stock Unit Agreement Under the W. R. Berkley Corporation 2018 Stock Incentive Plan. | | |
| --- | --- | --- | --- | --- | --- |
| | | | | | |
| | | | | | |
| ([97](https://www.sec.gov/Archives/edgar/data/11544/000001154424000005/wrb1231202310-kex97.htm)) | | | W. R. Berkley Corporation Clawback Policy. | | |
| | | | [Schedule IV — Reinsurance](#i35d9cb1974e34186ad62b3eebe1a5e07_217) | | | [129](#i35d9cb1974e34186ad62b3eebe1a5e07_217) | | |
Item 16. FORM 10-K Summary
107 rewritten, 23 added, 17 removed, 141 unchanged
| /s/ William R. Berkley | | | | | | Executive Chairman | | | | | | February [removed: 24, 2023] [added: 23, 2024] | | |
| /s/ W. Robert Berkley, Jr. | | | | | | President | | | | | | February [removed: 24, 2023] [added: 23, 2024] | | |
| /s/ Christopher L. Augostini | | | | | | Director | | | | | | February [removed: 24, 2023] [added: 23, 2024] | | |
| /s/ Ronald E. Blaylock | | | | | | Director | | | | | | February [removed: 24, 2023] [added: 23, 2024] | | |
| /s/ Mary C. Farrell | | | | | | Director | | | | | | February [removed: 24, 2023] [added: 23, 2024] | | |
| /s/ María Luisa Ferré | | | | | | Director | | | | | | February [removed: 24, 2023] [added: 23, 2024] | | |
| /s/ Daniel L. Mosley | | | | | | Director | | | | | | February [removed: 24, 2023] [added: 23, 2024] | | |
| /s/ Mark L. Shapiro | | | | | | Director | | | | | | February [removed: 24, 2023] [added: 23, 2024] | | |
| /s/ Jonathan Talisman | | | | | | Director | | | | | | February [removed: 24, 2023] [added: 23, 2024] | | |
| /s/ Richard M. Baio | | | | | | Executive Vice President | | | | | | February [removed: 24, 2023] [added: 23, 2024] | | |
| (In thousands) | | | [added: 2023 | | | | | |] 2022 | | | | | | 2021 | | |
| Cash and cash equivalents [removed: |] [added: at beginning of year] | | [removed: $] | 103,522 | | | | | [removed: $] | 684,037 | | [added: | | | | 296,960 | | |]
| Fixed maturity securities available for sale at fair value (cost [removed: $285,900] [added: $190,708] and [removed: $805,211] [added: $285,900] at December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] respectively) | | | [removed: 275,511] [added: 189,189] | | | | | | [removed: 806,074] [added: 275,511] | | |
| Loans receivable (net of allowance for expected credit losses of [removed: $559] [added: $1,146] and [removed: $647] [added: $559] at December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] respectively) | | | [removed: 109,793] [added: 91,304] | | | | | | [removed: 93,397] [added: 109,793] | | |
| Equity securities, at fair value (cost $3,430 in both [removed: 2022] [added: 2023] and [removed: 2021)] [added: 2022)] | | | 3,430 | | | | | | 3,430 | | |
| Investment in subsidiaries | | | [removed: 8,888,455] [added: 9,887,117] | | | | | | [removed: 8,516,916] [added: 8,888,455] | | |
| Current federal income taxes | | | [removed: 34,452] [added: —] | | | | | | [removed: 23,424] [added: 34,452] | | |
| Deferred federal income taxes | | | [removed: 304,191] [added: 278,946] | | | | | | [removed: 11,796] [added: 304,191] | | |
| Property, furniture and equipment at cost, less accumulated depreciation | | | [removed: 11,356] [added: 10,382] | | | | | | [removed: 11,916] [added: 11,356] | | |
| Other assets | | | [removed: 39,741] [added: 44,186] | | | | | | [removed: 43,793] [added: 39,741] | | |
| Total assets | | | $ | [removed: 9,770,451] [added: 10,632,988] | | | | | $ | [removed: 10,194,783] [added: 9,770,451] | |
| Due to subsidiaries | | | $ | [removed: 53,029] [added: 178,676] | | | | | $ | [removed: 138,376] [added: 53,029] | |
| Other liabilities | | | [removed: 139,150] [added: 166,399] | | | | | | [removed: 146,892] [added: 139,150] | | |
| Subordinated debentures | | | [removed: 1,008,371] [added: 1,009,090] | | | | | | [removed: 1,007,652] [added: 1,008,371] | | |
| Senior notes | | | [removed: 1,821,569] [added: 1,821,671] | | | | | | [removed: 2,248,852] [added: 1,821,569] | | |
| Total liabilities | | | [removed: 3,022,119] [added: 3,177,557] | | | | | | [removed: 3,541,772] [added: 3,022,119] | | |
| Preferred stock | | | [removed: —] | | | | | | — | | |
| Additional paid-in capital | | | [removed: 997,534] [added: 1,017,691] | | | | | | [removed: 981,104] [added: 997,534] | | |
| Retained earnings (including accumulated undistributed net income of subsidiaries of [removed: $7,975,360] [added: $8,497,674] and [removed: $6,463,882] [added: $7,975,360] at December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] respectively) | | | [removed: 10,161,005] [added: 11,040,908] | | | | | | [removed: 9,015,135] [added: 10,161,005] | | |
| Accumulated other comprehensive loss | | | [removed: (1,264,581)] [added: (925,838)] | | | | | | [removed: (281,955)] [added: (1,264,581)] | | |
| Treasury stock, at cost | | | [removed: (3,251,429)] [added: (3,783,133)] | | | | | | [removed: (3,167,076)] [added: (3,251,429)] | | |
| Total stockholders’ equity | | | [removed: 6,748,332] [added: 7,455,431] | | | | | | [removed: 6,653,011] [added: 6,748,332] | | |
| Total liabilities and stockholders’ equity | | | $ | [removed: 9,770,451] [added: 10,632,988] | | | | | $ | [removed: 10,194,783] [added: 9,770,451] | |
| (In thousands) | | | [removed: 2022] [added: 2023] | | | | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2020] [added: 2021] | | |
| Management fees and investment income including dividends from subsidiaries of [added: $1,261,166,] $22,807, [removed: $520,251,] and [removed: $617,424] [added: $520,251] for the years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020,] [added: 2021,] respectively | | | $ | [removed: 32,585] [added: 1,325,997] | | | | | $ | [removed: 548,512] [added: 32,585] | | | | | $ | [removed: 654,485] [added: 548,512] | |
| Net investment [added: (losses)] gains | | | [removed: 1,007] [added: (5,895)] | | | | | | [removed: 1,474] [added: 1,007] | | | | | | [removed: 3,580] [added: 1,474] | | |
| Other income | | | [removed: 1,916] [added: 368] | | | | | | [removed: 1,138] [added: 1,916] | | | | | | [removed: 568] [added: 1,138] | | |
| Total revenues | | | [removed: 35,508] [added: 1,320,470] | | | | | | [removed: 551,124] [added: 35,508] | | | | | | [removed: 658,633] [added: 551,124] | | |
| Operating costs and expense | | | [removed: 192,175] [added: 272,750] | | | | | | [removed: 214,995] [added: 192,175] | | | | | | [removed: 166,892] [added: 214,995] | | |
| Interest expense | | | [removed: 129,633] [added: 126,397] | | | | | | [removed: 144,837] [added: 129,633] | | | | | | [removed: 145,417] [added: 144,837] | | |
February 23, 2024
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| (In thousands) | | | 2023 | | | | | | 2022 | | |
| Cash and cash equivalents | | | $ | 128,434 | | | | | $ | 103,522 | |
| Current federal income taxes | | | 1,721 | | | | | | — | | |
| Net income | | | $ | 1,381,359 | | | | | $ | 1,381,062 | | | | | $ | 1,022,490 | |
December 31, 2023
| December 31, 2023 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Insurance | | | $ | 748,134 | | | | | $ | 15,386,761 | | | | | $ | 5,367,137 | | | | | $ | 9,130,324 | | | | | $ | 793,998 | | | | | $ | 5,689,263 | | | | | $ | 931,748 | | | | | $ | 1,699,703 | | | | | $ | 9,657,121 | |
| Reinsurance & Monoline Excess | | | 113,475 | | | | | | 3,352,891 | | | | | | 555,189 | | | | | | 1,270,363 | | | | | | 211,628 | | | | | | 682,879 | | | | | | 107,227 | | | | | | 253,120 | | | | | | 1,297,346 | | |
| Total | | | $ | 861,609 | | | | | $ | 18,739,652 | | | | | $ | 5,922,326 | | | | | $ | 10,400,687 | | | | | $ | 1,052,835 | | | | | $ | 6,372,142 | | | | | $ | 1,038,975 | | | | | $ | 2,324,961 | | | | | $ | 10,954,467 | |
| Insurance | | | $ | 11,310,709 | | | | | $ | 1,904,017 | | | | | $ | 250,429 | | | | | $ | 9,657,121 | | | | | 2.6 | | % |
| Reinsurance & Monoline Excess | | | 366,034 | | | | | | 113,522 | | | | | | 1,044,834 | | | | | | 1,297,346 | | | | | | 80.5 | | % |
| Total | | | $ | 11,676,743 | | | | | $ | 2,017,539 | | | | | $ | 1,295,263 | | | | | $ | 10,954,467 | | | | | 11.8 | | % |
| Year ended December 31, 2023 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Premiums, fees and other receivables | | | $ | 36,931 | | | | | | | | | | | $ | 13,637 | | | | | $ | (8,243) | | | | | $ | 42,325 | |
| Due from reinsurers | | | 8,064 | | | | | | | | | | | | 340 | | | | | | — | | | | | | 8,404 | | |
| Fixed maturity securities | | | 37,466 | | | | | | | | | | | | 5,013 | | | | | | (5,728) | | | | | | 36,751 | | |
| Loan loss reserves | | | 1,791 | | | | | | | | | | | | 1,782 | | | | | | (569) | | | | | | 3,004 | | |
| Total | | | $ | 131,418 | | | | | | | | | | | $ | 24,636 | | | | | $ | (29,287) | | | | | $ | 126,767 | |
Years Ended December 31, 2023, 2022 and 2021
| (In thousands) | | | 2023 | | | | | | 2022 | | | | | | 2021 | | |
February 24, 2023
| | | | | | | Director | | | | | | | | |
| Mark E. Brockbank | | | | | | | | | | | | | | |
| | | | | | | | | | | | |
| Cash and cash equivalents at beginning of year | | | 684,037 | | | | | | 296,960 | | | | | | 389,801 | | |
| December 31, 2020 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Insurance | | | $ | 467,871 | | | | | $ | 10,977,674 | | | | | $ | 3,660,758 | | | | | $ | 6,067,669 | | | | | $ | 375,554 | | | | | $ | 3,939,759 | | | | | $ | 734,062 | | | | | $ | 1,137,002 | | | | | $ | 6,347,101 | |
| Reinsurance & Monoline Excess | | | 88,297 | | | | | | 2,806,756 | | | | | | 412,433 | | | | | | 863,174 | | | | | | 146,029 | | | | | | 528,947 | | | | | | 170,893 | | | | | | 103,775 | | | | | | 915,336 | | |
| Total | | | $ | 556,168 | | | | | $ | 13,784,430 | | | | | $ | 4,073,191 | | | | | $ | 6,930,843 | | | | | $ | 583,821 | | | | | $ | 4,468,706 | | | | | $ | 904,955 | | | | | $ | 1,485,437 | | | | | $ | 7,262,437 | |
| Insurance | | | $ | 7,625,981 | | | | | $ | 1,490,395 | | | | | $ | 211,515 | | | | | $ | 6,347,101 | | | | | 3.3 | | % |
| Reinsurance & Monoline Excess | | | 248,069 | | | | | | 94,815 | | | | | | 762,082 | | | | | | 915,336 | | | | | | 83.3 | | % |
| Total | | | $ | 7,874,050 | | | | | $ | 1,585,210 | | | | | $ | 973,597 | | | | | $ | 7,262,437 | | | | | 13.4 | | % |
| Premiums, fees and other receivables | | | $ | 26,546 | | | | | $ | 1,270 | | | | | $ | 6,783 | | | | | $ | (6,744) | | | | | $ | 27,855 | |
| Due from reinsurers | | | 690 | | | | | | 5,927 | | | | | | 1,187 | | | | | | (3) | | | | | | 7,801 | | |
| Fixed maturity securities | | | — | | | | | | 35,714 | | | | | | 16,909 | | | | | | (50,043) | | | | | | 2,580 | | |
| Loan loss reserves | | | 2,146 | | | | | | (357) | | | | | | 3,648 | | | | | | — | | | | | | 5,437 | | |
| Total | | | $ | 62,632 | | | | | $ | 42,554 | | | | | $ | 75,283 | | | | | $ | (57,308) | | | | | $ | 123,161 | |
An excerpt. Shown here: 40 of 107 rewritten, all 23 added and all 17 removed. The counts are complete. For every sentence, read Item 16. FORM 10-K Summary in the FY2023 filing and the FY2020 filing.