 filings.tools
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
123K characters. Original on sec.gov · Markdown
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Non-GAAP Financial Measures
The following discussion includes financial information prepared in accordance with GAAP, as well as certain non-GAAP financial measures such as ongoing ROE, electric margin, natural gas margin, ongoing earnings and ongoing diluted EPS. Generally, a non-GAAP financial measure is a measure of a company’s financial performance, financial position or cash flows that excludes (or includes) amounts that are adjusted from measures calculated and presented in accordance with GAAP.
Xcel Energy’s management uses non-GAAP measures for financial planning and analysis, for reporting of results to the Board of Directors, in determining performance-based compensation, and communicating its earnings outlook to analysts and investors. Non-GAAP financial measures are intended to supplement investors’ understanding of our performance and should not be considered alternatives for financial measures presented in accordance with GAAP. These measures are discussed in more detail below and may not be comparable to other companies’ similarly titled non-GAAP financial measures.
Ongoing ROE
Ongoing ROE is calculated by dividing the net income or loss of Xcel Energy or each subsidiary, adjusted for certain nonrecurring items, by each entity’s average stockholder’s equity. We use these non-GAAP financial measures to evaluate and provide details of earnings results.
Electric and Natural Gas Margins
Electric margin is presented as electric revenues less electric fuel and purchased power expenses. Natural gas margin is presented as natural gas revenues less the cost of natural gas sold and transported. Expenses incurred for electric fuel and purchased power and the cost of natural gas are generally recovered through various regulatory recovery mechanisms. As a result, changes in these expenses are generally offset in operating revenues. Management believes electric and natural gas margins provide the most meaningful basis for evaluating our operations because they exclude the revenue impact of fluctuations in these expenses.
These margins can be reconciled to operating income, a GAAP measure, by including other operating revenues, cost of sales-other, O&M expenses, conservation and DSM expenses, depreciation and amortization and taxes (other than income taxes).
Earnings Adjusted for Certain Items (Ongoing Earnings and Ongoing Diluted EPS)
GAAP diluted EPS reflects the potential dilution that could occur if securities or other agreements to issue common stock (i.e., common stock equivalents) were settled. The weighted average number of potentially dilutive shares outstanding used to calculate Xcel Energy Inc.’s diluted EPS is calculated using the treasury stock method. Ongoing earnings reflect adjustments to GAAP earnings (net income) for certain items. Ongoing diluted EPS is calculated by dividing the net income or loss of each subsidiary, adjusted for certain items, by the weighted average fully diluted Xcel Energy Inc. common shares outstanding for the period. Ongoing diluted EPS for each subsidiary is calculated by dividing the net income or loss of such subsidiary, adjusted for certain items, by the weighted average fully diluted Xcel Energy Inc. common shares outstanding for the period.
We use these non-GAAP financial measures to evaluate and provide details of Xcel Energy’s core earnings and underlying performance. We believe these measurements are useful to investors to evaluate the actual and projected financial performance and contribution of our subsidiaries. For the years ended Dec. 31, 2019 and Dec. 31, 2018, there were no such adjustments to GAAP earnings and therefore GAAP earnings equal ongoing earnings.
| Results of Operations |
Diluted EPS for Xcel Energy at Dec. 31:
| 2019 | 2018 | |||||||
| Diluted Earnings (Loss) Per Share | GAAP and Ongoing Diluted EPS | GAAP and Ongoing Diluted EPS | ||||||
| PSCo | $ | 1.11 | $ | 1.08 | ||||
| NSP-Minnesota | 1.04 | 0.96 | ||||||
| SPS | 0.51 | 0.42 | ||||||
| NSP-Wisconsin | 0.15 | 0.19 | ||||||
| Equity earnings of unconsolidated subsidiaries (a) | 0.05 | 0.04 | ||||||
| Regulated utility (b) | 2.86 | 2.69 | ||||||
| Xcel Energy Inc. and other | (0.22 | ) | (0.22 | ) | ||||
| Total (b) | $ | 2.64 | $ | 2.47 |
| (a) | Includes income taxes. |
| (b) | Amounts may not add due to rounding. |
Xcel Energy’s management believes that ongoing earnings reflects management’s performance in operating the Company and provides a meaningful representation of the performance of Xcel Energy’s core business. In addition, Xcel Energy’s management uses ongoing earnings internally for financial planning and analysis, reporting results to the Board of Directors and when communicating its earnings outlook to analysts and investors.
2019 Comparison with 2018
Xcel Energy — GAAP and ongoing earnings increased $0.17 per share. Earnings increased as a result of higher electric margins primarily due to non-fuel riders and regulatory rate outcomes, higher natural gas margins and lower O&M expenses, primarily offset by lower AFUDC, increased depreciation and interest expenses.
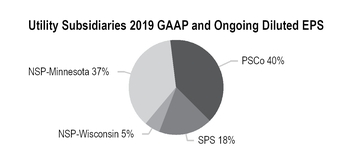
PSCo — Earnings increased $0.03 per share for 2019, reflecting higher electric margin due primarily to capital riders and increased natural gas margin attributable to capital riders, weather and sales growth, partially offset by lower AFUDC driven by the Rush Creek wind project that was placed in service in 2018 and higher depreciation, interest and O&M.
NSP-Minnesota — Earnings increased $0.08 per share for 2019, reflecting higher electric margin resulting from regulatory rate outcomes and capital riders and lower O&M, partially offset by increased depreciation.
SPS — Earnings increased $0.09 per share, reflecting higher electric margin attributable to purchased capacity costs, regulatory rate outcomes and demand revenue and higher AFUDC, partially offset by increased interest and depreciation.
NSP-Wisconsin — Earnings decreased $0.04 per share, reflecting lower electric margin, primarily related to sales decline and the impact of unfavorable weather, higher depreciation and lower AFUDC.
Xcel Energy Inc. and other — Xcel Energy Inc. and other primarily includes financing costs at the holding company.
Changes in Diluted EPS
Components significantly contributing to changes in EPS:
| 2019 vs. 2018 | ||||
| Diluted Earnings (Loss) Per Share | Dec. 31 | |||
| GAAP and ongoing diluted EPS - 2018 | $ | 2.47 | ||
| Components of change — 2019 vs. 2018 | ||||
| Higher electric margins | 0.29 | |||
| Lower ETR (a) | 0.15 | |||
| Higher natural gas margins | 0.08 | |||
| Lower O&M | 0.02 | |||
| Higher depreciation and amortization | (0.18 | ) | ||
| Higher interest | (0.11 | ) | ||
| Lower AFUDC | (0.08 | ) | ||
| GAAP and ongoing diluted EPS — 2019 | $ | 2.64 |
| (a) | Includes PTCs and timing of tax reform regulatory decisions, which are primarily offset in electric margin. |
ROE for Xcel Energy and its utility subsidiaries at Dec. 31:
| 2019 | 2018 | |||||
| ROE | GAAP and Ongoing ROE | GAAP and Ongoing ROE | ||||
| PSCo | 8.69 | % | 9.10 | % | ||
| NSP-Minnesota | 9.31 | 8.91 | ||||
| SPS | 9.71 | 9.14 | ||||
| NSP-Wisconsin | 8.27 | 10.77 | ||||
| Operating Companies | 9.06 | 9.14 | ||||
| Xcel Energy | 10.78 | 10.65 |
Statement of Income Analysis
The following summarizes the items that affected the individual revenue and expense items reported in the consolidated statements of income.
Estimated Impact of Temperature Changes on Earnings — Unusually hot summers or cold winters increase electric and natural gas sales, while mild weather reduces electric and natural gas sales. The estimated impact of weather on earnings is based on the number of customers, temperature variances, the amount of natural gas or electricity historically used per degree of temperature and excludes any incremental related operating expenses that could result due to storm activity or vegetation management requirements. As a result, weather deviations from normal levels can affect Xcel Energy’s financial performance.
Degree-day or THI data is used to estimate amounts of energy required to maintain comfortable indoor temperature levels based on each day’s average temperature and humidity. HDD is the measure of the variation in the weather based on the extent to which the average daily temperature falls below 65° Fahrenheit. CDD is the measure of the variation in the weather based on the extent to which the average daily temperature rises above 65° Fahrenheit. Each degree of temperature above 65° Fahrenheit is counted as one CDD, and each degree of temperature below 65° Fahrenheit is counted as one HDD. In Xcel Energy’s more humid service territories, a THI is used in place of CDD, which adds a humidity factor to CDD. HDD, CDD and THI are most likely to impact the usage of Xcel Energy’s residential and commercial customers. Industrial customers are less sensitive to weather.
Normal weather conditions are defined as either the 20-year or 30-year average of actual historical weather conditions. The historical period of time used in the calculation of normal weather differs by jurisdiction, based on regulatory practice. To calculate the impact of weather on demand, a demand factor is applied to the weather impact on sales. Extreme weather variations, windchill and cloud cover may not be reflected in weather-normalized estimates.
Percentage increase (decrease) in normal and actual HDD, CDD and THI:
| 2019 vs. Normal | 2018 vs. Normal | 2019 vs. 2018 | ||||||
| HDD | 10.4 | % | 2.2 | % | 6.8 | % | ||
| CDD | 5.4 | 26.7 | (15.5 | ) | ||||
| THI | (8.8 | ) | 37.3 | (33.2 | ) |
Weather — Estimated impact of temperature variations on EPS compared with normal weather conditions:
| 2019 vs. Normal | 2018 vs. Normal | 2019 vs. 2018 | |||||||||
| Retail electric | $ | 0.040 | $ | 0.114 | $ | (0.074 | ) | ||||
| Firm natural gas | 0.027 | 0.007 | 0.020 | ||||||||
| Total (excluding decoupling) | $ | 0.067 | $ | 0.121 | $ | (0.054 | ) | ||||
| Decoupling — Minnesota electric | — | (0.051 | ) | 0.051 | |||||||
| Total (adjusted for recovery from decoupling) | $ | 0.067 | $ | 0.070 | $ | (0.003 | ) |
Sales Growth (Decline) — Sales growth (decline) for actual and weather-normalized sales:
| 2019 vs. 2018 | |||||||||||||||
| PSCo | NSP-Minnesota | SPS | NSP-Wisconsin | Xcel Energy | |||||||||||
| Actual | |||||||||||||||
| Electric residential | 0.1 | % | (3.5 | )% | 0.3 | % | (1.8 | )% | (1.5 | )% | |||||
| Electric C&I | (0.6 | ) | (4.0 | ) | 3.5 | (3.2 | ) | (1.1 | ) | ||||||
| Total retail electric sales | (0.3 | ) | (3.9 | ) | 2.8 | (2.8 | ) | (1.2 | ) | ||||||
| Firm natural gas sales | 12.9 | 3.6 | N/A | (2.0 | ) | 8.8 |
| 2019 vs. 2018 | |||||||||||||||
| PSCo | NSP-Minnesota | SPS | NSP-Wisconsin | Xcel Energy | |||||||||||
| Weather-normalized | |||||||||||||||
| Electric residential | (0.1 | )% | 0.1 | % | 1.9 | % | 1.1 | % | 0.4 | % | |||||
| Electric C&I | (0.6 | ) | (3.0 | ) | 3.8 | (2.6 | ) | (0.5 | ) | ||||||
| Total retail electric sales | (0.3 | ) | (2.1 | ) | 3.4 | (1.6 | ) | (0.3 | ) | ||||||
| Firm natural gas sales | 4.1 | 1.1 | N/A | (2.5 | ) | 2.7 |
Weather-normalized 2019 Electric Sales Growth (Decline)
| • | PSCo — Residential sales declined due to lower use per customer, partially offset by an increased number of customers. The decline in C&I was mainly due to lower use per customer, primarily led by customers in the food products and service industries, partially offset by growth in the metal mining and fabricated metal and industries. The decrease in customer use was partially offset by an increase in the number of C&I customers; |
| • | NSP-Minnesota — Flat residential sales reflect lower use per customer offset by customer additions. The decline in C&I sales was a result of customer growth being offset by lower use per customer, and certain customers moving to co-generation. Decreased sales to C&I customers were driven by the energy and manufacturing sectors; |
| • | SPS — Residential sales grew largely due to an increase in customers and higher use per customer. C&I sales grew based on higher use per small C&I customer and an overall increase in the number of C&I customers. In addition, the increase in C&I sales was driven by the oil and natural gas industry in the Southeastern New Mexico, Permian Basin area; and |
| • | NSP-Wisconsin — Residential sales growth was primarily attributable to customer additions and more use per customer. The decline in C&I sales was largely due to lower use per customer and decreased sales to the frac sand mining, food and manufacturing sectors, which was partially offset by customer additions. |
Weather-normalized 2019 Natural Gas Sales Growth
| • | Overall natural gas sales reflect an increase in the number of customers combined with higher customer use, particularly C&I at PSCo. This was partially offset by a decline in C&I sales at NSP-Wisconsin, driven by the frac sand mining industry. |
Weather-normalized sales for 2020 are projected to increase ~1% over 2019 levels for retail electric and natural gas customers, including the impact of leap year.
Electric Margin
Electric revenues and fuel and purchased power expenses are impacted by fluctuations in the price of natural gas, coal and uranium used in the generation of electricity. However, these price fluctuations have minimal impact on electric margin due to fuel recovery mechanisms that recover fuel expenses. In addition, electric customers receive a credit for PTCs generated in a particular period.
Electric Margin
| (Millions of Dollars) | 2019 vs. 2018 | |||
| Non-fuel riders (a) | $ | 107 | ||
| Regulatory rate outcomes (Minnesota, New Mexico, North and South Dakota) | 95 | |||
| Implementation of lease accounting standard (offset in interest expense and amortization) | 22 | |||
| Purchased capacity costs | 22 | |||
| Demand revenue | 20 | |||
| Wholesale transmission revenue (net) | 11 | |||
| Timing of tax reform regulatory decisions (offset in income tax and amortization) | (37 | ) | ||
| Estimated impact of weather (net of Minnesota decoupling) | (25 | ) | ||
| Firm wholesale generation | (20 | ) | ||
| Sales declines (excluding weather impact) | (18 | ) | ||
| Other (net) | 23 | |||
| Total increase in electric margin | $ | 200 |
| (a) | Includes approximately $60 million of additional PTC benefit (grossed-up for tax) as compared to 2018, which are credited to customers through various regulatory mechanisms. |
Natural Gas Margin
Total natural gas expense varies with changing sales requirements and the cost of natural gas. However, fluctuations in the cost of natural gas has minimal impact on natural gas margin due to cost recovery mechanisms.
Natural Gas Margin
| (Millions of Dollars) | 2019 vs. 2018 | |||
| Infrastructure and integrity riders | $ | 19 | ||
| Estimated impact of weather | 14 | |||
| Transport sales | 7 | |||
| Retail sales growth | 7 | |||
| Other (net) | 7 | |||
| Total increase in natural gas margin | $ | 54 |
Non-Fuel Operating Expenses and Other Items
O&M Expenses — O&M expenses decreased $14 million, or 0.6%, for 2019. Significant changes are summarized below:
| (Millions of Dollars) | 2019 vs. 2018 | |||
| Plant generation | $ | (20 | ) | |
| Nuclear plant operations and amortization | (8 | ) | ||
| Transmission | (7 | ) | ||
| Distribution | 16 | |||
| Other (net) | 5 | |||
| Total decrease in O&M expenses | $ | (14 | ) |
| • | Plant generation, transmission and distribution costs were lower due to timing of maintenance activities; |
| • | Nuclear plant operations and amortization were lower largely reflecting improved operating efficiencies and reduced refueling outage costs; and |
| • | Distribution expenses in 2019 were higher than 2018 due to storms, labor and overtime incurred primarily in the first six months of 2019. |
Depreciation and Amortization — Depreciation and amortization increased $123 million, or 7%, for 2019. The increase was primarily driven by the Rush Creek, Hale, Foxtail and Lake Benton wind farms going into service, natural gas and distribution/transmission replacements, and various software solutions. These increases were partially offset by higher levels of accelerated amortization of PSCo’s prepaid pension asset in 2018.
Taxes (Other than Income Taxes) — Taxes (other than income taxes) increased $13 million, or 2.3%, for 2019. The increase was primarily due to higher property taxes in Colorado and Minnesota (net of deferred amounts).
AFUDC, Equity and Debt — AFUDC decreased $42 million for 2019. The decrease was primarily due to the Rush Creek wind project being placed in-service in 2018, partially offset by the Hale wind project, which went into service in June 2019, and other capital investments.
Interest Charges — Interest charges increased $73 million, or 10.4%, for 2019. The increase was primarily due to higher debt levels to fund capital investments, changes in short-term interest rates and implementation of lease accounting standard (offset in electric margin).
Income Taxes — Income taxes decreased $53 million for 2019, primarily driven by an increase in wind PTCs. Wind PTCs are credited to customers (recorded as a reduction to revenue) and do not have a material impact on net income. These were partially offset by higher pretax earnings in 2019 and ITCs in 2018. The ETR was 8.5% for 2019 compared with 12.6% for the same period in 2018, largely due to the adjustments above.
Xcel Energy Inc. and Other Results
Net income and diluted EPS contributions of Xcel Energy Inc. and its nonregulated businesses:
| Contribution (Millions of Dollars) | ||||||||
| 2019 | 2018 | |||||||
| Xcel Energy Inc. financing costs | $ | (128 | ) | $ | (110 | ) | ||
| Eloigne (a) | 1 | — | ||||||
| Xcel Energy Inc. taxes and other results | 12 | (5 | ) | |||||
| Total Xcel Energy Inc. and other costs | $ | (115 | ) | $ | (115 | ) |
| Contribution (Diluted Earnings (Loss) Per Share) | ||||||||
| 2019 | 2018 | |||||||
| Xcel Energy Inc. financing costs | $ | (0.21 | ) | $ | (0.21 | ) | ||
| Eloigne (a) | — | — | ||||||
| Xcel Energy Inc. taxes and other results | (0.01 | ) | (0.01 | ) | ||||
| Total Xcel Energy Inc. and other costs | $ | (0.22 | ) | $ | (0.22 | ) |
| (a) | Amounts include gains or losses associated with sales of properties held by Eloigne. |
Xcel Energy Inc.’s results include interest charges, which are incurred at Xcel Energy Inc. and are not directly assigned to individual subsidiaries.
2018 Comparison with 2017
A discussion of changes in Xcel Energy’s results of operations and liquidity and capital resources from the year ended Dec. 31, 2017 to Dec. 31, 2018 can be found in Part II, “Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations” of our Annual Report on Form 10-K for the fiscal year 2018, which was filed with the SEC on Feb. 22, 2019. However, such discussion is not incorporated by reference into, and does not constitute a part of, this Annual Report on Form 10-K.
| Public Utility Regulation |
The FERC and various state and local regulatory commissions regulate Xcel Energy Inc.’s utility subsidiaries and WGI. Xcel Energy is subject to rate regulation by state utility regulatory agencies, which have jurisdiction with respect to the rates of electric and natural gas distribution companies in Minnesota, North Dakota, South Dakota, Wisconsin, Michigan, Colorado, New Mexico, and Texas.
Rates are designed to recover plant investment, operating costs and an allowed return on investment. Our utility subsidiaries request changes in rates for utility services through filings with governing commissions. Changes in operating costs can affect Xcel Energy’s financial results, depending on the timing of rate case filings and implementation of final rates. Other factors affecting rate filings are new investments, sales, conservation and DSM efforts, and the cost of capital.
In addition, the regulatory commissions authorize the ROE, capital structure and depreciation rates in rate proceedings. Decisions by these regulators can significantly impact Xcel Energy’s results of operations.
See Rate Matters within Note 12 to the consolidated financial statements for further information.
NSP-Minnesota
Summary of Regulatory Agencies / RTO and Areas of Jurisdiction
| Regulatory Body / RTO | Additional Information | |
| MPUC (a) | Retail rates, services, security issuances, property transfers, mergers, disposition of assets, affiliate transactions, and other aspects of electric and natural gas operations. Reviews and approves IRPs for meeting future energy needs. Certifies the need and siting for generating plants greater than 50 MW and transmission lines greater than 100 KV in Minnesota. Reviews and approves natural gas supply plans. Pipeline safety compliance. | |
| NDPSC (a) | Retail rates, services and other aspects of electric and natural gas operations. Regulatory authority over generation and transmission facilities, along with the siting and routing of new generation and transmission facilities in North Dakota. Pipeline safety compliance. | |
| SDPUC | Retail rates, services and other aspects of electric operations. Regulatory authority over generation and transmission facilities, along with the siting and routing of new generation and transmission facilities in South Dakota. Pipeline safety compliance. | |
| FERC | Wholesale electric operations, hydroelectric licensing, accounting practices, wholesale sales for resale, transmission of electricity in interstate commerce, compliance with NERC electric reliability standards, asset transfers and mergers, and natural gas transactions in interstate commerce. | |
| MISO | NSP-Minnesota is a transmission owning member of the MISO RTO and operates within the MISO RTO and wholesale markets. NSP-Minnesota makes wholesale sales in other RTO markets at market-based rates. NSP-Minnesota and NSP-Wisconsin also make wholesale electric sales at market-based prices to customers outside of their balancing authority as jointly authorized by the FERC. | |
| DOT | Pipeline safety compliance. | |
| Minnesota Office of Pipeline Safety | Pipeline safety compliance. |
| (a) | Jurisdictional Cost Recovery Allocation — In December 2016, NSP-Minnesota filed a resource treatment framework with the NDPSC and MPUC to allow NSP-Minnesota’s operations in North Dakota and Minnesota to gradually become more independent of one another. The filing identified two options: a legal separation, creating a separate North Dakota operating company; or a pseudo-separation, which maintains the current corporate structure but directly assigns costs and benefits of each resource to the jurisdiction that supports it. Docket remains under consideration by the NDPSC. |
Recovery Mechanisms
| Mechanism | Additional Information | |
| CIP Rider (a) | Recovers costs of conservation and DSM programs. | |
| EIR | Recovers costs of environmental improvement projects. | |
| RDF | Allocates money collected from customers to support research and development of emerging renewable energy projects and technologies. | |
| RES | Recovers cost of renewable generation in Minnesota. | |
| RER | Recovers the cost of renewable generation in North Dakota. | |
| SEP | Recovers costs related to various energy policies approved by the Minnesota legislature. | |
| TCR | Recovers costs for investments in electric transmission and distribution grid modernization. | |
| Infrastructure Rider | Recovers costs for investments in generation and incremental property taxes in South Dakota. | |
| FCA (b) | Minnesota, North Dakota and South Dakota include a FCA for monthly billing adjustments to recover changes in prudently incurred costs of fuel related items and purchased energy. Capacity costs are recovered through base rates and are not recovered through the FCA. MISO costs are generally recovered through either the FCA or base rates. | |
| PGA | Provides for prospective monthly rate adjustments for costs of purchased natural gas, transportation and storage service. Includes a true-up process for difference between projected and actuals costs. | |
| GUIC Rider | Recovers costs for transmission and distribution pipeline integrity management programs, including: funding for pipeline assessments, deferred costs for sewer separation and pipeline integrity management programs. |
| (a) | Minnesota state law requires NSP-Minnesota to invest 2% of its state electric revenues and 0.5% of its state gas revenues in CIP. These costs are recovered through an annual cost-recovery mechanism. |
| (b) | In 2017, the MPUC changed the FCA process in Minnesota, which will implemented in 2020. Under the new process, each month utilities would collect amounts equal to the baseline cost of energy set at the start of the plan year (base would be reset annually). Monthly variations to the baseline costs would be tracked and netted over a 12-month period. Utilities would issue refunds above the baseline costs and could seek recovery of any overage. |
Pending and Recently Concluded Regulatory Proceedings
| Mechanism | Utility Service | Amount Requested (in millions) | Filing Date | Approval | Additional Information | |||||
| MPUC | ||||||||||
| 2018 TCR | Electric | $98 | November 2017 | Received | In November 2019, the MPUC issued an order setting an ROE of 9.06% and recovery of 2017-2018 expenses related to advanced grid investments. | |||||
| 2020 TCR | Electric | $82 | November 2019 | Pending | In November 2019, NSP-Minnesota filed the 2020 TCR Rider. The filing included an ROE of 9.06%. Timing of an MPUC ruling is uncertain. | |||||
| 2019 GUIC | Natural Gas | $29 | November 2018 | Pending | In November 2018, NSP-Minnesota filed the 2019 GUIC Rider with the MPUC. The filing included an ROE of 10.25%. Timing of an MPUC ruling is uncertain. | |||||
| 2020 GUIC | Natural Gas | $21 | November 2019 | Pending | In November 2019, NSP-Minnesota filed the 2020 GUIC Rider with the MPUC. The filing included an ROE of 9.04%. Timing of an MPUC ruling is uncertain. | |||||
| 2018 RES | Electric | $23 | November 2017 | Received | In November 2019, the MPUC approved an order setting an ROE of 9.06%. | |||||
| 2020 RES | Electric | $102 | November 2019 | Pending | In November 2019, NSP-Minnesota filed the 2020 RES Rider with the MPUC. The requested amount includes a true up for the 2019 rider of $38 million and the 2020 requested amount of $64 million. The filing included an ROE of 9.06%. Timing of an MPUC ruling is uncertain. |
Minnesota Electric Rate Case and Alternative Petition — In November 2019, NSP-Minnesota filed a three-year electric rate case with the MPUC. The proposed electric rates reflect a three-year increase in revenues of approximately $201.4 million (6.5%) in 2020, with subsequent incremental increases of $146.4 million (4.8%) in 2021 and $118.3 million (3.9%) in 2022. The rate case is based on a requested ROE of 10.2%, a 52.5% equity ratio, an average electric rate base of $9.0 billion for 2020, $9.3 billion for 2021 and $9.8 billion for 2022.
In addition, NSP-Minnesota requested interim rates, subject to refund, of $122.0 million to be implemented in January 2020 and an incremental $144.0 million to be implemented in January 2021.
NSP-Minnesota also filed a stay-out petition, in which NSP-Minnesota would withdraw its electric rate case and refrain from filing another rate case for one year if the MPUC were to approve an extension of true-up mechanisms for sales, capital and property taxes. NSP-Minnesota also requested that the MPUC delay any increase to the Nuclear Decommissioning Trust annual accrual until 2021.
In December 2019, the MPUC verbally approved the stay-out petition including extension of the sales, capital and property tax true-up mechanisms and the delay of any increase to the Nuclear Decommissioning Trust annual accrual until Jan. 1, 2021.
MEC Acquisition — In November 2018, NSP-Minnesota reached an agreement with Southern Power Company (a subsidiary of Southern Company) to purchase MEC, a 760 MW natural gas combined cycle facility, for approximately $650 million.
In September 2019, the MPUC denied NSP-Minnesota's request to purchase MEC as a rate base asset. In January 2020, the MPUC approved Xcel Energy’s plan to acquire MEC as a non-regulated investment and step into the terms of the existing PPAs with NSP-Minnesota. A newly formed non-regulated subsidiary of Xcel Energy completed the transaction to purchase MEC on Jan. 17, 2020.
Minnesota Resource Plan — In July 2019, NSP-Minnesota filed its Minnesota resource plan, which runs through 2034. The plan would result in an 80% carbon reduction by 2030 (from 2005) and puts NSP-Minnesota on a path to achieving its vision of being 100% carbon-free by 2050. The preferred plan includes the following:
| • | Extends the life of the Monticello nuclear plant from 2030 to 2040; |
| • | Continues to run PI through current end of life (2033 and 2034); |
| • | Includes the MEC acquisition and construction of the Sherco combined cycle natural gas plant; |
| • | Includes the early retirement of the King coal plant (511 MW) in 2028 and the Sherco 3 coal plant (517 MW) in 2030; |
| • | Adds approximately 1,700 MW of firm peaking (combustion turbine, pumped hydro, battery storage, demand response, etc.); |
| • | Adds approximately 1,200 MW of wind replacement; and |
| • | Adds approximately 4,000 MW of solar. |
Intervening parties will provide recommendations and comments on the resource plan. Following the MPUC’s denial of its request to purchase MEC, NSP-Minnesota will provide updates to remove its ownership of MEC from the preferred plan. The MPUC required NSP-Minnesota to update its filing to address issues related to its decision on MEC, including certain new modeling scenarios. An updated filing is required by April 1, 2020. The MPUC is anticipated to make a final decision on the resource plan in the first half of 2021.
Jeffers Wind and Community Wind North Repowering Acquisition — In October 2019, the MPUC approved NSP-Minnesota’s request to acquire the Jeffers and Community Wind North wind facilities in western Minnesota from Longroad Energy. The wind farms will have approximately 70 MW of capacity after being repowered. The repowering is expected to be completed by December 2020 and qualify for the full PTC. The $135 million asset acquisition is projected to provide customer savings of approximately $7 million over the life of the facilities.
Mower Wind Facility — In August 2019, NSP-Minnesota filed a petition with the MPUC to acquire the Mower wind facility from affiliates of NextEra Energy, Inc. for an undisclosed amount. The Mower facility is located in southeastern Minnesota and is currently contracted under a PPA with NSP-Minnesota through 2026. Mower is expected to continue to have approximately 99 MW of capacity following a planned repowering. The acquisition would occur after repowering, which is expected to be complete in 2020 and qualify for the full PTC. NSP-Minnesota will need approval from both the MPUC and FERC to complete the transaction. NSP-Minnesota filed reply comments addressing the DOC’s concerns with the transaction in February 2020.Timing of MPUC and FERC decisions are uncertain.
Purchased Power Arrangements and Transmission Service Provider
NSP-Minnesota expects to use power plants, power purchases, CIP/DSM options, new generation facilities and expansion of power plants to meet its system capacity requirements.
Purchased Power — NSP-Minnesota has contracts to purchase power from other utilities and IPPs. Long-term purchased power contracts for dispatchable resources typically require a capacity and an energy charge. NSP-Minnesota makes short-term purchases to meet system requirements, replace company owned generation, meet operating reserve obligations or obtain energy at a lower cost.
PPA Terminations and Amendments — In June 2018, NSP-Minnesota terminated the Benson and Laurentian PPAs, and purchased the Benson biomass facility. As a result, a $103 million regulatory asset was recognized for the costs of the Benson transaction. For Laurentian, a regulatory asset of $109 million was recognized for annual termination payments/obligations. Regulatory approvals provide for recovery of the Benson regulatory asset over 10 years and Laurentian termination payments as they occur (over six years). Termination of the PPAs is expected to save customers over $600 million throughout the next 10 years.
Purchased Transmission Services — NSP-Minnesota and NSP-Wisconsin have contracts with MISO and other regional transmission service providers to deliver power and energy to their customers.
Minnesota State ROFR Statute Complaint — In September 2017, LSP Transmission filed a complaint in the Minnesota District Court against the Minnesota Attorney General, MPUC and DOC. The complaint was in response to MISO assigning NSP-Minnesota and ITC Midwest, LLC to jointly own a new 345 KV transmission line from Mankato to Winnebago, Minnesota.
The project was estimated to cost $108 million and projected to be in-service by the end of 2021. It was assigned to NSP-Minnesota and ITC Midwest as the incumbent utilities, consistent with a Minnesota state ROFR statute. The complaint challenged the constitutionality of the statute and is seeking declaratory judgment that the statute violates the Commerce Clause of the U.S. Constitution and should not be enforced. The Minnesota state agencies and NSP-Minnesota filed motions to dismiss.
In June 2018, the Minnesota District Court granted the defendants’ motions to dismiss with prejudice. LSP Transmission filed an appeal in July 2018. In September 2019, the estimate was updated to approximately $140 million, due to various changes in build plans. In October 2019, oral arguments were held with the Eighth Circuit Court of Appeals. A decision is expected in the first or second quarter of 2020.
Nuclear Power Operations and Waste Disposal
Nuclear power plant operations produce gaseous, liquid and solid radioactive wastes, which are covered by federal regulation. High-level radioactive wastes primarily include used nuclear fuel. Low-level waste consists primarily of demineralizer resins, paper, protective clothing, rags, tools and equipment contaminated through use.
NRC Regulation — The NRC regulates nuclear operations. Costs of complying with NRC requirements can affect both operating expenses and capital investments of the plants. NSP-Minnesota has obtained recovery of these compliance costs and expects to recover future compliance costs.
Low-Level Waste Disposal — Low level waste disposal from Monticello and PI is disposed at the Clive facility located in Utah and the Waste Control Specialists facility in Texas. NSP-Minnesota has storage capacity available on-site at PI and Monticello which would allow both plants to continue to operate until the end of their current licensed lives if of-site low-level waste disposal facilities become unavailable.
High-Level Radioactive Waste Disposal — The federal government has responsibility to permanently dispose domestic spent nuclear fuel and other high-level radioactive wastes. The Nuclear Waste Policy Act requires the DOE to implement a program for nuclear high-level waste management. This includes the siting, licensing, construction and operation of a repository for spent nuclear fuel from civilian nuclear power reactors and other high-level radioactive wastes at a permanent federal storage or disposal facility. The federal government has been evaluating a nuclear geologic repository at Yucca Mountain, Nevada for many years. Currently, there are no definitive plans for a permanent federal storage facility site.
Nuclear Spent Fuel Storage — NSP-Minnesota has interim on-site storage for spent nuclear fuel at its Monticello and PI nuclear generating plants. Authorized storage capacity is sufficient to allow NSP-Minnesota to operate until the end of the operating licenses in 2030 for Monticello, 2033 for PI Unit 1, and 2034 for PI Unit 2. Authorizations for additional spent fuel storage capacity may be required at each site to support either continued operation or decommissioning if the federal government does not commence storage operations.
Wholesale and Commodity Marketing Operations
NSP-Minnesota conducts wholesale marketing operations, including the purchase and sale of electric capacity, energy, ancillary services and energy-related products. NSP-Minnesota uses physical and financial instruments to minimize commodity price and credit risk and hedge sales and purchases.
NSP-Minnesota also engages in trading activity unrelated to hedging. Sharing of any margins is determined through state regulatory proceedings as well as the operation of the FERC approved JOA. NSP-Minnesota does not serve any wholesale requirements customers at cost-based regulated rates.
NSP-Wisconsin
Summary of Regulatory Agencies / RTO and Areas of Jurisdiction
| Regulatory Body / RTO | Additional Information | |
| PSCW | Retail rates, services and other aspects of electric and natural gas operations. Certifies the need for new generating plants and electric transmission lines before the facilities may be sited and built. The PSCW has a biennial base rate filing requirement. By June of each odd numbered year, NSP-Wisconsin must submit a rate filing for the test year beginning the following January. Pipeline safety compliance. | |
| MPSC | Retail rates, services and other aspects of electric and natural gas operations. Certifies the need for new generating plants and electric transmission lines before the facilities may be sited and built. Pipeline safety compliance. | |
| FERC | Wholesale electric operations, hydroelectric generation licensing, accounting practices, wholesale sales for resale, transmission of electricity in interstate commerce, compliance with NERC electric reliability standards, asset transactions and mergers and natural gas transactions in interstate commerce. | |
| MISO | NSP-Wisconsin is a transmission owning member of the MISO RTO that operates within the MISO RTO and wholesale energy market. NSP-Wisconsin and NSP-Minnesota are jointly authorized by the FERC to make wholesale electric sales at market-based prices. | |
| DOT | Pipeline safety compliance. |
Recovery Mechanisms
| Mechanism | Additional Information | |
| Annual Fuel Cost Plan (a) | NSP-Wisconsin does not have an automatic electric fuel adjustment clause. Under Wisconsin rules, utilities submit a forward-looking annual fuel cost plan to the PSCW. Once the PSCW approves the plan, utilities defer the amount of any fuel cost under-recovery or over-recovery in excess of a 2% annual tolerance band, for future rate recovery or refund. Approval of a fuel cost plan and any rate adjustment for refund or recovery of deferred costs is determined by the PSCW. Rate recovery of deferred fuel cost is subject to an earnings test based on the most recently authorized ROE. Under-collections that exceed the 2% annual tolerance band may not be recovered if the utility earnings for that year exceed the authorized ROE. | |
| Power Supply Cost Recovery Factors | NSP-Wisconsin’s retail electric rate schedules for Michigan customers include power supply cost recovery factors, based on 12-month projections. After each 12-month period, a reconciliation is submitted whereby over-recoveries are refunded and any under-recoveries are collected from customers. | |
| Wisconsin Energy Efficiency Program | The primary energy efficiency program is funded by the utilities, but operated by independent contractors subject to oversight by the PSCW and utilities. NSP-Wisconsin recovers these costs from customers. | |
| PGA | NSP-Wisconsin has a retail PGA cost-recovery mechanism for Wisconsin to recover the actual cost of natural gas and transportation and storage services. | |
| Natural Gas Cost-Recovery Factor (MI) | NSP-Wisconsin’s natural gas rates for Michigan customers include a natural gas cost-recovery factor, based on 12-month projections and trued-up to actual amounts on an annual basis. |
| (a) | NSP-Wisconsin’s electric fuel costs were lower than authorized in rates and outside the 2% annual tolerance band in 2019. Under the fuel cost recovery rules, NSP-Wisconsin retained the $3.3 million of over-recovered fuel costs (amounts within annual tolerance band) and deferred $9.7 million (amounts in excess of annual tolerance band) as a regulatory liability. NSP-Wisconsin plans to file a reconciliation of 2019 fuel costs with the PSCW by March 2020. |
Pending and Recently Concluded Regulatory Proceedings
| Mechanism | Utility Service | Amount Requested (in millions) | Filing Date | Approval | Additional Information | |||||
| PSCW | ||||||||||
| Rate Case | Electric & Natural Gas | N/A | May 2019 | Received | In May 2019, NSP-Wisconsin filed an application with the PSCW seeking no change to base electric rates through Dec. 31, 2021; and a $3.2 million (4.6%) decrease to base natural gas rates, effective Jan. 1, 2020, and no additional changes to base natural gas rates through Dec. 31, 2021. The settlement is based on an ROE of 10.0% and an equity ratio of 52.5%. In September 2019, the PSCW issued an interim order approving the settlement agreement as filed with one minor modification, to remove the deferral of pension settlement accounting costs for 2021. A final order was received in December 2019. |
Purchased Power and Transmission Services
Purchased Power — Through the Interchange Agreement, NSP-Wisconsin receives power purchased by NSP-Minnesota from other utilities and independent power producers. Long-term purchased power contracts for dispatchable resources typically require a capacity charge and an energy charge. NSP-Minnesota makes short-term purchases to meet system requirements, replace company owned generation, meet operating reserve obligations or obtain energy at a lower cost.
Purchased Transmission Services — NSP-Minnesota and NSP-Wisconsin have contracts with MISO and other regional transmission service providers to deliver power and energy to their customers.
Wholesale and Commodity Marketing Operations
NSP-Wisconsin does not serve any wholesale requirements customers at cost-based regulated rates.
PSCo
Summary of Regulatory Agencies / RTO and Areas of Jurisdiction
| Regulatory Body / RTO | Additional Information | |
| CPUC | Retail rates, accounts, services, issuance of securities and other aspects of electric and natural gas operations. Pipeline safety compliance. | |
| FERC | Wholesale electric operations, accounting practices, hydroelectric licensing, wholesale sales for resale, transmission of electricity in interstate commerce, compliance with the NERC electric reliability standards, asset transactions and mergers and natural gas transactions in interstate commerce. Wholesale electric sales at cost-based prices to customers inside PSCo’s balancing authority area and at market-based prices to customers outside PSCo’s balancing authority area. PSCo holds a FERC certificate that allows it to transport natural gas in interstate commerce without PSCo becoming subject to full FERC jurisdiction. | |
| RTO | PSCo is not presently a member of an RTO and does not operate within an RTO energy market. However, PSCo does make certain sales to other RTO’s, including SPP and participates in a joint dispatch agreement with neighboring utilities. | |
| DOT | Pipeline safety compliance. |
Recovery Mechanisms
| Mechanism | Additional Information | |
| ECA | Recovers fuel and purchased energy costs. Short-term sales margins are shared with customers through the ECA. The ECA is revised quarterly. | |
| PCCA | Recovers purchased capacity payments. | |
| SCA | Recovers difference between actual fuel costs and costs recovered under steam service rates. The SCA rate is revised quarterly. | |
| DSMCA | Recovers DSM, interruptible service costs and performance initiatives for achieving energy savings goals. | |
| RESA | Recovers the incremental costs of compliance with the RES with a maximum of 2% of the customer’s bill. | |
| WCA | Recovers costs for customers who choose renewable resources. | |
| TCA | Recovers costs for transmission investment outside of rate cases. | |
| CACJA | Recovers costs associated with the CACJA. | |
| FCA | PSCo recovers fuel and purchased energy costs from wholesale electric customers through a fuel cost adjustment clause approved by the FERC. Wholesale customers pay production costs through a forecasted formula rate subject to true-up. | |
| GCA | Recovers costs of purchased natural gas and transportation and is revised quarterly to allow for changes in natural gas rates. | |
| PSIA | Recovers costs for transmission and distribution pipeline integrity management programs. |
Pending and Recently Concluded Regulatory Proceedings
| Mechanism | Utility Service | Amount Requested (in millions) | Filing Date | Approval | Additional Information | |||||
| CPUC | ||||||||||
| Rate Case | Steam | $7 | January 2019 | Received | In September 2019, the CPUC approved PSCo’s Settlement Agreement with CPUC Staff and the City of Denver. The settlement reflects an ROE of 9.67% for AFUDC purposes, an equity ratio of 56.04% and utilization of tax reform benefits. The first stepped increase went into effect Oct. 1, 2019, with full rates effective Oct. 1, 2020. | |||||
| Rate Case Appeal | Natural Gas | N/A | April 2019 | Pending | In April 2019, PSCo filed an appeal seeking judicial review of the CPUC’s prior ruling regarding PSCo’s last natural gas rate case (approved in December 2018). Appeal requests review of the following: denial of a return on the prepaid pension and retiree medical assets; the use of a capital structure that is not based on the actual historical test year level; and the use of an average rate base methodology rather than a year-end rate base methodology. Timeline on a final ruling is unknown. | |||||
| DSM Incentive | Electric & Natural Gas | $12 | April 2019 | Received | PSCo earned an electric and natural gas DSM incentive of $9 million and $3 million, respectively, for achieving its 2018 savings goals. |
PSCo — Electric Rate Case — In October 2019, PSCo filed rebuttal testimony with the CPUC requesting a net rate increase of $108 million. This is based on a $353 million increase offset by $245 million of previously authorized costs currently recovered through various rider mechanisms. The request was based on a ROE of 10.20%, an equity ratio of 55.61% and a current test year, which includes certain forecasted plant additions through December 2019.
In December 2019, the CPUC held deliberations and on Feb. 11, 2020 issued a written decision approving a current test year ended Aug. 31, 2019, a 9.3% ROE, an equity ratio of 55.61%, implementation of decoupling in 2020 and other items. This resulted in an estimated $35 million net base rate revenue increase.
| Revenue Request (Millions of Dollars) | 2020 | |||
| Company filed rebuttal | $ | 353 | ||
| ROE | (55 | ) | ||
| Impact of change in test year | (17 | ) | ||
| Property tax expense | 15 | |||
| Rate base adjustments | (11 | ) | ||
| Capital structure | (5 | ) | ||
| Total proposed revenue change | 280 | |||
| Estimated impact of previously authorized costs (existing riders) | 245 | |||
| Net revenue change | $ | 35 |
Final rates are expected to be implemented in February 2020. PSCo currently intends to file an application for rehearing/reconsideration in the first quarter of 2020.
PSCo — Gas Rate Case — On Feb. 5, 2020, PSCo filed a request with the CPUC seeking a net increase to retail gas rates of $127 million, reflecting a $145 million increase in base rate revenue, which is partially offset by $18 million previously authorized through the PSIA rider mechanism. The request is based on a test year that incorporates actual capital and expenses as of Sept. 30, 2019, adjusted for known and measurable differences for the 12-month period ended Sept. 30, 2020, a 9.95% ROE and an equity ratio of 55.81%. Proposed effective date is Nov. 1, 2020.
| Revenue Request (Millions of Dollars) | 2020 | |||
| Capital additions (through Sept. 30, 2019) | $ | 62 | ||
| Forecasted capital additions (through Sept. 30, 2020) | 33 | |||
| Sales growth (includes amounts forecasted through Sept. 30, 2020) | (29 | ) | ||
| Operations and maintenance, amortization and other expenses | 29 | |||
| Property tax expense | 19 | |||
| Cost of capital | 8 | |||
| Updated depreciation rates | 5 | |||
| Net increase to revenue | 127 | |||
| Previously authorized costs: | ||||
| Transfer PSIA rider costs to base rates | 18 | |||
| Total base request | $ | 145 | ||
| Expected year-end rate base | $ | 2,236 |
The request reflects $1.3 billion of capital additions since the 2016 test year used to set current rates. Capital investments are made to maintain the safety and reliability of the natural gas system, along with investments to connect new customers and perform mandated infrastructure relocation work.
Timing of a CPUC ruling is expected in the second half of 2020.
Resource Plan
CEP — In September 2018, the CPUC approved PSCo’s CEP portfolio, which included the retirement of two coal-fired generation units, Comanche Unit 1 (in 2022) and Comanche Unit 2 (in 2025), and the following additions:
| Total Capacity | PSCo's Ownership | |||
| Wind generation | 1,100 MW | 500 MW | ||
| Solar generation | 700 MW | — | ||
| Battery storage | 275 MW | — | ||
| Natural gas generation | 380 MW | 380 MW |
PSCo’s investment is expected to be approximately $1 billion, including transmission to support the increase in renewable generation.
CPCNs were granted by the CPUC for the Shortgrass Substation in February 2019, and for the 500 MW Cheyenne Ridge wind farm and 345 KV generation tie line in April 2019.
A CPCN for the acquisitions of the Valmont and Manchief natural gas generation facilities was filed in July 2019, and a settlement on those acquisitions was reached with CPUC Staff and the Colorado Office of Consumer Counsel in January 2020, pending a CPUC decision expected in approximately the second quarter of 2020.
A CPCN for voltage control facilities was also filed with the CPUC in December 2019, with another expected to follow in approximately the first quarter of 2020 for network transmission upgrades required for the CEP portfolio.
Purchased Power and Transmission Service Providers
PSCo expects to meet its system capacity requirements through electric generating stations, power purchases, new generation facilities, DSM options and expansion of generation plants.
Purchased Power — PSCo purchases power from other utilities and IPPs. Long-term purchased power contracts for dispatchable resources typically require capacity and energy charges. It also contracts to purchase power for both wind and solar resources. PSCo makes short-term purchases to meet system load and energy requirements, replace owned generation, meet operating reserve obligations, or obtain energy at a lower cost.
Purchased Transmission Services — In addition to using its own transmission system, PSCo has contracts with regional transmission service providers to deliver energy to its customers.
Boulder Municipalization
In 2011, Boulder passed a ballot measure authorizing the formation of an electric municipal utility, subject to certain conditions. Subsequently, there have been various legal proceedings in multiple venues with jurisdiction over Boulder’s plan. In 2014, the Boulder City Council passed an ordinance to establish an electric utility. PSCo challenged the formation of this utility and the Colorado Court of Appeals ruled in PSCo’s favor, vacating a lower court decision. In June 2018, the Colorado Supreme Court rejected Boulder’s request to dismiss the case and remanded it to the Boulder District Court. The case was then settled in June 2019 after Boulder agreed to repeal the ordinance establishing the utility.
Boulder has filed multiple separation applications with the CPUC, which have been challenged by PSCo and other intervenors. In September 2017, the CPUC issued a written decision, agreeing with several key aspects of PSCo’s position. The CPUC has approved the designation of some electrical distribution assets for transfer, subject to Boulder completing certain filings.
In the fourth quarter of 2018, the Boulder City Council also adopted an Ordinance authorizing Boulder to begin negotiations for the acquisition of certain property or to otherwise condemn that property after Feb. 1, 2019. In the first quarter of 2019, Boulder sent PSCo a notice of intent to acquire certain electric distribution assets. In the third quarter of 2019, Boulder filed its condemnation litigation, which was later dismissed by the Boulder District Court in September 2019 on the grounds that Boulder had not completed the pre-requisite CPUC process and filings. Boulder is currently appealing this order. In October 2019, the CPUC approved the subsequent filings regarding asset transfers outside of substations, reaffirmed its 2017 decision on assets outside of substations and closed the CPUC proceeding.
In December 2019, Boulder filed a new condemnation action despite its ongoing appeal of the last condemnation case. PSCo subsequently filed a motion to dismiss or stay the new condemnation action. In February 2020, Boulder filed an application under section 210 of the Federal Power Act asking FERC to order PSCo to interconnect its facilities with a future Boulder municipal utility under Boulder’s preferred terms and conditions.
Wholesale and Commodity Marketing Operations
PSCo conducts various wholesale marketing operations, including the purchase and sale of electric capacity, energy, ancillary services and energy related products. PSCo uses physical and financial instruments to minimize commodity price and credit risk and hedge sales and purchases. PSCo also engages in trading activity unrelated to hedging. Sharing of any margin is determined through state regulatory proceedings as well as the operation of the FERC approved JOA.
SPS
Summary of Regulatory Agencies / RTO and Areas of Jurisdiction
| Regulatory Body / RTO | Additional Information | |
| PUCT | Retail electric operations, rates, services, construction of transmission or generation and other aspects of SPS’ electric operations. The municipalities in which SPS operates in Texas have original jurisdiction over rates in those communities. The municipalities’ rate setting decisions are subject to PUCT review. | |
| NMPRC | Retail electric operations, retail rates and services and the construction of transmission or generation. | |
| FERC | Wholesale electric operations, accounting practices, wholesale sales for resale, the transmission of electricity in interstate commerce, compliance with NERC electric reliability standards, asset transactions and mergers, and natural gas transactions in interstate commerce. | |
| SPP RTO and SPP IM Wholesale Market | SPS is a transmission-owning member of the SPP RTO and operates within the SPP RTO and SPP IM wholesale market. SPS is authorized to make wholesale electric sales at market-based prices. |
Recovery Mechanisms
| Mechanism | Additional Information | |
| DCRF | Recovers distribution costs not included in rates in Texas. | |
| EECRF | Recovers costs for energy efficiency programs in Texas. | |
| Energy Efficiency Rider | Recovers costs for energy efficiency programs in New Mexico. | |
| FPPCAC | Adjusts monthly to recover actual fuel and purchased power costs in New Mexico. In October 2019, SPS filed an application to the NMPRC to approve SPS’ continued use of its FPPCAC and for reconciliation of fuel costs for the period Sept. 1, 2015, through June 30, 2019, which will determine whether all fuel costs incurred are eligible for recovery. No procedural schedule has yet been established for this matter. | |
| PCRF | Allows recovery of purchased power costs not included in Texas rates. | |
| RPS | Recovers deferred costs for renewable energy programs in New Mexico. | |
| TCRF | Recovers certain transmission infrastructure improvement costs and changes in wholesale transmission charges not included in Texas base rates. | |
| Fixed Fuel and Purchased Recovery Factor | Provides for the over- or under-recovery of energy expenses. Regulations require refunding or surcharging over- or under- recovery amounts, including interest, when they exceed 4% of the utility’s annual fuel and purchased energy costs on a rolling 12-month basis, if this condition is expected to continue. | |
| Wholesale Fuel and Purchased Energy Cost Adjustment | SPS recovers fuel and purchased energy costs from its wholesale customers through a monthly wholesale fuel and purchased energy cost adjustment clause accepted by the FERC. Wholesale customers also pay the jurisdictional allocation of production costs. |
Pending and Recently Concluded Regulatory Proceedings
| Mechanism | Utility Service | Amount Requested (in millions) | Filing Date | Approval | Additional Information | |||||
| SPS (NMPRC) | ||||||||||
| Rate Case | Electric | $51 | July 2019 | Pending | In July 2019, SPS filed an electric rate case with the NMPRC seeking an increase in retail electric base rates of approximately $51 million. The rate request is based on an ROE of 10.35%, an equity ratio of 54.77%, a rate base of approximately $1.3 billion and a historic test year with rate base additions through Aug. 31, 2019. In December 2019, SPS revised its base rate increase request to approximately $47 million, based on an ROE of 10.10% and updated information. The request also included an increase of $14.6 million for accelerated depreciation including the early retirement of the Tolk Coal Plant in 2032. On Jan. 13, 2020, SPS and various parties filed an uncontested comprehensive stipulation. The stipulation includes a base rate revenue increase of $31 million, based on an ROE of 9.45% and an equity ratio of 54.77%. The stipulation also includes an acceleration of depreciation on the Tolk Coal Plant to reflect early retirement in 2037, which results in a total increase in depreciation expense of $8 million. The Signatories will not oppose the full application of depreciation rates associated with the 2032 retirement date in SPS’ next base rate case. SPS anticipates final rates will go into effect in the second or third quarter of 2020. |
SPS — Texas Electric Rate Case
In August 2019, SPS filed an electric rate case with the PUCT seeking an increase in retail electric base rates of approximately $141 million. The filing requests an ROE of 10.35%, a 54.65% equity ratio, a rate base of approximately $2.6 billion and is built on a 12 month period that ended June 30, 2019. In September 2019, SPS filed an update to the electric rate case and revised its requested increase to approximately $137 million.
On Feb. 10, 2020, the Alliance of Xcel Municipalities (AXM), Texas Industrial Energy Consumers (TIEC), Office of Public Utility Counsel (OPUC) and Department of Energy (DOE) filed testimony along with several other parties.
On Feb. 18, 2020, the PUCT Staff filed testimony that included certain adjustments and various ring-fencing measures.
Proposed modifications to SPS’ request:
| (Millions of Dollars) | Staff | AXM | OPUC | TIEC | DOE | |||||||||||||||
| SPS Direct Testimony | $ | 137 | $ | 137 | $ | 137 | $ | 137 | $ | 137 | ||||||||||
| Recommended base rate adjustments: | ||||||||||||||||||||
| ROE | (22 | ) | (24 | ) | (15 | ) | (21 | ) | (24 | ) | ||||||||||
| Capital structure | (7 | ) | (10 | ) | — | (7 | ) | (3 | ) | |||||||||||
| Tolk/Harrington O&M disallowance | — | (7 | ) | — | — | — | ||||||||||||||
| Distribution and Transmission Capital Disallowances (a) | (7 | ) | — | — | — | — | ||||||||||||||
| Depreciation expense | (8 | ) | (15 | ) | (8 | ) | (20 | ) | — | |||||||||||
| Excess ADIT unprotected plant | — | — | (7 | ) | — | — | ||||||||||||||
| Income Tax Expense Differences | (12 | ) | — | — | — | — | ||||||||||||||
| Other, net | (6 | ) | (6 | ) | (1 | ) | (1 | ) | — | |||||||||||
| Total Adjustments | (62 | ) | (62 | ) | (31 | ) | (49 | ) | (27 | ) | ||||||||||
| Total proposed revenue change | $ | 75 | $ | 75 | $ | 106 | $ | 88 | $ | 110 |
| Recommended Position | Staff | AXM | OPUC (b) | TIEC | DOE | ||||||||||
| ROE | 9.1 | % | 9.0 | % | — | % | 9.2 | % | 9.0 | % | |||||
| Equity Ratio | 51.00 | % | 50.00 | % | — | % | 51.00 | % | 53.00 | % |
| (a) | Staff recommends exclusion of approximately $134 million in transmission, distribution, and general plant in service in this rate case resulting in an approximate $7 million decrease to the revenue requirement. |
| (b) | OPUC did not provide a recommendation for an ROE or equity ratio. For illustrative purposes an ROE of 9.5% was used. |
The next steps in the procedural schedule are expected to be as follows:
| • | Rebuttal testimony — March 11, 2020; and |
| • | Public hearing begins — March 30, 2020 |
A PUCT decision and implementation of final rates is anticipated in the third quarter of 2020.
Resource Plan
In December 2018, the NMPRC issued a final order accepting SPS’ IRP.
SPS is forecasting a surplus capacity of 382 MW in 2028, but a capacity deficit of approximately 2,896 MW in 2038. SPS’ optimal resource plan for the planning period incorporates the addition of wind, simple cycle combustion turbine generation, combined cycle energy and entering PPAs. Various factors may impact this IRP, which could potentially require updates to the action plan and will be the subject of future IRPs, including:
| • | New and revised environmental regulations; |
| • | Impacts of variability due to participation in the SPP; |
| • | Customer expectations; |
| • | Technological advances; |
| • | Groundwater aquifer depletion at SPS’s Tolk Station; |
| • | Aging generation fleet; |
| • | Load growth and gas price variability; |
| • | Changes to tax credits and incentives; and |
| • | Changes to renewable portfolio standard acquisitions. |
SPS is required to file an IRP in New Mexico every three years and will file its next IRP in July 2021.
Texas State ROFR
In May 2019, the Governor signed into law Senate Bill 1938, which grants incumbent utilities a ROFR to build transmission infrastructure when it directly interconnects to the utility’s existing facility. In June 2019, a complaint was filed in the United States District Court for the Western District of Texas claiming the new ROFR law to be unconstitutional. The Texas Attorney General has made a motion to dismiss the federal court complaint. A ruling on the dismissal motion is expected in the first quarter of 2020.
Purchased Power Arrangements and Transmission Service Providers
SPS expects to use electric generating stations, power purchases, DSM and new generation options to meet its system capacity requirements.
Purchased Power — SPS purchases power from other utilities and IPPs. Long-term purchased power contracts typically require periodic capacity and energy charges. SPS also makes short-term purchases to meet system load and energy requirements to replace owned generation, meet operating reserve obligations or obtain energy at a lower cost.
Purchased Transmission Services — SPS has contractual arrangements with SPP and regional transmission service providers to deliver power and energy to its native load customers.
Natural Gas
SPS does not provide retail natural gas service, but purchases and transports natural gas for its generation facilities and operates natural gas pipeline facilities connecting the generation facilities to interstate natural gas pipelines. SPS is subject to the jurisdiction of the FERC with respect to natural gas transactions in interstate commerce and the PHMSA and PUCT for pipeline safety compliance.
| Critical Accounting Policies and Estimates |
Preparation of the consolidated financial statements requires the application of accounting rules and guidance, as well as the use of estimates. Application of these policies involves judgments regarding future events, including the likelihood of success of particular projects, legal and regulatory challenges and anticipated recovery of costs. These judgments could materially impact the consolidated financial statements, based on varying assumptions. In addition, the financial and operating environment also may have a significant effect on the operation of the business and results reported.
Accounting policies and estimates that are most significant to Xcel Energy’s results of operations, financial condition or cash flows, and require management’s most difficult, subjective or complex judgments are outlined below. Each of these has a higher likelihood of resulting in materially different reported amounts under different conditions or using different assumptions. Each critical accounting policy has been reviewed and discussed with the Audit Committee of Xcel Energy Inc.’s Board of Directors on a quarterly basis.
Regulatory Accounting
Xcel Energy is subject to the accounting for Regulated Operations*,* which provides that rate-regulated entities report assets and liabilities consistent with the recovery of those incurred costs in rates, if it is probable that such rates will be charged and collected. Our rates are derived through the ratemaking process, which results in the recording of regulatory assets and liabilities based on the probability of future cash flows. Regulatory assets generally represent incurred or accrued costs that have been deferred because future recovery from customers is probable. Regulatory liabilities generally represent amounts that are expected to be refunded to customers in future rates or amounts collected in current rates for future costs. In other businesses or industries, regulatory assets and regulatory liabilities would generally be charged to net income or other comprehensive income.
Each reporting period we assess the probability of future recoveries and obligations associated with regulatory assets and liabilities. Factors such as the current regulatory environment, recently issued rate orders and historical precedents are considered. Decisions made by regulatory agencies can directly impact the amount and timing of cost recovery as well as the rate of return on invested capital, and may materially impact our results of operations, financial condition or cash flows.
As of Dec. 31, 2019 and 2018, Xcel Energy recorded regulatory assets of $3.4 billion and $3.8 billion, respectively, and regulatory liabilities of $5.5 billion and $5.6 billion, respectively. Each subsidiary is subject to regulation that varies from jurisdiction to jurisdiction. If future recovery of costs in any such jurisdiction is no longer probable, Xcel Energy would be required to charge these assets to current net income or other comprehensive income. In assessing the probability of recovery of recognized regulatory assets, Xcel Energy noted no current or anticipated proposals or changes in the regulatory environment that it expects will materially impact the probability of recovery of the assets.
See Note 4 to the consolidated financial statements for further information.
Income Tax Accruals
Judgment, uncertainty and estimates are a significant aspect of the income tax accrual process that accounts for the effects of current and deferred income taxes. Uncertainty associated with the application of tax statutes and regulations and outcomes of tax audits and appeals require that judgment and estimates be made in the accrual process and in the calculation of the ETR.
Changes in tax laws and rates may affect recorded deferred tax assets and liabilities and our future ETR. ETR calculations are revised every quarter based on best available year-end tax assumptions, adjusted in the following year after returns are filed. The tax accrual estimates are trued-up to the actual amounts claimed on the tax returns and further adjusted after examinations by taxing authorities, as needed.
In accordance with the interim period reporting guidance, income tax expense for the first three quarters in a year is based on the forecasted annual ETR. The forecasted ETR reflects a number of estimates, including forecasted annual income, permanent tax adjustments and tax credits.
Valuation allowances are applied to deferred tax assets if it is more likely than not that at least a portion may not be realized based on an evaluation of expected future taxable income. Accounting for income taxes also requires that only tax benefits that meet the more likely than not recognition threshold can be recognized or continue to be recognized. We may adjust our unrecognized tax benefits and interest accruals as disputes with the IRS and state tax authorities are resolved, and as new developments occur. These adjustments may increase or decrease earnings.
See Note 7 to the consolidated financial statements for further information.
Employee Benefits
We sponsor several noncontributory, defined benefit pension plans and other postretirement benefit plans that cover almost all employees and certain retirees. Projected benefit costs are based on historical information and actuarial calculations that include key assumptions (annual return level on pension and postretirement health care investment assets, discount rates, mortality rates and health care cost trend rates, etc.). In addition, the pension cost calculation uses a methodology to reduce the volatility of investment performance over time. Pension assumptions are continually reviewed.
At Dec. 31, 2019, Xcel Energy set the rate of return on assets used to measure pension costs at 6.87%, which is consistent with the rate set in 2018. The rate of return used to measure postretirement health care costs is 4.50% at Dec. 31, 2019, which represents a 80 basis point decrease from 2018. Xcel Energy’s pension investment strategy is based on plan-specific investments that seek to minimize investment and interest rate risk as a plan’s funded status increases over time. This strategy results in a greater percentage of interest rate sensitive securities being allocated to plans with a higher funded status and a greater percentage of growth assets being allocated to plans having a lower funded status ratios.
Xcel Energy set the discount rates used to value the pension obligations at 3.49% and postretirement health care obligations at 3.47% at Dec. 31, 2019. This represents a 82 basis point and 85 basis point decrease, respectively, from 2018. Xcel Energy uses a bond matching study as its primary basis for determining the discount rate used to value pension and postretirement health care obligations. The bond matching study utilizes a portfolio of high grade (Aa or higher) bonds that matches the expected cash flows of Xcel Energy’s benefit plans in amount and duration.
The effective yield on this cash flow matched bond portfolio determines the discount rate for the individual plans. The bond matching study is validated for reasonableness against the Merrill Lynch Corporate 15+ Bond Index. In addition, Xcel Energy reviews general actuarial survey data to assess the reasonableness of the discount rate selected.
If Xcel Energy were to use alternative assumptions, a 1% change would result in the following impact on 2019 pension costs:
| Pension Costs | ||||||||
| (Millions of Dollars) | +1% | -1% | ||||||
| Rate of return | $ | (16 | ) | $ | 18 | |||
| Discount rate (a) | (5 | ) | 9 |
| (a) | These costs include the effects of regulation. |
Mortality rates are developed from actual and projected plan experience for pension plan and postretirement benefits. Xcel Energy’s actuary conducts an experience study periodically as part of the process to determine an estimate of mortality. Xcel Energy considers standard mortality tables, improvement factors and the plans actual experience when selecting a best estimate.
As of Dec. 31, 2019, the initial medical trend cost claim assumptions for Pre-65 was 6.0% and Post-65 was 5.1%. The ultimate trend assumption remained at 4.5% for both Pre-65 and Post-65 claims costs. Xcel Energy bases its medical trend assumption on the long-term cost inflation expected in the health care market, considering the levels projected and recommended by industry experts, as well as recent actual medical cost experienced by Xcel Energy’s retiree medical plan.
A 1% change in the assumed health care cost trend rate would have the following effects on Xcel Energy:
| Accumulated Postretirement Benefit Obligation | Service and Interest Components | |||||||
| (Millions of Dollars) | +1% | -1% | +1% | -1% | ||||
| Health care cost trend | $51 | $(43) | $2 | $(2) |
Funding requirements in 2020 were $150 million and are expected to decline in the following years. Investment returns exceeded assumed levels in 2017 and 2019 and were below assumed levels in 2018.
The pension cost calculation uses a market-related valuation of pension assets. Xcel Energy uses a calculated value method to determine the market-related value of the plan assets. The market-related value is determined by adjusting the fair market value of assets at the beginning of the year to reflect the investment gains and losses (the difference between the actual investment return and the expected investment return on the market-related value) during each of the previous five years at the rate of 20% per year. As differences between actual and expected investment returns are incorporated into the market-related value, amounts are recognized in pension cost over the expected average remaining years of service for active employees (approximately 12 years in 2019).
Xcel Energy currently projects the pension costs recognized for financial reporting purposes will be $104 million in 2020 and $90 million in 2021, while the actual pension costs were $115 million in 2019 and $141 million in 2018. The expected decrease in 2020 and future year costs is primarily due to the reductions in loss amortizations.
Pension funding contributions across all four of Xcel Energy’s pension plans, both voluntary and required, for 2017 - 2020:
| • | $150 million in January 2020; |
| • | $154 million in 2019; |
| • | $150 million in 2018; and |
| • | $162 million in 2017. |
Future amounts may change based on actual market performance, changes in interest rates and any changes in governmental regulations. Therefore, additional contributions could be required in the future.
Xcel Energy contributed $15 million, $11 million and $20 million during 2019, 2018 and 2017, respectively, to the postretirement health care plans. Xcel Energy expects to contribute approximately $10 million during 2020. Xcel Energy recovers employee benefits costs in its utility operations consistent with accounting guidance with the exception of the areas noted below.
| • | NSP-Minnesota recognizes pension expense in all regulatory jurisdictions using the aggregate normal cost actuarial method. Differences between aggregate normal cost and expense as calculated by pension accounting standards are deferred as a regulatory liability; |
| • | In 2018, the PSCW approved NSP-Wisconsin’s request for deferred accounting treatment of the 2018 pension settlement accounting expense; |
| • | Regulatory Commissions in Colorado, Texas, New Mexico and FERC jurisdictions allow the recovery of other postretirement benefit costs only to the extent that recognized expense is matched by cash contributions to an irrevocable trust. Xcel Energy has consistently funded at a level to allow full recovery of costs in these jurisdictions; |
| • | PSCo and SPS recognize pension expense in all regulatory jurisdictions based on expense consistent with accounting guidance. The Texas and Colorado electric retail jurisdictions and the Colorado gas retail jurisdiction, each record the difference between annual recognized pension expense and the annual amount of pension expense approved in their last respective general rate case as a deferral to a regulatory asset; and |
| • | In 2018, PSCo was required to create a regulatory liability to adjust postretirement health care costs to zero in order to match the amounts collected in rates in the Colorado Gas retail jurisdiction. |
See Note 11 to the consolidated financial statements for further information.
Nuclear Decommissioning
Xcel Energy recognizes liabilities for the expected cost of retiring tangible long-lived assets for which a legal obligation exists. These AROs are recognized at fair value as incurred and are capitalized as part of the cost of the related long-lived assets. In the absence of quoted market prices, Xcel Energy estimates the fair value of its AROs using present value techniques, in which it makes assumptions including estimates of the amounts and timing of future cash flows associated with retirement activities, credit-adjusted risk free rates and cost escalation rates. When the Company revises any assumptions, it adjusts the carrying amount of both the ARO liability and related long-lived asset. ARO liabilities are accreted to reflect the passage of time using the interest method.
A significant portion of Xcel Energy’s AROs relates to the future decommissioning of NSP-Minnesota’s nuclear facilities. The nuclear decommissioning obligation is funded by the external decommissioning trust fund. Difference between regulatory funding (including depreciation expense less returns from the external trust fund) and expense recognized is deferred as a regulatory asset. The amounts recorded for AROs related to future nuclear decommissioning were $2.1 billion in 2019 and $2.0 billion in 2018.
NSP-Minnesota obtains periodic independent cost studies in order to estimate the cost and timing of planned nuclear decommissioning activities. Estimates of future cash flows are highly uncertain and may vary significantly from actual results. NSP-Minnesota is required to file a nuclear decommissioning filing every three years. The filing covers all expenses for the decommissioning of the nuclear plants, including decontamination and removal of radioactive material.
The most recent triennial filing was approved by the MPUC in January 2019. This approval did not result in a change to the ARO liability. In December 2019, the MPUC ordered Xcel Energy to maintain the current accrual through 2020 to align with the approved one year stay out of the previously filed three-year electric rate case. Xcel Energy will evaluate the scenarios and potentially propose a new accrual starting in 2022 when it submits the next triennial filing in December 2020.
The following assumptions have a significant effect on the estimated nuclear obligation:
Timing — Decommissioning cost estimates are impacted by each facility’s retirement date and timing of the actual decommissioning activities. Estimated retirement dates coincide with the expiration of each unit’s operating license with the NRC (i.e., 2030 for Monticello and 2033 and 2034 for PI’s Unit 1 and 2, respectively). The estimated timing of the decommissioning activities is based upon the DECON method, which assumes prompt removal and dismantlement. The use of the DECON method is required by the MPUC. Decommissioning activities are expected to begin at the end of the license date and be completed for both facilities by 2091.
Technology and Regulation — There is limited experience with actual decommissioning of large nuclear facilities. Changes in technology, experience and regulations could cause cost estimates to change significantly.
Escalation Rates — Escalation rates represent projected cost increases due to general inflation and increases in the cost of decommissioning activities. NSP-Minnesota used an escalation rate of 3.4% in calculating the ARO for nuclear decommissioning of its nuclear facilities, based on the weighted averages of labor and non-labor escalation factors calculated by Goldman Sachs Asset Management.
Discount Rates — Changes in timing or estimated cash flows that result in upward revisions to the ARO are calculated using the then-current credit-adjusted risk-free interest rate. The credit-adjusted risk-free rate in effect when the change occurs is used to discount the revised estimate of the incremental expected cash flows of the retirement activity.
If the change in timing or estimated expected cash flows results in a downward revision of the ARO, the undiscounted revised estimate of expected cash flows is discounted using the credit-adjusted risk-free rate in effect at the date of initial measurement and recognition of the original ARO. Discount rates ranging from approximately 4% to 7% have been used to calculate the net present value of the expected future cash flows over time.
Significant uncertainties exist in estimating future costs including the method to be utilized, ultimate costs to decommission and planned method of disposing spent fuel. If different cost estimates, life assumptions or cost escalation rates were utilized, the AROs could change materially.
However, changes in estimates have minimal impact on results of operations as NSP-Minnesota expects to continue to recover all costs in future rates.
The Company continually makes judgments and estimates related to these critical accounting policy areas, based on an evaluation of the assumptions and uncertainties for each area. The information and assumptions of these judgments and estimates will be affected by events beyond the control of Xcel Energy, or otherwise change over time. This may require adjustments to recorded results to better reflect updated information that becomes available. The accompanying financial statements reflect management’s best estimates and judgments of the impact of these factors as of Dec. 31, 2019.
See Note 12 to the consolidated financial statements for further information.
| Derivatives, Risk Management and Market Risk |
We are exposed to a variety of market risks in the normal course of business. Market risk is the potential loss that may occur as a result of adverse changes in the market or fair value of a particular instrument or commodity. All financial and commodity-related instruments, including derivatives, are subject to market risk.
Xcel Energy is also exposed to the impact of adverse changes in price for energy and energy-related products, which is partially mitigated by the use of commodity derivatives. In addition to ongoing monitoring and maintaining credit policies intended to minimize overall credit risk, management takes steps to mitigate changes in credit and concentration risks associated with its derivatives and other contracts, including parental guarantees and requests of collateral. While we expect that the counterparties will perform under the contracts underlying its derivatives, the contracts expose us to certain credit and non-performance risk.
Distress in the financial markets may impact counterparty risk, the fair value of the securities in the nuclear decommissioning fund and pension fund and Xcel Energy’s ability to earn a return on short-term investments.
Commodity Price Risk — We are exposed to commodity price risk in their electric and natural gas operations. Commodity price risk is managed by entering into long- and short-term physical purchase and sales contracts for electric capacity, energy and energy-related products and fuels used in generation and distribution activities. Commodity price risk is also managed through the use of financial derivative instruments. Our risk management policy allows it to manage commodity price risk within each rate-regulated operation per commission approved hedge plans.
Wholesale and Commodity Trading Risk — Xcel Energy conducts various wholesale and commodity trading activities, including the purchase and sale of electric capacity, energy, energy-related instruments and natural gas-related instruments, including derivatives. Our risk management policy allows management to conduct these activities within guidelines and limitations as approved by its risk management committee.
Fair value of net commodity trading contracts as of Dec. 31, 2019:
| Futures / Forwards Maturity | ||||||||||||||||||||
| (Millions of Dollars) | Less Than 1 Year | 1 to 3 Years | 4 to 5 Years | Greater Than 5 Years | Total Fair Value | |||||||||||||||
| NSP-Minnesota (a) | $ | (1 | ) | $ | 2 | $ | 2 | $ | 3 | $ | 6 | |||||||||
| NSP-Minnesota (b) | 2 | (3 | ) | (2 | ) | (10 | ) | (13 | ) | |||||||||||
| PSCo (b) | (4 | ) | (22 | ) | (31 | ) | — | (57 | ) | |||||||||||
| $ | (3 | ) | $ | (23 | ) | $ | (31 | ) | $ | (7 | ) | $ | (64 | ) |
| (a) | Prices actively quoted or based on actively quoted prices. |
| (b) | Prices based on models and other valuation methods. |
| Options Maturity | ||||||||||||||||||||
| (Millions of Dollars) | Less Than 1 Year | 1 to 3 Years | 4 to 5 Years | Greater Than 5 Years | Total Fair Value | |||||||||||||||
| NSP-Minnesota (a) | $ | 4 | $ | 1 | $ | — | $ | — | $ | 5 |
| (a) | Prices based on models and other valuation methods. |
Changes in the fair value of commodity trading contracts before the impacts of margin-sharing for the years ended Dec. 31:
| (Millions of Dollars) | 2019 | 2018 | ||||||
| Fair value of commodity trading net contract assets outstanding at Jan. 1 | $ | 17 | $ | 16 | ||||
| Contracts realized or settled during the period | (22 | ) | (10 | ) | ||||
| Commodity trading contract additions and changes during the period | (54 | ) | 11 | |||||
| Fair value of commodity trading net contract assets outstanding at Dec. 31 | $ | (59 | ) | $ | 17 |
At Dec. 31, 2019, a 10% increase in market prices for commodity trading contracts would increase pretax income by approximately $10 million, whereas a 10% decrease would decrease pretax income by approximately $10 million. At Dec. 31, 2018, a 10% increase in market prices for commodity trading contracts would increase pretax income by approximately $16 million, whereas a 10% decrease would decrease pretax income by approximately $16 million.
The utility subsidiaries’ commodity trading operations measure the outstanding risk exposure to price changes on contracts and obligations that have been entered into, but not closed, using an industry standard methodology known as VaR. VaR expresses the potential change in fair value on the outstanding contracts and obligations over a particular period of time under normal market conditions.
The VaRs for the NSP-Minnesota and PSCo commodity trading operations, excluding both non-derivative transactions and derivative transactions designated as normal purchase, normal sales, calculated on a consolidated basis using a Monte Carlo simulation with a 95% confidence level and a one-day holding period, were as follows:
| (Millions of Dollars) | Year Ended Dec. 31 | VaR Limit | Average | High | Low | |||||||||||||||
| 2019 | $ | 0.4 | $ | 3.0 | $ | 0.6 | $ | 0.8 | $ | 0.3 | ||||||||||
| 2018 | 4.8 | 6.0 | 0.6 | 5.6 | 0.1 |
In November 2018, management temporarily increased the VaR limit to accommodate a 10-year transaction. NSP-Minnesota systematically hedging the transaction and the consolidated VaR returned below $3 million in early January 2019.
Nuclear Fuel Supply — NSP-Minnesota has received all enriched nuclear material for 2019 and has contracted for approximately 51% of its 2020 enriched nuclear material requirements from sources that could be impacted by sanctions against entities doing business with Iran. Those sanctions may impact the supply of enriched nuclear material supplied from Russia. Long-term, through 2030, NSP-Minnesota is scheduled to take delivery of approximately 29% of its average enriched nuclear material requirements from these sources. Alternate potential sources provide the flexibility to manage NSP-Minnesota’s nuclear fuel supply. NSP-Minnesota periodically assesses if further actions are required to assure a secure supply of enriched nuclear material.
Interest Rate Risk — Xcel Energy is subject to interest rate risk. Our risk management policy allows interest rate risk to be managed through the use of fixed rate debt, floating rate debt and interest rate derivatives such as swaps, caps, collars and put or call options.
A 100 basis point change in the benchmark rate on Xcel Energy’s variable rate debt would impact annual pretax interest expense by approximately $6 million in 2019 and $10 million in 2018.
NSP-Minnesota maintains a nuclear decommissioning fund, as required by the NRC. The nuclear decommissioning fund is subject to interest rate risk and equity price risk. The fund is invested in a diversified portfolio of cash equivalents, debt securities, equity securities and other investments. These investments may be used only for the purpose of decommissioning NSP-Minnesota’s nuclear generating plants.
Realized and unrealized gains on the decommissioning fund investments are deferred as an offset of NSP-Minnesota’s regulatory asset for nuclear decommissioning costs. Fluctuations in equity prices or interest rates affecting the nuclear decommissioning fund do not have a direct impact on earnings due to the application of regulatory accounting.
Changes in discount rates and expected return on plan assets impact the value of pension and postretirement plan assets and/or benefit costs.
Credit Risk — Xcel Energy is also exposed to credit risk. Credit risk relates to the risk of loss resulting from counterparties’ nonperformance on their contractual obligations. The Company maintains credit policies intended to minimize overall credit risk and actively monitor these policies to reflect changes and scope of operations.
At Dec. 31, 2019, a 10% increase in commodity prices would have resulted in an increase in credit exposure of $19 million, while a decrease in prices of 10% would have resulted in an increase in credit exposure of $14 million. At Dec. 31, 2018, a 10% increase in commodity prices would have resulted in an increase in credit exposure of $14 million, while a decrease in prices of 10% would have resulted in an increase in credit exposure of $3 million.
Xcel Energy conducts credit reviews for all counterparties and employs credit risk controls, such as letters of credit, parental guarantees, master netting agreements and termination provisions. Credit exposure is monitored, and when necessary, the activity with a specific counterparty is limited until credit enhancement is provided. Distress in the financial markets could increase our credit risk.
Fair Value Measurements
Xcel Energy uses derivative contracts such as futures, forwards, interest rate swaps, options and FTRs to manage commodity price and interest rate risk. Derivative contracts, with the exception of those designated as normal purchase-normal sale contracts, are reported at fair value. The Company’s investments held in the nuclear decommissioning fund, rabbi trusts, pension and other postretirement funds are also subject to fair value accounting.
Commodity Derivatives — Xcel Energy monitors the creditworthiness of the counterparties to its commodity derivative contracts and assesses each counterparty’s ability to perform on the transactions. The impact of discounting commodity derivative assets for counterparty credit risk was not material to the fair value of commodity derivative assets at Dec. 31, 2019.
Adjustments to fair value for credit risk of commodity trading instruments are recorded in electric revenues. Credit risk adjustments for other commodity derivative instruments are recorded as other comprehensive income or deferred as regulatory assets and liabilities. Classification as a regulatory asset or liability is based on commission approved regulatory recovery mechanisms. The impact of discounting commodity derivative liabilities for credit risk was immaterial at Dec. 31, 2019.
See Notes 10 and 11 to the consolidated financial statements for further information.
| Liquidity and Capital Resources |
Cash Flows
| (Millions of Dollars) | 2019 | 2018 | 2017 | |||||||||
| Net cash provided by operating activities | $ | 3,263 | $ | 3,122 | $ | 3,126 |
Net cash provided by operating activities increased by $141 million for 2019 as compared to 2018. Increase was primarily due to additional net income (excluding amounts related to non-cash operating activities (e.g., depreciation and amortization and deferred tax expenses)), partially offset by increased refunds associated with TCJA.
Net cash provided by operating activities decreased by $4 million for 2018 as compared to 2017. Change was primarily due to refunds associated with the TCJA and timing of certain electric and natural gas recovery mechanisms, partially offset by the change in net income.
| (Millions of Dollars) | 2019 | 2018 | 2017 | |||||||||
| Net cash used in investing activities | $ | (4,343 | ) | $ | (3,986 | ) | $ | (3,296 | ) |
Net cash used in investing activities increased by $357 million for 2019 as compared to 2018. Increase was primarily attributable to additional capital expenditures, primarily for wind projects.
Net cash used in investing activities increased by $690 million for 2018 as compared to 2017. Increase was largely related to higher capital expenditures for the Rush Creek, Foxtail and Hale wind generation facilities.
| (Millions of Dollars) | 2019 | 2018 | 2017 | |||||||||
| Net cash provided by financing activities | $ | 1,181 | $ | 928 | $ | 168 |
Net cash provided by financing activities increased by $253 million for 2019 as compared to 2018. Increase was primarily attributable to higher proceeds from issuances of long-term debt and common stock (primarily due to the forward equity agreement settling in August 2019), partially offset by higher repayments of long-term debt and dividends paid.
Net cash provided by financing activities increased by $760 million for 2018 as compared to 2017. Increase was primarily due to lower repayments of long-term debt, proceeds from the issuances of common stock and additional debt financings, partially offset by lower short-term debt proceeds as compared to 2017.
Capital Requirements
Xcel Energy expects to meet future financing requirements by periodically issuing short-term debt, long-term debt, common stock, hybrid and other securities to maintain desired capitalization ratios.
Contractual Obligations and Other Commitments — Xcel Energy has contractual obligations and other commitments that will need to be funded in the future.
Contractual obligations and other commercial commitments as of Dec. 31, 2019:
| Payments Due by Period | ||||||||||||||||||||
| (Millions of Dollars) | Total | Less than 1 Year | 1 to 3 Years | 3 to 5 Years | After 5 Years | |||||||||||||||
| Long-term debt, principal and interest payments | $ | 31,433 | $ | 1,422 | $ | 2,702 | $ | 2,514 | $ | 24,795 | ||||||||||
| Finance lease obligations | 271 | 14 | 26 | 24 | 207 | |||||||||||||||
| Operating leases obligations (a) | 2,116 | 262 | 520 | 469 | 865 | |||||||||||||||
| Unconditional purchase obligations (b) | 5,831 | 1,302 | 1,940 | 1,178 | 1,411 | |||||||||||||||
| Other long-term obligations, including current portion | 680 | 64 | 89 | 59 | 468 | |||||||||||||||
| Other short-term obligations | 442 | 442 | — | — | — | |||||||||||||||
| Short-term debt | 595 | 595 | — | — | — | |||||||||||||||
| Total contractual cash obligations | $ | 41,368 | $ | 4,101 | $ | 5,277 | $ | 4,244 | $ | 27,746 |
| (a) | Included in operating lease obligations are $236 million, $463 million, $422 million and $750 million, for the less than 1 year, 1 - 3 years, 3 - 5 years and after 5 years categories, respectively, pertaining to PPAs that were accounted for as operating leases. |
| (b) | Xcel Energy Inc. and its subsidiaries have contracts providing for the purchase and delivery of a significant portion of its fuel (nuclear, natural gas and coal) requirements. Additionally, the utility subsidiaries of Xcel Energy Inc. have entered into non-lease purchase power agreements. Certain contractual purchase obligations are adjusted on indices. Effects of price changes are mitigated through cost of energy adjustment mechanisms. |
Capital Expenditures — Current estimated base capital expenditures:
| Capital Forecast | ||||||||||||||||||||||||
| (Millions of Dollars) | 2020 | 2021 | 2022 | 2023 | 2024 | 2020 - 2024 Total | ||||||||||||||||||
| By Subsidiary | ||||||||||||||||||||||||
| NSP-Minnesota | $ | 2,025 | $ | 1,580 | $ | 1,670 | $ | 1,800 | $ | 1,845 | $ | 8,920 | ||||||||||||
| PSCo | 1,415 | 1,445 | 1,720 | 1,565 | 1,530 | 7,675 | ||||||||||||||||||
| SPS | 1,025 | 530 | 700 | 750 | 800 | 3,805 | ||||||||||||||||||
| NSP-Wisconsin | 250 | 320 | 345 | 350 | 425 | 1,690 | ||||||||||||||||||
| Other (a) | (85 | ) | (65 | ) | 10 | 10 | 10 | (120 | ) | |||||||||||||||
| Total capital expenditures | $ | 4,630 | $ | 3,810 | $ | 4,445 | $ | 4,475 | $ | 4,610 | $ | 21,970 |
| (a) | Other category includes intercompany transfers for safe harbor wind turbines. The $650M non-regulated acquisition of MEC in 2020 is not included above. |
| Capital Forecast | ||||||||||||||||||||||||
| (Millions of Dollars) | 2020 | 2021 | 2022 | 2023 | 2024 | 2020 - 2024 Total | ||||||||||||||||||
| By Function | ||||||||||||||||||||||||
| Renewables | $ | 1,760 | $ | 315 | $ | — | $ | — | $ | — | $ | 2,075 | ||||||||||||
| Electric generation | 480 | 595 | 580 | 780 | 1,000 | 3,435 | ||||||||||||||||||
| Electric transmission | 625 | 835 | 1,295 | 1,270 | 1,260 | 5,285 | ||||||||||||||||||
| Electric distribution | 885 | 1,140 | 1,415 | 1,470 | 1,350 | 6,260 | ||||||||||||||||||
| Natural gas | 520 | 450 | 600 | 560 | 640 | 2,770 | ||||||||||||||||||
| Other | 360 | 475 | 555 | 395 | 360 | 2,145 | ||||||||||||||||||
| Total capital expenditures | $ | 4,630 | $ | 3,810 | $ | 4,445 | $ | 4,475 | $ | 4,610 | $ | 21,970 |
Xcel Energy’s capital expenditure program is subject to continuous review and modification. Actual capital expenditures may vary from estimates due to changes in electric and natural gas projected load growth, regulatory decisions, legislative initiatives, reserve margin requirements, availability of purchased power, alternative plans for meeting long-term energy needs, compliance with environmental requirements, RPS and mergers, acquisition and divestiture opportunities.
The Company issues debt and equity securities to refinance retiring maturities, reduce short-term debt, fund capital programs, infuse equity in subsidiaries, fund asset acquisitions and for other general corporate purposes.
Financing Capital Expenditures through 2024 — Xcel Energy issues debt and equity securities to refinance retiring maturities, reduce short-term debt, fund capital programs, infuse equity in subsidiaries, fund asset acquisitions and for other general corporate purposes.
Current estimated financing plans for 2020 - 2024:
| (Millions of Dollars) | ||||
| Funding Capital Expenditures | ||||
| Cash from operations (a) | $ | 13,905 | ||
| New debt (b) | 6,665 | |||
| Equity through the DRIP and benefit program | 400 | |||
| Equity through the at-the-market program | 250 | |||
| Equity through forward equity agreements (c) | 750 | |||
| Base capital expenditures 2020 - 2024 | $ | 21,970 | ||
| Maturing Debt | $ | 3,245 |
(a) Net of dividends and pension funding.
(b) Reflects a combination of short and long-term debt; net of refinancing.
(c) Equity forward issued in 2019, but has not yet settled; settlement expected by Dec. 31, 2020
Common Stock Dividends — Future dividend levels will be dependent on Xcel Energy’s results of operations, financial condition, cash flows, reinvestment opportunities and other factors, and will be evaluated by the Xcel Energy Inc. Board of Directors. In February 2020, Xcel Energy announced a quarterly dividend of $0.43 per share, which represents an increase of 6.2%.
Xcel Energy’s dividend policy balances the following:
| • | Projected cash generation; |
| • | Projected capital investment; |
| • | A reasonable rate of return on shareholder investment; and |
| • | The impact on Xcel Energy’s capital structure and credit ratings. |
In addition, there are certain statutory limitations that could affect dividend levels. Federal law places limits on the ability of public utilities within a holding company system to declare dividends. Specifically, under the Federal Power Act, a public utility may not pay dividends from any funds properly included in a capital account. The utility subsidiaries’ dividends may be limited directly or indirectly by state regulatory commissions or bond indenture covenants.
See Note 5 to the consolidated financial statements for further information.
Pension Fund — Xcel Energy’s pension assets are invested in a diversified portfolio of domestic and international equity securities, short-term to long-duration fixed income securities and alternative investments, including private equity, real estate and hedge funds.
Funded status and pension assumptions:
| (Millions of Dollars) | Dec. 31, 2019 | Dec. 31, 2018 | ||||||
| Fair value of pension assets | $ | 3,184 | $ | 2,742 | ||||
| Projected pension obligation (a) | 3,701 | 3,477 | ||||||
| Funded status | $ | (517 | ) | $ | (735 | ) |
| (a) | Excludes non-qualified plan of $39 million and $33 million at Dec. 31, 2019 and 2018, respectively. |
| Pension Assumptions | 2019 | 2018 | ||||
| Discount rate | 3.49 | % | 4.31 | % | ||
| Expected long-term rate of return | 6.87 | 6.87 |
Capital Sources
Short-Term Funding Sources — Xcel Energy uses a number of sources to fulfill short-term funding needs, including operating cash flow, notes payable, commercial paper and bank lines of credit. The amount and timing of short-term funding needs depend on financing needs for construction expenditures, working capital and dividend payments.
Short-Term Investments — Xcel Energy Inc., NSP-Minnesota, NSP-Wisconsin, PSCo and SPS maintain cash operating and short-term investment accounts.
Short-Term Debt — Xcel Energy Inc., NSP-Minnesota, NSP-Wisconsin, PSCo and SPS each have individual commercial paper programs. Authorized levels for these commercial paper programs are:
| • | $1.25 billion for Xcel Energy Inc.; |
| • | $700 million for PSCo; |
| • | $500 million for NSP-Minnesota; |
| • | $500 million for SPS; and |
| • | $150 million for NSP-Wisconsin. |
In addition, Xcel Energy Inc. borrowed $500 million under a 364-day term loan agreement that expires Dec. 1, 2020. Xcel Energy has an option to request an extension through Nov. 30, 2021.
Xcel Energy’s outstanding short-term debt:
| (Amounts in Millions, Except Interest Rates) | Three Months Ended Dec. 31, 2019 | |||
| Borrowing limit | $ | 3,600 | ||
| Amount outstanding at period end | 595 | |||
| Average amount outstanding | 663 | |||
| Maximum amount outstanding | 945 | |||
| Weighted average interest rate, computed on a daily basis | 2.40 | % | ||
| Weighted average interest rate at end of period | 2.34 |
| (Amounts in Millions, Except Interest Rates) | Year Ended Dec. 31, 2019 | Year Ended Dec. 31, 2018 | Year Ended Dec. 31, 2017 | |||||||||
| Borrowing limit | $ | 3,600 | $ | 3,250 | $ | 3,250 | ||||||
| Amount outstanding at period end | 595 | 1,038 | 814 | |||||||||
| Average amount outstanding | 1,115 | 788 | 644 | |||||||||
| Maximum amount outstanding | 1,780 | 1,349 | 1,247 | |||||||||
| Weighted average interest rate, computed on a daily basis | 2.72 | % | 2.34 | % | 1.35 | % | ||||||
| Weighted average interest rate at end of period | 2.34 | 2.97 | 1.90 |
Credit Facility Agreements — Xcel Energy Inc., NSP-Minnesota, PSCo and SPS each have the right to request an extension of the revolving credit facility for two additional one-year periods beyond the June 2024 termination date. NSP-Wisconsin has the right to request an extension of the revolving credit facility termination date for an additional one-year period. All extension requests are subject to majority bank group approval.
As of Feb. 18, 2020, Xcel Energy Inc. and its utility subsidiaries had the following committed credit facilities available to meet liquidity needs:
| (Millions of Dollars) | Facility | Drawn (a) | Available | Cash | Liquidity | |||||||||||||||
| Xcel Energy Inc. | $ | 1,250 | $ | 759 | $ | 491 | $ | — | $ | 491 | ||||||||||
| PSCo | 700 | 49 | 651 | 1 | 652 | |||||||||||||||
| NSP-Minnesota | 500 | 10 | 490 | 1 | 491 | |||||||||||||||
| SPS | 500 | 123 | 377 | 1 | 378 | |||||||||||||||
| NSP-Wisconsin | 150 | 62 | 88 | — | 88 | |||||||||||||||
| Total | $ | 3,100 | $ | 1,003 | $ | 2,097 | $ | 3 | $ | 2,100 |
| (a) | Includes outstanding commercial paper, term loan borrowings and letters of credit. |
Registration Statements — Xcel Energy Inc.’s Articles of Incorporation authorize the issuance of one billion shares of $2.50 par value common stock. As of Dec. 31, 2019 and 2018, the Company had approximately 525 million shares and 514 million shares of common stock outstanding, respectively.
Xcel Energy Inc. and its utility subsidiaries have registration statements on file with the SEC pursuant to which they may sell securities from time to time. These registration statements, which are uncapped, permit Xcel Energy Inc. and its utility subsidiaries to issue debt and other securities in the future at amounts, prices and with terms to be determined at the time of future offerings, and in the case of our utility subsidiaries, subject to commission approval.
Planned Financing Activity — Xcel Energy’s 2020 financing plans reflect the following:
| • | Xcel Energy Inc. — approximately $700 million of senior unsecured bonds and approximately $75 to $80 million of equity through the DRIP and benefit programs; |
| • | NSP-Minnesota — approximately $550 million of first mortgage bonds; |
| • | NSP-Wisconsin — approximately $100 million of first mortgage bonds |
| • | PSCo — approximately $750 million of first mortgage bonds; and |
| • | SPS — approximately $300 million of first mortgage bonds. |
Forward Equity Agreements — In November 2018, Xcel Energy Inc. entered into forward equity agreements in connection with a completed $459 million public offering of 9.4 million shares of common stock. In August 2019, we settled the forward equity agreements by physically delivering 9.4 million shares of common equity for cash proceeds of $453 million.
In November 2019, Xcel Energy Inc. entered into forward equity agreements for a $743 million public offering of 11.8 million shares of common stock.
Other Equity — Xcel Energy also plans to issue approximately $75 to $80 million of equity annually through the DRIP and benefit programs during the five-year forecast time period.
Long-Term Borrowings and Other Financing Instruments — See Note 5 to the consolidated financial statements for further information.
Earnings Guidance
2020 GAAP and ongoing earnings guidance is a range of $2.73 to $2.83 per share.(a)
Key assumptions:
| • | Constructive outcomes in all rate case and regulatory proceedings. |
| • | Normal weather patterns. |
| • | Weather-normalized retail electric sales are projected to increase ~1%, including impact of leap year. |
| • | Weather-normalized retail firm natural gas sales are projected to increase ~1%, including impact of leap year. |
| • | Capital rider revenue is projected to increase $45 million to $55 million (net of PTCs). PTCs are credited to customers, through capital riders and reductions to electric margin. |
| • | O&M expenses are projected to increase approximately 1% to 2%. |
| • | Depreciation expense is projected to increase approximately $160 million to $170 million. |
| • | Property taxes are projected to increase approximately $35 million to $45 million. |
| • | Interest expense (net of AFUDC — debt) is projected to increase $50 million to $60 million. |
| • | AFUDC — equity is projected to increase approximately $10 million to $20 million. |
| • | The ETR is projected to be approximately 0%. The ETR reflects benefits of PTCs which are credited to customers through electric margin and will not impact net income. |
| (a) | Ongoing earnings is calculated using net income and adjusting for certain nonrecurring or infrequent items that are, in management’s view, not reflective of ongoing operations. Ongoing earnings could differ from those prepared in accordance with GAAP for unplanned and/or unknown adjustments. Xcel Energy is unable to forecast if any of these items will occur or provide a quantitative reconciliation of the guidance for ongoing EPS to corresponding GAAP EPS. |
Off-Balance Sheet Arrangements
Xcel Energy does not have any off-balance-sheet arrangements, other than those currently disclosed, that have or are reasonably likely to have a current or future effect on financial condition, changes in financial condition, revenues or expenses, results of operations, liquidity, capital expenditures or capital resources that is material to investors.
Previous: Item 6. SELECTED FINANCIAL DATA · Next: Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK