 filings.tools
Zebra Technologies 10-K 2021-12-31
Filed 2022-02-10. 23 sections, 394K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the fiscal year ended December 31, 2021
OR
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
| For the transition period from to |
COMMISSION FILE NUMBER 000-19406
Zebra Technologies Corporation
(Exact name of registrant as specified in its charter)
| Delaware | 36-2675536 | ||||
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) |
3 Overlook Point, Lincolnshire, IL 60069
(Address of principal executive offices) (Zip Code)
Registrant’s telephone number, including area code: (847) 634-6700
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of exchange on which registered | ||||||||||||
| Class A Common Stock, par value $.01 per share | ZBRA | The NASDAQ Stock Market, LLC |
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☒ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Exchange Act. Yes ☐ No ☒
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☒ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer”, “accelerated filer”, “smaller reporting company”, and “emerging growth company” in Rule 12b-2 of the Exchange Act (Check one):
| Large accelerated filer | ☒ | Accelerated filer | ☐ | |||||||||||
| Non-accelerated filer | ☐ | Smaller reporting company | ☐ | |||||||||||
| Emerging growth company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☒
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Securities Act). Yes ☐ No ☒
The aggregate market value of the shares of Class A Common Stock held by non-affiliates of the registrant, computed by reference to the closing price of such stock as of the last business day of the registrant’s most recently completed second quarter, July 3, 2021, was $28.6 billion.
As of February 3, 2022, there were 53,079,740 shares of Class A Common Stock, par value $.01 per share, outstanding.
Documents Incorporated by Reference
Certain sections of the Registrant’s definitive proxy statement for its Annual Meeting of Stockholders to be held on May 12, 2022, are incorporated by reference into Part III of this report, as indicated herein. The definitive proxy statement shall be filed with the Securities and Exchange Commission within 120 days after the end of the fiscal year to which this report relates.
ZEBRA TECHNOLOGIES CORPORATION AND SUBSIDIARIES
YEAR ENDED DECEMBER 31, 2021
TABLE OF CONTENTS
PART I
References in this document to “the Company,” “we,” “us,” or “our” refer to Zebra Technologies Corporation and its subsidiaries, unless the context specifically indicates otherwise.
Safe Harbor
Forward-looking statements contained in this filing are subject to the safe harbor created by the Private Securities Litigation Reform Act of 1995 and are highly dependent upon a variety of important factors, which could cause actual results to differ materially from those expressed or implied in such forward-looking statements. When used in this document and documents referenced, the words “anticipate,” “believe,” “intend,” “estimate,” “will,” and “expect” and similar expressions as they relate to the Company or its management are intended to identify such forward-looking statements but are not the exclusive means of identifying these statements. The forward-looking statements include, but are not limited to, the Company’s financial outlook for the first quarter and full year of 2022. These forward-looking statements are based on current expectations, forecasts and assumptions, and are subject to the risks and uncertainties inherent in the Company’s industry, market conditions, general domestic and international economic conditions, and other factors. These factors include:
-
Market acceptance of the Company’s products, services and solution offerings and competitors’ offerings and the potential effects of emerging technologies and changes in customer requirements,
-
The effect of global market conditions, including the North America; Europe, Middle East, and Africa (“EMEA”); Latin America; and Asia-Pacific regions in which we do business,
-
The impact of changes in foreign exchange rates, customs duties and trade policies due to the large percentage of our sales and operations being outside the United States (“U.S.”),
-
Our ability to control manufacturing and operating costs,
-
Risks related to the manufacturing of the Company’s products and conducting business operations in non-U.S. countries, including the risk of depending on key suppliers who are also in non-U.S. countries,
-
The Company’s ability to purchase sufficient materials, parts, and components as well as our ability to provide services and software to meet customer demand, particularly in light of global economic conditions,
-
The availability of credit and the volatility of capital markets, which may affect our suppliers, customers, and ourselves,
-
Success of integrating acquisitions,
-
Our ability to attract, retain, develop, and motivate key personnel,
-
Interest rate and financial market conditions,
-
Access to cash and cash equivalents held outside the U.S.,
-
The effect of natural disasters, man-made disasters, public health issues (including pandemics), and cybersecurity incidents on our business,
-
The impact of changes in foreign and domestic governmental policies, laws, or regulations,
-
The outcome of litigation in which the Company may be involved, particularly litigation or claims related to infringement of third-party intellectual property rights, and
-
The outcome of any future tax matters or tax law changes.
We encourage readers of this report to review Item 1A, “Risk Factors,” in this report for further discussion of issues that could affect the Company’s future results. We undertake no obligation, other than as may be required by law, to publicly update or revise any forward-looking statements, whether as a result of new information, future events, changed circumstances, or any other reason after the date of this report.
Item 1. Business
The Company
We are a global leader providing Enterprise Asset Intelligence (“EAI”) solutions in the Automatic Identification and Data Capture (“AIDC”) industry. The AIDC market consists of mobile computing, data capture, radio frequency identification devices (“RFID”), barcode printing, and other workflow automation products and services. The Company’s solutions are proven to help our customers and end-users digitize and automate their workflows to achieve their critical business objectives, including improved productivity and operational efficiency, optimized regulatory compliance, and better customer experiences.
We design, manufacture, and sell a broad range of AIDC products, including: mobile computers, barcode scanners and imagers, RFID readers, specialty printers for barcode labeling and personal identification, real-time location systems (“RTLS”), related accessories and supplies, such as labels and other consumables, and related software applications. We also provide a full range of services, including maintenance, technical support, repair, managed and professional services, as well as cloud-based software subscriptions and robotics automation solutions. End-users of our products, solutions and services include those in the retail and e-commerce, manufacturing, transportation and logistics, healthcare, public sector, and other industries. We provide
our products, solutions and services globally through a direct sales force and extensive network of over 10,000 channel partners, operating in approximately 180 countries, with 128 facilities and approximately 9,800 employees worldwide.
Through continual innovation of our technologies, we are leading an evolution of the traditional AIDC market into EAI, which encompasses solutions that sense key operational information such as packages moving through a supply chain, equipment in a factory, workers and robots in a warehouse, shoppers in a store, and patients in a hospital. Data from enterprise assets, including status, condition, location, utilization, and preferences, is then analyzed to provide prioritized actionable insights. Finally, with the benefits of cloud computing and connectivity, these insights and directives can be delivered to the right user at the right time to drive the best next action. As a result, our solutions enable enterprises to “sense, analyze, and act” more effectively throughout their workflows.
The evolution of the AIDC market to transform workflows is being driven by strong underlying secular trends in technology, which include the internet of things (“IoT”), cloud-based data analytics, intelligent automation, mobility, computer vision, as well as artificial intelligence and machine learning. The IoT enables the real-time exchange of an increasingly broad set of information among a proliferation of smart, connected devices. Cloud computing and expanded data analytics are allowing enterprises to make better business decisions through improved timeliness and increased visibility into workflows. While traditional AIDC solutions sporadically capture limited amounts of data and populate static enterprise systems, newer solutions that can leverage artificial intelligence through machine learning can analyze real-time data from many sources to generate actionable insights. The continued rapid growth of mobile devices and application software are also significantly expanding mobile computing use cases throughout enterprises and supply chains. With these expanded capabilities, end-users can consume and act upon dynamic enterprise data and information anytime and anywhere. Additionally, computer vision (including machine vision) technology, which enables the automatic extraction and understanding of useful information from a digital image or video, provides a key element in many of our solutions.
Acquisitions
Antuit: On October 7, 2021, the Company acquired Antuit Holdings Pte. Ltd. (“Antuit”) for $145 million in cash, net of cash acquired. Antuit is a provider of demand-sensing and pricing optimization software solutions for retail and consumer products companies. Through this acquisition, the Company expands its portfolio of software solution offerings to customers in these industries by combining Antuit’s platform with its existing software solutions and EVM products. The operating results of Antuit are included in the EVM segment.
Fetch: On August 9, 2021, the Company acquired Fetch Robotics, Inc. (“Fetch”) for total purchase consideration of $301 million, which consisted of $290 million in cash paid, net of cash acquired, and the fair value of the Company’s existing minority ownership interest in Fetch of $11 million, as remeasured upon acquisition. Fetch is a provider of autonomous mobile robot solutions for customers who operate in the manufacturing, distribution, and fulfillment industries, enabling customers to optimize workflows through robotic automation. Through this acquisition, the Company intends to expand its automation solution offerings within these industries. The operating results of Fetch are included within the EVM segment.
Adaptive Vision: On May 17, 2021, the Company acquired Adaptive Vision Sp. z o.o. (“Adaptive Vision”) for $18 million in cash, net of cash acquired. Adaptive Vision is a provider of graphical machine vision software with applications in the manufacturing industry, as well as a provider of libraries and other offerings for machine vision developers. The operating results of Adaptive Vision are included within the EVM segment.
Reflexis: On September 1, 2020, the Company acquired Reflexis Systems, Inc. (“Reflexis”) for $547 million in cash, net of cash acquired. Reflexis is a provider of task and workforce management, execution, and communication software solutions for customers in the retail, food service, hospitality, and banking industries. Through this acquisition, the Company intends to enhance its solution offerings to customers in those industries by combining Reflexis’ platform with its existing software solutions and EVM products. The operating results of Reflexis are included within the EVM segment.
Cortexica: On November 5, 2019, the Company acquired Cortexica Vision Systems Limited (“Cortexica”) for $7 million in cash. Cortexica is a provider of computer vision-based artificial intelligence solutions primarily serving the retail industry. The operating results of Cortexica are included within the EVM segment.
Profitect: On May 31, 2019, the Company acquired Profitect, Inc. (“Profitect”) for total purchase consideration of $79 million, which consisted of $75 million in cash paid, net of cash acquired, and the fair value of the Company’s existing minority ownership interest in Profitect of $4 million, as remeasured upon acquisition. Profitect is a provider of prescriptive analytics software primarily serving the retail industry. Through this acquisition, the Company enhanced its existing software solutions within the retail industry by combining Profitect’s platform with its existing software solutions and EVM products. The operating results of Profitect are included within the EVM segment.
Temptime: On February 21, 2019, the Company acquired Temptime Corporation (“Temptime”) for $180 million in cash, net of cash acquired. Temptime is a developer and manufacturer of temperature-monitoring labels and devices. Through this acquisition, the Company expanded its product offerings within the healthcare industry, with possible future applications in other industries involving temperature-sensitive products. The operating results of Temptime are included within the AIT segment.
See Note 5, Business Acquisitions in the Notes to Consolidated Financial Statements for additional details.
Operations and Technologies
Our operations consist of two reportable segments that provide complementary offerings to our customers: Asset Intelligence & Tracking (“AIT”), which includes barcode and card printing, supplies, services, and location solutions; and Enterprise Visibility & Mobility (“EVM”), which includes mobile computing, data capture, RFID, fixed industrial scanning and machine vision, services and workflow optimization solutions.
Asset Intelligence & Tracking
Barcode and Card Printing: We design, manufacture, and sell printers, which produce high-quality labels, wristbands, tickets, receipts, and plastic cards on demand. Our customers use our printers in a wide range of applications, including routing and tracking, patient safety, transaction processing, personal identification, and product authentication. These applications require high levels of data accuracy, speed, and reliability. They also include specialty printing for receipts and tickets for improved customer service and productivity gains.
Our printers use thermal printing technology, which creates images by heating certain pixels of an electrical printhead to selectively image a ribbon or heat-sensitive substrate. Our printers integrate company-designed mechanisms, electrical systems, and firmware that supports serial, parallel, Ethernet, USB, Bluetooth, or 802.11 wireless communications with appropriate security protocols. Enclosures of metal or high-impact plastic help ensure durability of our printers. Printing instructions can be received as a proprietary language such as Zebra Programming Language II, as a print driver-provided image, or as user-defined Extensible Markup Language. These features make our printers easy to integrate into most computer systems.
We also provide dye-sublimination thermal card printers that produce high quality images and are used for secure, reliable personal identification (e.g. state identification cards, drivers’ licenses, and healthcare identification cards), access control (e.g. employee or student building access), and financial transactions (e.g. credit, debit and ATM cards). Additionally, we provide RFID printers that encode data into passive RFID transponders embedded in a label or card. We offer a wide range of accessories and options for our printers, including vehicle mounts and battery chargers.
Supplies: We produce and sell stock and customized thermal labels, receipts, ribbons, plastic cards, and RFID tags suitable for use with our printers, as well as wristbands for use in laser printers. We support our printing products, resellers, and end-users with an extensive line of superior quality, high-performance supplies optimized to a particular end-user’s needs, such as chemical or abrasion resistance, extreme temperature environments, exceptional image quality, or long life. We promote the use of supplies with our printing equipment. Our supplies business also includes temperature-monitoring labels primarily used in vaccine distribution, which incorporate chemical indicators designed to change color upon exceeding predefined time and/or temperature thresholds.
Services: We provide a full range of maintenance, technical support, and repair services. We also provide managed and professional services, including those which help customers manage their devices and related software applications. Our offerings include cloud-based subscriptions and multiple service levels. They are typically contracted through multi-year service agreements. We provide our services directly and through our global network of partners.
Location Solutions: The Company offers a range of RTLS and services that generate precise, on-demand information about the physical location and status of high-valued assets, equipment, and people. These solutions incorporate active and passive RFID technologies, beacons, and other tracking technologies to enable users to locate, track, manage, and optimize the utilization of enterprise assets and personnel. We provide substantially all elements of the location solution, including tags, sensors, exciters, middleware software, and application software. Our location solutions are deployed primarily in manufacturing, aerospace, transportation and logistics, sports, and healthcare industries.
Enterprise Visibility & Mobility
Mobile Computing: We design, manufacture, and sell rugged and enterprise-grade mobile computing products and accessories in a variety of specialized form factors and designs to meet a wide array of enterprise applications. Purpose-built devices ensure reliable operations for targeted use cases, surviving years of rough handling and harsh environments. Industrial applications include inventory management in warehouses and distribution centers; field mobility applications include field service, post and
parcel, and direct store delivery; and retail and customer facing applications include e-commerce, omnichannel, mobile point of sale, inventory look-up, staff collaboration, and analytics. Our mobile computing products primarily incorporate the Android™ operating system and support local-area and wide-area voice and data communications. Our products are also offered with software tools and services that enable secure data transmission while also supporting application development, device configuration, and field support to facilitate seamless, rapid deployment and maximum customer return on investment. Our products often incorporate barcode scanning, global position system and RFID features, and other sensory capabilities. Additionally, specialized features, such as advanced data capture technologies, data analytics technologies, voice and video collaboration tools, and advanced battery technologies, enable our customers to work more efficiently and better serve their own customers.
Data Capture, RFID, Fixed Industrial Scanning, and Machine Vision: We design, manufacture, and sell barcode scanners, RFID readers, industrial machine vision cameras, and fixed industrial scanners. Our portfolio of scanners includes laser scanning and imager products in a variety of form factors, including fixed, handheld, and embedded original equipment manufacturer (“OEM”) modules. Our scanners incorporate a range of technologies including area imagers, linear imagers, and lasers, as well as read linear and two-dimensional barcodes. They are used in a broad range of applications, ranging from supermarket checkouts to industrial warehouse optimization to patient management in hospitals. The design of these products reflects the diverse needs of these markets, with different ergonomics, multiple communication protocols, and varying levels of ruggedness. Our RFID products include fixed readers, RFID enabled mobile computers, and RFID sleds that utilize passive ultra-high frequency to provide high-speed, non-line of sight data capture from hundreds or thousands of RFID tags in near real-time. Using the Electronic Product Code (“EPC”) standard, end-users across multiple industries use our RFID technology to track high-value assets, monitor shipments, and drive increased retail sales through improved inventory accuracy. We also offer mobile computers that support high frequency near-field communications and low frequency radio technologies. In 2021, we introduced fixed industrial scanning and machine vision solutions. Our fixed industrial scanning products automatically track and trace items that move from production through distribution. Our industrial machine vision cameras extend scanning capabilities to help provide quality inspection on product lines. We also provide related software and accessories for these products.
Services: We provide a full range of maintenance, technical support, and repair services. We also provide managed and professional services that, among other things, help customers design, test, and deploy our solutions as well as manage their mobility devices, software applications and workflows. Our offerings include cloud-based subscriptions with multiple service levels, which are typically contracted through multi-year service agreements. We provide our services directly and through our global network of partners.
Workflow optimization solutions: We provide a portfolio of solutions that help our customers improve the agility and productivity of key operational workflows by analyzing and acting on data in real time. Our primary focus is on frontline workers in Zebra’s core customer segments, including retail, transportation and logistics, warehouse and distribution, and healthcare. Our workflow optimization solutions include:
-
Software-based solutions, which include workforce management, workflow execution and task management, demand-sensing, price optimization, prescriptive analytics, as well as communication and collaboration-based solutions. Such solutions are typically delivered through cloud-based software subscriptions and leverage big data, artificial intelligence, and mobile and web applications to provide customers with real-time visibility and actionable insights about their business. By analyzing labor, inventory, transactional and real-time situational data, these solutions are able to forecast demand, prescribe actions, schedule workers, and enhance collaboration. Our software-based solutions are available with multiple service levels, and are often contracted through multi-year service agreements;
-
Retail solutions, which include a range of physical inventory management solutions, including solutions for full store physical inventories, cycle counts, and analytics; and
-
Robotic automation solutions, which include software-powered autonomous robots that enable customers to orchestrate workflows alongside frontline workers, improving productivity and operational efficiency. Our robotic automation solutions are available in a variety of form factors to accommodate many use cases.
Our Competitive Strengths
The following are core competitive strengths that we believe enable us to differentiate ourselves from our competitors:
An industry leader focused on improving enterprise workflows
We are focused on the key technology solutions of EAI that drive improved enterprise workflows, including mobile computing, barcode and card printing, data capture, RFID, fixed industrial scanning, machine vision, and workflow optimization solutions, along with related software, services, and accessories. Our leadership position enables us to work with and support customers globally, in a variety of industries, who are focused on implementing leading-edge solutions.
High entry and switching barriers
On a global basis, we have long-standing relationships with end-users and with our extensive network of channel partners. We believe these customer relationships and our strong partner network are critical to our success and would be difficult for a new market entrant to replicate. We believe a significant portion of our products and solutions are deployed with specialized product performance and software application requirements, which could result in high switching costs.
Commitment to innovation and deep industry-specific expertise
Over time, we have developed and delivered improved, targeted end-to-end solutions for our customers. We remain committed to leveraging our technology portfolio and expertise in the industries that we service to continue to develop innovative solutions that meet the key needs of our customers.
Highly diversified business mix
We are highly diversified across business segments, end markets, geographies, and customers. Additionally, we have strong recurring business in services, supplies, and software driven by an extensive global installed base of purpose-built products and solutions.
Global reach and brand
We sell to customers directly and through our network of channel partners around the world. This global presence gives us the capability to supply our customers with products, solutions, and services no matter the location of their operations. In addition, we believe we have strong brand recognition with a reputation in the industry as a trusted and strategic partner, known for delivering high quality products that are reliable and durable.
Scale advantages
We believe the size and scope of our operations, including market leadership, product and solution development investment, portfolio breadth, and global distribution, give us advantages over our competitors. We believe we have the largest installed base of products compared to other companies in our industry. These characteristics enable us to compete successfully, achieve economies of scale, and develop industry-leading solutions.
Our Business Strategies
Leverage our market leadership position and innovation to profitably grow our core business
We expect to drive revenue growth by continuing to outpace our competition in our core businesses, including mobile computing, data capture, barcode printing, and services. We expect to achieve this by leveraging our broad portfolio of solutions and product innovation and continuing to be a strategic partner to end customers. We also expect to drive growth by capitalizing on technology transitions occurring in the industry, including the transition to the Android™ operating system in mobile computing and transitions in data capture to newer technologies involving 2D and 3D imaging and RFID. This includes increased focus on market segments and geographies that offer share-gain opportunities. In addition, we plan to leverage our market-leading installed base to accelerate growth in attach-oriented offerings, including services, supplies, accessories, and software applications. Our global channel partner network is vital to helping us achieve these goals. As such, we will ensure that we provide the necessary value and support for our partners to be successful.
Advance our Enterprise Asset Intelligence vision
Our EAI vision is for every asset and front-line worker to be connected, visible, and fully optimized. We believe that secular technology trends, particularly in IoT, cloud computing, intelligent automation, and mobility, advance our vision and are transforming our customers’ businesses and our industry, providing us with significant new opportunities to create value for our customers and for the Company. We expect to capitalize on these trends, and in particular the proliferation of smart connected sensors and devices in our core market segments, by providing end-to-end solutions that integrate these sensors and devices with cloud-based workflows and analytics applications. We plan to continue investing in the development of technologies that will enable intelligent automation solutions, providing increased visibility into the enterprise, real-time, actionable information, and improved customer experiences. Our solutions will also increasingly include advanced features, functions, and user experiences to drive additional competitive differentiation and elevate our role as a solutions provider.
Increase our opportunity for growth through expansion in adjacent market segments
We plan to drive growth through expansion, organically and inorganically, in adjacent market segments that are synergistic with our core markets. We will focus specifically on segments where our products and solutions, workflow expertise, and customer and industry relationships will enable us to provide significant value to end-users.
Enhance financial strength and flexibility
While maintaining our strong balance sheet, we intend to continue to improve profitability and cash flow generation through operational execution and increased productivity derived from continuous business process improvement, cost management, and focus on working capital efficiency.
Sustainable business model
Zebra’s foundational ESG priorities of human capital management, resource conservation, and climate align with our strategic focus and corporate values. Initiatives within these priorities are advanced by our cross-functional Sustainability Council, with executive sponsorship and board oversight. Our approach helps to ensure that our business is sustainable over the long term for the benefit of our primary stakeholder groups, including employees, customers, partners, and investors. We are driving a high-performance, inclusive and diverse culture, striving to consistently be the employer of choice in the communities where we work and live. We also focus on waste reduction, circular economy product innovation with certified refurbished devices, eco-packaging and sustainable product design. Additionally, we are committed to science-based targets on carbon emission reductions in Zebra’s operations and throughout our value chain.
Competition
We operate in a highly competitive environment. The need for companies to improve productivity and implement their strategies, as well as the secular trends around IoT, cloud computing, intelligent automation, and mobility, are some of the factors that are creating growth opportunities for established and new competitors.
Key competitive factors include the breadth and quality of products, solutions and services, as well as pricing, design, performance, durability, geographic availability, warranty coverage, brand recognition, relationships with customers and channel partners, and company reputation. We believe we compete effectively with respect to these factors.
Mobile Computing: Competitors in mobile computing and related services include companies that have historically served enterprises with ruggedized devices. For some applications, we compete with companies that provide tablets and smart phones. Competitors include: Datalogic, Honeywell, and Panasonic.
Data Capture, RFID, Fixed Industrial Scanning, and Machine Vision: Competitors that provide a broad portfolio of barcode scanning products and related services that are suitable for most global market applications include Datalogic and Honeywell. We also compete against smaller companies that focus on limited product subsets or specific regions, including Newland and Impinj. Competitors in our fixed industrial scanning and machine vision business include Cognex, SICK, and Keyence.
Barcode and Card Printing: We consider our direct competition in printing to be producers of on-demand thermal transfer and direct thermal label fixed and mobile printing systems and RFID printers/encoders. We also compete with companies engaged in the design, manufacture, and marketing of printing systems that use technologies such as ink-jet, direct marking and laser printing, as well as card printers based on ink-jet, thermal transfer, embossing, film-based systems, encoders, laser engraving, and large-scale dye sublimation printers. In addition, service bureaus, which provide centralized services, compete for end-user business and provide an alternative to our card printing solutions. Competitors include: Fargo Electronics (a unit of HID Global), Honeywell, Sato, Toshiba TEC, TSC, Brother, and Dymo.
Supplies: The supplies industry is highly fragmented with competition comprised of numerous companies of various sizes around the world.
Location Solutions: We compete with a diverse group of companies marketing location solutions that are primarily based on active RFID technologies. Competitors include: Cisco, Impinj, and Stanley Healthcare.
Workflow optimization solutions: We compete with a diverse and varied group of companies across our solution offerings worldwide. Competitors range from providers of software-based solutions serving customers in the retail industry to providers of autonomous mobile robot solutions serving customers in the manufacturing, distribution, and fulfillment industries.
Customers
End-users of our products, solutions and services are diversified across a wide variety of industries. We have three customers, who are distributors of the Company’s products and solutions, that individually accounted for more than 10% of our Net sales during the past three years. No other customer accounted for more than 10% of our Net sales during these years. See Note 20, Segment Information & Geographic Data in the Notes to Consolidated Financial Statements for further information.
Our Net sales to significant customers as a percentage of the Company’s total Net sales were as follows:
| Year Ended December 31, | |||||||||||||||||
| 2021 | 2020 | 2019 | |||||||||||||||
| Customer A | 22.3 | % | 20.7 | % | 16.6 | % | |||||||||||
| Customer B | 13.6 | % | 13.9 | % | 13.7 | % | |||||||||||
| Customer C | 12.6 | % | 17.7 | % | 18.3 | % |
Sales and Marketing
Sales: We sell our products and services primarily through distributors (two-tier distribution), value added resellers (“VARs”), independent software vendors (“ISVs”), direct marketers, and OEMs, and our software solutions primarily through our direct sales force. We also sell our products and services directly to a select number of customers through our direct sales force. Distributors purchase our products and sell to VARs, ISVs and others, thereby increasing the distribution of our products globally. VARs, ISVs, OEMs, and systems integrators provide end users with a variety of hardware, accessories, software applications, and services. VARs and ISVs typically customize solutions for specific end-user applications using their industry, systems, and applications expertise. Some OEMs resell Zebra-manufactured products and solutions under their own brands as part of their own product offerings. Because these sales channels provide specific software, configuration, installation, integration, and support services to end-users within various industry segments, these relationships are highly valued and allow our products to reach end users in a wide array of industries around the world. We believe that the breadth of our distributor and channel partner network is a competitive differentiator and enhances our ability to compete. Finally, we experience some seasonality in sales, depending upon the geographic region and industry served.
Marketing: Our marketing function aligns closely with sales and product management functions to market our products and to deliver and promote solutions that address the needs of our customers and partners. Our marketing organization includes regional and channel marketing teams that interface closely with customers, partners, and sellers. Our marketing organization also includes teams that support global strategies and communications, including portfolio marketing, digital marketing, marketing operations and communications, and strategic marketing functions.
Manufacturing and Outsourcing
Final assembly of our hardware products is performed by third-parties, including electronics manufacturing services companies (“EMSs”) and joint design manufacturers (“JDMs”). Our products are currently produced in facilities primarily located in the Asia-Pacific region, including China, Taiwan, Vietnam, and Malaysia, as well as Mexico and Brazil. In 2020, we completed our efforts to diversify our product sourcing footprint by establishing production in Taiwan, Vietnam, and Malaysia and reducing reliance on Chinese-based manufacturing. The EMSs and JDMs produce our products to our design specifications. We maintain control over portions of the supply chain, including supplier selection and price negotiations for key components. The manufacturers generally purchase all the components and subassemblies used in the production of our products. Our products are shipped to regional distribution centers, operated by third party logistics providers or the Company. A portion of products are reconfigured at the distribution centers through firmware downloads, packaging, and customer specific customization before they are shipped to customers. In addition, certain products are manufactured in accordance with procurement regulations and various international trade agreements and remain eligible for sale to the U.S. government.
Production facilities for our supplies products are located in the U.S. and Western Europe. We also supplement our in-house supplies production capabilities with third-party manufacturers, principally located in Asia-Pacific.
Repair services for our products are performed by either our own operations or through third-parties, with repair service hubs located in each of the regions in which we serve our customers.
Research and Development
The Company devotes significant resources to developing innovative solutions for our target markets and ensuring that our products, solutions, and services maintain high levels of reliability and provide value to end-users. Research and development expenditures for the years ended 2021, 2020, and 2019 were $567 million, $453 million, and $447 million, or 10.1%, 10.2% and 10.0% of Net sales, respectively. Worldwide, we have employed approximately 2,800 engineers and innovation and design experts, who along with contractors, are focused on strengthening and broadening our extensive portfolio of products and solutions.
Intellectual Property
We rely on a combination of trade secrets, patents, trademarks, copyrights, and contractual rights to establish and protect our innovations, and hold a large portfolio of intellectual property rights in the U.S. and other countries. As of December 31, 2021, the Company owned approximately 2,300 trademark registrations and trademark applications, and approximately 6,000 patents and patent applications, worldwide.
We believe that our intellectual property will continue to provide us with a competitive advantage in our core product areas as well as provide leverage for future technologies. Our success depends more upon our extensive know-how, deep understanding of end-user processes and work-flows, innovative culture, technical leadership and marketing and sales abilities. Although we do not rely only on patents or other intellectual property rights to protect or establish our market position, we will enforce our intellectual property rights when and where appropriate.
Human Capital
The Company is committed to attracting, developing, and retaining talent to enable our strategic vision. This commitment directly shapes our approach to fostering a culture of inclusion and diversity and ensuring employees can reach their potential.
We believe that our strong Company culture is a key enabler of our success. The values of accountability, integrity, teamwork, agility, and innovation are central to our culture and how we operate and work together. We take proactive steps to ensure that this culture continues to permeate throughout our organization. Employee engagement within the Company is consistently high with the most recent measures scoring above relevant benchmarks for technology companies. We consider our relations with our employees to be very good. In addition, we believe our compensation structure aligns with our stockholders’ long-term interests by balancing profitability and growth, as well as current market practices, and reflects the Company’s commitment to pay for performance.
In 2021, the Company conducted an employee survey focused on return to office initiatives, and created a new hybrid work model in response to employee feedback. In addition, we implemented new programs and resources to foster employee well-being.
As recognition of the Company’s strong culture and commitment to its employees, the Company was named a top workplace by a number of organizations in 2021, including Forbes, Newsweek, Chicago Tribune, ComputerWorld and Long Island Press among others.
As of December 31, 2021, the Company had approximately 9,800 employees globally, with a majority in sales and technical roles. Our employees work in 55 countries with a majority of our employees located outside of the U.S. Some portions of our business, primarily in Europe, China, and India, are subject to labor laws that differ significantly from those in the U.S. In Europe, for example, it is common for a works council to represent employees when discussing matters such as compensation, benefits, restructurings and layoffs.
Talent Development
We are a Company built on great minds, with unique points of view that come together to build something remarkable. We believe that empowered team members enable us to advance our strategic priorities.
As a result, we provide ample employee development opportunities, starting with our robust onboarding process. Our Zebra Education Network online learning platform offers a wide variety of learning and development resources such as formal learning courses, cross-functional development experiences, as well as tools for mentoring and career shadowing. We also offer annual training and certification programs. Additionally, on an annual basis, we conduct a comprehensive talent review to assess our leadership pipeline and align on the skills we need to proactively develop employees for the future. This annual exercise is complemented by quarterly sessions with management to ensure we make progress on our critical talent development efforts throughout the year.
Inclusion and Diversity
We are fostering a diverse workforce where employees are encouraged to bring their best selves to work, and where all are seen, heard, valued, and respected. We believe a diverse workforce and inclusive culture fosters innovation at the Company. We believe that to realize our inclusion and diversity vision, all employees should be engaged in promoting and actively driving inclusion and diversity. In 2020, we expanded our Inclusion & Diversity program, after formalizing the program in 2018, and launched our Inclusion & Diversity Advisory Council, comprised of Executive Leadership Team members and others from across the organization to oversee our strategy and champion our efforts. In 2021, we continued to expand our inclusion and diversity efforts by launching our Inclusion Champions program, which is comprised of employees who help to support key inclusion and diversity objectives and act as role models for inclusive behaviors. We also introduced formal inclusion and diversity goals for all people leaders and strongly encouraged all employees to create inclusion and diversity goals.
The Company is also fostering inclusion and diversity through the following mechanisms:
- Inclusion Networks: We have a number of employee-led inclusion groups including the Women’s Inclusion Network (WIN), the LGBTQ+ group called ZEAL (Zebra Equality Alliance), the Veterans group called VETZ, the Hispanic Inclusion Network called UNIDOZ, Zebras of African Descent (ZAD), a group advocating for inclusion and
accessibility for people of all abilities called ZoAA (Zebras of All Abilities), Asians and Allies (A2Z), and EDGE (Empowering Dynamic Generational Employees) which is geared towards our Millennial and Gen Z early career professionals. Each group is sponsored by one or more members of our Executive Leadership Team. We have collaborated with some of our inclusion groups to offer structured mentorship programs to focus on developing diverse talent.
-
Imbedding Inclusive Behaviors: We provide a variety of training including unconscious bias awareness for all employees, interviewing bias awareness training for hiring managers, and a mandatory Inclusive Leadership workshop for all people leaders. Additionally, our Inclusion Networks host a wide variety of events focused on increasing cultural competency. In 2021, we also launched additional diversity and inclusion learning tools and resources, including discussion forums and on-demand learning geared specifically on allyship.
-
External Outreach: The Company has set aspirational program goals, striving to increase the representation of women and ethnic racial minority groups across the entire organization, including in leadership roles (director level and above). To support these goals, we create a diverse slate of candidates wherever possible, with additional emphasis on our director level roles and above. We have established talent acquisition partnerships with organizations such as Catalyst, Society of Women Engineers (SWE), National Society of Black Engineers (NSBE), Disability IN, Hispanic Alliance for Career Enhancement (HACE), Hiring our Heroes (HOH), Out in STEM (oSTEM), as well as Historically Black Colleges and Universities to enhance our recruitment efforts and deepen our partnerships with diverse talent.
Regulatory Matters
Wireless Regulatory Matters
Our business is subject to certain wireless regulatory matters. The use of wireless voice, data, and video communications systems requires radio spectrum, which is regulated by government agencies throughout the world. In the U.S., the Federal Communications Commission (“FCC”) and the National Telecommunications and Information Administration (“NTIA”) regulate spectrum use by non-federal entities and federal entities, respectively. Similarly, countries around the world have one or more regulatory bodies that define and implement the rules for use of the radio spectrum, pursuant to their respective national laws and international coordination under the International Telecommunications Union. We manufacture and market products in spectrum bands already made available by regulatory bodies, these include voice and data infrastructure, mobile radios, and portable or hand-held devices. Consequently, our results of operations could be positively or negatively affected by the rules and regulations adopted from time-to-time by the FCC, NTIA, or regulatory agencies in other countries. Our products operate both on the licensed and unlicensed spectrum. The availability of additional radio spectrum may provide new business opportunities, and consequently, the loss of available radio spectrum may result in the loss of business opportunities. Regulatory changes in current spectrum bands may also provide opportunities or may require modifications to some products so they can continue to be manufactured and marketed.
Other Regulatory Matters
Some of our operations use substances regulated under various federal, state, local, and international laws governing the environment and worker health and safety, including those governing the discharge of pollutants into the ground, air and water, the management and disposal of hazardous substances and wastes and the cleanup of contaminated sites. Certain products are subject to various federal, state, local, and international laws governing chemical substances in electronic products. During 2021, compliance with U.S. federal, state and local, and foreign laws regulating the discharge of materials into the environment, or otherwise relating to the protection of the environment did not have a material effect on our business or results of operations.
Available Information
Our website address is www.zebra.com. The information on our website is not, and shall not be deemed to be, a part of this Annual Report on Form 10-K or incorporated into any other filings we make with the Securities and Exchange Commission (“SEC”). Our annual report on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, and any amendments to those reports, are made available free of charge on the Investor Relations page of our website as soon as reasonably practicable after we electronically file them with or furnish them to the SEC.
Item 1A. Risk Factors
Investors should carefully consider the risks, uncertainties, and other factors described below, as well as other disclosures in this report, including Management’s Discussion and Analysis of Financial Condition and Results of Operations, because they could have a material adverse effect on our business, financial condition, operating results, cash flows, and growth prospects. These risks are not the only risks we face. Our business operations could also be affected by additional factors that are not presently known to us or that we currently consider to be immaterial. No priority or significance is intended by, nor should be attached to, the order in which the risk factors appear.
General Business and Industry Risks
The Company is vulnerable to the potential difficulties associated with the increase in the complexity of our business. We have grown rapidly over the last several years through acquisition and worldwide growth. This growth has caused increased complexities in the business. We believe our future success depends in part on our ability to manage our growth and increased complexities of our business. The following factors could present difficulties to us:
-
Managing our distribution channel partners and end-user customers;
-
Managing our contract manufacturing and supply chain;
-
Manufacturing an increased number of products;
-
Developing and managing custom solutions offerings;
-
Managing parties to whom we have outsourced portions of our business operations;
-
Managing administrative and operational burdens;
-
Managing stakeholder interests including customer, investor and employee social responsibility matters;
-
Maintaining and improving information technology infrastructure to support growth;
-
Managing the integration of acquisitions;
-
Managing logistical problems common to complex, expansive operations;
-
Managing our international operations; and
-
Attracting, developing and retaining individuals with the requisite technical expertise to develop new technologies and introduce new products and solutions.
Inability to consummate future acquisitions at appropriate prices could negatively impact our growth rate and stock price. Our ability to expand revenues, earnings, and cash flow depends in part upon our ability to identify and successfully acquire and integrate businesses at appropriate prices and to realize anticipated synergies. Acquisitions can be difficult to identify and consummate due to competition among prospective buyers and the need to satisfy applicable closing conditions and obtain antitrust and other regulatory approval on acceptable terms.
The Company could encounter difficulties in any acquisition it undertakes, including unanticipated integration problems and business disruption. Acquisitions could also dilute stockholder value and adversely affect operating results. We may acquire or make investments in other businesses, technologies, services, products, or solutions. An acquisition may present business issues which are new to us. The process of integrating any acquired business, technology, service, product, or solution into our operations may result in unforeseen operating difficulties and expenditures. Integration of an acquired company also may consume considerable management time and attention, which could otherwise be available for ongoing operations and the further development of our existing business. These and other factors may result in benefits of an acquisition not being fully realized.
Acquisitions also may involve a number of risks, including, but not limited to:
-
Difficulties and uncertainties in retaining the customers, distributors, vendors, or other business relationships from the acquired entities;
-
The loss of key employees of acquired entities;
-
Disruptions in our business due to difficulties integrating and reorganizing operations, products, technologies and personnel;
-
The ability of acquired entities to fulfill their customers’ obligations;
-
The inheritance of known, and the discovery of unknown, issues or liabilities;
-
Pre-closing and post-closing acquisition-related earnings charges could adversely impact operating results and cash flows in any given period, and the impact may be substantially different from period to period;
-
The failure of acquired entities to meet or exceed expected operating results or cash flows could result in impairment of goodwill or intangible assets acquired;
-
The ability to implement internal controls and accounting systems necessary to be compliant with requirements applicable to public companies subject to SEC reporting, which could result in misstated financial reports; and
-
Future acquisitions could result in changes such as potentially dilutive issuances of equity securities, the incurrence of debt and contingent liabilities, and goodwill impairment charges.
The Company may not be able to continue to develop products or solutions to address user needs effectively in an industry characterized by ongoing change. To be successful, we must adapt to rapidly changing technological and application needs by continually improving our products and solutions, as well as introducing new products, solutions, and services, to address user demands.
The Company’s industry is characterized by:
-
Evolving industry standards;
-
Frequent new product, solution, and service introductions;
-
Evolving distribution channels;
-
Increasing demand for customized product and software solutions;
-
Changing customer demands; and
-
Changing security protocols.
Future success will depend on our ability to effectively and economically adapt in this evolving environment. We could incur substantial costs if we must modify our business to adapt to these changes, and may even be unable to adapt to these changes.
The Company participates in a competitive industry, which may become more competitive. Competitors may be able to respond more quickly to new or emerging technology and changes in customer requirements. The markets that we serve are rapidly evolving and highly competitive. Some of our products, solutions and services are in direct competition with similar or alternative products, solutions and services provided by our competitors. In addition, we often compete with local competitors that may have a substantial advantage in attracting customers in their countries due to more established branding in that country, greater knowledge with respect to the tastes and preferences of customers residing in that country or their focus on a single market. Because of the potential for consolidation in any market, such competitors may become larger, and increased size could permit them to operate in wider geographic areas. To remain competitive, we believe we must continue to effectively and economically:
-
Identify and evolve with customer needs, emerging technologies, and industry trends;
-
Monitor disruptive technologies and business models;
-
Innovate, develop and timely commercialize new technologies, solutions, and services;
-
Competitively price our products, solutions and services;
-
Offer superior customer service;
-
Provide products and solutions of high quality and reliability;
-
Provide dependable and efficient distribution networks; and
-
Attract, retain and develop employees with technical expertise and an understanding of our industry and customer needs.
We cannot assure that we will be able to compete successfully against current or future competitors or technologies. Current or future competitors are likely to continue to develop and introduce new and enhanced products, solutions and services that could cause a decline in market acceptance of our products, solutions or services, or result in the loss of major customers. Increased competition in our industry may result in price reductions, lower gross profit margins, and loss of market share, and could require increased spending on research and development, sales and
Showing the first 8K of 60K characters. Open the full section
Item 1B. Unresolved Staff Comments
None.
Item 2. Properties
Our corporate headquarters are located in Lincolnshire, Illinois; a northern suburb of Chicago. We also operate manufacturing, repair, distribution and warehousing, administrative, research, and sales facilities in other U.S. and international locations.
As of December 31, 2021, the Company owned three laboratory and warehouse facilities located in the U.S., U.K., and Canada.
As of December 31, 2021, the Company had a total of 125 leased facilities with locations spread globally; 38 of which are located in the U.S. and 87 of which are located in other countries. See Note 13, Leases in the Notes to Consolidated Financial Statements for further details related to the Company’s lease arrangements.
We generally consider the productive capacity of our facilities to be adequate and sufficient for our requirements. The extent of utilization of each manufacturing facility varies throughout the year.
Item 3. Legal Proceedings
On September 29-30, 2021, Honeywell filed patent litigation lawsuits against Zebra in multiple jurisdictions, including the International Trade Commission and Federal District Court in the Western District of Texas in the United States, as well as foreign courts in the United Kingdom, Germany and China. Honeywell has made substantially similar allegations of patent infringement in all cases filed. The technology addressed in the various actions generally includes aspects of data capture, barcode reading, and scanning. The allegedly infringing Zebra products identified in the actions are described as barcode scanners, mobile computers with barcode scanning capabilities, scan engines, and components thereof. The remedies sought in these lawsuits include damages and injunctive relief. The same Zebra products and technology are implicated in all of the lawsuits. The cases are in their earliest stages and Zebra intends to vigorously defend against these infringement allegations.
See Note 14, Accrued Liabilities, Commitments and Contingencies in the Notes to Consolidated Financial Statements for discussion of certain other matters.
Item 4. Mine Safety Disclosures
Not applicable.
PART II
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
Stock Information
Our Class A Common Stock is traded on the NASDAQ Stock Market, LLC under the symbol “ZBRA”.
As of February 3, 2022, the last reported price for the Company’s Class A Common Stock was $508.30 per share, and there were 94 registered stockholders of record for Zebra’s Class A Common Stock. The number of beneficial owners is substantially greater than the number of stockholders of record because a large portion of our Class A common stock is transacted through banks and brokers.
Dividend Policy
Since our initial public offering in 1991, we have not declared any cash dividends or distributions on our capital stock. We currently do not anticipate paying any cash dividends in the foreseeable future.
Treasury Shares
The following table sets forth information with respect to repurchases of the Company’s common stock for the three months ended December 31, 2021.
| Period | Total Number of Shares Purchased | Average Price Paid per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs (1) | Approximate Dollar Value of Shares that May Yet Be Purchased Under the Plans or Programs (in millions) (1) | ||||||||||||||||||||||
| October 3, 2021 - October 30, 2021 | 13,671 | $ | 494.74 | 13,671 | $ | 721 | ||||||||||||||||||||
| October 31, 2021 - November 27, 2021 | — | — | — | 721 | ||||||||||||||||||||||
| November 28, 2021 - December 31, 2021 | 43,055 | 580.61 | 43,055 | 696 | ||||||||||||||||||||||
| Total | 56,726 | $ | 559.91 | 56,726 | $ | 696 |
(1)On July 30, 2019, the Company announced that its Board of Directors authorized a share repurchase program for up to an aggregate amount of $1 billion of its outstanding shares of common stock. Repurchases may be effected from time to time through open market purchases, including pursuant to a pre-set trading plan meeting the requirements of Rule 10b5-1(c) of the Securities Exchange Act of 1934. The program does not have a stated expiration date.
Stock Performance Graph
The following graph compares the cumulative total stockholder return, calculated on a dividend-reinvested basis, in Zebra Technologies Corporation Class A Common Stock, the S&P 500 Index, and the S&P 500 Information Technology Index for the five years ended December 31, 2021. The comparison assumes that $100 was invested in each of the Company’s Class A Common Stock, the S&P 500 Index, and the S&P 500 Information Technology Index as of the market close on December 31, 2016. Note that historic stock price performance is not necessarily indicative of future stock price performance.
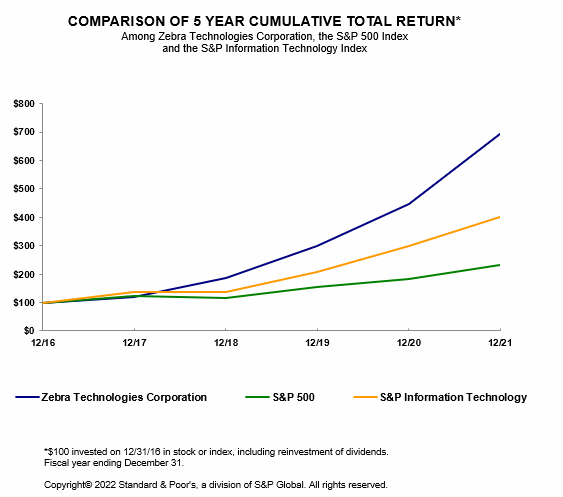
| Value at each year-end of $100 initial investment made on December 31, 2016 | ||||||||||||||||||||||||||||||||||||||
| 12/16 | 12/17 | 12/18 | 12/19 | 12/20 | 12/21 | |||||||||||||||||||||||||||||||||
| Zebra Technologies Corporation | $ | 100.00 | $ | 121.04 | $ | 185.67 | $ | 297.85 | $ | 448.15 | $ | 694.03 | ||||||||||||||||||||||||||
| S&P 500 | $ | 100.00 | $ | 121.83 | $ | 116.49 | $ | 153.17 | $ | 181.35 | $ | 233.41 | ||||||||||||||||||||||||||
| S&P 500 Information Technology | $ | 100.00 | $ | 138.83 | $ | 138.43 | $ | 208.05 | $ | 299.37 | $ | 402.73 |
Item 6. [Reserved]
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
This section generally discusses fiscal 2021 and 2020 items and year-over-year comparisons between 2021 and 2020. Discussions of 2019 items and year-over-year comparisons between 2020 and 2019 are not included herein. Refer to “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in Part II, Item 7 of the Company’s Annual Report on Form 10-K for the fiscal year ended December 31, 2020 for that discussion.
Overview
Zebra Technologies Corporation and its subsidiaries (“Zebra” or the “Company”) is a global leader respected for innovative Enterprise Asset Intelligence (“EAI”) solutions in the automatic identification and data capture solutions industry. We design, manufacture, and sell a broad range of products and solutions, including cloud-based subscriptions, that capture and move data. These products and solutions include mobile computers; barcode scanners and imagers; radio frequency identification device (“RFID”) readers; specialty printers for barcode labeling and personal identification; real-time location systems (“RTLS”); related accessories and supplies, such as self-adhesive labels and other consumables; and related software applications. We also provide a full range of services, including maintenance, technical support, repair, managed and professional services, as well as various workflow optimization solutions, including cloud-based software subscriptions and robotic automation solutions. End-users of our products, solutions and services include those in the retail and e-commerce, manufacturing, transportation and logistics, healthcare, public sector, and other industries within the following regions: North America; Europe, Middle East, and Africa (“EMEA”); Asia-Pacific; and Latin America. We provide our products, solutions, and services in approximately 180 countries, with 128 facilities and approximately 9,800 employees worldwide.
Our customers have traditionally benefited from proven solutions that increase productivity and improve asset efficiency and utilization. The Company is poised to drive, and capitalize on, the evolution of the data capture industry into the broader EAI industry, supported by technology trends including the Internet of Things (“IoT”), ubiquitous mobility, automation, cloud computing, and the increasingly on-demand global economy. EAI solutions offer additional benefits to our customers including real-time, data-driven insights that improve operational visibility and drive workflow optimization.
The Company’s operations consist of two reportable segments that provide complementary offerings to our customers: Asset Intelligence & Tracking (“AIT”) and Enterprise Visibility & Mobility (“EVM”).
*•*The AIT segment is an industry leader in barcode printing and asset tracking technologies. Its major product lines include barcode and card printers, supplies, including temperature-monitoring labels, services, and location solutions.
- The EVM segment is an industry leader in automatic information and data capture solutions. Its major product lines include mobile computing, data capture, RFID, fixed industrial scanning and machine vision, services, and workflow optimization solutions. Our workflow optimization solutions include cloud-based software subscriptions, retail solutions, and robotic automation solutions.
In the first quarter of 2021, the retail solutions product line, which provides a range of physical inventory management solutions with application in the retail industry, including solutions for full store physical inventories, cycle counts and analytics, moved from our AIT segment into our EVM segment contemporaneous with a change in our organizational structure and management of the business. We have reported our results reflecting this change, including historical periods, on a comparable basis. This change did not have an impact to the Consolidated Financial Statements.
Beginning in the first quarter of 2022, we will move the location solutions product line from our AIT segment into our EVM segment contemporaneously with a change in our organizational structure and management of the business. We will begin reporting our results reflecting this change in the first quarter of 2022 and will present historical periods on a comparable basis. This change will not have an impact to the Consolidated Financial Statements and is immaterial to our current and historical reportable segment results.
Recent Developments
COVID-19 Outbreak
The global coronavirus (“COVID-19”) pandemic continues to be complex and rapidly evolving. Governmental agencies, to varying degrees, have imposed, and continue to impose, several protocols and regulations restricting activities of individuals in an effort to limit the spread of COVID-19. We have implemented a number of measures in an effort to protect our employees’ health and well-being over the course of the pandemic tailored to address the local impacts, including having the majority of office workers work remotely during the height of the pandemic and gradually returning to offices as restrictions are lifted,
limiting employee travel, and implementing more strenuous health and safety measures for hosting and attending in-person industry events. Throughout the pandemic, distribution centers and repair centers have remained open at varying capacity levels to ensure continued support to our customers, many of whom provide essential goods and services to communities. As governments ease their restrictions, we have been allowing, and will continue to allow, our employees to come back to work in our offices in a controlled approach, with modified business practices, including masking and social distancing protocols consistent with government regulations, vaccine verification, health screening, office capacity restrictions and tracking and tracing protocols where applicable, provision of personal protective equipment, increasing air exchange/ventilation and extensively and frequently disinfecting our workspaces.
The negative impacts to Net sales from the pandemic, including declines in customer demand and impacts of operational closures within our supply chain, were most pronounced in the first half of 2020 and lessened later in 2020 as the global economic recovery took shape. While the ultimate duration of the pandemic and timing of recovery in each region remains highly uncertain, the Company’s 2021 sales and profitability, particularly in the first half of the year, have benefited from pent-up demand from customers who we believe had delayed purchases in 2020 due to the pandemic, as well as the resulting acceleration of the underlying trend to digitize and automate workflows. The level of demand for certain product components has resulted in lengthened lead times and higher input costs in 2021, including freight, which have become more significant during the second half of 2021 and, in some cases, have impacted our ability to meet customer demand. The Company expects input costs to remain elevated for some period of time, which we believe will be partially mitigated through higher pricing where permitted by market conditions. The availability of certain component parts has and may continue to negatively impact our ability to meet forecasted customer demand as suppliers of necessary parts allocate supply among their customers, including the Company.
Acquisitions
Antuit: On October 7, 2021, the Company acquired Antuit Holdings Pte. Ltd. (“Antuit”) for $145 million in cash, net of cash acquired. Antuit is a provider of demand-sensing and pricing optimization software solutions for retail and consumer products companies. Through this acquisition, the Company expands its portfolio of software solution offerings to customers in these industries by combining Antuit’s platform with its existing software solutions and EVM products. The operating results of Antuit are included in the EVM segment.
Fetch: On August 9, 2021, the Company acquired Fetch Robotics, Inc. (“Fetch”) for total purchase consideration of $301 million, which consisted of $290 million in cash paid, net of cash acquired, and the fair value of the Company’s existing minority ownership interest in Fetch of $11 million, as remeasured upon acquisition. Fetch is a provider of autonomous mobile robot solutions for customers who operate in the manufacturing, distribution, and fulfillment industries, enabling customers to optimize workflows through robotic automation. Through this acquisition, the Company intends to expand its automation solution offerings within these industries. The operating results of Fetch are included within the EVM segment.
Adaptive Vision: On May 17, 2021, the Company acquired Adaptive Vision Sp. z o.o. (“Adaptive Vision”) for $18 million in cash, net of cash acquired. Adaptive Vision is a provider of graphical machine vision software with applications in the manufacturing industry, as well as a provider of libraries and other offerings for machine vision developers. The operating results of Adaptive Vision are included within the EVM segment.
Reflexis: On September 1, 2020, the Company acquired Reflexis Systems, Inc. (“Reflexis”) for $547 million in cash, net of cash acquired. Reflexis is a provider of task and workforce management, execution, and communication solutions for customers in the retail, food service, hospitality, and banking industries. Through this acquisition, the Company intends to enhance its solution offerings to customers in those industries by combining Reflexis’ platform with its existing software solutions and EVM products. The operating results of Reflexis are included within the EVM segment.
Cortexica: On November 5, 2019, the Company acquired Cortexica Vision Systems Limited (“Cortexica”) for $7 million in cash. Cortexica is a provider of computer vision-based artificial intelligence solutions primarily serving the retail industry. The operating results of Cortexica are included within the EVM segment.
Profitect: On May 31, 2019, the Company acquired Profitect, Inc. (“Profitect”) for total purchase consideration of $79 million, which consisted of $75 million in cash paid, net of cash acquired, and the fair value of the Company’s existing minority ownership interest in Profitect of $4 million, as remeasured upon acquisition. Profitect is a provider of prescriptive analytics primarily serving the retail industry. Through this acquisition, the Company intends to enhance its solution offerings to customers in the retail industry by combining Profitect’s platform with its existing software solutions and EVM products. The operating results of Profitect are included within the EVM segment.
Temptime: On February 21, 2019, the Company acquired Temptime Corporation (“Temptime”) for $180 million in cash, net of cash acquired. Temptime is a developer and manufacturer of temperature-monitoring labels and devices. Through this
acquisition, the Company expanded its product offerings within the healthcare industry, with possible future applications in other industries involving temperature-sensitive products. The operating results of Temptime are included within the AIT segment.
Restructuring Programs
In the fourth quarter of 2021, the Company committed to organizational design changes intended to better meet its strategic objectives and improve cost efficiency (referred to as the “2021 Productivity Plan”), principally within the EMEA and North America regions. Exit and restructuring charges associated with the 2021 Productivity Plan, which primarily related to employee benefits and severance, were $7 million during the year ended December 31, 2021. Estimated remaining costs under the 2021 Productivity Plan, which is expected to be completed by 2022, are expected to be up to $3 million.
In the fourth quarter of 2019, the Company committed to certain organizational changes designed to generate operational efficiencies (referred to as the “2019 Productivity Plan”), principally in the North America and EMEA regions. The 2019 Productivity Plan was completed in 2020. Exit and restructuring charges associated with the 2019 Productivity Plan, which primarily related to employee severance and benefits, were $11 million and $8 million during the years ended December 31, 2020 and 2019, respectively.
Product Sourcing Diversification Initiative
In 2020, the Company completed its initiative to diversify its product sourcing footprint to include sourcing products from Taiwan, Vietnam, and Malaysia, thereby reducing its reliance on Chinese-based manufacturing and the impacts of related customs duties (“tariffs”) on U.S imports from China. In conjunction with this initiative, the Company incurred total one-time costs of $23 million, including $18 million and $5 million during the years ended December 31, 2020 and December 31, 2019, respectively, which are primarily reflected within Operating expenses on the Consolidated Statements of Operations. The Company also made $8 million of incremental equipment purchases during the year ended December 31, 2020.
Results of Operations: Year Ended 2021 versus 2020 and Year Ended 2020 versus 2019
Consolidated Results of Operations
(amounts in millions, except percentages)
| Year Ended December 31, | Percent Change 2021 vs 2020 | Percent Change 2020 vs 2019 | |||||||||||||||||||||||||||
| 2021 | 2020 | 2019 | |||||||||||||||||||||||||||
| Net sales: | |||||||||||||||||||||||||||||
| Tangible products | $ | 4,845 | $ | 3,813 | $ | 3,907 | 27.1 | % | (2.4) | % | |||||||||||||||||||
| Services and software | 782 | 635 | 578 | 23.1 | % | 9.9 | % | ||||||||||||||||||||||
| Total Net sales | 5,627 | 4,448 | 4,485 | 26.5 | % | (0.8) | % | ||||||||||||||||||||||
| Gross profit | 2,628 | 2,003 | 2,100 | 31.2 | % | (4.6) | % | ||||||||||||||||||||||
| Gross margin | 46.7 | % | 45.0 | % | 46.8 | % | 170 bps | (180) bps | |||||||||||||||||||||
| Operating expenses | 1,649 | 1,352 | 1,408 | 22.0 | % | (4.0) | % | ||||||||||||||||||||||
| Operating income | $ | 979 | $ | 651 | $ | 692 | 50.4 | % | (5.9) | % |
Net sales to customers by geographic region were as follows (amounts in millions, except percentages):
| Year Ended December 31, | Percent Change 2021 vs 2020 | Percent Change 2020 vs 2019 | |||||||||||||||||||||||||||
| 2021 | 2020 | 2019 | |||||||||||||||||||||||||||
| North America | $ | 2,819 | $ | 2,319 | $ | 2,261 | 21.6 | % | 2.6 | % | |||||||||||||||||||
| EMEA | 1,976 | 1,495 | 1,462 | 32.2 | % | 2.3 | % | ||||||||||||||||||||||
| Asia-Pacific | 543 | 439 | 518 | 23.7 | % | (15.3) | % | ||||||||||||||||||||||
| Latin America | 289 | 195 | 244 | 48.2 | % | (20.1) | % | ||||||||||||||||||||||
| Total Net sales | $ | 5,627 | $ | 4,448 | $ | 4,485 | 26.5 | % | (0.8) | % |
Operating expenses are summarized below (amounts in millions, except percentages):
| Year Ended December 31, | As a Percentage of Net sales | ||||||||||||||||||||||||||||||||||
| 2021 | 2020 | 2019 | 2021 | 2020 | 2019 | ||||||||||||||||||||||||||||||
| Selling and marketing | $ | 587 | $ | 483 | $ | 503 | 10.4 | % | 10.9 | % | 11.2 | % | |||||||||||||||||||||||
| Research and development | 567 | 453 | 447 | 10.1 | % | 10.2 | % | 10.0 | % | ||||||||||||||||||||||||||
| General and administrative | 348 | 304 | 323 | 6.2 | % | 6.8 | % | 7.2 | % | ||||||||||||||||||||||||||
| Amortization of intangible assets | 115 | 78 | 103 | NM | NM | NM | |||||||||||||||||||||||||||||
| Acquisition and integration costs | 25 | 23 | 22 | NM | NM | NM | |||||||||||||||||||||||||||||
| Exit and restructuring costs | 7 | 11 | 10 | NM | NM | NM | |||||||||||||||||||||||||||||
| Total Operating expenses | $ | 1,649 | $ | 1,352 | $ | 1,408 | 29.3 | % | 30.4 | % | 31.4 | % |
Consolidated Organic Net sales growth:
| Year Ended December 31, | |||||||||||
| 2021 | 2020 | ||||||||||
| Reported GAAP Consolidated Net sales growth | 26.5 | % | (0.8) | % | |||||||
| Adjustments: | |||||||||||
| Impact of foreign currency translations (1) | (2.1) | % | 0.6 | % | |||||||
| Impact of acquisitions (2) | (1.2) | % | (0.7) | % | |||||||
| Consolidated Organic Net sales growth (3) | 23.2 | % | (0.9) | % |
(1)Operating results reported in U.S. Dollars are affected by foreign currency exchange rate fluctuations. Foreign currency translation impact represents the difference in results that are attributable to fluctuations in the currency exchange rates used to convert the results for businesses where the functional currency is not the U.S. Dollar. This impact is calculated by translating the current period results at the currency exchange rates used in the comparable prior year period, inclusive of the Company’s foreign currency hedging program.
(2)For purposes of computing Organic Net sales growth, amounts directly attributable to business acquisitions are excluded for twelve months following their respective acquisitions.
(3)Consolidated Organic Net sales growth is a non-GAAP financial measure. See the Non-GAAP Measures section at the end of this item.
2021 compared to 2020
Total Net sales increased $1,179 million or 26.5% compared to the prior year primarily due to broad-based customer demand to digitize and automate their businesses. Net sales growth across both of our segments and all of our regions included pent-up demand from customers who we believe had delayed purchases in fiscal 2020 due to the COVID-19 pandemic. In addition, Net sales for the prior year included the negative impacts of supply chain disruptions within our EVM segment resulting from the temporary closure of a key distribution center supplying the Americas late in the first quarter. Excluding the effects of favorable currency changes and acquisitions, the increase in Consolidated Organic Net sales was 23.2%.
Gross margin increased to 46.7% for the current year compared to 45.0% in the prior year. Gross margins were higher than the prior year primarily due to favorable business mix and volume leverage, higher support service margins, favorable currency changes, the mitigation of Chinese import tariffs as of the fourth quarter of 2020, partial recovery of Chinese import tariffs in the current year, and contributions from our recent higher margin EVM acquisitions. These benefits were partially offset by higher premium freight costs.
Operating expenses for the years ended December 31, 2021 and 2020 were $1,649 million and $1,352 million, or 29.3% and 30.4% of Net sales, respectively. The increase in Operating expenses over the prior year was primarily due to higher employee compensation costs associated with higher incentive-based compensation related to improved financial performance in the current year, as well as prior year temporary salary reductions that began late in the second quarter; the inclusion of operating expenses and amortization of intangible assets associated with recently acquired businesses; and increased investment in research and development program projects, principally within our EVM segment. The prior year included costs associated with the diversification of the Company’s product sourcing footprint.
Operating income was $979 million for the current year compared to $651 million for the prior year. The increase was due to higher Gross profit, which was partially offset by higher Operating expenses.
Net income increased 66.1% compared to the prior year due to higher Operating income and favorability in Other expenses, net, partially offset by higher income tax expense detailed as follows:
-
Other expenses, net was $11 million for the current year, compared to $91 million in the prior year primarily due to lower interest expense and lower foreign exchange losses in the current year. The current year interest expense benefited from a $13 million gain on interest rate swaps compared to a $46 million loss in the prior year, lower average outstanding debt levels, and lower interest rates.
-
The Company’s effective tax rates for the years ended December 31, 2021 and December 31, 2020 were 13.5% and 10.0%, respectively. The increase in the effective tax rate compared to the prior year was primarily due to increases in pre-tax income in jurisdictions with higher tax rates, partially offset by a higher foreign-derived intangible income deduction, higher share-based compensation deductions, and the benefit of the enacted U.K. corporate tax rate increase from 19% to 25% on the Company’s deferred tax assets.
Diluted earnings per share increased to $15.52 as compared to $9.35 in the prior year primarily due to higher Net income.
Results of Operations by Segment
The following commentary should be read in conjunction with the financial results of each operating business segment as detailed in Note 20, Segment Information & Geographic Data in the Notes to Consolidated Financial Statements. To the extent applicable, segment results exclude purchase accounting adjustments, amortization of intangible assets, acquisition and integration costs, impairment of goodwill and other intangibles, exit and restructuring costs, and product sourcing diversification costs.
Asset Intelligence & Tracking Segment (“AIT”)
(amounts in millions, except percentages)
| Year Ended December 31, | Percent Change 2021 vs 2020 | Percent Change 2020 vs 2019 | |||||||||||||||||||||||||||
| 2021 | 2020 | 2019 | |||||||||||||||||||||||||||
| Net sales: | |||||||||||||||||||||||||||||
| Tangible products | $ | 1,577 | $ | 1,298 | $ | 1,347 | 21.5 | % | (3.6) | % | |||||||||||||||||||
| Services and software | 110 | 94 | 100 | 17.0 | % | (6.0) | % | ||||||||||||||||||||||
| Total Net sales | 1,687 | 1,392 | 1,447 | 21.2 | % | (3.8) | % | ||||||||||||||||||||||
| Gross profit | 769 | 658 | 720 | 16.9 | % | (8.6) | % | ||||||||||||||||||||||
| Gross margin | 45.6 | % | 47.3 | % | 49.8 | % | (170) bps | (250) bps | |||||||||||||||||||||
| Operating expenses | 395 | 340 | 369 | 16.2 | % | (7.9) | % | ||||||||||||||||||||||
| Operating income | $ | 374 | $ | 318 | $ | 351 | 17.6 | % | (9.4) | % |
AIT Organic Net sales growth:
| December 31, | |||||||||||
| 2021 | 2020 | ||||||||||
| AIT Reported GAAP Net sales growth | 21.2 | % | (3.8) | % | |||||||
| Adjustments: | |||||||||||
| Impact of foreign currency translations (1) | (1.9) | % | 0.4 | % | |||||||
| Impact of acquisition (2) | — | % | (0.5) | % | |||||||
| AIT Organic Net sales growth (3) | 19.3 | % | (3.9) | % |
(1)Operating results reported in U.S. Dollars are affected by foreign currency exchange rate fluctuations. Foreign currency translation impact represents the difference in results that are attributable to fluctuations in the currency exchange rates used to convert the results for businesses where the functional currency is not the U.S. Dollar. This impact is calculated by translating the current period results at the currency exchange rates used in the comparable prior year period, inclusive of the Company’s foreign currency hedging program.
(2)For purposes of computing AIT Organic Net sales growth, amounts directly attributable to the Temptime acquisition are excluded for twelve months following its acquisition date.
(3)AIT Organic Net sales growth is a non-GAAP financial measure. See the Non-GAAP Measures section at the end of this item.
2021 compared to 2020
Total Net sales for AIT increased $295 million or 21.2% compared to the prior year primarily due to higher sales of printing products (contributing the vast majority of the total increase) and supplies reflecting broad-based customer demand across all of our regions, inclusive of pent-up demand from customers who we believe had delayed purchases in fiscal 2020 due to the COVID-19 pandemic, as well as favorable currency changes. Excluding the impact of foreign currency changes, AIT Organic Net sales growth was 19.3%.
Gross margin decreased to 45.6% in the current year compared to 47.3% for the prior year, primarily due to higher premium freight costs, partially offset by favorable business mix and volume leverage, favorable currency changes, partial recovery of Chinese import tariffs in the current year, and the mitigation of Chinese import tariffs as of the fourth quarter of 2020.
Operating income increased 17.6% in the current year compared to the prior year. The increase was due to higher Gross profit, which was partially offset by higher Operating expenses.
Enterprise Visibility & Mobility Segment (“EVM”)
(amounts in millions, except percentages)
| Year Ended December 31, | Percent Change 2021 vs 2020 | Percent Change 2020 vs 2019 | |||||||||||||||||||||||||||
| 2021 | 2020 | 2019 | |||||||||||||||||||||||||||
| Net sales: | |||||||||||||||||||||||||||||
| Tangible products | $ | 3,268 | $ | 2,515 | $ | 2,560 | 29.9 | % | (1.8) | % | |||||||||||||||||||
| Services and software | 678 | 548 | 478 | 23.7 | % | 14.6 | % | ||||||||||||||||||||||
| Total Net sales | 3,946 | 3,063 | 3,038 | 28.8 | % | 0.8 | % | ||||||||||||||||||||||
| Gross profit | 1,865 | 1,358 | 1,387 | 37.3 | % | (2.1) | % | ||||||||||||||||||||||
| Gross margin | 47.3 | % | 44.3 | % | 45.7 | % | 300 bps | (140) bps | |||||||||||||||||||||
| Operating expenses | 1,107 | 888 | 900 | 24.7 | % | (1.3) | % | ||||||||||||||||||||||
| Operating income | $ | 758 | $ | 470 | $ | 487 | 61.3 | % | (3.5) | % |
EVM Organic Net sales growth:
| December 31, | |||||||||||
| 2021 | 2020 | ||||||||||
| EVM Reported GAAP Net sales growth | 28.8 | % | 0.8 | % | |||||||
| Adjustments: | |||||||||||
| Impact of foreign currency translations (1) | (1.9) | % | 0.7 | % | |||||||
| Impact of acquisitions (2) | (1.9) | % | (1.0) | % | |||||||
| EVM Organic Net sales growth (3) | 25.0 | % | 0.5 | % |
(1)Operating results reported in U.S. Dollars are affected by foreign currency exchange rate fluctuations. Foreign currency translation impact represents the difference in results that are attributable to fluctuations in the currency exchange rates used to convert the results for businesses where the functional currency is not the U.S. Dollar. This impact is calculated by translating the current period results at the currency exchange rates used in the comparable prior year period, inclusive of the Company’s foreign currency hedging program.
(2)For purposes of computing EVM Organic Net sales growth, amounts directly attributable to the acquisitions of Antuit, Fetch, Adaptive Vision, Reflexis, Cortexica, and Profitect are excluded for twelve months following their respective acquisitions.
(3)EVM Organic Net sales growth is a non-GAAP financial measure. See the Non-GAAP Measures section at the end of this item.
2021 compared to 2020
Total Net sales for EVM increased $883 million or 28.8% compared to the prior year primarily due to broad-based customer demand resulting in higher sales of mobile computing products (contributing the vast majority of the total increase) and support services across all regions, as well as higher sales of data capture products across most regions. In addition, our recent acquisitions contributed to the growth of Services and software sales in the current year. Excluding the impacts of foreign currency changes and acquisitions, EVM Organic Net sales growth was 25.0%.
Gross margin increased to 47.3% in the current year compared to 44.3% in the prior year, primarily due to favorable business mix and volume leverage, higher support service margins, favorable currency changes, the mitigation of Chinese import tariffs as of the fourth quarter of 2020, and contributions from our higher margin acquisitions. These benefits were partially offset by higher premium freight costs.
Operating income for the current year increased 61.3% compared to the prior year period. The increase was due to higher Gross profit, which was partially offset by higher Operating expenses.
Liquidity and Capital Resources
The primary factors that influence our liquidity include the amount and timing of our revenues, cash collections from our customers, cash payments to our suppliers, capital expenditures, repatriation of foreign cash, acquisitions, and share repurchases. Management believes that our existing capital resources, inclusive of available borrowing capacity on debt and other financing facilities and funds generated from operations, are sufficient to meet anticipated capital requirements and service our indebtedness. The following table summarizes our cash flow activities for the years indicated (in millions):
| Year Ended December 31, | $ Change 2021 vs 2020 | $ Change 2020 vs 2019 | |||||||||||||||||||||||||||
| 2021 | 2020 | 2019 | |||||||||||||||||||||||||||
| Cash flow provided by (used in): | |||||||||||||||||||||||||||||
| Operating activities | $ | 1,069 | $ | 962 | $ | 685 | $ | 107 | $ | 277 | |||||||||||||||||||
| Investing activities | (546) | (641) | (335) | 95 | (306) | ||||||||||||||||||||||||
| Financing activities | (371) | (157) | (365) | (214) | 208 | ||||||||||||||||||||||||
| Effect of exchange rates on cash balances | — | (2) | 1 | 2 | (3) | ||||||||||||||||||||||||
| Net increase (decrease) in cash and cash equivalents, including restricted cash | $ | 152 | $ | 162 | $ | (14) | $ | (10) | $ | 176 |
2021 vs. 2020
The change in our cash and cash equivalents balance during the current year is reflective of the following:
-
The increase in cash provided by operating activities compared to the prior year was primarily due to higher operating income, lower inventory levels, and lower employee incentive compensation payments. These benefits were partially offset by higher accounts receivable balances reflecting the timing of customer transactions within the period, higher income tax payments, as well as reduced benefits from our accounts receivable factoring programs.
-
The decrease in cash used in investing activities compared to the prior year was primarily due to lower cash paid for acquisitions. The current year includes cash payments for the acquisitions of Antuit, Fetch, and Adaptive Vision, whereas the prior year includes a cash payment for the acquisition of Reflexis.
-
The increase in net cash used in financing activities during the current year was primarily due to higher net debt repayments, as well as higher payments related to share-based compensation plans in the current year, which were partially offset by lower share repurchases. The prior year included a net source of cash associated with the timing of factored receivables servicing activities.
Company Debt
The following table shows the carrying value of the Company’s debt (in millions):
| December 31, | |||||||||||
| 2021 | 2020 | ||||||||||
| Term Loan A | $ | 888 | $ | 917 | |||||||
| 2020 Term Loan | — | 100 | |||||||||
| Receivables Financing Facilities | 108 | 235 | |||||||||
| Total debt | $ | 996 | $ | 1,252 | |||||||
| Less: Debt issuance costs | (3) | (5) | |||||||||
| Less: Unamortized discounts | (2) | (2) | |||||||||
| Less: Current portion of debt | (69) | (364) | |||||||||
| Total long-term debt | $ | 922 | $ | 881 |
Term Loan A
The principal on Term Loan A is due in quarterly installments, with the next quarterly installment due in March 2022 and the majority due upon the August 9, 2024 maturity date. The Company may make prepayments, in whole or in part, without premium or penalty, and would be required to prepay certain outstanding amounts in the event of certain circumstances or transactions. As of December 31, 2021, the Term Loan A interest rate was 1.35%. Interest payments are made monthly and are subject to variable rates plus an applicable margin.
2020 Term Loan
In September 2020, the Company entered into a new $200 million term loan (“2020 Term Loan”), with the proceeds used to partly fund the acquisition of Reflexis. The Company repaid $100 million of principal during the fourth quarter of 2020 and the remaining $100 million of principal in the first quarter of 2021.
Receivables Financing Facilities
The Company has two Receivables Financing Facilities with financial institutions that have a combined total borrowing limit of up to $280 million. As collateral, the Company pledges perfected first-priority security interests in its U.S. domestically originated accounts receivable. The Company has accounted for transactions under its Receivables Financing Facilities as secured borrowings. The Company’s first Receivables Financing Facility allows for borrowings of up to $180 million and matures on March 19, 2024. The Company’s second Receivable Financing Facility allows for borrowings of up to $100 million and matures on May 16, 2022.
As of December 31, 2021, the Company’s Consolidated Balance Sheets included $643 million of receivables that were pledged under the two Receivables Financing Facilities. As of December 31, 2021, $108 million had been borrowed, of which $13 million was classified as current. Borrowings under the Receivables Financing Facilities bear interest at a variable rate plus an applicable margin. As of December 31, 2021, the Receivables Financing Facilities had an average interest rate of 0.99%. Interest is paid on these borrowings on a monthly basis.
Revolving Credit Facility
The Company has a Revolving Credit Facility that is available for working capital and other general business purposes, including letters of credit. As of December 31, 2021, the Company had letters of credit totaling $7 million, which reduced funds available for borrowings under the Revolving Credit Facility from $1 billion to $993 million. No borrowings were outstanding under the Revolving Credit Facility as of December 31, 2021 or December 31, 2020.
See Note 12, Long-Term Debt in the Notes to Consolidated Financial Statements for further details related to the Company’s debt instruments.
Receivables Factoring
The Company currently has two Receivables Factoring arrangements, pursuant to which certain receivables are sold to banks without recourse in exchange for cash. One arrangement allows for the factoring of up to $25 million of uncollected receivables originated from the EMEA region. The second arrangement allows for the factoring of up to €150 million of uncollected receivables originated from the EMEA and Asia-Pacific regions. Transactions under the Receivables Factoring arrangements are accounted for as sales under Accounting Standards Codification 860, Transfers and Servicing of Financial Assets, with the sold receivables removed from the Company’s balance sheet. Under these Receivables Factoring arrangements, the Company does not maintain any beneficial interest in the receivables sold. The banks’ purchase of eligible receivables is subject to a maximum amount of uncollected receivables. The Company services the receivables on behalf of the banks, but otherwise maintains no significant continuing involvement with respect to the receivables. Sale proceeds that are representative of the fair value of factored receivables, less a factoring fee, are reflected in Net cash provided by operating activities on the Consolidated Statements of Cash Flows, while sale proceeds in excess of the fair value of factored receivables are reflected in Net cash used in financing activities on the Consolidated Statements of Cash Flows.
As of December 31, 2021 and 2020 there were a total of $24 million and $70 million, respectively, of uncollected receivables that had been sold and removed from the Company’s Consolidated Balance Sheets.
As servicer of sold receivables, the Company had $141 million and $142 million of obligations that were not yet remitted to banks as of December 31, 2021 and 2020, respectively. These obligations are included within Accrued liabilities on the Consolidated Balance Sheets, with changes in such obligations reflected within Net cash used in financing activities on the Consolidated Statements of Cash Flows.
See Note 19, Accounts Receivable Factoring in the Notes to Consolidated Financial Statements for further details.
Share Repurchases
On July 30, 2019, the Company announced that its Board of Directors authorized a share repurchase program for up to an aggregate amount of $1 billion of its outstanding shares of common stock. The share repurchase program does not have a stated expiration date. The level of the Company’s repurchases depends on a number of factors, including its financial condition, capital requirements, cash flows, results of operations, future business prospects and other factors its management may deem relevant. The timing, volume, and nature of repurchases are subject to market conditions, applicable securities laws and other factors and may be amended, suspended or discontinued at any time. Repurchases may be effected from time to time through open market purchases, including pursuant to a pre-set trading plan meeting the requirements of Rule 10b5-1(c) of the Securities Exchange Act of 1934. During the year ended December 31, 2021, the Company repurchased 109,115 shares of
common stock for $57 million. Comparatively, during the year ended December 31, 2020, the Company repurchased 948,740 shares of common stock for $200 million. As of December 31, 2021, approximately $696 million of common stock remained authorized for repurchase under the program. Subsequent to year end, the Company has repurchased 339,142 shares of common stock for $173 million through February 3, 2022.
Future Cash Requirements
We believe that our cash and cash equivalents, which totaled $332 million as of December 31, 2021, along with anticipated cash generation from operations and available borrowing capacity on debt and other financing facilities, will be sufficient to fund the Company’s cash requirements during the next 12 months and thereafter based on our current business plans.
Included in the Company’s Cash and cash equivalents are amounts held by foreign subsidiaries, which was $39 million and $37 million as of December 31, 2021 and 2020, respectively. We do not expect that Cash and cash equivalents held by foreign subsidiaries will need to be repatriated in order to fund the Company’s U.S. operations based on current cash requirements.
Our cash requirements during the next 12 months and thereafter include payments to satisfy the following obligations:
-
Purchase obligations — We generally procure inventories and other goods and services through purchase orders at levels to satisfy our operational needs for 12 months or less. We have a limited number of multi-year inventory and service-related purchase commitments which contain minimum purchase requirements and are non-cancellable. As of December 31, 2021, these commitments were approximately $360 million relating to the next five years, excluding amounts already reflected within Accounts payable or Accrued expenses on the Consolidated Balance Sheet. See Note 14, Accrued Liabilities, Commitments and Contingencies in the Notes to Consolidated Financial Statements for additional details.
-
Debt obligations — We expect to make total payments of approximately $101 million associated with the Company’s debt facilities in 2022. This expected use of cash is based on the Company’s current borrowings and applicable interest rates and margins as of December 31, 2021, and includes principal and interest payments along with expected cash settlements associated with the Company’s interest rate swaps. In the ordinary course of business, the Company may decide to borrow additional amounts or repay principal earlier than contractually owed, which would affect future cash payments. See Note 12, Long-Term Debt in the Notes to Consolidated Financial Statements for further details related to the Company’s debt facilities.
-
Leases obligations — We lease certain manufacturing facilities, distribution centers, sales and administrative offices, equipment, and vehicles. As of December 31, 2021, the Company’s fixed lease commitments totaled $215 million, of which $47 million is payable in 2022. See Note 13, Leases in the Notes to Consolidated Financial Statements for further details related to the Company’s lease arrangements.
In addition to the expected cash requirements described above, the Company may use cash to fund strategic acquisitions, investments, or repurchase common stock under its share repurchase program. We also expect to spend approximately $65 million to $75 million on capital expenditures in 2022.
Critical Accounting Estimates
Management prepared the consolidated financial statements of the Company under accounting principles generally accepted in the U.S. The application of these principles requires the use of estimates which affect the amounts reported in our consolidated financial statements. While we believe that our estimates are reasonable based upon available information, actual results may substantially differ from those estimates. Note 2, Significant Accounting Policies in the Notes to Consolidated Financial Statements provides additional discussion of these items along with other significant accounting policies of the Company. The accounting estimates described below have been identified by Management as those that are most critical to our financial statements, as they require management to make significant judgments and assumptions about inherently uncertain and complex matters.
Income Taxes
We estimate a provision or benefit for income taxes and amounts to be settled or recovered in several tax jurisdictions globally. Our estimates are complex and involve significant judgments and interpretations of regulations. Resolution of income tax treatments in individual jurisdictions may not be known for several years after completion of a given year. We are also required to evaluate the realizability of our deferred tax assets on an ongoing basis, which requires estimation of our ability to generate future taxable income. In particular, our income tax provision or benefit is dependent on our ability to forecast future taxable income in the U.S., U.K., Singapore, and other jurisdictions. Significant judgments included in our forecasts include projecting future sales volumes and pricing, costs to manufacture and procure products and to deliver services and solutions, among other factors. There were no significant changes in estimates to our income tax provision during the current year.
Acquisitions
We account for acquired businesses using the acquisition method of accounting. This method requires that the purchase price be allocated to the identifiable assets acquired and liabilities assumed at their estimated fair values. The excess of the purchase price over the identifiable assets acquired and liabilities assumed is recorded as goodwill. The estimates used to determine the fair values of long-lived intangible assets can be complex and require judgment. We generally value intangible assets using income-based valuation methodologies, such as the excess earnings method, which require a number of critical estimates that include, but are not limited to, future expected cash flows from revenues and operating activities, and the determination of discount rates.
Goodwill Impairment
Goodwill impairment testing consists of comparing the estimated fair value of each of our reporting units to its carrying value. Fair value determinations require judgment and are sensitive to changes in underlying assumptions, estimates, as well as market factors. We estimate the fair value of reporting units using both income and market-based valuation approaches. The income approach requires management to estimate a number of factors for each reporting unit, including projected future operating results and cash flows, and the determination of discount rates. The market approach estimates fair value using comparable marketplace fair value data from a comparable industry group. Estimating the fair value of reporting units also requires that we make a number of assumptions and estimates regarding our long-term growth and cash flow expectations, as well as overall industry and economic conditions. These estimates and assumptions include, but are not limited to, projections of revenue and income growth rates, capital investments, competitive and customer trends, appropriate peer group selection, market-based discount rates and other market factors. Our annual quantitative impairment test, most recently completed in the fourth quarter of 2021, continues to indicate that the fair values of each of our reporting units significantly exceed their respective carrying values.
Revenue Recognition
We recognize revenues when we transfer control of promised goods, solutions or services to our customers in an amount that reflects the consideration we expect to receive. The consideration that we expect to receive is estimated by reflecting reductions to our transaction price for product returns, rebates, and other incentives. These estimates are developed using the expected value that the Company anticipates receiving and are based on recent trends observed in similar transactions. Additionally, many of our contracts with customers contain multiple performance obligations, including various hardware, software, and/or services. For such contracts that contain multiple performance obligations, we allocate the estimated total transaction price to each performance obligation based on relative standalone selling prices (“SSP”). The determination of SSP is established at a regional level. SSP is based on observable prices in recent standalone transactions for the same or similar offerings, to the extent available, which is often applicable to tangible products and software licenses. Alternatively, in the absence of recent observable prices, the Company generally applies the expected cost-plus margin approach to professional services, repair and maintenance services, and solution offerings. There were no changes to our estimation processes for consideration received or SSP that materially affected revenues during the year.
New Accounting Pronouncements
See Note 2, Significant Accounting Policies in the Notes to Consolidated Financial Statements regarding recent accounting pronouncements.
Non-GAAP Measures
The Company has provided reconciliations of the supplemental non-GAAP financial measures, as defined under the rules of the Securities and Exchange Commission, presented herein to the most directly comparable financial measures calculated and presented in accordance with GAAP.
These supplemental non-GAAP financial measures – Consolidated Organic Net sales growth, AIT Organic Net sales growth, and EVM Organic Net sales growth – are presented because our management evaluates our financial results both including and
excluding the effects of business acquisitions and foreign currency translation, as applicable. Management believes that the supplemental non-GAAP financial measures presented provide additional perspective and insights when analyzing the core operating performance of our business from period to period and trends in our historical operating results. These supplemental non-GAAP financial measures should not be considered superior to, as a substitute for, or as an alternative to, and should be considered in conjunction with the GAAP financial measures presented.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
Market risk is the sensitivity of income to changes in interest rates, commodity prices, and foreign currency changes. Zebra is primarily exposed to the following types of market risk: interest rate and foreign currency.
Interest Rate Risk
We are exposed to interest rate volatility with regard to existing debt issuances. Our exposures include the London Inter-bank Offered Rate (“LIBOR”) and the Secured Overnight Financing Rate (“SOFR”). We use interest rate derivative contracts, including interest rate swaps, to mitigate the majority of the Company’s exposure from interest rate changes on existing debt and future debt issuances, thereby reducing the volatility of our financing costs and, based on current and projected market conditions, achieve a desired proportion of fixed versus floating-rate debt. Generally, under these interest rate swaps, we agree with a counterparty to exchange floating-rate for fixed-rate interest amounts with an agreed upon notional amount.
The United Kingdom’s Financial Conduct Authority, which regulates LIBOR, announced in 2017 the phase out of LIBOR. We continue to closely monitor the phase out of LIBOR to assess any impacts to our debt and interest rate swap contracts. We have already taken actions to amend certain contracts to incorporate a SOFR benchmark rate, and we expect other key contracts will be amended to incorporate a SOFR benchmark rate before the LIBOR phase out is completed. As of December 31, 2021, our remaining contracts containing exposure to LIBOR pertain only to LIBOR tenors that will be phased out by June 30, 2023.
As of December 31, 2021, we had approximately $1.0 billion of debt outstanding under our debt facilities, which bears interest determined by reference to a variable rate index. A one percentage point increase or decrease in interest rates would increase or decrease annual interest expense by approximately $2 million. This exposure includes the impact of associated forward interest rate swaps outstanding as of December 31, 2021. Refer to Note 11, Derivative Instruments in the Notes to Consolidated Financial Statements for further discussion of these risk mitigation activities. Exposure to variable interest may increase or decrease, to the extent that the Company’s borrowings under its debt facilities increase or decrease, respectively.
Foreign Exchange Risk
We provide products, solutions and services in approximately 180 countries throughout the world and, therefore, at times are exposed to risk based on movements in foreign exchange rates. In some instances, we invoice customers in their local currency and have a resulting foreign currency denominated revenue transaction and accounts receivable. We also purchase certain raw materials and other items in foreign currencies. We manage these risks using derivative financial instruments, including foreign currency exchange contracts. See Note 11, Derivative Instruments in the Notes to Consolidated Financial Statements for further discussions of hedging activities.
The currencies that we are primarily exposed to fluctuations in foreign currency exchange rates are the Euro, British Pound Sterling, and Czech Koruna. A one percentage point increase or decrease in exchange rates relative to the U.S. Dollar would increase or decrease our pre-tax income by approximately $2 million. This amount is inclusive of the impact of associated derivative contracts.
Item 8. Financial Statements and Supplementary Data
INDEX TO CONSOLIDATED FINANCIAL STATEMENTS
Report of Independent Registered Public Accounting Firm
To the Shareholders and the Board of Directors of Zebra Technologies Corporation
Opinion on the Financial Statements
We have audited the accompanying consolidated balance sheets of Zebra Technologies Corporation and subsidiaries (the Company) as of December 31, 2021 and 2020, the related consolidated statements of operations, comprehensive income, stockholders’ equity, and cash flows for each of the three years in the period ended December 31, 2021, and the related notes and financial statement schedule listed in the Index at Item 15 (collectively referred to as the “consolidated financial statements”). In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company at December 31, 2021 and 2020, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2021, in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company's internal control over financial reporting as of December 31, 2021, based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) and our report dated February 10, 2022 expressed an unqualified opinion thereon.
Basis for Opinion
These financial statements are the responsibility of the Company’s management. Our responsibility is to express an opinion on the Company’s financial statements based on our audits. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement, whether due to error or fraud. Our audits included performing procedures to assess the risks of material misstatement of the financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the financial statements. We believe that our audits provide a reasonable basis for our opinion.
Critical Audit Matter
The critical audit matter communicated below is a matter arising from the current period audit of the financial statements that was communicated or required to be communicated to the audit committee and that: (1) relates to accounts or disclosures that are material to the financial statements and (2) involved our especially challenging, subjective or complex judgments. The communication of the critical audit matter does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit matter below, providing a separate opinion on the critical audit matter or on the account or disclosure to which it relates.
Accounting for Income Taxes
| Description of the Matter | As discussed in Note 16 of the financial statements, the Company earns a significant amount of its operating income across multiple jurisdictions and the Company’s organizational structure and transactional flows are designed to reflect strategic and operational business imperatives that change over time. As the Company operates in a multinational tax environment and incurs income tax obligations in a number of jurisdictions, complexities and uncertainties can arise in the application of complex tax regulations to the Company’s multinational operations. Auditing the application of taxation legislation to the Company’s affairs is inherently complex, highly specialized and requires judgment. These factors impact the Company’s estimation of tax exposures, valuation allowances and income tax provisions. |
| How We Addressed the Matter in Our Audit | We obtained an understanding, evaluated the design and tested the operating effectiveness of controls over the Company’s identification of and accounting for the tax impact of changes in the business or significant changes in tax laws. This included controls over the Company’s evaluation of tax law changes, the evaluation of cross-jurisdictional transactions and the Company’s tax technical assessment over those changes and/or transactions. We involved our tax professionals in the Company’s significant operating jurisdictions to assist in the evaluation of the Company’s tax obligations. We evaluated the Company’s transactional flows to assess whether they aligned with the Company’s strategic and operational shifts. We made inquiries of management and inspected internally and externally prepared documentation to understand current disputes and uncertain tax positions. We assessed the completeness of the tax matters identified and evaluated the Company’s assessment regarding the related status, potential exposure and risk of loss. We assessed the consistency of assumptions used in estimating provisions for key tax exposures and evaluated the adequacy of the Company’s disclosures of tax and ongoing tax matters. |
/s/ Ernst & Young LLP
We have served as the Company’s auditor since 2005.
Chicago, Illinois
February 10, 2022
ZEBRA TECHNOLOGIES CORPORATION AND SUBSIDIARIES
CONSOLIDATED BALANCE SHEETS
(In millions, except share data)
| December 31, | |||||||||||
| 2021 | 2020 | ||||||||||
| Assets | |||||||||||
| Current assets: | |||||||||||
| Cash and cash equivalents | $ | 332 | $ | 168 | |||||||
| Accounts receivable, net of allowances for doubtful accounts of $1 million each |
Showing the first 8K of 171K characters. Open the full section
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure
None.
Item 9A. Controls and Procedures
Evaluation of Disclosure Controls and Procedures
We conducted an evaluation of the effectiveness of the design and operation of our disclosure controls and procedures (as defined in Rules 13a-15(e) and 15d-15(e) under the Securities Exchange Act of 1934 (the “Exchange Act”)) as of the end of the period covered by this Form 10-K. The evaluation was conducted under the supervision of our Disclosure Committee, and with the participation of management, including our Chief Executive Officer and Chief Financial Officer. Based on that evaluation, our Chief Executive Officer and Chief Financial Officer have concluded that our disclosure controls and procedures were effective to provide reasonable assurance that (i) the information required to be disclosed by us in this Form 10-K was recorded, processed, summarized and reported within the time periods specified in the SEC’s rules and forms, and (ii) information required to be disclosed by us in our reports that we file or furnish under the Exchange Act is accumulated and communicated to our management, including our principal executive and principal financial officers, or persons performing similar functions, as appropriate to allow timely decisions regarding required disclosure.
Management’s Report on Internal Control over Financial Reporting
Our management is responsible for establishing and maintaining adequate internal control over financial reporting as defined in Rules 13a-15(f) and 15d-15(f) under the Exchange Act to provide reasonable assurance regarding the reliability of our financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. Our management assessed the effectiveness of our internal control over financial reporting as of December 31, 2021. In making this assessment, our management used the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission in Internal Control-Integrated Framework as released in 2013. Based on this assessment and those criteria, our management believes that, as of December 31, 2021, our internal control over financial reporting is effective.
Our independent registered public accounting firm, Ernst & Young LLP, has issued an attestation report on Zebra’s internal control over financial reporting. Ernst & Young LLP’s report is included in the latter portion of this Item 9A.
Changes in Internal Control over Financial Reporting
There were no changes in the Company’s internal control over financial reporting during the fourth quarter of 2021, which were identified in connection with management’s evaluation required by paragraph (d) of Rules 13a-15 and 15d-15 under the Exchange Act, that have materially affected, or are reasonably likely to materially affect, the Company’s internal control over financial reporting.
Inherent Limitations on the Effectiveness of Controls
Our management, including our Chief Executive Officer and Chief Financial Officer, does not expect that our disclosure controls and procedures or our internal controls will prevent or detect all errors and all fraud. A control system, no matter how well conceived and operated, can provide only reasonable, not absolute, assurance that the objectives of the control system are met. Further, the design of a control system must reflect the fact that there are resource constraints, and the benefits of controls must be considered relative to their costs. Because of the inherent limitations in all control systems, no evaluation of controls can provide absolute assurance that misstatements due to error or fraud will not occur or that all control issues and instances of fraud, if any, within Zebra have been prevented or detected. These inherent limitations include the realities that judgments in decision-making can be faulty and that breakdowns can occur because of simple error or mistake. Controls can also be circumvented by the individual acts of some persons, by collusion of two or more people, or by management override of the controls. The design of any system of controls is based in part on certain assumptions about the likelihood of future events, and there can be no assurance that any design will succeed in achieving its stated goals under all potential future conditions. Projections of any evaluation of controls effectiveness to future periods are subject to risks. Over time, controls may become inadequate because of changes in conditions or deterioration in the degree of compliance with policies or procedures.
Report of Independent Registered Public Accounting Firm
To the Shareholders and the Board of Directors of Zebra Technologies Corporation
Opinion on Internal Control over Financial Reporting
We have audited Zebra Technologies Corporation and subsidiaries internal control over financial reporting as of December 31, 2021, based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) (the COSO criteria). In our opinion, Zebra Technologies Corporation (the Company) maintained, in all material respects, effective internal control over financial reporting as of December 31, 2021, based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated balance sheets of the Zebra Technologies Corporation as of December 31, 2021 and 2020, the related consolidated statements of operations, comprehensive income, stockholders’ equity, and cash flows, for each of the three years in the period ended December 31, 2021, and the related notes, and our report dated February 10, 2022 expressed an unqualified opinion thereon.
Basis for Opinion
The Company’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting included in the accompanying Management’s Report on Internal Control over Financial Reporting. Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audit in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects.
Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
Definition and Limitations of Internal Control Over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
/s/Ernst & Young LLP
Chicago, Illinois
February 10, 2022
Item 9B. Other Information
Not applicable.
Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections
Not applicable.
PART III
Item 10. Directors, Executive Officers and Corporate Governance
We have adopted a Code of Ethics for Senior Financial Officers (“Code of Ethics”) that applies to Zebra’s Chief Executive Officer, Chief Financial Officer and Chief Accounting Officer. The Code of Ethics is posted on the Investor Relations – Governance Documents page of Zebra’s Internet web site, www.zebra.com under “Investors-Governance-Governance Documents”, and is available for download. Any waiver from the Code of Ethics and any amendment to the Code of Ethics will be disclosed on such page of Zebra’s web site.
All other information in response to this item is incorporated by reference from the Proxy Statement sections entitled “Corporate Governance,” “Election of Directors,” “Committees of the Board,” “Executive Officers,” and “Delinquent Section 16(a) Reports.”
Item 11. Executive Compensation
The information in response to this item is incorporated by reference from the Proxy Statement sections entitled “Compensation Discussion and Analysis,” “Executive Compensation,” “Director Compensation,” “Executive Compensation – Compensation Committee Interlocks and Insider Participation” and “Compensation Committee Report.”
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
The information in response to this item is incorporated by reference from the Proxy Statement sections entitled “Ownership of our Common Stock” and “Executive Compensation – Equity Compensation Plan Information.”
Item 13. Certain Relationships and Related Transactions, and Director Independence
The information in response to this item is incorporated by reference from the Proxy Statement sections entitled “Corporate Governance – Related Party Transactions,” “Corporate Governance – Director Independence,” “Election of Directors,” and “Committees of the Board.”
Item 14. Principal Accounting Fees and Services
The information in response to this item is incorporated by reference from the Proxy Statement section entitled “Fees of Independent Auditors.”
PART IV
Item 15. Exhibits and Financial Statement Schedules
Index to Consolidated Financial Statements
Index to Financial Statement Schedules
Schedules are omitted because the information is not required or because the information required is included in the
Notes to Consolidated Financial Statements.
Index to Exhibits
| 32.1 | Certification of Principal Executive Officer Pursuant to 18 U.S.C Section 1350, as Adopted Pursuant to Section 906 of the Sarbanes-Oxley Act of 2002. | X | ||||||||||||||||||||||||||||||
| 32.2 | Certification of Principal Financial Officer Pursuant to 18 U.S.C Section 1350, as Adopted Pursuant to Section 906 of the Sarbanes-Oxley Act of 2002. | X | ||||||||||||||||||||||||||||||
| 101 | The following financial information from Zebra Technologies Corporation Annual Report on Form 10-K, for the year ended December 31, 2021, formatted in Inline XBRL: (i) the Consolidated Balance Sheets; (ii) the Consolidated Statements of Operations; (iii) the Consolidated Statements of Comprehensive Income; (iv) the Consolidated Statements of Stockholders’ Equity; (v) the Consolidated Statements of Cash Flows; and (vi) Notes to Consolidated Financial Statements. The instance document does not appear in the interactive data file because Inline XBRL tags are embedded in the iXBRL document. | |||||||||||||||||||||||||||||||
| 104 | The cover page from the Company’s Annual Report on Form 10-K for the year ended December 31, 2021, formatted in Inline XBRL (included in Exhibit 101). |
+ Management contract or compensatory plan or arrangement required to be filed as an exhibit to this Annual Report on Form 10-K.
Item 16. Form 10-K Summary
None.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized, on the 10th day of February 2022.
| ZEBRA TECHNOLOGIES CORPORATION | ||
| By: /s/ Anders Gustafsson | ||
| Anders Gustafsson | ||
| Chief Executive Officer |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons in the capacities and on the dates indicated.
| Signature | Title | Date | ||||||
| /s/ Anders Gustafsson Anders Gustafsson | Chief Executive Officer and Director (Principal Executive Officer) | February 10, 2022 | ||||||
| /s/ Nathan Winters Nathan Winters | Chief Financial Officer (Principal Financial Officer) | February 10, 2022 | ||||||
| /s/ Colleen M. O’Sullivan Colleen M. O’Sullivan | Senior Vice President, Chief Accounting and Treasury Officer (Principal Accounting Officer) | February 10, 2022 | ||||||
| /s/ Michael A. Smith Michael A. Smith | Director and Chairman of the Board of Directors | February 10, 2022 | ||||||
| /s/ Linda M. Connly Linda M. Connly | Director | February 10, 2022 | ||||||
| /s/ Ross W. Manire Ross W. Manire | Director | February 10, 2022 | ||||||
| /s/ Richard L. Keyser Richard L. Keyser | Director | February 10, 2022 | ||||||
| /s/ Janice M. Roberts Janice M. Roberts | Director | February 10, 2022 | ||||||
| /s/ Chirantan J. Desai Chirantan J. Desai | Director | February 10, 2022 | ||||||
| /s/ Frank B. Modruson Frank B. Modruson | Director | February 10, 2022 | ||||||
| /s/ Nelda J. Connors Nelda J. Connors | Director | February 10, 2022 |