 filings.tools
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
169K characters. Original on sec.gov · Markdown
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Executive Summary
Diluted loss per share from continuing operations for the year ended December 31, 2017 was $0.77, an increase of $0.73 compared to the year ended December 31, 2016. The increase was primarily due to a one-time transition tax on foreign earnings following the enactment of the U.S. Tax Cuts and Jobs Act in the fourth quarter of 2017. This impact was partially offset by lower impairment expense, primarily at DPL in the US SBU. Adjusted EPS, a non-GAAP financial measure, for the year ended December 31, 2017 increased $0.14 to $1.08, reflecting higher margins, primarily at the MCAC SBU, and contributions from new businesses in the U.S. and MCAC.
Strategic Priorities
As a result of our efforts to decrease our exposure to coal-fired generation and increase our portfolio of renewables, energy storage, and natural gas capacity, we are significantly reducing our carbon intensity. In 2017, AES and AIMCo completed the joint acquisition of sPower, the largest independent solar developer in the United States. In addition, we announced the sale or retirement of 4.5 GW of mostly merchant coal-fired generation, representing 31% of our coal-fired capacity.
In February 2018, we announced a reorganization as a part of our ongoing strategy to simplify our portfolio, optimize our cost structure, and reduce our carbon intensity. Reflecting this simplified portfolio, we will manage our global operations separate from our growth and commercial activities.
Overview of 2017 Results and Strategic Performance
Earnings Per Share and Free Cash Flow Results in 2017 (in millions, except per share amounts)
| Years Ended December 31, | 2017 | 2016 | 2015 | ||||||||
| Diluted earnings (loss) per share from continuing operations | $ | (0.77 | ) | $ | (0.04 | ) | $ | 0.46 | |||
| Adjusted EPS (a non-GAAP measure) (1) | 1.08 | 0.94 | 1.24 | ||||||||
| Net cash provided by operating activities | 2,489 | 2,884 | 2,134 | ||||||||
| Free Cash Flow (a non-GAAP measure) (1) | 1,921 | 2,244 | 1,628 |
| (1) | See reconciliation and definition under SBU Performance Analysis—Non-GAAP Measures. |
Diluted loss per share from continuing operations increased to a loss per share of $0.77 primarily due to a higher effective tax rate as a result of the U.S. Tax Reform Law enacted on December 22, 2017, partially offset by prior year impairments at DPL.
Adjusted EPS, a non-GAAP measure, increased by 15% to $1.08 primarily driven by higher margins at our MCAC SBU, contributions from new solar projects in the US, a one-time allowance on a non-trade receivable recognized in 2016, and the favorable impact of the YPF legal settlement at AES Uruguaiana, which was partially offset by higher adjusted effective tax rate.
Net cash provided by operating activities decreased by 14% to $2.5 billion primarily driven the collection of $360 million of overdue receivables at Maritza in 2016 and additional investments in working capital at Eletropaulo of $189 million. These decreases were partially offset by the $98 million increase in operating margin, excluding non cash drivers, at the Andes SBU.
Free Cash Flow, a non-GAAP measure, decreased by 14% to $1.9 billion primarily driven by a $395 million decrease in net cash provided by operating activities.
Review of Consolidated Results of Operations
| Years Ended December 31, | 2017 | 2016 | 2015 | % Change 2017 vs. 2016 | % Change 2016 vs. 2015 | ||||||||||||
| (in millions, except per share amounts) | |||||||||||||||||
| Revenue: | |||||||||||||||||
| US SBU | $ | 3,229 | $ | 3,429 | $ | 3,593 | -6 | % | -5 | % | |||||||
| Andes SBU | 2,710 | 2,506 | 2,489 | 8 | % | 1 | % | ||||||||||
| Brazil SBU | 542 | 450 | 962 | 20 | % | -53 | % | ||||||||||
| MCAC SBU | 2,448 | 2,172 | 2,353 | 13 | % | -8 | % | ||||||||||
| Eurasia SBU | 1,590 | 1,670 | 1,875 | -5 | % | -11 | % | ||||||||||
| Corporate and Other | 35 | 77 | 31 | -55 | % | NM | |||||||||||
| Intersegment eliminations | (24 | ) | (23 | ) | (43 | ) | -4 | % | 47 | % | |||||||
| Total Revenue | 10,530 | 10,281 | 11,260 | 2 | % | -9 | % | ||||||||||
| Operating Margin: | |||||||||||||||||
| US SBU | 567 | 582 | 621 | -3 | % | -6 | % | ||||||||||
| Andes SBU | 658 | 634 | 618 | 4 | % | 3 | % | ||||||||||
| Brazil SBU | 203 | 186 | 397 | 9 | % | -53 | % | ||||||||||
| MCAC SBU | 589 | 523 | 543 | 13 | % | -4 | % | ||||||||||
| Eurasia SBU | 423 | 429 | 452 | -1 | % | -5 | % | ||||||||||
| Corporate and Other | 23 | 15 | 33 | 53 | % | -55 | % | ||||||||||
| Intersegment eliminations | 1 | 11 | (1 | ) | 91 | % | NM | ||||||||||
| Total Operating Margin | 2,464 | 2,380 | 2,663 | 4 | % | -11 | % | ||||||||||
| General and administrative expenses | (215 | ) | (194 | ) | (196 | ) | 11 | % | -1 | % | |||||||
| Interest expense | (1,170 | ) | (1,134 | ) | (1,145 | ) | 3 | % | -1 | % | |||||||
| Interest income | 244 | 245 | 256 | — | % | -4 | % | ||||||||||
| Loss on extinguishment of debt | (68 | ) | (13 | ) | (182 | ) | NM | -93 | % | ||||||||
| Other expense | (57 | ) | (79 | ) | (24 | ) | -28 | % | NM | ||||||||
| Other income | 120 | 64 | 84 | 88 | % | -24 | % | ||||||||||
| Gain (loss) on disposal and sale of businesses | (52 | ) | 29 | 29 | NM | — | % | ||||||||||
| Goodwill impairment expense | — | — | (317 | ) | — | % | -100 | % | |||||||||
| Asset impairment expense | (537 | ) | (1,096 | ) | (285 | ) | -51 | % | NM | ||||||||
| Foreign currency transaction gains (losses) | 42 | (15 | ) | 106 | NM | NM | |||||||||||
| Income tax expense | (990 | ) | (32 | ) | (412 | ) | NM | -92 | % | ||||||||
| Net equity in earnings of affiliates | 71 | 36 | 105 | 97 | % | -66 | % | ||||||||||
| INCOME (LOSS) FROM CONTINUING OPERATIONS | (148 | ) | 191 | 682 | NM | -72 | % | ||||||||||
| Income (loss) from operations of discontinued businesses | (18 | ) | 151 | 80 | NM | 89 | % | ||||||||||
| Net loss from disposal and impairments of discontinued operations | (611 | ) | (1,119 | ) | — | -45 | % | NM | |||||||||
| NET INCOME (LOSS) | (777 | ) | (777 | ) | 762 | — | % | NM | |||||||||
| Noncontrolling interests: | |||||||||||||||||
| Less: Income from continuing operations attributable to noncontrolling interests and redeemable stock of subsidiaries | (359 | ) | (211 | ) | (364 | ) | 70 | % | -42 | % | |||||||
| Less: Income from discontinued operations attributable to noncontrolling interests | (25 | ) | (142 | ) | (92 | ) | -82 | % | 54 | % | |||||||
| NET INCOME (LOSS) ATTRIBUTABLE TO THE AES CORPORATION | $ | (1,161 | ) | $ | (1,130 | ) | $ | 306 | 3 | % | NM | ||||||
| AMOUNTS ATTRIBUTABLE TO THE AES CORPORATION COMMON STOCKHOLDERS: | |||||||||||||||||
| Income (loss) from continuing operations, net of tax | $ | (507 | ) | $ | (20 | ) | $ | 318 | NM | NM | |||||||
| Loss from discontinued operations, net of tax | (654 | ) | (1,110 | ) | (12 | ) | -41 | % | NM | ||||||||
| NET INCOME (LOSS) ATTRIBUTABLE TO THE AES CORPORATION | $ | (1,161 | ) | $ | (1,130 | ) | $ | 306 | 3 | % | NM | ||||||
| Net cash provided by operating activities | $ | 2,489 | $ | 2,884 | $ | 2,134 | -14 | % | 35 | % | |||||||
| DIVIDENDS DECLARED PER COMMON SHARE | $ | 0.49 | $ | 0.45 | $ | 0.41 | 9 | % | 10 | % |
Components of Revenue, Cost of Sales and Operating Margin — Revenue includes revenue earned from the sale of energy from our utilities and the production of energy from our generation plants, which are classified as regulated and non-regulated, respectively, on the Consolidated Statements of Operations. Revenue also includes the gains or losses on derivatives associated with the sale of electricity.
Cost of sales includes costs incurred directly by the businesses in the ordinary course of business. Examples include electricity and fuel purchases, operations and maintenance costs, depreciation and amortization expense, bad debt expense and recoveries, and general administrative and support costs (including employee-related costs
directly associated with the operations of the business). Cost of sales also includes the gains or losses on derivatives (including embedded derivatives other than foreign currency embedded derivatives) associated with the purchase of electricity or fuel.
Operating margin is defined as revenue less cost of sales.
Consolidated Revenue and Operating Margin
(in millions)
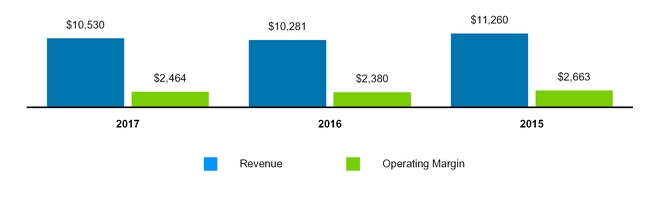
Year Ended December 31, 2017
Consolidated Revenue — Revenue increased $249 million, or 2%, in 2017 compared to 2016 primarily driven by:
| • | $276 million in MCAC primarily due to the commencement of the combined cycle operations at Los Mina in June 2017 as well as higher rates in the Dominican Republic and higher pass through costs in El Salvador, partially offset by hurricane impacts at Puerto Rico; and |
| • | $204 million in Andes primarily due to the start of commercial operations at Cochrane as well as higher availability at Argentina, partially offset by lower spot sales at Chivor. |
These positive impacts were partially offset by a decrease of $200 million in the U.S. mainly due to lower retail tariffs as well as lower wholesale volume and price at DPL.
Consolidated Operating Margin — Operating margin increased $84 million, or 4%, in 2017 compared to 2016 primarily driven by:
| • | The favorable impact of FX of $39 million, primarily in Brazil, Argentina, and Colombia. |
Excluding the FX impact mentioned above:
| • | $65 million in MCAC due to the commencement of the Los Mina combined cycle operations in June 2017 in the Dominican Republic as well as higher availability due to forced outages in 2016 at Mexico. |
These positive impacts were partially offset by a decrease of $15 million in the U.S. driven by lower retail margin, lower volumes, and lower commercial availability at DPL as well as a negative impact at IPL mainly due to one-off accruals due to the implementation of new base rates in Q2 2016.
Year Ended December 31, 2016
Consolidated Revenue — Revenue decreased $979 million, or 9%, in 2016 compared to 2015 primarily driven by:
| • | The unfavorable FX impacts of $326 million, primarily in Argentina of $94 million, Kazakhstan of $63 million and Colombia of $54 million. |
Excluding the FX impact mentioned above:
| • | $483 million in Brazil due to lower rates for energy sold under new contracts at Tietê as well as operations in 2015 but not in 2016 at Uruguaiana; |
| • | $164 million in the U.S. primarily due to the sale of DPLER in January 2016 as well as lower rates at DPL, partially offset by higher retail rates at IPL; |
| • | $141 million in MCAC primarily due to lower pass-through costs at El Salvador; and |
| • | $95 million in Eurasia primarily due to lower pass-through costs at IPP4 in Jordan, partially offset by the full operations at Mong Duong in 2016 compared to Unit 1 in March 2015 with principal operations commencing in April 2015. |
These decreases were partially offset by an increase of $165 million in Andes mainly due to the commencement of operations at Cochrane in Chile with Unit1 operational in July 2016 and principal operations in October.
Consolidated Operating Margin — Operating margin decreased $283 million, or 11%, in 2016 compared to 2015 primarily driven by:
| • | The unfavorable FX impacts of $88 million, primarily in Kazakhstan, Argentina, and Colombia. |
Excluding the FX impact mentioned above:
| • | $198 million in Brazil driven by the revenue drivers above; and |
| • | $39 million in the U.S. driven by the revenue drivers above. |
These decreases were partially offset by an increase of $52 million in Andes driven by the revenue drivers above as well as lower spot prices at Gener Chile.
See Item 7.—Management's Discussion and Analysis of Financial Condition and Results of Operations—SBU Performance Analysis of this Form 10-K for additional discussion and analysis of operating results for each SBU.
Consolidated Results of Operations — Other
General and administrative expenses
General and administrative expenses include expenses related to corporate staff functions and initiatives, executive management, finance, legal, human resources and information systems, as well as global development costs.
General and administrative expenses increased $21 million, or 11%, in 2017 from 2016 primarily due to severance costs related to workforce reductions associated with a major restructuring program, increased professional fees and increased business development activity.
General and administrative expenses decreased $2 million, or 1%, in 2016 from 2015 with no material drivers.
Interest expense
Interest expense increased $36 million, or 3%, in 2017 from 2016 primarily due to a $30 million increase at Andes SBU, driven by lower capitalized interest in 2017 due to Cochrane plant starting commercial operations in the second half of 2016.
Interest expense decreased $11 million, or 1% in 2016 from 2015 primarily due to a decrease in debt balance at the Parent Company and US SBU, partially offset by higher interest expense due to Mong Duong assets being placed in service, which ended the interest capitalization period at the Eurasia SBU.
Interest income
Interest income decreased $1 million in 2017 from 2016 with no material drivers.
Interest income decreased $11 million, or 4%, in 2016 from 2015 primarily due to prior year recognition of accumulated interest on VAT balances at the Andes SBU and lower short term investment balances at the Brazil SBU in 2016, partially offset by higher interest income recognized on the financing element of the service concession arrangement at Mong Duong in the Eurasia SBU, which became fully operational in April 2015.
Loss on extinguishment of debt
Loss on extinguishment of debt was $68 million for the year ended December 31, 2017 primarily related to losses of $92 million, $20 million, and $9 million on debt extinguishments at the Parent Company, AES Gener, and IPALCO, respectively. The loss was partially offset by a gain on early retirement of debt at Alicura of $65 million.
Loss on extinguishment of debt was $13 million for the year ended December 31, 2016. This loss was primarily related to losses of $14 million recognized on debt extinguishment at the Parent Company.
Loss on extinguishment of debt was $182 million for the year ended December 31, 2015. This loss was primarily related to losses of $105 million, $22 million, and $19 million recognized on debt extinguishments at the Parent Company, IPL, and the Dominican Republic, respectively.
Other income and expense
Other income increased $56 million, or 88%, in 2017 from 2016 primarily due to the favorable impact at Brazil SBU as a result of the settlement of legal proceeding at AES Uruguaiana related to YPF's breach of the parties’ gas supply agreement in 2017.
Other income decreased $20 million, or 24%, in 2016 from 2015 primarily due to gains on early contract termination in 2015.
Other expense decreased $22 million, or 28%, in 2017 from 2016 primarily due to the 2016 recognition of a full allowance on a non-trade receivable in the MCAC SBU as a result of payment delays. This decrease was partially offset by the 2017 loss on disposal of assets at DPL as a result of the decision to close the coal-fired and diesel-fired generating units at Stuart and Killen on or before June 1, 2018 and the write-off of water rights in the Andes SBU for projects that are no longer being pursued.
Other expense increased $55 million in 2016 from 2015 primarily due to the 2016 recognition of a full allowance on a non-trade receivable in the MCAC SBU as a result of payment delays.
See Note 18—Other Income and Expense included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Gain (loss) on disposal and sale of businesses
Loss on disposal and sale of businesses was $52 million for the year ended December 31, 2017 primarily due to the $49 million and $33 million loss on sale of Kazakhstan CHPs and hydroelectric plants, respectively, partially offset by the recognition of a $23 million gain related to the expiration of a contingency at Masinloc.
Gain on disposal and sale of businesses was $29 million for the year ended December 31, 2016 primarily due to the $49 million gain on sale of DPLER, partially offset by the $20 million loss on the deconsolidation of U.K. Wind.
Gain on disposal and sale of businesses was $29 million for the year ended December 31, 2015 primarily due to the $22 million gain on sale of Armenia Mountain.
Goodwill impairment expense
There were no goodwill impairments for the years ended December 31, 2017 or 2016.
Goodwill impairment expense was $317 million for the year ended December 31, 2015 due to a goodwill impairment at DP&L.
See Note 8—Goodwill and Other Intangible Assets included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Asset impairment expense
Asset impairment expense decreased $559 million, or 51%, in 2017 from 2016 mainly driven by the prior year US SBU impairment of $859 million at DPL, partially offset by a $121 million impairment in the current year at Laurel Mountain as a result of a decline in forward pricing.
Asset impairment expense increased $811 million in 2016 from 2015 primarily due to asset impairments recognized during 2016 at DPL in the US SBU, resulting from lower forecasted revenues from the PJM capacity auction and higher anticipated environmental compliance costs.
See Note 19—Asset Impairment Expense included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Foreign currency transaction gains (losses)
Foreign currency transaction gains (losses) in millions were as follows:
| Years Ended December 31, | 2017 | 2016 | 2015 | ||||||||
| Mexico | $ | 17 | $ | (8 | ) | $ | (6 | ) | |||
| Philippines | 15 | 12 | 8 | ||||||||
| Bulgaria | 14 | (8 | ) | 3 | |||||||
| Chile | 8 | (9 | ) | (18 | ) | ||||||
| AES Corporation | 3 | (50 | ) | (31 | ) | ||||||
| Argentina | 1 | 37 | 124 | ||||||||
| United Kingdom | (3 | ) | 13 | 11 | |||||||
| Colombia | (23 | ) | (8 | ) | 29 | ||||||
| Other | 10 | 6 | (14 | ) | |||||||
| Total (1) | $ | 42 | $ | (15 | ) | $ | 106 |
| (1) | Includes gains of $21 million, $17 million and $247 million on foreign currency derivative contracts for the years ended December 31, 2017, 2016 and 2015, respectively. |
The Company recognized net foreign currency transaction gains of $42 million for the year ended December 31, 2017 primarily driven by transactions associated with VAT activity in Mexico, the amortization of frozen embedded derivatives in the Philippines, and appreciation of the Euro in Bulgaria. These gains were partially offset by unfavorable foreign currency derivatives in Colombia.
The Company recognized net foreign currency transaction losses of $15 million for the year ended December 31, 2016 primarily due to remeasurement losses on intercompany notes, and losses on swaps and options at The AES Corporation. This loss was partially offset in Argentina, mainly due to the favorable impact of foreign currency derivatives related to government receivables.
The Company recognized net foreign currency transaction gains of $106 million for the year ended December 31, 2015 primarily due to foreign currency derivatives related to government receivables in Argentina and depreciation of the Colombian peso in Colombia. These gains were partially offset due to decreases in the valuation of intercompany notes at The AES Corporation and unfavorable devaluation of the Chilean peso in Chile.
Income tax expense
Income tax expense increased $958 million to $990 million in 2017 as compared to 2016. The Company's effective tax rates were 128% and 17% for the years ended December 31, 2017 and 2016, respectively.
The net increase in the 2017 effective tax rate was due primarily to expense related to the U.S. tax reform one-time transition tax and remeasurement of deferred tax assets. Further, the 2016 rate was impacted by the items described below.
Income tax expense decreased $380 million to $32 million in 2016 as compared to 2015. The Company's effective tax rates were 17% and 42% for the years ended December 31, 2016 and 2015, respectively.
The net decrease in the 2016 effective tax rate was due, in part, to the 2016 asset impairments in the U.S., as well as the devaluation of the peso in certain of our Mexican subsidiaries and the release of valuation allowance at certain of our Brazilian subsidiaries. These favorable items were partially offset by the unfavorable impact of Chilean income tax law reform enacted during the first quarter of 2016. Further, the 2015 rate was due, in part, to the nondeductible 2015 impairment of goodwill at DP&L and Chilean withholding taxes offset by the release of valuation allowance at certain of our businesses in Brazil, Vietnam and the U.S. See Note 19—Asset Impairment Expense included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for additional information regarding the 2016 U.S. asset impairments. See Note 20—Income Taxes included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for additional information regarding the 2016 Chilean income tax law reform.
Our effective tax rate reflects the tax effect of significant operations outside the U.S., which are generally taxed at rates different than the U.S. statutory rate. Foreign earnings may be taxed at rates higher than the new U.S. corporate rate of 21% and a greater portion of our foreign earnings may be subject to current U.S. taxation under the new tax rules. A future proportionate change in the composition of income before income taxes from foreign and domestic tax jurisdictions could impact our periodic effective tax rate. The Company also benefits from reduced tax rates in certain countries as a result of satisfying specific commitments regarding employment and capital investment. See Note 20—Income Taxes included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for additional information regarding these reduced rates.
Net equity in earnings of affiliates
Net equity in earnings of affiliates increased $35 million, or 97%, in 2017 from 2016 primarily due to earnings at the sPower equity method investment purchased in 2017, partially offset by fixed asset impairments in 2017 at the Distributed Energy entities, accounted for as equity affiliates. The $42 million equity earnings recorded for the investment in sPower includes the allocation of $53 million of project income to AES through the application of the HLBV model. This income includes the impact of day one gain described in Note 1—General and Summary of Significant Accounting Policies—Allocation of Earnings included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K. The net project income at sPower in the period after the acquisition was $20 million.
Net equity in earnings of affiliates decreased $69 million, or 66%, in 2016 from 2015 as a result of the restructuring of Guacolda in September 2015, which resulted in a $66 million benefit. No comparable transaction occurred in 2016.
See Note 7—Investments In and Advances to Affiliates included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Net income (loss) from discontinued operations
Net loss from discontinued operations was $629 million for the year ended December 31, 2017 primarily due to the after-tax loss on deconsolidation of Eletropaulo of $611 million recognized in the fourth quarter of 2017. The remaining loss was due to a loss contingency recognized by our equity affiliate, partially offset by the income from operations of Eletropaulo prior to the date of deconsolidation.
Net loss from discontinued operations was $968 million for the year ended December 31, 2016 due to the sale of Sul, partially offset by the income from operations of Eletropaulo. The loss includes an after-tax loss on the impairment of Sul of $382 million recognized in the second quarter of 2016 and an additional after-tax loss on the sale of Sul of $737 million recognized upon disposal in October 2016. There was no significant loss from operations related to the Sul discontinued business.
Net income from discontinued operations was $80 million for the year ended December 31, 2015 primarily due to the income from operations of Eletropaulo. There was no significant loss from operations related to the Sul discontinued business.
See Note 21—Discontinued Operations included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Net income attributable to noncontrolling interests and redeemable stock of subsidiaries
Net income attributable to noncontrolling interests and redeemable stock of subsidiaries increased $148 million, or 70%, in 2017 from 2016 primarily due to:
- Asset impairment at Buffalo Gap I and II in 2016.
Net income attributable to noncontrolling interests and redeemable stock of subsidiaries decreased $153 million, or 42%, in 2016 from 2015 primarily due to:
-
Lower earnings at Tietê,
-
Asset impairments at Buffalo Gap I and II.
These decreases were offset by:
| • | Lower asset impairment at Buffalo Gap III in 2015. |
Net income (loss) attributable to The AES Corporation
Net loss attributable to The AES Corporation increased $31 million, or 3%, in 2017 compared to 2016 as a result of:
| • | Impact due to U.S. Tax Reform Law enacted on December 22, 2017; |
| • | Current year losses on sale of Kazakhstan CHPs and hydroelectric plants; |
| • | Current year loss on deconsolidation of Eletropaulo; |
| • | Current year impairments at Laurel Mountain, Kazakhstan CHPs and hydroelectric plants and Kilroot; and |
| • | Higher loss on extinguishment of debt. |
These increases were partially offset by:
| • | Prior year impairments at DPL; |
| • | Prior year loss from discontinued operations as a result of the sale of Sul; |
| • | Higher margin at our MCAC SBU; |
| • | The favorable impact of the YPF legal settlement at AES Uruguaiana; and |
| • | Higher gains on foreign currency transactions. |
Net income attributable to The AES Corporation decreased $1.4 billion, to a loss of $1.1 billion in 2016 compared to income of $306 million in 2015 as result of:
| • | Impairments and loss on sale at discontinued businesses; |
| • | Higher impairment expense on long lived assets; |
| • | Lower operating margins at our US, Brazil and Eurasia SBUs; |
| • | Lower equity in earnings of affiliates due to the 2015 restructuring at Guacolda; and |
| • | Lower gains on foreign currency derivatives. |
These decreases were partially offset by:
| • | Lower effective tax rate; |
| • | Lower debt extinguishment expense; and |
| • | Absence of goodwill impairment expense. |
SBU Performance Analysis
Segments
We are organized into five market-oriented SBUs: US (United States), Andes (Chile, Colombia, and Argentina), Brazil, MCAC (Mexico, Central America, and the Caribbean), and Eurasia (Europe and Asia). In February 2018, we announced a reorganization as a part of our ongoing strategy to simplify our portfolio, optimize our cost structure, and reduce our carbon intensity. The evaluation of the impact this reorganization will have on our segment reporting structure is still ongoing.
Non-GAAP Measures
Adjusted Operating Margin, Adjusted PTC, Adjusted EPS, and Free Cash Flow are non-GAAP supplemental measures that are used by management and external users of our consolidated financial statements such as investors, industry analysts and lenders.
For the year ending December 31, 2017, the Company changed the definition of Adjusted Operating Margin, Adjusted PTC and Adjusted EPS to exclude (a) associated benefits and costs due to acquisitions, dispositions, and early plant closures; including the tax impact of decisions made at the time of sale to repatriate sales proceeds; (b) costs directly associated with a major restructuring program, including, but not limited to, workforce reduction efforts, relocations, and office consolidation; and (c) tax benefit or expense related to the enactment effects of 2017 U.S. tax law reform.
We have excluded from our adjusted financial results costs associated with non-recurring restructuring initiatives to simplify the organization and improve efficiency. These restructuring initiatives would result in significant incremental costs above normal operations and the inclusion of such costs would result in a lack of comparability in our results of operations and could be misleading to investors.
The Company amended its Adjusted EPS definition to exclude the specific enactment effects of the transformational U.S. tax reform enacted on December 22, 2017. Such effects include a one-time transition tax on foreign earnings and the remeasurement of deferred tax assets and liabilities to the lower corporate tax rate. As permitted by the SEC in SAB 118, the Company recorded provisional amounts for these effects in its 2017 income from continuing operations. Changes in our estimates of these enactment effects may occur in future periods.
We believe excluding these benefits and costs better reflect the business performance by removing the variability caused by strategic decisions to dispose of or acquire business interests or close plants early, as well as the costs directly associated with a major restructuring program and the impact of the 2017 U.S. tax law reform, which affect results in a given period or periods. The Company has also reflected these changes in the comparative periods ending December 31, 2016 and December 31, 2015.
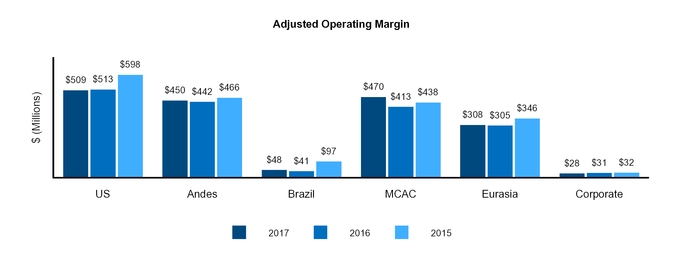
Adjusted Operating Margin
We define Adjusted Operating Margin as Operating Margin, adjusted for the impact of NCI, excluding (a) unrealized gains or losses related to derivative transactions; (b) gains, losses and associated benefits and costs due to dispositions and acquisitions of business interests, including early plant closures; and (c) costs directly associated with a major restructuring program, including, but not limited to, workforce reduction efforts, relocations, and office consolidation. See Review of Consolidated Results of Operations for definitions of Operating Margin and cost of sales.
The GAAP measure most comparable to Adjusted Operating Margin is Operating Margin. We believe that Adjusted Operating Margin better reflects the underlying business performance of the Company. Factors in this determination include the impact of NCI, where AES consolidates the results of a subsidiary that is not wholly owned by the Company, as well as the variability due to unrealized derivatives gains or losses related to derivative transactions and strategic decisions to dispose of or acquire business interests. Adjusted Operating Margin should not be construed as an alternative to Operating Margin, which is determined in accordance with GAAP.
| Reconciliation of Adjusted Operating Margin (in millions) | Years Ended December 31, | ||||||||||
| 2017 | 2016 | 2015 | |||||||||
| Operating Margin | $ | 2,464 | $ | 2,380 | $ | 2,663 | |||||
| Noncontrolling interests adjustment | (690 | ) | (644 | ) | (705 | ) | |||||
| Unrealized derivative losses (gains) | (5 | ) | 9 | 19 | |||||||
| Disposition/acquisition losses | 22 | — | — | ||||||||
| Restructuring costs | 22 | — | — | ||||||||
| Total Adjusted Operating Margin | $ | 1,813 | $ | 1,745 | $ | 1,977 |
Adjusted PTC
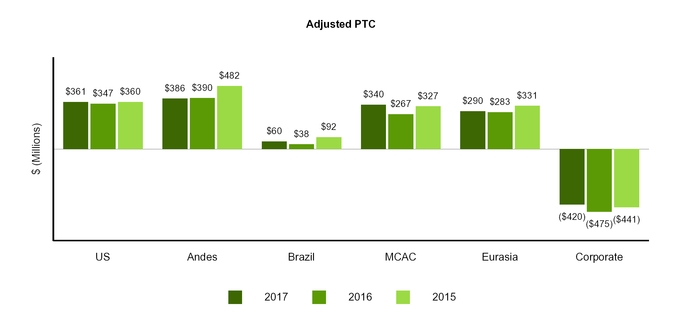
We define Adjusted PTC as pre-tax income from continuing operations attributable to The AES Corporation excluding gains or losses of the consolidated entity due to (a) unrealized gains or losses related to derivative transactions; (b) unrealized foreign currency gains or losses; (c) gains, losses and associated benefits and costs due to dispositions and acquisitions of business interests, including early plant closures; (d) losses due to impairments; (e) gains, losses and costs due to the early retirement of debt; and (f) costs directly associated with a major restructuring program, including, but not limited to, workforce reduction efforts, relocations, and office consolidation. Adjusted PTC also includes net equity in earnings of affiliates on an after-tax basis adjusted for the same gains or losses excluded from consolidated entities.
Adjusted PTC reflects the impact of NCI and excludes the items specified in the definition above. In addition to the revenue and cost of sales reflected in Operating Margin, Adjusted PTC includes the other components of our income statement, such as general and administrative expenses in the corporate segment, as well as business development costs, interest expense and interest income, other expense and other income, realized foreign currency transaction gains and losses, and net equity in earnings of affiliates.
The GAAP measure most comparable to Adjusted PTC is income from continuing operations attributable to The AES Corporation. We believe that Adjusted PTC better reflects the underlying business performance of the Company and is considered in the Company's internal evaluation of financial performance. Factors in this determination include the variability due to unrealized gains or losses related to derivative transactions, unrealized
foreign currency gains or losses, losses due to impairments and strategic decisions to dispose of or acquire business interests, retire debt or implement restructuring initiatives, which affect results in a given period or periods. In addition, earnings before tax represents the business performance of the Company before the application of statutory income tax rates and tax adjustments, including the effects of tax planning, corresponding to the various jurisdictions in which the Company operates. Adjusted PTC should not be construed as an alternative to income from continuing operations attributable to The AES Corporation, which is determined in accordance with GAAP.
| Reconciliation of Adjusted PTC (in millions) | Years Ended December 31, | ||||||||||
| 2017 | 2016 | 2015 | |||||||||
| Income (loss) from continuing operations, net of tax, attributable to The AES Corporation | $ | (507 | ) | $ | (20 | ) | $ | 318 | |||
| Income tax (benefit) expense attributable to The AES Corporation | 828 | (111 | ) | 263 | |||||||
| Pre-tax contribution | 321 | (131 | ) | 581 | |||||||
| Unrealized derivative gains | (3 | ) | (9 | ) | (166 | ) | |||||
| Unrealized foreign currency (gains) losses | (59 | ) | 22 | 95 | |||||||
| Disposition/acquisition (gains) losses | 123 | 6 | (42 | ) | |||||||
| Impairment losses | 542 | 933 | 504 | ||||||||
| Loss on extinguishment of debt | 62 | 29 | 179 | ||||||||
| Restructuring costs (1) | 31 | — | — | ||||||||
| Total Adjusted PTC | $ | 1,017 | $ | 850 | $ | 1,151 |
| (1) | In February 2018, the Company announced a reorganization as a part of its on-going strategy to simplify its portfolio, optimize its cost structure and reduce its carbon intensity. |
Adjusted EPS
We define Adjusted EPS as diluted earnings per share from continuing operations excluding gains or losses of both consolidated entities and entities accounted for under the equity method due to (a) unrealized gains or losses related to derivative transactions; (b) unrealized foreign currency gains or losses; (c) gains or losses and associated benefits and costs due to dispositions and acquisitions of business interests, including early plant closures, and the tax impact from the repatriation of sales proceeds; (d) losses due to impairments; (e) gains, losses and costs due to the early retirement of debt; (f) costs directly associated with a major restructuring program, including, but not limited to, workforce reduction efforts, relocations, and office consolidation; and (g) tax benefit or expense related to the enactment effects of 2017 U.S. tax law reform.
The GAAP measure most comparable to Adjusted EPS is diluted earnings per share from continuing operations. We believe that Adjusted EPS better reflects the underlying business performance of the Company and is considered in the Company's internal evaluation of financial performance. Factors in this determination include the variability due to unrealized gains or losses related to derivative transactions, unrealized foreign currency gains or losses, losses due to impairments and strategic decisions to dispose of or acquire business interests, retire debt or implement restructuring initiatives, which affect results in a given period or periods. Adjusted EPS should not be construed as an alternative to diluted earnings per share from continuing operations, which is determined in accordance with GAAP.
The Company reported a loss from continuing operations of $0.77 and $0.04 per share for the years ended December 31, 2017 and 2016. For purposes of measuring diluted loss per share under GAAP, common stock equivalents were excluded from weighted average shares as their inclusion would be anti-dilutive. However, for purposes of computing Adjusted EPS, the Company has included the impact of dilutive common stock equivalents. The table below reconciles the weighted average shares used in GAAP diluted loss per share to the weighted average shares used in calculating the non-GAAP measure of Adjusted EPS.
| Reconciliation of Denominator Used For Adjusted Earnings Per Share | Years Ended December 31, 2017 | Years Ended December 31, 2016 | ||||||||||||||||||||
| (in millions, except per share data) | Loss | Shares | $ per share | Loss | Shares | $ per share | ||||||||||||||||
| GAAP DILUTED LOSS PER SHARE | ||||||||||||||||||||||
| Loss from continuing operations attributable to The AES Corporation common stockholders | $ | (507 | ) | 660 | $ | (0.77 | ) | $ | (25 | ) | 660 | $ | (0.04 | ) | ||||||||
| EFFECT OF DILUTIVE SECURITIES | ||||||||||||||||||||||
| Restricted stock units | — | 2 | 0.01 | — | 2 | — | ||||||||||||||||
| NON-GAAP DILUTED LOSS PER SHARE | $ | (507 | ) | 662 | $ | (0.76 | ) | $ | (25 | ) | 662 | $ | (0.04 | ) |
| Reconciliation of Adjusted EPS | Years Ended December 31, | |||||||||||
| 2017 | 2016 | 2015 | ||||||||||
| Diluted earnings (loss) per share from continuing operations | $ | (0.76 | ) | $ | (0.04 | ) | $ | 0.46 | ||||
| Unrealized derivative gains | — | (0.01 | ) | (0.24 | ) | |||||||
| Unrealized foreign currency (gains) losses | (0.10 | ) | 0.03 | 0.15 | ||||||||
| Disposition/acquisition (gains) losses | 0.19 | (1) | 0.01 | (2) | (0.06 | ) | (3) | |||||
| Impairment losses | 0.82 | (4) | 1.41 | (5) | 0.73 | (6) | ||||||
| Loss on extinguishment of debt | 0.09 | (7) | 0.05 | (8) | 0.26 | (9) | ||||||
| Restructuring costs | 0.05 | — | — | |||||||||
| U.S. Tax Law Reform Impact | 1.08 | (10) | — | — | ||||||||
| Less: Net income tax benefit on adjustments | (0.29 | ) | (11) | (0.51 | ) | (12) | (0.06 | ) | (13) | |||
| Adjusted EPS | $ | 1.08 | $ | 0.94 | $ | 1.24 |
| (1) | Amount primarily relates to loss on sale of Kazakhstan CHPs of $49 million, or $0.07 per share, realized derivative losses associated with the sale of Sul of $38 million, or $0.06 per share, loss on sale of Kazakhstan Hydroelectric plants of $33 million, or $0.05 per share, costs associated with early plant closure of DPL of $24 million, or $0.04 per share; partially offset by gain on Masinloc contingent consideration of $23 million or $0.03 per share and gain on sale of Zimmer and Miami Fort of $13 million, or $0.02 per share. |
| (2) | Amount primarily relates to the loss on deconsolidation of UK Wind of $20 million, or $0.03 per share, and losses associated with the sale of Sul of $10 million, or $0.02; partially offset by the gain on sale of DPLER of $22 million, or $0.03 per share. |
| (3) | Amount primarily relates to the gains on the sale of Armenia Mountain of $22 million, or $0.03 per share and from the sale of Solar Spain and Solar Italy of $7 million, or $0.01 per share. |
| (4) | Amount primarily relates to asset impairment at Kazakhstan CHPs of $94 million, or $0.14 per share, at Kazakhstan hydroelectric plants of $92 million, or $0.14 per share, at Laurel Mountain wind farm of $121 million, or $0.18 per share, at DPL of $175 million, or $0.27 per share and at Kilroot of $37 million, or $0.05 per share. |
| (5) | Amount primarily relates to asset impairments at DPL of $859 million, or $1.30 per share; $159 million at Buffalo Gap II ($49 million, or $0.07 per share, net of NCI); and $77 million at Buffalo Gap I ($23 million, or $0.03 per share, net of NCI). |
| (6) | Amount primarily relates to the goodwill impairment at DPL of $317 million, or $0.46 per share, and asset impairments at Kilroot of $121 million ($119 million, or $0.17 per share, net of NCI), at Buffalo Gap III of $116 million ($27 million, or $0.04 per share, net of NCI), and at U.K. Wind (Development Projects) of $38 million ($30 million, or $0.04 per share, net of NCI). |
| (7) | Amount primarily relates to losses on early retirement of debt at the Parent Company of $92 million, or $0.14 per share, at AES Gener of $20 million, or $0.02 per share, at IPALCO of $9 million or $0.01 per share; partially offset by a gain on early retirement of debt at Alicura of $65 million, or $0.10 per share. |
| (8) | Amount primarily relates to the loss on early retirement of debt at the Parent Company of $19 million, or $0.03 per share. |
| (9) | Amount primarily relates to the loss on early retirement of debt at the Parent Company of $116 million, or $0.17 per share and at IPL of $22 million ($17 million, or $0.02 per share, net of NCI). |
| (10) | Amount relates to a one-time transition tax on foreign earnings of $675 million, or $1.02 per share and the remeasurement of deferred tax assets and liabilities to the lower corporate tax rate of $39 million, or $0.06 per share. |
| (11) | Amount primarily relates to the income tax benefit associated with asset impairment losses of $148 million, or $0.22 per share in the twelve months ended December 31, 2017. |
| (12) | Amount primarily relates to the income tax benefit associated with asset impairment of $332 million, or $0.50 per share in the twelve months ended December 31, 2016. |
| (13) | Amount primarily relates to the income tax benefit associated with losses on extinguishment of debt of $55 million, or $0.08 per share in the twelve months ended December 31, 2015. |
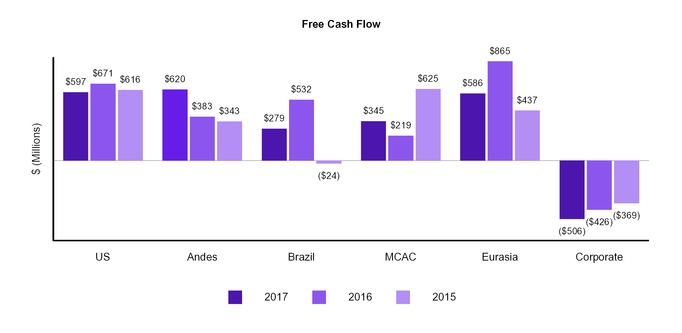
Free Cash Flow
We define Free Cash Flow as net cash from operating activities (adjusted for service concession asset capital expenditures) less maintenance capital expenditures (including non-recoverable environmental capital expenditures), net of reinsurance proceeds from third parties. Upon the Company's adoption of the accounting guidance for service concession arrangements effective January 1, 2015, capital expenditures related to service concession assets that would have been classified as investing activities on the Consolidated Statement of Cash Flows are now classified as operating activities. See Note 1—General and Summary of Significant Accounting Policies included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information on the adoption of this guidance.
We also exclude environmental capital expenditures that are expected to be recovered through regulatory, contractual or other mechanisms. An example of recoverable environmental capital expenditures is IPL's investment in MATS-related environmental upgrades that are recovered through a tracker. See Item 1.—Business—US SBU—IPL—Environmental Matters for details of these investments.
The GAAP measure most comparable to Free Cash Flow is net cash provided by operating activities. We believe that Free Cash Flow is a useful measure for evaluating our financial condition because it represents the amount of cash generated by the business after the funding of maintenance capital expenditures that may be available for investing in growth opportunities or for repaying debt.
The presentation of Free Cash Flow has material limitations. Free Cash Flow should not be construed as an alternative to net cash from operating activities, which is determined in accordance with GAAP. Free Cash Flow does not represent our cash flow available for discretionary payments because it excludes certain payments that are required or to which we have committed, such as debt service requirements and dividend payments. Our definition of Free Cash Flow may not be comparable to similarly titled measures presented by other companies.
| Reconciliation of Free Cash Flow (in millions) | Years Ended December 31, | ||||||||||
| 2017 | 2016 | 2015 | |||||||||
| Net Cash provided by operating activities | $ | 2,489 | $ | 2,884 | $ | 2,134 | |||||
| Add: capital expenditures related to service concession assets (1) | 6 | 29 | 165 | ||||||||
| Less: maintenance capital expenditures, net of reinsurance proceeds | (551 | ) | (624 | ) | (611 | ) | |||||
| Less: non-recoverable environmental capital expenditures (2) | (23 | ) | (45 | ) | (60 | ) | |||||
| Free Cash Flow | $ | 1,921 | $ | 2,244 | $ | 1,628 |
| (1) | Service concession asset expenditures are included in net cash provided by operating activities, but are excluded from the Free Cash Flow non-GAAP metric. |
| (2) | Excludes IPL's recoverable environmental capital expenditures of $54 million, $186 million and $262 million for the years ended December 31, 2017, 2016 and 2015, respectively. |
US SBU
The following table summarizes Operating Margin, Adjusted Operating Margin, Adjusted PTC, and Free Cash Flow (in millions) for the periods indicated:
| For the Years Ended December 31, | 2017 | 2016 | 2015 | $ Change 2017 vs. 2016 | % Change 2017 vs. 2016 | $ Change 2016 vs. 2015 | % Change 2016 vs. 2015 | |||||||||||||||||||
| Operating Margin | $ | 567 | $ | 582 | $ | 621 | $ | (15 | ) | -3 | % | $ | (39 | ) | -6 | % | ||||||||||
| Adjusted Operating Margin | 509 | 513 | 598 | (4 | ) | -1 | % | (85 | ) | -14 | % | |||||||||||||||
| Adjusted PTC | 361 | 347 | 360 | 14 | 4 | % | (13 | ) | -4 | % | ||||||||||||||||
| Operating Cash Flow | 776 | 912 | 845 | (136 | ) | -15 | % | 67 | 8 | % | ||||||||||||||||
| Free Cash Flow | 597 | 671 | 616 | (74 | ) | -11 | % | 55 | 9 | % | ||||||||||||||||
| Free Cash Flow Attributable to NCI | 41 | 57 | 25 | (16 | ) | -28 | % | 32 | NM |
| (1) | See Item 1.— Business for the respective ownership interest for key businesses. In addition, AES owns 70% of IPL as of March 2016 compared to 75% beginning April 2015, 85% beginning in February 2015 and 100% prior to February 2015. |
Fiscal year 2017 versus 2016
Operating Margin decreased $15 million, or 3%, which was driven primarily by the following (in millions):
| IPL | |||
| Decrease due to implementation of new base rates in Q2 2016 which resulted in a favorable change in accrual | $ | (18 | ) |
| Total IPL Decrease | (18 | ) | |
| DPL | |||
| Lower retail margin due to lower regulated rates | (22 | ) | |
| Lower volumes primarily due to the shutdown of Stuart Unit 1 and lower commercial availability | (21 | ) | |
| Lower depreciation expense driven by lower PP&E carrying values from impairments in 2016 and 2017 | 26 | ||
| Other | 7 | ||
| Total DPL Decrease | (10 | ) | |
| Other Business Drivers | 13 | ||
| Total US SBU Operating Margin Decrease | $ | (15 | ) |
Adjusted Operating Margin decreased $4 million due to the drivers above, adjusted for NCI and excluding unrealized gains and losses on derivatives, one-time restructuring charges and costs associated with early plant closures.
Adjusted PTC increased $14 million driven by earnings from equity affiliates due to the 2017 acquisition of sPower, the Company's share of earnings at Distributed Energy due to new project growth, and an increase in insurance recoveries at DPL. The increase in Adjusted PTC was partially offset by the decrease of $4 million in Adjusted Operating Margin described above and a 2016 gain on contract termination at DP&L.
Free Cash Flow decreased $74 million, of which $16 million was attributable to NCI. The decrease was driven by changes in net cash provided by operating activities comprising:
| • | A decrease of $49 million in Operating Margin (net of $34 million of decreased depreciation); |
| • | Increases in working capital of $144 million primarily related to an increase of $66 million in inventory balances as mild weather in 2015 drove inventory optimization efforts in 2016 and higher payments for purchased power and general accounts payable of $57 million at DPL and IPL; and |
| • | Decreases in working capital of $86 million primarily driven by higher collections at IPL of $27 million due to the monetization of higher receivable balances from December 2016 generated by favorable weather and rates and additional regulatory asset payments of $31 million primarily driven by higher MISO cost collection. |
Free Cash Flow was also impacted by a net increase of $33 million in other drivers, primarily related to a $51 million reduction in maintenance and non-recoverable environmental capital expenditures due to declining investment in our remaining coal generation capacity and $12 million in insurance proceeds at DPL.
Fiscal year 2016 versus 2015
Operating Margin decreased by $39 million, or 6%, which was driven primarily by the following (in millions):
| US Generation | |||
| Southland related to an increase in depreciation expense as a result of a change in estimated useful lives of the plants | $ | (17 | ) |
| Impact from sale of Armenia Mountain in July 2015 | (10 | ) | |
| Warrior Run due to lower availability and higher maintenance cost primarily due to major outages in 2016 | (8 | ) | |
| Laurel Mountain due to lower regulation dispatch as well as lower energy and regulation pricing | (8 | ) | |
| Other | (4 | ) | |
| Total US Generation Decrease | (47 | ) | |
| DPL | |||
| Impact of lower wholesale prices and completion of DP&L’s transition to a competitive-bid market | (42 | ) | |
| Decrease in RTO capacity and other revenues primarily due to lower capacity cleared in the auction | (21 | ) | |
| Lower depreciation expense due to June 2016 fixed asset impairment and decrease in generating facility maintenance and other expenses | 17 | ||
| Other | 2 | ||
| Total DPL Decrease | (44 | ) | |
| IPL | |||
| Higher retail margin driven by environmental revenues and higher rates due to a new rate order | 36 | ||
| Change in accrual resulting from the implementation of new rates | 18 | ||
| Other | (2 | ) | |
| Total IPL Increase | 52 | ||
| Total US SBU Operating Margin Decrease | $ | (39 | ) |
Adjusted Operating Margin decreased $85 million due to the drivers above, adjusted for NCI and excluding unrealized gains and losses on derivatives.
Adjusted PTC decreased $13 million driven by the decrease of $85 million in Adjusted Operating Margin described above, partially offset by a gain on contract termination at DP&L, lower interest expense at DPL and IPL in part due to the sell-down impacts and the impact of HLBV at our Distributed Energy business as a result of new projects achieving COD in 2016.
Free Cash Flow increased $55 million, of which $32 million was attributable to NCI. The increase was driven by changes in net cash provided by operating activities comprising:
| • | A decrease of $21 million in Operating Margin (net of $28 million in increased depreciation and $10 million in other non-cash impacts); |
| • | Decrease in working capital of $169 million primarily driven by a $142 million reduction in inventory holdings as we focused on inventory optimization efforts and reductions in working capital needs of $17 million resulting from the sale of MC2 and DPLER; and |
| • | Increases in working capital of $97 million primarily related to an increase in receivables of $80 million resulting from higher rates at IPL and favorable weather in Q4 2016. |
Free Cash was also impacted by a $12 million increase in maintenance capital expenditures due to higher expenditures at IPL. Free Cash Flow was also impacted by lower interest payments of $16 million due to debt repayments at DPL and lower interest rates.
ANDES SBU
The following table summarizes Operating Margin, Adjusted Operating Margin, Adjusted PTC, and Free Cash Flow (in millions) for the periods indicated:
| For the Years Ended December 31, | 2017 | 2016 | 2015 | $ Change 2017 vs. 2016 | % Change 2017 vs. 2016 | $ Change 2016 vs. 2015 | % Change 2016 vs. 2015 | |||||||||||||||||||
| Operating Margin | $ | 658 | $ | 634 | $ | 618 | $ | 24 | 4 | % | $ | 16 | 3 | % | ||||||||||||
| Adjusted Operating Margin | 450 | 442 | 466 | 8 | 2 | % | (24 | ) | -5 | % | ||||||||||||||||
| Adjusted PTC | 386 | 390 | 482 | (4 | ) | -1 | % | (92 | ) | -19 | % | |||||||||||||||
| Operating Cash Flow | 714 | 475 | 462 | 239 | 50 | % | 13 | 3 | % | |||||||||||||||||
| Free Cash Flow | 620 | 383 | 343 | 237 | 62 | % | 40 | 12 | % | |||||||||||||||||
| Free Cash Flow Attributable to NCI | 204 | 119 | 119 | 85 | 71 | % | — | — | % |
| (1) | See Item 1.—Business for the respective ownership interest for key businesses. In addition, AES owned 71% of Gener and Chivor prior to sell down effective December 2015 which resulted in ownership of 67%. The Alto Maipo (under construction) and Cochrane plants are owned 62% and 40% respectively. |
Fiscal year 2017 versus 2016
Including the favorable impact of foreign currency translation and remeasurement of $19 million, Operating Margin increased $24 million, or 4%, which was driven primarily by the following (in millions):
| Gener | |||
| Negative impact of new regulation on Emissions (Green Taxes) | $ | (41 | ) |
| Lower availability of efficient generation resulting in higher replacement energy and fixed costs mainly associated with major maintenance at Ventanas Complex | (29 | ) | |
| Lower margin at the SING market primarily associated with lower contract sales and increase in coal prices at Norgener partially offset by higher spot sales | (21 | ) | |
| Start of operations at Cochrane Units I and II in July and October 2016, respectively | 72 | ||
| Other | 1 | ||
| Total Gener Decrease | (18 | ) | |
| Argentina | |||
| Higher capacity payments primarily associated to changes in regulation in 2017 | 64 | ||
| Lower generation at CTSN mainly associated with lower demand | (26 | ) | |
| Higher fixed costs mainly associated with higher people costs driven by inflation | (11 | ) | |
| Favorable FX impact | 9 | ||
| Total Argentina Increase | 36 | ||
| Chivor | |||
| Higher contract sales primarily associated to an increase in contracted capacity at higher prices | 35 | ||
| Lower spot sales mainly associated to lower generation and lower spot prices | (37 | ) | |
| Other | 8 | ||
| Total Chivor Increase | 6 | ||
| Total Andes SBU Operating Margin Increase | $ | 24 |
Adjusted Operating Margin increased $8 million due to the drivers above, adjusted for NCI and excluding restructuring charges.
Adjusted PTC decreased $4 million, driven by higher interest expense, mainly due to the issuance of debt at Argentina and lower interest capitalization in Cochrane and Chivor, and the write-off of water rights at Gener resulting from a business development project that is no longer pursued. These negative impacts were partially offset by the increase in Adjusted Operating Margin, foreign currency gains in Argentina associated with the collection of financing receivables, prepayment of financial debt denominated in U.S. dollars in 2017, and lower foreign currency losses associated with the sale of Argentina’s sovereign bonds at Termoandes.
Free Cash Flow increased $237 million, of which $85 million was attributable to NCI. The increase was driven by changes in net cash provided by operating activities comprising:
| • | $98 million increase in Operating Margin (net of higher depreciation of $33 million and $41 million of environmental tax accruals in Chile impacting margin, but not free cash flow); |
| • | Decreases in working capital of $130 million primarily driven by higher VAT Refunds of $60 million at Alto Maipo and other Construction Projects and $38 million in collections of financing receivables related to the commencement of operations of Guillermo Brown and Cochrane; and |
| • | Increases in working capital of $55 million primarily related to $40 million in lower collections of receivables at Chivor. |
Free Cash Flow was also impacted by a net increase of $64 million in other drivers, primarily related to a $58 million decrease in taxes and $34 million in dividends received from Guacolda, partially offset by a $27 million increase in interest payments.
Fiscal year 2016 versus 2015
Including the unfavorable impact of foreign currency translation and remeasurement of $36 million, Operating Margin increased $16 million, or 3%, which was driven primarily by the following (in millions):
| Gener | |||
| Lower spot prices on energy and fuel purchases | $ | 82 | |
| Start of operations of Cochrane Plant | 36 | ||
| Other | (3 | ) | |
| Total Gener Increase | 115 | ||
| Argentina | |||
| Higher rates driven by annual price review granted by Resolution 22/2016 | 61 | ||
| Lower availability mainly associated with planned major maintenance | (20 | ) | |
| Higher fixed costs primarily driven by higher inflation and by higher maintenance cost | (44 | ) | |
| Unfavorable FX remeasurement impacts | (21 | ) | |
| Total Argentina Decrease | (24 | ) | |
| Chivor | |||
| Higher volume of energy sales to Spot Market | 14 | ||
| Unfavorable FX remeasurement impacts | (15 | ) | |
| Lower spot sales prices | (72 | ) | |
| Other | (2 | ) | |
| Total Chivor Decrease | (75 | ) | |
| Total Andes SBU Operating Margin Increase | $ | 16 |
Adjusted Operating Margin decreased $24 million due to the drivers above, adjusted for NCI.
Adjusted PTC decreased $92 million driven by the decrease in Equity Earnings of $54 million mainly related to Guacolda’s reorganization in September 2015, the decrease of $24 million in Adjusted Operating Margin and the increase of $12 million in interest expense primarily associated with lower interest capitalization after the beginning of commercial operations at Cochrane.
Free Cash Flow increased $40 million, none of which was attributable to NCI. The increase was driven by changes in net cash provided by operating activities comprising:
| • | An increase of $58 million in Operating Margin (net of $42 million in increased depreciation and other non-cash impacts); |
| • | Decrease in working capital of $178 million, primarily driven by $83 million in higher collections at Chivor related to Q4 2015 sales, a $38 million positive impact related to a one-time interest rate swap termination payment at Ventanas in July 2015, and $57 million in collections of financing receivables and maintenance remuneration from CAMMESSA in Argentina; and |
| • | Increases in working capital of $137 million primarily related to an increase in VAT accruals of $107 million related to our Cochrane and Alto Maipo construction projects. |
Free Cash Flow was also impacted by a $57 million increase in taxes at Chile and Chivor, a $29 million increase in interest payments at Gener due to new unsecured notes issued in July 2015 as part of the Ventanas refinancing, and a $27 million reduction in maintenance and non-recoverable capital expenditures due to lower expenditures on emissions and control equipment at Chile.
BRAZIL SBU
The following table summarizes Operating Margin, Adjusted Operating Margin, Adjusted PTC, and Free Cash Flow (in millions) for the periods indicated:
| For the Years Ended December 31, | 2017 | 2016 | 2015 | $ Change 2017 vs. 2016 | % Change 2017 vs. 2016 | $ Change 2016 vs. 2015 | % Change 2016 vs. 2015 | |||||||||||||||||||
| Operating Margin | $ | 203 | $ | 186 | $ | 397 | $ | 17 | 9 | % | $ | (211 | ) | -53 | % | |||||||||||
| Adjusted Operating Margin | 48 | 41 | 97 | 7 | 17 | % | (56 | ) | -58 | % | ||||||||||||||||
| Adjusted PTC | 60 | 38 | 92 | 22 | 58 | % | (54 | ) | -59 | % | ||||||||||||||||
| Operating Cash Flow | 469 | 716 | 136 | (247 | ) | (34 | )% | 580 | NM | |||||||||||||||||
| Free Cash Flow | 279 | 532 | (24 | ) | (253 | ) | (48 | )% | 556 | NM | ||||||||||||||||
| Free Cash Flow Attributable to NCI | 204 | 422 | 5 | (218 | ) | (52 | )% | 417 | NM |
| (1) | See Item 1.—Business for the respective ownership interest for key businesses. |
Fiscal year 2017 versus 2016
Including the favorable impact of foreign currency translation of $19 million, Operating Margin increased $17 million, or 9%, which was driven primarily by the following (in millions):
| Tietê | |||
| Net impact of volume and prices of bilateral contracts due to higher energy purchased | $ | (100 | ) |
| Net impact of volume and prices of lower energy purchased in spot market | 71 | ||
| Higher volume due to acquisition of new wind entities - Alto Sertão II | 23 | ||
| Favorable FX impacts | 21 | ||
| Other | 4 | ||
| Total Tietê Increase | 19 | ||
| Other Business Drivers | (2 | ) | |
| Total Brazil SBU Operating Margin Increase | $ | 17 |
Adjusted Operating Margin increased $7 million due to the drivers above, adjusted for NCI and excluding costs due to dispositions and acquisitions of business interests.
Adjusted PTC increased $22 million, driven by a $28 million increase from the settlement of a legal dispute with YPF at Uruguaiana as well as the $7 million of increase in Adjusted Operating Margin described above, partially offset by $5 million of higher interest expense over Alto Sertão II debt.
Free Cash Flow decreased $253 million, of which $218 million was attributable to NCI. The decrease was driven by changes in net cash provided by operating activities comprising:
| • | $35 million increase in Operating Margin (net of increased depreciation of $18 million); |
| • | $58 million decrease due to the sale of Sul in October 2016; |
| • | Increases in working capital of $913 million, primarily related to $600 million of higher costs deferred in net regulatory assets at Eletropaulo resulting from unfavorable hydrology in prior periods and $198 million of lower collections of energy sales at Eletropaulo due to higher tariff flags in 2016; and |
| • | Decreases in working capital of $445 million, primarily due to $411 million related to timing of payments for energy purchases due to lower energy costs and lower regulatory charges at Eletropaulo and Tietê. |
Free Cash Flow was also impacted by an increase of $240 million in other drivers, primarily related to $93 million of lower tax payments at Tietê and Eletropaulo, $71 million in lower interest paid at Tietê and Eletropaulo, and $60 million collected from a legal dispute settlement with YPF at Uruguaiana.
Fiscal year 2016 versus 2015
Including the unfavorable impact of foreign currency translation of $14 million, Operating Margin decreased $211 million, or 53%, which was driven primarily by the following (in millions):
| Tietê | |||
| Lower rates for energy sold under new contracts | $ | (239 | ) |
| Unfavorable FX impacts | (14 | ) | |
| Higher fixed costs due to higher legal settlements | (13 | ) | |
| Lower rates for energy purchases mainly due to decrease in spot market prices | 78 | ||
| Other | (2 | ) | |
| Total Tietê Decrease | (190 | ) | |
| Uruguaiana | |||
| Operations in 2015 compared to not operating in 2016 | (20 | ) | |
| Total Uruguaiana Decrease | (20 | ) | |
| Other Business Drivers | (1 | ) | |
| Total Brazil SBU Operating Margin Decrease | $ | (211 | ) |
Adjusted Operating Margin decreased $56 million due to the drivers above, adjusted for NCI and excluding unrealized gains and losses on derivatives.
Adjusted PTC decreased $54 million, driven by the decrease of $56 million in Adjusted Operating Margin described above.
Free Cash Flow increased $556 million, of which $417 million was attributable to NCI. The increase was driven by changes in net cash provided by operating activities comprising:
| • | $308 million decrease in Operating Margin (net of $45 million in non-cash impacts, primarily due to the reversal of a contingent regulatory liability at Eletropaulo in 2015); |
| • | Decreases in working capital of $1.5 billion, primarily due to $974 million in higher collections of costs deferred in net regulatory assets at Eletropaulo and Sul resulting from unfavorable hydrology in 2015 and $416 million of higher collections on energy sales in 2016; and |
| • | Increases in working capital of $623 million primarily due to $581 million related to regulatory charges and timing of payments for energy purchases at Eletropaulo and Sul in 2016. |
MCAC SBU
The following table summarizes Operating Margin, Adjusted Operating Margin, Adjusted PTC, and Free Cash Flow (in millions) for the periods indicated:
| For the Years Ended December 31, | 2017 | 2016 | 2015 | $ Change 2017 vs. 2016 | % Change 2017 vs. 2016 | $ Change 2016 vs. 2015 | % Change 2016 vs. 2015 | |||||||||||||||||||
| Operating Margin | $ | 589 | $ | 523 | $ | 543 | $ | 66 | 13 | % | $ | (20 | ) | -4 | % | |||||||||||
| Adjusted Operating Margin | 470 | 413 | 438 | 57 | 14 | % | (25 | ) | -6 | % | ||||||||||||||||
| Adjusted PTC | 340 | 267 | 327 | 73 | 27 | % | (60 | ) | -18 | % | ||||||||||||||||
| Operating Cash Flow | 427 | 312 | 705 | 115 | 37 | % | (393 | ) | -56 | % | ||||||||||||||||
| Free Cash Flow | 345 | 219 | 625 | 126 | 58 | % | (406 | ) | -65 | % | ||||||||||||||||
| Free Cash Flow Attributable to NCI | 61 | 51 | 127 | 10 | 20 | % | (76 | ) | -60 | % |
| (1) | See Item 1.—Business for the respective ownership interest for key businesses. AES owned 92% of Andres and Los Mina and 46% of Itabo in the Dominican Republic until December 2015 when the ownership changed to 90% at Andres and Los Mina and 45% at Itabo until October 2017. |
Fiscal year 2017 versus 2016
Operating Margin increased $66 million, or 13%, which was driven primarily by the following (in millions):
| Dominican Republic | |||
| Higher contracted energy sales net of LNG fuel consumption mainly driven by Los Mina combined cycle commencement of operations in June 2017 | $ | 34 | |
| Other | 6 | ||
| Total Dominican Republic Increase | 40 | ||
| Mexico | |||
| Higher availability as a result of a plant forced maintenance in 2016 | 13 | ||
| Other | 7 | ||
| Total Mexico Increase | 20 | ||
| Other Business Drivers | 6 | ||
| Total MCAC SBU Operating Margin Increase | $ | 66 |
Adjusted Operating Margin increased $57 million due to the drivers above, adjusted for NCI and excluding unrealized gains and losses on derivatives and one-time restructuring charges.
Adjusted PTC increased $73 million, driven by the increase in Adjusted Operating Margin of $57 million as described above.
Free Cash Flow increased $126 million, of which $10 million was attributable to NCI. The increase was driven by changes in net cash provided by operating activities comprising:
| • | $73 million increase in Operating Margin (net of higher depreciation of $7 million); |
| • | Decreases in working capital in Dominican Republic of $61 million primarily due to the collection of past overdue amounts as part of the sale of receivables executed with the distribution companies and CDEEE in 2017; and |
| • | Increases in working capital in Puerto Rico of $10 million primarily related to lower payments and collections caused by Hurricane Maria. |
Free Cash Flow was also impacted by lower tax payments of $17 million in El Salvador and a $10 million decrease in maintenance and non-recoverable environmental capital expenditures, partially offset by higher interest payments in Dominican Republic of $25 million due to the issuance of new Senior Notes in Los Mina.
Fiscal year 2016 versus 2015
Operating Margin decreased $20 million, or 4%, which was driven primarily by the following (in millions):
| Mexico | |||
| Lower availability and related costs | $ | (11 | ) |
| Other | (6 | ) | |
| Total Mexico Decrease | (17 | ) | |
| El Salvador | |||
| Higher fixed costs and lower energy sales margin | (10 | ) | |
| Total El Salvador Decrease | (10 | ) | |
| Panama | |||
| Expenses related to the ongoing construction of a natural gas generation plant and a liquefied natural gas terminal | (19 | ) | |
| Commencement of power barge operations at the end of March 2015 | 13 | ||
| Other | (3 | ) | |
| Total Panama Decrease | (9 | ) | |
| Dominican Republic | |||
| Higher contracted and spot energy sales | 24 | ||
| Total Dominican Republic Increase | 24 | ||
| Other Business Drivers | (8 | ) | |
| Total MCAC SBU Operating Margin Decrease | $ | (20 | ) |
Adjusted Operating Margin decreased $25 million due to the drivers above, adjusted for NCI and excluding unrealized gains and losses on derivatives.
Adjusted PTC decreased $60 million, driven by the decrease in Adjusted Operating Margin of $25 million described above as well as a 2015 compensation agreement regarding early termination of the original Barge PPA of $10 million and a $26 million allowance recognized in 2016 at Puerto Rico.
Free Cash Flow decreased $406 million, of which $76 million was attributable to NCI. The decrease was driven by changes in net cash provided by operating activities comprising:
| • | A decrease of $10 million in Operating Margin (net of $10 million in depreciation); and |
| • | Increases in working capital of $338 million, primarily related to higher accounts receivable balances for the Dominican Republic of $243 million due to collections of overdue receivables in September 2015 and for Puerto Rico of $47 million primarily due to lower sales in Q4 2015. |
Free Cash Flow was also impacted by a $13 million increase in maintenance and non-recoverable environmental capital expenditures.
EURASIA SBU
The following table summarizes Operating Margin, Adjusted Operating Margin, Adjusted PTC, and Free Cash Flow (in millions) for the periods indicated:
| For the Years Ended December 31, | 2017 | 2016 | 2015 | $ Change 2017 vs. 2016 | % Change 2017 vs. 2016 | $ Change 2016 vs. 2015 | % Change 2016 vs. 2015 | |||||||||||||||||||
| Operating Margin | $ | 423 | $ | 429 | $ | 452 | $ | (6 | ) | -1 | % | $ | (23 | ) | -5 | % | ||||||||||
| Adjusted Operating Margin | 308 | 305 | 346 | 3 | 1 | % | (41 | ) | -12 | % | ||||||||||||||||
| Adjusted PTC | 290 | 283 | 331 | 7 | 2 | % | (48 | ) | -15 | % | ||||||||||||||||
| Operating Cash Flow | 610 | 892 | 354 | (282 | ) | -32 | % | 538 | NM | |||||||||||||||||
| Free Cash Flow | 586 | 865 | 437 | (279 | ) | -32 | % | 428 | 98 | % | ||||||||||||||||
| Free Cash Flow Attributable to NCI | 173 | 177 | 112 | (4 | ) | -2 | % | 65 | 58 | % |
| (1) | See Item 1.—Business for the respective ownership interest for key businesses. |
Fiscal year 2017 versus 2016
Operating Margin decreased $6 million, or 1%, and Adjusted Operating Margin increased $3 million, or 1%, with no material drivers.
Adjusted PTC increased $7 million, primarily driven by the increase of in Adjusted Operating Margin, adjusted for NCI and excluding unrealized gains and losses on derivatives.
Free Cash Flow decreased $279 million, of which $4 million was attributable to NCI. The decrease was primarily driven by changes in net cash provided by operating activities, specifically:
| • | A decrease of $28 million in Operating Margin (net of $22 million in decreased depreciation); |
| • | A reduction in cash receipts of $362 million, primarily attributable to a $360 million payment made in April 2016 from NEK, net of payments to the fuel supplier, for Maritza related to overdue receivables; and |
| • | Decreases in working capital of $64 million primarily related to lower working capital requirements of $50 million at Masinloc and Mong Duong due to the timing of payments for coal purchases. |
Free Cash Flow was also impacted by a $25 million reduction in maintenance and non-recoverable environmental capital expenditures and a $20 million decrease in interest payments.
Fiscal year 2016 versus 2015
Including the unfavorable impact of foreign currency translation of $36 million, Operating Margin decreased $23 million, or 5%, which was driven primarily by the following (in millions):
| Kazakhstan | |||
| Unfavorable FX impact due to KZT depreciation against USD | $ | (29 | ) |
| Other | (1 | ) | |
| Total Kazakhstan Decrease | (30 | ) | |
| Maritza | |||
| Lower contracted capacity prices due to PPA amendment | (18 | ) | |
| Other | (2 | ) | |
| Total Maritza Decrease | (20 | ) | |
| Ballylumford | |||
| Higher contracted revenues | 27 | ||
| Lower plant capacity resulting from the retirement of one generation facility | (21 | ) | |
| Total Ballylumford Increase | 6 | ||
| Mong Duong | |||
| Impact of full year operations for 2016 compared to commencement of principal operations in April 2015 | 16 | ||
| Total Mong Duong Increase | 16 | ||
| Other Business Drivers | 5 | ||
| Total Eurasia SBU Operating Margin Decrease | $ | (23 | ) |
Adjusted Operating Margin decreased $41 million due to the drivers above, adjusted for NCI and excluding unrealized gains and losses on derivatives.
Adjusted PTC decreased $48 million, driven by the decrease of $41 million in Adjusted Operating Margin described above, lower equity earnings at OPGC in India due to lower tariffs and the net impact of higher interest expense and higher interest income at Mong Duong.
Free Cash Flow increased $428 million, of which $65 million was attributable to NCI. The increase was driven by a $26 million reduction in maintenance and non-recoverable environmental capital expenditures and changes in net cash provided by operating activities comprising:
| • | A decrease of $43 million in Operating Margin (net of $20 million in decreased depreciation and other non-cash impacts); |
| • | Increases in working capital of $472 million from increased collections of $360 million at Maritza from NEK, net of payments to the fuel supplier, and a reduction in working capital requirements of $58 million at Mong Duong due to higher working capital needs in 2015 in preparation for commencement of plant operations; and |
| • | Decreases in working capital of $47 million attributable to a $24 million decrease in CO2 allowances due to a price decrease at Maritza and a higher interest expense of $34 million as capitalization of interest ceased upon COD of Mong Duong in 2015. |
Key Trends and Uncertainties
During 2018 and beyond, we expect to face the following challenges at certain of our businesses. Management expects that improved operating performance at certain businesses, growth from new businesses, and global cost reduction initiatives may lessen or offset their impact. If these favorable effects do not occur, or if the challenges described below and elsewhere in this section impact us more significantly than we currently anticipate, or if volatile foreign currencies and commodities move more unfavorably, then these adverse factors (or other adverse factors unknown to us) may impact our operating margin, net income attributable to The AES Corporation and cash flows. We continue to monitor our operations and address challenges as they arise. For the risk factors related to our business, see Item 1.—Business and Item 1A.—Risk Factors of this Form 10-K.
Macroeconomic and Political
The political environments in some countries where our subsidiaries conduct business have changed during
- This could result in significant impacts to tax laws, and environmental and energy policies. Additionally, we operate in multiple countries and as such are subject to volatility in exchange rates at the subsidiary level. See Item 7A.—Quantitative and Qualitative Disclosures About Market Risk for further information.
United States Tax Law Reform
On December 22, 2017, the United States enacted the Tax Cuts and Jobs Act (the “2017 Act”). The legislation significantly revised the U.S. corporate income tax system by, among other things, lowering the corporate income tax rate, introducing new limitations on interest expense deductions, subjecting foreign earnings in excess of an allowable return to current U.S. taxation, and adopting a semi-territorial corporate tax system. These changes will materially impact our effective tax rate in future periods. Furthermore, we anticipate that higher U.S. tax expense may fully utilize our remaining net operating loss carryforwards in the near term, which could lead to material cash tax payments in the United States. Specific provisions of the 2017 Act and their potential impacts on the Company are noted below. Our interpretation of the 2017 Act may change as the U.S. Treasury and the Internal Revenue Service issue additional guidance. Such changes may be material.
Lower Tax Rate — The corporate tax rate decreased from 35 percent to 21 percent beginning in 2018. In addition to deferred tax remeasurement impacts, the lower tax rate will result in the recognition, at December 31, 2017, of a regulatory liability at IPL and DPL. The regulatory liability will reflect deferred taxes that will flow back to ratepayers over time.
Limitation on Interest Expense Deductions — The 2017 Act introduced a new limitation on the deductibility of net interest expense beginning January 1, 2018. The deduction will be limited to interest income, plus 30 percent of tax basis EBITDA through 2021 (30 percent of EBIT beginning January 1, 2022). This determination is made at the consolidated group level, although it applies separately to partnerships. The limitation does not apply to interest expense attributable to regulated utility property. The U.S. Treasury and Internal Revenue Service are expected to provide guidance to clarify how the exception will apply to regulated utility holding companies. Given typical project financing and current U.S. holding company debt levels, we anticipate that this limitation will materially, negatively impact our effective tax rate.
Cost Recovery — The 2017 Act amended depreciation rules to provide full expensing (100% bonus depreciation) for assets that commence construction and are placed in service before January 1, 2023. This provision is phased down by 20 percent ratably through 2027. The immediate full expensing provision is elective, but it does not apply to regulated utility property. This change is not expected to impact the Company’s effective tax rate; however, if elected, it could impact taxable income and cash taxes in future periods.
Transition to a Participation Exemption System — A transition tax will be imposed on previously untaxed, deferred foreign earnings at a rate of either 8 percent or 15.5 percent, depending on the liquidity of the underlying foreign earnings. Prospectively, a 100 percent dividends received deduction will apply to foreign source dividends upon repatriation.
Global Intangible Low Taxed Income (“GILTI”) — A new provision in the U.S. tax law subjects the foreign earnings of foreign subsidiaries to current U.S. taxation to the extent that those earnings exceed an allowable economic return on investment. The allowable return is 10 percent of the adjusted tax basis in the foreign subsidiaries’ tangible property, reduced by interest expense. The foreign earnings subject to current taxation under the GILTI provision are not limited to those derived from intangible property and may include gains derived from some future asset sales. Although the new GILTI rules provide for a reduced 10.5 percent effective tax rate on captured income (increasing to 13.125% January 1, 2026), by way of a 50 percent deduction, companies with a net operating loss or otherwise insufficient taxable income will not benefit from the lower effective tax rate and may not be able to utilize foreign tax credits.
We expect that the GILTI provision may capture a very significant portion of our foreign earnings and subject those foreign earnings to current U.S. taxation. As a result, we expect the GILTI provision to materially, negatively impact our effective tax rate. Prospectively, the consequences of the new GILTI provision may be mitigated by foreign tax credits. However, additional guidance from the U.S. Treasury and Internal Revenue Service will be required to determine the extent to which the Company will be able to claim such foreign tax credits and mitigate the negative consequences of the GILTI provision.
State Taxes — The reactions of the individual states to federal tax reform are still evolving. Most states will assess whether and how the federal changes will be incorporated into their state tax legislation. As we expect higher taxable income in the future due to the federal changes, this may also lead to higher state taxable income. Our current state tax provisions predominantly have full valuation allowances against state net operating losses. These positions will be re-assessed in the future as state tax law evolves and may result in
material changes in position.
Tax Equity Structures — Our U.S. renewable energy portfolio operates primarily through tax equity partnerships. We cannot be certain of the impacts U.S. tax reform may have on availability or pricing of tax equity for future growth opportunities. Impacts of provisions such as the lower tax rate and immediate expensing may impact the amount and timing of returns allocable to our partners in our existing tax equity structures.
SAB 118 — As further explained in Note 20—Income Taxes included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K we have included certain reasonable estimates of the impact of U.S. tax law reform subject to potential adjustments in future periods.
Puerto Rico — Our subsidiaries in Puerto Rico have long-term PPAs with state-owned PREPA, which has been facing economic challenges that could impact the Company.
In order to address these challenges, on June 30, 2016, the Puerto Rico Oversight, Management, and Economic Stability Act (“PROMESA”) was signed into law. PROMESA created a structure for exercising federal oversight over the fiscal affairs of U.S. territories and allowed for the establishment of an Oversight Board with broad powers of budgetary and financial control over Puerto Rico. PROMESA also created procedures for adjusting debts accumulated by the Puerto Rico government and, potentially, other territories (“Title III”). Finally, PROMESA expedites the approval of key energy projects and other critical projects in Puerto Rico.
PREPA entered into preliminary Restructuring Support Agreements (“RSAs”) with their lenders. Under PROMESA, PREPA submitted the RSA to the Oversight Board for approval on April 28, 2017, which the board denied on June 28, 2017. As a consequence, on July 2, 2017, the Oversight Board filed for bankruptcy on behalf of PREPA under Title III.
As a result of the bankruptcy filing, AES Puerto Rico and AES Ilumina’s non-recourse debt of $365 million and $36 million, respectively, are in default and have been classified as current as of December 31, 2017.
Additionally, on July 18, 2017, Moody's downgraded AES Puerto Rico to Caa1 from B3 due to the heightened default risk for AES Puerto Rico as a result of PREPA's bankruptcy protection. This protection gives PREPA the ability to renegotiate contracts, which could impact the value of our assets in Puerto Rico or otherwise have a material impact on the Company. In this regard, PREPA had requested the Company to renegotiate its 24 MW AES Ilumina’s PPA. After the event of the Hurricanes Maria and Irma, these negotiations were put on hold.
In September 2017, Puerto Rico and the U.S. Virgin Islands were severely impacted by Hurricanes Irma and Maria, disrupting the operations of AES Puerto Rico, AES Ilumina, and certain Distributed Energy assets. The Company sustained modest damage to its 24 MW AES Ilumina solar plant, resulting in a $2 million loss, and minor damage to its 524 MW AES Puerto Rico thermal plants, both located in Puerto Rico.
As a result of the hurricanes, PREPA has declared an event of Force Majeure. However, both units of AES Puerto Rico and approximately 75% of AES Ilumina have been available to generate electricity since mid-October which, in accordance with the PPAs, will allow AES Puerto Rico to invoice capacity, even under Force Majeure. Puerto Rico’s infrastructure was severely damaged, including electric infrastructure and transmission lines. The extensive structural damage caused by hurricane winds and flooding is expected to take significant time and cost to repair.
Due to the extensive damage from the hurricanes, energy demand in Puerto Rico has decreased and is expected to remain low until economic activity has recovered. Despite the decrease in demand, AES Puerto Rico has resumed generation and continues to be the lowest cost and EPA compliant energy provider in Puerto Rico. Therefore, we expect AES Puerto Rico to continue to be a critical supplier to PREPA.
On October 24, 2017, the U.S. Congress approved a $37 billion emergency disaster relief bill which will allow the U.S. Government to help victims from the hurricanes and assist with the infrastructure rebuild in the affected areas through the Federal Emergency Management Agency. This supplemental appropriation includes an allocation of $5 billion for the Disaster Assistance Direct Loan Program to assist local governments, like Puerto Rico, in providing essential services, such as reestablishing electricity.
In November 2017, AES Puerto Rico signed a Forbearance and Standstill Agreement with its lenders to prevent the lenders from taking any action against the company due to the default events. This agreement will expire on March 22, 2018.
The Company's receivable balances in Puerto Rico as of December 31, 2017 totaled $86 million, of which $53 million was overdue. Despite the disruption caused by the hurricanes and the Title III protection, PREPA has
restarted the payments to the generators. AES Puerto Rico has been able to collect $28 million of overdue amounts as of December 31, 2017.
In January 2018, Puerto Rico announced its intention to privatize PREPA. The plan will need to be approved by the Oversight Board, and, if approved, could take 18 months to complete. It is difficult to predict the outcome of the proposed privatization, but the impact on our businesses in Puerto Rico and AES could be material.
Considering the information available as of the filing date, Management believes the carrying amount of our assets in Puerto Rico of $627 million is recoverable and no reserve on the receivables is necessary as of December 31, 2017.
Brazil — Brazilian President Michael Temer continues to seek economic reforms that would improve the economic outlook in Brazil, which may benefit our businesses in the country. Corruption investigations and the 2018 presidential campaign have limited Mr. Temer's ability to implement these reforms. Despite these limitations, the Brazilian economy is showing moderate signs of improvement.
United Kingdom — In June 2016, the United Kingdom ("U.K.") held a referendum in which voters approved an exit from the European Union (“E.U.”), commonly referred to as “Brexit.” In December 2017, the U.K. and E.U. agreed terms to conclude Phase 1 negotiations and have moved into Phase 2 of negotiations with respect to long-term trading relationship and a potential transitional period. The U.K. is expected to exit the E.U. on March 29, 2019. While the full impact of the Brexit remains uncertain, these changes may adversely affect our operations and financial results.
Regulatory
International Trade Commission — In September 2017, the U.S. International Trade Commission ("ITC") determined that serious injury has been caused by foreign solar photovoltaic panels to U.S. manufacturers. The ITC proposed recommendations for remedies that include tariffs at various levels, a quota system and licensing fees. In January 2018, the U.S. President approved tariffs of 30% in the first year, which will gradually decrease to 15% over four years. AES is evaluating the impact of these tariffs, but they will likely increase the cost of solar photovoltaic panels in the short term. The Company has taken mitigating action to limit our exposure to these increased costs, such as acquiring solar panels for committed projects in 2017 in anticipation of the new tariff, however these tariffs may impact the economics of future solar development projects in the U.S., including those of our solar businesses.
Maritza PPA Review — The DG Comp continues to review whether Maritza’s PPA with NEK is compliant with the European Commission’s state aid rules. Although no formal investigation has been launched by DG Comp to date, Maritza has engaged in discussions with the DG Comp case team and representatives of Bulgaria to discuss the agency’s review. In the near term, Maritza expects that it will engage in discussions with Bulgaria to attempt to reach a negotiated resolution concerning DG Comp’s review. The anticipated discussions could involve a range of potential outcomes, including but not limited to termination of the PPA and payment of some level of compensation to Maritza. Any negotiated resolution would be subject to mutually acceptable terms, lender consent, and DG Comp approval. At this time, we cannot predict the outcome of the anticipated discussions between Maritza and Bulgaria, nor can we predict how DG Comp might resolve its review if the discussions fail to result in an agreement concerning the review. Maritza believes that its PPA is legal and in compliance with all applicable laws, and it will take all actions necessary to protect its interests, whether through negotiated agreement or otherwise. However, there can be no assurances that this matter will be resolved favorably; if it is not, there could be a material adverse impact on Maritza’s and the Company’s respective financial statements.
Alto Maipo
Alto Maipo has experienced construction difficulties which have resulted in increased projected costs over the original $2 billion budget. These overages led to a series of negotiations with the intention of restructuring the project’s existing financial structure and obtaining additional funding. On March 17, 2017, AES Gener completed a legal and financial restructuring of Alto Maipo. As a part of this restructuring, AES Gener simultaneously acquired a 40% ownership interest from Minera Los Pelambres (“MLP”), a noncontrolling shareholder, for nominal consideration, and sold a 6.7% ownership interest to Strabag, one of the construction contractors. Through its 67% ownership interest in AES Gener, the Company now has an effective 62% indirect economic interest in Alto Maipo. Additionally, certain construction milestones were amended and if Alto Maipo is unable to meet these milestones, there could be a material impact to the financing and value of the project. For additional information on risks regarding construction and development, refer to Item 1A.—Risk Factors—Our Business is Subject to Substantial Development Uncertainties of this Form 10-K.
Following the restructuring, the project continued to face construction difficulties, including greater than expected costs and slower than anticipated productivity by construction contractors towards agreed-upon
milestones. As a result of the failure to perform by one of its construction contractors, Constructora Nuevo Maipo S.A. (“CNM”), Alto Maipo terminated CNM’s contract during the second quarter of 2017. As a result of the termination of CNM, Alto Maipo’s construction debt of $618 million and derivative liabilities of $132 million are in technical default and presented as current on the balance sheet as of December 31, 2017.
Alto Maipo is currently a party to arbitration concerning the termination of CNM and other related matters. These include Alto Maipo’s draws on letters of credit securing CNM’s performance under the parties’ construction contract totaling $73 million (the “LC Funds”). The LC Funds were collected by Alto Maipo and are available to be utilized for on-going construction costs. In February 2018, CNM was denied their request for interim relief to recover the LC Funds. However, the overall arbitration concerning the termination of CNM, including a final ruling on CNM’s claim to recover the LC Funds, is still pending. Alto Maipo cannot predict the ultimate outcome of the arbitration or any related proceedings. For more information on the legal proceedings concerning CNM, see Item 3.—Legal Proceedings of this Form 10-K.
Construction at the project is continuing, and the project is over 61% complete. In February 2018, Alto Maipo signed an amended EPC contract with Strabag, the permanent replacement contractor selected to complete CNM’s work, subject to approval by the project's senior lenders as part of the second refinancing. Alto Maipo is working to resolve the challenges described above, however, there can be no assurance that Alto Maipo will succeed in these efforts and if there are further delays or cost overruns, or if Alto Maipo is unable to reach an agreement with the non-recourse lenders, there is a risk these lenders may seek to exercise remedies available as a result of the default noted above, or Alto Maipo may not be able to meet its contractual or other obligations and may be unable to continue with the project. If any of the above occur, there could be a material impairment for the Company.
The carrying value of long-lived assets and deferred tax assets of Alto Maipo as of December 31, 2017 was approximately $1.4 billion and $60 million, respectively. Through its 67% ownership interest in AES Gener, the Parent Company has invested approximately $375 million in Alto Maipo and has an additional equity funding commitment of $39 million required as part of the March 2017 restructuring described above. AES Gener may provide material additional funding commitments as part of ongoing negotiations and future project restructurings. Even though certain construction difficulties have not been formally resolved, construction costs continue to be capitalized as management believes the project is probable of completion. Management believes the carrying value of the long-lived asset group is recoverable and was not impaired as of December 31, 2017. In addition, management believes it is more likely than not the deferred tax assets will be realized; however, they could be reduced if estimates of future taxable income are decreased.
Changuinola Tunnel Leak
Increased water levels were noted in a creek near the Changuinola power plant, a 223 MW hydroelectric power facility in Panama. After the completion of an assessment, the Company has confirmed loss of water in specific sections of the tunnel. The plant is in operation and can generate up to its maximum capacity. Repairs will be needed to ensure the long term performance of the facility, during which time the affected units of the plant will be out of service. Subject to final inspection, the repairs may take up to 10 months to complete and are expected to commence during the first quarter of 2019. The Company has notified its insurers of a potential claim and has asserted claims against its construction contractor. However, there can be no assurance of collection. The Company continues to monitor the situation to identify any potential changes to the tunnel. The Company has not identified any indicators of impairment and believes the carrying value of the long-lived asset group is recoverable as of December 31, 2017.
Impairments
Long-lived Assets — During the year ended December 31, 2017, the Company recognized asset impairment expense of $186 million at the Kazakhstan CHP and Hydroelectric plants, $175 million at DPL, $121 million at Laurel Mountain, $37 million at Kilroot, and $18 million at other businesses in the PJM market. See Note 19—Asset Impairment Expense included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information. After recognizing these asset impairment expenses, the carrying value of the long-lived asset groups, including those that were assessed and not impaired, excluding Alto Maipo, totaled $1 billion at December 31, 2017.
Events or changes in circumstances that may necessitate further recoverability tests and potential impairment of long-lived assets may include, but are not limited to, adverse changes in the regulatory environment, unfavorable changes in power prices or fuel costs, increased competition due to additional capacity in the grid, technological advancements, declining trends in demand, or an expectation that it is more likely than not that the asset will be disposed of before the end of its previously estimated useful life.
Goodwill — The Company currently has no reporting units considered to be "at risk." A reporting unit is considered "at risk" when its fair value is not higher than its carrying amount by 10%. The Company monitors its reporting units at risk of Step 1 failure on an ongoing basis. It is possible that the Company may incur goodwill impairment charges at any reporting units containing goodwill in future periods if adverse changes in their business or operating environments occur. See Note 8—Goodwill and Other Intangible Assets included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Functional Currency
Argentina — In February 2017, the Argentina Ministry of Energy issued Resolution 19/2017, which established changes to the energy price framework. As a result of this resolution, tariffs are now priced in USD rather than Argentine pesos, and the retention of unpaid amounts and accumulation of receivables with CAMMESA was eliminated. Concurrent with the establishment of the new price framework, AES Argentina issued $300 million of bonds denominated in USD. Given these significant changes in economic facts and circumstances, the Company changed the functional currency of the Argentina businesses from the Argentine peso to the USD effective February 2017. Changes to the energy framework could have a material impact on the Company.
Chivor — In May 2017, the Company repaid its outstanding USD denominated debt held at Chivor. In addition, the Company updated Chivor’s future financing strategy to align with Colombian peso denominated operational cash flows of the business. Given these changes, the Colombian peso is now regarded as the currency of the economic environment in which Chivor primarily operates. Therefore, the Company changed the functional currency of the Chivor business from USD to the Colombian peso effective May 2017.
Capital Resources and Liquidity
Overview — As of December 31, 2017, the Company had unrestricted cash and cash equivalents of $949 million, of which $11 million was held at the Parent Company and qualified holding companies. The Company also had $424 million in short term investments, held primarily at subsidiaries. In addition, we had restricted cash and debt service reserves of $839 million. The Company also had non-recourse and recourse aggregate principal amounts of debt outstanding of $15.3 billion and $4.6 billion, respectively. Of the approximately $2.2 billion of our current non-recourse debt, $1.1 billion was presented as such because it is due in the next twelve months and $1 billion relates to debt considered in default due to covenant violations. Defaults at AES Puerto Rico are covenant and payment defaults, for which Forbearance and Standstill Agreements have been signed. All other defaults are not payment defaults, but are instead technical defaults triggered by failure to comply with other covenants and/or other conditions such as (but not limited to) failure to meet information covenants, complete construction or other milestones in an allocated time, meet certain minimum or maximum financial ratios, or other requirements contained in the non-recourse debt documents of the Company.
We expect such current maturities will be repaid from net cash provided by operating activities of the subsidiary to which the debt relates or through opportunistic refinancing activity or some combination thereof. We have $5 million of recourse debt which matures within the next twelve months. From time to time, we may elect to repurchase our outstanding debt through cash purchases, privately negotiated transactions or otherwise when management believes that such securities are attractively priced. Such repurchases, if any, will depend on prevailing market conditions, our liquidity requirements and other factors. The amounts involved in any such repurchases may be material.
We rely mainly on long-term debt obligations to fund our construction activities. We have, to the extent available at acceptable terms, utilized non-recourse debt to fund a significant portion of the capital expenditures and investments required to construct and acquire our electric power plants, distribution companies and related assets. Our non-recourse financing is designed to limit cross default risk to the Parent Company or other subsidiaries and affiliates. Our non-recourse long-term debt is a combination of fixed and variable interest rate instruments. Generally, a portion or all of the variable rate debt is fixed through the use of interest rate swaps. In addition, the debt is typically denominated in the currency that matches the currency of the revenue expected to be generated from the benefiting project, thereby reducing currency risk. In certain cases, the currency is matched through the use of derivative instruments. The majority of our non-recourse debt is funded by international commercial banks, with debt capacity supplemented by multilaterals and local regional banks.
Given our long-term debt obligations, the Company is subject to interest rate risk on debt balances that accrue interest at variable rates. When possible, the Company will borrow funds at fixed interest rates or hedge its variable rate debt to fix its interest costs on such obligations. In addition, the Company has historically tried to maintain at least 70% of its consolidated long-term obligations at fixed interest rates, including fixing the interest rate through the use of interest rate swaps. These efforts apply to the notional amount of the swaps compared to the amount of
related underlying debt. Presently, the Parent Company's only material unhedged exposure to variable interest rate debt relates to indebtedness under its $521 million outstanding secured term loan due 2022 and drawings of $207 million under its secured credit facility. On a consolidated basis, of the Company's $20 billion of total debt outstanding as of December 31, 2017, approximately $3.2 billion bore interest at variable rates that were not subject to a derivative instrument which fixed the interest rate. Brazil holds $1 billion of our floating rate non-recourse exposure as we have no ability to fix local debt interest rates efficiently.
In addition to utilizing non-recourse debt at a subsidiary level when available, the Parent Company provides a portion, or in certain instances all, of the remaining long-term financing or credit required to fund development, construction or acquisition of a particular project. These investments have generally taken the form of equity investments or intercompany loans, which are subordinated to the project's non-recourse loans. We generally obtain the funds for these investments from our cash flows from operations, proceeds from the sales of assets and/or the proceeds from our issuances of debt, common stock and other securities. Similarly, in certain of our businesses, the Parent Company may provide financial guarantees or other credit support for the benefit of counterparties who have entered into contracts for the purchase or sale of electricity, equipment or other services with our subsidiaries or lenders. In such circumstances, if a business defaults on its payment or supply obligation, the Parent Company will be responsible for the business' obligations up to the amount provided for in the relevant guarantee or other credit support. At December 31, 2017, the Parent Company had provided outstanding financial and performance-related guarantees or other credit support commitments to or for the benefit of our businesses, which were limited by the terms of the agreements, of approximately $842 million in aggregate (excluding those collateralized by letters of credit and other obligations discussed below).
As a result of the Parent Company's below investment grade rating, counterparties may be unwilling to accept our general unsecured commitments to provide credit support. Accordingly, with respect to both new and existing commitments, the Parent Company may be required to provide some other form of assurance, such as a letter of credit, to backstop or replace our credit support. The Parent Company may not be able to provide adequate assurances to such counterparties. To the extent we are required and able to provide letters of credit or other collateral to such counterparties, this will reduce the amount of credit available to us to meet our other liquidity needs. At December 31, 2017, we had $36 million in letters of credit outstanding, provided under our senior secured credit facility, $52 million in letters of credit outstanding, provided under our unsecured senior credit facility. These letters of credit operate to guarantee performance relating to certain project development activities and business operations. During the year ended December 31, 2017, the Company paid letter of credit fees ranging from 0.25% to 2.25% per annum on the outstanding amounts.
We expect to continue to seek, where possible, non-recourse debt financing in connection with the assets or businesses that we or our affiliates may develop, construct or acquire. However, depending on local and global market conditions and the unique characteristics of individual businesses, non-recourse debt may not be available on economically attractive terms or at all. If we decide not to provide any additional funding or credit support to a subsidiary project that is under construction or has near-term debt payment obligations and that subsidiary is unable to obtain additional non-recourse debt, such subsidiary may become insolvent, and we may lose our investment in that subsidiary. Additionally, if any of our subsidiaries lose a significant customer, the subsidiary may need to withdraw from a project or restructure the non-recourse debt financing. If we or the subsidiary choose not to proceed with a project or are unable to successfully complete a restructuring of the non-recourse debt, we may lose our investment in that subsidiary.
Many of our subsidiaries depend on timely and continued access to capital markets to manage their liquidity needs. The inability to raise capital on favorable terms, to refinance existing indebtedness or to fund operations and other commitments during times of political or economic uncertainty may have material adverse effects on the financial condition and results of operations of those subsidiaries. In addition, changes in the timing of tariff increases or delays in the regulatory determinations under the relevant concessions could affect the cash flows and results of operations of our businesses.
Long-Term Receivables — As of December 31, 2017, the Company had approximately $194 million of accounts receivable classified as Noncurrent assets—other primarily related to certain of its generation businesses in Argentina. The noncurrent receivables mostly consist of accounts receivable in Argentina that, pursuant to amended agreements or government resolutions, have collection periods that extend beyond December 31, 2018, or one year from the latest balance sheet date. The majority of Argentinian receivables have been converted into long-term financing for the construction of power plants. See Note 6—Financing Receivables included in Item 8.—Financial Statements and Supplementary Data and Item 1.—Business—Regulatory Matters—Argentina of this Form 10-K for further information.
Consolidated Cash Flows
The following table reflects the changes in operating, investing, and financing cash flows for the comparative twelve month periods (in millions):
| December 31, | $ Change | |||||||||||||||||||
| Cash flows provided by (used in): | 2017 | 2016 | 2015 | 2017 vs. 2016 | 2016 vs. 2015 | |||||||||||||||
| Operating activities | $ | 2,489 | $ | 2,884 | $ | 2,134 | $ | (395 | ) | $ | 750 | |||||||||
| Investing activities | (2,749 | ) | (2,108 | ) | (2,366 | ) | (641 | ) | 258 | |||||||||||
| Financing activities | 43 | (747 | ) | 28 | 790 | (775 | ) |
Operating Activities
The following table summarizes the key components of our consolidated operating cash flows (in millions):
| December 31, | $ Change | |||||||||||||||||||
| 2017 | 2016 | 2015 | 2017 vs. 2016 | 2016 vs. 2015 | ||||||||||||||||
| Net income (loss) | $ | (777 | ) | $ | (777 | ) | $ | 762 | $ | — | $ | (1,539 | ) | |||||||
| Depreciation and amortization | 1,169 | 1,176 | 1,144 | (7 | ) | 32 | ||||||||||||||
| Impairment expenses | 537 | 1,098 | 602 | (561 | ) | 496 | ||||||||||||||
| Loss on the extinguishment of debt | 68 | 20 | 186 | 48 | (166 | ) | ||||||||||||||
| Deferred income taxes | 672 | (793 | ) | (50 | ) | 1,465 | (743 | ) | ||||||||||||
| Net loss from disposal and impairments of discontinued businesses | 611 | 1,383 | — | (772 | ) | 1,383 | ||||||||||||||
| Other adjustments to net income | 275 | 225 | (73 | ) | 50 | 298 | ||||||||||||||
| Non-cash adjustments to net income (loss) | 3,332 | 3,109 | 1,809 | 223 | 1,300 | |||||||||||||||
| Net income, adjusted for non-cash items | $ | 2,555 | $ | 2,332 | $ | 2,571 | $ | 223 | $ | (239 | ) | |||||||||
| Net change in operating assets and liabilities (1) | (66 | ) | 552 | (437 | ) | (618 | ) | 989 | ||||||||||||
| Net cash provided by operating activities (2) | $ | 2,489 | $ | 2,884 | $ | 2,134 | $ | (395 | ) | $ | 750 |
| (1) | Refer to the table below for explanations of the variance in operating assets and liabilities. |
| (2) | Amounts included in the table above include the results of discontinued operations, where applicable. |
Fiscal Year 2017 versus 2016
Net change in operating assets and liabilities decreased by $618 million for the year ended December 31, 2017 compared to the year ended December 31, 2016, which was primarily driven by (in millions):
| Increases in: | |||
| Accounts receivable, primarily at Maritza and Eletropaulo | $ | (414 | ) |
| Prepaid expenses and other current assets, primarily short-term regulatory assets at Eletropaulo and Sul | (763 | ) | |
| Accounts payable and other current liabilities, primarily at Eletropaulo, Tietê, Gener and Maritza, partially offset by Corporate | 783 | ||
| Income taxes payable, net, and other taxes payable, primarily at Gener, Tietê and Eletropaulo | 252 | ||
| Decreases in: | |||
| Other liabilities, primarily due to higher deferrals into regulatory liabilities related to energy costs in 2016 compared to 2017 at Eletropaulo | (362 | ) | |
| Other | (114 | ) | |
| Total decrease in cash from changes in operating assets and liabilities | $ | (618 | ) |
Fiscal Year 2016 versus 2015
Net change in operating assets and liabilities increased by $989 million for the year ended December 31, 2016 compared to the year ended December 31, 2015, which was primarily driven by (in millions):
| Decreases in: | |||
| Other assets, primarily long-term regulatory assets at Eletropaulo and service concession assets at Vietnam | $ | 1,054 | |
| Accounts receivable, primarily at Maritza and Eletropaulo | 615 | ||
| Prepaid expenses and other current assets, primarily regulatory assets at Eletropaulo and Sul | 215 | ||
| Accounts payable and other current liabilities, primarily at Eletropaulo and Sul | (651 | ) | |
| Income taxes payable, net and other taxes payable, primarily at Tietê, Chivor and Gener | (252 | ) | |
| Increases in: | |||
| Other | 8 | ||
| Total increase in cash from changes in operating assets and liabilities | $ | 989 |
Investing Activities
Fiscal Year 2017 versus 2016
Net cash used in investing activities increased $641 million for the year ended December 31, 2017 compared to December 31, 2016, which was primarily driven by (in millions):
| Increases in: | |||
| Acquisitions of businesses, net of cash acquired, and equity method investees (related to the acquisitions of sPower and Alto Sertão II in 2017, partially offset by the lower acquisition of Distributed Energy projects in 2016) | $ | (570 | ) |
| Contributions to equity investments at OPGC and sPower | (83 | ) | |
| Restricted cash, debt service and other assets | (74 | ) | |
| Decreases in: | |||
| Proceeds from the sale of business, net of cash sold, related to the sale of Sul in 2016, partially offset by the sale of Zimmer and Miami Fort | (523 | ) | |
| Short-term investments | 477 | ||
| Capital expenditures (1) | 168 | ||
| Other investing activities | (36 | ) | |
| Total increase in net cash used in investing activities | $ | (641 | ) |
| (1) | Refer to the tables below for a breakout of capital expenditure by type and by primary business driver. |
The following table summarizes the Company's capital expenditures for growth investments, maintenance and environmental reported in investing cash activities for the periods indicated (in millions):
| December 31, | $ Change | |||||||||||
| 2017 | 2016 | 2017 vs. 2016 | ||||||||||
| Growth Investments | $ | (1,549 | ) | $ | (1,510 | ) | $ | (39 | ) | |||
| Maintenance | (552 | ) | (617 | ) | 65 | |||||||
| Environmental (1) | (76 | ) | (218 | ) | 142 | |||||||
| Total capital expenditures | $ | (2,177 | ) | $ | (2,345 | ) | $ | 168 |
| (1) | Includes both recoverable and non-recoverable environmental capital expenditures. See SBU Performance Analysis for more information. |
Cash used for capital expenditures decreased by $168 million for the year ended December 31, 2017 compared to December 31, 2016, which was primarily driven by (in millions):
| Decreases in: | |||
| Growth expenditures at the Andes SBU, primarily due to the completion of the Cochrane project and slower than anticipated productivity by construction contractors at Alto Maipo | $ | 114 | |
| Growth expenditure at the Eurasia SBU, primarily due to timing of payments resulting in more financed capex | 73 | ||
| Maintenance and environmental expenditures at the US SBU, primarily due to lower spending at IPALCO on the NPDES and MATS compliance and Harding Street refueling projects, decreased spending on CCR compliance and also, decreased spending at DPL on Stuart and Killen facilities due to planned plant closures | 180 | ||
| Increases in: | |||
| Growth expenditures at the US SBU, primarily due to increased spending at Southland re-powering and various Distributed Energy projects, offset by lower spending related to Eagle Valley at IPALCO | (233 | ) | |
| Other capital expenditures | 34 | ||
| Total decrease in net cash used for capital expenditures | $ | 168 |
Fiscal Year 2016 versus 2015
Net cash used in investing activities decreased $258 million for the year ended December 31, 2016 compared to December 31, 2015, which was primarily driven by (in millions):
| Increases in: | |||
| Capital expenditures (1) | $ | (37 | ) |
| Acquisitions, net of cash acquired (primarily Distributed Energy) | (38 | ) | |
| Proceeds from the sales of businesses, net of cash sold (primarily related to sales of DPLER and Sul) | 493 | ||
| Net purchases of short-term investments | (297 | ) | |
| Decreases in: | |||
| Restricted cash, debt service and other assets | 98 | ||
| Other investing activities | 39 | ||
| Total decrease in net cash used in investing activities | $ | 258 |
| (1) | Refer to the tables below for a breakout of capital expenditures by type and by primary business driver. |
The following table summarizes the Company's capital expenditures for growth investments, maintenance and environmental for the periods indicated (in millions):
| December 31, | $ Change | |||||||||||
| 2016 | 2015 | 2016 vs. 2015 | ||||||||||
| Growth Investments | $ | (1,510 | ) | $ | (1,401 | ) | $ | (109 | ) | |||
| Maintenance | (617 | ) | (606 | ) | (11 | ) | ||||||
| Environmental (1) | (218 | ) | (301 | ) | 83 | |||||||
| Total capital expenditures | $ | (2,345 | ) | $ | (2,308 | ) | $ | (37 | ) |
| (1) | Includes both recoverable and non-recoverable environmental capital expenditures. |
Cash used for capital expenditures increased by $37 million for the year ended December 31, 2016 compared to December 31, 2015, which was primarily driven by (in millions):
| Increases in: | |||
| Growth expenditures at the Eurasia SBU for the construction of the Masinloc expansion and retrofit related costs to the existing plant to increasing capacity | $ | (124 | ) |
| Growth expenditures at the MCAC SBU for the construction of Colon and Los Mina | (266 | ) | |
| Decreases In: | |||
| Growth expenditures at the Andes SBU, primarily due to lower spending at Cochrane and the Andes Solar plant; partially offset by higher investments in Alto Maipo | 280 | ||
| Growth expenditures at the US SBU, primarily due to lower spending related to Eagle Valley and Transmission & Distribution projects at IPALCO | 20 | ||
| Maintenance and environmental expenditures at the US SBU, primarily due to lower spending related to MATS compliance and the conversion of Harding Street Stations 5, 6 and 7 to natural gas upon being placed into service in late 2015 and early 2016; partially offset by higher spending on CCR compliance | 63 | ||
| Other capital expenditures | (10 | ) | |
| Total increase in net cash used for capital expenditures | $ | (37 | ) |
Financing Activities
Net cash used in financing activities decreased $790 million for the year ended December 31, 2017 compared to December 31, 2016, which was primarily driven by (in millions):
| Decreases in: | |||
| Proceeds from the sale of redeemable stock of subsidiaries at IPALCO | $ | (134 | ) |
| Contributions from noncontrolling interests and redeemable security holders at MCAC and US SBUs | (117 | ) | |
| Repayment of non-recourse debt, primarily at the Brazil, US, Eurasia and MCAC SBUs (1) | 550 | ||
| Increases in: | |||
| Borrowings under the revolving credit facilities, primarily at the Parent Company and net decrease in repayments at the US SBU | 382 | ||
| Proceeds from sale of noncontrolling interests primarily related to the sell down of Dominican Republic business in 2017 | 94 | ||
| Other financing activities | 15 | ||
| Total decrease in net cash used in financing activities | $ | 790 |
| (1) | See Note 10—Debt in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for more information regarding significant recourse debt transactions. |
Net cash provided by financing activities increased $775 million for the year ended December 31, 2016 compared to the year ended December 31, 2015, which was primarily driven by (in millions):
| Increases in: | |||
| Distributions to noncontrolling interests, primarily at the Brazil SBU | $ | (150 | ) |
| Contributions from noncontrolling interests, primarily at the MCAC SBU | 64 | ||
| Decreases in: | |||
| Net issuance of non-recourse debt, primarily at the Andes and Brazil SBUs | (624 | ) | |
| Proceeds from the sale of redeemable stock of subsidiaries at IPALCO | (327 | ) | |
| Proceeds from sales to noncontrolling interests, net of transaction costs | (154 | ) | |
| Purchases of treasury stock by the Parent Company | 403 | ||
| Net repayments of recourse debt at the Parent Company (1) | 32 | ||
| Other financing activities | (19 | ) | |
| Total increase in net cash provided by financing activities | $ | (775 | ) |
| (1) | See Note 10—Debt in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for more information regarding significant recourse debt transactions. |
Parent Company Liquidity
The following discussion of Parent Company Liquidity is included as a useful measure of the liquidity available to The AES Corporation, or the Parent Company, given the non-recourse nature of most of our indebtedness. Parent Company Liquidity as outlined below is a non-GAAP measure and should not be construed as an alternative
to cash and cash equivalents which is determined in accordance with GAAP as a measure of liquidity. Cash and cash equivalents is disclosed on the Consolidated Statements of Cash Flows. Parent Company Liquidity may differ from similarly titled measures used by other companies. The principal sources of liquidity at the Parent Company level are dividends and other distributions from our subsidiaries, including refinancing proceeds, proceeds from debt and equity financings at the Parent Company level, including availability under our credit facility, and proceeds from asset sales. Cash requirements at the Parent Company level are primarily to fund interest; principal repayments of debt; construction commitments; other equity commitments; common stock repurchases; acquisitions; taxes; Parent Company overhead and development costs; and dividends on common stock.
The Company defines Parent Company Liquidity as cash available to the Parent Company plus available borrowings under existing credit facility. The cash held at qualified holding companies represents cash sent to subsidiaries of the Company domiciled outside of the U.S. Such subsidiaries have no contractual restrictions on their ability to send cash to the Parent Company. Parent Company Liquidity is reconciled to its most directly comparable U.S. GAAP financial measure, Cash and cash equivalents, at December 31, 2017 and 2016 as follows:
| Parent Company Liquidity (in millions) | 2017 | 2016 | ||||||
| Consolidated cash and cash equivalents | $ | 949 | $ | 1,244 | ||||
| Less: Cash and cash equivalents at subsidiaries | 938 | 1,144 | ||||||
| Parent and qualified holding companies' cash and cash equivalents | 11 | 100 | ||||||
| Commitments under Parent Company credit facilities | 1,100 | 800 | ||||||
| Less: Letters of credit under the credit facilities | (35 | ) | (6 | ) | ||||
| Less: Borrowings under the credit facilities | (207 | ) | — | |||||
| Borrowings available under Parent Company credit facilities | 858 | 794 | ||||||
| Total Parent Company Liquidity | $ | 869 | $ | 894 |
The Parent Company paid dividends of $0.48 per share to its common stockholders during the year ended December 31, 2017. While we intend to continue payment of dividends and believe we will have sufficient liquidity to do so, we can provide no assurance that we will continue to pay dividends, or if continued, the amount of such dividends.
Recourse Debt
Our total recourse debt was $4.6 billion and $4.7 billion at December 31, 2017 and 2016, respectively. See Note 10—Debt in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for additional detail.
While we believe that our sources of liquidity will be adequate to meet our needs for the foreseeable future, this belief is based on a number of material assumptions, including, without limitation, assumptions about our ability to access the capital markets (see Key Trends and Uncertainties—Macroeconomic and Political), the operating and financial performance of our subsidiaries, currency exchange rates, power market pool prices, and the ability of our subsidiaries to pay dividends. In addition, our subsidiaries' ability to declare and pay cash dividends to us (at the Parent Company level) is subject to certain limitations contained in loans, governmental provisions and other agreements. We can provide no assurance that these sources will be available when needed or that the actual cash requirements will not be greater than anticipated. See Item 1A.—Risk Factors—The AES Corporation is a holding company and its ability to make payments on its outstanding indebtedness, including its public debt securities, is dependent upon the receipt of funds from its subsidiaries by way of dividends, fees, interest, loans or otherwise, of this Form 10-K.
Various debt instruments at the Parent Company level, including our senior secured credit facility, contain certain restrictive covenants. The covenants provide for — among other items — limitations on other indebtedness; liens, investments and guarantees; limitations on dividends, stock repurchases and other equity transactions; restrictions and limitations on mergers and acquisitions, sales of assets, leases, transactions with affiliates and off-balance sheet and derivative arrangements; maintenance of certain financial ratios; and financial and other reporting requirements. As of December 31, 2017, we were in compliance with these covenants at the Parent Company level.
Non-Recourse Debt
While the lenders under our non-recourse debt financings generally do not have direct recourse to the Parent Company, defaults thereunder can still have important consequences for our results of operations and liquidity, including, without limitation:
| • | reducing our cash flows as the subsidiary will typically be prohibited from distributing cash to the Parent Company during the time period of any default; |
| • | triggering our obligation to make payments under any financial guarantee, letter of credit or other credit support we have provided to or on behalf of such subsidiary; |
| • | causing us to record a loss in the event the lender forecloses on the assets; and |
| • | triggering defaults in our outstanding debt at the Parent Company. |
For example, our senior secured credit facility and outstanding debt securities at the Parent Company include events of default for certain bankruptcy related events involving material subsidiaries. In addition, our revolving credit agreement at the Parent Company includes events of default related to payment defaults and accelerations of outstanding debt of material subsidiaries.
Some of our subsidiaries are currently in default with respect to all or a portion of their outstanding indebtedness. The total non-recourse debt classified as current in the accompanying Consolidated Balance Sheets amounts to $2.2 billion. The portion of current debt related to such defaults was $1 billion at December 31, 2017, all of which was non-recourse debt related to three subsidiaries — Alto Maipo, AES Puerto Rico, and AES Ilumina. See Note 10—Debt in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for additional detail.
None of the subsidiaries that are currently in default are subsidiaries that met the applicable definition of materiality under AES' corporate debt agreements as of December 31, 2017 in order for such defaults to trigger an event of default or permit acceleration under AES' indebtedness. However, as a result of additional dispositions of assets, other significant reductions in asset carrying values or other matters in the future that may impact our financial position and results of operations or the financial position of the individual subsidiary, it is possible that one or more of these subsidiaries could fall within the definition of a "material subsidiary" and thereby upon an acceleration trigger an event of default and possible acceleration of the indebtedness under the Parent Company's outstanding debt securities. A material subsidiary is defined in the Company's senior secured revolving credit facility as any business that contributed 20% or more of the Parent Company's total cash distributions from businesses for the four most recently completed fiscal quarters. As of December 31, 2017, none of the defaults listed above individually or in the aggregate results in or is at risk of triggering a cross-default under the recourse debt of the Company.
Contractual Obligations and Parent Company Contingent Contractual Obligations
A summary of our contractual obligations, commitments and other liabilities as of December 31, 2017 is presented below and excludes any businesses classified as discontinued operations or held-for-sale (in millions):
| Contractual Obligations | Total | Less than 1 year | 1-3 years | 3-5 years | More than 5 years | Other | Footnote Reference(4) | |||||||||||||||||||
| Debt Obligations (1) | $ | 20,404 | $ | 2,250 | $ | 2,431 | $ | 5,003 | $ | 10,720 | $ | — | 10 | |||||||||||||
| Interest Payments on Long-Term Debt (2) | 9,103 | 1,172 | 2,166 | 1,719 | 4,046 | — | n/a | |||||||||||||||||||
| Capital Lease Obligations | 18 | 2 | 2 | 2 | 12 | — | 11 | |||||||||||||||||||
| Operating Lease Obligations | 935 | 58 | 116 | 117 | 644 | — | 11 | |||||||||||||||||||
| Electricity Obligations | 4,501 | 581 | 948 | 907 | 2,065 | — | 11 | |||||||||||||||||||
| Fuel Obligations | 5,859 | 1,759 | 1,642 | 992 | 1,466 | — | 11 | |||||||||||||||||||
| Other Purchase Obligations | 4,984 | 1,488 | 1,401 | 781 | 1,314 | — | 11 | |||||||||||||||||||
| Other Long-Term Liabilities Reflected on AES' Consolidated Balance Sheet under GAAP (3) | 701 | — | 284 | 118 | 277 | 22 | n/a | |||||||||||||||||||
| Total | $ | 46,505 | $ | 7,310 | $ | 8,990 | $ | 9,639 | $ | 20,544 | $ | 22 |
| (1) | Includes recourse and non-recourse debt presented on the Consolidated Balance Sheet. These amounts exclude capital lease obligations which are included in the capital lease category. |
| (2) | Interest payments are estimated based on final maturity dates of debt securities outstanding at December 31, 2017 and do not reflect anticipated future refinancing, early redemptions or new debt issuances. Variable rate interest obligations are estimated based on rates as of December 31, 2017. |
| (3) | These amounts do not include current liabilities on the Consolidated Balance Sheet except for the current portion of uncertain tax obligations. Noncurrent uncertain tax obligations are reflected in the "Other" column of the table above as the Company is not able to reasonably estimate the timing of the future payments. In addition, these amounts do not include: (1) regulatory liabilities (See Note 9—Regulatory Assets and Liabilities), (2) contingencies (See Note 12—Contingencies), (3) pension and other postretirement employee benefit liabilities (see Note 13—Benefit Plans), (4) derivatives and incentive compensation (See Note 5—Derivative Instruments and Hedging Activities) or (5) any taxes (See Note 20—Income Taxes) except for uncertain tax obligations, as the Company is not able to reasonably estimate the timing of future payments. See the indicated notes to the Consolidated Financial Statements included in Item 8 of this Form 10-K for additional information on the items excluded. |
| (4) | For further information see the note referenced below in Item 8.—Financial Statements and Supplementary Data of this Form 10-K. |
The following table presents our Parent Company's contingent contractual obligations as of December 31, 2017:
| Contingent contractual obligations | Amount (in millions) | Number of Agreements | Maximum Exposure Range for Each Agreement (in millions) | |||||
| Guarantees and commitments | $ | 815 | 21 | $1 — 272 | ||||
| Letters of credit under the unsecured credit facility | 52 | 4 | $2 — 26 | |||||
| Asset sale related indemnities (1) | 27 | 1 | 27 | |||||
| Letters of credit under the senior secured credit facility | 36 | 21 | <$1 — 13 | |||||
| Total | $ | 930 | 47 |
| (1) | Excludes normal and customary representations and warranties in agreements for the sale of assets (including ownership in associated legal entities) where the associated risk is considered to be nominal. |
We have a diverse portfolio of performance-related contingent contractual obligations. These obligations are designed to cover potential risks and only require payment if certain targets are not met or certain contingencies occur. The risks associated with these obligations include change of control, construction cost overruns, subsidiary default, political risk, tax indemnities, spot market power prices, sponsor support and liquidated damages under power sales agreements for projects in development, in operation and under construction. In addition, we have an asset sale program through which we may have customary indemnity obligations under certain assets sale agreements. While we do not expect that we will be required to fund any material amounts under these contingent contractual obligations beyond 2017, many of the events which would give rise to such obligations are beyond our control. We can provide no assurance that we will be able to fund our obligations under these contingent contractual obligations if we are required to make substantial payments thereunder.
Critical Accounting Policies and Estimates
The Consolidated Financial Statements of AES are prepared in conformity with U.S. GAAP, which requires the use of estimates, judgments and assumptions that affect the reported amounts of assets and liabilities at the date of the financial statements and the reported amounts of revenue and expenses during the periods presented. AES' significant accounting policies are described in Note 1—General and Summary of Significant Accounting Policies to the Consolidated Financial Statements included in Item 8 of this Form 10-K.
An accounting estimate is considered critical if the estimate requires management to make assumptions about matters that were highly uncertain at the time the estimate was made, different estimates reasonably could have been used, or the impact of the estimates and assumptions on financial condition or operating performance is material.
Management believes that the accounting estimates employed are appropriate and the resulting balances are reasonable; however, actual results could materially differ from the original estimates, requiring adjustments to these balances in future periods. Management has discussed these critical accounting policies with the Audit Committee, as appropriate. Listed below are the Company's most significant critical accounting estimates and assumptions used in the preparation of the Consolidated Financial Statements.
Income Taxes — We are subject to income taxes in both the U.S. and numerous foreign jurisdictions. Our worldwide income tax provision requires significant judgment and is based on calculations and assumptions that are subject to examination by the Internal Revenue Service and other taxing authorities. Certain of the Company's subsidiaries are under examination by relevant taxing authorities for various tax years. The Company regularly assesses the potential outcome of these examinations in each tax jurisdiction when determining the adequacy of the provision for income taxes. Accounting guidance for uncertainty in income taxes prescribes a more likely than not recognition threshold. Tax reserves have been established, which the Company believes to be adequate in relation to the potential for additional assessments. Once established, reserves are adjusted only when there is more information available or when an event occurs necessitating a change to the reserves. While the Company believes that the amounts of the tax estimates are reasonable, it is possible that the ultimate outcome of current or future examinations may be materially different than the reserve amounts.
Because we have a wide range of statutory tax rates in the multiple jurisdictions in which we operate, any changes in our geographical earnings mix could materially impact our effective tax rate. Furthermore, our tax position could be adversely impacted by changes in tax laws, tax treaties or tax regulations or the interpretation or enforcement thereof and such changes may be more likely or become more likely in view of recent economic trends in certain of the jurisdictions in which we operate. As an example, new tax laws were enacted in December 2017 in the U.S. which decreased the statutory income tax rate from 35% to 21%, required a one-time transition tax, and introduced numerous other changes. As further outlined in Key Trends and Uncertainties, the Company anticipates that the new GILTI provisions of U.S. tax reform could materially impact the effective tax rate in future periods.
Accordingly, in 2017 our net U.S. deferred tax liabilities were remeasured to the new rates. The potential future impacts of the changes in tax law may be material to continuing operations. See Note 20—Income Taxes to the Consolidated Financial Statements included in Item 8 of this Form 10-K for additional information.
The Company's provision for income taxes could be adversely impacted by changes to the U.S. taxation of earnings of our foreign subsidiaries. In accordance with SAB 118, the Company has made reasonable estimates of the impacts of U.S. tax reform on its 2017 financial results, subject to potential adjustments as we complete our analysis. Our expected effective tax rate could increase by amounts that may be material to the Company.
In addition, no taxes have been recorded on undistributed earnings for certain of our non-U.S. subsidiaries to the extent such earnings are considered to be indefinitely reinvested in the operations of those subsidiaries. Should the earnings be remitted as dividends, the Company may be subject to additional foreign withholding and state income taxes.
Deferred tax assets and liabilities are recognized for the future tax consequences attributable to differences between the financial statement carrying amounts of the existing assets and liabilities, and their respective income tax bases. The Company establishes a valuation allowance when it is more likely than not that all or a portion of a deferred tax asset will not be realized.
Sales of Noncontrolling Interests — The accounting for a sale of noncontrolling interest under the accounting standards depends on whether the sale is considered to be a sale of in-substance real estate, where the gain (loss) on sale would be recognized in earnings rather than within stockholders' equity. If management's estimation process determines that there is no significant value beyond the in-substance real estate, the gain (loss) on the sale of the noncontrolling interest is recognized in earnings. However, if it is determined that significant value likely exists beyond the in-substance real estate, the gain (loss) on the sale of the noncontrolling interest would be recognized within stockholders' equity.
In-substance real estate is composed of land plus improvements and integral equipment. The determination of whether property, plant and equipment is integral equipment is based on the significance of the costs to remove the equipment from its existing location (including the cost of repairing damage resulting from the removal), combined with the decrease in the fair value of the equipment as a result of those removal activities. When the combined total of removal costs and the decrease in fair value of the equipment exceeds 10% of the fair value of the equipment, the equipment is considered integral equipment. The accounting standards specifically identify power plants as an example of in-substance real estate. Where the consolidated entity in which noncontrolling interests have been sold contains in-substance real estate, management estimates the extent to which the total fair value of the assets of the entity is represented by the in-substance real estate and whether significant value exists beyond the in-substance real estate. This estimation considers all qualitative and quantitative factors relevant for each sale and, where appropriate, includes making quantitative estimates about the fair value of the entity and its identifiable assets and liabilities (including any favorable or unfavorable contracts) by analogy to the accounting standards on business combinations. As such, these estimates may require significant judgment and assumptions, similar to the critical accounting estimates discussed below for impairments and fair value.
Impairments — Our accounting policies on goodwill and long-lived assets are described in detail in Note 1—General and Summary of Significant Accounting Policies, included in Item 8 of this Form 10-K. The Company makes considerable judgments in its impairment evaluations of goodwill and long-lived assets, starting with determining if an impairment indicator exists. Events that may result in an impairment analysis being performed include, but are not limited to: adverse changes in the regulatory environment, unfavorable changes in power prices or fuel costs, increased competition due to additional capacity in the grid, technological advancements, declining trends in demand, or an expectation it is more likely than not that the asset will be disposed of before the end of its previously estimated useful life. The Company exercises judgment in determining if these events represent an impairment indicator requiring the computation of the fair value of goodwill and/or the recoverability of long-lived assets. The fair value determination is typically the most judgmental part in an impairment evaluation. Please see Fair Value below for further detail.
As part of the impairment evaluation process, management analyzes the sensitivity of fair value to various underlying assumptions. The level of scrutiny increases as the gap between fair value and carrying amount decreases. Changes in any of these assumptions could result in management reaching a different conclusion regarding the potential impairment, which could be material. Our impairment evaluations inherently involve uncertainties from uncontrollable events that could positively or negatively impact the anticipated future economic and operating conditions.
Further discussion of the impairment charges recognized by the Company can be found within Note 8—Goodwill and Other Intangible Assets and Note 19—Asset Impairment Expense to the Consolidated Financial
Statements included in Item 8 of this Form 10-K.
Fair Value
Fair Value — For information regarding the fair value hierarchy, see Note 1—General and Summary of Significant Accounting Policies included in Item 8 of this Form 10-K.
Fair Value of Financial Instruments — A significant number of the Company's financial instruments are carried at fair value with changes in fair value recognized in earnings or other comprehensive income each period. Investments are generally fair valued based on quoted market prices or other observable market data such as interest rate indices. The Company's investments are primarily certificates of deposit, government debt securities and money market funds. Derivatives are valued using observable data as inputs into internal valuation models. The Company's derivatives primarily consist of interest rate swaps, foreign currency instruments, and commodity and embedded derivatives. Additional discussion regarding the nature of these financial instruments and valuation techniques can be found in Note 4—Fair Value included in Item 8 of this Form 10-K.
Fair Value of Nonfinancial Assets and Liabilities — Significant estimates are made in determining the fair value of long-lived tangible and intangible assets (i.e., property, plant and equipment, intangible assets and goodwill) during the impairment evaluation process. In addition, the majority of assets acquired and liabilities assumed in a business combination are required to be recognized at fair value under the relevant accounting guidance.
The Company may engage an independent valuation firm to assist management with the valuation. The Company generally utilizes the income approach to value nonfinancial assets and liabilities, specifically a Discounted Cash Flow ("DCF") model to estimate fair value by discounting our internal budgets and cash flow forecasts, adjusted to reflect market participant assumptions, to the extent necessary, at an appropriate discount rate.
Management applies considerable judgment in selecting several input assumptions during the development of our internal budgets and cash flow forecasts. Examples of the input assumptions that our budgets and forecasts are sensitive to include macroeconomic factors such as growth rates, industry demand, inflation, exchange rates, power prices and commodity prices. Whenever appropriate, management obtains these input assumptions from observable market data sources (e.g., Economic Intelligence Unit) and extrapolates the market information if an input assumption is not observable for the entire forecast period. Many of these input assumptions are dependent on other economic assumptions, which are often derived from statistical economic models with inherent limitations such as estimation differences. Further, several input assumptions are based on historical trends which often do not recur. It is not uncommon that different market data sources have different views of the macroeconomic factor expectations and related assumptions. As a result, macroeconomic factors and related assumptions are often available in a narrow range; however, in some situations these ranges become wide and the use of a different set of input assumptions could produce significantly different budgets and cash flow forecasts.
A considerable amount of judgment is also applied in the estimation of the discount rate used in the DCF model. To the extent practical, inputs to the discount rate are obtained from market data sources (e.g., Bloomberg). The Company selects and uses a set of publicly traded companies from the relevant industry to estimate the discount rate inputs. Management applies judgment in the selection of such companies based on its view of the most likely market participants. It is reasonably possible that the selection of a different set of likely market participants could produce different input assumptions and result in the use of a different discount rate.
Accounting for Derivative Instruments and Hedging Activities — We enter into various derivative transactions in order to hedge our exposure to certain market risks. We primarily use derivative instruments to manage our interest rate, commodity and foreign currency exposures. We do not enter into derivative transactions for trading purposes. See Note 5—Derivative Instruments and Hedging Activities included in Item 8 of this Form 10-K for further information on the classification.
The fair value measurement standard requires the Company to consider and reflect the assumptions of market participants in the fair value calculation. These factors include nonperformance risk (the risk that the obligation will not be fulfilled) and credit risk, both of the reporting entity (for liabilities) and of the counterparty (for assets). Due to the nature of the Company's interest rate swaps, which are typically associated with non-recourse debt, credit risk for AES is evaluated at the subsidiary level rather than at the Parent Company level. Nonperformance risk on the Company's derivative instruments is an adjustment to the initial asset/liability fair value position that is derived from internally developed valuation models that utilize observable market inputs.
As a result of uncertainty, complexity and judgment, accounting estimates related to derivative accounting could result in material changes to our financial statements under different conditions or utilizing different
assumptions. As a part of accounting for these derivatives, we make estimates concerning nonperformance, volatilities, market liquidity, future commodity prices, interest rates, credit ratings (both ours and our counterparty's), and future exchange rates. Refer to Note 4—Fair Value included in Item 8 of this Form 10-K for additional details.
The fair value of our derivative portfolio is generally determined using internal and third party valuation models, most of which are based on observable market inputs, including interest rate curves and forward and spot prices for currencies and commodities. The Company derives most of its financial instrument market assumptions from market efficient data sources (e.g., Bloomberg, Reuters and Platt's). In some cases, where market data is not readily available, management uses comparable market sources and empirical evidence to derive market assumptions to determine a financial instrument's fair value. In certain instances, the published curve may not extend through the remaining term of the contract and management must make assumptions to extrapolate the curve. Specifically, where there is limited forward curve data with respect to foreign exchange contracts, beyond the traded points the Company utilizes the interest rate differential approach to construct the remaining portion of the forward curve. Additionally, in the absence of quoted prices, we may rely on "indicative pricing" quotes from financial institutions to input into our valuation model for certain of our foreign currency swaps. These indicative pricing quotes do not constitute either a bid or ask price and therefore are not considered observable market data. For individual contracts, the use of different valuation models or assumptions could have a material effect on the calculated fair value.
Regulatory Assets — Management continually assesses whether the regulatory assets are probable of future recovery by considering factors such as applicable regulatory changes, recent rate orders applicable to other regulated entities and the status of any pending or potential deregulation legislation. If future recovery of costs ceases to be probable, any asset write-offs would be required to be recognized in operating income.
Consolidation — The Company enters into transactions impacting the Company's equity interests in its affiliates. In connection with each transaction, the Company must determine whether the transaction impacts the Company's consolidation conclusion by first determining whether the transaction should be evaluated under the variable interest model or the voting model. In determining which consolidation model applies to the transaction, the Company is required to make judgments about how the entity operates, the most significant of which are whether (i) the entity has sufficient equity to finance its activities, (ii) the equity holders, as a group, have the characteristics of a controlling financial interest, and (iii) whether the entity has non-substantive voting rights.
If the entity is determined to be a variable interest entity, the most significant judgment in determining whether the Company must consolidate the entity is whether the Company, including its related parties and de facto agents, collectively have power and benefits. If AES is determined to have power and benefits, the entity will be consolidated by AES.
Alternatively, if the entity is determined to be a voting model entity, the most significant judgments involve determining whether the non-AES shareholders have substantive participating rights. The assessment of shareholder rights and whether they are substantive participating rights requires significant judgment since the rights provided under shareholders' agreements may include selecting, terminating, and setting the compensation of management responsible for implementing the subsidiary's policies and procedures, establishing operating and capital decisions of the entity, including budgets, in the ordinary course of business. On the other hand, if shareholder rights are only protective in nature (referred to as protective rights) then such rights would not overcome the presumption that the owner of a majority voting interest shall consolidate its investee. Significant judgment is required to determine whether minority rights represent substantive participating rights or protective rights that do not affect the evaluation of control. While both represent an approval or veto right, a distinguishing factor is the underlying activity or action to which the right relates.
Pension and Other Postretirement Plans — The Company recognizes a net asset or liability reflecting the funded status of pension and other postretirement plans with current-year changes in actuarial gains or losses recognized in AOCL, except for those plans at certain of the Company's regulated utilities that can recover portions of their pension and postretirement obligations through future rates. The valuation of the Company's benefit obligation, fair value of plan assets, and net periodic benefit costs requires various estimates and assumptions, the most significant of which include the discount rate and expected return on plan assets. These assumptions are reviewed by the Company on an annual basis. Refer to Note 1—General and Summary of Significant Accounting Policies included in Item 8 of this Form 10-K for further information.
New Accounting Pronouncements — See Note 1—General and Summary of Significant Accounting Policies included in Item 8 of this Form 10-K for further information about new accounting pronouncements adopted during 2017 and accounting pronouncements issued but not yet effective.
Previous: Item 6. SELECTED FINANCIAL DATA · Next: Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK