 filings.tools
Cover and table of contents
55K characters. Original on sec.gov · Markdown
Cover and table of contents
10-K 1 allcorp-12311810xk.htm 10-K
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
| ý | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the fiscal year ended December 31, 2018
OR
| o | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the transition period from to
Commission file number 1-11840
THE ALLSTATE CORPORATION
(Exact name of registrant as specified in its charter)
| Delaware | 36-3871531 | |
| (State or Other Jurisdiction of Incorporation or Organization) | (I.R.S. Employer Identification No.) |
2775 Sanders Road, Northbrook, Illinois 60062
(Address of principal executive offices) (Zip Code)
Registrant’s telephone number, including area code: (847) 402-5000
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Name of each exchange on which registered |
| Common Stock, par value $0.01 per share | New York Stock Exchange Chicago Stock Exchange |
| 5.10% Fixed-to-Floating Rate Subordinated Debentures due 2053 | New York Stock Exchange |
| Depositary Shares each representing a 1/1,000th interest in a share of Fixed Rate Noncumulative Perpetual Preferred Stock, Series A | New York Stock Exchange |
| Depositary Shares each representing a 1/1,000th interest in a share of Fixed Rate Noncumulative Perpetual Preferred Stock, Series D | New York Stock Exchange |
| Depositary Shares each representing a 1/1,000th interest in a share of Fixed Rate Noncumulative Perpetual Preferred Stock, Series E | New York Stock Exchange |
| Depositary Shares each representing a 1/1,000th interest in a share of Fixed Rate Noncumulative Perpetual Preferred Stock, Series F | New York Stock Exchange |
| Depositary Shares each representing a 1/1,000th interest in a share of Fixed Rate Noncumulative Perpetual Preferred Stock, Series G | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes X No
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes No X
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes X No
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes X No
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K (§ 229.405 of this chapter) is not contained herein, and will not be contained, to the best of registrant’s knowledge in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K.
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer X | Accelerated filer | |
| Non-accelerated filer | Smaller reporting company | |
| Emerging growth company |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ____
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes No X
The aggregate market value of the common stock held by non-affiliates of the registrant, computed by reference to the closing price as of the last business day of the registrant’s most recently completed second fiscal quarter, June 30, 2018, was approximately $31.24 billion.
As of January 31, 2019, the registrant had 331,963,104 shares of common stock outstanding.
Documents Incorporated By Reference
Portions of the following documents are incorporated herein by reference as follows:
Part III of this Form 10-K incorporates by reference certain information from the registrant’s definitive proxy statement for its annual stockholders meeting to be held on May 21, 2019, (the “Proxy Statement”) to be filed not later than 120 days after the end of the fiscal year covered by this Form 10-K.
Table of Contents
2018 Form 10-K Item 1. Business
Part I
Item 1. Business
The Allstate Corporation was incorporated under the laws of the State of Delaware on November 5, 1992 to serve as the holding company for Allstate Insurance Company. Its business is conducted principally through Allstate Insurance Company, Allstate Life Insurance Company and other subsidiaries (collectively, including The Allstate Corporation, “Allstate”).
Allstate’s purpose is to protect people from life’s uncertainties and prepare them for the future so they can realize their hopes and dreams. Allstate is primarily engaged in the property and casualty insurance business in the United States and Canada. Additionally, Allstate provides customers other protection offerings such as life, accident and health insurance and protection plans that cover electronic devices and personal identities.
The Allstate Corporation is one of the largest publicly held personal lines insurers in the United States. Allstate’s Property-Liability strategy is to serve distinct customer segments with differentiated offerings. The Allstate brand is widely known through the “You’re In Good Hands With Allstate®” slogan. Allstate is the 3rd largest personal property and casualty insurer in the United States on the basis of 2017 statutory direct premiums written according to A.M. Best.
In addition, Allstate also has strong market positions in other protection products. According to A.M. Best, Allstate is the nation’s 20th largest issuer of life insurance business on the basis of 2017 ordinary life insurance in force and 38th largest on the basis of 2017 statutory admitted assets. Allstate Benefits provides accident, health and life insurance through employers and is one of the top five voluntary benefits carriers in the market based on a 2017 voluntary/worksite industry survey. SquareTrade provides protection plans on a wide variety of consumer goods such as cell phones, tablets, computers and appliances, and has a leading position in distribution through major retailers. InfoArmor provides identity protection through employers and has a leading position in this distribution channel. In total, Allstate had 113.9 million policies in force (“PIF”) as of December 31, 2018.
In this Annual Report on Form 10-K, we occasionally refer to statutory financial information. All domestic United States insurance companies are required to prepare statutory-basis financial statements. As a result, industry data is available that enables comparisons between insurance companies, including competitors that are not required to prepare financial statements in conformity with accounting principles generally accepted in the United States of America (“GAAP”). We frequently use industry publications containing statutory financial information to assess our competitive position.
The Allstate Corporation  1
Item 1. Business 2018 Form 10-K
Strategy and Segment Information
Allstate's strategy is to grow personal property-liability market share and expand other protection businesses by leveraging our brand, customer base, investment expertise, distribution channels and capital.
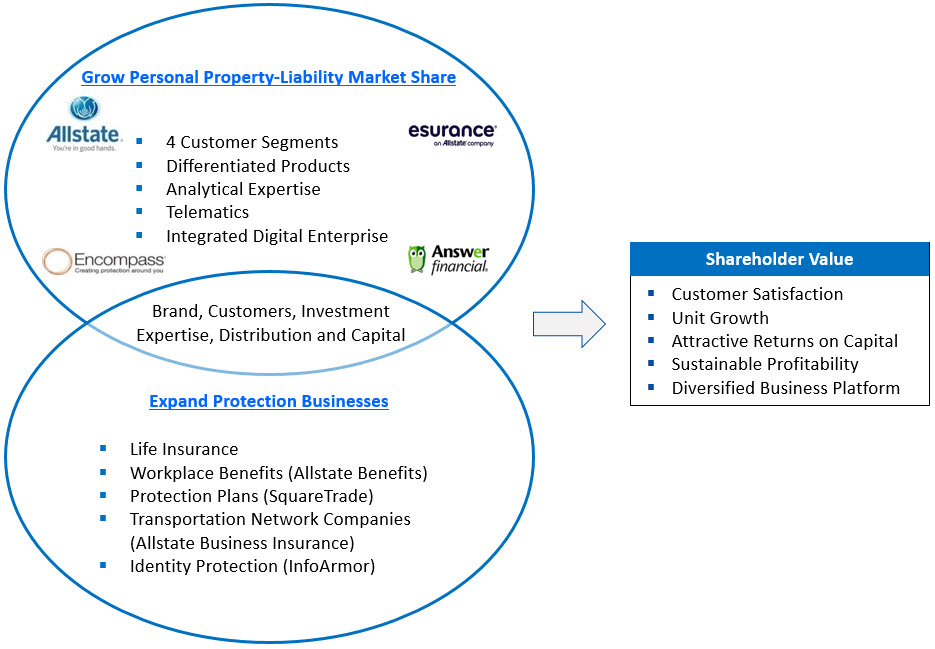
We evaluate performance and make resource and capital decisions across seven reportable segments.
| Reportable segments | ||
| Allstate Protection (1) | Includes the Allstate, Encompass and Esurance brands and Answer Financial. Offers private passenger auto, homeowners, other personal lines and commercial insurance through agencies and direct, including contact centers and the internet. | |
| Service Businesses | Includes SquareTrade, Arity, InfoArmor, Allstate Roadside Services and Allstate Dealer Services, which offer a broad range of products and services that expand and enhance our customer value propositions. InfoArmor is included in Service Businesses since its acquisition on October 5, 2018. | |
| Allstate Life | Offers traditional, interest-sensitive and variable life insurance products through Allstate exclusive agencies and exclusive financial specialists. | |
| Allstate Benefits | Offers voluntary benefits products, including life, accident, critical illness, short-term disability and other health insurance products sold through workplace enrolling independent agents and Allstate exclusive agencies. | |
| Allstate Annuities | Consists of deferred fixed annuities and immediate fixed annuities (including standard and sub-standard structured settlements) in run-off. | |
| Discontinued Lines and Coverages (1) | Relates to property and casualty insurance policies written during the 1960's through the mid-1980's with exposure to asbestos, environmental and other claims in run-off. | |
| Corporate and Other | Includes holding company activities and certain non-insurance operations. |
| (1) | Allstate Protection and Discontinued Lines and Coverages segments comprise Property-Liability. |
The Allstate Corporation 2
Item 1. Business 2018 Form 10-K
Allstate Protection Segment
Our Allstate Protection segment accounted for 90.2% of Allstate’s 2018 consolidated insurance premiums and contract charges and 29.2% of Allstate’s December 31, 2018 PIF. In this segment, private passenger auto, homeowners, and other personal lines insurance products are offered to consumers through agencies and directly through contact centers and online. Our strategy is to position product offerings and distribution channels to meet customers’ evolving needs and help them manage the risks they face.
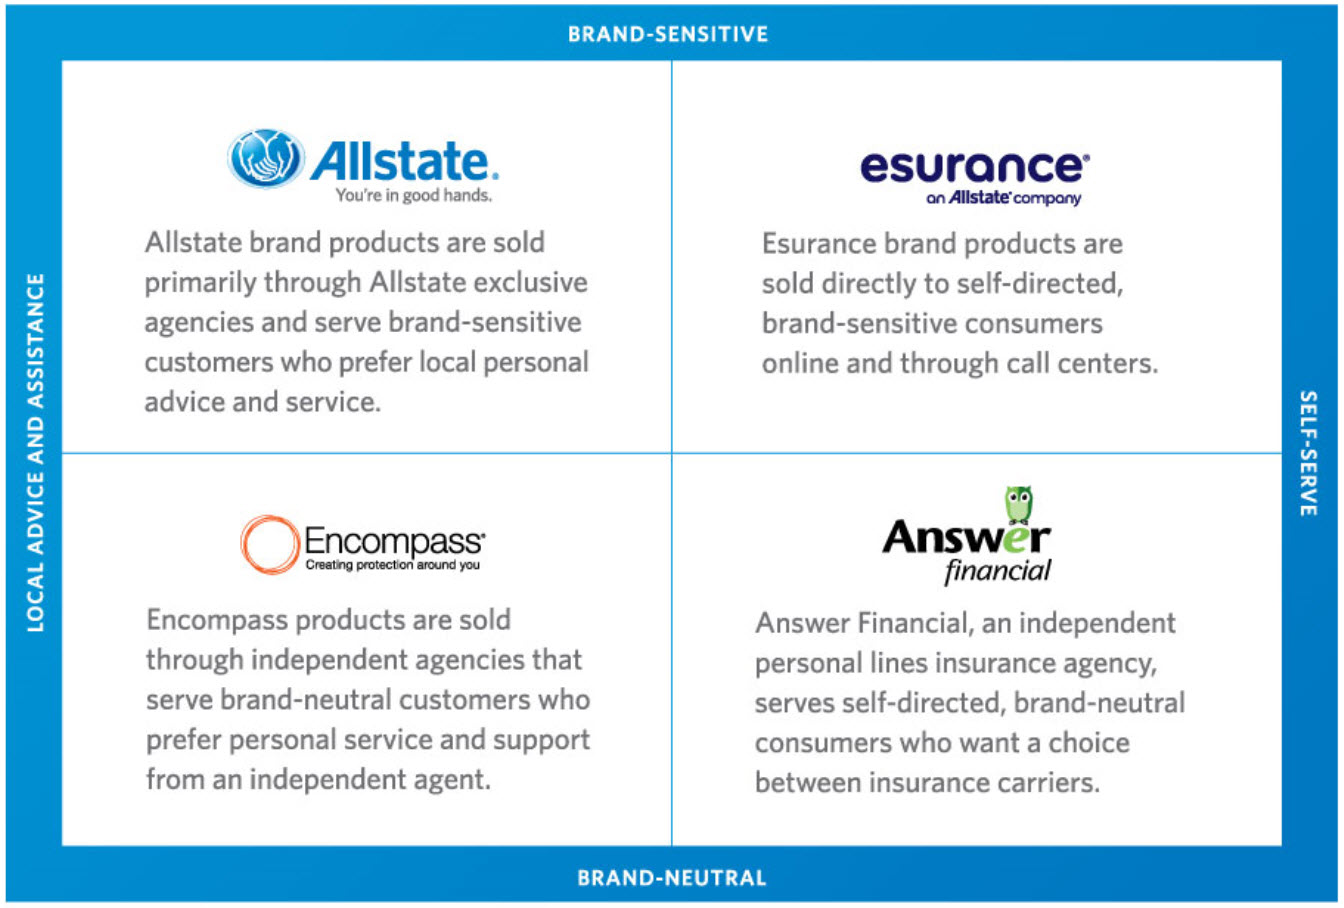
Allstate Protection has four market-facing businesses with products and services that cater to different customer preferences for advice and brand recognition to improve our competitive position and performance.
Strategy
We serve all four consumer segments using differentiated products, analytical expertise, telematics and an integrated digital enterprise that leverages data and technology to redesign our processes with a focus on greater effectiveness and efficiencies and long-term expense savings.
Allstate brand strategy
Our strategy is to grow profitably through exclusive agencies, who serve as trusted advisors to customers, while leveraging best-in-class operational capabilities to gain market share and efficiencies. The Allstate brand differentiates itself by offering comprehensive product options and features through agencies that provide local advice and service, including a partnership with exclusive financial specialists to deliver life and retirement solutions. This strategy focuses on four customer-centric themes to expand our trusted advisor initiative and deliver profitable growth:
| Available | Competitive | Simple | Connected | |||
| Provide products and services that protect what matters most | Offer products that make good use of our customers’ hard-earned money | Easy to interact with | Know our customers and proactively interact in value-added ways | |||
| Continue to build effective and efficient distribution systems and product offerings that provide a competitive advantage | Advance our pricing sophistication and improve cost competitiveness | Provide seamless, personalized customer interactions supported by contemporary products and technology | Expand the breadth of value-added products and services, enabled by connections with our customers |
The Allstate Corporation 3
2018 Form 10-K Item 1. Business
Available Allstate’s 10,700 exclusive agencies provide customized solutions and support based on our consumers’ needs. Agencies are established in 10,600 locations, supported by 26,900 licensed sales professionals and 1,100 exclusive financial specialists who are trusted advisors to our customers.
| Being a trusted advisor means that our agencies |
| • Have a local presence in our customers’ communities |
| • Know customers and understand the unique needs of their households |
| • Help customers assess the potential risks they face |
| • Provide local expertise and personalized guidance on how to protect what matters most to customers by offering customized solutions |
| • Support customers when they have changes in their lives and during their times of need |
Allstate exclusive agencies also offer life and retirement solutions and can partner with exclusive financial specialists who provide expertise with more complex life and retirement solutions and other financial needs of our customers.
Exclusive agencies and financial specialists are supported through marketing assistance, service and business processes, technology, education, offering financing to grow their businesses and other resources to help them enhance the customer experience and to acquire and retain more customers. We continue to focus on the effectiveness and efficiency of our distribution system and the breadth of our product offerings.
Competitive Data, analytics and technology support advancements in pricing sophistication for all lines of business. Pricing and underwriting strategies and decisions are designed to generate sustainable profitable growth.
Targeted marketing includes messaging that communicates the value of our Good Hands®, the importance of having proper coverage, product options, and the ease of doing business with Allstate and our exclusive agencies.
Enhanced loss cost management and expense control are a priority. To achieve this, we are continuing to modernize our operating platform (including enhanced digital capabilities) and optimizing vendor relationships. Investments are being made to increase efficiencies and reduce expenses.
Simple We are focused on creating value through simplicity, quality, rewarding engagement and improving ease of access and service through an integrated digital enterprise.
Emerging technologies and predictive analytics are being used to simplify the customer experience and expedite the claims process. To achieve this, we have opened several Digital Operating Centers to handle auto physical damage claims countrywide. The centers utilize virtual estimation capabilities, which include estimating damage through photos and video with the use of QuickFoto Claim® and Virtual Assist® (video chat technology used to review supplemental damage with auto body shops). We are also leveraging virtual
capabilities to handle property claims by estimating damage through video with Virtual Assist and aerial imagery using satellites, airplanes and drones.
Connected We will continue to leverage telematics to offer customers a highly individualized price, better understand their risks and improve customer experience delivered through innovative products and services.
Current capabilities are being expanded through our partnership with Arity, which uses telematics to offer personalized, engaging programs that empower drivers with insights about their vehicle’s health, costs and safety.
Exclusive agency compensation structure The compensation structure for Allstate exclusive agencies rewards agencies for delivering high value to customers and achieving certain business outcomes such as product profitability, growth and household penetration. Allstate exclusive agency remuneration comprises a base commission, variable compensation and a bonus.
| • | Agencies receive a monthly base commission payment as a percentage of their total eligible written premium. |
| • | Variable compensation rewards agencies for meeting customers’ needs for life insurance and retirement policies sold relative to the size of the agency. |
| • | Bonus compensation is based on a percentage of premiums and can be earned by agencies who are meeting certain sales goals and selling additional policies to meet customer needs profitably. |
Agencies have the ability to earn commissions and additional bonuses on non-proprietary products provided to customers when an Allstate product is not available. In 2018, Ivantage had $1.8 billion non-proprietary premiums under management and is a leading provider of property and casualty brokerage services.
Allstate exclusive financial specialists receive commissions for proprietary and non-proprietary sales and earn a bonus based on the volume of business produced with Allstate exclusive agencies.
Allstate independent agent remuneration comprises a base commission and a bonus that can be earned by agents who achieve sales goals and a target loss ratio.
Commercial lines strategy We are actively pursuing profitable expansion of our commercial lines, including the shared economy, such as transportation network companies. Profit improvement actions have been implemented for our traditional commercial lines insurance products, emphasizing pricing, claims, governance and operational improvements.
Esurance strategy
We are working to make insurance surprisingly painless by innovating to make it simple, transparent, and affordable. We plan to grow profitably by
Item 1. Business 2018 Form 10-K
delivering an excellent customer experience at an exceptional value through an engaged and high-performing workforce. To provide an enhanced customer experience we:
| • | Offer a seamless online and mobile experience with fast quoting for ease and convenience. |
| • | Provide hassle-free purchases and claims processing through intuitive tools and advanced technology. |
| • | Offer a broad suite of protection products and solutions to our customers. |
| • | Offer innovative product options and features. |
Encompass strategy
Our strategy is to expand the independent agency footprint, broaden geographic and product diversification, enhance pricing and underwriting sophistication and provide a superior customer and agent experience.
Over the past several years, Encompass has been executing on a profit improvement plan emphasizing pricing, governance and operational improvements at both the state and countrywide levels. These actions have improved underlying profitability but led to a reduction of policies in force compared to prior years for both auto and homeowners.
Answer Financial strategy
Answer Financial is an insurance agency that sells other insurance companies’ products directly to customers online. Our strategy as a technology-enabled insurance agency is to provide comparison shopping and related services for businesses, offering customers choice, convenience and ease of use.
Allstate Protection pricing and risk management strategies
Our pricing and underwriting strategies and decisions are designed to generate sustainable profitable growth.
A proprietary database of underwriting and loss experience enables sophisticated pricing algorithms and methodologies to more accurately price risks while also seeking to attract and retain customers in multiple risk segments.
| • | For auto insurance, risk evaluation factors can include, but are not limited to, vehicle make, model and year; driver age and marital status; territory; years licensed; loss history; years insured with prior carrier; prior liability limits; prior lapse in coverage; and insurance scoring utilizing telematics data and other consumer information. |
| • | For property insurance, risk evaluation factors can include, but are not limited to, the amount of insurance purchased; geographic location of the property; loss history; age, condition and construction characteristics of the property; and |
characteristics of the insured including insurance scoring utilizing other consumer information.
A combination of underwriting information, pricing and discounts are also used to achieve a more competitive position and growth. The pricing strategy involves local marketplace pricing and underwriting decisions based on risk evaluation factors and an evaluation of competitors to the extent permissible by applicable law.
Pricing of property products is intended to establish risk-adjusted returns that are acceptable over a long-term period. Rate increases are pursued to keep pace with loss trends, including losses from catastrophic events and those that are weather-related (such as wind, hail, lightning and freeze not meeting our criteria to be declared a catastrophe). We also take into consideration potential customer disruption, the impact on our ability to market our products, regulatory limitations, our competitive position and profitability.
In any reporting period, loss experience from catastrophic events and weather-related losses may contribute to negative or positive underwriting performance relative to the expectations incorporated into product pricing.
Property catastrophe exposure is managed with the goal of providing shareholders an acceptable return on the risks assumed in the property business and to reduce the variability of earnings. Our property business includes personal homeowners, commercial property and other property insurance lines. Our current catastrophe reinsurance program supports our risk tolerance framework that targets less than a 1% likelihood of annual aggregate catastrophe losses from hurricanes and earthquakes, net of reinsurance, exceeding $2 billion. The use of different assumptions and updates to industry models, and updates to our risk transfer program could materially change the projected loss. Growth strategies include areas where we believe diversification can be enhanced and an appropriate return can be earned for the risk. As a result, our modeled exposure may increase, but in aggregate remain lower than $2 billion as noted above. In addition, we have exposure to other severe weather events and wildfires, which impact catastrophe losses.
Property catastrophe exposure management includes purchasing reinsurance to provide coverage for known exposure to hurricanes, earthquakes, wildfires, fires following earthquakes and other catastrophes. We are also working to promote measures to prevent and mitigate losses and make homes and communities more resilient, including enactment of stronger building codes and effective enforcement of those codes, adoption of sensible land use policies, and development of effective and affordable methods of improving the resilience of existing structures.
The Allstate Corporation 5
2018 Form 10-K Item 1. Business
Products and distribution
Allstate Protection differentiates itself by offering solutions to meet broad-based household protection needs and a comprehensive range of innovative product options and features across distribution channels that best suit each consumer segment.
| Insurance products | |||
| Allstate brand | Auto | ||
| Homeowners | |||
| Specialty auto (motorcycle, trailer, motor home and off-road vehicle) | |||
| Other personal lines (renters, condominium, landlord, boat, umbrella, manufactured home and stand-alone scheduled personal property) | |||
| Commercial lines | |||
| Esurance brand | Auto | ||
| Homeowners | |||
| Motorcycle | |||
| Renters | |||
| Encompass brand | Auto | ||
| Homeowners | |||
| Other personal lines (renters, condominium, landlord, boat and umbrella) | |||
| Answer Financial | Comparison quotes for non-proprietary auto, homeowners and other personal lines (condominium, renters, motorcycle, recreational vehicle and boat) |
Item 1. Business 2018 Form 10-K
| Innovative product offerings and features | |||
| Market-leading solutions | |||
| Allstate brand | Your Choice Auto® | Qualified customers choose from a variety of options, such as Accident Forgiveness, Deductible Rewards®, Safe Driving Bonus® and New Car Replacement. | |
| Allstate House and Home® | Featured options include Claim RateGuard®, Claim-Free Bonus, deductible rewards and flexibility in options and coverages, including graduated roof coverage and pricing based on roof type and age for damage related to wind and hail events. | ||
| Claim Satisfaction Guarantee® | Promised return of premium to standard auto insurance customers dissatisfied with their claims experience. | ||
| Bundling Benefits | Auto customers with a qualifying property policy are provided an auto renewal guarantee and a deductible waiver (when the same event, with the same covered cause of loss, damages both auto and property). Offered in 15 states as of December 31, 2018. | ||
| Auto Replacement Protection | Replaces a qualifying customer’s vehicle involved in a total loss accident with a vehicle of the same or similar make and model that is one year newer. Offered in 15 states as of December 31, 2018. | ||
| Encompass brand | EncompassOne Policy® | Packaged insurance product with one premium, one bill, one policy deductible and one renewal date. Broad coverage options include customizable features such as enhanced accident forgiveness, new-car replacement coverage, walk-away home coverage option should the insured decide not to rebuild, flexible additional living expense coverage, water-sewer backup coverage options and roadside assistance. This product is offered in 36 states and the District of Columbia (“D.C.”) as of December 31, 2018. | |
| Surround Solutions by EncompassSM | Offers contemporary auto (6-months), homeowner and specialty lines products, pricing, services and support designed to provide flexibility and be customized based on consumer needs. Offered exclusively in four states for Encompass as of December 31, 2018. | ||
| Telematics offerings | |||
| Allstate brand | Drivewise® | Telematics-based insurance program, available in 49 states and the District of Columbia as of December 31, 2018, that uses a mobile application or an in-car device to capture driving behaviors and encourage safe driving. It provides customers with information and tools, incentives and driving challenges. For example, in most states, Allstate Rewards® provides reward points for safe driving. | |
| Milewise® | Usage-based insurance product, available in 6 states as of December 31, 2018, that gives customers flexibility to customize their insurance and pay based on the number of miles they drive. | ||
| Esurance brand | DriveSense® | Telematics-based insurance program, available in 32 states as of December 31, 2018, that primarily uses a mobile application to capture driving behaviors and reward customers for safe driving. | |
| Encompass brand | Route ReportSM | Telematics application, available in 4 states as of December 31, 2018, used to capture driving behaviors and reward customer participation. | |
| Answer Financial | StreetWiseSM | Telematics application, available in all 50 states and D.C. as of December 31, 2018, used to capture driving behaviors. | |
| Shared economy solutions | |||
| Allstate brand | Transportation Network Company Commercial Auto | Commercial coverage for drivers of transportation networking companies during various phases of the ridesharing service. | |
| Allstate Ride for Hire®/ HostAdvantage® | Supplemental personal insurance coverage for those using their vehicle to drive for a transportation network company or their house for peer-to-peer property sharing. |
| Distribution channels | |
| Allstate brand | In the U.S., we offer products through 10,700 Allstate exclusive agencies operating in 10,600 locations, supported by 26,900 licensed sales professionals, and 1,100 exclusive financial specialists. We also offer products through 2,700 independent agencies that are primarily in rural areas and through contact centers and online. In Canada, we offer Allstate brand products through 900 employee producers. |
| Esurance brand | Sold to customers online and through contact centers. |
| Encompass brand | Distributed through 2,600 independent agencies. |
| Answer Financial | Comparison quotes offered to customers online or through contact centers. |
Allstate exclusive agencies also support the Service Businesses, Allstate Life and Allstate Benefits segments through offering roadside assistance and protection plans, life insurance and voluntary benefits products.
The Allstate Corporation 7
2018 Form 10-K Item 1. Business
When an Allstate product is not available, we may offer non-proprietary products to consumers through arrangements made with other companies, agencies, and brokers. As of December 31, 2018, Allstate agencies had approximately $1.6 billion of non-proprietary personal insurance premiums under management, primarily related to property business in hurricane exposed areas, and approximately $220 million of non-proprietary commercial insurance premiums under management. Additionally, we offer a homeowners product through our subsidiary North Light Specialty Insurance Company in certain areas with higher risk of catastrophes or where customers do not meet the Allstate brand standard underwriting profile.
Competition
The personal lines insurance markets, including private passenger auto and homeowners insurance, are highly competitive. The following charts provide Allstate Protection’s combined market share compared to our principal competitors in the U.S. using statutory direct written premium for the year ended December 31, 2017, according to A.M. Best.
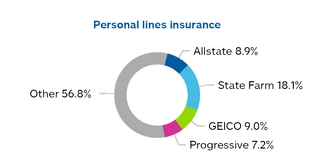
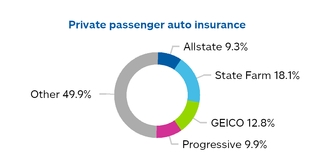
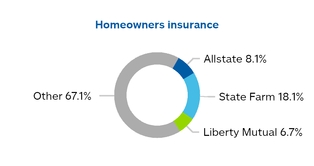
Esurance is among the top 25 largest providers of personal property and casualty insurance products in the U.S., and Encompass is among the top 20 largest providers of personal property and casualty insurance products through independent agencies in the U.S., based on statutory direct written premium according to A.M. Best for 2017.
Geographic markets
Our principal geographic markets are in the U.S. Through various subsidiaries, we are authorized to sell a variety of personal property and casualty products in all 50 states, D.C., Puerto Rico and Canada. The top U.S. geographic markets are reflected below based on 2018 information contained in statements filed with the state insurance departments.
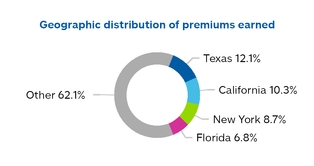
Item 1. Business 2018 Form 10-K
Service Businesses Segment
Our Service Businesses segment accounted for 3.3% of Allstate’s 2018 consolidated total revenue and 65.1% of Allstate’s December 31, 2018 PIF. Service Businesses include SquareTrade, Arity, InfoArmor, Allstate Roadside Services and Allstate Dealer Services, which offer a broad range of products and services that expand and enhance customer value propositions. Starting in the fourth quarter of 2018, the Service Businesses segment includes the results of InfoArmor, a leading provider of identity protection to more than 1 million employees and their family members at over 1,400 firms, which was acquired on October 5, 2018.
Strategy - To deliver superior value propositions and build strategic platforms to connect and engage with customers and effectively address their changing needs and preferences.
| SquareTrade® | Expand distribution of consumer protection plan and technical support products through new and existing retail and mobile operator accounts while increasing profitability and returns. | |
| Arity® | Build a strategic platform leveraging our analytics and deep understanding of driver risk. The platform will be used by those industries effected most by the changing face of transportation, including insurance companies, shared mobility companies and the automotive ecosystem. | |
| InfoArmor® | Create a leading position in the identity protection market, offering full identity protection monitoring with proactive alerts, digital exposure reporting, identity theft reimbursement and excellent customer service. | |
| Allstate Roadside Services® | Digitize the roadside assistance business and enhance capabilities to deliver a superior customer experience while lowering costs in the customer assistance centers and optimizing the rescue network. | |
| Allstate Dealer Services® | Expand distribution of Allstate branded finance and insurance products and services to auto dealerships, while pursuing additional distribution through strategic partnerships. |
Products and distribution
| Products and services | ||
| SquareTrade | Provides consumer protection plans and related technical support for mobile phones, consumer electronics and appliances which provide customers protection from mechanical or electrical failure, and in certain cases, accidental damage from handling. | |
| Arity | The Arity platform provides data and analytics solutions using automotive telematics information. Customers receive value from our solutions either by using web based software tools, white labeled mobile applications or through embedding our technology in their mobile applications. | |
| InfoArmor | Provides identity protection services including monitoring, alerts, remediation and a proprietary indicator of identity health. | |
| Allstate Roadside Services | A leading roadside assistance provider in North America offering towing, jump-start, lockout, fuel delivery and tire change services to retail customers and customers of our wholesale partners. Good Hands Rescue® is a pay-per-use mobile application service that connects users to a select countrywide network of third-party providers and a proprietary crowdsourced network to assist with emergencies. | |
| Allstate Dealer Services | Offers finance and insurance products, including vehicle service contracts, guaranteed asset protection waivers, road hazard tire and wheel protection, and paintless dent repair protection. |
| Distribution channels | ||
| SquareTrade | Major retailers in the U.S. and mobile operators in Europe. | |
| Arity | Sells directly to affiliate and non-affiliate customers and through strategic industry specific partners. | |
| InfoArmor | Workplace benefit programs provided to employees with a strategic focus to leverage relationships with our Allstate Benefits segment and expand into other distribution channels. | |
| Allstate Roadside Services | Allstate exclusive agencies, wholesale partners, affinity groups and a mobile application. | |
| Allstate Dealer Services | Independent agencies and brokers through auto dealerships in the U.S. to customers in conjunction with the purchase of a new or used vehicle. |
Geographic markets
The Service Businesses primarily operate in the U.S., with certain businesses offering services in Europe, Canada and Puerto Rico.
Competition
We compete on a variety of factors, including product offerings, brand recognition, financial strength, price, distribution and the customer experience. The market for these services is highly fragmented and competitive.
The Allstate Corporation 9
2018 Form 10-K Item 1. Business
Allstate Life Segment
Strategy
Our Allstate Life segment accounted for 4.8% of Allstate’s 2018 consolidated total revenue and 1.8% of Allstate’s December 31, 2018 PIF. Our overall strategy is to broaden Allstate’s customer relationships and value proposition. The Allstate Life segment’s product offerings are a part of the Allstate brand trusted advisor strategy. We also distribute non-proprietary retirement products offered by third-party providers. Our target customers are those who prefer local personalized advice and service and are brand-sensitive.
Our product positioning provides solutions to help meet customer needs during various phases of life. Term and whole life insurance products offer basic life protection solutions while universal life and financial planning solutions cover more advanced needs. Many Allstate exclusive agencies partner with exclusive financial specialists to deliver life and retirement solutions. These specialists have expertise with advanced life and retirement cases and other more complex customer needs. Successful partnerships assist agencies with building stronger and deeper customer relationships. Sales producer education and technology improvements are being made to ensure agencies have the tools and information needed to help customers meet their needs and build personal relationships as trusted advisors.
The operating model is being modernized through investments in data and analytics and technology capabilities, tailoring distribution support, product innovation and enhancing the underwriting process.
Products and distribution
| Insurance products | ||
| Term life | Interest-sensitive life | |
| Whole life | Variable life |
| Distribution channel |
| Allstate exclusive agencies and exclusive financial specialists. |
Allstate exclusive agencies and exclusive financial specialists also sell certain non-proprietary products, including mutual funds, fixed and variable annuities, disability insurance, and long-term care insurance to provide a broad suite of protection and retirement products. As of December 31, 2018, Allstate agencies had approximately $14.1 billion of non-proprietary mutual funds and fixed and variable annuity account balances under management. New and additional deposits into these non-proprietary products were $2.2 billion in 2018.
Competition
We compete on a variety of factors, including product offerings, brand recognition, financial strength and ratings, price, distribution and the level of customer service. The market for life insurance continues to be highly fragmented and competitive. As of December 31, 2017, there were approximately 360 groups of life insurance companies in the United States.
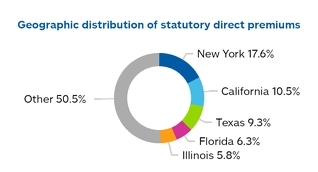
Geographic markets
Through subsidiaries, we are authorized to sell various types of life insurance products in all 50 states, D.C. and Puerto Rico. Our top geographic markets are reflected below.
Item 1. Business 2018 Form 10-K
Allstate Benefits Segment
Strategy
Our Allstate Benefits segment accounted for 3.0% of Allstate’s 2018 consolidated total revenue and 3.7% of Allstate’s December 31, 2018 PIF. The Allstate Benefits segment provides consumers with financial protection against the risk of accidents, illness and mortality. We are an industry leader in the rapidly growing voluntary benefits market, offering a broad range of products through workplace enrollment. The voluntary market continues to grow as voluntary benefits products have become a core component of employer benefit offerings. Our life insurance portfolio includes individual and group term life and permanent life solutions.
Our products are offered through a network of independent agents and Allstate exclusive agencies. A broad product portfolio, flexible enrollment solutions and technology (including significant presence on employer benefit administration systems), our strong national accounts team, and a well-recognized brand differentiates Allstate Benefits.
Our strategy for growth is to become the industry leader in the voluntary benefits market by delivering substantially more value through innovative products and technology, tailored solutions and exceptional service. Initiatives are focused on expanding into non-traditional products and becoming an integrated digital enterprise through investments in future-state technologies and data and analytics capabilities.
Products and distribution
Our target customers are middle market consumers with family financial protection needs employed by small, medium and large sized firms. Allstate Benefits is well represented in all market segments and is a leader in the large and mega (over 10,000 employees) market segments.
| Voluntary benefits products | ||
| Life | Short-term disability | |
| Accident | Other health | |
| Critical illness |
| Distribution channels |
| Primary distribution continues to be through 6,200 workplace enrolling independent agents. |
| Allstate exclusive agencies, focusing on small employers, also distribute products. |
Competition
We compete on a wide variety of factors, including product offerings, brand recognition, financial strength and ratings, price, distribution and customer service.
The market for voluntary benefits is growing as these products help employees fill the increasing gaps associated with continued medical cost inflation and the shifting of costs from employers to employees to cover co-pays and deductibles. Favorable industry and economic trends have increased competitive pressure and attracted new traditional and non-traditional entrants to the voluntary benefits market. Recent entrants, including large group medical, life and disability insurance carriers, are leveraging core benefit capabilities by bundling and discounting to capture voluntary market share.
Geographic markets
We are authorized to sell voluntary benefits products in all 50 states, D.C., Puerto Rico, the U.S. Virgin Islands, Guam and Canada. The top geographic markets are reflected below. 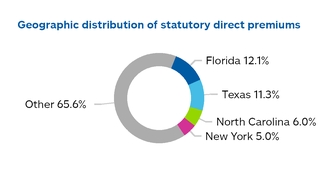
The Allstate Corporation 11
Item 1. Business 2018 Form 10-K
Allstate Annuities Segment
Strategy
Our Allstate Annuities segment accounted for 2.4% of Allstate’s 2018 consolidated total revenue and 0.2% of Allstate’s December 31, 2018 PIF. The Allstate Annuities segment consists primarily of deferred fixed annuities and immediate fixed annuities (including standard and sub-standard structured settlements). The segment is in run-off and is focused on increasing lifetime economic value. Both the deferred and immediate annuity businesses have been adversely impacted by the historically low interest rate environment. Our immediate annuity business has also been impacted by medical advancements that have resulted in annuitants living longer than anticipated when many of these contracts were originated.
Allstate Annuities focuses on the distinct risk and return profiles of the specific products when developing investment and liability management strategies. The level of legacy deferred annuities in force has been significantly reduced and the investment portfolio and crediting rates are proactively managed to improve profitability of the business while providing appropriate levels of liquidity.
The investment portfolio supporting our immediate annuities is managed to ensure the assets match the characteristics of the liabilities and provide the long-term returns needed to support this business. To better match the long-term nature of our immediate annuities, we use performance-based investments in which we have ownership interests and a greater proportion of return is derived from idiosyncratic asset or operating performance.
We continue to review strategic options to reduce exposure and improve returns of the business. As a result, we may take additional operational and financial actions that offer return improvement and risk reduction opportunities.
Products and distribution
We previously offered and continue to have in force deferred fixed annuities and immediate fixed annuities (including standard and sub-standard structured settlements). We exited the continuing sale of annuities over an eight year period from 2006 to 2014, reflecting our expectations of declining returns. In 2006, we disposed of substantially all of the variable annuity business through reinsurance agreements. For discussion of non-proprietary retirement and investment products sold through our Allstate exclusive agencies and exclusive financial specialists, see Part I, Item 1. Allstate Life Segment of this report.
Other Business Segments
Discontinued Lines and Coverages Segment
The Discontinued Lines and Coverages segment includes results from property and casualty insurance coverage that primarily relates to policies written during the 1960s through the mid-1980s.
Strategy Management of this segment has been assigned to a designated group of professionals with expertise in claims handling, policy coverage interpretation, exposure identification, litigation and reinsurance collection. As part of its responsibilities, this group may at times be engaged in policy buybacks, settlements and reinsurance assumed and ceded commutations.
Development in the reserves established for asbestos, environmental and other discontinued lines losses in the future may continue. Reserve changes can be caused by new information relating to new and additional claims or the impact of resolving unsettled claims based on unanticipated events such as arbitrations, litigation, legislative, judicial or regulatory actions. Environmental losses may also increase as the result of additional funding for environmental site clean-up.
Challenges related to the concentration of insurance and reinsurance claims from companies who specialize in this business continue to be addressed.
Corporate and Other Segment
Our Corporate and Other segment is comprised of holding company activities and certain non-insurance operations.
The Allstate Corporation 12
Next: Item 1. Business 2018 Form 10-K