 filings.tools
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
472K characters. Original on sec.gov · Markdown
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
| Page | |||
| Overview and 2018 Highlights | 36 | ||
| Consolidated Net Income | 40 | ||
| Property-Liability Operations | 41 | ||
| Allstate Protection | 44 | ||
| – Allstate brand | 51 | ||
| – Esurance brand | 56 | ||
| – Encompass brand | 60 | ||
| Discontinued Lines and Coverages | 64 | ||
| Service Businesses | 66 | ||
| Claims and Claims Expense Reserves | 68 | ||
| Allstate Life | 77 | ||
| Allstate Benefits | 82 | ||
| Allstate Annuities | 85 | ||
| Investments | 89 | ||
| Market Risk | 99 | ||
| Pension and Other Postretirement Plans | 103 | ||
| Capital Resources and Liquidity | 105 | ||
| Enterprise Risk and Return Management | 112 | ||
| Application of Critical Accounting Estimates | 114 | ||
| Regulation and Legal Proceedings | 127 | ||
| Pending Accounting Standards | 127 |
The Allstate Corporation  35
2018 Form 10-K
Overview
The following discussion highlights significant factors influencing the consolidated financial position and results of operations of The Allstate Corporation (referred to in this document as “we,” “our,” “us,” the “Company” or “Allstate”). It should be read in conjunction with the 5-year summary of selected financial data, consolidated financial statements and related notes found under Part II. Item 6. and Item 8. contained herein.
The most important factors we monitor to evaluate the financial condition and performance for our reportable segments and the Company include:
| • | Allstate Protection: premium, policies in force (“PIF”), new business sales, policy retention, price changes, claim frequency and severity, catastrophes, loss ratio, expenses, underwriting results, and relative competitive position. |
| • | Service Businesses: revenues, premium written, PIF, adjusted net income and net income. |
| • | Allstate Life: premiums and contract charges, new business sales, PIF, benefit spread, expenses, adjusted net income and net income. |
| • | Allstate Benefits: premiums, new business sales, PIF, benefit ratio, expenses, adjusted net income and net income. |
| • | Allstate Annuities: investment spread, asset-liability matching, contract benefits, expenses, adjusted net income, net income and invested assets. |
| • | Investments: exposure to market risk, asset allocation, credit quality/experience, total return, net investment income, cash flows, realized capital gains and losses, unrealized capital gains and losses, stability of long-term returns, and asset and liability duration. |
| • | Financial condition: liquidity, parent holding company deployable assets, financial strength ratings, operating leverage, debt levels, book value per share and return on equity. |
Measuring segment profit or loss
The measure of segment profit or loss used in evaluating performance is underwriting income for the Allstate Protection and Discontinued Lines and Coverages segments and adjusted net income for the Service Businesses, Allstate Life, Allstate Benefits, Allstate Annuities, and Corporate and Other segments.
Underwriting income is calculated as premiums earned and other revenue, less claims and claims expense (“losses”), amortization of deferred policy acquisition costs (“DAC”), operating costs and expenses and restructuring and related charges, as determined using accounting principles generally accepted in the United States of America (“GAAP”). We use this measure in our evaluation of results of operations to analyze the profitability of the Property-Liability insurance operations separately from investment results. Underwriting income is reconciled to net income applicable to common shareholders in the Property-Liability Operations section of Management’s Discussion and Analysis (“MD&A”).
Adjusted net income is net income applicable to common shareholders, excluding:
| • Realized capital gains and losses, after-tax, except for periodic settlements and accruals on non-hedge derivative instruments, which are reported with realized capital gains and losses but included in adjusted net income |
| • Valuation changes on embedded derivatives not hedged, after-tax |
| • Amortization of DAC and deferred sales inducement costs (“DSI”), to the extent they resulted from the recognition of certain realized capital gains and losses or valuation changes on embedded derivatives not hedged, after-tax |
| • Business combination expenses and the amortization of purchased intangible assets, after-tax |
| • Gain (loss) on disposition of operations, after-tax |
| • Adjustments for other significant non-recurring, infrequent or unusual items, when (a) the nature of the charge or gain is such that it is reasonably unlikely to recur within two years, or (b) there has been no similar charge or gain within the prior two years |
Adjusted net income is reconciled to net income applicable to common shareholders in the Service Businesses, Allstate Life, Allstate Benefits and Allstate Annuities Segment sections of MD&A.
2018 Form 10-K
2018 Highlights
| Allstate Delivered on 2018 Operating Priorities (1) | |||||
| Better Serve Customers | Net Promoter Score increased for all major businesses | ||||
| Renewal ratio improved across Allstate, Esurance and Encompass brands | |||||
| Achieve Target Economic Returns on Capital | Return on common shareholders’ equity of 10.5% for 2018 | ||||
| Grow Customer Base | Policy growth accelerated in Allstate and Esurance brands | ||||
| SquareTrade PIF grew 29.9 million, or 77.1%, compared to 2017 | |||||
| Proactively Manage Investments | Net investment income of $3.2 billion in 2018 | ||||
| Total return on $81 billion investment portfolio of 0.8% | |||||
| Building Long-Term Growth Platforms | Expanded telematics offerings, Arity collecting 10 billion miles of data per month | ||||
| SquareTrade continued its rapid growth, adding a leading U.S. retailer during the year | |||||
| Acquired InfoArmor, a fast growing identity protection service provider |
| (1) | 2019 operating priorities will remain consistent with the 2018 priorities. |
| Consolidated Net Income | ||||
| ($ in billions) |
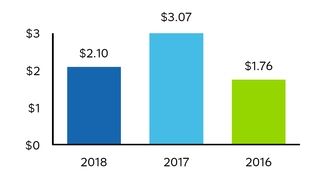
| Consolidated net income applicable to common shareholders decreased 31.5% in 2018 compared to 2017. The decrease was primarily driven by net realized capital losses compared to net realized capital gains in 2017, a lower tax benefit from the Tax Legislation, lower favorable prior year reserve reestimates and higher distribution expenses from growth, partially offset by higher premiums earned, a lower effective tax rate from the Tax Legislation and lower catastrophe losses. The Property-Liability combined ratio was 93.6 in both 2018 and 2017. Net realized capital losses on investments in 2018 were primarily due to declines in the valuation of equity investments, which are now recorded in net income due to the adoption of the recognition and measurement accounting standard effective January 1, 2018. 2017 vs. 2016 - Increase was primarily due to higher Allstate Protection premiums earned, a tax benefit from the Tax Legislation, net realized capital gains in 2017 compared to net realized capital losses in 2016, higher net investment income, lower claims and claims expense, partially offset by higher catastrophe losses. |
| Total Revenue | ||||
| ($ in billions) |
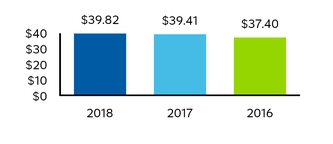
| Total revenue increased 1.0% in 2018 compared to 2017, driven by a 5.3% increase in insurance premiums and contract charges, which were partially offset by net realized capital losses in 2018 compared to net realized capital gains in 2017 and lower net investment income. Insurance premiums increased in the following segments: Allstate Protection (Allstate brand and Esurance), Service Businesses (SquareTrade and Allstate Dealer Services), Allstate Benefits and Allstate Life. 2017 vs. 2016 - Increase was primarily due to higher Allstate Protection insurance premiums, net realized capital gains in 2017 compared to net realized capital losses in 2016, higher net investment income and the acquisition of SquareTrade. |
The Allstate Corporation 37
2018 Form 10-K
| Net Investment Income | ||||
| ($ in billions) |
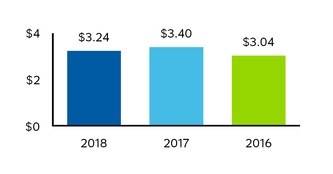
| Net investment income decreased 4.7% in 2018 compared to 2017, primarily due to strong performance-based investment results in 2017, partially offset by higher market-based portfolio income as interest rates increased during 2018. 2017 vs. 2016 - Increase reflected strong 2017 performance-based results, primarily from limited partnerships, an increase in invested assets and stable market-based yields, partially offset by higher employee-related expenses. |
Segment Highlights
Allstate Protection underwriting income totaled $2.19 billion in 2018, a 3.6% increase from $2.11 billion in 2017, primarily due to increased premiums earned, lower catastrophe losses and improved auto claim frequency, partially offset by higher claim severity, operating costs and expenses and lower favorable prior year reserve reestimates.
Premiums written increased 6.0% to $33.56 billion in 2018 compared to 2017.
Service Businesses adjusted net income was $2 million in 2018 compared to an adjusted net loss of $59 million in 2017. The improvement in 2018 was primarily due to increased revenue at SquareTrade, improved loss experience at SquareTrade and Allstate Dealer Services and lower restructuring charges in 2018 compared to 2017, partially offset by higher loss costs at Allstate Roadside Services.
Total revenues increased 24.5% or $259 million to $1.32 billion in 2018 from $1.06 billion in 2017. The increase was primarily due to SquareTrade’s growth through its U.S. retail and international channels and increased premiums earned on Allstate Dealer Services’ vehicle service contracts. 2018 revenue also includes $101 million from SquareTrade due to the adoption of the revenue from contracts with customers accounting standard.
Allstate Life adjusted net income was $289 million in 2018 compared to $253 million in 2017. The increase was primarily due to a lower effective tax rate from the Tax Legislation and increased premiums and contract charges, partially offset by higher contract benefits.
Premiums and contract charges totaled $1.32 billion in 2018, an increase of 2.7% from $1.28 billion in 2017.
Allstate Benefits adjusted net income was $119 million in 2018 compared to $95 million in 2017. The increase was primarily due to higher premiums and a lower effective tax rate from the Tax Legislation, partially offset by higher contract benefits and operating costs and expenses.
Premiums and contract charges totaled $1.14 billion in 2018, an increase of 4.7% from $1.08 billion in 2017.
Allstate Annuities adjusted net income was $130 million in 2018 compared to $204 million in 2017. The
decrease was primarily due to lower net investment income, driven by performance-based investment results and decreased average investment balances, partially offset by a lower effective tax rate from the Tax Legislation, decreased interest credited to contractholder funds and lower contract benefits.
Net investment income decreased 16.0% to $1.10 billion in 2018 from $1.31 billion in 2017.
Financial Highlights
Tax reform On December 22, 2017, the Tax Legislation became effective, permanently reducing the U.S. corporate income tax rate from 35% to 21% beginning January 1, 2018. As a result, the corporate tax rate is not comparable between years. During 2017, we revalued deferred tax assets and liabilities and recorded liabilities related to the transition to the modified territorial system for international taxation, resulting in a $506 million reduction to income tax expense or a $1.38 per share benefit to earnings per common share for the year ended December 31, 2017. During 2018, the impact of the Tax Legislation was adjusted from our preliminary estimate due to, among other things, changes in interpretations and assumptions we previously made, guidance that was issued and actions we took as a result of the Tax Legislation. During 2018, we recognized a net tax benefit of $29 million, as a reduction to income tax expense related to the provisional amounts. The accounting for income tax effects of the Tax Legislation has been completed. The impact of Tax Legislation is excluded from adjusted net income when evaluating segment performance.
InfoArmor On October 5, 2018, we acquired InfoArmor, Inc. (“InfoArmor”), a leading provider of identity protection in the employee benefits market, for $525 million in cash. InfoArmor primarily offers identity protection to employees and their family members through voluntary benefit programs at over 1,400 firms, including more than 100 of the Fortune 500 companies. Starting in the fourth quarter of 2018, the Service Businesses segment includes the results of InfoArmor.
PlumChoice On November 30, 2018, we acquired PlumChoice, Inc. (“PlumChoice”) for $30 million in cash
2018 Form 10-K
to provide technical support services to SquareTrade’s customers and small businesses.
Investments totaled $81.26 billion as of December 31, 2018, decreasing from $82.80 billion as of December 31, 2017.
Shareholders’ equity As of December 31, 2018, shareholders’ equity was $21.31 billion. This total included $1.50 billion in deployable assets at the parent holding company level comprising cash and investments that are generally saleable within one quarter.
Book value per diluted common share (ratio of common shareholders’ equity to total common shares outstanding and dilutive potential common shares outstanding) was $57.56 as of December 31, 2018, a decrease from $57.58 as of December 31, 2017.
Return on average common shareholders’ equity For the twelve months ended December 31, 2018, net income applicable to common shareholders’ return on the average of beginning and ending period common shareholders’ equity of 10.5% decreased by 5.0 points from 15.5% for the twelve months ended December 31, 2017.
Pension settlement loss During 2018 and 2017, the Company’s qualified employee pension plan lump sum payments exceeded a threshold of service and interest cost, which resulted in a pension settlement loss of $172 million and $122 million, pre-tax, respectively, and was recorded as part of operating costs and expenses in the Corporate and Other segment. The net periodic costs for the pension plans inclusive of pension settlement losses were $257 million and $255 million in 2018 and 2017, respectively.
Common share repurchases On October 31, 2018, the Board authorized a new $3.00 billion common share repurchase program that is expected to be completed by April 2020. As of December 31, 2018, there was $2.07 billion remaining on the repurchase program.
Adopted Accounting Standards
Recognition and Measurement of Financial Assets and Financial Liabilities (“recognition and measurement accounting standard”) Beginning January 1, 2018, equity securities are reported at fair value with changes in fair value recognized in realized capital gains and losses. Limited partnerships previously reported using the cost method are now reported at fair value with changes in fair value recognized in net investment income. See the Investments section of this Item for further details.
Revenue from Contracts with Customers Beginning January 1, 2018, we adopted the revenue from contracts with customers accounting standard, which revises the criteria for revenue recognition and impacted the Service Businesses segment by increasing deferred revenue by approximately $160 million with a corresponding increase in DAC for protection plans that are sold directly to retailers prior to January 1, 2018. The anticipated impact of these adjustments offset and do not impact net income, but impact premium and DAC comparability trends as they are recognized over the life of the policy.
See Note 2 of the consolidated financial statements for additional details on the adopted accounting standards.
The Allstate Corporation 39
2018 Form 10-K
| Consolidated net income | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Revenues | ||||||||||||
| Property and casualty insurance premiums | $ | 34,048 | $ | 32,300 | $ | 31,307 | ||||||
| Life premiums and contract charges | 2,465 | 2,378 | 2,275 | |||||||||
| Other revenue | 939 | 883 | 865 | |||||||||
| Net investment income (1) | 3,240 | 3,401 | 3,042 | |||||||||
| Realized capital gains and losses: | ||||||||||||
| Total other-than-temporary impairment (“OTTI”) losses | (13 | ) | (146 | ) | (313 | ) | ||||||
| OTTI losses reclassified (from) to other comprehensive income | (1 | ) | (4 | ) | 10 | |||||||
| Net OTTI losses recognized in earnings | (14 | ) | (150 | ) | (303 | ) | ||||||
| Sales and valuation changes on equity investments and derivatives | (863 | ) | 595 | 213 | ||||||||
| Total realized capital gains and losses (1) | (877 | ) | 445 | (90 | ) | |||||||
| Total revenues | 39,815 | 39,407 | 37,399 | |||||||||
| Costs and expenses | ||||||||||||
| Property and casualty insurance claims and claims expense | (22,839 | ) | (21,929 | ) | (22,221 | ) | ||||||
| Life contract benefits | (1,973 | ) | (1,923 | ) | (1,857 | ) | ||||||
| Interest credited to contractholder funds | (654 | ) | (690 | ) | (726 | ) | ||||||
| Amortization of deferred policy acquisition costs | (5,222 | ) | (4,784 | ) | (4,550 | ) | ||||||
| Operating costs and expenses | (5,869 | ) | (5,442 | ) | (4,939 | ) | ||||||
| Amortization of purchased intangible assets | (105 | ) | (99 | ) | (32 | ) | ||||||
| Restructuring and related charges | (83 | ) | (109 | ) | (30 | ) | ||||||
| Goodwill impairment | — | (125 | ) | — | ||||||||
| Interest expense | (332 | ) | (335 | ) | (295 | ) | ||||||
| Total costs and expenses | (37,077 | ) | (35,436 | ) | (34,650 | ) | ||||||
| Gain on disposition of operations | 6 | 20 | 5 | |||||||||
| Income tax expense (2) | (492 | ) | (802 | ) | (877 | ) | ||||||
| Net income | 2,252 | 3,189 | 1,877 | |||||||||
| Preferred stock dividends | (148 | ) | (116 | ) | (116 | ) | ||||||
| Net income applicable to common shareholders | $ | 2,104 | $ | 3,073 | $ | 1,761 |
| (1) | Due to the adoption of the recognition and measurement accounting standard, limited partnerships previously reported using the cost method are now reported at fair value with changes in fair value recognized in net investment income and equity securities are reported at fair value with changes in fair value recognized in valuation changes on equity investments in realized capital gains and losses. See the Investments section of this Item and Note 2 of the consolidated financial statements for further details. |
| (2) | Beginning January 1, 2018, the Tax Legislation reduced the U.S. corporate income tax rate from 35% to 21%. 2018 and 2017 results include a Tax Legislation benefit of $29 million and $506 million, respectively. 2017 results also include a tax benefit of $63 million related to the adoption of the new accounting standard for share-based payments on January 1, 2017. |
Property-Liability 2018 Form 10-K
Property-Liability Operations
Overview Our Property-Liability operations consist of two reportable segments: Allstate Protection and Discontinued Lines and Coverages. These segments are consistent with the groupings of financial information that management uses to evaluate performance and to determine the allocation of resources.
We do not allocate Property-Liability investment income, realized capital gains and losses, or assets to the Allstate Protection and Discontinued Lines and Coverages segments. Management reviews assets at the Property-Liability level for decision-making purposes.
The table below includes GAAP operating ratios we use to measure our profitability. We believe that they enhance an investor’s understanding of our profitability. They are calculated as follows:
| • | Loss ratio: the ratio of claims and claims expense to premiums earned. Loss ratios include the impact of catastrophe losses. |
| • | Expense ratio: the ratio of amortization of DAC, operating costs and expenses and restructuring and related charges, less other revenue to premiums earned. |
| • | Combined ratio: the ratio of claims and claims expense, amortization of DAC, operating costs and expenses, and restructuring and related charges, less other revenue to premiums earned. The combined ratio is the sum of the loss ratio and the expense ratio. The difference between 100% and the combined ratio represents underwriting income as a percentage of premiums earned, or underwriting margin. |
We have also calculated the following impacts of specific items on the GAAP operating ratios because of the volatility of these items between fiscal periods.
| • | Effect of catastrophe losses on combined ratio: the ratio of catastrophe losses included in claims and claims expense to premiums earned. This ratio includes prior year reserve reestimates of catastrophe losses. |
| • | Effect of prior year reserve reestimates on combined ratio: the ratio of prior year reserve reestimates included in claims and claims expense to premiums earned. This ratio includes prior year reserve reestimates of catastrophe losses. |
| • | Effect of amortization of purchased intangible assets on combined ratio: the ratio of amortization of purchased intangible assets to premiums earned. Amortization of purchased intangible assets is reported in operating costs and expenses on the Consolidated Statements of Operations. |
| • | Effect of restructuring and related charges on combined ratio: the ratio of restructuring and related charges to premiums earned. |
| • | Effect of Discontinued Lines and Coverages on combined ratio: the ratio of claims and claims expense and operating costs and expenses in the Discontinued Lines and Coverages segment to Property-Liability premiums earned. The sum of the effect of Discontinued Lines and Coverages on the combined ratio and the Allstate Protection combined ratio is equal to the Property-Liability combined ratio. |
The Allstate Corporation 41
2018 Form 10-K Property-Liability
| Summarized financial data | ||||||||||||
| ($ in millions, except ratios) | 2018 | 2017 | 2016 | |||||||||
| Premiums written | $ | 33,555 | $ | 31,648 | $ | 30,891 | ||||||
| Revenues | ||||||||||||
| Premiums earned | $ | 32,950 | $ | 31,433 | $ | 30,727 | ||||||
| Other revenue | 738 | 703 | 688 | |||||||||
| Net investment income | 1,464 | 1,478 | 1,253 | |||||||||
| Realized capital gains and losses | (639 | ) | 401 | (6 | ) | |||||||
| Total revenues | 34,513 | 34,015 | 32,662 | |||||||||
| Costs and expenses | ||||||||||||
| Claims and claims expense | (22,495 | ) | (21,566 | ) | (21,968 | ) | ||||||
| Amortization of DAC | (4,475 | ) | (4,205 | ) | (4,053 | ) | ||||||
| Operating costs and expenses | (4,545 | ) | (4,262 | ) | (4,145 | ) | ||||||
| Restructuring and related charges | (76 | ) | (91 | ) | (29 | ) | ||||||
| Total costs and expenses | (31,591 | ) | (30,124 | ) | (30,195 | ) | ||||||
| Gain on disposition of operations (1) | — | 14 | — | |||||||||
| Income tax expense | (581 | ) | (1,318 | ) | (806 | ) | ||||||
| Net income applicable to common shareholders | $ | 2,341 | $ | 2,587 | $ | 1,661 | ||||||
| Underwriting income | $ | 2,097 | $ | 2,012 | $ | 1,220 | ||||||
| Net investment income | 1,464 | 1,478 | 1,253 | |||||||||
| Income tax expense on operations | (715 | ) | (1,119 | ) | (812 | ) | ||||||
| Realized capital gains and losses, after-tax | (500 | ) | 272 | — | ||||||||
| Gain on disposition of operations, after-tax | — | 9 | — | |||||||||
| Tax Legislation expense | (5 | ) | (65 | ) | — | |||||||
| Net income applicable to common shareholders | $ | 2,341 | $ | 2,587 | $ | 1,661 | ||||||
| Catastrophe losses (2) | $ | 2,855 | $ | 3,228 | $ | 2,571 | ||||||
| GAAP operating ratios | ||||||||||||
| Claims and claims expense ratio | 68.2 | 68.6 | 71.5 | |||||||||
| Expense ratio (3) | 25.4 | 25.0 | 24.5 | |||||||||
| Combined ratio | 93.6 | 93.6 | 96.0 | |||||||||
| Effect of catastrophe losses on combined ratio | 8.7 | 10.3 | 8.4 | |||||||||
| Effect of prior year reserve reestimates on combined ratio (4) | (0.8 | ) | (1.6 | ) | (0.1 | ) | ||||||
| Effect of catastrophe losses included in prior year reserve reestimates on combined ratio | 0.1 | — | — | |||||||||
| Effect of amortization of purchased intangible assets on combined ratio | — | — | 0.1 | |||||||||
| Effect of restructuring and related charges on combined ratio | 0.2 | 0.3 | 0.1 | |||||||||
| Effect of Discontinued Lines and Coverages on combined ratio | 0.2 | 0.3 | 0.3 |
| (1) | 2017 results represented the conclusion of a contractual arrangement related to the sale of Sterling Collision Centers, Inc. in 2014. |
| (2) | Prior year reserve reestimates included in catastrophe losses totaled $25 million unfavorable, $18 million favorable and $6 million unfavorable in 2018, 2017 and 2016, respectively. |
| (3) | Other revenue is deducted from operating costs and expenses in the expense ratio calculation. |
| (4) | Prior year favorable reserve reestimates totaled $253 million, $505 million and $21 million in 2018, 2017 and 2016, respectively. |
Property-Liability 2018 Form 10-K
Net investment income decreased 0.9% or $14 million to $1.46 billion in 2018 from $1.48 billion in 2017 after increasing 18.0% in 2017 compared to 2016. The 2018 decrease was primarily due to lower performance-based investment results, primarily from limited partnerships, partially offset by higher market-based portfolio income. The 2017 increase benefited from strong performance-based results, primarily from limited partnerships, an increase in invested assets and stable market-based yields, partially offset by higher employee-related expenses. Limited partnership income includes asset appreciation and sales of underlying investments.
| Net investment income | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Fixed income securities | $ | 943 | $ | 909 | $ | 870 | ||||||
| Equity securities | 121 | 122 | 95 | |||||||||
| Mortgage loans | 17 | 12 | 11 | |||||||||
| Limited partnership interests (1) | 378 | 432 | 269 | |||||||||
| Short-term investments | 40 | 17 | 9 | |||||||||
| Other | 123 | 100 | 89 | |||||||||
| Investment income, before expense | 1,622 | 1,592 | 1,343 | |||||||||
| Investment expense (2) (3) | (158 | ) | (114 | ) | (90 | ) | ||||||
| Net investment income | $ | 1,464 | $ | 1,478 | $ | 1,253 |
| (1) | Due to the adoption of the recognition and measurement accounting standard, limited partnerships previously reported using the cost method are now reported at fair value with changes in fair value recognized in net investment income. |
| (2) | Investment expense includes $45 million, $22 million and $19 million of investee level expenses in 2018, 2017 and 2016, respectively, and has increased compared to prior year primarily due to growth in real estate investments. Investee level expenses include depreciation and asset level operating expenses on directly held real estate and other consolidated investments. |
| (3) | Investment expense includes $18 million, $4 million and zero related to the portion of reinvestment income on securities lending collateral paid to the counterparties in 2018, 2017 and 2016, respectively. |
Realized capital gains and losses Net realized capital losses in 2018, primarily related to decreases in the valuation of equity investments and losses on sales of fixed income securities. Realized capital gains and losses in 2017 primarily related to net gains on sales, as well as gains from valuation changes in public securities held in certain limited partnerships, partially offset by impairment and change in intent write-downs, and derivative valuation losses.
| Components of realized capital gains (losses) and the related tax effect | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Impairment write-downs (1) | $ | (5 | ) | $ | (56 | ) | $ | (130 | ) | |||
| Change in intent write-downs (1) | — | (44 | ) | (56 | ) | |||||||
| Net OTTI losses recognized in earnings | (5 | ) | (100 | ) | (186 | ) | ||||||
| Sales (1) | (148 | ) | 531 | 185 | ||||||||
| Valuation of equity investments (1)(2) | (522 | ) | — | — | ||||||||
| Valuation and settlements of derivative instruments | 36 | (30 | ) | (5 | ) | |||||||
| Realized capital gains and losses, pre-tax | (639 | ) | 401 | (6 | ) | |||||||
| Income tax benefit (expense) | 139 | (129 | ) | 6 | ||||||||
| Realized capital gains and losses, after-tax | $ | (500 | ) | $ | 272 | $ | — |
| (1) | Due to the adoption of the recognition and measurement accounting standard, equity securities are reported at fair value with changes in fair value recognized in valuation of equity investments and are no longer included in impairment write-downs, change in intent write-downs and sales. |
| (2) | 2018 results include $447 million of declines in the valuation of equity investments and $75 million of declines in value primarily related to certain limited partnerships where the underlying assets are predominately public equity securities. |
The Allstate Corporation 43
2018 Form 10-K Allstate Protection
Allstate Protection Segment
Private passenger auto, homeowners, and other personal lines insurance products are offered to consumers through agencies and directly through contact centers and online. Our strategy is to position product offerings and distribution channels to meet customers’ evolving needs and help them manage the risks they face. For additional information on our strategy and outlook, see Part I, Item 1. Business - Strategy and Segment Information.
| Underwriting results | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Premiums written | $ | 33,555 | $ | 31,648 | $ | 30,888 | ||||||
| Premiums earned | $ | 32,950 | $ | 31,433 | $ | 30,727 | ||||||
| Other revenue | 738 | 703 | 688 | |||||||||
| Claims and claims expense | (22,408 | ) | (21,470 | ) | (21,863 | ) | ||||||
| Amortization of DAC | (4,475 | ) | (4,205 | ) | (4,053 | ) | ||||||
| Other costs and expenses | (4,542 | ) | (4,259 | ) | (4,143 | ) | ||||||
| Restructuring and related charges | (76 | ) | (91 | ) | (29 | ) | ||||||
| Underwriting income | $ | 2,187 | $ | 2,111 | $ | 1,327 | ||||||
| Catastrophe losses | $ | 2,855 | $ | 3,228 | $ | 2,571 | ||||||
| Underwriting income (loss) by line of business | ||||||||||||
| Auto | $ | 1,681 | $ | 1,298 | $ | 156 | ||||||
| Homeowners | 457 | 658 | 1,075 | |||||||||
| Other personal lines (1) | 94 | 124 | 160 | |||||||||
| Commercial lines | (87 | ) | (19 | ) | (110 | ) | ||||||
| Other business lines (2) | 49 | 51 | 53 | |||||||||
| Answer Financial | (7 | ) | (1 | ) | (7 | ) | ||||||
| Underwriting income | $ | 2,187 | $ | 2,111 | $ | 1,327 |
| (1) | Other personal lines include renters, condominium, landlord and other personal lines products. |
| (2) | Other business lines represent Ivantage, a general agency for Allstate exclusive agencies. Ivantage provides agencies a solution for their customers when coverage through Allstate brand underwritten products is not available. |
Allstate Protection 2018 Form 10-K
| Changes in underwriting results from prior year by component and by line of business (1) | ||||||||||||||||||||||||||||||||||||||||
| For the years ended December 31, | ||||||||||||||||||||||||||||||||||||||||
| Auto | Homeowners | Other personal lines | Commercial lines | Allstate Protection (2) | ||||||||||||||||||||||||||||||||||||
| ($ in millions) | 2018 | 2017 | 2018 | 2017 | 2018 | 2017 | 2018 | 2017 | 2018 | 2017 | ||||||||||||||||||||||||||||||
| Underwriting income (loss) - prior year | $ | 1,298 | $ | 156 | $ | 658 | $ | 1,075 | $ | 124 | $ | 160 | $ | (19 | ) | $ | (110 | ) | $ | 2,111 | $ | 1,327 | ||||||||||||||||||
| Changes in underwriting income (loss) from: | ||||||||||||||||||||||||||||||||||||||||
| Increase (decrease) premiums earned | 1,092 | 614 | 207 | 53 | 58 | 50 | 160 | (11 | ) | 1,517 | 706 | |||||||||||||||||||||||||||||
| Increase (decrease) other revenue | 30 | 10 | 3 | — | 4 | 1 | (2 | ) | — | 35 | 15 | |||||||||||||||||||||||||||||
| (Increase) decrease incurred claims and claims expense (“losses”): | ||||||||||||||||||||||||||||||||||||||||
| Incurred losses, excluding catastrophe losses and reserve reestimates | (623 | ) | 623 | (262 | ) | (46 | ) | (71 | ) | (29 | ) | (137 | ) | 51 | (1,093 | ) | 599 | |||||||||||||||||||||||
| Catastrophe losses, excluding reserve reestimates | 336 | (150 | ) | 92 | (526 | ) | (13 | ) | (12 | ) | 1 | 7 | 416 | (681 | ) | |||||||||||||||||||||||||
| Catastrophe reserve reestimates | 24 | 7 | (72 | ) | 18 | 4 | (5 | ) | 1 | 4 | (43 | ) | 24 | |||||||||||||||||||||||||||
| Non-catastrophe reserve reestimates | (59 | ) | 328 | (73 | ) | 89 | 4 | (5 | ) | (90 | ) | 39 | (218 | ) | 451 | |||||||||||||||||||||||||
| Losses subtotal | (322 | ) | 808 | (315 | ) | (465 | ) | (76 | ) | (51 | ) | (225 | ) | 101 | (938 | ) | 393 | |||||||||||||||||||||||
| (Increase) decrease expenses | (417 | ) | (290 | ) | (96 | ) | (5 | ) | (16 | ) | (36 | ) | (1 | ) | 1 | (538 | ) | (330 | ) | |||||||||||||||||||||
| Underwriting income (loss) | $ | 1,681 | $ | 1,298 | $ | 457 | $ | 658 | $ | 94 | $ | 124 | $ | (87 | ) | $ | (19 | ) | $ | 2,187 | $ | 2,111 |
| (1) | The 2018 column presents changes in 2018 compared to 2017. The 2017 column presents changes in 2017 compared to 2016. |
| (2) | Includes other business lines underwriting income of $49 million and $51 million in 2018 and 2017, respectively, and Answer Financial underwriting loss of $7 million and $1 million in 2018 and 2017, respectively. |
Underwriting income totaled $2.19 billion in 2018, a 3.6% increase from $2.11 billion in 2017, primarily due to increased premiums earned, lower catastrophe losses and improved auto claim frequency, partially offset by higher claim severity, operating costs and expenses and lower favorable prior year reserve reestimates. Underwriting income totaled $2.11 billion in 2017, a 59.1% increase from $1.33 billion in 2016, primarily due to increased premiums earned, lower loss costs and higher favorable prior year reserve reestimates, partially offset by higher catastrophe losses.
Premiums written is the amount of premiums charged for policies issued during a fiscal period. Premiums are considered earned and are included in the financial results on a pro-rata basis over the policy period. The portion of premiums written applicable to the unexpired term of the policies is recorded as unearned premiums on our Consolidated Statements of Financial Position.
The Allstate Corporation 45
2018 Form 10-K Allstate Protection
| Premiums written and earned by line of business | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Premiums written | ||||||||||||
| Auto | $ | 23,367 | $ | 22,042 | $ | 21,425 | ||||||
| Homeowners | 7,698 | 7,350 | 7,240 | |||||||||
| Other personal lines | 1,831 | 1,768 | 1,724 | |||||||||
| Subtotal – Personal lines | 32,896 | 31,160 | 30,389 | |||||||||
| Commercial lines | 659 | 488 | 499 | |||||||||
| Total premiums written | $ | 33,555 | $ | 31,648 | $ | 30,888 | ||||||
| Reconciliation of premiums written to premiums earned: | ||||||||||||
| Increase in unearned premiums | (544 | ) | (258 | ) | (181 | ) | ||||||
| Other | (61 | ) | 43 | 20 | ||||||||
| Total premiums earned | $ | 32,950 | $ | 31,433 | $ | 30,727 | ||||||
| Auto | $ | 22,970 | $ | 21,878 | $ | 21,264 | ||||||
| Homeowners | 7,517 | 7,310 | 7,257 | |||||||||
| Other personal lines | 1,808 | 1,750 | 1,700 | |||||||||
| Subtotal – Personal lines | 32,295 | 30,938 | 30,221 | |||||||||
| Commercial lines | 655 | 495 | 506 | |||||||||
| Total premiums earned | $ | 32,950 | $ | 31,433 | $ | 30,727 |
Auto insurance premiums written totaled $23.37 billion in 2018, a 6.0% increase from $22.04 billion in 2017, following a 2.9% increase in 2017 from $21.43 billion in 2016.
Homeowners insurance premiums written totaled $7.70 billion in 2018, a 4.7% increase from $7.35 billion in 2017, following a 1.5% increase from $7.24 billion in 2016. Excluding the cost of catastrophe reinsurance, which is recorded as a reduction to premiums, premiums written increased 4.3% in 2018 compared to 2017. For a more detailed discussion on reinsurance, see the Claims and Claims Expense Reserves section of this Item and Note 10 of the consolidated financial statements.
| Unearned premium balance and the time frame in which we expect to recognize these premiums as earned | ||||||||||||||||||||
| ($ in millions) | as of December 31, | % earned after | ||||||||||||||||||
| 2018 | 2017 | Three months | Six months | Nine months | Twelve months | |||||||||||||||
| Allstate brand: | ||||||||||||||||||||
| Auto | $ | 5,635 | $ | 5,344 | 71.1 | % | 96.6 | % | 99.2 | % | 100.0 | % | ||||||||
| Homeowners | 3,908 | 3,745 | 43.3 | % | 75.4 | % | 94.1 | % | 100.0 | % | ||||||||||
| Other personal lines | 917 | 895 | 43.4 | % | 75.3 | % | 94.1 | % | 100.0 | % | ||||||||||
| Commercial lines | 250 | 246 | 44.0 | % | 75.2 | % | 93.9 | % | 100.0 | % | ||||||||||
| Total Allstate brand | 10,710 | 10,230 | 58.1 | % | 86.7 | % | 96.8 | % | 100.0 | % | ||||||||||
| Esurance brand: | ||||||||||||||||||||
| Auto | 471 | 404 | 74.4 | % | 99.1 | % | 99.8 | % | 100.0 | % | ||||||||||
| Homeowners | 53 | 42 | 43.4 | % | 75.5 | % | 94.2 | % | 100.0 | % | ||||||||||
| Other personal lines | 2 | 2 | 43.5 | % | 75.4 | % | 94.1 | % | 100.0 | % | ||||||||||
| Total Esurance brand | 526 | 448 | 71.1 | % | 96.6 | % | 99.2 | % | 100.0 | % | ||||||||||
| Encompass brand: | ||||||||||||||||||||
| Auto | 275 | 275 | 43.9 | % | 75.7 | % | 94.2 | % | 100.0 | % | ||||||||||
| Homeowners | 212 | 216 | 43.8 | % | 75.7 | % | 94.2 | % | 100.0 | % | ||||||||||
| Other personal lines | 42 | 44 | 44.1 | % | 75.8 | % | 94.2 | % | 100.0 | % | ||||||||||
| Total Encompass brand | 529 | 535 | 43.8 | % | 75.7 | % | 94.2 | % | 100.0 | % | ||||||||||
| Allstate Protection unearned premiums | $ | 11,765 | $ | 11,213 | 58.1 | % | 86.6 | % | 96.8 | % | 100.0 | % |
Allstate Protection 2018 Form 10-K
| Combined ratios by line of business | |||||||||||||||||||||||||||
| For the years ended December 31, | |||||||||||||||||||||||||||
| Loss ratio | Expense ratio (1) | Combined ratio | |||||||||||||||||||||||||
| 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | |||||||||||||||||||
| Auto | 67.0 | 68.9 | 74.7 | 25.7 | 25.2 | 24.6 | 92.7 | 94.1 | 99.3 | ||||||||||||||||||
| Homeowners | 69.5 | 67.2 | 61.3 | 24.4 | 23.8 | 23.9 | 93.9 | 91.0 | 85.2 | ||||||||||||||||||
| Other personal lines | 66.2 | 64.0 | 62.9 | 28.6 | 28.9 | 27.7 | 94.8 | 92.9 | 90.6 | ||||||||||||||||||
| Commercial lines | 91.5 | 75.5 | 93.9 | 21.8 | 28.3 | 27.8 | 113.3 | 103.8 | 121.7 | ||||||||||||||||||
| Total | 68.0 | 68.3 | 71.2 | 25.4 | 25.0 | 24.5 | 93.4 | 93.3 | 95.7 |
| (1) | Other revenue is deducted from operating costs and expenses in the expense ratio calculation. |
| Loss ratios by line of business | ||||||||||||||||||||||||||||||||||||
| For the years ended December 31, | ||||||||||||||||||||||||||||||||||||
| Loss ratio | Effect of catastrophe losses on combined ratio | Effect of prior year reserve reestimates on combined ratio | Effect of catastrophe losses included in prior year reserve reestimates on combined ratio | |||||||||||||||||||||||||||||||||
| 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | |||||||||||||||||||||||||
| Auto | 67.0 | 68.9 | 74.7 | 1.6 | 3.3 | 2.7 | (2.0 | ) | (2.2 | ) | (0.7 | ) | (0.2 | ) | (0.1 | ) | — | |||||||||||||||||||
| Homeowners | 69.5 | 67.2 | 61.3 | 30.0 | 31.2 | 24.4 | 0.2 | (1.8 | ) | (0.3 | ) | 0.9 | (0.1 | ) | 0.2 | |||||||||||||||||||||
| Other personal lines | 66.2 | 64.0 | 62.9 | 12.1 | 11.9 | 11.3 | (0.4 | ) | 0.1 | (0.5 | ) | — | 0.2 | (0.1 | ) | |||||||||||||||||||||
| Commercial lines | 91.5 | 75.5 | 93.9 | 3.4 | 4.8 | 6.9 | 16.5 | 3.8 | 12.2 | — | 0.2 | 1.0 | ||||||||||||||||||||||||
| Total | 68.0 | 68.3 | 71.2 | 8.7 | 10.3 | 8.4 | (1.0 | ) | (1.9 | ) | (0.4 | ) | 0.1 | (0.1 | ) | — |
Catastrophe losses were $2.86 billion in 2018, compared to $3.23 billion in 2017 and $2.57 billion in 2016. We define a “catastrophe” as an event that produces pre-tax losses before reinsurance in excess of $1 million and involves multiple first party policyholders, or a winter weather event that produces a number of claims in excess of a preset, per-event threshold of average claims in a specific area, occurring within a certain amount of time following the event. Catastrophes are caused by various natural events including high winds, winter storms and freezes, tornadoes, hailstorms, wildfires, tropical storms, tsunamis, hurricanes, earthquakes and volcanoes. We are also exposed to man-made catastrophic events, such as certain types of terrorism or industrial accidents. The nature and level of catastrophes in any period cannot be reliably predicted.
| Catastrophe losses in 2018 by the size of event | ||||||||||||||||||||
| ($ in millions) | Number of Events | Claims and claims expense | Combined ratio impact | Average catastrophe loss per event | ||||||||||||||||
| Size of catastrophe loss | ||||||||||||||||||||
| Greater than $250 million | 1 | 0.8 | % | $ | 469 | 16.4 | % | 1.4 | $ | 469 | ||||||||||
| $101 million to $250 million | 5 | 4.3 | 769 | 26.9 | 2.3 | 154 | ||||||||||||||
| $50 million to $100 million | 9 | 7.7 | 694 | 24.3 | 2.1 | 77 | ||||||||||||||
| Less than $50 million | 102 | 87.2 | 898 | 31.5 | 2.8 | 9 | ||||||||||||||
| Total | 117 | 100.0 | % | 2,830 | 99.1 | 8.6 | 24 | |||||||||||||
| Prior year reserve reestimates | 25 | 0.9 | 0.1 | |||||||||||||||||
| Total catastrophe losses | $ | 2,855 | 100.0 | % | 8.7 |
| Catastrophe losses by the type of event | |||||||||||||||||||||
| For the years ended December 31, | |||||||||||||||||||||
| ($ in millions) | Number of events | 2018 | Number of events | 2017 | Number of events | 2016 | |||||||||||||||
| Hurricanes/Tropical storms | 3 | $ | 200 | 3 | $ | 613 | 2 | $ | 156 | ||||||||||||
| Tornadoes | 3 | 17 | 3 | 100 | 2 | 7 | |||||||||||||||
| Wind/Hail | 99 | 1,752 | 93 | 1,973 | 72 | 2,255 | |||||||||||||||
| Wildfires | 10 | 745 | 10 | 536 | 8 | 92 | |||||||||||||||
| Other events | 2 | 116 | 2 | 24 | 2 | 55 | |||||||||||||||
| Prior year reserve reestimates | 25 | (18 | ) | 6 | |||||||||||||||||
| Total catastrophe losses | 117 | $ | 2,855 | 111 | $ | 3,228 | 86 | $ | 2,571 |
The Allstate Corporation 47
2018 Form 10-K Allstate Protection
Catastrophe management
Historical catastrophe experience For the last ten years, the average annual impact of catastrophes on our loss ratio was 8.4 points, but it has varied from 4.5 points to 14.7 points. The average annual impact of catastrophes on the homeowners loss ratio for the last ten years was 32.0 points. Over time, we have limited our aggregate insurance exposure to catastrophe losses in certain regions of the country that are subject to high levels of natural catastrophes, limited by our participation in various state facilities. For further discussion of these facilities, see Note 14 of the consolidated financial statements. However, the impact of these actions may be diminished by the growth in insured values, and the effect of state insurance laws and regulations. In addition, in various states we are required to participate in assigned risk plans, reinsurance facilities and joint underwriting associations that provide insurance coverage to individuals or entities that otherwise are unable to purchase such coverage from private insurers. Because of our participation in these and other state facilities such as wind pools, we may be exposed to losses that surpass the capitalization of these facilities and to assessments from these facilities.
We have continued to take actions to maintain an appropriate level of exposure to catastrophic events while continuing to meet the needs of our customers, including the following:
| • | Continuing to limit or not offer new homeowners, manufactured home and landlord package policy business in certain coastal geographies. |
| • | Increased capacity in our brokerage platform for customers not offered an Allstate policy. |
| • | In 2016, we began to write a limited number of homeowners policies in select areas of California. We continue to renew current policyholders and allow replacement policies for existing customers who buy a new home, or change their residence to rental property. Additionally, we write homeowners coverage through North Light Specialty Insurance Company (“North Light”), which includes earthquake coverage (other than fire following earthquakes) that is currently ceded via quota share reinsurance. |
| • | In certain states, we have been ceding wind exposure related to insured property located in wind pool eligible areas. |
| • | Starting in the second quarter of 2017, we began writing a limited number of homeowners policies in select areas of Florida and continue to support existing customers who replace their currently-insured home with an acceptable property. Encompass withdrew from property lines in Florida in 2009. |
| • | Tropical cyclone deductibles are generally higher than all peril deductibles and are in place for a large portion of coastal insured properties. |
| • | Auto physical damage coverage generally includes coverage for flood-related loss. We have additional catastrophe exposure, beyond the property lines, for auto customers who have purchased physical |
damage coverage. We manage this additional exposure through inclusion of auto losses in our nationwide reinsurance program, including Florida personal lines automobile business, as of June 1, 2016. New Jersey is excluded from the nationwide reinsurance program, but auto losses are included in our New Jersey reinsurance program.
| • | We offer a homeowners policy available in 42 states and the District of Columbia (“D.C.”), Allstate House and Home®, that provides options of coverage for roof damage, including graduated coverage and pricing based on roof type and age. |
Hurricanes We consider the greatest areas of potential catastrophe losses due to hurricanes generally to be major metropolitan centers in counties along the eastern and gulf coasts of the United States. Usually, the average premium on a property policy near these coasts is greater than in other areas. However, average premiums are often not considered commensurate with the inherent risk of loss. In addition and as explained in Note 14 of the consolidated financial statements, in various states Allstate is subject to assessments from assigned risk plans, reinsurance facilities and joint underwriting associations providing insurance for wind related property losses.
We have addressed our risk of hurricane loss by, among other actions, purchasing reinsurance for specific states and on a countrywide basis for our personal lines property insurance in areas most exposed to hurricanes, limiting personal homeowners, landlord package policy and manufactured home new business writings in coastal areas in southern and eastern states, implementing tropical cyclone deductibles where appropriate, and not offering continuing coverage on certain policies in coastal counties in certain states. We continue to seek appropriate returns for the risks we write. This may require further actions, similar to those already taken, in geographies where we are not getting appropriate returns. However, we may maintain or opportunistically increase our presence in areas where adequate risk adjusted returns can be achieved.
Earthquakes We do not offer earthquake coverage in most states. We retain approximately 23,000 PIF with earthquake coverage, primarily in Kentucky, due to regulatory and other reasons. We purchase reinsurance in Kentucky and enter into arrangements in many states to make earthquake coverage available through our brokerage platform.
We continue to have exposure to earthquake risk on certain policies that do not specifically exclude coverage for earthquake losses, including our auto policies, and to fires following earthquakes. Allstate policyholders in California are offered homeowners coverage through the California Earthquake Authority (“CEA”), a privately-financed, publicly-managed state agency created to provide insurance coverage for earthquake damage. Allstate is subject to assessments from the CEA under certain circumstances as explained in Note 14 of the consolidated financial statements. While North Light writes property policies in California, which can include
Allstate Protection 2018 Form 10-K
earthquake coverage, this coverage is 100% ceded via quota share reinsurance.
Fires Following Earthquakes Under a standard homeowners policy we cover fire losses, including those caused by an earthquake. Actions taken related to our risk of loss from fires following earthquakes include restrictive underwriting guidelines in California for new business writings, purchasing reinsurance for Kentucky personal lines property risks, and purchasing nationwide occurrence reinsurance, excluding Florida and New Jersey.
Wildfires Actions taken related to managing our risk of loss from wildfires include purchasing nationwide occurrence reinsurance, new and renewal inspection programs to identify and remediate wildfire risk as well as leveraging contemporary underwriting tools in select areas. While these programs are designed to mitigate risk, the exposure to wildfires still
exists. We continue to manage our exposure and seek appropriate returns for the risks we write. For example, despite writing a limited number of homeowner risks in select geographies in California over the last three years, our overall homeowner exposures in California have declined approximately 50% since 2007.
To manage the exposure, this may require further actions, similar to those already taken, in geographies where we are not achieving appropriate returns. However, we may maintain or opportunistically increase our presence in areas where adequate risk adjusted returns can be achieved.
Reinsurance A description of our current catastrophe reinsurance program appears in Note 10 of the consolidated financial statements.
Expense ratio increased 0.4 points in 2018 compared to 2017.
| Expense ratios by line of business | |||||||||
| For the years ended December 31, | |||||||||
| 2018 | 2017 | 2016 | |||||||
| Auto | 25.7 | 25.2 | 24.6 | ||||||
| Homeowners | 24.4 | 23.8 | 23.9 | ||||||
| Other personal lines | 28.6 | 28.9 | 27.7 | ||||||
| Commercial lines | 21.8 | 28.3 | 27.8 | ||||||
| Total expense ratio (1) | 25.4 | 25.0 | 24.5 |
| (1) | Other revenue is deducted from other costs and expenses in the expense ratio calculation. |
| Impact of specific costs and expenses on the expense ratio | |||||||||
| For the years ended December 31, | |||||||||
| 2018 | 2017 | 2016 | |||||||
| Amortization of DAC | 13.6 | 13.4 | 13.2 | ||||||
| Advertising expense | 2.5 | 2.2 | 2.5 | ||||||
| Amortization of purchased intangible assets | — | — | 0.1 | ||||||
| Other costs and expenses | 9.1 | 9.1 | 8.6 | ||||||
| Restructuring and related charges | 0.2 | 0.3 | 0.1 | ||||||
| Total expense ratio (1) | 25.4 | 25.0 | 24.5 |
(1) Other revenue is deducted from other costs and expenses in the expense ratio calculation.
Deferred acquisition costs We establish a DAC asset for costs that are related directly to the successful acquisition of new or renewal insurance policies, principally agency remuneration and premium taxes. DAC is amortized to income over the period in which premiums are earned.
| DAC balance as of December 31 by product type | ||||||||
| ($ in millions) | 2018 | 2017 | ||||||
| Auto | $ | 845 | $ | 789 | ||||
| Homeowners | 599 | 558 | ||||||
| Other personal lines | 141 | 132 | ||||||
| Commercial lines | 33 | 31 | ||||||
| Total DAC | $ | 1,618 | $ | 1,510 |
The Allstate Corporation 49
2018 Form 10-K Allstate Protection
The following table presents premiums written, PIF and underwriting income (loss) by line of business for Allstate brand, Esurance brand, Encompass brand and Allstate Protection as of or for the year ended December 31, 2018. Detailed analysis of underwriting results, premiums written and earned, and the combined ratios, including loss and expense ratios, are discussed in the brand sections below.
| Premiums written, policies in force and underwriting income (loss) | ||||||||||||||||||||||||||||
| ($ in millions) | Allstate brand | Esurance brand | Encompass brand | Allstate Protection | ||||||||||||||||||||||||
| Premiums written | Amount | Percent to total brand | Amount | Percent to total brand | Amount | Percent to total brand | Amount | Percent to total | ||||||||||||||||||||
| Auto | $ | 20,991 | 68.6 | % | $ | 1,839 | 94.4 | % | $ | 537 | 52.8 | % | $ | 23,367 | 69.6 | % | ||||||||||||
| Homeowners | 7,199 | 23.5 | 101 | 5.2 | 398 | 39.2 | 7,698 | 22.9 | ||||||||||||||||||||
| Other personal lines | 1,742 | 5.7 | 8 | 0.4 | 81 | 8.0 | 1,831 | 5.5 | ||||||||||||||||||||
| Commercial lines | 659 | 2.2 | — | — | — | — | 659 | 2.0 | ||||||||||||||||||||
| Total | $ | 30,591 | 100.0 | % | $ | 1,948 | 100.0 | % | $ | 1,016 | 100.0 | % | $ | 33,555 | 100.0 | % | ||||||||||||
| Percent to total Allstate Protection | 91.2 | % | 5.8 | % | 3.0 | % | 100.0 | % | ||||||||||||||||||||
| PIF (thousands) | ||||||||||||||||||||||||||||
| Auto | 20,104 | 65.2 | % | 1,488 | 91.4 | % | 502 | 61.3 | % | 22,094 | 66.4 | % | ||||||||||||||||
| Homeowners | 6,186 | 20.1 | 95 | 5.8 | 239 | 29.2 | 6,520 | 19.6 | ||||||||||||||||||||
| Other personal lines | 4,295 | 13.9 | 46 | 2.8 | 78 | 9.5 | 4,419 | 13.3 | ||||||||||||||||||||
| Commercial lines | 231 | 0.8 | — | — | — | — | 231 | 0.7 | ||||||||||||||||||||
| Total | 30,816 | 100.0 | % | 1,629 | 100.0 | % | 819 | 100.0 | % | 33,264 | 100.0 | % | ||||||||||||||||
| Percent to total Allstate Protection | 92.6 | % | 4.9 | % | 2.5 | % | 100.0 | % | ||||||||||||||||||||
| Underwriting income (loss) | ||||||||||||||||||||||||||||
| Auto | $ | 1,681 | 76.2 | % | $ | (11 | ) | 44.0 | % | $ | 11 | 84.6 | % | $ | 1,681 | 76.9 | % | |||||||||||
| Homeowners | 472 | 21.4 | (14 | ) | 56.0 | (1 | ) | (7.7 | ) | 457 | 20.9 | |||||||||||||||||
| Other personal lines | 91 | 4.1 | — | — | 3 | 23.1 | 94 | 4.3 | ||||||||||||||||||||
| Commercial lines | (87 | ) | (3.9 | ) | — | — | — | — | (87 | ) | (4.0 | ) | ||||||||||||||||
| Other business lines | 49 | 2.2 | — | — | — | — | 49 | 2.2 | ||||||||||||||||||||
| Answer Financial | — | — | — | — | — | — | (7 | ) | (0.3 | ) | ||||||||||||||||||
| Total | $ | 2,206 | 100.0 | % | $ | (25 | ) | 100.0 | % | $ | 13 | 100.0 | % | $ | 2,187 | 100.0 | % |
When analyzing premium measures and statistics for all three brands the following calculations are used as described below.
| • | PIF: Policy counts are based on items rather than customers. A multi-car customer would generate multiple item (policy) counts, even if all cars were insured under one policy. Commercial lines PIF for the agreement with a transportation network company reflects corporate contracts as opposed to individual driver counts. |
| • | New issued applications: Item counts of automobile or homeowner insurance applications for insurance policies that were issued during the period, regardless of whether the customer was previously insured by another Allstate Protection brand. Allstate brand includes automobiles added by existing customers when they exceed the number allowed (currently 10) on a policy. |
| • | Average premium-gross written (“average premium”): Gross premiums written divided by issued item count. Gross premiums written include the impacts from discounts, surcharges and ceded reinsurance premiums and exclude the impacts from mid-term premium adjustments and premium refund accruals. Average premiums represent the appropriate policy term for each line. Allstate and Esurance brand policy terms are 6 months for auto and 12 months for homeowners. Encompass brand policy terms are generally 12 months for auto and homeowners. |
| • | Renewal ratio: Renewal policy item counts issued during the period, based on contract effective dates, divided by the total policy item counts issued 6 months prior for auto (generally 12 months prior for Encompass brand) or 12 months prior for homeowners. |
Allstate Protection: Allstate brand 2018 Form 10-K
Allstate brand products are sold primarily through Allstate exclusive agencies and serve customers who prefer local personalized advice and service and are brand-sensitive. In 2018, the Allstate brand represented 91.2% of the Allstate Protection segment’s written premium. For additional information on our strategy and outlook, see Part I, Item 1. Business - Strategy and Segment Information.
| Underwriting results | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Premiums written | $ | 30,591 | $ | 28,885 | $ | 28,059 | ||||||
| Premiums earned | $ | 30,058 | $ | 28,631 | $ | 27,865 | ||||||
| Other revenue | 582 | 559 | 545 | |||||||||
| Claims and claims expense | (20,296 | ) | (19,352 | ) | (19,750 | ) | ||||||
| Amortization of DAC | (4,242 | ) | (3,963 | ) | (3,791 | ) | ||||||
| Other costs and expenses | (3,828 | ) | (3,591 | ) | (3,385 | ) | ||||||
| Restructuring and related charges | (68 | ) | (83 | ) | (27 | ) | ||||||
| Underwriting income | $ | 2,206 | $ | 2,201 | $ | 1,457 | ||||||
| Catastrophe losses | $ | 2,701 | $ | 2,985 | $ | 2,424 | ||||||
| Underwriting income (loss) by line of business | ||||||||||||
| Auto | $ | 1,681 | $ | 1,331 | $ | 250 | ||||||
| Homeowners | 472 | 725 | 1,098 | |||||||||
| Other personal lines (1) | 91 | 113 | 166 | |||||||||
| Commercial lines | (87 | ) | (19 | ) | (110 | ) | ||||||
| Other business lines (2) | 49 | 51 | 53 | |||||||||
| Underwriting income | $ | 2,206 | $ | 2,201 | $ | 1,457 |
| (1) | Other personal lines include renters, condominium, landlord and other personal lines products. |
| (2) | Other business lines represent Ivantage. |
| Changes in underwriting results from prior year by component (1) | ||||||||
| For the years ended December 31, | ||||||||
| ($ in millions) | 2018 | 2017 | ||||||
| Underwriting income - prior year | $ | 2,201 | $ | 1,457 | ||||
| Changes in underwriting income (loss) from: | ||||||||
| Increase (decrease) premiums earned | 1,427 | 766 | ||||||
| Increase (decrease) other revenue | 23 | 14 | ||||||
| (Increase) decrease incurred claims and claims expense (“losses”): | ||||||||
| Incurred losses, excluding catastrophe losses and reserve reestimates | (1,002 | ) | 506 | |||||
| Catastrophe losses, excluding reserve reestimates | 311 | (583 | ) | |||||
| Catastrophe reserve reestimates | (27 | ) | 22 | |||||
| Non-catastrophe reserve reestimates | (226 | ) | 453 | |||||
| Losses subtotal | (944 | ) | 398 | |||||
| (Increase) decrease expenses | (501 | ) | (434 | ) | ||||
| Underwriting income | $ | 2,206 | $ | 2,201 |
(1) The 2018 column presents changes in 2018 compared to 2017. The 2017 column presents changes in 2017 compared to 2016.
Underwriting income totaled $2.21 billion in 2018, a 0.2% increase from $2.20 billion in 2017, primarily due to increased premiums earned, lower catastrophe losses and improved auto claim frequency, partially offset by higher claim severity, agency and employee-related compensation costs and advertising costs and lower favorable non-catastrophe prior year reserve reestimates.
Underwriting income totaled $2.20 billion in 2017, a 51.1% increase from $1.46 billion in 2016, primarily due to increased premiums earned, lower claim frequency and higher favorable prior year reserve reestimates, partially offset by higher catastrophe losses and agency and employee-related compensation costs.
The Allstate Corporation 51
2018 Form 10-K Allstate Protection: Allstate brand
| Premiums written and earned by line of business | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Premiums written | ||||||||||||
| Auto | $ | 20,991 | $ | 19,859 | $ | 19,209 | ||||||
| Homeowners | 7,199 | 6,865 | 6,730 | |||||||||
| Other personal lines | 1,742 | 1,673 | 1,621 | |||||||||
| Subtotal – Personal lines | 29,932 | 28,397 | 27,560 | |||||||||
| Commercial lines | 659 | 488 | 499 | |||||||||
| Total | $ | 30,591 | $ | 28,885 | $ | 28,059 | ||||||
| Premiums earned | ||||||||||||
| Auto | $ | 20,662 | $ | 19,676 | $ | 19,031 | ||||||
| Homeowners | 7,025 | 6,811 | 6,736 | |||||||||
| Other personal lines | 1,716 | 1,649 | 1,592 | |||||||||
| Subtotal – Personal lines | 29,403 | 28,136 | 27,359 | |||||||||
| Commercial lines | 655 | 495 | 506 | |||||||||
| Total | $ | 30,058 | $ | 28,631 | $ | 27,865 |
| Auto premium measures and statistics | ||||||||||||
| 2018 | 2017 | 2016 | ||||||||||
| PIF (thousands) | 20,104 | 19,580 | 19,742 | |||||||||
| New issued applications (thousands) | 2,933 | 2,520 | 2,312 | |||||||||
| Average premium | $ | 570 | $ | 550 | $ | 523 | ||||||
| Renewal ratio (%) | 88.5 | 87.6 | 87.8 | |||||||||
| Approved rate changes (1): | ||||||||||||
| # of locations (2) | 47 | 49 | 53 | |||||||||
| Total brand (%) (3) | 1.1 | 4.0 | (6) | 7.2 | ||||||||
| Location specific (%) (4)(5) | 2.9 | 6.0 | (6) | 8.1 |
| (1) | Rate changes do not include rating plan enhancements, including the introduction of discounts and surcharges that result in no change in the overall rate level in a location. These rate changes do not reflect initial rates filed for insurance subsidiaries initially writing business in a location. |
| (2) | Allstate brand operates in 50 states, D.C. and 5 Canadian provinces. |
| (3) | Represents the impact in the states, D.C. and Canadian provinces where rate changes were approved during the period as a percentage of total brand prior year-end premiums written. |
| (4) | Represents the impact in the states, D.C. and Canadian provinces where rate changes were approved during the period as a percentage of their respective total prior year-end premiums written in those same locations. |
| (5) | Based on historical premiums written in the locations noted above, rate changes approved for auto totaled $215 million, $773 million and $1.33 billion in 2018, 2017 and 2016, respectively. |
| (6) | Includes a rate increase in California in first and fourth quarter 2017. Excluding California, Allstate brand auto total brand and location specific rate changes were 2.7% and 4.7% in 2017. |
Auto insurance premiums written totaled $20.99 billion in 2018, a 5.7% increase from $19.86 billion in 2017. Factors impacting premiums written were:
| • | 2.7% or 524 thousand increase in PIF as of December 31, 2018 compared to December 31, 2017. The rate of PIF change compared to the prior year improved throughout 2018. Auto PIF increased in 40 states, including 8 of our largest 10 states, as of December 31, 2018 compared to December 31, 2017. |
| • | 0.9 point increase in the renewal ratio in 2018 compared to 2017. 48 states, including 9 of our largest 10 states, experienced increases in the renewal ratio in 2018 compared to 2017. |
| • | 16.4% increase in new issued applications in 2018 compared to 2017. 43 states, including 9 of our largest 10 states, experienced increases in new issued applications in 2018 compared to 2017, with 34 states experiencing double digit increases. |
| • | 3.6% increase in average premium in 2018 compared to 2017, primarily due to rate increases approved in 2017. |
Auto insurance premiums written totaled $19.86 billion in 2017, a 3.4% increase from $19.21 billion in 2016. Factors impacting premiums written were:
| • | 0.8% or 162 thousand decrease in PIF as of December 31, 2017 compared to December 31, 2016. The rate of PIF change compared to the prior year improved throughout 2017. Auto PIF increased in 18 states, including 3 of our largest 10 states, as of December 31, 2017 compared to December 31, 2016. |
| • | 9.0% increase in new issued applications in 2017 compared to 2016. 38 states, including 9 of our largest 10 states, experienced increases in new issued applications in 2017 compared to 2016, with 20 states experiencing double digit increases. |
| • | 5.2% increase in average premium in 2017 compared to 2016, primarily due to rate increases. |
Allstate Protection: Allstate brand 2018 Form 10-K
| • | 0.2 point decrease in the renewal ratio in 2017 compared to 2016. 20 states, including 3 of our largest 10 states, experienced increases in the renewal ratio in 2017 compared to 2016. |
| Homeowners premium measures and statistics | |||||||||||||
| 2018 | 2017 | 2016 | |||||||||||
| PIF (thousands) | 6,186 | 6,088 | 6,120 | ||||||||||
| New issued applications (thousands) | 826 | 733 | 712 | ||||||||||
| Average premium | $ | 1,231 | $ | 1,197 | $ | 1,177 | |||||||
| Renewal ratio (%) | 88.0 | 87.3 | 87.8 | ||||||||||
| Approved rate changes (1): | |||||||||||||
| # of locations (2) | 40 | 30 | 40 | ||||||||||
| Total brand (%) | 2.7 | 1.8 | 1.1 | (4) | |||||||||
| Location specific (%) (3) | 4.3 | 3.7 | 2.2 | (4) |
| (1) | Includes rate changes approved based on our net cost of reinsurance. |
| (2) | Allstate brand operates in 50 states, D.C., and 5 Canadian provinces. |
| (3) | Based on historical premiums written in the locations noted above, rate changes approved for homeowners totaled $189 million, $122 million and $75 million in 2018, 2017 and 2016, respectively. |
| (4) | Includes the impact of a rate decrease in California in first quarter 2016. Excluding California, Allstate brand homeowners total brand and location specific rate changes were 2.1% and 5.1% in 2016, respectively. |
Homeowners insurance premiums written totaled $7.20 billion in 2018, a 4.9% increase from $6.87 billion in 2017. Factors impacting premiums written were:
| • | 1.6% or 98 thousand increase in PIF as of December 31, 2018 compared to December 31, 2017. Allstate brand homeowners PIF increased in 32 states, including 5 of our largest 10 states, as of December 31, 2018 compared to December 31, 2017. |
| • | 0.7 point increase in the renewal ratio in 2018 compared to 2017. Of our largest 10 states, 9 experienced an increase in the renewal ratio in 2018 compared to 2017. |
| • | 12.7% increase in new issued applications in 2018 compared to 2017. Of our largest 10 states, 8 experienced increases in new issued applications in 2018 compared to 2017. |
| • | 2.8% increase in average premium in 2018 compared to 2017 primarily due to rate increases and increasing insured home valuations due to inflation. |
| • | $19 million decrease in the cost of our catastrophe reinsurance program to $264 million in 2018 from $283 million in 2017. Catastrophe placement premiums are recorded primarily in the Allstate brand and are a reduction of premium. |
Premiums written for Allstate’s House and Home product, our homeowners offering currently available in 42 states and D.C., totaled $2.87 billion in 2018 compared to $2.34 billion in 2017.
Homeowners insurance premiums written totaled $6.87 billion in 2017, a 2.0% increase from $6.73 billion in 2016. Factors impacting premiums written were:
| • | 0.5% or 32 thousand decrease in PIF as of December 31, 2017 compared to December 31, 2016. Allstate brand homeowners PIF increased in 20 states, including 4 of our largest 10 states, as of |
December 31, 2017 compared to December 31, 2016.
| • | 2.9% increase in new issued applications in 2017 compared to 2016. Of our largest 10 states, 6 experienced increases in new issued applications in 2017 compared to 2016. |
| • | 1.7% increase in average premium in 2017 compared to 2016 primarily due to rate changes and increasing insured home valuations due to inflation. |
| • | 0.5 point decrease in the renewal ratio in 2017 compared to 2016. Of our largest 10 states, 1 experienced an increase in the renewal ratio in 2017 compared to 2016. |
| • | $52 million decrease in the cost of our catastrophe reinsurance program to $283 million in 2017 from $335 million in 2016. |
Other personal lines premiums written totaled $1.74 billion in 2018, a 4.1% increase from $1.67 billion in 2017, following a 3.2% increase in 2017 from $1.62 billion in 2016. The increase in 2018 was primarily due to increases in personal umbrella and condominium insurance premiums, partially offset by agreements to transfer our auto residual market obligations to third party carriers. The increase in 2017 was primarily due to increases in personal umbrella insurance premiums.
Commercial lines premiums written totaled $659 million in 2018, a 35.0% increase from $488 million in 2017, following a 2.2% decrease in 2017 from $499 million in 2016. The increase in 2018 was due to the agreement with a transportation network company to provide commercial auto insurance coverage in select states, partially offset by profit improvement actions. The decrease in 2017 was driven by decreased new business and lower renewals due to profit improvement actions, partially offset by increased average premiums.
The Allstate Corporation 53
2018 Form 10-K Allstate Protection: Allstate brand
| Combined ratios by line of business | |||||||||||||||||||||||||||
| For the years ended December 31, | |||||||||||||||||||||||||||
| Loss ratio | Expense ratio (1) | Combined ratio | |||||||||||||||||||||||||
| 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | |||||||||||||||||||
| Auto | 66.2 | 68.1 | 74.5 | 25.7 | 25.1 | 24.2 | 91.9 | 93.2 | 98.7 | ||||||||||||||||||
| Homeowners | 69.5 | 66.2 | 61.0 | 23.8 | 23.2 | 22.7 | 93.3 | 89.4 | 83.7 | ||||||||||||||||||
| Other personal lines | 66.5 | 64.3 | 62.0 | 28.2 | 28.8 | 27.6 | 94.7 | 93.1 | 89.6 | ||||||||||||||||||
| Commercial lines | 91.5 | 75.5 | 93.9 | 21.8 | 28.3 | 27.8 | 113.3 | 103.8 | 121.7 | ||||||||||||||||||
| Total | 67.6 | 67.6 | 70.9 | 25.1 | 24.7 | 23.9 | 92.7 | 92.3 | 94.8 |
| (1) | Other revenue is deducted from operating costs and expenses in the expense ratio calculation. |
| Loss ratios by line of business | ||||||||||||||||||||||||||||||||||||
| For the years ended December 31, | ||||||||||||||||||||||||||||||||||||
| Loss ratio | Effect of catastrophe losses | Effect of prior year reserve reestimates | Effect of catastrophe losses included in prior year reserve reestimates | |||||||||||||||||||||||||||||||||
| 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | |||||||||||||||||||||||||
| Auto | 66.2 | 68.1 | 74.5 | 1.6 | 3.4 | 2.8 | (2.1 | ) | (2.5 | ) | (0.7 | ) | (0.2 | ) | (0.1 | ) | (0.1 | ) | ||||||||||||||||||
| Homeowners | 69.5 | 66.2 | 61.0 | 30.5 | 30.7 | 24.6 | — | (1.9 | ) | (0.3 | ) | 0.7 | (0.1 | ) | 0.1 | |||||||||||||||||||||
| Other personal lines | 66.5 | 64.3 | 62.0 | 12.3 | 12.2 | 11.8 | 0.5 | 0.7 | (0.9 | ) | (0.1 | ) | 0.2 | (0.2 | ) | |||||||||||||||||||||
| Commercial lines | 91.5 | 75.5 | 93.9 | 3.4 | 4.8 | 6.9 | 16.5 | 3.8 | 12.2 | — | 0.2 | 1.0 | ||||||||||||||||||||||||
| Total | 67.6 | 67.6 | 70.9 | 9.0 | 10.4 | 8.7 | (1.1 | ) | (2.0 | ) | (0.4 | ) | — | — | — |
Frequency and severity statistics, which are influenced by driving patterns, inflation and other factors, are provided to describe the trends in loss costs of the business. Our reserving process incorporates changes in loss patterns, operational statistics and changes in claims reporting processes to determine our best estimate of recorded reserves. We use the following statistics to evaluate losses:
| • Paid claim frequency (1) is calculated as annualized notice counts closed with payment in the period divided by the average of PIF with the applicable coverage during the period. |
| • Gross claim frequency (1) is calculated as annualized notice counts received in the period divided by the average of PIF with the applicable coverage during the period. Gross claim frequency includes all actual notice counts, regardless of their current status (open or closed) or their ultimate disposition (closed with a payment or closed without payment). |
| • Paid claim severity is calculated by dividing the sum of paid losses and loss expenses by claims closed with a payment during the period. |
| • Percent change in frequency or severity statistics is calculated as the amount of increase or decrease in the paid or gross claim frequency or severity in the current period compared to the same period in the prior year divided by the prior year paid or gross claim frequency or severity. |
| (1) | Frequency statistics exclude counts associated with catastrophe events. |
Paid claim frequency trends will often differ from gross claim frequency trends due to differences in the timing of when notices are received and when claims are settled. For property damage claims, paid frequency trends reflect smaller differences as timing between opening and settlement is generally less. For bodily injury, gross frequency trends reflect emerging trends since the difference in timing between opening and settlement is much greater and gross frequency does not experience the same volatility in quarterly
fluctuations seen in paid frequency. In evaluating frequency, we typically rely upon paid frequency trends for physical damage coverages such as property damage and gross frequency for casualty coverages such as bodily injury to provide an indicator of emerging trends in overall claim frequency while also providing insights for our analysis of severity.
We are continuing to implement new technology and process solutions to provide continued loss cost accuracy, efficient processing and enhanced customer experiences that are simple, fast and produce high degrees of satisfaction. We have opened several Digital Operating Centers to handle auto physical damage claims countrywide utilizing our virtual estimation capabilities, which includes estimating damage through photos and video with the use of QuickFoto Claim® and Virtual AssistSM. We are also leveraging virtual capabilities to handle property claims by estimating damage through video with Virtual Assist and aerial imagery using satellites, airplanes and drones. These organizational and process changes impact frequency and severity statistics as changes in claim opening and closing practices and shifts in timing, if any, can impact comparisons to prior periods.
Auto loss ratio decreased 1.9 points in 2018 compared to 2017, primarily due to increased premiums earned, lower catastrophe losses and improved claim frequency, partially offset by higher claim severity and lower favorable non-catastrophe prior year reserve reestimates. Auto loss ratio decreased 6.4 points in 2017 compared to 2016, primarily due to increased premiums earned, lower claim frequency and higher favorable prior year reserve reestimates, partially offset by higher catastrophe losses and higher claim severity.
Property damage paid claim frequency decreased 1.7% in 2018 compared to 2017, following a decrease of 5.2% in 2017 compared to 2016. 36 states experienced
Allstate Protection: Allstate brand 2018 Form 10-K
a year over year decrease in property damage paid claim frequency in 2018 when compared to 2017. Property damage paid claim severities increased 5.9% in 2018 compared to 2017, following an increase of 4.5% in 2017 compared to 2016 due to the impact of higher costs to repair more sophisticated, newer model vehicles, higher third-party subrogation demands and increased costs associated with total losses.
Bodily injury gross claim frequency decreased 2.0% in 2018 compared to 2017, following a decrease of 4.8% in 2017 compared to 2016. Bodily injury severity trends have been impacted by higher medical costs, which after adjusting for company specific claims practices, policy provisions and coverage limits, generally increased consistent with medical care inflation indices.
Homeowners loss ratio increased 3.3 points to 69.5 in 2018 from 66.2 in 2017, primarily due to higher paid claim frequency and severity and lower favorable non-catastrophe prior year reserve reestimates, partially offset by increased premiums earned. Paid claim frequency excluding catastrophe losses increased 4.8% in 2018 compared to 2017 driven by weather related claims. Paid claim severity excluding catastrophe losses increased 5.5% in 2018 compared to 2017. Homeowner paid claim severity can be impacted by both the mix of perils and the magnitude of specific losses paid during the year. Homeowners loss ratio increased 5.2 points to 66.2 in 2017 from 61.0 in 2016, primarily due to higher catastrophe losses, partially
offset by higher favorable prior year reserve reestimates and increased premiums earned. Paid claim frequency excluding catastrophe losses decreased 0.1% in 2017 compared to 2016. Paid claim severity excluding catastrophe losses increased 5.0% in 2017 compared to 2016.
Other personal lines loss ratio increased 2.2 points in 2018 compared to 2017, primarily due to higher loss costs, including catastrophe losses, partially offset by increased premiums earned. Other personal lines loss ratio increased 2.3 points in 2017 compared to 2016, primarily due to unfavorable prior year reserve reestimates, higher catastrophe losses and higher claim severity, partially offset by increased premiums earned.
Commercial lines loss ratio increased 16.0 points in 2018 compared to 2017, primarily due to higher unfavorable non-catastrophe prior year reserve reestimates related to auto bodily injury coverages, partially offset by increased premiums earned. Commercial lines recorded losses related to an agreement with a transportation network company and are based on original pricing expectations given limited loss experience. Commercial lines loss ratio decreased 18.4 points in 2017 compared to 2016, primarily due to lower unfavorable prior year reserve reestimates, lower claim frequency and lower catastrophe losses.
| Expense ratios by line of business | |||||||||
| For the years ended December 31, | |||||||||
| 2018 | 2017 | 2016 | |||||||
| Auto | 25.7 | 25.1 | 24.2 | ||||||
| Homeowners | 23.8 | 23.2 | 22.7 | ||||||
| Other personal lines | 28.2 | 28.8 | 27.6 | ||||||
| Commercial lines | 21.8 | 28.3 | 27.8 | ||||||
| Total expense ratio (1) | 25.1 | 24.7 | 23.9 |
| (1) | Other revenue is deducted from other costs and expenses in the expense ratio calculation. |
| Impact of specific costs and expenses on the expense ratio | |||||||||
| For the years ended December 31, | |||||||||
| 2018 | 2017 | 2016 | |||||||
| Amortization of DAC | 14.1 | 13.8 | 13.6 | ||||||
| Advertising expense | 2.2 | 2.0 | 2.1 | ||||||
| Other costs and expenses (1) | 8.6 | 8.6 | 8.1 | ||||||
| Restructuring and related charges | 0.2 | 0.3 | 0.1 | ||||||
| Total expense ratio | 25.1 | 24.7 | 23.9 |
| (1) | Other revenue is deducted from other costs and expenses in the expense ratio calculation. |
Expense ratio increased 0.4 points in 2018 compared to 2017, primarily due to higher agency and employee-related compensation costs and higher advertising costs. Amortization of DAC primarily includes agent remuneration and premium taxes. Allstate agency total incurred base commissions, variable compensation and bonuses in 2018 were higher than 2017. Commercial lines expense ratio decreased 6.5 points in 2018 compared to 2017, primarily due to a lower expense ratio on business with a transportation network company.
Expense ratio increased 0.8 points in 2017 compared to 2016, primarily due to higher agency and employee-related compensation costs and restructuring and related costs. Amortization of DAC primarily includes agency remuneration and premium taxes.
The Allstate Corporation 55
2018 Form 10-K Allstate Protection: Esurance brand
Esurance brand products are sold directly to self-directed, brand-sensitive consumers online and through call centers. We manage the direct-to-customer business based on its profitability over the lifetime of the customer relationship. In 2018, the Esurance brand represented 5.8% of the Allstate Protection segment’s written premium. For additional information on our strategy and outlook, see Part I, Item 1. Business - Strategy and Segment Information.
| Underwriting results | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Premiums written | $ | 1,948 | $ | 1,728 | $ | 1,689 | ||||||
| Premiums earned | $ | 1,869 | $ | 1,712 | $ | 1,660 | ||||||
| Other revenue | 80 | 67 | 62 | |||||||||
| Claims and claims expense | (1,443 | ) | (1,329 | ) | (1,258 | ) | ||||||
| Amortization of DAC | (43 | ) | (41 | ) | (41 | ) | ||||||
| Other costs and expenses | (487 | ) | (462 | ) | (547 | ) | ||||||
| Restructuring and related charges | (1 | ) | (3 | ) | — | |||||||
| Underwriting loss | $ | (25 | ) | $ | (56 | ) | $ | (124 | ) | |||
| Catastrophe losses | $ | 52 | $ | 50 | $ | 36 | ||||||
| Underwriting income (loss) by line of business | ||||||||||||
| Auto | $ | (11 | ) | $ | (37 | ) | $ | (65 | ) | |||
| Homeowners | (14 | ) | (20 | ) | (59 | ) | ||||||
| Other personal lines | — | 1 | — | |||||||||
| Underwriting loss | $ | (25 | ) | $ | (56 | ) | $ | (124 | ) |
| Changes in underwriting results from prior year by component (1) | ||||||||
| For the years ended December 31, | ||||||||
| ($ in millions) | 2018 | 2017 | ||||||
| Underwriting income (loss) - prior year | $ | (56 | ) | $ | (124 | ) | ||
| Changes in underwriting income (loss) from: | ||||||||
| Increase (decrease) premiums earned | 157 | 52 | ||||||
| Increase (decrease) other revenue | 13 | 5 | ||||||
| (Increase) decrease incurred claims and claims expense (“losses”): | ||||||||
| Incurred losses, excluding catastrophe losses and reserve reestimates | (110 | ) | (37 | ) | ||||
| Catastrophe losses, excluding reserve reestimates | 1 | (15 | ) | |||||
| Catastrophe reserve reestimates | (3 | ) | 1 | |||||
| Non-catastrophe reserve reestimates | (2 | ) | (20 | ) | ||||
| Losses subtotal | (114 | ) | (71 | ) | ||||
| (Increase) decrease expenses | (25 | ) | 82 | |||||
| Underwriting loss | $ | (25 | ) | $ | (56 | ) |
(1) The 2018 column presents changes in 2018 compared to 2017. The 2017 column presents changes in 2017 compared to 2016.
Underwriting loss totaled $25 million in 2018, an improvement from $56 million in 2017, primarily due to increased premiums earned, partially offset by higher claim severities and additional marketing spend.
Underwriting loss totaled $56 million in 2017, an improvement from $124 million in 2016, primarily due to increased premiums earned, decreased homeowners marketing and lower amortization of purchased intangible assets, partially offset by lower favorable prior year reserve reestimates and higher catastrophe losses.
Allstate Protection: Esurance brand 2018 Form 10-K
| Premiums written and earned by line of business | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Premiums written | ||||||||||||
| Auto | $ | 1,839 | $ | 1,641 | $ | 1,625 | ||||||
| Homeowners | 101 | 79 | 56 | |||||||||
| Other personal lines | 8 | 8 | 8 | |||||||||
| Total | $ | 1,948 | $ | 1,728 | $ | 1,689 | ||||||
| Premiums earned | ||||||||||||
| Auto | $ | 1,771 | $ | 1,636 | $ | 1,610 | ||||||
| Homeowners | 90 | 68 | 42 | |||||||||
| Other personal lines | 8 | 8 | 8 | |||||||||
| Total | $ | 1,869 | $ | 1,712 | $ | 1,660 |
| Auto premium measures and statistics | ||||||||||||
| 2018 | 2017 | 2016 | ||||||||||
| PIF (thousands) | 1,488 | 1,352 | 1,391 | |||||||||
| New issued applications (thousands) | 633 | 484 | 597 | |||||||||
| Average premium | $ | 605 | $ | 574 | $ | 547 | ||||||
| Renewal ratio (%) | 83.3 | 81.5 | 79.4 | |||||||||
| Approved rate changes (1): | ||||||||||||
| # of locations (2) | 30 | 39 | 33 | |||||||||
| Total brand (%) (3) | 1.8 | 4.8 | 4.2 | |||||||||
| Location specific (%) (4) (5) | 2.7 | 5.5 | 6.1 |
| (1) | Rate changes do not include rating plan enhancements, including the introduction of discounts and surcharges that result in no change in the overall rate level in a location. These rate changes do not reflect initial rates filed for insurance subsidiaries initially writing business in a location. |
| (2) | Esurance brand operates in 43 states. In the second quarter of 2018, Esurance discontinued its operations in Canada. |
| (3) | Represents the impact in the states where rate changes were approved during the period as a percentage of total brand prior year-end premiums written. |
| (4) | Represents the impact in the states where rate changes were approved during the period as a percentage of their respective total prior year-end premiums written in those same locations. |
| (5) | Based on historical premiums written in the locations noted above, rate changes approved for auto totaled $28 million, $78 million and $65 million in 2018, 2017 and 2016, respectively. |
Auto insurance premiums written totaled $1.84 billion in 2018, a 12.1% increase from $1.64 billion in 2017. Factors impacting premiums written were:
| • | 10.1% or 136 thousand increase in PIF as of December 31, 2018 compared to December 31, 2017. |
| • | 1.8 point increase in the renewal ratio in 2018 compared to 2017, primarily due to improved customer experience. |
| • | 30.8% increase in new issued applications in 2018 compared to 2017, primarily due to improvements in the sales process as well as increases in quote volume driven in part by additional marketing spend. |
| • | 5.4% increase in average premium in 2018 compared to 2017, primarily due to rate changes and changes in business mix. |
Auto insurance premiums written totaled $1.64 billion in 2017, a 1.0% increase from $1.63 billion in 2016. Factors impacting premiums written were:
| • | 2.8% or 39 thousand decrease in PIF as of December 31, 2017 compared to December 31, 2016. |
| • | 18.9% decrease in new issued applications in 2017 compared to 2016, primarily due to the impact of rate increases, decreased marketing activities and underwriting guideline changes. |
| • | 4.9% increase in average premium in 2017 compared to 2016 primarily due to rate changes and changes in business mix. |
| • | 2.1 point increase in the renewal ratio in 2017 compared to 2016, primarily due to improved customer experience. |
.
The Allstate Corporation 57
2018 Form 10-K Allstate Protection: Esurance brand
| Homeowners premium measures and statistics | ||||||||||||
| 2018 | 2017 | 2016 | ||||||||||
| PIF (thousands) | 95 | 79 | 58 | |||||||||
| New issued applications (thousands) | 32 | 34 | 37 | |||||||||
| Average premium | $ | 982 | $ | 917 | $ | 875 | ||||||
| Renewal ratio (%) (1) | 85.3 | 85.5 | 82.6 | |||||||||
| Approved rate changes (2): | ||||||||||||
| # of locations (3) | 6 | 3 | 1 | |||||||||
| Total brand (%) | 2.1 | 4.5 | (0.5 | ) | ||||||||
| Location specific (%) (4) | 6.9 | 18.5 | (10.0 | ) |
| (1) | Esurance’s renewal ratios exclude the impact of risk related cancellations. Customers can enter into a policy without a physical inspection. During the underwriting review period, a number of policies may be canceled if upon inspection the condition is unsatisfactory. |
| (2) | Includes rate changes approved based on our net cost of reinsurance. |
| (3) | Esurance brand operates in 31 states. In the second quarter of 2018, Esurance discontinued its operations in Canada. |
| (4) | Based on historical premiums written in the locations noted above, rate changes approved for homeowners totaled $2 million and $3 million in 2018 and 2017, respectively. Rate changes were only approved in Texas in 2016. |
Homeowners insurance premiums written totaled $101 million in 2018 compared to $79 million in 2017. Factors impacting premiums written were:
| • | 16 thousand increase in PIF as of December 31, 2018 compared to December 31, 2017. |
| • | 2 thousand decrease in new issued applications in 2018 compared to 2017. |
| • | 7.1% increase in average premium in 2018 compared to 2017, primarily due to increased premium distribution in higher average premium states and rate increases. As of December 31, 2018, Esurance continues to write homeowners insurance in 31 states with lower hurricane risk, contributing to lower average premium compared to the industry. |
Homeowners insurance premiums written totaled $79 million in 2017 compared to $56 million in 2016. Factors impacting premiums written were:
| • | 21 thousand increase in PIF as of December 31, 2017 compared to December 31, 2016. |
| • | 3 thousand decrease in new issued applications in 2017 compared to 2016 due to reduced marketing activities. |
| • | 4.8% increase in average premium in 2017 compared to 2016, primarily due to increased premium distribution in higher average premium states and rate changes. As of December 31, 2017, Esurance writes homeowners insurance in 31 states with lower hurricane risk, contributing to lower average premium compared to the industry. |
| Combined ratios by line of business | |||||||||||||||||||||||||||
| For the years ended December 31, | |||||||||||||||||||||||||||
| Loss ratio | Expense ratio (1) | Combined ratio | |||||||||||||||||||||||||
| 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | |||||||||||||||||||
| Auto | 77.0 | 77.5 | 75.8 | 23.6 | 24.8 | 28.2 | 100.6 | 102.3 | 104.0 | ||||||||||||||||||
| Homeowners | 83.4 | 83.8 | 78.6 | 32.2 | 45.6 | 161.9 | 115.6 | 129.4 | 240.5 | ||||||||||||||||||
| Total | 77.2 | 77.6 | 75.8 | 24.1 | 25.7 | 31.7 | 101.3 | 103.3 | 107.5 |
| (1) | Other revenue is deducted from operating costs and expenses in the expense ratio calculation. |
| Loss ratios by line of business | ||||||||||||||||||||||||||||||||||||
| For the years ended December 31, | ||||||||||||||||||||||||||||||||||||
| Loss ratio | Effect of catastrophe losses | Effect of prior year reserve reestimates | Effect of catastrophe losses included in prior year reserve reestimates | |||||||||||||||||||||||||||||||||
| 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | |||||||||||||||||||||||||
| Auto | 77.0 | 77.5 | 75.8 | 1.5 | 2.1 | 1.5 | 0.1 | 0.1 | (1.3 | ) | — | — | — | |||||||||||||||||||||||
| Homeowners | 83.4 | 83.8 | 78.6 | 27.8 | 23.5 | 28.6 | 2.2 | (3.0 | ) | — | 2.2 | (1.5 | ) | — | ||||||||||||||||||||||
| Total | 77.2 | 77.6 | 75.8 | 2.8 | 2.9 | 2.2 | 0.2 | (0.1 | ) | (1.3 | ) | 0.1 | (0.1 | ) | — |
Auto loss ratio decreased 0.5 points in 2018 compared to 2017, primarily due to increased premiums earned, and lower catastrophe losses, partially offset by higher claim severity. Auto loss ratio increased 1.7 points in 2017 compared to 2016, primarily due to unfavorable prior year reserve reestimates in 2017 compared to favorable prior year reserve reestimates in 2016 and higher catastrophe losses.
Catastrophe losses were $52 million in 2018 compared to $50 million in 2017 and $36 million in 2016.
Allstate Protection: Esurance brand 2018 Form 10-K
| Expense ratios by line of business | |||||||||
| For the years ended December 31, | |||||||||
| 2018 | 2017 | 2016 | |||||||
| Auto | 23.6 | 24.8 | 28.2 | ||||||
| Homeowners | 32.2 | 45.6 | 161.9 | ||||||
| Total expense ratio (1) | 24.1 | 25.7 | 31.7 |
| (1) | Other revenue is deducted from other costs and expenses in the expense ratio calculation. |
| Impact of specific costs and expenses on the expense ratio | |||||||||
| For the years ended December 31, | |||||||||
| 2018 | 2017 | 2016 | |||||||
| Amortization of DAC | 2.3 | 2.4 | 2.5 | ||||||
| Advertising expense | 8.7 | 8.3 | 11.2 | ||||||
| Amortization of purchased intangible assets | 0.1 | 0.2 | 1.4 | ||||||
| Other costs and expenses (1) | 12.9 | 14.6 | 16.6 | ||||||
| Restructuring and related charges | 0.1 | 0.2 | — | ||||||
| Total expense ratio | 24.1 | 25.7 | 31.7 |
| (1) | Other revenue is deducted from other costs and expenses in the expense ratio calculation. |
Expense ratio decreased 1.6 points in 2018 compared to 2017. Other costs and expenses, including salaries of telephone sales personnel and other underwriting costs related to customer acquisition, were lower in 2018 compared to 2017 due to the continued implementation of process efficiencies. Esurance uses a direct distribution model, therefore its primary acquisition-related costs are advertising as opposed to commissions. Esurance advertising expense ratio increased 0.4 points in 2018 compared to 2017, primarily due to a new marketing campaign launched during the second half of 2018 and increased spending on targeted growth opportunities.
We manage our advertising spend to ensure our acquisition costs meet our targeted returns. Esurance incurs substantially all of its acquisition costs in the year of policy inception. As a result, the Esurance expense ratio will be higher or lower depending on the advertising expenditures incurred. Esurance’s annual combined ratio is below 100 after the year of policy inception (in which substantially all acquisition costs are incurred).
Expense ratio decreased 6.0 points in 2017 compared to 2016. Esurance advertising expense ratio decreased 2.9 points in 2017 compared to 2016, primarily due to reductions in homeowners marketing. Other costs and expenses, including salaries of phone sales personnel and other underwriting costs related to customer acquisition, were lower in 2017 compared to 2016 due to the implementation of process efficiencies. Expense ratio includes amortization of purchased intangible assets from the original acquisition in 2011.
Starting in 2017, the portion of the remaining purchased intangible asset related to the Esurance brand name was classified as an infinite-lived intangible and is no longer being amortized, but instead tested for impairment on an annual basis.
The Allstate Corporation 59
2018 Form 10-K Allstate Protection: Encompass brand
Encompass products are sold through independent agencies that serve brand-neutral customers who prefer personal service and support from an independent agent. In 2018, the Encompass brand represented 3.0% of the Allstate Protection segment’s written premium. For additional information on our strategy and outlook, see Part I, Item 1. Business - Strategy and Segment Information.
| Underwriting results | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Premiums written | $ | 1,016 | $ | 1,035 | $ | 1,140 | ||||||
| Premiums earned | $ | 1,023 | $ | 1,090 | $ | 1,202 | ||||||
| Other revenue | 5 | 6 | 6 | |||||||||
| Claims and claims expense | (669 | ) | (789 | ) | (855 | ) | ||||||
| Amortization of DAC | (190 | ) | (201 | ) | (221 | ) | ||||||
| Other costs and expenses | (149 | ) | (134 | ) | (130 | ) | ||||||
| Restructuring and related charges | (7 | ) | (5 | ) | (1 | ) | ||||||
| Underwriting income (loss) | $ | 13 | $ | (33 | ) | $ | 1 | |||||
| Catastrophe losses | $ | 102 | $ | 193 | $ | 111 | ||||||
| Underwriting income (loss) by line of business | ||||||||||||
| Auto | $ | 11 | $ | 4 | $ | (29 | ) | |||||
| Homeowners | (1 | ) | (47 | ) | 36 | |||||||
| Other personal lines | 3 | 10 | (6 | ) | ||||||||
| Underwriting income (loss) | $ | 13 | $ | (33 | ) | $ | 1 |
| Changes in underwriting results from prior year by component (1) | ||||||||
| For the years ended December 31, | ||||||||
| ($ in millions) | 2018 | 2017 | ||||||
| Underwriting income (loss) - prior year | $ | (33 | ) | $ | 1 | |||
| Changes in underwriting income (loss) from: | ||||||||
| Increase (decrease) premiums earned | (67 | ) | (112 | ) | ||||
| Increase (decrease) other revenue | (1 | ) | — | |||||
| (Increase) decrease incurred claims and claims expense (“losses”): | ||||||||
| Incurred losses, excluding catastrophe losses and reserve reestimates | 19 | 130 | ||||||
| Catastrophe losses, excluding reserve reestimates | 104 | (83 | ) | |||||
| Catastrophes reserve reestimates | (13 | ) | 1 | |||||
| Non-catastrophe reserve reestimates | 10 | 18 | ||||||
| Losses subtotal | 120 | 66 | ||||||
| (Increase) decrease expenses | (6 | ) | 12 | |||||
| Underwriting income (loss) | $ | 13 | $ | (33 | ) |
(1) The 2018 column presents changes in 2018 compared to 2017. The 2017 column presents changes in 2017 compared to 2016.
Underwriting income totaled $13 million in 2018 compared to an underwriting loss of $33 million in 2017. The improvement was primarily due to lower catastrophe losses and improved auto claim frequency, partially offset by decreased premiums earned.
Underwriting loss totaled $33 million in 2017 compared to underwriting income of $1 million in 2016, primarily due to higher homeowners catastrophe losses, partially offset by improved auto loss costs.
Allstate Protection: Encompass brand 2018 Form 10-K
| Premiums written and earned by line of business | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Premiums written | ||||||||||||
| Auto | $ | 537 | $ | 542 | $ | 591 | ||||||
| Homeowners | 398 | 406 | 454 | |||||||||
| Other personal lines | 81 | 87 | 95 | |||||||||
| Total | $ | 1,016 | $ | 1,035 | $ | 1,140 | ||||||
| Premiums earned | ||||||||||||
| Auto | $ | 537 | $ | 566 | $ | 623 | ||||||
| Homeowners | 402 | 431 | 479 | |||||||||
| Other personal lines | 84 | 93 | 100 | |||||||||
| Total | $ | 1,023 | $ | 1,090 | $ | 1,202 |
| Auto premium measures and statistics | ||||||||||||
| 2018 | 2017 | 2016 | ||||||||||
| PIF (thousands) | 502 | 530 | 622 | |||||||||
| New issued applications (thousands) | 76 | 52 | 54 | |||||||||
| Average premium | $ | 1,118 | $ | 1,079 | $ | 1,008 | ||||||
| Renewal ratio (%) (1) | 74.9 | 73.4 | 75.0 | |||||||||
| Approved rate changes (2): | ||||||||||||
| # of locations (3) | 17 | 27 | 24 | |||||||||
| Total brand (%) (4) | 2.4 | 6.2 | 10.5 | |||||||||
| Location specific (%) (5)(6) | 4.8 | 7.8 | 14.3 |
| (1) | Encompass announced a plan to exit business in Massachusetts in the second quarter of 2017 and previously announced a plan to exit business in North Carolina in the first half of 2016, which impacted the renewal ratio. Excluding Massachusetts and North Carolina, the renewal ratios were 76.5 points in 2018 compared to 74.5 points in 2017 and 75.0 points in 2016. |
| (2) | Rate changes that are indicated based on loss trend analysis to achieve a targeted return will continue to be pursued. Rate changes do not include rating plan enhancements, including the introduction of discounts and surcharges that result in no change in the overall rate level in a location. These rate changes do not reflect initial rates filed for insurance subsidiaries initially writing business in a location. |
| (3) | Encompass brand operates in 40 states and D.C. |
| (4) | Represents the impact in the states and D.C. where rate changes were approved during the period as a percentage of total brand prior year-end premiums written. |
| (5) | Represents the impact in the states and D.C. where rate changes were approved during the period as a percentage of their respective total prior year-end premiums written in those same locations. |
| (6) | Based on historical premiums written in the locations noted above, rate changes approved for auto totaled $13 million, $37 million and $68 million in 2018, 2017 and 2016, respectively. |
Auto insurance premiums written totaled $537 million in 2018, a 0.9% decrease from $542 million in 2017. Factors impacting premiums written were:
| • | 5.3% or 28 thousand decrease in PIF as of December 31, 2018 compared to December 31, 2017. |
| • | 1.5 point increase in the renewal ratio in 2018 compared to 2017, as profit improvement actions have moderated. Encompass sells a high percentage of package policies that include both auto and homeowners; therefore, declines in one product can contribute to declines in the other. |
| • | 46.2% or 24 thousand increase in new issued applications in 2018 compared to 2017. |
| • | 3.6% increase in average premium in 2018 compared to 2017, primarily due to rate changes. Encompass brand policy terms are generally 12 months for auto. |
Auto insurance premiums written totaled $542 million in 2017, an 8.3% decrease from $591 million in 2016. Factors impacting premiums written were:
| • | 14.8% or 92 thousand decrease in PIF as of December 31, 2017 compared to December 31, 2016. |
| • | 3.7% decrease in new issued applications in 2017 compared to 2016, primarily due to rate changes. |
| • | 7.0% increase in average premium in 2017 compared to 2016. |
| • | 1.4 point decrease in the renewal ratio in 2017 compared to 2016, primarily due to profit improvement actions taken, including exiting states with inadequate returns. |
The Allstate Corporation 61
2018 Form 10-K Allstate Protection: Encompass brand
| Homeowners premium measure and statistics | ||||||||||||
| 2018 | 2017 | 2016 | ||||||||||
| PIF (thousands) | 239 | 254 | 295 | |||||||||
| New issued applications (thousands) | 37 | 30 | 34 | |||||||||
| Average premium | $ | 1,724 | $ | 1,684 | $ | 1,639 | ||||||
| Renewal ratio (%) (1) | 80.0 | 78.5 | 79.8 | |||||||||
| Approved rate changes (2): | ||||||||||||
| # of locations (3) | 20 | 21 | 19 | |||||||||
| Total brand (%) | 4.7 | 4.8 | 5.1 | |||||||||
| Location specific (%) (4) | 8.1 | 8.4 | 9.0 |
| (1) | Encompass announced a plan to exit business in Massachusetts in the second quarter of 2017 and previously announced a plan to exit business in North Carolina in the first half of 2016, which has impacted the renewal ratio. Excluding Massachusetts and North Carolina, the renewal ratios were 80.8 points in 2018 compared to 79.0 points in 2017 and 79.9 points in 2016. |
| (2) | Includes rate changes approved based on our net cost of reinsurance. |
| (3) | Encompass brand operates in 40 states and D.C. |
| (4) | Based on historical premiums written in the locations noted above, rate changes approved for homeowner totaled $20 million, $23 million and $27 million in 2018, 2017 and 2016, respectively. |
Homeowners insurance premiums written totaled $398 million in 2018, a 2.0% decrease from $406 million in 2017. Factors impacting premiums written were the following:
| • | 5.9% or 15 thousand decrease in PIF as of December 31, 2018 compared to December 31, 2017. |
| • | 1.5 point increase in the renewal ratio in 2018 compared to 2017, as profit improvement actions have moderated. Encompass sells a high percentage of package policies that include both auto and homeowners; therefore, declines in one product can contribute to declines in the other. |
| • | 23.3% or 7 thousand increase in new issued applications in 2018 compared to 2017. |
| • | 2.4% increase in average premium in 2018 compared to 2017, primarily due to rate changes. |
Homeowners insurance premiums written totaled $406 million in 2017, a 10.6% decrease from $454 million in 2016. Factors impacting premiums written were the following:
| • | 13.9% or 41 thousand decrease in PIF as of December 31, 2017 compared to December 31, 2016. |
| • | 11.8% decrease in new issued applications in 2017 compared to 2016. |
| • | 2.7% increase in average premium in 2017 compared to 2016, primarily due to rate changes. |
| • | 1.3 point decrease in the renewal ratio in 2017 compared to 2016, primarily due to profit improvement actions taken to exit states with inadequate returns. |
| Combined ratios by line of business | |||||||||||||||||||||||||||
| For the years ended December 31, | |||||||||||||||||||||||||||
| Loss ratio | Expense ratio (1) | Combined ratio | |||||||||||||||||||||||||
| 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | |||||||||||||||||||
| Auto | 65.2 | 68.6 | 76.1 | 32.8 | 30.7 | 28.6 | 98.0 | 99.3 | 104.7 | ||||||||||||||||||
| Homeowners | 66.9 | 80.3 | 63.5 | 33.3 | 30.6 | 29.0 | 100.2 | 110.9 | 92.5 | ||||||||||||||||||
| Other personal lines | 59.5 | 59.1 | 77.0 | 36.9 | 30.1 | 29.0 | 96.4 | 89.2 | 106.0 | ||||||||||||||||||
| Total | 65.4 | 72.4 | 71.1 | 33.3 | 30.6 | 28.8 | 98.7 | 103.0 | 99.9 |
| (1) | Other revenue is deducted from operating costs and expenses in the expense ratio calculation. |
| Loss ratios by line of business | ||||||||||||||||||||||||||||||||||||
| For the years ended December 31, | ||||||||||||||||||||||||||||||||||||
| Loss ratio | Effect of catastrophe losses | Effect of prior year reserve reestimates | Effect of catastrophe losses included in prior year reserve reestimates | |||||||||||||||||||||||||||||||||
| 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | |||||||||||||||||||||||||
| Auto | 65.2 | 68.6 | 76.1 | 1.1 | 2.1 | 1.6 | (1.8 | ) | (1.1 | ) | — | (0.2 | ) | (0.2 | ) | (0.4 | ) | |||||||||||||||||||
| Homeowners | 66.9 | 80.3 | 63.5 | 22.1 | 40.1 | 20.3 | 3.2 | 0.5 | — | 3.0 | — | 0.5 | ||||||||||||||||||||||||
| Other personal lines | 59.5 | 59.1 | 77.0 | 8.3 | 8.6 | 4.0 | (16.7 | ) | (10.8 | ) | 5.0 | 1.2 | — | — | ||||||||||||||||||||||
| Total | 65.4 | 72.4 | 71.1 | 10.0 | 17.7 | 9.2 | (1.1 | ) | (1.3 | ) | 0.4 | 1.2 | (0.1 | ) | — |
Auto loss ratio decreased 3.4 points in 2018 compared to 2017, primarily due to lower claim frequency, lower catastrophe losses, higher favorable
non-catastrophe prior year reserve reestimates and a slower decline in premiums earned. Auto loss ratio decreased 7.5 points in 2017 compared to 2016,
Allstate Protection: Encompass brand 2018 Form 10-K
primarily due to lower frequency and severity, and favorable prior year reserve reestimates, partially offset by higher catastrophe losses.
Homeowners loss ratio decreased 13.4 points in 2018 compared to 2017, primarily due to lower catastrophe losses, partially offset by decreased
premiums earned. Homeowners loss ratio increased 16.8 points in 2017 compared to 2016, primarily due to higher catastrophe losses.
| Expense ratios by line of business | |||||||||
| For the years ended December 31, | |||||||||
| 2018 | 2017 | 2016 | |||||||
| Auto | 32.8 | 30.7 | 28.6 | ||||||
| Homeowners | 33.3 | 30.6 | 29.0 | ||||||
| Other personal lines | 36.9 | 30.1 | 29.0 | ||||||
| Total expense ratio (1) | 33.3 | 30.6 | 28.8 |
| (1) | Other revenue is deducted from other costs and expenses in the expense ratio calculation. |
| Impact of specific costs and expenses on the expense ratio | |||||||||
| For the years ended December 31, | |||||||||
| 2018 | 2017 | 2016 | |||||||
| Amortization of DAC | 18.5 | 18.3 | 18.4 | ||||||
| Advertising expense | 0.2 | 0.2 | 0.2 | ||||||
| Other costs and expenses (1) | 13.9 | 11.6 | 10.1 | ||||||
| Restructuring and related charges | 0.7 | 0.5 | 0.1 | ||||||
| Total expense ratio | 33.3 | 30.6 | 28.8 |
| (1) | Other revenue is deducted from other costs and expenses in the expense ratio calculation. |
Expense ratio increased 2.7 points in 2018 compared to 2017, primarily due to decreased premiums earned, increased investment in technology and higher employee-related compensation costs. The Encompass brand DAC amortization rate is higher on average than Allstate brand due to higher commission rates paid to independent agencies.
Expense ratio increased 1.8 points in 2017 compared to 2016, primarily due to higher employee-related and technology costs, and restructuring and related charges.
The Allstate Corporation 63
2018 Form 10-K Discontinued Lines and Coverages
Discontinued Lines and Coverages Segment
The Discontinued Lines and Coverages segment includes results from property and casualty insurance coverage that primarily relates to policies written during the 1960s through the mid-1980s. Our exposure to asbestos, environmental and other discontinued lines claims arises principally from direct excess commercial insurance, assumed reinsurance coverage, direct primary commercial insurance and other businesses in run-off. For additional information on our strategy and outlook, see Part I, Item 1. Business - Strategy and Segment Information.
| Underwriting Results | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Premiums written (1) | $ | — | $ | — | $ | 3 | ||||||
| Premiums earned | $ | — | $ | — | $ | — | ||||||
| Claims and claims expense | (87 | ) | (96 | ) | (105 | ) | ||||||
| Operating costs and expenses | (3 | ) | (3 | ) | (2 | ) | ||||||
| Underwriting loss | $ | (90 | ) | $ | (99 | ) | $ | (107 | ) |
| (1) | Primarily represents retrospective reinsurance premium recognized when billed. |
Underwriting losses of $90 million in 2018 primarily related to our annual reserve review using established industry and actuarial best practices. The annual review resulted in unfavorable reestimates of $76 million, including $44 million for asbestos exposures, primarily related to new reported information, changes in our projections of reported claims and settlement agreements, including bankruptcy proceedings; $20 million for environmental exposures and $13 million for other exposures, partially offset by a $1 million decrease in the allowance for uncollectible reinsurance.
Underwriting losses of $99 million in 2017 primarily related to our annual reserve review, resulting in unfavorable reestimates of $85 million, including $61 million for asbestos exposures, $10 million for
environmental exposures and $27 million for other exposures, partially offset by a $13 million decrease in the allowance for future uncollectible reinsurance.
Underwriting losses of $107 million in 2016 primarily related to our annual reserve review, resulting in unfavorable reestimates of $96 million, including a $67 million unfavorable reestimate of asbestos exposures, a $23 million unfavorable reestimate of environmental exposures and a $6 million increase in the allowance for future uncollectible reinsurance with other exposures essentially unchanged.
The cost of administering claims settlements totaled $11 million, $11 million and $10 million for 2018, 2017 and 2016, respectively.
| Reserves for asbestos, environmental and other discontinued lines claims before and after the effects of reinsurance | ||||||||
| ($ in millions) | December 31, 2018 | December 31, 2017 | ||||||
| Asbestos claims | ||||||||
| Gross reserves | $ | 1,266 | $ | 1,296 | ||||
| Reinsurance | (400 | ) | (412 | ) | ||||
| Net reserves | 866 | 884 | ||||||
| Environmental claims | ||||||||
| Gross reserves | 209 | 199 | ||||||
| Reinsurance | (39 | ) | (33 | ) | ||||
| Net reserves | 170 | 166 | ||||||
| Other discontinued lines | ||||||||
| Gross reserves | 389 | 398 | ||||||
| Reinsurance | (34 | ) | (41 | ) | ||||
| Net reserves | 355 | 357 | ||||||
| Total | ||||||||
| Gross reserves | 1,864 | 1,893 | ||||||
| Reinsurance | (473 | ) | (486 | ) | ||||
| Net reserves | $ | 1,391 | $ | 1,407 |
Discontinued Lines and Coverages 2018 Form 10-K
| Reserves by type of exposure before and after the effects of reinsurance | ||||||||
| ($ in millions) | December 31, 2018 | December 31, 2017 | ||||||
| Direct excess commercial insurance | ||||||||
| Gross reserves (1) | $ | 973 | $ | 997 | ||||
| Reinsurance (2) | (355 | ) | (378 | ) | ||||
| Net reserves | 618 | 619 | ||||||
| Assumed reinsurance coverage | ||||||||
| Gross reserves (3) | 625 | 622 | ||||||
| Reinsurance (4) | (53 | ) | (38 | ) | ||||
| Net reserves | 572 | 584 | ||||||
| Direct primary commercial insurance | ||||||||
| Gross reserves (5) | 171 | 177 | ||||||
| Reinsurance (6) | (48 | ) | (48 | ) | ||||
| Net reserves | 123 | 129 | ||||||
| Other run-off business | ||||||||
| Gross reserves | 19 | 24 | ||||||
| Reinsurance | (16 | ) | (21 | ) | ||||
| Net reserves | 3 | 3 | ||||||
| Unallocated loss adjustment expenses | ||||||||
| Gross reserves | 76 | 73 | ||||||
| Reinsurance | (1 | ) | (1 | ) | ||||
| Net reserves | 75 | 72 | ||||||
| Total | ||||||||
| Gross reserves | 1,864 | 1,893 | ||||||
| Reinsurance | (473 | ) | (486 | ) | ||||
| Net reserves | $ | 1,391 | $ | 1,407 |
(1) Gross reserves as of December 31, 2018 comprised 67% case reserves and 33% incurred but not reported (“IBNR”) reserves. Approximately 75% of the total gross case reserves are subject to settlement agreements. In 2018, total gross payments from case reserves were $105 million with approximately 88% attributable to settlements. Reserves as of December 31, 2017, comprised 65% case reserves and 35% IBNR reserves.
(2) Ceded reserves as of December 31, 2018 comprised 78% case reserves and 22% IBNR reserves. Approximately 82% of the total ceded case reserves are subject to settlement agreements. In 2018, reinsurance billings of ceded case reserves were $55 million with approximately 84% attributable to settlements. Reserves as of December 31, 2017, comprised 76% case reserves and 24% IBNR reserves.
(3) Gross reserves as of December 31, 2018 comprised 34% case reserves and 66% IBNR reserves. In 2018, total gross payments from case reserves were $39 million. Reserves as of December 31, 2017, comprised 31% case reserves and 69% IBNR reserves.
(4) Ceded reserves as of December 31, 2018 comprised 37% case reserves and 63% IBNR reserves. In 2018, reinsurance billings of ceded case reserves were $5 million. Reserves as of December 31, 2017, comprised 36% case reserves and 64% IBNR reserves.
(5) Gross reserves as of December 31, 2018 comprised 58% case reserves and 42% IBNR reserves. In 2018, total gross payments from case reserves were $8 million. Reserves as of December 31, 2017, comprised 54% case reserves and 46% IBNR reserves.
(6) Ceded reserves as of December 31, 2018 comprised 78% case reserves and 22% IBNR reserves. In 2018, reinsurance billings of ceded case reserves were $1 million. Reserves as of December 31, 2017, comprised 76% case reserves and 24% IBNR reserves.
Total net reserves were $1.39 billion, including $693 million or 50% of estimated IBNR reserves as of December 31, 2018 compared to total net reserves of $1.41 billion, including $733 million or 52% of estimated IBNR reserves as of December 31, 2017.
Total gross payments were $156 million and $192 million for 2018 and 2017, respectively, primarily related to payments on settlement agreements reached with several insureds on large claims, mainly asbestos related losses, where the scope of coverages has been agreed upon.
The claims associated with these settlement agreements are expected to be substantially paid out over the next several years as qualified claims are submitted by these insureds. Reinsurance collections were $62 million and $67 million for 2018 and 2017, respectively.
See the Claims and Claims Expense Reserves section of this Item for a more detailed discussion.
The Allstate Corporation 65
2018 Form 10-K Service Businesses
Service Businesses Segment

Service Businesses comprise SquareTrade, Arity, InfoArmor, Allstate Roadside Services and Allstate Dealer Services. In 2018, Service Businesses represented 3.3% of total revenue, 65.1% of total PIF and less than 1.0% of total adjusted net income. We offer consumer product protection plans, device and mobile data collection services and analytic solutions, identity protection, roadside assistance, and finance and insurance products (including vehicle service contracts, guaranteed asset protection waivers, road hazard tire and wheel and paintless dent repair protection).
Starting in the fourth quarter of 2018, the Service Businesses segment includes the results of InfoArmor, a leading provider of identity protection to more than 1 million employees and their family members at over 1,400 firms, which was acquired on October 5, 2018. For additional information on our strategy and outlook, see Part I, Item 1. Business - Strategy and Segment Information.
| Summarized financial information | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Premiums written | $ | 1,431 | $ | 1,094 | $ | 709 | ||||||
| Revenues | ||||||||||||
| Premiums | $ | 1,098 | $ | 867 | $ | 580 | ||||||
| Intersegment insurance premiums and service fees (1) | 122 | 110 | 105 | |||||||||
| Other revenue | 82 | 66 | 64 | |||||||||
| Net investment income | 27 | 16 | 13 | |||||||||
| Realized capital gains and losses | (11 | ) | — | — | ||||||||
| Total revenues | 1,318 | 1,059 | 762 | |||||||||
| Costs and expenses | ||||||||||||
| Claims and claims expense | (351 | ) | (369 | ) | (258 | ) | ||||||
| Amortization of DAC | (463 | ) | (296 | ) | (214 | ) | ||||||
| Operating costs and expenses | (511 | ) | (467 | ) | (287 | ) | ||||||
| Amortization of purchased intangible assets | (94 | ) | (92 | ) | — | |||||||
| Restructuring and related charges (2) | (4 | ) | (13 | ) | — | |||||||
| Total costs and expenses | (1,423 | ) | (1,237 | ) | (759 | ) | ||||||
| Income tax benefit | 20 | 193 | — | |||||||||
| Net (loss) income applicable to common shareholders | $ | (85 | ) | $ | 15 | $ | 3 | |||||
| Adjusted net income (loss) | $ | 2 | $ | (59 | ) | $ | 3 | |||||
| Realized capital gains and losses, after-tax | (9 | ) | — | — | ||||||||
| Amortization of purchased intangible assets, after-tax | (74 | ) | (60 | ) | — | |||||||
| Tax Legislation (expense) benefit | (4 | ) | 134 | — | ||||||||
| Net (loss) income applicable to common shareholders | $ | (85 | ) | $ | 15 | $ | 3 | |||||
| SquareTrade (3) | $ | 23 | $ | (22 | ) | $ | — | |||||
| Arity | (14 | ) | (15 | ) | 11 | |||||||
| InfoArmor (3) | 1 | — | — | |||||||||
| Allstate Roadside Services | (23 | ) | (20 | ) | (12 | ) | ||||||
| Allstate Dealer Services | 15 | (2 | ) | 4 | ||||||||
| Adjusted net income (loss) | $ | 2 | $ | (59 | ) | $ | 3 | |||||
| SquareTrade (3) | 68,588 | 38,719 | — | |||||||||
| InfoArmor (3) | 1,040 | — | — | |||||||||
| Allstate Roadside Services | 663 | 699 | 768 | |||||||||
| Allstate Dealer Services | 3,896 | 4,088 | 4,142 | |||||||||
| Policies in force as of December 31 (in thousands) | 74,187 | 43,506 | 4,910 |
| (1) | Primarily related to Arity and Allstate Roadside Services and are eliminated in our consolidated financial statements. |
| (2) | 2018 related to organizational changes at Allstate Roadside Services and 2017 related to a one-time contract termination of a SquareTrade European vendor. |
| (3) | SquareTrade was acquired on January 3, 2017 and InfoArmor was acquired on October 5, 2018. |
Service Businesses 2018 Form 10-K
Net loss applicable to common shareholders was $85 million in 2018 compared to net income applicable to common shareholders of $15 million and $3 million in 2017 and 2016, respectively. 2018 and 2017 results include a tax expense of $4 million and a tax benefit of $134 million, respectively, related to the Tax Legislation.
Adjusted net income was $2 million in 2018 compared to an adjusted net loss of $59 million in 2017 and an adjusted net income of $3 million in 2016. The improvement in 2018 was primarily due to increased revenue at SquareTrade, improved loss experience at SquareTrade and Allstate Dealer Services and lower restructuring charges in 2018 compared to 2017, partially offset by higher loss costs at Allstate Roadside Services. The loss in 2017 compared to income in 2016 was primarily due to investments in Arity’s research and development, strategic investments in SquareTrade and Allstate Roadside Services, a SquareTrade restructuring charge and Hurricane Harvey’s impacts on Allstate Dealer Services.
Total revenues increased 24.5% or $259 million to $1.32 billion in 2018 from $1.06 billion in 2017. The increase was primarily due to SquareTrade’s growth through its U.S. retail and international channels and increased premiums earned on Allstate Dealer Services’ vehicle service contracts. 2018 revenue also includes $101 million for SquareTrade protection plans sold directly to retailers prior to January 1, 2018 for which SquareTrade is deemed to be the principal. This increase in revenue is due to the adoption of the revenue from contracts with customers accounting standard and is offset by corresponding increases in amortization of DAC.
Premiums written increased 30.8% or $337 million to $1.43 billion in 2018 from $1.09 billion in 2017, primarily due to continued growth at SquareTrade, including the addition of a leading U.S. retailer in third quarter 2018. Premiums written increased 54.3% or $385 million to $1.09 billion in 2017 from $709 million in 2016, primarily due to the acquisition of SquareTrade and growth through its U.S. retail channel, partially offset by decreases in premiums written at Allstate Roadside Services.
Premiums written in 2019 will benefit from the full year impact of the addition of a leading U.S. retailer, but will be partially offset by the loss of existing retailer relationships in the normal course of business.
SquareTrade and Allstate Dealer Services issue contractual liability insurance policies or guaranteed asset protection reimbursement insurance policies to cover the liabilities of their products where required by state regulations. The products offered through SquareTrade and Allstate Dealer Services fall under the regulation of departments of insurance in many states with requirements for filing of forms and rates varying by product and by state.
PIF increased 70.5% or 30.7 million to 74.2 million as of December 31, 2018 compared to 43.5 million as of December 31, 2017 due to continued growth at SquareTrade, including the addition of a leading U.S.
retailer, and the acquisition of InfoArmor. PIF increased by 38.6 million to 43.5 million as of December 31, 2017 compared to 4.9 million as of December 31, 2016 due to the acquisition of SquareTrade.
Intersegment premiums and service fees of $122 million in 2018 increased from $110 million and $105 million in 2017 and 2016, respectively, primarily related to increased auto connections through Arity’s device and mobile data collection services and analytic solutions.
Other revenue of $82 million in 2018 increased from $66 million and $64 million in 2017 and 2016, respectively, primarily due to the acquisition of InfoArmor in 2018.
Claims and claims expense decreased 4.9% to $351 million in 2018 from $369 million in 2017, primarily due to improved loss experience at SquareTrade and Allstate Dealer Services, including a decrease in catastrophe losses as Allstate Dealer Services was impacted by Hurricane Harvey in 2017, partially offset by higher loss costs at Allstate Roadside Services. Claims and claims expense increased 43.0% to $369 million in 2017 from $258 million in 2016, primarily due to the acquisition of SquareTrade on January 3, 2017.
Amortization of DAC increased 56.4% or $167 million to $463 million in 2018 from $296 million in 2017, including $101 million in 2018 related to the adoption of the revenue from contracts with customers accounting standard. The remaining increase of $66 million is due to the growth experienced at SquareTrade and Allstate Dealer Services.
Operating costs and expenses increased 9.4% to $511 million in 2018 from $467 million in 2017, primarily due to higher product and advertising costs at SquareTrade, higher costs for device data collection services, investments in research and business expansion at Arity and the addition of InfoArmor. Operating costs and expenses increased 62.7% to $467 million in 2017 from $287 million in 2016, primarily due to the acquisition of SquareTrade on January 3, 2017, Allstate Roadside Services increase in strategic investments in the Good Hands Rescue Network, and investments in Arity’s research and business expansion.
Amortization of purchased intangible assets relates to the acquisitions of SquareTrade and InfoArmor. We recognized $555 million of intangible assets for SquareTrade and we recorded amortization expense of $81 million in 2018 compared to $92 million in 2017. We recognized $257 million of intangible assets for InfoArmor and we recorded amortization expense of $13 million in 2018.
The Allstate Corporation 67
2018 Form 10-K Claims and Claims Expense Reserves
Claims and Claims Expense Reserves
Underwriting results are significantly influenced by estimates of claims and claims expense reserves. For a description of our reserve process, see Note 8 of the consolidated financial statements. Further, for a description of our reserving policies and the potential variability in our reserve estimates, see the Application of Critical Accounting Estimates section of the MD&A. These reserves are an estimate of amounts necessary to settle all outstanding claims, including IBNR claims, as of the reporting date.
The facts and circumstances leading to our reestimates of reserves relate to revisions to the development factors used to predict how losses are likely to develop from the end of a reporting period until all claims have been paid. Reestimates occur because actual losses are likely different than those predicted by the estimated development factors used in prior reserve estimates.
We believe the net loss reserves exposures are appropriately established based on available facts, technology, laws and regulations.
| Total reserves, net of recoverables (“net reserves”), as of December 31, by line of business | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Allstate brand | $ | 17,272 | $ | 16,826 | $ | 16,108 | ||||||
| Esurance brand | 862 | 777 | 740 | |||||||||
| Encompass brand | 691 | 758 | 749 | |||||||||
| Total Allstate Protection | 18,825 | 18,361 | 17,597 | |||||||||
| Discontinued Lines and Coverages | 1,391 | 1,407 | 1,445 | |||||||||
| Total Property-Liability | 20,216 | 19,768 | 19,042 | |||||||||
| Service Businesses | 52 | 86 | 24 | |||||||||
| Total net reserves | $ | 20,268 | $ | 19,854 | $ | 19,066 |
The year-end 2018 gross reserves of $27.42 billion for insurance claims and claims expense were $8.52 billion more than the net reserve balance of $18.90 billion recorded on the basis of statutory accounting practices for reports provided to state regulatory authorities. The principal differences are recoverables from third parties totaling $7.16 billion, including $5.37 billion of indemnification recoverables related to the Michigan Catastrophic Claims Association (“MCCA”), that reduce reserves for statutory reporting, but are
recorded as assets for GAAP reporting, and a liability for the reserves of the Canadian subsidiaries for $1.26 billion that are a component of our consolidated reserves, but not included in our U.S. statutory reserves. The tables below show net reserves representing the estimated cost of outstanding claims as they were recorded at the beginning of years 2018, 2017 and 2016, and the effect of reestimates in each year.
| Net reserves | ||||||||||||
| January 1 reserves | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Allstate brand | $ | 16,826 | $ | 16,108 | $ | 14,953 | ||||||
| Esurance brand | 777 | 740 | 717 | |||||||||
| Encompass brand | 758 | 749 | 770 | |||||||||
| Total Allstate Protection | 18,361 | 17,597 | 16,440 | |||||||||
| Discontinued Lines and Coverages | 1,407 | 1,445 | 1,516 | |||||||||
| Total Property-Liability | 19,768 | 19,042 | 17,956 | |||||||||
| Service Businesses | 86 | 24 | 21 | |||||||||
| Total net reserves | $ | 19,854 | $ | 19,066 | $ | 17,977 |
Claims and Claims Expense Reserves 2018 Form 10-K
| Impact of reserve reestimates by brand on combined ratio and underwriting income | |||||||||||||||||||||
| ($ in millions, except ratios) | 2018 | 2017 | 2016 | ||||||||||||||||||
| Reserve reestimate (4) | Effect on combined ratio (5) | Reserve reestimate (4) | Effect on combined ratio (5) | Reserve reestimate (4) | Effect on combined ratio (5) | ||||||||||||||||
| Allstate brand (1) | $ | (332 | ) | (1.0 | ) | $ | (585 | ) | (1.8 | ) | $ | (110 | ) | (0.3 | ) | ||||||
| Esurance brand (2) | 3 | — | (2 | ) | — | (21 | ) | (0.1 | ) | ||||||||||||
| Encompass brand (3) | (11 | ) | — | (14 | ) | (0.1 | ) | 5 | — | ||||||||||||
| Total Allstate Protection | (340 | ) | (1.0 | ) | (601 | ) | (1.9 | ) | (126 | ) | (0.4 | ) | |||||||||
| Discontinued Lines and Coverages | 87 | 0.2 | 96 | 0.3 | 105 | 0.3 | |||||||||||||||
| Total Property-Liability (6) | (253 | ) | (0.8 | ) | (505 | ) | (1.6 | ) | (21 | ) | (0.1 | ) | |||||||||
| Service Businesses | (2 | ) | — | 2 | — | 4 | — | ||||||||||||||
| Total | $ | (255 | ) | $ | (503 | ) | $ | (17 | ) | ||||||||||||
| Reserve reestimates, after-tax | $ | (201 | ) | $ | (327 | ) | $ | (11 | ) | ||||||||||||
| Consolidated net income applicable to common shareholders | $ | 2,104 | $ | 3,073 | $ | 1,761 | |||||||||||||||
| Reserve reestimates as a % impact on consolidated net income applicable to common shareholders | 9.6 | % | 10.6 | % | 0.6 | % |
| (1) | Impact of reserve reestimates on Allstate brand underwriting income were 15.0%, 26.6% and 7.5% in 2018, 2017 and 2016, respectively. |
| (2) | Impact of reserve reestimates on Esurance brand underwriting loss were (12.0)%, 3.6% and 16.9% in 2018, 2017 and 2016, respectively. |
| (3) | Impact of reserve reestimates on Encompass brand underwriting income (loss) were 84.6% and 42.4% in 2018 and 2017, respectively. Impact on results in 2016 were not meaningful. |
| (4) | Favorable reserve reestimates are shown in parentheses. |
| (5) | Ratios are calculated using property and casualty premiums earned. |
| (6) | Prior year reserve reestimates included in catastrophe losses totaled $25 million unfavorable, $18 million favorable and $6 million unfavorable in 2018, 2017 and 2016, respectively. |
The following tables reflect the accident years to which the reestimates shown above are applicable. Favorable reserve reestimates are shown in parentheses.
| 2018 prior year reserve reestimates | ||||||||||||||||||||||||
| ($ in millions) | 2013 & prior | 2014 | 2015 | 2016 | 2017 | Total | ||||||||||||||||||
| Allstate brand | $ | (61 | ) | $ | (50 | ) | $ | (25 | ) | $ | (146 | ) | $ | (50 | ) | $ | (332 | ) | ||||||
| Esurance brand | (5 | ) | (6 | ) | 9 | 13 | (8 | ) | 3 | |||||||||||||||
| Encompass brand | (12 | ) | (11 | ) | (15 | ) | 1 | 26 | (11 | ) | ||||||||||||||
| Total Allstate Protection | (78 | ) | (67 | ) | (31 | ) | (132 | ) | (32 | ) | (340 | ) | ||||||||||||
| Discontinued Lines and Coverages | 87 | — | — | — | — | 87 | ||||||||||||||||||
| Total Property-Liability | 9 | (67 | ) | (31 | ) | (132 | ) | (32 | ) | (253 | ) | |||||||||||||
| Service Businesses | — | — | — | — | (2 | ) | (2 | ) | ||||||||||||||||
| Total | $ | 9 | $ | (67 | ) | $ | (31 | ) | $ | (132 | ) | $ | (34 | ) | $ | (255 | ) |
| 2017 prior year reserve reestimates | ||||||||||||||||||||||||
| ($ in millions) | 2012 & prior | 2013 | 2014 | 2015 | 2016 | Total | ||||||||||||||||||
| Allstate brand | $ | 3 | $ | (99 | ) | $ | (103 | ) | $ | (121 | ) | $ | (265 | ) | $ | (585 | ) | |||||||
| Esurance brand | (3 | ) | (1 | ) | (12 | ) | 1 | 13 | (2 | ) | ||||||||||||||
| Encompass brand | (6 | ) | (1 | ) | (4 | ) | (1 | ) | (2 | ) | (14 | ) | ||||||||||||
| Total Allstate Protection | (6 | ) | (101 | ) | (119 | ) | (121 | ) | (254 | ) | (601 | ) | ||||||||||||
| Discontinued Lines and Coverages | 96 | — | — | — | — | 96 | ||||||||||||||||||
| Total Property-Liability | 90 | (101 | ) | (119 | ) | (121 | ) | (254 | ) | (505 | ) | |||||||||||||
| Service Businesses | — | — | — | — | 2 | 2 | ||||||||||||||||||
| Total | $ | 90 | $ | (101 | ) | $ | (119 | ) | $ | (121 | ) | $ | (252 | ) | $ | (503 | ) |
The Allstate Corporation 69
2018 Form 10-K Claims and Claims Expense Reserves
| 2016 prior year reserve reestimates | ||||||||||||||||||||||||
| ($ in millions) | 2011 & prior | 2012 | 2013 | 2014 | 2015 | Total | ||||||||||||||||||
| Allstate brand | $ | (11 | ) | $ | (52 | ) | $ | (69 | ) | $ | (40 | ) | $ | 62 | $ | (110 | ) | |||||||
| Esurance brand | (7 | ) | (3 | ) | (5 | ) | (9 | ) | 3 | (21 | ) | |||||||||||||
| Encompass brand | (25 | ) | 7 | 3 | 14 | 6 | 5 | |||||||||||||||||
| Total Allstate Protection | (43 | ) | (48 | ) | (71 | ) | (35 | ) | 71 | (126 | ) | |||||||||||||
| Discontinued Lines and Coverages | 105 | — | — | — | — | 105 | ||||||||||||||||||
| Total Property-Liability | 62 | (48 | ) | (71 | ) | (35 | ) | 71 | (21 | ) | ||||||||||||||
| Service Businesses | — | — | — | — | 4 | 4 | ||||||||||||||||||
| Total | $ | 62 | $ | (48 | ) | $ | (71 | ) | $ | (35 | ) | $ | 75 | $ | (17 | ) |
Allstate Protection
The tables below show Allstate Protection net reserves representing the estimated cost of outstanding claims as they were recorded at the beginning of years 2018, 2017, and 2016, and the effect of reestimates in each year.
| Net reserves by line | ||||||||||||
| January 1 reserves | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Auto | $ | 14,051 | $ | 13,530 | $ | 12,459 | ||||||
| Homeowners | 2,205 | 1,990 | 1,937 | |||||||||
| Other personal lines | 1,489 | 1,456 | 1,490 | |||||||||
| Commercial lines | 616 | 621 | 554 | |||||||||
| Total Allstate Protection | $ | 18,361 | $ | 17,597 | $ | 16,440 |
| Impact of reserve reestimates by line on combined ratio and underwriting income | |||||||||||||||||||||
| ($ in millions, except ratios) | 2018 | 2017 | 2016 | ||||||||||||||||||
| Reserve reestimate | Effect on combined ratio | Reserve reestimate | Effect on combined ratio | Reserve reestimate | Effect on combined ratio | ||||||||||||||||
| Auto | $ | (455 | ) | (1.3 | ) | $ | (490 | ) | (1.5 | ) | $ | (155 | ) | (0.5 | ) | ||||||
| Homeowners | 14 | — | (131 | ) | (0.4 | ) | (24 | ) | (0.1 | ) | |||||||||||
| Other personal lines | (7 | ) | — | 1 | — | (9 | ) | — | |||||||||||||
| Commercial lines | 108 | 0.3 | 19 | — | 62 | 0.2 | |||||||||||||||
| Total Allstate Protection | $ | (340 | ) | (1.0 | ) | $ | (601 | ) | (1.9 | ) | $ | (126 | ) | (0.4 | ) | ||||||
| Underwriting income | $ | 2,187 | $ | 2,111 | $ | 1,327 | |||||||||||||||
| Reserve reestimates as a % impact on underwriting income | 15.5 | % | 28.5 | % | 9.5 | % |
Prior year reserve reestimates are developed based on factors that are calculated quarterly and periodically throughout the year for data elements such as claims reported and settled, paid losses and paid losses combined with case reserves. These data elements are primarily responsible for revisions to loss development factors used to predict how losses are likely to develop from the end of a reporting period until all claims have been paid. When actual development of these data elements is different than the historical development pattern used in a prior period reserve estimate, reserves are revised as actuarial studies validate new trends based on the indications of updated development factor calculations. On-going claims organizational and process changes that are occurring are considered within our estimation process.
Favorable reserve reestimates for auto in 2018 primarily related to continued favorable personal lines auto injury coverage development, offset by strengthening in our commercial lines and personal injury protection (“PIP”) coverage, including an unfavorable ruling against the insurance industry related to Florida PIP. Auto liability claims process
changes implemented in prior years, including a program requiring enhanced documentation of injuries and related medical treatments, have resulted in favorable severity trends compared to those originally estimated as we continue to develop greater experience in settling claims under these programs. The impact of these program changes have begun to moderate. Unfavorable results for commercial lines in 2018 were primarily due to non-catastrophe auto loss development being higher than anticipated in previous estimates.
Favorable reserve reestimates for auto and homeowners in 2017 were primarily related to a reduction in claim severity estimates for liability coverages. Auto liability claims process changes implemented in prior years also impacted 2017 results. Auto liability legislative reforms, higher limits and longer settlement periods in Canada resulted in uncertainty that has developed favorably as loss experience emerges. Unfavorable results for commercial lines in 2017 were primarily due to non-catastrophe auto loss development being higher than anticipated in previous estimates.
Claims and Claims Expense Reserves 2018 Form 10-K
Favorable auto reserve reestimates in 2016 were primarily due to severity development for auto liability coverages that was better than expected. Favorable homeowners reserve reestimates in 2016 were primarily due to severity development for liability coverages related to the timing of payments. Other personal lines reserve reestimates in 2016 were primarily due to non-catastrophe loss development lower than anticipated in previous estimates.
Commercial lines reserve reestimates in 2016 were primarily due to severity development for auto bodily injury coverage that was more than expected.
Estimating the ultimate cost of claims and claims expenses is an inherently uncertain and complex process involving a high degree of judgment and is subject to the evaluation of numerous variables.
Pending, new and closed claims for Allstate Protection are summarized in the following table for the years ended December 31. The increases in pending claims as of December 31, 2018 compared to December 31, 2017 were primarily due to increases in the amount of time to settle auto liability claims and growth in the business. The increases in pending claims as of December 31, 2017 compared to December 31, 2016 were primarily due to increases in the amount of time to settle claims.
| Summary of pending new and closed claims for Allstate Protection | |||||||||
| Number of claims | 2018 | 2017 | 2016 | ||||||
| Auto | |||||||||
| Pending, beginning of year | 538,424 | 534,531 | 521,890 | ||||||
| New | 6,494,554 | 6,448,747 | 6,844,491 | ||||||
| Total closed | (6,443,276 | ) | (6,444,854 | ) | (6,831,850 | ) | |||
| Pending, end of year | 589,702 | 538,424 | 534,531 | ||||||
| Homeowners | |||||||||
| Pending, beginning of year | 37,294 | 34,691 | 38,865 | ||||||
| New | 810,919 | 898,512 | 818,084 | ||||||
| Total closed | (806,559 | ) | (895,909 | ) | (822,258 | ) | |||
| Pending, end of year | 41,654 | 37,294 | 34,691 | ||||||
| Other personal lines | |||||||||
| Pending, beginning of year | 17,077 | 14,937 | 15,835 | ||||||
| New | 212,061 | 242,427 | 219,053 | ||||||
| Total closed | (211,309 | ) | (240,287 | ) | (219,951 | ) | |||
| Pending, end of year | 17,829 | 17,077 | 14,937 | ||||||
| Commercial lines | |||||||||
| Pending, beginning of year | 10,416 | 11,518 | 11,837 | ||||||
| New | 72,326 | 55,308 | 73,139 | ||||||
| Total closed | (70,203 | ) | (56,410 | ) | (73,458 | ) | |||
| Pending, end of year | 12,539 | 10,416 | 11,518 | ||||||
| Total Allstate Protection | |||||||||
| Pending, beginning of year | 603,211 | 595,677 | 588,427 | ||||||
| New | 7,589,860 | 7,644,994 | 7,954,767 | ||||||
| Total closed | (7,531,347 | ) | (7,637,460 | ) | (7,947,517 | ) | |||
| Pending, end of year | 661,724 | 603,211 | 595,677 |
Discontinued Lines and Coverages
We conduct an annual review in the third quarter of each year to evaluate and establish asbestos, environmental and other discontinued lines reserves. Reserves are recorded in the reporting period in which they are determined. Using established industry and actuarial best practices and assuming no change in the
regulatory or economic environment, this detailed and comprehensive methodology determines reserves based on assessments of the characteristics of exposure (e.g. claim activity, potential liability, jurisdiction, products versus non-products exposure) presented by policyholders.
| Discontinued Lines and Coverages reserve reestimates | ||||||||||||||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||||||||||||||
| January 1 reserves | Reserve reestimate | January 1 reserves | Reserve reestimate | January 1 reserves | Reserve reestimate | |||||||||||||||||||
| Asbestos claims | $ | 884 | $ | 44 | $ | 912 | $ | 61 | $ | 960 | $ | 67 | ||||||||||||
| Environmental claims | 166 | 20 | 179 | 10 | 179 | 23 | ||||||||||||||||||
| Other discontinued lines | 357 | 23 | 354 | 25 | 377 | 15 | ||||||||||||||||||
| Total | $ | 1,407 | $ | 87 | $ | 1,445 | $ | 96 | $ | 1,516 | $ | 105 | ||||||||||||
| Underwriting loss | $ | (90 | ) | $ | (99 | ) | $ | (107 | ) |
Reserve additions for asbestos in 2018 were primarily related to new reported information, changes
in our projections of reported claims and settlement agreements, including bankruptcy proceedings.
The Allstate Corporation 71
2018 Form 10-K Claims and Claims Expense Reserves
Reserve additions for asbestos in 2017 were primarily related to new reported information and settlement agreements, including bankruptcy proceedings. Reserve additions for asbestos in 2016 were primarily related to insured business and claim development, new reported information on insured’s claims, expanded expected exposure periods and other legal settlements including insured’s bankruptcy proceedings.
Reserve additions for environmental in 2018 were primarily related to expected greater loss activity for future claims. Reserve additions for environmental in 2017 and 2016 were primarily related to greater reported loss activity than expected.
| Reserves and claim activity before (Gross) and after (Net) the effects of reinsurance | ||||||||||||||||||||||||
| ($ in millions, except ratios) | 2018 | 2017 | 2016 | |||||||||||||||||||||
| Gross | Net | Gross | Net | Gross | Net | |||||||||||||||||||
| Asbestos claims | ||||||||||||||||||||||||
| Beginning reserves | $ | 1,296 | $ | 884 | $ | 1,356 | $ | 912 | $ | 1,418 | $ | 960 | ||||||||||||
| Incurred claims and claims expense | 89 | 44 | 79 | 61 | 96 | 67 | ||||||||||||||||||
| Claims and claims expense paid | (119 | ) | (62 | ) | (139 | ) | (89 | ) | (158 | ) | (115 | ) | ||||||||||||
| Ending reserves | $ | 1,266 | $ | 866 | $ | 1,296 | $ | 884 | $ | 1,356 | $ | 912 | ||||||||||||
| Annual survival ratio | 10.6 | 14.0 | 9.3 | 9.9 | 8.6 | 7.9 | ||||||||||||||||||
| 3-year survival ratio | 9.1 | 9.7 | 9.2 | 8.9 | 9.9 | 9.2 | ||||||||||||||||||
| Environmental claims | ||||||||||||||||||||||||
| Beginning reserves | $ | 199 | $ | 166 | $ | 219 | $ | 179 | $ | 222 | $ | 179 | ||||||||||||
| Incurred claims and claims expense | 30 | 20 | 9 | 10 | 24 | 23 | ||||||||||||||||||
| Claims and claims expense paid | (20 | ) | (16 | ) | (29 | ) | (23 | ) | (27 | ) | (23 | ) | ||||||||||||
| Ending reserves | $ | 209 | $ | 170 | $ | 199 | $ | 166 | $ | 219 | $ | 179 | ||||||||||||
| Annual survival ratio | 10.5 | 10.6 | 6.9 | 7.2 | 8.1 | 7.8 | ||||||||||||||||||
| 3-year survival ratio | 8.4 | 8.2 | 6.9 | 6.9 | 8.1 | 7.8 | ||||||||||||||||||
| Combined environmental and asbestos claims | ||||||||||||||||||||||||
| Annual survival ratio | 10.6 | 13.3 | 8.9 | 9.4 | 8.5 | 7.9 | ||||||||||||||||||
| 3-year survival ratio | 9.0 | 9.5 | 8.8 | 8.5 | 9.6 | 8.9 | ||||||||||||||||||
| Percentage of IBNR in ending reserves | 49.6 | % | 52.7 | % | 56.7 | % |
The survival ratio is calculated by taking our ending reserves divided by payments made during the year. This is a commonly used but extremely simplistic and imprecise approach to measuring the adequacy of asbestos and environmental reserve levels. Many factors, such as mix of business, level of coverage provided and settlement procedures have significant impacts on the amount of environmental and asbestos claims and claims expense reserves, claim payments and the resultant ratio. As payments result in
corresponding reserve reductions, survival ratios can be expected to vary over time. In 2018, the asbestos and environmental net 3-year survival ratio increased due to lower claim payments associated with settlement agreements. In 2017 and 2016, the asbestos and environmental net 3-year survival ratio decreased due to increased claim payments associated with settlement agreements expected to be substantially paid out over the next several years.
| Net asbestos reserves by type of exposure and total reserve additions | ||||||||||||||||||||||||||||||
| ($ in millions) | December 31, 2018 | December 31, 2017 | December 31, 2016 | |||||||||||||||||||||||||||
| Active policy-holders | Net reserves | % of reserves | Active policy-holders | Net reserves | % of reserves | Active policy-holders | Net reserves | % of reserves | ||||||||||||||||||||||
| Direct policyholders: | ||||||||||||||||||||||||||||||
| Primary | 51 | $ | 12 | 1 | % | 48 | $ | 10 | 1 | % | 51 | $ | 9 | 1 | % | |||||||||||||||
| Excess | 295 | 309 | 36 | 296 | 308 | 35 | 297 | 266 | 29 | |||||||||||||||||||||
| Total case reserves | 346 | 321 | 37 | 344 | 318 | 36 | 348 | 275 | 30 | |||||||||||||||||||||
| Assumed reinsurance | 138 | 16 | 117 | 13 | 125 | 14 | ||||||||||||||||||||||||
| IBNR | 407 | 47 | 449 | 51 | 512 | 56 | ||||||||||||||||||||||||
| Total net reserves | $ | 866 | 100 | % | $ | 884 | 100 | % | $ | 912 | 100 | % | ||||||||||||||||||
| Total reserve additions | $ | 44 | $ | 61 | $ | 67 |
Claims and Claims Expense Reserves 2018 Form 10-K
At December 31, 2018, there were 346 active policyholders with open asbestos claims.
| • | Active policyholders increased by 2 in 2018, including 13 policyholders reporting asbestos claims for the first time and the closing of all claims for 11 policyholders. |
| • | Active policyholders decreased by 4 in 2017, including 10 policyholders reporting asbestos claims for the first time and the closing of all claims for 14 policyholders. |
| • | Active policyholders increased by 2 in 2016, including 17 policyholders reporting asbestos claims for the first time and the closing of all claims for 15 policyholders. |
IBNR net reserves decreased $42 million as of December 31, 2018 compared to December 31, 2017, due to the transfer of IBNR to case reserves through settlement agreements with insureds on large claims where the scope of coverages have been agreed. IBNR provides for reserve development of known claims and future reporting of additional unknown claims from current policyholders and ceding companies.
| Claims counts for asbestos and environmental exposures | |||||||||
| For the years ended December 31, | |||||||||
| Number of claims | 2018 | 2017 | 2016 | ||||||
| Asbestos | |||||||||
| Pending, beginning of year | 6,659 | 6,883 | 7,151 | ||||||
| New | 427 | 406 | 477 | ||||||
| Closed | (646 | ) | (630 | ) | (745 | ) | |||
| Pending, end of year | 6,440 | 6,659 | 6,883 | ||||||
| Closed without payment | 446 | 377 | 373 | ||||||
| Environmental | |||||||||
| Pending, beginning of year | 3,351 | 3,399 | 3,504 | ||||||
| New | 335 | 375 | 292 | ||||||
| Closed | (457 | ) | (423 | ) | (397 | ) | |||
| Pending, end of year | 3,229 | 3,351 | 3,399 | ||||||
| Closed without payment | 320 | 299 | 211 |
Reinsurance and indemnification programs We utilize reinsurance to reduce exposure to catastrophe risk and manage capital, and to support the required statutory surplus and the insurance financial strength ratings of certain subsidiaries such as Castle Key Insurance Company (“CKIC”) and Allstate New Jersey Insurance Company (“ANJ”). We purchase significant reinsurance to manage our aggregate countrywide exposure to an acceptable level. The price and terms of reinsurance and the credit quality of the reinsurer are considered in the purchase process, along with whether the price can be appropriately reflected in the
costs that are considered in setting future rates charged to policyholders. We have also historically purchased reinsurance to mitigate long-tail liability lines, including environmental, asbestos and other discontinued lines exposures. We also participate in various indemnification mechanisms, including state-based industry pool or facility programs mandating participation by insurers offering certain coverage in their state and the federal government National Flood Insurance Program (“NFIP”). See Note 10 of the consolidated financial statements for additional details on these programs.
The Allstate Corporation 73
2018 Form 10-K Claims and Claims Expense Reserves
| Reinsurance and indemnification recoverable balances net of the allowance established for uncollectible amounts | ||||||||||
| S&P financial strength rating (1) | Reinsurance or indemnification recoverable on paid and unpaid claims, net | |||||||||
| ($ in millions) | 2018 | 2017 | ||||||||
| Indemnification programs | ||||||||||
| State-based industry pool or facility programs | ||||||||||
| MCCA (2) | N/A | $ | 5,400 | $ | 5,261 | |||||
| New Jersey Property-Liability Insurance Guaranty Association (“PLIGA”) | N/A | 461 | 493 | |||||||
| North Carolina Reinsurance Facility | N/A | 86 | 86 | |||||||
| Florida Hurricane Catastrophe Fund (“FHCF”) | N/A | 104 | 19 | |||||||
| Other | 9 | 6 | ||||||||
| Federal Government - NFIP | N/A | 31 | 88 | |||||||
| Subtotal | 6,091 | 5,953 | ||||||||
| Catastrophe reinsurance recoverables | ||||||||||
| Renaissance Reinsurance Limited | A+ | 65 | 1 | |||||||
| Swiss Reinsurance America Corporation | AA- | 39 | — | |||||||
| Arch Reinsurance Limited | A+ | 37 | — | |||||||
| Other | 412 | 10 | ||||||||
| Subtotal | 553 | 11 | ||||||||
| Other reinsurance recoverables (3) | ||||||||||
| Lloyd’s of London (“Lloyd’s”) (4) | A+ | 165 | 167 | |||||||
| Westport Insurance Corporation | AA- | 60 | 61 | |||||||
| TIG Insurance Company | N/A | 35 | 31 | |||||||
| Other, including allowance for future uncollectible recoverables | 344 | 326 | ||||||||
| Subtotal | 604 | 585 | ||||||||
| Total Property-Liability | 7,248 | 6,549 | ||||||||
| Service Businesses | 18 | 18 | ||||||||
| Total | $ | 7,266 | $ | 6,567 |
| (1) | N/A reflects no S&P Global Ratings (“S&P”) rating available. |
| (2) | As of December 31, 2018 and 2017, MCCA includes $30 million and $27 million of reinsurance recoverable on paid claims, respectively, and $5.37 billion and $5.23 billion of reinsurance recoverable on unpaid claims, respectively. |
| (3) | Other reinsurance recoverables primarily relate to asbestos, environmental and other liability exposures. |
| (4) | As of December 31, 2018, case reserves for Lloyd’s were 69% of the reinsurance recoverable for unpaid claims. |
Reinsurance and indemnification recoverables include an estimate of the amount of insurance claims and claims expense reserves that are ceded under the terms of the agreements, including incurred but not reported unpaid losses. We calculate our ceded reinsurance and indemnification estimates based on the terms of each applicable agreement, including an estimate of how IBNR losses will ultimately be ceded under the agreement. We also consider other limitations and coverage exclusions under our agreements. Accordingly, our estimate of recoverables is subject to similar risks and uncertainties as our estimate of reserves claims and claims expense. We believe the recoverables are appropriately established; however, as our underlying reserves continue to develop, the amount ultimately recoverable may vary from amounts currently recorded. We regularly evaluate the reinsurers and the respective amounts of our reinsurance recoverables, and a provision for uncollectible reinsurance recoverables is recorded, if needed. The establishment of reinsurance recoverables and the related allowance for uncollectible reinsurance is also an inherently uncertain process involving estimates. Changes in estimates
could result in additional changes to the Consolidated Statements of Operations.
Indemnification recoverables are considered collectible based on the industry pool and facility enabling legislation and the Company has not had any credit losses related to these programs. We also have not experienced credit losses on our catastrophe reinsurance programs. The allowance for uncollectible reinsurance relates to other reinsurance programs primarily related to our Discontinued Lines and Coverages segment. This allowance was $65 million and $70 million as of December 31, 2018 and 2017, respectively, which represents 11.8% and 12.0% of the related reinsurance recoverable balances as of December 31, 2018 and 2017, respectively. The allowance is based upon our ongoing review of amounts outstanding, length of collection periods, changes in reinsurer credit standing, and other relevant factors. In addition, in the ordinary course of business, we may become involved in coverage disputes with certain of our reinsurers that may ultimately result in lawsuits and arbitrations brought by or against such reinsurers to determine the parties’
Claims and Claims Expense Reserves 2018 Form 10-K
rights and obligations under the various reinsurance agreements. We employ dedicated specialists to manage reinsurance collections and disputes. We also consider recent developments in commutation activity between reinsurers and cedents, and recent trends in arbitration and litigation outcomes in disputes between cedents and reinsurers in seeking to maximize our reinsurance recoveries.
Adverse developments in the insurance industry have led to a decline in the financial strength of some of our reinsurance carriers, causing amounts recoverable from them and future claims ceded to them to be considered a higher risk. There has also been consolidation activity in the industry, which
causes reinsurance risk across the industry to be concentrated among fewer companies. In addition, some companies have segregated asbestos, environmental, and other discontinued lines exposures into separate legal entities with dedicated capital. Regulatory bodies in certain cases have supported these actions. We are unable to determine the impact, if any, that these developments will have on the collectability of reinsurance recoverables in the future.
For a detailed description of the MCCA, PLIGA and Lloyd’s, see Note 10 of the consolidated financial statements.
| Effects of reinsurance ceded and indemnification programs on our premiums earned and claims and claims expense | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Allstate Protection - Premiums | ||||||||||||
| Indemnification programs | ||||||||||||
| State-based industry pool or facility programs | ||||||||||||
| MCCA | $ | 77 | $ | 73 | $ | 73 | ||||||
| PLIGA | 9 | 9 | 8 | |||||||||
| FHCF | 10 | 11 | 12 | |||||||||
| Other | 90 | 108 | 99 | |||||||||
| Federal Government - NFIP | 258 | 263 | 274 | |||||||||
| Catastrophe reinsurance | 344 | 344 | 381 | |||||||||
| Other reinsurance programs | 54 | — | — | |||||||||
| Total Allstate Protection | 842 | 808 | 847 | |||||||||
| Discontinued Lines and Coverages | — | — | — | |||||||||
| Total Property-Liability | 842 | 808 | 847 | |||||||||
| Service Businesses | 174 | 163 | 140 | |||||||||
| Total effect on premiums earned | $ | 1,016 | $ | 971 | $ | 987 | ||||||
| Allstate Protection - Claims | ||||||||||||
| Indemnification programs | ||||||||||||
| State-based industry pool or facility programs | ||||||||||||
| MCCA | $ | 233 | $ | 410 | $ | 386 | ||||||
| PLIGA | (6 | ) | 3 | 20 | ||||||||
| FHCF | 148 | 19 | — | |||||||||
| Other | 90 | 89 | 82 | |||||||||
| Federal Government - NFIP | 118 | 1,116 | 537 | |||||||||
| Catastrophe reinsurance | 604 | 46 | (9 | ) | ||||||||
| Other reinsurance programs | 40 | — | — | |||||||||
| Total Allstate Protection | 1,227 | 1,683 | 1,016 | |||||||||
| Discontinued Lines and Coverages | 57 | 35 | 27 | |||||||||
| Total Property-Liability | 1,284 | 1,718 | 1,043 | |||||||||
| Service Businesses | 94 | 89 | 73 | |||||||||
| Total effect on claims and claims expense | $ | 1,378 | $ | 1,807 | $ | 1,116 |
In 2018, 2017 and 2016, ceded premiums earned increased primarily due to increased indemnification program reinsurance premium rates and a decrease in policies written for the NFIP.
In 2018, ceded claims and claims expenses decreased $429 million, primarily due to higher amounts related to the NFIP in 2017. In 2017, ceded claims and claims expenses increased $691 million, primarily due to higher amounts related to the NFIP related to claims as a result of Hurricanes Harvey and Irma. Ceded claims and claims expenses increased in
2016, primarily due to higher amounts related to the NFIP as the result of Louisiana flooding.
Our claim reserve development experience is consistent with the MCCA’s overall experience with reported and pending claims increasing in recent years. Moreover, the MCCA has reported severity increasing with nearly 57% of reimbursements for attendant and residential care services. Michigan’s unique no-fault motor vehicle insurance law provides unlimited lifetime coverage for medical expenses resulting from motor vehicle accidents. The reserve
The Allstate Corporation 75
2018 Form 10-K Claims and Claims Expense Reserves
increases in the MCCA program are attributable to an increased recognition of longer term paid loss trends. The paid loss trends are rising due to increased costs in medical and attendant care and increased longevity of claimants. As a result of continuing to originate
motor vehicle policies in Michigan with unlimited personal injury protection coverage, we expect the number of MCCA covered claims and losses to increase each year.
| Michigan personal injury protection reserve and claim activity before and after the effects of MCCA recoverables | |||||||||||||||||||||||||||
| For the years ended December 31, | |||||||||||||||||||||||||||
| 2018 | 2017 | 2016 | |||||||||||||||||||||||||
| ($ in millions) | Gross | Net | Gross | Net | Gross | Net | |||||||||||||||||||||
| Beginning reserves | $ | 5,799 | $ | 565 | $ | 5,443 | $ | 522 | $ | 5,121 | $ | 486 | |||||||||||||||
| Incurred claims and claims expense-current year | 449 | 189 | 513 | 195 | 578 | 214 | |||||||||||||||||||||
| Incurred claims and claims expense-prior years | 9 | 35 | 117 | 25 | 8 | (15 | ) | ||||||||||||||||||||
| Claims and claims expense paid-current year (1) | (52 | ) | (51 | ) | (54 | ) | (53 | ) | (60 | ) | (58 | ) | |||||||||||||||
| Claims and claims expense paid-prior years (1) | (230 | ) | (133 | ) | (220 | ) | (124 | ) | (204 | ) | (105 | ) | |||||||||||||||
| Ending reserves (2) | $ | 5,975 | $ | 605 | $ | 5,799 | $ | 565 | $ | 5,443 | $ | 522 |
| (1) | Paid claims and claims expenses reported in the table for the current and prior years, recovered from the MCCA totaled $98 million, $97 million and $101 million in 2018, 2017 and 2016, respectively. |
| (2) | Gross reserves for the year ended December 31, 2018, comprise 88% case reserves and 12% IBNR. Gross reserves for the year ended December 31, 2017, comprise 87% case reserves and 13% IBNR. Gross reserves for the year ended December 31, 2016 comprise 85% case reserves and 15% IBNR. The MCCA does not require member companies to report ultimate case reserves. |
Pending MCCA claims differ from most personal lines insurance pending claims as other personal lines policies have coverage limits and incurred claims settle in shorter periods. Claims are considered pending as long as payments are continuing pursuant to an outstanding MCCA claim, which can be for a claimant’s lifetime. Many of these injuries are catastrophic in
nature, resulting in serious permanent disabilities that require attendant and residential care for periods that may span decades. A significant portion of the ultimate incurred claim reserves and the recoverables can be attributed to a small number of catastrophic claims that occurred more than five years ago and continue to pay lifetime benefits.
| Pending, new and closed claims for Michigan personal injury protection exposures | |||||||||
| For the years ended December 31, | |||||||||
| Number of claims (1) | 2018 | 2017 | 2016 | ||||||
| Pending, beginning of year | 4,983 | 5,388 | 5,127 | ||||||
| New | 7,858 | 8,494 | 9,577 | ||||||
| Closed | (8,029 | ) | (8,899 | ) | (9,316 | ) | |||
| Pending, end of year | 4,812 | 4,983 | 5,388 |
| (1) | Total claims includes those covered and not covered by the MCCA indemnification. |
As of December 31, 2018, approximately 1,645 of our pending claims have been reported to the MCCA, of which approximately 50% represents claims that occurred more than 5 years ago. There are 75 Allstate brand claims with reserves in excess of $15 million as of December 31, 2018, which comprise approximately 37% of the gross ending reserves in the table above. As a result, significant developments with a single claimant can result in volatility in prior year incurred claims.
Intercompany reinsurance We enter into certain intercompany insurance and reinsurance transactions in order to maintain underwriting control and manage insurance risk among various legal entities. These reinsurance agreements have been approved by the appropriate regulatory authorities. All significant intercompany transactions have been eliminated in consolidation.
Catastrophe reinsurance Our catastrophe reinsurance program is designed, utilizing our risk management methodology, to address our exposure to catastrophes nationwide. Our program is designed to provide reinsurance protection for catastrophes resulting from multiple perils including hurricanes, windstorms, hail, tornadoes, fires following earthquakes, earthquakes and wildfires. These reinsurance agreements are part of our catastrophe management strategy, which is intended to provide our shareholders an acceptable return on the risks assumed in our property business, and to reduce variability of earnings, while providing protection to our customers.
We anticipate completing the placement of our 2019 nationwide catastrophe reinsurance program in the second quarter of 2019. We expect the program will be similar to our 2018 nationwide catastrophe reinsurance program, but will evaluate opportunities to improve the economic terms and conditions. For further details of the existing 2018 program, see Note 10 of the consolidated financial statements.
Allstate Life 2018 Form 10-K
Allstate Life Segment
Allstate Life offers traditional, interest-sensitive and variable life insurance. In 2018, Allstate Life represented 4.8% of total revenue, 1.8% of total PIF and 10.1% of total adjusted net income. Our target customers prefer local personalized advice and service and are brand-sensitive. For additional information on our strategy and outlook, see Part I, Item 1. Business - Strategy and Segment Information.
| Summarized financial information | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Revenues | ||||||||||||
| Premiums and contract charges | $ | 1,315 | $ | 1,280 | $ | 1,250 | ||||||
| Other revenue | 119 | 114 | 113 | |||||||||
| Net investment income | 505 | 489 | 482 | |||||||||
| Realized capital gains and losses | (14 | ) | 5 | (38 | ) | |||||||
| Total revenues | 1,925 | 1,888 | 1,807 | |||||||||
| Costs and expenses | ||||||||||||
| Contract benefits | (809 | ) | (765 | ) | (742 | ) | ||||||
| Interest credited to contractholder funds | (285 | ) | (282 | ) | (285 | ) | ||||||
| Amortization of DAC | (132 | ) | (134 | ) | (131 | ) | ||||||
| Operating costs and expenses | (369 | ) | (352 | ) | (338 | ) | ||||||
| Restructuring and related charges | (3 | ) | (2 | ) | (1 | ) | ||||||
| Total costs and expenses | (1,598 | ) | (1,535 | ) | (1,497 | ) | ||||||
| Income tax (expense) benefit | (73 | ) | 224 | (91 | ) | |||||||
| Net income applicable to common shareholders | $ | 254 | $ | 577 | $ | 219 | ||||||
| Adjusted net income | $ | 289 | $ | 253 | $ | 247 | ||||||
| Realized capital gains and losses, after-tax | (11 | ) | 2 | (24 | ) | |||||||
| DAC and DSI amortization related to realized capital gains and losses, after-tax | (8 | ) | (10 | ) | (4 | ) | ||||||
| Tax Legislation (expense) benefit | (16 | ) | 332 | — | ||||||||
| Net income applicable to common shareholders | $ | 254 | $ | 577 | $ | 219 | ||||||
| Reserve for life-contingent contract benefits as of December 31 | $ | 2,677 | $ | 2,636 | $ | 2,578 | ||||||
| Contractholder funds as of December 31 | $ | 7,656 | $ | 7,608 | $ | 7,464 | ||||||
| Policies in force as of December 31 by distribution channel (in thousands) | ||||||||||||
| Allstate agencies | 1,831 | 1,822 | 1,804 | |||||||||
| Closed channels | 191 | 204 | 219 | |||||||||
| Total | 2,022 | 2,026 | 2,023 |
Net income applicable to common shareholders was $254 million, $577 million and $219 million in 2018, 2017 and 2016, respectively. 2018 and 2017 results include a tax expense of $16 million and a tax benefit of $332 million, respectively, related to the Tax Legislation.
Adjusted net income was $289 million in 2018 compared to $253 million in 2017. The increase was primarily due to a lower effective tax rate from the Tax Legislation and increased premiums and contract charges, partially offset by higher contract benefits.
Adjusted net income was $253 million in 2017 compared to $247 million in 2016. The increase was primarily due to higher premiums and contract
charges, partially offset by higher contract benefits and operating costs and expenses.
Premiums and contract charges increased 2.7% or $35 million in 2018 compared to 2017. The increase primarily relates to growth in traditional life insurance as well as lower reinsurance premiums ceded. Approximately 85% of Allstate Life’s traditional life insurance premium relates to term life insurance products.
Premiums and contract charges increased 2.4% or $30 million in 2017 compared to 2016. The increase primarily relates to higher traditional life insurance renewal premiums as well as lower levels of reinsurance premiums ceded.
The Allstate Corporation 77
2018 Form 10-K Allstate Life
| Premiums and contract charges by product | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Traditional life insurance premiums | $ | 600 | $ | 568 | $ | 533 | ||||||
| Accident and health insurance premiums | 2 | 2 | 2 | |||||||||
| Interest-sensitive life insurance contract charges | 713 | 710 | 715 | |||||||||
| Premiums and contract charges (1) | $ | 1,315 | $ | 1,280 | $ | 1,250 |
| (1) | Contract charges related to the cost of insurance totaled $493 million, $487 million and $488 million in 2018, 2017 and 2016, respectively. |
Contract benefits increased 5.8% or $44 million in 2018 compared to 2017, primarily due to higher claim experience on both traditional and interest-sensitive life insurance. Contract benefits increased 3.1% or $23 million in 2017 compared to 2016, primarily due to growth in business in force.
Our annual review of assumptions in 2018 resulted in a $1 million increase in reserves primarily for secondary guarantees on interest-sensitive life insurance due to higher than anticipated policyholder persistency. In 2017, the review resulted in a $12 million increase in reserves, primarily for secondary guarantees on interest-sensitive life insurance due to increased projected exposure to benefits paid under secondary guarantees resulting from continued low interest rates.
Benefit spread reflects our mortality and morbidity results using the difference between premiums and contract charges earned for the cost of insurance and contract benefits (“benefit spread”). Benefit spread decreased 2.1% to $286 million in 2018 compared to $292 million in 2017, primarily due to higher claim experience, partially offset by growth in traditional life insurance premiums. Benefit spread increased 3.9% to
$292 million in 2017 compared to $281 million in 2016, primarily due to growth in business in force.
Investment spread reflects the difference between net investment income and interest credited to contractholder funds (“investment spread”) and is used to analyze the impact of net investment income and interest credited to contractholders on net income. Investment spread increased 6.3% to $220 million in 2018 compared to $207 million in 2017, primarily due to higher net investment income, partially offset by higher credited interest. Investment spread increased 5.1% to $207 million in 2017 compared to $197 million in 2016, primarily due to higher net investment income and lower credited interest.
Amortization of DAC decreased 1.5% or $2 million in 2018 compared to 2017, primarily due to lower gross profits on interest-sensitive life insurance, partially offset by amortization acceleration in 2018 compared to amortization deceleration in 2017 for changes in assumptions. Amortization of DAC increased 2.3% or $3 million in 2017 compared to 2016, primarily due to higher net realized capital gains and gross profits, partially offset by higher amortization deceleration for changes in assumptions.
| Components of amortization of DAC | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Amortization of DAC before amortization relating to realized capital gains and losses and changes in assumptions | $ | 117 | $ | 134 | $ | 131 | ||||||
| Amortization relating to realized capital gains and losses (1) | 10 | 14 | 6 | |||||||||
| Amortization acceleration (deceleration) for changes in assumptions (‘‘DAC unlocking’’) | 5 | (14 | ) | (6 | ) | |||||||
| Total amortization of DAC | $ | 132 | $ | 134 | $ | 131 |
| (1) | The impact of realized capital gains and losses on amortization of DAC is dependent upon the relationship between the assets that give rise to the gain or loss and the product liability supported by the assets. Fluctuations result from changes in the impact of realized capital gains and losses on actual and expected gross profits. |
Our annual comprehensive review of assumptions underlying estimated future gross profits for our interest-sensitive life contracts covers assumptions for mortality, persistency, expenses, investment returns, including capital gains and losses, interest crediting rates to policyholders, and the effect of any hedges.
In 2018, the review resulted in an acceleration of DAC amortization (decrease to income) of $5 million. DAC amortization acceleration primarily related to the investment margin component of estimated gross profits and was due to lower projected investment returns. This was partially offset by DAC amortization deceleration (increase to income) for changes in the
benefit margin due to a decrease in projected mortality.
In 2017, the review resulted in a deceleration of DAC amortization of $14 million. DAC amortization deceleration primarily related to the benefit margin component of estimated gross profits and was due to a decrease in projected mortality. This was partially offset by DAC amortization acceleration for changes in the investment margin due to continued low interest rates and lower projected investment returns.
In 2016, the review resulted in a deceleration of DAC amortization of $6 million. DAC amortization deceleration for changes in the investment margin was due to increased projected investment margins from a
Allstate Life 2018 Form 10-K
favorable asset portfolio mix. DAC amortization deceleration for changes in the expense margin related primarily to variable life insurance and was due to a decrease in projected expenses.
| Changes in DAC | ||||||||||||||||||||||||
| ($ in millions) | Traditional life and accident and health | Interest-sensitive life insurance | Total | |||||||||||||||||||||
| For the years ended December 31, | ||||||||||||||||||||||||
| 2018 | 2017 | 2018 | 2017 | 2018 | 2017 | |||||||||||||||||||
| Balance, beginning of year | $ | 465 | $ | 438 | $ | 687 | $ | 762 | $ | 1,152 | $ | 1,200 | ||||||||||||
| Acquisition costs deferred | 65 | 66 | 65 | 66 | 130 | 132 | ||||||||||||||||||
| Amortization of DAC before amortization relating to realized capital gains and losses and changes in assumptions (1) | (41 | ) | (39 | ) | (76 | ) | (95 | ) | (117 | ) | (134 | ) | ||||||||||||
| Amortization relating to realized capital gains and losses (1) | — | — | (10 | ) | (14 | ) | (10 | ) | (14 | ) | ||||||||||||||
| Amortization (acceleration) deceleration for changes in assumptions (“DAC unlocking”) (1) | — | — | (5 | ) | 14 | (5 | ) | 14 | ||||||||||||||||
| Effect of unrealized capital gains and losses (2) | — | — | 150 | (46 | ) | 150 | (46 | ) | ||||||||||||||||
| Ending balance | $ | 489 | $ | 465 | $ | 811 | $ | 687 | $ | 1,300 | $ | 1,152 |
| (1) | Included as a component of amortization of DAC on the Consolidated Statements of Operations. |
| (2) | Represents the change in the DAC adjustment for unrealized capital gains and losses. The DAC adjustment represents the amount by which the amortization of DAC would increase or decrease if the unrealized gains and losses in the respective product portfolios were realized. |
Operating costs and expenses increased 4.8% or $17 million in 2018 compared to 2017, primarily due to higher technology and employee-related costs and higher commissions on non-proprietary product sales.
Operating costs and expenses increased 4.1% or $14 million in 2017 compared to 2016, primarily due to
higher employee related costs and higher net distribution expenses reflecting increased regulatory compliance costs, partially offset by lower non-deferrable commissions.
Analysis of reserves and contractholder funds
| Reserve for life-contingent contract benefits | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Traditional life insurance | $ | 2,539 | $ | 2,460 | $ | 2,398 | ||||||
| Accident and health insurance | 138 | 176 | 180 | |||||||||
| Reserve for life-contingent contract benefits | $ | 2,677 | $ | 2,636 | $ | 2,578 |
The Allstate Corporation 79
2018 Form 10-K Allstate Life
Contractholder funds represent interest-bearing liabilities arising from the sale of products such as interest-sensitive life insurance. The balance of contractholder funds is equal to the cumulative deposits received and interest credited to the contractholder less cumulative contract benefits, surrenders, withdrawals and contract charges for mortality or administrative expenses.
| Change in contractholder funds | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Contractholder funds, beginning balance | $ | 7,608 | $ | 7,464 | $ | 7,359 | ||||||
| Deposits | 965 | 973 | 991 | |||||||||
| Interest credited | 284 | 282 | 284 | |||||||||
| Benefits, withdrawals and other adjustments | ||||||||||||
| Benefits | (232 | ) | (241 | ) | (245 | ) | ||||||
| Surrenders and partial withdrawals | (259 | ) | (254 | ) | (250 | ) | ||||||
| Contract charges | (704 | ) | (704 | ) | (705 | ) | ||||||
| Net transfers from separate accounts | 6 | 4 | 4 | |||||||||
| Other adjustments (1) | (12 | ) | 84 | 26 | ||||||||
| Total benefits, withdrawals and other adjustments | (1,201 | ) | (1,111 | ) | (1,170 | ) | ||||||
| Contractholder funds, ending balance | $ | 7,656 | $ | 7,608 | $ | 7,464 |
| (1) | The table above illustrates the changes in contractholder funds, which are presented gross of reinsurance recoverables on the Consolidated Statements of Financial Position. The table above is intended to supplement our discussion and analysis of revenues, which are presented net of reinsurance on the Consolidated Statements of Operations. As a result, the net change in contractholder funds associated with products reinsured is reflected as a component of the other adjustments line. |
Contractholder deposits decreased 0.8% in 2018 compared to 2017, and 1.8% in 2017 compared to 2016. The weighted average guaranteed crediting rate and weighted average current crediting rate for our interest-sensitive life insurance contracts, excluding variable life, are both 3.9% as of December 31, 2018.
Allstate Life 2018 Form 10-K
Allstate Life reinsurance ceded
In the normal course of business, we seek to limit aggregate and single exposure to losses on large risks by purchasing reinsurance. In addition, we have used reinsurance to effect the disposition of certain blocks of business.
We retain primary liability as a direct insurer for all risks ceded to reinsurers. As of December 31, 2018, approximately 15% of our face amount of life insurance in force was reinsured.
| Reinsurance recoverables by reinsurer | ||||||||||
| S&P financial strength rating (1) | Reinsurance recoverable on paid and unpaid benefits | |||||||||
| For the years ended December 31, | ||||||||||
| ($ in millions) | 2018 | 2017 | ||||||||
| RGA Reinsurance Company | AA- | $ | 210 | $ | 229 | |||||
| Swiss Re Life and Health America, Inc. | AA- | 156 | 159 | |||||||
| Munich American Reassurance | AA- | 87 | 91 | |||||||
| Transamerica Life Group | AA- | 76 | 77 | |||||||
| Scottish Re (U.S.), Inc. (2) | N/A | 66 | 87 | |||||||
| John Hancock Life & Health Insurance Company | AA- | 53 | 54 | |||||||
| Triton Insurance Company | N/A | 45 | 47 | |||||||
| American Health & Life Insurance Co. | N/A | 34 | 37 | |||||||
| Lincoln National Life Insurance | AA- | 25 | 28 | |||||||
| Security Life of Denver | A | 24 | 27 | |||||||
| SCOR Global Life | AA- | 14 | 17 | |||||||
| American United Life Insurance Company | AA- | 13 | 14 | |||||||
| Other (3) | 20 | 25 | ||||||||
| Total | $ | 823 | $ | 892 |
| (1) | N/A reflects no S&P rating available. |
| (2) | Scottish Re (U.S.), Inc. was last rated by S&P in 2009 and A.M. Best removed their rating in 2011. Scottish Re (U.S.), Inc. remains current on claims payments to Allstate. |
| (3) | As of December 31, 2018 and 2017, the other category includes $9 million and $19 million, respectively, of recoverables due from reinsurers rated A- or better by S&P. |
We continuously monitor the creditworthiness of reinsurers in order to determine our risk of recoverability on an individual and aggregate basis, and a provision for uncollectible reinsurance is recorded if needed. No amounts have been deemed unrecoverable in the three-years ended December 31, 2018.
We enter into certain intercompany reinsurance transactions for the Allstate Life operations in order to maintain underwriting control and manage insurance risk among various legal entities. These reinsurance agreements have been approved by the appropriate regulatory authorities. All significant intercompany transactions have been eliminated in consolidation.
The Allstate Corporation 81
2018 Form 10-K Allstate Benefits
Allstate Benefits Segment
Allstate Benefits offers voluntary benefits products, including life, accident, critical illness, short-term disability and other health products. In 2018, Allstate Benefits represented 3.0% of total revenue, 3.7% of total PIF and 4.2% of total adjusted net income. Our target customers are middle market consumers with family financial protection needs. For additional information on our strategy and outlook, see Part I, Item 1. Business - Strategy and Segment Information.
| Summarized financial information | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Revenues | ||||||||||||
| Premiums and contract charges | $ | 1,135 | $ | 1,084 | $ | 1,011 | ||||||
| Net investment income | 77 | 72 | 71 | |||||||||
| Realized capital gains and losses | (9 | ) | 1 | (5 | ) | |||||||
| Total revenues | 1,203 | 1,157 | 1,077 | |||||||||
| Costs and expenses | ||||||||||||
| Contract benefits | (595 | ) | (564 | ) | (509 | ) | ||||||
| Interest credited to contractholder funds | (35 | ) | (35 | ) | (36 | ) | ||||||
| Amortization of DAC | (145 | ) | (142 | ) | (145 | ) | ||||||
| Operating costs and expenses | (285 | ) | (266 | ) | (240 | ) | ||||||
| Restructuring and related charges | — | (3 | ) | — | ||||||||
| Total costs and expenses | (1,060 | ) | (1,010 | ) | (930 | ) | ||||||
| Income tax expense | (30 | ) | (1 | ) | (51 | ) | ||||||
| Net income applicable to common shareholders | $ | 113 | $ | 146 | $ | 96 | ||||||
| Adjusted net income | $ | 119 | $ | 95 | $ | 100 | ||||||
| Realized capital gains and losses, after-tax | (7 | ) | — | (4 | ) | |||||||
| DAC and DSI amortization related to realized capital gains and losses, after-tax | 1 | — | — | |||||||||
| Tax Legislation benefit | — | 51 | — | |||||||||
| Net income applicable to common shareholders | $ | 113 | $ | 146 | $ | 96 | ||||||
| Benefit ratio (1) | 52.4 | 52.0 | 50.3 | |||||||||
| Operating expense ratio (2) | 25.1 | 24.5 | 23.7 | |||||||||
| Reserve for life-contingent contract benefits as of December 31 | $ | 1,007 | $ | 979 | $ | 940 | ||||||
| Contractholder funds as of December 31 | $ | 898 | $ | 890 | $ | 881 | ||||||
| Policies in force as of December 31 by product type (in thousands) | 4,208 | 4,033 | 3,755 |
| (1) | Benefit ratio is calculated as contract benefits divided by premiums and contract charges. |
| (2) | Operating expense ratio is calculated as operating costs and expenses divided by premiums and contract charges. |
Net income applicable to common shareholders was $113 million, $146 million and $96 million in 2018, 2017 and 2016, respectively. 2017 results include a tax benefit of $51 million related to the Tax Legislation.
Adjusted net income was $119 million in 2018 compared to $95 million in 2017. The increase was primarily due to higher premiums and a lower effective tax rate from the Tax Legislation, partially offset by higher contract benefits and operating costs and expenses.
Adjusted net income was $95 million in 2017 compared to $100 million in 2016. The decrease was
primarily due to higher contract benefits and operating costs and expenses, partially offset by higher premiums and contract charges.
Premiums and contract charges increased 4.7% or $51 million in 2018 compared to 2017, primarily related to growth in hospital indemnity (included in other health), accident and critical illness products.
Premiums and contract charges increased 7.2% or $73 million in 2017 compared to 2016, primarily related to growth in critical illness, short-term disability and accident products.
Allstate Benefits 2018 Form 10-K
| Premiums and contract charges by product | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Life | $ | 155 | $ | 155 | $ | 154 | ||||||
| Accident | 297 | 280 | 270 | |||||||||
| Critical illness | 476 | 468 | 443 | |||||||||
| Short-term disability | 108 | 102 | 78 | |||||||||
| Other health | 99 | 79 | 66 | |||||||||
| Premiums and contract charges | $ | 1,135 | $ | 1,084 | $ | 1,011 |
New annualized premium sales (annualized premiums at initial customer enrollment) decreased 12.4% to $389 million in 2018 and increased 11.6% to $444 million in 2017. The decrease in 2018 relates to increased competition and higher initial enrollments for certain accounts in the prior year.
PIF increased 4.3% to 4,208 thousand as of December 31, 2018 compared to 4,033 thousand as of December 31, 2017. PIF increased 7.4% to 4,033 thousand as of December 31, 2017 compared to 3,755 thousand as of December 31, 2016.
Contract benefits increased 5.5% or $31 million in 2018 compared to 2017 and 10.8% or $55 million in 2017 compared to 2016. The increase in both periods was primarily due to higher claim experience and growth.
Benefit ratio increased to 52.4 in 2018 compared to 52.0 in 2017 due to higher claim experience related to life products, partially offset by lower claim experience in hospital indemnity products. Benefit ratio increased to 52.0 in 2017 compared to 50.3 in 2016 due to higher
claims experience in health products, including critical illness and accident.
Amortization of DAC increased 2.1% or $3 million to $145 million in 2018 compared to 2017, primarily due to growth, partially offset by a favorable adjustment associated with our annual review of assumptions. Amortization of DAC decreased 2.1% or $3 million to $142 million in 2017 compared to 2016, primarily due to lower amortization associated with our annual comprehensive review of assumptions and lower lapses, partially offset by higher amortization related to growth.
Our annual comprehensive review of assumptions underlying estimated future gross profits for our interest-sensitive life contracts resulted in a deceleration of DAC amortization (increase to income) of $4 million in 2018 compared to an acceleration of DAC amortization (decrease to income) of $1 million and $4 million in 2017 and 2016, respectively.
| Changes in DAC | ||||||||
| For the years ended | ||||||||
| ($ in millions) | 2018 | 2017 | ||||||
| Balance, beginning of year | $ | 542 | $ | 526 | ||||
| Acquisition costs deferred | 150 | 158 | ||||||
| Amortization of DAC before amortization relating to changes in assumptions (1) | (150 | ) | (141 | ) | ||||
| Amortization relating to realized capital gains and losses (1) | 1 | — | ||||||
| Amortization deceleration (acceleration) for changes in assumptions (“DAC unlocking”) (1) | 4 | (1 | ) | |||||
| Effect of unrealized capital gains and losses (2) | 2 | — | ||||||
| Ending balance | $ | 549 | $ | 542 |
| (1) | Included as a component of amortization of DAC on the Consolidated Statements of Operations. |
| (2) | Represents the change in the DAC adjustment for unrealized capital gains and losses. The DAC adjustment represents the amount by which the amortization of DAC would increase or decrease if the unrealized gains and losses in the respective product portfolios were realized. |
| Operating costs and expenses | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Non-deferrable commissions | $ | 109 | $ | 98 | $ | 91 | ||||||
| General and administrative expenses | 176 | 168 | 149 | |||||||||
| Total operating costs and expenses | $ | 285 | $ | 266 | $ | 240 |
Operating costs and expenses increased 7.1% or $19 million in 2018 compared to 2017, primarily due to higher non-deferrable commissions (associated with growth in premiums and contract charges) and employee-related costs consistent with growth.
Operating costs and expenses increased 10.8% or $26 million in 2017 compared to 2016, primarily due to higher employee-related costs and non-deferrable commissions related to growth, as well as higher technology expenses.
The Allstate Corporation 83
2018 Form 10-K Allstate Benefits
Operating expense ratio increased to 25.1 in 2018 compared to 24.5 in 2017, primarily due to policy growth and investments in the business. Operating expense ratio increased to 24.5 in 2017 compared to 23.7 in 2016.
Analysis of reserves and contractholder funds
| Reserve for life-contingent contract benefits | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Traditional life insurance | $ | 269 | $ | 262 | $ | 247 | ||||||
| Accident and health insurance | 738 | 717 | 693 | |||||||||
| Reserve for life-contingent contract benefits | $ | 1,007 | $ | 979 | $ | 940 |
Contractholder funds relate to interest-sensitive life insurance and totaled $898 million as of December 31, 2018 compared to $890 million as of December 31, 2017 and $881 million as of December 31, 2016.
Allstate Benefits reinsurance ceded
The vast majority of our reinsurance relates to the disposition of our long-term care and other closed blocks of business several years ago. We retain primary liability as a direct insurer for all risks ceded to reinsurers.
| Reinsurance recoverables by reinsurer | ||||||||||
| S&P financial strength rating | Reinsurance recoverable on paid and unpaid benefits | |||||||||
| For the years ended December 31, | ||||||||||
| ($ in millions) | 2018 | 2017 | ||||||||
| Mutual of Omaha Insurance | AA- | $ | 71 | $ | 68 | |||||
| General Re Life Corporation | AA+ | 19 | 19 | |||||||
| Other (1) | 5 | 5 | ||||||||
| Total | $ | 95 | $ | 92 |
| (1) | As of both December 31, 2018 and 2017, the other category includes $4 million of recoverables due from reinsurers rated A- or better by S&P. |
We continuously monitor the creditworthiness of reinsurers in order to determine our risk of recoverability on an individual and aggregate basis, and a provision for uncollectible reinsurance is recorded if needed. No amounts have been deemed unrecoverable in the three-years ended December 31, 2018.
We enter into certain intercompany reinsurance transactions for the Allstate Benefits operations in order to maintain underwriting control and manage insurance risk among various legal entities. These reinsurance agreements have been approved by the appropriate regulatory authorities. All significant intercompany transactions have been eliminated in consolidation.
Allstate Annuities 2018 Form 10-K
Allstate Annuities Segment
Allstate Annuities consists primarily of deferred fixed annuities and immediate fixed annuities (including standard and sub-standard structured settlements). In 2018, Allstate Annuities represented 2.4% of total revenue, 0.2% of total PIF and 4.6% of total adjusted net income. We exited the continuing sale of annuities over an eight year period from 2006 to 2014, reflecting our expectations of declining returns. This segment is in run-off, and we manage it with a focus on increasing economic value through our investment strategy. For additional information on our strategy and outlook, see Part I, Item 1. Business - Strategy and Segment Information.
| Summarized financial information | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Revenues | ||||||||||||
| Contract charges | $ | 15 | $ | 14 | $ | 14 | ||||||
| Net investment income | 1,096 | 1,305 | 1,181 | |||||||||
| Realized capital gains and losses | (166 | ) | 44 | (38 | ) | |||||||
| Total revenues | 945 | 1,363 | 1,157 | |||||||||
| Costs and expenses | ||||||||||||
| Contract benefits | (569 | ) | (594 | ) | (606 | ) | ||||||
| Interest credited to contractholder funds | (334 | ) | (373 | ) | (405 | ) | ||||||
| Amortization of DAC | (7 | ) | (7 | ) | (7 | ) | ||||||
| Operating costs and expenses | (32 | ) | (35 | ) | (32 | ) | ||||||
| Total costs and expenses | (942 | ) | (1,009 | ) | (1,050 | ) | ||||||
| Gain on disposition of operations | 6 | 6 | 5 | |||||||||
| Income tax benefit (expense) | 66 | 58 | (36 | ) | ||||||||
| Net income applicable to common shareholders | $ | 75 | $ | 418 | $ | 76 | ||||||
| Adjusted net income | $ | 130 | $ | 204 | $ | 101 | ||||||
| Realized capital gains and losses, after-tax | (131 | ) | 28 | (26 | ) | |||||||
| Valuation changes on embedded derivatives not hedged, after-tax | 3 | — | (2 | ) | ||||||||
| Gain on disposition of operations, after-tax | 4 | 4 | 3 | |||||||||
| Tax Legislation benefit | 69 | 182 | — | |||||||||
| Net income applicable to common shareholders | $ | 75 | $ | 418 | $ | 76 | ||||||
| Reserve for life-contingent contract benefits as of December 31 | $ | 8,524 | $ | 8,934 | $ | 8,721 | ||||||
| Contractholder funds as of December 31 | $ | 9,817 | $ | 10,936 | $ | 11,915 | ||||||
| Policies in force as of December 31 (in thousands) | ||||||||||||
| Deferred annuities | 127 | 142 | 156 | |||||||||
| Immediate annuities | 84 | 89 | 95 | |||||||||
| Total | 211 | 231 | 251 |
Net income applicable to common shareholders was $75 million, $418 million and $76 million in 2018, 2017 and 2016, respectively. 2018 and 2017 results include a tax benefit of $69 million and $182 million, respectively, related to the Tax Legislation.
Adjusted net income was $130 million in 2018 compared to $204 million in 2017. The decrease was primarily due to lower net investment income, driven by performance-based investment results and decreased average investment balances, partially offset by a lower effective tax rate from the Tax Legislation, decreased interest credited to contractholder funds and lower contract benefits.
Adjusted net income was $204 million in 2017 compared to $101 million in 2016. The increase was primarily due to higher net investment income, lower
interest credited to contractholder funds and lower contract benefits.
Net investment income decreased 16.0% or $209 million in 2018 compared to 2017, primarily due to lower performance-based investment results, mainly from limited partnerships, and lower average investment balances. Net investment income increased 10.5% or $124 million in 2017 compared to 2016, benefiting from strong performance-based investment results, primarily from limited partnerships, partially offset by lower average investment balances as a result of a decrease in contractholder funds.
The investment portfolio supporting immediate annuities is managed to ensure the assets match the characteristics of the liabilities and provide the long-term returns needed to support this business. To better match the long-term nature of our immediate
The Allstate Corporation 85
2018 Form 10-K Allstate Annuities
annuities, we use performance-based investments in which we have ownership interests, and a greater proportion of return is derived from idiosyncratic asset or operating performance. Performance-based income can vary significantly between periods and is influenced by economic conditions, equity market performance, comparable public company earnings multiples, capitalization rates, operating performance of the underlying investments and the timing of asset sales.
Net realized capital losses in 2018 primarily related to decreased valuation of equity investments and losses on sales of fixed income securities. Net realized capital gains in 2017 primarily related to net gains on sales, as well as gains from valuation changes in public securities held in certain limited partnerships, partially offset by impairment write-downs and derivative valuation losses. Net realized capital losses in 2016 primarily related to impairment write-downs, partially offset by net gains on sales in connection with ongoing portfolio management.
Contract benefits decreased 4.2% or $25 million in 2018 compared to 2017, primarily due to immediate annuity mortality experience that was favorable in comparison to the prior year. Contract benefits decreased 2.0% or $12 million in 2017 compared to 2016, primarily due to immediate annuity mortality experience.
Our annual review of assumptions in 2018 resulted in a $2 million increase in reserves primarily for guaranteed withdrawal benefits on equity-indexed annuities due to higher projected guaranteed benefits. In 2017, the review resulted in a $1 million increase in reserves.
As of December 31, 2018 and 2017, our premium deficiency and profits followed by losses evaluations
for our immediate annuities with life contingencies concluded that no adjustments were required to be recognized. For further detail on these evaluations, see Reserve for life-contingent contract benefits estimation in the Application of Critical Accounting Estimates section.
Benefit spread reflects our mortality results using the difference between contract charges earned and contract benefits excluding the portion related to the implied interest on immediate annuities with life contingencies. This implied interest totaled $492 million, $501 million and $511 million in 2018, 2017 and 2016, respectively. Total benefit spread was $(68) million, $(84) million and $(86) million in 2018, 2017 and 2016, respectively.
Interest credited to contractholder funds decreased 10.5% or $39 million in 2018 compared to 2017 and decreased 7.9% or $32 million in 2017 compared to 2016, primarily due to lower average contractholder funds. Valuation changes on derivatives embedded in equity-indexed annuity contracts that are not hedged decreased interest credited to contractholder funds by $3 million in 2018 compared to increases of $1 million in 2017 and $3 million in 2016.
Investment spread reflects the difference between net investment income and the sum of interest credited to contractholder funds and the implied interest on immediate annuities with life contingencies, which is included as a component of contract benefits and is used to analyze the impact of net investment income and interest credited to contractholders on net income.
| Investment spread | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Investment spread before valuation changes on embedded derivatives not hedged | $ | 267 | $ | 432 | $ | 268 | ||||||
| Valuation changes on derivatives embedded in equity-indexed annuity contracts that are not hedged | 3 | (1 | ) | (3 | ) | |||||||
| Total investment spread | $ | 270 | $ | 431 | $ | 265 |
Investment spread before valuation changes on embedded derivatives not hedged decreased 38.2% to $267 million in 2018 compared to $432 million in 2017, primarily due to lower investment income, mainly from limited partnership interests, partially offset by lower credited interest.
Investment spread before valuation changes on embedded derivatives not hedged increased 61.2% to $432 million in 2017 compared to $268 million in 2016, primarily due to higher net investment income and lower credited interest.
Allstate Annuities 2018 Form 10-K
To further analyze investment spreads, the following table summarizes the weighted average investment yield on assets supporting product liabilities, interest crediting rates and investment spreads. Investment spreads may vary significantly between periods due to the variability in investment income, particularly for immediate fixed annuities where the investment portfolio includes performance-based investments.
| Analysis of investment spread | |||||||||||||||||||||||||||
| Weighted average investment yield | Weighted average interest crediting rate | Weighted average investment spreads | |||||||||||||||||||||||||
| 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | |||||||||||||||||||
| Deferred fixed annuities | 4.1 | % | 4.2 | % | 4.1 | % | 2.8 | % | 2.8 | % | 2.8 | % | 1.3 | % | 1.4 | % | 1.3 | % | |||||||||
| Immediate fixed annuities with and without life contingencies | 6.4 | 8.0 | 6.5 | 6.0 | 6.0 | 5.9 | 0.4 | 2.0 | 0.6 |
The following table summarizes the weighted average guaranteed crediting rates and weighted average current crediting rates as of December 31, 2018 for certain fixed annuities where management has the ability to change the crediting rate, subject to a contractual minimum. Other products, including equity-indexed, variable and immediate annuities totaling $4.37 billion of contractholder funds, have been excluded from the analysis because management does not have the ability to change the crediting rate or the minimum crediting rate is not considered meaningful in this context.
| Weighted average guaranteed crediting rates and weighted average current crediting rates | ||||||||||
| ($ in millions) | Weighted average guaranteed crediting rates | Weighted average current crediting rates | Contractholder funds | |||||||
| Annuities with annual crediting rate resets | 3.14 | % | 3.14 | % | $ | 4,585 | ||||
| Annuities with multi-year rate guarantees (1): | ||||||||||
| Resettable in next 12 months | 1.27 | 3.23 | 198 | |||||||
| Resettable after 12 months | 2.14 | 2.67 | 660 |
| (1) | These contracts include interest rate guarantee periods which are typically 5, 6 or 10 years. |
Operating costs and expenses decreased 8.6% or $3 million in 2018 compared to 2017, primarily due to a reduction in premium tax accruals and lower employee-related costs.
Operating costs and expenses increased 9.4% or $3 million in 2017 compared to 2016, primarily due to higher guaranty fund expenses. 2016 included a reduction in the accrual for anticipated guaranty fund expenses.
Analysis of reserves and contractholder funds
| Product liabilities | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Immediate fixed annuities with life contingencies | ||||||||||||
| Sub-standard structured settlements and group pension terminations (1) | $ | 4,990 | $ | 5,284 | $ | 5,029 | ||||||
| Standard structured settlements and SPIA (2) | 3,425 | 3,565 | 3,592 | |||||||||
| Other | 109 | 85 | 100 | |||||||||
| Reserve for life-contingent contract benefits | $ | 8,524 | $ | 8,934 | $ | 8,721 | ||||||
| Deferred fixed annuities | $ | 7,156 | $ | 8,128 | $ | 8,921 | ||||||
| Immediate fixed annuities without life contingencies | 2,525 | 2,700 | 2,874 | |||||||||
| Other | 136 | 108 | 120 | |||||||||
| Contractholder funds | $ | 9,817 | $ | 10,936 | $ | 11,915 |
| (1) | Comprises structured settlement annuities for annuitants with severe injuries or other health impairments which increased their expected mortality rate at the time the annuity was issued (“sub-standard structured settlements”) and group annuity contracts issued to sponsors of terminated pension plans. |
| (2) | Comprises structured settlement annuities for annuitants with standard life expectancy (“standard structured settlements”) and single premium immediate annuities (“SPIA”) with life contingencies. |
The Allstate Corporation 87
2018 Form 10-K Allstate Annuities
Contractholder funds represent interest-bearing liabilities arising from the sale of products such as fixed annuities and funding agreements. The balance of contractholder funds is equal to the cumulative deposits received and interest credited to the contractholder less cumulative contract benefits, surrenders, withdrawals, maturities and contract charges for mortality or administrative expenses.
| Changes in contractholder funds | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Contractholder funds, beginning balance | $ | 10,936 | $ | 11,915 | $ | 13,070 | ||||||
| Deposits | 15 | 28 | 42 | |||||||||
| Interest credited | 331 | 370 | 403 | |||||||||
| Benefits, withdrawals, maturities and other adjustments | ||||||||||||
| Benefits | (587 | ) | (638 | ) | (705 | ) | ||||||
| Surrenders and partial withdrawals | (854 | ) | (723 | ) | (780 | ) | ||||||
| Maturities of and interest payments on institutional products | — | — | (86 | ) | ||||||||
| Contract charges | (9 | ) | (9 | ) | (9 | ) | ||||||
| Net transfers from separate accounts | — | 1 | 1 | |||||||||
| Other adjustments (1) | (15 | ) | (8 | ) | (21 | ) | ||||||
| Total benefits, withdrawals, maturities and other adjustments | (1,465 | ) | (1,377 | ) | (1,600 | ) | ||||||
| Contractholder funds, ending balance | $ | 9,817 | $ | 10,936 | $ | 11,915 |
| (1) | The table above illustrates the changes in contractholder funds, which are presented gross of reinsurance recoverables on the Consolidated Statements of Financial Position. The table above is intended to supplement our discussion and analysis of revenues, which are presented net of reinsurance on the Consolidated Statements of Operations. As a result, the net change in contractholder funds associated with products reinsured is reflected as a component of the other adjustments line. |
Contractholder funds decreased 10.2% and 8.2% in 2018 and 2017, respectively, primarily due to the continued runoff of our deferred fixed annuity business. We discontinued the sale of annuities but still accept additional deposits on existing contracts.
Surrenders and partial withdrawals increased 18.1% to $854 million in 2018 from $723 million in 2017. Surrenders and partial withdrawals decreased 7.3% to $723 million in 2017 from $780 million in 2016. 2018 had elevated surrenders on fixed annuities resulting from an increased number of contracts reaching the 30-45 day period (typically at their 5, 7 or 10 year anniversary) during which there is no surrender charge. The surrender and partial withdrawal rate on deferred fixed annuities, based on the beginning of year contractholder funds, was 11.4% in 2018 compared to 8.7% in 2017 and 8.6% in 2016.
Maturities of and interest payments on institutional products included an $85 million maturity in 2016. There were no institutional products outstanding as of December 31, 2018, 2017 or 2016.
Allstate Annuities reinsurance ceded
We ceded substantially all of the risk associated with our variable annuity business to Prudential Insurance Company of America (“Prudential”). Our reinsurance recoverables from Prudential totaled $1.36 billion and $1.35 billion as of December 31, 2018 and 2017, respectively. We also have reinsurance recoverables from other reinsurers of $17 million as of both December 31, 2018 and 2017.
We retain primary liability as a direct insurer for all risks ceded to reinsurers. We continuously monitor the creditworthiness of reinsurers in order to determine our risk of recoverability on an individual and aggregate basis, and a provision for uncollectible reinsurance is recorded if needed. No amounts have been deemed unrecoverable in the three-years ended December 31, 2018.
Investments 2018 Form 10-K
Investments
Overview and strategy The return on our investment portfolios is an important component of our ability to offer good value to customers, fund business improvements and create value for shareholders. Investment portfolios are held for Property-Liability, Service Businesses, Allstate Life, Allstate Benefits, Allstate Annuities, and Corporate and Other operations. While taking into consideration the investment portfolio in aggregate, management of the underlying portfolios is significantly influenced by the nature of each respective business and its corresponding liability profile. For each business, we identify a strategic asset allocation which considers both the nature of the liabilities and the risk and return characteristics of the various asset classes in which we invest. This allocation is informed by our long-term and market expectations, as well as other considerations such as risk appetite, portfolio diversification, duration, desired liquidity and capital. Within appropriate ranges relative to strategic allocations, tactical allocations are made in consideration of prevailing and potential future market conditions. We manage risks that involve uncertainty related to interest rates, credit spreads, equity returns and currency exchange rates.
The Property-Liability portfolio emphasizes protection of principal and consistent income generation, within a total return framework. This approach has produced competitive returns over the long term and is designed to ensure financial strength and stability for paying claims, while maximizing economic value and surplus growth. Products, such as auto insurance and discontinued lines and coverages, with lower liquidity needs and capital create capacity to invest in less liquid higher yielding fixed income securities, performance-based investments such as limited partnerships, and equity securities. Products with higher liquidity needs, such as homeowners insurance, are invested primarily in high quality liquid fixed income securities.
The Service Businesses portfolio is focused on protection of principal and consistent income generation, within a total return framework. The portfolio is largely comprised of fixed income securities with a lesser allocation to equity securities and short-term investments.
The Allstate Life portfolio is comprised of assets chosen to generate returns to support corresponding liabilities within an asset-liability framework that targets an appropriate return on capital. This portfolio is well diversified and primarily consists of longer duration fixed income securities and commercial mortgage loans.
The Allstate Benefits portfolio is focused on generating an appropriate return on capital. The portfolio is largely comprised of fixed income securities and commercial mortgage loans with a small allocation to equity securities.
The Allstate Annuities portfolio is managed to ensure the assets match the characteristics of the
liabilities. For longer-term immediate annuity liabilities, we invest primarily in performance-based investments such as limited partnerships and equity securities. For shorter-term annuity liabilities, we invest primarily in fixed income securities and commercial mortgage loans with maturity profiles aligned with liability cash flow requirements.
The Corporate and Other portfolio balances liquidity needs related to the corporate capital structure with the pursuit of returns.
Within each segment, we utilize two primary strategies to manage risks and returns and to position our portfolio to take advantage of market opportunities while attempting to mitigate adverse effects. As strategies and market conditions evolve, the asset allocation may change or assets may be moved between strategies.
Market-based strategies include investments primarily in public fixed income and equity securities. Market-based core seeks to deliver predictable earnings aligned to business needs and returns consistent with the markets in which we invest. Private fixed income assets, such as commercial mortgages, bank loans and privately placed debt that provide liquidity premiums are also included in this category. Market-based active seeks to outperform within the public markets through tactical positioning and by taking advantage of short-term opportunities. This category may generate results that meaningfully deviate from those achieved by market indices, both favorably and unfavorably.
Performance-based strategy seeks to deliver attractive risk-adjusted returns and supplement market risk with idiosyncratic risk. Returns are impacted by a variety of factors including general macroeconomic and public market conditions as public benchmarks are often used in the valuation of underlying investments. Variability in earnings will also result from the performance of the underlying assets or business and the timing of sales of those investments. Earnings from the sales of investments may be recorded as net investment income or realized capital gains and losses. The portfolio, which primarily includes private equity and real estate with a majority being limited partnerships, is diversified across a number of characteristics, including managers or partners, vintage years, strategies, geographies (including international) and industry sectors or property types. These investments are generally illiquid in nature, often require specialized expertise, typically involve a third party manager, and often enhance returns and income through transformation at the company or property level. A portion of these investments seek returns in markets or asset classes that are dislocated or special situations, primarily in private markets.
Outlook
In December 2018, the Federal Open Market Committee (“FOMC”) tightened monetary policy by setting the new target range for the federal funds rate
The Allstate Corporation 89
2018 Form 10-K Investments
at 2-1/4 percent to 2-1/2 percent and maintained their inflation target of 2 percent. The FOMC noted that some further gradual increases in the federal funds rate will be consistent with sustained expansion of economic activity, strong labor market conditions, and inflation near the target of 2 percent. We plan to focus on the following priorities:
| • | Enhance investment portfolio returns through use of a dynamic capital allocation framework and focus on tax efficiency. |
| • | Leverage our broad capabilities to shift the portfolio mix to earn higher risk-adjusted returns on capital. |
| • | Invest for the specific needs and characteristics of Allstate’s businesses, including its corresponding liability profile. |
We continue to increase performance-based investments in our Property-Liability portfolio, consistent with our ongoing strategy to have a greater
proportion of return derived from idiosyncratic asset or operating performance.
Invested assets and market-based income are expected to decline with reductions in contractholder funds and income related to performance-based investments will result in variability of earnings for the Allstate Annuities segment.
Adopted Recognition and Measurement of Financial Assets and Financial Liabilities Beginning January 1, 2018, equity securities are reported at fair value with changes in fair value recognized in realized capital gains and losses.
Limited partnerships previously reported using the cost method are now reported at fair value with changes in fair value recognized in net investment income.
See Note 2 of the consolidated financial statements.
| Portfolio composition and strategy by reporting segment (1) | ||||||||||||||||||||||||||||
| As of December 31, 2018 | ||||||||||||||||||||||||||||
| ($ in millions) | Property-Liability | Service Businesses | Allstate Life | Allstate Benefits | Allstate Annuities | Corporate and Other | Total | |||||||||||||||||||||
| Fixed income securities (2) | $ | 32,143 | $ | 981 | $ | 7,463 | $ | 1,224 | $ | 14,242 | $ | 1,117 | $ | 57,170 | ||||||||||||||
| Equity securities (3) | 3,488 | 131 | 40 | 51 | 1,299 | 27 | 5,036 | |||||||||||||||||||||
| Mortgage loans | 390 | — | 1,867 | 205 | 2,208 | — | 4,670 | |||||||||||||||||||||
| Limited partnership interests | 4,222 | — | — | — | 3,283 | — | 7,505 | |||||||||||||||||||||
| Short-term investments (4) | 1,759 | 91 | 187 | 27 | 638 | 325 | 3,027 | |||||||||||||||||||||
| Other | 1,632 | — | 1,252 | 302 | 666 | — | 3,852 | |||||||||||||||||||||
| Total | $ | 43,634 | $ | 1,203 | $ | 10,809 | $ | 1,809 | $ | 22,336 | $ | 1,469 | $ | 81,260 | ||||||||||||||
| Percent to total | 53.7 | % | 1.5 | % | 13.3 | % | 2.2 | % | 27.5 | % | 1.8 | % | 100.0 | % | ||||||||||||||
| Market-based core | $ | 30,689 | $ | 1,203 | $ | 10,809 | $ | 1,809 | $ | 17,548 | $ | 1,469 | $ | 63,527 | ||||||||||||||
| Market-based active | 8,451 | — | — | — | 1,245 | — | 9,696 | |||||||||||||||||||||
| Performance-based | 4,494 | — | — | — | 3,543 | — | 8,037 | |||||||||||||||||||||
| Total | $ | 43,634 | $ | 1,203 | $ | 10,809 | $ | 1,809 | $ | 22,336 | $ | 1,469 | $ | 81,260 |
| (1) | Balances reflect the elimination of related party investments between segments. |
| (2) | Fixed income securities are carried at fair value. Amortized cost basis for these securities was $32.44 billion, $984 million, $7.36 billion, $1.24 billion, $14.00 billion, $1.11 billion and $57.13 billion for Property-Liability, Service Businesses, Allstate Life, Allstate Benefits, Allstate Annuities, Corporate and Other, and in Total, respectively. |
| (3) | Equity securities are carried at fair value. The fair value of equity securities held as of December 31, 2018, was $547 million in excess of cost. These net gains were primarily concentrated in the consumer goods, technology and banking sectors. Beginning January 1, 2018, the periodic changes in fair value are reflected in realized capital gains and losses. |
| (4) | Short-term investments are carried at fair value. |
Investments totaled $81.26 billion as of December 31, 2018, decreasing from $82.80 billion as of December 31, 2017, primarily due to common share repurchases, lower fixed income and equity valuations, issuances and redemptions of debt and preferred stock, net reductions in contractholder funds, dividends paid to shareholders and the acquisition of InfoArmor, partially offset by positive operating cash flows.
Investments 2018 Form 10-K
| Portfolio composition by investment strategy | ||||||||||||||||
| As of December 31, 2018 | ||||||||||||||||
| ($ in millions) | Market-based core | Market-based active | Performance-based | Total | ||||||||||||
| Fixed income securities | $ | 48,903 | $ | 8,193 | $ | 74 | $ | 57,170 | ||||||||
| Equity securities | 4,253 | 522 | 261 | 5,036 | ||||||||||||
| Mortgage loans | 4,670 | — | — | 4,670 | ||||||||||||
| Limited partnership interests | 489 | 158 | 6,858 | 7,505 | ||||||||||||
| Short-term investments | 2,346 | 681 | — | 3,027 | ||||||||||||
| Other | 2,866 | 142 | 844 | 3,852 | ||||||||||||
| Total | $ | 63,527 | $ | 9,696 | $ | 8,037 | $ | 81,260 | ||||||||
| Percent to total | 78.2 | % | 11.9 | % | 9.9 | % | 100.0 | % | ||||||||
| Unrealized net capital gains and losses | ||||||||||||||||
| Fixed income securities | $ | 149 | $ | (112 | ) | $ | (1 | ) | $ | 36 | ||||||
| Other | (3 | ) | — | — | (3 | ) | ||||||||||
| Total | $ | 146 | $ | (112 | ) | $ | (1 | ) | $ | 33 |
During 2018, strategic actions focused on optimizing portfolio yield, return and risk in the rising interest rate environment.
We continued to increase performance-based investments in the Property-Liability portfolio.
We modestly increased the maturity profile of fixed income securities in our Property-Liability portfolio at a duration of 4.1 years, while maintaining duration at 5.6 and 4.2 years for the Allstate Life and Allstate Annuities portfolios, respectively.
In the Allstate Annuities portfolio, invested assets and market-based income declined with reductions in contractholder funds. Performance-based investments and equity securities will continue to be allocated primarily to the longer-term immediate annuity liabilities to reduce the risk that investment returns are below levels required to meet their funding needs while shorter-term annuity liabilities will be invested in market-based investments.
| Fixed income securities by type | ||||||||
| Fair value as of December 31, | ||||||||
| ($ in millions) | 2018 | 2017 | ||||||
| U.S. government and agencies | $ | 5,517 | $ | 3,616 | ||||
| Municipal | 9,169 | 8,328 | ||||||
| Corporate | 40,136 | 44,026 | ||||||
| Foreign government | 747 | 1,021 | ||||||
| Asset-backed securities (“ABS”) | 1,045 | 1,272 | ||||||
| Residential mortgage-backed securities (“RMBS”) | 464 | 578 | ||||||
| Commercial mortgage-backed securities (“CMBS”) | 70 | 128 | ||||||
| Redeemable preferred stock | 22 | 23 | ||||||
| Total fixed income securities | $ | 57,170 | $ | 58,992 |
Fixed income securities are rated by third party credit rating agencies and/or are internally rated. As of December 31, 2018, 90.8% of the consolidated fixed income securities portfolio was rated investment grade, which is defined as a security having a rating of Aaa, Aa, A or Baa from Moody’s, a rating of AAA, AA, A or BBB from S&P, a comparable rating from another nationally recognized rating agency, or a comparable internal rating if an externally provided rating is not available. Credit ratings below these designations are
considered low credit quality or below investment grade, which includes high yield bonds. Market prices for certain securities may have credit spreads which imply higher or lower credit quality than the current third party rating. Our initial investment decisions and ongoing monitoring procedures for fixed income securities are based on a thorough due diligence process which includes, but is not limited to, an assessment of the credit quality, sector, structure, and liquidity risks of each issue.
The Allstate Corporation 91
2018 Form 10-K Investments
| Fair value and unrealized net capital gains (losses) for fixed income securities by credit quality | ||||||||||||||||||||||||
| As of December 31, 2018 | ||||||||||||||||||||||||
| Investment grade | Below investment grade | Total | ||||||||||||||||||||||
| ($ in millions) | Fair value | Unrealized gain/(loss) | Fair value | Unrealized gain/(loss) | Fair value | Unrealized gain/(loss) | ||||||||||||||||||
| U.S. government and agencies | $ | 5,517 | $ | 131 | $ | — | $ | — | $ | 5,517 | $ | 131 | ||||||||||||
| Municipal | ||||||||||||||||||||||||
| Tax exempt | 6,969 | 6 | 31 | — | 7,000 | 6 | ||||||||||||||||||
| Taxable | 2,133 | 201 | 36 | (1 | ) | 2,169 | 200 | |||||||||||||||||
| Corporate | ||||||||||||||||||||||||
| Public | 26,435 | (160 | ) | 2,835 | (136 | ) | 29,270 | (296 | ) | |||||||||||||||
| Privately placed | 8,966 | (10 | ) | 1,900 | (94 | ) | 10,866 | (104 | ) | |||||||||||||||
| Foreign government | 738 | 8 | 9 | — | 747 | 8 | ||||||||||||||||||
| ABS | ||||||||||||||||||||||||
| Collateralized debt obligations (“CDO”) | 246 | (3 | ) | 23 | — | 269 | (3 | ) | ||||||||||||||||
| Consumer and other asset-backed securities (“Consumer and other ABS”) | 765 | — | 11 | (1 | ) | 776 | (1 | ) | ||||||||||||||||
| RMBS | ||||||||||||||||||||||||
| U.S. government sponsored entities (“U.S. Agency”) | 81 | 1 | — | — | 81 | 1 | ||||||||||||||||||
| Non-agency | 35 | 1 | 348 | 85 | 383 | 86 | ||||||||||||||||||
| CMBS | 30 | — | 40 | 7 | 70 | 7 | ||||||||||||||||||
| Redeemable preferred stock | 22 | 1 | — | — | 22 | 1 | ||||||||||||||||||
| Total fixed income securities | $ | 51,937 | $ | 176 | $ | 5,233 | $ | (140 | ) | $ | 57,170 | $ | 36 |
Municipal bonds, including tax exempt and taxable securities, totaled $9.17 billion as of December 31, 2018 with 99.3% rated investment grade and an unrealized net capital gain of $206 million. The municipal bond portfolio includes general obligations of state and local issuers and revenue bonds (including pre-refunded bonds, which are bonds for which an irrevocable trust has been established to fund the remaining payments of principal and interest).
Our practice for acquiring and monitoring municipal bonds is predominantly based on the underlying credit quality of the primary obligor. We currently rely on the primary obligor to pay all contractual cash flows and are not relying on bond insurers for payments. As a result of downgrades in the insurers’ credit ratings, the ratings of the insured municipal bonds generally reflect the underlying ratings of the primary obligor.
Corporate bonds, including publicly traded and privately placed, totaled $40.14 billion as of December 31, 2018, with 88.2% rated investment grade and an unrealized net capital loss of $400 million. Privately placed securities primarily consist of corporate issued senior debt securities that are directly negotiated with the borrower or are in unregistered form.
Our $10.87 billion portfolio of privately placed securities is diversified by issuer, industry sector and country. The portfolio is made up of 448 issuers. Privately placed corporate obligations may contain structural security features such as financial covenants and call protections that provide investors greater protection against credit deterioration, reinvestment risk or fluctuations in interest rates than those typically found in publicly registered debt securities. Additionally, investments in these securities are made
after due diligence of the issuer, typically including discussions with senior management and on-site visits to company facilities. Ongoing monitoring includes direct periodic dialog with senior management of the issuer and continuous monitoring of operating performance and financial position. Every issue not rated by an independent rating agency is internally rated with a formal rating affirmation at least once a year.
Our corporate bonds portfolio includes $4.74 billion of below investment grade bonds, $1.90 billion of which are privately placed. These securities are diversified by issuer and industry sector. The below investment grade corporate bonds portfolio is made up of 287 issuers. We employ fundamental analyses of issuers and sectors along with macro and asset class views to identify investment opportunities. This results in a portfolio with broad exposure to the high yield market with an emphasis on idiosyncratic positions reflective of our views of market conditions and opportunities.
Foreign government securities totaled $747 million as of December 31, 2018, with 98.8% rated investment grade and an unrealized net capital gain of $8 million. Of these securities, 78.2% are in Canadian governmental and provincial securities (73.8% of which are held by our Canadian companies), 19.9% are backed by the U.S. government and the remaining 1.9% are highly diversified in other foreign governments.
ABS, RMBS and CMBS are structured securities that are primarily collateralized by consumer or corporate borrowings and residential and commercial real estate loans. The cash flows from the underlying collateral paid to the securitization trust are generally applied in a pre-determined order and are designed so that each security issued by the trust, typically referred to as a “class”, qualifies for a specific original rating.
Investments 2018 Form 10-K
For example, the “senior” portion or “top” of the capital structure, or rating class, which would originally qualify for a rating of Aaa typically has priority in receiving principal repayments on the underlying collateral and retains this priority until the class is paid in full. In a sequential structure, underlying collateral principal repayments are directed to the most senior rated Aaa class in the structure until paid in full, after which principal repayments are directed to the next most senior Aaa class in the structure until it is paid in full. Senior Aaa classes generally share any losses from the underlying collateral on a pro-rata basis after losses are absorbed by classes with lower original ratings. The payment priority and class subordination included in these securities serves as credit enhancement for holders of the senior or top portions of the structures. These securities continue to retain the payment priority features that existed at the origination of the securitization trust. Other forms of credit enhancement may include structural features embedded in the securitization trust, such as overcollateralization, excess spread and bond insurance. The underlying collateral may contain fixed interest rates, variable interest rates (such as adjustable rate mortgages), or both fixed and variable rate features.
ABS, including CDO and Consumer and other ABS, totaled $1.05 billion as of December 31, 2018, with 96.7% rated investment grade and an unrealized net capital loss of $4 million. Credit risk is managed by monitoring the performance of the underlying collateral. Many of the securities in the ABS portfolio have credit enhancement with features such as overcollateralization, subordinated structures, reserve funds, guarantees and/or insurance.
CDO totaled $269 million as of December 31, 2018, with 91.4% rated investment grade and an unrealized net capital loss of $3 million. CDO consist of obligations collateralized by cash flow CDO, which are structures collateralized primarily by below investment grade senior secured corporate loans.
Consumer and other ABS totaled $776 million as of December 31, 2018, with 98.6% rated investment grade. Consumer and other ABS consists of $264 million of consumer auto, $215 million of credit card and $297
million of other ABS with unrealized net capital losses of $1 million, $1 million and an unrealized net capital gain of $1 million, respectively.
RMBS totaled $464 million as of December 31, 2018, with 25.0% rated investment grade and an unrealized net capital gain of $87 million. The RMBS portfolio is subject to interest rate risk, but unlike other fixed income securities, is additionally subject to prepayment risk from the underlying residential mortgage loans. RMBS consists of a U.S. Agency portfolio having collateral issued or guaranteed by U.S. government agencies and a non-agency portfolio consisting of securities collateralized by Prime, Alt-A and Subprime loans. The non-agency portfolio totaled $383 million as of December 31, 2018, with 9.1% rated investment grade and an unrealized net capital gain of $86 million.
CMBS totaled $70 million as of December 31, 2018, with 42.9% rated investment grade and an unrealized net capital gain of $7 million. The CMBS investments are primarily traditional conduit transactions collateralized by commercial mortgage loans, broadly diversified across property types and geographical area.
Equity securities primarily include common stocks, exchange traded and mutual funds, non-redeemable preferred stocks and real estate investment trust equity investments. Certain exchange traded and mutual funds have fixed income securities as their underlying investments. The equity securities portfolio was $5.04 billion as of December 31, 2018.
Mortgage loans, which are primarily held in the life and annuity portfolios, totaled $4.67 billion as of December 31, 2018 and primarily comprise loans secured by first mortgages on developed commercial real estate. Key considerations used to manage our exposure include property type and geographic diversification. For further detail on our mortgage loan portfolio, see Note 5 of the consolidated financial statements.
Limited partnership interests include interests in private equity funds, real estate funds and other funds.
| Carrying value and other information for limited partnership interests | ||||||||||||||
| As of December 31, 2018 | ||||||||||||||
| ($ in millions) | Limited partnership interests (1)(2) | Number of managers | Number of individual investments | Largest exposure to single investment | ||||||||||
| Private equity | $ | 5,724 | 145 | 287 | $ | 187 | ||||||||
| Real estate | 1,134 | 38 | 78 | 109 | ||||||||||
| Other | 647 | 11 | 12 | 316 | ||||||||||
| Total | $ | 7,505 | 194 | 377 |
| (1) | Due to the adoption of the recognition and measurement accounting standard, limited partnerships previously reported using the cost method are now reported at fair value. See Note 2 of the consolidated financial statements. |
| (2) | We have commitments to invest in additional limited partnership interests totaling $3.03 billion. |
Short-term investments totaled $3.03 billion as of December 31, 2018, which includes securities lending collateral of $1.19 billion.
Other investments primarily comprise $1.35 billion of bank loans, $891 million of policy loans, $791 million of real estate, $620 million of agent loans (loans issued
The Allstate Corporation 93
2018 Form 10-K Investments
to exclusive Allstate agents) and $117 million of derivatives as of December 31, 2018. For further detail on our use of derivatives, see Note 7 of the consolidated financial statements.
Unrealized net capital gains totaled $33 million as of December 31, 2018 compared to $2.63 billion as of December 31, 2017.
| Unrealized net capital gains (losses) | ||||||||
| As of December 31, | ||||||||
| ($ in millions) | 2018 | 2017 | ||||||
| U.S. government and agencies | $ | 131 | $ | 36 | ||||
| Municipal | 206 | 275 | ||||||
| Corporate | (400 | ) | 1,030 | |||||
| Foreign government | 8 | 16 | ||||||
| ABS | (4 | ) | 6 | |||||
| RMBS | 87 | 98 | ||||||
| CMBS | 7 | 4 | ||||||
| Redeemable preferred stock | 1 | 2 | ||||||
| Fixed income securities | 36 | 1,467 | ||||||
| Equity securities (1) | — | 1,160 | ||||||
| Derivatives | (3) | (1 | ) | |||||
| Equity method of accounting (“EMA”) limited partnerships | — | 1 | ||||||
| Unrealized net capital gains and losses, pre-tax | $ | 33 | $ | 2,627 |
| (1) | Due to the adoption of the recognition and measurement accounting standard, equity securities are reported at fair value with changes in fair value recognized in realized capital gains and losses and are no longer included in the table above. Upon adoption of the new guidance on January 1, 2018, $1.16 billion of pre-tax unrealized net capital gains for equity securities were reclassified from accumulated other comprehensive income (“AOCI”) to retained income. See Note 2 of the consolidated financial statements. |
We have a comprehensive portfolio monitoring process to identify and evaluate each fixed income security that may be other-than-temporarily impaired. The process includes a quarterly review of all securities to identify instances where the fair value of a security compared to its amortized cost is below established thresholds. The process also includes the monitoring of other impairment indicators such as ratings, ratings downgrades and payment defaults. The securities identified, in addition to other securities for which we may have a concern, are evaluated for potential other-than-temporary impairment using all reasonably available information relevant to the collectability or recovery of the security. Inherent in our evaluation of other-than-temporary impairment for these fixed income securities are assumptions and estimates about the financial condition and future earnings potential of the issue or issuer. Some of the factors that may be considered in evaluating whether a decline in fair value is other than temporary are: 1) the financial condition, near-term and long-term prospects of the issue or issuer, including relevant industry specific market conditions and trends, geographic location and
implications of rating agency actions and offering prices; 2) the specific reasons that a security is in an unrealized loss position, including overall market conditions which could affect liquidity; and 3) the length of time and extent to which the fair value has been less than amortized cost or cost. All investments in an unrealized loss position as of December 31, 2018 were included in our portfolio monitoring process for determining whether declines in value were other than temporary.
The unrealized net capital gain for the fixed income portfolio totaled $36 million, comprised of $993 million of gross unrealized gains and $957 million of gross unrealized losses as of December 31, 2018. This is compared to an unrealized net capital gain for the fixed income portfolio totaling $1.47 billion, comprised of $1.75 billion of gross unrealized gains and $283 million of gross unrealized losses as of December 31, 2017. Fixed income valuations decreased primarily due to an increase in risk-free interest rates and wider credit spreads.
Investments 2018 Form 10-K
| Gross unrealized gains (losses) on fixed income securities by type and sector | ||||||||||||||||
| As of December 31, 2018 | ||||||||||||||||
| Amortized cost | Gross unrealized | Fair value | ||||||||||||||
| ($ in millions) | Gains | Losses | ||||||||||||||
| Corporate: | ||||||||||||||||
| Consumer goods (cyclical and non-cyclical) | $ | 12,224 | $ | 78 | $ | (285 | ) | $ | 12,017 | |||||||
| Capital goods | 4,725 | 34 | (116 | ) | 4,643 | |||||||||||
| Utilities | 5,410 | 208 | (104 | ) | 5,514 | |||||||||||
| Banking | 3,929 | 8 | (69 | ) | 3,868 | |||||||||||
| Energy | 2,315 | 36 | (66 | ) | 2,285 | |||||||||||
| Communications | 2,740 | 19 | (66 | ) | 2,693 | |||||||||||
| Technology | 2,678 | 7 | (61 | ) | 2,624 | |||||||||||
| Financial services | 2,403 | 25 | (46 | ) | 2,382 | |||||||||||
| Basic industry | 1,970 | 30 | (46 | ) | 1,954 | |||||||||||
| Transportation | 1,794 | 41 | (26 | ) | 1,809 | |||||||||||
| Other | 348 | 4 | (5 | ) | 347 | |||||||||||
| Total corporate fixed income portfolio | 40,536 | 490 | (890 | ) | 40,136 | |||||||||||
| U.S. government and agencies | 5,386 | 137 | (6 | ) | 5,517 | |||||||||||
| Municipal | 8,963 | 249 | (43 | ) | 9,169 | |||||||||||
| Foreign government | 739 | 13 | (5 | ) | 747 | |||||||||||
| ABS | 1,049 | 6 | (10 | ) | 1,045 | |||||||||||
| RMBS | 377 | 89 | (2 | ) | 464 | |||||||||||
| CMBS | 63 | 8 | (1 | ) | 70 | |||||||||||
| Redeemable preferred stock | 21 | 1 | — | 22 | ||||||||||||
| Total fixed income securities | $ | 57,134 | $ | 993 | $ | (957 | ) | $ | 57,170 |
The consumer goods, utilities and capital goods sectors comprise 30%, 14% and 12%, respectively, of the carrying value of our corporate fixed income securities portfolio as of December 31, 2018. The consumer goods, capital goods and utilities sectors had the highest concentration of gross unrealized losses in our corporate fixed income securities portfolio as of December 31, 2018. In general, the gross unrealized losses are related to an increase in market yields, which may include increased risk-free interest rates and/or wider credit spreads since the time of initial
purchase. Similarly, gross unrealized gains reflect a decrease in market yields since the time of initial purchase.
As of December 31, 2018, we have not made the decision to sell and it is not more likely than not we will be required to sell fixed income securities with unrealized losses before recovery of the amortized cost basis.
The Allstate Corporation 95
2018 Form 10-K Investments
| Net investment income | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Fixed income securities | $ | 2,077 | $ | 2,078 | $ | 2,060 | ||||||
| Equity securities | 170 | 174 | 137 | |||||||||
| Mortgage loans | 217 | 206 | 217 | |||||||||
| Limited partnership interests (1) | 705 | 889 | 561 | |||||||||
| Short-term investments | 73 | 30 | 16 | |||||||||
| Other | 272 | 236 | 222 | |||||||||
| Investment income, before expense | 3,514 | 3,613 | 3,213 | |||||||||
| Investment expense (2) (3) | (274 | ) | (212 | ) | (171 | ) | ||||||
| Net investment income | $ | 3,240 | $ | 3,401 | $ | 3,042 | ||||||
| Market-based core | $ | 2,431 | $ | 2,360 | $ | 2,340 | ||||||
| Market-based active | 303 | 301 | 262 | |||||||||
| Performance-based | 780 | 952 | 611 | |||||||||
| Investment income, before expense | $ | 3,514 | $ | 3,613 | $ | 3,213 |
| (1) | Due to the adoption of the recognition and measurement accounting standard, limited partnerships previously reported using the cost method are now reported at fair value with changes in fair value recognized in net investment income. |
| (2) | Investment expense includes $71 million, $40 million and $36 million of investee level expenses in 2018, 2017 and 2016, respectively, and has increased compared to prior year primarily due to growth in real estate investments. Investee level expenses include depreciation and asset level operating expenses on directly held real estate and other consolidated investments. |
| (3) | Investment expense includes $28 million, $10 million and $1 million related to the portion of reinvestment income on securities lending collateral paid to the counterparties in 2018, 2017 and 2016, respectively. |
Net investment income decreased 4.7% or $161 million in 2018 compared to 2017, after increasing 11.8% or $359 million in 2017 compared to 2016. The 2018 decrease was primarily due to lower performance-based results, primarily from limited partnerships, partially offset by higher market-based income. The
2017 increase benefited from strong performance-based results, primarily from limited partnerships, an increase in invested assets and stable market-based yields, partially offset by higher employee-related expenses.
| Performance-based investment income | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Limited partnerships | ||||||||||||
| Private equity | $ | 582 | $ | 725 | $ | 455 | ||||||
| Real estate | 123 | 164 | 106 | |||||||||
| Performance-based - limited partnerships | 705 | 889 | 561 | |||||||||
| Non-limited partnerships | ||||||||||||
| Private equity | 9 | 19 | 9 | |||||||||
| Real estate | 66 | 44 | 41 | |||||||||
| Performance-based - non-limited partnerships | 75 | 63 | 50 | |||||||||
| Total | ||||||||||||
| Private equity | 591 | 744 | 464 | |||||||||
| Real estate | 189 | 208 | 147 | |||||||||
| Total performance-based | $ | 780 | $ | 952 | $ | 611 | ||||||
| Investee level expenses (1) | $ | (64 | ) | $ | (35 | ) | $ | (32 | ) |
| (1) | Investee level expenses include depreciation and asset level operating expenses reported in investment expense. |
Performance-based investment income decreased 18.1% or $172 million in 2018 compared to an increase of 55.8% or $341 million in 2017. The 2018 decrease reflects lower asset appreciation and fewer gains on sales of underlying investments held by limited partnerships compared to prior year. The 2017 increase reflects asset appreciation, sales of underlying investments, and the continued growth of our performance-based portfolio.
The five highest contributing performance-based investments in 2018 and 2017 generated investment income of $159 million and $210 million, respectively. Performance-based results and income can vary significantly between periods and are influenced by economic conditions, equity market performance, comparable public company earnings multiples, capitalization rates, operating performance of the underlying investments and the timing of asset sales.
Investments 2018 Form 10-K
| Components of realized capital gains (losses) and the related tax effect | ||||||||||||
| For the year December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Impairment write-downs | ||||||||||||
| Fixed income securities | $ | (10 | ) | $ | (26 | ) | $ | (44 | ) | |||
| Equity securities (1) | — | (38 | ) | (125 | ) | |||||||
| Mortgage Loans | — | (1 | ) | — | ||||||||
| Limited partnership interests | (3 | ) | (32 | ) | (56 | ) | ||||||
| Other investments | (1 | ) | (5 | ) | (9 | ) | ||||||
| Total impairment write-downs | (14 | ) | (102 | ) | (234 | ) | ||||||
| Change in intent write-downs (1) | — | (48 | ) | (69 | ) | |||||||
| Net OTTI losses recognized in earnings | (14 | ) | (150 | ) | (303 | ) | ||||||
| Sales (1) | (215 | ) | 641 | 213 | ||||||||
| Valuation of equity investments (1) | (691 | ) | — | — | ||||||||
| Valuation and settlements of derivative instruments | 43 | (46 | ) | — | ||||||||
| Realized capital gains and losses, pre-tax | (877 | ) | 445 | (90 | ) | |||||||
| Income tax benefit (expense) | 189 | (147 | ) | 34 | ||||||||
| Realized capital gains and losses, after-tax | $ | (688 | ) | $ | 298 | $ | (56 | ) | ||||
| Market-based core | $ | (794 | ) | $ | 309 | $ | (40 | ) | ||||
| Market-based active | (152 | ) | 177 | 21 | ||||||||
| Performance-based | 69 | (41 | ) | (71 | ) | |||||||
| Realized capital gains and losses, pre-tax | $ | (877 | ) | $ | 445 | $ | (90 | ) |
| (1) | Due to the adoption of the recognition and measurement accounting standard, equity securities are reported at fair value with changes in fair value recognized in valuation of equity investments and are no longer included in impairment write-downs, change in intent write-downs and sales. |
Realized capital losses in 2018 related primarily to decreased valuation of equity investments and sales of fixed income securities.
Impairment write-downs totaled $14 million, $102 million and $234 million in 2018, 2017 and 2016, respectively. Impairment write-downs on limited partnership interests and fixed income securities in 2018 and 2017 related to investment specific circumstances.
Impairment write-downs on fixed income securities in 2016 were primarily driven by corporate fixed income securities impacted by issuer specific circumstances. Limited partnership write-downs primarily related to investments with exposure to the energy sector, partially offset by the recovery in value of a limited partnership that was previously written-down.
Equity securities were written down in 2017 and 2016 primarily due to the length of time and extent to which fair value was below cost, considering our assessment of the financial condition and prospects of the issuer, including relevant industry conditions and trends. Beginning January 1, 2018, equity securities are reported at fair value with changes in fair value recognized in valuation of equity investments and are no longer included in impairment write-downs.
Sales resulted in $215 million of net realized capital losses and $641 million and $213 million of net realized capital gains in 2018, 2017 and 2016, respectively.
Sales in 2018 related primarily to fixed income securities in connection with ongoing portfolio management.
Sales in 2017 and 2016 included sales of equity and fixed income securities in connection with ongoing portfolio management, as well as gains from valuation changes in public securities held in certain limited partnerships. Sales in first quarter 2016 included $105 million of losses on $1.90 billion of sales to reduce our exposure to the energy, metals and mining sectors.
Valuation of equity investments resulted in losses of $691 million in 2018, which included $594 million of declines in the valuation of equity securities and $97 million of declines in value primarily for certain limited partnerships where the underlying assets are predominately public equity securities.
Valuation and settlements of derivative instruments generated gains of $43 million in 2018, losses of $46 million in 2017 and gains and losses that netted to zero in 2016. 2018 primarily comprised gains on foreign currency contracts due to the strengthening of the U.S. dollar and gains on equity options used for risk management due to a decrease in equity indices, partially offset by losses on total return swaps and equity options and futures used for asset replication due to decreases in equity indices. 2017 primarily comprised losses on foreign currency contracts due to the weakening of the U.S. dollar and losses on equity futures used for risk management due to increases in equity indices. 2016 primarily comprised gains on foreign currency contracts due to the strengthening of the U.S. dollar, offset by losses on equity futures used for risk management due to increases in equity indices and losses on credit default swaps due to the tightening of credit spreads on the underlying credit names.
The Allstate Corporation 97
2018 Form 10-K Investments
| Realized capital gains (losses) for performance-based investments | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Impairment write-downs | $ | (3 | ) | $ | (32 | ) | $ | (90 | ) | |||
| Change in intent write-downs | — | — | (1 | ) | ||||||||
| Net OTTI losses recognized in earnings | (3 | ) | (32 | ) | (91 | ) | ||||||
| Sales | 7 | 15 | 9 | |||||||||
| Valuation of equity investments | 36 | — | — | |||||||||
| Valuation and settlements of derivative instruments | 29 | (24 | ) | 11 | ||||||||
| Total performance-based | $ | 69 | $ | (41 | ) | $ | (71 | ) |
Performance based investments generated realized capital gains of $69 million in 2018 and realized capital losses of $41 million and $71 million in 2017 and 2016, respectively. 2018 primarily related to increased valuation on equity investments and gains on valuation and settlements of derivative instruments. 2017 included impairment write-downs on private equity investments and derivative losses related to the hedging of foreign currency risk, partially offset by gains on sale of real estate investments. 2016 included impairment write-downs on certain investments with exposure to the energy sector, partially offset by the recovery in value of a limited partnership that was previously written-down.
Market Risk 2018 Form 10-K
Market Risk
Market risk is the risk that we will incur losses due to adverse changes in interest rates, credit spreads, equity prices, commodity prices or currency exchange rates. Adverse changes to these rates and prices may occur due to changes in fiscal policy, the economic climate, the liquidity of a market or market segment, insolvency or financial distress of key market makers or participants or changes in market perceptions of credit worthiness and/or risk tolerance. Our primary market risk exposures are to changes in interest rates, credit spreads and equity prices. We also have direct and indirect exposure to commodity price changes through our diversified investments in timber, agriculture, infrastructure and energy primarily held in limited partnership interests and consolidated subsidiaries.
The active management of market risk is integral to our results of operations. We may use the following approaches to manage exposure to market risk within defined tolerance ranges: 1) rebalancing existing asset or liability portfolios, 2) changing the type of investments purchased in the future and 3) using derivative instruments to modify the market risk characteristics of existing assets and liabilities or assets expected to be purchased. For a more detailed discussion of our use of derivative instruments, see Note 7 of the consolidated financial statements.
Overview In formulating and implementing guidelines for investing funds, we seek to earn attractive risk-adjusted returns that enhance our ability to offer competitive rates and prices to customers while contributing to stable profits and long-term capital growth. Accordingly, our investment decisions and objectives are informed by the underlying risks and product profiles. Investment policies define the overall framework for managing market and other investment risks, including accountability and controls over risk management activities. Subsidiaries that conduct investment activities follow policies that have been approved by their respective boards of directors and which specify the investment limits and strategies that are appropriate given the liquidity, surplus, product profile and regulatory requirements of the subsidiary. Executive oversight of investment activities is conducted primarily through the subsidiaries’ boards of directors and legal entity investment committees, and aggregate portfolio risks are overseen by our board of directors and its committees.
For life and annuity products, the asset-liability management (“ALM”) policies further define the overall framework for managing market and investment risks and are approved by the subsidiaries’ respective boards of directors. ALM focuses on strategies to enhance yields, mitigate market risks and optimize capital to improve profitability and returns while incorporating future expected cash requirements to repay liabilities. These ALM policies specify limits, ranges and/or targets for investments that best meet business objectives in light of the unique demands and characteristics of the product liabilities and are intended to result in a prudent, methodical and effective adjudication of market risk and return.
We use widely-accepted quantitative and qualitative approaches to measure, monitor and manage market risk. We evaluate our market risk exposure using multiple measures including but not limited to:
| • Duration, a measure of the price sensitivity of assets and liabilities to changes in interest rates |
| • Value-at-risk, a statistical estimate of the probability that the change in fair value of a portfolio will exceed a certain amount over a given time horizon |
| • Scenario analysis, an estimate of the potential changes in the fair value of a portfolio that could occur under hypothetical market conditions defined by changes to multiple market risk factors: interest rates, credit spreads, equity prices or currency exchange rates |
| • Sensitivity analysis, an estimate of the potential changes in the fair value of a portfolio that could occur using hypothetical shocks to a market risk factor |
In general, we establish investment portfolio asset allocation and market risk limits based upon a combination of duration, value-at-risk, scenario analysis and sensitivity analysis. The asset allocation limits place restrictions on the total funds that may be invested within an asset class. Comprehensive day-to-day management of market risk within defined tolerance ranges occurs as portfolio managers buy and sell within their respective markets based upon the acceptable boundaries established by investment policies. Although we apply a similar overall philosophy to market risk, the underlying business frameworks and the accounting and regulatory environments may differ between our products and therefore affect investment decisions and risk parameters.
Interest rate risk is the risk that we will incur a loss due to adverse changes in interest rates relative to the characteristics of our interest-bearing assets and liabilities. Interest rate risk includes risks related to changes in U.S. Treasury yields and other key risk-free reference yields. This risk arises from many of our primary activities, as we invest substantial funds in interest-sensitive assets and issue interest-sensitive liabilities. Changes in interest rates can have favorable and unfavorable effects on our results. For example, increases in rates can improve investment income, but decrease the fair value of our fixed income securities portfolio and increase policyholder surrenders requiring us to liquidate assets. Decreases in rates could increase the fair value of our fixed income securities portfolio while decreasing investment income due to reinvesting at lower market yields and accelerating pay-downs and prepayments of certain investments.
For our corporate debt, we monitor market interest rates and evaluate refinancing opportunities as maturity dates approach. To mitigate this risk, we ladder the maturity dates of our debt. For our noncumulative perpetual preferred stock, we monitor market dividend rates and evaluate opportunities to redeem or refinance on or after specified dates. For further detail regarding our debt and our preferred stock, see Note 12 of the consolidated financial
The Allstate Corporation 99
2018 Form 10-K Market Risk
statements and the Capital Resources and Liquidity section of this Item.
We manage the interest rate risk in our assets relative to the interest rate risk in our liabilities and our assessment of overall economic and capital risk. One of the measures used to quantify this exposure is duration. The difference in the duration of our assets relative to our liabilities is our duration gap. To calculate the duration gap between assets and liabilities, we project asset and liability cash flows and calculate their net present value using a risk-free market interest rate adjusted for credit quality, sector attributes, liquidity and other specific risks. Duration is calculated by revaluing these cash flows at alternative interest rates and determining the percentage change in aggregate fair value. The cash flows used in this calculation include the expected maturity and repricing characteristics of our derivative financial instruments, all other financial instruments, and certain other items including, unearned premiums, claims and claims expense reserves, annuity liabilities and other interest-sensitive liabilities.
The projections include assumptions (based upon historical market experience and our experience) that reflect the effect of changing interest rates on the prepayment, lapse, leverage and/or option features of instruments, where applicable. The preceding assumptions relate primarily to callable municipal and corporate bonds, fixed rate single and flexible premium deferred annuities, mortgage-backed securities and municipal housing bonds. Additionally, the calculations include assumptions regarding the renewal of property and casualty products.
As of December 31, 2018, the difference between our asset and liability duration was a (1.16) gap compared to a (2.16) gap as of December 31, 2017. The calculation excludes traditional and interest-sensitive life insurance and accident and health insurance products that are not considered financial instruments. A negative duration gap indicates that the fair value of our liabilities is more sensitive to interest rate movements than the fair value of our assets, while a positive duration gap indicates that the fair value of our assets is more sensitive to interest rate movements than the fair value of our liabilities. Due to the relatively short duration of our property and casualty liabilities, primarily related to auto and homeowners claims, the investments generally maintain a positive duration gap between assets and liabilities. In contrast, for our annuity products the duration gap may be positive or negative as the assets and liabilities vary based on the characteristics of the products in-force and investing activity. As of December 31, 2018, property and casualty products had a positive duration gap while annuity products had a negative duration gap.
To reduce the risk that investment returns are below levels required to meet the funding needs of certain liabilities, we are executing our performance-based strategy that supplements market risk with idiosyncratic risk. We are using these investments, in addition to public equity securities, to support a portion of our property and casualty products and
long-term annuity liabilities. Shorter-term annuity liabilities will continue to be invested in market-based investments to generate cash flows that will fund future claims, benefits and expenses, and that will earn stable returns across a wide variety of interest rate and economic scenarios. Performance-based investments and public equity securities are generally not interest-bearing; accordingly, using them to support interest-bearing liabilities contributes toward a negative duration gap.
Based upon the information and assumptions used in the duration calculation, and market interest rates as of December 31, 2018, we estimate that a 100 basis point immediate, parallel increase in interest rates (“rate shock”) would increase the fair value of the assets net of liabilities by $889 million, compared to an increase of $1.65 billion as of December 31, 2017, reflecting year to year changes in duration and the amount of assets and liabilities. The selection of a 100 basis point immediate, parallel change in interest rates should not be construed as our prediction of future market events, but only as an illustration of the potential effect of such an event.
The estimate excludes traditional and interest-sensitive life insurance and accident and health insurance products that are not considered financial instruments and the $11.07 billion of assets supporting them and the associated liabilities. The $11.07 billion of assets excluded from the calculation increased from $11.06 billion as of December 31, 2017. Based on assumptions described above, in the event of a 100 basis point immediate increase in interest rates, the assets supporting the excluded products would decrease in value by $593 million compared to a decrease of $620 million as of December 31, 2017. To the extent that conditions differ from the assumptions we used in these calculations, duration and rate shock measures could be significantly impacted. Additionally, our calculations assume the current relationship between short-term and long-term interest rates (the term structure of interest rates) will remain constant over time. As a result, these calculations may not fully capture the effect of non-parallel changes in the term structure of interest rates and/or large changes in interest rates.
Credit spread risk is the risk that we will incur a loss due to adverse changes in credit spreads (“spreads”). Credit spread is the additional yield on fixed income securities and loans above the risk-free rate (typically referenced as the yield on U.S. Treasury securities) that market participants require to compensate them for assuming credit, liquidity and/or prepayment risks. The magnitude of the spread will depend on the likelihood that a particular issuer will default. This risk arises from many of our primary activities, as we invest substantial funds in spread-sensitive fixed income assets. We manage the spread risk in our assets. One of the measures used to quantify this exposure is spread duration. Spread duration measures the price sensitivity of the assets to changes in spreads. For example, if spreads increase 100 basis points, the fair value of an asset exhibiting a
100 www.allstate.com
Market Risk 2018 Form 10-K
spread duration of 5 is expected to decrease in value by 5%.
Spread duration is calculated similarly to interest rate duration. As of December 31, 2018, the spread duration was 4.28, compared to 3.99 as of December 31, 2017. Based upon the information and assumptions we use in this spread duration calculation, and market spreads as of December 31, 2018, we estimate that a 100 basis point immediate, parallel increase in spreads across all asset classes, industry sectors and credit ratings (“spread shock”) would decrease the net fair value of the assets by $2.49 billion compared to $2.46 billion as of December 31, 2017. Reflected in the spread duration calculation are the effects of tactical positions that include the use of credit default swaps to manage spread risk. The selection of a 100 basis point immediate parallel change in spreads should not be construed as our prediction of future market events, but only as an illustration of the potential effect of such an event.
Equity price risk is the risk that we will incur losses due to adverse changes in the general levels of the equity markets. As of December 31, 2018, we held $4.78 billion in common stocks and exchange traded and mutual funds and $7.76 billion in other investments with equity risk (including primarily limited partnership interests and non-redeemable preferred securities), compared to $6.33 billion and $7.03 billion, respectively, as of December 31, 2017. 68.4% of the common stocks and exchange traded and mutual funds and 57.2% of the other securities with equity risk supported property and casualty products as of December 31, 2018, compared to 71.1% and 54.8%, respectively, as of December 31, 2017.
As of December 31, 2018, our portfolio of common stocks and other investments with equity risk had a cash market portfolio beta of 1.07, compared to a beta of 1.03 as of December 31, 2017. Beta represents a widely used methodology to describe, quantitatively, an investment’s market risk characteristics relative to an index such as the Standard & Poor’s 500 Composite Price Index (“S&P 500”). Based on the beta analysis, we estimate that if the S&P 500 increases or decreases by 10%, the fair value of our equity investments will increase or decrease by 10.7%, respectively. Based upon the information and assumptions we used to calculate beta as of December 31, 2018, we estimate that an immediate increase or decrease in the S&P 500 of 10% would increase or decrease the net fair value of our equity investments by $1.34 billion, of which approximately 40% relates to public securities, compared to $1.37 billion as of December 31, 2017.
We periodically use put options to reduce equity price risk or call options to adjust our equity risk profile. Put options provide an offset to declines in equity market values below a targeted level, while call options provide participation in equity market appreciation above a targeted level. Options can expire, terminate early or the option can be exercised. If the equity index does not fall below the put’s strike price or rise above the call’s strike price, the maximum loss on purchased puts and calls is limited to the amount of the premium paid. Based on the equity put and call
options in place at December 31, 2018, we would recognize $18 million of losses in the event of a 10% increase in the S&P 500 index and $28 million in gains in the event of a 10% decrease.
The selection of a 10% immediate increase or decrease in the S&P 500 should not be construed as our prediction of future market events, but only as an illustration of the potential effect of such an event. The beta of our common stocks and other investments with equity risk was determined by calculating the change in the fair value of the portfolio resulting from stressing the equity market up and down 10%. For limited partnership interests, quarterly changes in fair values may not be highly correlated to equity indices in the short-term and changes in value of these investments are generally recognized on a three-month delay due to the availability of the related investee financial statements. The illustrations noted above may not reflect our actual experience if the future composition of the portfolio (hence its beta) and correlation relationships differ from the historical relationships.
As of December 31, 2018 and 2017, we had separate account assets related to variable annuity and variable life contracts with account values totaling $2.81 billion and $3.44 billion, respectively. Equity risk exists for contract charges based on separate account balances and guarantees for death and/or income benefits provided by our variable products. In 2006, we disposed of substantially all of the variable annuity business through reinsurance agreements with The Prudential Insurance Company of America, a subsidiary of Prudential Financial Inc. and therefore mitigated this aspect of our risk. Equity risk for our variable life business relates to contract charges and policyholder benefits. Total direct and assumed variable life contract charges for 2018 and 2017 were $44 million and $41 million, respectively. Separate account liabilities related to variable life contracts were $68 million and $70 million as of December 31, 2018 and 2017, respectively.
As of December 31, 2018 and 2017, we had $1.83 billion and $1.85 billion, respectively, in equity-indexed life and annuity liabilities that provide customers with interest crediting rates based on the performance of the S&P 500. We hedge the majority of the risk associated with these liabilities using equity-indexed options and futures and eurodollar futures, maintaining risk within specified value-at-risk limits.
Foreign currency exchange rate risk is the risk that we will incur economic losses due to adverse changes in foreign currency exchange rates. This risk primarily arises from our foreign equity investments, including common stocks, limited partnership interests, and our Canadian, Northern Ireland and Indian operations. We use foreign currency derivative contracts to partially offset this risk.
As of December 31, 2018, we also have $96 million in certain fixed income securities and emerging market fixed income funds that are denominated in foreign currencies, of which approximately 0.4% used derivatives to hedge foreign currency risk.
The Allstate Corporation 101
2018 Form 10-K Market Risk
As of December 31, 2018, we had $2.10 billion in foreign currency denominated equity investments, including the impact of foreign currency derivative contracts, $860 million net investment in our foreign subsidiaries, primarily related to our Canadian operations, and $96 million in unhedged non-U.S. dollar fixed income securities. These amounts were $2.18 billion, $1.02 billion, and $112 million, respectively, as of December 31, 2017.
Based upon the information and assumptions used, including the impact of foreign currency derivative contracts, as of December 31, 2018, we estimate that a 10% immediate unfavorable change in each of the foreign currency exchange rates to which we are exposed would decrease the value of our foreign currency denominated instruments by $306 million, compared with an estimated $326 million decrease as of December 31, 2017. The selection of a 10% immediate decrease in all currency exchange rates should not be construed as our prediction of future market events, but only as an illustration of the potential effect of such an event.
The modeling technique we use to report our currency exposure does not take into account correlation among foreign currency exchange rates. Even though we believe it is very unlikely that all of the foreign currency exchange rates that we are exposed to would simultaneously decrease by 10%, we nonetheless stress test our portfolio under this and other hypothetical extreme adverse market scenarios. Our actual experience may differ from these results because of assumptions we have used or because significant liquidity and market events could occur that we did not foresee.
102 www.allstate.com
Pension and Other Postretirement Plans 2018 Form 10-K
Pension and Other Postretirement Plans
Our defined benefit pension plans cover most full-time employees, certain part-time employees and employee-agents. Benefits are based primarily on a cash balance formula; however, certain participants have a significant portion of their benefits attributable to a former final average pay formula. 87% of the projected benefit obligation (“PBO”) of our primary qualified employee plan is related to the former final average pay formula. See Note 17 of the consolidated financial statements for a discussion of these plans and their effect on the consolidated financial statements.
Our pension and other postretirement benefit costs are calculated using various actuarial assumptions and methodologies. These assumptions include discount rates, compensation increases, health care cost trend rates, inflation, expected returns on plan assets, mortality and other factors. The assumptions utilized in recording the obligations under our pension plans represent our best estimates and we believe they are reasonable based on information as to historical experience and performance as well as other factors that might cause future expectations to differ from past trends.
2019 change in pension and other postretirement plan accounting At January 1, 2019, we changed our accounting principle for recognizing actuarial gains and losses and expected return on plan assets for our pension and other postretirement plans to a more preferable policy under U.S. GAAP. Prior to 2019, actuarial gains and losses were recognized as a component of AOCI, and were generally amortized into earnings in future periods. Under the new principle, actuarial gains and losses will be immediately recognized through earnings (“fair value accounting”).
In addition, we changed our policy for recognizing expected returns on plan assets by eliminating the permitted accounting practice allowing the five-year smoothing of equity returns and moving to an unadjusted fair value method.
We believe that fair value accounting is preferable as it provides greater transparency of our economic obligations in accounting results and better aligns with the fair value accounting principles by recognizing the effects of economic and interest rate changes on pension and other postretirement plan assets and liabilities in the year in which the gains and losses are incurred. These changes will be applied retrospectively thereby requiring restatement of prior periods presented and upon adoption will have no impact on shareholders’ equity or book value per share.
Differences in actual experience or changes in assumptions After the January 1, 2019 change to fair value accounting, differences in actual experience or changes in assumptions will affect our pension and other postretirement obligations and future expense. The primary factors contributing to actuarial gains and losses are 1) changes in the discount rate used to value pension and postretirement obligations as of the measurement date, 2) differences between the expected and the actual return on plan assets, 3)
changes in demographic assumptions, including mortality, and 4) participant experience different from demographic assumptions.
Impact of assumption changes to net periodic pension and benefit costs, following a retrospective change to fair value accounting The discount rate is based on rates at which expected pension benefits attributable to past employee service could effectively be settled on a present value basis at the measurement date. We develop the assumed discount rate by utilizing the weighted average yield of a theoretical dedicated portfolio derived from non-callable bonds and bonds with a make-whole provision available in the Bloomberg corporate bond universe having ratings of at least “AA” by S&P or at least “Aa” by Moody’s on the measurement date with cash flows that match expected plan benefit requirements. Significant changes in discount rates, such as those caused by changes in the credit spreads, yield curve, the mix of bonds available in the market, the duration of selected bonds and expected benefit payments, may result in volatility in pension cost.
Holding other assumptions constant, a hypothetical decrease of 100 basis points in the discount rate would result in an increase of $612 million, pre-tax, in net periodic pension cost as of December 31, 2018. A hypothetical increase of 100 basis points in the discount rate would decrease net periodic pension cost by $515 million, pre-tax, as of December 31, 2018. This non-symmetrical range results from the non-linear relationship between discount rates and pension obligations.
The expected long-term rate of return on plan assets reflects the average rate of earnings expected on plan assets. While this rate reflects long-term assumptions and is consistent with long-term historical returns, sustained changes in the market or changes in the mix of plan assets may lead to revisions in the assumed long-term rate of return on plan assets that may result in variability of pension cost. Differences between the actual return on plan assets and the expected long-term rate of return on plan assets are immediately recognized through earnings upon the annual remeasurement in the fourth quarter, or on an interim basis as triggering events warrant remeasurement. Short-term asset performance can differ significantly from the expected rate of return, especially in volatile markets.
Holding other assumptions constant, a hypothetical increase or decrease of 100 basis points in the expected long-term rate of return on plan assets would result in a decrease or increase, respectively, of $55 million, pre-tax, in net periodic pension cost as of December 31, 2018.
Assumed health care cost trend rates have a significant effect on the amounts reported for the postretirement health care plans. A one percentage-point increase in assumed health care cost trend rates would increase net periodic benefit cost for other postretirement benefits by $27 million. A one
The Allstate Corporation 103
2018 Form 10-K Pension and Other Postretirement Plans
percentage-point decrease in assumed health care cost trend rates would decrease net periodic benefit cost for other postretirement benefits by $24 million.
Target funding levels are established in accordance with applicable regulations, including those under the Internal Revenue Code for U.S. pension plans, and generally accepted actuarial principles. Our funding levels were within our targeted range as of December 31, 2018. In 2018, we contributed $16 million to our unfunded non-qualified plans and zero to the qualified funded pension plans. We expect to contribute $26 million and zero to these plans, respectively, for the 2019 fiscal year. This estimate could change significantly based on market conditions.
104 www.allstate.com
Capital Resources and Liquidity 2018 Form 10-K
Capital Resources and Liquidity
Capital resources consist of shareholders’ equity and debt, representing funds deployed or available to be deployed to support business operations or for general corporate purposes.
| Capital resources | ||||||||||||
| As of December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Preferred stock, common stock, treasury stock, retained income and other shareholders’ equity items | $ | 22,869 | $ | 22,245 | $ | 20,989 | ||||||
| Accumulated other comprehensive (loss) income | (1,557 | ) | 306 | (416 | ) | |||||||
| Total shareholders’ equity | 21,312 | 22,551 | 20,573 | |||||||||
| Debt | 6,451 | 6,350 | 6,347 | |||||||||
| Total capital resources | $ | 27,763 | $ | 28,901 | $ | 26,920 | ||||||
| Ratio of debt to shareholders’ equity | 30.3 | % | 28.2 | % | 30.9 | % | ||||||
| Ratio of debt to capital resources | 23.2 | % | 22.0 | % | 23.6 | % |
Shareholders’ equity decreased in 2018, primarily due to decreased net unrealized capital gains on investments, common share repurchases and dividends paid to shareholders, partially offset by net income and issuance of preferred stock. In 2018, we paid dividends of $614 million and $134 million related to our common and preferred shares, respectively. Shareholders’ equity increased in 2017, primarily due to net income, increased unrealized net capital gains on investments and lower unrecognized pension and other postretirement benefit costs, partially offset by common share repurchases and dividends paid to shareholders.
Preferred stock and debt issuances On March 29, 2018, we issued 23,000 shares of 5.625% Fixed Rate Noncumulative Perpetual Preferred Stock, Series G, for aggregate proceeds of $575 million, $250 million of Floating Rate Senior Notes due 2021 and $250 million of Floating Rate Senior Notes due 2023. The proceeds of these issuances were for general corporate purposes, including the redemption, repayment or repurchase of certain preferred stock or debt.
Redemption and repayment of preferred stock and debt On May 13, 2018, we redeemed our $224 million Series B 6.125% Fixed-to-Floating Rate Junior Subordinated Debentures at a redemption price equal to 100% of the outstanding principal.
On May 15, 2018, we repaid $176 million of 6.75% Senior Debentures at maturity.
On October 15, 2018, we redeemed all 15,400 shares of our Fixed Rate Noncumulative Perpetual Preferred Stock, Series C and the corresponding depository shares for $385 million. The redemption price in excess of the carrying value for the preferred shares was recognized as part of preferred stock dividends on the Consolidated Statements of Operations and Consolidated Statements of Shareholders’ Equity.
For additional details on these transactions, see Note 12 of the consolidated financial statements.
Debt $317 million of senior debt is scheduled to mature in May 2019. As of December 31, 2018 and 2017, there were no outstanding commercial paper
borrowings. For further information on outstanding debt, see Note 12 of the consolidated financial statements.
Common share repurchases On October 31, 2018, the Board authorized a new $3.00 billion common share repurchase program that is expected to be completed by April 2020. Funding for the repurchase program may include potential preferred stock issuances of up to $1.00 billion. As of December 31, 2018, there was $2.07 billion remaining on the repurchase program.
In November 2018, we completed the $2.00 billion common share repurchase program that commenced in August 2017.
In December 2018, we entered into an accelerated share repurchase agreement (“ASR agreement”) with Wells Fargo Bank, National Association (“Wells Fargo”), to purchase $1.00 billion of our outstanding common stock. Under the ASR agreement, we paid $1.00 billion upfront and initially acquired 10.7 million shares. The actual number of shares we repurchase under this ASR agreement, and the average price paid per share, will be determined at the completion of the ASR agreement based on the volume weighted average price of Allstate’s common stock during the period of Wells Fargo’s purchases. This ASR agreement is expected to be completed on or before May 2019.
During 2018, we repurchased 25.0 million common shares for $2.20 billion. The common share repurchases were completed through open market transactions and ASR agreements.
Since 1995, we have acquired 707 million shares of our common stock at a cost of $33.33 billion, primarily as part of various stock repurchase programs. We have reissued 141 million common shares since 1995, primarily associated with our equity incentive plans, the 1999 acquisition of American Heritage Life Investment Corporation and the 2001 redemption of certain mandatorily redeemable preferred securities. Since 1995, total common shares outstanding has decreased by 567 million shares or 63.1%, primarily due to our repurchase programs.
The Allstate Corporation 105
2018 Form 10-K Capital Resources and Liquidity
Common shareholder dividends On January 2, 2018, April 2, 2018, July 2, 2018 and October 1, 2018, we paid common shareholder dividends of $0.37, $0.46, $0.46 and $0.46, respectively. On November 16, 2018, we declared a common shareholder dividend of $0.46,
payable on January 2, 2019. On February 8, 2019, we declared a common shareholder dividend of $0.50, payable on April 1, 2019.
Financial ratings and strength
| Senior long-term debt, commercial paper and insurance financial strength ratings | ||||||
| As of December 31, 2018 | ||||||
| Moody’s | S&P Global Ratings | A.M. Best | ||||
| The Allstate Corporation (debt) | A3 | A- | a | |||
| The Allstate Corporation (short-term issuer) | P-2 | A-2 | AMB-1+ | |||
| Allstate Insurance Company (insurance financial strength) | Aa3 | AA- | A+ | |||
| Allstate Life Insurance Company (insurance financial strength) | A1 | A+ | A+ | |||
| Allstate Assurance Company (insurance financial strength) | A1 | N/A | A+ |
Our ratings are influenced by many factors including our operating and financial performance, asset quality, liquidity, asset/liability management, overall portfolio mix, financial leverage (i.e., debt), exposure to risks such as catastrophes and the current level of operating leverage. The preferred stock and subordinated debentures are viewed as having a common equity component by certain rating agencies and are given equity credit up to a pre-determined limit in our capital structure as determined by their respective methodologies. These respective methodologies consider the existence of certain terms and features in the instruments such as the noncumulative dividend feature in the preferred stock.
In August 2018, Moody’s affirmed The Allstate Corporation’s debt and short-term issuer ratings of A3 and P-2, respectively, and the insurance financial strength ratings of Aa3 for AIC and A1 for both Allstate Life Insurance Company (“ALIC”) and Allstate Assurance Company (“AAC”). The outlook for the ratings is stable. In August 2018, S&P affirmed The Allstate Corporation’s debt and short-term issuer ratings of A- and A-2, respectively, and the insurance financial strength ratings of AA- for AIC and A+ for ALIC. The outlook for the ratings is stable. In April 2018, A.M. Best upgraded The Allstate Corporation’s debt and short-term issuer ratings of a- and AMB-1 to a and AMB-1+, respectively, and affirmed the insurance financial strength ratings of A+ for AIC, ALIC and AAC. The outlook for the ratings is stable.
We have distinct and separately capitalized groups of subsidiaries licensed to sell property and casualty insurance that maintain separate group ratings. The ratings of these groups are influenced by the risks that relate specifically to each group. Many mortgage companies require property owners to have insurance from an insurance carrier with a secure financial strength rating from an accredited rating agency. In April 2018, A.M. Best affirmed the ANJ, which writes auto and homeowners insurance, rating of A, and affirmed the North Light, our excess and surplus lines carrier, rating of A+. The outlook for the ANJ rating and North Light rating is stable. ANJ also has a Financial Stability Rating® of A” from Demotech, which was
affirmed in November 2018. In February 2018, A.M. Best affirmed the CKIC, which underwrites personal lines property insurance in Florida, rating of B-. CKIC also has a Financial Stability Rating of A’ from Demotech that was affirmed in November 2018. ANJ, North Light and CKIC do not have support agreements with AIC.
Allstate’s domestic property and casualty and life insurance subsidiaries prepare their statutory-basis financial statements in conformity with accounting practices prescribed or permitted by the insurance department of the applicable state of domicile. Statutory surplus is a measure that is often used as a basis for determining dividend paying capacity, operating leverage and premium growth capacity, and it is also reviewed by rating agencies in determining their ratings.
The property and casualty business is comprised of 29 insurance companies, each of which has individual company dividend limitations. As of December 31, 2018, total statutory surplus is $18.15 billion compared to $18.63 billion as of December 31, 2017. Property and casualty subsidiaries surplus was $14.33 billion as of December 31, 2018, compared to $14.90 billion as of December 31, 2017. Life insurance subsidiaries surplus was $3.82 billion as of December 31, 2018, compared to $3.73 billion as of December 31, 2017.
The National Association of Insurance Commissioners (“NAIC”) has developed financial relationships or tests known as the Insurance Regulatory Information System to assist state insurance regulators in monitoring the financial condition of insurance companies and identifying companies that require special attention or actions by state insurance regulators. The NAIC analyzes financial data provided by insurance companies using prescribed ratios, each with defined “usual ranges”. Additional regulatory scrutiny may occur if a company’s ratios fall outside the usual ranges for four or more of the ratios. Our domestic insurance companies have no significant departure from these ranges.
106 www.allstate.com
Capital Resources and Liquidity 2018 Form 10-K
Liquidity sources and uses Our potential sources and uses of funds principally include the following activities below.
| Activities for potential sources of funds | ||||||||||||
| Property- Liability | Service Businesses | Allstate Life | Allstate Benefits | Allstate Annuities | Corporate and Other | |||||||
| Receipt of insurance premiums | ü | ü | ü | ü | ü | |||||||
| Recurring service fees | ü | ü | ||||||||||
| Contractholder fund deposits | ü | ü | ü | |||||||||
| Reinsurance and indemnification program recoveries | ü | ü | ü | ü | ü | |||||||
| Receipts of principal, interest and dividends on investments | ü | ü | ü | ü | ü | ü | ||||||
| Sales of investments | ü | ü | ü | ü | ü | ü | ||||||
| Funds from securities lending, commercial paper and line of credit agreements | ü | ü | ü | ü | ||||||||
| Intercompany loans | ü | ü | ü | ü | ü | ü | ||||||
| Capital contributions from parent | ü | ü | ü | ü | ü | |||||||
| Dividends or return of capital from subsidiaries | ü | ü | ü | ü | ||||||||
| Tax refunds/settlements | ü | ü | ü | ü | ü | ü | ||||||
| Funds from periodic issuance of additional securities | ü | |||||||||||
| Receipt of intercompany settlements related to employee benefit plans | ü |
| Activities for potential uses of funds | ||||||||||||
| Property- Liability | Service Businesses | Allstate Life | Allstate Benefits | Allstate Annuities | Corporate and Other | |||||||
| Payment of claims and related expenses | ü | ü | ||||||||||
| Payment of contract benefits, maturities, surrenders and withdrawals | ü | ü | ü | |||||||||
| Reinsurance cessions and indemnification program payments | ü | ü | ü | ü | ü | |||||||
| Operating costs and expenses | ü | ü | ü | ü | ü | ü | ||||||
| Purchase of investments | ü | ü | ü | ü | ü | ü | ||||||
| Repayment of securities lending, commercial paper and line of credit agreements | ü | ü | ü | ü | ||||||||
| Payment or repayment of intercompany loans | ü | ü | ü | ü | ü | ü | ||||||
| Capital contributions to subsidiaries | ü | ü | ü | ü | ||||||||
| Dividends or return of capital to shareholders/parent company | ü | ü | ü | ü | ü | ü | ||||||
| Tax payments/settlements | ü | ü | ü | ü | ü | |||||||
| Common share repurchases | ü | |||||||||||
| Debt service expenses and repayment | ü | ü | ||||||||||
| Payments related to employee and employee-agent benefit plans | ü | ü | ü | ü | ü | ü | ||||||
| Payments for acquisitions | ü | ü | ü | ü | ü | ü |
We actively manage our financial position and liquidity levels in light of changing market, economic, and business conditions. Liquidity is managed at both the entity and enterprise level across the Company, and is assessed on both base and stressed level liquidity needs. We believe we have sufficient liquidity to meet these needs. Additionally, we have existing intercompany agreements in place that facilitate liquidity management across the Company to enhance flexibility.
As of December 31, 2018, we held $8.96 billion of cash, U.S. government and agencies fixed income securities, and public equity securities (excluding non-redeemable preferred stocks and foreign equities)
which, under normal market conditions, we would expect to be able to liquidate within one week. In addition, we regularly estimate how much of the total portfolio, which includes high quality corporate fixed income and municipal holdings, can be reasonably liquidated within one quarter. These estimates are subject to considerable uncertainty associated with evolving market conditions. As of December 31, 2018, estimated liquidity available within one quarter without generating significant net realized capital losses was $21.34 billion. As of December 31, 2018, gross unrealized losses related to fixed income securities totaled $957 million.
The Allstate Corporation 107
2018 Form 10-K Capital Resources and Liquidity
Certain remote events and circumstances could constrain our liquidity. Those events and circumstances include, for example, a catastrophe resulting in extraordinary losses, a downgrade in our senior long-term debt ratings to non-investment grade status, or a downgrade in AIC’s or ALIC’s financial strength ratings. The rating agencies also consider the interdependence of our individually rated entities; therefore, a rating change in one entity could potentially affect the ratings of other related entities.
The Allstate Corporation is party to an Amended and Restated Intercompany Liquidity Agreement (“Liquidity Agreement”) with certain subsidiaries, which include, but are not limited to, ALIC and AIC. The Liquidity Agreement allows for short-term advances of funds to be made between parties for liquidity and other general corporate purposes. The Liquidity Agreement does not establish a commitment to advance funds on the part of any party. ALIC and AIC each serve as a lender and borrower, certain other subsidiaries serve only as borrowers, and the Corporation serves only as a lender. AIC also has a capital support agreement with ALIC. Under the capital support agreement, AIC is committed to providing capital to ALIC to maintain an adequate capital level. The maximum amount of potential funding under each of these agreements is $1.00 billion.
In addition to the Liquidity Agreement, the Corporation also has an intercompany loan agreement with certain of its subsidiaries, which include, but are not limited to, AIC and ALIC. The amount of intercompany loans available to the Corporation’s subsidiaries is at the discretion of the Corporation. The maximum amount of loans the Corporation will have outstanding to all its eligible subsidiaries at any given point in time is limited to $1.00 billion. The Corporation may use commercial paper borrowings, bank lines of credit and securities lending to fund intercompany borrowings.
Parent company capital capacity At the parent holding company level, we have deployable assets totaling $1.50 billion as of December 31, 2018, comprising cash and investments that are generally saleable within one quarter. The substantial earnings capacity of the operating subsidiaries is the primary source of capital generation for the Corporation.
The payment of dividends by AIC to The Allstate Corporation is limited by Illinois insurance law to formula amounts based on statutory net income and statutory surplus, as well as the timing and amount of dividends paid in the preceding twelve months. Based on the greater of 2018 statutory net income or 10% of statutory surplus, the maximum amount of dividends that AIC will be able to pay, without prior Illinois Department of Insurance approval, at a given point in time in 2019 is estimated at $2.73 billion, less dividends paid during the preceding twelve months measured at that point in time. Notification and approval of intercompany lending activities are also required by the Illinois Department of Insurance for those transactions that exceed formula amounts based on statutory admitted assets and statutory surplus.
This provides funds for the parent company’s fixed charges and other corporate purposes.
Intercompany dividends were paid in 2018, 2017 and 2016 between the following companies: AIC, Allstate Insurance Holdings, LLC (“AIH”), the Corporation, ALIC, American Heritage Life Insurance Company (“AHL”) and Allstate Financial Insurance Holdings Corporation (“AFIHC”).
| Intercompany dividends | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| AIC to AIH | $ | 2,874 | $ | 1,555 | $ | 1,905 | ||||||
| AIH to the Corporation | 2,897 | 1,613 | 1,865 | |||||||||
| ALIC to AIC | 250 | 600 | — | |||||||||
| AHL to AFIHC | 55 | 70 | 55 |
Dividends may not be paid or declared on our common stock and shares of common stock may not be repurchased unless the full dividends for the latest completed dividend period on our preferred stock have been declared and paid or provided for. We are prohibited from declaring or paying dividends on our preferred stock if we fail to meet specified capital adequacy, net income or shareholders’ equity levels, except out of the net proceeds of common stock issued during the 90 days prior to the date of declaration. As of December 31, 2018, we satisfied all of the tests with no current restrictions on the payment of preferred stock dividends. There were no capital contributions paid by the Corporation to AIC in 2018, 2017 or 2016. There were no capital contributions by AIC to ALIC in 2018, 2017 or 2016.
The terms of our outstanding subordinated debentures also prohibit us from declaring or paying any dividends or distributions on our common or preferred stock or redeeming, purchasing, acquiring, or making liquidation payments on our common stock or preferred stock if we have elected to defer interest payments on the subordinated debentures, subject to certain limited exceptions. In 2018, we did not defer interest payments on the subordinated debentures.
Additional borrowings to support liquidity are as follows:
| • | The Corporation has access to a commercial paper facility with a borrowing limit of $1.00 billion to cover short-term cash needs. As of December 31, 2018, there were no balances outstanding and therefore the remaining borrowing capacity was $1.00 billion; however, the outstanding balance can fluctuate daily. |
| • | The Corporation, AIC and ALIC have access to a $1.00 billion unsecured revolving credit facility that is available for short-term liquidity requirements. The maturity date of this facility is April 2021. The facility is fully subscribed among 11 lenders with the largest commitment being $115 million. The commitments of the lenders are several and no lender is responsible for any other lender’s commitment if such lender fails to make a loan under the facility. This facility contains an increase provision that would allow up to an additional $500 |
108 www.allstate.com
Capital Resources and Liquidity 2018 Form 10-K
million of borrowing. This facility has a financial covenant requiring that we not exceed a 37.5% debt to capitalization ratio as defined in the agreement. This ratio was 16.0% as of December 31, 2018. Although the right to borrow under the facility is not subject to a minimum rating requirement, the costs of maintaining the facility and borrowing under it are based on the ratings of our senior unsecured, unguaranteed long-term debt. There were no borrowings under the credit facility during 2018.
| • | The Corporation has access to a universal shelf registration statement with the Securities and |
Exchange Commission that expires in 2021. We can use this shelf registration to issue an unspecified amount of debt securities, common stock (including 568 million shares of treasury stock as of December 31, 2018), preferred stock, depositary shares, warrants, stock purchase contracts, stock purchase units and securities of trust subsidiaries. The specific terms of any securities we issue under this registration statement will be provided in the applicable prospectus supplements.
Liquidity exposure Contractholder funds were $18.37 billion as of December 31, 2018.
| Contractholder funds by contractual withdrawal provisions | |||||||
| ($ in millions) | December 31, 2018 | Percent to total | |||||
| Not subject to discretionary withdrawal | $ | 2,848 | 15.5 | % | |||
| Subject to discretionary withdrawal with adjustments: | |||||||
| Specified surrender charges (1) | 4,753 | 25.9 | |||||
| Market value adjustments (2) | 996 | 5.4 | |||||
| Subject to discretionary withdrawal without adjustments (3) | 9,774 | 53.2 | |||||
| Total contractholder funds (4) | $ | 18,371 | 100.0 | % |
| (1) | Includes $870 million of liabilities with a contractual surrender charge of less than 5% of the account balance. |
| (2) | $512 million of the contracts with market value adjusted surrenders have a 30-45 day period at the end of their initial and subsequent interest rate guarantee periods (which are typically 1, 5, 7 or 10 years) during which there is no surrender charge or market value adjustment. $225 million of these contracts have their 30-45 day window period in 2019. |
| (3) | 89% of these contracts have a minimum interest crediting rate guarantee of 3% or higher. |
| (4) | Includes $732 million of contractholder funds on variable annuities reinsured to The Prudential Insurance Company of America, a subsidiary of Prudential Financial Inc., in 2006. |
Retail life and annuity products may be surrendered by customers for a variety of reasons. Reasons unique to individual customers include a current or unexpected need for cash or a change in life insurance coverage needs. Other key factors that may impact the likelihood of customer surrender include the level of the contract surrender charge, the length of time the contract has been in force, distribution channel, market interest rates, equity market conditions and potential tax implications.
In addition, the propensity for retail life insurance policies to lapse is lower than it is for fixed annuities because of the need for the insured to be re-underwritten upon policy replacement.
The surrender and partial withdrawal rate on deferred fixed annuities and interest-sensitive life insurance products, based on the beginning of year contractholder funds, was 7.2% and 6.1% in 2018 and 2017, respectively. We strive to promptly pay customers who request cash surrenders; however, statutory regulations generally provide up to six months in most states to fulfill surrender requests.
Our asset-liability management practices enable us to manage the differences between the cash flows generated by our investment portfolio and the expected cash flow requirements of our life insurance and annuity product obligations.
The Allstate Corporation 109
2018 Form 10-K Capital Resources and Liquidity
Contractual obligations and commitments Our contractual obligations as of December 31, 2018, and the payments due by period are shown in the following table.
| Contractual obligations and payments due by period | ||||||||||||||||||||
| As of December 31, 2018 | ||||||||||||||||||||
| ($ in millions) | Total | Less than 1 year | 1 to 3 years | Over 3 years to 5 years | Over 5 years | |||||||||||||||
| Liabilities for collateral (1) | $ | 1,458 | $ | 1,458 | $ | — | $ | — | $ | — | ||||||||||
| Contractholder funds (2) | 37,570 | 2,185 | 4,094 | 3,736 | 27,555 | |||||||||||||||
| Reserve for life-contingent contract benefits (2) | 38,787 | 1,425 | 2,661 | 2,428 | 32,273 | |||||||||||||||
| Long-term debt (3) | 13,429 | 625 | 843 | 1,320 | 10,641 | |||||||||||||||
| Operating leases (4) | 650 | 139 | 217 | 144 | 150 | |||||||||||||||
| Unconditional purchase obligations (4) | 568 | 287 | 274 | 6 | 1 | |||||||||||||||
| Defined benefit pension plans and other postretirement benefit plans (4)(5) | 958 | 47 | 113 | 117 | 681 | |||||||||||||||
| Reserve for property and casualty insurance claims and claims expense (6) | 27,423 | 12,498 | 8,692 | 3,040 | 3,193 | |||||||||||||||
| Other liabilities and accrued expenses (7)(8) | 5,918 | 5,634 | 259 | 12 | 13 | |||||||||||||||
| Net unrecognized tax benefits (9) | 70 | 58 | 12 | — | — | |||||||||||||||
| Total contractual cash obligations | $ | 126,831 | $ | 24,356 | $ | 17,165 | $ | 10,803 | $ | 74,507 |
| (1) | Liabilities for collateral are typically fully secured with cash or short-term investments. We manage our short-term liquidity position to ensure the availability of a sufficient amount of liquid assets to extinguish short-term liabilities as they come due in the normal course of business, including utilizing potential sources of liquidity as disclosed previously. |
| (2) | Contractholder funds represent interest-bearing liabilities arising from the sale of products such as interest-sensitive life and fixed annuities, including immediate annuities without life contingencies. The reserve for life-contingent contract benefits relates primarily to traditional life insurance, immediate annuities with life contingencies and voluntary accident and health insurance. These amounts reflect the present value of estimated cash payments to be made to contractholders and policyholders. Certain of these contracts, such as immediate annuities without life contingencies, involve payment obligations where the amount and timing of the payment are essentially fixed and determinable. These amounts relate to (i) policies or contracts where we are currently making payments and will continue to do so and (ii) contracts where the timing of a portion or all of the payments has been determined by the contract. Other contracts, such as interest-sensitive life, fixed deferred annuities, traditional life insurance and voluntary accident and health insurance, involve payment obligations where a portion or all of the amount and timing of future payments is uncertain. For these contracts, we are not currently making payments and will not make payments until (i) the occurrence of an insurable event such as death or illness or (ii) the occurrence of a payment triggering event such as the surrender or partial withdrawal on a policy or deposit contract, which is outside of our control. For immediate annuities with life contingencies, the amount of future payments is uncertain since payments will continue as long as the annuitant lives. We have estimated the timing of payments related to these contracts based on historical experience and our expectation of future payment patterns. Uncertainties relating to these liabilities include mortality, morbidity, expenses, customer lapse and withdrawal activity, estimated additional deposits for interest-sensitive life contracts, and renewal premium for life policies, which may significantly impact both the timing and amount of future payments. Such cash outflows reflect adjustments for the estimated timing of mortality, retirement, and other appropriate factors, but are undiscounted with respect to interest. As a result, the sum of the cash outflows shown for all years in the table exceeds the corresponding liabilities of $18.37 billion for contractholder funds and $12.21 billion for reserve for life-contingent contract benefits as included in the Consolidated Statements of Financial Position as of December 31, 2018. The liability amount in the Consolidated Statements of Financial Position reflects the discounting for interest as well as adjustments for the timing of other factors as described above. Future premium collections are not included in the amounts presented in the table above. |
| (3) | Amount differs from the balance presented on the Consolidated Statements of Financial Position as of December 31, 2018, because the long-term debt amount above includes interest and excludes debt issuance costs. |
| (4) | Our payment obligations relating to operating leases, unconditional purchase obligations and pension and other postretirement benefits (“OPEB”) contributions are managed within the structure of our intermediate to long-term liquidity management program. |
| (5) | The pension plans’ obligations in the next 12 months represent our planned contributions to certain unfunded non-qualified plans where the benefit obligation exceeds the assets, and the remaining years’ contributions are projected based on the average remaining service period using the current underfunded status of the plans. The OPEB plans’ obligations are estimated based on the expected benefits to be paid. These liabilities are discounted with respect to interest, and as a result the sum of the cash outflows shown for all years in the table exceeds the corresponding liability amount of $510 million included in other liabilities and accrued expenses on the Consolidated Statements of Financial Position. |
| (6) | Reserve for property and casualty insurance claims and claims expense is an estimate of amounts necessary to settle all outstanding claims, including claims that have been IBNR as of the balance sheet date. We have estimated the timing of these payments based on our historical experience and our expectation of future payment patterns. However, the timing of these payments may vary significantly from the amounts shown above, especially for IBNR claims. The ultimate cost of losses may vary materially from recorded amounts that are our best estimates. |
| (7) | Other liabilities primarily include accrued expenses and certain benefit obligations and claim payments and other checks outstanding. Certain of these long-term liabilities are discounted with respect to interest, as a result the sum of the cash outflows shown for all years in the table exceeds the corresponding liability amount by $4 million. |
110 www.allstate.com
Capital Resources and Liquidity 2018 Form 10-K
| (8) | Balance sheet liabilities not included in the table above include unearned and advance premiums of $15.29 billion and gross deferred tax liabilities of $1.58 billion. These items were excluded as they do not meet the definition of a contractual liability as we are not contractually obligated to pay these amounts to third parties. Rather, they represent an accounting mechanism that allows us to present our financial statements on an accrual basis. In addition, other liabilities of $252 million were not included in the table above because they did not represent a contractual obligation or the amount and timing of their eventual payment was sufficiently uncertain. |
| (9) | Net unrecognized tax benefits represent our potential future obligation to the taxing authority for a tax position that was not recognized in the consolidated financial statements. We believe it is reasonably possible that a decrease of up to $58 million in unrecognized tax benefits may occur within the next twelve months due to IRS settlements. The resolution of this obligation may be for an amount different than what we have accrued. |
| Contractual commitments and periods in which commitments expire | ||||||||||||||||||||
| As of December 31, 2018 | ||||||||||||||||||||
| ($ in millions) | Total | Less than 1 year | 1 to 3 years | Over 3 years to 5 years | Over 5 years | |||||||||||||||
| Other commitments – conditional | $ | 280 | $ | 81 | $ | 97 | $ | 45 | $ | 57 | ||||||||||
| Other commitments – unconditional | 3,028 | 243 | 270 | 333 | 2,182 | |||||||||||||||
| Total commitments | $ | 3,308 | $ | 324 | $ | 367 | $ | 378 | $ | 2,239 |
Contractual commitments represent investment commitments such as private placements, limited partnership interests and other loans. Limited partnership interests are typically funded over the commitment period which is shorter than the contractual expiration date of the partnership and as a result, the actual timing of the funding may vary.
We have agreements in place for services we conduct, generally at cost, between subsidiaries relating to insurance, reinsurance, loans and capitalization. All material intercompany transactions have been appropriately eliminated in consolidation. Intercompany transactions among insurance subsidiaries and affiliates have been approved by the appropriate departments of insurance as required.
For a more detailed discussion of our off-balance sheet arrangements, see Note 7 of the consolidated financial statements.
The Allstate Corporation 111
2018 Form 10-K Enterprise Risk and Return Management
Enterprise Risk and Return Management
In addition to the normal risks of the business, Allstate is subject to significant risks as an insurer and a provider of other products and financial services. These risks are discussed in more detail in the Risk Factors section of this document. We regularly identify, measure, monitor and report all significant risks. The major categories of enterprise risks are insurance, financial, investment, operational and strategic.
Allstate manages these risks through Enterprise Risk and Return Management (“ERRM”) governance practices, culture, and activities that are performed on an integrated, enterprise-wide basis, following our risk and return principles. Our legal and capital structures are designed to manage capital and solvency on a legal entity basis. Our risk-return principles define how we operate and guide decision-making around risk and return. These principles state that our priority is to protect solvency, comply with laws and act with integrity. Building upon this foundation, we strive to build strategic value and optimize risk and return.
Governance ERRM governance includes board oversight, an executive management committee structure, and enterprise and business unit chief risk officers.
| • | The Allstate Corporation Board of Directors (“Allstate Board”) has overall responsibility for oversight of management’s design and implementation of ERRM. |
| • | The Risk and Return Committee (“RRC”) of the Allstate Board oversees effectiveness of the ERRM framework, governance structure and decision-making, while focusing on the Company’s overall risk profile. |
| • | The Audit Committee oversees effectiveness of management’s control framework for risks and cybersecurity. |
| • | The Enterprise Risk and Return Council (“ERRC”) is Allstate’s senior risk management committee that directs ERRM by establishing risk-return targets, determining economic capital levels and directing integrated strategies and actions from an enterprise perspective. The ERRC consists of Allstate’s chief executive officer and president, vice chair, chief financial officer, business unit presidents, chief investment and corporate strategy officer, chief risk officer, general counsel, treasurer, vice president of operational risk, business unit chief risk officers, and business unit chief financial officers. |
| • | Other key committees work with the ERRC to direct ERRM activities, including the Operating Committee, the Operational Risk Council, the Corporate Asset Liability Committee, legal entity liability governance committees, and legal entity investment committees. |
Key risks are assessed and reported quarterly through a comprehensive ERRM risk dashboard prepared for senior management and the RRC. The
risk dashboard communicates alignment of Allstate’s risk profile with risk and return principles while providing a perspective on quarterly risk position. Dashboard discussion promotes active engagement with management and the RRC. Internal controls over key risks are managed and reported to senior management and the Audit Committee of the Company through a semiannual risk control dashboard. Annually, we communicate with both the Allstate Board and the RRC about economic capital and risks related to the strategic plan, operating plan, and incentive compensation programs.
Framework We apply these principles using an integrated ERRM framework that focuses on measurement, transparency and dialogue. Our framework provides a comprehensive view of risks and is used by senior management and business managers to drive strategic and business decisions. We continually validate and improve our ERRM practices by benchmarking and obtaining external perspectives.
Allstate’s risk appetite is integrated with planning through our economic capital framework. Management and the ERRC rely on internal and external perspectives to determine an appropriate level of target economic capital. Internal perspectives include enterprise solvency and volatility measures, stress scenarios, model assumptions, and management judgment. External considerations include NAIC risk-based capital as well as S&P’s, Moody’s, and A.M. Best’s capital adequacy measurement. Our economic capital reflects management’s view of the aggregate level of capital necessary to satisfy stakeholder interests, manage Allstate’s risk profile and maintain financial strength over a multi-year time horizon. The impact of strategic initiatives on enterprise risk is evaluated through the economic capital framework.
The NAIC has adopted the Risk Management and Own Risk and Solvency Assessment Model Act (“ORSA Model Act”), which has been enacted by our insurance subsidiaries’ domiciliary states. The ORSA Model Act requires that insurers maintain a risk management framework and conduct an internal own risk and solvency assessment of the insurer’s material risks in normal and stressed environments. The assessment must be documented in a confidential annual summary report, a copy of which must be made available to regulators as required or upon request.
The enterprise risk appetite is cascaded into individual risk limits which set boundaries on the amount of risk we are willing to accept from one specific risk category before escalating for further management discussion and action. Risk limits are established based upon expected returns, volatility, potential tail losses, and impact on the enterprise portfolio. To effectively operate within risk limits and for risk-return optimization, business units establish risk limits and capital targets specific to their businesses. Allstate’s risk management strategies adapt to changes in business and market environments.
112 www.allstate.com
Enterprise Risk and Return Management 2018 Form 10-K
Process Our shared ERRM framework establishes a basis for transparency and dialogue across the enterprise and for continuous learning by embedding our risk and return management culture of identifying, measuring, managing, monitoring and reporting risks within the organization. Allstate designs business and enterprise strategies that seek to optimize risk-adjusted returns on capital. Risks are managed at both the legal entity and enterprise level. A summary of our process to manage each of our major risk categories follows:
Insurance risk management addresses fluctuations in the timing, frequency, and severity of benefits, expenses, and premiums relative to the return expectations at the time of pricing inclusive of systemic risk, concentration of insurance exposures, policy terms, reinsurance coverage, and claims handling practices. This includes credit risk that arises when an external party fails to meet a contractual obligation such as reinsurance for ceded claims.
Insurance risk exposures include our operating results and financial conditions, claims frequency and severity, catastrophes and severe weather, and mortality and morbidity risk.
Insurance risk exposures are measured and monitored with different approaches including:
| • | Stochastic methods: measures and monitors risks such as natural catastrophes and severe weather. We develop probabilistic estimates of risk based on our exposures, historical observed volatility and/or industry-recognized models in the case of catastrophe risk. |
| • | Scenario analysis: measures and monitors risks and estimated losses due to extreme but plausible insurance-related events such as multiple hurricanes and/or wildfires. Scenarios evaluated include combined multiple event scenarios across risk categories and time periods, considering the effects of macroeconomic conditions. |
Financial risk management addresses the risk of insufficient cash flows to meet corporate or policyholder needs, risk of inadequate aggregate capital or capital within any subsidiary, inability to access capital markets or risk associated with a business counterparty default.
Financial risk exposures include capital resources and liquidity sources and uses.
We actively manage our capital and liquidity levels in light of changing market, economic, and business conditions. Our capital position, capital generation capacity, and targeted risk profile provide strategic and financial flexibility.
We generally assess solvency on a statutory accounting basis, but also consider GAAP volatility. Current enterprise capital, which exceeds economic targeted levels, is based on a combination of statutory surplus and invested assets at the parent holding company level which were $18.15 billion and $1.50 billion, respectively, as of December 31, 2018.
Investment risk management addresses financial loss due to changes in the valuations of assets held in the Allstate investment portfolio. Such losses may be caused by macro developments, such as rising interest rates, widening credit spreads, and falling equity prices, or could be specific to individual investments in the portfolio. These losses can encompass both daily market volatility and permanent impairments of capital due to credit defaults and equity write-downs.
Investment risk exposures include interest rate risk, credit spread risk, equity price risk and foreign currency exchange rate risk.
Investment risk exposures are measured and monitored in a number of ways including:
| • | Sensitivity analysis: measures the impact from a unit change in a market risk input. |
| • | Stochastic and probabilistic estimation of potential losses: combines portfolio risk exposures with historical or recent market volatilities and correlations to assess the potential span of future investment results. |
| • | Scenario analysis: measures material adverse outcomes such as shock scenarios applied to credit, public and private equity markets. Some of the stress scenarios are a combination of multiple scenarios across risk categories and over multiple time periods, considering the effects of macroeconomic conditions. |
Operational risk management addresses loss as a result of the failure of people, processes, systems and culture. Operational risk exposures include human resources, privacy, regulatory compliance, ethics, fraud, system availability, cybersecurity, data quality, disaster recovery and business continuity.
Operational risk is managed at the enterprise and business unit levels, with business units identifying, measuring, monitoring, managing, and reporting these and other operational risks at a more detailed level.
Strategic risk management addresses loss associated with inadequate or flawed business planning or strategy setting, including product mix, mergers or acquisitions and market positioning, and unexpected changes within the market or regulatory environment in which Allstate operates. This includes reputational risk, which is the potential for negative publicity regarding a company’s conduct or business practices to adversely impact its profitability, operations, consumer base, or require costly litigation and other defensive measures.
We manage strategic risk through the Allstate Board and senior management strategy reviews that include a risk and return assessment of our strategic plans and ongoing monitoring of our strategic actions and the external competitive environment. Using the ERRM framework, Allstate designs strategies that seek to optimize risk-adjusted returns on economic capital for risk types including interest rate risk, credit risk to equity investments with idiosyncratic return potential, auto profitability, and growing property exposure.
The Allstate Corporation 113
2018 Form 10-K Application of Critical Accounting Estimates and Other Disclosures
Application of Critical Accounting Estimates
The preparation of financial statements in conformity with GAAP requires management to adopt accounting policies and make estimates and assumptions that affect amounts reported in the consolidated financial statements. The most critical estimates, presented in the order they appear in the Consolidated Statements of Financial Position, include those used in determining:
| • | Fair value of financial assets |
| • | Impairment of fixed income securities |
| • | Deferred policy acquisition costs amortization |
| • | Evaluation of goodwill for impairment |
| • | Reserve for property and casualty insurance claims and claims expense estimation |
| • | Reserve for life-contingent contract benefits estimation |
In making these determinations, management makes subjective and complex judgments that frequently require estimates about matters that are inherently uncertain. Many of these policies, estimates and related judgments are common in the insurance and financial services industries; others are specific to our businesses and operations. It is reasonably likely that changes in these estimates could occur from period to period and result in a material impact on our consolidated financial statements.
A summary of each of these critical accounting estimates follows. For a more detailed discussion of the effect of these estimates on our consolidated financial statements, and the judgments and assumptions related to these estimates, see the referenced sections of this document. For a more detailed summary of our significant accounting policies, see the notes to the consolidated financial statements.
Fair value of financial assets Fair value is defined as the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date. We are responsible for the determination of fair value of financial assets and the supporting assumptions and methodologies. We use independent third-party valuation service providers, broker quotes and internal pricing methods to determine fair values. We obtain or calculate only one single quote or price for each financial instrument.
Valuation service providers typically obtain data about market transactions and other key valuation model inputs from multiple sources and, through the use of proprietary models, produce valuation information in the form of a single fair value for individual fixed income and other securities for which a fair value has been requested under the terms of our agreements. The inputs used by the valuation service providers include, but are not limited to, market prices from recently completed transactions and transactions of comparable securities, interest rate yield curves, credit spreads, liquidity spreads, currency rates, and
other information, as applicable. Credit and liquidity spreads are typically implied from completed transactions and transactions of comparable securities. Valuation service providers also use proprietary discounted cash flow models that are widely accepted in the financial services industry and similar to those used by other market participants to value the same financial instruments. The valuation models take into account, among other things, market observable information as of the measurement date, as described above, as well as the specific attributes of the security being valued including its term, interest rate, credit rating, industry sector, and where applicable, collateral quality and other issue or issuer specific information. Executing valuation models effectively requires seasoned professional judgment and experience. For certain equity securities, valuation service providers provide market quotations for completed transactions on the measurement date. In cases where market transactions or other market observable data is limited, the extent to which judgment is applied varies inversely with the availability of market observable information.
For certain of our financial assets measured at fair value, where our valuation service providers cannot provide fair value determinations, we obtain a single non-binding price quote from a broker familiar with the security who, similar to our valuation service providers, may consider transactions or activity in similar securities among other information. The brokers providing price quotes are generally from the brokerage divisions of financial institutions with market making, underwriting and distribution expertise regarding the security subject to valuation.
The fair value of certain financial assets, including privately placed corporate fixed income securities and free-standing derivatives, for which our valuation service providers or brokers do not provide fair value determinations, is developed using valuation methods and models widely accepted in the financial services industry. Our internal pricing methods are primarily based on models using discounted cash flow methodologies that develop a single best estimate of fair value. Our models generally incorporate inputs that we believe are representative of inputs other market participants would use to determine fair value of the same instruments, including yield curves, quoted market prices of comparable securities or instruments, published credit spreads, and other applicable market data as well as instrument-specific characteristics that include, but are not limited to, coupon rates, expected cash flows, sector of the issuer, and call provisions. Because judgment is required in developing the fair values of these financial assets, they may differ from the amount actually received to sell an asset in an orderly transaction between market participants at the measurement date. Moreover, the use of different valuation assumptions may have a material effect on the financial assets’ fair values.
For most of our financial assets measured at fair value, all significant inputs are based on or corroborated by market observable data, and
114 www.allstate.com
Application of Critical Accounting Estimates and Other Disclosures 2018 Form 10-K
significant management judgment does not affect the periodic determination of fair value. The determination of fair value using discounted cash flow models involves management judgment when significant model inputs are not based on or corroborated by market observable data. However, where market observable data is available, it takes precedence, and as a result, no range of reasonably likely inputs exists from which the basis of a sensitivity analysis could be constructed.
We gain assurance that our financial assets are appropriately valued through the execution of various processes and controls designed to ensure the overall reasonableness and consistent application of valuation methodologies, including inputs and assumptions, and compliance with accounting standards. For fair values received from third parties or internally estimated, our processes and controls are designed to ensure that the valuation methodologies are appropriate and consistently applied, the inputs and assumptions are reasonable and consistent with the objective of determining fair value, and the fair values are accurately recorded. For example, on a continuing basis, we assess the reasonableness of individual fair values that have stale security prices or that exceed certain thresholds as compared to previous fair values received from valuation service providers or brokers or derived from internal models. We perform procedures to understand and assess the methodologies, processes and controls of valuation service providers. In addition, we may validate the reasonableness of fair values by comparing information obtained from
valuation service providers or brokers to other third party valuation sources for selected securities. We perform ongoing price validation procedures such as back-testing of actual sales, which corroborate the various inputs used in internal models to market observable data. When fair value determinations are expected to be more variable, we validate them through reviews by members of management who have relevant expertise and who are independent of those charged with executing investment transactions.
We also perform an analysis to determine whether there has been a significant decrease in the volume and level of activity for the asset when compared to normal market activity, and if so, whether transactions may not be orderly. Among the indicators we consider in determining whether a significant decrease in the volume and level of market activity for a specific asset has occurred include the level of new issuances in the primary market, trading volume in the secondary market, level of credit spreads over historical levels, bid-ask spread, and price consensuses among market participants and sources. If evidence indicates that prices are based on transactions that are not orderly, we place little, if any, weight on the transaction price and will estimate fair value using an internal model. As of December 31, 2018 and 2017, we did not adjust fair values provided by our valuation service providers or brokers or substitute them with an internal model for such securities.
| Fixed income, equity securities and short-term investments by source of fair value determination | |||||||
| December 31, 2018 | |||||||
| ($ in millions) | Fair value | Percent to total | |||||
| Fair value based on internal sources | $ | 3,138 | 4.8 | % | |||
| Fair value based on external sources (1) | 62,095 | 95.2 | |||||
| Total | $ | 65,233 | 100.0 | % |
| (1) | Includes $379 million that are valued using broker quotes and $268 million that are valued using quoted prices or quoted net asset values from deal sponsors. |
For additional detail on fair value measurements, see Note 6 of the consolidated financial statements.
Impairment of fixed income securities For fixed income securities classified as available-for-sale, the difference between fair value and amortized cost, net of certain other items and deferred income taxes (as disclosed in Note 5 of the consolidated financial statements), is reported as a component of AOCI on the Consolidated Statements of Financial Position and is not reflected in the operating results of any period until reclassified to net income upon the consummation of a transaction with an unrelated third party or when a write-down is recorded due to an other-than-temporary decline in fair value. We have a comprehensive portfolio monitoring process to identify and evaluate each fixed income security whose carrying value may be other-than-temporarily impaired.
For each fixed income security in an unrealized loss position, we assess whether management with the appropriate authority has made the decision to sell or
whether it is more likely than not we will be required to sell the security before recovery of the amortized cost basis for reasons such as liquidity, contractual or regulatory purposes. If a security meets either of these criteria, the security’s decline in fair value is considered other than temporary and is recorded in earnings.
If we have not made the decision to sell the fixed income security and it is not more likely than not we will be required to sell the fixed income security before recovery of its amortized cost basis, we evaluate whether we expect to receive cash flows sufficient to recover the entire amortized cost basis of the security. We use our best estimate of future cash flows expected to be collected from the fixed income security, discounted at the security’s original or current effective rate, as appropriate, to calculate a recovery value and determine whether a credit loss exists. The determination of cash flow estimates is inherently subjective and methodologies may vary depending on facts and circumstances specific to the security. All reasonably available information relevant to the
The Allstate Corporation 115
2018 Form 10-K Application of Critical Accounting Estimates and Other Disclosures
collectability of the security, including past events, current conditions, and reasonable and supportable assumptions and forecasts, is considered when developing the estimate of cash flows expected to be collected. That information generally includes, but is not limited to, the remaining payment terms of the security, prepayment speeds, foreign exchange rates, the financial condition and future earnings potential of the issue or issuer, expected defaults, expected recoveries, the value of underlying collateral, vintage, geographic concentration, available reserves or escrows, current subordination levels, third party guarantees and other credit enhancements. Other information, such as industry analyst reports and forecasts, sector credit ratings, financial condition of the bond insurer for insured fixed income securities, and other market data relevant to the realizability of contractual cash flows, may also be considered. The estimated fair value of collateral will be used to estimate recovery value if we determine that the security is dependent on the liquidation of collateral for ultimate settlement. If the estimated recovery value is less than the amortized cost of the security, a credit loss exists and an other-than-temporary impairment for the difference between the estimated recovery value and amortized cost is recorded in earnings. The portion of the unrealized loss related to factors other than credit remains classified in AOCI. If we determine that the fixed income security does not have sufficient cash flow or other information to estimate a recovery value for the security, we may conclude that the entire decline in fair value is deemed to be credit related and the loss is recorded in earnings.
Once assumptions and estimates are made, any number of changes in facts and circumstances could cause us to subsequently determine that a fixed income security is other-than-temporarily impaired, including: 1) general economic conditions that are worse than previously forecast or that have a greater adverse effect on a particular issuer or industry sector than originally estimated; 2) changes in the facts and circumstances related to a particular issue or issuer’s ability to meet all of its contractual obligations; and 3) changes in facts and circumstances that result in management’s decision to sell or result in our assessment that it is more likely than not we will be required to sell before recovery of the amortized cost basis. Changes in assumptions, facts and circumstances could result in additional charges to earnings in future periods to the extent that losses are realized. The charge to earnings, while potentially significant to net income, would not have a significant effect on shareholders’ equity, since our fixed income securities are designated as available-for-sale and carried at fair value and as a result, any related unrealized loss, net of deferred income taxes and related DAC, deferred sales inducement costs and reserves for life-contingent contract benefits, would already be reflected as a component of AOCI in shareholders’ equity.
The determination of the amount of other-than-temporary impairment is an inherently subjective process based on periodic evaluations of the factors described above. Such evaluations and assessments
are revised as conditions change and new information becomes available. We update our evaluations regularly and reflect changes in other-than-temporary impairments in our results of operations as such evaluations are revised. The use of different methodologies and assumptions in the determination of the amount of other-than-temporary impairments may have a material effect on the amounts recognized and presented within the consolidated financial statements.
For additional detail on investment impairments, see Note 5 of the consolidated financial statements.
Deferred policy acquisition costs amortization We incur significant costs in connection with acquiring insurance policies and investment contracts. In accordance with GAAP, costs that are related directly to the successful acquisition of new or renewal insurance policies and investment contracts are deferred and recorded as an asset on the Consolidated Statements of Financial Position.
DAC related to property and casualty contracts is amortized into income as premiums are earned, typically over periods of six or twelve months for personal lines policies or generally one to five years for protection plans and other contracts (primarily related to finance and insurance products).
DAC related to traditional life and voluntary accident and health insurance is amortized over the premium paying period of the related policies in proportion to the estimated revenues on such business. Significant assumptions relating to estimated premiums, investment returns, as well as mortality, persistency and expenses to administer the business are established at the time the policy is issued and are generally not revised during the life of the policy. The assumptions for determining the timing and amount of DAC amortization are consistent with the assumptions used to calculate the reserve for life-contingent contract benefits. Any deviations from projected business in force resulting from actual policy terminations differing from expected levels and any estimated premium deficiencies may result in a change to the rate of amortization in the period such events occur. Generally, the amortization periods for these policies approximate the estimated lives of the policies. The recovery of DAC is dependent upon the future profitability of the business. We periodically review the adequacy of reserves and recoverability of DAC for these policies using actual experience and current assumptions. Prior to fourth quarter 2017, we evaluated our traditional life insurance products and immediate annuities with life contingencies on an aggregate basis. In conjunction with the segment changes that occurred in the fourth quarter of 2017, traditional life insurance products, immediate annuities with life contingencies, and voluntary accident and health insurance products are reviewed individually. In the event actual experience and current assumptions are adverse compared to the original assumptions and a premium deficiency is determined to exist, any remaining unamortized DAC balance must be expensed to the extent not recoverable and a premium deficiency reserve may be required if the remaining
116 www.allstate.com
Application of Critical Accounting Estimates and Other Disclosures 2018 Form 10-K
DAC balance is insufficient to absorb the deficiency. In 2018, 2017 and 2016, our reviews concluded that no premium deficiency adjustments were necessary. For additional detail on reserve adequacy, see the Reserve for life-contingent contract benefits estimation section.
DAC related to interest-sensitive life insurance is amortized in proportion to the incidence of the total present value of gross profits, which includes both actual historical gross profits (“AGP”) and estimated future gross profits (“EGP”) expected to be earned over the estimated lives of the contracts. The amortization is net of interest on the prior period DAC balance using rates established at the inception of the contracts. Actual amortization periods generally range from 15-30 years; however, incorporating estimates of the rate of customer surrenders, partial withdrawals and deaths generally results in the majority of the DAC being amortized during the surrender charge period, which is typically 10-20 years for interest-sensitive life. The rate of DAC amortization is reestimated and adjusted by a cumulative charge or credit to income when there is a difference between the incidence of actual versus expected gross profits in a reporting period or when there is a change in total EGP.
AGP and EGP primarily consist of the following components: contract charges for the cost of insurance less mortality costs and other benefits (benefit margin); investment income and realized capital gains and losses less interest credited (investment margin); and surrender and other contract charges less maintenance expenses (expense margin). The principal assumptions for determining the amount of EGP are mortality, persistency, expenses, investment returns, including capital gains and losses on assets supporting contract liabilities, interest crediting rates to contractholders, and the effects of any hedges, and these assumptions are reasonably likely to have the greatest impact on the amount of DAC amortization. Changes in these assumptions can be offsetting and we are unable to reasonably predict their future movements or offsetting impacts over time.
Each reporting period, DAC amortization is recognized in proportion to AGP for that period adjusted for interest on the prior period DAC balance.
This amortization process includes an assessment of AGP compared to EGP, the actual amount of business remaining in force and realized capital gains and losses on investments supporting the product liability. The impact of realized capital gains and losses on amortization of DAC depends upon which product liability is supported by the assets that give rise to the gain or loss. If the AGP is greater than EGP in the period, but the total EGP is unchanged, the amount of DAC amortization will generally increase, resulting in a current period decrease to earnings. The opposite result generally occurs when the AGP is less than the EGP in the period, but the total EGP is unchanged. However, when DAC amortization or a component of gross profits for a quarterly period is potentially negative (which would result in an increase of the DAC balance) as a result of negative AGP, the specific facts and circumstances surrounding the potential negative amortization are considered to determine whether it is appropriate for recognition in the consolidated financial statements. Negative amortization is only recorded when the increased DAC balance is determined to be recoverable based on facts and circumstances. For products whose supporting investments are exposed to capital losses in excess of our expectations which may cause periodic AGP to become temporarily negative, EGP and AGP utilized in DAC amortization may be modified to exclude the excess capital losses.
Annually, we review and update the assumptions underlying the projections of EGP, including mortality, persistency, expenses, investment returns, comprising investment income and realized capital gains and losses, interest crediting rates and the effect of any hedges, using our experience and industry experience. At each reporting period, we assess whether any revisions to assumptions used to determine DAC amortization are required. These reviews and updates may result in amortization acceleration or deceleration, which are referred to as “DAC unlocking”. If the update of assumptions causes total EGP to increase, the rate of DAC amortization will generally decrease, resulting in a current period increase to earnings. A decrease to earnings generally occurs when the assumption update causes the total EGP to decrease.
| Effect on DAC amortization of changes in assumptions relating to gross profit components | ||||||||||||
| For the years ended December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Investment margin | $ | 10 | $ | 12 | $ | (1 | ) | |||||
| Benefit margin | (11 | ) | (23 | ) | 1 | |||||||
| Expense margin | 2 | (2 | ) | (2 | ) | |||||||
| Net acceleration (deceleration) | $ | 1 | $ | (13 | ) | $ | (2 | ) |
In 2018, DAC amortization acceleration for changes in the investment margin component of EGP related to interest-sensitive life insurance and was due to lower projected investment returns. The deceleration related to benefit margin primarily related to interest-sensitive life insurance and was due to a decrease in projected mortality.
In 2017, DAC amortization acceleration for changes in the investment margin component of EGP related to interest-sensitive life insurance and was due to continued low interest rates and lower projected investment returns. The deceleration related to benefit margin primarily related to interest-sensitive life insurance and was due to a decrease in projected mortality.
The Allstate Corporation 117
2018 Form 10-K Application of Critical Accounting Estimates and Other Disclosures
In 2016, DAC amortization deceleration for changes in the investment margin component of EGP related to interest-sensitive life insurance and was due to increased projected investment margins from a favorable asset portfolio mix. The acceleration related to benefit margin primarily related to interest-sensitive life insurance and was due to lower than expected persistency on non-guaranteed products. The expense margin deceleration related primarily to
variable life insurance and was due to a decrease in projected expenses.
The following table displays the sensitivity of reasonably likely changes in assumptions included in the gross profit components of investment margin or benefit margin to amortization of the DAC balance as of December 31, 2018.
| ($ in millions) | Increase/(reduction) | |||
| Increase in future investment margins of 25 basis points | $ | 57 | ||
| Decrease in future investment margins of 25 basis points | (63) | |||
| Decrease in future life mortality by 1% | $ | 15 | ||
| Increase in future life mortality by 1% | (16) |
Any potential changes in assumptions discussed above are measured without consideration of correlation among assumptions. Therefore, it would be inappropriate to add them together in an attempt to estimate overall variability in amortization.
For additional detail related to DAC, see the Allstate Life Segment section of the MD&A.
Evaluation of goodwill for impairment Goodwill represents the excess of amounts paid for acquiring businesses over the fair value of the net assets acquired, less any impairment of goodwill recognized. Our goodwill reporting units are equivalent to our reportable segments: Allstate Protection, Service Businesses, Allstate Life and Allstate Benefits to which goodwill has been assigned.
| Goodwill by reporting unit | ||||||||
| As of December 31, | ||||||||
| ($ in millions) | 2018 | 2017 | ||||||
| Allstate Protection | $ | 810 | $ | 810 | ||||
| Service Businesses | 1,449 | 1,100 | ||||||
| Allstate Life | 175 | 175 | ||||||
| Allstate Benefits | 96 | 96 | ||||||
| Total | $ | 2,530 | $ | 2,181 |
Goodwill is recognized when acquired and allocated to reporting units based on which unit is expected to benefit from the synergies of the business combination. Goodwill is not amortized but is tested for impairment at least annually. We perform our annual goodwill impairment testing during the fourth quarter of each year based upon data as of the close of the third quarter. We also review goodwill for impairment whenever events or changes in circumstances, such as deteriorating or adverse market conditions, indicate that it is more likely than not that the carrying amount of goodwill may exceed its implied fair value. Goodwill impairment is measured and recognized as the amount by which a reporting unit’s carrying value, including goodwill, exceeds its fair value, not to exceed the carrying amount of goodwill allocated to the reporting unit. The goodwill impairment analysis is performed at the reporting unit level which is equal to our reportable segments. The fair value of our goodwill reporting units exceeded their carrying values.
Upon acquisition, the purchase price of the acquired business is assumed to be its fair value. Subsequently, we estimate the fair value of our businesses in each goodwill reporting unit, utilizing a combination of widely accepted valuation techniques including a stock price and market capitalization analysis, discounted cash flow (“DCF”) calculations and an estimate of a business’s fair value using market to book multiples derived from peer company analysis. The stock price and market capitalization analysis takes into consideration the quoted market price of our outstanding common stock and includes a control premium, derived from relevant historical acquisition activity, in determining the estimated fair value of the consolidated entity before allocating that fair value to individual reporting units. The DCF analysis utilizes long term assumptions for revenues, investment income, benefits, claims, other operating expenses and income taxes to produce projections of both income and cash flows available for dividends that are present valued using weighted average cost of capital. Market to book multiples represent the mean market to book multiple for selected peer companies with operations similar to our goodwill reporting units to which the multiple is applied. The outputs from these methods are weighted based on the nature of the business and the relative amount of market observable assumptions supporting the estimates. The computed values are then weighted to reflect the fair value estimate based on the specific attributes of each goodwill reporting unit.
Estimating the fair value of reporting units is a subjective process that involves the use of significant estimates by management. Changes in market inputs or other events impacting the fair value of these businesses, including discount rates, operating results, investment returns, strategies and growth rate assumptions or increases in the level of equity required to support these businesses, could result in goodwill impairments, resulting in a charge to income. Most of our goodwill reporting units are comprised of a combination of legacy and acquired businesses and as a result have substantial internally generated and unrecognized intangibles and fair values that significantly exceed their carrying values. Our Service Businesses goodwill reporting unit is more heavily comprised of newly acquired businesses and as
118 www.allstate.com
Application of Critical Accounting Estimates and Other Disclosures 2018 Form 10-K
a result does not have a significant excess of fair value over its carrying value. Therefore, this reporting unit may be more susceptible to goodwill impairment based on changes to growth or margin assumptions.
The most significant assumptions utilized in the determination of the estimated fair value of the Service Businesses reporting unit are the earnings growth rate and discount rate. The growth rate utilized in our fair value estimates is consistent with our plans to grow these businesses rapidly over the near-term with more moderated growth rates in later years.
The discount rate, which is consistent with the weighted average cost of capital expected by a market participant, is based upon industry specific required rates of return, including consideration of both debt and equity components of the capital structure. Our discount rate may be impacted by changes in the risk free rate, cost of debt, equity risk premium and entity specific risks.
Changes in our growth assumptions, including the risk of loss of key customers, or adverse changes in the discount rates could result in a decline in fair value and result in a goodwill impairment charge.
Reserve for property and casualty insurance claims and claims expense estimation Reserves are established to provide for the estimated costs of paying claims and claims expenses under insurance policies we have issued. Underwriting results are significantly influenced by estimates of property and casualty insurance claims and claims expense reserves. These reserves are an estimate of amounts necessary to settle all outstanding claims, including IBNR, as of the financial statement date.
Characteristics of reserves Reserves are established independently of business segment management for each business segment and line of business based on estimates of the ultimate cost to settle claims, less losses that have been paid. The significant lines of business are auto, homeowners, and other personal lines for Allstate Protection, and asbestos, environmental, and other discontinued lines for Discontinued Lines and Coverages. Allstate Protection’s claims are typically reported promptly with relatively little reporting lag between the date of occurrence and the date the loss is reported. Auto and homeowners liability losses generally take an average of about two years to settle, while auto physical damage, homeowners property and other personal lines have an average settlement time of less than one year. Discontinued Lines and Coverages involve long-tail losses, such as those related to asbestos and environmental claims, which often involve substantial reporting lags and extended times to settle.
Reserves are the difference between the estimated ultimate cost of losses incurred and the amount of paid losses as of the reporting date. Reserves are estimated for both reported and unreported claims, and include estimates of all expenses associated with processing and settling all incurred claims. We update most of our reserve estimates quarterly and as new information becomes available or as events emerge that may affect the
resolution of unsettled claims. Changes in prior reserve estimates (reserve reestimates), which may be material, are determined by comparing updated estimates of ultimate losses to prior estimates, with the differences recorded as property and casualty insurance claims and claims expense in the Consolidated Statements of Operations in the period such changes are determined. Estimating the ultimate cost of claims and claims expenses is an inherently uncertain and complex process involving a high degree of judgment and is subject to the evaluation of numerous variables.
The actuarial methods used to develop reserve estimates Reserve estimates are derived by using several different actuarial estimation methods that are variations on one primary actuarial technique. The actuarial technique is known as a “chain ladder” estimation process in which historical loss patterns are applied to actual paid losses and reported losses (paid losses plus individual case reserves established by claim adjusters) for an accident year or a report year to create an estimate of how losses are likely to develop over time. An accident year refers to classifying claims based on the year in which the claims occurred. A report year refers to classifying claims based on the year in which the claims are reported. Both classifications are used to prepare estimates of required reserves for payments to be made in the future. The key assumptions affecting our reserve estimates comprise data elements including claim counts, paid losses, case reserves, and development factors calculated with this data.
See Discontinued and Lines and Coverages reserve estimates section for specific disclosures of industry and actuarial best practices for this segment.
In the chain ladder estimation technique, a ratio (development factor) is calculated which compares current period results to results in the prior period for each accident year. A three-year or two-year average development factor, based on historical results, is usually multiplied by the current period experience to estimate the development of losses of each accident year into the next time period. The development factors for the future time periods for each accident year are compounded over the remaining future periods to calculate an estimate of ultimate losses for each accident year. The implicit assumption of this technique is that an average of historical development factors is predictive of future loss development, as the significant size of our experience database achieves a high degree of statistical credibility in actuarial projections of this type. The effects of inflation are implicitly considered in the reserving process, the implicit assumption being that a multi-year average development factor includes an adequate provision. The development factor estimation methodology may require modification when data changes due to changing claim reporting practices, changing claim settlement patterns, external regulatory or financial influences, or contractual coverage changes. In these situations, actuarial estimation techniques are applied to appropriately modify the “chain ladder” assumptions. These actuarial techniques are
The Allstate Corporation 119
2018 Form 10-K Application of Critical Accounting Estimates and Other Disclosures
necessary to analyze the effects of changing loss data to develop modified development factor selections. The actuarial estimation techniques include exclusion of unusual losses or aberrations and adjustment of historical data to present conditions. Actuarially modified patterns of development are calculated with the adjusted historical data. Actuarial judgment is then applied to make appropriate development factor assumptions needed to develop a best estimate of gross ultimate losses. These developments are discussed further in the Allstate brand loss ratio disclosures in the Allstate Protection Segment section of the MD&A.
How reserve estimates are established and updated Reserve estimates are developed at a very detailed level, and the results of these numerous micro-level best estimates are aggregated to form a consolidated reserve estimate. For example, over one thousand actuarial estimates of the types described above are prepared each quarter to estimate losses for each line of insurance, major components of losses (such as coverages and perils), major states or groups of states and for reported losses and IBNR. The actuarial methods described above are used to analyze the settlement patterns of claims by determining the development factors for specific data elements that are necessary components of a reserve estimation process. Development factors are calculated quarterly and periodically throughout the year for data elements such as claim counts reported and settled, paid losses, and paid losses combined with case reserves. The calculation of development factors from changes in these data elements also impacts claim severity trends. The historical development patterns for these data elements are used as the assumptions to calculate reserve estimates.
Often, several different estimates are prepared for each detailed component, incorporating alternative analyses of changing claim settlement patterns and other influences on losses, from which we select our best estimate for each component, occasionally incorporating additional analyses and actuarial judgment, as described above. These micro-level estimates are not based on a single set of assumptions. Actuarial judgments that may be applied to these components of certain micro-level estimates generally do not have a material impact on the consolidated level of reserves. Moreover, this detailed
micro-level process does not permit or result in a compilation of a company-wide roll up to generate a range of needed loss reserves that would be meaningful. Based on our review of these estimates, our best estimate of required reserves for each state/line/coverage component is recorded for each accident year, and the required reserves for each component are summed to create the reserve balance carried on our Consolidated Statements of Financial Position.
Reserves are reestimated quarterly and periodically throughout the year, by combining historical results with current actual results to calculate new development factors. This process continuously incorporates the historic and latest actual trends, and other underlying changes in the data elements used to calculate reserve estimates. New development factors are likely to differ from previous development factors used in prior reserve estimates because actual results (claims reported or settled, losses paid, or changes to case reserves) occur differently than the implied assumptions contained in the previous development factor calculations. If claims reported, paid losses, or case reserve changes are greater or less than the levels estimated by previous development factors, reserve reestimates increase or decrease. When actual development of these data elements is different than the historical development pattern used in a prior period reserve estimate, a new reserve is determined. The difference between indicated reserves based on new reserve estimates and recorded reserves (the previous estimate) is the amount of reserve reestimate and is recognized as an increase or decrease in claims and claims expense in the Consolidated Statements of Operations. Total net reserve reestimates, after-tax, impact on net income applicable to common shareholders were 9.6% favorable in 2018, 10.6% favorable in 2017 and 0.6% favorable in 2016. The 3-year average of net reserve reestimates as a percentage of total reserves was a favorable 1.9% for Allstate Protection, an unfavorable 6.8% for Discontinued Lines and Coverages and an unfavorable 2.5% for Service Businesses, each of these results being consistent within a reasonable actuarial tolerance for the respective businesses. A more detailed discussion of reserve reestimates is presented in the Claims and Claims Expense Reserves section of the MD&A.
120 www.allstate.com
Application of Critical Accounting Estimates and Other Disclosures 2018 Form 10-K
| Net claims and claims expense reserves by segment and line of business | ||||||||||||
| As of December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Allstate Protection | ||||||||||||
| Auto | $ | 14,378 | $ | 14,051 | $ | 13,530 | ||||||
| Homeowners | 2,157 | 2,205 | 1,989 | |||||||||
| Other lines | 2,290 | 2,105 | 2,078 | |||||||||
| Total Allstate Protection | 18,825 | 18,361 | 17,597 | |||||||||
| Discontinued Lines and Coverages | ||||||||||||
| Asbestos | 866 | 884 | 912 | |||||||||
| Environmental | 170 | 166 | 179 | |||||||||
| Other discontinued lines | 355 | 357 | 354 | |||||||||
| Total Discontinued Lines and Coverages | 1,391 | 1,407 | 1,445 | |||||||||
| Total Service Businesses | 52 | 86 | 24 | |||||||||
| Total net claims and claims expense reserves | $ | 20,268 | $ | 19,854 | $ | 19,066 |
Allstate Protection reserve estimate
Factors affecting reserve estimates Reserve estimates are developed based on the processes and historical development trends described above. These estimates are considered in conjunction with known facts and interpretations of circumstances and factors including our experience with similar cases, actual claims paid, historical trends involving claim payment patterns and pending levels of unpaid claims, loss management programs, product mix and contractual terms, changes in law and regulation, judicial decisions, and economic conditions. When we experience changes of the type previously mentioned, we may need to apply actuarial judgment in the determination and selection of development factors considered more reflective of the new trends, such as combining shorter or longer periods of historical results with current actual results to produce development factors based on two-year, three-year, or longer development periods to reestimate our reserves. For example, if a legal change is expected to have a significant impact on the development of claim severity for a coverage which is part of a particular line of insurance in a specific state, actuarial judgment is applied to determine appropriate development factors that will most accurately reflect the expected impact on that specific estimate. Another example would be when a change in economic conditions is expected to affect the cost of repairs to damaged autos or property for a particular line, coverage, or state, actuarial judgment is applied to determine appropriate development factors to use in the reserve estimate that will most accurately reflect the expected impacts on severity development.
As claims are reported, for certain liability claims of sufficient size and complexity, the field adjusting staff establishes case reserve estimates of ultimate cost, based on their assessment of facts and circumstances related to each individual claim. For other claims which occur in large volumes and settle in a relatively short time frame, it is not practical or efficient to set case reserves for each claim, and a statistical case reserve is set for these claims based on estimation techniques described above. In the normal course of business, we may also supplement our claims processes by utilizing third party adjusters, appraisers, engineers, inspectors, and other professionals and information sources to
assess and settle catastrophe and non-catastrophe related claims.
Historically, the case reserves set by the field adjusting staff have not proven to be an entirely accurate estimate of the ultimate cost of claims. To provide for this, a development reserve is estimated using the processes described above, and allocated to pending claims as a supplement to case reserves. Typically, the case, including statistical case, and supplemental development reserves comprise about 90% of total reserves.
Another major component of reserves is IBNR, which comprises about 10% of total reserves. IBNR can be a small percentage of reserves for relatively short-term claims, such as auto physical damage claims, or a large percentage of reserves for claims that have uncertain payout requirements over a long period of time, such as auto injury and MCCA claims. All major components of reserves are affected by changes in claim frequency as well as claim severity.
Generally, the initial reserves for a new accident year are established based on actual claim frequency and severity assumptions for different business segments, lines and coverages based on historical relationships to relevant inflation indicators. Reserves for prior accident years are statistically determined using processes described above. Changes in auto claim frequency may result from changes in mix of business, the rate of distracted driving, miles driven or other macroeconomic factors. Changes in auto current year claim severity are generally influenced by inflation in the medical and auto repair sectors of the economy and the effectiveness and efficiency of our claim practices. We mitigate these effects through various loss management programs. Injury claims are affected largely by medical cost inflation while physical damage claims are affected largely by auto repair cost inflation and used car prices. For auto physical damage coverages, we monitor our rate of increase in average cost per claim against the auto maintenance, repair, parts and equipment price indices. We believe our claim settlement initiatives, such as improvements to the claim review and settlement process, the use of special investigative units to detect fraud and handle suspect claims, litigation management and defense strategies, as well as various other loss management
The Allstate Corporation 121
2018 Form 10-K Application of Critical Accounting Estimates and Other Disclosures
initiatives underway, contribute to the mitigation of injury and physical damage severity trends.
Changes in homeowners current year claim severity are generally influenced by inflation in the cost of building materials, the cost of construction and property repair services, the cost of replacing home furnishings and other contents, the types of claims that qualify for coverage, deductibles, other economic and environmental factors and the effectiveness and efficiency of our claim practices. We employ various loss management programs to mitigate the effect of these factors.
As loss experience for the current year develops for each type of loss, it is monitored relative to initial assumptions until it is judged to have sufficient statistical credibility. From that point in time and forward, reserves are reestimated using statistical actuarial processes to reflect the impact actual loss trends have on development factors incorporated into the actuarial estimation processes. Statistical credibility is usually achieved by the end of the first calendar year; however, when trends for the current accident year exceed initial assumptions sooner, they are usually determined to be credible, and reserves are increased accordingly.
The very detailed processes for developing reserve estimates, and the lack of a need and existence of a common set of assumptions or development factors, limits aggregate reserve level testing for variability of data elements. However, by applying standard actuarial methods to consolidated historic accident year loss data for major loss types, comprising auto injury losses, auto physical damage losses and homeowner losses, we develop variability analyses consistent with the way we develop reserves by measuring the potential variability of development factors, as described in the section titled “Potential Reserve Estimate Variability” below.
Causes of reserve estimate uncertainty Since reserves are estimates of unpaid portions of claims and claims expenses that have occurred, including IBNR losses, the establishment of appropriate reserves, including reserves for catastrophe losses, requires regular reevaluation and refinement of estimates to determine our ultimate loss estimate.
At each reporting date, the highest degree of uncertainty in estimates for most of our losses from ongoing businesses arise from claims remaining to be settled for the current accident year and the most recent preceding accident year. The greatest degree of uncertainty exists in the current accident year because the current accident year contains the greatest proportion of losses that have not been reported or settled but must be estimated as of the current reporting date. Most of these losses relate to damaged property such as automobiles and homes, and medical care for injuries from accidents. During the first year after the end of an accident year, a large portion of the total losses for that accident year are settled. When accident year losses paid through the end of the first year following the initial accident year are incorporated into updated actuarial estimates, the
trends inherent in the settlement of claims emerge more clearly. Consequently, this is the point in time at which we tend to make our largest reestimates of losses for an accident year. After the second year, the losses that we pay for an accident year typically relate to claims that are more difficult to settle, such as those involving serious injuries or litigation. Private passenger auto insurance provides a good illustration of the uncertainty of future loss estimates: our typical annual percentage payout of reserves remaining at December 31 for an accident year is approximately 45% in the first year after the end of the accident year, 20% in the second year, 15% in the third year, 10% in the fourth year, and the remaining 10% thereafter.
Reserves for catastrophe losses Catastrophe losses are an inherent risk of the property and casualty insurance industry that have contributed, and will continue to contribute, to potentially material year-to-year fluctuations in our results of operations and financial position. We define a “catastrophe” as an event that produces pre-tax losses before reinsurance in excess of $1 million and involves multiple first party policyholders, or a winter weather event that produces a number of claims in excess of a preset, per-event threshold of average claims in a specific area, occurring within a certain amount of time following the event. Catastrophes are caused by various natural events including high winds, winter storms and freezes, tornadoes, hailstorms, wildfires, tropical storms, hurricanes, earthquakes and volcanoes. We are also exposed to man-made catastrophic events, such as certain types of terrorism or industrial accidents. The nature and level of catastrophes in any period cannot be reliably predicted.
The estimation of claims and claims expense reserves for catastrophe losses also comprises estimates of losses from reported claims and IBNR, primarily for damage to property. In general, our estimates for catastrophe reserves are based on claim adjuster inspections and the application of historical loss development factors as described above. However, depending on the nature of the catastrophe, the estimation process can be further complicated. For example, for hurricanes, complications could include the inability of insureds to promptly report losses, limitations placed on claims adjusting staff affecting their ability to inspect losses, determining whether losses are covered by our homeowners policy (generally for damage caused by wind or wind driven rain) or specifically excluded coverage caused by flood, estimating additional living expenses, and assessing the impact of demand surge, exposure to mold damage, and the effects of numerous other considerations, including the timing of a catastrophe in relation to other events, such as at or near the end of a financial reporting period, which can affect the availability of information needed to estimate reserves for that reporting period. In these situations, we may need to adapt our practices to accommodate these circumstances in order to determine a best estimate of our losses from a catastrophe. For example, to complete estimates for certain areas affected by catastrophes not yet inspected by our claims adjusting staff, or where we believed our historical loss
122 www.allstate.com
Application of Critical Accounting Estimates and Other Disclosures 2018 Form 10-K
development factors were not predictive, we rely on analysis of actual claim notices received compared to total PIF, as well as visual, governmental and third party information, including aerial photos using drones and satellites, area observations, and data on wind speed and flood depth to the extent available.
Potential reserve estimate variability The aggregation of numerous micro-level estimates for each business segment, line of insurance, major components of losses (such as coverages and perils), and major states or groups of states for reported losses and IBNR forms the reserve liability recorded in the Consolidated Statements of Financial Position. Because of this detailed approach to developing our reserve estimates, there is not a single set of assumptions that determines our reserve estimates at the consolidated level. Given the numerous micro-level estimates for reported losses and IBNR, management does not believe the processes that we follow will produce a statistically credible or reliable actuarial reserve range that would be meaningful. Reserve estimates, by their very nature, are very complex to determine and subject to significant judgment, and do not represent an exact determination for each outstanding claim. Accordingly, as actual claims, paid losses, and/or case reserve results emerge, our estimate of the ultimate cost to settle will be different than previously estimated.
To develop a statistical indication of potential reserve variability within reasonably likely possible outcomes, an actuarial technique (stochastic modeling) is applied to the countrywide consolidated data elements for paid losses and paid losses combined with case reserves separately for injury losses, auto physical damage losses, and homeowners losses excluding catastrophe losses. Based on the combined historical variability of the development factors calculated for these data elements, an estimate of the standard error or standard deviation around these reserve estimates is calculated within each accident year for the last twelve years for each type of loss. The variability of these reserve estimates within one standard deviation of the mean (a measure of frequency of dispersion often viewed to be an acceptable level of accuracy) is believed by management to represent a reasonable and statistically probable measure of potential variability. Based on our products and coverages, historical experience, the statistical credibility of our extensive data and stochastic modeling of actuarial chain ladder methodologies used to develop reserve estimates, we estimate that the potential variability of our Allstate Protection reserves, excluding reserves for catastrophe losses, within a reasonable probability of other possible outcomes, may be approximately plus or minus 4%, or plus or minus $750 million in net income applicable to common shareholders. A lower level of variability exists for auto injury losses, which comprise approximately 80% of reserves, due to their relatively stable development patterns over a longer duration of time required to settle claims. Other types of losses, such as auto physical damage, homeowners losses and other personal lines losses, which comprise about 20% of reserves, tend to have greater variability but are
settled in a much shorter period of time. Although this evaluation reflects most reasonably likely outcomes, it is possible the final outcome may fall below or above these amounts. Historical variability of reserve estimates is reported in the Claims and Claims Expense Reserves section of the MD&A.
Reserves for Michigan and New Jersey unlimited personal injury protection Claims and claims expense reserves include reserves for Michigan mandatory unlimited personal injury protection coverage to insureds involved in qualifying motor vehicle accidents. The administration of this program is through the MCCA, a state-mandated, non-profit association of which all insurers actively writing automobile coverage in Michigan are members.
The process employed to estimate MCCA covered losses involves a number of activities including the comprehensive review and interpretation of MCCA actuarial reports, other MCCA members’ reports and our personal injury protection loss trends which have increased in severity over time. A significant portion of incurred claim reserves can be attributed to a small number of catastrophic claims and thus a large portion of the recoverable is similarly concentrated. We conduct comprehensive claim file reviews to develop case reserve type estimates of specific claims, which have increased our view of future claim development and longevity of claimants. Each year, we update the actuarial estimate of our ultimate reserves and recoverables. We report our paid and unpaid claims based on MCCA requirements. The MCCA has its own reserving estimates based on its own reserve methodologies, which may not align with our estimations. The MCCA does not provide member companies with its estimate of a company’s claim costs. We continue to update each comprehensive claim file case reserve estimate when there is a significant change in the status of the claimant, or once every three years if there have been no significant changes.
We provide similar personal injury protection coverage in New Jersey for auto policies issued or renewed in New Jersey prior to 1991 that is administered by PLIGA. We use similar actuarial estimating techniques as for the MCCA exposures to estimate loss reserves for unlimited personal injury protection coverage for policies covered by PLIGA. We continue to update our estimates for these claims as the status of claimant’s changes. However, unlimited coverage was no longer offered after 1991, therefore no new claimants are being added.
Reserve estimates are confidential and proprietary and by their nature are very complex to determine and subject to significant judgments. Reserve estimates do not represent an exact determination for each outstanding claim. Claims may be subject to litigation. As actual claims, paid losses and/or case reserve results emerge, our estimate of the ultimate cost to settle may be materially greater or less than previously estimated amounts.
Adequacy of reserve estimates We believe our net claims and claims expense reserves are appropriately
The Allstate Corporation 123
2018 Form 10-K Application of Critical Accounting Estimates and Other Disclosures
established based on available methodologies, facts, technology, laws and regulations. We calculate and record a single best reserve estimate, in conformance with generally accepted actuarial standards and practices, for each line of insurance, its components (coverages and perils) and state, for reported losses and for IBNR losses, and as a result we believe that no other estimate is better than our recorded amount. Due to the uncertainties involved, the ultimate cost of losses may vary materially from recorded amounts, which are based on our best estimates.
Discontinued Lines and Coverages reserve estimates
Characteristics of Discontinued Lines exposure Our exposure to asbestos, environmental and other discontinued lines claims arise principally from assumed reinsurance coverage written during the 1960s through the mid-1980s, including reinsurance on primary insurance written on large U.S. companies, and from direct excess commercial insurance written from 1972 through 1985, including substantial excess general liability coverages on large U.S. companies. Additional exposure stems from direct primary commercial insurance written during the 1960s through the mid-1980s. Asbestos claims relate primarily to bodily injuries asserted by claimants who were exposed to asbestos or products containing asbestos. Environmental claims relate primarily to pollution and related clean-up costs. Other discontinued lines exposures primarily relate to general liability and product liability mass tort claims, such as those for medical devices and other products, workers’ compensation claims and claims for various other coverage exposures other than asbestos and environmental.
In 1986, the general liability policy form used by us and others in the property and casualty industry was amended to introduce an “absolute pollution exclusion,” which excluded coverage for environmental damage claims, and to add an asbestos exclusion. Most general liability policies issued prior to 1987 contain annual aggregate limits for product liability coverage. General liability policies issued in 1987 and thereafter contain annual aggregate limits for product liability coverage and annual aggregate limits for all coverages. Our experience to date is that these policy form changes have limited the extent of our exposure to environmental and asbestos claim risks.
Our exposure to liability for asbestos, environmental and other discontinued lines losses manifests differently depending on whether it arises from assumed reinsurance coverage, direct excess commercial insurance or direct primary commercial insurance. The direct insurance coverage we provided that covered asbestos, environmental and other discontinued lines was substantially “excess” in nature.
Direct excess commercial insurance and reinsurance involve coverage written by us for specific layers of protection above retentions and other insurance plans. The nature of excess coverage and reinsurance provided to other insurers limits our exposure to loss to specific layers of protection in excess of policyholder retention on primary insurance
plans. Our exposure is further limited by the significant reinsurance that we had purchased on our direct excess business.
Our assumed reinsurance business involved writing generally small participations in other insurers’ reinsurance programs. The reinsured losses in which we participate may be a proportion of all eligible losses or eligible losses in excess of defined retentions. The majority of our assumed reinsurance exposure, approximately 85%, is for excess of loss coverage, while the remaining 15% is for pro-rata coverage.
Our direct primary commercial insurance business did not include coverage to large asbestos manufacturers. This business comprises a cross section of policyholders engaged in many diverse business sectors throughout the country.
How reserve estimates are established and updated We conduct an annual review in the third quarter to evaluate and establish asbestos, environmental and other discontinued lines reserves. Changes to reserves are recorded in the reporting period in which they are determined. Using established industry and actuarial best practices and assuming no change in the regulatory or economic environment, this detailed and comprehensive methodology determines asbestos reserves based on assessments of the characteristics of exposure (i.e. claim activity, potential liability, jurisdiction, products versus non-products exposure) presented by individual policyholders, and determines environmental reserves based on assessments of the characteristics of exposure (i.e. environmental damages, respective shares of liability of potentially responsible parties, appropriateness and cost of remediation) to pollution and related clean-up costs. The number and cost of these claims are affected by advertising by trial lawyers seeking asbestos plaintiffs, and entities with asbestos exposure seeking bankruptcy protection as a result of asbestos liabilities, initially causing a delay in the reporting of claims, often followed by an acceleration and an increase in claims and claims expenses as settlements occur.
After evaluating our insureds’ probable liabilities for asbestos and/or environmental claims, we evaluate our insureds’ coverage programs for such claims. We consider our insureds’ total available insurance coverage, including the coverage we issued. We also consider relevant judicial interpretations of policy language and applicable coverage defenses or determinations, if any.
Evaluation of both the insureds’ estimated liabilities and our exposure to the insureds depends heavily on an analysis of the relevant legal issues and litigation environment. This analysis is conducted by our specialized claims adjusting staff and legal counsel. Based on these evaluations, case reserves are established by claims adjusting staff and actuarial analysis is employed to develop an IBNR reserve, which includes estimated potential reserve development and claims that have occurred but have not been reported. As of December 31, 2018 and 2017, IBNR was 50% and
124 www.allstate.com
Application of Critical Accounting Estimates and Other Disclosures 2018 Form 10-K
53%, respectively, of combined net asbestos and environmental reserves.
For both asbestos and environmental reserves, we also evaluate our historical direct net loss and expense paid and incurred experience to assess any emerging trends, fluctuations or characteristics suggested by the aggregate paid and incurred activity.
Other Discontinued Lines and Coverages
Characteristics of other exposures Other mass torts includes direct excess commercial and
reinsurance general liability coverage provided for cumulative injury losses other than asbestos and environmental. Workers’ compensation and commercial and other include run-off from discontinued direct primary, direct excess commercial and reinsurance commercial insurance operations of various coverage exposures other than asbestos and environmental. Reserves are based on considerations similar to those described above, as they relate to the characteristics of specific individual coverage exposures.
| Reserves for other discontinued lines | ||||||||||||
| As of December 31, | ||||||||||||
| ($ in millions) | 2018 | 2017 | 2016 | |||||||||
| Other mass torts | $ | 148 | $ | 150 | $ | 142 | ||||||
| Workers’ compensation | 69 | 73 | 76 | |||||||||
| Commercial and other | 138 | 134 | 136 | |||||||||
| Other discontinued lines | $ | 355 | $ | 357 | $ | 354 |
Potential reserve estimate variability Establishing Discontinued Lines and Coverages net loss reserves for asbestos, environmental and other discontinued lines claims is subject to uncertainties that are much greater than those presented by other types of property and casualty claims. Among the complications are lack of historical data, long reporting delays, uncertainty as to the number and identity of insureds with potential exposure and unresolved legal issues regarding policy coverage; unresolved legal issues regarding the determination, availability and timing of exhaustion of policy limits; plaintiffs’ evolving and expanding theories of liability; availability and collectability of recoveries from reinsurance; retrospectively determined premiums and other contractual agreements; estimates of the extent and timing of any contractual liability; the impact of bankruptcy protection sought by various asbestos producers and other asbestos defendants; and other uncertainties. There are also complex legal issues concerning the interpretation of various insurance policy provisions and whether those losses are covered, or were ever intended to be covered, and could be recoverable through retrospectively determined premium, reinsurance or other contractual agreements. Courts have reached different and sometimes inconsistent conclusions as to when losses are deemed to have occurred and which policies provide coverage; what types of losses are covered; whether there is an insurer obligation to defend; how policy limits are determined; how policy exclusions and conditions are applied and interpreted; and whether clean-up costs represent insured property damage. Our reserves for asbestos and environmental exposures could be affected by tort reform, class action litigation, and other potential legislation and judicial decisions. Environmental exposures could also be affected by a change in the existing federal Superfund law and similar state statutes. There can be no assurance that any reform legislation will be enacted or that any such legislation will provide for a fair, effective and cost-efficient system for settlement of asbestos or environmental claims. We believe these issues are not likely to be resolved in the near future, and the ultimate costs may vary materially from the
amounts currently recorded resulting in material changes in loss reserves. Historical variability of reserve estimates is demonstrated in the Claims and Claims Expense Reserves section of the MD&A.
Adequacy of reserve estimates Management believes its net loss reserves for environmental, asbestos and other discontinued lines exposures are appropriately established based on available facts, technology, laws, regulations, and assessments of other pertinent factors and characteristics of exposure (i.e. claim activity, potential liability, jurisdiction, products versus non-products exposure) presented by individual policyholders, assuming no change in the legal, legislative or economic environment. Due to the uncertainties and factors described above, management believes it is not practicable to develop a meaningful range for any such additional net loss reserves that may be required.
Further discussion of reserve estimates For further discussion of these estimates and quantification of the impact of reserve estimates, reserve reestimates and assumptions, see Notes 8 and 14 of the consolidated financial statements and the Claims and Claims Expense Reserves section of the MD&A.
Reserve for life-contingent contract benefits estimation Due to the long term nature of traditional life insurance, life-contingent immediate annuities and voluntary accident and health insurance products, benefits are payable over many years; accordingly, the reserves are calculated as the present value of future expected benefits to be paid, reduced by the present value of future expected net premiums. Long-term actuarial assumptions of future investment yields, mortality, morbidity, policy terminations and expenses are used when establishing the reserve for life-contingent contract benefits payable under these insurance policies. These assumptions, which for traditional life insurance are applied using the net level premium method, include provisions for adverse deviation and generally vary by characteristics such as type of coverage, year of issue and policy duration. Future investment yield assumptions are determined
The Allstate Corporation 125
2018 Form 10-K Application of Critical Accounting Estimates and Other Disclosures
based upon prevailing investment yields as well as estimated reinvestment yields. Mortality, morbidity and policy termination assumptions are based on our experience and industry experience. Expense assumptions include the estimated effects of inflation and expenses to be incurred beyond the premium-paying period. These assumptions are established at the time the policy is issued, are consistent with assumptions for determining DAC amortization for these policies, and are generally not changed during the policy coverage period. However, if actual experience emerges in a manner that is significantly adverse relative to the original assumptions, adjustments to DAC or reserves may be required resulting in a charge to earnings which could have a material effect on our operating results and financial condition.
We periodically review the adequacy of reserves and recoverability of DAC for these policies using actual experience and current assumptions. In the event actual experience and current assumptions are adverse compared to the original assumptions and a premium deficiency is determined to exist, any remaining unamortized DAC balance must be expensed to the extent not recoverable and the establishment of a premium deficiency reserve may be required.
Prior to fourth quarter 2017, we evaluated our traditional life insurance products and immediate annuities with life contingencies on an aggregate basis. In conjunction with the segment changes that occurred in the fourth quarter of 2017, traditional life insurance products, immediate annuities with life contingencies, and voluntary accident and health insurance are reviewed individually. In 2018, 2017 and 2016, our reviews concluded that no premium deficiency
adjustments were necessary. As of December 31, 2018, traditional life insurance and accident and health insurance both have a substantial sufficiency. As of December 31, 2018, there is marginal sufficiency in the evaluation of immediate annuities with life contingencies which has been adversely impacted primarily by sub-standard structured settlement mortality expectations. The sufficiency represents approximately 4% of applicable reserves for Allstate Annuities as of December 31, 2018. Additional reserves may be required in future periods if the evaluation results in a premium deficiency.
In 2016, we completed a mortality study for our structured settlement annuities with life contingencies. The study indicated that annuitants are living longer and receiving benefits for a longer period than originally estimated due to medical advances and access to medical care. The results of the study were included in the premium deficiency and profits followed by losses evaluations as of December 31, 2016, and no adjustments were recognized.
In 2016, there was a favorable change in the long-term investment yield assumptions due to investment strategy changes to increase performance-based investments and equity securities. The favorable impact of higher long-term investment yield assumptions more than offset the impact of unfavorable mortality assumptions. The investment strategy changes for immediate annuities are discussed further in the Allstate Annuities Segment section of the MD&A.
The following table displays the sensitivity of changes in the future investment yield assumption included in the annuity premium deficiency evaluation to the sufficiency balance as of December 31, 2018.
| ($ in millions) | Increase/(reduction) in sufficiency | Change in sufficiency as a percentage of applicable reserves | ||
| Increase in future investment yields of 25 basis points | $198 | 3% | ||
| Decrease in future investment yields of 25 basis points | $(205) | (3)% |
We also review these policies for circumstances where projected profits would be recognized in early years followed by projected losses in later years. In 2018, 2017 and 2016, our reviews concluded that there were no projected losses following projected profits in each long-term projection.
We will continue to monitor the experience of our traditional life insurance and immediate annuities. We anticipate that mortality, investment and reinvestment yields, and policy terminations are the factors that would be most likely to require premium deficiency adjustments to these reserves or related DAC. Mortality rates and investment and reinvestment yields are the factors that would be most likely to require a profits followed by losses liability accrual.
For further detail on the reserve for life-contingent contract benefits, see Note 9 of the consolidated financial statements.
126 www.allstate.com
2018 Form 10-K
Regulation and Legal Proceedings
We are subject to extensive regulation and we are involved in various legal and regulatory actions, all of which have an effect on specific aspects of our business. For a detailed discussion of the legal and regulatory actions in which we are involved, see Note 14 of the consolidated financial statements.
Pending Accounting Standards
There are several pending accounting standards that we have not implemented because the implementation date has not yet occurred. For a discussion of these pending standards, see Note 2 of the consolidated financial statements.
The effect of implementing certain accounting standards on our financial results and financial condition is often based in part on market conditions at the time of implementation of the standard and other factors we are unable to determine prior to implementation. For this reason, we are sometimes unable to estimate the effect of certain pending accounting standards until the relevant authoritative body finalizes these standards or until we implement them.
Previous: Item 6. Selected Financial Data · Next: Item 7A. Quantitative and Qualitative Disclosures About Market Risk