 filings.tools
A. O. Smith 10-K 2015-12-31
Filed 2016-02-17. 21 sections, 240K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 d104769d10k.htm FORM 10-K
Table of Contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
| x | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
|---|
For the fiscal year ended December 31, 2015
OR
| ¨ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
|---|
For the transition period from to
Commission File Number 1-475
A. O. Smith Corporation
(Exact name of registrant as specified in its charter)
| Delaware | 39-0619790 | |
| (State of Incorporation) | (I.R.S. Employer Identification No.) |
| 11270 West Park Place, Milwaukee, Wisconsin | 53224-9508 | |
| (Address of Principal Executive Office) | (Zip Code) |
(414) 359-4000
Registrant’s telephone number, including area code
Securities registered pursuant to Section 12(b) of the Act:
| Title of Each Class | Shares of Stock Outstanding February 10, 2016 | Name of Each Exchange on Which Registered | ||
| Class A Common Stock (par value $5.00 per share) | 13,121,508 | Not listed | ||
| Common Stock (par value $1.00 per share) | 74,677,900 | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act: None.
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. x Yes ¨ No
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. ¨ Yes x No
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. x Yes ¨ No.
Indicate by check mark whether the registrant has submitted electronically and posted on its corporate Web site, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files). x Yes ¨ No
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K (§229.405 of this chapter) is not contained herein, and will not be contained, to the best of registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. x
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer or a smaller reporting company. See the definitions of “large accelerated filer,” “accelerated filer” and “smaller reporting company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | x | Accelerated filer | ¨ | |||
| Non-accelerated filer | ¨ (Do not check if a smaller reporting company) | Smaller reporting company | ¨ |
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act.) ¨ Yes x No
The aggregate market value of voting stock held by non-affiliates of the registrant was $41,422,906 for Class A Common Stock and $5,322,129,940 for Common Stock as of June 30, 2015.
DOCUMENTS INCORPORATED BY REFERENCE
| 1. | Portions of the company’s definitive Proxy Statement for the 2016 Annual Meeting of Stockholders (to be filed with the Securities and Exchange Commission under Regulation 14A within 120 days after the end of the registrant’s fiscal year and, upon such filing, to be incorporated by reference in Part III). |
|---|
Table of Contents
Table of Contents
A. O. Smith Corporation
Index to Form 10-K
Year Ended December 31, 2015
Table of Contents
PART 1
Item 1. BUSINESS
Our company is comprised of two reporting segments: North America and Rest of World. Our Rest of World segment is primarily comprised of China, Europe and India. Both segments manufacture and market comprehensive lines of residential and commercial gas, gas tankless and electric water heaters. Both segments primarily manufacture and market in their respective regions of the world. Our North America segment also manufactures and globally markets specialty commercial water heating equipment, condensing and non-condensing boilers and water systems tanks. Primarily for Asia, our Rest of World segment also manufactures and markets water treatment products. We also market in-home air purification products in China.
On August 22, 2011, we sold our Electrical Products business (EPC) to Regal Beloit Corporation (RBC) for approximately $760 million in cash and approximately 2.83 million shares of RBC common stock valued at $140.6 million as of that date. Due to the sale, EPC has been reflected as a discontinued operation in the accompanying financial information for all periods presented.
The following table summarizes our sales from continuing operations. This summary and all other information presented in this section should be read in conjunction with the Consolidated Financial Statements and Notes to Consolidated Financial Statements, which appear in Item 8 in this document.
| Years Ended December 31 (dollars in millions) | ||||||||||||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | ||||||||||||||||
| North America | $ | 1,703.0 | $ | 1,621.7 | $ | 1,520.0 | $ | 1,430.8 | $ | 1,289.5 | ||||||||||
| Rest of World | 866.1 | 768.3 | 668.0 | 542.5 | 455.6 | |||||||||||||||
| Inter-segment | (32.6 | ) | (34.0 | ) | (34.2 | ) | (34.0 | ) | (34.6 | ) | ||||||||||
| Total Sales | $ | 2,536.5 | $ | 2,356.0 | $ | 2,153.8 | $ | 1,939.3 | $ | 1,710.5 | ||||||||||
NORTH AMERICA
Sales in our North America segment increased 5.0 percent or $81.3 million in 2015 compared with the prior year. The sales increase in 2015 was the result of price increases in the U.S. and Canada for residential and commercial water heaters and higher volumes of commercial water heaters and condensing commercial boilers in the U.S. Lower volumes of U.S. residential water heaters and lower water heater sales in Canada, primarily due to a decline in the value of the Canadian dollar of approximately thirteen percent versus the U.S. dollar, partially offset these favorable factors. Our Lochinvar brand, which we acquired in August 2011, incrementally added approximately $143 million of sales in 2012 compared to 2011. Approximately 40 percent of Lochinvar-branded sales consist of residential and commercial water heaters while the remaining 60 percent of Lochinvar-branded sales consist primarily of boilers and related parts.
We serve residential and commercial end markets in North America with a broad range of products including:
Water heaters. Our residential and commercial water heaters come in sizes ranging from 2.5 gallon (point-of-use) models to 12,500 gallon products with varying efficiency ranges. We offer electric, natural gas, gas tankless and liquid propane models as well as solar tank units. Our North American residential water heater sales in 2015 were approximately $1.1 billion or 62 percent of North America sales. Typical applications for our water heaters include residences, restaurants, hotels and motels, office buildings, laundries, car washes and small businesses.
Boilers. Our residential and commercial boilers range in size from 40,000 British Thermal Units (BTUs) to 5.0 million BTUs. Our commercial boilers are used primarily in space heating applications for hospitals, schools, hotels and other large commercial buildings.
Other. Our North America segment also manufactures expansion tanks, commercial solar water heating systems, swimming pool and spa heaters, and related products and parts.
A significant portion of the sales in our North America segment is derived from the replacement of existing products.
We are the largest manufacturer and marketer of water heaters in North America, and we have a leading share in both the residential and commercial markets. In the commercial market, we believe our comprehensive product line including boilers
Table of Contents
and our high-efficiency products give us a competitive advantage in this portion of the water heating industry. Our wholesale distribution channel includes more than 1,200 independent wholesale plumbing distributors with more than 4,400 selling locations serving residential and commercial end markets. We also sell our residential water heaters through the retail channel. In this channel, our customers include five of the seven largest national hardware and home center chains, including long-standing exclusive relationships with both Lowe’s and Sears. Our boiler distribution channel is primarily comprised of manufacturer representative firms.
Our Lochinvar brand is one of the leading brands of residential and commercial boilers in the U.S.
Our energy efficient product offerings continue to be a sales driver for our business. Our Cyclone product family and our condensing boilers continue to be an option for commercial customers looking for high efficiency water and space heating with a short payback period through energy savings. We offer residential heat pump, condensing tank-type and tankless water heaters in North America, as well as other higher efficiency water heating solutions to round out our energy efficient product offerings.
We sell our water heating products in highly competitive markets. We compete in each of our targeted market segments based on product design, reliability, quality of products and services, advanced technologies, product performance, maintenance costs and price. Our principal water heating and boiler competitors in North America include Rheem, Bradford White, Rinnai, Aerco and Navien. Numerous other manufacturing companies also compete.
REST OF WORLD
Sales in our Rest of World segment increased 12.7 percent, or $97.8 million, in 2015 compared with the prior year. A 13.7 percent increase in sales in China to $789.2 million was the primary source of the increase. Excluding the impact from the stronger U.S. dollar, China sales increased 16.1 percent in 2015.
We have operated in China for 20 years. In that time, we have been aggressively expanding our presence while building A. O. Smith brand recognition in the Chinese residential and commercial markets. The Chinese water heater market is predominantly comprised of electric wall-hung, solar and gas tankless water heaters. We believe we are one of the leading suppliers of water heaters to the residential market in China, with a broad product offering including electric, gas, gas tankless, heat pump and solar units as well as combi boilers. Primarily for Asia, we also manufacture and market water treatment products. We also market air purification products primarily for the residential market in China.
We sell water heaters in more than 8,000 retail outlets in China, of which over 2,000 exclusively sell our products. Our water treatment products and air purification products are sold in over 5,500 and 1,200 retail outlets in China, respectively. Our online sales continue to grow in China and in 2015 reached $140 million.
In 2008, we established a sales office in India and began importing products specifically designed for India from our China operations. We began manufacturing water heaters in India in 2010. Our sales in India were $15.9 million in 2015 compared with $15.1 million in 2014.
Our primary competitor in China is Haier Appliances, a Chinese company, but we also compete with Midea in the electric water heater and water treatment markets and Rinnai and Noritz in the gas tankless and solar water heater markets. Additionally, we compete with numerous other Chinese private and state-owned water heater and water treatment companies in China. In India, we compete in the water heater and water treatment markets. We compete with Bajaj and MTS-Racold in the water heater market and Eureka Forbes and Kent in the water treatment market.
In addition, we sell water heaters in the European and Middle Eastern markets and water treatment products in Turkey, all of which combined comprised less than seven percent of total Rest of World sales in 2015.
RAW MATERIALS
Raw materials for our manufacturing operations, primarily consisting of steel, are generally available in adequate quantities. A portion of our customers are contractually obligated to accept price changes based on fluctuations in steel prices. There has been volatility in steel costs over the last several years.
Table of Contents
RESEARCH AND DEVELOPMENT
To improve our competitiveness by generating new products and processes, we conduct research and development at our Corporate Technology Center in Milwaukee, Wisconsin, at our Global Engineering Center in Nanjing, China, and at our operating locations. Our total expenditures for research and development in 2015, 2014 and 2013 were $73.7 million, $67.9 million and $57.8 million, respectively.
PATENTS AND TRADEMARKS
We own and use in our businesses various trademarks, trade names, patents, trade secrets and licenses. We do not believe that our business as a whole is materially dependent upon any such trademark, trade name, patent, trade secret or license. However, our trade name is important with respect to our products, particularly in China, India and the U.S.
EMPLOYEES
We employed approximately 13,400 employees as of December 31, 2015, primarily non-union.
BACKLOG
Due to the short-cycle nature of our businesses, none of our operations sustains significant backlogs.
ENVIRONMENTAL LAWS
Our operations are governed by a variety of federal, foreign, state and local laws intended to protect the environment. Compliance with environmental laws has not had and is not expected to have a material effect upon the capital expenditures, earnings, or competitive position of our company. See Item 3.
AVAILABLE INFORMATION
We maintain a website with the address www.aosmith.com. The information contained on our website is not included as a part of, or incorporated by reference into, this Annual Report on Form 10-K. Other than an investor’s own internet access charges, we make available free of charge through our website our Annual Report on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K and amendments to these reports as soon as reasonably practical after we have electronically filed such material with, or furnished such material to, the Securities and Exchange Commission (SEC).
We are committed to sound corporate governance and have documented our corporate governance practices by adopting the A. O. Smith Corporate Governance Guidelines. The Corporate Governance Guidelines, Criteria for Selection of Directors, Financial Code of Ethics, the A. O. Smith Guiding Principles, as well as the charters for the Audit, Personnel and Compensation, Nominating and Governance and the Investment Policy Committees of the Board of Directors and other corporate governance materials, may be viewed on the company’s website. Any waiver of or amendments to the Financial Code of Conduct or the A. O. Smith Guiding Principles also would be posted on this website; to date there have been none. Copies of these documents will be sent to stockholders free of charge upon written request of the corporate secretary at the address shown on the cover page of this Annual Report on Form 10-K.
Table of Contents
Item 1A. RISK FACTORS
You should carefully consider the risk factors set forth below and all other information contained in this Annual Report on Form 10-K, including the documents incorporated by reference, before making an investment decision regarding our common stock. If any of the events contemplated by the following risks actually occurs, then our business, financial condition, or results of operations could be materially adversely affected. As a result, the trading price of our common stock could decline, and you may lose all or part of your investment. The risks and uncertainties below are not the only risks facing our company.
| • | The effects of the global economic downturn could have a material adverse effect on our business |
|---|
The global economy is still showing signs of stress, and could stall or reverse the course of any recovery. If this were to occur it could adversely affect consumer confidence and spending patterns which could result in decreased demand for the products we sell, a delay in purchases, increased price competition, or slower adoption of energy efficient water heaters and boilers which could negatively impact our profitability and cash flows. In addition, a deterioration in current economic conditions, including credit market conditions, could negatively impact our vendors and customers, which could result in an increase in bad debt expense, customer and vendor bankruptcies, interruption or delay in supply of materials, or increased material prices, which could negatively impact our ability to distribute, market and sell our products and our financial condition, results of operations and cash flows.
| • | A portion of our business could be affected by a slowdown in the transition of the Chinese economy to a consumer driven ecomony |
|---|
Our sales growth in China has averaged approximately 19 percent per year over the past three years and we anticipate sales growth of approximately 15 percent in local currency in 2016. We continue to expand capacity for water heating and water treatment products in China to meet local demand. If a slowdown in the transition to a more consumer driven economy or the rate urbanization was to stall, it could adversely affect our financial condition, results of operations and cash flows.
| • | Sales growth of our Lochinvar-branded products could stall resulting in lower than expected revenues and earnings |
|---|
The compound annual growth rate of revenues of our Lochinvar-branded products has been approximately ten percent per year since our acquisition of Lochinvar, largely due to the transition in the boiler industry in the U.S. from lower efficiency, non-condensing boilers to higher efficiency, condensing boilers as well as new product introductions. In 2003, approximately five percent of the boilers sold in the U.S. were condensing boilers and by 2013, the percentage had grown to approximately 40 percent. Our Lochinvar brand is a leader in residential and commercial condensing boilers. We expect the transition to continue, which we believe would result in approximately ten percent sales growth in Lochinvar-branded products in 2016 and annually for the foreseeable future after 2016 in conjunction with new product introductions. If the transition to higher efficiency, condensing boilers stalls as a result of lower energy costs, another recession occurs, or our competitors’ technologies surpass our technology, our growth rate could be lower than expected.
| • | A material loss, cancellation, reduction, or delay in purchases by one or more of our largest customers could harm our business |
|---|
Net sales to our five largest customers represented approximately 38 percent of our sales in 2015. We expect that our customer concentration will continue for the foreseeable future. Our concentration of sales to a relatively small number of customers makes our relationship with each of these customers important to our business. We cannot assure that we will be able to retain our largest customers. Some of our customers may shift their purchases to our competitors in the future. The loss of one or more of our largest customers, any material reduction or delay in sales to these customers, our inability to successfully develop relationships with additional customers, or our inability to execute on pricing actions could have a material adverse effect on our financial position, results of operations and cash flows.
| • | A portion of our business could be adversely affected by a decline in new residential and commercial construction or a decline in replacement related volume |
|---|
The recovery in residential and commercial construction activity in North America remains fragile and construction could decline again after showing improvements in 2015. We believe that the majority of the market we serve is for replacement of existing products and replacement related volume growth was strong in 2013 and 2014 before declining in 2015. Changes in replacement volume and in the construction market could negatively affect us.
Table of Contents
| • | A failure in our implementation of a new enterprise resource planning system could disrupt our business |
|---|
We depend on information technology to record and process customers’ orders, manufacture and ship products in a timely manner, and maintain the financial accuracy of our business records. We are in the midst of implementing a global enterprise resource planning system that is core to our efforts to redesign and deploy new processes and migrate to a common information system across our plants over a period of several years. There is no certainty that this system will deliver the expected benefits. Implementation may impact our ability to process transactions accurately and efficiently, which could increase costs and thereby impact profitability or otherwise impact our business. In addition, the failure to either deliver the application on time, or anticipate the necessary readiness and training needs, could lead to business disruption and loss of customers and revenue and profit.
| • | We increasingly sell our products and operate outside the U.S., which may present additional risks to our business |
|---|
Approximately 40 percent of our net sales in 2015 were attributable to products sold outside of the U.S., primarily in China and Canada and to a lesser extent in Europe and India. Approximately 8,100 of our 13,400 employees as of December 31, 2015 were located in China. At December 31, 2015, approximately $458 million of our cash and marketable securities balances were located in China. International operations generally are subject to various risks, including political, religious, and economic instability, local labor market conditions, the imposition of foreign tariffs and other trade restrictions, the impact of foreign government regulations, the effects of income taxes, governmental expropriation, the imposition or increases in withholding and other taxes on remittances and other payments by foreign subsidiaries, labor relations problems, the imposition of environmental or employment laws, or other restrictions by foreign governments and differences in business practices. Unfavorable changes in the political, regulatory, and business climate could have a material adverse effect on our financial condition, results of operations and cash flows or our ability to repatriate funds to the U.S. As of December 31, 2015, approximately $645 million of cash, cash equivalents and marketable securities were held by our foreign subsidiaries. We would incur a cost to repatriate these funds to the U.S. and have recorded a liability of approximately $48 million associated with the repatriation of a portion of those funds.
| • | Because we participate in markets that are highly competitive, our revenues and earnings could decline as we respond to competition |
|---|
We sell all of our products in highly competitive markets. We compete in each of our targeted markets based on product design, reliability, quality of products and services, advanced technologies, product performance, maintenance costs and price. Some of our competitors may have greater financial, marketing, manufacturing, research and development and distribution resources than we have, and some are increasingly expanding beyond their existing manufacturing or geographic footprints. Consumer purchasing behavior may shift to distribution channels, including e-commerce, which is a rapidly developing area. Development of a successful e-commerce strategy involves significant time, investment and resources. We cannot assure that our products and services will continue to compete successfully with those of our competitors or that we will be able to retain our customer base or improve or maintain our profit margins on sales to our customers, all of which could materially and adversely affect our financial condition, results of operations and cash flows.
| • | Our international operations are subject to risks related to foreign currencies |
|---|
We have significant operations outside of the U.S., primarily in China and Canada and to a lesser extent Europe and India, and therefore, hold assets, incur liabilities, earn revenues and pay expenses in a variety of currencies other than the U.S. dollar. The financial statements of our foreign subsidiaries are translated into U.S. dollars in our consolidated financial statements. As a result, we are subject to risks associated with operating in foreign countries, including fluctuations in currency exchange rates and interest rates, or hyperinflation in some foreign countries. Furthermore, typically our products are priced in foreign countries in local currencies. As a result, an increase in the value of the U.S. dollar relative to the local currencies of our foreign markets has had and would continue to have a negative effect on our profitability. In addition to currency translation risks, we incur a currency transaction risk whenever one of our subsidiaries enters into either a purchase or sale transaction using a currency different from the operating subsidiaries’ functional currency. The majority of our foreign currency transaction risk is a result of our Canadian water heater operations. These risks may hurt our reported sales and profits in the future or negatively impact revenues and earnings translated from foreign currencies into U.S. dollars.
Table of Contents
| • | If we are unable to develop product innovations and improve our technology and expertise, we could lose customers or market share |
|---|
Our success may depend on our ability to adapt to technological changes in the water heating, boiler and water treatment industries. If we are unable to timely develop and introduce new products, or enhance existing products, in response to changing market conditions or customer requirements or demands, our competitiveness could be materially and adversely affected. Our ability to develop and successfully market new products and to develop, acquire, and retain necessary intellectual property rights is essential to our continued success, but cannot reasonably be assured.
| • | Changes in regulations or standards could adversely affect our business |
|---|
Our products are subject to a wide variety of statutory, regulatory and industry standards and requirements related to, among other items, energy efficiency, environmental emissions, labeling and safety. While we believe our products are currently efficient, safe and environment-friendly, a significant change to regulatory requirements, whether federal, foreign, state or local, or to industry standards, could substantially increase manufacturing costs, impact the size and timing of demand for our products, or put us at a competitive disadvantage, any of which could harm our business and have a material adverse effect on our financial condition, results of operations and cash flow.
| • | Our business may be adversely impacted by product defects |
|---|
Product defects can occur through our own product development, design and manufacturing processes or through our reliance on third parties for component design and manufacturing activities. We may incur various expenses related to product defects, including product warranty costs, product liability and recall or retrofit costs. While we maintain a reserve for product warranty costs based on certain estimates and our knowledge of current events and actions, our actual warranty costs may exceed our reserve, resulting in current period expenses and a need to increase our reserves for warranty charges. In addition, product defects and recalls may diminish the reputation of our brand. Further, our inability to cure a product defect could result in the failure of a product line or the temporary or permanent withdrawal from a product or market. Any of these events may have a material adverse impact on our financial condition, results of operations and cash flows.
| • | Acquisitions have contributed to our financial results and we may not be able to identify or complete future acquisitions, which could adversely affect our future growth |
|---|
Acquisitions we have made have positively impacted our results of operations. While we will continue to evaluate potential acquisitions and intend to use a significant portion of our available capital for future acquisitions, we may not be able to identify and successfully negotiate suitable acquisitions, obtain financing for future acquisitions on satisfactory terms, utilize cash flows from operations, obtain regulatory approval for certain acquisitions, or otherwise complete acquisitions in the future. If we complete any future acquisitions, then we may not be able to successfully integrate the acquired businesses or operate them profitably or accomplish our strategic objectives for those acquisitions. If we complete any future acquisitions in new geographies, our unfamiliarity with local regulations and market customs may impact our ability to operate them profitably or achieve our strategic objectives for those acquisitions. Our level of indebtedness may increase in the future if we finance acquisitions with debt, which would cause us to incur additional interest expense and could increase our vulnerability to general adverse economic and industry conditions and limit our ability to service our debt or obtain additional financing. The impact of future acquisitions may have a material adverse effect on our financial condition, results of operations and cash flows.
| • | Our operations could be adversely impacted by material price volatility and supplier concentration |
|---|
The market prices for certain raw materials we purchase, primarily steel, have been volatile. Significant increases in the cost of any of the key materials we purchase could increase our cost of doing business and ultimately could lead to lower operating earnings if we are not able to recover these cost increases through price increases to our customers. Historically, there has been a lag in our ability to recover increased material costs from customers, and that lag could negatively impact our profitability. In addition, in some cases we are dependent on a limited number of suppliers for some of the raw materials and components we require in the manufacture of our products. A significant disruption or termination of the supply from one of these suppliers could delay sales or increase costs which could result in a material adverse effect on our financial condition, results of operations and cash flows.
Table of Contents
| • | We are subject to regulation of our international operations that could adversely affect our business and results of operations |
|---|
Due to our global operations, we are subject to many laws governing international relations, including those that prohibit improper payments to government officials and restrict where we can do business, what information or products we can supply to certain countries and what information we can provide to a non-U.S. government, including but not limited to the Foreign Corrupt Practices Act and the U.S. Export Administration Act. Violations of these laws may result in criminal penalties or sanctions that could have a material adverse effect on our financial condition, results of operations and cash flows.
| • | Our results of operations may be negatively impacted by product liability lawsuits and claims |
|---|
Our water heating and boiler products expose us to potential product liability risks that are inherent in the design, manufacture, sale and use of our products. While we currently maintain what we believe to be suitable product liability insurance, we cannot be certain that we will be able to maintain this insurance on acceptable terms, that this insurance will provide adequate protection against potential liabilities or that our insurance providers will be able to ultimately pay all insured losses. In addition, we self-insure a portion of product liability claims. A series of successful claims against us could materially and adversely affect our reputation and our financial condition, results of operations and cash flows.
| • | Retention of key personnel is important to our business |
|---|
Attracting and retaining talented employees is important to the continued success of our business. Failure to retain key personnel, particularly on the leadership team, would have a material effect on our business and our ability to execute our business strategies in a timely and effective manner.
| • | An inability to adequately maintain our information systems and their security, as well as to protect data and other confidential information, could adversely affect our business and reputation |
|---|
In the ordinary course of business, we collect and store sensitive data and information, including our proprietary and regulated business information and that of our customers, suppliers and business partners, as well as personally identifiable information about our employees. Our information systems, like those of other companies, are susceptible to outages due to natural disasters, power loss, telecommunications failures, viruses, break-ins and similar events, or breaches of security. We continue to take steps to maintain and improve data security and address these risks and uncertainties by implementing security technologies, internal controls, network and data center resiliency and recovery processes. However, any operations failure or breach of security from increasingly sophisticated cyber threats could lead to the loss or disclosure of both our and our customers’ financial, product and other confidential information and could result in regulatory actions and have a material adverse effect on our business and reputation.
| • | Our underfunded pension plans require future pension contributions which could limit our flexibility in managing our company |
|---|
Due to the significant negative investment returns in 2008, flat returns in 2015 and falling interest rates in recent years, the projected benefit obligations of our defined benefit pension plans exceeded the fair value of the plan assets by approximately $134 million at December 31, 2015. U.S. employees hired after January 1, 2010 have not participated in our defined benefit plan, and benefit accruals for the majority of current salaried and hourly employees ended on December 31, 2014. We are forecasting that we will not be required to make a contribution to the plan in 2016, and we do not plan to make any voluntary contributions. However, we cannot provide any assurance that contributions will not be required in the future. Among the key assumptions inherent in our actuarially calculated pension plan obligation and pension plan expense are the discount rate and the expected rate of return on plan assets. If interest rates and actual rates of return on invested plan assets were to decrease significantly, our pension plan obligations could increase materially. The size of future required pension contributions could result in us dedicating a substantial portion of our cash flows from operations to making the contributions which could negatively impact our flexibility in managing the company.
| • | We have significant goodwill and indefinite-lived intangible assets and an impairment of our goodwill or indefinite-lived intangible assets could cause a decline in our net worth |
|---|
Our total assets include significant goodwill and indefinite-lived intangible assets. Our goodwill results from our acquisitions, representing the excess of the purchase prices we paid over the fair value of the net tangible and intangible assets we acquired.
Table of Contents
We assess whether there has been impairments in the value of our goodwill or indefinite-lived intangible assets during the fourth quarter of each calendar year or sooner if triggering events warrant. If future operating performance at our businesses does not meet expectations, we may be required to reflect non-cash charges to operating results for goodwill or indefinite-lived intangible asset impairments. The recognition of an impairment of a significant portion of goodwill or indefinite-lived intangible assets would negatively affect our results of operations and total capitalization, the effect of which could be material. A significant reduction in our stockholders’ equity due to an impairment of goodwill or indefinite-lived intangible assets may affect our ability to maintain the debt-to-capital ratio required under our existing debt arrangements. We have identified the valuation of goodwill and indefinite-lived intangible assets as a critical accounting policy. See “Management’s Discussion and Analysis of Financial Condition and Results of Operations – Critical Accounting Policies—Goodwill and Indefinite-lived Intangible Assets” included in Item 7 of this Annual Report on Form 10-K.
| • | Certain members of the founding family of our company and trusts for their benefit have the ability to influence all matters requiring stockholder approval |
|---|
We have two classes of common equity: our Common Stock and our Class A Common Stock. The holders of Common Stock currently are entitled, as a class, to elect only one-third of our board of directors. The holders of Class A Common Stock are entitled, as a class, to elect the remaining directors. Certain members of the founding family of our company and trusts for their benefit (Smith Family) have entered into a voting trust agreement with respect to shares of our Class A Common Stock and shares of our Common Stock they own. As of December 31, 2015, these members of the Smith Family own approximately 61.0 percent of the total voting power of our outstanding shares of Class A Common Stock and Common Stock, taken together as a single class, and approximately 95.6 percent of the voting power of the outstanding shares of our Class A Common Stock, as a separate class. Due to the differences in the voting rights between shares of our Common Stock and shares of our Class A Common Stock, the Smith Family is in a position to control to a large extent the outcome of matters requiring a stockholder vote, including the adoption of amendments to our certificate of incorporation or bylaws or approval of transactions involving a change of control. This ownership position may increase if other members of the Smith Family enter into the voting trust agreement, and the voting power relating to this ownership position may increase if shares of our Class A Common Stock held by stockholders who are not parties to the voting trust agreement are converted into shares of our Common Stock. The voting trust agreement provides that, in the event one of the parties to the voting trust agreement wants to withdraw from the trust or transfer any of its shares of our Class A Common Stock, such shares of our Class A Common Stock are automatically exchanged for shares of our Common Stock held by the trust to the extent available in the trust. In addition, the trust will have the right to purchase the shares of our Class A Common Stock and our Common Stock proposed to be withdrawn or transferred from the trust. As a result, the Smith Family members that are parties to the voting trust agreement have the ability to maintain their collective voting rights in our company even if certain members of the Smith Family decide to transfer their shares.
Table of Contents
Item 1B. UNRESOLVED STAFF COMMENTS
None.
Item 2. PROPERTIES
Properties utilized by us at December 31, 2015 were as follows:
North America
In this segment we have 12 manufacturing plants located in five states and two non-U.S. countries, of which ten are owned directly by us or our subsidiaries and two are leased from outside parties. The terms of leases in effect at December 31, 2015 expire between 2016 and 2025.
Rest of World
In this segment we have six manufacturing plants located in four non-U.S. countries, of which three are owned directly by us or our subsidiaries and three are leased from outside parties. Initial lease terms generally provide for minimum terms of one to six years and have one or more renewal options. The terms of leases in effect at December 31, 2015 expire between 2016 and 2020.
Corporate and General
We consider our plants and other physical properties to be suitable, adequate, and of sufficient productive capacity to meet the requirements of our business. The manufacturing plants operate at varying levels of utilization depending on the type of operation and market conditions. The executive offices of the company, which are leased, are located in Milwaukee, Wisconsin.
Item 3. LEGAL PROCEEDINGS
We are involved in various unresolved legal actions, administrative proceedings and claims in the ordinary course of our business involving product liability, property damage, insurance coverage, exposure to asbestos and other substances, patents and environmental matters, including the disposal of hazardous waste. Although it is not possible to predict with certainty the outcome of these unresolved legal actions or the range of possible loss or recovery, we believe, based on past experience, adequate reserves and insurance availability, that these unresolved legal actions will not have a material effect on our financial position or results of operations. A more detailed discussion of certain of these matters appears in Note 14 of Notes to Consolidated Financial Statements.
Item 4. MINE SAFETY DISCLOSURES
Not applicable.
Table of Contents
EXECUTIVE OFFICERS OF THE COMPANY
Pursuant to General Instruction of G(3) of Form 10-K, the following is a list of the executive officers which is included as an unnumbered Item in Part I of this report in lieu of being included in our Proxy Statement for our 2016 Annual Meeting of Stockholders.
| Name (Age) | Positions Held | Period Position Was Held | ||
| Randall S. Bednar (63) | Senior Vice President – Chief Information Officer | 2007 to Present | ||
| Senior Vice President – Information Technology | 2006 | |||
| Vice President – Information Technology | 2001 to 2006 | |||
| Wilfridus M. Brouwer (57) | Senior Vice President – Asia Corporate Development | 2015 to Present | ||
| Senior Vice President | 2013 to 2014 | |||
| President – A. O. Smith Holdings (Barbados) SRL | 2013 to Present | |||
| Senior Vice President – Asia | 2009 to 2012 | |||
| President and General Manager – A. O. Smith (China) Investment Co., Ltd. | 2009 to 2012 | |||
| Paul R. Dana (53) | Senior Vice President – Global Manufacturing | 2016 to Present | ||
| Vice President – Global Manufacturing | 2015 | |||
| President – APCOM, a division of State Industries, Inc., a subsidiary of the Company | 2011 to Present | |||
| Vice President – Product Engineering | 2006 to 2010 | |||
| Plant Manager – Productos de Agua, S. de R.L. de C.V. | 1998 to 2005 | |||
| Wei Ding (53) | Senior Vice President | 2013 to Present | ||
| President – A. O. Smith (China) Investment Co., Ltd.; General Manager – A. O. Smith (China) Water Heater Co., Ltd. and A. O. Smith (Shanghai) Water Treatment Products Co. Ltd. | 2013 to Present | |||
| President and General Manager – A. O. Smith (China) Water Heater Co., Ltd. | 2013 | |||
| Senior Vice President – A. O. Smith Water Products Company | 2011 to 2012 | |||
| Vice President – China – A. O. Smith Water Products Company | 2006 to 2011 | |||
| General Manager – A. O. Smith (China) Water Heater Co., Ltd. | 1999 to 2012 | |||
| Robert J. Heideman (49) | Senior Vice President – Chief Technology Officer | 2013 to Present | ||
| Senior Vice President – Engineering & Technology | 2011 to 2012 | |||
| Senior Vice President – Corporate Technology | 2010 to 2011 | |||
| Vice President – Corporate Technology | 2007 to 2010 | |||
| Director – Materials | 2005 to 2007 | |||
| Section Manager | 2002 to 2005 |
Table of Contents
| Name (Age) | Positions Held | Period Position Was Held | ||
| John J. Kita (60) | Executive Vice President and Chief Financial Officer | 2011 to Present | ||
| Senior Vice President, Corporate Finance and Controller | 2006 to 2011 | |||
| Vice President, Treasurer and Controller | 1996 to 2006 | |||
| Treasurer and Controller | 1995 to 1996 | |||
| Assistant Treasurer | 1988 to 1994 | |||
| Charles T. Lauber (53) | Senior Vice President, Strategy and Corporate Development | 2013 to Present | ||
| Senior Vice President – Chief Financial Officer – A. O. Smith Water Products Company | 2006 to 2012 | |||
| Vice President – Global Finance – A. O. Smith Electrical Products Company | 2004 to 2006 | |||
| Vice President and Controller – A. O. Smith Electrical Products Company | 2001 to 2004 | |||
| Director of Audit and Tax | 1999 to 2001 | |||
| Mark A. Petrarca (52) | Senior Vice President – Human Resources and Public Affairs | 2006 to Present | ||
| Vice President – Human Resources and Public Affairs | 2005 to 2006 | |||
| Vice President – Human Resources – A. O. Smith Water Products Company | 1999 to 2004 | |||
| Ajita G. Rajendra (64) | Chairman, President and Chief Executive Officer | 2014 to Present | ||
| President and Chief Executive Officer | 2013 to 2014 | |||
| President and Chief Operating Officer | 2011 to 2012 | |||
| Executive Vice President | 2006 to 2011 | |||
| President – A. O. Smith Water Products Company | 2005 to 2011 | |||
| Senior Vice President | 2005 to 2007 | |||
| James F. Stern (53) | Executive Vice President, General Counsel and Secretary | 2007 to Present | ||
| Partner – Foley & Lardner LLP | 1997 to 2007 | |||
| William L. Vallett Jr. (56) | Senior Vice President | 2013 to Present | ||
| Chief Executive Officer – Lochinvar, LLC | 2012 to Present | |||
| Chief Executive Officer – Lochinvar Corporation | 1992 to 2012 |
Table of Contents
| Name (Age) | Positions Held | Period Position Was Held | ||
| Kevin J. Wheeler (56) | Senior Vice President | 2013 to Present | ||
| President and General Manager – North America, India and Europe Water Heating | 2013 to Present | |||
| Senior Vice President and General Manager – North America, India and Europe – A. O. Smith Water Products Company | 2011 to 2012 | |||
| Senior Vice President and General Manager – U.S. Retail – A. O. Smith Water Products Company | 2007 to 2011 | |||
| Vice President – International – A. O. Smith Water Products Company | 2004 to 2007 | |||
| Managing Director – A. O. Smith Water Products Company B.V. | 1999 to 2004 |
Table of Contents
PART II
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
On April 15, 2013, our Board of Directors declared a two-for-one stock split of our Class A Common Stock and Common Stock in the form of a 100 percent stock dividend to stockholders of record on April 30, 2013 and payable on May 15, 2013. All references in this Item 5 to numbers of A. O. Smith Corporation shares or price per share have been adjusted to reflect the split.
| (a) | Market Information. Our Common Stock is listed on the New York Stock Exchange under the symbol AOS. Our Class A Common Stock is not listed. Wells Fargo Shareowner Services, N.A., P.O. Box 64854, St. Paul, Minnesota, 55164-0854 serves as the registrar, stock transfer agent and the dividend reinvestment agent for our Common Stock and Class A Common Stock. |
|---|
Quarterly Common Stock Price Range
| 2015 | 1st Qtr. | 2nd Qtr. | 3rd Qtr. | 4th Qtr. | ||||||||||||
| High | $ | 65.99 | $ | 74.40 | $ | 77.43 | $ | 81.15 | ||||||||
| Low | 53.49 | 63.53 | 50.09 | 64.23 | ||||||||||||
| 2014 | 1st Qtr. | 2nd Qtr. | 3rd Qtr. | 4th Qtr. | ||||||||||||
| High | $ | 53.98 | $ | 51.17 | $ | 50.91 | $ | 57.16 | ||||||||
| Low | 44.56 | 44.14 | 46.36 | 44.60 |
| (b) | Holders. As of January 31, 2016, the approximate number of stockholders of record of Common Stock and Class A Common Stock were 680 and 200, respectively. |
|---|
| (c) | Dividends. Dividends declared on the common stock are shown in Note 16 of Notes to Consolidated Financial Statements appearing elsewhere herein. |
|---|
| (d) | Stock Repurchases. In 2013, our Board of Directors approved adding 2,000,000 shares of Common Stock to an existing discretionary share repurchase authority. In 2014, our board of directors authorized the purchase of an additional 3,500,000 shares of our Common Stock. In 2015, our Board of Directors authorized the purchase of an additional 2,000,000 shares of our Common Stock. Under the share repurchase program, our Common Stock may be purchased through a combination of Rule 10b5-1 automatic trading plan and discretionary purchases in accordance with applicable securities laws. The number of shares purchased and the timing of the purchase will depend on a number of factors, including share price, trading volume and general market conditions, as well as on working capital requirements, general business conditions and other factors, including alternative investment opportunities. The stock repurchase authorization remains effective until terminated by our Board of Directors which may occur at any time, subject to the parameters of any Rule 10b5-1 automatic trading plan that we may then have in effect. In 2015, we repurchased 1,908,237 shares at an average price of $67.14 per share and at a total cost of $128.1 million. As of December 31, 2015, there were 2,589,756 shares remaining on the existing repurchase authorization. |
|---|
The following table sets forth the number of shares of common stock we repurchased during the fourth quarter of 2015:
| ISSUER PURCHASES OF EQUITY SECURITIES | ||||||||||||||||
| Period | Total Number of Shares Purchased | Average Price Paid per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | Maximum Number of Shares that may yet be Purchased Under the Plans or Programs | ||||||||||||
| October 1 – October 31, 2015 | 192,320 | $ | 69.10 | 192,320 | 726,446 | |||||||||||
| November 1 – November 30, 2015 | 136,690 | 76.98 | 136,690 | 589,756 | ||||||||||||
| December 1 – December 31, 2015 | — | — | — | 2,589,756 |
| (e) | Performance Graph. The following information in this Item 5 of this Annual Report on Form 10-K is not deemed to be “soliciting material” or to be “filed” with the SEC or subject to Regulation 14A or 14C under the Securities Exchange Act of 1934 or to the liabilities of Section 18 of the Securities Exchange Act of 1934, and will not be deemed to be incorporated by reference into any filing under the Securities Act of 1933 or the Securities Exchange Act of 1934, except to the extent we specifically incorporate it by reference into such a filing. |
|---|
Table of Contents
The graph below shows a five-year comparison of the cumulative shareholder return on our Common Stock with the cumulative total return of the Standard & Poor’s (S&P) Mid Cap 400 Index and the Russell 1000 Index, both of which are published indices.
Comparison of Five-Year Cumulative Total Return
From December 31, 2010 to December 31, 2015
Assumes $100 Invested with Reinvestment of Dividends
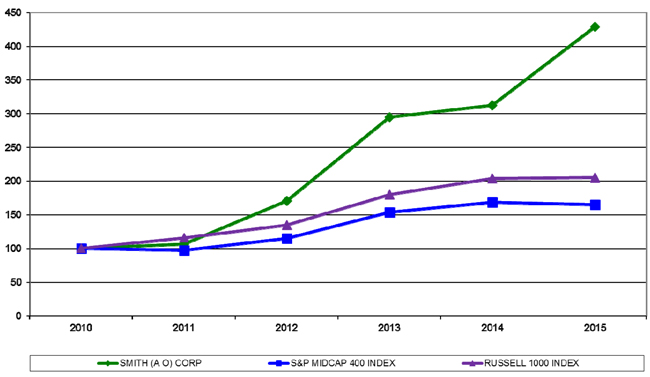
| Base Period | Indexed Returns | |||||||||||||||||||||||
| Company/Index | 12/31/10 | 12/31/11 | 12/31/12 | 12/31/13 | 12/31/14 | 12/31/15 | ||||||||||||||||||
| A. O. Smith Corporation | 100.0 | 107.0 | 170.7 | 295.1 | 312.5 | 429.0 | ||||||||||||||||||
| S&P Mid Cap 400 Index | 100.0 | 97.8 | 115.2 | 153.8 | 168.9 | 165.2 | ||||||||||||||||||
| Russell 1000 Index | 100.0 | 116.1 | 135.2 | 179.9 | 203.7 | 205.5 |
Table of Contents
Item 6. SELECTED FINANCIAL DATA
| (dollars in millions, except per share amounts) | ||||||||||||||||||||
| Years ended December 31 | ||||||||||||||||||||
| 2015 | 2014 | 2013(1) | 2012 | 2011(2)(3) | ||||||||||||||||
| Net sales – continuing operations | $ | 2,536.5 | $ | 2,356.0 | $ | 2,153.8 | $ | 1,939.3 | $ | 1,710.5 | ||||||||||
| Earnings (loss) | ||||||||||||||||||||
| Continuing operations | 282.9 | 207.8 | 169.7 | 162.6 | 111.2 | |||||||||||||||
| Discontinued operations | — | — | — | (3.9 | ) | 194.5 | ||||||||||||||
| Net earnings | $ | 282.9 | $ | 207.8 | $ | 169.7 | $ | 158.7 | $ | 305.7 | ||||||||||
| Basic earnings (loss) per share of common stock(1) | ||||||||||||||||||||
| Continuing operations | $ | 3.19 | $ | 2.30 | $ | 1.84 | $ | 1.76 | $ | 1.20 | ||||||||||
| Discontinued operations | — | — | — | (0.04 | ) | 2.11 | ||||||||||||||
| Net earnings | $ | 3.19 | $ | 2.30 | $ | 1.84 | $ | 1.72 | $ | 3.31 | ||||||||||
| Diluted earnings (loss) per share of common stock(1) | ||||||||||||||||||||
| Continuing operations | $ | 3.16 | $ | 2.28 | $ | 1.83 | $ | 1.75 | $ | 1.19 | ||||||||||
| Discontinued operations | — | — | — | (0.04 | ) | 2.09 | ||||||||||||||
| Net earnings | $ | 3.16 | $ | 2.28 | $ | 1.83 | $ | 1.71 | $ | 3.28 | ||||||||||
| Cash dividends per common share(1) | $ | 0.76 | $ | 0.60 | $ | 0.46 | $ | 0.36 | $ | 0.30 | ||||||||||
| December 31 | ||||||||||||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | ||||||||||||||||
| Total assets | $ | 2,646.5 | $ | 2,515.3 | $ | 2,391.5 | $ | 2,278.8 | $ | 2,349.0 | ||||||||||
| Long-term debt(4) | 236.1 | 210.1 | 177.7 | 225.1 | 443.0 | |||||||||||||||
| Total stockholders’ equity | 1,442.3 | 1,381.3 | 1,328.7 | 1,194.1 | 1,085.8 |
| (1) | In April 2013, we declared a 100 percent stock dividend to holders of Common Stock and Class A Common Stock which is not included in cash dividends. Basic and diluted earnings per share are calculated using the weighted average shares outstanding which were restated for all periods presented to reflect the stock dividend. |
|---|
| (2) | In August 2011, we sold EPC which is reflected as a discontinued operation for all periods presented. |
|---|
| (3) | In August 2011, we acquired Lochinvar. |
|---|
| (4) | Excludes the current portion of long-term debt. |
|---|
Table of Contents
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
OVERVIEW
Our company is comprised of two reporting segments: North America and Rest of World. Our Rest of World segment is primarily comprised of China, Europe and India. Both segments manufacture and market comprehensive lines of residential and commercial gas, gas tankless and electric water heaters. Both segments primarily manufacture and market in their respective region of the world. Our North America segment also manufactures and globally markets specialty commercial water heating equipment, condensing and non-condensing boilers and water systems tanks. Primarily for Asia, our Rest of World segment also manufactures and markets water treatment products. We also market in-home air purification products in China.
In 2015, our North America segment sales were $1,703.0 million and our Rest of World segment sales were $866.1 million. Sales of our products in China grew significantly in 2015, increasing 13.7 percent over 2014. Excluding the impact from the strengthening U.S. dollar, sales in China increased 16.1 percent in 2015. We expect sales in 2016 in China to grow at a rate of approximately 15 percent in local currency, as we believe overall water heater market growth, geographic expansion, market share gains, growth in water treatment products and air purification products and improved product mix will contribute to our growth. Price increases for residential and commercial water heaters and higher volumes of commercial water heaters and condensing commercial boilers contributed to 2015 sales increases in our North America segment. Partially offsetting these factors was a decline in residential water heater volumes in the U.S. The 13 percent decline in the value of the Canadian dollar against the U.S. dollar during 2015 also negatively impacted sales. We expect North America residential and commercial water heater industry unit to show modest growth in 2016. Lochinvar-branded products contributed $296.0 million to our net sales in 2015, and we expect ten percent sales growth of Lochinvar-branded products in 2016, driven by the U.S. industry transition to higher efficiency products and our introduction of new products; particularly condensing boilers. Approximately 40 percent of Lochinvar-branded product sales consist of residential and commercial water heaters while the remaining 60 percent of Lochinvar-branded product sales consist primarily of boilers and related parts.
Our stated acquisition strategy includes a number of our water-related strategic initiatives. We will look to continue to grow our core residential and commercial water heating, boiler and water treatment businesses throughout the world. We will also continue to look for opportunities to add to our existing operations in the high growth regions of China and India demonstrated by our introduction of air purification products in China in 2015.
Consistent with our stated strategy to expand our core product offering, we acquired Lochinvar in 2011. Lochinvar, one of the leading manufacturers of residential and commercial boilers in the U.S., fit squarely within our stated strategic growth initiative to expand our core water heating business. In 2013, approximately 40 percent of boilers sold in the U.S. were condensing boilers, compared with five percent in 2003. Our Lochinvar brand is a leading brand of higher efficiency, condensing boilers. We expect the transition in the U.S. to higher efficiency boilers will continue into the foreseeable future.
RESULTS OF OPERATIONS
Our sales in 2015 were a record $2,536.5 million surpassing 2014 sales of $2,356.0 million by 7.7 percent. Excluding the impact from the strengthening U.S. dollar against the Canadian and Chinese currencies, our sales grew over nine percent in 2015. The increase in sales was due to higher prices in North America, higher sales of Lochinvar-branded products and commercial water heaters in the U.S., as well as continued demand for our water heating and water treatment products in China. Sales in China grew 13.7 percent in 2015. Excluding the impact from the stronger U.S. dollar, China sales increased 16.1 percent in 2015. Our sales in 2014 were higher than 2013 sales of $2,153.8 million by 9.4 percent. The increase in 2014 in sales was attributable to higher volumes of water heaters and boilers in the U.S. and higher sales of water heaters and water treatment products in China. Sales of water heaters and water treatment products in China grew 18.4 percent to $694.0 million in 2014 compared to 2013.
Our gross profit margin in 2015 increased to 39.8 percent from 36.5 percent in 2014. The higher margin in 2015 was due to price increases in the U.S. and Canada, higher U.S. sales of commercial boilers and commercial water heaters which have higher margins, lower steel costs and a reduction in pension-related costs. Our gross profit margin in 2014 increased slightly from 35.9 percent in 2013, primarily due to higher volumes of water heaters and boilers in the U.S., partially offset by higher material costs in the U.S., as well as higher volumes of water heaters and water treatment products in the China.
Selling, general and administrative (SG&A) expenses were $38.6 million higher in 2015 than in 2014. The increase in SG&A expenses in 2015 to $610.7 million was primarily due to higher selling and engineering costs in support of increased volumes in China as well as higher costs associated with the 2015 launch of air purification products in China which more than offset
Table of Contents
lower pension costs in the U.S. SG&A expenses were $47.6 million higher in 2014 than in 2013 primarily due to higher selling and advertising costs in support of increased volumes in North America and China and approximately $9 million of incremental enterprise resource planning system (ERP) implementation costs.
On March 28, 2013, our Board of Directors approved a plan to transfer residential water heater production from our Fergus, Ontario plant to our other North American facilities. The majority of our production was consolidated in the second quarter of 2013. As a result of the capacity rationalization, we incurred pre-tax restructuring and impairment expenses of $22.0 million in 2013 related to employee severance costs, impairments of assets and equipment relocation costs. In addition, included in operating earnings in 2013 is a pre-tax gain of $11.0 million resulting from a settlement with a former supplier related to previous overcharges and warranty costs.
Pension expense in 2015 was $0.1 million compared to $28.6 million in 2014 and $27.9 million in 2013. The significant decrease in pension expense in 2015 compared to prior years was due to the sunset of our pension plan for the majority of our employees on December 31, 2014. In 2015, we began making additional Company contributions to a defined contribution plan in lieu of benefits earned in our pension plan.
Interest expense was $7.4 million in 2015 compared to $5.7 million in 2014. Interest expense in 2013 was also $5.7 million. The higher interest expense in 2015 was primarily related to interest rates on term notes in the amount of $75 million issued in January 2015 that were higher than the interest rate on the revolving credit facility that it replaced as well as higher overall debt levels related to share repurchases.
Other income was $10.8 million in 2015 compared to $5.2 million in 2014 and $3.8 million in 2013. The increases in other income in 2015 and 2014 were primarily due to higher interest income compared to the preceding year.
Our effective tax rate was 29.7 percent in 2015, compared with 27.5 percent in 2014 and 28.2 percent in 2013. The higher effective tax rate in 2015 was primarily due to a change in geographic earnings mix as compared to the prior year.
North America
Our North America segment sales were $1,703.0 million in 2015 or $81.3 million higher than sales of $1,621.7 million in 2014. The sales increase in 2015 resulted from higher prices in the U.S. and Canada and higher volumes of commercial water heaters and condensing commercial boilers in the U.S., partially offset by lower residential volumes in the U.S. and an unfavorable currency impact in Canada. Sales in 2014 were $101.7 million higher than sales of $1,520.0 million in 2013. The sales increase in 2014 was primarily due to higher volumes of water heaters and boilers in the U.S., which were partially offset by lower water heaters sales in Canada, primarily due to a decline in the value of the Canadian dollar of approximately seven percent versus the U.S. dollar.
North America operating earnings were $339.9 million in 2015 compared to operating earnings of $238.7 million and $211.9 million in 2014 and 2013, respectively. Operating margins were 20.0 percent, 14.7 percent and 13.9 percent in 2015, 2014 and 2013, respectively. The significantly higher operating earnings and operating margin in 2015 were primarily due to higher prices in the U.S. and Canada, higher sales of Lochinvar-branded products and commercial water heaters in the U.S., lower steel costs and lower pension costs which more than offset lower residential water heater volumes in the U.S. Higher operating earnings in 2014 compared to 2013 were primarily due to higher volumes in the U.S. which were partially offset by higher material costs and approximately $9 million of incremental ERP implementation costs.
Rest of World
Sales in our Rest of World segment in 2015 were $866.1 million or $97.8 million higher than sales of $768.3 million in 2014. Sales in China increased approximately $95 million due to higher demand for water heaters, approximately $35 million of incremental sales of water treatment products and approximately $9 million in sales of our newly launched in-home air purification products. Sales in China grew 13.7 percent in 2015. Excluding the impact from the stronger U.S. dollar, China sales increased 16.1 percent in 2015. Sales for our Rest of World segment in 2014 were $100.3 million higher than sales of $668.0 million in 2013 due to an 18.4 percent increase in sales in China, driven by increased demand for water heaters and water treatment products and a higher priced product mix that was partially offset by lower sales in India resulting from weakness in the housing market and the termination of a co-branding relationship with our largest distributor.
Rest of World operating earnings were $113.0 million in 2015 compared to operating earnings of $106.7 million and $88.0 million in 2014 and 2013, respectively. Segment operating margins were 13.0 percent in 2015 as compared to 13.9 percent and 13.2 percent in 2014 and 2013, respectively. Higher operating earnings in 2015 were primarily due to higher sales in China and lower steel costs that were partially offset by lower sales of highly profitable commercial water heaters in China, increased SG&A expenses and approximately $1.5 million of higher losses in India as compared to 2014. China earnings were reduced by approximately $2.5 million due to currency translation. Higher selling and engineering costs in China as well as higher
Table of Contents
SG&A costs associated with the 2015 launch of air purification products were the primary drivers for the decreased operating margin in 2015 as compared to 2014. Higher operating earnings and margins in 2014 as compared to 2013 were due to higher sales of water heaters and water treatment products in China as well as a higher priced product mix as a result of product introductions with higher value features which was partially offset by larger losses in India. Losses in India were $7.5 million in 2014, including approximately $1 million of product development and advertising expenses in advance of our 2015 launch of water treatment products.
LIQUIDITY AND CAPITAL RESOURCES
Our working capital was $802.1 million at December 31, 2015 compared with $713.8 million and $614.7 million at December 31, 2014 and December 31, 2013, respectively. Cash generated in China and sales-related increases in accounts receivable and inventory levels explain the majority of the increase in both 2015 and 2014. As of December 31, 2015, essentially all of the $645.2 million of cash, cash equivalents and marketable securities were held by our foreign subsidiaries. We would incur a cost to repatriate these funds to the U.S. and have an accrual of $47.9 million for the repatriation of a portion of these funds.
Cash provided by operating activities during 2015 was $344.4 million compared with $263.9 million during 2014 and $279.6 million during 2013. The improvement in cash flows in 2015 was primarily due to higher earnings from operations and lower outlays for working capital driven primarily by increases in accounts payable balances in China. Higher earnings in 2014 were more than offset by higher outlays for working capital. We expect cash provided by operating activities in 2016 to be approximately $320 million.
Our capital expenditures were $72.7 million in 2015, $86.1 million in 2014 and $97.7 million in 2013. Included in 2015 capital expenditures were approximately $16 million related to our ERP implementation and approximately $19 million related to capacity expansion in China and the U.S. to support growth. Included in 2014 capital expenditures was approximately $31 million related to our ERP implementation. Included in 2013 capital expenditures was approximately $45 million in China and India for the construction of a second water heater manufacturing plant in Nanjing, China and to continue the expansion of our manufacturing plant near Bangalore, India. Also included in 2013 capital expenditures was approximately $19 million related to the ERP implementation. We project 2016 capital expenditures will be between $120 and $130 million and depreciation and amortization expense in 2016 will be approximately $70 million. We expect capital spending in 2016 to include approximately $8 million related to our ERP implementation and approximately $40 million related to the initial phase of a new water treatment manufacturing facility in China as we will outgrow capacity in a leased facility in the next few years.
In December 2012, we completed a $400 million multi-currency five year revolving credit facility with a group of eight banks. The facility has an accordion provision which allows it to be increased up to $500 million if certain conditions (including lender approval) are satisfied. Borrowing rates under the facility are determined by our leverage ratio. The facility requires us to maintain two financial covenants, a leverage ratio test and an interest coverage test, and we were in compliance with the covenants as of December 31, 2015. The facility backs up commercial paper and credit line borrowings, and it expires on December 12, 2017. As a result of the long-term nature of this facility, the commercial paper and credit line borrowings, as well as drawings under the facility are classified as long-term debt.
At December 31, 2015, we had available borrowing capacity of $253.0 million under this facility. We believe that the combination of cash, available borrowing capacity and operating cash flow will provide sufficient funds to finance our existing operations for the foreseeable future.
In January 2015, we issued $75 million of fixed rate term notes to an insurance company. Principal payments commence in 2020 and the notes mature in 2030. The notes have an interest rate of 3.52 percent. We used proceeds of the notes to pay down borrowings under our revolving credit facility.
Our total debt increased to $249.0 million at December 31, 2015 compared with $223.8 million at December 31, 2014, as our cash flows generated in the U.S were more than offset by our share repurchase activity. As a result, our leverage, as measured by the ratio of total debt to total capitalization, was 14.7 percent at the end of 2015 compared with 13.9 percent at the end of 2014.
Our U.S. pension plan continues to meet all funding requirements under ERISA regulations. We were not required to make a contribution to our pension plan in 2015 and we did not make any voluntary contributions. We forecast that we will not be required to make a contribution to the plan in 2016 and we do not plan to make any voluntary contributions in 2016. For further information on our pension plans, see Note 11 of the Notes to Consolidated Financial Statements.
During 2015, our Board of Directors authorized the purchase of an additional 2,000,000 shares of our Common Stock. In 2015, we repurchased 1,908,237 shares at an average price of $67.14 per share and a total cost of $128.1 million. At December 31,
Table of Contents
2015, a total of 2,589,756 shares remained on the existing repurchase authorization. Depending on factors such as stock price, working capital requirements and alternative investment opportunities, we expect to spend approximately $150 million on stock repurchase activity in 2016.
We have paid dividends for 76 consecutive years with payments increasing each of the last 24 years. We paid total dividends of $0.76 per share in 2015 compared with $0.60 per share in 2014. In January 2016, we increased our dividend by 26 percent and anticipate paying total dividends of $0.96 per share in 2016.
Aggregate Contractual Obligations
A summary of our contractual obligations as of December 31, 2015, is as follows:
| (dollars in millions) | Payments due by period | |||||||||||||||||||
| Contractual Obligations | Total | Less Than 1 year | 1 - 2 Years | 3 - 5 Years | More than 5 years | |||||||||||||||
| Long-term debt | $ | 249.0 | $ | 12.9 | $ | 161.1 | $ | 6.8 | $ | 68.2 | ||||||||||
| Fixed rate interest | 25.6 | 3.8 | 6.0 | 5.0 | 10.8 | |||||||||||||||
| Operating leases | 39.5 | 19.7 | 8.1 | 4.5 | 7.2 | |||||||||||||||
| Purchase obligations | 98.0 | 97.2 | 0.8 | — | — | |||||||||||||||
| Pension and post-retirement obligations | 72.1 | 2.2 | 8.7 | 8.1 | 53.1 | |||||||||||||||
| Total | $ | 484.2 | $ | 135.8 | $ | 184.7 | $ | 24.4 | $ | 139.3 | ||||||||||
As of December 31, 2015, our liability for uncertain income tax positions was $2.6 million. Due to the high degree of uncertainty regarding timing of potential future cash flows associated with these liabilities, we are unable to make a reasonably reliable estimate of the amount and period in which these liabilities might be paid.
We utilize blanket purchase orders to communicate expected annual requirements to many of our suppliers. Requirements under blanket purchase orders generally do not become committed until several weeks prior to our scheduled unit production. The purchase obligation amount presented above represents the value of commitments that we consider firm.
Recent Accounting Pronouncements
In November 2015, the Financial Accounting Standards Board (FASB) amended Accounting Standard Codification (ASC) 740, Income Taxes (issued under Accounting Standards No. (ASN) 2015-17). This amendment requires that deferred tax assets and liabilities be classified as noncurrent in the statement of financial position. The amendment is effective for periods beginning January 1, 2016 and allows for either prospective adoption or retrospective adoption. We expect the adoption of amended ASC 740 to impact the classification of deferred taxes on our consolidated balance sheet.
In April 2015, the FASB amended ASC 835-30, Interest - Imputation of Interest (issued under ASN 2015-03). This amendment to ASC 835-30 requires that debt issuance costs related to a recognized debt liability be presented in the balance sheet as a direct deduction from the carrying amount of that debt liability, consistent with debt discounts. The recognition and measurement guidance for debt issuance costs is not affected by this amendment. The amendment is effective for periods beginning January 1, 2016 and requires using a retrospective approach. We do not expect the adoption of amended ASC 835-30 to have a material impact on our consolidated balance sheet.
In May 2014, the FASB issued ASC 606-10, Revenue from Contracts with Customers (issued under ASN 2014-09). ASC 606-10 will replace all existing revenue recognition guidance when effective. In July 2015, the FASB approved a one year deferral of the effective date, with application permitted as of the original effective date, or periods beginning January 1, 2017. Either full retrospective adoption or modified retrospective adoption is allowed under ASC 606-10. We are in the process of determining whether the adoption of ASC 606-10 will have an impact on our consolidated financial condition, results of operations or cash flows.
Critical Accounting Policies
Our accounting policies are described in Note 1 of Notes to Consolidated Financial Statements. Also as disclosed in Note 1, the preparation of financial statements in conformity with accounting principles generally accepted in the U.S. requires the use of estimates and assumptions about future events that affect the amounts reported in the financial statements and accompanying notes. Future events and their effects cannot be determined with absolute certainty. Therefore, the determination of estimates requires the exercise of judgment. Actual results inevitably will differ from those estimates, and such differences may be material to the financial statements.
Table of Contents
The most significant accounting estimates inherent in the preparation of our financial statements include estimates associated with the evaluation of the impairment of goodwill and indefinite-lived intangible assets, as well as significant estimates used in the determination of liabilities related to warranty activity, product liability and pensions. Various assumptions and other factors underlie the determination of these significant estimates. The process of determining significant estimates is fact-specific and takes into account factors such as historical experience and trends, and in some cases, actuarial techniques. We monitor these significant factors and adjustments are made as facts and circumstances dictate. Historically, actual results have not significantly deviated from those determined using the estimates described above.
Goodwill and Indefinite-lived Intangible Assets
In conformity with U.S. GAAP, goodwill and indefinite-lived intangible assets are tested for impairment annually or more frequently if events or changes in circumstances indicate that the assets might be impaired. We perform impairment reviews for our reporting units using a fair-value method based on management’s judgments and assumptions. The fair value represents the estimated amount at which a reporting unit could be bought or sold in a current transaction between willing parties on an arm’s-length basis. The estimated fair value is then compared with the carrying amount of the reporting unit, including recorded goodwill. We are subject to financial statement risk to the extent that goodwill and indefinite-lived intangible assets become impaired. Any impairment review is, by its nature, highly judgmental as estimates of future sales, earnings and cash flows are utilized to determine fair values. However, we believe that we conduct annual thorough and competent valuations of goodwill and indefinite-lived intangible assets and that there has been no impairment in goodwill or indefinite-lived assets in 2015.
Product warranty
Our products carry warranties that generally range from one to ten years and are based on terms that are generally accepted in the market. We provide for the estimated cost of product warranty at the time of sale. The product warranty provision is estimated based upon warranty loss experience using actual historical failure rates and estimated costs of product replacement. The variables used in the calculation of the provision are reviewed on a periodic basis. At times, warranty issues may arise which are beyond the scope of our historical experience. We provide for any such warranty issues as they become known and estimable. While our warranty costs have historically been within calculated estimates, it is possible that future warranty costs could differ significantly from those estimates. The allocation of the warranty liability between current and long-term is based on the expected warranty liability to be paid in the next year as determined by historical product failure rates.
Product liability
Due to the nature of our products, we are subject to product liability claims in the normal course of business. We maintain insurance to reduce our risk. Most insurance coverage includes self-insured retentions that vary by year. In 2015, we maintained a self-insured retention of $7.5 million per occurrence with an aggregate insurance limit of $125.0 million per occurrence.
We establish product liability reserves for our self-insured retention portion of any known outstanding matters based on the likelihood of loss and our ability to reasonably estimate such loss. There is inherent uncertainty as to the eventual resolution of unsettled matters due to the unpredictable nature of litigation. We make estimates based on available information and our best judgment after consultation with appropriate advisors and experts. We periodically revise estimates based upon changes to facts or circumstances. We also use an actuary to calculate reserves required for estimated incurred but not reported claims as well as to estimate the effect of adverse development of claims over time. At December 31, 2015, our reserve for product liability was $38.7 million.
Pensions
We have significant pension benefit costs that are developed from actuarial valuations. The valuations reflect key assumptions regarding, among other things, discount rates, expected return on plan assets, retirement ages, and years of service. Consideration is given to current market conditions, including changes in interest rates in making these assumptions. Our assumption for the expected return on plan assets was 7.75 percent in 2015 and 2014. The discount rate used to determine net periodic pension costs decreased to 4.05 percent in 2015 from 4.85 percent in 2014. For 2016, our expected return on plan assets is 7.50 percent and our discount rate is 4.40 percent.
In developing our expected return on plan assets, we evaluate our pension plan’s current and target asset allocation, the expected long-term rates of return of equity and bond indices and the actual historical returns of our pension plan. Our plan’s target allocation to equity managers is approximately 50 percent, with the remainder allocated primarily to bond managers and a small allocation to private equity managers and real estate managers. Our actual asset allocation as of December 31, 2015,
Table of Contents
was 47 percent to equity managers, 39 percent to bond managers, nine percent to real estate managers and five percent to private equity managers. We regularly review our actual asset allocation and periodically rebalance our investments to our targeted allocation when considered appropriate. Our pension plan’s historical ten-year and 25-year compounded annualized returns are 6.1 percent and 9.5 percent, respectively. We believe that with our target allocation and the expected long-term returns of equity and bond indices as well as our actual historical returns, our 7.50 percent expected return on plan assets for 2016 is reasonable.
The discount rate assumptions used to determine future pension obligations at December 31, 2015 and 2014 were based on the AonHewitt AA Only Above Median yield curve, which was designed by AonHewitt to provide a means for plan sponsors to value the liabilities of their postretirement benefit plans. The AA Only Above Median yield curve represents a series of annual discount rates from bonds with AA minimum average rating as rated by Moody’s Investor Service, Standard &Poor’s and Fitch Ratings. We will continue to evaluate our actuarial assumptions at least annually, and we will adjust the assumptions as necessary.
As of December 31, 2015, we changed the method we used to estimate the service and interest components of net periodic pension benefit cost for our pension plan and post-retirement benefit plan. The change will result in an approximate $7 million decrease in the service and interest components in 2016.
As a result, we estimate that we will recognize pension income of approximately $7 million in 2016 compared to $0.1 million of pension expense in 2015. We estimate that costs associated with our replacement retirement plan in 2016 will be approximately $6 million, consistent with 2015. We made changes to our pension plan including closing the plan to new entrants effective January 1, 2010, and the sunset of our plan for the majority of our employees on December 31, 2014 which significantly decreased pension expense beginning in 2015. Lowering the expected return on plan assets by 25 basis points would increase our net pension expense for 2015 by approximately $1.8 million. Lowering the discount rate by 25 basis points would decrease our 2015 net pension expense by approximately $0.3 million.
Outlook
Despite volatile conditions in China, we continue to expect strong, profitable sales growth in China in 2016 at the rate of approximately 15 percent in local currency terms. We continue to experience strong consumer demand for our water heating and water treatment products in China, and our new air purification products have been well received by Chinese consumers. In the U.S. we expect the transition from non-condensing, lower efficiency boilers to condensing, higher efficiency boilers to continue in 2016, which combined with new products, should allow sales growth of Lochinvar-branded products to continue at ten percent. We expect modest growth in commercial and residential water heater volumes in North America driven by modest assumptions for new construction and steady replacement demand. Other income is expected to be approximately $5 million lower in 2016 as compared to 2015 primarily due to expected lower interest rates than last year on cash deposits in China. We anticipate ERP implementation related costs will be approximately $9 million higher or approximately $25 million in 2016 due to the increase in the number of scheduled go-live events in 2016. We also expect our effective tax rate to be between 30.5 percent and 31 percent due to a change in geographic earnings mix.
Combining all these factors, we expect sales growth of between nine and ten percent in local currency terms and between seven and eight percent in U.S. dollars in 2016 and earnings to be in the range of $3.40 to $3.55 per share for 2016.
OTHER MATTERS
Environmental
Our operations are governed by a number of federal, foreign, state, local and environmental laws concerning the generation and management of hazardous materials, the discharge of pollutants into the environment and remediation of sites owned by the company or third parties. We have expended financial and managerial resources complying with such laws. Expenditures related to environmental matters were not material in 2015 and we do not expect them to be material in any single year. We have reserves associated with environmental obligations at various facilities and we believe these reserves are sufficient to cover reasonably anticipated remediation costs. Although we believe that our operations are substantially in compliance with such laws and maintain procedures designed to maintain compliance, there are no assurances that substantial additional costs for compliance will not be incurred in the future. However, since the same laws govern our competitors, we should not be placed at a competitive disadvantage.
Table of Contents
Market Risk
We are exposed to various types of market risks, primarily currency. We monitor our risks in such areas on a continuous basis and generally enter into forward contracts to minimize such exposures for periods of less than one year. We do not engage in speculation in our derivatives strategies. Further discussion regarding derivative instruments is contained in Note 1 of Notes to Consolidated Financial Statements.
We enter into foreign currency forward contracts to minimize the effect of fluctuating foreign currencies. At December 31, 2015, we had net foreign currency contracts outstanding of $79.8 million. Assuming a hypothetical ten percent movement in the respective currencies, the potential foreign exchange gain or loss associated with the change in rates would amount to $8.0 million. Gains and losses from our forward contract activities will be offset by gains and losses in the underlying transactions being hedged.
Our earnings exposure related to movements in interest rates is primarily derived from outstanding floating-rate debt instruments that are determined by short-term money market rates. At December 31, 2015, we had $147.0 million in outstanding floating-rate debt with a weighted-average interest rate of 1.3 percent at year end. A hypothetical ten percent annual increase or decrease in the year-end average cost of our outstanding floating-rate debt would result in a change in annual pre-tax interest expense of approximately $0.2 million.
Forward-Looking Statements
This filing contains statements that the company believes are “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. Forward-looking statements generally can be identified by the use of words such as “may,” “will,” “expect,” “intend,” “estimate,” “anticipate,” “believe,” “forecast,” “guidance” or words of similar meaning. All forward-looking statements are subject to risks and uncertainties that could cause actual results to differ materially from those anticipated as of the date of this filing. Important factors that could cause actual results to differ materially from these expectations include, among other things, the following: a further slowdown in the growth rate of the Chinese economy; potential weakening in the high efficiency boiler segment in the U.S.; significant volatility in raw material prices; inability to implement or maintain pricing actions; potential weakening in U.S. residential or commercial construction or instability in the Company’s replacement markets; uncertain costs, savings and timeframes associated with the implementation of the new enterprises resources planning system; foreign currency fluctuations; the ability to execute our acquisition strategy; competitive pressures on the company’s businesses and adverse general economic conditions and capital market deterioration. Forward-looking statements included in this filing are made only as of the date of this release, and the company is under no obligation to update these statements to reflect subsequent events or circumstances. All subsequent written and oral forward-looking statements attributed to the company, or persons acting on its behalf, are qualified entirely by these cautionary statements.
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
See “Market Risk” above.
Table of Contents
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
The Board of Directors and Stockholders
A. O. Smith Corporation
We have audited the accompanying consolidated balance sheets of A. O. Smith Corporation as of December 31, 2015 and 2014, and the related consolidated statements of earnings, comprehensive earnings, stockholders’ equity and cash flows for each of the three years in the period ended December 31, 2015. Our audits also included the financial statement schedule listed in the index at Item 15(a). These financial statements and schedule are the responsibility of the company’s management. Our responsibility is to express an opinion on these financial statements and schedule based on our audits.
We conducted our audits in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement. An audit includes examining, on a test basis, evidence supporting the amounts and disclosures in the financial statements. An audit also includes assessing the accounting principles used and significant estimates made by management, as well as evaluating the overall financial statement presentation. We believe that our audits provide a reasonable basis for our opinion.
In our opinion, the financial statements referred to above present fairly, in all material respects, the consolidated financial position of A. O. Smith Corporation at December 31, 2015 and 2014, and the consolidated results of its operations and its cash flows for each of the three years in the period ended December 31, 2015, in conformity with U.S. generally accepted accounting principles. Also, in our opinion, the related financial statement schedule, when considered in relation to the basic financial statements taken as a whole, presents fairly in all material respects the information set forth therein.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), A. O. Smith Corporation’s internal control over financial reporting as of December 31, 2015, based on criteria established in Internal Control - Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) and our report dated February 17, 2016 expressed an unqualified opinion thereon.
| Ernst & Young LLP |
Milwaukee, Wisconsin
February 17, 2016
Table of Contents
CONSOLIDATED BALANCE SHEETS
| December 31 (dollars in millions) | ||||||||
| 2015 | 2014 | |||||||
| Assets | ||||||||
| Current Assets | ||||||||
| Cash and cash equivalents | $ | 323.6 | $ | 319.4 | ||||
| Marketable securities | 321.6 | 222.5 | ||||||
| Receivables | 501.4 | 475.4 | ||||||
| Inventories | 222.9 | 208.3 | ||||||
| Deferred income taxes | 39.9 | 40.5 | ||||||
| Other current assets | 45.9 | 52.9 | ||||||
| Total Current Assets | 1,455.3 | 1,319.0 | ||||||
| Net property, plant and equipment | 442.7 | 427.7 | ||||||
| Goodwill | 420.9 | 428.8 | ||||||
| Other intangibles | 291.0 | 308.5 | ||||||
| Other assets | 36.6 | 31.3 | ||||||
| Total Assets | $ | 2,646.5 | $ | 2,515.3 | ||||
| Liabilities | ||||||||
| Current Liabilities | ||||||||
| Trade payables | $ | 424.9 | $ | 393.8 | ||||
| Accrued payroll and benefits | 81.5 | 70.3 | ||||||
| Accrued liabilities | 90.2 | 85.1 | ||||||
| Product warranties | 43.7 | 42.3 | ||||||
| Long-term debt due within one year | 12.9 | 13.7 | ||||||
| Total Current Liabilities | 653.2 | 605.2 | ||||||
| Long-term debt | 236.1 | 210.1 | ||||||
| Deferred income taxes | 21.3 | 21.4 | ||||||
| Product warranties | 95.6 | 93.9 | ||||||
| Post-retirement benefit obligation | 6.2 | 9.6 | ||||||
| Pension liabilities | 134.2 | 133.1 | ||||||
| Other liabilities | 57.6 | 60.7 | ||||||
| Total Liabilities | 1,204.2 | 1,134.0 | ||||||
| Commitments and contingencies | — | — | ||||||
| Stockholders’ Equity | ||||||||
| Preferred Stock | — | — | ||||||
| Class A Common Stock (shares issued 13,186,698 and 13,220,470) | 65.9 | 66.1 | ||||||
| Common Stock (shares issued 82,167,098 and 82,133,326) | 82.2 | 82.1 | ||||||
| Capital in excess of par value | 617.4 | 600.1 | ||||||
| Retained earnings | 1,350.7 | 1,135.5 | ||||||
| Accumulated other comprehensive loss | (313.4 | ) | (272.0 | ) | ||||
| Treasury stock at cost | (360.5 | ) | (230.5 | ) | ||||
| Total Stockholders’ Equity | 1,442.3 | 1,381.3 | ||||||
| Total Liabilities and Stockholders’ Equity | $ | 2,646.5 | $ | 2,515.3 | ||||
See accompanying notes which are an integral part of these statements.
Table of Contents
CONSOLIDATED STATEMENT OF EARNINGS
| Years ended December 31 (dollars in millions, except per share amounts) | ||||||||||||
| 2015 | 2014 | 2013 | ||||||||||
| Continuing Operations | ||||||||||||
| Net sales | $ | 2,536.5 | $ | 2,356.0 | $ | 2,153.8 | ||||||
| Cost of products sold | 1,526.7 | 1,496.7 | 1,380.0 | |||||||||
| Gross profit | 1,009.8 | 859.3 | 773.8 | |||||||||
| Selling, general and administrative expenses | 610.7 | 572.1 | 524.5 | |||||||||
| Restructuring, impairment and settlement expenses – net | — | — | 11.0 | |||||||||
| Interest expense | 7.4 | 5.7 | 5.7 | |||||||||
| Other income - net | (10.8 | ) | (5.2 | ) | (3.8 | ) | ||||||
| Earnings before provision for income taxes | 402.5 | 286.7 | 236.4 | |||||||||
| Provision for income taxes | 119.6 | 78.9 | 66.7 | |||||||||
| Net Earnings | $ | 282.9 | $ | 207.8 | $ | 169.7 | ||||||
| Net Earnings Per Share of Common Stock | $ | 3.19 | $ | 2.30 | $ | 1.84 | ||||||
| Diluted Net Earnings Per Share of Common Stock | $ | 3.16 | $ | 2.28 | $ | 1.83 | ||||||
CONSOLIDATED STATEMENT OF COMPREHENSIVE EARNINGS
| Years ended December 31 (dollars in millions) | ||||||||||||
| 2015 | 2014 | 2013 | ||||||||||
| Net Earnings | $ | 282.9 | $ | 207.8 | $ | 169.7 | ||||||
| Other comprehensive (loss) earnings | ||||||||||||
Showing the first 8K of 116K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
None.
Item 9A. CONTROLS AND PROCEDURES
Evaluation of Disclosure Controls and Procedures
Our management, with the participation of our Chief Executive Officer and Chief Financial Officer, has evaluated the effectiveness of our disclosure controls and procedures (as such term is defined in Rules 13a-15(e) under the Securities Exchange Act of 1934, as amended (“the Exchange Act”) as of the end of the period covered by this report. Based on such evaluations, our Chief Executive Officer and Chief Financial Officer have concluded that, as of the end of such period our disclosure controls and procedures are effective in recording, processing, summarizing, and reporting, on a timely basis, information required to be disclosed by us in the reports that we file or submit under the Exchange Act, and that information is accumulated and communicated to the Chief Executive Officer and Chief Financial Officer, as appropriate, to allow timely discussions regarding required disclosure.
Management Report on Internal Control Over Financial Reporting
Our management is responsible for establishing and maintaining adequate internal control over financial reporting, as such term is defined in Exchange Act Rule 13a-15(f). Our management, with the participation of our Chief Executive Officer and Chief Financial Officer, has evaluated the effectiveness of our internal control over financial reporting based on the Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework). Based on this evaluation, our management has concluded that, as of December 31, 2015, our internal control over financial reporting was effective.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Ernst & Young LLP, an independent registered public accounting firm, has audited our consolidated financial statements and the effectiveness of internal controls over financial reporting as of December 31, 2015 as stated in their report which is included herein.
Table of Contents
Changes in Internal Control Over Financial Reporting
In 2015, we continued the implementation of a new global enterprise resource planning system. This multi-year initiative is being conducted in phases and includes modifications to the design and operation of controls over financial reporting. We are testing internal controls over financial reporting for design effectiveness prior to the implementation of each phase, and we have monitoring controls in place over the implementation of these changes
Except as described above, there have been no changes in our internal control over financial reporting (as such term is defined in Rules 13a-15(f) and 15d-15(f) under the Securities and Exchange Act) during the year ended December 31, 2015 that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
Item 9B. OTHER INFORMATION
None
Table of Contents
Report of Independent Registered Public Accounting Firm
The Board of Directors and Stockholders
A. O. Smith Corporation
We have audited A. O. Smith Corporation’s internal control over financial reporting as of December 31, 2015, based on criteria established in Internal Control—Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) (the COSO criteria). A. O. Smith Corporation’s management is responsible for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting included in the accompanying Management Report on Internal Control over Financial Reporting. Our responsibility is to express an opinion on the company’s internal control over financial reporting based on our audit.
We conducted our audit in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
In our opinion, A. O. Smith Corporation maintained, in all material respects, effective internal control over financial reporting as of December 31, 2015, based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), the consolidated balance sheets of A. O. Smith Corporation as of December 31, 2015 and 2014, and the related consolidated statements of earnings, comprehensive earnings, stockholders’ equity, and cash flows for each of the three years in the period ended December 31, 2015, and our report dated February 17, 2016 expressed an unqualified opinion thereon.
| Ernst & Young LLP |
Milwaukee, Wisconsin
February 17, 2016
Table of Contents
PART III
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
The information included under the headings “Election of Directors” and “Board Committees” in our definitive Proxy Statement for the 2016 Annual Meeting of Stockholders (to be filed with the Securities and Exchange Commission under Regulation 14A within 120 days after the end of the registrant’s fiscal year) is incorporated herein by reference. The information required regarding Executive Officers of the company is included in Part I of this Annual Report on Form 10-K under the caption “Executive Officers of the Company.”
We have a separately designated Audit Committee on which Gene C. Wulf, Gloster B. Current, Jr., Mark D. Smith and Idelle K. Wolf serve, with Mr. Wulf, as Chairperson. All members are independent under applicable SEC and New York Stock Exchange rules; the Board of Directors of the company has concluded that Ms. Wolf and Mr. Wulf are “audit committee financial experts” in accordance with SEC rules.
We have adopted a Financial Code of Ethics applicable to our principal executive officer, principal financial officer and principal accounting officer. As a best practice, this code has been executed by all other company officers and key financial and accounting personnel as well. In addition, we have adopted a general code of business conduct for our directors, officers and all employees, which is known as the A. O. Smith Guiding Principles. The Financial Code of Ethics, the A. O. Smith Guiding Principles and other company corporate governance matters are available on our website at www.aosmith.com. We are not including the information contained on our website as a part of or incorporating it by reference into, this Form 10-K. We intend to disclose on this website any amendments to, or waivers from, the Financial Code of Ethics or the A. O. Smith Guiding Principles that are required to be disclosed pursuant to SEC rules. There have been no waivers of the Financial Code of Ethics or the A. O. Smith Guiding Principles. Stockholders may obtain copies of any of these corporate governance documents free of charge by writing to the Corporate Secretary at the address on the cover page of this Form 10-K.
The information included under the heading “Compliance with Section 16(a) of the Securities Exchange Act” in our definitive Proxy Statement for the 2016 Annual Meeting of Stockholders (to be filed with the Securities and Exchange Commission under Regulation 14A within 120 days after the end of the registrant’s fiscal year) is incorporated herein by reference.
Item 11. EXECUTIVE COMPENSATION
The information included under the headings “Executive Compensation,” “Director Compensation,” “Report of the Personnel and Compensation Committee” and “Compensation Committee Interlocks and Insider Participation” in the company’s definitive Proxy Statement for the 2016 Annual Meeting of Stockholders (to be filed with the Securities and Exchange Commission under Regulation 14A within 120 days after the end of the registrant’s fiscal year) is incorporated herein by reference.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
The information included under the headings “Principal Stockholders” and “Security Ownership of Directors and Management” in our definitive Proxy Statement for the 2016 Annual Meeting of Stockholders (to be filed with the Securities and Exchange Commission under Regulation 14A within 120 days after the end of the registrant’s fiscal year) is incorporated herein by reference.
Table of Contents
Equity Compensation Plan Information
The following table provides information about our equity compensation plans as of December 31, 2015.
| Plan Category | Number of securities to be issued upon the exercise of outstanding options, warrants and rights | Weighted-average exercise price of outstanding options, warrants and rights | Number of securities remaining available for future issuance under equity compensation plans (excluding securities reflected in the first column) | |||||||||
| Equity compensation plans approved by security holders | 1,817,959 | (1) | $ | 36.05 | (2) | 1,994,172 | (3) | |||||
| Equity compensation plans not approved by security holders | — | — | — | |||||||||
| Total | 1,817,959 | $ | 36.05 | 1,994,172 | ||||||||
| (1) | Consists of 1,326,779 shares subject to stock options, 329,262 shares subject to employee share units and 161,918 shares subject to director share units. |
|---|
| (2) | Represents the weighted average exercise price of outstanding options and does not take into account outstanding share units. |
|---|
| (3) | Represents securities remaining available for issuance under the A. O. Smith Combined Incentive Compensation Plan. If any awards lapse, expire, terminate or are cancelled without issuance of shares, or shares are forfeited under any award, then such shares will become available for issuance under the A. O. Smith Combined Incentive Compensation Plan, hereby increasing the number of securities remaining available. |
|---|
Item 13. CERTAIN RELATIONSHIPS, RELATED TRANSACTIONS AND DIRECTOR INDEPENDENCE
The information included under the headings “Director Independence and Financial Literacy”, “Compensation Committee Interlocks and Insider Participation” and “Procedure for Review of Related Party Transactions” in our definitive Proxy Statement for the 2016 Annual Meeting of Stockholders (to be filed with the Securities and Exchange Commission under Regulation 14A within 120 days after the end of the registrant’s fiscal year) is incorporated herein by reference.
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
The information included under the heading “Report of the Audit Committee” in our definitive Proxy Statement for the 2016 Annual Meeting of Stockholders (to be filed with the Securities and Exchange Commission under Regulation 14A within 120 days after the end of the registrant’s fiscal year) required by this Item 14 is incorporated herein by reference.
Table of Contents
PART IV
Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES
(a) The following documents are filed as part of this Annual Report on Form 10-K:
| 1. | Financial Statements of the Company |
|---|
| Form 10-K Page Number | ||||
| The following consolidated financial statements of A. O. Smith Corporation are included in Item 8: | ||||
| Consolidated Balance Sheets at December 31, 2015 and 2014 | 26 | |||
| For each of the three years in the period ended December 31, 2015: | ||||
| - Consolidated Statement of Earnings | 27 | |||
| - Consolidated Statement of Comprehensive Earnings | 27 | |||
| - Consolidated Statement of Cash Flows | 28 | |||
| - Consolidated Statement of Stockholders’ Equity | 29 | |||
| Notes to Consolidated Financial Statements | 30 - 53 |
| 2. | Financial Statement Schedules |
|---|
| Schedule II - Valuation and Qualifying Accounts | 62 | |||||
| Schedules not included have been omitted because they are not applicable. |
| 3. | Exhibits - see the Index to Exhibits on pages 60 - 61 of this report. Each management contract or compensatory plan or arrangement required to be filed as an exhibit to this report on Form 10-K are listed as Exhibits 10(a) through 10(m) in the Index to Exhibits. |
|---|
Pursuant to the requirements of Rule 14a-3(b)(10) of the Securities Exchange Act of 1934, as amended, we will, upon request and upon payment of a reasonable fee not to exceed the rate at which such copies are available from the Securities and Exchange Commission, furnish copies to our security holders of any exhibits listed in the Index to Exhibits.
Table of Contents
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on behalf of the undersigned, thereunto duly authorized.
| A. O. SMITH CORPORATION | ||||||
| Date: February 17, 2016 | By: | /s/ Ajita G. Rajendra | ||||
| Ajita G. Rajendra | ||||||
| Executive Chairman of | ||||||
| the Board of Directors |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below as of February 17, 2016 by the following persons on behalf of the registrant and in the capacities and on the dates indicated.
| Name and Title | Signature | |
| AJITA G. RAJENDRA | /s/ Ajita G. Rajendra | |
| Chairman of the Board, President and Chief Executive Officer | Ajita G. Rajendra | |
| JOHN J. KITA | /s/ John J. Kita | |
| Executive Vice President and Chief Financial Officer | John J. Kita | |
| DANIEL L. KEMPKEN | /s/ Daniel L. Kempken | |
| Vice President and Controller | Daniel L. Kempken | |
| RONALD D. BROWN | /s/ Ronald D. Brown | |
| Director | Ronald D. Brown | |
| GLOSTER B. CURRENT, Jr. | /s/ Gloster B. Current, Jr. | |
| Director | Gloster B. Current, Jr. | |
| WILLIAM P. GREUBEL | /s/ William P. Greubel | |
| Director | William P. Greubel | |
| PAUL W. JONES | /s/ Paul W. Jones | |
| Director | Paul W. Jones | |
| MATHIAS F. SANDOVAL | /s/ Mathias F. Sandoval | |
| Director | Mathias F. Sandoval | |
| BRUCE M. SMITH | /s/ Bruce M. Smith | |
| Director | Bruce M. Smith | |
| MARK D. SMITH | /s/ Mark D. Smith | |
| Director | Mark D. Smith | |
| IDELLE K. WOLF | /s/ Idelle K. Wolf | |
| Director | Idelle K. Wolf | |
| GENE C. WULF | /s/ Gene C. Wulf | |
| Director | Gene C. Wulf |
Table of Contents
INDEX TO EXHIBITS
| Exhibit Number | Description | |||
| (3)(i) | Amended and Restated Certificate of Incorporation of A. O. Smith Corporation as amended through April 15, 2013, incorporated by reference to the annual report on Form 10-K for the fiscal year ended December 31, 2013. | |||
| (3)(ii) | By-laws of A. O. Smith Corporation as amended April 11, 2006, incorporated by reference to Exhibit 3 to the quarterly report on Form 10-Q for the quarter ended June 30, 2006. | |||
| (4) | (a) | Amended and Restated Certificate of Incorporation of A. O. Smith Corporation as amended through April 15, 2013, incorporated by reference to the annual report on Form 10-K for the fiscal year ended December 31, 2013. | ||
| (b) | Amended and Restated Credit Agreement, dated as of December 12, 2012, among A. O. Smith Corporation, A. O Smith Enterprises Ltd., A. O. Smith International Holdings B.V., and the financial institutions and agents party thereto, incorporated by reference to the current report on Form 8-K dated December 12, 2012. | |||
| (c) | The corporation has instruments that define the rights of holders of long-term debt that are not being filed with this Registration Statement in reliance upon Item 601(b)(4)(iii) of Regulation S-K. The Registrant agrees to furnish to the Securities and Exchange Commission, upon request, copies of these instruments. | |||
| (10) | Material Contracts | |||
| (a) | A. O. Smith Combined Incentive Compensation Plan, incorporated by reference as Exhibit A to the Proxy Statement filed on March 5, 2012 for the 2012 Annual Meeting of Stockholders. | |||
| (b) | A. O. Smith Corporation Executive Life Insurance Plan, as amended January 1, 2009, incorporated by reference to the annual report on Form 10-K for the fiscal year ended December 31, 2008. | |||
| (c) | A. O. Smith Nonqualified Deferred Compensation Plan, adopted December 1, 2008, incorporated by reference to the annual report on Form 10-K for the fiscal year ended December 31, 2008. | |||
| (d) | A. O. Smith Corporation Executive Supplemental Pension Plan, as amended January 1, 2009, incorporated by reference to the annual report on Form 10-K for the fiscal year ended December 31, 2008. | |||
| (e) | A. O. Smith Corporation Executive Incentive Compensation Award Agreement, incorporated by reference to the Form S-8 Registration Statement filed by the corporation on July 30, 2007 (Reg. No. 333-144950). | |||
| (f) | A. O. Smith Corporation Executive Incentive Compensation Award Agreement, incorporated by reference to the quarterly report on Form 10-Q for the quarter ended March 31, 2012. | |||
| (g) | Offer Letter to Paul W. Jones, dated December 9, 2003, incorporated by reference to the annual report on Form 10-K for the fiscal year ended December 31, 2007. | |||
| (h) | Offer Letter to Ajita G. Rajendra, dated September 20, 2004, incorporated by reference to the annual report on Form 10-K for the fiscal year ended December 31, 2007. | |||
| (i) | Amendment to Offer Letter to Ajita G. Rajendra dated December 10, 2015. | |||
| (j) | Summary of Directors’ Compensation incorporated by reference to the quarterly report on Form 10-Q for the quarter ended June 30, 2015. |
Table of Contents
INDEX TO EXHIBITS (continued)
| Exhibit Number | Description | |||
| (k) | A. O. Smith Corporation Senior Leadership Severance Plan, incorporated by Reference to the quarterly report for Form 10-Q for the quarter ended June 30, 2009. | |||
| (l) | Form of A. O. Smith Corporation Special Retention Award Agreement, incorporated by reference to the quarterly report on Form 10-Q for the quarter ended March 31, 2011. | |||
| (m) | Stockholder Agreement dated as of December 9, 2008, between A. O. Smith Corporation and each Smith Investment Company stockholder who becomes a signatory thereto, incorporated by reference to the current report on Form 8-K dated December 9, 2008. | |||
| (21) | Subsidiaries. | |||
| (23) | Consent of Independent Registered Public Accounting Firm. | |||
| (31.1) | Certification by the Chief Executive Officer, pursuant to Section 302 of the Sarbanes-Oxley Act, dated February 17, 2016. | |||
| (31.2) | Certification by the Executive Vice-President and Chief Financial Officer, pursuant to Section 302 of the Sarbanes-Oxley Act, dated February 17, 2016. | |||
| (32.1) | Written Statement of the Chief Executive Officer Pursuant to 18 U.S.C. Section 1350. | |||
| (32.2) | Written Statement of the Chief Financial Officer Pursuant to 18 U.S.C. Section 1350. | |||
| (101) | The following materials from A. O. Smith Corporation’s Annual Report on Form 10-K for the fiscal year ended December 31, 2015 are filed herewith, formatted in XBRL (Extensive Business Reporting Language): (i) the Consolidated Balance Sheets as of December 31, 2015 and 2014, (ii) the Consolidated Statement of Earnings for the three years ended December 31, 2015, (iii) the Consolidated Statement of Comprehensive Earnings for the three years ended December 31, 2015, (iv) the Consolidated Statement of Cash Flows for the three years ended December 31, 2015, (v) the Consolidated Statement of Stockholders’ Equity for the three years ended December 31, 2015 and (vi) the Notes to Consolidated Financial Statements. |
Table of Contents
A. O. SMITH CORPORATION
SCHEDULE II - VALUATION AND QUALIFYING ACCOUNTS
(Dollars in millions)
Years ended December 31, 2015, 2014 and 2013
| Description | Balance at Beginning of Year | Charged to Costs and Expenses | Deductions | Balance at End of Year | ||||||||||||
| 2015: | ||||||||||||||||
| Valuation allowance for trade and notes receivable | $ | 3.7 | $ | 2.6 | $ | (0.3 | ) | $ | 6.0 | |||||||
| Valuation allowance for deferred tax assets | 9.8 | 1.4 | (0.2 | ) | 11.0 | |||||||||||
| 2014: | ||||||||||||||||
| Valuation allowance for trade and notes receivable | 2.8 | 1.4 | (0.5 | ) | 3.7 | |||||||||||
| Valuation allowance for deferred tax assets | 9.6 | 1.0 | (0.8 | ) | 9.8 | |||||||||||
| 2013: | ||||||||||||||||
| Valuation allowance for trade and notes receivable | 4.2 | 0.2 | (1.6 | ) | 2.8 | |||||||||||
| Valuation allowance for deferred tax assets | 7.4 | 2.2 | — | 9.6 |