 filings.tools
Item 2. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
295K characters. Original on sec.gov · Markdown
Item 2. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
The following discussion should be read in conjunction with Apollo Global Management, Inc.’s condensed consolidated financial statements and the related notes within this quarterly report. This discussion contains forward-looking statements that are subject to known and unknown risks and uncertainties. Actual results and the timing of events may differ significantly from those expressed or implied in such forward-looking statements due to a number of factors, including those included in our quarterly report on Form 10-Q filed with the SEC on May 10, 2022 and in the section of this report entitled “Item 1A. Risk Factors.” The highlights listed below have had significant effects on many items within our condensed consolidated financial statements and affect the comparison of the current period’s activity with those of prior periods. Target returns included in this report are presented gross and do not account for fees, expenses and taxes, which will reduce returns. Target returns are neither guarantees nor predictions or projections of future performance. There can be no assurance that target returns will be achieved or that Apollo will be successful in implementing the applicable strategy. Actual gross and net returns for funds managed by Apollo, and individual investors participating directly or indirectly in funds managed by Apollo, may vary significantly from the target returns set forth herein.
General
Our Businesses
Founded in 1990, Apollo is a high-growth, global alternative asset manager and a retirement services provider. Apollo conducts its business primarily in the United States through the following three reportable segments: Asset Management, Retirement Services and Principal Investing. These business segments are differentiated based on the investment services they provide as well as varying investing strategies.
Asset Management
Our Asset Management segment focuses on three investing strategies: yield, hybrid and equity. We have a flexible mandate in many of the funds we manage which enables our funds to invest opportunistically across a company’s capital structure. We raise, invest and manage funds on behalf of some of the world’s most prominent pension, endowment and sovereign wealth funds, as well as other institutional and individual investors. As of September 30, 2022, we had total AUM of $523.3 billion.
Our Asset Management segment had a team of 2,528 employees as of September 30, 2022, with offices throughout the world. This team possesses a broad range of transaction, financial, managerial and investment skills. We operate our asset management business in a highly integrated manner, which we believe distinguishes us from other alternative asset managers. Our investment teams frequently collaborate across disciplines and believe that this collaboration enables the funds we manage to more successfully invest across a company’s capital structure. Our objective is to achieve superior long-term risk-adjusted returns for our clients. The majority of the investment funds we manage are designed to invest capital over periods of seven or more years from inception, thereby allowing us to seek to generate attractive long-term returns throughout economic cycles. We have a contrarian, value-oriented investment approach, emphasizing downside protection, and the preservation of capital. We believe our contrarian investment approach is reflected in a number of ways, including:
-
our willingness to pursue investments in industries that our competitors typically avoid;
-
the often complex structures employed in some of the investments of our funds;
-
our experience investing during periods of uncertainty or distress in the economy or financial markets; and
-
our willingness to undertake transactions that have substantial business, regulatory or legal complexity.
We have applied this investment philosophy to identify what we believe are attractive investment opportunities, deploy capital across the balance sheet of industry leading, or “franchise,” businesses and create value throughout economic cycles.
The yield, hybrid and equity investing strategies of our Asset Management segment reflect the range of investment capabilities across our platform based on relative risk and return. As an asset manager, we earn fees for providing investment management services and expertise to our client base. The amount of fees charged for managing these assets depends on the underlying investment strategy, liquidity profile, and, ultimately, our ability to generate returns for our clients. We also earn transaction and advisory fees as part of our growing capital solutions business and as part of monitoring and deployment activity alongside our sizeable private equity franchise. After expenses, we call the resulting earnings stream “Fee Related Earnings” or “FRE”, which represents the primary performance measure for the Asset Management segment.
Yield
Yield is our largest asset management strategy with $372.6 billion of AUM as of September 30, 2022. Our yield strategy focuses on generating excess returns through high-quality credit underwriting and origination. Beyond participation in the traditional issuance and secondary credit markets, through our origination platforms and corporate solutions capabilities we seek to originate attractive and safe-yielding assets for our investors. Within our yield strategy, we target 4% to 10% returns for our clients. Since inception, the total return yield fund has generated a 5% gross Return on Equity (“ROE”) and 4% net ROE annualized through September 30, 2022. The investment portfolios of the yield-oriented funds Apollo manages include several asset classes, as described below:
-
Corporate Fixed Income ($97.7 billion of AUM), which generally includes investment grade corporate bonds, emerging markets investments and investment grade private placement investments;
-
Corporate Credit ($71.9 billion of AUM), which includes performing credit investments, including income-oriented, senior loan and bond investments involving issuers primarily domiciled in the U.S. and in Europe as well as investment grade asset-backed securities;
-
Structured Credit ($70.7 billion of AUM), which includes corporate structured and asset-backed securities as well consumer and residential real estate credit investments;
-
Real Estate Debt ($38.4 billion of AUM), including debt investments across a broad spectrum of property types and at various points within a property’s capital structure, including first mortgage and mezzanine financing and preferred equity; and
-
Direct Origination ($33.8 billion of AUM), which includes originations (both directly with sponsors and through banks) and investments in loans primarily related to middle market lending and aviation finance.
Hybrid
Our hybrid strategy, with $56.7 billion of AUM as of September 30, 2022, brings together our capabilities across debt and equity to seek to offer a differentiated risk-adjusted return with an emphasis on structured downside protected opportunities across asset classes. We target 8% to 15% returns within our hybrid strategy by pursuing investments in all market environments, deploying capital during both periods of dislocation and market strength, and focusing on different investing strategies and asset classes. Our flagship hybrid credit hedge fund has generated an 11% gross ROE and a 7% net ROE annualized and our hybrid value funds have generated a 21% gross IRR and a 17% net IRR from inception through September 30, 2022. The investing strategies and asset classes within our hybrid strategy are described below:
-
Accord and Credit Strategies ($10.0 billion of AUM), which refers to the investment strategy of certain funds managed by Apollo that invest opportunistically in both the primary and secondary markets in order to seek to capitalize on both near and longer-term relative value across market cycles. The investment portfolios of these funds include credit investments in a broad array of primary and secondary opportunities encompassing stressed and distressed public and private securities including senior loans (secured and unsecured), large corporate investment grade loan origination and structured capital solutions, high yield, mezzanine, derivative securities, debtor in possession financings, rescue or bridge financings, and other debt investments.
-
Hybrid Value ($11.2 billion of AUM), which refers to the investment strategy of certain funds managed by Apollo that focus on providing companies, among other things, rescue financing or customized capital solutions, including senior secured and unsecured debt or preferred equity securities, often with equity-linked or equity-like upside, as well as structured equity investments.
-
Infrastructure Equity ($5.5 billion of AUM), which refers to the investment strategy of certain funds managed by Apollo that focus on investing in a broad range of infrastructure assets, including communications, midstream energy, power and renewables, and transportation related assets.
-
Hybrid Real Estate ($5.0 billion of AUM), which includes our net lease and core plus investment strategies. In our net lease strategy, we seek to build net lease investment portfolios for our clients that are diversified by both geography and tenancy, while targeting attractive risk-adjusted returns. In our core plus strategy, we seek to build investment
portfolios for our clients that include stabilized real estate investments with attractive fundamentals in select cities in Europe.
Equity
Our equity strategy manages $93.9 billion of AUM as of September 30, 2022. Our equity strategy emphasizes flexibility, complexity, and purchase price discipline to drive opportunistic-like returns for our clients throughout market cycles. Apollo’s equity team has experience across sectors, industries, and geographies in both private equity and real estate equity. Our control equity transactions are principally buyouts, corporate carveouts and distressed investments, while our real estate funds generally transact in single asset, portfolio and platform acquisitions. Within our equity strategy, we target upwards of 15% returns in the funds we manage. We have consistently produced attractive long-term investment returns in our traditional private equity funds, generating a 39% gross IRR and a 24% net IRR on a compound annual basis from inception through September 30, 2022. Our equity strategy focuses on several investing strategies as described below:
- Flagship Private Equity ($66.1 billion of AUM), which refers to our investment strategy focused on creating investment opportunities with attractive risk-adjusted returns across industries and geographies and throughout market cycles, utilizing our value-oriented investment approach. Through this strategy, we seek to build portfolios of investments that are created at meaningful discounts to comparable market multiples of adjusted cash flow, thereby resulting in what we believe are portfolios focused on capital preservation. The transactions in this strategy include opportunistic buyouts, corporate carveouts and distressed investments. After acquisition by an Apollo-managed fund, Apollo works with its funds’ portfolio companies to seek to accelerate growth and execute a value creation strategy.
Included within flagship private equity are assets related to our impact investing strategy, which pursues private equity-like investment opportunities with the intention of generating a positive, measurable, social and/or environmental impact while also seeking attractive risk-adjusted returns. The impact investment strategy targets investment opportunities across five core impact-aligned investment themes including: (i) economic opportunity, (ii) education; (iii) health, safety and wellness; (iv) industry 4.0; and (v) climate and sustainability.
-
European Principal Finance (“EPF”) ($7.6 billion of AUM), which refers to our investment strategy focused on European commercial and residential real estate, performing loans, non-performing loans, and unsecured consumer loans, as well as acquiring assets as a result of distressed market situations. Certain of the European principal finance vehicles we manage also own captive pan-European financial institutions, loan servicing and property management platforms that perform banking and lending activities and manage and service consumer credit receivables and loans secured by commercial and residential properties.
-
Real Estate Equity ($5.4 billion of AUM), which refers to our investment strategy that targets investments in real estate and real estate-related assets, portfolios and platforms located in primary, secondary and tertiary markets across North America and Asia and across various real estate asset classes.
Perpetual Capital
Included within our investing strategies above is $305.4 billion of Perpetual Capital, out of the $523.3 billion of AUM as of September 30, 2022. As of September 30, 2022, Perpetual Capital includes, without limitation, certain assets in our Yield strategy, including assets relating to publicly traded and non-traded vehicles, certain origination platform assets and assets managed for certain of our retirement services clients. Perpetual Capital assets may be withdrawn under certain circumstances.
Retirement Services
Our retirement services business is conducted by Athene, a leading financial services company that specializes in issuing, reinsuring and acquiring retirement savings products designed for the increasing number of individuals and institutions seeking to fund retirement needs. Athene provides retail annuity retirement solutions to policyholders, and reinsures fixed indexed annuities (“FIA”), multi-year guaranteed annuities (“MYGA”), traditional one-year guarantee fixed deferred annuities, immediate annuities and institutional products from reinsurance partners. In addition, Athene offers institutional products, including funding agreements and pension group annuities. Apollo’s asset management business provides a full suite of services for Athene’s investment portfolio, including direct investment management, asset allocation, mergers and acquisition asset diligence and certain operational support services, including investment compliance, tax, legal and risk management support. As of September 30, 2022, Athene had 1,602 employees.
Our retirement services business focuses on generating spread income by combining the two core competencies of (1) sourcing long-term, generally illiquid liabilities and (2) using the global scale and reach of our asset management business to actively source or originate assets with Athene’s preferred risk and return characteristics. Athene’s investment philosophy is to invest a portion of its assets in securities that earn an incremental yield by taking measured liquidity and complexity risk and capitalizing on its long-dated, persistent liability profile to prudently achieve higher net investment earned rates, rather than solely assuming credit risk. A cornerstone of Athene’s investment philosophy is that given the operating leverage inherent in its business, modest investment outperformance can translate to outsized return performance. Because Athene maintains discipline in underwriting attractively priced liabilities, it has the ability to invest in a broad range of high-quality assets to generate attractive earnings.
Our asset management expertise supports the sourcing and underwriting of asset classes for Athene’s portfolio. Athene is invested in a diverse array of corporate bonds and more structured, but highly rated, asset classes. Athene establishes risk thresholds which in turn define risk tolerance across a wide range of factors, including credit risk, liquidity risk, concentration risk and caps on specific asset classes. In addition to other efforts, we partially mitigate the risk of rising interest rates by strategically allocating a meaningful portion of Athene’s investment portfolio into floating rate securities. Athene also maintains holdings in less interest rate-sensitive investments, including collateralized loan obligations (“CLO”), commercial mortgage loans, residential mortgage loans, non-agency residential mortgage-backed securities (“RMBS”) and various types of structured products, consistent with its strategy of pursuing incremental yield by assuming liquidity risk and complexity risk, rather than assuming solely credit risk.
Rather than increase Athene’s allocation to higher risk securities to increase yield, we pursue the direct origination of high-quality, predominantly senior secured assets, which we believe possess greater alpha-generating qualities than securities that would otherwise be readily available in public markets. These direct origination strategies include investments sourced by (1) affiliated platforms that originate loans to third parties and in which Athene gains exposure directly to the loan or indirectly through its ownership of the platform, and (2) our extensive network of direct relationships with predominantly investment-grade counterparties.
Athene uses, and may continue to use, derivatives, including swaps, options, futures and forward contracts, and reinsurance contracts to hedge risks such as current or future changes in the fair value of its assets and liabilities, current or future changes in cash flows, changes in interest rates, equity markets, currency fluctuations and changes in longevity.
Products
Athene principally offers two product lines: annuities and funding agreements.
Annuities
Athene’s primary product line is annuities, which include Fixed Indexed Annuities, Registered Index-Linked Annuities, Fixed Rate Annuities, Payout Annuities and Group Annuities.
Fixed Indexed Annuities (“FIAs”). FIAs are the majority of Athene’s net reserve liabilities. FIAs are a type of insurance contract in which the policyholder makes one or more premium deposits which earn interest, on a tax deferred basis, at a crediting rate based on a specified market index, subject to a specified cap, spread or participation rate. FIAs allow policyholders the possibility of earning interest without significant risk to principal, unless the contract is surrendered during a surrender charge period. A market index tracks the performance of a specific group of stocks or other assets representing a particular segment of the market, or in some cases, an entire market. Athene generally buys options on the indices to which the FIAs are tied to hedge the associated market risk. The cost of the option is priced into the overall economics of the product as an option budget. Athene generates income on FIA products by earning an investment spread, based on the difference between (1) income earned on the investments supporting the liabilities and (2) the cost of funds, including fixed interest credited to customers, option costs, the cost of providing guarantees (net of rider fees), policy issuance and maintenance costs, and commission costs.
Registered Index-Linked Annuities (“RILA”). A RILA is similar to an FIA in offering the policyholder the opportunity for tax-deferred growth based in part on the performance of a market index. Compared to an FIA, a RILA has the potential for higher returns but also has the potential for risk of loss to principal and related earnings. A RILA provides the ability for the policyholder to participate in the positive performance of certain market indices during a term, limited by a cap or adjusted for a
participation rate. Negative performance of the market indices during a term can result in negative policyholder returns, with downside protection typically provided in the form of either a “buffer” or a “floor” to limit the policyholder’s exposure to market loss. A “buffer” is protection from negative exposure up to a certain percentage, typically 10 or 20 percent. A “floor” is protection from negative exposure less than a stated percentage (i.e., the policyholder risks exposure of loss up to the “floor,” but is protected against any loss in excess of this amount).
Fixed Rate Annuities. Fixed rate annuities include annual reset annuities and MYGAs. Unlike FIAs, fixed rate annuities earn interest at a set rate (or declared crediting rate), rather than a rate that may vary based on an index. Fixed rate annual reset annuities have a crediting rate that is typically guaranteed for one year. After such period, Athene has the ability to change the crediting rate at its discretion, generally once annually, to any rate at or above a guaranteed minimum rate. MYGAs are similar to annual reset annuities except that the initial crediting rate is guaranteed for a specified number of years, rather than just one year, before it may be changed at Athene’s discretion. After the initial crediting period, MYGAs can generally be reset annually.
Withdrawal Options for Deferred Annuities. After the first year following the issuance of a deferred annuity, the policyholder is typically permitted to make withdrawals up to 5% or 10% (depending on the contract) of the prior year’s value without a surrender charge or market value adjustment (“MVA”), subject to certain limitations. Withdrawals in excess of the allowable amounts are assessed a surrender charge and MVA if such withdrawals are made during the surrender charge period of the policy. The surrender charge for most Athene products at contract inception is generally between 7% and 15% of the contract value and decreases by approximately one percentage point per year during the surrender charge period, which generally ranges from 3 to 20 years.
At maturity, the policyholder may elect to receive proceeds in the form of a single payment or an annuity. If the annuity option is selected, the policyholder will receive a series of payments either over the policyholder’s lifetime or over a fixed number of years, depending upon the terms of the contract. Some contracts permit annuitization prior to maturity. A fixed annuity policyholder may also elect to purchase an income rider.
Income Riders to Fixed Annuity Products. Athene’s income riders on its deferred annuities can be broadly categorized as either guaranteed or participating. Guaranteed income riders provide policyholders with a GLWB, which permits policyholders to elect to receive guaranteed payments for life from their contract without having to annuitize their policies. Participating income riders tend to have lower levels of guaranteed income than guaranteed income riders but provide policyholders the opportunity to receive greater levels of income if the policies’ indexed crediting strategies perform well. As of September 30, 2022, approximately 33% of Athene’s deferred annuity account value had rider benefits.
Payout Annuities. Payout annuities primarily consist of single premium immediate annuities (“SPIA”), supplemental contracts and structured settlements. Payout annuities provide a series of periodic payments for a fixed period of time or for the life of the policyholder, based upon the policyholder’s election at the time of issuance. The amounts, frequency and length of time of the payments are fixed at the outset of the annuity contract. SPIAs are often purchased by persons at or near retirement age who desire a steady stream of payments over a future period of years. Supplemental contracts are typically created upon the conversion of a death claim or the annuitization of a deferred annuity. Structured settlements generally relate to legal settlements.
Group Annuities. Group annuities issued in connection with pension group annuity transactions usually involve a single premium group annuity contract issued to discharge certain pension plan liabilities. The group annuities that Athene issues are non-participating contracts. The assets supporting the guaranteed benefits for each contract may be held in a separate account. Group annuity benefits may be purchased for current, retired and/or terminated employees and their beneficiaries covered under terminating or continuing pension plans. Both immediate and deferred annuity certificates may be issued pursuant to a single group annuity contract. Immediate annuity certificates cover those retirees and beneficiaries currently receiving payments, whereas deferred annuity certificates cover those participants who have not yet begun receiving benefit payments. Immediate annuity certificates have no cash surrender rights, whereas deferred annuity certificates may include an election to receive a lump sum payment, exercisable by the participant upon either the participant achieving a specified age or the occurrence of a specified event, such as termination of the participant’s employment.
Athene earns income on group annuities based upon the spread between the return on the assets received in connection with the pension group annuity transaction and the cost of the pension obligations assumed. Group annuities expose Athene to longevity risk, which would be realized if plan participants live longer than assumed in underwriting the transaction, resulting in aggregate payments that exceed Athene’s expectations.
Funding Agreements
Funding agreements are issued opportunistically to institutional investors at attractive risk-adjusted funding costs. Funding agreements are negotiated privately between an investor and an insurance company. They are designed to provide an agreement holder with a guaranteed return of principal and periodic interest payments, while offering competitive yields and predictable returns. The interest rate can be fixed or floating. Athene also includes repurchase agreements with a term that exceeds one year at the time of execution within the funding agreement product category.
Distribution Channels
Athene has developed four dedicated distribution channels to address the retirement services market: retail, flow reinsurance, institutional and acquisitions and block reinsurance, which support opportunistic origination across differing market environments. Additionally, Athene believes these distribution channels enable it to achieve stable asset growth while maintaining attractive returns.
Retail
Athene has built a scalable platform that allows it to originate and rapidly grow its business in deferred annuity products. Athene has developed a suite of retirement savings products, distributed through its network of approximately 54 independent marketing organizations; approximately 75,000 independent agents in all 50 states; and a growing network of 16 banks and 125 regional broker-dealers. Athene is focused in every aspect of its retail channel on providing high quality products and service to its policyholders and maintaining appropriate financial protection over the life of their policies.
Flow Reinsurance
Flow reinsurance provides another opportunistic channel for Athene to source liabilities with attractive cost of funds and offers insurance companies the opportunity to improve their product offerings and enhance their financial results. As in the retail channel, Athene does not pursue flow volume growth at the expense of profitability, and therefore tends to respond rapidly to adjust pricing for changes in asset yields.
Reinsurance is an arrangement under which an insurance company, the reinsurer, agrees to indemnify another insurance company, the ceding company or cedant, for all or a portion of certain insurance risks underwritten by the ceding company. Reinsurance is designed to (1) reduce the net amount at risk on individual risks, thereby enabling the ceding company to increase the volume of business it can underwrite, as well as increase the maximum risk it can underwrite on a single risk, (2) stabilize operating results by reducing volatility in the ceding company’s loss experience, (3) assist the ceding company in meeting applicable regulatory requirements and (4) enhance the ceding company’s financial strength and surplus position.
Within its flow reinsurance channel, Athene generally conducts third-party flow reinsurance transactions through its subsidiary, ALRe. As a fixed annuity reinsurer, ALRe partners with insurance companies to develop solutions to their capital requirements, enhance their presence in the retirement market and improve their financial results. The specific liabilities that ALRe targets to reinsure include FIAs, MYGAs, traditional one-year guarantee fixed deferred annuities, immediate annuities and institutional products. For various transaction-related reasons, from time to time, Athene’s US insurance subsidiaries will reinsure business from third-party ceding companies. In these instances, the respective US insurance subsidiary will generally retrocede a portion of the reinsured business to Athene Annuity Re Ltd. or ALRe.
Institutional
The Institutional channel includes pension group annuity transactions and funding agreements.
Pension Group Annuity Transactions. Athene partners with institutions seeking to transfer and thereby reduce their obligation to pay future pension benefits to retirees and deferred participants, through pension group annuities. Athene works with advisors, brokers and consultants to source pension group annuity transactions and design solutions that meet the needs of prospective pension group annuity counterparties.
Funding Agreements. Athene participates in a FABN program through which it may issue funding agreements to a special-purpose trust that issues marketable medium-term notes. The notes are underwritten and marketed by major investment banks’
broker-dealer operations and are sold to institutional investors. The proceeds of the issuance of notes are used by the trust to purchase one or more funding agreements from Athene subsidiaries with matching interest and maturity payment terms. Athene has established a funding agreement-backed repurchase program, in which a special-purpose, unaffiliated entity may enter into a repurchase agreement with a bank and the proceeds of the repurchase transactions are used by the special-purpose entity to purchase secured funding agreements from Athene subsidiaries. Athene is also a member of the FHLB and Athene has issued funding agreements to the FHLB in exchange for cash advances. Finally, repurchase agreements with an original maturity exceeding one year are also included within the funding agreement channel.
Acquisitions and Block Reinsurance
Acquisitions. Acquisitions are an important source of growth in our retirement services business. Athene has a proven ability to acquire businesses in complex transactions at favorable terms, manage the liabilities acquired and reinvest the associated assets. Athene plans to continue leveraging this expertise in sourcing and evaluating transactions to profitably grow its business. Athene believes its demonstrated ability to source transactions, consummate complex transactions and reinvest assets into higher yielding investments as well as its access to capital provide it with distinct advantages relative to other acquisition candidates.
Block Reinsurance. Through block reinsurance transactions, Athene partners with life and annuity companies to decrease their exposure to one or more products or to divest of lower-margin or non-core segments of their businesses. Unlike acquisitions in which Athene must acquire the assets or stock of a target company, block reinsurance allows Athene to contractually assume assets and liabilities associated with a certain book of business. In doing so, Athene contractually assumes responsibility for only that portion of the business that it deems desirable, without assuming additional liabilities.
Capital
We believe that Athene has a strong capital position and that it is well positioned to meet policyholder and other obligations. Athene measures capital sufficiency using an internal capital model which reflects management’s view on the various risks inherent to its business, the amount of capital required to support its core operating strategies and the amount of capital necessary to maintain its current ratings in a recessionary environment. The amount of capital required to support Athene’s core operating strategies is determined based upon internal modeling and analysis of economic risk, as well as inputs from rating agency capital models and consideration of both NAIC risk-based capital (“RBC”) and Bermuda capital requirements. Capital in excess of this required amount is considered excess equity capital, which is available to deploy.
Deployable Capital
Athene’s deployable capital is comprised of capital from three sources: excess equity capital, untapped debt capacity and available undrawn capital commitments from ACRA. As of September 30, 2022, we believe that Athene had approximately $5.8 billion in total excess equity capital, untapped debt capacity and available undrawn ACRA commitments available to be deployed, subject, in the case of debt capacity, to favorable market conditions and general availability.
ACRA
In order to support growth strategies and capital deployment opportunities, Athene established ACRA as a long-duration, on-demand capital vehicle. Athene owns 36.55% of ACRA’s economic interests and 100% of ACRA’s voting interests, with the remaining 63.45% of the economic interests being owned by ADIP, a series of funds managed by Apollo. ACRA participates in certain transactions by drawing a portion of the required capital for such transactions from third-party investors equal to ADIP’s proportionate economic interest in ACRA. This strategic capital solution allows us the flexibility to simultaneously deploy capital across multiple accretive avenues, while maintaining a strong financial position for Athene and its subsidiaries.
Uses of Capital
Capital deployment includes the payment for a business opportunity, such as the payment of a ceding commission to enter into a block reinsurance transaction, and the retention of capital based on our internal capital model. Currently, we deploy capital from our retirement services business in four primary ways: (1) supporting organic growth, (2) supporting inorganic growth, (3) making dividend payments to AGM from time to time, and (4) retaining capital to support financial strength ratings upgrades. Athene generally seeks mid-teen returns on its capital deployment.
Internal Reinsurance
Subject to quota shares generally ranging from 80% to 100%, substantially all of the existing deposits held and new deposits generated by Athene’s US insurance subsidiaries are reinsured to its Bermuda reinsurance subsidiaries. Athene maintains the same reserving standards for its Bermuda reinsurance subsidiaries as it does for its US insurance subsidiaries. Athene also retrocedes certain inorganic transactions, pension group annuity transactions and funding agreement transactions to ACRA, and effective January 1, 2022, it began to retrocede a quota share of its retail business to a subsidiary of ACRA. Athene’s internal reinsurance structure provides it with several strategic and operational advantages, including the aggregation of regulatory capital, which makes the aggregate capital of its Bermuda reinsurance subsidiaries available to support the risks assumed by each entity, and enhanced operating efficiencies. As a result of its internal reinsurance structure and third-party direct to Bermuda business, a significant majority of Athene’s aggregate capital is held by its Bermuda reinsurance subsidiaries.
Ratings
As of September 30, 2022, each of Athene’s significant insurance subsidiaries is rated “A+”, “A1” or “A” by the four rating agencies that evaluate the financial strength of such subsidiaries. To achieve financial strength ratings aspirations in the Retirement Services segment, Athene may choose to retain additional capital above the level required by the rating agencies to support operating needs. Athene believes there are numerous benefits to achieving stronger ratings over time, including increased recognition of and confidence in the financial strength by prospective business partners, particularly within product distribution, as well as potential profitability improvements in certain organic channels through lower funding costs.
Principal Investing
Our Principal Investing segment is comprised of our realized performance fee income, realized investment income from our balance sheet investments, and certain allocable expenses related to corporate functions supporting the entire company. The Principal Investing segment also includes our growth capital and liquidity resources at AGM. We expect to deploy capital into strategic investments over time that will help accelerate the growth of our Asset Management segment, by broadening our investment management and/or product distribution capabilities or increasing the efficiency of our operations. We believe these investments will translate into greater compounded annual growth of Fee Related Earnings.
Given the cyclical nature of performance fees, earnings from our Principal Investing segment, or Principal Investing Income (“PII”), is inherently more volatile in nature than earnings from the Asset Management and Retirement Services segments. We earn fees based on the investment performance of the funds we manage and compensate our employees, primarily investment professionals, with a meaningful portion of these proceeds to align our team with the investors in the funds we manage and incentivize them to deliver strong investment performance over time. We expect to increase the proportion of performance fee income we pay to our employees over time, and as such proportion increases, we expect PII to represent a relatively smaller portion of our total company earnings.
The diagram below depicts our current organizational structure:
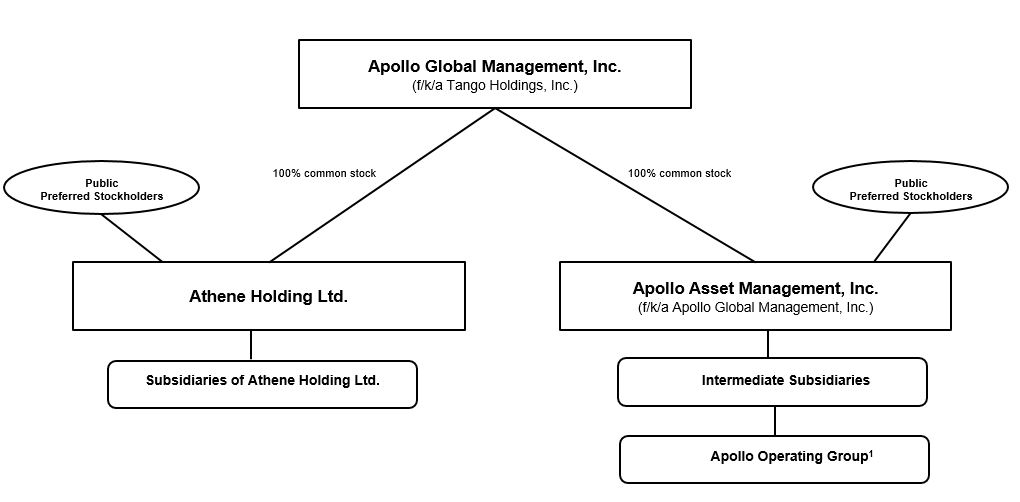
Note: The organizational structure chart above depicts a simplified version of the Apollo structure. It does not include all legal entities in the structure.
(1)Includes direct and indirect ownership by AGM.
Business Environment
Economic and Market Conditions
Our asset management and retirement services businesses are affected by the condition of global financial markets and the economy. Price fluctuations within equity, credit, commodity, foreign exchange markets, as well as interest rates and global inflation, which may be volatile and mixed across geographies, can significantly impact the performance of our business, including, but not limited to, the valuation of investments, including those of the funds we manage, and related income we may recognize.
We carefully monitor economic and market conditions that could potentially give rise to global market volatility and affect our business operations, investment portfolios and derivatives, which includes global inflation.
Adverse economic conditions may result from domestic and global economic and political developments, including plateauing or decreasing economic growth and business activity, civil unrest, geopolitical tensions or military action, such as the armed conflict between Ukraine and Russia and corresponding sanctions imposed by the United States and other countries, and new or evolving legal and regulatory requirements on business investment, hiring, migration, labor supply and global supply chains.
U.S. inflation remained heightened during the third quarter of 2022, and the U.S. Federal Reserve continued its interest rate hiking cycle as a result. The U.S. Bureau of Labor Statistics reported that the annual U.S. inflation rate increased to 8.2% as of September 30, 2022, compared to 9.1% as of June 30, 2022, and core inflation is at the highest level since the 1980s. In September 2022, the Federal Reserve raised the benchmark interest rate to a target range of 3.00% to 3.25% from a target range of 1.50% to 1.75% in June 2022. The increase in the U.S. inflation rate continues to be driven by various factors, including the armed conflict between Ukraine and Russia, supply chain disruptions, persistent consumer demand, tight labor markets, a distorted supply/demand housing imbalance, and residential vacancy rates.
In the U.S., the S&P 500 Index decreased by 5.3% during the third quarter of 2022, following a decrease of 16.4% during the second quarter of 2022. Global equity markets have also been impacted, with the MSCI All Country World ex USA Index decreasing 9.1% during the third quarter of 2022, following a decrease of 14.4% in the second quarter of 2022.
Conditions in the credit markets have a significant impact on our business. Credit markets are negative in 2022, with the BofAML HY Master II Index decreasing by 0.7% in the third quarter of 2022, while the S&P/LSTA Leveraged Loan Index increased by 1.3%. The U.S. 10-year Treasury yield at the end of the quarter was 3.83%.
In terms of economic conditions in the U.S., the Bureau of Economic Analysis reported real GDP increased at an annual rate of 2.6% in the third quarter of 2022, following a decrease of 0.9% in the second quarter of 2022. As of October 2022, the International Monetary Fund estimated that the U.S. economy will expand by 1.6% in 2022 and 1.0% in 2023. The U.S. Bureau of Labor Statistics reported that the U.S. unemployment rate decreased to 3.5% as of September 30, 2022.
Foreign exchange rates can materially impact the valuations of our investments and those of the funds we manage that are denominated in currencies other than the U.S. dollar. The increasing yield disparity globally drove the strengthening of the U.S.
dollar compared to the euro and the British pound. Relative to the U.S. dollar, the euro depreciated 6.5% during the third quarter of 2022, after depreciating 5.3% in the second quarter of 2022, while the British pound depreciated 8.3% during the third quarter of 2022, after depreciating 7.3% in the second quarter of 2022. The price of crude oil depreciated by 24.8% during the quarter, after appreciating by 5.5% in the second quarter of 2022, as recession fears counteracted constrained supply and oil export disruptions due to the ongoing conflict between Ukraine and Russia.
We are actively monitoring the developments in Ukraine resulting from the Russia/Ukraine conflict and the economic sanctions and restrictions imposed against Russia, Belarus, and certain Russian and Belarussian entities and individuals. The Company continues to (i) identify and assess any exposure to designated persons or entities across the Company’s business; (ii) ensure existing surveillance and controls are calibrated to the evolving sanctions; and (iii) ensure appropriate levels of communication across the Company, and with other relevant market participants, as appropriate.
As of September 30, 2022, the funds we manage have no investments that would cause Apollo or any Apollo managed fund to be in violation of current international sanctions, and we believe the direct exposure of investment portfolios of the funds we manage to Russia and Ukraine is insignificant. The Company and the funds we manage do not intend to make any new material investments in Russia, and have appropriate controls in place to ensure review of any new exposure.
Institutional investors continue to allocate capital towards alternative investment managers for more attractive risk-adjusted returns in a low interest rate environment, and we believe the business environment remains generally accommodative to raise larger successor funds, launch new products, and pursue attractive strategic growth opportunities.
Interest Rate Environment
Rates have already moved meaningfully higher than most predictions for 2022, and this trend continued in the third quarter. The ten-year US Treasury moved out of the 2.80%-3.20% range, reaching levels as high as 3.97% over the quarter. Given the Federal Reserve’s continued focus on curbing inflation and recessionary concerns, it is difficult to predict rates in the near term, although they will likely be higher.
With respect to Retirement Services, Athene’s investment portfolio consists predominantly of fixed maturity investments. If prevailing interest rates were to rise, we believe the yield on Athene’s new investment purchases may also rise and Athene’s investment income from floating rate investments would increase, while the value of Athene’s existing investments may decline. If prevailing interest rates were to decline, it is likely that the yield on Athene’s new investment purchases may decline and Athene’s investment income from floating rate investments would decrease, while the value of Athene’s existing investments may increase.
Athene addresses interest rate risk through managing the duration of the liabilities it sources with assets it acquires through asset liability management (“ALM”) modeling. As part of its investment strategy, Athene purchases floating rate investments, which we expect would perform well in a rising interest rate environment, as we are currently experiencing, and which we expect would underperform in a declining rate environment. As of September 30, 2022, Athene’s net invested asset portfolio includes $38.3 billion of floating rate investments, or 20% of its net invested assets, and its net reserve liabilities include $13.5 billion of floating rate liabilities at notional, or 7% of its net invested assets, translating to $24.8 billion of net floating rate assets, or 13% of its net invested assets.
If prevailing interest rates were to rise, we believe Athene’s products would be more attractive to consumers and its sales would likely increase. If prevailing interest rates were to decline, it is likely that Athene’s products would be less attractive to consumers and Athene’s sales would likely decrease. In periods of prolonged low interest rates, the net investment spread may
be negatively impacted by reduced investment income to the extent that Athene is unable to adequately reduce policyholder crediting rates due to policyholder guarantees in the form of minimum crediting rates or otherwise due to market conditions. A significant majority of Athene’s deferred annuity products have crediting rates that it may reset annually upon renewal following the expiration of the current guaranteed period. While Athene has the contractual ability to lower these crediting rates to the guaranteed minimum levels, its willingness to do so may be limited by competitive pressures.
See Part I - Item 3. Quantitative and Qualitative Disclosures About Market Risk, which includes a discussion regarding interest rate and other significant risks and our strategies for managing these risks.
Overview of Results of Operations
Financials Measures under U.S. GAAP - Asset Management
The following discussion of financial measures under U.S. GAAP is based on Apollo’s asset management business as of September 30, 2022.
Revenues
Management Fees
The significant growth of the assets we manage has had a positive effect on our revenues. Management fees are typically calculated based upon any of “net asset value,” “gross assets,” “adjusted par asset value,” “adjusted costs of all unrealized portfolio investments,” “capital commitments,” “invested capital,” “adjusted assets,” “capital contributions,” or “stockholders’ equity,” each as defined in the applicable limited partnership agreement and/or management agreement of the unconsolidated funds or accounts.
Advisory and Transaction Fees, Net
As a result of providing advisory services with respect to actual and potential investments, we are entitled to receive fees for transactions related to the acquisition and, in certain instances, disposition and financing of companies, some of which are portfolio companies of the funds we manage, as well as fees for ongoing monitoring of portfolio company operations and directors’ fees. We also receive advisory fees for advisory services provided to certain funds. In addition, monitoring fees are generated on certain structured portfolio company investments. Under the terms of the limited partnership agreements for certain funds, the management fee payable by the funds may be subject to a reduction based on a certain percentage (up to 100%) of such advisory and transaction fees, net of applicable broken deal costs (“Management Fee Offset”). Such amounts are presented as a reduction to advisory and transaction fees, net, in the condensed consolidated statements of operations (see note 2 to our condensed consolidated financial statements for more detail on advisory and transaction fees, net).
Performance Fees
The general partners of the funds we manage are entitled to an incentive return of normally up to 20% of the total returns of a fund’s capital, depending upon performance of the underlying funds and subject to preferred returns and high water marks, as applicable. Performance fees, categorized as performance allocations, are accounted for as an equity method investment, and effectively, the performance fees for any period are based upon an assumed liquidation of the funds’ assets at the reporting date, and distribution of the net proceeds in accordance with the funds’ allocation provisions. Performance fees categorized as incentive fees, which are not accounted as an equity method investment, are deferred until fees are probable to not be significantly reversed. The majority of performance fees are comprised of performance allocations.
As of September 30, 2022, approximately 45% of the value of our funds’ investments on a gross basis was determined using market-based valuation methods (i.e., reliance on broker or listed exchange quotes) and the remaining 55% was determined primarily by comparable company and industry multiples or discounted cash flow models. See “Item 1A. Risk Factors—Risks Relating to Our Asset Management Business—The performance of the funds we manage, and our performance, may be adversely affected by the financial performance of portfolio companies of the funds we manage and industries in which the funds we manage invest” in our quarterly report on Form 10-Q filed with the SEC on May 10, 2022 for discussion regarding certain industry-specific risks that could affect the fair value of our equity funds’ portfolio company investments.
In our equity strategy funds, the Company does not earn performance fees until the investors in the fund have achieved cumulative investment returns on invested capital (including management fees and expenses) in excess of an 8% hurdle rate. Additionally, certain of our yield and hybrid strategy funds have various performance fee rates and hurdle rates. Certain of our yield and hybrid strategy funds allocate performance fees to the general partner in a similar manner as the equity funds. In our equity, certain yield and hybrid funds, so long as the investors achieve their priority returns, there is a catch-up formula whereby the Company earns a priority return for a portion of the return until the Company’s performance fees equate to its incentive fee rate for that fund; thereafter, the Company participates in returns from the fund at the performance fee rate. Performance fees, categorized as performance allocations, are subject to reversal to the extent that the performance fees distributed exceed the amount due to the general partner based on a fund’s cumulative investment returns. The Company recognizes potential repayment of previously received performance fees as a general partner obligation representing all amounts previously distributed to the general partner that would need to be repaid to the Apollo funds if these funds were to be liquidated based on the current fair value of the underlying funds’ investments as of the reporting date. The actual general partner obligation, however, would not become payable or realized until the end of a fund’s life or as otherwise set forth in the respective limited partnership agreement of the fund.
The table below presents an analysis of Apollo’s (i) performance fees receivable on an unconsolidated basis and (ii) realized and unrealized performance fees:
| As of September 30, 2022 | Performance Fees for the Three Months Ended September 30, 2022 | Performance Fees for the Nine Months Ended September 30, 2022 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (In millions) | Performance Fees Receivable on an Unconsolidated Basis | Unrealized | Realized | Total | Unrealized | Realized | Total | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| AIOF I and II | $ | 30.2 | $ | 16.2 | $ | — | $ | 16.2 | $ | 14.2 | $ | 5.6 | $ | 19.8 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| ANRP I, II and III1 | 28.6 | (0.8) | 0.3 | (0.5) | (64.5) | 2.1 | (62.4) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| EPF Funds | 127.3 | 9.3 | 9.6 | 18.9 | (11.2) | 47.0 | 35.8 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| FCI Funds | 135.7 | (12.0) | — | (12.0) | (3.6) | — | (3.6) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Fund IX | 1,136.9 | (32.9) | 22.2 | (10.7) | 368.7 | 93.4 | 462.1 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Fund VIII | 293.8 | (35.5) | 8.1 | (27.4) | (432.4) | 14.4 | (418.0) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Fund VII2 | 39.7 | (9.6) | 9.2 | (0.4) | (37.7) | 43.7 | 6.0 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Fund VI | 16.6 | (0.3) | 0.9 | 0.6 | (0.8) | 1.2 | 0.4 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Fund IV and Fund V1 | — | 0.1 | — | 0.1 | (0.2) | — | (0.2) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| HVF I | 87.3 | 4.6 | 3.2 | 7.8 | (18.8) | 60.0 | 41.2 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Real Estate Equity Funds1 | 60.3 | 0.1 | 0.7 | 0.8 | 17.9 | 14.3 | 32.2 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Corporate Credit | 13.3 | 5.8 | 5.7 | 11.5 | 1.2 | 10.1 | 11.3 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Structured Finance and ABS | 75.1 | 6.8 | 3.9 | 10.7 | (4.6) | 14.2 | 9.6 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Direct Origination | 140.8 | 7.8 | 10.6 | 18.4 | 29.8 | 26.3 | 56.1 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other1,3 | 357.4 | (26.5) | 38.6 | 12.1 | 29.4 | 84.6 | 114.0 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total | $ | 2,543.0 | $ | (66.9) | $ | 113.0 | $ | 46.1 | $ | (112.6) | $ | 416.9 | $ | 304.3 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total, net of profit sharing payable4/expense | $ | 1,153.7 | $ | (47.1) | $ | 34.4 | $ | (12.7) | $ | (92.9) | $ | 52.3 | $ | (40.6) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1 As of September 30, 2022, certain funds had $88.6 million in general partner obligations to return previously distributed performance fees. The fair value gain on investments and income at the fund level needed to reverse the general partner obligations was $1.4 billion as of September 30, 2022. | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2 As of September 30, 2022, the remaining investments and escrow cash of Fund VII was valued at 112% of the fund’s unreturned capital, which was below the required escrow ratio of 115%. As a result, the fund is required to place in escrow current and future performance fee distributions to the general partner until the specified return ratio of 115% is met (at the time of a future distribution) or upon liquidation. As of September 30, 2022, Fund VII had $85.5 million of gross performance fees or $48.7 million net of profit sharing, in escrow. With respect to Fund VII, realized performance fees currently distributed to the general partner are limited to potential tax distributions and interest on escrow balances per the fund’s partnership agreements. Performance fees receivable as of September 30, 2022 and realized performance fees for the three and nine months ended September 30, 2022 include interest earned on escrow balances that is not subject to contingent repayment. | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 3 Other includes certain SIAs. | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 4 There was a corresponding profit sharing payable of $1.4 billion as of September 30, 2022, including profit sharing payable related to amounts in escrow and contingent consideration obligations of $103.0 million. |
The general partners of certain of our funds accrue performance fees, categorized as performance allocations, when the fair value of investments exceeds the cost basis of the individual investors’ investments in the fund, including any allocable share of expenses incurred in connection with such investments, which we refer to as “high water marks.” These high water marks are applied on an individual investor basis. Certain of the funds we manage have investors with various high water marks, the achievement of which is subject to market conditions and investment performance.
Performance fees from certain funds we manage are subject to contingent repayment by the general partner in the event of future losses to the extent that the cumulative performance fees distributed from inception to date exceeds the amount computed as due to the general partner at the final distribution. These general partner obligations, if applicable, are included in due to related parties on the condensed consolidated statements of financial condition.
The following table summarizes our performance fees since inception through September 30, 2022:
| Performance Fees Since Inception****1 | |||||||||||||||||||||||||||||
| Undistributed by Fund and Recognized | Distributed by Fund and Recognized****2 | Total Undistributed and Distributed by Fund and Recognized****3 | General Partner Obligation****3 | Maximum Performance Fees Subject to Potential Reversal****4 | |||||||||||||||||||||||||
| (in millions) | |||||||||||||||||||||||||||||
| AIOF I and II | $ | 30.2 | $ | 37.1 | $ | 67.3 | $ | — | $ | 47.8 | |||||||||||||||||||
| ANRP I, II and III | 28.6 | 158.6 | 187.2 | 15.1 | 50.1 | ||||||||||||||||||||||||
| EPF Funds | 127.3 | 457.5 | 584.8 | 26.9 | 348.0 | ||||||||||||||||||||||||
| FCI Funds | 135.7 | 24.2 | 159.9 | — | 135.7 | ||||||||||||||||||||||||
| Fund IX | 1,136.9 | 482.6 | 1,619.5 | — | 1,404.2 | ||||||||||||||||||||||||
| Fund VIII | 293.8 | 1,653.2 | 1,947.0 | — | 1,354.9 | ||||||||||||||||||||||||
| Fund VII | 39.7 | 3,225.1 | 3,264.8 | — | 14.9 | ||||||||||||||||||||||||
| Fund VI | 16.6 | 1,663.9 | 1,680.5 | — | — | ||||||||||||||||||||||||
| Fund IV and Fund V | — | 2,053.1 | 2,053.1 | 31.9 | 0.6 | ||||||||||||||||||||||||
| HVF I | 87.3 | 145.1 | 232.4 | — | 153.2 | ||||||||||||||||||||||||
| Real Estate Equity | 60.3 | 71.2 | 131.5 | 1.5 | 71.5 | ||||||||||||||||||||||||
| Corporate Credit | 13.3 | 926.0 | 939.3 | — | 7.6 | ||||||||||||||||||||||||
| Structured Finance and ABS | 75.1 | 52.2 | 127.3 | — | 60.9 | ||||||||||||||||||||||||
| Direct Origination | 140.8 | 69.6 | 210.4 | — | 127.8 | ||||||||||||||||||||||||
| Other5 | 357.4 | 1,681.2 | 2,038.6 | 13.2 | 538.7 | ||||||||||||||||||||||||
| Total | $ | 2,543.0 | $ | 12,700.6 | $ | 15,243.6 | $ | 88.6 | $ | 4,315.9 | |||||||||||||||||||
| 1 Certain funds are denominated in euros and historical figures are translated into U.S. dollars at an exchange rate of €1.00 to $0.98 as of September 30, 2022. Certain funds are denominated in pounds sterling and historical figures are translated into U.S. dollars at an exchange rate of £1.00 to $1.12 as of September 30, 2022. | |||||||||||||||||||||||||||||
| 2 Amounts in “Distributed by Fund and Recognized” for the Citi Property Investors (“CPI”), Gulf Stream Asset Management, LLC (“Gulf Stream”), Stone Tower Capital LLC and its related companies (“Stone Tower”) funds and SIAs are presented for activity subsequent to the respective acquisition dates. Amounts exclude certain performance fees from business development companies and Redding Ridge Holdings LP (“Redding Ridge Holdings”), an affiliate of Redding Ridge. | |||||||||||||||||||||||||||||
| 3 Amounts were computed based on the fair value of fund investments on September 30, 2022. Performance fees have been allocated to and recognized by the general partner. Based on the amount allocated, a portion is subject to potential reversal or, to the extent applicable, has been reduced by the general partner obligation to return previously distributed performance fees at September 30, 2022. The actual determination and any required payment of any such general partner obligation would not take place until the final disposition of the fund’s investments based on contractual termination of the fund. | |||||||||||||||||||||||||||||
| 4 Represents the amount of performance fees that would be reversed if remaining fund investments became worthless on September 30, 2022. Amounts subject to potential reversal of performance fees include amounts undistributed by a fund (i.e., the performance fees receivable), as well as a portion of the amounts that have been distributed by a fund, net of taxes and not subject to a general partner obligation to return previously distributed performance fees, except for those funds that are gross of taxes as defined in the respective funds’ governing documents. | |||||||||||||||||||||||||||||
| 5 Other includes certain SIAs. |
Expenses
Compensation and Benefits
The most significant expense in our asset management business is compensation and benefits expense. This consists of fixed salary, discretionary and non-discretionary bonuses, profit sharing expense associated with the performance fees earned and compensation expense associated with the vesting of non-cash equity-based awards.
Our compensation arrangements with certain employees contain a significant performance-based incentive component. Therefore, as our net revenues increase, our compensation costs rise. Our compensation costs also reflect the increased investment in people as we expand geographically and create new funds.
In addition, certain professionals and selected other individuals have a profit sharing interest in the performance fees earned in order to better align their interests with our own and with those of the investors in funds we manage. Profit sharing expense is part of our compensation and benefits expense and is generally based upon a fixed percentage of performance fees. Profit sharing expense can reverse during periods when there is a decline in performance fees that were previously recognized. Profit sharing amounts are normally distributed to employees after the corresponding investment gains have been realized and generally before preferred returns are achieved for the investors. Therefore, changes in our unrealized performance fees have the same effect on our profit sharing expense. Profit sharing expense increases when unrealized performance fees increase. Realizations only impact profit sharing expense to the extent that the effects on investments have not been recognized previously. If losses on other investments within a fund are subsequently realized, the profit sharing amounts previously distributed are normally subject to a general partner obligation to return performance fees previously distributed back to the funds. This general partner obligation due to the funds would be realized only when the fund is liquidated, which generally occurs at the end of the fund’s term. However, indemnification obligations also exist for realized gains with respect to Fund IV, Fund V and Fund VI, which, although our Former Managing Partners and Contributing Partners would remain personally liable, may indemnify our Former Managing Partners and Contributing Partners for 17.5% to 100% of the previously distributed profits regardless of the fund’s future performance. See note 16 to our condensed consolidated financial statements for further information regarding the Company’s indemnification liability.
The Company grants equity awards to certain employees, including RSUs, restricted shares of common stock and options, that generally vest and become exercisable in quarterly installments or annual installments depending on the award terms. In some instances, vesting of an RSU is also subject to the Company’s receipt of performance fees, within prescribed periods, sufficient to cover the associated equity-based compensation expense. See note 13 to our condensed consolidated financial statements for further discussion of equity-based compensation.
Other expenses
The balance of our other expenses includes interest, placement fees, and general, administrative and other operating expenses. Interest expense consists primarily of interest related to the 2024 Senior Notes, the 2026 Senior Notes, the 2029 Senior Notes, the 2030 Senior Notes, the 2048 Senior Notes and the 2050 Subordinated Notes as discussed in note 12 to our condensed consolidated financial statements. Placement fees are incurred in connection with our capital raising activities. In cases where the limited partners of the funds are determined to be the customer in an arrangement, placement fees may be capitalized as a cost to acquire a customer contract, and amortized over the life of the customer contract. General, administrative and other expenses includes occupancy expense, depreciation and amortization, professional fees and costs related to travel, information technology and administration. Occupancy expense represents charges related to office leases and associated expenses, such as utilities and maintenance fees. Depreciation and amortization of fixed assets is normally calculated using the straight-line method over their estimated useful lives, ranging from two to sixteen years, taking into consideration any residual value. Leasehold improvements are amortized over the shorter of the useful life of the asset or the expected term of the lease. Intangible assets are amortized based on the future cash flows over the expected useful lives of the assets.
Other Income (Loss)
Net Gains (Losses) from Investment Activities
Net gains (losses) from investment activities include both realized gains and losses and the change in unrealized gains and losses in our investment portfolio between the opening reporting date and the closing reporting date. Net unrealized gains (losses) are a result of changes in the fair value of unrealized investments and reversal of unrealized gains (losses) due to
dispositions of investments during the reporting period. Significant judgment and estimation goes into the assumptions that drive these models and the actual values realized with respect to investments could be materially different from values obtained based on the use of those models. The valuation methodologies applied impact the reported value of investment company holdings and their underlying portfolios in our condensed consolidated financial statements.
Net Gains (Losses) from Investment Activities of Consolidated Variable Interest Entities
Changes in the fair value of the consolidated VIEs’ assets and liabilities and related interest, dividend and other income and expenses subsequent to consolidation are presented within net gains (losses) from investment activities of consolidated variable interest entities and are attributable to non-controlling interests in the condensed consolidated statements of operations.
Other Income (Losses), Net
Other income (losses), net includes gains (losses) arising from the remeasurement of foreign currency denominated assets and liabilities, remeasurement of the tax receivable agreement liability and other miscellaneous non-operating income and expenses.
Financials Measures under U.S. GAAP - Retirement Services
The following discussion of financial measures under U.S. GAAP is based on the Company’s retirement services business which is operated by Athene as of September 30, 2022.
Revenues
Premiums
Premiums for long-duration contracts, including products with fixed and guaranteed premiums and benefits, are recognized as revenue when due from policyholders. Insurance revenues are reported net of amounts ceded.
Product charges
Revenues for universal life-type policies and investment contracts, including surrender and market value adjustments, costs of insurance, policy administration, GMDB, GLWB and no-lapse guarantee charges, are earned when assessed against policyholder account balances during the period.
Net investment income
Net investment income is a significant component of Athene’s total revenues. Athene recognizes investment income as it accrues or is legally due, net of investment management and custody fees. Investment income on fixed maturity securities includes coupon interest, as well as the amortization of any premium and the accretion of any discount. Investment income on equity securities represents dividend income and preferred coupons interest.
Investment related gains (losses)
Investment related gains (losses) primarily consist of (i) realized gains and losses on sales of investments, (ii) unrealized gains or losses relating to identified risks within AFS securities in fair value hedging relationships, (iii) gains and losses on trading securities, (iv) change in the fair value of the embedded derivatives and derivatives not designated as a hedge, (v) change in fair value of mortgage loan assets and (vi) allowance for expected credit losses recorded through credit loss expense.
Expenses
Interest sensitive contract benefits
Universal life-type policies and investment contracts include fixed indexed and traditional fixed annuities in the accumulation phase, funding agreements, universal life insurance, fixed indexed universal life insurance and immediate annuities without significant mortality risk (which includes pension group annuities without life contingencies). Liabilities for traditional fixed annuities, universal life insurance and funding agreements are carried at the account balances without reduction for potential surrender or withdrawal charges, except for a block of universal life business ceded to Global Atlantic which is carried at fair
value. Fixed indexed annuities and fixed indexed universal life insurance contracts contain an embedded derivative. Benefits reserves for fixed indexed annuities and fixed indexed universal life insurance contracts are reported as the sum of the fair value of the embedded derivative and the host (or guaranteed) component of the contracts. Liabilities for immediate annuities without significant mortality risk are calculated as the present value of future liability cash flows and policy maintenance expenses discounted at contractual interest rates.
Changes in the interest sensitive contract liabilities, excluding deposits and withdrawals, are recorded in interest sensitive contract benefits or product charges on the condensed consolidated statements of operations.
Future policy and other policy benefits
Athene issues contracts classified as long-duration, which includes term and whole life, accident and health, disability, and deferred and immediate annuities with life contingencies (which includes pension group annuities with life contingencies). Liabilities for non-participating long-duration contracts are established using accepted actuarial valuation methods which require the use of assumptions related to expenses, investment yields, mortality, morbidity and persistency at the date of issue or acquisition.
Changes in future policy benefits other than the adjustment for the OCI effects of unrealized investment gains and losses on AFS securities, are recorded in future policy and other policy benefits on the condensed consolidated statements of operations.
Amortization of deferred acquisition costs, deferred sales inducements, and value of business acquired
Costs related directly to the successful acquisition of new or renewal insurance or investment contracts are deferred to the extent they are recoverable from future premiums or gross profits. These costs consist of commissions and policy issuance costs, as well as sales inducements credited to policyholder account balances.
Deferred costs related to investment contracts without significant revenue streams from sources other than investment of the policyholder funds are amortized using the effective interest method. Deferred costs related to universal life-type policies and investment contracts with significant revenue streams from sources other than investment of the policyholder funds are amortized over the lives of the policies, based upon the proportion of the present value of actual and expected deferred costs to the present value of actual and expected gross profits to be earned over the life of the policies. VOBA associated with acquired contracts is amortized in relation to applicable policyholder liabilities.
Policy and other operating expenses
Policy and other operating expenses includes normal operating expenses, policy acquisition expenses, interest expense, dividends to policyholders, integration, restructuring and other non-operating expenses, and stock compensation expenses.
Other Financial Measures under U.S. GAAP
Income Taxes
Significant judgment is required in determining the provision for income taxes and in evaluating income tax positions, including evaluating uncertainties. We recognize the income tax benefits of uncertain tax positions only where the position is “more likely than not” to be sustained upon examination, including resolution of any related appeals or litigation, based on the technical merits of the positions. The tax benefit is measured as the largest amount of benefit that has a greater than 50% likelihood of being realized upon ultimate settlement. If a tax position is not considered more likely than not to be sustained, then no benefits of the position are recognized. The Company’s income tax positions are reviewed and evaluated quarterly to determine whether or not we have uncertain tax positions that require financial statement recognition or de-recognition.
Deferred tax assets and liabilities are recognized for the expected future tax consequences, using currently enacted tax rates, of differences between the carrying amount of assets and liabilities and their respective tax basis. The effect on deferred tax assets and liabilities of a change in tax rates is recognized in income in the period when the change is enacted. Deferred tax assets are reduced by a valuation allowance when it is more likely than not that some portion or all of the deferred tax assets will not be realized.
Non-Controlling Interests
For entities that are consolidated, but not 100% owned, a portion of the income or loss and corresponding equity is allocated to owners other than Apollo. The aggregate of the income or loss and corresponding equity that is not owned by the Company is included in non-controlling interests in the condensed consolidated financial statements. Non-controlling interests primarily include limited partner interests in certain consolidated funds and VIEs. Prior to the Mergers on January 1, 2022, the non-controlling interests relating to Apollo Global Management, Inc. also included the ownership interest in the Apollo Operating Group held by the Former Managing Partners and Contributing Partners through their limited partner interests in AP Professional Holdings, L.P. and the non-controlling interest in the Apollo Operating Group held by Athene.
The authoritative guidance for non-controlling interests in the condensed consolidated financial statements requires reporting entities to present non-controlling interest as equity and provides guidance on the accounting for transactions between an entity and non-controlling interests. According to the guidance, (1) non-controlling interests are presented as a separate component of stockholders’ equity on the Company’s condensed consolidated statements of financial condition, (2) net income (loss) includes the net income (loss) attributable to the non-controlling interest holders on the Company’s condensed consolidated statements of operations, (3) the primary components of non-controlling interest are separately presented in the Company’s condensed consolidated statements of changes in stockholders’ equity to clearly distinguish the interests in the Apollo Operating Group and other ownership interests in the consolidated entities and (4) profits and losses are allocated to non-controlling interests in proportion to their ownership interests regardless of their basis.
Results of Operations
Below is a discussion of our condensed consolidated results of operations for the three and nine months ended September 30, 2022 and 2021. For additional analysis of the factors that affected our results at the segment level, see “—Segment Analysis” below:
| For the Three Months ended September 30, | Total Change | Percentage Change | For the Nine Months Ended September 30, | Total Change | Percentage Change | ||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||||||||||||||||||||||||
| (In millions) | (In millions) | ||||||||||||||||||||||||||||||||||||||||||||||
| Revenues | |||||||||||||||||||||||||||||||||||||||||||||||
| Asset Management | |||||||||||||||||||||||||||||||||||||||||||||||
| Management fees | $ | 389 | $ | 475 | $ | (86) | (18.1)% | $ | 1,100 | $ | 1,402 | $ | (302) | (21.5)% | |||||||||||||||||||||||||||||||||
| Advisory and transaction fees, net | 110 | 63 | 47 | 74.6 | 286 | 205 | 81 | 39.5 | |||||||||||||||||||||||||||||||||||||||
| Investment income (loss) | (31) | 535 | (566) | NM | 475 | 3,125 | (2,650) | (84.8) | |||||||||||||||||||||||||||||||||||||||
| Incentive fees | 9 | 5 | 4 | 80.0 | 17 | 24 | (7) | (29.2) | |||||||||||||||||||||||||||||||||||||||
| 477 | 1,078 | (601) | (55.8) | 1,878 | 4,756 | (2,878) | (60.5) | ||||||||||||||||||||||||||||||||||||||||
| Retirement Services | |||||||||||||||||||||||||||||||||||||||||||||||
| Premiums | 3,045 | — | 3,045 | NM | 10,769 | — | 10,769 | NM | |||||||||||||||||||||||||||||||||||||||
| Product charges | 184 | — | 184 | NM | 525 | — | 525 | NM | |||||||||||||||||||||||||||||||||||||||
| Net investment income | 2,033 | — | 2,033 | NM | 5,667 | — | 5,667 | NM | |||||||||||||||||||||||||||||||||||||||
| Investment related gains (losses) | (2,847) | — | (2,847) | NM | (12,823) | — | (12,823) | NM | |||||||||||||||||||||||||||||||||||||||
| Revenues of consolidated variable interest entities | 114 | — | 114 | NM | 148 | — | 148 | NM | |||||||||||||||||||||||||||||||||||||||
| Other revenues | (27) | — | (27) | NM | (38) | — | (38) | NM | |||||||||||||||||||||||||||||||||||||||
| 2,502 | — | 2,502 | NM | 4,248 | — | 4,248 | NM | ||||||||||||||||||||||||||||||||||||||||
| Total Revenues | 2,979 | 1,078 | 1,901 | 176.3 | 6,126 | 4,756 | 1,370 | 28.8 | |||||||||||||||||||||||||||||||||||||||
| Expenses | |||||||||||||||||||||||||||||||||||||||||||||||
| Asset Management | |||||||||||||||||||||||||||||||||||||||||||||||
| Compensation and benefits: | |||||||||||||||||||||||||||||||||||||||||||||||
| Salary, bonus and benefits | 232 | 182 | 50 | 27.5 | 684 | 540 | 144 | 26.7 | |||||||||||||||||||||||||||||||||||||||
| Equity-based compensation | 104 | 56 | 48 | 85.7 | 373 | 165 | 208 | 126.1 | |||||||||||||||||||||||||||||||||||||||
| Profit sharing expense | 50 | 263 | (213) | (81.0) | 372 | 1,279 | (907) | (70.9) | |||||||||||||||||||||||||||||||||||||||
| Total compensation and benefits | 386 | 501 | (115) | (23.0) | 1,429 | 1,984 | (555) | (28.0) | |||||||||||||||||||||||||||||||||||||||
| Interest expense | 31 | 35 | (4) | (11.4) | 94 | 105 | (11) | (10.5) | |||||||||||||||||||||||||||||||||||||||
| General, administrative and other | 167 | 112 | 55 | 49.1 | 472 | 328 | 144 | 43.9 | |||||||||||||||||||||||||||||||||||||||
| 584 | 648 | (64) | (9.9) | 1,995 | 2,417 | (422) | (17.5) | ||||||||||||||||||||||||||||||||||||||||
| Retirement Services | |||||||||||||||||||||||||||||||||||||||||||||||
| Interest sensitive contract benefits | 89 | — | 89 | NM | (573) | — | (573) | NM | |||||||||||||||||||||||||||||||||||||||
| Future policy and other policy benefits | 3,294 | — | 3,294 | NM | 10,988 | — | 10,988 | NM | |||||||||||||||||||||||||||||||||||||||
| Amortization of deferred acquisition costs, deferred sales inducements and value of business acquired | 125 | — | 125 | NM | 375 | — | 375 | NM | |||||||||||||||||||||||||||||||||||||||
| Policy and other operating expenses | 343 | — | 343 | NM | 982 | — | 982 | NM | |||||||||||||||||||||||||||||||||||||||
| 3,851 | — | 3,851 | NM | 11,772 | — | 11,772 | NM | ||||||||||||||||||||||||||||||||||||||||
| Total Expenses | 4,435 | 648 | 3,787 | NM | 13,767 | 2,417 | 11,350 | 469.6 | |||||||||||||||||||||||||||||||||||||||
| Other income (loss) – Asset Management | |||||||||||||||||||||||||||||||||||||||||||||||
| Net gains (losses) from investment activities | (16) | 173 | (189) | NM | 164 | 1,439 | (1,275) | (88.6) | |||||||||||||||||||||||||||||||||||||||
| Net gains (losses) from investment activities of consolidated variable interest entities | 85 | 142 | (57) | (40.1) | 465 | 400 | 65 | 16.3 | |||||||||||||||||||||||||||||||||||||||
| Other income (loss), net | 28 | (13) | 41 | NM | 26 | (25) | 51 | NM | |||||||||||||||||||||||||||||||||||||||
| Total Other Income (Loss) | 97 | 302 | (205) | (67.9) | 655 | 1,814 | (1,159) | (63.9) | |||||||||||||||||||||||||||||||||||||||
| Income (loss) before income tax (provision) benefit | (1,359) | 732 | (2,091) | NM | (6,986) | 4,153 | (11,139) | NM | |||||||||||||||||||||||||||||||||||||||
| Income tax (provision) benefit | 185 | (101) | 286 | NM | 1,280 | (498) | 1,778 | NM | |||||||||||||||||||||||||||||||||||||||
| Net income (loss) | (1,174) | 631 | (1,805) | NM | (5,706) | 3,655 | (9,361) | NM | |||||||||||||||||||||||||||||||||||||||
| Net (income) loss attributable to non-controlling interests | 298 | (373) | 671 | NM | 1,909 | (2,060) | 3,969 | NM | |||||||||||||||||||||||||||||||||||||||
| Net income (loss) attributable to Apollo Global Management, Inc. | (876) | 258 | (1,134) | NM | (3,797) | 1,595 | (5,392) | NM | |||||||||||||||||||||||||||||||||||||||
| Preferred stock dividends | — | (9) | 9 | (100.0) | — | (27) | 27 | (100.0) | |||||||||||||||||||||||||||||||||||||||
| Net income (loss) available to Apollo Global Management, Inc. Common Stockholders | $ | (876) | $ | 249 | $ | (1,125) | NM | $ | (3,797) | $ | 1,568 | $ | (5,365) | NM | |||||||||||||||||||||||||||||||||
| Note: “NM” denotes not meaningful. Changes from negative to positive amounts and positive to negative amounts are not considered meaningful. Increases or decreases from zero and changes greater than 500% are also not considered meaningful. |
Three Months Ended September 30, 2022 Compared to Three Months Ended September 30, 2021
In this section, references to 2022 refer to the three months ended September 30, 2022 and references to 2021 refer to the three months ended September 30, 2021.
Asset Management
Revenues
Revenues were $477 million in 2022, a decrease of $601 million from $1.1 billion in 2021, primarily driven by lower investment income (loss). Investment income (loss) decreased $566 million in 2022 to $(31) million compared to $535 million in 2021. The investment income (loss) of $(31) million in 2022 is comprised of principal investment income (losses) of $(70) million, partially offset by performance allocations of $39 million.
The principal investment income (losses) were primarily attributable to the decreased unrealized value of investments held by certain funds managed by Apollo and other entities in which the Company has a direct interest, mainly with respect to Motive Partners and AP Liberty L.P., as a result of the equity market volatility and public share price fluctuations in 2022. Significant drivers for performance allocations in 2021 were performance allocations earned from Fund IX, HVF I and Fund VII of $177 million, $53 million and $48 million, respectively, primarily as a result of fund appreciation and realization activity. Significant drivers for performance allocations in 2022 were performance allocations earned from EPF III and MidCap of $20 million and $14 million, respectively, partially offset by performance allocation losses from Fund VIII of $29 million.
See below for details on the respective funds’ performance allocations in 2022.
The performance allocations from EPF III in 2022 were primarily driven by net foreign currency gains, as the U.S. dollar strengthened compared to the euro, as well as increased performance allocations related to private positions held in the consumer services and financial services industries.
The performance allocations from MidCap in 2022 were primarily driven by higher interest income.
The performance allocation losses from Fund VIII in 2022 were primarily driven by the depreciation in the value of the fund’s investments in the consumer services, leisure, and media, telecom and technology sectors.
Management fees decreased by $86 million to $389 million in 2022 from $475 million in 2021. The decrease for 2022 was primarily driven by the elimination of management fees between AAM and Athene subsidiaries upon consolidation, as a result of the Mergers. The decrease was partially offset by increases in management fees earned from Apollo Diversified Real Estate Fund (f/k/a Griffin Institutional Access Real Estate Fund) and Apollo Diversified Credit Fund (f/k/a Griffin Institutional Access Credit Fund) (collectively “ADREF and ADCF”) of $25 million, as a result of the management fee contribution from the Griffin Capital U.S. asset management business acquisition, and from MidCap of $12 million, driven by higher Fee-Generating AUM.
The decreases in investment income (loss) and management fees were offset, in part, by an increase in advisory and transaction fees. Advisory and transaction fees increased by $47 million to $110 million in 2022 from $63 million in 2021. Advisory and transaction fees earned in 2022 were primarily attributable to advisory and transaction fees earned from companies in the consumer services, financial services and natural resource sectors as well as structuring fees earned from companies in the financial services, real estate and consumer services sectors.
Expenses
Expenses were $584 million in 2022, a decrease of $64 million from $648 million in 2021 due to a decrease in profit sharing expense of $213 million resulting from lower investment income during 2022. In any period, the blended profit sharing percentage is impacted by the respective profit sharing ratios of the funds generating performance allocations in the period. This decrease was partially offset by an increase in salary, bonus and benefits of $50 million and an increase in equity-based compensation of $48 million due to accelerated headcount growth in 2022. In addition, equity-based compensation increased as a result of: (i) performance grants which are tied to the Company’s receipt of performance fees, within prescribed periods and are typically recognized on an accelerated recognition method over the requisite service period to the extent the performance revenue metrics are met or deemed probable, and (ii) the impact of one-time grants awarded to the Co-Presidents of AAM
which vest on a cliff basis subject to continued employment over five years and the Company’s achievement of FRE and SRE per share metrics.
General, administrative and other expenses were $167 million in 2022, an increase of $55 million from $112 million in 2021. The increase in 2022 was primarily driven by increases in the amortization expense associated with the Company’s commitment asset, higher travel and entertainment expenses, as well as the absorption of occupancy expense to support the Company’s increased headcount, including from the acquisition of Griffin Capital’s U.S. asset management business.
Other Income (Loss)
Other income (loss) was $97 million in 2022, a decrease of $205 million from $302 million in 2021 primarily due to a decrease in net gains from investment activities, as a result of AAM no longer holding an interest in Athene Holding following the Mergers, and a decrease in net gains from investment activities of consolidated VIEs as a result of the Company’s deconsolidation of VIEs in the first half of 2022. Other income (loss) in 2022 was primarily attributable to higher interest income earned on the Company’s money market funds and U.S. Treasury securities, as a result of a rising interest rate environment, as well as gains from consolidated VIEs, which was offset, in part, by losses from certain of the Company’s balance sheet investments. Other income (loss) in 2021 was primarily attributable to net gains from investment activities from the Company’s investment in Athene Holding during 2021.
Retirement Services
Revenues
Retirement Services revenues were $2.5 billion in 2022. Revenues were primarily driven by pension group annuity premiums and net investment income, partially offset by the adverse impact from investment related gains and losses. Investment related losses of $2.8 billion were primarily driven by unfavorable changes in the fair value of reinsurance assets, mortgage loans, FIA hedging derivatives, trading securities, and realized losses on AFS securities, partially offset by foreign exchange gains on derivatives. The losses on Retirement Services’ assets were primarily due to an increase in U.S. Treasury rates and credit spread widening in the current quarter. The change in fair value of FIA hedging derivatives decreased due to the unfavorable performance of the indices upon which Athene’s call options are based as the majority of the call options are based on the S&P 500 index, which decreased 5.3% during the quarter. The foreign exchange gains on derivatives were primarily driven by the strengthening of the U.S. dollar in the current quarter for assets denominated in foreign currencies.
Expenses
Retirement Services expenses were $3.9 billion in 2022. Expenses were primarily driven by pension group annuity obligations, interest credited to policyholders, interest paid on funding agreements, policy and other operating expenses and amortization of DAC and VOBA, partially offset by a decrease in the change of FIA fair value embedded derivatives. The change in FIA fair value embedded derivatives was primarily due to the performance of the equity indices to which Athene’s FIA policies are linked, primarily the S&P 500 index, which experienced a decrease of 5.3% during the quarter, as well as the favorable change in discount rates and favorable unlocking, partially offset by unfavorable economics impacting policyholder projected benefits. The FIA fair value embedded derivatives unlocking in 2022 was $41 million favorable due to changes to projected interest crediting, partially offset by the impact of higher rates on future account values.
Income Tax (Provision) Benefit
The Company’s income tax (provision) benefit totaled $185 million and $(101) million in 2022 and 2021, respectively. The change to the provision was primarily related to the decrease in pre-tax income. The provision for income taxes includes federal, state, local and foreign income taxes resulting in an effective income tax rate of 13.6% and 13.8% for 2022 and 2021, respectively. The most significant reconciling items between the U.S. federal statutory income tax rate and the effective income tax rate were due to the following: (i) income pass through to non-controlling interests, (ii) foreign, state and local income taxes, including NYC UBT, and (iii) equity-based compensation net of the limiting provisions for executive compensation under Internal Revenue Code Section 162(m) (see note 11 to the condensed consolidated financial statements for further details regarding the Company’s income tax provision).
Nine Months Ended September 30, 2022 Compared to Nine Months Ended September 30, 2021
In this section, references to 2022 refer to the nine months ended September 30, 2022 and references to 2021 refer to the nine months ended September 30, 2021.
Asset Management
Revenues
Revenues were $1.9 billion in 2022, a decrease of $2.9 billion from $4.8 billion in 2021 due to lower investment income (loss) and, to a lesser extent, a decrease in management fees. Investment income (loss) decreased $2.7 billion in 2022 to $475 million compared to $3.1 billion in 2021. The decrease in investment income (loss) of $2.7 billion in 2022 was primarily driven by decreases in performance allocations.
Significant drivers for performance allocations in 2021 were performance allocations earned from Fund IX, Fund VIII and Fund VII of $875 million, $683 million, $232 million, respectively, primarily as a result of fund appreciation and realization activity. Significant drivers for performance allocations in 2022 were performance allocations primarily earned from Fund IX of $474 million, partially offset by performance allocation losses from Fund VIII of $435 million, as a result of continued equity market volatility in 2022.
See below for details on the respective funds’ performance allocations in 2022.
The performance allocations from Fund IX in 2022 were primarily driven by the appreciation and realization of the fund’s investments in the consumer services, leisure, and media, telecom and technology sectors.
The performance allocation losses from Fund VIII were primarily driven by the depreciation in the value of the fund’s investments in the consumer services, leisure, and media, telecom and technology sectors.
Management fees decreased by $302 million to $1.1 billion in 2022 from $1.4 billion in 2021. The decrease for 2022 was primarily driven by the elimination of management fees between AAM and Athene subsidiaries upon consolidation, as a result of the Mergers. The decrease was partially offset by increases in management fees earned from ADREF and ADCF of $42 million, as a result of the management fee contribution from the Griffin Capital U.S. asset management business acquisition, and from MidCap of $23 million, driven by higher Fee-Generating AUM.
The decreases in investment income (loss) and management fees were offset, in part, by an increase in advisory and transaction fees. Advisory and transaction fees increased by $81 million to $286 million in 2022 from $205 million in 2021. Advisory and transaction fees earned during 2022 were primarily attributable to advisory and transaction fees earned from companies in the financial services, consumer services, healthcare, consumer and retail, real estate, natural resources and media, telecom and technology sectors, as well as structuring fees earned from companies in the financial services, consumer services, real estate and leisure sectors.
Expenses
Expenses were $2.0 billion in 2022, a decrease of $422 million from $2.4 billion in 2021 due to a decrease in profit sharing expense of $907 million resulting from the corresponding lower investment income during 2022. This decrease was partially offset by increases in equity-based compensation of $208 million and an increase in salary, bonus and benefits of $144 million due to accelerated headcount growth in 2022, including for certain senior level roles, as the Company strategically invests in talent that will seek to capture its next phase of growth. In addition, equity-based compensation increased as a result of: (i) performance grants which are tied to the Company’s receipt of performance fees, within prescribed periods and are typically recognized on an accelerated recognition method over the requisite service period to the extent the performance revenue metrics are met or deemed probable, and (ii) the impact of one-time grants awarded to the Co-Presidents of AAM which vest on a cliff basis subject to continued employment over five years and the Company’s achievement of FRE and SRE per share metrics.
General, administrative and other expenses were $472 million in 2022, an increase of $144 million from $328 million in 2021. The increase in 2022 was primarily driven by increases in the amortization expense associated with the Company’s
commitment asset, higher travel and entertainment expenses, as well as the absorption of occupancy expense to support the Company’s increased headcount, including from the acquisition of Griffin Capital’s U.S. asset management business.
Other Income (Loss)
Other income (loss) was $655 million in 2022, a decrease of $1.2 billion from $1.8 billion in 2021. This decrease was primarily driven by a decrease in net gains from investment activities, as a result of AAM no longer holding an interest in Athene Holding following the Mergers. Other income (loss) in 2022 was primarily attributable to net gains from investment activities of consolidated VIEs and income earned as a result of APSG I’s deconsolidation event. Other income (loss) in 2021 was primarily attributable to net gains from investment activities from the Company’s investment in Athene Holding during 2021.
Retirement Services
Revenues
Retirement Services revenues were $4.2 billion in 2022. Revenues were primarily driven by pension group annuity premiums and net investment income, partially offset by the adverse impact of investment related losses. Investment related losses of $12.8 billion were primarily driven by unfavorable changes in the fair value of reinsurance assets, mortgage loans, FIA hedging derivatives, trading and equity securities, realized losses on AFS securities and an increase in the provision for credit losses, partially offset by foreign exchange gains on derivatives. The losses on Retirement Services’ assets were primarily due to an increase in U.S. Treasury rates and credit spread widening in the current year. The change in fair value of FIA hedging derivatives decreased due to the unfavorable performance of the indices upon which Athene’s call options are based as the majority of the call options are based on the S&P 500 index, which decreased 24.8% during the year. The unfavorable change in the provision for credit losses was primarily driven by unfavorable economics. The foreign exchange gains on derivatives were primarily driven by the strengthening of the U.S. dollar in the current year for assets denominated in foreign currencies.
Expenses
Retirement Services expenses were $11.8 billion in 2022. Expenses were primarily driven by pension group annuity obligations, interest credited to policyholders, interest paid on funding agreements, policy and other operating expenses and amortization of DAC and VOBA, partially offset by a decrease in the change in FIA fair value embedded derivatives. The change in FIA fair value embedded derivatives was primarily due to the performance of the equity indices to which Athene’s FIA policies are linked, primarily the S&P 500 index, which experienced a decrease of 24.8% during the year, as well as the favorable change in discount rates and favorable unlocking, partially offset by unfavorable economics impacting policyholder projected benefits. The FIA fair value embedded derivatives unlocking in 2022 was $41 million favorable due to changes to projected interest crediting, partially offset by the impact of higher rates on future account values.
Income Tax (Provision) Benefit
The Company’s income tax (provision) benefit totaled $1,280 million and $(498) million in 2022 and 2021, respectively. The change to the provision was primarily related to the decrease in pre-tax income and a tax benefit from the derecognition of a deferred tax liability related to the Mergers. The provision for income taxes includes federal, state, local and foreign income taxes resulting in an effective income tax rate of 18.3% and 12.0% for 2022 and 2021, respectively. The most significant reconciling items between the U.S. federal statutory income tax rate and the effective income tax rate were due to the following: (i) a benefit realized from the derecognition of a deferred tax liability related to the Company’s historical holdings in Athene, (ii) foreign, state and local income taxes, including NYC UBT, (iii) income attributable to non-controlling interests and (iv) equity-based compensation net of the limiting provisions for executive compensation under IRC Section 162(m) (see note 11 to the condensed consolidated financial statements for further details regarding the Company’s income tax provision).
Managing Business Performance - Key Segment and Non-U.S. GAAP Performance Measures
We believe that the presentation of Adjusted Segment Income supplements a reader’s understanding of the economic operating performance of each of our segments.
Adjusted Segment Income and Adjusted Net Income
Adjusted Segment Income, or “ASI”, is the key performance measure used by management in evaluating the performance of the Asset Management, Retirement Services, and Principal Investing segments. Adjusted Net Income (“ANI”) represents Adjusted Segment Income less HoldCo interest and other financing costs and estimated income taxes. For purposes of calculating the Adjusted Net Income tax rate, Adjusted Segment Income is reduced by HoldCo interest and financing costs. Income taxes on FRE and PII represents the total current corporate, local, and non-U.S. taxes as well as the current payable under Apollo’s tax receivable agreement. Income taxes on FRE and PII excludes the impacts of deferred taxes and the remeasurement of the tax receivable agreement, which arise from changes in estimated future tax rates. Certain assumptions and methodologies that impact the implied FRE and PII income tax provision are similar to those used under U.S. GAAP. Specifically, certain deductions considered in the income tax provision under U.S. GAAP relating to transaction related charges, equity-based compensation, and tax deductible interest expense are taken into account for the implied tax provision. Income Taxes on SRE represent the total current and deferred tax expense or benefit on income before taxes adjusted to eliminate the impact of the tax expense or benefit associated with the non-operating adjustments. Management believes the methodologies used to compute income taxes on FRE, SRE, and PII are meaningful to each segment and increases comparability of income taxes between periods.
We believe that ASI is helpful for an understanding of our business and that investors should review the same supplemental financial measure that management uses to analyze our segment performance. This measure supplements and should be considered in addition to and not in lieu of the results of operations discussed below in “—Overview of Results of Operations” that have been prepared in accordance with U.S. GAAP. See note 18 to the condensed consolidated financial statements for more details regarding the components of ASI and management’s consideration of ASI.
Fee Related Earnings, Spread Related Earnings and Principal Investing Income
Fee Related Earnings, or “FRE”, is a component of ASI that is used as a supplemental performance measure to assess the performance of the Asset Management segment.
Spread Related Earnings, or “SRE”, is a component of ASI that is used as a supplemental performance measure to assess the performance of the Retirement Services segment, excluding certain market volatility and certain expenses related to integration, restructuring, equity-based compensation, and other expenses.
Principal Investing Income, or “PII”, is a component of ASI that is used as a supplemental performance measure to assess the performance of the Principal Investing segment.
See note 18 to the condensed consolidated financial statements for more details regarding the components of FRE, SRE, and PII.
We use ASI, ANI, FRE, SRE and PII as measures of operating performance, not as measures of liquidity. These measures should not be considered in isolation or as a substitute for net income or other income data prepared in accordance with U.S. GAAP. The use of these measures without consideration of their related U.S. GAAP measures is not adequate due to the adjustments described above.
Net Invested Assets
In managing its business, Athene analyzes net invested assets, which does not correspond to total Athene investments, including investments in related parties on the consolidated statements of financial condition. Net invested assets represent the investments that directly back its net reserve liabilities as well as surplus assets. Net invested assets is used in the computation of net investment earned rate, which is used to analyze the profitability of Athene’s investment portfolio. Net invested assets includes (a) total investments on the consolidated statements of financial condition with AFS securities at cost or amortized cost, excluding derivatives, (b) cash and cash equivalents and restricted cash, (c) investments in related parties, (d) accrued investment income, (e) VIE and VOE assets, liabilities and non-controlling interest adjustments, (f) net investment payables and receivables, (g) policy loans ceded (which offset the direct policy loans in total investments) and (h) an adjustment for the allowance for credit losses. Net invested assets also excludes assets associated with funds withheld liabilities related to business exited through reinsurance agreements and derivative collateral (offsetting the related cash positions). Athene includes the underlying investments supporting its assumed funds withheld and modco agreements in its net invested assets calculation in order to match the assets with the income received. Athene believes the adjustments for reinsurance provide a view of the assets
for which it has economic exposure. Net invested assets includes Athene’s proportionate share of ACRA investments, based on its economic ownership, but does not include the proportionate share of investments associated with the non-controlling interest. Net invested assets are averaged over the number of quarters in the relevant period to compute a net investment earned rate for such period. While Athene believes net invested assets is a meaningful financial metric and enhances the understanding of the underlying drivers of its investment portfolio, it should not be used as a substitute for Athene’s total investments, including related parties, presented under U.S. GAAP.
Segment Analysis
Discussed below are our results of operations for each of our reportable segments. They represent the segment information available and utilized by management to assess performance and to allocate resources. See note 18 to our condensed consolidated financial statements for more information regarding our segment reporting.
Asset Management
The following table presents Fee Related Earnings, the performance measure of our Asset Management segment.
| Three months ended September 30, | Total Change | Percentage Change | Nine months ended September 30, | Total Change | Percentage Change | ||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||||||||||||||||||||||||
| (In millions) | (In millions) | ||||||||||||||||||||||||||||||||||||||||||||||
| Asset Management: | |||||||||||||||||||||||||||||||||||||||||||||||
| Management fees - Yield | $ | 366.4 | $ | 299.2 | $ | 67.2 | 22.5% | $ | 1,042.0 | $ | 872.0 | $ | 170.0 | 19.5% | |||||||||||||||||||||||||||||||||
| Management fees - Hybrid | 52.9 | 43.5 | 9.4 | 21.6 | 153.9 | 124.3 | 29.6 | 23.8 | |||||||||||||||||||||||||||||||||||||||
| Management fees - Equity | 126.6 | 129.8 | (3.2) | (2.5) | 377.3 | 398.9 | (21.6) | (5.4) | |||||||||||||||||||||||||||||||||||||||
| Management fees | 545.9 | 472.5 | 73.4 | 15.5 | 1,573.2 | 1,395.2 | 178.0 | 12.8 | |||||||||||||||||||||||||||||||||||||||
| Advisory and transaction fees, net | 104.6 | 65.2 | 39.4 | 60.4 | 271.8 | 203.8 | 68.0 | 33.4 | |||||||||||||||||||||||||||||||||||||||
| Fee-related performance fees | 20.0 | 19.8 | 0.2 | 1.0 | 45.9 | 36.7 | 9.2 | 25.1 | |||||||||||||||||||||||||||||||||||||||
| Fee-related compensation | (193.8) | (160.7) | (33.1) | 20.6 | (556.4) | (476.7) | (79.7) | 16.7 | |||||||||||||||||||||||||||||||||||||||
| Other operating expenses | (112.1) | (76.7) | (35.4) | 46.2 | (318.8) | (218.3) | (100.5) | 46.0 | |||||||||||||||||||||||||||||||||||||||
| Fee Related Earnings (FRE) | $ | 364.6 | $ | 320.1 | $ | 44.5 | 13.9% | $ | 1,015.7 | $ | 940.7 | $ | 75.0 | 8.0% |
| Three months ended September 30, | Total Change | Percentage Change | Nine months ended September 30, | Total Change | Percentage Change | ||||||||||||||||||||||||||||||||||||||||||
| 2021 | 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||||||||||||
| (In millions) | (In millions) | ||||||||||||||||||||||||||||||||||||||||||||||
| Asset Management: | |||||||||||||||||||||||||||||||||||||||||||||||
| Management fees - Yield | $ | 299.2 | $ | 251.5 | $ | 47.7 | 19.0% | $ | 872.0 | $ | 693.7 | $ | 178.3 | 25.7% | |||||||||||||||||||||||||||||||||
| Management fees - Hybrid | 43.5 | 35.6 | 7.9 | 22.2 | 124.3 | 100.5 | 23.8 | 23.7 | |||||||||||||||||||||||||||||||||||||||
| Management fees - Equity | 129.8 | 139.4 | (9.6) | (6.9) | 398.9 | 416.5 | (17.6) | (4.2) | |||||||||||||||||||||||||||||||||||||||
| Management fees | 472.5 | 426.5 | 46.0 | 10.8 | 1,395.2 | 1,210.7 | 184.5 | 15.2 | |||||||||||||||||||||||||||||||||||||||
| Advisory and transaction fees, net | 65.2 | 72.3 | (7.1) | (9.8) | 203.8 | 170.8 | 33.0 | 19.3 | |||||||||||||||||||||||||||||||||||||||
| Fee-related performance fees | 19.8 | 2.2 | 17.6 | NM | 36.7 | 8.0 | 28.7 | 358.8 | |||||||||||||||||||||||||||||||||||||||
| Fee-related compensation | (160.7) | (137.9) | (22.8) | 16.5 | (476.7) | (384.4) | (92.3) | 24.0 | |||||||||||||||||||||||||||||||||||||||
| Other operating expenses | (76.7) | (70.9) | (5.8) | 8.2 | (218.3) | (197.4) | (20.9) | 10.6 | |||||||||||||||||||||||||||||||||||||||
| Fee Related Earnings (FRE) | $ | 320.1 | $ | 292.2 | $ | 27.9 | 9.5% | $ | 940.7 | $ | 807.7 | $ | 133.0 | 16.5% |
In this section, references to 2022 refer to the three months ended September 30, 2022, references to 2021 refer to the three months ended September 30, 2021, and references to 2020 refer to the three months ended September 30, 2020.
Three Months Ended September 30, 2022 Compared to Three Months Ended September 30, 2021
FRE was $364.6 million in 2022, an increase of $44.5 million compared to $320.1 million in 2021. This increase was primarily attributable to continued growth in management fees and record quarterly advisory and transaction fees. The increase in management fees was primarily attributable to management fees earned from Athene of $39.2 million and ADREF and ADCF of $25.4 million, as a result of higher Fee-Generating AUM. Advisory and transaction fees earned in 2022 were primarily
attributable to advisory and transaction fees earned from companies in the consumer services, financial services and natural resource sectors as well as structuring fees earned from companies in the financial services, real estate and consumer services sectors. The growth in revenues was offset, in part, by increases in other operating expenses and fee-related compensation expense associated with the re-basing of cost structure to support the Company’s next phase of growth, including costs associated with the acquisition of Griffin Capital’s U.S. asset management business.
Three Months Ended September 30, 2021 Compared to Three Months Ended September 30, 2020
FRE was $320.1 million in 2021, an increase of $27.9 million compared to $292.2 million in 2020. This increase was primarily attributable to the growth in management fees and fee-related performance fees. The increase in management fees was primarily driven by Athene and other funds we manage in our yield strategy. The increase in fee-related performance fees was primarily driven by fees earned from Redding Ridge Holdings and MFIC as each achieved its respective hurdle rates in 2021. The growth in revenues was offset, in part, by higher fee-related compensation expenses due to an increase in headcount as we continued to expand our global team in 2021.
In this section, references to 2022 refer to the nine months ended September 30, 2022, references to 2021 refer to the nine months ended September 30, 2021, and references to 2020 refer to the nine months ended September 30, 2020.
Nine Months Ended September 30, 2022 Compared to Nine Months Ended September 30, 2021
FRE was $1.0 billion in 2022, an increase of $75.0 million compared to $940.7 million in 2021. This increase was primarily attributable to the continued growth in management fees, and advisory and transaction fees. The increase in management fees was primarily attributable to an increase in management fees earned from Athene of $127.9 million and ADREF and ADCF of $41.7 million as a result of higher Fee-Generating AUM. Advisory and transaction fees earned in 2022 were primarily attributable to advisory and transaction fees earned from companies in the financial services, consumer services, consumer and retail, real estate, natural resources and media, telecom and technology sectors, as well as structuring fees earned from companies in the financial services, consumer services and real estate sectors. The growth in revenues was offset, in part, by increases in fee-related compensation expense associated with the re-basing of cost structure to support the Company’s next phase of growth, as well as costs associated with the acquisition of Griffin Capital’s U.S. asset management business.
Nine Months Ended September 30, 2021 Compared to Nine Months Ended September 30, 2020
FRE was $940.7 million in 2021, an increase of $133.0 million compared to $807.7 million in 2020. This increase was primarily attributable to the growth in management fees and advisory and transaction fees. The increase in management fees was primarily driven by Athene, Athora and other funds we manage in our yield strategy. The increase in advisory and transaction fees was primarily driven by transaction and advisory fees earned related to companies in the consumer and retail industries, and transaction and placement fees earned in relation to a company in the media, telecom and technology sector in 2021. The growth in revenues was offset, in part, by higher fee-related compensation expense due to an increase in headcount as we continued to expand our global team in 2021.
Asset Management Operating Metrics
We monitor certain operating metrics that are common to the alternative asset management industry and directly impact the performance of our Asset Management segment. These operating metrics include Assets Under Management, gross capital deployment and uncalled commitments.
Assets Under Management
The following presents Apollo’s Total AUM and Fee-Generating AUM by investing strategy (in billions):
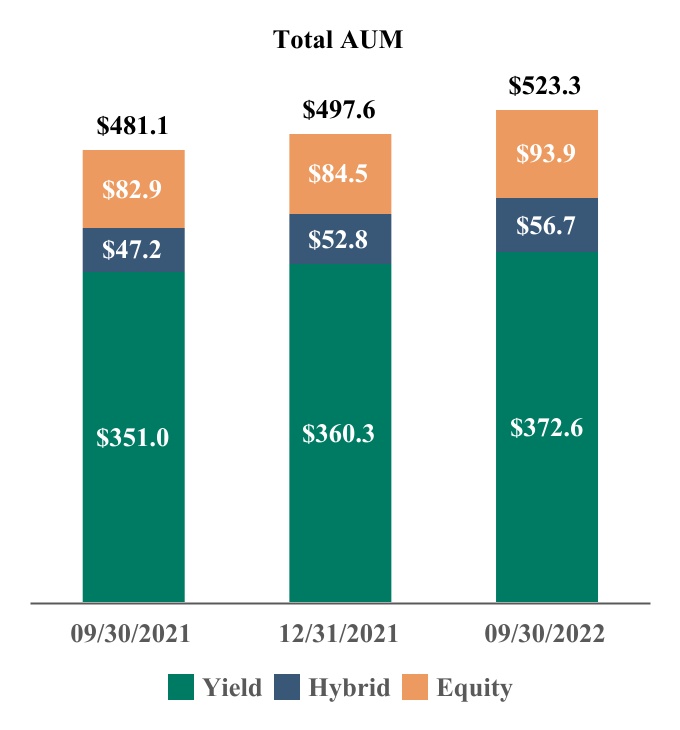
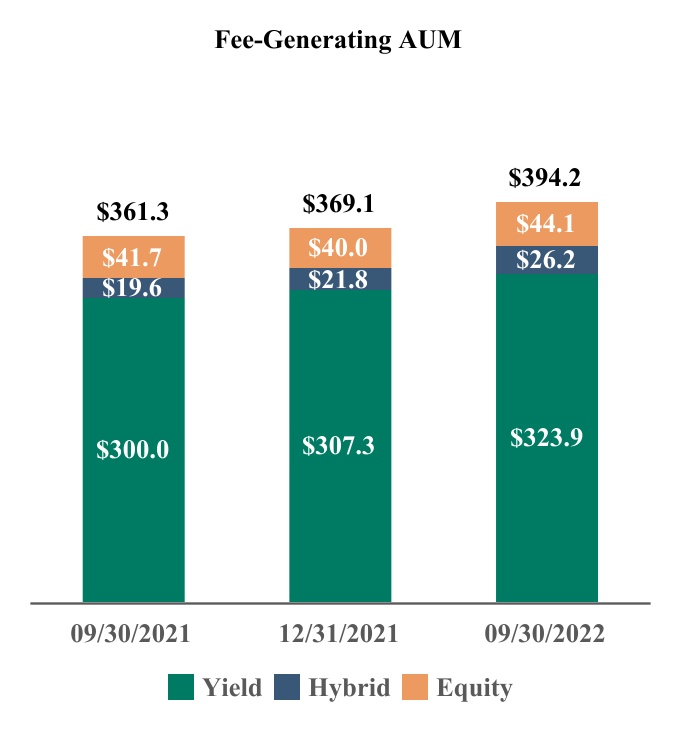
The following presents Apollo’s AUM with Future Management Fee Potential by investing strategy (in billions):

The following tables present the components of Performance Fee-Eligible AUM for each of Apollo’s three investing strategies within the asset management segment:
| As of September 30, 2022 | |||||||||||||||||||||||
| Yield | Hybrid | Equity | Total | ||||||||||||||||||||
| (In millions) | |||||||||||||||||||||||
| Performance Fee-Generating AUM 1 | $ | 37,271 | $ | 12,037 | $ | 40,807 | $ | 90,115 | |||||||||||||||
| AUM Not Currently Generating Performance Fees | 11,791 | 16,987 | 3,418 | 32,196 | |||||||||||||||||||
| Uninvested Performance Fee-Eligible AUM | 5,828 | 13,706 | 29,812 | 49,346 | |||||||||||||||||||
| Total Performance Fee-Eligible AUM | $ | 54,890 | $ | 42,730 | $ | 74,037 | $ | 171,657 |
| As of September 30, 2021 | |||||||||||||||||||||||
| Yield | Hybrid | Equity | Total | ||||||||||||||||||||
| (In millions) | |||||||||||||||||||||||
| Performance Fee-Generating AUM 1 | $ | 37,064 | $ | 16,733 | $ | 38,733 | $ | 92,530 | |||||||||||||||
| AUM Not Currently Generating Performance Fees | 1,318 | 4,593 | 3,175 | 9,086 | |||||||||||||||||||
| Uninvested Performance Fee-Eligible AUM | 2,524 | 15,350 | 21,468 | 39,342 | |||||||||||||||||||
| Total Performance Fee-Eligible AUM | $ | 40,906 | $ | 36,676 | $ | 63,376 | $ | 140,958 |
| As of December 31, 2021 | |||||||||||||||||||||||
| Yield | Hybrid | Equity | Total | ||||||||||||||||||||
| (In millions) | |||||||||||||||||||||||
| Performance Fee-Generating AUM 1 | $ | 37,756 | $ | 17,663 | $ | 37,447 | $ | 92,866 | |||||||||||||||
| AUM Not Currently Generating Performance Fees | 2,355 | 4,971 | 3,614 | 10,940 | |||||||||||||||||||
| Uninvested Performance Fee-Eligible AUM | 2,644 | 16,478 | 21,075 | 40,197 | |||||||||||||||||||
| Total Performance Fee-Eligible AUM | $ | 42,755 | $ | 39,112 | $ | 62,136 | $ | 144,003 | |||||||||||||||
| 1 Performance Fee-Generating AUM of $3.9 billion, $4.2 billion and $5.2 billion as of September 30, 2022, September 30, 2021 and December 31, 2021, respectively, are above the hurdle rates or preferred returns and have been deferred to future periods when the fees are probable to not be significantly reversed. |
The components of Fee-Generating AUM by investing strategy are presented below:
| As of September 30, 2022 | |||||||||||||||||||||||
| Yield | Hybrid | Equity | Total | ||||||||||||||||||||
| (In millions) | |||||||||||||||||||||||
| Fee-Generating AUM based on capital commitments | $ | — | $ | 2,521 | $ | 30,499 | $ | 33,020 | |||||||||||||||
| Fee-Generating AUM based on invested capital | 3,400 | 9,738 | 12,748 | 25,886 | |||||||||||||||||||
| Fee-Generating AUM based on gross/adjusted assets | 280,874 | 4,789 | 560 | 286,223 | |||||||||||||||||||
| Fee-Generating AUM based on NAV | 39,665 | 9,110 | 316 | 49,091 | |||||||||||||||||||
| Total Fee-Generating AUM | $ | 323,939 | $ | 26,158 | $ | 44,123 | 1 | $ | 394,220 | ||||||||||||||
| 1 The weighted average remaining life of the traditional private equity funds as of September 30, 2022 was 56 months. |
| As of September 30, 2021 | |||||||||||||||||||||||
| Yield | Hybrid | Equity | Total | ||||||||||||||||||||
| (In millions) | |||||||||||||||||||||||
| Fee-Generating AUM based on capital commitments | $ | — | $ | 2,576 | $ | 30,935 | $ | 33,511 | |||||||||||||||
| Fee-Generating AUM based on invested capital | 1,932 | 6,250 | 10,139 | 18,321 | |||||||||||||||||||
| Fee-Generating AUM based on gross/adjusted assets | 268,442 | 3,523 | 324 | 272,289 | |||||||||||||||||||
| Fee-Generating AUM based on NAV | 29,642 | 7,253 | 277 | 37,172 | |||||||||||||||||||
| Total Fee-Generating AUM | $ | 300,016 | $ | 19,602 | $ | 41,675 | 1 | $ | 361,293 | ||||||||||||||
| 1 The weighted average remaining life of the traditional private equity funds at September 30, 2021 was 67 months. |
| As of December 31, 2021 | |||||||||||||||||||||||
| Yield | Hybrid | Equity | Total | ||||||||||||||||||||
| (In millions) | |||||||||||||||||||||||
| Fee-Generating AUM based on capital commitments | $ | — | $ | 3,580 | $ | 27,277 | $ | 30,857 | |||||||||||||||
| Fee-Generating AUM based on invested capital | 2,321 | 6,826 | 12,075 | 21,222 | |||||||||||||||||||
| Fee-Generating AUM based on gross/adjusted assets | 273,695 | 4,293 | 406 | 278,394 | |||||||||||||||||||
| Fee-Generating AUM based on NAV | 31,290 | 7,146 | 192 | 38,628 | |||||||||||||||||||
| Total Fee-Generating AUM | $ | 307,306 | $ | 21,845 | $ | 39,950 | 1 | $ | 369,101 | ||||||||||||||
| 1 The weighted average remaining life of the traditional private equity funds as of December 31, 2021 was 64 months. |
Apollo, through its consolidated subsidiary, ISG, provides asset management services to Athene with respect to assets in the accounts owned by or related to Athene (“Athene Accounts”), including asset allocation services, direct asset management services, asset and liability matching management, mergers and acquisitions, asset diligence, hedging and other asset management services and receives management fees for providing these services. The Company, through ISG, also provides sub-allocation services with respect to a portion of the assets in the Athene Accounts. Apollo, through its asset management business, managed or advised $228.8 billion, $212.6 billion, and $203.6 billion of AUM on behalf of Athene as of September 30, 2022, December 31, 2021 and September 30, 2021, respectively.
Apollo, through ISGI, provides investment advisory services with respect to certain assets in certain portfolio companies of Apollo funds and sub-advises the Athora Accounts and broadly refers to “Athora Sub-Advised” assets as those assets in the Athora Accounts which the Company explicitly sub-advises as well as those assets in the Athora Accounts which are invested directly in funds and investment vehicles Apollo manages. The Company refers to the portion of the Athora AUM that is not Athora Sub-Advised AUM as “Athora Non-Sub Advised” AUM. See note 16 to the condensed consolidated financial statements for more details regarding the fee arrangements with respect to the assets in the Athora Accounts. Apollo managed or advised $45.3 billion, $59.0 billion, and $61.0 billion of AUM on behalf of Athora as of September 30, 2022, December 31, 2021 and September 30, 2021, respectively.
The following tables summarize changes in total AUM for each of Apollo’s three investing strategies within the asset management segment:
| For the Three Months Ended September 30, | |||||||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | ||||||||||||||||||||||||||||||||||||||||||||||
| Yield | Hybrid | Equity | Total | Yield | Hybrid | Equity | Total | ||||||||||||||||||||||||||||||||||||||||
| (In millions) | |||||||||||||||||||||||||||||||||||||||||||||||
| Change in Total AUM1: | |||||||||||||||||||||||||||||||||||||||||||||||
| Beginning of Period | $ | 375,753 | $ | 56,120 | $ | 82,889 | $ | 514,762 | $ | 338,729 | $ | 47,041 | $ | 86,005 | $ | 471,775 | |||||||||||||||||||||||||||||||
| Inflows | 18,232 | 2,686 | 13,175 | 34,093 | 17,035 | 1,598 | 1,703 | 20,336 | |||||||||||||||||||||||||||||||||||||||
| Outflows2 | (9,466) | (265) | (99) | (9,830) | (3,868) | (294) | — | (4,162) | |||||||||||||||||||||||||||||||||||||||
| Net Flows | 8,766 | 2,421 | 13,076 | 24,263 | 13,167 | 1,304 | 1,703 | 16,174 | |||||||||||||||||||||||||||||||||||||||
| Realizations | (6,555) | (1,548) | (2,026) | (10,129) | (759) | (2,174) | (5,900) | (8,833) | |||||||||||||||||||||||||||||||||||||||
| Market Activity3 | (5,332) | (255) | (17) | (5,604) | (173) | 1,033 | 1,088 | 1,948 | |||||||||||||||||||||||||||||||||||||||
| End of Period | $ | 372,632 | $ | 56,738 | $ | 93,922 | $ | 523,292 | $ | 350,964 | $ | 47,204 | $ | 82,896 | $ | 481,064 | |||||||||||||||||||||||||||||||
| 1 At the individual segment level, inflows include new subscriptions, commitments, capital raised, other increases in available capital, purchases, acquisitions, and portfolio company appreciation. Outflows represent redemptions, other decreases in available capital and portfolio company depreciation. Realizations represent fund distributions of realized proceeds. Market activity represents gains (losses), the impact of foreign exchange rate fluctuations and other income. | |||||||||||||||||||||||||||||||||||||||||||||||
| 2 Outflows for Total AUM include redemptions of $1.0 billion and $0.6 billion during the three months ended September 30, 2022 and 2021, respectively. | |||||||||||||||||||||||||||||||||||||||||||||||
| 3 Includes foreign exchange impacts of $(5.1) billion and $(2.1) billion during the three months ended September 30, 2022 and 2021, respectively. |
| For the Nine Months Ended September 30, | |||||||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | ||||||||||||||||||||||||||||||||||||||||||||||
| Yield | Hybrid | Equity | Total | Yield | Hybrid | Equity | Total | ||||||||||||||||||||||||||||||||||||||||
| (in millions) | |||||||||||||||||||||||||||||||||||||||||||||||
| Change in Total AUM1: | |||||||||||||||||||||||||||||||||||||||||||||||
| Beginning of Period | $ | 360,289 | $ | 52,772 | $ | 84,491 | $ | 497,552 | $ | 332,880 | $ | 42,317 | $ | 80,289 | $ | 455,486 | |||||||||||||||||||||||||||||||
| Inflows | 72,353 | 9,288 | 18,737 | 100,378 | 40,358 | 6,615 | 4,781 | 51,754 | |||||||||||||||||||||||||||||||||||||||
| Outflows2 | (30,058) | (1,009) | (101) | (31,168) | (18,131) | (563) | (1,312) | (20,006) | |||||||||||||||||||||||||||||||||||||||
| Net Flows | 42,295 | 8,279 | 18,636 | 69,210 | 22,227 | 6,052 | 3,469 | 31,748 | |||||||||||||||||||||||||||||||||||||||
| Realizations | (8,181) | (4,248) | (9,025) | (21,454) | (2,435) | (4,324) | (14,817) | (21,576) | |||||||||||||||||||||||||||||||||||||||
| Market Activity3 | (21,771) | (65) | (180) | (22,016) | (1,708) | 3,159 | 13,955 | 15,406 | |||||||||||||||||||||||||||||||||||||||
| End of Period | $ | 372,632 | $ | 56,738 | $ | 93,922 | $ | 523,292 | $ | 350,964 | $ | 47,204 | $ | 82,896 | $ | 481,064 | |||||||||||||||||||||||||||||||
| 1 At the individual strategy level, inflows include new subscriptions, commitments, capital raised, other increases in available capital, purchases, acquisitions and portfolio company appreciation. Outflows represent redemptions, other decreases in available capital and portfolio company depreciation. Realizations represent fund distributions of realized proceeds. Market activity represents gains (losses), the impact of foreign exchange rate fluctuations and other income. | |||||||||||||||||||||||||||||||||||||||||||||||
| 2 Outflows for Total AUM include redemptions of $2.4 billion and $1.9 billion during the nine months ended September 30, 2022 and 2021, respectively. | |||||||||||||||||||||||||||||||||||||||||||||||
| 3 Includes foreign exchange impacts of $(12.2) billion and $(4.5) billion during the nine months ended September 30, 2022 and 2021, respectively. |
Three Months Ended September 30, 2022
Total AUM was $523.3 billion at September 30, 2022, an increase of $8.5 billion, or 1.7%, compared to $514.8 billion at June 30, 2022. The net increase was primarily due to subscriptions across the platform, growth of our retirement services AUM, and increased leverage, partially offset by distributions driven by a one-time release of unfunded commitments, and market activity across our yield strategy due to foreign exchange depreciation and market related changes. More specifically, the net increase was due to:
-
Net flows of $24.3 billion primarily attributable to:
-
an $8.8 billion increase related to funds we manage in our yield strategy primarily consisting of (i) $4.9 billion related to the growth of our retirement services clients, (ii) $2.9 billion of subscriptions mostly related to the structured finance and ABS and corporate credit funds we manage, and (iii) a $1.7 billion increase in leverage; partially offsetting these increases were $0.7 billion of redemptions primarily in the corporate credit funds we manage;
-
a $2.4 billion increase related to funds we manage in our hybrid strategy primarily due to $1.7 billion of subscriptions across the hybrid value and hybrid credit funds we manage; and
-
a $13.1 billion increase related to funds we manage in the equity strategy primarily due to $12.7 billion of subscriptions mostly from the traditional private equity funds we manage.
-
Realizations of $(10.1) billion primarily attributable to:
-
$(6.6) billion related to funds we manage in our yield strategy primarily consisting of a $5.8 billion one-time release of unfunded commitments;
-
$(1.5) billion related to funds we manage in our hybrid strategy primarily consisting of $1.0 billion related to a fund liquidation; and
-
$(2.0) billion related to funds we manage in our equity strategy primarily consisting of distributions across our traditional private equity funds.
-
Market activity of $(5.6) billion, primarily attributable to:
-
$(5.3) billion related to funds we manage in our yield strategy primarily consisting of $(3.8) billion driven by Athora and $(1.5) billion related to the corporate credit funds we manage.
Nine Months Ended September 30, 2022
Total AUM was $523.3 billion at September 30, 2022, an increase of $25.7 billion, or 5.2%, compared to $497.6 billion at December 31, 2021. The net increase was primarily due to subscriptions across the platform, growth of our retirement services AUM, increased leverage, and the acquisition of Griffin Capital’s U.S. asset management business; partially offset by
distributions driven by a one-time release of unfunded commitments, and market activity across our yield strategy due to foreign exchange depreciation and market related changes. More specifically, the net increase was due to:
- Net flows of $69.2 billion primarily attributable to:
*•*a $42.3 billion increase related to funds we manage in our yield strategy primarily consisting of (i) $16.4 billion related to the growth of our retirement services clients, (ii) $16.0 billion of subscriptions mostly related to the corporate credit funds we manage, (iii) an $11.9 billion increase in leverage, and (iv) $6.5 billion related to the acquisition of Griffin Capital’s U.S. asset management business; partially offsetting these increases were (i) $(4.1) billion of net transfers and (ii) $(1.5) billion of redemptions primarily in the corporate credit funds we manage;
-
an $8.3 billion increase related to funds we manage in our hybrid strategy due to (i) $7.1 billion of fundraising primarily across the hybrid credit and hybrid value funds we manage, and (ii) $1.1 billion of net transfers primarily from the yield strategy; and
-
an $18.6 billion increase related to funds we manage in our equity strategy primarily consisting of (i) $14.4 billion of fundraising primarily related to the traditional private equity funds we manage, and (ii) $3.0 billion of net transfers primarily from the yield strategy.
-
Realizations of $(21.5) billion primarily attributable to:
-
$(8.2) billion related to funds we manage in our yield strategy primarily consisting of a $5.8 billion one-time release of unfunded commitments;
-
$(4.2) billion related to funds we manage in our hybrid strategy primarily consisting of distributions from the hybrid credit and illiquid opportunistic funds we manage; and
-
$(9.0) billion related to funds we manage in our equity strategy primarily consisting of distributions across our traditional private equity funds.
-
Market activity of $(22.0) billion, primarily attributable to:
-
$(21.8) billion related to funds we manage in our yield strategy primarily consisting of $(15.0) billion driven by Athora and $(5.3) billion related to our corporate credit funds.
The following tables summarize changes in Fee-Generating AUM for each of Apollo’s three investing strategies within the asset management segment:
| For the Three Months ended September 30, | |||||||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | ||||||||||||||||||||||||||||||||||||||||||||||
| Yield | Hybrid | Equity | Total | Yield | Hybrid | Equity | Total | ||||||||||||||||||||||||||||||||||||||||
| (In millions) | |||||||||||||||||||||||||||||||||||||||||||||||
| Change in Fee-Generating AUM1: | |||||||||||||||||||||||||||||||||||||||||||||||
| Beginning of Period | $ | 314,062 | $ | 25,123 | $ | 41,609 | $ | 380,794 | $ | 291,680 | $ | 19,128 | $ | 42,752 | $ | 353,560 | |||||||||||||||||||||||||||||||
| Inflows | 26,446 | 3,089 | 3,551 | 33,086 | 14,627 | 1,379 | 268 | 16,274 | |||||||||||||||||||||||||||||||||||||||
| Outflows2 | (11,007) | (1,431) | (154) | (12,592) | (5,713) | (833) | (163) | (6,709) | |||||||||||||||||||||||||||||||||||||||
| Net Flows | 15,439 | 1,658 | 3,397 | 20,494 | 8,914 | 546 | 105 | 9,565 | |||||||||||||||||||||||||||||||||||||||
| Realizations | (317) | (436) | (681) | (1,434) | (623) | (244) | (1,107) | (1,974) | |||||||||||||||||||||||||||||||||||||||
| Market Activity3 | (5,245) | (187) | (202) | (5,634) | 45 | 172 | (75) | 142 | |||||||||||||||||||||||||||||||||||||||
| End of Period | $ | 323,939 | $ | 26,158 | $ | 44,123 | $ | 394,220 | $ | 300,016 | $ | 19,602 | $ | 41,675 | $ | 361,293 | |||||||||||||||||||||||||||||||
| 1 At the individual strategy level, inflows include new subscriptions, commitments, capital raised, other increases in available capital, purchases, acquisitions and portfolio company appreciation. Outflows represent redemptions, other decreases in available capital and portfolio company depreciation. Realizations represent fund distributions of realized proceeds. Market activity represents gains (losses), the impact of foreign exchange rate fluctuations and other income. | |||||||||||||||||||||||||||||||||||||||||||||||
| 2 Outflows for Fee-Generating AUM include redemptions of $0.7 billion and $0.6 billion during the three months ended September 30, 2022 and 2021, respectively. | |||||||||||||||||||||||||||||||||||||||||||||||
| 3 Includes foreign exchange impacts of $(3.9) billion and $(1.7) billion during the three months ended September 30, 2022 and 2021, respectively. |
| For the Nine Months Ended September 30, | |||||||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | ||||||||||||||||||||||||||||||||||||||||||||||
| Yield | Hybrid | Equity | Total | Yield | Hybrid | Equity | Total | ||||||||||||||||||||||||||||||||||||||||
| (in millions) | |||||||||||||||||||||||||||||||||||||||||||||||
| Change in Fee-Generating AUM1: | |||||||||||||||||||||||||||||||||||||||||||||||
| Beginning of Period | $ | 307,306 | $ | 21,845 | $ | 39,950 | $ | 369,101 | $ | 285,830 | $ | 17,622 | $ | 45,222 | $ | 348,674 | |||||||||||||||||||||||||||||||
| Inflows | 64,799 | 8,248 | 6,262 | 79,309 | 36,070 | 4,402 | 1,098 | 41,570 | |||||||||||||||||||||||||||||||||||||||
| Outflows2 | (28,191) | (2,187) | (636) | (31,014) | (19,149) | (2,402) | (1,159) | (22,710) | |||||||||||||||||||||||||||||||||||||||
| Net Flows | 36,608 | 6,061 | 5,626 | 48,295 | 16,921 | 2,000 | (61) | 18,860 | |||||||||||||||||||||||||||||||||||||||
| Realizations | (993) | (1,327) | (1,101) | (3,421) | (1,581) | (880) | (3,374) | (5,835) | |||||||||||||||||||||||||||||||||||||||
| Market Activity3 | (18,982) | (421) | (352) | (19,755) | (1,154) | 860 | (112) | (406) | |||||||||||||||||||||||||||||||||||||||
| End of Period | $ | 323,939 | $ | 26,158 | $ | 44,123 | $ | 394,220 | $ | 300,016 | $ | 19,602 | $ | 41,675 | $ | 361,293 | |||||||||||||||||||||||||||||||
| 1 At the individual strategy level, inflows include new subscriptions, commitments, capital raised, other increases in available capital, purchases, acquisitions and portfolio company appreciation. Outflows represent redemptions, other decreases in available capital and portfolio company depreciation. Realizations represent fund distributions of realized proceeds. Market activity represents gains (losses), the impact of foreign exchange rate fluctuations and other income. | |||||||||||||||||||||||||||||||||||||||||||||||
| 2 Outflows for Fee-Generating AUM include redemptions of $1.6 billion and $1.8 billion during the nine months ended September 30, 2022 and 2021, respectively. | |||||||||||||||||||||||||||||||||||||||||||||||
| 3 Includes foreign exchange impacts of $(9.6) billion and $(3.8) billion during the nine months ended September 30, 2022 and 2021, respectively. |
Three Months Ended September 30, 2022
Total Fee-Generating AUM was $394.2 billion at September 30, 2022, an increase of $13.4 billion, or 3.5%, compared to $380.8 billion at June 30, 2022. The net increase was primarily due to growth of our retirement services AUM, fundraising, and deployment, partially offset by market activity across our yield strategy due to foreign exchange depreciation and market related changes. More specifically, the net increase was due to:
- Net flows of $20.5 billion primarily attributable to:
*•*a $15.4 billion increase related to funds we manage in our yield strategy primarily consisting of (i) $11.0 billion of fee-generating capital deployment mostly related to Athora and the corporate credit funds we manage, (ii) $4.9 billion related to the growth of our retirement services clients, and (iii) $1.8 billion of subscriptions mostly related to the corporate credit funds we manage; partially offset by redemptions mostly related to the corporate credit funds we manage;
-
a $1.7 billion increase related to funds we manage in our hybrid strategy primarily due to fee-generating capital deployment related to the hybrid credit funds we manage, partially offset by capital reductions in our financial credit instruments strategy; and
-
a $3.4 billion increase related to funds we manage in our equity strategy primarily related to fundraising.
-
Net flows were partially offset by:
-
$(5.6) billion of market activity primarily related to funds we manage in our yield strategy driven by $(4.1) billion related to Athora and $(1.2) billion related to the corporate credit funds we manage; and
-
$(1.4) billion of realizations across the platform.
Nine Months Ended September 30, 2022
Total Fee-Generating AUM was $394.2 billion at September 30, 2022, an increase of $25.1 billion, or 6.8%, compared to $369.1 billion at December 31, 2021. The net increase was primarily due to growth of our retirement services AUM, deployment, fundraising, and the acquisition of Griffin Capital’s U.S. asset management business, partially offset by market activity across our yield strategy due to foreign exchange depreciation, market related changes and realizations. More specifically, the net increase was due to:
- Net flows of $48.3 billion primarily attributable to:
*•*a $36.6 billion increase related to funds we manage in our yield strategy primarily consisting of (i) a $16.4 billion increase in AUM related to the growth of our retirement services clients, (ii) $15.1 billion of fee-generating capital deployment mostly related to the corporate credit funds we manage and Athora, (iii) $6.5 billion related to the
acquisition of Griffin Capital’s U.S. asset management business, and (iv) $5.3 billion of subscriptions mostly related to the corporate credit funds we manage; partially offset by $(1.4) billion of redemptions mostly related to the corporate credit funds we manage and $(1.2) billion of net transfers;
-
a $6.1 billion increase related to funds we manage in our hybrid strategy primarily due to (i) $5.5 billion of fee-generating capital deployment, (ii) $1.7 billion of subscriptions mostly related to the hybrid credit funds we manage, and (iii) $1.0 billion of transfers in primarily from the yield strategy we manage, offset by ($1.0) billion of fee-generating capital reductions related to the financial credit instruments strategy; and
-
a $5.6 billion increase related to funds we manage in our equity strategy primarily related to (i) $3.3 billion of fee-generating capital deployment and (ii) $2.1 billion of fundraising.
-
Net flows were partially offset by:
-
$(19.8) billion of market activity primarily related to funds we manage in our yield strategy, consisting of $(13.1) billion related to Athora and $(4.5) billion related to the corporate credit funds we manage; and
-
$(3.4) billion of realizations across the yield, hybrid and equity strategies.
Gross Capital Deployment and Uncalled Commitments
Gross capital deployment represents the gross capital that has been invested in investments by the funds and accounts we manage during the relevant period, but excludes certain investment activities primarily related to hedging and cash management functions at the Company. Gross Capital Deployment is not reduced or netted down by sales or refinancings, and takes into account leverage used by the funds and accounts we manage in gaining exposure to the various investments that they have made.
Uncalled commitments, by contrast, represent unfunded capital commitments that certain of Apollo’s funds have received from fund investors to fund future or current fund investments and expenses.
Gross capital deployment and uncalled commitments are indicative of the pace and magnitude of fund capital that is deployed or will be deployed, and which therefore could result in future revenues that include management fees, transaction fees and performance fees to the extent they are fee-generating. Gross capital deployment and uncalled commitments can also give rise to future costs that are related to the hiring of additional resources to manage and account for the additional capital that is deployed or will be deployed. Management uses gross capital deployment and uncalled commitments as key operating metrics since we believe the results are measures of investment activities of the funds we manage.
The following presents gross capital deployment and uncalled commitments (in billions):
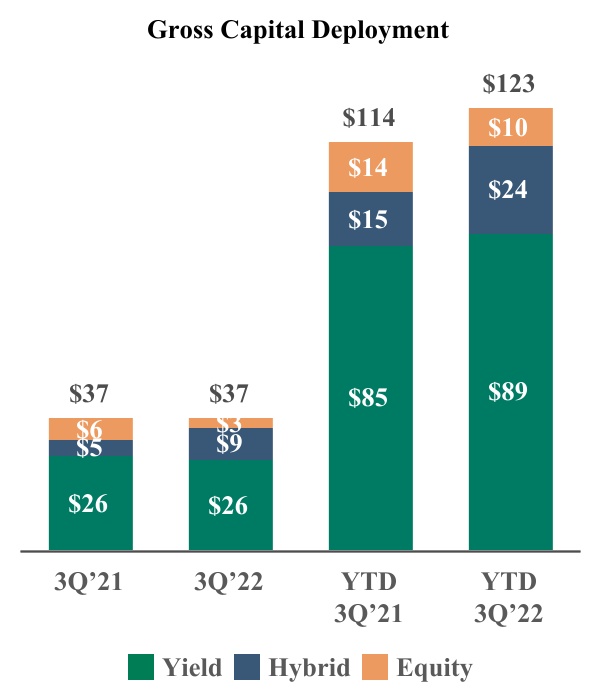
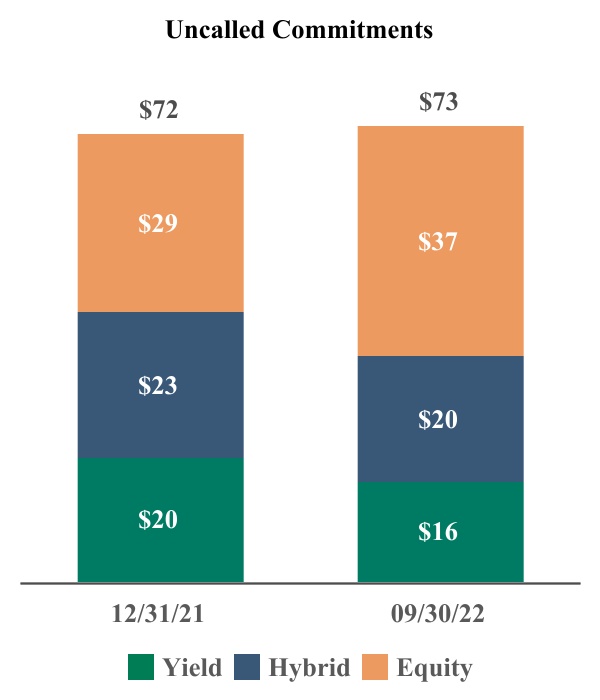
As of September 30, 2022 and December 31, 2021, Apollo had $51 billion and $47 billion of dry powder, respectively, which represents the amount of capital available for investment or reinvestment subject to the provisions of the applicable limited partnership agreements or other governing agreements of the funds, partnerships and accounts we manage. These amounts exclude uncalled commitments which can only be called for fund fees and expenses and commitments from perpetual capital vehicles.
Retirement Services
The following table presents Spread Related Earnings, the performance measure of our Retirement Services segment.
| Three months ended September 30, 2022 | Nine months ended September 30, 2022 | ||||||||||
| (In millions) | |||||||||||
| Retirement Services: | |||||||||||
| Fixed income and other investment income, net | $ | 1,470.4 | $ | 3,979.3 | |||||||
| Alternative investment income, net | 249.6 | 883.6 | |||||||||
| Strategic capital management fees | 13.6 | 38.6 | |||||||||
| Cost of funds | (965.5) | (2,677.8) | |||||||||
| Net investment spread | 768.1 | 2,223.7 | |||||||||
| Other operating expenses | (117.1) | (334.9) | |||||||||
| Interest and other financing costs | (72.9) | (198.8) | |||||||||
| Spread Related Earnings (SRE) | $ | 578.1 | $ | 1,690.0 | |||||||
In this section, references to 2022 refer to the three months ended September 30, 2022.
Three Months Ended September 30, 2022
Spread Related Earnings
SRE was $578.1 million for the three months ended September 30, 2022. SRE is comprised of investment income from Athene’s fixed income and other and alternative portfolios as well as strategic capital management fees less cost of funds on Athene’s liabilities, other operating expenses, and interest and other financing costs. SRE for the three months ended September 30, 2022 was mainly attributed to fixed income and other investment income and alternative investment income, partially offset by cost of funds, other operating expenses and financing costs. Fixed income and other investment income benefited from strong growth in organic inflows as well as floating rate income driven by the increase in rates. As a result of purchase accounting, the book value of Athene’s investment portfolio was marked up to fair value resulting in an adverse impact to fixed income and other investment income. Alternative investment income benefited from the deployment of inflows into alternative investments as well as strong performance on real estate funds, yield funds and MidCap but was adversely impacted by unfavorable economics. Cost of funds was primarily driven by interest credited and option costs on annuity products, pension group annuity obligations, interest on funding agreement issuances, income rider reserve and DAC and VOBA amortization as well as other liability costs. As a result of purchase accounting, Athene marked its reserve liabilities to fair value resulting in a favorable impact to cost of funds. Additionally, cost of funds was favorably impacted by an adjustment to exclude the non-operating change in funding agreement reserves from SRE, actuarial experience and unlocking. Unlocking, net of noncontrolling interests, was favorable $6 million primarily related to the impact of higher rates on future account values, partially offset by changes to projected interest crediting.
Net Investment Spread
| Three months ended September 30, 2022 | |||||
| Fixed income and other net investment earned rate | 3.27 | % | |||
| Alternative net investment earned rate | 8.26 | % | |||
| Net investment earned rate | 3.58 | % | |||
| Strategic capital management fees | 0.03 | % | |||
| Cost of funds | (2.01) | % | |||
| Net investment spread | 1.60 | % |
Net investment earned rate of 3.58% for the three months ended September 30, 2022 is comprised of a fixed income and other net investment earned rate of 3.27% and alternative net investment earned rate of 8.26%. The fixed income earned rate was adversely impacted by unfavorable purchase accounting impacts, partially offset by floating rate income due to the increase in rates. The alternative investment earned rate was driven by strong performance on real estate funds, Foundation Home Loans and MidCap but was adversely impacted by unfavorable economics.
Strategic capital management fees of 0.03% for the three months ended September 30, 2022 consisted of the management fee for ADIP’s portion of Athene’s business ceded to ACRA.
Cost of funds of 2.01% for the three months ended September 30, 2022 was primarily driven by interest credited and option costs on annuity products, pension group annuity obligations, interest on funding agreement issuances, income rider reserve and DAC and VOBA amortization, as well as other liability costs. As a result of purchase accounting, Athene marked its reserve liabilities to fair value resulting in a favorable impact to cost of funds. Additionally, cost of funds was favorably impacted by an adjustment to exclude the non-operating change in funding agreement reserves from SRE, actuarial experience and unlocking.
In this section, references to 2022 refer to the nine months ended September 30, 2022.
Nine Months Ended September 30, 2022
Spread Related Earnings
SRE was $1,690.0 million for the nine months ended September 30, 2022. SRE was mainly attributed to fixed income and other investment income and strong alternative investment income, partially offset by cost of funds, other operating expenses and interest and other financing costs. Fixed income and other investment income benefited from strong growth in organic inflows as well as floating rate income driven by the increase in rates. As a result of purchase accounting, the book value of Athene’s investment portfolio was marked up to fair value resulting in an adverse impact to fixed income and other investment income. Alternative investment income benefited from the deployment of inflows into alternative investments as well as strong performance on real estate funds, Athora and MidCap but was adversely impacted by unfavorable economics. Cost of funds was primarily driven by interest credited and option costs on annuity products, pension group annuity obligations, interest on funding agreement issuances, income rider reserve and DAC and VOBA amortization as well as other liability costs. As a result of purchase accounting, Athene marked its reserve liabilities to fair value resulting in a favorable impact to cost of funds. Additionally, cost of funds was favorably impacted by actuarial experience and unlocking. Unlocking, net of noncontrolling interests, was favorable $6 million primarily related to the impact of higher rates on future account values, partially offset by changes to projected interest crediting.
Net Investment Spread
| Nine months ended September 30, 2022 | |||||
| Fixed income and other net investment earned rate | 3.03 | % | |||
| Alternative net investment earned rate | 10.30 | % | |||
| Net investment earned rate | 3.47 | % | |||
| Strategic capital management fees | 0.03 | % | |||
| Cost of funds | (1.91) | % | |||
| Net investment spread | 1.59 | % |
Net investment earned rate of 3.47% for the nine months ended September 30, 2022 is comprised of a fixed income and other net investment earned rate of 3.03% and alternative net investment earned rate of 10.30%. The fixed income earned rate was adversely impacted by unfavorable purchase accounting impacts, partially offset by floating rate income due to the increase in rates. The alternative investment earned rate was driven by strong performance on real estate funds, Athora and MidCap but was adversely impacted by unfavorable economics.
Strategic capital management fees of 0.03% for the nine months ended September 30, 2022 consisted of the management fee for ADIP’s portion of Athene’s business ceded to ACRA.
Cost of funds of 1.91% for the nine months ended September 30, 2022 was primarily driven by interest credited and option costs on annuity products, pension group annuity obligations, interest on funding agreement issuances, income rider reserve and DAC and VOBA amortization, as well as other liability costs. As a result of purchase accounting, Athene marked its reserve liabilities to fair value resulting in a favorable impact to cost of funds. Additionally, cost of funds was favorably impacted by actuarial experience and unlocking.
Investment Portfolio
Athene had investments, including related parties and VIEs, of $200.3 billion as of September 30, 2022. Athene’s investment strategy seeks to achieve sustainable risk-adjusted returns through the disciplined management of its investment portfolio against its long-duration liabilities, coupled with the diversification of risk. The investment strategies focus primarily on a buy and hold asset allocation strategy that may be adjusted periodically in response to changing market conditions and the nature of Athene’s liability profile. Athene takes advantage of its generally illiquid liability profile by identifying investment opportunities with an emphasis on earning incremental yield by taking liquidity and complexity risk rather than assuming solely credit risk. Athene has selected a diverse array of corporate bonds and more structured, but highly rated asset classes. Athene also maintains holdings in floating rate and less rate-sensitive instruments, including CLOs, non-agency RMBS and various types of structured products. In addition to its fixed income portfolio, Athene opportunistically allocates approximately 5% – 6% of its portfolio to alternative investments where it primarily focuses on fixed income-like, cash flow-based investments.
The following table presents the carrying values of Athene’s total investments including related parties and VIEs:
| September 30, 2022 | |||||||||||||||||||||||
| (In millions, except percentages) | Carrying Value | Percent of Total | |||||||||||||||||||||
| AFS securities | |||||||||||||||||||||||
| US government and agencies | $ | 2,498 | 1.3 | % | |||||||||||||||||||
| US state, municipal and political subdivisions | 920 | 0.5 | % | ||||||||||||||||||||
| Foreign governments | 861 | 0.4 | % | ||||||||||||||||||||
| Corporate | 56,908 | 28.4 | % | ||||||||||||||||||||
| CLO | 14,146 | 7.1 | % | ||||||||||||||||||||
| ABS | 9,872 | 4.9 | % | ||||||||||||||||||||
| CMBS | 3,063 | 1.5 | % | ||||||||||||||||||||
| RMBS | 5,325 | 2.7 | % | ||||||||||||||||||||
| Total AFS securities, at fair value | 93,593 | 46.8 | % | ||||||||||||||||||||
| Trading securities, at fair value | 1,590 | 0.8 | % | ||||||||||||||||||||
| Equity securities | 1,607 | 0.8 | % | ||||||||||||||||||||
| Mortgage loans | 25,145 | 12.6 | % | ||||||||||||||||||||
| Investment funds | 29 | — | % | ||||||||||||||||||||
| Policy loans | 353 | 0.2 | % | ||||||||||||||||||||
| Funds withheld at interest | 34,706 | 17.3 | % | ||||||||||||||||||||
| Derivative assets | 4,065 | 2.0 | % | ||||||||||||||||||||
| Short-term investments | 318 | 0.2 | % | ||||||||||||||||||||
| Other investments | 682 | 0.3 | % | ||||||||||||||||||||
| Total investments | 162,088 | 81.0 | % | ||||||||||||||||||||
| Investments in related parties | |||||||||||||||||||||||
| AFS securities | |||||||||||||||||||||||
| Corporate | 1,022 | 0.5 | % | ||||||||||||||||||||
| CLO | 2,481 | 1.2 | % | ||||||||||||||||||||
| ABS | 5,552 | 2.8 | % | ||||||||||||||||||||
| Total AFS securities, at fair value | 9,055 | 4.5 | % | ||||||||||||||||||||
| Trading securities, at fair value | 901 | 0.4 | % | ||||||||||||||||||||
| Equity securities, at fair value | 340 | 0.2 | % | ||||||||||||||||||||
| Mortgage loans | 1,331 | 0.7 | % | ||||||||||||||||||||
| Investment funds | 1,272 | 0.6 | % | ||||||||||||||||||||
| Funds withheld at interest | 9,961 | 5.0 | % | ||||||||||||||||||||
| Other investments | 274 | 0.1 | % | ||||||||||||||||||||
| Total related party investments | 23,134 | 11.5 | % | ||||||||||||||||||||
| Total investments including related parties | 185,222 | 92.5 | % | ||||||||||||||||||||
| Investments owned by consolidated VIEs | |||||||||||||||||||||||
| Trading securities, at fair value | 988 | 0.5 | % | ||||||||||||||||||||
| Equity securities, at fair value | 15 | — | % | ||||||||||||||||||||
| Mortgage loans | 2,000 | 1.0 | % | ||||||||||||||||||||
| Investment funds, at fair value | 11,885 | 5.9 | % | ||||||||||||||||||||
| Other investments, at fair value | 152 | 0.1 | % | ||||||||||||||||||||
| Total investments owned by consolidated VIEs | 15,040 | 7.5 | % | ||||||||||||||||||||
| Total investments including related parties and VIEs | $ | 200,262 | 100.0 | % |
Athene’s investment portfolio consists largely of high quality fixed maturity securities, loans and short-term investments, as well as additional opportunistic holdings in investment funds and other instruments, including equity holdings. Fixed maturity securities and loans include publicly issued corporate bonds, government and other sovereign bonds, privately placed corporate bonds and loans, mortgage loans, CMBS, RMBS, CLOs and ABS. A significant majority of Athene’s AFS portfolio, 95.4% as of September 30, 2022, was invested in assets considered investment grade with a NAIC designation of 1 or 2.
Athene invests a portion of its investment portfolio in mortgage loans, which are generally comprised of high quality commercial first lien and mezzanine real estate loans. Athene has acquired mortgage loans through acquisitions and reinsurance arrangements, as well as through an active program to invest in new mortgage loans. It invests in CMLs on income producing
properties including hotels, apartments, retail and office buildings, and other commercial and industrial properties. Athene’s RML portfolio primarily consists of first lien RMLs collateralized by properties located in the U.S.
Funds withheld at interest represent a receivable for amounts contractually withheld by ceding companies in accordance with modco and funds withheld reinsurance agreements in which Athene acts as the reinsurer. Generally, assets equal to statutory reserves are withheld and legally owned by the ceding company.
While the substantial majority of Athene’s investment portfolio has been allocated to corporate bonds and structured credit products, a key component of Athene’s investment strategy is the opportunistic acquisition of investment funds with attractive risk and return profiles. Athene’s investment fund portfolio consists of funds that employ various strategies including real estate and other real asset funds, credit funds and private equity funds. Athene has a strong preference for assets that have some or all of the following characteristics, among others: (1) investments that constitute a direct investment or an investment in a fund with a high degree of co-investment; (2) investments with credit- or debt-like characteristics (for example, a stipulated maturity and par value), or alternatively, investments with reduced volatility when compared to pure equity; or (3) investments that Athene believes have less downside risk.
Athene holds derivatives for economic hedging purposes to reduce its exposure to the cash flow variability of assets and liabilities, equity market risk, interest rate risk, credit risk and foreign exchange risk. Athene’s primary use of derivative instruments relates to providing the income needed to fund the annual indexed credits on its FIA products. Athene primarily uses fixed indexed options to economically hedge index annuity products that guarantee the return of principal to the policyholder and credit interest based on a percentage of the gain in a specific market index.
Net Invested Assets
The following summarizes Athene’s net invested assets:
| September 30, 2022 | |||||||||||||||||||||||
| (In millions, except percentages) | Net Invested Asset Value****1 | Percent of Total | |||||||||||||||||||||
| Corporate | $ | 81,912 | 42.0 | % | |||||||||||||||||||
| CLO | 19,249 | 9.9 | % | ||||||||||||||||||||
| Credit | 101,161 | 51.9 | % | ||||||||||||||||||||
| CML | 23,793 | 12.2 | % | ||||||||||||||||||||
| RML | 9,818 | 5.0 | % | ||||||||||||||||||||
| RMBS | 7,063 | 3.6 | % | ||||||||||||||||||||
| CMBS | 3,859 | 2.0 | % | ||||||||||||||||||||
| Real estate | 44,533 | 22.8 | % | ||||||||||||||||||||
| ABS | 20,154 | 10.3 | % | ||||||||||||||||||||
| Alternative investments | 12,335 | 6.3 | % | ||||||||||||||||||||
| State, municipal, political subdivisions and foreign government | 2,723 | 1.4 | % | ||||||||||||||||||||
| Equity securities | 1,823 | 0.9 | % | ||||||||||||||||||||
| Short-term investments | 452 | 0.2 | % | ||||||||||||||||||||
| US government and agencies | 2,649 | 1.4 | % | ||||||||||||||||||||
| Other investments | 40,136 | 20.5 | % | ||||||||||||||||||||
| Cash and equivalents | 7,161 | 3.7 | % | ||||||||||||||||||||
| Policy loans and other | 2,166 | 1.1 | % | ||||||||||||||||||||
| Net invested assets | 195,157 | 100.0 | % | ||||||||||||||||||||
| 1 See Managing Business Performance - Key Segment and Non-U.S. GAAP Performance Measures for the definition of net invested assets. |
Athene’s net invested assets were $195.2 billion as of September 30, 2022. In managing its business, Athene utilizes net invested assets as presented in the above table. Net invested assets do not correspond to Athene’s total investments, including related parties, on the condensed consolidated statements of financial condition, as discussed previously in Managing Business Performance - Key Segment and Non-U.S. GAAP Performance Measures. Net invested assets represent Athene’s investments that directly back the net reserve liabilities and surplus assets. Athene believes this view of its portfolio provides a view of the assets for which it has economic exposure. Athene adjusts the presentation for funds withheld and modco transactions to
include or exclude the underlying investments based upon the contractual transfer of economic exposure to such underlying investments. Athene also adjusts for VIEs to show the net investment in the funds, which are included in the alternative investments line above, as well as adjust for the allowance for credit losses. Net invested assets includes its proportionate share of ACRA investments, based on its economic ownership, but excludes the proportionate share of investments associated with the non-controlling interest.
Net invested assets is utilized by management to evaluate Athene’s investment portfolio. Net invested assets is used in the computation of net investment earned rate, which allows Athene to analyze the profitability of the investment portfolio. Net invested assets is also used in Athene’s risk management processes for asset purchases, product design and underwriting, stress scenarios, liquidity, and ALM.
Principal Investing
The following table presents Principal Investing Income, the performance measure of our Principal Investing segment.
| Three months ended September 30, | Total Change | Percentage Change | Nine months ended September 30, | Total Change | Percentage Change | ||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||||||||||||||||||||||||
| (In millions) | (In millions) | ||||||||||||||||||||||||||||||||||||||||||||||
| Principal Investing: | |||||||||||||||||||||||||||||||||||||||||||||||
| Realized performance fees | $ | 92.9 | $ | 608.0 | $ | (515.1) | (84.7)% | $ | 371.0 | $ | 1,183.6 | $ | (812.6) | (68.7)% | |||||||||||||||||||||||||||||||||
| Realized investment income | 61.4 | 295.2 | (233.8) | (79.2) | 324.7 | 397.6 | (72.9) | (18.3) | |||||||||||||||||||||||||||||||||||||||
| Principal investing compensation | (90.3) | (309.0) | 218.7 | (70.8) | (401.3) | (631.3) | 230.0 | (36.4) | |||||||||||||||||||||||||||||||||||||||
| Other operating expenses | (13.9) | (11.8) | (2.1) | 17.8 | (37.6) | (34.1) | (3.5) | 10.3 | |||||||||||||||||||||||||||||||||||||||
| Principal Investing Income (PII) | $ | 50.1 | $ | 582.4 | $ | (532.3) | (91.4) | $ | 256.8 | $ | 915.8 | $ | (659.0) | (72.0) |
| Three months ended September 30, | Total Change | Percentage Change | Nine months ended September 30, | Total Change | Percentage Change | ||||||||||||||||||||||||||||||||||||||||||
| 2021 | 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||||||||||||
| (In millions) | (In millions) | ||||||||||||||||||||||||||||||||||||||||||||||
| Principal Investing: | |||||||||||||||||||||||||||||||||||||||||||||||
| Realized performance fees | $ | 608.0 | $ | 17.4 | $ | 590.6 | NM | $ | 1,183.6 | $ | 94.0 | $ | 1,089.6 | NM | |||||||||||||||||||||||||||||||||
| Realized investment income | 295.2 | 5.1 | 290.1 | NM | 397.6 | 22.2 | 375.4 | NM | |||||||||||||||||||||||||||||||||||||||
| Principal investing compensation | (309.0) | (26.2) | (282.8) | NM | (631.3) | (119.8) | (511.5) | 427.0 | |||||||||||||||||||||||||||||||||||||||
| Other operating expenses | (11.8) | (9.9) | (1.9) | 19.2 | (34.1) | (42.5) | 8.4 | (19.8) | |||||||||||||||||||||||||||||||||||||||
| Principal Investing Income (PII) | $ | 582.4 | $ | (13.6) | $ | 596.0 | NM | $ | 915.8 | $ | (46.1) | $ | 961.9 | NM |
As described in “Item 2. Management’s Discussion and Analysis of Financial Condition and Results of Operations — General”, earnings from our Principal Investing segment are inherently more volatile in nature than earnings from our Asset Management segment due to the intrinsic cyclical nature of performance fees, one of the key drivers of PII performance.
In this section, references to 2022 refer to the three months ended September 30, 2022, references to 2021 refer to the three months ended September 30, 2021, and references to 2020 refer to the three months ended September 30, 2020.
Three Months Ended September 30, 2022 Compared to Three Months Ended September 30, 2021
PII was $50.1 million in 2022, a decrease of $532.3 million, as compared to $582.4 million in 2021. This decrease was primarily attributable to decreases in realized performance fees and realized investment income of $515.1 million and $233.8 million, respectively, as equity market volatility delayed monetization activity. Realized investment income of $61.4 million in 2022 was primarily driven by realized gains from the transfer of the Company’s investment in Redding Ridge to AAA. The decrease in PII was partially offset by a decrease in principal investing compensation expense.
Principal investing compensation expense decreased as a result of a corresponding decrease in realized performance fees. In any period, the blended profit sharing percentage is impacted by the respective profit sharing ratios of the funds generating performance allocations in the period. Additionally, included in principal investing compensation are expenses related to the Incentive Pool, a compensation program through which certain employees are allocated discretionary compensation based on realized performance fees in a given year. The Incentive Pool is separate from the fund related profit sharing expense and may
result in greater variability in compensation and have a variable impact on the blended profit sharing percentage during a particular period.
Three Months Ended September 30, 2021 Compared to Three Months Ended September 30, 2020
PII was $582.4 million in 2021, an increase of $596.0 million, as compared to $(13.6) million in 2020. This increase was primarily attributable to increases in realized performance fees and realized investment income, partially offset by an increase in principal investing compensation expense. Realized performance fees increased to $608.0 million in 2021 from $17.4 million in 2020 driven by an increase in realized performance fees generated from Fund IX, Fund VIII and Fund VII of $269.5 million, $182.0 million and $49.4 million, respectively. The increase in realized investment income was primarily attributable to an increase in realizations driven by the sale of a platform investment to certain funds we manage and Athora in 2021. Principal investing compensation expense increased as a result of a corresponding increase in realized performance fees as described above.
In this section, references to 2022 refer to the nine months ended September 30, 2022, references to 2021 refer to the nine months ended September 30, 2021, and references to 2020 refer to the nine months ended September 30, 2020.
Nine Months Ended September 30, 2022 Compared to Nine Months Ended September 30, 2021
PII was $256.8 million in 2022, a decrease of $659.0 million, as compared to $915.8 million in 2021. This decrease was primarily attributable to reduced realized performance fees and realized investment income as a result of delayed monetization activity in 2022, offset, in part, by a corresponding decrease in principal investing compensation. Realized investment income in 2022 was primarily attributable to realized gains on the transfer of certain of Apollo’s general partner fund co-investments transferred to Athene that were subsequently transferred to AAA and realized gains from the transfer of the Company’s investment in Redding Ridge to AAA.
Nine Months Ended September 30, 2021 Compared to Nine Months Ended September 30, 2020
PII was $915.8 million in 2021, an increase of $961.9 million, as compared to $(46.1) million in 2020. This increase was primarily attributable to increases in realized performance fees and realized investment income, partially offset by an increase in principal investing compensation expense. Realized performance fees increased to $1.2 billion in 2021 from $94.0 million in 2020 driven by an increase in performance fees generated from Fund VIII and Fund IX of $577.1 million and $273.2 million, respectively. In 2020, the COVID-19 pandemic and the actions taken in response caused severe disruption to the global economy and financial markets. In line with public equity and credit indices, the Company experienced significant unrealized mark-to-market losses in underlying funds which significantly delayed monetization activity. The increase in realized investment income in 2021 was primarily attributable to an increase in realizations from the sale of a platform investment to certain funds we manage and Athora and an increase in realizations from Apollo’s equity ownership in Fund VIII. Principal investing compensation expense increased as a result of a corresponding increase in realized performance fees as described above.
The Historical Investment Performance of Our Funds
Below we present information relating to the historical performance of the funds we manage, including certain legacy Apollo funds that do not have a meaningful amount of unrealized investments, and in respect of which the general partner interest has not been contributed to us.
When considering the data presented below, you should note that the historical results of funds we manage are not indicative of the future results that you should expect from such funds, from any future funds we may raise or from your investment in our common shares.
An investment in our common stock is not an investment in any of the Apollo funds, and the assets and revenues of our funds are not directly available to us. The historical and potential future returns of the funds we manage are not directly linked to returns on our common stock. Therefore, you should not conclude that continued positive performance of the funds we manage will necessarily result in positive returns on an investment in our common stock. However, poor performance of the funds that we manage would cause a decline in our revenue from such funds, and would therefore have a negative effect on our performance and in all likelihood the value of our common stock.
Moreover, the historical returns of funds we manage should not be considered indicative of the future results you should expect from such funds or from any future funds we may raise. There can be no assurance that any Apollo fund will continue to achieve the same results in the future.
Finally, our private equity IRRs have historically varied greatly from fund to fund. For example, Fund VI generated a 12% gross IRR and a 9% net IRR since its inception through September 30, 2022, while Fund V generated a 61% gross IRR and a 44% net IRR since its inception through September 30, 2022. Accordingly, the IRR going forward for any current or future fund may vary considerably from the historical IRR generated by any particular fund, or for our private equity funds as a whole. Future returns will also be affected by the applicable risks, including risks of the industries and businesses in which a particular fund invests. See “Item 1A. Risk Factors—Risks Relating to Our Asset Management Business—Historical performance metrics are unreliable indicators of our current or future results of operations” in our quarterly report on Form 10-Q filed with the SEC on May 10, 2022.
Investment Record
The following table summarizes the investment record by strategy of Apollo’s significant commitment-based funds that have a defined maturity date in which investors make a commitment to provide capital at the formation of such funds and deliver capital when called as investment opportunities become available. The funds included in the investment record table below have greater than $500 million of AUM and/or form part of a flagship series of funds. All amounts are as of September 30, 2022, unless otherwise noted:
| (in millions, except IRR) | Vintage Year | Total AUM | Committed Capital | Total Invested Capital | Realized Value | Remaining Cost | Unrealized Value | Total Value | Gross IRR | Net IRR | |||||||||||||||||||||||||||||||||||||||||||||||||
| Yield: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Apollo Origination Partners1 | 2022 | $ | 2,407 | $ | 2,348 | $ | 2,135 | $ | 374 | $ | 1,891 | $ | 1,838 | $ | 2,212 | NM2 | NM2 | ||||||||||||||||||||||||||||||||||||||||||
| Hybrid: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Apollo Infrastructure Opportunity Fund II | 2021 | $ | 2,683 | $ | 2,542 | $ | 921 | $ | 30 | $ | 900 | $ | 1,135 | $ | 1,165 | 28 | % | 23 | % | ||||||||||||||||||||||||||||||||||||||||
| Apollo Infrastructure Opportunity Fund | 2018 | 598 | 897 | 802 | 1,022 | 205 | 248 | 1,270 | 25 | 19 | |||||||||||||||||||||||||||||||||||||||||||||||||
| FCI IV | 2021 | 1,349 | 1,123 | 154 | 5 | 154 | 155 | 160 | NM2 | NM2 | |||||||||||||||||||||||||||||||||||||||||||||||||
| FCI III | 2017 | 2,530 | 1,906 | 3,101 | 2,395 | 1,810 | 1,716 | 4,111 | 16 | 13 | |||||||||||||||||||||||||||||||||||||||||||||||||
| FCI II | 2013 | 2,069 | 1,555 | 3,449 | 2,818 | 1,719 | 1,436 | 4,254 | 7 | 5 | |||||||||||||||||||||||||||||||||||||||||||||||||
| FCI I | 2012 | — | 559 | 1,516 | 1,975 | — | — | 1,975 | 12 | 8 | |||||||||||||||||||||||||||||||||||||||||||||||||
| HVF II | 2022 | 4,455 | 4,592 | 1,790 | 8 | 1,782 | 1,682 | 1,690 | NM2 | NM2 | |||||||||||||||||||||||||||||||||||||||||||||||||
| HVF I | 2019 | 3,873 | 3,238 | 3,682 | 2,372 | 2,202 | 2,811 | 5,183 | 25 | 20 | |||||||||||||||||||||||||||||||||||||||||||||||||
| SCRF I, II, III, IV3 | Various | 2,679 | 3,963 | 8,323 | 8,729 | 780 | 670 | 9,399 | 13 | 10 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Accord V4 | 2022 | 1,868 | 1,922 | 1,095 | 311 | 788 | 725 | 1,036 | NM2 | NM2 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Accord I, II, III, III B & IV4 | Various | — | 6,070 | 4,765 | 5,137 | — | — | 5,137 | 22 | 17 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Accord+ | 2021 | 2,438 | 2,255 | 2,170 | 499 | 1,705 | 1,638 | 2,137 | NM2 | NM2 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total Hybrid | $ | 24,542 | $ | 30,622 | $ | 31,768 | $ | 25,301 | $ | 12,045 | $ | 12,216 | $ | 37,517 | |||||||||||||||||||||||||||||||||||||||||||||
| Equity: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Fund IX | 2018 | $ | 31,845 | $ | 24,729 | $ | 17,293 | $ | 7,063 | $ | 13,293 | $ | 20,648 | $ | 27,711 | 40 | % | 26 | % | ||||||||||||||||||||||||||||||||||||||||
| Fund VIII | 2013 | 11,513 | 18,377 | 16,273 | 20,332 | 5,716 | 7,850 | 28,182 | 15 | 11 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Fund VII | 2008 | 413 | 14,677 | 16,461 | 34,205 | 19 | 77 | 34,282 | 33 | 25 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Fund VI | 2006 | 366 | 10,136 | 12,457 | 21,136 | 405 | — | 21,136 | 12 | 9 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Fund V | 2001 | 62 | 3,742 | 5,192 | 12,721 | 120 | 3 | 12,724 | 61 | 44 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Fund I, II, III, IV & MIA5 | Various | 9 | 7,320 | 8,753 | 17,400 | — | — | 17,400 | 39 | 26 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Traditional Private Equity Funds6 | $ | 44,208 | $ | 78,981 | $ | 76,429 | $ | 112,857 | $ | 19,553 | $ | 28,578 | $ | 141,435 | 39 | 24 | |||||||||||||||||||||||||||||||||||||||||||
| ANRP III | 2020 | 1,618 | 1,400 | 781 | 87 | 771 | 1,054 | 1,141 | NM2 | NM2 | |||||||||||||||||||||||||||||||||||||||||||||||||
| ANRP II | 2016 | 1,711 | 3,454 | 2,931 | 2,965 | 1,153 | 1,155 | 4,120 | 16 | 9 | |||||||||||||||||||||||||||||||||||||||||||||||||
| ANRP I | 2012 | 220 | 1,323 | 1,149 | 1,209 | 461 | 22 | 1,231 | 2 | (2) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Impact Mission Fund1 | N/A | 1,053 | 947 | 547 | 44 | 503 | 626 | 670 | NM2 | NM2 | |||||||||||||||||||||||||||||||||||||||||||||||||
| EPF IV1,7 | N/A | 1,628 | 1,618 | 251 | — | 251 | 251 | 251 | NM2 | NM2 | |||||||||||||||||||||||||||||||||||||||||||||||||
| EPF III7 | 2017 | 4,534 | 4,326 | 4,605 | 3,123 | 2,282 | 3,075 | 6,198 | 19 | 11 | |||||||||||||||||||||||||||||||||||||||||||||||||
| EPF II7 | 2012 | 864 | 3,315 | 3,020 | 4,437 | 466 | 213 | 4,650 | 13 | 8 | |||||||||||||||||||||||||||||||||||||||||||||||||
| EPF I7 | 2007 | 199 | 1,269 | 1,668 | 2,814 | — | — | 2,814 | 23 | 17 | |||||||||||||||||||||||||||||||||||||||||||||||||
| U.S. RE Fund III8 | 2021 | 1,087 | 1,114 | 502 | 61 | 481 | 671 | 732 | 40 | 33 | |||||||||||||||||||||||||||||||||||||||||||||||||
| U.S. RE Fund II8 | 2016 | 1,341 | 1,264 | 1,067 | 663 | 747 | 1,111 | 1,774 | 16 | 14 | |||||||||||||||||||||||||||||||||||||||||||||||||
| U.S. RE Fund I8 | 2012 | 36 | 641 | 626 | 938 | 70 | 4 | 942 | 13 | 10 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Asia RE Fund II8 | 2022 | 972 | 978 | 515 | 195 | 345 | 353 | 548 | 6 | 3 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Asia RE Fund I8 | 2017 | 692 | 691 | 471 | 248 | 297 | 448 | 696 | 14 | 10 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total Equity | $ | 60,163 | $ | 101,321 | $ | 94,562 | $ | 129,641 | $ | 27,380 | $ | 37,561 | $ | 167,202 |
1Vintage Year is not yet applicable as these funds have not had their final closings.
2Data has not been presented as the fund’s effective date is less than 24 months prior to the period indicated and such information was deemed not meaningful.
3Remaining cost for certain of the hybrid funds we manage may include physical cash called, invested or reserved for certain levered investments.
4Accord funds have investment periods shorter than 24 months, therefore Gross and Net IRR are presented after 12 months of investing.
5The general partners and managers of Funds I, II and MIA, as well as the general partner of Fund III, were excluded assets in connection with the reorganization of the Company that occurred in 2007. As a result, Apollo did not receive the economics associated with these entities. The investment performance of these funds, combined with Fund IV, is presented to illustrate fund performance associated with Apollo’s investment professionals.
6Total IRR is calculated based on total cash flows for all funds presented.
7Includes funds denominated in euros with historical figures translated into U.S. dollars at an exchange rate of €1.00 to $0.98 as of September 30, 2022.
8U.S. RE Fund I, U.S. RE Fund II, U.S. RE Fund III, Asia RE Fund I and Asia RE Fund II had $145 million, $792 million, $439 million, $348 million and $515 million of co-investment commitments as of September 30, 2022, respectively, which are included in the figures in the table. A co-invest entity within U.S. RE Fund I is denominated in pounds sterling and translated into U.S. dollars at an exchange rate of £1.00 to $1.12 as of September 30, 2022.
Equity
The following table summarizes the investment record for distressed investments made in our traditional private equity fund portfolios since the Company’s inception. All amounts are as of September 30, 2022:
| (In millions, except percentages) | Total Invested Capital | Total Value | Gross IRR | ||||||||||||||
| Distressed for Control | $ | 7,795 | $ | 18,875 | 29 | % | |||||||||||
| Non-Control Distressed | 6,302 | 10,670 | 71 | ||||||||||||||
| Total | 14,097 | 29,545 | 49 | ||||||||||||||
| Corporate Carve-outs, Opportunistic Buyouts and Other Credit1 | 62,332 | 111,890 | 21 | ||||||||||||||
| Total | $ | 76,429 | $ | 141,435 | 39 | % | |||||||||||
| 1 Other Credit is defined as investments in debt securities of issuers other than portfolio companies that are not considered to be distressed. |
The following tables provide additional detail on the composition of the Fund IX, Fund VIII and Fund VII private equity portfolios based on investment strategy. Amounts for Fund I, II, III, IV, V and VI are included in the table above but not presented below as their remaining value is less than $100 million or the fund has been liquidated and such information was deemed not meaningful. All amounts are as of September 30, 2022:
Fund IX1
| (In millions) | Total Invested Capital | Total Value | |||||||||
| Corporate Carve-outs | $ | 4,082 | $ | 7,476 | |||||||
| Opportunistic Buyouts | 12,427 | 17,988 | |||||||||
| Distressed2 | 784 | 2,247 | |||||||||
| Total | $ | 17,293 | $ | 27,711 |
Fund VIII1
| (In millions) | Total Invested Capital | Total Value | |||||||||
| Corporate Carve-outs | $ | 2,704 | $ | 6,935 | |||||||
| Opportunistic Buyouts | 13,002 | 20,493 | |||||||||
| Distressed2 | 567 | 754 | |||||||||
| Total | $ | 16,273 | $ | 28,182 |
Fund VII1
| (In millions) | Total Invested Capital | Total Value | |||||||||
| Corporate Carve-outs | $ | 2,539 | $ | 4,845 | |||||||
| Opportunistic Buyouts | 4,338 | 10,799 | |||||||||
| Distressed/Other Credit2 | 9,584 | 18,638 | |||||||||
| Total | $ | 16,461 | $ | 34,282 | |||||||
1Committed capital less unfunded capital commitments for Fund IX, Fund VIII and Fund VII were $16.1 billion, $17.7 billion and $14.7 billion, respectively, which represents capital commitments from limited partners to invest in such funds less capital that is available for investment or reinvestment subject to the provisions of the applicable governing agreements.
2The distressed investment strategy includes distressed for control, non-control distressed and other credit. Other Credit is defined as investments in debt securities of issuers other than portfolio companies that are not considered to be distressed.
During the recovery and expansionary periods of 1994 through 2000 and late 2003 through the first half of 2007, our private equity funds invested or committed to invest approximately $13.7 billion primarily in traditional and corporate partner buyouts. During the recessionary periods of 1990 through 1993, 2001 through late 2003 and the recessionary and post recessionary periods (beginning the second half of 2007 through September 30, 2022), our private equity funds have invested $76.2 billion, of which $22.0 billion was in distressed buyouts and debt investments when the debt securities of quality companies traded at deep discounts to par value. Our average entry multiple for Fund VIII, VII and VI was 5.7x, 6.1x and 7.7x, respectively, as of September 30, 2022. Our average entry multiple for a private equity fund is the average of the total enterprise value over an applicable adjusted earnings before interest, taxes, depreciation and amortization, which may incorporate certain adjustments based on the investment team’s estimates and we believe captures the true economics of our funds’ investments in portfolio companies. The average entry multiple of actively investing funds may include committed investments not yet closed.
Perpetual Capital
The following table summarizes the investment record for our Perpetual Capital vehicles, excluding Athene-related and Athora-related assets managed or advised by ISG and ISGI:
| Total Returns****1 | |||||||||||||||||||||||||||||||||||||||||||||||
| IPO Year****2 | Total AUM | For the Three Months Ended September 30, 2022 | For the Three Months Ended September 30, 2021 | For the Nine Months Ended September 30, 2022 | For the Nine Months Ended September 30, 2021 | ||||||||||||||||||||||||||||||||||||||||||
| (In millions) | |||||||||||||||||||||||||||||||||||||||||||||||
| MidCap3 | N/A | $ | 11,558 | 4 | % | 3 | % | 15 | % | 16 | % | ||||||||||||||||||||||||||||||||||||
| AIF | 2013 | 343 | — | % | 3 | % | (18) | % | 15 | % | |||||||||||||||||||||||||||||||||||||
| AFT | 2011 | 355 | — | % | 2 | % | (18) | % | 15 | % | |||||||||||||||||||||||||||||||||||||
| MFIC/Other4 | 2004 | 9,266 | (2) | % | (2) | % | (13) | % | 32 | % | |||||||||||||||||||||||||||||||||||||
| ARI | 2009 | 9,860 | (17) | % | (5) | % | (30) | % | 42 | % | |||||||||||||||||||||||||||||||||||||
| Total | $ | 31,382 |
1Total returns are based on the change in closing trading prices during the respective periods presented taking into account dividends and distributions, if any, as if they were reinvested without regard to commission.
2An initial public offering (“IPO”) year represents the year in which the vehicle commenced trading on a national securities exchange.
3MidCap is not a publicly traded vehicle and therefore IPO year is not applicable. The returns presented are a gross return based on NAV. The net returns based on NAV were 3% and 2% for the three months ended September 30, 2022 and 2021, respectively, and 12% and 12% for the nine months ended September 30, 2022 and 2021, respectively.
4Included within total AUM of MFIC/Other, is $4.6 billion of AUM related to a non-traded business development company and $1.9 billion of AUM related to a publicly traded business development company from which Apollo earns investment-related service fees, but for which Apollo does not provide management or advisory services. Total returns exclude performance related to this AUM.
Summary of Non-U.S. GAAP Measures
The table below sets forth a reconciliation of net income attributable to Apollo Global Management, Inc. common stockholders to our non-U.S. GAAP performance measure:
| Three months ended September 30, | Nine months ended September 30, | |||||||||||||||||||||||||
| (In millions) | 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||
| GAAP Net Income (Loss) Attributable to Apollo Global Management, Inc. | $ | (876) | $ | 249 | $ | (3,797) | $ | 1,568 | ||||||||||||||||||
| Preferred dividends | — | 9 | — | 27 | ||||||||||||||||||||||
| Net income (loss) attributable to non-controlling interests | (298) | 373 | (1,909) | 2,060 | ||||||||||||||||||||||
| GAAP Net Income (Loss) | $ | (1,174) | $ | 631 | $ | (5,706) | $ | 3,655 | ||||||||||||||||||
| Income tax provision (benefit) | (185) | 101 | (1,280) | 498 | ||||||||||||||||||||||
| GAAP Income (Loss) Before Income Tax Provision (Benefit) | $ | (1,359) | $ | 732 | $ | (6,986) | $ | 4,153 | ||||||||||||||||||
| Asset Management Adjustments: | ||||||||||||||||||||||||||
| Equity-based profit sharing expense and other1 | 55 | 32 | 219 | 94 | ||||||||||||||||||||||
| Equity-based compensation | 46 | 20 | 139 | 55 | ||||||||||||||||||||||
| Preferred dividends | — | (9) | — | (27) | ||||||||||||||||||||||
| Transaction-related charges2 | (5) | (1) | (6) | 27 | ||||||||||||||||||||||
| Merger-related transaction and integration costs3 | 14 | 15 | 50 | 39 | ||||||||||||||||||||||
| (Gains) losses from change in tax receivable agreement liability | — | — | 14 | (2) | ||||||||||||||||||||||
| Net (income) loss attributable to non-controlling interests in consolidated entities | 328 | (113) | 1,882 | (300) | ||||||||||||||||||||||
| Unrealized performance fees | 66 | 159 | 109 | (1,411) | ||||||||||||||||||||||
| Unrealized profit sharing expense | (19) | (41) | (16) | 646 | ||||||||||||||||||||||
| HoldCo interest and other financing costs4 | 29 | 42 | 103 | 128 | ||||||||||||||||||||||
| Unrealized principal investment income (loss) | 128 | 219 | 138 | (154) | ||||||||||||||||||||||
| Unrealized net (gains) losses from investment activities and other | (15) | (152) | (138) | (1,391) | ||||||||||||||||||||||
| Retirement Services Adjustments: | ||||||||||||||||||||||||||
| Investment (gains) losses, net of offsets | 1,737 | — | 6,913 | — | ||||||||||||||||||||||
| Non-operating change in insurance liabilities and related derivatives, net of offsets | (64) | — | 398 | — | ||||||||||||||||||||||
| Integration, restructuring and other non-operating expenses | 37 | — | 104 | — | ||||||||||||||||||||||
| Equity-based compensation expense | 15 | — | 40 | — | ||||||||||||||||||||||
| Adjusted Segment Income | 993 | 903 | 2,963 | 1,857 | ||||||||||||||||||||||
| HoldCo interest and other financing costs4 | (29) | (42) | (103) | (128) | ||||||||||||||||||||||
| Taxes and related payables | (163) | (108) | (578) | (180) | ||||||||||||||||||||||
| Adjusted Net Income | $ | 801 | $ | 753 | $ | 2,282 | $ | 1,549 | ||||||||||||||||||
| 1 Equity-based profit sharing expense and other includes certain profit sharing arrangements in which a portion of performance fees distributed to the general partner are required to be used by employees of Apollo to purchase restricted shares of common stock or is delivered in the form of RSUs, which are granted under the Equity Plan. Equity-based profit sharing expense and other also includes performance grants which are tied to the Company’s receipt of performance fees, within prescribed periods, sufficient to cover the associated equity-based compensation expense. | ||||||||||||||||||||||||||
| 2 Transaction-related charges include contingent consideration, equity-based compensation charges and the amortization of intangible assets and certain other charges associated with acquisitions, and restructuring charges. | ||||||||||||||||||||||||||
| 3 Merger-related transaction and integration costs includes advisory services, technology integration, equity-based compensation charges and other costs associated with the Mergers. | ||||||||||||||||||||||||||
| 4 Represents interest and other financing costs related to AGM not attributable to any specific segment. | ||||||||||||||||||||||||||
The table below sets forth a reconciliation of common stock outstanding to our Adjusted Net Income Shares Outstanding:
| As of September 30, 2022 | As of September 30, 2021 | As of December 31, 2021 | |||||||||||||||
| Total GAAP Common Stock Outstanding | 572,670,634 | 245,393,192 | 248,896,649 | ||||||||||||||
| Non-GAAP Adjustments: | |||||||||||||||||
| Participating Apollo Operating Group Units | — | 187,406,688 | 184,787,638 | ||||||||||||||
| Vested RSUs | 13,492,457 | 253,953 | 17,700,688 | ||||||||||||||
| Unvested RSUs Eligible for Dividend Equivalents | 14,181,682 | 7,311,733 | 9,809,245 | ||||||||||||||
| Adjusted Net Income Shares Outstanding | 600,344,773 | 440,365,566 | 461,194,220 |
The table below sets forth a reconciliation of Athene’s total investments, including related parties, to net invested assets:
| (In millions) | September 30, 2022 | December 31, 2021 | ||||||||||||
| Total investments, including investment in related parties | $ | 185,222 | $ | — | ||||||||||
| Derivative assets | (4,065) | — | ||||||||||||
| Cash and cash equivalents (including restricted cash) | 10,847 | — | ||||||||||||
| Accrued investment income | 1,226 | — | ||||||||||||
| Payables for collateral on derivatives | (2,538) | — | ||||||||||||
| Reinsurance funds withheld and modified coinsurance | 7,156 | — | ||||||||||||
| VIE and VOE assets, liabilities and non-controlling interest | 13,259 | — | ||||||||||||
| Unrealized (gains) losses | 25,098 | — | ||||||||||||
| Ceded policy loans | (180) | — | ||||||||||||
| Net investment receivables (payables) | 249 | — | ||||||||||||
| Allowance for credit losses | 446 | — | ||||||||||||
| Total adjustments to arrive at gross invested assets | 51,498 | — | ||||||||||||
| Gross invested assets | 236,720 | — | ||||||||||||
| ACRA non-controlling interest | (41,563) | — | ||||||||||||
| Net invested assets | $ | 195,157 | $ | — |
Liquidity and Capital Resources
Overview
The Company primarily derives revenues and cash flows from the assets it manages and the retirement savings products it issues, reinsures and acquires. Based on management’s experience, we believe that the Company’s current liquidity position, together with the cash generated from revenues will be sufficient to meet the Company’s anticipated expenses and other working capital needs for at least the next 12 months. For the longer-term liquidity needs of the asset management business, we expect to continue to fund the asset management business’ operations through management fees and performance fees received. The principal sources of liquidity for the retirement services business, in the ordinary course of business, are operating cash flows and holdings of cash, cash equivalents and other readily marketable assets.
AGM is a holding company whose primary source of cash flow is distributions from its subsidiaries, which are expected to be sufficient to fund cash flow requirements based on current estimates of future obligations. AGM’s primary liquidity needs include the cash-flow requirements relating to its corporate activities, including its day-to-day operations, common stock dividend payments and strategic transactions, such as acquisitions.
At September 30, 2022, the Company had $10.9 billion of unrestricted cash and cash equivalents and $1.0 billion of U.S. Treasury securities as well as $4.5 billion of available funds from the AMH credit facility, AHL credit facility, and AHL liquidity facility.
Primary Uses of Cash
Over the next 12 months, we expect the Company’s primary liquidity needs will be to:
-
support the future growth of Apollo’s businesses through strategic corporate investments
-
pay the Company’s operating expenses, including, compensation, general, administrative, and other expense
-
make payments to policyholders for surrenders, withdrawals and payout benefits
-
make interest and principal payments on funding agreements
-
make payments to satisfy pension group annuity obligations and policy acquisition costs
-
pay taxes and tax related payments
-
pay cash dividends
-
make payments related to the AOG Unit Payment
-
repurchase common stock
-
make payments under the tax receivable agreement
Over the long term, we believe we will be able to (i) grow Apollo’s Assets Under Management and generate positive investment performance in the funds we manage, which we expect will allow us to grow the Company’s management fees and performance fees and (ii) grow the investment portfolio of retirement services, in each case in amounts sufficient to cover our long-term liquidity requirements, which may include:
-
supporting the future growth of our businesses
-
creating new or enhancing existing products and investment platforms
-
making payments to policyholders
-
pursuing new strategic corporate investment opportunities
-
paying interest and principal on the Company’s financing arrangements
-
repurchasing common stock
-
making payments under the tax receivable agreement
-
making payments related to the AOG Unit Payment
-
paying cash dividends
Cash Flow Analysis
The section below discusses in more detail the Company’s primary sources and uses of cash and the primary drivers of cash flows within the Company’s consolidated statements of cash flows:
| For the Nine Months Ended September 30, | |||||||||||||||||
| (In millions) | 2022 | 2021 | |||||||||||||||
| Operating Activities | $ | 2,324 | $ | 2,137 | |||||||||||||
| Investing Activities | (12,171) | (344) | |||||||||||||||
| Financing Activities | 21,013 | (444) | |||||||||||||||
| Effect of exchange rate changes on cash and cash equivalents | (18) | — | |||||||||||||||
| Net Increase in Cash and Cash Equivalents, Restricted Cash and Cash Equivalents, and Cash and Cash Equivalents Held at Consolidated Variable Interest Entities | $ | 11,148 | $ | 1,349 |
The assets of our consolidated funds and VIEs, on a gross basis, could have a substantial effect on the accompanying statement of cash flows. Because our consolidated funds and VIEs are generally treated as investment companies for accounting purposes, their investing cash flow amounts are included in our cash flows from operating activities. The table below summarizes our consolidated statements of cash flow by activity attributable to the Company and to our consolidated funds and VIEs.
| For the Nine Months Ended September 30, | |||||||||||||||||
| (In millions) | 2022 | 2021 | |||||||||||||||
| Net cash provided by the Company's operating activities | $ | 6,923 | $ | 2,061 | |||||||||||||
| Net cash provided by (used in) the Consolidated Funds and VIEs operating activities | (4,599) | 76 | |||||||||||||||
| Net cash provided by operating activities | 2,324 | 2,137 | |||||||||||||||
| Net cash used in the Company's investing activities | (10,491) | (368) | |||||||||||||||
| Net cash provided by (used in) the Consolidated Funds and VIEs investing activities | (1,680) | 24 | |||||||||||||||
| Net cash used in investing activities | (12,171) | (344) | |||||||||||||||
| Net cash provided by (used in) the Company's financing activities | 14,740 | (1,161) | |||||||||||||||
| Net cash provided by the Consolidated Funds and VIEs financing activities | 6,273 | 717 | |||||||||||||||
| Net cash provided by (used in) financing activities | $ | 21,013 | $ | (444) |
Operating Activities
The Company’s operating activities support its Asset Management, Retirement Services and Principal Investing activities. The primary sources of cash within operating activities include: (a) management fees, (b) advisory and transaction fees, (c) realized performance revenues, (d) realized principal investment income, (e) investment sales from our consolidated funds and VIEs, (f) net investment income, (g) annuity considerations and (h) insurance premiums. The primary uses of cash within operating activities include: (a) compensation and non-compensation related expenses, (b) interest and taxes, (c) investment purchases from our consolidated funds and VIEs, (d) benefit payments and (e) other operating expenses.
-
During the nine months ended September 30, 2022, cash used in operating activities primarily includes net cash used in our consolidated funds and VIEs for purchases of investments. Net cash provided by operating activities reflects cash inflows of management fees, advisory and transaction fees, realized performance revenues, and realized principal investment income, as well as cash received from pension group annuity transactions net of outflows.
-
During the nine months ended September 30, 2021, cash provided by operating activities primarily includes cash inflows from the receipt of management fees, advisory and transaction fees, realized performance revenues, and realized principal investment income, offset by cash outflows for compensation, general, administrative, and other expenses. Net cash provided by operating activities also reflects the operating activity of our consolidated funds and VIEs, which primarily includes cash inflows from consolidated funds and from the sale of investments offset by cash outflows for purchases of investments.
Investing Activities
The Company’s investing activities support the growth of its business. The primary sources of cash within investing activities include: (a) distributions from investments and (b) sales, maturities and repayments of investments. The primary uses of cash within investing activities include: (a) capital expenditures, (b) purchases and acquisitions of new investments, including purchases of U.S. Treasury securities and (c) equity method investments in the funds we manage.
-
During the nine months ended September 30, 2022, cash used in investing activities primarily reflects the purchase of investments due to the deployment of significant cash inflows from Athene’s organic growth, partially offset by Athene cash acquired as a result of the Mergers and the sale, repayment and maturity of investments.
-
During the nine months ended September 30, 2021, cash used in investing activities primarily reflects purchases of investments in Motive Partners and Challenger Ltd. and net contributions to equity method investments. Net cash used in investing activities also reflects the investing activity of our consolidated funds and VIEs, which primarily reflects net proceeds from maturities of U.S. Treasury securities.
Financing Activities
The Company’s financing activities reflect its capital market transactions and transactions with equity holders. The primary sources of cash within the financing activities section includes: (a) proceeds from debt and preferred equity issuances, (b)
inflows on Athene’s investment-type policies, (c) changes of cash collateral posted for derivative transactions, and (d) capital contributions and proceeds from other borrowing activities. The primary uses of cash within the financing activities section include: (a) dividends, (b) payments under the tax receivable agreement, (c) share repurchases, (d) cash paid to settle tax withholding obligations in connection with net share settlements of equity-based awards, (e) repayments of debt, (f) withdrawals on Athene’s investment-type policies and (g) changes of cash collateral posted for derivative transactions.
-
During the nine months ended September 30, 2022, cash provided by financing activities primarily reflects the strong organic inflows from retail, flow reinsurance and funding agreements, net of withdrawals, partially offset by the payment of stock dividends. Cash provided by financing activities of our consolidated funds and VIEs primarily includes proceeds from the issuance of debt.
-
During the nine months ended September 30, 2021, cash used in financing activities primarily reflects dividends to common stockholders, distributions to non-controlling interest holders, and repurchases of common stock. Net cash used in financing activities also reflects the financing activity of our consolidated funds and VIEs, which primarily includes cash inflows from the issuance of debt, net contributions from non-controlling interests in consolidated entities, proceeds from issuance of securities of a SPAC, partially offset by payment of underwriting discounts and cash outflows for the principal repayment of debt.
Contractual Obligations, Commitments and Contingencies
For a summary and a description of the nature of the Company’s commitments, contingencies and contractual obligations, see note 17 to the condensed consolidated financial statements and “—Contractual Obligations, Commitments and Contingencies.” The Company’s commitments are primarily fulfilled through cash flows from operations and financing activities.
Consolidated Funds and VIEs
The Company manages its liquidity needs by evaluating unconsolidated cash flows; however, the Company’s financial statements reflect the financial position of Apollo as well as Apollo’s consolidated funds and VIEs (including SPACs). The primary sources and uses of cash at Apollo’s consolidated funds and VIEs include: (a) raising capital from their investors, which have been reflected historically as non-controlling interests of the consolidated subsidiaries in our financial statements, (b) using capital to make investments, (c) generating cash flows from operations through distributions, interest and the realization of investments, (d) distributing cash flow to investors, (e) issuing debt to finance investments (CLOs) and (f) raising capital through SPAC vehicles for future acquisition of targeted entities.
Dividends and Distributions
For information regarding the quarterly dividends and distributions that were made to common stockholders and non-controlling interest holders in the Apollo Operating Group and participating securities, see note 14 to the condensed consolidated financial statements. Although the Company currently expects to pay dividends, we may not pay dividends if, among other things, we do not have the cash necessary to pay the dividends. To the extent we do not have cash on hand sufficient to pay dividends, we may have to borrow funds to pay dividends, or we may determine not to pay dividends. The declaration, payment and determination of the amount of our dividends are at the sole discretion of our board of directors.
On November 2, 2022, AGM declared a cash dividend of $0.40 per share of its common stock, which will be paid on November 30, 2022 to holders of record at the close of business on November 17, 2022.
Repurchase of Securities
Share Repurchase Program
For information regarding the Company’s share repurchase program, see note 14 to the condensed consolidated financial statements.
Repurchase of Other Securities
We may from time to time seek to retire or purchase our other outstanding debt or equity securities through cash purchases and/or exchanges for other securities, purchases in the open market, privately negotiated transactions or otherwise. Any such
repurchases will be dependent upon several factors, including our liquidity requirements, contractual restrictions, general market conditions and applicable regulatory, legal and accounting factors. Whether or not we repurchase any of our other securities and the size and timing of any such repurchases will be determined at our discretion.
Asset Management Liquidity
Our asset management business requires limited capital resources to support the working capital or operating needs of the business. For the asset management business’ longer-term liquidity needs, we expect to continue to fund the asset management business’ operations through management fees and performance fees received. Liquidity needs are also met (to a limited extent) through proceeds from borrowings and equity issuances as described in notes 12 and 14 to the condensed consolidated financial statements, respectively. From time to time, if the Company determines that market conditions are favorable after taking into account our liquidity requirements, we may seek to raise proceeds through the issuance of additional debt or equity instruments.
At September 30, 2022, the asset management business had $1.1 billion of unrestricted cash and cash equivalents and $1.0 billion of U.S. Treasury securities as well as $750 million of available funds from the AMH credit facility.
Future Debt Obligations
The asset management business had long-term debt of $2.8 billion at September 30, 2022, which includes notes with maturities in 2024, 2026, 2029, 2030, 2048 and 2050. See note 12 to the condensed consolidated financial statements for further information regarding the asset management business’ debt arrangements.
Future Cash Flows
Our ability to execute our business strategy, particularly our ability to increase our AUM, depends on our ability to establish new funds and to raise additional investor capital within such funds. Our liquidity will depend on a number of factors, such as our ability to project our financial performance, which is highly dependent on the funds we manage and our ability to manage our projected costs, fund performance, access to credit facilities, compliance with existing credit agreements, as well as industry and market trends. Also during economic downturns the funds we manage might experience cash flow issues or liquidate entirely. In these situations we might be asked to reduce or eliminate the management fee and performance fees we charge, which could adversely impact our cash flow in the future.
An increase in the fair value of the investments of the funds we manage, by contrast, could favorably impact our liquidity through higher management fees where the management fees are calculated based on the net asset value, gross assets or adjusted assets. Additionally, higher performance fees not yet realized would generally result when investments appreciate over their cost basis which would not have an impact on the asset management business’ cash flow until realized.
Consideration of Financing Arrangements
As noted above, in limited circumstances, the asset management business may issue debt or equity to supplement its liquidity. The decision to enter into a particular financing arrangement is made after careful consideration of various factors including the asset management business’ cash flows from operations, future cash needs, current sources of liquidity, demand for the asset management business’ debt or equity, and prevailing interest rates.
Revolver Facility
Under the 2022 AMH credit facility, AMH may borrow in an aggregate amount not to exceed $1.0 billion and may incur incremental facilities in an aggregate amount not to exceed $250 million plus additional amounts so long as AMH is in compliance with a net leverage ratio not to exceed 4.00 to 1.00. Borrowings under the 2022 AMH credit facility may be used for working capital and general corporate purposes, including without limitation, permitted acquisitions. The 2022 AMH credit facility has a final maturity date of October 12, 2027. See note 12 to the condensed consolidated financial statements for details regarding the AMH credit facility refinancing, which occurred during the fourth quarter of 2022.
Tax Receivable Agreement
The tax receivable agreement provides for the payment to the Former Managing Partners and Contributing Partners of 85% of the amount of cash savings, if any, in U.S. federal, state, local and foreign income taxes that AGM and its subsidiaries realizes
subject to the agreement. For more information regarding the tax receivable agreement, see note 16 to the condensed consolidated financial statements.
AOG Unit Payment
On December 31, 2021, holders of AOG Units (other than Athene and Apollo) sold and transferred a portion of such AOG Units to a wholly-owned subsidiary of the Company, in exchange for an amount equal to $3.66 multiplied by the total number of AOG Units held by such holders immediately prior to such transaction (such payment, the “AOG Unit Payment”). The remainder of the AOG Units held by such holders were exchanged for shares of AGM common stock concurrently with the consummation of the Mergers on January 1, 2022.
As of September 30, 2022, the outstanding AOG Unit Payment amount was $394 million, payable in equal installments through December 31, 2024. See note 16 for more information.
Athora
On April 14, 2017, Apollo made a commitment of €125 million to purchase new Class B-1 equity interests in Athora, a strategic platform that acquires and reinsures traditional closed life insurance policies and provides capital and reinsurance solutions to insurers in Europe which, as of April 2020 was fully drawn. In January 2018, Apollo purchased Class C-1 equity interests in Athora that represent a profits interest in Athora which, upon meeting certain vesting triggers, will be convertible by Apollo into additional Class B-1 equity interests in Athora.
In connection with Athora’s acquisition of VIVAT N.V., Apollo exercised its preemptive rights and made an additional incremental commitment of approximately €58 million to purchase new Class B-1 equity interests in Athora. In addition, in April 2020, Apollo purchased Class C-2 equity interests in Athora that represent a profits interest in Athora which, upon meeting certain vesting triggers, will be convertible by Apollo into additional Class B-1 equity interests in Athora.
In November 2021, Apollo made an additional commitment to purchase up to €120 million of new Class B-1 equity interests in Athora, to be drawn in connection with three separate offerings over a period of three years, with a commitment of up to €30 million in 2021, up to €40 million in 2022 and up to €50 million in 2023. Athora’s other common shareholders may exercise preemptive rights to acquire common shares in connection with each offering and any such exercise will reduce the total amount of new Class B-1 equity interests ultimately purchased by Apollo. In connection with the 2021 offering, Apollo acquired approximately €21.9 million of new Class B-1 equity interests. In addition, Apollo purchased Class C-3 equity interests in Athora in connection with the 2021 offering that represent a profits interest in Athora which, upon meeting certain vesting triggers, will be convertible by Apollo into additional Class B-1 equity interests in Athora. The remaining commitments are drawable in four installments between 2022 and 2024.
In December 2021, Apollo committed an additional €250 million to purchase new Class B-1 equity interests to support Athora’s ongoing growth initiatives, of which €180 million was drawn as of December 31, 2021. Apollo expects the remaining €70 million will be drawn in 2022, pending regulatory approvals.
Apollo Asset Management and Athene are minority investors in Athora with a long-term strategic relationship. Through its share ownership, Apollo has approximately 19.9% of the total voting power in Athora, and Athene holds shares in Athora representing 10% of the total voting power in Athora. In addition, Athora shares held by funds and other accounts managed by Apollo Asset Management represent, in the aggregate, approximately 15.1% of the total voting power in Athora.
Fund Escrow
As of September 30, 2022, the remaining investments and escrow cash of Fund VII was valued at 112% of the fund’s unreturned capital which was below the required escrow ratio of 115%. As a result, the fund is required to place in escrow current and future performance fee distributions to the general partner until the specified return ratio of 115% is met (at the time of a future distribution) or upon liquidation. Realized performance fees currently distributed to the general partner are limited to potential tax distributions and interest on escrow balances per the fund’s partnership agreement.
Clawback
Performance fees from certain of the funds we manage are subject to contingent repayment by the general partner in the event of future losses to the extent that the cumulative performance fees distributed from inception to date exceeds the amount computed as due to the general partner at the final distribution. See “—Overview of Results of Operations—Performance Fees” for the maximum performance fees subject to potential reversal by each fund.
Indemnification Liability
The asset management business recorded an indemnification liability in the event that the Former Managing Partners, Contributing Partners and certain investment professionals are required to pay amounts in connection with a general partner obligation to return previously distributed performance fees. See note 16 to the consolidated financial statements for further information regarding the asset management business’ indemnification liability.
Retirement Services Liquidity
There are two forms of liquidity relevant to our retirement services business, funding liquidity and balance sheet liquidity. Funding liquidity relates to the ability to fund operations. Balance sheet liquidity relates to the ability to liquidate or rebalance Athene’s balance sheet without incurring significant costs from fees, bid-offer spreads, or market impact. Athene manages the liquidity position of its business by matching projected cash demands with adequate sources of cash and other liquid assets. The principal sources of liquidity for our retirement services business, in the ordinary course of business, are operating cash flows and holdings of cash, cash equivalents and other readily marketable assets.
Athene’s investment portfolio is structured to ensure a strong liquidity position over time in order to permit timely payment of policy and contract benefits without requiring asset sales at inopportune times or at depressed prices. In general, liquid assets include cash and cash equivalents, highly rated corporate bonds, unaffiliated preferred stock and public common stock, all of which generally have liquid markets with a large number of buyers. Assets included in modified coinsurance and funds withheld portfolios are available to fund the benefits for the associated obligations but are restricted from other uses. Although the investment portfolio of our retirement services’ business does contain assets that are generally considered illiquid for liquidity monitoring purposes (primarily mortgage loans, policy loans, real estate, investment funds, and affiliated common stock), there is some ability to raise cash from these assets if needed. Athene has access to additional liquidity through the $1.25 billion AHL credit facility, the AHL liquidity facility with a current borrowing capacity of $2.5 billion, and its $2.0 billion of committed repurchase facilities. Both the AHL credit facility and AHL liquidity facility were undrawn as of September 30, 2022. Athene also has a registration statement on Form S-3 to provide it with access to the capital markets, subject to favorable market conditions and other factors. Athene is also party to repurchase agreements with several different financial institutions, pursuant to which it may obtain short-term liquidity, to the extent available. In addition, through Athene’s membership in the FHLB, it is eligible to borrow under variable rate short-term federal funds arrangements to provide additional liquidity.
Athene proactively manages its liquidity position to meet cash needs while minimizing adverse impacts on investment returns. Athene analyzes its cash-flow liquidity over the upcoming 12 months by modeling potential demands on liquidity under a variety of scenarios, taking into account the provisions of its policies and contracts in force, its cash flow position, and the volume of cash and readily marketable securities in its portfolio.
Liquidity risk is monitored, managed and mitigated through a number of stress tests and analyses to assess Athene’s ability to meet its cash flow requirements, as well as the ability of its reinsurance and insurance subsidiaries to meet their collateral obligations, under various stress scenarios. Athene further seeks to mitigate liquidity risk by maintaining access to alternative, external sources of liquidity.
Insurance Subsidiaries’ Operating Liquidity
The primary cash flow sources for Athene’s insurance subsidiaries include retirement services product inflows (premiums), investment income, principal repayments on its investments, net transfers from separate accounts and financial product inflows. Uses of cash include investment purchases, payments to policyholders for surrenders, withdrawals and payout benefits, interest and principal payments on funding agreements, payments to satisfy pension group annuity obligations, policy acquisition costs and general operating costs.
Athene’s policyholder obligations are generally long-term in nature. However, policyholders may elect to withdraw some, or all, of their account value during the surrender charge period of an annuity contract. Athene includes provisions within its annuity policies, such as surrender charges and MVAs, which are intended to protect it from early withdrawals. As of September 30, 2022, approximately 75% of Athene’s deferred annuity liabilities were subject to penalty upon surrender. In addition, as of September 30, 2022, approximately 53% of policies contained MVAs that may also have the effect of limiting early withdrawals if interest rates increase, but may encourage early withdrawals by effectively subsidizing a portion of surrender charges when interest rates decrease. Athene’s funding agreements, group annuities and payout annuities are generally non-surrenderable, which accounts for approximately 31% of Athene’s net reserve liabilities as of September 30, 2022.
Membership in Federal Home Loan Bank
Through its membership in the FHLB, Athene is eligible to borrow under variable rate short-term federal funds arrangements to provide additional liquidity. The borrowings must be secured by eligible collateral such as mortgage loans, eligible CMBS or RMBS, government or agency securities and guaranteed loans. As of September 30, 2022, Athene had no outstanding borrowings under these arrangements.
Athene has issued funding agreements to the FHLB. These funding agreements were issued in an investment spread strategy, consistent with other investment spread operations. As of September 30, 2022, Athene had funding agreements outstanding with the FHLB in the aggregate principal amount of $3.7 billion.
The maximum FHLB indebtedness by a member is determined by the amount of collateral pledged, and cannot exceed a specified percentage of the member’s total statutory assets dependent on the internal credit rating assigned to the member by the FHLB. As of September 30, 2022, the total maximum borrowings under the FHLB facilities were limited to $48.6 billion. However, Athene’s ability to borrow under the facilities is constrained by the availability of assets that qualify as eligible collateral under the facilities and certain other limitations. Considering these limitations, as of September 30, 2022 Athene had the ability to draw up to an estimated $5.3 billion, inclusive of borrowings then outstanding. This estimate is based on Athene’s internal analysis and assumptions, and may not accurately measure collateral which is ultimately acceptable to the FHLB.
Securities Repurchase Agreements
Athene engages in repurchase transactions whereby it sells fixed income securities to third parties, primarily major brokerage firms or commercial banks, with a concurrent agreement to repurchase such securities at a determined future date. Athene requires that, at all times during the term of the repurchase agreements, it maintains sufficient cash or other liquid assets sufficient to allow it to fund substantially all of the repurchase price. Proceeds received from the sale of securities pursuant to these arrangements are generally invested in short-term investments, with the offsetting obligation to repurchase the security included within payables for collateral on derivatives and securities to repurchase on the condensed consolidated statements of financial condition. As per the terms of the repurchase agreements, Athene monitors the market value of the securities sold and may be required to deliver additional collateral (which may be in the form of cash or additional securities) to the extent that the value of the securities sold decreases prior to the repurchase date.
As of September 30, 2022, the payables for repurchase agreements were $4.5 billion, while the fair value of securities and collateral held by counterparties backing the repurchase agreements was $4.6 billion. As of September 30, 2022, payables for repurchase agreements were comprised of $1.6 billion of short-term and $2.9 billion of long-term repurchase agreements.
Dividends from Insurance Subsidiaries
AHL is a holding company whose primary liquidity needs include the cash-flow requirements relating to its corporate activities, including its day-to-day operations, debt servicing, preferred and common stock dividend payments and strategic transactions, such as acquisitions. The primary source of AHL’s cash flow is dividends from its subsidiaries, which are expected to be adequate to fund cash flow requirements based on current estimates of future obligations.
The ability of AHL’s insurance subsidiaries to pay dividends is limited by applicable laws and regulations of the jurisdictions where the subsidiaries are domiciled, as well as agreements entered into with regulators. These laws and regulations require, among other things, the insurance subsidiaries to maintain minimum solvency requirements and limit the amount of dividends these subsidiaries can pay.
Subject to these limitations and prior notification to the appropriate regulatory agency, Athene’s U.S. insurance subsidiaries are permitted to pay ordinary dividends based on calculations specified under insurance laws of the relevant state of domicile. Any distributions above the amount permitted by statute in any twelve month period are considered to be extraordinary dividends, and require the approval of the appropriate regulator prior to payment. AHL does not currently plan on having the U.S. subsidiaries pay any dividends to their parents.
Dividends from AHL’s subsidiaries are projected to be the primary source of AHL’s liquidity. Under the Bermuda Insurance Act, each of Athene’s Bermuda insurance subsidiaries is prohibited from paying a dividend in an amount exceeding 25% of the prior year’s statutory capital and surplus, unless at least two members of the board of directors of the Bermuda insurance subsidiary and its principal representative in Bermuda sign and submit to the Bermuda Monetary Authority (“BMA”) an affidavit attesting that a dividend in excess of this amount would not cause the Bermuda insurance subsidiary to fail to meet its relevant margins. In certain instances, the Bermuda insurance subsidiary would also be required to provide prior notice to the BMA in advance of the payment of dividends. In the event that such an affidavit is submitted to the BMA in accordance with the Bermuda Insurance Act, and further subject to the Bermuda insurance subsidiary meeting its relevant margins, the Bermuda insurance subsidiary is permitted to distribute up to the sum of 100% of statutory surplus and an amount less than 15% of its total statutory capital. Distributions in excess of this amount require the approval of the BMA.
The maximum distribution permitted by law or contract is not necessarily indicative of the insurance subsidiaries’ actual ability to pay such distributions, which may be further restricted by business and other considerations, such as the impact of such distributions on surplus, which could affect our ratings or competitive position and the amount of premiums that can be written. Specifically, the level of capital needed to maintain desired financial strength ratings from rating agencies, including S&P, A.M. Best, Fitch and Moody’s, is of particular concern when determining the amount of capital available for distributions. AHL believes its insurance subsidiaries have sufficient statutory capital and surplus, combined with additional capital available to be provided by AHL, to meet their financial strength ratings objectives. Finally, state insurance laws and regulations require that the statutory surplus of Athene’s insurance subsidiaries following any dividend or distribution must be reasonable in relation to their outstanding liabilities and adequate for the insurance subsidiaries’ financial needs.
Other Sources of Funding
Athene may seek to secure additional funding at the AHL level by means other than dividends from subsidiaries, such as by drawing on the undrawn $1.25 billion AHL credit facility, drawing on the undrawn $2.5 billion AHL liquidity facility or by pursuing future issuances of debt or preference shares to third-party investors. The AHL credit facility contains various standard covenants with which Athene must comply, including maintaining a Consolidated Debt to Capitalization Ratio (as such term is defined in the AHL credit facility) of not greater than 35% at the end of any quarter, maintaining a minimum Consolidated Net Worth (as such term is defined in the AHL credit facility) of no less than $7.3 billion, and restrictions on the ability to incur debt and liens, in each case with certain exceptions. The AHL liquidity facility also contains various standard covenants with which Athene must comply, including maintaining an ALRe minimum Consolidated Net Worth (as such term is defined in the AHL liquidity facility) of no less than $9.3 billion and restrictions on the ability to incur debt and liens, in each case with certain exceptions.
Future Debt Obligations
Athene had long-term debt of $3.3 billion as of September 30, 2022, which includes notes with maturities in 2028, 2030, 2031, 2051, and 2052. See note 12 to the condensed consolidated financial statements for further information regarding Athene’s debt arrangements.
Capital
Athene believes it has a strong capital position and that it is well positioned to meet policyholder and other obligations. Athene measures capital sufficiency using an internal capital model which reflects management’s view on the various risks inherent to its business, the amount of capital required to support its core operating strategies and the amount of capital necessary to maintain its current ratings in a recessionary environment. The amount of capital required to support Athene’s core operating strategies is determined based upon internal modeling and analysis of economic risk, as well as inputs from rating agency capital models and consideration of NAIC RBC and Bermuda capital requirements. Capital in excess of this required amount is considered excess equity capital, which is available to deploy.
ACRA
ACRA provides Athene with access to on-demand capital to support its growth strategies and capital deployment opportunities. ACRA provides a capital source to fund both Athene’s inorganic and organic channels, including pension group annuity, funding agreement and retail channels. This strategic capital solution allows Athene the flexibility to simultaneously deploy capital across multiple accretive avenues, while maintaining a strong financial position.
Critical Accounting Estimates and Policies
Other than as described in this Item 2, there have been no material changes to the Company’s critical accounting estimates and judgments from those previously disclosed in Apollo and Athene’s 2021 Annual Reports. The following updates and supplements the critical accounting estimates and judgments in Athene’s 2021 Annual Report.
Investments
Valuation of Mortgage Loans
Athene has elected the fair value option on its mortgage loan portfolio. Athene uses independent commercial pricing services to value its mortgage loans portfolio. Discounted cash flow analysis is performed through which the loans’ contractual cash flows are modeled and an appropriate discount rate is determined to discount the cash flows to arrive at a present value. Financial factors, credit factors, collateral characteristics and current market conditions are all taken into consideration when performing the discounted cash flow analysis. Athene performs vendor due diligence exercises annually to review vendor processes, models and assumptions. Additionally, Athene reviews price movements on a quarterly basis to ensure reasonableness.
Future Policy Benefits
The future policy benefit liabilities associated with long duration contracts include term and whole-life products, accident and health, disability, and deferred and immediate annuities with life contingencies. Liabilities for non-participating long duration contracts are established using accepted actuarial valuation methods which require Athene to make certain assumptions regarding expenses, investment yields, mortality, morbidity, and persistency, with a provision for adverse deviation, at the date of issue or acquisition. As of September 30, 2022, the reserve investment yield assumptions for non-participating contracts range from 2.3% to 5.9% and are specific to Athene’s expected earned rate on the asset portfolio supporting the reserves. Athene bases other key assumptions, such as mortality and morbidity, on industry standard data adjusted to align with actual company experience, if necessary. Premium deficiency tests are performed periodically using current assumptions, without provisions for adverse deviation, in order to test the appropriateness of the established reserves. If the reserves using current assumptions are greater than the existing reserves, the excess is recorded and the initial assumptions are revised.
Liabilities for Guaranteed Living Withdrawal Benefits and Guaranteed Minimum Death Benefits
Athene issues and reinsures deferred annuity contracts which contain GLWB and GMDB riders. Athene establishes future policy benefits for GLWB and GMDB by estimating the expected value of withdrawal and death benefits in excess of the projected account balance. Athene recognizes the excess proportionally over the accumulation period based on total actual and expected assessments. The methods used to estimate the liabilities have assumptions about policyholder behavior, which includes lapses, withdrawals and utilization of the benefit riders; mortality; and market conditions affecting the account balance.
Projected policyholder lapse and withdrawal behavior assumptions are set in one of two ways. For certain blocks of business, this behavior is a function of our predictive analytics model which considers various observable inputs. For the remaining blocks of business, these assumptions are set at the product level by grouping individual policies sharing similar features and guarantees and reviewed periodically against experience. Base lapse rates consider the level of surrender charges and are dynamically adjusted based on the level of current interest rates relative to the guaranteed rates and the amount by which any rider guarantees are in a net positive position. Rider utilization assumptions consider the number and timing of policyholders electing the riders. Athene tracks and updates this assumption as experience emerges. Mortality assumptions are set at the product level and generally based on standard industry tables, adjusted for historical experience and a provision for mortality improvement. Projected guaranteed benefit amounts in excess of the underlying account balances are considered over a range of scenarios in order to capture Athene’s exposure to the guaranteed withdrawal and death benefits.
The assessments used to accrue liabilities are based on interest margins, rider charges, surrender charges and realized gains (losses). As such, future reserve changes can be sensitive to changes in investment results and the impacts of shadow adjustments, which represent the impact of assuming unrealized gains (losses) are realized in future periods. As of September 30, 2022, the GLWB and GMDB liability balance, including the impacts of shadow adjustments, totaled $5.1 billion. The relative sensitivity of the GLWB and GMDB liability balance from changes to these assumptions, including the impacts of shadow adjustments from hypothetical changes in projected assessments, changes in the discount rate and annual equity growth, has decreased following the business combination and purchase accounting described in note 3. Using factors consistent with those previously disclosed in Athene’s 2021 Annual Report, changes to the GLWB and GMDB liability balance from these hypothetical changes in assumptions are not significant.
Derivatives
Valuation of Embedded Derivatives on indexed annuities
Athene issues and reinsures products, primarily indexed annuity products, or purchases investments that contain embedded derivatives. If Athene determines the embedded derivative has economic characteristics not clearly and closely related to the economic characteristics of the host contract, and a separate instrument with the same terms would qualify as a derivative instrument, the embedded derivative is bifurcated from the host contract and accounted for separately, unless the fair value option is elected on the host contract.
Indexed annuities and indexed universal life insurance contracts allow the policyholder to elect a fixed interest rate return or an equity market component for which interest credited is based on the performance of certain equity market indices. The equity market option is an embedded derivative, similar to a call option. The benefit reserve is equal to the sum of the fair value of the embedded derivative and the host (or guaranteed) component of the contracts. The fair value of the embedded derivatives represents the present value of cash flows attributable to the indexed strategies. The embedded derivative cash flows are based on assumptions for future policy growth, which include assumptions for expected index credits on the next policy anniversary date, future equity option costs, volatility, interest rates, and policyholder behavior. The embedded derivative cash flows are discounted using a rate that reflects Athene’s credit rating. The host contract is established at contract inception as the initial account value less the initial fair value of the embedded derivative and accreted over the policy’s life. Contracts acquired through a business combination which contain an embedded derivative are re-bifurcated as of the acquisition date.
In general, the change in the fair value of the embedded derivatives will not directly correspond to the change in fair value of the hedging derivative assets. The derivatives are intended to hedge the index credits expected to be granted at the end of the current term. The options valued in the embedded derivatives represent the rights of the policyholder to receive index credits over the period indexed strategies are made available to the policyholder, which is typically longer than the current term of the options. From an economic basis, Athene believes it is suitable to hedge with options that align with index terms of our indexed annuity products because policyholder accounts are credited with index performance at the end of each index term. However, because the value of an embedded derivative in an indexed annuity contract is longer-dated, there is a duration mismatch which may lead to differences in the recognition of income and expense for accounting purposes.
A significant assumption in determining policy liabilities for indexed annuities is the vector of rates used to discount indexed strategy cash flows. The change in risk free rates is expected to drive most of the movement in the discount rates between periods. Changes to credit spreads for a given credit rating as well as any change to Athene’s credit rating requiring a revised level of nonperformance risk would also be factors in the changes to the discount rate. If the discount rates used to discount the indexed strategy cash flows were to fluctuate, there would be a resulting change in reserves for indexed annuities recorded through the condensed consolidated statements of operations.
As of September 30, 2022, Athene had embedded derivative liabilities classified as Level 3 in the fair value hierarchy of $5.0 billion. The increase (decrease) to the embedded derivatives on FIA products from hypothetical changes in discount rates is summarized as follows:
| (In millions) | September 30, 2022 | ||||
| +100 bps discount rate | $ | (248) | |||
| –100 bps discount rate | 274 |
However, these estimated effects do not take into account potential changes in other variables, such as equity price levels and market volatility, which can also contribute significantly to changes in carrying values. Therefore, the quantitative impact presented in the table above does not necessarily correspond to the ultimate impact on the condensed consolidated financial statements. In determining the ranges, Athene has considered current market conditions, as well as the market level of discount rates that can reasonably be anticipated over the near-term. For additional information regarding sensitivities to interest rate risk and public equity risk, see Item 3. Quantitative and Qualitative Disclosures About Market Risk.
Deferred Acquisition Costs, Deferred Sales Inducements, and Value of Business Acquired
Costs related directly to the successful acquisition of new or renewal insurance or investment contracts are deferred to the extent they are recoverable from future premiums or gross profits. These costs consist of commissions and policy issuance costs, as well as sales inducements credited to policyholder account balances. Athene performs periodic tests, including at issuance, to determine if the deferred costs are recoverable. If it is determined that the deferred costs are not recoverable, Athene records a cumulative charge to the current period.
Deferred costs related to universal life-type policies and investment contracts with significant revenue streams from sources other than investment of the policyholder funds are amortized over the lives of the policies, based upon the proportion of the present value of actual and expected deferred costs to the present value of actual and expected gross profits to be earned over the life of the policies. Gross profits include investment spread margins, surrender charge income, policy administration, changes in the GLWB and GMDB reserves, and realized gains (losses) on investments. Current period gross profits for indexed annuities also include the change in fair value of both freestanding and embedded derivatives.
The estimates of expected gross profits and margins are based on assumptions using accepted actuarial methods related to policyholder behavior, including lapses and the utilization of benefit riders, mortality, yields on investments supporting the liabilities, future interest credited amounts (including indexed related credited amounts on fixed indexed annuity products), and other policy changes as applicable, and the level of expenses necessary to maintain the policies over their expected lives. Each reporting period, Athene updates estimated gross profits with actual gross profits as part of the amortization process. Athene also periodically revises the key assumptions used in the amortization calculation which results in revisions to the estimated future gross profits. The effects of changes in assumptions are recorded as unlocking in the period in which the changes are made.
Athene establishes VOBA for blocks of insurance contracts acquired through the acquisition of insurance entities. The fair value of the liabilities purchased is determined using market participant assumptions at the time of acquisition and represents the amount an acquirer would expect to be compensated to assume the contracts. Athene records the fair value of the liabilities assumed in two components: reserves and VOBA. Reserves are established using best estimate assumptions, plus a provision for adverse deviation where applicable, as of the business combination date. VOBA is the difference between the fair value of the liabilities and the reserves. VOBA can be either positive or negative. Any negative VOBA is recorded to the same financial statement line on the condensed consolidated statements of financial condition as the associated reserves. Positive VOBA is recorded in DAC, DSI and VOBA on the condensed consolidated statements of financial condition.
VOBA and negative VOBA are amortized in relation to applicable policyholder liabilities. Significant assumptions which impact VOBA and negative VOBA amortization are consistent with those which impact the measurement of policyholder liabilities.
Estimated future gross profits vary based on a number of factors but are typically most sensitive to changes in investment spread margins, which are the most significant component of gross profits. If estimated gross profits for all future years on business in force were to change, including the impacts of shadow adjustments, there would be a resulting increase or decrease to the balances of DAC and DSI recorded as an increase or decrease to amortization of DAC and DSI on the condensed consolidated statements of operations or AOCI.
Actual gross profits will depend on actual margins, including the changes in the value of embedded derivatives. The most sensitive assumption in determining the value of the embedded derivative is the vector of rates used to discount the embedded derivative cash flows. If the discount rates used to discount the embedded derivative cash flows were to change, there would be a resulting increase or decrease to the balances of DAC and DSI recorded as an increase or decrease in amortization of DAC and DSI on the condensed consolidated statements of operations.
Following the business combination and application of purchase accounting described in note 3, DAC and DSI balances exhibit less sensitivity to hypothetical changes in estimated future gross profits and changes in the embedded derivative discount rate as they are relatively less material following the business combination. VOBA balances no longer amortize based on estimated gross profits, and accordingly, are not sensitive to changes to actual or estimated gross profits.
Recent Accounting Pronouncements
A list of recent accounting pronouncements that are relevant to Apollo and its industry is included in note 2 to our condensed consolidated financial statements.
Contractual Obligations, Commitments and Contingencies
Fixed and determinable payments due in connection with the Company’s material contractual obligations are as follows as of September 30, 2022:
| Remaining 2022 | 2023 - 2024 | 2025 - 2026 | 2027 and Thereafter | Total | |||||||||||||||||||||||||
| (In millions) | |||||||||||||||||||||||||||||
| Asset Management | |||||||||||||||||||||||||||||
| Operating lease obligations1 | $ | 16 | $ | 140 | $ | 135 | $ | 538 | $ | 829 | |||||||||||||||||||
| Other long-term obligations2 | 16 | 17 | — | — | 33 | ||||||||||||||||||||||||
| AMH credit facility3 | — | 1 | 1 | — | 2 | ||||||||||||||||||||||||
| Debt obligations3 | 30 | 741 | 700 | 2,570 | 4,041 | ||||||||||||||||||||||||
| AOG Unit payment 4 | 44 | 350 | — | — | 394 | ||||||||||||||||||||||||
| 106 | 1,249 | 836 | 3,108 | 5,299 | |||||||||||||||||||||||||
| Retirement Services | |||||||||||||||||||||||||||||
| Interest sensitive contract liabilities | 4,131 | 40,546 | 34,262 | 87,955 | 166,894 | ||||||||||||||||||||||||
| Future policy benefits | 446 | 4,135 | 4,057 | 46,071 | 54,709 | ||||||||||||||||||||||||
| Debt3 | 34 | 253 | 253 | 4,172 | 4,712 | ||||||||||||||||||||||||
| Securities to repurchase5 | 1,448 | 422 | 1,269 | 1,807 | 4,946 | ||||||||||||||||||||||||
| 6,059 | 45,356 | 39,841 | 140,005 | 231,261 | |||||||||||||||||||||||||
| Obligations | $ | 6,165 | $ | 46,605 | $ | 40,677 | $ | 143,113 | $ | 236,560 | |||||||||||||||||||
| 1 Operating lease obligations excludes $196 million of other operating expenses associated with operating leases. | |||||||||||||||||||||||||||||
| 2 Includes (i) payments on management service agreements related to certain assets and (ii) payments with respect to certain consulting agreements entered into by the Company. Note that a significant portion of these costs are reimbursable by funds. | |||||||||||||||||||||||||||||
| 3 The obligations for debt payments include contractual maturities of principal and estimated future interest payments based on the terms of the debt agreements. See note 12 of the condensed consolidated financial statements for further discussion of these debt obligations. | |||||||||||||||||||||||||||||
| 4 On December 31, 2021, each holder of AOG Units (other than those held by the Company and Athene) sold a portion of their limited partnership interests to the Company in exchange for the AOG Unit Payment. See note 16 to the condensed consolidated financial statements for more information. | |||||||||||||||||||||||||||||
| 5 The obligations for securities for repurchase payments include contractual maturities of principal and estimated future interest payments based on the terms of the agreements. Future interest payments on floating rate repurchase agreements were calculated using the September 30, 2022 interest rate. |
Note: Due to the fact that the timing of certain amounts to be paid cannot be determined or for other reasons discussed below, the following contractual commitments have not been presented in the table above.
(i)As noted previously, the tax receivable agreement requires us to pay to our Former Managing Partners and Contributing Partners 85% of any tax savings received by AGM and its subsidiaries from our step-up in tax basis. The tax savings achieved may not ensure that we have sufficient cash available to pay this liability and we might be required to incur additional debt to satisfy this liability.
(ii)Debt amounts related to the consolidated VIEs are not presented in the table above as the Company is not a guarantor of these non-recourse liabilities.
(iii)In connection with the Stone Tower acquisition, Apollo agreed to pay the former owners of Stone Tower a specified percentage of any future performance fees earned from certain of the Stone Tower funds, CLOs and strategic investment accounts. In connection with the acquisition of Griffin Capital’s U.S. asset management business on May 3, 2022, Apollo agreed to pay the former owners certain share-based consideration contingent on specified AUM and capital raising thresholds. These contingent consideration liabilities are remeasured to fair value at each reporting period until the obligations are satisfied. See note 17 to the condensed consolidated financial statements for further information regarding the contingent consideration liabilities.
(iv)Commitments from certain of our subsidiaries to contribute to the funds we manage and certain related parties.
Previous: Item 1A. UNAUDITED SUPPLEMENTAL PRESENTATION OF STATEMENTS OF FINANCIAL CONDITION · Next: Item 3. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK