 filings.tools
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
257K characters. Original on sec.gov · Markdown
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
The following discussion should be read in conjunction with our consolidated financial statements and notes thereto under “Item 15. Exhibits and financial statement schedules” in this annual report on Form 10-K. Forward-looking statements involve inherent risks and uncertainties regarding events, conditions, and financial trends that may affect our future plans of operations, business strategy, results of operations, and financial position. A number of important factors could cause actual results to differ materially from those included within or contemplated by such forward-looking statements, including, but not limited to, those described under “Item 7. Management’s discussion and analysis of financial condition and results of operations” in this annual report on Form 10-K. We do not undertake any responsibility to update any of these factors or to announce publicly any revisions to any of the forward-looking statements contained in this or any other document, whether as a result of new information, future events, or otherwise.
As used in this annual report on Form 10-K, references to the “Company,” “Alexandria,” “we,” “us,” and “our” refer to Alexandria Real Estate Equities, Inc. and its consolidated subsidiaries.
The COVID-19 pandemic
In December 2019, a novel coronavirus, which causes respiratory illness and spreads from person to person (COVID-19), was first identified during an investigation into an outbreak in Wuhan, China. The first case of COVID-19 in the U.S. was reported on January 20, 2020. On March 11, 2020, the World Health Organization declared COVID-19 a pandemic, and on March 13, 2020, the U.S. declared a national emergency with respect to COVID-19. As of January 29, 2021, according to the World Health Organization, over 101.0 million novel coronavirus cases have been reported worldwide. The U.S. has reported more than 25.3 million cases of COVID-19 and over 425,670 deaths as of January 29, 2021.
COVID-19 disease, treatment, and measures to combat the pandemic
Most patients with COVID-19 have had mild to severe respiratory illness with symptoms of fever, chills, cough, shortness of breath, fatigue, and loss of taste. Many individuals with COVID-19 are asymptomatic and show limited to no symptoms, highlighting the ongoing challenge of containing the continued spread of COVID-19. Some patients develop pneumonia in both lungs and/or multi-organ failure, which in some cases leads to death. Since scientists shared the virus’s genetic makeup in January 2020, intense research has been underway around the world to develop treatments and vaccines for COVID-19. This has led to the FDA issuing Emergency Use Authorizations (“EUA”s) for therapeutics to treat patients with COVID-19 and, most recently, approving two vaccines for use in the prevention of coronavirus disease caused by COVID-19.
The two approved vaccines were created by Pfizer Inc. (in partnership with BioNTech) and Moderna, Inc. (in partnership with the National Institutes of Health), each a tenant of ours. The U.S. began a large-scale COVID-19 vaccination campaign in December 2020. As of January 29, 2021, according to the U.S. Centers for Disease Control and Prevention, over 4.7 million individuals in the U.S. have been fully vaccinated for COVID-19, and the U.S. will continue to roll out vaccines across the nation, prioritizing frontline and essential workers, the elderly, and individuals considered high risk.
Although the U.S. FDA has approved two vaccines and certain therapies for use as of the date of this report, the initial rollout of vaccine distribution has encountered significant delays, and uncertainties remain as to the amount of vaccine available for distribution, the logistics of implementing a national vaccine program, and the overall efficacy of the vaccines once widely administered, especially as new strains of COVID-19 have been discovered, and the level of resistance these new strains have to the existing vaccines, if any, remains unknown.
In response to the supply and distribution issues surrounding the vaccine, in January 2021, President Biden outlined a plan to create additional vaccination sites, increase the supply and distribution of vaccines, and increase the number of vaccinations administered to Americans. The Biden administration plans to utilize the Defense Production Act to maximize the manufacturing and distribution of vaccines in order to administer 100 million vaccination shots within the first 100 days of holding office.
In addition to the currently approved vaccines, as of January 29, 2021, there are over 60 other potential vaccines in clinical development that may contribute to increasing the supply of vaccines in 2021. The current vaccines in development use a myriad of different scientific approaches to attempt to provoke an immune response, including:
-
Genetic vaccines that use part of the coronavirus’s genetic code;
-
Viral vector vaccines that use a virus to deliver coronavirus genes into cells;
-
Protein-based vaccines that use a coronavirus protein or protein fragment to stimulate the immune system; and
-
Whole-virus vaccines that use a weakened or inactivated version of the coronavirus.
Over 60 potential vaccines are currently in human clinical trials, with nearly a third of these in later stages of clinical development. Phase I trials typically include a small number of participants to test safety and dosage as well as to confirm that the vaccine stimulates the immune system. Phase II trials involve hundreds of participants split into groups, such as children and the elderly, to determine whether the vaccine acts differently in each subpopulation. Phase III trials involve delivering the vaccine to tens of thousands of people, observing how many subsequently become infected, and determining the severity of symptoms when compared with volunteer subjects who received a placebo. Regulators in each country will review the trial results to make a determination as to
whether the drug or vaccine should be approved. As of January 29, 2021, there were 20 potential vaccines in Phase III trials, including a number that require only a single dose, rather than two doses for the currently approved vaccines and that are potentially easier to distribute.
Shelter-in-place and stay-at-home orders
On March 19, 2020, California became the first state to set mandatory stay-at-home restrictions to help combat the spread of the coronavirus. The order included the shutdown of all nonessential services, such as dine-in restaurants, bars, gyms, conference or convention centers, and other businesses not deemed to support critical infrastructure. Exceptions for essential services, such as grocery stores, pharmacies, gas stations, food banks, convenience stores, and delivery restaurants, have allowed these services to remain open. Subsequently, almost all states issued similar orders, including New York, Massachusetts, Washington, Maryland, and North Carolina, where our remaining properties outside California are located. Countries around the world also implemented measures to slow the spread of the coronavirus, from national quarantines to school closures or similar types of stay-at-home orders or movement limitations.
Most state orders expired or were rescinded between May and early June 2020, and authorities began reopening businesses, including retail stores, restaurants, bars, salons, houses of worship, entertainment venues such as movie theaters and museums, and manufacturing facilities and offices. Daily new COVID-19 cases in the U.S., which had declined to approximately 18,000 new daily cases by June 9, 2020, from the low- to mid-30,000 daily range in April 2020, began to surge, leading to additional restrictions in many parts of the country. Additionally, in recent months, new COVID-19 variants were discovered in the U.K, among other countries, which have spread globally, including the U.S. While these strains do not appear to cause more severe symptoms in individuals, they have shown to be more infectious than the original strain discovered in China. As a result, more stringent lockdown restrictions have been implemented globally and within the U.S. On January 29, 2021, according to the World Health Organization, 155,203 new cases and 4,100 deaths were reported in the U.S.
Impact to the global and U.S. economy
As a result of the unprecedented measures taken in the U.S. and around the world, the disruption and impact to the U.S. and global economies and financial markets by the COVID-19 pandemic have been significant. In January 2021, the IMF estimated that the global and U.S. economies contracted by 3.5% and 3.4%, respectively, during 2020, in contrast to the expansion of 3.3% and 2.0%, respectively, that IMF projected for the year 2020 in January 2020. However, multiple vaccine approvals have raised hopes for an eventual end to the pandemic, and the rollout of vaccines has contributed to the positive global and U.S. growth projections for 2021, as estimated by IMF in January 2021, of 5.5% and 5.1%, respectively. These projections may be negatively impacted by potential new strains of the virus, renewed lockdowns, or logistical problems with vaccine distribution.
Based on the data provided by the U.S. Bureau of Labor Statistics on January 8, 2021, the unemployment rate in the U.S. is up by 3.2% since February 2020 to 6.7%. The December 2020 data reported 140 thousand jobs lost in December 2020. Stock markets around the globe have rebounded substantially since March 2020; however, since the pandemic was declared, access to capital has become much more challenging for most companies or non-existent for some.
The unprecedented disruption and impact to the U.S. and global economies and financial markets from the COVID-19 pandemic resulted in the U.S. President Trump’s signing into law on March 27, 2020, the Coronavirus Aid, Relief, and Economic Security Act (“CARES Act”), a $2 trillion economic stimulus package. The CARES Act allocated over $140 billion to the U.S. health system to support COVID-19-related manufacturing, production, diagnostics, and treatments, and to accelerate the market entrance of necessary vaccines and cures. The CARES Act also designated $945.4 million specifically to the NIH, a tenant of ours in our Maryland market, to combat COVID-19, which includes, but is not limited to, providing support for research, construction, and acquisition of equipment for vaccine and infectious disease research facilities, including the acquisition of real property.
In addition, on April 24, 2020, the President Trump signed the Paycheck Protection Program and Health Care Enhancement Act into law, which provided an additional $484 billion of relief primarily to assist distressed small businesses and prevent them from shutting their operations and laying off employees. This package designated $75 billion to hospitals and $25 billion for a new COVID-19 testing program. It is too early to determine if the CARES Act and the $484 billion relief package were effective or sufficient to offset some of the most severe economic effects of the pandemic.
On August 8, 2020, President Trump signed four executive actions to provide additional COVID-19 relief along with unemployment benefits of $400 weekly payment to those receiving more than $100 a week in state-funded unemployment benefits through December 6, 2020. On December 27, 2020, a second stimulus package was passed to provide relief aid to Americans during financial hardship, aggregating $900 billion in provisions, which included an additional $600 payment to eligible American adults and $600 for qualifying child dependents, a reinstatement of unemployment benefits of $300 per week through March 14, 2021, an additional $285 billion towards loan programs for small businesses, $82 billion towards education, and additional aid for hard-hit industries, including the airline industry.
On January 14, 2020, then President-elect Biden unveiled a $1.9 trillion “American Rescue Plan” proposal to combat the pandemic and stimulate the economy. The proposal provides additional provisions for increased unemployment benefits, rental assistance, small businesses, state and local governments, educational institutions, and substantial funding towards accelerated distribution of vaccinations and for COVID-19 testing, as well as direct payments of $1,400 to all eligible Americans. The American Rescue Plan is the first of two major spending initiatives expected to be proposed by President Biden in the coming weeks.
Potential ineffectiveness or delay of such relief measures could lead to further deterioration of economic conditions, higher unemployment rates, and prolonged recession, which in turn could materially affect our (or our tenants’ or venture investment portfolio companies’) performance, financial condition, results of operations, and cash flows. See “Item 1A. Risk factors” within “Part I” in this annual report on Form 10-K for additional discussion of the risks posed by the COVID-19 pandemic, and uncertainties we, our tenants, and the national and global economies face as a result.
Executive summary
Operating results
| Year Ended December 31, | ||||||||||||||||||||||||||
| 2020 | 2019 | |||||||||||||||||||||||||
| Net income attributable to Alexandria’s common stockholders – diluted: | ||||||||||||||||||||||||||
| In millions | $ | 760.8 | $ | 351.0 | ||||||||||||||||||||||
| Per share | $ | 6.01 | $ | 3.12 | ||||||||||||||||||||||
| Funds from operations attributable to Alexandria’s common stockholders – diluted, as adjusted: | ||||||||||||||||||||||||||
| In millions | $ | 923.8 | $ | 783.0 | ||||||||||||||||||||||
| Per share | $ | 7.30 | $ | 6.96 |
The operating results shown above include certain items related to corporate-level investing and financing decisions. For additional information, refer to “Funds from operations and funds from operations, as adjusted, attributable to Alexandria Real Estate Equities, Inc.’s common stockholders” in the “Non-GAAP measures and definitions” section and to the tabular presentation of these items in the “Results of operations” section within this Item 7 in this annual report on Form 10-K.
Alexandria and our tenants at the vanguard and heart of the life science ecosystem
Bringing together our unique and pioneering strategic vertical platforms of essential Labspace® real estate, strategic venture investments, impactful thought leadership, and purposeful corporate responsibility, Alexandria is at the vanguard and heart of the vital life science ecosystem that is advancing solutions for COVID-19 and other key challenges to human health. Owing to the efforts of numerous Alexandria tenants, including Pfizer and Moderna, in developing and delivering safe and effective vaccines and therapies to people around the world, the inherent value and critical need for the life science industry has been globally recognized. The essential R&D engine of the biopharma industry continued with productivity and resilience throughout this past year. By maintaining continuous operations across our campuses and facilities, Alexandria has enabled our tenants to continue to pursue their essential, mission-critical research, development, manufacturing, and commercialization efforts to solve the most pressing current and future healthcare challenges.
Strong and flexible balance sheet with significant liquidity
-
Investment-grade credit ratings ranked in the top 10% among all publicly traded REITs as of December 31, 2020.
-
Net debt and preferred stock to Adjusted EBITDA of 5.3x and fixed-charge coverage ratio of 4.6x represent the lowest and highest, respectively, in the past 10 years.
-
$4.1 billion of liquidity as of December 31, 2020.
-
No debt maturing prior to 2024.
-
10.6 years weighted-average remaining term of debt as of December 31, 2020.
Continued dividend strategy to share growth in cash flows with stockholders
Common stock dividend declared for the three months ended December 31, 2020 of $1.09 per common share, aggregating $4.24 per common share for the year ended December 31, 2020, up 24 cents, or 6%, over the year ended December 31, 2019. Our FFO payout ratio of 60% for the three months ended December 31, 2020, allows us to share growth in cash flows from operating activities with our stockholders while also retaining a significant portion for reinvestment.
A REIT industry-leading, high-quality tenant roster
-
55% of annual rental revenue from investment-grade or publicly traded large cap tenants.
-
Weighted-average remaining lease term of 7.6 years.
Key strategic transactions that generated capital for investment into our highly leased value-creation pipeline and strategic acquisitions
-
During the three months ended December 31, 2020, we completed two strategic transactions that generated capital aggregating $874.6 million for investment into our highly leased development and redevelopment projects and strategic acquisitions:
-
Sale of 70% ownership interest in our properties at 1201 and 1208 Eastlake Avenue East and 199 East Blaine Street in our Lake Union submarket for an aggregate sales price of $314.5 million, representing a capitalization rate of 4.2% (cash basis), and setting a new record in Seattle of $1,399 per RSF; and
-
Disposition of two tech office buildings at 510 Townsend Street and 505 Brannan Street in our SoMa submarket for an aggregate sales price of $560.2 million, or $1,263 per RSF, representing capitalization rates of 5.3% and 5.0% (cash basis), and a gain on sale of $151.9 million.
Continued solid net operating income and internal growth
-
Total revenues of $1.9 billion, up 23.1%, for the year ended December 31, 2020, compared to $1.5 billion for the year ended December 31, 2019.
-
Net operating income (cash basis) of $1.2 billion for the year ended December 31, 2020, increased by $249.7 million, or 26.2%, compared to the year ended December 31, 2019.
-
94% of our leases contain contractual annual rent escalations approximating 3%.
-
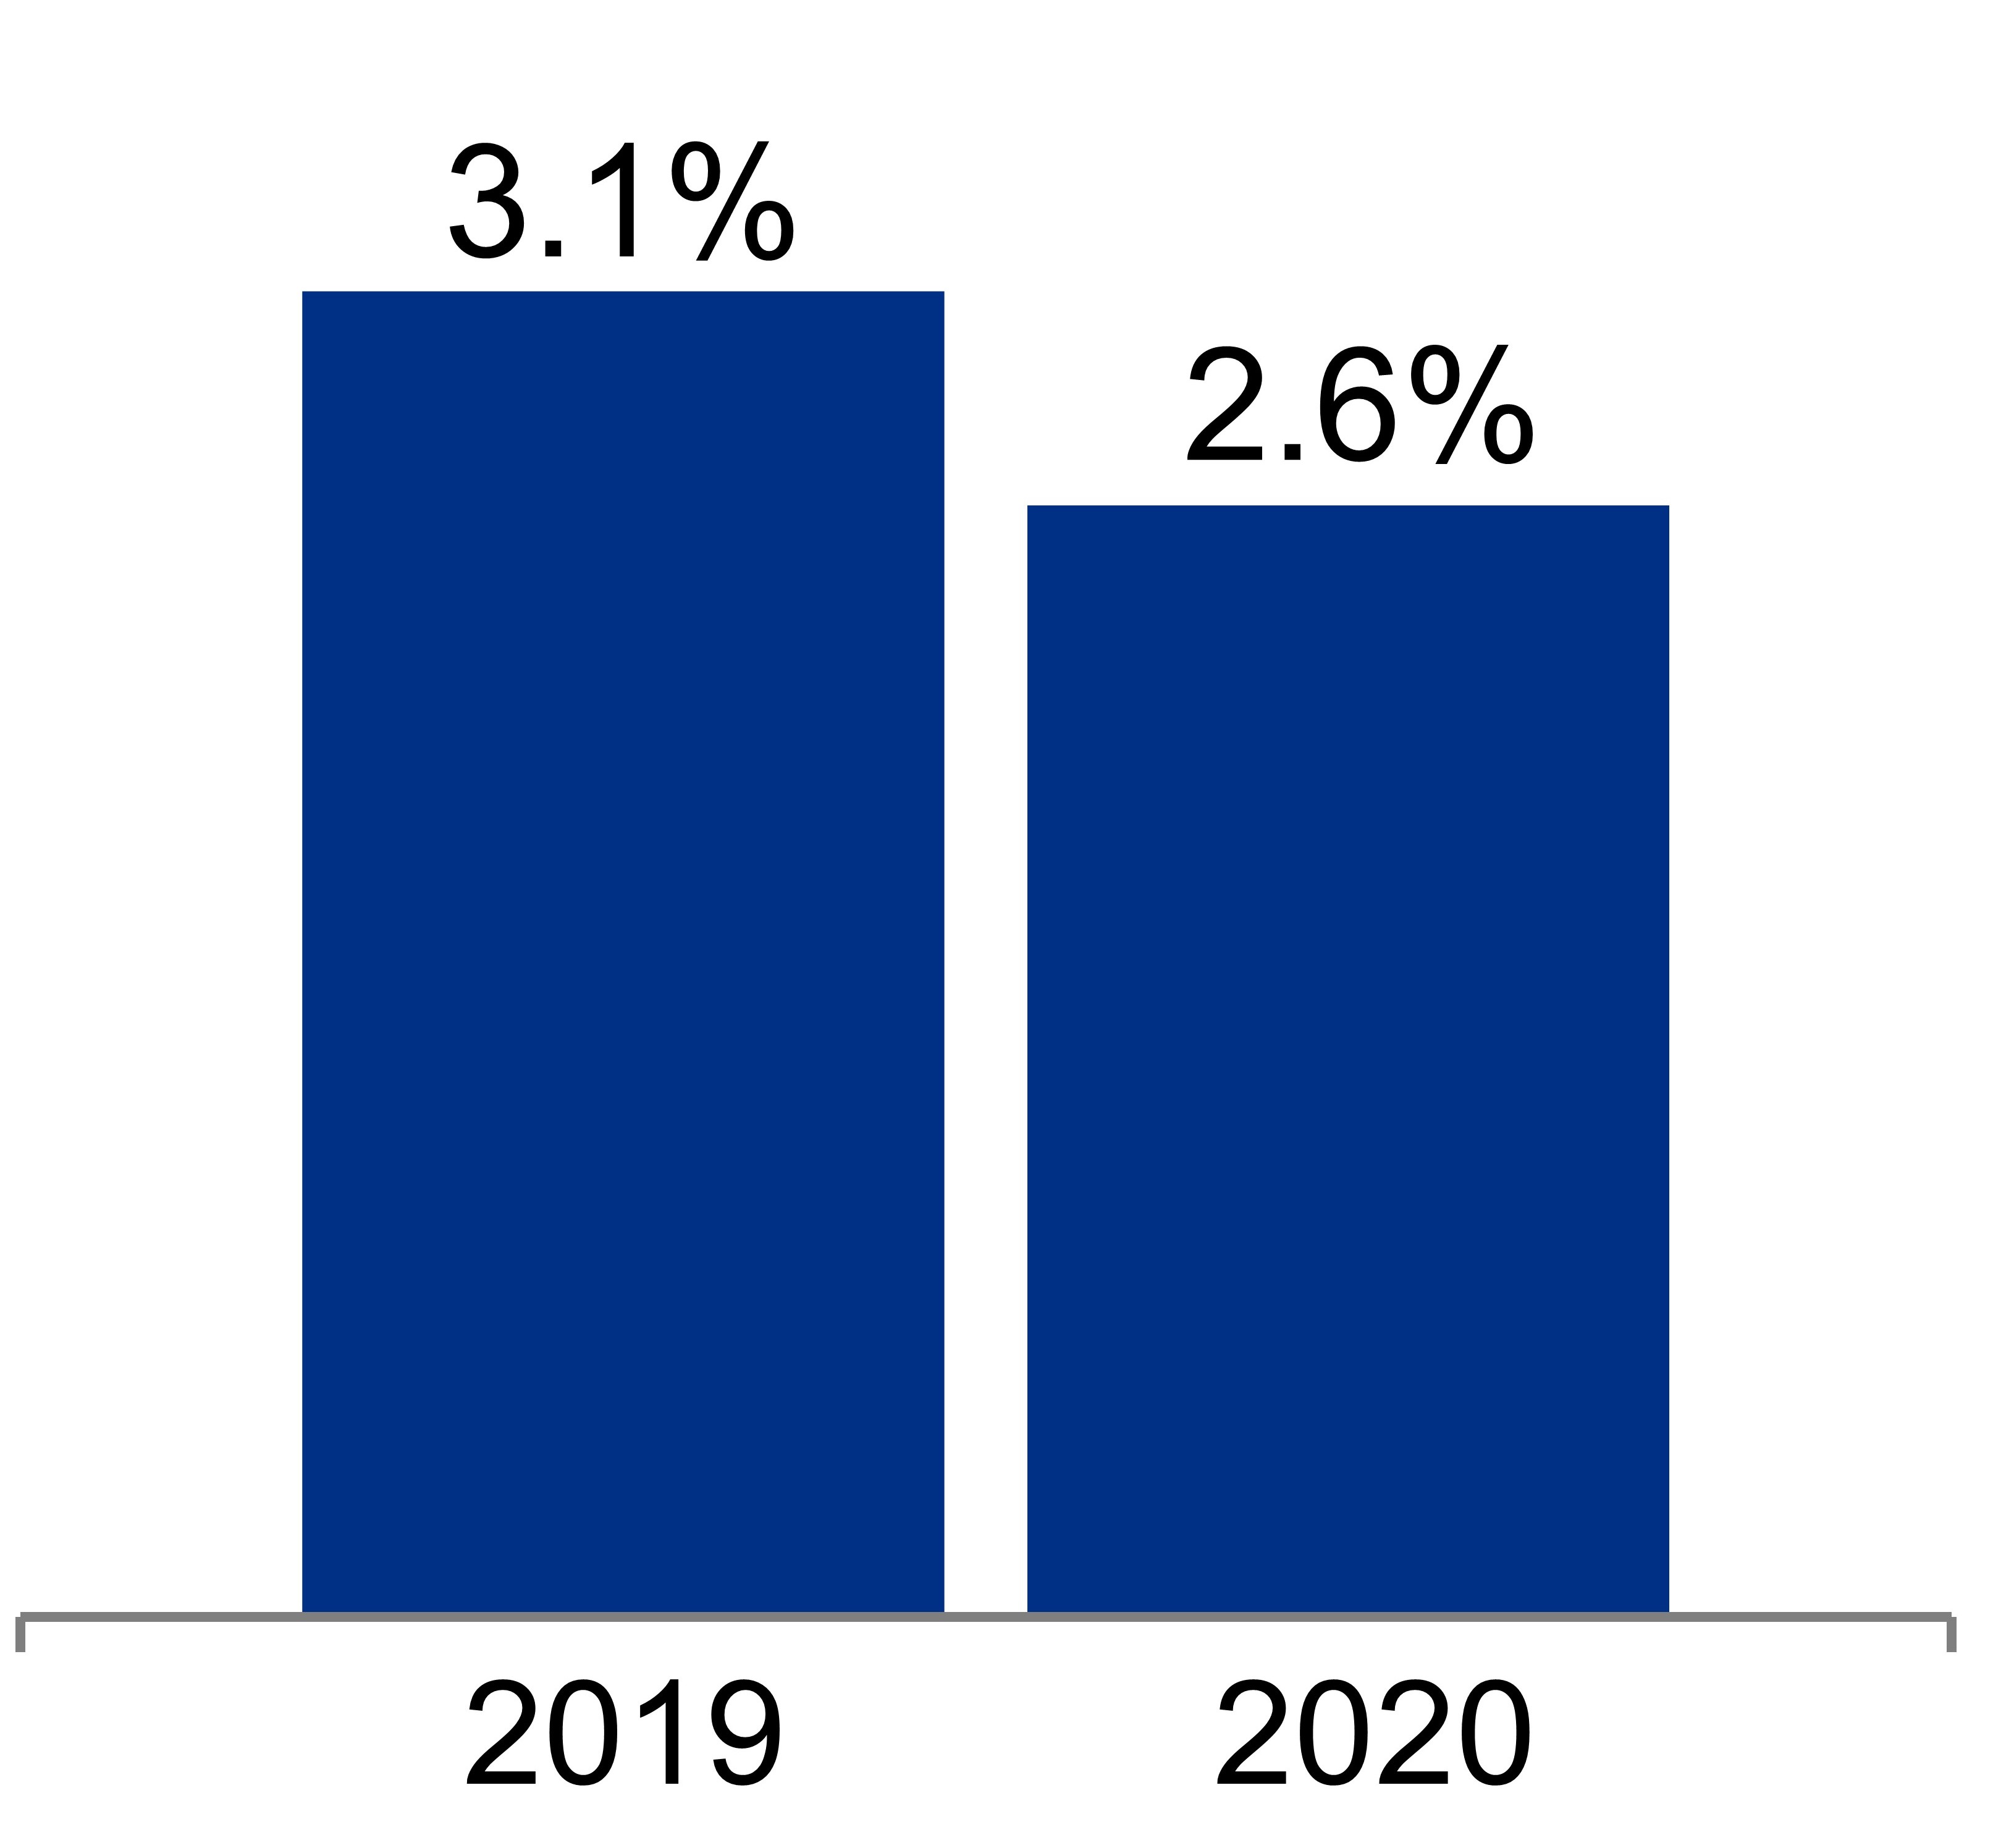
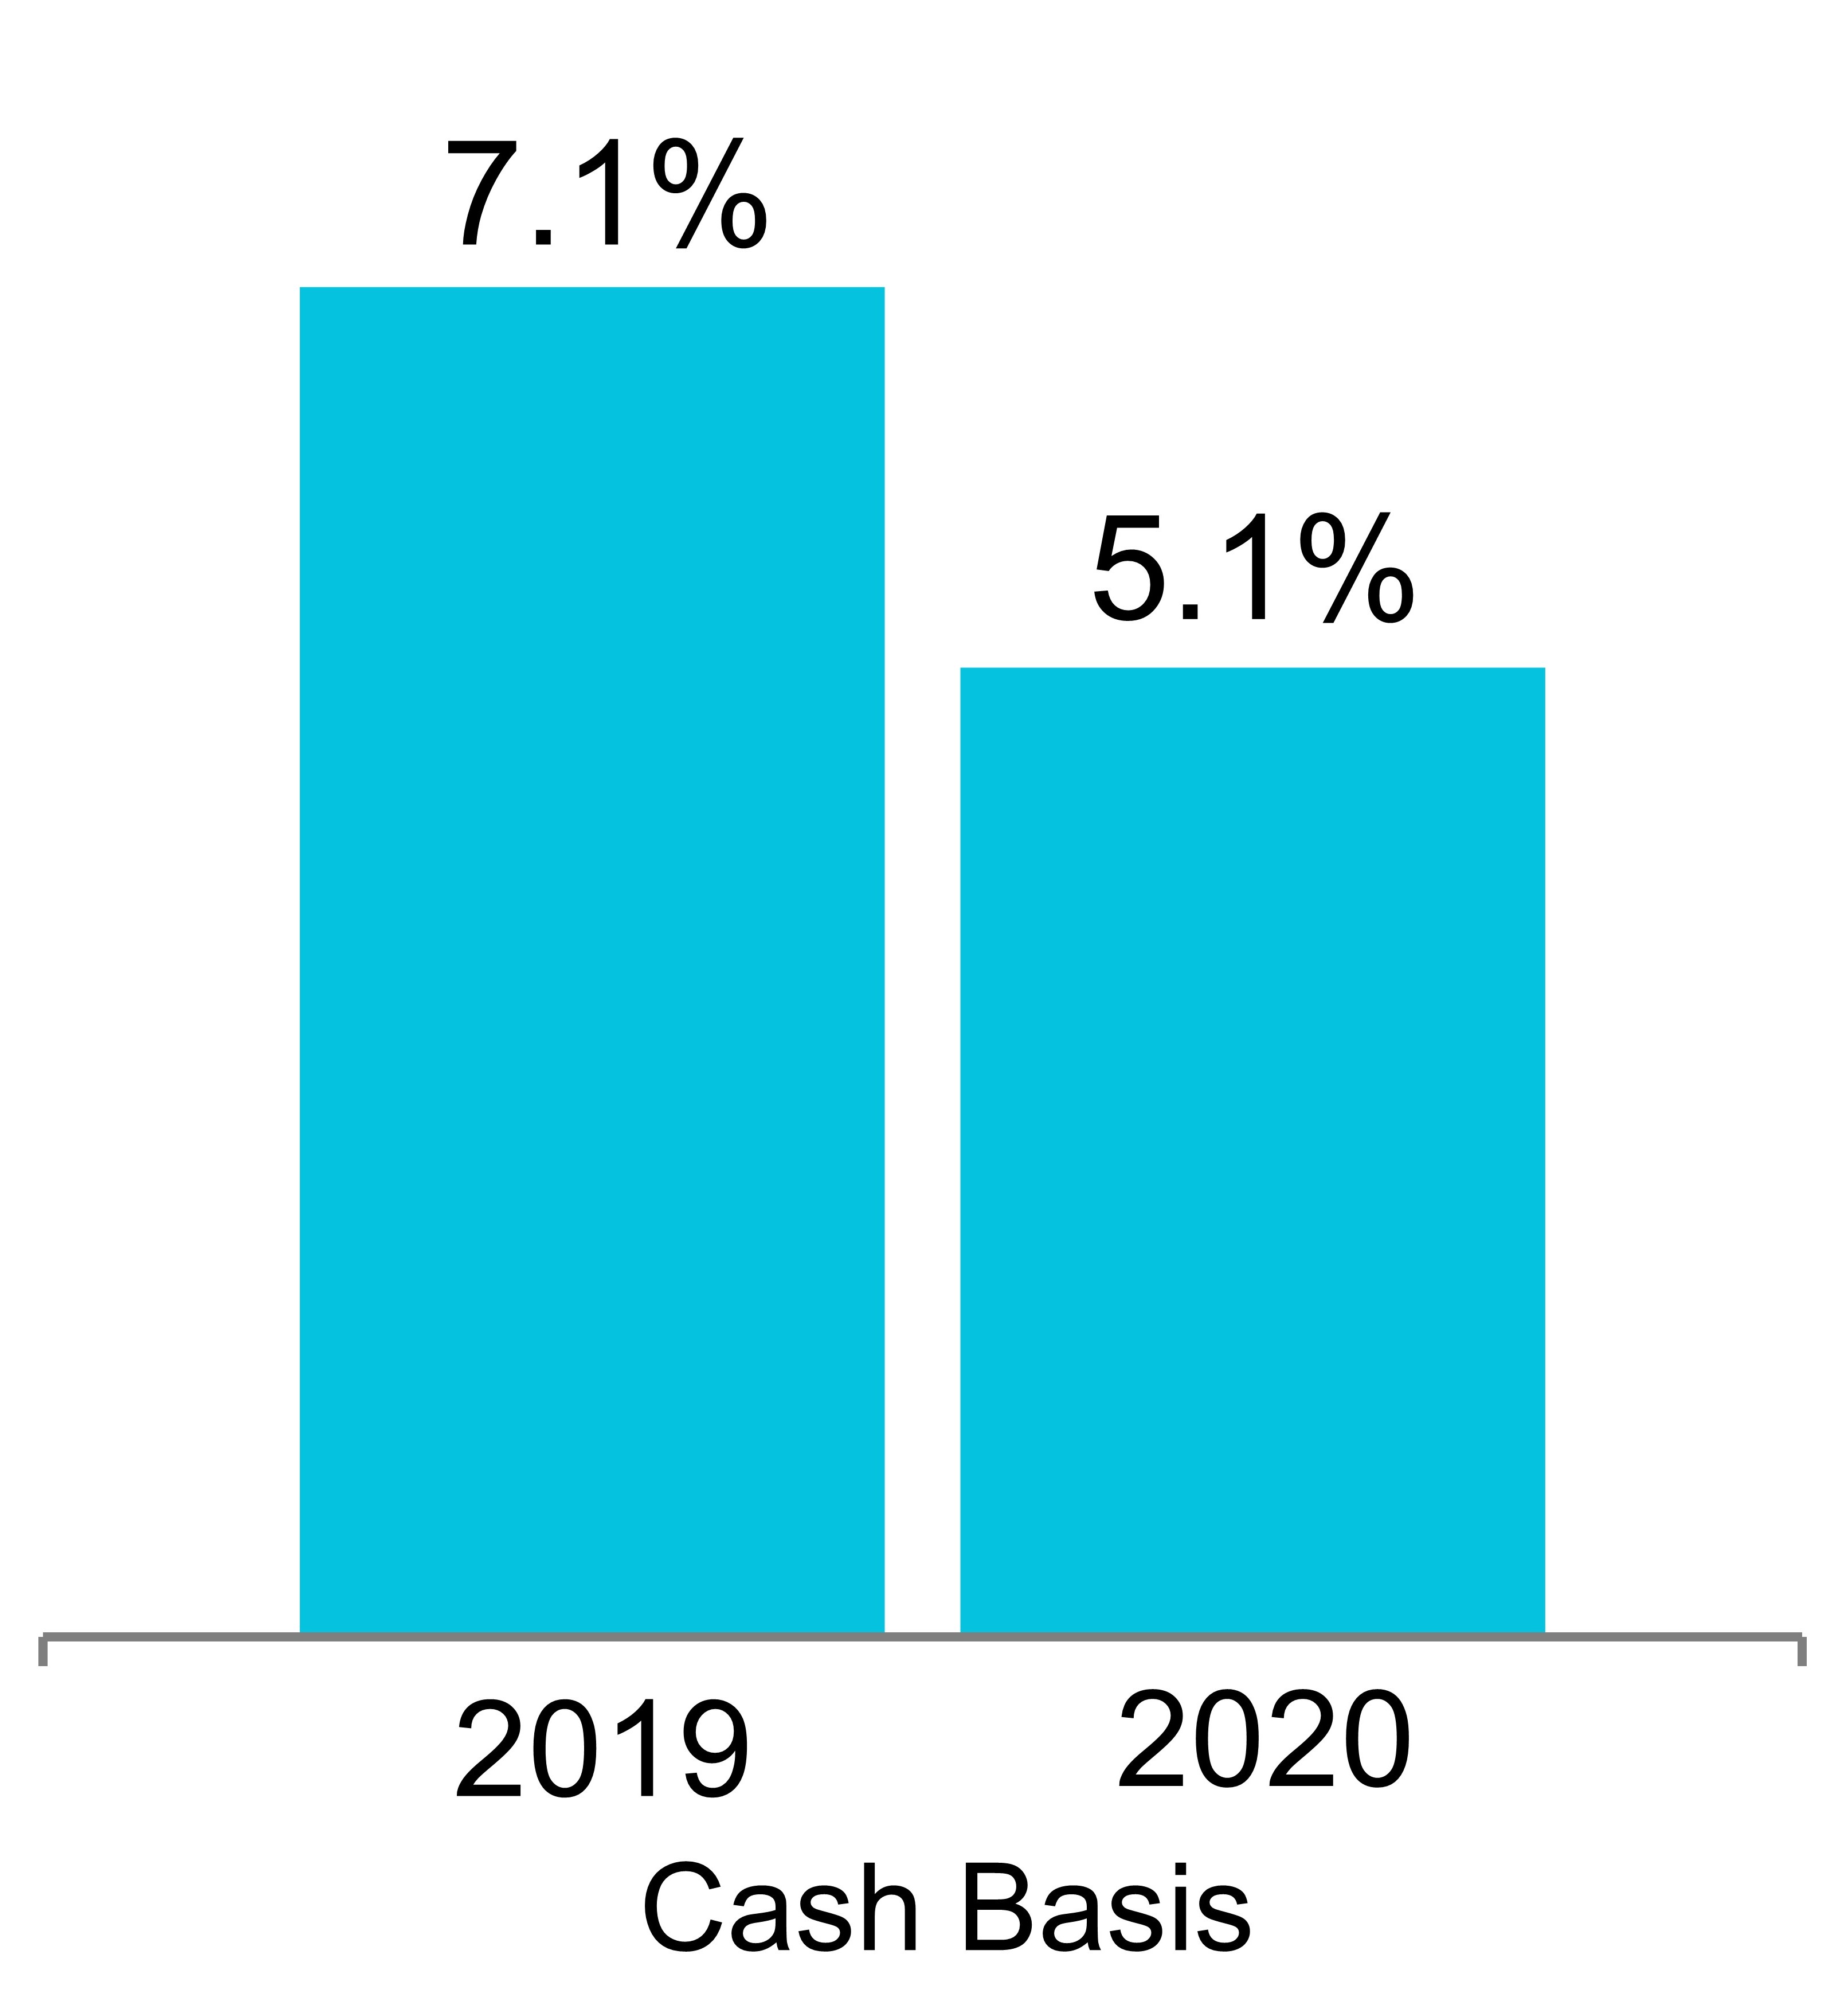
Same property net operating income growth of 2.6% and 5.1% (cash basis) for the year ended December 31, 2020, compared to the year ended December 31, 2019.
-
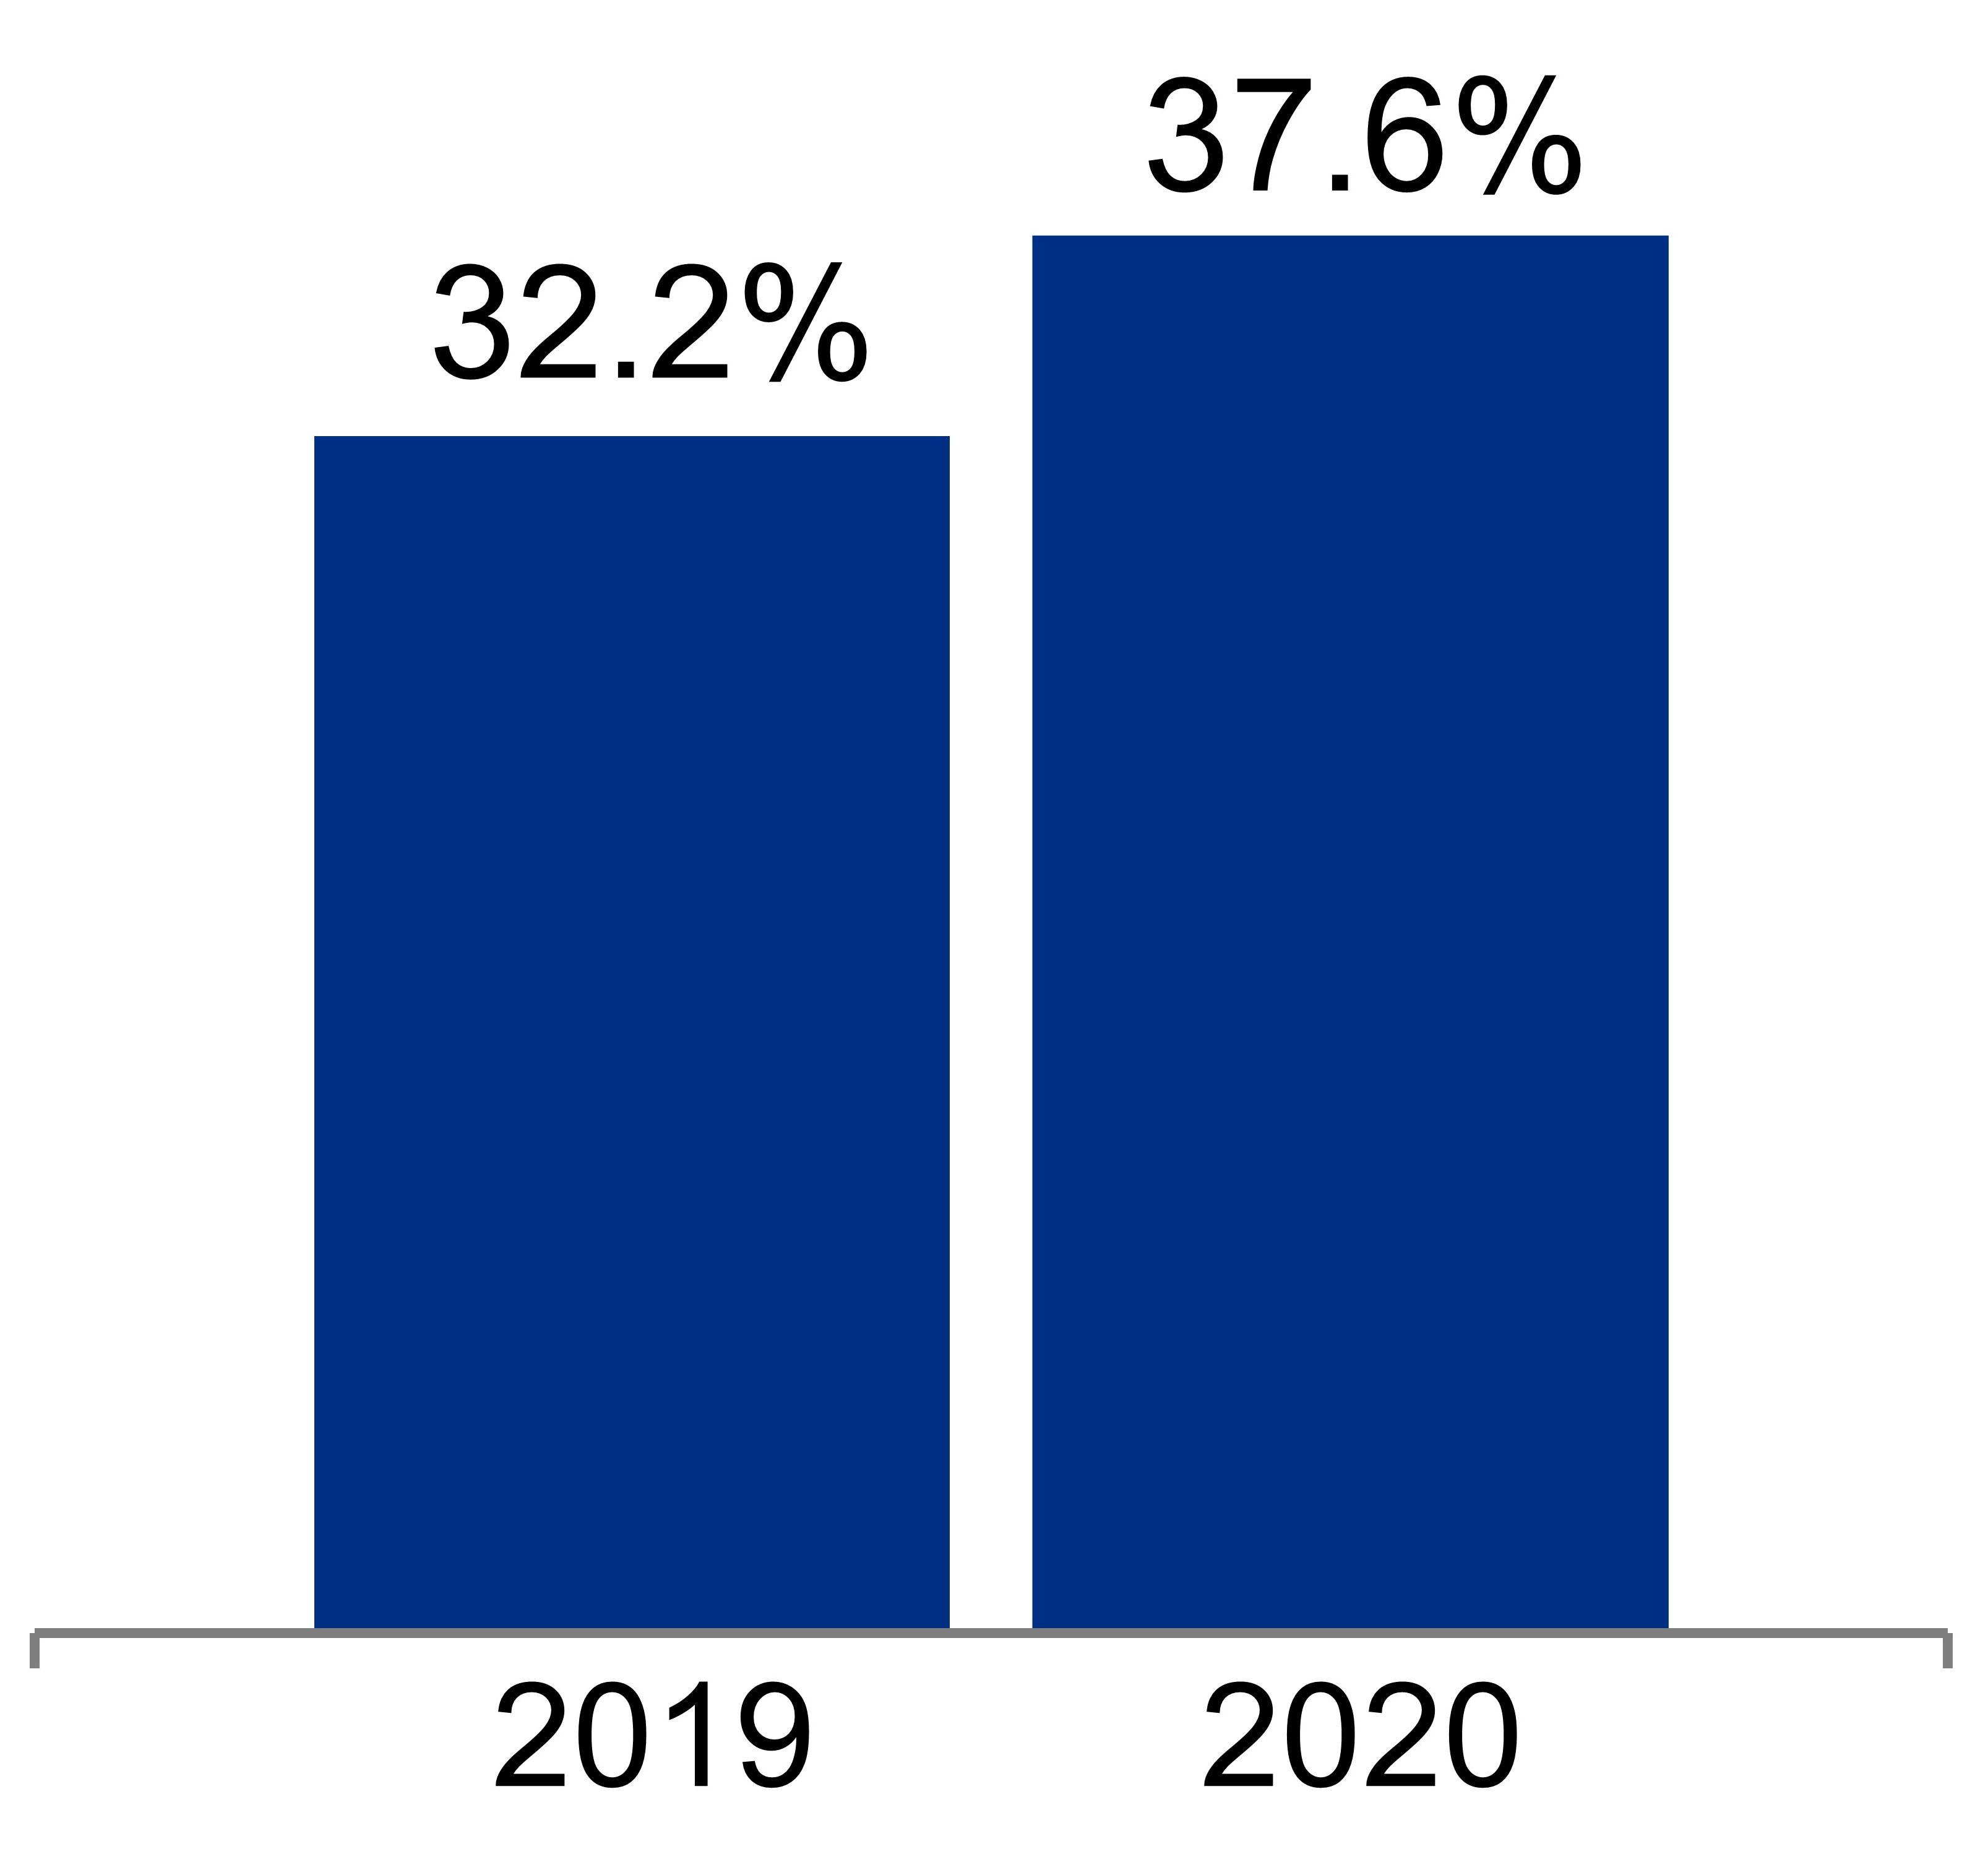
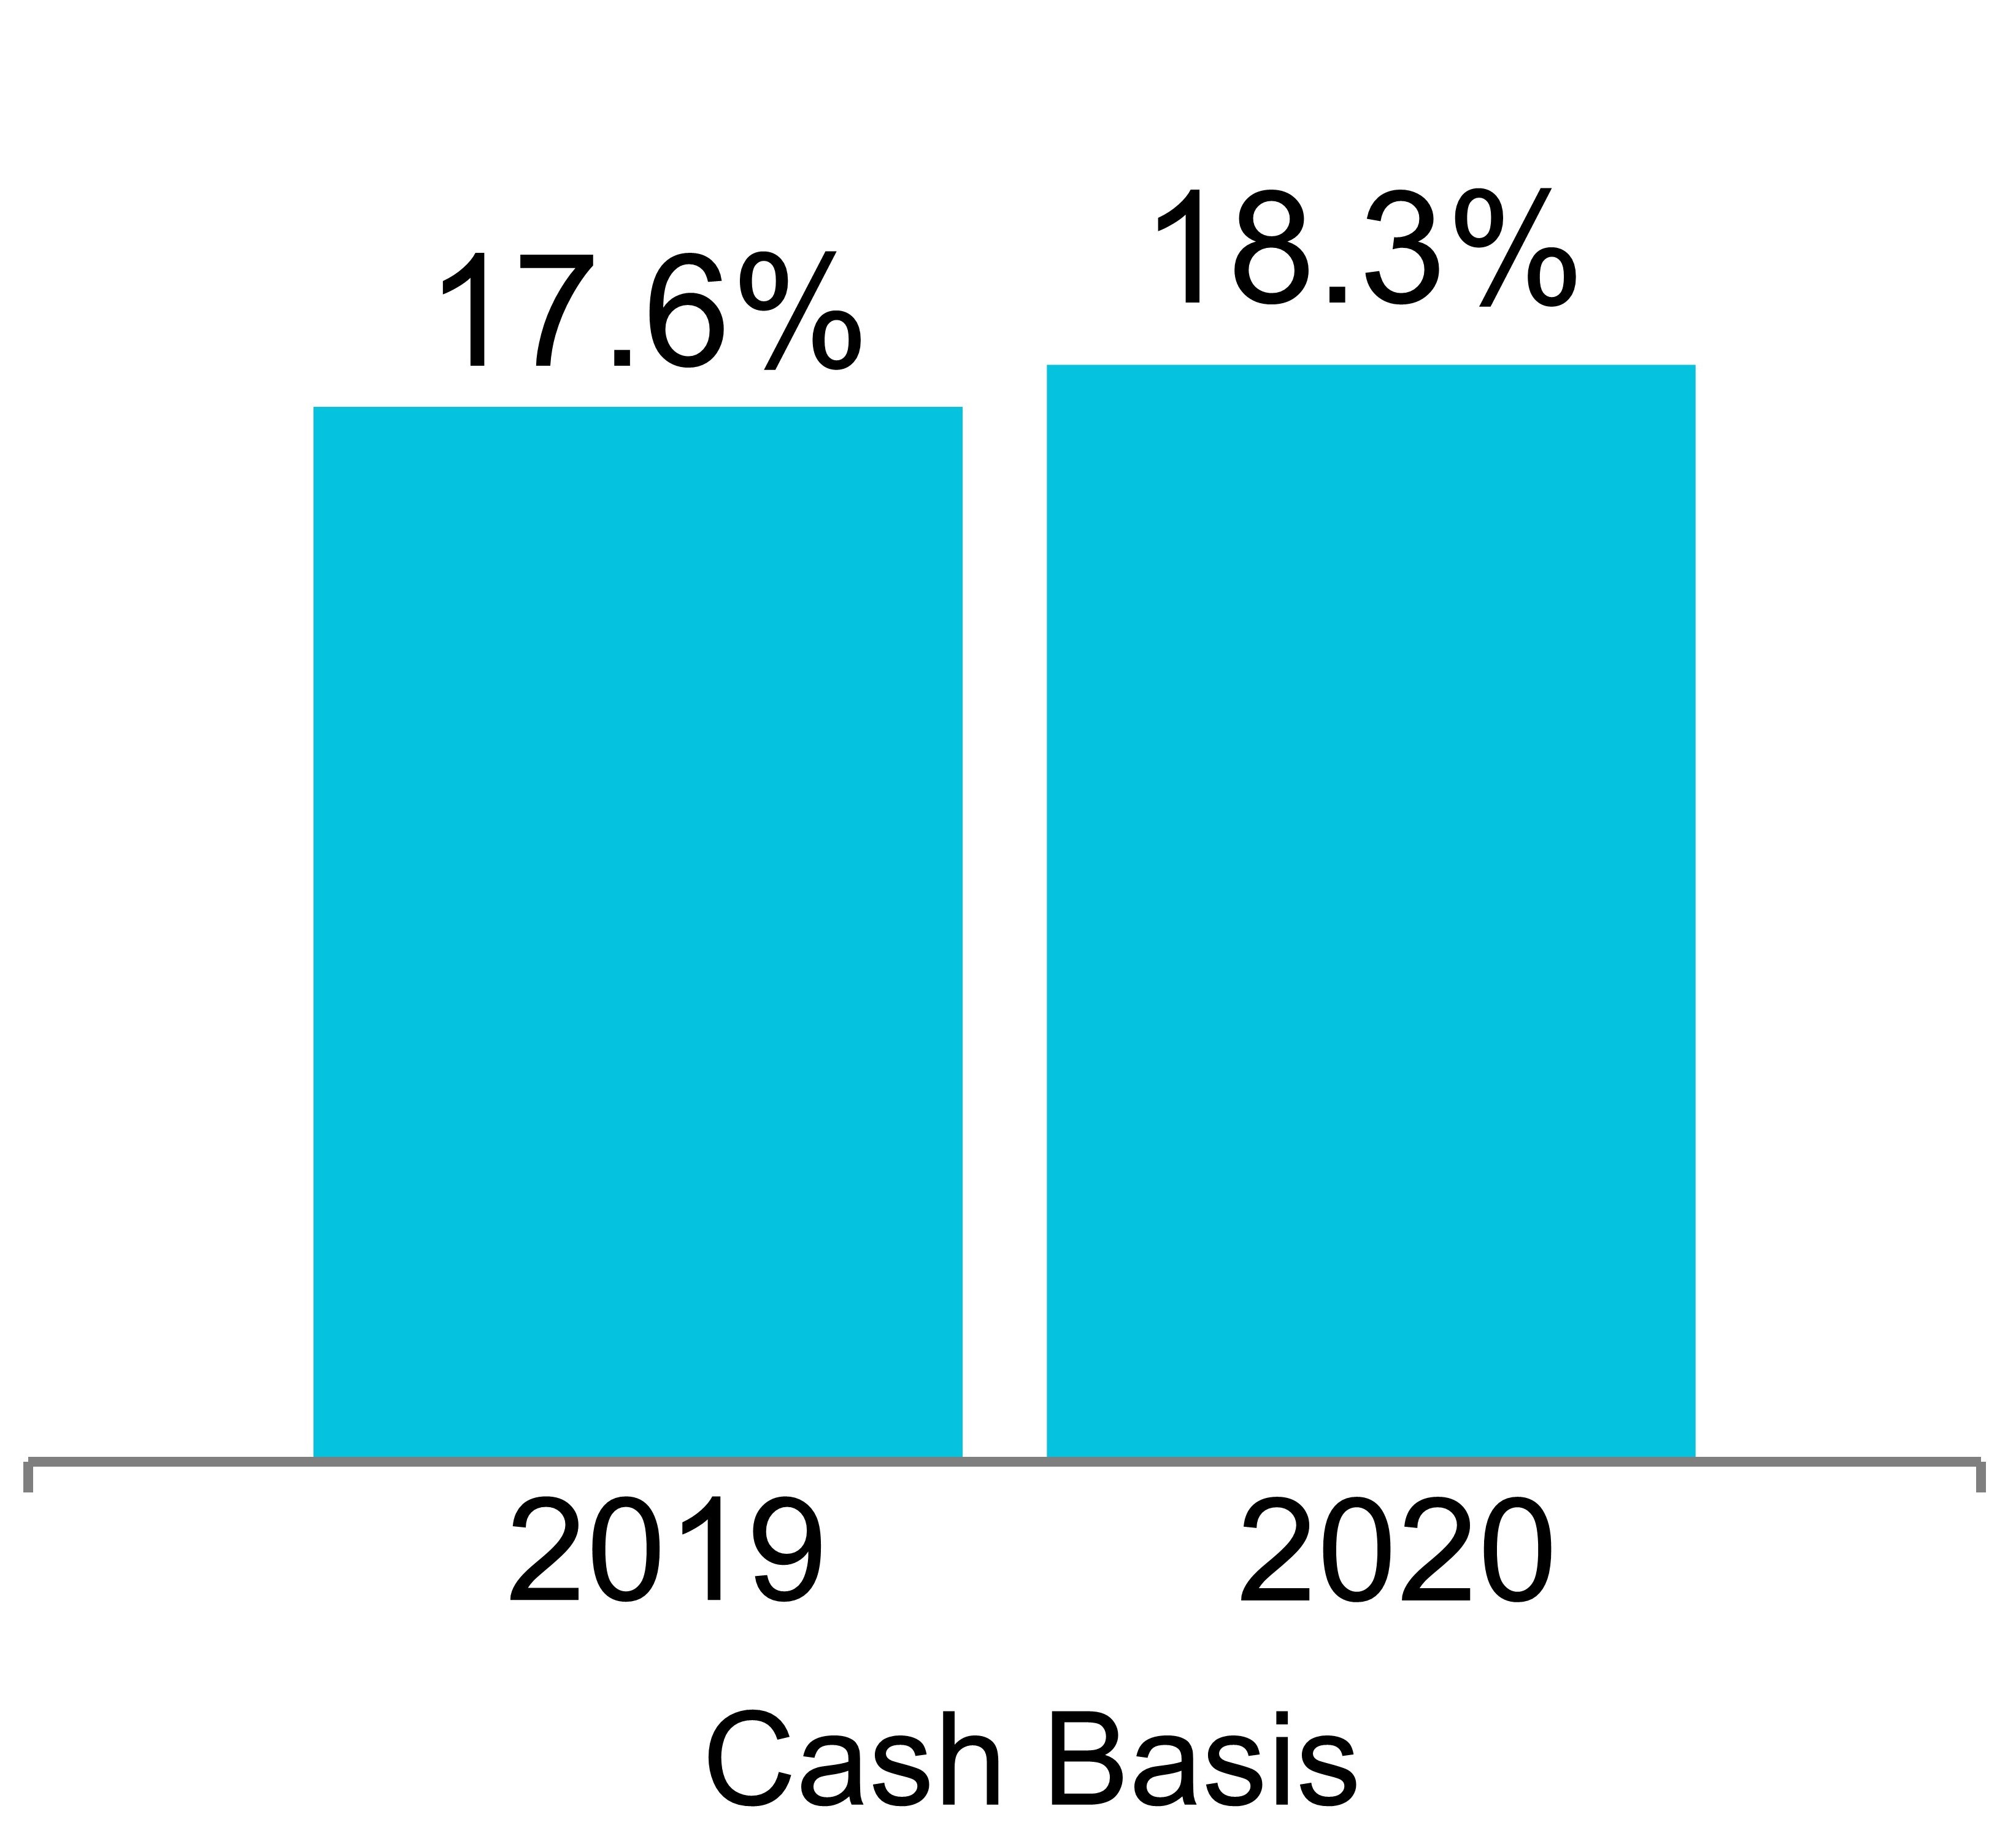
Continued solid leasing activity and rental rate growth during 2020 over expiring rates on renewed and re-leased space, representing our highest annual rental rate increases during the past 10 years:
| 2020 | ||||||||||||||
| Total leasing activity – RSF | 4,358,846 | |||||||||||||
| Leasing of development and redevelopment space – RSF | 1,012,364 | |||||||||||||
| Lease renewals and re-leasing of space: | ||||||||||||||
| RSF (included in total leasing activity above) | 2,556,833 | |||||||||||||
| Rental rate increases | 37.6% | |||||||||||||
| Rental rate increases (cash basis) | 18.3% | |||||||||||||
- Guidance ranges for expected 2021 rental rate increases on lease renewals and re-leasing of space are 29.0% to 32.0%, and 16.0% to 19.0% (cash basis).
High-quality revenues and cash flows, strong margins, and operational excellence
| As of December 31, 2020 | ||||||||||||||
| Percentage of annual rental revenue in effect from investment-grade or publicly traded large cap tenants | 55 | % | ||||||||||||
| Occupancy of operating properties in North America | 94.6 | % | (1) | |||||||||||
| Operating margin | 71 | % | (2) | |||||||||||
| Adjusted EBITDA margin | 69 | % | (2) | |||||||||||
| Weighted-average remaining lease term: | ||||||||||||||
| All tenants | 7.6 | years | ||||||||||||
| Top 20 tenants | 11.0 | years | ||||||||||||
(1)Includes 970,199 RSF, or 3.1%, of vacancy in our North America markets, representing lease-up opportunities that will contribute to growth in cash flows at recently acquired properties. Excluding these acquired vacancies, occupancy of operating properties in North America was 97.7% as of December 31, 2020. Refer to the “Summary of occupancy percentages in North America” section under Item 2 in this annual report on Form 10-K for additional information regarding vacancy from recently acquired properties.
(2)For the three months ended December 31, 2020.
Sustained strength in tenant collections during the ongoing COVID-19 pandemic
-
We have collected rents and tenant recoveries as follows:
-
99.8% for April 1, 2020 through December 31, 2020; and
-
99.2% for January 2021 as of January 29, 2021.
-
As of December 31, 2020, our tenant receivables balance was $7.3 million.
Strategic acquisitions with significant value-creation opportunities in key submarkets
*•*During the three months ended December 31, 2020, we completed acquisitions of 16 properties in key submarkets aggregating 3.3 million SF, with significant value-creation opportunities including, 1.9 million RSF of future developments, 383,396 RSF of active redevelopments, and 1.0 million of operating RSF, currently 80% occupied, for an aggregate purchase price of $580.7 million.
- In January 2021, we completed the acquisition of 401 Park Drive, 201 Brookline Avenue, and one future development opportunity, as described in further detail below.
Acquisition of 401 Park Drive and 201 Brookline Avenue
-
In January 2021, we acquired 401 Park Drive, 201 Brookline Avenue, and one future development opportunity, located in the heart of our Greater Boston life science cluster market, for a purchase price of $1.48 billion. The future collaborative life science campus, aggregating 1.8 million SF, consists of the following:
-
401 Park Drive (operating property with future redevelopment opportunity):
-
Highly amenitized Class A office/R&D building aggregating 973,145 RSF, currently 93% occupied with a weighted-average remaining lease term of 8.8 years;
-
50% of annual rental revenue generated from investment-grade tenants;
-
In-place rents are 38% below market; 30% of the RSF has a weighted-average remaining lease term of 3.3 years with in-place rents approximately 41% below market;
-
Initial stabilized yields of 5.7% and 4.5% (cash basis); and
-
Future opportunity to redevelop up to 221,000 RSF, or 23% of the building, to office/laboratory space.
-
201 Brookline Avenue (active development):
-
Office/laboratory building undergoing ground-up development, aggregating 510,116 RSF, targeting initial occupancy in 2022; and
-
17% pre-leased to high-quality tenants.
-
Future development opportunity for one office/laboratory building for which we are pursuing net new entitlement rights totaling approximately 400,000 SF of office/laboratory along with retail and common spaces.
Highly leased value-creation pipeline, including COVID-19-focused R&D spaces
-
Current and pre-leased near-term projects aggregating 4.8 million RSF, including COVID-19-focused R&D spaces, are highly leased/negotiating at 78% and will generate significant revenues and cash flows.
-
We commenced development and redevelopment of four projects aggregating 609,797 RSF during the three months ended December 31, 2020, and two projects aggregating 640,116 RSF during January 2021.
-
Key development and redevelopment projects placed into service during the three months ended December 31, 2020:
-
63,774 RSF at our redevelopment project at 9877 Waples Street in our Sorrento Mesa submarket, 100% leased to Cue Health Inc.; and
-
96,463 RSF at our development project at the Alexandria Center® for Life Science – San Carlos in our Greater Stanford submarket, leased to ChemoCentryx, Inc.
-
Annual net operating income (cash basis), including our share of unconsolidated real estate joint ventures, is expected to increase by $28 million upon the burn-off of initial free rent on recently delivered projects.
Balance sheet management
Refer to the “Execution of capital strategy” section below within this Item 7 in this annual report on Form 10-K.
Operating summary
| Same Property Net Operating Income Growth | Favorable Lease Structure**(1)** | ||||||||||||||||||||||||||||
 |  | Strategic Lease Structure by Owner and Operator of Collaborative Life Science, Technology, and Agtech Campuses | |||||||||||||||||||||||||||
| Increasing cash flows | |||||||||||||||||||||||||||||
| Percentage of leases containing annual rent escalations | 94% | ||||||||||||||||||||||||||||
| Stable cash flows | |||||||||||||||||||||||||||||
| Percentage of triple net leases | 94% | ||||||||||||||||||||||||||||
| Lower capex burden | |||||||||||||||||||||||||||||
| Percentage of leases providing for the recapture of capital expenditures | 93% | ||||||||||||||||||||||||||||
| Rental Rate Growth: Renewed/Re-Leased Space | Margins**(2)** | ||||||||||||||||||||||||||||
 |  | ||||||||||||||||||||||||||||
| Operating | Adjusted EBITDA | ||||||||||||||||||||||||||||
| 71% | 69% | ||||||||||||||||||||||||||||
(1)Percentages calculated based on RSF as of December 31, 2020.
(2)Represents percentages for the three months ended December 31, 2020.
Execution of capital strategy
During 2020, we continued to execute on many of the long-term components of our capital strategy. Some of our key accomplishments include the following:
2020 capital strategy
Key metrics as of December 31, 2020
-
$31.9 billion(1) of total market capitalization.
-
$24.4 billion of total equity capitalization.
-
$4.1 billion of liquidity as of December 31, 2020.
(1) Refer to the “Non-GAAP measures and definitions” section under this Item 7 in this annual report on Form 10-K for the definition of “Total market capitalization.”
| As of December 31, 2020 | Goal for Fourth Quarter of 2021, Annualized | ||||||||||||||||||||||
| Quarter Annualized | Trailing 12 Months | ||||||||||||||||||||||
| Net debt and preferred stock to Adjusted EBITDA | 5.3x | 5.5x | Less than or equal to 5.2x | ||||||||||||||||||||
| Fixed-charge coverage ratio | 4.6x | 4.4x | Greater than or equal to 4.5x | ||||||||||||||||||||
| Value-creation pipeline of new Class A development and redevelopment projects as a percentage of gross investments in real estate | As of December 31, 2020 | |||||||||||||
| Current and pre-leased near-term projects 78% leased/negotiating | 8% | |||||||||||||
| Income-producing/potential cash flows/covered land play(1) | 7% | |||||||||||||
| Land | 3% | |||||||||||||
(1)Includes projects that have existing buildings that are generating or can generate operating cash flows. Also includes development rights associated with existing operating campuses.
Key capital events in 2020
Unsecured senior line of credit
- On October 6, 2020, we amended our unsecured senior line of credit. Key changes include the following:
| New Agreement | Change | |||||||||||||
| Commitments available for borrowing | $3.0 billion | Up $800 million | ||||||||||||
| Interest rate | LIBOR+0.825% | Added a 0% LIBOR floor | ||||||||||||
| Maturity date | January 6, 2026 | Extended 2 years | ||||||||||||
- In April 2020, we closed an additional unsecured senior line of credit with $750.0 million of available commitments, which had a maturity date of April 14, 2022, and bore interest at LIBOR plus 1.05%. In addition to the cost of borrowing, this line of credit was subject to an annual facility fee of 0.20% based on the aggregate commitment outstanding. The terms of the $750.0 million unsecured senior line of credit agreement required that the outstanding commitments be reduced by 100% of net cash proceeds from certain new debt transactions and 50% of net cash proceeds from new equity offerings as defined in the agreement. In August 2020, we received cash proceeds from the issuance of our $1.0 billion 1.875% Unsecured Senior Notes, and, pursuant to the terms of the $750.0 million unsecured senior line of credit agreement, all outstanding commitments from the line of credit were reduced to zero, and we terminated this facility.
Commercial paper program
- During 2020, we increased the aggregate amount we may issue under our commercial paper program from $750.0 million to $1.5 billion as of December 31, 2020. Borrowings under our commercial paper program are backed by our $3.0 billion unsecured senior line of credit.
Unsecured senior notes payable
-
In March 2020, we completed an offering of $700.0 million of unsecured senior notes payable due on December 15, 2030, at an interest rate of 4.90% for net proceeds of $691.6 million.
-
In August 2020, we opportunistically issued $1.0 billion of unsecured senior notes payable due in 2033 at an interest rate of 1.875% (“1.875% Unsecured Senior Notes”).
-
We used a portion of the proceeds from our 1.875% Unsecured Senior Notes to refinance $500.0 million of our 3.90% unsecured senior notes payable due in 2023, pursuant to a partial cash tender offer completed on August 5, 2020, and a subsequent call for redemption for the remaining outstanding amounts, which settled on September 4, 2020. As a result of our debt refinancing, we recognized a loss on early extinguishment of debt of $50.8 million, including the write-off of unamortized loan fees
Extinguishment of unsecured senior notes payable, unsecured senior line of credit, and secured notes payable
-
In August 2020, we refinanced our 3.90% unsecured senior notes payable due in 2023 aggregating $500.0 million and recognized a loss on early extinguishment of debt aggregating $50.8 million, including the write-off of unamortized loan fees. Additionally, we recognized a loss on early extinguishment of debt aggregating $1.9 million due to the termination of our $750.0 million unsecured senior line of credit.
-
In December 2020, we extinguished two secured notes payable aggregating $108.2 million, due in 2023 with a weighted-average interest rate of 3.67%, and recognized losses on early extinguishment of debt aggregating $7.3 million. As a result of these extinguishments, we have no debt maturing until 2024.
Forward equity sales agreements
*•*In January 2020 and July 2020, we entered into forward equity sales agreements aggregating $1.0 billion and $1.1 billion, respectively, to sell an aggregate of 6.9 million shares for each offering (13.8 million in aggregate) of our common stock, including the exercise of underwriters’ options, at public offering prices of $155.00 per share and $160.50 per share, respectively, before underwriting discounts. During 2020, we issued all 13.8 million shares under these forward equity sales agreements and received net proceeds of $2.1 billion.
- In January 2021, we entered into forward equity sales agreements aggregating $1.1 billion to sell an aggregate of 6.9 million shares of our common stock (including the exercise of underwriters’ option) at a public offering price of $164.00 per share, before underwriting discounts and commissions. We expect to settle these forward equity sales agreements in March 2021.
ATM common stock offering program
-
In February 2020, we entered into a new ATM common stock offering program, which allows us to sell up to an aggregate of $850.0 million of our common stock.
-
We issued 1.5 million shares of common stock under our ATM program at a price of $159.09 per share (before underwriting discounts), and received net proceeds of $235.0 million in 2020.
-
We have 362 thousand shares under our ATM program subject to forward equity sales agreements that remain outstanding at a price of $159.09 per share (before underwriting discounts) as of December 31, 2020. We expect to settle these forward equity sales agreements in 2021 and receive net proceeds of approximately $56.3 million.
-
The remaining availability of $547.3 million under this ATM program expired in December 2020 concurrently with the expiration of the associated shelf registration. In January 2021, we filed a new shelf registration and we expect to establish a new ATM program soon in 2021.
Unconsolidated real estate joint venture loan
- In March 2020, our unconsolidated joint venture at 1655 and 1725 Third Street, in which we own a 10% interest, located in Mission Bay/SoMa, refinanced an existing variable-rate secured construction loan with a fixed-rate loan with terms as follows:
| 100% at Joint Venture Level | Amended Agreement | Change | ||||||||||||
| Aggregate commitments | $600.0 million | Increase of $225.0 million | ||||||||||||
| Maturity date | March 2025 | Extended by 45 months | ||||||||||||
| Interest rate | Fixed at 4.50% | Previously LIBOR + 3.70% | ||||||||||||
Investments
-
Our investments in publicly traded companies and privately held entities aggregated a carrying amount of $1.6 billion, including an adjusted cost basis of $835.4 million and unrealized gains of $775.7 million, as of December 31, 2020.
-
Investment income of $421.3 million during the year ended December 31, 2020, consisted of $47.3 million of realized gains, which included $24.5 million of impairments related to investments in privately held entities that do not report NAV, and $374.0 million of unrealized gains.
2021 Capital strategy
During 2021, we intend to continue to execute our capital strategy to achieve further improvements to our credit profile, which will allow us to further improve our cost of capital and continue our disciplined approach to capital allocation. For further information, refer to the “Projected results” section below under this Item 7 in this annual report on Form 10-K. Consistent with 2020, our capital strategy for 2021 includes the following elements:
-
Allocate capital to Class A properties located in collaborative life science, technology, and agtech campuses in AAA urban innovation clusters;
-
Continue to improve our credit profile;
-
Maintain prudent access to diverse sources of capital, which include cash flows from operating activities after dividends, incremental debt supported by our growth in EBITDA, real estate asset sales, non-real estate investment sales, joint venture capital, and other capital such as sales of equity;
-
Maintain commitment to long-term capital to fund growth;
-
Prudently ladder debt maturities;
-
Reduce short-term variable-rate debt;
-
Prudently manage equity investments to support corporate-level investment strategies;
-
Maintain significant balance sheet liquidity; and
-
Maintain a stable and flexible balance sheet.
Given the anticipated delivery of significant incremental EBITDA from our development and redevelopment of new Class A properties, we expect to be able to debt fund a significant portion of construction on a leverage-neutral basis. We expect to continue to maintain access to a diverse source of debt, including unsecured senior notes payable, as well as secured construction loans for our development and redevelopment projects from time to time. We expect to continue to maintain a significant proportion of our net operating income on an unencumbered basis to allow for future flexibility for accessing both unsecured and secured debt markets, although we expect traditional secured mortgage notes payable will remain a small component of our capital structure. In addition to debt funding on a leverage-neutral basis, we intend to supplement our remaining capital needs with net cash flows from operating activities, after dividends and proceeds from real estate asset sales, non-real estate investment sales, partial interest sales, and other debt and equity capital.
Improved cost of capital
As part of our capital strategy to continue strengthening our credit profile, we expect to complete and place into service development and redevelopment projects currently under construction, which we expect will deliver significant incremental EBITDA. The expected growth in our EBITDA in 2021 and beyond should allow us to obtain debt funding on a leverage-neutral basis and provide significant capital to fund our development and redevelopment projects. Additionally, the resulting expected improvement in our balance sheet leverage ratio should allow us to access diverse sources of capital, strengthen our credit profile, and reduce our cost of capital. In addition, we expect to continue to maintain a significant proportion of unencumbered net operating income. For the year ended December 31, 2020, our unencumbered net operating income as a percentage of total net operating income was 96%.
Investments
We present our equity investments at fair value whenever fair value or NAV is readily available. Adjustments for our limited partnership investments represent changes in reported NAV as a practical expedient to estimate fair value. For investments without readily available fair values, we adjust the carrying amount whenever such investments have an observable price change, and further adjustments are not made until another price change, if any, is observed. Refer to Note 7 – “Investments” to our consolidated financial statements under Item 15 in this annual report on Form 10-K for additional information.
| December 31, 2020 | |||||||||||||||||||||||||||||
| (In thousands) | Three Months Ended | Year Ended | Year Ended December 31, 2019 | ||||||||||||||||||||||||||
| Realized gains | $ | 21,599 | $ | 47,288 | (1) | $ | 33,158 | (2) | |||||||||||||||||||||
| Unrealized gains | 233,538 | 374,033 | 161,489 | ||||||||||||||||||||||||||
| Investment income | $ | 255,137 | $ | 421,321 | $ | 194,647 | |||||||||||||||||||||||
| Investments (In thousands) | Cost | Adjustments | Carrying Amount | ||||||||||||||||||||||||||
| Fair value: | |||||||||||||||||||||||||||||
| Publicly traded companies | $ | 208,754 | $ | 351,076 | (3) | $ | 559,830 | ||||||||||||||||||||||
| Entities that report NAV | 334,341 | 327,741 | 662,082 | ||||||||||||||||||||||||||
| Entities that do not report NAV: | |||||||||||||||||||||||||||||
| Entities with observable price changes | 47,545 | 96,859 | 144,404 | ||||||||||||||||||||||||||
| Entities without observable price changes | 244,798 | — | 244,798 | ||||||||||||||||||||||||||
| December 31, 2020 | $ | 835,438 | (4) | $ | 775,676 | $ | 1,611,114 | ||||||||||||||||||||||
| September 30, 2020 | $ | 788,807 | $ | 542,138 | $ | 1,330,945 |
(1)Includes impairments related to investments in privately held entities that do not report NAV of $24.5 million for the year ended December 31, 2020.
(2)Includes impairments related to investments in privately held entities that do not report NAV of $17.1 million for the year ended December 31, 2019.
(3)Includes gross unrealized gains and losses of $366.9 million and $15.8 million, respectively, as of December 31, 2020.
(4)Represents 3.2% of total gross assets as of December 31, 2020.
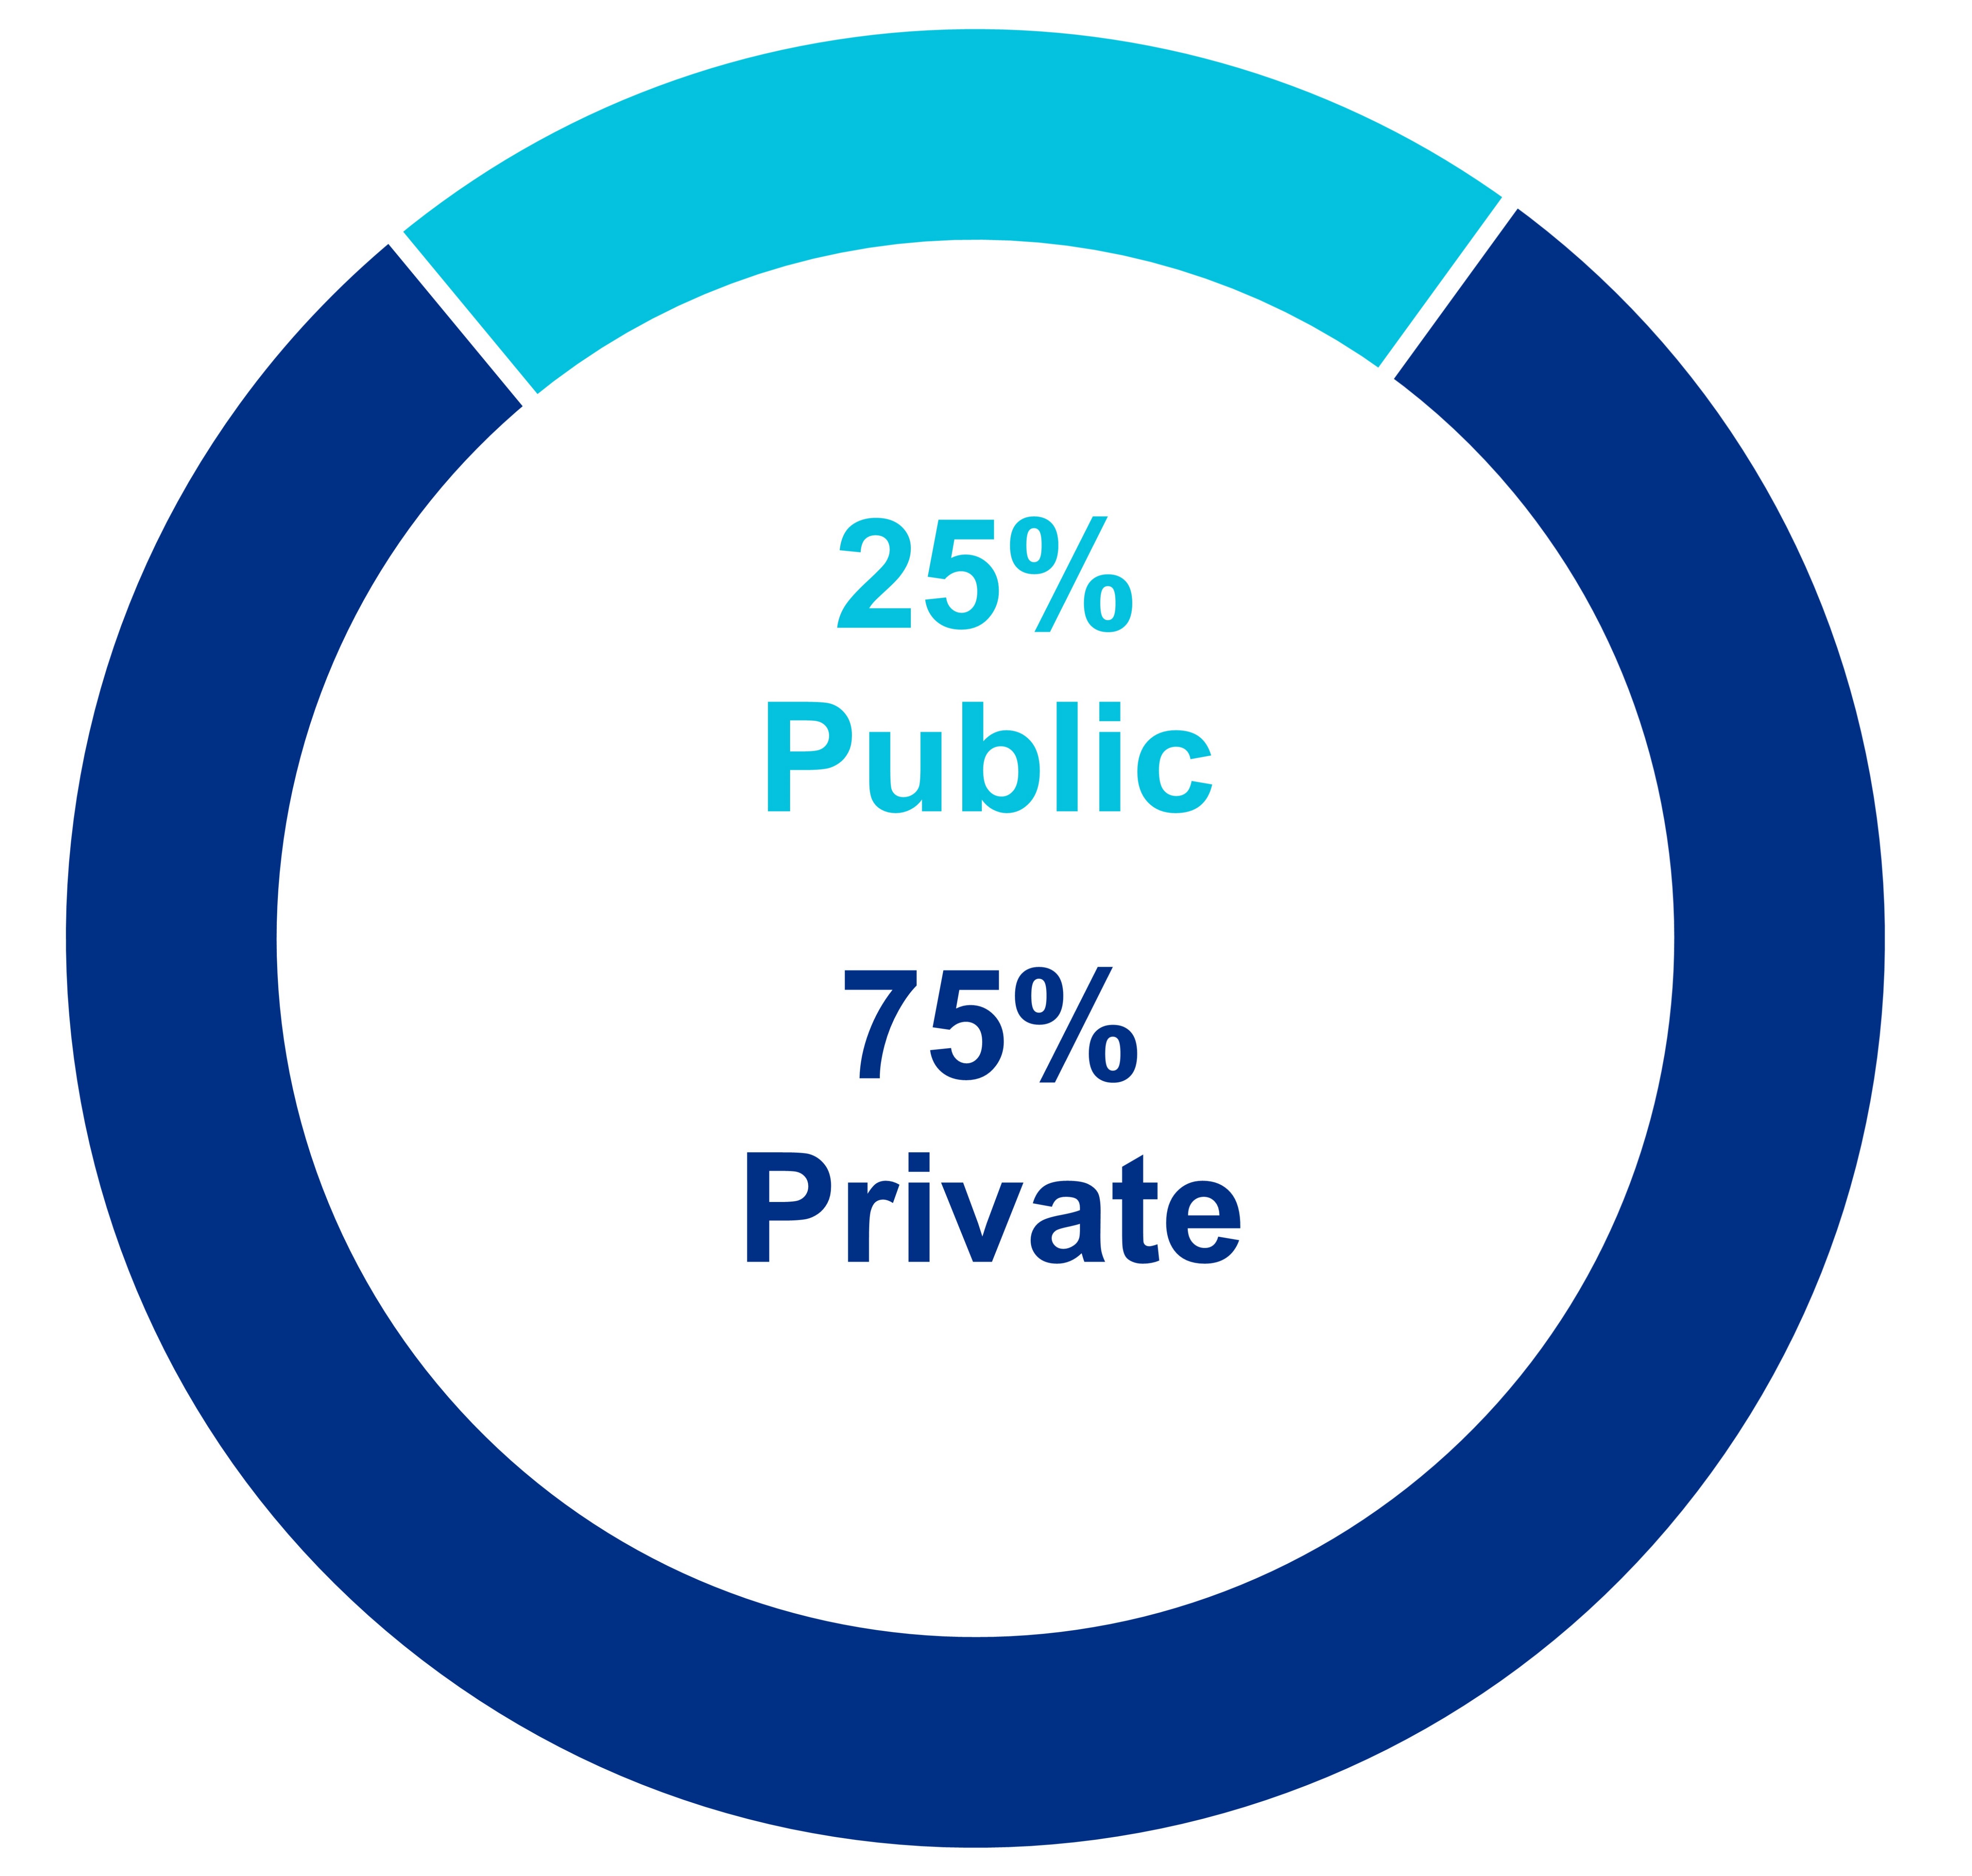
| Public/Private Mix (Cost) | ||||||||
 | ||||||||
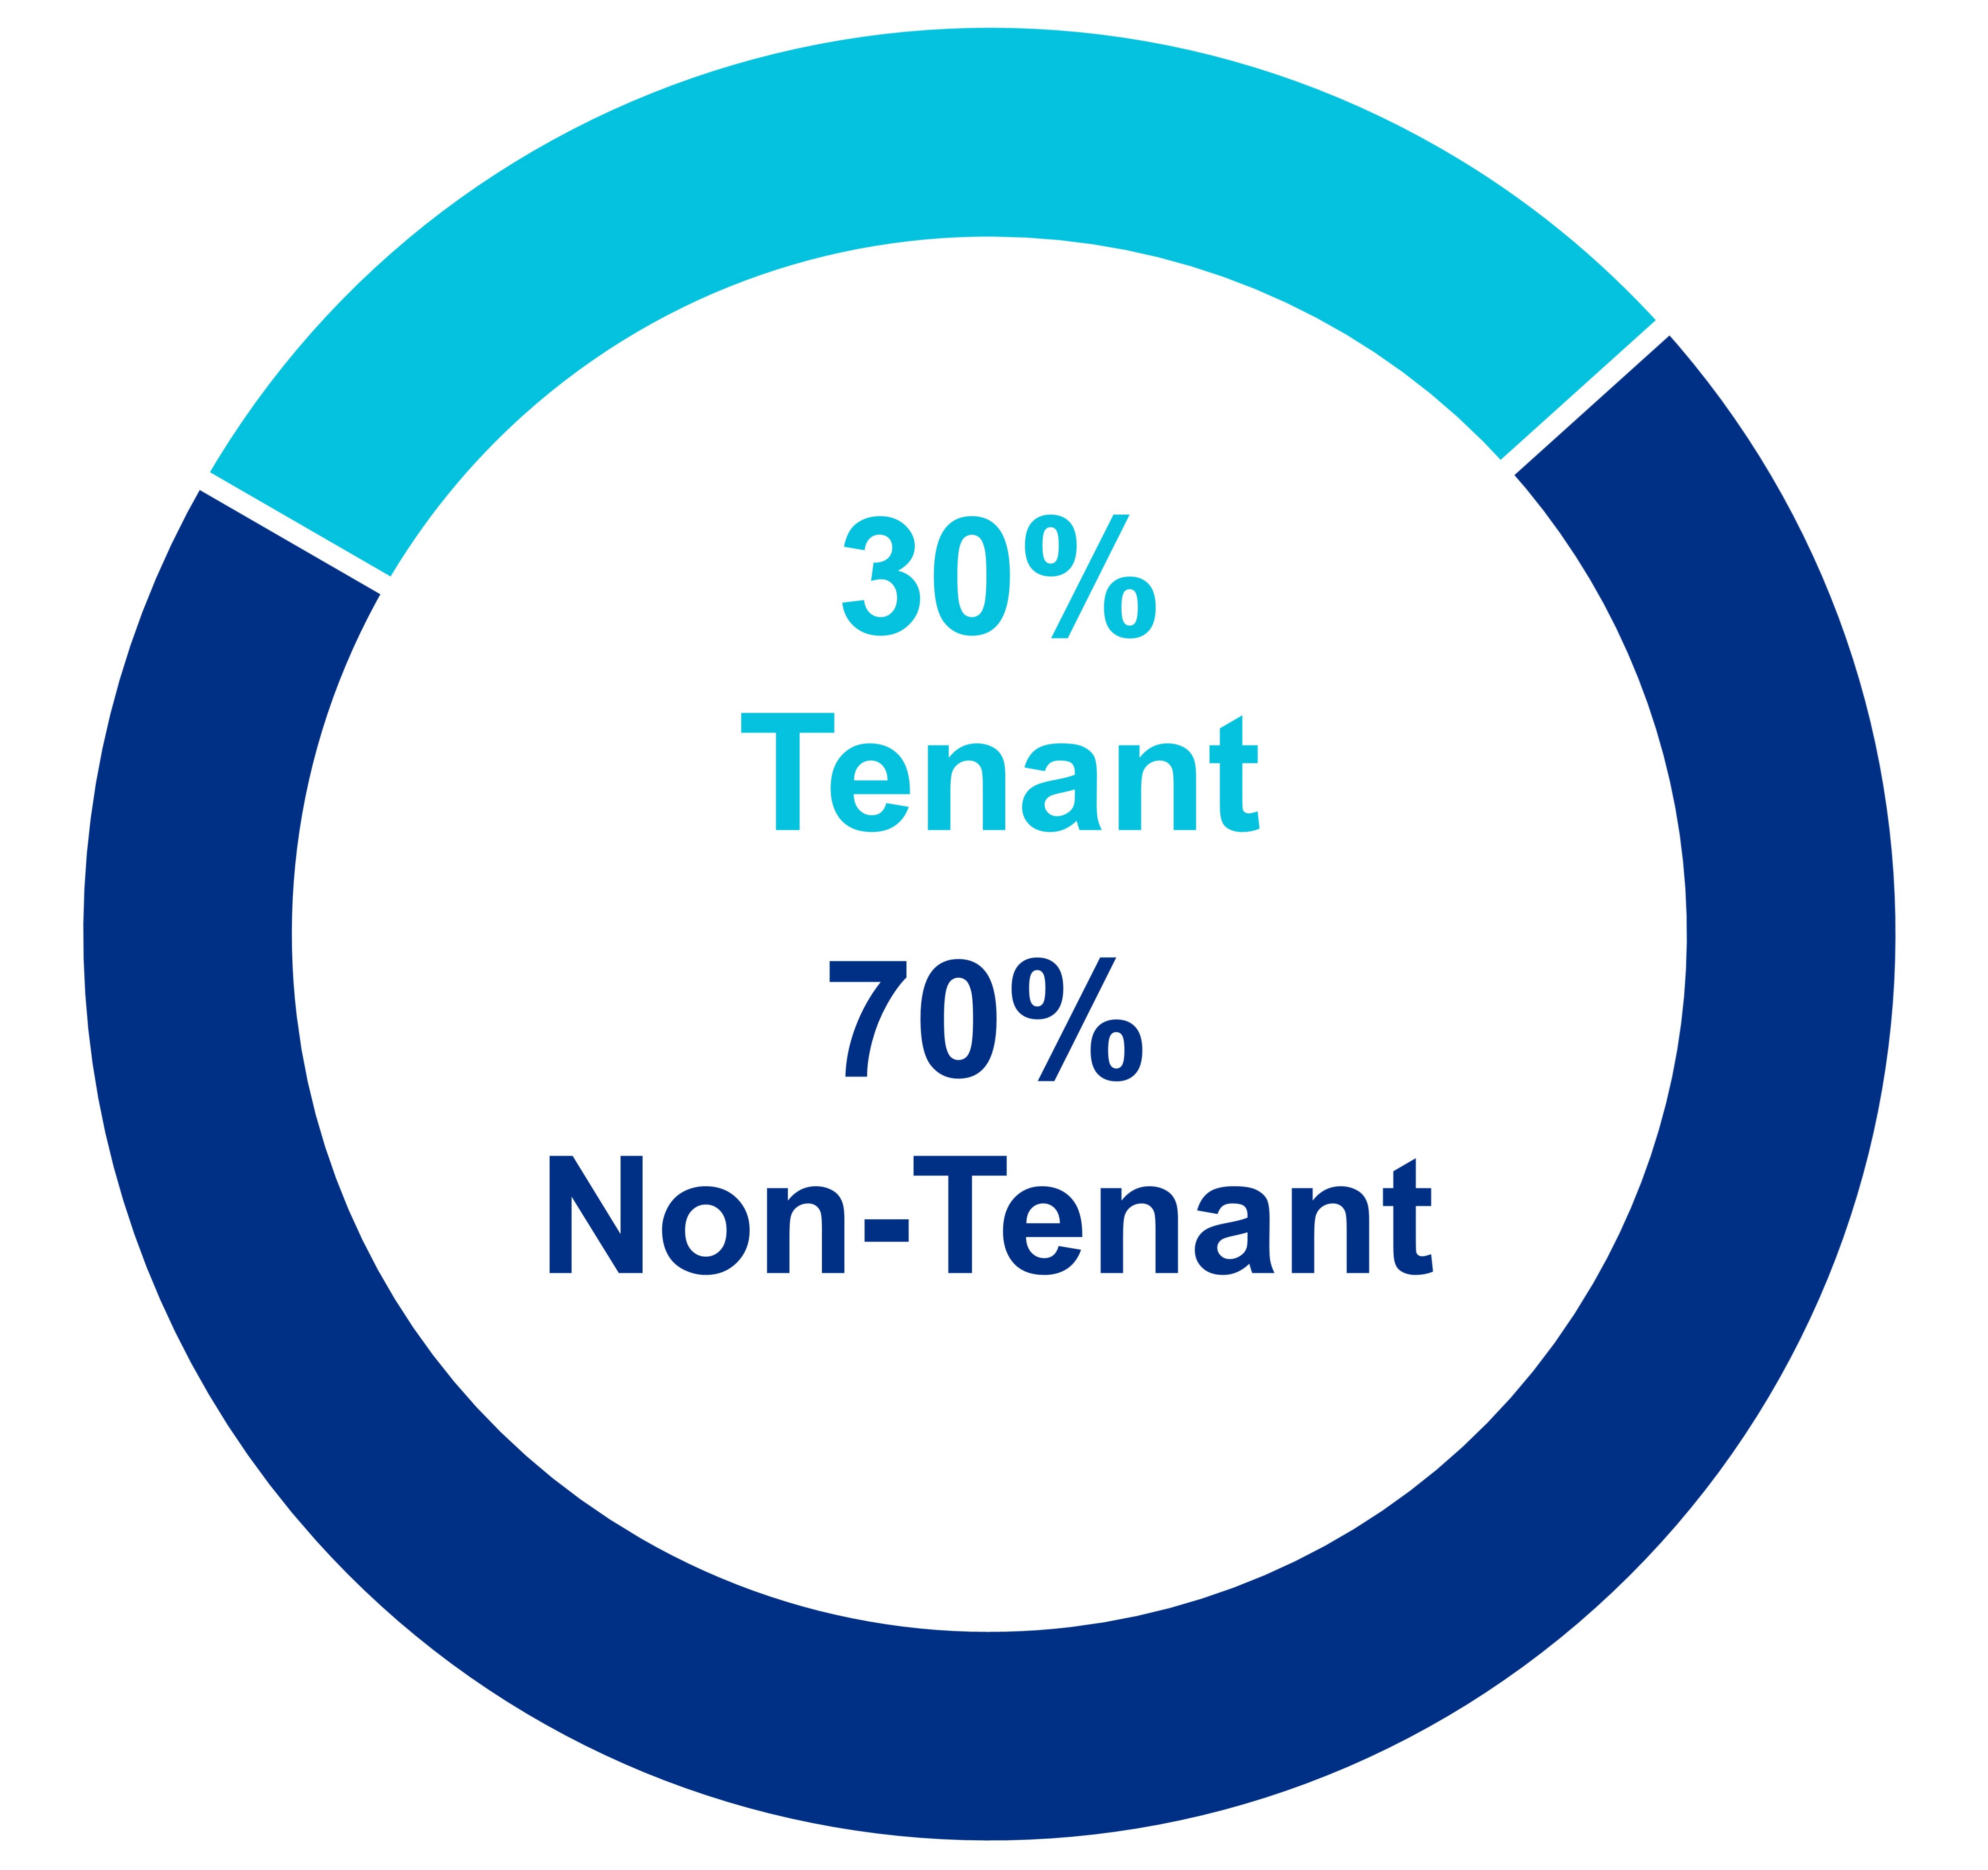
| Tenant/Non-Tenant Mix (Cost) | ||||||||
 |
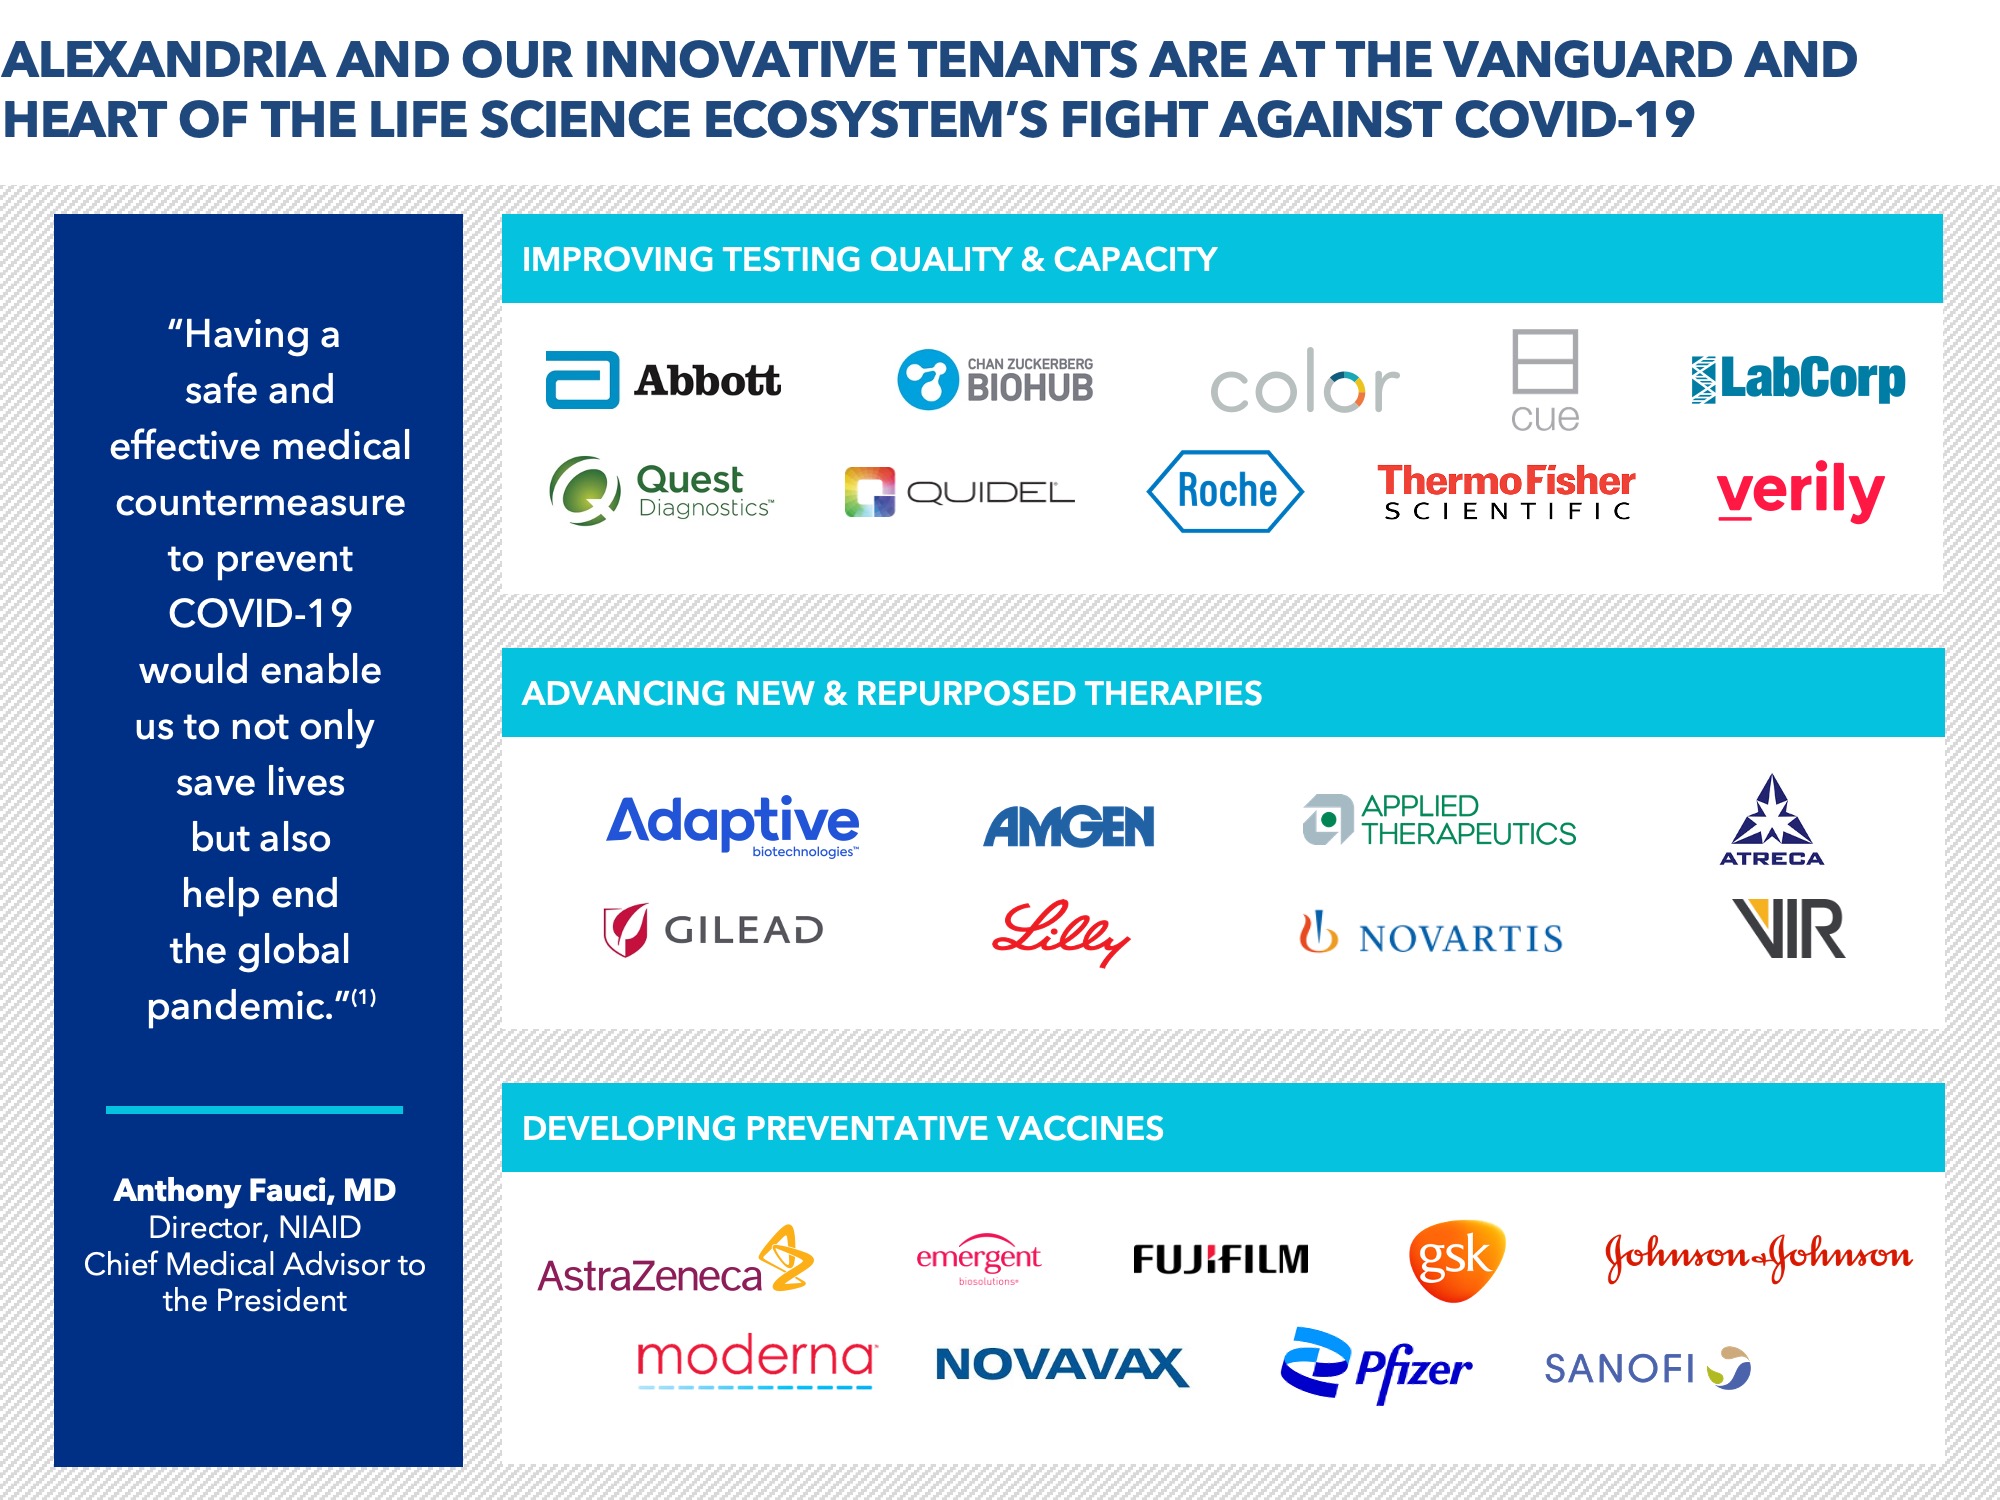
Represents an illustrative subset of approximately 100 tenants focused on COVID-19-related efforts, with some of these companies working on multiple efforts that span testing, treatment, and/or vaccine development.
(1)Source: National Institutes of Health, “NIH launches clinical trials network to test COVID-19-related vaccines and other preventive tools,” July 8, 2020.
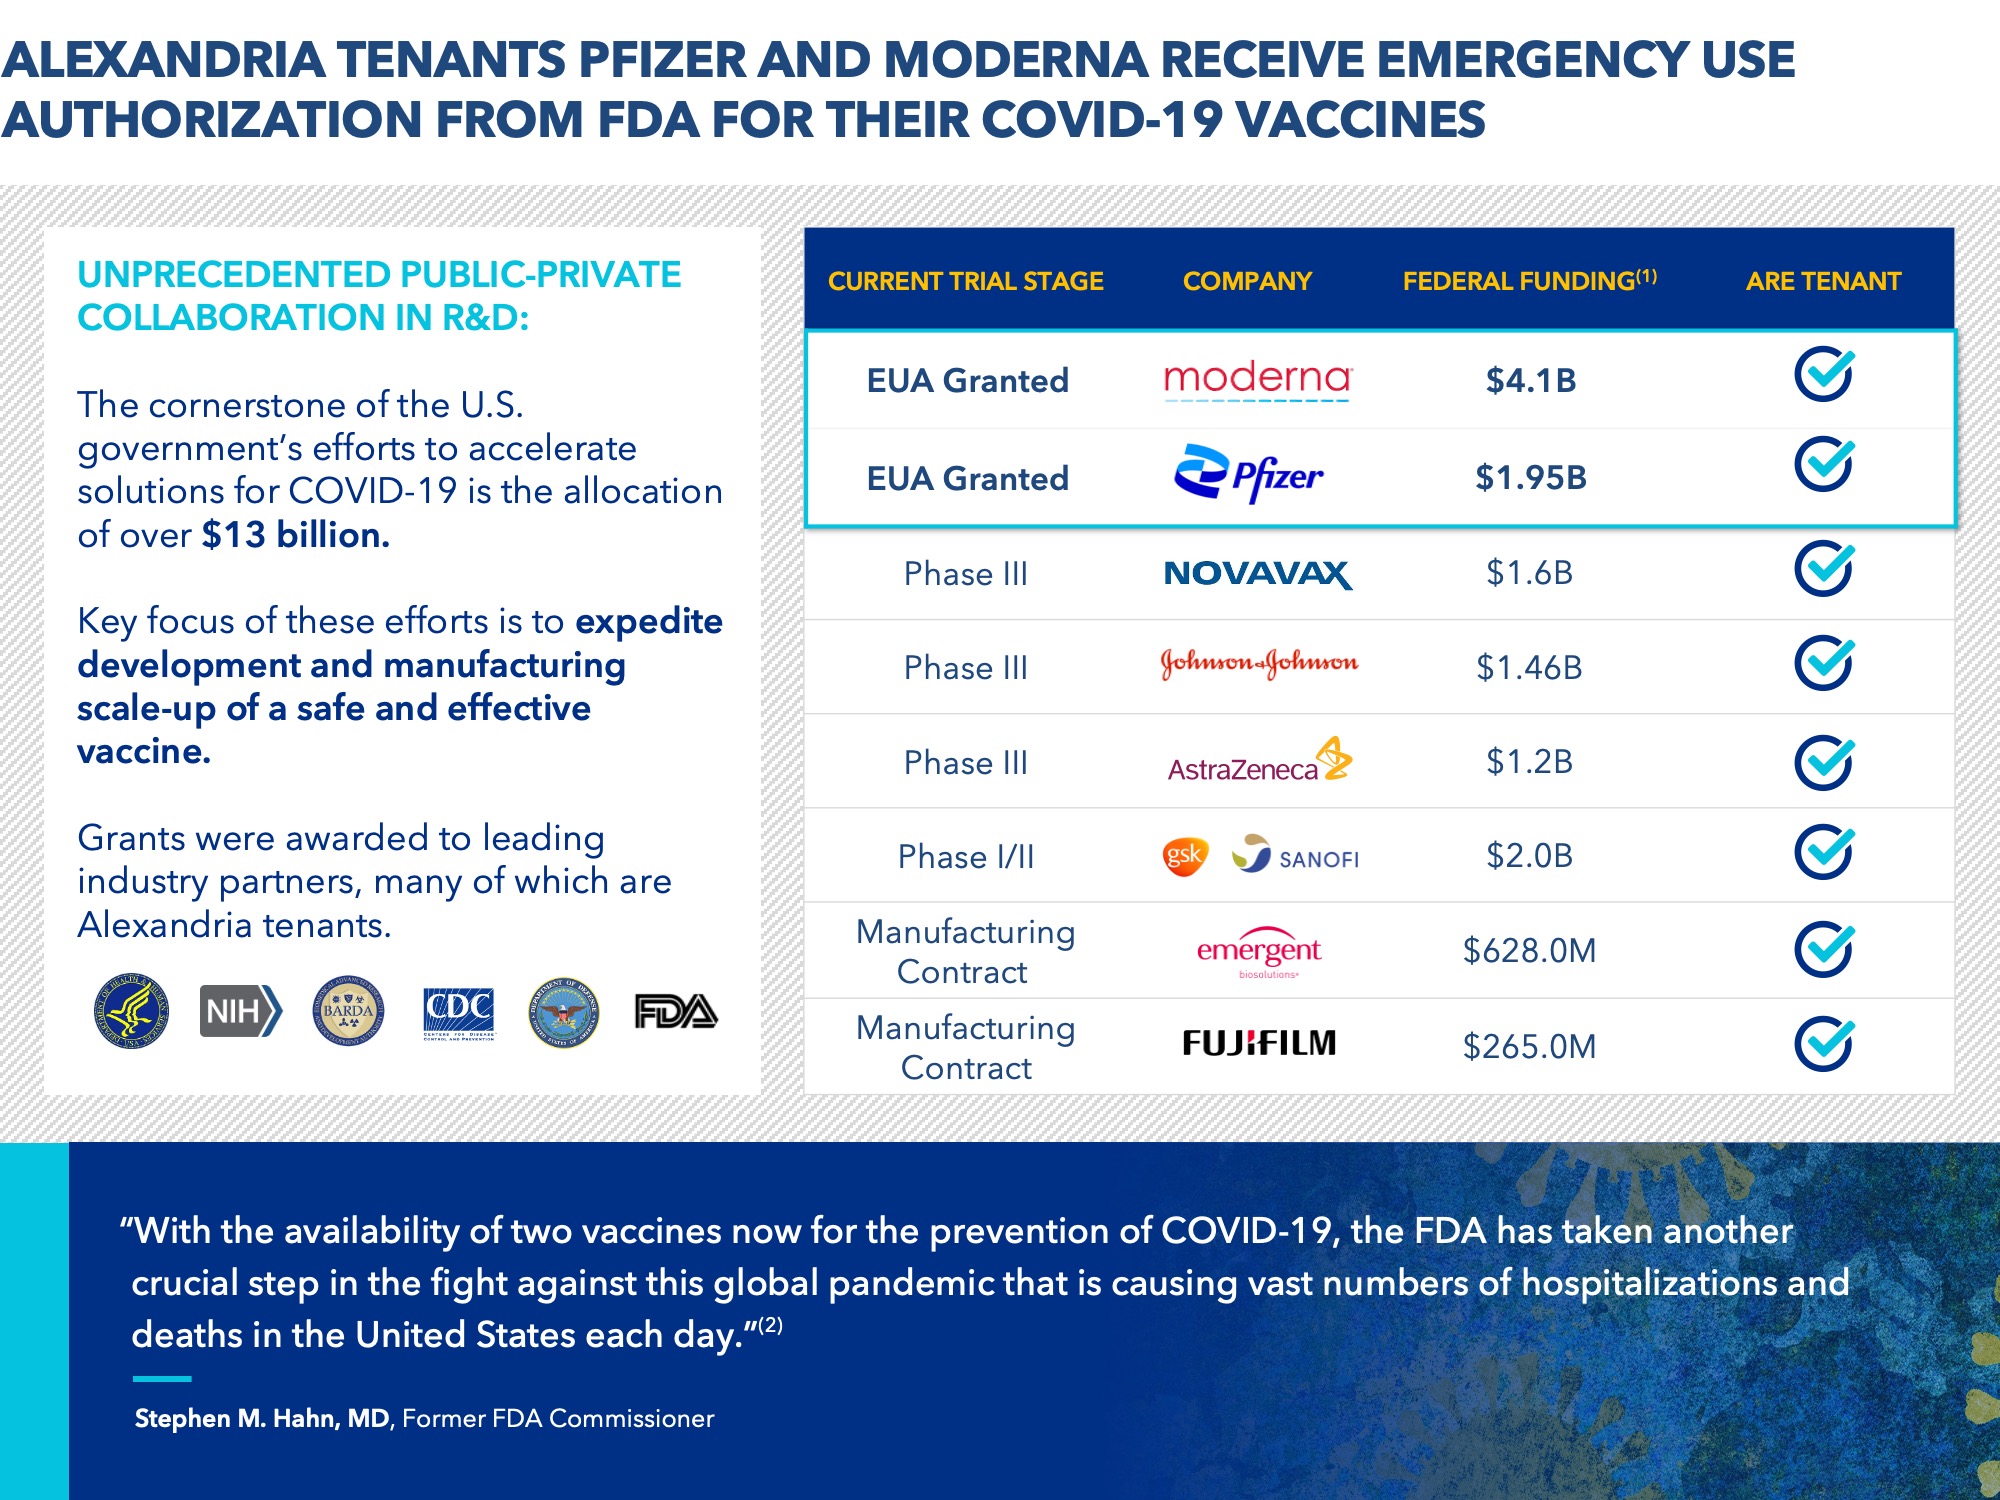
(1)As of January 29, 2021. Source: U.S. Department of Health & Human Services. Federal funding presented includes the total commitment value.
(2)Source: U.S. Food and Drug Administration, “FDA Takes Additional Action in Fight Against COVID-19 By Issuing Emergency Use Authorization for Second COVID-19 Vaccine,” December 18, 2020.
Alexandria and our innovative tenants are at the vanguard and heart of the life science ecosystem advancing solutions for COVID-19
Safe and effective vaccines and therapies, in addition to widespread testing, continue to be critically needed to combat the global COVID-19 pandemic. By maintaining essential continuous operations across our campuses, Alexandria has enabled several of our life science tenants to pursue mission-critical COVID-19-related research and development. The heroic work being done by so many of our tenants and campus community members to help test for, treat, and prevent COVID-19, as well as provide medical supplies and protective equipment to neighboring hospitals, is profound and inspiring. We are currently tracking approximately 100 tenants across our cluster markets that have contributed meaningful time and resources to advancing solutions for COVID-19.
Developing preventative vaccines
-
A prophylactic vaccine is critically needed to resolve the global COVID-19 pandemic. As such, researchers around the world are working tirelessly to develop a safe and effective vaccine in record time. Furthermore to help expedite the development, manufacturing, and distribution of COVID-19 vaccines, the U.S. government initiated an unprecedented public-private collaboration, allocating several billions of dollars to these efforts.
-
This support along with the internal vaccine development expertise and innovative technology platforms of our tenants Pfizer Inc. (in partnership with BioNTech) and Moderna, Inc. (in partnership with the National institutes of Health), culminated in the FDA providing Emergency Use Authorization (“EUA”) in December 2020 for their respective mRNA based COVID-19 vaccines. The U.S. has begun a large-scale COVID-19 vaccination campaign and will continue to roll out vaccines across the nation, prioritizing frontline and essential workers, the elderly, and individuals considered high-risk.
-
Additional tenants, including AstraZeneca plc, Emergent BioSolutions Inc., FUJIFILM Diosynth Biotechnologies, GlaxoSmithKline, Johnson & Johnson, Novavax, Inc., and Sanofi, have similarly received strong government support for their efforts in the development, manufacturing, and/or distribution of COVID-19 vaccines. Many of these companies will report critical trial data over the coming months, which, if positive, could help bolster the widespread delivery of a safe and effective COVID-19 vaccine around the world.
Advancing new and repurposed therapies
-
Safe and effective therapies are important for mitigating the impact of COVID-19, decreasing hospitalizations, and improving patient outcomes overall. On October 22, 2020, the FDA approved Veklury® (remdesivir), developed by our tenant Gilead Sciences, Inc., as the first antiviral treatment approved for COVID-19 patients requiring hospitalization. Subsequently, in November 2020, the FDA granted EUAs to tenant Eli Lilly and Company’s bamlanivimab for the treatment of newly infected high-risk patients with mild or moderate disease, as well as to Regeneron Pharmaceutical’s antibody cocktail for a similar indication.
-
In addition, over 300 experimental therapies to treat COVID-19 are being studied in over 900 clinical trials around the world, as well as over more than 150 therapeutic candidates in preclinical development. A substantial number of these programs are sponsored by our tenants, including the following:
-
Vir Biotechnology, Inc. and GlaxoSmithKline announced on October 6, 2020, that their most advanced antibody therapy for the early treatment of patients with COVID-19 has entered Phase III and that they expect complete results in the first quarter of 2021.
-
AbbVie Inc.**, Amgen, AstraZeneca plc, Atreca Inc., Enanta Pharmaceuticals, Inc., Novartis AG, and Pfizer Inc. are similarly endeavoring to develop novel therapies and repurpose existing and investigational drugs to provide near-term treatments for moderate and severe COVID-19 patients and those at highest risk.
Improving testing quality and capacity
- Abbott Laboratories**, Adaptive Biotechnologies Corporation, Color, Cue Health Inc., Laboratory Corporation of America Holdings, Quest Diagnostics, Quidel Corporation, Roche, Thermo Fisher Scientific Inc., Verily Life Sciences, and others are working to improve testing quality, capacity, and turnaround time to more effectively determine who has an active COVID-19 infection, who has been exposed to the virus, and who has developed immunity against it. The increased availability of widespread COVID-19 testing is critical for curtailing the pandemic and facilitating a safer reopening of workplaces, communities, and society overall.
Industry and corporate leadership: catalyzing and leading the way for positive change to benefit human health and society
Industry leadership
-
In January 2020, we announced our first national $100,000 AgTech Innovation Prize competition to recognize startup and early-stage agtech and foodtech companies that demonstrate innovative approaches to addressing challenges related to agriculture, food, and nutrition.
-
In June 2020, we announced that Alexandria LaunchLabs® – AgTech awarded its inaugural $100,000 AgTech Innovation Prize to TerMir Inc., an early-stage agtech company aiming to address key, unresolved agricultural, environmental, and human health challenges.
-
In January 2020, Alexandria Venture Investments, our strategic venture capital arm, was recognized for a third consecutive year as the most active biopharma investor by new deal volume by Silicon Valley Bank in its “2020 Healthcare Investments and Exits Report.” Alexandria’s venture activity provides us with, among other things, mission-critical data and knowledge of innovations and trends.
-
In July 2020, Alexandria Venture Investments was recognized as the most active biopharma investor by new deal volume from 2019 to the six months ended June 30, 2020, by Silicon Valley Bank in its “Mid-Year 2020 Healthcare Investments and Exits Report.”
-
In January 2021, Alexandria Venture Investments, our strategic venture capital platform, was recognized for a fourth consecutive year as the most active biopharma corporate investor by new deal volume from 2019 to 2020 by Silicon Valley Bank in its “Healthcare Investments and Exits: Annual Report 2021.”
-
In February 2020, Alexandria LaunchLabs® at the Alexandria Center® at One Kendall Square earned the Fitwel Impact Award for the highest Fitwel certification of all time, as well as the highest score in 2019 for a commercial interior space, in the Fitwel 2020 Best in Building Health awards program. This marks the second consecutive year Alexandria LaunchLabs® – Cambridge has held the record for Fitwel’s top certification score. The award recognizes our commitment to supporting high levels of health, wellness, and productivity through the design, construction, and operation of our best-in-class buildings and spaces.
-
In March 2020, the Navy SEAL Foundation honored Joel S. Marcus, our executive chairman and founder, and the company with the 2020 Navy SEAL Foundation Patriot Award, which highlights our contributions and unwavering support for the Naval Special Warfare community. We have proudly supported the Navy SEAL Foundation in its mission to provide immediate and ongoing support and assistance to the Naval Special Warfare community and their families since 2010.
-
In June 2020, our executive chairman and founder, Joel S. Marcus, had the honor of serving as the keynote speaker for a special fireside chat at the virtual BIO Health Caucus hosted by the Association of University Research Parks, an organization dedicated to guiding leaders to cultivate communities of innovation at global anchor institutions. The virtual fireside, titled “Three Decades of Building Bio Health Facilities and Companies,” covered a broad array of topics that provided a comprehensive view of our essential business, our dynamic cluster locations, and our critical role at the vanguard of the life science ecosystem fighting COVID-19.
-
In June 2020, we released our 2019 Corporate Responsibility Report, which reinforces Alexandria’s longstanding environmental, social, and governance commitment, strong progress toward our 2025 environmental impact goals, and critical role at the vanguard and heart of the life science ecosystem advancing solutions for COVID-19.
-
In September 2020, Alexandria won the Commercial Brokers Association (“CBA”) Boston Landlord of the Year award. The CBA was established as a freestanding division of the Greater Boston Real Estate Board in 2001 and represents over 400 members in the commercial brokerage community throughout Massachusetts.
-
In November 2020, Alexandria was ranked as the #1 public REIT for construction-in-progress in 2019 from Engineering News-Record’s (ENR) Top 50 List. ENR recognize leaders in the construction industry, and its top ranking of our construction activity highlights our commitment to creating and delivering life-changing and essential facilities to our tenant community.
-
In December 2020, we achieved the following in the 2020 Global Real Estate Sustainability Benchmark (“GRESB”) Real Estate Assessment: (i) #1 global ranking in the Science & Technology sector, (ii) #1 global ranking and 5 Star Rating (out of 5 stars) in our Diversified Listed Peer Group for highly sustainable development initiatives, and (iii) our third consecutive “A” disclosure score.
Pioneering social responsibility initiatives to continue to drive unique, disruptive, and highly impactful solutions to tackle some of society’s most complex and pressing challenges
Alexandria is profoundly committed to driving forward significant collaborative and innovative solutions to address some of today’s most urgent and widespread societal challenges, including the COVID-19 pandemic, the opioid epidemic, and the educational achievement gap.
At the vanguard and heart of the life science ecosystem’s fight against COVID-19
-
As a testament to our comprehensive and industry-leading COVID‑19 prevention guidelines and practices, in October 2020, we became the first-ever company to achieve a Fitwel Viral Response Certification with Distinction, the highest designation within the new Viral Response Module developed by the world’s leading healthy building certification system. Additionally, in November 2020, we achieved the world’s first WELL Health-Safety Rating for Laboratory Space at Alexandria LaunchLabs® – New York City. This latest evidence-based, third-party-verified rating further affirms our longstanding and robust practices to help keep our tenants, employees, visitors, service providers, and key industry stakeholders healthy and safe.
-
Throughout the COVID-19 pandemic, Alexandria has been a critical partner to several impactful organizations supporting communities adversely affected by the COVID-19 pandemic. In total, Alexandria has donated more than $1 million to non-profit organizations on the front lines of combating the devastating impact of the COVID-19 pandemic, including Robin Hood, New York City’s largest poverty-fighting organization. As a member of the Robin Hood Board of Directors, Joel S. Marcus has played a key leadership role in the distribution of over $60 million to 575 organizations across all five New York City boroughs, providing critical emergency support for New Yorkers in need through food, housing, financial assistance, job security, and more.
-
In lieu of tenant holiday gifts, in December 2020, Alexandria made donations to several regional COVID-19-related non-profit programs, including Seattle Foundation’s COVID-19 Relief Fund, Robin Hood COVID-19 Relief Fund, SF New Deal COVID-19 Relief for San Francisco, Nourish Now in Maryland, and the Greg Hill Foundation’s Restaurant Strong Fund in Boston.
Pioneering a groundbreaking, data-driven, and evidence-based model to help solve the opioid epidemic
-
Determined to reverse the trajectory of the U.S. opioid epidemic, which is one of the most pervasive public health challenges in our nation’s history, Alexandria partnered with Verily Life Sciences to establish an innovative, non-profit healthcare ecosystem dedicated to the full and sustained recovery of people living with addiction. Together, we pioneered a fully integrated campus in Dayton, Ohio, to house an evidence-based comprehensive treatment model encompassing a full continuum of care with dedicated facilities and services for treatment, residential housing, group therapy, family reunification, workforce development programs, job placement, and community transition.
-
Over the last year, we completed construction of the OneFifteen Outpatient Clinic; the Crisis Stabilization Unit; and most recently, OneFifteen Living, the residential housing component that opened in late 2020.
-
Overdose deaths continue to rise dramatically during the COVID-19 pandemic, demonstrating the tremendous need for the OneFifteen ecosystem. Since opening in the fall of 2019, OneFifteen has made a positive and comprehensive impact on the local community and the way addiction is treated, seeing approximately 2,200 patients in 2020, including over 1,150 people during the three months ended December 31, 2020. It is our hope that OneFifteen’s unique approach to treatment will serve as a model of recovery for the rest of the country to replicate.
Building educational foundations for students to pave paths for long-term success and close the achievement gap
-
Alexandria is deeply committed to driving educational opportunities and providing the support and resources needed to build the foundations for underserved, low-income students to succeed and become engaged and leading members of society. Understanding that education is one of the most fundamental foundations for a safe, healthy, and good life and essential for opportunity and economic mobility, we have forged deep partnerships in our communities with highly impactful organizations that provide holistic educational resources to underserved populations.
-
In December 2020, Alexandria celebrated the culmination of the Emily Krzyzewski Center’s $15 million Game Changer Campaign, in which Alexandria played a critical leadership role. The Emily K Center paves a path to success in higher education for academically focused, low-income K–12 students in Durham, North Carolina. Students receive holistic support that encompasses academic skills development, personal management and leadership training, college planning, and career exploration. Of those who complete Emily K’s Scholars to College program, nearly 100% are accepted to college each year.
-
The campaign funds will support ongoing programs to prepare students for life-changing college access while bolstering their achievement and developing their character and leadership; an endowment to ensure support for students in years to come; and a new 7,500 square foot facility designed for the specific needs of college-access programs to provide much needed classroom space as well as rooms for quiet study and one-on-one advising and financial aid discussions.
Results of operations
We present a tabular comparison of items, whether gain or loss, that may facilitate a high-level understanding of our results and provide context for the disclosures included in this annual report on Form 10-K. We believe such tabular presentation promotes a better understanding for investors of the corporate-level decisions made and activities performed that significantly affect comparison of our operating results from period to period. We also believe this tabular presentation will supplement for investors an understanding of our disclosures and real estate operating results. Gains or losses on sales of real estate and impairments of held for sale assets are related to corporate-level decisions to dispose of real estate. Gains or losses on early extinguishment of debt, gains or losses on early termination of interest rate hedge agreements, and preferred stock redemption charges are related to corporate-level financing decisions focused on our capital structure strategy. Significant realized and unrealized gains or losses on non-real estate investments, impairments of real estate and non-real estate investments, and significant termination fees are not related to the operating performance of our real estate assets as they result from strategic corporate-level decisions and external market conditions. Impairments of non-real estate investments are not related to the operating performance of our real estate as they represent the write-down of non-real estate investments when their fair values decline below their respective carrying values due to changes in general market or other conditions outside of our control. Significant items included in the tabular disclosure for current periods are described in further detail under this Item 7 in this annual report on Form 10-K. Items included in net income attributable to Alexandria’s common stockholders were as follows:
| Year Ended December 31, | |||||||||||||||||||||||
| (In millions, except per share amounts) | 2020 | 2019 | 2020 | 2019 | |||||||||||||||||||
| Amount | Per Share – Diluted | ||||||||||||||||||||||
| Unrealized gains on non-real estate investments | $ | 374.0 | $ | 161.5 | $ | 2.96 | $ | 1.44 | |||||||||||||||
| Gain on sales of real estate | 154.1 | 0.5 | 1.22 | — | |||||||||||||||||||
| Impairment of real estate | (55.7) | (1) | (12.3) | (0.44) | (0.11) | ||||||||||||||||||
| Impairment of non-real estate investments | (24.5) | (17.1) | (0.19) | (0.15) | |||||||||||||||||||
| Loss on early extinguishment of debt | (60.7) | (47.6) | (0.48) | (0.42) | |||||||||||||||||||
| Loss on early termination of interest rate hedge agreements | — | (1.7) | — | (0.02) | |||||||||||||||||||
| Termination fee(2) | 86.2 | — | 0.68 | — | |||||||||||||||||||
| Acceleration of stock compensation expense due to executive officer resignation | (4.5) | — | (0.04) | — | |||||||||||||||||||
| Preferred stock redemption charge | — | (2.6) | — | (0.02) | |||||||||||||||||||
| Total | $ | 468.9 | $ | 80.7 | $ | 3.71 | $ | 0.72 |
(1)Amount includes $7.6 million impairment of our investment in a recently developed retail property held by our unconsolidated real estate joint venture. This impairment was recognized during the three months ended March 31, 2020, and was classified in equity in earnings from unconsolidated real estate joint ventures within our consolidated statements of operations.
(2)Refer to “Income from rentals” in Note 5 – “Leases” to our consolidated financial statements under Item 15 in this annual report on Form 10-K for more information.
Same properties
We supplement an evaluation of our results of operations with an evaluation of operating performance of certain of our properties, referred to as “Same Properties.” For additional information on the determination of our Same Properties portfolio, refer to the definition of “Same property comparisons” in the “Non-GAAP measures and definitions” section under this Item 7 in this annual report on Form 10-K. The following table presents information regarding our Same Properties as of December 31, 2020 and 2019:
| December 31, | ||||||||||||||
| 2020 | 2019 | |||||||||||||
| Percentage change in net operating income over comparable period from prior year | 2.6% | 3.1 | % | |||||||||||
| Percentage change in net operating income (cash basis) over comparable period from prior year | 5.1% | 7.1 | % | |||||||||||
| Operating margin | 73% | 71% | ||||||||||||
| Number of Same Properties | 209 | 192 | ||||||||||||
| RSF | 20,707,818 | 18,519,783 | ||||||||||||
| Occupancy – current-period average | 96.6% | 96.6 | % | |||||||||||
| Occupancy – same-period prior-year average | 96.7% | 96.3 | % |
The following table reconciles the number of Same Properties to total properties for the year ended December 31, 2020:
| Development – under construction | Properties | ||||||||||
| 9804 Medical Center Drive | 1 | ||||||||||
| 9950 Medical Center Drive | 1 | ||||||||||
| Alexandria Center® for Life Science – San Carlos | 2 | ||||||||||
| 3115 Merryfield Row | 1 | ||||||||||
| 201 Haskins Way | 1 | ||||||||||
| 1165 Eastlake Avenue East | 1 | ||||||||||
| 9 Laboratory Drive | 1 | ||||||||||
| Alexandria Center® for Advanced Technologies | 2 | ||||||||||
| 10 | |||||||||||
| Development – placed into service after January 1, 2019 | Properties | ||||||||||
| 399 Binney Street | 1 | ||||||||||
| 279 East Grand Avenue | 1 | ||||||||||
| 188 East Blaine Street | 1 | ||||||||||
| 3 | |||||||||||
| Redevelopment – under construction | Properties | ||||||||||
| 5505 Morehouse Drive | 1 | ||||||||||
| Alexandria Center® – Long Island City | 1 | ||||||||||
| 3160 Porter Drive | 1 | ||||||||||
| The Arsenal on the Charles | 5 | ||||||||||
| 700 Quince Orchard Road | 1 | ||||||||||
| Alexandria Center® for Life Science – Durham | 3 | ||||||||||
| 12 | |||||||||||
| Redevelopment – placed into service after January 1, 2019 | Properties | ||||||||||
| Alexandria PARC | 4 | ||||||||||
| 9877 Waples Street | 1 | ||||||||||
| 681 and 685 Gateway Boulevard | 2 | ||||||||||
| 266 and 275 Second Avenue | 2 | ||||||||||
| 5 Laboratory Drive | 1 | ||||||||||
| 10 | |||||||||||
| Acquisitions after January 1, 2019 | Properties | ||||||||||
| 25, 35, and 45 West Watkins Mill Road | 3 | ||||||||||
| 3170 and 3181 Porter Drive | 2 | ||||||||||
| Shoreway Science Center | 2 | ||||||||||
| 3911, 3931, and 4075 Sorrento Valley Boulevard | 3 | ||||||||||
| 5 Necco Street | 1 | ||||||||||
| 601 Dexter Avenue North | 1 | ||||||||||
| 4224/4242 Campus Point Court and 10210 Campus Point Drive | 3 | ||||||||||
| 3825 and 3875 Fabian Way | 2 | ||||||||||
| SD Tech by Alexandria | 10 | ||||||||||
| The Arsenal on the Charles | 6 | ||||||||||
| 275 Grove Street | 1 | ||||||||||
| 601, 611, and 651 Gateway Boulevard | 3 | ||||||||||
| 3330, 3412, 3450, and 3460 Hillview Avenue | 4 | ||||||||||
| 9605 Medical Center Drive | 1 | ||||||||||
| 987 and 1075 Commercial Street | 2 | ||||||||||
| 4555 Executive Drive | 1 | ||||||||||
| Alexandria Center® for Life Science – Durham | 13 | ||||||||||
| Reservoir Woods | 3 | ||||||||||
| One Upland Road | 1 | ||||||||||
| 830 4th Avenue South | 1 | ||||||||||
| 11255 and 11355 North Torrey Pines Road | 2 | ||||||||||
| 6420 and 6450 Sequence Drive | 2 | ||||||||||
| 380 and 420 E Street | 2 | ||||||||||
| Other | 15 | ||||||||||
| 84 | |||||||||||
| Unconsolidated real estate JV | 6 | ||||||||||
| Properties held for sale | 4 | ||||||||||
| Total properties excluded from Same Properties | 129 | ||||||||||
| Same Properties | 209 | (1) | |||||||||
| Total properties in North America as of December 31, 2020 | 338 | ||||||||||
(1)Includes 9880 Campus Point Drive and 3545 Cray Court. The 9880 Campus Point Drive building was occupied through January 2018 and was placed into service during the three months ended September 30, 2020, and 3545 Cray Court is currently undergoing renovations.
Comparison of results for the year ended December 31, 2020, to the year ended December 31, 2019
The following table presents a comparison of the components of net operating income for our Same Properties and Non-Same Properties for the year ended December 31, 2020, compared to the year ended December 31, 2019. Refer to the “Non-GAAP measures and definitions” section under this Item 7 in this annual report on Form 10-K for definitions of “Tenant recoveries” and “Net operating income” and their reconciliations from the most directly comparable financial measures presented in accordance with GAAP, income from rentals and net income, respectively. We provide a comparison of the results for the year ended December 31, 2019, to the year ended December 31, 2018, including a comparison of the components of net operating income for our Same Properties and Non-Same Properties for the year ended December 31, 2019, compared to the year ended December 31, 2018, within the “Results of operations” section in Item 7 of our annual report on Form 10-K for the year ended December 31, 2019.
For additional discussion related to the COVID-19 pandemic and its impact to us, refer to “The COVID-19 pandemic” section under Item 7 in this annual report on Form 10-K. In addition, refer to “Item 1A. Risk factors” in this annual report on Form 10-K for a discussion about risks that COVID-19 directly or indirectly may pose to our business.
| Year Ended December 31, | |||||||||||||||||||||||||||||
| (Dollars in thousands) | 2020 | 2019 | $ Change | % Change | |||||||||||||||||||||||||
| Income from rentals: | |||||||||||||||||||||||||||||
| Same Properties | $ | 1,031,126 | $ | 1,017,749 | $ | 13,377 | 1.3 | % | |||||||||||||||||||||
| Non-Same Properties(1) | 440,714 | 148,039 | 292,675 | 197.7 | |||||||||||||||||||||||||
| Rental revenues | 1,471,840 | 1,165,788 | 306,052 | 26.3 | |||||||||||||||||||||||||
| Same Properties | 327,815 | 313,705 | 14,110 | 4.5 | |||||||||||||||||||||||||
| Non-Same Properties | 78,553 | 37,371 | 41,182 | 110.2 | |||||||||||||||||||||||||
| Tenant recoveries | 406,368 | 351,076 | 55,292 | 15.7 | |||||||||||||||||||||||||
| Income from rentals | 1,878,208 | 1,516,864 | 361,344 | 23.8 | |||||||||||||||||||||||||
| Same Properties | 368 | 444 | (76) | (17.1) | |||||||||||||||||||||||||
| Non-Same Properties | 7,061 | 13,988 | (6,927) | (49.5) | |||||||||||||||||||||||||
| Other income | 7,429 | 14,432 | (7,003) | (48.5) | |||||||||||||||||||||||||
| Same Properties | 1,359,309 | 1,331,898 | 27,411 | 2.1 | |||||||||||||||||||||||||
| Non-Same Properties | 526,328 | 199,398 | 326,930 | 164.0 | |||||||||||||||||||||||||
| Total revenues | 1,885,637 | 1,531,296 | 354,341 | 23.1 | |||||||||||||||||||||||||
| Same Properties | 373,416 | 370,926 | 2,490 | 0.7 | |||||||||||||||||||||||||
| Non-Same Properties | 156,808 | 74,566 | 82,242 | 110.3 | |||||||||||||||||||||||||
| Rental operations | 530,224 | 445,492 | 84,732 | 19.0 | |||||||||||||||||||||||||
| Same Properties | 985,893 | 960,972 | 24,921 | 2.6 | |||||||||||||||||||||||||
| Non-Same Properties | 369,520 | 124,832 | 244,688 | 196.0 | |||||||||||||||||||||||||
| Net operating income | $ | 1,355,413 | $ | 1,085,804 | $ | 269,609 | 24.8 | % | |||||||||||||||||||||
| Net operating income – Same Properties | $ | 985,893 | $ | 960,972 | $ | 24,921 | 2.6 | % | |||||||||||||||||||||
| Straight-line rent revenue | (67,243) | (84,167) | 16,924 | (20.1) | |||||||||||||||||||||||||
| Amortization of acquired below-market leases | (10,791) | (13,372) | 2,581 | (19.3) | |||||||||||||||||||||||||
| Net operating income – Same Properties (cash basis) | $ | 907,859 | $ | 863,433 | $ | 44,426 | 5.1 | % |
(1)Includes a termination fee recognized during the three months ended September 30, 2020. Refer to “Income from rentals” in Note 5 – “Leases” to our consolidated financial statements under Item 15 in this annual report on Form 10-K for detail.
Income from rentals
Total income from rentals for the year ended December 31, 2020, increased by $361.3 million, or 23.8%, to $1.9 billion, compared to $1.5 billion for the year ended December 31, 2019, as a result of increases in rental revenues and tenant recoveries, as discussed below.
Rental revenues
Total rental revenues for the year ended December 31, 2020, increased by $306.1 million, or 26.3%, to $1.5 billion, compared to $1.2 billion for the year ended December 31, 2019. The increase was primarily due to an increase in rental revenues from our Non-Same Properties aggregating $292.7 million primarily related to 1,008,382 RSF of development and redevelopment projects placed into service subsequent to January 1, 2019, and 84 operating properties aggregating 7.8 million RSF acquired subsequent to January 1, 2019, as well as a termination fee of $89.5 million recognized in connection with the termination of our contract for a future lease at our development project at 88 Bluxome Street in our SoMa submarket during the three months ended September 30, 2020. Our annual rental revenue per RSF was $49.08 as of December 31, 2020 compared to $51.04 as of December 31, 2019. The decrease in our rental revenue per RSF was due to our recent acquisitions of Alexandria Center® for Life Science – Durham in our Research Triangle submarket, and acquisitions made during the three months ended December 31, 2020, including 6420 and 6450 Sequence Drive in our Sorrento Mesa submarket of San Diego, and 380 and 420 E Street in our Seaport Innovation District submarket of Greater Boston. Annual rental rates per RSF in our Research Triangle and Seattle markets, in which most of the operating RSF of the aforementioned acquisitions is concentrated, is generally lower than annual rental rates per RSF in our Greater Boston and San Francisco markets where the majority of our operating RSF is located. Excluding these acquisitions, our annual rental revenue per RSF as of December 31, 2020, would have been $51.26. For the definition of “Annual rental revenue” refer to the “Non-GAAP measures and definitions” section under Item 7 in this annual report on Form 10-K.
Rental revenues from our Same Properties for the year ended December 31, 2020, increased by $13.4 million, or 1.3%, to $1.03 billion, compared to $1.02 billion for the year ended December 31, 2019. The increase was primarily due to rental rate increases on lease renewals and re-leasing of space since January 1, 2019. Refer to the “Leasing activity” section of “Item 2. Properties” within “Part I” in this annual report on Form 10-K for additional details. The increase was partially offset by the effect of reduced revenues generated from our transient parking, retail tenants, and amenities, which had limited operations due to COVID-19 restrictions.
The increase in total rental revenues was also partially offset by a $5.4 million reduction to rental revenues recognized during the year ended December 31, 2020, due to specific write-offs and a general allowance related to deferred rent balances of tenants that are or may potentially be impacted by uncertainties surrounding COVID-19.
Tenant recoveries
Tenant recoveries for the year ended December 31, 2020, increased by $55.3 million, or 15.7%, to $406.4 million, compared to $351.1 million for the year ended December 31, 2019. This increase is consistent with the increase in our rental operating expenses of $84.7 million, or 19.0%, as discussed under “Rental operations” below.
Same Properties’ tenant recoveries for the year ended December 31, 2020, increased by $14.1 million, or 4.5%, to $327.8 million, compared to $313.7 million for the year ended December 31, 2019, primarily due to the increase in property tax expenses resulting from higher assessed values of our properties, higher property insurance, and higher repairs and maintenance expenses during the year ended December 31, 2020, as discussed under “Rental operations” below. As of December 31, 2020, 94% of our leases (on an RSF basis) were triple net leases, which require tenants to pay substantially all real estate taxes, insurance, utilities, repairs and maintenance, common area expenses, and other operating expenses (including increases thereto) in addition to base rent.
Other income
Other income for the years ended December 31, 2020 and 2019, was $7.4 million and $14.4 million, respectively, primarily consisting of construction management fees and interest income earned during each respective period. The decrease was primarily a result of lower construction management fees recognized due to the completion of certain projects.
Rental operations
Total rental operating expenses for the year ended December 31, 2020, increased by $84.7 million, or 19.0%, to $530.2 million, compared to $445.5 million for the year ended December 31, 2019. The increase was primarily due to incremental expenses from our Non-Same Properties, primarily related to 1,008,382 RSF of development and redevelopment projects placed into service subsequent to January 1, 2019, and 84 operating properties aggregating 7.8 million RSF acquired subsequent to January 1, 2019.
Same Properties’ rental operating expenses increased by $2.5 million, or 0.7%, to $373.4 million, compared to $370.9 million for the year ended December 31, 2019. The increase was primarily due to an increase in property tax expenses resulting from higher assessed values of our properties, higher property insurance, and higher repairs and maintenance expenses, which were partially offset by reduced operating expenses related to retail tenants and amenities, which had no or limited operations due to COVID-19 restrictions during the year ended December 31, 2020.
General and administrative expenses
General and administrative expenses for the year ended December 31, 2020, increased by $24.5 million, or 22.5%, to $133.3 million, compared to $108.8 million for the year ended December 31, 2019. Approximately $4.5 million of the increase was the result of the acceleration of stock compensation expense recognized in connection with the resignation of an executive officer during the three months ended September 2020. This former executive officer remains a consultant to the Company. A portion of unvested stock outstanding will continue to vest pursuant to the original terms of the awards. This was deemed a modification for accounting purposes due to a significant reduction in future services to the Company, which resulted in an accelerated vesting and recognition of the fair value of the modified award. The remaining increase was primarily due to continued growth in the depth and breadth of our operations in multiple markets, including development and redevelopment projects placed into service and properties acquired subsequent to January 1, 2019, as discussed under “Income from rentals” above. As a percentage of net operating income, our general and administrative expenses for the years ended December 31, 2020 and 2019, were 9.8% and 10.0%, respectively.
Interest expense
Interest expense for the years ended December 31, 2020 and 2019, consisted of the following (dollars in thousands):
| Year Ended December 31, | ||||||||||||||||||||
| Component | 2020 | 2019 | Change | |||||||||||||||||
| Interest incurred | $ | 297,227 | $ | 262,238 | $ | 34,989 | ||||||||||||||
| Capitalized interest | (125,618) | (88,563) | (37,055) | |||||||||||||||||
| Interest expense | $ | 171,609 | $ | 173,675 | $ | (2,066) | ||||||||||||||
| Average debt balance outstanding(1) | $ | 7,762,498 | $ | 6,416,773 | $ | 1,345,725 | ||||||||||||||
| Weighted-average annual interest rate(2) | 3.8 | % | 4.1 | % | (0.3) | % |
(1)Represents the average debt balance outstanding during the respective periods.
(2)Represents total interest incurred divided by the average debt balance outstanding in the respective periods.
The net change in interest expense during the year ended December 31, 2020, compared to the year ended December 31, 2019, resulted from the following (dollars in thousands):
| Component | Interest Rate(1) | Effective Date | Change | ||||||||||||||||||||||||||
| Increases in interest incurred due to: | |||||||||||||||||||||||||||||
| Issuances of debt: | |||||||||||||||||||||||||||||
| $650 million unsecured senior notes payable – green bond | 4.03 | % | June 2018/ March 2019 | $ | 1,776 | ||||||||||||||||||||||||
| $350 million unsecured senior notes payable – green bond | 3.96 | % | March 2019 | 2,969 | |||||||||||||||||||||||||
| $300 million unsecured senior notes payable | 4.93 | % | March 2019 | 3,236 | |||||||||||||||||||||||||
| $750 million unsecured senior notes payable | 3.48 | % | July 2019 | 13,685 | |||||||||||||||||||||||||
| $700 million unsecured senior notes payable | 3.91 | % | July/September 2019 | 16,572 | |||||||||||||||||||||||||
| $400 million unsecured senior notes payable | 2.87 | % | September 2019 | 7,712 | |||||||||||||||||||||||||
| $700 million unsecured senior notes payable | 5.05 | % | March 2020 | 26,232 | |||||||||||||||||||||||||
| $1.0 billion unsecured senior notes payable | 1.97 | % | August 2020 | 7,661 | |||||||||||||||||||||||||
| Fluctuations in interest rate and average balance: | |||||||||||||||||||||||||||||
| $1.5 billion commercial paper program | 1,778 | ||||||||||||||||||||||||||||
| Other increase in interest | 1,570 | ||||||||||||||||||||||||||||
| Total increases | 83,191 | ||||||||||||||||||||||||||||
| Decreases in interest incurred due to: | |||||||||||||||||||||||||||||
| Repayments of debt: | |||||||||||||||||||||||||||||
| $550 million unsecured senior notes payable | 4.75 | % | July/August 2019 | (14,424) | |||||||||||||||||||||||||
| $400 million unsecured senior notes payable | 2.96 | % | July/August 2019 | (6,257) | |||||||||||||||||||||||||
| $500 million unsecured senior notes payable | 4.04 | % | August/September 2020 | (7,166) | |||||||||||||||||||||||||
| Secured construction loan | 3.29 | % | March 2019 | (1,778) | |||||||||||||||||||||||||
| Unsecured senior bank term loan | Various | Various | (7,335) | ||||||||||||||||||||||||||
| Fluctuations in interest rate and average balance: | |||||||||||||||||||||||||||||
| Unsecured senior line of credit | (11,242) | ||||||||||||||||||||||||||||
| Total decreases | (48,202) | ||||||||||||||||||||||||||||
| Change in interest incurred | 34,989 | ||||||||||||||||||||||||||||
| Increase in capitalized interest | (37,055) | ||||||||||||||||||||||||||||
| Total change in interest expense | $ | (2,066) |
(1)Represents the weighted-average interest rate as of the end of the applicable period, including amortization of loan fees, amortization of debt premiums (discounts), and other bank fees.
In anticipation of LIBOR cessation at the end of 2021, we have been actively reducing LIBOR-based borrowings outstanding on our loans. As of December 31, 2020, the outstanding balance on our unsecured senior line of credit, our only LIBOR-based debt (excluding debt held by our unconsolidated joint ventures), was zero.
Depreciation and amortization
Depreciation and amortization expense for the year ended December 31, 2020, increased by $153.5 million, or 28.2%, to $698.1 million, compared to $544.6 million for the year ended December 31, 2019. The increase was primarily due to additional depreciation from 1,008,382 RSF of development and redevelopment projects placed into service subsequent to January 1, 2019, and 84 operating properties aggregating 7.8 million RSF acquired subsequent to January 1, 2019.
Gain on sales of real estate
During the year ended December 31, 2020, we recognized a gain on sales of real estate aggregating $154.1 million, which primarily consisted of the following:
-
Gain on sale of $151.9 million recognized in connection with the sale of two tech office properties aggregating 443,479 RSF at 510 Townsend Street and 505 Brannan Street in our SoMa submarket. We completed the sale in November 2020 for an aggregate sales price of $560.2 million.
-
Gain on sale of $1.6 million recognized in connection with the sale of 30 Bearfoot Road in our Route 495 submarket. We completed the sale of the real estate asset in August 2020 for a sales price of $3.4 million.
During the year ended December 31, 2019, we recognized a gain on sale of real estate of $474 thousand in connection with the sale of our property at 6138/6150 Nancy Ridge Drive aggregating 56,698 RSF, located in our Sorrento Mesa submarket, which was classified as held for sale during the three months ended June 30, 2019. The gain on sale was recognized in December 2019, upon completion of the sale of the property for a sales price of $6.6 million, or $117 per RSF.
Impairment charges
During the year ended December 31, 2020, we recognized impairment charges aggregating $48.1 million, primarily including:
-
Impairment charges aggregating $15.2 million, which mainly consisted of a $10 million write-off of the pre-acquisition deposit for a previously pending acquisition of an operating tech office property for which our revised economic projections declined from our initial underwriting. We recognized this impairment charge in April 2020 concurrently with the submission of our notice to terminate the transaction.
-
Impairment charge of $13.5 million recognized during the three months ended December 31, 2020, upon classification of our real estate assets located at 260 Townsend Street in our SoMa submarket as held for sale. We expect to sell this real estate asset during 2021.
-
Impairment charge of $11.7 million recognized during the three months ended December 31, 2020, upon classification of our real estate asset located at 220 and 240 2nd Avenue South in our SoDo submarket as held for sale. We expect to sell this real estate asset during 2021.
-
Impairment charge of $6.8 million recognized during the three months ended September 30, 2020, upon classification of our real estate asset located at 945 Market Street in our SoMa submarket as held for sale. In September 2020, we completed the sale of the real estate asset for a sales price of $198.0 million with no gain or loss.
During the three months ended December 31, 2019, we decided to sell two of our real estate assets aggregating 123,862 RSF in non-cluster markets to allow for reinvestment of this capital into our highly leased value-creation pipeline. Upon classification as held for sale, we recognized impairment charges aggregating $12.3 million to lower the carrying amounts of these real estate assets to their respective estimated fair value less cost to sell.
For additional information, refer to Note 18 – “Assets classified as held for sale” to our consolidated financial statements under Item 15 in this annual report on Form 10-K.
Investment income
During the year ended December 31, 2020, we recognized investment income aggregating $421.3 million, which consisted of $47.3 million of realized gains and $374.0 million of unrealized gains. Realized gains primarily consisted of $72.5 million of gains on non-real estate investments, partially offset by realized losses on investments in privately held entities that do not report NAV. Unrealized gains of $374.0 million during the year ended December 31, 2020, primarily consisted of increases in fair values of our investments in publicly traded companies and in privately held entities that report NAV. For more information about our investments, refer to Note 7 – “Investments” to our consolidated financial statements under Item 15 in this annual report on Form 10-K. For our impairments accounting policy, refer to the “Investments” section in Note 2 – “Summary of significant accounting policies” to our consolidated financial statements under Item 15 in this annual report on Form 10-K.
During the year ended December 31, 2019, we recognized investment income aggregating $194.6 million, which consisted of $33.2 million of realized gains and $161.5 million of unrealized gains.
Loss on early extinguishment of debt
During the year ended December 31, 2020, we recognized losses on early extinguishment of debt aggregating $60.7 million, consisting of the following:
-
$50.8 million, including the write-off of unamortized loan fees, related to the refinancing of our 3.90% unsecured senior notes payable due in 2023 aggregating $500.0 million.
-
$7.3 million related to the extinguishment of two secured notes payable in December 2020 aggregating $108.2 million, which were originally due in 2023 and had a weighted-average interest rate of 3.67%. This amount includes a $2.8 million loss on early extinguishment of debt recognized in connection with a legal defeasance that extinguished our secured note payable related to 3545 Cray Court.
-
$1.9 million due to the termination of our $750.0 million unsecured senior line of credit.
-
$651 thousand related to the write-off of unamortized loan fees upon the amendment of our unsecured senior line of credit in October 6, 2020.
For more information about our extinguishment of debt, refer to the “Extinguishment of unsecured senior notes payable, unsecured senior line of credit, and secured notes payable” section in Note 10 – “Secured and unsecured senior debt” to our consolidated financial statements under Item 15 in this annual report on Form 10-K.
During the year ended December 31, 2019, we recognized losses on early extinguishment of debt aggregating $47.6 million, consisting of the following:
-
$40.2 million related to the repayment of the outstanding balance of our unsecured senior bank term loan of $350.0 million and the refinancing of unsecured senior notes payable comprising $400.0 million of 2.75% unsecured senior notes payable due 2020 and $550.0 million of 4.60% unsecured senior notes payable due in 2022.
-
$7.1 million, including the write-off of unamortized loan fees, related to early repayment of one secured note payable aggregating $106.7 million, which was originally due in 2020 and bore interest at 7.75%.
-
$269 thousand related to the early repayment of the remaining $193.1 million balance of our secured construction loan related to 50/60 Binney Street.
Equity in earnings of unconsolidated real estate joint ventures
During the year ended December 31, 2020, we recognized equity in earnings of unconsolidated real estate joint ventures of $8.1 million. This balance consisted of earnings from our unconsolidated real estate joint ventures of approximately $15.8 million, partially offset by the impairment charge discussed below.
In March 2020, the impact of COVID-19 pandemic and the resulting State of Maryland’s shelter-in-place order led to the closure of a retail center owned by one of our unconsolidated joint ventures. We evaluated the recoverability of our investment in this joint venture and recognized a $7.6 million impairment charge to lower the carrying amount of our investment balance, which primarily consisted of real estate, to its estimated fair value less costs to sell. This impairment charge was classified in equity in earnings of unconsolidated real estate joint ventures within our consolidated statements of operations for the year ended December 31, 2020. Refer to Note 4 – “Consolidated and unconsolidated real estate joint ventures” to our consolidated financial statements under Item 15 in this annual report on Form 10-K for additional information.
During the year ended December 31, 2019, we recognized equity in earnings of unconsolidated real estate joint ventures of $10.1 million, which consisted primarily of earnings recognized due to the delivery of our development project at Menlo Gateway in our Greater Stanford submarket during the three months ended September 30, 2019.
Preferred stock redemption charge
During the year ended December 31, 2019, we repurchased, in privately negotiated transactions, 275,000 outstanding shares of our 7.00% Series D cumulative convertible preferred stock and recognized a preferred stock redemption charge of $2.6 million. As of December 31, 2019 and 2020, we had no outstanding shares of preferred stock.
Other comprehensive income
Total other comprehensive income for the year ended December 31, 2020, increased by $2.4 million to aggregate net unrealized gains of $3.1 million, compared to net unrealized gains of $686 thousand for the year ended December 31, 2019, primarily due to the unrealized gains (losses) on foreign currency translation related to our operations in Canada and China.
Projected results
Based on our current view of existing market conditions and certain current assumptions, we present guidance for EPS attributable to Alexandria’s common stockholders – diluted and funds from operations per share attributable to Alexandria’s common stockholders – diluted for the year ending December 31, 2021, as set forth in the table below. The tables below also provide a reconciliation of EPS attributable to Alexandria’s common stockholders – diluted, the most directly comparable financial measure presented in accordance with GAAP, to funds from operations per share, a non-GAAP measure, and other key assumptions included in our updated guidance for the year ending December 31, 2021. There can be no assurance that actual amounts will be materially higher or lower than these expectations. Refer to our discussion of “Forward-looking statements” in this annual report on Form 10-K.
| Projected 2021 Earnings per Share and Funds From Operations per Share Attributable to Alexandria’s Common Stockholders – Diluted | ||||||||||||||
| Earnings per share(1) | $2.14 to $2.34 | |||||||||||||
| Depreciation and amortization of real estate assets | 5.50 | |||||||||||||
| Allocation of unvested restricted stock awards | (0.04) | |||||||||||||
| Funds from operations per share(2) | $7.60 to $7.80 | |||||||||||||
| Midpoint | $7.70 | |||||||||||||
(1)Excludes unrealized gains or losses after December 31, 2020, that are required to be recognized in earnings and are excluded from funds from operations per share, as adjusted.
(2)Calculated in accordance with standards established by the Advisory Board of Governors of Nareit (the “Nareit Board of Governors”). Refer to the definition of “Funds from operations and funds from operations, as adjusted, attributable to Alexandria Real Estate Equities, Inc.’s common stockholders” in the “Non-GAAP measures and definitions” section under this Item 7 in this annual report on Form 10-K for additional information.
| Key Assumptions(1) (Dollars in millions) | 2021 Guidance | ||||||||||||||||
| Low | High | ||||||||||||||||
| Occupancy percentage for operating properties in North America as of December 31, 2021 | 95.6% | 96.2% | |||||||||||||||
| Lease renewals and re-leasing of space: | |||||||||||||||||
| Rental rate increases | 29.0% | 32.0% | |||||||||||||||
| Rental rate increases (cash basis) | 16.0% | 19.0% | |||||||||||||||
| Same property performance: | |||||||||||||||||
| Net operating income increase | 1.0% | 3.0% | |||||||||||||||
| Net operating income increase (cash basis) | 4.0% | 6.0% | |||||||||||||||
| Straight-line rent revenue | $ | 114 | $ | 124 | |||||||||||||
| General and administrative expenses | $ | 146 | $ | 151 | |||||||||||||
| Capitalization of interest | $ | 167 | $ | 177 | |||||||||||||
| Interest expense | $ | 133 | $ | 143 | |||||||||||||
(1)Our assumptions presented in the table above are subject to a number of variables and uncertainties, including those discussed as “Forward-looking statements” under “Part I”; “Item 1A. Risk factors”; and “Item 7. Management’s discussion and analysis of financial condition and results of operations” in this annual report on Form 10-K. To the extent our full-year earnings guidance is updated during the year, we will provide additional disclosure supporting reasons for any significant changes to such guidance.
| Key Credit Metrics | 2021 Guidance | ||||||||||
| Net debt and preferred stock to Adjusted EBITDA – fourth quarter of 2021, annualized | Less than or equal to 5.2x | ||||||||||
| Fixed-charge coverage ratio – fourth quarter of 2021, annualized | Greater than or equal to 4.5x | ||||||||||
Consolidated and unconsolidated real estate joint ventures
We present components of balance sheet and operating results information for the noncontrolling interest share of our consolidated real estate joint ventures and for our share of investments in unconsolidated real estate joint ventures to help investors estimate balance sheet and operating results information related to our partially owned entities. These amounts are estimated by computing, for each joint venture that we consolidate in our financial statements, the noncontrolling interest percentage of each financial item to arrive at the cumulative noncontrolling interest share of each component presented. In addition, for our real estate joint ventures that we do not control and do not consolidate, we apply our economic ownership percentage to the unconsolidated real estate joint ventures to arrive at our proportionate share of each component presented. Refer to Note 4 – “Consolidated and unconsolidated real estate joint ventures” to our consolidated financial statements under Item 15 in this annual report on Form 10-K for further discussion.
| Consolidated Real Estate Joint Ventures | ||||||||||||||||||||||||||
| Property/Market/Submarket | Noncontrolling(1) Interest Share | Operating RSF at 100% | ||||||||||||||||||||||||
| 225 Binney Street/Greater Boston/Cambridge/Inner Suburbs | 70.0 | % | 305,212 | |||||||||||||||||||||||
| 75/125 Binney Street/Greater Boston/Cambridge/Inner Suburbs | 60.0 | % | 388,270 | |||||||||||||||||||||||
| 57 Coolidge Avenue/Greater Boston/Cambridge/Inner Suburbs | 25.0 | % | — | (2) | ||||||||||||||||||||||
| 409 and 499 Illinois Street/San Francisco/Mission Bay | 40.0 | % | 455,069 | |||||||||||||||||||||||
| 1500 Owens Street/San Francisco/Mission Bay | 49.9 | % | 158,267 | |||||||||||||||||||||||
| Alexandria Technology Center® – Gateway/San Francisco/South San Francisco(3) | 54.9 | % | 1,089,265 | |||||||||||||||||||||||
| 500 Forbes Boulevard/San Francisco/South San Francisco | 90.0 | % | 155,685 | |||||||||||||||||||||||
| Alexandria Point/San Diego/University Town Center(4) | 45.0 | % | 1,337,916 | |||||||||||||||||||||||
| 5200 Illumina Way/San Diego/University Town Center | 49.0 | % | 792,687 | |||||||||||||||||||||||
| 9625 Towne Centre Drive/San Diego/University Town Center | 49.9 | % | 163,648 | |||||||||||||||||||||||
| SD Tech by Alexandria/San Diego/Sorrento Mesa(5) | 50.0 | % | 677,597 | |||||||||||||||||||||||
| The Eastlake Life Science Campus by Alexandria/Seattle/Lake Union(6) | 70.0 | % | 321,218 | |||||||||||||||||||||||
| Unconsolidated Real Estate Joint Ventures | ||||||||||||||||||||||||||
| Property/Market/Submarket | Our Ownership Share(7) | Operating RSF at 100% | ||||||||||||||||||||||||
| 1655 and 1725 Third Street/San Francisco/Mission Bay | 10.0 | % | 586,208 | |||||||||||||||||||||||
| Menlo Gateway/San Francisco/Greater Stanford | 49.0 | % | 772,983 | |||||||||||||||||||||||
| 704 Quince Orchard Road/Maryland/Gaithersburg | 56.8 | % | (8) | 80,032 | ||||||||||||||||||||||
(1)In addition to the consolidated real estate joint ventures listed, various partners hold insignificant noncontrolling interests in five other joint ventures in North America.
(2)We expect to commence vertical construction of 275,000 RSF during 2021.
(3)Excludes 600, 630, 650, 901, and 951 Gateway Boulevard in our South San Francisco submarket. Noncontrolling interest share is anticipated to be 49% as we make further contributions over time.
(4)Excludes 9880 Campus Point Drive in our University Town Center submarket.
(5)Excludes 5505 Morehouse Drive and 10121 and 10151 Barnes Canyon Road in our Sorrento Mesa submarket.
(6)Excludes 1165, 1616, and 1551 Eastlake Avenue East, 188 East Blaine Street, and 1600 Fairview Avenue East in our Lake Union submarket.
(7)In addition to the unconsolidated real estate joint ventures listed, we hold an interest in two other insignificant unconsolidated real estate joint ventures in North America.
(8)Represents our ownership interest; our voting interest is limited to 50%.
Our unconsolidated real estate joint ventures have the following secured loans that include the following key terms as of December 31, 2020 (dollars in thousands):
| Unconsolidated Joint Venture | Our Share | Maturity Date | Stated Rate | Interest Rate(1) | Debt Balance at 100%(2) | ||||||||||||||||||||||||||||||||||||||||||
| 704 Quince Orchard Road | 56.8% | 3/16/23 | L+1.95% | 3.22% | (3) | $ | 12,660 | ||||||||||||||||||||||||||||||||||||||||
| 1655 and 1725 Third Street | 10.0% | 3/10/25 | 4.50% | 4.57% | 598,232 | ||||||||||||||||||||||||||||||||||||||||||
| Menlo Gateway, Phase II | 49.0% | 5/1/35 | 4.53% | 4.59% | 155,942 | ||||||||||||||||||||||||||||||||||||||||||
| Menlo Gateway, Phase I | 49.0% | 8/10/35 | 4.15% | 4.18% | 139,558 | ||||||||||||||||||||||||||||||||||||||||||
| $ | 906,392 |
(1)Includes interest expense and amortization of loan fees.
(2)Represents outstanding principal, net of unamortized deferred financing costs, as of December 31, 2020.
(3)Includes a 1.00% LIBOR floor on the interest rate.
The following tables present information related to the operating results and financial positions of our consolidated and unconsolidated real estate joint ventures (in thousands):
| Noncontrolling Interest Share of Consolidated Real Estate Joint Ventures | Our Share of Unconsolidated Real Estate Joint Ventures | ||||||||||||||||||||||
| December 31, 2020 | December 31, 2020 | ||||||||||||||||||||||
| Three Months Ended | Year Ended | Three Months Ended | Year Ended | ||||||||||||||||||||
| Total revenues | $ | 42,203 | $ | 160,676 | $ | 10,474 | $ | 41,638 | |||||||||||||||
| Rental operations | (11,622) | (42,930) | (1,679) | (5,932) | |||||||||||||||||||
| 30,581 | 117,746 | 8,795 | 35,706 | ||||||||||||||||||||
| General and administrative | (120) | (504) | (29) | (217) | |||||||||||||||||||
| Interest | — | — | (2,197) | (8,284) | |||||||||||||||||||
| Depreciation and amortization | (15,032) | (61,933) | (2,976) | (11,413) | |||||||||||||||||||
| Impairment of real estate | — | — | — | (7,644) | |||||||||||||||||||
| Fixed returns allocated to redeemable noncontrolling interests(1) | 220 | 903 | — | — | |||||||||||||||||||
| $ | 15,649 | $ | 56,212 | $ | 3,593 | $ | 8,148 | ||||||||||||||||
| Straight-line rent and below-market lease revenue | $ | 1,055 | $ | 5,341 | $ | 3,946 | $ | 21,210 | |||||||||||||||
| Funds from operations(2) | $ | 30,681 | $ | 118,145 | $ | 6,569 | $ | 27,205 |
(1)Represents an allocation of joint venture earnings to redeemable noncontrolling interests primarily in one property in our South San Francisco submarket. These redeemable noncontrolling interests earn a fixed return on their investment rather than participate in the operating results of the property.
(2)Refer to the definition of “Funds from operations and funds from operations, as adjusted, attributable to Alexandria Real Estate Equities, Inc.’s common stockholders” in the “Non-GAAP measures and definitions” section under this Item 7 in this annual report on Form 10-K for the definition and the reconciliation from the most directly comparable financial measure presented in accordance with GAAP.
| December 31, 2020 | ||||||||||||||
| Noncontrolling Interest Share of Consolidated Real Estate Joint Ventures | Our Share of Unconsolidated Real Estate Joint Ventures | |||||||||||||
| Investments in real estate | $ | 1,568,665 | $ | 457,672 | ||||||||||
| Cash, cash equivalents, and restricted cash | 49,633 | 32,981 | ||||||||||||
| Other assets | 179,699 | 59,342 | ||||||||||||
| Secured notes payable | — | (210,201) | ||||||||||||
| Other liabilities | (79,931) | (7,445) | ||||||||||||
| Redeemable noncontrolling interests | (11,342) | — | ||||||||||||
| $ | 1,706,724 | $ | 332,349 |
During the years ended December 31, 2020 and 2019, our consolidated real estate joint ventures distributed an aggregate of $87.3 million and $48.2 million, respectively, to our joint venture partners. Refer to our consolidated statements of cash flows and Note 4 – “Consolidated and unconsolidated real estate joint ventures” to our consolidated financial statements under Item 15 in this annual report on Form 10-K for additional information.
Liquidity
| Liquidity | Minimal Outstanding Borrowings and Significant Availability on Unsecured Senior Line of Credit | |||||||||||||||||||
| (in millions) | ||||||||||||||||||||
| $4.1B | 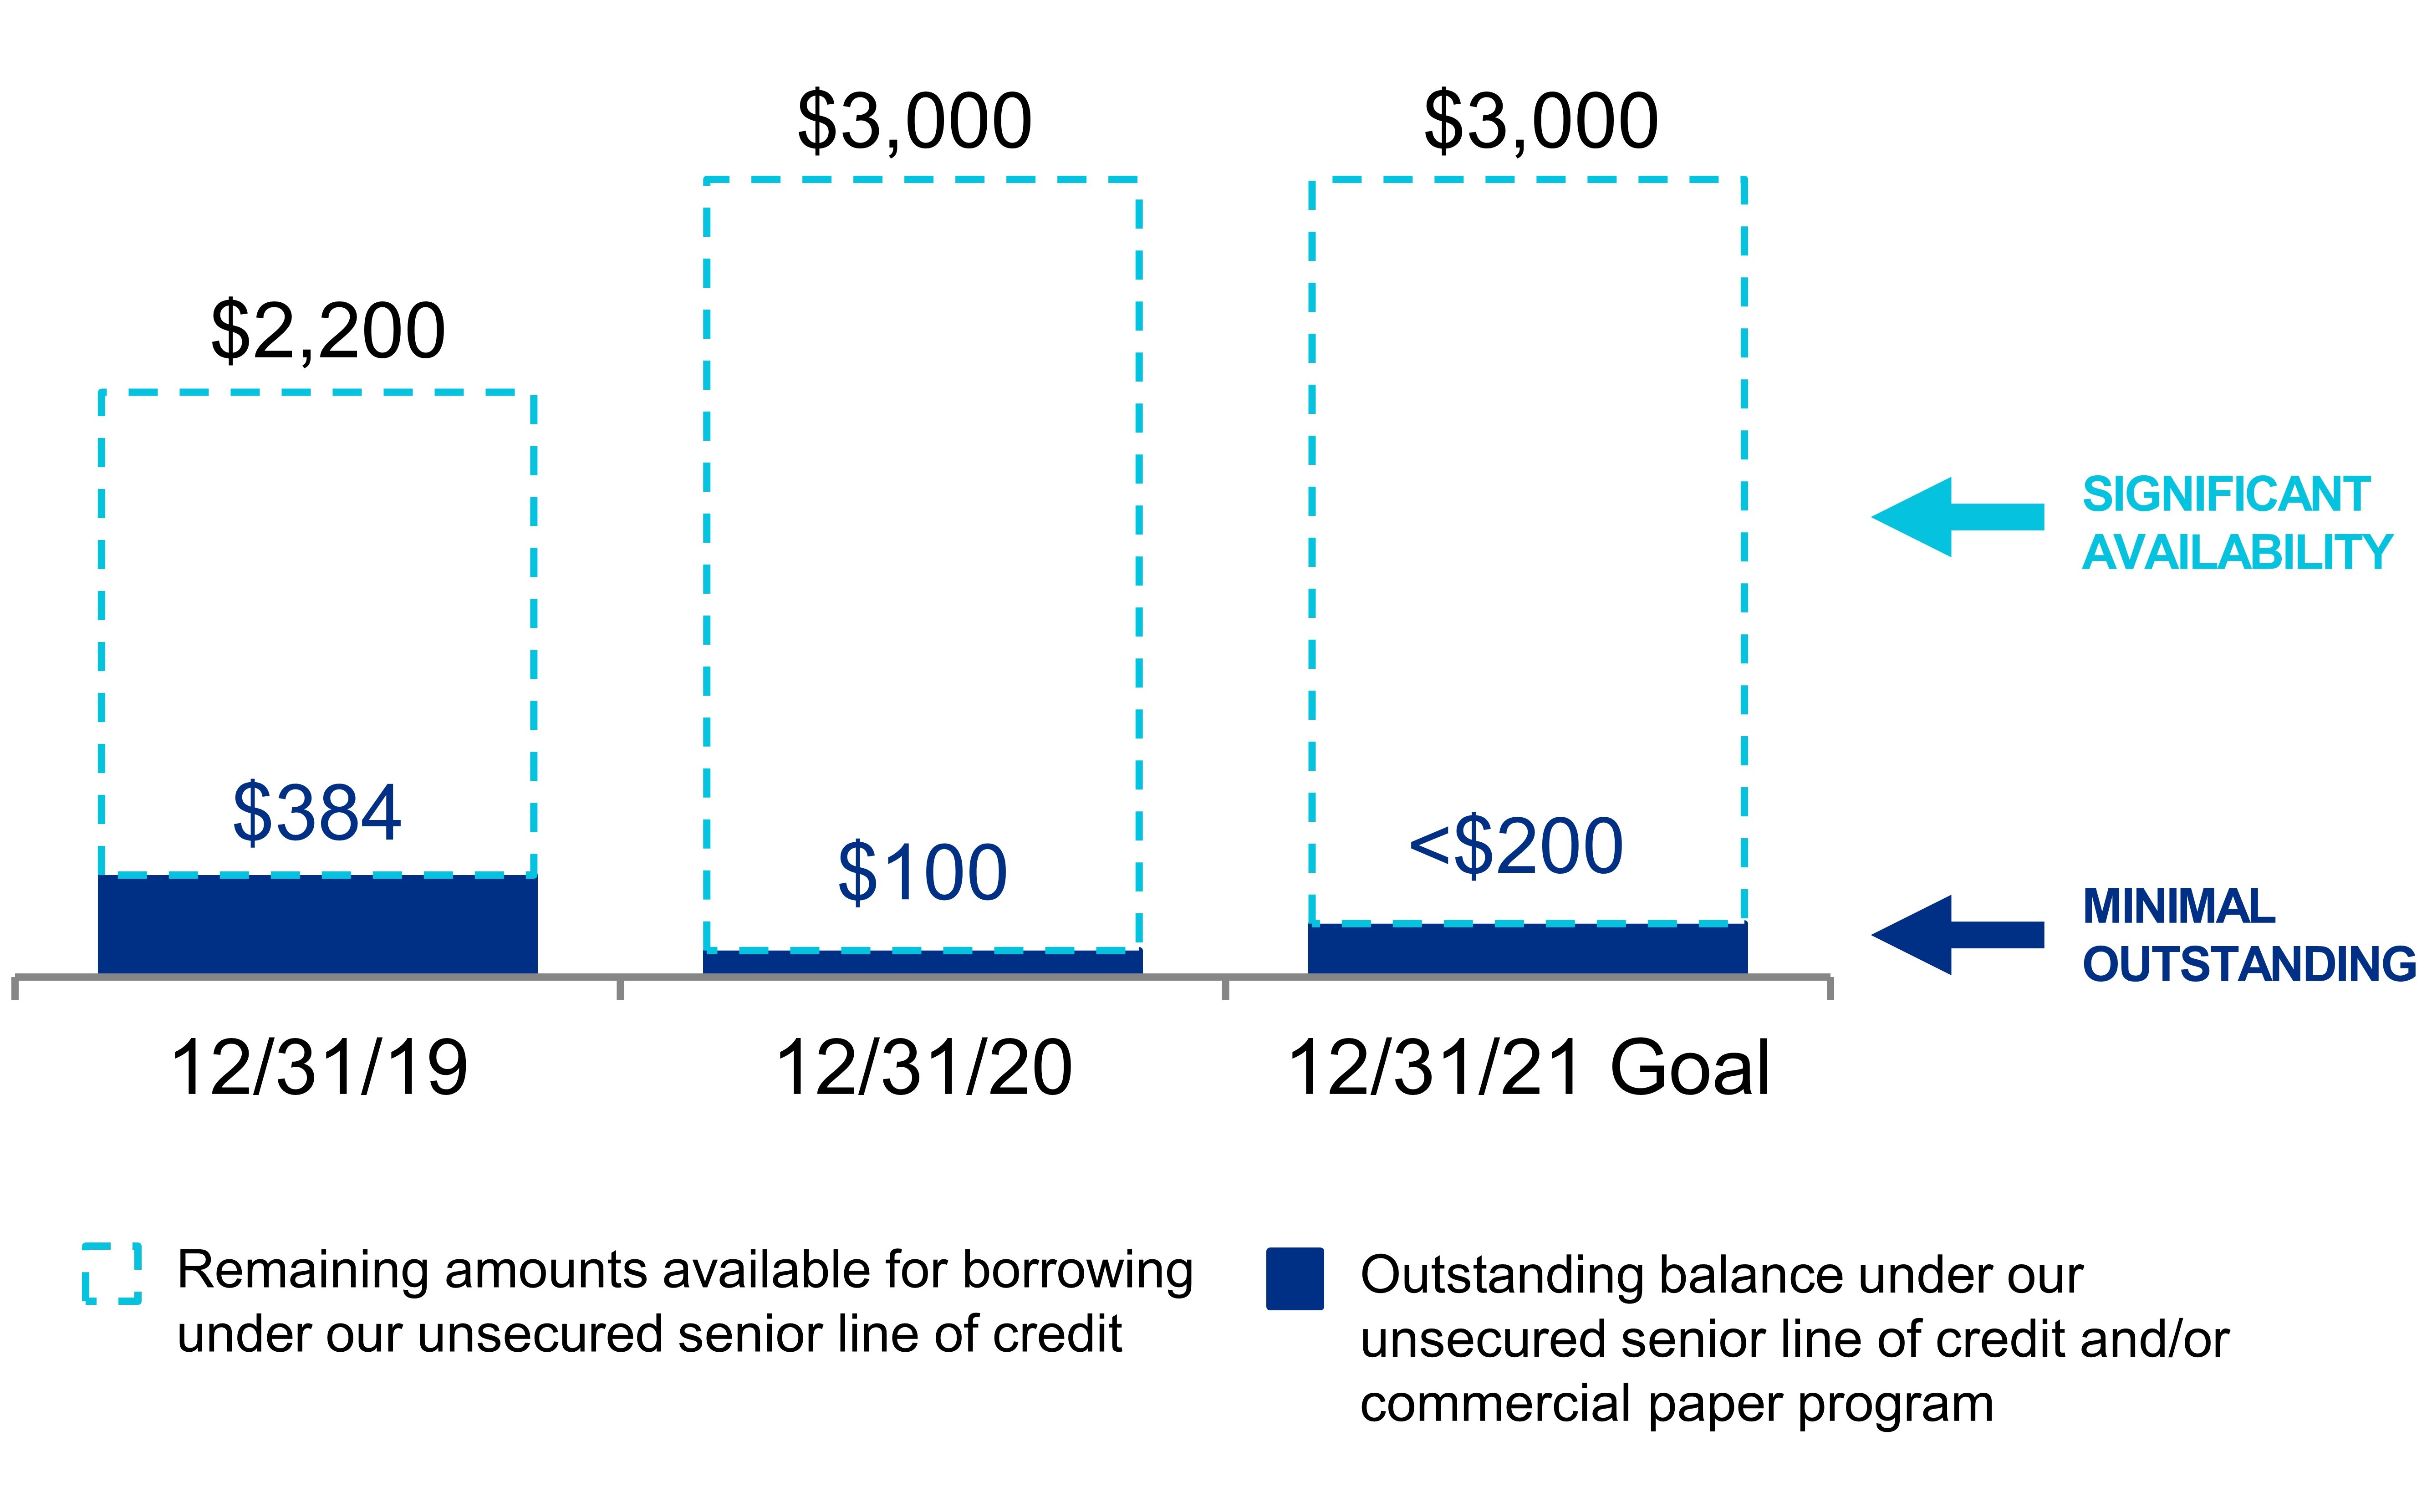 | |||||||||||||||||||
| (In millions) | ||||||||||||||||||||
| Availability under our unsecured senior line of credit, net of amounts outstanding under our commercial paper program | $ | 2,900 | ||||||||||||||||||
| Outstanding forward equity sales agreements(1) | 56 | |||||||||||||||||||
| Cash, cash equivalents, and restricted cash | 598 | |||||||||||||||||||
| Investments in publicly traded companies | 560 | |||||||||||||||||||
| Liquidity as of December 31, 2020 | $ | 4,114 | ||||||||||||||||||
| Net Debt and Preferred Stock to Adjusted EBITDA**(2)** | Fixed-Charge Coverage Ratio**(2)** | |||||||||||||||||||
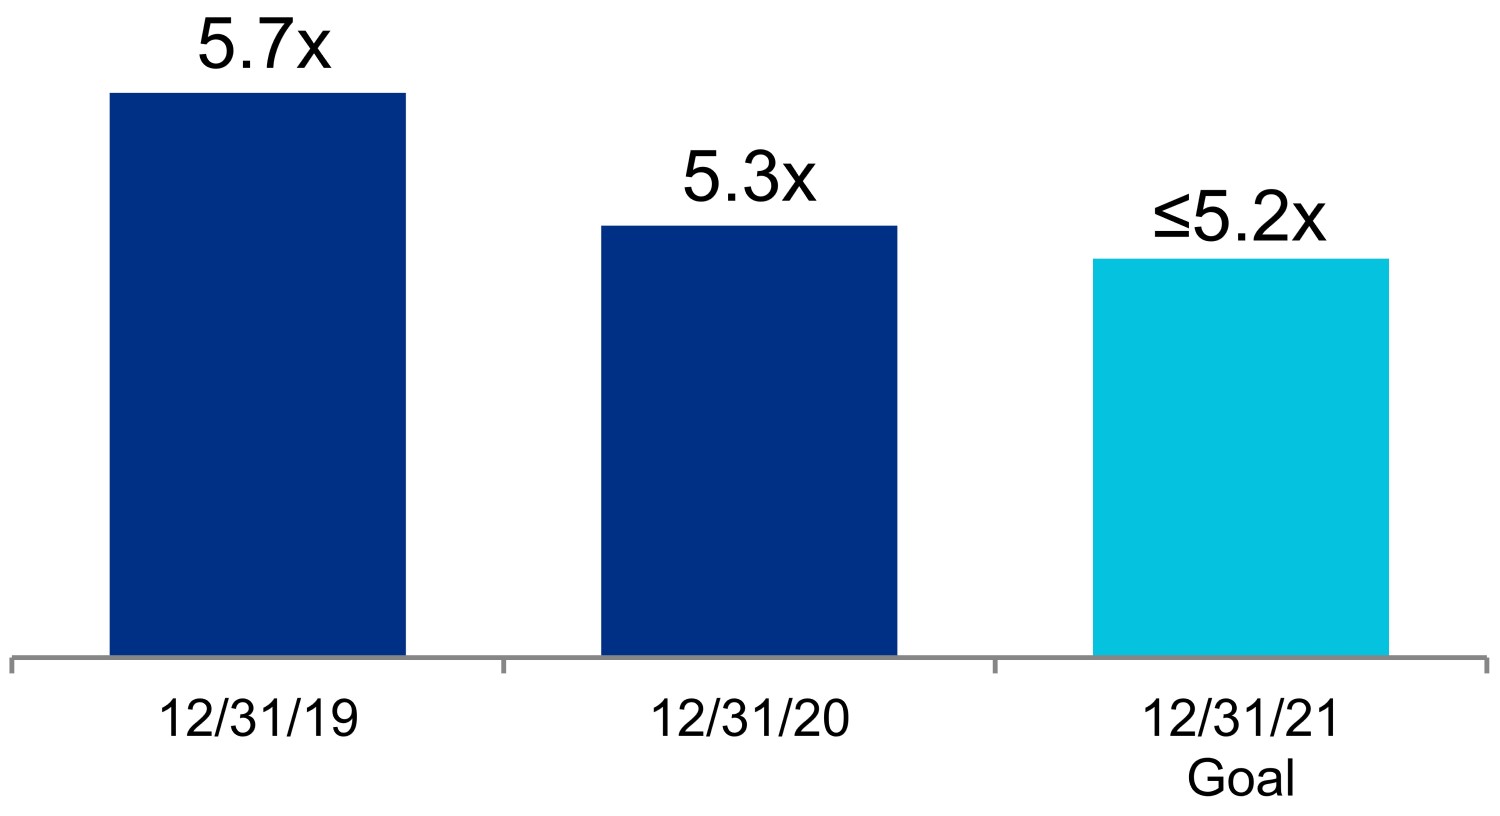 | 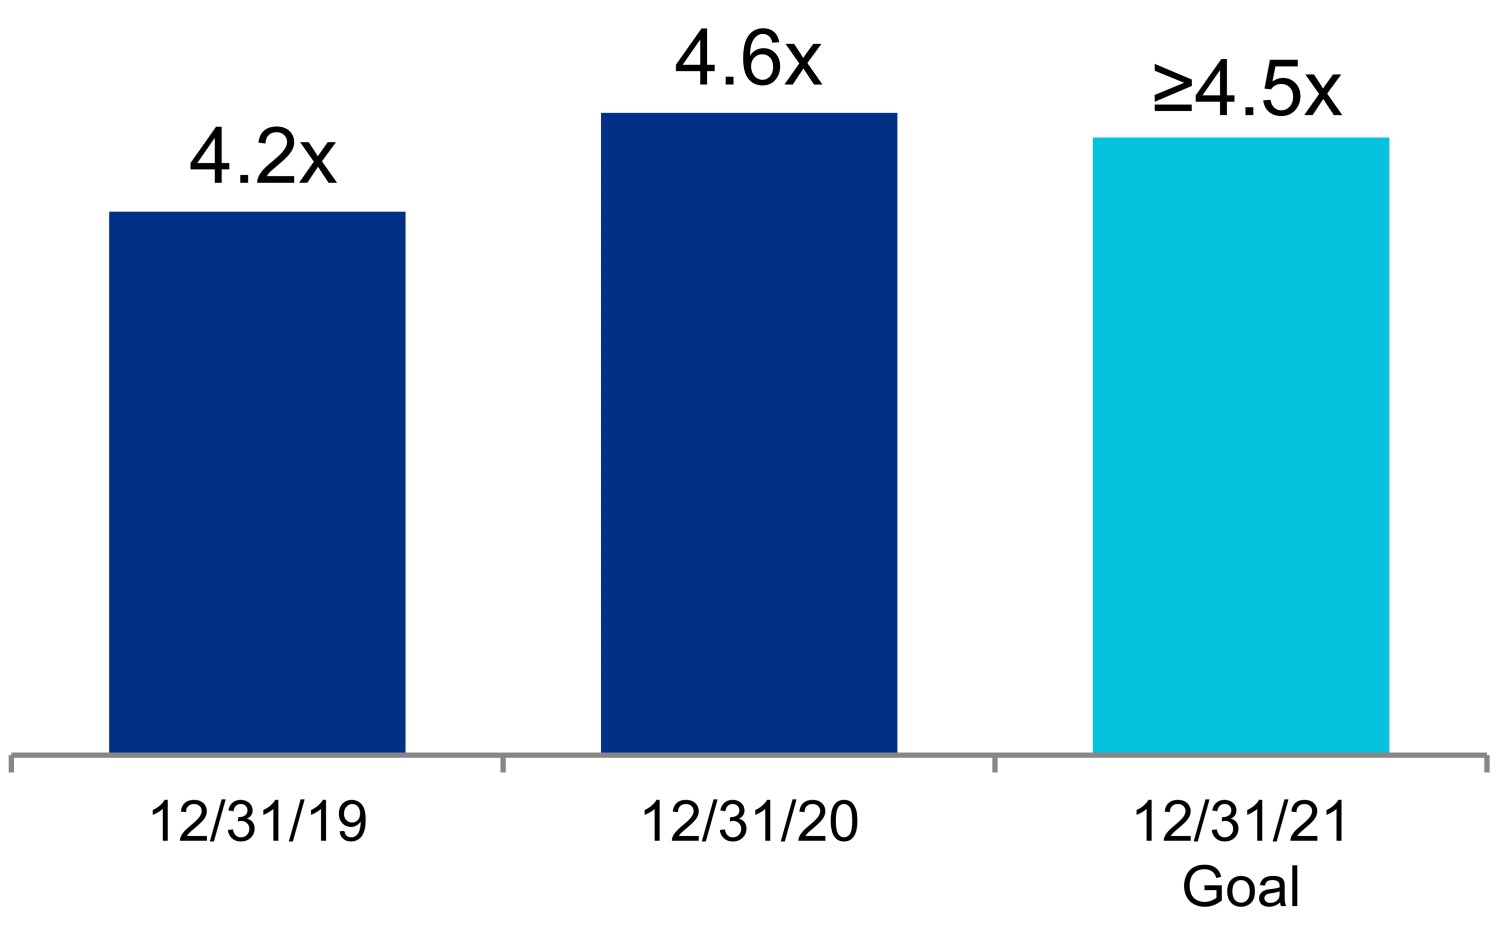 | |||||||||||||||||||
(1)Represents expected net proceeds from the future settlement of the remaining 362 thousand shares outstanding under our forward equity sales agreements as of December 31, 2020. Excludes forward equity sales agreements aggregating $1.1 billion entered into in January 2021.
(2)Quarter annualized.
We expect to meet certain long-term liquidity requirements, such as requirements for development, redevelopment, other construction projects, capital improvements, tenant improvements, property acquisitions, leasing costs, non-revenue-enhancing capital expenditures, scheduled debt maturities, distributions to noncontrolling interests, and payment of dividends through net cash provided by operating activities, periodic asset sales, strategic real estate joint venture capital, and long-term secured and unsecured indebtedness, including borrowings under our unsecured senior line of credit, issuances under our commercial paper program, and issuances of additional debt and/or equity securities.
We expect to continue meeting our short-term liquidity and capital requirements, as further detailed in this section, generally through our working capital and net cash provided by operating activities. We believe that the net cash provided by operating activities will continue to be sufficient to enable us to make the distributions necessary to continue qualifying as a REIT.
Over the next several years, our balance sheet, capital structure, and liquidity objectives are as follows:
-
Retain positive cash flows from operating activities after payment of dividends and distributions to noncontrolling interests for investment in development and redevelopment projects and/or acquisitions;
-
Improve credit profile and relative long-term cost of capital;
-
Maintain diverse sources of capital, including sources from net cash provided by operating activities, unsecured debt, secured debt, selective real estate asset sales, partial interest sales, non-real estate investment sales, preferred stock, and common stock;
-
Maintain commitment to long-term capital to fund growth;
-
Maintain prudent laddering of debt maturities;
-
Maintain solid credit metrics;
-
Maintain significant balance sheet liquidity;
-
Mitigate variable-rate debt exposure through the reduction of short-term and medium-term variable-rate bank debt;
-
Maintain a large unencumbered asset pool to provide financial flexibility;
-
Fund common stock dividends and distributions to noncontrolling interests from net cash provided by operating activities;
-
Manage a disciplined level of value-creation projects as a percentage of our gross investments in real estate; and
-
Maintain high levels of pre-leasing and percentage leased in value-creation projects.
In addition, refer to “Item 1A. Risk factors” in this annual report on Form 10-K for a discussion about risks that COVID-19 directly or indirectly may pose to our business.
The following table presents the availability under our unsecured senior line of credit less amounts outstanding under our commercial paper program; outstanding forward equity sales agreements; cash, cash equivalents, and restricted cash; and investments in publicly traded companies as of December 31, 2020 (dollars in thousands):
| Description | Stated Rate | Aggregate Commitments | Outstanding Balance under our Commercial Paper Program | Remaining Commitments/Liquidity | ||||||||||||||||||||||
| Availability under our unsecured senior line of credit | L+0.825% | $ | 3,000,000 | $ | 99,991 | $ | 2,900,000 | |||||||||||||||||||
| Outstanding forward equity sales agreements | 56,291 | |||||||||||||||||||||||||
| Cash, cash equivalents, and restricted cash | 597,705 | |||||||||||||||||||||||||
| Investments in publicly traded companies | 559,830 | |||||||||||||||||||||||||
| Total liquidity | $ | 4,113,826 |
Cash, cash equivalents, and restricted cash
As of December 31, 2020 and 2019, we had $597.7 million and $242.7 million, respectively, of cash, cash equivalents, and restricted cash. We expect existing cash, cash equivalents, and restricted cash, net cash from operating activities, proceeds from real estate asset sales and partial interest sales, non-real estate investment sales, borrowings under our unsecured senior line of credit, issuances under our commercial paper program, issuances of unsecured notes payable, and issuances of common stock to continue to be sufficient to fund our operating activities and cash commitments for investing and financing activities, such as regular quarterly dividends, distributions to noncontrolling interests, scheduled debt repayments, acquisitions, and certain capital expenditures, including expenditures related to construction activities.
Cash flows
We report and analyze our cash flows based on operating activities, investing activities, and financing activities. The following table summarizes changes in our cash flows for the years ended December 31, 2020 and 2019 (in thousands):
| Year Ended December 31, | |||||||||||||||||
| 2020 | 2019 | Change | |||||||||||||||
| Net cash provided by operating activities | $ | 882,510 | $ | 683,857 | $ | 198,653 | |||||||||||
| Net cash used in investing activities | $ | (3,278,161) | $ | (3,641,320) | $ | 363,159 | |||||||||||
| Net cash provided by financing activities | $ | 2,750,356 | $ | 2,927,482 | $ | (177,126) |
Operating activities
Cash flows provided by operating activities are primarily dependent upon the occupancy level of our asset base, the rental rates of our leases, the collectibility of rent and recovery of operating expenses from our tenants, the timing of completion of development and redevelopment projects, and the timing of acquisitions and dispositions of operating properties. Net cash provided by operating activities for the year ended December 31, 2020, increased to $882.5 million, compared to $683.9 million for the year ended December 31, 2019. This increase was primarily attributable to (i) cash flows generated from our highly leased development and redevelopment projects recently placed into service, (ii) income-producing acquisitions since January 1, 2019, and (iii) increases in rental rates on lease renewals and re-leasing of space since January 1, 2019.
Investing activities
Cash used in investing activities for the years ended December 31, 2020 and 2019, consisted of the following (in thousands):
| Year Ended December 31, | |||||||||||||||||
| 2020 | 2019 | Increase (Decrease) | |||||||||||||||
| Sources of cash from investing activities: | |||||||||||||||||
| Sales of non-real estate investments | $ | 141,149 | $ | 147,332 | $ | (6,183) | |||||||||||
| Proceeds from sales of real estate | 747,020 | 6,619 | 740,401 | ||||||||||||||
| Return of capital from unconsolidated real estate joint ventures | 20,225 | 14 | 20,211 | ||||||||||||||
| Change in escrow deposits | 7,408 | — | 7,408 | ||||||||||||||
| 915,802 | 153,965 | 761,837 | |||||||||||||||
| Uses of cash for investing activities: | |||||||||||||||||
| Purchases of real estate | 2,570,693 | 2,259,778 | 310,915 | ||||||||||||||
| Additions to real estate | 1,445,171 | 1,224,541 | 220,630 | ||||||||||||||
| Investments in unconsolidated real estate joint ventures | 3,444 | 102,081 | (98,637) | ||||||||||||||
| Change in escrow deposits | — | 18,107 | (18,107) | ||||||||||||||
| Additions to non-real estate investments | 174,655 | 190,778 | (16,123) | ||||||||||||||
| 4,193,963 | 3,795,285 | 398,678 | |||||||||||||||
| Net cash used in investing activities | $ | 3,278,161 | $ | 3,641,320 | $ | (363,159) |
The decrease in net cash used in investing activities for the year ended December 31, 2020, was primarily due to an increased source of cash from proceeds from sales of real estate, partially offset by cash used in purchases of real estate and additions to real estate. Refer to Note 3 – “Investments in real estate” to our consolidated financial statements under Item 15 in this annual report on Form 10-K for further information.
Financing activities
Cash flows provided by financing activities for the years ended December 31, 2020 and 2019, consisted of the following (in thousands):
| Year Ended December 31, | |||||||||||||||||
| 2020 | 2019 | Change | |||||||||||||||
| Repayments of borrowings from secured notes payable | $ | (84,104) | $ | (306,199) | $ | 222,095 | |||||||||||
| Payment for the defeasance of secured note payable | (32,865) | — | (32,865) | ||||||||||||||
| Proceeds from issuance of unsecured senior notes payable | 1,697,651 | 2,721,169 | (1,023,518) | ||||||||||||||
| Repayments of unsecured senior notes payable | (500,000) | (950,000) | 450,000 | ||||||||||||||
| Borrowings from unsecured senior line of credit | 2,700,000 | 5,056,000 | (2,356,000) | ||||||||||||||
| Repayments of borrowings from unsecured senior line of credit | (3,084,000) | (4,880,000) | 1,796,000 | ||||||||||||||
| Repayments of borrowings from unsecured senior bank term loan | — | (350,000) | 350,000 | ||||||||||||||
| Premium paid for early extinguishment of debt | (54,385) | (41,351) | (13,034) | ||||||||||||||
| Proceeds from issuance under commercial paper program | 23,539,400 | 2,233,000 | 21,306,400 | ||||||||||||||
| Repayments of borrowings from commercial paper program | (23,439,400) | (2,233,000) | (21,206,400) | ||||||||||||||
| Payments of loan fees | (32,309) | (27,182) | (5,127) | ||||||||||||||
| Changes related to debt | 709,988 | 1,222,437 | (512,449) | ||||||||||||||
| Contributions from and sales of noncontrolling interests | 367,613 | 1,022,712 | (655,099) | ||||||||||||||
| Distributions to and purchases of noncontrolling interests | (88,805) | (48,225) | (40,580) | ||||||||||||||
| Proceeds from the issuance of common stock | 2,315,862 | 1,216,445 | 1,099,417 | ||||||||||||||
| Dividend payments | (532,980) | (451,170) | (81,810) | ||||||||||||||
| Taxes paid related to net settlement of equity awards | (21,322) | (25,477) | 4,155 | ||||||||||||||
| Repurchase of 7.00% Series D cumulative convertible preferred stock | — | (9,240) | 9,240 | ||||||||||||||
| Net cash provided by financing activities | $ | 2,750,356 | $ | 2,927,482 | $ | (177,126) |
Inflation
As of December 31, 2020, approximately 94% of our leases (on an RSF basis) were triple net leases, which require tenants to pay substantially all real estate taxes, insurance, utilities, repairs and maintenance, common area expenses, and other operating expenses (including increases thereto) in addition to base rent. Approximately 94% of our leases (on an RSF basis) contained effective annual rent escalations that were either fixed (generally ranging from 3.0% to 3.5%) or indexed based on a consumer price index or other indices. Accordingly, we do not believe that our cash flows or earnings from real estate operations are subject to significant risks from inflation. A period of inflation, however, could cause an increase in the cost of our variable-rate borrowings, including borrowings related to our unsecured senior line of credit and secured construction loans held by our unconsolidated joint ventures.
Capital resources
We expect that our principal liquidity needs for the year ending December 31, 2021, will be satisfied by the following multiple sources of capital, as shown in the table below. There can be no assurance that our sources and uses of capital will not be materially higher or lower than these expectations.
| Key Sources and Uses of Capital (In millions) | 2021 Guidance | Certain Completed Items | |||||||||||||||||||||||||||
| Range | Midpoint | ||||||||||||||||||||||||||||
| Sources of capital: | |||||||||||||||||||||||||||||
| Net cash provided by operating activities after dividends | $ | 210 | $ | 250 | $ | 230 | |||||||||||||||||||||||
| Incremental debt | 730 | 740 | 735 | ||||||||||||||||||||||||||
| 2020 debt capital proceeds held in cash | 150 | 250 | 200 | ||||||||||||||||||||||||||
| Real estate dispositions and partial interest sales(1) | 1,250 | 1,500 | 1,375 | ||||||||||||||||||||||||||
| Common equity | 1,700 | 2,100 | 1,900 | $ | 1,141 | (2) | |||||||||||||||||||||||
| Total sources of capital | $ | 4,040 | $ | 4,840 | $ | 4,440 | |||||||||||||||||||||||
| Uses of capital: | |||||||||||||||||||||||||||||
| Construction | $ | 1,590 | $ | 1,890 | $ | 1,740 | |||||||||||||||||||||||
| Acquisitions | 2,450 | 2,950 | 2,700 | $ | 1,602 | ||||||||||||||||||||||||
| Total uses of capital | $ | 4,040 | $ | 4,840 | $ | 4,440 | |||||||||||||||||||||||
| Incremental debt (included above): | |||||||||||||||||||||||||||||
| Issuance of unsecured senior notes payable(3) | $ | 700 | $ | 1,100 | $ | 900 | |||||||||||||||||||||||
| Unsecured senior line of credit, commercial paper program, and other | 30 | (360) | (165) | ||||||||||||||||||||||||||
| Incremental debt | $ | 730 | $ | 740 | $ | 735 |
(1)In December 2020, three office buildings aggregating 146,842 RSF met the criteria to be classified as held for sale. We expect to complete the sale of these properties in 2021 for a total estimated sales price of $78.1 million, including the buyer’s assumption of a $28.2 million secured note payable related to one of the buildings. Upon the buildings being classified as held for sale, we recognized impairment charges aggregating $25.2 million.
(2)Represents forward equity sales agreements that we expect to settle in 2021 and receive net proceeds of approximately $1.1 billion.
(3)In addition to our guidance range, we may seek opportunities to refinance our $650 million unsecured senior notes payable green bond due in 2024 prior to its maturity, subject to market conditions.
The key assumptions behind the sources and uses of capital in the table above include a favorable capital market environment, performance of our core operating properties, lease-up and delivery of current and future development and redevelopment projects, and leasing activity. Our expected sources and uses of capital are subject to a number of variables and uncertainties, including those discussed as “Forward-looking statements” under “Part 1”; “Item 1A. Risk factors” and “Item 7. Management’s discussion and analysis of financial condition and results of operations” in this annual report on Form 10-K. We expect to update our forecast of sources and uses of capital on a quarterly basis.
Sources of capital
Net cash provided by operating activities after dividends
We expect to retain $210.0 million to $250.0 million of net cash flows from operating activities after payment of common stock dividends, and distributions to noncontrolling interests for the year ending December 31, 2021. For purposes of this calculation, changes in operating assets and liabilities are excluded as they represent timing differences. We also excluded significant contract termination fees that represent an ancillary source of cash that is not associated with any ongoing activity at any of our operating properties. For the year ending December 31, 2021, we expect our recently delivered projects, our highly pre-leased value-creation projects expected to be completed and along with contributions from Same Properties and recently acquired properties, to contribute significant increases in income from rentals, net operating income, and cash flows. We anticipate significant contractual near-term growth in annual cash rents of $28 million related to the commencement of contractual rents on the projects recently placed into service that are near the end of their initial free rent period. Refer to the “Cash flows” section within this Item 7 in this annual report on Form 10-K for a discussion of cash flows provided by operating activities for the year ended December 31, 2020.
Debt
As of December 31, 2020, we have no outstanding balance on our unsecured senior line of credit. Our unsecured senior line of credit bears an interest rate of LIBOR plus 0.825%. In addition to the cost of borrowing, the unsecured senior line of credit is subject to an annual facility fee of 0.15% based on the aggregate commitments outstanding. On October 6, 2020, we amended our unsecured senior line of credit to increase commitments available for borrowing by $800 million to an aggregate of $3.0 billion and to extend the maturity date to January 6, 2026. Among other things, the amended credit agreement includes a 0% LIBOR floor on the interest rate and is subject to certain annual sustainability measures entitling us to a temporary reduction in the interest rate margin of one basis point, but not below zero percent per year.
We use our unsecured senior line of credit to fund working capital, construction activities, and, from time to time, acquisition of properties. Borrowings under the unsecured senior line of credit bear interest at a “Eurocurrency Rate,” a “LIBOR Floating Rate,” or a “Base Rate” specified in the unsecured senior line of credit agreement plus, in any case, the Applicable Margin. The Eurocurrency Rate specified in the unsecured senior line of credit agreement is, as applicable, the rate per annum equal to either (i) the LIBOR or a successor rate thereto as agreed to by the administrative agent and the Company for loans denominated in a LIBOR quoted currency (i.e., U.S. dollars, euro, sterling, or yen), (ii) the average annual yield rates applicable to Canadian dollar bankers’ acceptances for loans denominated in Canadian dollars, (iii) the Bank Bill Swap Reference Bid rate for loans denominated in Australian dollars, or (iv) the rate designated with respect to the applicable alternative currency for loans denominated in a non-LIBOR quoted currency (other than Canadian or Australian dollars). The LIBOR Floating Rate means, for any day, one-month LIBOR, or a successor rate thereto as agreed to by the administrative agent and the Company for loans denominated in U.S. dollars. The Base Rate means, for any day, a fluctuating rate per annum equal to the highest of (i) the federal funds rate plus 1/2 of 1.00%, (ii) the rate of interest in effect for such day as publicly announced from time to time by the Administrative Agent as its “prime rate,” and (iii) the Eurocurrency Rate plus 1.00%. Our unsecured senior line of credit contains a feature that allows lenders to competitively bid on the interest rate for borrowings under the facility. This may result in an interest rate that is below the stated rate.
We expect to fund a portion of our capital needs in 2021 from the settlement of our outstanding forward equity sales agreements, from sales of our common stock under our ATM program, from issuances under our commercial paper program discussed below, from borrowings under our unsecured senior line of credit, and from real estate dispositions and partial interest sales.
We established a commercial paper program that provides us with the ability to issue up to $1.5 billion of commercial paper notes generally with a maturity of 30 days or less and with a maximum maturity of 397 days from the date of issuance. Our commercial paper program is backed by our unsecured senior line of credit, and at all times we expect to retain a minimum undrawn amount of borrowing capacity under our unsecured senior line of credit equal to any outstanding balance on our commercial paper program. We use borrowings under the program to fund short-term capital needs. The notes issued under our commercial paper program are sold under customary terms in the commercial paper market. They are typically issued at a discount to par, representing a yield to maturity dictated by market conditions at the time of issuance. In the event we are unable to issue commercial paper notes or refinance outstanding commercial paper notes under terms equal to or more favorable than those under the unsecured senior line of credit, we expect to borrow under the unsecured senior line of credit at LIBOR plus 0.825%. The commercial paper notes sold during the year ended December 31, 2020, were issued at a weighted-average yield to maturity of 0.26%. As of December 31, 2020, we had $100.0 million of outstanding notes under our commercial paper program.
In March 2020, we completed an offering of $700.0 million of unsecured senior notes payable due on December 15, 2030, at an interest rate of 4.90% for net proceeds of $691.6 million. The net proceeds were used to reduce the outstanding indebtedness under our unsecured senior line of credit and commercial paper program.
In August 2020, we completed an offering of $1.0 billion of unsecured senior notes payable due on February 1, 2033, at an interest rate of 1.875% for net proceeds of $989.1 million. A portion of the proceeds was used to refinance our 3.90% unsecured senior notes payable due in 2023, aggregating $500.0 million, pursuant to a partial cash tender offer and a subsequent call for redemption. On August 5, 2020, we tendered $247.0 million, or 49.4%, of our outstanding 3.90% unsecured senior notes payable and settled the call for redemption of the remaining outstanding balance on September 4, 2020. As a result of our debt refinancing, we recognized a loss on early extinguishment of debt of $50.8 million, including the write-off of unamortized loan fees.
In December 2020, we extinguished two secured notes payable aggregating $108.2 million due in 2023 with a weighted-average interest rate of 3.67% and recognized losses on early extinguishment of debt aggregating $7.3 million. As a result of these extinguishments, we have no debt maturing until 2024.
Since January 1, 2019, we have completed the issuances of $4.4 billion in unsecured senior notes, with a weighted-average interest rate of 3.48% and a weighted-average maturity of 14.1 years, as of December 31, 2020.
Refer to Note 10 – “Secured and unsecured senior debt” to our consolidated financial statements under Item 15 in this annual report on Form 10-K for additional information.
Proactive management of transition away from LIBOR
LIBOR has been used extensively in the U.S. and globally as a reference rate for various commercial and financial contracts, including variable-rate debt and interest rate swap contracts. However, it is expected that LIBOR will no longer be used after June 30, 2023. To address the increased risk of LIBOR discontinuation, in the U.S. the Alternative Reference Rates Committee (“ARRC”) was established to help ensure the successful transition from LIBOR. In June 2017, the ARRC selected SOFR, a new index calculated by reference to short-term repurchase agreements backed by U.S. Treasury securities, as its preferred replacement for U.S. dollar LIBOR. We have been closely monitoring developments related to the transition away from LIBOR and have implemented numerous proactive measures to minimize the potential impact of the transition to the Company, specifically:
-
We have proactively eliminated outstanding LIBOR-based borrowings under our unsecured senior bank term loans and secured construction loans through repayments. From January 2017 through December 2020, we retired approximately $1.5 billion of such debt.
-
During 2020, we increased the aggregate amount of our commercial paper program to $1.5 billion from $750.0 million. This program provides us with ability to issue commercial paper notes bearing interest at short-term fixed rates, generally with a maturity of 30 days or less and with a maximum maturity of 397 days from the date of issuance. Our commercial paper program is not subject to LIBOR and is used for funding short-term working capital needs. As of December 31, 2020, we had $100.0 million of outstanding notes under our commercial paper program.
-
We continue to prudently manage outstanding borrowings under our unsecured senior line of credit, our only LIBOR-based debt (excluding $12.7 million LIBOR-based debt held by one of our unconsolidated joint ventures as of December 31, 2020). As of December 31, 2020, we had no borrowings outstanding under our unsecured senior line of credit.
-
Our unsecured senior line of credit contains fallback language generally consistent with the ARRC’s Amendment Approach, which provides a streamlined amendment approach for negotiating a benchmark replacement and introduces clarity with respect to the fallback trigger events and an adjustment to be applied to the successor rate.
-
We continue to monitor developments by the ARRC and other governing bodies involved in LIBOR transition.
Refer to Note 10 – “Secured and unsecured senior debt” to our consolidated financial statements under Item 15 and “Item 1A. Risk factors” in this annual report on Form 10-K for additional information about our management of risks related to the transition away from LIBOR.
Real estate dispositions and partial interest sales
We expect to continue the disciplined execution of select sales of operating assets. Future sales will provide an important source of capital to fund a portion of pending and recently completed opportunistic acquisitions and our highly leased value-creation development and redevelopment projects, and also provide significant capital for growth over the next two to three quarters. We may also consider additional sales of partial interests in core Class A properties and/or development projects. For 2021, we expect real estate dispositions and partial interest sales ranging from $1.3 billion to $1.5 billion. The amount of asset sales necessary to meet our forecasted sources of capital will vary depending upon the amount of EBITDA associated with the assets sold.
During the year ended December 31, 2020, we received proceeds of $1.1 billion, primarily related to our sale of properties at 510 Townsend Street, 505 Brannan Street, and 945 Market Street in our SoMa submarket, our sale of properties at 9808 and 9868 Scranton Road in our Sorrento Mesa submarket, and our partial interest sale of properties at 1201 and 1208 Eastlake Avenue East and 199 East Blaine Street in our Lake Union submarket. The proceeds received were used primarily to fund development and redevelopment projects in our highly leased value-creation pipeline and to fund acquisitions completed in 2020.
As a REIT, generally we are subject to a 100% tax on the net income from real estate asset sales that the IRS characterizes as “prohibited transactions.” We do not expect our sales will be categorized as prohibited transactions. However, unless we meet certain “safe harbor” requirements, whether a real estate asset sale is a prohibited transaction will be based on the facts and circumstances of the sale. Our real estate asset sales may not always meet such safe harbor requirements. Refer to “Item 1A. Risk factors” in this annual report on Form 10-K for additional information about the “prohibited transaction” tax.
Common equity transactions
During the year ended December 31, 2020, we completed issuances and executed forward equity sales agreements for an aggregate of 15.7 million shares of common stock, including the exercise of an underwriters’ option, for aggregate net proceeds of approximately $2.4 billion, as follows:
-
In January 2020 and July 2020, we entered into forward equity sales agreements aggregating $1.0 billion and $1.1 billion, respectively, to sell an aggregate of 6.9 million shares for each offering (13.8 million in aggregate) of our common stock, including the exercise of underwriters’ options, at public offering prices of $155.00 per share and $160.50 per share, respectively, before underwriting discounts. During 2020, we issued all 13.8 million shares under these forward equity sales agreements and received net proceeds of $2.1 billion.
-
In February 2020, we entered into an ATM common stock offering program, which allowed us to sell up to an aggregate of $850.0 million of our common stock.
-
We issued 1.5 million shares of common stock under our ATM program at a price of $159.09 per share (before underwriting discounts), and received net proceeds of $235.0 million during 2020.
-
We have 362 thousand shares under our ATM program subject to forward equity sales agreements that remain outstanding at a price of $159.09 per share (before underwriting discounts) As of December 31, 2020. We expect to settle these forward equity sales agreements in 2021 and receive net proceeds of approximately $56.3 million.
-
The remaining availability of $547.3 million under this ATM program expired in December 2020 concurrently with the expiration of the associated shelf registration. In January 2021, we filed a new shelf registration statement and expect to establish a new ATM program soon in 2021.
Other sources
Under our current shelf registration statement filed with the SEC, we may offer common stock, preferred stock, debt, and other securities. These securities may be issued, from time to time, at our discretion based on our needs and market conditions, including, as necessary, to balance our use of incremental debt capital.
Additionally, we hold interests, together with joint venture partners, in real estate joint ventures that we consolidate in our financial statements. These joint venture partners may contribute equity into these entities primarily related to their share of funds for construction and financing-related activities. During the year ended December 31, 2020, we received $367.6 million of contributions from and sales of noncontrolling interests.
Uses of capital
Summary of capital expenditures
One of our primary uses of capital relates to the development, redevelopment, pre-construction, and construction of properties. We currently have projects in our growth pipeline aggregating 3.3 million RSF of Class A office/laboratory and tech office space undergoing construction, 7.1 million RSF of near-term and intermediate-term development and redevelopment projects, and 7.4 million SF of future development projects in North America. We incur capitalized construction costs related to development, redevelopment, pre-construction, and other construction activities. We also incur additional capitalized project costs, including interest, property taxes, insurance, and other costs directly related and essential to the development, redevelopment, pre-construction, or construction of a project, during periods when activities necessary to prepare an asset for its intended use are in progress. Refer to the “New Class A development and redevelopment properties: current projects” and “Summary of capital expenditures” subsections of the “Investments in real estate” section under Item 2 in this annual report on Form 10-K for more information on our capital expenditures.
We capitalize interest cost as a cost of the project only during the period for which activities necessary to prepare an asset for its intended use are ongoing, provided that expenditures for the asset have been made and interest cost has been incurred. Capitalized interest for the years ended December 31, 2020 and 2019, of $125.6 million and $88.6 million, respectively, was classified in investments in real estate. Indirect project costs, including construction administration, legal fees, and office costs that clearly relate to projects under development or construction, are capitalized as incurred during the period an asset is undergoing activities to prepare it for its intended use. We capitalized payroll and other indirect project costs related to development, redevelopment, pre-construction, and construction projects, which aggregated $61.0 million and $43.2 million for the years ended December 31, 2020 and 2019, respectively. The increase in capitalized payroll and other indirect project costs for the year ended December 31, 2020, compared to the same period in 2019 was primarily due to an increase in our value-creation pipeline projects undergoing construction and pre-construction activities aggregating 11 projects with 7.2 million RSF in 2020 over 2019. Pre-construction activities include entitlements, permitting, design, site work, and other activities preceding commencement of construction of aboveground building improvements. The advancement of pre-construction efforts is focused on reducing the time required to deliver projects to prospective tenants. These critical activities add significant value for future ground-up development and are required for the vertical construction of buildings. Should we cease activities necessary to prepare an asset for its intended use, the interest, taxes, insurance, and certain other direct project costs related to this asset would be expensed as incurred. Expenditures for repairs and maintenance are expensed as incurred.
Fluctuations in our development, redevelopment, and construction activities could result in significant changes to total expenses and net income. For example, had we experienced a 10% reduction in development, redevelopment, and construction activities without a corresponding decrease in indirect project costs, including interest and payroll, total expenses would have increased by approximately $18.7 million for the year ended December 31, 2020.
We use third-party brokers to assist in our leasing activity, who are paid on a contingent basis upon successful leasing. We are required to capitalize initial direct costs related to successful leasing transactions that result directly from and are essential to the lease transaction and would not have been incurred had that lease transaction not been successfully executed. During the year ended December 31, 2020, we capitalized total initial direct leasing costs of $61.2 million. Costs that we incur to negotiate or arrange a lease regardless of its outcome, such as fixed employee compensation, tax, or legal advice to negotiate lease terms, and other costs, are expensed as incurred.
Acquisitions
Refer to the “Acquisitions” section in Note 3 – “Investments in real estate” and to Note 4 – “Consolidated and unconsolidated real estate joint ventures” to our consolidated financial statements under Item 15 in this annual report on Form 10-K for detailed information on our acquisitions.
Dividends
During the years ended December 31, 2020 and 2019, we paid the following dividends (in thousands):
| Year Ended December 31, | |||||||||||||||||
| 2020 | 2019 | Change | |||||||||||||||
| Common Stock | $ | 532,980 | $ | 447,029 | $ | 85,951 | |||||||||||
| Series D Convertible Preferred Stock | — | 4,141 | (4,141) | ||||||||||||||
| $ | 532,980 | $ | 451,170 | $ | 81,810 |
The increase in dividends paid on our common stock during the year ended December 31, 2020, compared to the year ended December 31, 2019, was primarily due to an increase in number of common shares outstanding subsequent to January 1, 2019, as a result of issuances of common stock under our ATM program and settlement of forward equity sales agreements, and partially due to the increase in the related dividends to $4.18 per common share paid during the year ended December 31, 2020, from $3.94 per common share paid during the year ended December 31, 2019.
The decrease in dividends paid on our Series D Convertible Preferred Stock during the year ended December 31, 2020, compared to the year ended December 31, 2019, was due to the repurchase of 275,000 outstanding shares of our Series D Convertible Preferred Stock and the conversion of the remaining 2.3 million outstanding shares of our Series D Convertible Preferred Stock into shares of our common stock during 2019. As a result, we had no outstanding shares of Series D Convertible Preferred Stock as of December 31, 2020.
Contractual obligations and commitments
Contractual obligations as of December 31, 2020, consisted of the following (in thousands):
| Payments by Period | |||||||||||||||||||||||||||||
| Total | 2021 | 2022–2023 | 2024–2025 | Thereafter | |||||||||||||||||||||||||
| Secured and unsecured debt(1)(2) | $ | 7,598,130 | $ | 3,420 | $ | 7,364 | $ | 1,433,593 | $ | 6,153,753 | |||||||||||||||||||
| Estimated interest payments on fixed-rate debt(3) | 3,077,819 | 279,393 | 558,689 | 492,553 | 1,747,184 | ||||||||||||||||||||||||
| Ground lease obligations – operating leases | 798,589 | 17,127 | 34,750 | 35,115 | 711,597 | ||||||||||||||||||||||||
| Ground lease obligations – finance lease | 35,868 | 415 | 836 | 844 | 33,773 | ||||||||||||||||||||||||
| Other obligations | 27,215 | 1,776 | 5,253 | 5,583 | 14,603 | ||||||||||||||||||||||||
| Total | $ | 11,537,621 | $ | 302,131 | $ | 606,892 | $ | 1,967,688 | $ | 8,660,910 |
(1)Amounts represent principal amounts due and exclude unamortized premiums (discounts) and deferred financing costs reflected in the consolidated balance sheets under Item 15 in this annual report on Form 10-K.
(2)Payment dates reflect any extension options that we control.
(3)Amounts are based upon contractual interest rates, including interest payment dates and scheduled maturity dates.
Secured notes payable
Secured notes payable as of December 31, 2020, consisted of four notes secured by nine properties. Our secured notes payable typically require monthly payments of principal and interest and had a weighted-average interest rate of approximately 3.53%. As of December 31, 2020, the total book value of our investments in real estate securing debt was approximately $880.1 million. Additionally, as of December 31, 2020, our entire secured notes payable balance of $230.9 million, including unamortized discounts and deferred financing costs, was fixed-rate debt. Refer to Note 10 – “Secured and unsecured senior debt” to our consolidated financial statements under Item 15 in this annual report on Form 10-K for information on our repayments of secured notes payable during the year ended December 31, 2020.
Unsecured senior notes payable and unsecured senior line of credit
The requirements of, and our actual performance with respect to, the key financial covenants under our unsecured senior notes payable as of December 31, 2020, were as follows:
| Covenant Ratios(1) | Requirement | December 31, 2020 | ||||||||||||
| Total Debt to Total Assets | Less than or equal to 60% | 31% | ||||||||||||
| Secured Debt to Total Assets | Less than or equal to 40% | 1% | ||||||||||||
| Consolidated EBITDA(2) to Interest Expense | Greater than or equal to 1.5x | 8.6x | ||||||||||||
| Unencumbered Total Asset Value to Unsecured Debt | Greater than or equal to 150% | 305% |
(1)All covenant ratio titles utilize terms as defined in the respective debt agreements.
(2)The calculation of consolidated EBITDA is based on the definitions contained in our loan agreements and is not directly comparable to the computation of EBITDA as described in Exchange Act Release No. 47226.
In addition, the terms of the indentures, among other things, limit the ability of the Company, Alexandria Real Estate Equities, L.P., and the Company’s subsidiaries to (i) consummate a merger, or consolidate or sell all or substantially all of the Company’s assets, and (ii) incur certain secured or unsecured indebtedness.
The requirements of, and our actual performance with respect to, the key financial covenants under our unsecured senior line of credit as of December 31, 2020, were as follows:
| Covenant Ratios (1) | Requirement | December 31, 2020 | |||||||||||||||
| Leverage Ratio | Less than or equal to 60.0% | 27.5% | |||||||||||||||
| Secured Debt Ratio | Less than or equal to 45.0% | 0.8% | |||||||||||||||
| Fixed-Charge Coverage Ratio | Greater than or equal to 1.50x | 3.91x | |||||||||||||||
| Unsecured Interest Coverage Ratio | Greater than or equal to 1.75x | 6.64x |
(1)All covenant ratio titles utilize terms as defined in each respective credit agreement.
Estimated interest payments
Estimated interest payments on our fixed-rate debt were calculated based upon contractual interest rates, including interest payment dates and scheduled maturity dates. As of December 31, 2020, 99% of our debt was fixed-rate debt. For additional information regarding our debt, refer to Note 10 – “Secured and unsecured senior debt” to our consolidated financial statements under Item 15 in this annual report on Form 10-K.
Ground lease obligations
Operating lease agreements
Ground lease obligations as of December 31, 2020, included leases for 36 of our properties, which accounted for approximately 11% of our total number of properties. Excluding one ground lease that expires in 2036 related to one operating property with a net book value of $7.1 million as of December 31, 2020, our ground lease obligations have remaining lease terms ranging from approximately 33 to 94 years, including available extension options that we are reasonably certain to exercise.
As of December 31, 2020, the remaining contractual payments under ground and office lease agreements in which we are the lessee aggregated $798.6 million and $27.2 million, respectively. We are required to recognize a right-of-use asset and a related liability to account for our future obligations under operating lease arrangements in which we are the lessee. The operating lease liability is measured based on the present value of the remaining lease payments, including payments during the term under our extension options that we are reasonably certain to exercise. The right-of-use asset is equal to the corresponding operating lease liability, adjusted for the initial direct leasing cost and any other consideration exchanged with the landlord prior to the commencement of the lease, as well as adjustments to reflect favorable or unfavorable terms of an acquired lease when compared with market terms at the time of acquisition. As of December 31, 2020, the present value of the remaining contractual payments, aggregating $825.8 million, under our operating lease agreements, including our extension options that we are reasonably certain to exercise, was $345.8 million, which was classified in accounts payable, accrued expenses, and other liabilities in our consolidated balance sheets. As of December 31, 2020, the weighted-average remaining lease term of operating leases in which we are the lessee was approximately 43 years, and the weighted-average discount rate was 4.88%. Our corresponding operating lease right-of-use assets, adjusted for initial direct leasing costs and other consideration exchanged with the landlord prior to the commencement of the lease, aggregated $335.9 million. We classify the right-of-use asset in other assets in our consolidated balance sheets. Refer to the “Lease accounting” section in Note 2 – “Summary of significant accounting policies” to our consolidated financial statements under Item 15 in this annual report on Form 10-K.
Commitments
As of December 31, 2020, remaining aggregate costs under contract for the construction of properties undergoing development, redevelopment, and improvements under the terms of leases approximated $1.2 billion. We expect payments for these obligations to occur over one to three years, subject to capital planning adjustments from time to time. We may have the ability to cease the construction of certain properties, which would result in the reduction of our commitments. In addition, we have letters of credit and performance obligations aggregating $11.1 million primarily related to construction projects.
We are committed to funding approximately $210.6 million for non-real estate investments primarily related to our investments in privately held entities that report NAV. Our funding commitments expire at various dates over the next 11 years, with a weighted-average expiration of 8.3 years as of December 31, 2020.
Exposure to environmental liabilities
In connection with the acquisition of all of our properties, we have obtained Phase I environmental assessments to ascertain the existence of any environmental liabilities or other issues. The Phase I environmental assessments of our properties have not revealed any environmental liabilities that we believe would have a material adverse effect on our financial condition or results of operations taken as a whole, nor are we aware of any material environmental liabilities that have occurred since the Phase I environmental assessments were completed. In addition, we carry a policy of pollution legal liability insurance covering exposure to certain environmental losses at substantially all of our properties.
Accumulated other comprehensive loss
The following table presents the change in accumulated other comprehensive loss attributable to Alexandria Real Estate Equities, Inc.’s stockholders during the year ended December 31, 2020, due to the changes in the foreign exchange rates for our real estate investments in Canada and Asia. We reclassify unrealized foreign currency translation gains and losses into net income as we dispose of these holdings.
| Total | ||||||||
| Balance as of December 31, 2019 | $ | (9,749) | ||||||
| Other comprehensive income before reclassifications | 3,124 | |||||||
| Net other comprehensive income | 3,124 | |||||||
| Balance as of December 31, 2020 | $ | (6,625) |
Issuer and guarantor subsidiary summarized financial information
Alexandria Real Estate Equities, Inc. (the “Issuer”) has sold certain debt securities registered under the Securities Act of 1933, as amended, that are fully and unconditionally guaranteed by Alexandria Real Estate Equities, L.P. (the “LP” or the “Guarantor Subsidiary”), an indirectly 100% owned subsidiary of the Issuer. The Issuer’s other subsidiaries, including, but not limited to, the subsidiaries that own substantially all of its real estate (collectively, the “Combined Non-Guarantor Subsidiaries”), will not provide a guarantee of such securities, including the subsidiaries that are partially or 100% owned by the LP. The following summarized financial information presents on a combined basis for the Issuer and the Guarantor Subsidiary balance sheet financial information as of December 31, 2020 and 2019, and results of operations and comprehensive income for the years ended December 31, 2020 and 2019. The information presented below excludes eliminations necessary to arrive at the information on a consolidated basis. In presenting the summarized financial statements, the equity method of accounting has been applied to (i) the Issuer’s interests in the Guarantor Subsidiary, (ii) the Guarantor Subsidiary’s interests in the Combined Non-Guarantor Subsidiaries, and (iii) the Combined Non-Guarantor Subsidiaries’ interests in the Guarantor Subsidiary, where applicable, even though all such subsidiaries meet the requirements to be consolidated under GAAP. All assets and liabilities have been allocated to the Issuer and the Guarantor Subsidiary generally based on legal entity ownership.
The following tables present combined summarized financial information as of December 31, 2020 and 2019, and for the years ended December 31, 2020 and 2019, for the Issuer and Guarantor Subsidiary. Amounts provided do not represent our total consolidated amounts (in thousands):
| December 31, | ||||||||||||||
| 2020 | 2019 | |||||||||||||
| Assets: | ||||||||||||||
| Cash, cash equivalents, and restricted cash | $ | 404,802 | $ | 4,432 | ||||||||||
| Other assets | 100,689 | 71,036 | ||||||||||||
| Total assets | $ | 505,491 | $ | 75,468 | ||||||||||
| Liabilities: | ||||||||||||||
| Unsecured senior notes payable | $ | 7,232,370 | $ | 6,044,127 | ||||||||||
| Unsecured senior line of credit and commercial paper | 99,991 | 384,000 | ||||||||||||
| Other liabilities | 341,621 | 278,858 | ||||||||||||
| Total liabilities | $ | 7,673,982 | $ | 6,706,985 | ||||||||||
| Year Ended December 31, | ||||||||||||||
| 2020 | 2019 | |||||||||||||
| Total revenues | $ | 22,946 | $ | 22,731 | ||||||||||
| Total expenses | (355,370) | (317,896) | ||||||||||||
| Net loss | (332,424) | (295,165) | ||||||||||||
| Net income attributable to unvested restricted stock awards and preferred stock | (10,168) | (12,170) | ||||||||||||
| Net loss attributable to Alexandria Real Estate Equities, Inc.’s common stockholders | $ | (342,592) | $ | (307,335) | ||||||||||
Critical accounting policies
Our consolidated financial statements have been prepared in accordance with GAAP. The preparation of these financial statements in conformity with GAAP requires us to make estimates, judgments, and assumptions that affect the reported amounts of assets, liabilities, revenues, and expenses. We base these estimates, judgments, and assumptions on historical experience and on various other factors that we believe to be reasonable under the circumstances.
We continually evaluate the policies and estimates we use to prepare our consolidated financial statements. Changes in estimates or policies applied could affect our financial position and specific items in our results of operations that are used by our stockholders, potential investors, industry analysts, and lenders in their evaluation of our performance. Our significant accounting policies are described in Note 2 – “Summary of significant accounting policies” to our consolidated financial statements under Item 15 in this annual report on Form 10-K.
REIT compliance
We have elected to be taxed as a REIT under the Internal Revenue Code. Qualification as a REIT involves the application of highly technical and complex provisions of the Internal Revenue Code to our operations and financial results, and the determination of various factual matters and circumstances not entirely within our control. We believe that our current organization and method of operation comply with the rules and regulations promulgated under the Internal Revenue Code to enable us to qualify, and continue to qualify, as a REIT. However, it is possible that we have been organized or have operated in a manner that would not allow us to qualify as a REIT, or that our future operations could cause us to fail to qualify.
If we fail to qualify as a REIT in any taxable year, then we will be required to pay federal and state income taxes on our taxable income at regular corporate rates. If we lose our REIT status, then our net earnings available for investment or distribution to our stockholders will be significantly reduced for each of the years involved and we will no longer be required to make distributions to our stockholders.
Investments in real estate
Recognition of real estate acquired
We evaluate each acquisition of real estate or in-substance real estate (including equity interests in entities that predominantly hold real estate assets) to determine whether the integrated set of assets and activities acquired meets the definition of a business and needs to be accounted for as a business combination. An acquisition of an integrated set of assets and activities that does not meet the definition of a business is accounted for as an asset acquisition.
For acquisitions of real estate or in-substance real estate that are accounted for as business combinations, we allocate the acquisition consideration (excluding acquisition costs) to the assets acquired, liabilities assumed, noncontrolling interests, and previously existing ownership interests at fair value as of the acquisition date. Assets include intangible assets such as tenant relationships, acquired in-place leases, and favorable intangibles associated with in-place leases in which we are the lessor. Liabilities include unfavorable intangibles associated with in-place leases in which we are the lessor. In addition, for acquired in-place finance or operating leases in which we are the lessee, acquisition consideration is allocated to lease liabilities and related right-of-use assets, adjusted to reflect favorable or unfavorable terms of the lease when compared with market terms. Any excess (deficit) of the consideration transferred relative to the fair value of the net assets acquired is accounted for as goodwill (bargain purchase gain). Acquisition costs related to business combinations are expensed as incurred.
Generally, we expect that acquisitions of real estate or in-substance real estate will not meet the definition of a business because substantially all of the fair value is concentrated in a single identifiable asset or group of similar identifiable assets (i.e., land, buildings, and related intangible assets). The accounting model for asset acquisitions is similar to the accounting model for business combinations except that the acquisition consideration (including acquisition costs) is allocated to the individual assets acquired and liabilities assumed on a relative fair value basis. Any excess (deficit) of the consideration transferred relative to the sum of the fair value of the assets acquired and liabilities assumed is allocated to the individual assets and liabilities based on their relative fair values. As a result, asset acquisitions do not result in the recognition of goodwill or a bargain purchase gain. Incremental and external direct acquisition costs (such as legal and other third-party services) are capitalized.
We exercise judgment to determine the key assumptions used to allocate the purchase price of real estate acquired among its components. The allocation of the consideration to the various components of properties acquired during the year can have an effect on our net income due to the useful depreciable and amortizable lives applicable to each component and the recognition of the related depreciation and amortization expense in our consolidated statements of operations. We apply judgment in utilizing available comparable market information to assess relative fair value. We assess the relative fair values of tangible and intangible assets and liabilities based on available comparable market information, including estimated replacement costs, rental rates, and recent market transactions. In addition, we may use estimated cash flow projections that utilize appropriate discount and capitalization rates.
Estimates of future cash flows are based on a number of factors, including the historical operating results, known and anticipated trends, and market/economic conditions that may affect the property.
The value of tangible assets acquired is based upon our estimation of fair value on an “as if vacant” basis. The value of acquired in-place leases includes the estimated costs during the hypothetical lease-up period and other costs that would have been incurred in the execution of similar leases under the market conditions at the acquisition date of the acquired in-place lease. The value of above-market lease assets and below-market lease liabilities reflects the difference between (i) the contractual rents to be paid over the remaining term for each in-place lease and (ii) the estimated current market lease rates using available comparable market information and tenant credit quality. If there is a bargain fixed-rate renewal option for the period beyond the noncancelable lease term of an in-place lease, we evaluate intangible factors such as the business conditions in the industry in which the lessee operates, the economic conditions in the area in which the property is located, and the ability of the lessee to sublease the property during the renewal term, in order to determine the likelihood that the lessee will renew. When we determine there is reasonable assurance that such bargain purchase option will be exercised, we consider the option in determining the intangible value of such lease and its related amortization period. We also recognize the relative fair values of assets acquired, the liabilities assumed, and any noncontrolling interest in acquisitions of less than a 100% interest when the acquisition constitutes a change in control of the acquired entity.
We completed acquisitions of 55 properties for a total purchase price of $2.6 billion during the year ended December 31, 2020. These transactions were accounted for as asset acquisitions, and the purchase price of each was allocated based on the relative fair value of the asset acquired and liabilities assumed.
Depreciation and amortization
The values allocated to buildings and building improvements, land improvements, tenant improvements, and equipment are depreciated on a straight-line basis using the shorter of the respective ground lease term, estimated useful life, or up to 40 years, for buildings and building improvements; estimated life, or up to 20 years, for land improvements; the respective lease term or estimated useful life for tenant improvements; and the shorter of the lease term or estimated useful life for equipment. The values of acquired in-place leases and associated favorable intangibles (i.e., acquired above-market leases) are classified in other assets in our consolidated balance sheets and are amortized over the remaining terms of the related leases as a reduction of income from rentals in our consolidated statements of operations. The values of unfavorable intangibles (i.e., acquired below-market leases) associated with acquired in-place leases are classified in accounts payable, accrued expenses, and other liabilities in our consolidated balance sheets and are amortized over the remaining terms of the related leases, as an increase in income from rentals in our consolidated statements of operations.
Capitalized project costs
We capitalize project costs, including pre-construction costs, interest, property taxes, insurance, and other costs directly related and essential to the development, redevelopment, pre-construction, or construction of a project. Capitalization of development, redevelopment, pre-construction, and construction costs is required while activities are ongoing to prepare an asset for its intended use. Fluctuations in our development, redevelopment, pre-construction, and construction activities could result in significant changes to total expenses and net income. Costs incurred after a project is substantially complete and ready for its intended use are expensed as incurred. Should development, redevelopment, pre-construction, or construction activity cease, interest, property taxes, insurance, and certain other costs would no longer be eligible for capitalization and would be expensed as incurred. Expenditures for repairs and maintenance are expensed as incurred.
Properties classified as held for sale
A property is classified as held for sale when all of the following criteria for a plan of sale have been met: (i) management, having the authority to approve the action, commits to a plan to sell the property; (ii) the property is available for immediate sale in its present condition, subject only to terms that are usual and customary; (iii) an active program to locate a buyer and other actions required to complete the plan to sell have been initiated; (iv) the sale of the property is probable and is expected to be completed within one year; (v) the property is being actively marketed for sale at a price that is reasonable in relation to its current fair value; and (vi) actions necessary to complete the plan of sale indicate that it is unlikely that significant changes to the plan will be made or that the plan will be withdrawn. Depreciation of assets ceases upon designation of a property as held for sale.
If the disposal of a property represents a strategic shift that has (or will have) a major effect on our operations or financial results, such as (i) a major line of business, (ii) a major geographic area, (iii) a major equity method investment, or (iv) other major parts of an entity, then the operations of the property, including any interest expense directly attributable to it, are classified as discontinued operations in our consolidated statements of operations, and amounts for all prior periods presented are reclassified from continuing operations to discontinued operations. The disposal of an individual property generally will not represent a strategic shift and therefore will typically not meet the criteria for classification as a discontinued operation.
Impairment of long-lived assets
Prior to and subsequent to the end of each quarter, we review current activities and changes in the business conditions of all of our long-lived assets to determine the existence of any triggering events or impairment indicators requiring an impairment analysis. If triggering events or impairment indicators are identified, we review an estimate of the future undiscounted cash flows, including, if necessary, a probability-weighted approach if multiple outcomes are under consideration.
Long-lived assets to be held and used, including our rental properties, CIP, land held for development, right-of-use assets related to operating leases in which we are the lessee, and intangibles, are individually evaluated for impairment when conditions exist that may indicate that the carrying amount of a long-lived asset may not be recoverable. The carrying amount of a long-lived asset to be held and used is not recoverable if it exceeds the sum of the undiscounted cash flows expected to result from the use and eventual disposition of the asset. Triggering events or impairment indicators for long-lived assets to be held and used, including our rental properties, CIP, land held for development, and intangibles, are assessed by project and include significant fluctuations in estimated net operating income, occupancy changes, significant near-term lease expirations, current and historical operating and/or cash flow losses, construction costs, estimated completion dates, rental rates, and other market factors. We assess the expected undiscounted cash flows based upon numerous factors, including, but not limited to, construction costs, available market information, current and historical operating results, known trends, current market/economic conditions that may affect the property, and our assumptions about the use of the asset, including, if necessary, a probability-weighted approach if multiple outcomes are under consideration.
Upon determination that an impairment has occurred, a write-down is recognized to reduce the carrying amount to its estimated fair value. If an impairment loss is not required to be recognized, the recognition of depreciation or amortization is adjusted prospectively, as necessary, to reduce the carrying amount of the real estate to its estimated disposition value over the remaining period that the asset is expected to be held and used. We may adjust depreciation of properties that are expected to be disposed of or redeveloped prior to the end of their useful lives.
We use the held for sale impairment model for our properties classified as held for sale. The held for sale impairment model is different from the held and used impairment model. Under the held for sale impairment model, an impairment loss is recognized if the carrying amount of the long-lived asset classified as held for sale exceeds its fair value less cost to sell. Because of these two different models, it is possible for a long-lived asset previously classified as held and used to require the recognition of an impairment charge upon classification as held for sale.
Equity investments
We hold investments in publicly traded companies and privately held entities primarily involved in the life science, technology, and agtech industries. As a REIT, we generally limit our ownership percentage in the voting stock of each individual entity to less than 10%.
Our investments in publicly traded companies are classified as investments with readily determinable fair values and are carried at fair value, with changes in fair value recognized in net income. The fair values for our investments in publicly traded companies are determined based on sales prices/quotes available on securities exchanges and therefore generally require no judgment to determine fair value. Investments in privately held entities that report NAV per share, such as our privately held investments in limited partnerships, are carried at fair value using NAV as a practical expedient, with changes in fair value recognized in net income. As a result, fair value estimation for these investments generally requires limited judgment. Investments in privately held entities that do not report NAV are measured at cost, adjusted for observable price changes and impairments, with changes recognized in net income. Observable price changes result from, among other things, equity transactions for the same issuer executed during the reporting period, including subsequent equity offerings or other reported equity transactions related to the same issuer. For these equity transactions to be considered observable price changes of the same issuer, we evaluate whether these transactions have similar rights and obligations, including voting rights, distribution preferences, conversion rights, and other factors, to the investments we hold.
We monitor investments in privately held entities that do not report NAV per share throughout the year for new developments, including operating results, prospects and results of clinical trials, new product initiatives, new collaborative agreements, capital-raising events, and merger and acquisition activities. These investments are evaluated on the basis of a qualitative assessment for indicators of impairment by monitoring the presence of the following triggering events or impairment indicators: (i) a significant deterioration in the earnings performance, asset quality, or business prospects of the investee; (ii) a significant adverse change in the regulatory, economic, or technological environment of the investee, (iii) a significant adverse change in the general market condition, including the research and development of technology and products that the investee is bringing or attempting to bring to the market, or (iv) significant concerns about the investee’s ability to continue as a going concern. If such indicators are present, we are required to estimate the investment’s fair value and immediately recognize an impairment loss in an amount equal to the investment’s carrying value in excess of its estimated fair value.
Liability and right-of-use assets related to operating leases in which we are the lessee
We have operating lease agreements in which we are the lessee consisting of ground and office leases. At the lease commencement date (or at the acquisition date if the lease is acquired as part of a real estate acquisition), we are required to recognize a liability to account for our future obligations under these operating leases, and a corresponding right-of-use asset.
The lease liability is measured based on the present value of the future lease payments, including payments during the term under our extension options that we are reasonably certain to exercise. The present value of the future lease payments is calculated for each operating lease using each respective remaining lease term and a corresponding estimated incremental borrowing rate, which is the interest rate that we estimate we would have to pay to borrow on a collateralized basis over a similar term for an amount equal to the lease payments. Subsequently, the lease liability is accreted by applying a discount rate established at the lease commencement date to the lease liability balance as of the beginning of the period and is reduced by the payments made during the period. We classify the operating lease liability in accounts payable, accrued expenses, and other liabilities in our consolidated balance sheets.
The right-of-use asset is measured based on the corresponding lease liability, adjusted for initial direct leasing costs and any other consideration exchanged with the landlord prior to the commencement of the lease, as well as adjustments to reflect favorable or unfavorable terms of an acquired lease when compared with market terms at the time of acquisition. Subsequently, the right-of-use asset is amortized on a straight-line basis during the lease term. We classify the right-of-use asset in other assets in our consolidated balance sheets. Refer to the “Lessee Accounting” subsection of “Lease Accounting” section within Note 2 – “Summary of significant accounting policies” to our consolidated financial statements under Item 15 in this annual report on Form 10-K.
Monitoring of tenant credit quality
During the term of each lease, we monitor the credit quality and any related material changes of our tenants by (i) monitoring the credit rating of tenants that are rated by a nationally recognized credit rating agency, (ii) reviewing financial statements of the tenants that are publicly available or that are required to be delivered to us pursuant to the applicable lease, (iii) monitoring news reports regarding our tenants and their respective businesses, and (iv) monitoring the timeliness of lease payments.
Allowance for credit losses
On January 1, 2020, we adopted an accounting standard that requires companies to estimate and recognize lifetime expected losses, rather than incurred losses, which results in the earlier recognition of credit losses even if the expected risk of credit loss is remote. The accounting standard applies to most financial assets including trade receivables and direct financing leases. The standard does not apply to the receivables arising from operating leases. Upon adoption of the new standard on January 1, 2020, we recognized a credit loss adjustment related to adoption of this accounting standard as a cumulative adjustment to retained earnings. For details, refer to the “Allowance for credit losses” section in Note 2 – “Summary of significant accounting policies”
We have one lease classified as a direct financing lease subject to this standard. In this direct financing lease, the payment obligation of the lessee is collateralized by real estate property. At each reporting date, we estimate the current credit loss related to this asset by assessing the probability of default on this lease based on the lessee’s financial condition, credit rating, business prospects, remaining lease term, and expected value of the underlying collateral upon its repossession, and, if necessary, we recognize a credit loss adjustment. We recognized subsequent credit loss adjustments related to our direct financing lease in our consolidated statements of operations during the year ended December 31, 2020. For further details, refer to Note 5 – “Leases” to our consolidated financial statements.
Non-GAAP measures and definitions
This section contains additional information of certain non-GAAP financial measures and the reasons why we use these supplemental measures of performance and believe they provide useful information to investors, as well as the definitions of other terms used in this annual report on Form 10-K.
Funds from operations and funds from operations, as adjusted, attributable to Alexandria Real Estate Equities, Inc.’s common stockholders
GAAP-basis accounting for real estate assets utilizes historical cost accounting and assumes that real estate values diminish over time. In an effort to overcome the difference between real estate values and historical cost accounting for real estate assets, the Nareit Board of Governors established funds from operations as an improved measurement tool. Since its introduction, funds from operations has become a widely used non-GAAP financial measure among equity REITs. We believe that funds from operations is helpful to investors as an additional measure of the performance of an equity REIT. Moreover, we believe that funds from operations, as adjusted, allows investors to compare our performance to the performance of other real estate companies on a consistent basis, without having to account for differences recognized because of real estate acquisition and disposition decisions, financing decisions, capital structure, capital market transactions, variances resulting from the volatility of market conditions outside of our control, or other corporate activities that may not be representative of the operating performance of our properties.
On January 1, 2019, we adopted standards established by the Nareit Board of Governors in its November 2018 White Paper (the “Nareit White Paper”) on a prospective basis. The Nareit White Paper defines funds from operations as net income (computed in accordance with GAAP), excluding gains or losses on sales of real estate, and impairments of real estate, plus depreciation and amortization of operating real estate assets, and after adjustments for our share of consolidated and unconsolidated partnerships and real estate joint ventures. Impairments represent the write-down of assets when fair value over the recoverability period is less than the carrying value due to changes in general market conditions and do not necessarily reflect the operating performance of the properties during the corresponding period.
We compute funds from operations, as adjusted, as funds from operations calculated in accordance with the Nareit White Paper, excluding significant gains, losses, and impairments realized on non-real estate investments, unrealized gains or losses on non-real estate investments, gains or losses on early extinguishment of debt, gains or losses on early termination of interest rate hedge agreements, significant termination fees, acceleration of stock compensation expense due to the resignation of an executive officer, preferred stock redemption charges, deal costs, the income tax effect related to such items, and the amount of such items that is allocable to our unvested restricted stock awards. Neither funds from operations nor funds from operations, as adjusted, should be considered as alternatives to net income (determined in accordance with GAAP) as indications of financial performance, or to cash flows from operating activities (determined in accordance with GAAP) as measures of liquidity, nor are they indicative of the availability of funds for our cash needs, including our ability to make distributions.
The following table reconciles net income to funds from operations for the share of consolidated real estate joint ventures attributable to noncontrolling interests and our share of unconsolidated real estate joint ventures for the year ended December 31, 2020:
| Noncontrolling Interest Share of Consolidated Real Estate Joint Ventures | Our Share of Unconsolidated Real Estate Joint Ventures | ||||||||||||||||||||||
| December 31, 2020 | December 31, 2020 | ||||||||||||||||||||||
| (in thousands) | Three Months Ended | Year Ended | Three Months Ended | Year Ended | |||||||||||||||||||
| Net income | $ | 15,649 | $ | 56,212 | $ | 3,593 | $ | 8,148 | |||||||||||||||
| Depreciation and amortization | 15,032 | 61,933 | 2,976 | 11,413 | |||||||||||||||||||
| Impairment of real estate | — | — | — | 7,644 | |||||||||||||||||||
| Funds from operations | $ | 30,681 | $ | 118,145 | $ | 6,569 | $ | 27,205 | |||||||||||||||
The following tables present a reconciliation of net income attributable to Alexandria Real Estate Equities, Inc.’s common stockholders, the most directly comparable financial measure presented in accordance with GAAP, including our share of amounts from consolidated and unconsolidated real estate joint ventures, to funds from operations attributable to Alexandria Real Estate Equities, Inc.’s common stockholders – diluted, and funds from operations attributable to Alexandria Real Estate Equities, Inc.’s common stockholders – diluted, as adjusted, and the related per share amounts for the years ended December 31, 2020, 2019, and 2018. Per share amounts may not add due to rounding.
| Year Ended December 31, | |||||||||||||||||
| (In thousands) | 2020 | 2019 | 2018 | ||||||||||||||
| Net income attributable to Alexandria Real Estate Equities, Inc.’s common stockholders – basic and diluted | $ | 760,791 | $ | 350,995 | $ | 363,983 | |||||||||||
| Depreciation and amortization of real estate assets | 684,682 | 541,855 | 477,661 | ||||||||||||||
| Noncontrolling share of depreciation and amortization from consolidated real estate JVs | (61,933) | (30,960) | (16,077) | ||||||||||||||
| Our share of depreciation and amortization from unconsolidated real estate JVs | 11,413 | 6,366 | 3,181 | ||||||||||||||
| Gain on sales of real estate | (154,089) | (474) | (8,704) | ||||||||||||||
| Our share of gain on sales of real estate from unconsolidated real estate JVs | — | — | (35,678) | ||||||||||||||
| Impairment of real estate – rental properties | 40,501 | (1) | 12,334 | — | |||||||||||||
| Assumed conversion of 7.00% Series D cumulative convertible preferred stock | — | 3,204 | 5,060 | ||||||||||||||
| Allocation to unvested restricted stock awards | (7,018) | (5,904) | (5,961) | ||||||||||||||
| Funds from operations attributable to Alexandria Real Estate Equities, Inc.’s common stockholders – diluted(2) | 1,274,347 | 877,416 | 783,465 | ||||||||||||||
| Unrealized gains on non-real estate investments | (374,033) | (161,489) | (99,634) | ||||||||||||||
| Realized gains on non-real estate investments | — | — | (14,680) | ||||||||||||||
| Impairment of real estate | 15,221 | — | — | ||||||||||||||
| Impairment of real estate – land parcels | — | — | 6,311 | ||||||||||||||
| Impairment of non-real estate investments | 24,482 | 17,124 | 5,483 | ||||||||||||||
| Loss on early extinguishment of debt | 60,668 | 47,570 | 1,122 | ||||||||||||||
| Loss on early termination of interest rate hedge agreements | — | 1,702 | — | ||||||||||||||
| Termination fee | (86,179) | — | — | ||||||||||||||
| Acceleration of stock compensation expense due to executive officer resignation | 4,499 | — | — | ||||||||||||||
| Our share of gain on early extinguishment of debt from unconsolidated real estate JVs | — | — | (761) | ||||||||||||||
| Preferred stock redemption charge | — | 2,580 | 4,240 | ||||||||||||||
| Removal of assumed conversion of 7.00% Series D cumulative convertible preferred stock | — | (3,204) | (5,060) | ||||||||||||||
| Allocation to unvested restricted stock awards | 4,790 | 1,307 | 1,517 | ||||||||||||||
| Funds from operations attributable to Alexandria Real Estate Equities, Inc.’s common stockholders – diluted, as adjusted | $ | 923,795 | $ | 783,006 | $ | 682,003 |
(1)Includes a $7.6 million impairment of our investment in a recently developed retail property held by our unconsolidated real estate joint venture recognized during the three months ended March 31, 2020. This impairment is classified in equity in earnings of unconsolidated real estate joint ventures within our consolidated statements of operations.
(2)Calculated in accordance with standards established by the Nareit Board of Governors.
| Year Ended December 31, | ||||||||||||||||||||
| (Per share) | 2020 | 2019 | 2018 | |||||||||||||||||
| Net income per share attributable to Alexandria Real Estate Equities, Inc.’s common stockholders – diluted | $ | 6.01 | $ | 3.12 | $ | 3.52 | ||||||||||||||
| Depreciation and amortization of real estate assets | 5.01 | 4.60 | 4.50 | |||||||||||||||||
| Gain on sales of real estate | (1.22) | — | (0.08) | |||||||||||||||||
| Our share of gain on sales of real estate from unconsolidated real estate JVs | — | — | (0.35) | |||||||||||||||||
| Impairment of real estate – rental properties | 0.32 | 0.11 | — | |||||||||||||||||
| Allocation to unvested restricted stock awards | (0.05) | (0.06) | (0.06) | |||||||||||||||||
| Funds from operations per share attributable to Alexandria Real Estate Equities, Inc.’s common stockholders – diluted | 10.07 | 7.77 | 7.53 | |||||||||||||||||
| Unrealized gains on non-real estate investments | (2.96) | (1.44) | (0.96) | |||||||||||||||||
| Realized losses (gains) on non-real estate investments | — | — | (0.14) | |||||||||||||||||
| Impairment of real estate | 0.12 | — | — | |||||||||||||||||
| Impairment of real estate – land parcels | — | — | 0.06 | |||||||||||||||||
| Impairment of non-real estate investments | 0.19 | 0.15 | 0.05 | |||||||||||||||||
| Loss on early extinguishment of debt | 0.48 | 0.42 | 0.01 | |||||||||||||||||
| Loss on early termination of interest rate hedge agreements | — | 0.02 | — | |||||||||||||||||
| Termination fee | (0.68) | — | — | |||||||||||||||||
| Acceleration of stock compensation expense due to executive officer resignation | 0.04 | — | — | |||||||||||||||||
| Our share of gain on early extinguishment of debt from unconsolidated real estate JVs | — | — | (0.01) | |||||||||||||||||
| Preferred stock redemption charge | — | 0.02 | 0.04 | |||||||||||||||||
| Allocation to unvested restricted stock awards | 0.04 | 0.02 | 0.02 | |||||||||||||||||
| Funds from operations per share attributable to Alexandria Real Estate Equities, Inc.’s common stockholders – diluted, as adjusted | $ | 7.30 | $ | 6.96 | $ | 6.60 | ||||||||||||||
| Weighted-average shares of common stock outstanding(1) for calculations of: | ||||||||||||||||||||
| EPS – diluted | 126,490 | 112,524 | 103,321 | |||||||||||||||||
| Funds from operations – diluted, per share | 126,490 | 112,966 | 104,048 | |||||||||||||||||
| Funds from operations – diluted, as adjusted, per share | 126,490 | 112,524 | 103,321 |
(1)Refer to the definition of “Weighted-average shares of common stock outstanding – diluted” within this section of this Item 7 in this annual report on Form 10-K for additional information.
Adjusted EBITDA and Adjusted EBITDA margin
We use Adjusted EBITDA as a supplemental performance measure of our operations, for financial and operational decision-making, and as a supplemental means of evaluating period-to-period comparisons on a consistent basis. Adjusted EBITDA is calculated as earnings before interest, taxes, depreciation, and amortization (“EBITDA”), excluding stock compensation expense, gains or losses on early extinguishment of debt, gains or losses on sales of real estate, impairments of real estate, and significant termination fees. Adjusted EBITDA also excludes unrealized gains or losses and significant realized gains and impairments that result from our non-real estate investments. These non-real estate investment amounts are classified in our consolidated statements of operations outside of revenues.
We believe Adjusted EBITDA provides investors with relevant and useful information as it allows investors to evaluate the operating performance of our business activities without having to account for differences recognized because of investing and financing decisions related to our real estate and non-real estate investments, our capital structure, capital market transactions, and variances resulting from the volatility of market conditions outside of our control. For example, we exclude gains or losses on the early extinguishment of debt to allow investors to measure our performance independent of our indebtedness and capital structure. We believe that adjusting for the effects of impairments and gains or losses on sales of real estate, significant impairments and gains on the sale of non-real estate investments, and significant termination fees allows investors to evaluate performance from period to period on a consistent basis without having to account for differences recognized because of investing and financing decisions related to our real estate and non-real estate investments or other corporate activities that may not be representative of the operating performance of our properties.
In addition, we believe that excluding charges related to stock compensation and unrealized gains or losses facilitates for investors a comparison of our business activities across periods without the volatility resulting from market forces outside of our control. Adjusted EBITDA has limitations as a measure of our performance. Adjusted EBITDA does not reflect our historical expenditures or future requirements for capital expenditures or contractual commitments. While Adjusted EBITDA is a relevant measure of performance, it does not represent net income (loss) or cash flows from operations calculated and presented in accordance with GAAP, and it should not be considered as an alternative to those indicators in evaluating performance or liquidity.
In order to calculate Adjusted EBITDA margin, we also make comparable adjustments to our revenues. We adjust our total revenues by realized gains, losses, and impairments related to our non-real estate investments and significant termination fees to arrive at revenues, as adjusted. Our calculation of Adjusted EBITDA margin divides Adjusted EBITDA by our revenues, as adjusted. We believe that consistent application of these comparable adjustments to both components of Adjusted EBITDA margin provides a more useful calculation for the comparison across periods.
The following table reconciles net income (loss) and revenues, the most directly comparable financial measures calculated and presented in accordance with GAAP, to Adjusted EBITDA and revenues, as adjusted, respectively, for the three months and years ended December 31, 2020 and 2019 (dollars in thousands):
| Three Months Ended December 31, | Year Ended December 31, | |||||||||||||||||||||||||
| 2020 | 2019 | 2020 | 2019 | |||||||||||||||||||||||
| Net income | $ | 457,133 | $ | 216,053 | $ | 827,171 | $ | 404,047 | ||||||||||||||||||
| Interest expense | 37,538 | 45,493 | 171,609 | 173,675 | ||||||||||||||||||||||
| Income taxes | 2,053 | 1,269 | 7,230 | 4,343 | ||||||||||||||||||||||
| Depreciation and amortization | 177,750 | 140,518 | 698,104 | 544,612 | ||||||||||||||||||||||
| Stock compensation expense | 11,394 | 10,239 | 43,502 | 43,640 | ||||||||||||||||||||||
| Loss on early extinguishment of debt | 7,898 | — | 60,668 | 47,570 | ||||||||||||||||||||||
| Gain on sales of real estate | (152,503) | (474) | (154,089) | (474) | ||||||||||||||||||||||
| Unrealized gains on non-real estate investments | (233,538) | (148,268) | (374,033) | (161,489) | ||||||||||||||||||||||
| Impairment of real estate | 25,177 | 12,334 | 55,722 | 12,334 | ||||||||||||||||||||||
| Impairment of non-real estate investments | — | 9,991 | 24,482 | 17,124 | ||||||||||||||||||||||
| Termination fee | — | — | (86,179) | — | ||||||||||||||||||||||
| Adjusted EBITDA | $ | 332,902 | $ | 287,155 | $ | 1,274,187 | $ | 1,085,382 | ||||||||||||||||||
| Revenues | $ | 463,720 | $ | 408,114 | $ | 1,885,637 | $ | 1,531,296 | ||||||||||||||||||
| Non-real estate investments – realized gains | 21,599 | 4,399 | 47,288 | 33,158 | ||||||||||||||||||||||
| Impairment of non-real estate investments | — | 9,991 | 24,482 | 17,124 | ||||||||||||||||||||||
| Termination fee | — | — | (86,179) | — | ||||||||||||||||||||||
| Revenues, as adjusted | $ | 485,319 | $ | 422,504 | $ | 1,871,228 | $ | 1,581,578 | ||||||||||||||||||
| Adjusted EBITDA margin | 69% | 68% | 68% | 69% |
Annual rental revenue
Annual rental revenue represents the annualized fixed base rental obligations, calculated in accordance with GAAP, for leases in effect as of the end of the period, related to our operating RSF. Annual rental revenue is presented using 100% of the annual rental revenue of our consolidated properties and our share of annual rental revenue for our unconsolidated real estate joint ventures. Annual rental revenue per RSF is computed by dividing annual rental revenue by the sum of 100% of the RSF of our consolidated properties and our share of the RSF of properties held in unconsolidated real estate joint ventures. As of December 31, 2020, approximately 94% of our leases (on an RSF basis) were triple net leases, which require tenants to pay substantially all real estate taxes, insurance, utilities, repairs and maintenance, common area expenses, and other operating expenses (including increases thereto) in addition to base rent. Annual rental revenue excludes these operating expenses recovered from our tenants. Amounts recovered from our tenants related to these operating expenses, along with base rent, are classified in income from rentals in our consolidated statements of operations.
Cash interest
Cash interest is equal to interest expense calculated in accordance with GAAP plus capitalized interest, less amortization of loan fees and debt premiums (discounts). Refer to the definition of “Fixed-charge coverage ratio” in this section under this Item 7 in this annual report on 10-K for a reconciliation of interest expense, the most directly comparable financial measure calculated and presented in accordance with GAAP, to cash interest.
Class A properties and AAA locations
Class A properties are properties clustered in AAA locations that provide innovative tenants with highly dynamic and collaborative environments that enhance their ability to successfully recruit and retain world-class talent and inspire productivity, efficiency, creativity, and success. Class A properties generally command higher annual rental rates than other classes of similar properties.
AAA locations are in close proximity to concentrations of specialized skills, knowledge, institutions, and related businesses. Such locations are generally characterized by high barriers to entry for new landlords, high barriers to exit for tenants, and a limited supply of available space.
Development, redevelopment, and pre-construction
A key component of our business model is our disciplined allocation of capital to the development and redevelopment of new Class A properties, and property enhancements identified during the underwriting of certain acquired properties, located in collaborative life science, technology, and agtech campuses in AAA urban innovation clusters. These projects are generally focused on providing high-quality, generic, and reusable spaces that meet the real estate requirements of, and are reusable by, a wide range of tenants. Upon completion, each value-creation project is expected to generate a significant increase in rental income, net operating income, and cash flows. Our development and redevelopment projects are generally in locations that are highly desirable to high-quality entities, which we believe results in higher occupancy levels, longer lease terms, higher rental income, higher returns, and greater long-term asset value.
Development projects generally consist of the ground-up development of generic and reusable facilities. Redevelopment projects consist of the permanent change in use of office, warehouse, and shell space into office/laboratory, tech office, or agtech space. We generally will not commence new development projects for aboveground construction of new Class A office/laboratory, tech office, and agtech space without first securing significant pre-leasing for such space, except when there is solid market demand for high-quality Class A properties.
Pre-construction activities include entitlements, permitting, design, site work, and other activities preceding commencement of construction of aboveground building improvements. The advancement of pre-construction efforts is focused on reducing the time required to deliver projects to prospective tenants. These critical activities add significant value for future ground-up development and are required for the vertical construction of buildings. Ultimately, these projects will provide high-quality facilities and are expected to generate significant revenue and cash flows.
Development, redevelopment, and pre-construction spending also includes the following costs: (i) certain tenant improvements and renovations that will be reimbursed, (ii) amounts to bring certain acquired properties up to market standard and/or other costs identified during the acquisition process (generally within two years of acquisition), and (iii) permanent conversion of space for highly flexible, move-in-ready office/laboratory space to foster the growth of promising early- and growth-stage life science companies.
Revenue-enhancing and repositioning capital expenditures represent spending to reposition or significantly change the use of a property, including through improvement in the asset quality from Class B to Class A.
Non-revenue-enhancing capital expenditures represent costs required to maintain the current revenues of a stabilized property, including the associated costs for renewed and re-leased space.
Fixed-charge coverage ratio
Fixed-charge coverage ratio is a non-GAAP financial measure representing the ratio of Adjusted EBITDA to fixed charges. We believe this ratio is useful to investors as a supplemental measure of our ability to satisfy fixed financing obligations and preferred stock dividends. Cash interest is equal to interest expense calculated in accordance with GAAP plus capitalized interest, less amortization of loan fees and debt premiums (discounts).
The following table reconciles interest expense, the most directly comparable financial measure calculated and presented in accordance with GAAP, to cash interest and fixed charges for the three months ended December 31, 2020 and 2019 (dollars in thousands):
| Three Months Ended December 31, | ||||||||||||||
| 2020 | 2019 | |||||||||||||
| Adjusted EBITDA | $ | 332,902 | $ | 287,155 | ||||||||||
| Interest expense | $ | 37,538 | $ | 45,493 | ||||||||||
| Capitalized interest | 37,589 | 23,822 | ||||||||||||
| Amortization of loan fees | (2,905) | (2,241) | ||||||||||||
| Amortization of debt premiums | 869 | 907 | ||||||||||||
| Cash interest and fixed charges | $ | 73,091 | $ | 67,981 | ||||||||||
| Fixed-charge coverage ratio: | ||||||||||||||
| – period annualized | 4.6x | 4.2x | ||||||||||||
| – trailing 12 months | 4.4x | 4.2x |
Initial stabilized yield (unlevered)
Initial stabilized yield is calculated as the estimated amounts of net operating income at stabilization divided by our investment in the property. Our initial stabilized yield excludes the benefit of leverage. Our cash rents related to our value-creation projects are generally expected to increase over time due to contractual annual rent escalations. Our estimates for initial stabilized yields, initial stabilized yields (cash basis), and total costs at completion represent our initial estimates at the commencement of the project. We expect to update this information upon completion of the project, or sooner if there are significant changes to the expected project yields or costs.
-
Initial stabilized yield reflects rental income, including contractual rent escalations and any rent concessions over the term(s) of the lease(s), calculated on a straight-line basis.
-
Initial stabilized yield (cash basis) reflects cash rents at the stabilization date after initial rental concessions, if any, have elapsed and our total cash investment in the property.
Investment-grade or publicly traded large cap tenants
Investment-grade or publicly traded large cap tenants represent tenants that are investment-grade rated or publicly traded companies with an average daily market capitalization greater than $10 billion for the twelve months ended December 31, 2020, as reported by Bloomberg Professional Services. In addition, we monitor the credit quality and related material changes of our tenants. Material changes that cause a tenant’s market capitalization to decline below $10 billion, which are not immediately reflected in the twelve-month average, may result in their exclusion from this measure.
Investments in real estate – value-creation square footage currently in rental properties
The square footage presented in the table below includes RSF of buildings in operation as of December 31, 2020, primarily representing lease expirations at recently acquired properties that also have inherent future development or redevelopment opportunities, for which we have the intent to demolish or redevelop the existing property upon expiration of the existing in-place leases and commencement of future construction:
| Dev/Redev | RSF lease expirations going into development and redevelopment | |||||||||||||||||||||||||||||||
| Property/Submarket | 2021 | 2022 | Thereafter | Total | ||||||||||||||||||||||||||||
| Near-term projects: | ||||||||||||||||||||||||||||||||
| The Arsenal on the Charles/Cambridge/Inner Suburbs | Redev | 64,056 | — | — | 64,056 | |||||||||||||||||||||||||||
| 50 and 60 Sylvan Road/Route 128 | Redev | 202,428 | — | — | 202,428 | |||||||||||||||||||||||||||
| 651 Gateway Boulevard/South San Francisco | Redev | — | 197,787 | 102,223 | (1) | 300,010 | ||||||||||||||||||||||||||
| Other/Seattle | Redev | — | 51,255 | — | 51,255 | |||||||||||||||||||||||||||
| 266,484 | 249,042 | 102,223 | 617,749 | |||||||||||||||||||||||||||||
| Intermediate-term projects: | ||||||||||||||||||||||||||||||||
| 3825 Fabian Way/Greater Stanford | Redev | — | 250,000 | — | 250,000 | |||||||||||||||||||||||||||
| 3450 and 3460 Hillview Avenue/Greater Stanford | Redev | — | 42,340 | 34,611 | 76,951 | |||||||||||||||||||||||||||
| 987 and 1075 Commercial Street/Greater Stanford | Dev | 26,738 | — | — | 26,738 | |||||||||||||||||||||||||||
| 10931 and 10933 North Torrey Pines Road/Torrey Pines | Dev | — | 92,450 | — | 92,450 | |||||||||||||||||||||||||||
| 10260 Campus Point Drive/University Town Center | Dev | — | — | 109,164 | 109,164 | |||||||||||||||||||||||||||
| 9363 and 9393 Towne Centre Drive/ University Town Center | Dev | — | — | 87,252 | 87,252 | |||||||||||||||||||||||||||
| 4555 Executive Drive/University Town Center | Dev | 41,475 | — | — | 41,475 | |||||||||||||||||||||||||||
| 68,213 | 384,790 | 231,027 | 684,030 | |||||||||||||||||||||||||||||
| Future projects: | ||||||||||||||||||||||||||||||||
| 380 and 420 E Street/Seaport Innovation District | Dev | — | — | 195,506 | 195,506 | |||||||||||||||||||||||||||
| 40 Sylvan Road/Route 128 | Redev | — | — | 312,845 | 312,845 | |||||||||||||||||||||||||||
| 3875 Fabian Way/Greater Stanford | Redev | — | — | 228,000 | 228,000 | |||||||||||||||||||||||||||
| 960 Industrial Road/Greater Stanford | Dev | — | — | 110,000 | 110,000 | |||||||||||||||||||||||||||
| 219 East 42nd Street/New York City | Dev | — | — | 349,947 | 349,947 | |||||||||||||||||||||||||||
| 11255 and 11355 North Torrey Pines Road/Torrey Pines | Dev | — | 139,135 | — | 139,135 | |||||||||||||||||||||||||||
| 4161 Campus Point Court/University Town Center | Dev | — | — | 159,884 | 159,884 | |||||||||||||||||||||||||||
| 6450 Sequence Drive/Sorrento Mesa | Redev | — | — | 202,915 | 202,915 | |||||||||||||||||||||||||||
| 4045 and 4075 Sorrento Valley Boulevard/Sorrento Valley | Dev | — | — | 50,926 | 50,926 | |||||||||||||||||||||||||||
| 601 Dexter Avenue North/Lake Union | Dev | — | — | 18,680 | 18,680 | |||||||||||||||||||||||||||
| 830 4th Avenue South/SoDo | Dev | — | — | 42,380 | 42,380 | |||||||||||||||||||||||||||
| — | 139,135 | 1,671,083 | 1,810,218 | |||||||||||||||||||||||||||||
| 334,697 | 772,967 | 2,004,333 | 3,111,997 |
(1) Represents vacant square footage as of December 31, 2020.
Joint venture financial information
We present components of balance sheet and operating results information related to our real estate joint ventures, which are not presented, or intended to be presented, in accordance with GAAP. We present the proportionate share of certain financial line items as follows: (i) for each real estate joint venture that we consolidate in our financial statements, which are controlled by us through contractual rights or majority voting rights, but of which we own less than 100%, we apply the noncontrolling interest economic ownership percentage to each financial item to arrive at the amount of such cumulative noncontrolling interest share of each component presented; and (ii) for each real estate joint venture that we do not control and do not consolidate, and are instead controlled jointly or by our joint venture partners through contractual rights or majority voting rights, we apply our economic ownership percentage to each financial item to arrive at our proportionate share of each component presented.
The components of balance sheet and operating results information related to our real estate joint ventures do not represent our legal claim to those items. For each entity that we do not wholly own, the joint venture agreement generally determines what equity holders can receive upon capital events, such as sales or refinancing, or in the event of a liquidation. Equity holders are normally entitled to their respective legal ownership of any residual cash from a joint venture only after all liabilities, priority distributions, and claims have been repaid or satisfied.
We believe this information can help investors estimate the balance sheet and operating results information related to our partially owned entities. Presenting this information provides a perspective not immediately available from consolidated financial statements and one that can supplement an understanding of the joint venture assets, liabilities, revenues, and expenses included in our consolidated results.
The components of balance sheet and operating results information related to our real estate joint ventures are limited as an analytical tool as the overall economic ownership interest does not represent our legal claim to each of our joint ventures’ assets, liabilities, or results of operations. In addition, joint venture financial information may include financial information related to the unconsolidated real estate joint ventures that we do not control. We believe that in order to facilitate for investors a clear understanding of our operating results and our total assets and liabilities, joint venture financial information should be examined in conjunction with our consolidated statements of operations and balance sheets. Joint venture financial information should not be considered an alternative to our consolidated financial statements, which are prepared in accordance with GAAP.
Net cash provided by operating activities after dividends
Net cash provided by operating activities after dividends includes the deduction for distributions to noncontrolling interests. For purposes of this calculation, changes in operating assets and liabilities are excluded as they represent timing differences.
Net debt and preferred stock to Adjusted EBITDA
Net debt and preferred stock to Adjusted EBITDA is a non-GAAP financial measure that we believe is useful to investors as a supplemental measure in evaluating our balance sheet leverage. Net debt and preferred stock is equal to the sum of total consolidated debt less cash, cash equivalents, and restricted cash, plus preferred stock outstanding as of the end of the period. Refer to the definition of “Adjusted EBITDA and Adjusted EBITDA margin” under Item 7 in this annual report on Form 10-K for further information on the calculation of Adjusted EBITDA.
The following table reconciles debt to net debt and preferred stock and computes the ratio to Adjusted EBITDA as of December 31, 2020 and 2019 (dollars in thousands):
| December 31, | |||||||||||
| 2020 | 2019 | ||||||||||
| Secured notes payable | $ | 230,925 | $ | 349,352 | |||||||
| Unsecured senior notes payable | 7,232,370 | 6,044,127 | |||||||||
| Unsecured senior line of credit and commercial paper | 99,991 | 384,000 | |||||||||
| Unamortized deferred financing costs | 56,312 | 47,299 | |||||||||
| Cash and cash equivalents | (568,532) | (189,681) | |||||||||
| Restricted cash | (29,173) | (53,008) | |||||||||
| Preferred stock | — | — | |||||||||
| Net debt and preferred stock | $ | 7,021,893 | $ | 6,582,089 | |||||||
| Adjusted EBITDA: | |||||||||||
| – quarter annualized | $ | 1,331,608 | $ | 1,148,620 | |||||||
| – trailing 12 months | $ | 1,274,187 | $ | 1,085,382 | |||||||
| Net debt and preferred stock to Adjusted EBITDA: | |||||||||||
| – quarter annualized | 5.3 | x | 5.7 | x | |||||||
| – trailing 12 months | 5.5 | x | 6.1 | x |
Net operating income, net operating income (cash basis), and operating margin
The following table reconciles net income to net operating income, and to net operating income (cash basis) for the years ended December 31, 2020, 2019, and 2018 (dollars in thousands):
| Year Ended December 31, | ||||||||||||||||||||
| 2020 | 2019 | 2018 | ||||||||||||||||||
| Net income | $ | 827,171 | $ | 404,047 | $ | 402,793 | ||||||||||||||
| Equity in earnings of unconsolidated real estate joint ventures | (8,148) | (10,136) | (43,981) | |||||||||||||||||
| General and administrative expenses | 133,341 | 108,823 | 90,405 | |||||||||||||||||
| Interest expense | 171,609 | 173,675 | 157,495 | |||||||||||||||||
| Depreciation and amortization | 698,104 | 544,612 | 477,661 | |||||||||||||||||
| Impairment of real estate | 48,078 | 12,334 | 6,311 | |||||||||||||||||
| Loss on early extinguishment of debt | 60,668 | 47,570 | 1,122 | |||||||||||||||||
| Gain on sales of real estate | (154,089) | (474) | (8,704) | |||||||||||||||||
| Investment income | (421,321) | (194,647) | (136,763) | |||||||||||||||||
| Net operating income | 1,355,413 | 1,085,804 | 946,339 | |||||||||||||||||
| Straight-line rent revenue | (96,676) | (104,235) | (93,883) | |||||||||||||||||
| Amortization of acquired above- and below-market leases | (57,244) | (29,813) | (21,938) | |||||||||||||||||
| Net operating income (cash basis) | $ | 1,201,493 | $ | 951,756 | $ | 830,518 | ||||||||||||||
| Net operating income (from above) | $ | 1,355,413 | $ | 1,085,804 | $ | 946,339 | ||||||||||||||
| Total revenues | $ | 1,885,637 | $ | 1,531,296 | $ | 1,327,459 | ||||||||||||||
| Operating margin | 72% | 71% | 71% |
Net operating income is a non-GAAP financial measure calculated as net income, the most directly comparable financial measure calculated and presented in accordance with GAAP, excluding equity in the earnings of our unconsolidated real estate joint ventures, general and administrative expenses, interest expense, depreciation and amortization, impairments of real estate, gains or losses on early extinguishment of debt, gains or losses on sales of real estate, and investment income or loss. We believe net operating income provides useful information to investors regarding our financial condition and results of operations because it primarily reflects
those income and expense items that are incurred at the property level. Therefore, we believe net operating income is a useful measure for investors to evaluate the operating performance of our consolidated real estate assets. Net operating income on a cash basis is net operating income adjusted to exclude the effect of straight-line rent and amortization of acquired above- and below-market lease revenue adjustments required by GAAP. We believe that net operating income on a cash basis is helpful to investors as an additional measure of operating performance because it eliminates straight-line rent revenue and the amortization of acquired above- and below-market leases.
Furthermore, we believe net operating income is useful to investors as a performance measure for our consolidated properties because, when compared across periods, net operating income reflects trends in occupancy rates, rental rates, and operating costs, which provide a perspective not immediately apparent from net income or loss. Net operating income can be used to measure the initial stabilized yields of our properties by calculating net operating income generated by a property divided by our investment in the property. Net operating income excludes certain components from net income in order to provide results that are more closely related to the results of operations of our properties. For example, interest expense is not necessarily linked to the operating performance of a real estate asset and is often incurred at the corporate level rather than at the property level. In addition, depreciation and amortization, because of historical cost accounting and useful life estimates, may distort comparability of operating performance at the property level. Impairments of real estate have been excluded in deriving net operating income because we do not consider impairments of real estate to be property-level operating expenses. Impairments of real estate relate to changes in the values of our assets and do not reflect the current operating performance with respect to related revenues or expenses. Our impairments of real estate represent the write-down in the value of the assets to the estimated fair value less cost to sell. These impairments result from investing decisions or a deterioration in market conditions. We also exclude realized and unrealized investment income or loss, which results from investment decisions that occur at the corporate level related to non-real estate investments in publicly traded companies and certain privately held entities. Therefore, we do not consider these activities to be an indication of operating performance of our real estate assets at the property level. Our calculation of net operating income also excludes charges incurred from changes in certain financing decisions, such as losses on early extinguishment of debt, as these charges often relate to corporate strategy. Property operating expenses included in determining net operating income primarily consist of costs that are related to our operating properties, such as utilities, repairs, and maintenance; rental expense related to ground leases; contracted services, such as janitorial, engineering, and landscaping; property taxes and insurance; and property-level salaries. General and administrative expenses consist primarily of accounting and corporate compensation, corporate insurance, professional fees, office rent, and office supplies that are incurred as part of corporate office management. We calculate operating margin as net operating income divided by total revenues.
We believe that in order to facilitate for investors a clear understanding of our operating results, net operating income should be examined in conjunction with net income or loss as presented in our consolidated statements of operations. Net operating income should not be considered as an alternative to net income or loss as an indication of our performance, nor as an alternative to cash flows as a measure of our liquidity or our ability to make distributions.
Operating statistics
We present certain operating statistics related to our properties, including number of properties, RSF, occupancy percentage, leasing activity, and contractual lease expirations as of the end of the period. We believe these measures are useful to investors because they facilitate an understanding of certain trends for our properties. We compute the number of properties, RSF, occupancy percentage, leasing activity, and contractual lease expirations at 100% for all properties in which we have an investment, including properties owned by our consolidated and unconsolidated real estate joint ventures. For operating metrics based on annual rental revenue, refer to the definition of “Annual rental revenue” in this “Non-GAAP measures and definitions” section.
Same property comparisons
As a result of changes within our total property portfolio during the comparative periods presented, including changes from assets acquired or sold, properties placed into development or redevelopment, and development or redevelopment properties recently placed into service, the consolidated total income from rentals, as well as rental operating expenses in our operating results, can show significant changes from period to period. In order to supplement an evaluation of our results of operations over a given quarterly or annual period, we analyze the operating performance for all consolidated properties that were fully operating for the entirety of the comparative periods presented, referred to as same properties. We separately present quarterly and year-to-date same property results to align with the interim financial information required by the SEC in our management’s discussion and analysis of our financial condition and results of operations. These same properties are analyzed separately from properties acquired subsequent to the first day in the earliest comparable quarterly or year-to-date period presented, properties that underwent development or redevelopment at any time during the comparative periods, unconsolidated real estate joint ventures, properties classified as held for sale, and corporate entities (legal entities performing general and administrative functions), which are excluded from same property results. Additionally, termination fees, if any, are excluded from the results of same properties. Refer to the “Same properties” subsection in the “Results of operations” section within this Item 7 in this annual report on Form 10-K for additional information.
Stabilized occupancy date
The stabilized occupancy date represents the estimated date on which the project is expected to reach occupancy of 95% or greater.
Tenant recoveries
Tenant recoveries represent revenues comprising reimbursement of real estate taxes, insurance, utilities, repairs and maintenance, common area expenses, and other operating expenses and earned in the period during which the applicable expenses are incurred and the tenant’s obligation to reimburse us arises.
We classify rental revenues and tenant recoveries generated through the leasing of real estate assets within revenue in income from rentals in our consolidated statements of operations. We provide investors with a separate presentation of rental revenues and tenant recoveries in the “Comparison of results for the year ended December 31, 2020, to the year ended December 31, 2019” subsection of the “Results of operations” section within this Item 7 because we believe it promotes investors’ understanding of our operating results. We believe that the presentation of tenant recoveries is useful to investors as a supplemental measure of our ability to recover operating expenses under our triple net leases, including recoveries of utilities, repairs and maintenance, insurance, property taxes, common area expenses, and other operating expenses, and of our ability to mitigate the effect to net income for any significant variability to components of our operating expenses.
The following table reconciles income from rentals to tenant recoveries for the years ended December 31, 2020, 2019, and 2018 (in thousands):
| Year Ended December 31, | ||||||||||||||||||||
| 2020 | 2019 | 2018 | ||||||||||||||||||
| Income from rentals | $ | 1,878,208 | $ | 1,516,864 | $ | 1,314,781 | ||||||||||||||
| Rental revenues | (1,471,840) | (1,165,788) | (1,010,718) | |||||||||||||||||
| Tenant recoveries | $ | 406,368 | $ | 351,076 | $ | 304,063 | ||||||||||||||
Total market capitalization
Total market capitalization is equal to the outstanding shares of common stock at the end of the period multiplied by the closing price on the last trading day of the period (i.e., total equity capitalization), plus total debt outstanding at period-end.
Unencumbered net operating income as a percentage of total net operating income
Unencumbered net operating income as a percentage of total net operating income is a non-GAAP financial measure that we believe is useful to investors as a performance measure of the results of operations of our unencumbered real estate assets as it reflects those income and expense items that are incurred at the unencumbered property level. Unencumbered net operating income is derived from assets classified in continuing operations, which are not subject to any mortgage, deed of trust, lien, or other security interest, as of the period for which income is presented.
The following table summarizes unencumbered net operating income as a percentage of total net operating income for the years ended December 31, 2020 and 2019 (dollars in thousands):
| Year Ended December 31, | |||||||||||
| 2020 | 2019 | ||||||||||
| Unencumbered net operating income | $ | 1,295,520 | $ | 1,024,619 | |||||||
| Encumbered net operating income | 59,893 | 61,185 | |||||||||
| Total net operating income | $ | 1,355,413 | $ | 1,085,804 | |||||||
| Unencumbered net operating income as a percentage of total net operating income | 96% | 94% |
Weighted-average shares of common stock outstanding – diluted
From time to time, we enter into capital market transactions, including forward equity sales agreements (“Forward Agreements”), to fund acquisitions, to fund construction of our highly leased development and redevelopment projects, and for general working capital purposes. We are required to consider the potential dilutive effect of our forward equity sales agreements under the treasury stock method while the forward equity sales agreements are outstanding. As of December 31, 2020, we had Forward Agreements outstanding to sell an aggregate of 362 thousand shares of common stock.
Prior to the conversion of our remaining outstanding shares in October 2019, we considered the effect of assumed conversion of our outstanding 7.00% Series D Convertible Preferred Stock when determining potentially dilutive incremental shares to our common stock. When calculating the assumed conversion, we add back to net income or loss the dividends paid on our Series D Convertible Preferred Stock to the numerator and then include additional common shares assumed to have been issued (as displayed in the table below) to the denominator of the per share calculation. The effect of the assumed conversion is considered separately for our per share calculations of net income or loss; funds from operations, computed in accordance with the definition in the Nareit White Paper; and funds from operations, as adjusted. Prior to the conversion of our remaining outstanding shares in October 2019, our Series D Convertible Preferred Stock was dilutive and assumed to be converted when quarterly and annual basic EPS, funds from operations, or funds from operations, as adjusted, exceeded approximately $1.75 and $7.00 per share, respectively, subject to conversion ratio adjustments and the impact of repurchases of our Series D Convertible Preferred Stock. The effect of the assumed conversion was included when it was dilutive on a per share basis. The dilutive effect to both numerator and denominator may result in a per share effect of less than a half cent, which would appear as zero in our per share calculation, even when the dilutive effect to the numerator alone appears in our reconciliation. Refer to Note 12 – “Earnings per share” and Note 15 – “Stockholders’ equity” to our consolidated financial statements under Item 15 in this annual report on Form 10-K for more information related to our forward equity sales agreements.
The weighted-average shares of common stock outstanding used in calculating EPS – diluted, funds from operations per share – diluted, and funds from operations per share – diluted, as adjusted, for the years ended December 31, 2020, 2019 and 2018, are calculated as follows (in thousands):
| Year Ended December 31, | |||||||||||||||||
| 2020 | 2019 | 2018 | |||||||||||||||
| Weighted-average shares of common stock outstanding: | |||||||||||||||||
| Basic shares for EPS | 126,106 | 112,204 | 103,010 | ||||||||||||||
| Outstanding forward equity sales agreements | 384 | 320 | 311 | ||||||||||||||
| Series D Convertible Preferred Stock | — | — | — | ||||||||||||||
| Diluted shares for EPS | 126,490 | 112,524 | 103,321 | ||||||||||||||
| Basic shares for EPS | 126,106 | 112,204 | 103,010 | ||||||||||||||
| Outstanding forward equity sales agreements | 384 | 320 | 311 | ||||||||||||||
| Series D Convertible Preferred Stock | — | 442 | 727 | ||||||||||||||
| Diluted shares for FFO | 126,490 | 112,966 | 104,048 | ||||||||||||||
| Basic shares for EPS | 126,106 | 112,204 | 103,010 | ||||||||||||||
| Outstanding forward equity sales agreements | 384 | 320 | 311 | ||||||||||||||
| Series D Convertible Preferred Stock | — | — | — | ||||||||||||||
| Diluted shares for FFO, as adjusted | 126,490 | 112,524 | 103,321 |
Previous: Item 6. SELECTED FINANCIAL DATA (CONTINUED) · Next: Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK