 filings.tools
Berkshire Hathaway (BRK-B) 10-K risk factor changes: FY2021 vs FY2020
The 2021-12-31 10-K against the 2020-12-31 one, compared heading by heading and sentence by sentence.
Item 1A10 rewritten6 added10 removed94 unchanged
All filing items1,588 rewritten627 added597 removed2,394 unchanged
Summary
counted, not written
- Item 1A headings could not be compared: only 0 carried over between the two years, which usually means one filing was read wrongly, so none is reported as new or removed.
- Sentence by sentence, 627 added, 597 removed, 1,588 rewritten and 2,394 unchanged across 14 items that differ.
- Not in this year's filing: Item 6. Selected Financial Data.
Sentences by item
16 items, with every count and a link to each item that changed
| Item | Added | Removed | Rewritten | Unchanged |
|---|---|---|---|---|
| Item 1A. Risk Factors | 6 | 10 | 10 | 94 |
| Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations | 272 | 233 | 440 | 508 |
| Item 7A. Quantitative and Qualitative Disclosures About Market Risk | 1 | 1 | 3 | 6 |
| Item 1. Business Description | 71 | 30 | 207 | 535 |
| Item 3. Legal Proceedings | 1 | 1 | 0 | 5 |
| Cover and table of contents | 2 | 2 | 28 | 66 |
| Item 1B. Unresolved Staff Comments | 0 | 0 | 0 | 1 |
| Item 2. Description of Properties | 5 | 7 | 34 | 41 |
| Item 4. Mine Safety Disclosures | 0 | 0 | 7 | 13 |
| Item 5. Market for Registrant’s Common Equity, Related Security Holder Matters and Issuer Purchases of Equity Securities | 6 | 8 | 6 | 21 |
| Item 8. Financial Statements and Supplementary Data | 249 | 264 | 763 | 967 |
| Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure | 0 | 0 | 0 | 1 |
| Item 9A. Controls and Procedures | 0 | 0 | 2 | 3 |
| Item 9B. Other Information | 0 | 0 | 1 | 3 |
| Item 15. Exhibits and Financial Statement Schedules | 14 | 9 | 87 | 130 |
| Item 6. Selected Financial Datadropped | 0 | 32 | 0 | 0 |
Underlined words on a shaded ground are new in FY2021; struck-through words were in FY2020. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors
10 rewritten, 6 added, 10 removed, 94 unchanged
Although we have taken steps intended to mitigate these risks, including business continuity planning, disaster recovery planning and business impact analysis, a significant disruption or cyber intrusion [added: at one or more of our significant operations] could adversely affect our results of operations, financial condition and liquidity.
Buffett, Chairman of the Board of Directors and Chief Executive Officer, age [removed: 90,] [added: 91,] in consultation with Charles T.
Munger, Vice Chairman of the Board of Directors, age [removed: 97.][added: 98.]
Mr. [removed: Abel and Mr. Jain each report directly to Mr.] Buffett [removed: and Mr. Buffett] continues to be responsible for major capital allocation and investment decisions.
[removed: We] [added: We] need [removed: qualified] [added: qualified] personnel to manage and operate our various businesses.
[removed: Competition] [added: Competition] and technology may erode our business franchises and result in lower earnings.
[removed: The] [added: The] degree of estimation error inherent in the process of estimating property and casualty insurance loss reserves may result in significant underwriting [removed: losses.][added: losses.]
Our estimated unpaid losses arising under contracts covering property and casualty insurance risks are large [removed: ($120.8] [added: ($125] billion at December 31, [removed: 2020),] [added: 2021),] and a small percentage increase to those liabilities can result in materially lower reported earnings.
Regulations broadly apply and may limit management’s ability to independently make and implement decisions regarding numerous matters including: acquiring businesses; constructing, acquiring, disposing or retiring of operating assets; operating and maintaining generating facilities and transmission and distribution system assets; complying with pipeline safety and integrity and environmental requirements; setting rates charged to customers; establishing capital structures and issuing debt; [removed: transacting] [added: managing and reporting transactions] between our domestic utilities and our other subsidiaries and affiliates; and paying dividends or similar distributions.
The [removed: risk of] operational or financial failure of capital projects [removed: is] [added: may] not [removed: necessarily] [added: be] recoverable through rates that are charged to customers.
Mr. Abel and Mr. Jain each report directly to Mr. Buffett.
Should a replacement for Mr. Buffett be needed currently, Berkshire’s Board of Directors has agreed that Mr. Abel should replace Mr. Buffett.
Climate change may impact our businesses.
Climate change could cause increases in hurricanes, floods, wildfires, and other risks that could produce losses affecting our businesses.
Also, failure to comply with new or existing regulations or reinterpretations of existing regulations relating to climate change could have a significant adverse effect on our financial results.
K-26
K-22
However, Berkshire’s Board of Directors has identified certain current Berkshire managers who, in their judgment, are capable of succeeding Mr. Buffett and has agreed on a replacement for Mr. Buffett should a replacement be needed currently.
Over ten years ago, we assumed the risk of potentially significant losses under a number of equity index put option contracts, which contain equity price risks.
Most of the contracts remaining at year end 2020 will expire by February 2023.
Risks of losses under these contracts are based on declines in equity prices of stocks comprising certain major U.S. and international stock indexes.
We received considerable cash premiums as compensation for accepting these risks.
Absent major reductions in future equity securities prices, our ultimate payment obligations are not likely to be significant.
Nevertheless, there can be no assurance that equity securities prices will not decline significantly resulting in significant settlement payments upon contract expirations.
K-23
Currently, we estimate that our aggregate exposure from a single event under outstanding policies is significantly below $10 billion.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
440 rewritten, 272 added, 233 removed, 508 unchanged
| | | [removed: 2020] [added: 2021] | | | | [removed: 2019] [added: 2020] | | | | [removed: 2018] [added: 2019] | | |
| Insurance – underwriting | | $ | [removed: 657] [added: 728] | | | $ | [removed: 325] [added: 657] | | | $ | [removed: 1,566] [added: 325] | |
| Insurance – investment income | | | [removed: 5,039] [added: 4,807] | | | | [removed: 5,530] [added: 5,039] | | | | [removed: 4,554] [added: 5,530] | |
| Railroad | | | [removed: 5,161] [added: 5,990] | | | | [removed: 5,481] [added: 5,161] | | | | [removed: 5,219] [added: 5,481] | |
| Utilities and energy | | | [removed: 3,091] [added: 3,495] | | | | [removed: 2,840] [added: 3,091] | | | | [removed: 2,621] [added: 2,840] | |
| Manufacturing, service and retailing | | | [removed: 8,300] [added: 11,120] | | | | [removed: 9,372] [added: 8,300] | | | | [removed: 9,364] [added: 9,372] | |
| Investment and derivative gains/losses | | | [removed: 31,591] [added: 62,340] | | | | [removed: 57,445] [added: 31,591] | | | | [removed: (17,737] [added: 57,445] | [removed: )] |
| Other* | | | [removed: (11,318] [added: 1,315] | [removed: )] | | | [removed: 424] [added: (11,318] | [added: )] | | | [removed: (1,566] [added: 424] | [removed: )] |
| Net earnings attributable to Berkshire Hathaway shareholders | | $ | [removed: 42,521] [added: 89,795] | | | $ | [removed: 81,417] [added: 42,521] | | | $ | [removed: 4,021] [added: 81,417] | |
| * | Includes goodwill and indefinite-lived intangible asset impairment charges of [added: $259 million in 2021,] $11.0 billion in [removed: 2020,] [added: 2020 and] $435 million in [removed: 2019 and $3.0 billion in 2018,] [added: 2019,] which includes our share of charges recorded by Kraft Heinz. |
Through our subsidiaries, we engage in [removed: a number of] [added: numerous] diverse business activities.
The business segment data (Note [removed: 27] [added: 25] to the accompanying Consolidated Financial Statements) should be read in conjunction with this discussion.
[removed: As the] [added: The] COVID-19 pandemic [removed: accelerated beginning in the second half of March,] [added: negatively affected] most of our businesses [removed: were negatively affected,] [added: beginning in March of 2020,] with the effects to date ranging from relatively minor to severe.
[removed: Revenues and earnings] [added: Earnings] of most of our manufacturing, service and retailing businesses declined considerably, and in certain instances severely, in the second quarter [removed: due to closures] of [removed: facilities where crowds gather, such as retail stores, restaurants and entertainment venues as well as from public travel restrictions and from closures of certain of our businesses.][added: 2020.]
We cannot reliably predict future economic effects of the pandemic or when business activities at [removed: all of] our [removed: numerous and diverse] operations will [added: completely] normalize.
Our insurance businesses generated after-tax earnings from underwriting of [removed: $657] [added: $728] million in [removed: 2020, $325] [added: 2021, $657] million in [removed: 2019] [added: 2020] and [removed: $1.6 billion] [added: $325 million] in [removed: 2018.][added: 2019.]
Insurance underwriting results included after-tax losses from significant catastrophe events of approximately [added: $2.3 billion in 2021,] $750 million in [removed: 2020,] [added: 2020 and] $800 million in [removed: 2019 and $1.3 billion in 2018.][added: 2019.]
Underwriting results in 2020 [removed: also reflected] [added: included] the effects of the pandemic, arising from premium reductions from the GEICO Giveback program, reduced claims frequencies for private passenger automobile insurance and increased loss estimates for certain commercial insurance and property and casualty reinsurance business.
After-tax earnings of our railroad business [added: in 2021 rose 16.1% compared to 2020 and] decreased 5.8% in 2020 [removed: as] compared to 2019.
After-tax earnings of our utilities and energy business [added: in 2021] increased [added: 13.1% versus 2020 and increased] 8.8% [removed: as] [added: in 2020] compared to 2019.
The increase [added: in 2021 included higher earnings from the utilities and natural gas pipelines businesses, including the effects of a business acquisition, and from the real estate brokerage business, while the earnings increase in 2020] reflected increased tax benefits from renewable energy and increased earnings from the real estate brokerage business.
Earnings in [removed: 2020] [added: 2021] from our manufacturing, service and retailing businesses [added: increased 34.0% versus 2020 and] declined 11.4% [added: in 2020] versus 2019.
The effects of the COVID-19 pandemic [added: have] varied among our [removed: manufacturing] businesses relative to significance and duration.
Other earnings included after-tax goodwill and indefinite-lived intangible asset impairment charges of [added: $259 million in 2021,] $11.0 billion in [removed: 2020,] [added: 2020 and] $435 million in [removed: 2019 and $3.0 billion in 2018.][added: 2019.]
Approximately $9.8 billion of the charges in 2020 were attributable to impairments of goodwill and [removed: identifiable] [added: indefinite-lived] intangible assets recorded in connection with Berkshire’s acquisition of Precision Castparts in 2016.
Other earnings in [removed: 2020] [added: 2021] also included after-tax foreign exchange rate [added: gains of $955 million and after-tax] losses of $764 million [added: in 2020] related to non-U.S. Dollar denominated debt issued by Berkshire and its U.S.-based finance subsidiary, Berkshire Hathaway Finance Corporation (“BHFC”).
Investment and derivative gains/losses in each of the three years presented [removed: included significant gains and losses on] [added: predominantly derived from] our investments in equity [removed: securities, including] [added: securities and included significant net] unrealized gains [removed: and losses] from market price [removed: changes on securities we continue to hold.][added: changes.]
We believe that investment and derivative gains/losses, whether realized from dispositions or unrealized from changes in market prices of equity securities, are generally meaningless in understanding our reported [added: quarterly or annual] results or evaluating the economic performance of our [added: operating] businesses.
Accordingly, we evaluate performance of underwriting operations without any allocation of investment income or investment [removed: gains/losses.][added: gains and losses.]
However, we consider investment gains and losses, whether realized or [removed: unrealized] [added: unrealized,] as [removed: non-operating, based on our long-held strategy of acquiring securities and holding those securities for long periods.][added: non-operating.]
We believe that such gains and losses are not meaningful in understanding the [added: periodic] operating results of our insurance businesses.
The timing and [removed: amount] [added: magnitude] of catastrophe losses can produce significant volatility in our periodic underwriting results, particularly with respect to our reinsurance businesses.
Generally, we consider [removed: pre-tax] [added: incurred] losses [removed: in excess of] [added: exceeding] $100 million from a current year catastrophic event to be significant.
Unpaid loss estimates, including estimates under retroactive reinsurance contracts, were approximately [removed: $120.8] [added: $125] billion as of December 31, [removed: 2020.][added: 2021.]
Underwriting results [removed: in 2020] of certain of our commercial insurance and reinsurance businesses were negatively affected [added: in 2021 and 2020] by estimated losses and costs associated with the COVID-19 pandemic, including [removed: estimated] [added: incremental] provisions for claims and uncollectible premiums and incremental operating costs to maintain customer service levels.
The effects of the pandemic [removed: in the] [added: on] future [added: periods] may be [removed: further] affected by judicial rulings and regulatory and legislative actions pertaining to insurance coverage and claims and by its effects on general economic activity, which we cannot reasonably estimate at this time.
Our insurance and reinsurance businesses are GEICO, Berkshire Hathaway Primary Group and Berkshire Hathaway Reinsurance [removed: Group (“BHRG”).][added: Group.]
| | [removed: 2020] [added: 2021] | | | | [removed: 2019] [added: 2020] | | | | [removed: 2018] [added: 2019] | | |
| GEICO | $ | [removed: 3,428] [added: 1,259] | | | $ | [removed: 1,506] [added: 3,428] | | | $ | [removed: 2,449] [added: 1,506] | |
| Berkshire Hathaway Primary Group | | [removed: 110] [added: 607] | | | | [removed: 383] [added: 110] | | | | [removed: 670] [added: 383] | |
Over the second half of 2020 and continuing in 2021, many of these businesses experienced significant recoveries in revenues and earnings, in some instances exceeding pre-pandemic levels.
However, many of our businesses were negatively affected by ongoing global supply chain disruptions, including those attributable to major winter storms and a hurricane in North America, which contributed to higher input costs.
Underwriting results in 2021 were favorably impacted by reductions in incurred losses for prior accident years under property and casualty contracts.
Underwriting results in 2021 were negatively impacted by reductions in earned premium from the GEICO Giveback program, higher private passenger auto claims frequencies and severities estimates and higher losses in the life reinsurance business.
After-tax earnings from insurance investment income in 2021 decreased 4.6% compared to 2020 and declined 8.9% in 2020 versus 2019.
Earnings in 2021 and 2020 were negatively affected by declines in interest rates on our substantial holdings of cash and U.S. Treasury Bills.
K-32
The earnings increase in 2021 reflected overall higher freight volumes, higher average revenue per car/unit and improved productivity, partly offset by higher average fuel prices and volume related costs.
Many of our businesses generated significantly higher earnings in 2021 compared to 2020.
While customer demand for products was relatively high during the year, several of our businesses experienced higher materials, freight and other input costs attributable to ongoing disruptions in global supply chains.
The significant catastrophe events in 2021 included Hurricane Ida and floods in Europe in the third quarter, as well as Winter Storm Uri in the first quarter.
GEICO’s pre-tax underwriting earnings in 2021 and 2020 were significantly affected by changes in average claims frequencies.
Beginning in the first quarter of 2020 and continuing through the first quarter of 2021, average claims frequencies were significantly below historical levels from the effects of less driving by policyholders during the COVID-19 pandemic.
Starting in the second quarter of 2021, average claims frequencies began to increase as driving by policyholders increased.
In addition, average property claims severities increased due to increases in used vehicle valuations.
2021 versus 2020
Premiums earned in 2021 increased $2.6 billion (7.4%) compared to 2020.
The GEICO Giveback Program reduced earned premiums by approximately $2.5 billion in 2020 with the remainder of the impact included in 2021.
Voluntary auto policies-in-force in 2021 were slightly higher compared to 2020.
The increase in the loss ratio reflected an increase in average claims frequencies and severities and higher losses from significant catastrophe events, partially offset by increased reductions of ultimate estimated losses for claims occurring in prior years.
Ultimate claim loss estimates for claims occurring in prior years were reduced approximately $1.8 billion in 2021 and $253 million in 2020, which produced corresponding reductions in losses and loss adjustment expenses.
Losses incurred attributable to Hurricane Ida in 2021 were $375 million, while losses in 2020 included $81 million attributable to Hurricanes Laura and Sally and U.S. wildfires.
Underwriting expenses decreased $199 million (3.5%) compared to 2020, reflecting lower advertising expenses.
GEICO’s expense ratio (underwriting expenses to premiums earned) decreased 1.6 percentage points in 2021, reflecting lower nominal expenses and higher premiums earned.
GEICO’s loss ratio was 74.1%, a decrease of 7.2 percentage points compared to 2019.
Premiums written increased $2.4 billion (23.3%) in 2021 compared to 2020, reflecting increases from BH Specialty (36%), MedPro Group (16%), NICO Primary (25%), GUARD (7%), BHHC (5%) and USLI (20%).
The increases were across multiple coverages and occurred in several markets.
BH Primary’s loss ratios were 70.0% in 2021, 74.1% in 2020 and 69.1% in 2019.
Underwriting expenses increased $485 million (20.4%) in 2021 compared to 2020, reflecting the increase in business, changes in business mix and the costs associated with new product development.
The expense ratio in 2021 was relatively unchanged versus 2020.
The expense ratio in 2020 declined 2.0 percentage points compared to 2019 and reflected changes in business mix and the impact of the Applied Underwriters divestiture.
We also write life and health reinsurance coverages through General Re Life Corporation, General Reinsurance AG and Berkshire Hathaway Life Insurance Company of Nebraska (“BHLN”).
Premiums written increased $854 million (6.4%) in 2021 compared to 2020, primarily attributable to net new business, increased participations and improved prices on renewals and favorable currency translation effects.
The increase was primarily attributable to property coverages.
Losses and loss adjustment expenses were relatively unchanged in 2021 compared to 2020, while the loss ratio decreased 9.1 percentage points.
Losses incurred arising from significant catastrophe events in 2021 (Hurricane Ida, flooding in Europe and Winter Storm Uri) were $2.1 billion, which were partially offset by reductions in estimated ultimate liabilities for losses occurring in prior years of $718 million.
Incurred losses from significant catastrophe events during 2019 were $1.0 billion and derived from Typhoons Faxai and Hagibis and various U.S. and non-U.S. wildfires, which were partially offset by reductions in estimated ultimate liabilities for losses occurring in prior years of $295 million.
The expense ratio in 2021 decreased 2.3 percentage points compared to 2020, primarily attributable to changes in business mix and foreign currency effects.
Premiums written in 2020 included $710 million from a contract that covered U.S. health risks that incepted in the fourth quarter of 2019 and did not renew in 2021.
Otherwise, premiums written in 2021 increased 9.4% versus 2020, primarily due to volume growth in the Asia Pacific region and favorable foreign currency translation effects.
| --- | --- |
In each of the third and fourth quarters of 2020, several of these businesses experienced significant increases in revenues and earnings as compared to the second quarter.
Our businesses that were deemed essential continued to operate through the pandemic, including our railroad, utilities and energy, insurance and certain of our manufacturing, wholesale distribution and service businesses.
In response to the effects of the pandemic, our businesses implemented various business continuity plans to protect our employees and customers.
Such plans include a variety of actions, such as temporarily closing certain retail stores, manufacturing facilities and service centers of businesses that were not subject to government mandated closure.
Our businesses also implemented practices to protect employees while at work.
Such practices included work-from-home, staggered or reduced work schedules, increased cleaning and sanitation of workspaces, providing employee health screenings, eliminating non-essential travel and face-to-face meetings and providing general health reminders intended to lower the risk of spreading COVID-19.
We also took actions in response to the economic losses from reductions in consumer demand for products and services we offer and our temporary inability to produce goods and provide services at certain of our businesses.
These actions included employee furloughs, wage and salary reductions, capital spending reductions and other actions intended to help mitigate the economic losses and preserve capital and liquidity.
Certain of our businesses undertook and may continue to undertake restructuring activities to resize their operations to better fit expected customer demand.
After-tax earnings from insurance investment income in 2020 declined $491 million (8.9%) versus 2019, reflecting lower interest income primarily attributable to declines in interest rates on our substantial holdings of cash and U.S. Treasury Bills.
After-tax earnings from insurance investment income in 2019 increased 21.4% over 2018, attributable to increases in interest and dividend income.
After-tax earnings of our railroad business increased 5.0% in 2019 compared to 2018.
Earnings in 2019 benefitted from higher rates per car/unit, a curtailment gain related to an amendment to defined benefit retirement plans and ongoing operating cost control initiatives, partly offset by lower freight volumes and incremental costs associated with the persistent flooding conditions and severe winter weather in the first half of 2019.
After-tax earnings of our utilities and energy business increased 8.4% in 2019 compared to 2018.
Earnings from our manufacturing, service and retailing businesses in 2019 were relatively unchanged from 2018, reflecting mixed operating results with several of these businesses experiencing lower earnings in 2019 from a variety of factors.
Revenues and pre-tax earnings in 2019 of certain of these businesses were negatively affected by the unfavorable effects of foreign currency translation attributable to a stronger U.S. Dollar, international trade tensions and U.S. trade tariffs.
GEICO’s pre-tax underwriting earnings for 2020 reflected significant declines in losses and loss adjustment expenses attributable to lower claims frequencies from the effects of less driving by policyholders during the COVID-19 pandemic offset by the effects of the GEICO Giveback program (see following paragraph) on earned premiums.
GEICO (Continued)
The increase reflected a 7.3% decrease in new business sales and a 2.5% decrease in non-renewals and policy cancellations.
2019 versus 2018
Premiums written and earned in 2019 increased 5.5% and 6.6%, respectively, compared to 2018.
These increases were primarily attributable to voluntary auto policies-in-force growth of 6.4%, partially offset by a decrease in average premiums per auto policy.
The increase in voluntary auto policies-in-force primarily resulted from an increase in new business sales and a decrease in policies cancelled or not renewed.
Voluntary auto policies-in-force increased approximately 1,068,000 during 2019.
The loss ratio in 2019 was 81.3%, an increase of 2.5 percentage points over 2018, primarily due to increases in average claims severities.
Underwriting expenses in 2019 increased $493 million (10.6%) over 2018.
GEICO’s underwriting expense ratio in 2019 was 14.5%, an increase of 0.6 percentage points compared to 2018.
The underwriting expense increase was primarily attributable to increases in advertising expenses and employee-related costs, which reflected wage and staffing increases.
Other BH Primary insurers include U.S. Liability Insurance Company, Central States Indemnity Company and MLMIC Insurance Company (“MLMIC”), acquired October 1, 2018.
The increase at BH Specialty was driven by increased casualty business globally and the increase at MedPro Group reflected increases across several product categories.
The declines in workers’ compensation and commercial auto business written reflected the effects of reduced exposures and premium refunds related to the COVID-19 pandemic and volume reductions attributable to increased price competition in the market.
Premiums written increased $1.3 billion (15.0%) in 2019 compared to 2018.
The increase was attributable to higher volumes from BH Specialty, MedPro Group and GUARD, as well as from the effects of the MLMIC acquisition.
These increases were partly offset by lower volume at BHHC and the effect of the Applied Underwriters divestiture.
BH Primary’s combined loss ratios were 74.1% in 2020, 69.1% in 2019 and 64.9% in 2018, which reflected the effects of significant catastrophe events during the year and changes in estimated losses for prior years’ loss events.
We incurred no losses from significant catastrophe events in 2019.
Finally, losses and loss adjustment expenses were reduced $265 million in 2020, $499 million in 2019 and $715 million in 2018 for net reductions in estimated ultimate liabilities for prior years’ loss events.
Premiums written in 2019 increased $1.0 billion (10.8%) compared to 2018.
The increase was primarily attributable to new business, net of non-renewals, and increased participations on renewal business, partly offset by the unfavorable foreign currency translation effects of a stronger U.S. Dollar.
An excerpt. Shown here: 40 of 440 rewritten, 40 of 272 added and 40 of 233 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations in the FY2021 filing and the FY2020 filing.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
3 rewritten, 1 added, 1 removed, 6 unchanged
Under the supervision and with the participation of our management, including our principal executive officer and principal financial officer, we conducted an evaluation of the effectiveness of the Company’s internal control over financial reporting as of December 31, [removed: 2020] [added: 2021,] as required by the Securities Exchange Act of 1934 Rule 13a-15(c).
Based on our evaluation under the framework in *Internal Control—Integrated Framework* (2013), our management concluded that our internal control over financial reporting was effective as of December 31, [removed: 2020.][added: 2021.]
The effectiveness of our internal control over financial reporting as of December 31, [removed: 2020] [added: 2021] has been audited by Deloitte & Touche LLP, an independent registered public accounting firm, as stated in their report which appears on page K-67.
February 26, 2022
February 27, 2021
Item 1. Business Description
207 rewritten, 71 added, 30 removed, 535 unchanged
Berkshire Hathaway Inc. (“Berkshire,” “Company” or “Registrant”) is a holding company owning subsidiaries engaged in [removed: a large number of] [added: numerous] diverse business activities.
Berkshire also owns and operates numerous other businesses engaged in a variety of [removed: activities, as identified herein.][added: manufacturing, services, retailing and other activities.]
Berkshire and its consolidated subsidiaries employed approximately [removed: 360,000] [added: 372,000] people worldwide at the end of [removed: 2020.][added: 2021, of which approximately 77% were in the United States and 21% were represented by unions.]
Consistent with Berkshire’s decentralized management philosophy, Berkshire’s operating businesses [added: individually] establish specific policies and practices [removed: for their businesses] concerning the attraction and retention of personnel within the organizations.
[removed: Such policies] [added: Policies] and practices [removed: generally] [added: commonly] address, among other things: maintaining a safe work environment [removed: for employees, customers] and [removed: other business partners,] [added: minimizing or eliminating workplace injuries;] offering competitive compensation to employees, [removed: including] [added: which includes various] health insurance and retirement [added: benefits, as well as other] benefits [added: such as incentives to recognize] and [removed: incentives, providing] [added: reward performance; wellness programs; training,] learning and career [removed: development opportunities,] [added: advancement opportunities;] and hiring practices intended to identify qualified candidates and promote diversity and inclusion in the workforce.
Berkshire’s insurance and reinsurance business activities are conducted through numerous domestic and foreign-based insurance [removed: entities.][added: subsidiaries.]
Berkshire’s insurance [removed: businesses] [added: subsidiaries] provide insurance and reinsurance of property and casualty [added: risks] and [removed: life, accident] [added: reinsurance of life] and health risks worldwide.
Berkshire’s [removed: insurance] [added: retailing] businesses employed approximately [removed: 51,000] [added: 26,000] people at the end of [removed: 2020.][added: 2021.]
In reinsurance activities, the [removed: reinsurer] [added: insurer] assumes defined portions of risks that other direct insurers or reinsurers assumed in their own insuring activities.
Treaty reinsurance refers to reinsurance coverage for all or a portion of a specified group or class of risks ceded by [removed: the] [added: a] direct [removed: insurer,] [added: insurer or reinsurer,] while facultative reinsurance involves coverage of specific individual underlying risks.
Insurers [removed: and reinsurers] compete on the basis of reliability, financial strength and stability, financial ratings, underwriting consistency, service, business ethics, price, performance, capacity, policy terms and coverage conditions.
The NAIC adopts forms, instructions and accounting procedures for use by U.S. insurers [removed: and reinsurers] in preparing and filing annual statutory financial statements.
The [added: IAIS] standards address a variety of topics regarding supervision, coordination of regulators, insurance capital standards, risk management and governance.
While the IAIS standards do not have legal effect, the states and the NAIC are implementing various [added: group supervision] regulatory tools and mandates that are responsive to certain IAIS standards.
[removed: For example, the] U.S. state regulators now require insurance groups to file an annual report, [removed: called an] [added: the] Own Risk Solvency Assessment or ORSA, with the group’s lead [removed: regulator.][added: supervisor.]
U.S. state regulators [added: have] formed supervisory colleges intended to promote communication and cooperation amongst the various domestic [added: and] international insurance regulators.
The Nebraska Department of Insurance acts as the lead [removed: group wide] supervisor for our group of insurance companies and chairs the Berkshire supervisory college.
The NAIC is also developing further tools, including [removed: a group capital calculation tool and] various liquidity assessments, that [removed: could] [added: will likely] be imposed on insurance groups in the [added: near] future.
Collectively, the combined statutory surplus of Berkshire’s U.S.-based insurers was approximately [removed: $237] [added: $301] billion at December 31, [removed: 2020.][added: 2021.]
The Program currently extends to December 31, 2027 through other Acts, most recently the Terrorism Risk Insurance Program Reauthorization Act of [removed: 2019 (the “2019 TRIA Reauthorization”).][added: 2019.]
Under TRIA, the Department of the Treasury is charged with certifying “acts of terrorism.” Coverage under TRIA occurs if the industry insured loss for certified events occurring during the calendar year exceeds $200 million in [removed: 2020, or] any calendar [removed: year thereafter.][added: year.]
[removed: During 2020 and thereafter, in] [added: In] the event of a certified act of terrorism, the federal government will reimburse insurers (conditioned on their satisfaction of policyholder notification requirements) for 80% of their insured losses in excess of an insurance group’s deductible.
The aggregate deductible in [removed: 2021] [added: 2022] for Berkshire’s insurance group is expected to approximate [removed: $1.4] [added: $1.6] billion.
While each country imposes licensing, solvency, [removed: auditing,] [added: auditing] and financial reporting requirements, the type and extent of the requirements differ substantially.
Significant variations can also be found in the size, [removed: structure,] [added: structure] and resources of the local regulatory departments that oversee insurance activities.
Berkshire insurance subsidiaries are located in several countries, including Germany, the United Kingdom [removed: (“UK”),] [added: (“U.K.”),] Ireland, Australia and South Africa, and also maintain branches in [added: several] other [removed: countries, including Canada, various members of the European Union (“EU”), Australia, New Zealand, Singapore, Hong Kong, Macau and Dubai.][added: countries.]
[removed: On June 23,] [added: In] 2016, the [removed: UK] [added: U.K.] voted in a national referendum to withdraw from the [removed: EU] [added: European Union (“EU”)] (“Brexit”), which resulted in the [removed: UK’s] [added: U.K.’s] withdrawal from the EU on January 31, 2020.
In anticipation of the [removed: UK] [added: U.K.] leaving the EU, Berkshire Hathaway European Insurance DAC in Ireland was established to permit property and casualty insurance and reinsurance businesses to continue to operate in the [removed: EU] [added: EU, and Berkshire continues to maintain a substantial presence in London] following Brexit.
Except for retroactive reinsurance and periodic payment annuity products that generate significant amounts of up-front premiums along with estimated claims expected to be paid over [removed: very] long time periods (creating “float,” see Investments [removed: section below),] [added: section),] Berkshire expects to achieve [removed: a net] [added: an] underwriting profit over time and to reject inadequately priced risks.
GEICO’s insurance subsidiaries consist of Government Employees Insurance Company, GEICO General Insurance Company, GEICO Indemnity Company, GEICO Casualty Company, GEICO Advantage Insurance Company, GEICO Choice Insurance Company, GEICO Secure Insurance Company, GEICO County Mutual Insurance [added: Company, GEICO Texas County Mutual Insurance] Company and GEICO Marine Insurance Company.
GEICO competes for private passenger automobile insurance customers in the preferred, standard and non-standard risk markets with other companies that sell directly to the customer [removed: as well as] [added: and] with companies that use agency sales forces, including State Farm, Allstate, Progressive and USAA.
GEICO’s advertising campaigns and competitive rates contributed to a cumulative increase in voluntary policies-in-force of approximately [removed: 36%] [added: 26.0%] over the past five years.
According to the most recently published A.M. Best data for [removed: 2019,] [added: 2020,] the five largest automobile insurers had a combined market share in [removed: 2019] [added: 2020] of approximately [removed: 58%] [added: 59.7%] based on written premiums, with GEICO’s market share being [added: the] second largest at approximately [removed: 13.8%.][added: 13.5%.]
The name and reputation of GEICO are material assets and management protects [removed: it] [added: those] and other service marks through appropriate registrations.
[removed: NICO] [added: National Indemnity Company (“NICO”), domiciled in Nebraska,] and certain affiliates (“NICO Primary”) underwrite commercial motor vehicle and general liability insurance on an admitted basis and on an excess and surplus basis.
Additionally, MedPro provides HCL insurance solutions to [removed: the] international markets through other Berkshire insurance affiliates, delivers liability insurance to other professionals, and offers specialized accident and health insurance solutions to colleges and other customers through its subsidiaries and other Berkshire [added: insurance] affiliates.
U.S. Liability Insurance Company (“USLI”) includes a group of five specialty insurers that underwrite commercial, professional and personal lines insurance on an admitted basis, as well as [added: on] an excess and surplus basis.
USLI markets policies in all 50 [removed: states and] [added: states,] the District of Columbia and Canada through wholesale and retail insurance agents.
[removed: The] Berkshire Hathaway GUARD Insurance Companies (“GUARD”) is a group of five insurance companies that provide [removed: workers’ compensation, business owners’, commercial auto,] [added: a full suite of] commercial [removed: package and homeowners’ products] [added: insurance products, as well as homeowners policies] to over 350,000 small [removed: and] [added: to] mid-sized [removed: businesses.][added: businesses and homeowners.]
[removed: Policies] [added: These offerings] are [removed: offered] [added: made] through independent agents and retail and wholesale brokers.
Employees engage in a wide variety of occupations.
Given the wide variations in the nature and size of business activities, policies and practices often vary widely among Berkshire’s operating subsidiaries.
For purposes of this discussion, entities that provide insurance or reinsurance are referred to as insurers.
The IAIS is developing capital standards for internationally active insurance groups (the “Insurance Capital Standard”) based on a consolidated group approach and is also evaluating a potentially comparable group capital standard based on the aggregation of regulated entities and their underlying local capital requirements (the “Aggregation Method”).
The NAIC recently adopted a group capital calculation based on methodology similar to the Aggregation Method, which leverages the NAIC’s existing Risk Based Capital standards.
The NAIC’s group capital calculation is a tool designed to help the lead supervisor understand the capital adequacy across an insurance group.
GEICO’s written premiums in 2020 were reduced by the effects of the GEICO Giveback Program implemented in response to significant reductions in claim frequencies attributable to reduced policyholder driving during the initial stages of the COVID-19 pandemic.
Pandemic-related premium credit programs of other private passenger insurers may not have been reported as premium reductions, which impacts the industry data reported by A.M Best.
Since the publication of that data, GEICO’s management estimates its current market share is approximately 14.2%.
Consumption of diesel fuel by locomotives accounted for approximately 80% of BNSF’s greenhouse gas (“GHG”) emissions in its baseline year of 2018.
BNSF management has committed to a broad sustainability model, applying science-based approaches, that will provide a 30% reduction in BNSF’s GHG-emissions by 2030 from its baseline year of 2018.
BNSF intends to continue improvements in fuel efficiency and increased utilization of renewable diesel fuel.
Long-term solutions, such as battery-electric and hydrogen locomotives, are also being evaluated and field-tested.
New commitments to the Paris Agreement were announced in April 2021, with the United States pledging to cut its overall greenhouse gas emissions by 50-52% below 2005 levels by 2030 and to reach 100% carbon pollution-free electricity by 2035.
On January 19, 2021, the D.C. Circuit Court of Appeals vacated the Affordable Clean Energy Rule in its entirety.
In October 2021, the U.S. Supreme Court agreed to hear an appeal of that decision.
Arguments in the case will be held in February 2022 and a decision regarding the scope of the EPA’s authority to regulate greenhouse gas emissions under the Clean Air Act is expected by June 2022.
BHE’s primary source of GHG emissions is the generation of electricity from its power plants that are fueled by coal or natural gas.
In managing its electricity generation, BHE works with its regulators to protect the energy and economic needs of customers by considering costs, reliability and sources of electric generation.
Over the years, BHE has invested heavily in owned wind, solar and geothermal generation, with cumulative investments of $30.1 billion through 2021 and has retired 16 coal generation units.
As a result, BHE has reduced its annual GHG emissions by about 20% from 2005 levels.
BHE plans to continue investing in wind, solar and other low-carbon generation in the future and to retire an additional 16 coal generation units between 2022 and 2030 in a reliable and cost-effective manner, thereby achieving a 50% reduction in GHG emissions from 2005 levels in 2030.
Since the onset of the COVID-19 pandemic in 2020, delay requests increased, with delivery dates extending in some cases beyond 2021.
The grounding of the Boeing 737 MAX also adversely impacted 2020 and 2021 and quality issues with the Boeing 787 negatively impacted 2021.
PCC is currently subject to various federal, state and foreign environmental laws concerning, among other things, water discharges, air emissions, waste management, toxic materials use reduction and environmental cleanup.
Laws and regulations continue to evolve, and it is reasonably possible that environmental standards will become more stringent in the future, particularly under air quality and water quality laws and standards related to climate change, including reporting of greenhouse gas emissions.
As a result, it is also reasonably likely that PCC will be regularly required to make additional expenditures, including capital expenditures, which could be significant, relating to environmental matters.
In 2021, the COVID-19 pandemic continued to have an adverse effect on many of the markets that Lubrizol serves, as did worldwide supply chain disruptions, affecting both the availability of raw materials and fulfillment of customer orders.
In addition, the occurrence and duration of the February 2021 winter storms and freezing temperatures in Texas significantly interrupted operations at Lubrizol’s manufacturing facilities.
Lubrizol expends significant capital to ensure the safety of its employees and the communities where it operates, as well as delivering on its commitments to operational excellence and cybersecurity.
Lubrizol also makes significant capital investments to ensure reliable supply and compliance with regulations governing its operations, while reducing their environmental footprint.
Lubrizol also suffered a fire in 2021 that resulted in a total loss of its grease manufacturing facility.
IMC
Cemented tungsten carbide powder is the main raw material used in manufacturing cutting tools.
Most of IMC’s metalworking insert products are made from tungsten.
While supplies are currently adequate, a significant disruption or constraints in production processing facilities could cause a price increase.
IMC is committed to follow, comply and obey all government and environmental regulations and requirements of all applicable laws.
IMC considers environmental preservation and pollution prevention as important factors in all operations and activities.
IMC production facilities are built with the highest standards and follow all applicable regulations.
Certain Marmon business, including the Rail and Medical groups, are subject to government regulation and oversight.
Following the withdrawal of the UK from the EU as a result of Brexit, Berkshire expects to continue to maintain a substantial presence in London.
Since that data was published, GEICO’s management estimates its current market share may have declined, depending on how the effects of pandemic-related premium credit programs will be reflected in A.M. Best’s measurements.
GUARD also offers complementary professional liability and umbrella products nationwide.
Central States Indemnity Company of Omaha, based in Omaha, Nebraska, primarily writes credit card credit insurance, Medicare Supplement insurance and agricultural equipment insurance.
On October 1, 2018, NICO acquired MLMIC Insurance Company (“MLMIC”).
MLMIC distributes its policies mostly on a
In October 2019, Berkshire sold its 81% interest in Applied Underwriters, Inc.
For instance, an excess contract written in January 2017 provides indemnification for 80% of up to $25 billion in excess of $25 billion retained by the ceding company.
The EPA’s repeal and replacement of the Clean Power Plan is not expected to have a material impact on BHE and its energy subsidiaries.
For example, through December 31, 2020, BHE’s cumulative investment in wind, solar, geothermal and biomass generation is approximately $34 billion.
In 2020, delay requests increased due to the COVID-19 pandemic.
Lubrizol is an industry leader in many of the markets in which it competes.
In 2020, the global pandemic had an adverse effect on many of the markets that Lubrizol serves, including the transportation and industrial markets.
This was offset in part by strong demand for Lubrizol’s technology that is used in personal care applications, such as hand sanitizers.
Lubrizol continues to expend necessary capital to upgrade and optimize operations, ensure compliance with health, safety and environmental requirements, and increase global manufacturing capacity, while reducing the environmental footprint of its operations.
Lubrizol also makes a significant investment in its human capital to ensure that it attracts, develops and retains a talented and diverse employee workforce.
IMC International Metalworking Companies
Crane Services is a provider of mobile cranes and operators in North America and Australia.
MiTek Industries, Inc.
MiTek’s commercial businesses provide products and services sold to the commercial construction industry.
Commercial products include curtain wall systems, masonry and stone anchoring systems, light gauge steel framing products, engineering services for a proprietary high-performance steel frame connection and a comprehensive range of ductwork for the ventilation market, customized air handling systems for commercial, institutional and industrial markets, design and supply of nuclear safety related HVAC systems and components, energy recovery and dehumidification systems for commercial applications and pre-engineered and pre-fabricated custom structural mezzanines and platforms for distribution and manufacturing facilities.
In 2020, approximately 58% of FOL’s sales were to five customers.
Additionally, raw materials are subject to price volatility caused by weather, supply conditions, government regulations, economic climate and other unpredictable factors.
FOL has secured contracts to purchase cotton, either directly or through the yarn suppliers, to meet a large percentage of its production plans for 2021.
Forest River has numerous manufacturing facilities located in seven states.
Management believes there are currently sufficient sources of raw materials available, which are primarily steel, zinc and manganese.
Business Wire provides electronic dissemination of full-text news releases to the media, online services and databases and the global investment community in 150 countries and in 45 languages.
Approximately 93% of Business Wire’s revenues derive from its core news distribution business.
OTC offers a unique assortment of over 50,000 products and utilizes sophisticated digital and print marketing efforts to drive significant traffic and industry leading customer satisfaction.
Information concerning these investments is included in Note 5 to Berkshire’s Consolidated Financial Statements.
An excerpt. Shown here: 40 of 207 rewritten, 40 of 71 added and all 30 removed. The counts are complete. For every sentence, read Item 1. Business Description in the FY2021 filing and the FY2020 filing.
Item 3. Legal Proceedings
0 rewritten, 1 added, 1 removed, 5 unchanged
K-29
K-28
Cover and table of contents
28 rewritten, 2 added, 2 removed, 66 unchanged
For the fiscal year ended December 31, [removed: 2020][added: 2021]
State the aggregate market value of the voting stock held by non-affiliates of the Registrant as of June 30, [removed: 2020: $336,500,000,000*][added: 2021: $503,600,000,000*]
| February [removed: 16, 2021—Class] [added: 14, 2022—Class] A common stock, $5 par value | [removed: 640,586] [added: 615,333] shares |
| February [removed: 16, 2021—Class] [added: 14, 2022—Class] B common stock, $0.0033 par value | [removed: 1,336,348,609] [added: 1,291,212,661] shares |
Portions of the Proxy Statement for the Registrant’s Annual Meeting to be held [removed: May 1, 2021] [added: April 30, 2022] are incorporated in Part III.
| * | This aggregate value is computed at the last sale price of the common stock as reported on the New York Stock Exchange on June 30, [removed: 2020.] [added: 2021.] It does not include the value of Class A common stock and Class B common stock held by Directors and Executive Officers of the Registrant and members of their immediate families, some of whom may not constitute “affiliates” for purpose of the Securities Exchange Act of 1934. |
| Item 1A. | [Risk Factors](#ITEM_1A_RISK_FACTORS) | [removed: K-22] [added: K-24] |
| Item 1B. | [Unresolved Staff Comments](#ITEM_1B_UNRESOLVED_STAFF_COMMENTS) | [removed: K-26] [added: K-27] |
| Item 2. | [Description of Properties](#ITEM_2_DESCRIPTION_PROPERTIES) | [removed: K-26] [added: K-27] |
| Item 3. | [Legal Proceedings](#ITEM_3_LEGAL_PROCEEDINGS) | [removed: K-28] [added: K-29] |
| Item 4. | [Mine Safety Disclosures](#ITEM_4_MINE_SAFETY_DISCLOSURES) | [removed: K-29] [added: K-30] |
| Item 5. | [Market for Registrant’s Common Equity, Related Security Holder Matters and Issuer Purchases of Equity Securities](#ITEM_5_MARKET_FOR_REGISTRANTS_COMMON_EQU) | [removed: K-29] [added: K-30] |
| Item 7. | [Management’s Discussion and Analysis of Financial Condition and Results of Operations](#ITEM_7_MANAGEMENTS_DISCUSSION_ANALYSIS_F) | [removed: K-33] [added: K-32] |
| | [Consolidated Balance Sheets— December 31, [removed: 2020] [added: 2021] and December 31, [removed: 201](#CONSOLIDATED_BALANCE_SHEETS)9] [added: 2020](#CONSOLIDATED_BALANCE_SHEETS)] | K-70 |
| | [Consolidated Statements of Earnings— Years Ended December 31, [removed: 2020,] [added: 2021,] December 31, [removed: 2019,] [added: 2020,] and December 31, [removed: 201](#CONSOLIDATED_STATEMENTS_EARNINGS)8] [added: 2019](#CONSOLIDATED_STATEMENTS_EARNINGS)] | K-72 |
| | [Consolidated Statements of Comprehensive Income— Years Ended December 31, [removed: 2020,] [added: 2021,] December 31, [removed: 2019,] [added: 2020,] and December 31, [removed: 201](#CONSOLIDATED_STATEMENTS_COMPREHENSIVE_IN)8] [added: 2019](#CONSOLIDATED_STATEMENTS_COMPREHENSIVE_IN)] | K-73 |
| | [Consolidated Statements of Changes in Shareholders’ Equity— Years Ended December 31, [removed: 2020,] [added: 2021,] December 31, [removed: 2019,] [added: 2020,] and December 31, [removed: 201](#CONSOLIDATED_STATEMENTS_CHANGES_IN_SHARE)8] [added: 2019](#CONSOLIDATED_STATEMENTS_CHANGES_IN_SHARE)] | K-73 |
| | [Consolidated Statements of Cash Flows— Years Ended December 31, [removed: 2020,] [added: 2021,] December 31, [removed: 2019,] [added: 2020,] and December 31, [removed: 201](#CONSOLIDATED_STATEMENTS_CASH_FLOWS)8] [added: 2019](#CONSOLIDATED_STATEMENTS_CASH_FLOWS)] | K-74 |
| Item 9. | [Changes in and Disagreements with Accountants on Accounting and Financial Disclosure](#ITEM_9_CHANGES_IN_DISAGREEMENTS_WITH_ACC) | [removed: K-116] [added: K-113] |
| Item 9A. | [Controls and Procedures](#ITEM_9A_CONTROLS_PROCEDURES) | [removed: K-116] [added: K-113] |
| Item 9B. | [Other Information](#ITEM_9B_OR_INFORMATION) | [removed: K-116] [added: K-113] |
| Item 10. | [Directors, Executive Officers and Corporate Governance](#PART_III) | [removed: K-116] [added: K-113] |
| Item 11. | [Executive Compensation](#PART_III) | [removed: K-116] [added: K-113] |
| Item 12. | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters](#PART_III) | [removed: K-116] [added: K-113] |
| Item 13. | [Certain Relationships and Related Transactions and Director Independence](#PART_III) | [removed: K-116] [added: K-113] |
| Item 14. | [Principal Accountant Fees and Services](#PART_III) | [removed: K-116] [added: K-113] |
| Item 15. | [Exhibits and Financial Statement Schedules](#ITEM_15_EXHIBITS_FINANCIAL_STATEMENT_SCH) | [removed: K-116] [added: K-113] |
| [Exhibit Index](#EXHIBIT_INDEX) | | [removed: K-120] [added: K-117] |
| Item 6. | \[Reserved\] | |
| [Signatures](#SIGNATURES) | | K-119 |
| Item 6. | [Selected Financial Data](#ITEM_6_SELECTED_FINANCIAL_DATA) | K-32 |
| [Signatures](#SIGNATURES) | | K-122 |
Item 2. Description of Properties
34 rewritten, 5 added, 7 removed, 41 unchanged
Through BNSF Railway, BNSF operates [removed: approximately] [added: over] 32,500 route miles of track (excluding multiple main tracks, yard tracks and sidings) in 28 states, and also operates in three Canadian provinces.
As of December 31, [removed: 2020,] [added: 2021,] the total BNSF Railway system, including single and multiple main tracks, yard tracks and sidings, consisted of over 50,000 operated miles of track.
BNSF owns or holds under non-cancelable leases exceeding one year approximately [removed: 7,700] [added: 7,500] locomotives and [removed: 66,000] [added: 63,600] freight cars, in addition to maintenance of way and other equipment.
In [removed: 2020,] [added: 2021,] BNSF recorded approximately $2 billion in repairs and maintenance expense.
BHE or its affiliates own or have interests in the following types of operating electric generating facilities at December 31, [removed: 2020:][added: 2021:]
| Natural gas | | PacifiCorp, MEC, NV [removed: Energy and] [added: Energy,] BHE Renewables [added: and BHE Canada] | | Nevada, Utah, Iowa, Illinois, Washington, Wyoming, Oregon, Texas, New [removed: York and] [added: York,] Arizona [added: and Canada] | | | [removed: 11,171] [added: 11,112] | | | | [removed: 10,892] [added: 10,833] | |
| Wind | | PacifiCorp, MEC and BHE Renewables | | Iowa, Wyoming, Texas, Nebraska, Washington, California, Illinois, [removed: Oregon, Kansas] [added: Montana, Oregon] and [removed: Montana] [added: Kansas] | | | [removed: 10,302] [added: 11,517] | | | | [removed: 10,302] [added: 11,517] | |
| Coal | | PacifiCorp, MEC and NV Energy | | Wyoming, Iowa, Utah, Nevada, Colorado and Montana | | | [removed: 13,249] [added: 13,235] | | | | [removed: 8,198] [added: 8,193] | |
| Solar | | BHE Renewables and NV Energy | | California, Texas, Arizona, Minnesota and Nevada | | | [removed: 1,699] [added: 1,719] | | | | [removed: 1,551] [added: 1,571] | |
| Hydroelectric | | PacifiCorp, MEC and BHE Renewables | | Washington, Oregon, [removed: The Philippines,] Idaho, California, Utah, Hawaii, Montana, Illinois and Wyoming | | | [removed: 1,299] [added: 1,149] | | | | [removed: 1,277] [added: 1,149] | |
| Nuclear | | MEC | | Illinois | | | [removed: 1,815] [added: 1,823] | | | | [removed: 454] [added: 456] | |
As of December 31, [removed: 2020,] [added: 2021,] BHE’s subsidiaries also have electric generating facilities that are under construction in [removed: Iowa, Wyoming] [added: Nevada, Iowa] and [removed: Montana] [added: Canada] having total Facility Net Capacity and Net Owned Capacity of [removed: 603] [added: 421] MW.
PacifiCorp, MEC and NV Energy own electric transmission and distribution systems, including approximately [removed: 27,600] [added: 27,700] miles of transmission lines and approximately [removed: 1,650] [added: 1,660] substations and gas distribution facilities, including approximately [removed: 27,600] [added: 27,700] miles of gas mains and service lines.
Northern Powergrid (Northeast) and Northern Powergrid (Yorkshire) operate an electricity distribution network that includes approximately [removed: 17,300] [added: 17,400] miles of overhead lines, approximately [removed: 42,800] [added: 43,300] miles of underground cables and approximately [removed: 770] [added: 780] major substations.
The BHE GT&S pipeline system consists of approximately 5,400 miles of natural gas transmission, gathering and storage [removed: pipelines.][added: pipelines located in portions of Maryland, New York, Ohio, Pennsylvania, Virginia, West Virginia, South Carolina and Georgia.]
Northern Natural’s pipeline system consists of approximately [removed: 14,500] [added: 14,300] miles of natural gas pipelines, including approximately [removed: 6,000] [added: 5,800] miles of mainline transmission pipelines and approximately 8,500 miles of branch and lateral pipelines.
| GEICO | | U.S. | | | | Offices and claims centers | | | 10 | | | | [removed: 122] [added: 113] | |
| BHRG | | U.S. | | | | Offices | | | 1 | | | | [removed: 30] [added: 27] | |
| | | Non-U.S. | | Locations in [removed: 22] [added: 23] countries | | Offices | | | 1 | | | | 37 | |
| BH Primary | | U.S. | | | | Offices | | | [removed: 7] [added: 5] | | | | [removed: 51] [added: 48] | |
| | | Non-U.S. | | Locations in 7 countries | | Offices | | | — | | | | [removed: 16] [added: 15] | |
| Manufacturing | | U.S. | | | | Manufacturing facility | | | [removed: 485] [added: 484] | | | | [removed: 119] [added: 113] | |
| | | | | | | [removed: Retail/Showroom] [added: Leasing/Showroom/Retail] | | | [removed: 261] [added: 31] | | | | [removed: 213] [added: 49] | |
| | | Non-U.S. | | Locations in 63 countries | | Manufacturing facility | | | [removed: 199] [added: 179] | | | | [removed: 124] [added: 111] | |
| | | | | | | Offices/Warehouses | | | [removed: 88] [added: 214] | | | | [removed: 448] [added: 476] | |
| Service | | U.S. | | | | Training facilities/Hangars | | | [removed: 19] [added: 12] | | | | [removed: 94] [added: 93] | |
| | | | | | | Offices/Distribution | | | [removed: 15] [added: —] | | | | [removed: 144] [added: 47] | |
| | | | | | | [removed: Leasing/Showroom/Retail] [added: Retail/Showroom] | | | [removed: 31] [added: 231] | | | | [removed: 48] [added: 195] | |
| | | Non-U.S. | | Locations in [removed: 18] [added: 19] countries | | Training facilities/Hangars | | | [removed: 2] [added: 1] | | | | 12 | |
| | | | | | | Offices/Distribution | | | [removed: —] [added: 15] | | | | [removed: 48] [added: 135] | |
| McLane [removed: Company] | | U.S. | | | | Distribution centers | | | 59 | | | | [removed: 26] [added: 27] | |
| Retailing | | U.S. | | | | Offices/Warehouses | | | [removed: 21] [added: 23] | | | | [removed: 26] [added: 27] | |
| | | Non-U.S. | | Locations in 6 countries | | Offices/Warehouses | | | 1 | | | | [removed: 9] [added: 7] | |
| | | | | | | Retail/Offices | | | — | | | | [removed: 93] [added: 91] | |
| | | | | Total | | | 40,932 | | | | 34,096 | |
K-28
| | | | | | | Housing subdivisions | | | 319 | | | | — | |
| | | | | | | Offices/Warehouses | | | 106 | | | | 437 | |
| | | | | | | Retail/Showroom | | | 139 | | | | 498 | |
K-26
| | | | | Total | | | 39,912 | | | | 33,051 | |
BHE GT&S provides natural gas storage and transportation service to on-system customers in Maryland, New York, Ohio, Pennsylvania, South Carolina, Virginia and West Virginia.
Additionally, through multiple interconnects with other pipelines, BHE GT&S provides services to off-system customers broadly in the Northeast, Southeast and Mid-Atlantic regions.
| | | | | | | Offices/Warehouses | | | 207 | | | | 443 | |
| | | | | | | Housing communities | | | 312 | | | | — | |
| | | | | | | Retail/Showroom | | | 142 | | | | 543 | |
Item 4. Mine Safety Disclosures
7 rewritten, 0 added, 0 removed, 13 unchanged
| Warren E. Buffett | | [removed: 90] [added: 91] | | Chairman and Chief Executive Officer | | 1970 |
| Charles T. Munger | | [removed: 97] [added: 98] | | Vice Chairman | | 1978 |
| Gregory E. Abel | | [removed: 58] [added: 59] | | Vice Chairman – Non-Insurance Operations | | 2018 |
| Ajit Jain | | [removed: 69] [added: 70] | | Vice Chairman – Insurance Operations | | 2018 |
| Marc D. Hamburg | | [removed: 71] [added: 72] | | Senior Vice-President – Chief Financial Officer | | 1992 |
Forward-looking statements include statements which are predictive in nature, which depend upon or refer to future events or conditions, [added: or] which include words such as “expects,” “anticipates,” “intends,” “plans,” “believes,” “estimates” or similar expressions.
The principal risk factors that could cause our actual performance and future events and actions to differ materially from such forward-looking statements include, but are not limited to, changes in market prices of our investments in fixed maturity and equity [removed: securities,] [added: securities;] losses realized from derivative [removed: contracts,] [added: contracts;] the occurrence of one or more catastrophic events, such as an earthquake, hurricane, act of terrorism or [removed: cyber attack] [added: cyber-attack] that causes losses insured by our insurance subsidiaries and/or losses to our business [removed: operations,] [added: operations;] the frequency and severity of epidemics, pandemics or other outbreaks, including COVID-19, that negatively affect our operating results and restrict our access to borrowed funds through the capital markets at reasonable [removed: rates,] [added: rates;] changes in laws or regulations affecting our insurance, railroad, utilities and energy and finance [removed: subsidiaries,] [added: subsidiaries;] changes in federal income tax [removed: laws,] [added: laws;] and changes in general economic and market factors that affect the prices of securities or the industries in which we do business.
Item 5. Market for Registrant’s Common Equity, Related Security Holder Matters and Issuer Purchases of Equity Securities
6 rewritten, 6 added, 8 removed, 21 unchanged
Berkshire had approximately [removed: 1,600] [added: 1,400] record holders of its Class A common stock and [removed: 18,900] [added: 18,400] record holders of its Class B common stock at February [removed: 16, 2021.][added: 15, 2022.]
Record owners included nominees holding at least [removed: 351,000] [added: 346,000] shares of Class A common stock and [removed: 1,332,000,000] [added: 1,287,000,000] shares of Class B common stock on behalf of beneficial-but-not-of-record owners.
Information with respect to Berkshire’s Class A and Class B common stock repurchased during the fourth quarter of [removed: 2020] [added: 2021] follows.
| * | The program does not specify a maximum number of shares to be repurchased or obligate Berkshire to repurchase any specific dollar amount or number of Class A or Class B shares and there is no expiration date to the repurchase program. Berkshire will not repurchase its common stock if the repurchases reduce the total value of Berkshire’s consolidated cash, cash equivalents and U.S. Treasury Bills holdings to less than [removed: $20] [added: $30] billion. |
The following chart compares the subsequent value of $100 invested in Berkshire common stock on December 31, [removed: 2015] [added: 2016] with a similar investment in the Standard & Poor’s 500 Stock Index and in the Standard & Poor’s Property – Casualty Insurance Index.
[removed: 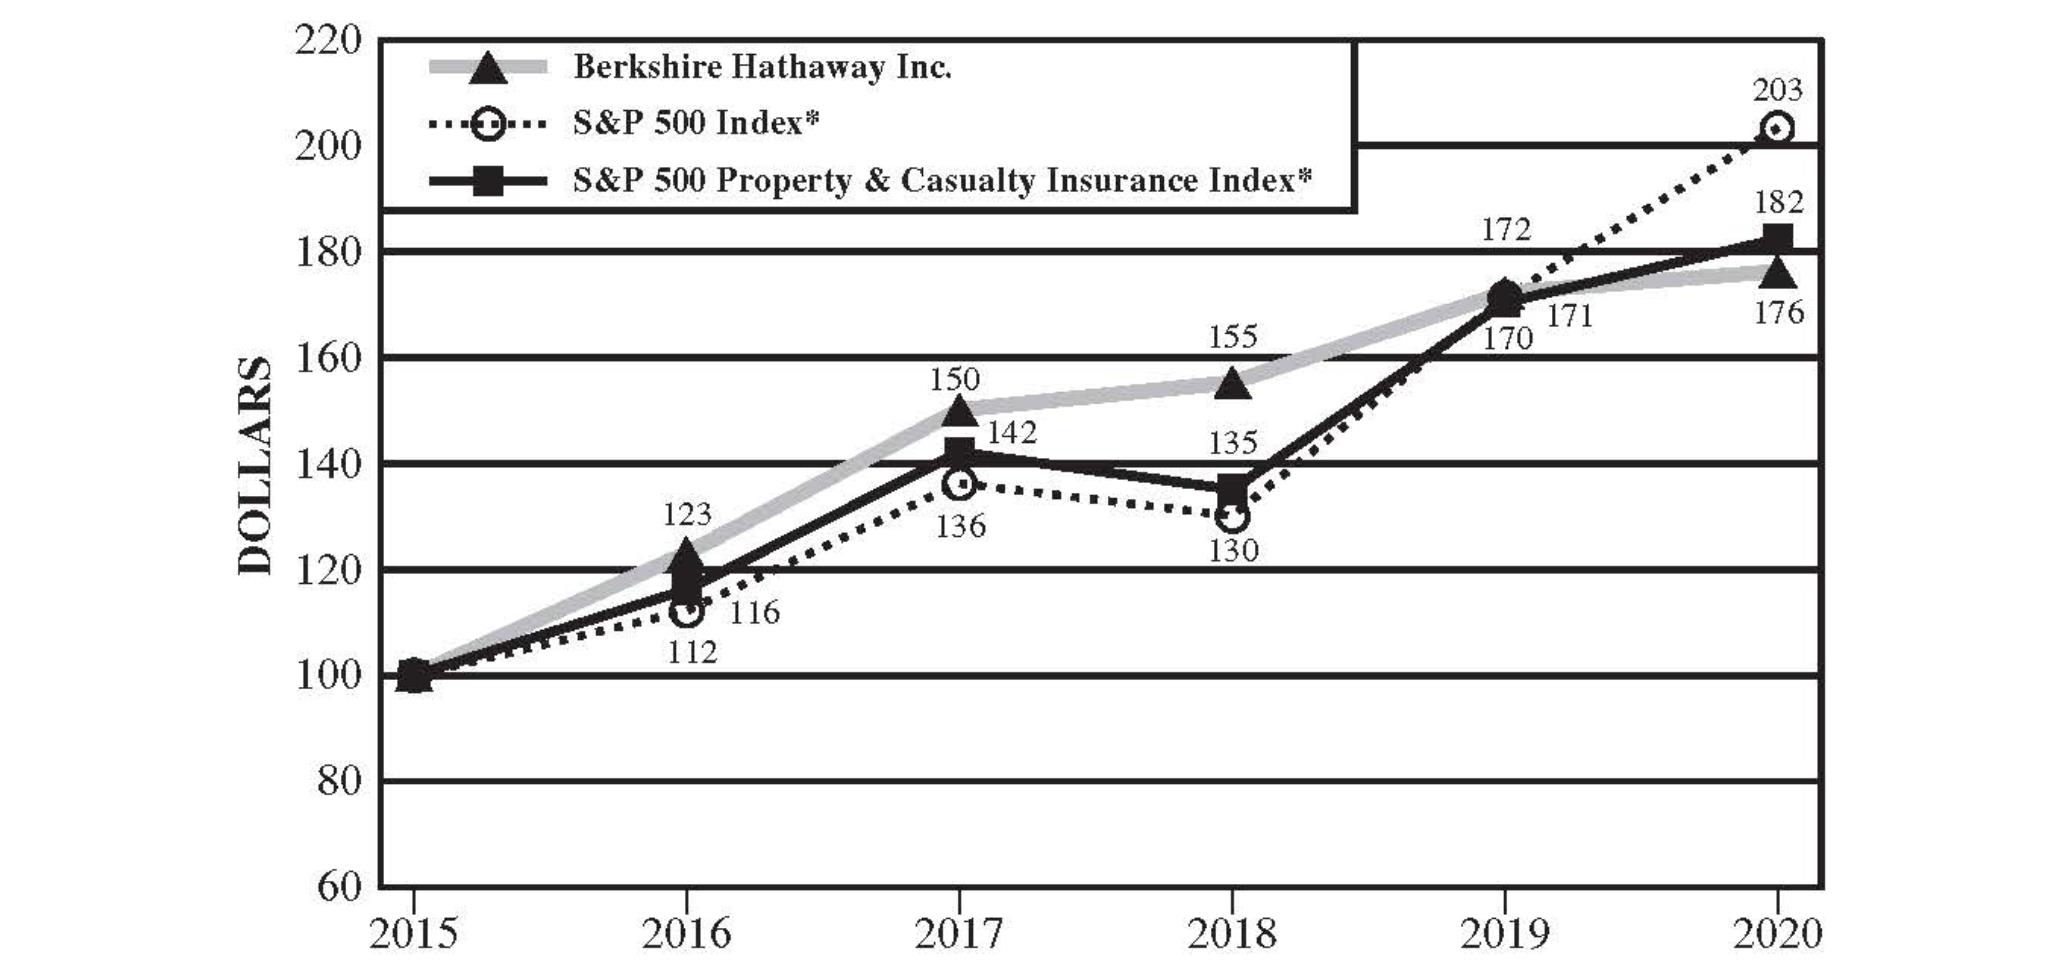][added: ]
| Class A common stock | | 680 | | $ | 431,525.72 | | | 680 | | * |
| Class B common stock | | 5,862,551 | | $ | 282.86 | | | 5,862,551 | | * |
| Class A common stock | | 403 | | $ | 430,172.46 | | | 403 | | * |
| Class B common stock | | 7,013,482 | | $ | 284.39 | | | 7,013,482 | | * |
| Class A common stock | | 1,828 | | $ | 439,625.92 | | | 1,828 | | * |
| Class B common stock | | 6,259,164 | | $ | 287.62 | | | 6,259,164 | | * |
K-29
| Class A common stock | | 1,894 | | $ | 316,292.44 | | | 1,894 | | * |
| Class B common stock | | 11,097,536 | | $ | 209.92 | | | 11,097,536 | | * |
| Class A common stock | | 2,244 | | $ | 341,117.06 | | | 2,244 | | * |
| Class B common stock | | 7,423,729 | | $ | 219.12 | | | 7,423,729 | | * |
| Class A common stock | | 1,787 | | $ | 342,577.29 | | | 1,787 | | * |
| Class B common stock | | 12,605,335 | | $ | 225.73 | | | 12,605,335 | | * |
Market for Registrant’s Common Equity, Related Security Holder Matters and Issuer Purchases of Equity Securities *(Continued)*
Item 8. Financial Statements and Supplementary Data
763 rewritten, 249 added, 264 removed, 967 unchanged
We have audited the accompanying consolidated balance sheets of Berkshire Hathaway Inc. and subsidiaries (the “Company”) as of December 31, [removed: 2020] [added: 2021] and [removed: 2019,] [added: 2020,] the related consolidated statements of earnings, comprehensive income, changes in shareholders’ equity, and cash flows, for each of the three years in the period ended December 31, [removed: 2020,] [added: 2021,] and the related notes (collectively referred to as the “financial statements”).
We also have audited the Company’s internal control over financial reporting as of December 31, [removed: 2020,] [added: 2021,] based on criteria established in *Internal Control — Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, [removed: 2020] [added: 2021] and [removed: 2019,] [added: 2020,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2020,] [added: 2021,] in conformity with accounting principles generally accepted in the United States of America.
Also, in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2020,] [added: 2021,] based on criteria established in *Internal Control — Integrated Framework (2013)* issued by COSO.
[removed: REPORT] [added: REPORT] OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING [removed: FIRM (Continued)][added: FIRM (Continued)]
Unpaid Losses and Loss Adjustment Expenses— Refer to Notes 1 and [removed: 15] [added: 16] to the financial statements
The Company’s unpaid losses and loss adjustment expenses (“claim liabilities”) under short duration property and casualty insurance and reinsurance contracts are [removed: $79,854] [added: $86,664] million as of December 31, [removed: 2020.][added: 2021.]
Given the subjectivity of estimating these key assumptions, performing audit procedures to evaluate whether claim liabilities were appropriately recorded as of December 31, [removed: 2020,] [added: 2021,] required a high degree of auditor judgment and an increased extent of effort, including the need to involve our actuarial specialists.
Unpaid Losses and Loss Adjustment Expenses Under Retroactive Reinsurance Contracts — Refer to Notes 1 and [removed: 16] [added: 17] to the financial statements
The Company’s unpaid losses and loss adjustment expenses (“claim liabilities”) for property and casualty retroactive reinsurance contracts are [removed: $40,966] [added: $38,256] million as of December 31, [removed: 2020.][added: 2021.]
The Precision Castparts Corp. (“PCC”) reporting unit reported approximately [removed: $31] [added: $21] billion of goodwill and indefinite-lived intangible assets as of December 31, [removed: 2019.][added: 2021.]
[removed: As a result] [added: The carrying values] of [removed: the reevaluation, the Company recognized] [added: PCC-related] goodwill and indefinite-lived intangible [removed: asset] [added: assets prior to the] impairment charges [removed: in the amount of approximately $10 billion, as the fair values of the PCC reporting unit and indefinite-lived intangible assets] were [removed: less than their respective carrying values.][added: approximately $31 billion.]
[removed: | | |] December 31, [removed: | | | | | | |][added: 2021]
| | | [added: 2021 | | | |] 2020 | | | | 2019 | | |
| Cash and cash equivalents* | | $ | [removed: 44,714] [added: 85,319] | | | $ | [removed: 61,151] [added: 44,714] | |
| Short-term investments in U.S. Treasury Bills | | | [removed: 90,300] [added: 58,535] | | | | [removed: 63,822] [added: 90,300] | |
| Investments in fixed maturity securities | | | [removed: 20,410] [added: 16,434] | | | | [removed: 18,685] [added: 20,410] | |
| Investments in equity securities | | | [removed: 281,170] [added: 350,719] | | | | [removed: 248,027] [added: 281,170] | |
| Equity method investments | | | [removed: 17,303] [added: 17,375] | | | | [removed: 17,505] [added: 17,303] | |
| Loans and finance receivables | | | [removed: 19,201] [added: 20,751] | | | | [removed: 17,527] [added: 19,201] | |
| Other receivables | | | [removed: 32,310] [added: 35,388] | | | | [removed: 32,418] [added: 32,310] | |
| Inventories | | | [removed: 19,208] [added: 20,954] | | | | [removed: 19,852] [added: 19,208] | |
| Property, plant and equipment | | | [removed: 21,200] [added: 20,834] | | | | [removed: 21,438] [added: 21,200] | |
| Equipment held for lease | | | [removed: 14,601] [added: 14,918] | | | | [removed: 15,065] [added: 14,601] | |
| Goodwill | | | [removed: 47,121] [added: 47,117] | | | | [removed: 57,052] [added: 47,121] | |
| Other intangible assets | | | [removed: 29,462] [added: 28,486] | | | | [removed: 31,051] [added: 29,462] | |
| Deferred charges [removed: under] [added: -] retroactive reinsurance [removed: contracts] | | | [removed: 12,441] [added: 10,639] | | | | [removed: 13,747] [added: 12,441] | |
| Other | | | [removed: 14,580] [added: 15,854] | | | | [removed: 13,232] [added: 14,580] | |
| Cash and cash equivalents* | | | [removed: 3,276] [added: 2,865] | | | | [removed: 3,024] [added: 3,276] | |
| Receivables | | | [removed: 3,542] [added: 4,177] | | | | [removed: 3,417] [added: 3,542] | |
| Property, plant and equipment | | | [removed: 151,216] [added: 155,530] | | | | [removed: 137,838] [added: 151,216] | |
| Goodwill | | | [removed: 26,613] [added: 26,758] | | | | [removed: 24,830] [added: 26,613] | |
| Regulatory assets | | | [removed: 3,440] [added: 3,963] | | | | [removed: 2,881] [added: 3,440] | |
| Other | | | [removed: 21,621] [added: 22,168] | | | | [removed: 15,167] [added: 21,621] | |
| | | [added: | | | | | | | | | | | |] $ | [added: 958,784 | | | $ |] 873,729 | | | $ | 817,729 | |
| * | Includes U.S. Treasury Bills with maturities of three months or less when purchased of [removed: $23.2] [added: $61.7] billion at December 31, [removed: 2020] [added: 2021] and [removed: $37.1] [added: $23.2] billion at December 31, [removed: 2019.] [added: 2020.] |
| Unpaid losses and loss adjustment expenses | | $ | [removed: 79,854] [added: 86,664] | | | $ | [removed: 73,019] [added: 79,854] | |
| Unpaid losses and loss adjustment expenses under retroactive reinsurance contracts | | | [removed: 40,966] [added: 38,256] | | | | [removed: 42,441] [added: 40,966] | |
| Unearned premiums | | | [removed: 21,395] [added: 23,512] | | | | [removed: 19,782] [added: 21,395] | |
| Life, annuity and health insurance benefits | | | [removed: 21,616] [added: 22,452] | | | | [removed: 20,155] [added: 21,616] | |
Given the subjectivity of estimating these key assumptions, performing audit procedures to evaluate whether claim liabilities were appropriately recorded as of December 31, 2021, required a high degree of auditor judgment and an increased extent of effort, including the need to involve our actuarial specialists.
February 26, 2022
| | | | 743,323 | | | | 664,021 | |
| | | | 215,461 | | | | 209,708 | |
| | | $ | 958,784 | | | $ | 873,729 | |
| | | | 255,711 | | | | 250,223 | |
| | | | 97,900 | | | | 98,072 | |
| | | $ | 958,784 | | | $ | 873,729 | |
| Unrealized appreciation of fixed maturity securities | | | (217 | ) | | | 74 | | | | 142 | |
| Net earnings | | | — | | | | — | | | | 89,795 | | | | — | | | | 1,012 | | | | 90,807 | |
| Balance December 31, 2021 | | $ | 35,600 | | | $ | (4,027 | ) | | $ | 534,421 | | | $ | (59,795 | ) | | $ | 8,731 | | | $ | 514,930 | |
| Net earnings | | $ | 90,807 | | | $ | 43,253 | | | $ | 81,792 | |
| | *(d)* | Investments in fixed maturity securities (Continued) |
Premiums for periodic payment annuity contracts are usually received in full at the inception of the contracts.
For short duration contracts, we subsequently amortize such costs to underwriting expenses as the related premiums are earned.
Acquisition costs related to long duration life insurance contracts are amortized over the expected premium-paying period in proportion to the anticipated premiums over the life of the policy.
Such anticipated premiums are estimated using the same assumptions used for computing liabilities for future policy benefits.
In August 2018, the Financial Accounting Standards Board issued Accounting Standards Update 2018-12 “Targeted Improvements to the Accounting for Long-Duration Contracts” (“ASU 2018-12”).
The effects from changes in cash flow assumptions are reflected in earnings and the effects from changes in discount rate assumptions are reflected in other comprehensive income.
We currently intend to adopt ASU 2018-12 as of January 1, 2023 using the modified retrospective method, which provides that the revised cash flow and discount rate assumptions as of January 1, 2021 (the transition date) be applied to contracts then in-force, with liabilities then remeasured as provided under the standard.
The cumulative effects from discount rate assumption changes as of the transition date will be reflected in accumulated other comprehensive income and the cumulative effect from cash flow assumption changes will be included in retained earnings.
While we have not finalized our assessment of the impact of the adoption as of the transition date, we currently believe that the changes in discount rate assumptions will have a greater effect on our recorded liabilities than changes in cash flow assumptions.
We also preliminarily estimate that the changes in discount rate assumptions as of January 1, 2021 will increase our life, health and annuity benefit liabilities from the amounts previously reported due to the historically low interest rate environment at that time.
However, the ultimate impact of adopting ASU 2018-12 will be based on the discount rate and cash flow assumptions determined as of the January 1, 2023 adoption date.
The closing of the second agreement was subject to regulatory and customary closing conditions; however, in July 2021, BHE and Dominion agreed to terminate the second agreement.
| Property, plant and equipment | $ | 9,264 | |
| Goodwill | | 1,741 | |
| Other | | 2,398 | |
| Other | | 1,358 | |
| December 31, 2021 | | | | | | | | | | | | | | | | |
| Foreign governments | | | 10,998 | | | | 29 | | | | (33 | ) | | | 10,994 | |
| Corporate bonds | | | 1,363 | | | | 412 | | | | (1 | ) | | | 1,774 | |
| | | $ | 15,964 | | | $ | 510 | | | $ | (40 | ) | | $ | 16,434 | |
| Amortized cost | | $ | 9,171 | | | $ | 6,044 | | | $ | 307 | | | $ | 207 | | | $ | 235 | | | $ | 15,964 | |
| Fair value | | | 9,165 | | | | 6,086 | | | | 559 | | | | 347 | | | | 277 | | | | 16,434 | |
| December 31, 2021 * | | | | | | | | | | | | |
| Banks, insurance and finance | | $ | 26,822 | | | $ | 62,236 | | | $ | 89,058 | |
| Consumer products | | | 36,076 | | | | 154,945 | | | | 191,021 | |
| | | $ | 104,605 | | | $ | 246,114 | | | $ | 350,719 | |
Investments in commercial, industrial and other equity securities include our investments in Occidental Corporation (“Occidental”), which we acquired in 2019.
| --- | --- |
During the second quarter of 2020, the Company performed an interim reevaluation of the goodwill and indefinite-lived intangible assets at the PCC reporting unit.
This determination was made due to disruptions arising from the COVID-19 pandemic that had an adverse impact on the industries in which PCC operates.
As a result, PCC reported goodwill and indefinite-lived intangible assets of approximately $21 billion as of December 31, 2020.
February 27, 2021
| --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | 664,021 | | | | 630,572 | |
| | | | 209,708 | | | | 187,157 | |
| Derivative contract liabilities | | | 1,065 | | | | 968 | |
| | | | 250,223 | | | | 234,570 | |
| | | | 98,072 | | | | 87,797 | |
| | | | | | | | | | | | | |
| Balance December 31, 2017 | | $ | 35,702 | | | $ | 58,571 | | | $ | 255,786 | | | $ | (1,763 | ) | | $ | 3,658 | | | $ | 351,954 | |
| Adoption of new accounting pronouncements | | | — | | | | (61,375 | ) | | | 61,305 | | | | — | | | | — | | | | (70 | ) |
| Net earnings | | | — | | | | — | | | | 4,021 | | | | — | | | | 301 | | | | 4,322 | |
The risks and uncertainties resulting from the pandemic that may affect our future earnings, cash flows and financial condition include the time necessary to distribute safe and effective vaccines and to vaccinate a significant number of people in the U.S. and throughout the world as well as the long-term effect from the pandemic on the demand for certain of our products and services.
| (1) | Significant accounting policies and practices *(Continued)* |
See Note 1(w).
We do not measure an allowance for expected credit losses on accrued interest and instead, as permitted, we elected to reverse uncollectible accrued interest through interest income on a timely basis.
Berkshire adopted ASC 842 “Leases” on January 1, 2019.
We also reduced other assets by approximately $300 million.
Consequently, our consolidated assets and liabilities increased by approximately $5.9 billion.
ASC 842 did not have a material effect on our accounting for our lessor contracts or for lessee contracts classified as financing leases.
On January 1, 2018, we adopted Accounting Standards Update (“ASU”) 2016-01 “Financial Instruments—Recognition and Measurement of Financial Assets and Financial Liabilities,” ASU 2018-02 “Reclassification of Certain Tax Effects from Accumulated Other Comprehensive Income” and ASC 606 “Revenues from Contracts with Customers.” Prior year financial statements were not restated.
A summary of the effects of the initial adoption of ASU 2016-01, ASU 2018-02 and ASC 606 on our shareholders’ equity follows (in millions).
| | | ASU 2016-01 | | | | ASU 2018-02 | | | | ASC 606 | | | | Total | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Increase (decrease): | | | | | | | | | | | | | | | | |
| Retained earnings | | | 61,459 | | | | (84 | ) | | | (70 | ) | | | 61,305 | |
| Shareholders’ equity | | | — | | | | — | | | | (70 | ) | | | (70 | ) |
In adopting ASU 2016-01, as of January 1, 2018, we reclassified the net after-tax unrealized gains on equity securities from accumulated other comprehensive income to retained earnings.
In adopting ASU 2018-02, we reclassified certain deferred income tax effects as of January 1, 2018 attributable to the reduction in the U.S. statutory income tax rate under the Tax Cuts and Jobs Act of 2017 from accumulated other comprehensive income to retained earnings.
In adopting ASC 606, we recorded increases to certain assets and other liabilities, with the cumulative net effect recorded to retained earnings.
| | *(z)* | New accounting pronouncements to be adopted subsequent to December 31, 2020 |
Under the terms of the second acquisition agreement, BHE agreed to acquire the Excluded Assets for approximately $1.3 billion in cash.
The closing of this second acquisition is subject to receiving necessary regulatory approvals and other customary closing conditions and is expected to occur during the first half of 2021.
| Goodwill | | 1,732 | |
| Other | | 2,376 | |
On October 1, 2018, we acquired MLMIC Insurance Company (“MLMIC”), a writer of medical professional liability insurance domiciled in New York.
The acquisition price was approximately $2.5 billion.
An excerpt. Shown here: 40 of 763 rewritten, 40 of 249 added and 40 of 264 removed. The counts are complete. For every sentence, read Item 8. Financial Statements and Supplementary Data in the FY2021 filing and the FY2020 filing.
Item 9A. Controls and Procedures
2 rewritten, 0 added, 0 removed, 3 unchanged
The attestation report called for by Item 308(b) of Regulation S-K is incorporated herein by reference to [added: the] Report of Independent Registered Public Accounting Firm, included on page K-67 of this report.
There has been no change in the Corporation’s internal control over financial reporting during the quarter ended December 31, [removed: 2020] [added: 2021] that has materially affected, or is reasonably likely to materially affect, the Corporation’s internal control over financial reporting.
Item 9B. Other Information
1 rewritten, 0 added, 0 removed, 3 unchanged
Except for the information set forth under the caption “Executive Officers of the Registrant” in Part I hereof, information required by this Part (Items 10, 11, 12, 13 and 14) is incorporated by reference from the Registrant’s definitive proxy statement, filed pursuant to Regulation 14A, for the Annual Meeting of Shareholders of the Registrant to be held on [removed: May 1, 2021,] [added: April 30, 2022,] which meeting will involve the election of directors.
Item 15. Exhibits and Financial Statement Schedules
87 rewritten, 14 added, 9 removed, 130 unchanged
| [Report of Independent Registered Public Accounting [removed: Firm](#ITEM_8_FINANCIAL_STATEMENTS_SUPPLEMENTAR)] [added: Firm](#REPORT_OF_INDEPENDENT_REGISTERED_2)] | | [removed: K-67] [added: K-114] |
| [Consolidated Balance Sheets— December 31, [removed: 2020] [added: 2021] and December 31, [removed: 201](#CONSOLIDATED_BALANCE_SHEETS)9] [added: 2020](#CONSOLIDATED_BALANCE_SHEETS)] | | K-70 |
| [Consolidated Statements of Earnings— Years Ended December 31, [removed: 2020,] [added: 2021,] December 31, [removed: 2019,] [added: 2020,] and December 31, [removed: 201](#CONSOLIDATED_STATEMENTS_EARNINGS)8] [added: 2019](#CONSOLIDATED_STATEMENTS_EARNINGS)] | | K-72 |
| [Consolidated Statements of Comprehensive Income— Years Ended December 31, [removed: 2020,] [added: 2021,] December 31, [removed: 2019,] [added: 2020,] and December 31, [removed: 201](#CONSOLIDATED_STATEMENTS_COMPREHENSIVE_IN)8] [added: 2019](#CONSOLIDATED_STATEMENTS_COMPREHENSIVE_IN)] | | K-73 |
| [Consolidated Statements of Changes in Shareholders’ Equity— Years Ended December 31, [removed: 2020,] [added: 2021,] December 31, [removed: 2019,] [added: 2020,] and December 31, [removed: 201](#CONSOLIDATED_STATEMENTS_CHANGES_IN_SHARE)8] [added: 2019](#CONSOLIDATED_STATEMENTS_CHANGES_IN_SHARE)] | | K-73 |
| [Consolidated Statements of Cash Flows— Years Ended December 31, [removed: 2020,] [added: 2021,] December 31, [removed: 2019,] [added: 2020,] and December 31, [removed: 201](#CONSOLIDATED_STATEMENTS_CASH_FLOWS)8] [added: 2019](#CONSOLIDATED_STATEMENTS_CASH_FLOWS)] | | K-74 |
| [Report of Independent Registered Public Accounting Firm](#REPORT_INDEPENDENT_REGISTERED_PUBLIC_ACC) [added: (PCAOB ID No. 34)] | | [removed: K-117] [added: K-67] |
| [Schedule I—Parent Company Condensed Financial Information Balance Sheets as of December 31, [removed: 2020] [added: 2021] and [removed: 2019,] [added: 2020,] Statements of Earnings and Comprehensive Income and Cash Flows for the years ended December 31, [removed: 2020,] [added: 2021,] December 31, [removed: 2019] [added: 2020] and December 31, [removed: 2018] [added: 2019] and Note to Condensed Financial Information](#SCHEDULE_I) | | [removed: K-118] [added: K-115] |
See the “Exhibit Index” at page [removed: K-120.][added: K-117.]
We have audited the consolidated financial statements of Berkshire Hathaway Inc. and subsidiaries (the “Company”) as of December 31, [removed: 2020] [added: 2021] and [removed: 2019,] [added: 2020,] and for each of the three years in the period ended December 31, [removed: 2020,] [added: 2021,] and the Company’s internal control over financial reporting as of December 31, [removed: 2020,] [added: 2021,] and have issued our report thereon dated February [removed: 27, 2021;] [added: 26, 2022;] such consolidated financial statements and report are included elsewhere in this Form 10-K.
| | | [added: 2021 | | | |] 2020 | | | | 2019 | | |
| Cash and cash equivalents | | $ | [removed: 12,329] [added: 18,797] | | | $ | [removed: 15,004] [added: 12,329] | |
| Short-term investments in U.S. Treasury Bills | | | [removed: 29,773] [added: 9,681] | | | | [removed: 25,514] [added: 29,773] | |
| Investments in and advances to/from consolidated subsidiaries | | | [removed: 411,826] [added: 486,862] | | | | [removed: 392,162] [added: 411,826] | |
| Investment in The Kraft Heinz Company | | | [removed: 13,336] [added: 13,112] | | | | [removed: 13,757] [added: 13,336] | |
| Other assets | | | [removed: 108] [added: 140] | | | | [removed: 131] [added: 108] | |
| Accounts payable, accrued interest and other liabilities | | $ | [removed: 369] [added: 237] | | | $ | [removed: 320] [added: 369] | |
| Income taxes, principally deferred | | | [removed: 1,174] [added: 747] | | | | [removed: 1,554] [added: 1,174] | |
| Notes payable and other borrowings | | | [removed: 22,665] [added: 21,409] | | | | [removed: 19,903] [added: 22,665] | |
| Berkshire Hathaway shareholders’ equity | | | [removed: 443,164] [added: 506,199] | | | | [removed: 424,791] [added: 443,164] | |
| | | [removed: 2020] [added: 2021] | | | | [removed: 2019] [added: 2020] | | | | [removed: 2018] [added: 2019] | | |
| Dividends and distributions | | $ | [removed: 26,110] [added: 13,462] | | | $ | [removed: 15,603] [added: 26,110] | | | $ | [removed: 9,658] [added: 15,603] | |
| Undistributed earnings [removed: (losses)] | | | [removed: 17,402] [added: 74,819] | | | | [removed: 65,237] [added: 17,402] | | | | [removed: (3,952] [added: 65,237] | [removed: )] |
| | | | [removed: 43,512] [added: 88,281] | | | | [removed: 80,840] [added: 43,512] | | | | [removed: 5,706] [added: 80,840] | |
| Investment gains (losses) | | | [removed: (24] [added: 35] | [removed: )] | | | [removed: (125] [added: (24] | ) | | | [removed: (4] [added: (125] | ) |
| Equity in net earnings [removed: (losses)] of The Kraft Heinz Company | | | [removed: 95] [added: 269] | | | | [removed: 493] [added: 95] | | | | [removed: (2,730] [added: 493] | [removed: )] |
| Other income | | | [removed: 328] [added: 73] | | | | [removed: 780] [added: 328] | | | | [removed: 649] [added: 780] | |
| | | | [removed: 43,911] [added: 88,658] | | | | [removed: 81,988] [added: 43,911] | | | | [removed: 3,621] [added: 81,988] | |
| General and administrative | | | [removed: 194] [added: 136] | | | | [removed: 122] [added: 194] | | | | [removed: 216] [added: 122] | |
| Interest expense | | | [removed: 489] [added: 444] | | | | [removed: 591] [added: 489] | | | | [removed: 601] [added: 591] | |
| Foreign exchange (gains) losses on non-U.S. Dollar denominated debt | | | [removed: 970] [added: (1,281] | [added: )] | | | [removed: (193] [added: 970] | [removed: )] | | | [removed: (366] [added: (193] | ) |
| Income tax expense (benefit) | | | [removed: (263] [added: (436] | ) | | | [removed: 51] [added: (263] | [added: )] | | | [removed: (851] [added: 51] | [removed: )] |
| | | | [removed: 1,390] [added: (1,137] | [added: )] | | | [removed: 571] [added: 1,390] | | | | [removed: (400] [added: 571] | [removed: )] |
| Net earnings attributable to Berkshire Hathaway shareholders | | | [removed: 42,521] [added: 89,795] | | | | [removed: 81,417] [added: 42,521] | | | | [removed: 4,021] [added: 81,417] | |
| Other comprehensive income attributable to Berkshire Hathaway shareholders | | | [removed: 1,000] [added: 216] | | | | [removed: (228] [added: 1,000] | [removed: )] | | | [removed: (2,211] [added: (228] | ) |
| Comprehensive income attributable to Berkshire Hathaway shareholders | | $ | [removed: 43,521] [added: 90,011] | | | $ | [removed: 81,189] [added: 43,521] | | | $ | [removed: 1,810] [added: 81,189] | |
| Net earnings attributable to Berkshire Hathaway shareholders | | $ | [removed: 42,521] [added: 89,795] | | | $ | [removed: 81,417] [added: 42,521] | | | $ | [removed: 4,021] [added: 81,417] | |
| Investment gains/losses | | | [removed: 24] [added: (35] | [added: )] | | | [removed: 125] [added: 24] | | | | [removed: 4] [added: 125] | |
| Undistributed earnings of consolidated subsidiaries | | | [removed: (17,402] [added: (74,819] | ) | | | [removed: (65,237] [added: (17,402] | ) | | | [removed: 3,952] [added: (65,237] | [added: )] |
| Non-cash dividends from subsidiaries | | | [removed: (8,296] [added: (2,126] | ) | | | [removed: —] [added: (8,296] | [added: )] | | | — | |
K-113
February 26, 2022
K-114
| | | 2021 | | | | 2020 | | |
| | | $ | 528,592 | | | $ | 467,372 | |
| | | | 22,393 | | | | 24,208 | |
| | | $ | 528,592 | | | $ | 467,372 | |
K-115
In January 2022, Berkshire repaid $600 million of maturing debt and issued ¥128.5 billion (approximately $1.1 billion) of senior notes with maturity dates ranging from 2027 to 2052 and a weighted average interest rate of 0.5%.
| 4.6 | | [Indenture, dated as of January 28, 2022, by and among Berkshire Hathaway Inc., as an issuer and a guarantor of the debt securities issued by Berkshire Hathaway Finance Corporation, Berkshire Hathaway Finance Corporation, as an issuer, and The Bank of New York Mellon Trust Company, N.A., as trustee. Incorporated by reference to Exhibit 4.1 to Berkshire’s Registration Statement on Form S-3 filed on January 28, 2022. SEC File No 333-262384.](http://www.sec.gov/Archives/edgar/data/1067983/000119312522021211/d277039dex41.htm) |
| /S/ SUSAN A. BUFFETT Susan A. Buffett | Director | February 26, 2022 Date |
| /S/ CHRISTOPHER C. DAVIS Christopher C. Davis | Director | February 26, 2022 Date |
| | | |
| | | |
February 27, 2021
| | | $ | 467,372 | | | $ | 446,568 | |
| | | | 24,208 | | | | 21,777 | |
See Note 17 to the accompanying Consolidated Financial Statements for additional information.
K-120
K-121
| /S/ THOMAS S. MURPHY Thomas S. Murphy | Director | February 27, 2021 Date |
| /S/ WALTER SCOTT, JR. Walter Scott, Jr. | Director | February 27, 2021 Date |
K-122
An excerpt. Shown here: 40 of 87 rewritten, all 14 added and all 9 removed. The counts are complete. For every sentence, read Item 15. Exhibits and Financial Statement Schedules in the FY2021 filing and the FY2020 filing.
Item 6. Selected Financial Data
0 rewritten, 0 added, 32 removed, 0 unchanged
Dropped this year
Selected Financial Data for the Past Five Years
(dollars in millions except per-share data)
| | | 2020 | | | | 2019 | | | | 2018 | | | | 2017 | | | | 2016 | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Revenues: | | | | | | | | | | | | | | | | | | | | |
| Insurance premiums earned | | $ | 63,401 | | | $ | 61,078 | | | $ | 57,418 | | | $ | 60,597 | | | $ | 45,881 | |
| Sales and service revenues | | | 127,044 | | | | 134,989 | | | | 133,336 | | | | 130,243 | | | | 123,053 | |
| Leasing revenue | | | 5,209 | | | | 5,856 | | | | 5,732 | | | | 2,552 | | | | 2,553 | |
| Railroad, utilities and energy revenues | | | 41,764 | | | | 43,453 | | | | 43,673 | | | | 40,005 | | | | 37,447 | |
| Interest, dividend and other investment income | | | 8,092 | | | | 9,240 | | | | 7,678 | | | | 6,536 | | | | 6,180 | |
| Total revenues | | $ | 245,510 | | | $ | 254,616 | | | $ | 247,837 | | | $ | 239,933 | | | $ | 215,114 | |
| | | | | | | | | | | | | | | | | | | | | |
| Investment and derivative gains/losses | | $ | 40,746 | | | $ | 72,607 | | | $ | (22,455 | ) | | $ | 2,128 | | | $ | 8,304 | |
| | | | | | | | | | | | | | | | | | | | | |
| Earnings: | | | | | | | | | | | | | | | | | | | | |
| Net earnings attributable to Berkshire Hathaway (1) | | $ | 42,521 | | | $ | 81,417 | | | $ | 4,021 | | | $ | 44,940 | | | $ | 24,074 | |
| Net earnings per share attributable to Berkshire Hathaway shareholders (2) | | $ | 26,668 | | | $ | 49,828 | | | $ | 2,446 | | | $ | 27,326 | | | $ | 14,645 | |
| | | | | | | | | | | | | | | | | | | | | |
| Year-end data: | | | | | | | | | | | | | | | | | | | | |
| Total assets | | $ | 873,729 | | | $ | 817,729 | | | $ | 707,794 | | | $ | 702,095 | | | $ | 620,854 | |
| Notes payable and other borrowings: | | | | | | | | | | | | | | | | | | | | |
| Insurance and other | | | 41,522 | | | | 37,590 | | | | 34,975 | | | | 40,409 | | | | 42,559 | |
| Railroad, utilities and energy | | | 75,373 | | | | 65,778 | | | | 62,515 | | | | 62,178 | | | | 59,085 | |
| | | | | | | | | | | | | | | | | | | | | |
| Berkshire Hathaway shareholders’ equity | | | 443,164 | | | | 424,791 | | | | 348,703 | | | | 348,296 | | | | 282,070 | |
| Class A equivalent common shares outstanding, in thousands | | | 1,544 | | | | 1,625 | | | | 1,641 | | | | 1,645 | | | | 1,644 | |
| Berkshire Hathaway shareholders’ equity per outstanding Class A equivalent common share | | $ | 287,031 | | | $ | 261,417 | | | $ | 212,503 | | | $ | 211,750 | | | $ | 171,542 | |
| *(1)* | Includes after-tax investment and derivative gains/losses of $31.6 billion in 2020, $57.4 billion in 2019, $(17.7) billion in 2018, $1.4 billion in 2017 and $6.5 billion in 2016. Beginning in 2018, investment gains/losses include the changes in fair values of equity securities during the period. Previously, investment gains/losses of equity securities were recognized in earnings when securities were sold. Net earnings in 2017 includes a one-time net benefit of $29.1 billion attributable to the enactment of the Tax Cuts and Jobs Act of 2017. |
| --- | --- |
| *(2)* | Represents net earnings per average equivalent Class A share outstanding. Net earnings per average equivalent Class B common share outstanding is equal to 1/1,500 of such amount. |
| --- | --- |
K-32