 filings.tools
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
259K characters. Original on sec.gov · Markdown
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
| --- | --- |
The following discussion and analysis should be read in conjunction with The Blackstone Group L.P.’s consolidated financial statements and the related notes included within this Annual Report on Form 10-K.
Our Business
Blackstone is one of the largest independent managers of private capital in the world. Our business is organized into four segments:
| • | Real Estate. Our real estate group is one of the largest real estate investment managers in the world. We operate as one globally integrated business, with investments in North America, Europe, Asia and Latin America. Our real estate investment team seeks to establish a differentiated view and capitalizes on our scale and proprietary information advantages to invest with conviction and generate attractive risk-adjusted returns for our investors over the long-term. |
|---|
Our Blackstone Real Estate Partners (“BREP”) funds are geographically diversified and target a broad range of “opportunistic” real estate and real estate related investments. The BREP funds include global funds as well as funds focused specifically on Europe or Asia investments. We seek to acquire high quality, well-located yet undermanaged assets at an attractive basis, address any property or business issues through active asset management and sell the assets once our business plan is accomplished. BREP has made significant investments in hotels, office buildings, industrial assets, residential and shopping centers, as well as a variety of real estate operating companies.
Our core+ real estate business, Blackstone Property Partners (“BPP”) has assembled a global portfolio of high quality core+ investments across the U.S., Europe and Asia. We manage several core+ real estate funds, which target substantially stabilized assets in prime markets with a focus on industrial, multifamily, office and retail assets.
BREIT, a non-exchange traded real estate investment trust (“REIT”), is focused on investing primarily in stabilized income-oriented commercial real estate in the U.S.
Our Blackstone Real Estate Debt Strategies (“BREDS”) vehicles target debt investment opportunities collateralized by commercial real estate in both public and private markets, primarily in the U.S. and Europe. BREDS’ scale and investment mandates enable it to provide a variety of lending and investment options including mezzanine loans, senior loans and liquid securities. The BREDS platform includes a number of high yield real estate debt funds, liquid real estate debt funds and BXMT, a NYSE-listed REIT.
| • | Private Equity. We are a world leader in private equity investing, having managed seven general private equity funds, as well as three sector-focused funds and a geographically-focused fund, since we established this business in 1987. Our Private Equity segment includes our corporate private equity business, which consists of (a) our flagship private equity funds (Blackstone Capital Partners (“BCP”) funds), (b) our sector-focused private equity funds, including our energy-focused funds (Blackstone Energy Partners (“BEP”) funds), (c) our Asia-focused fund (Blackstone Capital Partners Asia (“BCP Asia”) fund) and (d) our core private equity fund, Blackstone Core Equity Partners (“BCEP”). In addition, our Private Equity segment includes (a) our opportunistic investment platform that invests globally across asset classes, industries and geographies, Blackstone Tactical Opportunities (“Tactical Opportunities”), (b) our secondary fund of funds business, Strategic Partners Fund Solutions (“Strategic Partners”), (c) our infrastructure-focused funds, Blackstone Infrastructure Partners (“BIP”), (d) our life sciences private investment platform, Blackstone Life Sciences (“BXLS”), (e) a multi-asset investment program for eligible high net worth investors offering exposure to certain of Blackstone’s key illiquid investment strategies through a single commitment, Blackstone Total Alternatives Solution (“BTAS”) and (f) our capital markets services business, Blackstone Capital Markets (“BXCM”). |
|---|
Our corporate private equity business pursues transactions throughout the world across a variety of transaction types, including large buyouts, mid-cap buyouts, buy and build platforms (which involve
Table of Contents
multiple acquisitions behind a single management team and platform) and growth equity/development projects (which involve significant minority investments in mature companies and greenfield development projects in energy and power). Within our corporate private equity business, our core private equity fund targets control-oriented investments in high quality companies with durable businesses and seeks to offer a lower level of risk and a longer hold period than traditional private equity. Tactical Opportunities invests globally across asset classes, industries and geographies, seeking to identify and execute on attractive, differentiated investment opportunities, leveraging the intellectual capital across our various businesses while continuously optimizing its approach in the face of ever-changing market conditions. Strategic Partners is a total fund solutions provider that acquires interests in high quality private funds from original holders seeking liquidity, co-investments alongside financial sponsors and provides investment advisory services to clients investing in primary and secondary investments in private funds and co-investments. BIP focuses on infrastructure investments in the energy, transportation, communications and water and waste sectors.
| • | Hedge Fund Solutions. The largest component of our Hedge Fund Solutions segment is Blackstone Alternative Asset Management (“BAAM”). BAAM is the world’s largest discretionary allocator to hedge funds, managing a broad range of commingled and customized fund solutions since its inception in 1990. The Hedge Fund Solutions segment also includes investment platforms that seed new hedge fund businesses, purchase minority ownership interests in more established hedge funds, invest in special situation opportunities, create alternative solutions in the form of mutual funds and UCITS and trade directly. |
|---|
| • | Credit. Our Credit segment consists principally of GSO Capital Partners LP (“GSO”). GSO is one of the largest credit alternative asset managers in the world and is the largest manager of collateralized loan obligations (“CLOs”) globally. The investment portfolios of the funds GSO manages or sub-advises predominantly consist of loans and securities of non-investment grade companies spread across the capital structure including senior debt, subordinated debt, preferred stock and common equity. |
|---|
The GSO business is organized into three overarching strategies: performing credit, distressed and long only. Our performing credit strategies include mezzanine lending funds, middle market direct lending funds and other performing credit strategy funds. Our distressed strategies include credit alpha strategies, stressed/distressed funds and energy strategies. GSO’s long only strategies consist of CLOs, closed end funds, open ended funds and separately managed accounts.
In addition, our Credit segment includes our publicly traded master limited partnership (“MLP”) investment platform, which is managed by Harvest. Harvest, which was founded in 2005 and subsequently acquired by Blackstone in 2017, primarily invests capital raised from institutional investors in separately managed accounts and pooled vehicles, investing in publicly traded MLPs holding primarily midstream energy assets in the U.S.
Our insurer-focused platform, BIS, also a part of our Credit segment, delivers to insurers bespoke, capital efficient investments and diversified portfolios of Blackstone products across asset classes tailored to their needs and risk profile.
We generate revenue from fees earned pursuant to contractual arrangements with funds, fund investors and fund portfolio companies (including management, transaction and monitoring fees), and from capital markets services. We invest in the funds we manage and we are entitled to a pro-rata share of the results of the fund (a “pro-rata allocation”). In addition to a pro-rata allocation, and assuming certain investment returns are achieved, we are entitled to a disproportionate allocation of the income otherwise allocable to the limited partners, commonly referred to as carried interest (“Performance Allocations”). In certain structures, we receive a contractual, incentive fee from an investment fund in the event that specified cumulative investment returns are achieved (an “Incentive Fee”, and together with Performance Allocations, “Performance Revenues”). The composition of our revenues will vary based on market conditions and the cyclicality of the different businesses in which we operate. Net investment gains and investment income generated by the Blackstone Funds, principally private equity and real estate funds, are
Table of Contents
driven by value created by our operating and strategic initiatives as well as overall market conditions. Fair values are affected by changes in the fundamentals of the portfolio company, the portfolio company’s industry, the overall economy and other market conditions.
Business Environment
Blackstone’s businesses are materially affected by conditions in the financial markets and economic conditions in the U.S., Europe, Asia and, to a lesser extent, elsewhere in the world.
For the first three quarters of 2018, equity indices rose in the U.S., supported by continued healthy economic growth and additional benefits to corporate earnings from the Tax Reform Bill. After reaching record highs in September, U.S. equity indices declined sharply and volatility spiked, as investor sentiment turned negative due to signs of slowing global economic growth, continued monetary policy tightening in the U.S., and concerns over the impact of trade disputes, particularly between the U.S. and China. While underlying fundamentals in the U.S. remain positive, most economists expect slower U.S. and global growth in the near term. The S&P 500 ended the year down 4%, while the Dow and Nasdaq declined 6% and 4%, respectively. During the first six weeks of 2019, U.S. equity markets rebounded and volatility declined.
Globally, other equity indices also declined. The MSCI World index ended the year down 10% while the MSCI Europe index declined 17% and the MSCI Asia index declined 16%. The MSCI Emerging Markets Index was down 17% for the year.
In Europe, economic growth continues to slow amid lower manufacturing exports and ongoing political unrest. As concerns over Brexit persisted, the FTSE 100 declined, ending the year down 13%, with the British pound down 6% versus the U.S. dollar.
In Asia, slower growth, along with trade conflicts and rising U.S. interest rates, contributed to market declines. The Hang Seng index fell 14% and the Nikkei declined 12% for the year. In Japan, GDP contracted in the first quarter of 2018, the first decline since 2015, as private consumption waned. In China, equities posted their worst decline since 2011 amid decelerating economic growth.
The CBOE volatility index more than doubled in 2018, reaching 36.07 in December, before ending the year at 25.42, up 130%. Oil prices declined significantly in the fourth quarter of 2018, with West Texas Intermediate Crude falling 38% to $45 per barrel, down 25% for the year. The S&P 500 Energy Index ended the year down 21% and the Bloomberg Commodity Index declined 13% while the Henry Hub Natural Gas spot price was flat for the year. Despite facing pressure in 2018, oil prices and energy indices both rebounded sharply in the first six weeks of 2019.
In fixed income, the Bloomberg Barclays U.S. Aggregate was flat, U.S. investment grade corporates were down 2.5% and high yield corporates declined 2.1% during the year. The U.S. Federal Reserve continued monetary tightening and raised interest rates four times in 2018, with the current target range set to 2.25-2.5%, but indicated they would be patient with regard to any future adjustments. 10-year U.S. Treasury yields rose to 3.24% in November, the highest level in more than four years, prompting investor concerns over the potential negative impact to values of fixed income and longer duration assets. High yield spreads widened 181 basis points during the year and issuance decreased 39% year over year. Global equity capital markets activity for both initial public offerings and follow-on offerings declined, with year to date 2018 activity down 18% year over year.
U.S. merger and acquisition (“M&A”) volume rose 16% during the year, following a strong backlog after the passage of the Tax Reform Bill. Global M&A volume reached $3.4 trillion, its highest level since 2015, and the outlook for deal activity remains positive.
Most economists expect moderate, albeit slowing, economic growth characterized by less synchronized global expansion in the near term, with virtually no signals of a recession in the U.S. in 2019. While global trade tensions and geopolitical instability pose additional risks, the broader outlook remains constructive.
Table of Contents
Notable Transactions
On April 9, 2018, Blackstone concluded its investment sub-advisory relationship with FS Investments’ funds (the “FS Funds”), as previously announced. At March 31, 2018, the FS Funds represented $20.0 billion of Total Assets Under Management. As part of the transaction, Blackstone received proceeds from FS Investments of $580.9 million which is recorded as Other Revenues within the Consolidated Statement of Operations for the year ended December 31, 2018. This amount is characterized as a Transaction-Related Charge and therefore is not included in Fee Related Earnings, or Distributable Earnings for the year ended December 31, 2018. Blackstone distributed a portion of the after-tax proceeds to unitholders resulting in an incremental $0.30 per common unit and per Blackstone Holdings Partnership Unit over the second, third and fourth quarters of 2018, of which $0.10 per common unit and Blackstone Holdings Partnership Unit was distributed on each of August 6, 2018, November 5, 2018 and February 19, 2019.
On September 21, 2018, Blackstone Holdings Finance Co L.L.C., an indirect subsidiary of the Partnership, entered into an amended and restated $1.6 billion revolving credit facility. The amendment and restatement to the Issuer’s credit facility, among other things, increased the amount of available borrowings and extended the maturity date from August 31, 2021 to September 21, 2023.
On November 30, 2018, Blackstone closed the acquisition of Clarus Ventures, LLC and certain of its affiliates (“Clarus”), a leading global life sciences investment firm that has raised $2.6 billion since its founding. Clarus is focused on funding growth-stage investments, often in partnership with major biopharmaceutical companies through research and development collaborations (the “Clarus Acquisition”). The Clarus Acquisition launched BXLS, a private investment platform with capabilities to invest across the life-cycle of companies and products within the life sciences sector. BXLS is included in our Private Equity segment.
Organizational Structure
The simplified diagram below depicts our current organizational structure. The diagram does not depict all of our subsidiaries, including intermediate holding companies through which certain of the subsidiaries depicted are held.
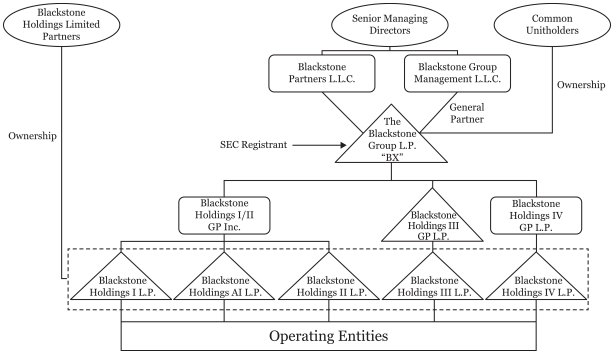
Table of Contents
Key Financial Measures and Indicators
We manage our business using traditional financial measures and key operating metrics since we believe these metrics measure the productivity of our investment activities. We prepare our Consolidated Financial Statements in accordance with GAAP. See Note 2. “Summary of Significant Accounting Policies” in the “Notes to Consolidated Financial Statements” in “— Item 8. Financial Statements and Supplementary Data” and “— Critical Accounting Policies.” Our key non-GAAP financial measures and operating indicators and metrics are discussed below.
Distributable Earnings
Distributable Earnings, is derived from Blackstone’s segment reported results, and is used to assess performance and amounts available for distributions to Blackstone unitholders, including Blackstone personnel and others who are limited partners of the Blackstone Holdings Partnerships. Distributable Earnings is the sum of Segment Distributable Earnings plus Net Interest Income (Loss) less Taxes and Related Payables. Distributable Earnings excludes unrealized activity and is derived from and reconciled to, but not equivalent to, its most directly comparable GAAP measure of Income (Loss) Before Provision for Taxes. See “— Non-GAAP Financial Measures” for our reconciliation of Distributable Earnings.
Net Interest Income (Loss) is presented on a segment basis and is equal to Interest and Dividend Revenue less Interest Expense, adjusted for the impact of consolidation of Blackstone Funds, and interest expense associated with the Tax Receivable Agreement.
Taxes and Related Payables represent the total GAAP tax provision adjusted to include only the current tax provision (benefit) calculated on Income (Loss) Before Provision for Taxes excluding the tax impact of any divestitures and including the Payable under the Tax Receivable Agreement.
Segment Distributable Earnings
Effective as of and for the three months ended December 31, 2018, Blackstone senior management determined that Segment Distributable Earnings, and not Economic Income, is the measure that it uses to assess the performance of its business segments. Segment Distributable Earnings is used by management to make operating decisions, allocate resources and determine the compensation of employees across all of its business segments. All prior periods have been recast to reflect these updates.
Segment Distributable Earnings is Blackstone’s segment profitability measure used to make operating decisions and assess performance across Blackstone’s four segments. Segment Distributable Earnings represents the net realized earnings of Blackstone’s segments and is the sum of Fee Related Earnings and Net Realizations for each segment. Blackstone’s segments are presented on a basis that deconsolidates Blackstone Funds, eliminates non-controlling ownership interests in Blackstone’s consolidated Operating Partnerships, removes the amortization of intangible assets and removes Transaction-Related Charges. Transaction-Related Charges arise from corporate actions including acquisitions, divestitures and Blackstone’s initial public offering. They consist primarily of equity-based compensation charges, gains and losses on contingent consideration arrangements, changes in the balance of the tax receivable agreement resulting from a change in tax law or similar event, transaction costs and any gains or losses associated with these corporate actions. Segment Distributable Earnings excludes unrealized activity and is derived from and reconciled to, but not equivalent to, its most directly comparable GAAP measure of Income (Loss) Before Provision for Taxes. See “— Non-GAAP Financial Measures” for our reconciliation of Segment Distributable Earnings.
Net Realizations is presented on a segment basis and is the sum of Realized Principal Investment Income and Realized Performance Revenues (which refers to Realized Performance Revenues excluding Fee Related Performance Revenues), less Realized Performance Compensation (which refers to Realized Performance Compensation excluding Fee Related Performance Compensation and Equity-Based Performance Compensation).
Table of Contents
Fee Related Earnings
Fee Related Earnings is a performance measure used to assess Blackstone’s ability to generate profits from revenues that are measured and received on a recurring basis and not subject to future realization events. Fee Related Earnings equals management and advisory fees (net of management fee reductions and offsets) plus Fee Related Performance Revenues less (a) Fee Related Compensation on a segment basis, and (b) Other Operating Expenses. Fee Related Earnings is derived from and reconciled to, but not equivalent to, its most directly comparable GAAP measure of Income (Loss) Before Provision for Taxes. See “— Non-GAAP Financial Measures” for our reconciliation of Fee Related Earnings.
Fee Related Compensation is presented on a segment basis and refers to the compensation expense, excluding Equity-Based Compensation, directly related to Management and Advisory Fees, Net and Fee Related Performance Revenues.
Fee Related Performance Revenues refers to the realized portion of Performance Revenues from Perpetual Capital that are (a) measured and received on a recurring basis, and (b) not dependent on realization events from the underlying investments.
Fee Related Performance Compensation is included in Fee Related Compensation on a segment basis and refers to compensation expense directly related to Fee Related Performance Revenues.
Adjusted Earnings Before Interest, Taxes and Depreciation and Amortization
Adjusted Earnings Before Interest, Taxes and Depreciation and Amortization (“Adjusted EBITDA”), is a supplemental measure used to assess performance derived from Blackstone’s segment results and may be used to assess its ability to service its borrowings. Adjusted EBITDA represents Distributable Earnings plus the addition of (a) Interest Expense on a segment basis, (b) Taxes and Related Payables, and (c) Depreciation and Amortization. Adjusted EBITDA is derived from and reconciled to, but not equivalent to, its most directly comparable GAAP measure of Income (Loss) Before Provision for Taxes. See “— Non-GAAP Financial Measures” for our reconciliation of Adjusted EBITDA.
Operating Metrics
The alternative asset management business is a complex business that is primarily based on managing third party capital and does not require substantial capital investment to support rapid growth. However, there also can be volatility associated with its earnings and cash flows. Since our inception, we have developed and used various key operating metrics to assess and monitor the operating performance of our various alternative asset management businesses in order to monitor the effectiveness of our value creating strategies.
Assets Under Management. Assets Under Management refers to the assets we manage. Our Assets Under Management equals the sum of:
| (a) | the fair value of the investments held by our carry funds and our side-by-side and co-investment entities managed by us, plus (1) the capital that we are entitled to call from investors in those funds and entities pursuant to the terms of their respective capital commitments, including capital commitments to funds that have yet to commence their investment periods, or (2) for certain credit-focused funds the amounts available to be borrowed under asset based credit facilities, |
|---|
| (b) | the net asset value of (1) our hedge funds and real estate debt carry funds, BPP, certain co-investments managed by us, and our Hedge Fund Solutions carry and drawdown funds (plus, in each case, the capital that we are entitled to call from investors in those funds, including commitments yet to commence their investment periods), and (2) our funds of hedge funds, our Hedge Fund Solutions registered investment companies, and BREIT, |
|---|
Table of Contents
| (c) | the invested capital, fair value or net asset value of assets we manage pursuant to separately managed accounts, |
|---|
| (d) | the amount of debt and equity outstanding for our CLOs during the reinvestment period, |
|---|
| (e) | the aggregate par amount of collateral assets, including principal cash, for our CLOs after the reinvestment period, |
|---|
| (f) | the gross or net amount of assets (including leverage where applicable) for our credit-focused registered investment companies, and |
|---|
| (g) | the fair value of common stock, preferred stock, convertible debt, or similar instruments issued by BXMT. |
|---|
Our carry funds are commitment-based drawdown structured funds that do not permit investors to redeem their interests at their election. Our funds of hedge funds, hedge funds, funds structured like hedge funds and other open ended funds in our Hedge Fund Solutions, Credit and Real Estate segments generally have structures that afford an investor the right to withdraw or redeem their interests on a periodic basis (for example, annually or quarterly), typically with 30 to 95 days’ notice, depending on the fund and the liquidity profile of the underlying assets. Investment advisory agreements related to certain separately managed accounts in our Hedge Fund Solutions and Credit segments, excluding our BIS separately managed accounts, may generally be terminated by an investor on 30 to 90 days’ notice.
Fee-Earning Assets Under Management. Fee-Earning Assets Under Management refers to the assets we manage on which we derive management fees and/or performance revenues. Our Fee-Earning Assets Under Management equals the sum of:
| (a) | for our Private Equity segment funds and Real Estate segment carry funds, including certain BREDS and Hedge Fund Solutions funds, the amount of capital commitments, remaining invested capital, fair value, net asset value or par value of assets held, depending on the fee terms of the fund, |
|---|
| (b) | for our credit-focused carry funds, the amount of remaining invested capital (which may include leverage) or net asset value, depending on the fee terms of the fund, |
|---|
| (c) | the remaining invested capital or fair value of assets held in co-investment vehicles managed by us on which we receive fees, |
|---|
| (d) | the net asset value of our funds of hedge funds, hedge funds, BPP, certain co-investments managed by us, certain registered investment companies, BREIT, and certain of our Hedge Fund Solutions drawdown funds, |
|---|
| (e) | the invested capital, fair value of assets or the net asset value we manage pursuant to separately managed accounts, |
|---|
| (f) | the net proceeds received from equity offerings and accumulated core earnings of BXMT, subject to certain adjustments, |
|---|
| (g) | the aggregate par amount of collateral assets, including principal cash, of our CLOs, and |
|---|
| (h) | the gross amount of assets (including leverage) or the net assets (plus leverage where applicable) for certain of our credit-focused registered investment companies. |
|---|
Each of our segments may include certain Fee-Earning Assets Under Management on which we earn performance revenues but not management fees.
Our calculations of assets under management and fee-earning assets under management may differ from the calculations of other asset managers, and as a result this measure may not be comparable to similar measures presented by other asset managers. In addition, our calculation of assets under management includes commitments to, and the fair value of, invested capital in our funds from Blackstone and our personnel, regardless of whether such
Table of Contents
commitments or invested capital are subject to fees. Our definitions of assets under management and fee-earning assets under management are not based on any definition of assets under management and fee-earning assets under management that is set forth in the agreements governing the investment funds that we manage.
For our carry funds, total assets under management includes the fair value of the investments held, whereas fee-earning assets under management includes the amount of capital commitments, the remaining amount of invested capital at cost depending on whether the investment period has or has not expired or the fee terms of the fund. As such, fee-earning assets under management may be greater than total assets under management when the aggregate fair value of the remaining investments is less than the cost of those investments.
Perpetual Capital. Perpetual Capital refers to the component of assets under management with an indefinite term, that is not in liquidation, and for which there is no requirement to return capital to investors through redemption requests in the ordinary course of business, except where funded by new capital inflows. Perpetual Capital includes co-investment capital with an investor right to convert into Perpetual Capital.
Limited Partner Capital Invested. Limited Partner Capital Invested represents the aggregate amount of third party capital invested by our funds and vehicles, including investments closed but not yet funded by investors during each period presented, including (a) capital invested by our carry and drawdown funds and vehicles, (b) certain perpetual capital invested including undistributed proceeds that are reinvested, and (c) capital invested through fee-paying co-investments made by third parties in investments of our carry and perpetual funds and vehicles.
Dry Powder. Dry Powder represents the amount of capital available for investment or reinvestment, including general partner and employee capital, and is an indicator of the capital we have available for future investments.
Performance Revenue Eligible Assets Under Management. Performance Revenue Eligible Assets Under Management represents invested and to be invested capital at fair value, including capital closed for funds whose investment period has not yet commenced, on which performance fees could be earned if certain hurdles are met.
Income Tax Current Developments
Certain past legislative proposals would treat certain publicly traded partnerships as corporations for federal income tax purposes. If similar legislation were enacted and applied to us, we would not qualify as a partnership for U.S. federal income tax purposes. If we were taxed as a corporation, our effective tax rate could increase significantly.
States and other jurisdictions have also considered legislation to increase taxes with respect to carried interest. For example, New Jersey recently enacted legislation which eliminates an exclusion from New Jersey source income (for non-residents) for carried interest and income from providing investment management services, which is not expected to materially affect our common unitholders, and authorizes a contingent 17% surtax on such management income for gross income tax and corporate income tax purposes. These carried interest provisions remain non-operative as they are dependent upon Connecticut, New York and Massachusetts enacting legislation with identical provisions. In addition, New York State recently introduced legislation which would tax income from certain investment management services provided by a partner (whether or not a New York resident), which could cause a non-resident of New York State who holds our common units to be subject to New York State income tax on carried interest earned by entities in which we hold an indirect interest, thereby requiring the non-resident to file a New York State income tax return reporting such carried interest income. As part of that legislation, New York also proposed a state tax surcharge of 19% on carried interest in addition to the personal income tax. Similar to the New Jersey legislation, the New York legislation would not take effect until similar legislation is enacted by Connecticut, New Jersey and Massachusetts. Similar proposals are under consideration in other jurisdictions such as California. Whether or when similar legislation will be enacted is unclear.
Table of Contents
Finally, several state and local jurisdictions are evaluating ways to subject partnerships to entity level taxation through the imposition of state or local income, franchise or other forms of taxation or to increase the amount of such taxation. For example, although we believe it would not affect us materially, Connecticut recently enacted an income tax on pass through entities doing business in Connecticut, and states in which we do business may consider similar tax changes. These and other proposals have recently been under heightened consideration in light of U.S. federal income tax legislation, known as the Tax Cuts and Jobs Act, which was signed into law on December 22, 2017 (the “Tax Reform Bill”).
Meaningfully quantifying the potential impact on Blackstone of this potential future legislation or any similar legislation is not possible at this time. Multiple versions of legislation in this area have been proposed over the last few years that have included significantly different provisions regarding effective dates and the treatment of invested capital, tiered entities and cross-border operations, among other matters. Depending upon what version of the legislation, if any, were enacted, the potential impact on a public company such as Blackstone in a given year could differ significantly and could be material. In addition, even if these legislative proposals would not themselves impose a tax on a publicly traded partnership such as Blackstone, they could force Blackstone and other publicly traded partnerships to restructure their operations so as to prevent disqualifying income from reaching the publicly traded partnership in amounts that would disqualify the partnership from treatment as a partnership for U.S. federal income tax purposes. Such a restructuring could result in more income being earned in corporate subsidiaries, thereby increasing corporate income tax liability indirectly borne by the publicly traded partnership. In addition, we, and our common unitholders, could be taxed on any such restructuring. The nature of any such restructuring would depend on the precise provisions of the legislation that was ultimately enacted, as well as the particular facts and circumstances of Blackstone’s operations at the time any such legislation were to take effect, making the task of predicting the amount of additional tax highly speculative.
The Tax Reform Bill has resulted in fundamental changes to the Internal Revenue Code. Changes to U.S. tax laws resulting from the Tax Reform Bill, including reduction to the federal corporate income tax rate, partial limitation on the deductibility of business interest expense, and a longer three-year holding period requirement for carried interest to be treated as long-term capital gain could have an adverse effect on our business operations and our funds’ investment activities. These and other changes from the Tax Reform Bill — including limitations on the use, carryback and carryforward of net operating losses and changes relating to the scope and timing of U.S. taxation on earnings from international business operations — could also have an adverse effect on our portfolio companies. The exact impact of the Tax Reform Bill for future years is difficult to quantify, but these changes could have an adverse effect on our business, results of operations and financial condition. In addition, other changes could be enacted in the future to increase the corporate tax rate, limit further the deductibility of interest, subject carried interest to more onerous taxation or effect other changes that could have a material adverse effect on our business, results of operations and financial condition.
Congress, the Organization for Economic Co-operation and Development (“OECD”) and other government agencies in jurisdictions in which we and our affiliates invest or do business have maintained a focus on issues related to the taxation of multinational companies. The OECD, which represents a coalition of member countries, is contemplating changes to numerous long-standing tax principles through its base erosion and profit shifting (“BEPS”) project, which is focused on a number of issues, including the shifting of profits between affiliated entities in different tax jurisdictions, interest deductibility and eligibility for the benefits of double tax treaties. Several of the proposed measures are potentially relevant to some of our structures and could have an adverse tax impact on our funds, investors and/or our portfolio companies. Some member countries have been moving forward on the BEPS agenda but, because timing of implementation and the specific measures adopted will vary among participating states, significant uncertainty remains regarding the impact of BEPS proposals. If implemented, these proposals could result in a loss of tax treaty benefits and increased taxes on income from our investments.
A number of European jurisdictions have enacted taxes on financial transactions, and the European Commission has proposed legislation to harmonize these taxes under the so-called “enhanced cooperation procedure,” which provides for adoption of EU-level legislation applicable to some but not all EU Member States.
Table of Contents
These contemplated changes, if adopted by individual countries, could increase tax uncertainty and/or costs faced by us, our portfolio companies and our investors, and cause other adverse consequences. The timing or impact of these proposals is unclear at this point. In addition, tax laws, regulations and interpretations are subject to continual changes, which could adversely affect our structures or returns to our investors. For instance, various countries have adopted or proposed tax legislation that may adversely affect portfolio companies and investment structures in countries in which our funds have invested and may limit the benefits of additional investments in those countries.
In addition, legislation enacted in 2015 significantly changed the rules for U.S. federal income tax audits of partnerships. Such audits will be conducted at the partnership level, and unless a partnership qualifies for and affirmatively elects an alternative procedure, any adjustments to the amount of tax due (including interest and penalties) will be payable by the partnership. Under an elective alternative procedure, a partnership would issue information returns to persons who were partners in the audited year, who would then be required to take the adjustments into account in calculating their own tax liability, and the partnership would not be liable for the adjustments. If a partnership elects the alternative procedure for a given adjustment, the amount of taxes for which its partners would be liable would be increased by any applicable penalties and a special interest charge. There can be no assurance that we will be eligible to make such an election or that we will, in fact, make such an election for any given adjustment. If we do not or are not able to make such an election, then (a) our then-current common unitholders, in the aggregate, could indirectly bear income tax liabilities in excess of the aggregate amount of taxes that would have been due had we elected the alternative procedure, and (b) a given common unitholder may indirectly bear taxes attributable to income allocable to other common unitholders or former common unitholders, including taxes (as well as interest and penalties) with respect to periods prior to such holder’s ownership of common units. Amounts available for distribution to our common unitholders may be reduced as a result of our obligation to pay any taxes associated with an adjustment. Many issues with respect to, and the overall effect of, this legislation on us are uncertain, and common unitholders should consult their own tax advisors regarding all aspects of this legislation as it affects their particular circumstances.
Consolidated Results of Operations
Following is a discussion of our consolidated results of operations for each of the years in the three-year period ended December 31, 2018. For a more detailed discussion of the factors that affected the results of our four business segments (which are presented on a basis that deconsolidates the investment funds we manage) in these periods, see “— Segment Analysis” below.
Table of Contents
The following table sets forth information regarding our consolidated results of operations and certain key operating metrics for the years ended December 31, 2018, 2017 and 2016:
| Year Ended December 31, | 2018 vs. 2017 | 2017 vs. 2016 | ||||||||||||||||||||||||||
| 2018 | 2017 | 2016 | $ | % | $ | % | ||||||||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||||||||||
| Revenues | ||||||||||||||||||||||||||||
| Management and Advisory Fees, Net | $ | 3,027,796 | $ | 2,751,322 | $ | 2,464,290 | $ | 276,474 | 10 | % | $ | 287,032 | 12 | % | ||||||||||||||
| Incentive Fees | 57,540 | 242,514 | 149,928 | (184,974 | ) | -76 | % | 92,586 | 62 | % | ||||||||||||||||||
| Investment Income (Loss) | ||||||||||||||||||||||||||||
| Performance Allocations | ||||||||||||||||||||||||||||
| Realized | 1,876,507 | 3,571,811 | 1,495,439 | (1,695,304 | ) | -47 | % | 2,076,372 | 139 | % | ||||||||||||||||||
| Unrealized | 561,373 | (105,473 | ) | 530,114 | 666,846 | N/M | (635,587 | ) | N/M | |||||||||||||||||||
| Principal Investments | ||||||||||||||||||||||||||||
| Realized | 415,862 | 635,769 | 278,737 | (219,907 | ) | -35 | % | 357,032 | 128 | % | ||||||||||||||||||
| Unrealized | 49,917 | 42,605 | 77,314 | 7,312 | 17 | % | (34,709 | ) | -45 | % | ||||||||||||||||||
| Total Investment Income | 2,903,659 | 4,144,712 | 2,381,604 | (1,241,053 | ) | -30 | % | 1,763,108 | 74 | % | ||||||||||||||||||
| Interest and Dividend Revenue | 171,947 | 139,696 | 95,724 | 32,251 | 23 | % | 43,972 | 46 | % | |||||||||||||||||||
| Other | 672,317 | (133,229 | ) | 54,753 | 805,546 | N/M | (187,982 | ) | N/M | |||||||||||||||||||
| Total Revenues | 6,833,259 | 7,145,015 | 5,146,299 | (311,756 | ) | -4 | % | 1,998,716 | 39 | % | ||||||||||||||||||
| Expenses | ||||||||||||||||||||||||||||
| Compensation and Benefits | ||||||||||||||||||||||||||||
| Compensation | 1,609,957 | 1,442,485 | 1,335,408 | 167,472 | 12 | % | 107,077 | 8 | % | |||||||||||||||||||
| Incentive Fee Compensation | 33,916 | 105,279 | 68,921 | (71,363 | ) | -68 | % | 36,358 | 53 | % | ||||||||||||||||||
| Performance Allocations Compensation | ||||||||||||||||||||||||||||
| Realized | 711,076 | 1,281,965 | 465,129 | (570,889 | ) | -45 | % | 816,836 | 176 | % | ||||||||||||||||||
| Unrealized | 319,742 | 103,794 | 333,528 | 215,948 | 208 | % | (229,734 | ) | -69 | % | ||||||||||||||||||
| Total Compensation and Benefits | 2,674,691 | 2,933,523 | 2,202,986 | (258,832 | ) | -9 | % | 730,537 | 33 | % | ||||||||||||||||||
| General, Administrative and Other | 594,873 | 488,582 | 541,624 | 106,291 | 22 | % | (53,042 | ) | -10 | % | ||||||||||||||||||
| Interest Expense | 163,990 | 197,486 | 152,654 | (33,496 | ) | -17 | % | 44,832 | 29 | % | ||||||||||||||||||
| Fund Expenses | 78,486 | 132,787 | 52,181 | (54,301 | ) | -41 | % | 80,606 | 154 | % | ||||||||||||||||||
| Total Expenses | 3,512,040 | 3,752,378 | 2,949,445 | (240,338 | ) | -6 | % | 802,933 | 27 | % | ||||||||||||||||||
| Other Income | ||||||||||||||||||||||||||||
| Reduction of Tax Receivable Agreement Liability | — | 403,855 | — | (403,855 | ) | -100 | % | 403,855 | N/M | |||||||||||||||||||
| Net Gains from Fund Investment Activities | 191,722 | 321,597 | 184,750 | (129,875 | ) | -40 | % | 136,847 | 74 | % | ||||||||||||||||||
| Total Other Income | 191,722 | 725,452 | 184,750 | (533,730 | ) | -74 | % | 540,702 | 293 | % | ||||||||||||||||||
| Income Before Provision for Taxes | 3,512,941 | 4,118,089 | 2,381,604 | (605,148 | ) | -15 | % | 1,736,485 | 73 | % | ||||||||||||||||||
| Provision for Taxes | 249,390 | 743,147 | 132,362 | (493,757 | ) | -66 | % | 610,785 | 461 | % | ||||||||||||||||||
| Net Income | 3,263,551 | 3,374,942 | 2,249,242 | (111,391 | ) | -3 | % | 1,125,700 | 50 | % | ||||||||||||||||||
| Net Income (Loss) Attributable to Redeemable Non-Controlling Interests in Consolidated Entities | (2,104 | ) | 13,806 | 3,977 | (15,910 | ) | N/M | 9,829 | 247 | % | ||||||||||||||||||
| Net Income Attributable to Non-Controlling Interests in Consolidated Entities | 358,878 | 497,439 | 246,152 | (138,561 | ) | -28 | % | 251,287 | 102 | % | ||||||||||||||||||
| Net Income Attributable to Non-Controlling Interests in Blackstone Holdings | 1,364,989 | 1,392,323 | 960,099 | (27,334 | ) | -2 | % | 432,224 | 45 | % | ||||||||||||||||||
| Net Income Attributable to The Blackstone Group L.P. | $ | 1,541,788 | $ | 1,471,374 | $ | 1,039,014 | $ | 70,414 | 5 | % | $ | 432,360 | 42 | % | ||||||||||||||
| N/M | Not meaningful. |
|---|
Year Ended December 31, 2018 Compared to Year Ended December 31, 2017
Revenues
Revenues were $6.8 billion for the year ended December 31, 2018, a decrease of $311.8 million compared to $7.1 billion for the year ended December 31, 2017. The decrease in Revenues was primarily attributable to decreases of $1.2 billion in Investment Income and $185.0 million in Incentive Fees, partially offset by increases of $805.5 million in Other Revenues and $276.5 million in Management and Advisory Fees, Net.
Table of Contents
The decrease in Investment Income was primarily attributable to decreases in our Real Estate, Credit and Hedge Fund Solution segments of $1.2 billion, $272.5 million and $74.0 million, respectively, partially offset by an increase in our Private Equity segment of $363.4 million. The decrease in our Real Estate segment was attributable to lower net appreciation of investment holdings in our BREP funds compared to the comparable 2017 period. For the year ended December 31, 2018, the carrying value of investments for our BREP funds increased 9.8% compared to 19.4% for the year ended December 31, 2017. The decrease in our Credit segment was primarily attributable to the negative impact on 2018 returns as a result of decreases in certain public positions, and volatility in the energy and credit markets. The decrease in our Hedge Fund Solutions segment was primarily due to lower returns in investments of which Blackstone owns a share compared to the year ended December 31, 2017. The increase in our Private Equity segment was driven by corporate private equity. Corporate private equity carrying value increased 19.1% for the year ended December 31, 2018 compared to 17.6% for the year ended December 31, 2017.
The decrease in Incentive Fees was primarily attributable to decreases in our Credit and Hedge Fund Solutions segments of $104.5 million and $84.4 million, respectively. The decrease in our Credit segment was primarily attributable to the conclusion of our sub-advisory relationship with FS Investments. The decrease in our Hedge Fund Solutions segment was driven by lower returns across a number of strategies, including customized solutions, commingled products and individual investor solutions and specialized solutions, compared to the year ended December 31, 2017.
The increase in Other Revenue was primarily due to the fixed payment we received in connection with the conclusion of our sub-advisory relationship with FS Investments’ funds and a foreign exchange gain on our euro denominated bonds.
The increase in Management and Advisory Fees, Net was primarily due to increases in our Real Estate and Private Equity segments of $187.4 million and $65.4 million, respectively. The increase in our Real Estate segment was primarily attributable to increases in Base Management Fees of $113.2 million driven by Assets Under Management growth in core+ and Transaction and Other Fees, Net of $69.7 million, which were due to $27.1 million of BREP breakup fees related to two transactions and increased investment activity in our BREP global funds. The increase in our Private Equity segment was primarily attributable to the launch of BCP Asia and the third vintage of Tactical Opportunities.
Expenses
Expenses were $3.5 billion for the year ended December 31, 2018, a decrease of $240.3 million compared to $3.8 billion for the year ended December 31, 2017. The decrease was primarily attributable to decreases of $258.8 million in Total Compensation and Benefits and $54.3 million in Fund Expenses, partially offset by an increase of $106.3 million in General, Administrative and Other Expenses. The decrease in Total Compensation and Benefits was primarily due to decreases of $354.9 million in Performance Allocations Compensation and $71.4 million in Incentive Fee Compensation, partially offset by an increase of $167.5 million in Compensation. The decrease in Performance Allocations Compensation was primarily due to the decrease in Investment Income. The decrease in Incentive Fee Compensation was primarily due to the decrease in Incentive Fees in our Credit and Hedge Fund Solutions segments, on which a portion of Incentive Fee Compensation is based. The increase in Compensation was due to the increase in Management and Advisory Fees, Net, on which a portion of compensation is based, as well as investment in our infrastructure initiative and a lower deferral on Compensation. The decrease in Fund Expenses was due to a decrease of $55.7 million in our Credit segment primarily from the deconsolidation of certain CLO and other vehicles in 2018. The increase in General, Administrative and Other Expenses was primarily due to the growth in BIS as well as a full year of Harvest-related expenses following our acquisition of Harvest in the fourth quarter of 2017.
Year Ended December 31, 2017 Compared to Year Ended December 31, 2016
Revenues
Total Revenues were $7.1 billion for the year ended December 31, 2017, an increase of $2.0 billion compared to $5.1 billion for the year ended December 31, 2016. The increase in Total Revenues was attributable to increases
Table of Contents
of $1.8 billion in Investment Income and $287.0 million in Management and Advisory Fees, Net, partially offset by a decrease in Other Revenue of $188.0 million.
The increase in Investment Income was primarily attributable to increases in our Real Estate and Private Equity segments of $966.1 million and $507.7 million, respectively. The increase in our Real Estate segment was primarily attributable to a net increase in the appreciation of investment holdings in our opportunistic funds. For the year ended December 31, 2017, the carrying value of investments for our opportunistic funds increased 19.4% versus 11.1% for the year ended December 31, 2016. Our core+ real estate funds, real estate debt drawdown funds and real estate hedge funds appreciated 12.0%, 14.7% and 8.9%, respectively for the year ended December 31, 2017. The increase in our Private Equity segment was driven by corporate private equity and Tactical Opportunities. Corporate private equity carrying value increased 17.6% in 2017 versus 10.7% for the year ended December 31, 2016. Tactical Opportunities carrying value increased 14.5% in 2017 versus 10.9% for the year ended December 31, 2016.
The increase in Management and Advisory Fees, Net was primarily due to increases in our Private Equity, Real Estate and Credit segments of $204.4 million, $55.9 million and $51.4 million, respectively. The increase in our Private Equity segment was primarily due to assets earning higher base management fees, principally due to the conclusion of a six-month fee holiday for BCP VII in the fourth quarter of 2016. The increase in our Real Estate segment was primarily due to growth in our core+ real estate funds and the launch of BREP Europe V in the fourth quarter of 2016 and the corresponding expiration of its fee holiday in the second quarter of 2017. The increase in our Credit segment was primarily due to our performing credit and energy portfolios, as well as Harvest.
The decrease in Other Revenue was primarily the result of foreign exchange loss on the revaluation of our euro denominated bonds.
Expenses
Expenses were $3.8 billion for the year ended December 31, 2017, an increase of $802.9 million compared to $2.9 billion for the year ended December 31, 2016. The increase was primarily attributable to increases in Performance Allocations Compensation, Compensation and Fund Expenses. The increase of $587.1 million in Performance Allocations Compensation was due to related increases in Investment Income in our Real Estate and Private Equity. The increase of $107.1 million in Compensation was primarily due to the increase in Management and Advisory Fees, Net in our Private Equity, Real Estate and Credit segments, on which a portion of compensation is based. The increase of $80.6 million in Fund Expenses was due to an increase of $73.9 million in our Credit segment. The increase in our Credit segment was primarily the result of newly launched CLOs.
Other Income
Year Ended December 31, 2018 Compared to Year Ended December 31, 2017
Other Income was $191.7 million for the year ended December 31, 2018, a decrease of $533.7 million compared to $725.5 million for the year ended December 31, 2017. The decrease in Other Income was due to the absence of the $403.9 million in Reduction of Tax Receivable Agreement Liability that was recognized during the year ended December 31, 2017 and a decrease of $129.9 million in Net Gains from Fund Investment Activities.
The absence of the Other Income — Reduction of Tax Receivable Agreement Liability was primarily due to the reduction in the federal tax rate from 35% to 21% pursuant to the Tax Reform Bill during the year ended December 31, 2017.
The decrease in Other Income — Net Gains from Fund Investment Activities was driven by decreases of $62.5 million in our Credit segment, $58.2 million in our Real Estate segment and $21.4 million in our Hedge Fund Solutions segment, partially offset by an increase of $12.3 million in our Private Equity segment. The decrease in our Credit segment was primarily driven by the deconsolidation of certain CLO and other vehicles in 2018, partially
Table of Contents
offset by newly launched CLOs. The decrease in our Real Estate segment was primarily due to a year over year net decrease in the appreciation of investments in our BREP funds. The decrease in our Hedge Fund Solutions segment was primarily due to lower returns across the segment year over year. The increase in our Private Equity segment was primarily due to a year over year net increase in the appreciation of investments in our private equity funds.
Year Ended December 31, 2017 Compared to Year Ended December 31, 2016
Other Income was $725.5 million for the year ended December 31, 2017, an increase of $540.7 million compared to $184.8 million for the year ended December 31, 2016. The increase in Other Income was primarily due to increases of $403.9 million in Reduction of Tax Receivable Agreement Liability and $136.8 million in Net Gains from Fund Investment Activities.
Other Income — Reduction of Tax Receivable Agreement Liability was $403.9 million for the year ended December 31, 2017. The Reduction of the Tax Receivable Agreement Liability was primarily attributable to the reduction in the corporate federal tax rate from 35% to 21% pursuant to the Tax Reform Bill.
Other Income — Net Gains from Fund Investment Activities was $321.6 million for the year ended December 31, 2017, an increase of $136.8 million compared to $184.8 million for the year ended December 31, 2016. The increase was principally driven by increases in our Credit and Real Estate segments of $75.2 million and $47.4 million, respectively. The increase in our Credit segment was primarily due to newly launched CLOs. The increase in our Real Estate segment was primarily the result of a year over year net increase in the appreciation of investments across the Real Estate funds.
Provision for Taxes
The following table summarizes Blackstone’s tax position:
| Year Ended December 31, | ||||||||||||
| 2018 | 2017 | 2016 | ||||||||||
| Income Before Provision for Taxes | $ | 3,512,941 | $ | 4,118,089 | $ | 2,381,604 | ||||||
| Provision for Taxes | $ | 249,390 | $ | 743,147 | $ | 132,362 | ||||||
| Effective Income Tax Rate | 7.1 | % | 18.0 | % | 5.6 | % |
The following table reconciles the effective income tax rate to the U.S. federal statutory tax rate:
| Year Ended December 31, | 2018 vs. 2017 | 2017 vs. 2016 | ||||||||||||||||||
| 2018 | 2017 | 2016 | ||||||||||||||||||
| Statutory U.S. Federal Income Tax Rate | 21.0 | % | 35.0 | % | 35.0 | % | -14.0 | % | — | |||||||||||
| Income Passed Through to Common Unitholders and Non-Controlling Interest Holders (a) | -15.5 | % | -25.9 | % | -28.6 | % | 10.4 | % | 2.7 | % | ||||||||||
| State and Local Income Taxes | 1.8 | % | 1.5 | % | 1.3 | % | 0.3 | % | 0.2 | % | ||||||||||
| Equity-Based Compensation | — | -0.1 | % | -0.2 | % | 0.1 | % | 0.1 | % | |||||||||||
| Impact of the Tax Reform Bill | — | 8.3 | % | — | -8.3 | % | 8.3 | % | ||||||||||||
| Other | -0.2 | % | -0.8 | % | -1.9 | % | 0.6 | % | 1.1 | % | ||||||||||
| Effective Income Tax Rate | 7.1 | % | 18.0 | % | 5.6 | % | -10.9 | % | 12.4 | % | ||||||||||
| (a) | Includes income that is not taxable to the Partnership and its subsidiaries. Such income is directly taxable to the Partnership’s unitholders and the non-controlling interest holders. |
|---|
Blackstone’s Provision for Taxes for the years ended December 31, 2018, 2017 and 2016 was $249.4 million, $743.1 million and $132.4 million, respectively. This resulted in an effective tax rate of 7.1%, 18.0% and 5.6%, respectively, based on our Income Before Provision for Taxes of $3.5 billion, $4.1 billion and $2.4 billion, respectively.
Table of Contents
The Tax Reform Bill enacted in late 2017 reduced the federal corporate income tax rate from 35% to 21% effective January 1, 2018. The decrease in the effective tax rate from the rate reduction was partially offset by the corresponding reduction in the benefit for the exclusion of income passed through to common unitholders and non-controlling interests. This, along with the increase in the 2017 effective tax rate for the one-time remeasurement of the Deferred Tax Assets as a result of the Tax Reform Bill, resulted in an overall decrease in the effective tax rate for the twelve months ended December 31, 2018 compared with the twelve months ended December 31, 2017.
The difference in Blackstone’s effective tax rate for the year ended December 31, 2017 compared to the year ended December 31, 2016 resulted primarily from two items. First, the Income Before Provision for Taxes that was not taxable to the Partnership or its subsidiaries (and therefore was passed through to common unitholders and non-controlling interest holders) was $3.1 billion in 2017 (of $4.1 billion of 2017 total pretax income), compared to $1.9 billion in 2016 (of $2.4 billion of 2016 total pretax income). Second, the Tax Reform Bill that was signed into law on December 22, 2017 included a reduction in the federal corporate income tax rate from 35% to 21%. The remeasurement of the Deferred Tax Assets resulted in income tax expense of $500.6 million partially offset by $160.3 million tax benefit resulting from the $403.9 million reduction to the liability under the Tax Receivable Agreement. The net impact to the effective tax rate was an 8.3% increase. All factors except for the remeasurement of the Deferred Tax Assets and the liability under the Tax Receivable Agreement are expected to impact the effective tax rate for future years.
Additional information regarding our income taxes can be found in Note 14. “Income Taxes” in the “Notes to Consolidated Financial Statements” in “— Item 8. Financial Statements and Supplementary Data” of this filing.
Non-Controlling Interests in Consolidated Entities
The Net Income Attributable to Redeemable Non-Controlling Interests in Consolidated Entities and Net Income Attributable to Non-Controlling Interests in Consolidated Entities is attributable to the consolidated Blackstone Funds. The amounts of these items vary directly with the performance of the consolidated Blackstone Funds and largely eliminate the amount of Other Income — Net Gains from Fund Investment Activities from the Net Income (Loss) Attributable to The Blackstone Group L.P.
Net Income Attributable to Non-Controlling Interests in Blackstone Holdings is derived from the Income Before Provision for Taxes, excluding the Net Gains from Fund Investment Activities and the percentage allocation of the income between Blackstone personnel and others who are limited partners of Blackstone Holdings and The Blackstone Group L.P. after considering any contractual arrangements that govern the allocation of income (loss) such as fees allocable to The Blackstone Group L.P.
For the years ended December 31, 2018, 2017 and 2016, the Net Income Before Taxes allocated to Blackstone personnel and others who are limited partners of Blackstone Holdings was 44.0%, 44.9% and 46.1%, respectively. The decreases of 0.9% and 1.2% were primarily due to conversions of Blackstone Holdings Partnership Units to Blackstone common units and the vesting of common units.
The Other Income — Reduction of Tax Receivable Agreement Liability was entirely allocated to The Blackstone Group L.P.
Table of Contents
Operating Metrics
The following graphs and tables summarize the Fee-Earning Assets Under Management by Segment and Total Assets Under Management by Segment, followed by a rollforward of activity for the years ended December 31, 2018, 2017 and 2016. For a description of how Assets Under Management and Fee-Earning Assets Under Management are determined, please see “— Key Financial Measures and Indicators — Operating Metrics — Assets Under Management and Fee-Earning Assets Under Management.”

Note: Totals may not add due to rounding.
Table of Contents
| Year Ended December 31, | ||||||||||||||||||||||||||||||||||||||||
| 2018 | 2017 | |||||||||||||||||||||||||||||||||||||||
| Real Estate | Private Equity | Hedge Fund Solutions | Credit | Total | Real Estate | Private Equity | Hedge Fund Solutions | Credit | Total | |||||||||||||||||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||||||||||||||||||||||
| Fee-Earning Assets Under Management | ||||||||||||||||||||||||||||||||||||||||
| Balance, Beginning of Period | $ | 83,984,824 | $ | 70,140,883 | $ | 69,914,061 | $ | 111,304,230 | $ | 335,343,998 | $ | 72,030,054 | $ | 69,110,457 | $ | 66,987,553 | $ | 68,964,608 | $ | 277,092,672 | ||||||||||||||||||||
| Inflows, including Commitments (a) | 17,961,223 | 16,096,543 | 12,354,410 | 24,587,957 | 71,000,133 | 23,555,866 | 8,257,430 | 10,302,444 | 55,099,845 | 97,215,585 | ||||||||||||||||||||||||||||||
| Outflows, including Distributions (b) | (2,000,367 | ) | (1,888,223 | ) | (10,278,403 | ) | (27,640,908 | ) | (41,807,901 | ) | (2,773,181 | ) | (1,196,502 | ) | (9,777,064 | ) | (4,364,916 | ) | (18,111,663 | ) | ||||||||||||||||||||
| Realizations (c) | (8,781,140 | ) | (4,729,843 | ) | (429,912 | ) | (6,672,539 | ) | (20,613,434 | ) | (11,851,866 | ) | (6,558,390 | ) | (2,182,220 | ) | (10,396,313 | ) | (30,988,789 | ) | ||||||||||||||||||||
| Net Inflows (Outflows) | 7,179,716 | 9,478,477 | 1,646,095 | (9,725,490 | ) | 8,578,798 | 8,930,819 | 502,538 | (1,656,840 | ) | 40,338,616 | 48,115,133 | ||||||||||||||||||||||||||||
| Market Appreciation (Depreciation) (d)(f) | 2,088,184 | 388,806 | 720,450 | (4,592,729 | ) | (1,395,289 | ) | 3,023,951 | 527,888 | 4,583,348 | 2,001,006 | 10,136,193 | ||||||||||||||||||||||||||||
| Balance, End of Period | $ | 93,252,724 | $ | 80,008,166 | $ | 72,280,606 | $ | 96,986,011 | $ | 342,527,507 | $ | 83,984,824 | $ | 70,140,883 | $ | 69,914,061 | $ | 111,304,230 | $ | 335,343,998 | ||||||||||||||||||||
| Increase (Decrease) | $ | 9,267,900 | $ | 9,867,283 | $ | 2,366,545 | $ | (14,318,219 | ) | $ | 7,183,509 | $ | 11,954,770 | $ | 1,030,426 | $ | 2,926,508 | $ | 42,339,622 | $ | 58,251,326 | |||||||||||||||||||
| Increase (Decrease) | 11 | % | 14 | % | 3 | % | -13 | % | 2 | % | 17 | % | 1 | % | 4 | % | 61 | % | 21 | % | ||||||||||||||||||||
| Annualized Base Management Fee Rate (e) | 1.09 | % | 1.00 | % | 0.73 | % | 0.56 | % | 0.84 | % | 1.06 | % | 1.07 | % | 0.74 | % | 0.56 | % | 0.83 | % |
| Year Ended December 31, | ||||||||||||||||||||
| 2016 | ||||||||||||||||||||
| Real Estate | Private Equity | Hedge Fund Solutions | Credit | Total | ||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||
| Fee-Earning Assets Under Management | ||||||||||||||||||||
| Balance, Beginning of Period | $ | 67,345,357 | $ | 51,451,196 | $ | 65,665,439 | $ | 61,684,380 | $ | 246,146,372 | ||||||||||
| Inflows, including Commitments (a) | 14,230,164 | 28,896,280 | 10,132,407 | 15,066,802 | 68,325,653 | |||||||||||||||
| Outflows, including Distributions (b) | (2,180,183 | ) | (3,135,750 | ) | (9,744,077 | ) | (4,616,966 | ) | (19,676,976 | ) | ||||||||||
| Realizations (c) | (8,019,202 | ) | (8,193,322 | ) | (416,583 | ) | (5,976,564 | ) | (22,605,671 | ) | ||||||||||
| Net Inflows (Outflows) | 4,030,779 | 17,567,208 | (28,253 | ) | 4,473,272 | 26,043,006 | ||||||||||||||
| Market Appreciation (d)(f) | 653,918 | 92,053 | 1,350,367 | 2,806,956 | 4,903,294 | |||||||||||||||
| Balance, End of Period | $ | 72,030,054 | $ | 69,110,457 | $ | 66,987,553 | $ | 68,964,608 | $ | 277,092,672 | ||||||||||
| Increase | $ | 4,684,697 | $ | 17,659,261 | $ | 1,322,114 | $ | 7,280,228 | $ | 30,946,300 | ||||||||||
| Increase | 7 | % | 34 | % | 2 | % | 12 | % | 13 | % | ||||||||||
| Annualized Base Management Fee Rate (e) | 1.09 | % | 0.93 | % | 0.78 | % | 0.78 | % | 0.90 | % |
Table of Contents
| Year Ended December 31, | ||||||||||||||||||||||||||||||||||||||||
| 2018 | 2017 | |||||||||||||||||||||||||||||||||||||||
| Real Estate | Private Equity | Hedge Fund Solutions | Credit | Total | Real Estate | Private Equity | Hedge Fund Solutions | Credit | Total | |||||||||||||||||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||||||||||||||||||||||
| Total Assets Under Management | ||||||||||||||||||||||||||||||||||||||||
| Balance, Beginning of Period | $ | 115,340,363 | $ | 105,560,576 | $ | 75,090,834 | $ | 138,136,470 | $ | 434,128,243 | $ | 101,963,652 | $ | 100,189,994 | $ | 71,119,718 | $ | 93,280,101 | $ | 366,553,465 | ||||||||||||||||||||
| Inflows, including Commitments (a) | 31,478,431 | 26,639,963 | 13,278,327 | 29,578,890 | 100,975,611 | 23,844,270 | 12,631,106 | 12,106,471 | 59,373,876 | 107,955,723 | ||||||||||||||||||||||||||||||
| Outflows, including Distributions (b) | (2,162,958 | ) | (1,617,585 | ) | (10,780,055 | ) | (28,057,658 | ) | (42,618,256 | ) | (1,399,741 | ) | (1,230,409 | ) | (10,661,542 | ) | (6,165,216 | ) | (19,456,908 | ) | ||||||||||||||||||||
| Realizations (c) | (14,675,095 | ) | (10,396,611 | ) | (471,931 | ) | (8,516,996 | ) | (34,060,633 | ) | (24,527,951 | ) | (15,760,727 | ) | (2,409,985 | ) | (12,487,834 | ) | (55,186,497 | ) | ||||||||||||||||||||
| Net Inflows (Outflows) | 14,640,378 | 14,625,767 | 2,026,341 | (6,995,764 | ) | 24,296,722 | (2,083,422 | ) | (4,360,030 | ) | (965,056 | ) | 40,720,826 | 33,312,318 | ||||||||||||||||||||||||||
| Market Appreciation (Depreciation) (d)(g) | 6,266,488 | 10,478,943 | 697,341 | (3,625,420 | ) | 13,817,352 | 15,460,133 | 9,730,612 | 4,936,172 | 4,135,543 | 34,262,460 | |||||||||||||||||||||||||||||
| Balance, End of Period | $ | 136,247,229 | $ | 130,665,286 | $ | 77,814,516 | $ | 127,515,286 | $ | 472,242,317 | $ | 115,340,363 | $ | 105,560,576 | $ | 75,090,834 | $ | 138,136,470 | $ | 434,128,243 | ||||||||||||||||||||
| Increase (Decrease) | $ | 20,906,866 | $ | 25,104,710 | $ | 2,723,682 | $ | (10,621,184 | ) | $ | 38,114,074 | $ | 13,376,711 | $ | 5,370,582 | $ | 3,971,116 | $ | 44,856,369 | $ | 67,574,778 | |||||||||||||||||||
| Increase (Decrease) | 18 | % | 24 | % | 4 | % | -8 | % | 9 | % | 13 | % | 5 | % | 6 | % | 48 | % | 18 | % |
| Year Ended December 31, | ||||||||||||||||||||
| 2016 | ||||||||||||||||||||
| Real Estate | Private Equity | Hedge Fund Solutions | Credit | Total | ||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||
| Total Assets Under Management | ||||||||||||||||||||
| Balance, Beginning of Period | $ | 93,917,824 | $ | 94,280,074 | $ | 69,105,425 | $ | 79,081,252 | $ | 336,384,575 | ||||||||||
| Inflows, including Commitments (a) | 19,047,473 | 16,845,959 | 10,782,839 | 22,984,504 | 69,660,775 | |||||||||||||||
| Outflows, including Distributions (b) | (500,727 | ) | (1,526,205 | ) | (9,871,709 | ) | (6,408,231 | ) | (18,306,872 | ) | ||||||||||
| Realizations (c) | (17,926,238 | ) | (14,221,866 | ) | (436,973 | ) | (6,798,762 | ) | (39,383,839 | ) | ||||||||||
| Net Inflows | 620,508 | 1,097,888 | 474,157 | 9,777,511 | 11,970,064 | |||||||||||||||
| Market Appreciation (d)(g) | 7,425,320 | 4,812,032 | 1,540,136 | 4,421,338 | 18,198,826 | |||||||||||||||
| Balance, End of Period | $ | 101,963,652 | $ | 100,189,994 | $ | 71,119,718 | $ | 93,280,101 | $ | 366,553,465 | ||||||||||
| Increase | $ | 8,045,828 | $ | 5,909,920 | $ | 2,014,293 | $ | 14,198,849 | $ | 30,168,890 | ||||||||||
| Increase | 9 | % | 6 | % | 3 | % | 18 | % | 9 | % |
| (a) | Inflows represent contributions in our hedge funds and closed ended mutual funds, increases in available capital for our carry funds (capital raises, recallable capital and increased side-by-side commitments) and CLOs, increases in the capital we manage pursuant to separately managed account programs, allocations from multi-asset products to other strategies and acquisitions. |
|---|
| (b) | Outflows represent redemptions in our hedge funds and closed ended mutual funds, client withdrawals from our separately managed account programs and decreases in available capital for our carry funds (expired capital, expense drawdowns and decreased side-by-side commitments). |
|---|
| (c) | Realizations represent realizations from the disposition of assets or capital returned to investors from CLOs. |
|---|
| (d) | Market appreciation (depreciation) includes realized and unrealized gains (losses) on portfolio investments and the impact of foreign exchange rate fluctuations. |
|---|
| (e) | Represents the annualized current quarter’s Base Management Fee divided by period end Fee-Earning Assets Under Management. |
|---|
Table of Contents
| (f) | For the year ended December 31, 2018, the impact to Fee-Earning Assets Under Management due to foreign exchange rate fluctuations was $(904.2) million, $(626.6) million and $(1.5) billion for the Real Estate, Credit and Total segments, respectively. For the year ended December 31, 2017, the impact to Fee-Earning Assets Under Management due to foreign exchange rate fluctuations was $1.4 billion, $1.3 million, $1.4 billion and $2.8 billion for the Real Estate, Private Equity, Credit and Total segments, respectively. For the year ended December 31, 2016, such impact was $(463.8) million, $1.0 million, $(335.8) million and $(798.5) million for the Real Estate, Private Equity, Credit and Total segments, respectively. |
|---|
| (g) | For the year ended December 31, 2018, the impact to Total Assets Under Management due to foreign exchange rate fluctuations was $(2.1) billion, $(354.1) million, $(821.9) million and $(3.3) billion for the Real Estate, Private Equity, Credit and Total segments, respectively. For the year ended December 31, 2017, the impact to Total Assets Under Management due to foreign exchange rate fluctuations was $3.1 billion, $1.1 billion, $1.8 billion and $5.9 billion for the Real Estate, Private Equity, Credit and Total segments, respectively. For the year ended December 31, 2016, such impact was $(1.4) billion, $86.5 million, $(490.4) million and $(1.8) billion for the Real Estate, Private Equity, Credit and Total segments, respectively. |
|---|
Fee-Earning Assets Under Management
Fee-Earning Assets Under Management were $342.5 billion at December 31, 2018, an increase of $7.2 billion, compared to $335.3 billion at December 31, 2017. The net increase was due to:
| • | Inflows of $71.0 billion related to: |
|---|
| • | $24.6 billion in our Credit segment driven by $12.2 billion from certain long only and MLP strategies, $7.7 billion of capital raised from new CLO launches and CLO refinancings, $4.0 billion from BIS, $3.3 billion from our distressed strategies, $2.4 billion from our mezzanine funds and $1.5 billion from our new direct lending platform, partially offset by $6.5 billion of allocations from insurance multi-asset products to other strategies, |
|---|
| • | $18.0 billion in our Real Estate segment driven by $7.4 billion from BREDS, $3.0 billion from BREIT, $2.8 billion from BPP U.S. and co-investment, $2.2 billion from BPP Europe and co-investment and $2.0 billion from BREP funds and co-investment, |
|---|
| • | $16.1 billion in our Private Equity segment driven by $6.1 billion from Tactical Opportunities, $5.4 billion from BIP, $1.4 billion as a result of the Clarus Acquisition, $1.1 billion from Strategic Partners, $862.5 million from corporate private equity, $742.5 million from core private equity and $503.1 million from multi-asset products, and |
|---|
| • | $12.4 billion in our Hedge Fund Solutions segment driven by $5.4 billion in customized solutions, $5.3 billion in individual investor and specialized solutions and $1.6 billion in commingled products. |
|---|
Offsetting these increases were:
| • | Outflows of $41.8 billion primarily attributable to: |
|---|
| • | $27.6 billion in our Credit segment driven by the conclusion of our sub-advisory relationship with FS Investments. The remaining outflows were mainly related to certain long only and MLP strategies, |
|---|
| • | $10.3 billion in our Hedge Fund Solutions segment driven by $4.1 billion from customized solutions, $3.3 billion from individual investor and specialized solutions and $2.9 billion from commingled products, |
|---|
| • | $2.0 billion in our Real Estate segment primarily driven by $798.9 million of redemptions from the BREDS liquids funds and $787.0 million uninvested capital at the close of a BPP separately managed account’s investment period, and |
|---|
| • | $1.9 billion in our Private Equity segment driven by $856.3 million from Tactical Opportunities, $606.0 million from multi-asset products, $298.3 million from Strategic Partners and $127.7 million from corporate private equity. |
|---|
Table of Contents
| • | Realizations of $20.6 billion primarily driven by: |
|---|
| • | $8.8 billion in our Real Estate segment driven by $3.9 billion from BREP funds and co-investment, $3.2 billion from BREDS and $1.7 billion from core+ real estate funds, |
|---|
| • | $6.7 billion in our Credit segment driven by $2.8 billion from distressed strategies, $1.9 billion of capital returned to investors from CLOs that are post their re-investment periods and $1.2 billion from mezzanine funds, and |
|---|
| • | $4.7 billion in our Private Equity segment driven by $1.7 billion from Strategic Partners, $1.5 billion from Tactical Opportunities and $1.5 billion from corporate private equity. |
|---|
| • | Market depreciation of $1.4 billion due to: |
|---|
| • | $4.6 billion depreciation in our Credit segment driven by $4.0 billion of depreciation from market activity ($1.8 billion from certain long only and MLP strategies, $1.4 billion from BIS, $414.9 million from CLOs and $315.2 million from distressed strategies), and foreign exchange depreciation of $626.6 million mainly related to CLOs, certain long only and MLP strategies and mezzanine funds, |
|---|
| • | Partially offset by $2.1 billion appreciation in our Real Estate segment primarily driven by $2.0 billion of appreciation from core+ real estate funds ($2.7 billion from market appreciation offset by $629.7 million from foreign exchange depreciation), and |
|---|
| • | $720.5 million appreciation in our Hedge Fund Solutions segment driven by returns from BAAM’s Principal Solutions Composite of 2.0% gross (1.2% net). |
|---|
Hedge Fund Solutions had net inflows of $1.2 billion from January 1 through February 1, 2019.
Fee-Earning Assets Under Management were $335.3 billion at December 31, 2017, an increase of $58.3 billion, compared to $277.1 billion at December 31, 2016. The net increase was due to:
| • | Inflows of $97.2 billion related to: |
|---|
| • | $55.1 billion in our Credit segment driven by $22.4 billion from BIS, $11.2 billion from the acquisition of Harvest, $5.8 billion of capital raised from new CLO launches, $5.8 billion of inflows from mezzanine funds, $4.3 billion of inflows from long only and MLP strategies, $3.3 billion of inflows from distressed strategies and $2.3 billion of inflows from business development companies (“BDCs”), |
|---|
| • | $23.6 billion in our Real Estate segment driven by $5.9 billion from the Logicor asset management mandate, $5.8 billion from the second Asian opportunistic fund, $5.2 billion from BREDS, $1.7 billion from BREIT and $3.2 billion from other core+ real estate funds, |
|---|
| • | $10.3 billion in our Hedge Fund Solutions segment driven by $4.6 billion from customized solutions, $4.0 billion from individual investor and specialized solutions and $1.7 billion from commingled products, and |
|---|
| • | $8.3 billion in our Private Equity segment driven by $3.0 billion from Tactical Opportunities, $2.0 billion from Strategic Partners, $1.7 billion from corporate private equity and $1.3 billion from core private equity. |
|---|
| • | Market appreciation of $10.1 billion due to: |
|---|
| • | $4.6 billion in our Hedge Fund Solutions segment driven by solid returns from BAAM’s Principal Solutions Composite of 8.3% gross (7.3% net), |
|---|
| • | $3.0 billion in our Real Estate segment driven by $1.4 billion of foreign exchange appreciation as well as appreciation of $1.3 billion from core+ real estate funds, and |
|---|
| • | $2.0 billion in our Credit segment driven by $697.9 million of appreciation from long only and MLP strategies ($427.3 million from market appreciation and $270.6 million from foreign exchange appreciation), $387.9 million of appreciation from CLOs and $382.5 million of market appreciation from BDCs. |
|---|
Table of Contents
Offsetting these increases were:
| • | Realizations of $31.0 billion primarily driven by: |
|---|
| • | $11.9 billion in our Real Estate segment driven by $6.8 billion from BREP funds, $3.4 billion from BREDS, $816.4 million from BREP co-investment and $801.7 million from core+ real estate funds, |
|---|
| • | $10.4 billion in our Credit segment driven by $4.4 billion of capital returned to investors from CLOs that are post their re-investment periods, $3.0 billion of realizations from distressed strategies, $1.6 billion of realizations from mezzanine funds and $983.0 million in dividends from BDCs, |
|---|
| • | $6.6 billion in our Private Equity segment driven by $3.1 billion from corporate private equity, $2.4 billion from Strategic Partners and $1.1 billion from Tactical Opportunities, and |
|---|
| • | $2.2 billion in our Hedge Fund Solutions segment driven by $2.1 billion from individual investor and specialized solutions. |
|---|
| • | Outflows of $18.1 billion primarily attributable to: |
|---|
| • | $9.8 billion in our Hedge Fund Solutions segment driven by $4.0 billion from individual investor and specialized solutions, $3.2 billion from customized solutions and $2.6 billion from commingled products, |
|---|
| • | $4.4 billion in our Credit segment driven by $2.1 billion from long only and MLP strategies, $1.1 billion from BDCs and $689.4 million from distressed strategies, |
|---|
| • | $2.8 billion in our Real Estate segment driven by $2.1 billion of uninvested reserves at the close of BREP Asia’s investment period, and |
|---|
| • | $1.2 billion in our Private Equity segment driven by reductions of $467.4 million from Strategic Partners and $452.5 million from corporate private equity assets that no longer earn fees. |
|---|
Total Assets Under Management
Total Assets Under Management were $472.2 billion at December 31, 2018, an increase of $38.1 billion, compared to $434.1 billion at December 31, 2017. The net increase was due to:
| • | Inflows of $101.0 billion related to: |
|---|
| • | $31.5 billion in our Real Estate segment driven by $15.4 billion from the first closing of BREP’s ninth global opportunistic fund, $5.3 billion from BREDS, $3.0 billion from BREIT, $2.7 billion from BPP U.S. and co-investment, $1.6 billion from BPP Europe and co-investment and $1.4 billion from BREP Asia II, |
|---|
| • | $29.6 billion in our Credit segment driven by $12.8 billion from certain long only and MLP strategies, $7.8 billion of capital raised from CLO launches and CLO refinancings, $6.1 billion from distressed strategies, $4.4 billion from our new direct lending platform, $4.0 billion from BIS and $788.8 million from mezzanine funds, partially offset by $6.5 billion of allocations from insurance multi-asset products to other strategies, |
|---|
| • | $26.6 billion in our Private Equity segment driven by $7.0 billion from Tactical Opportunities, $5.7 billion from corporate private equity, $5.7 billion from BIP, $5.3 billion from Strategic Partners, $2.1 billion as a result of the Clarus Acquisition and $800.1 million from multi-asset products, and |
|---|
| • | $13.3 billion in our Hedge Fund Solutions segment driven by $6.0 billion in customized solutions, $5.5 billion in individual investor and specialized solutions and $1.7 billion in commingled products. |
|---|
| • | Market appreciation of $13.8 billion due to: |
|---|
| • | $10.5 billion appreciation in our Private Equity segment driven by carrying value increase in corporate private equity, Strategic Partners and Tactical Opportunities of 19.1%, 18.6% and 12.2%, respectively, which included $354.1 million of foreign exchange depreciation across the segment, |
|---|
Table of Contents
| • | $6.3 billion appreciation in our Real Estate segment driven by carrying value increases in our opportunistic and core+ real estate funds of 9.8% and 10.7%, respectively, which includes $2.1 billion of foreign exchange depreciation across the segment, and |
|---|
| • | Partially offset by $3.6 billion depreciation in our Credit segment driven by $2.8 billion of depreciation from market activity ($1.7 billion from certain long only and MLP strategies, $1.4 billion from BIS, and $262.3 million from distressed strategies, partially offset by $754.4 million of market appreciation in mezzanine funds), and foreign exchange depreciation of $821.9 million mainly related to CLOs, certain long only and MLP strategies and mezzanine funds. |
|---|
Total Assets Under Management market appreciation (depreciation) in our Private Equity and Real Estate segments generally represents the change in fair value of the investments held and typically exceeds the Fee-Earning Assets Under Management market appreciation (depreciation).
Offsetting these increases were:
| • | Outflows of $42.6 billion primarily attributable to: |
|---|
| • | $28.1 billion in our Credit segment driven by the conclusion of our sub-advisory relationship with FS Investments. The remaining outflows were primarily related to certain long only and MLP strategies, |
|---|
| • | $10.8 billion in our Hedge Fund Solutions segment driven by $4.1 billion from customized solutions, $3.7 billion from individual investor and specialized solutions and $3.0 billion from commingled products, |
|---|
| • | $2.2 billion in our Real Estate segment driven by redemptions from the BREDS liquids funds and the expiration of the BREP VI fund term, and |
|---|
| • | $1.6 billion in our Private Equity segment driven by $576.9 million from Tactical Opportunities, $557.4 million from Strategic Partners and $213.1 million from corporate private equity. |
|---|
| • | Realizations of $34.1 billion primarily driven by: |
|---|
| • | $14.7 billion in our Real Estate segment driven by $10.5 billion from BREP funds and co-investment, $2.2 billion from BREDS and $2.0 billion from core+ real estate funds, |
|---|
| • | $10.4 billion in our Private Equity segment driven by continued disposition activity across the segment, mainly related to $5.8 billion from corporate private equity, $2.4 billion from Strategic Partners and $2.1 billion from Tactical Opportunities, and |
|---|
| • | $8.5 billion in our Credit segment driven by $3.7 billion from our distressed strategies, $2.0 billion from our mezzanine strategies and $1.9 billion from capital returned to investors from CLOs that are post their re-investment periods. |
|---|
Total Assets Under Management realizations in our Private Equity and Real Estate segments generally represent the total proceeds and typically exceed the Fee-Earning Assets Under Management realizations which generally represent only the invested capital.
Total Assets Under Management were $434.1 billion at December 31, 2017, an increase of $67.6 billion, compared to $366.6 billion at December 31, 2016. The net increase was due to:
| • | Inflows of $108.0 billion primarily related to: |
|---|
| • | $59.4 billion in our Credit segment driven by $22.4 billion of inflows from BIS, $11.2 billion from the acquisition of Harvest, $8.8 billion of inflows from distressed strategies, $5.8 billion of capital raised from CLO launches, $4.7 billion of inflows from long only and MLP strategies, $3.8 billion from mezzanine funds and $2.3 billion of inflows from BDCs, |
|---|
Table of Contents
| • | $23.8 billion in our Real Estate segment driven by $6.0 billion from the Logicor asset management mandate, $5.9 billion from the second Asian opportunistic fund, $4.3 billion from other core+ real estate funds, $3.1 billion from BREDS, $2.9 billion from recycled capital for BREP funds, $1.7 billion from BREIT, |
|---|
| • | $12.6 billion in our Private Equity segment driven by $5.9 billion from Tactical Opportunities, $2.4 billion from Strategic Partners, $2.2 billion from BCP co-investment and $1.9 million from corporate private equity, and |
|---|
| • | $12.1 billion in our Hedge Fund Solutions driven by capital raised of $5.1 billion from individual investor and specialized solutions, $5.0 billion from customized solutions and $1.9 billion from commingled products. |
|---|
| • | Market appreciation of $34.3 billion due to: |
|---|
| • | $15.5 billion in our Real Estate segment driven by carrying value increases of 19.4% and 12.0%, respectively, in opportunistic and core+ real estate funds, which includes $3.1 billion of foreign exchange appreciation, |
|---|
| • | $9.7 billion in our Private Equity segment driven by carrying value increases in corporate private equity, Strategic Partners and Tactical Opportunities of 17.6%, 22.5% and 14.5%, respectively, which includes $1.1 billion of foreign exchange appreciation, |
|---|
| • | $4.9 billion in our Hedge Fund Solutions segment due to the reasons noted above in Fee-Earning Assets Under Management, and |
|---|
| • | $4.1 billion in our Credit segment driven by $1.1 billion of appreciation from mezzanine funds ($709.5 million from market appreciation and $429.7 million from foreign exchange appreciation), $954.5 million appreciation from distressed strategies ($866.4 million from market appreciation and $88.1 million from foreign exchange appreciation), $787.7 million of appreciation from long only and MLP strategies ($437.9 million from market appreciation and $349.8 million from foreign exchange appreciation) and $648.8 million of appreciation from CLOs. |
|---|
Offsetting these increases were:
| • | Realizations of $55.2 billion driven by: |
|---|
| • | $24.5 billion in our Real Estate segment driven by $19.6 billion from BREP funds, $2.1 billion from BREP co-investment, $1.8 million from BREDS and $934.6 million from core+ real estate funds, |
|---|
| • | $15.8 billion in our Private Equity segment driven by continued disposition activity across the segment, mainly $9.2 billion from corporate private equity, $2.8 billion from Strategic Partners and $2.7 billion from Tactical Opportunities, |
|---|
| • | $12.5 billion in our Credit segment driven by $4.7 billion of capital returned to investors from CLOs that are post their re-investment periods, $4.0 billion of realizations from distressed strategies, $2.3 billion of realizations from mezzanine funds and $983.0 million in dividends from BDCs, and |
|---|
| • | $2.4 billion in our Hedge Fund Solutions segment driven by $2.2 billion of realizations from individual investor and specialized solutions. |
|---|
| • | Outflows of $19.5 billion primarily attributable to: |
|---|
| • | $10.7 billion in our Hedge Fund Solutions segment driven by outflows of $4.7 billion from individual investor and specialized solutions, $3.3 billion from customized solutions and $2.7 billion from commingled products, |
|---|
| • | $6.2 billion in our Credit segment driven by $2.2 billion from long only and MLP strategies, $1.8 billion from distressed strategies and $1.1 billion from BDCs, and |
|---|
Table of Contents
| • | $1.4 billion in our Real Estate segment driven by an $803.6 million release of reserves in BREDS II and $394.3 million of redemptions from BREDS liquid funds. |
|---|
Limited Partner Capital Invested
The following presents our Limited Partner Capital Invested for each of the years ended December 31:

Note: Totals may not add due to rounding.
| Year Ended December 31, | ||||||||||||
| 2016 | 2017 | 2018 | ||||||||||
| (Dollars in Thousands) | ||||||||||||
| Limited Partner Capital Invested | ||||||||||||
| Real Estate | $ | 10,969,746 | $ | 19,586,515 | $ | 18,374,432 | ||||||
| Private Equity | 7,443,607 | 16,923,385 | 14,181,675 | |||||||||
| Hedge Fund Solutions (a) | 753,548 | 901,230 | 1,470,718 | |||||||||
| Credit | 3,254,849 | 8,805,283 | 6,900,422 | |||||||||
| $ | 22,421,750 | $ | 46,216,413 | $ | 40,927,247 | |||||||
| (a) | Limited Partner Capital Invested for the Hedge Fund Solutions segment has been updated for an adjustment applicable to each of the three month periods ended September 30, 2016, December 31, 2016 and March 31, 2017. |
|---|
Table of Contents
Dry Powder
The following presents our Dry Powder as of December 31 of each year:

Note: Totals may not add due to rounding.
| (a) | Represents illiquid drawdown funds, a component of perpetual capital and fee-paying co-investments; includes fee-paying third party capital as well as general partner and employee capital that does not earn fees. Amounts are reduced by outstanding capital commitments, for which capital has not yet been invested. |
|---|
| December 31, | ||||||||||||
| 2016 | 2017 | 2018 | ||||||||||
| (Dollars in Thousands) | ||||||||||||
| Dry Powder Available for Investment | ||||||||||||
| Real Estate | $ | 32,134,990 | $ | 32,251,005 | $ | 40,627,676 | ||||||
| Private Equity | 43,618,496 | 36,302,497 | 44,431,881 | |||||||||
| Hedge Fund Solutions | 4,309,901 | 3,943,358 | 3,275,768 | |||||||||
| Credit | 21,279,670 | 22,285,149 | 24,542,243 | |||||||||
| $ | 101,343,057 | $ | 94,782,009 | $ | 112,877,568 | |||||||
Net Accrued Performance Revenues
The following table presents the Accrued Performance Revenues, net of performance compensation, of the Blackstone Funds as of December 31, 2018 and 2017. Net Accrued Performance Revenues presented do not include clawback amounts, if any, which are disclosed in Note 18. “Commitments and Contingencies — Contingencies — Contingent Obligations (Clawback)” in the “Notes to Consolidated Financial Statements” in “— Item 8. Financial
Table of Contents
Statements and Supplementary Data” of this filing. The Net Accrued Performance Revenues as of each reporting date were principally unrealized; if realized, such amount can be a significant component of Distributable Earnings.
| December 31, | ||||||||
| 2018 | 2017 | |||||||
| (Dollars in Millions) | ||||||||
| Real Estate | ||||||||
| BREP IV | $ | 3 | $ | 9 | ||||
| BREP V | 55 | 203 | ||||||
| BREP VI | 89 | 190 | ||||||
| BREP VII | 484 | 587 | ||||||
| BREP VIII | 429 | 255 | ||||||
| BREP Europe III | — | 67 | ||||||
| BREP Europe IV | 200 | 207 | ||||||
| BREP Europe V | 110 | 25 | ||||||
| BREP Asia I | 114 | 102 | ||||||
| BPP | 215 | 134 | ||||||
| BREIT | 23 | 10 | ||||||
| BREDS | 17 | 35 | ||||||
| BTAS | 36 | 16 | ||||||
| Total Real Estate (a) | 1,775 | 1,840 | ||||||
| Private Equity | ||||||||
| BCP IV | 72 | 87 | ||||||
| BCP V | — | 73 | ||||||
| BCP VI | 746 | 668 | ||||||
| BCP VII | 225 | 16 | ||||||
| BEP I | 103 | 95 | ||||||
| BEP II | 73 | 5 | ||||||
| Tactical Opportunities | 155 | 104 | ||||||
| Strategic Partners | 94 | 66 | ||||||
| BCEP | 19 | — | ||||||
| BTAS | 41 | 13 | ||||||
| Other | 1 | 3 | ||||||
| Total Private Equity (a) | 1,529 | 1,130 | ||||||
| Hedge Fund Solutions | 24 | 89 | ||||||
| Credit | 195 | 289 | ||||||
| Total Blackstone Net Accrued Performance Revenues | $ | 3,523 | $ | 3,348 | ||||
| (a) | Real Estate and Private Equity include Co-Investments, as applicable. |
|---|
Net Accrued Performance Revenues receivable was increased by net Performance Revenues of $1.4 billion for the year ended December 31, 2018 and decreased by net realized distributions of $1.3 billion for the year ended December 31, 2018.
Table of Contents
Performance Revenue Eligible Assets Under Management
The following presents our Invested Performance Revenue Eligible Assets Under Management as of December 31 of each year:

Note: Totals may not add due to rounding.
Table of Contents
Perpetual Capital
The following presents our Perpetual Capital as of December 31 of each year:

Note: Totals may not add due to rounding.
Investment Record
Fund returns information for our significant funds is included throughout this discussion and analysis to facilitate an understanding of our results of operations for the periods presented. The fund returns information reflected in this discussion and analysis is not indicative of the financial performance of The Blackstone Group L.P. and is also not necessarily indicative of the future performance of any particular fund. An investment in The Blackstone Group L.P. is not an investment in any of our funds. There can be no assurance that any of our funds or our other existing and future funds will achieve similar returns.
Table of Contents
The following table presents the investment record of our significant drawdown funds from inception through December 31, 2018:
| Unrealized Investments | Realized Investments | Total Investments | Net IRRs (c) | |||||||||||||||||||||||||||||||||||||||||
| Fund (Investment Period Beginning Date / Ending Date) | Committed Capital | Available Capital (a) | Value | MOIC (b) | % Public | Value | MOIC (b) | Value | MOIC (b) | Realized | Total | |||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Except Where Noted) | ||||||||||||||||||||||||||||||||||||||||||||
| Real Estate | ||||||||||||||||||||||||||||||||||||||||||||
| Pre-BREP | $ | 140,714 | $ | — | $ | — | N/A | — | $ | 345,190 | 2.5x | $ | 345,190 | 2.5x | 33 | % | 33 | % | ||||||||||||||||||||||||||
| BREP I (Sep 1994 / Oct 1996) | 380,708 | — | — | N/A | — | 1,327,708 | 2.8x | 1,327,708 | 2.8x | 40 | % | 40 | % | |||||||||||||||||||||||||||||||
| BREP II (Oct 1996 / Mar 1999) | 1,198,339 | — | — | N/A | — | 2,531,614 | 2.1x | 2,531,614 | 2.1x | 19 | % | 19 | % | |||||||||||||||||||||||||||||||
| BREP III (Apr 1999 / Apr 2003) | 1,522,708 | — | — | N/A | — | 3,330,406 | 2.4x | 3,330,406 | 2.4x | 21 | % | 21 | % | |||||||||||||||||||||||||||||||
| BREP IV (Apr 2003 / Dec 2005) | 2,198,694 | — | 212,309 | 0.3x | 21 | % | 4,290,218 | 2.2x | 4,502,527 | 1.6x | 33 | % | 12 | % | ||||||||||||||||||||||||||||||
| BREP V (Dec 2005 / Feb 2007) | 5,539,418 | — | 542,613 | 1.4x | 31 | % | 12,697,555 | 2.4x | 13,240,168 | 2.3x | 12 | % | 11 | % | ||||||||||||||||||||||||||||||
| BREP VI (Feb 2007 / Aug 2011) | 11,060,444 | — | 1,215,191 | 1.6x | 2 | % | 26,334,443 | 2.6x | 27,549,634 | 2.5x | 14 | % | 13 | % | ||||||||||||||||||||||||||||||
| BREP VII (Aug 2011 / Apr 2015) | 13,495,496 | 2,001,683 | 10,154,856 | 1.6x | 18 | % | 18,332,067 | 2.1x | 28,486,923 | 1.9x | 27 | % | 16 | % | ||||||||||||||||||||||||||||||
| BREP VIII (Apr 2015 / Oct 2020) | 16,457,804 | 5,762,268 | 14,427,542 | 1.4x | 1 | % | 4,740,239 | 1.5x | 19,167,781 | 1.4x | 27 | % | 16 | % | ||||||||||||||||||||||||||||||
| BREP IX (TBD) | 15,445,659 | 15,445,659 | — | N/A | — | — | N/A | — | N/A | N/A | N/A | |||||||||||||||||||||||||||||||||
| Total Global BREP | $ | 67,439,984 | $ | 23,209,610 | $ | 26,552,511 | 1.4x | — | $ | 73,929,440 | 2.3x | $ | 100,481,951 | 2.0x | 19 | % | 16 | % | ||||||||||||||||||||||||||
| BREP Int’l (Jan 2001 / Sep 2005) | € | 824,172 | € | — | € | — | N/A | — | € | 1,366,553 | 2.1x | € | 1,366,553 | 2.1x | 23 | % | 23 | % | ||||||||||||||||||||||||||
| BREP Int’l II (Sep 2005 / Jun 2008) (d) | 1,629,748 | — | 106,396 | 1.1x | — | 2,347,656 | 1.8x | 2,454,052 | 1.8x | 8 | % | 8 | % | |||||||||||||||||||||||||||||||
| BREP Europe III (Jun 2008 / Sep 2013) | 3,205,167 | 464,566 | 660,005 | 0.9x | — | 5,494,293 | 2.5x | 6,154,298 | 2.1x | 21 | % | 15 | % | |||||||||||||||||||||||||||||||
| BREP Europe IV (Sep 2013 / Dec 2016) | 6,709,145 | 1,340,701 | 4,358,327 | 1.6x | 12 | % | 7,147,829 | 2.0x | 11,506,156 | 1.8x | 25 | % | 17 | % | ||||||||||||||||||||||||||||||
| BREP Europe V (Dec 2016 / Jun 2022) | 7,877,201 | 3,224,734 | 5,662,031 | 1.3x | — | 77,038 | 2.4x | 5,739,069 | 1.3x | N/M | 18 | % | ||||||||||||||||||||||||||||||||
| Total Euro BREP | € | 20,245,433 | € | 5,030,001 | € | 10,786,759 | 1.3x | 5 | % | € | 16,433,369 | 2.1x | € | 27,220,128 | 1.7x | 16 | % | 14 | % | |||||||||||||||||||||||||
| BREP Asia I (Jun 2013 / Dec 2017) | $ | 5,096,359 | $ | 1,729,439 | $ | 4,128,651 | 1.4x | — | $ | 2,989,011 | 1.8x | $ | 7,117,662 | 1.5x | 21 | % | 15 | % | ||||||||||||||||||||||||||
| BREP Asia II (Dec 2017 / Jun 2023) | 7,126,830 | 6,415,884 | 880,798 | 1.0x | — | — | N/A | 880,798 | 1.0x | N/M | N/M | |||||||||||||||||||||||||||||||||
| BREP Co-Investment (e) | 7,055,644 | 172,062 | 2,124,456 | 1.6x | 41 | % | 11,834,696 | 2.1x | 13,959,152 | 2.0x | 16 | % | 15 | % | ||||||||||||||||||||||||||||||
| Total BREP | $ | 111,511,210 | $ | 37,294,898 | $ | 46,355,732 | 1.4x | 8 | % | $ | 109,719,753 | 2.2x | $ | 156,075,485 | 1.9x | 18 | % | 15 | % | |||||||||||||||||||||||||
| BPP (f) | $ | 26,569,578 | $ | 2,964,457 | $ | 28,054,480 | 1.2x | — | $ | 3,602,356 | 2.6x | $ | 31,656,836 | 1.2x | N/M | 11 | % | |||||||||||||||||||||||||||
| BREDS | $ | 13,228,639 | $ | 3,582,239 | $ | 3,739,330 | 1.1x | — | $ | 10,333,439 | 1.3x | $ | 14,072,769 | 1.2x | 11 | % | 10 | % | ||||||||||||||||||||||||||
| Private Equity | ||||||||||||||||||||||||||||||||||||||||||||
| BCP I (Oct 1987 / Oct 1993) | $ | 859,081 | $ | — | $ | — | N/A | — | $ | 1,741,738 | 2.6x | $ | 1,741,738 | 2.6x | 19 | % | 19 | % | ||||||||||||||||||||||||||
| BCP II (Oct 1993 / Aug 1997) | 1,361,100 | — | — | N/A | — | 3,256,819 | 2.5x | 3,256,819 | 2.5x | 32 | % | 32 | % | |||||||||||||||||||||||||||||||
| BCP III (Aug 1997 / Nov 2002) | 3,967,422 | — | — | N/A | — | 9,184,688 | 2.3x | 9,184,688 | 2.3x | 14 | % | 14 | % | |||||||||||||||||||||||||||||||
| BCOM (Jun 2000 / Jun 2006) | 2,137,330 | 24,575 | 17,244 | 1.4x | — | 2,953,649 | 1.4x | 2,970,893 | 1.4x | 7 | % | 6 | % | |||||||||||||||||||||||||||||||
| BCP IV (Nov 2002 / Dec 2005) | 6,773,182 | 205,984 | 610,391 | 0.7x | 33 | % | 20,861,706 | 3.1x | 21,472,097 | 2.8x | 41 | % | 36 | % | ||||||||||||||||||||||||||||||
| BCP V (Dec 2005 / Jan 2011) | 21,022,215 | 1,048,362 | 1,748,350 | 0.9x | 33 | % | 36,298,422 | 2.0x | 38,046,772 | 1.9x | 9 | % | 8 | % | ||||||||||||||||||||||||||||||
| BCP VI (Jan 2011 / May 2016) | 15,191,118 | 1,756,975 | 14,645,713 | 1.7x | 31 | % | 11,915,798 | 2.1x | 26,561,511 | 1.9x | 21 | % | 13 | % | ||||||||||||||||||||||||||||||
| BEP I (Aug 2011 / Feb 2015) | 2,435,285 | 224,784 | 2,364,512 | 1.5x | 41 | % | 1,954,527 | 2.3x | 4,319,039 | 1.8x | 26 | % | 13 | % | ||||||||||||||||||||||||||||||
| BEP II (Feb 2015 / Feb 2021) | 4,929,718 | 1,203,693 | 4,215,603 | 1.4x | — | 210,362 | 2.0x | 4,425,965 | 1.4x | 40 | % | 15 | % | |||||||||||||||||||||||||||||||
| BCP VII (May 2016 / May 2022) | 18,590,630 | 8,252,225 | 10,446,740 | 1.4x | — | 434,736 | 1.3x | 10,881,476 | 1.4x | 21 | % | 21 | % | |||||||||||||||||||||||||||||||
| BCP Asia (Dec 2017 / Dec 2023) | 2,369,469 | 2,040,455 | 165,694 | 1.5x | — | — | N/A | 165,694 | 1.5x | N/A | N/M | |||||||||||||||||||||||||||||||||
| BEP III (TBD) | 3,515,891 | 3,515,891 | — | N/A | — | — | N/A | — | N/A | N/A | N/A | |||||||||||||||||||||||||||||||||
| Total Corporate Private Equity | $ | 83,152,441 | $ | 18,272,944 | $ | 34,214,247 | 1.4x | 18 | % | $ | 88,812,445 | 2.2x | $ | 123,026,692 | 1.9x | 17 | % | 15 | % | |||||||||||||||||||||||||
| Tactical Opportunities | 22,053,992 | 10,234,751 | 9,559,311 | 1.3x | 9 | % | 6,342,454 | 1.7x | 15,901,765 | 1.4x | 21 | % | 11 | % | ||||||||||||||||||||||||||||||
| Tactical Opportunities Co-Investment and Other | 5,426,066 | 1,603,582 | 3,853,442 | 1.2x | 1 | % | 1,310,719 | 1.6x | 5,164,161 | 1.3x | 28 | % | 14 | % | ||||||||||||||||||||||||||||||
| Total Tactical Opportunities | $ | 27,480,058 | $ | 11,838,333 | $ | 13,412,753 | 1.2x | 7 | % | $ | 7,653,173 | 1.7x | $ | 21,065,926 | 1.4x | 22 | % | 11 | % | |||||||||||||||||||||||||
| Strategic Partners I-V and Co-Investment (g) | 11,913,121 | 1,800,737 | 1,742,846 | N/M | — | 15,970,061 | N/M | 17,712,907 | 1.5x | N/A | 13 | % | ||||||||||||||||||||||||||||||||
| Strategic Partners VI LBO, RE and SMA (g) | 7,402,171 | 1,943,044 | 3,016,474 | N/M | — | 3,407,157 | N/M | 6,423,631 | 1.5x | N/A | 19 | % | ||||||||||||||||||||||||||||||||
| Strategic Partners VII (g) | 8,221,982 | 3,227,165 | 5,948,522 | N/M | — | 730,088 | N/M | 6,678,610 | 1.3x | N/A | 37 | % | ||||||||||||||||||||||||||||||||
| Strategic Partners RA II (g) | 1,898,154 | 1,036,103 | 451,971 | N/M | — | 36,438 | N/M | 488,409 | 1.2x | N/A | 17 | % | ||||||||||||||||||||||||||||||||
| Strategic Partners VIII | 3,422,804 | 3,422,804 | — | N/A | — | — | N/A | — | N/A | N/A | N/A | |||||||||||||||||||||||||||||||||
| Total Strategic Partners | $ | 32,858,232 | $ | 11,429,853 | $ | 11,159,813 | N/M | — | $ | 20,143,744 | N/M | $ | 31,303,557 | 1.5x | N/A | 14 | % | |||||||||||||||||||||||||||
continued ...
Table of Contents
| Unrealized Investments | Realized Investments | Total Investments | Net IRRs (c) | |||||||||||||||||||||||||||||||||||||||||
| Fund (Investment Period Beginning Date / Ending Date) | Committed Capital | Available Capital (a) | Value | MOIC (b) | % Public | Value | MOIC (b) | Value | MOIC (b) | Realized | Total | |||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Except Where Noted) | ||||||||||||||||||||||||||||||||||||||||||||
| BCEP (Jan 2017 / Jan 2021) (h) | $ | 4,755,613 | $ | 2,601,681 | $ | 2,505,183 | 1.2x | — | $ | — | N/A | $ | 2,505,183 | 1.2x | N/A | 10 | % | |||||||||||||||||||||||||||
| BIP (TBD) | 5,686,000 | 5,686,000 | — | N/A | — | — | N/A | — | N/A | N/A | N/A | |||||||||||||||||||||||||||||||||
| Other Funds and Co-Investment (i) | 1,557,393 | 325,028 | 96,990 | 1.0x | 17 | % | 635,564 | 0.9x | 732,554 | 1.0x | N/M | N/M | ||||||||||||||||||||||||||||||||
| Hedge Fund Solutions | ||||||||||||||||||||||||||||||||||||||||||||
| BSCH (Dec 2013 / Jun 2020) (j) | $ | 3,298,575 | $ | 2,083,559 | $ | 1,308,188 | 1.1x | — | $ | 312,539 | N/A | $ | 1,620,727 | 1.3x | N/A | 8 | % | |||||||||||||||||||||||||||
| BSCH Co-Investment | 276,000 | 98,070 | 195,414 | 1.1x | — | 28,573 | N/A | 223,987 | 1.3x | N/A | 9 | % | ||||||||||||||||||||||||||||||||
| Total Hedge Fund Solutions | $ | 3,574,575 | $ | 2,181,629 | $ | 1,503,602 | 1.1x | — | $ | 341,112 | N/A | $ | 1,844,714 | 1.3x | N/A | 9 | % | |||||||||||||||||||||||||||
| Credit (k) | ||||||||||||||||||||||||||||||||||||||||||||
| Mezzanine I (Jul 2007 / Oct 2011) | $ | 2,000,000 | $ | 97,114 | $ | 25,716 | 1.3x | — | $ | 4,772,118 | 1.6x | $ | 4,797,834 | 1.6x | N/A | 17 | % | |||||||||||||||||||||||||||
| Mezzanine II (Nov 2011 / Nov 2016) | 4,120,000 | 1,146,274 | 2,034,118 | 1.0x | — | 4,526,585 | 1.6x | 6,560,703 | 1.3x | N/A | 12 | % | ||||||||||||||||||||||||||||||||
| Mezzanine III (Sep 2016 / Sep 2021) | 6,639,133 | 2,589,498 | 3,573,397 | 1.1x | — | 1,003,295 | 1.6x | 4,576,692 | 1.1x | N/A | 11 | % | ||||||||||||||||||||||||||||||||
| Stressed / Distressed Investing I (Sep 2009 / May 2013) | 3,253,143 | 135,000 | 228,105 | 0.4x | — | 5,732,348 | 1.6x | 5,960,453 | 1.4x | N/A | 11 | % | ||||||||||||||||||||||||||||||||
| Stressed / Distressed Investing II (Jun 2013 / Jun 2018) | 5,125,000 | 570,214 | 2,119,618 | 0.9x | — | 3,597,716 | 1.4x | 5,717,334 | 1.2x | N/A | 8 | % | ||||||||||||||||||||||||||||||||
| Stressed / Distressed Investing III (Dec 2017 / Dec 2022) | 7,356,380 | 6,007,292 | 1,356,095 | 1.0x | — | 302,613 | 1.3x | 1,658,708 | 1.1x | N/A | N/A | |||||||||||||||||||||||||||||||||
| Energy Select Opportunities (Nov 2015 / Nov 2018) | 2,856,867 | 943,281 | 1,968,152 | 1.1x | — | 544,630 | 1.7x | 2,512,782 | 1.2x | N/A | 13 | % | ||||||||||||||||||||||||||||||||
| Euro | ||||||||||||||||||||||||||||||||||||||||||||
| European Senior Debt Fund (Feb 2015 / Feb 2019) | € | 1,964,689 | € | 1,503,470 | € | 2,045,708 | 1.0x | — | € | 842,857 | 1.6x | € | 2,888,565 | 1.1x | N/A | 9 | % | |||||||||||||||||||||||||||
| Total Credit | $ | 33,616,933 | $ | 13,207,440 | $ | 13,643,752 | 1.0x | — | $ | 21,445,271 | 1.5x | $ | 35,089,023 | 1.3x | N/A | 12 | % | |||||||||||||||||||||||||||
The returns presented herein represent those of the applicable Blackstone Funds and not those of The Blackstone Group L.P.
| N/M | Not meaningful. |
|---|
| N/A | Not applicable. |
|---|
| (a) | Available Capital represents total investable capital commitments, including side-by-side, adjusted for certain expenses and expired or recallable capital and may include leverage, less invested capital. This amount is not reduced by outstanding commitments to investments. |
|---|
| (b) | Multiple of Invested Capital (“MOIC”) represents carrying value, before management fees, expenses and Performance Revenues, divided by invested capital. |
|---|
| (c) | Net Internal Rate of Return (“IRR”) represents the annualized inception to December 31, 2018 IRR on total invested capital based on realized proceeds and unrealized value, as applicable, after management fees, expenses and Performance Revenues. |
|---|
| (d) | The 8% Realized Net IRR and 8% Total Net IRR exclude investors that opted out of the Hilton investment opportunity. Overall BREP International II performance reflects a 7% Realized Net IRR and a 6% Total Net IRR. |
|---|
| (e) | BREP Co-Investment represents co-investment capital raised for various BREP investments. The Net IRR reflected is calculated by aggregating each co-investment’s realized proceeds and unrealized value, as applicable, after management fees, expenses and Performance Revenues. |
|---|
| (f) | BPP represents the core+ real estate funds which invest with a more modest risk profile and lower leverage. Excludes BREIT. |
|---|
| (g) | Realizations are treated as return of capital until fully recovered and therefore unrealized and realized MOICs are not meaningful. |
|---|
| (h) | BCEP, or Blackstone Core Equity Partners, is a core private equity fund which invests with a more modest risk profile and longer hold period. |
|---|
| (i) | Returns for Other Funds and Co-Investment are not meaningful as these funds have limited transaction activity. |
|---|
| (j) | BSCH, or Blackstone Strategic Capital Holdings, is focused on acquiring strategic minority positions in alternative asset managers. |
|---|
| (k) | Funds presented represent the flagship credit drawdown funds only. The Total Credit Net IRR is the combined IRR of the eight credit drawdown funds presented. |
|---|
Table of Contents
Segment Analysis
Discussed below is our Segment Distributable Earnings for each of our segments. This information is reflected in the manner utilized by our senior management to make operating decisions, assess performance and allocate resources. References to “our” sectors or investments may also refer to portfolio companies and investments of the underlying funds that we manage.
Real Estate
The following table presents the results of operations for our Real Estate segment:
| Year Ended December 31, | 2018 vs. 2017 | 2017 vs. 2016 | ||||||||||||||||||||||||||
| 2018 | 2017 | 2016 | $ | % | $ | % | ||||||||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||||||||||
| Management Fees, Net | ||||||||||||||||||||||||||||
| Base Management Fees | $ | 985,399 | $ | 872,191 | $ | 795,161 | $ | 113,208 | 13 | % | $ | 77,030 | 10 | % | ||||||||||||||
| Transaction and Other Fees, Net | 152,513 | 82,781 | 95,324 | 69,732 | 84 | % | (12,543 | ) | -13 | % | ||||||||||||||||||
| Management Fee Offsets | (11,442 | ) | (15,934 | ) | (7,322 | ) | 4,492 | -28 | % | (8,612 | ) | 118 | % | |||||||||||||||
| Total Management Fees, Net | 1,126,470 | 939,038 | 883,163 | 187,432 | 20 | % | 55,875 | 6 | % | |||||||||||||||||||
| Fee Related Performance Revenues | 124,502 | 79,500 | 18,178 | 45,002 | 57 | % | 61,322 | 337 | % | |||||||||||||||||||
| Fee Related Compensation | (459,430 | ) | (437,311 | ) | (379,331 | ) | (22,119 | ) | 5 | % | (57,980 | ) | 15 | % | ||||||||||||||
| Other Operating Expenses | (146,260 | ) | (136,042 | ) | (137,581 | ) | (10,218 | ) | 8 | % | 1,539 | -1 | % | |||||||||||||||
| Fee Related Earnings | 645,282 | 445,185 | 384,429 | 200,097 | 45 | % | 60,756 | 16 | % | |||||||||||||||||||
| Realized Performance Revenues | 914,984 | 2,141,374 | 1,214,931 | (1,226,390 | ) | -57 | % | 926,443 | 76 | % | ||||||||||||||||||
| Realized Performance Compensation | (284,319 | ) | (751,526 | ) | (335,147 | ) | 467,207 | -62 | % | (416,379 | ) | 124 | % | |||||||||||||||
| Realized Principal Investment Income | 92,525 | 255,903 | 122,712 | (163,378 | ) | -64 | % | 133,191 | 109 | % | ||||||||||||||||||
| Net Realizations | 723,190 | 1,645,751 | 1,002,496 | (922,561 | ) | -56 | % | 643,255 | 64 | % | ||||||||||||||||||
| Segment Distributable Earnings | $ | 1,368,472 | $ | 2,090,936 | $ | 1,386,925 | $ | (722,464 | ) | -35 | % | $ | 704,011 | 51 | % | |||||||||||||
| N/M | Not meaningful. |
|---|
Year Ended December 31, 2018 Compared to Year Ended December 31, 2017
Segment Distributable Earnings was $1.4 billion for the year ended December 31, 2018, a decrease of $722.5 million compared to $2.1 billion for the year ended December 31, 2017. The decrease in Distributable Earnings was primarily attributable to a decrease of $922.6 million in Net Realizations, partially offset by an increase of $200.1 million in Fee Related Earnings.
Segment Distributable Earnings in our Real Estate segment in 2018 were lower compared to 2017, primarily driven by lower realizations in 2018 compared to 2017, which was a record year for realizations in our Real Estate segment. Growing macroeconomic and geopolitical concerns, such as concerns over U.S. Federal Reserve policy, Brexit, the “trade war” with China and the rate of global growth, contributed to volatility in the fourth quarter of 2018. Although our Real Estate funds had $14.7 billion of realizations in 2018, ongoing volatility could contribute to a more challenging environment for realizations going forward. Overall, operating trends in our Real Estate portfolio remain stable and supply-demand fundamentals remain positive in most markets, although decelerating growth in certain sectors, including retail, may contribute to a more challenging environment for our portfolio companies. Capital deployment in opportunistic investments in the United States continues to be challenging, as distress levels are low and asset values are relatively high. Nonetheless, our Real Estate funds deployed or committed an aggregate of $21.3 billion of capital in 2018, with approximately 50% of such aggregate capital invested or committed outside of North America. In the event global markets enter a period of slower growth relative to recent years, periods of difficult market conditions or economic slowdown (which may be across
Table of Contents
industries, sectors or geographies) may contribute to adverse operating performance at our portfolio companies. In turn, this may limit attractive realization opportunities for our funds. To the extent interest rates continue to rise in 2019, the cost of debt financing for our real estate businesses and assets will likely increase. Rising interest rates, as well as a stronger U.S. dollar and higher inflation, would also potentially negatively impact Segment Distributable Earnings in our Real Estate segment, particularly if occurring against a backdrop of slowing economic growth. Segment Distributable Earnings in our Real Estate segment would also potentially be negatively impacted if pressure on wages and other inputs increasingly pressure profit margins. See “Part I. Item 1A. Risk Factors — Risks Related to Our Business — Difficult market conditions can adversely affect our business in many ways, including by reducing the value or performance of the investments made by our investment funds, making it more difficult to find opportunities for our funds to exit and realize value from existing investments and reducing the ability of our investment funds to raise or deploy capital, each of which could materially reduce our revenue, earnings and cash flow and adversely affect our financial prospects and condition.”
Fee Related Earnings
Fee Related Earnings was $645.3 million for the year ended December 31, 2018, an increase of $200.1 million, compared to $445.2 million for the year ended December 31, 2017. The increase in Fee Related Earnings was primarily attributable to increases of $187.4 million in Management Fees, Net and $45.0 million in Fee Related Performance Revenues, partially offset by an increase of $22.1 million in Fee Related Compensation.
Management Fees, Net were $1.1 billion for the year ended December 31, 2018, an increase of $187.4 million compared to $939.0 million for the year ended December 31, 2017, primarily driven by an increase in Base Management Fees. Base Management Fees were $985.4 million for the year ended December 31, 2018, an increase of $113.2 million compared to $872.2 million for the year ended December 31, 2017, primarily due to Assets Under Management growth in our core+ real estate funds. Transaction and Other Fees, Net were $152.5 million for the year ended December 31, 2018, an increase of $69.7 million compared to $82.8 million for the year ended December 31, 2017, primarily due to $27.1 million of BREP breakup fees related to two transactions as well as increased fees from investment activity in our BREP global funds.
Fee Related Performance Revenues were $124.5 million for the year ended December 31, 2018, an increase of $45.0 million, compared to $79.5 million for the year ended December 31, 2017. The increase was due to crystallizations in BREIT and BPP U.S., and an increase in BXMT earnings.
Fee Related Compensation was $459.4 million for the year ended December 31, 2018, an increase of $22.1 million, compared to $437.3 million for the year ended December 31, 2017. The increase was primarily due to the increase in Management and Advisory Fees, Net and Fee Related Performance Revenues, on which a portion of Fee Related Compensation is based.
Net Realizations
Net Realizations were $723.2 million for the year ended December 31, 2018, a decrease of $922.6 million, compared to $1.6 billion for the year ended December 31, 2017. The decrease in Net Realizations was primarily attributable to decreases of $1.2 billion in Realized Performance Revenues and $163.4 million in Realized Principal Investment Income, partially offset by a decrease of $467.2 million in Realized Performance Compensation.
Realized Performance Revenues were $915.0 million for the year ended December 31, 2018, a decrease of $1.2 billion, compared to $2.1 billion for the year ended December 31, 2017. The decrease was due to record realization activity in the year ended December 31, 2017.
Realized Principal Investment Income was $92.5 million for the year ended December 31, 2018, a decrease of $163.4 million, compared to $255.9 million for the year ended December 31, 2017. The decrease was primarily due to lower Realized Principal Investment Income for BREP VI.
Table of Contents
Realized Performance Compensation was $284.3 million for the year ended December 31, 2018, a decrease of $467.2 million, compared to $751.5 million for the year ended December 31, 2017. The decrease was due to the decrease in Realized Performance Revenues.
Year Ended December 31, 2017 Compared to Year Ended December 31, 2016
Segment Distributable Earnings were $2.1 billion for the year ended December 31, 2017, an increase of $704.0 million compared to $1.4 billion for the year ended December 31, 2016. The increase in Distributable Earnings was primarily attributable to increases of $60.8 million in Fee Related Earnings and $643.3 million in Net Realizations.
Fee Related Earnings
Fee Related Earnings was $445.2 million for the year ended December 31, 2017, an increase of $60.8 million, compared to $384.4 million for the year ended December 31, 2016. The increase in Fee Related Earnings was primarily attributable to increases of $61.3 million in Fee Related Performance Revenues and $55.9 million in Management Fees, Net, partially offset by an increase of $58.0 million in Fee Related Compensation.
Fee Related Performance Revenues were $79.5 million for the year ended December 31, 2017, an increase of $61.3 million, compared to $18.2 million for the year ended December 31, 2016. The increase was due to crystallizations in BPP U.S. and BREIT.
Management Fees, Net were $939.0 million for the year ended December 31, 2017, an increase of $55.9 million compared to $883.2 million for the year ended December 31, 2016, driven by an increase in Base Management Fees, partially offset by a decrease in Transactions and Other Fees, Net. Base Management Fees were $872.2 million for the year ended December 31, 2017, an increase of $77.0 million compared to $795.2 million for the year ended December 31, 2016, primarily due to growth in our core+ real estate funds and the launch of BREP Europe V in the fourth quarter of 2016 and the corresponding expiration of its fee holiday in the second quarter of 2017. Transaction and Other Fees, Net were $82.8 million for the year ended December 31, 2017, a decrease of $12.5 million compared to $95.3 million for the year ended December 31, 2016, primarily due to the timing of investment closings in our BREP global funds.
Fee Related Compensation was $437.3 million for the year ended December 31, 2017, an increase of $58.0 million, compared to $379.3 million for the year ended December 31, 2016. The increase was primarily due to the increase in Fee Related Performance Revenues and Management Fees, Net, on which a portion of Fee Related Compensation is based.
Net Realizations
Net Realizations were $1.6 billion for the year ended December 31, 2017, an increase of $643.3 million compared to $1.0 billion for the year ended December 31, 2016. The increase in Net Realizations was primarily attributable to increases of $926.4 million in Realized Performance Revenues and $133.2 million in Realized Principal Investment Income, partially offset by an increase of $416.4 million in Realized Performance Compensation.
Realized Performance Revenues were $2.1 billion for the year ended December 31, 2017, an increase of $926.4 million compared to $1.2 billion for the year ended December 31, 2016. The increase was driven by record realization activity.
Realized Principal Investment Income was $255.9 million for the year ended December 31, 2017, an increase of $133.2 million, compared to $122.7 million for the year ended December 31, 2016. The increase was due to higher Realized Principal Investment Income for BREP VI.
Table of Contents
Realized Performance Compensation was $751.5 million for the year ended December 31, 2017, an increase of $416.4 million compared to $335.1 million for the year ended December 31, 2016. The increase was due to the increase in Realized Performance Revenues.
Fund Returns
Fund return information for our significant funds is included throughout this discussion and analysis to facilitate an understanding of our results of operations for the periods presented. The fund returns information reflected in this discussion and analysis is not indicative of the financial performance of The Blackstone Group L.P. and is also not necessarily indicative of the future performance of any particular fund. An investment in The Blackstone Group L.P. is not an investment in any of our funds. There can be no assurance that any of our funds or our other existing and future funds will achieve similar returns.
The following table presents the internal rates of return, except where noted, of our significant real estate funds:
| Year Ended December 31, | December 31, 2018 Inception to Date | |||||||||||||||||||||||||||||||||||||||
| 2018 | 2017 | 2016 | Realized | Total | ||||||||||||||||||||||||||||||||||||
| Fund (a) | Gross | Net | Gross | Net | Gross | Net | Gross | Net | Gross | Net | ||||||||||||||||||||||||||||||
| BREP IV | -14 | % | -12 | % | 3 | % | 3 | % | -12 | % | -10 | % | 56 | % | 33 | % | 22 | % | 12 | % | ||||||||||||||||||||
| BREP V | -6 | % | -5 | % | 11 | % | 10 | % | 7 | % | 7 | % | 15 | % | 12 | % | 14 | % | 11 | % | ||||||||||||||||||||
| BREP VI | 7 | % | 5 | % | 28 | % | 23 | % | 21 | % | 17 | % | 18 | % | 14 | % | 17 | % | 13 | % | ||||||||||||||||||||
| BREP VII | 3 | % | 2 | % | 22 | % | 17 | % | 7 | % | 4 | % | 37 | % | 27 | % | 23 | % | 16 | % | ||||||||||||||||||||
| BREP VIII | 20 | % | 14 | % | 24 | % | 16 | % | 29 | % | 19 | % | 39 | % | 27 | % | 25 | % | 16 | % | ||||||||||||||||||||
| BREP International II (b)(c) | 34 | % | 29 | % | 23 | % | 21 | % | 23 | % | 23 | % | 10 | % | 8 | % | 9 | % | 8 | % | ||||||||||||||||||||
| BREP Europe III (b) | -18 | % | -15 | % | 25 | % | 20 | % | -4 | % | -4 | % | 30 | % | 21 | % | 23 | % | 15 | % | ||||||||||||||||||||
| BREP Europe IV (b) | 20 | % | 14 | % | 33 | % | 26 | % | 14 | % | 10 | % | 34 | % | 25 | % | 24 | % | 17 | % | ||||||||||||||||||||
| BREP Europe V (b) | 25 | % | 17 | % | N/M | N/M | N/A | N/A | N/M | N/M | 29 | % | 18 | % | ||||||||||||||||||||||||||
| BREP Asia I | 10 | % | 7 | % | 27 | % | 19 | % | 30 | % | 21 | % | 30 | % | 21 | % | 22 | % | 15 | % | ||||||||||||||||||||
| BREP Asia II | N/M | N/M | N/A | N/A | N/A | N/A | N/M | N/M | N/M | N/M | ||||||||||||||||||||||||||||||
| BREP Co-Investment (d) | -1 | % | — | 24 | % | 22 | % | 16 | % | 14 | % | 18 | % | 16 | % | 17 | % | 15 | % | |||||||||||||||||||||
| BPP (e) | 11 | % | 10 | % | 13 | % | 10 | % | 11 | % | 10 | % | N/M | N/M | 13 | % | 11 | % | ||||||||||||||||||||||
| BREDS Drawdown | 8 | % | 5 | % | 15 | % | 11 | % | 14 | % | 10 | % | 15 | % | 11 | % | 15 | % | 10 | % | ||||||||||||||||||||
| BREDS Liquid (f) | 6 | % | 4 | % | 11 | % | 8 | % | 2 | % | — | N/A | N/A | 11 | % | 8 | % | |||||||||||||||||||||||
| BXMT (g) | N/A | 7 | % | N/A | 16 | % | N/A | 23 | % | N/A | N/A | N/A | 12 | % | ||||||||||||||||||||||||||
| BREIT (g) | N/A | 8 | % | N/A | 10 | % | N/A | N/A | N/A | N/A | N/A | 9 | % |
The returns presented herein represent those of the applicable Blackstone Funds and not those of The Blackstone Group L.P.
| N/M | Not meaningful. |
|---|
| N/A | Not applicable. |
|---|
| (a) | Net returns are based on the change in carrying value (realized and unrealized) after management fees, expenses and Performance Revenues. |
|---|
| (b) | Euro-based internal rates of return. |
|---|
| (c) | The 8% Realized Net IRR and 8% Total Net IRR exclude investors that opted out of the Hilton investment opportunity. Overall BREP International II Performance reflects an 7% Realized Net IRR and a 6% Total Net IRR. |
|---|
| (d) | Excludes fully realized co-investments prior to Blackstone’s IPO. |
|---|
| (e) | BPP represents the core+ real estate funds which invest with a more modest risk profile and lower leverage. Excludes BREIT. |
|---|
Table of Contents
| (f) | BREDS Liquid represents BREDS funds that invest in liquid real estate debt securities, except funds in liquidation and insurance mandates with specific investment objectives. Effective June 30, 2018, the returns presented represent summarized asset-weighted gross and net rates of return. Inception to Date returns are presented on an annualized basis. Prior periods have been updated to reflect such rates of return. |
|---|
| (g) | Reflects annualized return of a shareholder invested in the REIT as of the beginning of each period presented, assuming reinvestment of all dividends received during the period, and no upfront selling commission for BREIT, net of all fees and expenses incurred by the REIT. For BXMT, return incorporates the closing NYSE stock price as of each period end, and for BREIT, return incorporates the final Class S NAV/share as of each period end. Inception to date returns are from May 22, 2013 and January 1, 2017 for BXMT and BREIT, respectively. |
|---|
As of December 31, 2018, the investment period for BREP International II had expired and the fund was not above its carried interest threshold. BREP International II Investors that opted out of the Hilton investment opportunity are not expected to exceed the carried interest threshold in future periods. However, since gains are not earned pro-rata, it is possible that certain BREP International II investors who participated in the Hilton investment opportunity will exceed the carried interest threshold in future periods.
The Real Estate segment has three funds in their investment period, which were above their respective carried interest thresholds as of December 31, 2018: BREP VIII, BREP Europe V and BREDS III.
Private Equity
The following table presents the results of operations for our Private Equity segment:
| Year Ended December 31, | 2018 vs. 2017 | 2017 vs. 2016 | ||||||||||||||||||||||||||
| 2018 | 2017 | 2016 | $ | % | $ | % | ||||||||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||||||||||
| Management and Advisory Fees, Net | ||||||||||||||||||||||||||||
| Base Management Fees | $ | 785,223 | $ | 724,818 | $ | 555,593 | $ | 60,405 | 8 | % | $ | 169,225 | 30 | % | ||||||||||||||
| Transaction, Advisory and Other Fees, Net | 58,165 | 57,624 | 39,283 | 541 | 1 | % | 18,341 | 47 | % | |||||||||||||||||||
| Management Fee Offsets | (13,504 | ) | (18,007 | ) | (34,810 | ) | 4,503 | -25 | % | 16,803 | -48 | % | ||||||||||||||||
| Total Management and Advisory Fees, Net | 829,884 | 764,435 | 560,066 | 65,449 | 9 | % | 204,369 | 36 | % | |||||||||||||||||||
| Fee Related Compensation | (375,446 | ) | (347,562 | ) | (298,149 | ) | (27,884 | ) | 8 | % | (49,413 | ) | 17 | % | ||||||||||||||
| Other Operating Expenses | (133,096 | ) | (120,997 | ) | (130,685 | ) | (12,099 | ) | 10 | % | 9,688 | -7 | % | |||||||||||||||
| Fee Related Earnings | 321,342 | 295,876 | 131,232 | 25,466 | 9 | % | 164,644 | 125 | % | |||||||||||||||||||
| Realized Performance Revenues | 757,406 | 1,157,188 | 245,268 | (399,782 | ) | -35 | % | 911,920 | 372 | % | ||||||||||||||||||
| Realized Performance Compensation | (318,167 | ) | (404,544 | ) | (110,882 | ) | 86,377 | -21 | % | (293,662 | ) | 265 | % | |||||||||||||||
| Realized Principal Investment Income | 109,731 | 154,837 | 73,377 | (45,106 | ) | -29 | % | 81,460 | 111 | % | ||||||||||||||||||
| Net Realizations | 548,970 | 907,481 | 207,763 | (358,511 | ) | -40 | % | 699,718 | 337 | % | ||||||||||||||||||
| Segment Distributable Earnings | $ | 870,312 | $ | 1,203,357 | $ | 338,995 | $ | (333,045 | ) | -28 | % | $ | 864,362 | 255 | % | |||||||||||||
| N/M | Not meaningful. |
|---|
Year Ended December 31, 2018 Compared to Year Ended December 31, 2017
Segment Distributable Earnings was $870.3 million for the year ended December 31, 2018, a decrease of $333.0 million compared to $1.2 billion for the year ended December 31, 2017. The decrease in Distributable Earnings was primarily attributable to a decrease of $358.5 million in Net Realizations, partially offset by an increase of $25.5 million in Fee Related Earnings.
Segment Distributable Earnings in our Private Equity segment in 2018 were lower compared to 2017, primarily driven by lower Realized Performance Revenues for BCP V, which had a number of large realizations in the
Table of Contents
comparable 2017 period. Growing macroeconomic and geopolitical concerns, such as concerns over U.S. Federal Reserve policy, Brexit, the “trade war” with China and the rate of global growth, contributed to volatility in the fourth quarter of 2018. Although realizations of $10.4 billion in 2018 reflected solid realization activity across corporate private equity, Tactical Opportunities and Strategic Partners, ongoing volatility could contribute to a more challenging environment for realizations going forward. The market environment continues to be generally characterized by high prices, and this can make deployment of capital more difficult. Nonetheless, we deployed or committed an aggregate of $19.3 billion of capital across the segment in 2018. Decelerating growth in certain sectors may contribute to a more challenging environment for our portfolio companies. In the event global markets enter a period of slower growth relative to recent years, periods of difficult market conditions or economic slowdown (which may be across industries, sectors or geographies) may contribute to adverse operating performance at our portfolio companies. In turn, this may limit attractive realization opportunities for our funds. To the extent interest rates continue to rise in 2019, the cost of debt financing for us and our portfolio companies will likely increase. Rising interest rates, as well as a stronger U.S. dollar and higher inflation, would also potentially negatively impact Segment Distributable Earnings in our Private Equity segment, particularly if occurring against a backdrop of slowing economic growth. Segment Distributable Earnings in the Private Equity segment would also potentially be negatively impacted if pressure on wages and other inputs and higher tariffs increasingly pressure profit margins. See “Part I. Item 1A. Risk Factors — Risks Related to Our Business — Difficult market conditions can adversely affect our business in many ways, including by reducing the value or performance of the investments made by our investment funds, making it more difficult to find opportunities for our funds to exit and realize value from existing investments and reducing the ability of our investment funds to raise or deploy capital, each of which could materially reduce our revenue, earnings and cash flow and adversely affect our financial prospects and condition.”
Fee Related Earnings
Fee Related Earnings was $321.3 million for the year ended December 31, 2018, an increase of $25.5 million, compared to $295.9 million for the year ended December 31, 2017. The increase in Fee Related Earnings was primarily attributable to an increase of $65.4 million in Management and Advisory Fees, Net, partially offset by an increase of $27.9 million in Fee Related Compensation.
Management and Advisory Fees, Net were $829.9 million for the year ended December 31, 2018, an increase of $65.4 million compared to $764.4 million for the year ended December 31, 2017, primarily driven by an increase in Base Management Fees. Base Management Fees were $785.2 million for the year ended December 31, 2018, an increase of $60.4 million compared to $724.8 million for the year ended December 31, 2017, primarily due to the launch of BCP Asia and the third vintage of Tactical Opportunities.
Fee Related Compensation was $375.4 million for the year ended December 31, 2018, an increase of $27.9 million, compared to $347.6 million for the year ended December 31, 2017. The increase was primarily due to the increase in Management and Advisory Fees, Net, on which a portion of Fee Related Compensation is based, as well as investment in our infrastructure initiative.
Net Realizations
Net Realizations were $549.0 million for the year ended December 31, 2018, a decrease of $358.5 million, compared to $907.5 million for the year ended December 31, 2017. The decrease in Net Realizations was primarily attributable to decreases of $399.8 million in Realized Performance Revenues and $45.1 million in Realized Principal Investment Income, partially offset by a decrease of $86.4 million in Realized Performance Compensation.
Realized Performance Revenues were $757.4 million for the year ended December 31, 2018, a decrease of $399.8 million, compared to $1.2 billion for the year ended December 31, 2017. The decrease was primarily due to lower Realized Performance Revenues for BCP V.
Table of Contents
Realized Principal Investment Income was $109.7 million for the year ended December 31, 2018, a decrease of $45.1 million, compared to $154.8 million for the year ended December 31, 2017. The decrease was primarily due to lower Realized Principal Investment income for BCP V.
Realized Performance Compensation was $318.2 million for the year ended December 31, 2018, a decrease of $86.4 million, compared to $404.5 million for the year ended December 31, 2017. The decrease was due to the decrease in Realized Performance Revenues.
Year Ended December 31, 2017 Compared to Year Ended December 31, 2016
Segment Distributable Earnings was $1.2 billion for the year ended December 31, 2017, an increase of $864.4 million compared to $339.0 million for the year ended December 31, 2016. The increase in Distributable Earnings was primarily attributable to increases of $164.6 million in Fee Related Earnings and $699.7 million in Net Realizations.
Fee Related Earnings
Fee Related Earnings was $295.9 million for the year ended December 31, 2017, an increase of $164.6 million compared to $131.2 million for the year ended December 31, 2016. The increase in Fee Related Earnings was primarily attributable to an increase of $204.4 million in Management and Advisory Fees, Net, partially offset by an increase of $49.4 million in Fee Related Compensation.
Management and Advisory Fees, Net were $764.4 million for the year ended December 31, 2017, an increase of $204.4 million compared to $560.1 million for the year ended December 31, 2016, driven primarily by an increase in Base Management Fees. Base Management Fees were $724.8 million for the year ended December 31, 2017, an increase of $169.2 million compared to $555.6 million for the year ended December 31, 2016, primarily due to higher management fees, as a result of the conclusion of a six-month fee holiday for BCP VII in the fourth quarter of 2016.
The Annualized Base Management Fee Rate increased from 0.93% at December 31, 2016 to 1.07% at December 31, 2017. The increase was principally due to the conclusion of a six-month fee holiday for BCP VII, which commenced its investment period in the second quarter of 2016.
Fee Related Compensation was $347.6 million for the year ended December 31, 2017, an increase of $49.4 million, compared to $298.1 million for the year ended December 31, 2016. The increase was primarily due to the increase in Management and Advisory Fees, Net, on which a portion of Fee Related Compensation is based.
Net Realizations
Net Realizations were $907.5 million for the year ended December 31, 2017, an increase of $699.7 million compared to $207.8 million for the year ended December 31, 2016. The increase in Net Realizations was primarily attributable to an increase of $911.9 million in Realized Performance Revenues, partially offset by an increase of $293.7 million in Realized Performance Compensation.
Realized Performance Revenues were $1.2 billion for the year ended December 31, 2017, an increase of $911.9 million compared to $245.3 million for the year ended December 31, 2016. The increase was primarily due to higher Realized Performance Revenues for BCP V and BCP VI.
Realized Performance Compensation was $404.5 million for the year ended December 31, 2017, an increase of $293.7 million compared to $110.9 million for the year ended December 31, 2016. The increase was due to the increase in Realized Performance Revenues.
Fund Returns
Fund returns information for our significant funds is included throughout this discussion and analysis to facilitate an understanding of our results of operations for the periods presented. The fund returns information
Table of Contents
reflected in this discussion and analysis is not indicative of the financial performance of The Blackstone Group L.P. and is also not necessarily indicative of the future performance of any particular fund. An investment in The Blackstone Group L.P. is not an investment in any of our funds. There can be no assurance that any of our funds or our other existing and future funds will achieve similar returns.
The following table presents the internal rates of return of our significant private equity funds:
| Year Ended December 31, | December 31, 2018 Inception to Date | |||||||||||||||||||||||||||||||||||||||
| 2018 | 2017 | 2016 | Realized | Total | ||||||||||||||||||||||||||||||||||||
| Fund (a) | Gross | Net | Gross | Net | Gross | Net | Gross | Net | Gross | Net | ||||||||||||||||||||||||||||||
| BCP IV | 6 | % | 5 | % | 1 | % | 1 | % | 22 | % | 19 | % | 55 | % | 41 | % | 50 | % | 36 | % | ||||||||||||||||||||
| BCP V | -6 | % | -5 | % | 12 | % | 9 | % | 9 | % | 7 | % | 11 | % | 9 | % | 10 | % | 8 | % | ||||||||||||||||||||
| BCP VI | 17 | % | 14 | % | 27 | % | 22 | % | 12 | % | 9 | % | 27 | % | 21 | % | 18 | % | 13 | % | ||||||||||||||||||||
| BCP VII | 43 | % | 28 | % | 29 | % | 12 | % | N/M | N/M | 65 | % | 21 | % | 38 | % | 21 | % | ||||||||||||||||||||||
| BEP I | 18 | % | 15 | % | 16 | % | 13 | % | 9 | % | 7 | % | 32 | % | 26 | % | 17 | % | 13 | % | ||||||||||||||||||||
| BEP II | 32 | % | 20 | % | 15 | % | 6 | % | 93 | % | 51 | % | 66 | % | 40 | % | 28 | % | 15 | % | ||||||||||||||||||||
| BCOM | 3 | % | 2 | % | -3 | % | -4 | % | 18 | % | 16 | % | 13 | % | 7 | % | 13 | % | 6 | % | ||||||||||||||||||||
| Tactical Opportunities | 13 | % | 9 | % | 16 | % | 13 | % | 12 | % | 9 | % | 26 | % | 21 | % | 15 | % | 11 | % | ||||||||||||||||||||
| Tactical Opportunities Co-Investment and Other | 13 | % | 11 | % | 28 | % | 21 | % | 8 | % | 5 | % | 28 | % | 28 | % | 17 | % | 14 | % | ||||||||||||||||||||
| Strategic Partners I-Vand Co-Investment (b) | 9 | % | 6 | % | 12 | % | 11 | % | -5 | % | -5 | % | N/A | N/A | 16 | % | 13 | % | ||||||||||||||||||||||
| Strategic Partners VI LBO, RE and SMA (b) | 16 | % | 13 | % | 17 | % | 13 | % | 6 | % | 4 | % | N/A | N/A | 24 | % | 19 | % | ||||||||||||||||||||||
| Strategic Partners VII (b) | 32 | % | 27 | % | 103 | % | 82 | % | N/M | N/M | N/A | N/A | 47 | % | 37 | % | ||||||||||||||||||||||||
| Strategic Partners RA II (b) | 31 | % | 20 | % | N/M | N/M | N/A | N/A | N/A | N/A | 26 | % | 17 | % |
The returns presented herein represent those of the applicable Blackstone Funds and not those of The Blackstone Group L.P.
| N/M | Not meaningful. |
|---|
| N/A | Not applicable. |
|---|
| (a) | Net returns are based on the change in carrying value (realized and unrealized) after management fees, expenses and Performance Revenues. |
|---|
| (b) | Realizations are treated as return of capital until fully recovered and therefore inception to date realized returns are not applicable. |
|---|
The corporate private equity funds within the Private Equity segment have five funds with closed investment periods: BCP IV, BCP V, BCP VI, BCOM and BEP I. As of December 31, 2018, BCP IV was above its carried interest threshold (i.e., the preferred return payable to its limited partners before the general partner is eligible to receive carried interest) and would still be above its carried interest threshold even if all remaining investments were valued at zero. BCP V is comprised of two fund classes based on the timings of fund closings, the BCP V “main fund” and BCP V-AC fund. Within these fund classes, the general partner is subject to equalization such that (a) the general partner accrues carried interest when the respective carried interest for either fund class is positive and (b) the general partner realizes carried interest so long as clawback obligations, if any, for either of the respective fund classes are fully satisfied. During the quarter, BCP V is currently below its carried interest threshold, while BCP V-AC is above its carried interest threshold. BCP VI is currently above its carried interest threshold. BCOM is currently above its carried interest threshold. We are entitled to retain previously realized carried interest up to 20% of BCOM’s net gains. As a result, Performance Revenues are recognized from BCOM on current period gains and losses. BEP I is currently above its carried interest threshold.
Table of Contents
Hedge Fund Solutions
The following table presents the results of operations for our Hedge Fund Solutions segment:
| Year Ended December 31, | 2018 vs. 2017 | 2017 vs. 2016 | ||||||||||||||||||||||||||
| 2018 | 2017 | 2016 | $ | % | $ | % | ||||||||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||||||||||
| Management Fees, Net | ||||||||||||||||||||||||||||
| Base Management Fees | $ | 519,782 | $ | 516,048 | $ | 521,736 | $ | 3,734 | 1 | % | $ | (5,688 | ) | -1 | % | |||||||||||||
| Transaction and Other Fees, Net | 3,180 | 2,980 | 1,061 | 200 | 7 | % | 1,919 | 181 | % | |||||||||||||||||||
| Management Fee Offsets | (93 | ) | (93 | ) | — | — | — | (93 | ) | N/M | ||||||||||||||||||
| Total Management Fees, Net | 522,869 | 518,935 | 522,797 | 3,934 | 1 | % | (3,862 | ) | -1 | % | ||||||||||||||||||
| Fee Related Compensation | (162,172 | ) | (146,924 | ) | (153,645 | ) | (15,248 | ) | 10 | % | 6,721 | -4 | % | |||||||||||||||
| Other Operating Expenses | (77,772 | ) | (68,265 | ) | (75,870 | ) | (9,507 | ) | 14 | % | 7,605 | -10 | % | |||||||||||||||
| Fee Related Earnings | 282,925 | 303,746 | 293,282 | (20,821 | ) | -7 | % | 10,464 | 4 | % | ||||||||||||||||||
| Realized Performance Revenues | 42,419 | 154,343 | 42,177 | (111,924 | ) | -73 | % | 112,166 | 266 | % | ||||||||||||||||||
| Realized Performance Compensation | (21,792 | ) | (40,707 | ) | (15,029 | ) | 18,915 | -46 | % | (25,678 | ) | 171 | % | |||||||||||||||
| Realized Principal Investment Income (Loss) | 17,039 | 9,074 | (7,224 | ) | 7,965 | 88 | % | 16,298 | N/M | |||||||||||||||||||
| Net Realizations | 37,666 | 122,710 | 19,924 | (85,044 | ) | -69 | % | 102,786 | 516 | % | ||||||||||||||||||
| Segment Distributable Earnings | $ | 320,591 | $ | 426,456 | $ | 313,206 | $ | (105,865 | ) | -25 | % | $ | 113,250 | 36 | % | |||||||||||||
| N/M | Not meaningful. |
|---|
Year Ended December 31, 2018 Compared to Year Ended December 31, 2017
Segment Distributable Earnings was $320.6 million for the year ended December 31, 2018, a decrease of $105.9 million compared to $426.5 million for the year ended December 31, 2017. The decrease in Distributable Earnings was primarily attributable to decreases of $20.8 million in Fee Related Earnings and $85.0 million in Net Realizations.
Segment Distributable Earnings in our Hedge Fund Solutions segment in 2018 were lower compared to 2017 driven primarily by lower Realized Performance Revenues as a result of lower returns in a number of strategies, including equities and credit. Segment Distributable Earnings in the Hedge Fund Solutions segment would likely be negatively impacted in the event of a significant or sustained decline in global, regional or sector asset prices, deterioration of global market conditions, or withdrawal of assets by investors as a result of liquidity needs, performance or other reasons. In addition, Segment Distributable Earnings in our Hedge Fund Solutions segment may be negatively impacted by a prolonged weak equity market environment, which may be caused by concerns over macroeconomic and geopolitical factors such as a rise in interest rate and concerns over Brexit, the “trade war” with China and the rate of global growth. See “Part I. Item 1A. Risk Factors — Risks Related to Our Business — Difficult market conditions can adversely affect our business in many ways, including by reducing the value or performance of the investments made by our investment funds, making it more difficult to find opportunities for our funds to exit and realize value from existing investments and reducing the ability of our investment funds to raise or deploy capital, each of which could materially reduce our revenue, earnings and cash flow and adversely affect our financial prospects and condition” and “— Hedge fund investments are subject to numerous additional risks.” The segment operates multiple business lines, manages strategies that are both long and short asset classes and generates a majority of its revenue through management fees, which we believe may provide a level of downside protection to Hedge Fund Solutions Segment Distributable Earnings. Over time we anticipate an increasing change in the mix of our product offerings to products whose performance based fees represent a more significant proportion of the fees than has historically been the case for such products.
Table of Contents
Fee Related Earnings
Fee Related Earnings was $282.9 million for the year ended December 31, 2018, a decrease of $20.8 million, compared to $303.7 million for the year ended December 31, 2017. The decrease in Fee Related Earnings was primarily attributable to increases of $15.2 million in Fee Related Compensation and $9.5 million in Other Operating Expenses.
Fee Related Compensation was $162.2 million for the year ended December 31, 2018, an increase of $15.2 million, compared to $146.9 million for the year ended December 31, 2017. The increase was primarily due to a lower deferral on Compensation.
Other Operating Expenses were $77.8 million for the year ended December 31, 2018, an increase of $9.5 million, compared to $68.3 million for the year ended December 31, 2017. The increase was primarily due to an increase in professional fees, including legal expenses.
Net Realizations
Net Realizations were $37.7 million for the year ended December 31, 2018, a decrease of $85.0 million, compared to $122.7 million for the year ended December 31, 2017. The decrease in Net Realizations was primarily attributable to a decrease of $111.9 million in Realized Performance Revenues, partially offset by a decrease of $18.9 million in Realized Performance Compensation.
Realized Performance Revenues were $42.4 million for the year ended December 31, 2018, a decrease of $111.9 million, compared to $154.3 million for the year ended December 31, 2017. The decrease was primarily driven by lower returns across a number of strategies, including customized solutions, commingled products, individual investor and specialized solutions, compared to the year ended December 31, 2017.
Realized Performance Compensation was $21.8 million for the year ended December 31, 2018, a decrease of $18.9 million, compared to $40.7 million for the year ended December 31, 2017. The decrease was due to the decrease in Realized Performance Revenues.
Year Ended December 31, 2017 Compared to Year Ended December 31, 2016
Segment Distributable Earnings was $426.5 million for the year ended December 31, 2017, an increase of $113.3 million compared to $313.2 million for the year ended December 31, 2016. The increase in Distributable Earnings was primarily attributable to an increase of $102.8 million in Net Realizations, while Fee Related Earnings stayed relatively flat.
Net Realizations
Net Realizations were $122.7 million for the year ended December 31, 2017, an increase of $102.8 million compared to $19.9 million for the year ended December 31, 2016. The increase in Net Realizations was primarily attributable to increases of $112.2 million in Realized Performance Revenues and $16.3 million in Realized Principal Investment Income, partially offset by an increase of $25.7 million in Realized Performance Compensation.
Realized Performance Revenues were $154.3 million for the year ended December 31, 2017, an increase of $112.2 million compared to $42.2 million for the year ended December 31, 2016. The increase in Realized Performance Revenues in our Hedge Fund Solutions segment was primarily driven by higher returns in our BPS Composite, 8.3% gross (7.3% net) for the year ended December 31, 2017 compared to 3.5% gross (2.7% net) for the year ended December 31, 2016.
Realized Principal Investment Income was $9.1 million for the year ended December 31, 2017, an increase of $16.3 million, compared to $(7.2) million for the year ended December 31, 2016. The increase was primarily driven by the year over year net appreciation of investments of which Blackstone owns a share.
Table of Contents
Realized Performance Compensation was $40.7 million for the year ended December 31, 2017, an increase of $25.7 million compared to $15.0 million for the year ended December 31, 2016. The increase was due to the increase in Realized Performance Revenues.
Operating Metrics
The following table presents information regarding our Incentive Fee-Earning Assets Under Management:
| Fee-Earning Assets Under Management Eligible for Incentive Fees | Estimated % Above High Water Mark/Benchmark (a) | |||||||||||||||||||||||
| December 31, | December 31, | |||||||||||||||||||||||
| 2018 | 2017 | 2016 | 2018 | 2017 | 2016 | |||||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||||||
| Hedge Fund Solutions Managed Funds (b) | $ | 42,393,275 | $ | 41,238,330 | $ | 36,664,203 | 46 | % | 91 | % | 78 | % |
| (a) | Estimated % Above High Water Mark/Benchmark represents the percentage of Fee-Earning Assets Under Management Eligible for Incentive Fees that as of the dates presented would earn incentive fees when the applicable Hedge Fund Solutions managed fund has positive investment performance relative to a benchmark, where applicable. Incremental positive performance in the applicable Blackstone Funds may cause additional assets to reach their respective High Water Mark or clear a benchmark return, thereby resulting in an increase in Estimated % Above High Water Mark/Benchmark. |
|---|
| (b) | For the Hedge Fund Solutions managed funds, at December 31, 2018, the incremental appreciation needed for the 54% of Fee-Earning Assets Under Management below their respective High Water Marks/Benchmarks to reach their respective High Water Marks/Benchmarks was $856.7 million, an increase of $457.2 million, compared to $399.6 million at December 31, 2017. Of the Fee-Earning Assets Under Management below their respective High Water Marks/ Benchmarks as of December 31, 2018, 91% were within 5% of reaching their respective High Water Mark. |
|---|
Composite Returns
Composite returns information is included throughout this discussion and analysis to facilitate an understanding of our results of operations for the periods presented. The composite returns information reflected in this discussion and analysis is not indicative of the financial performance of The Blackstone Group L.P. and is also not necessarily indicative of the future results of any particular fund. An investment in The Blackstone Group L.P. is not an investment in any of our funds or composites. There can be no assurance that any of our funds or composites or our other existing and future funds or composites will achieve similar returns.
The following table presents the return information of the BAAM Principal Solutions Composite:
| Average Annual Returns (a) | ||||||||||||||||||||||||||||||||
| Periods Ended December 31, 2018 | ||||||||||||||||||||||||||||||||
| One Year | Three Year | Five Year | Historical | |||||||||||||||||||||||||||||
| Composite | Gross | Net | Gross | Net | Gross | Net | Gross | Net | ||||||||||||||||||||||||
| BAAM Principal Solutions Composite (b) | 2 | % | 1 | % | 5 | % | 4 | % | 5 | % | 4 | % | 7 | % | 6 | % |
The returns presented herein represent those of the applicable Blackstone Funds and not those of The Blackstone Group L.P.
| (a) | Composite returns present a summarized asset-weighted return measure to evaluate the overall performance of the applicable class of Blackstone Funds. |
|---|
| (b) | BAAM’s Principal Solutions (“BPS”) Composite covers the period from January 2000 to present, although BAAM’s inception date is September 1990. The BPS Composite includes only BAAM-managed commingled and customized multi-manager funds and accounts. None of the other platforms/strategies managed through the Blackstone Hedge Fund Solutions Group are included in the composite (except for investments by BPS funds/ |
|---|
Table of Contents
| accounts directly into those platforms/strategies). BAAM-managed funds in liquidation and non-fee-paying assets (in the case of net returns) are excluded from the composite. The historical return is from January 1, 2000. |
|---|
Credit
The following table presents the results of operations for our Credit segment:
| Year Ended December 31, | 2018 vs. 2017 | 2017 vs. 2016 | ||||||||||||||||||||||||||
| 2018 | 2017 | 2016 | $ | % | $ | % | ||||||||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||||||||||
| Management Fees, Net | ||||||||||||||||||||||||||||
| Base Management Fees | $ | 553,921 | $ | 567,334 | $ | 525,289 | $ | (13,413 | ) | -2 | % | $ | 42,045 | 8 | % | |||||||||||||
| Transaction and Other Fees, Net | 15,640 | 13,431 | 9,190 | 2,209 | 16 | % | 4,241 | 46 | % | |||||||||||||||||||
| Management Fee Offsets | (12,332 | ) | (32,382 | ) | (37,512 | ) | 20,050 | -62 | % | 5,130 | -14 | % | ||||||||||||||||
| Total Management Fees, Net | 557,229 | 548,383 | 496,967 | 8,846 | 2 | % | 51,416 | 10 | % | |||||||||||||||||||
| Fee Related Performance Revenues | (666 | ) | 89,945 | 83,252 | (90,611 | ) | N/M | 6,693 | 8 | % | ||||||||||||||||||
| Fee Related Compensation | (219,098 | ) | (253,842 | ) | (223,313 | ) | 34,744 | -14 | % | (30,529 | ) | 14 | % | |||||||||||||||
| Other Operating Expenses | (131,200 | ) | (99,562 | ) | (87,700 | ) | (31,638 | ) | 32 | % | (11,862 | ) | 14 | % | ||||||||||||||
| Fee Related Earnings | 206,265 | 284,924 | 269,206 | (78,659 | ) | -28 | % | 15,718 | 6 | % | ||||||||||||||||||
| Realized Performance Revenues | 96,962 | 194,902 | 43,210 | (97,940 | ) | -50 | % | 151,692 | 351 | % | ||||||||||||||||||
| Realized Performance Compensation | (53,863 | ) | (100,834 | ) | (22,199 | ) | 46,971 | -47 | % | (78,635 | ) | 354 | % | |||||||||||||||
| Realized Principal Investment Income | 16,763 | 16,380 | 11,004 | 383 | 2 | % | 5,376 | 49 | % | |||||||||||||||||||
| Net Realizations | 59,862 | 110,448 | 32,015 | (50,586 | ) | -46 | % | 78,433 | 245 | % | ||||||||||||||||||
| Segment Distributable Earnings | $ | 266,127 | $ | 395,372 | $ | 301,221 | $ | (129,245 | ) | -33 | % | $ | 94,151 | 31 | % | |||||||||||||
| N/M | Not meaningful. |
|---|
Year Ended December 31, 2018 Compared to Year Ended December 31, 2017
Segment Distributable Earnings was $266.1 million for the year ended December 31, 2018, a decrease of $129.2 million compared to $395.4 million for the year ended December 31, 2017. The decrease in Distributable Earnings was primarily attributable to decreases of $78.7 million in Fee Related Earnings and $50.6 million in Net Realizations.
Segment Distributable Earnings in our Credit segment in 2018 were lower compared to 2017, primarily driven by lower Fee Related Earnings a as a result of the conclusion of our investment sub-advisory relationship with FS Investments in April 2018. Lower Segment Distributable Earnings were also driven by lower Net Realizations in 2018 compared to 2017 as a result of a mezzanine fund crossing its carried interest threshold in 2017, which resulted in higher Realized Performance Revenues in such prior period. In 2018, the investment pace across our Credit segment remained active, with $7.6 billion of capital deployed. To the extent interest rates continue to rise in 2019, and such rise occurs concurrently with a period of economic weakness or slowdown in growth, capital deployment in our Credit segment may be challenged. In addition, interest rate increases could adversely affect Segment Distributable Earnings in our Credit segment, although we believe our current portfolio is somewhat insulated because much of our debt portfolio is floating rate, short duration and/or held to maturity. Our Segment Distributable Earnings in our Credit segment may also be negatively impacted by our failure to accurately assess and react to risk, such as, for example, a sustained period of depressed energy and commodity prices or weakened market fundamentals, which may lead to, among other things, ratings downgrades. See “Part I. Item 1A. Risk Factors — Risks Related to Our Business — Difficult market conditions can adversely affect our business in many ways, including by reducing the value or performance of the investments made by our investment funds, making it more difficult to find opportunities for our funds to exit and realize value from existing investments and reducing
Table of Contents
the ability of our investment funds to raise or deploy capital, each of which could materially reduce our revenue, earnings and cash flow and adversely affect our financial prospects and condition.”
Fee Related Earnings
Fee Related Earnings was $206.3 million for the year ended December 31, 2018, a decrease of $78.7 million, compared to $284.9 million for the year ended December 31, 2017. The decrease in Fee Related Earnings was primarily attributable to a decrease of $90.6 million in Fee Related Performance Revenues and an increase of $31.6 million in Other Operating Expenses, partially offset by a decrease of $34.7 million in Fee Related Compensation.
Fee Related Performance Revenues were $(0.7) million for the year ended December 31, 2018, a decrease of $90.6 million, compared to $89.9 million for the year ended December 31, 2017. The decrease was due to the conclusion of our sub-advisory relationship with FS Investments (see “— Notable Transactions”).
Other Operating Expenses were $131.2 million for the year ended December 31, 2018, an increase of $31.6 million, compared to $99.6 million for the year ended December 31, 2017. The increase was primarily due to the growth in our new business initiatives, including our BIS, as well as a full year of Harvest-related expenses following its acquisition in the fourth quarter of 2017.
Fee Related Compensation was $219.1 million for the year ended December 31, 2018, a decrease of $34.7 million, compared to $253.8 million for the year ended December 31, 2017. The decrease was primarily due to the decrease in Fee Related Performance Revenues, on which a portion of Fee Related Compensation is based.
Net Realizations
Net Realizations were $59.9 million for the year ended December 31, 2018, a decrease of $50.6 million, compared to $110.4 million for the year ended December 31, 2017. The decrease in Net Realizations was primarily attributable to a decrease of $97.9 million in Realized Performance Revenues, partially offset by a decrease of $47.0 million in Realized Performance Compensation.
Realized Performance Revenues were $97.0 million for the year ended December 31, 2018, a decrease of $97.9 million, compared to $194.9 million for the year ended December 31, 2017. The decrease was primarily attributable to a mezzanine fund crossing its carry threshold during the year ended December 31, 2017, resulting in higher Realized Performance Revenues compared to the year ended December 31, 2018.
Realized Performance Compensation was $53.9 million for the year ended December 31, 2018, a decrease of $47.0 million, compared to $100.8 million for the year ended December 31, 2017. The decrease was due to the decrease in Realized Performance Revenues.
Year Ended December 31, 2017 Compared to December 31, 2016
Segment Distributable Earnings was $395.4 million for the year ended December 31, 2017, an increase of $94.2 million compared to $301.2 million for the year ended December 31, 2016. The increase in Distributable Earnings was primarily attributable to increases of $15.7 million in Fee Related Earnings and $78.4 million in Net Realizations.
Fee Related Earnings
Fee Related Earnings was $284.9 million for the year ended December 31, 2017, an increase of $15.7 million, compared to $269.2 million for the year ended December 31, 2016. The increase in Fee Related Earnings was primarily attributable to an increase of $51.4 million in Management Fees, Net, partially offset by increases of $30.5 million in Fee Related Compensation and $11.9 million in Other Operating Expenses.
Table of Contents
Management Fees, Net were $548.4 million for the year ended December 31, 2017, an increase of $51.4 million compared to $497.0 million for the year ended December 31, 2016. The increase was primarily attributable to our performing credit and energy portfolios, as well as Harvest.
The Annualized Base Management Fee Rate decreased from 0.78% at December 31, 2016 to 0.56% at December 31, 2017. The decrease was principally due to the inclusion of our insurance solutions initiative and the related fee holiday in the fourth quarter of 2017.
Fee Related Compensation was $253.8 million for the year ended December 31, 2017, an increase of $30.5 million, compared to $223.3 million for the year ended December 31, 2016. The increase was primarily due to the increase in Management Fees, Net, on which a portion of Fee Related Compensation is based.
Other Operating Expenses were $99.6 million for the year ended December 31, 2017, an increase of $11.9 million compared to $87.7 million for the year ended December 31, 2016. The increase was driven by increases in professional fees, fundraising costs and certain one-time expenses.
Net Realizations
Net Realizations were $110.4 million for the year ended December 31, 2017, an increase of $78.4 million compared to $32.0 million for the year ended December 31, 2016. The increase in Net Realizations was primarily attributable to an increase of $151.7 million in Realized Performance Revenues, partially offset by an increase of $78.6 million in Realized Performance Compensation.
Realized Performance Revenues were $194.9 million for the year ended December 31, 2017, an increase of $151.7 million compared to $43.2 million for the year ended December 31, 2016. The increase was primarily attributable to a mezzanine fund crossing its carry threshold during the year ended December 31, 2017, resulting in higher Realized Performance Revenues compared to the year ended December 31, 2016.
Realized Performance Compensation was $100.8 million for the year ended December 31, 2017, an increase of $78.6 million compared to $22.2 million for the year ended December 31, 2016. The increase was due to the increase in Realized Performance Revenues.
Fund Returns
Fund return information for our significant businesses is included throughout this discussion and analysis to facilitate an understanding of our results of operations for the periods presented. The fund returns information reflected in this discussion and analysis is not indicative of the financial performance of The Blackstone Group L.P. and is also not necessarily indicative of the future results of any particular fund. An investment in The Blackstone Group L.P. is not an investment in any of our funds. There can be no assurance that any of our funds or our other existing and future funds will achieve similar returns.
The following table presents combined internal rates of return of the segment’s performing credit and distressed strategies funds:
| Year Ended December 31, | Inception to December 31, 2018 | |||||||||||||||||||||||||||||||
| 2018 | 2017 | 2016 | Total | |||||||||||||||||||||||||||||
| Composite (a) | Gross | Net | Gross | Net | Gross | Net | Gross | Net | ||||||||||||||||||||||||
| Performing Credit Strategies (b) | 9 | % | 6 | % | 11 | % | 6 | % | 23 | % | 17 | % | 14 | % | 8 | % | ||||||||||||||||
| Distressed Strategies (c) | -3 | % | -3 | % | 8 | % | 5 | % | 18 | % | 13 | % | 10 | % | 6 | % |
Table of Contents
The returns presented herein represent those of the applicable Blackstone Funds and not those of The Blackstone Group L.P.
| (a) | Net returns are based on the change in carrying value (realized and unrealized) after management fees, expenses and Performance Allocations, net of tax advances. |
|---|
| (b) | Performing Credit Strategies include mezzanine lending funds, BDCs and other performing credit strategy funds. Performing Credit Strategies’ returns represent the IRR of the combined cash flows of the fee-earning funds exceeding $100 million of fair value at each respective quarter end excluding the Blackstone Funds that were contributed to GSO as part of Blackstone’s acquisition of GSO in March 2008. The inception to date returns are from July 16, 2007. |
|---|
| (c) | Distressed Strategies include stressed/distressed funds, credit alpha strategies and energy strategies. Distressed Strategies’ returns represent the IRR of the combined cash flows of the fee-earning funds exceeding $100 million of fair value at each respective quarter end. The inception to date returns are from August 1, 2005. |
|---|
As of December 31, 2018, there was $15.4 billion of Performance Revenue eligible assets under management invested in Credit strategies that were above the hurdle necessary to generate Incentive Fees or Performance Allocations. This represented 34% of the total Performance Revenue eligible assets at fair value across all Credit strategies.
Non-GAAP Financial Measures
These non-GAAP financial measures are presented without the consolidation of any Blackstone Funds that are consolidated into the Consolidated Financial Statements. Consequently, all non-GAAP financial measures exclude the assets, liabilities and operating results related to the Blackstone Funds. See “— Key Financial Measures and Indicators” for our definitions of Distributable Earnings, Segment Distributable Earnings, Fee Related Earnings and Adjusted EBITDA.
Effective July 1, 2018, Fee Related Earnings has been redefined to include Fee Related Performance Revenues and Fee Related Performance Compensation. There was no change to Distributable Earnings. All prior periods have been recast to reflect this definition.
Effective as of and for the three months ended December 31, 2018, Blackstone senior management determined that Segment Distributable Earnings, and not Economic Income, is the measure that it uses to assess the performance of its business segments. Segment Distributable Earnings is used by management to make operating decisions, allocate resources and determine the compensation of employees across all of its business segments. All prior periods have been recast to reflect these updates.
Table of Contents
The following table is a reconciliation of Net Income Attributable to The Blackstone Group L.P. to Distributable Earnings, Total Segment Distributable Earnings, Fee Related Earnings and Adjusted EBITDA for the years ended December 31, 2018, 2017 and 2016:

| (a) | This adjustment removes Transaction-Related Charges, which are excluded from Blackstone’s segment presentation. Transaction-Related Charges arise from corporate actions including acquisitions, divestitures, and Blackstone’s initial public offering. They consist primarily of equity-based compensation charges, gains and losses on contingent consideration arrangements, changes in the balance of the tax receivable agreement resulting from a change in tax law or similar event, transaction costs and any gains or losses associated with these corporate actions. |
|---|
| (b) | This adjustment removes the amortization of transaction-related intangibles, which are excluded from Blackstone’s segment presentation. This amount includes amortization of intangibles associated with Blackstone’s investment in Pátria, which is accounted for under the equity method. |
|---|
Table of Contents
| (c) | This adjustment reverses the effect of consolidating Blackstone Funds, which are excluded from Blackstone’s segment presentation. This adjustment includes the elimination of Blackstone’s interest in these funds, the increase to revenue representing the reimbursement of certain expenses by Blackstone Funds, which are presented gross under GAAP but netted against Other Operating Expenses in the segment presentation, and the removal of amounts associated with the ownership of Blackstone consolidated operating partnerships held by non-controlling interests. |
|---|
| (d) | This adjustment removes Unrealized Performance Revenues on a segment basis. The Segment Adjustment represents the add back of performance revenues earned from consolidated Blackstone Funds which have been eliminated in consolidation. |
|---|
| Year Ended December 31, | ||||||||||||
| 2018 | 2017 | 2016 | ||||||||||
| GAAP Unrealized Performance Allocations | $ | 561,373 | $ | (105,473 | ) | $ | 530,114 | |||||
| Segment Adjustment | (210 | ) | 41 | 6 | ||||||||
| Unrealized Performance Revenues | $ | 561,163 | $ | (105,432 | ) | $ | 530,120 | |||||
| (e) | This adjustment removes Unrealized Performance Allocations Compensation. |
|---|
| (f) | This adjustment removes Unrealized Principal Investment Income (Loss) on a segment basis. The Segment Adjustment represents (1) the add back of Principal Investment Income, including general partner income, earned from consolidated Blackstone Funds which have been eliminated in consolidation, and (2) the removal of amounts associated with the ownership of Blackstone consolidated operating partnerships held by non-controlling interests. |
|---|
| Year Ended December 31, | ||||||||||||
| 2018 | 2017 | 2016 | ||||||||||
| GAAP Unrealized Principal Investment Income | $ | 49,917 | $ | 42,605 | $ | 77,314 | ||||||
| Segment Adjustment | (115,768 | ) | (173,811 | ) | (56,893 | ) | ||||||
| Unrealized Principal Investment Income (Loss) | $ | (65,851 | ) | $ | (131,206 | ) | $ | 20,421 | ||||
| (g) | This adjustment removes Other Revenues on a segment basis. The Segment Adjustment represents (1) the add back of Other Revenues earned from consolidated Blackstone Funds which have been eliminated in consolidation, and (2) the removal of certain Transaction-Related Charges. For the year ended December 31, 2018, Transaction-Related Charges included $580.9 million of Other Revenues received upon the conclusion of Blackstone’s investment sub-advisory relationship with FS Investments’ funds. |
|---|
| Year Ended December 31, | ||||||||||||
| 2018 | 2017 | 2016 | ||||||||||
| GAAP Other Revenue | $ | 672,317 | $ | (133,229 | ) | $ | 54,753 | |||||
| Segment Adjustment | (582,849 | ) | (6,822 | ) | (41 | ) | ||||||
| Other Revenue | $ | 89,468 | $ | (140,051 | ) | $ | 54,712 | |||||
| (h) | This adjustment removes Equity-Based Compensation on a segment basis. |
|---|
| (i) | Taxes represent the total GAAP tax provision adjusted to include only the current tax provision (benefit) calculated on Income (Loss) Before Provision for Taxes and adjusted to exclude the tax impact of any |
|---|
Table of Contents
| divestitures. Related Payables represent tax-related payables including the amount payable under the Tax Receivable Agreement. |
|---|
| Year Ended December 31, | ||||||||||||
| 2018 | 2017 | 2016 | ||||||||||
| Taxes | $ | 90,022 | $ | 101,531 | $ | 92,263 | ||||||
| Related Payables | 63,843 | 88,457 | 74,886 | |||||||||
| Taxes and Related Payables | $ | 153,865 | $ | 189,988 | $ | 167,149 | ||||||
| (j) | This adjustment removes Interest and Dividend Revenue less Interest Expense on a segment basis. The Segment Adjustment represents (1) the add back of Other Revenues earned from consolidated Blackstone Funds which have been eliminated in consolidation, and (2) the removal of interest expense associated with the Tax Receivable Agreement. |
|---|
| Year Ended December 31, | ||||||||||||
| 2018 | 2017 | 2016 | ||||||||||
| GAAP Interest and Dividend Revenue | $ | 171,947 | $ | 139,696 | $ | 95,724 | ||||||
| Segment Adjustment | 9,816 | 3,224 | 675 | |||||||||
| Interest and Dividend Revenue | 181,763 | 142,920 | 96,399 | |||||||||
| GAAP Interest Expense | 163,990 | 197,486 | 152,654 | |||||||||
| Segment Adjustment | (4,152 | ) | (4,648 | ) | (4,632 | ) | ||||||
| Interest Expense | 159,838 | 192,838 | 148,022 | |||||||||
| Net Interest Income (Loss) | $ | 21,925 | $ | (49,918 | ) | $ | (51,623 | ) | ||||
| (k) | This adjustment removes the total segment amounts of Realized Performance Revenues. |
|---|
| (l) | This adjustment removes the total segment amounts of Realized Performance Compensation. |
|---|
| (m) | This adjustment removes the total segment amount of Realized Principal Investment Income. |
|---|
| (n) | This adjustment adds back Interest Expense on a segment basis. |
|---|
Liquidity and Capital Resources
General
Blackstone’s business model derives revenue primarily from third party assets under management. Blackstone is not a capital or balance sheet intensive business and targets operating expense levels such that total management and advisory fees exceed total operating expenses each period. As a result, we require limited capital resources to support the working capital or operating needs of our businesses. We draw primarily on the long-term committed capital of our limited partner investors to fund the investment requirements of the Blackstone Funds and use our own realizations and cash flows to invest in growth initiatives, make commitments to our own funds, where our minimum general partner commitments are generally less than 5% of the limited partner commitments of a fund, and pay distributions to unitholders.
Fluctuations in our statement of financial condition result primarily from activities of the Blackstone Funds which are consolidated as well as business transactions, such as the issuance of senior notes described below. The majority economic ownership interests of the Blackstone Funds are reflected as Redeemable Non-Controlling Interests in Consolidated Entities, and Non-Controlling Interests in Consolidated Entities in the Consolidated Financial Statements. The consolidation of these Blackstone Funds has no net effect on the Partnership’s Net Income or Partners’ Capital. Additionally, fluctuations in our statement of financial condition also include appreciation or depreciation in Blackstone investments in the Blackstone Funds, additional investments and redemptions of such interests in the Blackstone Funds and the collection of receivables related to management and advisory fees.
Table of Contents
Total assets were $28.9 billion as of December 31, 2018, a net decrease of $5.5 billion from December 31, 2017. The decrease was principally due to a decrease of $6.3 billion in total assets attributable to consolidated Blackstone funds. The decrease in total assets attributable to consolidated Blackstone funds was primarily due to a decrease of $8.9 billion from the deconsolidation of CLOs and other fund entities, partially offset by an increase of $2.7 billion from the launch of new consolidated CLOs.
Total liabilities were $15.2 billion as of December 31, 2018, a net decrease of $5.5 billion from December 31, 2017. The decrease was principally due to a decrease of $5.9 billion in total liabilities attributable to consolidated Blackstone funds. The decrease in total liabilities attributable to consolidated Blackstone funds was primarily due to a decrease of $8.7 billion from the deconsolidation of CLOs and other fund entities, partially offset by an increase of $2.7 billion from the launch of new consolidated CLOs.
The deconsolidation of the CLOs and fund vehicles was the result of the dilution of Blackstone’s ownership interests in these vehicles during the year ended December 31, 2018. As a result of the dilution, Blackstone determined that it was no longer the primary beneficiary of these VIEs under GAAP guidance and deconsolidated these vehicles. See Note 9. “Variable Interest Entities” in the “Notes to Consolidated Financial Statements” in “Part II. Item 8. Financial Statements and Supplementary Data” of this filing.
Sources and Uses of Liquidity
We have multiple sources of liquidity to meet our capital needs, including annual cash flows, accumulated earnings in the businesses, the proceeds from our issuances of senior notes, liquid investments we hold on our balance sheet for our own use and access to our $1.6 billion committed revolving credit facility. On September 21, 2018, Blackstone amended and restated its revolving credit facility to, among other things, increase the amount of the revolving credit facility from $1.5 billion to $1.6 billion and to extend the maturity date of the revolving credit facility from August 31, 2021 to September 21, 2023. As of December 31, 2018, Blackstone had $2.2 billion in cash and cash equivalents, $2.5 billion invested in corporate treasury investment, $1.9 billion invested in Blackstone Funds and other investments, against $3.5 billion in borrowings from our bond issuances, and no borrowings outstanding under our revolving credit facility.
In addition to the cash we received from our debt offerings and availability under our committed revolving credit facility, we expect to receive (a) cash generated from operating activities, (b) Performance Allocations and Incentive Fee realizations, and (c) realizations on the carry and hedge fund investments that we make. The amounts received from these three sources in particular may vary substantially from year to year and quarter to quarter depending on the frequency and size of realization events or net returns experienced by our investment funds. Our available capital could be adversely affected if there are prolonged periods of few substantial realizations from our investment funds accompanied by substantial capital calls for new investments from those investment funds. Therefore, Blackstone’s commitments to our funds are taken into consideration when managing our overall liquidity and cash position.
We expect that our primary liquidity needs will be cash to (a) provide capital to facilitate the growth of our existing businesses which principally includes funding our general partner and co-investment commitments to our funds, (b) provide capital to facilitate our expansion into new businesses that are complementary, (c) pay operating expenses, including cash compensation to our employees and other obligations as they arise, (d) fund modest capital expenditures, (e) repay borrowings and related interest costs, (f) pay income taxes, (g) repurchase our common units and Blackstone Holdings Partnership Units pursuant to our unit repurchase program and (h) make distributions to
Table of Contents
our unitholders and the holders of Blackstone Holdings Partnership Units. Our own capital commitments to our funds, the funds we invest in and our investment strategies as of December 31, 2018 consisted of the following:
| Blackstone and General Partner | Senior Managing Directors and Certain Other Professionals (a) | |||||||||||||||
| Fund | Original Commitment | Remaining Commitment | Original Commitment | Remaining Commitment | ||||||||||||
| (Dollars in Thousands) | ||||||||||||||||
| Real Estate | ||||||||||||||||
| BREP VII | $ | 300,000 | $ | 44,053 | $ | 100,000 | $ | 14,684 | ||||||||
| BREP VIII | 300,000 | 105,197 | 100,000 | 35,066 | ||||||||||||
| BREP IX | 300,000 | 300,000 | 100,000 | 100,000 | ||||||||||||
| BREP Europe III | 100,000 | 13,231 | 35,000 | 4,410 | ||||||||||||
| BREP Europe IV | 130,000 | 23,842 | 43,333 | 7,947 | ||||||||||||
| BREP Europe V | 150,000 | 66,991 | 43,333 | 22,330 | ||||||||||||
| BREP Asia I | 50,000 | 14,809 | 16,667 | 4,936 | ||||||||||||
| BREP Asia II | 70,707 | 62,439 | 23,569 | 20,813 | ||||||||||||
| BREDS II | 50,000 | 6,227 | 16,667 | 2,076 | ||||||||||||
| BREDS III | 50,000 | 21,942 | 16,667 | 7,314 | ||||||||||||
| BPP | 108,320 | 29,484 | — | — | ||||||||||||
| Other (b) | 64,984 | 10,717 | — | — | ||||||||||||
| Private Equity | ||||||||||||||||
| BCP V | 629,356 | 30,642 | — | — | ||||||||||||
| BCP VI | 719,718 | 107,631 | 250,000 | 37,386 | ||||||||||||
| BCP VII | 500,000 | 293,509 | 225,000 | 132,079 | ||||||||||||
| BEP I | 50,000 | 4,728 | — | — | ||||||||||||
| BEP II | 80,000 | 28,535 | 26,667 | 9,512 | ||||||||||||
| BEP III | 68,939 | 68,939 | 22,980 | 22,980 | ||||||||||||
| BCEP | 120,000 | 66,408 | 18,992 | 10,510 | ||||||||||||
| BCP Asia | 40,000 | 37,961 | 13,333 | 12,654 | ||||||||||||
| Tactical Opportunities | 402,821 | 252,382 | 116,540 | 84,127 | ||||||||||||
| Strategic Partners | 416,150 | 221,313 | 58,627 | 27,650 | ||||||||||||
| BIP | 112,333 | 112,333 | — | — | ||||||||||||
| Blackstone Life Sciences | 10,500 | 9,188 | — | — | ||||||||||||
| Other (b) | 255,307 | 28,377 | — | — | ||||||||||||
| Hedge Fund Solutions | ||||||||||||||||
| Strategic Alliance | 50,000 | 2,033 | — | — | ||||||||||||
| Strategic Alliance II | 50,000 | 1,482 | — | — | ||||||||||||
| Strategic Alliance III | 22,000 | 17,379 | — | — | ||||||||||||
| Strategic Holdings LP | 154,610 | 97,476 | — | — | ||||||||||||
| Other (b) | 4,200 | 2,410 | — | — | ||||||||||||
| Credit | ||||||||||||||||
| Capital Opportunities Fund II LP | 120,000 | 33,950 | 110,527 | 31,270 | ||||||||||||
| Capital Opportunities Fund III LP | 130,783 | 77,334 | 30,431 | 18,304 | ||||||||||||
| GSO Euro Senior Debt Fund LP | 63,000 | 19,358 | 57,194 | 17,574 | ||||||||||||
| GSO Capital Solutions | 50,000 | 5,780 | 27,666 | 3,198 | ||||||||||||
| GSO Capital Solutions II | 125,000 | 52,036 | 120,534 | 50,177 | ||||||||||||
| GSO Capital Solutions III | 151,000 | 136,377 | 30,542 | 27,589 | ||||||||||||
| GSO Energy Select Opportunities Fund | 80,000 | 41,942 | 74,742 | 39,186 | ||||||||||||
| GSO Energy Select Opportunities Fund II | 40,165 | 40,165 | 13,388 | 13,388 | ||||||||||||
| GSO Credit Alpha Fund LP | 52,102 | 7,465 | 50,285 | 7,205 | ||||||||||||
| GSO Credit Alpha Fund II LP | 25,500 | 22,400 | 5,979 | 5,225 | ||||||||||||
| Other (b) | 166,737 | 55,239 | 21,672 | 5,117 | ||||||||||||
| Other | ||||||||||||||||
| Treasury | 263,759 | 72,734 | — | — | ||||||||||||
| $ | 6,627,991 | $ | 2,646,438 | $ | 1,770,335 | $ | 774,707 | |||||||||
Table of Contents
| (a) | For some of the general partner commitments shown in the table above we require our senior managing directors and certain other professionals to fund a portion of the commitment even though the ultimate obligation to fund the aggregate commitment is ours pursuant to the governing agreements of the respective funds. The amounts of the aggregate applicable general partner original and remaining commitment are shown in the table above. In addition, certain senior managing directors and other professionals are required to fund a de minimis amount of the commitment in the other private equity, real estate and credit-focused carry funds. We expect our commitments to be drawn down over time and to be funded by available cash and cash generated from operations and realizations. Taking into account prevailing market conditions and both the liquidity and cash or liquid investment balances, we believe that the sources of liquidity described above will be more than sufficient to fund our working capital requirements. |
|---|
| (b) | Represents capital commitments to a number of other funds in each respective segment. |
|---|
As of December 31, 2018, Blackstone Holdings Finance Co. L.L.C. (the “Issuer”), an indirect subsidiary of the Partnership, had issued and outstanding the following senior notes (collectively the “Notes”):
| Senior Notes (a) | Aggregate Principal Amount (Dollars/Euros in Thousands) | |||
| 5.875%, Due 3/15/2021 | $ | 400,000 | ||
| 4.750%, Due 2/15/2023 | $ | 400,000 | ||
| 2.000%, Due 5/19/2025 | € | 300,000 | ||
| 1.000%, Due 10/5/2026 | € | 600,000 | ||
| 3.150%, Due 10/2/2027 | $ | 300,000 | ||
| 6.250%, Due 8/15/2042 | $ | 250,000 | ||
| 5.000%, Due 6/15/2044 | $ | 500,000 | ||
| 4.450%, Due 7/15/2045 | $ | 350,000 | ||
| 4.000%, Due 10/2/2047 | $ | 300,000 |
| (a) | The Notes are unsecured and unsubordinated obligations of the Issuer and are fully and unconditionally guaranteed, jointly and severally, by The Blackstone Group L.P. and each of the Blackstone Holdings Partnerships. The Notes contain customary covenants and financial restrictions that, among other things, limit the Issuer and the guarantors’ ability, subject to certain exceptions, to incur indebtedness secured by liens on voting stock or profit participating equity interests of their subsidiaries or merge, consolidate or sell, transfer or lease assets. The Notes also contain customary events of default. All or a portion of the Notes may be redeemed at our option, in whole or in part, at any time and from time to time, prior to their stated maturity, at the make-whole redemption price set forth in the Notes. If a change of control repurchase event occurs, the Notes are subject to repurchase at the repurchase price as set forth in the Notes. |
|---|
Blackstone, through indirect subsidiaries, has a $1.6 billion unsecured revolving credit facility (the “Credit Facility”) with Citibank, N.A., as administrative agent with a maturity date of September 21, 2023. Borrowings may also be made in U.K. sterling, euros, Swiss francs, Japanese yen or Canadian dollars, in each case subject to certain sub-limits. The Credit Facility contains customary representations, covenants and events of default. Financial covenants consist of a maximum net leverage ratio and a requirement to keep a minimum amount of fee-earning assets under management, each tested quarterly.
On April 16, 2018, the Board of Directors of our general partner, Blackstone Group Management L.L.C., authorized the repurchase of up to $1.0 billion of Blackstone common units and Blackstone Holdings Partnership Units. Under the unit repurchase program, units may be repurchased from time to time in open market transactions, in privately negotiated transactions or otherwise. The timing and the actual number of units repurchased will depend on a variety of factors, including legal requirements, price and economic and market conditions. The unit repurchase program may be changed, suspended or discontinued at any time and does not have a specified expiration date.
Table of Contents
During the year ended December 31, 2018, we repurchased 16.0 million Blackstone common units as part of the unit repurchase program at a total cost of $541.5 million. As of December 31, 2018, the amount remaining available for repurchases under the program was $458.5 million.
Distributions
Our intention is to distribute quarterly to common unitholders approximately 85% of The Blackstone Group L.P.’s share of Distributable Earnings, subject to adjustment by amounts determined by Blackstone’s general partner to be necessary or appropriate to provide for the conduct of its business, to make appropriate investments in its business and funds, to comply with applicable law, any of its debt instruments or other agreements, or to provide for future cash requirements such as tax-related payments, clawback obligations and distributions to unitholders for any ensuing quarter. The amount to be distributed could also be adjusted upward in any one quarter.
For Blackstone’s definition of Distributable Earnings, see “— Key Financial Measures and Indicators”.
All of the foregoing is subject to the qualification that the declaration and payment of any distributions are at the sole discretion of our general partner, and our general partner may change our distribution policy at any time, including, without limitation, to reduce the quarterly distribution payable to our common unitholders or even to eliminate such distributions entirely.
Because the subsidiaries of The Blackstone Group L.P. must pay taxes and make payments under the tax receivable agreements, the amounts ultimately distributed by The Blackstone Group L.P. to its common unitholders in respect of each fiscal year are generally expected to be less, on a per unit basis, than the amounts distributed by the Blackstone Holdings Partnerships to the Blackstone personnel and others who are limited partners of the Blackstone Holdings Partnerships in respect of their Blackstone Holdings Partnership Units.
The following graph shows fiscal quarterly and annual per common unitholder distributions for 2016, 2017 and 2018. Distributions are declared and paid in the quarter subsequent to the quarter in which they are earned.

Table of Contents
With respect to fiscal year 2018, we have paid to common unitholders distributions of $0.35, $0.58, $0.64 and $0.58 per common unit in respect of the first, second, third and fourth quarters, respectively, aggregating $2.15 per common unit. The second, third and fourth quarter fiscal 2018 per common unit distributions of $0.58, $0.64 and $0.58 each include $0.10 per common unit distributed from a portion of the after-tax proceeds received in connection with the conclusion of Blackstone’s sub-advisory relationship with FS Investments, as noted below. With respect to fiscal years 2017 and 2016, we paid aggregate common unitholder distributions of $2.70 per common unit and $1.52 per common unit, respectively.
Blackstone distributed a portion of the after-tax proceeds from the conclusion of its sub-advisory relationship with FS Investments, resulting in an incremental $0.30 per common unit and per Blackstone Holdings Partnership Unit over the second, third and fourth quarters of 2018, of which $0.10 per common unit and Blackstone Holdings Partnership Unit was distributed on each of August 6, 2018, November 5, 2018 and February 19, 2019.
Leverage
We may under certain circumstances use leverage opportunistically and over time to create the most efficient capital structure for Blackstone and our public common unitholders. In addition to the borrowings from our bond issuances and our revolving credit facility, we may use reverse repurchase agreements, repurchase agreements and securities sold, not yet purchased. All of these positions are held in a separately managed portfolio. Reverse repurchase agreements are entered into primarily to take advantage of opportunistic yields otherwise absent in the overnight markets and also to use the collateral received to cover securities sold, not yet purchased. Repurchase agreements are entered into primarily to opportunistically yield higher spreads on purchased securities. The balances held in these financial instruments fluctuate based on Blackstone’s liquidity needs, market conditions and investment risk profiles.
Generally our funds in our Private Equity segment, our opportunistic real estate funds, funds of hedge funds and certain credit-focused funds have not utilized substantial leverage at the fund level other than for (a) short-term borrowings between the date of an investment and the receipt of capital from the investing fund’s investors, and (b) long-term borrowings for certain investments in aggregate amounts which are generally 1% to 25% of the capital commitments of the respective fund. Our carry funds make direct or indirect investments in companies that utilize leverage in their capital structure. The degree of leverage employed varies among portfolio companies.
Certain of our Real Estate debt hedge funds, Hedge Fund Solutions funds and credit-focused funds use leverage in order to obtain additional market exposure, enhance returns on invested capital and/or to bridge short-term cash needs. The forms of leverage primarily employed by these funds include purchasing securities on margin, utilizing collateralized financing and using derivative instruments.
The following table presents information regarding these financial instruments in our Consolidated Statements of Financial Condition:
| Repurchase Agreements | Securities Sold, Not Yet Purchased | |||||||
| (Dollars in Millions) | ||||||||
| Balance, December 31, 2018 | $ | 222.2 | $ | 142.6 | ||||
| Balance, December 31, 2017 | $ | 118.8 | $ | 154.4 | ||||
| Year Ended December 31, 2018 | ||||||||
| Average Daily Balance | $ | 178.4 | $ | 152.7 | ||||
| Maximum Daily Balance | $ | 224.1 | $ | 174.7 |
Table of Contents
Critical Accounting Policies
We prepare our Consolidated Financial Statements in accordance with GAAP. In applying many of these accounting principles, we need to make assumptions, estimates and/or judgments that affect the reported amounts of assets, liabilities, revenues and expenses in our consolidated financial statements. We base our estimates and judgments on historical experience and other assumptions that we believe are reasonable under the circumstances. These assumptions, estimates and/or judgments, however, are often subjective. Actual results may be affected negatively based on changing circumstances. If actual amounts are ultimately different from our estimates, the revisions are included in our results of operations for the period in which the actual amounts become known. We believe the following critical accounting policies could potentially produce materially different results if we were to change underlying assumptions, estimates and/or judgments. For a description of our accounting policies, see Note 2. “Summary of Significant Accounting Policies” in the “Notes to Consolidated Financial Statements” in “— Item 8. Financial Statements and Supplementary Data” of this filing.
Principles of Consolidation
For a description of our accounting policy on consolidation, see Note 2. “Summary of Significant Accounting Policies — Consolidation” and Note 9. “Variable Interest Entities” in the “Notes to Consolidated Financial Statements” in “— Item 8. Financial Statements and Supplementary Data” of this filing for detailed information on Blackstone’s consolidation policy and its involvement with VIEs. The following discussion is intended to provide supplemental information about how the application of consolidation principles impact our financial results, and management’s process for implementing those principles including areas of significant judgment.
The determination that the Partnership holds a controlling financial interest in a Blackstone Fund significantly changes the presentation of our consolidated financial statements. In our Consolidated Statements of Financial Position included in this filing, we present 100% of the assets and liabilities of consolidated VIEs along with a non-controlling interest which represents the portion of the consolidated vehicle’s interests held by third parties. However, assets of our consolidated VIEs can only be used to settle obligations of the consolidated VIE and are not available for general use by the Partnership. Further, the liabilities of our consolidated VIEs do not have recourse to the general credit of Blackstone. In the Consolidated Statements of Operations, we eliminate any management fees, Incentive Fees, or Performance Allocations received or accrued from consolidated VIEs as they are considered intercompany transactions. We recognize 100% of the consolidated VIE’s investment income (loss) and allocate the portion of that income (loss) attributable to third party ownership to non-controlling interests in arriving at Net Income Attributable to The Blackstone Group L.P.
The assessment of whether we consolidate a Blackstone Fund we manage requires the application of significant judgment. These judgments are applied both at the time we become involved with the VIE and on an ongoing basis and include, but are not limited to:
| • | Determining whether our management fees, Incentive Fees or Performance Allocations represent variable interests — We make judgments as to whether the fees we earn are commensurate with the level of effort required for those fees and at market rates. In making this judgment, we consider, among other things, the extent of third party investment in the entity and the terms of any other interests we hold in the VIE. |
|---|
| • | Determining whether kick-out rights are substantive — We make judgments as to whether the third party investors in a partnership entity have the ability to remove the general partner, the investment manager or its equivalent, or to dissolve (liquidate) the partnership entity, through a simple majority vote. This includes an evaluation of whether barriers to exercise these rights exist. |
|---|
| • | Concluding whether the Partnership has an obligation to absorb losses or the right to receive benefits that could potentially be significant to the VIE — As there is no explicit threshold in GAAP to define “potentially significant,” management must apply judgment and evaluate both quantitative and qualitative factors to conclude whether this threshold is met. |
|---|
Table of Contents
Revenue Recognition
For a description of our accounting policy on revenue recognition, see Note 2. “Summary of Significant Accounting Policies — Revenue Recognition” in the “Notes to Consolidated Financial Statements” in “— Item 8. Financial Statements and Supplementary Data.” For additional description of the nature of our revenue arrangements, including how management fees, Incentive Fees, and Performance Allocations are generated, please refer to “Part I. Item 1. Business — Incentive Arrangements / Fee Structure.” The following discussion is intended to provide supplemental information about how the application of revenue recognition principles impact our financial results, and management’s process for implementing those principles including areas of significant judgment.
Management and Advisory Fees, Net — The Partnership earns base management fees from the investors in each of its managed funds and investment vehicles, at a fixed percentage of a calculation base which is typically assets under management, net asset value, total assets, committed capital or invested capital. The range of management fee rates and the calculation base from which they are earned, generally, are as follows:
On private equity, real estate, and certain of our hedge fund solutions and credit-focused funds:
| • | 0.25% to 2.00% of committed capital or invested capital during the investment period, |
|---|
| • | 0.25% to 1.50% of invested capital, committed capital and investment fair value subsequent to the investment period for private equity and real estate funds, and |
|---|
| • | 0.75% to 1.50% of invested capital or net asset value subsequent to the investment period for certain of our hedge fund solutions and credit-focused funds. |
|---|
On real estate, credit and MLP-focused funds structured like hedge funds:
| • | 0.50% to 1.50% of net asset value. |
|---|
On credit and MLP-focused separately managed accounts:
| • | 0.25% to 1.50% of net asset value or total assets. |
|---|
On real estate separately managed accounts:
| • | 0.50% to 2.00% of invested capital, net operating income or net asset value. |
|---|
On funds of hedge funds, certain hedge funds and separately managed accounts invested in hedge funds:
| • | 0.50% to 1.25% of net asset value. |
|---|
On CLO vehicles:
| • | 0.40% to 0.65% of the aggregate par amount of collateral assets, including principal cash. |
|---|
On credit-focused registered and non-registered investment companies:
| • | 0.35% to 1.50% of total assets or net asset value. |
|---|
The investment adviser of BXMT receives annual management fees based upon 1.50% of BXMT’s net proceeds received from equity offerings and accumulated “core earnings” (which is generally equal to its GAAP net income excluding certain non-cash and other items), subject to certain adjustments. The investment adviser of BREIT receives a management fee of 1.25% per annum of net asset value, payable monthly.
Table of Contents
Management fee calculations based on committed capital or invested capital are mechanical in nature and therefore do not require the use of significant estimates or judgments. Management fee calculations based on net asset value, total assets, or investment fair value depend on the fair value of the underlying investments within the funds. Estimates and assumptions are made when determining the fair value of the underlying investments within the funds and could vary depending on the valuation methodology that is used as well as economic conditions. See “— Fair Value” below for further discussion of the judgment required for determining the fair value of the underlying investments.
Investment Income (Loss) — Performance Allocations are made to the general partner based on cumulative fund performance to date, subject to a preferred return to limited partners. Blackstone has concluded that investments made alongside its limited partners in a partnership which entitle Blackstone to a Performance Allocation represent equity method investments that are not in the scope of the GAAP guidance on accounting for revenues from contracts with customers. Blackstone accounts for these arrangements under the equity method of accounting. Under the equity method Blackstone’s share of earnings (losses) from equity method investments is determined using a balance sheet approach referred to as the hypothetical liquidation at book value (“HLBV”) method. Under the HLBV method, at the end of each reporting period Blackstone calculates the accrued Performance Allocations that would be due to Blackstone for each fund pursuant to the fund agreements as if the fair value of the underlying investments were realized as of such date, irrespective of whether such amounts have been realized. Performance Allocations are subject to clawback to the extent that the Performance Allocation received to date exceeds the amount due to Blackstone based on cumulative results.
The change in the fair value of the investments held by certain Blackstone Funds is a significant input into the accrued Performance Allocation calculation and accrual for potential repayment of previously received Performance Allocations. Estimates and assumptions are made when determining the fair value of the underlying investments within the funds. See “— Fair Value” below for further discussion related to significant estimates and assumptions used for determining fair value of the underlying investments.
Fair Value
The Partnership uses fair value throughout the reporting process. For a description of our accounting policies related to valuation, see Note 2. “Summary of Significant Accounting Policies — Fair Value of Financial Instruments” and “Summary of Significant Accounting Policies — Investments at Fair Value” in the “Notes to Consolidated Financial Statements” in “— Item 8. Financial Statements and Supplementary Data” of this filing. The following discussion is intended to provide supplemental information about how the application of fair value principles impact our financial results, and management’s process for implementing those principles including areas of significant judgment.
The fair value of the investments held by Blackstone Funds is the primary input to the calculation of certain of our management fees, Incentive Fees, Performance Allocations and the related Compensation we recognize. The Blackstone Funds are accounted for as investment companies under the American Institute of Certified Public Accountants Accounting and Auditing Guide, Investment Companies, and in accordance with the GAAP guidance on investment companies and reflect their investments, including majority-owned and controlled investments (the “Portfolio Companies”), at fair value. In the absence of observable market prices, we utilize valuation methodologies applied on a consistent basis and assumptions that we believe market participants would use to determine the fair value of the investments. For some investments where little market activity may exist management’s determination of fair value is then based on the best information available in the circumstances, may incorporate management’s own assumptions and involves a significant degree of judgment, taking into consideration a combination of internal and external factors, including the appropriate risk adjustments for non-performance and liquidity risks.
The Partnership has also elected the fair value option for certain instruments it owns directly, including loans and receivables and investments in private debt securities, the assets of consolidated CLO vehicles and other
Table of Contents
proprietary investments. The Partnership is required to measure certain financial instruments at fair value, including debt instruments, equity securities and freestanding derivatives.
Fair Value of Investments or Instruments that are Publicly Traded
Securities that are publicly traded and for which a quoted market exists will be valued at the closing price of such securities in the principal market in which the security trades, or in the absence of a principal market, in the most advantageous market on the valuation date. When a quoted price in an active market exists, no block discounts or control premiums are permitted regardless of the size of the public security held. In some cases, securities will include legal and contractual restrictions limiting their purchase and sale for a period of time, such as may be required under SEC Rule 144 or by underwriters in certain transactions. A discount to publicly traded price may be appropriate in those cases; the amount of the discount shall be determined based on the time period that must pass before the restricted security becomes unrestricted or otherwise available for sale.
Fair Value of Investments or Instruments that are not Publicly Traded
Investments for which market prices are not observable include private investments in the equity or debt of operating companies or real estate properties. Our primary methodology for determining the fair values of such investments is the income approach which provides an indication of fair value based on the present value of cash flows that a business, security, or property is expected to generate in the future. The most widely used methodology under the income approach is the discounted cash flow method which includes significant assumptions about the underlying investment’s projected net earnings or cash flows, discount rate, capitalization rate and exit multiple. Our secondary methodology, generally used to corroborate the results of the income approach, is the market approach. The most widely used methodology under the market approach relies upon valuations for comparable public companies, transactions, or assets, and includes making judgments about which companies, transactions, or assets are comparable.
In certain cases debt and equity securities are valued on the basis of prices from an orderly transaction between market participants provided by reputable dealers or pricing services. In determining the value of a particular investment, pricing services may use certain information with respect to transactions in such investments, quotations from dealers, pricing matrices and market transactions in comparable investments and various relationships between investments.
Management Process on Fair Value
Due to the importance of fair value throughout the consolidated financial statements and the significant judgment required to be applied in arriving at those fair values, we have developed a process around valuation that incorporates several levels of approval and review from both internal and external sources. Blackstone Fund investments are valued on a quarterly basis by our internal valuation teams, which are independent from our investment teams.
For investments valued utilizing the income method, our valuation team generally has a direct line of communication with each of the Portfolio Company finance teams and collects financial data used to support projections used in a discounted cash flow analysis. The valuation team then analyzes the data received and updates the valuation models reflecting any changes in the underlying discounted cash flow projections, weighted-average cost of capital, exit multiple, and any other valuation input relevant economic conditions.
The results of all valuations of investments held by Blackstone Fund and investment vehicles are reviewed by the relevant business unit’s sub-committee, which is made up of key personnel, typically the chief investment officer, chief operating officer, chief financial officer, chief compliance officer (or their respective equivalents where applicable) and other Senior Managing Directors in the business. Following review and approval by each business unit’s sub-committee, the results are reviewed and must be approved by Blackstone’s firm-wide valuation
Table of Contents
committee chaired by Blackstone’s Chief Financial Officer and including senior heads of each of Blackstone’s businesses, as well as representatives from legal and finance. To further corroborate our results, we generally obtain a positive assurance opinion by an independent valuation party, at least annually for all investments and quarterly for certain investments. Each quarter, the valuations of Blackstone’s investments are also reviewed by the Audit Committee comprised of our non-employee directors in a meeting attended by the chairman of the valuation committee.
Off-Balance Sheet Arrangements
In the normal course of business, we engage in off-balance sheet arrangements, including transactions in derivatives, guarantees, commitments, indemnifications and potential contingent repayment obligations. We do not have any off-balance sheet arrangements that would require us to fund losses or guarantee target returns to investors in our funds.
Further disclosure on our off-balance sheet arrangements is presented in the “Notes to Consolidated Financial Statements” in “— Item 8. Financial Statements and Supplementary Data” of this filing as follows:
| • | Note 9. “Variable Interest Entities”, and |
|---|
| • | Note 18. “Commitments and Contingencies — Commitments, Operating Leases; — Commitments, Investment Commitments; and — Contingencies, Guarantees.” |
|---|
Recent Accounting Developments
Information regarding recent accounting developments and their impact on Blackstone can be found in Note 2. “Summary of Significant Accounting Policies” in the “Notes to Consolidated Financial Statements” in “— Item 8. Financial Statements and Supplementary Data” of this filing.
Table of Contents
Contractual Obligations, Commitments and Contingencies
The following table sets forth information relating to our contractual obligations as of December 31, 2018 on a consolidated basis and on a basis deconsolidating the Blackstone Funds:
| Contractual Obligations | 2019 | 2020-2021 | 2022-2023 | Thereafter | Total | |||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||
| Operating Lease Obligations (a) | $ | 78,506 | $ | 153,105 | $ | 156,342 | $ | 273,347 | $ | 661,300 | ||||||||||
| Purchase Obligations | 44,014 | 21,259 | 33 | — | 65,306 | |||||||||||||||
| Blackstone Issued Notes and Revolving Credit Facility (b) | — | 400,000 | 400,000 | 2,732,030 | 3,532,030 | |||||||||||||||
| Interest on Blackstone Issued Notes and Revolving Credit Facility (c) | 133,910 | 256,071 | 211,321 | 1,512,226 | 2,113,528 | |||||||||||||||
| Blackstone Funds and CLO Vehicles Debt Obligations Payable (d) | — | — | — | 6,863,285 | 6,863,285 | |||||||||||||||
| Interest on Blackstone Funds and CLO Vehicles Debt Obligations Payable (e) | 274,573 | 549,146 | 549,146 | 1,749,751 | 3,122,616 | |||||||||||||||
| Blackstone Funds Capital Commitments to Investee Funds (f) | 94,457 | — | — | — | 94,457 | |||||||||||||||
| Due to Certain Non-Controlling Interest Holders in Connection with Tax Receivable Agreements (g) | 84,688 | 140,422 | 143,140 | 437,327 | 805,577 | |||||||||||||||
| Unrecognized Tax Benefits, Including Interest and Penalties (h) | 2,467 | — | — | — | 2,467 | |||||||||||||||
| Blackstone Operating Entities Capital Commitments to Blackstone Funds and Other (i) | 2,646,438 | — | — | — | 2,646,438 | |||||||||||||||
| Consolidated Contractual Obligations | 3,359,053 | 1,520,003 | 1,459,982 | 13,567,966 | 19,907,004 | |||||||||||||||
| Blackstone Funds and CLO Vehicles Debt Obligations Payable (d) | — | — | — | (6,863,285 | ) | (6,863,285 | ) | |||||||||||||
| Interest on Blackstone Funds and CLO Vehicles Debt Obligations Payable (e) | (274,573 | ) | (549,146 | ) | (549,146 | ) | (1,749,751 | ) | (3,122,616 | ) | ||||||||||
| Blackstone Funds Capital Commitments to Investee Funds (f) | (94,457 | ) | — | — | — | (94,457 | ) | |||||||||||||
| Blackstone Operating Entities Contractual Obligations | $ | 2,990,023 | $ | 970,857 | $ | 910,836 | $ | 4,954,930 | $ | 9,826,646 | ||||||||||
| (a) | We lease our primary office space and certain office equipment under agreements that expire through 2030. In connection with certain office space lease agreements, we are responsible for escalation payments. The contractual obligation table above includes only guaranteed minimum lease payments for such leases and does not project potential escalation or other lease-related payments. These leases are classified as operating leases for financial statement purposes and as such are not recorded as liabilities on the Consolidated Statements of Financial Condition. The amounts are presented net of contractual sublease commitments. |
|---|
| (b) | Represents the principal amount due on the senior notes we issued. As of December 31, 2018, we had no outstanding borrowings under our revolver. |
|---|
| (c) | Represents interest to be paid over the maturity of our senior notes and borrowings under our revolving credit facility which has been calculated assuming no pre-payments are made and debt is held until its final maturity date. These amounts exclude commitment fees for unutilized borrowings under our revolver. |
|---|
| (d) | These obligations are those of the Blackstone Funds including the consolidated CLO vehicles. |
|---|
| (e) | Represents interest to be paid over the maturity of the related consolidated Blackstone Funds’ and CLO vehicles’ debt obligations which has been calculated assuming no pre-payments will be made and debt will be held until its final maturity date. The future interest payments are calculated using variable rates in effect as of |
|---|
Table of Contents
| December 31, 2018, at spreads to market rates pursuant to the financing agreements, and range from 0.8% to 9.2%. The majority of the borrowings are due on demand and for purposes of this schedule are assumed to mature within one year. Interest on the majority of these borrowings rolls over into the principal balance at each reset date. |
|---|
| (f) | These obligations represent commitments of the consolidated Blackstone Funds to make capital contributions to investee funds and portfolio companies. These amounts are generally due on demand and are therefore presented in the less than one year category. |
|---|
| (g) | Represents obligations by the Partnership’s corporate subsidiary to make payments under the Tax Receivable Agreements to certain non-controlling interest holders for the tax savings realized from the taxable purchases of their interests in connection with the reorganization at the time of Blackstone’s IPO in 2007 and subsequent purchases. The obligation represents the amount of the payments currently expected to be made, which are dependent on the tax savings actually realized as determined annually without discounting for the timing of the payments. As required by GAAP, the amount of the obligation included in the Consolidated Financial Statements and shown in Note 17. “Related Party Transactions” (see “— Item 8. Financial Statements and Supplementary Data”) differs to reflect the net present value of the payments due to certain non-controlling interest holders. |
|---|
| (h) | The total represents gross unrecognized tax benefits of $1.1 million and interest and penalties of $1.4 million. In addition, Blackstone is not able to make a reasonably reliable estimate of the timing of payments in individual years in connection with gross unrecognized benefits of $19.8 million and interest of $1.8 million; therefore, such amounts are not included in the above contractual obligations table. |
|---|
| (i) | These obligations represent commitments by us to provide general partner capital funding to the Blackstone Funds, limited partner capital funding to other funds and Blackstone principal investment commitments. These amounts are generally due on demand and are therefore presented in the less than one year category; however, a substantial amount of the capital commitments are expected to be called over the next three years. We expect to continue to make these general partner capital commitments as we raise additional amounts for our investment funds over time. |
|---|
Guarantees
Blackstone and certain of its consolidated funds provide financial guarantees. The amounts and nature of these guarantees are described in Note 18. “Commitments and Contingencies — Contingencies — Guarantees” in the “Notes to Consolidated Financial Statements” in “— Item 8. Financial Statements and Supplementary Data” of this filing.
Indemnifications
In many of its service contracts, Blackstone agrees to indemnify the third party service provider under certain circumstances. The terms of the indemnities vary from contract to contract and the amount of indemnification liability, if any, cannot be determined and has not been included in the table above or recorded in our Consolidated Financial Statements as of December 31, 2018.
Clawback Obligations
Performance Allocations are subject to clawback to the extent that the Performance Allocations received to date with respect to a fund exceeds the amount due to Blackstone based on cumulative results of that fund. The actual clawback liability, however, generally does not become realized until the end of a fund’s life except for certain Blackstone real estate funds, multi-asset class investment funds and credit-focused funds, which may have an interim clawback liability. The lives of the carry funds, including available contemplated extensions, for which a liability for potential clawback obligations has been recorded for financial reporting purposes, are currently anticipated to expire at various points through 2028. Further extensions of such terms may be implemented under given circumstances.
Table of Contents
For financial reporting purposes, when applicable, the general partners record a liability for potential clawback obligations to the limited partners of some of the carry funds due to changes in the unrealized value of a fund’s remaining investments and where the fund’s general partner has previously received Performance Allocation distributions with respect to such fund’s realized investments.
As of December 31, 2018, the total clawback obligations were $29.5 million, of which $30.4 million related to Blackstone Holdings and $(0.9) million related to current and former Blackstone personnel. The split of clawback between Blackstone Holdings and current and former personnel is based on the performance of individual investments held by a fund rather than on a fund by fund basis. If, at December 31, 2018, all of the investments held by our carry funds were deemed worthless, a possibility that management views as remote, the amount of Performance Allocations subject to potential clawback would be $7.0 billion, on an after tax basis where applicable, of which Blackstone Holdings is potentially liable for $6.4 billion if current and former Blackstone personnel default on their share of the liability, a possibility that management also views as remote. See Note 17. “Related Party Transactions” and Note 18. “Commitments and Contingencies” in the “Notes to Consolidated Financial Statements” in “— Item 8. Financial Statements and Supplementary Data” of this filing.
Previous: Item 6. SELECTED FINANCIAL DATA · Next: Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK