 filings.tools
Item 2. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
139K characters. Original on sec.gov · Markdown
Item 2. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Citizens Financial Group, Inc. | 5
FORWARD-LOOKING STATEMENTS
This document contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Any statement that does not describe historical or current facts is a forward-looking statement. These statements often include the words “believes,” “expects,” “anticipates,” “estimates,” “intends,” “plans,” “goals,” “targets,” “initiatives,” “potentially,” “probably,” “projects,” “outlook,” “guidance” or similar expressions or future conditional verbs such as “may,” “will,” “should,” “would,” and “could.”
Forward-looking statements are based upon the current beliefs and expectations of management, and on information currently available to management. Our statements speak as of the date hereof, and we do not assume any obligation to update these statements or to update the reasons why actual results could differ from those contained in such statements in light of new information or future events. We caution you, therefore, against relying on any of these forward-looking statements. They are neither statements of historical fact nor guarantees or assurances of future performance. While there is no assurance that any list of risks and uncertainties or risk factors is complete, important factors that could cause actual results to differ materially from those in the forward-looking statements include the following, without limitation:
-
Negative economic, business and political conditions, including as a result of the interest rate environment, supply chain disruptions, inflationary pressures and labor shortages, that adversely affect the general economy, housing prices, the job market, consumer confidence and spending habits;
-
The general state of the economy and employment, as well as general business and economic conditions, and changes in the competitive environment;
-
Our capital and liquidity requirements under regulatory standards and our ability to generate capital and liquidity on favorable terms;
-
The effect of changes in the level of commercial and consumer deposits on our funding costs and net interest margin;
-
Our ability to implement our business strategy, including the cost savings and efficiency components, and achieve our financial performance goals, including the anticipated benefits of the Investors acquisition and HSBC transaction;
-
The effects of geopolitical instability, including as a result of Russia’s invasion of Ukraine and the imposition of sanctions on Russia and other actions in response, on economic and market conditions, inflationary pressures and the interest rate environment, commodity price and foreign exchange rate volatility, and heightened cybersecurity risks;
-
Our ability to meet heightened supervisory requirements and expectations;
-
Liabilities and business restrictions resulting from litigation and regulatory investigations;
-
The effect of changes in interest rates on our net interest income, net interest margin and our mortgage originations, mortgage servicing rights and mortgages held for sale;
-
Changes in interest rates and market liquidity, as well as the magnitude of such changes, which may reduce interest margins, impact funding sources and affect the ability to originate and distribute financial products in the primary and secondary markets;
-
Financial services reform and other current, pending or future legislation or regulation that could have a negative effect on our revenue and businesses;
-
Environmental risks, such as physical or transitional risks associated with climate change, and social and governance risks, that could adversely affect our reputation, operations, business, and customers;
-
A failure in or breach of our operational or security systems or infrastructure, or those of our third-party vendors or other service providers, including as a result of cyber-attacks; and
-
Management’s ability to identify and manage these and other risks.
In addition to the above factors, we also caution that the actual amounts and timing of any future common stock dividends or share repurchases will be subject to various factors, including our capital position,
Citizens Financial Group, Inc. | 6
financial performance, capital impacts of strategic initiatives, market conditions, receipt of required regulatory approvals and other regulatory considerations, as well as any other factors that our Board of Directors deems relevant in making such a determination. Therefore, there can be no assurance that we will repurchase shares from or pay any dividends to holders of our common stock, or as to the amount of any such repurchases or dividends.
More information about factors that could cause actual results to differ materially from those described in the forward-looking statements can be found in the “Risk Factors” section in Part I, Item 1A of our 2022 Form 10-K.
INTRODUCTION
Citizens Financial Group, Inc. is one of the nation’s oldest and largest financial institutions, with $222.3 billion in assets as of March 31, 2023. Headquartered in Providence, Rhode Island, we offer a broad range of retail and commercial banking products and services to individuals, small businesses, middle-market companies, large corporations and institutions. We help our customers reach their potential by listening to them and by understanding their needs in order to offer tailored advice, ideas and solutions. In Consumer Banking, we provide an integrated experience that includes mobile and online banking, a full-service customer contact center and the convenience of approximately 3,400 ATMs and more than 1,100 branches in 14 states and the District of Columbia. Consumer Banking products and services include a full range of banking, lending, savings, wealth management and small business offerings. In Commercial Banking, we offer a broad complement of financial products and solutions, including lending and leasing, deposit and treasury management services, foreign exchange, interest rate and commodity risk management solutions, as well as loan syndication, corporate finance, merger and acquisition, and debt and equity capital markets capabilities. More information is available at www.citizensbank.com.
The following MD&A is intended to assist readers in their analysis of the accompanying unaudited interim Consolidated Financial Statements and supplemental financial information. It should be read in conjunction with the unaudited interim Consolidated Financial Statements and Notes to the unaudited interim Consolidated Financial Statements in Part I, Item 1, as well as other information contained in this document and our 2022 Form 10-K.
Non-GAAP Financial Measures
This document contains non-GAAP financial measures denoted as “Underlying” results and “including AOCI impact”. Underlying results for any given reporting period exclude certain items that may occur in that period which management does not consider indicative of our on-going financial performance. We believe these non-GAAP financial measures provide useful information to investors because they are used by management to evaluate our operating performance and make day-to-day operating decisions. In addition, we believe our Underlying results in any given reporting period reflect our on-going financial performance in that period and, accordingly, are useful to consider in addition to our GAAP financial results. We further believe the presentation of Underlying results increases comparability of period-to-period results.
Other companies may use similarly titled non-GAAP financial measures that are calculated differently from the way we calculate such measures. Accordingly, our non-GAAP financial measures may not be comparable to similar measures used by such companies. We caution investors not to place undue reliance on such non-GAAP financial measures, but to consider them with the most directly comparable GAAP measures. Non-GAAP financial measures have limitations as analytical tools and should not be considered in isolation or as a substitute for our results reported under GAAP.
Non-GAAP measures are denoted throughout our MD&A by the use of the term Underlying. Where there is a reference to these metrics in that paragraph, all measures that follow are on the same basis when applicable. For more information on the computation of non-GAAP financial measures, see “Non-GAAP Financial Measures and Reconciliations.”
Citizens Financial Group, Inc. | 7
FINANCIAL PERFORMANCE
Key Highlights
Net income increased $91 million for the three months ended March 31, 2023, with earnings per diluted common share up $0.07 to $1.00 compared to the same period in 2022.
Results reflect notable items of $49 million or $0.10 per diluted common share, net of tax benefit, for the three months ended March 31, 2023, compared to $56 million or $0.14 per diluted common share, net of tax benefit, for the same period in 2022.
| Table 1: Notable Items | Three Months Ended March 31, 2023 | ||||||||||||||||
| Less: notable items | |||||||||||||||||
| (dollars in millions) | Reported results (GAAP) | Integration related costs**(1)** | TOP and other**(2)** | Provision | Underlying results (non-GAAP) | ||||||||||||
| Provision (benefit) for credit losses | $168 | $— | $— | $— | $168 | ||||||||||||
| Noninterest expense | 1,296 | 52 | 14 | — | 1,230 | ||||||||||||
| Income tax expense | 153 | (13) | (4) | — | 170 |
| Three Months Ended March 31, 2022 | |||||||||||||||||
| Less: notable items | |||||||||||||||||
| (dollars in millions) | Reported results (GAAP) | Integration related costs**(1)** | TOP and other**(2)** | Provision**(3)** | Underlying results (non-GAAP) | ||||||||||||
| Provision (benefit) for credit losses | $3 | $— | $— | $24 | ($21) | ||||||||||||
| Noninterest expense | 1,106 | 37 | 11 | — | 1,058 | ||||||||||||
| Income tax expense | 116 | (10) | — | (6) | 132 |
(1) Includes integration related costs associated with acquisitions.
(2) Includes our TOP transformational and revenue and efficiency initiatives for the three months ended March 31, 2023 and 2022, and income tax impacts related to legacy tax matters for the three months ended March 31, 2022.
(3) Includes the initial provision for credit losses of $24 million tied to the HSBC transaction. As required by purchase accounting, a fair value mark for performing loans including both credit and interest rate components is recorded in addition to the provision for credit losses expense, thus the credit exposure has been “double counted”.
- Net income available to common stockholders increased $92 million to $488 million for the three months ended March 31, 2023, compared to the same period in 2022.
**◦**On an Underlying basis, which excludes notable items, net income available to common stockholders of $537 million for the three months ended March 31, 2023, compared with $452 million for the same period in 2022.
**◦**On an Underlying basis, earnings per diluted common share of $1.10 for the three months ended March 31, 2023, compared to $1.07 for the same period in 2022.
-
Total revenue increased $483 million to $2.1 billion for the three months ended March 31, 2023, compared to the same period in 2022, driven by an increase of 43% in net interest income, including the impacts of the HSBC transaction and Investors acquisition.
-
The efficiency ratio of 60.9% for the three months ended March 31, 2023, compared to 67.2% for the same period in 2022.
**◦**On an Underlying basis, the efficiency ratio of 57.8% for the three months ended March 31, 2023, compared to 64.3% for the same period in 2022.
- ROTCE of 14.4% for the three months ended March 31, 2023, compared to 11.4% for the same period in 2022.
**◦**On an Underlying basis, ROTCE of 15.8% for the three months ended March 31, 2023, compared to 13.0% for the same period in 2022.
- Tangible book value per common share of $29.44 increased 6% from December 31, 2022.
For additional information regarding our financial performance, see “Results of Operations” included in this report.
Citizens Financial Group, Inc. | 8
RESULTS OF OPERATIONS
Net Interest Income
Net interest income is our largest source of revenue and is the difference between the interest earned on interest-earning assets (generally loans, leases and investment securities) and the interest expense incurred in connection with interest-bearing liabilities (generally deposits and borrowed funds). The level of net interest income is primarily a function of the difference between the effective yield on our average interest-earning assets and the effective cost of our interest-bearing liabilities. These factors are influenced by the pricing and mix of interest-earning assets and interest-bearing liabilities which, in turn, are impacted by external factors such as local economic conditions, competition for loans and deposits, the monetary policy of the FRB and market interest rates. For further discussion, refer to the “Market Risk” and “Risk Governance” sections of our 2022 Form 10-K.
| Table 2: Major Components of Net Interest Income | ||||||||||||||||||||||||||||||||
| Three Months Ended March 31, | ||||||||||||||||||||||||||||||||
| 2023 | 2022 | Change | ||||||||||||||||||||||||||||||
| (dollars in millions) | Average Balances | Income/ Expense | Yields/ Rates | Average Balances | Income/ Expense | Yields/ Rates | Average Balances | Yields/ Rates (bps) | ||||||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||||||||
| Interest-bearing cash and due from banks and deposits in banks | $5,899 | $69 | 4.65 | % | $8,055 | $4 | 0.21 | % | ($2,156) | 444 bps | ||||||||||||||||||||||
| Taxable investment securities | 38,953 | 266 | 2.74 | 29,245 | 138 | 1.88 | 9,708 | 86 | ||||||||||||||||||||||||
| Non-taxable investment securities | 2 | — | 2.68 | 2 | — | 2.60 | — | 8 | ||||||||||||||||||||||||
| Total investment securities | 38,955 | 266 | 2.74 | 29,247 | 138 | 1.88 | 9,708 | 86 | ||||||||||||||||||||||||
| Commercial and industrial | 51,993 | 735 | 5.66 | 44,947 | 328 | 2.91 | 7,046 | 275 | ||||||||||||||||||||||||
| Commercial real estate | 28,892 | 416 | 5.75 | 14,066 | 90 | 2.57 | 14,826 | 318 | ||||||||||||||||||||||||
| Leases | 1,436 | 12 | 3.33 | 1,560 | 11 | 2.81 | (124) | 52 | ||||||||||||||||||||||||
| Total commercial | 82,321 | 1,163 | 5.65 | 60,573 | 429 | 2.83 | 21,748 | 282 | ||||||||||||||||||||||||
| Residential mortgages | 30,075 | 250 | 3.33 | 23,461 | 169 | 2.88 | 6,614 | 45 | ||||||||||||||||||||||||
| Home equity | 14,073 | 240 | 6.92 | 12,124 | 90 | 3.02 | 1,949 | 390 | ||||||||||||||||||||||||
| Automobile | 11,937 | 119 | 4.04 | 14,534 | 127 | 3.55 | (2,597) | 49 | ||||||||||||||||||||||||
| Education | 12,796 | 154 | 4.88 | 13,034 | 131 | 4.07 | (238) | 81 | ||||||||||||||||||||||||
| Other retail | 5,290 | 121 | 9.25 | 5,428 | 102 | 7.63 | (138) | 162 | ||||||||||||||||||||||||
| Total retail | 74,171 | 884 | 4.81 | 68,581 | 619 | 3.65 | 5,590 | 116 | ||||||||||||||||||||||||
| Total loans and leases | 156,492 | 2,047 | 5.25 | 129,154 | 1,048 | 3.26 | 27,338 | 199 | ||||||||||||||||||||||||
| Loans held for sale, at fair value | 1,009 | 15 | 5.87 | 2,366 | 16 | 2.70 | (1,357) | 317 | ||||||||||||||||||||||||
| Other loans held for sale | 197 | 5 | 9.98 | 454 | 7 | 5.89 | (257) | 409 | ||||||||||||||||||||||||
| Interest-earning assets | 202,552 | 2,402 | 4.76 | 169,276 | 1,213 | 2.88 | 33,276 | 188 | ||||||||||||||||||||||||
| Noninterest-earning assets | 20,159 | 19,041 | 1,118 | |||||||||||||||||||||||||||||
| Total assets | $222,711 | $188,317 | $34,394 | |||||||||||||||||||||||||||||
| Liabilities and Stockholders’ Equity | ||||||||||||||||||||||||||||||||
| Checking with interest | $35,974 | $97 | 1.09 | % | $30,417 | $5 | 0.07 | % | $5,557 | 102 | ||||||||||||||||||||||
| Money market | 49,942 | 287 | 2.33 | 47,220 | 12 | 0.10 | 2,722 | 223 | ||||||||||||||||||||||||
| Savings | 29,460 | 79 | 1.09 | 23,835 | 5 | 0.08 | 5,625 | 101 | ||||||||||||||||||||||||
| Term | 12,839 | 87 | 2.72 | 4,970 | 3 | 0.29 | 7,869 | 243 | ||||||||||||||||||||||||
| Total interest-bearing deposits | 128,215 | 550 | 1.74 | 106,442 | 25 | 0.10 | 21,773 | 164 | ||||||||||||||||||||||||
| Short-term borrowed funds | 542 | 6 | 4.97 | 29 | — | 3.50 | 513 | 147 | ||||||||||||||||||||||||
| Long-term borrowed funds | 17,780 | 203 | 4.55 | 6,066 | 41 | 2.66 | 11,714 | 189 | ||||||||||||||||||||||||
| Total borrowed funds | 18,322 | 209 | 4.57 | 6,095 | 41 | 2.66 | 12,227 | 191 | ||||||||||||||||||||||||
| Total interest-bearing liabilities | 146,537 | 759 | 2.09 | 112,537 | 66 | 0.23 | 34,000 | 186 | ||||||||||||||||||||||||
| Demand deposits | 46,135 | 48,641 | (2,506) | |||||||||||||||||||||||||||||
| Other noninterest-bearing liabilities | 6,323 | 4,144 | 2,179 | |||||||||||||||||||||||||||||
| Total liabilities | 198,995 | 165,322 | 33,673 | |||||||||||||||||||||||||||||
| Stockholders’ equity | 23,716 | 22,995 | 721 | |||||||||||||||||||||||||||||
| Total liabilities and stockholders’ equity | $222,711 | $188,317 | $34,394 | |||||||||||||||||||||||||||||
| Interest rate spread | 2.67 | % | 2.65 | % | 2 | |||||||||||||||||||||||||||
| Net interest income and net interest margin | $1,643 | 3.29 | % | $1,147 | 2.75 | % | 54 | |||||||||||||||||||||||||
| Net interest income and net interest margin, FTE(1) | $1,647 | 3.30 | % | $1,149 | 2.75 | % | 55 | |||||||||||||||||||||||||
| Memo: Total deposits (interest-bearing and demand) | $174,350 | $550 | 1.28 | % | $155,083 | $25 | 0.07 | % | $19,267 | 121 | bps |
(1) Net interest income and net interest margin is presented on a FTE basis using the federal statutory tax rate of 21%. The FTE impact is predominantly attributable to commercial and industrial loans for the periods presented.
Citizens Financial Group, Inc. | 9
Net interest income increased $496 million, or 43%, for the three months ended March 31, 2023, compared to the same period in 2022, reflecting higher net interest margin and growth of 20% in average interest-earning assets, including the impacts of the HSBC transaction and Investors acquisition.
Net interest margin on a FTE basis increased 55 basis points to 3.30% for the three months ended March 31, 2023, compared to the same period in 2022, reflecting higher interest-earning asset yields given higher market interest rates and interest-earning asset growth, partially offset by increased funding costs. Average interest-earning asset yields increased 188 basis points to 4.76%, while average interest-bearing liability costs increased 186 basis points to 2.09%, compared to the same period.
Average interest-earning assets increased $33.3 billion, or 20%, for the three months ended March 31, 2023, compared to the same period in 2022, reflecting the impacts of the HSBC transaction and Investors acquisition. Growth of $27.3 billion in loans and leases and $9.7 billion in investments was partially offset by a decline of $2.2 billion in cash held in interest-bearing deposits and $1.6 billion in LHFS.
Average deposits increased $19.3 billion, or 12%, for the three months ended March 31, 2023, compared to the same period in 2022, primarily attributable to the HSBC transaction and Investors acquisition.
Average total borrowed funds increased $12.2 billion for the three months ended March 31, 2023, compared to the same period in 2022, driven by the Investors acquisition, an increase in FHLB advances and the issuance of senior debt.
Noninterest Income
| Table 3: Noninterest Income | |||||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended March 31, | |||||||||||||||||||||||||||||||||||||||||||||||
| (dollars in millions) | 2023 | 2022 | Change | Percent | |||||||||||||||||||||||||||||||||||||||||||
| Service charges and fees | $100 | $98 | $2 | 2 | % | ||||||||||||||||||||||||||||||||||||||||||
| Capital markets fees | 83 | 93 | (10) | (11) | |||||||||||||||||||||||||||||||||||||||||||
| Card fees | 72 | 60 | 12 | 20 | |||||||||||||||||||||||||||||||||||||||||||
| Mortgage banking fees | 57 | 69 | (12) | (17) | |||||||||||||||||||||||||||||||||||||||||||
| Trust and investment services fees | 63 | 61 | 2 | 3 | |||||||||||||||||||||||||||||||||||||||||||
| Foreign exchange and derivative products | 48 | 51 | (3) | (6) | |||||||||||||||||||||||||||||||||||||||||||
| Letter of credit and loan fees | 40 | 38 | 2 | 5 | |||||||||||||||||||||||||||||||||||||||||||
| Securities gains, net | 5 | 4 | 1 | 25 | |||||||||||||||||||||||||||||||||||||||||||
| Other income(1) | 17 | 24 | (7) | (29) | |||||||||||||||||||||||||||||||||||||||||||
| Noninterest income | $485 | $498 | ($13) | (3 | %) |
(1) Includes bank-owned life insurance income and other income for all periods presented.
Noninterest income decreased for the three months ended March 31, 2023, compared to the same period in 2022, highlighted by the following significant changes.
-
Mortgage banking fees declined driven by lower production volumes, partially offset by improved gain-on-sale margins and higher servicing revenue.
-
Card fees increased given higher transaction volumes.
-
Capital markets fees decreased reflecting lower syndication fees, partially offset by higher merger and acquisition advisory, and underwriting fees.
-
Other income decreased reflecting higher derivative expense associated with hedging customer risk given wider spreads.
Citizens Financial Group, Inc. | 10
Noninterest Expense
| Table 4: Noninterest Expense | |||||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended March 31, | |||||||||||||||||||||||||||||||||||||||||||||||
| (dollars in millions) | 2023 | 2022 | Change | Percent | |||||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | $658 | $594 | $64 | 11 | % | ||||||||||||||||||||||||||||||||||||||||||
| Outside services | 176 | 169 | 7 | 4 | |||||||||||||||||||||||||||||||||||||||||||
| Equipment and software | 169 | 150 | 19 | 13 | |||||||||||||||||||||||||||||||||||||||||||
| Occupancy | 124 | 83 | 41 | 49 | |||||||||||||||||||||||||||||||||||||||||||
| Other operating expense | 169 | 110 | 59 | 54 | |||||||||||||||||||||||||||||||||||||||||||
| Noninterest expense | $1,296 | $1,106 | $190 | 17 | % |
Noninterest expense increased for the three months ended March 31, 2023, compared to the same period in 2022, driven primarily by acquisition and integration-related costs, and higher other operating expense associated with FDIC insurance and fraud losses, partially offset by the benefit of efficiency initiatives.
Provision for Credit Losses
The provision for credit losses is the result of a detailed analysis performed to estimate our ACL. The total provision for credit losses includes the provision for loan and lease losses and the provision for unfunded commitments. Refer to “—Analysis of Financial Condition — Allowance for Credit Losses and Nonaccrual Loans and Leases” for more information.
Credit provision expense of $168 million for the three months ended March 31, 2023, compared to $3 million for the same period in 2022. The provision expense for the three months ended March 31, 2023 reflects an increased net charge-off level and a focus on the CRE general office portfolio given return to office dynamics and rising interest rates. For the three months ended March 31, 2022, the provision expense reflects low charge-off levels and reduced reserve requirements as COVID concerns subsided.
Income Tax Expense
Income tax expense of $153 million increased $37 million for the three months ended March 31, 2023, compared to the same period in 2022. The effective income tax rate of 23.0% for the same period increased from 21.7%, compared to the same period in 2022, primarily driven by the adoption of the proportional amortization method for qualified investments in tax credit structures and increased non-deductible FDIC premium expense. Provision for income taxes is calculated by applying the estimated annual effective tax rate to year-to-date pre-tax income, adjusting for discrete items that occurred during the period.
Business Operating Segments
We have two business operating segments: Consumer Banking and Commercial Banking. Segment results are determined based on our management reporting system, which assigns balance sheet and statement of operations items to each of the business segments. The process is designed around our organizational and management structure. The results derived are not necessarily comparable with similar information published by other financial institutions.
Developing and applying methodologies used to allocate items among the business operating segments is a dynamic process. Accordingly, financial results may be revised periodically as management systems are enhanced, methods of evaluating performance or product lines are updated, or our organizational structure changes.
There have been no significant changes in our methodologies used to allocate items to our business operating segments as described in Note 26 in our 2022 Form 10-K.
Citizens Financial Group, Inc. | 11
The following table presents certain financial data of our business operating segments. Total business operating segment financial results differ from total consolidated financial results. These differences are reflected in Other non-segment operations. See Note 16 for additional information.
| Table 5: Selected Financial Data for Business Operating Segments | |||||||||||||||||||||||
| Consumer Banking | Commercial Banking | ||||||||||||||||||||||
| Three Months Ended March 31, | Three Months Ended March 31, | ||||||||||||||||||||||
| (dollars in millions) | 2023 | 2022 | 2023 | 2022 | |||||||||||||||||||
| Net interest income | $1,096 | $857 | $597 | $416 | |||||||||||||||||||
| Noninterest income | 256 | 257 | 201 | 213 | |||||||||||||||||||
| Total revenue | 1,352 | 1,114 | 798 | 629 | |||||||||||||||||||
| Noninterest expense | 889 | 784 | 331 | 272 | |||||||||||||||||||
| Profit before credit losses | 463 | 330 | 467 | 357 | |||||||||||||||||||
| Net charge-offs | 83 | 49 | 47 | 12 | |||||||||||||||||||
| Income before income tax expense | 380 | 281 | 420 | 345 | |||||||||||||||||||
| Income tax expense | 99 | 72 | 101 | 74 | |||||||||||||||||||
| Net income | $281 | $209 | $319 | $271 | |||||||||||||||||||
| Average Balances: | |||||||||||||||||||||||
| Total assets | $87,558 | $77,551 | $78,891 | $61,118 | |||||||||||||||||||
| Total loans and leases(1) | 81,190 | 73,233 | 75,734 | 58,007 | |||||||||||||||||||
| Deposits | 115,578 | 104,663 | 48,966 | 44,520 | |||||||||||||||||||
| Interest-earning assets | 81,871 | 74,052 | 76,130 | 58,312 |
(1) Includes LHFS.
Consumer Banking
Net interest income increased $239 million, or 28%, for the three months ended March 31, 2023, compared to the same period in 2022, driven by higher net interest margin and growth in average interest-earning assets, including the impacts of the HSBC transaction and Investors acquisition, partially offset by higher funding costs. Average loans increased $8.0 billion, or 11%, for the same period, reflecting the impacts of the HSBC transaction and Investors acquisition, as well as growth in home equity and mortgage, partially offset by planned runoff in auto. Average deposits increased $10.9 billion, or 10%, for the same period, reflecting the impacts of the HSBC transaction and Investors acquisition.
Noninterest income decreased $1 million for the three months ended March 31, 2023, compared to the same period in 2022, driven by a decline in mortgage banking fees reflecting lower production volumes, partially offset by improved gain-on-sale margins and higher servicing revenue, and service charges and fees given the elimination of non-sufficient funds fees. These decreases were partially offset by higher card fees given higher transactions volumes and higher trust and investment services fees reflecting increased investment sales, partially offset by lower fees on assets under management.
Noninterest expense increased $105 million, or 13%, for the three months ended March 31, 2023, compared to the same period in 2022, driven primarily by acquisition and integration-related costs, and higher other operating expense associated with FDIC insurance and fraud losses, partially offset by the benefit of efficiency initiatives.
Net charge-offs increased $34 million, or 69%, for the three months ended March 31, 2023, compared to the same period in 2022, driven by other retail, auto and home equity as credit losses continue to gradually normalize off pandemic-era lows.
Commercial Banking
Net interest income increased $181 million, or 44%, for the three months ended March 31, 2023, compared to the same period in 2022, reflecting higher net interest margin and growth in average interest-earning assets, including the impact of the Investors acquisition. The increase in net interest margin reflects higher interest-earning asset yields given higher market interest rates and interest-earning asset growth, partially offset by higher funding costs.
Citizens Financial Group, Inc. | 12
Noninterest income decreased $12 million, or 6%, for the three months ended March 31, 2023, compared to the same period in 2022, driven by a decline in capital markets fees reflecting lower syndication fees, partially offset by higher mergers and acquisitions advisory, and underwriting fees, and other income reflecting higher derivative expense associated with hedging customer risk given wider spreads. These decreases were partially offset by higher service charges and fees reflecting the benefit of acquisitions and improvement in Treasury Solutions fees and higher card fees given higher transaction volumes.
Noninterest expense increased $59 million, or 22%, for the three months ended March 31, 2023, compared to the same period in 2022, driven primarily by acquisition and integration-related costs, and higher other operating expense associated with FDIC insurance, partially offset by the benefit of efficiency initiatives.
Net charge-offs increased $35 million for the three months ended March 31, 2023, compared to the same period in 2022, as credit losses continue to gradually normalize off pandemic-era lows.
ANALYSIS OF FINANCIAL CONDITION
Securities
| Table 6: Amortized Cost and Fair Value of AFS and HTM Securities | |||||||||||||||||||||||||||||||||||
| March 31, 2023 | December 31, 2022 | ||||||||||||||||||||||||||||||||||
| (dollars in millions) | Amortized Cost | Fair Value | Amortized Cost | Fair Value | |||||||||||||||||||||||||||||||
| U.S. Treasury and other | $3,378 | $3,252 | $3,678 | $3,486 | |||||||||||||||||||||||||||||||
| State and political subdivisions | 2 | 2 | 2 | 2 | |||||||||||||||||||||||||||||||
| Mortgage-backed securities: | |||||||||||||||||||||||||||||||||||
| Federal agencies and U.S. government sponsored entities | 20,957 | 19,125 | 21,250 | 19,062 | |||||||||||||||||||||||||||||||
| Other/non-agency | 280 | 251 | 280 | 251 | |||||||||||||||||||||||||||||||
| Total mortgage-backed securities | 21,237 | 19,376 | 21,530 | 19,313 | |||||||||||||||||||||||||||||||
| Collateralized loan obligations | 1,248 | 1,215 | 1,248 | 1,206 | |||||||||||||||||||||||||||||||
| Total debt securities available for sale | $25,865 | $23,845 | $26,458 | $24,007 | |||||||||||||||||||||||||||||||
| Mortgage-backed securities: | |||||||||||||||||||||||||||||||||||
| Federal agencies and U.S. government sponsored entities | $9,125 | $8,540 | $9,253 | $8,506 | |||||||||||||||||||||||||||||||
| Total mortgage-backed securities | 9,125 | 8,540 | 9,253 | 8,506 | |||||||||||||||||||||||||||||||
| Asset-backed securities | 552 | 524 | 581 | 536 | |||||||||||||||||||||||||||||||
| Total debt securities held to maturity | $9,677 | $9,064 | $9,834 | $9,042 | |||||||||||||||||||||||||||||||
| Total debt securities available for sale and held to maturity | $35,542 | $32,909 | $36,292 | $33,049 | |||||||||||||||||||||||||||||||
| Equity securities (at cost) | $1,228 | $1,228 | $1,058 | $1,058 | |||||||||||||||||||||||||||||||
| Equity securities (at fair value) | 143 | 143 | 153 | 153 | |||||||||||||||||||||||||||||||
The primary objective of the securities portfolio is to provide a ready source of liquidity and is an effective mitigant of interest rate risk. The portfolio primarily includes high-quality, highly-liquid investments reflecting our ongoing commitment to maintain strong contingent liquidity levels and pledging capacity. The amount by which amortized cost exceeded fair value improved by approximately $600 million from $3.2 billion at December 31, 2022, to $2.6 billion at March 31, 2023.
As of March 31, 2023, U.S. Treasury, GNMA and GSE-issued mortgage-backed securities represent 94% of the fair value of our debt securities portfolio holdings, with approximately $27.3 billion in fair value of unencumbered high-quality liquid securities serving as potential collateral for borrowings from the FHLB, FRB discount window, the Fixed Income Clearing Corporation bilateral repurchase agreement market, and the Bank Term Funding Program. Under the Bank Term Funding Program, securities are pledged at par value instead of fair value.
For further discussion of the use of our securities as liquidity collateral see the “Liquidity Risk Management and Governance” section in this document. For further discussion of liquidity requirements, see “Regulation and Supervision — Liquidity Requirements” in our 2022 Form 10-K.
We manage our securities portfolio duration and convexity risk through asset selection and securities structure, and maintain duration levels within our risk appetite in the context of the broader interest rate risk
Citizens Financial Group, Inc. | 13
framework and limits. As of March 31, 2023 and December 31, 2022, the portfolio’s average effective duration remained stable at 5.8 years.
Loans and Leases
| Table 7: Composition of Loans and Leases, Excluding LHFS | |||||||||||||||||||||||
| (dollars in millions) | March 31, 2023 | December 31, 2022 | Change | Percent | |||||||||||||||||||
| Commercial and industrial | $50,450 | $51,836 | ($1,386) | (3) | % | ||||||||||||||||||
| Commercial real estate | 28,999 | 28,865 | 134 | — | |||||||||||||||||||
| Leases | 1,417 | 1,479 | (62) | (4) | |||||||||||||||||||
| Total commercial | 80,866 | 82,180 | (1,314) | (2) | |||||||||||||||||||
| Residential mortgages | 30,362 | 29,921 | 441 | 1 | |||||||||||||||||||
| Home equity | 14,135 | 14,043 | 92 | 1 | |||||||||||||||||||
| Automobile | 11,535 | 12,292 | (757) | (6) | |||||||||||||||||||
| Education | 12,634 | 12,808 | (174) | (1) | |||||||||||||||||||
| Other retail | 5,156 | 5,418 | (262) | (5) | |||||||||||||||||||
| Total retail | 73,822 | 74,482 | (660) | (1) | |||||||||||||||||||
| Total loans and leases | $154,688 | $156,662 | ($1,974) | (1) | % |
Total loans and leases as of March 31, 2023 decreased compared to December 31, 2022, reflecting a $1.3 billion decrease in commercial given loan sales as part of balance sheet optimization actions and reduced line utilization by companies in anticipation of a softer economic environment, and a $660 million decrease in retail, given planned runoff in auto, partially offset by growth in mortgage and home equity.
Allowance for Credit Losses and Nonaccrual Loans and Leases
The ACL is a reserve to absorb estimated future credit losses in accordance with GAAP. For additional information regarding the ACL, see “Critical Accounting Estimates — Allowance for Credit Losses” and Note 4 of this report, and “Critical Accounting Estimates — Allowance for Credit Losses” and Note 6 in our 2022 Form 10-K.
The ACL of $2.3 billion at March 31, 2023 compared with an ACL of $2.2 billion as of December 31, 2022, reflecting a reserve increase of $35 million. For further information see Note 4.
| Table 8: ACL and Related Coverage Ratios by Portfolio | |||||||||||||||||||||||
| March 31, 2023 | December 31, 2022 | ||||||||||||||||||||||
| (dollars in millions) | Loans and Leases | Allowance | Coverage | Loans and Leases | Allowance | Coverage | |||||||||||||||||
| Allowance for Loan and Lease Losses | |||||||||||||||||||||||
| Commercial and industrial | $50,450 | $601 | 1.19 | % | $51,836 | $581 | 1.12 | % | |||||||||||||||
| Commercial real estate | 28,999 | 486 | 1.67 | 28,865 | 456 | 1.58 | |||||||||||||||||
| Leases | 1,417 | 24 | 1.72 | 1,479 | 23 | 1.59 | |||||||||||||||||
| Total commercial | 80,866 | 1,111 | 1.37 | 82,180 | 1,060 | 1.29 | |||||||||||||||||
| Residential mortgages | 30,362 | 207 | 0.68 | 29,921 | 207 | 0.69 | |||||||||||||||||
| Home equity | 14,135 | 95 | 0.67 | 14,043 | 89 | 0.63 | |||||||||||||||||
| Automobile | 11,535 | 121 | 1.05 | 12,292 | 131 | 1.07 | |||||||||||||||||
| Education | 12,634 | 266 | 2.11 | 12,808 | 268 | 2.09 | |||||||||||||||||
| Other retail | 5,156 | 217 | 4.22 | 5,418 | 228 | 4.21 | |||||||||||||||||
| Total retail | 73,822 | 906 | 1.23 | 74,482 | 923 | 1.24 | |||||||||||||||||
| Total loans and leases | $154,688 | $2,017 | 1.30 | % | $156,662 | $1,983 | 1.27 | % | |||||||||||||||
| Allowance for Unfunded Lending Commitments | |||||||||||||||||||||||
| Commercial(1) | $215 | 1.64 | % | $207 | 1.54 | % | |||||||||||||||||
| Retail(2) | 43 | 1.29 | 50 | 1.31 | |||||||||||||||||||
| Total allowance for unfunded lending commitments | 258 | 257 | |||||||||||||||||||||
| Allowance for credit losses | $154,688 | $2,275 | 1.47 | % | $156,662 | $2,240 | 1.43 | % |
(1) Coverage ratio includes total commercial allowance for unfunded lending commitments and total commercial allowance for loan and lease losses in the numerator and total commercial loans and leases in the denominator.
(2) Coverage ratio includes total retail allowance for unfunded lending commitments and total retail allowance for loan losses in the numerator and total retail loans in the denominator.
Citizens Financial Group, Inc. | 14
| Table 9: Nonaccrual Loans and Leases | |||||||||||||||||||||||
| (dollars in millions) | March 31, 2023 | December 31, 2022 | Change | Percent | |||||||||||||||||||
| Commercial and industrial | $297 | $249 | $48 | 19 | % | ||||||||||||||||||
| Commercial real estate | 140 | 103 | 37 | 36 | |||||||||||||||||||
| Leases | — | — | — | — | |||||||||||||||||||
| Total commercial | 437 | 352 | 85 | 24 | |||||||||||||||||||
| Residential mortgages | 216 | 234 | (18) | (8) | |||||||||||||||||||
| Home equity | 240 | 241 | (1) | — | |||||||||||||||||||
| Automobile | 50 | 56 | (6) | (11) | |||||||||||||||||||
| Education | 23 | 33 | (10) | (30) | |||||||||||||||||||
| Other retail | 30 | 28 | 2 | 7 | |||||||||||||||||||
| Total retail | 559 | 592 | (33) | (6) | |||||||||||||||||||
| Nonaccrual loans and leases | $996 | $944 | $52 | 6 | % | ||||||||||||||||||
| Nonaccrual loans and leases to total loans and leases | 0.64 | % | 0.60 | % | 4 | bps | |||||||||||||||||
| Allowance for loan and lease losses to nonaccrual loans and leases | 203 | % | 210 | % | (7 | %) | |||||||||||||||||
| Allowance for credit losses to nonaccrual loans and leases | 229 | % | 237 | % | (8 | %) |
| Table 10: Ratio of Net Charge-Offs to Average Loans and Leases | |||||||||||||||||||||||
| Three Months Ended March 31, | |||||||||||||||||||||||
| 2023 | 2022 | ||||||||||||||||||||||
| (dollars in millions) | Net Charge-Offs | Average Balance | Ratio | Net Charge-Offs | Average Balance | Ratio | |||||||||||||||||
| Commercial and industrial | $52 | $51,993 | 0.40 | % | $11 | $44,947 | 0.10 | % | |||||||||||||||
| Commercial real estate | 3 | 28,892 | 0.05 | — | 14,066 | — | |||||||||||||||||
| Leases | (3) | 1,436 | (0.85) | — | 1,560 | 0.10 | |||||||||||||||||
| Total commercial | 52 | 82,321 | 0.26 | 11 | 60,573 | 0.08 | |||||||||||||||||
| Residential mortgages | 1 | 30,075 | 0.01 | — | 23,461 | — | |||||||||||||||||
| Home equity | (3) | 14,073 | (0.07) | (9) | 12,124 | (0.32) | |||||||||||||||||
| Automobile | 15 | 11,937 | 0.51 | 6 | 14,534 | 0.18 | |||||||||||||||||
| Education | 18 | 12,796 | 0.57 | 16 | 13,034 | 0.49 | |||||||||||||||||
| Other retail | 50 | 5,290 | 3.81 | 35 | 5,428 | 2.61 | |||||||||||||||||
| Total retail | 81 | 74,171 | 0.44 | 48 | 68,581 | 0.28 | |||||||||||||||||
| Total loans and leases | $133 | $156,492 | 0.34 | % | $59 | $129,154 | 0.19 | % |
For the three months ended March 31, 2023, the NCO ratio increased 15 basis points and net charge-offs of $133 million increased $74 million compared to the same period in 2022. The increase in net charge-offs reflects a $33 million increase in retail, primarily other retail, auto and home equity, and a $41 million increase in commercial as credit losses continue to gradually normalize off pandemic-era lows.
Commercial Loan Asset Quality
Our commercial portfolio consists of traditional commercial and industrial loans, commercial leases and commercial real estate loans. As discussed in our 2022 Form 10-K, we utilize regulatory classification ratings to monitor credit quality for commercial loans and leases.
Total commercial criticized balances of $7.4 billion at March 31, 2023 increased $1.9 billion compared with December 31, 2022.
Commercial and industrial criticized balances of $3.6 billion at March 31, 2023, increased from $3.1 billion at December 31, 2022, primarily driven by the impact of increasing interest rates and certain sector-specific employment and reimbursement challenges in Healthcare and Social Assistance.
Commercial real estate criticized balances of $3.7 billion increased from $2.4 billion at December 31, 2022, primarily driven by the combined impacts of interest rates and return-to-office dynamics on the Office sector and the impacts of interest rates on the Multi-family sector. In the general office commercial real estate sector, approximately 24% of the $4.1 billion in balances are criticized at March 31, 2023.
Citizens Financial Group, Inc. | 15
| Table 11: Commercial Loans and Leases | |||||||||||||||||
| March 31, 2023 | December 31, 2022 | ||||||||||||||||
| (dollars in millions) | Balance | % of Total Loans and Leases | Balance | % of Total Loans and Leases | |||||||||||||
| Sector | |||||||||||||||||
| Finance and insurance | |||||||||||||||||
| Capital call facilities | $6,507 | 4 | % | $6,753 | 4 | % | |||||||||||
| Other | 5,815 | 4 | 5,310 | 3 | |||||||||||||
| Other manufacturing | 4,325 | 3 | 4,474 | 3 | |||||||||||||
| Technology | 4,211 | 3 | 4,367 | 3 | |||||||||||||
| Accommodation and food services | 3,440 | 2 | 3,572 | 2 | |||||||||||||
| Health, pharma, and social assistance | 3,061 | 2 | 3,056 | 2 | |||||||||||||
| Professional, scientific, and technical services | 2,839 | 2 | 3,067 | 2 | |||||||||||||
| Wholesale trade | 2,817 | 2 | 2,955 | 2 | |||||||||||||
| Retail trade | 2,345 | 1 | 2,391 | 2 | |||||||||||||
| Other services | 2,516 | 2 | 2,713 | 2 | |||||||||||||
| Energy and related | 2,076 | 1 | 2,299 | 1 | |||||||||||||
| Real estate and rental and leasing | 1,586 | 1 | 1,542 | 1 | |||||||||||||
| Consumer products manufacturing | 1,428 | 1 | 1,511 | 1 | |||||||||||||
| Administrative and waste management services | 1,733 | 1 | 1,710 | 1 | |||||||||||||
| Arts, entertainment, and recreation | 1,550 | 1 | 1,587 | 1 | |||||||||||||
| Automotive | 1,260 | 1 | 1,316 | 1 | |||||||||||||
| All other(1) | 2,941 | 2 | 3,091 | 2 | |||||||||||||
| Total commercial and industrial | 50,450 | 33 | 51,715 | 33 | |||||||||||||
| Property type | |||||||||||||||||
| Multi-family | 8,612 | 6 | 8,696 | 6 | |||||||||||||
| Office | 6,282 | 4 | 6,253 | 4 | |||||||||||||
| Retail | 3,476 | 2 | 3,208 | 2 | |||||||||||||
| Industrial | 3,554 | 2 | 3,344 | 2 | |||||||||||||
| Co-op | 1,859 | 1 | 1,824 | 1 | |||||||||||||
| Data centers | 808 | 1 | 870 | 1 | |||||||||||||
| Hospitality | 656 | — | 638 | — | |||||||||||||
| All other(1) | 3,752 | 2 | 4,032 | 2 | |||||||||||||
| Total commercial real estate | 28,999 | 18 | 28,865 | 18 | |||||||||||||
| Total leases | 1,417 | 1 | 1,479 | 1 | |||||||||||||
| Total commercial(2) | $80,866 | 52 | % | $82,059 | 52 | % |
(1) Includes deferred fees and costs.
(2) Excludes PPP loans of $121 million as of December 31, 2022.
Retail Loan Asset Quality
We utilize credit scores provided by FICO, which are generally refreshed on a quarterly basis, and payment and delinquency status, among other data points, to monitor credit quality for retail loans. Management believes FICO credit scores are the strongest indicator of potential credit losses over the contractual life of the loan. These scores represent current and historical national industry-wide consumer level credit performance data, which management considers to predict a borrower’s future payment performance. The largest portion of the retail portfolio is represented by borrowers located in the New England, Mid-Atlantic and Midwest regions. However, we do lend selectively in areas outside the footprint, primarily in automobile finance and education lending.
Citizens Financial Group, Inc. | 16
| Table 12: Retail Loan Portfolio Analysis | |||||||||||||||||||||||||||||||||||
| March 31, 2023 | December 31, 2022 | ||||||||||||||||||||||||||||||||||
| Days Past Due and Accruing | Days Past Due and Accruing | ||||||||||||||||||||||||||||||||||
| Current | 30-59 | 60-89 | 90+ | Nonaccrual | Current | 30-59 | 60-89 | 90+ | Nonaccrual | ||||||||||||||||||||||||||
| Residential mortgages(1) | 97.35 | % | 0.67 | % | 0.24 | % | 1.03 | % | 0.71 | % | 97.68 | % | 0.32 | % | 0.15 | % | 1.07 | % | 0.78 | % | |||||||||||||||
| Home equity | 97.66 | 0.48 | 0.16 | — | 1.70 | 97.68 | 0.46 | 0.14 | — | 1.72 | |||||||||||||||||||||||||
| Automobile | 98.17 | 1.11 | 0.29 | — | 0.43 | 97.93 | 1.24 | 0.37 | — | 0.46 | |||||||||||||||||||||||||
| Education | 99.43 | 0.26 | 0.11 | 0.02 | 0.18 | 99.30 | 0.28 | 0.13 | 0.03 | 0.26 | |||||||||||||||||||||||||
| Other retail | 97.64 | 0.81 | 0.52 | 0.45 | 0.58 | 97.71 | 0.81 | 0.55 | 0.41 | 0.52 | |||||||||||||||||||||||||
| Total retail | 97.91 | % | 0.64 | % | 0.23 | % | 0.46 | % | 0.76 | % | 98.02 | % | 0.52 | % | 0.21 | % | 0.46 | % | 0.79 | % |
(1) 90+ days past due and accruing includes $309 million and $316 million of loans fully or partially guaranteed by the FHA, VA, and USDA at March 31, 2023 and December 31, 2022, respectively.
| Table 13: Retail Asset Quality Metrics | |||||||||||
| March 31, 2023 | December 31, 2022 | ||||||||||
| Average refreshed FICO for total portfolio | 771 | 770 | |||||||||
| CLTV ratio for secured real estate(1) | 51 | % | 50 | % |
(1) The real estate secured portfolio CLTV is calculated as the mortgage and second lien loan balance divided by the most recently available value of the property.
For more information on the aging of accruing and nonaccrual retail loans, and the distribution of retail loans by vintage date and FICO score, see Note 4.
Deposits
| Table 14: Composition of Deposits | |||||||||||||||||||||||||||||
| (dollars in millions) | March 31, 2023 | % of Total Deposits | December 31, 2022 | % of Total Deposits | |||||||||||||||||||||||||
| Demand | $44,326 | 26 | % | $49,283 | 27 | % | |||||||||||||||||||||||
| Money market | 48,905 | 28 | 49,905 | 28 | |||||||||||||||||||||||||
| Checking with interest | 34,496 | 20 | 39,721 | 22 | |||||||||||||||||||||||||
| Savings | 29,789 | 17 | 29,805 | 16 | |||||||||||||||||||||||||
| Term | 14,678 | 9 | 12,010 | 7 | |||||||||||||||||||||||||
| Total deposits | $172,194 | 100 | % | $180,724 | 100 | % |
Total deposits as of March 31, 2023 decreased compared to December 31, 2022, driven by seasonal and rate-related outflows.
| Table 15: Insured/Secured Deposits | |||||
| (dollars in millions) | March 31, 2023 | ||||
| Total deposits | $172,194 | ||||
| Estimated uninsured deposits(1) | 78,395 | ||||
| Less: Uninsured affiliate deposits eliminated in consolidation | 15,406 | ||||
| Less: Secured deposits(1) | 8,344 | ||||
| CFG adjusted uninsured, excluding secured deposits | 54,645 | ||||
| Total estimated insured/secured deposits | $117,549 | ||||
| Insured/secured deposits to total deposits | 68 | % |
(1) As reported on CBNA’s 3/31/23 Call Report.
Estimated CFG insured/secured deposits totaled $117.5 billion, comprised of $109.2 billion of insured deposits and $8.3 billion of collateralized preferred deposits from states and municipalities, making up 68% of our consolidated deposit base of $172.2 billion as of March 31, 2023.
Citizens Financial Group, Inc. | 17
| Table 16: Term Deposits in Excess of the FDIC Insurance Limit by Remaining Maturity | |||||
| (dollars in millions) | March 31, 2023 | ||||
| Three months or less | $793 | ||||
| After three months through six months | 39 | ||||
| After six months through twelve months | 422 | ||||
| After twelve months | 25 | ||||
| Total term deposits(1) | $1,279 |
(1) Includes term deposits per account in excess of $250,000.
Borrowed Funds
Total borrowed funds of $19.9 billion as of March 31, 2023 increased $4.0 billion compared to December 31, 2022, primarily driven by an increase in FHLB advances. For more information regarding our borrowed funds, see “Liquidity” and Note 7.
CAPITAL AND REGULATORY MATTERS
As a bank holding company and financial holding company, we are subject to regulation and supervision by the FRB. Our banking subsidiary, CBNA, is a national banking association primarily regulated by the OCC. Our regulation and supervision continues to evolve as the legal and regulatory frameworks governing our operations continue to change.
Capital Adequacy Process
Our assessment of capital adequacy begins with our Board-approved risk appetite and risk management framework. This framework provides for the identification, measurement and management of material risks. There have been no significant changes to our capital adequacy risk appetite and risk management framework as described in “Capital and Regulatory Matters” in our 2022 Form 10-K.
The FRB regularly supervises and evaluates our capital adequacy and capital planning processes, including the submission of an annual capital plan approved by our Board of Directors or one of its committees. Under the FRB’s Tailoring Rules, Category IV firms, such as us, are subject to biennial supervisory stress testing in even-numbered years. To incorporate the effects of the Investors acquisition on our capital requirements, the FRB is requiring that we participate in the 2023 CCAR supervisory stress test.
Under the SCB framework, firms must maintain capital ratios above the sum of its minimum and SCB requirements to avoid restrictions on capital distributions and discretionary bonus payments. Our SCB will be re-calibrated with each biennial supervisory stress test and updated annually to reflect our planned common stock dividends. Our SCB associated with the 2022 supervisory stress test is 3.4%, effective until September 30, 2023. We submitted our 2023 Capital Plan to the FRB on April 4, 2023 and expect the FRB to provide us with our preliminary SCB requirement in June and our final SCB requirement by August 31, 2023. The final SCB requirement will become effective on October 1, 2023 and will remain in effect until September 30, 2024.
Regulations relating to capital planning, regulatory reporting, stress testing and capital buffer requirements applicable to firms like us are presently subject to rule-making and potential further guidance and interpretation by the applicable federal regulators. We will continue to evaluate the impact of these and any other prudential regulatory changes, including their potential resultant changes in our regulatory and compliance costs and expenses.
For more information on our capital adequacy process, see the “Regulation and Supervision”, “Capital and Regulatory Matters” and “Tailoring of Prudential Requirements” sections in our 2022 Form 10-K.
Regulatory Capital Ratios and Capital Composition
Under the current U.S. Basel III capital framework, we and our banking subsidiary, CBNA, must meet the following specific minimum requirements: CET1 capital ratio of 4.5%, tier 1 capital ratio of 6.0%, total capital ratio of 8.0% and tier 1 leverage ratio of 4.0%. As a bank holding company, our SCB of 3.4% is imposed on top of the three minimum risk-based capital ratios listed above and a CCB of 2.5% is imposed on top of the three minimum risk-based capital ratios listed above for CBNA.
Citizens Financial Group, Inc. | 18
For additional discussion of the U.S. Basel III capital framework and its related application, see “Regulation and Supervision” in our 2022 Form 10-K. The table below presents our regulatory capital ratios under the U.S. Basel III Standardized rules:
| Table 17: Regulatory Capital Ratios Under the U.S. Basel III Standardized Rules | ||||||||||||||||||||
| March 31, 2023 | December 31, 2022 | Required Minimum Capital Ratios**(1)** | ||||||||||||||||||
| (dollars in millions) | Amount | Ratio | Amount | Ratio | ||||||||||||||||
| CET1 capital | $18,370 | 10.0 | % | $18,574 | 10.0 | % | 7.9 | % | ||||||||||||
| Tier 1 capital | 20,384 | 11.1 | 20,588 | 11.1 | 9.4 | |||||||||||||||
| Total capital | 23,720 | 12.9 | 23,755 | 12.8 | 11.4 | |||||||||||||||
| Tier 1 leverage | 20,384 | 9.4 | 20,588 | 9.3 | 4.0 | |||||||||||||||
| Risk-weighted assets | 183,246 | 185,224 | ||||||||||||||||||
| Quarterly adjusted average assets(2) | 217,998 | 220,779 |
(1) Represents minimum requirement under the current capital framework plus the SCB of 3.4%. The SCB is not applicable to the Tier 1 leverage ratio.
(2) Represents total average assets less certain amounts deducted from Tier 1 capital.
At March 31, 2023, our CET1 and tier 1 capital ratios were flat compared to December 31, 2022. Net income and a $2.0 billion decrease in RWA driven by a decline in commercial and auto loans, was offset by dividends, common share repurchases and a decrease in the modified CECL transition amount as we entered the second year of the CECL three-year transition period. A slight increase in the total capital ratio was driven by an increase in the modified AACL transition amount. At March 31, 2023, our CET1, tier 1 and total capital ratios were approximately 210, 170 and 150 bps, respectively, above their required minimums.
At March 31, 2023, our tier 1 leverage ratio increased slightly compared to December 31, 2022, driven by a decline in quarterly adjusted average assets of $2.8 billion, partially offset by lower tier 1 capital.
| Table 18: Capital Composition Under the U.S. Basel III Capital Framework | |||||||||||
| (dollars in millions) | March 31, 2023 | December 31, 2022 | |||||||||
| Total common stockholders' equity | $22,187 | $21,676 | |||||||||
| Exclusions: | |||||||||||
| Modified CECL transitional amount | 192 | 288 | |||||||||
| Net unrealized (gains)/losses recorded in accumulated other comprehensive income (loss), net of tax: | |||||||||||
| Debt securities | 2,424 | 2,771 | |||||||||
| Derivatives | 1,149 | 1,416 | |||||||||
| Unamortized net periodic benefit costs | 370 | 373 | |||||||||
| Deductions: | |||||||||||
| Goodwill, net of deferred tax liability | (7,783) | (7,780) | |||||||||
| Other intangible assets, net of deferred tax liability | (159) | (170) | |||||||||
| Deferred tax assets that arise from tax loss and credit carryforwards | (10) | — | |||||||||
| Total common equity tier 1 capital | 18,370 | 18,574 | |||||||||
| Qualifying preferred stock | 2,014 | 2,014 | |||||||||
| Total tier 1 capital | 20,384 | 20,588 | |||||||||
| Qualifying subordinated debt(1) | 1,429 | 1,427 | |||||||||
| Allowance for credit losses | 2,275 | 2,240 | |||||||||
| Exclusions from tier 2 capital: | |||||||||||
| Modified AACL transitional amount | (249) | (374) | |||||||||
| Allowance on PCD assets | (119) | (126) | |||||||||
| Adjusted allowance for credit losses | 1,907 | 1,740 | |||||||||
| Total capital | $23,720 | $23,755 |
(1) As of March 31, 2023 and December 31, 2022, the amount of non-qualifying subordinated debt excluded from regulatory capital was $367 million. See Note 7 for more details on our outstanding subordinated debt.
Citizens Financial Group, Inc. | 19
Capital Transactions
We completed the following capital transactions during the first quarter of 2023:
-
Repurchased $400 million of our outstanding common stock;
-
Declared and paid quarterly common stock dividends of $0.42 per share, aggregating to $205 million; and
-
Declared and paid preferred stock dividends aggregating to $23 million and $33 million, respectively.
For additional detail regarding our common and preferred stock dividends see Note 10.
In February 2023, our Board of Directors increased our common share repurchase authorization to $2.0 billion, which was an increase of $1.15 billion above the $850 million of capacity remaining as of December 31, 2022 under the prior June 2022 authorization. All future capital distributions are subject to consideration and approval by our Board of Directors prior to execution. The timing and amount of future dividends and share repurchases will depend on various factors, including our capital position, financial performance, capital impacts of strategic initiatives, market conditions, receipt of required regulatory approvals and other regulatory considerations.
Banking Subsidiary’s Capital
| Table 19: CBNA's Capital Ratios Under the U.S. Basel III Standardized Rules | ||||||||||||||||||||
| March 31, 2023 | December 31, 2022 | Required Minimum Capital Ratios**(1)** | ||||||||||||||||||
| (dollars in millions) | Amount | Ratio | Amount | Ratio | ||||||||||||||||
| CET1 capital | $20,233 | 11.1 | % | $20,669 | 11.2 | % | 7.0 | % | ||||||||||||
| Tier 1 capital | 20,233 | 11.1 | 20,669 | 11.2 | 8.5 | |||||||||||||||
| Total capital | 23,265 | 12.7 | 23,534 | 12.7 | 10.5 | |||||||||||||||
| Tier 1 leverage | 20,233 | 9.3 | 20,669 | 9.4 | 4.0 | |||||||||||||||
| Risk-weighted assets | 182,794 | 184,781 | ||||||||||||||||||
| Quarterly adjusted average assets(2) | 217,371 | 220,182 |
(1) Represents minimum requirement under the current capital framework plus the CCB of 2.5%. The CCB is not applicable to the Tier 1 leverage ratio.
(2) Represents total average assets less certain amounts deducted from Tier 1 capital.
At March 31, 2023, CBNA’s CET1 and tier 1 capital ratios decreased slightly compared to December 31, 2022, driven by a dividend payment to the Parent Company and a decrease in the modified CECL transition amount as we entered the second year of the CECL three-year transition period, partially offset by net income and a $2.0 billion decrease in RWA, primarily driven by a decline in commercial and auto loans. CBNA’s total capital ratio was flat compared to December 31, 2022. At March 31, 2023, CBNA’s CET1, tier 1 and total capital ratios were approximately 410, 260 and 220 bps, respectively, above their required minimums.
At March 31, 2023, CBNA’s tier 1 leverage ratio decreased slightly compared to December 31, 2022, driven by lower tier 1 capital, partially offset by a decline in quarterly adjusted average assets of $2.8 billion.
Citizens Financial Group, Inc. | 20
Potential Regulatory Agency Action Considerations
Given recent U.S. bank failures, regulatory agencies are considering a range of potential changes to capital, liquidity, and other prudential standard-related requirements.
AOCI from Securities Impact on Regulatory Capital
Under the applicable regulatory capital rules we have made the AOCI opt-out election, which enables us to exclude all components of AOCI from regulatory capital. The following table presents the impact of AOCI from securities on our regulatory capital ratios, which we believe provides useful information.
| Table 20: AOCI from Securities Impact on Regulatory Capital | |||||||||||||||||||||||
| March 31, 2023 | |||||||||||||||||||||||
| CFG | CBNA | ||||||||||||||||||||||
| (dollars in millions) | CET1 | Tier 1 | Total | CET1 | Tier 1 | Total | |||||||||||||||||
| Regulatory capital, including AOCI impact from securities: | |||||||||||||||||||||||
| Regulatory capital (as reported) | $18,370 | $20,384 | $23,720 | $20,233 | $20,233 | $23,265 | |||||||||||||||||
| Unrealized gains (losses) on securities | (2,424) | (2,424) | (2,424) | (2,424) | (2,424) | (2,424) | |||||||||||||||||
| Deferred tax assets - securities AOCI | (18) | (18) | (18) | (18) | (18) | (18) | |||||||||||||||||
| Regulatory capital, including AOCI impact from securities (non-GAAP) | $15,928 | $17,942 | $21,278 | $17,791 | $17,791 | $20,823 | |||||||||||||||||
| Risk-weighted assets, including AOCI impact from securities: | |||||||||||||||||||||||
| Risk-weighted assets (as reported) | $183,246 | $183,246 | $183,246 | $182,794 | $182,794 | $182,794 | |||||||||||||||||
| Unrealized gains (losses) on securities | (428) | (428) | (428) | (428) | (428) | (428) | |||||||||||||||||
| Deferred tax assets - securities AOCI | 1,969 | 1,969 | 1,969 | 1,969 | 1,969 | 1,969 | |||||||||||||||||
| Risk-weighted assets, including AOCI impact from securities (non-GAAP) | $184,787 | $184,787 | $184,787 | $184,335 | $184,335 | $184,335 | |||||||||||||||||
| Ratio: | |||||||||||||||||||||||
| Regulatory capital ratio (as reported) | 10.0 | % | 11.1 | % | 12.9 | % | 11.1 | % | 11.1 | % | 12.7 | % | |||||||||||
| Regulatory capital ratio, including AOCI impact from securities (non-GAAP) | 8.6 | % | 9.7 | % | 11.5 | % | 9.7 | % | 9.7 | % | 11.3 | % |
FDIC Special Assessment
In connection with recent bank failures, the FDIC was appointed as receiver of the failed institutions and announced that, as required by the Federal Deposit Insurance Act, any losses to the Deposit Insurance Fund to support uninsured depositors would be recovered by a special assessment. Proposed FDIC rulemaking for the special assessment is expected in the near term, with the FDIC having discretion over its design and timeframe. As a result, the timing, amount and allocation of the special assessment that will ultimately be imposed on banking organizations is uncertain and its impact on our noninterest expense and results of operations may be material.
LIQUIDITY
We define liquidity as our ability to meet our cash-flow and collateral obligations in a timely manner, at a reasonable cost. As a financial institution, we must maintain operating liquidity to meet expected daily and forecasted cash-flow requirements, as well as contingent liquidity to meet unexpected (stress scenario) funding requirements. Reflecting the importance of meeting all unexpected and stress-scenario funding requirements, we identify and manage contingent liquidity, consisting of cash balances at the FRB, unencumbered high-quality liquid securities and unused FHLB borrowing capacity. Separately, we also identify and manage asset liquidity as a subset of contingent liquidity, consisting of cash balances at the FRB and unencumbered high-quality liquid securities. We consider the effective and prudent management of liquidity fundamental to our health and strength. We manage liquidity at the consolidated enterprise level and at each material legal entity.
Parent Company Liquidity
Our Parent Company’s primary sources of cash are dividends and interest received from CBNA resulting from investing in bank equity and subordinated debt as well as externally issued preferred stock, senior debt and subordinated debt. Uses of cash include the routine cash flow requirements as a bank holding company, including periodic share repurchases and payments of dividends, interest and expenses; the needs of subsidiaries, including CBNA for additional equity and, as required, its need for debt financing; and the support for extraordinary funding requirements when necessary. To the extent the Parent Company has relied on wholesale borrowings, uses also include payments of related principal and interest.
Citizens Financial Group, Inc. | 21
During the three months ended March 31, 2023 and 2022, the Parent Company declared dividends on common stock of $205 million and $165 million, respectively, and declared dividends on preferred stock of $23 million and $24 million, respectively.
During the three months ended March 31, 2023, the Parent Company repurchased $400 million of its outstanding common stock.
Our Parent Company’s cash and cash equivalents represent a source of liquidity that can be used to meet various needs and totaled $2.0 billion and $1.6 billion as of March 31, 2023 and December 31, 2022, respectively. The Parent Company’s double-leverage ratio (the combined equity investment in Parent Company subsidiaries divided by Parent Company equity) is a measure of reliance on equity cash flows from subsidiaries to fund Parent Company obligations. The Parent Company’s double-leverage ratio was 100.2% and 101.2% as of March 31, 2023 and December 31, 2022, respectively.
CBNA Liquidity
As CBNA’s primary business involves taking deposits and making loans, a key role of liquidity management is to ensure that customers have timely access to funds from deposits and for loans. Liquidity management also involves maintaining sufficient liquidity to repay wholesale borrowings, pay operating expenses and support extraordinary funding requirements when necessary. In the ordinary course of business the liquidity of CBNA is managed by matching sources and uses of cash. The primary sources of bank liquidity include deposits from our consumer and commercial customers; payments of principal and interest on loans and debt securities; and wholesale borrowings, as needed, and as described under “Liquidity Risk Management and Governance.” The primary uses of bank liquidity include withdrawals and maturities of deposits; payment of interest on deposits; funding of loans and related commitments; and funding of securities purchases. To the extent that CBNA has relied on wholesale borrowings, uses also include payments of related principal and interest. For further information on CBNA’s outstanding debt, see Note 7.
During the three months ended March 31, 2023, CBNA completed the following transactions:
-
Issued $450 million of 5.284% fixed-to-floating rate senior notes; and
-
Redeemed $750 million of senior notes due March 2023.
Liquidity Risk
We define liquidity risk as the risk that an entity will be unable to meet its payment obligations in a timely manner, at a reasonable cost. Liquidity risk can arise due to contingent liquidity risk and/or funding liquidity risk.
Contingent liquidity risk is the risk that market conditions may reduce an entity’s ability to liquidate, pledge and/or finance certain assets and thereby substantially reduce the liquidity value of such assets. Drivers of contingent liquidity risk include general market disruptions as well as specific issues regarding the credit quality and/or valuation of a security or loan, issuer or borrower and/or asset class.
Funding liquidity risk is the risk that market conditions and/or entity-specific events may reduce an entity’s ability to raise funds from depositors and/or wholesale market counterparties. Drivers of funding liquidity risk may be idiosyncratic or systemic, reflecting impediments to operations and/or damaged market confidence.
Factors Affecting Liquidity
Given the composition of assets and borrowing sources, contingent liquidity risk at CBNA would be materially affected by events such as deterioration of financing markets for high-quality securities (e.g., mortgage-backed securities and other instruments issued by GNMA, FNMA and FHLMC), by any inability of the FHLBs to provide collateralized advances and/or by a refusal of the FRB to act as a lender of last resort in systemic stress.
Similarly, the funding liquidity risk of CBNA could be materially affected by an adverse idiosyncratic event (e.g., a major loss, causing a perceived or actual deterioration in its financial condition), an adverse systemic event (e.g., default or bankruptcy of a significant capital markets participant), or a combination of both. Consequently, and despite ongoing exposure to a variety of idiosyncratic and systemic events, we view our contingent liquidity risk and our funding liquidity risk to be relatively low.
Citizens Financial Group, Inc. | 22
An additional variable affecting our access to unsecured wholesale market funds and to large denomination (i.e., uninsured) customer deposits is the credit ratings assigned by such agencies as Moody’s, Standard and Poor’s, and Fitch. Moody’s initiated coverage of CFG during the first quarter of 2023.
| Table 21: Credit Ratings | |||||||||||||||||
| March 31, 2023 | |||||||||||||||||
| Moody’s | Standard and Poor’s | Fitch | |||||||||||||||
| Citizens Financial Group, Inc.: | |||||||||||||||||
| Long-term issuer | Baa1 | BBB+ | BBB+ | ||||||||||||||
| Short-term issuer | NR | A-2 | F1 | ||||||||||||||
| Subordinated debt | Baa1 | BBB | BBB | ||||||||||||||
| Preferred Stock | Baa3 | BB+ | BB | ||||||||||||||
| Citizens Bank, National Association: | |||||||||||||||||
| Long-term issuer | Baa1 | A- | BBB+ | ||||||||||||||
| Short-term issuer | NR | A-2 | F1 | ||||||||||||||
| Long-term deposits | A1 | NR | A- | ||||||||||||||
| Short-term deposits | P-1 | NR | F1 | ||||||||||||||
| NR = Not rated |
Changes in our public credit ratings could affect both the cost and availability of our wholesale funding. As a result, and in order to maintain a conservative funding profile, CBNA continues to minimize reliance on unsecured wholesale funding. At March 31, 2023, our wholesale funding consisted primarily of term debt issued by the Parent Company and CBNA, and collateralized advances from the FHLB.
Existing and evolving regulatory liquidity requirements represent another key driver of systemic liquidity conditions and liquidity management practices. The FRB, OCC, and FDIC regularly evaluate our liquidity as part of the overall supervisory process. In addition, we are subject to existing and evolving regulatory liquidity requirements, some of which are subject to further rulemaking, guidance and interpretation by the applicable federal regulators. For further discussion, see “Regulation and Supervision — Tailoring of Prudential Requirements” and “—Liquidity Requirements” in our 2022 Form 10-K.
Liquidity Risk Management and Governance
Liquidity risk is measured and managed by the Funding and Liquidity unit within our Treasury group in accordance with policy guidelines promulgated by our Board and the Asset Liability Committee. The Funding and Liquidity unit maintains a robust liquidity management framework designed to effectively manage liquidity risk. Processes within this framework include, but are not limited to, regular and comprehensive reporting, including current levels versus threshold limits for a broad set of liquidity metrics and early warning indicators, explanatory commentary relating to emerging risk trends and, as appropriate, recommended remedial strategies, liquidity stress testing, contingency funding plans, and collateral management.
Citizens Financial Group, Inc. | 23
Our Funding and Liquidity unit’s primary goals are to deliver and maintain prudent levels of operating liquidity to support expected and projected funding requirements, contingent liquidity to support unexpected funding requirements resulting from idiosyncratic, systemic, and combination stress events, and regulatory liquidity requirements in a timely manner from stable and cost-efficient funding sources. We seek to accomplish these goals by funding loans with stable deposits, by prudently controlling dependence on wholesale funding, particularly short-term unsecured funding, and by maintaining ample available liquidity, including a contingent liquidity buffer of unencumbered high-quality loans and securities.
In response to the recent U.S. bank failures, the FRB established the Bank Term Funding Program to make additional funding available to eligible depository institutions to ensure the ability to meet the needs of all depositors. This program was designed to provide another source of liquidity against the par value of high-quality securities, eliminating the need to sell these securities during times of stress. Citizens is eligible to borrow under this program based on its existing eligibility for primary credit under the Federal Reserve discount window.
As of March 31, 2023:
- Organically generated deposits continue to be our primary source of funding, resulting in a consolidated period-end loans-to-deposits ratio, excluding LHFS, of 89.8%;
◦Estimated insured/secured deposits comprise 68% of our consolidated deposit base of $172.2 billion.
- Our total available liquidity, comprised of contingent liquidity and available discount window capacity, was approximately $66.0 billion;
◦Contingent liquidity was $40.7 billion, consisting of unencumbered high-quality liquid securities of $27.3 billion, unused FHLB capacity of $6.8 billion, and our cash balances at the FRB of $6.6 billion; and
◦Available discount window capacity was $25.3 billion, defined as available total borrowing capacity from the FRB based on identified collateral, which is primarily secured by non-mortgage commercial and retail loans.
For a summary of our sources and uses of cash by type of activity for the three months ended March 31, 2023 and 2022, see the Consolidated Statements of Cash Flows in Item 1.
The Funding and Liquidity unit monitors a variety of liquidity and funding metrics and early warning indicators and metrics, including specific risk thresholds limits. These monitoring tools are broadly classified as follows:
-
Current liquidity sources and capacities, including cash balances at the FRB, free and liquid securities, and secured FHLB borrowing capacity;
-
Liquidity stress sources, including idiosyncratic, systemic and combined stresses, in addition to evolving regulatory requirements; and
-
Current and prospective exposures, including secured and unsecured wholesale funding, and spot and cumulative cash-flow gaps across a variety of horizons.
Further, certain of these metrics are monitored individually for CBNA and for our consolidated enterprise on a daily basis, including cash position, unencumbered securities, asset liquidity and available FHLB borrowing capacity. In order to identify emerging trends and risks and inform funding decisions, specific metrics are also forecasted over a one-year horizon.
Off-Balance Sheet Arrangements
We engage in a variety of activities that are not reflected in our Consolidated Balance Sheets that are generally referred to as “off-balance sheet arrangements.” For more information on these types of activities, see Note 11.
CRITICAL ACCOUNTING ESTIMATES
Our unaudited interim Consolidated Financial Statements included in this Report are prepared in accordance with GAAP. The preparation of financial statements in conformity with GAAP requires us to establish accounting policies and make estimates that affect amounts reported in our audited Consolidated Financial Statements.
Citizens Financial Group, Inc. | 24
An accounting estimate requires assumptions and judgments about uncertain matters that could have a material effect on our unaudited interim Consolidated Financial Statements. Estimates are made using facts and circumstances known at a point in time. Changes in those facts and circumstances could produce results substantially different from those estimates. Our most significant accounting policies and estimates and their related application are discussed below. For additional information regarding fair value measurements, see “Critical Accounting Estimates” in our 2022 Form 10-K.
Allowance for Credit Losses
The ACL increased from $2.2 billion at December 31, 2022 to $2.3 billion at March 31, 2023.
Our ACL as of March 31, 2023 accounts for an economic forecast over our two-year reasonable and supportable period with peak unemployment of approximately 6% and peak-to-trough GDP decline of approximately 1%. This forecast reflects a moderate recession over the two-year reasonable and supportable period. This compares to our December 31, 2022 forecast which reflected the same unemployment rate with a slightly more adverse peak-to-trough GDP decline of approximately 1.4%.
Our determination of the ACL is sensitive to changes in forecasted macroeconomic conditions during the reasonable and supportable forecast period. To illustrate the sensitivity, we applied a more pessimistic scenario than that described above which assumes that monetary tightening triggers a deeper real GDP contraction across our two-year reasonable and supportable forecast period, resulting in a 1.7% peak-to-trough decline in real GDP. Excluding consideration of qualitative adjustments, this scenario would result in a quantitative lifetime loss estimate of approximately 1.15x our modeled period-end ACL, or an increase of approximately $275 million. This analysis relates only to the modeled credit loss estimate and not to the overall period-end ACL, which includes qualitative adjustments.
Because several quantitative and qualitative factors are considered in determining the ACL, this sensitivity analysis does not necessarily reflect the nature and extent of future changes in the ACL or even what the ACL would be under these economic circumstances. The sensitivity is intended to provide insights into the impact of adverse changes in the macroeconomic environment and the corresponding impact to modeled loss estimates. The hypothetical determination does not incorporate the impact of management judgment or other qualitative factors that could be applied in the actual estimation of the ACL and does not imply any expectation of future deterioration in our loss rates.
It remains difficult to estimate how changes in economic forecasts might affect our ACL because such forecasts consider a wide variety of variables and inputs, and changes in the variables and inputs may not occur at the same time or in the same direction, and such changes may have differing impacts by product type. The variables and inputs may be idiosyncratically affected by risks to the economy, including changing monetary and fiscal policies, impacts from the recent stress on the banking industry, and their impact on inflationary trends. Changes in one or multiple of the key macroeconomic variables may have a material impact to our estimation of expected credit losses.
For additional information regarding the ACL, see Note 4 of this report, and “Critical Accounting Estimates - Allowance for Credit Losses” and Note 6 in our 2022 Form 10-K.
RISK GOVERNANCE
We are committed to maintaining a strong, integrated, and proactive approach to the management of all risks to which we are exposed in pursuit of our business objectives. A key aspect of our Board’s responsibility as the main decision making body is setting our risk appetite to ensure that the levels of risk that we are willing to accept in the attainment of our strategic business and financial objectives are clearly understood.
To enable our Board to carry out its objectives, it has delegated authority for risk management activities, as well as governance and oversight of those activities, to a number of Board and executive management level risk committees. The Executive Risk Committee, chaired by the Chief Risk Officer, is responsible for oversight of risk across the enterprise and actively considers our inherent material risks, analyzes our overall risk profile and seeks confirmation that the risks are being appropriately identified, assessed and mitigated. Reporting to the Executive Risk Committee are the following committees covering specific areas of risk: Compliance and Operational Risk, Model Risk, Credit Policy, Asset Liability, Business Initiatives Review, and Conduct and Ethics.
There have been no significant changes in our risk governance practices, risk framework, risk appetite, or credit risk as described in “Risk Governance” in our 2022 Form 10-K.
Citizens Financial Group, Inc. | 25
MARKET RISK
Market risk refers to potential losses arising from changes in interest rates, foreign exchange rates, equity prices, commodity prices and/or other relevant market rates or prices. Modest market risk arises from trading activities that serve customer needs, including the hedging of interest rate and foreign exchange risk. As described below, more material market risk arises from our non-trading banking activities, such as the origination of loans and deposit-gathering. We have established enterprise-wide policies and methodologies to identify, measure, monitor and report market risk. We actively manage market risk for both non-trading and trading activities.
Non-Trading Risk
Our non-trading banking activities expose us to market risk. This market risk is composed of interest rate risk, as we have no commodity risk and de minimis direct currency and equity risk. We also have market risk related to capital markets loan originations, as well as the valuation of our MSRs. There have been no significant changes in our sources of interest rate risk, interest rate risk practices, risk framework, metrics or assumptions as described in “Market Risk — Non-Trading Risk” in our 2022 Form 10-K.
The table below reports net interest income exposures against a variety of interest rate scenarios. Our policies involve measuring exposures as a percentage change in net interest income over the next year due to either instantaneous or gradual parallel changes in rates relative to the market implied forward yield curve. As the following table illustrates, our balance sheet is asset-sensitive; net interest income would benefit from an increase in interest rates, while exposure to a decline in interest rates is within limits established and monitored by senior management. While an instantaneous and severe shift in interest rates is included in this analysis, we believe that any actual shift in interest rates would be more gradual and, therefore, have a more modest impact.
The table below presents the sensitivity of net interest income to various parallel yield curve shifts from the market implied forward yield curve:
| Table 22: Sensitivity of Net Interest Income | |||||||||||
| Estimated % Change in Net Interest Income over 12 Months | |||||||||||
| Basis points | March 31, 2023 | December 31, 2022 | |||||||||
| Instantaneous Change in Interest Rates | |||||||||||
| +200 | 2.5 | % | 4.8 | % | |||||||
| +100 | 1.0 | 2.4 | |||||||||
| -100 | (2.1) | (2.5) | |||||||||
| -200 | (4.8) | (5.6) | |||||||||
| Gradual Change in Interest Rates | |||||||||||
| +200 | 1.1 | % | 2.7 | % | |||||||
| +100 | 0.3 | 1.4 | |||||||||
| -100 | (1.2) | (1.4) | |||||||||
| -200 | (2.6) | (3.0) |
We continue to manage asset sensitivity within the scope of our policy, changing market conditions and changes in our balance sheet. Asset sensitivity against a 200-basis point gradual increase in rates was 1.1% on March 31, 2023, compared with 2.7% on December 31, 2022. This decrease reflects the effects of our ongoing hedge activity combined with changes in our current and projected balance sheet mix due to the higher interest rate environment. Current and projected levels of asset sensitivity minimize the effects of changes in short-term policy rates from the FRB and mitigate the impact on the Company’s net interest income and margin. Changes in interest rates can also affect risk management activities, which impact the repricing sensitivity or beta of the deposit base as well as the cash flows on assets that allow for early payoff without a penalty. The risk position is managed within our risk limits, and long-term view of interest rates through occasional adjustments to securities investments, interest rate swaps and mix of funding.
Citizens Financial Group, Inc. | 26
We use a valuation measure of exposure to structural interest rate risk, EVE, as a supplement to net interest income simulations. EVE complements net interest income simulation analysis as it estimates risk exposure over a long-term horizon. EVE measures the extent to which the economic value of assets, liabilities and off-balance sheet instruments may change in response to fluctuations in interest rates. This analysis is highly dependent upon assumptions applied to assets and liabilities with non-contractual maturities, and we employ sophisticated models for prepayments and deposit pricing and attrition, which provide a granular view of cash flows based on the unique characteristics of the underlying products and customer segments. The change in value is expressed as a percentage of regulatory capital.
We use interest rate contracts to manage the interest rate exposure to the variability in the interest cash flows on our floating-rate assets and wholesale funding, and to hedge market risk on fixed-rate capital markets debt issuances.
The following table presents interest rate derivative contracts that we have entered into as of March 31, 2023 and December 31, 2022.
| Table 23: Interest Rate Derivative Contracts Used to Manage Non-Trading Interest Rate Exposure | |||||||||||||||||||||||||||||
| March 31, 2023 | December 31, 2022 | ||||||||||||||||||||||||||||
| Weighted Average | Weighted Average | ||||||||||||||||||||||||||||
| (dollars in millions) | Notional Amount | Maturity (Years) | Receive Rate | Pay Rate | Notional Amount | Maturity (Years) | Receive Rate | Pay Rate | |||||||||||||||||||||
| Swaps - conventional ALM**(1)** | |||||||||||||||||||||||||||||
| Cash flow - receive fixed/pay variable | |||||||||||||||||||||||||||||
| Active | $9,750 | 0.5 | 1.1 | % | 1.3 | % | $15,750 | 3.9 | 1.9 | % | 4.4 | % | |||||||||||||||||
| Forward-starting(2) | 36,500 | 2.7 | 3.5 | 4.3 | 15,500 | 3.5 | 3.0 | 4.5 | |||||||||||||||||||||
| Fair value - receive fixed/pay variable | 500 | 2.6 | 2.6 | 4.9 | 1,000 | 1.6 | 2.7 | 4.7 | |||||||||||||||||||||
| Total | 46,750 | 32,250 | |||||||||||||||||||||||||||
| Forward-starting cash flow - basis swaps(3)(4) | 7,000 | 3.1 | 4.3 | 4.3 | 7,000 | 3.3 | 4.4 | 4.4 | |||||||||||||||||||||
| Total swaps | $53,750 | $39,250 | |||||||||||||||||||||||||||
| Options | |||||||||||||||||||||||||||||
| Interest rate collars(5)(6) | $1,500 | 2.6 | 2.6 | 3.9 | $1,500 | 2.8 | 2.6 | 3.9 | |||||||||||||||||||||
| Floor spread(5)(6) | 500 | 2.9 | 4.1 | 3.0 | — | — | — | — |
(1) We use interest rate contracts as part of our ALM strategy to manage exposure to the variability in the interest cash flows on our floating-rate commercial loans and wholesale funding, as well as the variability in the fair value of AFS securities.
(2) As of March 31, 2023, start dates range from the second quarter of 2023 to the fourth quarter of 2024.
(3) As of March 31, 2023, start dates range from the third quarter of 2023 to the third quarter of 2024.
(4) Receive and pay rates represent SOFR and 1-month term SOFR, respectively.
(5) Represents forward-starting interest rate options with effective dates ranging from the fourth quarter of 2023 to the second quarter of 2024.
(6) Receive and pay rates represent the minimum interest rate received for interest rate floors and the maximum interest rate paid for interest rate caps, respectively.
The following table presents the average active notional amounts for our interest rate derivatives, based on contract effective date, during the remainder of 2023 and for the next five years:
| Table 24: Schedule of Average Active Notional for Interest Rate Derivative Contracts | |||||||||||||||||||||||
| Year Ended | |||||||||||||||||||||||
| (dollars in millions) | 2023 | 2024 | 2025 | 2026 | 2027 | 2028 | |||||||||||||||||
| Swaps | |||||||||||||||||||||||
| Cash flow - receive fixed/pay variable | $20,941 | $26,477 | $27,172 | $16,112 | $5,375 | $501 | |||||||||||||||||
| Fair value - receive fixed/pay variable | 500 | 500 | 441 | — | — | — | |||||||||||||||||
| Forward-starting cash flow - basis swaps | 715 | 6,277 | 5,634 | 2,810 | 785 | — | |||||||||||||||||
| Options | |||||||||||||||||||||||
| Interest rate collars | 109 | 1,261 | 1,001 | 240 | — | — | |||||||||||||||||
| Floor spread | — | 407 | 500 | 93 | — | — | |||||||||||||||||
| Total | $22,265 | $34,922 | $34,748 | $19,255 | $6,160 | $501 | |||||||||||||||||
| Weighted average receive rate(1) | 4.2 | % | 3.2 | % | 3.1 | % | 3.2 | % | 3.2 | % | 2.8 | % | |||||||||||
| Weighted average pay rate(1) | — | — | — | — | — | — |
(1) Represents the weighted average rate relative to the fixed leg of the interest rate derivative contracts.
Citizens Financial Group, Inc. | 27
| Table 25: Pre-Tax Gains (Losses) Recorded in the Consolidated Statements of Operations and the Consolidated Statements of Comprehensive Income on Cash Flow Hedges | ||||||||||||||||||||||||||||||||
| Three Months Ended March 31, | ||||||||||||||||||||||||||||||||
| (dollars in millions) | 2023 | 2022 | ||||||||||||||||||||||||||||||
| Amount of pre-tax net gains (losses) recognized in OCI | $233 | ($661) | ||||||||||||||||||||||||||||||
| Amount of pre-tax net gains (losses) reclassified from AOCI into interest income | (127) | 37 | ||||||||||||||||||||||||||||||
| Amount of pre-tax net gains (losses) reclassified from AOCI into interest expense | — | (5) |
Using the interest rate curve at March 31, 2023 with respect to cash flow hedge strategies, we estimate that approximately $514 million in pre-tax net losses will be reclassified from AOCI to net interest income over the next 12 months, including $452 million related to terminated swaps. This amount could differ from amounts recognized due to changes in interest rates, hedge de-designations and the addition of other hedges after March 31, 2023.
LIBOR Transition
For details regarding our LIBOR Transition Program and associated efforts to plan for the discontinuation of LIBOR, see “Market Risk — LIBOR Transition” in our 2022 Form 10-K. There were no significant changes relative to the program during the three months ended March 31, 2023.
Capital Markets
A key component of our capital markets activities is the underwriting and distribution of corporate credit facilities to partially finance merger and acquisition transactions for our clients. We have a rigorous risk management process around these activities, including a limit structure capping our underwriting risk, potential loss, and sub-limits for specific asset classes. Further, the ability to approve underwriting exposure is delegated only to senior level individuals in the credit risk management and capital markets organizations with each transaction adjudicated in the Loan Underwriting Approval Committee.
Mortgage Servicing Rights
We have market risk associated with the value of residential MSRs, which are impacted by various types of inherent risks, including duration, basis, convexity, volatility and yield curve.
As part of our overall risk management strategy relative to the fair market value of the MSRs we enter into various free-standing derivatives, such as interest rate swaps, interest rate swaptions, interest rate futures and forward contracts to purchase mortgage-backed securities to economically hedge the changes in fair value. As of March 31, 2023 and December 31, 2022, the fair value of our MSRs was $1.5 billion, and the total notional amount of related derivative contracts was $19.7 billion and $12.9 billion, respectively. Gains and losses on MSRs and the related derivatives used for hedging are included in mortgage banking fees in the Consolidated Statements of Operations.
As with our traded market risk-based activities, earnings at risk excludes the impact of MSRs. MSRs are captured under our single price risk management framework that is used for calculating a management value at risk that is consistent with the definition used by banking regulators.
Trading Risk
We are exposed to market risk primarily through client facilitation activities including derivatives and foreign exchange products as well as underwriting and market making activities. Exposure is created as a result of changes in interest rates and related basis spreads and volatility, foreign exchange rates, equity prices, and credit spreads on a select range of interest rates, foreign exchange, commodities, equity securities, corporate bonds and secondary loan instruments. These securities underwriting and trading activities are conducted through CBNA, CCMI and JMP. There have been no significant changes in our market risk governance, market risk measurement, or market risk practices including VaR, stressed VaR, sensitivity analysis, stress testing, or VaR model review and validation as described in “Market Risk — Trading Risk” in our 2022 Form 10-K.
Market Risk Regulatory Capital
The U.S. banking regulators’ “Market Risk Rule” covers the calculation of market risk capital. Under this rule all our client facing trades and associated hedges maintain a net low risk and qualify as “covered positions.” The internal management VaR measure is calculated based on the same population of trades that is utilized for regulatory VaR.
Citizens Financial Group, Inc. | 28
| Table 26: Results of Modeled and Non-Modeled Measures for Regulatory Capital Calculations | ||||||||||||||||||||||||||||||||||||||||||||||||||
| (dollars in millions) | For the Three Months Ended March 31, 2023 | For the Three Months Ended March 31, 2022 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Market Risk Category | Period End | Average | High | Low | Period End | Average | High | Low | ||||||||||||||||||||||||||||||||||||||||||
| Interest Rate | $2 | $3 | $4 | $2 | $1 | $2 | $6 | $— | ||||||||||||||||||||||||||||||||||||||||||
| Foreign Exchange Currency Rate | — | — | — | — | — | — | 3 | — | ||||||||||||||||||||||||||||||||||||||||||
| Credit Spread | 1 | 1 | 2 | 1 | 3 | 9 | 14 | 3 | ||||||||||||||||||||||||||||||||||||||||||
| Commodity | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||
| General VaR | 2 | 3 | 5 | 2 | 3 | 10 | 17 | 3 | ||||||||||||||||||||||||||||||||||||||||||
| Specific Risk VaR | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||
| Total VaR | $2 | $3 | $5 | $2 | $3 | $10 | $17 | $3 | ||||||||||||||||||||||||||||||||||||||||||
| Stressed General VaR | $5 | $8 | $13 | $4 | $15 | $13 | $19 | $4 | ||||||||||||||||||||||||||||||||||||||||||
| Stressed Specific Risk VaR | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||
| Total Stressed VaR | $5 | $8 | $13 | $4 | $15 | $13 | $19 | $4 | ||||||||||||||||||||||||||||||||||||||||||
| Market Risk Regulatory Capital | $32 | $67 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Specific Risk Not Modeled Add-on | 20 | 25 | ||||||||||||||||||||||||||||||||||||||||||||||||
| de Minimis Exposure Add-on | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
| Total Market Risk Regulatory Capital | $52 | $92 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Market Risk-Weighted Assets | $654 | $1,154 |
VaR Backtesting
Backtesting is one form of validation of the VaR model and is run daily. The Market Risk Rule requires a comparison of our internal VaR measure to the actual net trading revenue (excluding fees, commissions, reserves, intra-day trading and net interest income) for each day over the preceding year (the most recent 250 business days). Any observed loss in excess of the VaR number is taken as an exception. The level of exceptions determines the multiplication factor used to derive the VaR and SVaR-based capital requirement for regulatory reporting purposes, when applicable. We perform sub-portfolio backtesting as required under the Market Risk Rule, using models approved by our banking regulators for interest rate, credit spread and foreign exchange positions.
The following graph shows our daily net trading revenue and total internal, modeled VaR for the twelve months ended March 31, 2023.
Daily VaR Backtesting
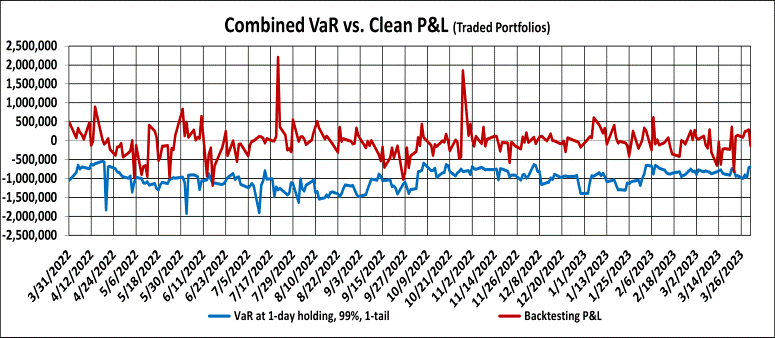
Citizens Financial Group, Inc. | 29
NON-GAAP FINANCIAL MEASURES AND RECONCILIATIONS
For more information on the computation of our non-GAAP financial measures, see “Introduction — Non-GAAP Financial Measures,” included in this Report. The following table presents computations of non-GAAP financial measures representing our “Underlying” results used in the MD&A:
| Table 27: Reconciliations of Non-GAAP Measures | ||||||||||||||||||||||||||
| As of and for the Three Months Ended March 31, | ||||||||||||||||||||||||||
| (dollars in millions, except per share data) | Ref. | 2023 | 2022 | |||||||||||||||||||||||
| Total revenue, Underlying: | ||||||||||||||||||||||||||
| Total revenue (GAAP) | C | $2,128 | $1,645 | |||||||||||||||||||||||
| Less: Notable items | — | — | ||||||||||||||||||||||||
| Total revenue, Underlying (non-GAAP) | D | $2,128 | $1,645 | |||||||||||||||||||||||
| Noninterest expense, Underlying: | ||||||||||||||||||||||||||
| Noninterest expense (GAAP) | E | $1,296 | $1,106 | |||||||||||||||||||||||
| Less: Notable items | 66 | 48 | ||||||||||||||||||||||||
| Noninterest expense, Underlying (non-GAAP) | F | $1,230 | $1,058 | |||||||||||||||||||||||
| Pre-provision profit: | ||||||||||||||||||||||||||
| Total revenue (GAAP) | C | $2,128 | $1,645 | |||||||||||||||||||||||
| Less: Noninterest expense (GAAP) | E | 1,296 | 1,106 | |||||||||||||||||||||||
| Pre-provision profit (GAAP) | $832 | $539 | ||||||||||||||||||||||||
| Pre-provision profit, Underlying | ||||||||||||||||||||||||||
| Total revenue, Underlying (non-GAAP) | D | $2,128 | $1,645 | |||||||||||||||||||||||
| Less: Noninterest expense, Underlying (non-GAAP) | F | 1,230 | 1,058 | |||||||||||||||||||||||
| Pre-provision profit, Underlying (non-GAAP) | $898 | $587 | ||||||||||||||||||||||||
| Provision (benefit) for credit losses, Underlying: | ||||||||||||||||||||||||||
| Provision (benefit) for credit losses (GAAP) | $168 | $3 | ||||||||||||||||||||||||
| Less: Notable items | — | 24 | ||||||||||||||||||||||||
| Provision (benefit) for credit losses, Underlying (non-GAAP) | $168 | ($21) | ||||||||||||||||||||||||
| Income before income tax expense, Underlying: | ||||||||||||||||||||||||||
| Income before income tax expense (GAAP) | G | $664 | $536 | |||||||||||||||||||||||
| Less: Income (loss) before income tax expense (benefit) related to notable items | (66) | (72) | ||||||||||||||||||||||||
| Income before income tax expense, Underlying (non-GAAP) | H | $730 | $608 | |||||||||||||||||||||||
| Income tax expense and effective income tax rate, Underlying: | ||||||||||||||||||||||||||
| Income tax expense (GAAP) | I | $153 | $116 | |||||||||||||||||||||||
| Less: Income tax expense (benefit) related to notable items | (17) | (16) | ||||||||||||||||||||||||
| Income tax expense, Underlying (non-GAAP) | J | $170 | $132 | |||||||||||||||||||||||
| Effective income tax rate (GAAP) | I/G | 22.97 | % | 21.70 | % | |||||||||||||||||||||
| Effective income tax rate, Underlying (non-GAAP) | J/H | 23.25 | 21.70 | |||||||||||||||||||||||
| Net income, Underlying: | ||||||||||||||||||||||||||
| Net income (GAAP) | K | $511 | $420 | |||||||||||||||||||||||
| Add: Notable items, net of income tax benefit | 49 | 56 | ||||||||||||||||||||||||
| Net income, Underlying (non-GAAP) | L | $560 | $476 | |||||||||||||||||||||||
| Net income available to common stockholders, Underlying: | ||||||||||||||||||||||||||
| Net income available to common stockholders (GAAP) | M | $488 | $396 | |||||||||||||||||||||||
| Add: Notable items, net of income tax benefit | 49 | 56 | ||||||||||||||||||||||||
| Net income available to common stockholders, Underlying (non-GAAP) | N | $537 | $452 | |||||||||||||||||||||||
| Return on average common equity and return on average common equity, Underlying: | ||||||||||||||||||||||||||
| Average common equity (GAAP) | O | $21,702 | $20,981 | |||||||||||||||||||||||
| Return on average common equity | M/O | 9.11 | % | 7.65 | % | |||||||||||||||||||||
| Return on average common equity, Underlying (non-GAAP) | N/O | 10.01 | 8.75 |
Citizens Financial Group, Inc. | 30
| As of and for the Three Months Ended March 31, | ||||||||||||||||||||||||||
| (dollars in millions, except per share data) | Ref. | 2023 | 2022 | |||||||||||||||||||||||
| Return on average tangible common equity and return on average tangible common equity, Underlying: | ||||||||||||||||||||||||||
| Average common equity (GAAP) | O | $21,702 | $20,981 | |||||||||||||||||||||||
| Less: Average goodwill (GAAP) | 8,177 | 7,156 | ||||||||||||||||||||||||
| Less: Average other intangibles (GAAP) | 192 | 80 | ||||||||||||||||||||||||
| Add: Average deferred tax liabilities related to goodwill and other intangible assets (GAAP) | 422 | 383 | ||||||||||||||||||||||||
| Average tangible common equity | P | $13,755 | $14,128 | |||||||||||||||||||||||
| Return on average tangible common equity | M/P | 14.38 | % | 11.36 | % | |||||||||||||||||||||
| Return on average tangible common equity, Underlying (non-GAAP) | N/P | 15.80 | 12.99 | |||||||||||||||||||||||
| Return on average total assets and return on average total assets, Underlying: | ||||||||||||||||||||||||||
| Average total assets (GAAP) | Q | $222,711 | $188,317 | |||||||||||||||||||||||
| Return on average total assets | K/Q | 0.93 | % | 0.90 | % | |||||||||||||||||||||
| Return on average total assets, Underlying (non-GAAP) | L/Q | 1.02 | 1.03 | |||||||||||||||||||||||
| Return on average total tangible assets and return on average total tangible assets, Underlying: | ||||||||||||||||||||||||||
| Average total assets (GAAP) | Q | $222,711 | $188,317 | |||||||||||||||||||||||
| Less: Average goodwill (GAAP) | 8,177 | 7,156 | ||||||||||||||||||||||||
| Less: Average other intangibles (GAAP) | 192 | 80 | ||||||||||||||||||||||||
| Add: Average deferred tax liabilities related to goodwill and other intangible assets (GAAP) | 422 | 383 | ||||||||||||||||||||||||
| Average tangible assets | R | $214,764 | $181,464 | |||||||||||||||||||||||
| Return on average total tangible assets | K/R | 0.97 | % | 0.94 | % | |||||||||||||||||||||
| Return on average total tangible assets, Underlying (non-GAAP) | L/R | 1.06 | 1.06 | |||||||||||||||||||||||
| Efficiency ratio and efficiency ratio, Underlying: | ||||||||||||||||||||||||||
| Efficiency ratio | E/C | 60.90 | % | 67.23 | % | |||||||||||||||||||||
| Efficiency ratio, Underlying (non-GAAP) | F/D | 57.84 | 64.28 | |||||||||||||||||||||||
| Operating leverage and operating leverage, Underlying: | ||||||||||||||||||||||||||
| Increase in total revenue | 29.39 | % | (0.85) | % | ||||||||||||||||||||||
| Increase in noninterest expense | 17.22 | 8.65 | ||||||||||||||||||||||||
| Operating leverage | 12.17 | % | (9.50) | % | ||||||||||||||||||||||
| Increase in total revenue, Underlying (non-GAAP) | 29.39 | % | (0.85) | % | ||||||||||||||||||||||
| Increase in noninterest expense, Underlying (non-GAAP) | 16.43 | 5.89 | ||||||||||||||||||||||||
| Operating leverage, Underlying (non-GAAP) | 12.96 | % | (6.74) | % | ||||||||||||||||||||||
| Tangible book value per common share: | ||||||||||||||||||||||||||
| Common shares - at period end (GAAP) | S | 483,982,264 | 423,031,985 | |||||||||||||||||||||||
| Common stockholders' equity (GAAP) | $22,187 | $20,060 | ||||||||||||||||||||||||
| Less: Goodwill (GAAP) | 8,177 | 7,232 | ||||||||||||||||||||||||
| Less: Other intangible assets (GAAP) | 185 | 115 | ||||||||||||||||||||||||
| Add: Deferred tax liabilities related to goodwill and other intangible assets (GAAP) | 422 | 387 | ||||||||||||||||||||||||
| Tangible common equity | T | $14,247 | $13,100 | |||||||||||||||||||||||
| Tangible book value per common share | T/S | $29.44 | $30.97 | |||||||||||||||||||||||
| Net income per average common share - basic and diluted and net income per average common share - basic and diluted, Underlying: | ||||||||||||||||||||||||||
| Average common shares outstanding - basic (GAAP) | U | 485,444,313 | 422,401,747 | |||||||||||||||||||||||
| Average common shares outstanding - diluted (GAAP) | V | 487,712,146 | 424,670,871 | |||||||||||||||||||||||
| Net income per average common share - basic (GAAP) | M/U | $1.00 | $0.94 | |||||||||||||||||||||||
| Net income per average common share - diluted (GAAP) | M/V | 1.00 | 0.93 | |||||||||||||||||||||||
| Net income per average common share - basic, Underlying (non-GAAP) | N/U | 1.10 | 1.07 | |||||||||||||||||||||||
| Net income per average common share - diluted, Underlying (non-GAAP) | N/V | 1.10 | 1.07 | |||||||||||||||||||||||
| Dividend payout ratio and dividend payout ratio, Underlying: | ||||||||||||||||||||||||||
| Cash dividends declared and paid per common share | W | $0.42 | $0.39 | |||||||||||||||||||||||
| Dividend payout ratio | W/(M/U) | 42 | % | 41 | % | |||||||||||||||||||||
| Dividend payout ratio, Underlying (non-GAAP) | W/(N/U) | 38 | 36 |
Citizens Financial Group, Inc. | 31
Previous: Cover and table of contents · Next: Item 1. FINANCIAL STATEMENTS