 filings.tools
Item 1. Business.
67K characters. Original on sec.gov · Markdown
Item 1. Business.
Introduction
We are the second largest cable operator in the United States and a leading broadband communications services company providing video, Internet and voice services to approximately 29.2 million residential and small and medium business customers at December 31, 2019. We also offer mobile service to residential customers and recently launched mobile service to small and medium business customers. In addition, we sell video and online advertising inventory to local, regional and national advertising customers and tailored communications and managed solutions to larger enterprise customers. We also own and operate regional sports networks and local sports, news and community channels.
We own and operate a high-capacity, two-way telecommunications network which passes over 52 million households and small and medium businesses across the United States. Our core strategy is to use our network to deliver high quality products at competitive prices, combined with outstanding service. This strategy, combined with simple, easy to understand pricing and packaging, is central to our goal of growing our customer base while selling more of our core connectivity services, which include both fixed and mobile Internet, video and voice services, to each individual customer. We execute this strategy by managing our operations in a consumer-friendly, efficient and cost-effective manner. Our operating strategy includes insourcing nearly all of our customer care and field operations workforces, which results in higher quality service delivery. While an insourced operating model can increase the field operations and customer care costs associated with individual service transactions, the higher quality nature of insourced labor service transactions significantly reduces the volume of service transactions per customer, more than offsetting the higher investment made in each insourced service transaction. As we reduce the number of service transactions and recurring costs per customer relationship, we continue to provide our customers with products and prices that we believe provide more value than what our competitors offer. The combination of offering high quality, competitively priced products and outstanding service, allows us to both increase the number of customers we serve over our fully deployed network, and to increase the number of products we sell to each customer. This combination also reduces the number of service transactions we perform per relationship, yielding higher customer satisfaction and lower customer churn, resulting in lower costs to acquire and serve customers.
We have enhanced our service operations to allow our customers to (1) more frequently interact with us through our customer website and Spectrum TV application, online chat and social media, (2) have their services installed at the time and in the manner of their own choosing, including self-installation, and (3) receive a variety of video packages on an increasing number of connected devices including those owned by us and those owned by the customer. By offering our customers growing levels of choices in how they receive and install their services and how they interact with us, we are driving higher overall levels of customer satisfaction and reducing our operating costs and capital expenditures per customer relationship. Ultimately, our operating strategy enables us to offer high quality, competitively priced services profitably, while continuing to invest in new products and services.
The capability and functionality of our two-way network continues to grow in a number of areas, especially with respect to wireless connectivity. Our Internet service offers consumers the ability to wirelessly connect to our network using WiFi technology. We estimate that over 300 million devices are wirelessly connected to our network through WiFi. Initially, our wireless strategy focused on offering wireless connectivity solutions inside the home and business using WiFi. Through our mobile virtual network operator (“MVNO”) reseller agreement with Verizon Communications Inc. ("Verizon"), we are now able to offer Internet connectivity to our customers beyond the home via our Spectrum Mobile product. We are also actively testing and evaluating opportunities for our customers to wirelessly connect to our network using a combination of licensed and unlicensed radio spectrum to deliver fixed and mobile service directly from our distributed, high capacity network.
Our principal executive offices are located at 400 Atlantic Street, Stamford, Connecticut 06901. Our telephone number is (203) 905-7801, and we have a website accessible at www.charter.com. Our Annual Reports on Form 10-K, Quarterly Reports on Form 10-Q and Current Reports on Form 8-K, and all amendments thereto, are available on our website free of charge as soon as reasonably practicable after they have been filed. The information posted on our website is not incorporated into this annual report.
Corporate Entity Structure
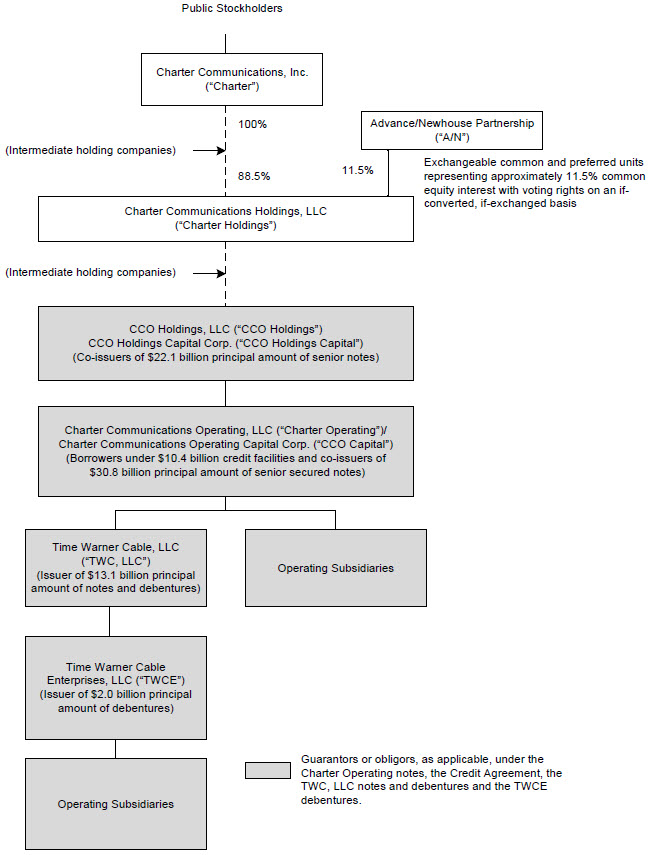
The chart below sets forth our entity structure and that of our direct and indirect subsidiaries. The chart does not include all of our affiliates and subsidiaries and, in some cases, we have combined separate entities for presentation purposes. The equity ownership percentages shown below are approximations. Indebtedness amounts shown below are principal amounts as of December 31, 2019. See Note 9 to the accompanying consolidated financial statements contained in “Part II. Item 8. Financial Statements and Supplementary Data,” which also includes the accreted values of the indebtedness described below.
Products and Services
We offer our customers subscription-based video services, Internet services, and voice and mobile services. Our services are offered to residential and commercial customers on a subscription basis, with prices and related charges based on the types of service selected, whether the services are sold as a “bundle” or on an individual basis, and based on the equipment necessary to receive our services. Bundled services are available to substantially all of our passings, and approximately 57% of our residential customers subscribe to a bundle of services including some combination of our video, Internet and/or voice products.
The following table summarizes our customer statistics for video, Internet, mobile and voice as of December 31, 2019 and 2018 (in thousands except per customer data and footnotes).
| Approximate as of | |||||||
| December 31, | |||||||
| 2019 (a) | 2018 (a) | ||||||
| Customer Relationships (b) | |||||||
| Residential | 27,277 | 26,270 | |||||
| Small and Medium Business | 1,958 | 1,833 | |||||
| Total Customer Relationships | 29,235 | 28,103 | |||||
| Residential Primary Service Units ("PSUs") | |||||||
| Video | 15,620 | 16,104 | |||||
| Internet | 24,908 | 23,625 | |||||
| Voice | 9,443 | 10,135 | |||||
| Monthly Residential Revenue per Residential Customer (c) | $ | 112.63 | $ | 111.56 | |||
| Small and Medium Business PSUs | |||||||
| Video | 524 | 502 | |||||
| Internet | 1,756 | 1,634 | |||||
| Voice | 1,144 | 1,051 | |||||
| Monthly Small and Medium Business Revenue per Customer (d) | $ | 169.90 | $ | 174.88 | |||
| Mobile Lines | 1,082 | 134 | |||||
| Enterprise PSUs (e) | 267 | 248 |
| (a) | We calculate the aging of customer accounts based on the monthly billing cycle for each account. On that basis, as of December 31, 2019 and 2018, customers include approximately 154,200 and 217,600 customers, respectively, whose accounts were over 60 days past due, approximately 13,500 and 24,000 customers, respectively, whose accounts were over 90 days past due, and approximately 10,000 and 19,200 customers, respectively, whose accounts were over 120 days past due. |
| (b) | Customer relationships include the number of customers that receive one or more levels of service, encompassing video, Internet and voice services, without regard to which service(s) such customers receive. Customers who reside in residential multiple dwelling units (“MDUs”) and that are billed under bulk contracts are counted based on the number of billed units within each bulk MDU. Total customer relationships exclude enterprise and mobile-only customer relationships. |
| (c) | Monthly residential revenue per residential customer is calculated as total residential video, Internet and voice annual revenue divided by twelve divided by average residential customer relationships during the respective year. Monthly residential revenue per residential customers excludes mobile revenue and customers. |
| (d) | Monthly small and medium business revenue per customer is calculated as total small and medium business annual revenue divided by twelve divided by average small and medium business customer relationships during the respective year. Monthly small and medium business revenue per small and medium customer excludes mobile revenue and customers. |
| (e) | Enterprise PSUs represent the aggregate number of fiber service offerings counting each separate service offering at each customer location as an individual PSU. |
Residential Services
Video Services
Our video customers receive a package of programming which generally includes a digital set-top box that provides an interactive electronic programming guide with parental controls, access to pay-per-view services, including video on demand (“VOD”) (available to nearly all of our passings) and the ability to view certain video services on third-party devices inside and outside the residence. Customers have the option to purchase additional tiers of services including premium channels which provide original programming, commercial-free movies, sports, and other special event entertainment programming. Substantially all of our video programming is available in high definition. We also offer certain video packages containing a limited number of channels via our cable television systems.
In the vast majority of our footprint, we offer VOD service which allows customers to select from over 60,000 titles at any time. VOD programming options may be accessed for free if the content is associated with a customer’s linear subscription, or for a fee on a transactional basis. VOD services are also offered on a subscription basis included in a digital tier premium channel subscription or for a monthly fee. Pay-per-view channels allow customers to pay on a per-event basis to view a single showing of a one-time special sporting event, music concert, or similar event on a commercial-free basis.
Our goal is to provide our video customers with the programming they want, when they want it, on any device. Digital video recorder (“DVR”) service enables customers to digitally record programming and to pause and rewind live programming. Customers can also use our Spectrum TV application on Internet Protocol ("IP") devices to watch over 375 channels of cable TV in home and approximately 275 channels out of home and view VOD programming. Customers are increasingly accessing their subscription video content through connected IP devices via our IP network. In 2019, we launched cloud DVR service which allows customers to schedule, record and watch their favorite programming anytime from connected IP devices as well as SpectrumTV.com. Our video customers also have access to programmer authenticated applications and websites (known as TV Everywhere services) such as HBO Go, Fox Now, Discovery Go and ESPN. We deploy Spectrum Guide®, our network or “cloud-based” user interface, to new video customers in the majority of our service areas. Spectrum Guide runs on traditional set-top boxes but offers a look and feel similar to that of our Spectrum TV application. Spectrum Guide also provides access to third-party video applications such as Netflix.
Internet Services
Our Spectrum pricing and packaging (“SPP”) offers an entry level Internet download speed of at least 200 megabits per second (“Mbps”) in approximately 60% of our footprint and 100 Mbps across approximately 40% of our footprint, which among other things, allows several people within a single household to stream high definition (“HD”) television video content while simultaneously using our Internet service for other purposes. Additionally, leveraging DOCSIS 3.1 technology, we offer 940 Mbps speed service ("Spectrum Internet Gig") in nearly all of our footprint. Finally, we offer a security suite with our Internet services which, upon installation by customers, provides protection against computer viruses and spyware and includes parental control features.
We offer an in-home WiFi product that provides customers with high performance wireless routers to maximize their in-home wireless Internet experience. At the end of 2019, we launched our advanced in-home WiFi product in select service areas and we plan to continue to roll this product out to our entire footprint throughout 2020 and 2021. Advanced in-home WiFi provides connected device visibility, management and control to customers in a single application and to customer service agents to help support our customers. Advanced in-home WiFi is built on a software platform that will allow us to integrate and launch additional network based security and control features.
Voice Services
We provide voice communications services using voice over Internet protocol ("VoIP") technology to transmit digital voice signals over our network. Our voice services include unlimited local and long distance calling to the United States, Canada, Mexico and Puerto Rico, voicemail, call waiting, caller ID, call forwarding and other features and offers international calling either by the minute, or through packages of minutes per month. For customers that subscribe to both our voice and video offerings, caller ID on TV is also available in most areas.
Mobile Services
At the end of the second quarter of 2018, we launched our mobile product, Spectrum Mobile, to residential customers under our MVNO reseller agreement with Verizon. We currently offer our Spectrum Mobile service to residential customers subscribing to
our Internet service and recently launched mobile service to small and medium business customers. In the second quarter of 2019, we expanded our Spectrum Mobile bring-your-own-device ("BYOD") program across all sales channels to include a broader set of devices which we believe lowers the cost for consumers of switching mobile carriers, and reduces the short-term working capital impact of selling new mobile devices on installment plans. We believe Spectrum-branded mobile services will drive more sales of our core products, create longer customer lives and increase profitability and cash flow over time. As we continue to grow our mobile services, including 5G in 2020, we expect that Spectrum Mobile will require an initial funding period to grow the product as well as negative working capital impacts from the timing of device-related cash flows when we sell the handset or tablet to customers pursuant to equipment installment plans.
We plan to use our WiFi network in conjunction with additional unlicensed, and potentially licensed, spectrum to improve network performance and expand capacity to offer consumers a superior mobile service at a lower total cost to us. Further, we have experimental wireless licenses from the Federal Communications Commission ("FCC") that we are utilizing to test next generation mobile services in several service areas around the country. We intend to consider and pursue opportunities in the mobile space which may include the acquisition of licensed spectrum and may include entering into or expanding joint ventures or partnerships with wireless or cable providers which may require significant investment.
Commercial Services
We offer scalable broadband communications solutions for businesses and carrier organizations of all sizes, selling Internet access, data networking, fiber connectivity to cellular towers and office buildings, video entertainment services and business telephone services.
Small and Medium Business
Spectrum Business® offers Internet, voice and video services to small and medium businesses over our hybrid fiber coaxial network. In addition, in 2019, we began offering our Spectrum Mobile service to small and medium business customers. Spectrum Business includes a full range of video programming and entry-level Internet speeds of 200 Mbps downstream and 10 Mbps upstream in virtually all of our markets. Additionally, customers can upgrade their Internet speeds by purchasing Internet Ultra (400 Mbps downstream) or Internet Gig (940 Mbps downstream). Spectrum Business also includes a set of business services including static IP and business WiFi, e-mail and security, and multi-line telephone services with more than 30 business features including web-based service management, that are generally not available to residential customers.
Enterprise
Spectrum Enterprise offers more tailored communications products and managed service solutions to larger businesses, as well as high-capacity last-mile data connectivity services to mobile and wireline carriers on a wholesale basis. Spectrum Enterprise's product portfolio includes fiber Internet access, voice trunking services, unified messaging/unified communications (“UM/UC”), Ethernet services that privately and securely connect geographically dispersed client locations, and video solutions designed to meet the needs of hospitality, education, and healthcare clients. In addition, in 2019, Spectrum Enterprise launched an innovative Hybrid Software-Defined Wide Area Network ("SD-WAN") that enables businesses to leverage the performance of Ethernet, the ubiquity of Internet connectivity and the flexibility of a software-defined solution to solve a wide array of business communications and networking challenges. Spectrum Enterprise combines its large, serviceable footprint and robust portfolio of fiber lit buildings with a sizeable partner network to effectively serve enterprise customers nationally. These customers can benefit from obtaining advanced services from a single provider, receiving a consistent solution while simplifying procurement and potentially reducing their costs.
Advertising Services
Our advertising sales division, Spectrum Reach®, offers local, regional and national businesses the opportunity to advertise in individual and multiple service areas on cable television networks and digital outlets. We receive revenues from the sale of local advertising across various platforms for networks such as MTV, CNN and ESPN. In any particular service area, we typically insert local advertising on 40 to 90 channels. Our large footprint provides opportunities for advertising customers to address broader regional audiences from a single provider and thus reach more customers with a single transaction. Our size also provides scale to invest in new technology to create more targeted and addressable advertising capabilities.
Available advertising time is generally sold by our advertising sales force. In some service areas, we have formed advertising interconnects or entered into representation agreements with other video distributors, including, among others, Verizon, AT&T Inc. (“AT&T”) and Comcast Corporation, under which we sell advertising on behalf of those operators. In other service areas, we enter into representation agreements under which another operator in the area will sell advertising on our behalf. These
arrangements enable us and our partners to deliver linear commercials across wider geographic areas, replicating the reach of local broadcast television stations to the extent possible. In addition, we enter into interconnect agreements from time to time with other cable operators, which, on behalf of a number of video operators, sells advertising time to national and regional advertisers in individual or multiple service areas.
Additionally, we sell the advertising inventory of our owned and operated local sports and news channels, of our regional sports networks that carry Los Angeles Lakers’ basketball games and other sports programming and of SportsNet LA, a regional sports network that carries Los Angeles Dodgers’ baseball games and other sports programming.
In 2019, we began expanding our deployment of household addressability, which allows for more precise targeting within various parts of our footprint. We also began the roll-out of our Ad Portal, which allows small businesses to purchase local cable advertising and/or creative services via our web portal with no sales personnel interaction at a fee within their budgets. Both products will be more widely deployed in 2020. They join our fully deployed Audience App, which uses our proprietary set-top box viewership data (all anonymized and aggregated) to optimize linear inventory, in our suite of advanced advertising products available to the marketplace.
Other Services
Regional Sports and News Networks
We have an agreement with the Los Angeles Lakers for rights to distribute all locally available Los Angeles Lakers’ games through 2033. We broadcast those games on our regional sports network, Spectrum SportsNet. American Media Productions, LLC ("American Media Productions"), an unaffiliated third party, owns SportsNet LA, a regional sports network carrying the Los Angeles Dodgers’ baseball games and other sports programming. In accordance with agreements with American Media Productions, we act as the network’s exclusive affiliate and advertising sales representative and have certain branding and programming rights with respect to the network. In addition, we provide certain production and technical services to American Media Productions. The affiliate, advertising, production and programming agreements continue through 2038. We also own 26.8% of Sterling Entertainment Enterprises, LLC (doing business as SportsNet New York), a New York City-based regional sports network that carries New York Mets’ baseball games as well as other regional sports programming.
We manage 28 local news channels, including Spectrum News NY1® and LA1, 24-hour news channels focused on New York City and Los Angeles. Our local news channels provide 24/7 hyperlocal content, focusing on news, programming and storytelling that addresses the deeper needs and interests of the diverse communities and neighborhoods we serve.
Pricing of Our Products and Services
Our revenues are principally derived from the monthly fees customers pay for the services we provide. We typically charge a one-time installation fee which is sometimes waived or discounted in certain sales channels during certain promotional periods.
Our Spectrum pricing and packaging ("SPP") generally offers a standardized price for each tier of service, bundle of services, and add-on service in a service area. We believe SPP:
| • | offers a higher quality and more value-based set of services relative to our competitors, including faster Internet speeds, more HD channels, lower equipment fees and a more transparent pricing structure; |
| • | offers simplicity for customers to understand our offers, and for our employees in service delivery; |
| • | drives our ability to package more services at the time of sale, thus increasing revenue per customer; |
| • | drives higher customer satisfaction, lower service calls and churn; and |
| • | allows for gradual price increases at the end of promotional periods. |
We sell video and Internet packages with the option to add on voice and mobile services at attractive pricing. Our mobile customers can choose one of two simple ways to pay for data. Customers can choose an unlimited data plan or a by-the-gig data usage plan. Both plans include free nationwide talk and text and customers can easily switch between mobile data plans during the month. Customers can also purchase mobile devices and accessory products and have the option to pay for devices under interest-free monthly installment plans.
Our Network Technology
Our network includes three key components: a national backbone, regional/metro networks and a “last-mile” network. Both our national backbone and regional/metro network components utilize a redundant IP ring/mesh architecture. The national backbone
component provides connectivity from regional demarcation points to nationally centralized content, connectivity and services. The regional/metro network components provide connectivity between the regional demarcation points and headends within a specific geographic area and enable the delivery of content and services between these network components.
Our last-mile network utilizes a hybrid fiber coaxial cable (“HFC”) architecture, which combines the use of fiber optic cable with coaxial cable. In most systems, we deliver our signals via fiber optic cable from the headend to a group of nodes, and use coaxial cable to deliver the signal from individual nodes to the homes served by that node. For our fiber Internet, Ethernet, carrier wholesale, Session Initiation Protocol ("SIP") and Primary Rate Interface ("PRI") Spectrum Enterprise customers, fiber optic cable is extended from individual nodes to the customer’s site. For certain new build and MDU sites, we increasingly bring fiber to the customer site. Our design standard allows spare fiber strands to each node to be utilized for additional residential traffic capacity, and enterprise customer needs as they arise. We believe that this hybrid network design provides high capacity and signal quality.
HFC architecture benefits include:
| • | bandwidth capacity to enable traditional and two-way video and broadband services; |
| • | dedicated bandwidth for two-way services; and |
| • | signal quality and high service reliability. |
Our systems provide an all-digital platform, leveraging DOCSIS 3.1 technology and bandwidth of 750 megahertz or greater to approximately 100% of our estimated passings. This bandwidth capacity enables us to offer two-way signal capabilities necessary to provide HD television, interactive video services such as VOD, high-speed Internet and voice services. An all-digital platform leveraging DOCSIS 3.1 technology enables us to offer a larger selection of HD channels, Spectrum Internet Gig and better picture quality while providing greater plant security and enabling lower installation and disconnect service truck rolls. We believe this architecture also allows us to continue to enhance our network to enable multi-gigabit services with low latency at a lower incremental capital cost relative to our competitors.
Management, Customer Operations and Marketing
Our operations are centralized, with senior executives located at several key corporate offices, responsible for coordinating and overseeing operations, including establishing company-wide strategies, policies and procedures. Sales and marketing, network operations, field operations, customer operations, engineering, advertising sales, human resources, legal, government relations, information technology and finance are all directed at the corporate level. Regional and local field operations are responsible for customer premise service transactions and maintaining and constructing that portion of our network which is located outdoors.
We continue to focus on improving the customer experience through enhanced product offerings, reliability of services, and delivery of quality customer service. As part of our operating strategy, we insource most of our customer operations workload. Our in-house call centers handle over 90% of our total customer service calls. We manage our customer service call centers centrally to ensure a consistent, high quality customer experience. In addition, we route calls by call type to specific agents that only handle such call types, enabling agents to become experts in addressing specific customer needs, creating a better customer experience. We implemented a new call center agent desktop interface tool in 2019 which enables virtualization of all call centers thereby better serving our customers. Virtualization allows calls to be routed across our call centers regardless of the location origin of the call, reducing call wait times, and saving costs. We continue to migrate our call centers to full virtualization and expect all our call centers to be fully virtualized by 2020.
We also provide customers with the opportunity to interact with us through a variety of forums in addition to telephonic communications, including through our customer website, mobile device applications, online chat and social media. Our customer websites and mobile applications enable customers to pay their bills, manage their accounts, order new services and utilize self-service help and support.
We sell our residential and commercial services using a national brand platform known as Spectrum, Spectrum Business and Spectrum Enterprise. These brands reflect our comprehensive approach to industry-leading products, driven by speed, performance and innovation. Our marketing strategy emphasizes the sale of our bundled services through targeted direct response marketing programs to existing and potential customers, and increases awareness and the value of the Spectrum brand. Our marketing organization creates and executes marketing programs intended to grow customer relationships, increase the number of services we sell per relationship, retain existing customers and cross-sell additional products to current customers. We monitor the effectiveness of our marketing efforts, customer perception, competition, pricing, and service preferences, among other factors, in order to increase our responsiveness to our customers and to improve our sales and customer retention. The marketing organization manages all sales channels including inbound, direct sales, on-line, outbound telemarketing and stores.
Programming
We believe that offering a wide variety of video programming choices influences a customer’s decision to subscribe and retain our cable video services. We obtain basic and premium programming, usually pursuant to written contracts from a number of suppliers. Media corporation consolidation has, however, resulted in fewer suppliers and additional selling power on the part of programming suppliers. Although an insignificant amount of our programming budget, recently we have begun entering into agreements to co-produce or exclusively license original content which give us the right to provide our customers with certain exclusive content for a period of time.
Programming is usually made available to us for a license fee, which is generally paid based on the number of customers to whom we make that programming available. Programming license fees may include “volume” discounts and financial incentives to support the launch of a channel and/or ongoing marketing support, as well as discounts for channel placement or service penetration. For home shopping channels, we typically receive a percentage of the revenue attributable to our customers’ purchases. We also offer VOD and pay-per-view channels of movies and events that are subject to a revenue split with the content provider.
Our programming costs have increased in excess of customary inflationary and cost-of-living type increases. We expect programming costs per customer to continue to increase due to a variety of factors including, annual increases pursuant to our programming contracts, contract renewals with programmers and the carriage of incremental programming, including new services and VOD programming. Increases in the cost of sports programming and the amounts paid for broadcast station retransmission consent have been the largest contributors to the growth in our programming costs over the last few years. Additionally, the demands of large media companies who link carriage of their most popular networks to carriage and cost increases of their less popular networks and who require us to carry their most popular networks to a large percentage of our video subscribers, has limited our flexibility in creating more tailored and cost-sensitive programming packages for consumers.
Federal law allows commercial television broadcast stations to make an election between “must-carry” rights and an alternative “retransmission-consent” regime. When a station opts for retransmission-consent, we are not allowed to carry the station’s signal without that station’s permission. Continuing demands by owners of broadcast stations for cash payments at substantial increases over amounts paid in prior years in exchange for retransmission consent will increase our programming costs or require us to cease carriage of popular programming, potentially leading to a loss of customers in affected service areas.
Over the past several years, increases in our video service rates have not fully offset the increases in our programming costs, and with the impact of increasing competition and other marketplace factors, we do not expect the increases in our video service rates to fully offset the increase in our programming costs for the foreseeable future. Although we pass along a portion of amounts paid for retransmission consent to the majority of our customers, our inability to fully pass programming cost increases on to our video customers has had, and is expected in the future to have, an adverse impact on our cash flow and operating margins associated with our video product. In order to mitigate reductions of our operating margins due to rapidly increasing programming costs, we continue to review our pricing and programming packaging strategies.
Our programming contracts are generally for a fixed period of time, usually for multiple years, and are subject to negotiated renewal. The contracts set to expire in any particular year vary. We will seek to renew these agreements on terms that we believe are favorable. There can be no assurance, however, that these agreements will be renewed on favorable or comparable terms. To the extent that we are unable to reach agreements with certain programmers on terms that we believe are reasonable, we have been, and may in the future be, forced to remove such programming channels from our line-up, which may result in a loss of customers.
Regions
We operate in geographically diverse areas which are organized in regional clusters. These regions are managed centrally on a consolidated level. Our eleven regions and the customer relationships within each region as of December 31, 2019 are as follows (in thousands):
| Regions | Total Customer Relationships | |
| Carolinas | 3,020 | |
| Central | 3,058 | |
| Florida | 2,619 | |
| Great Lakes | 2,270 | |
| Northeast | 3,068 | |
| Northwest | 1,626 | |
| New York City | 1,381 | |
| South | 2,094 | |
| Southern Ohio | 2,313 | |
| Texas | 3,070 | |
| West | 4,716 |
Competition
Residential Services
We face intense competition for residential customers, both from existing competitors and, as a result of the rapid development of new technologies, services and products, from new entrants. We face triple play competition, consisting of wireline multichannel video, wireline Internet, and wireline voice service, from three primary competitors, AT&T, Frontier Communications Corporation (“Frontier”) and Verizon. As of December 31, 2019, AT&T, Frontier and Verizon offered these triple play packages in approximately 33%, 7% and 5% of our operating areas, respectively. AT&T also owns DIRECTV, and as a combined company provides video service (via IP or satellite) and voice service (via fixed or wireless) across our entire footprint.
Video Competition
Our residential video service faces competition from DBS service providers, which have a national footprint and compete in all of our operating areas. DBS providers offer satellite-delivered pre-packaged programming services that can be received by relatively small and inexpensive receiving dishes. DBS providers offer aggressive promotional pricing, exclusive programming (e.g., NFL Sunday Ticket) and video services that are comparable in many respects to our residential video service. Our residential video service also faces competition from large telecommunications companies, primarily AT&T U-verse, Frontier fiber optic service (“FiOS" or "Fios") and Verizon Fios, which offer wireline video services in significant portions of our operating areas.
Our residential video service also faces growing competition from a number of other sources, including companies that deliver linear network programming, movies and television shows on demand and other video content over broadband Internet connections to televisions, computers, tablets and mobile devices. These competitors include virtual multichannel video programming distributors (“V-MVPDs”) such as AT&T TV NOW, Sling TV, YouTube TV and Hulu Live. Other online video business models and products have also developed, some offered by programmers that have not traditionally sold programming directly to consumers, including, (i) subscription video on demand (“SVOD”) services such as Netflix, Apple TV+, Amazon Prime, Hulu Plus, Disney+, HBO Now, CBS All Access, Starz and Showtime Anytime, (ii) ad-supported free online video products, including YouTube and Pluto TV, some of which offer programming for free to consumers that we currently purchase for a fee, (iii) pay-per-view products, such as iTunes and Amazon Instant, and (iv) additional offerings from mobile providers which continue to integrate and bundle video services and mobile products. Historically, we have generally viewed SVOD online video services as complementary to our own video offering, and we have developed a cloud-based guide that is capable of incorporating video from online video services currently offered in the marketplace. As the proliferation of online video services grows, however, services from V-MVPDs and new direct to consumer offerings, as well as piracy and password sharing, negatively impact the number of customers purchasing our video product.
Internet Competition
Our residential Internet service faces competition from fiber-to-the-home ("FTTH"), fiber-to-the-node ("FTTN"), DSL and wireless broadband offerings, as well as from a variety of companies that offer other forms of online services, including fixed wireless and satellite-based broadband services. AT&T, Frontier FiOS and Verizon’s Fios are our primary FTTH competitors. Given the FTTH deployments of our competitors, launches of broadband services offering 1 gigabit per second (“Gbps”) speed have recently grown. Several competitors, including AT&T, Frontier FiOS, Verizon's Fios, WideOpenWest Finance, LLC ("WOW") and Google Fiber, deliver 1 Gbps broadband speed in at least a portion of their footprints which overlap our footprint. DSL service is often offered at prices lower than our Internet services, although typically at speeds much lower than the minimum speeds we offer as part of SPP. Various mobile phone companies offer wireless Internet services delivered over networks which they continue to enhance to deliver faster speeds. AT&T, Verizon, Sprint Corporation ("Sprint") and T-Mobile US, Inc. ("T-Mobile") all began deploying fifth generation (5G) mobile services in 2019, although generally in limited geographies, with plans to expand 5G more broadly in 2020. In April 2018, Sprint and T-Mobile announced their intent to merge. If the transaction closes, the resulting company would be one of the nation’s largest mobile carriers bringing increased competition with a stated intent of pursuing broad 5G network deployment and offering fixed wireless broadband service. Some mobile phone companies offer unlimited data packages to customers. In addition, a growing number of commercial areas, such as retail malls, restaurants and airports, offer WiFi Internet service. Numerous local governments are also considering or actively pursuing publicly subsidized WiFi Internet access networks. These options offer alternatives to cable-based Internet access.
Voice Competition
Our residential voice service competes with wireless and wireline phone providers, as well as other forms of communication, such as text messaging on cellular phones, instant messaging, social networking services, video conferencing and email. We also compete with “over-the-top” phone providers, such as Vonage, Skype, magicJack, Google Voice and Ooma, Inc., as well as companies that sell phone cards at a cost per minute for both national and international service. The increase in the number of different technologies capable of carrying voice services and the number of alternative communication options available to customers as well as the replacement of wireline services by wireless have intensified the competitive environment in which we operate our residential voice service. Our mobile service competes with other mobile providers such as Verizon, AT&T, T-Mobile and Sprint, as well as various regional wireless service providers. We also compete for retail activations with other resellers that buy bulk wholesale service from wireless service providers for resale.
Regional Competitors
In some of our operating areas, other competitors have built networks that offer video, Internet and voice services that compete with our services. For example, in certain service areas, our residential video, Internet and voice services compete with Google Fiber, Cincinnati Bell Inc., Hawaiian Telcom (owned by Cincinnati Bell Inc.), RCN Telecom Services, LLC, Grande Communications Networks, LLC and WOW.
Additional Competition
In addition to multi-channel video providers, cable systems compete with other sources of news, information and entertainment, including over-the-air television broadcast reception, live events, movie theaters and the Internet. Competition is also posed by fixed wireless and satellite master antenna television systems, or SMATV systems, serving MDUs, such as condominiums, apartment complexes, and private residential communities.
Business Services
We face intense competition across each of our business services product offerings. Our small and medium business video, Internet, networking and voice services face competition from a variety of providers as described above. Our enterprise solutions also face competition from the competitors described above as well as application-service providers and other telecommunications carriers, such as metro and regional fiber-based carriers.
Advertising
We face intense competition for advertising revenue across many different platforms and from a wide range of local and national competitors. Advertising competition has increased and will likely continue to increase as new advertising avenues seek to attract the same advertisers. We compete for advertising revenue against, among others, local broadcast stations, national cable and broadcast networks, radio stations, print media and online advertising companies and content providers.
Seasonality and Cyclicality
Our business is subject to seasonal and cyclical variations. Our results are impacted by the seasonal nature of customers receiving our cable services in college and vacation service areas. Our revenue is subject to cyclical advertising patterns and changes in viewership levels. Our advertising revenue is generally higher in the second and fourth calendar quarters of each year, due in part to increases in consumer advertising in the spring and in the period leading up to and including the holiday season. U.S. advertising revenue is also cyclical, benefiting in even-numbered years from advertising related to candidates running for political office and issue-oriented advertising. Our capital expenditures and trade working capital are also subject to significant seasonality based on the timing of subscriber growth, network programs, specific projects and construction.
Regulation and Legislation
The following summary addresses the key regulatory and legislative developments affecting the cable industry and our services for both residential and commercial customers. Cable system operations are extensively regulated by the federal government (primarily the FCC), certain state governments and many local governments. A failure to comply with these regulations could subject us to substantial penalties. Our business can be dramatically impacted by changes to the existing regulatory framework, whether triggered by legislative, administrative, or judicial rulings. Congress and the FCC have frequently revisited the subject of communications regulation and they are likely to do so again in the future. We could be materially disadvantaged in the future if we are subject to new laws, regulations or regulatory actions that do not equally impact our key competitors. We cannot provide assurance that the already extensive regulation of our business will not be expanded in the future. In addition, we are already subject to Charter-specific conditions regarding certain business practices as a result of the FCC’s approval of the merger in 2016 with Time Warner Cable Inc. ("TWC") and acquisition of Bright House Networks, LLC ("Bright House").
Video Service
Must Carry/Retransmission Consent
There are two alternative legal methods for carriage of local broadcast television stations on cable systems. Federal “must carry” regulations require cable systems to carry local broadcast television stations upon the request of the local broadcaster. Alternatively, federal law includes “retransmission consent” regulations, by which popular commercial television stations can prohibit cable carriage unless the cable operator first negotiates for “retransmission consent,” which may be conditioned on significant payments or other concessions. Popular stations invoking “retransmission consent” have been demanding substantial compensation increases in their recent negotiations with cable operators, thereby significantly increasing our operating costs.
Pole Attachments
The Communications Act of 1934, as amended (the "Communications Act") requires most utilities owning utility poles to provide cable systems with access to poles and conduits and also subjects the rates charged for this access to either federal or state regulation. The federally regulated rates now applicable to pole attachments used for cable, Internet, and telecommunications services are substantially similar. The FCC's approach does not directly affect the rate in states that self-regulate, but many of those states have substantially the same rate for all communications attachments.
Some municipalities have enacted “one-touch” make-ready pole attachment ordinances, which permit third parties to alter components of our network attached to utility poles in ways that could adversely affect our businesses. Some of these ordinances have been challenged with differing results. In 2018, the FCC adopted “one-touch” make-ready (“OTMR”) rules that will apply in states where pole attachments are FCC regulated, and they may impact many of our existing pole attachments. Various utilities have sought review of the OTMR rules in federal court.
Cable Rate Regulation
Pursuant to federal law, a cable system's video offerings are universally exempt from rate regulation, except for a cable system’s minimum level of video programming service, referred to as “basic service,” and associated equipment. FCC regulations require a local franchise authority interested in regulating rates for basic service and associated equipment to first make an affirmative showing that there is no “effective competition” (as defined under federal law) in the community. Given the competitive nature of our markets, the FCC recently rescinded certifications for the relatively few communities where we had been subject to rate regulation. It is possible that the competitive situation could change, and that some local franchising authorities may be certified to regulate rates in the future, and existing and potential laws and regulations may affect our marketing practices (including our disclosure and itemization of subscriber fees).
Other FCC Regulatory Matters
The Communications Act and FCC regulations cover a variety of additional areas, including, among other things: (1) licensing of systems and facilities; (2) equal employment opportunity obligations; (3) customer service standards; (4) technical service standards; (5) mandatory blackouts of certain network and syndicated programming; (6) restrictions on political advertising; (7) restrictions on advertising in children’s programming; (8) ownership restrictions; (9) maintenance of public files; (10) emergency alert systems; (11) inside wiring and exclusive contracts for MDU complexes; (12) disability access, including requirements governing video-description and closed-captioning; (13) competitive availability of cable equipment; (14) the provision of up to 15% of video channel capacity for commercial leased access by unaffiliated third parties; and (15) public, education and government entity access requirements. Each of these regulations restricts our business practices to varying degrees and may impose additional costs on our operations. Further, the FCC regulates spectrum usage and other communications enterprises in ways that could impact our operations. For example, the FCC is currently considering proposals to reallocate certain spectrum for new wireless communications purposes, which could be disruptive to the satellite platform we rely upon to provide our video services. The FCC is also preparing to make additional spectrum available for commercial services, which we might use to deliver services in the future. Our ability to access and use such spectrum is uncertain and may be limited by further FCC auction or allocation decisions.
It is possible that Congress or the FCC will expand or modify its regulation of cable systems in the future, and we cannot predict at this time how that might impact our business.
Copyright
Cable systems are subject to a federal compulsory copyright license covering carriage of television and radio broadcast signals. The copyright law provides copyright owners the right to audit our payments under the compulsory license, and the Copyright Office is currently considering modifications to the license’s royalty calculations and reporting obligations. The possible modification or elimination of this license is the subject of continuing legislative proposals and administrative review and could adversely affect our ability to obtain desired broadcast programming.
Franchise Matters
Our cable systems generally are operated pursuant to nonexclusive franchises, permits, and similar authorizations granted by a municipality or other state or local government entity in order to utilize and cross public rights-of-way.
Cable franchises generally are granted for fixed terms and in many cases include monetary penalties for noncompliance and may be terminable if the franchisee fails to comply with material provisions. The specific terms and conditions of cable franchises vary significantly between jurisdictions. They generally contain provisions governing cable operations, franchise fees, system construction, maintenance, technical performance, customer service standards, supporting and carrying public access channels, and changes in the ownership of the franchisee. Although local franchising authorities have considerable discretion in establishing franchise terms, certain federal protections benefit cable operators. For example, federal law imposes a 5% cap on franchise fees. In August 2019, the FCC clarified that in-kind contribution requirements set forth in cable franchises are subject to the statutory cap on franchise fees, and it reaffirmed that state and local authorities are barred from imposing duplicative franchise and/or fee requirements on franchised cable systems providing non-cable services. An appeal of the FCC’s order is pending in federal court.
A number of states have adopted franchising laws that provide for statewide franchising. Generally, state-wide cable franchises are issued for a fixed term, but streamline many of the traditional local cable franchise requirements and eliminate local negotiation.
The Communications Act provides for an orderly franchise renewal process in which granting authorities may not unreasonably deny renewals. If we fail to obtain renewals of franchises representing a significant number of our customers, it could have a material adverse effect on our consolidated financial condition, results of operations, or our liquidity. Similarly, if a franchising authority’s consent is required for the purchase or sale of a cable system, the franchising authority may attempt to impose more burdensome requirements as a condition for providing its consent.
Internet Service
The FCC originally classified broadband Internet access services, such as those we offer, as an “information service,” which exempted the service from traditional communications common carrier laws and regulations. In 2015, the FCC reclassified broadband Internet access services as “telecommunications service” and, on that basis, imposed a number of “net neutrality” rules governing the provision of broadband service. In 2017, the FCC reversed its 2015 decision. The Commission's 2017 Order restored the “information service” classification and eliminated the 2015 rules, other than a transparency requirement, which
created an obligation to disclose performance statistics and other service information to consumers. The 2017 FCC decision also ruled that state regulators may not impose obligations similar to federal network neutrality obligations that the FCC eliminated.
In 2019, the U.S. Court of Appeals for the District of Columbia upheld the FCC’s information service reclassification, but vacated the FCC’s blanket prohibition of state utility regulation of broadband services. The court left open the possibility that individual state laws could be deemed preempted on a case by case basis if it is shown that they conflict with federal law. We understand that this decision may be subject to further judicial review. Several states (including California) have already adopted state obligations, and additional states may consider the imposition of new regulations on our Internet services, such as rules similar to the network neutrality requirements that were eliminated by the FCC. California’s legislation has been challenged in court, and we cannot predict how the challenge to California’s legislation or challenges to any future state legislation will be resolved. As recent history has shown, it is possible that the FCC might further revise its approach to broadband Internet access, or that Congress might enact legislation affecting the rules applicable to the service. The application of new legal requirements to our Internet services could adversely affect our business.
In recent years, the FCC has demonstrated an interest in accelerating advancements in, and deployment of, wired and wireless broadband infrastructure, including advanced 5G wireless service. For example, the FCC and some state regulatory commissions direct certain subsidies to telephone and other companies deploying broadband to areas deemed to be “unserved” or “underserved.” We have opposed such subsidies when directed to areas that we serve. However, continued regulatory efforts to accelerate competitive wireline and wireless broadband deployment, including reforms that create regulatory imbalances, could adversely affect our business.
Aside from the FCC’s generally applicable regulations, we have made certain commitments to comply with the FCC’s order in connection with the FCC’s approval of the merger with TWC and acquisition of Bright House (discussed below).
Wireline Voice Service
The FCC has never classified the VoIP telephone services we offer as “telecommunications services” that are subject to traditional federal common carrier regulation, but instead has imposed some of these requirements on a case-by-case basis, such as requirements relating to 911 emergency services (“E911”), Communications Assistance for Law Enforcement Act ("CALEA") (the statute governing law enforcement access to and surveillance of communications), Universal Service Fund contributions, customer privacy and Customer Proprietary Network Information protections, number portability, network outage reporting, rural call completion, disability access, regulatory fees, back-up power obligations, and discontinuance of service. It is possible that the FCC or Congress will impose additional requirements on our VoIP telephone services in the future.
Although we believe that VoIP telephone services should be governed only by federal regulation, some states have attempted to subject cable VoIP services to state level regulation, and at least one state has asserted jurisdiction over our VoIP services. We prevailed on a legal challenge to that state’s assertion of jurisdiction, which was affirmed by a federal appellate court, but that ruling is limited to the seven states in that circuit. Although we have registered with, or obtained certificates or authorizations from the FCC and the state regulatory authorities in those states in which we offer competitive voice services in order to ensure the continuity of our services, it is unclear whether and how these and other ongoing regulatory matters ultimately will be resolved. State regulatory commissions and legislatures in other jurisdictions may continue to consider imposing regulatory requirements on our fixed telephone services.
Mobile Service
Our Spectrum Mobile service offers mobile Internet access and telephone service. We provide this service as an MVNO using Verizon’s network and our network of Spectrum Wi-Fi hotspots. As an MVNO, we are subject to many of the same FCC regulations that apply to facilities-based wireless carriers, as well as certain state or local regulations, including (but not limited to): E911, local number portability, customer privacy, CALEA, universal service fund contribution, and hearing aid compatibility and safety and emission requirements for mobile devices. Spectrum Mobile’s broadband Internet access service is also subject to the FCC’s transparency rule. The FCC or other regulatory authorities may adopt new or different regulations for MVNOs and/or mobile service providers in the future, or impose new taxes or fees applicable to Spectrum Mobile, which could adversely affect the service offering or our business generally.
Privacy and Information Security Regulation
The Communications Act limits our ability to collect, use, and disclose customers’ personally identifiable information for our video, voice, and Internet services. We are subject to additional federal, state, and local laws and regulations that impose additional restrictions on the collection, use and disclosure of consumer information. All broadband providers are also obliged by CALEA
to configure their networks in a manner that facilitates the ability of state and federal law enforcement, with proper legal process authorized under the Electronic Communications Privacy Act, to obtain records and information concerning our customers, including the content of their communications. Further, the FCC, Federal Trade Commission (“FTC”), and many states regulate and restrict the marketing practices of communications service providers, including telemarketing and sending unsolicited commercial emails. The FTC currently has the authority, pursuant to its general authority to enforce against unfair or deceptive acts and practices, to protect the privacy of Internet service customers, including our use and disclosure of certain customer information.
Our operations are also subject to federal and state laws governing information security. In the event of an information security breach, such rules may require consumer and government agency notification and may result in regulatory enforcement actions with the potential of monetary forfeitures. The FCC, the FTC and state attorneys general regularly bring enforcement actions against companies related to information security breaches and privacy violations.
Various security standards provide guidance to telecommunications companies in order to help identify and mitigate cybersecurity risks. One such standard is the voluntary framework released by the National Institute for Standards and Technologies (“NIST”) in 2014 and updated in 2018, in cooperation with other federal agencies and owners and operators of U.S. critical infrastructure. The NIST cybersecurity framework provides a prioritized and flexible model for organizations to identify and manage cyber risks inherent to their business. It was designed to supplement, not supersede, existing cybersecurity regulations and requirements. Several government agencies have encouraged compliance with the NIST cybersecurity framework, including the FCC, which is also considering expansion of its cybersecurity guidelines or the adoption of cybersecurity requirements.
Many states and local authorities have considered legislative or other actions that would impose restrictions on our ability to collect, use and disclose, and safeguard certain consumer information, particularly with regard to our broadband Internet business. For example, the California Consumer Privacy Act and Maine’s Act to Protect Privacy of Online Customer Information are both scheduled go into effect in 2020. The California law will, under certain circumstances, regulate companies’ use and disclosure of the personal information of California residents and authorizes enforcement actions by the California Attorney General and private class actions for data breaches. The Maine law regulates how Internet service providers use and disclose customers’ personal information and requires Internet service providers to take reasonable measures to protect customers’ personal information. We expect state and local efforts to regulate consumer privacy to continue in 2020. Additionally, several state legislatures are considering the adoption of new data security and cybersecurity legislation that could result in additional network and information security requirements for our business. We expect such state activity to increase as a result of the recent U.S. Court of Appeals decision that, while affirming the FCC’s reclassification of Internet access as an “information service,” vacated the FCC’s blanket prohibition of state regulation of broadband service and instead left open the possibility that individual state laws could be deemed preempted on a case by case basis if it is shown that they conflict with federal law. There are also bills pending in both the U.S. House of Representatives and Senate that could impose new privacy and data security obligations. We cannot predict whether any of these efforts will be successful or preempted, or how new legislation and regulations, if any, would affect our business.
Commitments Related to the 2016 Merger with TWC and Acquisition of Bright House
In connection with approval of the 2016 merger with TWC and acquisition of Bright House (the "Transactions"), federal and state regulators imposed a number of post-transaction conditions on us including but not limited to the following.
FCC Conditions
| • | Offer settlement-free Internet interconnection to any party that meets the requirements of our Interconnection Policy (available on Charter’s website) on terms generally consistent with the policy for seven years (with a possible reduction to five years from FCC approval in 2016); |
| • | Deploy and offer high-speed broadband Internet access service to an additional two million locations over five years; |
| • | Refrain from charging usage-based prices or imposing data caps on any fixed mass market broadband Internet access service plans for seven years (with a possible reduction to five); |
| • | Offer 30/4 Mbps discounted broadband where technically feasible to eligible customers throughout our service area for four years from the offer’s commencement; and |
| • | Continue to provide CableCARDs to any new or existing customer upon request for use in third-party retail devices for four years and continue to support such CableCARDs for seven years (in each case, unless the FCC changes the relevant rules). |
The FCC conditions also contain a number of compliance reporting requirements.
DOJ Conditions
The Department of Justice (“DOJ”) Order prohibits us from entering into or enforcing any agreement with a video programmer that forbids, limits or creates incentives to limit the video programmer’s provision of content to online video distributors ("OVDs"). We will not be able to avail ourself of other distributors’ most favored nation (“MFN”) provisions if they are inconsistent with this prohibition. The DOJ’s conditions are effective for seven years after entry of the final judgment in 2016, although we may petition the DOJ to eliminate the conditions after five years.
State Conditions
Certain state regulators, including California, New York, Hawaii and New Jersey also imposed conditions in connection with the approval of the Transactions. These conditions include requirements related to:
| • | Building out our network to certain households and business locations that are not currently served by cable within the designated states; |
| • | Offering LifeLine service discounts and low-income broadband to eligible households served within the applicable states; |
| • | Investing in service improvement programs and customer service enhancements and maintaining customer-facing jobs within the designated state; and |
| • | Complying with reporting requirements. |
Employees
As of December 31, 2019, we had approximately 95,100 active full-time equivalent employees.
Previous: Cover and table of contents · Next: Item 1A. Risk Factors.