 filings.tools
Cincinnati Financial (CINF) 10-K risk factor changes: FY2022 vs FY2021
The 2022-12-31 10-K against the 2021-12-31 one, compared heading by heading and sentence by sentence.
Item 1A54 rewritten48 added18 removed242 unchanged
All filing items2,219 rewritten462 added411 removed2,670 unchanged
Sentence counts leave out repeated page headers and footers. 197 of those lines differ and are listed apart under each item.
Summary
counted, not written
- Item 1A lists 21 risk factor headings: 4 new, 3 reworded and 14 unchanged since FY2021. 1 heading from FY2021 no longer appears.
- Sentence by sentence, 462 added, 411 removed, 2,219 rewritten and 2,670 unchanged across 17 items that differ.
- Not counted above: 197 repeated page header or footer lines also differ. They are listed apart under each item.
New Item 1A headings (4)
- Climate change may adversely impact our results of operations and/or our financial position.
- Developments relating to the Russian war against Ukraine could adversely affect our insurance operations or other financial matters.
- Elevated inflation may negatively impact profit and the value of investments.
- Any failure to protect the confidentiality of customer information could adversely affect our reputation or expose us to fines, penalties or litigation, which could have a material adverse effect on our business, financial condition and results of operations.
Removed Item 1A headings (1)
- The anticipated benefits may not be realized for our acquisition of Cincinnati Global.
Reworded Item 1A headings (3)
- We could experience an unusually high level of losses due to
[removed: catastrophic,][added: natural or man-made catastrophe,] terrorism or epidemic events or risk concentrations. [removed: Cincinnati Global’s international][added: International] operations subject us to additional regulation and[removed: could]expose us to additional investment, political and economic risks.- Developments relating to the United
[removed: Kingdom’s][added: Kingdom] leaving the European Union could adversely affect Cincinnati Global’s operations.
A heading is new when no FY2021 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
23 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2022; struck-through words were in FY2021. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors
54 rewritten, 48 added, 18 removed, 242 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
We could experience an unusually high level of losses due to [removed: catastrophic,] [added: natural or man-made catastrophe,] terrorism or epidemic events or risk concentrations.
Man-made catastrophes to which we may be exposed include, but are not limited to, industrial accidents, terrorist attacks, [added: cyberattacks, infrastructure failures,] social unrest and riot.
[removed: Additionally,] [added: Other] man-made events, such as hydraulic fracturing, could cause damage from earth movement or create environmental and/or health hazards.
According to these models, probable maximum loss estimates from a single hurricane event that combine the effects of property casualty insurance written on a direct basis by The Cincinnati Insurance Companies, the Cincinnati Re reinsurance portfolio and risks insured by Cincinnati Global include the following amounts, net of amounts recoverable through reinsurance ceded and also income taxes, and including the effects of estimated reinstatement premiums: [removed: $428] [added: $540] million for a once-in-a-100-year event and [removed: $602] [added: $798] million for a once-in-a-250-year event.
Please see Item 7, Liquidity and Capital Resources, [removed: 2022] [added: 2023] Reinsurance Programs, for a discussion of modeled losses considered in evaluating our risk mitigation strategy, which includes our ceded reinsurance program.
Our geographic concentration [removed: ties] [added: links] our performance to business, economic, environmental and regulatory conditions in certain states.
We also have exposure in states where we do not actively market insurance when clients of our independent agencies have businesses or properties in multiple [removed: states.][added: states or we provide insurance through Cincinnati Global and reinsurance through Cincinnati Re.]
The Cincinnati Insurance Company continues to expand its Cincinnati Re reinsurance assumed operations and has staffed it with seasoned underwriting and analytical [removed: talent] [added: associates] who strive to assume risks that we [removed: understand well,] [added: understand,] both quantitatively and qualitatively.
Based on treaties in effect at January 1, [removed: 2022,] [added: 2023,] the largest loss exposure to us for Cincinnati Re is from natural catastrophe events.
That exposure includes probable maximum loss estimates, on a marginal basis, of the following amounts: [removed: $174] [added: $167] million for a once-in-a-100-year event and [removed: $167] [added: $198] million for a once-in-a-250-year event.
They are based on probable maximum loss estimates from the Applied Insurance Research Touchstone® version [removed: 8.0] [added: 10.0] catastrophe model.
Ignoring diversification effects provided by those two components, on a standalone basis, probable maximum loss estimates for Cincinnati Re include the following amounts: [removed: $201] [added: $204] million for a once-in-a-100-year event and [removed: $230] [added: $244] million for a once-in-a-250-year event.
[removed: We] [added: Given its seasoned underwriting associates, we] are also expanding Cincinnati Global, our global specialty underwriter with premiums primarily for U.S. and international property [removed: exposures, given its seasoned underwriting talent.][added: exposures.]
At January 1, [removed: 2022,] [added: 2023,] the largest loss exposure to us for Cincinnati Global is from natural catastrophe events.
[removed: That] [added: Cincinnati Global's] exposure [added: from such events] includes probable maximum loss estimates of the following amounts: [removed: $49] [added: $71] million for a once-in-a-100-year event and [removed: $78] [added: $106] million for a once-in-a-250-year event.
[added: They are] based on probable maximum loss estimates from the Applied Insurance Research Touchstone version [removed: 8.0] [added: 10.0] catastrophe model.
[added: If there is a high frequency of large property catastrophe or terrorism events, or a single extreme] event, during the coverage period of its policies, our financial position and results of operations could be materially affected.
If we cannot obtain adequate [added: reinsurance or primary insurance] coverage at a reasonable cost, it could constrain where we can write business or reduce the amount of business we can write in certain areas.
Our estimates for COVID-19 losses and loss adjustment expenses represent our best estimates as of December 31, [removed: 2021,] [added: 2022,] based upon information currently available.
While we believe our net reserves for losses and loss adjustment expenses for COVID-19 as of December 31, [removed: 2021,] [added: 2022,] are adequate based on information available at this time, we continue to closely monitor reported claims, government actions, judicial decisions and changes in the levels of worldwide social disruption and economic activity arising from the pandemic and will adjust our estimates of gross and net losses as new information becomes available.
Factors that affect our estimates of losses and loss adjustment expenses or our ability to reasonably estimate such losses include the [removed: continuing duration of the pandemic and governmental actions to limit the spread of the virus that may produce additional economic losses; the] number of policyholders that will ultimately submit claims or file lawsuits; the lack of submitted proofs of loss for allegedly covered claims; judicial rulings in similar litigation involving other companies in the insurance industry; difference in state law and developing case law; litigation trends, including varying legal theories advanced by policyholders; whether and to what degree any class of policyholders may be certified; and the inherent unpredictability of litigation.
To properly price our products, we must collect, properly analyze and use data to make decisions and take appropriate action; the data must be sufficient, reliable and accessible; [added: Cincinnati Global has risks due to its reliance on coverholders in underwriting parts of its business;] we need to develop appropriate rating methodologies and formulae; and we may need to identify and respond to trends quickly.
[added: Inflation trends, especially outside of] historical norms, [added: such as we experienced during 2022,] may make it more difficult to determine adequate pricing.
- Underwriting and pricing methodologies that allow insurers to identify and [removed: flexibly] [added: appropriately] price risks
Unforeseen losses, [added: or unintended coverages,] the type and magnitude of which we cannot predict, may emerge.
Similar risks exist for Cincinnati Global due to [removed: reliance on coverholders] [added: potential delays] in [removed: underwriting parts of its business.][added: loss reporting.]
[removed: Cincinnati Global’s international] [added: International] operations subject us to additional regulation and [removed: could] expose us to additional investment, political and economic risks.
We have international operations that [removed: could] expose us to a number of additional risks.
Our business activities outside the United States, including the [removed: United Kingdom (U.K.), could also be] [added: U.K.,] subject [added: us] to political and economic risks, including foreign currency and credit risk.
[removed: Additionally, business] [added: Business] activities outside the United States will subject us to additional domestic and foreign laws and regulations, including the Foreign Corrupt Practices Act, the U.K. Bribery Act and similar laws in other countries that prohibit the making of improper payments to foreign officials.
There is risk that [removed: plans] [added: Cincinnati Global's plan] will not be approved or will be limited.
As a Lloyd’s managing agent and syndicate, Cincinnati Global is exposed to various risks and [removed: the uncertainties associated,] [added: their associated uncertainties,] including [removed: its] [added: Lloyd’s rating agency ratings, reputation, and Cincinnati Global’s] obligation to maintain funds at Lloyd’s to support its underwriting activities and periodic assessment of its capital, governance and other aspects of its business.
Developments relating to the United [removed: Kingdom’s] [added: Kingdom] leaving the European Union could adversely affect Cincinnati Global’s operations.
With a view to mitigating the potential effects of Brexit on business underwritten through it, Lloyd’s has set up an insurance company subsidiary in Belgium, [removed: with the intention of] [added: Lloyd's Europe,] underwriting European Economic Area insurance business via that subsidiary.
Please see Item 7, Liquidity and Capital Resources, [removed: 2022] [added: 2023] Reinsurance Ceded Programs, for a discussion of selected reinsurance transactions.
[removed: The] [added: Recent events, including the] outbreak of [removed: COVID-19] [added: COVID-19, global supply chain disruptions, increasing interest rate environment and inflationary pressures, have] contributed to significant disruption and volatility for financial markets and decreased economic activity.
In the event that these conditions [removed: recur] [added: continue] or result in a prolonged economic [removed: downturn,] [added: downturn or recession,] they could [added: further] adversely impact our financial condition, results of operations or cash flows.
For fixed-maturity investments such as bonds, which represented [removed: 53.5%] [added: 55.2%] of the fair value of our investment portfolio at the end of [removed: 2021,] [added: 2022,] the inverse relationship between interest rates and bond prices leads to falling bond values during periods of increasing interest rates.
[removed: A significant increase] [added: Significant increases] in the general level of interest [removed: rates] [added: rates, such as we experienced during 2022,] could have an adverse effect on our shareholders’ equity.
These events [added: have in the past and] may [added: in the future] adversely affect the economy generally and [removed: could] cause our investment income or the value of securities we own to decrease.
Premium revenues and underwriting profit could also be adversely affected by marked or prolonged economic downturns or other events.
Economic events experienced during 2022 included elevated inflation, global supply chain disruptions, increasing interest rates, tightening credit markets and higher fuel costs.
Our insurance operations expose us to claims arising out of catastrophes.
- Tornadoes, wind and hail.
- Winter storms.
Cincinnati Global also writes North American and United Kingdom (U.K.) contingency and event cancellation coverage and worldwide credit and political risk coverage and political violence coverage.
Climate change may adversely impact our results of operations and/or our financial position.
Global climate change from rising planet temperatures over the last several decades has been linked to a number of factors that contribute to the increased unpredictability, frequency, duration and severity of weather events, including: changing weather patterns, a rise in ocean temperatures and sea level rise.
Further increases or persistence in these conditions would lead to higher overall losses, which we may not be able to recoup, particularly in a highly regulated and competitive environment, and higher reinsurance costs.
Certain catastrophe models assume an increase in frequency and severity of certain weather or other events, which could result in a disproportionate impact on insurers with certain geographic concentrations of risk.
This would also likely increase the risks of writing property insurance in coastal areas or areas susceptible to wildfires or flooding, particularly in jurisdictions that restrict pricing and underwriting flexibility.
The threat of rising seas or other catastrophe losses as a result of global climate change may also cause property values in coastal or such other communities to decrease, reducing the total amount of insurance coverage that is required.
Our life policy reserves are also subject to uncertainty.
Periods of higher death claims outside of long-term historical norms, such as the COVID-19 pandemic, and not anticipated within our actuarial models could make our life policy reserves inadequate to cover actual future death claims.
Increases in estimates of future death claims would increase life policy reserve levels and in turn decrease earnings.
Because of the inherent uncertainties involved in setting reserves, we cannot provide assurance that our existing reserves or future reserves will prove adequate in light of subsequent events.
Our results of operations and financial condition have in the past been, and in the future could be, materially affected by adverse loss development for events that we insured in prior periods.
Developments relating to the Russian war against Ukraine could adversely affect our insurance operations or other financial matters.
We have limited direct exposure within our insurance operations to businesses or individuals in Russia or the Ukraine reported in our consolidated property casualty insurance catastrophe losses and loss expenses incurred, net of reinsurance.
We do not have material exposure to investments subject to embargos or Russian reinsurance counterparties.
However, the ongoing Russian war against Ukraine is impacting global economic, banking, commodity, and financial markets, exacerbating ongoing economic challenges, including inflation and supply chain disruption, which impacts insurance loss costs, premiums and investment valuation.
We also have life policy reserves established for traditional life policies including term, whole and other products.
Reserve variability could increase with the adoption of ASU 2018-12 as discussed in Item 8, Note 1 of the Consolidated Financial Statements, as reserves are based on certain cash flow assumptions as well as a discount rate assumption.
This discount rate assumption is based on updated market value discount rates.
Life policy reserves are required to be remeasured using an updated discount rate assumption quarterly.
Remeasurement adjustments for the updated discount rate are recorded as an increase or decrease to life policy reserves with an offsetting increase or decrease to accumulated other comprehensive income (AOCI).
As the discount rate increases during the quarter, life policy reserves decrease and AOCI increases.
Conversely, as the discount rate decreases during the quarter, life policy reserves increase and AOCI decreases.
A significant decrease in discount rates, relative to the prior quarter, could have an adverse effect on shareholders' equity.
Elevated inflation may negatively impact profit and the value of investments.
Inflation in various forms, such as we experienced in 2022, can reduce underwriting profitability due to higher losses and loss expenses to repair damaged autos or other property that we insure.
Elevated inflation can also be in the form of social inflation of litigation costs, jury awards and settlement expectations.
In addition to potential adverse effects on the fair value of our equity portfolio, inflationary pressures can also cause or contribute to, or are the result of, increases in interest rates, which would reduce the fair value of our fixed-maturity portfolio.
During some periods, such as we experienced in 2022, labor markets are tight and there is intense competition for associates qualified to execute important business functions.
In addition, global climate change and global climate change transitions could lead to new or enhanced regulation, which may be difficult or costly to comply with, or impact assets that we invest in, which may result in realized and unrealized losses in future periods that could have a material adverse impact on our results of operations and/or financial position.
It is not possible to foresee the impacts of potential future climate regulation, or which, if any, assets, industries or markets may be materially and adversely affected by global climate change and global climate change transitions, nor is it possible to foresee the magnitude of such effects.
From time to time we have had to, and in the future we may need to, increase or expend resources to investigate or remediate vulnerabilities as a result of data security incidents.
Such resources are costly in time and expense, and detract from resources spent on or are otherwise devoted to our core operations.
In addition, depending on the nature of an incident, we may not be able to detect an incident readily, assess its severity or impact, or appropriately respond in a timely manner, which could increase our risk and exposures.
Any failure to protect the confidentiality of customer information could adversely affect our reputation or expose us to fines, penalties or litigation, which could have a material adverse effect on our business, financial condition and results of operations.
In the normal course of our business, both in our insurance and reinsurance operations, we provide coverage against perils for which estimates of losses are highly uncertain, in particular catastrophic and terrorism events.
Various scientists and other experts believe that changing climate conditions have added to the unpredictability, frequency and severity of such natural disasters in certain parts of the world and have created additional uncertainty as to future trends and exposures.
We cannot predict the impact that changing climate conditions may have on our results of operations nor can we predict how any legal, regulatory or social responses to concerns about climate change may impact our business.
- Tornadoes, wind and hail in the Midwest, South, Southeast, Southwest and the mid-Atlantic.
They are
If there is a high frequency of large property catastrophe or terrorism events, or a single extreme
Inflation trends, especially outside of
The anticipated benefits may not be realized for our acquisition of Cincinnati Global.
Cincinnati Global, our London-based global specialty underwriter for Lloyd's Syndicate 318, was acquired on February 28, 2019.
We can provide no assurance that the anticipated benefits of the transaction will be fully realized in the time frame anticipated or at all, or that the costs or difficulties related to further developing its operations will not be greater than expected.
The success of the transaction will depend, in part, on our ability to realize the anticipated business opportunities and growth prospects from acquiring Cincinnati Global.
We may never realize these business opportunities and growth prospects, and our management might have its attention diverted while trying to further develop ongoing operations.
It is uncertain how effective Lloyd's proposed Brexit contingency plan will be.
This risk is exacerbated because approximately 64% of our associates typically work at our Fairfield, Ohio, headquarters.
As stay-at-home actions were enacted in 2020, we promptly and effectively transitioned most of our headquarters associates to working from home.
adapt to changing business needs.
In the event of a disaster such as a natural
Threats to data security, including unauthorized access and cyberattacks, rapidly emerge and change, exposing us to additional costs for protection or remediation and competing time constraints to secure our data in accordance with customer expectations and statutory and regulatory requirements.
An excerpt. Shown here: 40 of 54 rewritten, 40 of 48 added and all 18 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors in the FY2022 filing and the FY2021 filing.
Page headers and footers: 12 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 32
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 33
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 34
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 35
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 36
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 37
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 38
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 39
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 40
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 41
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 42
Cincinnati Financial Corporation - 2022 10-K - Page 43
Item 7. Management's Discussion and Analysis of Financial Condition and
784 rewritten, 188 added, 179 removed, 856 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
Through The Cincinnati Insurance Company, Cincinnati Financial Corporation is one of the 25 largest property casualty insurers in the nation, based on net written premium volume for the first nine months of [removed: 2021,] [added: 2022,] among approximately 2,000 U.S. stock and mutual insurer groups.
Those revenues are further reduced by underwriting expenses associated with marketing policies or related to administration of our insurance [removed: operation.][added: operations.]
| [removed: As] [added: As] of December 31, [removed: 2021] [added: 2021] | | | | | | [removed: 25.7] [added: 25.7] | | [removed: %] | | | | [removed: 23.6] [added: 23.6] | | [removed: %] | | | | [removed: 18.7] [added: 18.7] | | [removed: %] |
[removed: We also exceeded] [added: It was within] the [removed: high end of] [added: range for] the [added: five-year period, but below the] range for [removed: both] the three-year [removed: and five-year periods] [added: period, both] that ended in December [removed: 2021.][added: 2022.]
| | | | | | | Years ended December 31, | | | | | | | | | | | | | | | | | | [removed: 2021-2020] [added: 2022-2021] | | | | | | [removed: 2020-2019] [added: 2021-2020] | | |
| | | | | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2020] [added: 2021] | | | | | | [removed: 2019] [added: 2020] | | | | | | Pt. Change | | | | | | Pt. Change | | |
| Net income before investment gains | | | | | | [removed: 9.7] [added: 5.2] | | % | | | | [removed: 5.5] [added: 9.7] | | % | | | | [removed: 8.9] [added: 5.5] | | % | | | | [removed: 4.2] [added: (4.5)] | | | | | | [removed: (3.4)] [added: 4.2] | | |
| Change in fixed-maturity securities, realized and unrealized gains | | | | | | [removed: (1.5)] [added: (10.1)] | | | | | | [removed: 3.0] [added: (1.5)] | | | | | | [removed: 5.5] [added: 3.0] | | | | | | [removed: (4.5)] [added: (8.6)] | | | | | | [removed: (2.5)] [added: (4.5)] | | |
| Change in equity securities, investment gains | | | | | | [removed: 16.8] [added: (9.3)] | | | | | | [removed: 7.5] [added: 16.8] | | | | | | [removed: 16.6] [added: 7.5] | | | | | | [removed: 9.3] [added: (26.1)] | | | | | | [removed: (9.1)] [added: 9.3] | | |
| Other | | | | | | [removed: 0.7] [added: (0.4)] | | | | | | [removed: (1.3)] [added: 0.7] | | | | | | [removed: (0.5)] [added: (1.3)] | | | | | | [removed: 2.0] [added: (1.1)] | | | | | | [removed: (0.8)] [added: 2.0] | | |
| Value creation ratio | | | | | | [removed: 25.7] [added: (14.6)] | | % | | | | [removed: 14.7] [added: 25.7] | | % | | | | [removed: 30.5] [added: 14.7] | | % | | | | [removed: 11.0] [added: (40.3)] | | | | | | [removed: (15.8)] [added: 11.0] | | |
The [removed: 2021 value creation ratio increased by 11.0 percentage points,] [added: increase in 2021,] compared with 2020, [removed: including] [added: included] improved operating results and a higher valuation for our investment [removed: portfolio, as shown in the table above.][added: portfolio.]
| | | | | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2020] [added: 2021] | | | | | | [removed: 2019] [added: 2020] | | |
| End of period book value* | | | | | | $ | [removed: 81.72] [added: 67.01] | | | | | $ | [removed: 67.04] [added: 81.72] | | | | | $ | [removed: 60.55] [added: 67.04] | |
| Less beginning of period book value | | | | | | [removed: 67.04] [added: 81.72] | | | | | | [removed: 60.55] [added: 67.04] | | | | | | [removed: 48.10] [added: 60.55] | | |
| Change in book value | | | | | | [removed: 14.68] [added: (14.71)] | | | | | | [removed: 6.49] [added: 14.68] | | | | | | [removed: 12.45] [added: 6.49] | | |
| Dividend declared to shareholders | | | | | | [removed: 2.52] [added: 2.76] | | | | | | [removed: 2.40] [added: 2.52] | | | | | | [removed: 2.24] [added: 2.40] | | |
| Total value creation | | | | | | $ | [removed: 17.20] [added: (11.95)] | | | | | $ | [removed: 8.89] [added: 17.20] | | | | | $ | [removed: 14.69] [added: 8.89] | |
| Value creation ratio from change in book value | | | | | | [removed: 21.9] [added: (18.0)] | | % | | | | [removed: 10.7] [added: 21.9] | | % | | | | [removed: 25.9] [added: 10.7] | | % |
| Value creation ratio from dividends declared to shareholders* | | | | | | [removed: 3.8] [added: 3.4] | | | | | | [removed: 4.0] [added: 3.8] | | | | | | [removed: 4.6] [added: 4.0] | | |
| Value creation ratio | | | | | | [removed: 25.7] [added: (14.6)] | | % | | | | [removed: 14.7] [added: 25.7] | | % | | | | [removed: 30.5] [added: 14.7] | | % |
The compound annual growth rate of our net written premiums was [removed: 7.2%] [added: 8.6%] over the five-year period [removed: 2017] [added: 2018] through [removed: 2021,] [added: 2022,] exceeding the [removed: 5.8%] [added: 7.3%] estimated growth rate for the property casualty insurance industry, with [removed: 2021] [added: 2022] representing industry data reported through the first nine months of [removed: 2021.][added: 2022.]
Our GAAP combined ratio averaged [removed: 94.8%] [added: 94.9%] over the five-year period [removed: 2017] [added: 2018] through [removed: 2021,] [added: 2022,] slightly better than the performance target range.
Our statutory combined ratio averaged [removed: 94.2%] [added: 94.3%] over the five-year period [removed: 2017] [added: 2018] through [removed: 2021,] [added: 2022,] compared with an estimated [removed: 100.3%] [added: 99.7%] for the property casualty industry, with [removed: 2021] [added: 2022] representing industry data reported through the first nine months of [removed: 2021.][added: 2022.]
◦Investment income growth, on a pretax basis, had a compound annual growth rate of [removed: 3.7%] [added: 5.1%] over the five-year period [removed: 2017] [added: 2018] through [removed: 2021.][added: 2022.]
◦Over the five years ended December 31, [removed: 2021,] [added: 2022,] our equity portfolio compound annual total return was [removed: 18.0%] [added: 11.1%] compared with a compound annual total return of [removed: 18.5%] [added: 9.4%] for the Index.
For the year [removed: 2021,] [added: 2022,] our equity portfolio total return was [removed: 29.6%,] [added: negative 10.9%,] compared with [removed: 28.7%] [added: negative 18.1%] for the Index.
Through [removed: 2021,] [added: 2022,] the company has increased the annual cash dividend rate for [removed: 61] [added: 62] consecutive years, a record we believe is matched by only seven other publicly traded U.S. companies.
The board regularly evaluates relevant factors in dividend-related decisions, and the [removed: 2021] [added: 2022] increase to the regular dividend reflected confidence in our [removed: strong] [added: outstanding] capital, liquidity and financial flexibility, as well as progress of our initiatives to improve earnings performance while growing insurance premium revenues.
| | | | | | | [removed: 2021] [added: 2022] | | | | | | [added: 2021 | | | | | |] 2020 | | | [added: | | | Change % | | | | | | Change % | | |]
| Total investments | | | | | | $ | [removed: 24,666] [added: 22,425] | | | | | $ | [removed: 21,542] [added: 24,666] | |
| Total assets | | | | | | [removed: 31,387] [added: 29,736] | | | | | | [removed: 27,542] [added: 31,387] | | |
| Short-term debt | | | | | | [removed: 54] [added: 50] | | | | | | 54 | | |
| Long-term debt | | | | | | 789 | | | | | | [removed: 788] [added: 789] | | |
| Shareholders' equity | | | | | | [removed: 13,105] [added: 10,531] | | | | | | [removed: 10,789] [added: 13,105] | | |
| Book value per share | | | | | | [removed: 81.72] [added: 67.01] | | | | | | [removed: 67.04] [added: 81.72] | | |
| Debt-to-total-capital ratio | | | | | | [removed: 6.0] [added: 7.4] | | % | | | | [removed: 7.2] [added: 6.0] | | % |
Total investments [removed: increased] [added: decreased] by [removed: 15%] [added: 9%] during [removed: 2021] [added: 2022] on a fair value basis, [removed: with an increase] [added: and included a decrease] in our securities portfolio valuation that [removed: added to] [added: offset] a [removed: 7%] [added: 6%] increase in its cost basis.
Entering [removed: 2022,] [added: 2023,] we believe the portfolio continues to be well diversified and is well positioned to withstand short-term fluctuations.
Shareholders’ equity [removed: increased] [added: decreased] by [removed: 21%] [added: 20%] and book value per share [removed: increased] [added: decreased] by [removed: 22%,] [added: 18%,] for reasons discussed in the preceding Executive Summary.
| As of December 31, 2022 | | | | | | (14.6) | | % | | | | 8.6 | | % | | | | 11.2 | | % |
At negative 14.6% for 2022, our performance was significantly below the low end of that range.
The 2022 value creation ratio decreased by 40.3 percentage points, compared with 2021, and again included a significant contribution from operating results, as shown in the table above.
The 2022 ratio decrease was primarily due to a reduction in overall net gains from our investment portfolio, with reductions of 26.1 percentage-points from our equity securities investment portfolio and 8.6 points from our fixed-maturity securities investment portfolio.
| | | | | | | 2022 | | | | | | 2021 | | |
Total assets decreased by 5%, compared with year-end 2021.
A net loss of $486 million in 2022 represented a decrease of $3.432 billion, compared with net income for 2021, including a $3.062 billion reduction in net investment gains on an after-tax basis.
During 2022, SARS-CoV-2, also known as COVID-19 and recognized as a pandemic by the World Health Organization, continued to cause various effects in parts of the world.
We believe it did not have a significant effect on our premium revenues during 2022 and there were no material changes to our estimates for incurred losses and expenses related to the pandemic.
In 2021, it caused dampening economic effects in some areas where we
During the first half of 2022, most of our headquarters associates transitioned to a hybrid work schedule, regularly alternating between work at our headquarters and work from remote locations.
The $591 million decrease in 2022, compared with excellent results in 2021, included higher current accident year loss and loss expenses before catastrophe losses, reflecting increased uncertainty of estimated ultimate losses, due in part to elevated paid losses reflecting economic or other forms of inflation.
| At December 31, 2022 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Total | | | | | | $ | 7,931 | | | | | $ | 7,393 | | | | | $ | 8,099 | | | | | $ | 353 | | | | | $ | 279 | |
| Commercial casualty | | | | | | $ | 2,779 | | | | | $ | 2,424 | | | | | $ | 2,964 | | | | | $ | 270 | | | | | $ | 213 | |
| Commercial property | | | | | | 581 | | | | | | 441 | | | | | | 682 | | | | | | 121 | | | | | | 96 | | |
| Commercial auto | | | | | | 834 | | | | | | 791 | | | | | | 877 | | | | | | 43 | | | | | | 34 | | |
| Workers' compensation | | | | | | 983 | | | | | | 870 | | | | | | 1,037 | | | | | | 83 | | | | | | 66 | | |
| Personal auto | | | | | | 321 | | | | | | 300 | | | | | | 343 | | | | | | 22 | | | | | | 17 | | |
| Homeowners | | | | | | 353 | | | | | | 330 | | | | | | 375 | | | | | | 23 | | | | | | 18 | | |
| Excess and surplus | | | | | | 731 | | | | | | 679 | | | | | | 783 | | | | | | 55 | | | | | | 43 | | |
Profit decreased in 2022, reflecting increased uncertainty of estimated ultimate losses, due in part to elevated paid losses reflecting economic or other forms of inflation.
The 2022 ratio for current accident year losses and loss expenses before catastrophes increased by 4.2 percentage points, reflecting inflation effects discussed below.
The combined ratio increase and related decrease in property casualty underwriting income in 2022 included higher insured loss experience before catastrophe effects driven by various forms of inflation.
Effects of the pandemic also contributed to increased uncertainty regarding ultimate losses.
We believe the past two years distorted paid loss cost trends for reasons such as slowed activity for many businesses, reduced driving and closed courts that delayed progress on some litigated insurance claims.
Until longer-term paid loss cost trends become more clear, we intend to remain prudent in reserving for estimated ultimate losses.
As a result, incurred losses in 2022 for several lines of business were higher than in prior years and are further discussed in results for our commercial lines and personal lines insurance segments.
Elevated inflation was a driver of higher losses and loss expenses as costs have increased significantly to repair damaged autos or other property that we insure.
In addition to inflation affecting historic loss patterns, we believe reduced driving during the pandemic resulted in a relatively low level of loss activity in 2021, distorting paid loss cost trends for autos.
We also experienced higher losses for liability coverages for some of our lines of business, particularly for commercial umbrella insurance.
We believe future property casualty underwriting results will continue to benefit from price increases and our ongoing initiatives to improve pricing precision and loss experience related to claims and loss control practices.
Losses estimated for Hurricane Ian as of December 31, 2022, resulted in an estimated recovery of $19 million.
Ultimate loss experience could be lower or higher than that estimate.
Reserve estimates are inherently uncertain and our proprietary adjustments and ultimate loss estimates will develop as more information is reported by affected ceding companies.
Effective in May 2022, to provide more capacity to retain risks, we added a quota share reinsurance arrangement for our personal lines risks in California that we insure through excess and surplus lines policies.
Approximately 27% of the risk is reinsured through ceded premiums.
Included in all other 2022 catastrophes is an estimate of $8 million for catastrophe losses and loss expenses incurred, net of reinsurance, for direct exposure within our Other insurance operation to businesses or individuals in Russia or Ukraine.
| 2022 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| All other 2022 catastrophes | | | | | | | | | 151 | | | | | | 130 | | | | | | 3 | | | | | | 20 | | | | | | 304 | | |
| As of December 31, 2019 | | | | | | 30.5 | | | | | | 17.8 | | | | | | 14.2 | | |
At 25.7% for 2021, our performance exceeded the high end of that range.
The decrease in 2020, compared with 2019, was primarily due to a less favorable valuation for our investment portfolio.
Total assets rose 14%.
Net income in 2020 decreased by $781 million, compared with 2019, including a $620 million decrease for 2020 net investment gains after taxes.
to shelter-in-place, stay-at-home and other governmental actions.
In 2020, the pandemic slowed the growth of our premium revenues, including new business written premiums.
For our long-tail lines such as workers’ compensation, commercial casualty and certain other liability lines, models from the probabilistic trend family tend to provide superior fits and to validate well, compared with models underlying the loss development and Bornhuetter-Ferguson methods.
| Total | | | | | | $ | 6,902 | | | | | $ | 6,446 | | | | | $ | 7,014 | | | | | $ | 284 | | | | | $ | 224 | |
| Commercial casualty | | | | | | $ | 2,464 | | | | | $ | 2,222 | | | | | $ | 2,655 | | | | | $ | 217 | | | | | $ | 171 | |
| Commercial property | | | | | | 456 | | | | | | 314 | | | | | | 527 | | | | | | 107 | | | | | | 85 | | |
| Commercial auto | | | | | | 759 | | | | | | 708 | | | | | | 798 | | | | | | 45 | | | | | | 36 | | |
| Workers' compensation | | | | | | 965 | | | | | | 815 | | | | | | 989 | | | | | | 87 | | | | | | 69 | | |
| Personal auto | | | | | | 292 | | | | | | 272 | | | | | | 313 | | | | | | 21 | | | | | | 17 | | |
| Homeowners | | | | | | 299 | | | | | | 282 | | | | | | 316 | | | | | | 17 | | | | | | 13 | | |
| Excess and surplus | | | | | | 562 | | | | | | 521 | | | | | | 603 | | | | | | 43 | | | | | | 34 | | |
Pandemic-related incurred losses and expenses of $85 million in 2020 were discussed in more detail in Corporate Financial Highlights of Management’s Discussion and Analysis.
We believe the COVID-19 pandemic did not have a significant effect on our consolidated property casualty premium revenues for the last three quarters of 2021, while it had a modestly slowing effect on premium growth for the first quarter.
The pandemic and a weakened economy reduced premium volume during the first quarter of 2021 and during much of 2020.
A strengthening economy in 2021 contributed to premium growth, compared with the same period a year ago.
Consolidated property casualty net written premiums grew 10% in 2021, compared with 2020, including a contribution of 3% from Cincinnati Re.
For policies that renewed during 2021, higher average pricing also contributed to premium growth.
Regardless of pricing changes, new business and renewal premium amounts could decline if the exposure basis for policy premiums, such as sales and payrolls of businesses we insure, decrease as a result of a weakened economy.
Loss experience for our insurance operations is influenced by many factors as discussed in further detail in Financial Results by property casualty insurance segment.
For future periods, factors that reduce exposure to certain insurance losses, such as fewer vehicular miles driven or reduced sales and payrolls for businesses, could cause a reduction in future losses that generally correspond to reduced premiums.
However, there could be losses or legal expenses that occur independent of changes in mileage, sales or payrolls of businesses we insure, due to pandemic effects or other factors.
The 2021 ratio for current accident year losses and loss expenses before catastrophes improved by 1.0 percentage point, largely reflecting what we believe are improvements to some of our loss experience due to recent-year initiatives to improve pricing precision and claims and loss control practices.
was 99.5% in 2021, 99.1% in 2020 and 99.2% in 2019.
Effective June 1, 2021, we nonrenewed our combined property catastrophe occurrence excess of loss treaty that provided coverage for business written on a direct basis and by Cincinnati Re.
We determined that the coverage was no longer cost effective.
It provided a recovery based on Hurricane Ida losses estimated as of December 31, 2021.
The estimated recovery from the program was $16 million, with a net incurred loss of $80 million for Cincinnati Re in 2021, excluding the benefit of reinstatement premiums estimated at approximately $11 million.
| Jul. 8-10 | | | Flood, Hail, Wind | | | Midwest | | | | | | 5 | | | | | | 6 | | | | | | — | | | | | | — | | | | | | 11 | | |
| Aug. 29 - Sep. 2 | | | Flood, Hail, Wind | | | Northeast, South (Ida) | | | | | | 14 | | | | | | 36 | | | | | | — | | | | | | 118 | | | | | | 168 | | |
| Dec. 10-12 | | | Flood, Hail, Wind | | | Midwest, Northeast, South | | | | | | 40 | | | | | | 22 | | | | | | — | | | | | | — | | | | | | 62 | | |
| Dec. 13-16 | | | Flood, Lightning, Wind | | | Midwest, West | | | | | | 10 | | | | | | 9 | | | | | | — | | | | | | — | | | | | | 19 | | |
| 2020 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Jan. 10-12 | | | Flood, hail, wind | | | Midwest, Northeast, South | | | | | | $ | 6 | | | | | $ | 4 | | | | | $ | — | | | | | $ | — | | | | | $ | 10 | |
| Feb. 5-8 | | | Flood, hail, wind | | | Northeast, South | | | | | | 9 | | | | | | 5 | | | | | | — | | | | | | — | | | | | | 14 | | |
| Mar. 2-4 | | | Flood, hail, wind | | | Midwest, South | | | | | | 58 | | | | | | 8 | | | | | | — | | | | | | 5 | | | | | | 71 | | |
An excerpt. Shown here: 40 of 784 rewritten, 40 of 188 added and 40 of 179 removed. The counts are complete. For every sentence, read Item 7. Management's Discussion and Analysis of Financial Condition and in the FY2022 filing and the FY2021 filing.
Page headers and footers: 66 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 46][added: 47]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 47][added: 48]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 48][added: 49]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 49][added: 50]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 50][added: 51]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 51][added: 52]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 52][added: 53]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 53][added: 54]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 54][added: 55]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 55][added: 56]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 56][added: 57]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 57][added: 58]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 58][added: 59]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 59][added: 60]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 60][added: 61]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 61][added: 62]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 62][added: 63]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 63][added: 64]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 64][added: 65]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 65][added: 66]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 66][added: 67]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 67][added: 68]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 68][added: 69]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 69][added: 70]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 70][added: 71]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 71][added: 72]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 72][added: 73]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 73][added: 74]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 74][added: 75]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 75][added: 76]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 76][added: 77]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 77][added: 78]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 78][added: 79]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 79][added: 80]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 80][added: 81]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 81][added: 82]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 82][added: 83]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 83][added: 84]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 84][added: 85]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 85][added: 86]
Cincinnati Financial Corporation - 2021 10-K - Page 111
Shown here: 40 of 65 changed, all 0 added and all 1 removed.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
43 rewritten, 11 added, 10 removed, 96 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
| Revaluation | | | | | | [removed: A] [added: H] | | | | | | [removed: A] [added: H] | | | | | | H | | | | | | [removed: A] [added: H] | | |
| [removed: At] [added: At] December 31, [removed: 2021] [added: 2021] | | | | | | [removed: $] [added: $] | [removed: 14,327] [added: 14,327] | | | | | [removed: $] [added: $] | [removed: 13,656] [added: 13,656] | | | | | [removed: $] [added: $] | [removed: 13,022] [added: 13,022] | | | | | [removed: $] [added: $] | [removed: 12,399] [added: 12,399] | | | | | [removed: $] [added: $] | [removed: 11,768] [added: 11,768] | |
The effective duration of the fixed-maturity portfolio was [removed: 4.8] [added: 4.7] years at year-end [removed: 2021, up] [added: 2022, down] from [removed: 4.5] [added: 4.8] years at year-end [removed: 2020.][added: 2021.]
| [removed: At] [added: At] December 31, [removed: 2021] [added: 2021] | | | | | | [removed: $] [added: $] | [removed: 7,921] [added: 7,921] | | | | | [removed: $] [added: $] | [removed: 9,052] [added: 9,052] | | | | | [removed: $] [added: $] | [removed: 10,184] [added: 10,184] | | | | | [removed: $] [added: $] | [removed: 11,315] [added: 11,315] | | | | | [removed: $] [added: $] | [removed: 12,447] [added: 12,447] | | | | | [removed: $] [added: $] | [removed: 13,578] [added: 13,578] | | | | | [removed: $] [added: $] | [removed: 14,710] [added: 14,710] | |
No holding had a fair value greater than [removed: 8.0%] [added: 6.4%] of our [removed: $10.862] [added: $9.454] billion publicly traded common stock portfolio.
We had 42 holdings among [removed: 10] [added: nine] different sectors each with a fair value greater than $100 million.
The application of our impairment policy resulted in write-downs of impaired securities intended to be sold that reduced our income before income taxes by [removed: $1] [added: $5] million in [removed: 2021, $78] [added: 2022, $1] million in [removed: 2020] [added: 2021] and [removed: OTTI charges of $9] [added: $78] million in [removed: 2019.][added: 2020.]
At year-end [removed: 2021, 278] [added: 2022, 3,272] of the [removed: 4,329] [added: 4,521] fixed-maturity securities we owned had a fair value below 100% of cost or amortized cost compared with [removed: 128] [added: 278] of the [removed: 4,128] [added: 4,329] at year-end [removed: 2020] [added: 2021] and [removed: 157] [added: 128] of the [removed: 3,911] [added: 4,128] at year-end [removed: 2019.][added: 2020.]
The [removed: 278] [added: 3,272] holdings fair valued below cost or amortized cost at year-end [removed: 2021] [added: 2022] represented [removed: 8.3%] [added: 78.8%] of our fixed-maturity portfolio and [removed: $16] [added: $908] million in unrealized losses.
- [removed: 274] [added: 2,080] of these holdings were fair valued between 90% and 100% of cost or amortized cost.
The fair value of these [removed: 274] [added: 2,080] securities was [removed: $1.069] [added: $6.907] billion at year-end [removed: 2021,] [added: 2022,] and they accounted for [removed: $15] [added: $267] million in unrealized losses.
- [removed: 4] [added: 1,143] of these holdings were fair valued between 70% and 90% of cost or amortized cost.
The fair value of these holdings was [removed: $6] [added: $61] million, and they accounted for [removed: $1] [added: $30] million in unrealized losses.
- [removed: No fixed-maturity securities] [added: 49 of these holdings] had a fair value below 70% of cost or amortized cost.
| At December 31, [removed: 2021] [added: 2022] | | | | | | Fair value | | | | | | Unrealized losses | | | | | | Fair value | | | | | | Unrealized losses | | | | | | Fair value | | | | | | Unrealized losses | | |
| Corporate | | | | | | [removed: $] [added: $] | [removed: 861] [added: 861] | | | | | [removed: $] [added: $] | [removed: 13] [added: 13] | | | | | [removed: $] [added: $] | [removed: 15] [added: 15] | | | | | [removed: $] [added: $] | [removed: —] [added: —] | | | | | [removed: $] [added: $] | [removed: 876] [added: 876] | | | | | [removed: $] [added: $] | [removed: 13] [added: 13] | |
| States, municipalities and political subdivisions | | | | | | [removed: 105] [added: 105] | | | | | | [removed: 2] [added: 2] | | | | | | [removed: 2] [added: 2] | | | | | | [removed: 1] [added: 1] | | | | | | [removed: 107] [added: 107] | | | | | | [removed: 3] [added: 3] | | |
| Commercial mortgage-backed | | | | | | [removed: 10] [added: 10] | | | | | | [removed: —] [added: —] | | | | | | [removed: 11] [added: 11] | | | | | | [removed: —] [added: —] | | | | | | [removed: 21] [added: 21] | | | | | | [removed: —] [added: —] | | |
| United States government | | | | | | [removed: 48] [added: 48] | | | | | | [removed: —] [added: —] | | | | | | [removed: —] [added: —] | | | | | | [removed: —] [added: —] | | | | | | [removed: 48] [added: 48] | | | | | | [removed: —] [added: —] | | |
| Foreign government | | | | | | [removed: 16] [added: 25] | | | | | | [removed: —] [added: 1] | | | | | | [removed: —] [added: 4] | | | | | | — | | | | | | [removed: 16] [added: 29] | | | | | | [removed: —] [added: 1] | | |
| Government-sponsored enterprises | | | | | | [removed: 7] [added: 7] | | | | | | [removed: —] [added: —] | | | | | | [removed: —] [added: —] | | | | | | [removed: —] [added: —] | | | | | | [removed: 7] [added: 7] | | | | | | [removed: —] [added: —] | | |
| Total | | | | | | [removed: $] [added: $] | [removed: 1,047] [added: 1,047] | | | | | [removed: $] [added: $] | [removed: 15] [added: 15] | | | | | [removed: $] [added: $] | [removed: 28] [added: 28] | | | | | [removed: $] [added: $] | [removed: 1] [added: 1] | | | | | [removed: $] [added: $] | [removed: 1,075] [added: 1,075] | | | | | [removed: $] [added: $] | [removed: 16] [added: 16] | |
| States, municipalities and political subdivisions | | | | | | [removed: 31] [added: 2,600] | | | | | | [removed: 2] [added: 274] | | | | | | [removed: 2] [added: 77] | | | | | | [removed: —] [added: 29] | | | | | | [removed: 33] [added: 2,677] | | | | | | [removed: 2] [added: 303] | | |
| Commercial mortgage-backed | | | | | | [removed: 23] [added: 215] | | | | | | [removed: 1] [added: 13] | | | | | | [removed: 6] [added: 14] | | | | | | [removed: —] [added: 3] | | | | | | [removed: 29] [added: 229] | | | | | | [removed: 1] [added: 16] | | |
| United States government | | | | | | [removed: 12] [added: 146] | | | | | | [removed: —] [added: 3] | | | | | | [removed: —] [added: 41] | | | | | | [removed: —] [added: 2] | | | | | | [removed: 12] [added: 187] | | | | | | [removed: —] [added: 5] | | |
| Foreign government | | | | | | [removed: 10] [added: 16] | | | | | | — | | | | | | — | | | | | | — | | | | | | [removed: 10] [added: 16] | | | | | | — | | |
| Government-sponsored enterprises | | | | | | [removed: —] [added: 123] | | | | | | [removed: —] [added: 3] | | | | | | [removed: —] [added: 3] | | | | | | [removed: —] [added: —] | | | | | | [removed: —] [added: 126] | | | | | | [removed: —] [added: 3] | | |
| [removed: At] [added: At] December 31, [removed: 2021] [added: 2021] | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | [added: | | | | | |]
| Fair valued below 70% of amortized cost | | | | | | [removed: —] [added: 34] | | | | | | $ | [removed: —] [added: 64] | | | | | $ | [removed: —] [added: 43] | | | | | $ | [removed: —] [added: (21)] | | | | | $ | [removed: —] [added: 2] | |
| Fair valued at 70% to less than 100% of amortized cost | | | | | | [removed: 258] [added: 278] | | | | | | [removed: 1,059] [added: 1,091] | | | | | | [removed: 1,044] [added: 1,075] | | | | | | [removed: (15)] [added: (16)] | | | | | | [removed: 16] [added: 17] | | |
| Fair valued at 100% and above of amortized cost | | | | | | [removed: 1,820] [added: 172] | | | | | | [removed: 7,285] [added: 646] | | | | | | [removed: 7,814] [added: 686] | | | | | | [removed: 529] [added: 40] | | | | | | [removed: 307] [added: 33] | | |
| Investment income on securities sold in current year | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | [removed: 30] [added: 20] | | |
| Fair valued below 70% of amortized cost | | | | | | [removed: —] [added: 15] | | | | | | [removed: —] [added: 27] | | | | | | [removed: —] [added: 18] | | | | | | [removed: —] [added: (9)] | | | | | | [removed: —] [added: 1] | | |
| Fair valued at 70% to less than 100% of amortized cost | | | | | | [removed: 20] [added: 1,225] | | | | | | [removed: 32] [added: 2,067] | | | | | | [removed: 31] [added: 1,929] | | | | | | [removed: (1)] [added: (138)] | | | | | | [removed: 1] [added: 61] | | |
| Fair valued at 100% and above of amortized cost | | | | | | [removed: 2,231] [added: 1,077] | | | | | | [removed: 3,854] [added: 1,865] | | | | | | [removed: 4,133] [added: 1,886] | | | | | | [removed: 279] [added: 21] | | | | | | [removed: 120] [added: 59] | | |
| Fair valued below 70% of amortized cost | | | | | | [removed: —] [added: 49] | | | | | | [removed: —] [added: 91] | | | | | | [removed: —] [added: 61] | | | | | | [removed: —] [added: (30)] | | | | | | [removed: —] [added: 3] | | |
| Fair valued at 70% to less than 100% of amortized cost | | | | | | [removed: 278] [added: 1,998] | | | | | | [removed: 1,091] [added: 8,310] | | | | | | [removed: 1,075] [added: 7,570] | | | | | | [removed: (16)] [added: (740)] | | | | | | [removed: 17] [added: 331] | | |
| Fair valued at 100% and above of amortized cost | | | | | | [removed: 4,051] [added: 4,051] | | | | | | [removed: 11,139] [added: 11,139] | | | | | | [removed: 11,947] [added: 11,947] | | | | | | [removed: 808] [added: 808] | | | | | | [removed: 427] [added: 427] | | |
| Investment income on securities sold in current year | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | [removed: 33] [added: 23] | | |
| Total | | | | | | [removed: 4,329] [added: 4,329] | | | | | | [removed: $] [added: $] | [removed: 12,230] [added: 12,230] | | | | | [removed: $] [added: $] | [removed: 13,022] [added: 13,022] | | | | | [removed: $] [added: $] | [removed: 792] [added: 792] | | | | | [removed: $] [added: $] | [removed: 477] [added: 477] | |
| At December 31, 2022 | | | | | | $ | 13,300 | | | | | $ | 12,714 | | | | | $ | 12,132 | | | | | $ | 11,548 | | | | | $ | 10,974 | |
| At December 31, 2022 | | | | | | $ | 6,889 | | | | | $ | 7,873 | | | | | $ | 8,857 | | | | | $ | 9,841 | | | | | $ | 10,825 | | | | | $ | 11,809 | | | | | $ | 12,793 | |
Our equity holdings represented $9.841 billion in fair value.
The fair value of these holdings was $2.592 billion, and they accounted for $611 million in unrealized losses.
| Corporate | | | | | | $ | 5,651 | | | | | $ | 412 | | | | | $ | 661 | | | | | $ | 168 | | | | | $ | 6,312 | | | | | $ | 580 | |
| Total | | | | | | $ | 8,760 | | | | | $ | 706 | | | | | $ | 800 | | | | | $ | 202 | | | | | $ | 9,560 | | | | | $ | 908 | |
| At December 31, 2022 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Total | | | | | | 2,204 | | | | | | 9,020 | | | | | | 8,299 | | | | | | (721) | | | | | | 386 | | |
| Total | | | | | | 2,317 | | | | | | 3,959 | | | | | | 3,833 | | | | | | (126) | | | | | | 124 | | |
| Total | | | | | | 4,521 | | | | | | $ | 12,979 | | | | | $ | 12,132 | | | | | $ | (847) | | | | | $ | 510 | |
| At December 31, 2021 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| At December 31, 2020 | | | | | | $ | 13,493 | | | | | $ | 12,900 | | | | | $ | 12,338 | | | | | $ | 11,774 | | | | | $ | 11,195 | |
| At December 31, 2020 | | | | | | $ | 6,199 | | | | | $ | 7,085 | | | | | $ | 7,970 | | | | | $ | 8,856 | | | | | $ | 9,742 | | | | | $ | 10,627 | | | | | $ | 11,513 | |
Our equity holdings represented $11.315 billion in fair value and accounted for approximately 90.1% of the net unrealized gains and losses of the entire portfolio at year-end 2021.
| At December 31, 2020 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Corporate | | | | | | $ | 330 | | | | | $ | 5 | | | | | $ | 46 | | | | | $ | 2 | | | | | $ | 376 | | | | | $ | 7 | |
| Total | | | | | | $ | 406 | | | | | $ | 8 | | | | | $ | 54 | | | | | $ | 2 | | | | | $ | 460 | | | | | $ | 10 | |
| Total | | | | | | 2,078 | | | | | | 8,344 | | | | | | 8,858 | | | | | | 514 | | | | | | 353 | | |
| Total | | | | | | 2,251 | | | | | | 3,886 | | | | | | 4,164 | | | | | | 278 | | | | | | 124 | | |
| At December 31, 2020 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Total | | | | | | 4,128 | | | | | | $ | 11,312 | | | | | $ | 12,338 | | | | | $ | 1,026 | | | | | $ | 455 | |
An excerpt. Shown here: 40 of 43 rewritten, all 11 added and all 10 removed. The counts are complete. For every sentence, read Item 7A. Quantitative and Qualitative Disclosures About Market Risk in the FY2022 filing and the FY2021 filing.
Page headers and footers: 6 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 112
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 113
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 114
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 115
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 116
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 117
Item 1. Business
188 rewritten, 53 added, 46 removed, 446 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
At year-end [removed: 2021,] [added: 2022,] a select group of independent agencies in 46 states actively marketed our property casualty insurance within their communities.
Standard market commercial lines and excess and surplus lines policies were marketed in [removed: 41] [added: 42] of those states.
We continue to increase our capabilities to successfully underwrite both larger commercial policies, which we refer to as key accounts, [removed: or] [added: and] small business accounts that require greater efficiency.
| Property casualty agency relationships, January 1 | | | | | | [removed: 1,848] [added: 1,921] | | | | | | [removed: 1,796] [added: 1,848] | | |
| New appointments that market all or most of The Cincinnati Insurance Companies' products | | | | | | [removed: 155] [added: 145] | | | | | | [removed: 133] [added: 155] | | |
| New appointments that market only personal lines insurance products for Cincinnati Insurance | | | | | | [removed: 59] [added: 64] | | | | | | [removed: 58] [added: 59] | | |
| Changes due to consolidation and other | | | | | | [removed: (141)] [added: (146)] | | | | | | [removed: (139)] [added: (141)] | | |
| Property casualty agency relationships, December 31 | | | | | | [removed: 1,921] [added: 1,984] | | | | | | [removed: 1,848] [added: 1,921] | | |
| Property casualty reporting locations | | | | | | [removed: 2,721] [added: 2,861] | | | | | | [removed: 2,578] [added: 2,721] | | |
| New relationship appointments | | | | | | [removed: 159] [added: 146] | | | | | | [removed: 119] [added: 159] | | |
| Active states | | | | | | 46 | | | | | | [removed: 45] [added: 46] | | |
On average, we have a [removed: 5.5%] [added: 5.1%] share of the standard lines property casualty insurance purchased through our reporting agency locations, according to [removed: 2020] [added: 2021] data from agency surveys.
Our share is [removed: 11.6%] [added: 11.3%] in reporting agency locations that have represented us for more than 10 years; [removed: 4.3%] [added: 3.9%] in agencies that have represented us for six to 10 years; [removed: 1.9%] [added: 1.5%] in agencies that have represented us for two to five years; and [removed: 0.3%] [added: 0.4%] in agencies that have represented us for one year or less.
Our largest single agency relationship accounted for approximately 0.6% of our total property casualty earned premiums in [removed: 2021.][added: 2022.]
No aggregate locations under a single ownership structure accounted for more than 5% of our earned premiums in [removed: 2021.][added: 2022.]
- Our [removed: $13.022] [added: $12.132] billion fixed-maturity portfolio is diversified and exceeds total insurance reserves.
The portfolio had an average rating of [removed: A3/A,] [added: A2/A,] and its fair value exceeded total insurance reserve liabilities by approximately [removed: 26%] [added: 6%] at December 31, [removed: 2021.][added: 2022.]
Our [removed: $11.315] [added: $9.841] billion equity portfolio minimizes concentrations in single stocks or industries.
At December 31, [removed: 2021,] [added: 2022,] no single security accounted for more than [removed: 8.0%] [added: 6.4%] of our portfolio of publicly traded common stocks, and no single sector accounted for more than [removed: 32%.][added: 27%.]
At December 31, [removed: 2021,] [added: 2022,] we held [removed: $5.099] [added: $4.230] billion of our cash and invested assets at the parent-company level, of which [removed: $4.774] [added: $3.974] billion, or [removed: 93.6%,] [added: 93.9%,] was invested in common stocks, and [removed: $211] [added: $121] million, or [removed: 4.1%,] [added: 2.9%,] was cash and cash equivalents.
We minimize reliance on debt as a source of capital, with a debt-to-total-capital ratio of [removed: 6.0%] [added: 7.4%] at year-end [removed: 2021.][added: 2022.]
Long-term debt at year-end [removed: 2021] [added: 2022] totaled $789 million, [removed: up $1 million from] [added: matching] year-end [removed: 2020,] [added: 2021,] and our short-term debt was [removed: $54] [added: $50] million, [removed: matching] [added: down from $54 million at] the end of the prior year.
At year-end [removed: 2021] [added: 2022] and [removed: 2020,] [added: 2021,] risk-based capital (RBC) for our standard market property casualty insurance, excess and surplus lines insurance and life insurance subsidiaries was strong, far exceeding regulatory requirements.
- We ended [removed: 2021] [added: 2022] with a [removed: 0.9-to-1] [added: 1.1-to-1] ratio of property casualty premiums to surplus, a key measure of property casualty insurance company capacity and security.
The estimated industry average ratio was [removed: 0.7-to-1] [added: 0.8-to-1] at year-end [removed: 2021,] [added: 2022,] based on industry data reported through the first nine months of [removed: 2021.][added: 2022.]
On a statutory consolidated property casualty insurance basis, our ratio of investments in common stock, at fair value, to statutory capital and surplus was [removed: 83.6%] [added: 83.7%] at year-end [removed: 2021] [added: 2022] compared with [removed: 82.6%] [added: 83.6%] at year-end [removed: 2020.][added: 2021.]
- We ended [removed: 2021] [added: 2022] with a [removed: 7.4%] [added: 9.5%] ratio of life statutory adjusted risk-based surplus to liabilities, a key measure of life insurance company capital strength.
Our life insurance subsidiary’s RBC at year-end [removed: 2021] [added: 2022] was [removed: 5.0] [added: 6.1] times the authorized control level RBC.
| Statutory capital and surplus | | | | | | $ | [removed: 7,247] [added: 6,512] | | | | | $ | [removed: 5,838] [added: 7,247] | |
| Risk-based capital | | | | | | [removed: 7,279] [added: 6,551] | | | | | | [removed: 5,860] [added: 7,279] | | |
| Authorized control level risk-based capital | | | | | | [removed: 1,093] [added: 1,186] | | | | | | [removed: 924] [added: 1,093] | | |
| Risk-based capital to authorized control level risk-based capital ratio | | | | | | [removed: 6.7] [added: 5.5] | | | | | | [removed: 6.3] [added: 6.7] | | |
| Written premium to surplus ratio | | | | | | [removed: 0.9] [added: 1.1] | | | | | | [removed: 1.0] [added: 0.9] | | |
At February [removed: 23, 2022,] [added: 22, 2023,] our insurance subsidiaries continued to be highly rated.
On February [removed: 2, 2022,] [added: 9, 2023,] A.M. Best affirmed its ratings, continuing its stable outlook.
On November [removed: 17, 2021,] [added: 1, 2022,] Fitch affirmed its ratings, continuing its stable outlook.
On July [removed: 30, 2021,] [added: 19, 2022,] Moody's affirmed its ratings, continuing its stable outlook.
On July [removed: 26, 2021,] [added: 12, 2022,] S&P affirmed its ratings, continuing its stable outlook.
In our 10 highest volume states for consolidated property casualty premiums, [removed: 1,359] [added: 1,386] reporting agency locations wrote [removed: 52.1%] [added: 50.1%] of our [removed: 2021] [added: 2022] consolidated property casualty earned premium volume compared with [removed: 1,316] [added: 1,359] locations and [removed: 53.3%] [added: 52.1%] in [removed: 2020.][added: 2021.]
| Year ended December 31, [removed: 2021] [added: 2022] | | | | | | | | | | | | | | |
Pricing property casualty insurance policies includes estimates for expected losses, loss expenses to settle claims and expenses from underwriting policies while also considering the time value of money related to expected cash flows and a reasonable profit margin.
| | | | | | | 2022 | | | | | | 2021 | | |
| | | | | | | 2022 | | | | | | 2021 | | |
| Ohio | | | $ | 930 | | 13.4 | | % | 257 | | | $ | 3.6 | |
| Illinois | | | 376 | | | 5.4 | | | 177 | | | 2.1 | | |
| New York | | | 327 | | | 4.7 | | | 184 | | | 1.8 | | |
| North Carolina | | | 314 | | | 4.5 | | | 113 | | | 2.8 | | |
| Pennsylvania | | | 308 | | | 4.4 | | | 155 | | | 2.0 | | |
| Georgia | | | 300 | | | 4.3 | | | 110 | | | 2.7 | | |
| Indiana | | | 279 | | | 4.0 | | | 127 | | | 2.2 | | |
| Tennessee | | | 220 | | | 3.2 | | | 74 | | | 3.0 | | |
| Missouri | | | 216 | | | 3.1 | | | 73 | | | 3.0 | | |
| Texas | | | 214 | | | 3.1 | | | 116 | | | 1.8 | | |
The associate voluntary turnover rate was 8% in 2022, 7% in 2021 and 3% in 2020.
| Whole life insurance | | | | | | 47 | | | | | | 47 | | | | | | 43 | | | | | | 0.6 | | |
| Universal life and other | | | | | | 66 | | | | | | 81 | | | | | | 83 | | | | | | 0.8 | | |
| Other: | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Cincinnati Re | | | | | | 585 | | | | | | 461 | | | | | | 302 | | | | | | 7.7 | | |
| Cincinnati Global | | | | | | 230 | | | | | | 187 | | | | | | 177 | | | | | | 3.0 | | |
| Ohio | | | $ | 570 | | 14.2 | | % | 243 | | | $ | 2.3 | |
| Illinois | | | 245 | | | 6.1 | | | 154 | | | 1.6 | | |
| Pennsylvania | | | 238 | | | 5.9 | | | 145 | | | 1.6 | | |
| Indiana | | | 190 | | | 4.7 | | | 123 | | | 1.5 | | |
| New York | | | 165 | | | 4.1 | | | 150 | | | 1.1 | | |
| Virginia | | | 163 | | | 4.1 | | | 77 | | | 2.1 | | |
| Georgia | | | 160 | | | 4.0 | | | 96 | | | 1.7 | | |
| Tennessee | | | 158 | | | 3.9 | | | 71 | | | 2.2 | | |
| Missouri | | | 157 | | | 3.9 | | | 61 | | | 2.6 | | |
Beginning in 2023, we’re renaming our high net worth products and services, Cincinnati Private ClientSM.
Private client is a term used in the financial services industry to describe people who have complex needs based on their affluence, investments and belongings.
This change allows agencies and their customers to easily recognize that we stand ready to serve this client segment.
| Ohio | | | $ | 326 | | 19.3 | | % | 235 | | | $ | 1.4 | |
| New York | | | 133 | | | 7.9 | | | 108 | | | 1.2 | | |
| California | | | 104 | | | 6.2 | | | 74 | | | 1.4 | | |
| Illinois | | | 96 | | | 5.7 | | | 131 | | | 0.7 | | |
| Indiana | | | 69 | | | 4.1 | | | 107 | | | 0.6 | | |
| Alabama | | | 63 | | | 3.8 | | | 56 | | | 1.1 | | |
| Texas | | | 52 | | | 3.1 | | | 62 | | | 0.8 | | |
| Connecticut | | | 51 | | | 3.0 | | | 43 | | | 1.2 | | |
| Illinois | | | $ | 35 | | 7.2 | | % |
| | | | | | | 2021 | | | | | | 2020 | | |
| | | | | | | 2021 | | | | | | 2020 | | |
| Ohio | | | $ | 889 | | 14.4 | | % | 253 | | | $ | 3.5 | |
| Illinois | | | 339 | | | 5.5 | | | 173 | | | 2.0 | | |
| North Carolina | | | 291 | | | 4.7 | | | 110 | | | 2.6 | | |
| Georgia | | | 289 | | | 4.7 | | | 110 | | | 2.6 | | |
| Pennsylvania | | | 282 | | | 4.6 | | | 152 | | | 1.9 | | |
| Indiana | | | 266 | | | 4.3 | | | 113 | | | 2.4 | | |
| New York | | | 264 | | | 4.3 | | | 160 | | | 1.7 | | |
| Tennessee | | | 204 | | | 3.3 | | | 69 | | | 3.0 | | |
| Michigan | | | 200 | | | 3.2 | | | 143 | | | 1.4 | | |
| Virginia | | | 195 | | | 3.1 | | | 76 | | | 2.6 | | |
The associate voluntary turnover rate had been approximately 5% for several years prior to 2021, when it increased to approximately 10%.
| Universal life insurance | | | | | | 34 | | | | | | 34 | | | | | | 37 | | | | | | 0.5 | | |
| Other life insurance and annuity products | | | | | | 94 | | | | | | 92 | | | | | | 85 | | | | | | 1.4 | | |
| Other | | | | | | 648 | | | | | | 479 | | | | | | 368 | | | | | | 9.5 | | |
| Ohio | | | $ | 539 | | 14.7 | | % | 242 | | | $ | 2.2 | |
| Illinois | | | 225 | | | 6.1 | | | 152 | | | 1.5 | | |
| Pennsylvania | | | 219 | | | 6.0 | | | 140 | | | 1.6 | | |
| Indiana | | | 183 | | | 5.0 | | | 109 | | | 1.7 | | |
| Virginia | | | 152 | | | 4.1 | | | 70 | | | 2.2 | | |
| Georgia | | | 151 | | | 4.1 | | | 96 | | | 1.6 | | |
| Tennessee | | | 146 | | | 4.0 | | | 69 | | | 2.1 | | |
| Missouri | | | 137 | | | 3.7 | | | 55 | | | 2.5 | | |
| Ohio | | | $ | 319 | | 20.7 | | % | 231 | | | $ | 1.4 | |
| New York | | | 106 | | | 6.9 | | | 105 | | | 1.0 | | |
| Illinois | | | 82 | | | 5.3 | | | 123 | | | 0.7 | | |
| California | | | 70 | | | 4.6 | | | 70 | | | 1.0 | | |
| Indiana | | | 67 | | | 4.3 | | | 92 | | | 0.7 | | |
| Alabama | | | 63 | | | 4.1 | | | 49 | | | 1.3 | | |
| Michigan | | | 51 | | | 3.3 | | | 100 | | | 0.5 | | |
| Kentucky | | | 47 | | | 3.1 | | | 53 | | | 0.9 | | |
| Illinois | | | $ | 31 | | 7.8 | | % |
| Ohio | | | 30 | | | 7.6 | | |
| Texas | | | 24 | | | 6.1 | | |
| Pennsylvania | | | 22 | | | 5.5 | | |
| Georgia | | | 20 | | | 5.0 | | |
| Minnesota | | | 16 | | | 3.9 | | |
| Ohio | | | $ | 57 | | 15.7 | | % |
| Pennsylvania | | | 27 | | | 7.4 | | |
An excerpt. Shown here: 40 of 188 rewritten, 40 of 53 added and 40 of 46 removed. The counts are complete. For every sentence, read Item 1. Business in the FY2022 filing and the FY2021 filing.
Page headers and footers: 27 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 5
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 6
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 7
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 8
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 9
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 10
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 11
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 12
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 13
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 14
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 15
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 16
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 17
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 18
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 19
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 20
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 21
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 22
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 23
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 24
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 25
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 26
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 27
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 28
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 29
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 30
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 31
Cover and table of contents
44 rewritten, 10 added, 8 removed, 41 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
For the fiscal year ended December 31, [removed: 2021.][added: 2022.]
The aggregate market value of voting stock held by nonaffiliates of the Registrant based on the closing price of [removed: $116.62] [added: $118.98] per share as reported on Nasdaq Global Select Market on June 30, [removed: 2021,] [added: 2022,] was [removed: $18,398,492,958.][added: $18,533,373,847.]
As of February 15, [removed: 2022,] [added: 2023,] there were [removed: 160,433,769] [added: 157,240,556] shares of common stock outstanding.
Portions of the definitive Proxy Statement for Cincinnati Financial Corporation’s Annual Meeting of Shareholders to be held on May [removed: 7, 2022,] [added: 6, 2023,] are incorporated by reference into Part III of this Form 10-K.
[removed: 2021] [added: 2022] ANNUAL REPORT ON FORM 10-K
| Item 1. | | | Business | | | [removed: [5](#ib516704f6c694dd39ca65eef55d59c29_13)] [added: [5](#i02093e9754da48e991fe7fbb3df85a22_13)] | | |
| | | | Cincinnati Financial Corporation – Introduction | | | [removed: [5](#ib516704f6c694dd39ca65eef55d59c29_16)] [added: [5](#i02093e9754da48e991fe7fbb3df85a22_16)] | | |
| | | | Our Business and Our Strategy | | | [removed: [6](#ib516704f6c694dd39ca65eef55d59c29_19)] [added: [6](#i02093e9754da48e991fe7fbb3df85a22_19)] | | |
| | | | Our Segments | | | [removed: [14](#ib516704f6c694dd39ca65eef55d59c29_22)] [added: [14](#i02093e9754da48e991fe7fbb3df85a22_22)] | | |
| Item 1A. | | | Risk Factors | | | [removed: [32](#ib516704f6c694dd39ca65eef55d59c29_31)] [added: [32](#i02093e9754da48e991fe7fbb3df85a22_31)] | | |
| Item 1B. | | | Unresolved Staff Comments | | | [removed: [43](#ib516704f6c694dd39ca65eef55d59c29_34)] [added: [44](#i02093e9754da48e991fe7fbb3df85a22_34)] | | |
| Item 2. | | | Properties | | | [removed: [43](#ib516704f6c694dd39ca65eef55d59c29_37)] [added: [44](#i02093e9754da48e991fe7fbb3df85a22_37)] | | |
| Item 3. | | | Legal Proceedings | | | [removed: [43](#ib516704f6c694dd39ca65eef55d59c29_40)] [added: [44](#i02093e9754da48e991fe7fbb3df85a22_40)] | | |
| Item 4. | | | Mine Safety Disclosures | | | [removed: [43](#ib516704f6c694dd39ca65eef55d59c29_43)] [added: [44](#i02093e9754da48e991fe7fbb3df85a22_43)] | | |
| Item 5. | | | Market for the Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities | | | [removed: [44](#ib516704f6c694dd39ca65eef55d59c29_49)] [added: [45](#i02093e9754da48e991fe7fbb3df85a22_49)] | | |
| Item 6. | | | \[Reserved\] | | | [removed: [45](#ib516704f6c694dd39ca65eef55d59c29_2655)] [added: [46](#i02093e9754da48e991fe7fbb3df85a22_52)] | | |
| Item 7. | | | Management’s Discussion and Analysis of Financial Condition and Results of Operations | | | [removed: [46](#ib516704f6c694dd39ca65eef55d59c29_55)] [added: [47](#i02093e9754da48e991fe7fbb3df85a22_58)] | | |
| | | | Executive Summary | | | [removed: [47](#ib516704f6c694dd39ca65eef55d59c29_61)] [added: [48](#i02093e9754da48e991fe7fbb3df85a22_64)] | | |
| | | | Critical Accounting Estimates | | | [removed: [52](#ib516704f6c694dd39ca65eef55d59c29_64)] [added: [53](#i02093e9754da48e991fe7fbb3df85a22_67)] | | |
| | | | Recent Accounting Pronouncements | | | [removed: [58](#ib516704f6c694dd39ca65eef55d59c29_67)] [added: [59](#i02093e9754da48e991fe7fbb3df85a22_70)] | | |
| | | | Financial Results | | | [removed: [59](#ib516704f6c694dd39ca65eef55d59c29_70)] [added: [60](#i02093e9754da48e991fe7fbb3df85a22_73)] | | |
| | | | Liquidity and Capital Resources | | | [removed: [93](#ib516704f6c694dd39ca65eef55d59c29_91)] [added: [93](#i02093e9754da48e991fe7fbb3df85a22_94)] | | |
| | | | Safe Harbor Statement | | | [removed: [109](#ib516704f6c694dd39ca65eef55d59c29_94)] [added: [109](#i02093e9754da48e991fe7fbb3df85a22_97)] | | |
| Item 7A. | | | Quantitative and Qualitative Disclosures About Market Risk | | | [removed: [112](#ib516704f6c694dd39ca65eef55d59c29_97)] [added: [112](#i02093e9754da48e991fe7fbb3df85a22_100)] | | |
| Item 8. | | | Financial Statements and Supplementary Data | | | [removed: [118](#ib516704f6c694dd39ca65eef55d59c29_112)] [added: [118](#i02093e9754da48e991fe7fbb3df85a22_115)] | | |
| | | | Responsibility for Financial Statements | | | [removed: [118](#ib516704f6c694dd39ca65eef55d59c29_115)] [added: [118](#i02093e9754da48e991fe7fbb3df85a22_118)] | | |
| | | | Management’s Annual Report on Internal Control Over Financial Reporting | | | [removed: [119](#ib516704f6c694dd39ca65eef55d59c29_118)] [added: [119](#i02093e9754da48e991fe7fbb3df85a22_121)] | | |
| | | | Report of Independent Registered Public Accounting Firm (PCAOB ID No. 34) | | | [removed: [120](#ib516704f6c694dd39ca65eef55d59c29_121)] [added: [120](#i02093e9754da48e991fe7fbb3df85a22_124)] | | |
| | | | Consolidated Balance Sheets | | | [removed: [122](#ib516704f6c694dd39ca65eef55d59c29_124)] [added: [122](#i02093e9754da48e991fe7fbb3df85a22_127)] | | |
| | | | Consolidated Statements of Income | | | [removed: [123](#ib516704f6c694dd39ca65eef55d59c29_130)] [added: [123](#i02093e9754da48e991fe7fbb3df85a22_130)] | | |
| | | | Consolidated Statements of Comprehensive Income | | | [removed: [124](#ib516704f6c694dd39ca65eef55d59c29_133)] [added: [124](#i02093e9754da48e991fe7fbb3df85a22_133)] | | |
| | | | Consolidated Statements of Shareholders’ Equity | | | [removed: [125](#ib516704f6c694dd39ca65eef55d59c29_139)] [added: [125](#i02093e9754da48e991fe7fbb3df85a22_136)] | | |
| | | | Consolidated Statements of Cash Flows | | | [removed: [126](#ib516704f6c694dd39ca65eef55d59c29_142)] [added: [126](#i02093e9754da48e991fe7fbb3df85a22_139)] | | |
| | | | Notes to Consolidated Financial Statements | | | [removed: [127](#ib516704f6c694dd39ca65eef55d59c29_145)] [added: [127](#i02093e9754da48e991fe7fbb3df85a22_142)] | | |
| Item 9. | | | Changes in and Disagreements with Accountants on Accounting and Financial Disclosure | | | [removed: [174](#ib516704f6c694dd39ca65eef55d59c29_238)] [added: [175](#i02093e9754da48e991fe7fbb3df85a22_202)] | | |
| Item 9A. | | | Controls and Procedures | | | [removed: [174](#ib516704f6c694dd39ca65eef55d59c29_241)] [added: [175](#i02093e9754da48e991fe7fbb3df85a22_205)] | | |
| Item 9B. | | | Other Information | | | [removed: [174](#ib516704f6c694dd39ca65eef55d59c29_244)] [added: [175](#i02093e9754da48e991fe7fbb3df85a22_208)] | | |
| Item 9C. | | | Disclosure Regarding Foreign Jurisdictions that Prevent Inspections | | | [removed: [174](#ib516704f6c694dd39ca65eef55d59c29_2641)] [added: [175](#i02093e9754da48e991fe7fbb3df85a22_211)] | | |
| Item 10. | | | Directors, Executive Officers and Corporate Governance | | | [removed: [175](#ib516704f6c694dd39ca65eef55d59c29_250)] [added: [176](#i02093e9754da48e991fe7fbb3df85a22_217)] | | |
| Item 11. | | | Executive Compensation | | | [removed: [177](#ib516704f6c694dd39ca65eef55d59c29_253)] [added: [178](#i02093e9754da48e991fe7fbb3df85a22_220)] | | |
If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the registrant included in the filing reflect the correction of an error to previously issued financial statements.
Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant’s executive officers during the relevant recovery period pursuant to §240.10D-1(b).
| Part I | | | | | | [5](#i02093e9754da48e991fe7fbb3df85a22_13) | | |
| | | | Other | | | [27](#i02093e9754da48e991fe7fbb3df85a22_25) | | |
| | | | Regulation | | | [28](#i02093e9754da48e991fe7fbb3df85a22_28) | | |
| Part II | | | | | | [45](#i02093e9754da48e991fe7fbb3df85a22_46) | | |
| | | | Introduction | | | [47](#i02093e9754da48e991fe7fbb3df85a22_61) | | |
| Part III | | | | | | [176](#i02093e9754da48e991fe7fbb3df85a22_214) | | |
| Part IV | | | | | | [180](#i02093e9754da48e991fe7fbb3df85a22_232) | | |
| Item 16 | | | Form 10-K Summary | | | [180](#i02093e9754da48e991fe7fbb3df85a22_235) | | |
| Part I | | | | | | [5](#ib516704f6c694dd39ca65eef55d59c29_13) | | |
| | | | Other | | | [27](#ib516704f6c694dd39ca65eef55d59c29_25) | | |
| | | | Regulation | | | [28](#ib516704f6c694dd39ca65eef55d59c29_28) | | |
| Part II | | | | | | [44](#ib516704f6c694dd39ca65eef55d59c29_46) | | |
| | | | Introduction | | | [46](#ib516704f6c694dd39ca65eef55d59c29_58) | | |
| Part III | | | | | | [175](#ib516704f6c694dd39ca65eef55d59c29_247) | | |
| Part IV | | | | | | [179](#ib516704f6c694dd39ca65eef55d59c29_265) | | |
| Item 16 | | | Form 10-K Summary | | | [179](#ib516704f6c694dd39ca65eef55d59c29_268) | | |
An excerpt. Shown here: 40 of 44 rewritten, all 10 added and all 8 removed. The counts are complete. For every sentence, read Cover and table of contents in the FY2022 filing and the FY2021 filing.
Page headers and footers: 4 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 1
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 2
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 3
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 4
Item 2. Properties
5 rewritten, 0 added, 0 removed, 10 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
The property, including [removed: land] [added: land,] is recorded in our financial statements at [removed: $131] [added: $8] million at December 31, [removed: 2021,] [added: 2022,] and is classified as Land, building and equipment, net, for company use.
Schiff & Co. Inc., a related party, occupies [removed: 8,991] [added: 9,056] square feet (less than 1%).
The property is recorded in the financial statements at $4 million at December 31, [removed: 2021,] [added: 2022,] and is classified as investment property in Other invested assets.
At December 31, [removed: 2021,] [added: 2022,] unaffiliated tenants occupied 86%, Cincinnati Financial affiliates occupied 14%.
The property, including [removed: land,] [added: land] is recorded in our financial statements at [removed: $8] [added: $129] million at December 31, [removed: 2021,] [added: 2022,] and is classified as Land, building and equipment, net, for company use.
Item 4. Mine Safety Disclosures
0 rewritten, 0 added, 0 removed, 2 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
Page headers and footers: 1 line differs, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 43][added: 44]
Item 5. Market for the Registrant’s Common Equity, Related Stockholder Matters and
16 rewritten, 6 added, 5 removed, 18 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
Cincinnati Financial Corporation had approximately [removed: 243,000] [added: 245,000] shareholders of record as of December 31, [removed: 2021.][added: 2022.]
While approximately [removed: 13,500] [added: 13,700] shareholders are registered, the majority of shareholders are beneficial owners whose shares are held in “street name” by brokers and institutional accounts.
We believe many of our independent agent representatives and most of the [removed: 5,166] [added: 5,148] associates of our subsidiaries own the company’s common stock.
As depicted in the graph below, the five-year total return on a $100 investment made December 31, [removed: 2016,] [added: 2017,] assuming the reinvestment of all dividends, was [removed: 72.8%] [added: 55.5%] for Cincinnati Financial Corporation’s common stock compared with [removed: 82.3%] [added: 56.9%] for the S&P [added: 500 Index and 73.9% for the S&P] Composite 1500 Property & Casualty Insurance [removed: Index and 133.4% for the S&P 500] Index.
The following graph depicts $100 invested on December 31, [removed: 2016,] [added: 2017,] in stock or index, including reinvestment of dividends.
[removed: ][added: 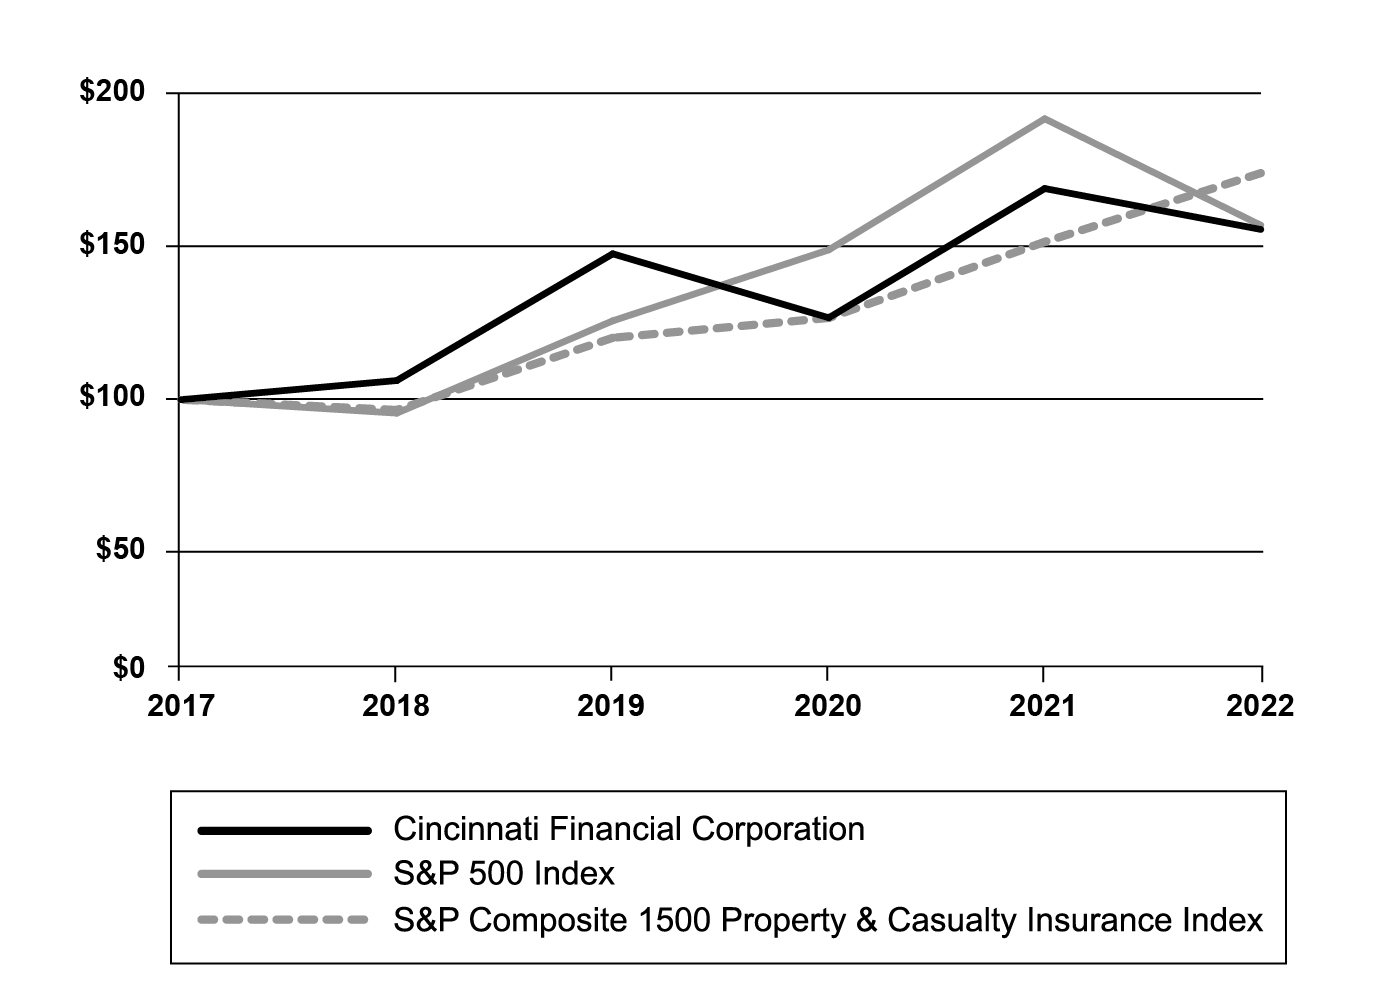]
At year-end [removed: 2021,] [added: 2022,] the S&P Composite 1500 Property & Casualty Insurance Index included [removed: 28] [added: 29] companies.
The following summarizes securities authorized for issuance under our equity compensation plans as of December 31, [removed: 2021:][added: 2022:]
| Plan category | | | | | | Number of securities to be issued upon exercise of outstanding options, warrants and rights at December 31, [removed: 2021] [added: 2022] | | | | | | Weighted-average exercise price of outstanding options, warrants and rights | | | | | | Number of securities remaining available for future issuance under equity compensation plan (excluding securities reflected in column (a)) at December 31, [removed: 2021] [added: 2022] | | |
| Equity compensation plans approved by security holders | | | | | | [removed: 3,552,336] [added: 3,608,347] | | | | | | $ | [removed: 78.52] [added: 86.21] | | | | | [removed: 5,867,608] [added: 4,556,968] | | |
The number of securities remaining available for future issuance includes: [removed: 5,538,245] [added: 4,313,579] shares available for issuance under the Cincinnati Financial Corporation 2016 Stock Compensation Plan (the 2016 [removed: Plan), 74,411 shares available for issuance under the Cincinnati Financial Corporation 2012 Stock Compensation Plan (the 2012 Plan),] [added: Plan)] and [removed: 254,952] [added: 243,389] shares available for issuance of share grants under the Director’s Stock Plan of 2018.
[removed: Both the] [added: The] 2016 Plan [removed: and 2012 Plan allow] [added: allows] for issuance of stock options, service-based or performance-based restricted stock units, stock appreciation rights or other equity-based grants.
Awards other than stock options granted from the 2016 [removed: and 2012 plans] [added: Plan] are counted as three shares against the plan for each one share of common stock actually issued.
We did not sell any of our shares that were not registered under the Securities Act during [removed: 2021.][added: 2022.]
We have [removed: 11,076,785] [added: 7,326,785] shares available for purchase under our programs at December 31, [removed: 2021.][added: 2022.]
During [removed: 2021,] [added: 2022,] we repurchased [removed: 1,250,000] [added: 3,750,000] shares at an average price of [removed: $115.19.][added: $109.33.]
| Total | | | | | | 3,608,347 | | | | | | $ | 86.21 | | | | | 4,556,968 | | |
The Cincinnati Financial Corporation 2012 Stock Compensation Plan expired in April 2022.
| October 1-31, 2022 | | | | | | — | | | | | | — | | | | | | — | | | | | | 7,428,512 | | |
| November 1-30, 2022 | | | | | | — | | | | | | — | | | | | | — | | | | | | 7,428,512 | | |
| December 1-31, 2022 | | | | | | 101,727 | | | | | | $ | 109.55 | | | | | 101,727 | | | | | | 7,326,785 | | |
| Totals | | | | | | 101,727 | | | | | | 109.55 | | | | | | 101,727 | | | | | | | | |
| Total | | | | | | 3,552,336 | | | | | | $ | 78.52 | | | | | 5,867,608 | | |
| October 1-31, 2021 | | | | | | — | | | | | | — | | | | | | — | | | | | | 11,942,698 | | |
| November 1-30, 2021 | | | | | | 715,913 | | | | | | $ | 120.27 | | | | | 715,913 | | | | | | 11,226,785 | | |
| December 1-31, 2021 | | | | | | 150,000 | | | | | | 116.21 | | | | | | 150,000 | | | | | | 11,076,785 | | |
| Totals | | | | | | 865,913 | | | | | | 119.56 | | | | | | 865,913 | | | | | | | | |
Page headers and footers: 1 line differs, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 44][added: 45]
Item 6. [Reserved]
0 rewritten, 0 added, 0 removed, 0 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
Page headers and footers: 1 line differs, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 45][added: 46]
Item 8. Financial Statements and Supplementary Data
737 rewritten, 131 added, 128 removed, 731 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
We have prepared the consolidated financial statements of Cincinnati Financial Corporation and our subsidiaries for the year ended December 31, [removed: 2021,] [added: 2022,] in accordance with accounting principles generally accepted in the United States of America (GAAP).
Deloitte & Touche LLP, our independent registered public accounting firm, audited the consolidated financial statements of Cincinnati Financial Corporation and subsidiaries for the year ended December 31, [removed: 2021.][added: 2022.]
The company’s management assessed the effectiveness of the company’s internal control over financial reporting as of December 31, [removed: 2021,] [added: 2022,] as required by Section 404 of the Sarbanes Oxley Act of 2002.
Management’s assessment was based on the criteria established in the Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission and was designed to provide reasonable assurance that the company maintained effective internal control over financial reporting as of December 31, [removed: 2021.][added: 2022.]
The assessment led management to conclude that, as of December 31, [removed: 2021,] [added: 2022,] the company’s internal control over financial reporting was effective based on those criteria.
The company’s independent registered public accounting firm has issued an audit report on our internal control over financial reporting as of December 31, [removed: 2021.][added: 2022.]
[removed: Chairman, President] [added: Chairman] and Chief Executive Officer
Chief Financial Officer, [removed: Senior] [added: Executive] Vice President and Treasurer
We have audited the accompanying consolidated balance sheets of Cincinnati Financial Corporation and subsidiaries (the [removed: “Company”)] [added: "Company")] as of December 31, [removed: 2021] [added: 2022] and [removed: 2020,] [added: 2021,] the related consolidated statements of income, comprehensive income, shareholders' equity, and cash flows for each of the three years in the period ended December 31, [removed: 2021,] [added: 2022,] and the related notes and the schedules listed in the Index at Item 15(c) (collectively referred to as the [removed: “financial statements”).][added: "financial statements").]
We also have audited the Company’s internal control over financial reporting as of December 31, [removed: 2021,] [added: 2022,] based on criteria established in *Internal Control [removed: -] [added: —] Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, [removed: 2021] [added: 2022] and [removed: 2020,] [added: 2021,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2021,] [added: 2022,] in conformity with accounting principles generally accepted in the United States of America.
Also, in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2021,] [added: 2022,] based on criteria established in *Internal Control [removed: -] [added: —] Integrated Framework (2013)* issued by COSO.
- We tested the effectiveness of controls related to loss and loss expense reserves, including those over the review of [added: actuarial] methods, models, assumptions and judgments used, and management’s review of the estimates.
- We tested the underlying data that served as the basis for the actuarial [removed: analysis,] [added: analyses,] including historical claims data, to test the reasonableness of key inputs to the actuarial estimates.
| | | | | | | [removed: 2021] [added: 2022] | | | | | | [added: 2021 | | | | | |] 2020 | | |
| Fixed maturities, at fair value (amortized cost: [removed: 2021—$12,230; 2020—$11,312)] [added: 2022—$12,979; 2021—$12,230)] | | | | | | $ | [removed: 13,022] [added: 12,132] | | | | | $ | [removed: 12,338] [added: 13,022] | |
| Equity securities, at fair value (cost: [removed: 2021—$4,121; 2020—$3,927)] [added: 2022—$4,294; 2021—$4,121)] | | | | | | [removed: 11,315] [added: 9,841] | | | | | | [removed: 8,856] [added: 11,315] | | |
| Other invested assets | | | | | | [removed: 329] [added: 452] | | | | | | [removed: 348] [added: 329] | | |
| Total investments | | | | | | [removed: 24,666] [added: 22,425] | | | | | | [removed: 21,542] [added: 24,666] | | |
| Cash and cash equivalents | | | | | | [removed: 1,139] [added: 1,264] | | | | | | [removed: 900] [added: 1,139] | | |
| Investment income receivable | | | | | | [removed: 144] [added: 160] | | | | | | [removed: 136] [added: 144] | | |
| Finance receivable | | | | | | [removed: 98] [added: 92] | | | | | | [removed: 95] [added: 98] | | |
| Premiums receivable | | | | | | [removed: 2,053] [added: 2,322] | | | | | | [removed: 1,879] [added: 2,053] | | |
| Reinsurance recoverable | | | | | | [removed: 570] [added: 640] | | | | | | [removed: 517] [added: 570] | | |
| Prepaid reinsurance premiums | | | | | | [removed: 78] [added: 79] | | | | | | [removed: 65] [added: 78] | | |
| Deferred policy acquisition costs | | | | | | [removed: 905] [added: 1,014] | | | | | | [removed: 805] [added: 905] | | |
| Land, building and equipment, net, for company use (accumulated depreciation: [removed: 2021—$303; 2020—$285)] [added: 2022—$322; 2021—$303)] | | | | | | [removed: 205] [added: 202] | | | | | | [removed: 213] [added: 205] | | |
| Other assets | | | | | | [removed: 570] [added: 646] | | | | | | [removed: 438] [added: 570] | | |
| Separate accounts | | | | | | [removed: 959] [added: 892] | | | | | | [removed: 952] [added: 959] | | |
| Total assets | | | | | | $ | [removed: 31,387] [added: 29,736] | | | | | $ | [removed: 27,542] [added: 31,387] | |
| Loss and loss expense reserves | | | | | | $ | [removed: 7,305] [added: 8,400] | | | | | $ | [removed: 6,746] [added: 7,305] | |
| Life policy and investment contract reserves | | | | | | [removed: 3,014] [added: 3,059] | | | | | | [removed: 2,915] [added: 3,014] | | |
| Unearned premiums | | | | | | [removed: 3,271] [added: 3,689] | | | | | | [removed: 2,960] [added: 3,271] | | |
| Other liabilities | | | | | | [removed: 1,092] [added: 1,229] | | | | | | [removed: 982] [added: 1,092] | | |
| Deferred income tax | | | | | | [removed: 1,744] [added: 1,045] | | | | | | [removed: 1,299] [added: 1,744] | | |
| Note payable | | | | | | [removed: 54] [added: 50] | | | | | | 54 | | |
| Long-term debt and lease obligations | | | | | | [removed: 843] [added: 841] | | | | | | [removed: 845] [added: 843] | | |
| Separate accounts | | | | | | [removed: 959] [added: 892] | | | | | | [removed: 952] [added: 959] | | |
| Total liabilities | | | | | | [removed: 18,282] [added: 19,205] | | | | | | [removed: 16,753] [added: 18,282] | | |
| Common stock, par value—$2 per share; (authorized: [removed: 2021] [added: 2022] and [removed: 2020—500] [added: 2021—500] million shares; issued: [removed: 2021] [added: 2022] and [removed: 2020—198.3] [added: 2021—198.3] million shares) | | | | | | 397 | | | | | | 397 | | |
February 23, 2023
February 23, 2023
| Sale, call or maturity of fixed maturities | | | 1,113 | | | | | | 1,461 | | | | | | 1,091 | | | | | | | | |
insurance policies and measure profitability.
At December 31, 2022, the current fair value of the contract holders’ account value exceeded the current fair value of the BOLI invested assets and cash by approximately $64 million.
traditionally used for the types of exposures written.
We adopted these ASUs on a modified retrospective basis on January 1, 2023, resulting in an after-tax increase to shareholders' equity of approximately $30 million.
Quarterly updates to the life policy and investment contract reserves and corresponding adjustments to shareholders' equity due to changes in the market value discount rates and other assumptions in subsequent periods could be material.
| Corporate | | | | | | $ | 7,412 | | | | | $ | 37 | | | | | $ | 580 | | | | | $ | 6,869 | |
| Total | | | | | | $ | 12,979 | | | | | $ | 61 | | | | | $ | 908 | | | | | $ | 12,132 | |
The net unrealized investment losses in our fixed-maturity portfolio at December 31, 2022, are primarily due to an increase in U.S. Treasury yields and widening of corporate credit spreads.
| Corporate | | | | | | $ | 5,651 | | | | | $ | 412 | | | | | $ | 661 | | | | | $ | 168 | | | | | $ | 6,312 | | | | | $ | 580 | |
| Total | | | | | | $ | 8,760 | | | | | $ | 706 | | | | | $ | 800 | | | | | $ | 202 | | | | | $ | 9,560 | | | | | $ | 908 | |
| At December 31, 2022 | | | | | | | | | | | | | | | | | | | | |
| Total | | | | | | $ | 12,979 | | | | | $ | 12,132 | | | | | 100.0 | | % |
At December 31, 2022, the allowance for credit losses on fixed-maturity securities was $1 million.
Changes in the amount during the period were also $1 million.
There were three fixed-maturity securities that were written down to fair value, due to an intention to be sold, primarily in the real estate sector.
At December 31, 2022, 3,272 fixed-maturity securities with a total unrealized loss of $908 million were in an unrealized loss position.
| (Dollars in millions) | | | | | | Level 1 | | | | | | | | | | | | Level 3 | | | | | | | | |
| At December 31, 2022 | | | | | | | | | Level 2 | | | | | | | | | Total | | | | | | | | |
| Subtotal | | | | | | 191 | | | | | | 11,941 | | | | | | — | | | | | | 12,132 | | |
| Total | | | | | | $ | 9,702 | | | | | $ | 13,143 | | | | | $ | — | | | | | $ | 22,845 | |
| (Dollars in millions) | | | | | | Level 1 | | | | | | Level 2 | | | | | | Level 3 | | | | | | Total | | |
| At December 31, 2022 | | | | | | | | | | | | | | | | | | | | | | | | | | |
| (Dollars in millions) | | | | | | Level 1 | | | | | | Level 2 | | | | | | Level 3 | | | | | | Total | | |
| At December 31, 2022 | | | | | | | | | | | | | | | | | | | | | | | | | | |
| (Dollars in millions) | | | | | | Level 1 | | | | | | Level 2 | | | | | | Level 3 | | | | | | Total | | |
| At December 31, 2022 | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Total | | | | | | $ | — | | | | | $ | 143 | | | | | $ | 621 | | | | | $ | 764 | |
This was partially offset by unfavorable development of $25 million for the commercial casualty line and $23 million for the commercial auto line.
Within commercial lines, we recognized favorable development of $120 million for the commercial casualty line, $97 million for the commercial property line,
| Commercial casualty | | | | | | $ | 5,932 | | | | | $ | 3,396 | | | | | $ | 86 | | | | | $ | 2,622 | | | | | $ | 43 | | | | | $ | 2,665 | |
| Workers' compensation | | | | | | 1,865 | | | | | | 1,215 | | | | | | 311 | | | | | | 961 | | | | | | 57 | | | | | | 1,018 | | |
| Commercial auto | | | | | | 2,332 | | | | | | 1,581 | | | | | | 40 | | | | | | 791 | | | | | | 5 | | | | | | 796 | | |
| Commercial property | | | | | | 3,312 | | | | | | 2,774 | | | | | | 15 | | | | | | 553 | | | | | | 47 | | | | | | 600 | | |
| Personal auto | | | | | | 1,831 | | | | | | 1,557 | | | | | | 13 | | | | | | 287 | | | | | | 28 | | | | | | 315 | | |
| Homeowner | | | | | | 2,275 | | | | | | 1,952 | | | | | | 6 | | | | | | 329 | | | | | | 8 | | | | | | 337 | | |
| Excess and surplus | | | | | | 1,272 | | | | | | 587 | | | | | | 2 | | | | | | 687 | | | | | | 37 | | | | | | 724 | | |
| 2022 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | 924 | | | | | | 613 | | | | | | 10 | | |
February 24, 2022
February 24, 2022
| Investment income receivable | | | (8) | | | | | | (3) | | | | | | (1) | | |
| Sale of fixed maturities | | | 118 | | | | | | 179 | | | | | | 102 | | |
| Call or maturity of fixed maturities | | | 1,343 | | | | | | 912 | | | | | | 1,241 | | |
| Collection of finance receivables | | | 37 | | | | | | 35 | | | | | | 29 | | |
| Share-based compensation | | | 26 | | | | | | 19 | | | | | | 9 | | |
Cincinnati Global, our London-based global specialty underwriter, was acquired effective February 28, 2019.
Beginning in mid-March 2020, the coronavirus (SARS-CoV-2 or COVID-19) pandemic outbreak, and unprecedented
actions taken to contain the virus, caused an economic downturn on a global scale as well as market disruption and
volatility.
The 2019 consolidated financial statements include Cincinnati Global's results for the period from February 28, 2019, through December 31, 2019.
approximately 0.6% of our total property casualty earned premiums in 2021.
fees and assessments accrues to us and is transferred from the separate account to our general account and is recognized as revenue or expense.
We plan to adopt these ASUs on a modified retrospective basis on January 1, 2023, with a transition date of January 1, 2021.
Management has identified that the requirement to measure term and whole life policy reserves using updated discount rates is expected to have a material impact on shareholders' equity, through an increase to life policy reserves and a decrease to AOCI, at the transition date.
The company is in the process of addressing necessary implementation-related items, including modifications to reporting and analysis capabilities as well as actuarial systems and associated data processes.
Further, the company continues to refine its accounting policy decisions associated with the new guidance.
Additional impacts of these ASUs on our company's consolidated financial position, results of operations and cash flows are being further evaluated by management.
| Corporate | | | | | | $ | 6,281 | | | | | $ | 621 | | | | | $ | 7 | | | | | $ | 6,895 | |
The net unrealized investment gains in our fixed-maturity portfolio at December 31, 2021, are primarily the result of the continued low interest rate environment that increased the fair value of our fixed-maturity portfolio.
| Corporate | | | | | | $ | 330 | | | | | $ | 5 | | | | | $ | 46 | | | | | $ | 2 | | | | | $ | 376 | | | | | $ | 7 | |
| Total | | | | | | $ | 406 | | | | | $ | 8 | | | | | $ | 54 | | | | | $ | 2 | | | | | $ | 460 | | | | | $ | 10 | |
| Total | | | | | | $ | 12,230 | | | | | $ | 13,022 | | | | | 100.0 | | % |
During 2019, we other-than-temporarily impaired three securities.
At December 31, 2019, 38 fixed-maturity investments with a total unrealized loss of $3 million had been in an unrealized loss position for 12 months or more.
| (Dollars in millions) | | | | | | Quoted prices in active markets for identical assets (Level 1) | | | | | | | | | | | | Significant unobservable inputs (Level 3) | | | | | | | | |
| At December 31, 2021 | | | | | | | | | Significant other observable inputs (Level 2) | | | | | | | | | Total | | | | | | | | |
| At December 31, 2020 | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Subtotal | | | | | | 120 | | | | | | 12,218 | | | | | | — | | | | | | 12,338 | | |
| Total | | | | | | $ | 8,712 | | | | | $ | 13,436 | | | | | $ | — | | | | | $ | 22,148 | |
| (Dollars in millions) | | | | | | Quoted prices in active markets for identical assets (Level 1) | | | | | | Significant other observable inputs (Level 2) | | | | | | Significant unobservable inputs (Level 3) | | | | | | Total | | |
| At December 31, 2020 | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Total | | | | | | $ | — | | | | | $ | 1,126 | | | | | $ | — | | | | | $ | 1,126 | |
| (Dollars in millions) | | | | | | Quoted prices in active markets for identical assets (Level 1) | | | | | | Significant other observable inputs (Level 2) | | | | | | Significant unobservable inputs (Level 3) | | | | | | Total | | |
| At December 31, 2020 | | | | | | | | | | | | | | | | | | | | | | | | | | |
| (Dollars in millions) | | | | | | Quoted prices in active markets for identical assets (Level 1) | | | | | | Significant other observable inputs (Level 2) | | | | | | Significant unobservable inputs (Level 3) | | | | | | Total | | |
| At December 31, 2020 | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Total | | | | | | $ | — | | | | | $ | 227 | | | | | $ | 836 | | | | | $ | 1,063 | |
| Net loss and loss expense reserves related to acquisition of Cincinnati Global at February 28, 2019 | | | | | | — | | | | | | — | | | | | | 246 | | |
An excerpt. Shown here: 40 of 737 rewritten, 40 of 131 added and 40 of 128 removed. The counts are complete. For every sentence, read Item 8. Financial Statements and Supplementary Data in the FY2022 filing and the FY2021 filing.
Page headers and footers: 57 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 118
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 119
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 120
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 121
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 122
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 123
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 124
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 125
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 126
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 127
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 128
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 129
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 130
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 131
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 132
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 133
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 134
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 135
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 136
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 137
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 138
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 139
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 140
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 141
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 142
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 143
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 144
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 145
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 146
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 147
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 148
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 149
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 150
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 151
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 152
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 153
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 154
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 155
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 156
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page 157
Cincinnati Financial Corporation - 2022 10-K - Page 174
Shown here: 40 of 56 changed, all 1 added and all 0 removed.
Item 9A. Controls and Procedures
3 rewritten, 0 added, 0 removed, 7 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
The company’s management, with the participation of the company’s chief executive officer and chief financial officer, has evaluated the effectiveness of the design and operation of the company’s disclosure controls and procedures as of December 31, [removed: 2021.][added: 2022.]
Changes in Internal Control over Financial Reporting – During the three months ended December 31, [removed: 2021,] [added: 2022,] there were no changes in our internal controls over financial reporting that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
There was no significant impact to our internal controls over financial reporting while the majority of our [added: headquarters] associates [removed: are working remotely due] [added: transitioned] to [removed: the COVID-19 pandemic.][added: a hybrid work schedule, regularly alternating between work at our headquarters and work from remote locations.]
Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections
1 rewritten, 0 added, 0 removed, 3 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
Our Proxy Statement will be filed with the SEC no later than April 30, [removed: 2022,] [added: 2023,] in preparation for the [removed: 2022] [added: 2023] Annual Meeting of Shareholders scheduled for May [removed: 7, 2022.][added: 6, 2023.]
Page headers and footers: 1 line differs, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 174][added: 175]
Item 10. Directors, Executive Officers and Corporate Governance
16 rewritten, 1 added, 0 removed, 5 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
a) The following sections of our Proxy Statement for our [removed: 2022] [added: 2023] Annual Meeting of Shareholders to be held May [removed: 7, 2022,] [added: 6, 2023,] are incorporated herein by reference: “Delinquent Section 16(a) Reports,” “Information about the Board of Directors,” and “Governance of Your Company.”
c) Set forth below is information concerning the company’s executive officers who are not also directors of the company, as of February [removed: 24, 2022.][added: 23, 2023.]
| February [removed: 24, 2022] [added: 23, 2023] | | | | | | Since February [removed: 2017] [added: 2018] | | | | | | Officer Since | | |
| Roger A. Brown, FSA, MAAA, CLU [removed: (50)] [added: (51)] | | | | | | Senior vice president and chief operating officer of The Cincinnati Life Insurance Company. Responsible for life insurance underwriting and operations. | | | | | | 2016 | | |
| Teresa C. Cracas, Esq. [removed: (56)] [added: (57)] | | | | | | Chief risk officer and executive vice president of The Cincinnati Insurance Company. Senior vice president until 2022. Responsible for strategic planning and risk management, including oversight of modeling for financial analysis, property casualty reserving and pricing, strategic innovation, reinsurance assumed operations and the activities of Cincinnati Global Underwriting Ltd., a London-based, global specialty underwriter for Lloyd's Syndicate 318. | | | | | | 2011 | | |
| Angela O. Delaney [removed: (53)] [added: (54)] | | | | | | Senior vice president of The Cincinnati Insurance Company. Responsible for property casualty insurance sales and marketing operations since 2019, including management of field underwriters and independent agency relationships. Field sales supervisor for Idaho, Iowa, Montana, Oregon, South Dakota and Washington from 2017 to 2019. | | | | | | 2020 | | |
| Donald J. Doyle, Jr., CPCU, AIM [removed: (55)] [added: (56)] | | | | | | Senior vice president of The Cincinnati Insurance Company. Responsible for excess and surplus lines underwriting and operations of The Cincinnati Specialty Underwriters Insurance Company and CSU Producer Resources Inc. | | | | | | 2008 | | |
| Sean M. Givler, CIC, CRM [removed: (46)] [added: (47)] | | | | | | Senior vice president of The Cincinnati Insurance Company. Responsible for standard market commercial lines underwriting and operations, including management liability and surety insurance, machinery and equipment insurance, loss control and premium audit. Until 2019, responsible for sales and marketing, including management of field underwriters and independent agency relationships. | | | | | | 2017 | | |
| Theresa A. Hoffer [removed: (60)] [added: (61)] | | | | | | Senior vice president and treasurer of The Cincinnati Insurance Company since 2016. Responsible for corporate accounting and SEC reporting operations. | | | | | | 2017 | | |
| [removed: Martin F. Hollenbeck,] [added: Steven A. Soloria,] CFA, CPCU [removed: (62)] [added: (56)] | | | | | | Chief investment [removed: officer, senior vice president, assistant secretary and assistant treasurer of Cincinnati Financial Corporation. Chief investment] officer and [removed: executive] [added: senior] vice president of The Cincinnati Insurance Company. [removed: Senior vice president until 2022.] Responsible for all investment operations. [added: Vice president of investments until 2022.] | | | | | | [removed: 2008] [added: 2023] | | |
| John S. Kellington [removed: (60)] [added: (61)] | | | | | | Chief information officer and executive vice president of The Cincinnati Insurance Company. Senior vice president until 2022. Responsible for enterprise [removed: strategic] technology [added: platforms] and [removed: oversight of all technology] [added: related] activities. | | | | | | 2010 | | |
| February [removed: 24, 2022] [added: 23, 2023] | | | | | | Since February [removed: 2017] [added: 2018] | | | | | | Officer Since | | |
| Lisa A. Love, Esq. [removed: (62)] [added: (63)] | | | | | | [removed: Senior vice president, general counsel and corporate secretary of Cincinnati Financial Corporation.] Chief legal officer, executive vice president and corporate secretary of [removed: The] Cincinnati [removed: Insurance Company.] [added: Financial Corporation.] Senior vice president [added: and general counsel] until 2022. Responsible for corporate legal, governance and compliance activities, including oversight of regulatory and compliance, shareholder services, government relations, litigation and contract administration. | | | | | | 2011 | | |
| Michael J. Sewell, CPA [removed: (58)] [added: (59)] | | | | | | Chief financial officer, principal accounting officer, [removed: senior] [added: executive] vice president and treasurer of Cincinnati Financial Corporation. [removed: Chief financial officer and executive vice president of The Cincinnati Insurance Company.] Senior vice president until 2022. Chief operating officer of CFC Investment Company, a commercial lease and finance subsidiary. Responsible for oversight of all accounting, finance, financial reporting, purchasing, investor relations, administrative services and facilities maintenance and security. | | | | | | 2011 | | |
| Stephen M. Spray [removed: (55)] [added: (56)] | | | | | | President of [removed: The] Cincinnati [removed: Insurance Company and its subsidiaries; CFC Investment Company; and CSU Producer Resources Inc. since 2022. Chief insurance officer of The Cincinnati Insurance Company and its property casualty subsidiaries since 2019.] [added: Financial Corporation.] Responsible for executive oversight of [added: life insurance,] commercial and personal standard market and excess and surplus lines property and casualty insurance sales, marketing, underwriting, related field services, relationships with independent agents, ceded reinsurance programs, corporate communications and human resources. [added: Chief insurance officer of The Cincinnati Insurance Company and its property casualty subsidiaries until 2022.] Until 2019, senior vice president responsible for commercial lines underwriting and operations. | | | | | | 2012 | | |
| William H. Van Den Heuvel [removed: (55)] [added: (56)] | | | | | | Senior vice president of The Cincinnati Insurance Company. Responsible for all aspects of personal lines operations, including underwriting, insurance regulatory filings, product management and risk management. | | | | | | 2014 | | |
| Marc J. Schambow, CPCU, AIM, ASLI (57) | | | | | | Chief claims officer and senior vice president of The Cincinnati Insurance Company. Responsible for all headquarters and field claims operations, including special investigations and claims administration. Until 2020, vice president of field claims. | | | | | | 2022 | | |
Page headers and footers: 2 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 175][added: 176]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 176][added: 177]
Item 11. Executive Compensation
1 rewritten, 0 added, 0 removed, 1 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
The “Compensation of Named Executive Officers and Directors,” section of our Proxy Statement for our Annual Meeting of Shareholders to be held May [removed: 7, 2022,] [added: 6, 2023,] is incorporated herein by reference.
Item 12. Security Ownership of Certain Beneficial Owners and Management and
1 rewritten, 0 added, 0 removed, 3 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
a) The “Security Ownership of Principal Shareholders and Management” section of our Proxy Statement for our Annual Meeting of Shareholders to be held May [removed: 7, 2022,] [added: 6, 2023,] is incorporated herein by reference.
Page headers and footers: 1 line differs, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 177][added: 178]
Item 13. Certain Relationships and Related Transactions, and Director Independence
1 rewritten, 0 added, 0 removed, 0 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
The following sections of our Proxy Statement for our Annual Meeting of Shareholders to be held May [removed: 7, 2022,] [added: 6, 2023,] are incorporated herein by reference: “Governance of Your Company – Director Independence” and “Governance of Your Company – Certain Relationships and Transactions.”
Item 14. Principal Accounting Fees and Services
2 rewritten, 0 added, 0 removed, 1 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
The “Audit-Related Matters,” section of our Proxy Statement for our Annual Meeting of Shareholders to be held May [removed: 7, 2022,] [added: 6, 2023,] is incorporated herein by reference.
It includes the “Proposal [removed: 3] [added: 5] – Ratification of Selection of Independent Registered Public Accounting Firm,” “Report of the Audit Committee,” “Fees Billed by the Independent Registered Public Accounting Firm” and “Services Provided by the Independent Registered Public Accounting Firm.”
Page headers and footers: 1 line differs, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 178][added: 179]
Item 15. Exhibit and Financial Statement Schedules
8 rewritten, 0 added, 0 removed, 1 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
a) Financial Statements – information contained in Part II, Item 8, of this report, Page [removed: [118](#ib516704f6c694dd39ca65eef55d59c29_112)] [added: [118](#i02093e9754da48e991fe7fbb3df85a22_115)] to Page [removed: 173][added: [174](#i3e3d009a2fa245adbc6f1cb50e4c5b94_2907)]
b) Exhibits – see Index of Exhibits, Page [removed: [191](#ib516704f6c694dd39ca65eef55d59c29_274)][added: [192](#i02093e9754da48e991fe7fbb3df85a22_241)]
Schedule I – Summary of Investments – Other Than Investments in Related Parties, Page [removed: 180][added: [181](#i02093e9754da48e991fe7fbb3df85a22_2281)]
Schedule II – Condensed Financial Statements of Parent Company, Page [removed: 182][added: [183](#i02093e9754da48e991fe7fbb3df85a22_2310)]
Schedule III – Supplementary Insurance Information, Page [removed: 185][added: [186](#i02093e9754da48e991fe7fbb3df85a22_2338)]
Schedule IV – Reinsurance, Page [removed: 187][added: [188](#i02093e9754da48e991fe7fbb3df85a22_2366)]
Schedule V – Valuation and Qualifying Accounts, Page [removed: 188][added: [189](#i02093e9754da48e991fe7fbb3df85a22_2394)]
Schedule VI – Supplementary Information Concerning Property Casualty Insurance Operations, Page [removed: 189][added: [190](#i02093e9754da48e991fe7fbb3df85a22_2422)]
Item 16. Form 10-K Summary
315 rewritten, 14 added, 17 removed, 202 unchanged
Read the full itemFY2022 item · filed February 23, 2023FY2021 item · filed February 24, 2022
| (Dollars in millions) | | | | | | At December 31, [removed: 2021] [added: 2022] | | | | | | | | | | | | | | |
| The Cincinnati Insurance Company | | | | | | [removed: $] [added: 15] | [removed: 3,343] | | | | | [removed: $] [added: 15] | [removed: 3,583] | | | | | [removed: $] [added: 15] | [removed: 3,583] | |
| The Cincinnati Casualty Company | | | | | | [removed: 230] [added: 243] | | | | | | [removed: 246] [added: 230] | | | | | | [removed: 246] [added: 230] | | |
| The Cincinnati Indemnity Company | | | | | | [removed: 49] [added: 48] | | | | | | [removed: 53] [added: 46] | | | | | | [removed: 53] [added: 46] | | |
| The Cincinnati Life Insurance Company | | | | | | [removed: 446] [added: 13] | | | | | | [removed: 471] [added: 11] | | | | | | [removed: 471] [added: 11] | | |
| The Cincinnati Specialty Underwriters Insurance Company | | | | | | [removed: 643] [added: 10] | | | | | | [removed: 685] [added: 10] | | | | | | [removed: 685] [added: 10] | | |
| Cincinnati Financial Corporation | | | | | | [removed: 57] [added: 62] | | | | | | [removed: 57] [added: 52] | | | | | | [removed: 57] [added: 52] | | |
| The Cincinnati Insurance Company [added: (1)] | | | | | | [removed: 69] [added: 38] | | | | | | [removed: 71] [added: —] | | | | | | [removed: 71] [added: 38] | | |
| Cincinnati Global Underwriting Ltd. | | | | | | [removed: 50] [added: 55] | | | | | | [removed: 50] [added: 54] | | | | | | [removed: 50] [added: 54] | | |
| Cincinnati Global Underwriting Ltd. | | | | | | [removed: 16] [added: 9] | | | | | | [removed: 16] [added: 9] | | | | | | [removed: 16] [added: 9] | | |
| Total | | | | | | [removed: 26] [added: 34] | | | | | | [removed: 26] [added: 33] | | | | | | [removed: 26] [added: 33] | | |
| Cincinnati Global Underwriting Ltd. | | | | | | [removed: 8] [added: 24] | | | | | | [removed: 8] [added: 23] | | | | | | [removed: 8] [added: 23] | | |
| Total [added: (1)] | | | | | | [removed: 8] [added: $] | [added: 41] | | | | | [removed: 8] [added: $] | [added: 53] | | | | | [removed: 8] [added: $] | [added: 46] | |
| The Cincinnati Insurance Company [added: (1)] | | | | | | [removed: 3,443] [added: 288] | | | | | | [removed: 3,628] [added: —] | | | | | | [removed: 3,628] [added: 288] | | |
| The Cincinnati Casualty Company | | | | | | [removed: 102] [added: 5] | | | | | | [removed: 106] [added: 5] | | | | | | [removed: 106] [added: 5] | | |
| The Cincinnati Indemnity Company | | | | | | [removed: 33] [added: 2] | | | | | | [removed: 35] [added: 2] | | | | | | [removed: 35] [added: 2] | | |
| The Cincinnati Life Insurance Company [added: (1)] | | | | | | [removed: 3,339] [added: 5] | | | | | | [removed: 3,595] [added: —] | | | | | | [removed: 3,595] [added: 5] | | |
| The Cincinnati Specialty Underwriters Insurance Company | | | | | | [removed: 300] [added: 688] | | | | | | [removed: 316] [added: 640] | | | | | | [removed: 316] [added: 640] | | |
| CSU Producer Resources Inc. | | | | | | [removed: 1] [added: 17] | | | | | | [removed: 1] [added: 27] | | | | | | [removed: 1] [added: 27] | | |
| Cincinnati Global Underwriting Ltd. | | | | | | [removed: 82] [added: 32] | | | | | | [removed: 82] [added: —] | | | | | | [removed: 82] [added: 32] | | |
| Cincinnati Financial Corporation | | | | | | [removed: 7] [added: 29] | | | | | | [removed: 7] [added: 26] | | | | | | [removed: 7] [added: 26] | | |
| Total | | | | | | [removed: 7,307] [added: $] | [added: 7,307] | | | | | [removed: 7,770] [added: $] | [added: 6,479] | | | | | [removed: 7,770] [added: $] | [added: 5,864] | |
| Total fixed maturities | | | | | | $ | [removed: 12,230] [added: 12,979] | | | | | $ | [removed: 13,022] [added: 12,132] | | | | | $ | [removed: 13,022] [added: 12,132] | |
| (Dollars in millions) | | | | | | At December 31, [removed: 2021] [added: 2022] | | | | | | | | | | | | | | |
| The Cincinnati Insurance Company | | | | | | $ | [removed: 1,848] [added: 3,401] | | | | | $ | [removed: 5,543] [added: 3,271] | | | | | $ | [removed: 5,543] [added: 3,271] | |
| The Cincinnati Casualty Company | | | | | | [removed: 59] [added: 96] | | | | | | [removed: 186] [added: 85] | | | | | | [removed: 186] [added: 85] | | |
| The Cincinnati Indemnity Company | | | | | | [removed: 18] [added: 33] | | | | | | [removed: 44] [added: 31] | | | | | | [removed: 44] [added: 31] | | |
| The Cincinnati Specialty Underwriters Insurance Company | | | | | | [removed: 101] [added: 323] | | | | | | 287 | | | | | | 287 | | |
| Cincinnati Financial Corporation | | | | | | [removed: 1,656] [added: 5] | | | | | | [removed: 4,774] [added: —] | | | | | | [removed: 4,774] [added: 5] | | |
| The Cincinnati Insurance Company | | | | | | [removed: 407] [added: 139] | | | | | | [removed: 436] [added: 135] | | | | | | [removed: 436] [added: 135] | | |
| The Cincinnati Life Insurance Company | | | | | | [removed: 13] [added: 459] | | | | | | [removed: 13] [added: 383] | | | | | | [removed: 13] [added: 383] | | |
| Total equity securities | | | | | | $ | [removed: 4,121] [added: 4,294] | | | | | $ | [removed: 11,315] [added: 9,841] | | | | | $ | [removed: 11,315] [added: 9,841] | |
| Cincinnati Global Underwriting Ltd. | | | | | | [removed: 29] [added: 104] | | | | | | [removed: —] [added: 102] | | | | | | [removed: 29] [added: 102] | | |
| Cincinnati Financial Corporation [added: (1)] | | | | | | [removed: 6] [added: 44] | | | | | | — | | | | | | [removed: 6] [added: 44] | | |
| The Cincinnati Insurance Company [removed: (1)] | | | | | | [removed: 191] [added: 3,794] | | | | | | [removed: —] [added: 3,527] | | | | | | [removed: 191] [added: 3,527] | | |
| Cincinnati Financial Corporation [removed: (1)] | | | | | | [removed: 36] [added: 1,730] | | | | | | [removed: —] [added: 3,974] | | | | | | [removed: 36] [added: 3,974] | | |
| The Cincinnati Insurance Company [removed: (1)] | | | | | | [removed: 27] [added: $] | [added: 1,925] | | | | | [removed: —] [added: $] | [added: 5,013] | | | | | [removed: 27] [added: $] | [added: 5,013] | |
| Total other invested assets | | | | | | $ | [removed: 329] [added: 452] | | | | | — | | | | | | $ | [removed: 329] [added: 452] | |
| | | | | | | [removed: 2021] [added: 2022] | | | | | | [added: 2021 | | | | | |] 2020 | | |
| Fixed maturities, at fair value (amortized cost: [removed: 2021—$64; 2020—$69)] [added: 2022—$91; 2021—$64)] | | | | | | $ | [removed: 64] [added: 78] | | | | | $ | [removed: 68] [added: 64] | |
| Total | | | | | | 4,901 | | | | | | 4,622 | | | | | | 4,622 | | |
| Total | | | | | | 196 | | | | | | 191 | | | | | | 191 | | |
| The Cincinnati Life Insurance Company | | | | | | 145 | | | | | | 142 | | | | | | 142 | | |
| Total | | | | | | 186 | | | | | | 183 | | | | | | 183 | | |
| The Cincinnati Life Insurance Company | | | | | | 3,283 | | | | | | 3,045 | | | | | | 3,045 | | |
| Total | | | | | | 7,662 | | | | | | 7,103 | | | | | | 7,103 | | |
| The Cincinnati Casualty Company | | | | | | 59 | | | | | | 162 | | | | | | 162 | | |
| The Cincinnati Indemnity Company | | | | | | 18 | | | | | | 40 | | | | | | 40 | | |
| The Cincinnati Specialty Underwriters Insurance Company | | | | | | 102 | | | | | | 238 | | | | | | 238 | | |
| Total | | | | | | 3,851 | | | | | | 9,454 | | | | | | 9,454 | | |
| The Cincinnati Insurance Company | | | | | | 426 | | | | | | 372 | | | | | | 372 | | |
| Total | | | | | | 443 | | | | | | 387 | | | | | | 387 | | |
| Total investments | | | | | | $ | 17,725 | | | | | — | | | | | | $ | 22,425 | |
| | | | | | | 2022 | | | | | | 2021 | | |
| Total | | | | | | 4,768 | | | | | | 5,095 | | | | | | 5,095 | | |
| Total | | | | | | 121 | | | | | | 123 | | | | | | 123 | | |
| CSU Producer Resources Inc. | | | | | | 15 | | | | | | 28 | | | | | | 28 | | |
| Total | | | | | | 3,697 | | | | | | 10,862 | | | | | | 10,862 | | |
| Total | | | | | | 424 | | | | | | 453 | | | | | | 453 | | |
| Total investments | | | | | | $ | 16,680 | | | | | — | | | | | | $ | 24,666 | |
| Investment income receivable | | | | | | (1) | | | | | | (1) | | | | | | (1) | | |
| Purchase of fixed maturities | | | | | | (19) | | | | | | (23) | | | | | | (39) | | |
| Cash paid for acquisition | | | | | | — | | | | | | — | | | | | | (63) | | |
| Total (1) | | | | | | $ | 53 | | | | | $ | 46 | | | | | $ | 35 | |
| | | | | | | 2021 | | | | | | 2020 | | | | | | 2019 | | |
| Total | | | | | | $ | 6,479 | | | | | $ | 5,864 | | | | | $ | 5,516 | |
| 10.33 | | | [Cincinnati Financial Corporation Executive Deferred Compensation Agreement by and between the Cincinnati Financial Corporation and Michael J. Sewell, dated as of October 25, 2011 (incorporated by reference to Exhibit 10.2 filed with the company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2011)](http://www.sec.gov/Archives/edgar/data/20286/000114420411059805/v237330_ex10-2.htm) | | |
| /S/ William F. Bahl | | | Director | | | February 24, 2022 | | |
| William F. Bahl | | | | | | | | |
| /S/ Kenneth C. Lichtendahl | | | Director | | | February 24, 2022 | | |
| Kenneth C. Lichtendahl | | | | | | | | |
An excerpt. Shown here: 40 of 315 rewritten, all 14 added and all 17 removed. The counts are complete. For every sentence, read Item 16. Form 10-K Summary in the FY2022 filing and the FY2021 filing.
Page headers and footers: 17 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 179][added: 180]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 180][added: 181]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 181][added: 182]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 182][added: 183]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 183][added: 184]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 184][added: 185]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 185][added: 186]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 186][added: 187]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 187][added: 188]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 188][added: 189]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 189][added: 190]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 190][added: 191]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 191][added: 192]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 192][added: 193]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 193][added: 194]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 194][added: 195]
Cincinnati Financial Corporation - [removed: 2021] [added: 2022] 10-K - Page [removed: 195][added: 196]