 filings.tools
Cincinnati Financial (CINF) 10-K risk factor changes: FY2023 vs FY2022
The 2023-12-31 10-K against the 2022-12-31 one, compared heading by heading and sentence by sentence.
Item 1A63 rewritten37 added15 removed266 unchanged
All filing items2,063 rewritten1,143 added910 removed2,378 unchanged
Sentence counts leave out repeated page headers and footers. 220 of those lines differ and are listed apart under each item.
Summary
counted, not written
- Item 1A lists 20 risk factor headings: 0 new, 1 reworded and 19 unchanged since FY2022. 1 heading from FY2022 no longer appears.
- Sentence by sentence, 1,143 added, 910 removed, 2,063 rewritten and 2,378 unchanged across 20 items that differ.
- Not counted above: 220 repeated page header or footer lines also differ. They are listed apart under each item.
- New this year: Item 1C. Cybersecurity.
New Item 1A headings (0)
No risk factor heading in this filing is absent from FY2022.
Removed Item 1A headings (1)
- Developments relating to the Russian war against Ukraine could adversely affect our insurance operations or other financial matters.
Reworded Item 1A headings (1)
- Elevated inflation
[removed: may]negatively[removed: impact][added: impacts] profit and the value of investments.
A heading is new when no FY2022 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
24 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2023; struck-through words were in FY2022. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors
63 rewritten, 37 added, 15 removed, 266 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
- Mergers and acquisitions [added: of agencies] could result in a concentration of a significant amount of premium in one agency.
A reduction in the number of independent agencies marketing our products, the failure of agencies to successfully market our products or pay amounts due to us, changes in the strategy or operations of agencies or the choice of agencies to reduce their writings of our products could affect our results of operations if we [removed: were] [added: are] unable to replace them with agencies that produce adequate and profitable premiums.
[removed: Economic] [added: Such economic] events experienced during [removed: 2022] [added: recent periods] included elevated inflation, global supply chain disruptions, increasing interest rates, tightening credit markets and higher fuel costs.
Man-made catastrophes to which we [added: have been exposed in the past, and] may be exposed [added: in the future,] include, but are not limited to, industrial accidents, terrorist attacks, [added: wars,] cyberattacks, infrastructure failures, social unrest and riot.
Natural peril catastrophe events to which we [added: have been exposed in the past, and] may be exposed [added: in the future,] include, but are not limited to, hurricanes, [removed: tornadoes, windstorms, earthquakes, landslides, hailstorms, flooding,] severe winter [removed: weather] [added: weather, wildfires, earthquakes, landslides] and [removed: wildfires.][added: severe convective storm effects such as tornadoes, windstorms, hailstorms and flooding.]
Due to the nature of these events, we are unable to predict precisely the [removed: frequency] [added: frequency, severity] or potential cost of catastrophe occurrences.
According to these models, probable maximum loss estimates from a single hurricane event that combine the effects of property casualty insurance written on a direct basis by The Cincinnati Insurance Companies, the Cincinnati Re reinsurance portfolio and risks insured by Cincinnati Global include the following amounts, net of amounts recoverable through reinsurance ceded and also income taxes, and including the effects of estimated reinstatement premiums: [removed: $540] [added: $570] million for a once-in-a-100-year event and [removed: $798] [added: $848] million for a once-in-a-250-year event.
Please see Item 7, Liquidity and Capital Resources, [removed: 2023] [added: 2024] Reinsurance Programs, for a discussion of modeled losses considered in evaluating our risk mitigation strategy, which includes our ceded reinsurance program.
- Hurricanes in the gulf, eastern, southeastern and northeastern coastal [removed: regions.][added: regions]
- Earthquakes in many regions, most particularly in the New Madrid fault zone, California, the Northwest and [removed: Southwest.][added: Southwest]
- Tornadoes, wind and [removed: hail.][added: hail]
Additionally, our life insurance subsidiary could be adversely affected in the event of a terrorist event or an epidemic, particularly if the epidemic were to affect a broad range of the population, or [removed: affects] [added: affect] the overall economy.
Based on treaties in effect at January 1, [removed: 2023,] [added: 2024,] the largest loss exposure to us for Cincinnati Re is from natural catastrophe events.
That exposure includes probable maximum loss estimates, on a marginal basis, of the following amounts: [removed: $167] [added: $194] million for a once-in-a-100-year event and [removed: $198] [added: $224] million for a once-in-a-250-year event.
Ignoring diversification effects provided by those two components, on a standalone basis, probable maximum loss estimates for Cincinnati Re include the following amounts: [removed: $204] [added: $231] million for a once-in-a-100-year event and [removed: $244] [added: $281] million for a once-in-a-250-year event.
[removed: If there is a] high frequency of large property catastrophe or terrorism events, or a single extreme event, during the coverage period of these treaties, our financial position and results of operations could be materially affected.
[removed: Given its seasoned underwriting associates, we] [added: We] are also expanding Cincinnati Global, our global specialty underwriter with premiums primarily for U.S. and international property exposures.
At January 1, [removed: 2023,] [added: 2024,] the largest loss exposure to us for Cincinnati Global is from natural catastrophe events.
Cincinnati Global's exposure from such events includes probable maximum loss estimates of the following amounts: [removed: $71] [added: $46] million for a once-in-a-100-year event and [removed: $106] [added: $64] million for a once-in-a-250-year event.
[removed: Global] [added: Various scientists have linked global] climate change from rising planet temperatures over the last several decades [removed: has been linked] to a number of factors that contribute to the increased unpredictability, frequency, duration and severity of weather events, including: changing weather patterns, a rise in ocean temperatures and sea level rise.
[removed: This] [added: A continuation of these trends] would also likely increase the risks of writing property insurance in coastal areas or areas susceptible to wildfires or flooding, particularly in jurisdictions that restrict pricing and underwriting flexibility.
The outbreak was widespread in the [removed: United States,] [added: U.S.,] including in the markets in which we operate.
Our estimates for COVID-19 losses and loss adjustment expenses represent our best estimates as of December 31, [removed: 2022,] [added: 2023,] based upon information currently available.
These estimates are based on reported claims, policy level [removed: reviews and recent] [added: reviews,] judicial [removed: rulings.][added: rulings and other litigation developments.]
[removed: However, assumptions about coverage,] liability and reinsurance continue to be subject to on-going judicial review and may be subject to further government action.
While we believe our net reserves for losses and loss adjustment expenses for COVID-19 as of December 31, [removed: 2022,] [added: 2023,] are adequate based on information available at this time, we continue to closely monitor reported claims, government actions, judicial decisions and changes in the levels of worldwide social disruption and economic activity arising from the pandemic and will adjust our estimates of gross and net losses as new information becomes available.
To properly price our products, we must collect, properly analyze and use data to make decisions and take appropriate action; the data must be sufficient, reliable and [removed: accessible; Cincinnati Global has risks due to its reliance on coverholders in underwriting parts of its business; we need to develop appropriate rating methodologies and formulae; and we may need to identify and respond to trends quickly.][added: accessible.]
We may overestimate or underestimate loss cost trends or these trends may unexpectedly change, [added: such as inflation in recent years outside of historical norms,] leading to losing business by pricing risks above our competitors or charging rates too low to maintain profitability.
Our ability to set appropriate rates [removed: could be] [added: are] hampered if states where we write business refuse to allow rate increases that we believe are necessary to cover the risks insured.
A state could also hamper our ability to set appropriate rates if it no longer [removed: allowed] [added: allows] us to use factors that we believe are predictive of loss, such as credit-based factors.
These additional losses could arise from changes in the legal environment, laws and regulations, climate change, catastrophic events, increases in loss severity or frequency, environmental claims, mass torts or other causes such [removed: as social inflation.]
Periods of higher death claims outside of long-term historical norms, such as [added: during] the COVID-19 pandemic, and not anticipated within our actuarial models could make our life policy reserves inadequate to cover actual future death claims.
Our business activities outside the [removed: United States,] [added: U.S.,] including [added: in] the U.K., subject us to political and economic risks, including foreign currency and credit risk.
Business activities outside the [removed: United States] [added: U.S.] will subject us to additional domestic and foreign laws and regulations, including the Foreign Corrupt Practices Act, the U.K. Bribery Act and similar laws in other countries that prohibit the making of improper payments to foreign officials.
We have limited direct exposure within our insurance operations to businesses or individuals in [removed: Russia or the] [added: Russia,] Ukraine [removed: reported in our consolidated property casualty insurance catastrophe losses and loss expenses incurred, net of reinsurance.][added: or Gaza.]
The ultimate impact of Brexit is uncertain and will depend on any agreements that the U.K. makes to retain access to [removed: European Union markets.]
Please see Item 7, Liquidity and Capital Resources, [removed: 2023] [added: 2024] Reinsurance Ceded Programs, for a discussion of selected reinsurance transactions.
Recent events, including the [removed: outbreak of COVID-19,] global supply chain disruptions, increasing interest rate environment and inflationary pressures, have contributed to significant disruption and volatility for financial markets and decreased economic activity.
In the event that these conditions [removed: continue] [added: continue, recur] or result in a prolonged economic downturn or recession, they could further adversely impact our financial condition, results of operations or cash flows.
These market conditions [added: have in the past, and] could [removed: also] [added: in the future,] cause our investment income or the value of securities we own to decrease.
Marked or prolonged economic downturns or other events have in the past and may in the future result in a softening of the insurance market and agents or consumers choosing a competitor’s product that may in turn adversely affect our premium revenues and underwriting profit.
- Wildfires
- Winter storms
Cincinnati Re and Cincinnati Global provide reinsurance or insurance coverage in many parts of the world, including coverage for losses due to war, terrorism or political violence.
Wars can occur anywhere, and our results of operations could be adversely affected, especially if effects of wars expand over time and space.
We have exposure within our insurance operations, primarily through reinsurance treaties, to insured losses related to wars that include risks in the Middle East region.
If effects related to the war in Gaza expand significantly in the Middle East region, causing a high frequency of loss events, or a single extreme event, during the coverage period of our treaties or policies, our financial position and results of operations could be materially affected.
If there is a
Changes in climate and/or weather patterns may increase the frequency and/or intensity of severe weather and natural catastrophe events, including hurricanes, heavy precipitation events, heavy wind events, flash flooding, sea level rise, droughts, heat waves and wildfires potentially leading to increased insured losses.
We cannot predict how legal, regulatory or social responses to concerns about climate change may impact our business.
However, assumptions about coverage,
Cincinnati Global has risks due to its reliance on coverholders in underwriting parts of its business.
We also need to develop appropriate rating methodologies and formulae; and we may need to identify and respond to trends quickly.
Legal trends in recent years have also made it more difficult to determine adequate pricing, including adverse changes in the tort environment caused by more aggressive attorney involvement in insurance claims, increased litigation, expanded theories of liability, higher jury awards, lawsuit abuse and third-party litigation finance.
Limitations on our ability to use various types of artificial intelligence (AI) in the development of pricing precision could adversely affect underwriting results.
Examples of inflation effects include adverse changes in the tort environment caused by more aggressive attorney involvement in insurance claims, increased litigation, expanded theories of liability, higher jury awards, lawsuit abuse and third-party litigation finance.
as social inflation.
The increase in inflation in recent periods has significantly increased our loss costs in our auto and property businesses.
It is possible that inflation could remain
at high levels for a prolonged period, or increase from these high levels, which could in turn lead to further increases in our loss costs.
In addition, a significant portion of claims costs consists of medical costs.
As a result, an increase in medical inflation could materially and adversely impact our loss costs and our loss reserves.
Recent changes in the macroeconomic environment have impacted medical labor and materials costs, the potential persistency of which could result in future loss costs which are higher than our current expectations.
European Union markets.
inactions of the U.S. government, epidemic events, terrorism attacks or threats, war, adverse events affecting other companies in our industry or the industries in which we invest, market events leading to credit constriction, and other widespread unpredictable events.
Wars can occur anywhere in the world and have an adverse effect on our investment portfolio, especially if effects of wars expand over time and space.
We do not have material exposure to investments based in Russia, Ukraine, Israel or Gaza.
If there is significant expansion of wars to regions beyond these countries, it may have an adverse effect.
A BOLI is designed with the bank as the policy owner and the policy beneficiary.
We legally segregate and record as separate accounts the assets and liabilities for certain BOLIs, when required by the specific contract provisions.
Minimum investment returns, account values and death benefits are guaranteed by us for our separate account BOLIs.
We could incur losses in the performance of these guarantees.
There has been increased regulatory scrutiny of the use of machine learning and AI, and it is likely that we will be subject to new regulations that could materially adversely affect our operations or ability to write business profitably in one or more jurisdictions.
Some of our existing or potential shareholders, policyholders, associates, regulators, and other stakeholders will evaluate our business practices according to a variety of environmental, social and governance (ESG) standards and expectations, including those related to climate change, inclusive diversity and equity, data privacy, and the well-being of our employees.
Our business practices and disclosures are evaluated against ESG standards which are continually evolving and not always well defined or readily measurable today.
Our practices may not change in the particular ways or at the rate stakeholders expect, leading to business or reputational challenges.
Please see Item 1C, Cybersecurity, for further discussion of our cybersecurity risk management, strategy and governance.
Premium revenues and underwriting profit could also be adversely affected by marked or prolonged economic downturns or other events.
- Wildfires.
- Winter storms.
Further increases or persistence in these conditions would lead to higher overall losses, which we may not be able to recoup, particularly in a highly regulated and competitive environment, and higher reinsurance costs.
The threat of rising seas or other catastrophe losses as a result of global climate change may also cause property values in coastal or such other communities to decrease, reducing the total amount of insurance coverage that is required.
Inflation trends, especially outside of historical norms, such as we experienced during 2022, may make it more difficult to determine adequate pricing.
Inflationary scenarios may cause the cost of claims, especially medical claims, to rise, impacting reserve adequacy and our results of operations.
Developments relating to the Russian war against Ukraine could adversely affect our insurance operations or other financial matters.
We do not have material exposure to investments subject to embargos or Russian reinsurance counterparties.
However, the ongoing Russian war against Ukraine is impacting global economic, banking, commodity, and financial markets, exacerbating ongoing economic challenges, including inflation and supply chain disruption, which impacts insurance loss costs, premiums and investment valuation.
BOLI investment assets must meet certain criteria established by the regulatory authorities in the jurisdiction for which the group contract holder is subject.
Therefore, sales of investments may be mandated to maintain compliance with these regulations, possibly requiring gains or losses to be recorded.
We could experience losses if the assets in the accounts were less than liabilities at the time of maturity or termination.
While we take commercially reasonable measures to keep our systems and data secure, it is difficult or impossible to defend against every risk being posed by changing technologies as well as criminal and state-sponsored cybercrime and cyber threats.
While we are not aware of having experienced a material breach of our cybersecurity systems, administrative, internal accounting and technical controls as well as other preventative actions may be insufficient to prevent security breaches to our systems or those of third parties with whom we do business.
An excerpt. Shown here: 40 of 63 rewritten, all 37 added and all 15 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors in the FY2023 filing and the FY2022 filing.
Page headers and footers: 13 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 32][added: 30]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 33][added: 31]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 34][added: 32]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 35][added: 33]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 36][added: 34]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 37][added: 35]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 38][added: 36]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 39][added: 37]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 40][added: 38]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 41][added: 39]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 42][added: 40]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 43][added: 41]
Cincinnati Financial Corporation - 2023 10-K - Page 42
Item 7. Management's Discussion and Analysis of Financial Condition and
665 rewritten, 146 added, 575 removed, 588 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
Through The Cincinnati Insurance Company, Cincinnati Financial Corporation is one of the 25 largest property casualty insurers in the nation, based on net written premium volume for the first nine months of [removed: 2022,] [added: 2023,] among approximately 2,000 U.S. stock and mutual insurer groups.
| [removed: As] [added: As] of December 31, [removed: 2022] [added: 2022] | | | | | | [removed: (14.6)] [added: (14.6)] | | [removed: %] | | | | [removed: 8.6] [added: 8.6] | | [removed: %] | | | | [removed: 11.2] [added: 11.2] | | [removed: %] |
At [removed: negative 14.6%] [added: 19.5%] for [removed: 2022,] [added: 2023,] our performance was [removed: significantly below] [added: above] the [removed: low] [added: high] end of that range.
It was within the range for the [removed: five-year period, but below] [added: three-year period and above] the [added: high end of the] range for the [removed: three-year] [added: five-year] period, both that ended in December [removed: 2022.][added: 2023.]
The table below shows the primary [removed: components] [added: contributors] of our value creation ratio on a percentage basis.
Analysis of the [removed: components] [added: contributors] aids understanding of our financial performance.
| | | | | | | Years ended December 31, | | | | | | | | | | | | | | | | | | [removed: 2022-2021] [added: 2023-2022] | | | | | | [removed: 2021-2020] [added: 2022-2021] | | |
| | | | | | | [removed: 2022] [added: 2023] | | | | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2020] [added: 2021] | | | | | | Pt. Change | | | | | | Pt. Change | | |
| Value creation ratio major [removed: components:] [added: contributors:] | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Net income before investment gains | | | | | | [removed: 5.2] [added: 9.1] | | % | | | | [removed: 9.7] [added: 5.2] | | % | | | | [removed: 5.5] [added: 9.7] | | % | | | | [removed: (4.5)] [added: 3.9] | | | | | | [removed: 4.2] [added: (4.5)] | | |
| Change in fixed-maturity securities, realized and unrealized gains | | | | | | [removed: (10.1)] [added: 1.9] | | | | | | [removed: (1.5)] [added: (10.1)] | | | | | | [removed: 3.0] [added: (1.5)] | | | | | | [removed: (8.6)] [added: 12.0] | | | | | | [removed: (4.5)] [added: (8.6)] | | |
| Change in equity securities, investment gains | | | | | | [removed: (9.3)] [added: 8.6] | | | | | | [removed: 16.8] [added: (9.3)] | | | | | | [removed: 7.5] [added: 16.8] | | | | | | [removed: (26.1)] [added: 17.9] | | | | | | [removed: 9.3] [added: (26.1)] | | |
| Other | | | | | | [removed: (0.4)] [added: (0.1)] | | | | | | [removed: 0.7] [added: (0.4)] | | | | | | [removed: (1.3)] [added: 0.7] | | | | | | [removed: (1.1)] [added: 0.3] | | | | | | [removed: 2.0] [added: (1.1)] | | |
| Value creation ratio | | | | | | [removed: (14.6)] [added: 19.5] | | % | | | | [removed: 25.7] [added: (14.6)] | | % | | | | [removed: 14.7] [added: 25.7] | | % | | | | [removed: (40.3)] [added: 34.1] | | | | | | [removed: 11.0] [added: (40.3)] | | |
The [removed: 2022] [added: 2023] value creation ratio [removed: decreased] [added: improved] by [removed: 40.3] [added: 34.1] percentage points, compared with [removed: 2021,] [added: 2022,] and again included a significant contribution from operating results, as shown in the table [removed: above.][added: above, that was 3.9 percentage-points higher than last year.]
The [removed: 2022 ratio] decrease [added: in 2022, compared with 2021,] was primarily due to a reduction in overall net gains from our investment [removed: portfolio, with reductions of 26.1 percentage-points from our equity securities investment portfolio and 8.6 points from our fixed-maturity securities investment] portfolio.
| | | | | | | [removed: 2022] [added: 2023] | | | | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2020] [added: 2021] | | |
| End of period book value* | | | | | | $ | [removed: 67.01] [added: 77.06] | | | | | $ | [removed: 81.72] [added: 67.01] | | | | | $ | [removed: 67.04] [added: 81.72] | |
| Less beginning of period book value | | | | | | [removed: 81.72] [added: 67.01] | | | | | | [removed: 67.04] [added: 81.72] | | | | | | [removed: 60.55] [added: 67.04] | | |
| Change in book value | | | | | | [removed: (14.71)] [added: 10.05] | | | | | | [removed: 14.68] [added: (14.71)] | | | | | | [removed: 6.49] [added: 14.68] | | |
| Dividend declared to shareholders | | | | | | [removed: 2.76] [added: 3.00] | | | | | | [removed: 2.52] [added: 2.76] | | | | | | [removed: 2.40] [added: 2.52] | | |
| Total value creation | | | | | | $ | [removed: (11.95)] [added: 13.05] | | | | | $ | [removed: 17.20] [added: (11.95)] | | | | | $ | [removed: 8.89] [added: 17.20] | |
| Value creation ratio from change in book value | | | | | | [removed: (18.0)] [added: 15.0] | | % | | | | [removed: 21.9] [added: (18.0)] | | % | | | | [removed: 10.7] [added: 21.9] | | % |
| Value creation ratio from dividends declared to shareholders* | | | | | | [removed: 3.4] [added: 4.5] | | | | | | [removed: 3.8] [added: 3.4] | | | | | | [removed: 4.0] [added: 3.8] | | |
| Value creation ratio | | | | | | [removed: (14.6)] [added: 19.5] | | % | | | | [removed: 25.7] [added: (14.6)] | | % | | | | [removed: 14.7] [added: 25.7] | | % |
The compound annual growth rate of our net written premiums was [removed: 8.6%] [added: 9.9%] over the five-year period [removed: 2018] [added: 2019] through [removed: 2022,] [added: 2023,] exceeding the [removed: 7.3%] [added: 6.9%] estimated growth rate for the property casualty insurance industry, with [removed: 2022] [added: 2023] representing industry data reported through the first nine months of [removed: 2022.][added: 2023.]
- Combined ratio – We believe our underwriting philosophy and initiatives can drive performance to achieve our underwriting profitability target of a GAAP combined ratio over any five-year period that consistently averages within the range of [added: 92% to 98% in the future, better than our target of] 95% to [removed: 100%.][added: 100% during 2012 through 2023.]
Our GAAP combined ratio averaged [removed: 94.9%] [added: 94.6%] over the five-year period [removed: 2018] [added: 2019] through [removed: 2022,] [added: 2023,] slightly better than the performance target [removed: range.][added: range for that period.]
Our statutory combined ratio averaged [removed: 94.3%] [added: 94.1%] over the five-year period [removed: 2018] [added: 2019] through [removed: 2022,] [added: 2023,] compared with an estimated [removed: 99.7%] [added: 101.1%] for the property casualty industry, with [removed: 2022] [added: 2023] representing industry data reported through the first nine months of [removed: 2022.][added: 2023.]
◦Investment income growth, on a pretax basis, had a compound annual growth rate of [removed: 5.1%] [added: 7.6%] over the five-year period [removed: 2018] [added: 2019] through [removed: 2022.][added: 2023.]
◦Over the five years ended December 31, [removed: 2022,] [added: 2023,] our equity portfolio compound annual total return was [removed: 11.1%] [added: 15.0%] compared with a compound annual total return of [removed: 9.4%] [added: 15.7%] for the Index.
For the year [removed: 2022,] [added: 2023,] our equity portfolio total return was [removed: negative 10.9%,] [added: 15.2%,] compared with [removed: negative 18.1%] [added: 26.3%] for the Index.
Through [removed: 2022,] [added: 2023,] the company has increased the annual cash dividend rate for [removed: 62] [added: 63] consecutive years, a record we believe is matched by only seven other publicly traded U.S. companies.
The board regularly evaluates relevant factors in dividend-related decisions, and the [removed: 2022] [added: 2023] increase to the regular dividend reflected confidence in our outstanding capital, liquidity and financial flexibility, as well as progress of our initiatives to improve earnings performance while growing insurance premium revenues.
| | | | | | | [removed: 2022] [added: 2023] | | | | | | [added: 2022 | | | | | |] 2021 | | | [added: | | | Change % | | | | | | Change % | | |]
| Total investments | | | | | | $ | [removed: 22,425] [added: 25,357] | | | | | $ | [removed: 24,666] [added: 22,425] | |
| Short-term debt | | | | | | [removed: 50] [added: 25] | | | | | | [removed: 54] [added: 50] | | |
| Long-term debt | | | | | | [removed: 789] [added: 790] | | | | | | 789 | | |
| [removed: Book] [added: Book] value [added: change] per [removed: share] [added: share] | | | | | | [removed: 67.01] | | | | | | [removed: 81.72] | | | [added: | | | | | |]
| Debt-to-total-capital ratio | | | | | | [removed: 7.4] [added: 6.3] | | % | | | | [removed: 6.0] [added: 7.4] | | % |
As discussed in Item 8, Note 1, Summary of Significant Accounting Policies, effective January 1, 2023, we adopted ASU 2018-12, *Financial Services - Insurance (Topic 944): Targeted Improvements to the Accounting for Long-Duration Contracts*.
We adjusted applicable financial statements.
Related financial data shown in Management's Discussion and Analysis of Financial Condition and Results of Operations also have been adjusted.
| As of December 31, 2023 | | | | | | 19.5 | | % | | | | 10.2 | | % | | | | 15.2 | | % |
The 2023 ratio improvement was primarily due to a higher valuation for our investment portfolio, with increases of 17.9 percentage-points from our equity securities investment portfolio and 12.0 points from our fixed-maturity securities investment portfolio.
| Book value as originally reported December 31, 2022 | | | | | | | | | | | | $ | 67.01 | | | | | | | |
| Cumulative effect of change in accounting for long-duration insurance contracts, net of tax | | | | | | | | | | | | 0.20 | | | | | | | | |
| Book value as adjusted December 31, 2022 | | | | | | | | | | | | $ | 67.21 | | | | | | | |
We changed the target because we believe we can continue to perform at a high level.
| Total assets | | | | | | 32,769 | | | | | | 29,732 | | |
| Shareholders' equity | | | | | | 12,098 | | | | | | 10,562 | | |
| Book value per share | | | | | | 77.06 | | | | | | 67.21 | | |
| Earned premiums | | | | | | $ | 7,958 | | | | | $ | 7,225 | | | | | $ | 6,478 | | | | | 10 | | | | | | 12 | | |
| Total revenues | | | | | | 10,013 | | | | | | 6,563 | | | | | | 9,626 | | | | | | 53 | | | | | | (32) | | |
| Net income (loss) | | | | | | 1,843 | | | | | | (487) | | | | | | 2,968 | | | | | | nm | | | | | | nm | | |
| Comprehensive income (loss) | | | | | | 2,022 | | | | | | (1,398) | | | | | | 2,930 | | | | | | nm | | | | | | nm | | |
We believe it did not have a significant effect on our premium or investment revenues during 2023, 2022 or 2021.
For future periods, renewal premium or new business premium amounts could decline due to reduced spending by businesses or consumers,
Underwriting results improved in 2023, compared with 2022, due to improved overall insured loss experience before catastrophe effects, as price increases helped to offset elevated losses reflecting economic or other forms of inflation that increased our uncertainty regarding ultimate losses.
Loss experience in 2022 was much worse than in 2021, including higher current accident year loss and loss expenses before catastrophe losses that rose 20%, exceeding earned premium growth of 12%.
Loss experience is discussed further in Financial Results for our property casualty business and related segments.
Obligations and Reserves.
Our life insurance segment reported a profit of $41 million in 2023 and profit of $27 million in 2022.
| At December 31, 2023 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Total | | | | | | $ | 8,613 | | | | | $ | 7,926 | | | | | $ | 8,704 | | | | | $ | 389 | | | | | $ | 307 | |
| Commercial casualty | | | | | | $ | 3,090 | | | | | $ | 2,661 | | | | | $ | 3,272 | | | | | $ | 305 | | | | | $ | 241 | |
| Commercial property | | | | | | 509 | | | | | | 382 | | | | | | 589 | | | | | | 103 | | | | | | 81 | | |
| Commercial auto | | | | | | 859 | | | | | | 803 | | | | | | 896 | | | | | | 46 | | | | | | 36 | | |
| Workers' compensation | | | | | | 1,005 | | | | | | 900 | | | | | | 1,064 | | | | | | 82 | | | | | | 65 | | |
| Personal auto | | | | | | 344 | | | | | | 320 | | | | | | 369 | | | | | | 24 | | | | | | 19 | | |
| Homeowners | | | | | | 381 | | | | | | 351 | | | | | | 408 | | | | | | 29 | | | | | | 23 | | |
| Excess and surplus | | | | | | 898 | | | | | | 852 | | | | | | 944 | | | | | | 49 | | | | | | 39 | | |
We establish the reserves for traditional life policies, including term, whole life and other products based on certain cash flow assumptions including mortality and lapse rates.
These assumptions are established based on our current expectations and are reviewed annually to determine any necessary updates.
They are also updated on an interim basis if evidence suggests that they should be revised.
These reserves also include a discount rate assumption that is based on upper-medium grade fixed-income instrument yields (market value discount rates) and is updated quarterly.
The gross reserve balance for term and whole life policy reserves was $1.500 billion, or 48.9%, of total life policy and investment contract reserves at December 31, 2023.
The following table summarizes the sensitivity, on a net basis, of our term and whole life policy reserves and reinsurance recoverable amounts to hypothetical changes in key assumptions and the resulting increase/(decrease) to pretax net income and pretax other comprehensive income:
| (Dollars in millions) | | | | | | | | | | | | | | | | | | At December 31, 2023 | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | Pretax Net Income | | | | | | Pretax Other Comprehensive Income | | | | | | | | | | | | | | |
| As of December 31, 2020 | | | | | | 14.7 | | | | | | 15.0 | | | | | | 16.5 | | |
The increase in 2021, compared with 2020, included improved operating results and a higher valuation for our investment portfolio.
| Total assets | | | | | | 29,736 | | | | | | 31,387 | | |
| Shareholders' equity | | | | | | 10,531 | | | | | | 13,105 | | |
| Earned premiums | | | | | | $ | 7,219 | | | | | $ | 6,482 | | | | | $ | 5,980 | | | | | 11 | | | | | | 8 | | |
| Total revenues | | | | | | 6,557 | | | | | | 9,630 | | | | | | 7,536 | | | | | | (32) | | | | | | 28 | | |
| Net income (loss) | | | | | | (486) | | | | | | 2,946 | | | | | | 1,216 | | | | | | nm | | | | | | 142 | | |
| Comprehensive income (loss) | | | | | | (1,770) | | | | | | 2,825 | | | | | | 1,537 | | | | | | nm | | | | | | 84 | | |
In 2021, it caused dampening economic effects in some areas where we
operate, while many areas experienced strengthening economic effects due to increased business activity and consumer spending.
In 2020, it caused significant effects, including temporary closures of many businesses and reduced consumer spending due to shelter-in-place, stay-at-home and other governmental actions.
Those orders and the uncertainty surrounding COVID-19 had broad financial market effects and caused significant market disruption and volatility, including to our investment portfolio during 2020.
As the pandemic unfolded in 2020 and continued into 2021, management met with the board of directors frequently to discuss matters such as our response to prioritize the health and safety of our associates, agents and policyholders.
Discussion also included near-term and longer-term financial effects.
As stay-at-home orders were enacted, we promptly and effectively transitioned most of our headquarters associates to working from home.
We provided the technology necessary to keep the business running, as associates continued writing and collecting insurance premiums, responding to claims and performing other operational functions.
They joined our field associates who already worked from home, providing agents and policyholders with outstanding service.
At the end of 2021, most of our associates continued to work from home.
During the first half of 2022, most of our headquarters associates transitioned to a hybrid work schedule, regularly alternating between work at our headquarters and work from remote locations.
While we believe the COVID-19 pandemic did not have a significant effect on our premium revenues for the last three quarters of 2021, in 2020 and early 2021 it slowed the growth of our premium revenues, including new business written premiums.
We are not able to determine premium effects for future periods.
During 2021, changes to our estimates for incurred losses and expenses related to the pandemic included a $2 million increase in Cincinnati Re® losses, a $1 million decrease in Cincinnati Global Underwriting Ltd.SM (Cincinnati Global) losses and an $8 million decrease in ultimate credit losses related to uncollectible premiums.
For full-year 2020, pandemic-related incurred losses and expenses totaled $85 million.
The total included $30 million for legal expenses in defense of business interruption claims, $19 million for Cincinnati Re losses, $12 million for Cincinnati Global losses, $8 million for credit losses related to uncollectible premiums and $16 million for the Stay-at-Home policyholder credit for personal auto policies.
Approximately half of the losses for Cincinnati Re represent its estimated share from reinsurance treaties with companies that provided affirmative coverage for pandemic-related business interruption, and most of the remainder is an estimated share of treaties covering professional liability.
Most of the losses for Cincinnati Global represent its share of potential losses from business interruption coverage for large risks with customized policy terms and conditions.
Most of our commercial property policies are written to preclude coverage for business interruption claims unless there is direct physical loss or damage to property.
For this reason, most of our standard market commercial property policies in states where we actively write business do not contain a specific virus exclusion.
We are not able to determine loss effects for future periods.
As discussed in Investments Results, we reported a net investment loss in 2022, primarily due to a $1.526 billion net unfavorable change in fair value for equity securities still held.
In both 2021 and 2020, we reported net investment gains, including $2.278 billion in 2021 and $841 million in 2020 from net favorable changes in fair value for equity securities still held.
The $591 million decrease in 2022, compared with excellent results in 2021, included higher current accident year loss and loss expenses before catastrophe losses, reflecting increased uncertainty of estimated ultimate losses, due in part to elevated paid losses reflecting economic or other forms of inflation.
Our life insurance segment reported a gain of $28 million in 2022 and a loss of $16 million in 2021.
| Total | | | | | | $ | 7,931 | | | | | $ | 7,393 | | | | | $ | 8,099 | | | | | $ | 353 | | | | | $ | 279 | |
| Commercial casualty | | | | | | $ | 2,779 | | | | | $ | 2,424 | | | | | $ | 2,964 | | | | | $ | 270 | | | | | $ | 213 | |
| Commercial property | | | | | | 581 | | | | | | 441 | | | | | | 682 | | | | | | 121 | | | | | | 96 | | |
| Commercial auto | | | | | | 834 | | | | | | 791 | | | | | | 877 | | | | | | 43 | | | | | | 34 | | |
| Workers' compensation | | | | | | 983 | | | | | | 870 | | | | | | 1,037 | | | | | | 83 | | | | | | 66 | | |
| Personal auto | | | | | | 321 | | | | | | 300 | | | | | | 343 | | | | | | 22 | | | | | | 17 | | |
| Homeowners | | | | | | 353 | | | | | | 330 | | | | | | 375 | | | | | | 23 | | | | | | 18 | | |
An excerpt. Shown here: 40 of 665 rewritten, 40 of 146 added and 40 of 575 removed. The counts are complete. For every sentence, read Item 7. Management's Discussion and Analysis of Financial Condition and in the FY2023 filing and the FY2022 filing.
Page headers and footers: 65 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 47
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 48
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 49
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 50
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 51
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 52
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 53
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 54
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 55
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 56
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 57
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 58
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 59
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 60
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 61
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 62
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 63
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 64
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 65
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 66
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 67
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 68
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 69
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 70
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 71
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 72
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 73
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 74
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 75
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 76
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 77
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 78
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 79
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 80
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 81
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 82
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 83
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 84
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 85
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 86
Cincinnati Financial Corporation - 2022 10-K - Page 97
Cincinnati Financial Corporation - 2022 10-K - Page 98
Cincinnati Financial Corporation - 2022 10-K - Page 99
Cincinnati Financial Corporation - 2022 10-K - Page 100
Cincinnati Financial Corporation - 2022 10-K - Page 101
Cincinnati Financial Corporation - 2022 10-K - Page 102
Cincinnati Financial Corporation - 2022 10-K - Page 103
Cincinnati Financial Corporation - 2022 10-K - Page 104
Cincinnati Financial Corporation - 2022 10-K - Page 105
Cincinnati Financial Corporation - 2022 10-K - Page 106
Cincinnati Financial Corporation - 2022 10-K - Page 107
Cincinnati Financial Corporation - 2022 10-K - Page 108
Cincinnati Financial Corporation - 2022 10-K - Page 109
Cincinnati Financial Corporation - 2022 10-K - Page 110
Cincinnati Financial Corporation - 2022 10-K - Page 111
Shown here: 40 of 50 changed, all 0 added and all 15 removed.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
51 rewritten, 9 added, 9 removed, 90 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
| Interest rate | | | | | | [removed: H] [added: A] | | | | | | [removed: H] [added: A] | | | | | | A | | | | | | [removed: H] [added: A] | | |
The table below summarizes the effect of [added: an instantaneous] hypothetical [removed: changes] [added: change] in interest rates on [added: the] fair value of our fixed-maturity portfolio.
| [removed: At] [added: At] December 31, [removed: 2022] [added: 2022] | | | | | | [removed: $] [added: $] | [removed: 13,300] [added: 13,300] | | | | | [removed: $] [added: $] | [removed: 12,714] [added: 12,714] | | | | | [removed: $] [added: $] | [removed: 12,132] [added: 12,132] | | | | | [removed: $] [added: $] | [removed: 11,548] [added: 11,548] | | | | | [removed: $] [added: $] | [removed: 10,974] [added: 10,974] | |
The effective duration of the fixed-maturity portfolio was [removed: 4.7] [added: 4.3] years at year-end [removed: 2022,] [added: 2023,] down from [removed: 4.8] [added: 4.7] years at year-end [removed: 2021.][added: 2022.]
A 100-basis-point movement in interest rates would result in an approximately [removed: 4.8%] [added: 4.3%] change in the fair value of the fixed-maturity portfolio.
The table below summarizes the effect of hypothetical changes in market prices on [added: the] fair value of our equity portfolio.
| [removed: At] [added: At] December 31, [removed: 2022] [added: 2022] | | | | | | [removed: $] [added: $] | [removed: 6,889] [added: 6,889] | | | | | [removed: $] [added: $] | [removed: 7,873] [added: 7,873] | | | | | [removed: $] [added: $] | [removed: 8,857] [added: 8,857] | | | | | [removed: $] [added: $] | [removed: 9,841] [added: 9,841] | | | | | [removed: $] [added: $] | [removed: 10,825] [added: 10,825] | | | | | [removed: $] [added: $] | [removed: 11,809] [added: 11,809] | | | | | [removed: $] [added: $] | [removed: 12,793] [added: 12,793] | |
Our equity holdings represented [removed: $9.841] [added: $10.989] billion in fair [removed: value.][added: value at year-end 2023.]
No holding had a fair value greater than [removed: 6.4%] [added: 8.0%] of our [removed: $9.454] [added: $10.641] billion publicly traded common stock portfolio.
We had [removed: 42] [added: 39] holdings among nine different sectors each with a fair value greater than $100 million.
The application of our impairment policy resulted in write-downs of impaired securities intended to be sold that reduced our income before income taxes by [removed: $5] [added: $4] million in [removed: 2022, $1] [added: 2023, $5] million in [removed: 2021] [added: 2022] and [removed: $78] [added: $1] million in [removed: 2020.][added: 2021.]
Further, [removed: cost or] amortized cost for some securities have been revised due to impairment charges recognized in prior periods.
At year-end [removed: 2022, 3,272] [added: 2023, 2,840] of the [removed: 4,521] [added: 4,738] fixed-maturity securities we owned had a fair value below 100% of [removed: cost or] amortized cost compared with [removed: 278] [added: 3,272] of the [removed: 4,329] [added: 4,521] at year-end [removed: 2021] [added: 2022] and [removed: 128] [added: 278] of the [removed: 4,128] [added: 4,329] at year-end [removed: 2020.][added: 2021.]
The [removed: 3,272] [added: 2,840] holdings fair valued below [removed: cost or] amortized cost at year-end [removed: 2022] [added: 2023] represented [removed: 78.8%] [added: 67.4%] of our fixed-maturity portfolio and [removed: $908] [added: $687] million in unrealized losses.
- [removed: 2,080] [added: 1,963] of these holdings were fair valued between 90% and 100% of [removed: cost or] amortized cost.
The fair value of these [removed: 2,080] [added: 1,963] securities was [removed: $6.907] [added: $7.208] billion at year-end [removed: 2022,] [added: 2023,] and they accounted for [removed: $267] [added: $226] million in unrealized losses.
- [removed: 1,143] [added: 857] of these holdings were fair valued between 70% and 90% of [removed: cost or] amortized cost.
The fair value of these holdings was [removed: $2.592] [added: $2.044] billion, and they accounted for [removed: $611] [added: $438] million in unrealized losses.
- [removed: 49] [added: 20] of these holdings had a fair value below 70% of [removed: cost or] amortized cost.
The fair value of these holdings was [removed: $61] [added: $44] million, and they accounted for [removed: $30] [added: $23] million in unrealized losses.
| At December 31, [removed: 2022] [added: 2023] | | | | | | Fair value | | | | | | Unrealized losses | | | | | | Fair value | | | | | | Unrealized losses | | | | | | Fair value | | | | | | Unrealized losses | | |
| Corporate | | | | | | [removed: $] [added: $] | [removed: 5,651] [added: 5,651] | | | | | [removed: $] [added: $] | [removed: 412] [added: 412] | | | | | [removed: $] [added: $] | [removed: 661] [added: 661] | | | | | [removed: $] [added: $] | [removed: 168] [added: 168] | | | | | [removed: $] [added: $] | [removed: 6,312] [added: 6,312] | | | | | [removed: $] [added: $] | [removed: 580] [added: 580] | |
| States, municipalities and political subdivisions | | | | | | [removed: 2,600] [added: 2,600] | | | | | | [removed: 274] [added: 274] | | | | | | [removed: 77] [added: 77] | | | | | | [removed: 29] [added: 29] | | | | | | [removed: 2,677] [added: 2,677] | | | | | | [removed: 303] [added: 303] | | |
| [removed: Commercial mortgage-backed] [added: Mortgage-backed] | | | | | | [removed: 215] [added: 215] | | | | | | [removed: 13] [added: 13] | | | | | | [removed: 14] [added: 14] | | | | | | [removed: 3] [added: 3] | | | | | | [removed: 229] [added: 229] | | | | | | [removed: 16] [added: 16] | | |
| United States government | | | | | | [removed: 146] [added: 146] | | | | | | [removed: 3] [added: 3] | | | | | | [removed: 41] [added: 41] | | | | | | [removed: 2] [added: 2] | | | | | | [removed: 187] [added: 187] | | | | | | [removed: 5] [added: 5] | | |
| Government-sponsored enterprises | | | | | | [removed: 123] [added: 123] | | | | | | [removed: 3] [added: 3] | | | | | | [removed: 3] [added: 3] | | | | | | [removed: —] [added: —] | | | | | | [removed: 126] [added: 126] | | | | | | [removed: 3] [added: 3] | | |
| Foreign government | | | | | | [removed: 25] [added: 3] | | | | | | [removed: 1] [added: —] | | | | | | [removed: 4] [added: 6] | | | | | | — | | | | | | [removed: 29] [added: 9] | | | | | | [removed: 1] [added: —] | | |
| Total | | | | | | [removed: $] [added: $] | [removed: 8,760] [added: 8,760] | | | | | [removed: $] [added: $] | [removed: 706] [added: 706] | | | | | [removed: $] [added: $] | [removed: 800] [added: 800] | | | | | [removed: $] [added: $] | [removed: 202] [added: 202] | | | | | [removed: $] [added: $] | [removed: 9,560] [added: 9,560] | | | | | [removed: $] [added: $] | [removed: 908] [added: 908] | |
| States, municipalities and political subdivisions | | | | | | [removed: 105] [added: 313] | | | | | | [removed: 2] [added: 2] | | | | | | [removed: 2] [added: 1,932] | | | | | | [removed: 1] [added: 206] | | | | | | [removed: 107] [added: 2,245] | | | | | | [removed: 3] [added: 208] | | |
| [removed: Commercial mortgage-backed] [added: Mortgage-backed] | | | | | | [removed: 10] [added: 5] | | | | | | [removed: —] [added: —] | | | | | | [removed: 11] [added: 172] | | | | | | [removed: —] [added: 16] | | | | | | [removed: 21] [added: 177] | | | | | | [removed: —] [added: 16] | | |
| United States government | | | | | | [removed: 48] [added: 32] | | | | | | [removed: —] [added: —] | | | | | | [removed: —] [added: 129] | | | | | | [removed: —] [added: 3] | | | | | | [removed: 48] [added: 161] | | | | | | [removed: —] [added: 3] | | |
| Government-sponsored enterprises | | | | | | [removed: 7] [added: 652] | | | | | | [removed: —] [added: 3] | | | | | | [removed: —] [added: 113] | | | | | | [removed: —] [added: 3] | | | | | | [removed: 7] [added: 765] | | | | | | [removed: —] [added: 6] | | |
| Foreign government | | | | | | [removed: 16] [added: 25] | | | | | | [removed: —] [added: 1] | | | | | | [removed: —] [added: 4] | | | | | | — | | | | | | [removed: 16] [added: 29] | | | | | | [removed: —] [added: 1] | | |
| [removed: At] [added: At] December 31, [removed: 2022] [added: 2022] | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | [added: | | | | | |]
| Fair valued below 70% of amortized cost | | | | | | [removed: 34] [added: 16] | | | | | | $ | [removed: 64] [added: 55] | | | | | $ | [removed: 43] [added: 36] | | | | | $ | [removed: (21)] [added: (19)] | | | | | $ | 2 | |
| Fair valued at 70% to less than 100% of amortized cost | | | | | | [removed: 1,998] [added: 966] | | | | | | [removed: 8,310] [added: 1,600] | | | | | | [removed: 7,570] [added: 1,518] | | | | | | [removed: (740)] [added: (82)] | | | | | | [removed: 331] [added: 47] | | |
| Fair valued at 100% and above of amortized cost | | | | | | [removed: 172] [added: 494] | | | | | | [removed: 646] [added: 2,043] | | | | | | [removed: 686] [added: 2,119] | | | | | | [removed: 40] [added: 76] | | | | | | [removed: 33] [added: 83] | | |
| Investment income on securities sold in current year | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | [removed: 20] [added: 22] | | |
| Fair valued below 70% of amortized cost | | | | | | [removed: 15] [added: 4] | | | | | | [removed: 27] [added: 12] | | | | | | [removed: 18] [added: 8] | | | | | | [removed: (9)] [added: (4)] | | | | | | 1 | | |
| Fair valued at 70% to less than 100% of amortized cost | | | | | | [removed: 1,225] [added: 1,854] | | | | | | [removed: 2,067] [added: 8,316] | | | | | | [removed: 1,929] [added: 7,734] | | | | | | [removed: (138)] [added: (582)] | | | | | | [removed: 61] [added: 362] | | |
| At December 31, 2023 | | | | | | $ | 14,962 | | | | | $ | 14,375 | | | | | $ | 13,791 | | | | | $ | 13,179 | | | | | $ | 12,543 | |
| At December 31, 2023 | | | | | | $ | 7,692 | | | | | $ | 8,791 | | | | | $ | 9,890 | | | | | $ | 10,989 | | | | | $ | 12,088 | | | | | $ | 13,187 | | | | | $ | 14,286 | |
| Corporate | | | | | | $ | 379 | | | | | $ | 13 | | | | | $ | 5,560 | | | | | $ | 441 | | | | | $ | 5,939 | | | | | $ | 454 | |
| Total | | | | | | $ | 1,384 | | | | | $ | 18 | | | | | $ | 7,912 | | | | | $ | 669 | | | | | $ | 9,296 | | | | | $ | 687 | |
| At December 31, 2023 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Total | | | | | | 2,364 | | | | | | 10,414 | | | | | | 9,889 | | | | | | (525) | | | | | | 469 | | |
| Total | | | | | | 2,374 | | | | | | 3,947 | | | | | | 3,902 | | | | | | (45) | | | | | | 131 | | |
| Total | | | | | | 4,738 | | | | | | $ | 14,361 | | | | | $ | 13,791 | | | | | $ | (570) | | | | | $ | 600 | |
| At December 31, 2022 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| At December 31, 2021 | | | | | | $ | 14,327 | | | | | $ | 13,656 | | | | | $ | 13,022 | | | | | $ | 12,399 | | | | | $ | 11,768 | |
| At December 31, 2021 | | | | | | $ | 7,921 | | | | | $ | 9,052 | | | | | $ | 10,184 | | | | | $ | 11,315 | | | | | $ | 12,447 | | | | | $ | 13,578 | | | | | $ | 14,710 | |
| At December 31, 2021 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Corporate | | | | | | $ | 861 | | | | | $ | 13 | | | | | $ | 15 | | | | | $ | — | | | | | $ | 876 | | | | | $ | 13 | |
| Total | | | | | | $ | 1,047 | | | | | $ | 15 | | | | | $ | 28 | | | | | $ | 1 | | | | | $ | 1,075 | | | | | $ | 16 | |
| Total | | | | | | 2,204 | | | | | | 9,020 | | | | | | 8,299 | | | | | | (721) | | | | | | 386 | | |
| Total | | | | | | 2,317 | | | | | | 3,959 | | | | | | 3,833 | | | | | | (126) | | | | | | 124 | | |
| At December 31, 2021 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Total | | | | | | 4,329 | | | | | | $ | 12,230 | | | | | $ | 13,022 | | | | | $ | 792 | | | | | $ | 477 | |
An excerpt. Shown here: 40 of 51 rewritten, all 9 added and all 9 removed. The counts are complete. For every sentence, read Item 7A. Quantitative and Qualitative Disclosures About Market Risk in the FY2023 filing and the FY2022 filing.
Page headers and footers: 6 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 112][added: 113]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 113][added: 114]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 114][added: 115]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 115][added: 116]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 116][added: 117]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 117][added: 118]
Item 1. Business
191 rewritten, 48 added, 47 removed, 449 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
At year-end [removed: 2022,] [added: 2023,] a select group of independent agencies in 46 states actively marketed our property casualty insurance within their communities.
Standard market commercial lines and excess and surplus lines policies were [removed: marketed in 42 of those states.]
[removed: Better] [added: We believe] profit margins [removed: may] [added: can] be [removed: achieved] [added: improved] with additional information and expanded pricing capabilities we can access with the use of technology and analytics.
Distribution through independent insurance agents or brokers represents [removed: nearly] [added: approximately] 60% of overall U.S. property casualty insurance premiums and approximately 80% of commercial property casualty insurance premiums, according to studies by the Independent Insurance Agents and Brokers of America.
| Property casualty agency relationships, January 1 | | | | | | [removed: 1,921] [added: 1,984] | | | | | | [removed: 1,848] [added: 1,921] | | |
| New appointments that market all or most of The Cincinnati Insurance Companies' products | | | | | | [removed: 145] [added: 216] | | | | | | [removed: 155] [added: 145] | | |
| New appointments that market only personal lines insurance products for Cincinnati Insurance | | | | | | [removed: 64] [added: 84] | | | | | | [removed: 59] [added: 64] | | |
| Changes due to consolidation and other | | | | | | [removed: (146)] [added: (204)] | | | | | | [removed: (141)] [added: (146)] | | |
| Property casualty agency relationships, December 31 | | | | | | [removed: 1,984] [added: 2,080] | | | | | | [removed: 1,921] [added: 1,984] | | |
| Property casualty reporting locations | | | | | | [removed: 2,861] [added: 3,116] | | | | | | [removed: 2,721] [added: 2,861] | | |
| New relationship appointments | | | | | | [removed: 146] [added: 206] | | | | | | [removed: 159] [added: 146] | | |
On average, we have a [removed: 5.1%] [added: 4.6%] share of the standard lines property casualty insurance purchased through our reporting agency locations, according to [removed: 2021] [added: 2022] data from agency surveys.
Our share is [removed: 11.3%] [added: 9.2%] in reporting agency locations that have represented us for more than 10 years; [removed: 3.9%] [added: 3.1%] in agencies that have represented us for six to 10 years; [removed: 1.5%] [added: 1.3%] in agencies that have represented us for two to five years; and 0.4% in agencies that have represented us for one year or less.
Our largest single agency relationship accounted for approximately 0.6% of our total property casualty earned premiums in [removed: 2022.][added: 2023.]
No aggregate locations under a single ownership structure accounted for more than [removed: 5%] [added: 6%] of our earned premiums in [removed: 2022.][added: 2023.]
- Our [removed: $12.132] [added: $13.791] billion fixed-maturity portfolio is diversified and exceeds total insurance reserves.
The portfolio had an average rating of A2/A, and its fair value exceeded total insurance reserve liabilities by approximately [removed: 6%] [added: 14%] at December 31, [removed: 2022.][added: 2023.]
No corporate bond exposure accounted for more than [removed: 0.9%] [added: 0.8%] of our fixed-maturity portfolio, and no municipal exposure accounted for more than 0.2%.
Our [removed: $9.841] [added: $10.989] billion equity portfolio minimizes concentrations in single stocks or industries.
At December 31, [removed: 2022,] [added: 2023,] no single security accounted for more than [removed: 6.4%] [added: 8.0%] of our portfolio of publicly traded common stocks, and no single sector accounted for more than [removed: 27%.][added: 34%.]
At December 31, [removed: 2022,] [added: 2023,] we held [removed: $4.230] [added: $4.907] billion of our cash and invested assets at the parent-company level, of which [removed: $3.974] [added: $4.542] billion, or [removed: 93.9%,] [added: 92.6%,] was invested in common stocks, and [removed: $121] [added: $138] million, or [removed: 2.9%,] [added: 2.8%,] was cash and cash equivalents.
We minimize reliance on debt as a source of capital, with a debt-to-total-capital ratio of [removed: 7.4%] [added: 6.3%] at year-end [removed: 2022.][added: 2023.]
Long-term debt at year-end [removed: 2022] [added: 2023] totaled [removed: $789] [added: $790] million, [removed: matching] [added: compared with $789 million at] year-end [removed: 2021,] [added: 2022,] and our short-term debt was [removed: $50] [added: $25] million, down from [removed: $54] [added: $50] million at the end of the prior year.
At year-end [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] risk-based capital (RBC) for our standard market property casualty insurance, excess and surplus lines insurance and life insurance subsidiaries was strong, far exceeding regulatory requirements.
- We ended [removed: 2022] [added: 2023] with a 1.1-to-1 ratio of property casualty premiums to surplus, a key measure of property casualty insurance company capacity and security.
The estimated industry average ratio was [removed: 0.8-to-1] [added: 0.9-to-1] at year-end [removed: 2022,] [added: 2023,] based on industry data reported through the first nine months of [removed: 2022.][added: 2023.]
On a statutory consolidated property casualty insurance basis, our ratio of investments in common stock, at fair value, to statutory capital and surplus was [removed: 83.7%] [added: 83.2%] at year-end [removed: 2022] [added: 2023] compared with [removed: 83.6%] [added: 83.7%] at year-end [removed: 2021.][added: 2022.]
- We ended [removed: 2022] [added: 2023] with [removed: a 9.5%] [added: an 11.8%] ratio of life statutory adjusted risk-based surplus to liabilities, a key measure of life insurance company capital strength.
Our life insurance subsidiary’s RBC at year-end [removed: 2022] [added: 2023] was [removed: 6.1] [added: 7.5] times the authorized control level RBC.
| Statutory capital and surplus | | | | | | $ | [removed: 6,512] [added: 7,294] | | | | | $ | [removed: 7,247] [added: 6,512] | |
| Risk-based capital | | | | | | [removed: 6,551] [added: 7,335] | | | | | | [removed: 7,279] [added: 6,551] | | |
| Authorized control level risk-based capital | | | | | | [removed: 1,186] [added: 1,354] | | | | | | [removed: 1,093] [added: 1,186] | | |
| Risk-based capital to authorized control level risk-based capital ratio | | | | | | [removed: 5.5] [added: 5.4] | | | | | | [removed: 6.7] [added: 5.5] | | |
| Written premium to surplus ratio | | | | | | 1.1 | | | | | | [removed: 0.9] [added: 1.1] | | |
In addition, the rating firms award our property casualty and life operations [removed: insurance] [added: insurer] financial strength ratings based on their quantitative and qualitative analyses.
At February [removed: 22, 2023,] [added: 23, 2024,] our insurance subsidiaries continued to be highly rated.
On February 9, [removed: 2023,] [added: 2024,] A.M. Best affirmed its ratings, continuing its stable outlook.
On [removed: November 1, 2022,] [added: October 25, 2023,] Fitch affirmed its ratings, continuing its stable outlook.
On July [removed: 19, 2022,] [added: 14, 2023,] Moody's affirmed its ratings, continuing its stable outlook.
On [removed: July 12, 2022,] [added: June 29, 2023,] S&P affirmed its ratings, continuing its stable outlook.
marketed in 43 of those states.
| | | | | | | 2023 | | | | | | 2022 | | |
| | | | | | | 2023 | | | | | | 2022 | | |
| Ohio | | | $ | 1,027 | | 13.4 | | % | 261 | | | $ | 3.9 | |
| Illinois | | | 408 | | | 5.3 | | | 190 | | | 2.1 | | |
| New York | | | 386 | | | 5.0 | | | 200 | | | 1.9 | | |
| Pennsylvania | | | 321 | | | 4.2 | | | 168 | | | 1.9 | | |
| Georgia | | | 320 | | | 4.2 | | | 123 | | | 2.6 | | |
| Indiana | | | 299 | | | 3.9 | | | 140 | | | 2.1 | | |
| Missouri | | | 255 | | | 3.3 | | | 78 | | | 3.3 | | |
| Texas | | | 234 | | | 3.1 | | | 123 | | | 1.9 | | |
| Ohio | | | $ | 621 | | 14.6 | | % | 252 | | | $ | 2.5 | |
| Illinois | | | 244 | | | 5.7 | | | 167 | | | 1.5 | | |
| Pennsylvania | | | 240 | | | 5.6 | | | 155 | | | 1.5 | | |
| North Carolina | | | 230 | | | 5.4 | | | 115 | | | 2.0 | | |
| Indiana | | | 200 | | | 4.7 | | | 138 | | | 1.4 | | |
| New York | | | 185 | | | 4.3 | | | 169 | | | 1.1 | | |
| Missouri | | | 173 | | | 4.0 | | | 61 | | | 2.8 | | |
| Tennessee | | | 172 | | | 4.0 | | | 78 | | | 2.2 | | |
| Virginia | | | 171 | | | 4.0 | | | 89 | | | 1.9 | | |
| Georgia | | | 167 | | | 3.9 | | | 106 | | | 1.6 | | |
We estimate those policyholders represent
| Ohio | | | $ | 372 | | 18.2 | | % | 241 | | | $ | 1.5 | |
| New York | | | 163 | | | 8.0 | | | 111 | | | 1.5 | | |
| California | | | 151 | | | 7.4 | | | 75 | | | 2.0 | | |
| Georgia | | | 128 | | | 6.3 | | | 99 | | | 1.3 | | |
| Illinois | | | 125 | | | 6.1 | | | 142 | | | 0.9 | | |
| Indiana | | | 77 | | | 3.8 | | | 116 | | | 0.7 | | |
| Texas | | | 67 | | | 3.3 | | | 65 | | | 1.0 | | |
| Ohio | | | 34 | | | 6.3 | | |
| Texas | | | 32 | | | 5.9 | | |
| Pennsylvania | | | 26 | | | 4.8 | | |
| Georgia | | | 25 | | | 4.5 | | |
| Michigan | | | 22 | | | 4.2 | | |
| Ohio | | | $ | 58 | | 15.2 | | % |
| Pennsylvania | | | 26 | | | 6.8 | | |
| Illinois | | | 23 | | | 5.9 | | |
| Georgia | | | 22 | | | 5.7 | | |
The net investment gain position at year-end 2023, compared with year-end 2022, included a net increase for our equity security portfolio, reflecting a general increase in equity market valuations.
It also included a smaller net unrealized loss position in our fixed-maturity investments, due to lower short-term interest rates in addition to a tightening of corporate credit spreads.
| | | | | | | 2022 | | | | | | 2021 | | |
| | | | | | | 2022 | | | | | | 2021 | | |
| Ohio | | | $ | 930 | | 13.4 | | % | 257 | | | $ | 3.6 | |
| Illinois | | | 376 | | | 5.4 | | | 177 | | | 2.1 | | |
| New York | | | 327 | | | 4.7 | | | 184 | | | 1.8 | | |
| Pennsylvania | | | 308 | | | 4.4 | | | 155 | | | 2.0 | | |
| Georgia | | | 300 | | | 4.3 | | | 110 | | | 2.7 | | |
| Indiana | | | 279 | | | 4.0 | | | 127 | | | 2.2 | | |
| Missouri | | | 216 | | | 3.1 | | | 73 | | | 3.0 | | |
| Texas | | | 214 | | | 3.1 | | | 116 | | | 1.8 | | |
| Ohio | | | $ | 570 | | 14.2 | | % | 243 | | | $ | 2.3 | |
| Illinois | | | 245 | | | 6.1 | | | 154 | | | 1.6 | | |
| Pennsylvania | | | 238 | | | 5.9 | | | 145 | | | 1.6 | | |
| North Carolina | | | 214 | | | 5.3 | | | 108 | | | 2.0 | | |
| Indiana | | | 190 | | | 4.7 | | | 123 | | | 1.5 | | |
| New York | | | 165 | | | 4.1 | | | 150 | | | 1.1 | | |
| Virginia | | | 163 | | | 4.1 | | | 77 | | | 2.1 | | |
| Georgia | | | 160 | | | 4.0 | | | 96 | | | 1.7 | | |
| Tennessee | | | 158 | | | 3.9 | | | 71 | | | 2.2 | | |
| Missouri | | | 157 | | | 3.9 | | | 61 | | | 2.6 | | |
| Ohio | | | $ | 326 | | 19.3 | | % | 235 | | | $ | 1.4 | |
| New York | | | 133 | | | 7.9 | | | 108 | | | 1.2 | | |
| Georgia | | | 117 | | | 6.9 | | | 92 | | | 1.3 | | |
| California | | | 104 | | | 6.2 | | | 74 | | | 1.4 | | |
| Illinois | | | 96 | | | 5.7 | | | 131 | | | 0.7 | | |
| Texas | | | 52 | | | 3.1 | | | 62 | | | 0.8 | | |
| Ohio | | | 35 | | | 7.2 | | |
| Texas | | | 32 | | | 6.6 | | |
| Pennsylvania | | | 25 | | | 5.1 | | |
| Georgia | | | 23 | | | 4.8 | | |
| Indiana | | | 19 | | | 4.0 | | |
| Michigan | | | 18 | | | 3.7 | | |
| Ohio | | | $ | 57 | | 15.4 | | % |
| Pennsylvania | | | 26 | | | 7.0 | | |
| Illinois | | | 22 | | | 6.0 | | |
| Georgia | | | 21 | | | 5.5 | | |
The 2022 decreases reflected a general decline in equity markets and movement from a net unrealized gain position in our fixed-maturity investments to a net unrealized loss position, primarily due to an increase in interest rates, such as U.S. Treasury yields, and widening of corporate credit spreads.
During 2021, purchases and a net increase in fair value offset sales.
| | | | 2022 | | | | | | 2021 | | | | | |
| | | | 2022 | | | | | | 2021 | | |
An excerpt. Shown here: 40 of 191 rewritten, 40 of 48 added and 40 of 47 removed. The counts are complete. For every sentence, read Item 1. Business in the FY2023 filing and the FY2022 filing.
Page headers and footers: 27 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 5
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 6
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 7
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 8
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 9
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 10
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 11
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 12
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 13
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 14
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 15
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 16
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 17
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 18
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 19
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 20
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 21
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 22
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 23
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 24
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 25
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 26
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 27
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 28
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 29
Cincinnati Financial Corporation - 2022 10-K - Page 30
Cincinnati Financial Corporation - 2022 10-K - Page 31
Cover and table of contents
42 rewritten, 12 added, 11 removed, 42 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
For the fiscal year ended December 31, [removed: 2022.][added: 2023.]
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 [removed: if] [added: of] Regulation [removed: S-T(§232.405] [added: S-T (§232.405] of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files).
The aggregate market value of voting stock held by nonaffiliates of the Registrant based on the closing price of [removed: $118.98] [added: $97.32] per share as reported on Nasdaq Global Select Market on June 30, [removed: 2022,] [added: 2023,] was [removed: $18,533,373,847.][added: $14,988,706,711.]
As of February [removed: 15, 2023,] [added: 16, 2024,] there were [removed: 157,240,556] [added: 156,665,018] shares of common stock outstanding.
Portions of the definitive Proxy Statement for Cincinnati Financial Corporation’s Annual Meeting of Shareholders to be held on May [removed: 6, 2023,] [added: 4, 2024,] are incorporated by reference into Part III of this Form 10-K.
[removed: 2022] [added: 2023] ANNUAL REPORT ON FORM 10-K
| [removed: Item 1.] [added: [Item 1.](#ia6ac93763b1b4c649a509de92246d484_13)] | | | [removed: Business] [added: [Business](#ia6ac93763b1b4c649a509de92246d484_13)] | | | [removed: [5](#i02093e9754da48e991fe7fbb3df85a22_13)] [added: [5](#ia6ac93763b1b4c649a509de92246d484_13)] | | |
| | | | [removed: Cincinnati] [added: [Cincinnati] Financial Corporation – [removed: Introduction] [added: Introduction](#ia6ac93763b1b4c649a509de92246d484_16)] | | | [removed: [5](#i02093e9754da48e991fe7fbb3df85a22_16)] [added: [5](#ia6ac93763b1b4c649a509de92246d484_16)] | | |
| | | | [removed: Our] [added: [Our] Business and Our [removed: Strategy] [added: Strategy](#ia6ac93763b1b4c649a509de92246d484_19)] | | | [removed: [6](#i02093e9754da48e991fe7fbb3df85a22_19)] [added: [6](#ia6ac93763b1b4c649a509de92246d484_19)] | | |
| | | | [removed: Our Segments] [added: [Our Segments](#ia6ac93763b1b4c649a509de92246d484_22)] | | | [removed: [14](#i02093e9754da48e991fe7fbb3df85a22_22)] [added: [14](#ia6ac93763b1b4c649a509de92246d484_22)] | | |
| [removed: Item 1A.] [added: [Item 1A.](#ia6ac93763b1b4c649a509de92246d484_31)] | | | [removed: Risk Factors] [added: [Risk Factors](#ia6ac93763b1b4c649a509de92246d484_31)] | | | [removed: [32](#i02093e9754da48e991fe7fbb3df85a22_31)] [added: [30](#ia6ac93763b1b4c649a509de92246d484_31)] | | |
| [removed: Item 1B.] [added: [Item 1B.](#ia6ac93763b1b4c649a509de92246d484_43)] | | | [removed: Unresolved] [added: [Unresolved] Staff [removed: Comments] [added: Comments](#ia6ac93763b1b4c649a509de92246d484_43)] | | | [removed: [44](#i02093e9754da48e991fe7fbb3df85a22_34)] [added: [43](#ia6ac93763b1b4c649a509de92246d484_43)] | | |
| [removed: Item 2.] [added: [Item 2.](#ia6ac93763b1b4c649a509de92246d484_46)] | | | [removed: Properties] [added: [Properties](#ia6ac93763b1b4c649a509de92246d484_46)] | | | [removed: [44](#i02093e9754da48e991fe7fbb3df85a22_37)] [added: [44](#ia6ac93763b1b4c649a509de92246d484_46)] | | |
| [removed: Item 3.] [added: [Item 3.](#ia6ac93763b1b4c649a509de92246d484_49)] | | | [removed: Legal Proceedings] [added: [Legal Proceedings](#ia6ac93763b1b4c649a509de92246d484_49)] | | | [removed: [44](#i02093e9754da48e991fe7fbb3df85a22_40)] [added: [44](#ia6ac93763b1b4c649a509de92246d484_49)] | | |
| [removed: Item 4.] [added: [Item 4.](#ia6ac93763b1b4c649a509de92246d484_52)] | | | [removed: Mine] [added: [Mine] Safety [removed: Disclosures] [added: Disclosures](#ia6ac93763b1b4c649a509de92246d484_52)] | | | [removed: [44](#i02093e9754da48e991fe7fbb3df85a22_43)] [added: [44](#ia6ac93763b1b4c649a509de92246d484_52)] | | |
| [removed: Item 5.] [added: [Item 5.](#ia6ac93763b1b4c649a509de92246d484_58)] | | | [removed: Market] [added: [Market] for the Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities] [added: Securities](#ia6ac93763b1b4c649a509de92246d484_58)] | | | [removed: [45](#i02093e9754da48e991fe7fbb3df85a22_49)] [added: [45](#ia6ac93763b1b4c649a509de92246d484_58)] | | |
| [removed: Item 6.] [added: [Item 6.](#ia6ac93763b1b4c649a509de92246d484_61)] | | | [removed: \[Reserved\]] [added: [\[Reserved\]](#ia6ac93763b1b4c649a509de92246d484_61)] | | | [removed: [46](#i02093e9754da48e991fe7fbb3df85a22_52)] [added: [46](#ia6ac93763b1b4c649a509de92246d484_61)] | | |
| [removed: Item 7.] [added: [Item 7.](#ia6ac93763b1b4c649a509de92246d484_67)] | | | [removed: Management’s] [added: [Management’s] Discussion and Analysis of Financial Condition and Results of [removed: Operations] [added: Operations](#ia6ac93763b1b4c649a509de92246d484_67)] | | | [removed: [47](#i02093e9754da48e991fe7fbb3df85a22_58)] [added: [47](#ia6ac93763b1b4c649a509de92246d484_67)] | | |
| | | | [removed: Executive Summary] [added: [Executive Summary](#ia6ac93763b1b4c649a509de92246d484_73)] | | | [removed: [48](#i02093e9754da48e991fe7fbb3df85a22_64)] [added: [48](#ia6ac93763b1b4c649a509de92246d484_73)] | | |
| | | | [removed: Critical] [added: [Critical] Accounting [removed: Estimates] [added: Estimates](#ia6ac93763b1b4c649a509de92246d484_76)] | | | [removed: [53](#i02093e9754da48e991fe7fbb3df85a22_67)] [added: [53](#ia6ac93763b1b4c649a509de92246d484_76)] | | |
| | | | [removed: Recent] [added: [Recent] Accounting [removed: Pronouncements] [added: Pronouncements](#ia6ac93763b1b4c649a509de92246d484_79)] | | | [removed: [59](#i02093e9754da48e991fe7fbb3df85a22_70)] [added: [60](#ia6ac93763b1b4c649a509de92246d484_79)] | | |
| | | | [removed: Financial Results] [added: [Financial Results](#ia6ac93763b1b4c649a509de92246d484_82)] | | | [removed: [60](#i02093e9754da48e991fe7fbb3df85a22_73)] [added: [61](#ia6ac93763b1b4c649a509de92246d484_82)] | | |
| | | | [removed: Liquidity] [added: [Liquidity] and Capital [removed: Resources] [added: Resources](#ia6ac93763b1b4c649a509de92246d484_103)] | | | [removed: [93](#i02093e9754da48e991fe7fbb3df85a22_94)] [added: [94](#ia6ac93763b1b4c649a509de92246d484_103)] | | |
| [removed: Item 7A.] [added: [Item 7A.](#ia6ac93763b1b4c649a509de92246d484_109)] | | | [removed: Quantitative] [added: [Quantitative] and Qualitative Disclosures About Market [removed: Risk] [added: Risk](#ia6ac93763b1b4c649a509de92246d484_109)] | | | [removed: [112](#i02093e9754da48e991fe7fbb3df85a22_100)] [added: [113](#ia6ac93763b1b4c649a509de92246d484_109)] | | |
| [removed: Item 8.] [added: [Item 8.](#ia6ac93763b1b4c649a509de92246d484_124)] | | | [removed: Financial] [added: [Financial] Statements and Supplementary [removed: Data] [added: Data](#ia6ac93763b1b4c649a509de92246d484_124)] | | | [removed: [118](#i02093e9754da48e991fe7fbb3df85a22_115)] [added: [119](#ia6ac93763b1b4c649a509de92246d484_124)] | | |
| | | | [removed: Responsibility] [added: [Responsibility] for Financial [removed: Statements] [added: Statements](#ia6ac93763b1b4c649a509de92246d484_127)] | | | [removed: [118](#i02093e9754da48e991fe7fbb3df85a22_118)] [added: [119](#ia6ac93763b1b4c649a509de92246d484_127)] | | |
| | | | [removed: Management’s] [added: [Management’s] Annual Report on Internal Control Over Financial [removed: Reporting] [added: Reporting](#ia6ac93763b1b4c649a509de92246d484_130)] | | | [removed: [119](#i02093e9754da48e991fe7fbb3df85a22_121)] [added: [120](#ia6ac93763b1b4c649a509de92246d484_130)] | | |
| | | | [removed: Report] [added: [Report] of Independent Registered Public Accounting [removed: Firm] [added: Firm](#ia6ac93763b1b4c649a509de92246d484_133)] (PCAOB ID No. 34) | | | [removed: [120](#i02093e9754da48e991fe7fbb3df85a22_124)] [added: [121](#ia6ac93763b1b4c649a509de92246d484_133)] | | |
| | | | [removed: Consolidated] [added: [Consolidated] Statements of [removed: Comprehensive Income] [added: Income](#ia6ac93763b1b4c649a509de92246d484_139)] | | | [removed: [124](#i02093e9754da48e991fe7fbb3df85a22_133)] [added: [124](#ia6ac93763b1b4c649a509de92246d484_139)] | | |
| | | | [removed: Consolidated] [added: [Consolidated] Statements of Shareholders’ [removed: Equity] [added: Equity](#ia6ac93763b1b4c649a509de92246d484_145)] | | | [removed: [125](#i02093e9754da48e991fe7fbb3df85a22_136)] [added: [126](#ia6ac93763b1b4c649a509de92246d484_145)] | | |
| | | | [removed: Consolidated] [added: [Consolidated] Statements of Cash [removed: Flows] [added: Flows](#ia6ac93763b1b4c649a509de92246d484_148)] | | | [removed: [126](#i02093e9754da48e991fe7fbb3df85a22_139)] [added: [127](#ia6ac93763b1b4c649a509de92246d484_148)] | | |
| | | | [removed: Notes] [added: [Notes] to Consolidated Financial [removed: Statements] [added: Statements](#ia6ac93763b1b4c649a509de92246d484_151)] | | | [removed: [127](#i02093e9754da48e991fe7fbb3df85a22_142)] [added: [128](#ia6ac93763b1b4c649a509de92246d484_151)] | | |
| [removed: Item 9.] [added: [Item 9.](#ia6ac93763b1b4c649a509de92246d484_211)] | | | [removed: Changes] [added: [Changes] in and Disagreements with Accountants on Accounting and Financial [removed: Disclosure] [added: Disclosure](#ia6ac93763b1b4c649a509de92246d484_211)] | | | [removed: [175](#i02093e9754da48e991fe7fbb3df85a22_202)] [added: [182](#ia6ac93763b1b4c649a509de92246d484_211)] | | |
| [removed: Item 9A.] [added: [Item 9A.](#ia6ac93763b1b4c649a509de92246d484_214)] | | | [removed: Controls] [added: [Controls] and [removed: Procedures] [added: Procedures](#ia6ac93763b1b4c649a509de92246d484_214)] | | | [removed: [175](#i02093e9754da48e991fe7fbb3df85a22_205)] [added: [182](#ia6ac93763b1b4c649a509de92246d484_214)] | | |
| [removed: Item 9B.] [added: [Item 9B.](#ia6ac93763b1b4c649a509de92246d484_217)] | | | [removed: Other Information] [added: [Other Information](#ia6ac93763b1b4c649a509de92246d484_217)] | | | [removed: [175](#i02093e9754da48e991fe7fbb3df85a22_208)] [added: [182](#ia6ac93763b1b4c649a509de92246d484_217)] | | |
| [removed: Item 9C.] [added: [Item 9C.](#ia6ac93763b1b4c649a509de92246d484_220)] | | | [removed: Disclosure] [added: [Disclosure] Regarding Foreign Jurisdictions that Prevent [removed: Inspections] [added: Inspections](#ia6ac93763b1b4c649a509de92246d484_220)] | | | [removed: [175](#i02093e9754da48e991fe7fbb3df85a22_211)] [added: [182](#ia6ac93763b1b4c649a509de92246d484_220)] | | |
| [removed: Item 10.] [added: [Item 10.](#ia6ac93763b1b4c649a509de92246d484_226)] | | | [removed: Directors,] [added: [Directors,] Executive Officers and Corporate [removed: Governance] [added: Governance](#ia6ac93763b1b4c649a509de92246d484_226)] | | | [removed: [176](#i02093e9754da48e991fe7fbb3df85a22_217)] [added: [183](#ia6ac93763b1b4c649a509de92246d484_226)] | | |
| [removed: Item 11.] [added: [Item 11.](#ia6ac93763b1b4c649a509de92246d484_229)] | | | [removed: Executive Compensation] [added: [Executive Compensation](#ia6ac93763b1b4c649a509de92246d484_229)] | | | [removed: [178](#i02093e9754da48e991fe7fbb3df85a22_220)] [added: [185](#ia6ac93763b1b4c649a509de92246d484_229)] | | |
| [removed: Item 12.] [added: [Item 12.](#ia6ac93763b1b4c649a509de92246d484_232)] | | | [removed: Security] [added: [Security] Ownership of Certain Beneficial Owners and Management and Related Stockholder [removed: Matters] [added: Matters](#ia6ac93763b1b4c649a509de92246d484_232)] | | | [removed: [178](#i02093e9754da48e991fe7fbb3df85a22_223)] [added: [185](#ia6ac93763b1b4c649a509de92246d484_232)] | | |
| [removed: Item 13.] [added: [Item 13.](#ia6ac93763b1b4c649a509de92246d484_235)] | | | [removed: Certain] [added: [Certain] Relationships and Related Transactions, and Director [removed: Independence] [added: Independence](#ia6ac93763b1b4c649a509de92246d484_235)] | | | [removed: [179](#i02093e9754da48e991fe7fbb3df85a22_226)] [added: [186](#ia6ac93763b1b4c649a509de92246d484_235)] | | |
| [Part I](#ia6ac93763b1b4c649a509de92246d484_10) | | | | | | [5](#ia6ac93763b1b4c649a509de92246d484_13) | | |
| | | | [Other](#ia6ac93763b1b4c649a509de92246d484_25) | | | [25](#ia6ac93763b1b4c649a509de92246d484_25) | | |
| | | | [Regulation](#ia6ac93763b1b4c649a509de92246d484_28) | | | [26](#ia6ac93763b1b4c649a509de92246d484_28) | | |
| [Item 1C.](#ia6ac93763b1b4c649a509de92246d484_2517) | | | [Cybersecurity](#ia6ac93763b1b4c649a509de92246d484_2517) | | | | | |
| [Part II](#ia6ac93763b1b4c649a509de92246d484_55) | | | | | | [45](#ia6ac93763b1b4c649a509de92246d484_55) | | |
| | | | [Introduction](#ia6ac93763b1b4c649a509de92246d484_70) | | | [47](#ia6ac93763b1b4c649a509de92246d484_70) | | |
| | | | [Safe Harbor Statement](#ia6ac93763b1b4c649a509de92246d484_106) | | | [110](#ia6ac93763b1b4c649a509de92246d484_106) | | |
| | | | [Consolidated Balance Sheets](#ia6ac93763b1b4c649a509de92246d484_136) | | | [123](#ia6ac93763b1b4c649a509de92246d484_136) | | |
| | | | [Consolidated Statements of Comprehensive Income](#ia6ac93763b1b4c649a509de92246d484_142) | | | [125](#ia6ac93763b1b4c649a509de92246d484_142) | | |
| [Part III](#ia6ac93763b1b4c649a509de92246d484_223) | | | | | | [183](#ia6ac93763b1b4c649a509de92246d484_223) | | |
| [Part IV](#ia6ac93763b1b4c649a509de92246d484_241) | | | | | | [187](#ia6ac93763b1b4c649a509de92246d484_241) | | |
| [Item 16.](#ia6ac93763b1b4c649a509de92246d484_244) | | | [Form 10-K Summary](#ia6ac93763b1b4c649a509de92246d484_244) | | | [187](#ia6ac93763b1b4c649a509de92246d484_244) | | |
| Part I | | | | | | [5](#i02093e9754da48e991fe7fbb3df85a22_13) | | |
| | | | Other | | | [27](#i02093e9754da48e991fe7fbb3df85a22_25) | | |
| | | | Regulation | | | [28](#i02093e9754da48e991fe7fbb3df85a22_28) | | |
| Part II | | | | | | [45](#i02093e9754da48e991fe7fbb3df85a22_46) | | |
| | | | Introduction | | | [47](#i02093e9754da48e991fe7fbb3df85a22_61) | | |
| | | | Safe Harbor Statement | | | [109](#i02093e9754da48e991fe7fbb3df85a22_97) | | |
| | | | Consolidated Balance Sheets | | | [122](#i02093e9754da48e991fe7fbb3df85a22_127) | | |
| | | | Consolidated Statements of Income | | | [123](#i02093e9754da48e991fe7fbb3df85a22_130) | | |
| Part III | | | | | | [176](#i02093e9754da48e991fe7fbb3df85a22_214) | | |
| Part IV | | | | | | [180](#i02093e9754da48e991fe7fbb3df85a22_232) | | |
| Item 16 | | | Form 10-K Summary | | | [180](#i02093e9754da48e991fe7fbb3df85a22_235) | | |
An excerpt. Shown here: 40 of 42 rewritten, all 12 added and all 11 removed. The counts are complete. For every sentence, read Cover and table of contents in the FY2023 filing and the FY2022 filing.
Page headers and footers: 4 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 1
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 2
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 3
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 4
Item 1C. Cybersecurity
0 rewritten, 35 added, 0 removed, 0 unchanged
New section this year
Read the full itemFY2023 item · filed February 26, 2024
Risk Management and Strategy
As discussed further in Item 1, Regulation, Enterprise Risk Management, we manage cybersecurity as part of our overall enterprise risk programs.
As part of this program to keep our systems and data secure and to assist in understanding, assessing, identifying and managing material risks from cybersecurity threats, we take various measures through internal risk management efforts and testing by third-party experts.
Those measures assess our cybersecurity program structure and capabilities and include blocking attempted cyber intrusions, defending against service disruptions, performing frequent vulnerability assessments and maintaining procedures to ensure timely notification of critical cybersecurity incidents and performance of related disclosure controls.
We also have developed procedures and reporting processes when we identify an attempted cyber intrusion to the systems of one of our independent agents.
Additionally, the company uses third-party service providers, or vendors, in the course of conducting its operations.
As such, the company has measures in place to help identify material risks from cybersecurity threats associated with the use of those vendors.
When work with a vendor is evaluated, we consider, among other items, the availability of system and organization controls reports, interactions with our systems, the data involved and its level of sensitivity, the amount of data the vendor will process, where the data will be stored, what they will do with the data and destruction of data.
Once a vendor is approved by the appropriate personnel, expectations regarding incident reporting are established and followed.
We are not aware of having experienced a material cybersecurity incident and we take commercially reasonable measures, described above and below, to monitor and respond to threats to keep our systems and data secure.
However, we acknowledge that administrative, technical and internal accounting controls as well as other preventative actions may be insufficient to prevent security breaches to our systems or those of third parties with whom we do business due to, among other factors, changing technologies as well as criminal and state-sponsored cybercrime and cyber threats.
Further, a material breach of our security or the security of a vendor that results in unauthorized access to our data could expose us to a disruption or challenges relating to our daily operations as well as to data loss, litigation, damages, fines and penalties, significant increases in compliance costs and reputational damage and could affect the company's strategy, results of operations or financial condition.
See Item 1A, Risk Factors, for additional details.
Governance
Cybersecurity matters are an important part of reporting to our board of directors, executive management team, risk committee and disclosure committee.
From a board perspective, the audit committee oversees the company's cybersecurity efforts along with additional oversight from the entire board.
Several members of the audit committee have obtained certifications in cybersecurity oversight.
Each quarter, the chief information officer and chief information security officer report to the audit committee on cybersecurity risks and controls.
Also occurring each quarter, the entire board, and our senior executive team, as appropriate, receives a comprehensive report from the chief risk officer on the status and management of risk and other metrics relative to identified tolerances and limits, risk assessments and risk plans.
Additionally, the chief risk officer has direct access to all members of the board of directors and presents in person at board meetings twice each year.
At the executive management and management levels, the chief information security officer leads the process of assessing and managing material risks from cybersecurity threats.
Our chief information security officer has over 25 years of experience as a technology professional with in-depth knowledge of IT management processes and holds multiple degrees and professional designations, including as a certified information systems security professional (CISSP).
The chief information security officer also works in collaboration with our chief information officer and chief risk officer and is supported by a cross-functional group of qualified and experienced professionals across various committees and functions.
On a quarterly basis, the chief information officer provides a cybersecurity update to the disclosure committee and, on a monthly basis, the information security office team delivers a cybersecurity report to the senior executive team.
Also refer to Item 10, Directors, Executive Officers and Corporate Governance, for additional qualification, experience and responsibility details.
Associates involved in this area stay informed of industry trends and evolving threats using various resources including government authorities, peers, continuous education, industry publications, news outlets and other external parties that provide pertinent information.
We take administrative, technical and internal accounting control measures to protect against cybersecurity incidents, including actions to monitor for, prevent, detect, mitigate and remediate any incidents that occur.
These measures and actions include endpoint controls, multi-factor authentication and general cybersecurity education directed at our workforce and independent agents.
From a monitoring perspective, generally speaking, our information security office associates monitor the environment for threats, events and potential incidents.
Depending on the potential severity of any identified incident, the company's incident response process, modeled after National Institute for Standards and Technology (NIST) frameworks, is initiated.
As part of this process, each incident is evaluated and inventoried by our incident response team and reported to our legal compliance subcommittee for further action.
Depending on severity, certain other internal and external parties may participate in the incident response process from a compliance and financial reporting perspective.
Incidents, regardless of severity, are evaluated and documented and are shared with the audit committee.
In 2023, the audit committee received four updates on matters related to cybersecurity.
The process of evaluating and documenting individual incidents, even when not deemed material, assists in determining how previous incidents have or may reasonably likely have a material effect on the company in the future.
Page headers and footers: 1 line differs, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - 2023 10-K - Page 43
Item 2. Properties
5 rewritten, 0 added, 0 removed, 10 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
The property, including [removed: land] [added: land,] is recorded in our financial statements at [removed: $129] [added: $7] million at December 31, [removed: 2022,] [added: 2023,] and is classified as Land, building and equipment, net, for company use.
The property is recorded in the financial statements at [removed: $4] [added: $3] million at December 31, [removed: 2022,] [added: 2023,] and is classified as investment property in Other invested assets.
At December 31, [removed: 2022,] [added: 2023,] unaffiliated tenants occupied 86%, Cincinnati Financial affiliates occupied 14%.
The property, including [removed: land,] [added: land] is recorded in our financial statements at [removed: $8] [added: $133] million at December 31, [removed: 2022,] [added: 2023,] and is classified as Land, building and equipment, net, for company use.
We also lease office space throughout the [removed: United States] [added: U.S.] to support our insurance operations.
Item 4. Mine Safety Disclosures
0 rewritten, 41 added, 0 removed, 2 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
ITEM 5.
Market for the Registrant’s Common Equity, Related Stockholder Matters and
Issuer Purchases of Equity Securities
Cincinnati Financial Corporation had approximately 205,000 shareholders of record as of December 31, 2023.
While approximately 13,800 shareholders are registered, the majority of shareholders are beneficial owners whose shares are held in “street name” by brokers and institutional accounts.
We believe many of our independent agent representatives and most of the 5,426 associates of our subsidiaries own the company’s common stock.
Our common shares are traded under the symbol CINF on Nasdaq.
Cumulative Total Return
As depicted in the graph below, the five-year total return on a $100 investment made December 31, 2018, assuming the reinvestment of all dividends, was 52.2% for Cincinnati Financial Corporation’s common stock compared with 107.2% for the S&P 500 Index and 99.6% for the S&P Composite 1500 Property & Casualty Insurance Index.
The following graph depicts $100 invested on December 31, 2018, in stock or index, including reinvestment of dividends.
The years shown represent each respective fiscal year ending December 31.
Comparison of Five-Year Cumulative Total Return
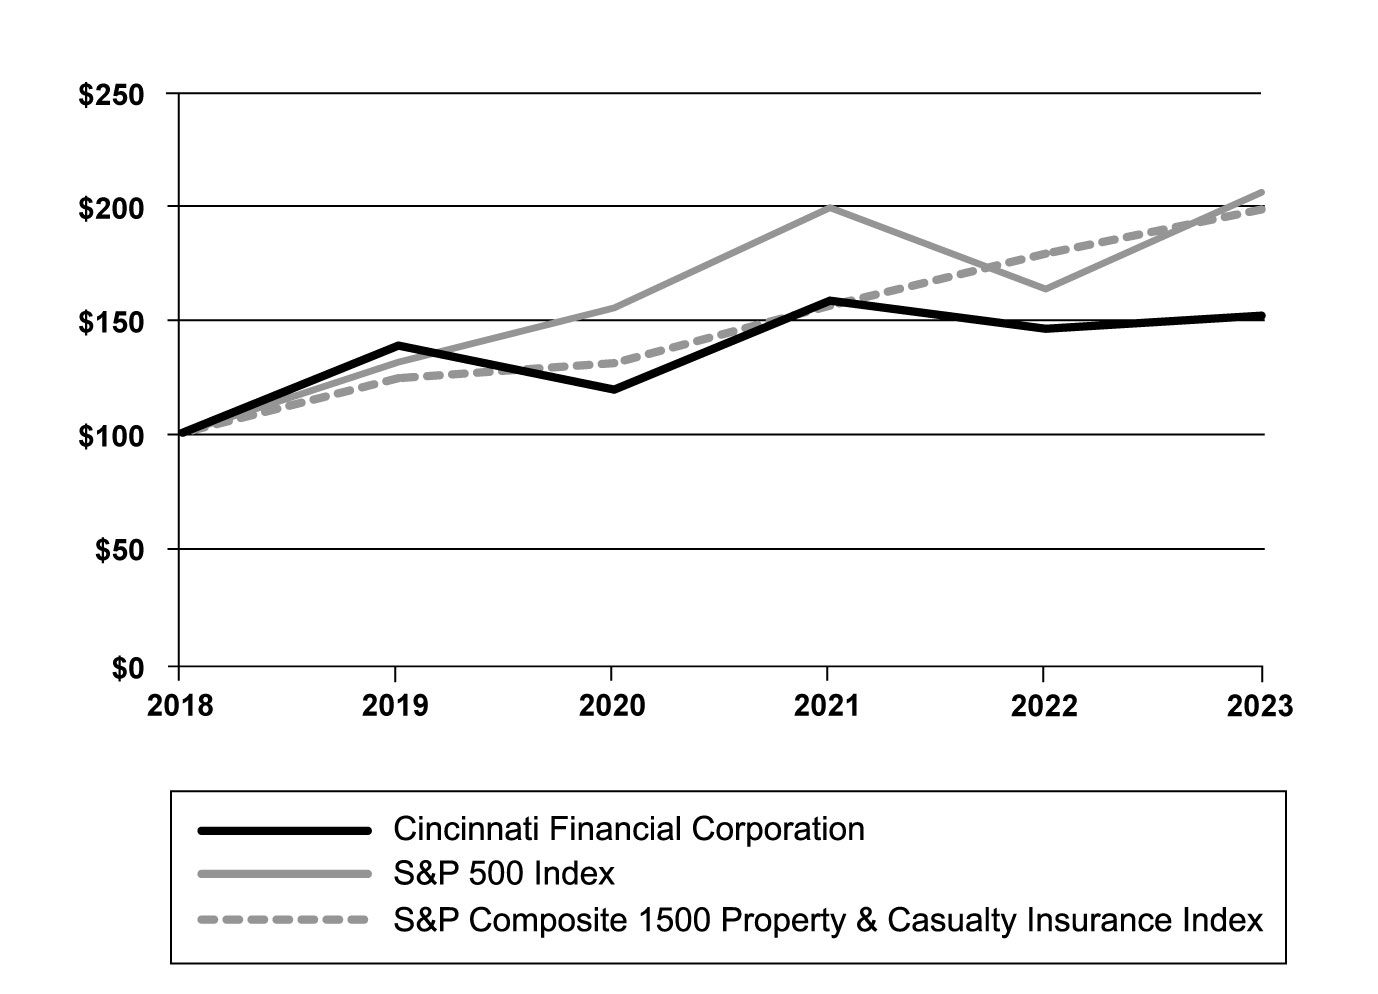
The S&P 500 Index includes a representative sample of 500 leading companies in a cross section of industries of the U.S. economy.
At year-end 2023, the S&P Composite 1500 Property & Casualty Insurance Index included 31 companies.
Issuances and Purchases of Equity Securities
The following summarizes securities authorized for issuance under our equity compensation plans as of December 31, 2023:
| Plan category | | | | | | Number of securities to be issued upon exercise of outstanding options, warrants and rights at December 31, 2023 | | | | | | Weighted-average exercise price of outstanding options, warrants and rights | | | | | | Number of securities remaining available for future issuance under equity compensation plan (excluding securities reflected in column (a)) at December 31, 2023 | | |
| | | | | | | (a) | | | | | | (b) | | | | | | (c) | | |
| Equity compensation plans approved by security holders | | | | | | 3,647,437 | | | | | | $ | 92.36 | | | | | 3,627,346 | | |
| Equity compensation plans not approved by security holders | | | | | | — | | | | | | — | | | | | | — | | |
| Total | | | | | | 3,647,437 | | | | | | $ | 92.36 | | | | | 3,627,346 | | |
The number of securities remaining available for future issuance includes: 3,395,481 shares available for issuance under the Cincinnati Financial Corporation 2016 Stock Compensation Plan (the 2016 Plan) and 231,865 shares available for issuance of share grants under the Director’s Stock Plan of 2018.
The number of securities remaining available for future issuance assumes the number of securities to be issued from performance-based awards are issued at the target-level performance level.
The 2016 Plan allows for issuance of stock options, service-based or performance-based restricted stock units, stock appreciation rights or other equity-based grants.
Awards other than stock options granted from the 2016 Plan are counted as three shares against the plan for each one share of common stock actually issued.
Additional information about share-based associate compensation granted under our equity compensation plans is available in Item 8, Note 17 of the Consolidated Financial Statements.
We discuss the factors that affect our ability to pay cash dividends and repurchase shares, as well as the objectives of our repurchase program, in Item 7, Liquidity and Capital Resources.
Regulatory restrictions on dividends our insurance subsidiaries can pay to the parent company are discussed in Item 8, Note 9 of the Consolidated Financial Statements.
The following summarizes shares purchased under our repurchase programs:
| Period | | | | | | Total number of shares purchased | | | | | | Average price paid per share | | | | | | Total number of shares purchased as part of publicly announced plans or programs | | | | | | Maximum number of shares that may yet be purchased under the plans or programs | | |
| October 1-31, 2023 | | | | | | — | | | | | | $ | — | | | | | — | | | | | | 6,726,785 | | |
| November 1-30, 2023 | | | | | | — | | | | | | — | | | | | | — | | | | | | 6,726,785 | | |
| December 1-31, 2023 | | | | | | — | | | | | | — | | | | | | — | | | | | | 6,726,785 | | |
| Totals | | | | | | — | | | | | | — | | | | | | — | | | | | | | | |
We did not sell any of our shares that were not registered under the Securities Act during 2023.
Our repurchase program does not have an expiration date.
Our repurchase program was expanded on January 26, 2018, by
15 million shares.
We have 6,726,785 shares available for purchase under our programs at December 31, 2023.
An excerpt. Shown here: all 0 rewritten, 40 of 41 added and all 0 removed. The counts are complete. For every sentence, read Item 4. Mine Safety Disclosures in the FY2023 filing and the FY2022 filing.
Page headers and footers: 2 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 44
Cincinnati Financial Corporation - 2023 10-K - Page 45
Item 6. [Reserved]
0 rewritten, 0 added, 0 removed, 0 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
Page headers and footers: 1 line differs, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page 46
Item 5. , Market for the Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
0 rewritten, 410 added, 40 removed, 0 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
Obligations
We pay obligations to customers, suppliers and associates in the normal course of our business operations.
Some are contractual obligations that define the amount, circumstances and/or timing of payments.
We have other commitments for business expenditures; such as $223 million we expect to fund for our private equity and real estate investments, however, the amount, circumstances and/or timing of our other commitments are not dictated by contractual arrangements.
Contractual Obligations
At December 31, 2023, we estimated our significant future contractual obligations as follows:
| (Dollars in millions) | | | | | | Year | | | | | | Years | | | | | | | | | | | | There- | | | | | | | | |
| Payment due by period | | | | | | 2024 | | | | | | 2025-2028 | | | | | | | | | | | | after | | | | | | Total | | |
| Gross property casualty loss and loss expense payments | | | | | | $ | 2,963 | | | | | $ | 4,742 | | | | | | | | | | | $ | 1,270 | | | | | $ | 8,975 | |
| Gross life policyholder obligations | | | | | | 145 | | | | | | 500 | | | | | | | | | | | | 5,709 | | | | | | 6,354 | | |
| Long-term debt | | | | | | — | | | | | | — | | | | | | | | | | | | 793 | | | | | | 793 | | |
| Interest on long-term debt | | | | | | 52 | | | | | | 193 | | | | | | | | | | | | 126 | | | | | | 371 | | |
| Profit-sharing commissions | | | | | | 208 | | | | | | — | | | | | | | | | | | | — | | | | | | 208 | | |
| Other liabilities | | | | | | 123 | | | | | | 83 | | | | | | | | | | | | 1 | | | | | | 207 | | |
| Total | | | | | | $ | 3,491 | | | | | $ | 5,518 | | | | | | | | | | | $ | 7,899 | | | | | $ | 16,908 | |
Liquidity and Capital Resources Outlook
At December 31, 2023, we had $907 million in cash and cash equivalents.
During 2024, our lead insurance subsidiary may pay a maximum of $729 million in dividends to our parent company without regulatory approval.
That strong liquidity and our consistent cash flows give us the flexibility to meet current obligations and commitments while building value by prudently investing where we see potential for both current income and long-term return.
Our cash and cash equivalents provide adequate financial cushion when short-term operating results do not meet our objectives.
A long-term perspective governs our liquidity and capital resources decisions, with the goal of benefiting our policyholders, agents, shareholders and associates over time.
Our underwriting philosophy and initiatives can drive performance to achieve underwriting profit.
Our GAAP combined ratio averaged 94.6% over the five-year period 2019 through 2023, resulting in strong underwriting profits.
In any year, we consider the most likely source of pressure on liquidity would be an unusually high level of catastrophe loss payments within a short period of time.
There could be additional obligations for our insurance operations due to increasing severity or frequency of noncatastrophe claims.
To address the risk of unusually large insurance loss obligations, including catastrophe events, we maintain property casualty reinsurance contracts with highly rated reinsurers, as discussed under 2024 Reinsurance Ceded Programs.
We also monitor the financial condition of our reinsurers because their insolvency could jeopardize a portion of our $651 million reinsurance recoverable asset at December 31, 2023.
Parent-company liquidity could also be constrained by Ohio regulatory requirements that restrict the dividends insurance subsidiaries can pay.
Economic weakness also has the potential to affect our liquidity and capital resources in a number of different ways, including delinquent payments from agencies, defaults on interest payments by fixed-maturity holdings in our portfolio, dividend reductions by holdings in our equity portfolio or declines in the market value of holdings in our portfolio.
Off-Balance-Sheet Arrangements
We do not use any special-purpose financing vehicles or have any undisclosed off-balance-sheet arrangements (as that term is defined in applicable SEC rules) that are reasonably likely to have a current or future material effect on the company’s financial condition, results of operation, liquidity, capital expenditures or capital resources.
Property Casualty Loss and Loss Expense Obligations and Reserves
Our estimate of future gross property casualty loss and loss expense payments of $8.975 billion is lower than loss and loss expense reserves of $9.050 billion reported on our balance sheet at December 31, 2023.
The $75 million difference is due to certain life and health loss reserves.
Reserving practices are discussed in Critical Accounting Estimates, Property Casualty Insurance Loss and Loss Expense Reserves.
For the business lines in the commercial and personal lines insurance segments, and in total for the excess and surplus lines insurance segment and for other parts of our property casualty insurance operations, the following table details gross reserves among case, IBNR and loss expense reserves, net of salvage and subrogation.
The $639 million increase in total gross reserves included an $86 million increase in case loss reserves, a $395 million increase in IBNR loss reserves and a $158 million increase in loss expense reserves.
The increase in total gross reserves included $285 million for our commercial casualty line of business, $179 million for excess and surplus lines and $110 million for Cincinnati Re.
Property Casualty Gross Loss and Loss Expense Reserves
| (Dollars in millions) | | | | | | Loss reserves | | | | | | | | | | | | Loss expense reserves | | | | | | Total gross reserves | | | | | | | | |
Issuer Purchases of Equity Securities
Cincinnati Financial Corporation had approximately 245,000 shareholders of record as of December 31, 2022.
While approximately 13,700 shareholders are registered, the majority of shareholders are beneficial owners whose shares are held in “street name” by brokers and institutional accounts.
We believe many of our independent agent representatives and most of the 5,148 associates of our subsidiaries own the company’s common stock.
Our common shares are traded under the symbol CINF on Nasdaq.
Cumulative Total Return
As depicted in the graph below, the five-year total return on a $100 investment made December 31, 2017, assuming the reinvestment of all dividends, was 55.5% for Cincinnati Financial Corporation’s common stock compared with 56.9% for the S&P 500 Index and 73.9% for the S&P Composite 1500 Property & Casualty Insurance Index.
The following graph depicts $100 invested on December 31, 2017, in stock or index, including reinvestment of dividends.
The years shown represent each respective fiscal year ending December 31.
Comparison of Five-Year Cumulative Total Return
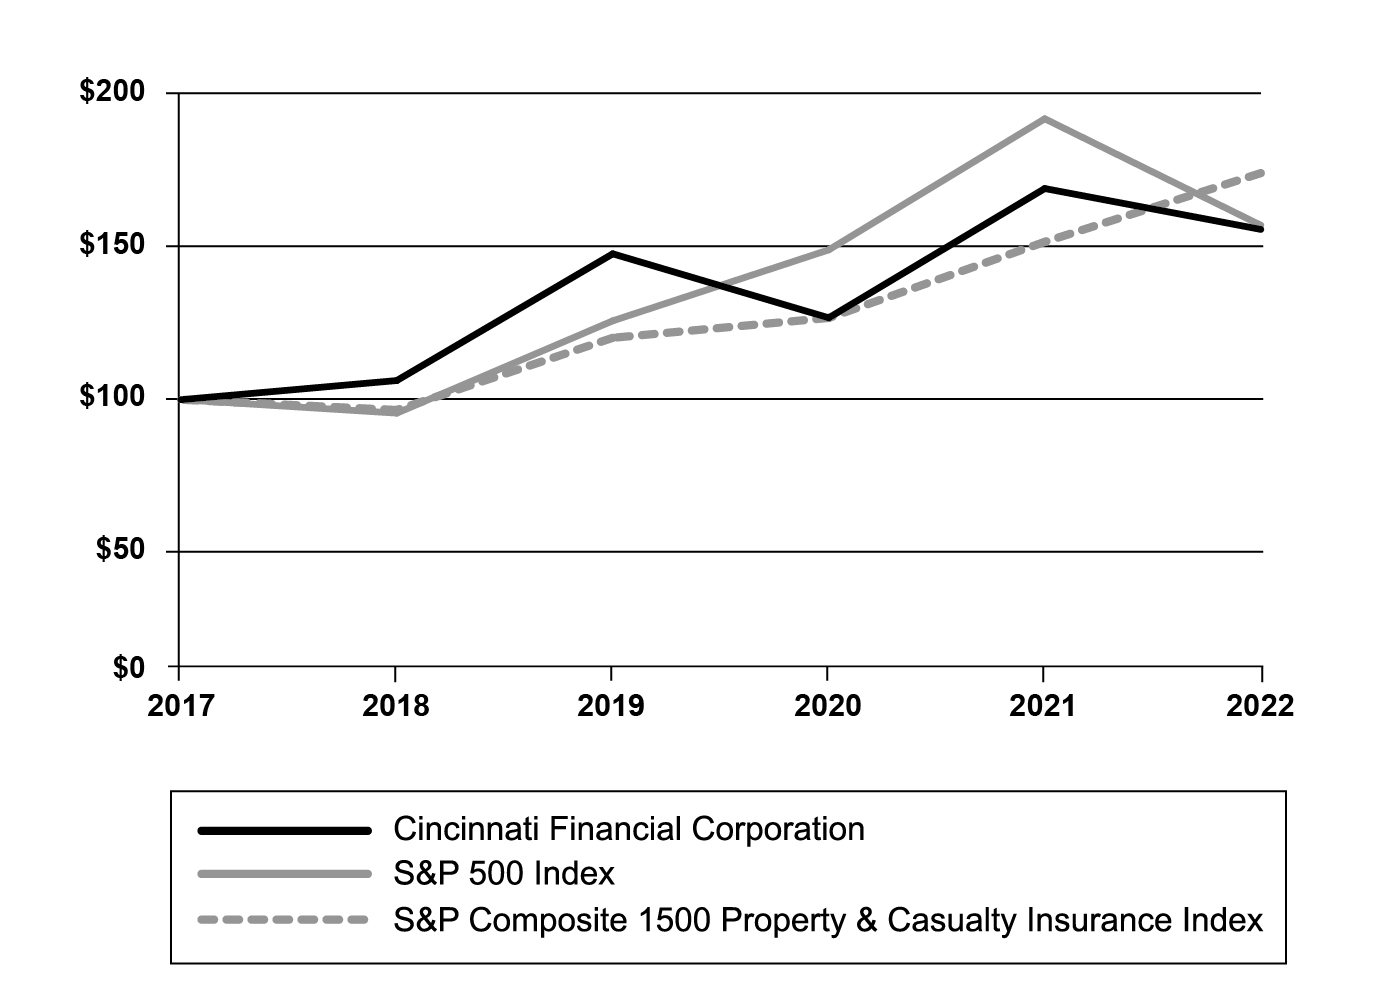
The S&P 500 Index includes a representative sample of 500 leading companies in a cross section of industries of the U.S. economy.
At year-end 2022, the S&P Composite 1500 Property & Casualty Insurance Index included 29 companies.
Issuances and Purchases of Equity Securities
The following summarizes securities authorized for issuance under our equity compensation plans as of December 31, 2022:
| Plan category | | | | | | Number of securities to be issued upon exercise of outstanding options, warrants and rights at December 31, 2022 | | | | | | Weighted-average exercise price of outstanding options, warrants and rights | | | | | | Number of securities remaining available for future issuance under equity compensation plan (excluding securities reflected in column (a)) at December 31, 2022 | | |
| | | | | | | (a) | | | | | | (b) | | | | | | (c) | | |
| Equity compensation plans approved by security holders | | | | | | 3,608,347 | | | | | | $ | 86.21 | | | | | 4,556,968 | | |
| Equity compensation plans not approved by security holders | | | | | | — | | | | | | — | | | | | | — | | |
| Total | | | | | | 3,608,347 | | | | | | $ | 86.21 | | | | | 4,556,968 | | |
The number of securities remaining available for future issuance includes: 4,313,579 shares available for issuance under the Cincinnati Financial Corporation 2016 Stock Compensation Plan (the 2016 Plan) and 243,389 shares available for issuance of share grants under the Director’s Stock Plan of 2018.
The Cincinnati Financial Corporation 2012 Stock Compensation Plan expired in April 2022.
The number of securities remaining available for future issuance assumes the number of securities to be issued from performance-based awards are issued at the target-level performance level.
The 2016 Plan allows for issuance of stock options, service-based or performance-based restricted stock units, stock appreciation rights or other equity-based grants.
Awards other than stock options granted from the 2016 Plan are counted as three shares against the plan for each one share of common stock actually issued.
Additional information about share-based associate compensation granted under our equity compensation plans is available in Item 8, Note 17 of the Consolidated Financial Statements.
We discuss the factors that affect our ability to pay cash dividends and repurchase shares in Item 7, Liquidity and Capital Resources.
Regulatory restrictions on dividends our insurance subsidiaries can pay to the parent company are discussed in Item 8, Note 9 of the Consolidated Financial Statements.
The following summarizes shares purchased under our repurchase programs:
| Period | | | | | | Total number of shares purchased | | | | | | Average price paid per share | | | | | | Total number of shares purchased as part of publicly announced plans or programs | | | | | | Maximum number of shares that may yet be purchased under the plans or programs | | |
| October 1-31, 2022 | | | | | | — | | | | | | — | | | | | | — | | | | | | 7,428,512 | | |
| November 1-30, 2022 | | | | | | — | | | | | | — | | | | | | — | | | | | | 7,428,512 | | |
| December 1-31, 2022 | | | | | | 101,727 | | | | | | $ | 109.55 | | | | | 101,727 | | | | | | 7,326,785 | | |
| Totals | | | | | | 101,727 | | | | | | 109.55 | | | | | | 101,727 | | | | | | | | |
We did not sell any of our shares that were not registered under the Securities Act during 2022.
Our repurchase program does not have an expiration date.
Our repurchase program was expanded on January 26, 2018, by
15 million shares.
We have 7,326,785 shares available for purchase under our programs at December 31, 2022.
During 2022, we repurchased 3,750,000 shares at an average price of $109.33.
An excerpt. Shown here: all 0 rewritten, 40 of 410 added and all 40 removed. The counts are complete. For every sentence, read Item 5. , Market for the Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities. in the FY2023 filing and the FY2022 filing.
Page headers and footers: 16 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 45][added: 97]
Cincinnati Financial Corporation - 2023 10-K - Page 98
Cincinnati Financial Corporation - 2023 10-K - Page 99
Cincinnati Financial Corporation - 2023 10-K - Page 100
Cincinnati Financial Corporation - 2023 10-K - Page 101
Cincinnati Financial Corporation - 2023 10-K - Page 102
Cincinnati Financial Corporation - 2023 10-K - Page 103
Cincinnati Financial Corporation - 2023 10-K - Page 104
Cincinnati Financial Corporation - 2023 10-K - Page 105
Cincinnati Financial Corporation - 2023 10-K - Page 106
Cincinnati Financial Corporation - 2023 10-K - Page 107
Cincinnati Financial Corporation - 2023 10-K - Page 108
Cincinnati Financial Corporation - 2023 10-K - Page 109
Cincinnati Financial Corporation - 2023 10-K - Page 110
Cincinnati Financial Corporation - 2023 10-K - Page 111
Cincinnati Financial Corporation - 2023 10-K - Page 112
Item 8. Financial Statements and Supplementary Data
708 rewritten, 369 added, 178 removed, 713 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
We have prepared the consolidated financial statements of Cincinnati Financial Corporation and our subsidiaries for the year ended December 31, [removed: 2022,] [added: 2023,] in accordance with accounting principles generally accepted in the United States of America (GAAP).
Deloitte & Touche LLP, our independent registered public accounting firm, audited the consolidated financial statements of Cincinnati Financial Corporation and subsidiaries for the year ended December 31, [removed: 2022.][added: 2023.]
The company’s management assessed the effectiveness of the company’s internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] as required by Section 404 of the Sarbanes Oxley Act of 2002.
Management’s assessment was based on the criteria established in the Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission and was designed to provide reasonable assurance that the company maintained effective internal control over financial reporting as of December 31, [removed: 2022.][added: 2023.]
The assessment led management to conclude that, as of December 31, [removed: 2022,] [added: 2023,] the company’s internal control over financial reporting was effective based on those criteria.
The company’s independent registered public accounting firm has issued an audit report on our internal control over financial reporting as of December 31, [removed: 2022.][added: 2023.]
We have audited the accompanying consolidated balance sheets of Cincinnati Financial Corporation and subsidiaries (the "Company") as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] the related consolidated statements of income, comprehensive income, shareholders' equity, and cash flows for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] and the related notes and the schedules listed in the Index at Item 15(c) (collectively referred to as the "financial statements").
We also have audited the Company’s internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in *Internal Control — Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] in conformity with accounting principles generally accepted in the United States of America.
Also, in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in *Internal Control — Integrated Framework (2013)* issued by COSO.
A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable [removed: assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.]
| | | | | | | [removed: 2022] [added: 2023] | | | | | | [added: 2022 | | | | | |] 2021 | | |
| Fixed maturities, at fair value (amortized cost: [removed: 2022—$12,979; 2021—$12,230)] [added: 2023—$14,361; 2022—$12,979)] | | | | | | $ | [removed: 12,132] [added: 13,791] | | | | | $ | [removed: 13,022] [added: 12,132] | |
| Equity securities, at fair value (cost: [removed: 2022—$4,294; 2021—$4,121)] [added: 2023—$4,282; 2022—$4,294)] | | | | | | [removed: 9,841] [added: 10,989] | | | | | | [removed: 11,315] [added: 9,841] | | |
| Other invested assets | | | | | | [removed: 452] [added: 577] | | | | | | [removed: 329] [added: 452] | | |
| Total investments | | | | | | [removed: 22,425] [added: 25,357] | | | | | | [removed: 24,666] [added: 22,425] | | |
| Cash and cash equivalents | | | | | | [removed: 1,264] [added: 907] | | | | | | [removed: 1,139] [added: 1,264] | | |
| Investment income receivable | | | | | | [removed: 160] [added: 192] | | | | | | [removed: 144] [added: 160] | | |
| Finance receivable | | | | | | [removed: 92] [added: 108] | | | | | | [removed: 98] [added: 92] | | |
| Premiums receivable | | | | | | [removed: 2,322] [added: 2,592] | | | | | | [removed: 2,053] [added: 2,322] | | |
| Reinsurance recoverable | | | [added: $] | [added: 651] | | [removed: 640] | | | [added: $] | [added: 640] | | [removed: 570] [added: $] | [added: 665] | | [added: $ | 25 | |]
| Prepaid reinsurance premiums | | | | | | [removed: 79] [added: 55] | | | | | | [removed: 78] [added: 51] | | |
| Deferred policy acquisition costs | | | [added: (80)] | | | [removed: 1,014] | | | [added: (96)] | | | [removed: 905] | | | [added: (78) | | | | | | | | |]
| Land, building and equipment, net, for company use (accumulated depreciation: [removed: 2022—$322; 2021—$303)] [added: 2023—$337; 2022—$322)] | | | | | | [removed: 202] [added: 208] | | | | | | [removed: 205] [added: 202] | | |
| Other assets | | | | | | [removed: 646] [added: 681] | | | | | | [removed: 570] [added: 646] | | |
| Separate accounts | | | | | | [removed: 892] [added: 925] | | | | | | [removed: 959] [added: 892] | | |
| Total assets | | | [added: 32,769] | | | [removed: $] | [removed: 29,736] | | [added: 29,736] | | | [removed: $] [added: 29,732] | [removed: 31,387] | | [added: (4) | | |]
| Loss and loss expense reserves | | | | | | $ | [removed: 8,400] [added: 9,050] | | | | | $ | [removed: 7,305] [added: 8,400] | |
| Life policy and investment contract reserves | | | [added: 99] | | | [removed: 3,059] | | | [added: 78] | | | [removed: 3,014] | | | [added: 76 | | | | | | | | |]
| Unearned premiums | | | | | | [removed: 3,689] [added: 4,119] | | | | | | [removed: 3,271] [added: 3,689] | | |
| Other liabilities | | | | | | [removed: 1,229] [added: 1,311] | | | | | | [removed: 1,092] [added: 1,229] | | |
| Deferred income tax | | | [added: 1,324] | | | [removed: 1,045] | | | [added: 1,045] | | | [removed: 1,744] [added: 1,054] | | | [added: 9 | | |]
| Note payable | | | | | | [removed: 50] [added: 25] | | | | | | [removed: 54] [added: 50] | | |
| Long-term debt and lease obligations | | | | | | [removed: 841] [added: 849] | | | | | | [removed: 843] [added: 841] | | |
| Separate accounts | | | | | | [removed: 892] [added: 925] | | | | | | [removed: 959] [added: 892] | | |
| Total liabilities | | | [added: 20,671] | | | [removed: 19,205] | | | [added: 19,205] | | | [removed: 18,282] [added: 19,170] | | | [added: (35) | | |]
| Common stock, par value—$2 per share; (authorized: [removed: 2022] [added: 2023] and [removed: 2021—500] [added: 2022—500] million shares; issued: [removed: 2022] [added: 2023] and [removed: 2021—198.3] [added: 2022—198.3] million shares) | | | | | | 397 | | | | | | 397 | | |
| Paid-in capital | | | | | | [removed: 1,392] [added: 1,437] | | | | | | [removed: 1,356] [added: 1,392] | | |
| Retained earnings | | | [added: 13,084] | | | [removed: 11,702] | | | [added: 11,702] | | | [removed: 12,625] [added: 11,711] | | | [added: 9 | | |]
| Accumulated other comprehensive income | | | [added: (435)] | | | [removed: (636)] | | | [added: (636)] | | | [removed: 648] [added: (614)] | | | [added: 22 | | |]
February 26, 2024
Change in Accounting Principle
As discussed in Note 1 to the financial statements, the Company changed its method of accounting, measurement, and disclosure of long duration contracts effective January 1, 2023, using the modified retrospective method applied as of the transition date of January 1, 2021, due to adoption of ASU 2018-12, *Financial Services - Insurance (Topic 944): Targeted Improvements to the Accounting for Long-Duration Contracts.*
assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
February 26, 2024
| Reinsurance recoverable | | | | | | 651 | | | | | | 665 | | |
| Deferred policy acquisition costs | | | | | | 1,093 | | | | | | 1,013 | | |
| Total assets | | | | | | $ | 32,769 | | | | | $ | 29,732 | |
| Deferred income tax | | | | | | 1,324 | | | | | | 1,054 | | |
| Total liabilities | | | | | | 20,671 | | | | | | 19,170 | | |
| Retained earnings | | | | | | 13,084 | | | | | | 11,711 | | |
| Accumulated other comprehensive income | | | | | | (435) | | | | | | (614) | | |
| Total shareholders' equity | | | | | | 12,098 | | | | | | 10,562 | | |
| Total liabilities and shareholders' equity | | | | | | $ | 32,769 | | | | | $ | 29,732 | |
| Earned premiums | | | | | | $ | 7,958 | | | | | $ | 7,225 | | | | | $ | 6,478 | |
| Total revenues | | | | | | 10,013 | | | | | | 6,563 | | | | | | 9,626 | | |
| Insurance losses and contract holders' benefits | | | | | | 5,274 | | | | | | 5,019 | | | | | | 3,909 | | |
| Underwriting, acquisition and insurance expenses | | | | | | 2,384 | | | | | | 2,162 | | | | | | 1,946 | | |
| Deferred | | | | | | 223 | | | | | | (355) | | | | | | 483 | | |
| Net Income (Loss) | | | | | | $ | 1,843 | | | | | $ | (487) | | | | | $ | 2,968 | |
| Net Income (Loss) | | | | | | $ | 1,843 | | | | | $ | (487) | | | | | $ | 2,968 | |
| Comprehensive Income (Loss) | | | | | | $ | 2,022 | | | | | $ | (1,398) | | | | | $ | 2,930 | |
| Cumulative effect of change in accounting for long-duration insurance contracts (Note 1) | | | — | | | | | | — | | | | | | (12) | | |
| Adjusted beginning of year | | | 11,711 | | | | | | 12,635 | | | | | | 10,073 | | |
| Net income (loss) | | | 1,843 | | | | | | (487) | | | | | | 2,968 | | |
| End of year | | | 13,084 | | | | | | 11,711 | | | | | | 12,635 | | |
| Cumulative effect of change in accounting for long-duration insurance contracts (Note 1) | | | — | | | | | | — | | | | | | (434) | | |
| Adjusted beginning of year | | | (614) | | | | | | 297 | | | | | | 335 | | |
| Other comprehensive income (loss) | | | 179 | | | | | | (911) | | | | | | (38) | | |
| End of year | | | (435) | | | | | | (614) | | | | | | 297 | | |
| Total Shareholders' Equity | | | $ | 12,098 | | | | | $ | 10,562 | | | | | $ | 12,764 | |
| Net income (loss) | | | $ | 1,843 | | | | | $ | (487) | | | | | $ | 2,968 | | | | | | | |
| Deferred income tax expense | | | 223 | | | | | | (355) | | | | | | 483 | | | | | | | | |
The private equity investments provide their financial statements to us
We establish reserves for traditional long-duration contracts, including term, whole life and other products, based on the present value of future benefits and claim expenses less the present value of future net premiums.
The cash flow assumptions are established based on our current expectations and are reviewed annually to determine any necessary updates.
These assumptions are also updated on an interim basis if evidence suggests that they should be revised.
Certain assumptions, including the mortality, lapse and long-term interest rate reversion targets, were updated in 2023 as part of our annual assumption unlocking.
See Note 5, Life Policy and Investment Contract Reserves, for further detail regarding the measurement impact on traditional long-duration contract reserves due to changes in the inputs, judgments and assumptions during the period.
We also offer universal life, deferred annuity and other investment contracts.
February 23, 2023
February 23, 2023
| Total revenues | | | | | | 6,557 | | | | | | 9,630 | | | | | | 7,536 | | |
| Deferred | | | | | | (355) | | | | | | 477 | | | | | | 136 | | |
| Net Income (Loss) | | | | | | $ | (486) | | | | | $ | 2,946 | | | | | $ | 1,216 | |
| Cumulative effect of change in accounting for credit losses as of January 1, 2020 | | | — | | | | | | — | | | | | | (2) | | |
| Adjusted beginning of year | | | 12,625 | | | | | | 10,085 | | | | | | 9,255 | | |
| Net income (loss) | | | (486) | | | | | | 2,946 | | | | | | 1,216 | | |
| End of year | | | 11,702 | | | | | | 12,625 | | | | | | 10,085 | | |
| End of year | | | (636) | | | | | | 648 | | | | | | 769 | | |
| Total Shareholders' Equity | | | $ | 10,531 | | | | | $ | 13,105 | | | | | $ | 10,789 | |
| Net income (loss) | | | $ | (486) | | | | | $ | 2,946 | | | | | $ | 1,216 | | | | | | | |
The company continues to monitor the impact of the coronavirus (SARS-CoV-2 or COVID-19) pandemic outbreak.
The estimated pandemic-related incurred losses and expenses were immaterial in 2022 and 2021 and $85 million in 2020.
The company cannot predict the impact the pandemic will have on its future consolidated financial position, results of operations and cash flows, however the impact could be material.
insurance policies and measure profitability.
A significant portion of the increase in the allowance to $19 million at December 31, 2020, was due to consideration of pandemic-related factors.
We establish a liability for traditional long-duration contracts as we receive premiums.
The amount of this liability is the present value of future expenses and benefits less the present value of future net premiums.
We include a provision for deviation, meaning we allow for some uncertainty in making our assumptions.
We establish our assumptions when the contract is issued, and we generally maintain those assumptions for the life of the contract.
We use our own experience and historical trends for setting our assumption for expected expenses.
We base our assumption for expected investment income on our own experience, adjusted for current and future economic conditions.
We charge these capitalized costs associated with successfully acquiring traditional long-duration contract insurance policies in proportion to premium revenue recognized.
We use the same assumptions used in establishing the liability for the contract.
We maintain a policy reserve liability equal to the policyholder account value.
There is no provision for adverse deviation.
We capitalize acquisition costs associated with successfully acquiring universal life long-duration contracts.
We charge these capitalized costs to expenses over the term of coverage of the contract in accordance with the recognition of gross profit from the contract or notional benefit base.
When we charge deferred policy acquisition costs to expenses, we use assumptions based on our best estimates of long-term experience.
We review and modify these assumptions on a regular basis.
At December 31, 2021, the current fair value of the BOLI invested assets and cash exceeded the current fair value of the contract holders’ account value by approximately $79 million.
If the BOLI projected fair value were to fall below the value we guaranteed, a liability would be established with a corresponding charge to the company’s earnings.
traditionally used for the types of exposures written.
Quarterly updates to the life policy and investment contract reserves and corresponding adjustments to shareholders' equity due to changes in the market value discount rates and other assumptions in subsequent periods could be material.
| Corporate | | | | | | $ | 7,043 | | | | | $ | 467 | | | | | $ | 13 | | | | | $ | 7,497 | |
| Commercial mortgage-backed | | | | | | 264 | | | | | | 9 | | | | | | — | | | | | | 273 | | |
| Total | | | | | | $ | 12,230 | | | | | $ | 808 | | | | | $ | 16 | | | | | $ | 13,022 | |
| At December 31, 2021 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Corporate | | | | | | $ | 861 | | | | | $ | 13 | | | | | $ | 15 | | | | | $ | — | | | | | $ | 876 | | | | | $ | 13 | |
An excerpt. Shown here: 40 of 708 rewritten, 40 of 369 added and 40 of 178 removed. The counts are complete. For every sentence, read Item 8. Financial Statements and Supplementary Data in the FY2023 filing and the FY2022 filing.
Page headers and footers: 63 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 118][added: 119]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 119][added: 120]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 120][added: 121]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 121][added: 122]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 122][added: 123]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 123][added: 124]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 124][added: 125]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 125][added: 126]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 126][added: 127]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 127][added: 128]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 128][added: 129]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 129][added: 130]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 130][added: 131]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 131][added: 132]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 132][added: 133]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 133][added: 134]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 134][added: 135]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 135][added: 136]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 136][added: 137]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 137][added: 138]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 138][added: 139]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 139][added: 140]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 140][added: 141]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 141][added: 142]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 142][added: 143]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 143][added: 144]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 144][added: 145]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 145][added: 146]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 146][added: 147]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 147][added: 148]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 148][added: 149]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 149][added: 150]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 150][added: 151]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 151][added: 152]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 152][added: 153]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 153][added: 154]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 154][added: 155]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 155][added: 156]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 156][added: 157]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 157][added: 158]
Cincinnati Financial Corporation - 2023 10-K - Page 176
Cincinnati Financial Corporation - 2023 10-K - Page 177
Cincinnati Financial Corporation - 2023 10-K - Page 178
Cincinnati Financial Corporation - 2023 10-K - Page 179
Cincinnati Financial Corporation - 2023 10-K - Page 180
Cincinnati Financial Corporation - 2023 10-K - Page 181
Shown here: 40 of 57 changed, all 6 added and all 0 removed.
Item 9A. Controls and Procedures
3 rewritten, 0 added, 1 removed, 6 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
The company’s management, with the participation of the company’s chief executive officer and chief financial officer, has evaluated the effectiveness of the design and operation of the company’s disclosure controls and procedures as of December 31, [removed: 2022.][added: 2023.]
Changes in Internal Control over Financial Reporting – During the three months ended December 31, [removed: 2022,] [added: 2023,] there were no changes in our internal controls over financial reporting that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
We are continually monitoring and assessing any potential impact on the design and operating effectiveness of our internal controls over financial [removed: reporting, caused by or] [added: reporting] related to the [removed: pandemic.][added: alternating of associate schedules between working at our headquarters and working from remote locations.]
There was no significant impact to our internal controls over financial reporting while the majority of our headquarters associates transitioned to a hybrid work schedule, regularly alternating between work at our headquarters and work from remote locations.
Item 9B. Other Information
0 rewritten, 1 added, 1 removed, 0 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
Neither the company nor any of our officers or directors adopted or terminated a Rule 10b5-1 or non-Rule 10b5-1 trading arrangement as defined by Item 408(a) and Item 408(d) of Regulation S-K during the last fiscal quarter.
None
Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections
1 rewritten, 0 added, 0 removed, 3 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
Our Proxy Statement will be filed with the SEC no later than April [removed: 30, 2023,] [added: 29, 2024,] in preparation for the [removed: 2023] [added: 2024] Annual Meeting of Shareholders scheduled for May [removed: 6, 2023.][added: 4, 2024.]
Page headers and footers: 1 line differs, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 175][added: 182]
Item 10. Directors, Executive Officers and Corporate Governance
16 rewritten, 0 added, 1 removed, 5 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
a) The following sections of our Proxy Statement for our [removed: 2023] [added: 2024] Annual Meeting of Shareholders to be held May [removed: 6, 2023,] [added: 4, 2024,] are incorporated herein by reference: “Delinquent Section 16(a) Reports,” “Information about the Board of Directors,” and “Governance of Your Company.”
c) Set forth below is information concerning the company’s executive officers who are not also directors of the company, as of February [removed: 23, 2023.][added: 26, 2024.]
| February [removed: 23, 2023] [added: 26, 2024] | | | | | | Since February [removed: 2018] [added: 2019] | | | | | | Officer Since | | |
| Roger A. Brown, FSA, MAAA, CLU [removed: (51)] [added: (52)] | | | | | | Senior vice president and chief operating officer of The Cincinnati Life Insurance Company. Responsible for life insurance underwriting and operations. | | | | | | 2016 | | |
| Teresa C. Cracas, Esq. [removed: (57)] [added: (58)] | | | | | | Chief risk officer and executive vice president of The Cincinnati Insurance Company. Senior vice president until 2022. Responsible for strategic planning and risk management, including oversight of modeling for financial analysis, property casualty reserving and pricing, strategic innovation, [added: ceded] reinsurance [added: programs, reinsurance] assumed operations and the activities of Cincinnati Global Underwriting Ltd., a London-based, global specialty underwriter for Lloyd's Syndicate 318. | | | | | | 2011 | | |
| Angela O. Delaney [removed: (54)] [added: (55)] | | | | | | Senior vice president of The Cincinnati Insurance Company. Responsible for property casualty insurance sales and marketing operations since 2019, including management of field underwriters and independent agency relationships. [removed: Field sales supervisor for Idaho, Iowa, Montana, Oregon, South Dakota and Washington from 2017 to 2019.] | | | | | | 2020 | | |
| Donald J. Doyle, Jr., CPCU, AIM [removed: (56)] [added: (57)] | | | | | | Senior vice president of The Cincinnati Insurance Company. Responsible for excess and surplus lines underwriting and operations of The Cincinnati Specialty Underwriters Insurance Company and CSU Producer Resources Inc. | | | | | | 2008 | | |
| Sean M. Givler, CIC, CRM [removed: (47)] [added: (48)] | | | | | | Senior vice president of The Cincinnati Insurance Company. Responsible for standard market commercial lines underwriting and operations, including management liability and surety insurance, machinery and equipment insurance, loss control and premium [removed: audit. Until 2019, responsible for sales and marketing, including management of field underwriters and independent agency relationships.] [added: audit since 2019.] | | | | | | 2017 | | |
| Theresa A. Hoffer [removed: (61)] [added: (62)] | | | | | | Senior vice president and treasurer of The Cincinnati Insurance Company since 2016. Responsible for corporate accounting and SEC reporting operations. | | | | | | 2017 | | |
| John S. Kellington [removed: (61)] [added: (62)] | | | | | | Chief information officer and executive vice president of The Cincinnati Insurance Company. Senior vice president until 2022. Responsible for enterprise technology platforms and related activities. | | | | | | 2010 | | |
| February [removed: 23, 2023] [added: 26, 2024] | | | | | | Since February [removed: 2018] [added: 2019] | | | | | | Officer Since | | |
| Lisa A. Love, Esq. [removed: (63)] [added: (64)] | | | | | | Chief legal officer, executive vice president and corporate secretary of Cincinnati Financial Corporation. Senior vice president and general counsel until 2022. Responsible for corporate legal, governance and compliance activities, including oversight of regulatory and compliance, shareholder services, government relations, litigation and contract administration. | | | | | | 2011 | | |
| Marc J. Schambow, CPCU, AIM, ASLI [removed: (57)] [added: (58)] | | | | | | Chief claims officer and senior vice president of The Cincinnati Insurance Company. Responsible for all headquarters and field claims operations, including special investigations and claims administration. Until 2020, vice president of field claims. | | | | | | 2022 | | |
| Michael J. Sewell, CPA [removed: (59)] [added: (60)] | | | | | | Chief financial officer, principal accounting officer, executive vice president and treasurer of Cincinnati Financial Corporation. Senior vice president until 2022. Chief operating officer of CFC Investment Company, a commercial lease and finance subsidiary. Responsible for oversight of [removed: all] accounting, finance, financial reporting, purchasing, investor relations, administrative services and facilities maintenance and security. | | | | | | 2011 | | |
| Steven A. Soloria, CFA, CPCU [removed: (56)] [added: (57)] | | | | | | Chief investment officer and [removed: senior] [added: executive] vice president of [removed: The] Cincinnati [removed: Insurance Company.] [added: Financial Corporation.] Responsible for all investment operations. [added: Senior vice president of The Cincinnati Insurance Company until 2023.] Vice president of investments until 2022. | | | | | | 2023 | | |
| William H. Van Den Heuvel [removed: (56)] [added: (57)] | | | | | | Senior vice president of The Cincinnati Insurance Company. Responsible for all aspects of personal lines operations, including underwriting, insurance regulatory filings, product management and risk management. | | | | | | 2014 | | |
| Stephen M. Spray (56) | | | | | | President of Cincinnati Financial Corporation. Responsible for executive oversight of life insurance, commercial and personal standard market and excess and surplus lines property and casualty insurance sales, marketing, underwriting, related field services, relationships with independent agents, ceded reinsurance programs, corporate communications and human resources. Chief insurance officer of The Cincinnati Insurance Company and its property casualty subsidiaries until 2022. Until 2019, senior vice president responsible for commercial lines underwriting and operations. | | | | | | 2012 | | |
Page headers and footers: 2 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 176][added: 183]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 177][added: 184]
Item 11. Executive Compensation
1 rewritten, 0 added, 0 removed, 1 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
The “Compensation of Named Executive Officers and Directors,” section of our Proxy Statement for our Annual Meeting of Shareholders to be held May [removed: 6, 2023,] [added: 4, 2024,] is incorporated herein by reference.
Item 12. Security Ownership of Certain Beneficial Owners and Management and
1 rewritten, 0 added, 0 removed, 3 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
a) The “Security Ownership of Principal Shareholders and Management” section of our Proxy Statement for our Annual Meeting of Shareholders to be held May [removed: 6, 2023,] [added: 4, 2024,] is incorporated herein by reference.
Page headers and footers: 1 line differs, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 178][added: 185]
Item 13. Certain Relationships and Related Transactions, and Director Independence
1 rewritten, 0 added, 0 removed, 0 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
The following sections of our Proxy Statement for our Annual Meeting of Shareholders to be held May [removed: 6, 2023,] [added: 4, 2024,] are incorporated herein by reference: “Governance of Your Company – Director Independence” and “Governance of Your Company – Certain Relationships and Transactions.”
Item 14. Principal Accounting Fees and Services
1 rewritten, 0 added, 0 removed, 2 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
The “Audit-Related Matters,” section of our Proxy Statement for our Annual Meeting of Shareholders to be held May [removed: 6, 2023,] [added: 4, 2024,] is incorporated herein by reference.
Page headers and footers: 1 line differs, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 179][added: 186]
Item 15. Exhibit and Financial Statement Schedules
7 rewritten, 1 added, 2 removed, 0 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
a) Financial Statements – information contained in Part II, Item 8, of this report, Page [removed: [118](#i02093e9754da48e991fe7fbb3df85a22_115)] [added: [119](#ia6ac93763b1b4c649a509de92246d484_124)] to Page [removed: [174](#i3e3d009a2fa245adbc6f1cb50e4c5b94_2907)][added: [181](#i0bd744c34a67421395bc440d5a58ba4f_2750)]
b) Exhibits – see Index of Exhibits, Page [removed: [192](#i02093e9754da48e991fe7fbb3df85a22_241)][added: [199](#ia6ac93763b1b4c649a509de92246d484_268)]
Schedule I – Summary of Investments – Other Than Investments in Related Parties, Page [removed: [181](#i02093e9754da48e991fe7fbb3df85a22_2281)][added: [188](#ia6ac93763b1b4c649a509de92246d484_247)]
Schedule II – Condensed Financial Statements of Parent Company, Page [removed: [183](#i02093e9754da48e991fe7fbb3df85a22_2310)][added: [190](#ia6ac93763b1b4c649a509de92246d484_250)]
Schedule III – Supplementary Insurance Information, Page [removed: [186](#i02093e9754da48e991fe7fbb3df85a22_2338)][added: [193](#ia6ac93763b1b4c649a509de92246d484_253)]
Schedule V – Valuation and Qualifying Accounts, Page [removed: [189](#i02093e9754da48e991fe7fbb3df85a22_2394)][added: [196](#ia6ac93763b1b4c649a509de92246d484_259)]
Schedule VI – Supplementary Information Concerning Property Casualty Insurance Operations, Page [removed: [190](#i02093e9754da48e991fe7fbb3df85a22_2422)][added: [197](#ia6ac93763b1b4c649a509de92246d484_262)]
Schedule IV – Reinsurance, Page [195](#ia6ac93763b1b4c649a509de92246d484_256)
c) Financial Statement Schedules
Schedule IV – Reinsurance, Page [188](#i02093e9754da48e991fe7fbb3df85a22_2366)
Item 16. Form 10-K Summary
307 rewritten, 34 added, 30 removed, 194 unchanged
Read the full itemFY2023 item · filed February 26, 2024FY2022 item · filed February 23, 2023
| (Dollars in millions) | | | | | | At December 31, [removed: 2022] [added: 2023] | | | | | | | | | | | | | | |
| The Cincinnati Insurance Company [added: (1)] | | | | | | [removed: $] [added: 58] | [removed: 3,401] | | | | | [removed: $] [added: —] | [removed: 3,271] | | | | | [removed: $] [added: 58] | [removed: 3,271] | |
| The Cincinnati Casualty Company | | | | | | [removed: 243] [added: 25] | | | | | | [removed: 230] [added: 25] | | | | | | [removed: 230] [added: 25] | | |
| The Cincinnati Indemnity Company | | | | | | [removed: 48] [added: 50] | | | | | | [removed: 46] [added: 49] | | | | | | [removed: 46] [added: 49] | | |
| The Cincinnati Life Insurance Company | | | | | | [removed: 459] [added: 13] | | | | | | [removed: 383] [added: 12] | | | | | | [removed: 383] [added: 12] | | |
| The Cincinnati Specialty Underwriters Insurance Company | | | | | | [removed: 688] [added: 126] | | | | | | [removed: 640] [added: 126] | | | | | | [removed: 640] [added: 126] | | |
| Cincinnati Financial Corporation | | | | | | [removed: 62] [added: 54] | | | | | | [removed: 52] [added: 47] | | | | | | [removed: 52] [added: 47] | | |
| The Cincinnati Insurance Company | | | | | | [removed: 139] [added: 641] | | | | | | [removed: 135] [added: 641] | | | | | | [removed: 135] [added: 641] | | |
| Cincinnati Global Underwriting Ltd. | | | | | | [removed: 55] [added: 79] | | | | | | [removed: 54] [added: 79] | | | | | | [removed: 54] [added: 79] | | |
| The Cincinnati [added: Life] Insurance Company | | | | | | [removed: 15] [added: $] | [added: 33] | | | | | [removed: 15] [added: —] | | | | | | [removed: 15] [added: $] | [added: 33] | |
| The Cincinnati Casualty Company | | | | | | [removed: 5] [added: 98] | | | | | | [removed: 5] [added: 89] | | | | | | [removed: 5] [added: 89] | | |
| The Cincinnati Indemnity Company | | | | | | [removed: 2] [added: 6] | | | | | | [removed: 2] [added: 6] | | | | | | [removed: 2] [added: 6] | | |
| The Cincinnati Life Insurance Company [added: (1)] | | | | | | [removed: 145] [added: 4] | | | | | | [removed: 142] [added: —] | | | | | | [removed: 142] [added: 4] | | |
| The Cincinnati Specialty Underwriters Insurance Company | | | | | | [removed: 10] [added: 738] | | | | | | [removed: 10] [added: 710] | | | | | | [removed: 10] [added: 710] | | |
| Cincinnati Global Underwriting Ltd. | | | | | | [removed: 9] [added: 6] | | | | | | [removed: 9] [added: 5] | | | | | | [removed: 9] [added: 5] | | |
| The Cincinnati Insurance Company [added: (1)] | | | | | | [removed: 10] [added: 389] | | | | | | [removed: 10] [added: —] | | | | | | [removed: 10] [added: 389] | | |
| Cincinnati Global Underwriting Ltd. | | | | | | [removed: 24] [added: 25] | | | | | | [removed: 23] [added: 25] | | | | | | [removed: 23] [added: 25] | | |
| Total | | | | | | [removed: 34] [added: 25] | | | | | | [removed: 33] [added: 25] | | | | | | [removed: 33] [added: 25] | | |
| The Cincinnati Insurance Company | | | | | | [removed: 3,794] [added: $] | [added: 3,339] | | | | | [removed: 3,527] [added: $] | [added: 3,278] | | | | | [removed: 3,527] [added: $] | [added: 3,278] | |
| The Cincinnati Casualty Company | | | | | | [removed: 96] [added: 58] | | | | | | [removed: 85] [added: 171] | | | | | | [removed: 85] [added: 171] | | |
| The Cincinnati Indemnity Company | | | | | | [removed: 33] [added: 35] | | | | | | [removed: 31] [added: 33] | | | | | | [removed: 31] [added: 33] | | |
| The Cincinnati Life Insurance Company | | | | | | [removed: 3,283] [added: 447] | | | | | | [removed: 3,045] [added: 388] | | | | | | [removed: 3,045] [added: 388] | | |
| The Cincinnati Specialty Underwriters Insurance Company | | | | | | [removed: 323] [added: 398] | | | | | | [removed: 287] [added: 373] | | | | | | [removed: 287] [added: 373] | | |
| Cincinnati Global Underwriting Ltd. | | | | | | [removed: 104] [added: 39] | | | | | | [removed: 102] [added: —] | | | | | | [removed: 102] [added: 39] | | |
| Cincinnati Financial Corporation | | | | | | [removed: 29] [added: 27] | | | | | | 26 | | | | | | 26 | | |
| Total fixed maturities | | | | | | $ | [removed: 12,979] [added: 14,361] | | | | | $ | [removed: 12,132] [added: 13,791] | | | | | $ | [removed: 12,132] [added: 13,791] | |
| (Dollars in millions) | | | | | | At December 31, [removed: 2022] [added: 2023] | | | | | | | | | | | | | | |
| The Cincinnati Insurance Company | | | | | | [removed: $] [added: 122] | [removed: 1,925] | | | | | [removed: $] [added: 119] | [removed: 5,013] | | | | | [removed: $] [added: 119] | [removed: 5,013] | |
| The Cincinnati Casualty Company | | | | | | [removed: 59] [added: 239] | | | | | | [removed: 162] [added: 231] | | | | | | [removed: 162] [added: 231] | | |
| The Cincinnati Specialty Underwriters Insurance Company | | | | | | [removed: 102] [added: 109] | | | | | | [removed: 238] [added: 302] | | | | | | [removed: 238] [added: 302] | | |
| CSU Producer Resources Inc. | | | | | | 17 | | | | | | [removed: 27] [added: 28] | | | | | | [removed: 27] [added: 28] | | |
| Cincinnati Financial Corporation | | | | | | [removed: 1,730] [added: 3] | | | | | | [removed: 3,974] [added: 2] | | | | | | [removed: 3,974] [added: 2] | | |
| The Cincinnati Insurance Company | | | | | | [removed: 426] [added: 4,147] | | | | | | [removed: 372] [added: 3,955] | | | | | | [removed: 372] [added: 3,955] | | |
| The Cincinnati Life Insurance Company | | | | | | [removed: 13] [added: 320] | | | | | | [removed: 11] [added: 318] | | | | | | [removed: 11] [added: 318] | | |
| Cincinnati Financial Corporation [added: (1)] | | | | | | [removed: 4] [added: 40] | | | | | | [removed: 4] [added: —] | | | | | | [removed: 4] [added: 40] | | |
| Total | | | | | | [removed: 443] [added: $] | [added: 569] | | | | | [removed: 387] [added: $] | [added: 561] | | | | | [removed: 387] [added: $] | [added: 443] | |
| Total equity securities | | | | | | $ | [removed: 4,294] [added: 4,282] | | | | | $ | [removed: 9,841] [added: 10,989] | | | | | $ | [removed: 9,841] [added: 10,989] | |
| The Cincinnati Life Insurance Company | | | | | | [removed: $] [added: 3,176] | [removed: 31] | | | | | [removed: —] [added: 3,005] | | | | | | [removed: $] [added: 3,005] | [removed: 31] | |
| Cincinnati Global Underwriting Ltd. | | | | | | [removed: 32] [added: 158] | | | | | | [removed: —] [added: 158] | | | | | | [removed: 32] [added: 158] | | |
| The Cincinnati Insurance Company [removed: (1)] | | | | | | [removed: 288] [added: $] | [added: 2,025] | | | | | [removed: —] [added: $] | [added: 5,558] | | | | | [removed: 288] [added: $] | [added: 5,558] | |
| Total | | | | | | 4,867 | | | | | | 4,703 | | | | | | 4,703 | | |
| Total | | | | | | 203 | | | | | | 200 | | | | | | 200 | | |
| Total | | | | | | 1,227 | | | | | | 1,224 | | | | | | 1,224 | | |
| Total | | | | | | 8,039 | | | | | | 7,639 | | | | | | 7,639 | | |
| Cincinnati Financial Corporation | | | | | | 1,642 | | | | | | 4,542 | | | | | | 4,542 | | |
| Total | | | | | | 3,869 | | | | | | 10,641 | | | | | | 10,641 | | |
| Total | | | | | | 413 | | | | | | 348 | | | | | | 348 | | |
| Total investments | | | | | | $ | 19,220 | | | | | — | | | | | | $ | 25,357 | |
| | | | | | | 2023 | | | | | | 2022 | | |
| Total assets | | | | | | $ | 13,733 | | | | | $ | 12,027 | |
| Retained earnings | | | | | | 13,084 | | | | | | 11,711 | | |
| Increase in equity of subsidiaries | | | | | | 1,299 | | | | | | 112 | | | | | | 2,106 | | |
| Net Income (Loss) | | | | | | $ | 1,843 | | | | | $ | (487) | | | | | $ | 2,968 | |
| Comprehensive Income (Loss) | | | | | | $ | 2,022 | | | | | $ | (1,398) | | | | | $ | 2,930 | |
| Net income | | | | | | $ | 1,843 | | | | | $ | (487) | | | | | $ | 2,968 | |
| Increase in equity of subsidiaries | | | | | | (1,299) | | | | | | (112) | | | | | | (2,106) | | |
| Total | | | | | | $ | 1,093 | | | | | $ | 1,013 | | | | | $ | 916 | |
| Total (1) | | | | | | $ | 12,069 | | | | | $ | 11,374 | | | | | $ | 10,727 | |
| Life insurance | | | | | | 313 | | | | | | 301 | | | | | | 294 | | |
| Total | | | | | | $ | 7,958 | | | | | $ | 7,225 | | | | | $ | 6,478 | |
| Total | | | | | | $ | 5,274 | | | | | $ | 5,019 | | | | | $ | 3,909 | |
| Total (3) | | | | | | $ | 1,450 | | | | | $ | 1,330 | | | | | $ | 1,176 | |
| Total (3) | | | | | | $ | 934 | | | | | $ | 832 | | | | | $ | 770 | |
| Life insurance | | | | | | 394 | | | | | | 379 | | | | | | 370 | | |
| Total | | | | | | $ | 7,801 | | | | | $ | 7,056 | | | | | $ | 6,366 | |
| Life insurance | | | | | | 313 | | | | | | 301 | | | | | | 294 | | |
| Total | | | | | | $ | 7,958 | | | | | $ | 7,225 | | | | | $ | 6,478 | |
| 10.34 | | | [Fifth Amendment of the Amended and Restated Credit Agreement by and among Cincinnati Financial Corporation, CFC Investment Company, PNC Bank, N.A., as Administrative Agent, PNC Capital Markets, LLC, as Sole Bookrunner and Joint Lead Arranger, Fifth Third Bank, N.A. as Joint Lead Arranger and Syndication Agent, The Huntington National Bank and U.S. Bank, N.A. as Documentation Agents, dated March 23, 2023 (incorporated by reference to Exhibit 10.1 filed with the company’s Current Report on Form 8-K dated March 23, 2023)](https://www.sec.gov/Archives/edgar/data/20286/000002028623000025/exhibit101-5thamendmenta.htm) | | |
| 19 | | | [Cincinnati Financial Corporation Securities Trading Policy And Addendum to Securities Trading Policy For Pre-Clearance And Blackout Procedures](https://www.sec.gov/Archives/edgar/data/20286/000002028624000014/exhibit1902-26x24.htm) | | |
| 97 | | | [Cincinnati Financial Corporation Policy For The Recovery of Erroneously Awarded Compensation](https://www.sec.gov/Archives/edgar/data/20286/000002028624000014/exhibit9702-26x24.htm) | | |
| /S/ Stephen M. Spray | | | President and Director | | | February 26, 2024 | | |
| Stephen M. Spray | | | | | | | | |
| /S/ Chengsheng Peter Wu | | | Director | | | February 26, 2024 | | |
| Chengsheng Peter Wu | | | | | | | | |
| Total | | | | | | 4,901 | | | | | | 4,622 | | | | | | 4,622 | | |
| Total | | | | | | 196 | | | | | | 191 | | | | | | 191 | | |
| Total | | | | | | 186 | | | | | | 183 | | | | | | 183 | | |
| Total | | | | | | 7,662 | | | | | | 7,103 | | | | | | 7,103 | | |
| Total | | | | | | 3,851 | | | | | | 9,454 | | | | | | 9,454 | | |
| The Cincinnati Insurance Company (1) | | | | | | 38 | | | | | | — | | | | | | 38 | | |
| Total investments | | | | | | $ | 17,725 | | | | | — | | | | | | $ | 22,425 | |
| Total assets | | | | | | $ | 11,996 | | | | | $ | 14,754 | |
| Retained earnings | | | | | | 11,702 | | | | | | 12,625 | | |
| Increase in equity of subsidiaries | | | | | | 113 | | | | | | 2,084 | | | | | | 763 | | |
| Net Income (Loss) | | | | | | $ | (486) | | | | | $ | 2,946 | | | | | $ | 1,216 | |
| Comprehensive Income (Loss) | | | | | | $ | (1,770) | | | | | $ | 2,825 | | | | | $ | 1,537 | |
| Net income | | | | | | $ | (486) | | | | | $ | 2,946 | | | | | $ | 1,216 | |
| Increase in equity of subsidiaries | | | | | | (113) | | | | | | (2,084) | | | | | | (763) | | |
| Total | | | | | | $ | 1,014 | | | | | $ | 905 | | | | | $ | 805 | |
| Total (1) | | | | | | $ | 11,418 | | | | | $ | 10,266 | | | | | $ | 9,615 | |
| Total | | | | | | $ | 7,219 | | | | | $ | 6,482 | | | | | $ | 5,980 | |
| Total | | | | | | $ | 5,012 | | | | | $ | 3,936 | | | | | $ | 4,134 | |
| Total (3) | | | | | | $ | 1,347 | | | | | $ | 1,197 | | | | | $ | 1,106 | |
| Total (3) | | | | | | $ | 815 | | | | | $ | 754 | | | | | $ | 723 | |
| Life insurance | | | | | | 373 | | | | | | 374 | | | | | | 362 | | |
| Total | | | | | | $ | 7,050 | | | | | $ | 6,370 | | | | | $ | 5,985 | |
| Total | | | | | | $ | 561 | | | | | $ | 443 | | | | | $ | 285 | |
| Life insurance in force | | | | | | $ | 80,482 | | | | | $ | 77,493 | | | | | $ | 73,475 | |
| Life insurance | | | | | | 295 | | | | | | 298 | | | | | | 289 | | |
| Total | | | | | | $ | 7,219 | | | | | $ | 6,482 | | | | | $ | 5,980 | |
| Cumulative effect of change in accounting for credit losses as of January 1, 2020, pretax | | | | | | — | | | | | | — | | | | | | 3 | | |
| | | | | | | 2022 | | | | | | 2021 | | | | | | 2020 | | |
| 10.30 | | | [Amended and Restated Cincinnati Financial Corporation Top Hat Savings Plan dated January 1, 2018 (incorporated by reference to Exhibit 10.31 filed with the company's Form 10-K dated February 23, 2018)](http://www.sec.gov/Archives/edgar/data/20286/000002028618000012/exhibit103102-23x18.htm) | | |
| 10.31 | | | [Cincinnati Financial Corporation Executive Deferred Compensation Agreement by and between the Cincinnati Financial Corporation and Michael J. Sewell, dated as of October 25, 2011 (incorporated by reference to Exhibit 10.2 filed with the company’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2011)](http://www.sec.gov/Archives/edgar/data/20286/000114420411059805/v237330_ex10-2.htm) | | |
An excerpt. Shown here: 40 of 307 rewritten, all 34 added and all 30 removed. The counts are complete. For every sentence, read Item 16. Form 10-K Summary in the FY2023 filing and the FY2022 filing.
Page headers and footers: 17 lines differ, not counted above
Lines that repeat across the filing's pages, such as a footer with the company, form, year and page number. A change here is a change in the page, not in what was disclosed.
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 180][added: 187]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 181][added: 188]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 182][added: 189]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 183][added: 190]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 184][added: 191]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 185][added: 192]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 186][added: 193]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 187][added: 194]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 188][added: 195]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 189][added: 196]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 190][added: 197]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 191][added: 198]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 192][added: 199]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 193][added: 200]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 194][added: 201]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 195][added: 202]
Cincinnati Financial Corporation - [removed: 2022] [added: 2023] 10-K - Page [removed: 196][added: 203]