 filings.tools
Cooper Companies 10-K 2013-10-31
Filed 2013-12-20. 21 sections, 369K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 coo_20131031-10k.htm 10-K
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 10-K
ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF
THE SECURITIES EXCHANGE ACT OF 1934
FOR THE FISCAL YEAR ENDED OCTOBER 31, 2013
COMMISSION FILE NO. 1-8597
THE COOPER COMPANIES, INC.
(Exact name of registrant as specified in its charter)
| Delaware | 94-2657368 |
| (State or other jurisdiction of incorporation) | (I.R.S. Employer Identification No.) |
| 6140 Stoneridge Mall Road, Suite 590 Pleasanton, California | 94588 |
| (Address of principal executive offices) | (Zip Code) |
(925) 460-3600
(Registrant’s telephone number, including area code)
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Name of each exchange on which registered | |
| Common Stock, $.10 par value, and associated rights | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act:
None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes x No ¨
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ¨ No x
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months, and (2) has been subject to such filing requirements for the past 90 days. Yes x No ¨
Indicate by check mark whether the registrant has submitted electronically and posted on its corporate Web site, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files). Yes x No ¨
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K is not contained herein, and will not be contained, to the best of registrant's knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. x
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer or a smaller reporting company. See definitions of “large accelerated filer,” “accelerated filer” and “smaller reporting company” in Rule 12b-2 of the Exchange Act (check one).
Large accelerated filer x Accelerated filer ¨ Non-accelerated filer ¨ Smaller reporting company ¨
(Do not check if a smaller reporting company)
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes ¨ No x
On November 30, 2013, there were 47,655,018 shares of the registrant's common stock held by non-affiliates with aggregate market value of $5.2 billion on April 30, 2013, the last day of the registrant's most recently completed fiscal second quarter.
Number of shares outstanding of the registrant's common stock, as of November 30, 2013: 48,000,571
Documents Incorporated by Reference:
| Document | Part of Form 10-K | |
| Portions of the Proxy Statement for the Annual Meeting of Stockholders scheduled to be held in March 2014 | Part III |
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Annual Report on Form 10-K
for the Fiscal Year Ended October 31, 2013
Table of Contents
| PART I | Page | |
| Item 1. | Business | 6 |
| Item 1A. | Risk Factors | 18 |
| Item 1B. | Unresolved Staff Comments | 32 |
| Item 2. | Properties | 33 |
| Item 3. | Legal Proceedings | 35 |
| Item 4. | Submission of Matters to a Vote of Security Holders | 36 |
| PART II | ||
| Item 5. | Market for Registrant's Common Equity and Related Stockholder Matters | 37 |
| Item 6. | Selected Financial Data | 41 |
| Item 7. | Management's Discussion and Analysis of Financial Condition and Results of Operations | 42 |
| Item 7A. | Quantitative and Qualitative Disclosure about Market Risk | 61 |
| Item 8. | Financial Statements and Supplementary Data | 63 |
| Item 9. | Changes In and Disagreements With Accountants on Accounting and Financial Disclosure | 103 |
| Item 9A. | Controls and Procedures | 103 |
| Item 9B. | Other Information | 104 |
| PART III | ||
| Item 10. | Directors, Executive Officers and Corporate Governance | 105 |
| Item 11. | Executive Compensation | 105 |
| Item 12. | Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters | 105 |
| Item 13. | Certain Relationships and Related Transactions, and Director Independence | 105 |
| Item 14. | Principal Accounting Fees and Services | 105 |
| PART IV | ||
| Item 15. | Exhibits and Financial Statement Schedules | 106 |
PART I
Forward-Looking Statements
This Annual Report on Form 10-K contains “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1934 and Section 21E of the Securities Exchange Act of 1934. These include statements relating to plans, prospects, goals, strategies, future actions, events or performance and other statements which are other than statements of historical fact. In addition, all statements regarding anticipated growth in our revenue, anticipated effects of any product recalls, anticipated market conditions, planned product launches and expected results of operations and integration of any acquisition are forward-looking. To identify these statements look for words like “believes,” “expects,” “may,” “will,” “should,” “could,” “seeks,” “intends,” “plans,” “estimates” or “anticipates” and similar words or phrases. Forward-looking statements necessarily depend on assumptions, data or methods that may be incorrect or imprecise and are subject to risks and uncertainties. Among the factors that could cause our actual results and future actions to differ materially from those described in forward-looking statements are:
| • | Adverse changes in global or regional general business, political and economic conditions due to the current global economic downturn, including the impact of continuing uncertainty and instability of certain European Union countries which could adversely affect our global markets. |
| • | Foreign currency exchange rate and interest rate fluctuations including the risk of further declines in the value of the yen that would decrease our revenues and earnings. |
| • | Acquisition integration delays or costs or the requirement to record significant adjustments to the preliminary fair value of assets acquired and liabilities assumed within the measurement period. |
| • | A major disruption in the operations of our manufacturing, research and development or distribution facilities, due to technological problems, natural disasters or other causes. |
| • | Disruptions in supplies of raw materials, particularly components used to manufacture our silicone hydrogel lenses. |
| • | The impact of acquisitions or divestitures on revenues, earnings or margins. |
| • | Limitations on sales following new product introductions due to poor market acceptance. |
| • | New competitors, product innovations or technologies. |
| • | Reduced sales, loss of customers and costs and expenses related to recalls. |
| • | New U.S. and foreign government laws and regulations, and changes in existing laws, regulations and enforcement guidance, which affect the medical device industry and the healthcare industry generally. |
| • | Failures to receive, or delays in receiving, U.S. or foreign regulatory approvals for products. |
| • | Failure to obtain adequate coverage and reimbursement from third party payors for our products. |
| • | Compliance costs and potential liability in connection with U.S. and foreign healthcare regulations, including product recalls, and potential losses resulting from sales of counterfeit and other infringing products. |
| • | Legal costs, insurance expenses, settlement costs and the risk of an adverse decision or settlement related to product liability, patent protection or other litigation. |
| • | Changes in tax laws or their interpretation and changes in statutory tax rates. |
| • | The requirement to provide for a significant liability or to write off, or accelerate depreciation on, a significant asset, including goodwill. |
| • | The success of the Company’s research and development activities and other start-up projects. |
| • | Dilution to earnings per share from acquisitions or issuing stock. |
| • | Changes in accounting principles or estimates. |
| • | Environmental risks. |
| • | Other events described in our Securities and Exchange Commission filings, including the “Business” and “Risk Factors” sections in this Annual Report on Form 10-K for the fiscal year ended October 31, 2013, as such Risk Factors may be updated in quarterly filings. |
We caution investors that forward-looking statements reflect our analysis only on their stated date. We disclaim any intent to update them except as required by law.
Item 1. Business.
The Cooper Companies, Inc. (Cooper, we or the Company), a Delaware corporation organized in 1980, is a global medical device company publicly traded on the NYSE Euronext (NYSE: COO). Cooper is dedicated to being A Quality of Life CompanyTM with a focus on shareholder value. Cooper operates through two business units, CooperVision, Inc. and CooperSurgical, Inc.
CooperVision is a global manufacturer providing products for contact lens wearers. CooperVision develops, manufactures and markets a broad range of monthly, two-week and single-use contact lenses, featuring advanced materials and optics. CooperVision's products are designed to solve vision challenges such as astigmatism, presbyopia and ocular dryness; with a broad collection of spherical, toric and multifocal contact lenses. CooperVision's products are primarily manufactured at its facilities located in Hampshire, United Kingdom, Juana Diaz, Puerto Rico, and Scottsville, New York. CooperVision distributes products from West Henrietta, New York, Fareham, United Kingdom, Liege, Belgium, and various smaller international distribution facilities.
CooperSurgical focuses on supplying women's health clinicians with products and treatment options to improve the delivery of healthcare to women. CooperSurgical's primary objectives include internal growth and growth through acquisitions to expand its core businesses and the introduction of advanced technology-based products to aid clinicians in the management and treatment of commonly seen conditions. CooperSurgical customers are healthcare professionals and institutions providing care to and for women. CooperSurgical products support the point of healthcare delivery in the hospital, clinicians office and fertility clinics. CooperSurgical's major manufacturing and distribution facilities are located in Trumbull, Connecticut, Malov, Denmark, Pasadena, California, Stafford, Texas, Golden, Colorado, and Berlin, Germany.
CooperVision and CooperSurgical each operate in highly competitive environments. Competition in the medical device industry involves the search for technological and therapeutic innovations. Both of Cooper's businesses compete primarily on the basis of product quality and differentiation, technological benefit, service and reliability.
COOPERVISION
CooperVision competes in the worldwide soft contact lens market and services three primary regions: the Americas, EMEA (Europe, Middle East and Africa) and Asia Pacific. The contact lens market has two major product categories:
| • | Spherical lenses including lenses that correct near- and farsightedness uncomplicated by more complex visual defects. |
| • | Toric and multifocal lenses including lenses that, in addition to correcting near- and farsightedness, address more complex visual defects such as astigmatism and presbyopia by adding optical properties of cylinder and axis, which correct for irregularities in the shape of the cornea. |
In order to achieve comfortable and healthy contact lens wear, products are sold with recommended replacement schedules, often defined as modalities, with the primary modalities being single-use, two-week and monthly.
CooperVision offers spherical, aspherical, toric, multifocal and toric multifocal lens products in most modalities. We believe that in order to compete successfully in the numerous niches of the contact lens market, companies must offer differentiated products that are priced competitively and manufactured efficiently. CooperVision believes that it is the only contact lens manufacturer to use three different manufacturing processes to produce its lenses: lathing, cast molding and FIPS™, a cost-effective combination of lathing and molding. This manufacturing flexibility allows CooperVision to compete in its markets by:
| • | Producing high, medium and low volumes of lenses made with a variety of materials for a broader range of market niches: single-use, two-week, monthly and quarterly disposable sphere and toric lenses and custom toric lenses for patients with a high degree of astigmatism. |
| • | Offering a wide range of lens parameters, leading to a higher rate of successful fitting for practitioners and better visual acuity for patients. |
Sales of contact lenses utilizing silicone hydrogel materials, a major product material in the industry, have grown significantly. Silicone hydrogel materials supply a higher level of oxygen to the cornea, as measured by the transmissibility of oxygen through a given thickness of material, or “dk/t,” than traditional hydrogel lenses. Silicone hydrogel lenses now represent a significant portion of CooperVision's contact lens sales and our Biofinity® brand is CooperVision's leading product line. Under the Biofinity brand, CooperVision has launched monthly silicone hydrogel spherical, toric and multifocal lens products over the past five years. CooperVision has also launched two-week silicone hydrogel spherical and toric lens products under our Avaira® brand. In fiscal 2013, we launched MyDayTM, our single-use spherical silicone hydrogel lens, in Europe.
In addition, CooperVision lenses compete based on providing superior comfort through the use of lens edge technology. CooperVision lenses have a round to partial round edge which we believe increases comfort. CooperVision's Proclear® line of spherical, toric and multifocal lenses are manufactured with omafilcon, a material that incorporates Phosphorylcholine (PC) Technology™ that helps enhance tissue-device compatibility. Proclear lenses are the only lenses with FDA clearance for the claim "… may provide improved comfort for contact lens wearers who experience mild discomfort or symptoms relating to dryness during lens wear." Mild discomfort relating to dryness during lens wear is a condition that often causes patients to discontinue contact lens wear.
In addition to its PC Technology™ and silicone hydrogel product offerings, CooperVision competes in the contact lens market with its traditional hydrogel products.
Contact Lens Product Sales
Spheres: Net sales of CooperVision's spherical lenses, representing 56 percent of CooperVision's net sales, grew 4 percent in fiscal 2013, as compared to fiscal 2012. Single-use spherical lens net sales, representing 21 percent of net sales, grew 1 percent.
Toric and Multifocal: Net sales of CooperVision's toric lenses, representing 31 percent of CooperVision's net sales, grew 9 percent in fiscal 2013, as compared to fiscal 2012. Multifocal lens net sales, representing 10 percent of net sales, grew 29 percent in fiscal 2013.
Proclear: Net sales of CooperVision's PC Technology products - which consist of spherical, toric and multifocal products, including Biomedics® XC and Proclear® 1 Day - grew 6 percent in fiscal 2013 as compared to fiscal 2012 and represented 25 percent of CooperVision's net sales.
Silicone Hydrogel: CooperVision's silicone hydrogel spherical, toric and multifocal lens products grew 26 percent in fiscal 2013 as compared to fiscal 2012 and represented 43 percent of CooperVision's net sales as compared to 36 percent in fiscal 2012.
CooperVision Competition
The contact lens market is highly competitive. CooperVision's three largest competitors in the worldwide market and its primary competitors in the spherical, toric and multifocal lens categories of that market are Johnson & Johnson Vision Care, Inc., CIBA Vision (owned by Novartis AG) and Bausch & Lomb Incorporated (owned by Valeant Pharmaceuticals International, Inc.).
Over the past decade, the contact lens industry has experienced a global shift toward silicone hydrogel lenses and toward single-use lenses. CooperVision's primary competitors control the majority of the silicone hydrogel segment of the market. CooperVision was late in entering the silicone hydrogel segment of the market but now has significant sales of monthly and two-week spherical, toric and multifocal silicone hydrogel offerings, and it has recently introduced a silicone hydrogel single-use spherical lens.
In the toric lens market, a similar shift toward silicone hydrogel lenses has occurred but we believe that lens manufacturers also continue to compete to provide the highest possible level of visual acuity and patient satisfaction by offering a wide range of lens parameters, superior wearing comfort and a high level of customer service, both for patients and contact lens practitioners. CooperVision competes based on its three manufacturing processes yielding wider ranges of toric lens parameters, providing wide choices for patient and practitioner and superior visual acuity, as well as by offering excellent customer service, including high standards of on-time product delivery.
CooperVision's primary competitors have greater financial resources and larger research and development budgets and sales forces. CooperVision seeks to offer a high level of customer service through its direct sales organizations around the world and through telephone sales and technical service representatives who consult with eye care professionals about the use of the Company's lens products.
CooperVision also competes with manufacturers of eyeglasses and with refractive surgical procedures that correct visual defects. CooperVision believes that its contact lenses will continue to compete favorably against eyeglasses and there are opportunities for contact lenses to gain market share, particularly in markets where the penetration of contact lenses in the vision correction market is low. CooperVision also believes that laser vision correction is not a significant threat to its sales of contact lenses.
COOPERSURGICAL
CooperSurgical offers a broad array of products used in the care and treatment of women's health. The Company participates in the women's healthcare market through offering quality products, innovative technologies and superior service to clinicians worldwide. CooperSurgical collaborates with clinicians to identify products and new technologies from disposable products to sophisticated instruments and equipment. The result is a broad portfolio of products that aid in the delivery of improved clinical outcomes that healthcare professionals use routinely in the diagnosis and treatment of a wide spectrum of women's health issues.
Since its inception in 1990, CooperSurgical has steadily grown its market presence and distribution system by developing products and acquiring products and companies that complement its business model.
Acquisition of Origio
In July 2012, CooperSurgical completed a voluntary tender offer for the outstanding shares of Origio a/s. Origio is a global in-vitro fertilization (IVF) medical device company that develops, manufactures and distributes highly specialized products that target IVF treatment with a goal to make fertility treatment safer, more efficient and convenient. Based in Malov, Denmark, Origio, with approximately 320 employees, is a leader in delivering innovative Assisted Reproductive Technology (ART) solutions that enhance the work of ART professionals to the benefit of families. With 13 subsidiaries and several distributors, Origio has a worldwide presence with a broad product portfolio for the ART market along with professional training programs.
Market for Women's Healthcare
CooperSurgical participates in the market for women's healthcare with its diversified product lines of over 600 products. CooperSurgical products are in three major categories based on the point of healthcare delivery: hospitals, obstetricians and gynecologists (ob/gyns) medical offices and fertility clinics.
Based on United States Census estimates, CooperSurgical expects patient visits to United States ob/gyns to increase over the next decade. Driving this growth is an increasing base of reproductive age women, a large and stable middle-aged population and a rapidly growing population of women over the age of 65. CooperSurgical believes that the resurgence of population growth in the reproductive age group will result in increased office visits related to birth control and childbearing. CooperSurgical expects growth in fertility treatments as more women choose to delay childbearing to the mid-thirties and beyond. Office visit activity related to menopausal problems, including abnormal bleeding, incontinence and osteoporosis, are also expected to increase slightly over the next decade. CooperSurgical believes that in the past clinicians primarily saw women only during their reproductive years. Now, with new treatment options available and a more educated population, CooperSurgical expects the relationship between the patient and clinician will continue into the middle years and later.
Another trend in the market for women's healthcare includes the migration of ob/gyn clinicians away from private practice ownership and toward aligning with group practices or employment with hospitals and health systems. CooperSurgical believes that the market factors that are driving this trend will continue in the near term.
While general medical practitioners play an important role in women's primary care, the ob/gyn specialist is the primary market for associated medical devices.
Some significant features of this market are:
| • | Patient visits are for annual checkups, cancer screening, menstrual disorders, vaginitis (inflammation of vaginal tissue), treatment of abnormal Pap smears, osteoporosis (reduction in bone mass) and the management of menopause, pregnancy and reproductive management. |
| • | Ob/gyns traditionally provide the initial evaluation for women and their partners who seek infertility assistance. Ovulatory drugs and intrauterine insemination (IUI) are common treatments of these cases along with embryo transfer procedures. |
| • | Osteoporosis and incontinence have become frequent diagnoses as the female population ages. Early identification and treatment of these conditions will both improve women's health and help reduce overall costs of treatment. |
| • | Sterilization is a frequently performed surgical procedure. |
| • | Hysterectomy, one of the most commonly performed surgical procedures, is increasingly performed using a laparoscopic approach. |
| • | The trend to move hospital-based procedures to an office or clinical setting is continuing as seen with the endometrial ablation procedure. |
CooperSurgical's Fiscal 2013 Net Sales Growth
During fiscal 2013, CooperSurgical's net sales grew 25 percent, or 3 percent excluding acquisitions, to $319.4 million from $255.9 million in fiscal 2012, representing 20 percent of Cooper's net sales in fiscal 2013 compared to 18 percent in fiscal 2012. With the acquisition of Origio in July 2012, sales of fertility products now represent 33 percent of CooperSurgical's net sales as compared to 16 percent in fiscal 2012.
CooperSurgical Competition
CooperSurgical focuses on selected segments of the women's healthcare market, supplying diagnostic products and surgical instruments and accessories. In some instances, CooperSurgical offers all of the items needed for a complete procedure. CooperSurgical believes that opportunities exist for continued market consolidation of smaller technology-driven firms that generally offer only one or two product lines. Most are privately owned or divisions of public companies including some owned by companies with greater financial resources than Cooper.
Competitive factors in these segments include technological and scientific advances, product quality, price, customer service and effective communication of product information to physicians and hospitals. CooperSurgical competes based on its sales and marketing expertise and the technological advantages of its products. CooperSurgical's strategy includes developing and acquiring new products, including those used in new medical procedures. As CooperSurgical expands its product line, it also offers training for medical professionals in the appropriate use of its products.
CooperSurgical is seeking to expand its presence in the significantly larger hospital and outpatient surgical procedure segment of the market that is at present dominated by bigger competitors such as Johnson & Johnson's Ethicon Endo-Surgery and Ethicon Women's Health and Urology companies, Boston Scientific, Gyrus ACMI and Covidien. These competitors have well established positions within the operating room
environment. CooperSurgical intends to leverage its relationship with gynecologic surgeons and focus on devices specific to gynecologic surgery to facilitate its expansion within the surgical segment of the market.
RESEARCH AND DEVELOPMENT
Cooper employs about 245 people in its research and development and manufacturing engineering departments. Most of these employees are in CooperVision. CooperVision product development and clinical research is supported by internal and external specialists in lens design, formulation science, polymer chemistry, clinical trials, microbiology and biochemistry. CooperVision's research and development activities primarily include programs to develop new contact lens designs.
CooperSurgical conducts research and development in-house and also has consulting agreements with external surgical specialists. CooperSurgical's research and development activities include the design and upgrading of surgical procedure devices, the upgrade and expansion of CooperSurgical's portfolio of assisted reproductive technology products, including Origio products, as well as products within the general obstetrics and gynecology offerings.
Cooper-sponsored research and development expenditures during fiscal 2013, 2012 and 2011 were $58.8 million, $51.7 million and $43.6 million, respectively. Research and development expenditures represented 4 percent of net sales in fiscal 2013 and 2012, and 3 percent in 2011. During fiscal 2013, CooperVision represented 79 percent and CooperSurgical represented 21 percent of the total research and development expenses. We did not participate in any customer-sponsored research and development programs during fiscal 2011 - 2013.
GOVERNMENT REGULATION
Medical Device Regulation
Our products are medical devices subject to extensive regulation by the United States Food and Drug Administration (FDA) in the United States and other regulatory bodies abroad. FDA regulations govern, among other things, medical device design and development, testing, manufacturing, labeling, storage, recordkeeping, premarket clearance or approval, advertising and promotion, and sales and distribution. Unless an exemption applies, each medical device we wish to distribute commercially in the United States will require either prior 510(k) clearance or prior premarket approval (PMA) from the FDA. A majority of the medical devices we currently market have received FDA clearance through the 510(k) process or approval through the PMA process. Because we cannot be assured that any new products we develop, or any product enhancements, will be subject to the shorter 510(k) clearance process, significant delays in the introduction of any new products or product enhancements may occur.
Device Classification
The FDA classifies medical devices into one of three classes - Class I, II or III - depending on the degree of risk associated with each medical device and the extent of control needed to ensure its safety and effectiveness. Both CooperVision and CooperSurgical develop and market medical devices under different levels of FDA regulation depending on the classification of the device. Class III devices, such as flexible and extended wear contact lenses, require extensive premarket testing and approval, while Class I and II devices require lower levels of regulation. The majority of CooperSurgical's products are Class II devices.
Class I devices are those for which safety and effectiveness can be assured by adherence to the FDA's general regulatory controls for medical devices, which include compliance with the applicable portions of the FDA's
Quality System Regulation, facility registration and product listing, reporting of adverse medical events, and appropriate, truthful and non-misleading labeling, advertising, and promotional materials (General Controls). Some Class I devices also require premarket clearance by the FDA through the 510(k) premarket notification process described below.
Class II devices are subject to the FDA's General Controls, and any other special controls as deemed necessary by the FDA to ensure the safety and effectiveness of the device. Premarket review and clearance by the FDA for Class II devices is accomplished through the 510(k) premarket notification procedure. Pursuant to the Medical Device User Fee and Modernization Act of 2002 (MDUFMA), unless a specific exemption applies, 510(k) premarket notification submissions are subject to user fees. Certain Class II devices are exempt from this premarket review process.
Class III devices are those devices which have a new intended use, or use advanced technology that is not substantially equivalent to that of a legally marketed device. The safety and effectiveness of Class III devices cannot be assured solely by the General Controls and the other requirements described above. These devices almost always require formal clinical studies to demonstrate safety and effectiveness and must be approved through the premarket approval process described below. Premarket approval applications (and supplemental premarket approval applications) are subject to significantly higher user fees under MDUFMA than are 510(k) premarket notifications.
510(k) Clearance Pathway
When we are required to obtain a 510(k) clearance for a device that we wish to market, we must submit a premarket notification to the FDA demonstrating that the device is substantially equivalent to a previously cleared 510(k) device or a device that was in commercial distribution before May 28, 1976, for which the FDA has not yet called for the submission of premarket approval applications. By regulation, the FDA is required to respond to a 510(k) premarket notification within 90 days of submission of the notification. As a practical matter, clearance can take significantly longer. If the FDA determines that the device, or its intended use, is not substantially equivalent to a previously-cleared device or use, the FDA will place the device, or the particular use of the device, into Class III.
After a device receives 510(k) clearance, any modification that could significantly affect its safety or effectiveness, or that changes its intended use, will require a new 510(k) clearance or could require premarket approval. The FDA requires each manufacturer to make this determination initially, but the FDA can review any such decision and can disagree with a manufacturer's determination. If the FDA disagrees with a manufacturer's determination that a new clearance or approval is not required for a particular modification, the FDA can require the manufacturer to cease marketing and/or recall the modified device until 510(k) clearance or premarket approval is obtained. In these circumstances, a manufacturer also may be subject to significant regulatory fines or penalties. We have made and plan to continue to make additional product enhancements and modifications to our devices that we believe do not require new 510(k) clearances.
Premarket Approval Pathway
A PMA application must be submitted if the device cannot be cleared through the 510(k) premarket notification procedures. The PMA process is much more demanding than the 510(k) premarket notification process. A PMA application must be supported by extensive data including, but not limited to, technical, preclinical, clinical trials, manufacturing and labeling to demonstrate to the FDA's satisfaction the safety and effectiveness of the device for its intended use.
After a PMA application is complete, the FDA begins an in-depth review of the submitted information. The FDA, by statute and regulation, has 180 days to review an accepted PMA application, although the review generally occurs over a significantly longer period of time, and can take up to several years. During this review period, the FDA may request additional information, including clinical data, or clarification of information already provided. Also during the review period, an advisory panel of experts from outside the FDA may be convened to review and evaluate the application and provide recommendations to the FDA as to the approvability of the device. In addition, the FDA will conduct a preapproval inspection of the manufacturing facility to ensure compliance with the Quality System Regulation (QSR). New PMA applications or PMA application supplements are required for significant modifications to the manufacturing process, labeling and design of a device that is approved through the premarket approval process. Premarket approval supplements often require submission of the same type of information as a premarket approval application, except that the supplement is limited to information needed to support any changes from the device covered by the original premarket approval application, and may not require as extensive clinical data or the convening of an advisory panel.
Clinical Trials
A clinical trial is almost always required to support a PMA application and is sometimes required for a 510(k) premarket notification. These trials generally require submission of an application for an investigational device exemption (IDE) to the FDA. The IDE application must be supported by appropriate data, such as animal and laboratory testing results, showing that the potential benefits of testing the device in humans outweighs the risks and that the testing protocol is scientifically sound. The IDE application must be approved in advance by the FDA for a specified number of patients, unless the product is deemed a non-significant risk device and eligible for more abbreviated investigational device exemption requirements. Clinical trials for a significant risk device may begin once the IDE application is approved by both the FDA and the appropriate institutional review boards at the clinical trial sites. All of Cooper's currently marketed products have been cleared by all appropriate regulatory agencies, and Cooper has no product currently being marketed under an IDE.
Continuing FDA Regulation
After a device is placed on the market, numerous regulatory requirements apply. These include: the QSR, which requires manufacturers to follow design, testing, control, documentation and other quality assurance procedures during the manufacturing process; labeling regulations, which prohibit the promotion of products for unapproved or “off-label” uses and impose other restrictions on labeling; new FDA unique device identifier legislation which requires changes to labeling and packaging; the recently enacted Physician Payments Sunshine Act requiring the reporting of certain payments to health care practitioners made after August 1, 2013; and medical device reporting regulations, which require that manufacturers report to the FDA if their device may have caused or contributed to a death or serious injury or malfunctioned in a way that would likely cause or contribute to a death or serious injury if it were to recur. The FDA has broad post-market and regulatory enforcement powers. We are subject to unannounced inspections by the FDA to determine our compliance with the QSR and other regulations.
Failure to comply with applicable regulatory requirements can result in enforcement action by the FDA, which may include any of the following sanctions: fines, injunctions and civil penalties; recall, seizure or import holds of our products; operating restrictions, suspension of production; refusing our request for 510(k) clearance or premarket approval of new products; withdrawing 510(k) clearance or premarket approvals that are already granted and criminal prosecution.
Even if regulatory approval or clearance of a medical device is granted, the FDA may impose limitations or restrictions on the uses and indications for which the device may be labeled and promoted. Medical devices may be marketed only for the uses and indications for which they are cleared or approved. FDA regulations prohibit a manufacturer from promoting a device for an unapproved or “off-label” use. Failure to comply with this prohibition on “off-label” promotion can result in enforcement action by the FDA, including, among other things, warning letters, fines, injunctions, consent decrees and civil or criminal penalties.
Foreign Regulation
Health authorities in foreign countries regulate Cooper's clinical trials and medical device sales. The regulations vary widely from country to country. Even if the FDA has approved a product, the regulatory agencies in each country must approve new products before they may be marketed there. The worldwide Medical Device regulations are increasing, with many countries becoming regulated for the first time. For example, Hong Kong and Singapore are now regulated and following the Global Harmonization Task Force model for regulating medical devices. These emerging regulated countries require the same rigorous safety data compiled in pre-clinical and clinical studies for the rest of the world. Japan has one of the most rigorous regulatory systems in the world and requires in-country clinical trials. The Japanese quality and regulatory standards remain stringent even with the more recent harmonization efforts and updated Japanese regulations. China is also updating its regulations and is requiring rigorous in-country product testing.
These regulatory procedures require a considerable investment in time and resources and usually result in a substantial delay between new product development and marketing. If the Company does not maintain compliance with regulatory standards or if problems occur after marketing, product approval may be withdrawn.
In addition to FDA regulatory requirements, the Company also maintains ISO 13485 certification and CE mark approvals for its products. A CE mark is an international symbol of adherence to certain standards and compliance with applicable European medical device requirements. These quality programs and approvals are required by the European Medical Device Directive and must be maintained for all products intended to be sold in the European market. The ISO 13485 Quality Measurement System registration is now also required for registration of products in Asia Pacific and Latin American countries. In order to maintain these quality benchmarks, the Company is subjected to rigorous biannual reassessment audits of its quality systems and procedures.
Other Health Care Regulation
We may be subject to various federal, state and foreign laws pertaining to healthcare fraud and abuse, including anti-kickback laws and physician self-referral laws, and laws pertaining to healthcare privacy and security. Violations of these laws are punishable by criminal and civil sanctions, including, in some instances, exclusion from participation in federal and state healthcare programs, including Medicare, Medicaid, Veterans Administration health programs and TRICARE. Similarly if the physicians or other providers or entities with whom we do business are found to be noncompliant with applicable laws, they may be subject to sanctions, which could indirectly have a negative impact on our business, financial conditions and results of operations. While we believe that our operations are in material compliance with such laws, as applicable to us, because of the complex and far-reaching nature of these laws, there can be no assurance that we would not be required to alter one or more of our practices to be in compliance with these laws.
RAW MATERIALS
CooperVision's raw materials primarily consist of various chemicals and packaging materials and are generally available from more than one source. However, CooperVision relies on sole suppliers for certain raw materials used to make our silicone hydrogel contact lens products. If current raw material suppliers fail to supply sufficient materials on a timely basis or at all for any reason, we may suffer a disruption in the supply of our silicone hydrogel contact lens products.
Raw materials used by CooperSurgical are generally available from more than one source. However, because some products require specialized manufacturing procedures, we could experience inventory shortages if we were required to use an alternative supplier on short notice.
MARKETING AND DISTRIBUTION
CooperVision markets its products in the United States through its field sales representatives, who call on optometrists, ophthalmologists, opticians, optical chains and distributors. CooperVision augments its United States sales and marketing efforts with e-commerce, telemarketing, social media and advertising in professional journals. In the EMEA and Asia Pacific regions, CooperVision primarily markets its products through its field sales representatives. In other countries, CooperVision uses distributors and has given some of them the exclusive right to market its products within specific geographic areas.
CooperSurgical's products are marketed by a network of dedicated field sales representatives, independent agents and distributors. In the United States, CooperSurgical augments its sales and marketing activities by participating in national and regional industry tradeshows, professional educational programs and internet promotions including e‑commerce, social media and collaborative efforts with professional organizations, telemarketing, direct mail and advertising in professional journals. Origio products are marketed globally through its field sales representatives and distributors.
PATENTS, TRADEMARKS AND LICENSING AGREEMENTS
Cooper owns or licenses a variety of domestic and foreign patents, which, in total, are material to its overall business. The names of certain of Cooper's products are protected by trademark registrations in the United States Patent and Trademark Office and, in some cases, also in foreign trademark offices. Applications are pending for additional trademark and patent registrations. Cooper intends to protect its intellectual property rights aggressively.
No individual patent or license is material to the Company or either of its principal business units other than our License Agreement effective as of November 19, 2007, between CooperVision and CIBA Vision AG and CIBA Vision Corporation. This license relates to patents covering CooperVision's silicone hydrogel contact lens products. The Company’s royalty obligations under this License Agreement extend until the expiration of the applicable patent rights, which the Company believes will occur in September 2014 in the United States and in March 2016 outside of the United States.
In addition to trademarks and patent licenses, the Company owns certain trade secrets, copyrights, know-how and other intellectual property.
DEPENDENCE ON CUSTOMERS
Neither of our business units depends to any material extent on any one customer or any one affiliated group of customers.
GOVERNMENT CONTRACTS
Neither of our business units is materially subject to profit renegotiation or termination of contracts or subcontracts at the election of the United States government.
BACKLOG
Backlog is not a material factor in either of Cooper's business units.
SEASONALITY
CooperVision's contact lens sales in its fiscal first quarter, which runs from November 1 through January 31, are typically lower than subsequent quarters, as patient traffic to practitioners' offices is relatively light during the holiday season.
COMPLIANCE WITH ENVIRONMENTAL LAWS
Federal, state and local provisions that regulate the discharge of materials into the environment, or relate to the protection of the environment, do not currently materially affect Cooper's capital expenditures, earnings or competitive position.
FINANCIAL INFORMATION ABOUT BUSINESS SEGMENTS, GEOGRAPHIC AREAS, FOREIGN OPERATIONS AND EXPORT SALES
The information required by this item is included in the "Business Segment Information" of our notes to consolidated financial statements and "Risk Factors" as part of this Annual Report on Form 10-K for the fiscal year ended October 31, 2013.
EMPLOYEES
On October 31, 2013, the Company had about 8,000 employees. The Company believes that its relations with its employees are good.
NEW YORK STOCK EXCHANGE CERTIFICATION
We submitted our 2013 annual Section 12(a) CEO certification with the New York Stock Exchange. The certification was not qualified in any respect. Additionally, we filed with the Securities and Exchange Commission as exhibits to this Annual Report on Form 10-K for the year ended October 31, 2013, the CEO and CFO certifications required under Section 302 of the Sarbanes-Oxley Act of 2002.
AVAILABLE INFORMATION
The Cooper Companies, Inc. Internet address is http://www.coopercos.com. The information on the Company's Web site is not part of this or any other report we file with, or furnish to, the SEC. Our annual reports on Form 10-K, quarterly reports on Form 10-Q and current reports on Form 8-K, along with all other reports and amendments filed with or furnished to the Securities and Exchange Commission (SEC), are publicly available free of charge on our Web site as soon as reasonably practicable. The public may read and copy these materials at the SEC's Public Reference Room at 100 F Street, NE, Washington, DC 20549. The public may obtain information on the operation of the Public Reference Room by calling the SEC at 1-800-SEC-0330. The SEC maintains a Web site that contains such reports, proxy and information statements and other information whose Internet address is http://www.sec.gov. The Company's Corporate Governance Principles, Ethics and Business Conduct Policy and charters of each standing committee of the Board of Directors are also posted on the Company's Web site.
Item 1A. Risk Factors.
Our business faces significant risks. These risks include those described below and may include additional risks and uncertainties not presently known to us or that we currently deem immaterial. Our business, financial condition and results of operations could be materially adversely affected by any of these risks, and the trading prices of our common stock could decline by virtue of these risks. These risks should be read in conjunction with the other information in this report.
Risks Relating to Our Business
We operate in the highly competitive healthcare industry and there can be no assurance that we will be able to compete successfully.
Each of our businesses operates within a highly competitive environment. In our soft contact lens business, CooperVision faces intense competition from competitors' products, in particular silicone hydrogel contact lenses, and may face increasing competition as other new products enter the market. Our major competitors in the contact lens business, Johnson & Johnson Vision Care, Inc., CIBA Vision (owned by Novartis AG) and Bausch & Lomb, Inc. (owned by Valeant Pharmaceuticals International, Inc.), have substantially greater financial resources, larger research and development budgets, larger sales forces, greater market penetration and/or larger manufacturing volumes than CooperVision. They offer competitive products and differentiated materials, plus a variety of other eye care products including lens care products and ophthalmic pharmaceuticals, which may give them a competitive advantage in marketing their lenses. The market for contact lenses is intensely competitive and is characterized by declining sales volumes for older product lines and growing demand for silicone hydrogel based products. Our ability to respond to these competitive pressures will depend on our ability to decrease our costs and maintain gross margins and operating results and to introduce new products successfully, on a timely basis in the Americas, EMEA and Asia Pacific, and to achieve manufacturing efficiencies and sufficient manufacturing capacity and capabilities for such products. Any significant decrease in our costs per lens will depend, in part, on our ability to increase sales volume and production capabilities. Our failure to respond to competitive pressures in a timely manner could have a material adverse effect on our business, financial condition and results of operations.
To a lesser extent, CooperVision also competes with manufacturers of eyeglasses and providers of other forms of vision correction including ophthalmic surgery.
There can be no assurance that we will not encounter increased competition in the future, or that our competitors' newer contact lens products will not successfully erode CooperVision's contact lens business, which could have a material adverse effect on our business, financial condition and results of operations.
In the women's healthcare market, competitive factors include technological and scientific advances, product quality, price and effective communication of product information to physicians and hospitals. CooperSurgical competes with a number of manufacturers in each of its niche areas, some of which have substantially greater financial and personnel resources and sell a much broader range of products, which may give them an advantage in marketing competitive products.
Acquisitions that we have made and may make in the future involve numerous risks.
We have a history of acquiring businesses and products that have significantly contributed to our growth in recent years. As part of our growth strategy, particularly at CooperSurgical, we intend to continue to consider acquiring complementary technologies, products and businesses. Future acquisitions could result in
potentially dilutive issuances of equity securities, the incurrence of debt and contingent liabilities and an increase in amortization and/or write-offs of goodwill and other intangible assets, which could have a material adverse effect upon our business, financial condition and results of operations. In fiscal 2012, CooperSurgical completed the acquisition of Origio a/s. This acquisition added significant operations to CooperSurgical and greatly expanded its international business. The Origio acquisition has correspondingly added risks to CooperSurgical. Risks we could face with respect to acquisitions, including the Origio acquisition, include:
| • | difficulties in, and expenses related to, the integration of the operations, technologies, products and personnel of the acquired company and establishment of appropriate accounting controls and reporting procedures and other regulatory compliance procedures; |
| • | risks of entering markets in which we have no or limited prior experience; |
| • | potential loss of employees; |
| • | an inability to identify and consummate future acquisitions on favorable terms or at all; |
| • | diversion of management's attention away from other business concerns; |
| • | expenses of any undisclosed or potential liabilities of the acquired company; |
| • | expenses, including restructuring expenses, to shut-down our own locations or terminate our employees; |
| • | a dilution of earnings per share; and |
| • | risks inherent in accounting allocations. |
Product innovations are important in the industry in which we operate, and we face the risk of product obsolescence if we are unable to develop new products or gain regulatory approvals or if our competitors introduce new products.
Product innovations are important in the contact lens market in which CooperVision competes and in the areas of the healthcare industry in which CooperSurgical competes. CooperSurgical does not allocate substantial resources to new product development, but rather it has historically purchased, leveraged or licensed the technology developments of others. CooperVision has been investing in new product development since 2005, including the development of silicone hydrogel-based contact lenses. Although CooperVision focuses on products that will be marketable immediately or in the short to medium term rather than on funding longer-term, higher risk research and development projects, time commitments, the cost of obtaining necessary regulatory approval and other costs related to product innovations can be substantial. There can be no assurance that we will successfully obtain necessary regulatory approvals or clearances for our new products or that our new products will successfully compete in the marketplace and, as a result, justify the expense involved in their development and regulatory approval. In addition, our competitors may have developed or may in the future develop new products or technologies, such as contact lenses with anti-microbial or anti-allergenic features, that could lead to the obsolescence of one or more of our products. Competitors may also introduce new uses for contact lenses, such as for drug delivery or the control of myopia. Failure to develop new product offerings and technological changes and to offer products that provide performance that is at least comparable to competing products could have a material adverse effect on our business, financial condition, or results of operations.
If our products are not accepted by the market, we will not be able to sustain or expand our business.
Certain of our proposed products have not yet been clinically tested or commercially introduced, and we cannot assure that any of them, assuming they receive necessary regulatory approvals, will achieve market acceptance or generate operating profits. In addition, we have been slower to introduce new silicone hydrogel contact lens products than our competitors which put these products at a competitive disadvantage. The
development of a market for our products may be influenced by many factors, some of which are out of our control, including:
| • | acceptance of our products by eye care and women's healthcare practitioners; |
| • | the cost competitiveness of our products; |
| • | consumer reluctance to try and use a new product; |
| • | regulatory requirements; |
| • | adequate coverage and reimbursement by third party payors; |
| • | the earlier release of competitive products, such as silicone hydrogel products, into the market by our competitors; and |
| • | the emergence of newer and more competitive products. |
New medical and technological developments may reduce the need for our products.
Technological developments in the eye care and women's healthcare industries, such as new surgical procedures or medical devices, may limit demand for our products. Corneal refractive surgical procedures such as Lasik surgery and the development of new pharmaceutical products may decrease the demand for our optical products. If these new advances provide a practical alternative to traditional vision correction, the demand for contact lenses and eyeglasses may materially decrease. We cannot assure that medical advances and technological developments will not have a material adverse effect on our businesses.
Our substantial and expanding international operations are subject to uncertainties which could affect our operating results.
A significant portion of our current operations for CooperVision and our newly acquired Origio business are conducted and located outside the United States, and our growth strategy involves expanding our existing foreign operations and entering into new foreign jurisdictions. We have significant manufacturing and distribution sites in North America and Europe. Approximately two-thirds of our net sales for CooperVision for the fiscal years ended October 31, 2013 and 2012, respectively, were derived from the sale of products outside the United States. We believe that sales outside the United States will continue to account for a material portion of our total net sales for the foreseeable future. International operations and business expansion plans are subject to numerous additional risks, including:
| • | we may have difficulty enforcing intellectual property rights in some foreign countries; |
| • | we may have difficulty gaining market share in countries such as Japan because of regulatory restrictions and customer preferences; |
| • | we may find it difficult to grow in emerging markets such as China, India and other developing nations due to, among other things, customer acceptance, undeveloped distribution channels, regulatory restrictions and business knowledge of these new markets; |
| • | tax rates in some foreign countries may exceed those of the United States, and foreign earnings may be subject to withholding requirements or the imposition of tariffs, exchange controls or other restrictions; |
| • | we may find it difficult to comply with a variety of United States and foreign compliance and regulatory requirements such as the Foreign Corrupt Practices Act, the Dodd-Frank Act and the U.K. Bribery Act; |
| • | we may find it difficult to manage a large organization spread throughout various countries; |
| • | fluctuations in currency exchange rates could adversely affect our results; |
| • | foreign customers may have longer payment cycles than customers in the United States; |
| • | failure to comply with United States Department of Commerce export controls may result in fines and/or penalties; |
| • | general economic and political conditions in the countries where we operate may have an adverse effect on our operations in those countries or not be favorable to our growth strategy; |
| • | foreign governments may adopt regulations or take other actions that would have a direct or indirect adverse impact on our business and market opportunities; and |
| • | we may have difficulty enforcing agreements and collecting receivables through some foreign legal systems. |
As we continue to expand our business globally, our success will depend, in large part, on our ability to anticipate and effectively manage these and other risks associated with our international operations. However, any of these factors could adversely affect our international operations and, consequently, our operating results.
Current market conditions and recessionary pressures in one or more of our markets could impact our ability to grow our business.
In the United States and globally, market and economic conditions have been unprecedented over the past few years and challenging with tighter credit conditions and slower economic growth. The U.S. economy has experienced a recession and faces continued concerns about the systemic impacts of adverse economic conditions such as the growing U.S. deficit, high energy costs, geopolitical issues, the availability and cost of credit, and an unstable real estate market. Foreign countries, in particular the Euro zone, are affected by similar systemic impacts. As a result, we continue to have lower than historical expectations for market growth in fiscal 2014.
Continued turbulence in the United States and international markets and economic conditions may adversely affect our liquidity and financial condition, and the liquidity and financial condition of our customers. If these market conditions continue, they may limit our ability, and the ability of our customers, to replace maturing liabilities and to access the capital markets to meet liquidity needs, which could have a material adverse effect on our financial condition and results of operations.
We face risks associated with disruption of manufacturing and distribution operations and failure to develop new manufacturing processes that could adversely affect our profitability or competitive position.
We manufacture a significant portion of the medical device products we sell. Any prolonged disruption in the operations of our existing manufacturing or distribution facilities, whether due to technical or labor difficulties, destruction of or damage to any facility (as a result of natural disaster, use and storage of hazardous materials or other events), enforcement action by the FDA or other regulatory body if we are found to be in non-compliance with current Good Manufacturing Practices (cGMP) or other reasons, could have a material adverse effect on our business, financial condition and results of operations. In addition, materials such as silicone hydrogel require improvements to our manufacturing processes to make them cost effective. While we have improved our manufacturing capabilities for our silicone hydrogel products, our failure to continue to develop improvements to our manufacturing processes and reduce our cost of goods could significantly impact our ability to compete.
CooperVision manufactures molded contact lenses, which represent the majority of our contact lens revenues, primarily at our facilities in the United Kingdom and Puerto Rico. CooperSurgical manufactures the majority of its products in Trumbull, Connecticut, Stafford, Texas, Malov, Denmark, and Pasadena, California. We manufacture certain products at only one manufacturing site for certain markets, and certain of our products are approved for manufacturing only at one site. Before we can use a second manufacturing site, we must obtain the approval of regulatory authorities, and because this process is expensive, we generally have not sought approvals needed to manufacture at an additional site. If there were any prolonged disruption in the operations of the approved facility, it could take a significant amount of time to validate a second site and replace lost product, which could result in lost customers and thereby reduce sales, profitability and market share.
CooperVision distributes products out of West Henrietta, New York, Hampshire, United Kingdom, Liege, Belgium and various smaller international distribution facilities. CooperSurgical's products are primarily distributed out of its facilities in Trumbull, Connecticut, and Malov, Denmark. Any prolonged disruption in the operations of our existing distribution facilities, whether due to technical or labor difficulties, destruction of or damage to any facility (as a result of natural disaster, use and storage of hazardous materials or other events) or other reasons, could have a material adverse effect on our business, financial condition and results of operations.
If our manufacturing operations fail to comply with applicable regulations, our manufacturing could be delayed or disrupted, our products could be subject to recall, and sales and profitability could suffer.
Our manufacturing operations and processes are required to comply with numerous federal, state and foreign regulatory requirements, including the FDA's cGMP for medical devices, known as the QSR regulations, which govern the procedures related to the design, testing, production processes, controls, quality assurance, labeling, packaging, storage, importing, exporting and shipping of our products. We also are subject to state requirements and licenses applicable to manufacturers of medical devices. In addition, we must engage in extensive recordkeeping and reporting and must make available our manufacturing facilities and records for periodic unscheduled inspections by governmental agencies, including the FDA, state authorities and comparable agencies in other countries. Failure to pass a cGMP, QSR or similar foreign inspection or to comply with these and other applicable regulatory requirements could result in disruption of our operations and manufacturing delays in addition to, among other things, significant fines, suspension of approvals, seizures, recalls or import holds of products, operating restrictions and criminal prosecutions. As a result, any failure to comply with applicable requirements could adversely affect our product sales and profitability.
We rely on independent suppliers for raw materials and we could experience inventory shortages if we were required to use an alternative supplier on short notice.
We rely on independent suppliers for key raw materials, consisting primarily of various chemicals and packaging materials. Raw materials used in our operations are generally available from more than one source. However, because some products require specialized manufacturing procedures, we could experience inventory shortages if we were required to use an alternative manufacturer on short notice. For example, some of the primary material used to make our silicone hydrogel contact lens products, including MyDay, Biofinity and Avaira, are supplied by a sole supplier. We may suffer a disruption in the supply of our silicone hydrogel contact lens products if our suppliers, particularly those which are the sole source of any necessary material, fail to supply sufficient material on a timely basis or at all for any reason and/or we need to switch to an alternative supplier. A disruption in the supply of raw materials could disrupt production of our silicone hydrogel contact lens products, thereby adversely impacting our ability to market and sell such products and our ability to compete in this important segment of the contact lens market.
If we fail to protect our intellectual property adequately, our business could suffer.
We consider our intellectual property rights, including patents, trademarks and licensing agreements, to be an integral component of our business. We attempt to protect our intellectual property rights through a combination of patent, trademark, copyright and trade secret laws, as well as licensing agreements and third-party nondisclosure and assignment agreements. Our failure to obtain or maintain adequate protection of our intellectual property rights for any reason could have a material adverse effect on our business, financial condition and results of operations.
We also may seek to enforce our intellectual property rights on others through litigation. Our claims, even if meritorious, may be found invalid or inapplicable to a party we believe infringes or has misappropriated our intellectual property rights. In addition, litigation can:
| • | be expensive and time consuming to prosecute or defend; |
| • | result in a finding that we do not have certain intellectual property rights or that such rights lack sufficient scope or strength; |
| • | divert management's attention and resources; or |
| • | require us to license our intellectual property. |
We have applied for patent protection in the United States and other foreign jurisdictions relating to certain existing and proposed processes and products. We cannot assure that any of our patent applications will be approved. Patent applications in the United States and other foreign jurisdictions are maintained in secrecy for a period of time, which may last until patents are issued, and since publication of discoveries in the scientific or patent literature tends to lag behind actual discoveries by several months, we cannot be certain that we will be the first creator of inventions covered by any patent application we make or the first to file patent applications on such inventions. The patents we own could be challenged, invalidated or circumvented by others and may not be of sufficient scope or strength to provide us with any meaningful protection or commercial advantage. We also cannot assure that we will have adequate resources to enforce our patents.
Both CooperVision and CooperSurgical also rely on unpatented proprietary technology or technology where patents will expire in less than a few years. It is possible that others will independently develop the same or similar technology or otherwise obtain access to our unpatented technology. To protect our trade secrets and other proprietary information, we require employees, consultants, advisors and collaborators to enter into confidentiality agreements and assignment agreements, which generally provide that inventions conceived by the party in the course of rendering services to us will be our exclusive property. However, we cannot assure that these confidentiality agreements will provide meaningful protection for our trade secrets, know-how or other proprietary information in the event of any unauthorized use, misappropriation or disclosure of such trade secrets, know-how or other proprietary information. Enforcing a claim that a party illegally obtained and is using our trade secrets is difficult, expensive and time consuming and the outcome is unpredictable.
We rely on trademarks to establish a market identity for our products. To maintain the value of our trademarks, we might have to file lawsuits against third parties to prevent them from using trademarks confusingly similar to or dilutive of our registered or unregistered trademarks. We also might not obtain registrations for our pending or future trademark applications, and might have to defend our registered trademark and pending applications from challenge by third parties. Enforcing or defending our registered and unregistered trademarks might result in significant litigation costs and damages, including the inability to continue using certain trademarks.
The laws of foreign countries in which we do business or contemplate doing business in the future may not recognize intellectual property rights or protect them to the same extent as do the laws of the United States. Adverse determinations in a judicial or administrative proceeding could prevent us from manufacturing and selling our products or prevent us from stopping others from manufacturing and selling competing products, and thereby have a material adverse affect on our business, financial condition and results of operations.
Our products or processes could be subject to claims of infringement of the intellectual property of others.
Our competitors in both the United States and foreign countries, many of which have substantially greater resources and have made substantial investments in competing technologies, may have applied for or obtained, or may in the future apply for and obtain, patents that will prevent, limit or otherwise interfere with our ability to make and sell our existing and planned products. In the contact lens industry, CooperVision and its competitors all hold patents covering contact lens designs, business methods, processes and materials. Claims that our products, business methods or processes infringe upon the proprietary rights of others often are not asserted until after commencement of commercial sales of products incorporating our technology.
Significant litigation regarding intellectual property rights exists in our industries. For example, CooperVision has faced significant patent litigation over its silicone hydrogel contact lens products. Third parties have made, and may make in the future, claims of infringement against us or our contract manufacturers in connection with the use of our technology. Any claims, even those without merit, could:
| • | be expensive and time consuming to defend; |
| • | cause us to cease making, licensing or using products that incorporate the challenged intellectual property; |
| • | require us to redesign or reengineer our products, if feasible; |
| • | divert management's attention and resources; or |
| • | require us to enter into royalty or licensing agreements in order to obtain the right to use a necessary product, component or process. |
We cannot be certain of the outcome of any litigation. Any royalty or licensing agreement, if required, may not be available to us on acceptable terms or at all. Our failure to obtain the necessary licenses or other rights could prevent the sale, manufacture, or distribution of some of our products and, therefore, could have a material adverse effect on our business.
A successful claim of infringement against us or our contract manufacturers in connection with the use of our technology, in particular if we are unable to manufacture or sell any of our planned products in any major market, could adversely affect our business.
We could experience losses from product liability claims, including such claims and other losses resulting from sales of counterfeit and other infringing products.
We face an inherent risk of exposure to product liability claims in the event that the use of our products results in personal injury. We also face the risk that defects in the design or manufacture of our products or sales of counterfeit or other infringing products might necessitate a product recall and other actions by manufacturers, distributors or retailers in order to safeguard the health of consumers and protect the integrity of the subject brand. Consumers may halt or delay purchases of a product that is the subject of a claim or recall, or has been counterfeited. We handle some risk with third-party carrier policies that are subject to deductibles and limitations. There can be no assurance that we will not experience material losses due to
product liability claims or recalls, or a decline in sales resulting from sales of counterfeit or other infringing products, in the future.
We face risks related to environmental matters.
Our facilities are subject to a broad range of United States federal, state, local and foreign environmental laws and requirements, including those governing discharges to the air and water, the handling or disposal of solid and hazardous substances and wastes, remediation of contamination associated with the release of hazardous substances at our facilities and offsite disposal locations and occupational safety and health. We have made, and will continue to make, expenditures to comply with such laws and requirements. Future events, such as changes in existing laws and regulations, or the enforcement thereof, or the discovery of contamination at our facilities, may give rise to additional compliance or remediation costs that could have a material adverse effect on our business, financial condition and results of operations. Such laws and requirements are constantly changing, are different in every jurisdiction and can impose substantial fines and sanctions for violations. As a manufacturer of various products, we are exposed to some risk of claims with respect to environmental matters, and there can be no assurance that material costs or liabilities will not be incurred in connection with any such claims.
Our indebtedness could adversely affect our financial health and prevent us from fulfilling our debt obligations.
We have now and expect to continue to have a significant amount of indebtedness.
Our indebtedness could:
| • | increase our vulnerability to general adverse economic and industry conditions; |
| • | require us to dedicate a substantial portion of our cash flow from operations to payments on our indebtedness, thereby reducing the availability of our cash flow to fund working capital, capital expenditures, acquisitions, research and development efforts and other general corporate purposes; |
| • | limit our flexibility in planning for, or reacting to, changes in our business and the industry in which we operate; |
| • | place us at a competitive disadvantage compared to our competitors that have less debt; |
| • | limit our ability to borrow additional funds; and |
| • | make it more difficult for us to satisfy our obligations with respect to our debt, including our obligation to repay our credit facilities under certain circumstances. |
Our credit facilities contain financial and other restrictive covenants that could limit our ability to engage in activities that may be in our long-term best interests. Our failure to comply with those covenants could result in an event of default which, if not cured or waived, could result in the acceleration of all of our debt, which could adversely affect our business, earnings and financial condition.
We are vulnerable to interest rate risk with respect to our debt.
We are subject to interest rate risk in connection with the issuance of variable and fixed-rate debt. In order to maintain our desired mix of fixed-rate and variable-rate debt, we currently use, and may continue to use, interest rate swap agreements and exchange fixed and variable-rate interest payment obligations over the life of the arrangements, without exchange of the underlying principal amounts. We may not be successful
in structuring such swap agreements to manage our risks effectively, which could adversely affect our business, earnings and financial condition.
Exchange rate fluctuations and our foreign currency hedges could adversely affect our financial results.
As a result of our international operations, currency exchange rate fluctuations may affect our results of operations and financial position. Our most significant currency exposures are the British pound sterling, euro and Japanese yen. We expect to generate an increasing portion of our revenue and incur a significant portion of our expenses in currencies other than U.S. dollars. To the extent we are unable to materially offset non-nonfunctional currency flows, exchange rate fluctuations could have a positive or negative impact on our financial condition and results of operations. Because our consolidated financial results are reported in U.S. dollars, if we generate sales or earnings in other currencies, the translation of those results into U.S. dollars can result in a significant increase or decrease in the amount of those sales or earnings and can make it more difficult for our shareholders to understand the relative strengths or weaknesses of the underlying business on a period-over-period comparative basis. Although from time to time we enter into foreign exchange agreements with financial institutions to reduce our net exposure to fluctuations in foreign currency values relative to our non-functional currency obligations or balances, these hedging transactions do not eliminate that risk entirely.
Increases in our effective tax rates or adverse outcomes resulting from examination of income tax returns could adversely affect our results.
Our future effective tax rates could be adversely affected by earnings being higher than anticipated in countries where the Company has higher statutory rates or lower than anticipated in countries where it has lower statutory rates, by changes in valuation of our deferred tax assets and liabilities, or by changes in tax laws or interpretations of those laws. We are also subject to the examination of our income tax returns by other tax authorities and the outcome of these examinations could have a material adverse effect on our operating results and financial condition.
We operate globally and changes in tax laws could adversely affect our results.
We operate globally and changes in tax laws could adversely affect our results. We have overseas manufacturing, administrative and sales offices and generate substantial revenues and profits in foreign jurisdictions. Recently, a number of countries, including the United States, have proposed changes to their tax laws, some of which affect taxation of earnings recognized in foreign jurisdictions. Such changes in tax laws or their interpretation, if adopted, could adversely affect our effective tax rates and our results.
Volatility in the securities markets, interest rates, and other factors could substantially increase our defined benefit pension costs.
We sponsor a defined benefit pension plan for employees in the United States. This defined benefit pension plan is funded with trust assets invested in a diversified portfolio of securities and other investments. Changes in interest rates, mortality rates, early retirement rates, investment returns, discount rates and the market value of plan assets can affect the funded status of our defined benefit pension plan and cause volatility in the net periodic benefit cost and future funding requirements of the plan. A significant increase in our obligations or future funding requirements could have a negative impact on our results of operations and cash flows from operations.
We manage our businesses utilizing complex computer systems that are regularly maintained and upgraded; an interruption to these systems could disrupt our business or force us to expend excessive costs.
We utilize complex computer systems, including enterprise resource planning and warehouse management systems, to support our business units and we have a continuous improvement strategy in place to keep our systems and overarching technology stable and in line with business needs and growth. Regular upgrades of our computer hardware and software revisions are typical and expected. We employ controlled change management methodologies to plan, test and execute all such system upgrades and improvements, and we believe that we assign adequate staffing and other resources to projects to ensure successful implementation. However, we cannot assure that our systems will meet our future business needs or that upgrades will operate as designed. We cannot assure that there will not be associated excessive costs or disruptions in portions of our business in the course of our maintenance, support and/or upgrade of these systems.
If we do not retain our key personnel and attract and retain other highly skilled employees, our business could suffer.
If we fail to recruit and retain the necessary personnel, our business and our ability to obtain new customers, develop new products and provide acceptable levels of customer service could suffer. The success of our business is heavily dependent on the leadership of our key management personnel. Our success also depends on our ability to recruit, retain and motivate highly skilled sales, marketing, engineering and scientific personnel. Competition for these persons in our industry is intense, and we may not be able to successfully recruit, train or retain qualified personnel.
Provisions of our governing documents and Delaware law, and our rights plan, may have anti-takeover effects.
Certain provisions of our Second Restated Certificate of Incorporation and Amended and Restated By-laws may inhibit changes in control of the Company not approved by our Board of Directors. These provisions include: (i) advance notice requirements for stockholder proposals and nominations and (ii) the authority of our board to issue without stockholder approval preferred stock with such terms as our board may determine. We also have the protections of Section 203 of the Delaware General Corporation Law, which could have similar effects. Our Board of Directors extended our preferred stock purchase rights plan, commonly known as a “poison pill,” pursuant to an amended rights agreement dated as of October 29, 2007, that expires on October 29, 2017. The rights agreement is intended to prevent abusive hostile takeover attempts by requiring a potential acquirer to negotiate the terms of an acquisition with our Board of Directors. However, it could have the effect of deterring or preventing an acquisition of our Company, even if a majority of our stockholders would be in favor of such acquisition, and could also have the effect of making it more difficult for a person or group to gain control of the Company or to change existing management.
Risks Relating to Government Regulation of Manufacture and Sale of Our Products
Our failure to comply with regulatory requirements or to receive regulatory clearance or approval for our products or operations could adversely affect our business.
Our products and operations are subject to rigorous regulation by the FDA, and numerous other federal, state and foreign governmental authorities. In the United States, the FDA regulates virtually all aspects of a medical device's design, development, testing, manufacture, safety, labeling (including, for example the upcoming FDA unique device identifier regulations), storage, recordkeeping, reporting, marketing, promotion and distribution, as well as the export of medical devices manufactured in the United States to foreign markets.
Our failure to comply with FDA regulations could lead to the imposition of administrative or judicial sanctions, including injunctions, suspensions or the loss of regulatory approvals, product recalls, termination of distribution or product seizures. In the most egregious cases, criminal sanctions or closure of our manufacturing facilities are possible.
Our medical devices require clearance or approval by the FDA before they can be commercially distributed in the United States and may require similar approvals by foreign regulatory agencies before distribution in foreign jurisdictions. Medical devices may only be marketed for the indications for which they are approved or cleared. The process of obtaining regulatory clearances and approvals to market a medical device, particularly from the FDA, can be costly and time consuming. There can be no assurance that such clearances and approvals will be granted on a timely basis, if at all, or that significant delays in the introduction of any new products or product enhancements will occur, which could adversely affect our competitive position and results of operations. In addition, the FDA may change its policies, adopt additional regulations or revise existing regulations, each of which could prevent or delay premarket approval or clearance of our products or could impact our ability to market our currently approved or cleared products. For example, the FDA recently has been reviewing the premarket clearance process in response to internal and external concerns regarding the 510(k) program. In January 2011, the FDA announced a plan of action that included twenty-five action items designed to make the process more rigorous and transparent. Since then the FDA has implemented some changes intended to improve its premarket programs. Some of these changes and proposals under consideration could impose additional regulatory requirements on us that could delay our ability to obtain new 510(k) clearances for our products, increase the cost of compliance, or restrict our ability to maintain our current clearances.
Modifications and enhancements to a medical device also require a new FDA clearance or approval if they could significantly affect its safety or effectiveness or would constitute a major change in its intended use, design or manufacture. The FDA requires every manufacturer to make this determination in the first instance, but the FDA may review any manufacturer's decision. We have made modifications and enhancements to our medical devices that we do not believe require a new clearance or application, but we cannot confirm that the FDA will agree with our decisions. If the FDA requires us to seek clearance or approval for modification of a previously cleared product for which we have concluded that new clearances or approvals are unnecessary, we may be required to cease marketing or to recall the modified product until we obtain clearance or approval, and we may be subject to significant regulatory fines or penalties, which could have a material adverse effect on our financial results and competitive position. We also cannot assure that we will be successful in obtaining clearances or approvals for our modifications, if required.
Even if regulatory approval or clearance of a medical device is granted, the FDA may impose limitations or restrictions on the uses and indications for which the device may be labeled and promoted, and failure to comply with FDA regulations prohibiting a manufacturer from promoting a device for an unapproved, or “off-label” use could result in enforcement action by the FDA, including, among other things, warning letters, fines, injunctions, consent decrees, and civil or criminal penalties.
Development and marketing of our products are subject to strict governmental regulation by foreign regulatory agencies, and failure to receive, or delay in receiving, foreign qualifications could have a material adverse effect on our business.
In many of the foreign countries in which we market our products, we are subject to regulations affecting, among other things, product standards, packaging requirements, labeling requirements, import restrictions, tariff regulations, the reporting of certain payments to health care practitioners in certain markets (for example, the French Sunshine Act of 2013), duties and tax requirements. Many of the regulations applicable to our devices and products in such countries are similar to those of the FDA.
In the European Economic Area, a medical device can only be placed on the market if it is in conformity with the essential requirements set out in the European Directives and implementing regulations that govern medical devices. These Directives prescribe quality programs and standards which must be maintained in order to achieve required ISO certification and to approve the use of CE marking. In order to maintain ISO certification and CE marking quality benchmarks, firms' quality systems and procedures are subjected to rigorous periodic inspections and reassessment audits.
In many countries, the national health or social security organizations require our products to be qualified before they can be marketed with the benefit of reimbursement eligibility. To date, we have not experienced difficulty in complying with these regulations. However, our failure to receive, or delays in the receipt of, relevant foreign qualifications could have a material adverse effect on our business, financial condition and results of operations.
Our products are subject to reporting requirements and recalls, even after receiving regulatory clearance or approval, which could harm our reputation, business and financial results.
After a device is placed on the market, numerous regulatory requirements apply, including the FDA's QSR regulations, which require manufacturers to follow design, testing, control, documentation and other quality assurance procedures during the manufacturing process; labeling regulations, which prohibit the promotion of products for unapproved or “off-label” uses and impose other restrictions on labeling; and medical device reporting regulations that require us to report to FDA or similar governmental bodies in other countries if our products malfunction in a way that would be reasonably likely to contribute to death or serious injury if the malfunction were to recur. The FDA and similar governmental bodies in other countries have the authority to require the recall of our products in the event of material deficiencies or defects in design or manufacture. Medical device manufacturers, such as CooperVision and CooperSurgical, may under their own initiative recall a product if a reasonable possibility of serious injury or any material deficiency in a device is found. For example, CooperVision recently concluded a recall of limited lots of Avaira Toric contact lenses and Avaira Sphere contact lenses. Recalls of any of our products may divert managerial and financial resources and have an adverse effect on our financial condition and results of operations. A recall could harm our reputation with customers and consumers which could reduce the sales of our products. In addition, the FDA or other foreign governmental agencies may implement enforcement actions in connection with a recall which could impair our product offerings and be harmful to our business and financial results.
Changes in legislation and government regulation of the healthcare industry as well as third-party payors' efforts to control the costs of healthcare could materially adversely affect our business.
In recent years, an increasing number of healthcare reform proposals have been formulated by the legislative and executive branches of the United States federal and state governments. In March 2010, the President signed the Patient Protection and Affordable Care Act, as amended by the Health Care and Education Reconciliation Act, which we refer to collectively as the Health Care Reform Law. The Health Care Reform Law makes extensive changes to the delivery of health care in the United States. Among the provisions of the Health Care Reform Law, of greatest importance to the medical device industry are the following:
| • | A 2.3 percent excise tax on any entity that manufactures or imports medical devices offered for sale in the United States, with limited exceptions, which exceptions include all contact lenses; |
| • | A new Patient-Centered Outcomes Research Institute to oversee, identify priorities in, and conduct comparative clinical effectiveness research, along with funding for such research; |
| • | New reporting and disclosure requirements on medical device manufacturers for any “transfer of value” made or distributed to prescribers and other healthcare providers, and any ownership and investment |
interests held by physicians or their immediate family members, and any payments or other “transfers of value” to such owners. Manufacturers were required to begin data collection on August 1, 2013 and will be required to report such data to the government by March 31, 2014 and by the 90th calendar day of each year thereafter;
| • | Payment system reforms including a national pilot program on payment bundling to encourage hospitals, physicians and other providers to improve the coordination, quality and efficiency of certain healthcare services through bundled payment models; |
| • | Creation of the Independent Payment Advisory Board which, beginning in 2014, will have authority to recommend certain changes to reduce Medicare spending and those recommendations could have the effect of law even if Congress doesn't act on the recommendations; and |
| • | Establishment of a Center for Medicare Innovation at the Centers for Medicare & Medicaid Services to test innovative payment and service delivery models to lower Medicare and Medicaid spending. |
These measures could result in decreased net revenues or increased expenses from our medical device products and decrease potential returns from our development efforts. At this time, the full effect that the Health Care Reform Law would have on our business remains unclear. For example, the Health Care Reform Law imposes a new excise tax of 2.3 percent of the price for which certain medical devices are sold, which went into effect on January 1, 2013. CooperVision is not affected by this new tax because contact lenses are excluded from the tax. However, United States sales of almost all of CooperSurgical's products are subject to this new tax. We cannot anticipate at this time the magnitude of this new tax as there are significant uncertainties concerning key definitions and terms within the law.
Other legislative changes have been proposed and adopted since the Health Care Reform Law was enacted. On August 2, 2011, the President signed into law the Budget Control Act of 2011, which, among other things, created the Joint Select Committee on Deficit Reduction to recommend proposals in spending reductions to Congress. The Joint Select Committee did not achieve its targeted deficit reduction of at least $1.2 trillion for the years 2013 through 2021, triggering the legislation’s automatic reductions to several government programs. These reductions include aggregate reductions to Medicare payments to providers of up to 2% per fiscal year, which went into effect on April 1, 2013. On January 2, 2013, President Obama signed into law the American Taxpayer Relief Act of 2012, which, among other things, further reduced Medicare payments to several providers, including hospitals, imaging centers and cancer treatment centers.
We expect that additional state and federal healthcare reform measures will be adopted in the future, including those initiatives affecting coverage and reimbursement for our products, any of which could limit the amounts that federal and state governments will pay for healthcare products and services, which could adversely affect the growth of the market for our products or demand for our products, or result in additional pricing pressures. Also, any adoption of healthcare reform proposals on a state-by-state basis could require us to develop state-specific marketing and sales approaches. We cannot predict the effect such reforms or the prospect of their enactment may have on our business.
In addition, third-party payors, whether governmental or commercial, whether inside the United States or abroad, increasingly attempt to contain or reduce the costs of healthcare. These cost-control methods include prospective payment systems, capitated rates, group purchasing, redesign of benefits, requiring pre-authorizations or second opinions prior to certain medical procedures, encouragement of healthier lifestyles and exploration of more cost-effective methods of delivering healthcare. Although cost controls or other requirements imposed by third-party payors have not historically had a significant effect on contact lens prices or distribution practices, this could change in the future and could adversely affect our business, financial condition and results of operations.
The costs of complying with the requirements of federal laws pertaining to the privacy and security of health information and the potential liability associated with failure to do so could materially adversely affect our business and results of operations.
Other federal legislation affects the manner in which we use and disclose health information. The Health Insurance Portability and Accountability Act of 1996, or HIPAA, mandates, among other things, the adoption of standards for the electronic exchange of health information that may require significant and costly changes to current practices. The United States Department of Health and Human Services (HHS) has released several rules mandating the use of specified standards with respect to certain healthcare transactions and health information. The electronic transactions rule requires the use of uniform standards for common healthcare transactions, including healthcare claims information, plan eligibility, referral certification and authorization, claims status, plan enrollment and disenrollment, payment and remittance advice, plan premium payments and coordination of benefits. The privacy rule imposes standards governing the use and disclosure of individually identifiable health information. The security rule released by HHS establishes minimum standards for the security of electronic health information, and requires the adoption of administrative, physical and technical safeguards.
Additionally, the Health Information Technology for Economic and Clinical Health (HITECH) Act of 2009 was signed into law as part of the America's Recovery and Reinvestment Act in February 2009. Previously, HIPAA directly regulated only certain covered entities, such as health care providers and health plans. Under the HITECH Act, certain of HIPAA's privacy and security standards are now also directly applicable to covered entities' business associates. As a result, business associates are now subject to civil and criminal penalties for failure to comply with applicable privacy and security rule requirements. Moreover, the HITECH Act set forth new notification requirements for health data security breaches, increased the civil and criminal penalties that may be imposed against covered entities, business associates and possibly other persons, and gave state attorneys general new authority to file civil actions for damages or injunctions in federal courts to enforce HIPAA and seek attorney's fees and costs associated with pursuing federal actions.
While we do not believe that we are a covered entity or a business associate under HIPAA, many of our customers may be covered entities or business associates subject to HIPAA. Some customers as an expectation of transacting business with us may require us to enter into business associate agreements, which would obligate us to safeguard and restrict the manner in which we use certain protected health information (as defined by HIPAA) that we obtain in the course of our commercial relationship with them, triggering potential liability on us for failure to meet our contractual obligations. Alternatively, some customers may limit the scope of our commercial relationship with them with regard to our access to certain protected health information. Pursuant to the HITECH Act, if the government determines that we are a business associate, we could be additionally subject to direct governmental enforcement for failure to comply with certain privacy and security requirements. In addition, the final omnibus rule released in January 2013, among other things, modifies the breach reporting standard in a manner that will likely make more data security incidents qualify as reportable breaches. The costs of complying with these contractual obligations and new legal and regulatory requirements, and the potential liability associated with failure to do so could have a material adverse effect on our business, financial condition and results of operations.
Laws pertaining to healthcare fraud and abuse could materially adversely affect our business, financial condition and results of operations.
We may be subject to various federal, state and foreign laws pertaining to healthcare fraud and abuse, including anti-kickback laws, physician self-referral laws and false claims laws. Violations of these laws are punishable by criminal and civil sanctions, including, in some instances, exclusion from participation in federal and state healthcare programs, including Medicare, Medicaid, Veterans Administration health programs and TRICARE. Similarly, if the physicians or other providers or entities with whom we do business are found to be non-compliant with applicable laws, they may be subject to sanctions, which could indirectly have a negative impact on our business, financial condition and results of operations. While we believe that our operations are in material compliance with such laws, because of the complex and far-reaching nature of these laws, there can be no assurance that we would not be required to alter one or more of our practices to be in compliance with these laws.
Indeed, changes in state laws and model codes of ethics have required us to alter certain of our compliance efforts. For example, in April of 2009, Massachusetts issued regulations governing the conduct of pharmaceutical and medical device manufacturers with respect to healthcare practitioners. This regulation became effective on July 1, 2009 and sets forth what medical device manufacturers may and may not permissibly do with respect to providing meals, sponsoring continuing medical education and otherwise providing payments or items of economic benefit to healthcare practitioners located within the state. Additionally, the regulation requires medical device manufacturers to have in place robust fraud and abuse compliance programs. Other states (e.g., California, Vermont and Nevada) have adopted similar laws. The Advanced Medical Technology Association (AdvaMed), a trade association representing the interests of medical device manufacturers, has also released a revised code of ethics outlining permissible interactions with health care professionals. This code became effective July 1, 2009. These laws, regulations and guidance documents act to limit our marketing practices, require the dedication of resources to ensure compliance, and expose us to additional liabilities.
In addition, the recent Health Care Reform Law, among other things, amends the intent requirement of the federal Anti-Kickback Statute and certain criminal healthcare fraud statutes so that a person or entity no longer needs to have actual knowledge of the statute or specific intent to violate it in order to have committed a violation. The Health Care Reform Law also provides that the government may assert that a claim including items or services resulting from a violation of these statutes constitutes a false or fraudulent claim for purposes of the civil False Claims Act or the civil monetary penalties statute.
Any violations of these laws or regulations could result in a material adverse effect on our business, financial condition and results of operations. In addition, changes in these laws, regulations, or administrative or judicial interpretations, may require us to further change our business practices or subject our existing business practices to legal challenges, which could have a material adverse effect on our business, financial condition and results of operations.
Item 1B. Unresolved Staff Comments.
None.
Item 2. Properties.
The following is a summary of Cooper's principal facilities as of October 31, 2013. Cooper generally leases its office and operations facilities but owns several manufacturing and research and development facilities, including 205,850 square feet in Hamble, United Kingdom, 49,500 square feet in Scottsville, New York, 63,787 square feet in Malov, Denmark, and 33,630 square feet in Stafford, Texas. Our lease agreements expire at various dates through the year 2030. The Company believes its properties are suitable and adequate for its businesses.
| Location | Approximate Square Feet | Operations | ||
| AMERICAS | ||||
| United States | ||||
| California | 112,727 | Executive offices; CooperVision research & development and CooperVision administrative offices; CooperSurgical manufacturing and distribution | ||
| New York | 390,277 | CooperVision manufacturing, marketing, distribution and administrative offices | ||
| Connecticut | 210,837 | CooperSurgical manufacturing, marketing, distribution, research & development and administrative offices | ||
| Texas | 33,630 | CooperSurgical manufacturing | ||
| Wisconsin | 18,000 | CooperSurgical manufacturing | ||
| New Jersey | 10,600 | CooperSurgical marketing | ||
| Puerto Rico | ||||
| Juana Diaz | 333,124 | CooperVision manufacturing and distribution | ||
| Canada | ||||
| Ontario | 11,647 | CooperVision marketing | ||
| Brazil | ||||
| Sao Paulo | 17,545 | CooperVision marketing and distribution | ||
| EMEA | ||||
| United Kingdom | ||||
| Hampshire | 493,128 | CooperVision manufacturing, marketing, distribution, research & development and administrative offices; CooperSurgical marketing | ||
| Belgium | ||||
| Liege | 119,146 | CooperVision distribution | ||
| Denmark | ||||
| Malov | 63,787 | CooperSurgical manufacturing, marketing and administrative offices | ||
| Germany | ||||
| Berlin | 13,255 | CooperSurgical manufacturing, marketing and distribution | ||
| Frankfurt | 14,694 | CooperVision marketing and distribution | ||
| Italy | ||||
| Milan | 29,150 | CooperVision marketing and distribution | ||
| Firenze | 2,047 | CooperSurgical marketing | ||
| Spain | ||||
| Madrid | 29,301 | CooperVision marketing and distribution | ||
| Barcelona | 1,377 | CooperSurgical marketing | ||
| South Africa | ||||
| Johannesburg | 13,250 | CooperVision marketing and distribution | ||
| France | ||||
| Nice | 12,184 | CooperVision marketing and distribution | ||
| ASIA PACIFIC | ||||
| Japan | 63,590 | CooperVision manufacturing, marketing, distribution and administrative offices; CooperSurgical marketing | ||
| Australia | 29,973 | CooperVision manufacturing, marketing, distribution and administrative offices | ||
| Other Asia Pacific | 45,187 | CooperVision and CooperSurgical marketing and distribution |
Item 3. Legal Proceedings.
Securities Litigation
On November 28, 2011, Harold Greenberg filed a complaint in the United States District Court for the Northern District of California, Case No. 4:11-cv-05697-YGR, against the following defendants: the Company; Robert S. Weiss, its President, Chief Executive Officer and a director; Eugene J. Midlock, its former Senior Vice President and Chief Financial Officer; and Albert G. White, III, its Vice President and Chief Strategy Officer. On December 12, 2011, a second individual, Ross Wallen, filed a related complaint against the same defendants in the Northern District of California, Case No. 4:11-cv-06214-YGR. The Wallen complaint largely repeats the allegations in the Greenberg complaint. Greenberg and Wallen each sought to represent a class of persons who purchased the Company's common stock between March 4, 2011 and November 15, 2011.
On February 29, 2012, the court ordered the Greenberg and Wallen actions consolidated and appointed Universal-Investment-Gesellschaft mbH as lead plaintiff. On May 4, 2012, the lead plaintiff filed a Consolidated Amended Complaint, which alleges that the Company, Robert S. Weiss and Eugene J. Midlock violated Section 10(b) of the Securities Exchange Act of 1934 by, among other things, making misrepresentations with an intent to deceive investors concerning the safety of the Avaira® Toric and Avaira Sphere contact lenses, which the Company recalled in 2011. On August 7, 2012, the Court heard argument on defendants' motion to dismiss the Consolidated Amended Complaint. On January 7, 2013, the Court granted defendants' motion to dismiss the Consolidated Amended Complaint, with leave to amend. On February 4, 2013, the lead plaintiff filed a Second Consolidated Amended Complaint, which again alleges that the Company, Robert S. Weiss and Eugene J. Midlock violated Section 10(b) of the Securities Exchange Act of 1934 by, among other things, making misrepresentations with an intent to deceive investors concerning the 2011 recall of Avaira contact lenses. The Second Consolidated Amended Complaint seeks unspecified damages on behalf of a purported class of persons who purchased the Company's common stock between August 19, 2011 and November 15, 2011. On March 6, 2013, the defendants moved to dismiss the Second Consolidated Amended Complaint. On April 16, 2013 the Court heard argument on defendants' motion to dismiss the Second Consolidated Amended Complaint. On May 31, 2013, the Court granted defendants' motion to dismiss the Second Consolidated Amended Complaint without leave to amend and entered final judgment in favor of defendants. Plaintiff did not file a notice of appeal within the time prescribed by law.
Derivative Litigation
On January 9, 2012, Joseph Operman filed a purported shareholder derivative complaint in the United States District Court for the Northern District of California, Case No. 4:12-cv-00143-YGR, against members of the Company's board of directors. The derivative complaint seeks recovery on behalf of the Company, which is named as a “nominal defendant.” The derivative complaint purports to allege causes of action for breach of fiduciary duties and failure to exercise oversight responsibilities against all defendants and a cause of action for contribution against Mr. Weiss for alleged violations of Section 10(b) of the Securities Exchange Act of 1934. On May 18, 2012, Operman filed an amended derivative complaint. The amended derivative complaint largely repeats the allegations of misrepresentations in the securities class action complaints described above, and includes allegations of false projections of future financial results. On June 13, 2013, Operman voluntarily moved the Court to dismiss the derivative action without prejudice. On July 24, 2013, after the Company's shareholders were provided with notice of the voluntary motion for dismissal and an opportunity to object, and no objections were received, the Court entered a final order of dismissal in the derivative action.
Item 4. Submission of Matters to a Vote of Security Holders.
During the fiscal fourth quarter of 2013, the Company did not submit any matters to a vote of the Company's security holders.
PART II
Item 5. Market for Registrant's Common Equity and Related Stockholder Matters.
Cooper's common stock, par value $0.10 per share, is traded on the New York Stock Exchange under the symbol “COO.” In the table that follows, we indicate the high and low selling prices of our common stock for each three-month period of 2013 and 2012:
| 2013 | 2012 | ||||||||||||||
| Quarterly Common Stock Price Range Years Ended October 31, | High | Low | High | Low | |||||||||||
| Fiscal Quarter Ended | |||||||||||||||
| January 31 | $ | 102.47 | $ | 88.80 | $ | 73.28 | $ | 52.60 | |||||||
| April 30 | $ | 110.85 | $ | 100.24 | $ | 88.74 | $ | 72.41 | |||||||
| July 31 | $ | 129.06 | $ | 105.71 | $ | 89.31 | $ | 72.44 | |||||||
| October 31 | $ | 135.41 | $ | 124.00 | $ | 100.92 | $ | 71.40 |
At November 30, 2013, there were 544 common stockholders of record.
Dividend Policy
Our current policy is to pay annual cash dividends on our common stock of $0.06 per share, in two semiannual payments of $0.03 per share each. In dollar terms, we paid cash for dividends of about $2.9 million in fiscal 2013 and $2.9 million in fiscal 2012. Dividends are paid when, as and if declared at the discretion of our Board of Directors from funds legally available for that purpose. Our Board of Directors periodically reviews our dividend policy and considers the Company's earnings, financial condition, liquidity needs, business plans and opportunities and other factors in making and setting dividend policy.
Performance Graph
The following graph compares the cumulative total return on the Company's common stock with the cumulative total return of the Standard & Poor's Smallcap 600 Stock Index and the Standard & Poor's Health Care Equipment Index for the five-year period ended October 31, 2013. The graph assumes that the value of the investment in the Company and in each index was $100 on October 31, 2008, and assumes that all dividends were reinvested.
COMPARISON OF 5 YEAR CUMULATIVE TOTAL RETURN*
Among The Cooper Companies, Inc., the S&P Smallcap 600 Index
and the S&P Health Care Equipment Index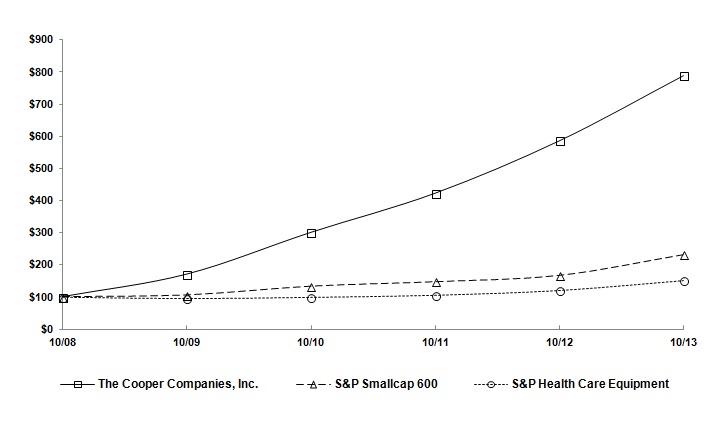
*$100 invested on 10/31/08 in stock or index, including reinvestment of dividends. Fiscal year ending October 31.
Copyright© 2013 S&P, a division of The McGraw-Hill Companies Inc. All rights reserved.
| 10/08 | 1 | 10/09 | 10/10 | 10/11 | 10/12 | 10/13 | ||||||||||||||||||
| The Cooper Companies, Inc. | $ | 100.00 | $ | 170.42 | $ | 300.66 | $ | 422.67 | $ | 585.89 | $ | 789.16 | ||||||||||||
| S&P Smallcap 600 | $ | 100.00 | $ | 105.56 | $ | 133.30 | $ | 147.34 | $ | 167.38 | $ | 232.80 | ||||||||||||
| S&P Health Care Equipment | $ | 100.00 | $ | 95.53 | $ | 99.35 | $ | 105.90 | $ | 120.91 | $ | 151.80 |
Unregistered Sales of Equity Securities and Use of Proceeds
Issuer Purchases of Equity Securities
During the three-month period ended October 31, 2013, we repurchased shares of our common stock as follows:
| Period | Total Number of Shares Purchased | Average Price Paid Per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | Maximum Approximate Dollar Value of Shares that May Yet Be Purchased Under Publicly Announced Plans or Programs | ||||||||||
| 8/1/13 – 8/31/13 | — | $ | — | — | $ | 184,500,000 | ||||||||
| 9/1/13 – 9/30/13 | 177,526 | $ | 129.72 | 177,526 | $ | 161,500,000 | ||||||||
| 10/1/13 – 10/31/13 | 782,725 | $ | 127.68 | 782,725 | $ | 61,500,000 | ||||||||
| Total | 960,251 | $ | 128.06 | 960,251 |
The transactions described in the table above represent the repurchase of the Company’s common stock on the New York Stock Exchange as part of the share repurchase program approved by the Company’s Board of Directors in December 2011 (2012 Share Repurchase Program). The program as amended in December 2012 and December 2013 provides authorization for a total of $500.0 million. Purchases under the 2012 Share Repurchase Program may be made from time-to-time on the open market at prevailing market prices or in privately negotiated transactions and are subject to a review of the circumstances in place at the time and will be made from time to time as permitted by securities laws and other legal requirements. This program has no expiration date and may be discontinued at any time. At October 31, 2013, the remaining repurchase authorization under the 2012 Share Repurchase Program was approximately $61.5 million and was subsequently increased $200.0 million, by a December 12, 2013 amendment to the program, for a total remaining repurchase authorization of $261.5 million.
Equity Compensation Plan Information
| Plan Category | Number of Securities to be Issued Upon Exercise of Outstanding Options, Warrants and Rights(1) (A) | Weighted-Average Exercise Price of Outstanding Options, Warrants and Rights (B) | Number of Securities Remaining Available for Future Issuance Under Equity Compensation Plans (Excluding Securities Reflected in Column A) (C) | ||
| Equity compensation plans approved by shareholders(2) | 2,355,861 | $54.58 | 1,855,841 | ||
| Equity compensation plans not approved by shareholders | — | — | — | ||
| Total | 2,355,861 | $54.58 | 1,855,841 |
(1) The amount of total securities to be issued under equity plans shown in Column A includes 647,185 Restricted Stock Units granted pursuant to the Company's equity plans. These awards allow for the distribution of shares to the grant recipient upon the completion of time-based holding periods and do not have an associated exercise price. Accordingly, these awards are not reflected in the weighted-average exercise price disclosed in Column B. Amounts in Column A do not reflect performance share awards without a final payout.
(2) Includes information with respect to the Second Amended and Restated 2007 Long-Term Incentive Plan for Employees of The Cooper Companies, Inc. (2007 Plan), which was approved by stockholders on March 16, 2011, and provides for the issuance of up to 5,230,000 shares of common stock, and the Second Amended and Restated 2006 Long Term Incentive Plan for Non-Employee Directors of The Cooper Companies, Inc. (the Directors’ Plan), which was approved by stockholders on March 16, 2011, and provides for the issuance of up to 950,000 shares of common stock. As of October 31, 2013, up to 1,609,325 shares of common stock may be issued pursuant to the 2007 Plan and 246,516 shares of common stock may be issued pursuant to the 2006 Directors’ Plan.
Also includes information with respect to the 1996 Long Term Incentive Plan for Non-Employee Directors (1996 Directors' Plan) and the Second Amended and Restated 2001 Long Term Incentive Plan (2001 Plan) of The Cooper Companies, Inc., which were originally approved by stockholders on March 21, 1996 and March 28, 2001. The 1996 Directors' Plan and 2001 Plan have expired by their terms, but up to 354,200 shares of common stock may be issued pursuant to awards that remain outstanding under these plans.
Item 6. Selected Financial Data.
Five Year Financial Highlights
| Years Ended October 31, (In thousands, except per share amounts) | 2013 | 2012 | 2011 | 2010 | 2009 | ||||||||||||||
| Consolidated Operations | |||||||||||||||||||
| Net sales | $ | 1,587,725 | $ | 1,445,136 | $ | 1,330,835 | $ | 1,158,517 | $ | 1,080,421 | |||||||||
| Gross profit | $ | 1,026,808 | $ | 924,010 | $ | 804,804 | $ | 676,723 | $ | 596,494 | |||||||||
| Income before income taxes | $ | 312,271 | $ | 275,452 | $ | 192,764 | $ | 124,426 | $ | 114,828 | |||||||||
| Net income attributable to Cooper stockholders | $ | 296,151 | $ | 248,339 | $ | 175,430 | $ | 112,803 | $ | 100,548 | |||||||||
| Diluted earnings per share attributable to Cooper stockholders | $ | 5.96 | $ | 5.05 | $ | 3.63 | $ | 2.43 | $ | 2.21 | |||||||||
| Number of shares used to compute diluted earnings per share | 49,685 | 49,152 | 48,309 | 46,505 | 45,478 | ||||||||||||||
| Dividends paid per share | $ | 0.06 | $ | 0.06 | $ | 0.06 | $ | 0.06 | $ | 0.06 | |||||||||
| Consolidated Financial Position | |||||||||||||||||||
| Current assets | $ | 747,241 | $ | 657,860 | $ | 540,347 | $ | 491,340 | $ | 503,878 | |||||||||
| Property, plant and equipment, net | 739,867 | 640,255 | 609,205 | 593,887 | 602,568 | ||||||||||||||
| Goodwill | 1,387,611 | 1,370,247 | 1,276,567 | 1,261,976 | 1,257,029 | ||||||||||||||
| Other intangible assets, net | 198,769 | 214,783 | 128,341 | 114,177 | 114,700 | ||||||||||||||
| Other assets | 63,773 | 58,239 | 70,058 | 63,638 | 73,732 | ||||||||||||||
| $ | 3,137,261 | $ | 2,941,384 | $ | 2,624,518 | $ | 2,525,018 | $ | 2,551,907 | ||||||||||
| Short-term debt | $ | 42,987 | $ | 25,284 | $ | 52,979 | $ | 19,159 | $ | 9,844 | |||||||||
| Other current liabilities | 278,266 | 237,268 | 214,227 | 180,361 | 165,570 | ||||||||||||||
| Long-term debt | 301,670 | 348,422 | 327,453 | 591,977 | 771,630 | ||||||||||||||
| Other liabilities | 90,844 | 117,252 | 92,371 | 66,745 | 64,521 | ||||||||||||||
| Total liabilities | 713,767 | 728,226 | 687,030 | 858,242 | 1,011,565 | ||||||||||||||
| Stockholders' equity | 2,423,494 | 2,213,158 | 1,937,488 | 1,666,776 | 1,540,342 | ||||||||||||||
| $ | 3,137,261 | $ | 2,941,384 | $ | 2,624,518 | $ | 2,525,018 | $ | 2,551,907 |
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations.
Note numbers refer to “Notes to Consolidated Financial Statements” in Item 8. Financial Statements and Supplementary Data.
RESULTS OF OPERATIONS
We discuss below the results of our operations for fiscal 2013 compared with fiscal 2012 and the results of our operations for fiscal 2012 compared with fiscal 2011. Certain prior period amounts have been reclassified to conform to the current period's presentation. We discuss our cash flows and current financial condition under “Capital Resources and Liquidity.”
Outlook
Overall, we remain optimistic about the long-term prospects for the worldwide contact lens and women’s healthcare markets. However, events affecting the economy as a whole, including the uncertainty and instability of global markets driven by United States debt and uncertainty surrounding employment, housing and credit concerns together with the European debt crisis and related foreign currency volatility impact our current performance and continue to represent a risk to our performance for fiscal year 2014.
We compete in the worldwide contact lens market with our spherical, toric and multifocal contact lenses offered in a variety of materials including using silicone hydrogel Aquaform® technology and phosphorylcholine technology (PC Technology™). We believe that there will be lower contact lens wearer dropout rates as technology improves and enhances the wearing experience through a combination of improved designs and materials and the growth of preferred modalities such as single-use and monthly wearing options. CooperVision is focused on greater worldwide market penetration as we introduce new products and continue to expand our presence in existing and emerging markets, including through acquisitions.
Sales of contact lenses utilizing silicone hydrogel materials, a major product material in the industry, have grown significantly. Our ability to compete successfully with a full range of silicone hydrogel products is an important factor to achieving our projected future levels of sales growth and profitability. CooperVision markets monthly and two-week silicone hydrogel spherical and toric lens products under our Biofinity® and Avaira® brands and a multifocal lens under Biofinity.
We believe that the global market for single-use contact lenses is expanding and will continue to grow. In fiscal 2013, we launched MyDayTM, our single-use spherical silicone hydrogel lens, in Europe, and in fiscal 2012 we launched Proclear® 1 Day multifocal. We forecast increasing demand for our existing and future single-use products. To meet this anticipated demand, in fiscal 2014 we plan to continue the implementation of capital projects to invest in increased single-use manufacturing capacity. Competitive silicone hydrogel single-use lens products are gaining market share and represent a risk to our business.
On October 31, 2013, we completed a transaction to sell Aime, our rigid gas-permeable contact lens and solutions business in Japan, to Nippon Contact Lens Inc. In our fiscal fourth quarter of 2013, we recorded a pre-tax loss of approximately $21.1 million. The business was originally obtained as part of the December 1, 2010, acquisition which included obtaining the rights to market Biofinity in Japan. The divestiture is consistent with the strategy to focus on our core soft contact lens business. Additionally, Aime revenue has declined in recent periods, and the products have lower than average company margins. Results from operations of Aime are included in our Consolidated Statements of Income for fiscal 2013, 2012 and 2011. Post divestiture, we expect the transaction to be neutral to earnings per share.
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
The medical device segment of the women's healthcare market is highly fragmented. CooperSurgical has steadily grown its market presence and distribution system by developing products and acquiring companies and products that complement its business model. We intend to continue to invest in CooperSurgical's business through acquisitions of companies and product lines. CooperSurgical product sales are categorized based on the point of healthcare delivery including products used in medical office and surgical procedures by obstetricians and gynecologists (ob/gyns) representing 67% of CooperSurgical's net sales. CooperSurgical's remaining sales represent products used in fertility clinics that now represent 33% of CooperSurgical's net sales up from 16% in the prior year period due to the July 2012 acquisition of Origio, a global in-vitro fertilization medical device company.
As part of the new health care reform law, a 2.3% excise tax on any entity that manufactures or imports medical devices offered for sale in the United States, with limited exceptions, became effective January 1, 2013. CooperVision's products are not subject to this new tax because contact lenses are excluded from the tax. However, United States sales of CooperSurgical's products are subject to this new tax which is primarily recorded in selling, general and administrative expense on the Statement of Income.
On September 12, 2013, we entered into a five-year, $300.0 million, senior unsecured term loan agreement (Term Loan) that will mature on September 12, 2018, and will be subject to amortization of principal of 5% per year payable quarterly beginning October 31, 2016, with the balance payable at maturity. We utilized the funds provided by this Term Loan to repay amounts outstanding on our revolving Credit Agreement, and at October 31, 2013, $300.0 million remained outstanding on the Term Loan.
At October 31, 2013, we had $999.8 million available under the revolving Credit Agreement. We believe that our cash and cash equivalents, cash flow from operating activities and borrowing capacity under existing credit facilities will fund operations both in the next 12 months and in the longer term as well as current and long-term cash requirements for capital expenditures, acquisitions, share repurchases and cash dividends.
2013 Compared with 2012
Highlights: 2013 vs. 2012
| • | Net sales up 10% to $1.6 billion from $1.4 billion in fiscal year 2012. |
| • | Gross margin 65% of net sales up from 64%. |
| • | Operating income up 8% to $305.9 million from $283.4 million. |
| • | Interest expense down 22% to $9.2 million from $11.8 million. |
| • | Diluted earnings per share up 18% to $5.96 from $5.05. |
| • | Operating cash flow $415.9 million up 32% from $315.1 million. |
Fiscal 2013 pre-tax results include a $21.1 million loss on divestiture of Aime, $14.1 million of insurance proceeds related to a business interruption claim and $0.6 million of costs related to the acquisition of Origio. Fiscal 2012 pre-tax results include a $1.4 million loss related to the May 31, 2012, amendment to our revolving Credit Agreement, and costs related to the acquisition of Origio consisting of $4.9 million in direct acquisition costs and a $0.4 million net gain related to the repayment of debt acquired recorded in interest expense.
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
Selected Statistical Information – Percentage of Net Sales
| Years Ended October 31, | 2013 | 2013 vs. 2012 % Change | 2012 | 2012 vs. 2011 % Change | 2011 | |||||||||
| Net sales | 100 | % | 10 | % | 100 | % | 9 | % | 100 | % | ||||
| Cost of sales | 35 | % | 8 | % | 36 | % | (1 | )% | 40 | % | ||||
| Gross profit | 65 | % | 11 | % | 64 | % | 15 |
Showing the first 8K of 69K characters. Open the full section
Item 7A. Quantitative and Qualitative Disclosure about Market Risk.
We are exposed to market risks that relate principally to changes in interest rates and foreign currency fluctuations. Our policy is to reduce, to the extent reasonable and practical, its exposure to the impact of changing interest rates and foreign currency fluctuations by entering into a limited number of interest rate swaps and foreign currency forward exchange contracts, respectively. We do not emphasize such transactions to the same degree as some other companies with international operations. We do not enter into derivative financial instrument transactions for speculative purposes.
We operate multiple foreign subsidiaries that manufacture and market our products worldwide. As a result, our earnings, cash flow and financial position are exposed to foreign currency risk from foreign currency denominated receivables and payables, sales transactions, capital expenditures and net investment in certain foreign operations. We are exposed to risks caused by changes in foreign exchange, primarily to the British pound, euro and Japanese yen. Our policy is to minimize, to the extent reasonable and practical, transaction, remeasurement and specified economic exposures with derivatives instruments. Although we may enter into foreign exchange agreements with financial institutions to reduce our nonfunctional currency exposure, these hedging transactions do not eliminate that risk entirely. A hypothetical 10% increase or decrease in the foreign currency exchange rates in comparison to the United States dollar would not have a material adverse impact on our financial condition or results of operations. For additional information, see Item 1A. Risk Factors and Note 1 to the consolidated financial statements.
We are also exposed to risks associated with changes in interest rates, as the interest rate on our senior unsecured syndicated credit facilities, including the revolving Credit Agreement and Term Loan, may vary with the London Interbank Offered Rate (LIBOR). We have decreased this interest rate risk by hedging a significant portion of variable rate debt effectively converting it to fixed rate debt for varying periods through December 2014.
On September 12, 2013, we entered into a five-year, $300.0 million, senior unsecured term loan agreement (Term Loan) that will mature on September 12, 2018, and will be subject to amortization of principal of 5% per year payable quarterly beginning October 31, 2016, with the balance payable at maturity. We utilized the funds provided by this Term Loan to repay amounts outstanding on our revolving Credit Agreement, and at October 31, 2013, $300.0 million remained outstanding on the Term Loan.
On May 31, 2012, we entered into an amendment to our Credit Agreement, originally entered into on January 12, 2011. The aggregate revolving commitment was increased to $1.0 billion from $750.0 million. This facility offers additional availability, lower interest rates and extends the maturity date to May 31, 2017, from January 12, 2016. In addition, we have the ability to increase the facility by up to an additional $500.0 million. KeyBank led the refinancing with certain banks that participated in the Credit Agreement retaining or increasing their participation.
In February 2011, we redeemed all $339.0 million aggregate principal amount outstanding of our 7.125% Senior Notes issued on January 31, 2007, in accordance with the terms of the Indenture from borrowings under the Credit Agreement. In accordance with the Indenture, the redemption price for the Notes was 103.563% of their principal amount plus accrued and unpaid interest to February 15, 2011, the redemption date. In fiscal 2011, we recorded a $16.5 million loss on the repurchase that includes the write-off of about $4.4 million of unamortized costs and the redemption premium of $12.1 million related to the Senior Notes on our Consolidated Statement of Income.
| October 31, (In millions) | 2013 | 2012 | |||||
| Short-term debt | $ | 43.0 | $ | 25.3 | |||
| Long-term debt | 301.7 | 348.4 | |||||
| Total | $ | 344.7 | $ | 373.7 |
At October 31, 2013 the scheduled maturities of our fixed and variable rate long-term debt obligations, their weighted average interest rates and their estimated fair values were as follows:
| Expected Maturity Date Fiscal Year ($ in millions) | 2014 | 2015 | 2016 | 2017 | 2018 | Thereafter | Total | Fair Value | |||||||||||||||||||||||
| Long-term debt: | |||||||||||||||||||||||||||||||
| Fixed interest rate | $ | — | $ | 0.4 | $ | 0.4 | $ | 0.4 | $ | — | $ | 0.5 | $ | 1.7 | $ | 1.7 | |||||||||||||||
| Average interest rate | 2.1 | % | 2.5 | % | 3.1 | % | 4.8 | % | 4.8 | % | 4.8 | % | |||||||||||||||||||
| Variable interest rate | $ | — | $ | — | $ | 3.8 | $15.0 | $281.2 | $ | — | $300.0 | $300.0 | |||||||||||||||||||
| Average interest rate | 1.0 | % | 1.0 | % | 1.0 | % | 1.0 | % | 1.0 | % | — |
As the table incorporates only those exposures that existed as of October 31, 2013, it does not consider those exposures or positions which could arise after that date. As a result, our ultimate realized gain or loss with respect to interest rate fluctuations will depend on interest rates, the exposures that arise during the period and our hedging strategies at that time. As of October 31, 2013, we had interest rate swaps outstanding that are designed to fix the variable borrowing costs related to $200.0 million of the outstanding balance on our credit agreements. If interest rates were to increase or decrease by 1% or 100 basis points, annual interest expense would increase or decrease by about $1.0 million. For further information about our debt, see Item 1A. Risk Factors and Note 1 and Note 4 to the consolidated financial statements.
Item 8. Financial Statements and Supplementary Data.
Report of Independent Registered Public Accounting Firm
The Board of Directors and Stockholders
The Cooper Companies, Inc.:
We have audited the accompanying consolidated balance sheets of The Cooper Companies, Inc. and subsidiaries (the Company) as of October 31, 2013 and 2012, and the related consolidated statements of income, comprehensive income (loss), stockholders' equity, and cash flows for each of the years in the three-year period ended October 31, 2013. We also have audited the Company's internal control over financial reporting as of October 31, 2013, based on criteria established in Internal Control - Integrated Framework (1992) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO). The Company's management is responsible for these consolidated financial statements, for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting included in the accompanying Management's Annual Report on Internal Control Over Financial Reporting appearing under item 9A. Our responsibility is to express an opinion on these consolidated financial statements and an opinion on the Company's internal control over financial reporting based on our audits.
We conducted our audits in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audits to obtain reasonable assurance about whether the financial statements are free of material misstatement and whether effective internal control over financial reporting was maintained in all material respects. Our audits of the consolidated financial statements included examining, on a test basis, evidence supporting the amounts and disclosures in the financial statements, assessing the accounting principles used and significant estimates made by management, and evaluating the overall financial statement presentation. Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audits also included performing such other procedures as we considered necessary in the circumstances. We believe that our audits provide a reasonable basis for our opinions.
A company's internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company's internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company's assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of The Cooper Companies, Inc. and subsidiaries as of October 31, 2013 and 2012, and the results of their operations and their cash flows for each of the years in the three-year period ended October 31, 2013, in conformity with U.S. generally accepted accounting principles. Also in our opinion, The Cooper Companies, Inc. and subsidiaries maintained, in all material respects, effective internal control over financial reporting as of October 31, 2013, based on criteria established in Internal Control - Integrated Framework (1992) issued by the Committee of Sponsoring Organizations of the Treadway Commission.
KPMG LLP
San Francisco, California
December 20, 2013
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Consolidated Statements of Income
| Years Ended October 31, (In thousands, except per share amounts) | 2013 | 2012 | 2011 | ||||||||
| Net sales | $ | 1,587,725 | $ | 1,445,136 | $ | 1,330,835 | |||||
| Cost of sales | 560,917 | 521,126 | 526,031 | ||||||||
| Gross profit | 1,026,808 | 924,010 | 804,804 | ||||||||
| Selling, general and administrative expense | 610,735 | 564,903 | 513,138 | ||||||||
| Research and development expense | 58,827 | 51,730 | 43,581 | ||||||||
| Amortization of intangibles | 30,239 | 23,979 | 20,529 | ||||||||
| Loss on divestiture of Aime | 21,062 | — | — | ||||||||
| Operating income | 305,945 | 283,398 | 227,556 | ||||||||
| Interest expense | 9,168 | 11,771 | 17,342 | ||||||||
| Gain on insurance proceeds | 14,084 | 5,000 | — | ||||||||
| Loss on extinguishment of debt | — | 1,404 | 16,487 | ||||||||
| Other income (expense), net | 1,410 | 229 | (963 | ) | |||||||
| Income before income taxes | 312,271 | 275,452 | 192,764 | ||||||||
| Provision for income taxes | 15,365 | 26,808 | 17,334 | ||||||||
| Net income | 296,906 | 248,644 | 175,430 | ||||||||
| Income attributable to noncontrolling interests | 755 | 305 | — | ||||||||
| Net income attributable to Cooper stockholders | $ | 296,151 | $ | 248,339 | $ | 175,430 | |||||
| Earnings per share attributable to Cooper stockholders - basic | $ | 6.09 | $ | 5.18 | $ | 3.74 | |||||
| Earnings per share attributable to Cooper stockholders - diluted | $ | 5.96 | $ | 5.05 | $ | 3.63 | |||||
| Number of shares used to compute earnings per share attributable to Cooper stockholders: | |||||||||||
| Basic | 48,615 | 47,913 | 46,904 | ||||||||
| Diluted | 49,685 | 49,152 | 48,309 |
See accompanying notes to consolidated financial statements.
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Consolidated Statements of Comprehensive Income (Loss)
| Years Ended October 31, (In thousands) | 2013 | 2012 | 2011 | ||||||||
| Net income | $ | 296,906 | $ | 248,644 | $ | 175,430 | |||||
| Other comprehensive income (loss): | |||||||||||
| Foreign currency translation adjustment | 2,607 | (4,658 | ) | 5,817 | |||||||
| Change in value of derivative instruments, net of tax provision (benefit) of $857, $289 and $(1,307), respectively | 1,341 | 452 | (3,798 | ) | |||||||
| Change in minimum pension liability, net of tax provision (benefit) $7,399, $(5,764) and $(1,806), respectively | 11,601 | (8,986 | ) | (2,804 | ) | ||||||
| Unrealized gain on marketable securities, net of tax provision of |
Showing the first 8K of 137K characters. Open the full section
Item 9. Changes In and Disagreements With Accountants on Accounting and Financial Disclosure.
None.
Item 9A. Controls and Procedures.
Evaluation of Disclosure Controls and Procedures
The Company has established and currently maintains disclosure controls and procedures designed to ensure that information required to be disclosed in its reports filed under the Securities Exchange Act of 1934 is recorded, processed, summarized and reported within the time periods specified by the Securities and Exchange Commission and that such information is accumulated and communicated to management, including the Chief Executive Officer and Chief Financial Officer, to allow timely decisions regarding required disclosures. In designing and evaluating the disclosure controls and procedures, management recognizes that controls and procedures, no matter how well designed and operated, can provide only reasonable assurance of achieving desired control objectives. In reaching a reasonable level of assurance, management necessarily was required to apply its judgment in evaluating the cost-benefit relationship of possible controls and procedures.
In conjunction with the close of each fiscal quarter, the Company conducts a review and evaluation, under the supervision and with the participation of the Company's management, including the Chief Executive Officer and Chief Financial Officer, of the effectiveness of the design and operation of the Company's disclosure controls and procedures. The Company's Chief Executive Officer and Chief Financial Officer, based upon their evaluation as of October 31, 2013, the end of the fiscal period covered in this report, concluded that the Company's disclosure controls and procedures were effective at the reasonable assurance level.
Management's Annual Report on Internal Control Over Financial Reporting
Management is responsible for establishing and maintaining adequate internal control over financial reporting, as such term is defined in Rule 13a-15(f) under the Securities Exchange Act of 1934. Internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. Because of its inherent limitations, internal control over financial reporting may not prevent or detect all misstatements, errors or fraud.
Management assessed the effectiveness of the Company's internal control over financial reporting as of October 31, 2013, based on the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission in Internal Control - Integrated Framework (1992). Based on this assessment, management, under the supervision and with the participation of the Company's Chief Executive Officer and Chief Financial Officer, concluded that the Company's internal control over financial reporting was effective as of October 31, 2013.
The Company's independent registered public accounting firm, KPMG LLP, has audited the effectiveness of the Company's internal control over financial reporting as of October 31, 2013, as stated in their report in Part II, Item 8 of this Annual Report on Form 10-K.
Changes in Internal Control Over Financial Reporting
There has been no change in the Company's internal control over financial reporting during the Company's fiscal quarter ended October 31, 2013, that has materially affected, or is reasonably likely to materially affect, the Company's internal control over financial reporting.
Item 9B. Other Information.
None.
PART III
Item 10. Directors, Executive Officers and Corporate Governance.
The information required by this item is incorporated by reference to the subheadings, “Proposal 1 - Election of Directors,” “Executive Officers of the Company,” “Ownership of the Company - Section 16(a) Beneficial Ownership Reporting Compliance,” “Corporate Governance - The Board of Directors,” “Corporate Governance - Ethics and Business Conduct Policy,” “Corporate Governance - Board Committees - The Audit Committee” and “Report of the Audit Committee” of the Company's Proxy Statement for the Annual Meeting of Stockholders scheduled to be held in March 2014 (the “2014 Proxy Statement”).
Item 11. Executive Compensation.
The information required by this item is incorporated by reference to the subheadings “Compensation Committee Report,” “Compensation Discussion and Analysis,” “Executive Compensation Tables” and “Director Compensation” of the 2014 Proxy Statement.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
See Item 5. Market for Registrant's Common Equity and Related Stockholder Matters - Equity Compensation Plan Information. Additional information required by this item is incorporated by reference to the subheadings “Securities Held by Management” and “Principal Securityholders” of the “Ownership of the Company” section of the 2014 Proxy Statement.
Item 13. Certain Relationships and Related Transactions, and Director Independence.
The information required by this item is incorporated by reference to the subheadings “Corporate Governance - Related Party Transactions,” “Proposal 1 - Election of Directors” and “Corporate Governance - The Board of Directors” of the 2014 Proxy Statement.
Item 14. Principal Accounting Fees and Services.
The information required by this item is incorporated by reference to “Report of the Audit Committee” section of the 2014 Proxy Statement.
PART IV
Item 15. Exhibits and Financial Statement Schedules.
(a) 1. Financial Statements
The following financial statements are filed as a part of this report:
Report of KPMG LLP, Independent Registered Public Accounting Firm
Consolidated Financial Statements:
Statements of Income for the years ended October 31, 2013, 2012 and 2011
Statements of Comprehensive Income (Loss) for the years ended October 31, 2013, 2012 and 2011
Balance Sheets as of October 31, 2013 and 2012
Statements of Stockholders' Equity for the years ended October 31, 2013, 2012 and 2011
Statements of Cash Flows for the years ended October 31, 2013, 2012 and 2011
Notes to Consolidated Financial Statements
- Financial Statement Schedules of the Company.
Schedule Number Description
Schedule II Valuation and Qualifying Accounts
(b) Exhibits.
The exhibits listed on the accompanying Exhibit Index are filed as part of this report.
All other schedules which are included in the applicable accounting regulations of the Securities and Exchange Commission are not required here because they are not applicable.
Schedule II
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
VALUATION AND QUALIFYING ACCOUNTS
Three Years Ended October 31, 2013
| (In thousands) | Balance Beginning of Year | Additions Charged to Costs and Expenses | (Deductions) Recoveries/ Other (1) | Balance at End of Year | |||||||||||
| Allowance for doubtful accounts: | |||||||||||||||
| Year Ended October 31, 2013 | $ | 4,374 | $ | 1,524 | $ | (637 | ) | $ | 5,261 | ||||||
| Year Ended October 31, 2012 | $ | 4,826 | $ | (257 | ) | $ | (195 | ) | $ | 4,374 | |||||
| Year Ended October 31, 2011 | $ | 4,238 | $ | 2,282 | $ | (1,694 | ) | $ | 4,826 |
(1) Consists of additions representing allowances and recoveries, less deductions representing receivables written off as uncollectible.
| (In thousands) | Balance Beginning of Year | Additions | Reductions/ Charges (2) | Balance at End of Year | |||||||||||
| Income tax valuation allowance: | |||||||||||||||
| Year Ended October 31, 2013 | $ | 1,107 | $ | — | $ | (139 | ) | $ | 968 | ||||||
| Year Ended October 31, 2012 | $ | — | $ | 1,107 | $ | — | $ | 1,107 | |||||||
| Year Ended October 31, 2011 | $ | — | $ | — | $ | — | $ | — |
(2) During the fiscal third quarter of 2013, the Company revalued its deferred tax assets and liabilities residing in Denmark, along with the related valuation allowance to reflect the newly enacted tax rate change that incrementally decreased the corporate tax rate.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized, on December 20, 2013.
THE COOPER COMPANIES, INC.
By: /s/ ROBERT S. WEISS
Robert S. Weiss
Chief Executive Officer and Director
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities indicated on the dates set forth opposite their respective names.
| Signature | Capacity | Date | ||
| /s/ ROBERT S. WEISS | President, Chief Executive Officer and Director | December 20, 2013 | ||
| (Robert S. Weiss) | ||||
| /s/ A. THOMAS BENDER | Chairman of the Board | December 20, 2013 | ||
| (A. Thomas Bender) | ||||
| /s/ ALLAN E. RUBENSTEIN, M.D. | Vice Chairman of the Board and Lead Director | December 20, 2013 | ||
| (Allan E. Rubenstein) | ||||
| /s/ GREG W. MATZ | Vice President, Chief Financial Officer and Chief Risk Officer | December 20, 2013 | ||
| (Greg W. Matz) | (Principal Financial Officer) | |||
| /s/ RODNEY E. FOLDEN | Vice President and Corporate Controller | December 20, 2013 | ||
| (Rodney E. Folden) | (Principal Accounting Officer) | |||
| /s/ MICHAEL H. KALKSTEIN | Director | December 20, 2013 | ||
| (Michael H. Kalkstein) | ||||
| /s/ JODY S. LINDELL | Director | December 20, 2013 | ||
| (Jody S. Lindell) | ||||
| /s/ GARY S. PETERSMEYER | Director | December 20, 2013 | ||
| (Gary S. Petersmeyer) | ||||
| /s/ DONALD PRESS | Director | December 20, 2013 | ||
| (Donald Press) | ||||
| /s/ STEVEN ROSENBERG | Director | December 20, 2013 | ||
| (Steven Rosenberg) | ||||
| /s/ STANLEY ZINBERG, M.D. | Director | December 20, 2013 | ||
| (Stanley Zinberg) |
EXHIBIT INDEX
Location of
Exhibit in
Exhibit Sequential
Number Description of Document Number System
| 3.1 | - Second Restated Certificate of Incorporation filed with the Delaware Secretary of State, incorporated by reference to Exhibit 3.1 of the Company's Current Report on Form 8-K dated January 13, 2006 |
| 3.2 | - Amended and Restated By-Laws, The Cooper Companies, Inc., dated December 14, 2010, incorporated by reference to Exhibit 3.1 to the Company's Current Report on Form 8-K dated December 15, 2010 |
| 4.1 | - Amended and Restated Rights Agreement, dated as of October 29, 2007, between the Company and American Stock Transfer & Trust Company, as Rights Agent, incorporated by reference to Exhibit 4.1 to the Company's Current Report on Form 8-K dated October 30, 2007 |
| 4.2 | - Indenture, dated as of January 31, 2007, by and among The Cooper Companies, Inc., the Subsidiary Guarantors listed on the signatures pages thereto, and HSBC Bank USA, National Association, including the form of 7.125% Senior Notes due 2015, incorporated by reference to Exhibit 4.1 to the Company's Current Report on Form 8-K filed on February 6, 2007 |
| 4.3 | - Registration Rights Agreement, dated as of January 31, 2007, by and among The Cooper Companies, Inc., Citigroup Global Markets Inc., Credit Suisse Securities (USA) LLC, J.P. Morgan Securities Inc. and KeyBanc Capital Markets, a division of McDonald Investments, Inc., incorporated by reference to Exhibit 4.2 to the Company's Current Report on Form 8-K filed on February 6, 2007 |
| 10.1 | - Change in Control Agreement entered into as of August 21, 1989, by and between Robert S. Weiss and the Company, incorporated by reference to Exhibit 10.28 to Amendment No. 1 to the Company's Annual Report on Form 10‑K for the fiscal year ended October 31, 1992 |
| 10.2 | - Change in Control Agreement entered into as of January 3, 2007, and amended September 9, 2008, by and between Albert G. White III and the Company |
| 10.3 | - The Cooper Companies, Inc. Change in Control Severance Plan, dated May 21, 2007, incorporated by reference to Exhibit 10.1 to the Company's Quarterly Report on Form 10‑Q for the fiscal quarter ended July 31, 2007 |
| 10.4 | - Change in Control Agreement entered into as of June 8, 2007, by and between The Cooper Companies, Inc. and Eugene J. Midlock, incorporated by reference to Exhibit 10.8 to the Company's Annual Report on Form 10-K for the fiscal year ended October 31, 2007 |
| 10.5 | - Change in Control Agreement dated as of June 8, 2007, by and between The Cooper Companies, Inc. and John A. Weber, incorporated by reference to Exhibit 10.6 to the Company's Annual Report on form 10-K for the fiscal year ended October 31, 2008 |
| 10.6 | - Change in Control Agreement dated as of June 8, 2007, by and between The Cooper Companies, Inc. and Carol R. Kaufman, incorporated by reference to Exhibit 10.2 to the Company's Annual Report on form 10-K for the fiscal year ended October 31, 2009 |
| 10.7 | - Change in Control Agreement dated as of June 1, 2010, by and between The Cooper Companies, Inc. and Gregory W. Matz , incorporated by reference to Exhibit 10.7 to the Company's Annual Report on Form 10-K for the fiscal year ended October 31, 2011 |
| 10.8 | - 1996 Long-term Incentive Plan for Non-Employee Directors of The Cooper Companies, Inc., incorporated by reference to Appendix A to the Company's Proxy Statement for its 1996 Annual Meeting of Stockholders |
Location of
Exhibit in
Exhibit Sequential
Number Description of Document Number System
| 10.9 | - Amendment No. 1 to 1996 Long-term Incentive Plan for Non‑Employee Directors of The Cooper Companies, Inc., dated October 10, 1996, incorporated by reference to Exhibit 10.14 to the Company's Annual Report on Form 10-K for the fiscal year ended October 31, 1996 |
| 10.10 | - Amendment No. 2 to 1996 Long-term Incentive Plan for Non‑Employee Directors of The Cooper Companies, Inc., dated October 29, 1997, incorporated by reference to Exhibit 10.15 to the Company's Annual Report on Form 10-K for the fiscal year ended October 31, 1997 |
| 10.11 | - Amendment No. 3 to 1996 Long-term Incentive Plan for Non‑Employee Directors of The Cooper Companies, Inc., dated October 29, 1999, incorporated by reference to Exhibit 10.15 to the Company's Annual Report on Form 10-K for the fiscal year ended October 31, 2001 |
| 10.12 | - Amendment No. 4 to 1996 Long-term Incentive Plan for Non‑Employee Directors of The Cooper Companies, Inc., dated October 24, 2000, incorporated by reference to Exhibit 10.16 to the Company's Annual Report on Form 10-K for the fiscal year ended October 31, 2001 |
| 10.13 | - Amendment No. 5 to the 1996 Long-term Incentive Plan for Non-employee Directors of The Cooper Companies, Inc., incorporated by reference to Exhibit 10.17 to the Company's Annual Report on Form 10-K for the fiscal year ended October 31, 2001 |
| 10.14- | Amendment No. 6 to the 1996 Long-term Incentive Plan for Non-employee Directors of The Cooper Companies, Inc., incorporated by reference to Exhibit 4.15 to the Company's Registration Statement on form S-8 dated November 21, 2002 |
| 10.15- | Amendment No. 7 to the 1996 Long-term Incentive Plan for Non-employee Directors of The Cooper Companies, Inc. dated November 4, 2002, incorporated by reference to Exhibit 10.16 to the Company's Annual Report on Form 10-K for the fiscal year ended October 31, 2002 |
| 10.16 | - Amendment No. 8 to 1996 Long-term Incentive Plan for Non‑Employee Directors of The Cooper Companies, Inc. dated October 29, 2003, incorporated by reference to Exhibit 10.16 to the Company's Annual Report on Form 10-K for the fiscal year ended October 31, 2003 |
| 10.17- | Amendment No. 9 to 1996 Long-term Incentive Plan for Non‑Employee Directors of The Cooper Companies, Inc. dated November 9, 2005, incorporated by reference to Exhibit 10.17 to the Company's Annual Report on Form 10-K for the fiscal year ended October 31, 2006 |
| 10.18 | - Form of Non-Qualified Stock Option Agreement Pursuant to The Cooper Companies, Inc. 1996 Long Term Incentive Plan for Non-Employee Directors, incorporated by reference to the Company's Current Report on Form 8-K dated December 13, 2004 |
| 10.19 | - Form of Restricted Stock Agreement Pursuant to The Cooper Companies, Inc. 1996 Long Term Incentive Plan for Non-Employee Directors, incorporated by reference to the Company's Current Report on Form 8-K dated December 13, 2004 |
| 10.20 | - The Second Amended and Restated 2006 Long Term Incentive Plan for Non-Employee Directors of The Cooper Companies, Inc., incorporated by reference to the Company's Proxy Statement filed February 2, 2011 |
| 10.21 | - Amendment No. 1 to the Second Amended and Restated 2006 Long-term Incentive Plan for Non-Employee Directors of The Cooper Companies, Inc., incorporated by reference to Exhibit 10.21 to the Company's Annual Report on Form 10-K for the fiscal year ended October 31, 2011 |
Location of
Exhibit in
Exhibit Sequential
Number Description of Document Number System
| 10.22 | - Amendment No. 2 to the Second Amended and Restated 2006 Long-term Incentive Plan for Non-Employee Directors of The Cooper Companies, Inc., incorporated by reference to Exhibit 10.22 to the Company's Annual Report on Form 10-K for the fiscal year ended October 31, 2012 |
| 10.23 - | Amendment No. 3 to the Second Amended and Restated 2006 Long-term Incentive Plan for Non-Employee Directors of The Cooper Companies, Inc. |
| 10.24 | - Form of Non-Qualified Stock Option Agreement Pursuant to The Cooper Companies, Inc. 2006 Long Term Incentive Plan for Non-Employee Directors, incorporated by reference to Exhibit 10.25 of the Company's Annual Report on Form 10-K for the fiscal year ended October 31, 2007 |
| 10.25 | - Form of Restricted Stock Agreement Pursuant to The Cooper Companies, Inc. 2006 Long Term Incentive Plan for Non-Employee Directors, incorporated by reference to Exhibit 10.26 of the Company's Annual Report on Form 10-K for the fiscal year ended October 31, 2007 |
| 10.26 | - Second Amended and Restated 2001 Long-Term Incentive Plan, incorporated by reference to Appendix 10.2 to the Company's Quarterly Report on Form 10‑Q for the fiscal quarter ended April 30, 2006 |
| 10.27 | - Form of Incentive Stock Option Agreement Pursuant to The Cooper Companies, Inc. 2001 Long Term Incentive Plan, incorporated by reference to the Company's Current Report on Form 8-K dated December 13, 2004 |
| 10.28 | - The Second Amended and Restated 2007 Long-Term Incentive Plan of The Cooper Companies, Inc., incorporated by reference to the Company's Proxy Statement filed February 2, 2011 |
| 10.29 | - Form of Non-Qualified Stock Option Agreement Pursuant to the 2007 Long-Term Incentive Plan of The Cooper Companies, Inc., incorporated by reference to Exhibit 10.32 of the Company's Annual Report on Form 10-K for the fiscal year ended October 31, 2007 |
| 10.30 | - Form of UK Tax Approved Stock Option Agreement Pursuant to the 2007 Long-Term Incentive Plan of The Cooper Companies, Inc., incorporated by reference to Exhibit 10.33 of the Company's Annual Report on Form 10-K for the fiscal year ended October 31, 2007 |
| 10.31 | - Form of Deferred Stock Agreement Pursuant to the 2007 Long-Term Incentive Plan of The Cooper Companies, Inc., incorporated by reference to Exhibit 10.34 of the Company's Annual Report on Form 10-K for the fiscal year ended October 31, 2007 |
| 10.32(a)- | License Agreement dated as of November 19, 2007, by and among CIBA Vision AG, CIBA Vision Corporate and CooperVision, Inc., incorporated by reference to Exhibit 10.41 to the Company's Annual Report on Form 10-K for the fiscal year ended October 31, 2008 |
| 10.33(a)- | Amendment No. 1 to the License Agreement dated as of November 19, 2007, by and among CIBA Vision AG, CIBA Vision Corporate and CooperVision, Inc., incorporated by reference to Exhibit 99.1 of the Company’s Current Report on Form 8-K filed on December 21, 2012 |
| 10.34- | Lease Contract dated as of November 6, 2003, by and between The Puerto Rico Industrial Development Company and Ocular Sciences Puerto Rico, Inc., incorporated by reference to Exhibit 10.1 to the Company's Current Report on Form 8-K dated January 11, 2005 |
| 10.35 | - First Supplement and Amendment to Lease Contract dated as of December 30, 2003, by and between The Puerto Rico Industrial Development Company and Ocular Sciences Puerto Rico, Inc., incorporated by reference to Exhibit 10.2 to the Company's Current Report on Form 8-K dated January 11, 2005 |
Location of
Exhibit in
Exhibit Sequential
Number Description of Document Number System
| 10.36- | Assignment of Lease Agreement dated as of June 29, 2004, by and among Ocular Sciences Puerto Rico, Inc., Ocular Sciences Cayman Islands Corporation and The Puerto Rico Industrial Development Company, incorporated by reference to Exhibit 10.3 to the Company's Current Report on Form 8-K dated January 11, 2005 |
| 10.37 | - Credit Agreement, dated as of January 12, 2011, among The Cooper Companies, Inc., CooperVision International Holding Company LP, the lenders from time to time party thereto, KeyBank National Association, as a bookrunner, a lead arranger, and sole administrative agent, swing line lender and LC issuer, J.P. Morgan Securities LLC, as a lead arranger, bookrunner and syndication agent, Citigroup Global Markets Inc., as a lead arranger, bookrunner and syndication agent, Bank of America, N.A., as a lead arranger and documentation agent, and Wells Fargo Bank, National Association, as lead arranger and documentation agent, incorporated by reference to Exhibit 10.2 to the Company's Quarterly Report on Form 10-Q filed March 4, 2011 |
| 10.38 - | Amendment No. 1 to Credit Agreement, dated as of May 31, 2012, among The Cooper Companies, Inc., CooperVision International Holding Company, LP, the lenders party thereto and KeyBank National Association, as administrative agent, incorporated by reference to Exhibit 10.1 to the Company's Current Report on Form 8-K dated May 31, 2012 |
| 10.39 - | Amendment No. 2 to Credit Agreement, dated as of September 12, 2013, among The Cooper Companies, Inc., CooperVision International Holding Company, LP, the lenders party thereto and KeyBank National Association, as administrative agent, incorporated by reference to Exhibit 10.2 to the Company's Current Report on Form 8-K dated September 17, 2013 |
| 10.40 | - The Cooper Companies, Inc. 2013 Incentive Payment Plan, incorporated by reference to Exhibit 10.1 of the Company's Current Report on Form 8-K filed January 4, 2013 |
| 10.41 - | The Cooper Companies, Inc. 2014 Incentive Payment Plan, incorporated by reference to Exhibit 10.1 of the Company's Current Report on Form 8-K filed December 16, 2013 |
| 10.42 | - Form of Long Term Performance Share Award Agreement Pursuant to the 2007 Long-Term Incentive Plan of The Cooper Companies, Inc., incorporated by reference to Exhibit 10.1 of the Company's Current Report on Form 8-K dated February 13, 2009 |
| 10.43 - | Term loan agreement, dated as of September 12, 2013, among The Cooper Companies, Inc., the lenders party thereto, and KeyBank National Association, as Administrative Agent, incorporated by reference to Exhibit 10.1 to the Company's Current Report on Form 8-K dated September 17, 2013 |
| 11(b) | - Calculation of earnings per share |
| 21 | - Subsidiaries |
| 23 | - Consent and Report on Schedule of Independent Registered Public Accounting Firm |
| 31.1 | - Certification of the Chief Executive Officer, pursuant to Rule 13a-14(a) of the Securities Exchange Act of 1934 |
| 31.2 | - Certification of the Chief Financial Officer pursuant to Rule 13a-14(a) of the Securities Exchange Act of 1934 |
| 32.1 | - Certification of the Chief Executive Officer, pursuant to 18 U.S.C. Section 1350 |
| 32.2 | - Certification of the Chief Financial Officer, pursuant to 18 U.S.C. Section 1350 |
Location of
Exhibit in
Exhibit Sequential
Number Description of Document Number System
| 101 | The following materials from the Company's Annual Report on Form 10-K for the year ended October 31, 2013, formatted in Extensible Business Reporting Language (XBRL); (i) Consolidated Statements of Income for the years ended October 31, 2013, 2012 and 2011, (ii) Consolidated Statements of Comprehensive Income (Loss) for the years ended October 31, 2013, 2012 and 2011, (iii) Consolidated Balance Sheets at October 2013 and 2012, (iv) Consolidated Statements of Stockholders' Equity for the years ended October 31, 2013, 2012 and 2011, (v) Consolidated Statements of Cash Flows for the years ended October 31, 2013, 2012 and 2011, (vi) related notes to consolidated financial statements and (vii) Schedule II Valuation and Qualifying Accounts. |
| (a) | The agreement received confidential treatment from the Securities and Exchange Commission with respect to certain portions of this exhibit. Omitted portions have been filed separately with the Commission. |
| (b) | The information required in this exhibit is provided in Note 6, Earnings Per Share, in this report. |
CORPORATE INFORMATION
| BOARD OF DIRECTORS A. Thomas Bender Chairman of the Board Allan E. Rubenstein, M.D. Vice Chairman and Lead Director, Chairman of the Board, CalAsia Pharmaceuticals, Inc. Michael H. Kalkstein Of Counsel, Palo Alto Office, Dechert LLP Jody S. Lindell President and Chief Executive Officer, S.G. Management, Inc. Gary S. Petersmeyer Director Donald Press Executive Vice President, Broadway Management Co., Inc. Steven Rosenberg Director Robert S. Weiss President, Chief Executive Officer and Director Stanley Zinberg, M.D. Director COMMITTEES OF THE BOARD Audit Committee Steven Rosenberg (Chairman) Michael H. Kalkstein Jody S. Lindell Corporate Governance and Nominating Committee Donald Press (Chairman) Steven Rosenberg Allan E. Rubenstein, M.D. Stanley Zinberg, M.D. Organization and Compensation Committee Michael H. Kalkstein (Chairman) Jody S. Lindell Donald Press Gary S. Petersmeyer Allan E. Rubenstein, M.D. Science and Technology Committee Stanley Zinberg, M.D. (Chairman) A. Thomas Bender Gary S. Petersmeyer Allan E. Rubenstein, M.D. Robert S. Weiss | EXECUTIVE OFFICERS Robert S. Weiss President and Chief Executive Officer Rodney E. Folden Vice President and Corporate Controller Carol R. Kaufman Executive Vice President, Secretary, Chief Administrative Officer and Chief Governance Officer Greg W. Matz Vice President, Chief Financial Officer and Chief Risk Officer Daniel G. McBride, Esq. Executive Vice President, Chief Operating Officer and General Counsel Nicholas J. Pichotta President and Chief Executive Officer, Cooper Medical, Inc. Paul Remmell President and Chief Executive Officer, CooperSurgical, Inc. John A. Weber President, CooperVision, Inc. Albert G. White III Vice President and Chief Strategy Officer PRINCIPAL SUBSIDIARIES CooperVision, Inc. 6150 Stoneridge Mall Road Suite 370 Pleasanton, CA 94588 585-385-6810 www.coopervision.com CooperSurgical, Inc. 75 Corporate Drive Trumbull, CT 06611 203-601-5200 www.coopersurgical.com CORPORATE OFFICES The Cooper Companies, Inc. 6140 Stoneridge Mall Road Suite 590 Pleasanton, CA 94588 925-460-3600 www.coopercos.com | INVESTOR INFORMATION Recent news releases, the annual report on Securities and Exchange Commission Form 10-K, information about the Company's corporate governance program, recent investor presentations, replays of quarterly conference calls and historical stock quotes are available on our Web site at www.coopercos.com. INVESTOR RELATIONS CONTACT Albert G. White III Vice President and Chief Strategy Officer 6140 Stoneridge Mall Road Suite 590 Pleasanton, CA 94588 Voice: 925-460-3663 Fax: 925-460-3648 E-mail: ir@cooperco.com ANNUAL MEETING The Cooper Companies will hold its Annual Stockholders' Meeting in March 2014. TRANSFER AGENT American Stock Transfer & Trust Company 59 Maiden Lane - Plaza Level New York, NY 10038 800-937-5449 TRADEMARKS The Cooper Companies, Inc., its subsidiaries or affiliates own, license or distribute the registered trademarks, common law trademarks and trade names referenced in this report. INDEPENDENT AUDITORS KPMG LLP STOCK EXCHANGE LISTING The New York Stock Exchange Ticker Symbol “COO” |