 filings.tools
Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations.
67K characters. Original on sec.gov · Markdown
Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations.
Note numbers refer to “Notes to Consolidated Financial Statements” in Item 8. Financial Statements and Supplementary Data.
RESULTS OF OPERATIONS
In this section, we discuss the results of our operations for fiscal 2018 compared with fiscal 2017 and the results of our operations for fiscal 2017 compared with fiscal 2016. We discuss our cash flows and current financial condition under “Capital Resources and Liquidity.” Within the tables presented, percentages are calculated based on the underlying whole-dollar amounts and, therefore, may not recalculate exactly from the rounded numbers used for disclosure purposes.
Outlook
Overall, we remain optimistic about the long-term prospects for the worldwide contact lens and general health care markets. However, events affecting the economy as a whole, including but not limited to the uncertainty and instability of global markets driven by foreign currency volatility, global tax reform, debt concerns, the uncertainty caused by the United Kingdom's upcoming withdrawal from the European Union, and the trend of consolidations within the health care industry, impact our current performance and continue to represent a risk to our future performance.
CooperVision - We compete in the worldwide contact lens market with our spherical, toric and multifocal contact lenses offered in a variety of materials including using silicone hydrogel Aquaform® technology and phosphorylcholine technology (PC) Technology™. We believe that there will be lower contact lens wearer dropout rates as technology improves and enhances the wearing experience through a combination of improved designs and materials and the growth of preferred modalities such as single-use and monthly wearing options. CooperVision is focused on greater worldwide market penetration using recently introduced products, and we continue to expand our presence in existing and emerging markets, including through acquisitions.
CooperVision acquired the following entities during fiscal 2018:
| • | Blueyes on January 4, 2018 - a long-standing distribution partner, which has a leading position in the distribution of contact lenses to the optical and pharmacy sector in Israel |
| • | Paragon Vision Sciences on December 1, 2017 - a leading provider of ortho-k specialty contact lenses and oxygen permeable rigid contact lens materials |
CooperVision acquired the following entities in fiscal 2017:
| • | Procornea on August 3, 2017 - a Netherlands based manufacturer of specialty contact lenses, which expanded CooperVision's access to myopia (nearsightedness) management markets with new products |
| • | Grand Vista LLC on June 30, 2017 - a distributor in Russia of soft contact lenses |
Our ability to compete successfully with a full range of silicone hydrogel products is an important factor to achieving our desired future levels of sales growth and profitability. CooperVision manufactures and markets a wide variety of silicone hydrogel contact lenses within the daily, two-week and monthly modalities along with manufacturing some of these lenses as toric and/or multifocal lenses, including but not limited to Biofinity®, MyDay®, Avaira Vitality® and clariti®. Single-use lenses are designed for daily replacement and frequently replaced lenses are designed for two-week or monthly replacement. We expect increasing demand for clariti® 1day and MyDay® products, as well as future single-use products.
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
CooperSurgical - Our CooperSurgical business competes in the general health care market with a focus on advancing the health of women, babies and families through a diversified portfolio of products and services focusing on women's health, fertility, diagnostics and contraception. CooperSurgical has established its market presence and distribution system by developing products and acquiring companies, products and services that complement its business model.
CooperSurgical acquired the following entities and assets during fiscal 2018:
| • | LifeGlobal Group on April 3, 2018 - a privately held company that specializes primarily in IVF media. LifeGlobal’s product categories include media products, IVF laboratory air filtration products and dishware. This acquisition fits CooperSurgical product portfolio and strengthens our fertility media offerings |
| • | PARAGARD on November 1, 2017 - CooperSurgical acquired the assets of the PARAGARD IUD business from Teva for $1.1 billion. PARAGARD broadens and strengthens CooperSurgical's current women's health product portfolio and it is the only non-hormonal, long lasting, reversible contraceptive option approved by the FDA and available in the United States. IUDs represent a large and growing segment of the contraceptive market and this acquisition allows CooperSurgical to accelerate growth providing opportunities for operational synergies. |
In fiscal 2017, CooperSurgical acquired Wallace within Fertility, the IVF segment of Smiths Medical International Ltd. Wallace manufactures a range of IVF and ob/gyn products.
We intend to continue investing in CooperSurgical's business with the goal of expanding our integrated solutions model within the areas of women's health, fertility, diagnostics and contraception.
In the second quarter of fiscal 2018, CooperSurgical recognized an impairment charge of $24.4 million on the intangible assets acquired from Recombine Inc. (Recombine) as the cash flows expected to be generated by this asset group over its estimated remaining life were not sufficient to recover its carrying value. CooperSurgical acquired Recombine in fiscal 2016, a clinical genetic testing company specializing in carrier screening. In connection with the impairment charge, on June 1, 2018, CooperSurgical announced the exit of the carrier screening and non-invasive prenatal testing (NIPT) product lines in fertility. Exit and restructuring charges which were substantially completed at the end of fiscal 2018, consisted primarily of compensation and benefits to terminated employees, were approximately $10.0 million. The net loss from both product lines are not material to the Company's consolidated results of operations.
Capital Resources - At October 31, 2018, we had $77.7 million in cash, primarily outside the United States, and $560.5 million available under our 2016 Revolving Credit Facility (as defined below). On October 31, 2018, we had $125.0 million outstanding on the $830.0 million 2016 Term Loan Facility (as defined below), and we had the full amount of $1.425 billion outstanding under the 2017 Term Loan Agreement (as defined below).
On November 1, 2018, subsequent to our fiscal year ended October 31, 2018, the Company entered into a 364-day, $400.0 million senior unsecured term loan which matures on October 31, 2019 (the 2018 Term Loan Agreement). The Company used the funds to partially repay outstanding borrowings under the 2016 Revolving Credit Facility. See Note 14. Subsequent Event of the Consolidated Financial Statements for additional information.
On November 1, 2017, we entered into a $1.425 billion syndicated Term Loan Agreement (2017 Term Loan Agreement) which matures on November 1, 2022, to fund the acquisition of PARAGARD, to partially repay outstanding amounts under the 2016 Revolving Credit Facility, and for general corporate purposes. On March 1, 2016, we entered into a syndicated revolving Credit and Term Loan Agreement
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
(the 2016 Credit Agreement). This agreement, maturing on March 1, 2021, provides for a multi-currency revolving credit facility in an aggregate principal amount of $1.0 billion (the 2016 Revolving Credit Facility) and a term loan facility in the aggregate principal amount of $830.0 million (the 2016 Term Loan Facility). We paid down $705.0 million of the 2016 Term Loan Facility in the fiscal fourth quarter of 2018 and had $125.0 million outstanding at October 31, 2018. See Note 4. Debt of the Consolidated Financial Statements for additional information.
The Company believes that current cash, cash equivalents and future cash flow from operating activities will be sufficient to meet the Company’s anticipated cash needs, including working capital needs, capital expenditures and contractual obligations for at least 12 months from the issuance date of the financial statements included in this annual report. To the extent additional funds are necessary to meet our liquidity needs such as that for acquisitions, share repurchases, cash dividends or other activities as we execute our business strategy, we anticipate that additional funds will be obtained through the incurrence of additional indebtedness, additional equity financings or a combination of these potential sources of funds; however, such financing may not be available on favorable terms, or at all.
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
2018 Compared with 2017

Highlights: 2018 vs. 2017
| • | Gross margin remained at 64% of net sales compared with 64% in fiscal 2017 |
| • | Operating income decreased 6% to $403.1 million from $429.1 million, primarily due to an increase in amortization expenses as a result of acquisitions and a non-recurring impairment charge |
| • | Interest expense increased to $82.7 million from $33.4 million due to higher debt balance in connection with acquisitions and higher interest rates |
| • | Diluted earnings per share decreased 63% to $2.81 from $7.52 due to U.S. tax reform charges, an increase in amortization expense and a non-recurring impairment charge |
| • | Operating cash flow $668.9 million increased 12.7% from $593.6 million |
Selected Statistical Information – Percentage of Net Sales
| Years Ended October 31, | 2018 | 2017 | 2018 vs. 2017 % Change in Absolute Values | |||||
| Net sales | 100 | % | 100 | % | 18 | % | ||
| Cost of sales | 36 | % | 36 | % | 16 | % | ||
| Gross profit | 64 | % | 64 | % | 20 | % | ||
| Selling, general and administrative expense | 38 | % | 37 | % | 22 | % | ||
| Research and development expense | 3 | % | 3 | % | 23 | % | ||
| Amortization of intangibles | 6 | % | 3 | % | 114 | % | ||
| Impairment of intangibles | 1 | % | — | — | ||||
| Operating income | 16 | % | 20 | % | (6 | )% |
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
Net Sales Growth by Business Unit
| ($ in millions) | 2018 | 2017 | Increase | 2018 vs 2017 % Change | ||||||||||
| CooperVision | $ | 1,882.0 | $ | 1,674.1 | $ | 207.9 | 12 | % | ||||||
| CooperSurgical | 650.8 | 464.9 | 185.9 | 40 | % | |||||||||
| Net Sales | $ | 2,532.8 | $ | 2,139.0 | $ | 393.8 | 18 | % |
CooperVision Net Sales
The contact lens market has two major product categories:
| • | Spherical lenses including lenses that correct near- and farsightedness uncomplicated by more complex visual defects. |
| • | Toric and multifocal lenses including lenses that, in addition to correcting near- and farsightedness, address more complex visual defects such as astigmatism and presbyopia by adding optical properties of cylinder and axis, which correct for irregularities in the shape of the cornea. |
CooperVision Net Sales by Category
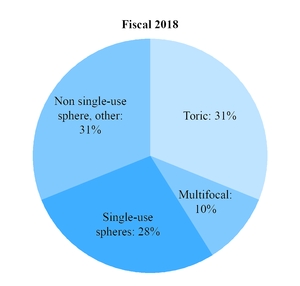

| ($ in millions) | 2018 | 2017 | 2018 vs. 2017 % Change | |||||||
| Toric | $ | 591.4 | $ | 526.8 | 12 | % | ||||
| Multifocal | 196.6 | 177.2 | 11 | % | ||||||
| Single-use spheres | 520.1 | 438.3 | 19 | % | ||||||
| Non single-use sphere, other | 573.9 | 531.8 | 8 | % | ||||||
| $ | 1,882.0 | $ | 1,674.1 | 12 | % |
In the fiscal year ended October 31, 2018:
| • | Toric and multifocal lenses grew primarily through the success of Biofinity, clariti and MyDay |
| • | Single-use sphere lenses growth was primarily attributed to clariti and MyDay lenses |
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
| • | Non single-use spheres grew primarily on sales of Biofinity |
| • | Increased sales of silicone hydrogel products were partially offset by lower sales of older hydrogel products. Total silicone hydrogel products grew 19% in fiscal 2018, representing 69% of net sales compared to 65% in the prior fiscal year |
| • | "Other" products primarily include lens care which represent 2% of net sales in fiscal 2018 compared to 3% in prior fiscal year |
| • | Foreign exchange rates positively increased sales by $43.9 million in fiscal 2018, primarily attributable to the Euro and British Pound |
| • | Sales growth was driven primarily by increases in the volume of lenses sold. Average realized prices by product did not materially influence sales growth |
CooperVision Net Sales by Geography
CooperVision competes in the worldwide soft contact lens market and services in three primary regions: the Americas, EMEA and Asia Pacific.
| ($ in millions) | 2018 | 2017 | 2018 vs. 2017 % Change | |||||||
| Americas | $ | 722.9 | $ | 675.4 | 7 | % | ||||
| EMEA | 744.3 | 651.2 | 14 | % | ||||||
| Asia Pacific | 414.8 | 347.5 | 19 | % | ||||||
| $ | 1,882.0 | $ | 1,674.1 | 12 | % |
CooperVision's regional growth was primarily attributed to market gains of silicone hydrogel contact lenses and positive foreign exchange rates in EMEA. Refer to CooperVision Net Sales by Category above for further discussion.
CooperSurgical Net Sales by Category
CooperSurgical supplies the family health care market with a diversified portfolio of products and services for use in surgical and other medical procedures that are performed primarily by obstetricians and gynecologists in hospitals, surgical centers, fertility clinics and the medical office. Fertility offerings include highly specialized products and services that target the IVF process, including diagnostics testing with a goal to make fertility treatment safer, more efficient and convenient.
The chart below shows the percentage of net sales of office and surgical products and fertility:
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations


The change in product mix was attributable to recent acquisitions, primarily PARAGARD which increased the revenue of office and surgical products.
| Year Ended October 31, ($ in millions) | 2018 | 2017 | 2018 vs. 2017 % Change | ||||||||
| Office and surgical procedures | $ | 400.4 | $ | 214.7 | 86 | % | |||||
| Fertility | 250.4 | 250.2 | — | % | |||||||
| $ | 650.8 | $ | 464.9 | 40 | % |
In the fiscal year ended October 31, 2018:
| • | CooperSurgical’s net sales growth was primarily due to incremental revenues from the acquisition of PARAGARD IUD, which is categorized in office and surgical products |
| • | Fertility net sales remained relatively flat in fiscal 2018 compared to the prior year primarily due to increased sales of IVF equipment and consumables and incremental revenue from LifeGlobal, offset by reduction of revenue from genetic testing primarily from the exit of NIPT and carrier screening product lines in the third quarter of fiscal 2018 |
| • | Office and surgical products increased compared to prior year periods due to continued growth in surgical products and recently acquired products, primarily PARAGARD |
| • | Unit growth and product mix positively impacted sales growth |
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
2017 Compared with 2016

Highlights: 2017 vs. 2016
| • | Gross margin increased to 64% of net sales compared with 60% in fiscal 2016 |
| • | Operating income increased 32% to $429.1 million from $324.1 million |
| • | Interest expense increased to $33.4 million from $26.2 million |
| • | Diluted earnings per share increased 35% to $7.52 from $5.59 |
| • | Operating cash flow increased 16% to $593.6 million from $509.6 million |
Selected Statistical Information – Percentage of Net Sales
| Years Ended October 31, | 2017 | 2016 | 2017 vs. 2016 % Change in Absolute Values | |||||
| Net sales | 100 | % | 100 | % | 9 | % | ||
| Cost of sales | 36 | % | 40 | % | (3 | )% | ||
| Gross profit | 64 | % | 60 | % | 16 | % | ||
| Selling, general and administrative expense | 37 | % | 37 | % | 11 | % | ||
| Research and development expense | 3 | % | 3 | % | 6 | % | ||
| Amortization of intangibles | 3 | % | 3 | % | 13 | % | ||
| Operating income | 20 | % | 16 | % | 32 | % |
Net Sales Growth by Business Unit
| ($ in millions) | 2017 | 2016 | Increase | 2017 vs 2016 % Change | ||||||||||
| CooperVision | $ | 1,674.1 | $ | 1,577.2 | $ | 96.8 | 6 | % | ||||||
| CooperSurgical | 464.9 | 389.6 | 75.4 | 19 | % | |||||||||
| Net Sales | $ | 2,139.0 | $ | 1,966.8 | $ | 172.2 | 9 | % |
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
CooperVision Net Sales by Category
| ($ in millions) | 2017 | % Net Sales | 2016 | %Net sales | 2017 vs. 2016 % Change | |||||||||||
| Toric | $ | 526.8 | 31 | % | $ | 480.2 | 30 | % | 10 | % | ||||||
| Multifocal | 177.2 | 11 | % | 169.8 | 11 | % | 4 | % | ||||||||
| Single-use spheres | 438.3 | 26 | % | 403.1 | 26 | % | 9 | % | ||||||||
| Non single-use sphere, other | 531.8 | 32 | % | 524.1 | 33 | % | 1 | % | ||||||||
| $ | 1,674.1 | 100 | % | $ | 1,577.2 | 100 | % | 6 | % |
In fiscal 2017, CooperVision's toric and multifocal lenses grew largely through the success of our Biofinity, clariti and MyDay portfolios, offset by declines in older hydrogel products. Single-use sphere lenses growth was largely attributed to clariti and MyDay lenses offset by declines in older hydrogel products. Non single-use spheres grew largely on sales of Biofinity offset by declines in older hydrogel products. The term "other" products primarily includes lens care, approximately 3% of net sales in fiscal 2017. Total silicone hydrogel products, including clariti, Biofinity, Avaira and MyDay grew 16% in fiscal 2017, representing 65% of net sales compared to 60% in the prior fiscal year.
CooperVision competes in the worldwide soft contact lens market and services in three primary regions: the Americas, EMEA and Asia Pacific.
CooperVision Net Sales by Geography
| ($ in millions) | 2017 | 2016 | 2017 vs. 2016 % Change | |||||||
| Americas | $ | 675.4 | $ | 650.7 | 4 | % | ||||
| EMEA | 651.2 | 612.3 | 6 | % | ||||||
| Asia Pacific | 347.5 | 314.2 | 11 | % | ||||||
| $ | 1,674.1 | $ | 1,577.2 | 6 | % |
CooperVision fiscal 2017 net sales growth was partially offset by foreign exchange rate fluctuations which had a negative impact on net sales of $19.8 million. Americas net sales growth was primarily due to market gains of silicone hydrogel contact lenses including Biofinity, clariti and MyDay, partially offset by a decrease in sales of older hydrogel lens products. EMEA net sales growth was largely due to market gains of silicone hydrogel contact lenses including Biofinity, clariti and MyDay, offset by a decrease in sales of older hydrogel products and weakening foreign currencies, primarily the British pound, compared to the prior year against the United States Dollar for the first three fiscal quarters and euro, for the first half of the fiscal year. Net sales in the Asia Pacific region grew on market gains of silicone hydrogel and hydrogel lenses, including Biofinity, clariti and MyDay, partially offset by weakening foreign currencies, primarily the Japanese yen, for the second half of the fiscal year.
CooperVision’s net sales growth was driven primarily by increases in the volume of lenses sold, including recently introduced silicone hydrogel products. While unit growth and product mix have influenced CooperVision’s net sales, average realized prices by product have not materially influenced sales growth.
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
CooperSurgical Net Sales
| Year Ended October 31, ($ in millions) | 2017 | % Net Sales | 2016 | % Net Sales | 2017 vs. 2016 % Change | ||||||||||||
| Fertility | $ | 250.2 | 54 | % | $ | 175.8 | 45 | % | 42 | % | |||||||
| Office and surgical procedures | 214.7 | 46 | % | 213.8 | 55 | % | — | % | |||||||||
| $ | 464.9 | 100 | % | $ | 389.6 | 100 | % | 19 | % |
CooperSurgical's net sales increase in fertility products compared to the prior year period was mainly due to incremental sales from products and services of acquired companies. The net sales of medical office and surgical procedures remained relatively flat in fiscal 2017 compared to the prior year due to declines in sales of disposable products, partially offset by growth in recently launched products used in surgical procedures. Unit growth and product mix, primarily sales of recently acquired products and services, influenced sales growth. Net sales growth was partially offset by the negative impact from the weakening of foreign currencies compared to the United States dollar during the year.
2018 Compared to 2017 and 2017 Compared to 2016
Gross Margin
| Gross Margin | 2018 | 2017 | 2016 | |||||
| CooperVision | 66 | % | 65 | % | 59 | % | ||
| CooperSurgical | 61 | % | 60 | % | 62 | % | ||
| Consolidated | 64 | % | 64 | % | 60 | % |
CooperVision's increase in gross margin in fiscal 2018 compared to fiscal 2017 was primarily due to:
| • | an increase in sales of higher margin products including Biofinity; |
| • | the favorable impact to revenue from exchange rate fluctuations, primarily attributable to the Euro and British Pound; and |
| • | was offset by $10.1 million of primarily product transition and integration costs in fiscal 2018. |
CooperVision's increase in gross margin in fiscal 2017 compared to fiscal 2016 was primarily due to:
| • | an increase in sales of higher margin products including Biofinity; |
| • | the favorable currency impact to CooperVision's cost of sales primarily led by the weakening of the British pound compared to the United States dollar; and |
| • | was offset by $10.9 million of primarily incremental costs associated with the impact of Hurricane Maria on our Puerto Rico manufacturing facility, $5.7 million of product write off costs related to the product transition from Avaira sphere to Avaira Vitality, and $0.6 million of facility start up in fiscal 2017. Fiscal 2016 gross margin was also negatively impacted by higher restructuring and integrations costs. |
CooperSurgical's gross margin in fiscal 2018 was positively impacted by the inclusion of our PARAGARD IUD product with higher gross margin; however, it was offset by:
| • | $49.3 million of inventory step-up relating to the PARAGARD and LifeGlobal acquisitions; and |
| • | $16.2 million of primarily integration and acquisition costs. |
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
CooperSurgical’s decrease in gross margin in fiscal 2017, compared to fiscal 2016 was primarily due to a change in product mix arising from sales of acquired lower margin fertility products and services. Cost of sales included $5.8 million of integration costs compared to $4.4 million in fiscal 2016.
Selling, General and Administrative Expense (SGA)
| ($ in millions) | 2018 | % Net Sales | 2018 vs. 2017 % Change | 2017 | % Net Sales | 2017 vs. 2016 % Change | 2016 | % Net Sales | ||||||||||||||||||
| CooperVision | $ | 657.2 | 35 | % | 13 | % | $ | 583.5 | 35 | % | 9 | % | $ | 535.3 | 34 | % | ||||||||||
| CooperSurgical | 259.3 | 40 | % | 55 | % | 167.8 | 36 | % | 19 | % | 141.6 | 36 | % | |||||||||||||
| Corporate | 56.8 | — | 19 | % | 47.8 | — | 4 | % | 45.9 | — | ||||||||||||||||
| $ | 973.3 | 38 | % | 22 | % | $ | 799.1 | 37 | % | 11 | % | $ | 722.8 | 37 | % |
CooperVision's sequential increase in SGA in fiscal 2018, compared to fiscal 2017 and 2016 was due to investments to support our long-term objectives, including increased headcount, investments in information technology and higher distribution expenses to support revenue growth. CooperVision's SGA in fiscal 2018 included $8.7 million of integration and third-party consulting costs.
CooperVision's SGA in fiscal 2017 included $9.1 million of legal costs related to Unilateral Pricing Policy (UPP) and $4.7 million of acquisition and integration costs, compared to $2.9 million of UPP costs and $9.0 million of restructuring and integration costs in fiscal 2016.
The increases in CooperSurgical's SGA in the fiscal 2018 compared to fiscal 2017 in absolute dollars and as a percentage of sales were primarily due to the addition of PARAGARD marketing expenses and sales headcount investment to support growth. CooperSurgical's SGA in fiscal 2018, included approximately $10.0 million of carrier screening and NIPT exit costs and $24.0 million primarily related to acquisition and integration expenses of acquired companies.
The increase in CooperSurgical's SGA in fiscal 2017 compared to fiscal 2016 in absolute dollars was primarily due to the inclusion of operating expenses of acquired companies and investment in headcount to support growth. CooperSurgical's SGA included $16.3 million primarily related to acquisition and integration expenses of acquired companies compared to $11.3 million in fiscal 2016.
The increases in Corporate SGA in fiscal 2018 compared to fiscal 2017 were primarily due to $6.2 million of compensation costs related to executives' retirements. The increase in fiscal 2017 compared to fiscal 2016 was primarily due to share based compensation related expenses.
Research and Development Expense (R&D)
| ($ in millions) | 2018 | % Net Sales | 2018 vs. 2017 % Change | 2017 | % Net Sales | 2017 vs. 2016 % Change | 2016 | % Net Sales | ||||||||||||||||||
| CooperVision | $ | 54.3 | 3 | % | 15 | % | $ | 47.3 | 3 | % | 1 | % | $ | 46.9 | 3 | % | ||||||||||
| CooperSurgical | 30.5 | 5 | % | 40 | % | 21.9 | 5 | % | 18 | % | 18.5 | 5 | % | |||||||||||||
| $ | 84.8 | 3 | % | 23 | % | $ | 69.2 | 3 | % | 6 | % | $ | 65.4 | 3 | % |
In fiscal 2018, CooperVision's R&D increased mainly due to increased costs from acquisitions and increase clinical studies. As a percentage of sales, R&D expense remained flat. CooperVision's R&D activities are primarily focused on the development of contact lenses, manufacturing technology and product enhancements. CooperVision's R&D expense remained relatively flat in fiscal 2017 compared to fiscal 2016.
The sequential increases in CooperSurgical's R&D in fiscal 2018 compared to fiscal 2017 and 2016 were primarily due to acquisitions, increased investment and activities in developing new products and services
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
and upgrades of existing products. As a percentage of sales, R&D expense remained flat. CooperSurgical's R&D activities include diagnostics, IVF product development and the design and upgrade of surgical procedure devices.
Amortization of Intangibles
| ($ in millions) | 2018 | % Net Sales | 2018 vs. 2017 % Change | 2017 | % Net Sales | 2017 vs. 2016 % Change | 2016 | % Net Sales | ||||||||||||||||||
| CooperVision | $ | 43.6 | 2 | % | 19 | % | $ | 36.7 | 2 | % | (9 | )% | $ | 40.1 | 3 | % | ||||||||||
| CooperSurgical | 103.1 | 16 | % | 224 | % | 31.7 | 7 | % | 54 | % | 20.7 | 5 | % | |||||||||||||
| $ | 146.7 | 6 | % | 114 | % | $ | 68.4 | 3 | % | 13 | % | $ | 60.8 | 3 | % |
The increases in amortization expense in fiscal 2018 compared to fiscal 2017 and 2016 were primarily due to amortization of intangible assets acquired in recent acquisitions in CooperVision and CooperSurgical, primarily PARAGARD which increased amortization expense by $70.8 million.
Impairment of Intangible Assets
In the second quarter of fiscal 2018, CooperSurgical recognized an impairment charge of $24.4 million on the intangible assets acquired from Recombine Inc. as the cash flows expected to be generated by this asset group over its estimated remaining life were not sufficient to recover its carrying value. CooperSurgical acquired Recombine Inc., a clinical genetic testing company specializing in carrier screening, in fiscal 2016. In connection with the impairment charge, on June 1, 2018, CooperSurgical announced the exit of the carrier screening and NIPT product lines in fertility. Exit and restructuring charges which were substantially completed at the end of fiscal 2018, consisted primarily of compensation and benefits to terminated employees, were approximately $10.0 million. The net loss from both product lines are not material to the Company's consolidated results of operations.
Operating Income
| ($ in millions) | 2018 | % Net Sales | 2018 vs. 2017 % Change | 2017 | % Net Sales | 2017 vs. 2016 % Change | 2016 | % Net Sales | ||||||||||||||||||
| CooperVision | $ | 479.8 | 25 | % | 15 | % | $ | 418.4 | 25 | % | 35 | % | $ | 309.8 | 20 | % | ||||||||||
| CooperSurgical | (19.9 | ) | (3 | )% | (134 | )% | 58.5 | 13 | % | (3 | )% | 60.2 | 15 | % | ||||||||||||
| Corporate | (56.8 | ) | — | (19 | )% | (47.8 | ) | — | (4 | )% | (45.9 | ) | — | |||||||||||||
| $ | 403.1 | 16 | % | (6 | )% | $ | 429.1 | 20 | % | 32 | % | $ | 324.1 | 16 | % |
The decrease in consolidated operating income in fiscal 2018 compared to fiscal 2017 was primarily due to the increase in amortization expense from the PARAGARD intangible assets, impairment of intangible asset and investments in SGA in both businesses, partially offset by the increase in consolidated gross margin.
The increase in consolidated operating income in fiscal 2017 compared to fiscal 2016 in absolute dollars and as a percentage of net sales was primarily due to the increase in consolidated gross margins and lower restructuring and integration costs in CooperVision compared to fiscal 2016. This was partially offset by a decrease in CooperSurgical operating income due to higher operating expenses relating to acquisitions and investments to support growth.
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
Interest Expense
| ($ in millions) | 2018 | % Net Sales | 2018 vs. 2017 % Change | 2017 | % Net Sales | 2017 vs. 2016 % Change | 2016 | % Net Sales | ||||||||||||||||||
| Interest expense | $ | 82.7 | 3 | % | 147 | % | $ | 33.4 | 2 | % | 28 | % | $ | 26.2 | 1 | % |
The increase in interest expense in fiscal 2018 compared to fiscal 2017 in absolute dollars and as a percentage of sales reflects higher average debt balances mainly due to the $1.425 billion term loan entered into on November 1, 2017 to primarily fund the PARAGARD acquisition and higher interest rates. Fiscal 2018 interest expense also included $2.5 million write off of debt issuance costs related to partial prepayments of the 2016 term loan and $1.7 million of Bridge Loan Facility fees that were incurred related to the PARAGARD acquisition.
The increase in interest expense in fiscal 2017 compared to fiscal 2016 in absolute dollars and as a percentage of sales reflect higher average debt balances as a result of debt incurred in connection with acquisitions as well as higher interest rates. Fiscal 2017 interest expense also included $2.2 million of Bridge Loan Facility fees that were incurred related to the PARAGARD acquisition.
Other (Income) Expense, Net
| Years Ended October 31, (In millions) | 2018 | 2017 | 2016 | ||||||||
| Foreign exchange loss | $ | 3.4 | $ | 1.4 | $ | 1.6 | |||||
| Other (income) expense, net | (14.9 | ) | 0.3 | 0.7 | |||||||
| $ | (11.5 | ) | $ | 1.7 | $ | 2.3 |
Foreign exchange loss primarily resulted from the revaluation and settlement of foreign currencies-denominated balances. Other income in fiscal 2018 is primarily from the realization of a Puerto Rico research and development credit of $14.2 million as we had the intent and ability to sell the credit.
Other expense in fiscal 2017 includes a $0.2 million foreign exchange loss on forward contracts related to an acquisition. Other expense in fiscal 2016 includes a $0.6 million foreign exchange loss on forward contracts related to an acquisition and a $0.4 million loss related to extinguishment of debt.
Provision for Income Taxes
The Company’s effective tax rate (ETR) was 57.9%, 5.3% and 7.0% for fiscal 2018, 2017 and 2016, respectively. The ETR in fiscal 2018 increased in comparison to fiscal 2017 primarily due to the net charge related to the enactment of the 2017 Act which was partially offset by a shift in the geographic mix of income. The ETR in fiscal 2017 decreased in comparison to fiscal 2016 due to the shift in the geographic mix of income as well as excess tax benefits from share-based compensation.
The ETR for 2018 was greater than the U.S. federal statutory tax rate primarily due to the tax expense related to the enactment of the 2017 Act. The ETR for 2017 and 2016 was less than the U.S. federal statutory tax rate because a majority of our taxable income was earned in foreign jurisdictions with lower tax rates. The ratio of domestic income to worldwide income significantly impacted our overall tax rate due to the fact that the tax rates in the majority of foreign jurisdictions where we operate are significantly lower than the statutory rate in the United States. The foreign jurisdictions with lower tax rates compared to the U.S. federal statutory tax rate that had the most significant impact on our provision for foreign income taxes in the fiscal years presented include the United Kingdom, Barbados and Puerto Rico. See Note 5. Income Taxes of the Consolidated Financial Statements for additional information.
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
ASC 740, Income Taxes, requires companies to recognize the effect of the tax law changes in the period of enactment. However, in December 2017, the SEC provided regulatory guidance for accounting referred to as Staff Accounting Bulletin (SAB) 118. Under the guidance in SAB 118, the income tax effects for which the accounting under ASC 740 is incomplete, are reported as a provisional amount based on a reasonable estimate. The reasonable estimate is subject to adjustment during a "measurement period," not to exceed one year, until the accounting is complete. The estimate is also subject to the finalization of management’s analysis related to certain matters, such as developing interpretations of the provision, changes to certain estimates and amounts related to the earnings and profits of certain subsidiaries and the filing of tax returns. The Company recorded a provisional charge for fiscal 2018, utilizing the most recent information and guidance available related to the calculation of the tax liability and the impact to its deferred tax assets and liabilities, including those recorded for foreign, local and withholding taxes that the Company assessed as of October 31, 2018. The provisional charge may require further adjustments and changes as new guidance is made available. Revisions to the provisional charge may be material to the Company's financial results and will be recorded in the quarter in which we complete the analysis.
Share-Based Compensation Plans
We grant various share-based compensation awards, including stock options, performance shares and restricted stock units. The share-based compensation and related income tax benefit recognized in the Consolidated Financial Statements in fiscal 2018 was $43.2 million and $8.8 million, respectively, compared to $37.2 million and $11.4 million, respectively, in fiscal 2017. As of October 31, 2018, there was $79.2 million of total unrecognized share-based compensation cost related to non-vested awards. See Note 8. Stock Plans of the Consolidated Financial Statements for additional information.
We estimate the fair value of each stock option award on the date of grant using the Black-Scholes valuation model, which requires management to make estimates regarding expected option life, stock price volatility and other assumptions. The use of different assumptions could lead to a different estimate of fair value. The expected life of the stock option is based on the observed and expected time to post-vesting forfeiture and/or exercise. Groups of employees that have similar historical exercise behavior are considered separately for valuation purposes. If our assumption for the expected life increased by one year, the fair value of an individual option granted in fiscal 2018 would have increased by approximately $5.69. To determine the stock price volatility, management considers implied volatility from publicly-traded options on the Company's stock at the date of grant, historical volatility and other factors. If our assumption for stock price volatility increased by one percentage point, the fair value of an individual option granted in fiscal 2018 would have increased by approximately $1.91.
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
CAPITAL RESOURCES AND LIQUIDITY
2018 Highlights
| • | Operating cash flow $668.9 million up from $593.6 million in fiscal 2017 |
| • | Expenditures for purchases of property, plant and equipment $193.6 million up from $127.2 million in fiscal 2017 |
| • | Cash payments for acquisitions and others, $1,323.9 million compared to $254.1 million in fiscal 2017 |
| • | Total debt, net of debt issuance cost at $2.02 billion at the end of fiscal 2018 compared to $1.17 billion at the end of fiscal 2017 |
Comparative Statistics
| Years Ended October 31, ($ in millions) | 2018 | 2017 | |||||
| Cash and cash equivalents | $ | 77.7 | $ | 88.8 | |||
| Total assets | $ | 6,112.8 | $ | 4,858.7 | |||
| Working capital | $ | 554.4 | $ | 557.1 | |||
| Total debt | $ | 2,022.8 | $ | 1,172.7 | |||
| Stockholders’ equity | $ | 3,307.8 | $ | 3,175.8 | |||
| Ratio of debt to equity | 0.61:1 | 0.37:1 | |||||
| Debt as a percentage of total capitalization | 38 | % | 27 | % |
Working Capital
The decrease in working capital at the end of fiscal 2018 from the end of fiscal 2017 was primarily due to an increase in accrued and other current liabilities ($122.4 million) mainly due to an increase in charge backs, an increase in short term notes payable ($13.7 million), an increase in accounts payable ($4.3 million) and a decrease in cash and cash equivalents ($11.1 million). This was partially offset by an increase in accounts receivable ($58.1 million) from increased revenue, an increase in prepayments and other current assets ($76.0 million) primarily from the $42.0 million (GBP 31 million) payment to U.K. Tax Authorities relating to DPT, and an increase in inventories ($14.7 million).
At October 31, 2018, our inventory months on hand were 6.3 compared to 6.5 at October 31, 2017. The $14.7 million increase in inventories was primarily due to increase in finished goods and raw materials to support product launches and production levels. Our days sales outstanding (DSO) remained flat at 53 days at October 31, 2018 and at October 31, 2017.
We have reviewed our needs in the United States and have determined there is sufficient cash to fund working capital without repatriating cash from our foreign subsidiaries. For purposes of recording the provisional tax expense for the year ended October 31, 2018, we are no longer asserting that earnings from our foreign subsidiaries are indefinitely reinvested. However, the Company has not completed its analysis and will make a final decision within the measurement period. If the Company changes its assertion to not indefinitely reinvest foreign earnings, there will be more flexibility in using the cash from our foreign operations to fund future working capital in the United States.
Accounts Receivable Factoring Program - We may factor certain designated trade receivables with one or more third party financial institutions pursuant to a factoring agreement. These are non-recourse factoring arrangements to assist us in managing operating cash flow and meet the requirements to be accounted for
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
as sales in accordance with the “Transfers and Servicing” guidance in ASC 860, where the Company’s continuing involvement subsequent to the transfer is limited to providing certain servicing and collection actions on behalf of the purchasers of the designated trade receivables. See Note 1. Accounting Policies of the Consolidated Financial Statements for additional information.
Operating Cash Flow
Cash flow provided by operating activities in fiscal 2018 is one of our major sources of liquidity, at $668.9 million compared to $593.6 million in fiscal 2017 and $509.6 million in fiscal 2016. Cash provided by operating activities increased by $75.3 million in fiscal 2018. This increase in cash flow provided by operating activities primarily consists of an increase of $182.5 million in non-cash items, from $226.9 million in the fiscal 2017 to $409.4 million in fiscal 2018, and increase in assets and liabilities of $125.8 million. This increase was offset by a decrease in net income of $233.0 million from $372.9 million in fiscal 2017 to $139.9 million in fiscal 2018, primarily due to $214.6 million of provisional tax expense related to the 2017 Act.
The $182.5 million increase from non-cash items compared to fiscal 2017 is primarily due to a $86.7 million increase in depreciation and amortization, a $50.5 million release of a fair value adjustment to inventory acquired mainly from PARAGARD, impairment of intangibles of $24.4 million and an increase in share-based compensation expense of $6.0 million.
The $125.8 million increase in the net cash from changes in assets and liabilities compared to fiscal 2017 is mainly due to an increase in long-term liabilities of $150.7 million, primarily from a provisional tax liability for the mandatory deemed repatriation of deferred foreign earnings under the 2017 Act of $141.5 million, a $25.9 million increase in the net changes of inventories, driven by acquisitions and higher raw materials to support production levels, and a $62.3 million increase in accrued liabilities mainly due to increase in charge backs. This increase is partially offset by a $34.4 million decrease in net changes in receivables, a $51.1 million decrease in changes to prepayments and other assets primarily due to a $42.0 million payment to the U.K. Tax Authorities, a $22.1 million decrease in net changes to accounts payable and a $5.5 million decrease in accrued income taxes.
Cash flow provided by operating activities in fiscal 2017 was at $593.6 million compared to $509.6 million in fiscal 2016. Fiscal 2017 results include $372.9 million of net income and non-cash items primarily made up of $188.4 million related to depreciation and amortization, $37.2 million of share-based compensation and $6.1 million of loss on disposal of property, partially offset by $7.1 million related to deferred income taxes. Cash flow from operating capital reflect the changes in operating assets and liabilities, which are primarily a $25.1 million increase in accounts receivable, driven by higher revenue, an increase in inventories of $30.9 million, driven by higher raw materials to support production levels and inventories from acquisitions, and other assets of $13.8 million, offset by an increase in accounts payable of $25.0 million, an increase in accrued expenses of $18.9 million, and an increase in other long term liabilities of $9.8 million. The $84.0 million increase in cash flows provided by operating activities in fiscal 2017 compared to fiscal 2016 is primarily due to the increase in net income and inclusion of excess tax benefit from share based compensation awards in operating activities from the adoption of ASU2016-09.
Investing Cash Flow
Cash used in investing activities increased by $1,136.2 million to $1,517.5 million in fiscal 2018. The increase was driven by a $66.4 million increase in capital expenditures, primarily to invest in the
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
expansion of distribution and manufacturing capacity, and an increase in payments for business and asset acquisitions of $1,069.8 million. The increase in payments related to acquisitions was largely due to the acquisition of PARAGARD as discussed in Outlook above and in Note 2. Acquisitions of the Consolidated Financial Statements.
Cash used in investing activities of $381.3 million in fiscal 2017 was for capital expenditures of $127.2 million primarily to increase manufacturing capacity and payments of $254.1 million primarily related to acquisitions in fiscal 2017. In fiscal 2017, payments related to the acquisitions are Procornea Holding B.V, Wallace and Grand Vista LLC.
Financing Cash Flow
Cash provided by financing activities increased by $1,072.3 million to $844.4 million in fiscal 2018. The increase was driven by a $1,012.1 million increase of net proceeds from short and long-term debt primarily due to additional debt taken on to fund the PARAGARD acquisition, and $7.1 million increase in net proceeds related to share-based compensation awards. No share repurchases were made in fiscal 2018 compared to $55.0 million in fiscal 2017.
Cash used in financing activities of $227.9 million in fiscal 2017 was driven by $211.7 million net repayments of short term debt, $55.0 million for repurchase of common stock, $5.3 million net payments related to share-based compensation awards, $4.3 million of payments of contingent consideration for prior acquisitions and $2.9 million for dividends, partially offset by $49.2 million net proceeds from long term debt.
The 2017 Term Loan Agreement contains customary restrictive covenants, as well as financial covenants that require the Company to maintain a certain Total Leverage Ratio and Interest Coverage Ratio (each as defined in the 2017 Term Loan Agreement) consistent with the 2016 Credit Agreement. As defined, in both the 2017 Term Loan Agreement and the 2016 Credit Agreement, we are required to maintain an Interest Coverage Ratio of at least 3.00 to 1.00, and a Total Leverage Ratio of no higher than 3.75 to 1.00. At October 31, 2018, we were in compliance with the Interest Coverage Ratio at 10.66 to 1.00 and the Total Leverage Ratio at 2.21 to 1.00.
At October 31, 2018, we had $1.425 billion outstanding under the 2017 Term Loan Agreement, $125.0 million outstanding under the 2016 Term Loan Facility and $560.5 million available under the 2016 Revolving Credit Facility.
At October 31, 2018, we had $77.7 million in cash & cash equivalents, predominantly outside the United States.
On November 1, 2018, subsequent to the fiscal year ended October 31, 2018, the Company entered into a 364-day, $400.0 million, senior unsecured term loan agreement by and among the Company, the lenders party thereto and PNC Bank, National Association, as administrative agent which matures on October 31, 2019 (the 2018 Term Loan Agreement). The Company used the funds to partially repay outstanding borrowings under the 2016 Revolving Credit Facility. See Note 14. Subsequent Event of the Consolidated Financial Statements for additional information.
Share Repurchases
In December 2011, our Board of Directors authorized the 2012 Share Repurchase Program and through subsequent amendments, the most recent in March 2017, the total repurchase authorization was increased from $500.0 million to $1.0 billion of the Company's common stock. The program has no expiration date
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
and may be discontinued at any time. We did not repurchase any shares during fiscal 2018. At October 31, 2018, we had remaining authorization to repurchase $563.5 million of our common stock
During fiscal 2017, we repurchased 108 thousand shares of our common stock for $25.5 million at an average purchase price of $237.12 per share in the fourth quarter of fiscal 2017; and repurchased 150 thousand shares of our common stock for $29.5 million at an average purchase price of $196.82 per share in the second quarter of fiscal 2017. We did not repurchase any shares during fiscal 2016.
OFF BALANCE SHEET ARRANGEMENTS
None.
CONTRACTUAL OBLIGATIONS AND COMMERCIAL COMMITMENTS
As of October 31, 2018, we had the following contractual obligations and commercial commitments:
| Payments Due by Period (In millions) | Total | 2019 | 2020 & 2021 | 2022 & 2023 | 2024 & Beyond | ||||||||||||||
| Contractual obligations: | |||||||||||||||||||
| Long-term debt | $ | 1,989.2 | $ | — | $ | 564.2 | $ | 1,425.0 | $ | — | |||||||||
| Interest payments | 228.0 | 62.0 | 116.0 | 50.0 | — | ||||||||||||||
| Operating leases | 304.2 | 37.5 | 60.6 | 46.4 | 159.7 | ||||||||||||||
| Transition tax on unremitted foreign earnings and profits (1) | 153.8 | 12.3 | 24.6 | 24.6 | 92.3 | ||||||||||||||
| Total contractual obligations | 2,675.2 | 111.8 | 765.4 | 1,546.0 | 252.0 | ||||||||||||||
| Commercial commitments: | |||||||||||||||||||
| Stand-by letters of credit | 4.7 | 4.7 | — | — | — | ||||||||||||||
| Total | $ | 2,679.9 | $ | 116.5 | $ | 765.4 | $ | 1,546.0 | $ | 252.0 |
(1) As of October 31, 2018, we had recorded $153.8 million of income tax liabilities related to the provisional one-time transition tax that resulted from the enactment of the 2017 Act, which will be payable in eight annual installments. The first installment is classified as a current income tax payable on our consolidated balance sheet. The remaining installment amounts will be equal to 8% of the total liability, payable in fiscal 2020 through 2023, 15% in fiscal year 2024, 20% in fiscal year 2025, and 25% in fiscal year 2026.
The expected future benefit payments for pension plans through 2028 are disclosed in Note 9. Employee Benefits of the Consolidated Financial Statements.
We are unable to reliably estimate the timing of future payments related to uncertain tax positions; therefore, about $68.9 million of our long-term income taxes payable have been excluded from the table above. However, other long-term liabilities, included in our consolidated balance sheet, include these uncertain tax positions. See Note 5. Income Taxes of the Consolidated Financial Statements for additional information.
Inflation and Changing Prices
Inflation has had no appreciable effect on our operations in the last three fiscal years.
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
Accounting Pronouncements
Information regarding new accounting pronouncements is included in Note 1. Accounting Policies of the Consolidated Financial Statements.
Estimates and Critical Accounting Policies
Management estimates and judgments are an integral part of financial statements prepared in accordance with accounting principles generally accepted in the United States of America (GAAP). We believe that the critical accounting policies described in this section address the more significant estimates required of management when preparing the Consolidated Financial Statements in accordance with GAAP. We consider an accounting estimate critical if changes in the estimate may have a material impact on our financial condition or results of operations. We believe that the accounting estimates employed are appropriate and resulting balances are reasonable; however, actual results could differ from the original estimates, requiring adjustment to these balances in future periods.
| • | Revenue recognition - We recognize product net sales, net of discounts, returns and rebates in accordance with related accounting standards and SEC Staff Accounting Bulletins. As required by these standards, we recognize revenue when it is realized or realizable and earned, based on terms of sale with the customer, where persuasive evidence of an agreement exists, delivery has occurred, the seller's price is fixed and determinable and collectability is reasonably assured. For contact lenses as well CooperSurgical's office and surgical products, fertility and diagnostic products and services, this occurs when title and risk of ownership transfers to our customers, and/or when services are rendered. We believe our revenue recognition policies are appropriate in all circumstances, and that our policies are reflective of our customer arrangements. We record, based on historical statistics, estimated reductions to revenue for customer incentive programs offered including cash discounts, promotional and advertising allowances, volume discounts, contractual pricing allowances, chargebacks, rebates and specifically established customer product return programs. We record taxes collected from customers on a net basis, as these taxes are not included in net sales. |
| • | Valuation of goodwill - We evaluate our goodwill balances and test them for impairment annually during the fiscal third quarter and when an event occurs or circumstances change such that it is reasonably possible that impairment may exist in accordance with related accounting standards. We performed our annual impairment test in our fiscal third quarter of 2018, and our analysis indicated that we had no impairment of goodwill. We performed our annual impairment test in our fiscal third quarter of 2017 and concluded that we had no impairment of goodwill in that year. |
Goodwill impairment analysis and measurement is a process that requires significant judgment. If our common stock price trades below book value per share, there are changes in market conditions or a future downturn in our business, or a future annual goodwill impairment test indicates an impairment of our goodwill, we may have to recognize a non-cash impairment of our goodwill that could be material, and could adversely affect our results of operations in the period recognized and also adversely affect our total assets, stockholders' equity and financial condition.
We test goodwill impairment in accordance with ASU 2017-04, Intangibles - Goodwill and other (Topic 350): Simplifying the Test for Goodwill Impairment. We perform a qualitative assessment to test each reporting unit's goodwill for impairment. Qualitative factors considered in this assessment include industry and market considerations, overall financial performance and other relevant events and factors affecting each reporting unit. Based on our qualitative assessment, if we determine that the fair value of a reporting unit is more likely than not to be less than its
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
carrying amount, the fair value of a reporting unit will be compared with its carrying amount and an impairment charge will be recognized for the carrying amount which exceeds the reporting unit's fair value. A reporting unit is the level of reporting at which goodwill is tested for impairment. Our reporting units are the same as our business segments - CooperVision and CooperSurgical - reflecting the way that we manage our business.
| • | Business combinations - We routinely consummate business combinations. Results of operations for acquired companies are included in our consolidated results of operations from the date of acquisition. We recognize separately from goodwill, the identifiable assets acquired, including acquired in-process research and development, the liabilities assumed, and any noncontrolling interest in the acquiree at the acquisition date fair values as defined by accounting standards related to fair value measurements. Key assumptions routinely utilized in allocation of purchase price to intangible assets include projected financial information such as revenue projections for companies acquired. As of the acquisition date, goodwill is measured as the excess of consideration given, generally measured at fair value, and the net of the acquisition date fair values of the identifiable assets acquired and the liabilities assumed. Direct acquisition costs are expensed as incurred. |
| • | Income taxes - We account for income taxes under the asset and liability method. Deferred tax assets and liabilities are recognized for the future tax consequences attributable to differences between the financial statement carrying amounts of existing assets and liabilities and their respective tax bases, and for tax losses and tax credit carryforwards. Deferred tax assets and liabilities are measured using enacted tax rates expected to apply to taxable income in the years in which those temporary differences are expected to be recovered or settled. The effect on deferred tax assets and liabilities of a change in tax rates is recognized in income in the period that includes the enactment date. In assessing the realizability of deferred tax assets, management considers whether it is more likely than not that some portion or all of the deferred tax assets will not be realized. |
As part of the process of preparing the Consolidated Financial Statements, we must estimate our income tax expense for each of the jurisdictions in which we operate. This process requires significant management judgments and involves estimating our current tax exposures in each jurisdiction including the impact, if any, of additional taxes resulting from tax examinations as well as judging the recoverability of deferred tax assets. To the extent recovery of deferred tax assets is not likely based on our estimation of future taxable income in each jurisdiction, a valuation allowance is established. Tax exposures can involve complex issues and may require an extended period to resolve. Frequent changes in tax laws in each jurisdiction complicate future estimates. To determine the tax rate, we are required to estimate full-year income and the related income tax expense in each jurisdiction. We update the estimated effective tax rate for the effect of significant unusual items as they are identified. Changes in the geographic mix or estimated level of annual pre-tax income can affect the overall effective tax rate, and such changes could be material.
Regarding accounting for uncertainty in income taxes, we recognize the benefit from a tax position only if it is more likely than not that the position would be sustained upon audit based solely on the technical merits of the tax position. We classify interest and penalties related to uncertain tax positions as additional income tax expense.
THE COOPER COMPANIES, INC. AND SUBSIDIARIES
Management’s Discussion and Analysis of Financial Condition and Results of Operations
Trademarks
Aquaform®, Avaira®, Avaira Vitality®, Biofinity®, MyDay® and Proclear® are registered trademarks of The Cooper Companies, Inc., its affiliates and/or subsidiaries. PC Technology™, FIPS™, and A Quality of Life Company™ are trademarks of The Cooper Companies, Inc., its affiliates and/or subsidiaries. The clariti® mark is a registered trademark of The Cooper Companies, Inc., its affiliates and/or subsidiaries worldwide except in the United States where the use of clariti® is licensed. PARAGARD® is a registered trademark of CooperSurgical, Inc.
Previous: Item 6. Selected Financial Data. · Next: Item 7A. Quantitative and Qualitative Disclosure about Market Risk.