 filings.tools
Copart (CPRT) 10-K risk factor changes: FY2017 vs FY2016
The 2017-07-31 10-K against the 2016-07-31 one, compared heading by heading and sentence by sentence. One of these filings carries no fiscal year tag, so its year is the calendar year of the period end.
Item 1A28 rewritten23 added24 removed393 unchanged
All filing items887 rewritten546 added287 removed1,742 unchanged
Summary
counted, not written
- Item 1A headings could not be compared: only 0 carried over between the two years, which usually means one filing was read wrongly, so none is reported as new or removed.
- Sentence by sentence, 546 added, 287 removed, 887 rewritten and 1,742 unchanged across 16 items that differ.
Sentences by item
20 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2017; struck-through words were in FY2016. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors
28 rewritten, 23 added, 24 removed, 393 unchanged
No single customer accounted for more than 10% of our [added: consolidated] revenue for fiscal [removed: 2016.][added: 2017.]
Our expansion into markets outside the U.S., including [removed: recent] expansions in Europe, Brazil, the Middle East, and India expose us to risks arising from operating in international markets.
Subsequently, in fiscal 2008 we made a significant acquisition in the U.K., followed by acquisitions in the U.A.E., Brazil, Germany, and Spain in fiscal 2013, expansions into Bahrain and Oman in fiscal 2015, and expansion into [added: the Republic of] Ireland and India in fiscal 2016.
Among other things, we [removed: will] [added: plan to] ultimately deploy our proprietary auction technologies at all of our foreign operations and we cannot predict whether this deployment will be successful or will result in increases in the revenues or operating efficiencies of any acquired companies relative to their historic operating performance.
| • | the [removed: difficulty of managing and staffing foreign offices and the] increased travel, infrastructure and legal compliance costs associated with multiple international locations; |
On June 23, 2016, the U.K. held a referendum in which voters approved an exit from the European Union, commonly referred to as “Brexit.” [removed: As a result of] [added: In February 2017,] the [removed: referendum, it is expected that] [added: British Parliament voted in favor of allowing] the British government [removed: will] [added: to] begin negotiating the terms of the U.K.’s withdrawal from the European Union and [removed: the U.K.’s future relationships] [added: discussions] with [added: the] European Union [removed: member states.][added: began in March 2017.]
[removed: Adverse] [added: The ultimate effects of Brexit on us are difficult to predict, but adverse] consequences concerning Brexit or the European Union could include deterioration in global economic conditions, instability in global financial markets, political uncertainty, volatility in currency exchange rates, or adverse changes in the cross-border agreements currently in place, any of which could have an adverse impact on our financial results in the future.
In many countries outside of the United States, particularly in those with developing economies, it may be common for persons to engage in business practices prohibited by laws and regulations applicable to us, such as the U.S. Foreign Corrupt Practices Act (FCPA), U.K. Bribery Act, Brazil Clean Companies Act, [removed: India's] [added: India’s] Prevention of Corruption Act, [removed: 1998] [added: 1988] or similar local anti-bribery laws.
[removed: In general, acquisitions] [added: Acquisitions typically will] increase our sales and profitability although, given the typical size of our [removed: acquisitions,] [added: acquisitions to date,] most acquisitions will not individually have a material impact on our consolidated results of operations and financial position.
We began using our new internally developed proprietary system with our expansion into Spain and India in fiscal [removed: 2016.][added: 2016 and Germany in fiscal 2017.]
[removed: In] [added: For example, in] April 2015, we identified that unauthorized third parties had gained access to data provided to us by our members that is considered to be personal information in certain jurisdictions.
[removed: As such, we have implemented certain anti-fraud measures, including credit card verification procedures; however,] [added: However,] a failure to adequately prevent fraudulent credit card transactions could adversely affect our consolidated financial position and results of operations.
In considering new markets, we consider the potential synergies from the implementation of our model based in large part on our experience in the U.S., Canada, and the U.K. [removed: We] [added: However, we] cannot predict whether these synergies will also be realized in new markets.
[removed: In] [added: For example, in] fiscal 2015, we opened new facilities in Bahrain, Oman, and Moncton, Canada.
[removed: In fiscal 2016, we opened new facilities in Castledermot, Ireland; Sonepat, India; Algete, Spain; and in the U.S. Promising acquisitions] [added: Acquisitions] are difficult to identify and complete for a number of reasons, including competition among prospective buyers, the availability of affordable financing in the capital markets and the need to satisfy applicable closing conditions and obtain antitrust and other regulatory approvals on acceptable terms.
We rely [removed: solely] [added: primarily] upon independent subhaulers to pick up and deliver vehicles to and from our storage facilities in the U.S., Canada, Brazil, U.A.E., Oman, Bahrain, [added: Germany, the Republic of] Ireland, [added: India,] and [removed: India.][added: Spain.]
Our executive officers, directors and their affiliates beneficially own, in the aggregate, [removed: 21.1%] [added: 15.9%] of our common stock as of July 31, [removed: 2016.][added: 2017.]
We have certain provisions in our certificate of incorporation and [removed: bylaws,] [added: bylaws] which may have an anti-takeover effect or that may delay, defer or prevent acquisition bids for us that a stockholder might consider favorable and limit attempts by our stockholders to replace or remove our current management.
A material reduction in accident rates, whether due to, among other things, a reduction in miles driven per car, vehicle-related technological advances such as accident avoidance systems and, to the extent widely adopted, the advent of [removed: driverless cars,] [added: autonomous vehicles,] could have a material impact on revenue growth.
In addition, under our Percentage Incentive Program contracts, [removed: or] [added: which we refer to as] PIP, the cost of towing the vehicle to one of our facilities is included in the PIP fee.
[removed: Environmental laws] and regulations could become more stringent over time and there can be no assurance that we or [added: our operations will not be subject to significant costs in the future.]
As of July 31, [removed: 2016,] [added: 2017,] the amount of goodwill on our consolidated balance sheet subject to future impairment testing was [removed: $260.2] [added: $340.2] million.
Pursuant to ASC 350, Intangibles—Goodwill and Other, we are required to annually test goodwill [removed: and intangible assets with indefinite lives] to determine if impairment has [removed: occurred.][added: occurred, either through a quantitative or qualitative analysis.]
If the testing performed indicates that impairment has occurred, we are required to record a non-cash impairment charge for the difference between the carrying value of the goodwill [removed: or other intangible assets] and the implied fair value of the goodwill [removed: or other intangible assets] in the period the determination is made.
Changes in these factors, or changes in actual performance [removed: compared with estimates of our future performance,] could affect the fair value of [removed: goodwill or other intangible assets,] [added: goodwill,] which may result in an impairment charge.
For example, [removed: continued] deterioration in worldwide economic conditions could affect these assumptions and lead us to determine that goodwill impairment is [removed: required with respect to our acquisitions in the U.S., Canada, the U.K., Brazil, Germany, the U.A.E. or Spain.][added: required.]
Should the value of our goodwill [removed: or other intangible assets] become impaired, it could have a material adverse effect on our consolidated results of operations and could result in our incurring net losses in future periods.
Fluctuations in the rate of exchange between the U.S. dollar and foreign currencies, primarily the British pound, Canadian dollar, U.A.E. dirham, Bahraini dinar, Omani rial, Brazilian real, Indian rupee, [added: Chinese renminbi,] and [added: European Union] Euro could adversely affect our consolidated results of operations and financial position.
| • | the difficulty of managing and staffing foreign offices; |
The ultimate effects of Brexit on us will also depend on the terms of agreements, if any, that the U.K. and the European Union make to retain access to each other’s respective markets either during a transitional period or more permanently.
For example, during fiscal 2017, we recognized a $19.4 million charge primarily related to fully impairing costs previously capitalized in connection with the development of business operating software.
As such, we have implemented certain anti-fraud measures, including credit card verification procedures.
In fiscal 2016, we opened new facilities in Castledermot, Republic of Ireland; Sonepat, India; Algete, Spain; and six new facilities in the U.S. In fiscal 2017, we opened a new facility in Bad Fallingbostel, Germany, a new facility in Betim, Minas Gerais, Brazil, nine new facilities in the U.S and acquired Cycle Express, LLC, which conducts business primarily as National Powersport Auctions (NPA), a leading non-salvage auction platform for motorcycles, snowmobiles, watercraft and other powersports vehicles.
NPA currently operates facilities in Atlanta, Georgia; Cincinnati, Ohio; Dallas, Texas; Philadelphia, Pennsylvania; and San Diego, California.
| | |
| --- | --- |
In some cases, we may acquire land with existing environmental issues, including landfills as an example.
Environmental laws
The annual goodwill impairment analysis, which was performed qualitatively in the fourth quarter of fiscal 2017, considered all relevant factors specific to our reporting units, including macroeconomic conditions; industry and market considerations; overall financial performance and relevant entity-specific events.
We considered the above factors noting none involved significant uncertainty.
In addition, the industry in which we operate improved over the observable period, and our calculated fair value exceeded carrying value for each reporting unit by a substantial amount in our prior year quantitative analysis, indicating no material risk as of July 31, 2017, with respect to potential goodwill impairments.
Changes in federal, state and local, or foreign tax laws, changing interpretations of existing tax laws, or adverse determinations by tax authorities could increase our tax burden or otherwise adversely affect our financial condition or results of operations.
We are subject to taxation at the federal, state, provincial, and local levels in the United States, the United Kingdom, and various other countries and jurisdictions in which we operate, including income taxes, sales taxes, value-added (VAT) taxes, and similar taxes and assessments.
The laws and regulations related to tax matters are extremely complex and subject to varying interpretations.
Although we believe our tax positions are reasonable, we are subject to audit by the Internal Revenue Service in the United States, HM Revenue and Customs in the United Kingdom, state tax authorities in the states in which we operate, and other similar tax authorities in international jurisdictions.
As previously disclosed, we have been subject to challenge by the Georgia Department of Revenue with respect to sales taxes and could face similar audits or challenges from applicable federal, state, or foreign tax authorities in the future.
While we believe we comply with all applicable tax laws, rules, and regulations in the relevant jurisdictions, tax authorities may elect to audit us and determine that we owe additional taxes, which could result in a significant increase in our liabilities for taxes, interest, and penalties in excess of our accrued liabilities.
New tax legislative initiatives may be proposed from time to time, such as proposals for comprehensive tax reform in the United States, which may impact our effective tax rate and which could adversely affect our tax positions or tax liabilities.
Our future effective tax rate could be adversely affected by, among other things, changes in the composition of earnings in jurisdictions with differing tax rates, changes in statutory rates and other legislative changes, changes in interpretations of existing tax laws, or changes in determinations regarding the jurisdictions in which we are subject to tax.
From time to time, U.S. federal, state and local, and foreign governments make substantive changes to tax rules and their application, which could result in materially higher taxes than would be incurred under existing tax law and which could adversely affect our financial condition or results of operations.
On June 23, 2016, the U.K. held a referendum in which voters approved an exit from the European Union, commonly referred to as “Brexit.” In February 2017, the British Parliament voted in favor of allowing the British government to begin negotiating the terms of the U.K.’s withdrawal from the European Union and discussions with the European Union began in March 2017.
During fiscal 2014, we recognized a $29.1 million impairment charge primarily related to capitalized software development costs, as we ceased development of a third-party enterprise operating system and decided to address our international technology needs through an internally developed proprietary solution.
For example, in fiscal 2014, we acquired a facility in Montreal, Canada.
our operations will not be subject to significant costs in the future.
The testing of goodwill and other intangible assets for impairment requires us to make significant estimates about our future performance and cash flows, as well as other assumptions.
These estimates can be affected by numerous factors, including changes in the definition of a business segment in which we operate; changes in economic, industry or market conditions; changes in business operations; changes in competition; or potential changes in the share price of our common stock and market capitalization.
An adverse outcome of our appeal to the Georgia Tax Tribunal of the Georgia Department of Revenue's final assessment in connection with its sales tax audit could have a material adverse effect on our consolidated results of operations and financial condition.
The Georgia Department of Revenue, or DOR, has conducted a sales and use tax audit of our operations in Georgia for the period from January 1, 2007 through June 30, 2011.
As a result of their initial audit, the DOR issued a notice of proposed assessment for uncollected sales taxes in which it asserted that we failed to collect and remit sales taxes totaling $73.8 million, including penalties and interest.
According to the DOR, the proposed assessment was based on its initial determination that our sales did not constitute nontaxable sales for resale.
Subsequently, we engaged a Georgia law firm and outside tax advisors to review the conduct of our business operations in Georgia, the notice of proposed assessment, and the DOR’s policy position.
In particular, our outside legal counsel provided us with an opinion that the sales for resale to non-U.S. registered resellers should not be subject to Georgia sales and use tax.
In rendering its opinion, our counsel noted that non-U.S. registered resellers are unable to comply strictly with technical requirements for a Georgia certificate of exemption but concluded that our sales for resale to non-U.S. registered resellers should not be subject to Georgia sales and use tax notwithstanding this technical inability to comply.
Since our receipt of the notice of proposed assessment, our counsel and we have engaged in active discussions with the DOR to resolve the matter.
On June 5, 2015, following our discussions and after additional review of documentation, the DOR provided us with revised audit work papers computing a sales tax liability of $2.7 million before interest and any penalties.
On June 22, 2015, representatives of the DOR and the Office of the Attorney General for the State of Georgia informed our counsel that the DOR intended to issue a formal notice of assessment for an estimated $100.0 million, based on the DOR’s original proposed assessment of $73.8 million plus additional accumulated interest and penalties.
On August 4, 2015, the DOR issued an official Assessment and Demand for Payment for $96.1 million for sales taxes, penalties, and interest that the DOR alleges we owe the State of Georgia.
We filed an appeal of this notice of assessment from the DOR with the Georgia Tax Tribunal on September 3, 2015.
On August 5, 2016, the DOR filed a response in which it denied all allegations noted in our appeal of the notice of assessment.
We continue to substantiate our position that these transactions are nontaxable sales for resale by providing the DOR with documentation supporting the exempt nature of these sales.
Based on the opinion from our outside law firm, advice from our outside tax advisors, and our best estimate of a probable outcome, we believe that we have adequately provided for the payment of any assessment in our consolidated financial statements.
We believe we have strong defenses to the DOR’s notice of assessment and intend to defend this matter.
There can be no assurance that this matter will be resolved in our favor or that we will not ultimately be required to make a substantial payment to the Georgia DOR.
We understand that litigating and defending the matter in Georgia could be expensive and time-consuming and result in substantial management distraction.
If the matter were to be resolved in a manner adverse to us, it could have a material adverse effect on our consolidated results of operations and financial position.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
185 rewritten, 118 added, 43 removed, 294 unchanged
This Annual Report on Form 10-K for the fiscal year ended July 31, [removed: 2016,] [added: 2017,] or this Form 10-K, including the information incorporated by reference herein, contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended (the Securities Act), and Section 21E of the Securities Exchange Act of 1934, as amended (the Exchange Act).
We are a leading provider of online auctions and vehicle remarketing services [added: with operations] in the United States (U.S.), Canada, the United Kingdom (U.K.), [added: the Republic of Ireland,] Brazil, [added: Germany,] the United Arab Emirates (U.A.E.), Oman, Bahrain, [removed: Ireland, Spain] [added: India,] and [removed: India.][added: Spain.]
Vehicle sellers consist primarily of insurance companies, but also include [removed: banks and financial institutions,] [added: banks, finance companies,] charities, [removed: car dealerships,] fleet [removed: operators] [added: operators, dealers] and [removed: vehicle rental companies.][added: vehicles sourced directly from individual owners.]
In the U.S., Canada, [added: the Republic of Ireland,] Brazil, the U.A.E., Oman, Bahrain, [removed: Ireland, Spain and] India, [added: and Spain,] we sell vehicles primarily as an agent and derive revenue primarily from fees paid by vehicle sellers and vehicle buyers as well as related fees for services, such as towing and storage.
In the U.K., we operate both [added: as an agent and] on a principal basis, purchasing the salvage vehicles outright from the insurance companies and reselling the vehicles for our own [removed: account, and as an agent.][added: account.]
In Germany and Spain, we [added: also] derive revenue from sales listing fees for listing vehicles on behalf of many insurance companies.
Revenues from sellers are generally generated either on a fixed fee contract basis, where our fees are fixed based on the sale of each vehicle regardless of the selling price of the vehicle or under our Percentage Incentive [removed: Program (PIP),] [added: Program, which we refer to as PIP,] where our fees are generally based on a predetermined percentage of the vehicle sales price.
Under the [removed: consignment program,]
[added: consignment program,] only the fees associated with vehicle processing are recorded in revenue, not the actual sales price (gross proceeds).
Our revenue is impacted by several factors, including [removed: salvage] [added: total loss] frequency and the average vehicle auction selling price, as a significant amount of our service revenue is associated in some manner to the ultimate selling price of the vehicle.
Vehicle auction selling prices are driven primarily by: (i) changes in commodity prices, particularly the per ton price for crushed car bodies, as we believe this has an impact on the ultimate selling price of vehicles sold for scrap and vehicles sold for dismantling; (ii) used car pricing, which we [added: also] believe has an impact on [removed: salvage] [added: total loss] frequency; (iii) the mix of cars sold; and (iv) changes in the U.S. dollar exchange rate to foreign currencies, which we believe has an impact on auction participation by international buyers.
[removed: Salvage] [added: Total loss] frequency is the percentage of cars involved in accidents which insurance companies salvage rather than repair and is driven by the relationship between repairs costs, used car values, and auction returns.
Over the last several years, we believe there has been an increase in overall growth in the salvage market driven by an increase in [removed: salvage] [added: total loss] frequency.
Conversely, increases in used car prices, such as occurred during the most recent recession, may decrease [removed: salvage] [added: total loss] frequency and adversely affect our growth rate.
[removed: Additionally, the] [added: The] average age of cars on the road continued to increase, growing from 9.6 years in 2002 to [removed: 11.5] [added: 11.6] years in [removed: 2015.][added: 2016.]
Accordingly, we cannot predict future trends in [removed: salvage] [added: total loss] frequency.
The primary factors affecting cash operating results are: (i) seasonality; (ii) market wins and losses; (iii) supplier mix; (iv) accident frequency; (v) [removed: salvage] [added: total loss] frequency; (vi) increased volume from our existing suppliers; (vii) commodity pricing; (viii) used car pricing; (ix) foreign currency exchange rates; (x) product mix; (xi) contract mix to the extent applicable; and (xii) our capital expenditures.
Potential internal sources of additional working capital are the sale of assets or the issuance of [removed: equity] [added: shares] through option exercises and shares issued under our Employee Stock Purchase Plan.
We believe that these acquisitions and openings will strengthen our coverage, as we have facilities located in the U.S., Canada, the U.K., Brazil, the U.A.E., Oman, Bahrain, Germany, Spain, [added: the Republic of] Ireland and India with the intention of providing national coverage for our sellers.
The following table sets forth facilities that we have acquired or opened from August 1, [removed: 2013] [added: 2014] through July 31, [removed: 2016:][added: 2017:]
| Wilmer, Texas [added: (Dallas)] | | Greenfield | | April 2016 | | United States |
| Castledermot, [added: Republic of] Ireland | | Greenfield | | April 2016 | | [added: Republic of] Ireland |
The following table shows certain data from our consolidated statements of income expressed as a percentage of total service revenues and vehicle sales for fiscal [removed: 2016, 2015] [added: 2017, 2016] and [removed: 2014:][added: 2015:]
| | [added: |] Year Ended July 31, | | | | | | | |
| (In percentages) | [removed: 2016] | [added: 2017] | | [removed: 2015] | [added: 2016] | | [removed: 2014] | [added: 2015] | [added: |]
| Service revenues and vehicle sales: | | | | | | | | | [added: |]
| Service revenues | [removed: 87] | [added: 89 |] % | | [removed: 86] [added: 87] | % | | [removed: 82] [added: 86] | % |
| Vehicle sales | [removed: 13] | [added: 11 |] % | | [removed: 14] [added: 13] | % | | [removed: 18] [added: 14] | % |
| Total service revenues and vehicle sales | [added: |] 100 | % | | 100 | % | | 100 | % |
| Operating expenses: | | | | | | | | | [added: |]
| Yard operations | [removed: 46] | [added: 47 |] % | | 46 | % | | [removed: 45] [added: 46] | % |
| Cost of vehicle sales | [removed: 11] | [added: 9 |] % | | [removed: 12] [added: 11] | % | | [removed: 15] [added: 12] | % |
| General and administrative | [added: |] 11 | % | | [removed: 12] [added: 11] | % | | [removed: 14] [added: 12] | % |
| Impairment of long-lived assets | [removed: —] | [added: 1 |] % | | — | % | | [removed: 3] [added: —] | % |
| Total operating expenses | [added: |] 68 | % | | [removed: 70] [added: 68] | % | | [removed: 77] [added: 70] | % |
| Operating income | [added: |] 32 | % | | [removed: 30] [added: 32] | % | | [removed: 23] [added: 30] | % |
| Other (expense) income | [removed: (1] | [added: (2 |] )% | | (1 | )% | | [removed: —] [added: (1] | [removed: %] [added: )%] |
| Income before income taxes | [removed: 31] | [added: 30 |] % | | [removed: 29] [added: 31] | % | | [removed: 23] [added: 29] | % |
| Income taxes | [removed: 10] | [added: 3 |] % | | 10 | % | | [removed: 8] [added: 10] | % |
| Net income | [removed: 21] | [added: 27 |] % | | [removed: 19] [added: 21] | % | | [removed: 15] [added: 19] | % |
A potential external source of additional working capital is the issuance of additional debt with new lenders and equity.
However, we cannot predict if these sources will be available in the future or on commercially acceptable terms.
| Brighton, Colorado (Denver) | | Greenfield | | August 2016 | | United States |
| Sun Valley, California (Los Angeles) | | Greenfield | | November 2016 | | United States |
| Casper, Wyoming | | Greenfield | | January 2017 | | United States |
| Littleton, Colorado (Denver) | | Greenfield | | January 2017 | | United States |
| Apopka, Florida (Orlando) | | Greenfield | | January 2017 | | United States |
| Alorton, Illinois (St. Louis) | | Greenfield | | February 2017 | | United States |
| Okeechobee, Florida | | Greenfield | | March 2017 | | United States |
| Ogden, Utah (Salt Lake City) | | Greenfield | | March 2017 | | United States |
| Wilmington, California (Long Beach) | | Greenfield | | March 2017 | | United States |
| Cycle Express, LLC (1) | | Acquisition | | June 2017 | | United States |
| Bad Fallingbostel, Germany (Hanover) | | Greenfield | | September 2016 | | Germany |
| Newbury, United Kingdom | | Greenfield | | September 2016 | | United Kingdom |
| Betim, Minas Gerais | | Greenfield | | April 2017 | | Brazil |
| (1) | Cycle Express, LLC conducts business primarily as National Powersport Auctions (NPA), a leading non-salvage auction platform for motorcycles, snowmobiles, watercraft and other powersports vehicles. NPA currently operates facilities in Atlanta, Georgia; Cincinnati, Ohio; Dallas, Texas; Philadelphia, Pennsylvania; and San Diego, California. |
| | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | |
The increase in volume in the U.S. was derived from (i) growth in the number of units sold from new and expanded contracts with insurance companies, and (ii) growth from existing suppliers, driven by what we believe was an increase in salvage frequency.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | |
The increase in the U.S. was primarily the result of higher average auction selling prices, which we believe was due to higher commodity prices and a change in the mix of vehicles sold, partially offset by a shift in volume for certain sellers from principal to agency business.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | |
The increase in yard operations depreciation and amortization expenses resulted primarily from depreciating new and expanded facilities and certain technology assets placed into service in the U.S.
Included in yard operations expenses were depreciation and amortization expenses.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | Year Ended July 31, | | | | | | | | | | | | 2017 vs. 2016 | | | | | | | 2016 vs. 2015 | | | | | |
| (In thousands) | | | 2017 | | | | 2016 | | | | 2015 | | | | Change | | | | % Change | | | Change | | | | % Change | |
The decrease in cost of vehicle sales for fiscal 2017 of $3.4 million, or 2.4% as compared to fiscal 2016 was the result of (i) a decrease in International of $9.0 million; partially offset by (ii) an increase in the U.S. of $5.6 million.
We also provide vehicle remarketing services in Germany and Spain.
New car sales grew on a year over year basis, increasing the supply of used cars.
A potential external source of additional working capital is the issuance of debt and equity; however, we cannot predict if these sources will be available in the future and, if available, if they can be issued under terms commercially acceptable to us.
| Seaford, Delaware | | Greenfield | | July 2014 | | United States |
| Montreal, Quebec | | Acquisition | | November 2013 | | Canada |
| Itaquaquecetuba, Brazil (São Paulo) | | Greenfield | | January 2014 | | Brazil |
| | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
The increase in volume in the U.S. primarily came from existing suppliers as we believe there may have been an increase in the overall growth in the salvage market driven by increased salvage frequency.
Included in our U.S. yard operations expenses for fiscal 2014 were severance and lease termination costs of $4.0 million, primarily associated with the integration of the Salvage Parent, Inc. acquisition.
The decrease in cost of vehicle sales for fiscal 2015 of $38.1 million, or 21.8% as compared to fiscal 2014 came from (i) a decline in International of $30.4 million, which included the beneficial impact of $4.1 million due to changes in foreign currency exchange rates, primarily from the change in the British pound to U.S. dollar exchange rate, and (ii) a decline in the U.S. of $7.7 million.
The decline in International resulted primarily from decreased volume in the U.K. from insurance sellers and lower average purchase prices, driven by decreased insurance volume and increased open market purchase activity from the general public.
The decline in the U.S. was primarily the result of decreased open market purchase activity from the general public and lower average purchase prices.
| Total vehicle sales | | $ | 138,116 | | | $ | 138,975 | | | $ | 164,535 | | | $ | (859 | ) | | (0.6 | )% | | $ | (25,560 | ) | | (15.5 | )% |
The decrease in general and administrative expenses for fiscal 2015 of $25.6 million, or 15.5% as compared to fiscal 2014 came primarily from a decrease in the U.S. of $23.4 million as a result of the integration of the Salvage Parent, Inc. acquisition, the relocation of our technology department being completed in fiscal 2014, decreased expenditures on technology development, a decrease in stock-based payment compensation and a decrease in depreciation and amortization expenses.
Included in fiscal 2014 was $7.5 million in lease termination, severance and relocation costs associated with the integration of the Salvage Parent, Inc. acquisition, which was finalized in fiscal 2014, and the relocation of our technology department from California to our Dallas, Texas corporate headquarters.
The decrease in depreciation and amortization expenses came primarily from a decrease in the U.S. as a result of certain assets becoming fully amortized.
| | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
During fiscal 2014, we terminated a contract with KPIT (formerly known as Sparta Consulting, Inc.), whereby KPIT was engaged to design and implement an SAP-based replacement for our existing business operating software that, among other things, would address our international expansion needs.
Following a review of KPIT’s work performed and an assessment of the cost to complete, deployment risk, and other factors, we ceased development of KPIT’s software and internally developed a proprietary solution in its place.
The increase in total other expense for fiscal 2015 of $7.4 million, or 151.7% as compared to fiscal 2014 was primarily due to an increase in interest expense of $9.4 million as a result of the additional long-term debt issued in December 2014, partially offset by increased currency gains in International, primarily in the U.K. of $2.1 million.
| | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Acquisitions | — | | | | — | | | | (14,300 | | ) | | — | | | | — | % | | 14,300 | | | | 100.0 | % |
| FY 2014—Q1 | | 14,000 | | | $ | 16.43 | | | 7,241 | | | 2,519 | | | 4,240 | | | $ | 31.77 | | | $ | 80 | |
| FY 2015—Q1 | | 201,333 | | | 19.59 | | | | 124,621 | | | 35,416 | | | 41,296 | | | 31.65 | | | | 1,121 | | |
| FY 2015—Q3 | | 139,690 | | | 20.27 | | | | 76,021 | | | 20,656 | | | 43,013 | | | 37.27 | | | | 770 | | |
| FY 2015—Q4 | | 200,000 | | | 12.02 | | | | 66,602 | | | 52,158 | | | 81,240 | | | 36.08 | | | | 1,882 | | |
| FY 2016—Q4 | | 1,130,000 | | | 18.64 | | | | 410,648 | | | 293,152 | | | 426,200 | | | 51.30 | | | | 15,039 | | |
| Operating leases (2) | 23,217 | | | | 36,333 | | | | 22,624 | | | | 61,904 | | | | — | | | | 144,078 | | |
| Capital leases (2) | 1,124 | | | | 2,002 | | | | — | | | | — | | | | — | | | | 3,126 | | |
| Total contractual obligations | $ | 119,827 | | | $ | 240,721 | | | $ | 61,774 | | | $ | 576,395 | | | $ | 25,641 | | | $ | 1,024,358 | |
Credit Facility
On December 14, 2010, we entered into an Amended and Restated Credit Facility Agreement (Credit Facility), with Bank of America, N.A. The Credit Facility was an unsecured credit agreement providing for (i) a $100.0 million revolving credit facility, including a $100.0 million alternative currency borrowing sublimit and a $50.0 million letter of credit sublimit and (ii) a term loan facility of $400.0 million.
On September, 29, 2011, we amended the Credit Facility increasing the amount of the term loan facility from $400.0 million to $500.0 million.
Proceeds from the Credit Agreement were used to repay all outstanding amounts under the Credit Facility totaling $275.0 million at December 3, 2014.
Pre-sale services, including towing, title processing,
An excerpt. Shown here: 40 of 185 rewritten, 40 of 118 added and 40 of 43 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations in the FY2017 filing and the FY2016 filing.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
7 rewritten, 0 added, 0 removed, 19 unchanged
To achieve this objective in the current uncertain global financial markets, all cash and cash equivalents were held in bank deposits and money market funds as of July 31, [removed: 2016.][added: 2017.]
As of July 31, [removed: 2016,] [added: 2017,] we held no direct investments in auction rate securities, collateralized debt obligations, structured investment vehicles or mortgaged-backed securities.
Based on the average cash balance held for fiscal [removed: 2016,] [added: 2017,] a hypothetical 10% adverse change in our interest yield would not have materially affected our operating results.
Our total borrowings under the Revolving Loan Facility under the Credit Agreement were [removed: $238.0] [added: $231.0] million as of July 31, [removed: 2016.][added: 2017.]
A hypothetical 10% adverse change in the value of the U.S. dollar relative to the Canadian dollar, British pound, U.A.E. dirham, Bahraini dinar, Omani rial, Brazilian real, Euro and Indian rupee would have resulted in a decrease in operating income of [removed: $6.6] [added: $6.8] million for fiscal [removed: 2016.][added: 2017.]
At July 31, [removed: 2016,] [added: 2017,] the cumulative effect of foreign exchange rate fluctuations on our consolidated financial position was a net translation loss of [removed: $109.2] [added: $100.7] million.
A hypothetical 10% adverse change in the value of the U.S. dollar relative to the Canadian dollar, British pound, U.A.E. dirham, Bahraini dinar, Omani rial, Brazilian real, [removed: Euro and] Indian [removed: rupee] [added: rupee, Chinese renminbi, and European Union Euro] would not have materially affected our consolidated financial position.
Item 1. Business
48 rewritten, 22 added, 12 removed, 331 unchanged
We were incorporated in California in 1982, became a public company in 1994 and [removed: we] reincorporated into Delaware in January 2012.
We are a leading provider of online auctions and vehicle remarketing services [added: with operations] in the United States (U.S.), Canada, the United Kingdom (U.K.), the [added: Republic of Ireland, Brazil, Germany, the] United Arab Emirates (U.A.E.), Oman, Bahrain, [removed: Brazil, Ireland, Spain,] [added: India,] and [removed: India.][added: Spain.]
Vehicle sellers consist primarily of insurance companies, but also include [removed: banks and financial institutions,] [added: banks, finance companies,] charities, [removed: car dealerships, municipalities,] fleet [removed: operators] [added: operators, dealers] and [removed: vehicle rental companies.][added: vehicles sourced directly from individual owners.]
In the U.S., Canada, [added: the Republic of Ireland,] Brazil, the U.A.E., Oman, Bahrain, [removed: Ireland, Spain, and] India, [added: and Spain,] we sell vehicles primarily as an agent and derive revenue primarily from fees paid by vehicle sellers and vehicle [removed: buyers] [added: buyers,] as well as related fees for services, such as towing and storage.
In the U.K., we operate both [added: as an agent and] on a principal basis, [added: in some cases] purchasing [removed: the] salvage vehicles outright from the insurance companies and reselling the vehicles for our own [removed: account, and as an agent.][added: account.]
We converted all of our U.S. and Canada sales to [removed: VB2] [added: our Virtual Bidding Second Generation (VB2)] during fiscal 2004 and we converted our U.K. sales to VB2 during fiscal 2008.
This technology and model [removed: employs] [added: employ] a two-step bidding process.
For fiscal [removed: 2016,] [added: 2017,] sales of U.S. vehicles, on a unit basis, to members registered outside the state where the vehicle was located accounted for [removed: 49.1%] [added: 49.8%] of total vehicles sold; [removed: 29.3%] [added: 29.7%] of vehicles were sold to out of state members within the U.S. and [removed: 19.8%] [added: 20.1%] were sold to International members, based on [added: the address submitted during] registration.
| • | providing a comprehensive range of [removed: customer] services that includes [removed: merchandising services,] [added: merchandising,] efficient title processing, timely pick-up and delivery of vehicles, and Internet sales; |
| • | applying technology to enhance operating efficiency through Internet bidding, web-based order processing, salvage value quotes, electronic communication with members and sellers, [removed: vehicle imaging,] and [removed: an online used] vehicle [removed: parts locator service;] [added: imaging;] and |
| • | providing [removed: the] [added: a] venue for insurance customers through our Virtual Insured Exchange (VIX) product to contingently sell a vehicle through [removed: the] [added: our] auction process to [removed: establish its] [added: assess] true [added: market] value, [removed: enabling the] [added: equipping our] insurance [removed: customer to access] [added: customers with] market [removed: value information when negotiating] [added: data in its negotiations] with owners who wish to retain their damaged vehicles. |
Historically, we believe our business has grown as a result of (i) acquisitions, (ii) increases in [removed: the] overall volume in the salvage car market, (iii) growth in market share, (iv) increases in the amount of revenue generated per sales transaction resulting from increases in the gross selling price and the addition of value-added services for both members and sellers, and (v) [removed: the] growth in non-insurance company sellers.
For fiscal [removed: 2016,] [added: 2017,] our revenues were [removed: $1.3] [added: $1.4] billion and our operating income was [removed: $406.5] [added: $461.3] million.
In fiscal 2016, we opened facilities in Sonepat, India; Castledermot, [added: Republic of] Ireland; Algete, Spain; Dallas, Wilmer and Temple, Texas; Colorado Springs and Denver, Colorado; and Cartersville, Georgia.
Revenues from sellers are generally generated either on a fixed fee contract basis, where we collect a fixed amount for selling each vehicle regardless of the selling price of the vehicle or under our Percentage Incentive [removed: Program (PIP),] [added: Program, which we refer to as PIP,] where our fees are generally based on a predetermined percentage of the vehicle sales price.
Operating costs consist primarily of operating personnel (which includes yard management, clerical and yard employees), rent, contract vehicle towing, insurance, fuel, equipment maintenance and repair, and costs of vehicles sold under [removed: the] purchase contracts.
While most companies in this industry remarket vehicles through a physical [added: auction or a hybrid internet and physical] auction, we sell [removed: substantially] [added: virtually] all of our vehicles on our Internet selling platform VB3, thus eliminating the requirement for buyers to travel to an auction location to participate in the sales process.
Although there are other sellers of vehicles, such as [removed: banks and financial institutions,] [added: banks, finance companies,] charities, [removed: car dealerships,] fleet [removed: operators] [added: operators, dealers] and [removed: vehicle rental companies, the] [added: vehicles sourced directly from individual owners, our] primary sellers of vehicles are insurance companies.
The primary buyers of [removed: the] vehicles [added: at our auctions] are vehicle dismantlers, rebuilders, repair licensees, used vehicle dealers, exporters, and in some states, the general public.
Vehicle dismantlers, which we believe are the largest group of vehicle buyers, [added: based on volume of vehicles purchased,] either dismantle a salvage vehicle and sell parts individually or sell the entire vehicle to rebuilders, used vehicle dealers, or the general public.
The vehicle is inspected by the insurance company’s adjuster, who estimates the costs of repairing the vehicle and gathers information regarding the damaged vehicle’s mileage, options and condition in order to estimate its pre-accident value (PAV), [removed: or] [added: otherwise known as] actual cash value (ACV).
The adjuster determines whether to pay for repairs or to classify the vehicle as a total loss based upon the adjuster’s estimate of repair costs, vehicle’s salvage value, and the [removed: PAV or ACV,] [added: PAV,] as well as customer service considerations.
| • | the anticipated percentage return on salvage (i.e., gross salvage proceeds, minus vehicle handling and selling expenses, divided by the [removed: ACV);] [added: PAV);] |
The vehicle is then sold [removed: either] at [removed: a live] auction [removed: or, in our case,] on VB3 typically within seven days.
Since our inception in 1982, we have expanded from a single facility in Vallejo, California to an integrated network of facilities located in the U.S., Canada, the U.K., the U.A.E., Oman, Bahrain, Brazil, [added: Germany, the Republic of] Ireland, Spain and India.
In Germany and [removed: Spain] [added: Spain,] we also provide online vehicle remarketing services.
| • | mobile applications, which [removed: allows] [added: allow] members to search, bid, create watch lists, join auctions and bid [added: in numerous languages] from anywhere; |
| • | e-mail notifications [added: available in numerous languages] to potential buyers of vehicles that match desired characteristics; |
We also assign a special integration team to help convert newly acquired facilities to our own management information and proprietary software systems, [removed: enabling] [added: helping enable] us to ensure a smooth and consistent transition to our business operating and sales systems.
We believe that our integrated technology systems generate improved capacity and financial returns for our clients, resulting in [removed: high client retention, and allow us to expand our national supply contracts.]
Our revenues for the year ended July 31, [removed: 2016] [added: 2017] were distributed as follows: U.S. [removed: 80.1%] [added: 82.4%] and International [removed: 19.9%.][added: 17.6%.]
Geographic information as well as comparative segment revenues and related financial information pertaining to the U.S. and International segments for the years ended July 31, [removed: 2016, 2015] [added: 2017, 2016] and [removed: 2014] [added: 2015] are presented in the tables in Note 14 — Segments and Other Geographic Reporting, to the Notes to Consolidated Financial Statements, which are included under in Part II, Item 8 of this 10-K.
We have over [removed: 70] [added: 80] vehicle inspection stations at our facilities.
At the election of the seller, we sell vehicles pursuant to our Percentage Incentive [removed: Program (PIP),] [added: Program, which we refer to as PIP,] Consignment Program, or Purchase Program.
Under the purchase program, we purchase vehicles from a vehicle seller at a formula price, based on a percentage of the vehicles’ estimated pre-accident value (PAV), [removed: or] [added: otherwise known as] actual cash value (ACV), and sell the vehicles for our own account.
Buy It [removed: Now][added: Now, Make An Offer]
No single customer accounted for more than 10% of our revenues for fiscal [removed: 2016, 2015] [added: 2017, 2016] and [removed: 2014.][added: 2015.]
We obtained 83% of the total number of vehicles processed during fiscal 2016 and [removed: 2015 and 81% for fiscal 2014,] [added: 2015,] from insurance company sellers.
We market our services to franchise and independent dealerships, as well as the general [removed: public under CashForCars.com.][added: public.]
To become a registered [removed: member] [added: member,] a person [added: or business] must complete a basic application either online or through our mobile applications.
In fiscal 2017, we opened facilities in Bad Fallingbostel, Germany; Newbury, U.K.; Betim, Minas Gerais, Brazil; Brighton and Littleton, Colorado; Sun Valley and Wilmington, California; Apopka and Okeechobee, Florida; Casper, Wyoming; Alorton, Illinois; Ogden, Utah; acquired the assets of an excavation company, which engages in earthwork, soil stabilization, equipment hauling and erosion control commercial contractor services; and acquired Cycle Express, LLC, which conducts business primarily as National Powersport Auctions (NPA), a leading non-salvage auction platform for motorcycles, snowmobiles, watercraft and other powersports vehicles.
NPA currently operates facilities in Atlanta, Georgia; Cincinnati, Ohio; Dallas, Texas; Philadelphia, Pennsylvania; and San Diego, California.
| • | attractiveness and efficiency to buyers, leading to enhanced selling prices for vehicles; |
| | |
| --- | --- |
high client retention, and allow us to expand our national supply contracts.
The segments continue to share similar business models, services and economic characteristics.
Additionally, in some cases a service offering may be applicable only to a particular subsidiary or operating segment.
We provide a venue for insurance customers through our Virtual Insured Exchange (VIX) product to contingently sell a vehicle through our auction process to assess true market value, equipping our insurance customers with market data in its negotiations with owners who wish to retain their damaged vehicles.
Additionally, members have the option of submitting an offer amount on certain selected vehicles.
If an offer is accepted, the member can purchase the vehicle before the live auction process.
National Powersport Auctions
In the U.S., we provide non-salvage powersport vehicle remarketing services through live and online auction platforms to dealers, financial institutions and OEMs through our subsidiary National Powersport Auctions, or NPA.
NPA, also offers comprehensive data services including the NPA Value GuideTM, which we believe is the industry’s most accurate wholesale valuation tool.
NPA has facilities in San Diego, California; Philadelphia, Pennsylvania; Dallas, Texas; Cincinnati, Ohio; and Atlanta, Georgia.
We obtained 84% of the total number of vehicles processed during fiscal 2017 from insurance company sellers.
| | | |
| --- | --- | --- |
| | | |
| United States | | 4,012 |
| International | | 1,311 |
| Total employees | | 5,323 |
We also provide vehicle remarketing services in Germany.
In fiscal 2014, we acquired one facility in Montreal, Canada; a salvage vehicle auction business in Brazil, which did not include any facilities; as well as the assets of an online marketing company, which included the rights to hundreds of web domains including www.cashforcars.com and www.cash4cars.com; and opened facilities in Seaford, Delaware and Itaquaquecetuba, Brazil.
The segments continue to share similar business models, services and economic characteristics although recent changes in management structure and continued growth in our International region have resulted in the change in our reportable segments.
We provide the venue for insurance customers to enter a vehicle into a sealed bid sale to establish its true value, thereby enabling the insurance customer to access market value information when negotiating with owners who wish to retain their damaged vehicles.
During fiscal 2014, we terminated a contract with KPIT (formerly known as Sparta Consulting, Inc.), whereby KPIT was engaged to design and implement an SAP-based replacement for our existing business operating software that, among other things, would address our international expansion needs.
Following a review of KPIT’s work performed and an assessment of the cost to complete, deployment risk, and other factors, we ceased development of KPIT’s software and internally developed a proprietary solution in its place.
As a result in fiscal 2014, we recognized a charge of $29.1 million resulting primarily from the impairment of costs previously capitalized in connection with the development of the software.
See Notes to Consolidated Financial Statements, Capitalized Software Costs in Note 1 — Summary of Significant Accounting Policies.
| | | | | |
| --- | --- | --- | --- | --- |
| United States | | International | | Total Employees |
| 3,823 | | 1,021 | | 4,844 |
An excerpt. Shown here: 40 of 48 rewritten, all 22 added and all 12 removed. The counts are complete. For every sentence, read Item 1. Business in the FY2017 filing and the FY2016 filing.
Item 3. Legal Proceedings
7 rewritten, 11 added, 4 removed, 27 unchanged
The Georgia Department of Revenue, or DOR, [removed: has] conducted a sales and use tax audit of our operations in Georgia for the period from January 1, 2007 through June 30, 2011.
[removed: Since] [added: Following] our receipt of the notice of proposed assessment, [added: we and] our counsel [removed: and we have] engaged in active discussions with the DOR to resolve the matter.
On August 4, 2015, the DOR issued an official Assessment and Demand for Payment [added: (the “Assessment”)] for $96.1 million for sales taxes, penalties, and interest that the DOR [removed: alleges] [added: alleged] we owe [added: to] the State of Georgia.
We filed an appeal of this [removed: notice of assessment] [added: Assessment] from the DOR with the Georgia Tax Tribunal on September 3, 2015.
On August 5, 2016, the DOR filed a response in which it denied all allegations noted in our appeal of the [removed: notice of assessment.][added: Assessment.]
We believe we have strong defenses to the [removed: DOR’s notice of assessment] [added: remaining tax liability set forth above] and intend to [added: continue to] defend this matter.
There can be no assurance that this matter will be resolved in our favor or that we will not ultimately be required to make a substantial payment to the [removed: Georgia] DOR.
We and KPIT filed competing motions for summary judgment in January 2017.
The Court issued its ruling on the motions on September 25, 2017.
The order granted some of the relief sought by us, and some of the relief sought by KPIT.
Our core claims remain in the case after the ruling, including our claims for fraud, fraudulent inducement, breach of contract, professional negligence, trade secret misappropriation, unfair competition, unjust enrichment, and computer hacking.
KPIT’s claims are now limited to breach of contract, breach of the implied covenant of good faith and fair dealing, and declaratory relief.
During an extended remand period, it was determined that grounds exist for a substantial reduction in the Official Assessment, on the basis that (i) the transactions and resulting tax at issue were erroneously double-counted by the DOR in the audit sales transaction work papers on which the Assessment was based; and (ii) we were ultimately able to provide documentation showing that most of the remaining transactions were sales at wholesale, therefore qualifying for the sale for resale exemption from Georgia Sales and Use Tax.
After these reductions, the remaining amount of principal Georgia Sales and Use Tax still in dispute between the parties is $2.6 million, plus applicable interest.
A Consent Order to this effect was entered by the Georgia Tax Tribunal on May 22, 2017.
Since the date of entry of the Consent Order, we and the DOR have exchanged discovery requests and initial discovery responses.
We expect that discovery will be completed in the fall of 2017.
We and the DOR will then present the case to the Tax Tribunal for final disposition.
According to the DOR, the proposed assessment was based on its initial determination that our sales did not constitute nontaxable sales for resale.
On June 5, 2015, following our discussions and after additional review of documentation, the DOR provided us with revised audit work papers computing a sales tax liability of $2.7 million before interest and any penalties.
On June 22, 2015, representatives of the DOR and the Office of the Attorney General for the State of Georgia informed our counsel that the DOR intended to issue a formal notice of assessment for an estimated $100.0 million, based on the DOR’s original proposed assessment of $73.8 million plus additional accumulated interest and penalties.
We continue to substantiate our position that these transactions are nontaxable sales for resale by providing the DOR with documentation supporting the exempt nature of these sales.
Cover and table of contents
38 rewritten, 17 added, 13 removed, 70 unchanged
For the fiscal year ended July 31, [removed: 2016][added: 2017]
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, [removed: or a] smaller reporting [added: company, or an emerging growth] company.
See the definitions of “large accelerated filer,” “accelerated [removed: filer” and] [added: filer,”] “smaller reporting [added: company,” and “emerging growth] company” in Rule 12b-2 of the Act (check one):
| [removed: Large Accelerated Filer ý | | Accelerated Filer o |] [added: Non-accelerated filer] | [removed: Non-Accelerated Filer o] [added: ¨] | [added: (Do not check if a smaller reporting company)] | Smaller [removed: Reporting Company o] [added: reporting company] | [added: ¨ |]
The aggregate market value of the voting and non-voting Common Stock held by non-affiliates of the registrant as of January [removed: 29, 2016] [added: 31, 2017] (the last business day of the registrant’s most recently completed second fiscal quarter) was [removed: $3,337,942,326] [added: $5,644,908,664] based upon the closing sales price reported for such date on the NASDAQ Global Select Market.
As of September [removed: 27, 2016, 114,161,199] [added: 26, 2017, 230,773,342] shares of the registrant’s common stock were outstanding.
Portions of our definitive Proxy Statement for the [removed: 2016] [added: 2017] Annual Meeting of Stockholders, also referred to in this Annual Report on Form 10-K as our Proxy Statement, which will be filed with the Securities and Exchange Commission, or SEC, pursuant to Regulation 14A within 120 days after the registrant’s fiscal year end of July 31, [removed: 2016,] [added: 2017,] have been incorporated by reference in Part III hereof.
| Item 1 | | [removed: [Business](#s27A9D7684274510E8685200B79B0CB6F)] [added: [Business](#s0681F2DABE33542A8F8756BA1D26525E)] | [removed: [1](#s27A9D7684274510E8685200B79B0CB6F)] [added: [1](#s0681F2DABE33542A8F8756BA1D26525E)] |
| | | [Industry [removed: Overview](#s8DDF7591CEF95F69AAA3D7CDC56A3C50)] [added: Overview](#sDA6F1E4A718A50E681C4BA706079181D)] | [removed: [3](#s8DDF7591CEF95F69AAA3D7CDC56A3C50)] [added: [3](#sDA6F1E4A718A50E681C4BA706079181D)] |
| | | [Operating and Growth [removed: Strategy](#s779247C679455023A18C57250408C100)] [added: Strategy](#sEEA06D6570C953E283F2773842A7B946)] | [removed: [4](#s779247C679455023A18C57250408C100)] [added: [5](#sEEA06D6570C953E283F2773842A7B946)] |
| | | [Our Competitive [removed: Advantages](#s8FA5DF6B1B1852E7A3D5A5FE0CBA75B4)] [added: Advantages](#sB2D57B917034544593E0AAFAF9156812)] | [removed: [5](#s8FA5DF6B1B1852E7A3D5A5FE0CBA75B4)] [added: [5](#sB2D57B917034544593E0AAFAF9156812)] |
| | | [Business [removed: Segments](#sea40d6c1933b4047b34adc5d4db83b34)] [added: Segments](#s5E35F57223555D9B9283ED5BB0E07E3C)] | [removed: [5](#s8FA5DF6B1B1852E7A3D5A5FE0CBA75B4)] [added: [7](#s5E35F57223555D9B9283ED5BB0E07E3C)] |
| | | [Our Service [removed: Offerings](#sD30D712C28945CDC8C82A3C4FB4723DD)] [added: Offerings](#s2C02A8A78A9D5200B7F41A38871CD9E7)] | [removed: [7](#sD30D712C28945CDC8C82A3C4FB4723DD)] [added: [7](#s2C02A8A78A9D5200B7F41A38871CD9E7)] |
| | | [Management Information [removed: Systems](#s07BF7844226A5C1CA0D4BFBC84726C51)] [added: Systems](#s1ED97E7D6D7C5B3880475B49AF37B61A)] | [removed: [10](#s07BF7844226A5C1CA0D4BFBC84726C51)] [added: [10](#s1ED97E7D6D7C5B3880475B49AF37B61A)] |
| | | [Environmental [removed: Matters](#sCC20B8444A825118BBC60FDE47CEC658)] [added: Matters](#sF54D6795B50056BCB0599C722BC59076)] | [removed: [11](#sCC20B8444A825118BBC60FDE47CEC658)] [added: [11](#sF54D6795B50056BCB0599C722BC59076)] |
| | | [Governmental [removed: Regulations](#s7458A8BF48E05C1CA68DF7F3B3CE4F80)] [added: Regulations](#s4441580DC61D5D2F94D6F2712786DB1A)] | [removed: [11](#s7458A8BF48E05C1CA68DF7F3B3CE4F80)] [added: [11](#s4441580DC61D5D2F94D6F2712786DB1A)] |
| | | [Intellectual Property and Proprietary [removed: Rights](#s33D347F217DF5DCEA456F6015CCCC0C6)] [added: Rights](#s1B601A58930F51B8A685AA5447CFEDE7)] | [removed: [11](#s33D347F217DF5DCEA456F6015CCCC0C6)] [added: [11](#s1B601A58930F51B8A685AA5447CFEDE7)] |
| Item 1A. | | [Risk [removed: Factors](#s7F424E05EE2053DCA7995298DF0B83A5)] [added: Factors](#s50B5F3640366547A8B7AB51C440D8A54)] | [removed: [12](#s7F424E05EE2053DCA7995298DF0B83A5)] [added: [12](#s50B5F3640366547A8B7AB51C440D8A54)] |
| Item 1B. | | [Unresolved Staff [removed: Comments](#s9AB2D3CBD05351B3818278739C745668)] [added: Comments](#s4D4F162474FA50FA8EDCBD8883DDAA61)] | [removed: [24](#s9AB2D3CBD05351B3818278739C745668)] [added: [24](#s4D4F162474FA50FA8EDCBD8883DDAA61)] |
| Item 2. | | [removed: [Properties](#s5EDFAB25D71750AB971EA43E84224EC0)] [added: [Properties](#s19A398EDCBE75A72B94620A52D7CE1EF)] | [removed: [25](#s5EDFAB25D71750AB971EA43E84224EC0)] [added: [24](#s19A398EDCBE75A72B94620A52D7CE1EF)] |
| Item 3. | | [Legal [removed: Proceedings](#s05C332076BF858F7AFD856DB5E712354)] [added: Proceedings](#s7A4D9F76DFAE5B3CBD2C5C2FFA67010B)] | [removed: [25](#s05C332076BF858F7AFD856DB5E712354)] [added: [25](#s7A4D9F76DFAE5B3CBD2C5C2FFA67010B)] |
| Item 4. | | [Mine Safety [removed: Disclosures](#s3DF778FB970E5776BE3B95058FC513A3)] [added: Disclosures](#s6DCC251F23D05C90B8044D77635D2B55)] | [removed: [26](#s3DF778FB970E5776BE3B95058FC513A3)] [added: [26](#s6DCC251F23D05C90B8044D77635D2B55)] |
| Item 5. | | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities](#sD12F09266A9E52BC9DDEF3DF4EB575F0)] [added: Securities](#s05C0984985F4527E94DEEAE134D4AF12)] | [removed: [27](#sD12F09266A9E52BC9DDEF3DF4EB575F0)] [added: [27](#s05C0984985F4527E94DEEAE134D4AF12)] |
| Item 6. | | [Selected Financial [removed: Data](#s7D971730C9145CEDAE3EDD76D595CBF8)] [added: Data](#s498C0A92818D5D3BB166B86E5FBE7A5B)] | [removed: [30](#s7D971730C9145CEDAE3EDD76D595CBF8)] [added: [30](#s498C0A92818D5D3BB166B86E5FBE7A5B)] |
| Item 7. | | [Management’s Discussion and Analysis of Financial Condition and Results of [removed: Operations](#s76A6896DE7725C21B683284853108914)] [added: Operations](#s9497EA34BFF75B439E5BA422E126F070)] | [removed: [31](#s76A6896DE7725C21B683284853108914)] [added: [31](#s9497EA34BFF75B439E5BA422E126F070)] |
| Item 7A. | | [Quantitative and Qualitative Disclosures About Market [removed: Risk](#s2A6698138A635213B6E44D3CCF4FE187)] [added: Risk](#s797C3655527359668603872C071E8C1F)] | [removed: [48](#s2A6698138A635213B6E44D3CCF4FE187)] [added: [49](#s797C3655527359668603872C071E8C1F)] |
| Item 8. | | [Financial Statements and Supplementary [removed: Data](#s756B0F9751B354A69D008DE8462A047D)] [added: Data](#s20025221C39A507088210751058CFF0C)] | [removed: [49](#s756B0F9751B354A69D008DE8462A047D)] [added: [50](#s20025221C39A507088210751058CFF0C)] |
| Item 9. | | [Changes in and Disagreements with Accountants on Accounting and Financial [removed: Disclosure](#s74702A619350579D8F04B7DE0B65B8C4)] [added: Disclosure](#s3CA650DF0CE95A14810EFCFBDB36EA10)] | [removed: [49](#s74702A619350579D8F04B7DE0B65B8C4)] [added: [50](#s3CA650DF0CE95A14810EFCFBDB36EA10)] |
| Item 9A. | | [Controls and [removed: Procedures](#s67FCFFAEBB145DC0BED4E903DE8B62E7)] [added: Procedures](#s4625427A94985C7BAE6ABA823CECA110)] | [removed: [50](#s67FCFFAEBB145DC0BED4E903DE8B62E7)] [added: [51](#s4625427A94985C7BAE6ABA823CECA110)] |
| Item 9B. | | [Other [removed: Information](#s92D231C2DC415162B768F18FF9DB9BD9)] [added: Information](#s42042B61716352C1B134B3F6D863BCA5)] | [removed: [52](#s92D231C2DC415162B768F18FF9DB9BD9)] [added: [53](#s42042B61716352C1B134B3F6D863BCA5)] |
| [PART [removed: III](#sE62DD9AC81D4512CA89E8E3EEB07EF2D)] [added: III](#sAFFE42688F485D03996567742E7CD5B9)] | | | [removed: [53](#sE62DD9AC81D4512CA89E8E3EEB07EF2D)] [added: [54](#sAFFE42688F485D03996567742E7CD5B9)] |
| Item 10. | | [Directors, Executive Officers and Corporate [removed: Governance](#s44BF4357B3715B4994C3A7A2069E6290)] [added: Governance](#sDB41A23EA5D45E0CBEB34429DFFE279F)] | [removed: [53](#s44BF4357B3715B4994C3A7A2069E6290)] [added: [54](#sDB41A23EA5D45E0CBEB34429DFFE279F)] |
| Item 11. | | [Executive [removed: Compensation](#s0AECFA5C46E55F5C8CCCA18A1F5A96B7)] [added: Compensation](#sA1445A7585325C8392634290BD16483A)] | [removed: [53](#s0AECFA5C46E55F5C8CCCA18A1F5A96B7)] [added: [54](#sA1445A7585325C8392634290BD16483A)] |
| Item 12. | | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder [removed: Matters](#sE4351950A4A4566F89A4764DDC58889F)] [added: Matters](#s2CBAC618E8E0502283996C4BAF279B7C)] | [removed: [54](#sE4351950A4A4566F89A4764DDC58889F)] [added: [54](#s2CBAC618E8E0502283996C4BAF279B7C)] |
| Item 13. | | [Certain Relationships and Related Transactions, and Director [removed: Independence](#s6D9C1EF8B9D155339F763F30923D2EBB)] [added: Independence](#sB09FC47811A5515DB78E44BD86F423BC)] | [removed: [54](#s6D9C1EF8B9D155339F763F30923D2EBB)] [added: [54](#sB09FC47811A5515DB78E44BD86F423BC)] |
| Item 14. | | [Principal Accounting Fees and [removed: Services](#sAEE4BC4105DC593CB112B3931595B33F)] [added: Services](#s34FA217173935A1799045EBF89413AEF)] | [removed: [54](#sAEE4BC4105DC593CB112B3931595B33F)] [added: [54](#s34FA217173935A1799045EBF89413AEF)] |
| Item 15. | | [Exhibits, Financial Statement [removed: Schedules](#s5E33C1C855EE53D49306A08DEA7656A6)] [added: Schedules](#s719DDAE91D185C1B9BB002C52BBA957B)] | [removed: [55](#s5E33C1C855EE53D49306A08DEA7656A6)] [added: [55](#s719DDAE91D185C1B9BB002C52BBA957B)] |
This Annual Report on Form 10-K for the fiscal year ended July 31, [removed: 2016,] [added: 2017,] or this Form 10-K, including the information incorporated by reference herein, contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended (the Securities Act), and Section 21E of the Securities Exchange Act of 1934, as amended (the Exchange Act).
10-K 1 cprt07312017-10k.htm 10-K
| | | | | |
| --- | --- | --- | --- | --- |
| | | | | |
| Large accelerated filer | x | | Accelerated filer | ¨ |
| | | | Emerging growth company | ¨ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act.
For the Fiscal Year Ended July 31, 2017
| [PART I](#sD2476079E48E5DE6AB57CC9D2233E43B) | | | [1](#sD2476079E48E5DE6AB57CC9D2233E43B) |
| | | [Sales](#s8C2FADA45CBA519983B53BFBA9C780F6) | [9](#s8C2FADA45CBA519983B53BFBA9C780F6) |
| | | [Members](#s7BDA39672E045705B737DB4DB7592173) | [10](#s7BDA39672E045705B737DB4DB7592173) |
| | | [Competition](#s752CBA08CD5357F38A7616AC8A903B18) | [10](#s752CBA08CD5357F38A7616AC8A903B18) |
| | | [Employees](#s8F2E302F544F59AEA193262D45D21185) | [11](#s8F2E302F544F59AEA193262D45D21185) |
| | | [Seasonality](#sE23D2A3625375BF8A5C44233FCADFB6E) | [11](#sE23D2A3625375BF8A5C44233FCADFB6E) |
| [PART II](#sAB24A140E75254A29344CD3BA18881C9) | | | [27](#sAB24A140E75254A29344CD3BA18881C9) |
| [PART IV](#s5BD2019B4CAA5485874D97E95D9FB04D) | | | [55](#s5BD2019B4CAA5485874D97E95D9FB04D) |
| [Signatures](#s2B193D1404D25958A0AB01284A034698) | | | [56](#s2B193D1404D25958A0AB01284A034698) |
10-K 1 cprt07312016-10k.htm 10-K
| | | | | | | |
| --- | --- | --- | --- | --- | --- | --- |
| | | | | (Do not check if a smaller reporting company) | | |
| [PART I](#s2DF5BB9FE5935B438D89CAF9F3B0CA35) | | | [1](#s2DF5BB9FE5935B438D89CAF9F3B0CA35) |
| | | [Sales](#s538E35AC6A345F9F860BB338FCFB78C9) | [9](#s538E35AC6A345F9F860BB338FCFB78C9) |
| | | [Members](#s595DEC7E75D951199D17ED0BFC4D4F5A) | [9](#s595DEC7E75D951199D17ED0BFC4D4F5A) |
| | | [Competition](#s73870276AB5D57EFBE8BFF7A5C937633) | [10](#s73870276AB5D57EFBE8BFF7A5C937633) |
| | | [Employees](#s203DDFE71CD95613887B56141B4DA313) | [10](#s203DDFE71CD95613887B56141B4DA313) |
| | | [Seasonality](#sCBC3402D729F5C61BDA8BD120650C102) | [11](#sCBC3402D729F5C61BDA8BD120650C102) |
| [PART II](#sE0AB470730C2589EAA32D14BA47A68F9) | | | [27](#sE0AB470730C2589EAA32D14BA47A68F9) |
| [PART IV](#s41D4B2698EE7587186E8406F2FE2CC06) | | | [55](#s41D4B2698EE7587186E8406F2FE2CC06) |
| [Signatures](#s1FC4EE6E7D2F5659B8ECFBA25FE5016F) | | | [56](#s1FC4EE6E7D2F5659B8ECFBA25FE5016F) |
Item 2. Properties
6 rewritten, 1 added, 1 removed, 3 unchanged
This facility consists of approximately [removed: 70,000] [added: 96,000] square feet of office space under a lease which expires in fiscal 2024.
In the U.S., we own or lease facilities in every state except North Dakota, [removed: Rhode Island,] South Dakota, [removed: Vermont] and [removed: Wyoming.][added: Vermont.]
In Canada, we own or lease facilities in the provinces of Ontario, Quebec, [removed: Alberta] [added: Alberta, Nova Scotia] and New Brunswick.
In the U.K., we own or lease [removed: 16] [added: 17] operating facilities.
In Brazil, we own or lease [removed: six] [added: eight] operating facilities.
In [removed: Ireland and Spain] [added: the Republic of Ireland,] we own one operating facility.
In Germany and Spain, we operate online platforms and own one operating facility in each country.
In Germany and Spain, we operate online platforms.
Item 4. Mine Safety Disclosure
28 rewritten, 42 added, 36 removed, 38 unchanged
As of September [removed: 27, 2016,] [added: 26, 2017,] we had [removed: 1,044] [added: 946] stockholders of record.
On July 31, [removed: 2016,] [added: 2017,] the last reported sale price of our common stock on the NASDAQ Global Select Market was [removed: $50.44] [added: $31.49] per share.
| | [added: |] High | | | | Low | | | | High | | | | Low | | |
For further detail see Notes to Consolidated Financial Statements, Note 8 — Long-Term Debt and Note 11 — Stockholders’ Equity and under the subheadings [removed: "Credit Agreement"] [added: “Credit Agreement”] and [removed: "Note] [added: “Note] Purchase [removed: Agreement".][added: Agreement” in the Liquidity and Capital Resources sections of this Annual Report on Form 10-K.]
On September 22, 2011, our Board of Directors approved [removed: a 40] [added: an 80] million share increase in the stock repurchase program, bringing the total current authorization to [removed: 98] [added: 196] million shares.
For fiscal 2016, we repurchased [removed: 2,938,519] [added: 5,877,038] shares of our common stock at a weighted average price of [removed: $40.13] [added: $20.065] per share totaling $117.9 million.
For fiscal 2015, we repurchased [removed: 231,500] [added: 463,000] shares of our common stock at a weighted average price of [removed: $36.02] [added: $18.01] per share totaling $8.3 million.
For fiscal [removed: 2014,] [added: 2017,] we did not repurchase any shares of our common [removed: stock.][added: stock under the program.]
As of July 31, [removed: 2016,] [added: 2017,] the total number of shares repurchased under the program was [removed: 53,456,801] [added: 106,913,602,] and [removed: 44,543,199] [added: 89,086,398] shares were available for repurchase under our program.
On July 9, 2015, we completed a modified [removed: "Dutch Auction"] [added: “Dutch Auction”] tender offer, or tender offer, to purchase up to [removed: 13,888,888] [added: 27,777,776] shares of our common stock at a purchase price not greater than [removed: $36.00] [added: $18.00] nor less than [removed: $34.75] [added: $17.375] per share.
In connection with the tender offer, we accepted for payment an aggregate of [removed: 6,254,061] [added: 12,508,122] shares of our common stock at a purchase price of [removed: $36.00] [added: $18.00] per share for a total value of $225.1 million.
Additionally, on December 30, 2015, [removed: the Company] [added: we] completed a modified [removed: "Dutch Auction"] [added: “Dutch Auction”] tender offer, or tender offer, to purchase up to [removed: 7,317,073] [added: 14,634,146] shares of [removed: its] [added: our] common stock at a price not greater than [removed: $41.00] [added: $20.50] nor less than [removed: $38.00] [added: $19.00] per share.
In connection with the tender offer, [removed: the Company] [added: we] accepted for payment an aggregate of [removed: 8,333,333] [added: 16,666,666] shares of [removed: its] [added: our] common stock at a purchase price of [removed: $39.00] [added: $19.50] per share for a total value of $325.0 million.
| Period | [added: |] Total Number of Shares | | | Average Price Paid Per Share | | | | Total Number of Shares Purchased as Part of Publicly Announced Program | | | Maximum Number of Shares That May Yet be Purchased Under the Program(1) | |
| Fiscal 2015 | | | | | | | | | | | | | [added: |]
| Fiscal 2016 | | | | | | | | | | | | | [added: |]
| (1) | The [removed: Company's] [added: Company’s] stock repurchase program was announced on February 20, 2003. On September 22, 2011, the [removed: Company's] [added: Company’s] board of directors approved [removed: a 40] [added: an 80] million share increase in the [removed: Company's] [added: Company’s] stock repurchase program, bringing the total current authorization to [removed: 98] [added: 196] million shares. The repurchase may be effected through solicited or unsolicited transactions in the open market or in privately negotiated transactions. No time limit has been placed on the duration of the stock repurchase program. Subject to applicable securities laws, such repurchases will be made at such times and in such amounts as the Company deems appropriate and may be discontinued at any time. |
| (2) | Consists of [removed: 6,254,061] [added: 12,508,122] shares repurchased in connection with the tender offer at a purchase price of [removed: $36.00] [added: $18.00] per share and [removed: 231,500] [added: 463,000] shares repurchased through our publicly announced stock repurchase program. |
| (3) | [removed: 8,333,333] [added: 16,666,666] shares were repurchased by the Company through its modified [removed: "Dutch Auction"] [added: “Dutch Auction”] tender offer under which the Company was to purchase up to [removed: 7,317,073] [added: 14,634,146] shares of its common stock at a price not greater than [removed: $41.00] [added: $20.50] nor less than [removed: $38.00] [added: $19.00] per share. The tender offer was announced on November 23, 2015 and was completed on December 30, 2015. |
During fiscal [removed: 2016, 2015] [added: 2017, 2016] and [removed: 2014,] [added: 2015,] certain executive officers and employees exercised stock options through cashless exercises.
The Company remitted [removed: $15.0] [added: $134.6] million, [removed: $3.8] [added: $15.0] million and [removed: $0.1] [added: $3.8] million for the years ended July 31, [removed: 2016, 2015] [added: 2017, 2016] and [removed: 2014,] [added: 2015,] respectively, to the proper taxing authorities in satisfaction of the employees’ minimum statutory withholding requirements.
| Period | [added: |] Options Exercised | | | [added: Weighted Average] Exercise Price | | | | Shares Net Settled for Exercise | | | Shares Withheld for Taxes(1) | | | Net Shares to [removed: Employee] [added: Employees] | | | [added: Weighted Average] Share Price for Withholding | | | | [added: Employee Stock Based] Tax Withholding (in 000s) | | |
There were no issuances of unregistered securities in the year ended July 31, [removed: 2016.][added: 2017.]
The following is a line graph comparing the cumulative total return to stockholders of our common stock at July 31, [removed: 2016] [added: 2017] since July 31, [removed: 2011,] [added: 2012,] to the cumulative total return over such period of (i) the NASDAQ Composite Index, (ii) the NASDAQ Industrial Index, and (iii) the NASDAQ Q-50 (NXTQ).
[removed: 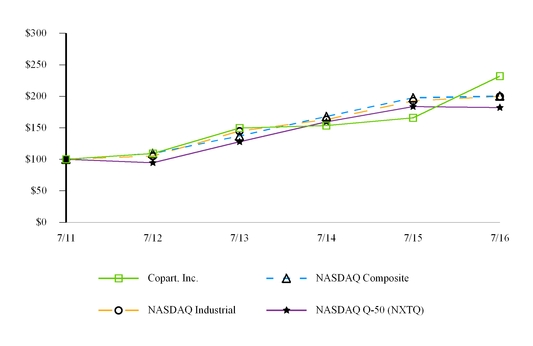][added: 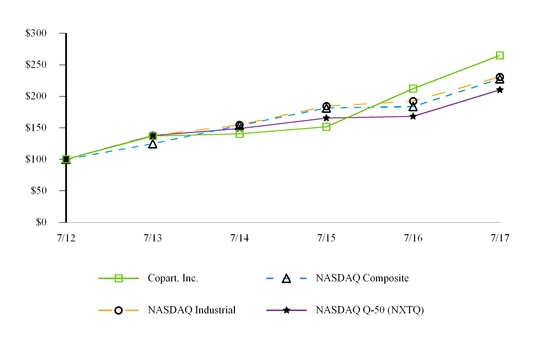]
| | [added: |] Fiscal Year Ended July 31, | | | | | | | | | | | | | | | | | | | | | | |
| | [removed: 2011] | [removed: | | |] 2012 | | | | 2013 | | | | 2014 | | | | 2015 | | | | 2016 | | | [added: | 2017 | | |]
| * | Assumes that $100.00 was invested on July 31, [removed: 2011] [added: 2012] in our common stock, in the NASDAQ Composite Index, the NASDAQ Industrial Index and the NASDAQ Q-50 (NXTQ), and that all dividends were reinvested. No dividends have been declared on our common stock. Stockholder returns over the indicated period should not be considered indicative of future stockholder returns. |
As of July 31, 2017, there were 230,488,296 shares outstanding.
| | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | |
| | | 2017 | | | | | | | | 2016 | | | | | | |
| Fourth Quarter | | $ | 31.95 | | | $ | 29.18 | | | $ | 25.66 | | | $ | 21.25 | |
| Third Quarter | | $ | 31.20 | | | $ | 27.83 | | | $ | 21.42 | | | $ | 16.56 | |
| Second Quarter | | $ | 28.81 | | | $ | 25.40 | | | $ | 19.84 | | | $ | 16.51 | |
| First Quarter | | $ | 27.23 | | | $ | 24.87 | | | $ | 18.37 | | | $ | 16.45 | |
| | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | |
| First Quarter | | — | | | $ | — | | | — | | | 95,426,436 | |
| Second Quarter | | — | | | $ | — | | | — | | | 95,426,436 | |
| Third Quarter | | — | | | $ | — | | | — | | | 95,426,436 | |
| Fourth Quarter(2) | | 12,971,122 | | | $ | 18.00 | | | 463,000 | | | 94,963,436 | |
| First Quarter | | — | | | $ | — | | | — | | | 94,963,436 | |
| Second Quarter(3) | | 16,666,666 | | | $ | 19.50 | | | — | | | 94,963,436 | |
| Third Quarter | | 5,877,038 | | | $ | 20.07 | | | 5,877,038 | | | 89,086,398 | |
| Fourth Quarter | | — | | | $ | — | | | — | | | 89,086,398 | |
| Fiscal 2017 | | | | | | | | | | | | | |
| First Quarter | | — | | | $ | — | | | — | | | 89,086,398 | |
| Second Quarter | | — | | | $ | — | | | — | | | 89,086,398 | |
| Third Quarter | | — | | | $ | — | | | — | | | 89,086,398 | |
| May 1, 2017 through May 31, 2017 | | — | | | $ | — | | | — | | | 89,086,398 | |
| June 1, 2017 through June 30, 2017 | | — | | | $ | — | | | — | | | 89,086,398 | |
| July 1, 2017 through July 31, 2017 | | — | | | $ | — | | | — | | | 89,086,398 | |
| | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | | | | | | | |
| FY 2015—Q1 | | 402,666 | | | $ | 9.80 | | | 249,242 | | | 70,832 | | | 82,592 | | | $ | 15.83 | | | $ | 1,121 | |
| FY 2015—Q3 | | 279,380 | | | 10.14 | | | | 152,042 | | | 41,312 | | | 86,026 | | | 18.64 | | | | 770 | | |
| FY 2015—Q4 | | 400,000 | | | 6.01 | | | | 133,204 | | | 104,316 | | | 162,480 | | | 18.04 | | | | 1,882 | | |
| FY 2016—Q4 | | 2,260,000 | | | 9.32 | | | | 821,296 | | | 586,304 | | | 852,400 | | | 25.65 | | | | 15,039 | | |
| FY 2017—Q1 | | 18,000,000 | | | 7.70 | | | | 5,408,972 | | | 5,255,322 | | | 7,335,706 | | | 25.62 | | | | 134,615 | | |
| | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | | | | | | | |
| Copart, Inc. | | $ | 100.00 | | | $ | 136.83 | | | $ | 140.49 | | | $ | 151.64 | | | $ | 212.29 | | | $ | 265.07 | |
| NASDAQ Composite | | $ | 100.00 | | | $ | 124.83 | | | $ | 153.69 | | | $ | 181.45 | | | $ | 183.70 | | | $ | 227.57 | |
As of July 31, 2016, there were 110,122,060 shares outstanding.
| | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | 2016 | | | | | | | | 2015 | | | | | | |
| Fourth Quarter | $ | 51.31 | | | $ | 42.49 | | | $ | 36.80 | | | $ | 33.36 | |
| Third Quarter | $ | 42.84 | | | $ | 33.11 | | | $ | 38.50 | | | $ | 35.48 | |
| Second Quarter | $ | 39.67 | | | $ | 33.01 | | | $ | 37.81 | | | $ | 33.14 | |
| First Quarter | $ | 36.74 | | | $ | 32.90 | | | $ | 34.92 | | | $ | 29.93 | |
We expect to continue to use cash flows from operations to finance our working capital needs and to develop and grow our business.
In addition to our stock repurchase program and our recently completed modified "Dutch Auction" tender offer, we are considering a variety of alternative potential uses for our remaining cash balances and our cash flows from operations.
These alternative potential uses include additional stock repurchases, repayments of long-term debt, the payment of dividends and acquisitions.
| | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Fiscal 2014 | | | | | | | | | | | | |
| First Quarter | — | | | $ | — | | | — | | | 47,713,218 | |
| Second Quarter | — | | | $ | — | | | — | | | 47,713,218 | |
| Third Quarter | — | | | $ | — | | | — | | | 47,713,218 | |
| Fourth Quarter | — | | | $ | — | | | — | | | 47,713,218 | |
| Fourth Quarter(2) | 6,485,561 | | | $ | 36.00 | | | 231,500 | | | 47,481,718 | |
| First Quarter | — | | | $ | — | | | — | | | 47,481,718 | |
| Second Quarter(3) | 8,333,333 | | | $ | 39.00 | | | — | | | 47,481,718 | |
| Third Quarter | 2,938,519 | | | $ | 40.13 | | | 2,938,519 | | | 44,543,199 | |
| May 1, 2016 through May 31, 2016 | — | | | $ | — | | | — | | | 44,543,199 | |
| June 1, 2016 through June 30, 2016 | — | | | $ | — | | | — | | | 44,543,199 | |
| July 1, 2016 through July 31, 2016 | — | | | $ | — | | | — | | | 44,543,199 | |
| | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| FY 2014—Q1 | 14,000 | | | $ | 16.43 | | | 7,241 | | | 2,519 | | | 4,240 | | | $ | 31.77 | | | $ | 80 | |
| FY 2015—Q1 | 201,333 | | | 19.59 | | | | 124,621 | | | 35,416 | | | 41,296 | | | 31.65 | | | | 1,121 | | |
| FY 2015—Q3 | 139,690 | | | 20.27 | | | | 76,021 | | | 20,656 | | | 43,013 | | | 37.27 | | | | 770 | | |
| FY 2015—Q4 | 200,000 | | | 12.02 | | | | 66,602 | | | 52,158 | | | 81,240 | | | 36.08 | | | | 1,882 | | |
| FY 2016—Q4 | 1,130,000 | | | 18.64 | | | | 410,648 | | | 293,152 | | | 426,200 | | | 51.30 | | | | 15,039 | | |
| Copart, Inc. | $ | 100.00 | | | $ | 109.37 | | | $ | 149.64 | | | $ | 153.65 | | | $ | 165.85 | | | $ | 232.17 | |
| NASDAQ Composite | $ | 100.00 | | | $ | 109.35 | | | $ | 137.07 | | | $ | 167.99 | | | $ | 197.62 | | | $ | 200.22 | |
| NASDAQ Industrial | $ | 100.00 | | | $ | 105.11 | | | $ | 145.01 | | | $ | 162.89 | | | $ | 192.89 | | | $ | 199.91 | |
| NASDAQ Q-50 (NXTQ) | $ | 100.00 | | | $ | 94.53 | | | $ | 127.70 | | | $ | 159.62 | | | $ | 183.66 | | | $ | 182.06 | |
An excerpt. Shown here: all 28 rewritten, 40 of 42 added and all 36 removed. The counts are complete. For every sentence, read Item 4. Mine Safety Disclosure in the FY2017 filing and the FY2016 filing.
Item 6. Selected Financial Data
17 rewritten, 7 added, 8 removed, 5 unchanged
| | [added: |] Fiscal Year Ended July 31, | | | | | | | | | | | | | | | | | | |
| | [removed: 2016] [added: | 2017] (1) | | | | [removed: 2015 (2)] [added: 2016 (1)] | | | | [removed: 2014 (2)] [added: 2015 (1)] | | | | [removed: 2013 (2)] [added: 2014 (1)] | | | | [removed: 2012 (2)] [added: 2013 (1)] | | |
| (In thousands, except per share) | | | | | | | | | | | | | | | | | | | | [added: |]
| Operating Data | | | | | | | | | | | | | | | | | | | | [added: |]
| Revenues | [added: |] $ | [removed: 1,268,449] [added: 1,447,981] | | | $ | [removed: 1,146,079] [added: 1,268,449] | | | $ | [removed: 1,163,489] [added: 1,146,079] | | | $ | [removed: 1,046,386] [added: 1,163,489] | | | $ | [removed: 924,191] [added: 1,046,386] | |
| Operating income | [removed: 406,470] | [added: 461,299] | | | [removed: 344,401] | [added: 406,470] | | | [removed: 274,934] | [added: 344,401] | | | [removed: 282,992] | [added: 274,934] | | | [removed: 286,353] | [added: 282,992] | | [added: |]
| Income before income taxes | [removed: 395,865] | [added: 440,100] | | | [removed: 332,069] | [added: 395,865] | | | [removed: 270,035] | [added: 332,069] | | | [removed: 276,872] | [added: 270,035] | | | [removed: 278,056] | [added: 276,872] | | [added: |]
| Income taxes | [removed: 125,505] | [added: 45,839] | | | [removed: 112,286] | [added: 125,505] | | | [removed: 91,348] | [added: 112,286] | | | [removed: 96,847] | [added: 91,348] | | | [removed: 95,937] | [added: 96,847] | | [added: |]
| Net income | [added: |] $ | [removed: 270,360] [added: 394,261] | | | $ | [removed: 219,783] [added: 270,360] | | | $ | [removed: 178,687] [added: 219,783] | | | $ | [removed: 180,025] [added: 178,687] | | | $ | [removed: 182,119] [added: 180,025] | |
| Basic net income per common share | [added: |] $ | [removed: 2.36] [added: 1.72] | | | $ | [removed: 1.75] [added: 1.18] | | | $ | [removed: 1.42] [added: 0.87] | | | $ | [removed: 1.44] [added: 0.71] | | | $ | [removed: 1.42] [added: 0.72] | |
| Diluted net income per common share | [added: |] $ | [removed: 2.21] [added: 1.66] | | | $ | [removed: 1.67] [added: 1.11] | | | $ | [removed: 1.36] [added: 0.84] | | | $ | [removed: 1.39] [added: 0.68] | | | $ | [removed: 1.39] [added: 0.69] | |
| Balance Sheet Data | | | | | | | | | | | | | | | | | | | | [added: |]
| Cash and cash equivalents | [added: |] $ | [removed: 155,849] [added: 210,100] | | | $ | [removed: 456,012] [added: 155,849] | | | $ | [removed: 158,668] [added: 456,012] | | | $ | [removed: 63,631] [added: 158,668] | | | $ | [removed: 140,112] [added: 63,631] | |
| Working capital | [removed: 220,523] | [added: 285,108] | | | [removed: 521,456] | [added: 220,523] | | | [removed: 168,007] | [added: 521,456] | | | [removed: 67,893] | [added: 168,007] | | | [removed: 134,908] | [added: 67,893] | | [added: |]
| Total assets | [removed: 1,649,820] | [added: 1,982,501] | | | [removed: 1,798,660] | [added: 1,649,820] | | | [removed: 1,506,121] | [added: 1,798,660] | | | [removed: 1,333,316] | [added: 1,506,121] | | | [removed: 1,155,648] | [added: 1,333,316] | | [added: |]
| Total debt | [removed: 640,492] | [added: 633,038] | | | [removed: 644,514] | [added: 640,492] | | | [removed: 302,218] | [added: 644,514] | | | [removed: 371,292] | [added: 302,218] | | | [removed: 442,472] | [added: 371,292] | | [added: |]
| Stockholders’ equity | [removed: 774,456] | [added: 1,098,600] | | | [removed: 964,464] | [added: 774,456] | | | [removed: 1,003,499] | [added: 964,464] | | | [removed: 762,401] | [added: 1,003,499] | | | [removed: 561,117] | [added: 762,401] | | [added: |]
| | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | | | |
| Weighted average common shares outstanding | | 228,686 | | | | 228,846 | | | | 251,829 | | | | 251,387 | | | | 249,824 | | |
| Diluted weighted average common shares outstanding | | 237,019 | | | | 244,295 | | | | 262,851 | | | | 262,459 | | | | 259,562 | | |
| | | | | | | | | | | | | | | | | | | | | |
| (1) | Shares and earnings per share data were revised from previously reported amounts due to a two-for-one common stock split effected in the form of a stock dividend. See Notes to Consolidated Financial Statements, Note 1 — Summary of Significant Accounting Policies. |
| | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Weighted average common shares outstanding | 114,423 | | | | 125,914 | | | | 125,693 | | | | 124,912 | | | | 128,120 | | |
| Diluted weighted average common shares outstanding | 122,147 | | | | 131,425 | | | | 131,230 | | | | 129,781 | | | | 131,428 | | |
| | |
| --- | --- |
| (1) | In March 2016, the FASB issued ASU No. 2016-09, Improvements to Employee Share-Based Payment Accounting. Under this standard, all excess tax benefits and tax deficiencies related to exercises of stock options are recognized as income tax expense or benefit in the income statement as discrete items in the reporting period in which they occur. Additionally, excess tax benefits are classified as an operating activity on the consolidated statements of cash flows. We early adopted ASU 2016-09 during the fourth quarter of fiscal 2016 on a modified retrospective basis. |
| (2) | In connection with our adoption of ASU 2015-03, Simplifying the Presentation of Debt Issuance Costs, as of July 31, 2016, prior year debt balances have been retrospectively adjusted to include a direct deduction of unamortized debt issuance costs, resulting in a reclassification of $1.3 million, $0.7 million, $1.2 million, and $1.6 million of debt issuance costs as of July 31, 2015, 2014, 2013, and 2012, respectively, to long-term debt for the respective periods. Prior to the adoption of ASU 2015-03, the unamortized debt issuance costs were included in other assets on our consolidated balance sheets. |
Item 9A. Controls and Procedures
5 rewritten, 1 added, 1 removed, 43 unchanged
Management assessed our internal control over financial reporting for the fiscal year ended July 31, [removed: 2016.][added: 2017.]
Our independent registered public accounting firm, Ernst & Young LLP, independently assessed the effectiveness of our internal control over financial reporting as of July 31, [removed: 2016.][added: 2017.]
We have audited Copart, Inc.’s internal control over financial reporting as of July 31, [removed: 2016,] [added: 2017,] based on criteria established in Internal Control — Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 [removed: Framework)] [added: framework)] (the COSO criteria).
In our opinion, Copart, Inc. maintained, in all material respects, effective internal control over financial reporting as of July 31, [removed: 2016,] [added: 2017,] based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), the consolidated balance sheets of Copart, Inc. as of July 31, [removed: 2016] [added: 2017] and [removed: 2015,] [added: 2016,] and the related consolidated statements of income, comprehensive income, stockholders’ equity, and cash flows for each of the three years in the period ended July 31, [removed: 2016] [added: 2017] of Copart, Inc. and our report dated September [removed: 28, 2016] [added: 27, 2017] expressed an unqualified opinion thereon.
September 27, 2017
September 28, 2016
Item 9B. Other Information
1 rewritten, 0 added, 0 removed, 2 unchanged
Certain information required by Part III is omitted from this Annual Report on Form 10-K because we intend to file a definitive proxy statement for our [removed: 2016] [added: 2017] Annual Meeting of Stockholders (the Proxy Statement) not later than 120 days after the end of the fiscal year covered by this Annual Report on Form 10-K, and certain information to be included therein is incorporated herein by reference.
Item 11. Executive Compensation
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this item is incorporated herein by reference from the Proxy Statement (to be filed with the Securities and Exchange Commission within 120 days of our July 31, [removed: 2016] [added: 2017] fiscal year end) under the heading “Executive Compensation,” “Compensation of Directors,” and “Corporate Governance and Board of Directors.”
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this item is incorporated herein by reference from the Proxy Statement (to be filed with the Securities and Exchange Commission within 120 days of our July 31, [removed: 2016] [added: 2017] fiscal year end) under the headings “Security Ownership” and “Executive Compensation,” subheading “Equity Compensation Plan Information.”
Item 13. Certain Relationships and Related Transactions, and Director Independence
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this item is incorporated herein by reference from the Proxy Statement (to be filed with the Securities and Exchange Commission within 120 days of our July 31, [removed: 2016] [added: 2017] fiscal year end) under the heading “Related Person Transactions and Section 16(a) Beneficial Ownership Compliance,” “Corporate Governance and Board of Directors,” and “Proposal Number One [added: —] Election of Directors.”
Item 14. Principal Accounting Fees and Services
1 rewritten, 0 added, 0 removed, 1 unchanged
The information required by this item is incorporated herein by reference from the section captioned “Proposal Number [removed: Three] [added: Four] — Ratification of Appointment of Independent Registered Public Accounting Firm” in the Proxy Statement (to be filed with the Securities and Exchange Commission within 120 days of our July 31, [removed: 2016] [added: 2017] fiscal year end).
Item 15. Exhibits, Financial Statement Schedules
513 rewritten, 304 added, 145 removed, 506 unchanged
Our consolidated financial statements at July 31, [removed: 2016] [added: 2017] and [removed: 2015] [added: 2016] and for each of the three years in the period ended July 31, [removed: 2016] [added: 2017] and the notes thereto, together with the report of the independent registered public accounting firm on those consolidated financial statements are hereby filed as part of this annual report on Form 10-K.
Date: September [removed: 28, 2016][added: 27, 2017]
| /s/ A. JAYSON ADAIR | | Chief Executive Officer (Principal Executive Officer and Director) | | September [removed: 28, 2016] [added: 27, 2017] |
| /s/ Jeffrey Liaw | | Chief Financial Officer (Principal Financial and Accounting Officer) | | September [removed: 28, 2016] [added: 27, 2017] |
| /s/ WILLIS J. JOHNSON | | Chairman of the Board | | September [removed: 28, 2016] [added: 27, 2017] |
| /s/ VINCENT W. MITZ | | President and Director | | September [removed: 28, 2016] [added: 27, 2017] |
| /s/ JAMES E. MEEKS | | Director | | September [removed: 28, 2016] [added: 27, 2017] |
| /s/ STEVEN D. COHAN | | Director | | September [removed: 28, 2016] [added: 27, 2017] |
| /s/ DANIEL ENGLANDER | | Director | | September [removed: 28, 2016] [added: 27, 2017] |
| /s/ THOMAS N. TRYFOROS | | Director | | September [removed: 28, 2016] [added: 27, 2017] |
| /s/ MATT BLUNT | | Director | | September [removed: 28, 2016] [added: 27, 2017] |
| [Report of Independent Registered Public Accounting [removed: Firm](#s019FEA280D6454569CD6D6D9FC5F4A3F)] [added: Firm](#s61F4723F430C5FB694E3CF116E25D59D)] | [removed: [59](#s019FEA280D6454569CD6D6D9FC5F4A3F)] [added: [59](#s61F4723F430C5FB694E3CF116E25D59D)] |
| [Consolidated Balance Sheets as of July 31, [removed: 2016] [added: 2017] and [removed: 2015](#sC92FF61D2F6B55D18CEA704E36B03E58)] [added: 2016](#sBD590C7C06C65480BC9C40A3E31F5460)] | [removed: [60](#sC92FF61D2F6B55D18CEA704E36B03E58)] [added: [60](#sBD590C7C06C65480BC9C40A3E31F5460)] |
| [Consolidated Statements of Income for the years ended July 31, [removed: 2016, 2015] [added: 2017, 2016] and [removed: 2014](#s5BA195F9027C5C52B89BE1D5DA1EBDDA)] [added: 2015](#sD89A4D6F19D053CA943EA5A43B0A21E5)] | [removed: [61](#s5BA195F9027C5C52B89BE1D5DA1EBDDA)] [added: [61](#sD89A4D6F19D053CA943EA5A43B0A21E5)] |
| [Consolidated Statements of Comprehensive Income for the years ended July 31, [removed: 2016, 2015] [added: 2017, 2016] and [removed: 2014](#s97E97CEB8E1D5D43AE07C59CE559A942)] [added: 2015](#sC99B8488FF0F54CAB09B70CDDB85B1E0)] | [removed: [62](#s97E97CEB8E1D5D43AE07C59CE559A942)] [added: [62](#sC99B8488FF0F54CAB09B70CDDB85B1E0)] |
| [Consolidated Statement of Stockholder’s Equity for the years ended July 31, [removed: 2016, 2015] [added: 2017, 2016] and [removed: 2014](#s17BA06312CDD5E54BDB5BCD6CFE841D4)] [added: 2015](#sC832B18BEBE2535CB309F32AEC087093)] | [removed: [63](#s17BA06312CDD5E54BDB5BCD6CFE841D4)] [added: [63](#sC832B18BEBE2535CB309F32AEC087093)] |
| [Consolidated Statements of Cash Flows for the years ended July 31, [removed: 2016, 2015] [added: 2017, 2016] and [removed: 2014](#s7FDDE29284F655F6B77A22FBE612CA21)] [added: 2015](#s6DB4383FEE565DF7ACC2F74C76369436)] | [removed: [64](#s7FDDE29284F655F6B77A22FBE612CA21)] [added: [64](#s6DB4383FEE565DF7ACC2F74C76369436)] |
| [Notes to Consolidated Financial [removed: Statements](#sC4C45EE07B4A552EAC3A506D3395B828)] [added: Statements](#sDEE0B644E7D25AC3A12EB1A62CAA0CB5)] | [removed: [65](#sC4C45EE07B4A552EAC3A506D3395B828)] [added: [65](#sDEE0B644E7D25AC3A12EB1A62CAA0CB5)] |
We have audited the accompanying consolidated balance sheets of Copart, Inc. as of July 31, [removed: 2016] [added: 2017] and [removed: 2015,] [added: 2016,] and the related consolidated statements of income, comprehensive income, stockholders’ equity, and cash flows for each of the three years in the period ended July 31, [removed: 2016.][added: 2017.]
In our opinion, the financial statements referred to above present fairly, in all material respects, the consolidated financial position of Copart, Inc. at July 31, [removed: 2016] [added: 2017] and [removed: 2015,] [added: 2016,] and the consolidated results of its operations and its cash flows for each of the three years in the period ended July 31, [removed: 2016,] [added: 2017,] in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), Copart, Inc.’s internal control over financial reporting as of July 31, [removed: 2016,] [added: 2017,] based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 [removed: Framework)] [added: framework)] and our report dated September [removed: 28, 2016] [added: 27, 2017] expressed an unqualified opinion thereon.
| | [added: |] July 31, | | | | | | |
| | [added: | 2017 | | | |] 2016 | | | | 2015 | | |
| ASSETS | | | | | | | | [added: |]
| Current assets: | | | | | | | | [added: |]
| Cash and cash equivalents [added: at beginning of period] | [removed: $] | 155,849 | | | [removed: $] | 456,012 | | [added: | | 158,668 | | |]
| Accounts receivable, net | [removed: 266,270] | [added: 311,846] | | | [removed: 215,696] | [added: 266,270] | | [added: |]
| Vehicle pooling costs | [removed: 28,599] | [added: 31,118] | | | [removed: 24,949] | [added: 28,599] | | [added: |]
| Inventories | [removed: 10,388] | [added: 10,163] | | | [removed: 8,613] | [added: 10,388] | | [added: |]
| Income taxes receivable | [removed: 18,751] | [added: 6,418] | | | [removed: 6,092] | [added: 18,751] | | [added: |]
| Deferred income taxes | [removed: 1,444] | [added: —] | | | [removed: 3,396] | [added: 1,444] | | [added: |]
| Prepaid expenses and other assets | [removed: 18,005] | [added: 17,616] | | | [removed: 19,824] | [added: 18,005] | | [added: |]
| Total current assets | [removed: 499,306] | [added: 587,261] | | | [removed: 734,582] | [added: 499,306] | | [added: |]
| Property and equipment, net | [removed: 816,791] | [added: 944,056] | | | [removed: 700,402] | [added: 816,791] | | [added: |]
| Intangibles, net | [removed: 11,761] | [added: 75,938] | | | [removed: 17,857] | [added: 11,761] | | [added: |]
| [removed: Goodwill] [added: Beginning balance] | [added: | $ |] 260,198 | | | [added: $] | 271,850 | | [removed: |]
| Deferred income taxes | [removed: 23,506] | [added: 1,287] | | | [removed: 28,840] | [added: 23,506] | | [added: |]
| Other assets | [removed: 38,258] | [added: 33,716] | | | [removed: 45,129] | [added: 38,258] | | [added: |]
| Total assets | [added: |] $ | [removed: 1,649,820] [added: 1,982,501] | | | $ | [removed: 1,798,660] [added: 1,649,820] | |
| LIABILITIES AND STOCKHOLDERS’ EQUITY | | | | | | | | [added: |]
Date: September 27, 2017
September 27, 2017
| | | 2017 | | | | 2016 | | |
| Cash and cash equivalents | | $ | 210,100 | | | $ | 155,849 | |
| Goodwill | | 340,243 | | | | 260,198 | | |
| Deferred income taxes | | 92 | | | | — | | |
| Noncontrolling interest | | 534 | | | | — | | |
| Net income attributable to noncontrolling interest | | 34 | | | | — | | | | — | | |
| Net income attributable to Copart, Inc. | | $ | 394,227 | | | $ | 270,360 | | | $ | 219,783 | |
| Weighted average common shares outstanding | | 228,686 | | | | 228,846 | | | | 251,829 | | |
| Diluted weighted average common shares outstanding | | 237,019 | | | | 244,295 | | | | 262,851 | | |
| | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | |
| Net income | | $ | 394,261 | | | $ | 270,360 | | | $ | 219,783 | |
| Comprehensive income attributable to noncontrolling interest | | 34 | | | | — | | | | — | | |
| Comprehensive income attributable to Copart, Inc. | | $ | 402,745 | | | $ | 229,959 | | | $ | 171,050 | |
| Net income | | — | | | — | | | | — | | | | — | | | | 394,227 | | | | 34 | | | | 394,261 | | |
| Acquisition of noncontrolling interest | | — | | | — | | | | — | | | | — | | | | — | | | | 500 | | | | 500 | | |
| Balances at July 31, 2017 | | 230,488,296 | | | $ | 23 | | | $ | 453,349 | | | $ | (100,676 | ) | | $ | 745,370 | | | $ | 534 | | | $ | 1,098,600 | |
| | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | |
| Net income | | $ | 394,261 | | | $ | 270,360 | | | $ | 219,783 | |
| Repurchases of common stock | | — | | | | (442,855 | | ) | | (233,484 | | ) |
| Payments for employee stock-based tax withholdings | | (135,433 | | ) | | (15,039 | | ) | | (3,822 | | ) |
JULY 31, 2017
On March 23, 2017, the Company’s Board of Directors approved a two-for-one common stock split effected in the form of a stock dividend.
The additional shares resulting from the stock split were distributed after the closing of trading on April 10, 2017 to stockholders of record on April 3, 2017.
The stock dividend increased the number of shares of common stock outstanding and all share and per share amounts have been adjusted for the stock dividend, as of the date earliest presented in these financial statements.
Certain prior year amounts have been adjusted to conform to current year presentation.
The Company also has a 59.5% voting interest in a company, which was acquired as part of the Cycle Express, LLC acquisition (“majority-owned subsidiary”), which provides various repossession services for the powersports auction industry.
Noncontrolling interest consists of a 40.5% outside voting interest in the majority-owned subsidiary.
Net income or loss of the majority-owned subsidiary is allocated to the members’ interests in accordance with the operating agreement.
The accounts and balances of the majority-owned subsidiary have been consolidated with those of the Company.
| | | | | |
| --- | --- | --- | --- | --- |
| | | | | |
Income Taxes and Deferred Tax Assets
Income taxes are accounted for under the asset and liability method.
| | | | |
| --- | --- | --- | --- |
As discussed in Note 1 — Summary of Significant Accounting Policies to the consolidated financial statements, the Company changed its method for certain aspects of share-based payments to employees as a result of the early adoption of the FASB Accounting Standards Update No. 2016-09, “Improvements to Employee Share-based Payment Accounting,” effective August 1, 2015.
September 28, 2016
| | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Weighted average common shares outstanding | 114,423 | | | | 125,914 | | | | 125,693 | | |
| Diluted weighted average common shares outstanding | 122,147 | | | | 131,425 | | | | 131,230 | | |
| | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Balances at July 31, 2013 | 125,494,995 | | | $ | 13 | | | $ | 368,769 | | | $ | (47,161 | ) | | $ | 440,780 | | | $ | 762,401 | |
| Net income | — | | | — | | | | — | | | | — | | | | 178,687 | | | | 178,687 | | |
| Interest rate swaps, net of tax effects | — | | | — | | | | — | | | | 283 | | | | — | | | | 283 | | |
| Repurchases of common stock | (457,894 | | ) | | (237,306 | | ) | | (572 | | ) |
| Change in bank overdraft | — | | | | — | | | | (16,291 | | ) |
| Cash and cash equivalents at end of period | $ | 155,849 | | | $ | 456,012 | | | $ | 158,668 | |
Goodwill and Other Identifiable Intangible Assets
The Company performed its annual impairment test for goodwill during the fourth quarter of the year ended July 31, 2016, utilizing a market value and discounted cash flow approach.
The impairment test for identifiable intangible assets not subject to amortization is also performed annually or when impairment indicators exist.
The impairment test consists of a comparison of the fair value of the intangible asset with its carrying amount.
Identifiable intangible assets that are subject to amortization are evaluated for impairment using a process similar to that used to evaluate other long-lived assets.
The Company reassessed its strategy of utilizing a third-party enterprise operating system to address its international expansion needs based on the projected cost to complete, deployment risk and certain other factors.
The Company decided to cease development of this software and address its international technology needs through an internally developed proprietary solution.
As a result of the adoption, the Company recognized excess tax benefits of $14.7 million as a reduction to tax expense in the consolidated statements of income, as though ASU 2016-09 had been in effect since the beginning of fiscal 2016, instead of reflected in stockholders' equity.
The Company realized an income tax benefit of $3.0 million and $2.3 million from stock option exercises during the years ended July 31, 2015 and 2014, respectively.
The segments continue to share similar business models, services and economic characteristics although recent changes in management structure and continued growth in the Company's International region have resulted in the change in the reportable segments.
Prior period reportable segment information has been adjusted to reflect the change in reportable segments.
Additionally, excess tax benefits will be classified as an operating activity on the consolidated statements of cash flows.
In regards to forfeitures, the entity can make an accounting policy election to either recognize forfeitures as they occur or estimate the number of awards expected to be forfeited.
The Company early adopted ASU 2016-09 during the fourth quarter of fiscal 2016 on a modified retrospective basis.
The benefit was previously recorded within additional paid-in capital, representing the cumulative windfall tax benefit related to
exercises of stock options.
With respect to forfeitures, the Company will continue to estimate the number of awards expected to be forfeited in accordance with our existing accounting policy.
In April 2015, the FASB issued ASU 2015-03, Interest - Imputation of Interest (Subtopic 835-30), which required that debt issuance costs related to a recognized debt liability be presented in the balance sheet as a direct deduction from the carrying amount of that debt liability, consistent with debt discounts.
The recognition and measurement guidance for debt issuance costs are not affected by the amendments in this ASU.
The amendments are effective for financial statements issued for annual and interim periods beginning after December 15, 2015.
The Company early adopted this guidance as of July 31, 2016.
In connection with the Company's adoption of ASU 2015-03, prior year debt balances have been retrospectively adjusted to include a direct deduction of unamortized debt issuance costs, resulting in a reclassification of $1.3 million of debt issuance costs to long-term debt obligation.
An excerpt. Shown here: 40 of 513 rewritten, 40 of 304 added and 40 of 145 removed. The counts are complete. For every sentence, read Item 15. Exhibits, Financial Statement Schedules in the FY2017 filing and the FY2016 filing.