 filings.tools
Copart (CPRT) 10-K risk factor changes: FY2018 vs FY2017
The 2018-07-31 10-K against the 2017-07-31 one, compared heading by heading and sentence by sentence. One of these filings carries no fiscal year tag, so its year is the calendar year of the period end.
Item 1A53 rewritten32 added7 removed384 unchanged
All filing items727 rewritten311 added273 removed2,139 unchanged
Summary
counted, not written
- Item 1A headings could not be compared: only 0 carried over between the two years, which usually means one filing was read wrongly, so none is reported as new or removed.
- Sentence by sentence, 311 added, 273 removed, 727 rewritten and 2,139 unchanged across 16 items that differ.
Sentences by item
20 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2018; struck-through words were in FY2017. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors
53 rewritten, 32 added, 7 removed, 384 unchanged
No single customer accounted for more than 10% of our consolidated revenue for fiscal [removed: 2017.][added: 2018.]
Our expansion into markets outside the U.S., including expansions in Europe, Brazil, [added: and] the Middle [removed: East, and India] [added: East] expose us to risks arising from operating in international markets.
Any failure to successfully integrate businesses acquired [added: or operational capabilities established] outside the U.S. [removed: into our operations] could have an adverse effect on our consolidated results of operations, financial position or cash flows.
Subsequently, in fiscal 2008 we made a significant acquisition in the U.K., followed by acquisitions in the U.A.E., Brazil, Germany, and Spain in fiscal 2013, expansions into Bahrain and Oman in fiscal 2015, [removed: and] expansion into the Republic of Ireland and India in fiscal [removed: 2016.][added: 2016, and an acquisition in Finland in fiscal 2018.]
We have and may continue to incur substantial expenses establishing new yards [removed: or operations] [added: and operations, acquiring buyers and sellers, and implementing shared services capabilities] in international markets.
[removed: In many countries outside of the United States, particularly in those with developing] economies, it may be common for persons to engage in business practices prohibited by laws and regulations applicable to us, such as the U.S. Foreign Corrupt Practices Act (FCPA), U.K. Bribery Act, Brazil Clean Companies Act, India’s Prevention of Corruption Act, 1988 or similar local anti-bribery laws.
These laws generally prohibit companies and their employees or agents from making improper payments [removed: to government officials] for the purpose of obtaining or retaining business.
In other markets, [added: including Germany,] insurers have traditionally been less involved in the disposition of salvage vehicles.
As we expand into markets outside the U.S., Canada, and the U.K., [added: including Germany in particular,] we cannot predict whether markets will readily adapt to our strategy of online auctions of automobiles sourced principally through vehicle insurers.
We have [removed: transitioned various functionality of our previously planned third-party enterprise operating system to an internally] developed [added: a new] proprietary [added: enterprise operating] system, and we may experience difficulties operating our business as we [removed: work] [added: continue] to [removed: develop and] design [added: and develop] this system.
We began using our new internally developed proprietary system with our expansion into Spain [removed: and India] in fiscal 2016 and Germany in fiscal 2017.
[removed: Any failure to maintain the integrity of our systems and infrastructure may result in loss of customers due to] among other things, slow delivery times, unreliable service levels or insufficient capacity, which could have a material adverse effect on our business, consolidated financial position and results of operations.
The impairment of [added: internally developed] capitalized [removed: development] [added: software] costs could adversely affect our consolidated results of operations and financial condition.
[removed: Any] [added: Disruptions to our information technology systems, including] failure to [added: prevent outages,] maintain [removed: security and] [added: security,] prevent unauthorized access to [removed: electronic] [added: our information technology systems] and other confidential [removed: information] [added: information,] could disrupt our business and materially and adversely affect our reputation, consolidated results of operations and financial condition.
Information [added: availability and] security risks for online commerce companies have significantly increased in recent years because of, in addition to other factors, the proliferation of new technologies, the use of the [removed: Internet] [added: internet] and telecommunications technologies to conduct financial transactions, and the increased sophistication and activities of organized crime, hackers, terrorists, and other external parties.
In addition, human error or accidental technological failure could make us vulnerable to [added: information technology system disruptions and/or] cyber-attacks, including the introduction of malicious computer viruses or code into our system, phishing attacks, or other information technology data security incidents.
Our customers and other parties in the payments value chain rely on our digital technologies, computer and [removed: e-mail] [added: email] systems, software and networks to conduct their operations.
In addition, to access our products and services, our customers [removed: and cardholders] increasingly use personal smartphones, tablet PCs and other mobile devices that may be beyond our control.
[removed: Cyber-attacks] [added: Information technology system disruptions, cyber-attacks] or other cyber security incidents could materially and adversely affect our reputation, operating results, or financial condition by, among other things, making our auction platform inoperable for a period of time, damaging our reputation with buyers, sellers, and insurance companies as a result of the unauthorized disclosure of confidential information (including account data information), or resulting in governmental investigations, litigation, liability, fines, or penalties against us.
In addition, as cyber-threats continue to evolve, we may be required to expend significant additional resources to continue to modify or enhance our protective measures or to investigate [removed: and remediate any information security vulnerabilities.]
Complying with [added: the GDPR and similar] emerging and changing privacy and data protection requirements may cause us to incur substantial costs or require us to change our business practices.
For example, Hurricanes Katrina, [removed: Rita] [added: Rita, Sandy,] and [removed: Sandy] [added: Harvey] had, in certain quarters, an adverse effect on our operating results, in part because of yard capacity constraints in the impacted areas of the United States.
[removed: In] [added: For example, in] fiscal 2016, we opened new [added: operational] facilities in Castledermot, Republic of Ireland; [removed: Sonepat, India;] Algete, [removed: Spain;] [added: Spain (Madrid);] and six new [added: operational] facilities in the U.S. In fiscal 2017, we opened a new [added: operational] facility in Bad Fallingbostel, [removed: Germany,] [added: Germany (Hanover),] a new [added: operational] facility in Betim, Minas Gerais, Brazil, nine new [added: operational] facilities in the [removed: U.S] [added: U.S.] and acquired Cycle Express, LLC, which conducts business primarily as National Powersport Auctions (NPA), a leading non-salvage auction platform for motorcycles, snowmobiles, watercraft and other powersports vehicles.
| • | the availability of salvage [removed: vehicles;] [added: vehicles or other vehicles we sell;] |
| • | changes in international, state or federal [removed: laws] [added: laws, regulations,] or [removed: regulations] [added: treaties] affecting [removed: salvage vehicles;] [added: the vehicles we sell;] |
| • | changes in [removed: local] laws affecting who may purchase [removed: salvage vehicles;] [added: the vehicles we sell;] |
| • | the ability to obtain [added: or maintain] necessary permits to operate. |
We rely primarily upon independent subhaulers to pick up and deliver vehicles to and from our storage facilities in the U.S., Canada, Brazil, [removed: U.A.E., Oman, Bahrain, Germany,] the Republic of Ireland, [removed: India,] [added: Germany, Finland, the U.A.E., Oman, Bahrain,] and Spain.
In connection therewith, we are subject to the risks associated with providing trucking services, including inclement weather, disruptions in transportation infrastructure, [added: accidents and related injury claims,] availability and price of fuel, any of which could result in an increase in our operating expenses and reduction in our net income.
We are partially self-insured for certain losses related to [added: our different lines of insurance coverage including, without limitation,] medical insurance, general liability, workers’ compensation and auto liability.
Our executive officers, directors and their affiliates beneficially own, in the aggregate, 15.9% of our common stock as of July 31, [removed: 2017.][added: 2018.]
Johnson, our [removed: Chairman;] [added: Chairman, or] A.
[removed: Mitz,] [added: Jayson Adair,] our [removed: President,] [added: Chief Executive Officer,] or if one or more of these executives decide to join a competitor or otherwise compete directly or indirectly with us, we may not be able to successfully manage our business or achieve our business objectives.
For example, during fiscal [removed: 2006] [added: 2006, fiscal 2013] and fiscal [removed: 2013,] [added: 2018,] we recognized substantial additional costs associated with Hurricanes Katrina, [removed: Rita] [added: Rita, Sandy,] and [removed: Sandy.][added: Harvey.]
Weather events have had, in certain quarters, an adverse effect on our operating results, in part because of yard capacity constraints in the impacted areas of the U.S. These additional costs were characterized as “abnormal” under ASC 330, Inventory, and included [removed: the additional subhauling,] [added: premiums for subhaulers,] payroll, equipment and facilities expenses directly related to the operating conditions created by the hurricanes.
In addition, under our Percentage Incentive Program contracts, which we refer to as PIP, the cost of towing the vehicle to one of our [removed: facilities is included in the PIP fee.]
The [removed: salvage] vehicle sales industry is highly competitive and we may not be able to compete successfully.
We face significant competition for the supply of salvage [added: and other] vehicles and for the buyers of those vehicles.
Due to the limited number of vehicle sellers, particularly in the U.K., [added: and other foreign markets,] the absence of long-term contractual commitments between us and our sellers and the increasingly competitive market environment, there can be no assurance that our competitors will not gain market share at our expense.
Government regulation of the [removed: salvage] vehicle sales industry may impair our operations, increase our costs of doing business and create potential liability.
For example, although we continue to operate a technology and operations center in India for administrative support, we recently decided to suspend our salvage operations in India, which did not have a material effect on our consolidated results of operations and financial position, until the Indian market develops in a manner better suited to our business model.
Moreover, success in opening and operating facilities in markets can be dependent upon establishing new relationships with buyers and sellers, and our failure to establish those relationships could have an adverse effect on our consolidated results of operations and future operating results.
Although we face risks associated with international expansion in each of the non-U.S. markets where we operate, our current focus on the German market heightens the risks we face relating to our expansion plans in Germany.
In many countries outside of the United States, particularly in those with developing
We have developed a new proprietary enterprise operating system to address our international expansion needs.
Any failure to maintain the integrity of our systems and infrastructure may result in loss of customers due to
and remediate any information security vulnerabilities.
Recent regulatory changes in Europe have created compliance uncertainty regarding certain transfers of personal data from Europe to the United States.
For example, the General Data Protection Regulation (“GDPR”), which went into effect in the European Union (“EU”) on May 25, 2018, applies to all of our activities conducted from an establishment in the EU and may also apply to related products and services that we offer to EU users.
In fiscal 2018, we opened new operational facilities in Andrews, Texas (Midland), Exeter, Rhode Island, and Lumberton, North Carolina, a new operational facility in Belfast, Northern Ireland, a new operational facility in Nobitz, Germany (Leipzig), and acquired locations in the municipalities of Espoo; Pirkkala; Oulu; and Turku, Finland.
| • | obtain or retain buyers, sellers, and sales volumes in new markets or facilities; |
| • | changes in the application, interpretation, and enforcement of existing laws, regulations or treaties; |
| • | trade disputes and other political, diplomatic, legal, or regulatory developments; |
| • | inconsistent application or enforcement of laws or regulations by regulators, governmental or quasi-governmental entities, or law enforcement or quasi-law enforcement agencies, as compared to our competitors; |
| | |
| --- | --- |
| | |
| --- | --- |
| | |
| --- | --- |
| | |
| --- | --- |
facilities is included in the PIP fee.
For example, in March 2008, a decree issued by the president of Mexico became effective that placed restrictions on the types of vehicles that can be imported into Mexico from the U.S. The adoption of similar laws or regulations in other jurisdictions that have the effect of reducing or curtailing our activities abroad, changes in the
Should the value of our goodwill become impaired, it could
The Tax Cuts and Jobs Act (“Tax Reform” or “Tax Act”) was enacted on December 22, 2017.
The Tax Act significantly revamped U.S. taxation of corporations, including a reduction of the federal income tax rate from 35% to 21%, a repeal of the exceptions to the $1.0 million deduction limitation for performance-based compensation to covered employees, and a new tax regime for foreign earnings.
The repeal of the $1.0 million deduction limit for performance-based compensation, the new U.S. taxes on accumulated and future foreign earnings and other adverse changes resulting from the Tax Act, or a change in the mix of domestic and foreign earnings, might offset the benefit from the reduced tax rate, and our future effective tax rates and/or cash taxes may increase, even significantly, or not decrease much, compared to recent or historical trends.
Many of the provisions of the Tax Act are highly complex and may be subject to further interpretive guidance from the IRS or others.
Some of the provisions of the Tax Act may be changed by a future Congress or challenged by the World Trade Organization (“WTO”).
Although we cannot predict the nature or outcome of such future interpretive guidance, or actions by a future Congress or WTO, they could adversely impact our consolidated results of operations and financial position.
Income tax expense on accumulated foreign earnings recorded as a result of the Tax Act is a provisional amount and reflects our current best estimate, which may be adjusted over the course of the next year and could adversely affect our consolidated results of operations and financial position.
Seller arrangements are either written or oral agreements typically subject to cancellation by either party upon 30 to 90 days’ notice.
During fiscal 2014, we terminated a contract with KPIT (formerly known as Sparta Consulting, Inc.), whereby KPIT was engaged to design and implement an SAP-based replacement for our existing business operating software that, among other things, would address our international expansion needs.
Following a review of KPIT’s work performed to date, and an assessment of the cost to complete, deployment risk, and other factors, we ceased development of KPIT’s software and internally developed a proprietary solution in its place.
For example, in October 2015, a European court decision invalidated the U.S.-EU Safe Harbor framework which allowed us and other companies to meet certain European legal requirements for the transfer of personal data from the European Economic Area to the U.S. We may find it necessary or desirable to modify our data handling practices as a result of this court decision, and it may serve as a basis for our personal data handling practices to be challenged or otherwise adversely impact our business.
For example, in fiscal 2015, we opened new facilities in Bahrain, Oman, and Moncton, Canada.
Jayson Adair, our Chief Executive Officer; and Vincent W.
Environmental laws
An excerpt. Shown here: 40 of 53 rewritten, all 32 added and all 7 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors in the FY2018 filing and the FY2017 filing.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
147 rewritten, 60 added, 55 removed, 383 unchanged
This Annual Report on Form 10-K for the fiscal year ended July 31, [removed: 2017,] [added: 2018,] or this Form 10-K, including the information incorporated by reference herein, contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended (the Securities Act), and Section 21E of the Securities Exchange Act of 1934, as amended (the Exchange Act).
We are a leading provider of online auctions and vehicle remarketing services with operations in the United States (U.S.), Canada, the United Kingdom (U.K.), [added: Brazil,] the Republic of Ireland, [removed: Brazil,] Germany, [added: Finland,] the United Arab Emirates (U.A.E.), Oman, Bahrain, [removed: India,] and Spain.
We offer vehicle sellers a full range of services that [added: help] expedite each stage of the vehicle sales process, minimize administrative and processing costs, and maximize the ultimate sales price.
In the U.S., Canada, [added: Brazil,] the Republic of Ireland, [removed: Brazil,] [added: Germany, Finland,] the U.A.E., Oman, Bahrain, [removed: India,] and Spain, we sell vehicles primarily as an agent and derive revenue primarily from fees paid by vehicle [removed: sellers] [added: buyers (“members”)] and vehicle [removed: buyers] [added: sellers] as well as related fees for services, such as towing and storage.
In the [removed: U.K.,] [added: U.K. and Germany,] we operate both as an agent and on a principal basis, [added: in some cases] purchasing [removed: the] salvage vehicles outright [removed: from the insurance companies] and reselling the vehicles for our own account.
In Germany and Spain, we also derive revenue from [removed: sales] listing [removed: fees for listing] vehicles on behalf of [removed: many] insurance [removed: companies.][added: companies and insurance experts to determine the vehicle’s residual value and/or to facilitate a sale for the insured.]
[added: Under the] consignment program, only the fees associated with vehicle processing are recorded in revenue, not the actual sales price (gross proceeds).
Purchased vehicle revenue includes the gross sales price of the [removed: vehicle] [added: vehicles] which we have purchased or are otherwise considered to own, and is primarily generated in the U.K. We have certain contracts with insurance companies in which we act as a principal, purchasing vehicles and reselling them for our own account.
Our revenue is impacted by several factors, including total loss frequency and the average vehicle auction selling price, as a significant amount of our service revenue is associated in some manner [removed: to] [added: with] the ultimate selling price of the vehicle.
Total loss frequency is the percentage of cars involved in accidents [removed: which] [added: that] insurance companies salvage rather than repair and is driven by the relationship between repairs costs, used car values, and auction returns.
The increase in [removed: salvage] [added: total loss] frequency may have been driven by the decline in used car values relative to repair costs, which we believe are generally trending upward.
The average age of cars on the road continued to increase, growing from 9.6 years in 2002 to [removed: 11.6] [added: 12.1] years in [removed: 2016.][added: 2018.]
The factors that [added: can] influence repair costs, used car pricing, and auction returns are many and varied and we cannot predict their movements.
See Notes to Consolidated Financial Statements, Note [removed: 8] [added: 2] — [removed: Long-Term Debt.][added: Acquisitions.]
We believe that these acquisitions and openings will strengthen our coverage, as we have facilities located in the U.S., Canada, the U.K., Brazil, the [added: Republic of Ireland, Germany, Finland, the] U.A.E., Oman, Bahrain, [removed: Germany, Spain, the Republic of Ireland] and [removed: India] [added: Spain] with the intention of providing national coverage for our sellers.
The following table sets forth [added: operational] facilities that we have acquired or opened [added: and began operations] from August 1, [removed: 2014] [added: 2015] through July 31, [removed: 2017:][added: 2018:]
It has been our practice and remains our intention, where possible, to migrate these [removed: contracts to the agency model in future periods.]
The following table shows certain data from our consolidated statements of income expressed as a percentage of total service revenues and vehicle sales for fiscal [removed: 2017, 2016] [added: 2018, 2017] and [removed: 2015:][added: 2016:]
| (In percentages) | | [removed: 2017] [added: 2018] | | | [removed: 2016] [added: 2017] | | | [removed: 2015] [added: 2016] | |
| Service revenues | | [removed: 89] [added: 87] | % | | [removed: 87] [added: 89] | % | | [removed: 86] [added: 87] | % |
| Vehicle sales | | [removed: 11] [added: 13] | % | | [removed: 13] [added: 11] | % | | [removed: 14] [added: 13] | % |
| Yard operations | | 47 | % | | [removed: 46] [added: 47] | % | | 46 | % |
| Cost of vehicle sales | | [removed: 9] [added: 11] | % | | [removed: 11] [added: 9] | % | | [removed: 12] [added: 11] | % |
| General and administrative | | [removed: 11] [added: 10] | % | | 11 | % | | [removed: 12] [added: 11] | % |
| Impairment of long-lived assets | | [removed: 1] [added: —] | % | | [removed: —] [added: 1] | % | | — | % |
| Total operating expenses | | 68 | % | | 68 | % | | [removed: 70] [added: 68] | % |
| Operating income | | 32 | % | | 32 | % | | [removed: 30] [added: 32] | % |
| Other (expense) income | | [removed: (2] [added: (1] | )% | | [removed: (1] [added: (2] | )% | | (1 | )% |
| Income before income taxes | | [removed: 30] [added: 31] | % | | [removed: 31] [added: 30] | % | | [removed: 29] [added: 31] | % |
| Income taxes | | [removed: 3] [added: 8] | % | | [removed: 10] [added: 3] | % | | 10 | % |
| Net income | | [removed: 27] [added: 23] | % | | [removed: 21] [added: 27] | % | | [removed: 19] [added: 21] | % |
Comparison of Fiscal Years ended July 31, [removed: 2017, 2016] [added: 2018, 2017] and [removed: 2015][added: 2016]
The following table presents a comparison of service revenues for fiscal [removed: 2017, 2016] [added: 2018, 2017] and [removed: 2015:][added: 2016:]
| | | | Year Ended July 31, | | | | | | | | | | | | [removed: 2017] [added: 2018] vs. [removed: 2016] [added: 2017] | | | | | | | [removed: 2016] [added: 2017] vs. [removed: 2015] [added: 2016] | | | | | |
| (In thousands) | | | [removed: 2017] [added: 2018] | | | | [removed: 2016] [added: 2017] | | | | [removed: 2015] [added: 2016] | | | | Change | | | | % Change | | | Change | | | | % Change | |
| | United States | | $ | [removed: 1,128,990] [added: 1,385,238] | | | $ | [removed: 958,558] [added: 1,128,990] | | | $ | [removed: 848,149] [added: 958,558] | | | $ | [removed: 170,432] [added: 256,248] | | | [removed: 17.8] [added: 22.7] | % | | $ | [removed: 110,409] [added: 170,432] | | | [removed: 13.0] [added: 17.8] | % |
| | International | | [removed: 157,262] [added: 193,264] | | | | [removed: 145,821] [added: 157,262] | | | | [removed: 137,214] [added: 145,821] | | | | [removed: 11,441] [added: 36,002] | | | | [removed: 7.8] [added: 22.9] | % | | [removed: 8,607] [added: 11,441] | | | | [removed: 6.3] [added: 7.8] | % |
| Total service revenues | | | $ | [removed: 1,286,252] [added: 1,578,502] | | | $ | [removed: 1,104,379] [added: 1,286,252] | | | $ | [removed: 985,363] [added: 1,104,379] | | | $ | [removed: 181,873] [added: 292,250] | | | [removed: 16.5] [added: 22.7] | % | | $ | [removed: 119,016] [added: 181,873] | | | [removed: 12.1] [added: 16.5] | % |
The increase in service revenues for fiscal [removed: 2016] [added: 2018] of [removed: $119.0] [added: $292.3] million, or [removed: 12.1%] [added: 22.7%] as compared to fiscal [removed: 2015] [added: 2017] came from (i) [removed: growth] [added: an increase] in the U.S. of [removed: $110.4] [added: $256.2] million and (ii) [removed: growth] [added: an increase] in International of [removed: $8.6] [added: $36.0] million.
The [removed: growth] [added: increase] in the U.S. was [removed: driven] primarily [removed: by] [added: the result of] increased [removed: volume,] [added: volume] partially [removed: offset] [added: driven] by [removed: lower] [added: higher] average auction selling prices, which we believe was due to [removed: lower] [added: a change in the mix of vehicles sold and higher] commodity prices.
Our goals are to generate sustainable profits for our stockholders, while also producing environmental and social benefits for the world, by promoting vehicle restoration, repair, and recycling; parts refurbishment and re-use; and facilitating the recovery and resilience of communities affected by severe climate events.
| Andrews, Texas (Midland) | | Greenfield | | August 2017 | | United States |
| Exeter, Rhode Island | | Greenfield | | October 2017 | | United States |
| Lumberton, North Carolina | | Greenfield | | June 2018 | | United States |
| Nobitz, Germany (Leipzig) | | Greenfield | | April 2018 | | Germany |
| Belfast, Northern Ireland | | Greenfield | | April 2018 | | United Kingdom |
| Espoo, Finland | | Acquisition | | March 2018 | | Finland |
| Pirkkala, Finland | | Acquisition | | March 2018 | | Finland |
| Oulu, Finland | | Acquisition | | March 2018 | | Finland |
| Turku, Finland | | Acquisition | | March 2018 | | Finland |
types of contracts to the agency model in future periods.
The increase in the cost to process each car in the U.S. was negatively impacted by abnormal costs of $68.6 million for temporary storage facilities; premiums for subhaulers; labor costs incurred from overtime; travel and lodging due to the reassignment of employees to the affected region; and equipment lease expenses to handle the increased volume associated with Hurricane Harvey, as the storm produced extraordinary volumes of flood damaged vehicles.
These costs do not include normal expenses associated with the increased unit volume created by the hurricane, which are deferred until the sale of the units and are recognized as vehicle pooling costs on the balance sheet.
The increase in yard operations depreciation and amortization expenses resulted primarily from depreciating new and expanded facilities and certain technology assets placed into service in the U.S. and International locations as well as changes to the useful lives of certain fixed assets.
| | | | Year Ended July 31, | | | | | | | | | | | | 2018 vs. 2017 | | | | | | | 2017 vs. 2016 | | | | | |
| (In thousands) | | | 2018 | | | | 2017 | | | | 2016 | | | | Change | | | | % Change | | | Change | | | | % Change | |
The increase in the U.S. was primarily the result of increased volume partially driven by
| | | | Year Ended July 31, | | | | | | | | | | | | 2018 vs. 2017 | | | | | | | 2017 vs. 2016 | | | | | |
| (In thousands) | | | 2018 | | | | 2017 | | | | 2016 | | | | Change | | | | % Change | | | Change | | | | % Change | |
The increase in general and administrative expenses for fiscal 2018 of $25.5 million, or 16.9% as compared to fiscal 2017 came primarily from an increase in the U.S. of $13.7 million, and an increase in International of $11.8 million, primarily from the impact of payroll taxes from the exercise of employee stock options.
Excluding depreciation and amortization, the increase in the U.S. of $9.0 million resulted due to the acquisition of Cycle Express, LLC, and litigation costs partially offset by a decrease in payroll taxes from the exercise of employee stock options.
| | | Year Ended July 31, | | | | | | | | | | | | 2018 vs. 2017 | | | | | | | 2017 vs. 2016 | | | | | |
| (In thousands) | | 2018 | | | | 2017 | | | | 2016 | | | | Change | | | | % Change | | | Change | | | | % Change | |
During fiscal 2018, we recognized a $1.1 million charge primarily related to fully impairing a supply contract in the International segment.
The increase in total other expense for fiscal 2018 of $0.6 million, or 3.0% as compared to fiscal 2017 was primarily due to a decrease in currency gains in International, primarily due to the change in the British pound to U.S. dollar exchange rate and to a decrease in interest expense of $3.4 million as a result of the paydown of our Revolving Loan Facility.
The tax rates in the prior year were impacted primarily from the result of recognizing excess tax benefits from the exercise of employee stock options of $21.3 million and $107.6 million for fiscal years 2018 and 2017, respectively.
The current year’s effective tax rate was computed based on the reduced blended U.S. federal corporate tax rate of 26.9% for the fiscal year ending July 31, 2018, and included the effects of the Tax Cuts and Jobs Act (“Tax Reform” or “Tax Act”).
See Note 12 — Income Taxes for a detailed discussion of the Tax Act.
| (In thousands) | | 2018 | | | | 2017 | | | | 2016 | | | | Change | | | | % Change | | | Change | | | | % Change | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | Year Ended July 31, | | | | | | | | | | | | 2018 vs. 2017 | | | | | | | 2017 vs. 2016 | | | | | |
| (In thousands) | | 2018 | | | | 2017 | | | | 2016 | | | | Change | | | | % Change | | | Change | | | | % Change | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | |
exercise of stock options, partially offset by a net repayments on our Revolving Loan Facility and a decline in cash used for acquisitions.
If these funds are needed for our operations in the U.S. the repatriation of these funds could still be subject to the foreign withholding tax related to the U.S. Tax Reform and the mandatory Transition Tax, which is imposed on the post-1986 undistributed foreign earnings and profits.
Net cash used in investing activities decreased for fiscal 2018 as compared to fiscal 2017 due primarily to a decline in acquisitions and proceeds from the sale of assets, including the majority-owned subsidiary, partially offset by increases in capital expenditures.
We acquired Autovahinkokeskus Oy (AVK), a salvage auto auction company based in Finland.
AVK currently operates facilities in the municipalities of Espoo; Pirkkala; Oulu; and Turku, Finland.
We also acquired the assets of an excavation company, which engages in earthwork, soil stabilization, equipment hauling, and erosion control commercial contractor services.
Under the
| Manama, Bahrain | | Greenfield | | May 2015 | | Bahrain |
| Muscat, Oman | | Greenfield | | June 2015 | | Oman |
| Moncton, New Brunswick | | Greenfield | | July 2015 | | Canada |
| Sonepat, India (New Delhi) | | Greenfield | | October 2015 | | India |
The decrease in yard operations depreciation and amortization expenses resulted primarily from certain assets becoming fully depreciated in the U.S.
The decrease in general and administrative expenses for fiscal 2016 of $0.9 million, or 0.6% as compared to fiscal 2015 came primarily from a decrease in the U.S. of $1.8 million, partially offset by an increase in International of $1.0 million as we continue to expand in these markets.
The decrease in the U.S. of $5.6 million, excluding depreciation and amortization, resulted from decreased expenditures on technology development; partially offset by the overall growth in labor costs and professional services associated with domestic expansion and increased stock-based payment compensation.
| | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
The decrease in total other expense for fiscal 2016 of $1.7 million, or 14.0% as compared to fiscal 2015 was primarily due to increased currency gains in International, primarily in the U.K. of $8.3 million, partially offset by an increase in interest expense of $5.5 million as a result of the additional long-term debt issued in December 2014, March 2016 and July 2016.
The decrease in the effective income tax rate for fiscal 2016 as compared to fiscal 2015 was driven by the geographical allocation of our taxable income and the adoption of ASU 2016-09.
If these funds are needed for our operations in the U.S., we would be required to accrue and pay U.S. taxes to repatriate these funds.
Net cash used in investing activities increased for fiscal 2016 as compared to fiscal 2015 due primarily to increases in capital expenditures.
Net cash used in financing activities increased in fiscal 2016 as compared to fiscal 2015 primarily due to the repurchases of our common stock as part of our stock repurchase program and our tender offer as discussed in further detail under the subheading “Stock Repurchases”, and a decrease in proceeds from the issuance of long-term debt.
For fiscal 2015, we repurchased 463,000 shares of our common stock at a weighted average price of $18.01 per share totaling $8.3 million.
In connection with the tender offer, we accepted for payment an aggregate of 12,508,122 shares of our common stock at a purchase price of $18.00 per share for a total value of $225.1 million.
Additionally, on December 30, 2015, we completed a modified “Dutch Auction” tender offer, or tender offer, to purchase up to 14,634,146 shares of our common stock at a price not greater than $20.50 nor less than $19.00 per share.
| FY 2015—Q1 | | 402,666 | | | $ | 9.80 | | | 249,242 | | | 70,832 | | | 82,592 | | | $ | 15.83 | | | $ | 1,121 | |
| FY 2015—Q3 | | 279,380 | | | 10.14 | | | | 152,042 | | | 41,312 | | | 86,026 | | | 18.64 | | | | 770 | | |
| FY 2015—Q4 | | 400,000 | | | 6.01 | | | | 133,204 | | | 104,316 | | | 162,480 | | | 18.04 | | | | 1,882 | | |
| Operating leases (2) | | 28,126 | | | | 40,649 | | | | 24,556 | | | | 59,436 | | | | — | | | | 152,767 | | |
| Capital leases (2) | | 1,153 | | | | 996 | | | | 13 | | | | — | | | | — | | | | 2,162 | | |
| Total contractual obligations | | $ | 130,941 | | | $ | 232,055 | | | $ | 61,589 | | | $ | 541,657 | | | $ | 24,573 | | | $ | 990,815 | |
extension of the termination date of the revolving credit facility under the Credit Agreement from March 15, 2021 to July 21, 2021, and (d) increased covenant flexibility.
ASU 2014-09 will be effective for us beginning with the first quarter of fiscal year 2019, the three months ended October 31, 2018.
We are currently evaluating the impact of implementing ASU 2014-09 on the consolidated financial statements, as well as evaluating the transition alternatives.
While we are continuing to assess all potential impacts of ASU 2014-09, we currently believe the most significant impact relates to our performance obligations through the determination of distinct and separately identifiable services, which may be different from our current separate units of accounting under ASU 2009-13.
Additionally, changes in revenue recognition requirements regarding our performance obligations within our service contracts could potentially result in either the earlier recognition of revenue and associated costs for certain performance obligations or the deferral of a significant portion of revenue and associated costs for a vehicle until the sale is substantially complete.
Due to the variety and complexity of our contracts, the actual revenue recognition treatment required under ASU 2014-09 may be dependent on contract-specific terms and vary in some instances.
Long-lived Asset Valuation, Including Intangible Assets
We evaluate long-lived assets, including property and equipment, and certain identifiable intangibles, for impairment whenever events or changes in circumstances indicate that the carrying amount of an asset may not be recoverable.
Recoverability of assets is measured by comparing the carrying amount of an asset to the estimated undiscounted future cash flows expected to be generated by the use of the asset.
If the estimated undiscounted cash flows change in the future, we may be required to reduce the carrying amount of an asset.
Allowance for Doubtful Accounts
We maintain an allowance for doubtful accounts in order to provide for estimated losses resulting from disputed amounts billed to sellers or members and the inability of our sellers or members to make required payments.
If billing disputes exceed expectations and/or if the financial condition of our sellers or members were to deteriorate, additional allowances may be required.
The allowance is calculated by taking both seller and buyer accounts receivables written off during the previous 12 month period as a percentage of the total accounts receivable balance.
A one percentage point adverse change to the write-off percentage would have resulted in an increase to the allowance for doubtful accounts balance of $2.6 million.
Retained Insurance Liabilities
An excerpt. Shown here: 40 of 147 rewritten, 40 of 60 added and 40 of 55 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations in the FY2018 filing and the FY2017 filing.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
13 rewritten, 1 added, 0 removed, 13 unchanged
To achieve this objective in the current uncertain global financial markets, all cash and cash equivalents were held in bank deposits and money market funds as of July 31, [removed: 2017.][added: 2018.]
As of July 31, [removed: 2017,] [added: 2018,] we held no direct investments in auction rate securities, collateralized debt obligations, structured investment vehicles or mortgaged-backed securities.
Based on the average cash balance held for fiscal [removed: 2017,] [added: 2018,] a hypothetical 10% adverse change in our interest yield would not have materially affected our operating results.
Our total borrowings under the Revolving Loan Facility under the Credit Agreement were [removed: $231.0 million] [added: zero] as of July 31, [removed: 2017.][added: 2018.]
If interest rates were to increase by 10%, our interest expense would increase by [removed: $2.4] [added: $2.0] million.
International net revenues are typically denominated in the local currency of each country and result from transactions by our operations in Canada, the U.K., [removed: the U.A.E.,] Brazil, [removed: Spain,] [added: the Republic of Ireland,] Germany, [added: Finland, the U.A.E., Oman, Bahrain,] and [removed: India.][added: Spain.]
These operations also incur a majority of their expenses in the local currency, the Canadian dollar, British pound, [added: Brazilian real, European Union euro,] U.A.E. dirham, [removed: Bahraini dinar,] Omani rial, [removed: Brazilian real, Euro] and [removed: Indian rupee.][added: Bahraini dinar.]
A hypothetical 10% adverse change in the value of the U.S. dollar relative to the Canadian dollar, British pound, [added: Brazilian real, European Union euro,] U.A.E. dirham, [removed: Bahraini dinar,] Omani rial, [removed: Brazilian real, Euro] and [removed: Indian rupee] [added: Bahraini dinar] would have resulted in a decrease in operating income of [removed: $6.8] [added: $7.6] million for fiscal [removed: 2017.][added: 2018.]
On June 23, 2016, the U.K. held a referendum in which voters approved an exit from the European Union, commonly referred to as “Brexit.” [removed: As a result of] [added: In February 2017,] the [removed: referendum, it is expected that] [added: British Parliament voted in favor of allowing] the British government [removed: will] [added: to] begin negotiating the terms of the U.K.’s withdrawal from the European Union and [removed: the U.K.’s future relationships] [added: discussions] with [added: the] European Union [removed: member states.][added: began in March 2017.]
[removed: Adverse] [added: The ultimate effects of Brexit on us are difficult to predict, but adverse] consequences concerning Brexit or the European Union could include deterioration in global economic conditions, instability in global financial markets, political uncertainty, volatility in currency exchange rates, or adverse changes in the cross-border agreements currently in place, any of which could have an adverse impact on our financial results in the future.
Fluctuations in foreign currencies also create volatility in our consolidated financial [removed: position,] [added: position] because we are required to remeasure substantially all assets and liabilities held by our foreign subsidiaries at the current exchange rate at the close of the accounting period.
At July 31, [removed: 2017,] [added: 2018,] the cumulative effect of foreign exchange rate fluctuations on our consolidated financial position was a net translation loss of [removed: $100.7] [added: $107.9] million.
A hypothetical 10% adverse change in the value of the U.S. dollar relative to the Canadian dollar, British pound, [added: Brazilian real, European Union euro,] U.A.E. dirham, [removed: Bahraini dinar,] Omani rial, [removed: Brazilian real, Indian rupee, Chinese renminbi,] [added: Bahraini dinar,] and [removed: European Union Euro] [added: Indian rupee] would not have materially affected our consolidated financial position.
The ultimate effects of Brexit on us will also depend on the terms of agreements, if any, that the U.K. and the European Union make to retain access to each other’s respective markets either during a transitional period or more permanently.
Item 1. Business
45 rewritten, 12 added, 12 removed, 344 unchanged
[removed: Copart™, VB2™, BID4U™, CI & Design™, Cars with Heart™, 1-800 CAR BUYER™, VB3™ and CrashedToys.com™ are trademarks of Copart, Inc.] This Form 10-K also includes other trademarks of Copart and of other companies.
We are a leading provider of online auctions and vehicle remarketing services with operations in the United States (U.S.), Canada, the United Kingdom (U.K.), [added: Brazil,] the Republic of Ireland, [removed: Brazil,] Germany, [added: Finland,] the United Arab Emirates (U.A.E.), Oman, Bahrain, [removed: India,] and Spain.
We offer vehicle sellers a full range of services that [added: help] expedite each stage of the vehicle sales process, minimize administrative and processing costs, and maximize the ultimate sales price.
In the U.S., Canada, [added: Brazil,] the Republic of Ireland, [removed: Brazil,] [added: Germany, Finland,] the U.A.E., Oman, Bahrain, [removed: India,] and Spain, we sell vehicles primarily as an agent and derive revenue primarily from fees paid by vehicle sellers and vehicle buyers, as well as related fees for services, such as towing and storage.
In the [removed: U.K.,] [added: U.K. and Germany,] we operate both as an agent and on a principal basis, in some cases purchasing salvage vehicles outright [removed: from the insurance companies] and reselling the vehicles for our own account.
In Germany and Spain, we also derive revenue from [removed: sales] listing [removed: fees for listing] vehicles on behalf of [removed: many] insurance [removed: companies.][added: companies and insurance experts to determine the vehicle’s residual value and/or to facilitate a sale for the insured.]
[removed: VB2 opened] [added: Through] our [added: Virtual Bidding Third Generation (VB3) auction platform our] sales process [added: is open] to registered buyers (whom we refer to as “members”) anywhere in the world with access to the [removed: Internet.][added: internet.]
To improve the effectiveness of bidding, the [removed: VB2] [added: VB3] system lets members see the current high bids on the vehicles they want to purchase.
Members enter the maximum price they are willing to pay for a vehicle and [removed: VB2’s] [added: VB3’s] BID4U feature will incrementally bid on the vehicle on their behalf during all phases of the auction.
If no bids are received during the [removed: countdown,] [added: countdown or any extensions,] the vehicle sells to the highest bidder.
We believe the [removed: implementation] [added: introduction] of [removed: VB2] [added: our virtual auction platform] increased the pool of available buyers for each sale, which resulted in added competition and an increase in the amount buyers are willing to pay for vehicles.
For fiscal [removed: 2017,] [added: 2018,] sales of U.S. vehicles, on a unit basis, to members registered outside the state where the vehicle was located accounted for [removed: 49.8%] [added: 52.3%] of total vehicles sold; [removed: 29.7%] [added: 30.9%] of vehicles were sold to out of state members within the U.S. and [removed: 20.1%] [added: 21.4%] were sold to International members, based on the address submitted during registration.
For fiscal [removed: 2017,] [added: 2018,] our revenues were [removed: $1.4] [added: $1.8] billion and our operating income was [removed: $461.3] [added: $584.3] million.
In fiscal 2016, we opened [added: new] facilities [added: and continue to operate] in [removed: Sonepat, India;] Castledermot, Republic of Ireland; Algete, [removed: Spain;] [added: Spain (Madrid);] Dallas, Wilmer and Temple, Texas; Colorado Springs and Denver, Colorado; and Cartersville, Georgia.
In fiscal 2017, we opened [added: new] facilities [added: and continue to operate] in Bad Fallingbostel, [removed: Germany;] [added: Germany (Hanover);] Newbury, U.K.; Betim, Minas Gerais, Brazil; Brighton and Littleton, [removed: Colorado;] [added: Colorado (Denver);] Sun Valley [added: (Los Angeles)] and [removed: Wilmington,] [added: Wilmington (Long Beach),] California; Apopka [added: (Orlando)] and Okeechobee, Florida; Casper, Wyoming; Alorton, [removed: Illinois;] [added: Illinois (St. Louis);] Ogden, [removed: Utah;] [added: Utah (Salt Lake City);] acquired the assets of an excavation company, which engages in earthwork, soil stabilization, equipment hauling and erosion control commercial contractor services; and acquired Cycle Express, LLC, which conducts business primarily as National Powersport Auctions [removed: (NPA),] [added: (“NPA”),] a leading non-salvage auction platform for motorcycles, snowmobiles, watercraft and other powersports vehicles.
The majority of our vehicles are sold on behalf of insurance companies and are usually vehicles involved in an [removed: accident.][added: accident or to a lesser extent a natural disaster.]
If the cost of repair is greater than the [removed: pre-accident value] [added: PAV] less the estimated salvage value, the insurance company generally will classify the vehicle as a total loss.
We believe that one effect of these additional features is that newer vehicles involved in accidents are [removed: costlier] [added: more costly] to repair and, accordingly, more likely to be deemed a total loss for insurance purposes.
Proceeds are then collected from the member, [added: typically] seller fees are [removed: subtracted] [added: subtracted,] and the remainder is remitted to the seller.
Since our inception in 1982, we have expanded from a single facility in Vallejo, California to an integrated network of facilities located in the U.S., Canada, the U.K., [removed: the U.A.E., Oman, Bahrain,] Brazil, [removed: Germany,] the Republic of Ireland, [removed: Spain] [added: Germany, Finland, the U.A.E., Oman, Bahrain,] and [removed: India.][added: Spain.]
| • | [removed: e-mail] [added: email] notifications available in numerous languages to potential buyers of vehicles that match desired characteristics; |
Since becoming a public company in 1994, we have completed acquisitions of facilities in the U.S., Canada, the U.K., [added: Brazil,] the U.A.E., [removed: Brazil,] Germany, [added: Finland,] and Spain.
Our full range of [removed: Internet] [added: internet] services allows us to expedite each stage of the vehicle sales process and [removed: minimizes] [added: helps to minimize] the administrative and processing costs for us, as well as our sellers.
We believe that our integrated technology systems generate improved capacity and financial returns for our clients, resulting in [added: high client retention, and allow us to expand our national supply contracts.]
Our revenues for the year ended July 31, [removed: 2017] [added: 2018] were distributed as follows: U.S. [removed: 82.4%] [added: 82.6%] and International [removed: 17.6%.][added: 17.4%.]
Geographic information as well as comparative segment revenues and related financial information pertaining to the U.S. and International segments for the years ended July 31, [removed: 2017, 2016] [added: 2018, 2017] and [removed: 2015] [added: 2016] are presented in the tables in Note 14 — Segments and Other Geographic Reporting, to the Notes to Consolidated Financial Statements, which are included [removed: under] in Part II, Item 8 of this [added: Form] 10-K.
We offer vehicle sellers a full range of vehicle services, which expedite each stage of the vehicle sales process, [removed: maximizing] [added: helping to maximize] proceeds and [removed: minimizing] [added: minimize] costs.
We have over [removed: 80] [added: 90] vehicle inspection stations at our facilities.
Under the [removed: purchase program,] [added: Purchase Program,] we purchase vehicles from a vehicle seller at a formula price, based on a percentage of the vehicles’ estimated [removed: pre-accident value (PAV),] [added: PAV,] otherwise known as [removed: actual cash value (ACV),] [added: ACV,] and sell the vehicles for our own account.
We maintain a database of thousands of [added: registered] members in the vehicle [removed: dismantling,] [added: dismantling and recycling,] rebuilding, [removed: repair licensee,] used vehicle dealer and export industries, as well as [added: members that are a part of] the general public, [removed: as we sell directly to the general public at certain locations.][added: where applicable.]
This data enables us to notify prospective buyers throughout the world via [removed: e-mail] [added: email] of vehicles available for bidding that match their vehicle preferences.
VB3 opens our sales process to members and to individuals who have not registered to view auctions via our website and our mobile [removed: application,] [added: application] anywhere in the world where [removed: Internet] [added: internet] access is available.
Anyone can [removed: call 1-800-Cash-For-Cars or] go to CashForCars.com [added: or call 1-888-961-5389] and arrange to obtain a valid offer to purchase their vehicle.
No single customer accounted for more than 10% of our revenues for fiscal [removed: 2017, 2016] [added: 2018, 2017] and [removed: 2015.][added: 2016.]
We obtained 84% [added: and 83%] of the total number of vehicles processed during fiscal 2017 [added: and 2016, respectively,] from insurance company sellers.
We obtained [removed: 83%] [added: 78%] of the total number of vehicles processed during fiscal [removed: 2016 and 2015,] [added: 2018] from insurance company sellers.
We maintain a database of thousands of registered members in the vehicle dismantling and recycling, rebuilding, used vehicle dealer and export [removed: industries.][added: industries, as well as members that are a part of the general public, where applicable.]
In certain venues, we may sell to the general public either directly or members may [removed: transact business] [added: purchase a vehicle offered] at [removed: any of our sales via] [added: Copart through] a registered broker who meets local licensing and permitting requirements.
We market to members online and via [removed: e-mail] [added: email] notifications, sales notices, telemarketing, direct mail, in-location marketing, search engines, social media, radio, television, trade publications and participation in trade show events.
We began using our new internally developed proprietary system with our expansion into Spain [removed: and India] in fiscal 2016 and Germany in fiscal 2017.
Copart®, VB2®, BID4U®, CI & Design®, DRIVE Auto Auctions™, 1-800 CAR BUYER®, CA$HFORCARS.COM®, COPART & DESIGN®, VB2 & DESIGN®, VB3 & DESIGN®, VB3® and CrashedToys.com® are trademarks of Copart, Inc. or one of its direct or indirect wholly-owned subsidiaries.
Our goals are to generate sustainable profits for our stockholders, while also producing environmental and social benefits for the world, by promoting vehicle restoration, repair, and recycling; parts refurbishment and re-use; and facilitating the recovery and resilience of communities affected by severe climate events.
In fiscal 2018, we opened new facilities and continue to operate in Andrews, Texas (Midland); Exeter, Rhode Island; Lumberton, North Carolina; Belfast, Northern Ireland; Nobitz, Germany (Leipzig); and acquired locations in the municipalities of Espoo; Pirkkala; Oulu; and Turku, Finland.
| • | a tailored experience by way of predictive analytics through collaborative filtering, such as the Recommendations Engine feature that suggests similar makes and models based on a member’s behavior; |
| • | Buy It Now, which provides an option to our members to purchase specific pre-qualified vehicles immediately at a set price before the live auction process; |
| | |
| --- | --- |
| | |
| --- | --- |
In the U.S. and Canada, we perform transportation services through a combination of our fleet of over 50 vehicles and predominately using third-party vehicle transport companies.
| International | | 1,595 |
In 2008, we obtained a patent issued by the United States Patent and Trademark Office that covers certain aspects of our virtual bidding auction platform.
We converted all of our U.S. and Canada sales to our Virtual Bidding Second Generation (VB2) during fiscal 2004 and we converted our U.K. sales to VB2 during fiscal 2008.
In August 2013, we launched our Virtual Bidding Third Generation (VB3), an Internet auction-style sales technology that was built on VB2.
VB3 adds several enhancements which focuses on expanding auction attendance and increasing bidding volume.
To attract new members and grow our membership base, VB3 allows non-registered members to view auctions via our website and our mobile applications.
In addition, VB3 includes a completely redesigned auction interface, enabling members to fit multiple auction windows on their screen, while simultaneously viewing more vehicle photos and information at the time of live Internet bidding.
In fiscal 2015, we opened facilities in Manama, Bahrain; Muscat, Oman; and Moncton, Canada.
high client retention, and allow us to expand our national supply contracts.
Our arrangements with our sellers are typically subject to cancellation by either party upon 30 to 90 days’ notice.
| International | | 1,311 |
In June 2003, we filed a provisional U.S. patent application on VB2 in the United States.
This provisional patent application was followed by a U.S. utility application filed in July 2003.
The patent was issued by the United States Patent and Trademark Office on January 1, 2008.
An excerpt. Shown here: 40 of 45 rewritten, all 12 added and all 12 removed. The counts are complete. For every sentence, read Item 1. Business in the FY2018 filing and the FY2017 filing.
Item 3. Legal Proceedings
1 rewritten, 7 added, 17 removed, 27 unchanged
The suit [removed: arises] [added: arose] out of our September 17, 2013 decision to terminate the Implementation Services Agreement, under which KPIT was to design, implement, and deliver a customized replacement enterprise resource planning system for us.
On November 1, 2013, we filed suit against Sparta Consulting, Inc. (now known as KPIT).
The case was tried in April and May 2018.
On May 22, 2018, the jury returned a verdict for us on our fraud claim against KPIT for $4.7 million, and on our professional negligence claim against KPIT for $16.3 million, and the jury found for KPIT on its implied covenant counterclaim against us for $4.9 million.
In a September 10, 2018, post-trial order, the Court reduced our professional negligence award to $9.1 million, found KPIT liable under California’s Unfair Competition Law (UCL) for fraudulent and unfair conduct and held that we could recover restitution of $6.3 million if the we choose to forego our fraud and professional negligence damages, found that we were not entitled to restitution on our unjust enrichment claim, and awarded KPIT prejudgment interest on its implied covenant counterclaim starting from December 26, 2016.
Further post-trial proceedings are expected in this lawsuit, including the determination of our right to prejudgment interest on our successful claims.
Since the date of entry of the Consent Order, the DOR filed a Motion for Summary Judgment related to the remaining $2.6 million in dispute.
We opposed the DOR’s motion and are awaiting a decision by the Court regarding the DOR’s motion.
On November 1, 2013, we filed suit against Sparta Consulting, Inc. (now known as KPIT) in the 44th Judicial District Court of Dallas County, Texas, alleging fraud, fraudulent inducement, and/or promissory fraud, negligent misrepresentation, unfair business practices pursuant to California Business and Professions Code § 17200, breach of contract, declaratory judgment, and attorney’s fees.
We seek compensatory and exemplary damages, disgorgement of amounts paid, attorney’s fees, pre- and post-judgment interest, costs of suit, and a judicial declaration of the parties’ rights, duties, and obligations under the Implementation Services Agreement dated October 6, 2011.
On January 2, 2014, KPIT removed this suit to the United States District Court for the Northern District of Texas.
On August 11, 2014, the Northern District of Texas transferred the suit to the United States District Court for the Eastern District of California for convenience.
KPIT seeks compensatory and exemplary damages, prejudgment interest, costs of suit, and a judicial declaration of the parties’ rights, duties, and obligations under the Implementation Services Agreement.
We are pursuing our claim for damages, and defending against KPIT’s claim for damages.
We and KPIT filed competing motions for summary judgment in January 2017.
The Court issued its ruling on the motions on September 25, 2017.
The order granted some of the relief sought by us, and some of the relief sought by KPIT.
Our core claims remain in the case after the ruling, including our claims for fraud, fraudulent inducement, breach of contract, professional negligence, trade secret misappropriation, unfair competition, unjust enrichment, and computer hacking.
KPIT’s claims are now limited to breach of contract, breach of the implied covenant of good faith and fair dealing, and declaratory relief.
On August 4, 2015, the DOR issued an official Assessment and Demand for Payment (the “Assessment”) for $96.1 million for sales taxes, penalties, and interest that the DOR alleged we owe to the State of Georgia.
We filed an appeal of this Assessment from the DOR with the Georgia Tax Tribunal on September 3, 2015.
On August 5, 2016, the DOR filed a response in which it denied all allegations noted in our appeal of the Assessment.
Since the date of entry of the Consent Order, we and the DOR have exchanged discovery requests and initial discovery responses.
We expect that discovery will be completed in the fall of 2017.
We and the DOR will then present the case to the Tax Tribunal for final disposition.
Cover and table of contents
36 rewritten, 11 added, 10 removed, 78 unchanged
For the fiscal year ended July 31, [removed: 2017][added: 2018]
| Non-accelerated filer | ¨ | [removed: (Do not check if a smaller reporting company)] | Smaller reporting company | ¨ |
The aggregate market value of the voting and non-voting Common Stock held by non-affiliates of the registrant as of January 31, [removed: 2017] [added: 2018] (the last business day of the registrant’s most recently completed second fiscal quarter) was [removed: $5,644,908,664] [added: $8,903,622,911] based upon the closing sales price reported for such date on the NASDAQ Global Select Market.
As of September [removed: 26, 2017, 230,773,342] [added: 28, 2018, 233,916,190] shares of the registrant’s common stock were outstanding.
Portions of our definitive Proxy Statement for the [removed: 2017] [added: 2018] Annual Meeting of Stockholders, also referred to in this Annual Report on Form 10-K as our Proxy Statement, which will be filed with the Securities and Exchange Commission, or SEC, pursuant to Regulation 14A within 120 days after the registrant’s fiscal year end of July 31, [removed: 2017,] [added: 2018,] have been incorporated by reference in Part III hereof.
| Item 1 | | [removed: [Business](#s0681F2DABE33542A8F8756BA1D26525E)] [added: [Business](#sF8D7366DE7AF5742925EE5CE3CE632B2)] | [removed: [1](#s0681F2DABE33542A8F8756BA1D26525E)] [added: [1](#sF8D7366DE7AF5742925EE5CE3CE632B2)] |
| | | [Industry [removed: Overview](#sDA6F1E4A718A50E681C4BA706079181D)] [added: Overview](#s1D2EA62E1AA4531C908F5E56E75B1B8F)] | [removed: [3](#sDA6F1E4A718A50E681C4BA706079181D)] [added: [3](#s1D2EA62E1AA4531C908F5E56E75B1B8F)] |
| | | [Operating and Growth [removed: Strategy](#sEEA06D6570C953E283F2773842A7B946)] [added: Strategy](#s30C3A508CF3A54C693768E6C14089DF3)] | [removed: [5](#sEEA06D6570C953E283F2773842A7B946)] [added: [5](#s30C3A508CF3A54C693768E6C14089DF3)] |
| | | [Our Competitive [removed: Advantages](#sB2D57B917034544593E0AAFAF9156812)] [added: Advantages](#sA199911CFF34581193B258C2E9D38DF6)] | [removed: [5](#sB2D57B917034544593E0AAFAF9156812)] [added: [5](#sA199911CFF34581193B258C2E9D38DF6)] |
| | | [removed: [Business Segments](#s5E35F57223555D9B9283ED5BB0E07E3C)] [added: [Our Business Segments](#sB813234346A25E98BA21734692B03C9E)] | [removed: [7](#s5E35F57223555D9B9283ED5BB0E07E3C)] [added: [7](#sB813234346A25E98BA21734692B03C9E)] |
| | | [Our Service [removed: Offerings](#s2C02A8A78A9D5200B7F41A38871CD9E7)] [added: Offerings](#s11241F60761D5CAEBC4191BD5102B248)] | [removed: [7](#s2C02A8A78A9D5200B7F41A38871CD9E7)] [added: [7](#s11241F60761D5CAEBC4191BD5102B248)] |
| | | [Management Information [removed: Systems](#s1ED97E7D6D7C5B3880475B49AF37B61A)] [added: Systems](#s787024EEDFAB56B89183575EEBC15BA1)] | [removed: [10](#s1ED97E7D6D7C5B3880475B49AF37B61A)] [added: [10](#s787024EEDFAB56B89183575EEBC15BA1)] |
| | | [Environmental [removed: Matters](#sF54D6795B50056BCB0599C722BC59076)] [added: Matters](#s492BE37602305FBAB61DA2F7CEB67C2A)] | [removed: [11](#sF54D6795B50056BCB0599C722BC59076)] [added: [11](#s492BE37602305FBAB61DA2F7CEB67C2A)] |
| | | [Governmental [removed: Regulations](#s4441580DC61D5D2F94D6F2712786DB1A)] [added: Regulations](#sB71F8D4FA48052B5B7E145DC028C999E)] | [removed: [11](#s4441580DC61D5D2F94D6F2712786DB1A)] [added: [11](#sB71F8D4FA48052B5B7E145DC028C999E)] |
| | | [Intellectual Property and Proprietary [removed: Rights](#s1B601A58930F51B8A685AA5447CFEDE7)] [added: Rights](#s7E2C1564B6A45E9AB9A3B9CED9FBE27B)] | [removed: [11](#s1B601A58930F51B8A685AA5447CFEDE7)] [added: [11](#s7E2C1564B6A45E9AB9A3B9CED9FBE27B)] |
| Item 1A. | | [Risk [removed: Factors](#s50B5F3640366547A8B7AB51C440D8A54)] [added: Factors](#s559BE4A2A6295748A447E74CB09D4427)] | [removed: [12](#s50B5F3640366547A8B7AB51C440D8A54)] [added: [12](#s559BE4A2A6295748A447E74CB09D4427)] |
| Item 1B. | | [Unresolved Staff [removed: Comments](#s4D4F162474FA50FA8EDCBD8883DDAA61)] [added: Comments](#sEBDDD7289BA1576AB587663B48203699)] | [removed: [24](#s4D4F162474FA50FA8EDCBD8883DDAA61)] [added: [25](#sEBDDD7289BA1576AB587663B48203699)] |
| Item 2. | | [removed: [Properties](#s19A398EDCBE75A72B94620A52D7CE1EF)] [added: [Properties](#sDC1E2A23859D5CD5BA605466B1B47365)] | [removed: [24](#s19A398EDCBE75A72B94620A52D7CE1EF)] [added: [25](#sDC1E2A23859D5CD5BA605466B1B47365)] |
| Item 3. | | [Legal [removed: Proceedings](#s7A4D9F76DFAE5B3CBD2C5C2FFA67010B)] [added: Proceedings](#s38795C9F5D055380B79E8F9E4448E859)] | [removed: [25](#s7A4D9F76DFAE5B3CBD2C5C2FFA67010B)] [added: [25](#s38795C9F5D055380B79E8F9E4448E859)] |
| Item 4. | | [Mine Safety [removed: Disclosures](#s6DCC251F23D05C90B8044D77635D2B55)] [added: Disclosure](#sB2298FF4FF56560E9C594159DFA2DCDA)] | [removed: [26](#s6DCC251F23D05C90B8044D77635D2B55)] [added: [26](#sB2298FF4FF56560E9C594159DFA2DCDA)] |
| Item 5. | | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities](#s05C0984985F4527E94DEEAE134D4AF12)] [added: Securities](#sEFA65643DABA5625B1007D7B05667164)] | [removed: [27](#s05C0984985F4527E94DEEAE134D4AF12)] [added: [27](#sEFA65643DABA5625B1007D7B05667164)] |
| Item 6. | | [Selected Financial [removed: Data](#s498C0A92818D5D3BB166B86E5FBE7A5B)] [added: Data](#sD17D0EDA21F75647A276735D8C92068A)] | [removed: [30](#s498C0A92818D5D3BB166B86E5FBE7A5B)] [added: [30](#sD17D0EDA21F75647A276735D8C92068A)] |
| Item 7. | | [Management’s Discussion and Analysis of Financial Condition and Results of [removed: Operations](#s9497EA34BFF75B439E5BA422E126F070)] [added: Operations](#sC9A80554AE435BC686121DF0E7BE223E)] | [removed: [31](#s9497EA34BFF75B439E5BA422E126F070)] [added: [31](#sC9A80554AE435BC686121DF0E7BE223E)] |
| Item 7A. | | [Quantitative and Qualitative Disclosures About Market [removed: Risk](#s797C3655527359668603872C071E8C1F)] [added: Risk](#sFE4B5D12294457469481D81DB4E02468)] | [removed: [49](#s797C3655527359668603872C071E8C1F)] [added: [48](#sFE4B5D12294457469481D81DB4E02468)] |
| Item 8. | | [Financial Statements and Supplementary [removed: Data](#s20025221C39A507088210751058CFF0C)] [added: Data](#s9A185BCCB627514F91A66224008A835B)] | [removed: [50](#s20025221C39A507088210751058CFF0C)] [added: [49](#s9A185BCCB627514F91A66224008A835B)] |
| Item 9. | | [Changes in and Disagreements with Accountants on Accounting and Financial [removed: Disclosure](#s3CA650DF0CE95A14810EFCFBDB36EA10)] [added: Disclosure](#s3209109AF56658A9AFE43BCFC9CDB05D)] | [removed: [50](#s3CA650DF0CE95A14810EFCFBDB36EA10)] [added: [49](#s3209109AF56658A9AFE43BCFC9CDB05D)] |
| Item 9A. | | [Controls and [removed: Procedures](#s4625427A94985C7BAE6ABA823CECA110)] [added: Procedures](#s779FF3E93E8E5762AA7240C0ABEB15F4)] | [removed: [51](#s4625427A94985C7BAE6ABA823CECA110)] [added: [49](#s779FF3E93E8E5762AA7240C0ABEB15F4)] |
| Item 9B. | | [Other [removed: Information](#s42042B61716352C1B134B3F6D863BCA5)] [added: Information](#s106A6902B4A05046909CD3D12425459B)] | [removed: [53](#s42042B61716352C1B134B3F6D863BCA5)] [added: [52](#s106A6902B4A05046909CD3D12425459B)] |
| [PART [removed: III](#sAFFE42688F485D03996567742E7CD5B9)] [added: III](#s25CC3B9EA4CE5D9DB79801003BA01EE7)] | | | [removed: [54](#sAFFE42688F485D03996567742E7CD5B9)] [added: [53](#s25CC3B9EA4CE5D9DB79801003BA01EE7)] |
| Item 10. | | [Directors, Executive Officers and Corporate [removed: Governance](#sDB41A23EA5D45E0CBEB34429DFFE279F)] [added: Governance](#sF1923B47545B5C71BBFE92B0E4853ED6)] | [removed: [54](#sDB41A23EA5D45E0CBEB34429DFFE279F)] [added: [53](#sF1923B47545B5C71BBFE92B0E4853ED6)] |
| Item 11. | | [Executive [removed: Compensation](#sA1445A7585325C8392634290BD16483A)] [added: Compensation](#sA875353305A6500AABC35847406B2C7B)] | [removed: [54](#sA1445A7585325C8392634290BD16483A)] [added: [53](#sA875353305A6500AABC35847406B2C7B)] |
| Item 12. | | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder [removed: Matters](#s2CBAC618E8E0502283996C4BAF279B7C)] [added: Matters](#sB495DA768B11551C8A8D55C2848DDF34)] | [removed: [54](#s2CBAC618E8E0502283996C4BAF279B7C)] [added: [53](#sB495DA768B11551C8A8D55C2848DDF34)] |
| Item 13. | | [Certain Relationships and Related Transactions, and Director [removed: Independence](#sB09FC47811A5515DB78E44BD86F423BC)] [added: Independence](#s2422C3ACFF775C26BF88FE34987ABB7E)] | [removed: [54](#sB09FC47811A5515DB78E44BD86F423BC)] [added: [53](#s2422C3ACFF775C26BF88FE34987ABB7E)] |
| Item 14. | | [Principal Accounting Fees and [removed: Services](#s34FA217173935A1799045EBF89413AEF)] [added: Services](#s96294CCA8D9A5B4AA111F89A9159EBF5)] | [removed: [54](#s34FA217173935A1799045EBF89413AEF)] [added: [53](#s96294CCA8D9A5B4AA111F89A9159EBF5)] |
| Item 15. | | [Exhibits, Financial Statement [removed: Schedules](#s719DDAE91D185C1B9BB002C52BBA957B)] [added: Schedules](#s0E8E96C7C78F57BEAAB81AC1F1DFAB7C)] | [removed: [55](#s719DDAE91D185C1B9BB002C52BBA957B)] [added: [54](#s0E8E96C7C78F57BEAAB81AC1F1DFAB7C)] |
This Annual Report on Form 10-K for the fiscal year ended July 31, [removed: 2017,] [added: 2018,] or this Form 10-K, including the information incorporated by reference herein, contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended (the Securities Act), and Section 21E of the Securities Exchange Act of 1934, as amended (the Exchange Act).
10-K 1 cprt07312018-10k.htm 10-K
For the Fiscal Year Ended July 31, 2018
| [PART I](#sBF974C32CEA752E787BF683BAE73DD2A) | | | [1](#sBF974C32CEA752E787BF683BAE73DD2A) |
| | | [Sales](#s68463425E0AD5CE58FF187EDEA666001) | [9](#s68463425E0AD5CE58FF187EDEA666001) |
| | | [Members](#s03AC4DC059595048B33C750485165934) | [10](#s03AC4DC059595048B33C750485165934) |
| | | [Competition](#s7294884CCE945C1ABFC92F5590D8722F) | [10](#s7294884CCE945C1ABFC92F5590D8722F) |
| | | [Employees](#sD1AFBE1A9326595CB6EE9226CC0419EE) | [11](#sD1AFBE1A9326595CB6EE9226CC0419EE) |
| | | [Seasonality](#s521533DE6E1B5BDD97E791209050021F) | [11](#s521533DE6E1B5BDD97E791209050021F) |
| [PART II](#s7F243CD3A2F656A7B08746591A1A1632) | | | [27](#s7F243CD3A2F656A7B08746591A1A1632) |
| [PART IV](#sCC874A3FB62A5F21B97C38538437914C) | | | [54](#sCC874A3FB62A5F21B97C38538437914C) |
| [Signatures](#s24132E396ECF5184B15AB57FB7940769) | | | [55](#s24132E396ECF5184B15AB57FB7940769) |
10-K 1 cprt07312017-10k.htm 10-K
| [PART I](#sD2476079E48E5DE6AB57CC9D2233E43B) | | | [1](#sD2476079E48E5DE6AB57CC9D2233E43B) |
| | | [Sales](#s8C2FADA45CBA519983B53BFBA9C780F6) | [9](#s8C2FADA45CBA519983B53BFBA9C780F6) |
| | | [Members](#s7BDA39672E045705B737DB4DB7592173) | [10](#s7BDA39672E045705B737DB4DB7592173) |
| | | [Competition](#s752CBA08CD5357F38A7616AC8A903B18) | [10](#s752CBA08CD5357F38A7616AC8A903B18) |
| | | [Employees](#s8F2E302F544F59AEA193262D45D21185) | [11](#s8F2E302F544F59AEA193262D45D21185) |
| | | [Seasonality](#sE23D2A3625375BF8A5C44233FCADFB6E) | [11](#sE23D2A3625375BF8A5C44233FCADFB6E) |
| [PART II](#sAB24A140E75254A29344CD3BA18881C9) | | | [27](#sAB24A140E75254A29344CD3BA18881C9) |
| [PART IV](#s5BD2019B4CAA5485874D97E95D9FB04D) | | | [55](#s5BD2019B4CAA5485874D97E95D9FB04D) |
| [Signatures](#s2B193D1404D25958A0AB01284A034698) | | | [56](#s2B193D1404D25958A0AB01284A034698) |
Item 2. Properties
3 rewritten, 2 added, 0 removed, 7 unchanged
In the U.K., we own or lease [removed: 17] [added: 18] operating facilities.
In the U.A.E., Oman, [removed: Bahrain,] and [removed: India,] [added: Bahrain,] we lease one operating facility in each country.
In [removed: Germany and] Spain, we operate [added: an] online [removed: platforms and] [added: platform,] own one operating facility [removed: in each country.][added: and lease three additional storage locations.]
In Finland, we own or lease four operating facilities.
In Germany we operate an online platform and own two operating facilities.
Item 4. Mine Safety Disclosure
24 rewritten, 12 added, 20 removed, 64 unchanged
As of September [removed: 26, 2017,] [added: 28, 2018,] we had [removed: 946] [added: 906] stockholders of record.
On July 31, [removed: 2017,] [added: 2018,] the last reported sale price of our common stock on the NASDAQ Global Select Market was [removed: $31.49] [added: $57.39] per share.
| Fourth Quarter | | $ | [removed: 31.95] [added: 60.43] | | | $ | [removed: 29.18] [added: 50.87] | | | $ | [removed: 25.66] [added: 31.95] | | | $ | [removed: 21.25] [added: 29.18] | |
| Third Quarter | | $ | [removed: 31.20] [added: 52.73] | | | $ | [removed: 27.83] [added: 39.21] | | | $ | [removed: 21.42] [added: 31.20] | | | $ | [removed: 16.56] [added: 27.83] | |
| Second Quarter | | $ | [removed: 28.81] [added: 46.09] | | | $ | [removed: 25.40] [added: 35.32] | | | $ | [removed: 19.84] [added: 28.81] | | | $ | [removed: 16.51] [added: 25.40] | |
| First Quarter | | $ | [removed: 27.23] [added: 36.65] | | | $ | [removed: 24.87] [added: 30.46] | | | $ | [removed: 18.37] [added: 27.23] | | | $ | [removed: 16.45] [added: 24.87] | |
For fiscal [added: 2018 and] 2017, we did not repurchase any shares of our common stock under the program.
As of July 31, [removed: 2017,] [added: 2018,] the total number of shares repurchased under the program was 106,913,602, and 89,086,398 shares were available for repurchase under our program.
On [removed: July 9,] [added: December 30,] 2015, we completed a modified “Dutch Auction” tender offer, or tender offer, to purchase up to [removed: 27,777,776] [added: 14,634,146] shares of our common stock at a [removed: purchase] price not greater than [removed: $18.00] [added: $20.50] nor less than [removed: $17.375] [added: $19.00] per share.
[removed: Additionally, on December 30, 2015, we completed a] [added: | (2) | 16,666,666 shares were repurchased by the Company through its] modified “Dutch Auction” tender [removed: offer, or tender offer,] [added: offer under which the Company was] to purchase up to 14,634,146 shares of [removed: our] [added: its] common stock at a price not greater than $20.50 nor less than $19.00 per share. [added: The tender offer was announced on November 23, 2015 and was completed on December 30, 2015. |]
| Second [removed: Quarter] [added: Quarter(2)] | | [removed: —] [added: 16,666,666] | | | $ | [removed: —] [added: 19.50] | | | — | | | [removed: 95,426,436] [added: 94,963,436] | |
| May 1, [removed: 2017] [added: 2018] through May 31, [removed: 2017] [added: 2018] | | — | | | $ | — | | | — | | | 89,086,398 | |
| June 1, [removed: 2017] [added: 2018] through June 30, [removed: 2017] [added: 2018] | | — | | | $ | — | | | — | | | 89,086,398 | |
| July 1, [removed: 2017] [added: 2018] through July 31, [removed: 2017] [added: 2018] | | — | | | $ | — | | | — | | | 89,086,398 | |
During fiscal [removed: 2017, 2016] [added: 2018, 2017] and [removed: 2015,] [added: 2016,] certain executive [removed: officers] [added: officers, members of the Company’s Board of Directors] and [added: other] employees exercised stock options through cashless exercises.
A portion of the options exercised were net settled in satisfaction of the exercise price and federal and state [removed: minimum] statutory tax withholding requirements.
The Company remitted $134.6 [removed: million, $15.0] million and [removed: $3.8] [added: $15.0] million for the years ended July 31, [removed: 2017, 2016] [added: 2017] and [removed: 2015,] [added: 2016,] respectively, to the proper taxing authorities in satisfaction of the employees’ [removed: minimum] statutory withholding requirements.
| Period | | Options Exercised | | | Weighted Average Exercise Price | | | | Shares Net Settled for Exercise | | | Shares Withheld for [removed: Taxes(1)] [added: Taxes (1)] | | | Net Shares to Employees | | | Weighted Average Share Price for Withholding | | | | Employee Stock Based Tax Withholding (in 000s) | | |
| FY 2016—Q4 | | 2,260,000 | | | [removed: 9.32] [added: $] | [added: 9.32] | | | 821,296 | | | 586,304 | | | 852,400 | | | [added: $ |] 25.65 | | | [added: $] | 15,039 | | [removed: |]
There were no issuances of unregistered securities in the year ended July 31, [removed: 2017.][added: 2018.]
The following is a line graph comparing the cumulative total return to stockholders of our common stock at July 31, [removed: 2017] [added: 2018] since July 31, [removed: 2012,] [added: 2013,] to the cumulative total return over such period of (i) the NASDAQ Composite Index, (ii) the NASDAQ Industrial Index, and (iii) the NASDAQ Q-50 (NXTQ).
[removed: 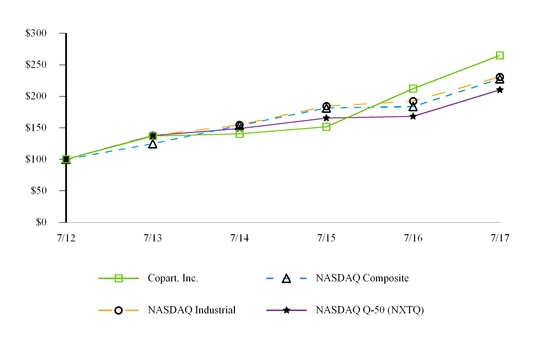][added: ]
| | | [removed: 2012 | | | |] 2013 | | | | 2014 | | | | 2015 | | | | 2016 | | | | 2017 | | | [added: | 2018 | | |]
| * | Assumes that $100.00 was invested on July 31, [removed: 2012] [added: 2013] in our common stock, in the NASDAQ Composite Index, the NASDAQ Industrial Index and the NASDAQ Q-50 (NXTQ), and that all dividends were reinvested. No dividends have been declared on our common stock. Stockholder returns over the indicated period should not be considered indicative of future stockholder returns. |
As of July 31, 2018, there were 233,898,841 shares outstanding.
| | | 2018 | | | | | | | | 2017 | | | | | | |
| Fourth Quarter | | — | | | $ | — | | | — | | | 89,086,398 | |
| Fiscal 2018 | | | | | | | | | | | | | |
| First Quarter | | — | | | $ | — | | | — | | | 89,086,398 | |
| Second Quarter | | — | | | $ | — | | | — | | | 89,086,398 | |
| Third Quarter | | — | | | $ | — | | | — | | | 89,086,398 | |
| FY 2018—Q2 | | 80,000 | | | 6.54 | | | | 11,996 | | | — | | | 68,004 | | | 43.60 | | | | — | | |
| Copart, Inc. | | $ | 100.00 | | | $ | 102.68 | | | $ | 110.83 | | | $ | 155.15 | | | $ | 193.73 | | | $ | 353.06 | |
| NASDAQ Composite | | $ | 100.00 | | | $ | 123.49 | | | $ | 145.85 | | | $ | 148.64 | | | $ | 183.99 | | | $ | 223.06 | |
| NASDAQ Industrial | | $ | 100.00 | | | $ | 113.05 | | | $ | 134.93 | | | $ | 142.76 | | | $ | 171.09 | | | $ | 204.84 | |
| NASDAQ Q-50 (NXTQ) | | $ | 100.00 | | | $ | 114.47 | | | $ | 127.30 | | | $ | 127.71 | | | $ | 152.84 | | | $ | 198.33 | |
| | |
| --- | --- |
As of July 31, 2017, there were 230,488,296 shares outstanding.
| | | 2017 | | | | | | | | 2016 | | | | | | |
For fiscal 2015, we repurchased 463,000 shares of our common stock at a weighted average price of $18.01 per share totaling $8.3 million.
In connection with the tender offer, we accepted for payment an aggregate of 12,508,122 shares of our common stock at a purchase price of $18.00 per share for a total value of $225.1 million.
| Fiscal 2015 | | | | | | | | | | | | | |
| First Quarter | | — | | | $ | — | | | — | | | 95,426,436 | |
| Third Quarter | | — | | | $ | — | | | — | | | 95,426,436 | |
| Fourth Quarter(2) | | 12,971,122 | | | $ | 18.00 | | | 463,000 | | | 94,963,436 | |
| Second Quarter(3) | | 16,666,666 | | | $ | 19.50 | | | — | | | 94,963,436 | |
| (2) | Consists of 12,508,122 shares repurchased in connection with the tender offer at a purchase price of $18.00 per share and 463,000 shares repurchased through our publicly announced stock repurchase program. |
| (3) | 16,666,666 shares were repurchased by the Company through its modified “Dutch Auction” tender offer under which the Company was to purchase up to 14,634,146 shares of its common stock at a price not greater than $20.50 nor less than $19.00 per share. The tender offer was announced on November 23, 2015 and was completed on December 30, 2015. |
| FY 2015—Q1 | | 402,666 | | | $ | 9.80 | | | 249,242 | | | 70,832 | | | 82,592 | | | $ | 15.83 | | | $ | 1,121 | |
| FY 2015—Q3 | | 279,380 | | | 10.14 | | | | 152,042 | | | 41,312 | | | 86,026 | | | 18.64 | | | | 770 | | |
| FY 2015—Q4 | | 400,000 | | | 6.01 | | | | 133,204 | | | 104,316 | | | 162,480 | | | 18.04 | | | | 1,882 | | |
| Copart, Inc. | | $ | 100.00 | | | $ | 136.83 | | | $ | 140.49 | | | $ | 151.64 | | | $ | 212.29 | | | $ | 265.07 | |
| NASDAQ Composite | | $ | 100.00 | | | $ | 124.83 | | | $ | 153.69 | | | $ | 181.45 | | | $ | 183.70 | | | $ | 227.57 | |
| NASDAQ Industrial | | $ | 100.00 | | | $ | 137.68 | | | $ | 154.66 | | | $ | 184.57 | | | $ | 192.33 | | | $ | 230.88 | |
| NASDAQ Q-50 (NXTQ) | | $ | 100.00 | | | $ | 137.58 | | | $ | 148.90 | | | $ | 165.49 | | | $ | 168.11 | | | $ | 210.32 | |
Item 6. Selected Financial Data
16 rewritten, 0 added, 3 removed, 10 unchanged
of this [added: Form] 10-K, and “Financial Statements and Supplementary Data” in Part II, Item 8 of this [added: Form] 10-K.
| | | [removed: 2017 (1)] [added: 2018] | | | | [removed: 2016 (1)] [added: 2017] | | | | [removed: 2015 (1)] [added: 2016] | | | | [removed: 2014 (1)] [added: 2015] | | | | [removed: 2013 (1)] [added: 2014] | | |
| Revenues | | $ | [removed: 1,447,981] [added: 1,805,695] | | | $ | [removed: 1,268,449] [added: 1,447,981] | | | $ | [removed: 1,146,079] [added: 1,268,449] | | | $ | [removed: 1,163,489] [added: 1,146,079] | | | $ | [removed: 1,046,386] [added: 1,163,489] | |
| Operating income | | [removed: 461,299] [added: 584,345] | | | | [removed: 406,470] [added: 461,299] | | | | [removed: 344,401] [added: 406,470] | | | | [removed: 274,934] [added: 344,401] | | | | [removed: 282,992] [added: 274,934] | | |
| Income before income taxes | | [removed: 440,100] [added: 562,511] | | | | [removed: 395,865] [added: 440,100] | | | | [removed: 332,069] [added: 395,865] | | | | [removed: 270,035] [added: 332,069] | | | | [removed: 276,872] [added: 270,035] | | |
| Income taxes | | [removed: 45,839] [added: 144,504] | | | | [removed: 125,505] [added: 45,839] | | | | [removed: 112,286] [added: 125,505] | | | | [removed: 91,348] [added: 112,286] | | | | [removed: 96,847] [added: 91,348] | | |
| Net income | | $ | [removed: 394,261] [added: 418,007] | | | $ | [removed: 270,360] [added: 394,261] | | | $ | [removed: 219,783] [added: 270,360] | | | $ | [removed: 178,687] [added: 219,783] | | | $ | [removed: 180,025] [added: 178,687] | |
| Basic net income per common share | | $ | [removed: 1.72] [added: 1.80] | | | $ | [removed: 1.18] [added: 1.72] | | | $ | [removed: 0.87] [added: 1.18] | | | $ | [removed: 0.71] [added: 0.87] | | | $ | [removed: 0.72] [added: 0.71] | |
| Weighted average common shares outstanding | | [removed: 228,686] [added: 231,793] | | | | [removed: 228,846] [added: 228,686] | | | | [removed: 251,829] [added: 228,846] | | | | [removed: 251,387] [added: 251,829] | | | | [removed: 249,824] [added: 251,387] | | |
| Diluted net income per common share | | $ | [removed: 1.66] [added: 1.73] | | | $ | [removed: 1.11] [added: 1.66] | | | $ | [removed: 0.84] [added: 1.11] | | | $ | [removed: 0.68] [added: 0.84] | | | $ | [removed: 0.69] [added: 0.68] | |
| Diluted weighted average common shares outstanding | | [removed: 237,019] [added: 241,877] | | | | [removed: 244,295] [added: 237,019] | | | | [removed: 262,851] [added: 244,295] | | | | [removed: 262,459] [added: 262,851] | | | | [removed: 259,562] [added: 262,459] | | |
| Cash and cash equivalents | | $ | [removed: 210,100] [added: 274,520] | | | $ | [removed: 155,849] [added: 210,100] | | | $ | [removed: 456,012] [added: 155,849] | | | $ | [removed: 158,668] [added: 456,012] | | | $ | [removed: 63,631] [added: 158,668] | |
| Working capital | | [removed: 285,108] [added: 431,860] | | | | [removed: 220,523] [added: 285,108] | | | | [removed: 521,456] [added: 220,523] | | | | [removed: 168,007] [added: 521,456] | | | | [removed: 67,893] [added: 168,007] | | |
| Total assets | | [removed: 1,982,501] [added: 2,307,698] | | | | [removed: 1,649,820] [added: 1,982,501] | | | | [removed: 1,798,660] [added: 1,649,820] | | | | [removed: 1,506,121] [added: 1,798,660] | | | | [removed: 1,333,316] [added: 1,506,121] | | |
| Total debt | | [removed: 633,038] [added: 399,898] | | | | [removed: 640,492] [added: 633,038] | | | | [removed: 644,514] [added: 640,492] | | | | [removed: 302,218] [added: 644,514] | | | | [removed: 371,292] [added: 302,218] | | |
| Stockholders’ equity | | [removed: 1,098,600] [added: 1,581,099] | | | | [removed: 774,456] [added: 1,098,600] | | | | [removed: 964,464] [added: 774,456] | | | | [removed: 1,003,499] [added: 964,464] | | | | [removed: 762,401] [added: 1,003,499] | | |
| | |
| --- | --- |
| (1) | Shares and earnings per share data were revised from previously reported amounts due to a two-for-one common stock split effected in the form of a stock dividend. See Notes to Consolidated Financial Statements, Note 1 — Summary of Significant Accounting Policies. |
Item 9A. Controls and Procedures
8 rewritten, 5 added, 1 removed, 40 unchanged
Management assessed our internal control over financial reporting for the fiscal year ended July 31, [removed: 2017.][added: 2018.]
Our independent registered public accounting firm, Ernst & Young LLP, independently assessed the effectiveness of our internal control over financial reporting as of July 31, [removed: 2017.][added: 2018.]
[removed: The] [added: To the Stockholders and the] Board of Directors [removed: and Stockholders] of Copart, Inc.
We have audited [removed: Copart, Inc.’s] [added: the] internal control over financial reporting [added: of Copart, Inc. (the Company)] as of July 31, [removed: 2017,] [added: 2018,] based on criteria established in Internal [removed: Control — Integrated] [added: Control—Integrated] Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) (the COSO criteria).
[removed: Copart, Inc.’s] [added: The Company’s] management is responsible for maintaining effective internal control over financial [removed: reporting,] [added: reporting] and for its assessment of the effectiveness of internal control over financial reporting included in the accompanying [removed: “Management’s] [added: Management’s] Report on Internal Control Over Financial [removed: Reporting”.][added: Reporting.]
We conducted our audit in accordance with the standards of the [removed: Public Company Accounting Oversight Board (United States).][added: PCAOB.]
In our opinion, Copart, Inc. maintained, in all material respects, effective internal control over financial reporting as of July 31, [removed: 2017,] [added: 2018,] based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United [removed: States), the consolidated balance sheets of Copart, Inc. as of July 31, 2017 and 2016, and] [added: States) (PCAOB),] the [removed: related] [added: 2018] consolidated [added: financial] statements of [removed: income, comprehensive income, stockholders’ equity, and cash flows for each of] the [removed: three years in the period ended July 31, 2017 of Copart, Inc.] [added: Company,] and our report dated [removed: September 27, 2017] [added: October 1, 2018] expressed an unqualified opinion thereon.
Opinion on Internal Control Over Financial Reporting
Basis for Opinion
We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
Definition and Limitations of Internal Control Over Financial Reporting
October 1, 2018
September 27, 2017
Item 9B. Other Information
1 rewritten, 0 added, 0 removed, 2 unchanged
Certain information required by Part III is omitted from this Annual Report on Form 10-K because we intend to file a definitive proxy statement for our [removed: 2017] [added: 2018] Annual Meeting of Stockholders (the Proxy Statement) not later than 120 days after the end of the fiscal year covered by this Annual Report on Form 10-K, and certain information to be included therein is incorporated herein by reference.
Item 11. Executive Compensation
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this item is incorporated herein by reference from the Proxy Statement (to be filed with the Securities and Exchange Commission within 120 days of our July 31, [removed: 2017] [added: 2018] fiscal year end) under the heading “Executive Compensation,” “Compensation of Directors,” and “Corporate Governance and Board of Directors.”
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this item is incorporated herein by reference from the Proxy Statement (to be filed with the Securities and Exchange Commission within 120 days of our July 31, [removed: 2017] [added: 2018] fiscal year end) under the headings “Security Ownership” and “Executive Compensation,” subheading “Equity Compensation Plan Information.”
Item 13. Certain Relationships and Related Transactions, and Director Independence
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this item is incorporated herein by reference from the Proxy Statement (to be filed with the Securities and Exchange Commission within 120 days of our July 31, [removed: 2017] [added: 2018] fiscal year end) under the heading “Related Person Transactions and Section 16(a) Beneficial Ownership Compliance,” “Corporate Governance and Board of Directors,” and “Proposal Number One — Election of Directors.”
Item 14. Principal Accounting Fees and Services
1 rewritten, 0 added, 0 removed, 1 unchanged
The information required by this item is incorporated herein by reference from the section captioned “Proposal Number Four — Ratification of Appointment of Independent Registered Public Accounting Firm” in the Proxy Statement (to be filed with the Securities and Exchange Commission within 120 days of our July 31, [removed: 2017] [added: 2018] fiscal year end).
Item 15. Exhibits, Financial Statement Schedules
376 rewritten, 169 added, 148 removed, 776 unchanged
Our consolidated financial statements at July 31, [removed: 2017] [added: 2018] and [removed: 2016] [added: 2017] and for each of the three years in the period ended July 31, [removed: 2017] [added: 2018] and the notes thereto, together with the report of the independent registered public accounting firm on those consolidated financial statements are hereby filed as part of this annual report on Form 10-K.
| /s/ A. JAYSON ADAIR | | Chief Executive Officer (Principal Executive Officer and Director) | | [removed: September 27, 2017] [added: October 1, 2018] |
| /s/ Jeffrey Liaw | | Chief Financial Officer (Principal Financial and Accounting Officer) | | [removed: September 27, 2017] [added: October 1, 2018] |
| /s/ WILLIS J. JOHNSON | | Chairman of the Board | | [removed: September 27, 2017] [added: October 1, 2018] |
| /s/ VINCENT W. MITZ | | President and Director | | [removed: September 27, 2017] [added: October 1, 2018] |
| /s/ JAMES E. MEEKS | | Director | | [removed: September 27, 2017] [added: October 1, 2018] |
| /s/ STEVEN D. COHAN | | Director | | [removed: September 27, 2017] [added: October 1, 2018] |
| /s/ DANIEL ENGLANDER | | Director | | [removed: September 27, 2017] [added: October 1, 2018] |
| /s/ THOMAS N. TRYFOROS | | Director | | [removed: September 27, 2017] [added: October 1, 2018] |
| /s/ MATT BLUNT | | Director | | [removed: September 27, 2017] [added: October 1, 2018] |
| Consolidated Financial Statements | [added: |] Page Number |
| [Report of Independent Registered Public Accounting [removed: Firm](#s61F4723F430C5FB694E3CF116E25D59D)] [added: Firm](#s690C062B387B51FDB40721E08FB4F831)] | [removed: [59](#s61F4723F430C5FB694E3CF116E25D59D)] | [added: [58](#s690C062B387B51FDB40721E08FB4F831) |]
| [Consolidated Balance Sheets as of July 31, [removed: 2017] [added: 2018] and [removed: 2016](#sBD590C7C06C65480BC9C40A3E31F5460)] [added: 2017](#sE793E8E214595ADDA98A3451095087EC)] | [removed: [60](#sBD590C7C06C65480BC9C40A3E31F5460)] | [added: [59](#sE793E8E214595ADDA98A3451095087EC) |]
| [Consolidated Statements of Income for the years ended July 31, [removed: 2017, 2016] [added: 2018, 2017] and [removed: 2015](#sD89A4D6F19D053CA943EA5A43B0A21E5)] [added: 2016](#s67D41BD9F2565077A67A7D26F07AF8EA)] | [removed: [61](#sD89A4D6F19D053CA943EA5A43B0A21E5)] | [added: [60](#s67D41BD9F2565077A67A7D26F07AF8EA) |]
| [Consolidated Statements of Comprehensive Income for the years ended July 31, [removed: 2017, 2016] [added: 2018, 2017] and [removed: 2015](#sC99B8488FF0F54CAB09B70CDDB85B1E0)] [added: 2016](#sA3D3A80FBC525342A33B830859FDBE87)] | [removed: [62](#sC99B8488FF0F54CAB09B70CDDB85B1E0)] | [added: [61](#sA3D3A80FBC525342A33B830859FDBE87) |]
| [Consolidated [removed: Statement] [added: Statements] of Stockholder’s Equity for the years ended July 31, [removed: 2017, 2016] [added: 2018, 2017] and [removed: 2015](#sC832B18BEBE2535CB309F32AEC087093)] [added: 2016](#sB11ED38CFDE05131A34D11C4874ED401)] | [removed: [63](#sC832B18BEBE2535CB309F32AEC087093)] | [added: [62](#sB11ED38CFDE05131A34D11C4874ED401) |]
| [Consolidated Statements of Cash Flows for the years ended July 31, [removed: 2017, 2016] [added: 2018, 2017] and [removed: 2015](#s6DB4383FEE565DF7ACC2F74C76369436)] [added: 2016](#s127349671F385AD395EE22253DEC3154)] | [removed: [64](#s6DB4383FEE565DF7ACC2F74C76369436)] | [added: [63](#s127349671F385AD395EE22253DEC3154) |]
| [Notes to Consolidated Financial [removed: Statements](#sDEE0B644E7D25AC3A12EB1A62CAA0CB5)] [added: Statements](#sB1399CAA2A7E57CEA5B64CB916AEB310)] | [removed: [65](#sDEE0B644E7D25AC3A12EB1A62CAA0CB5)] | [added: [64](#sB1399CAA2A7E57CEA5B64CB916AEB310) |]
[removed: The] [added: To the Stockholders and the] Board of Directors [removed: and Stockholders] of Copart, Inc.
We have audited the accompanying consolidated balance sheets of Copart, Inc. [added: (the Company)] as of July 31, [removed: 2017 and 2016,] [added: 2018] and [added: 2017,] the related consolidated statements of income, comprehensive income, stockholders’ equity, and cash flows for each of the three years in the period ended July 31, [removed: 2017.][added: 2018, and the related notes (collectively referred to as the “consolidated financial statements”).]
Our responsibility is to express an opinion on [removed: these] [added: the Company’s] financial statements based on our audits.
We conducted our audits in accordance with the standards of the [removed: Public Company Accounting Oversight Board (United States).][added: PCAOB.]
Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material [removed: misstatement.][added: misstatement, whether due to error or fraud.]
[removed: An audit includes] [added: Such procedures included] examining, on a test basis, evidence [removed: supporting] [added: regarding] the amounts and disclosures in the financial statements.
[removed: An audit] [added: Our audits] also [removed: includes assessing] [added: included evaluating] the accounting principles used and significant estimates made by management, as well as evaluating the overall [added: presentation of the] financial [removed: statement presentation.][added: statements.]
In our opinion, the [added: consolidated] financial statements [removed: referred to above] present fairly, in all material respects, the consolidated financial position of [removed: Copart, Inc.] [added: the Company] at July 31, [removed: 2017] [added: 2018] and [removed: 2016,] [added: 2017,] and the [removed: consolidated] results of its operations and its cash flows for each of the three years in the period ended July 31, [removed: 2017,] [added: 2018,] in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United [removed: States), Copart, Inc.’s] [added: States) (PCAOB), the Company’s] internal control over financial reporting as of July 31, [removed: 2017,] [added: 2018,] based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) and our report dated [removed: September 27, 2017] [added: October 1, 2018] expressed an unqualified opinion thereon.
| | | [added: 2018 | | | |] 2017 | | | | 2016 | | |
| Cash and cash equivalents [removed: |] [added: at beginning of period] | [removed: $] | 210,100 | | | [removed: $] | 155,849 | | [added: | | 456,012 | | |]
| Accounts receivable, net | | [removed: 311,846] [added: 351,601] | | | | [removed: 266,270] [added: 311,846] | | |
| Vehicle pooling costs | | [removed: 31,118] [added: 34,284] | | | | [removed: 28,599] [added: 31,118] | | |
| Inventories | | [removed: 10,163] [added: 16,734] | | | | [removed: 10,388] [added: 10,163] | | |
| Income taxes receivable | | [removed: 6,418] [added: 15,312] | | | | [removed: 18,751] [added: 6,418] | | |
| Deferred income taxes | | — | | | | [removed: 1,444] [added: 92] | | |
| Prepaid expenses and other assets | | [removed: 17,616] [added: 16,665] | | | | [removed: 18,005] [added: 17,616] | | |
| Total current assets | | [removed: 587,261] [added: 709,116] | | | | [removed: 499,306] [added: 587,261] | | |
| Property and equipment, net | | [removed: 944,056] [added: 1,163,425] | | | | [removed: 816,791] [added: 944,056] | | |
| Intangibles, net | | [removed: 75,938] [added: 64,892] | | | | [removed: 11,761] [added: 75,938] | | |
| [removed: Goodwill] [added: Beginning balance] | | [added: $ |] 340,243 | | | [added: $] | 260,198 | | [removed: |]
| Deferred income taxes | | [removed: 1,287] [added: 470] | | | | [removed: 23,506] [added: 1,287] | | |
Date: October 1, 2018
Date: October 1, 2018
| | | |
| --- | --- | --- |
| | | |
Opinion on the Financial Statements
Basis for Opinion
We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
Our audits included performing procedures to assess the risks of material misstatement of the financial statements, whether due to error or fraud, and performing procedures that respond to those risks.
We have served as the Company’s auditor since fiscal year 2006.
October 1, 2018
| | | 2018 | | | | 2017 | | |
| Cash and cash equivalents | | $ | 274,520 | | | $ | 210,100 | |
| Goodwill | | 337,235 | | | | 340,243 | | |
| Net income | | — | | | — | | | | — | | | | — | | | | 417,867 | | | | 140 | | | | 418,007 | | |
| Distribution to noncontrolling interest | | — | | | — | | | | — | | | | — | | | | — | | | | (235 | | ) | | (235 | | ) |
| Sale of majority-owned subsidiary | | — | | | — | | | | — | | | | — | | | | — | | | | (439 | | ) | | (439 | | ) |
| Exercise of stock options, net of repurchased shares | | 3,225,377 | | | — | | | | 44,459 | | | | — | | | | (1,115 | | ) | | — | | | | 43,344 | | |
| Balances at July 31, 2018 | | 233,898,841 | | | $ | 23 | | | $ | 526,858 | | | $ | (107,928 | ) | | $ | 1,162,146 | | | $ | — | | | $ | 1,581,099 | |
| Net income | | $ | 418,007 | | | $ | 394,261 | | | $ | 270,360 | |
| Impairment of long-lived assets | | 1,157 | | | | 19,365 | | | | — | | |
| Proceeds from sale of majority-owned subsidiary | | 1,796 | | | | — | | | | — | | |
| Distributions to noncontrolling interest | | (235 | | ) | | — | | | | — | | |
JULY 31, 2018
During the year ended July 31, 2018, the Company sold the majority-owned subsidiary and disposed of its related goodwill.
The proceeds from the sale of the majority-owned subsidiary were $1.8 million resulting in a realized gain of $0.9 million recorded in other income.
recognition.
The Company reports sales taxes on relevant transactions on a net basis in the Company’s consolidated results of operations, and therefore does not include sales taxes in revenues or costs.
In August 2017, Hurricane Harvey hit the Texas Gulf Coast.
As a result of the extensive flooding that it caused, the Company expended $68.6 million in additional costs for the year ended July 31, 2018, for (i) temporary storage facilities, (ii) premiums for subhaulers, (iii) labor costs incurred for overtime, (iv) travel and lodging due to the reassignment of employees to the affected region, and (v) equipment lease expenses to handle the increased volume.
These costs, which are characterized as "abnormal" under ASC 330, Inventory, were expensed as incurred and not included in vehicle pooling costs.
As of July 31, 2018, substantially all of the incremental salvage vehicles received as a result of Hurricane Harvey have been sold.
In the fourth quarter of 2018, the Company modified its estimate of the useful life of its land improvements to better reflect the estimated periods during which these assets will remain in service.
The change in estimate was accounted for prospectively as of the first day of the fourth quarter, and this change will not have a material effect on future periods.
| | | 2018 | | | | 2017 | | | | 2016 | | |
The allocation of the purchase consideration for acquisitions can require extensive use of accounting estimates and judgments to allocate the purchase consideration to the identifiable tangible and intangible assets acquired and liabilities assumed based on their respective fair values.
The excess of the fair value of purchase consideration over the values of the identifiable assets and liabilities is recorded as goodwill.
Critical estimates in valuing certain identifiable assets include but are not limited to expected long-term revenues; future expected operating expenses; cost of capital; appropriate attrition; and discount rates.
In February 2018, the FASB issued ASU 2018-02, Income Statement-Reporting Comprehensive Income (Topic 220): Reclassification of Certain Tax Effects from Accumulated Other Comprehensive Income.
The current standard, ASC Topic 740 - Income Taxes, requires deferred tax liabilities and assets to be adjusted for the effect of a change in tax laws or rates with the effect included in income from continuing operations in the reporting period that includes the enactment date.
| | |
| --- | --- |
Date: September 27, 2017
September 27, 2017
| Deferred income taxes | | 3,192 | | | | 3,816 | | |
| Balances at July 31, 2014 | | 252,286,732 | | | $ | 26 | | | $ | 404,529 | | | $ | (20,060 | ) | | $ | 619,004 | | | $ | — | | | $ | 1,003,499 | |
| Net income | | — | | | — | | | | — | | | | — | | | | 219,783 | | | | — | | | | 219,783 | | |
| Interest rate swaps, net of tax effects | | — | | | — | | | | — | | | | 785 | | | | — | | | | — | | | | 785 | | |
| Exercise of stock options, net of repurchased shares | | 795,040 | | | — | | | | 2,193 | | | | — | | | | (1,509 | | ) | | — | | | | 684 | | |
| Shares repurchased | | (12,971,122 | ) | | (2 | | ) | | (21,641 | | ) | | — | | | | (211,841 | | ) | | — | | | | (233,484 | | ) |
| Excess tax benefit from stock-based payment compensation | | — | | | | — | | | | (2,971 | | ) |
| Proceeds from sale of assets held for sale | | 105 | | | | 100 | | | | 217 | | |
| Excess tax benefit from stock-based payment compensation | | — | | | | — | | | | 2,971 | | |
| Cash and cash equivalents at beginning of period | | 155,849 | | | | 456,012 | | | | 158,668 | | |
On March 23, 2017, the Company’s Board of Directors approved a two-for-one common stock split effected in the form of a stock dividend.
The additional shares resulting from the stock split were distributed after the closing of trading on April 10, 2017 to stockholders of record on April 3, 2017.
The stock dividend increased the number of shares of common stock outstanding and all share and per share amounts have been adjusted for the stock dividend, as of the date earliest presented in these financial statements.
Certain prior year amounts have been adjusted to conform to current year presentation.
The accounts and balances of the majority-owned subsidiary have been consolidated with those of the Company.
The Company maintains an allowance for doubtful accounts in order to provide for estimated losses resulting from disputed amounts billed to sellers or members and the inability of sellers or members to make required payments.
If billing disputes exceed expectations and/or if the financial condition of sellers or members were to deteriorate, additional allowances may be required.
The allowance is calculated by considering both seller and member accounts receivables written off during the previous twelve-month period as a percentage of the total accounts receivable balance.
As of July 31, 2016, one customer accounted for more than 10% of the Company’s accounts receivable.
Long-Lived Asset Valuation
The Company evaluates long-lived assets, including property and equipment, for impairment whenever events or changes in circumstances indicate that the carrying amount of an asset may not be recoverable.
In accordance with ASC 360, Property, Plant, and Equipment, a long-lived asset is initially measured at the lower of its carrying amount or fair value.
An impairment loss is recognized when the estimated undiscounted future cash flows expected to be generated from the use of the asset are less than the carrying amount of the asset.
The impairment loss is then calculated by comparing the carrying amount with its fair value, which is usually estimated using discounted cash flows expected to be generated from the use of the asset.
This change in the annual assessment date does not delay, accelerate, or avoid an impairment charge.
This change was not applied retrospectively as it was impracticable to do so because retrospective application would require application of significant estimates and assumptions with the use of hindsight.
Accordingly, the change has been applied prospectively.
In the fourth quarters of fiscal 2016 and fiscal 2015, we performed quantitative assessments for our annual goodwill impairment analyses, which did not result in any impairment charge.
Retained Insurance Liabilities
The Company is partially self-insured for certain losses related to medical, general liability, workers’ compensation and auto liability.
The Company’s insurance policies are subject to a $250,000 deductible per claim, with the exception of its medical policy which has a $500,000 stop loss per person.
Our liability represents an estimate of the ultimate cost of claims incurred as of the balance sheet date, including an estimate for reported and unreported claims.
The estimated liability is not discounted and is established based upon analysis of historical data and actuarial estimates.
The primary estimates used in the actuarial analysis include total payroll and revenue.
The Company’s estimates have not materially fluctuated from actual results.
While the Company believes these estimates are reasonable based on the information currently available, if actual trends, including the severity of claims and medical cost inflation, differ from the Company’s estimates, the Company’s consolidated results of operations, financial position or cash flows could be impacted.
An excerpt. Shown here: 40 of 376 rewritten, 40 of 169 added and 40 of 148 removed. The counts are complete. For every sentence, read Item 15. Exhibits, Financial Statement Schedules in the FY2018 filing and the FY2017 filing.