 filings.tools
Domino's Pizza 10-K 2018-12-30
Filed 2019-02-21. 23 sections, 410K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 d696297d10k.htm 10-K
Table of Contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
(Mark One)
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
|---|
For the fiscal year ended December 30, 2018
or
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
|---|
Commission File Number 001-32242
Domino’s Pizza, Inc.
(Exact name of registrant as specified in its charter)
| DELAWARE | 38-2511577 | |
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) | |
| 30 Frank Lloyd Wright Drive Ann Arbor, Michigan | 48105 | |
| (Address of principal executive offices) | (Zip Code) |
Registrant’s telephone number, including area code (734) 930-3030
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class: | Name of each exchange on which registered: | |
| Domino’s Pizza, Inc. Common Stock, $0.01 par value | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act: Yes ☒ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act: Yes ☐ No ☒
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days: Yes ☒ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files): Yes ☒ No ☐
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K (§229.405 of this chapter) is not contained herein, and will not be contained, to the best of registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K: ☒
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | ☒ | Accelerated filer | ☐ | |||
| Non-accelerated filer | ☐ | Smaller reporting company | ☐ | |||
| Emerging growth company | ☐ |
If emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act): Yes ☐ No ☒
The aggregate market value of the voting and non-voting common stock held by non-affiliates of Domino’s Pizza, Inc. as of June 17, 2018 computed by reference to the closing price of Domino’s Pizza, Inc.’s common stock on the New York Stock Exchange on such date was $11,546,079,722.
As of February 14, 2019, Domino’s Pizza, Inc. had 41,040,704 shares of common stock, par value $0.01 per share, outstanding.
Documents incorporated by reference:
Portions of the definitive proxy statement to be furnished to shareholders of Domino’s Pizza, Inc. in connection with the annual meeting of shareholders to be held on April 23, 2019 are incorporated by reference into Part III.
Table of Contents
TABLE OF CONTENTS
Throughout this document, Domino’s Pizza, Inc. (NYSE: DPZ) is referred to as the “Company,” “Domino’s”, “Domino’s Pizza” or in the first-person notations of “we,” “us” and “our.”
In this document, we rely on and refer to information regarding the U.S. quick service restaurant, or QSR, sector and the U.S. QSR pizza category from the CREST® report (years ending November) prepared by The NPD Group, as well as market research reports, analyst reports and other publicly-available information. Although we believe this information to be reliable, we have not independently verified it. Domestic sales information relating to the U.S. QSR sector and the U.S. QSR pizza category represent reported consumer spending obtained by The NPD Group’s CREST® report from consumer surveys. This information relates to both our Company-owned and franchised stores.
Table of Contents
Part I
Item 1. Business.
Overview
Domino’s is the largest pizza company in the world based on global retail sales, with more than 15,900 locations in over 85 markets around the world. Founded in 1960, our roots are in convenient pizza delivery, while a significant amount of our sales also come from carryout customers. Although we are a highly-recognized global brand, we focus on serving the local neighborhoods in which we live and do business through our large global network of franchise owners and 390 U.S. Company-owned stores. On average, we and our franchisees sell more than 3 million pizzas each day throughout our global system.
The Domino’s business model is straightforward: we handcraft and serve quality food at a competitive price, with easy ordering access and efficient service, enhanced by our technology innovations. Our dough is generally made fresh and distributed to stores around the world by us and our franchisees.
Domino’s generates revenues and earnings by charging royalties and fees to our franchisees. Royalties are ongoing percent-of-sales fees for use of the Domino’s® brand marks. The Company also generates revenues and earnings by selling food, equipment and supplies to franchisees primarily in the U.S. and Canada, and by operating a number of our own stores. Franchisees profit by selling pizza and other complementary items to their local customers. In our international markets, we generally grant geographical rights to the Domino’s Pizza® brand to master franchisees. These master franchisees are charged with developing their geographical area, and they may profit by sub-franchising and selling food and equipment to those sub-franchisees, as well as by running pizza stores. Everyone in the system can benefit, including the end consumer, who can purchase Domino’s menu items for themselves and their family conveniently and economically.
The Domino’s business model can yield strong returns for our franchise owners and Company-owned stores. It can also yield significant cash flow to us, through a consistent franchise royalty payment and supply chain revenue stream, with moderate capital expenditures. We have historically returned cash to shareholders through dividend payments and share repurchases since becoming a publicly-traded company.
Our History
We pioneered the pizza delivery business and built Domino’s Pizza into one of the most widely-recognized consumer brands in the world. We have been delivering quality, affordable food to our customers since 1960, when brothers Thomas and James Monaghan borrowed $900 to purchase a small pizza store in Ypsilanti, Michigan. Thomas purchased his brother’s share of the business shortly thereafter. Concentrating first on building stores near college campuses and military bases in the 1960s and 1970s, the brand grew quickly in the 1980s in urban markets and near residential communities. We became “Domino’s Pizza” in 1965 and opened our first franchised store in 1967. The first international stores opened in 1983, in Canada and Australia.
Monaghan sold 93% of his economic stake in the Company in 1998 to Bain Capital, LLC, then sold and transferred his remaining stake in the Company in 2004, when we completed our initial public offering.
Since 1998, the Company has been structured with a leveraged balance sheet and has completed a number of recapitalization events. The Company’s most recent recapitalization transaction in 2018 (the “2018 Recapitalization”) primarily consisted of the issuance of $825.0 million of fixed rate notes and the repurchase and retirement of $490.0 million of previously outstanding fixed rate notes. As of December 30, 2018, the Company had $3.53 billion in total debt, which included debt from its 2018 Recapitalization and its previous recapitalization transactions in 2017 and 2015 (the “2017 Recapitalization” and the “2015 Recapitalization,” and together with the 2018 Recapitalization, the “2018, 2017 and 2015 Recapitalizations”). Excess proceeds from our 2018, 2017 and 2015 Recapitalizations were used primarily to repurchase shares of our common stock.
We re-launched our brand in the U.S. in late 2009 by introducing a new recipe for our core pizza product. Since 2008, the majority of our menu has changed, either through the improvement of existing products or the introduction of new products, such as our Handmade Pan Pizza and Specialty Chicken. During this time frame, we also began expanding our focus on technology through our development of innovative ordering platforms and other technological advancements, such as the launch of our Piece of the Pie Rewards® loyalty program in 2015 and the launch of Domino’s Delivery HotSpots® in 2018. Globally, we opened our 10,000th store in 2012 and our 15,000th store in 2018. In 2013, we announced a plan requiring all stores to adopt our new carry-out friendly “Pizza Theater” store design, which is more inviting to customers and allows them to see their orders being made fresh in front of them. The majority of our U.S. and international stores have completed these remodels as of the end of 2018.
Table of Contents
Our Industry
The U.S. QSR pizza category is large and fragmented. From 2008 through 2018, the U.S. QSR pizza category has grown from $32.8 billion to $36.5 billion. It is the second-largest category within the $299.6 billion U.S. QSR sector. The U.S. QSR pizza category is primarily comprised of delivery, dine-in and carryout.
In the U.S., we compete primarily in the delivery and carryout segments of the pizza industry. We are the market share leader in the delivery segment and we are amongst the top three chains in share in the carryout segment. Delivery segment sales of $9.8 billion in 2018 (down from $10.3 billion in 2008) account for approximately 27% of total U.S. QSR pizza. The delivery segment declined slightly during the period from 2008 to 2012, and has increased slightly since 2012, from $9.7 billion in 2012 to $9.8 billion in 2018. The three industry leaders, including Domino’s, account for over 56% of U.S. pizza delivery, based on reported consumer spending, with the remaining sales going to regional chains and independent establishments. From 2008 to 2018, the carryout segment grew from $14.1 billion to $17.1 billion. The four industry leaders, including Domino’s, account for approximately 48% of the carryout segment.
In contrast to the U.S., international pizza delivery is relatively underdeveloped, with only Domino’s and two other competitors having a significant global presence. We believe that demand for pizza and pizza delivery is large and growing throughout the world, driven by international consumers’ increasing emphasis on convenience, and the proven success of our 35 years of conducting business abroad.
Our Competition
The global pizza delivery and carryout segments are highly competitive. In the U.S., we compete against regional and local companies as well as national chains Pizza Hut®, Papa John’s® and Little Caesars Pizza®. Internationally, we compete primarily with Pizza Hut®, Papa John’s® and country-specific national and local pizzerias. We generally compete on the basis of product quality, location, image, service, technology, convenience and price. Our business and those of our competitors can be affected by changes in consumer tastes, economic conditions, demographic trends and consumers’ disposable income. We also compete on a broader scale with other food and food delivery companies. We compete not only for customers, but also for employees, suitable real estate sites and qualified franchisees.
Our Customers
The Company’s business is not dependent upon a single retail customer or small group of customers, including franchisees. No customer accounted for more than 10% of total consolidated revenues in 2018, 2017 or 2016. Our largest franchisee based on store count, Domino’s Pizza Enterprises (DMP: ASX), operates 2,383 stores in seven international markets, and accounts for 15% of our total store count. Revenues from this master franchisee accounted for 1.4% of our consolidated revenues in 2018. Our international business unit only requires a modest amount of general and administrative expenses to support its markets and does not have costs of sales. Therefore, the vast majority of these royalty revenues result in profits to us.
Our Menu
We offer a menu designed to present an attractive, quality offering to customers, while keeping it simple enough to minimize order errors and expedite order-taking and food preparation. Our basic menu features pizza products with varying sizes and crust types. Our typical store also offers oven-baked sandwiches, pasta, boneless chicken and wings, bread side items, desserts and soft drink products. International markets vary toppings by country and culture, such as squid topping in Japan or spicy cheese in India, and often feature regional specialty items, such as a banana and cinnamon dessert pizza in Brazil.
Store Image and Operations
We have been focused primarily on pizza delivery for nearly 60 years, as well as carryout as a significant component of our business. In 2012, we introduced our carryout-friendly Pizza Theater store design; the majority of our U.S. and international stores have converted to this design as of the end of 2018. Many stores offer casual seating and enable customers to watch the preparation of their orders, but do not offer a full-service dine-in experience. As a result, our stores generally do not require expensive restaurant facilities and staffing.
Table of Contents
Our Business Segments
We operate, and report, three business segments: U.S. stores, international franchise and supply chain.
U.S. Stores
Our U.S. stores segment consists primarily of our franchise operations, which consist of 5,486 franchised stores located in the United States. We also operate a network of 390 U.S. Company-owned stores.
During 2018, our U.S. stores segment accounted for $1.26 billion, or 37% of our consolidated revenues. We use our Company-owned stores as test sites for new products and promotions as well as operational improvements. We also use them for training new store managers and operations team members, as well as developing prospective franchisees. While we are primarily a franchised business, we continuously evaluate our mix of U.S. Company-owned and franchise stores.
We maintain a productive relationship with our independent franchise owners through regional franchise teams, distributing materials that help franchise stores comply with our standards and using franchise advisory groups that facilitate communications between us and our franchisees.
U.S. Franchise Profile
As of December 30, 2018, our network of 5,486 U.S. franchise stores were owned and operated by 793 independent U.S. franchisees. Our franchise formula enables franchisees to benefit from our brand name with a relatively low initial capital investment. As of December 30, 2018, the average U.S. franchisee owned and operated seven stores and had been in our franchise system for over 18 years. At the same time, 17 of our U.S. franchisees operated more than 50 stores (including our largest U.S. franchisee who operated 179 stores) and 262 of our U.S. franchisees each operated one store.
We apply rigorous standards to prospective U.S. franchisees. We generally require them to manage a store for at least one year and graduate from our franchise management school before being granted a franchise. This enables us to observe the operational and financial performance of a potential franchisee prior to entering into a long-term contract. Substantially all of our 793 independent U.S. franchise owners started their careers with us as delivery drivers or in other in-store positions, which we believe offers advantages in terms of familiarity with our business and store operations. In addition, we generally restrict the ability of U.S. franchisees to be involved in other businesses, which we believe helps focus our franchisees’ attention on operating their stores. We believe these characteristics and standards are largely unique within the franchise industry and have resulted in qualified and focused franchisees operating Domino’s stores.
U.S. Franchise Agreements
We enter into franchise agreements with U.S. franchisees under which the franchisee is generally granted the right to operate a store in a particular location for a term of ten years, with an ability to renew for an additional term of ten years. We have a franchise contract renewal rate of approximately 99%. Under the current standard franchise agreement, we assign an exclusive area of primary responsibility to each franchised store. Each franchisee is generally required to pay a 5.5% royalty fee on sales. In certain instances, we will collect lower rates based on new store incentives.
Our U.S. stores currently contribute 6% of their sales to fund national marketing and advertising campaigns (subject, in certain instances, to lower rates based on certain incentives and waivers). These funds are administered by Domino’s National Advertising Fund Inc. (“DNAF”), our consolidated not-for-profit advertising subsidiary. The funds are primarily used to purchase media for advertising, but also support market research, field communications, public relations, commercial production, talent payments and other activities to promote the brand. In addition to the national and market-level advertising contributions, U.S. stores spend additional funds on local store marketing activities.
We have the contractual right, subject to state law, to terminate a franchise agreement for a variety of reasons, including, but not limited to, a franchisee’s failure to adhere to the Company’s franchise agreement, failure to make required payments, or failure to adhere to specified Company policies and standards.
Table of Contents
International Franchise
Our international franchise segment is comprised of a network of franchised stores in more than 85 international markets. At December 30, 2018, we had 10,038 international franchise stores. During 2018, this segment accounted for $224.7 million, or 6% of our consolidated revenues. The principal sources of revenues from those operations are royalty payments generated by retail sales from franchised stores.
Our international franchisees employ our basic standard operating model and adapt it to satisfy the local eating habits and consumer preferences of various regions outside the U.S. Currently, the vast majority of our international stores operate under master franchise agreements.
We believe Domino’s appeals to potential international franchisees because of our recognized brand name and technological leadership, the moderate capital expenditures required to open and operate our stores and our system’s favorable store economics. Stores in eight of our top ten international markets in terms of store count are operated by master franchise companies that are publicly traded on stock exchanges in India (JUBLFOOD: NS), the United Kingdom (DOM: L), Mexico (ALSEA: MX), Australia (DMP: ASX) (which operates the stores in our Australia, Japan, France and Germany markets) and Turkey (DPEU: L). The following table shows our store count as of December 30, 2018 in our top ten international markets, which accounted for approximately 64% of our international stores as of December 30, 2018.
| Market | Number of stores | |||
| India | 1,195 | |||
| United Kingdom | 1,100 | |||
| Mexico | 760 | |||
| Australia | 693 | |||
| Japan | 550 | |||
| Turkey | 535 | |||
| Canada | 487 | |||
| South Korea | 447 | |||
| France | 387 | |||
| Germany | 283 |
International Franchisee Profile
The vast majority of our markets outside of the U.S. are operated by master franchisees with franchise and distribution rights for entire regions or countries. In a few select markets, we franchise directly to individual store operators. Prospective master franchisees are required to possess local market knowledge to establish and develop Domino’s Pizza stores, with the ability to identify and access targeted real estate sites, as well as expertise in local laws, customs, culture and consumer behavior. We also seek candidates that have access to sufficient capital to meet growth and development plans.
Master Franchise Agreements
Our master franchise agreements generally grant the franchisee exclusive rights to develop and sub-franchise stores and the right to operate supply chain centers in particular geographic areas. Agreements are generally for a term of ten years, with options to renew for additional terms. The agreements typically contain growth clauses requiring franchisees to open a minimum number of stores within a specified period. The master franchisee is generally required to pay an initial, one-time franchise fee as well as an additional franchise fee upon the opening of each new store. The master franchisee is also required to pay a continuing royalty fee as a percentage of sales, which varies among international markets, and averaged approximately 3.0% in 2018.
Supply Chain
Our supply chain segment operates 19 regional dough manufacturing and food supply chain centers in the U.S., one thin crust manufacturing center, one vegetable processing center and one center providing equipment and supplies to our U.S. and certain international stores. We plan to continue investing in additional supply chain centers and capacity initiatives in the future. We also operate five dough manufacturing and food supply chain centers in Canada. Our supply chain segment leases a fleet of more than 800 tractors and trailers. During 2018, our supply chain segment accounted for $1.94 billion, or nearly 57% of our consolidated revenues.
Our centers produce fresh dough and purchase, receive, store and deliver quality food and other complementary items to our U.S. stores and most of our Canadian franchised stores. We regularly supply over 6,300 stores with various food and supplies. Our supply chain segment made approximately 766,000 full-service deliveries in 2018 or approximately 2.5 deliveries per store per week, and we produced over 573 million pounds of fresh dough during 2018.
Table of Contents
We believe our franchisees voluntarily choose to obtain food, supplies and equipment from us because we offer the most efficient, convenient and cost-effective alternative, while also offering both quality and consistency. Our supply chain segment offers profit-sharing arrangements to franchisees who purchase all of their food for their stores from our centers. These profit-sharing arrangements generally offer participating franchisees and Company-owned stores with 50% (or a higher percentage in the case of Company-owned stores and certain franchisees who operate a larger number of stores) of their regional supply chain center’s pre-tax profits. We believe these arrangements strengthen our ties and provide aligned benefits with franchisees.
Third-Party Suppliers
Over half of our annual food spend is with suppliers with whom we have maintained a partnership of at least 20 years. Our supply partners are required to meet strict quality standards to ensure food safety. We review and evaluate these partners’ quality assurance programs through (among other actions) on-site visits, third-party audits and product evaluations to ensure compliance with our standards. We believe the length and quality of our relationships with third-party suppliers provides us with priority service and quality products at competitive prices.
Cheese is our largest food cost. The price we charge to our U.S. franchisees for cheese is based on the Chicago Mercantile Exchange cheddar block price, plus a supply chain markup. As cheese prices fluctuate, our revenues and margin percentages in our supply chain segment also fluctuate; however, actual supply chain dollar margins remain unchanged. We currently purchase our U.S. pizza cheese from a single supplier. Under our September 2017 agreement, our U.S. supplier agreed to provide an uninterrupted supply of cheese and the Company agreed to a seven-year pricing schedule to purchase all of its U.S. pizza cheese from this supplier. While we expect to meet the terms of this agreement, if we do not, we will be required to repay the certain negotiated cost savings as outlined in the agreement. The majority of our meat toppings in the U.S. come from a single supplier under a contract that expires in June 2022. We have the right to terminate these arrangements for quality failures and for uncured breaches.
We are party to a multi-year agreement with Coca-Cola® for the contiguous U.S. This contract, renegotiated in December 2013, provides for Coca-Cola to continue to be our exclusive beverage supplier and expires in March 2019.
We believe alternative third-party suppliers are available for all of these referenced products. While we may incur additional costs if we are required to replace any of our supply partners, we do not believe such additional costs would have a material adverse effect on our business. We continually evaluate each supply category to determine the optimal sourcing strategy.
We have not experienced any significant shortages of supplies or delays in receiving our inventories or products. Prices charged to us by our supply partners are subject to fluctuation, and we have historically been able to pass increased costs and savings on to stores. We periodically enter into supplier contracts to manage the risk from changes in commodity prices. We do not engage in speculative transactions, nor do we hold or issue financial instruments for trading purposes.
Our Strengths
Strong Brand Equity
We are the largest pizza company in the world based on global retail sales. We believe our Domino’s Pizza brand is one of the most widely-recognized consumer brands in the world. We are the recognized world leader in pizza delivery and have a significant business in carryout. We believe consumers associate our brand with the timely delivery of quality, affordable food.
Over the past five years, our U.S. franchise and Company-owned stores have invested an estimated $1.9 billion in national, co-operative and local advertising. Our international franchisees also invest significant amounts in advertising efforts in their markets. We continue to reinforce our brand with extensive advertising through various media channels. We have also enhanced the strength of our brand through marketing affiliations with brands such as Coca-Cola.
We are the number one pizza delivery company in the U.S. with a 31.1% share of pizza delivery based on reported consumer spending. With 5,876 stores located in the U.S., our store delivery areas cover a majority of U.S. households. Our share position and scale allow us to leverage our purchasing power, supply chain strength and marketing investments. We believe our scale and market coverage allow us to effectively serve our customers’ demands for convenience and timely delivery. Outside the U.S., we have significant market share positions in many of the markets in which we compete.
Table of Contents
Strong and Proven Business Model
Our business model generates U.S. and international franchise royalties and fees, supply chain revenue and retail sales at Company-owned stores. We have developed this model over our many years of operation and it is anchored by strong store-level economics, which provide an entrepreneurial incentive for our franchisees and historically has generated demand for new stores. Our franchise system, in turn, has produced strong and consistent earnings for us through royalty payments and through supply chain revenues, with moderate capital expenditures by us.
We developed a cost-efficient store model, characterized by a delivery- and carryout-oriented store design, with moderate capital requirements and a menu of quality, affordable items. At the store level, we believe the simplicity and efficiency of our operations give us significant advantages over our competitors, who, in many cases, also focus on dine-in or have broader menu offerings. At the supply chain level, we believe we provide quality, good value and consistency for our franchise customers while also driving profits for us, which we share with our franchisees.
Our menu simplifies and streamlines production and delivery processes and maximizes economies of scale on purchases of our principal food items. In addition, our stores are generally smaller and less expensive to build, furnish and maintain as compared to many other restaurant concepts. New stores built in our Pizza Theater design are often slightly larger than stores we have built in the past to create a better experience for our carryout and dine-in customers; however, they are still generally smaller and less expensive than many other restaurant concepts. The combination of this efficient store model and strong sales volume has resulted in favorable store-level financial returns and, we believe, makes Domino’s Pizza an attractive business opportunity for existing and prospective franchisees around the world. We and our franchisees are continuing to focus on growing our store count around the world to increase our presence in all of our markets to better serve our customers.
We believe our store economics have led to a strong, well-diversified franchise system. This established franchise system has produced strong cash flows and earnings for us, enabling us to invest in the Domino’s Pizza brand, stores, technology and supply chain centers, pay significant dividends, repurchase and retire shares of our common stock and service our debt obligations.
Technological Innovation
Technological innovation is vital to our brand and our long-term success. Digital ordering is critical to competing in the global pizza industry. In 2018, more than half of all global retail sales were derived from digital channels, primarily through our online ordering website and mobile applications. We believe we are among the largest e-commerce retailers in terms of annual transactions. After launching digital ordering in the U.S. in 2008, we made the strategic decision in 2010 to develop our own online ordering platform and to manage this important and growing area of our business internally. Over the next five years, we launched mobile applications that cover 95% of the smartphones and tablets on the U.S. market. In 2013, we launched an enhanced online ordering profiles platform, allowing customers the ability to reorder their favorite order in as few as five clicks, or 30 seconds. In 2014, we introduced “Dom,” a voice ordering application, which we believe is the first in the restaurant industry, and we also made the Domino’s Tracker® available on our ordering platforms. In 2015, we introduced several innovative ordering platforms including Samsung Smart TV®, Twitter, and text message using a pizza emoji. We continued this trend of innovation in 2016 with the introduction of zero-click ordering as well as adding Google Home, Facebook Messenger, Apple Watch, and Amazon Echo to our ordering platforms. In 2017, as part of an industry-first collaboration with Ford Motor Company, we began a meaningful test of delivery using self-driving vehicles. In April 2018, we launched Domino’s Delivery HotSpots, featuring over 200,000 non-traditional delivery locations including parks, beaches, local landmarks and other unique gathering spots.
The Company’s Piece of the Pie Rewards loyalty program, launched in 2015, is meant to reward customers with a program that is simple to understand and easy to use. Upon signing up for the program, customers become rewards members and can earn points for online orders. When rewards members reach a certain amount of points, they can redeem their points for free pizza. Rewards members may also receive exclusive members-only discounts and bonus offers. We may also occasionally provide additional opportunities for participating customers to benefit under the Piece of the Pie Rewards program.
All of this improved functionality has been developed to work seamlessly with our Domino’s PULSE™ point-of-sale system. Our Domino’s PULSE system is designed to drive operating efficiencies for our franchisees and our corporate management and assist franchisees in independently managing their business. We have installed Domino’s PULSE in every Company-owned store in the U.S., in more than 99% of our U.S. franchised stores and in approximately 72% of our international stores.
We believe utilizing Domino’s PULSE with our integrated technology solutions throughout our system provides us with competitive advantages over other concepts. We intend to continue to enhance and grow our online ordering, digital marketing and technological capabilities.
Table of Contents
Product Innovation
In late 2009, we reintroduced our core hand-tossed pizza in the U.S. with a new recipe, which we believe has contributed to continued growth in customer reorder rate, consumer traffic and increased sales. This recipe is now in use in other markets around the world. Our nearly 60 years of innovation have resulted in numerous new product developments, including our more recent innovations of Handmade Pan Pizza, Specialty Chicken, Parmesan Bread Bites, Stuffed Cheesy Bread, Marbled Cookie Brownie and Bread Twists, among others. Product innovation is also present in our global markets, where our master franchisees have the ability to recommend products to suit their local market tastes. Products include the Mayo Jaga in Japan (bacon, potatoes and sweet mayonnaise) and the Saumoneta in France (light cream, potatoes, onions, smoked salmon and dill).
Internal Dough Manufacturing and Supply Chain System
In addition to generating significant revenues and earnings in the U.S. and Canada, we believe our vertically integrated dough manufacturing and supply chain system enhances the quality and consistency of our products, enhances our relationships with franchisees and leverages economies of scale to offer lower costs to our stores. It also allows store managers to better focus on store operations and customer service by relieving them of the responsibility of mixing dough in the stores and sourcing other ingredients. Many of our international master franchisees also profit from running supply chain businesses.
Our Ideals
We believe in: opportunity, hard work, inspired solutions, winning together, embracing community and uncommon honesty.
Opportunity abounds at Domino’s. You can start in an entry-level position and become a store owner – in fact, substantially all of our independent U.S. franchise owners started their careers with us as delivery drivers or in other in-store positions. Thousands of other team members – supervisors, trainers, quality auditors, international business consultants, marketers and executives – also began their careers in the stores. Internal growth and providing opportunities for anyone willing to work hard are the foundation of our core beliefs.
The ideals of inspired solutions, uncommon honesty and winning together were driving forces behind the relaunch of our brand. We were inspired by our harshest critics when it came to the perceived taste of our pizza. Our solution was not simply more advertising; the solution was to create a new recipe and a broader menu of great-tasting products. Our marketing campaign was shockingly honest in its approach: telling consumers (and showing them via television ads) that we heard their negative feedback and were listening. And, without the buy-in from our franchise owners, we couldn’t have done it. We believe that we can’t focus solely on the Company’s success; we must focus on making our stores and our franchisees successful. That’s winning together.
Community Involvement
We believe in supporting the communities we serve through donating our time, money and pizza. You can find more information about our community giving at biz.dominos.com. Here are two organizations worthy of note:
Our national philanthropic partner is St. Jude Children’s Research Hospital®. St. Jude is internationally-recognized for its pioneering work in finding cures and saving children with cancer and other catastrophic diseases. Through a variety of internal and consumer-based activities, including a national fundraising campaign called St. Jude Thanks and Giving_®, the Domino’s system has contributed $57.5 million to St. Jude since our partnership began in 2004, including raising $10.5 million in 2018. In addition to raising funds, we have supported St. Jude through in-kind donations, including hosting hospital-wide pizza parties for patients and their families. Our system also helps St. Jude build awareness through the inclusion of the St. Jude logo on millions of our pizza boxes and through a link on our consumer website, as well as a St. Jude-themed Pizza Tracker during Thanks and Giving®__._
We also support the Domino’s Pizza Partners Foundation (“the Partners Foundation”). Founded in 1986, the mission of the Partners Foundation is “Team Members Helping Team Members.” Primarily funded by team member and franchise contributions, the foundation is a separate, not-for-profit organization that has disbursed more than $6.7 million over the past five years. The Partners Foundation is committed to meeting the needs of Domino’s team members facing crisis situations, such as fire, illness, natural disasters or other personal tragedies.
Table of Contents
Additional Disclosures
Employees
As of December 30, 2018, we had approximately 14,500 employees in our Company-owned stores, supply chain centers, World Resource Center and regional offices. None of our employees is covered by a collective bargaining agreement. As franchisees are independent business owners, they and their employees are not included in our employee count. We consider our relationship with our employees and franchisees to be good. We estimate the total number of people who work in the Domino’s system, including our employees, franchisees and the employees of franchisees, was more than 320,000 as of December 30, 2018.
Working Capital
Information about the Company’s working capital is included in Management’s Discussion and Analysis of Financial Condition and Results of Operations in Part II, Item 7., pages 35 through 39.
Government Regulation
We, along with our franchisees, are subject to various federal, state and local laws affecting the operation of our business. Each store is subject to licensing and regulation by a number of governmental authorities, which include zoning, health, safety, sanitation, building and fire agencies in the jurisdiction in which the store is located. In connection with maintaining our stores, we may be required to expend funds to meet certain federal, state and local regulations, including regulations requiring that remodeled or altered stores be accessible to persons with disabilities. Difficulties in obtaining, or the failure to obtain, required licenses or approvals could delay or prevent the opening of a new store in a particular area or cause an existing store to cease operations. Our supply chain facilities are also licensed and subject to similar regulations by federal, state and local health and fire codes.
We are also subject to the Fair Labor Standards Act and various other federal and state laws governing such matters as minimum wage requirements, overtime and other working conditions and citizenship requirements. A significant number of both our and our franchisees’ food service personnel are paid at rates related to the applicable minimum wage, and past increases in the minimum wage have increased labor costs, as would future increases.
We are subject to the rules and regulations of the Federal Trade Commission and various state laws regulating the offer and sale of franchises. The Federal Trade Commission and various state laws require that we furnish a franchise disclosure document containing certain information to prospective franchisees, and a number of states require registration of the franchise disclosure document with state authorities. We are operating under exemptions from registration in several states based on the net worth of our subsidiary, Domino’s Pizza Franchising LLC, and experience. We believe our franchise disclosure document, together with any applicable state versions or supplements, and franchising procedures comply in all material respects with both the Federal Trade Commission guidelines and all applicable state laws regulating franchising in those states in which we have offered franchises.
Internationally, our franchise stores are subject to national and local laws and regulations that are often similar to those affecting our U.S. stores, including laws and regulations concerning franchises, labor, health, sanitation and safety. Our international stores are also often subject to tariffs and regulations on imported commodities and equipment, and laws regulating foreign investment. We believe our international disclosure statements, franchise offering documents and franchising procedures comply in all material respects with the laws of the foreign countries in which we have offered franchises.
Privacy and Data Protection
We are subject to a number of privacy and data protection laws and regulations globally. The legislative and regulatory landscape for privacy and data protection continues to evolve, and there has been an increase in attention given to privacy and data protection issues with the potential to directly affect our business. This includes recently-enacted laws and regulations in the U.S. and internationally requiring notification to individuals and government authorities of security breaches involving certain categories of personal information. We have a privacy policy posted on our website at www.dominos.com. The security of our financial data, customer information and other personal information is a priority for us.
Trademarks
We have many registered trademarks and believe that the Domino’s mark and Domino’s Pizza names and logos, in particular, have significant value and are important to our business. Our policy is to pursue registration of our trademarks and to vigorously oppose the infringement of any of our trademarks. We license the use of our registered marks to franchisees through franchise agreements.
Table of Contents
Environmental Matters
We are not aware of any federal, state or local environmental laws or regulations that we would expect to materially affect our earnings or competitive position or result in material capital expenditures. However, we cannot predict the effect of possible future environmental legislation or regulations. During 2018, there were no material environmental compliance-related capital expenditures, and no such material expenditures are anticipated in 2019.
Seasonal Operations
The Company’s business is not typically seasonal.
Backlog Orders
The Company has no backlog orders as of December 30, 2018.
Government Contracts
No material portion of the Company’s business is subject to renegotiation of profits or termination of contracts or subcontracts at the election of the U.S. government.
Available Information
The Company makes available, free of charge, through its internet website biz.dominos.com, its annual report on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, proxy statements and amendments to those reports filed or furnished pursuant to Section 13(a), 15(d), or 16 of the Securities Exchange Act of 1934, as amended, as soon as reasonably practicable after electronically filing such material with the Securities and Exchange Commission. Materials filed with the Securities and Exchange Commission are available at www.sec.gov. Retail orders from Domino’s stores can be made through its internet website dominos.com. The reference to these website addresses does not constitute incorporation by reference of the information contained on the websites and information appearing on those websites, including biz.dominos.com and dominos.com, should not be considered a part of this document.
Table of Contents
Item 1A. Risk Factors.
The quick service restaurant pizza category is highly competitive and such competition could adversely affect our operating results.
In the U.S., we compete against regional and local companies as well as national chains Pizza Hut®, Papa John’s® and Little Caesars Pizza®. Internationally, we compete primarily with Pizza Hut®, Papa John’s® and country-specific national and local companies. We could experience increased competition from existing or new companies in the pizza category which could create increasing pressures to grow our business in order to maintain our market share. Additionally, we face growing competition from the supermarket industry and meal kit and food delivery providers, with the improvement of prepared food offerings and the trend towards convergence in grocery, deli, retail and restaurant services. If we are unable to maintain our competitive position, we could experience downward pressure on prices, lower demand for our products, reduced margins, the inability to take advantage of new business opportunities and the loss of market share, all of which would have an adverse effect on our operating results and could cause our stock price to decline.
We also compete on a broader scale with quick service and other international, national, regional and local restaurants. Competition from delivery aggregators and other food delivery services has also increased in recent years. The overall food service market and the quick service restaurant sector are intensely competitive with respect to food quality, price, service, image, convenience and concept, and are often affected by changes in:
| • | consumer tastes; |
|---|
| • | international, national, regional or local economic conditions; |
|---|
| • | disposable purchasing power; |
|---|
| • | demographic trends; and |
|---|
| • | currency fluctuations related to international operations. |
|---|
We compete within the food service market and the quick service restaurant sector not only for customers, but also for management and hourly employees, including drivers, suitable real estate sites and qualified franchisees. Our supply chain segment is also subject to competition from outside suppliers. While all U.S. franchisees purchased food, equipment and supplies from us in 2018, U.S. franchisees are not required to purchase food, equipment or supplies from us and they may choose to purchase from outside suppliers. If other suppliers who meet our qualification standards were to offer lower prices or better service to our franchisees for their ingredients and supplies and, as a result, our franchisees chose not to purchase from our U.S. supply chain centers, our financial condition, business and results of operations would be adversely affected.
If we fail to successfully implement our growth strategy, which includes opening new U.S. and international stores, our ability to increase our revenues and operating profits could be adversely affected.
A significant component of our growth strategy includes the opening of new U.S. and international stores. We and our franchisees face many challenges in opening new stores, including, among others:
| • | availability of financing with acceptable terms; |
|---|
| • | selection and availability of suitable new store sites and the ability to renew leases in quality locations; |
|---|
| • | negotiation of acceptable lease or financing terms; |
|---|
| • | securing required U.S. or foreign governmental permits, licenses and approvals; |
|---|
| • | employment and training of qualified personnel; and |
|---|
| • | general economic and business conditions. |
|---|
The opening of additional franchise stores also depends, in part, upon the availability of prospective franchisees who meet our criteria. Our failure to add a significant number of new stores would adversely affect our ability to increase revenues and operating income. Additionally, our growth strategy and the success of new stores depend in large part on the availability of suitable store sites. If we and our franchisees are not able to secure leases in desired locations on favorable terms, or to renew such leases, our business and results of operations may be adversely affected.
We and our franchisees are currently planning to expand our U.S. and international operations in many of the markets where we currently operate and in select new markets. This may require considerable management time as well as start-up expenses for market development before any significant revenues and earnings are generated. Operations in new foreign markets may achieve low margins or may be unprofitable, and expansion in existing markets may be affected by local economic and market conditions. Therefore, as we continue to expand internationally, we or our franchisees may not experience the operating margins we expect, our results of operations may be negatively impacted and our common stock price may decline.
Table of Contents
We may also pursue strategic acquisitions as part of our business. If we are able to identify acquisition candidates, such acquisitions may be financed, to the extent permitted under our debt agreements, with substantial debt or with potentially dilutive issuances of equity securities.
The food service market is affected by consumer preferences and perceptions. Changes in these preferences and perceptions may reduce the demand for our products, which would reduce sales and harm our business.
Food service businesses are affected by changes in consumer tastes, international, national, regional and local economic conditions, and demographic trends. For instance, if prevailing health or dietary preferences cause consumers to avoid pizza and other products we offer in favor of foods that are perceived as healthier, our business and operating results would be harmed. Moreover, because we are primarily dependent on a single product, if consumer demand for pizza should decrease, our business would suffer more than if we had a more diversified menu, as many other food service businesses do. The preferences of customers also may change as a result of advances in technology or alternative delivery methods or channels. If we are not able to respond to these changes, or our competitors respond to these changes more effectively, our business and operating results could be adversely affected.
Our inability or failure to recognize, respond to and effectively manage the accelerated impact of social media could adversely impact our business.
In recent years, there has been a marked increase in the use of social media platforms, including blogs, chat platforms, social media websites, and other forms of internet-based communications that allow individuals access to a broad audience of consumers and other persons. The rising popularity of social media and other consumer-oriented technologies has increased the speed and accessibility of information dissemination. The dissemination of information via social media could harm our business, brand, reputation, marketing partners, financial condition, and results of operations, regardless of the information’s accuracy. This could include negative publicity related to our food products or stores or negative publicity related to actions by our executives, team members or franchisees.
In addition, we frequently use social media to communicate with consumers and the public in general. Failure to use social media effectively could lead to a decline in brand value and revenue. Other risks associated with the use of social media include improper disclosure of proprietary information, negative comments about our brand, exposure of personally identifiable information, fraud, hoaxes or malicious dissemination of false information.
Reports of food-borne illness or food tampering could reduce sales and harm our business.
Reports, whether true or not, of food-borne illnesses (such as E. coli, avian flu, bovine spongiform encephalopathy, hepatitis A, trichinosis or salmonella) and injuries caused by food tampering have in the past severely injured the reputations of participants in the QSR sector and could in the future as well. The potential for acts of terrorism affecting our global food supply also exists and, if such an event occurs, it could have a negative impact on us and could severely hurt sales and profits. In addition, our reputation is an important asset; as a result, anything that damages our reputation could immediately and severely affect our sales and profits. Media reports of illnesses and injuries, whether accurate or not, could force some stores to close or otherwise reduce sales at such stores. Moreover, as described above, social media has dramatically increased the rate at which negative publicity, including as it relates to food-borne illness, can be disseminated before there is any meaningful opportunity to respond to or address an issue. Even reports of food-borne illnesses or food tampering occurring solely at the restaurants of competitors could, by resulting in negative publicity about the restaurant industry, adversely affect us on a local, regional, national or international basis.
We do not have long-term contracts with certain of our suppliers, and as a result they could seek to significantly increase prices or fail to deliver.
We do not have long-term contracts or arrangements with certain of our suppliers. Although in the past we have not experienced significant problems with our suppliers, our suppliers may implement significant price increases or may not meet our requirements in a timely fashion, or at all. The occurrence of any of the foregoing could have a material adverse effect on our results of operations.
Shortages or interruptions in the supply or delivery of fresh food products could adversely affect our operating results.
We and our franchisees are dependent on frequent deliveries of food products that meet our specifications. In addition, we have single suppliers or a limited number of suppliers for certain of our ingredients, including pizza cheese and meat toppings. While we believe there are adequate reserve quantities and potential alternative suppliers, shortages or interruptions in the supply of food products caused by increased demand, capacity constraints, problems in production or distribution, financial or other difficulties of suppliers, inclement weather or other conditions could adversely affect the availability, quality and cost of ingredients, could adversely affect our operating results.
Table of Contents
Increases in food, labor and other costs could adversely affect our profitability and operating results.
An increase in our operating costs could adversely affect our profitability. Factors such as inflation, increased food costs, increased labor and employee health and benefit costs, increased rent costs and increased energy costs may adversely affect our operating costs. Most of the factors affecting costs are beyond our control and, in many cases, we may not be able to pass along these increased costs to our customers or franchisees. Most ingredients used in our pizza, particularly cheese, are subject to significant price fluctuations as a result of seasonality, weather, demand and other factors. Cheese is a significant cost to us, representing approximately 20-25% of the market basket purchased by our Company-owned stores. Additionally, while we strive to engage in a competitive bidding process for our ingredients, because certain of these ingredients, including meat products, may only be available from a limited number of vendors, we may not always be able to do so effectively. Furthermore, if we need to seek new suppliers, we may be subject to pricing or other terms less favorable to us than those reflected in our current supply arrangements. Labor costs are largely a function of the minimum wage for a majority of our store personnel and certain supply chain center personnel and, generally, are also a function of the availability of labor. Several states in which we operate have recently approved minimum wage increases. As minimum wage increases are implemented in these states or if such increases are approved and implemented in other states in which we operate, we expect our labor costs will continue to increase. The advent of legislation aimed at predictive scheduling could impact labor for our stores and our franchisees’ stores. Additionally, while we do not currently have any unionized employees, if a significant portion of our employees were to become unionized, our labor costs could increase and our business could be negatively affected by other union requirements that increase our costs, disrupt our business, reduce our flexibility and impact our employee culture. Labor costs and food costs, including cheese, generally represent approximately 50% to 60% of the sales at a typical Company-owned store.
Any prolonged disruption in the operations of any of our dough manufacturing and supply chain centers could harm our business.
We operate 19 regional dough manufacturing and supply chain centers, one thin crust manufacturing center and one vegetable processing center in the U.S. and five dough manufacturing and supply chain centers in Canada. We plan to continue investing in additional supply chain capacity in the future.
Our U.S. dough manufacturing and supply chain centers service all of our Company-owned and U.S. franchise stores. As a result, any prolonged disruption in the operations of any of these facilities, whether due to technical or labor difficulties, destruction or damage to the facility, real estate issues, limited capacity or other reasons, could adversely affect our business and operating results.
Our success depends in part upon effective advertising, and lower advertising funds may reduce our ability to adequately market the Domino’s Pizza brand.
We have been routinely named a Leading National Advertiser by Advertising Age. Each Domino’s store located in the contiguous U.S. is obligated to pay a percentage of its sales in advertising fees. In fiscal 2018, each store in the contiguous U.S. generally was required to contribute 6% of their sales to DNAF (subject, in certain instances, to lower rates based on certain incentives and waivers), which uses such fees for national advertising in addition to contributions for local market-level advertising. We currently anticipate that this 6% contribution rate will remain in place for the foreseeable future. While additional funds for advertising in the past have been provided by us, our franchisees and other third parties, none of these additional funds are legally required. The lack of continued financial support for advertising activities could significantly curtail our marketing efforts, which may in turn materially and adversely affect our business and our operating results.
We face risks of litigation, investigations, enforcement actions and negative publicity from customers, franchisees, suppliers, employees, regulators and others in the ordinary course of business, which can or could divert our financial and management resources. Litigation, investigations, enforcement actions or publicity may adversely impact our financial condition and results of operations.
Claims of illness or injury relating to food quality or food handling are common in the food service industry, and vehicular accidents and injuries occur in the food delivery business. Claims within our industry of improper supplier actions also occasionally arise that, if made against one of our suppliers, could potentially damage our brand image. In addition, class action lawsuits have been filed, and may continue to be filed, against various quick service restaurants alleging, among other things, that quick service restaurants have failed to disclose the health risks associated with high-fat foods and that quick service restaurant marketing practices have encouraged obesity. State attorney general offices or other regulators may initiate investigations or enforcement actions against us. In addition to decreasing our sales and profitability and diverting our management resources, adverse publicity or a substantial settlement, fine, penalty or judgment against us could negatively impact our financial condition, results of operations and brand reputation, thereby hindering our ability to attract and retain franchisees and grow our business.
Table of Contents
Further, we may be subject to employee, franchisee and other claims in the future based on, among other things, discrimination, harassment, wrongful termination and wage, rest break and meal break issues, and those claims relating to overtime compensation. We have been and continue to be subject to these types of claims. If one or more of these claims were to be successful or if there is a significant increase in the number of these claims or if we receive significant negative publicity, our business, financial condition and operating results could be harmed.
Loss of key employees or our inability to attract and retain new qualified employees could hurt our business and inhibit our ability to operate and grow successfully.
Our success in the highly competitive pizza delivery and carry-out business will continue to depend to a significant extent on our leadership team and other key management personnel. Although we have entered into employment agreements with Richard E. Allison Jr., and Russell J. Weiner, each of these executives may terminate his agreement on ninety days’ notice. Our other executive officers may terminate their employment pursuant to their employment agreements at any time. As a result, we may not be able to retain our executive officers and key personnel or attract additional qualified management. While we do not have long-term employment agreements with our executive officers, for all of our executive officers we have non-compete and non-solicitation agreements that extend for 24 months following the termination of such executive officer’s employment. Our success will also continue to depend on our ability to attract and retain qualified personnel to operate our stores, dough manufacturing and supply chain centers and international operations. The loss of these employees or our inability to recruit and retain qualified personnel could have a material adverse effect on our operating results.
Adverse global economic conditions subject us to additional risk.
Our financial condition and results of operations are impacted by global markets and economic conditions over which neither we nor our franchisees have control. An economic downturn, including deterioration in the economic conditions in the U.S. or international markets where we compete, may result in a reduction in the demand for our products, longer payment cycles, slower adoption of new technologies and increased price competition.
Poor economic conditions may adversely affect the ability of our franchisees to pay royalties or amounts owed and could have a material adverse impact on our ability to pursue our growth strategy, which would reduce cash collections and in turn, may materially and adversely affect our ability to service our debt obligations.
Our international operations subject us to additional risk. Such risks and costs may differ in each country in which we and our franchisees do business and may cause our profitability to decline due to increased costs.
We conduct a significant and growing portion of our business outside the U.S. Our financial condition and results of operations may be adversely affected if global markets in which our franchise stores compete are affected by changes in political, economic or other factors. These factors, over which neither we nor our franchisees have control, may include:
| • | recessionary or expansive trends in international markets; |
|---|
| • | changing labor conditions and difficulties in staffing and managing our foreign operations; |
|---|
| • | increases in the taxes we pay and other changes in applicable tax laws; |
|---|
| • | tariffs and trade barriers; |
|---|
| • | legal and regulatory changes, and the burdens and costs of our compliance with a variety of foreign laws; |
|---|
| • | changes in inflation rates; |
|---|
| • | changes in exchange rates and the imposition of restrictions on currency conversion or the transfer of funds; |
|---|
| • | difficulty in collecting our royalties and longer payment cycles; |
|---|
| • | expropriation of private enterprises; |
|---|
| • | increases in anti-American sentiment and the identification of the Domino’s Pizza brand as an American brand; |
|---|
| • | political and economic instability and uncertainty around the world, including uncertainty arising as a result of the United Kingdom’s referendum in June 2016 in which voters approved an exit from the European Union, commonly referred to as “Brexit”; and |
|---|
| • | other external factors. |
|---|
Table of Contents
Fluctuations in the value of the U.S. dollar in relation to other currencies may lead to lower revenues and earnings.
Exchange rate fluctuations could have an adverse effect on our results of operations. Approximately 6.5% of our total revenues in 2018, 7.4% of our total revenues in 2017 and 7.2% of our total revenues in 2016 were derived from our international franchise segment, a majority of which were denominated in foreign currencies. We also operate dough manufacturing and distribution facilities in Canada, which generate revenues denominated in Canadian dollars. Sales made by franchise stores outside the U.S. are denominated in the currency of the country in which the store is located, and this currency could become less valuable in U.S. dollars as a result of exchange rate fluctuations. Unfavorable currency fluctuations could lead to increased prices to customers outside the U.S. or lower profitability to our franchisees outside the U.S., or could result in lower revenues for us, on a U.S. dollar basis, from such customers and franchisees. A hypothetical 10% adverse change in the foreign currency rates in our international markets would have resulted in a negative impact on international royalty revenues of approximately $20.0 million in 2018.
Our earnings and business growth strategy depends on the success of our franchisees, and we may be harmed by actions taken by our franchisees, or employees of our franchisees, that are outside of our control.
A significant portion of our earnings comes from royalties and fees generated by our franchise stores. Franchisees are independent operators, and their employees are not our employees. We provide tools for franchisees to use in training their employees, but the quality of franchise store operations and our brand and branded products may be diminished by any number of factors beyond our control. Franchisees may not operate stores in a manner consistent with our standards and requirements or they or their employees may take other actions that adversely affect the value of our brand. In such event, our business and reputation may suffer, and as a result our revenues and stock price could decline.
As of December 30, 2018, we had 793 U.S. franchisees operating 5,486 U.S. stores. Seventeen of these franchisees each own and operate more than 50 U.S. stores, including our largest U.S. franchisee who owns and operates 179 stores, and the average franchisee owns and operates seven stores.
Our international master franchisees are generally responsible for the development of significantly more stores than our U.S. franchisees. As a result, our international operations are more closely tied to the success of a smaller number of franchisees than our U.S. operations. Our largest international master franchisee operates 2,383 stores in seven markets, which accounts for approximately 24% of our total international store count. Our U.S. and international franchisees may not operate their franchises successfully. If one or more of our key franchisees were to become insolvent or otherwise were unable or unwilling to pay us our royalties or other amounts owed, our business and results of operations would be adversely affected.
We may not be able to adequately protect our intellectual property, which could harm the value of our brand and branded products and adversely affect our business.
We depend in large part on our brand and branded products and believe that they are very important to our business. We rely on a combination of trademarks, copyrights, trade secrets and similar intellectual property rights to protect our brand and branded products. The success of our business depends on our continued ability to use our existing trademarks in order to increase brand awareness and further develop our branded products in both U.S. and international markets. We have registered certain trademarks and have other trademark applications pending in the U.S. and foreign jurisdictions. Not all of the trademarks that we currently use have been registered in all of the countries in which we do business, and they may never be registered in all of these countries. We may not be able to adequately protect our trademarks and our use of these trademarks may result in liability for trademark infringement, trademark dilution or unfair competition. All of the steps we have taken to protect our intellectual property in the U.S. and in foreign countries may not be adequate. In addition, the laws of some foreign countries do not protect intellectual property rights to the same extent as the laws of the U.S. Further, through acquisitions of third parties, we may acquire brands and related trademarks that are subject to the same risks as the brands and trademarks we currently own.
We may, from time to time, be required to institute or defend litigation to enforce our trademarks or other intellectual property rights, or to protect our trade secrets. Such litigation could result in substantial costs and diversion of resources and could negatively affect our sales, profitability and prospects regardless of whether we are able to successfully enforce our rights.
Table of Contents
The occurrence of cyber incidents, or a deficiency in cybersecurity, could negatively impact our business by causing a disruption to our operations, a compromise or corruption of confidential information, or damage to our employee and business relationships, any of which could subject us to loss and harm our brand.
A cyber incident is considered to be any adverse event that threatens the confidentiality, integrity or availability of information resources. More specifically, a cyber incident is an intentional attack or an unintentional event that can include gaining unauthorized access to systems to disrupt operations, corrupt data or steal confidential information about customers, franchisees, suppliers or employees. A number of retailers and other companies have recently experienced serious cyber incidents and breaches of their information technology systems. As our reliance on technology has increased, so have the risks posed to our systems, both internal and those we have outsourced. The three primary risks that could directly result from the occurrence of a cyber incident include operational interruption, damage to our relationships with customers, franchisees and employees and private data exposure. In addition to maintaining insurance coverage to address cyber incidents, we have also implemented processes, procedures and controls to help mitigate these risks. However, our cyber insurance coverage may not fully cover the costs of a cyber incident and these measures, as well as our increased awareness of the risk of a cyber incident, do not guarantee that our reputation and financial results will not be adversely affected by such an incident.
Because we and our franchisees accept electronic forms of payment from customers, our business requires the collection and retention of customer data, including sensitive financial data and other personally identifiable information in various information systems that we and our franchisees maintain and in those maintained by third parties with whom we and our franchisees contract to provide payment processing. A weakness in such third party’s systems or software products may provide a mechanism for a cyber threat. In recent years, a significant number of companies have experienced security breaches in which customer information was stolen through vendor access channels. While we select our third-party suppliers carefully, cyber attacks and security breaches at a payment processing contractor could compromise confidential information or adversely affect our ability to deliver products and services to our customers. These problems could negatively affect our results of operations, and remediation could result in significant, unplanned capital investments.
We also maintain important internal Company data, such as personally identifiable information about our employees and franchisees and information relating to our operations. In addition, more than half of all global retail sales in 2018 were derived from digital channels, primarily through our online ordering website and mobile applications, where customers enter personally identifiable information that we retain. Our use and retention of personally identifiable information is regulated by foreign, federal and state laws and regulations, as well as by certain third-party agreements. For example, the European Union adopted a new regulation that became effective in May 2018, the European Union General Data Protection Regulation, which requires companies to meet new requirements regarding the handling of personal data. As privacy and information security laws and regulations change, we may incur additional costs to ensure that we remain in compliance with those laws and regulations. If our security and information systems are compromised or if we, our employees or franchisees fail to comply with these laws, regulations or contract terms, or to successfully implement appropriate processes related to applicable requirements, laws and regulations governing cyber incidents could require us to notify customers, employees or other groups, and could result in adverse publicity, loss of sales and profits, increased fees payable to third parties and penalties or remediation and other costs that could adversely affect our reputation, business and results of operations. Any other material disruption or other adverse event affecting one or more of our digital ordering platforms, including, for instance, power loss, technological failures, user error or cyber attacks, could similarly result in adverse publicity, loss of sales and profits and other costs, which could adversely affect our reputation, business and results of operations.
We may also become subject to private lawsuits or other proceedings for purportedly fraudulent transactions arising out of the actual or alleged theft of our consumers’ credit or debit card information or if consumer or employee information is obtained by unauthorized persons or used inappropriately. Any such claim or proceeding, or any adverse publicity resulting from such an event, may have a material adverse effect on our business and the potential of incurring significant remediation costs.
Table of Contents
We are subject to extensive government regulation and requirements issued by other groups and our failure to comply with existing or increased regulations could adversely affect our business and operating results.
We are subject to numerous federal, state, local and foreign laws and regulations, as well as requirements issued by other groups, including those relating to:
| • | the preparation, sale and labeling of food; |
|---|
| • | building and zoning requirements; |
|---|
| • | environmental protection; |
|---|
| • | labor and employment, including minimum wage, overtime, insurance and other labor requirements; |
|---|
| • | working and safety conditions; |
|---|
| • | franchise arrangements; |
|---|
| • | public company compliance, disclosure and governance matters; |
|---|
| • | taxation; |
|---|
| • | antitrust; |
|---|
| • | discrimination; |
|---|
| • | payment card industry standards and requirements; and |
|---|
| • | information privacy and consumer protection. |
|---|
We are subject to a Federal Trade Commission rule and to various state and foreign laws that govern the offer and sale of franchises. These laws regulate various aspects of the franchise relationship, including terminations and the refusal to renew franchises. The failure to comply with these laws and regulations in any jurisdiction or to obtain required government approvals could result in a ban or temporary suspension on future franchise sales, fines or other penalties or require us to make offers of rescission or restitution, any of which could adversely affect our business and operating results.
In 2015, the National Labor Relations Board adopted a new and broader standard for determining when two or more otherwise unrelated employers may be found to be a joint employer of the same employees under the National Labor Relations Act. Although elements of this joint employer liability standard continue to be subject to judicial review, if this standard is generally upheld or adopted by other government agencies such as the Department of Labor, the Equal Employment Opportunity Commission, and the Occupational Safety and Health Administration and/or applied generally to franchise relationships, it could cause us to be liable or held responsible for unfair labor practices and other violations of our franchisees and subject us to other liabilities, and require us to conduct collective bargaining negotiations regarding employees of totally separate, independent employers, most notably our franchisees. In such event, our operating expenses may increase as a result of required modifications to our business practices, increased litigation, governmental investigations or proceedings, administrative enforcement actions, fines and civil liability.
The Patient Protection and Affordable Care Act (as amended, the “Affordable Care Act”) requires employers such as us to provide health insurance for all qualifying employees or pay penalties for not providing coverage. The majority of the increases in these costs began in 2015, and while the incremental costs of this program have not been material to us to date, we cannot predict what effect these costs will have on our results of operations and financial position, or the effects of the Affordable Care Act on some of our larger franchisees. Modifications to, or repeal of, all or certain provisions of the Affordable Care Act are possible, consistent with statements made by certain elected officials.
The Tax Cuts and Jobs Act of 2017 (the “2017 Tax Act”) was signed into law on December 22, 2017, significantly reforming the Internal Revenue Code of 1986, as amended. The 2017 Tax Act, among other things, includes changes to U.S. Federal tax rates, imposes significant additional limitations on the deductibility of interest, allows for the expensing of capital expenditures, puts into effect the migration from a “worldwide” system of taxation to a territorial system and modifies or repeals many business deductions and credits. We continue to examine the impact the 2017 Tax Act may have on our business. The estimated impact of the 2017 Tax Act is based on our management’s current knowledge and assumptions and recognized impacts could be materially different from current estimates based on our actual results and our further analysis of the new law. We revalued our net deferred tax assets and liabilities at the newly enacted corporate tax rate in fiscal 2017 and recorded a significantly lower effective tax rate in 2018. Although some uncertainty remains about the effects of this new legislation on our business, we currently expect lower effective tax rates for the Company in 2018 will continue in future periods.
We may also become subject to legislation or regulation seeking to tax and/or regulate high-fat foods, foods with high sugar and salt content, or foods otherwise deemed to be “unhealthy,” and our capital expenditures could increase due to remediation and compliance measures related to these laws or regulations.
Table of Contents
If we fail to comply with existing or future laws and regulations, we may be subject to governmental or judicial fines, sanctions and other enforcement measures.
Our current insurance coverage may not be adequate, insurance premiums for such coverage may increase and we may not be able to obtain insurance at acceptable rates, or at all.
We have retention programs for workers’ compensation, general liability and owned and non-owned automobile liabilities. We are generally responsible for up to $1.0 million per occurrence under these retention programs for workers’ compensation and general liability. We are generally responsible for between $500,000 and $3.0 million per occurrence under these retention programs for owned and non-owned automobile liabilities. Total insurance limits under these retention programs vary depending upon the period covered and range up to $110.0 million per occurrence for general liability and owned and non-owned automobile liabilities and up to the applicable statutory limits for workers’ compensation. These insurance policies may not be adequate to protect us from liabilities that we incur in our business. In addition, in the future our insurance premiums may increase and we may not be able to obtain similar levels of insurance on reasonable terms, or at all. Any such inadequacy of, or inability to obtain insurance coverage could have a material adverse effect on our business, financial condition and results of operations.
Our annual and quarterly financial results are subject to significant fluctuations depending on various factors, many of which are beyond our control, and if we fail to meet the expectations of securities analysts or investors, our share price may decline significantly.
Our sales and operating results can vary significantly from quarter-to-quarter and year-to-year depending on various factors, many of which are beyond our control. These factors include, among other things:
| • | variations in the timing and volume of our sales and our franchisees’ sales; |
|---|
| • | the timing of expenditures in anticipation of future sales; |
|---|
| • | sales promotions by us and our competitors; |
|---|
| • | changes in competitive and economic conditions generally; |
|---|
| • | changes in the cost or availability of our ingredients or labor; and |
|---|
| • | foreign currency exposure. |
|---|
As a result, our operational performance may decline quickly and significantly in response to changes in order patterns or rapid decreases in demand for our products. We anticipate that fluctuations in operating results will continue in the future.
Our common stock price could be subject to significant fluctuations and/or may decline.
The market price of our common stock could be subject to significant fluctuations. Among the factors that could affect our stock price are:
| • | planned or actual changes to our capital or debt structure; |
|---|
| • | variations in our operating results; |
|---|
| • | changes in revenues or earnings estimates or publication of research reports by analysts; |
|---|
| • | speculation in the press or investment community; |
|---|
| • | strategic actions by us or our competitors, such as sales promotions, acquisitions or restructurings; |
|---|
| • | actions by institutional and other stockholders; |
|---|
| • | changes in our dividend policy or any share repurchase program; |
|---|
| • | changes in the market values of public companies that operate in our business segments; |
|---|
| • | maintenance and growth of the value of our brand; |
|---|
| • | significant litigation; |
|---|
| • | legislation or other regulatory developments affecting us or our industry; |
|---|
| • | general market conditions; and |
|---|
| • | U.S. and international economic factors unrelated to our performance. |
|---|
The stock markets in general have experienced volatility that has sometimes been unrelated to the operating performance of particular companies. These broad market fluctuations may cause the trading price of our common stock to decline.
Table of Contents
Our substantial indebtedness could adversely affect our business and limit our ability to plan for or respond to changes in our business.
We have a substantial amount of indebtedness. As of December 30, 2018, our consolidated total indebtedness was approximately $3.53 billion. We may also incur additional debt, which would not be prohibited under the terms of our current securitized debt agreements. Our substantial indebtedness could have important consequences for our business and our shareholders. For example, it could:
| • | make it more difficult for us to satisfy our obligations with respect to our debt agreements; |
|---|
| • | increase our vulnerability to general adverse economic and industry conditions; |
|---|
| • | require us to dedicate a substantial portion of our cash flow from operations to payments on our indebtedness, thereby reducing the availability of our cash flow for other purposes; and |
|---|
| • | limit our flexibility in planning for, or reacting to, changes in our business and the industry in which we operate, thereby placing us at a competitive disadvantage compared to our peers that may have less debt. |
|---|
Further, a portion of our indebtedness bears interest at fluctuating interest rates based on the London interbank offered rate (“LIBOR”), and there is currently uncertainty around whether LIBOR will continue to exist after 2021. If LIBOR ceases to exist, we may need to renegotiate certain loan documents and we cannot predict what alternative index would be negotiated with our lenders. As a result, our interest expense could increase, in which event we may have difficulties making interest payments and funding our other fixed costs, and our available cash flow for general corporate requirements may be adversely affected.
In addition, the financial and other covenants we agreed to with our lenders may limit our ability to incur additional indebtedness, make investments, pay dividends and engage in other transactions, and the leverage may cause potential lenders to be less willing to loan funds to us in the future. Our failure to comply with these covenants could result in an event of default that, if not cured or waived, could result in the acceleration of repayment of all of our indebtedness.
Downgrades in our credit ratings could impact our ability to access capital and materially adversely affect our business, financial condition and results of operations.
Our debt is rated by credit rating agencies. These agencies may downgrade their credit ratings for us based on the performance of our business, our capital strategies or their overall view of our industry. There can be no assurance that any rating assigned to our currently outstanding indebtedness will remain in effect for any given period of time or that any such ratings will not be lowered, suspended or withdrawn entirely by a rating agency if, in that agency’s judgment, circumstances so warrant. A downgrade of our credit ratings could, among other things, increase our cost of borrowing, limit our ability to access capital, result in more restrictive covenants in agreements governing the terms of any future indebtedness that we may incur, including restrictions on our ability to pay dividends or repurchase shares, or require us to provide collateral for future borrowings, and thereby adversely impact our business, financial condition and results of operations.
We may be unable to generate sufficient cash flow to satisfy our significant debt service obligations, which would adversely affect our financial condition and results of operations.
Our ability to make principal and interest payments on and to refinance our indebtedness will depend on our ability to generate cash in the future. This, to a certain extent, is subject to general economic, financial, competitive, legislative, regulatory and other factors that are beyond our control. If our business does not generate sufficient cash flow from operations, in the amounts projected or at all, or if future borrowings are not available to us under our variable funding notes in amounts sufficient to fund our other liquidity needs, our financial condition and results of operations may be adversely affected. If we cannot generate sufficient cash flow from operations to make scheduled principal amortization and interest payments on our debt obligations in the future, we may need to refinance all or a portion of our indebtedness on or before maturity, sell assets, delay capital expenditures or seek additional equity. If we are unable to refinance any of our indebtedness on commercially reasonable terms or at all or to effect any other action relating to our indebtedness on satisfactory terms or at all, our business may be harmed.
Table of Contents
The terms of our securitized debt financing of certain of our wholly-owned subsidiaries have restrictive terms and our failure to comply with any of these terms could put us in default, which would have an adverse effect on our business and prospects.
Unless and until we repay all outstanding borrowings under our securitized debt, we will remain subject to the restrictive terms of these borrowings. The securitized debt, under which certain of our wholly-owned subsidiaries issued and guaranteed fixed rate notes and variable funding senior revolving notes, contain a number of covenants, with the most significant financial covenant being a debt service coverage calculation. These covenants limit the ability of certain of our subsidiaries to, among other things:
| • | sell assets; |
|---|
| • | alter the business we conduct; |
|---|
| • | engage in mergers, acquisitions and other business combinations; |
|---|
| • | declare dividends or redeem or repurchase capital stock; |
|---|
| • | incur, assume or permit to exist additional indebtedness or guarantees; |
|---|
| • | make loans and investments; |
|---|
| • | incur liens; and |
|---|
| • | enter into transactions with affiliates. |
|---|
The securitized debt also requires us to maintain specified financial ratios at the end of each fiscal quarter. These restrictions could affect our ability to pay dividends or repurchase shares of our common stock. Our ability to meet these financial ratios can be affected by events beyond our control, and we may not satisfy such a test. A breach of this covenant could result in a rapid amortization event or default under the securitized debt. If amounts owed under the securitized debt are accelerated because of a default under the securitized debt and we are unable to pay such amounts, the investors may have the right to assume control of substantially all of the securitized assets.
During the term following issuance, the outstanding senior notes will accrue interest in accordance with the terms of the debt agreements. Additionally, our senior notes have original scheduled principal payments of $35.3 million in each of 2019 through 2021, $888.0 million in 2022, $26.3 million in each of 2023 and 2024, $1.14 billion in 2025, $14.0 million in 2026 and $1.27 billion in 2027. In accordance with our debt agreements, the payment of principal on the outstanding senior notes shall be suspended if the leverage ratios for the Company are less than or equal to 5.0x total debt, as defined, to adjusted EBITDA, as defined, and no catch-up provisions are applicable. As of December 30, 2018, we also had $65.0 million outstanding under our variable funding notes with a legal maturity date in July 2022, subject to two additional one-year extensions at the option of the Company, subject to certain conditions.
If we are unable to refinance or repay amounts under the securitized debt prior to the expiration of the term, our cash flow would be directed to the repayment of the securitized debt and, other than a weekly management fee sufficient to cover minimal selling, general and administrative expenses, would not be available for operating our business.
No assurance can be given that any refinancing or additional financing will be possible when needed or that we will be able to negotiate acceptable terms. In addition, our access to capital is affected by prevailing conditions in the financial and capital markets and other factors beyond our control. There can be no assurance that market conditions will be favorable at the times that we require new or additional financing.
The indenture governing the securitized debt will restrict the cash flow from the entities subject to the securitization to any of our other entities and upon the occurrence of certain events, cash flow would be further restricted.
In the event that a rapid amortization event occurs under the indenture (including, without limitation, upon an event of default under the indenture or the failure to repay the securitized debt at the end of its term), the funds available to us would be reduced or eliminated, which would in turn reduce our ability to operate or grow our business.
Table of Contents
Item 1B. Unresolved Staff Comments.
None.
Item 2. Properties.
We lease approximately 270,000 square feet for our World Resource Center located in Ann Arbor, Michigan under an operating lease with Domino’s Farms Office Park, L.L.C., an unrelated company. Under an amendment to this lease, Domino’s Farms Office Park, L.L.C. is currently constructing a new 33,000 square foot building that will be leased to the Company upon completion, which is expected to occur in 2019. The lease, as amended, expires in 2029 and has two five-year renewal options.
We own five supply chain center buildings. We also own two store buildings that we lease to U.S. franchisees. All other U.S. Company-owned stores are leased by us, typically under five-year leases with one or two five-year renewal options. All other U.S. and international supply chain centers are leased by us, typically under leases ranging between five and 20 years with one or two five-year renewal options. All other franchise stores are leased or owned directly by the respective franchisees. We believe that our existing headquarters and other leased and owned facilities are adequate to meet our current requirements.
Item 3. Legal Proceedings.
We are a party to lawsuits, revenue agent reviews by taxing authorities and administrative proceedings in the ordinary course of business which include, without limitation, workers’ compensation, general liability, automobile and franchisee claims. We are also subject to suits related to employment practices.
Litigation is subject to many uncertainties, and the outcome of individual litigated matters is not predictable with assurance. These matters referenced above could be decided unfavorably to us and could require us to pay damages or make other expenditures in amounts or a range of amounts that cannot be estimated with accuracy. In management’s opinion, these matters, individually and in the aggregate, should not have a significant adverse effect on the financial condition of the Company, and the established accruals adequately provide for the estimated resolution of such claims.
On February 14, 2011, Domino’s Pizza LLC was named as a defendant in a lawsuit along with Fischler Enterprises of C.F., Inc., a franchisee, and Jeffrey S. Kidd, the franchisee’s delivery driver, filed by Yvonne Wiederhold, the plaintiff, as Personal Representative of the Estate of Richard E. Wiederhold, deceased. The case involved a traffic accident in which the franchisee’s delivery driver is alleged to have caused an accident involving a vehicle driven by Richard Wiederhold. Mr. Wiederhold sustained spinal injuries resulting in quadriplegia and passed away several months after the accident. The jury returned a $10.1 million judgment for the plaintiff where the Company and Mr. Kidd were found to be 90% liable (after certain offsets and other deductions the final verdict was $8.9 million). In the second quarter of 2016, the trial court ruled on all post-judgment motions and entered the judgment. The Company denies liability and in the third quarter of 2016 filed an appeal of the verdict on a variety of grounds. On May 11, 2018, the court of appeals reversed and remanded the case to the trial court for a new trial based on the plaintiff’s improper closing argument. The Company continues to deny liability in this matter.
While we may occasionally be party to large claims, including class action suits, we do not believe that any existing matters, individually or in the aggregate, will materially affect our financial position, results of operations or cash flows.
Item 4. Mine Safety Disclosures.
Not applicable.
Item 4A. Executive Officers of the Registrant.
The listing of executive officers of the Company is set forth under Part III Item 10. Directors, Executive Officers and Corporate Governance on pages 76 through 78, which is incorporated herein by reference.
Table of Contents
Part II
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
As of February 14, 2019, Domino’s Pizza, Inc. had 170,000,000 authorized shares of common stock, par value $0.01 per share, of which 41,040,704 were issued and outstanding. Domino’s Pizza, Inc.’s common stock is traded on the New York Stock Exchange (“NYSE”) under the ticker symbol “DPZ.”
Our Board of Directors declared a quarterly dividend of $0.65 per common share on February 20, 2019 payable on March 29, 2019 to shareholders of record at the close of business on March 15, 2019.
We currently anticipate continuing the payment of quarterly cash dividends. The actual amount of such dividends, if any, will depend upon future earnings, results of operations, capital requirements, our financial condition and certain other factors. There can be no assurance as to the amount of free cash flow that we will generate in future years and, accordingly, dividends will be considered after reviewing returns to shareholders, profitability expectations and financing needs and will be declared at the discretion of our Board of Directors.
As of February 14, 2019, there were 1,565 registered holders of record of Domino’s Pizza, Inc.’s common stock.
As of December 30, 2018, we had a Board of Directors-approved share repurchase program for up to $750.0 million of our common stock, of which $158.8 million remained available for future purchases of our common stock. Any future purchases of our common stock would be funded by current cash amounts, available borrowings or future excess cash flow. The following table summarizes our repurchase activity during the fourth quarter ended December 30, 2018:
| Period | Total Number of Shares Purchased (1) | Average Price Paid per Share | Total Number of Shares Purchased as Part of Publicly Announced Program (2) | Maximum Approximate Dollar Value of Shares that May Yet Be Purchased Under the Program (in thousands) | ||||||||||||
| Period #10 (September 10, 2018 to October 7, 2018) | 5,574 | $ | 276.41 | 4,424 | $ | 319,595 | ||||||||||
| Period #11 (October 8, 2018 to November 4, 2018) | 331,613 | 264.29 | 330,291 | 232,305 | ||||||||||||
| Period #12 (November 5, 2018 to December 2, 2018) | 76,562 | 254.79 | 75,391 | 213,119 | ||||||||||||
| Period #13 (December 3, 2018 to December 30, 2018) | 226,270 | 240.11 | 226,270 | 158,788 | ||||||||||||
| Total | 640,019 | $ | 254.71 | 636,376 | $ | 158,788 | ||||||||||
| (1) | 3,643 shares were purchased as part of the Company’s employee stock purchase discount plan. During the fourth quarter, the shares were purchased at an average price of $274.26. |
|---|
| (2) | From December 31, 2018 through February 14, 2019, the Company repurchased and retired an additional 33,549 shares of common stock for a total of approximately $8.1 million, or an average price of $242.74 per share. Authorization for the repurchase program may be modified, suspended, or discontinued at any time. The repurchase of shares in any particular period and the actual amount of such purchases remain at the discretion of the Board of Directors, and no assurance can be given that shares will be repurchased in the future. |
|---|
Table of Contents
The following comparative stock performance line graph compares the cumulative shareholder return on the common stock of Domino’s Pizza, Inc. (NYSE: DPZ) for the five-year period between December 31, 2013 and December 31, 2018, with cumulative total return on (i) the Total Return Index for the New York Stock Exchange (the “NYSE Composite Index”), (ii) the Standard & Poor’s 500 Index (the “S&P 500”) and (iii) the peer group, the Standard & Poor’s 400 Restaurant Index (the “S&P 400 Restaurant Index”). Management believes that the companies included in the S&P 400 Restaurant Index appropriately reflect the scope of the Company’s operations and match the competitive market in which the Company operates. The cumulative total return computations set forth in the performance graph assume the investment of $100 in the Company’s common stock, the NYSE Composite Index, the S&P 500 Index and the S&P 400 Restaurant Index on December 31, 2013.
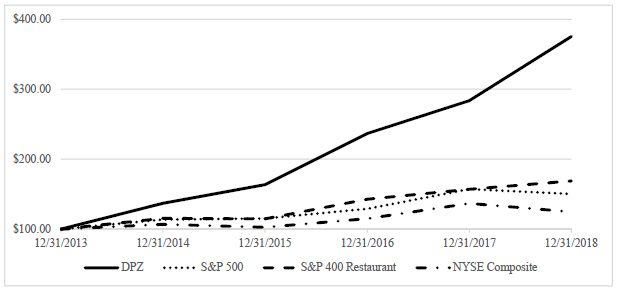
Table of Contents
Item 6. Selected Financial Data.
The following selected financial data set forth should be read in conjunction with, and is qualified by reference to, Management’s Discussion and Analysis of Financial Condition and Results of Operations and the consolidated financial statements and related notes included in this Form 10-K. The selected financial data, with the exception of store counts and same store sales growth, has been derived from the audited consolidated financial statements of Domino’s Pizza, Inc. and subsidiaries. This historical data is not necessarily indicative of results to be expected for any future period.
| Fiscal year ended (8) | ||||||||||||||||||||
| (dollars in millions, except per share data) | December 30, 2018 (4) (5) | December 31, 2017 (6) | January 1, 2017 | January 3, 2016 (7) | December 28, 2014 | |||||||||||||||
| Income statement data: | ||||||||||||||||||||
| Revenues: | ||||||||||||||||||||
| U.S. Company-owned stores | $ | 514.8 | $ | 490.8 | $ | 439.0 | $ | 396.9 | $ | 348.5 | ||||||||||
| U.S. franchise royalties and fees | 391.5 | 351.4 | 312.3 | 272.8 | 230.2 | |||||||||||||||
| U.S. franchise advertising (1) | 358.5 | — | — | — | — | |||||||||||||||
| U.S. stores | 1,264.8 | 842.2 | 751.3 | 669.7 | 578.7 | |||||||||||||||
| Supply chain | 1,943.3 | 1,739.0 | 1,544.3 | 1,383.2 | 1,262.5 | |||||||||||||||
| International franchise royalties and fees | 224.7 | 206.7 | 177.0 | 163.6 | 152.6 | |||||||||||||||
| Total revenues | 3,432.9 | 2,788.0 | 2,472.6 | 2,216.5 | 1,993.8 | |||||||||||||||
| Cost of sales | 2,130.2 | 1,922.0 | 1,704.9 | 1,533.4 | 1,399.1 | |||||||||||||||
| Operating margin | 1,302.7 | 866.0 | 767.7 | 683.1 | 594.8 | |||||||||||||||
| General and administrative expense | 372.5 | 344.8 | 313.6 | 277.7 | 249.4 | |||||||||||||||
| U.S. franchise advertising (1) | 358.5 | — | — | — | — | |||||||||||||||
| Income from operations | 571.7 | 521.2 | 454.0 | 405.4 | 345.4 | |||||||||||||||
| Interest income | 3.3 | 1.5 | 0.7 | 0.3 | 0.1 | |||||||||||||||
| Interest expense | (146.3 | ) | (122.5 | ) | (110.1 | ) | (99.5 | ) | (86.9 | ) | ||||||||||
| Income before provision for income taxes | 428.7 | 400.2 | 344.7 | 306.2 | 258.6 | |||||||||||||||
| Provision for income taxes | 66.7 | 122.2 | 130.0 | 113.4 | 96.0 | |||||||||||||||
| Net income | $ | 362.0 | $ | 277.9 | $ | 214.7 | $ | 192.8 | $ | 162.6 | ||||||||||
| Earnings per share: | ||||||||||||||||||||
| Common stock – basic | $ | 8.65 | $ | 6.05 | $ | 4.41 | $ | 3.58 | $ | 2.96 | ||||||||||
| Common stock – diluted | 8.35 | 5.83 | 4.30 | 3.47 | 2.86 | |||||||||||||||
| Dividends declared per share | $ | 2.20 | $ | 1.84 | $ | 1.52 | $ | 1.24 | $ | 1.00 | ||||||||||
| Balance sheet data (at end of period): | ||||||||||||||||||||
| Cash and cash equivalents | $ | 25.4 | $ | 35.8 | $ | 42.8 | $ | 133.4 | $ | 30.9 | ||||||||||
| Restricted cash and cash equivalents | 167.0 | 191.8 | 126.5 | 180.9 | 121.0 | |||||||||||||||
| Cash and cash equivalents included in advertising fund assets, restricted | 45.0 | 27.3 | 25.1 | 19.9 | 25.1 | |||||||||||||||
| Working capital (2) | 14.6 | (10.3 | ) | (34.3 | ) | 45.7 | 41.8 | |||||||||||||
| Total assets | 907.4 | 836.8 | 716.3 | 799.8 | 596.3 | |||||||||||||||
| Total debt net of debt issuance cost | 3,531.6 | 3,153.8 | 2,187.9 | 2,240.8 | 1,500.6 | |||||||||||||||
| Total stockholders’ deficit | (3,039.9 | ) | (2,735.4 | ) | (1,883.1 | ) | (1,800.3 | ) | (1,219.5 | ) |
Table of Contents
| Fiscal year ended (8) | ||||||||||||||||||||
| (dollars in millions) | December 30, 2018 (4) (5) | December 31, 2017 (6) | January 1, 2017 | January 3, 2016 (7) | December 28, 2014 | |||||||||||||||
| Other financial data: | ||||||||||||||||||||
| Depreciation and amortization | $ | 53.7 | $ | 44.4 | $ | 38.1 | $ | 32.4 | $ | 35.8 | ||||||||||
| Capital expenditures | 119.7 | 90.3 | 61.5 | 62.4 | 71.8 | |||||||||||||||
| Same store sales growth (3): | ||||||||||||||||||||
| U.S. Company-owned stores | 4.8 | % | 8.7 | % | 10.4 | % | 12.2 | % | 6.2 | % | ||||||||||
| U.S. franchise stores | 6.8 | % | 7.6 | % | 10.5 | % | 11.9 | % | 7.7 | % | ||||||||||
| U.S. stores | 6.6 | % | 7.7 | % | 10.5 | % | 12.0 | % | 7.5 | % | ||||||||||
| International stores | 3.5 | % | 3.4 | % | 6.3 | % | 7.8 | % | 6.9 | % | ||||||||||
| Store counts (at end of period): | ||||||||||||||||||||
| U.S. Company-owned stores | 390 | 392 | 392 | 384 | 377 | |||||||||||||||
| U.S. franchise stores | 5,486 | 5,195 | 4,979 | 4,816 | 4,690 | |||||||||||||||
| U.S. stores | 5,876 | 5,587 | 5,371 | 5,200 | 5,067 | |||||||||||||||
| International stores | 10,038 | 9,269 | 8,440 | 7,330 | 6,562 | |||||||||||||||
| Total stores | 15,914 | 14,856 | 13,811 | 12,530 | 11,629 | |||||||||||||||
| (1) | The adoption of ASC 606 in 2018 resulted in the recognition of $358.5 million in revenue in 2018 related to U.S. franchise contributions to DNAF. In prior years, under accounting standards in effect at that time, we had presented these contributions net with the related disbursements in our consolidated statement of income. Refer to Note 1 to the consolidated financial statements for additional information related to the adoption of this new accounting standard. |
|---|
| (2) | The working capital amounts exclude restricted cash and cash equivalents, advertising fund assets, restricted, and advertising fund liabilities. |
|---|
| (3) | Same store sales growth is calculated including only sales from stores that also had sales in the comparable period of the prior year. International same store sales growth is calculated similarly to U.S. same store sales growth. Changes in international same store sales are reported on a constant dollar basis which reflects changes in international local currency sales. The 53rd week in fiscal 2015 had no impact on reported same store sales growth amounts. |
|---|
| (4) | In 2018, the Company began managing its franchised stores in Alaska and Hawaii as part of its U.S. Stores segment. Prior to 2018, store counts and retail sales from these franchised stores were included in the Company’s international stores in the table above. Consolidated results of the Company have not been impacted by this change and prior year amounts have not been reclassified to conform to the current year presentation due to immateriality. |
|---|
| (5) | In connection with our 2018 Recapitalization, the Company issued $825.0 million of fixed rate notes. A portion of the proceeds from the 2018 Recapitalization was used to repay the remaining $490.1 million in outstanding principal and interest under the Company’s 2015 five-year fixed rate notes, pre-fund a portion of the principal and interest payable on the 2018 Notes, pay transaction fees and expenses and repurchase and retire shares of the Company’s common stock. Refer to Note 4 of the consolidated financial statements for additional detail related to the 2018 Recapitalization. |
|---|
| (6) | In connection with our 2017 Recapitalization, the Company issued $1.9 billion of fixed and floating rate notes. A portion of the proceeds from the 2017 Recapitalization was used to repay the remaining $910.2 million in outstanding principal under the Series 2012-1 5.216% Fixed Rate Senior Secured Notes, Class A-2 (the “2012 Fixed Rate Notes”), pre-fund a portion of the principal and interest payable on the 2017 fixed and floating rate notes and pay transaction fees and expenses. The Company also used a portion of the proceeds from the 2017 Recapitalization to enter into a $1.0 billion accelerated share repurchase agreement to repurchase the Company’s common stock. Refer to Note 4 of the consolidated financial statements for additional detail related to the 2017 Recapitalization. |
|---|
| (7) | In connection with our 2015 Recapitalization, the Company issued $1.3 billion of fixed rate notes. A portion of the proceeds from the 2015 Recapitalization was used to make an optional prepayment of approximately $551.3 million in aggregate principal amount of its 2012 Fixed Rate Notes, at par, pay scheduled principal catch-up amounts on its 2012 Fixed Rate Notes, make an interest reserve deposit, pre-fund a portion of the principal and interest payable on the 2015 fixed rate notes and pay transaction fees and expenses. The Company also used a portion of the proceeds from the 2015 Recapitalization to enter into a $600.0 million accelerated share repurchase agreement to repurchase the Company’s common stock. Refer to Note 4 of the consolidated financial statements for additional detail related to the 2015 Recapitalization. |
|---|
| (8) | The 2015 fiscal year includes 53 weeks and the 2018, 2017, 2016, and 2014 fiscal years each include 52 weeks. |
|---|
Table of Contents
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
Overview
Our fiscal year typically includes 52 weeks, comprised of three twelve-week quarters and one sixteen-week quarter. Every five or six years our fiscal year includes an extra (or 53rd) week in the fourth quarter. Fiscal 2018, 2017 and 2016 each consisted of 52 weeks.
Description of the Business
Domino’s is the largest pizza company in the world based on global retail sales, with more than 15,900 locations in over 85 markets around the world. Founded in 1960, our roots are in convenient pizza delivery, while a significant amount of our sales also come from carryout customers. Although we are a highly-recognized global brand, we focus on serving the local neighborhoods in which we live and do business through our large network of franchise owners and Company-owned stores. On average, we and our franchisees sell more than 3 million pizzas each day throughout our global system.
Our business model is straightforward: we handcraft and serve quality food at a competitive price, with easy ordering access and efficient service, enhanced by our technology innovations. Our dough is generally made fresh and distributed to stores around the world by us and our franchisees.
Domino’s generates revenues and earnings by charging royalties to our franchisees. Royalties are ongoing percent-of-sales fees for use of the Domino’s brand marks. The Company also generates revenues and earnings by selling food, equipment and supplies to franchisees primarily in the U.S. and Canada, and by operating a number of our own stores. Franchisees profit by selling pizza and other complementary items to their local customers. In our international markets, we generally grant geographical rights to the Domino’s Pizza brand to master franchisees. These master franchisees are charged with developing their geographical area, and they may profit by sub-franchising and selling food and equipment to those sub-franchisees, as well as by running pizza stores. Everyone in the system can benefit, including the end consumer, who can purchase Domino’s menu items for themselves and their family conveniently and economically.
Our business model can yield strong returns for our franchise owners and Company-owned stores. It can also yield significant cash flow to us, through a consistent franchise royalty payment and supply chain revenue stream, with moderate capital expenditures. We have historically returned cash to shareholders through dividend payments and share repurchases since becoming a publicly-traded company.
Fiscal 2018 Highlights
| • | Global retail sales (which are total retail sales at Company-owned and franchised stores worldwide) increased 10.6% as compared to 2017. |
|---|
| • | Same store sales increased 6.6% in our U.S. stores and increased 3.5% in our international stores. |
|---|
| • | Our revenues increased 23.1%. |
|---|
| • | Our income from operations increased 9.7%. |
|---|
| • | Our net income increased 30.3%. |
|---|
| • | Our diluted earnings per share increased 43.2%. |
|---|
The adoption of Accounting Standards Codification 606, Revenue from Contracts with Customers (“ASC 606”) in 2018 resulted in the recognition of $358.5 million in revenue in 2018 related to U.S. franchise contributions to Domino’s National Advertising Fund Inc. (“DNAF”), our consolidated not-for-profit advertising fund. In 2017, under accounting standards in effect at that time, we had presented these contributions net with the related disbursements in our consolidated statement of income. Refer to Note 1 to the consolidated financial statements for additional information related to the adoption of this new accounting standard.
During 2018, we continued our rapid global expansion with the opening of 1,058 net new stores. Our international franchise segment led the way with 800 net new store openings, including the opening of our 10,000th international store. We also continued our strong U.S. and international same store sales performance with 31 straight quarters of positive U.S. same store sales and 100 straight quarters of positive international same store sales. Our Domino’s Piece of the Pie Rewards loyalty program continues to contribute to our U.S. same store sales performance. Additionally, we remained focused on growing online ordering and improving the digital customer experience through our technology platforms, including the recent launch of Domino’s Delivery HotSpots. Our emphasis on technology innovation helped the Domino’s system generate more than half of global retail sales from digital channels in 2018. Overall, we believe our focus in 2018 on global growth and technology will continue to strengthen our brand in the future.
Table of Contents
Fiscal 2017 Highlights
| • | Global retail sales increased 12.7% as compared to 2016. |
|---|
| • | Same store sales increased 7.7% in our U.S. stores and increased 3.4% in our international stores. |
|---|
| • | Our revenues increased 12.8%. |
|---|
| • | Our income from operations increased 14.8%. |
|---|
| • | Our net income increased 29.5%. |
|---|
| • | Our diluted earnings per share increased 35.6%. |
|---|
During 2017, we continued our rapid global expansion with the opening of 1,045 net new stores. Our international franchise segment led the way with 829 net new store openings. We continued our focus on growing online ordering and the digital customer experience as well as other technological advancements. In 2017, as part of an industry-first collaboration with Ford Motor Company, Domino’s began a meaningful test of delivery using self-driving vehicles. Our emphasis on technology innovation helped the Domino’s system generate more than half of global retail sales from digital channels in 2017.
Critical accounting policies and estimates
The following discussion and analysis of financial condition and results of operations is based on our consolidated financial statements, which have been prepared in accordance with accounting principles generally accepted in the United States. The preparation of these financial statements requires our management to make estimates and judgments that affect the reported amounts of assets, liabilities, revenues and expenses and related disclosures of contingent assets and liabilities. On an ongoing basis, our management evaluates its estimates, including those related to revenue recognition, long-lived and intangible assets, insurance and legal matters, share-based payments and income taxes. We base our estimates on historical experience and on various other assumptions that we believe are reasonable under the circumstances, the results of which form the basis for making judgments about the carrying values of assets and liabilities that are not readily apparent from other sources. Actual results may differ from those estimates. Changes in our accounting policies and estimates could materially impact our results of operations and financial condition for any particular period. We believe that our most critical accounting policies and estimates are:
Revenue recognition. We earn revenues through our network of U.S. Company-owned and franchised stores, dough manufacturing and supply chain centers and international operations. Retail sales from franchise stores are reported to the Company by its franchisees and are not included in Company revenues. Retail sales from Company-owned stores and royalty revenues resulting from the retail sales from franchised stores are recognized as revenues when the items are delivered to or carried out by customers. Retail sales are generally reported and related royalties paid to the Company based on a pe
Showing the first 8K of 87K characters. Open the full section
Item 7A. Quantitative and Qualitative Disclosures About Market Risk.
Market risk
We do not engage in speculative transactions nor do we hold or issue financial instruments for trading purposes. In connection with the 2017 Recapitalization, we issued fixed and floating rate notes and, at December 30, 2018, we are exposed to interest rate risk on borrowings under our 2017 Floating Rate Notes and our 2017 Variable Funding Notes. As of December 30, 2018, we had $65.0 million in outstanding borrowings under our 2017 Variable Funding Notes. Our 2017 Floating Rate Notes and our 2017 Variable Funding Notes bear interest at fluctuating interest rates based on LIBOR. A hypothetical 1.0% adverse change in the LIBOR rate would have resulted in higher interest expense of approximately $3.0 million in 2018.
There is currently uncertainty around whether LIBOR will continue to exist after 2021. If LIBOR ceases to exist, we may need to renegotiate our loan documents and we cannot predict what alternative index would be negotiated with our lenders. As a result, our interest expense could increase, in which event we may have difficulties making interest payments and funding our other fixed costs, and our available cash flow for general corporate requirements may be adversely affected.
Our fixed rate debt exposes the Company to changes in market interest rates reflected in the fair value of the debt and to the risk that the Company may need to refinance maturing debt with new debt at a higher rate.
We are exposed to market risks from changes in commodity prices. During the normal course of business, we purchase cheese and certain other food products that are affected by changes in commodity prices and, as a result, we are subject to volatility in our food costs. We may periodically enter into financial instruments to manage this risk. We do not engage in speculative transactions nor do we hold or issue financial instruments for trading purposes. In instances when we use fixed pricing agreements with our suppliers, these agreements cover our physical commodity needs, are not net-settled and are accounted for as normal purchases.
Foreign currency exchange rate risk
We have exposure to various foreign currency exchange rate fluctuations for revenues generated by our operations outside the U.S., which can adversely impact our net income and cash flows. Approximately 6.5% of our total revenues in 2018, 7.4% of our total revenues in 2017 and 7.2% of our total revenues in 2016 were derived from our international franchise segment, a majority of which were denominated in foreign currencies. We also operate dough manufacturing and distribution facilities in Canada, which generate revenues denominated in Canadian dollars. We do not enter into financial instruments to manage this foreign currency exchange risk. A hypothetical 10% adverse change in the foreign currency rates for our international markets would have resulted in a negative impact on royalty revenues of approximately $20.0 million in 2018.
Table of Contents
Item 8. Financial Statements and Supplementary Data.
Report of Independent Registered Public Accounting Firm
To the Stockholders and Board of Directors
of Domino’s Pizza, Inc.:
Opinions on the Financial Statements and Internal Control over Financial Reporting
We have audited the accompanying consolidated balance sheets of Domino’s Pizza, Inc. and its subsidiaries (the “Company”) as of December 30, 2018 and December 31, 2017, and the related consolidated statements of income, statements of comprehensive income, statements of stockholders’ deficit, and statements of cash flows for each of the three years in the period ended December 30, 2018, including the related notes, the schedules of condensed financial information of the registrant as of December 30, 2018 and December 31, 2017 and for the three years in the period ended December 30, 2018 and valuation and qualifying accounts for each of the three years in the period December 30, 2018 appearing under Item 16 (collectively referred to as the “consolidated financial statements”). We also have audited the Company’s internal control over financial reporting as of December 30, 2018, based on criteria established in Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 30, 2018 and December 31, 2017, and the results of its operations and its cash flows for each of the three years in the period ended December 30, 2018 in conformity with accounting principles generally accepted in the United States of America. Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 30, 2018, based on criteria established in Internal Control – Integrated Framework (2013) issued by the COSO.
Change in Accounting Principles
As discussed in Note 1 to the consolidated financial statements, the Company changed the manner in which it accounts for revenue and the manner in which it accounts for restricted cash and cash equivalents in 2018. As discussed in Note 6 to the consolidated financial statements, the Company changed the manner in which it accounts for share-based compensation in 2017.
Basis for Opinions
The Company’s management is responsible for these consolidated financial statements, for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting, included in Management’s Annual Report on Internal Control over Financial Reporting, appearing under item 9A. Our responsibility is to express opinions on the Company’s [consolidated] financial statements and on the Company’s internal control over financial reporting based on our audits. We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) (PCAOB) and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audits to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement, whether due to error or fraud, and whether effective internal control over financial reporting was maintained in all material respects.
Our audits of the consolidated financial statements included performing procedures to assess the risks of material misstatement of the consolidated financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the consolidated financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the consolidated financial statements. Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audits also included performing such other procedures as we considered necessary in the circumstances. We believe that our audits provide a reasonable basis for our opinions.
Table of Contents
Definition and Limitations of Internal Control over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (i) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (ii) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (iii) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
/s/ PricewaterhouseCoopers LLP
Detroit, Michigan
February 21, 2019
We have served as the Company’s auditor since 2002.
Table of Contents
Domino’s Pizza, Inc. and Subsidiaries
CONSOLIDATED BALANCE SHEETS
(In thousands, except share and per share amounts)
| December 30, 2018 | December 31, 2017 | |||||||
| Assets | ||||||||
| Current assets: | ||||||||
| Cash and cash equivalents | $ | 25,438 | $ | 35,768 | ||||
| Restricted cash and cash equivalents | 166,993 | 191,762 | ||||||
| Accounts receivable, net of reserves of $1,879 in 2018 and $1,424 in 2017 | 190,091 | 173,677 | ||||||
| Inventories | 45,975 | 39,961 | ||||||
| Prepaid expenses and other | 25,710 | 18,389 | ||||||
| Advertising fund assets, restricted | 112,744 | 120,223 | ||||||
| Total current assets | 566,951 | 579,780 | ||||||
| Property, plant and equipment: | ||||||||
| Land and buildings | 41,147 | 29,171 | ||||||
| Leasehold and other improvements | 170,498 | 128,613 | ||||||
| Equipment | 243,654 | 216,599 | ||||||
| Construction in progress | 31,822 | 32,482 | ||||||
| 487,121 | 406,865 | |||||||
| Accumulated depreciation and amortization | (252,182 | ) | (237,279 | ) | ||||
| Property, plant and equipment, net | 234,939 | 169,586 | ||||||
| Othe |
Showing the first 8K of 138K characters. Open the full section
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure.
None.
Item 9A. Controls and Procedures.
(a) Evaluation of Disclosure Controls and Procedures.
The Company carried out an evaluation as of the end of the period covered by this report, under the supervision and with the participation of the Company’s management, including the Company’s Chief Executive Officer and Chief Financial Officer, of the effectiveness of the design and operation of the Company’s disclosure controls and procedures pursuant to Rules 13a-15 and 15d-15 of the Securities Exchange Act of 1934, as amended (the “Exchange Act”). Based upon that evaluation, the Chief Executive Officer and Chief Financial Officer concluded that the Company’s disclosure controls and procedures are effective in ensuring that all information required in the reports it files or submits under the Exchange Act was accumulated and communicated to the Company’s management, including its Chief Executive Officer and Chief Financial Officer, as appropriate to allow timely decisions regarding required disclosure and was recorded, processed, summarized and reported within the time period required by the rules and regulations of the Securities and Exchange Commission.
(b) Changes in Internal Control over Financial Reporting.
There have been no changes in internal control over financial reporting that occurred during the last fiscal quarter that have materially affected, or are reasonably likely to materially affect, the Company’s internal control over financial reporting.
(c) Management’s Annual Report on Internal Control over Financial Reporting.
The management of Domino’s Pizza, Inc. is responsible for establishing and maintaining adequate internal control over financial reporting. Internal control over financial reporting is defined in Rule 13a-15(f) promulgated under the Exchange Act, as a process designed by, or under the supervision of, the Company’s principal executive and principal financial officers and effected by the Company’s board of directors, management and other personnel, to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate. Under the supervision and with the participation of the Company’s management, including its Chief Executive Officer and Chief Financial Officer, the Company conducted an evaluation of the effectiveness of its internal control over financial reporting as of December 30, 2018 based on the framework in Internal Control — Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission. Based on that evaluation, management concluded that its internal control over financial reporting was effective as of December 30, 2018. The effectiveness of the Company’s internal control over financial reporting as of December 30, 2018, has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in their report which appears herein.
Item 9B. Other Information.
Item 10. Directors, Executive Officers and Corporate Governance.
The following table sets forth information about our executive officers and directors.
| Name | Age | Position | ||
| David A. Brandon | 66 | Chairman of the Board of Directors | ||
| Richard E. Allison, Jr. | 52 | Chief Executive Officer | ||
| Jeffrey D. Lawrence | 45 | Executive Vice President, Chief Financial Officer | ||
| Russell J. Weiner | 50 | Chief Operating Officer and President of the Americas | ||
| Thomas B. Curtis | 55 | Executive Vice President, Team USA | ||
| Scott R. Hinshaw | 56 | Executive Vice President, Franchise Operations and Development | ||
| Joseph H. Jordan | 45 | Executive Vice President, International | ||
| Stuart A. Levy | 47 | Executive Vice President, Supply Chain Services | ||
| Timothy P. McIntyre | 56 | Executive Vice President, Communication, Investor Relations and Legislative Affairs | ||
| Kevin S. Morris | 58 | Executive Vice President, General Counsel | ||
| J. Kevin Vasconi | 58 | Executive Vice President, Chief Information Officer | ||
| C. Andrew Ballard | 46 | Director | ||
| Andrew B. Balson | 52 | Director | ||
| Corie S. Barry | 43 | Director | ||
| Diana F. Cantor | 61 | Director | ||
| Richard L. Federico | 64 | Director | ||
| James A. Goldman | 60 | Director | ||
| Patricia E. Lopez | 57 | Director |
David A. Brandon has served as Domino’s Chairman of the Board of Directors since March 1999. Mr. Brandon most recently served as Chairman and Chief Executive Officer of Toys “R” Us, Inc., the world’s largest specialty retailer of toy and baby products, a position he held from July 2015 to December 2018. Previously, he was the Director of Athletics at the University of Michigan from March 2010 to October 2014. Mr. Brandon served as Domino’s Chief Executive Officer from March 1999 to March 2010 and was retained by the Company as a Special Advisor from March 2010 to January 2011. Prior to joining Domino’s, Mr. Brandon was President and Chief Executive Officer of Valassis, Inc., a company in the sales promotion and coupon industries, from 1989 to 1998 and Chairman of the Board of Directors of Valassis, Inc. from 1997 to 1998. In addition to serving on the Board of Directors for Domino’s, Mr. Brandon also serves on the Board of Directors of DTE Energy Co. and Herman Miller Inc. He previously served on the Boards of Directors of Toys “R” Us, Inc., Burger King Corporation, Kaydon Corporation, Northwest Airlines and the TJX Companies, Inc.
Richard E. Allison, Jr. has served as Domino’s Chief Executive Officer since July 2018 and was elected to Domino’s Board of Directors in July 2018 in conjunction with his appointment as Chief Executive Officer. He previously served as President, Domino’s International from October 2014 to July 2018, after joining the Company in March 2011 as Executive Vice President of International. Prior to joining Domino’s, Mr. Allison worked at Bain & Company, Inc. for more than 13 years, serving as a Partner from 2004 to December 2010, and as co-leader of Bain’s restaurant practice.
Jeffrey D. Lawrence has served as Domino’s Executive Vice President and Chief Financial Officer since August 2015. He previously served as Vice President – Finance and Treasurer from January 2014 to August 2015, and as Vice President of International Finance, Strategy & Insights and Administration from 2008 to January 2014. Prior to joining the International team, Mr. Lawrence served as Vice President and Corporate Controller from 2002 to 2008. Mr. Lawrence began his career at Domino’s in 2000. Prior to joining Domino’s, Mr. Lawrence was a Manager of Audit and Business Advisory Services in the Detroit office of Arthur Andersen LLP.
Russell J. Weiner has served as Domino’s Chief Operating Officer and President of the Americas since July 2018. He previously served as President, Domino’s USA from October 2014 to July 2018. Mr. Weiner served as Executive Vice President and Chief Marketing Officer, from September 2008 to October 2014. Prior to joining Domino’s, Mr. Weiner held various marketing positions at PepsiCo, Inc. from 1998 to 2008, most recently serving as Vice President of Marketing, Colas for Pepsi-Cola North America. Mr. Weiner serves on the Board of Directors of The Clorox Company.
Table of Contents
Thomas B. Curtis has served as Domino’s Executive Vice President, Team USA (which represents our Company-owned store division) since July 2018. Prior to his appointment, Mr. Curtis served as Vice President of Franchise Relations and Operations Innovation from March 2017 to July 2018, after serving as Vice President of Operations Support from August 2016 to March 2017 and as West Region Vice President from November 2012 to August 2016. Mr. Curtis joined Domino’s in 2006, after being a Domino’s franchisee since 1987.
Scott R. Hinshaw has served as Domino’s Executive Vice President, Franchise Operations and Development since January 2008. Mr. Hinshaw served as Executive Vice President, Team USA from September 2007 to January 2008. Mr. Hinshaw also served as a Vice President within Team USA from 1994 through September 2007. Mr. Hinshaw joined Domino’s in 1986.
Joseph H. Jordan has served as Domino’s Executive Vice President of International since April 2018. Prior to his appointment, Mr. Jordan had served as Senior Vice President and Chief Marketing Officer since May 2015, after joining Domino’s as Vice President of Innovation in September 2011. Prior to joining Domino’s, Mr. Jordan served as Senior Director of Marketing at Pepsi-Cola North America for six years, held marketing roles at Philips Electronics and Unilever and was a consultant for Accenture.
Stuart A. Levy has served as Domino’s Executive Vice President, Supply Chain Services since January 2019. Prior to joining Domino’s, Mr. Levy had served as Executive Vice President, Chief Transformation Officer for Republic Services, Inc. since 2014. Prior to joining Republic, Mr. Levy had served as a Partner with Bain & Company since 2008.
Timothy P. McIntyre has served as Domino’s Executive Vice President, Communication, Investor Relations and Legislative Affairs since May 2016. Mr. McIntyre served as Vice President of Communication from August 1997 to May 2016. Mr. McIntyre joined Domino’s in 1985.
Kevin S. Morris has served as Domino’s Executive Vice President, General Counsel since January 2017. Prior to joining Domino’s, Mr. Morris served at New York-based Equinox Holdings, Inc. and its various operating subsidiaries and affiliates from December 2012 to January 2017, most recently as Senior Vice President, General Counsel and Corporate Secretary. Mr. Morris operated his own private legal practice from July 2009 to November 2012. Prior to 2009, Mr. Morris served as Vice President and Associate General Counsel at Global Hyatt Corporation (the predecessor in interest to Hyatt Hotels Corporation) from 1999 to 2008. Prior to 1999, Mr. Morris served as a Senior International Attorney and Staff Director at McDonald’s Corporation after beginning his career as an attorney at Rudnick & Wolfe LLP (the predecessor to DLA Piper).
J. Kevin Vasconi has served as Domino’s Executive Vice President and Chief Information Officer since March 2012. Mr. Vasconi served as Chief Information Officer and Vice President of Engineering at Stanley Black & Decker – Stanley Security Solutions from 2011 to March 2012. Prior to his role at Stanley Security Solutions, Mr. Vasconi served in a variety of roles at R.L. Polk & Co. from 2003 to 2011, most recently as Senior Vice President and Chief Information Officer of Polk Global Automotive.
C. Andrew Ballard has served on Domino’s Board of Directors since July 2015 and is a member of the Compensation Committee of the Board of Directors. Mr. Ballard currently serves as the Chief Executive Officer and Co-Founder of Wiser Solutions, Inc., a technology and data company, a position he has held since December 2012. Mr. Ballard is also Founder of Figtree Partners, an investment firm focused on software and technology, and has served as its Managing Partner since November 2012. In addition, he has served as a Senior Advisor at the private equity firm Hellman & Friedman LLC since December 2012, where he previously served as Managing Director from 2006 to 2012 and as a Director from 2004 to 2006. Prior to joining Hellman & Friedman in 2003, Mr. Ballard worked at Bain Capital, LLC in San Francisco and Boston, as well as Bain & Company, Inc. from 1994 to 2002. In addition to serving on Domino’s Board of Directors, Mr. Ballard is currently Chairman of Datacor, Inc. and Vice Chairman of Zignal Labs, and has held previous board roles at Activant Solutions Inc., Catalina Marketing Corporation, DoubleClick Inc., Getty Images, Inc., Internet Brands, Inc. and Vertafore, Inc. Mr. Ballard is the Chair of the Board of Trustees and Chair of the Investment Committee of the San Francisco Foundation. He is also actively involved with Family Connections, a tuition-free preschool for under-served families.
Andrew B. Balson has served on our Board of Directors since March 1999 and serves as the Chairperson of the Compensation Committee of the Board of Directors. Mr. Balson is currently the Managing Partner of Cove Hill Partners, L.P., a firm formed to make private equity investments. Previously, Mr. Balson was the Chief Executive Officer of Match Beyond, an innovative college completion program that helps low-income young adults attain college degrees and prepare for the workforce, a position he held from January 2015 to June 2016. Prior to becoming the Chief Executive Officer of Match Beyond, Mr. Balson was a Managing Director at Bain Capital, LLC, a global investment company, from 2001 to 2013. Mr. Balson became a Principal of Bain Capital in January 1998. Mr. Balson previously served on the Boards of Directors of Bloomin’ Brands, Inc., FleetCor Technologies, Inc., Dunkin’ Brands, Inc., Skylark Co., Ltd., BELLSYSTEM24, Inc., Burger King Corporation and Bright Horizons Family Solutions, Inc., as well as numerous private companies.
Table of Contents
Corie S. Barry has served on our Board of Directors since July 2018 and is a member of the Audit Committee of the Board of Directors. Ms. Barry currently serves as Senior Executive Vice President and Chief Financial and Strategic Transformation Officer of Best Buy Co., Inc., a specialty retailer of consumer electronics, personal computers, entertainment software and appliances, a position she has held since June 2016. Ms. Barry previously served as Best Buy’s Chief Strategic Growth Officer from October 2015 to June 2016, Interim President of Geek Squad Services from March 2015 to May 2016, Senior Vice President of Domestic Finance from May 2013 to October 2015 and in a variety of financial and operational roles, both in the field and at the corporate campus, since joining Best Buy in 1999. Prior to Best Buy, Ms. Barry worked at Deloitte Touche Tohmatsu Limited from 1997 to 1999.
Diana F. Cantor has served on Domino’s Board of Directors since October 2005 and serves as the Chairperson of the Audit Committee of the Board of Directors. Ms. Cantor is currently a Partner at Alternative Investment Management, LLC, a position she has held since January 2010, and she is the Vice Chairman of the Virginia Retirement System, where she also serves on the Audit and Compliance Committee. Ms. Cantor was a Managing Director with New York Private Bank and Trust from January 2008 to the end of 2009. Ms. Cantor served as founding Executive Director of the Virginia College Savings Plan, the state’s 529 college savings program, from 1996 to January 2008. Ms. Cantor served seven years as Vice President of Richmond Resources, Ltd. from 1990 to 1996, and as Vice President of Goldman, Sachs & Co. from 1985 to 1990. Ms. Cantor also serves on the Boards of Directors of Universal Corporation and VICI Properties, Inc., and she previously served on the Boards of Directors of Media General, Inc., Revlon, Inc., The Edelman Financial Group Inc., Vistage International, Inc., Knowledge Universe Education LLC, Edelman Financial Services, LLC and Service King Body and Paint LLC.
Richard L. Federico Mr. Federico has served on Domino’s Board of Directors since February 2011 and is a member of the Compensation Committee and Nominating and Corporate Governance Committee of the Board of Directors. Mr. Federico is currently the Non-Executive Chairman of P.F. Chang’s China Bistro, Inc., based in Scottsdale, AZ, a position he has held since February 2016. Mr. Federico previously served as the Chairman and Chief Executive Officer or Co-Chief Executive Officer of P.F. Chang’s from September 1997 to March 2015 and as Executive Chairman from March 2015 to February 2016. Mr. Federico joined P.F. Chang’s as President in 1996, when he also began his service on its Board of Directors. Mr. Federico started his career in the restaurant industry as a Manager at Steak & Ale, and later at Orville Beans and Bennigan’s restaurants. He went on to develop Grady’s Goodtimes, serving as Co-Founder/Partner and Vice President of Operations until Brinker International, Inc. acquired Grady’s in 1989. Upon joining Brinker International, Mr. Federico served as Senior Vice President and concept head for Macaroni Grill before being promoted to President of the Italian Concept division. As President, he directed operations and development for Macaroni Grill and Spageddies. Mr. Federico currently serves on the Boards of Directors of Prime Steak Concepts and RPT Realty, a publicly-traded REIT, and previously served as Chairman of the Board of Directors of Jamba, Inc. He is a Founding Director of Chances for Children.
James A. Goldman has served on Domino’s Board of Directors since March 2010, serves as Chairperson of the Nominating and Corporate Governance Committee of the Board of Directors and also serves on the Audit Committee of the Board of Directors. Mr. Goldman served as President and Chief Executive Officer and as a member of the Board of Directors of Godiva Chocolatier, Inc. from 2004 to 2014. Mr. Goldman was President of the Food and Beverage Division at Campbell Soup Company from 2001 to 2004. Mr. Goldman served in various executive positions at Nabisco, Inc. from 1992 to 2000. Prior to his work at Nabisco, Mr. Goldman was a senior consulting associate at McKinsey & Company, Inc. Mr. Goldman is currently a Senior Advisor at Eurazeo SE, a private equity firm listed on the Paris Stock Exchange. Mr. Goldman is also currently on the Board of Trustees and the Executive Committee of Save the Children in Fairfield, CT, the Executive Board of the International Tennis Hall of Fame in Newport, RI and the Advisory Board of FEED Projects in New York, NY. Mr. Goldman previously served as a member of the Board of Directors at The Children’s Place Retail and served on its Compensation Committee. Mr. Goldman previously served on the Board of Trustees at the YMCA Camps Becket and Chimney Corners in Becket, MA.
Patricia E. Lopez has served on Domino’s Board of Directors since July 2018 and is a member of the Nominating and Corporate Governance Committee of the Board of Directors. Ms. Lopez currently serves as Chief Executive Officer and as a member of the Board of Directors of High Ridge Brands Co., roles she has held since July 2017. Prior to her current role, Ms. Lopez served as a Senior Vice President at Estée Lauder Companies Inc. from January 2015 to July 2016, a Senior Vice President at Avon Products, Inc. from December 2012 to November 2014 and previously held various positions at The Procter & Gamble Co. over a span of 25 years, most recently serving as a Vice President and General Manager overseeing its Eastern Europe business.
The remaining information required by this item is incorporated by reference from Domino’s Pizza, Inc.’s definitive proxy statement, which will be filed within 120 days of December 30, 2018.
Table of Contents
Item 11. Executive Compensation.
Information regarding executive compensation is incorporated by reference from Domino’s Pizza, Inc.’s definitive proxy statement, which will be filed within 120 days of December 30, 2018. However, no information set forth in the proxy statement regarding the Audit Committee Report shall be deemed incorporated by reference into this Form 10-K.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
Information regarding security ownership of certain beneficial owners and management and related stockholder matters is incorporated by reference from Domino’s Pizza, Inc.’s definitive proxy statement, which will be filed within 120 days of December 30, 2018.
Item 13. Certain Relationships and Related Transactions, and Director Independence.
Information regarding certain relationships and related transactions is incorporated by reference from Domino’s Pizza, Inc.’s definitive proxy statement, which will be filed within 120 days of December 30, 2018.
Item 14. Principal Accountant Fees and Services.
Information regarding principal accountant fees and services is incorporated by reference from Domino’s Pizza, Inc.’s definitive proxy statement, which will be filed within 120 days of December 30, 2018.
Table of Contents
Part IV
Item 15. Exhibits, Financial Statement Schedules.
| (a)1. | Financial Statements: The following financial statements for Domino’s Pizza, Inc. and subsidiaries are included in Item 8, “Financial Statements and Supplementary Data”: |
|---|
Report of Independent Registered Public Accounting Firm
Consolidated Balance Sheets as of December 30, 2018 and December 31, 2017
Consolidated Statements of Income for the Years Ended December 30, 2018, December 31, 2017 and January 1, 2017
Consolidated Statements of Comprehensive Income for the Years Ended December 30, 2018, December 31, 2017 and January 1, 2017
Consolidated Statements of Stockholders’ Deficit for the Years Ended December 30, 2018, December 31, 2017 and January 1, 2017
Consolidated Statements of Cash Flows for the Years Ended December 30, 2018, December 31, 2017 and January 1, 2017
Notes to Consolidated Financial Statements
| 2. | Financial Statement Schedules: The following financial statement schedules are attached to this report. |
|---|
Schedule I – Condensed Financial Information of the Registrant
Schedule II – Valuation and Qualifying Accounts
All other schedules are omitted because they are not applicable, not required, or the information is included in the financial statements or the notes thereto.
| 3. | Exhibits: Certain of the following Exhibits have been previously filed with the Securities and Exchange Commission pursuant to the requirements of the Securities Act of 1933 and the Securities Exchange Act of 1934. Such exhibits are identified by the parenthetical references following the listing of each such exhibit and are incorporated herein by reference. |
|---|
Table of Contents
Table of Contents
Table of Contents
Table of Contents
Table of Contents
| * | A management contract or compensatory plan or arrangement required to be filed as an exhibit to this report pursuant to Item 15(b) of Form 10-K. |
|---|
Item 16. Form 10-K Summary.
Not applicable**.**
Table of Contents
SCHEDULE I – CONDENSED FINANCIAL INFORMATION OF THE REGISTRANT
Domino’s Pizza, Inc.
PARENT COMPANY CONDENSED BALANCE SHEETS
(In thousands, except share and per share amounts)
| December 30, 2018 | December 31, 2017 | |||||||
| ASSETS | ||||||||
| ASSETS: | ||||||||
| Cash | $ | 6 | $ | 6 | ||||
| Total assets | $ | 6 | $ | 6 | ||||
| LIABILITIES AND STOCKHOLDERS’ DEFICIT | ||||||||
| LIABILITIES: | ||||||||
| Equity in net deficit of subsidiaries | $ | 3,039,921 | $ | 2,735,384 | ||||
| Due to subsidiary | 6 | 6 | ||||||
| Total liabilities | 3,039,927 | 2,735,390 | ||||||
| STOCKHOLDERS’ DEFICIT: | ||||||||
| Common stock, par value $0.01 per share; 170,000,000 shares authorized; 40,977,561 in 2018 and 42,898,329 in 2017 issued and outstanding | 410 | 429 | ||||||
| Preferred stock, par value $0.01 per share; 5,000,000 shares authorized, none issued | — | — | ||||||
| Additional paid-in capital | 569 | 5,654 | ||||||
| Retained deficit | (3,036,471 | ) | (2,739,437 | ) | ||||
| Accumulated other comprehensive loss | (4,429 | ) | (2,030 | ) | ||||
| Total stockholders’ deficit | (3,039,921 | ) | (2,735,384 | ) | ||||
| Total liabilities and stockholders’ deficit | $ | 6 | $ | 6 | ||||
See accompanying notes to the Schedule I.
Table of Contents
Domino’s Pizza, Inc.
PARENT COMPANY CONDENSED STATEMENTS OF INCOME AND COMPREHENSIVE INCOME
(In thousands, except share and per share amounts)
| For the Years Ended | ||||||||||||
| December 30, 2018 | December 31, 2017 | January 1, 2017 | ||||||||||
| REVENUES | $ | — | $ | — | $ | — | ||||||
| Total revenues | — | — | — | |||||||||
| OPERATING EXPENSES | — | — | — | |||||||||
| Total operating expenses | — | — | — | |||||||||
| INCOME FROM OPERATIONS | — | — | — | |||||||||
| Equity earnings in subsidiaries | 361,972 | 277,905 | 214,678 | |||||||||
| INCOME BEFORE PROVISION FOR INCOME TAXES | 361,972 | 277,905 | 214,678 | |||||||||
| PROVISION FOR INCOME TAXES | — | — | — | |||||||||
| NET INCOME | $ | 361,972 | $ | 277,905 | $ | 214,678 | ||||||
| COMPREHENSIVE INCOME | $ | 359,924 | $ | 278,985 | $ | 215,116 | ||||||
| EARNINGS PER SHARE: | ||||||||||||
| Common Stock – basic | $ | 8.65 | $ | 6.05 | $ | 4.41 | ||||||
| Common Stock – diluted | $ | 8.35 | $ | 5.83 | $ | 4.30 |
See accompanying notes to the Schedule I.
Table of Contents
Domino’s Pizza, Inc.
PARENT COMPANY CONDENSED STATEMENTS OF CASH FLOWS
(In thousands)
| For the Years Ended | ||||||||||||
| December 30, 2018 | December 31, 2017 | January 1, 2017 | ||||||||||
| CASH FLOWS FROM OPERATING ACTIVITIES: | ||||||||||||
| Net cash provided by operating activities | $ | 382,716 | $ | 299,576 | $ | 281,731 | ||||||
| CASH FLOWS FROM INVESTING ACTIVITIES: | ||||||||||||
| Dividends from subsidiaries | 297,792 | 852,325 | 82,856 | |||||||||
| Net cash provided by investing activities | 297,792 | 852,325 | 82,856 | |||||||||
| CASH FLOWS FROM FINANCING ACTIVITIES: | ||||||||||||
| Payments of common stock dividends | (92,166 | ) | (84,298 | ) | (73,925 | ) | ||||||
| Purchase of common stock | (591,212 | ) | (1,064,253 | ) | (300,250 | ) | ||||||
| Other | 2,870 | (3,350 | ) | 9,588 | ||||||||
| Net cash used in financing activities | (680,508 | ) | (1,151,901 | ) | (364,587 | ) | ||||||
| CHANGE IN CASH AND CASH EQUIVALENTS | — | — | — | |||||||||
| CASH AND CASH EQUIVALENTS, AT BEGINNING OF PERIOD | 6 | 6 | 6 | |||||||||
| CASH AND CASH EQUIVALENTS, AT END OF PERIOD | $ | 6 | $ | 6 | $ | 6 | ||||||
See accompanying notes to the Schedule I.
Table of Contents
Domino’s Pizza, Inc.
NOTES TO PARENT COMPANY FINANCIAL STATEMENTS
| (1) | Introduction and Basis of Presentation |
|---|
Domino’s Pizza, Inc., on a stand-alone basis, (the “Parent Company”) has accounted for majority-owned subsidiaries using the equity method of accounting. The accompanying condensed financial statements of the Parent Company should be read in conjunction with the consolidated financial statements of Domino’s Pizza, Inc. and its subsidiaries (the “Company”) and the notes thereto included in Item 8 of this Form 10-K. These financial statements have been provided to comply with Rule 4-08(e) of Regulation S-X.
Use of Estimates
The use of estimates is inherent in the preparation of financial statements in accordance with generally accepted accounting principles. Actual results could differ from those estimates.
New Accounting Pronouncements
During 2018, the Company adopted the below new accounting pronouncements that impacted the Parent Company financial statements.
Accounting Standards Update 2014-09, Revenue from Contracts with Customers (Topic 606)
In May 2014, the Financial Accounting Standards Board (“FASB”) issued Accounting Standards Update 2014-09, Revenue from Contracts with Customers (Topic 606) and has since issued various amendments which provide additional clarification and implementation guidance. This standard has been codified as ASC 606. This guidance outlines a single, comprehensive model for entities to use in accounting for revenue arising from contracts with customers and superseded most revenue recognition guidance issued by the FASB, including industry specific guidance. On January 1, 2018, the Company adopted ASC 606 using the modified retrospective method.
The Parent Company recorded a $6.7 million adjustment to equity in net deficit of subsidiaries and recorded a $6.7 million adjustment to retained deficit related to this new accounting standard in 2018. See Note 1 to the Company’s consolidated financial statements as filed in this Form 10-K for additional information related to the adoption of this new accounting standard.
ASU 2018-02, Income Statement – Reporting Comprehensive Income (Topic 220)
In February 2018, the FASB issued ASU 2018-02, Income Statement – Reporting Comprehensive Income (Topic 220): Reclassification of Certain Tax Effects from Accumulated Other Comprehensive Income. The amendments in this updated standard allow a reclassification from accumulated other comprehensive income to retained earnings for stranded tax effects resulting from the Tax Cuts and Jobs Act of 2017. The Parent Company adopted this standard in 2018 and, as a result, recorded a $0.4 million reclassification from accumulated other comprehensive loss to the beginning balance of retained deficit in 2018.
| (2) | Supplemental Disclosures of Cash Flow Information |
|---|
During 2018, 2017 and 2016, the Parent Company received dividends from its subsidiaries primarily consisting of amounts received to repurchase common stock in connection with the Company’s 2018 and 2017 recapitalization transactions. See Note 4 to the Company’s consolidated financial statements as filed in this Form 10-K for a description of the recapitalization transactions that occurred in 2018 and 2017.
Table of Contents
SCHEDULE II – VALUATION AND QUALIFYING ACCOUNTS
Domino’s Pizza, Inc. and Subsidiaries
| (in thousands) | Balance Beginning of Year | Provision (Benefit) | Additions/ Deductions from Reserves* | Balance End of Year | ||||||||||||
| Allowance for doubtful accounts receivable: | ||||||||||||||||
| 2018 | $ | 1,424 | $ | 903 | $ | (448 | ) | 1,879 | ||||||||
| 2017 | 2,342 | (88 | ) | (830 | ) | 1,424 | ||||||||||
| 2016 | 2,662 | (51 | ) | (269 | ) | 2,342 |
| * | Consists primarily of write-offs, recoveries of bad debt and certain reclassifications. |
|---|
Table of Contents
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrants have duly caused this annual report to be signed on their behalf by the undersigned, thereunto duly authorized.
| DOMINO’S PIZZA, INC. |
| /s/ Jeffrey D. Lawrence |
| Jeffrey D. Lawrence |
| Chief Financial Officer |
| February 21, 2019 |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrants and in the capacities and on the dates indicated.
| /s/ Richard E. Allison, Jr. Richard E. Allison, Jr. February 21, 2019 | Chief Executive Officer and Director (Principal Executive Officer) | |
| /s/ Jeffrey D. Lawrence Jeffrey D. Lawrence February 21, 2019 | Chief Financial Officer (Principal Financial and Accounting Officer) | |
| /s/ David A. Brandon David A. Brandon February 21, 2019 | Chairman of the Board of Directors | |
| /s/ C. Andrew Ballard C. Andrew Ballard February 21, 2019 | Director | |
| /s/ Andrew B. Balson Andrew B. Balson February 21, 2019 | Director | |
| /s/ Corie S. Barry Corie S. Barry February 21, 2019 | Director | |
| /s/ Diana F. Cantor Diana F. Cantor February 21, 2019 | Director | |
| /s/ Richard L. Federico Richard L. Federico February 21, 2019 | Director | |
| /s/ James A. Goldman James A. Goldman February 21, 2019 | Director | |
| /s/ Patricia E. Lopez Patricia E. Lopez February 21, 2019 | Director |