 filings.tools
Domino's Pizza (DPZ) 10-K risk factor changes: FY2018 vs FY2017
The 2018-12-30 10-K against the 2017-12-31 one, compared heading by heading and sentence by sentence. One of these filings carries no fiscal year tag, so its year is the calendar year of the period end.
Item 1A107 rewritten116 added16 removed160 unchanged
All filing items1,082 rewritten756 added424 removed1,586 unchanged
Summary
counted, not written
- Item 1A lists 26 risk factor headings: 2 new, 2 reworded and 22 unchanged since FY2017. 0 headings from FY2017 no longer appear.
- Sentence by sentence, 756 added, 424 removed, 1,082 rewritten and 1,586 unchanged across 23 items that differ.
New Item 1A headings (2)
- _Our inability or failure to recognize, respond to and effectively manage the accelerated impact of social media could adversely impact our business._
- _Downgrades in our credit ratings could impact our ability to access capital and materially adversely affect our business, financial condition and results of operations._
Removed Item 1A headings (0)
Every FY2017 risk factor heading is still here, word for word or reworded.
Reworded Item 1A headings (2)
- _If we fail to successfully implement our growth strategy, which includes opening new
[removed: domestic][added: U.S.] and international stores, our ability to increase our revenues and operating profits could be adversely affected._ - _We face risks of
[removed: litigation][added: litigation, investigations, enforcement actions] and negative publicity from customers, franchisees, suppliers,[removed: employees][added: employees, regulators] and others in the ordinary course of business, which can or could divert our financial and management resources.[removed: Any adverse litigation][added: Litigation, investigations, enforcement actions] or publicity may[removed: negatively][added: adversely] impact our financial condition and results of operations._
A heading is new when no FY2017 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
23 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2018; struck-through words were in FY2017. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors.
107 rewritten, 116 added, 16 removed, 160 unchanged
Internationally, we compete primarily with Pizza Hut®, Papa John’s® and country-specific national and local [removed: pizzerias.][added: companies.]
| [added: |] • | | consumer tastes; |
| [added: |] • | | international, national, regional or local economic conditions; |
| [added: |] • | | disposable purchasing power; |
| [added: |] • | | demographic trends; and |
| [added: |] • | | currency fluctuations related to international operations. |
While all [removed: domestic] [added: U.S.] franchisees purchased food, equipment and supplies from us in [removed: 2017, domestic] [added: 2018, U.S.] franchisees are not required to purchase food, equipment or supplies from us and they may choose to purchase from outside suppliers.
If other suppliers who meet our qualification standards were to offer lower prices or better service to our franchisees for their ingredients and supplies and, as a result, our franchisees chose not to purchase from our [removed: domestic] [added: U.S.] supply chain centers, our financial condition, business and results of operations would be adversely affected.
_If we fail to successfully implement our growth strategy, which includes opening new [removed: domestic] [added: U.S.] and international stores, our ability to increase our revenues and operating profits could be adversely affected._
A significant component of our growth strategy includes the opening of new [removed: domestic] [added: U.S.] and international stores.
| [added: |] • | | availability of financing with acceptable terms; |
| [added: |] • | | selection and availability of suitable new store sites and the ability to renew leases in quality locations; |
| [added: |] • | | negotiation of acceptable lease or financing terms; |
| [added: |] • | | securing required [removed: domestic] [added: U.S.] or foreign governmental permits, licenses and approvals; |
| [added: |] • | | employment and training of qualified personnel; and |
| [added: |] • | | general economic and business conditions. |
We and our franchisees are currently planning to expand our [removed: domestic] [added: U.S.] and international operations in many of the markets where we currently operate and in select new markets.
Therefore, as we [added: continue to] expand internationally, we or our franchisees may not experience the operating margins we expect, our results of operations may be negatively impacted and our common stock price may decline.
The potential for acts of terrorism [removed: on] [added: affecting] our global food supply also exists and, if such an event occurs, it could have a negative impact on us and could severely hurt sales and profits.
[removed: In addition,] [added: Even] reports of food-borne illnesses or food [removed: tampering, even those] [added: tampering] occurring solely at the restaurants of [removed: competitors,] [added: competitors] could, by resulting in negative publicity about the restaurant industry, adversely affect us on a local, regional, national or international basis.
As minimum wage increases are implemented in these states or if such increases are approved and implemented in other states in which we operate, we expect our labor costs will [added: continue to] increase.
Labor costs and food costs, including cheese, [added: generally] represent approximately 50% to 60% of the sales at a typical Company-owned store.
In addition, we have single suppliers or a limited number of suppliers for certain of our ingredients, including pizza [removed: cheese.][added: cheese and meat toppings.]
We operate [removed: 18] [added: 19] regional dough manufacturing and supply chain centers, one thin crust manufacturing center and one vegetable processing center in the [removed: United States] [added: U.S.] and five dough manufacturing and supply chain centers in Canada.
Our [removed: domestic] [added: U.S.] dough manufacturing and supply chain centers service all of our Company-owned and [removed: domestic] [added: U.S.] franchise stores.
Each Domino’s store located in the contiguous [removed: United States] [added: U.S.] is obligated to pay a percentage of its sales in advertising fees.
In fiscal [removed: 2017,] [added: 2018,] each store in the contiguous [removed: United States] [added: U.S.] generally was required to contribute 6% of their sales to DNAF (subject, in [removed: limited] [added: certain] instances, to lower rates based on certain incentives and waivers), which uses such fees for national advertising in addition to contributions for local market-level advertising.
_We face risks of [removed: litigation] [added: litigation, investigations, enforcement actions] and negative publicity from customers, franchisees, suppliers, [removed: employees] [added: employees, regulators] and others in the ordinary course of business, which can or could divert our financial and management resources.
[removed: Any adverse litigation] [added: Litigation, investigations, enforcement actions] or publicity may [removed: negatively] [added: adversely] impact our financial condition and results of operations._
In addition to decreasing our sales and profitability and diverting our management resources, adverse publicity or a substantial [added: settlement, fine, penalty or] judgment against us could negatively impact our financial condition, results of operations and brand reputation, thereby hindering our ability to attract and retain franchisees and grow our business.
We [removed: are currently subject to these types of claims and] have been [added: and continue to be] subject to these types of [removed: claims in the past.][added: claims.]
Poor economic conditions may adversely affect the ability of our franchisees to pay royalties or amounts [removed: owed,] [added: owed] and could have a material adverse impact on our ability to pursue our growth strategy, which would reduce cash collections and in turn, may materially and adversely affect our ability to service our debt obligations.
[added: We conduct a significant and growing portion of our business outside the U.S.] Our financial condition and results of operations may be adversely affected if global markets in which our franchise stores compete are affected by changes in political, economic or other factors.
| [added: |] • | | recessionary or expansive trends in international markets; |
| [added: |] • | | changing labor conditions and difficulties in staffing and managing our foreign operations; |
| [added: |] • | | increases in the taxes we pay and other changes in applicable tax laws; |
| [added: |] • | | legal and regulatory changes, and the burdens and costs of our compliance with a variety of foreign laws; |
| [added: |] • | | changes in inflation rates; |
| [added: |] • | | changes in exchange rates and the imposition of restrictions on currency conversion or the transfer of funds; |
| [added: |] • | | difficulty in collecting our royalties and longer payment cycles; |
Additionally, we face growing competition from the supermarket industry and meal kit and food delivery providers, with the improvement of prepared food offerings and the trend towards convergence in grocery, deli, retail and restaurant services.
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| --- | --- | --- | --- |
_Our inability or failure to recognize, respond to and effectively manage the accelerated impact of social media could adversely impact our business._
In recent years, there has been a marked increase in the use of social media platforms, including blogs, chat platforms, social media websites, and other forms of internet-based communications that allow individuals access to a broad audience of consumers and other persons.
The rising popularity of social media and other consumer-oriented technologies has increased the speed and accessibility of information dissemination.
The dissemination of information via social media could harm our business, brand, reputation, marketing partners, financial condition, and results of operations, regardless of the information’s accuracy.
This could include negative publicity related to our food products or stores or negative publicity related to actions by our executives, team members or franchisees.
In addition, we frequently use social media to communicate with consumers and the public in general.
Failure to use social media effectively could lead to a decline in brand value and revenue.
Other risks associated with the use of social media include improper disclosure of proprietary information, negative comments about our brand, exposure of personally identifiable information, fraud, hoaxes or malicious dissemination of false information.
Moreover, as described above, social media has dramatically increased the rate at which negative publicity, including as it relates to food-borne illness, can be disseminated before there is any meaningful opportunity to respond to or address an issue.
Additionally, while we strive to engage in a competitive bidding process for our ingredients, because certain of these ingredients, including meat products, may only be available from a limited number of vendors, we may not always be able to do so effectively.
Furthermore, if we need to seek new suppliers, we may be subject to pricing or other terms less favorable to us than those reflected in our current supply arrangements.
The advent of legislation aimed at predictive scheduling could impact labor for our stores and our franchisees’ stores.
Additionally, while we do not currently have any unionized employees, if a significant portion of our employees were to become unionized, our labor costs could increase and our business could be negatively affected by other union requirements that increase our costs, disrupt our business, reduce our flexibility and impact our employee culture.
We plan to continue investing in additional supply chain capacity in the future.
State attorney general offices or other regulators may initiate investigations or enforcement actions against us.
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| | • | | tariffs and trade barriers; |
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| --- | --- | --- | --- |
| --- | --- |
| --- | --- | --- |
An additional regional dough manufacturing and food supply chain center is expected to open in fiscal 2018.
We conduct a significant and growing portion of our business outside the United States.
In addition, the laws of some foreign countries do not protect intellectual property rights to the same extent as the laws of the United States.
As of December 31, 2017, we had 789 domestic franchisees operating 5,195 domestic stores.
identifiable information that we retain.
If our security and information systems are compromised or if our employees or franchisees fail to comply with these laws, regulations or contract terms, and this information is obtained by unauthorized persons or used inappropriately, it could adversely affect our reputation and could disrupt our operations and result in costly litigation, judgments or penalties.
| • | | compliance with securities laws and New York Stock Exchange listed company rules; |
| • | | compliance with the Americans with Disabilities Act of 1990, as amended; |
| • | | menu labeling and other nutritional requirements; |
| • | | compliance with the Patient Protection and Affordable Care Act, and subsequent amendments (the “Affordable Care Act”); |
| • | | compliance with the Dodd-Frank Wall Street Reform and Consumer Protection Act and any rules promulgated thereunder; and |
| • | | regulations under the Tax Cuts and Jobs Act of 2017 (the “2017 Tax Act”). |
While the impact of this new legislation was not material to our 2017 financial statements, we expect to have a significantly lower effective tax rate in future periods.
In addition, our capital expenditures could increase due to remediation measures that may be required if we are found to be noncompliant with any of these laws or regulations.
An excerpt. Shown here: 40 of 107 rewritten, 40 of 116 added and all 16 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors. in the FY2018 filing and the FY2017 filing.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
156 rewritten, 136 added, 139 removed, 370 unchanged
Fiscal [added: 2018,] 2017 and 2016 each consisted of 52 [removed: weeks, while fiscal 2015 consisted of 53] weeks._
Domino’s is the largest pizza company in the world based on global retail sales, with more than [removed: 14,800] [added: 15,900] locations in over 85 markets around the world.
On average, we and our franchisees sell more than [removed: 2.5] [added: 3] million pizzas each day throughout our global system.
Everyone in the system can benefit, including the end consumer, who can [removed: feed] [added: purchase] Domino’s menu items [removed: to] [added: for themselves and] their family conveniently and economically.
| | • | | Global retail sales (which are total retail sales at Company-owned and franchised stores worldwide) increased [removed: 12.7%] [added: 10.6%] as compared to [removed: 2016.] [added: 2017.] |
| | • | | Same store sales increased 7.7% in our [removed: domestic] [added: U.S.] stores and increased 3.4% in our international stores. |
Overall, we believe our focus in [removed: 2017] [added: 2018] on global growth and technology will continue to strengthen our brand in the future.
Fiscal [removed: 2016] [added: 2018] Highlights
| | • | | Global retail sales increased [removed: 9.8%] [added: 12.7%] as compared to [removed: 2015.] [added: 2016.] |
| | • | | Same store sales increased [removed: 10.5%] [added: 6.6%] in our [removed: domestic] [added: U.S.] stores and increased [removed: 6.3%] [added: 3.5%] in our international stores. |
| | • | | Our revenues increased [removed: 11.6%.] [added: 23.1%.] |
| | • | | Our income from operations increased [removed: 12.0%.] [added: 9.7%.] |
| | • | | Our net income increased [removed: 11.4%.] [added: 30.3%.] |
During [removed: 2016,] [added: 2018,] we continued our rapid global expansion with the opening of [removed: 1,281] [added: 1,058] net new stores.
Our international franchise segment led the way with [removed: a record 1,110] [added: 800] net new store [removed: openings.][added: openings, including the opening of our 10,000th international store.]
Our emphasis on technology innovation helped the Domino’s system generate more than half of global retail sales from digital channels in [removed: 2016.][added: 2018.]
We earn revenues through our network of [removed: domestic] [added: U.S.] Company-owned and franchised stores, dough manufacturing and supply chain centers and international operations.
Retail sales are generally reported and related royalties paid to the Company based on a percentage of retail sales, as specified in the related standard franchise agreement (generally 5.5% of [removed: domestic] [added: U.S.] franchise retail sales and, on average, 3.0% of international franchise retail sales).
Revenues from Company-owned stores and [removed: royalty] revenues [removed: and fees] from franchised stores [added: (including U.S. franchise royalties and fees and U.S. franchise advertising revenues)] can fluctuate from time-to-time as a result of store count and sales level changes.
If a Company-owned store that generated $1,000,000 in revenue in fiscal [removed: 2016] [added: 2017] was sold to a franchisee in fiscal [removed: 2017,] [added: 2018,] revenues from Company-owned stores would have declined by $1,000,000 in fiscal [removed: 2017,] [added: 2018,] while [added: U.S.] franchise royalty revenues would have increased by [removed: only] $55,000 [added: and U.S. franchise advertising revenues would have increased by $60,000] in fiscal [removed: 2017,] [added: 2018,] as we generally collect 5.5% of a [removed: domestic] [added: U.S.] franchisee’s retail [removed: sales.][added: sales as royalty revenue and 6.0% of a U.S. franchisee’s retail sales for advertising contributions.]
The Company did not record any impairment charges during fiscal [removed: 2017,] [added: 2018,] fiscal [removed: 2016] [added: 2017] or fiscal [removed: 2015.][added: 2016.]
A significant portion of our goodwill relates to acquisitions of [removed: domestic] [added: U.S.] franchise stores and is included in our [removed: domestic] [added: U.S.] stores segment, specifically, in our Company-owned stores division.
At December [removed: 31, 2017,] [added: 30, 2018,] the fair value of our business operations with [added: associated goodwill exceeded their recorded carrying value, including the related goodwill.]
We had accruals for legal matters of approximately [removed: $1.7] [added: $1.9] million at December [removed: 31, 2017] [added: 30, 2018] and [removed: $2.7] [added: $1.7] million at [removed: January 1,] [added: December 31,] 2017.
A 10% change in our self-insurance liability at December [removed: 31, 2017] [added: 30, 2018] would have affected our income before provision for income taxes by approximately [removed: $5.1] [added: $5.3] million for fiscal [removed: 2017.][added: 2018.]
We had accruals for insurance matters of approximately [removed: $51.4] [added: $53.3] million at December [removed: 31, 2017] [added: 30, 2018] and [removed: $43.9] [added: $51.4] million at [removed: January 1,] [added: December 31,] 2017.
The grant date fair value of each stock option award is estimated using [removed: a] [added: the] Black-Scholes option pricing model.
The Company did not have any valuation allowances recorded for deferred tax assets as of December [added: 30, 2018 or December] 31, [removed: 2017 and had valuation allowances recorded for deferred tax assets of approximately $0.1 million as of January 1,] 2017.
| | | [removed: 2017] [added: 2018 (1)] | | | | [removed: 2016] [added: 2017] | | | | [removed: 2015] [added: 2016] | | |
| [removed: Domestic] [added: U.S.] Company-owned stores | | | [removed: 8.7] [added: 4.8] | % | | | [removed: 10.4] [added: 8.7] | % | | | [removed: 12.2] [added: 10.4] | % |
| [removed: Domestic] [added: U.S.] franchise stores | | | [removed: 7.6] [added: 6.8] | % | | | [removed: 10.5] [added: 7.6] | % | | | [removed: 11.9] [added: 10.5] | % |
| [removed: Domestic] [added: U.S.] stores | | | [removed: 7.7] [added: 6.6] | % | | | [removed: 10.5] [added: 7.7] | % | | | [removed: 12.0] [added: 10.5] | % |
| International stores (excluding foreign currency impact) | | | [removed: 3.4] [added: 3.5] | % | | | [removed: 6.3] [added: 3.4] | % | | | [removed: 7.8] [added: 6.3] | % |
| | | [removed: Domestic Company-owned] [added: U.S. Company- owned] Stores | | | | [removed: Domestic] [added: U.S.] Franchise [added: Stores] | | | | Total [removed: Domestic] [added: U.S.] Stores | | | | International Stores | | | | Total | | |
| Transfers [added: (1)] | | | [removed: (4] [added: (14] | ) | | | [removed: 4] [added: 45] | | | | [removed: —] [added: 31] | | | | [removed: —] [added: (31] | [added: )] | | | — | |
| [removed: (dollars] [added: (dollars] in [removed: millions)] [added: millions)] | | [removed: 2017] [added: 2018 (1) (2)] | | | | | | | | [removed: 2016] [added: 2017] | | | | | | | | [removed: 2015] [added: 2016] | | | | | | |
| [removed: Domestic] [added: U.S.] Company-owned stores | | $ | [removed: 490.8] [added: 514.8] | | | | | | | $ | [removed: 439.0] [added: 490.8] | | | | | | | $ | [removed: 396.9] [added: 439.0] | | | | | |
| Supply chain | | | [removed: 1,739.0] [added: 1,943.3] | | | | | | | | [removed: 1,544.3] [added: 1,739.0] | | | | | | | | [removed: 1,383.2] [added: 1,544.3] | | | | | |
| International franchise [added: royalties and fees] | | | [removed: 206.7] [added: 224.7] | | | | | | | | [removed: 177.0] [added: 206.7] | | | | | | | | [removed: 163.6] [added: 177.0] | | | | | |
| Total revenues | | | [removed: 2,788.0] [added: 3,432.9] | | | | 100.0 | % | | | [removed: 2,472.6] [added: 2,788.0] | | | | 100.0 | % | | | [removed: 2,216.5] [added: 2,472.6] | | | | 100.0 | % |
| | • | | Our diluted earnings per share increased 43.2%. |
The adoption of Accounting Standards Codification 606, _Revenue from Contracts with Customers_ (“ASC 606”) in 2018 resulted in the recognition of $358.5 million in revenue in 2018 related to U.S. franchise contributions to Domino’s National Advertising Fund Inc. (“DNAF”), our consolidated not-for-profit advertising fund.
In 2017, under accounting standards in effect at that time, we had presented these contributions net with the related disbursements in our consolidated statement of income.
Refer to Note 1 to the consolidated financial statements for additional information related to the adoption of this new accounting standard.
We also continued our strong U.S. and international same store sales performance with 31 straight quarters of positive U.S. same store sales and 100 straight quarters of positive international same store sales.
Our Domino’s Piece of the Pie Rewards loyalty program continues to contribute to our U.S. same store sales performance.
Additionally, we remained focused on growing online ordering and improving the digital customer experience through our technology platforms, including the recent launch of Domino’s Delivery HotSpots.
| | • | | Our diluted earnings per share increased 35.6%. |
The Company also generates revenues from U.S. franchise advertising contributions to DNAF, its consolidated not-for-profit advertising fund (generally 6.0% of U.S. franchise retail sales).
As the fair value of our business operations exceeded their recorded carrying value in “Step 1” of the impairment test, the adoption of this standard did not have an impact on our evaluation of goodwill impairment.
| (1) | In the first quarter of 2018, the Company began managing its franchised stores in Alaska and Hawaii as part of its U.S. Stores segment. Prior to 2018, store counts, retail sales and royalty revenues from these franchised stores were included in the Company’s international operations in the tables above. Consolidated results of the Company have not been impacted by this change and prior year amounts have not been reclassified to conform to the current year presentation due to immateriality. |
| Openings | | | 12 | | | | 255 | | | | 267 | | | | 916 | | | | 1,183 | |
| Closings | | | — | | | | (9 | ) | | | (9 | ) | | | (116 | ) | | | (125 | ) |
| Store count at December 30, 2018 | | | 390 | | | | 5,486 | | | | 5,876 | | | | 10,038 | | | | 15,914 | |
| U.S. franchise royalties and fees | | | 391.5 | | | | | | | | 351.4 | | | | | | | | 312.3 | | | | | |
| U.S. franchise advertising | | | 358.5 | | | | | | | | — | | | | | | | | — | | | | | |
| U.S. franchise advertising | | | 358.5 | | | | 10.4 | % | | | — | | | | — | % | | | — | | | | — | % |
| | | | | | | | | | | | | | | | | | | | | | | | | |
| (1) | In 2018, the Company began managing its franchised stores in Alaska and Hawaii as part of its U.S. Stores segment. Prior to 2018, store counts, retail sales and royalty revenues from these franchised stores were included in the Company’s international operations in the tables above. Consolidated results of the Company have not been impacted by this change and prior year amounts have not been reclassified to conform to the current year presentation due to immateriality. Also, see Note 12 to the consolidated financial statements for additional information related to the store transfers between U.S. Company-owned stores and U.S. franchise stores. |
| (2) | The adoption of ASC 606 in 2018 resulted in the recognition of $358.5 million in revenue in 2018 related to U.S. franchise contributions to DNAF. In prior years, under accounting standards in effect at that time, we had presented these contributions net with the related disbursements in our consolidated statement of income. Refer to Note 1 to the consolidated financial statements for additional information related to the adoption of this new accounting standard. |
2018 compared to 2017
The adoption of ASC 606 in 2018 resulted in the recognition of $358.5 million in revenue in 2018 related to U.S. franchise contributions to DNAF.
In 2017, under accounting standards in effect at that time, we had presented these contributions net with the related disbursements in our consolidated statement of income.
Refer to Note 1 to the consolidated financial statements for additional information related to the adoption of this new accounting standard.
The remaining increase was due primarily to higher supply chain food volumes as well as higher U.S. franchise, Company-owned store and international franchise revenues resulting from retail sales growth.
| | | 2018 | | | | | | | | 2017 | | | | | | |
| U.S. Company-owned stores | | $ | 514.8 | | | | 40.7 | % | | $ | 490.8 | | | | 58.3 | % |
| U.S. franchise royalties and fees | | | 391.5 | | | | 31.0 | % | | | 351.4 | | | | 41.7 | % |
| U.S. franchise advertising | | | 358.5 | | | | 28.3 | % | | | — | | | | — | % |
U.S. stores revenues increased $422.6 million, or 50.2%, in 2018.
This increase was driven by the adoption of ASC 606, which requires a gross presentation of U.S. franchise advertising contributions in our consolidated statement of income, as well as higher royalty revenues earned on higher franchise same store sales and an increase in the average number of stores open in 2018 as compared to the prior year.
Higher U.S. Company-owned same store sales also contributed to the increase in revenue.
_U.S.
Company-owned stores._ Revenues from U.S. Company-owned store operations increased $24.0 million or 4.9% in 2018 due primarily to a 4.8% increase in same store sales as compared to 2017.
_U.S. franchise royalties and fees._ Revenues from U.S. franchise operations increased $40.1 million or 11.4% in 2018.
U.S. franchise royalties and fees were reduced by $17.9 million in 2018 due to the adoption of ASC 606, primarily related to the reclassification of certain advertising revenues from U.S. franchise royalties and fees to U.S. franchise advertising revenues.
_U.S. franchise advertising_.
Revenues from U.S. franchise advertising contributions were $358.5 million in 2018.
In years prior to 2018, based on accounting guidance in effect at the time, the U.S. franchise advertising contributions were shown net with the related disbursements in our consolidated statement of income.
In 2018, we adopted ASC 606, which required these revenues and expenses to be presented gross on our consolidated statement of income.
We continued our focus on growing online ordering and the digital customer experience as we introduced new innovative ordering platforms including zero-click ordering, Google Home, Facebook Messenger, Apple Watch and Amazon Echo.
associated goodwill exceeded their recorded carrying value, including the related goodwill.
| Store count at December 28, 2014 | | | 377 | | | | 4,690 | | | | 5,067 | | | | 6,562 | | | | 11,629 | |
| Openings | | | 12 | | | | 148 | | | | 160 | | | | 867 | | | | 1,027 | |
| Closings | | | (1 | ) | | | (26 | ) | | | (27 | ) | | | (99 | ) | | | (126 | ) |
| Domestic franchise | | | 351.4 | | | | | | | | 312.3 | | | | | | | | 272.8 | | | | | |
The impact of the 2017 Tax Act was not material to our 2017 financial statements.
For further discussion of risks and uncertainties associated with the implementation of the 2017 Tax Act, see Item 1A.
Risk Factors.
2016 compared to 2015
These increases were offset in part by the inclusion of the 53rd week in 2015, which positively impacted revenues by an estimated $49.7 million in 2015.
The negative impact of changes in foreign currency exchange rates on international franchise royalties and international supply chain revenues also partially offset the increases in revenues.
| | | 2016 | | | | | | | | 2015 | | | | | | |
| Domestic Company-owned stores | | $ | 439.0 | | | | 58.4 | % | | $ | 396.9 | | | | 59.3 | % |
| Domestic franchise | | | 312.3 | | | | 41.6 | % | | | 272.8 | | | | 40.7 | % |
Higher franchise same store sales, store count growth and higher domestic Company-owned same store sales drove an increase in overall domestic store revenues of $81.6 million or 12.2%.
_Domestic Company-owned stores._ Revenues from domestic Company-owned store operations increased $42.1 million or 10.6% in 2016.
This increase was due to a 10.4% increase in same store sales as compared to 2015 and an increase in the average number of stores open during the year, and was offset in part by the estimated $9.1 million positive impact in 2015 related to the inclusion of the 53rd week.
Revenues further benefited from fees paid by franchisees for our internally developed online ordering platform, and were offset in part by the estimated $6.1 million positive impact in 2015 related to the inclusion of the 53rd week.
| Domestic supply chain | | $ | 1,408.8 | | | | 91.2 | % | | $ | 1,266.4 | | | | 91.6 | % |
| International supply chain | | | 135.5 | | | | 8.8 | % | | | 116.8 | | | | 8.4 | % |
_Domestic supply chain._ Domestic supply chain revenues increased $142.4 million or 11.3% in 2016.
They were partially offset by lower commodity prices and the estimated $27.8 million positive impact in 2015 related to the inclusion of the 53rd week.
The lower cheese block price (passed through directly in domestic supply chain pricing to franchisees) did not have a material impact on domestic supply chain revenues in 2016.
We estimate that lower commodity prices resulted in an approximate $3.0 million decrease in domestic supply chain revenues during 2016.
_International supply chain._ Revenues from international supply chain operations increased $18.7 million or 16.0% in 2016.
This increase resulted primarily from higher volumes from increased order counts at the store level in 2016 and was offset in part by the negative impact of foreign currency exchange rates of approximately $4.3 million in 2016 and the estimated $2.6 million positive impact in 2015 related to the inclusion of the 53rd week.
_International franchise._ Revenues from international franchise operations increased $13.4 million or 8.2% in 2016.
This increase was due to an increase in the average number of international stores open during 2016 as well as higher same store sales, and was offset in part by the negative impact of changes in foreign currency exchange rates of approximately $8.9 million in 2016 and the estimated $4.1 million positive impact in 2015 related to the inclusion of the 53rd week.
| Consolidated cost of sales | | | 1,704.9 | | | | 69.0 | % | | | 1,533.4 | | | | 69.2 | % |
| Consolidated operating margin | | $ | 767.7 | | | | 31.0 | % | | $ | 683.1 | | | | 30.8 | % |
The increase in the consolidated operating margin was offset in part by the estimated $16.6 million positive impact in 2015 related to the inclusion of the 53rd week.
As a percentage of total revenues, our consolidated operating margin increased 0.2 percentage points in 2016, due to higher supply chain margins as a percentage of their revenues and a higher mix of franchise revenues.
Lower Company-owned stores operating margins as a percentage of their revenues partially offset these increases.
| Revenues | | $ | 439.0 | | | | 100.0 | % | | $ | 396.9 | | | | 100.0 | % |
| Cost of sales | | | 331.9 | | | | 75.6 | % | | | 299.3 | | | | 75.4 | % |
| Store operating margin | | $ | 107.2 | | | | 24.4 | % | | $ | 97.6 | | | | 24.6 | % |
The estimated $3.1 million positive impact in 2015 related to the inclusion of the 53rd week partially offset this increase.
| | • | | Food costs increased 0.5 percentage points to 26.6% in 2016, due primarily to promotional activities. Lower overall commodity prices partially offset these increases. |
| | • | | Labor costs increased 0.3 percentage points to 28.8% in 2016, due primarily to an increase in labor rates in certain markets as well as higher performance based compensation and overtime as a result of increased same store sales. The leveraging impact of higher same store sales partially offset these increases. |
An excerpt. Shown here: 40 of 156 rewritten, 40 of 136 added and 40 of 139 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations. in the FY2018 filing and the FY2017 filing.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk.
5 rewritten, 5 added, 1 removed, 12 unchanged
In connection with the 2017 Recapitalization, we issued fixed and floating rate notes and, at December [removed: 31, 2017,] [added: 30, 2018,] we are exposed to interest rate risk on borrowings under our 2017 Floating Rate Notes and our 2017 Variable Funding Notes.
As of December [removed: 31, 2017,] [added: 30, 2018,] we had [removed: no] [added: $65.0 million in] outstanding borrowings under our 2017 Variable Funding Notes.
We have exposure to various foreign currency exchange rate fluctuations for revenues generated by our operations outside the [removed: United States,] [added: U.S.,] which can adversely impact our net income and cash flows.
Approximately [removed: 7.4%] [added: 6.5%] of our total revenues in [removed: 2017, 7.2%] [added: 2018, 7.4%] of our total revenues in [removed: 2016] [added: 2017] and [removed: 7.4%] [added: 7.2%] of our total revenues in [removed: 2015] [added: 2016] were derived from our international franchise segment, a majority of which were denominated in foreign currencies.
A hypothetical 10% adverse change in the foreign currency rates for our international markets would have resulted in a negative impact on royalty revenues of approximately [removed: $17.9] [added: $20.0] million in [removed: 2017.][added: 2018.]
Our 2017 Floating Rate Notes and our 2017 Variable Funding Notes bear interest at fluctuating interest rates based on LIBOR.
A hypothetical 1.0% adverse change in the LIBOR rate would have resulted in higher interest expense of approximately $3.0 million in 2018.
There is currently uncertainty around whether LIBOR will continue to exist after 2021.
If LIBOR ceases to exist, we may need to renegotiate our loan documents and we cannot predict what alternative index would be negotiated with our lenders.
As a result, our interest expense could increase, in which event we may have difficulties making interest payments and funding our other fixed costs, and our available cash flow for general corporate requirements may be adversely affected.
| --- | --- |
Item 1. Business.
99 rewritten, 19 added, 26 removed, 203 unchanged
Domino’s is the largest pizza company in the world based on global retail sales, with more than [removed: 14,800] [added: 15,900] locations in over 85 markets around the world.
Although we are a highly-recognized global brand, we focus on serving the local neighborhoods in which we live and do business through our large [added: global] network of franchise owners and [added: 390 U.S.] Company-owned stores.
On average, we and our franchisees sell more than [removed: 2.5] [added: 3] million pizzas each day throughout our global system.
[removed: Our] [added: The Domino’s] business model is straightforward: we handcraft and serve quality food at a competitive price, with easy ordering access and efficient service, enhanced by our technology innovations.
Everyone in the system can benefit, including the end consumer, who can [removed: feed] [added: purchase] Domino’s menu items [removed: to] [added: for themselves and] their family conveniently and economically.
[removed: Our] [added: The Domino’s] business model can yield strong returns for our franchise owners and Company-owned stores.
The Company’s most recent recapitalization transaction in [removed: 2017] [added: 2018] (the [removed: “2017] [added: “2018] Recapitalization”) primarily consisted of the issuance of [removed: $1.9 billion] [added: $825.0 million] of fixed [removed: and floating] rate notes and the repurchase and retirement of [removed: $910.2] [added: $490.0] million of previously outstanding fixed rate notes.
[removed: Following] [added: As of December 30, 2018,] the [removed: 2017 Recapitalization, and including] [added: Company had $3.53 billion in total debt, which included] debt from its [added: 2018 Recapitalization and its] previous recapitalization [added: transactions] in [added: 2017 and] 2015 (the [added: “2017 Recapitalization” and the] “2015 [removed: Recapitalization”),] [added: Recapitalization,” and together with] the [removed: Company had $3.15 billion in total debt.][added: 2018 Recapitalization, the “2018, 2017 and 2015 Recapitalizations”).]
Excess proceeds from [removed: both] our [removed: 2015 and] [added: 2018,] 2017 [added: and 2015] Recapitalizations were [removed: primarily] used [added: primarily] to repurchase shares of our common stock.
During this time frame, we also began expanding our focus on technology through our development of innovative ordering platforms and other technological advancements, such as the launch of our Piece of the Pie Rewards® loyalty program in [removed: 2015.][added: 2015 and the launch of Domino’s Delivery HotSpots® in 2018.]
Globally, we opened our 10,000th store in 2012 and our [removed: 14,000th] [added: 15,000th] store in [removed: 2017.][added: 2018.]
The majority of our [removed: domestic] [added: U.S.] and international stores have completed these remodels as of the end of [removed: 2017.][added: 2018.]
From [removed: 2007] [added: 2008] through [removed: 2017,] [added: 2018,] the U.S. QSR pizza category has grown from [removed: $32.9] [added: $32.8] billion to [removed: $36.0] [added: $36.5] billion.
It is the second-largest category within the [removed: $290.2] [added: $299.6] billion U.S. QSR sector.
Delivery segment sales of $9.8 billion in [removed: 2017] [added: 2018] (down from [removed: $10.9] [added: $10.3] billion in [removed: 2007)] [added: 2008)] account for approximately 27% of total U.S. QSR pizza.
The delivery segment declined [added: slightly] during the period from [removed: 2007] [added: 2008] to 2012, and has increased slightly since 2012, from $9.7 billion in 2012 to $9.8 billion in [removed: 2017.][added: 2018.]
From [removed: 2007] [added: 2008] to [removed: 2017,] [added: 2018,] the carryout segment grew from [removed: $13.5] [added: $14.1] billion to [removed: $16.7] [added: $17.1] billion.
No customer accounted for more than 10% of total consolidated revenues in [removed: 2017, 2016] [added: 2018, 2017] or [removed: 2015.][added: 2016.]
Our largest franchisee based on store count, Domino’s Pizza Enterprises (DMP: ASX), operates [removed: 2,170] [added: 2,383] stores in seven international markets, and accounts for 15% of our total store count.
Revenues from this master franchisee accounted for [removed: 1.5%] [added: 1.4%] of our consolidated revenues in [removed: 2017.][added: 2018.]
Our international business unit only requires a [removed: minimal] [added: modest] amount of general and administrative expenses to support its [removed: markets,] [added: markets] and does not have costs of sales.
We have been focused primarily on pizza delivery for [removed: over 55] [added: nearly 60] years, as well as carryout as a significant component of our business.
In 2012, we introduced our carryout-friendly Pizza Theater store design; the majority of our [removed: domestic] [added: U.S.] and international stores have converted to this design as of the end of [removed: 2017.][added: 2018.]
We operate, and report, three business segments: [removed: domestic] [added: U.S.] stores, international franchise and supply chain.
Our [removed: domestic] [added: U.S.] stores segment consists primarily of our franchise operations, which consist of [removed: 5,195] [added: 5,486] franchised stores located in the [removed: contiguous] United States.
During [removed: 2017, our domestic stores] [added: 2018, this] segment accounted for [removed: $842.2] [added: $224.7] million, or [removed: over 30%] [added: 6%] of our consolidated revenues.
While we are primarily a franchised business, we continuously evaluate our mix of [removed: domestic] [added: U.S.] Company-owned and franchise stores.
[removed: _Domestic] Franchise Profile_
As of December [removed: 31, 2017,] [added: 30, 2018,] our network of [removed: 5,195 domestic] [added: 5,486 U.S.] franchise stores were owned and operated by [removed: 789] [added: 793] independent [removed: domestic] [added: U.S.] franchisees.
As of December [removed: 31, 2017,] [added: 30, 2018,] the average [removed: domestic] [added: U.S.] franchisee owned and operated seven stores and had been in our franchise system for over 18 years.
At the same time, [removed: 14] [added: 17] of our [removed: domestic] [added: U.S.] franchisees operated more than 50 stores (including our largest [removed: domestic] [added: U.S.] franchisee who operated [removed: 187] [added: 179] stores) and [removed: 271] [added: 262] of our [removed: domestic] [added: U.S.] franchisees each operated one store.
We apply rigorous standards to prospective [removed: domestic] [added: U.S.] franchisees.
We generally require them to manage a store for at least one year [added: and graduate from our franchise management school] before being granted a franchise.
[removed: Significantly] [added: Substantially] all of our [removed: 789] [added: 793] independent [removed: domestic] [added: U.S.] franchise owners started their careers with us as delivery drivers or in other in-store positions, which we believe offers advantages in terms of familiarity with our business and store operations.
In addition, we generally restrict the ability of [removed: domestic] [added: U.S.] franchisees to be involved in other businesses, which we believe helps focus our franchisees’ attention on operating their stores.
[removed: _Domestic] Franchise Agreements_
We enter into franchise agreements with [removed: domestic] [added: U.S.] franchisees under which the franchisee is generally granted the right to operate a store in a particular location for a term of ten years, with an ability to renew for an additional term of ten years.
In certain instances, we will collect lower rates based on [removed: area development agreements, sales initiatives and] new store incentives.
Our [removed: domestic] [added: U.S.] stores currently contribute 6% of their sales to fund national marketing and advertising campaigns (subject, in [removed: limited] [added: certain] instances, to lower rates based on certain incentives and waivers).
These funds are administered by Domino’s National Advertising Fund Inc. (“DNAF”), our [added: consolidated] not-for-profit advertising subsidiary.
U.S. Stores
We also operate a network of 390 U.S. Company-owned stores.
During 2018, our U.S. stores segment accounted for $1.26 billion, or 37% of our consolidated revenues.
_U.S.
_U.S.
| India | | | 1,195 | |
| Mexico | | | 760 | |
| Australia | | | 693 | |
| Japan | | | 550 | |
| Turkey | | | 535 | |
| Canada | | | 487 | |
| France | | | 387 | |
| Germany | | | 283 | |
We plan to continue investing in additional supply chain centers and capacity initiatives in the future.
We and our franchisees are continuing to focus on growing our store count around the world to increase our presence in all of our markets to better serve our customers.
In April 2018, we launched Domino’s Delivery HotSpots, featuring over 200,000 non-traditional delivery locations including parks, beaches, local landmarks and other unique gathering spots.
The security of our financial data, customer information and other personal information is a priority for us.
Materials filed with the Securities and Exchange Commission are available at www.sec.gov.
Retail orders from Domino’s stores can be made through its internet website dominos.com.
| --- | --- |
_Research and Development_
We conduct research and product development at our World Resource Center (our corporate headquarters) in Ann Arbor, Michigan.
Company-sponsored research and development activities, which include testing new products for possible menu additions, are an important activity for us and our franchisees.
We do not consider the amounts spent on research and development to be material.
Domestic Stores
We also operate a network of 392 domestic Company-owned stores located in the contiguous United States.
During 2017, this segment accounted for $206.7 million, or over 7% of our consolidated revenues.
Currently, the vast majority of our international stores operate under master franchise agreements.
| India | | | 1,126 | |
| Mexico | | | 701 | |
| Australia | | | 670 | |
| Turkey | | | 508 | |
| Japan | | | 503 | |
| Canada | | | 472 | |
| France | | | 370 | |
| Netherlands | | | 242 | |
An additional regional dough manufacturing and food supply chain center is expected to open in fiscal 2018.
We are currently in negotiations for a longer-term contract that would extend through June 2022.
We are party to a multi-year agreement with Coca-Cola® for the contiguous United States.
Financial Information about Business Segments and Geographic Areas
Financial information about international and United States markets and business segments is incorporated herein by reference to Selected Financial Data, Management’s Discussion and Analysis of Financial Condition and Results of Operations and the consolidated financial statements and related footnotes in Part II, Item 6., pages 22 through 23, Item 7.
and 7A., pages 24 through 40 and Item 8., pages 41 through 74, respectively, of this Form 10-K.
You may read and copy any materials filed with the Securities and Exchange Commission at the Securities and Exchange Commission’s Public Reference Room at 100 F Street, NE, Washington, D.C. 20549.
You may obtain information on the operation of the Public Reference Room by calling the Securities and Exchange Commission at 1-800-SEC-0330.
This information is also available at www.sec.gov.
An excerpt. Shown here: 40 of 99 rewritten, all 19 added and all 26 removed. The counts are complete. For every sentence, read Item 1. Business. in the FY2018 filing and the FY2017 filing.
Item 3. Legal Proceedings.
0 rewritten, 1 added, 1 removed, 15 unchanged
On May 11, 2018, the court of appeals reversed and remanded the case to the trial court for a new trial based on the plaintiff’s improper closing argument.
| --- | --- |
Cover and table of contents
34 rewritten, 14 added, 14 removed, 45 unchanged
For the fiscal year ended December [removed: 31, 2017][added: 30, 2018]
| (State or other jurisdiction of [added: incorporation or organization)] | | (I.R.S. Employer [added: Identification No.)] |
| 30 Frank Lloyd Wright Drive [added: Ann Arbor, Michigan] | | [added: 48105] |
Securities registered pursuant to Section 12(g) of the [removed: Act: None][added: Act: None]
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities [added: Act: Yes ☒ No ☐]
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the [added: Act: Yes ☐ No ☒]
Indicate by check mark whether the registrant has submitted electronically [removed: and posted on its corporate Web site, if any,] every Interactive Data File required to be submitted [removed: and posted] pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit [removed: and post] such files): Yes ☒ No ☐
| Non-accelerated filer | | ☐ [removed: (do not check if a smaller reporting company)] | | Smaller reporting company | | ☐ |
| [removed: Emerging growth company] | | [removed: ☐] | | [added: Emerging growth company] | | [added: ☐] |
The aggregate market value of the voting and non-voting common stock held by non-affiliates of Domino’s Pizza, Inc. as of June [removed: 18, 2017] [added: 17, 2018] computed by reference to the closing price of Domino’s Pizza, Inc.’s common stock on the New York Stock Exchange on such date was [removed: $10,126,535,325.][added: $11,546,079,722.]
As of February [removed: 13, 2018,] [added: 14, 2019,] Domino’s Pizza, Inc. had [removed: 43,018,242] [added: 41,040,704] shares of common stock, par value $0.01 per share, outstanding.
Portions of the definitive proxy statement to be furnished to shareholders of Domino’s Pizza, Inc. in connection with the annual meeting of shareholders to be held on April [removed: 24, 2018] [added: 23, 2019] are incorporated by reference into Part III.
| | | | | Page No. | [removed: | |]
| Item 1A. | | [Risk [removed: Factors](#tx531906_3) |] [added: Factors.](#tx696297_3)] | | 11 | [removed: |]
| Item 1B. | | [Unresolved Staff [removed: Comments](#tx531906_4) | |] [added: Comments.](#tx696297_4)] | [removed: 19] | [added: 21] |
| Item 4. | | [Mine Safety [removed: Disclosures](#tx531906_7) | |] [added: Disclosures.](#tx696297_7)] | [removed: 19] | [added: 21] |
| Item 4A. | | [Executive Officers of the [removed: Registrant](#tx531906_8) | |] [added: Registrant.](#tx696297_8)] | [removed: 19] | [added: 21] |
| Item 5. | | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities](#tx531906_10) | |] [added: Securities.](#tx696297_10)] | [removed: 20] | [added: 22] |
| Item 6. | | [Selected Financial [removed: Data](#tx531906_11) | |] [added: Data.](#tx696297_11)] | [removed: 22] | [added: 24] |
| Item 7. | | [Management’s Discussion and Analysis of Financial Condition and Results of [removed: Operations](#tx531906_12) | |] [added: Operations.](#tx696297_12)] | [removed: 24] | [added: 26] |
| Item 7A. | | [Quantitative and Qualitative Disclosures About Market [removed: Risk](#tx531906_13) | |] [added: Risk.](#tx696297_13)] | [removed: 40] | [added: 42] |
| Item 8. | | [Financial Statements and Supplementary [removed: Data](#tx531906_14) | |] [added: Data.](#tx696297_14)] | [removed: 41] | [added: 43] |
| Item 9. | | [Changes in and Disagreements with Accountants on Accounting and Financial [removed: Disclosure](#tx531906_15) |] [added: Disclosure.](#tx696297_15)] | | 75 | [removed: |]
| Item 9A. | | [Controls and [removed: Procedures](#tx531906_16) |] [added: Procedures.](#tx696297_16)] | | 75 | [removed: |]
| Item 9B. | | [Other [removed: Information](#tx531906_17) |] [added: Information.](#tx696297_17)] | | 75 | [removed: |]
| | | [Part [removed: III](#tx531906_18) | |] [added: III](#tx696297_18)] | | |
| Item 10. | | [Directors, Executive Officers and Corporate [removed: Governance](#tx531906_19) |] [added: Governance.](#tx696297_19)] | | 76 | [removed: |]
| Item 11. | | [Executive [removed: Compensation](#tx531906_20) |] [added: Compensation.](#tx696297_20)] | | 79 | [removed: |]
| Item 12. | | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder [removed: Matters](#tx531906_21) |] [added: Matters.](#tx696297_21)] | | 79 | [removed: |]
| Item 13. | | [Certain Relationships and Related Transactions, and Director [removed: Independence](#tx531906_22) |] [added: Independence.](#tx696297_22)] | | 79 | [removed: |]
| Item 14. | | [Principal Accountant Fees and [removed: Services](#tx531906_23) |] [added: Services.](#tx696297_23)] | | 79 | [removed: |]
| Item 15. | | [Exhibits, Financial Statement [removed: Schedules](#tx531906_25) |] [added: Schedules.](#tx696297_25)] | | 80 | [removed: |]
| Item 16. | | [Form 10-K [removed: Summary](#tx531906_26) |] [added: Summary.](#tx696297_26)] | | 85 | [removed: |]
Throughout this document, Domino’s Pizza, Inc. (NYSE: DPZ) is referred to as the “Company,” “Domino’s”, “Domino’s Pizza” or in the [removed: first person] [added: first-person] notations of “we,” “us” and “our.”
10-K 1 d696297d10k.htm 10-K
| | | | | |
| --- | --- | --- | --- | --- |
| | | [Part I](#tx696297_1) | | |
| Item 1. | | [Business.](#tx696297_2) | | 2 |
| Item 2. | | [Properties.](#tx696297_5) | | 21 |
| Item 3. | | [Legal Proceedings.](#tx696297_6) | | 21 |
| | | [Part II](#tx696297_9) | | |
| | | | | |
| | | | | |
| | | [Part IV](#tx696297_24) | | |
| | | | | |
| | | | | |
| [SIGNATURES](#tx696297_27) | | | | 91 |
10-K 1 d531906d10k.htm FORM 10-K
| incorporation or organization) | | Identification No.) |
| Ann Arbor, Michigan | | 48105 |
Act: Yes ☒ No ☐
Act: Yes ☐ No ☒
| | | | | | | |
| --- | --- | --- | --- | --- | --- | --- |
| | | [Part I](#tx531906_1) | | | | |
| Item 1. | | [Business](#tx531906_2) | | | 2 | |
| Item 2. | | [Properties](#tx531906_5) | | | 19 | |
| Item 3. | | [Legal Proceedings](#tx531906_6) | | | 19 | |
| | | [Part II](#tx531906_9) | | | | |
| | | [Part IV](#tx531906_24) | | | | |
| [SIGNATURES](#tx531906_27) | | | | | 91 | |
Item 1B. Unresolved Staff Comments.
0 rewritten, 0 added, 1 removed, 1 unchanged
| --- | --- |
Item 2. Properties.
5 rewritten, 1 added, 1 removed, 3 unchanged
We lease approximately [removed: 260,000] [added: 270,000] square feet for our World Resource Center located in Ann Arbor, Michigan under an operating lease with Domino’s Farms Office Park, L.L.C., an unrelated company.
The lease, as amended, expires in [removed: December 2022] [added: 2029] and has two five-year renewal options.
We also own two store buildings that we lease to [removed: domestic] [added: U.S.] franchisees.
All other [removed: domestic] [added: U.S.] Company-owned stores are leased by us, typically under five-year leases with one or two five-year renewal options.
All other [removed: domestic] [added: U.S.] and international supply chain centers are leased by us, typically under leases ranging between five and [removed: 15] [added: 20] years with one or two five-year renewal options.
Under an amendment to this lease, Domino’s Farms Office Park, L.L.C. is currently constructing a new 33,000 square foot building that will be leased to the Company upon completion, which is expected to occur in 2019.
| --- | --- |
Item 4. Mine Safety Disclosures.
0 rewritten, 0 added, 1 removed, 1 unchanged
| --- | --- |
Item 4A. Executive Officers of the Registrant.
0 rewritten, 0 added, 1 removed, 4 unchanged
| --- | --- |
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
10 rewritten, 6 added, 24 removed, 14 unchanged
As of February [removed: 13, 2018,] [added: 14, 2019,] Domino’s Pizza, Inc. had 170,000,000 authorized shares of common stock, par value $0.01 per share, of which [removed: 43,018,242] [added: 41,040,704] were issued and outstanding.
Our Board of Directors declared a quarterly dividend of [removed: $0.55] [added: $0.65] per common share on February [removed: 14, 2018] [added: 20, 2019] payable on March [removed: 30, 2018] [added: 29, 2019] to shareholders of record at the close of business on March 15, [removed: 2018.][added: 2019.]
As of February [removed: 13, 2018,] [added: 14, 2019,] there were [removed: 1,499] [added: 1,565] registered holders of record of Domino’s Pizza, Inc.’s common stock.
As of December [removed: 31, 2017,] [added: 30, 2018,] we had a Board of Directors-approved share repurchase program for up to [removed: $1.25 billion] [added: $750.0 million] of our common stock, of which [removed: $198.5] [added: $158.8] million remained available for future purchases of our common stock.
The following table summarizes our repurchase activity during the fourth quarter ended December [removed: 31, 2017:][added: 30, 2018:]
| Period | | [removed: Total Number of Shares Purchased (1)] [added: Total Number of Shares Purchased (1)] | | | | [removed: Average Price Paid per] [added: Average Price Paid per] Share | | | | [removed: Total Number] [added: Total Number] of [removed: Shares Purchased as Part of Publicly Announced Program (2)] [added: Shares Purchased as Part of Publicly Announced Program (2)] | | | | Maximum [removed: Approximate Dollar Value of Shares that] [added: Approximate Dollar Value of Shares that] May [removed: Yet Be Purchased Under the Program (in] [added: Yet Be Purchased Under the Program (in] thousands) | | |
| (1) | [removed: 4,506] [added: 3,643] shares were purchased as part of the Company’s employee stock purchase discount plan. During the fourth quarter, the shares were purchased at an average price of [removed: $190.97.] [added: $274.26.] |
The following comparative stock performance line graph compares the cumulative shareholder return on the common stock of Domino’s Pizza, Inc. (NYSE: DPZ) for the five-year period between December 31, [removed: 2012] [added: 2013] and December 31, [removed: 2017,] [added: 2018,] with cumulative total return on (i) the Total Return Index for the New York Stock Exchange (the “NYSE Composite Index”), (ii) the Standard & Poor’s 500 Index (the “S&P 500”) and (iii) the peer group, the Standard & Poor’s 400 Restaurant Index (the “S&P 400 Restaurant Index”).
The cumulative total return computations set forth in the performance graph assume the investment of $100 in the Company’s common stock, the NYSE Composite Index, the S&P 500 Index and the S&P 400 Restaurant Index on December 31, [removed: 2012.][added: 2013.]
[removed: 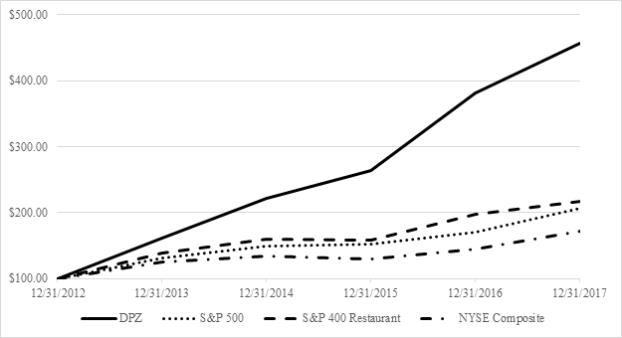][added: 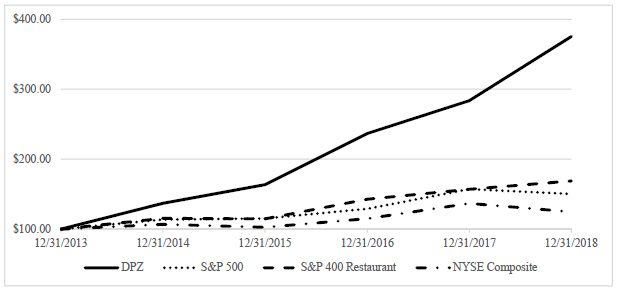]
| Period #10 (September 10, 2018 to October 7, 2018) | | | 5,574 | | | $ | 276.41 | | | | 4,424 | | | $ | 319,595 | |
| Period #11 (October 8, 2018 to November 4, 2018) | | | 331,613 | | | | 264.29 | | | | 330,291 | | | | 232,305 | |
| Period #12 (November 5, 2018 to December 2, 2018) | | | 76,562 | | | | 254.79 | | | | 75,391 | | | | 213,119 | |
| Period #13 (December 3, 2018 to December 30, 2018) | | | 226,270 | | | | 240.11 | | | | 226,270 | | | | 158,788 | |
| Total | | | 640,019 | | | $ | 254.71 | | | | 636,376 | | | $ | 158,788 | |
| (2) | From December 31, 2018 through February 14, 2019, the Company repurchased and retired an additional 33,549 shares of common stock for a total of approximately $8.1 million, or an average price of $242.74 per share. Authorization for the repurchase program may be modified, suspended, or discontinued at any time. The repurchase of shares in any particular period and the actual amount of such purchases remain at the discretion of the Board of Directors, and no assurance can be given that shares will be repurchased in the future. |
| --- | --- |
The following table presents the high and low closing prices by quarter for Domino’s Pizza, Inc.’s common stock, as reported by the NYSE, and dividends declared per common share.
| | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| 2017: | | High | | | | Low | | | | Dividends Declared Per Share | | |
| First quarter (January 2, 2017 – March 26, 2017) | | $ | 189.81 | | | $ | 158.36 | | | $ | 0.46 | |
| Second quarter (March 27, 2017 – June 18, 2017) | | | 218.15 | | | | 173.75 | | | | 0.46 | |
| Third quarter (June 19, 2017 – September 10, 2017) | | | 218.88 | | | | 178.38 | | | | 0.46 | |
| Fourth quarter (September 11, 2017 – December 31, 2017) | | | 209.44 | | | | 168.71 | | | | 0.46 | |
| 2016: | | | | | | | | | | | | |
| First quarter (January 4, 2016 – March 27, 2016) | | $ | 134.39 | | | $ | 104.16 | | | $ | 0.38 | |
| Second quarter (March 28, 2016 – June 19, 2016) | | | 140.01 | | | | 118.56 | | | | 0.38 | |
| Third quarter (June 20, 2016 – September 11, 2016) | | | 151.00 | | | | 122.08 | | | | 0.38 | |
| Fourth quarter (September 12, 2016 – January 1, 2017) | | | 172.26 | | | | 149.66 | | | | 0.38 | |
| Period #10 (September 11, 2017 to October 8, 2017) | | | — | | | $ | — | | | | — | | | $ | 250,000 | |
| Period #11 (October 9, 2017 to November 5, 2017) (2) | | | 799,561 | | | | 191.93 | | | | 797,649 | | | | 223,368 | |
| Period #12 (November 6, 2017 to December 3, 2017) | | | 140,697 | | | | 178.64 | | | | 139,377 | | | | 198,468 | |
| Period #13 (December 4, 2017 to December 31, 2017) | | | 1,274 | | | | 183.61 | | | | — | | | | 198,468 | |
| Total | | | 941,532 | | | $ | 189.93 | | | | 937,026 | | | $ | 198,468 | |
| (2) | On July 27, 2017, the Company’s Board of Directors authorized a new share repurchase program to repurchase up to $1.25 billion of the Company’s common stock. This repurchase program replaced the previously existing $250.0 million share repurchase program. On August 2, 2017, the Company entered into a $1.0 billion accelerated share repurchase agreement (the “2017 ASR Agreement”) with a counterparty. In connection with the 2017 ASR Agreement, the Company received and retired a total of 5,218,670 shares of its common stock, including 4,558,863 shares received and retired during the third quarter and 659,807 shares received and retired at final settlement during the fourth quarter. |
The average price paid per share of $191.93 for Period #11 (October 9, 2017 to November 5, 2017) includes the 659,807 shares received and retired at final settlement of the 2017 ASR Agreement.
The average purchase price per share for the 5,218,670 shares the Company received and retired through the $1.0 billion ASR program was $191.62.
On February 14, 2017, the Company’s Board of Directors authorized a new share repurchase program to repurchase up to $750.0 million of the Company’s common stock.
This repurchase program replaces the remaining availability of approximately $198.5 million under the Company’s previously approved $1.25 billion share repurchase program.
Item 6. Selected Financial Data.
43 rewritten, 10 added, 2 removed, 32 unchanged
| | | Fiscal year ended [removed: (5)] [added: (8)] | | | | | | | | | | | | | | | | | | |
| [removed: (dollars] [added: (dollars] in millions, except per share [removed: data)] [added: data)] | | December [added: 30, 2018 (4) (5) | | | | December] 31, 2017 [removed: (3)] [added: (6)] | | | | January 1, 2017 | | | | January 3, 2016 [removed: (4)] [added: (7)] | | | | December 28, 2014 | | | [removed: | December 29, 2013 | | |]
| [removed: Domestic] [added: U.S.] Company-owned stores | | $ | [removed: 490.8] [added: 514.8] | | | $ | [removed: 439.0] [added: 490.8] | | | $ | [removed: 396.9] [added: 439.0] | | | $ | [removed: 348.5] [added: 396.9] | | | $ | [removed: 337.4] [added: 348.5] | |
| [removed: Domestic] [added: U.S.] franchise [added: royalties and fees] | | | [removed: 351.4] [added: 391.5] | | | | [removed: 312.3] [added: 351.4] | | | | [removed: 272.8] [added: 312.3] | | | | [removed: 230.2] [added: 272.8] | | | | [removed: 212.4] [added: 230.2] | |
| [removed: Domestic] [added: U.S.] stores | | | [removed: 842.2] [added: 1,264.8] | | | | [removed: 751.3] [added: 842.2] | | | | [removed: 669.7] [added: 751.3] | | | | [removed: 578.7] [added: 669.7] | | | | [removed: 549.8] [added: 578.7] | |
| Supply chain | | | [removed: 1,739.0] [added: 1,943.3] | | | | [removed: 1,544.3] [added: 1,739.0] | | | | [removed: 1,383.2] [added: 1,544.3] | | | | [removed: 1,262.5] [added: 1,383.2] | | | | [removed: 1,118.9] [added: 1,262.5] | |
| International franchise [added: royalties and fees] | | | [removed: 206.7] [added: 224.7] | | | | [removed: 177.0] [added: 206.7] | | | | [removed: 163.6] [added: 177.0] | | | | [removed: 152.6] [added: 163.6] | | | | [removed: 133.6] [added: 152.6] | |
| Total revenues | | | [removed: 2,788.0] [added: 3,432.9] | | | | [removed: 2,472.6] [added: 2,788.0] | | | | [removed: 2,216.5] [added: 2,472.6] | | | | [removed: 1,993.8] [added: 2,216.5] | | | | [removed: 1,802.2] [added: 1,993.8] | |
| Cost of sales | | | [removed: 1,922.0] [added: 2,130.2] | | | | [removed: 1,704.9] [added: 1,922.0] | | | | [removed: 1,533.4] [added: 1,704.9] | | | | [removed: 1,399.1] [added: 1,533.4] | | | | [removed: 1,253.2] [added: 1,399.1] | |
| Operating margin | | | [removed: 866.0] [added: 1,302.7] | | | | [removed: 767.7] [added: 866.0] | | | | [removed: 683.1] [added: 767.7] | | | | [removed: 594.8] [added: 683.1] | | | | [removed: 549.0] [added: 594.8] | |
| General and administrative expense | | | [removed: 344.8] [added: 372.5] | | | | [removed: 313.6] [added: 344.8] | | | | [removed: 277.7] [added: 313.6] | | | | [removed: 249.4] [added: 277.7] | | | | [removed: 235.2] [added: 249.4] | |
| Income from operations | | | [removed: 521.2] [added: 571.7] | | | | [removed: 454.0] [added: 521.2] | | | | [removed: 405.4] [added: 454.0] | | | | [removed: 345.4] [added: 405.4] | | | | [removed: 313.8] [added: 345.4] | |
| Interest income | | | [removed: 1.5] [added: 3.3] | | | | [removed: 0.7] [added: 1.5] | | | | [removed: 0.3] [added: 0.7] | | | | [removed: 0.1] [added: 0.3] | | | | [removed: 0.2] [added: 0.1] | |
| Interest expense | | | [removed: (122.5] [added: (146.3] | ) | | | [removed: (110.1] [added: (122.5] | ) | | | [removed: (99.5] [added: (110.1] | ) | | | [removed: (86.9] [added: (99.5] | ) | | | [removed: (88.9] [added: (86.9] | ) |
| Income before provision for income taxes | | | [removed: 400.2] [added: 428.7] | | | | [removed: 344.7] [added: 400.2] | | | | [removed: 306.2] [added: 344.7] | | | | [removed: 258.6] [added: 306.2] | | | | [removed: 225.1] [added: 258.6] | |
| Provision for income taxes | | | [removed: 122.2] [added: 66.7] | | | | [removed: 130.0] [added: 122.2] | | | | [removed: 113.4] [added: 130.0] | | | | [removed: 96.0] [added: 113.4] | | | | [removed: 82.1] [added: 96.0] | |
| Net income | | $ | [removed: 277.9] [added: 362.0] | | | $ | [removed: 214.7] [added: 277.9] | | | $ | [removed: 192.8] [added: 214.7] | | | $ | [removed: 162.6] [added: 192.8] | | | $ | [removed: 143.0] [added: 162.6] | |
| Common stock – basic | | $ | [removed: 6.05] [added: 8.65] | | | $ | [removed: 4.41] [added: 6.05] | | | $ | [removed: 3.58] [added: 4.41] | | | $ | [removed: 2.96] [added: 3.58] | | | $ | [removed: 2.58] [added: 2.96] | |
| Common stock – diluted | | | [removed: 5.83] [added: 8.35] | | | | [removed: 4.30] [added: 5.83] | | | | [removed: 3.47] [added: 4.30] | | | | [removed: 2.86] [added: 3.47] | | | | [removed: 2.48] [added: 2.86] | |
| Dividends declared per share | | $ | [removed: 1.84] [added: 2.20] | | | $ | [removed: 1.52] [added: 1.84] | | | $ | [removed: 1.24] [added: 1.52] | | | $ | [removed: 1.00] [added: 1.24] | | | $ | [removed: 0.80] [added: 1.00] | |
| Cash and cash equivalents | | $ | [removed: 35.8] [added: 25.4] | | | $ | [removed: 42.8] [added: 35.8] | | | $ | [removed: 133.4] [added: 42.8] | | | $ | [removed: 30.9] [added: 133.4] | | | $ | [removed: 14.4] [added: 30.9] | |
| Restricted cash and cash equivalents | | | [removed: 191.8] [added: 167.0] | | | | [removed: 126.5] [added: 191.8] | | | | [removed: 180.9] [added: 126.5] | | | | [removed: 121.0] [added: 180.9] | | | | [removed: 125.5] [added: 121.0] | |
| Working capital [removed: (1)] [added: (2)] | | | [added: 14.6 | | | |] (10.3 | ) | | | (34.3 | ) | | | 45.7 | | | | 41.8 | | [removed: | | (28.5 | ) |]
| Total assets | | | [removed: 836.8] [added: 907.4] | | | | [removed: 716.3] [added: 836.8] | | | | [removed: 799.8] [added: 716.3] | | | | [removed: 596.3] [added: 799.8] | | | | [removed: 496.6] [added: 596.3] | |
| Total debt net of debt issuance cost | | | [removed: 3,153.8] [added: 3,531.6] | | | | [removed: 2,187.9] [added: 3,153.8] | | | | [removed: 2,240.8] [added: 2,187.9] | | | | [removed: 1,500.6] [added: 2,240.8] | | | | [removed: 1,507.7] [added: 1,500.6] | |
| Total stockholders’ deficit | | | [removed: (2,735.4] [added: (3,039.9] | ) | | | [removed: (1,883.1] [added: (2,735.4] | ) | | | [removed: (1,800.3] [added: (1,883.1] | ) | | | [removed: (1,219.5] [added: (1,800.3] | ) | | | [removed: (1,290.2] [added: (1,219.5] | ) |
| [removed: (dollars] [added: (dollars] in [removed: millions)] [added: millions)] | | December [removed: 31, 2017 (3)] [added: 30, 2018 (4) (5)] | | | | [added: December 31, 2017 (6) | | | |] January 1, 2017 | | | | January [removed: 3, 2016 (4)] [added: 3, 2016 (7)] | | | | December 28, 2014 | | | [removed: | December 29, 2013 | | |]
| Depreciation and amortization | | $ | [removed: 44.4] [added: 53.7] | | | $ | [removed: 38.1] [added: 44.4] | | | $ | [removed: 32.4] [added: 38.1] | | | $ | [removed: 35.8] [added: 32.4] | | | $ | [removed: 25.8] [added: 35.8] | |
| Capital expenditures | | | [removed: 90.3] [added: 119.7] | | | | [removed: 61.5] [added: 90.3] | | | | [removed: 62.4] [added: 61.5] | | | | [removed: 71.8] [added: 62.4] | | | | [removed: 40.4] [added: 71.8] | |
| Same store sales growth [removed: (2):] [added: (3):] | | | | | | | | | | | | | | | | | | | | |
| [removed: Domestic] [added: U.S.] Company-owned stores | | | [removed: 8.7] [added: 4.8] | % | | | [removed: 10.4] [added: 8.7] | % | | | [removed: 12.2] [added: 10.4] | % | | | [removed: 6.2] [added: 12.2] | % | | | [removed: 3.9] [added: 6.2] | % |
| [removed: Domestic] [added: U.S.] franchise stores | | | [removed: 7.6] [added: 6.8] | % | | | [removed: 10.5] [added: 7.6] | % | | | [removed: 11.9] [added: 10.5] | % | | | [removed: 7.7] [added: 11.9] | % | | | [removed: 5.5] [added: 7.7] | % |
| [removed: Domestic] [added: U.S.] stores | | | [removed: 7.7] [added: 6.6] | % | | | [removed: 10.5] [added: 7.7] | % | | | [removed: 12.0] [added: 10.5] | % | | | [removed: 7.5] [added: 12.0] | % | | | [removed: 5.4] [added: 7.5] | % |
| International stores | | | [removed: 3.4] [added: 3.5] | % | | | [removed: 6.3] [added: 3.4] | % | | | [removed: 7.8] [added: 6.3] | % | | | [removed: 6.9] [added: 7.8] | % | | | [removed: 6.2] [added: 6.9] | % |
| [removed: Domestic] [added: U.S.] Company-owned stores | | | [removed: 392] [added: 390] | | | | 392 | | | | [removed: 384] [added: 392] | | | | [removed: 377] [added: 384] | | | | [removed: 390] [added: 377] | |
| [removed: Domestic] [added: U.S.] franchise stores | | | [removed: 5,195] [added: 5,486] | | | | [removed: 4,979] [added: 5,195] | | | | [removed: 4,816] [added: 4,979] | | | | [removed: 4,690] [added: 4,816] | | | | [removed: 4,596] [added: 4,690] | |
| [removed: Domestic] [added: U.S.] stores | | | [removed: 5,587] [added: 5,876] | | | | [removed: 5,371] [added: 5,587] | | | | [removed: 5,200] [added: 5,371] | | | | [removed: 5,067] [added: 5,200] | | | | [removed: 4,986] [added: 5,067] | |
| International stores | | | [removed: 9,269] [added: 10,038] | | | | [removed: 8,440] [added: 9,269] | | | | [removed: 7,330] [added: 8,440] | | | | [removed: 6,562] [added: 7,330] | | | | [removed: 5,900] [added: 6,562] | |
| Total stores | | | [removed: 14,856] [added: 15,914] | | | | [removed: 13,811] [added: 14,856] | | | | [removed: 12,530] [added: 13,811] | | | | [removed: 11,629] [added: 12,530] | | | | [removed: 10,886] [added: 11,629] | |
| [removed: (2)] [added: (3)] | Same store sales growth is calculated including only sales from stores that also had sales in the comparable period of the prior year. International same store sales growth is calculated similarly to [removed: domestic] [added: U.S.] same store sales growth. Changes in international same store sales are reported on a constant dollar basis which reflects changes in international local currency sales. The 53rd week in fiscal 2015 had no impact on reported same store sales growth amounts. |
| U.S. franchise advertising (1) | | | 358.5 | | | | — | | | | — | | | | — | | | | — | |
| U.S. franchise advertising (1) | | | 358.5 | | | | — | | | | — | | | | — | | | | — | |
| Cash and cash equivalents included in advertising fund assets, restricted | | | 45.0 | | | | 27.3 | | | | 25.1 | | | | 19.9 | | | | 25.1 | |
| | | Fiscal year ended (8) | | | | | | | | | | | | | | | | | | |
| (1) | The adoption of ASC 606 in 2018 resulted in the recognition of $358.5 million in revenue in 2018 related to U.S. franchise contributions to DNAF. In prior years, under accounting standards in effect at that time, we had presented these contributions net with the related disbursements in our consolidated statement of income. Refer to Note 1 to the consolidated financial statements for additional information related to the adoption of this new accounting standard. |
| (2) | The working capital amounts exclude restricted cash and cash equivalents, advertising fund assets, restricted, and advertising fund liabilities. |
| (4) | In 2018, the Company began managing its franchised stores in Alaska and Hawaii as part of its U.S. Stores segment. Prior to 2018, store counts and retail sales from these franchised stores were included in the Company’s international stores in the table above. Consolidated results of the Company have not been impacted by this change and prior year amounts have not been reclassified to conform to the current year presentation due to immateriality. |
| (5) | In connection with our 2018 Recapitalization, the Company issued $825.0 million of fixed rate notes. A portion of the proceeds from the 2018 Recapitalization was used to repay the remaining $490.1 million in outstanding principal and interest under the Company’s 2015 five-year fixed rate notes, pre-fund a portion of the principal and interest payable on the 2018 Notes, pay transaction fees and expenses and repurchase and retire shares of the Company’s common stock. Refer to Note 4 of the consolidated financial statements for additional detail related to the 2018 Recapitalization. |
| --- | --- |
| --- | --- |
| | | | | | | | | | | | | | | | | | | | | |
| (1) | The working capital amounts exclude restricted cash and cash equivalents amounts of $191.8 million in 2017, $126.5 million in 2016, $180.9 million in 2015, $121.0 million in 2014 and $125.5 million in 2013. |
An excerpt. Shown here: 40 of 43 rewritten, all 10 added and all 2 removed. The counts are complete. For every sentence, read Item 6. Selected Financial Data. in the FY2018 filing and the FY2017 filing.
Item 8. Financial Statements and Supplementary Data.
446 rewritten, 363 added, 130 removed, 474 unchanged
We have audited the accompanying consolidated balance sheets of Domino’s Pizza, Inc. and its subsidiaries [added: (the “Company”)] as of December [removed: 31, 2017] [added: 30, 2018] and [removed: January 1,] [added: December 31,] 2017, and the related consolidated statements of income, [added: statements of] comprehensive income, [added: statements of] stockholders’ deficit, and [added: statements of] cash flows for each of the three years in the period ended December [removed: 31, 2017,] [added: 30, 2018,] including the related notes, the [removed: schedule] [added: schedules] of condensed financial information of the registrant as of December [removed: 31, 2017] [added: 30, 2018] and [removed: January 1,] [added: December 31,] 2017 and for the three years in the period ended December [removed: 31, 2017 appearing under Item 16,] [added: 30, 2018] and [removed: the schedule of] valuation and qualifying accounts for each of the three years in the period [removed: ended] December [removed: 31, 2017] [added: 30, 2018] appearing under Item 16 (collectively referred to as the “consolidated financial statements”).
We also have audited the Company’s internal control over financial reporting as of December [removed: 31, 2017,] [added: 30, 2018,] based on criteria established in [removed: _Internal Control—Integrated Framework_] [added: Internal Control – Integrated Framework] (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December [removed: 31, 2017] [added: 30, 2018] and [removed: January 1,] [added: December 31,] 2017, and the results of its operations and its cash flows for each of the three years in the period ended December [removed: 31, 2017] [added: 30, 2018] in conformity with accounting principles generally accepted in the United States of America.
Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December [removed: 31, 2017,] [added: 30, 2018,] based on criteria established in [removed: _Internal Control—Integrated Framework_] [added: Internal Control – Integrated Framework] (2013) issued by the COSO.
_Change in Accounting [removed: Principle_][added: Principles_]
As discussed in Note [removed: 1] [added: 6] to the consolidated financial statements, the Company changed the manner in which it accounts for share-based compensation in 2017.
Our responsibility is to express opinions on the Company’s [removed: consolidated] [added: \[consolidated\]] financial statements and on the Company’s internal control over financial reporting based on our audits.
We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) [removed: (“PCAOB”)] [added: (PCAOB)] and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
[removed: DOMINO’S PIZZA, INC. AND SUBSIDIARIES][added: Domino’s Pizza, Inc. and Subsidiaries]
[removed: CONSOLIDATED] [added: CONSOLIDATED] BALANCE [removed: SHEETS][added: SHEETS]
[removed: (In] [added: (In] thousands, except share and per share [removed: amounts)][added: amounts)]
| | | [removed: December 31, 2017] [added: December 30,] | | | | [removed: January 1, 2017] [added: December 31,] | | | [added: | January 1, | | |]
| [removed: ASSETS] [added: Assets] | | | | | | | | |
| Cash and cash equivalents | | $ | [removed: 35,768] [added: 25,438] | | | $ | [removed: 42,815] [added: 35,768] | |
| Restricted cash and cash [removed: equivalents] [added: equivalents, beginning of period] | | | 191,762 | | | | 126,496 | | [added: | | 180,940 | |]
| Accounts receivable, net of reserves of [removed: $1,424] [added: $1,879] in [removed: 2017] [added: 2018] and [removed: $2,342] [added: $1,424] in [removed: 2016] [added: 2017] | | | [removed: 173,677] [added: 190,091] | | | | [removed: 150,369] [added: 173,677] | |
| Inventories | | | [removed: 39,961] [added: 45,975] | | | | [removed: 40,181] [added: 39,961] | |
| Prepaid expenses and other | | | [removed: 18,389] [added: 25,710] | | | | [removed: 17,635] [added: 18,389] | |
| Advertising fund assets, restricted | | | [removed: 120,223] [added: 112,744] | | | | [removed: 118,377] [added: 120,223] | |
| Total current assets | | | [removed: 579,780] [added: 566,951] | | | | [removed: 495,873] [added: 579,780] | |
| Land and buildings | | | [removed: 29,171] [added: 41,147] | | | | [removed: 29,129] [added: 29,171] | |
| Leasehold and other improvements | | | [removed: 128,613] [added: 170,498] | | | | [removed: 120,726] [added: 128,613] | |
| Equipment | | | [removed: 216,599] [added: 243,654] | | | | [removed: 201,827] [added: 216,599] | |
| Construction in progress | | | [removed: 32,482] [added: 31,822] | | | | [removed: 7,816] [added: 32,482] | |
| Accumulated depreciation and amortization | | | [removed: (237,279] [added: (252,182] | ) | | | [removed: (220,964] [added: (237,279] | ) |
| Property, plant and equipment, net | | | [removed: 169,586] [added: 234,939] | | | | [removed: 138,534] [added: 169,586] | |
| Investments in marketable securities, restricted | | | [removed: 8,119] [added: 8,718] | | | | [removed: 7,260] [added: 8,119] | |
| Goodwill | | | [removed: 15,423] [added: 14,919] | | | | [removed: 16,058] [added: 15,423] | |
| Capitalized software, net of accumulated amortization of [removed: $78,696] [added: $89,161] in [removed: 2017] [added: 2018] and [removed: $68,727] [added: $78,696] in [removed: 2016] [added: 2017] | | | [removed: 52,823] [added: 63,809] | | | | [removed: 40,256] [added: 52,823] | |
| Other assets, net of accumulated amortization of $776 in [removed: 2017] [added: 2018] and $776 in [removed: 2016] [added: 2017] | | | [removed: 8,272] [added: 12,523] | | | | [removed: 9,379] [added: 8,272] | |
| Deferred income taxes | | | [removed: 2,750] [added: 5,526] | | | | [removed: 8,935] [added: 2,750] | |
| Total other assets | | | [removed: 87,387] [added: 105,495] | | | | [removed: 81,888] [added: 87,387] | |
| Total assets | | $ | [removed: 836,753] [added: 907,385] | | | $ | [removed: 716,295] [added: 836,753] | |
[removed: (Continued)][added: (Continued)]
| [removed: LIABILITIES AND STOCKHOLDERS’ DEFICIT] [added: Liabilities and stockholders’ deficit] | | | | | | | | |
| Current portion of long-term debt | | $ | [removed: 32,324] [added: 35,893] | | | $ | [removed: 38,887] [added: 32,324] | |
| Accounts payable | | | [removed: 106,894] [added: 92,546] | | | | [removed: 111,510] [added: 106,894] | |
| Accrued compensation | | | [removed: 37,417] [added: 40,962] | | | | [removed: 42,089] [added: 37,417] | |
| Accrued interest | | | [removed: 22,095] [added: 25,981] | | | | [removed: 18,826] [added: 22,095] | |
| Insurance reserves | | | [removed: 20,754] [added: 22,210] | | | | [removed: 16,742] [added: 20,754] | |
As discussed in Note 1 to the consolidated financial statements, the Company changed the manner in which it accounts for revenue and the manner in which it accounts for restricted cash and cash equivalents in 2018.
February 21, 2019
| | | December 30, 2018 | | | | December 31, 2017 | | |
| Restricted cash and cash equivalents | | | 166,993 | | | | 191,762 | |
| | | | 487,121 | | | | 406,865 | |
Domino’s Pizza, Inc. and Subsidiaries
| U.S. franchise royalties and fees | | | 391,493 | | | | 351,387 | | | | 312,260 | |
| U.S. franchise advertising | | | 358,526 | | | | — | | | | — | |
| U.S. franchise advertising | | | 358,526 | | | | — | | | | — | |
Domino’s Pizza, Inc. and Subsidiaries
| | | For the Years Ended | | | | | | | | | | |
| | | 2018 | | | | 2017 | | | | 2017 | | |
| Net income | | $ | 361,972 | | | $ | 277,905 | | | $ | 214,678 | |
Domino’s Pizza, Inc. and Subsidiaries
| Net income | | | — | | | | — | | | | — | | | | 361,972 | | | | — | |
| Purchases of common stock | | | (2,387,430 | ) | | | (24 | ) | | | (30,743 | ) | | | (560,445 | ) | | | — | |
| Exercises of stock options | | | 414,102 | | | | 4 | | | | 9,828 | | | | — | | | | — | |
| Adoption of ASC 606 (Note 1) | | | — | | | | — | | | | — | | | | (6,701 | ) | | | — | |
| Reclassification adjustment for stranded taxes (Note 1) | | | — | | | | — | | | | — | | | | 351 | | | | (351 | ) |
| Balance at December 30, 2018 | | | 40,977,561 | | | $ | 410 | | | $ | 569 | | | $ | (3,036,471 | ) | | $ | (4,429 | ) |
Domino’s Pizza, Inc. and Subsidiaries
(In thousands)
| | | For the Years Ended | | | | | | | | | | |
| | | 2018 | | | | 2017 | | | | 2017 | | |
| Net income | | $ | 361,972 | | | $ | 277,905 | | | $ | 214,678 | |
| Changes in advertising fund assets and liabilities, restricted | | | (5,352 | ) | | | 2,225 | | | | 5,187 | |
| Net cash provided by operating activities | | | 394,171 | | | | 341,261 | | | | 292,460 | |
| Maturities of advertising fund investments, restricted | | | 94,007 | | | | — | | | | — | |
| Purchases of advertising fund investments, restricted | | | (70,152 | ) | | | — | | | | — | |
| Net cash used in investing activities | | | (88,257 | ) | | | (83,738 | ) | | | (55,280 | ) |
| Change in cash and cash equivalents, restricted cash and cash equivalents | | $ | (17,427 | ) | | $ | 60,444 | | | $ | (139,891 | ) |
| Cash and cash equivalents included in advertising fund assets, restricted, beginning of period | | | 27,316 | | | | 25,091 | | | | 19,904 | |
| Cash and cash equivalents, restricted cash and cash equivalents and cash and cash equivalents included in advertising fund assets, restricted, beginning of period | | $ | 254,846 | | | $ | 194,402 | | | $ | 334,293 | |
| Restricted cash and cash equivalents, end of period | | | 166,993 | | | | 191,762 | | | | 126,496 | |
| Cash and cash equivalents included in advertising fund assets, restricted, end of period | | | 44,988 | | | | 27,316 | | | | 25,091 | |
| Cash and cash equivalents, restricted cash and cash equivalents and cash and cash equivalents included in advertising fund assets, restricted, end of period | | $ | 237,419 | | | $ | 254,846 | | | $ | 194,402 | |
Domino’s Pizza, Inc. and Subsidiaries
As of December 30, 2018, the Company also held $45.0 million of advertising fund restricted cash and cash equivalents, which can only be used for activities that promote the Domino’s Pizza brand.
As of December 31, 2017, the Company also held $27.3 million of advertising fund restricted cash and cash equivalents, which can only be used for activities that promote the Domino’s Pizza brand.
| | | 2018 | | | | 2017 | | |
##### [Table of Contents](#toc)
February 20, 2018
| --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | 406,865 | | | | 359,498 | |
The accompanying notes are an integral part of these consolidated statements.
| Domestic franchise | | | 351,387 | | | | 312,260 | | | | 272,808 | |
| BALANCE AT DECEMBER 28, 2014 | | | 55,553,149 | | | $ | 556 | | | $ | 29,561 | | | $ | (1,246,921 | ) | | $ | (2,661 | ) |
| Net income | | | — | | | | — | | | | — | | | | 192,789 | | | | — | |
| Purchases of common stock | | | (6,152,918 | ) | | | (62 | ) | | | (55,008 | ) | | | (683,487 | ) | | | — | |
| Exercises of stock options | | | 428,433 | | | | 4 | | | | 4,810 | | | | — | | | | — | |
| Other | | | — | | | | — | | | | (389 | ) | | | — | | | | — | |
| Net cash provided by operating activities | | | 339,036 | | | | 287,273 | | | | 291,786 | |
| Change in restricted cash | | | (65,266 | ) | | | 54,444 | | | | (59,986 | ) |
| Net cash used in investing activities | | | (149,004 | ) | | | (836 | ) | | | (109,292 | ) |
| CHANGE IN CASH AND CASH EQUIVALENTS | | | (7,047 | ) | | | (90,634 | ) | | | 102,594 | |
| | | |
These revenues are recognized consistently with the policies applied for franchise revenues generated in the contiguous United States.
Advertising costs are expensed as incurred.
Advertising expense, which relates primarily to Company-owned stores, was approximately $39.8 million, $34.5 million and $32.0 million during 2017, 2016 and 2015, respectively.
Included in advertising expense were advertising contributions from Company-owned stores to DNAF of approximately $30.4 million, $27.2 million and $24.9 million in 2017, 2016 and 2015, respectively.
DNAF also received advertising contributions from franchisees of approximately $323.8 million, $293.8 million and $266.0 million during 2017, 2016 and 2015, respectively.
Franchisee contributions to DNAF and offsetting disbursements are presented net in the accompanying consolidated statements of income, as we have determined we are an agent for accounting purposes in this arrangement.
DNAF assets, consisting primarily of cash received from franchisees and accounts receivable from franchisees, can only be used for activities that promote the Domino’s Pizza brand.
Accordingly, all assets held by the DNAF are considered restricted.
The Company also paid dividends of $13.8 million in 2015 related to a dividend declaration in 2014.
Specifically, the Company recorded $3.4 million for the renewal of a capital lease of a supply chain center building in the first quarter of 2015, and recorded $0.6 million as a result of entering into a capital lease for a corporate store in the third quarter of 2015.
ASU 2016-09 is intended to simplify several areas of accounting for share-based compensation arrangements, including the income tax impact, classification on the statement of cash flows and forfeitures.
The new standard was effective for the Company beginning January 2, 2017.
As a result, excess tax benefits or deficiencies from equity-based compensation activity are reflected in the consolidated statements of income as a component of the provision for income taxes, whereas they previously were recognized in the consolidated statement of stockholders’ deficit.
The Company also elected to account for forfeitures as they occur, rather than to use an estimate of expected forfeitures for financial statement reporting purposes.
The Company’s election to account for forfeitures as they occur had an immaterial impact on its equity-based compensation expense.
The Company adopted the cash flow presentation prospectively, and accordingly, excess tax benefits from equity-based compensation of $27.2 million in fiscal 2017 are presented as an operating activity, while $48.1 million and $17.8 million of excess tax benefits from equity-based compensation in fiscal 2016 and fiscal 2015, respectively, are presented as a financing activity.
The presentation requirements for cash flows related to taxes paid for restricted stock upon vesting had no impact on our consolidated statements of cash flows for any of the periods presented because such cash flows have historically been presented as a financing activity.
Under the new revenue recognition standard, entities apply a five-step model that depicts the transfer of promised goods or services to customers in an amount that reflects the consideration to which the entity expects to be entitled in exchange for those goods or services.
Specifically, companies identify the performance obligations within their contracts with customers, allocate the transaction price received from customers to each performance obligation identified within their contracts, and recognize revenue as the performance obligations are satisfied.
During 2015, 2016, and 2017, the FASB issued various amendments which provide additional clarification and implementation guidance on ASC 606.
Specifically, these amendments clarify how an entity should identify the specified good or service for the principal versus agent evaluation and how it should apply the control principle to certain types of arrangements, clarify how an entity should identify performance obligations and licensing implementation guidance, as well as account for shipping and handling fees and freight service, assess collectability, present sales tax, treat non-cash consideration, and account for completed and modified contracts at the time of transition.
The new guidance requires enhanced disclosures, including revenue recognition policies to identify performance obligations to customers and significant judgments in measurement and recognition.
The effective date and transition requirements for ASC 606 and amendments is for fiscal years, and for interim periods within those years, beginning after December 15, 2017, and the Company will adopt this guidance using the modified retrospective approach effective January 1, 2018.
The Company has substantially completed its assessment of ASC 606, and the adoption of this guidance is not expected to have a material impact on its recognition of sales from Company-owned stores, ongoing royalty fees which are based on a percentage of franchise sales, revenues from its supply chain centers, development fees or technology fees.
An excerpt. Shown here: 40 of 446 rewritten, 40 of 363 added and 40 of 130 removed. The counts are complete. For every sentence, read Item 8. Financial Statements and Supplementary Data. in the FY2018 filing and the FY2017 filing.
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure.
0 rewritten, 0 added, 1 removed, 1 unchanged
| --- | --- |
Item 9A. Controls and Procedures.
3 rewritten, 0 added, 1 removed, 10 unchanged
Under the supervision and with the participation of the Company’s management, including its Chief Executive Officer and Chief Financial Officer, the Company conducted an evaluation of the effectiveness of its internal control over financial reporting as of December [removed: 31, 2017] [added: 30, 2018] based on the framework in _Internal Control_ _— Integrated Framework (2013)_ issued by the Committee of Sponsoring Organizations of the Treadway Commission.
Based on that evaluation, management concluded that its internal control over financial reporting was effective as of December [removed: 31, 2017.][added: 30, 2018.]
The effectiveness of the Company’s internal control over financial reporting as of December [removed: 31, 2017,] [added: 30, 2018,] has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in their report which appears herein.
| --- | --- |
Item 9B. Other Information.
0 rewritten, 0 added, 1 removed, 3 unchanged
| --- | --- |
Item 10. Directors, Executive Officers and Corporate Governance.
53 rewritten, 32 added, 27 removed, 45 unchanged
| David A. Brandon | | [removed: 65] [added: 66] | | Chairman of the Board of Directors |
| Jeffrey D. Lawrence | | [removed: 44] [added: 45] | | Executive Vice President, Chief Financial Officer |
| [removed: Troy] [added: Stuart] A. [removed: Ellis] [added: Levy] | | [removed: 52] [added: 47] | | Executive Vice President, Supply Chain Services |
| [removed: Stanley J. Gage] [added: Thomas B. Curtis] | | [removed: 51] [added: 55] | | Executive Vice President, Team USA |
| Scott R. Hinshaw | | [removed: 55] [added: 56] | | Executive Vice President, Franchise Operations and Development |
| Timothy P. McIntyre | | [removed: 55] [added: 56] | | Executive Vice President, Communication, Investor Relations and Legislative Affairs |
| Kevin S. Morris | | [removed: 57] [added: 58] | | Executive Vice President, General Counsel |
| J. Kevin Vasconi | | [removed: 57] [added: 58] | | Executive Vice President, Chief Information Officer |
| C. Andrew Ballard | | [removed: 45] [added: 46] | | Director |
| Andrew B. Balson | | [removed: 51] [added: 52] | | Director |
| Diana F. Cantor | | [removed: 60] [added: 61] | | Director |
| Richard L. Federico | | [removed: 63] [added: 64] | | Director |
| James A. Goldman | | [removed: 59] [added: 60] | | Director |
Brandon_ has served as [removed: our] [added: Domino’s] Chairman of the Board of Directors since March 1999.
Mr. Brandon [removed: is currently] [added: most recently served as] Chairman and [removed: CEO] [added: Chief Executive Officer] of Toys “R” Us, Inc., the world’s largest specialty retailer of toy and baby products, a position he [removed: has] held [removed: since] [added: from] July [removed: 2015.][added: 2015 to December 2018.]
Mr. Brandon served as [removed: our] [added: Domino’s] Chief Executive Officer from March 1999 to March 2010 and was retained by the Company as a Special Advisor from March 2010 to January 2011.
In addition to serving on the [removed: Boards] [added: Board] of Directors for [removed: Domino’s and Toys “R” Us,] [added: Domino’s,] Mr. Brandon also serves on the [removed: boards] [added: Board] of [added: Directors of] DTE Energy [added: Co.] and Herman Miller Inc. He previously served on the [removed: boards] [added: Boards] of [added: Directors of Toys “R” Us, Inc.,] Burger King Corporation, Kaydon Corporation, Northwest Airlines and the TJX Companies, Inc.
Lawrence_ has served as [added: Domino’s] Executive Vice President and Chief Financial Officer since August 2015.
[removed: Allison, Jr._ has] [added: He previously] served as [removed: our] President, Domino’s International [removed: since] [added: from] October [removed: 2014,] [added: 2014 to July 2018,] after joining the Company in March 2011 as Executive Vice President of International.
Prior to joining Domino’s, Mr. Allison [removed: served as a Partner] [added: worked] at Bain & Company, Inc. [added: for more than 13 years, serving as a Partner] from 2004 [removed: through] [added: to] December 2010, [added: and] as co-leader of Bain’s restaurant [removed: practice and was employed with Bain & Company for more than 13 years.][added: practice.]
[removed: Weiner_] [added: Curtis_] has served as [removed: President,] Domino’s [added: Executive Vice President, Team] USA (which represents our [removed: domestic franchised and] Company-owned store [removed: operations, in addition to U.S. marketing)] [added: division)] since [removed: October 2014.][added: July 2018.]
[removed: In January 2018, the Company announced that the Board of Directors] [added: Weiner_] has [removed: appointed Mr. Weiner to the newly-created role of] [added: served as Domino’s] Chief Operating Officer and President of the [removed: Americas, effective] [added: Americas since] July [removed: 1,] 2018.
[removed: Ellis_] [added: Levy_] has served as [removed: our] [added: Domino’s] Executive Vice President, Supply Chain Services since [removed: June 2015.][added: January 2019.]
Hinshaw_ has served as [removed: our] [added: Domino’s] Executive Vice President, Franchise Operations and Development since January 2008.
McIntyre_ has served as [added: Domino’s] Executive Vice President, Communication, Investor Relations and Legislative Affairs since May 2016.
Morris_ has served as [removed: our] [added: Domino’s] Executive Vice President, General Counsel since January 2017.
Prior to 1999, Mr. Morris served as a Senior International Attorney and Staff Director at McDonald’s Corporation after beginning his career as an attorney at Rudnick & [removed: Wolfe.][added: Wolfe LLP (the predecessor to DLA Piper).]
Kevin Vasconi_ has served as [removed: our] [added: Domino’s] Executive Vice President and Chief Information Officer since March 2012.
Andrew Ballard_ has served on [removed: our] [added: Domino’s] Board of Directors since July 2015 and is a member of the Compensation Committee [removed: and the Nominating and Corporate Governance Committee] of the Board of Directors.
Mr. Ballard [removed: currently serves as the CEO and Co-founder of Wiser Solutions, Inc., a technology and data company, and] is also [removed: the] Founder [removed: and Managing Partner] of Figtree Partners, an investment firm focused on [removed: digital media.][added: software and technology, and has served as its Managing Partner since November 2012.]
In addition, he [removed: is] [added: has served as] a Senior Advisor at the private equity firm Hellman & [removed: Friedman,] [added: Friedman LLC since December 2012,] where he [removed: was] previously [removed: a] [added: served as] Managing [removed: Director.][added: Director from 2006 to 2012 and as a Director from 2004 to 2006.]
Prior to joining Hellman & Friedman in 2003, Mr. Ballard worked at Bain [removed: Capital] [added: Capital, LLC] in San Francisco and Boston, as well as Bain & [removed: Company] [added: Company, Inc.] from 1994 to 2002.
In addition to serving on Domino’s [removed: Board,] [added: Board of Directors,] Mr. Ballard is currently Chairman of Datacor, Inc. and Vice Chairman of Zignal Labs, and has held previous board roles at Activant Solutions Inc., Catalina Marketing Corporation, DoubleClick Inc., Getty Images, [added: Inc.,] Internet Brands, Inc. and Vertafore, Inc. Mr. Ballard is the Chair of the Board of Trustees and Chair of the Investment Committee of the San Francisco Foundation.
He is also actively involved with Family Connections, a [removed: tuition free] [added: tuition-free] preschool for under-served families.
Mr. Balson is currently the Managing Partner of Cove Hill Partners, [added: L.P.,] a firm formed to make private equity investments.
Previously, Mr. Balson was the [removed: CEO] [added: Chief Executive Officer] of Match Beyond, [added: an innovative college completion program that helps low-income young adults attain college degrees and prepare for the workforce,] a position he held from January 2015 to June 2016.
Prior to becoming the [removed: CEO] [added: Chief Executive Officer] of Match Beyond, Mr. Balson was a Managing Director at Bain Capital, [added: LLC,] a global investment company, from 2001 to 2013.
Mr. Balson previously served on the Boards of Directors of Bloomin’ Brands, Inc., FleetCor Technologies, Inc., Dunkin’ Brands, Inc., Skylark Co., Ltd., [removed: Bellsystem24,] [added: BELLSYSTEM24, Inc.,] Burger King [removed: Corporation,] [added: Corporation] and Bright Horizons [added: Family] Solutions, [added: Inc.,] as well as numerous private companies.
Cantor_ has served on [removed: our] [added: Domino’s] Board of Directors since October [removed: 2005,] [added: 2005 and] serves as the Chairperson of the Audit Committee of the Board of [removed: Directors and also serves on the Nominating and Corporate Governance Committee of the Board of] Directors.
Ms. Cantor is currently a Partner at Alternative Investment Management, LLC, a position she has held since January 2010, and [added: she] is the Vice Chairman of the Virginia Retirement System, where she also serves on the Audit and Compliance Committee.
| Richard E. Allison, Jr. | | 52 | | Chief Executive Officer |
| Russell J. Weiner | | 50 | | Chief Operating Officer and President of the Americas |
| Joseph H. Jordan | | 45 | | Executive Vice President, International |
| Corie S. Barry | | 43 | | Director |
| Patricia E. Lopez | | 57 | | Director |
Allison, Jr._ has served as Domino’s Chief Executive Officer since July 2018 and was elected to Domino’s Board of Directors in July 2018 in conjunction with his appointment as Chief Executive Officer.
He previously served as President, Domino’s USA from October 2014 to July 2018.
_Thomas B.
Prior to his appointment, Mr. Curtis served as Vice President of Franchise Relations and Operations Innovation from March 2017 to July 2018, after serving as Vice President of Operations Support from August 2016 to March 2017 and as West Region Vice President from November 2012 to August 2016.
Mr. Curtis joined Domino’s in 2006, after being a Domino’s franchisee since 1987.
_Joseph H.
Jordan_ has served as Domino’s Executive Vice President of International since April 2018.
Prior to his appointment, Mr. Jordan had served as Senior Vice President and Chief Marketing Officer since May 2015, after joining Domino’s as Vice President of Innovation in September 2011.
Prior to joining Domino’s, Mr. Jordan served as Senior Director of Marketing at Pepsi-Cola North America for six years, held marketing roles at Philips Electronics and Unilever and was a consultant for Accenture.
_Stuart A.
Prior to joining Domino’s, Mr. Levy had served as Executive Vice President, Chief Transformation Officer for Republic Services, Inc. since 2014.
Prior to joining Republic, Mr. Levy had served as a Partner with Bain & Company since 2008.
Mr. Ballard currently serves as the Chief Executive Officer and Co-Founder of Wiser Solutions, Inc., a technology and data company, a position he has held since December 2012.
_Corie S.
Barry_ has served on our Board of Directors since July 2018 and is a member of the Audit Committee of the Board of Directors.
Ms. Barry currently serves as Senior Executive Vice President and Chief Financial and Strategic Transformation Officer of Best Buy Co., Inc., a specialty retailer of consumer electronics, personal computers, entertainment software and appliances, a position she has held since June 2016.
Ms. Barry previously served as Best Buy’s Chief Strategic Growth Officer from October 2015 to June 2016, Interim President of Geek Squad Services from March 2015 to May 2016, Senior Vice President of Domestic Finance from May 2013 to October 2015 and in a variety of financial and operational roles, both in the field and at the corporate campus, since joining Best Buy in 1999.
Prior to Best Buy, Ms. Barry worked at Deloitte Touche Tohmatsu Limited from 1997 to 1999.
Mr. Federico joined P.F. Chang’s as President in 1996, when he also began his service on its Board of Directors.
Mr. Federico started his career in the restaurant industry as a Manager at Steak & Ale, and later at Orville Beans and Bennigan’s restaurants.
He went on to develop Grady’s Goodtimes, serving as Co-Founder/Partner and Vice President of Operations until Brinker International, Inc. acquired Grady’s in 1989.
Upon joining Brinker International, Mr. Federico served as Senior Vice President and concept head for Macaroni Grill before being promoted to President of the Italian Concept division.
As President, he directed operations and development for Macaroni Grill and Spageddies.
_Patricia E.
Lopez_ has served on Domino’s Board of Directors since July 2018 and is a member of the Nominating and Corporate Governance Committee of the Board of Directors.
Ms. Lopez currently serves as Chief Executive Officer and as a member of the Board of Directors of High Ridge Brands Co., roles she has held since July 2017.
Prior to her current role, Ms. Lopez served as a Senior Vice President at Estée Lauder Companies Inc. from January 2015 to July 2016, a Senior Vice President at Avon Products, Inc. from December 2012 to November 2014 and previously held various positions at The Procter & Gamble Co. over a span of 25 years, most recently serving as a Vice President and General Manager overseeing its Eastern Europe business.
| --- | --- |
| J. Patrick Doyle | | 54 | | President, Chief Executive Officer and Director |
| Richard E. Allison, Jr. | | 51 | | President, Domino’s International |
| Russell J. Weiner | | 49 | | President, Domino’s USA |
| Judith L. Werthauser | | 52 | | Executive Vice President, Chief People Officer |
_J.
Patrick Doyle_ has served as our President and Chief Executive Officer since March 2010 and was appointed to the Board of Directors in February 2010.
Mr. Doyle served as President, Domino’s USA from September 2007 to March 2010, Executive Vice President, Team USA from 2004 to 2007, Executive Vice President of International from May 1999 to October 2004 and as interim Executive Vice President of Build the Brand from December 2000 to July 2001.
Mr. Doyle served as Senior Vice President of Marketing from the time he joined Domino’s in 1997 until May 1999.
Mr. Doyle serves on the Board of Directors of Best Buy Co., Inc. and also previously served on the Board of Directors of G&K Services, Inc. In January 2018, Mr. Doyle announced that he will resign from his position as President, Chief Executive Officer and Director of the Company effective June 30, 2018.
In January 2018, the Company announced that the Board of Directors has appointed Mr. Allison to succeed Mr. Doyle as the Company’s Chief Executive Officer, effective July 1, 2018.
Mr. Allison shall also be appointed to the Company’s Board of Directors as soon as practical after July 1, 2018.
_Troy A.
Prior to joining Domino’s, Mr. Ellis served as Senior Vice President of Conversion of Coca-Cola Refreshments, overseeing manufacturing, transportation planning and third-party logistics.
Prior to that role, he spent nearly three years as Senior Vice President of Manufacturing after joining Coca-Cola Refreshments in 2010.
From 2000 to 2010, Mr. Ellis held various leadership roles with Coca-Cola Enterprises including Central Business Unit Vice President of Supply Chain.
Prior to joining Coca-Cola, he worked for PepsiCo and Kimberly Clark Corp., after serving in the U.S. Army from 1988-1991.
_Stanley J.
Gage_ has served as our Executive Vice President, Team USA (which represents our Company-owned store division) since August 2014.
Prior to his appointment, Mr. Gage served as Vice President of the Americas Region and International Training since October 2012 and as Vice President of Operations Training and Support from 2008 through October 2012.
Mr. Gage joined Domino’s in 1985.
Mr. McIntyre serves on Eastern Michigan University’s College of Business Marketing Advisory Board and served on the Board of Directors of Food Gatherers through December 2017.
_Judith L.
Werthauser_ has served as Executive Vice President and Chief People Officer since January 2016.
Ms. Werthauser previously served as Senior Vice President of Human Resources at Target Corp. Ms. Werthauser joined Target in 2008, holding increasing levels of human resources responsibilities.
Prior to Target, Ms. Werthauser was Senior Vice President of Human Resources for U.S. Bancorp in Minneapolis, held several senior human resources positions at Marshall Field’s department stores and directed student programs at the University of Minnesota.
Ms. Werthauser was also the co-owner and operations leader of Aljohn’s and Junkyard Retailers, a diverse retailing and manufacturing company that she grew from one to 11 locations.
An excerpt. Shown here: 40 of 53 rewritten, all 32 added and all 27 removed. The counts are complete. For every sentence, read Item 10. Directors, Executive Officers and Corporate Governance. in the FY2018 filing and the FY2017 filing.
Item 11. Executive Compensation.
1 rewritten, 0 added, 1 removed, 1 unchanged
Information regarding executive compensation is incorporated by reference from Domino’s Pizza, Inc.’s definitive proxy statement, which will be filed within 120 days of December [removed: 31, 2017.][added: 30, 2018.]
| --- | --- |
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
1 rewritten, 0 added, 1 removed, 0 unchanged
Information regarding security ownership of certain beneficial owners and management and related stockholder matters is incorporated by reference from Domino’s Pizza, Inc.’s definitive proxy statement, which will be filed within 120 days of December [removed: 31, 2017.][added: 30, 2018.]
| --- | --- |
Item 13. Certain Relationships and Related Transactions, and Director Independence.
1 rewritten, 0 added, 1 removed, 0 unchanged
Information regarding certain relationships and related transactions is incorporated by reference from Domino’s Pizza, Inc.’s definitive proxy statement, which will be filed within 120 days of December [removed: 31, 2017.][added: 30, 2018.]
| --- | --- |
Item 14. Principal Accountant Fees and Services.
1 rewritten, 0 added, 1 removed, 2 unchanged
Information regarding principal accountant fees and services is incorporated by reference from Domino’s Pizza, Inc.’s definitive proxy statement, which will be filed within 120 days of December [removed: 31, 2017.][added: 30, 2018.]
| --- | --- |
Item 15. Exhibits, Financial Statement Schedules.
67 rewritten, 9 added, 5 removed, 116 unchanged
[added: | (a)1. |] Financial Statements: The following financial statements for Domino’s Pizza, Inc. and subsidiaries are included in Item 8, “Financial Statements and Supplementary Data”: [added: |]
[removed: |] Report of Independent Registered Public Accounting Firm [removed: | | |]
[removed: |] Consolidated Balance Sheets as of December [removed: 31, 2017] [added: 30, 2018] and [removed: January 1,] [added: December 31,] 2017 [removed: | | |]
[removed: |] Consolidated Statements of Income for the Years Ended December [added: 30, 2018, December] 31, [removed: 2017, January 1,] 2017 and January [removed: 3, 2016 | | |][added: 1, 2017]
[removed: |] Consolidated Statements of Comprehensive Income for the Years Ended December [added: 30, 2018, December] 31, [removed: 2017, January 1,] 2017 and January [removed: 3, 2016 | | |][added: 1, 2017]
[removed: |] Consolidated Statements of Stockholders’ Deficit for the Years Ended December [added: 30, 2018, December] 31, [removed: 2017, January 1,] 2017 and January [removed: 3, 2016 | | |][added: 1, 2017]
[removed: |] Consolidated Statements of Cash Flows for the Years Ended December [added: 30, 2018, December] 31, [removed: 2017, January 1,] 2017 and January [removed: 3, 2016 | | |][added: 1, 2017]
[removed: |] Notes to Consolidated Financial Statements [removed: | | |]
| [removed: Exhibit Number] [added: Exhibit Number] | | [removed: Description] [added: Description] |
| 10.8 | | [Tenth Amendment to a Lease Agreement between Domino’s Farms Office Park, L.L.C. and Domino’s Pizza LLC, dated as of November 7, [removed: 2017.](https://www.sec.gov/Archives/edgar/data/1286681/000119312518049576/d531906dex108.htm)] [added: 2017 (Incorporated by reference to Exhibit 10.8 to the registrant’s annual report on Form 10-K for the year ended December 31, 2017).](http://www.sec.gov/Archives/edgar/data/1286681/000119312518049576/d531906dex108.htm)] |
| [removed: 10.9*] [added: 10.11*] | | [Domino’s Pizza, Inc. Deferred Compensation Plan adopted effective January 1, 2005 (Incorporated by reference to Exhibit 10.9 to the registrant’s annual report on Form 10-K for the year ended January 1, 2006).](http://www.sec.gov/Archives/edgar/data/1079458/000119312506045179/dex109.htm) |
| [removed: 10.10*] [added: 10.12*] | | [First Amendment to the Domino’s Pizza Deferred Compensation Plan effective January 1, 2007 (Incorporated by reference to Exhibit 10.9 to the registrant’s annual report on Form 10-K for the year ended December 31, 2006).](http://www.sec.gov/Archives/edgar/data/1079458/000119312507037666/dex109.htm) |
| [removed: 10.11*] [added: 10.13*] | | [Second Amendment to the Domino’s Pizza Deferred Compensation Plan effective February 8, 2013 (Incorporated by reference to Exhibit 10.5 to the 2012 10-K).](http://www.sec.gov/Archives/edgar/data/1286681/000119312513081957/d466015dex105.htm) |
| [removed: 10.12*] [added: 10.14*] | | [Amended Domino’s Pizza, Inc. 2004 Equity Incentive Plan (Incorporated by reference to Exhibit 10.1 to the registrant’s quarterly report on Form 10-Q for the quarter ended March 22, 2009 (the “March 2009 10-Q”)).](http://www.sec.gov/Archives/edgar/data/1286681/000119312509093037/dex101.htm) |
| [removed: 10.13*] [added: 10.15*] | | [Form of Employee Stock Option Agreement under the Amended Domino’s Pizza, Inc. 2004 Equity Incentive Plan (Incorporated by reference to Exhibit 10.8 to the 2012 10-K).](http://www.sec.gov/Archives/edgar/data/1286681/000119312513081957/d466015dex108.htm) |
| [removed: 10.14*] [added: 10.16*] | | [Form of 2013 Special Employee Stock Option Agreement under the Amended Domino’s Pizza, Inc. 2004 Equity Incentive Plan (Incorporated by reference to Exhibit 10.9 to the 2012 10-K).](http://www.sec.gov/Archives/edgar/data/1286681/000119312513081957/d466015dex109.htm) |
| [removed: 10.15*] [added: 10.17*] | | [Form of Director Stock Option Agreement under the Amended Domino’s Pizza, Inc. 2004 Equity Incentive Plan (Incorporated by reference to Exhibit 10.3 to the March 2009 10-Q).](http://www.sec.gov/Archives/edgar/data/1286681/000119312509093037/dex103.htm) |
| [removed: 10.16*] [added: 10.18*] | | [Form of Amendment to Existing Director Stock Option Grants (Incorporated by reference to Exhibit 10.5 to the March 2009 10-Q).](http://www.sec.gov/Archives/edgar/data/1286681/000119312509093037/dex105.htm) |
| [removed: 10.17*] [added: 10.19*] | | [Form of Performance-Based Restricted Stock Agreement (Incorporated by reference to Exhibit 10.12 to the 2012 10-K).](http://www.sec.gov/Archives/edgar/data/1286681/000119312513081957/d466015dex1012.htm) |
| [removed: 10.18*] [added: 10.20*] | | [Form of 2013 Special Performance-Based Restricted Stock Agreement (Incorporated by reference to Exhibit 10.13 to the 2012 10-K).](http://www.sec.gov/Archives/edgar/data/1286681/000119312513081957/d466015dex1013.htm) |
| [removed: 10.19*] [added: 10.21*] | | [Form of Performance-Based Restricted Stock Unit Award Agreement (Incorporated by reference to Exhibit 10.14 to the 2012 10-K).](http://www.sec.gov/Archives/edgar/data/1286681/000119312513081957/d466015dex1014.htm) |
| [removed: 10.20*] [added: 10.22*] | | [Form of 2013 Special Performance-Based Restricted Stock Unit Award Agreement (Incorporated by reference to Exhibit 10.15 to the 2012 10-K).](http://www.sec.gov/Archives/edgar/data/1286681/000119312513081957/d466015dex1015.htm) |
| [removed: 10.21*] [added: 10.23*] | | [Form of Domino’s Pizza, Inc. 2004 Equity Incentive Plan Restricted Stock Agreement for Directors (Incorporated by reference to Exhibit 10.19 to the registrant’s annual report on Form 10-K for the year ended January 3, 2010).](http://www.sec.gov/Archives/edgar/data/1286681/000119312510045334/dex1019.htm) |
| [removed: 10.22*] [added: 10.24*] | | [Amended and Restated Domino’s Pizza Senior Executive Annual Incentive Plan. (Incorporated by reference to Exhibit 10.20 to the registrant’s annual report on Form 10-K for the year ended January 2, 2011).](http://www.sec.gov/Archives/edgar/data/1286681/000119312511050979/dex1020.htm) |
| [removed: 10.23*] [added: 10.25*] | | [Amended and Restated Domino’s Pizza, Inc. Employee Stock Payroll Deduction Plan (Incorporated by reference to Exhibit 10.18 to the registrant’s annual report on Form 10-K for the year ended December 29, 2013).](http://www.sec.gov/Archives/edgar/data/1286681/000119312514066092/d661353dex1018.htm) |
| [removed: 10.24*] [added: 10.26*] | | [Form of Domino’s Pizza, Inc. Dividend Reinvestment & Direct Stock Purchase and Sale Plan (Incorporated by reference to Exhibit 10.32 to the S-1).](http://www.sec.gov/Archives/edgar/data/1286681/000119312504102056/dex1032.htm) |
| [removed: 10.25*] [added: 10.27*] | | [Form of 2018 Restricted Stock Agreement (Incorporated by reference to Exhibit 10.4 to the registrant’s current report on Form 8-K filed on January 11, 2018 (the “January 2018 8-K”)).](http://www.sec.gov/Archives/edgar/data/1286681/000119312518008592/d505807dex104.htm) |
| [removed: 10.26*] [added: 10.28*] | | [Employment Agreement dated as of February 23, 2015 between Domino’s Pizza LLC and J. Patrick Doyle (Incorporated by reference to Exhibit 10.20 to the registrant’s annual report on Form 10-K for the year ended December 28, [removed: 2014 (the “2014 10-K”)).](http://www.sec.gov/Archives/edgar/data/1286681/000119312515059100/d866504dex1020.htm)] [added: 2014).](http://www.sec.gov/Archives/edgar/data/1286681/000119312515059100/d866504dex1020.htm)] |
| [removed: 10.27*] [added: 10.36*] | | [Time Sharing Agreement dated as of [removed: February 23, 2015] [added: January 8, 2018] between Domino’s Pizza LLC and [removed: J. Patrick Doyle] [added: Richard E. Allison, Jr.] (Incorporated by reference to Exhibit [removed: 10.21] [added: 10.3] to the [removed: 2014 10-K).](http://www.sec.gov/Archives/edgar/data/1286681/000119312515059100/d866504dex1021.htm)] [added: January 2018 8-K).](http://www.sec.gov/Archives/edgar/data/1286681/000119312518008592/d505807dex103.htm)] |
| [removed: 10.28*] [added: 10.29*] | | [Employment Agreement dated as of August 28, 2015 between Domino’s Pizza LLC and Jeffrey Lawrence (Incorporated by reference to Exhibit 10.1 to the registrant’s quarterly report on Form 10-Q for the quarter ended September 6, 2015).](http://www.sec.gov/Archives/edgar/data/1286681/000119312515339829/d67435dex101.htm) |
| [removed: 10.29*] [added: 10.30*] | | [Employment Agreement dated as of September 2, 2008 between Domino’s Pizza LLC and Russell J. Weiner (Incorporated by reference to Exhibit 1.01 to the registrant’s current report on Form 8-K filed on September 4, 2008).](http://www.sec.gov/Archives/edgar/data/1286681/000119312508190324/dex101.htm) |
| [removed: 10.30*] [added: 10.31*] | | [Amendment to the Employment agreement dated as of September 2, 2008 between Domino’s Pizza LLC and Russell J. Weiner (Incorporated by reference to Exhibit 10.4 to the registrant’s current report on Form 8-K filed on December 24, 2008).](http://www.sec.gov/Archives/edgar/data/1286681/000119312508260125/dex104.htm) |
| [removed: 10.31*] [added: 10.32*] | | [Amendment to the Employment Agreement dated as of July 26, 2010 between Domino’s Pizza LLC and Russell J. Weiner (Incorporated by reference to Exhibit 10.3 to the registrant’s quarterly report on Form 10-Q for the quarter ended June 20, 2010).](http://www.sec.gov/Archives/edgar/data/1286681/000119312510166716/dex103.htm) |
| [removed: 10.32*] [added: 10.33*] | | [Employment Agreement dated as of January 8, 2018 between Domino’s Pizza, Inc., Domino’s Pizza LLC and Russell J. Weiner (Incorporated by reference to Exhibit 10.2 to the January 2018 8-K).](http://www.sec.gov/Archives/edgar/data/1286681/000119312518008592/d505807dex102.htm) |
| [removed: 10.33*] [added: 10.34*] | | [Employment Agreement dated as of March 14, 2011 between Domino’s Pizza LLC and Richard E. Allison, Jr. (Incorporated by reference to Exhibit 10.1 to the registrant’s quarterly report on Form 10-Q for the quarter ended March 27, 2011).](http://www.sec.gov/Archives/edgar/data/1286681/000119312511127320/dex101.htm) |
| [removed: 10.34*] [added: 10.35*] | | [Employment Agreement dated as of January 8, 2018 between Domino’s Pizza, Inc., Domino’s Pizza LLC and Richard E. Allison, Jr. (Incorporated by reference to Exhibit 10.1 to the January 2018 8-K).](http://www.sec.gov/Archives/edgar/data/1286681/000119312518008592/d505807dex101.htm) |
| [removed: 10.35*] [added: 10.38*] | | [removed: [Time Sharing Agreement] [added: [Addendum to the Employment agreement] dated as of [removed: January 8,] [added: July 16,] 2018 between Domino’s Pizza LLC and [removed: Richard E. Allison, Jr.] [added: J. Patrick Doyle] (Incorporated by reference to Exhibit [removed: 10.3] [added: 10.2] to the [removed: January] [added: June] 2018 [removed: 8-K).](http://www.sec.gov/Archives/edgar/data/1286681/000119312518008592/d505807dex103.htm)] [added: 10-Q).](http://www.sec.gov/Archives/edgar/data/1286681/000119312518220984/d513733dex102.htm)] |
| [removed: 10.36*] [added: 10.41*] | | [Employment Agreement dated as of [removed: December 7, 2016] [added: February 11, 2012] between Domino’s Pizza LLC and [added: J.] Kevin [removed: S. Morris.](https://www.sec.gov/Archives/edgar/data/1286681/000119312518049576/d531906dex1036.htm)] [added: Vasconi.](https://www.sec.gov/Archives/edgar/data/1286681/000119312519046191/d696297dex1041.htm)] |
| [removed: 10.37] [added: 10.43] | | [Form of Indemnification Agreement [added: between the Company and its officers and directors] (Incorporated by reference to Exhibit 10.33 to the S-1).](http://www.sec.gov/Archives/edgar/data/1286681/000119312504091718/dex1033.htm) |
| [removed: 10.38] [added: 10.44] | | [Amended and Restated Base Indenture dated March 15, 2012 among Domino’s Pizza Master Issuer LLC, Domino’s Pizza Distribution LLC, Domino’s IP Holder LLC and Domino’s SPV Canadian Holding Company Inc., each as Co-Issuer, and Citibank, N.A., as Trustee and Securities Intermediary (Incorporated by reference to Exhibit 4.1 to the registrant’s current report on Form 8-K filed on March 19, 2012 (the “March 2012 8-K”)).](http://www.sec.gov/Archives/edgar/data/1286681/000119312512120642/d318279dex41.htm) |
| 10.9 | | [Eleventh Amendment to a Lease Agreement between Domino’s Farms Office Park, L.L.C. and Domino’s Pizza LLC, dated as of July 13, 2018 (Incorporated by reference to Exhibit 10.1 to the registrant’s quarterly report on Form 10-Q for the quarter ended September 9, 2018 (the “September 2018 10-Q”)).](http://www.sec.gov/Archives/edgar/data/1286681/000119312518299738/d632190dex101.htm) |
| 10.10 | | [Twelfth Amendment to a Lease Agreement between Domino’s Farms Office Park, L.L.C. and Domino’s Pizza LLC, dated as of July 13, 2018 (Incorporated by reference to Exhibit 10.2 to the September 2018 10-Q).](http://www.sec.gov/Archives/edgar/data/1286681/000119312518299738/d632190dex102.htm) |
| 10.37* | | [Addendum to Amended and Restated Employment Agreement dated as of June 22, 2018 between Domino’s Pizza LLC and David A. Brandon (Incorporated by reference to Exhibit 10.1 to the registrant’s quarterly report on Form 10-Q for the quarter ended June 17, 2018 (the “June 2018 10-Q”)).](http://www.sec.gov/Archives/edgar/data/1286681/000119312518220984/d513733dex101.htm) |
| 10.39* | | [Addendum to Amended and Restated Employment Agreement dated as of December 29, 2018 between Domino’s Pizza LLC and David A. Brandon.](https://www.sec.gov/Archives/edgar/data/1286681/000119312519046191/d696297dex1039.htm) |
| 10.40* | | [Addendum to the Employment agreement dated as of December 30, 2018 between Domino’s Pizza LLC and J. Patrick Doyle.](https://www.sec.gov/Archives/edgar/data/1286681/000119312519046191/d696297dex1040.htm) |
| 10.42* | | [Employment Agreement dated as of April 9, 2018 between Domino’s Pizza LLC and Joseph H. Jordan.](https://www.sec.gov/Archives/edgar/data/1286681/000119312519046191/d696297dex1042.htm) |
| 10.54 | | [Purchase Agreement, dated April 18, 2018, by and among Domino’s Pizza Master Issuer LLC, Domino’s SPV Canadian Holding Company Inc., Domino’s Pizza Distribution LLC, Domino’s IP Holder LLC, Domino’s Pizza, Inc., Domino’s Pizza LLC, Domino’s, Inc., the guarantors party thereto and Guggenheim Securities, LLC, as representative of the initial purchasers named in Schedule I thereto (Incorporated by reference to Exhibit 1.1 to the April 2018 8-K).](http://www.sec.gov/Archives/edgar/data/1286681/000119312518131454/d538225dex11.htm) |
| | | |
| | | |
(a)1.
| --- | --- | --- |
| 10.58 | | [Fixed Dollar Accelerated Share Repurchase Transaction Confirmation, dated August 2, 2017 (Incorporated by reference to Exhibit 10.1 to the Domino’s Pizza, Inc. Current Report on Form 8-K, filed on August 2, 2017).](http://www.sec.gov/Archives/edgar/data/1286681/000119312517244950/d413019dex101.htm) |
| 10.59 | | [Omnibus Amendment No. 1, dated December 15, 2017, among Domino’s Pizza Master Issuer LLC, Domino’s SPV Canadian Holding Company Inc., Domino’s Pizza Distribution LLC and Domino’s IP Holder LLC, each as Co-Issuer, Domino’s SPV Guarantor LLC, Domino’s Pizza Franchising LLC, Domino’s Pizza International Franchising Inc., Domino’s Pizza Canadian Distribution ULC, Domino’s RE LLC and Domino’s EQ LLC, each as Guarantor, Domino’s Pizza LLC, as manager, certain conduit investors, financial institutions and funding agents, and Coöperatieve Rabobank U.A., New York Branch, as provider of letters of credit, as swingline lender and as administrative agent (Incorporated by reference to Exhibit 10.1 to the Domino’s Pizza, Inc. Current Report on Form 8-K, filed on December 19, 2017).](http://www.sec.gov/Archives/edgar/data/1286681/000119312517373784/d513737dex101.htm) |
| 12.1 | | [Ratio of Earnings to Fixed Charges.](https://www.sec.gov/Archives/edgar/data/1286681/000119312518049576/d531906dex121.htm) |
An excerpt. Shown here: 40 of 67 rewritten, all 9 added and all 5 removed. The counts are complete. For every sentence, read Item 15. Exhibits, Financial Statement Schedules. in the FY2018 filing and the FY2017 filing.
Item 16. Form 10-K Summary.
50 rewritten, 44 added, 28 removed, 74 unchanged
[removed: DOMINO’S PIZZA, INC.][added: Domino’s Pizza, Inc.]
[removed: PARENT] [added: PARENT] COMPANY CONDENSED BALANCE [removed: SHEETS][added: SHEETS]
[removed: (In] [added: (In] thousands, except share and per share [removed: amounts)][added: amounts)]
| | | [removed: December] [added: December 30, 2018 | | | | December] 31, [added: 2017] | | | | [removed: January] [added: January] 1, [added: 2017] | | |
| [removed: ASSETS] [added: ASSETS] | | | | | | | | |
| [removed: LIABILITIES] [added: LIABILITIES] AND STOCKHOLDERS’ [removed: DEFICIT] [added: DEFICIT] | | | | | | | | |
| Equity in net deficit of subsidiaries | | $ | [removed: 2,735,384] [added: 3,039,921] | | | $ | [removed: 1,883,143] [added: 2,735,384] | |
| Total liabilities | | | [removed: 2,735,390] [added: 3,039,927] | | | | [removed: 1,883,149] [added: 2,735,390] | |
| Common stock, par value $0.01 per share; 170,000,000 shares authorized; [removed: 42,898,329] [added: 40,977,561] in [removed: 2017] [added: 2018] and [removed: 48,100,143] [added: 42,898,329] in [removed: 2016] [added: 2017] issued and outstanding | | | [removed: 429] [added: 410] | | | | [removed: 481] [added: 429] | |
| Additional paid-in capital | | | [removed: 5,654] [added: 569] | | | | [removed: 1,006] [added: 5,654] | |
| Retained deficit | | | [removed: (2,739,437] [added: (3,036,471] | ) | | | [removed: (1,881,520] [added: (2,739,437] | ) |
| Accumulated other comprehensive loss | | | [removed: (2,030)] [added: (4,429] | [added: )] | | | [removed: (3,110)] [added: (2,030] | [added: )] |
| Total stockholders’ deficit | | | [removed: (2,735,384)] [added: (3,039,921] | [added: )] | | | [removed: (1,883,143)] [added: (2,735,384] | [added: )] |
[removed: PARENT] [added: PARENT] COMPANY CONDENSED STATEMENTS OF INCOME AND COMPREHENSIVE [removed: INCOME][added: INCOME]
[removed: (In] [added: (In] thousands, except [added: share and] per share [removed: amounts)][added: amounts)]
| | | [removed: For] [added: For] the Years [removed: Ended] [added: Ended] | | | | | | | | | | |
| | | [removed: December 31, 2017] [added: December 30, 2018] | | | | [removed: January 1, 2017] [added: December 31, 2017] | | | | [removed: January 3, 2016] [added: January 1, 2017] | | |
| Equity earnings in subsidiaries | | | [removed: 277,905] [added: 361,972] | | | | [removed: 214,678] [added: 277,905] | | | | [removed: 192,789] [added: 214,678] | |
| INCOME BEFORE PROVISION FOR INCOME TAXES | | | [removed: 277,905] [added: 361,972] | | | | [removed: 214,678] [added: 277,905] | | | | [removed: 192,789] [added: 214,678] | |
| NET INCOME | | $ | [removed: 277,905] [added: 361,972] | | | $ | [removed: 214,678] [added: 277,905] | | | $ | [removed: 192,789] [added: 214,678] | |
| COMPREHENSIVE INCOME | | $ | [removed: 278,985] [added: 359,924] | | | $ | [removed: 215,116] [added: 278,985] | | | $ | [removed: 191,902] [added: 215,116] | |
| Common Stock – basic | | $ | [removed: 6.05] [added: 8.65] | | | $ | [removed: 4.41] [added: 6.05] | | | $ | [removed: 3.58] [added: 4.41] | |
| Common Stock – diluted | | $ | [removed: 5.83] [added: 8.35] | | | $ | [removed: 4.30] [added: 5.83] | | | $ | [removed: 3.47] [added: 4.30] | |
[removed: PARENT] [added: PARENT] COMPANY CONDENSED STATEMENTS OF CASH [removed: FLOWS][added: FLOWS]
[removed: (In thousands)][added: (In thousands)]
| Net cash provided by operating activities | | $ | [removed: 299,576] [added: 382,716] | | | $ | [removed: 281,731] [added: 299,576] | | | $ | [removed: 226,912] [added: 281,731] | |
| Dividends from subsidiaries | | | [removed: 852,325] [added: 297,792] | | | | [removed: 82,856] [added: 852,325] | | | | [removed: 594,591] [added: 82,856] | |
| Net cash provided by investing activities | | | [removed: 852,325] [added: 297,792] | | | | [removed: 82,856] [added: 852,325] | | | | [removed: 594,591] [added: 82,856] | |
| Payments of common stock dividends | | | [removed: (84,298] [added: (92,166] | ) | | | [removed: (73,925] [added: (84,298] | ) | | | [removed: (80,329] [added: (73,925] | ) |
| Purchase of common stock | | | [removed: (1,064,253] [added: (591,212] | ) | | | [removed: (300,250] [added: (1,064,253] | ) | | | [removed: (738,557] [added: (300,250] | ) |
| Other | | | [removed: (3,350] [added: 2,870] | [removed: )] | | | [removed: 9,588] [added: (3,350] | [added: )] | | | [removed: (2,617] [added: 9,588] | [removed: )] |
| Net cash used in financing activities | | | [removed: (1,151,901] [added: (680,508] | ) | | | [removed: (364,587] [added: (1,151,901] | ) | | | [removed: (821,503] [added: (364,587] | ) |
[removed: NOTES] [added: NOTES] TO PARENT COMPANY FINANCIAL [removed: STATEMENTS][added: STATEMENTS]
| [removed: (1)] [added: (1)] | [removed: INTRODUCTION AND BASIS OF PRESENTATION] [added: Introduction and Basis of Presentation] |
[removed: Use] [added: Use] of [removed: Estimates][added: Estimates]
| [removed: (2)] [added: (2)] | [removed: SUPPLEMENTAL DISCLOSURES OF CASH FLOW INFORMATION] [added: Supplemental Disclosures of Cash Flow Information] |
During [removed: 2017, 2016] [added: 2018, 2017] and [removed: 2015,] [added: 2016,] the Parent Company received dividends from its subsidiaries primarily consisting of amounts received to repurchase common stock in connection with the Company’s [removed: 2017] [added: 2018] and [removed: 2015] [added: 2017] recapitalization transactions.
See Note 4 to the Company’s consolidated financial statements as filed in this Form 10-K for a description of the recapitalization transactions that occurred in [removed: 2017] [added: 2018] and [removed: 2015.][added: 2017.]
| (in thousands) | | [removed: Balance Beginning] [added: Balance Beginning] of Year | | | | [removed: Provision (Benefit)] [added: Provision (Benefit)] | | | | Additions/ Deductions [removed: from Reserves * | | | | Translation Adjustments] [added: from Reserves*] | | | | Balance End of Year | | |
| Allowance for doubtful accounts receivable: | | | | | | | | | | | | | | | | | [removed: | | | |]
| | | December 30, 2018 | | | | December 31, 2017 | | |
| | | | | | | | | |
| | | | | | | | | |
| | | | | | | | | |
| | | | | | | | | |
| | | | | | | | | |
Domino’s Pizza, Inc.
Domino’s Pizza, Inc.
| | | For the Years Ended | | | | | | | | | | |
| | | | | | | | | | | | | |
| | | | | | | | | | | | | |
| | | | | | | | | | | | | |
Domino’s Pizza, Inc.
New Accounting Pronouncements
During 2018, the Company adopted the below new accounting pronouncements that impacted the Parent Company financial statements.
_Accounting Standards Update 2014-09, Revenue from Contracts with Customers (Topic 606)_
In May 2014, the Financial Accounting Standards Board (“FASB”) issued Accounting Standards Update 2014-09, _Revenue from Contracts with Customers (Topic 606)_ and has since issued various amendments which provide additional clarification and implementation guidance.
This standard has been codified as ASC 606.
This guidance outlines a single, comprehensive model for entities to use in accounting for revenue arising from contracts with customers and superseded most revenue recognition guidance issued by the FASB, including industry specific guidance.
On January 1, 2018, the Company adopted ASC 606 using the modified retrospective method.
The Parent Company recorded a $6.7 million adjustment to equity in net deficit of subsidiaries and recorded a $6.7 million adjustment to retained deficit related to this new accounting standard in 2018.
See Note 1 to the Company’s consolidated financial statements as filed in this Form 10-K for additional information related to the adoption of this new accounting standard.
_ASU 2018-02, Income Statement – Reporting Comprehensive Income (Topic 220)_
In February 2018, the FASB issued ASU 2018-02, _Income Statement – Reporting Comprehensive Income (Topic 220): Reclassification of Certain Tax Effects from Accumulated Other Comprehensive Income_.
The amendments in this updated standard allow a reclassification from accumulated other comprehensive income to retained earnings for stranded tax effects resulting from the Tax Cuts and Jobs Act of 2017.
The Parent Company adopted this standard in 2018 and, as a result, recorded a $0.4 million reclassification from accumulated other comprehensive loss to the beginning balance of retained deficit in 2018.
| | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| 2018 | | $ | 1,424 | | | $ | 903 | | | $ | (448 | ) | | | 1,879 | |
| February 21, 2019 |
| | | |
| --- | --- | --- |
| | | |
| | | |
| | | |
| | | |
| | | |
| | | |
| /s/ Corie S. Barry Corie S. Barry February 21, 2019 | | Director |
| | | |
| --- | --- |
| | | 2017 | | | | 2017 | | |
| | | December 31, | | | | January 1, | | | | January 3, | | |
| | | 2017 | | | | 2017 | | | | 2016 | | |
Recently Adopted Accounting Standards
In March 2016, the Financial Accounting Standards Board (“FASB”) issued ASU 2016-09, _Compensation – Stock Compensation (Topic 718): Improvements to Employee Share-Based Payment Accounting_ (ASU 2016-09).
ASU 2016-09 is intended to simplify several areas of accounting for share-based compensation arrangements, including the income tax impact, classification on the statement of cash flows and forfeitures.
The new standard was effective for the Parent Company beginning January 2, 2017.
As a result, excess tax benefits or deficiencies from equity-based compensation activity are reflected in the parent company condensed statements of income and comprehensive income as a component of equity earnings in subsidiaries.
The Company also elected to account for forfeitures as they occur, rather than to use an estimate of expected forfeitures for financial statement reporting purposes.
The adoption of ASU 2016-09 resulted in an increase to net income of $27.2 million in fiscal 2017, primarily due to the recognition of excess tax benefits for options exercised and the vesting of equity awards.
The Company’s election to account for forfeitures as they occur had an immaterial impact on its equity-based compensation expense.
| | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| 2015 | | | 3,361 | | | | (582 | ) | | | (109 | ) | | | (8 | ) | | | 2,662 | |
| February 20, 2018 |
| | | | | |
| --- | --- | --- | --- | --- |
| J. Patrick Doyle | | | | |
| February 20, 2018 | | | | |
| Jeffrey D. Lawrence | | | | (Principal Financial and Accounting Officer) |
| David A. Brandon | | | | |
| C. Andrew Ballard | | | | |
| Andrew B. Balson | | | | |
| Diana F. Cantor | | | | |
| Richard L. Federico | | | | |
| James A. Goldman | | | | |
February 20, 2018
An excerpt. Shown here: 40 of 50 rewritten, 40 of 44 added and all 28 removed. The counts are complete. For every sentence, read Item 16. Form 10-K Summary. in the FY2018 filing and the FY2017 filing.