 filings.tools
Domino's Pizza (DPZ) 10-K risk factor changes: FY2023 vs FY2022
The 2023-01-01 10-K against the 2022-01-02 one, compared heading by heading and sentence by sentence.
Item 1A93 rewritten21 added24 removed284 unchanged
All filing items941 rewritten270 added216 removed1,667 unchanged
Summary
counted, not written
- Item 1A lists 27 risk factor headings: 0 new, 4 reworded and 23 unchanged since FY2022. 2 headings from FY2022 no longer appear.
- Sentence by sentence, 270 added, 216 removed, 941 rewritten and 1,667 unchanged across 16 items that differ.
New Item 1A headings (0)
No risk factor heading in this filing is absent from FY2022.
Removed Item 1A headings (2)
- We and our franchisees are subject to extensive laws and government regulation and requirements issued by other groups and our failure to comply with existing or increased laws and regulations could adversely affect our business and operating results.
- Actions of activist investors could negatively impact our business and the value of our stock price.
Reworded Item 1A headings (4)
[removed: Labor shortages and increases][added: Increases] in food, labor and other[removed: costs][added: costs, labor shortages or negative economic conditions] could adversely affect our profitability and operating results.- Reports of product contamination, food-borne illness or food tampering [added: or other events which] may [added: impact our reputation may] reduce sales and harm our business.
- We do not have long-term contracts with certain of our suppliers, [added: or have contracts which are set to expire,] and as a result they could seek to significantly increase prices or fail to deliver.
- We cannot predict the impact that new or improved
[removed: technologies in general,][added: technologies,] alternative methods of delivery, including autonomous vehicle delivery, or changes in consumer or employee behavior facilitated by these technologies and alternative methods of delivery will have on our business.
A heading is new when no FY2022 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
23 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2023; struck-through words were in FY2022. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors.
93 rewritten, 21 added, 24 removed, 284 unchanged
Internationally, we compete primarily with Pizza Hut®, Papa John’s® and country-specific [removed: national] [added: national, regional] and local companies.
We and our franchisees have [removed: recently] faced an increasingly competitive labor market due to sustained labor shortages and increased turnover resulting in part from the [added: ongoing] COVID-19 pandemic which has caused us and our franchisees to in certain cases reduce store hours and delay store openings, and has [added: in the past] prevented us from running promotions, which has impacted our sales, service levels and customer [added: acquisition and] experience and could ultimately impact our growth and competitive position.
While substantially all U.S. franchisees purchased food, equipment and supplies from us in [removed: 2021,] [added: 2022,] U.S. franchisees are not required to purchase food, equipment or supplies from us and they may choose to purchase from outside suppliers.
A public health pandemic such as COVID-19 poses the risk that we and/or our employees, franchisees, supply chain centers, suppliers, customers and other partners may [removed: be, or may continue to be,] [added: be] prevented [removed: from] [added: from, or be limited in,] conducting business activities for an indefinite period of time, including due to [removed: shutdowns, travel restrictions, social distancing requirements, and other] restrictions that have been or may be suggested or mandated by governmental authorities, or due to the impact of the disease itself on a business’ workforces.
In response to governmental requirements, we and our franchisees have [added: in the past] implemented a number of measures, including, among others, temporarily closing certain [removed: of our] stores, modifying [removed: certain] stores’ hours and closing locations to in-store [removed: dining, though some of these measures have since been rolled back.][added: dining.]
While it is not possible at this time to estimate the full impact that COVID-19 could have on our business going forward, the continued spread of the virus and the measures taken in response have [removed: disrupted] [added: in the past disrupted, and in the future may disrupt,] our operations and could disrupt our supply chain, which could adversely impact our business, financial condition and results of operations.
The Company’s sales and operating results may be affected by uncertain or changing economic and market conditions arising in connection with and in response to the COVID-19 pandemic, including inflation, changes to consumer demand, availability of [removed: labor, political instability] [added: labor] or other changes.
[removed: Potential] [added: We continue to monitor ongoing developments, and future potential] federal, [removed: state,] [added: state] or local [removed: COVID-19 vaccine and/or testing] [added: COVID-19-related] mandates could [removed: also] materially impact our [removed: results if we or our franchised stores face a reduction in available labor and/or incur] [added: results, including due to] additional compliance costs as a result of any imposed mandate.
While the Company has seen an increase in sales in certain markets, including within the U.S., [added: at times] during the COVID-19 pandemic, including increased sales related to heightened reliance on delivery and [removed: carry-out] [added: carryout] businesses, future sales [added: and same store sales] are not possible to estimate and it is unclear whether and to what extent sales will return to more normalized levels [added: or lessen] if and when consumer behavior and general economic and business activity return to pre-pandemic levels.
construction, permitting or development [removed: delays] [added: delays, including those] relating to the ongoing COVID-19 pandemic;
general economic and business conditions, including increases in food costs and labor costs which could impact [removed: profitability.][added: profitability and demand for new stores.]
The opening of additional franchise stores also depends, in part, upon the availability of prospective franchisees who meet our [removed: criteria and] [added: criteria,] the ability of these franchisees to attract and retain qualified [removed: personnel.][added: personnel and their desire to open new stores.]
Additionally, our growth strategy and the success of new stores depend in large part on the availability of suitable store [removed: sites.][added: sites and leases.]
Operations in new [removed: foreign] markets may achieve low margins or may be unprofitable, and expansion in existing markets may be affected by local economic and market conditions.
Therefore, as we continue to expand, we or our franchisees may not experience the [removed: operating] [added: gross] margins we expect, our results of operations may be negatively impacted, and our stock price may decline.
[removed: Labor shortages and increases] [added: Increases] in food, labor and other [removed: costs] [added: costs, labor shortages or negative economic conditions] could adversely affect our profitability and operating results.
We have [removed: recently] experienced increased labor shortages at many of our stores and supply chain centers and our franchisees have experienced similar labor shortages at their stores.
While there historically has been some level of ordinary course turnover of employees, the [added: ongoing] COVID-19 pandemic and resulting actions and impacts have exacerbated labor shortages and increased turnover.
Given the inflation rates in fiscal [removed: 2021,] [added: 2022, which we anticipate may continue,] there has been and may continue to be [added: significant] increases in food costs and labor costs which have [added: impacted] and could further impact our profitability and that of our franchisees and which could impact the opening of new U.S. and international franchised stores and adversely affect our operating results.
Factors such as inflation, increased food costs, increased labor and employee health and benefit costs, increased rent [added: costs, increased transportation] costs and increased energy costs may adversely affect our operating costs and profitability and those of our franchisees and could result in menu price [removed: increases.][added: increases, which could impact consumer demand.]
For example, we have experienced increased volatility in prices for some ingredients [added: in recent years and] during the [added: ongoing] COVID-19 pandemic, which may continue even if the pandemic recedes.
Furthermore, if we need to seek new suppliers, [added: including as a result of expiration of existing supply agreements,] we may be subject to pricing or other terms less favorable to us than those reflected in our current supply arrangements.
In addition to the increases in labor costs described above, several jurisdictions in which we [added: and our franchisees] operate have recently approved minimum wage increases.
Federal, state and local proposals that increase minimum wage requirements or mandate other employee matters could, to the extent implemented, materially increase [removed: our] labor and other costs.
As more jurisdictions implement minimum wage increases, we expect [removed: our] [added: that] labor costs will continue to increase.
The advent of legislation aimed at predictive scheduling [removed: could] [added: may] impact labor for our stores and our franchisees’ stores.
Labor costs and food costs, including cheese, generally represent approximately [removed: 50%] [added: 55%] to [removed: 60%] [added: 65%] of the sales at a typical Company-owned store.
While we believe there are adequate reserve quantities and potential alternative suppliers, shortages, interruptions, or disruptions in the supply of food products and store equipment caused by increased demand, capacity constraints, [added: expiration of existing agreements,] problems in production or distribution, product recalls, financial or other difficulties of suppliers, inclement weather or other conditions could adversely affect the availability, quality and cost of ingredients and equipment.
For instance, if prevailing health or dietary preferences cause consumers to avoid pizza and other products we offer in favor of foods that are perceived as healthier, [added: or consumers shift away from delivery or carryout food,] our business and operating results would be harmed.
If we are not able to respond to these changes, or our competitors respond to these changes more [removed: effectively,] [added: effectively than us,] our business and operating results could be adversely affected.
Reports of product contamination, food-borne illness or food tampering [added: or other events which] may [added: impact our reputation may] reduce sales and harm our business.
A decrease in sales due to these health [removed: concerns or] [added: concerns, any] negative publicity or as a result of the closure of any Domino’s stores could adversely affect our results of operations.
We do not have long-term contracts with certain of our suppliers, [added: or have contracts which are set to expire,] and as a result they could seek to significantly increase prices or fail to deliver.
We do not have long-term contracts or [removed: arrangements] [added: arrangements, or have contracts which are set to expire,] with certain of our suppliers.
[removed: We] [added: In the U.S., we] operate [removed: 21] [added: 22] regional dough manufacturing and supply chain [removed: centers in the U.S.,] [added: centers,] two thin crust manufacturing facilities, one vegetable processing center and one center providing equipment and supplies to our U.S. and certain international stores.
As a result, any prolonged disruption in the operations of any of these facilities, whether due to technical, systems, operational or labor difficulties, destruction or damage to the facility, real estate issues, limited capacity or other reasons, [added: or our failure to successfully increase capacity and open new centers,] could adversely affect our business and operating results.
The use of social media [removed: platforms, including blogs, social media websites, chat platforms, and other forms of internet-based communications that allow individuals access to a broad audience of consumers and other persons, including to our customers and the general public,] [added: platforms] and other consumer-oriented technologies has increased the speed and accessibility of information dissemination and given users the ability to more effectively organize collective actions such as boycotts and other brand-damaging behaviors.
Negative publicity related to our food [removed: products] [added: products, operations,] or stores or [removed: negative publicity] related to [added: our operations or] actions by our executives, team members or franchisees and their team members or others perceived to be associated with [removed: us or] our [removed: franchisees] [added: brand] could harm our business, brand, reputation, marketing partners, financial [removed: condition,] [added: condition] and results of operations, regardless of the accuracy of such negative publicity.
We have been routinely named a Leading National Advertiser by [removed: *Advertising Age*] [added: Advertising Age] and our success depends in part on continued effective advertising.
Each Domino’s store located in the U.S. is obligated to contribute 6% of its sales [removed: (subject, in certain instances,] to [removed: lower rates based on certain incentives and waivers) to] DNAF, which uses such fees for national advertising in addition to contributions for local market-level advertising.
As part of our growth strategy, we may decide to increase or decrease the number of Company-owned stores, either by refranchising existing Company-owned stores or by purchasing existing franchised stores, as we have done in the past.
Our failure to successfully execute these transactions could have an adverse effect on our operating results and could cause our stock price to decline.
Inflationary pressures may also impact the discretionary purchasing power of our customers, especially customers with less disposable income or for whom discretionary spending represents a smaller portion of their disposable income, resulting in decreased demand for our products.
Matters having a broad global economic impact may also significantly impact particular costs, such as the ongoing Russia-Ukraine conflict’s impact on our transportation and energy costs.
An economic environment characterized by high unemployment, rising interest rates, cautious consumer spending, or changes in consumer practices due to a possible recession could also impact consumer spending or demand and our operating results.
For example, labor and regulatory compliance costs could be adversely impacted as a result of California Assembly Bill No. 257, the Fast Food Accountability and Standards Recovery Act (“FAST Act”), which was signed into law in September 2022.
The FAST Act, which is currently subject to a referendum campaign, authorizes the creation of a council to set minimum standards for workers in the industry, including for wages, working hours and other health and safety conditions.
The implementation of the FAST Act could result in increased labor cost at franchised restaurants in California, thereby potentially impacting their profitability.
Further, this bill could prompt similar legislation in other states or localities.
Further, a boycott or other campaign critical of us, through social media or otherwise, could negatively impact our brand’s reputation and, consequently, sales.
We plan to continue investing in supply chain productivity initiatives in the future.
Weiner and Joseph H.
changes in inflation rates or foreign exchange rates and the imposition of restrictions on currency conversion or the transfer of funds;
national and international conflicts, sanctions, acts of war or terrorist acts;
There is also a potential heightened risk of cyber security incidents as a result of geopolitical events outside of our control, such as the ongoing Russia-Ukraine conflict.
The SEC has included in its regulatory agenda proposed rulemaking on climate change disclosures that, if adopted, could significantly increase compliance burdens and associated regulatory costs and the complexity of the regulatory framework.
Our 2021 Variable Funding Notes loan documents provide that after the date on which the administrator for LIBOR permanently or indefinitely ceases to provide all available settings of U.S. dollar LIBOR, any new advances under the 2021 Variable Funding Notes that would otherwise have borne interest based on LIBOR, as well as any existing LIBOR advances for which the interest period has expired, will instead bear interest at a forward-looking term rate based on the Secured Overnight Financing Rate (“Term SOFR”), plus a spread adjustment, that in each case have been selected or recommended by the Board of Governors of the Federal Reserve System or the Federal Reserve Bank of New York.
The loan documents also permit the lenders to effect a transition from LIBOR to Term SOFR at an earlier date, subject to certain conditions.
Our interest expense could also be increased by the rising interest rate environment, which could potentially have an adverse impact on our 2021 Variable Funding Notes, as well as on our 2022 Variable Funding Notes, which bear interest at fluctuating interest rates that in certain circumstances are based on Term SOFR.
On April 22, 2022, a federal appellate court rejected an appeal seeking to overturn that decision.
The NLRB issued a proposed rule on September 6, 2022 that largely reestablishes the August 2015 joint employer standard.
In addition, COVID-19 may impact the willingness of customers to purchase food prepared outside of the home.
The COVID-19 pandemic may also have the effect of heightening many of the other risks described throughout this report, including but not limited to those relating to our growth strategy, our supply chain and increased food and labor costs, availability of labor, disruption in operations, loss of key employees, our indebtedness, general economic conditions and our international operations.
We continue to monitor additional developments.
We have also made additional operating changes in response to changes in consumer behavior and preferences resulting from COVID-19, including offering contactless delivery and carryout options to our customers.
If we and our franchisees are not able to secure leases in desired locations on favorable terms, or to renew such leases, our business and results of operations may be adversely affected.
We may also pursue strategic acquisitions as part of our business.
If we are able to identify acquisition candidates, such acquisitions may be financed, to the extent permitted under our debt agreements, with substantial debt or with potentially dilutive issuances of equity securities and may not be successful.
We plan to continue investing in additional supply chain capacity in the future given the capacity limitations we are currently facing resulting from the growth of our business.
In addition, a failure of us, our employees, our franchisees or third parties acting at our direction to abide by applicable laws and regulations in the use of social media may adversely impact our brand, reputation, marketing partners, financial condition, and results of operations or subject us or our franchisees to fines or other penalties.
Allison Jr. and Russell J.
Some of our systems are not fully redundant, and our system’s disaster recovery planning cannot account for all eventualities.
Furthermore, as a result of the COVID-19 pandemic, certain of our employees have been required to work from home for an extended period of time.
The Financial Conduct Authority (the “FCA”) also stated that, while most available tenors for U.S. dollar LIBOR will be available for legacy contracts after December 31, 2021, such tenors may not be used in new contracts.
The FCA will consult regarding the use of new powers to be granted by the EU and UK governments which would permit the FCA to require panel banks to continue to publish certain LIBOR settings on a “synthetic” basis until the end of 2022, including the use of such powers for one-month, three-month and six-month U.S. dollar LIBOR settings.
However, the FCA also stated that any continued publication of “synthetic” LIBOR would not be representative and would only be for use in legacy contracts.
In addition, the Federal Reserve Board, the Office of the Comptroller of the Currency and the Federal Deposit Insurance Corporation had previously released a statement that (i) encouraged banks to cease entering into new contracts that use U.S. dollar LIBOR as a reference rate as soon as practicable and in any event by December 31, 2021, (ii) indicated that new contracts entered into before December 31, 2021 should either utilize a reference rate other than U.S. dollar LIBOR or have robust fallback language that includes a clearly defined alternative reference rate after the discontinuation of U.S. dollar LIBOR and (iii) explained that extending the publication of certain U.S. dollar LIBOR tenors until June 30, 2023 would allow most legacy U.S. dollar LIBOR contracts to mature before LIBOR begins experiencing disruptions.
In the United States, the U.S. Federal Reserve, in conjunction with the Alternative Reference Rates Committee, a steering committee comprised of large U.S. financial institutions, is considering replacing LIBOR with a new index calculated by short-term repurchase agreements, backed by Treasury securities called the Secured Overnight Financing Rate (“SOFR”).
Our 2021 Variable Funding Notes loan documents contemplate a transition from LIBOR to SOFR in the event that LIBOR ceases to exist.
make loans and investments;
The National Labor Relations Board (NLRB) announced on December 10, 2021 that it will again revisit its joint employer standard.
Actions of activist investors could negatively impact our business and the value of our stock price.
Publicly-traded companies have increasingly become subject to activist investor campaigns.
Responding to actions of an activist investor may be a significant distraction for our management and staff and could require us to expend significant time and resources, including legal fees and potential proxy solicitation expenses.
Any of these conditions could materially and adversely affect our financial performance.
An excerpt. Shown here: 40 of 93 rewritten, all 21 added and all 24 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors. in the FY2023 filing and the FY2022 filing.
Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations.
166 rewritten, 76 added, 66 removed, 261 unchanged
Fiscal [removed: 2021] [added: 2022] and [removed: 2019] [added: 2021] each consisted of 52 weeks and fiscal 2020 consisted of 53 weeks.*
In this section, we discuss the results of our operations for the [added: fiscal] year ended January [removed: 2, 2022] [added: 1, 2023] compared to the [added: fiscal] year ended January [removed: 3, 2021.][added: 2, 2022.]
For a discussion of the [added: fiscal] year ended January [removed: 3, 2021] [added: 2, 2022] compared to the [added: fiscal] year ended [removed: December 29, 2019,] [added: January 3, 2021,] please refer to Part II, Item 7, “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in our Annual Report on Form 10-K for the [added: fiscal] year ended January [removed: 3, 2021.][added: 2, 2022.]
Domino’s is the largest pizza company in the world, with more than [removed: 18,800] [added: 19,800] locations in over 90 markets around the world as of January [removed: 2, 2022,] [added: 1, 2023,] and operates two distinct service models within its stores with a significant business in both delivery and carryout.
[removed: Although] [added: Founded in 1960,] we are a highly-recognized global brand, [added: and] we focus on value while serving neighborhoods locally through our large network of franchise owners and Company-owned [removed: stores.][added: stores through both the delivery and carryout service models.]
We also generate revenues and earnings by selling food, equipment and supplies to [removed: franchisees,] [added: franchisees] primarily in the U.S. and [removed: Canada,] [added: Canada] and by operating a number of Company-owned stores in the U.S. Franchisees profit by selling pizza and other complementary items to their local customers.
Our financial results are driven largely by retail sales at our [removed: franchise] [added: franchised] and Company-owned stores.
We believe we have a proven business model for success, which includes leading with technology, service and product innovation and leveraging our global scale, which has historically provided strong returns for our [removed: shareholders][added: shareholders.]
There were no triggering events in [removed: 2021, 2020] [added: 2022, 2021] or [removed: 2019,] [added: 2020,] and accordingly, we did not record any impairment losses on long-lived assets in [removed: 2021, 2020] [added: 2022, 2021] and [removed: 2019.][added: 2020.]
A 10% change in our casualty insurance liability at January [removed: 2, 2022] [added: 1, 2023] would have affected our income before provision for income taxes by approximately [removed: $5.6] [added: $5.8] million in [removed: 2021.][added: 2022.]
We had accruals for casualty insurance reserves of [removed: $56.5] [added: $57.6] million and [removed: $54.6] [added: $56.5] million at January [removed: 2, 2022] [added: 1, 2023] and January [removed: 3, 2021,] [added: 2, 2022,] respectively.
The U.S. Federal statutory income tax rate was 21% in each of [removed: 2021, 2020] [added: 2022, 2021] and [removed: 2019.][added: 2020.]
Our Federal income tax provision calculated based on the Federal statutory rate was [removed: $131.4] [added: $120.3] million, [removed: $116.6] [added: $131.4] million and [removed: $101.4] [added: $116.6] million in [removed: 2021, 2020] [added: 2022, 2021] and [removed: 2019,] [added: 2020,] respectively.
As of January [removed: 2, 2022] [added: 1, 2023] and January [removed: 3, 2021,] [added: 2, 2022,] we had total foreign tax credits of [removed: $10.2] [added: $13.5] million and [removed: $6.6] [added: $10.2] million, respectively, each of which were fully offset with a corresponding valuation allowance.
We also had valuation allowances related to interest deductibility in separately filed states of [removed: $1.2] [added: $1.5] million and [removed: $1.0] [added: $1.2] million as of January [removed: 2, 2022] [added: 1, 2023] and January [removed: 3, 2021,] [added: 2, 2022,] respectively.
Fiscal [removed: 2021] [added: 2022] Highlights
Global retail sales, excluding foreign currency impact (which includes total retail sales at Company-owned and franchised stores worldwide) increased [removed: 8.9%] [added: 3.9%] as compared to [removed: 2020.][added: 2021.]
U.S. retail sales increased [removed: 4.3%] [added: 1.3%] and international retail sales, excluding foreign currency impact, increased [removed: 13.9%] [added: 6.3% each] as compared to [removed: 2020.][added: 2021.]
Same store sales [removed: increased 3.5%] [added: declined 0.8%] in our U.S. stores and increased [removed: 8.0%] [added: 0.1%] in our international [removed: stores.][added: stores, excluding foreign currency impact.]
[removed: Our revenues] [added: Revenues] increased [removed: 5.8%.][added: 4.1%.]
[removed: Our diluted] [added: Diluted] earnings per share [removed: increased 9.3%.][added: decreased 7.5%.]
During [removed: 2021,] [added: 2022,] we experienced global retail sales [removed: growth and] [added: growth, excluding foreign currency impact, in both our] U.S. and international [removed: same store sales growth.][added: businesses.]
Our U.S. and international same store sales [removed: results] [added: (excluding foreign currency impact)] continue to be [removed: impacted] [added: pressured] by our fortressing strategy, which includes increasing store concentration in certain markets where we compete, as well as from aggressive competitive activity.
During [removed: 2021,] [added: 2022,] we continued our global expansion with the opening of [removed: 1,204] [added: 1,032] net stores.
We had [removed: 205] [added: 126] net stores open in the U.S. comprised of [removed: 214] [added: 141] store openings and [removed: 9] [added: 15] closures.
We had [removed: 999] [added: 906] net stores open internationally comprised of [removed: 1,094] [added: 1,135] store openings and [removed: 95 closures.][added: 229 closures, primarily in Brazil, Russia and Italy.]
We remained focused on improving the customer experience through our technology initiatives, including [removed: through] our GPS delivery tracking technology, which allows customers to monitor the progress of their food, from the preparation stages to the time it is in the oven to the time it arrives at their doors.
Our emphasis on technological innovation helped the Domino’s system generate [removed: more than half] [added: approximately two-thirds] of global retail sales from digital channels in [removed: 2021.][added: 2022.]
Overall, we believe our [added: continued] global store growth, [removed: strong sales,] [added: along with our global retail sales growth (excluding foreign currency impact),] emphasis on [removed: technology, operations] [added: technology] and marketing [removed: initiatives] [added: initiatives,] have combined to strengthen our brand.
Global retail sales growth refers to total worldwide retail sales at Company-owned and [removed: franchise] [added: franchised] stores.
| | | [removed: 2021] [added: 2022] | | | | [removed: 2020] [added: 2021] | | | | [removed: 2019] [added: 2020] | | |
| U.S. stores | | | [removed: +4.3%] [added: \+ 1.3%] | | | | [removed: +17.6%] [added: \+ 4.3%] | | | | [removed: +6.9%] [added: \+ 17.6%] | |
| International stores (excluding foreign currency impact) | | | [removed: +13.9%] [added: \+ 6.3%] | | | | [removed: +8.8%] [added: \+ 13.9%] | | | | [removed: +9.0%] [added: \+ 8.8%] | |
| Total (excluding foreign currency impact) | | | [removed: +8.9%] [added: \+ 3.9%] | | | | [removed: +13.2%] [added: \+ 8.9%] | | | | [removed: +8.0%] [added: \+ 13.2%] | |
Same store sales growth is calculated for a given period by including only sales from stores that also had sales in the comparable weeks of both [removed: years.][added: periods.]
Changes in international same store sales are reported on a constant dollar [removed: basis] [added: basis,] which reflects changes in international local currency sales.
| | | [removed: 2021] [added: 2022] | | [removed: 2020] [added: 2021] | | [removed: 2019] [added: 2020] |
| U.S. Company-owned stores [added: (1)] | | [removed: (3.6)%] [added: (2.6)%] | | [removed: +11.0%] [added: (3.6)%] | | [removed: +2.8%] [added: \+ 11.0%] |
| U.S. franchise stores [added: (1)] | | [removed: +3.9%] [added: (0.7)%] | | [removed: +11.5%] [added: \+ 3.9%] | | [removed: +3.2%] [added: \+ 11.5%] |
| U.S. stores | | [removed: +3.5%] [added: (0.8)%] | | [removed: +11.5%] [added: \+ 3.5%] | | [removed: +3.2%] [added: \+ 11.5%] |
We are primarily a franchisor, with approximately 99% of Domino’s global stores owned and operated by our independent franchisees as of January 1, 2023.
Income from operations decreased 1.6%.
Net income decreased 11.4%.
Excluding the negative impact of foreign currency, Domino’s experienced global retail sales growth during 2022.
U.S. same store sales declined 0.8% during 2022, rolling over an increase in U.S. same store sales of 3.5% in 2021.
The decline in U.S. same store sales in 2022 was attributable to lower order counts due in part to labor shortages affecting store hours and staffing levels in many of our markets and economic stimulus activity in the U.S in 2021 in response to the COVID-19 pandemic which did not recur in 2022.
A higher average ticket per transaction resulting from higher menu and national offer pricing as well as increases to our average delivery fee partially offset the decline in U.S. same store sales in 2022.
International same store sales (excluding foreign currency impact) increased 0.1% during 2022, rolling over an increase in international same store sales (excluding foreign currency impact) of 8.0% in 2021.
International same store sales (excluding foreign currency impact) were pressured in 2022 due in part to a value added tax holiday in the United Kingdom in 2021 that expired during the first quarter of 2022.
During fiscal 2022, we experienced significant inflationary pressures in our commodity, labor and fuel costs resulting from the macroeconomic environment in the U.S., which had a significant impact on our overall operating results as compared to 2021.
Our overall operating results in fiscal 2022 were also negatively impacted by changes in foreign currency exchange rates resulting from the global macroeconomic environment.
| | | |
| --- | --- | --- |
| (1) | | During the first quarter of 2022, we purchased 23 U.S. franchised stores from certain of our existing U.S. franchisees (the “2022 Store Purchase”). The same store sales growth for these stores is reflected in U.S. Company-owned stores in 2022. During the fourth quarter of 2022, we refranchised 114 U.S. Company-owned stores (the “2022 Store Sale”). The same store sales growth for these stores is reflected in U.S. franchise stores in 2022. |
| Openings | | | 5 | | | | 136 | | | | 141 | | | | 1,135 | | | | 1,276 | |
| Closings | | | (3 | ) | | | (12 | ) | | | (15 | ) | | | (229 | ) | | | (244 | ) |
| Store count at January 1, 2023 | | | 286 | | | | 6,400 | | | | 6,686 | | | | 13,194 | | | | 19,880 | |
| Revenues: | | | | | | | | | | | | | | | | | | | | | | | | |
| Cost of sales: | | | | | | | | | | | | | | | | | | | | | | | | |
| Refranchising gain | | | (21.2 | ) | | | (0.5 | )% | | | — | | | | 0.0 | % | | | — | | | | 0.0 | % |
| | | 2022 | | | | | | | | 2021 | | | | | | |
Consolidated revenues increased $179.8 million, or 4.1%, in 2022 due primarily to higher supply chain revenues due to increases in our market basket pricing to stores.
U.S. franchise royalties and fee revenues increased primarily due to retail sales growth resulting from net store growth and the 2022 Store Sale as well as an increase in revenues from fees paid by our franchisees for the use of our technology platforms, but were partially offset by lower same store sales and, to a lesser extent, the 2022 Store Purchase.
U.S. franchise advertising revenues increased primarily due to retail sales growth resulting from net store growth and the 2022 Store Sale as well as lower advertising incentives related to brand promotions, but were partially offset by lower same store sales and, to a lesser extent, the 2022 Store Purchase.
International franchise royalties and fee revenues declined primarily due to the negative impact of foreign currency exchange rates.
U.S. Company-owned store revenues declined primarily due to the 2022 Store Sale as well as lower same store sales, but were partially offset by higher revenues resulting from the 2022 Store Purchase.
| | | 2022 | | | | | | | | 2021 | | | | | | |
Revenues from U.S. Company-owned store operations decreased $33.2 million, or 6.9%, in 2022 primarily driven by the 2022 Store Sale.
This decrease was partially offset by an increase in revenues resulting from the 2022 Store Purchase.
The decrease in U.S. Company-owned store revenue was also a result of lower U.S. Company-owned same store sales in 2022.
The 2022 Store Sale also contributed to the increase in U.S. franchise royalties and fee revenues.
These increases were partially offset by a decline in U.S. franchise same store sales in 2022 and, to a lesser extent, the 2022 Store Purchase.
Additionally, the Company recorded approximately $3.7 million less in advertising incentives related to certain brand promotions in 2022 as compared to 2021, which also contributed to the increase in U.S. franchise advertising revenues.
These increases were partially offset by a decline in U.S. franchise same store sales in 2022 and, to a lesser extent, the 2022 Store Purchase.
Supply chain revenues increased $193.8 million, or 7.6%, in 2022 due to higher market basket pricing to stores, and was partially offset by lower order volumes at our U.S. franchised stores during 2022.
The market basket pricing change, a statistical measure utilized by management, is calculated as the percentage change of the market basket purchased by an average U.S. store (based on average weekly unit sales) from our U.S. supply chain centers against the comparable period of the prior year.
We believe this measure is important to understanding Company performance because as our market basket prices fluctuate, our revenues, cost of sales and gross margin percentages in our supply chain segment also fluctuate.
The impact of changes in foreign currency exchange rates on international franchise royalty revenues, a statistical measure utilized by management, is calculated as the difference in international franchise royalty revenues resulting from translating current year local currency results to U.S. dollars at current year exchange rates as compared to prior year exchange rates.
We believe this measure is important to understanding Company performance given the significant variability in international franchise royalty revenues that can be driven by changes in foreign currency exchange rates.
| | | 2022 | | | | | | | | 2021 | | | | | | |
Founded in 1960, our roots are in convenient pizza delivery, while a significant amount of our sales also come from carryout customers.
Our estimates of the useful lives of our long-lived assets have not changed during the periods presented.
Our income from operations increased 7.5%.
Our net income increased 3.9%.
The inclusion of the 53rd week in 2020 negatively impacted our results as compared to the prior year.
We believe our commitment to value, convenience, quality and new products continues to keep consumers engaged with the brand.
We launched our newest side item in the U.S., Domino’s Oven-Baked Dips in three unique flavors including Cheesy Marinara, Five Cheese and Baked Apple to pair with our Domino’s Bread Twists.
Same store sales in the U.S. continue to be positively affected by changes in consumer ordering behavior observed since the onset of the COVID-19 pandemic, but have been pressured in part in recent quarters due to labor shortages affecting store hours and staffing levels in many of our markets, as well as a waning in the level of economic stimulus activity in fiscal 2021 in the U.S. as compared to the prior year.
Our strong international same store sales performance continued with 112 straight quarters of positive international same store sales.
We also continued to experience sustained increases in retail sales during fiscal 2021 resulting from evolving consumer trends, as well as the reopening and resumption of normal store hours and operating procedures at certain of our international franchised stores that had been temporarily closed or affected by changes in operating procedures and store hours for portions of fiscal 2020 as a result of the COVID-19 pandemic.
Additionally, we offer contactless carryout nationwide – via Domino’s Carside Delivery®, which customers can choose when placing a prepaid online order.
| Store count at December 30, 2018 | | | 390 | | | | 5,486 | | | | 5,876 | | | | 10,038 | | | | 15,914 | |
| Openings | | | 12 | | | | 253 | | | | 265 | | | | 939 | | | | 1,204 | |
| Closings | | | (1 | ) | | | (14 | ) | | | (15 | ) | | | (83 | ) | | | (98 | ) |
| | | 2021 | | | | | | | | 2020 | | | | | | |
Consolidated revenues increased $240.0 million, or 5.8%, in 2021 due primarily to higher global retail sales, which resulted in higher supply chain revenues, international franchise royalties and fees, U.S. franchise royalties and fees, and U.S. franchise advertising revenues.
These increases were partially offset by the inclusion of the 53rd week in 2020 which positively impacted revenues in 2020 by an estimated $88.4 million.
Revenues from U.S. Company-owned store operations decreased $6.6 million, or 1.4%, in 2021 due primarily to an estimated $10.6 million impact of the 53rd week in fiscal 2020, as well as a decrease in U.S. Company-owned same store sales.
Revenues were also benefited by approximately $3.0 million related to funding we provided to our franchisees for an effort to donate 10 million slices of pizza to people and organizations at the frontlines of the COVID-19 pandemic in the franchisees’ local communities during 2020 which did not recur in 2021.
These increases were partially offset by an estimated $11.4 million impact of the 53rd week in fiscal 2020.
Revenues from U.S. franchise advertising increased $17.3 million, or 3.7%, in 2021 due primarily to higher same store sales and an increase in the average number of U.S. franchised stores open during the year resulting from net store growth.
These increases were partially offset by an estimated $10.4 million impact of the 53rd week in fiscal 2020 as well as approximately $9.3 million in advertising incentives related to the Domino’s Surprise FreesTM promotion in 2021.
Supply chain revenues increased $144.3 million or 6.0% in 2021 due primarily to higher volumes resulting from retail sales growth.
These increases were partially offset by an estimated $49.6 million impact of the 53rd week in fiscal 2020.
The reopening and resumption of normal store hours and operating procedures at certain of the Company’s international franchised stores that had been temporarily closed or affected by changes in operating procedures and store hours for portions of 2020 as a result of the COVID-19 pandemic also contributed to the increase in revenues.
Changes in foreign currency exchange rates positively impacted revenue from international royalties and fees by approximately $4.9 million in 2021.
These increases were partially offset by an estimated $6.4 million impact of the 53rd week in fiscal 2020.
| Consolidated operating margin | | $ | 1,688.2 | | | | 38.7 | % | | $ | 1,594.5 | | | | 38.7 | % |
We estimate that the 53rd week resulted in an increase of approximately $50.6 million to consolidated cost of sales in fiscal 2020.
Consolidated operating margin (which we define as revenues less cost of sales) increased $93.7 million, or 5.9%, in 2021 due primarily to higher global franchise revenues and higher supply chain volumes.
These increases were partially offset by an estimated $37.8 million impact on consolidated operating margin related to the 53rd week in fiscal 2020.
As a percentage of revenues, the consolidated operating margin was flat at 38.7% in 2021 and 2020.
Higher food and occupancy costs also contributed to the decrease in U.S. Company-owned store operating margin.
These decreases were partially offset by lower labor costs.
As a percentage of store revenues, the store operating margin increased 0.1 percentage points in 2021.
Labor costs decreased 1.9 percentage points to 29.0% in 2021 due primarily to additional bonus pay incurred during 2020 for frontline team members, as well as lower team member headcount in 2021.
These decreases were partially offset by higher volumes.
General and administrative expenses increased $21.7 million, or 5.3%, in 2021 driven primarily by higher labor costs, including non-cash equity-based compensation expense.
Higher travel and event costs also contributed to the increase in general and administrative expenses.
These increases were partially offset by lower professional fees and an estimated $5.6 million impact of the 53rd week in 2020.
An excerpt. Shown here: 40 of 166 rewritten, 40 of 76 added and 40 of 66 removed. The counts are complete. For every sentence, read Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations. in the FY2023 filing and the FY2022 filing.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk.
6 rewritten, 4 added, 2 removed, 13 unchanged
In connection with the recapitalizations of our business, we have issued fixed rate notes and entered into variable funding notes and, at January [removed: 2, 2022,] [added: 1, 2023,] we are exposed to interest rate risk on borrowings under our variable funding notes.
As of January [removed: 2, 2022,] [added: 1, 2023,] we did not have any outstanding borrowings under our [added: 2022 and] 2021 Variable Funding Notes.
Because the composition and characteristics of [added: Term] SOFR are not the same as those of LIBOR, [removed: in such event,] there can be no assurance that [added: Term] SOFR will perform the same way LIBOR would have at any given time or for any applicable period.
Our [removed: fixed rate] [added: fixed-rate] debt exposes the Company to changes in market interest rates reflected in the fair value of the debt and to the risk that the Company may need to refinance maturing debt with new debt at a higher rate.
Approximately [removed: 6.8%] [added: 6.5%] of our total revenues in [removed: 2021, 6.1%] [added: 2022, 6.8%] of our total revenues in [removed: 2020] [added: 2021] and [removed: 6.7%] [added: 6.1%] of our total revenues in [removed: 2019] [added: 2020] were derived from our international franchise segment, a majority of which were denominated in foreign currencies.
A hypothetical 10% adverse change in the foreign currency rates for our international markets would have resulted in a negative impact on royalty revenues of approximately [removed: $26.5] [added: $26.1] million in [removed: 2021.][added: 2022.]
Our 2021 Variable Funding Notes loan documents provide that after the date on which the administrator for LIBOR permanently or indefinitely ceases to provide all available settings of U.S. dollar LIBOR, any new advances under the 2021 Variable Funding Notes that would otherwise have borne interest based on LIBOR, as well as any existing LIBOR advances for which the interest period has expired, will instead bear interest at a forward-looking term rate based on the Secured Overnight Financing Rate (“Term SOFR”), plus a spread adjustment, that in each case have been selected or recommended by the Board of Governors of the Federal Reserve System or the Federal Reserve Bank of New York.
The loan documents also permit the lenders to effect a transition from LIBOR to Term SOFR at an earlier date, subject to certain conditions.
Our interest expense could also be increased by the rising interest rate environment, which could potentially have an adverse impact on our 2021 Variable Funding Notes, as well as on our 2022 Variable Funding Notes, which bear interest at fluctuating interest rates that are based on Term SOFR.
Severe increases in commodity prices or food costs, including as a result of inflation, could affect the global and U.S. economies and could also adversely impact our business, financial condition or results of operations.
There is currently uncertainty around whether LIBOR will continue to exist after 2023.
Our 2021 Variable Funding Notes loan documents contemplate a transition from LIBOR to secured overnight financing rate (“SOFR”) in the event that LIBOR ceases to exist.
Item 1. Business.
89 rewritten, 9 added, 16 removed, 242 unchanged
Domino’s is the largest pizza company in the world with more than [removed: 18,800] [added: 19,800] locations in over 90 markets around the world as of January [removed: 2, 2022,] [added: 1, 2023,] and operates two distinct service models within its stores with a significant business in both delivery and carryout.
[removed: We] [added: Founded in 1960, we] are a highly recognized global brand, and we focus on value while serving neighborhoods locally through our large worldwide network of franchise owners and U.S. Company-owned [removed: stores.][added: stores through both the delivery and carryout service models.]
We are primarily a franchisor, with approximately [removed: 98%] [added: 99%] of Domino’s [added: global] stores [removed: currently] owned and operated by our independent [removed: franchisees.][added: franchisees as of January 1, 2023.]
We also generate revenues and earnings by selling food, equipment and supplies to franchisees through our supply chain [removed: operations,] [added: operations] primarily in the U.S. and [removed: Canada,] [added: Canada] and by operating a number of Company-owned stores in the United States.
We [removed: pioneered the pizza delivery business and] have been [removed: delivering] [added: selling] quality, affordable food [added: through both the carryout and delivery service models] to our customers since 1960.
[removed: Additionally, emphasis] [added: Emphasis] on technological innovation helped us achieve [removed: more than half] [added: approximately two-thirds] of all global retail sales in [removed: 2021] [added: 2022] from digital channels.
As of January [removed: 2, 2022,] [added: 1, 2023,] the Company had [removed: $5.07] [added: $5.02] billion in total debt, which [removed: included] [added: includes] debt [added: resulting] from its [removed: 2021 Recapitalization and its previous] recapitalization transactions [added: completed] in [added: 2021,] 2019, 2018, 2017 and 2015 (the [added: “2021 Recapitalization,”] “2019 Recapitalization,” “2018 Recapitalization,” “2017 Recapitalization” and the “2015 Recapitalization,” respectively, and [removed: together with the 2021 Recapitalization,] [added: collectively,] the “2021, 2019, 2018, 2017 and 2015 Recapitalizations”).
From [removed: 2016] [added: 2017] through [removed: 2021,] [added: 2022,] the U.S. QSR pizza category has grown from [removed: $35.9] [added: $36.4] billion to [removed: $40.6] [added: $40.7] billion.
It is the second-largest category within the [removed: $304.8] [added: $320.3] billion U.S. QSR sector.
In the U.S., we compete in the delivery and carryout segments of the pizza industry, and we are the dollar market share leader for delivery and [removed: a growing leader in carryout.][added: carryout among pizza QSRs.]
The four industry leaders, including Domino’s, account for [removed: over 59%] [added: approximately 60%] of U.S. pizza delivery, based on reported consumer spending, with the remaining dollars going to regional chains and independent establishments.
From [removed: 2016] [added: 2017] to [removed: 2021,] [added: 2022,] the carryout segment grew from [removed: $16.3] [added: $16.4] billion to [removed: $17.5] [added: $18.9] billion.
The four industry leaders, including Domino’s, account for approximately [removed: 48%] [added: 50%] of the U.S. carryout segment.
(Source: The NPD Group/CREST®, year ending [removed: November 2021).][added: December 2022).]
We believe that demand for pizza delivery and pizza carryout is large and growing throughout the world, driven by international consumers’ increasing emphasis on convenience, and our proven success of [removed: more than 35] [added: 40] years of conducting business abroad.
Internationally, we compete primarily with Pizza Hut®, Papa John’s® and country-specific [removed: national] [added: national, regional] and local pizzerias.
No customer accounted for more than 10% of total consolidated revenues in [removed: 2021, 2020] [added: 2022, 2021] or [removed: 2019.][added: 2020.]
As of January [removed: 2, 2022,] [added: 1, 2023,] our largest franchisee based on store count, Domino’s Pizza Enterprises (DMP: ASX), operated [removed: 3,229] [added: 3,751] stores in [removed: ten] [added: 13] international markets, and accounted for [removed: 17%] [added: 19%] of our total store count.
Revenues from this master franchisee accounted for 1.7% of our consolidated revenues in [removed: 2021.][added: 2022.]
We offer a menu designed to present an attractive, quality offering to customers, while keeping it simple enough to minimize [removed: order errors] [added: operational complexity] and expedite order-taking and food preparation.
International markets vary toppings by country and culture, such as the [removed: Cheese and Corn pizza] [added: Paratha Pizza] in India, [added: Durian Pizza in China] or the Octopus Bomb Shrimp in Korea, featuring shrimp, octopus, vegetables, feta cream and horseradish sauce.
We have [removed: been focused on] [added: delivered] pizza [removed: delivery] for over 60 years, and we also emphasize carryout as a significant component of our business.
During [removed: 2021,] [added: 2022,] our U.S. stores segment accounted for [removed: $1.50] [added: $1.49] billion, or [removed: 34%,] [added: 33%,] of our consolidated revenues.
Our U.S. stores segment consists primarily of our franchise operations, which consisted of [removed: 6,185] [added: 6,400] franchised stores located in the United States as of January [removed: 2, 2022.][added: 1, 2023.]
We also operated a network of [removed: 375] [added: 286] U.S. Company-owned stores as of January [removed: 2, 2022.][added: 1, 2023.]
While we are primarily a franchised business, we continuously evaluate our mix of U.S. Company-owned and [removed: franchise] [added: franchised] stores.
As of January [removed: 2, 2022,] [added: 1, 2023,] franchised stores represented approximately [removed: 94%] [added: 96%] of our total store count within our U.S. stores segment.
As of January [removed: 2, 2022,] [added: 1, 2023,] our network of [removed: 6,185] [added: 6,400] U.S. franchise stores was owned and operated by [removed: 735] [added: 725] independent U.S. franchisees.
As of January [removed: 2, 2022,] [added: 1, 2023,] the average U.S. franchisee owned and operated approximately [removed: eight] [added: nine] stores and had been in our franchise system for over [removed: 18] [added: 17] years.
Additionally, 22 of our U.S. franchisees operated more than 50 stores (including our largest U.S. franchisee who operated [removed: 177] [added: 162] stores) and [removed: 216] [added: 204] of our U.S. franchisees each operated one [removed: store, each] [added: store] as of [removed: that date.][added: January 1, 2023.]
We had a franchise agreement renewal rate of approximately 99% in [removed: 2021.][added: 2022.]
We have the contractual right, subject to state law, to terminate a franchise agreement for a variety of reasons, including, but not limited to, a franchisee’s failure to adhere to the Company’s franchise agreement, failure to make required [removed: payments,] [added: payments] or failure to adhere to specified Company policies and standards.
During [removed: 2021,] [added: 2022,] our international franchise segment accounted for [removed: $298.0] [added: $295.0] million, or [removed: 7%,] [added: 6%,] of our consolidated revenues.
This segment is comprised of a network of franchised stores in [removed: more than] [added: over] 90 international markets.
As of January [removed: 2, 2022,] [added: 1, 2023,] we had [removed: 12,288] [added: 13,194] international franchise stores.
We believe [added: that] Domino’s appeals to potential international franchisees because of our recognized brand name and technological leadership, the moderate capital expenditures required to open and operate the stores and the system’s desirable store-level profitability.
The following table shows our store count as of January [removed: 2, 2022] [added: 1, 2023] in our ten largest international markets, which accounted for approximately [removed: 62%] [added: 63%] of our international stores as of that date.
| India (JUBLFOOD: NS) | | | [removed: 1,495] [added: 1,758] | |
| United Kingdom (DOM: L) | | | [removed: 1,169] [added: 1,197] | |
| Japan (DMP: ASX) | | | [removed: 882] [added: 957] | |
Delivery segment dollars of $17.3 billion in 2022 (up from $13.6 billion in 2017) account for approximately 43% of total U.S. consumer spend at pizza QSRs.
| China | | | 589 | |
| Canada | | | 585 | |
We plan to continue investing in supply chain productivity initiatives in the future.
We are actively negotiating a new contract with this supplier and we do not anticipate any significant impacts to our supply following the expiration of our current extension.
Domino’s offers a comprehensive benefits package to eligible team members, including several benefits designed to promote an inclusive workplace like paid parental leaves, adoption support, discounted childcare tuition, and health plans that are available to dependents, spouses and domestic partners and include fertility and gender transition support.
In certain periods of 2022, we experienced labor shortages affecting store hours and staffing levels in many of our markets which contributed to lower order counts.
We also continue to highlight important stewardship topics with consumers, including our recent efforts to promote the ability to recycle pizza boxes throughout the U.S. We also launched a fleet of electric vehicles in 2022 as part of an initiative to solve a business need with a solution that is also good for the planet.
Labor costs are largely a function of the minimum wage for a majority of our store personnel and certain supply chain personnel.
Founded in 1960, our roots are in convenient pizza delivery, while a significant amount of our retail sales also come from carryout customers.
During 2021, the uncertain environment created by the novel coronavirus (“COVID-19”) pandemic persisted.
However, we continued to increase global retail sales, while our supply chain operations experienced higher volumes as a result of the increase in retail sales.
In the U.S. we launched our newest side item, Domino’s Oven-Baked Dips in three unique flavors including Cheesy Marinara, Five Cheese and Baked Apple to pair with our Domino’s Bread Twists.
In 2019, we announced a partnership with Nuro to further our exploration and testing of autonomous pizza delivery.
In 2021 we began a test of pizza delivery with Nuro vehicles in Houston, Texas.
In 2020, we also launched a new way to order contactless carryout nationwide – via Domino’s Carside Delivery®, which customers can choose when placing a prepaid online order, with a two-minute guarantee launched in 2021.
This new service method emphasizes our commitment to serving hot and delicious pizza in a convenient, contactless manner.
The Company’s most recent recapitalization transaction completed in April 2021, (the “2021 Recapitalization”), primarily consisted of the issuance of $1.85 billion of fixed rate notes and a new $200.0 million variable funding note facility.
Delivery segment dollars of $19.8 billion in 2021 (up from $13.1 billion in 2016) account for approximately 49% of total U.S. QSR pizza.
| Canada | | | 568 | |
| China | | | 472 | |
We plan to continue investing in additional supply chain centers and capacity initiatives in the future, including one additional regional dough manufacturing and supply chain center that is expected to open in fiscal 2022.
In mid-2020, we launched a new way to order contactless carryout nationwide – via Domino’s Carside Delivery, which customers can choose when placing a prepaid online order.
During 2021, we launched our newest side item, Domino’s Oven-Baked Dips, in three unique flavors including Cheesy Marinara, Five Cheese and Baked Apple to pair with our Domino’s Bread Twists.
Domino’s offers a comprehensive benefits package to eligible team members.
An excerpt. Shown here: 40 of 89 rewritten, all 9 added and all 16 removed. The counts are complete. For every sentence, read Item 1. Business. in the FY2023 filing and the FY2022 filing.
Cover and table of contents
31 rewritten, 8 added, 0 removed, 55 unchanged
For the fiscal year ended January [removed: 2, 2022][added: 1, 2023]
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act: [removed: Yes \[X\] No \[ \]]
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act: [removed: Yes \[ \] No \[X\]]
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days: [removed: Yes \[X\] No \[ \]]
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files): [removed: Yes \[X\] No \[ \]]
The aggregate market value of the voting and non-voting common stock held by non-affiliates of Domino’s Pizza, Inc. as of June [removed: 20, 2021] [added: 19, 2022] computed by reference to the closing price of Domino’s Pizza, Inc.’s common stock on the New York Stock Exchange on such date was [removed: $16,864,015,144.][added: $13,537,240,820.]
As of February [removed: 22, 2022,] [added: 16, 2023,] Domino’s Pizza, Inc. had [removed: 36,036,184] [added: 35,419,653] shares of common stock, par value $0.01 per share, outstanding.
Portions of the definitive proxy statement to be furnished to shareholders of Domino’s Pizza, Inc. in connection with the annual meeting of shareholders to be held on April [removed: 26, 2022] [added: 25, 2023] are incorporated by reference into Part III.
| Item 1. | [Business.](#item1_business) | [removed: 3] [added: 4] |
| Item 1A. | [Risk Factors.](#item1a_riskfactors) | [removed: 14] [added: 15] |
| Item 1B. | [Unresolved Staff Comments.](#item1b_unresolved_staff_comments) | [removed: 29] [added: 30] |
| Item 2. | [Properties.](#item2_properties) | [removed: 29] [added: 30] |
| Item 3. | [Legal Proceedings.](#item3_legal_proceedings) | [removed: 29] [added: 30] |
| Item 4. | [Mine Safety Disclosures.](#item4_mine_safety_disclosures) | [removed: 29] [added: 30] |
| Item 4A. | [Executive Officers of the Registrant](#item4a_executiveofficers_registrant). | [removed: 29] [added: 30] |
| Item 5. | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.](#item5_market_registrants_common_equity) | [removed: 30] [added: 31] |
| Item 6. | [\[Reserved\].](#part_ii_item_6) | [removed: 31] [added: 32] |
| Item 7. | [Management’s Discussion and Analysis of Financial Condition and Results of Operations.](#item7_mda) | [removed: 32] [added: 33] |
| Item 9. | [Changes in and Disagreements with Accountants on Accounting and Financial Disclosure.](#item9_changes_disagreements) | [removed: 81] [added: 80] |
| Item 9A. | [Controls and Procedures.](#item9a_controls_procedures) | [removed: 81] [added: 80] |
| Item 9B. | [Other Information.](#item9b_other_information) | [removed: 81] [added: 80] |
| Item 9C. | [Disclosure Regarding Foreign Jurisdictions that Prevent Inspections.](#item9c_foreign_jurisdictions) | [removed: 81] [added: 80] |
| Item 10. | [Directors, Executive Officers and Corporate Governance.](#item10_directors_executiveofficers) | [removed: 82] [added: 81] |
| Item 11. | [Executive Compensation.](#item11_executive_compensation) | [removed: 83] [added: 82] |
| Item 12. | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.](#item12_security_ownership) | [removed: 83] [added: 82] |
| Item 13. | [Certain Relationships and Related Transactions, and Director Independence.](#item13_certainrelationships) | [removed: 83] [added: 82] |
| Item 14. | [Principal Accountant Fees and Services.](#item14_principal_accountant_fees) | [removed: 83] [added: 82] |
| Item 15. | [Exhibits and Financial Statement Schedules.](#item15_exhibits) | [removed: 84] [added: 83] |
| Item 16. | [Form 10-K Summary.](#item16_form10k_summary) | [removed: 96] [added: 94] |
| [SIGNATURES](#signatures) | | [removed: 97] [added: 95] |
In this document, we rely on and refer to information regarding the U.S. quick service restaurant, or QSR, sector and the U.S. QSR pizza category from CREST® ongoing foodservice market research (years ending [removed: November)] [added: December)] prepared by The NPD Group, as well as market research reports, analyst reports and other publicly-available information.
Yes \[X\] No \[ \]
Yes \[ \] No \[X\]
Yes \[X\] No \[ \]
Yes \[X\] No \[ \]
If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the registrant included in the filing reflect the correction of an error to previously issued financial statements.
\[ \]
Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant’s executive officers during the relevant recovery period pursuant to §240.10D-1(b).
\[ \]
Item 2. Properties.
3 rewritten, 0 added, 0 removed, 4 unchanged
All other U.S. and [removed: international] [added: Canadian] supply chain centers are leased by us, under leases ranging between five and 21 years with one or two five-year renewal options.
All [removed: other] franchise stores are leased or owned directly by the respective franchisees.
We believe that our existing headquarters and other leased and owned facilities are adequate to meet our current requirements, but we plan to continue investing in additional [removed: capacity] [added: supply chain productivity] initiatives in the future.
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
11 rewritten, 6 added, 6 removed, 12 unchanged
As of February [removed: 22, 2022,] [added: 16, 2023,] Domino’s Pizza, Inc. had 170,000,000 authorized shares of common stock, par value $0.01 per share, of which [removed: 36,036,184] [added: 35,419,653] were issued and outstanding.
As of February [removed: 22, 2022,] [added: 16, 2023,] there were [removed: 1,563] [added: 1,507] registered holders of record of Domino’s Pizza, Inc.’s common stock.
Our Board of Directors declared a quarterly dividend of [removed: $1.10] [added: $1.21] per common share on February [removed: 24, 2022] [added: 21, 2023] payable on March 30, [removed: 2022] [added: 2023] to shareholders of record at the close of business on March 15, [removed: 2022.][added: 2023.]
As of January [removed: 2, 2022,] [added: 1, 2023,] we had a Board of Directors-approved share repurchase program for up to $1.0 billion of our common stock, of which [removed: $704.1] [added: $410.4] million remained available for future purchases of our common stock.
The following table summarizes our repurchase activity during the fourth quarter ended January [removed: 2, 2022:][added: 1, 2023:]
[removed: 2,728] [added: 3,557] shares were purchased as part of the Company’s employee stock purchase discount plan.
During the fourth quarter, the shares were purchased at an average price of [removed: $495.08.][added: $335.34.]
The following comparative stock performance line graph compares the cumulative shareholder return on the common stock of Domino’s Pizza, Inc. (NYSE: DPZ) for the five-year period between December 31, [removed: 2016] [added: 2017] and December 31, [removed: 2021,] [added: 2022,] with [added: the] cumulative total return on (i) the Standard & Poor’s 500 Index (the “S&P [removed: 500”) and] [added: 500”),] (ii) the [removed: peer group, the] Standard & Poor’s 400 Restaurant Index (the “S&P 400 Restaurant [added: Index”), which was the Company’s previously-utilized comparison index, and (iii) the Company’s current comparison index, the Standard & Poor’s Composite 1500 Restaurant Index (the “S&P 1500 Restaurant] Index”).
Management believes that the companies included in the S&P [removed: 400] [added: 1500] Restaurant Index [added: more] appropriately reflect the scope [added: and scale] of the Company’s operations and [added: better] match the competitive market in which the Company [removed: operates.][added: operates than the S&P 400 Restaurant Index.]
The cumulative total return computations set forth in the performance graph assume the investment of $100 in [added: each of] the Company’s common stock, the S&P [removed: 500] [added: 500, the S&P 400 Restaurant] Index and the S&P [removed: 400] [added: 1500] Restaurant Index on December 31, [removed: 2016.][added: 2017.]
[removed: 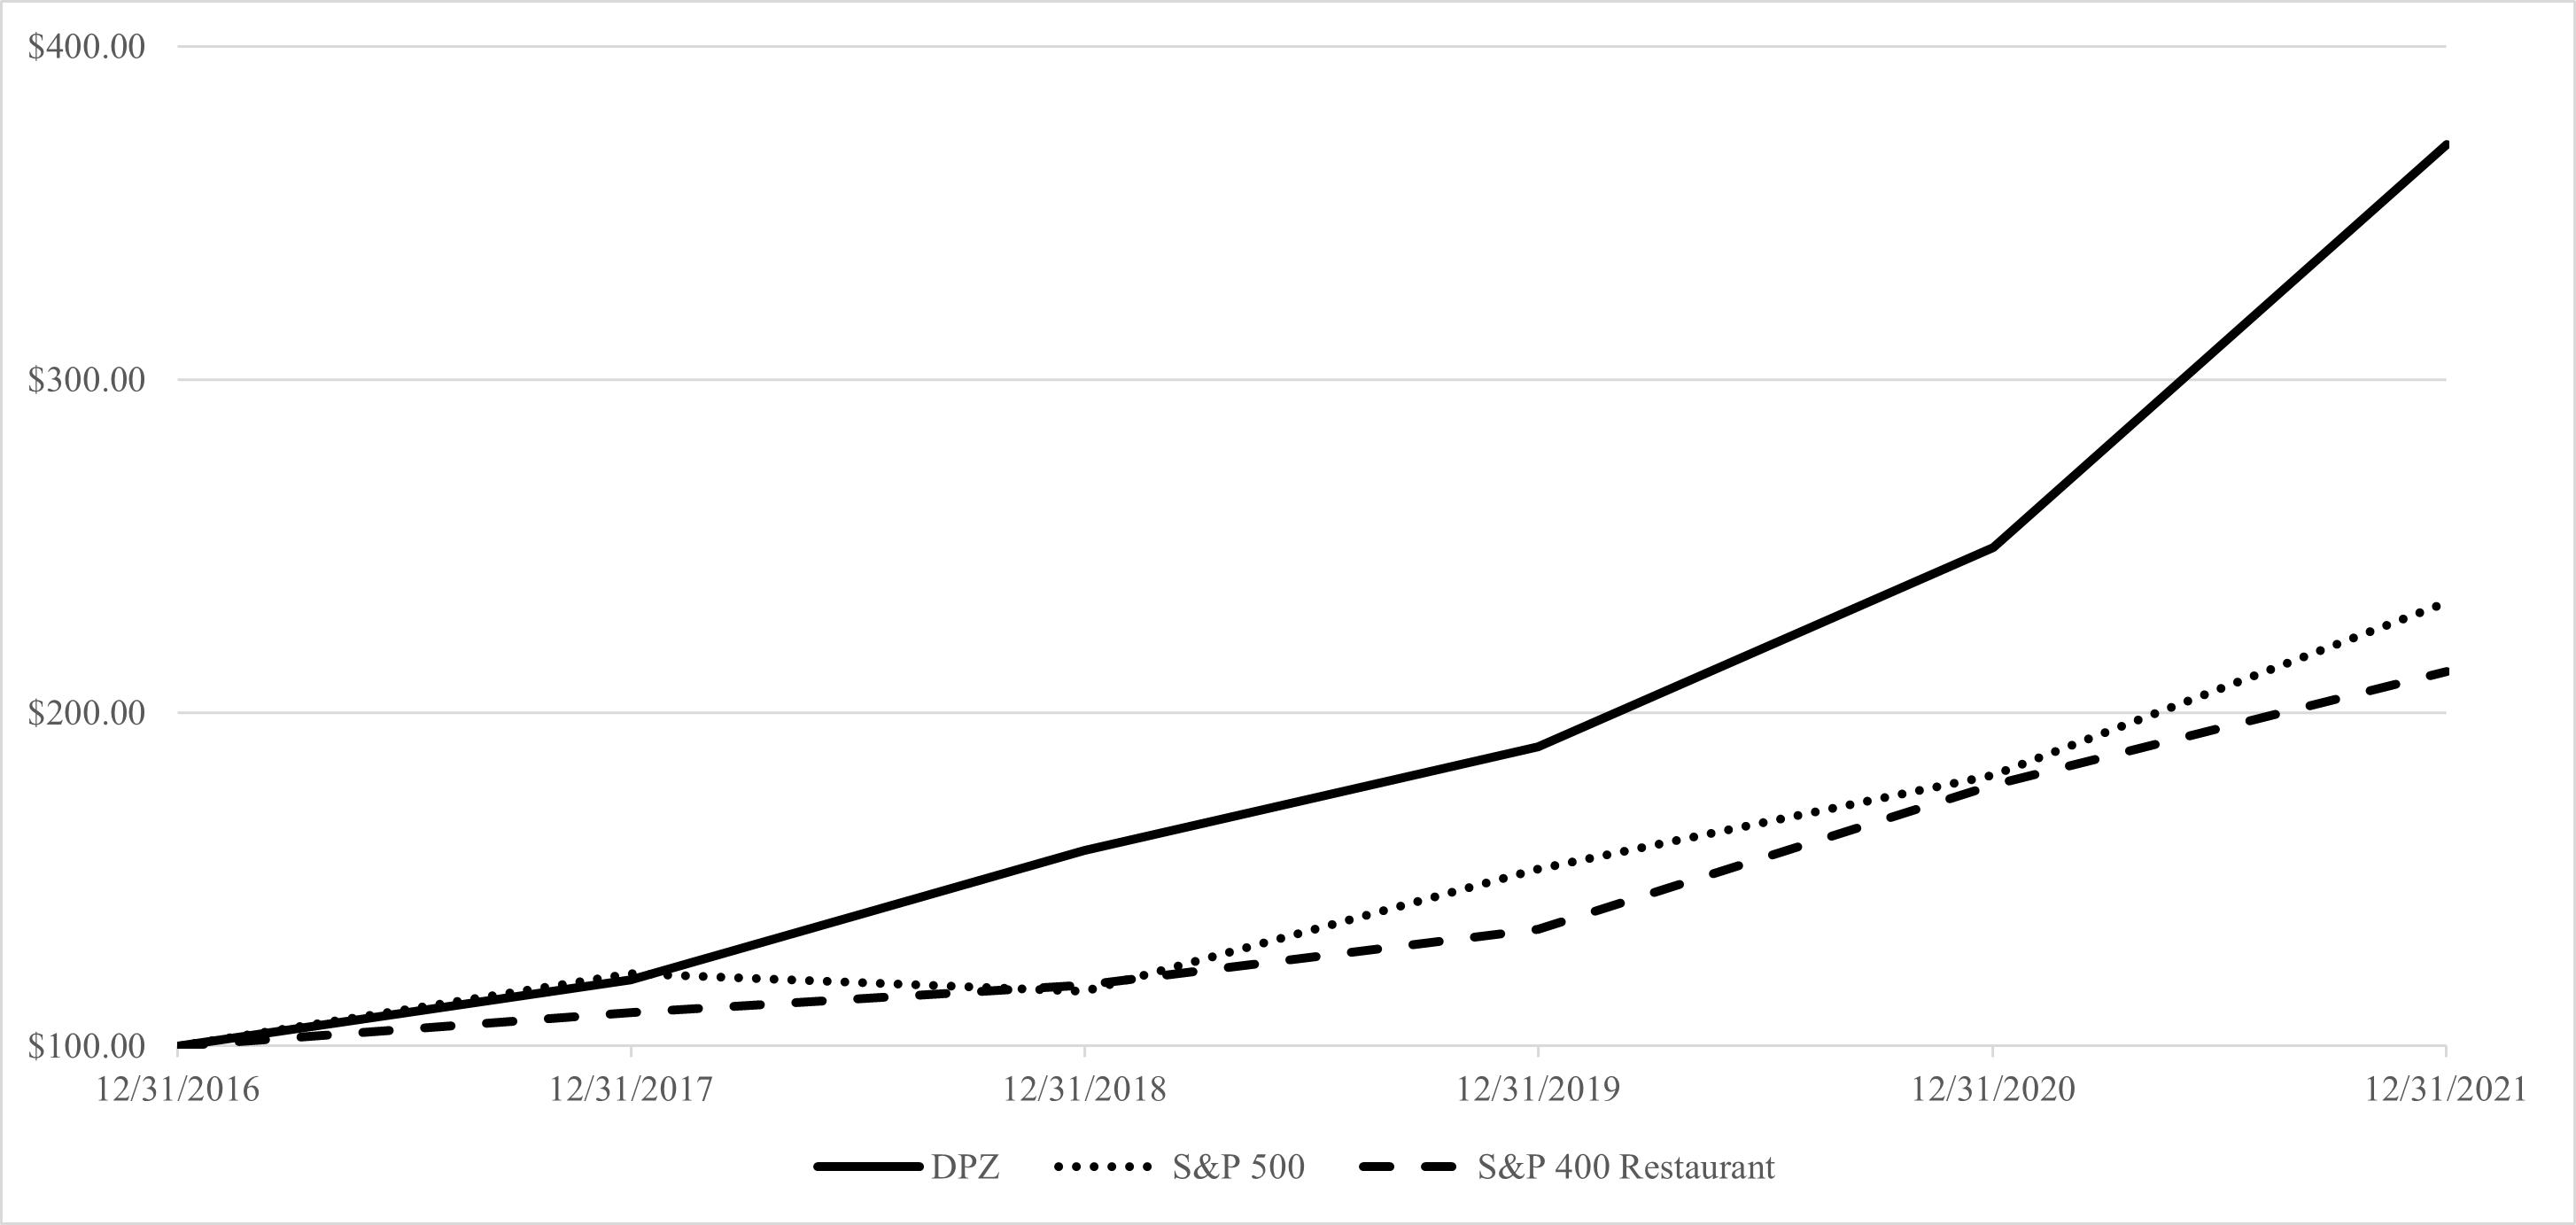][added: 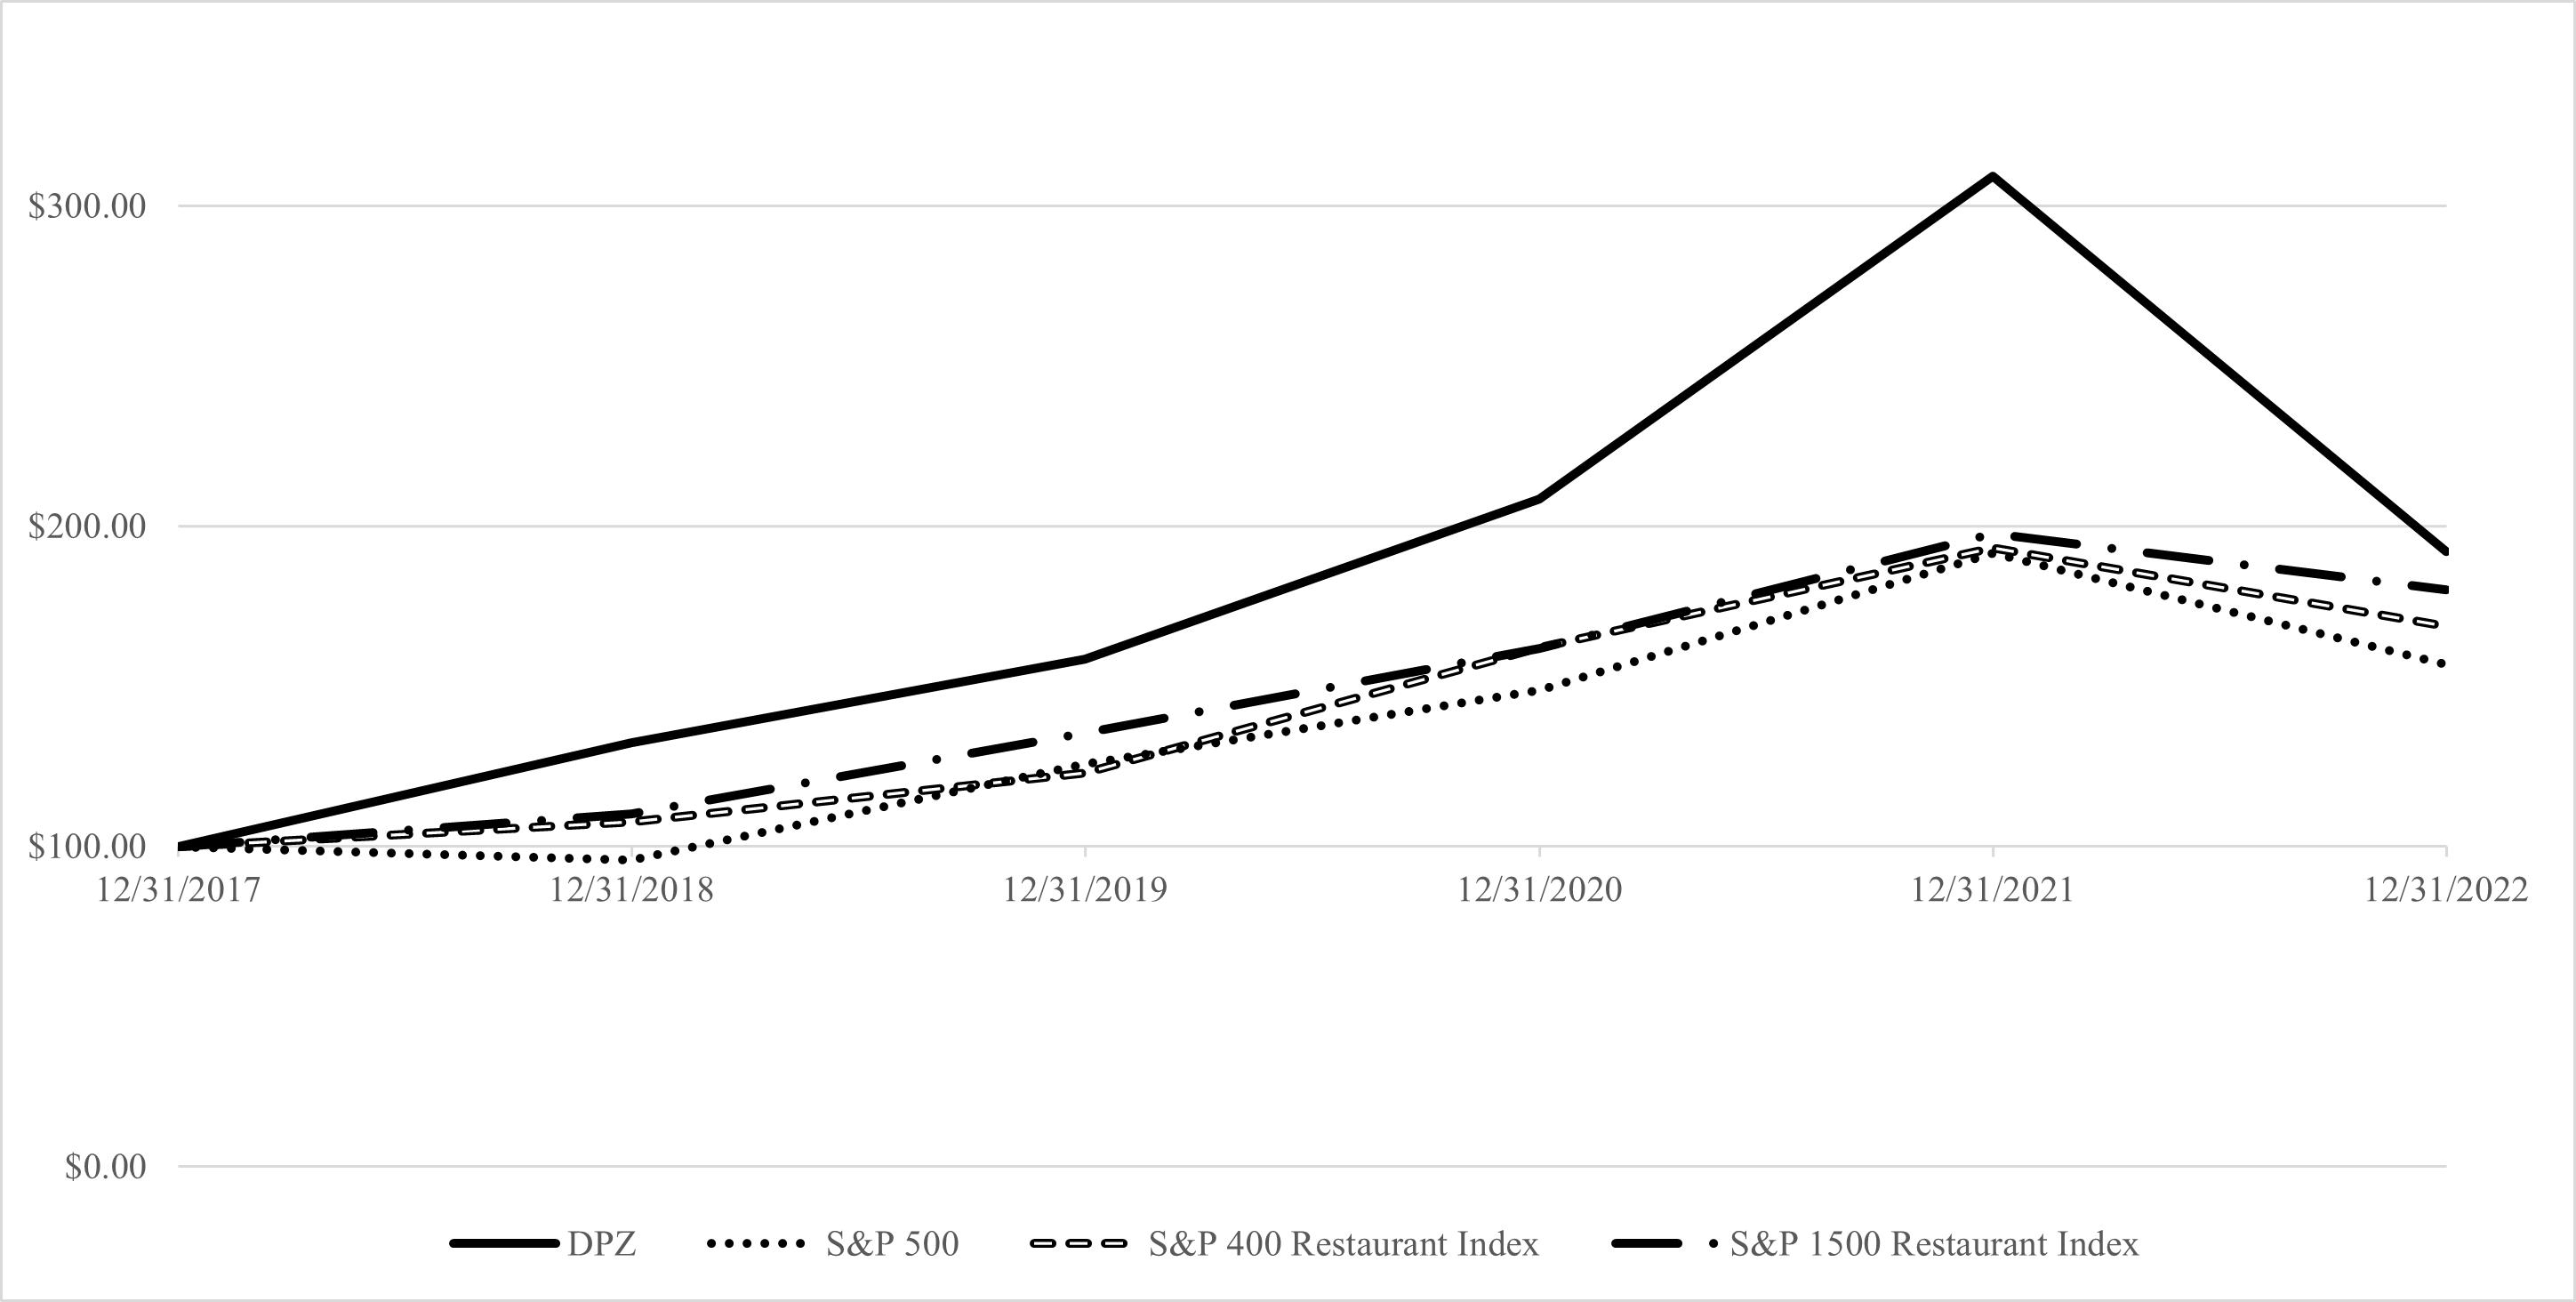]
| Period #10 (September 12, 2022 to October 9, 2022) | | | 1,651 | | | $ | 310.40 | | | | — | | | $ | 410,358 | |
| Period #11 (October 10, 2022 to November 6, 2022) | | | 1,052 | | | | 338.17 | | | | — | | | | 410,358 | |
| Period #12 (November 7, 2022 to December 4, 2022) | | | — | | | | — | | | | — | | | | 410,358 | |
| Period #13 (December 5, 2022 to January 1, 2023) | | | 854 | | | | 380.09 | | | | — | | | | 410,358 | |
| Total | | | 3,557 | | | $ | 335.34 | | | | — | | | $ | 410,358 | |
Due to the change in selected comparative indices, we are presenting the current comparative index and the comparative index that was used in the prior year.
| Period #10 (September 13, 2021 to October 10, 2021) | | | 195,777 | | | $ | 487.96 | | | | 194,860 | | | $ | 825,219 | |
| Period #11 (October 11, 2021 to November 7, 2021) | | | 162,877 | | | | 472.37 | | | | 161,770 | | | | 748,822 | |
| Period #12 (November 8, 2021 to December 5, 2021) | | | 53,711 | | | | 512.64 | | | | 53,007 | | | | 721,660 | |
| Period #13 (December 6, 2021 to January 2, 2022) | | | 33,448 | | | | 525.04 | | | | 33,448 | | | | 704,098 | |
| Total | | | 445,813 | | | $ | 488.02 | | | | 443,085 | | | $ | 704,098 | |
Subsequent to the end of the fourth quarter of 2021, the Company repurchased and retired an additional 100,810 shares of common stock for $47.7 million, or an average price of $472.78 per share.
Item 8. Financial Statements and Supplementary Data.
409 rewritten, 106 added, 79 removed, 580 unchanged
To the Stockholders and Board of Directors [added: of Domino’s Pizza, Inc.]
We have audited the accompanying consolidated balance sheets of Domino’s Pizza, Inc. and its subsidiaries (the “Company”) as of January [removed: 2, 2022] [added: 1, 2023] and January [removed: 3, 2021,] [added: 2, 2022,] and the related consolidated statements of income, [added: of] comprehensive income, [added: of] stockholders’ deficit and [added: of] cash flows for each of the three years in the period ended January [removed: 2, 2022,] [added: 1, 2023,] including the related notes and schedule of condensed financial information of the registrant as of January [removed: 2, 2022] [added: 1, 2023] and January [removed: 3, 2021] [added: 2, 2022] and for each of the three years in the period ended January [removed: 2, 2022] [added: 1, 2023] appearing under Item 15 (collectively referred to as the “consolidated financial statements”).
We also have audited the Company’s internal control over financial reporting as of January [removed: 2, 2022,] [added: 1, 2023,] based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of January [removed: 2, 2022] [added: 1, 2023] and January [removed: 3, 2021,] [added: 2, 2022,] and the results of its operations and its cash flows for each of the three years in the period ended January [removed: 2, 2022] [added: 1, 2023] in conformity with accounting principles generally accepted in the United States of America.
Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of January [removed: 2, 2022,] [added: 1, 2023,] based on criteria established in Internal Control - Integrated Framework (2013) issued by the COSO.
As of January [removed: 2, 2022,] [added: 1, 2023,] the Company had accruals for these casualty insurance matters of [removed: $56.5] [added: $57.6] million.
| | | January [removed: 2,] [added: 1,] | | | | January [removed: 3,] [added: 2,] | | |
| Cash and cash [removed: equivalents] [added: equivalents, end of period] | | [removed: $] | [added: 60,356 | | | |] 148,160 | | | [removed: $] | 168,821 | |
| Restricted cash and cash [removed: equivalents] [added: equivalents, beginning of period] | | | 180,579 | | | | 217,453 | | [added: | | 209,269 | |]
| Accounts receivable, net of reserves of [removed: $1,869] [added: $4,762] in [removed: 2021] [added: 2022] and [removed: $1,793] [added: $1,869] in [removed: 2020] [added: 2021] | | | [removed: 255,327] [added: 257,492] | | | | [removed: 244,560] [added: 255,327] | |
| Inventories | | | [removed: 68,328] [added: 81,570] | | | | [removed: 66,683] [added: 68,328] | |
| Prepaid expenses and other | | | [removed: 27,242] [added: 37,287] | | | | [removed: 24,169] [added: 27,242] | |
| Advertising fund assets, restricted | | | [removed: 180,904] [added: 162,660] | | | | [removed: 147,698] [added: 180,904] | |
| Total current assets | | | [removed: 860,540] [added: 790,654] | | | | [removed: 869,384] [added: 860,540] | |
| Land and buildings | | | [removed: 108,372] [added: 105,659] | | | | [removed: 88,063] [added: 108,372] | |
| Leasehold and other improvements | | | [removed: 193,572] [added: 172,725] | | | | [removed: 186,456] [added: 193,572] | |
| Equipment | | | [removed: 312,772] [added: 333,787] | | | | [removed: 292,456] [added: 312,772] | |
| Construction in progress | | | [removed: 27,815] [added: 22,536] | | | | [removed: 13,014] [added: 27,815] | |
| Accumulated depreciation and amortization | | | [removed: (318,466] [added: (332,472] | ) | | | [removed: (282,625] [added: (318,466] | ) |
| Property, plant and equipment, net | | | [removed: 324,065] [added: 302,235] | | | | [removed: 297,364] [added: 324,065] | |
| Operating lease right-of-use assets | | | [removed: 210,702] [added: 219,202] | | | | [removed: 228,268] [added: 210,702] | |
| Investments in marketable securities, restricted | | | [removed: 15,433] [added: 13,395] | | | | [removed: 13,251] [added: 15,433] | |
| Goodwill | | | [removed: 15,034] [added: 11,763] | | | | [removed: 15,061] [added: 15,034] | |
| Capitalized software, net of accumulated amortization of [removed: $142,509] [added: $165,457] in [removed: 2021] [added: 2022] and [removed: $124,043] [added: $142,509] in [removed: 2020] [added: 2021] | | | [removed: 95,558] [added: 108,354] | | | | [removed: 81,306] [added: 95,558] | |
| Investments | | | 125,840 | | | | [removed: 40,000] [added: 125,840] | |
| Other assets | | | [removed: 22,535] [added: 28,852] | | | | [removed: 20,630] [added: 22,535] | |
| Total other assets | | | [removed: 487,211] [added: 509,332] | | | | [removed: 400,420] [added: 487,211] | |
| Total assets | | $ | [removed: 1,671,816] [added: 1,602,221] | | | $ | [removed: 1,567,168] [added: 1,671,816] | |
| Current portion of long-term debt | | $ | [removed: 55,588] [added: 54,813] | | | $ | [removed: 2,855] [added: 55,588] | |
| Accounts payable | | | [removed: 91,547] [added: 89,715] | | | | [removed: 94,499] [added: 91,547] | |
| Accrued compensation | | | [removed: 59,567] [added: 40,442] | | | | [removed: 58,520] [added: 59,567] | |
| Accrued interest | | | [removed: 37,982] [added: 34,473] | | | | [removed: 31,695] [added: 37,982] | |
| Operating lease liabilities | | | [removed: 37,155] [added: 34,877] | | | | [removed: 35,861] [added: 37,155] | |
| Insurance reserves | | | [removed: 32,588] [added: 31,435] | | | | [removed: 26,377] [added: 32,588] | |
| Advertising fund liabilities | | | [removed: 173,737] [added: 157,909] | | | | [removed: 141,175] [added: 173,737] | |
| Other accrued liabilities | | | [removed: 102,577] [added: 92,957] | | | | [removed: 79,837] [added: 102,577] | |
| Total current liabilities | | | [removed: 590,741] [added: 536,621] | | | | [removed: 470,819] [added: 590,741] | |
| Long-term debt, less current portion | | | [removed: 5,014,638] [added: 4,967,420] | | | | [removed: 4,116,018] [added: 5,014,638] | |
| Operating lease liabilities | | | [removed: 184,471] [added: 195,244] | | | | [removed: 202,268] [added: 184,471] | |
| Insurance reserves | | | [removed: 36,913] [added: 40,179] | | | | [removed: 37,125] [added: 36,913] | |
February 23, 2023
| | | 2023 | | | | 2022 | | |
| | | | 634,707 | | | | 642,531 | |
| Deferred income tax assets, net | | | 1,926 | | | | 2,109 | |
| Deferred income tax liabilities | | | 7,761 | | | | 3,922 | |
| | | 2023 | | | | 2022 | | | | 2021 | | |
| U.S. franchise advertising | | | 485,330 | | | | 479,501 | | | | 462,238 | |
| Refranchising gain | | | (21,173 | ) | | | — | | | | — | |
The accompanying notes are an integral part of these consolidated financial statements.
| | | 2023 | | | | 2022 | | | | 2021 | | |
| Net income | | $ | 452,263 | | | $ | 510,467 | | | $ | 491,296 | |
The accompanying notes are an integral part of these consolidated financial statements.
| Net income | | | — | | | | — | | | | — | | | | 452,263 | | | | — | |
| Purchases of common stock | | | (739,847 | ) | | | (7 | ) | | | (12,819 | ) | | | (280,914 | ) | | | — | |
| Exercises of stock options | | | 32,979 | | | | — | | | | 3,312 | | | | — | | | | — | |
| Balance at January 1, 2023 | | | 35,419,718 | | | $ | 354 | | | $ | 9,693 | | | $ | (4,194,418 | ) | | $ | (4,694 | ) |
The accompanying notes are an integral part of these consolidated financial statements.
| | | January 1, | | | | January 2, | | | | January 3, | | |
| | | 2023 | | | | 2022 | | | | 2021 | | |
| Net income | | $ | 452,263 | | | $ | 510,467 | | | $ | 491,296 | |
| Refranchising gain | | | (21,173 | ) | | | — | | | | — | |
The accompanying notes are an integral part of these consolidated financial statements.
| 2023 | | $ | 22,657 | |
| 2024 | | | 16,250 | |
| 2025 | | | 10,336 | |
| 2026 | | | 7,286 | |
| 2027 | | | 6,506 | |
| | | $ | 89,025 | |
| | | January 1, 2023 | | | | January 2, 2022 | | |
| 2023 | | $ | 5,510 | |
| 2024 | | | 5,200 | |
| 2025 | | | 4,847 | |
| 2026 | | | 4,458 | |
| 2027 | | | 2,942 | |
| Thereafter | | | 5,268 | |
| | | $ | 28,225 | |
The Company had $29.2 million and $23.8 million included in other current accrued liabilities related to unredeemed gift cards as of January 1, 2023 and January 2, 2022, respectively.
However, the associated loan documents provide that after the date on which the administrator for LIBOR permanently or indefinitely ceases to provide all available settings of U.S. dollar LIBOR, any new advances under the 2021 Variable Funding Notes that would otherwise have borne interest based on LIBOR, as well as any existing LIBOR advances for which the interest period has expired, will instead bear interest at a forward-looking term rate based on the Secured Overnight Financing Rate (“Term SOFR”), plus a spread adjustment.
The loan documents also permit the lenders to effect a transition from LIBOR to Term SOFR at an earlier date, subject to certain conditions.
The Company’s 2022 Variable Funding Notes (Note 3) bear interest at fluctuating interest rates based on Term SOFR.
of Domino’s Pizza, Inc.
March 1, 2022
| | | | 642,531 | | | | 579,989 | |
| Deferred income taxes | | | 2,109 | | | | 1,904 | |
| Deferred income taxes | | | 3,922 | | | | 6,099 | |
| Balance at December 30, 2018 | | | 40,977,561 | | | $ | 410 | | | $ | 569 | | | $ | (3,036,471 | ) | | $ | (4,429 | ) |
| Net income | | | — | | | | — | | | | — | | | | 400,709 | | | | — | |
| Purchases of common stock | | | (2,493,560 | ) | | | (25 | ) | | | (27,700 | ) | | | (671,282 | ) | | | — | |
| Exercises of stock options | | | 425,601 | | | | 4 | | | | 13,060 | | | | — | | | | — | |
| Maturities of advertising fund investments, restricted | | | — | | | | — | | | | 50,152 | |
Amortization expense for implementation costs for cloud-based computing arrangements in 2019 was not material.
| | | | | |
| --- | --- | --- | --- | --- |
| 2022 | | $ | 19,059 | |
| 2023 | | | 10,075 | |
| 2024 | | | 3,522 | |
| 2025 | | | 1,158 | |
| 2026 | | | 768 | |
| | | $ | 34,582 | |
| 2022 | | $ | 5,403 | |
| 2023 | | | 5,162 | |
| 2024 | | | 4,855 | |
| 2025 | | | 4,406 | |
| 2026 | | | 4,003 | |
| Thereafter | | | 5,865 | |
| | | $ | 29,694 | |
*Accounting Standards Update (“ASU”) 2019-12, Income Taxes – Simplifying the Accounting for Income Taxes (Topic 740)*
In December 2019, the Financial Accounting Standards Board (“FASB”) issued ASU 2019-12, *Income Taxes (Topic 740): Simplifying the Accounting for Income Taxes (“ASU 2019-12”)*, which simplifies the accounting for income taxes.
ASU 2019-12 was effective for fiscal years beginning after December 15, 2020, including applicable interim periods.
ASC 326 requires companies to measure credit losses utilizing a methodology that reflects expected credit losses and requires a consideration of a broader range of reasonable and supportable information to inform credit loss estimates.
The comparative information has not been restated and continues to be reported under the accounting standards in effect for that period.
However, the associated loan documents contemplate a transition from LIBOR to secured overnight financing rate (“SOFR”) in the event that LIBOR ceases to exist.
If the Company further needs to renegotiate its loan documents, the Company cannot predict what alternative index would be negotiated with its lenders.
The Company is currently assessing the impact of adopting this standard but does not expect the adoption of this guidance to have a material impact on its consolidated financial statements.
The proceeds from the 2019 Recapitalization were used to prefund a portion of the principal and interest payable on the 2019 Notes, pay transaction fees and expenses and repurchase and retire shares of the Company’s common stock.
During 2019 and in connection with the 2019 Recapitalization, the Company incurred $0.5 million of net pre-tax 2019 Recapitalization-related general and administrative expenses, including legal and professional fees.
Accordingly, all principal amounts of the Company’s then outstanding 2019 Notes, 2018 Notes, the 2017 Notes and the 2015 Notes were classified as long-term debt in the consolidated balance sheet as of January 3, 2021.
As of the third quarter of 2019, the Company had a leverage ratio of less than 5.0x, and, in accordance with the Company’s debt agreements, ceased debt amortization payments in the fourth quarter of 2019.
Subsequent to the 2019 Recapitalization, the Company’s leverage ratios exceeded the leverage ratio of 5.0x and, accordingly, the Company resumed making the scheduled amortization payments on its then outstanding notes in the first quarter of 2020.
| 2017 Five-Year Fixed Rate Notes | | | — | | | | 582,000 | |
An excerpt. Shown here: 40 of 409 rewritten, 40 of 106 added and 40 of 79 removed. The counts are complete. For every sentence, read Item 8. Financial Statements and Supplementary Data. in the FY2023 filing and the FY2022 filing.
Item 9A. Controls and Procedures.
5 rewritten, 0 added, 0 removed, 11 unchanged
The Company carried out an evaluation as of the end of the period covered by this report, under the supervision and with the participation of the Company’s management, including the Company’s Chief Executive Officer [removed: (who is also serving as the Company’s principal financial officer),] [added: and Chief Financial Officer,] of the effectiveness of the design and operation of the Company’s disclosure controls and procedures pursuant to Rules 13a-15 and 15d-15 of the Securities Exchange Act of 1934, as amended (the “Exchange Act”).
Based upon that evaluation, the Chief Executive Officer [added: and Chief Financial Officer] concluded that the Company’s disclosure controls and procedures are effective in ensuring that all information required in the reports it files or submits under the Exchange Act was accumulated and communicated to the Company’s management, including its Chief Executive [added: Officer and Chief Financial] Officer, as appropriate to allow timely decisions regarding required disclosure and was recorded, processed, summarized and reported within the time period required by the rules and regulations of the Securities and Exchange Commission.
Under the supervision and with the participation of the Company’s management, including its Chief Executive Officer [removed: (who is also serving as the Company’s principal financial officer),] [added: and Chief Financial Officer,] the Company conducted an evaluation of the effectiveness of its internal control over financial reporting as of January [removed: 2, 2022] [added: 1, 2023] based on the framework in *Internal Control — Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission.
Based on that evaluation, management concluded that its internal control over financial reporting was effective as of January [removed: 2, 2022.][added: 1, 2023.]
The effectiveness of the Company’s internal control over financial reporting as of January [removed: 2, 2022,] [added: 1, 2023,] has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in their report which appears herein.
Item 10. Directors, Executive Officers and Corporate Governance.
16 rewritten, 7 added, 9 removed, 35 unchanged
| [removed: Richard E. Allison, Jr.] [added: Russell J. Weiner] | [removed: 55] [added: 54] | Chief Executive Officer and Director |
| Arthur P. [removed: D'Elia] [added: D’Elia] | [removed: 44] [added: 45] | Executive Vice President, [removed: Chief Marketing Officer] [added: International] |
| Kelly E. Garcia | [removed: 46] [added: 47] | Executive Vice President, Chief Technology Officer |
| Frank R. Garrido | [removed: 51] [added: 52] | Executive Vice President, U.S. Operations and Support |
| Cynthia A. Headen | [removed: 53] [added: 54] | Executive Vice President, Supply Chain Services |
| Kevin S. Morris | [removed: 61] [added: 62] | Executive Vice President, General Counsel and Corporate Secretary |
| Lisa V. Price | [removed: 49] [added: 50] | Executive Vice President, Chief Human Resources Officer |
[removed: Allison, Jr.] [added: Weiner] has served as [added: Domino’s] Chief Executive Officer [removed: of Domino’s] since [removed: July 2018.][added: May 2022.]
Mr. [removed: Allison] [added: Weiner] has served on Domino’s Board of Directors since [removed: July 2018,] [added: May 2022] when he was elected in conjunction with his appointment as Chief Executive Officer.
Mr. [removed: Allison] [added: Weiner] also serves on the Board of Directors of [removed: Starbucks Corporation.][added: The Clorox Company.]
[removed: Weiner has] [added: Prior to becoming CEO, Mr. Weiner] served as Chief Operating Officer and President, Domino’s U.S. [removed: since] [added: from] July 2020 [removed: and as] [added: to April 2022,] Chief Operating Officer and President of the Americas from July 2018 to July [removed: 2020.][added: 2020, President, Domino’s USA from October 2014 to July 2018 and joined Domino’s as Executive Vice President and Chief Marketing Officer in September 2008.]
Mr. [removed: Weiner] [added: D’Elia] served as Executive Vice [removed: President] [added: President, Chief Marketing Officer from July 2020 to April 2022] and [added: as Senior Vice President,] Chief Marketing Officer from [removed: September 2008] [added: February 2020] to [removed: October 2014.][added: July 2020.]
Prior to Domino’s, Mr. D'Elia served as Chief Marketing Officer for Danone Dairy’s UBN business unit from July 2017 to January [removed: 2018,] [added: 2018] after joining Danone U.S. in [added: April 2010, and worked at PepsiCo in corporate strategy, development and marketing for the North American beverage business from June 2003 to March] 2010.
[removed: Jordan] [added: D’Elia] has served as Domino’s Executive Vice [removed: President of] [added: President,] International since [removed: April 2018.][added: May 2022.]
[removed: Prior to his current role,] Mr. Jordan [added: previously] served as [added: Executive Vice President of International from April 2018 to April 2022,] Senior Vice President and Chief Marketing Officer [removed: since] [added: from] May [removed: 2015, after joining] [added: 2015 to April 2018, and joined] Domino’s as Vice President of Innovation in September 2011.
The remaining information required by this item is incorporated by reference from Domino’s Pizza, Inc.'s definitive proxy statement, which will be filed within 120 days of January [removed: 2, 2022.][added: 1, 2023.]
| Joseph H. Jordan | 49 | President, U.S. and Global Services |
| Sandeep Reddy | 52 | Executive Vice President, Chief Financial Officer |
Jordan has served as Domino’s President, U.S. and Global Services since May 2022.
Sandeep Reddy has served as Domino’s Executive Vice President, Chief Financial Officer since April 2022.
Prior to joining Domino’s, Mr. Reddy served as Executive Vice President and Chief Financial Officer of Six Flags Entertainment from July 2020 to March 2022, and as Chief Financial Officer of Guess?, Inc. from July 2013 to December 2019, after joining Guess?, Inc. in 2010 as the Vice President and European CFO.
From 1997 to 2010, Mr. Reddy held a variety of positions with increasing responsibility for Mattel Inc.
Mr. Garcia also serves on the Board of Directors of Ulta Beauty, Inc.
| Russell J. Weiner | 53 | Chief Operating Officer and President - Domino's U.S. |
| Joseph H. Jordan | 48 | Executive Vice President, International |
Richard E.
Mr. Allison oversees all company operations, strategy and vision in his role as Chief Executive Officer.
He previously served as President, Domino’s International from October 2014 to July 2018, after joining the Company in March 2011 as Executive Vice President of International.
Prior to joining Domino’s, Mr. Allison worked at Bain & Company, Inc. for more than 13 years, serving as a Partner from 2004 to December 2010, and as co-leader of Bain’s restaurant practice, working with some of the world’s most well-known restaurant brands.
He previously served as President, Domino’s USA from October 2014 to July 2018.
Mr. Weiner serves on the Board of Directors of The Clorox Company.
D’Elia has served as Domino’s Executive Vice President, Chief Marketing Officer since July 2020 and as Senior Vice President, Chief Marketing Officer from February 2020 to July 2020.
Item 11. Executive Compensation.
1 rewritten, 0 added, 0 removed, 1 unchanged
Information regarding executive compensation is incorporated by reference from Domino’s Pizza, Inc.’s definitive proxy statement, which will be filed within 120 days of January [removed: 2, 2022.][added: 1, 2023.]
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
1 rewritten, 0 added, 0 removed, 0 unchanged
Information regarding security ownership of certain beneficial owners and management and related stockholder matters is incorporated by reference from Domino’s Pizza, Inc.’s definitive proxy statement, which will be filed within 120 days of January [removed: 2, 2022.][added: 1, 2023.]
Item 13. Certain Relationships and Related Transactions, and Director Independence.
1 rewritten, 0 added, 0 removed, 0 unchanged
Information regarding certain relationships and related transactions is incorporated by reference from Domino’s Pizza, Inc.’s definitive proxy statement, which will be filed within 120 days of January [removed: 2, 2022.][added: 1, 2023.]
Item 14. Principal Accountant Fees and Services.
1 rewritten, 0 added, 0 removed, 1 unchanged
Information regarding principal accountant fees and services is incorporated by reference from Domino’s Pizza, Inc.’s definitive proxy statement, which will be filed within 120 days of January [removed: 2, 2022.][added: 1, 2023.]
Item 15. Exhibits, Financial Statement Schedules.
104 rewritten, 16 added, 8 removed, 115 unchanged
Consolidated Balance Sheets as of January [removed: 2, 2022] [added: 1, 2023] and January [removed: 3, 2021][added: 2, 2022]
Consolidated Statements of Income for the Years Ended January [added: 1, 2023, January] 2, [removed: 2022,] [added: 2022 and] January 3, 2021 [removed: and December 29, 2019]
Consolidated Statements of Comprehensive Income for the Years Ended January [added: 1, 2023, January] 2, [removed: 2022,] [added: 2022 and] January 3, 2021 [removed: and December 29, 2019]
Consolidated Statements of Stockholders’ Deficit for the Years Ended January [added: 1, 2023, January] 2, [removed: 2022,] [added: 2022 and] January 3, 2021 [removed: and December 29, 2019]
Consolidated Statements of Cash Flows for the Years Ended January [added: 1, 2023, January] 2, [removed: 2022,] [added: 2022 and] January 3, 2021 [removed: and December 29, 2019]
| [added: Exhibit] Number | | Description |
| [removed: 3.3] [added: 10.29*] | | [removed: [Second Amended] [added: [Amended] and Restated [removed: By-Laws of] Domino’s [removed: Pizza, Inc.] [added: Pizza Senior Executive Annual Incentive Plan] (Incorporated by reference to Exhibit [removed: 3.3] [added: 10.20] to the registrant’s annual report on Form 10-K for the year ended January [removed: 3, 2016).](https://www.sec.gov/Archives/edgar/data/1286681/000119312516476935/d128680dex33.htm)] [added: 2, 2011).](https://www.sec.gov/Archives/edgar/data/1286681/000119312511050979/dex1020.htm)] |
| [removed: 4.1] [added: 10.30*] | | [removed: [Description of Securities of the Registrant.] [added: [Amended and Restated Domino’s Pizza, Inc. Employee Stock Payroll Deduction Plan] (Incorporated by reference to Exhibit [removed: 4.1] [added: 10.18] to the registrant’s annual report on Form 10-K for the year ended December 29, [removed: 2019 (the “2019 10-K”)).](https://www.sec.gov/Archives/edgar/data/1286681/000119312520042675/d796357dex41.htm)] [added: 2013).](https://www.sec.gov/Archives/edgar/data/1286681/000119312514066092/d661353dex1018.htm)] |
| [removed: 10.13] [added: 10.14] | | [removed: [Fifteenth] [added: [Sixteenth] Amendment to a Lease Agreement between Domino’s Farms Office Park, L.L.C. and Domino’s Pizza LLC, dated as of July 21, [removed: 2021.](https://www.sec.gov/Archives/edgar/data/1286681/000095017022002426/dpz-ex10_13.htm)] [added: 2021 (Incorporated by reference to Exhibit 10.14 to the 2021 10-K).](https://www.sec.gov/Archives/edgar/data/1286681/000095017022002426/dpz-ex10_14.htm)] |
| [removed: 10.14] [added: 10.13] | | [removed: [Sixteenth] [added: [Fifteenth] Amendment to a Lease Agreement between Domino’s Farms Office Park, L.L.C. and Domino’s Pizza LLC, dated as of July 21, [removed: 2021.](https://www.sec.gov/Archives/edgar/data/1286681/000095017022002426/dpz-ex10_14.htm)] [added: 2021 (Incorporated by reference to Exhibit 10.13 to the registrant's annual report on Form 10-K for the year ended January 2, 2022 (the “2021 10-K”)).](https://www.sec.gov/Archives/edgar/data/1286681/000095017022002426/dpz-ex10_13.htm)] |
| [removed: 10.18*] [added: 10.19*] | | [Amended Domino’s Pizza, Inc. 2004 Equity Incentive Plan (Incorporated by reference to Exhibit 10.1 to the registrant’s quarterly report on Form 10-Q for the quarter ended March 22, 2009 (the “March 2009 10-Q”)).](https://www.sec.gov/Archives/edgar/data/1286681/000119312509093037/dex101.htm) |
| [removed: 10.19*] [added: 10.20*] | | [Form of Employee Stock Option Agreement under the Amended Domino’s Pizza, Inc. 2004 Equity Incentive Plan (Incorporated by reference to Exhibit 10.8 to the 2012 10-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312513081957/d466015dex108.htm) |
| [removed: 10.20*] [added: 10.21*] | | [Form of 2013 Special Employee Stock Option Agreement under the Amended Domino’s Pizza, Inc. 2004 Equity Incentive Plan (Incorporated by reference to Exhibit 10.9 to the 2012 10-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312513081957/d466015dex109.htm) |
| [removed: 10.21*] [added: 10.22*] | | [Form of Director Stock Option Agreement under the Amended Domino’s Pizza, Inc. 2004 Equity Incentive Plan (Incorporated by reference to Exhibit 10.3 to the March 2009 10-Q).](https://www.sec.gov/Archives/edgar/data/1286681/000119312509093037/dex103.htm) |
| [removed: 10.22*] [added: 10.23*] | | [Form of Amendment to Existing Director Stock Option Grants (Incorporated by reference to Exhibit 10.5 to the March 2009 10-Q).](https://www.sec.gov/Archives/edgar/data/1286681/000119312509093037/dex105.htm) |
| [removed: 10.23*] [added: 10.24*] | | [Form of Performance-Based Restricted Stock Agreement (Incorporated by reference to Exhibit 10.12 to the 2012 10-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312513081957/d466015dex1012.htm) |
| [removed: 10.24*] [added: 10.25*] | | [Form of 2013 Special Performance-Based Restricted Stock Agreement (Incorporated by reference to Exhibit 10.13 to the 2012 10-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312513081957/d466015dex1013.htm) |
| [removed: 10.25*] [added: 10.26*] | | [Form of Performance-Based Restricted Stock Unit Award Agreement (Incorporated by reference to Exhibit 10.14 to the 2012 10-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312513081957/d466015dex1014.htm) |
| [removed: 10.26*] [added: 10.27*] | | [Form of 2013 Special Performance-Based Restricted Stock Unit Award Agreement (Incorporated by reference to Exhibit 10.15 to the 2012 10-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312513081957/d466015dex1015.htm) |
| [removed: 10.27*] [added: 10.28*] | | [Form of Domino’s Pizza, Inc. 2004 Equity Incentive Plan Restricted Stock Agreement for Directors (Incorporated by reference to Exhibit 10.19 to the registrant’s annual report on Form 10-K for the year ended January 3, 2010).](https://www.sec.gov/Archives/edgar/data/1286681/000119312510045334/dex1019.htm) |
| [removed: 10.28*] [added: 10.49*] | | [removed: [Amended] [added: [Second Addendum to Amended] and Restated [added: Employment Agreement dated as of December 29, 2018 between] Domino’s Pizza [removed: Senior Executive Annual Incentive Plan.] [added: LLC and David A. Brandon] (Incorporated by reference to Exhibit [removed: 10.20] [added: 10.39] to the registrant’s annual report on Form 10-K for the year ended [removed: January 2, 2011).](https://www.sec.gov/Archives/edgar/data/1286681/000119312511050979/dex1020.htm)] [added: December 30, 2018 (the “December 2018 10-K”)).](https://www.sec.gov/Archives/edgar/data/1286681/000119312519046191/d696297dex1039.htm)] |
| [removed: 10.29*] [added: 10.31*] | | [removed: [Amended] [added: [First Amendment to the Amended] and Restated Domino’s Pizza, Inc. Employee Stock Payroll Deduction Plan [added: dated as of January 1, 2019] (Incorporated by reference to Exhibit [removed: 10.18] [added: 10.1] to the registrant’s [removed: annual] [added: quarterly] report on Form [removed: 10-K] [added: 10-Q] for the [removed: year] [added: quarter] ended [removed: December 29, 2013).](https://www.sec.gov/Archives/edgar/data/1286681/000119312514066092/d661353dex1018.htm)] [added: March 24, 2019).](https://www.sec.gov/Archives/edgar/data/1286681/000119312519115719/d661429dex101.htm)] |
| [removed: 10.30*] [added: 10.50*] | | [removed: [First Amendment] [added: [Third Addendum] to [removed: the] Amended and Restated [removed: Domino’s Pizza, Inc. Employee Stock Payroll Deduction Plan] [added: Employment Agreement] dated as of January [removed: 1, 2019] [added: 30, 2020 between Domino’s Pizza LLC and David A. Brandon] (Incorporated by reference to Exhibit 10.1 to the registrant’s quarterly report on Form 10-Q for the quarter ended March [removed: 24, 2019).](https://www.sec.gov/Archives/edgar/data/1286681/000119312519115719/d661429dex101.htm)] [added: 22, 2020).](https://www.sec.gov/Archives/edgar/data/1286681/000119312520115907/d914156dex101.htm)] |
| [removed: 10.31*] [added: 10.32*] | | [Form of Domino’s Pizza, Inc. Dividend Reinvestment & Direct Stock Purchase and Sale Plan (Incorporated by reference to Exhibit 10.32 to the S-1).](https://www.sec.gov/Archives/edgar/data/1286681/000119312504102056/dex1032.htm) |
| [removed: 10.32*] [added: 10.33*] | | [Form of 2018 Restricted Stock Agreement (Incorporated by reference to Exhibit 10.4 to the registrant’s current report on Form 8-K filed on January 11, 2018 (the “January 2018 8-K”)).](https://www.sec.gov/Archives/edgar/data/1286681/000119312518008592/d505807dex104.htm) |
| [removed: 10.33*] [added: 10.34*] | | [Form of 2021 Employee Stock Option Agreement under the Amended Domino’s Pizza, Inc. 2004 Equity Incentive Plan (Incorporated by reference to Exhibit 10.1 to the registrant's quarterly report on Form 10-Q for the quarter ended June 20, 2021 (the [removed: ""June] [added: “June] 2021 [removed: 10-Q"")).](https://www.sec.gov/Archives/edgar/data/1286681/000119312521221398/d164949dex101.htm)] [added: 10-Q”)).](https://www.sec.gov/Archives/edgar/data/1286681/000119312521221398/d164949dex101.htm)] |
| [removed: 10.34*] [added: 10.35*] | | [Form of Performance-Based Restricted Stock Unit Award Agreement under the Amended Domino’s Pizza, Inc. 2004 Equity Incentive Plan (Incorporated by reference to Exhibit 10.2 to the June 2021 10-Q).](https://www.sec.gov/Archives/edgar/data/1286681/000119312521221398/d164949dex102.htm) |
| [removed: 10.35*] [added: 10.36*] | | [Form of Restricted Stock Unit Award Agreement (three-year vesting) under the Amended Domino’s Pizza, Inc. 2004 Equity Incentive Plan (Incorporated by reference to Exhibit 10.3 to the June 2021 10-Q).](https://www.sec.gov/Archives/edgar/data/1286681/000119312521221398/d164949dex103.htm) |
| [removed: 10.36*] [added: 10.37*] | | [Form of Restricted Stock Unit Award Agreement (two vesting dates) under the Amended Domino’s Pizza, Inc. 2004 Equity Incentive Plan (Incorporated by reference to Exhibit 10.1 to the registrant's quarterly report on Form 10-Q for the quarter ended September 12, 2021).](https://www.sec.gov/Archives/edgar/data/1286681/000095017021002121/dpz-ex10_1.htm) |
| [removed: 10.37*] [added: 10.52*] | | [Employment Agreement dated as of August [removed: 28, 2015] [added: 20, 2020] between Domino’s Pizza LLC and [removed: Jeffrey Lawrence] [added: Stuart A. Levy] (Incorporated by reference to Exhibit 10.1 to the [removed: registrant’s] [added: registrant's] quarterly report on Form 10-Q for the quarter ended September 6, [removed: 2015).](https://www.sec.gov/Archives/edgar/data/1286681/000119312515339829/d67435dex101.htm)] [added: 2020).](https://www.sec.gov/Archives/edgar/data/1286681/000119312520265920/d935823dex101.htm)] |
| [removed: 10.38*] [added: 10.41*] | | [removed: [Employment] [added: [Amended and Restated Employment] Agreement dated as of [removed: September 2, 2008] [added: February 24, 2022] between Domino’s [added: Pizza, Inc., Domino’s] Pizza LLC and Russell J. Weiner (Incorporated by reference to Exhibit [removed: 1.01] [added: 10.1] to the registrant’s current report on Form 8-K filed on [removed: September 4, 2008).](https://www.sec.gov/Archives/edgar/data/1286681/000119312508190324/dex101.htm)] [added: March 1, 2022 (the “March 2022 8-K”)).](https://www.sec.gov/Archives/edgar/data/1286681/000119312522059952/d291533dex101.htm)] |
| [removed: 10.39*] [added: 10.51*] | | [removed: [Amendment to the] [added: [Amended and Restated] Employment Agreement dated as of [removed: September] [added: March] 2, [removed: 2008] [added: 2022 by and] between Domino’s Pizza LLC and [removed: Russell J. Weiner] [added: Joseph H. Jordan] (Incorporated by reference to Exhibit [removed: 10.4] [added: 10.1] to the registrant’s current report on Form 8-K filed on [removed: December 24, 2008).](https://www.sec.gov/Archives/edgar/data/1286681/000119312508260125/dex104.htm)] [added: March 4, 2022).](https://www.sec.gov/Archives/edgar/data/1286681/000119312522065165/d312023dex101.htm)] |
| [removed: 10.40*] [added: 10.48*] | | [removed: [Amendment] [added: [Addendum] to [removed: the] [added: Amended and Restated] Employment Agreement dated as of [removed: July 26, 2010] [added: June 22, 2018] between Domino’s Pizza LLC and [removed: Russell J. Weiner] [added: David A. Brandon] (Incorporated by reference to Exhibit [removed: 10.3] [added: 10.1] to the registrant’s quarterly report on Form 10-Q for the quarter ended June [removed: 20, 2010).](https://www.sec.gov/Archives/edgar/data/1286681/000119312510166716/dex103.htm)] [added: 17, 2018 (the “June 2018 10-Q”)).](https://www.sec.gov/Archives/edgar/data/1286681/000119312518220984/d513733dex101.htm)] |
| [removed: 10.41*] [added: 10.45*] | | [Employment Agreement dated as of January 8, 2018 between Domino’s Pizza, Inc., Domino’s Pizza LLC and [removed: Russell J. Weiner] [added: Richard E. Allison, Jr.] (Incorporated by reference to Exhibit [removed: 10.2] [added: 10.1] to the January 2018 [removed: 8-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312518008592/d505807dex102.htm)] [added: 8-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312518008592/d505807dex101.htm)] |
| [removed: 10.42*] [added: 10.44*] | | [Employment Agreement dated as of March 14, 2011 between Domino’s Pizza LLC and Richard E. Allison, Jr. (Incorporated by reference to Exhibit 10.1 to the registrant’s quarterly report on Form 10-Q for the quarter ended March 27, 2011).](https://www.sec.gov/Archives/edgar/data/1286681/000119312511127320/dex101.htm) |
| [removed: 10.43*] [added: 10.46*] | | [removed: [Employment] [added: [Time Sharing] Agreement dated as of January 8, 2018 between Domino’s [removed: Pizza, Inc., Domino’s] Pizza LLC and Richard E. Allison, Jr. (Incorporated by reference to Exhibit [removed: 10.1] [added: 10.3] to the January 2018 [removed: 8-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312518008592/d505807dex101.htm)] [added: 8-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312518008592/d505807dex103.htm)] |
| [removed: 10.44*] [added: 10.42*] | | [Time Sharing Agreement dated as of [removed: January 8, 2018] [added: February 24, 2022 by and] between Domino’s Pizza LLC and [removed: Richard E. Allison, Jr.] [added: Russell J. Weiner] (Incorporated by reference to Exhibit [removed: 10.3] [added: 10.2] to the [removed: January 2018 8-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312518008592/d505807dex103.htm)] [added: March 2022 8-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312522059952/d291533dex102.htm)] |
| [removed: 10.45*] [added: 10.43*] | | [removed: [Addendum to Amended and Restated Employment] [added: [Employment] Agreement dated as of [removed: June 22, 2018] [added: February 25, 2022 by and] between Domino’s Pizza LLC and [removed: David A. Brandon] [added: Sandeep Reddy] (Incorporated by reference to Exhibit [removed: 10.1] [added: 10.3] to the [removed: registrant’s quarterly report on Form 10-Q for the quarter ended June 17, 2018 (the “June 2018 10-Q”)).](https://www.sec.gov/Archives/edgar/data/1286681/000119312518220984/d513733dex101.htm)] [added: March 2022 8-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312522059952/d291533dex103.htm)] |
| [removed: 10.46*] [added: 10.54*] | | [removed: [Second Addendum to Amended and Restated Employment] [added: [Employment] Agreement dated as of December [removed: 29, 2018] [added: 7, 2016] between Domino’s Pizza LLC and [removed: David A. Brandon] [added: Kevin S. Morris] (Incorporated by reference to Exhibit [removed: 10.39] [added: 10.36] to the [removed: registrant’s annual report on Form 10-K for the year ended December 30, 2018 (the “December 2018 10-K”)).](https://www.sec.gov/Archives/edgar/data/1286681/000119312519046191/d696297dex1039.htm)] [added: 2017 10-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312518049576/d531906dex1036.htm)] |
| [removed: 10.48*] [added: 10.53*] | | [removed: [Employment] [added: [Separation] Agreement dated as of [removed: February 11, 2012] [added: May 19, 2021] between Domino’s Pizza LLC and [removed: J. Kevin Vasconi] [added: Stuart A. Levy] (Incorporated by reference to Exhibit [removed: 10.39] [added: 10.9] to the [removed: December 2018 10-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312519046191/d696297dex1041.htm)] [added: June 2021 10-Q).](https://www.sec.gov/Archives/edgar/data/1286681/000119312521221398/d164949dex109.htm)] |
| 3.3 | | [Third Amended and Restated By-Laws of Domino’s Pizza, Inc. (Incorporated by reference to Exhibit 3.1 to the registrant’s current report on Form 8-K filed on October 14, 2022).](https://www.sec.gov/Archives/edgar/data/1286681/000119312522262941/d394450dex31.htm) |
| 4.1 | | [Description of Securities of the Registrant.](https://www.sec.gov/Archives/edgar/data/1286681/000095017023003938/dpz-ex4_1.htm) |
| 10.18* | | [Third Amendment to the Domino’s Pizza Deferred Compensation Plan effective as of October 11, 2022.](https://www.sec.gov/Archives/edgar/data/1286681/000095017023003938/dpz-ex10_18.htm) |
| 10.38* | | [Form of Restricted Stock Unit Award Agreement (three vesting dates) under the Amended Domino’s Pizza, Inc. 2004 Equity Incentive Plan (Incorporated by reference to Exhibit 10.6 to the registrant's quarterly report on Form 10-Q for the quarter ended March 27, 2022 (the “March 2022 10-Q”)).](https://www.sec.gov/Archives/edgar/data/1286681/000095017022006436/dpz-ex10_6.htm) |
| 10.39* | | [Form of Restricted Stock Unit Award Agreement (two-year vesting with acceleration events) under the Amended Domino’s Pizza, Inc. 2004 Equity Incentive Plan (Incorporated by reference to Exhibit 10.1 to the registrant's quarterly report on Form 10-Q for the quarter ended June 19, 2022 (the “June 2022 8-K”)).](https://www.sec.gov/Archives/edgar/data/1286681/000095017022012843/dpz-ex10_1.htm) |
| 10.40* | | [Form of Restricted Stock Unit Award Agreement (three-year vesting with acceleration events) under the Amended Domino’s Pizza, Inc. 2004 Equity Incentive Plan (Incorporated by reference to Exhibit 10.2 to the June 2022 8-K).](https://www.sec.gov/Archives/edgar/data/1286681/000095017022012843/dpz-ex10_2.htm) |
| 10.47* | | [Addendum to Employment Agreement effective as of February 24, 2022 by and among Domino’s Pizza, Inc., Domino’s Pizza LLC and Richard E. Allison, Jr. (Incorporated by reference to Exhibit 10.5 to the March 2022 10-Q).](https://www.sec.gov/Archives/edgar/data/1286681/000095017022006436/dpz-ex10_5.htm) |
| 10.67 | | [Supplemental Indenture, dated November 19, 2019, among Domino’s Pizza Master Issuer LLC, Domino’s SPV Canadian Holding Company Inc., Domino’s Pizza Distribution LLC and Domino’s IP](https://www.sec.gov/Archives/edgar/data/1286681/000119312519295552/d806337dex41.htm) |
| 10.69 | | [Series 2022-1 Supplement to the Amended and Restated Base Indenture, dated as of September 16, 2022, by and among Domino’s Pizza Master Issuer LLC, Domino’s SPV Canadian Holding Company Inc., Domino’s Pizza Distribution LLC and Domino’s IP Holder LLC, each as Co-Issuer, and Citibank, N.A., as Trustee and Securities Intermediary (Incorporated by reference to Exhibit 4.1 to the registrant's current report on Form 8-K filed on September 16, 2022 (the “September 2022 8-K”)).](https://www.sec.gov/Archives/edgar/data/1286681/000119312522246362/d394498dex41.htm) |
| 10.76 | | [Class A-1 Note Purchase Agreement, dated September 16, 2022, among Domino’s Pizza Master Issuer LLC, Domino’s SPV Canadian Holding Company Inc., Domino’s Pizza Distribution LLC and Domino’s IP Holder LLC, each as Co-Issuer, Domino’s SPV Guarantor LLC, Domino’s Pizza Franchising LLC, Domino’s Pizza International Franchising Inc., Domino’s Pizza Canadian Distribution ULC, Domino’s RE LLC and Domino’s EQ LLC, each as Guarantor, Domino’s Pizza LLC, as manager, certain conduit](https://www.sec.gov/Archives/edgar/data/1286681/000119312522246362/d394498dex101.htm) |
| | | [investors, financial institutions and funding agents, and Barclays Bank PLC, as provider of letters of credit, as swingline lender and as administrative agent (Incorporated by reference to Exhibit 10.1 to the September 2022 8-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312522246362/d394498dex101.htm) |
| 10.83 | | [Amendment No. 5 dated as of September 16, 2022 to the Amended and Restated Management Agreement dated as of March 15, 2012 by and among Domino’s Pizza Master Issuer LLC, certain subsidiaries of Domino’s Pizza Master Issuer LLC party thereto, Domino’s SPV Guarantor LLC, Domino’s Pizza LLC, as manager and in its individual capacity, Domino’s Pizza NS Co., and Citibank, N.A., as Trustee (Incorporated by reference to Exhibit 10.2 to the September 2022 8-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312522246362/d394498dex102.htm) |
| 31.2 | | [Certification of Chief Financial Officer pursuant to Section 302 of the Sarbanes-Oxley Act of 2002, relating to Domino’s Pizza, Inc.](https://www.sec.gov/Archives/edgar/data/1286681/000095017023003938/dpz-ex31_2.htm) |
| 32.2 | | [Certification of Chief Financial Officer pursuant to Section 1350, Chapter 63 of Title 18, United States Code, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of 2002, relating to Domino’s Pizza, Inc.](https://www.sec.gov/Archives/edgar/data/1286681/000095017023003938/dpz-ex32_2.htm) |
| | | 2023 | | | | 2022 | | |
| | | January 1, | | | | January 2, | | | | January 3, | | |
| --- | --- | --- |
| Exhibit | | |
| 10.47* | | [Third Addendum to Amended and Restated Employment Agreement dated as of January 30, 2020 between Domino’s Pizza LLC and David A. Brandon (Incorporated by reference to Exhibit 10.1 to the registrant’s quarterly report on Form 10-Q for the quarter ended March 22, 2020).](https://www.sec.gov/Archives/edgar/data/1286681/000119312520115907/d914156dex101.htm) |
| 10.49* | | [Separation Agreement dated as of October 2, 2020 between Domino’s Pizza LLC and J. Kevin Vasconi (Incorporated by reference to Exhibit 10.43 the registrant's annual report on Form 10-K for the year ended January 3, 2021).](https://www.sec.gov/Archives/edgar/data/1286681/000119312521055734/d326373dex1043.htm) |
| 10.50* | | [Employment Agreement dated as of April 9, 2018 between Domino’s Pizza LLC and Joseph H. Jordan (Incorporated by reference to Exhibit 10.39 to the December 2018 10-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312519046191/d696297dex1042.htm) |
| 10.51* | | [Employment Agreement dated as of August 20, 2020 between Domino’s Pizza LLC and Stuart A. Levy (Incorporated by reference to Exhibit 10.1 to the registrant's quarterly report on Form 10-Q for the quarter ended September 6, 2020).](https://www.sec.gov/Archives/edgar/data/1286681/000119312520265920/d935823dex101.htm) |
| 10.52* | | [Separation Agreement dated as of May 19, 2021 between Domino’s Pizza LLC and Stuart A. Levy (Incorporated by reference to Exhibit 10.9 to the June 2021 10-Q).](https://www.sec.gov/Archives/edgar/data/1286681/000119312521221398/d164949dex109.htm) |
| 10.53* | | [Employment Agreement dated as of December 7, 2016 between Domino’s Pizza LLC and Kevin S. Morris (Incorporated by reference to Exhibit 10.36 to the 2017 10-K).](https://www.sec.gov/Archives/edgar/data/1286681/000119312518049576/d531906dex1036.htm) |
An excerpt. Shown here: 40 of 104 rewritten, all 16 added and all 8 removed. The counts are complete. For every sentence, read Item 15. Exhibits, Financial Statement Schedules. in the FY2023 filing and the FY2022 filing.
Item 16. Form 10-K Summary.
4 rewritten, 17 added, 6 removed, 36 unchanged
| [removed: Chief] Executive [added: Vice President, Chief Financial] Officer |
| [added: February 23, 2023 | |] (Principal Executive [removed: Officer and Principal Financial] Officer) |
| [removed: Richard E. Allison, Jr.] [added: Russell J. Weiner] | | Chief Executive Officer and Director |
| David A. Brandon | | [added: Executive] Chairman of the Board of Directors |
| /s/ Sandeep Reddy |
| Sandeep Reddy |
| February 23, 2023 |
| /s/ Russell J. Weiner | | |
| /s/ Sandeep Reddy | | |
| Sandeep Reddy | | Executive Vice President, Chief Financial Officer |
| February 23, 2023 | | (Principal Financial Officer) |
| February 23, 2023 | | |
| February 23, 2023 | | |
| February 23, 2023 | | |
| February 23, 2023 | | |
| February 23, 2023 | | |
| February 23, 2023 | | |
| February 23, 2023 | | |
| February 23, 2023 | | |
| | | |
| February 23, 2023 | | |
| /s/ Richard E. Allison, Jr. |
| Richard E. Allison, Jr. |
| March 1, 2022 |
| /s/ Richard E. Allison, Jr. | | |
| March 1, 2022 | | (Principal Executive Officer and Principal Financial Officer) |
| March 1, 2022 | | |