 filings.tools
Fifth Third Bancorp (FITB) 10-K risk factor changes: FY2022 vs FY2021
The 2022-12-31 10-K against the 2021-12-31 one, compared heading by heading and sentence by sentence.
Item 1A61 rewritten48 added48 removed481 unchanged
All filing items2,916 rewritten1,136 added1,155 removed4,274 unchanged
Summary
counted, not written
- Item 1A lists 47 risk factor headings: 1 new, 4 reworded and 42 unchanged since FY2021. 0 headings from FY2021 no longer appear.
- Sentence by sentence, 1,136 added, 1,155 removed, 2,916 rewritten and 4,274 unchanged across 18 items that differ.
New Item 1A headings (1)
- Inability to refinance in capital markets could cause a default that impacts Fifth Third borrowers.
Removed Item 1A headings (0)
Every FY2021 risk factor heading is still here, word for word or reworded.
Reworded Item 1A headings (4)
- Fifth Third may have more credit risk and higher credit losses to the extent loans are concentrated by [added: exposure to individual borrowers,] location or industry of the borrowers or collateral.
- Regulation of Fifth Third by the
[removed: Commodity Futures Trading Commission (“CFTC”)][added: CFTC] imposes additional operational and compliance costs. - Fifth Third may sell or consider selling one or more of its businesses or investments. Should it determine to sell such a business or investment, it may not be able to generate gains on sale or related
[removed: increase][added: increases] in shareholders’ equity commensurate with desirable levels. Moreover, if Fifth Third sold such businesses or investments, the loss of income could have an adverse effect on its earnings and future growth. [removed: Global][added: The effects of global] climate change, natural disasters or health emergencies may have an effect on the performance of Fifth Third’s loan portfolios, thereby adversely impacting its results of operations.
A heading is new when no FY2021 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
22 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2022; struck-through words were in FY2021. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. RISK FACTORS
61 rewritten, 48 added, 48 removed, 481 unchanged
- Fifth Third may have more credit risk and higher credit losses to the extent loans are concentrated by [added: exposure to individual borrowers,] location or industry of the borrowers or collateral.
- Regulation of Fifth Third by the [removed: Commodity Futures Trading Commission (“CFTC”)] [added: CFTC] imposes additional operational and compliance costs.
[Table of [removed: Contents](#i90d310f8677f475ebab3cfafe66c6b5b_49)][added: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)]
Should it determine to sell such a business or investment, it may not be able to generate gains on sale or related [removed: increase] [added: increases] in shareholders’ equity commensurate with desirable levels.
- [removed: Global] [added: The effects of global] climate change, [removed: other] natural [removed: disasters,] [added: disasters] or health emergencies may have an effect on the performance of Fifth Third’s loan portfolios, thereby adversely impacting its results of operations.
[removed: Such determination] requires difficult, subjective and complex judgments about the environment, including analysis of economic or market conditions that may impair the ability of borrowers to repay their loans.
Fifth Third believes that both the ALLL and the reserve for unfunded commitments are adequate to cover expected losses at December 31, [removed: 2021;] [added: 2022;] however, there is no assurance that they will be sufficient to cover future credit losses associated with exposures existing at December 31, [removed: 2021,] [added: 2022,] especially if [added: economic conditions decline, including but not limited to] housing and employment [removed: conditions decline.][added: conditions.]
Fifth Third may have more credit risk and higher credit losses to the extent loans are concentrated by [added: exposure to individual borrowers,] location or industry of the borrowers or collateral.
Fifth Third’s credit risk and credit losses can increase if its loans are concentrated among [added: individual borrowers,] borrowers engaged in the same or similar activities, industries or geographies or to borrowers who as a group may be uniquely or disproportionately affected by economic or market [removed: conditions such as those most impacted by the COVID-19 pandemic.][added: conditions.]
Deterioration in economic conditions, [added: including] housing conditions or commodity and real estate values in certain states or locations could result in materially higher credit losses if loans are concentrated in those [removed: locations.][added: locations or by other factors.]
Certain [added: industries, including] segments of the healthcare industry (including skilled nursing, physician offices and surgery/outpatient centers) [removed: have also been] [added: that were] impacted by the [added: COVID-19] pandemic [removed: given delays and restrictions on in-person visits and elective procedures.][added: continue to struggle with recovery.]
[removed: Many] [added: Additionally, many other] affected businesses that have reopened are experiencing increased costs and labor shortages, which create wide-ranging effects on several industries.
Core deposits, which include transaction deposits and certificates of deposit $250,000 or less, have historically provided Fifth Third with a sizeable source of relatively stable and low-cost funds (average core deposits funded [removed: 79%] [added: 78%] of average total assets for the year ending December 31, [removed: 2021).][added: 2022).]
[removed: In addition to customer deposits, sources of liquidity include investments in the] securities portfolio, Fifth Third’s sale or securitization of loans in secondary markets, the pledging of loans and investment securities to access secured borrowing facilities through the FHLB and the FRB, and Fifth Third’s ability to raise funds in money and capital markets.
- reductions in one or more of Fifth Third’s credit ratings; [removed: and]
- increased utilization of revolving lines of credit by [removed: customers.][added: customers; and]
[removed: Fifth Third must make investments in its ability to oversee third- and fourth-party] providers and its failure to do so could result in customer losses, operational issues, litigation, regulatory actions and reputational loss.
Third-party service providers with which the Bancorp does business both domestically and offshore, as well as vendors and other third parties with which the Bancorp’s customers do business, can also be sources of operational risk to the Bancorp, particularly where [added: processes are highly concentrated or] activities of customers are beyond the Bancorp’s security and control systems, such as through the use of the internet, personal computers, tablets, smart phones and other mobile services.
Fifth Third faces operational risk from [added: the effects of] climate change as an increase in severe weather may cause closures, damage to infrastructure, or damage to Fifth Third’s physical locations that may disrupt the physical operation of the Bancorp.
Future changes in laws or regulations (including tax laws and [removed: regulations)] [added: regulations such as the Inflation Reduction Act)] or their interpretations or enforcement may also be materially adverse to Fifth Third and its shareholders or may require Fifth Third to expend significant time and resources to comply with such requirements.
[removed: Fifth Third expects that the] [added: The] Biden Administration [removed: will seek] [added: has sought] to implement a regulatory agenda that is significantly different than that of the Trump Administration.
This agenda could include a heightened focus on the risks arising from climate change, [added: fair lending,] consumer protection, Bank Secrecy Act and anti-money laundering requirements, topics related to social equity, executive compensation, and increased capital and liquidity, as well as limits on share buybacks and dividends.
There can be no assurance that such approvals, if required, would be [added: forthcoming or that such approvals would be granted in a timely manner.]
Failure by the Bancorp or the Bank to meet the applicable eligibility requirements for FHC status (including capital and management requirements and that the Bank maintain at least a “Satisfactory” CRA rating) may result in restrictions on certain activities of the Bancorp, including the commencement of new activities and mergers with or acquisitions of other financial institutions and could ultimately result in the loss of [removed: financial holding company] [added: FHC] status.
Fifth Third and other financial institutions are subject to scrutiny from government authorities, including bank regulatory authorities, stemming from broader systemic regulatory concerns, including with respect to stress testing, liquidity and capital levels, asset quality, provisioning, AML/BSA, [added: fair lending,] consumer compliance and other prudential matters and efforts to ensure that financial institutions take steps to improve their risk management and prevent future crises.
Further changes to applicable capital and liquidity requirements could result in unexpected or new limitations on [removed: our] [added: the Bancorp’s] ability to pay dividends and engage in share repurchases.
Regulation of Fifth Third by the [removed: Commodity Futures Trading Commission (“CFTC”)] [added: CFTC] imposes additional operational and compliance costs.
For more information, refer to Regulation and [removed: Supervision—Derivatives.][added: Supervision—Derivatives in Item 1 of this Annual Report on Form 10-K.]
[removed: LIBOR] [added: London Interbank Offered Rate (“LIBOR”)] and certain other “benchmarks” are the subject of recent national, international and other regulatory guidance and proposals for reform.
On July 27, 2017, the United Kingdom’s Financial Conduct Authority (the “FCA”), which regulates LIBOR, publicly announced that it [removed: intends to] [added: would] stop persuading or compelling banks to submit LIBOR rates after 2021.
Deterioration or continued weakness in any of these conditions could result in a decrease in demand for Fifth Third’s products and [removed: services, a deterioration in credit quality or a reduced demand for credit, including a resultant effect on Fifth Third’s loan portfolio and ALLL and in the receipt of lower proceeds from the sale of loans and foreclosed properties.][added: services.]
Worldwide financial markets have recently experienced periods of extraordinary disruption and volatility, which have been [removed: exacerbated] [added: driven] by [added: factors such as] the COVID-19 [removed: pandemic,] [added: pandemic and the Russia/Ukraine conflict,] resulting in heightened credit risk, reduced valuation of investments, decreased economic activity, [added: heightened risk of cyberattacks,] and inflation.
In addition, as a result of recent financial [added: and political] events, Fifth Third may face increased regulation.
Many of the other risk factors discussed in this Risk Factors section identify risks that result from, or are [removed: exacerbated] [added: impacted] by, [added: a] financial economic downturn.
Global financial markets, including the United States, face political and economic uncertainties [added: (such as recent budget deficit concerns and political conflict over legislation to raise the U.S. government’s debt limit)] that may delay investment and hamper economic activity.
International events such as trade disputes, separatist movements, leadership changes and political and military conflicts (such as the [removed: escalating] [added: ongoing] military tension between Russia and Ukraine) could adversely affect global financial activity and markets and could negatively affect the U.S. economy.
In [removed: addition, in] response to the outbreak of the COVID-19 pandemic and its economic consequences, the FRB lowered its target for the federal funds rate to a range of 0% to [removed: 0.25%.][added: 0.25%, but a recent pronounced rise in inflation has prompted the FRB to raise certain benchmark interest rates to combat it.]
[removed: Such an occurrence] [added: Conversely, a lowering in interest rates] would likely further reduce the interest Fifth Third earns on loans and other earning assets.
Fifth Third cannot predict the nature or timing of future changes in monetary policies [removed: in response to the COVID-19 pandemic,] or [removed: otherwise, or] the precise effects that they may have on Fifth Third’s activities and financial results.
Fifth Third may use hedging instruments tied to U.S. Treasury rates, [removed: LIBOR] [added: LIBOR, SOFR] or Eurodollars that may not perfectly correlate with the value or income being hedged.
- Inability to refinance in capital markets could cause a default that impacts Fifth Third borrowers.
Such determination
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
Inability to refinance in capital markets could cause a default that impacts Fifth Third borrowers.
Some Fifth Third customers rely on additional sources of capital from outside the Bancorp.
If capital markets are disrupted or unavailable to these borrowers such that they cannot obtain funds for refinancing, those borrowers may experience a shortfall that would leave them unable to honor short-term and/or long-term obligations to the Bancorp.
In addition to customer deposits, sources of liquidity include investments in the
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
- systematic failure of financial market utilities relied upon by Fifth Third to settle intrabank payment activity.
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
Furthermore, financial services companies are regularly the target of cyber-attacks such as distributed denial of service attacks and ransomware attacks.
Fifth Third must make investments in its ability to oversee third- and fourth-party
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
Fifth Third may not be sufficiently resilient and may not recover from significant operational events in a timely manner which could create operational and reputational risks.
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
In addition, as climate change issues become more prevalent, the U.S. and foreign governments are beginning to respond to these issues.
The increasing government focus on climate change may result in new environmental regulations, including disclosure required by the SEC, that could result in additional compliance costs.
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
The Bancorp is subject to the stress capital buffer requirement and must maintain capital ratios above its buffered minimum (regulatory minimum plus stress capital buffer) in order to avoid certain limitations on capital distributions and discretionary bonuses to executive officers.
The FRB uses the supervisory stress test to determine the Bancorp’s stress capital buffer, subject to a floor of 2.5%.
The Bancorp’s stress capital buffer requirement has been 2.5% since the introduction of this framework and was most recently affirmed as part of the FRB’s 2022 supervisory stress test for the period from October 1, 2022 to September 30, 2023, based on the Bancorp’s 2022 supervisory stress
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
testing results, subject to potential adjustments by the FRB.
On March 15, 2022, President Biden signed the Adjustable Interest Rate (LIBOR) Act (the “LIBOR Act”) into law.
The LIBOR Act offers a federal solution for transitioning legacy instruments that lack sufficient provisions addressing LIBOR’s cessation by outlining a uniform process to govern the transition from LIBOR to a replacement rate.
The LIBOR Act also establishes a safe harbor for lenders, shielding lenders from litigation as a result of their choice of a replacement rate (such as SOFR) per FRB recommendations.
On December 16, 2022, the FRB issued its final regulations which carry out the terms of the LIBOR Act.
These regulations: (i) address the applicability of the LIBOR Act to various LIBOR contracts, (ii) identify the
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
FRB-selected benchmark replacements for various types of LIBOR contracts, (iii) include certain benchmark replacement conforming changes, (iv) address the issue of preemption and (v) provide other clarifications, definitions and information.
The regulations will become effective on February 27, 2023, which is thirty (30) days after the regulations were published in the Federal Register.
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
As inflation increases and market interest rates rise, the value of Fifth Third’s investment securities, particularly those that have fixed rates or longer maturities, could decrease.
Increasing rates would also increase debt service requirements for some of Fifth Third’s borrowers and may adversely affect those borrowers’ ability to pay as contractually obligated and could result in additional delinquencies or charge-offs.
Further, the increase in market interest rates is likely to reduce Fifth Third’s loan origination volume, particularly refinance volume, and/or reduce its interest rate spread, which could have an adverse effect on Fifth Third’s profitability and results of operations.
In addition to the challenge of competing
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
The COVID-19 pandemic has caused certain industries to experience increased stress.
These include consumer-driven industries that require gathering or congregation such as leisure and recreation (including casinos, restaurants, sports, fitness, hotels and other industries), non-essential retail and leisure travel (primarily including airlines and cruise lines).
Furthermore, there has been a well-publicized series of apparently related distributed denial of service attacks on large financial services companies and “ransom” attacks where hackers have requested payments in exchange for not disclosing customer information.
forthcoming or that such approvals would be granted in a timely manner.
Furthermore, regulatory capital requirements may constrain the Bancorp’s ability to return capital to its shareholders.
The FRB implemented the stress capital buffer (“SCB”) rule, which was effective for the Bancorp on October 1, 2020, pursuant to which the FRB will use the results of the supervisory stress tests required under the Dodd-Frank Act to determine the size of a large banking institution’s stress capital buffer requirement.
The SCB rule replaces the previous 2.5% capital conservation buffer under the Basel III standardized approach.
Our initial SCB requirement is 2.5%, for the period from October 1, 2020 to October 1, 2022, based on our 2020 stress testing results, subject to potential adjustments by the FRB.
In response to the uncertainty caused by the COVID-19 pandemic, certain large BHCs, including the Bancorp, were subject to certain limitations on share repurchases and dividend payments during the third and fourth quarters of 2020 and the first and second quarters of 2021.
These restrictions were lifted effective June 30, 2021.
- result in certain LIBOR-based instruments such as the Bancorp's Series H, Series I and Series J preferred stock moving from floating-rate instruments to fixed-rate instruments if the fallback language is unable to be amended to adopt alternative rates;
These factors could result in higher delinquencies, greater charge-offs and increased losses in future periods, which could materially adversely affect Fifth Third’s financial condition and results of operations.
As a result of the high percentage of Fifth Third’s assets and liabilities that are in the form of interest-bearing or interest-related instruments, this change in interest rates could adversely affect Fifth Third’s profitability.
Moreover, such low rates increase the risk in the U.S. of a negative interest rate environment in which interest rates drop below zero, either broadly or for some types of instruments.
For example, yields on one-month and three-month Treasuries briefly dropped below zero in March 2020.
well as large retailers who seek to offer one-stop financial services in addition to other products and services desired by consumers that may include services that banks have not been able or allowed to offer to their customers in the past or may not be currently able or allowed to offer.
Additionally, Fifth Third’s reputation may be harmed if it fails to properly identify and manage potential conflicts of interest.
The failure to adequately address, or the perceived failure to adequately address, conflicts of interest could affect the willingness of clients to use Fifth Third’s products and services, or give rise to litigation or enforcement actions, which could adversely affect Fifth Third’s business.
ratings to evaluate companies based upon ESG metrics.
In addition, the pandemic resulted in temporary closures of many businesses and the institution of social distancing and sheltering in place requirements in many states and communities, including those in major markets in which the Bancorp is located or does business.
As a result, the demand for the Bancorp’s products and services has been, and is expected to continue to be, significantly impacted.
Furthermore, the pandemic could influence the recognition of credit losses in the Bancorp’s loan and lease portfolios and increase its allowance for credit losses as both businesses and consumers are negatively impacted by the economic downturn.
In addition, governmental actions are meaningfully influencing the interest-rate environment, which could continue to adversely affect the Bancorp’s results of operations and financial condition.
The business operations of subsidiaries of the Bancorp, such as Fifth Third Bank, National Association, have been, and may also be disrupted in the future, if significant portions of their workforce are unable to work effectively, including because of illness, quarantines, government actions, travel restrictions, technology limitations and/or disruptions or other restrictions in connection with the pandemic.
Furthermore, the business operations of subsidiaries of the Bancorp have been, and may again in the future be, disrupted due to vendors and third-party service providers being unable to work or provide services effectively, including because of illness, quarantines, government actions, or other restrictions in connection with the pandemic.
In response to the pandemic, the Bancorp provided financial hardship relief to borrowers that were negatively impacted by the pandemic and its related economic impacts.
These programs included payment deferrals and forbearances for both commercial and retail borrowers.
The Bancorp had temporarily suspended initiating any new repossession actions on vehicles and temporarily suspended all residential foreclosure activity.
Repossession actions and residential foreclosure activity have since resumed.
It is uncertain how effective these programs have been in mitigating the effects of the COVID-19 pandemic on the Bancorp’s customers and there is potential that these actions may adversely affect the Bancorp’s business and results of operations more substantially over a longer period of time.
Governmental authorities have taken significant measures to provide economic assistance to households and businesses, to stabilize the markets and to support economic growth.
For example, in response to the COVID-19 pandemic, the FRB and other U.S. state and federal financial regulatory agencies took action to mitigate the resulting disruptions to economic activity and financial stability by implementing a number of facilities to provide emergency liquidity to various segments of the U.S. economy and financial markets.
Many of these facilities expired on or before December 31, 2020 or were extended for brief periods into 2021.
The expiration of these facilities could have an adverse effect on U.S. economy and ultimately on the Bancorp’s business.
Among other relief programs, the Bancorp participated in the SBA’s Paycheck Protection Program.
Paycheck Protection Program loans are fixed, unsecured, low interest rate loans that are guaranteed by the SBA and subject to numerous other regulatory requirements, and a borrower may apply to have all or a portion of the loan forgiven.
If Paycheck Protection Program borrowers fail to qualify for loan forgiveness, the Bancorp faces a heightened risk of holding these loans at unfavorable interest rates for an extended period of time.
While the Paycheck Protection Program loans are guaranteed by the SBA, the Bancorp’s ability to fully recover against the loan guarantee or to seek full recourse against the borrower may be limited in certain circumstances.
If a borrower defaults on a Paycheck Protection Program loan, these requirements and uncertainties may limit the Bancorp’s ability to fully recover against the loan guarantee or to seek full recourse against the borrower.
These assistance efforts may adversely affect the Bancorp’s revenue and results of operations and may make the Bancorp’s results more difficult to forecast.
An excerpt. Shown here: 40 of 61 rewritten, 40 of 48 added and 40 of 48 removed. The counts are complete. For every sentence, read Item 1A. RISK FACTORS in the FY2022 filing and the FY2021 filing.
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
1,022 rewritten, 449 added, 500 removed, 1,044 unchanged
For the year ended December 31, [removed: 2021,] [added: 2022,] net interest income on an FTE basis and noninterest income provided [removed: 61%] [added: 67%] and [removed: 39%] [added: 33%] of total revenue, respectively.
The Bancorp derives the majority of its revenues within the U.S. from customers domiciled in the U.S. Revenue from foreign countries and external customers domiciled in foreign countries was immaterial to the Consolidated Financial Statements for the year ended December 31, [removed: 2021.][added: 2022.]
Noninterest income is derived from [removed: commercial banking revenue,] service charges on deposits, wealth and asset management revenue, [added: commercial banking revenue,] card and processing revenue, leasing business revenue, mortgage banking net revenue, other noninterest income and net securities gains or losses.
[Table of [removed: Contents](#i90d310f8677f475ebab3cfafe66c6b5b_49)][added: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)]
For further [removed: information about these programs,] [added: discussion on credit quality,] refer to the Credit Risk Management subsection of the Risk Management section of MD&A [removed: included herein, and also] [added: as well as] Note [removed: 1] [added: 6] of the Notes to Consolidated Financial Statements.
The Bancorp entered into and settled a number of accelerated share repurchase transactions during the [removed: year] [added: years] ended December 31, [added: 2022 and] 2021.
[removed: The following table presents a summary of] [added: Under this authorization,] the [removed: Bancorp’s accelerated share repurchase transactions that were] [added: Bancorp] entered into and settled [added: one accelerated share repurchase transaction] during the year ended December 31, [removed: 2021:][added: 2022.]
Senior Notes [removed: Offering][added: Offerings]
In July 2017, the Chief Executive of the United Kingdom Financial Conduct Authority (the “FCA”), which regulates LIBOR, announced that the FCA [removed: will] [added: would] stop persuading or compelling banks to submit rates for the calculation of LIBOR to the administrator of LIBOR after 2021.
Although the full impact of LIBOR reforms and actions remains unclear, [removed: as of December 31, 2021,] the Bancorp has [removed: substantially] discontinued entering into new LIBOR-based contracts in accordance with regulatory guidance, except for permissible limited [removed: use] [added: use, such] as part of hedging and risk management programs.
As of December 31, [removed: 2021,] [added: 2022,] the Bancorp had substantial exposure to LIBOR-based products throughout several of its lines of business.
These exposures included derivative contracts with a total notional value of approximately [removed: $110] [added: $96] billion, loans outstanding of approximately [removed: $53] [added: $24] billion, preferred stock of approximately $1.4 billion and long-term debt of approximately [removed: $535] [added: $237] million.
The Bancorp currently estimates that approximately [removed: 20%] [added: 8%] of the existing exposures will mature before June 30, 2023.
Existing exposures without fallback provisions are expected to [added: either] be amended prior to June 30, 2023 to include such [removed: terms] [added: provisions] or [added: to] transition to an alternative reference [removed: rate.][added: rate pursuant to the terms of the LIBOR Act and its related regulations.]
| TABLE [removed: 2:] [added: 1:] Earnings Summary | | | | | | | | | | | | | | | | | |
| For the years ended December 31 ($ in millions, except per share data) | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2020] [added: 2021] | | | | | | [removed: 2019] [added: 2020] | | |
| Net interest income (U.S. GAAP) | | | $ | [removed: 4,770] [added: 5,609] | | | | | [removed: 4,782] [added: 4,770] | | | | | | [removed: 4,797] [added: 4,782] | | |
| Net interest income (FTE)*(a)(b)* | | | [removed: 4,782] [added: 5,625] | | | | | | [removed: 4,795] [added: 4,782] | | | | | | [removed: 4,814] [added: 4,795] | | |
| Noninterest income | | | [removed: 3,118] [added: 2,766] | | | | | | [removed: 2,830] [added: 3,118] | | | | | | [removed: 3,536] [added: 2,830] | | |
| Total revenue (FTE)*(a)(b)* | | | [removed: 7,900] [added: 8,391] | | | | | | [removed: 7,625] [added: 7,900] | | | | | | [removed: 8,350] [added: 7,625] | | |
| [removed: (Benefit from) provision] [added: Provision] for [added: (benefit from)] credit losses | | | [removed: (377)] [added: 563] | | | | | | [removed: 1,097] [added: (377)] | | | | | | [removed: 471] [added: 1,097] | | |
| Noninterest expense | | | [removed: 4,748] [added: 4,719] | | | | | | [removed: 4,718] [added: 4,748] | | | | | | [removed: 4,660] [added: 4,718] | | |
| Net income | | | [removed: 2,770] [added: 2,446] | | | | | | [removed: 1,427] [added: 2,770] | | | | | | [removed: 2,512] [added: 1,427] | | |
| Net income available to common shareholders | | | [removed: 2,659] [added: 2,330] | | | | | | [removed: 1,323] [added: 2,659] | | | | | | [removed: 2,419] [added: 1,323] | | |
| Earnings per share - basic | | | $ | [removed: 3.78] [added: 3.38] | | | | | [removed: 1.84] [added: 3.78] | | | | | | [removed: 3.38] [added: 1.84] | | |
| Earnings per share - diluted | | | [removed: 3.73] [added: 3.35] | | | | | | [removed: 1.83] [added: 3.73] | | | | | | [removed: 3.33] [added: 1.83] | | |
| Cash dividends declared per common share | | | [removed: 1.14] [added: 1.26] | | | | | | [removed: 1.08] [added: 1.14] | | | | | | [removed: 0.94] [added: 1.08] | | |
| Book value per share | | | [removed: 29.43] [added: 22.26] | | | | | | [removed: 29.46] [added: 29.43] | | | | | | [removed: 27.41] [added: 29.46] | | |
| Market value per share | | | [removed: 43.55] [added: 32.81] | | | | | | [removed: 27.57] [added: 43.55] | | | | | | [removed: 30.74] [added: 27.57] | | |
| Return on average assets | | | [removed: 1.34] [added: 1.18] | | % | | | | [removed: 0.73] [added: 1.34] | | | | | | [removed: 1.53] [added: 0.73] | | |
| Return on average common equity | | | [removed: 12.8] [added: 13.7] | | | | | | [removed: 6.4] [added: 12.8] | | | | | | [removed: 13.1] [added: 6.4] | | |
| Return on average tangible common equity*(b)* | | | [removed: 16.6] [added: 19.7] | | | | | | [removed: 8.4] [added: 16.6] | | | | | | [removed: 17.1] [added: 8.4] | | |
| Dividend payout | | | [removed: 30.2] [added: 37.3] | | | | | | [removed: 58.7] [added: 30.2] | | | | | | [removed: 27.8] [added: 58.7] | | |
The FTE adjustments were [removed: $12, $13] [added: $16, $12] and [removed: $17] [added: $13] for the years ended December 31, [removed: 2021, 2020] [added: 2022, 2021] and [removed: 2019,] [added: 2020,] respectively.*
The Bancorp’s net income available to common shareholders for the year ended December 31, [removed: 2020] [added: 2022] was [removed: $1.3] [added: $2.3] billion, or [removed: $1.83] [added: $3.35] per diluted share, which was net of [removed: $104] [added: $116] million in preferred stock dividends.
Net interest income on an FTE basis (non-GAAP) was [removed: $4.8] [added: $5.6] billion for the year ended December 31, [removed: 2021, a decrease] [added: 2022, an increase] of [removed: $13] [added: $843] million compared to the [removed: same period in the] prior [removed: year primarily due to the impact of lower market rates.][added: year.]
These [removed: negative] [added: positive] impacts were partially offset by [removed: a decrease] [added: increases] in [removed: rates paid] [added: FTP charges] on [removed: average interest-bearing liabilities, primarily driven by decreases] [added: commercial loans and leases as well as increases] in rates paid on [removed: average] interest checking deposits and [removed: average] [added: savings and] money market deposits.
Net interest margin on an FTE basis (non-GAAP) was [removed: 2.59%] [added: 3.02%] for the year ended December 31, [removed: 2021] [added: 2022] compared to [removed: 2.78%] [added: 2.59%] for the year ended December 31, [removed: 2020.][added: 2021.]
The [removed: benefit from] [added: provision for] credit losses was [removed: $377] [added: $563] million for the year ended December 31, [removed: 2021] [added: 2022] compared to a [removed: provision for] [added: benefit from] credit losses of [removed: $1.1 billion] [added: $377 million] in the prior year.
Net losses charged off as a percent of average portfolio loans and leases were [removed: 0.16%] [added: 0.19%] and [removed: 0.42%] [added: 0.16%] for the years ended December 31, [removed: 2021] [added: 2022] and [removed: 2020,] [added: 2021,] respectively.
Current Economic Conditions
In response to these inflationary pressures, the FRB raised benchmark interest rates and may continue to raise interest rates in response to economic conditions, particularly a continued high rate of inflation.
Amidst these uncertainties, some financial markets continued to experience volatility.
Changes in interest rates can affect numerous aspects of the Bancorp’s business and may impact the Bancorp’s future performance.
If financial markets remain volatile, this may impact the future performance of various segments of the Bancorp’s business, including the value of the Bancorp’s investment securities portfolio.
The Bancorp continues to closely monitor the pace of inflation and the impacts of inflation on the larger market, including labor and supply chain impacts.
Additionally, refer to the Interest Rate and Price Risk Management subsection of the Risk Management section of MD&A for additional information about the Bancorp’s interest rate risk management activities.
During the year ended December 31, 2022, the Bancorp (including both the parent company and its banking subsidiary) issued and sold fixed-rate/floating-rate senior notes in a number of debt offerings.
These transactions included:
- A Bancorp issuance on April 25, 2022 of $1 billion of fixed-rate/floating-rate senior notes which included $400 million of notes maturing on April 25, 2028 and $600 million of notes maturing on April 25, 2033.
- A Bancorp issuance on July 28, 2022 of $1 billion of fixed-rate/floating-rate senior notes maturing on July 28, 2030.
- A Bancorp issuance on October 27, 2022 of $1 billion of fixed-rate/floating-rate senior notes maturing on October 27, 2028.
- A Bank issuance on October 27, 2022 of $1 billion of fixed-rate/floating-rate senior notes maturing on October 27, 2025.
In each of these transactions, the parent company and banking subsidiary entered into interest rate swaps designated as fair value hedges to convert the fixed-rate period of the notes to a floating rate of interest.
Business Combination
During the second quarter of 2022, the Bancorp completed the acquisition of a national point-of-sale consumer lender specializing in home improvement and solar energy installation loans originated through a network of contractors and installers.
The acquisition was accounted for under the acquisition method of accounting which generally requires assets acquired and liabilities assumed to be recorded at their estimated fair values at acquisition date.
These fair value estimates are considered preliminary as of December 31, 2022 and are subject to change for up to one year after the acquisition date as additional information becomes available.
On March 15, 2022, President Biden signed the Adjustable Interest Rate (LIBOR) Act (the “LIBOR Act”) into law.
The LIBOR Act offers a federal solution for transitioning legacy instruments that lack sufficient provisions addressing LIBOR’s cessation by outlining a uniform process to govern the transition from LIBOR to a replacement rate.
The LIBOR Act also establishes a safe harbor for lenders, shielding lenders from litigation as a result of their choice of a replacement rate (such as SOFR) per FRB recommendations.
On December 16, 2022, the FRB issued its final regulations which carry out the terms of the LIBOR Act.
These regulations: (i) address the applicability of the LIBOR Act to various LIBOR contracts, (ii) identify the FRB-selected benchmark replacements for various types of LIBOR contracts, (iii) include certain benchmark replacement conforming changes, (iv) address the issue of preemption and (v) provide other clarifications, definitions and information.
The regulations will become effective on February 27, 2023, which is thirty (30) days after the regulations were published in the Federal Register.
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
- Return on Average Common Equity, Excluding AOCI (non-GAAP): Net income available to common shareholders divided by total equity, excluding AOCI and preferred stock
- Household Growth: Change in the number of consumer households with retail relationship-based checking accounts
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
Net interest income benefited from increases in market interest rates, resulting in increases in yields on average loans and leases and average other short-term investments for the year ended December 31, 2022 compared to the prior year.
Net interest income also benefited from increases in average taxable securities and average commercial and industrial loans for the year ended December 31, 2022 compared to the prior year.
These positive impacts were partially offset by an increase in rates paid on average interest-bearing core deposits, an increase in the average balance of FHLB advances and an increase in rates paid on average long-term debt as well as a decrease in interest income recognized from PPP loans for the year ended December 31, 2022 compared to the prior year.
Provision expense increased for the year ended December 31, 2022 compared to the prior year primarily driven by factors which caused increases in the ACL during the year ended December 31, 2022 including deterioration in forecasted macroeconomic conditions and higher period-end loan and lease balances, primarily driven by commercial and industrial loan growth, originations of point-of-sale solar energy installation loans in the second half of 2022 and loans acquired in a business acquisition completed in the second quarter of 2022.
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
| Net interest income (U.S. GAAP) | | | $ | 5,609 | | | | | 4,770 | | | | | | 4,782 | | |
| Add: FTE adjustment | | | 16 | | | | | | 12 | | | | | | 13 | | |
Pre-provision net revenue is net interest income plus noninterest income minus noninterest expense.
The Bancorp believes this measure is important because it provides a ready view of the Bancorp’s pre-tax earnings before the impact of provision expense.
The following table reconciles the non-GAAP financial measure of pre-provision net revenue to U.S. GAAP:
| TABLE 3: Non-GAAP Financial Measures - Pre-Provision Net Revenue | | | | | | | | | | | | | | | | | |
COVID-19 Global Pandemic
The COVID-19 pandemic created significant economic uncertainty and financial disruptions during the year ended December 31, 2020, which continued during 2021.
Government and public responses to the COVID-19 pandemic, including temporary closures of businesses and the implementation of social distancing protocols, caused reductions and instability in economic activity that resulted in increased unemployment levels in certain industries and volatility in the financial markets.
Markets continue to remain volatile as a result of the pandemic and its evolving impacts, including inflationary concerns as well as stresses in labor markets and supply chains.
During the years ended December 31, 2021 and 2020, low interest rates, reduced economic activity and market volatility have had the most immediate negative impacts on the Bancorp’s performance.
The Bancorp is unable to estimate the extent of the impact that these factors have had on its operating results since the pandemic began and these factors may adversely impact its future operating results.
Although the increased availability of COVID-19 vaccinations has begun to mitigate the public health effects of the pandemic, there has been a rise of certain variants of COVID-19 and slowing progress on vaccination rates.
The recovery from the related economic crisis continues to disproportionately affect certain industries, geographies and demographics more than others, and when combined with the unprecedented nature of the government response to the pandemic, it becomes difficult to predict the extent to which the pandemic will continue to adversely impact the Bancorp and its customers.
Furthermore, resurgence risk remains as new virus variants are identified.
The Bancorp continues to closely monitor the pandemic and its effects on customers, employees, communities and markets.
MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
The Bancorp has provided a variety of relief options for both commercial and consumer customers that were affected by the COVID-19 pandemic, including loan covenant relief, loan maturity extensions, payment deferrals, forbearances and fee waivers.
Government Response to the COVID-19 Pandemic
Congress, the FRB and the other U.S. state and federal financial regulatory agencies have taken actions to mitigate disruptions to economic activity and financial stability resulting from the COVID-19 pandemic.
The descriptions below summarize certain significant government actions taken in response to the COVID-19 pandemic.
The descriptions are qualified in their entirety by reference to the particular statutory or regulatory provisions or government programs summarized.
*The CARES Act*
The Coronavirus Aid, Relief and Economic Security (“CARES”) Act was signed into law on March 27, 2020 and has subsequently been amended several times, including by the Consolidated Appropriations Act, 2021.
Among other provisions, the CARES Act included funding for the SBA to expand lending, relief from certain U.S. GAAP requirements to allow COVID-19-related loan modifications to not be categorized as TDRs, direct stimulus payments and a range of incentives to encourage deferment, forbearance or modification of consumer credit and mortgage contracts.
One of the key CARES Act programs is the Paycheck Protection Program, discussed further below, which temporarily expanded the SBA’s business loan guarantee program.
The CARES Act contained additional protections for homeowners and renters of properties with federally-backed mortgages, including a 60-day moratorium on the initiation of foreclosure proceedings beginning on March 18, 2020 and a 120-day moratorium on initiating eviction proceedings effective March 27, 2020.
Borrowers of federally-backed mortgages had the right under the CARES Act to request up to 360 days of forbearance on their mortgage payments if they experienced financial hardship directly or indirectly due to the COVID-19 public health emergency.
The foreclosure moratorium and forbearance provisions of the CARES Act expired in 2020 but the FHA and Federal Housing Finance Agency independently extended these assistance programs.
The extended foreclosure moratorium expired in the third quarter of 2021.
COVID-19 related forbearance opportunities for new enrollees were set to expire on September 30, 2021, though this has been revised and currently the program has no set end date.
The provisions set forth in Section 4013 of the CARES Act related to TDRs expired on January 1, 2022.
Future loan modifications will be assessed based on existing TDR evaluation policies as appropriate.
Also pursuant to the CARES Act, the U.S. Treasury had authority to provide loans, guarantees and other investments in support of eligible businesses, states and municipalities affected by the economic effects of COVID-19.
Some of these funds have been used to support several FRB programs and facilities described below or additional programs or facilities that are established by its authority under Section 13(3) of the Federal Reserve Act that meet certain criteria.
*FRB Actions*
The FRB has taken a range of actions to support the flow of credit to households and businesses, offset forced liquidations and restore liquidity in the financial markets due to the COVID-19 pandemic.
For example, on March 15, 2020, the FRB reduced the target range for the federal funds rate to 0 to 0.25% and announced that it would increase its holdings of U.S. Treasury securities and agency mortgage-backed securities and begin purchasing agency commercial mortgage-backed securities.
The FRB has also encouraged depository institutions to borrow from the discount window and has lowered the primary credit rate for such borrowings by 150 basis points while extending the term of such loans up to 90 days.
Reserve requirement ratios were reduced to zero effective March 26, 2020.
During late 2021, the FRB stated that it will begin to reduce some of the monetary stimulus put in place in response to the COVID-19 pandemic, which could include raising the target range for the federal funds rate and reducing the size of its holdings of securities.
The FRB has indicated that it has no plans to re-impose reserve requirements but may do so in the future if conditions warrant.
In addition, the FRB established a range of facilities and programs to support the U.S. economy and U.S. marketplace participants in response to economic disruptions associated with COVID-19.
Through these facilities and programs, the FRB, relying on its authority under Section 13(3) of the Federal Reserve Act, has taken steps to directly or indirectly purchase assets from, or make loans to, U.S. companies, financial institutions, municipalities and other market participants.
*Paycheck Protection Program*
The Bancorp is a participating lender in the PPP, which is a program administered by the SBA to provide forgivable, guaranteed loans to eligible borrowers that have been affected by the COVID-19 pandemic.
An excerpt. Shown here: 40 of 1,022 rewritten, 40 of 449 added and 40 of 500 removed. The counts are complete. For every sentence, read Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS in the FY2022 filing and the FY2021 filing.
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
1 rewritten, 0 added, 0 removed, 2 unchanged
Refer to page [removed: [19](#i90d310f8677f475ebab3cfafe66c6b5b_13)] [added: [19](#i48540c50bc474a4186cf9dc1957cda5d_10)] for cautionary information regarding forward-looking statements.
Item 1. BUSINESS
73 rewritten, 45 added, 47 removed, 258 unchanged
As of December 31, [removed: 2021,] [added: 2022,] Fifth Third had [removed: $211] [added: $207] billion in assets and operates [removed: 1,117] [added: 1,087] full-service Banking Centers and [removed: 2,322] [added: 2,132] Fifth Third branded ATMs in Ohio, Kentucky, Indiana, Michigan, Illinois, Florida, Tennessee, West Virginia, Georgia, North Carolina and South Carolina.
The Bancorp operates [removed: four] [added: three] main businesses: Commercial Banking, [removed: Branch Banking,] Consumer [removed: Lending] and [added: Small Business Banking and] Wealth & Asset Management.
Fifth Third is among the largest money managers in the Midwest and, as of December 31, [removed: 2021,] [added: 2022,] had [removed: $554] [added: $510] billion in assets under care, of which it managed [removed: $65] [added: $55] billion for individuals, corporations and not-for-profit organizations.
Refer to Exhibit 21 filed as an attachment to this Annual Report on Form 10-K for a list of subsidiaries of the Bancorp as of February 15, [removed: 2022.][added: 2023.]
[removed: At] [added: As of] December 31, [removed: 2021,] [added: 2022,] the Bancorp had [removed: 19,112] [added: 19,319] full-time equivalent employees, compared to [removed: 19,872 at] [added: 19,112 as of] December 31, [removed: 2020.][added: 2021.]
These employees support [removed: Fifth Third’s Vision] [added: the organization’s ambition] to be the One Bank people most value and trust by upholding its four Core Values: Be Respectful & Inclusive, Take Accountability, Work as One Bank and Act with Integrity.
In [removed: 2021,] [added: 2022,] the Bancorp continued to face a rapidly changing work environment and [removed: workforce, complicated by the ongoing pandemic.][added: workforce.]
[Table of [removed: Contents](#i90d310f8677f475ebab3cfafe66c6b5b_49)][added: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)]
[removed: *Equity, Equality,] [added: *Equality, Equity] and Inclusion*
As of December 31, [removed: 2021,] [added: 2022,] the Bancorp’s employees were approximately [removed: 59%] [added: 58%] female and approximately [removed: 27%] [added: 28%] persons of color: [removed: 73%] [added: 72%] White, 13% Black/African American, [removed: 7%] [added: 8%] Hispanic/Latino, 5% Asian, and 2% Other.
- [removed: Complete] [added: Complete] Unconscious Bias Awareness training for 100% of employees
- [removed: Ensure] [added: Ensure] the diversity of the Bancorp’s workforce matches the markets it serves
- [removed: Grow] [added: Grow] leadership positions at each management level for women and persons of color
- [removed: Create] [added: Create] a work environment where there is no disparity in race or gender
- [removed: Advance] [added: Advance] the Bancorp as a leader in diversity and inclusion
- Achieve and [removed: sustain] [added: sustain] a 10% supplier diversity spend
These groups: African American, Asian & Pacific Islander, Individuals with Disabilities, Latino, LGBTQ+, Military, [removed: Women’s and] [added: Women’s,] Young Professionals, [added: and Sustainability] support the Bancorp’s three BRG Pillars; to drive business innovation, [added: encourage] community [removed: volunteerism] [added: volunteerism,] and provide an environment that supports employee [added: development,] engagement and networking.
The [removed: Bancorp engages] [added: Bancorp’s holistic approach to collecting, measuring and responding to employee feedback enhances engagement] with [removed: its] employees at critical points during their careers and during times of change in [removed: the] business [removed: environment.][added: or work environments.]
Each year, the Bancorp requires all employees and [removed: contingent/contract] [added: contingent] workers to complete [removed: a series of] courses related to risk and compliance on topics that support strong risk management behaviors and accountability.
The Bancorp is committed to providing competitive compensation programs that attract and retain top talent to drive [removed: our] [added: its] business strategy, effectively manage risk within incentive programs designed to pay for performance, consider applicable regulatory expectations with attention to [removed: our] corporate values and behavioral expectations, and align with the creation of long-term shareholder value.
The Bancorp continuously analyzes its compensation [added: and benefits] programs and practices [removed: to help ensure that] [added: with the objective of providing] all employees [removed: have] [added: with] an equal opportunity to maximize their potential.
In addition to traditional benefit offerings, the Bancorp offers a 401(k) retirement program that pays a match up to 7% of an employee’s eligible compensation, parental bonding leave, [removed: an enhanced military leave policy] [added: telemedicine services,] and [removed: services] [added: tools] that [removed: assist employees in maintaining a healthy work-life balance.][added: help find the highest quality and lowest cost treatment options.]
[removed: The Tailoring Rules establish four risk-based categories of institutions, and the extent to] which enhanced prudential standards and certain other capital and liquidity standards apply to these BHCs and banks depends on the banking organization’s category.
[added: The Bancorp is also subject] to regulation by the SEC by virtue of its status as a public company and due to the nature of some of its businesses.
The Bancorp and the Bank are required to file various reports with and are subject to examination by various regulators, including the [removed: FRB] [added: FRB, the OCC,] and the [removed: OCC.][added: CFPB.]
[removed: Certain] [added: Some] of the Bancorp’s and the Bank’s regulators are also empowered to assess civil money penalties against companies or individuals in certain situations, such as when there is a violation of a law or regulation.
Applicable state and federal laws also grant [removed: certain] [added: the Bancorp’s] regulators the authority to impose additional requirements and restrictions on the activities of the Bancorp and the Bank and, in some situations, the imposition of such additional requirements and restrictions will not be publicly available information.
The BHCA requires the prior approval of the FRB for a BHC to acquire substantially all the assets of a bank or to acquire direct or indirect ownership or control of more than 5% of any class of the voting shares of any bank, BHC or savings association, or to [removed: increase any such non-majority ownership or control of any bank, BHC or savings association, or to] merge or consolidate with any BHC.
The BHCA generally prohibits a BHC from [added: engaging in, or] acquiring a direct or indirect interest in or control of more than 5% of any class of the voting shares of a company that is not a bank or a BHC [removed: and from engaging] [added: that engages] directly or indirectly in activities other than those of banking, managing or controlling banks or furnishing services to its banking subsidiaries, except that it may engage in and may own shares of companies engaged in certain activities the FRB has determined to be so closely related to banking or managing or controlling banks as to be proper incident thereto.
In addition, the Bancorp’s ability to make capital distributions, including paying dividends and repurchasing shares, is subject to [added: the Bancorp complying with the automatic restrictions on capital distributions under the FRBs “Capital Rules” process discussed below (see Regulatory Capital Requirements below).]
The FDIC could [added: further] increase the deposit insurance assessments for certain insured depository institutions, including the Bank, if the DIF reserve ratio is not restored as projected.
The CRA requires the OCC to evaluate the performance of [added: national banks (including the Bank) with respect to these CRA obligations.]
For purposes of CRA examinations, the OCC rates each institution’s compliance with the CRA as “Outstanding,” “Satisfactory,” “Needs to Improve” or “Substantial Noncompliance.” The [removed: FRB, which was responsible for CRA evaluations of the] Bank [removed: prior to] [added: received an “Outstanding” rating on] its [removed: conversion to a national bank charter, conducted a regularly scheduled] [added: most recent CRA performance] examination [removed: covering 2014 through 2016 to determine the Bank’s compliance with] [added: from] the [removed: CRA.][added: OCC.]
[removed: In July 2021,] [added: On May 5, 2022,] the OCC, FRB, and FDIC issued [removed: an interagency statement announcing] a [added: notice of proposed rulemaking to provide for a] coordinated approach to modernize their respective CRA regulations, such that all banks will be subject to the same set of CRA rules.
[removed: These revisions have not yet] [added: No final rule has] been [removed: proposed,] [added: issued,] but [added: the rulemaking] may affect the Bank’s CRA compliance obligations in the future.
The Bancorp and the Bank are subject to certain risk-based capital and leverage ratio requirements under the capital adequacy rules (the [removed: “Final Capital] [added: “Capital] Rules”) adopted by the FRB, for the Bancorp, and by the OCC, for the Bank.
Under the [removed: Final] Capital Rules, the Bancorp’s and the Bank’s assets, exposures, and certain off-balance sheet items are subject to risk weights used to determine the institutions’ risk-weighted assets pursuant to the federal banking agencies’ Standardized Approach to risk-weighting of assets.
[removed: In the first quarter of 2015, under the Final Capital Rules, the] [added: The] Bancorp [removed: made a one-time election] [added: has elected] to exclude certain AOCI components, with the result that those components are not recognized in the Bancorp’s CET1.
[removed: In July 2019, the] [added: The] FDIC, [removed: the] FRB and [removed: the] OCC [added: have jointly] issued [removed: final] rules for institutions that do not apply advanced approaches to regulatory capital, including the Bancorp and the Bank.
As of December 31, [removed: 2021,] [added: 2022,] the Bancorp was permitted to use 100% of its eligible retained income for these purposes in the first quarter of [removed: 2022.][added: 2023.]
The Bancorp has continued to focus on accelerating racial equality, equity and inclusion as a key priority.
The Bancorp has an Executive Diversity Leadership Council which continues to lead concentrated strategies across several key workstreams that focus on employees, customers, and the community.
In 2022, Fifth Third launched a new Sustainability BRG.
The group focuses on social, environmental and related matters which include, but are not limited to, community engagement initiatives, philanthropy, environmental programs and corporate governance practices.
The Bancorp continued to drive meaningful change in our inclusion and diversity efforts by progressing towards the Six Bold Goals it plans to achieve by 2025:
Progressing on these goals, the Bancorp has seen an increase in diversity of its workforce in seven of the nine states in its branch network footprint that include 250 or more employees and continues to be recognized in various nationwide rankings for advancing as a leader in inclusion and diversity.
The Bancorp has also continued to progress towards its goal of achieving and sustaining a 10% supplier diversity spend during the year ended December 31, 2022.
The Bancorp’s continuous listening strategy forms the foundation of its employee culture.
Employees completed over 775,000 training hours during 2022, including content covering unconscious bias.
In 2022, the Bancorp raised its minimum wage to $20 per hour and concurrently provided a wage adjustment for its first four job levels.
These changes resulted in a compensation increase for more than 40% of the Bancorp’s employees.
These services help assist employees in maintaining a healthy work-life balance.
In 2022, the Bancorp conducted a Total Rewards Survey to assess which components of its compensation and benefit programs were most important to employees.
In response to feedback obtained in this survey, the Bancorp made enhancements to its benefits packages, effective
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
in 2023.
These included minimizing benefit cost increases on its medical plans, transitioning to a new paid time off structure that provides employees more control and flexibility to manage their time away and updating its short-term disability program to enhance the value it provides to employees.
The Bancorp responded proactively by reinforcing its employee value proposition which centers around inclusion and diversity, employee health and wellness and career development.
Through strategic actions and decisions as well as its human capital policies, programs and practices, the Bancorp helped support a culture of belonging and performance where employees feel valued and motivated to succeed.
Full year 2022 turnover decreased to 21.0% from 21.2% in 2021.
Fifth Third executed several retention strategies in 2022 to address trends in employee attrition including a focus on employee development and career progression, workplace flexibility and continued employee listening strategies.
The Bancorp’s multicultural recruitment strategy strengthens the organization by developing an employee base that reflects the communities it serves while also enhancing the lives of tomorrow’s leaders.
The Bancorp has strong partnerships with diversity-focused affinity groups, both with universities and partner organizations, that drive engagement with a diverse candidate population which includes women, minorities, LGBTQ+ communities, individuals with disabilities and veterans.
The Tailoring Rules establish four risk-based categories of institutions, and the extent to
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
On October 18, 2022, the FDIC adopted an amended restoration plan to increase the likelihood that the reserve ratio would be restored to at least 1.35% by September 30, 2028.
The FDIC’s amended restoration plan increases the initial base deposit insurance assessment rate schedules uniformly by 2 basis points, beginning in the first quarterly assessment period of 2023.
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
a Tier 1 Risk-Based Capital Ratio of 6.0% or greater and a Total Risk-Based Capital Ratio of 10.0% or greater.
The final rule is applicable to BHCs with $100
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
The Bancorp’s capital ratios have exceeded the stress capital buffer requirement for all periods presented.
There have been a number of significant
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
On August 25, 2022, the SEC finalized rules implementing the pay versus performance disclosure requirement mandated by Dodd–Frank.
Under the new rules, reporting companies are required to include a tabular and narrative disclosure of specified executive compensation and financial performance measures for the five most recently completed fiscal years in proxy statements for fiscal years ending on or after December 16, 2022.
Additionally, companies are required to use the company information in the table to give a clear description of the relationships between compensation actually paid to specified executive officers to the cumulative total shareholder return, net income, and company-selected financial measures.
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
The Human Capital division responded proactively and kept employee health and wellness, flexibility, and inclusion and diversity at the forefront of its strategic actions and decisions.
In 2020, the Bancorp outlined Six Bold Goals to support our vision of inclusion and diversity throughout our workforce and among our suppliers.
The Bancorp continues to make progress toward these goals that it plans to achieve by 2025:
Since 2018, these efforts have resulted in a 20% increase in employee participation and engagement in our BRGs.
The Bancorp has continued its efforts to accelerate racial equality, equity and inclusion guided by its Executive Diversity Leadership Council and has developed dashboards to monitor, measure and drive a culture of inclusion.
These efforts support the Bancorp’s goals to be differentiated in the marketplace and recognized as an employer of choice.
Through a continuous listening strategy, the Bancorp takes a holistic approach to collecting, measuring and responding to employee feedback and assessing engagement.
Employees completed over 765,000 training hours in 2021.
A combination of competitive compensation, best-in-class benefits, innovative programs that foster work-life balance, flexible work options, financial rewards for physical and financial wellness activities and the Bancorp’s reputation for being a business and community leader forms an attractive value proposition for current and prospective employees.
The Bancorp’s diversity recruiting outreach strategy enables it to build strong relationships with a qualified and diverse applicant pool that reflects the demographics of its markets through a focus on women, minority and LGBTQ+ populations, along with individuals with disabilities and veterans.
Consistent with external trends, the Bancorp experienced increased attrition in 2021 (21.2%).
To provide stability and support to its employees’ needs outside of work, the Bancorp updated its time away policies, provided additional vacation time in 2021 and offered back-up family care.
Several retention actions have been executed in alignment with the Bancorp’s compensation philosophy, including special bonus programs implemented for certain roles.
The Bancorp has also had an $18 per hour minimum wage since 2019.
*Human Capital Response to COVID-19 Pandemic*
The Bancorp’s continued response to the pandemic aimed to address the concerns and needs of its employees, customers and communities while showing the dedication and resilience of its workforce.
In 2021, Fifth Third was recognized as the #1 Bank in COVID-19 response.
Employee-focused highlights included:
- Awarded 7,500+ eligible front-line employees with a special COVID staffing bonus
- Delivered ongoing COVID-19 education and communication
- Offered on-site vaccinations in high density areas
- Provided paid time off for getting vaccinations and boosters
- Expanded back-up family care support for employees
- Continued offering non-worked paid time off and additional sick time
It is possible that the intensity of regulation and supervision will be higher in the Biden Administration.
The Bancorp is also subject
the Bancorp complying with the automatic restrictions on capital distributions under the FRBs capital rules (“CCAR”) process discussed below (see Regulatory Capital Requirements below).
In response to the uncertainty caused by the COVID-19 pandemic, certain large BHCs, including the Bancorp, were not permitted to make share repurchases, subject to certain limited exceptions, during the third and fourth quarters of 2020, but were permitted to make dividend payments subject to limits based on the amount of dividends paid in the second quarter and the firm’s average net income for the four preceding quarters.
The FRB extended these restrictions into the first and second quarters of 2021, with certain modifications to permit a limited amount of share repurchases.
During the first and second quarters of 2021, provided that a BHC did not increase its common stock dividends higher than the level paid in the second quarter of 2020, BHCs, including the Bancorp, were permitted to pay common dividends and make share repurchases that, in the aggregate, did not exceed an amount equal to the average of the firm’s net income for the four preceding calendar quarters.
BHCs could also make additional share repurchases up to the amount of share issuances related to expensed employee compensation.
In June 2021, the FRB lifted the COVID-19 pandemic induced capital distribution limitations and authorized the Bancorp, beginning July 1, 2021, to make capital distributions that are consistent with the requirements in the Board’s capital plan rule, inclusive of the Bancorp’s stress capital buffer requirement.
The FDIC has required that large insured depository institutions, defined as those insured depository institutions with 2 million or more deposit accounts, including the Bank, enhance their deposit account record keeping and related information technology system capabilities to facilitate prompt payment of insured deposits if such an institution were to fail.
The FDIC established an initial compliance date of April 1, 2020 while granting institutions an optional extension of the compliance date for up to one year, to a date no later than April 1, 2021.
The Bank elected to utilize the optional extension of the compliance date and issued its Certification of Compliance to the FDIC on March 26, 2021.
The FDIC’s restoration plan projects the reserve ratio to exceed 1.35% without increasing the deposit insurance assessment rate, subject to ongoing monitoring over the next eight years.
national banks (including the Bank) with respect to these CRA obligations.
This CRA examination resulted in a change in rating from “Needs to Improve” to “Outstanding.”
The OCC finalized revised CRA rules in June 2020, with compliance required by January 1, 2023.
However, effective January 1, 2022, the OCC rescinded those rules, reverting to the 1995 CRA rules, as amended, which are also the operative rules in place for FRB- and FDIC-regulated banks.
An excerpt. Shown here: 40 of 73 rewritten, 40 of 45 added and 40 of 47 removed. The counts are complete. For every sentence, read Item 1. BUSINESS in the FY2022 filing and the FY2021 filing.
Cover and table of contents
37 rewritten, 10 added, 7 removed, 69 unchanged
[Table of [removed: Contents](#i90d310f8677f475ebab3cfafe66c6b5b_49)][added: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)]
For the fiscal year ended December 31, [removed: 2021][added: 2022]
[removed: ][added: ]
There were [removed: 683,679,363] [added: 678,585,140] shares of the Bancorp’s Common Stock, without par value, outstanding as of January 31, [removed: 2022.][added: 2023.]
The Aggregate Market Value of the Voting Stock held by non-affiliates of the Bancorp was [removed: $23,662,337,082] [added: $20,129,206,051] as of June 30, [removed: 2021.][added: 2022.]
Sections of the Bancorp’s Proxy Statement for the [removed: 2022] [added: 2023] Annual Meeting of Shareholders are incorporated by reference into Part III of this report.
Only those sections of this [removed: 2021] [added: 2022] Annual Report to Shareholders that are specified in this Cross Reference Index constitute part of the registrant’s Form 10-K for the year ended December 31, [removed: 2021.][added: 2022.]
No other information contained in this [removed: 2021] [added: 2022] Annual Report to Shareholders shall be deemed to constitute any part of this Form 10-K nor shall any such information be incorporated into the Form 10-K and shall not be deemed “filed” as part of the registrant’s Form 10-K.
| Item 1. | | | [removed: [Business](#i90d310f8677f475ebab3cfafe66c6b5b_19)] [added: [Business](#i48540c50bc474a4186cf9dc1957cda5d_16)] | | | 20 | | |
| | | | [Average Balance [removed: Sheets](#i90d310f8677f475ebab3cfafe66c6b5b_76)] [added: Sheets](#i48540c50bc474a4186cf9dc1957cda5d_73)] | | | [removed: 70] [added: 66] | | |
| | | | [Analysis of Net Interest Income and Net Interest Income [removed: Changes](#i90d310f8677f475ebab3cfafe66c6b5b_76)] [added: Changes](#i48540c50bc474a4186cf9dc1957cda5d_73)] | | | [removed: 69] [added: 65] | | |
| | | | [Loan and Lease [removed: Portfolio](#i90d310f8677f475ebab3cfafe66c6b5b_115)] [added: Portfolio](#i48540c50bc474a4186cf9dc1957cda5d_112)] | | | [removed: 84, 151] [added: 81, 143] | | |
| | | | [Risk Elements of Loan and Lease [removed: Portfolio](#i90d310f8677f475ebab3cfafe66c6b5b_133)] [added: Portfolio](#i48540c50bc474a4186cf9dc1957cda5d_133)] | | | [removed: 92] [added: 89] | | |
| | | | [Return on Equity and [removed: Assets](#i90d310f8677f475ebab3cfafe66c6b5b_61)] [added: Assets](#i48540c50bc474a4186cf9dc1957cda5d_58)] | | | [removed: 60] [added: 57] | | |
| | | | [Short-term [removed: Borrowings](#i90d310f8677f475ebab3cfafe66c6b5b_127)] [added: Borrowings](#i48540c50bc474a4186cf9dc1957cda5d_127)] | | | [removed: 89, 181] [added: 86, 172] | | |
| Item 1A. | | | [Risk [removed: Factors](#i90d310f8677f475ebab3cfafe66c6b5b_22)] [added: Factors](#i48540c50bc474a4186cf9dc1957cda5d_19)] | | | [removed: 31] [added: 30] | | |
| Item 1B. | | | [Unresolved Staff [removed: Comments](#i90d310f8677f475ebab3cfafe66c6b5b_25)] [added: Comments](#i48540c50bc474a4186cf9dc1957cda5d_22)] | | | [removed: 49] [added: 47] | | |
| Item 2. | | | [removed: [Properties](#i90d310f8677f475ebab3cfafe66c6b5b_28)] [added: [Properties](#i48540c50bc474a4186cf9dc1957cda5d_25)] | | | [removed: 49] [added: 47] | | |
| Item 3. | | | [Legal [removed: Proceedings](#i90d310f8677f475ebab3cfafe66c6b5b_31)] [added: Proceedings](#i48540c50bc474a4186cf9dc1957cda5d_28)] | | | [removed: 49] [added: 47] | | |
| Item 4. | | | [Mine Safety [removed: Disclosures](#i90d310f8677f475ebab3cfafe66c6b5b_34)] [added: Disclosures](#i48540c50bc474a4186cf9dc1957cda5d_31)] | | | [removed: 49] [added: 47] | | |
| | | | [Information about our Executive [removed: Officers](#i90d310f8677f475ebab3cfafe66c6b5b_37)] [added: Officers](#i48540c50bc474a4186cf9dc1957cda5d_34)] | | | [removed: 50] [added: 48] | | |
| Item 5. | | | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities](#i90d310f8677f475ebab3cfafe66c6b5b_43)] [added: Securities](#i48540c50bc474a4186cf9dc1957cda5d_40)] | | | [removed: 52] [added: 50] | | |
| Item 7. | | | [Management’s Discussion and Analysis of Financial Condition and Results of [removed: Operations](#i90d310f8677f475ebab3cfafe66c6b5b_58)] [added: Operations](#i48540c50bc474a4186cf9dc1957cda5d_55)] | | | [removed: 56] [added: 54] | | |
| Item 7A. | | | [Quantitative and Qualitative Disclosures About Market [removed: Risk](#i90d310f8677f475ebab3cfafe66c6b5b_166)] [added: Risk](#i48540c50bc474a4186cf9dc1957cda5d_175)] | | | [removed: 123] [added: 117] | | |
| Item 8. | | | [Financial Statements and Supplementary [removed: Data](#i90d310f8677f475ebab3cfafe66c6b5b_166)] [added: Data](#i48540c50bc474a4186cf9dc1957cda5d_175)] | | | [removed: 123] [added: 117] | | |
| Item 9. | | | [Changes in and Disagreements with Accountants on Accounting and Financial [removed: Disclosure](#i90d310f8677f475ebab3cfafe66c6b5b_304)] [added: Disclosure](#i48540c50bc474a4186cf9dc1957cda5d_301)] | | | [removed: 225] [added: 215] | | |
| Item 9A. | | | [Controls and [removed: Procedures](#i90d310f8677f475ebab3cfafe66c6b5b_307)] [added: Procedures](#i48540c50bc474a4186cf9dc1957cda5d_304)] | | | [removed: 225] [added: 215] | | |
| Item 9B. | | | [Other [removed: Information](#i90d310f8677f475ebab3cfafe66c6b5b_313)] [added: Information](#i48540c50bc474a4186cf9dc1957cda5d_310)] | | | [removed: 227] [added: 217] | | |
| Item 9C. | | | [Disclosure Regarding Foreign Jurisdictions that Prevent [removed: Inspection](#i90d310f8677f475ebab3cfafe66c6b5b_2715)] [added: Inspection](#i48540c50bc474a4186cf9dc1957cda5d_313)] | | | [removed: 227] [added: 217] | | |
| Item 10. | | | [Directors, Executive Officers and Corporate [removed: Governance](#i90d310f8677f475ebab3cfafe66c6b5b_319)] [added: Governance](#i48540c50bc474a4186cf9dc1957cda5d_319)] | | | [removed: 227] [added: 217] | | |
| Item 11. | | | [Executive [removed: Compensation](#i90d310f8677f475ebab3cfafe66c6b5b_322)] [added: Compensation](#i48540c50bc474a4186cf9dc1957cda5d_322)] | | | [removed: 227] [added: 217] | | |
| Item 12. | | | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder [removed: Matters](#i90d310f8677f475ebab3cfafe66c6b5b_325)] [added: Matters](#i48540c50bc474a4186cf9dc1957cda5d_325)] | | | [removed: 227] [added: 217] | | |
| Item 13. | | | [Certain Relationships and Related Transactions, and Director [removed: Independence](#i90d310f8677f475ebab3cfafe66c6b5b_328)] [added: Independence](#i48540c50bc474a4186cf9dc1957cda5d_328)] | | | [removed: 227] [added: 217] | | |
| Item 14. | | | [Principal Accounting Fees and [removed: Services](#i90d310f8677f475ebab3cfafe66c6b5b_331)] [added: Services](#i48540c50bc474a4186cf9dc1957cda5d_331)] | | | [removed: 227] [added: 217] | | |
| Item 15. | | | [Exhibits, Financial Statement [removed: Schedules](#i90d310f8677f475ebab3cfafe66c6b5b_337)] [added: Schedules](#i48540c50bc474a4186cf9dc1957cda5d_337)] | | | [removed: 228] [added: 218] | | |
| Item 16. | | | [Form 10–K [removed: Summary](#i90d310f8677f475ebab3cfafe66c6b5b_340)] [added: Summary](#i48540c50bc474a4186cf9dc1957cda5d_340)] | | | [removed: 232] [added: 222] | | |
Factors that might cause such a difference include, but are not limited to: (1) effects of the global COVID-19 pandemic; (2) deteriorating credit quality; (3) loan concentration by location or industry of borrowers or collateral; (4) problems encountered by other financial institutions; (5) inadequate sources of funding or liquidity; (6) unfavorable actions of rating agencies; (7) inability to maintain or grow deposits; (8) limitations on the ability to receive dividends from subsidiaries; (9) cyber-security risks; (10) Fifth Third’s ability to secure confidential information and deliver products and services through the use of computer systems and telecommunications networks; (11) failures by third-party service providers; (12) inability to manage strategic initiatives and/or organizational changes; (13) inability to implement technology system enhancements; (14) failure of internal controls and other risk management systems; (15) losses related to fraud, theft, misappropriation or violence; (16) inability to attract and retain skilled personnel; (17) adverse impacts of government regulation; (18) governmental or regulatory changes or other actions; (19) failures to meet applicable capital requirements; (20) regulatory objections to Fifth Third’s capital plan; (21) regulation of Fifth Third’s derivatives activities; (22) deposit insurance premiums; (23) assessments for the orderly liquidation fund; (24) replacement of LIBOR; (25) weakness in the national or local economies; (26) global political and economic uncertainty or negative actions; (27) changes in interest [removed: rates;] [added: rates and the effects of inflation;] (28) changes and trends in capital markets; (29) fluctuation of Fifth Third’s stock price; (30) volatility in mortgage banking revenue; (31) litigation, investigations, and enforcement proceedings by governmental authorities; (32) breaches of contractual covenants, representations and warranties; (33) competition and changes in the financial services industry; (34) changing retail distribution strategies, customer preferences and behavior; (35) difficulties in identifying, acquiring or integrating suitable strategic partnerships, investments or acquisitions; (36) potential dilution from future acquisitions; (37) loss of income and/or difficulties encountered in the sale and separation of businesses, investments or other assets; (38) results of investments or acquired entities; (39) changes in accounting standards or interpretation or declines in the value of Fifth Third’s goodwill or other intangible assets; (40) inaccuracies or other failures from the use of models; (41) effects of critical accounting policies and judgments or the use of inaccurate estimates; (42) weather-related events, other natural disasters, or health emergencies (including pandemics); (43) the impact of reputational risk created by these or other developments on such matters as business generation and retention, funding and liquidity; (44) changes in law or requirements imposed by Fifth Third’s regulators impacting our capital actions, including dividend payments and stock repurchases; and (45) Fifth Third’s ability to meet its [removed: sustainability] [added: environmental and/or social] targets, goals and commitments.
If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the registrant included in the filing reflect the correction of an error to previously issued financial statements.
Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant’s executive officers during the relevant recovery period pursuant to §240.10D-1(b).
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
| | | | [Employees](#i48540c50bc474a4186cf9dc1957cda5d_16) | | | 20, 70 | | |
| | | | [Segment Information](#i48540c50bc474a4186cf9dc1957cda5d_88) | | | 72, 211 | | |
| | | | [Investment Securities Portfolio](#i48540c50bc474a4186cf9dc1957cda5d_115) | | | 82, 140 | | |
| | | | [Deposits](#i48540c50bc474a4186cf9dc1957cda5d_121) | | | 84 | | |
| SIGNATURES | | | | | | 223 | | |
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
| | | | [Employees](#i90d310f8677f475ebab3cfafe66c6b5b_19) | | | 20, 75 | | |
| | | | [Segment Information](#i90d310f8677f475ebab3cfafe66c6b5b_91) | | | 77, 221 | | |
| | | | [Investment Securities Portfolio](#i90d310f8677f475ebab3cfafe66c6b5b_118) | | | 85, 148 | | |
| | | | [Deposits](#i90d310f8677f475ebab3cfafe66c6b5b_124) | | | 87 | | |
| SIGNATURES | | | | | | 233 | | |
When considering these forward-looking statements, you should keep in mind these risks and uncertainties, as well as any cautionary statements we may make.
We undertake no obligation to release revisions to these forward-looking statements or reflect events or circumstances after the date of this document.
Item 2. PROPERTIES
1 rewritten, 0 added, 0 removed, 7 unchanged
At December 31, [removed: 2021,] [added: 2022,] the Bancorp, through its banking and non-banking subsidiaries, operated [removed: 1,117] [added: 1,087] banking centers, of which [removed: 767] [added: 744] were owned, [removed: 224] [added: 203] were leased and [removed: 126] [added: 140] for which the buildings are owned but the land is leased.
Item 4. MINE SAFETY DISCLOSURES
14 rewritten, 22 added, 14 removed, 47 unchanged
[Table of [removed: Contents](#i90d310f8677f475ebab3cfafe66c6b5b_49)][added: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)]
The names, ages and positions of the Executive Officers of the Bancorp as of February [removed: 25, 2022] [added: 24, 2023] are listed below along with their business experience during the past five years:
[removed: Previously, Mr. Carmichael] [added: He] was [added: also] President of the Bancorp from September 2012 to October 2020, Chief Operating Officer of the Bancorp from June 2006 to August 2015, Executive Vice President of the Bancorp from June 2006 to September 2012 and Chief Information Officer of the Bancorp from June 2003 to June 2006.
[added: Ms. Garrett has been] Executive Vice President and Head of Wealth & Asset Management since November 2020.
[removed: Previously] [added: Previously,] she was Senior Vice President and Head of Wealth & Asset Management from July 2019 to November 2020 and Head of Fifth Third Private Bank from October 2017 until July 2019.
Executive Vice President and Chief Corporate [removed: Social] Responsibility Officer since February 2022.
Howard Hammond, [removed: 56.][added: 57.]
Executive Vice President and Head of Commercial [removed: Banking] [added: Bank] of the Bancorp since January 2020.
[added: Mr. Spence has been] President since October 2020.
[removed: Previously, Mr. Stein was Chief Credit Officer from March 2018 through November 2020, Head] of the Commercial Bank from March 2016 through March 2018 and Senior Vice President and Chief Credit Officer from November 2014 through March 2016.
[removed: *50] [added: *47] Fifth Third Bancorp*
Executive Vice President and Chief [removed: Digital] [added: Marketing] Officer [removed: and Head of Digital, Marketing, Design and Innovation] since [removed: November 2020.][added: February 2023.]
[removed: Previously, Ms. Stevens] [added: She also] served as Senior Vice President, Chief Digital Officer, and Head of Omnichannel Banking Experiences, Design, and Innovation from May 2016 through November 2020.
[removed: *51] [added: *48] Fifth Third Bancorp*
Spence, 44.
President and Chief Executive Officer since July 2022.
Carmichael, 61.
Executive Chairman of the Bancorp since July 2022.
Mr. Carmichael has been Chairman of the Board since February 2018.
Previously, Mr. Carmichael was Chief Executive Officer from November 2015 to July 2022.
Garrett, 64.
Executive Vice President, Group Regional President and Head of Wealth & Asset Management since July 2022.
Gibson, 50.
Hazel, 57.
Lavender, 61.
Leonard, 53.
Pinckney, 59.
Schramm, 50.
Shaffer, 53.
Stein, 53.
Previously, Mr. Stein was Chief Credit Officer from March 2018 through November 2020, Head
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
Stevens, 48.
Previously, Ms. Stevens was Chief Digital Officer and Head of Digital, Marketing, Design and Innovation from November 2020 to February 2023.
Zaunbrecher, 63.
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
Carmichael, 60.
Chairman of the Board since February 2018 and Chief Executive Officer of the Bancorp since November 2015.
Garrett, 63.
Gibson, 49.
Hazel, 56.
Lavender, 60.
Leonard, 52.
Pinckney, 58.
Schramm, 49.
Shaffer, 52.
Spence, 43.
Stein, 52.
Stevens, 47.
Zaunbrecher, 62.
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
55 rewritten, 36 added, 33 removed, 41 unchanged
Additionally, as of December 31, [removed: 2021,] [added: 2022,] the Bancorp had [removed: 35,266] [added: 34,165] common shareholders of record.
[removed: *(a)Include 170,351] [added: *(a)Includes 106,433] shares repurchased during the fourth quarter of [removed: 2021] [added: 2022] in connection with various employee compensation plans of the Bancorp.
[Table of [removed: Contents](#i90d310f8677f475ebab3cfafe66c6b5b_49)][added: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)]
The graphs below summarize the cumulative return experienced by the Bancorp’s shareholders over the five and ten year periods ended December 31, [removed: 2021,] [added: 2022,] respectively, compared to the S&P 500 Stock, the S&P Banks and the KBW Banks indices.
[removed: 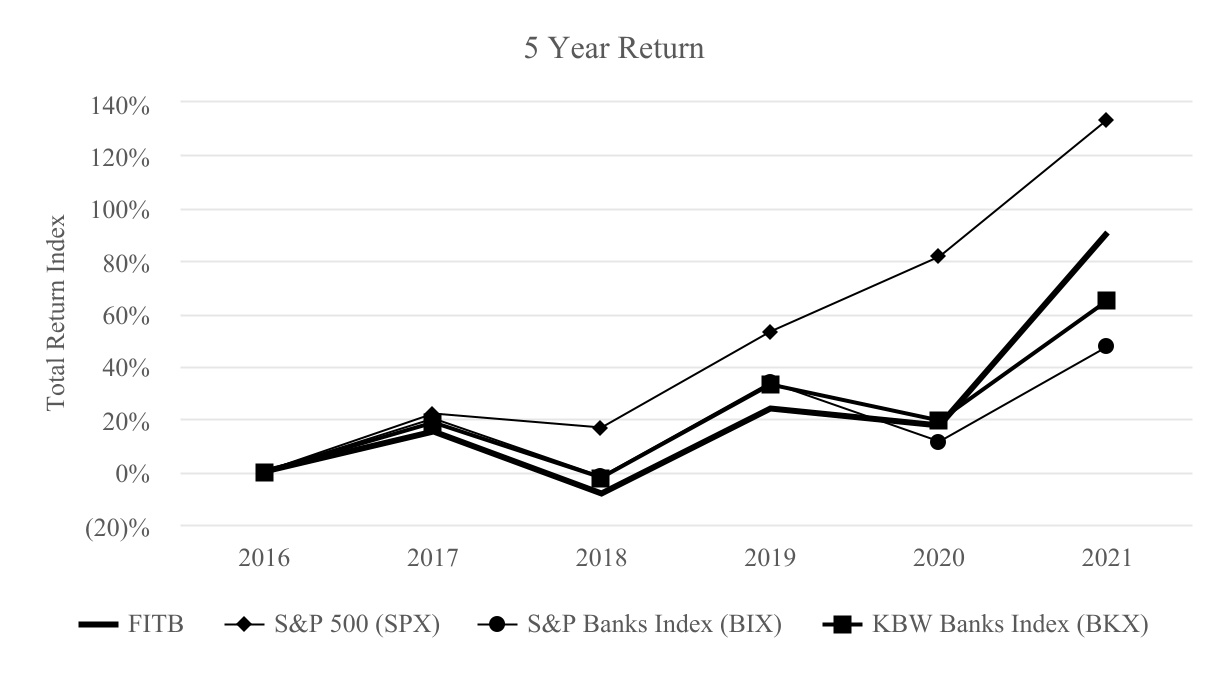][added: 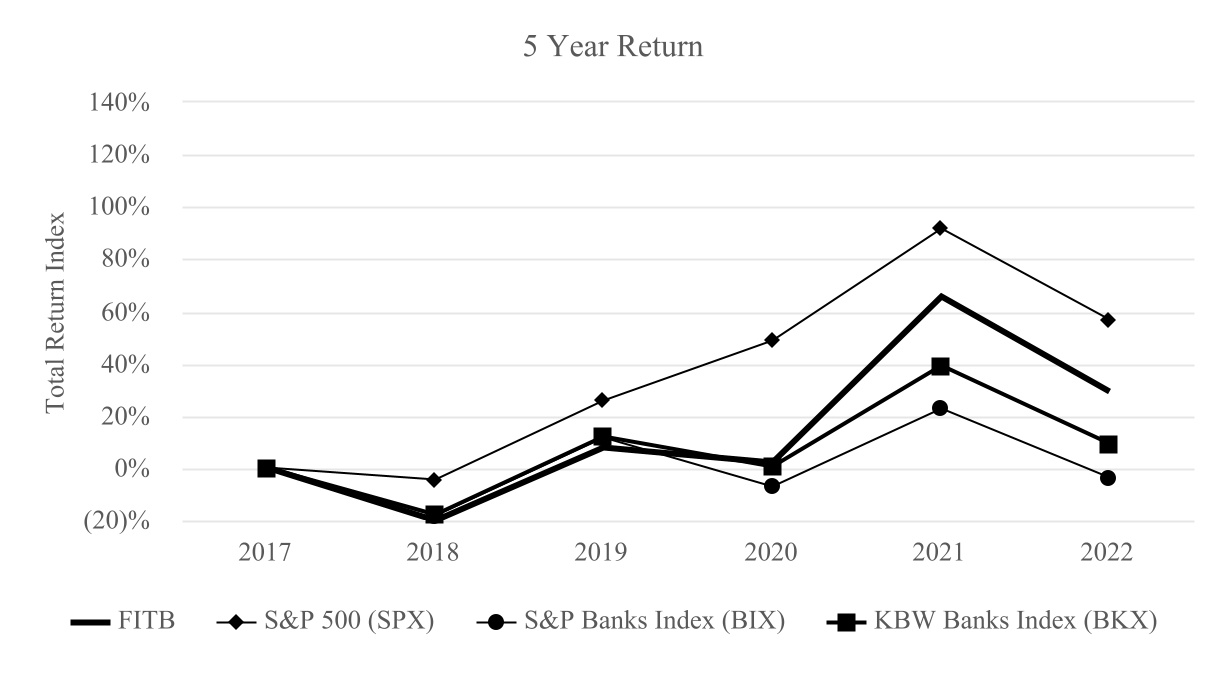]
[removed: 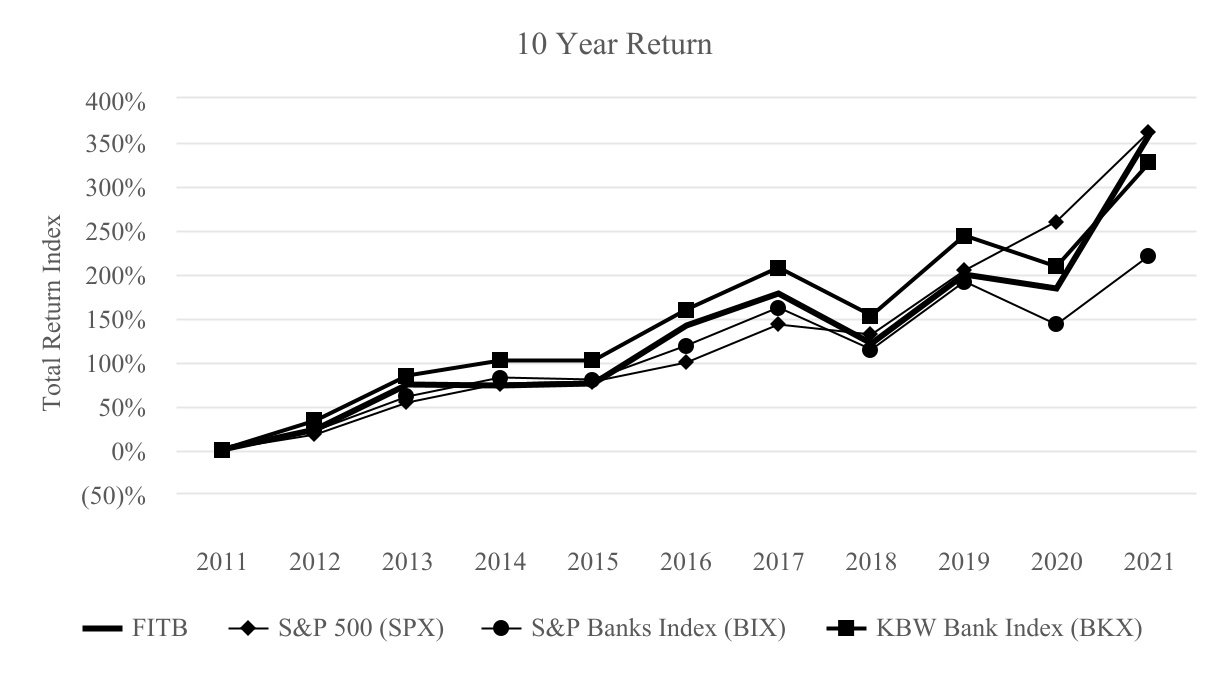][added: 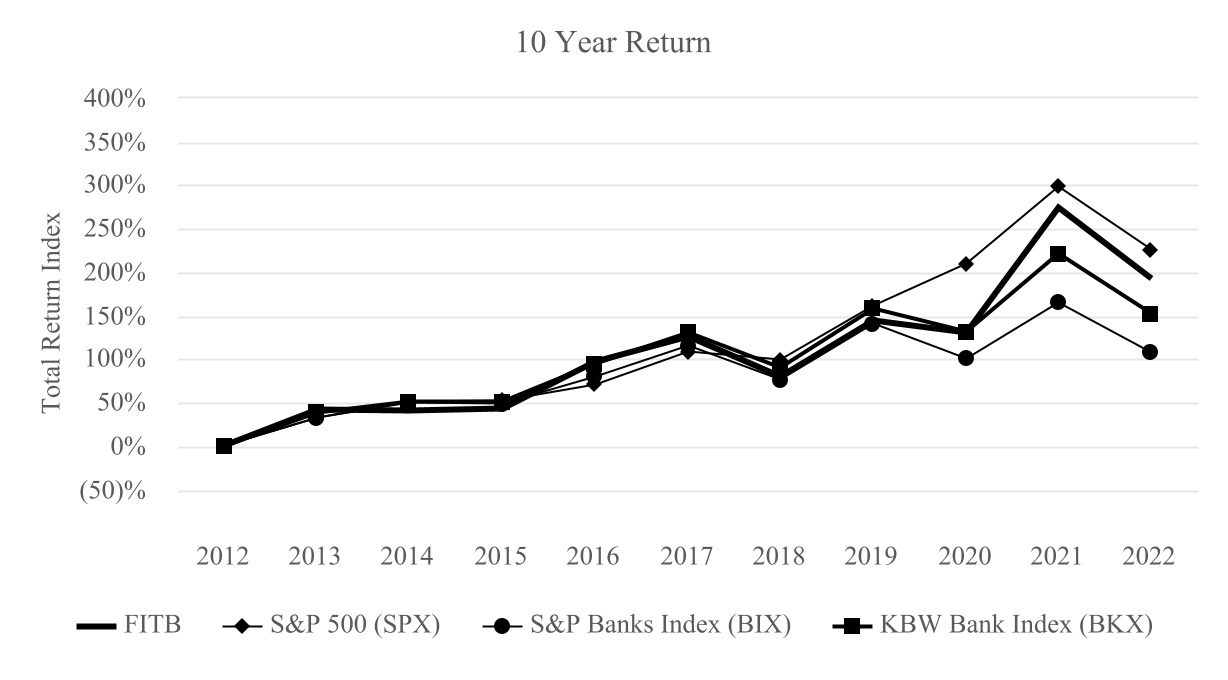]
[removed: ][added: ]
[removed: 2021] [added: 2022] ANNUAL REPORT
| [Glossary of Abbreviations and [removed: Acronyms](#i90d310f8677f475ebab3cfafe66c6b5b_52)] [added: Acronyms](#i48540c50bc474a4186cf9dc1957cda5d_49)] | | | | | | | | | [removed: [55](#i90d310f8677f475ebab3cfafe66c6b5b_52)] [added: [53](#i48540c50bc474a4186cf9dc1957cda5d_49)] | | |
| [Management’s Discussion and Analysis of Financial Condition and Results of [removed: Operations](#i90d310f8677f475ebab3cfafe66c6b5b_58)] [added: Operations](#i48540c50bc474a4186cf9dc1957cda5d_55)] | | | | | | | | | | | |
| [Non-GAAP Financial [removed: Measures](#i90d310f8677f475ebab3cfafe66c6b5b_64)] [added: Measures](#i48540c50bc474a4186cf9dc1957cda5d_61)] | | | | | | | | | [removed: [62](#i90d310f8677f475ebab3cfafe66c6b5b_64)] [added: [59](#i48540c50bc474a4186cf9dc1957cda5d_61)] | | |
| [Recent Accounting [removed: Standards](#i90d310f8677f475ebab3cfafe66c6b5b_67)] [added: Standards](#i48540c50bc474a4186cf9dc1957cda5d_64)] | | | | | | | | | [removed: [64](#i90d310f8677f475ebab3cfafe66c6b5b_67)] [added: [61](#i48540c50bc474a4186cf9dc1957cda5d_64)] | | |
| [Critical Accounting [removed: Policies](#i90d310f8677f475ebab3cfafe66c6b5b_70)] [added: Policies](#i48540c50bc474a4186cf9dc1957cda5d_67)] | | | | | | | | | [removed: [64](#i90d310f8677f475ebab3cfafe66c6b5b_70)] [added: [61](#i48540c50bc474a4186cf9dc1957cda5d_67)] | | |
| [Statements of Income [removed: Analysis](#i90d310f8677f475ebab3cfafe66c6b5b_73)] [added: Analysis](#i48540c50bc474a4186cf9dc1957cda5d_70)] | | | | | | | | | [removed: [69](#i90d310f8677f475ebab3cfafe66c6b5b_73)] [added: [65](#i48540c50bc474a4186cf9dc1957cda5d_70)] | | |
| [Business Segment [removed: Review](#i90d310f8677f475ebab3cfafe66c6b5b_91)] [added: Review](#i48540c50bc474a4186cf9dc1957cda5d_88)] | | | | | | | | | [removed: [77](#i90d310f8677f475ebab3cfafe66c6b5b_91)] [added: [72](#i48540c50bc474a4186cf9dc1957cda5d_88)] | | |
| [Balance Sheet [removed: Analysis](#i90d310f8677f475ebab3cfafe66c6b5b_112)] [added: Analysis](#i48540c50bc474a4186cf9dc1957cda5d_109)] | | | | | | | | | [removed: [84](#i90d310f8677f475ebab3cfafe66c6b5b_112)] [added: [81](#i48540c50bc474a4186cf9dc1957cda5d_109)] | | |
| [Risk Management - [removed: Overview](#i90d310f8677f475ebab3cfafe66c6b5b_130)] [added: Overview](#i48540c50bc474a4186cf9dc1957cda5d_130)] | | | | | | | | | [removed: [91](#i90d310f8677f475ebab3cfafe66c6b5b_130)] [added: [88](#i48540c50bc474a4186cf9dc1957cda5d_130)] | | |
| [Credit Risk [removed: Management](#i90d310f8677f475ebab3cfafe66c6b5b_133)] [added: Management](#i48540c50bc474a4186cf9dc1957cda5d_133)] | | | | | | | | | [removed: [92](#i90d310f8677f475ebab3cfafe66c6b5b_133)] [added: [89](#i48540c50bc474a4186cf9dc1957cda5d_133)] | | |
| [Interest Rate and Price Risk [removed: Management](#i90d310f8677f475ebab3cfafe66c6b5b_145)] [added: Management](#i48540c50bc474a4186cf9dc1957cda5d_154)] | | | | | | | | | [removed: [111](#i90d310f8677f475ebab3cfafe66c6b5b_145)] [added: [106](#i48540c50bc474a4186cf9dc1957cda5d_154)] | | |
| [Legal and Regulatory Compliance Risk [removed: Management](#i90d310f8677f475ebab3cfafe66c6b5b_154)] [added: Management](#i48540c50bc474a4186cf9dc1957cda5d_166)] | | | | | | | | | [removed: [120](#i90d310f8677f475ebab3cfafe66c6b5b_154)] [added: [115](#i48540c50bc474a4186cf9dc1957cda5d_166)] | | |
| [Report of Independent Registered Public Accounting [removed: Firm](#i90d310f8677f475ebab3cfafe66c6b5b_169)] [added: Firm](#i48540c50bc474a4186cf9dc1957cda5d_178)] | | | | | | | | | [removed: [124](#i90d310f8677f475ebab3cfafe66c6b5b_169)] [added: [118](#i48540c50bc474a4186cf9dc1957cda5d_178)] | | |
| [Consolidated Statements of Comprehensive [removed: Income](#i90d310f8677f475ebab3cfafe66c6b5b_178)] [added: Income](#i48540c50bc474a4186cf9dc1957cda5d_187)] | | | | | | | | | [removed: [128](#i90d310f8677f475ebab3cfafe66c6b5b_178)] [added: [122](#i48540c50bc474a4186cf9dc1957cda5d_187)] | | |
| [Consolidated Statements of Changes in [removed: Equity](#i90d310f8677f475ebab3cfafe66c6b5b_181)] [added: Equity](#i48540c50bc474a4186cf9dc1957cda5d_190)] | | | | | | | | | [removed: [129](#i90d310f8677f475ebab3cfafe66c6b5b_181)] [added: [123](#i48540c50bc474a4186cf9dc1957cda5d_190)] | | |
| [Consolidated Statements of Cash [removed: Flows](#i90d310f8677f475ebab3cfafe66c6b5b_187)] [added: Flows](#i48540c50bc474a4186cf9dc1957cda5d_196)] | | | | | | | | | [removed: [131](#i90d310f8677f475ebab3cfafe66c6b5b_187)] [added: [125](#i48540c50bc474a4186cf9dc1957cda5d_196)] | | |
| [Summary of Significant Accounting and Reporting [removed: Policies](#i90d310f8677f475ebab3cfafe66c6b5b_193)] [added: Policies](#i48540c50bc474a4186cf9dc1957cda5d_202)] | | | [removed: [132](#i90d310f8677f475ebab3cfafe66c6b5b_193)] [added: [126](#i48540c50bc474a4186cf9dc1957cda5d_202)] | | | [Long-Term [removed: Debt](#i90d310f8677f475ebab3cfafe66c6b5b_250)] [added: Debt](#i48540c50bc474a4186cf9dc1957cda5d_250)] | | | [removed: [182](#i90d310f8677f475ebab3cfafe66c6b5b_250)] [added: [173](#i48540c50bc474a4186cf9dc1957cda5d_250)] | | |
| [Supplemental Cash Flow [removed: Information](#i90d310f8677f475ebab3cfafe66c6b5b_196)] [added: Information](#i48540c50bc474a4186cf9dc1957cda5d_205)] | | | [removed: [147](#i90d310f8677f475ebab3cfafe66c6b5b_196)] [added: [139](#i48540c50bc474a4186cf9dc1957cda5d_205)] | | | [Commitments, Contingent Liabilities and [removed: Guarantees](#i90d310f8677f475ebab3cfafe66c6b5b_256)] [added: Guarantees](#i48540c50bc474a4186cf9dc1957cda5d_253)] | | | [removed: [186](#i90d310f8677f475ebab3cfafe66c6b5b_256)] [added: [177](#i48540c50bc474a4186cf9dc1957cda5d_253)] | | |
| [Restrictions [removed: on Dividends] [added: on](#i48540c50bc474a4186cf9dc1957cda5d_208) [](#i48540c50bc474a4186cf9dc1957cda5d_208)[Dividends] and Capital [removed: Actions](#i90d310f8677f475ebab3cfafe66c6b5b_202)] [added: Actions](#i48540c50bc474a4186cf9dc1957cda5d_208)] | | | [removed: [147](#i90d310f8677f475ebab3cfafe66c6b5b_202)] [added: [139](#i48540c50bc474a4186cf9dc1957cda5d_208)] | | | [Legal and Regulatory [removed: Proceedings](#i90d310f8677f475ebab3cfafe66c6b5b_259)] [added: Proceedings](#i48540c50bc474a4186cf9dc1957cda5d_256)] | | | [removed: [190](#i90d310f8677f475ebab3cfafe66c6b5b_259)] [added: [181](#i48540c50bc474a4186cf9dc1957cda5d_256)] | | |
| [Credit Quality and the Allowance for Loan and Lease [removed: Losses](#i90d310f8677f475ebab3cfafe66c6b5b_211)] [added: Losses](#i48540c50bc474a4186cf9dc1957cda5d_217)] | | | [removed: [153](#i90d310f8677f475ebab3cfafe66c6b5b_211)] [added: [145](#i48540c50bc474a4186cf9dc1957cda5d_217)] | | | [Retirement and Benefit [removed: Plans](#i90d310f8677f475ebab3cfafe66c6b5b_268)] [added: Plans](#i48540c50bc474a4186cf9dc1957cda5d_265)] | | | [removed: [196](#i90d310f8677f475ebab3cfafe66c6b5b_268)] [added: [187](#i48540c50bc474a4186cf9dc1957cda5d_265)] | | |
| [Bank Premises and [removed: Equipment](#i90d310f8677f475ebab3cfafe66c6b5b_214)] [added: Equipment](#i48540c50bc474a4186cf9dc1957cda5d_220)] | | | [removed: [164](#i90d310f8677f475ebab3cfafe66c6b5b_214)] [added: [155](#i48540c50bc474a4186cf9dc1957cda5d_220)] | | | [Accumulated Other Comprehensive [removed: Income](#i90d310f8677f475ebab3cfafe66c6b5b_271)] [added: Income](#i48540c50bc474a4186cf9dc1957cda5d_268)] | | | [removed: [199](#i90d310f8677f475ebab3cfafe66c6b5b_271)] [added: [190](#i48540c50bc474a4186cf9dc1957cda5d_268)] | | |
| [Operating Lease [removed: Equipment](#i90d310f8677f475ebab3cfafe66c6b5b_217)] [added: Equipment](#i48540c50bc474a4186cf9dc1957cda5d_223)] | | | [removed: [165](#i90d310f8677f475ebab3cfafe66c6b5b_217)] [added: [156](#i48540c50bc474a4186cf9dc1957cda5d_223)] | | | [Common, Preferred and Treasury [removed: Stock](#i90d310f8677f475ebab3cfafe66c6b5b_274)] [added: Stock](#i48540c50bc474a4186cf9dc1957cda5d_271)] | | | [removed: [201](#i90d310f8677f475ebab3cfafe66c6b5b_274)] [added: [192](#i48540c50bc474a4186cf9dc1957cda5d_271)] | | |
| [Sales of Receivables and Servicing [removed: Rights](#i90d310f8677f475ebab3cfafe66c6b5b_235)] [added: Rights](#i48540c50bc474a4186cf9dc1957cda5d_238)] | | | [removed: [172](#i90d310f8677f475ebab3cfafe66c6b5b_235)] [added: [163](#i48540c50bc474a4186cf9dc1957cda5d_238)] | | | [Regulatory Capital Requirements and Capital [removed: Ratios](#i90d310f8677f475ebab3cfafe66c6b5b_292)] [added: Ratios](#i48540c50bc474a4186cf9dc1957cda5d_289)] | | | [removed: [218](#i90d310f8677f475ebab3cfafe66c6b5b_292)] [added: [208](#i48540c50bc474a4186cf9dc1957cda5d_289)] | | |
| [Derivative Financial [removed: Instruments](#i90d310f8677f475ebab3cfafe66c6b5b_241)] [added: Instruments](#i48540c50bc474a4186cf9dc1957cda5d_241)] | | | [removed: [174](#i90d310f8677f475ebab3cfafe66c6b5b_241)] [added: [165](#i48540c50bc474a4186cf9dc1957cda5d_241)] | | | [Parent Company Financial [removed: Statements](#i90d310f8677f475ebab3cfafe66c6b5b_295)] [added: Statements](#i48540c50bc474a4186cf9dc1957cda5d_292)] | | | [removed: [219](#i90d310f8677f475ebab3cfafe66c6b5b_295)] [added: [209](#i48540c50bc474a4186cf9dc1957cda5d_292)] | | |
| [Management’s Assessment as to the Effectiveness of Internal Control over Financial [removed: Reporting](#i90d310f8677f475ebab3cfafe66c6b5b_307)] [added: Reporting](#i48540c50bc474a4186cf9dc1957cda5d_304)] | | | [removed: [225](#i90d310f8677f475ebab3cfafe66c6b5b_307)] [added: [215](#i48540c50bc474a4186cf9dc1957cda5d_304)] | | | | | | | | |
| [Report of Independent Registered Public Accounting [removed: Firm](#i90d310f8677f475ebab3cfafe66c6b5b_310)] [added: Firm](#i48540c50bc474a4186cf9dc1957cda5d_307)] | | | [removed: [226](#i90d310f8677f475ebab3cfafe66c6b5b_310)] [added: [216](#i48540c50bc474a4186cf9dc1957cda5d_307)] | | | | | | | | |
| [Consolidated Ten Year [removed: Comparison](#i90d310f8677f475ebab3cfafe66c6b5b_346)] [added: Comparison](#i48540c50bc474a4186cf9dc1957cda5d_346)] | | | [removed: [234](#i90d310f8677f475ebab3cfafe66c6b5b_346)] [added: [224](#i48540c50bc474a4186cf9dc1957cda5d_346)] | | | | | | | | |
| [Directors and [removed: Officers](#i90d310f8677f475ebab3cfafe66c6b5b_349)] [added: Officers](#i48540c50bc474a4186cf9dc1957cda5d_349)] | | | [removed: [235](#i90d310f8677f475ebab3cfafe66c6b5b_349)] [added: [225](#i48540c50bc474a4186cf9dc1957cda5d_349)] | | | | | | | | |
[removed: *54] [added: *50] Fifth Third Bancorp*
| ACL: Allowance for Credit Losses | | | [removed: IPO: Initial Public Offering] [added: HTM: Held-To-Maturity] | | |
| ALLL: Allowance for Loan and Lease Losses | | | [removed: IRS: Internal Revenue Service] [added: IRLC: Interest Rate Lock Commitment] | | |
| CCAR: Comprehensive Capital Analysis and Review | | | [removed: NII:] [added: NAV:] Net [removed: Interest Income] [added: Asset Value] | | |
| October 1 - October 31, 2022 | | | 73,176 | | | | | | $ | 33.08 | | | | | — | | | | | | 40,785,269 | | |
| November 1 - November 30, 2022 | | | 23,625 | | | | | | 34.93 | | | | | | — | | | | | | 40,785,269 | | |
| December 1 - December 31, 2022 | | | 3,089,094 | | | | | | 32.47 | | | | | | 3,079,462 | | | | | | 37,705,807 | | |
| Total | | | 3,185,895 | | | | | | $ | 32.51 | | | | | 3,079,462 | | | | | | 37,705,807 | | |
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
| [Overview](#i48540c50bc474a4186cf9dc1957cda5d_58) | | | | | | | | | [54](#i48540c50bc474a4186cf9dc1957cda5d_58) | | |
| [Liquidity Risk Management](#i48540c50bc474a4186cf9dc1957cda5d_160) | | | | | | | | | [112](#i48540c50bc474a4186cf9dc1957cda5d_160) | | |
| [Operational Risk Management](#i48540c50bc474a4186cf9dc1957cda5d_163) | | | | | | | | | [114](#i48540c50bc474a4186cf9dc1957cda5d_163) | | |
| [Capital Management](#i48540c50bc474a4186cf9dc1957cda5d_169) | | | | | | | | | [116](#i48540c50bc474a4186cf9dc1957cda5d_169) | | |
| [Consolidated Balance Sheets](#i48540c50bc474a4186cf9dc1957cda5d_181) | | | | | | | | | [120](#i48540c50bc474a4186cf9dc1957cda5d_181) | | |
| [Consolidated Statements of Income](#i48540c50bc474a4186cf9dc1957cda5d_184) | | | | | | | | | [121](#i48540c50bc474a4186cf9dc1957cda5d_184) | | |
| [Investment Securities](#i48540c50bc474a4186cf9dc1957cda5d_211) | | | [140](#i48540c50bc474a4186cf9dc1957cda5d_211) | | | [Related Party Transactions](#i48540c50bc474a4186cf9dc1957cda5d_259) | | | [183](#i48540c50bc474a4186cf9dc1957cda5d_259) | | |
| [Loans and Leases](#i48540c50bc474a4186cf9dc1957cda5d_214) | | | [143](#i48540c50bc474a4186cf9dc1957cda5d_214) | | | [Income Taxes](#i48540c50bc474a4186cf9dc1957cda5d_262) | | | [185](#i48540c50bc474a4186cf9dc1957cda5d_262) | | |
| [Lease Obligations – Lessee](#i48540c50bc474a4186cf9dc1957cda5d_226) | | | [156](#i48540c50bc474a4186cf9dc1957cda5d_226) | | | [Stock-Based Compensation](#i48540c50bc474a4186cf9dc1957cda5d_274) | | | [194](#i48540c50bc474a4186cf9dc1957cda5d_274) | | |
| [Goodwill](#i48540c50bc474a4186cf9dc1957cda5d_229) | | | [158](#i48540c50bc474a4186cf9dc1957cda5d_229) | | | [Other Noninterest Income and Other Noninterest Expense](#i48540c50bc474a4186cf9dc1957cda5d_280) | | | [197](#i48540c50bc474a4186cf9dc1957cda5d_280) | | |
| [Intangible Assets](#i48540c50bc474a4186cf9dc1957cda5d_232) | | | [159](#i48540c50bc474a4186cf9dc1957cda5d_232) | | | [Earnings Per Share](#i48540c50bc474a4186cf9dc1957cda5d_283) | | | [198](#i48540c50bc474a4186cf9dc1957cda5d_283) | | |
| [Variable Interest Entities](#i48540c50bc474a4186cf9dc1957cda5d_235) | | | [160](#i48540c50bc474a4186cf9dc1957cda5d_235) | | | [Fair Value Measurements](#i48540c50bc474a4186cf9dc1957cda5d_286) | | | [199](#i48540c50bc474a4186cf9dc1957cda5d_286) | | |
| [Other Assets](#i48540c50bc474a4186cf9dc1957cda5d_244) | | | [171](#i48540c50bc474a4186cf9dc1957cda5d_244) | | | [Business Segments](#i48540c50bc474a4186cf9dc1957cda5d_295) | | | [211](#i48540c50bc474a4186cf9dc1957cda5d_295) | | |
| [Short-Term Borrowings](#i48540c50bc474a4186cf9dc1957cda5d_247) | | | [172](#i48540c50bc474a4186cf9dc1957cda5d_247) | | | [Subsequent Event](#i48540c50bc474a4186cf9dc1957cda5d_298) | | | [214](#i48540c50bc474a4186cf9dc1957cda5d_298) | | |
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
| AFS: Available-For-Sale | | | IPO: Initial Public Offering | | |
| ALCO: Asset Liability Management Committee | | | IRC: Internal Revenue Code | | |
| CD: Certificate of Deposit | | | NII: Net Interest Income | | |
| CDC: Fifth Third Community Development Corporation and Fifth Third | | | NM: Not Meaningful | | |
| C&I: Commercial and Industrial | | | PCD: Purchased Credit Deteriorated | | |
| DCF: Discounted Cash Flow | | | PPP: Paycheck Protection Program | | |
| DTCC: Depository Trust & Clearing Corporation | | | PSA: Performance Share Award | | |
| ERMC: Enterprise Risk Management Committee | | | RSA: Restricted Stock Award | | |
| FHLMC: Federal Home Loan Mortgage Corporation | | | TBA: To Be Announced | | |
| FINRA: Financial Industry Regulatory Authority | | | TILA: Truth in Lending Act | | |
| FNMA: Federal National Mortgage Association | | | TRA: Tax Receivable Agreement | | |
| FRB: Federal Reserve Bank | | | U.S.: United States of America | | |
| FTS: Fifth Third Securities, Inc. | | | Principles | | |
| GNMA: Government National Mortgage Association | | | VIE: Variable Interest Entity | | |
| | | | | | |
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
| October 1 - October 31, 2021 | | | 6,302,831 | | | | | | $ | 43.39 | | | | | 6,211,841 | | | | | | 41,857,841 | | |
| November 1 - November 30, 2021 | | | 18,150 | | | | | | 44.30 | | | | | | — | | | | | | 41,857,841 | | |
| December 1 - December 31, 2021 | | | 1,133,783 | | | | | | 43.37 | | | | | | 1,072,572 | | | | | | 40,785,269 | | |
| Total | | | 7,454,764 | | | | | | $ | 43.39 | | | | | 7,284,413 | | | | | | 40,785,269 | | |
| [Overview](#i90d310f8677f475ebab3cfafe66c6b5b_61) | | | | | | | | | [56](#i90d310f8677f475ebab3cfafe66c6b5b_61) | | |
| [Liquidity Risk Management](#i90d310f8677f475ebab3cfafe66c6b5b_148) | | | | | | | | | [117](#i90d310f8677f475ebab3cfafe66c6b5b_148) | | |
| [Operational Risk Management](#i90d310f8677f475ebab3cfafe66c6b5b_151) | | | | | | | | | [119](#i90d310f8677f475ebab3cfafe66c6b5b_151) | | |
| [Capital Management](#i90d310f8677f475ebab3cfafe66c6b5b_157) | | | | | | | | | [121](#i90d310f8677f475ebab3cfafe66c6b5b_157) | | |
| [Consolidated Balance Sheets](#i90d310f8677f475ebab3cfafe66c6b5b_172) | | | | | | | | | [126](#i90d310f8677f475ebab3cfafe66c6b5b_172) | | |
| [Consolidated Statements of Income](#i90d310f8677f475ebab3cfafe66c6b5b_175) | | | | | | | | | [127](#i90d310f8677f475ebab3cfafe66c6b5b_175) | | |
| [Investment Securities](#i90d310f8677f475ebab3cfafe66c6b5b_205) | | | [148](#i90d310f8677f475ebab3cfafe66c6b5b_205) | | | [Related Party Transactions](#i90d310f8677f475ebab3cfafe66c6b5b_262) | | | [193](#i90d310f8677f475ebab3cfafe66c6b5b_262) | | |
| [Loans and Leases](#i90d310f8677f475ebab3cfafe66c6b5b_208) | | | [151](#i90d310f8677f475ebab3cfafe66c6b5b_208) | | | [Income Taxes](#i90d310f8677f475ebab3cfafe66c6b5b_265) | | | [194](#i90d310f8677f475ebab3cfafe66c6b5b_265) | | |
| [Lease Obligations – Lessee](#i90d310f8677f475ebab3cfafe66c6b5b_220) | | | [165](#i90d310f8677f475ebab3cfafe66c6b5b_220) | | | [Stock-Based Compensation](#i90d310f8677f475ebab3cfafe66c6b5b_277) | | | [203](#i90d310f8677f475ebab3cfafe66c6b5b_277) | | |
| [Goodwill](#i90d310f8677f475ebab3cfafe66c6b5b_226) | | | [167](#i90d310f8677f475ebab3cfafe66c6b5b_226) | | | [Other Noninterest Income and Other Noninterest Expense](#i90d310f8677f475ebab3cfafe66c6b5b_283) | | | [207](#i90d310f8677f475ebab3cfafe66c6b5b_283) | | |
| [Intangible Assets](#i90d310f8677f475ebab3cfafe66c6b5b_229) | | | [168](#i90d310f8677f475ebab3cfafe66c6b5b_229) | | | [Earnings Per Share](#i90d310f8677f475ebab3cfafe66c6b5b_286) | | | [208](#i90d310f8677f475ebab3cfafe66c6b5b_286) | | |
| [Variable Interest Entities](#i90d310f8677f475ebab3cfafe66c6b5b_232) | | | [169](#i90d310f8677f475ebab3cfafe66c6b5b_232) | | | [Fair Value Measurements](#i90d310f8677f475ebab3cfafe66c6b5b_289) | | | [209](#i90d310f8677f475ebab3cfafe66c6b5b_289) | | |
| [Other Assets](#i90d310f8677f475ebab3cfafe66c6b5b_244) | | | [180](#i90d310f8677f475ebab3cfafe66c6b5b_244) | | | [Business Segments](#i90d310f8677f475ebab3cfafe66c6b5b_298) | | | [221](#i90d310f8677f475ebab3cfafe66c6b5b_298) | | |
| [Short-Term Borrowings](#i90d310f8677f475ebab3cfafe66c6b5b_247) | | | [181](#i90d310f8677f475ebab3cfafe66c6b5b_247) | | | | | | | | |
| AFS: Available-For-Sale | | | IRC: Internal Revenue Code | | |
| ALCO: Asset Liability Management Committee | | | IRLC: Interest Rate Lock Commitment | | |
| CARES: Coronavirus Aid, Relief and Economic Security | | | NAV: Net Asset Value | | |
| CD: Certificate of Deposit | | | NM: Not Meaningful | | |
| C&I: Commercial and Industrial | | | OTTI: Other-Than-Temporary Impairment | | |
| DCF: Discounted Cash Flow | | | PCD: Purchased Credit Deteriorated | | |
| DTCC: Depository Trust & Clearing Corporation | | | PPP: Paycheck Protection Program | | |
| DTI: Debt-to-Income Ratio | | | PSA: Performance Share Award | | |
| FDIC: Federal Deposit Insurance Corporation | | | SAR: Stock Appreciation Right | | |
| FINRA: Financial Industry Regulatory Authority | | | TDR: Troubled Debt Restructuring | | |
| FNMA: Federal National Mortgage Association | | | TILA: Truth in Lending Act | | |
| FOMC: Federal Open Market Committee | | | TRA: Tax Receivable Agreement | | |
| FTS: Fifth Third Securities, Inc. | | | U.S. GAAP: United States Generally Accepted Accounting | | |
| GNMA: Government National Mortgage Association | | | VA: United States Department of Veterans Affairs | | |
| HTM: Held-To-Maturity | | | VRDN: Variable Rate Demand Note | | |
An excerpt. Shown here: 40 of 55 rewritten, all 36 added and all 33 removed. The counts are complete. For every sentence, read Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES in the FY2022 filing and the FY2021 filing.
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
1,496 rewritten, 487 added, 475 removed, 2,073 unchanged
[Table of [removed: Contents](#i90d310f8677f475ebab3cfafe66c6b5b_49)][added: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)]
We have audited the accompanying consolidated balance sheets of Fifth Third Bancorp and subsidiaries (the “Bancorp”) as of December 31, [removed: 2021] [added: 2022] and [removed: 2020,] [added: 2021,] the related consolidated statements of income, comprehensive income, changes in equity, and cash flows for each of the three years in the period ended December 31, [removed: 2021,] [added: 2022,] and the related notes (collectively referred to as the “financial statements”).
In our opinion, the financial statements present fairly, in all material respects, the financial position of the Bancorp as of December 31, [removed: 2021] [added: 2022] and [removed: 2020,] [added: 2021,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2021,] [added: 2022,] in conformity with accounting principles generally accepted in the United States of America.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Bancorp’s internal control over financial reporting as of December 31, [removed: 2021,] [added: 2022,] based on criteria established in Internal Control—Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission and our report dated February [removed: 25, 2022] [added: 24, 2023] expressed an unqualified opinion on the Bancorp’s internal control over financial reporting.
[removed: Change] [added: | Impact of cumulative effect of change] in [removed: Accounting Principle][added: accounting principle | | | | | | | | | | | | (472) | | | | | | | | | (472) | | |]
Qualitative factors are used to capture characteristics in the portfolio that impact expected credit losses but that are not fully captured within the Bancorp’s [removed: quantitative] [added: expected credit loss] models.
At December 31, [removed: 2021,] [added: 2022,] the key qualitative factors included adjustments [added: to the expected credit losses on the commercial loan portfolio] associated with the current economic [removed: environment and the COVID-19 pandemic.][added: environment.]
The ALLL for the commercial portfolio segment was $1.1 billion at December 31, [removed: 2021,] [added: 2022,] which includes adjustments for the qualitative factors noted above.
- We tested the completeness and accuracy and evaluated the relevance of the key data used as inputs to the [removed: direct impact] qualitative adjustment estimation process, including:
- With the assistance of our credit specialists, we [removed: evaluated the methodology and] tested the mathematical accuracy of the underlying support used as a basis for the qualitative adjustments.
[removed: February 25, 2022][added: | | | | 2022 | | | | | | | | | | | |]
| As of December 31 ($ in millions, except share data) | | | [removed: 2021] [added: 2022] | | | [removed: 2020] [added: 2021] | | |
| Cash and due from banks | | | [removed: $] [added: $] | [removed: 2,994] [added: 2,994] | | [removed: 3,147] [added: 2,994] | | | [added: — | | | — | | | 2,994 | | |]
| Other short-term [removed: investments*(a)*] [added: investments] | | | [removed: 34,572] [added: 34,572] | | | [removed: 33,399] [added: 34,572] | | | [added: — | | | — | | | 34,572 | | |]
| Available-for-sale debt and other securities*(b)* | | | [removed: 38,110] [added: 51,503] | | | [removed: 37,513] [added: 38,110] | | |
| Held-to-maturity securities*(c)* | | | [removed: 8] [added: 5] | | | [removed: 11] [added: 8] | | |
| Trading debt securities | | | [removed: 512] [added: 414] | | | [removed: 560] [added: 512] | | |
| Equity securities | | | [removed: 376] [added: 317] | | | [removed: 313] [added: 376] | | |
| Loans and leases held for sale*(d)* | | | [removed: 4,415] [added: 1,007] | | | [removed: 4,741] [added: 4,415] | | |
| Portfolio loans and leases*(a)(e)* | | | [removed: 112,050] [added: 121,480] | | | [removed: 108,782] [added: 112,050] | | |
| Allowance for loan and lease losses*(a)* | | | [removed: (1,892)] [added: (2,194)] | | | [removed: (2,453)] [added: (1,892)] | | |
| Portfolio loans and leases, net | | | [removed: 110,158] [added: 119,286] | | | [removed: 106,329] [added: 110,158] | | |
| Bank premises and equipment*(f)* | | | [removed: 2,120] [added: 2,187] | | | [removed: 2,088] [added: 2,120] | | |
| Operating lease equipment | | | [removed: 616] [added: 627] | | | [removed: 777] [added: 616] | | |
| Goodwill | | | [removed: 4,514] [added: 4,915] | | | [removed: 4,258] [added: 4,514] | | |
| Intangible assets | | | [removed: 156] [added: 169] | | | [removed: 139] [added: 156] | | |
| Servicing rights | | | [removed: 1,121] [added: —] | | | [removed: 656] [added: —] | | | [added: 1,121 | | | 1,121 | | |]
| Other assets*(a)* | | | [removed: 11,444] [added: 13,459] | | | [removed: 10,749] [added: 11,444] | | |
| Total Assets | | | $ | [removed: 211,116] [added: 207,452] | | [removed: 204,680] [added: 211,116] | | |
| Noninterest-bearing deposits | | | $ | [removed: 65,088] [added: 53,125] | | [removed: 57,711] [added: 65,088] | | |
| Interest-bearing [removed: deposits*(g)*] [added: deposits] | | | [removed: 104,236] [added: 110,565] | | | [removed: 101,370] [added: 104,236] | | |
| Total deposits | | | [removed: 169,324] [added: 163,690] | | | [removed: 159,081] [added: 169,324] | | |
| Federal funds purchased | | | [removed: 281] [added: 281] | | | [removed: 300] [added: 281] | | | [added: — | | | — | | | 281 | | |]
| Other short-term borrowings | | | [removed: 980] [added: 980] | | | [removed: 1,192] [added: —] | | | [added: 980 | | | — | | | 980 | | |]
| Accrued taxes, interest and expenses | | | [removed: 2,233] [added: 1,822] | | | [removed: 2,614] [added: 2,233] | | |
| Other liabilities*(a)* | | | [removed: 4,267] [added: 5,881] | | | [removed: 3,409] [added: 4,267] | | |
| Long-term debt*(a)* | | | [removed: 11,821] [added: 13,714] | | | [removed: 14,973] [added: 11,821] | | |
| Total Liabilities | | | $ | [removed: 188,906] [added: 190,125] | | [removed: 181,569] [added: 188,906] | | |
| Common [removed: stock*(h)*] [added: stock*(g)*] | | | $ | 2,051 | | 2,051 | | |
| Preferred [removed: stock*(i)*] [added: stock*(h)*] | | | 2,116 | | | 2,116 | | |
These considerations inherently require significant management judgment to determine the appropriate factors to be considered and the extent of their impact on the ALLL estimate.
When evaluating the adequacy of allowances, consideration is given to the effect that changing economic conditions may have on the Bancorp’s customers.
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
Overall, the collective evaluation process requires significant management judgment when determining the estimation methodology and inputs into the models, as well as in evaluating the reasonableness of the modeled results and the appropriateness of qualitative adjustments.
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
| Series L ($1,125.00 per share) | | | | | | | | | | | | (16) | | | | | | | | | (16) | | |
| Balance at December 31, 2021 | | | $ | 2,051 | | 2,116 | | | 3,624 | | | 20,236 | | | 1,207 | | | (7,024) | | | 22,210 | | |
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
| Cash dividends declared: | | | | | | | | | | | | | | | | | | | | | | | |
| Preferred stock:*(a)* | | | | | | | | | | | | | | | | | | | | | | | |
| Series J ($1,249.19 per share) | | | | | | | | | | | | (15) | | | | | | | | | (15) | | |
| Balance at December 31, 2022 | | | $ | 2,051 | | 2,116 | | | 3,684 | | | 21,689 | | | (5,110) | | | (7,103) | | | 17,327 | | |
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
| Provision for (benefit from) credit losses | | | 563 | | | (377) | | | 1,097 | | |
| Net cash paid on acquisitions | | | (917) | | | (297) | | | (23) | | |
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
The Bancorp places loans and leases on nonaccrual status when full repayment of principal and interest is not expected, unless the loan or lease is well-secured and in the process of collection.
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
previously accrued and unpaid interest is reversed against income.
The Bancorp utilizes the following policies to determine when full repayment of principal and interest on a loan or lease is not expected:
The Bancorp maintains a reserve for the portion of accrued interest receivable that it estimates will be uncollectible, at the portfolio level, for residential mortgage loans which are past due 90 days or more and on accrual status.
This reserve is recorded as a component of other assets on the Bancorp’s Consolidated Balance Sheets, consistent with the classification of the related accrued interest receivable.
- Credit card accounts that have been modified in a TDR are placed on nonaccrual status at the time of the modification.
Subsequent to the modification, accounts are placed on nonaccrual status when required payments become past due 90 days or more.
- Indirect secured consumer loans and other consumer loans are generally placed on nonaccrual status when principal or interest becomes past due 90 days or more.
In certain circumstances when the remaining amortized cost basis of a nonaccrual loan or lease is deemed to be fully collectible, the Bancorp may utilize the cash basis method to account for interest payments received on a nonaccrual loan or lease.
The Bancorp records a charge-off to the ALLL when all or a portion of a loan or lease is deemed to be uncollectible, after considering the net realizable value of any underlying collateral.
The Bancorp records charge-offs on consumer loans in accordance with applicable regulatory guidelines, which are primarily based on a loan’s delinquency status.
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
However, the Bancorp does record a reserve for the portion of accrued interest receivable that it expects to be uncollectible.
For collectively evaluated loans and leases, the Bancorp uses models to forecast expected credit losses based on the probability of a loan or lease defaulting, the expected balance at the estimated date of default and the expected loss percentage given a default.
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
as geopolitical events, natural disasters and their effects on regional borrowers, and changes in product structures.
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
As discussed in Note 1 to the Consolidated Financial Statements, the Bancorp has changed its method of accounting for financial assets measured at amortized cost in 2020 due to adoption of ASU 2016-13, *Financial Instruments - Credit Losses (Topic 326): Measurement of Credit Losses on Financial Instruments.*
For loans that are not individually evaluated, the Bancorp develops its estimate of expected credit losses using quantitative models, subject to certain qualitative adjustments.
The expected credit loss models consider historical credit loss experience, current market and economic conditions, and forecasted changes in market and economic conditions to the extent such forecasts are considered reasonable and supportable.
These qualitative factors primarily address the incremental loss exposures relating to commercial borrowers in certain industries which have been severely impacted by the COVID-19 pandemic or are otherwise experiencing prolonged distress.
| | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- |
*(g)Includes $351 of interest checking deposits held for sale at December 31, 2020.*
| | | | Bancorp Shareholders’ Equity | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Balance at December 31, 2018 | | | $ | 2,051 | | 1,331 | | | 2,873 | | | 16,578 | | | (112) | | | (6,471) | | | 16,250 | | | — | | | 16,250 | | |
| Impact of cumulative effect of change in accounting principle | | | | | | | | | | | | 10 | | | | | | | | | 10 | | | | | | 10 | | |
| Balance at January 1, 2019 | | | $ | 2,051 | | 1,331 | | | 2,873 | | | 16,588 | | | (112) | | | (6,471) | | | 16,260 | | | — | | | 16,260 | | |
| Other*(b)* ($30.00 per share) | | | | | | | | | | | | (6) | | | | | | | | | (6) | | | | | | (6) | | |
| Conversion of outstanding preferred stock issued by a Bancorp subsidiary | | | | | | 197 | | | | | | | | | | | | | | | 197 | | | (197) | | | — | | |
| Impact of MB Financial, Inc. acquisition | | | | | | | | | 712 | | | | | | | | | 2,447 | | | 3,159 | | | 197 | | | 3,356 | | |
| Impact of cumulative effect of change in accounting principle | | | | | | | | | | | | (472) | | | | | | | | | (472) | | | | | | (472) | | |
| Balance at December 31, 2020 | | | $ | 2,051 | | 2,116 | | | 3,635 | | | 18,384 | | | 2,601 | | | (5,676) | | | 23,111 | | |
*(b)Dividends declared for Perpetual Preferred Stock, Series C, of MB Financial, Inc., previously a subsidiary of the Bancorp.*
| Gain on sale of Worldpay, Inc. shares | | | — | | | — | | | (562) | | |
| Other | | | (99) | | | (47) | | | (58) | | |
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
Updates to Significant Accounting and Reporting Policies
In conjunction with the prospective adoption of ASU 2016-13 and ASU 2017-04 on January 1, 2020, the Bancorp updated its accounting and reporting policies for investment securities, portfolio loans and leases, the ALLL, the reserve for unfunded commitments and goodwill.
The accounting and reporting policies for these sections for periods prior to January 1, 2020 are provided in the Significant Accounting and Reporting Policies Applicable Prior to January 1, 2020 section below.
Further, for loans and leases that were part of the Bancorp’s COVID-19 customer relief programs, the Bancorp has elected certain accounting relief provisions that were provided by the FASB and/or various national banking regulatory agencies.
Refer to the Regulatory Developments Related to the COVID-19 Pandemic section for additional information.
Trading
The Bancorp believes the cost recovery method is appropriate for nonaccrual commercial loans and nonaccrual credit card loans because the assessment of collectability of the remaining amortized cost basis of these loans involves a high degree of subjectivity and uncertainty due to the nature or absence of underlying collateral.
Nonaccrual residential mortgage loans and other nonaccrual consumer loans are generally accounted for on the cash basis method.
The Bancorp believes the cash basis method is appropriate for nonaccrual residential mortgage and other nonaccrual consumer loans because such loans have generally been written down to estimated collateral values and the collectability of the remaining investment involves only an assessment of the fair value of the underlying collateral, which can be measured more objectively with a lesser degree of uncertainty than assessments of typical commercial loan collateral.
Residential mortgage loans, home equity loans and lines of credit and credit card loans that have principal and interest payments that have become past due 180 days are assessed for a charge-off to the ALLL, unless such loans are both well-secured and in the process of collection.
Home equity loans and lines of credit are also assessed for charge-off to the ALLL when such loans or lines of credit have become past due 120 days if the senior lien is also 120 days past due, unless such loans are both well-secured and in the process of collection.
Automobile and other consumer loans that have principal and interest payments that have become past due 120 days are assessed for a charge-off to the ALLL, unless such loans are both well-secured and in the process of collection.
Loans discharged in a Chapter 7 bankruptcy and not reaffirmed by the borrower are classified as collateral-dependent TDRs and placed on nonaccrual status regardless of the
borrower’s payment history or capacity to repay in the future.
In certain cases, commercial TDRs on nonaccrual status may be accounted for using the cash basis method for income recognition, provided that full repayment of principal under the modified terms of the loan is reasonably assured.
Residential mortgage loans that were restructured after receiving a forbearance related to the COVID-19 pandemic but that were not classified as a TDR as a result of the CARES Act are placed on nonaccrual status if they subsequently become past due 90 days unless the loan is both well-secured and in the process of collection, consistent with the Bancorp’s treatment of residential mortgage loan TDRs which subsequently become past due.
Contractual terms are adjusted for expected prepayments but are not extended for expected extensions,
These include adjustments
included in other noninterest income in the Consolidated Statements of Income at the time of sale.
or circumstances indicate that there may be impairment.
An excerpt. Shown here: 40 of 1,496 rewritten, 40 of 487 added and 40 of 475 removed. The counts are complete. For every sentence, read Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA in the FY2022 filing and the FY2021 filing.
Item 9A. CONTROLS AND PROCEDURES
12 rewritten, 5 added, 4 removed, 28 unchanged
The Bancorp’s management assessed the effectiveness of the Bancorp’s internal control over financial reporting as of December 31, [removed: 2021.][added: 2022.]
Management’s assessment is based on the criteria established in the *Internal Control — Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission and was designed to provide reasonable assurance that the Bancorp maintained effective internal control over financial reporting as of December 31, [removed: 2021.][added: 2022.]
Based on this assessment, management believes that the Bancorp maintained effective internal control over financial reporting as of December 31, [removed: 2021.][added: 2022.]
The Bancorp’s independent registered public accounting firm, that audited the Bancorp’s consolidated financial statements included in this annual report, has issued an audit report on our internal control over financial reporting as of December 31, [removed: 2021.][added: 2022.]
This report appears on page [removed: [226](#i90d310f8677f475ebab3cfafe66c6b5b_310)] [added: [216](#i48540c50bc474a4186cf9dc1957cda5d_307)] of the annual report.
| [removed: Chairman] [added: President] and Chief Executive Officer | | | | | | Executive Vice President and Chief Financial Officer | | |
[removed: *225] [added: *215] Fifth Third Bancorp*
[Table of [removed: Contents](#i90d310f8677f475ebab3cfafe66c6b5b_49)][added: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)]
We have audited the internal control over financial reporting of Fifth Third Bancorp and subsidiaries (the “Bancorp”) as of December 31, [removed: 2021,] [added: 2022,] based on criteria established in *Internal Control — Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the Bancorp maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2021,] [added: 2022,] based on criteria established in *Internal Control — Integrated Framework (2013)* issued by COSO.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated financial statements as of and for the year ended December 31, [removed: 2021,] [added: 2022,] of the Bancorp and our report dated February [removed: 25, 2022] [added: 24, 2023] expressed an unqualified opinion on those consolidated financial statements.
[removed: *226] [added: *216] Fifth Third Bancorp*
| /s/ Timothy N. Spence | | | | | | /s/ James C. Leonard | | |
| Timothy N. Spence | | | | | | James C. Leonard | | |
| February 24, 2023 | | | | | | February 24, 2023 | | |
February 24, 2023
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
| /s/ Greg D. Carmichael | | | | | | /s/ James C. Leonard | | |
| Greg D. Carmichael | | | | | | James C. Leonard | | |
| February 25, 2022 | | | | | | February 25, 2022 | | |
February 25, 2022
Item 9B. OTHER INFORMATION
0 rewritten, 1 added, 2 removed, 0 unchanged
None.
On February 22, 2022, the Board of Directors of the Bancorp approved an annual base salary of $500,000, a variable compensation target of $500,000 and a long-term incentive target of $600,000 for Lars Anderson’s 2022 fiscal year compensation.
Mr. Anderson will continue to serve as Executive Vice President & Vice Chairman of Commercial Banking, Strategic Growth Initiatives.
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
3 rewritten, 0 added, 0 removed, 3 unchanged
The information required by this item concerning Directors and the nomination process is incorporated herein by reference under the caption “Election of Directors” of the Bancorp’s Proxy Statement for the [removed: 2022] [added: 2023] Annual Meeting of Shareholders.
The information required by this item concerning the Audit Committee and Code of Business Conduct and Ethics is incorporated herein by reference under the captions “Corporate Governance” and “Board of Directors, Its Committees, Meetings, and Functions” of the Bancorp’s Proxy Statement for the [removed: 2022] [added: 2023] Annual Meeting of Shareholders.
The information required by this item concerning Delinquent Section 16(a) Reports is incorporated herein by reference under the caption “Delinquent Section 16(a) Reports” of the Bancorp’s Proxy Statement for the [removed: 2022] [added: 2023] Annual Meeting of Shareholders.
Item 11. EXECUTIVE COMPENSATION
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this item is incorporated herein by reference under the captions “Compensation Discussion and Analysis,” “Compensation of Named Executive Officers,” “Board of Directors Compensation,” “CEO Pay Ratio,” “Human Capital and Compensation Committee Report” and “Compensation Committee Interlocks and Insider Participation” of the Bancorp’s Proxy Statement for the [removed: 2022] [added: 2023] Annual Meeting of Shareholders.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
1 rewritten, 0 added, 0 removed, 1 unchanged
Security ownership information of certain beneficial owners and management is incorporated herein by reference under the captions “Certain Beneficial Owners,” “Election of Directors,” “Compensation Discussion and Analysis,” “Board of Directors Compensation,” and “Compensation of Named Executive Officers” of the Bancorp’s Proxy Statement for the [removed: 2022] [added: 2023] Annual Meeting of Shareholders.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this item is incorporated herein by reference under the captions “Certain Transactions”, “Election of Directors”, “Corporate Governance” and “Board of Directors, Its Committees, Meetings, and Functions” of the Bancorp’s Proxy Statement for the [removed: 2022] [added: 2023] Annual Meeting of Shareholders.
Item 14. PRINCIPAL ACCOUNTING FEES AND SERVICES
3 rewritten, 0 added, 0 removed, 2 unchanged
The information required by this item is incorporated herein by reference under the caption “Principal Independent External Audit Firm Fees” of the Bancorp’s Proxy Statement for the [removed: 2022] [added: 2023] Annual Meeting of Shareholders.
[removed: *227] [added: *217] Fifth Third Bancorp*
[Table of [removed: Contents](#i90d310f8677f475ebab3cfafe66c6b5b_49)][added: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)]
Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES
105 rewritten, 8 added, 8 removed, 56 unchanged
| [removed: Fifth] [added: [Fifth] Third Bancorp and Subsidiaries Consolidated Financial [removed: Statements] [added: Statements](#i48540c50bc474a4186cf9dc1957cda5d_181)] | | | [removed: [126](#i90d310f8677f475ebab3cfafe66c6b5b_172)] [added: [120](#i48540c50bc474a4186cf9dc1957cda5d_181)] | | |
| [removed: Notes] [added: [Notes] to Consolidated Financial [removed: Statements] [added: Statements](#i48540c50bc474a4186cf9dc1957cda5d_199)] | | | [removed: [132](#i90d310f8677f475ebab3cfafe66c6b5b_190)] [added: [126](#i48540c50bc474a4186cf9dc1957cda5d_199)] | | |
| 3.2 | | | [Regulations of Fifth Third Bancorp, as Amended as [removed: of March 23, 2020.] [added: of](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm) [April 12](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)[, 202](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)[2](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)[.] Incorporated by reference to Exhibit 3.2 to the [removed: Registrant’s Current Report] [added: Registrant’s](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm) [Quarte](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)[rly](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm) [Report] on [removed: Form 8-K filed] [added: Form](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm) [10-Q](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm) [filed] with the SEC on [removed: March 24, 2020.](https://www.sec.gov/Archives/edgar/data/35527/000119312520083207/d874033dex32.htm)] [added: M](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)[ay](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm) [](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)[9](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)[, 202](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)[2](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)[.](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)] | | |
| [removed: 4.7] [added: 4.10] | | | [Global Security dated as of [removed: March 7, 2012] [added: November 20, 2013] representing Fifth Third Bancorp’s $500,000,000 [removed: 3.500% Senior] [added: 4.30% Subordinated] Notes due [removed: 2022.] [added: 2024.] Incorporated by reference to Exhibit [removed: 4.2 to] [added: 4.1 of] the Registrant’s Current Report on Form [removed: 8-K/A] [added: 8-K] filed with the SEC on [removed: March 7, 2012.](https://www.sec.gov/Archives/edgar/data/35527/000119312512100271/d312151dex42.htm)] [added: November 20, 2013.](https://www.sec.gov/Archives/edgar/data/35527/000119312513447864/d629513dex41.htm) (2)] | | |
| [removed: 4.8] [added: 4.7] | | | [Deposit Agreement dated as of May 16, 2013, between Fifth Third Bancorp, as issuer, Wilmington Trust, National Association, as depositary and calculation agent, American Stock Transfer & Trust Company, LLC, as transfer agent and registrar, and the holders from time to time of the depositary receipts issued thereunder. Incorporated by reference to Exhibit 4.3 of the Registrant’s Current Report on Form 8-K filed with the SEC on May 16, 2013.](https://www.sec.gov/Archives/edgar/data/35527/000119312513223516/d540151dex43.htm) | | |
| [removed: 4.9] [added: 4.8] | | | [Form of Certificate Representing the 5.10% Fixed-to-Floating Rate Non-Cumulative Perpetual Preferred Stock, Series H, of Fifth Third Bancorp. Incorporated by reference to Exhibit 4.2 of the Registrant’s Current Report on Form 8-K filed with the SEC on May 16, 2013.](https://www.sec.gov/Archives/edgar/data/35527/000119312513223516/d540151dex42.htm) | | |
| [removed: 4.10] [added: 4.9] | | | [Form of Depositary Receipt for the 5.10% Fixed-to-Floating Rate Non-Cumulative Perpetual Preferred Stock, Series H, of Fifth Third Bancorp. Incorporated by reference as Exhibit A to Exhibit 4.3 of the Registrant’s Current Report on Form 8-K filed with the SEC on May 16, 2013.](https://www.sec.gov/Archives/edgar/data/35527/000119312513223516/d540151dex43.htm) | | |
| [removed: 4.11] [added: 4.25] | | | [removed: [Global Security dated as] [added: [Form] of [removed: November 20, 2013 representing Fifth Third Bancorp’s $500,000,000 4.30% Subordinated] [added: 3.650% Senior] Notes due 2024. Incorporated by reference to Exhibit [removed: 4.1 of] [added: 4.2 to] the Registrant’s Current Report on Form 8-K filed with the SEC on [removed: November 20, 2013.](https://www.sec.gov/Archives/edgar/data/35527/000119312513447864/d629513dex41.htm) (2)] [added: January 25, 2019.](https://www.sec.gov/Archives/edgar/data/35527/000119312519017133/d677927dex42.htm)] | | |
| [removed: 4.12] [added: 4.11] | | | [Deposit Agreement dated December 9, 2013, between Fifth Third Bancorp, as issuer, Wilmington Trust, National Association, as depositary and calculation agent, American Stock Transfer & Trust Company, LLC as transfer agent and registrar, and the holders from time to time of the depositary receipts issued thereunder. Incorporated by reference to Exhibit 4.3 of the Registrant’s Current Report on Form 8-K filed with the SEC on December 9, 2013.](https://www.sec.gov/Archives/edgar/data/35527/000119312513465956/d640696dex43.htm) | | |
| [removed: 4.13] [added: 4.12] | | | [Form of Certificate Representing the 6.625% Fixed-to-Floating Rate Non-Cumulative Perpetual Preferred Stock, Series I, of Fifth Third Bancorp. [removed: Incorporated by] [added: Incorporated](https://www.sec.gov/Archives/edgar/data/35527/000119312513465956/d640696dex42.htm) [](https://www.sec.gov/Archives/edgar/data/35527/000119312513465956/d640696dex42.htm)[by] reference to Exhibit 4.2 of the Registrant’s Current Report on Form 8-K filed with the SEC on December 9, 2013.](https://www.sec.gov/Archives/edgar/data/35527/000119312513465956/d640696dex42.htm) | | |
| [removed: 4.14] [added: 4.13] | | | [Form of Depositary Receipt for the 6.625% Fixed-to-Floating Rate Non-Cumulative Perpetual Preferred Stock, Series I, of Fifth Third Bancorp. Incorporated by reference as Exhibit A to Exhibit 4.3 of the Registrant’s Current Report on Form 8-K filed with the SEC on December 9, 2013.](https://www.sec.gov/Archives/edgar/data/35527/000119312513465956/d640696dex43.htm) | | |
| [removed: 4.15] [added: 4.14] | | | [Deposit Agreement dated June 5, 2014, among Fifth Third Bancorp, as issuer, Wilmington Trust, National Association, as depositary and calculation agent, American Stock Transfer & Trust Company, LLC as transfer agent and registrar, and the holders from time to time of the depositary receipts issued thereunder. Incorporated by reference to Exhibit 4.3 of the Registrant’s Current Report on Form 8-K filed with the SEC on June 5, 2014.](https://www.sec.gov/Archives/edgar/data/35527/000119312514226503/d739691dex43.htm) | | |
| [removed: 4.16] [added: 4.15] | | | [Form of Certificate Representing the 4.90% Fixed-to-Floating Rate Non-Cumulative Perpetual Preferred Stock, Series J, of Fifth Third Bancorp. Incorporated by reference to Exhibit 4.2 of the Registrant’s Current Report on Form 8-K filed with the SEC on June 5, 2014.](https://www.sec.gov/Archives/edgar/data/35527/000119312514226503/d739691dex42.htm) | | |
| [removed: 4.17] [added: 4.16] | | | [Form of Depositary Receipt for the 4.90% Fixed-to-Floating Rate Non-Cumulative Perpetual Preferred Stock, Series J, of Fifth Third Bancorp. Incorporated by reference as Exhibit A to Exhibit 4.3 of the Registrant’s Current Report on Form 8-K filed with the SEC on June 5, 2014.](https://www.sec.gov/Archives/edgar/data/35527/000119312514226503/d739691dex43.htm) | | |
| [removed: 4.18] [added: 4.17] | | | [Third Supplemental Indenture dated as of February 28, 2014 between Fifth Third Bancorp and Wilmington Trust Company, as Trustee, to the Indenture for Senior Debt Securities dated as of April 30, 2008 between Fifth Third Bancorp and the Trustee. Incorporated by reference to Exhibit 4.1 of the Registrant’s Current Report on Form 8-K filed with the SEC on February 28, 2014.](https://www.sec.gov/Archives/edgar/data/35527/000119312514075106/d683662dex41.htm) | | |
| [removed: 4.19] [added: 4.18] | | | [Fourth Supplemental Indenture dated as of July 27, 2015 between Fifth Third Bancorp and Wilmington Trust Company, as Trustee, to the Indenture for Senior Debt Securities dated as of April 30, 2008 between Fifth Third Bancorp and the Trustee. Incorporated by reference to Exhibit 4.1 to the Registrant’s Current Report on Form 8-K filed with the SEC on July 27, 2015.](https://www.sec.gov/Archives/edgar/data/35527/000119312515263455/d31544dex41.htm) | | |
| [removed: 4.20] [added: 4.19] | | | [Fifth Supplemental Indenture dated as of June 15, 2017 between Fifth Third Bancorp and Wilmington Trust Company, as Trustee, to the Indenture for Senior Debt Securities dated as of April 30, 2008 between Fifth Third Bancorp and the Trustee. Incorporated by reference to Exhibit 4.1 to the Registrant’s Current Report on Form 8-K filed with the SEC on June 15, 2017.](https://www.sec.gov/Archives/edgar/data/35527/000119312517204099/d409073dex41.htm) | | |
[removed: *228] [added: *218] Fifth Third Bancorp*
[Table of [removed: Contents](#i90d310f8677f475ebab3cfafe66c6b5b_49)][added: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)]
| 4.21 | | | [Form of [removed: 2.600%] [added: 3.950%] Senior Notes due [removed: 2022.] [added: 2028.] Incorporated by reference to Exhibit 4.2 to the Registrant’s Current Report on Form 8-K filed with the SEC on [removed: June 15, 2017.](https://www.sec.gov/Archives/edgar/data/35527/000119312517204099/d409073dex42.htm)] [added: March 14, 2018](https://www.sec.gov/Archives/edgar/data/35527/000119312518081489/d507686dex42.htm).] | | |
| [removed: 4.22] [added: 4.20] | | | [Sixth Supplemental Indenture dated as of March 14, 2018 between Fifth Third Bancorp and Wilmington Trust Company, as Trustee, to the Indenture for Senior Debt Securities dated as of April 30, 2008 between Fifth Third Bancorp and the Trustee. Incorporated by reference to Exhibit 4.1 to the Registrant’s Current Report on Form 8-K filed with the SEC on March 14, 2018.](https://www.sec.gov/Archives/edgar/data/35527/000119312518081489/d507686dex41.htm) | | |
| [removed: 4.23] [added: 4.32] | | | [Form of [removed: 3.950%] [added: 2.375%] Senior Notes due [removed: 2028.] [added: 2025.] Incorporated by reference to Exhibit 4.2 to the Registrant’s Current Report on Form 8-K filed with the SEC on [removed: March 14, 2018.](https://www.sec.gov/Archives/edgar/data/35527/000119312518081489/d507686dex42.htm)] [added: October 28, 2019.](https://www.sec.gov/Archives/edgar/data/35527/000119312519276267/d820639dex42.htm)] | | |
| [removed: 4.24] [added: 4.22] | | | [Seventh Supplemental Indenture dated as of June 5, 2018 between Fifth Third Bancorp and Wilmington Trust Company, as Trustee, to the Indenture for Senior Debt Securities dated as of April 30, 2008 between Fifth Third Bancorp and the Trustee. Incorporated by reference to Exhibit 4.1 to the Registrant’s Current Report on Form 8-K filed with the SEC on June 5, 2018.](https://www.sec.gov/Archives/edgar/data/35527/000119312518184483/d472226dex41.htm) | | |
| [removed: 4.25] [added: 4.23] | | | [Amendment dated as of August 31, 2018 to Seventh Supplemental Indenture dated as of June 5, 2018 between Fifth Third Bancorp and Wilmington Trust Company, as Trustee, to the Indenture for Senior Debt Securities dated as of April 30, 2008 between Fifth Third Bancorp and the Trustee. Incorporated by reference to Exhibit 4.1 to the Registrant’s Quarterly Report on Form 10-Q for the fiscal quarter ended September 30, 2018.](https://www.sec.gov/Archives/edgar/data/35527/000119312518319637/d634357dex41.htm) | | |
| [removed: 4.26] [added: 4.24] | | | [Eighth Supplemental Indenture dated as of January 25, 2019 between Fifth Third Bancorp and Wilmington Trust Company, as Trustee, to the Indenture for Senior Debt Securities dated as of April 30, 2008 between Fifth Third Bancorp and the Trustee. Incorporated by reference to Exhibit 4.1 to the Registrant’s Current Report on Form 8-K filed with the SEC on January 25, 2019.](https://www.sec.gov/Archives/edgar/data/35527/000119312519017133/d677927dex41.htm) | | |
| [removed: 4.27] [added: 4.34] | | | [Form of [removed: 3.650%] [added: 1.625%] Senior Notes due [removed: 2024.] [added: 2023.] Incorporated by reference to Exhibit 4.2 to the Registrant’s Current Report on Form 8-K filed with the SEC on [removed: January 25, 2019.](https://www.sec.gov/Archives/edgar/data/35527/000119312519017133/d677927dex42.htm)] [added: May 5, 2020.](https://www.sec.gov/Archives/edgar/data/35527/000119312520133774/d849424dex42.htm)] | | |
| [removed: 4.28] [added: 4.26] | | | [Second Amended and Restated Deposit Agreement, dated as of August 26, 2019, among Fifth Third Bancorp, as issuer, and American Stock Transfer & Trust Company, LLC, as depositary, transfer agent and registrar, and the holders from time to time of the depositary receipts issued. Incorporated by reference to Exhibit 4.1 to the Registrant’s Form 8-A filed with the SEC on August 26, 2019.](https://www.sec.gov/Archives/edgar/data/35527/000119312519229493/d791174dex41.htm) | | |
| [removed: 4.29] [added: 4.27] | | | [Form of depositary receipt representing the Depositary Shares (included as Exhibit A to Exhibit 4.34). Incorporated by reference to Exhibit 4.1 to the Registrant’s Form 8-A filed with the SEC on August 26, 2019.](https://www.sec.gov/Archives/edgar/data/35527/000119312519229493/d791174dex41.htm) | | |
| [removed: 4.30] [added: 4.28] | | | [Deposit Agreement dated September 17, 2019, between Fifth Third Bancorp, as issuer, American Stock Transfer & Trust Company, LLC, as depositary, transfer agent and registrar, relating to receipts, Depositary Shares and related 4.95% Non-Cumulative Perpetual Preferred Stock, Series K. Incorporated by reference to Exhibit 4.3 to the Registrant’s Current Report on Form 8-K filed with the SEC on September 17, 2019.](https://www.sec.gov/Archives/edgar/data/35527/000119312519246907/d803099dex43.htm) | | |
| [removed: 4.31] [added: 4.29] | | | [Form of Certificate Representing the 4.95% Non-Cumulative Perpetual Preferred Stock, Series K, of Fifth Third Bancorp. Incorporated by reference to Exhibit 4.2 to the Registrant’s Current Report on Form 8-K filed with the SEC on September 17, 2019.](https://www.sec.gov/Archives/edgar/data/35527/000119312519246907/d803099dex42.htm) | | |
| [removed: 4.32] [added: 4.30] | | | [Form of Depositary Receipt for the 4.95% Non-Cumulative Perpetual Preferred Stock, Series K, of Fifth Third Bancorp. Incorporated by reference to Exhibit 4.4 to the Registrant’s Current Report on Form 8-K filed with the SEC on September 17, 2019.](https://www.sec.gov/Archives/edgar/data/35527/000119312519246907/d803099dex44.htm) | | |
| [removed: 4.33] [added: 4.31] | | | [Ninth Supplemental Indenture dated as of October 28, 2019 between Fifth Third Bancorp and Wilmington Trust Company, as Trustee, to the Indenture for Senior Debt Securities dated as of April 30, 2008 between Fifth Third Bancorp and the Trustee. Incorporated by reference to Exhibit 4.1 to the Registrant’s Current Report on Form 8-K filed with the SEC on October 28, 2019.](https://www.sec.gov/Archives/edgar/data/35527/000119312519276267/d820639dex41.htm) | | |
| [removed: 4.34] [added: 4.47] | | | [Form of [removed: 2.375%] [added: 6.361% Fixed Rate/Floating Rate] Senior Notes due [removed: 2025.] [added: 2028.] Incorporated by reference to Exhibit 4.2 to the Registrant’s Current Report on Form 8-K filed with the SEC on October [removed: 28, 2019.](https://www.sec.gov/Archives/edgar/data/35527/000119312519276267/d820639dex42.htm)] [added: 27, 2022.](https://www.sec.gov/Archives/edgar/data/35527/000119312522271002/d354612dex42.htm)] | | |
| [removed: 4.35] [added: 4.33] | | | [Tenth Supplemental Indenture dated as of May 5, 2020 between Fifth Third Bancorp and Wilmington Trust Company, as Trustee, to the Indenture for Senior Debt Securities dated as of April 30, 2008 between Fifth Third Bancorp and the Trustee. Incorporated by reference to Exhibit 4.1 to the Registrant’s Current Report on Form 8-K filed with the SEC on May 5, 2020.](https://www.sec.gov/Archives/edgar/data/35527/000119312520133774/d849424dex41.htm) | | |
| [removed: 4.36] [added: 4.35] | | | [Form of [removed: 1.625%] [added: 2.550%] Senior Notes due [removed: 2023.] [added: 2027.] Incorporated by reference to Exhibit [removed: 4.2] [added: 4.3] to the Registrant’s Current Report on Form 8-K filed with the SEC on May 5, [removed: 2020.](https://www.sec.gov/Archives/edgar/data/35527/000119312520133774/d849424dex42.htm)] [added: 2020.](https://www.sec.gov/Archives/edgar/data/35527/000119312520133774/d849424dex43.htm)] | | |
| [removed: 4.37] [added: 4.43] | | | [Form of [removed: 2.550%] [added: 4.337% Fixed Rate/Floating Rate] Senior Notes due [removed: 2027.] [added: 2033.] Incorporated by reference to Exhibit 4.3 to the Registrant’s Current Report on Form 8-K filed with the SEC on [removed: May 5, 2020.](https://www.sec.gov/Archives/edgar/data/35527/000119312520133774/d849424dex43.htm)] [added: April 25, 2022.](https://www.sec.gov/Archives/edgar/data/35527/000119312522117623/d303267dex43.htm)] | | |
| [removed: 4.38] [added: 4.36] | | | [Form of Certificate Representing the 4.500% Fixed-Rate Reset Non-Cumulative Perpetual Preferred Stock, Series L, of Fifth Third Bancorp. Incorporated by reference to Exhibit 4.2 of the Registrant’s Current Report on Form 8-K filed with the SEC on July 30, 2020.](https://www.sec.gov/Archives/edgar/data/35527/000119312520204323/d935766dex42.htm) | | |
| [removed: 4.39] [added: 4.37] | | | [Deposit Agreement dated July 30, 2020, between Fifth Third Bancorp, as issuer, American Stock Transfer & Trust Company, LLC, as depositary, transfer agent and registrar, and the holders from time to time of depositary receipts issued. Incorporated by reference to Exhibit 4.3 to the Registrant’s Current Report on Form 8-K filed with the SEC on July 30, 2020.](https://www.sec.gov/Archives/edgar/data/35527/000119312520204323/d935766dex43.htm) | | |
| [removed: 4.40] [added: 4.38] | | | [Form of Depositary Receipt for the 4.500% Fixed-Rate Reset Non-Cumulative Perpetual Preferred Stock, Series L, of Fifth Third Bancorp. Incorporated by reference to Exhibit A of Exhibit 4.3 to the Registrant’s Current Report [removed: o](https://www.sec.gov/Archives/edgar/data/35527/000119312520204323/d935766dex43.htm)[n](https://www.sec.gov/Archives/edgar/data/35527/000119312520204323/d935766dex43.htm) [Form] [added: on Form] 8-K filed with the SEC on July 30, 2020.](https://www.sec.gov/Archives/edgar/data/35527/000119312520204323/d935766dex43.htm) | | |
| [removed: 4.41] [added: 4.39] | | | [Eleventh Supplemental Indenture dated as of November 1, 2021 between Fifth Third Bancorp and Wilmington Trust Company, as Trustee, to the Indenture for Senior Debt Securities dated as of April 30, 2008 between Fifth Third Bancorp and the Trustee. Incorporated by reference to Exhibit 4.1 to the Registrant’s Current Report on Form 8-K filed with the SEC on November 1, 2021.](https://www.sec.gov/Archives/edgar/data/0000035527/000119312521315460/d251543dex41.htm) | | |
| [Public Accounting Firm](#i48540c50bc474a4186cf9dc1957cda5d_178) | | | [118](#i48540c50bc474a4186cf9dc1957cda5d_178), [216](#i48540c50bc474a4186cf9dc1957cda5d_307) | | |
| 4.42 | | | [Form of 4.055% Fixed Rate/Floating Rate Senior Notes due 2028. Incorporated by reference to Exhibit 4.2 to the Registrant’s Current Report on Form 8-K filed with the SEC on April 25, 2022.](https://www.sec.gov/Archives/edgar/data/35527/000119312522117623/d303267dex42.htm) | | |
| 4.44 | | | [Thirteenth Supplemental Indenture dated as of July 28, 2022 between Fifth Third Bancorp and Wilmington Trust Company, as Trustee, to the Indenture for Senior Debt Securities dated as of April 30, 2008 between Fifth Third Bancorp and the Trustee, as amended by Article 4 of the Twelfth Supplemental Indenture dated April 25, 2022 between Fifth Third Bancorp and the Trustee. Incorporated by reference to Exhibit 4.1 to the Registrant’s Current Report on Form 8-K filed with the SEC on July 28, 2022.](https://www.sec.gov/Archives/edgar/data/35527/000119312522204836/d387881dex41.htm) | | |
| 4.45 | | | [Form of 4.772% Fixed Rate/Floating Rate Senior Notes due 2030. Incorporated by reference to Exhibit 4.2 to the Registrant’s Current Report on Form 8-K filed with the SEC on July 28, 2022](https://www.sec.gov/Archives/edgar/data/35527/000119312522204836/d387881dex42.htm). | | |
| 4.46 | | | [Fourteenth Supplemental Indenture dated as of October 27, 2022 between Fifth Third Bancorp and Wilmington Trust Company, as Trustee, to the Indenture for Senior Debt Securities dated as of April 30, 2008 between Fifth Third Bancorp and the Trustee, as amended by Article 4 of the Twelfth Supplemental Indenture dated April 25, 2022 between Fifth Third Bancorp and the Trustee. Incorporated by reference to Exhibit 4.1 to the Registrant’s Current Report on Form 8-K filed with the SEC on October 27, 2022.](https://www.sec.gov/Archives/edgar/data/35527/000119312522271002/d354612dex41.htm) | | |
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
| Public Accounting Firm | | | [124](#i90d310f8677f475ebab3cfafe66c6b5b_169), [226](#i90d310f8677f475ebab3cfafe66c6b5b_310) | | |
| 10.64 | | | [2020 Restricted Stock Unit Grant Agreement (for Directors). Incorporated by reference to Exhibit 10.1 to the Registrant’s Quarterly Report on Form 10-Q for the fiscal quarter ended March 31, 2020.](https://www.sec.gov/Archives/edgar/data/35527/000119312520137598/d840512dex101.htm)* | | |
| 10.67 | | | [2021 Restricted Stock Unit Agreement (for Executive Officers). Incorporated by reference to Exhibit 10.65 to the Registrant’s Annual Report on Form 10-K for the fiscal year ended December 31, 2020](https://www.sec.gov/Archives/edgar/data/0000035527/000003552721000100/fitb-12312020xexx1065.htm)[.](https://www.sec.gov/Archives/edgar/data/0000035527/000003552721000100/fitb-12312020xexx1065.htm)[*](https://www.sec.gov/Archives/edgar/data/0000035527/000003552721000100/fitb-12312020xexx1065.htm) | | |
| 10.68 | | | [2021 Stock Appreciation Right Award Agreement (for Executive Officers). Incorporated by reference to Exhibit 10.66 to the Registrant’s Annual Report on Form 10-K for the fiscal year ended December 31, 2020.](https://www.sec.gov/Archives/edgar/data/0000035527/000003552721000100/fitb-12312020xexx1066.htm)[*](https://www.sec.gov/Archives/edgar/data/0000035527/000003552721000100/fitb-12312020xexx1066.htm) | | |
| 10.69 | | | [2021 Restricted Stock Unit Grant Agreement (](https://www.sec.gov/Archives/edgar/data/35527/000003552721000221/a10qfitb-06302021xexx103.htm)[for](https://www.sec.gov/Archives/edgar/data/35527/000003552721000221/a10qfitb-06302021xexx103.htm) [Directors). Incorporated by reference to Exhibit 10.3 to the Registrant’s Quarterly Report on Form 10-Q for the fiscal quarter ended June 30, 2021](https://www.sec.gov/Archives/edgar/data/35527/000003552721000221/a10qfitb-06302021xexx103.htm).* | | |
| 10.70 | | | [Fifth Third Bancorp 2021 Incentive Compensation Plan. Incorporated by reference to Annex A to the Registrant’s Proxy Statement filed on March 2, 2021](https://www.sec.gov/Archives/edgar/data/35527/000119312521065580/d58594ddef14a.htm).* | | |
| 10.80 | | | [Supplemental Confirmations each dated July 23, 2021, to Master Confirmation dated August 7, 2019, for accelerated share repurchase transaction between Fifth Third Bancorp and Citibank, N.A. Incorporated by reference to Exhibit 10.1 to the Registrant’s Quarterly Report on Form 10-Q for the fiscal quarter ended September 30, 2021.](https://www.sec.gov/Archives/edgar/data/35527/000003552721000253/a10qfitb-09302021xexx101.htm)* | | |
| 10.81 | | | [Supplemental Confirmation dated October 27, 2021, to Master Confirmation dated July 29, 2015, for accelerated share repurchase transaction between Fifth Third Bancorp and Morgan Stanley & Co. LLC.](https://www.sec.gov/Archives/edgar/data/35527/000003552722000119/a202110-kexhibit1081.htm) [*](https://www.sec.gov/Archives/edgar/data/35527/000003552722000119/a202110-kexhibit1081.htm) | | |
An excerpt. Shown here: 40 of 105 rewritten, all 8 added and all 8 removed. The counts are complete. For every sentence, read Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES in the FY2022 filing and the FY2021 filing.
Item 16. FORM 10–K SUMMARY
30 rewritten, 25 added, 17 removed, 157 unchanged
[removed: *232 Fifth] [added: | *Fifth] Third Bancorp* [added: | | | | | | | | | | | | | | |]
[Table of [removed: Contents](#i90d310f8677f475ebab3cfafe66c6b5b_49)][added: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)]
| [removed: Chairman] [added: President] and CEO | | |
*Pursuant to requirements of the Securities Exchange Act of 1934, this report has been signed on February [removed: 25, 2022] [added: 24, 2023] by the following persons on behalf of the Registrant and in the capacities indicated.*
| [added: Executive] Chairman | | |
[removed: *233] [added: *222] Fifth Third Bancorp*
| [removed: 2021] [added: 2021] | | | [removed: $] [added: 114,117] | [removed: 114,117] | | [removed: 33,243] [added: 33,243] | | | [removed: 37,018] [added: 37,018] | | | [removed: 184,378] [added: 184,378] | | | [removed: 3,055] [added: 3,055] | | | [removed: 21,050] [added: 21,050] | | | [removed: 206,324] [added: 206,324] | | |
| [removed: 2021] [added: 2021] | | | [removed: $] [added: 62,028] | [removed: 62,028] | | [removed: 45,850] [added: 45,850] | | | [removed: 20,531] [added: 20,531] | | | [removed: 30,631] [added: 30,631] | | | [removed: 3,744] [added: 3,744] | | | [removed: 164] [added: 164] | | | [removed: 162,948] [added: 162,948] | | | [removed: 1,440] [added: 1,440] | | | [removed: 164,388] [added: 164,388] | | |
| [removed: 2021] [added: 2021] | | | [removed: $] [added: 5,211] | [removed: 5,211] | | [removed: 441] [added: 441] | | | [removed: 3,118] [added: 3,118] | | | [removed: 4,748] [added: 4,748] | | | [removed: 2,659] [added: 2,659] | | | [removed: 3.78] [added: 3.78] | | | [removed: 3.73] [added: 3.73] | | | [removed: 1.14] [added: 1.14] | | |
| Year | | | Common Shares Outstanding | | | Common Stock | | | Preferred Stock | | | Capital Surplus | | | Retained Earnings | | | Accumulated Other Comprehensive [removed: Income (Loss)] [added: (Loss) Income] | | | Treasury Stock | | | Total | | | Book Value Per Share | | | Allowance for Loan and Lease Losses | | |
| [removed: 2021] [added: 2021] | | | [removed: 682,777,664] [added: 682,777,664] | | | [removed: $] [added: 2,051] | [removed: 2,051] | | [removed: 2,116] [added: 2,116] | | | [removed: 3,624] [added: 3,624] | | | [removed: 20,236] [added: 20,236] | | | [removed: 1,207] [added: 1,207] | | | [removed: (7,024)] [added: (7,024)] | | | [removed: 22,210] [added: 22,210] | | | [removed: 29.43] [added: 29.43] | | | [removed: 1,892] [added: 1,892] | | |
[removed: *234] [added: *223] Fifth Third Bancorp*
| [removed: *Chairman & Chief Executive Officer*] [added: *Executive Chairman*] | | | | | | [removed: *Chairman &*] [added: *President & Chief Executive Officer*] | | | | | | | | |
| [added: Timothy N. Spence *President & Chief Executive Officer*] *Fifth Third Bancorp* | | | | | | [removed: *Chief Executive Officer*] | | | | | | | | |
| [removed: Marsha C. Williams, Lead Director] [added: *American Electric Power Company*] | | | | | | Kristine R. Garrett *Executive Vice [added: President,* *Group Regional] President &* *Head of Wealth & Asset Management* | | | | | | | | |
| [added: Marsha C. Williams] *Retired Chief Financial Officer* [added: *Orbitz Worldwide, Inc*] | | | | | | | | | | | | | | |
| [added: Greg D. Carmichael] | | | [removed: Howard Hammond *Executive Vice President &* *Head of Consumer Bank*] | | | [added: Timothy N. Spence] | | | [added: | | | Michael Ash David Briggs Timothy Elsbrock Lee Fite David Girodat Kimberly Halbauer Mark Heckler Francie Henry Randy Koporc Tom Partridge Cary Putrino Jim Weiss Thomas G. Welch, Jr. Joseph Yurosek] FIFTH THIRD BANCORP BOARD COMMITTEES Audit Committee Eileen A. Mallesch, Chair Katherine B. Blackburn Thomas H. Harvey Jewell D. Hoover Michael B. McCallister Finance Committee Gary R. Heminger, Chair Nicholas K. Akins Jorge L. Benitez Emerson L. Brumback [added: Thomas H. Harvey] Eileen A. Mallesch Michael B. McCallister Marsha C. Williams Human Capital and Compensation Committee Michael B. McCallister, Chair [added: Nicholas K. Akins] Emerson L. Brumback Gary R. Heminger Eileen A. Mallesch Marsha C. Williams Nominating and Corporate Governance Committee [added: Thomas H. Harvey, Chair] Nicholas K. [removed: Akins, Chair] [added: Akins] B. Evan Bayh, III Jorge L. Benitez Katherine B. Blackburn [removed: Thomas H. Harvey] Marsha C. Williams Risk and Compliance Committee Emerson L. Brumback, Chair Linda W. Clement-Holmes C. Bryan Daniels Gary R. Heminger Jewell D. Hoover Eileen A. Mallesch Technology Committee Jorge L. Benitez, Chair [removed: Nicholas K. Akins] B. Evan Bayh, III Linda W. Clement-Holmes C. Bryan Daniels Thomas H. Harvey | | | [removed: | | |]
| Jorge L. Benitez *Retired Chief Executive Officer* *North America of Accenture plc* | | | | | | [added: Kala J. Gibson *Executive Vice President &* *Chief Corporate Responsibility Officer*] | | | | | | | | |
| [added: Emerson L. Brumback *Retired President & Chief Operating Officer* *M&T Bank*] | | | [added: | | |] Mark D. Hazel *Executive Vice President &* *Controller* | | | | | | | | | [removed: | | |]
| Katherine B. Blackburn *Executive Vice President* *Cincinnati Bengals, Inc.* | | | | | | [added: Howard Hammond *Executive Vice President &* *Head of Consumer Bank*] | | | | | | | | |
| [added: C. Bryan Daniels *Founding Partner* *Prairie Capital*] | | | [added: | | |] James C. Leonard *Executive Vice President &* *Chief Financial Officer* | | | | | | | | | [removed: | | |]
| Linda W. Clement-Holmes *Retired Chief Information Officer* *The Procter & Gamble Company* | | | | | | [added: Kevin P. Lavender *Executive Vice President &* *Head of Commercial Bank*] | | | | | | | | |
| [added: Mitchell S. Feiger *Retired CEO and President* *MB Financial, Inc.*] | | | [added: | | |] Nancy [removed: A.] [added: C.] Pinckney *Executive Vice President &* *Chief Human Resource Officer* | | | | | | | | | [removed: | | |]
| [added: Thomas H. Harvey *Chief Executive Officer* *Energy Innovation: Policy and Technology, LLC*] | | | [added: | | |] Jude A. Schramm *Executive Vice President &* *Chief Information Officer* | | | | | | | | | [removed: | | |]
| [added: Gary R. Heminger *Retired Chief Executive Officer & Chairman* *Marathon Petroleum Corporation*] | | | [added: | | |] Robert P. Shaffer *Executive Vice President &* *Chief Risk Officer* | | | | | | | | | [removed: | | |]
| [removed: | | |] [added: /s/] Timothy N. Spence [removed: *President*] | | | [removed: | | | | | | | | |]
| [removed: Gary R. Heminger] [added: Jewell D. Hoover] *Retired [removed: Chief Executive Officer & Chairman* *Marathon Petroleum Corporation*] [added: Senior Official* *Comptroller of the Currency*] | | | | | | Richard L. Stein *Executive Vice President &* *Chief Credit Officer* | | | | | | | | |
| Eileen A. Mallesch *Retired Chief Financial Officer* *Nationwide Property & Casualty [removed: Segment,* *Nationwide] [added: Segment, Nationwide] Mutual Insurance Company* | | | | | | [added: Melissa S. Stevens *Executive Vice President &* *Chief Marketing Officer*] | | | | | | | | |
| [added: Michael B. McCallister *Retired Chairman & Chief Executive Officer* *Humana, Inc.*] | | | [added: | | |] Susan B. Zaunbrecher *Executive Vice President &* *Chief Legal Officer* | | | | | | | | | [removed: | | |]
[removed: *235] [added: *224] Fifth Third Bancorp*
| Timothy N. Spence | | |
| February 24, 2023 | | |
| /s/ Timothy N. Spence | | |
| Timothy N. Spence | | |
| President and CEO | | |
| /s/ Timothy N. Spence | | |
| Timothy N. Spence | | |
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
| 2022 | | | $ | 120,561 | | 12,419 | | | 53,346 | | | 186,326 | | | 3,093 | | | 19,490 | | | 206,929 | | |
| 2022 | | | $ | 60,185 | | 45,835 | | | 23,445 | | | 29,326 | | | 4,030 | | | 170 | | | 162,991 | | | 4,925 | | | 167,916 | | |
| 2022 | | | $ | 6,587 | | 978 | | | 2,766 | | | 4,719 | | | 2,330 | | | 3.38 | | | 3.35 | | | 1.26 | | |
| 2022 | | | 683,385,880 | | | $ | 2,051 | | 2,116 | | | 3,684 | | | 21,689 | | | (5,110) | | | (7,103) | | | 17,327 | | | 22.26 | | | 2,194 | | |
[Table of Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)
| | | | | | | Greg D.Carmichael | | | | | | | | |
| Nicholas K. Akins, Lead Director | | | | | | *Executive Chairman* | | | | | | | | |
| *Executive Chair* | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
*225 Fifth Third Bancorp*
| /s/ Greg D. Carmichael | | |
| Greg D. Carmichael | | |
| February 25, 2022 | | |
| 2012 | | | 84,822 | | | 1,495 | | | 15,319 | | | 101,636 | | | 2,355 | | | 15,643 | | | 117,562 | | |
| 2012 | | | 27,196 | | | 23,096 | | | 21,393 | | | 4,903 | | | 7,408 | | | 1,555 | | | 85,551 | | | 4,806 | | | 90,357 | | |
| 2012 | | | 4,107 | | | 512 | | | 2,999 | | | 4,083 | | | 1,541 | | | 1.69 | | | 1.66 | | | 0.36 | | |
| 2012 | | | 882,152,057 | | | 2,051 | | | 398 | | | 2,758 | | | 8,768 | | | 375 | | | (634) | | | 13,716 | | | 15.10 | | | 1,854 | | |
| Greg D. Carmichael | | | | | | Greg D. Carmichael | | | | | | Michael Ash David Briggs Joseph DiRocco Timothy Elsbrock Lee Fite David Girodat Kimberly Halbauer Francie Henry Mark Hoppe Randy Koporc Cary Putrino Jim Weiss Thomas G. Welch, Jr. Joseph Yurosek | | |
| *Orbitz Worldwide, Inc.* | | | | | | | | | | | | | | |
| Nicholas K. Akins *Chairman, President & Chief Executive Officer* *American Electric Power Company* | | | | | | Kala J. Gibson *Executive Vice President &* *Chief Corporate Social Responsibility Officer* | | | | | | | | |
| | | | Kevin P. Lavender *Executive Vice President &* *Head of Commercial Banking* | | | | | | | | | | | |
| Emerson L. Brumback *Retired President & Chief Operating Officer* *M&T Bank* | | | | | | | | | | | | | | |
| C. Bryan Daniels *Founding Partner* *Prairie Capital* | | | | | | | | | | | | | | |
| Mitchell S. Feiger *Retired CEO and President* *MB Financial, Inc.* | | | | | | | | | | | | | | |
| Thomas H. Harvey *Chief Executive Officer* *Energy Innovation: Policy and Technology, LLC* | | | | | | | | | | | | | | |
| Jewell D. Hoover *Retired Senior Official* *Comptroller of the Currency* | | | | | | Melissa S. Stevens *Executive Vice President &* *Head of Digital, Marketing, Design and Innovation* | | | | | | | | |
| Michael B. McCallister *Retired Chairman & Chief Executive Officer* *Humana, Inc.* | | | | | | | | | | | | | | |