 filings.tools
Fifth Third Bancorp (FITB) 10-K risk factor changes: FY2023 vs FY2022
The 2023-12-31 10-K against the 2022-12-31 one, compared heading by heading and sentence by sentence.
Item 1A62 rewritten57 added122 removed390 unchanged
All filing items2,861 rewritten1,321 added895 removed4,262 unchanged
Summary
counted, not written
- Item 1A lists 47 risk factor headings: 3 new, 3 reworded and 41 unchanged since FY2022. 3 headings from FY2022 no longer appear.
- Sentence by sentence, 1,321 added, 895 removed, 2,861 rewritten and 4,262 unchanged across 19 items that differ.
- New this year: Item 1C. CYBERSECURITY.
New Item 1A headings (3)
- Industry adoption of real-time payments networks could negatively impact financial performance through reductions in product profitability, increased liquidity reserves and the potential for increased fraud losses, among other risks.
- Fifth Third has businesses other than banking that are subject to a variety of risks.
- Recent bank failures have created significant market volatility and regulatory uncertainty which could have a material adverse effect on Fifth Third’s business and financial condition.
Removed Item 1A headings (3)
- Regulation of Fifth Third by the CFTC imposes additional operational and compliance costs.
- The replacement of LIBOR could adversely affect Fifth Third’s revenue or expenses and the value of those assets or obligations.
- The COVID-19 pandemic creates significant risks and uncertainties for Fifth Third’s business.
Reworded Item 1A headings (3)
- Problems encountered by [added: other] financial institutions
[removed: larger than or similar to Fifth Third]could adversely affect financial markets generally and have direct and indirect adverse effects on Fifth Third. - Fifth Third relies on its systems and certain third-party service providers and certain failures (including those
[removed: driven by climate-related][added: related to cybersecurity or] weather[removed: events)][added: events exacerbated by climate change)] could materially adversely affect operations. - Deposit insurance premiums levied against the Bank
[removed: may][added: could] increase [added: further] if the number of bank failures increase or the cost of resolving failed banks increases.
A heading is new when no FY2022 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
23 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2023; struck-through words were in FY2022. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. RISK FACTORS
62 rewritten, 57 added, 122 removed, 390 unchanged
[removed: - Problems] [added: Problems] encountered by [added: other] financial institutions [removed: larger than or similar to Fifth Third] could adversely affect financial markets generally and have direct and indirect adverse effects on Fifth [removed: Third.][added: Third.]
[removed: - Fifth] [added: Fifth] Third is exposed to [removed: cyber security] [added: cybersecurity] risks that create both operational and reputational risk for the Bank and its customers across all lines of [removed: business.][added: business.]
[removed: - Fifth] [added: Fifth] Third relies on its systems and certain third-party service providers and certain failures (including those [removed: driven by climate-related] [added: related to cybersecurity or] weather [removed: events)] [added: events exacerbated by climate change)] could materially adversely affect [removed: operations.][added: operations.]
[removed: -] Fifth Third and/or its affiliates are or may become involved from time to time in information-gathering requests, [added: reviews,] investigations and [removed: litigation, regulatory or other enforcement] proceedings [added: (both formal and informal)] by [removed: various] governmental regulatory agencies and law enforcement authorities, [added: including but not limited to the FRB, OCC, CFPB, SEC, FINRA, U.S. Department of Justice, etc.,] as well as [added: state and other governmental authorities and] self-regulatory [removed: agencies which may lead to adverse consequences.][added: bodies, regarding their respective customers and businesses.]
[removed: - Deposit] [added: Deposit] insurance premiums levied against the Bank [removed: may] [added: could] increase [added: further] if the number of bank failures increase or the cost of resolving failed banks [removed: increases.][added: increases.]
[Table of [removed: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)][added: Contents](#i1f68b48eea92495388df6551a4f9ea63_52)]
[added: Such determination] requires difficult, subjective and complex judgments about the environment, including analysis of economic or market conditions that may impair the ability of borrowers to repay their loans.
Fifth Third believes that both the ALLL and the reserve for unfunded commitments are adequate to cover expected losses at December 31, [removed: 2022;] [added: 2023;] however, there is no assurance that they will be sufficient to cover future credit losses associated with exposures existing at December 31, [removed: 2022,] [added: 2023,] especially if economic conditions decline, including but not limited to housing and employment conditions.
Core deposits, which include transaction deposits and certificates of deposit $250,000 or less, have historically provided Fifth Third with a sizeable source of relatively stable and low-cost funds (average core deposits funded [removed: 78%] [added: 76%] of average total assets for the year ending December 31, [removed: 2022).][added: 2023).]
[added: In addition to customer deposits, sources of liquidity include investments in the] securities portfolio, Fifth Third’s sale or securitization of loans in secondary markets, the pledging of loans and investment securities to access secured borrowing facilities through the FHLB and the FRB, and Fifth Third’s ability to raise funds in money and capital markets.
- a lack of market or customer confidence in Fifth Third or negative news about Fifth [removed: Third] [added: Third, regional banks] or the financial services industry generally, which also may result in a loss of customer deposits and/or negatively affect Fifth Third’s ability to access the capital markets;
A reduction in Fifth Third’s credit rating could adversely affect its ability to [added: retain deposits,] borrow [removed: funds, including] [added: funds (including] by raising the cost of borrowings [removed: substantially] [added: substantially)] and could cause creditors and business counterparties to raise collateral requirements or take other actions that could adversely affect Fifth Third’s ability to raise [added: liquidity or] capital.
Fifth Third’s bank customers could take their money out of the Bank and put it in alternative investments, causing Fifth Third to lose a [removed: lower cost] [added: lower-cost] source of funding.
[removed: Failures, interruptions of service or breaches in the security of these environments occur across the financial services industry with some frequency and, if a material] [added: If an] event of this nature occurred at Fifth Third or one of its third-party [removed: providers,] [added: providers and such event proved to be material,] this could result in disruptions to Fifth Third’s accounting, deposit, lending and other systems, and adversely affect its customer relationships.
In addition, because the techniques used to cause such security breaches change frequently, often are not recognized until launched against a target and may originate from [added: remote and] less regulated [removed: and remote] areas around the world, Fifth Third may be unable to proactively address these techniques or to implement adequate preventative measures.
Despite Fifth Third’s efforts to prevent a cyber-attack, a successful cyber-attack could persist for an extended period of time before being detected, and, following detection, it could take considerable time for Fifth Third to obtain full and reliable information about the [removed: cyber security] [added: cybersecurity] incident and the extent, amount and type of information compromised.
During the course of an investigation, Fifth Third may not necessarily know the full effects of the incident or how to remediate it, and actions and decisions that are taken or made in an effort to mitigate risk may further increase the costs and other negative [removed: consequences of the incident.]
Furthermore, financial services companies are regularly the target of cyber-attacks such as distributed denial of [removed: service attacks] [added: service, social engineering] and ransomware attacks.
The unintentional or willful acts or omissions of employees also remains the primary avenue through which threat actors attempt to gain access to company networks, information [removed: systems] [added: systems, data] and [removed: data.][added: credentials.]
An [removed: emerging] [added: additional] risk is the use of third- and fourth-party providers to host critical data and platforms for Fifth Third, or in some cases provide IT services to Fifth Third domestically and internationally.
Fifth Third must make investments in its ability to oversee third- and fourth-party [added: providers and its failure to do so could result in customer losses, operational issues, litigation, regulatory actions and reputational loss.]
These [removed: emerging] [added: additional] risks are further heightened through the increasing use of near real-time money movement solutions such as Zelle, and increase the difficulty to detect, prevent and recover fraudulent transactions.
These [removed: emerging] [added: additional] risks are increasing the costs of Fifth Third’s investment in technology and [removed: cyber security] [added: cybersecurity] and require further investment in cyber-related and data loss event insurance which Fifth Third has in place.
Though Fifth Third has insurance against some [removed: cyber security] [added: cybersecurity] risks and attacks, it may not be sufficient to offset the impact of a material loss event.
Any failures or disruptions of the Bancorp’s systems or operations could give rise to losses in service to customers and clients, adversely affect the Bancorp’s business and results of operations by subjecting the Bancorp to losses or liability, or require the Bancorp to expend significant resources to correct the failure or disruption, as well as by exposing the Bancorp to reputational harm, litigation, regulatory fines [removed: or penalties or losses not covered by insurance.]
Fifth Third has established processes and procedures intended to identify, measure, monitor, report and manage the types of risk to which it is [removed: subject,] [added: exposed,] including liquidity risk, credit risk, interest rate risk, price risk, legal and regulatory compliance risk, strategic risk, reputational risk and operational risk related to its employees, systems and vendors, among others.
[removed: Fifth Third also considers the physical and transition risks arising from climate change to be transverse risk drivers] that impact all of these material risks and [removed: have] [added: has] therefore integrated climate change considerations into its risk management framework.
Fifth Third continues to devote a significant amount of effort, time and resources to improving its controls and ensuring compliance with complex [removed: regulations.][added: regulations, and overall safety and soundness.]
If Fifth Third’s risk management framework proves ineffective, Fifth Third could incur [removed: litigation,] [added: litigation costs,] negative regulatory consequences, reputational damages among other adverse consequences and Fifth Third could suffer unexpected losses that may affect its financial condition or results of operations.
Competition for qualified candidates in the activities and markets that Fifth Third serves is intense, which may increase Fifth Third’s expenses and may result in Fifth Third not being [added: able to hire candidates or retain them.]
Fifth Third may be required to repurchase residential mortgage loans, indemnify the securitization trust, investor or insurer, or reimburse the securitization trust, investor or insurer, for credit losses incurred on loans in the event of a breach of contractual representations or warranties that is not remedied within a specified [added: period (usually 60 days or less) after Fifth Third receives notice of the breach.]
[removed: This] [added: The Biden Administration has sought to implement a regulatory] agenda [added: that has included, or] could [removed: include] [added: include,] a heightened focus on the risks arising from climate change, fair lending, consumer protection, Bank Secrecy Act and anti-money laundering requirements, topics related to social equity, executive compensation, and increased capital and liquidity, as well as limits on share buybacks and dividends.
In addition, mergers and acquisitions [removed: could] [added: may] be hindered by increased antitrust and other regulatory scrutiny.
It is uncertain [removed: which,] if [removed: any,] [added: the implementation] of [added: any of] these policies would [removed: be implemented] [added: impact Fifth Third,] and [added: if so,] what [removed: their] [added: the] impact would [removed: be on Fifth Third.][added: be.]
Such actions and activities that may be subject to prior approval include, but are not limited to, increasing dividends or other [removed: capital distributions by the Bancorp or the Bank, entering into a merger or acquisition transaction, acquiring or establishing new branches, and entering into certain new businesses.]
Fifth Third [removed: and other financial institutions are] [added: is also] subject to [removed: scrutiny from government authorities, including bank regulatory authorities, stemming from broader systemic] [added: certain] regulatory [removed: concerns,] [added: requirements as a result of its banking activity] including with respect to stress testing, liquidity and capital levels, asset quality, provisioning, AML/BSA, fair lending, consumer compliance and other prudential matters and efforts to ensure that financial institutions take steps to improve their risk management and prevent future crises.
The Bancorp’s stress capital buffer requirement has been 2.5% since the introduction of this framework and was most recently affirmed as part of [removed: the FRB’s 2022 supervisory stress test for the period from] [added: Fifth Third’s 2023 Capital Plan submission with an effective date of] October 1, [removed: 2022 to September 30, 2023, based on the Bancorp’s 2022 supervisory stress][added: 2023.]
For more information, refer to Regulation and [removed: Supervision—Derivatives] [added: Supervision—Regulatory Regime for Derivatives] in Item 1 of this Annual Report on Form 10-K.
Worldwide financial markets have recently experienced periods of extraordinary disruption and volatility, which have been driven by factors such as the COVID-19 [removed: pandemic and] [added: pandemic,] the Russia/Ukraine [removed: conflict,] [added: conflict and the evolving conflict in Israel and Gaza,] resulting in heightened credit risk, reduced valuation of investments, decreased economic activity, heightened risk of [removed: cyberattacks,] [added: cyber-attacks,] and inflation.
International events such as trade disputes, separatist movements, leadership changes and political and military conflicts (such as the ongoing military tension between Russia and [removed: Ukraine)] [added: Ukraine and the evolving conflict in Israel and Gaza)] could adversely affect global financial activity and markets and could negatively affect the U.S. economy.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
Failures, interruptions of service or breaches in the security of these environments occur across the financial services industry with some frequency, including at Fifth Third and its third-party providers.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
consequences of the incident.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
or penalties or losses not covered by insurance.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
Investigations by regulatory authorities may from time to time result in civil or criminal referrals to law enforcement.
Additionally, in some cases, regulatory authorities may take supervisory actions that are considered to be confidential supervisory information which may not be publicly disclosed.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
Similarly, the impact of domestic and international events related to financial crime such as fraud, money laundering, and economic sanctions will continue to be an area of constant change, risk, and regulatory focus which pose ongoing regulatory, compliance, operational and financial risks.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
capital distributions by the Bancorp or the Bank, entering into a merger or acquisition transaction, acquiring or establishing new branches, and entering into certain new businesses.
Fifth Third and other financial institutions are highly regulated and subject to extensive oversight, supervision and examination by regulators, including the FRB, OCC, FDIC, CFPB, SEC, CFTC, FINRA, the National Futures Association and other state, federal and self-regulatory entities.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
As of June 30, 2020, the DIF reserve ratio fell to 1.30%, below the statutory minimum of 1.35%.
In order to restore the DIF to its statutorily mandated minimums, the FDIC significantly increased deposit insurance premium rates, including the Bank’s, resulting in increased expenses.
The revised assessment rate schedules became effective January 1, 2023, and are applicable to the first quarterly assessment period of 2023.
Additionally, on November 16, 2023, the FDIC finalized a special assessment to recover the loss to the DIF caused by the bank failures that occurred in 2023 to be collected at an annual rate of approximately 13.4 basis points for an anticipated total of eight quarterly assessment periods, beginning the first quarterly assessment period of 2024.
The FDIC may further increase the assessment rates or impose additional special assessments in the future, which may require the Bank to pay significantly higher FDIC premiums.
The United States is also facing a potentially contentious Presidential election as well as elections to determine the control of Congress and State governments.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
policies of various governmental and regulatory agencies (in particular, the FRB).
Throughout 2022 and 2023, the Federal Reserve raised the federal funds rate to its current targeted rate between 5.25% and 5.5% in an effort to curb inflation.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
Industry adoption of real-time payments networks could negatively impact financial performance through reductions in product profitability, increased liquidity reserves and the potential for increased fraud losses, among other risks.
With the launch of real-time payments networks, such as RTP® from The Clearing House and FedNow® from the Federal Reserve, instantaneous cash settlement capabilities are available 24 hours a day and 7 days a week.
The implications of the new settlement capabilities are far reaching and have not yet significantly affected the banking industry.
As market adoption increases, Fifth Third may be required to hold more liquidity reserves in cash to facilitate cash settlement activity outside of traditional business hours.
Additionally, instantaneous settlement will likely reduce float benefits associated with providing deposit and banking services, as well as pose incremental fraud risk due to a reduced ability to reverse fraudulent transactions due to the speed of money movement.
Future acquisition and investment activities and efforts to monitor newly acquired businesses or reap the benefits of a new strategic relationship may
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
Fifth Third has businesses other than banking that are subject to a variety of risks.
Fifth Third is a diversified financial services company.
As a result, the Bancorp is subject to additional risks and uncertainties.
Other businesses that the Bancorp operates include investment banking, securities underwriting and market making, investment management, and retail and institutional brokerage services offered through the Bancorp’s subsidiaries.
These business activities are subject to rigorous regulatory oversight by federal, state and self-regulatory entities, and may incur substantial market, operational, credit, regulatory, legal and other risks that could adversely impact the Bancorp’s results of operations.
For more information, refer to Regulation and Supervision—Regulatory Regime for Derivatives in Item 1 of this Annual Report on Form 10-K.
Because Fifth Third conducts most of its businesses under the “Fifth Third” brand, negative public opinion about one business could affect its other businesses.
If
RISK FACTORS SUMMARY
The following is a summary of the Risk Factors disclosure in this Item 1A:
CREDIT RISKS
- Deteriorating credit quality has adversely impacted Fifth Third in the past and may adversely impact Fifth Third in the future.
- Fifth Third may have more credit risk and higher credit losses to the extent loans are concentrated by exposure to individual borrowers, location or industry of the borrowers or collateral.
- Inability to refinance in capital markets could cause a default that impacts Fifth Third borrowers.
LIQUIDITY RISKS
- Fifth Third must maintain adequate sources of funding and liquidity.
- Fifth Third and/or the holders of its securities could be adversely affected by unfavorable ratings from rating agencies.
- If Fifth Third is unable to maintain or grow its deposits, it may be subject to paying higher funding costs.
- The Bancorp’s ability to receive dividends from its subsidiaries accounts for most of its revenue and could affect its liquidity and ability to pay dividends.
OPERATIONAL RISKS
- Fifth Third may not be able to effectively manage organizational changes and implement key initiatives in a timely fashion, or at all, due to competing priorities which could adversely affect its business, results of operations, financial condition and reputation.
- Fifth Third may not be able to successfully implement future information technology system enhancements, which could adversely affect Fifth Third’s business operations and profitability.
- Fifth Third’s framework for managing risks may not be effective in mitigating its risk and loss.
- Fifth Third may experience losses related to fraud, theft or violence.
- Fifth Third could suffer if it fails to attract and retain skilled personnel.
- Fifth Third may experience operational disruption from the effects of climate change.
LEGAL AND REGULATORY COMPLIANCE RISKS
- Fifth Third may be required to repurchase residential mortgage loans or reimburse investors and others as a result of breaches in contractual representations and warranties.
- Fifth Third is subject to extensive governmental regulation which could adversely impact Fifth Third or the businesses in which Fifth Third is engaged.
- Fifth Third could suffer from unauthorized use of intellectual property.
- Fifth Third is subject to various regulatory requirements that may limit its operations and potential growth.
- Fifth Third could face serious negative consequences if its third-party service providers, business partners or investments fail to comply with applicable laws, rules or regulations.
- As a regulated entity, the Bancorp is subject to certain capital requirements that may limit its operations, potential growth and ability to pay or increase dividends on its common stock or to repurchase its capital stock.
- Regulation of Fifth Third by the CFTC imposes additional operational and compliance costs.
- If an orderly liquidation of a systemically important BHC or non-bank financial company were triggered, Fifth Third could face assessments for the Orderly Liquidation Fund.
MARKET RISKS: INTEREST RATE RISKS AND PRICE RISKS
- The replacement of LIBOR could adversely affect Fifth Third’s revenue or expenses and the value of those assets or obligations.
- Weakness in the U.S. economy, including within Fifth Third’s geographic footprint, has adversely affected Fifth Third in the past and may adversely affect Fifth Third in the future.
- Global and domestic political, social and economic uncertainties and changes may adversely affect Fifth Third.
- Changes in interest rates could affect Fifth Third’s income and cash flows.
- Changes and trends in the capital markets may affect Fifth Third’s income and cash flows.
- Fifth Third’s stock price is volatile.
- Fifth Third’s mortgage banking net revenue can be volatile from quarter to quarter.
STRATEGIC RISKS
- If Fifth Third does not respond to intense competition and rapid changes in the financial services industry or otherwise adapt to changing customer preferences, its financial performance may suffer.
- Changes in retail distribution strategies and consumer behavior may adversely impact Fifth Third’s investments in its bank premises and equipment and other assets and may lead to increased expenditures to change its retail distribution channel.
- Difficulties in identifying suitable opportunities or combining the operations of acquired entities or assets with Fifth Third’s own operations or assessing the effectiveness of businesses in which Fifth Third makes strategic investments or with which Fifth Third enters into strategic contractual relationships may prevent Fifth Third from achieving the expected benefits from these acquisitions, investments or relationships.
- Future acquisitions may dilute current shareholders’ ownership of Fifth Third and may cause Fifth Third to become more susceptible to adverse economic events.
An excerpt. Shown here: 40 of 62 rewritten, 40 of 57 added and 40 of 122 removed. The counts are complete. For every sentence, read Item 1A. RISK FACTORS in the FY2023 filing and the FY2022 filing.
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
1,044 rewritten, 379 added, 333 removed, 1,013 unchanged
For the year ended December 31, [removed: 2022,] [added: 2023,] net interest income on an FTE basis and noninterest income provided 67% and 33% of total revenue, respectively.
The Bancorp derives the majority of its revenues within the U.S. from customers domiciled in the U.S. Revenue from foreign countries and external customers domiciled in foreign countries was immaterial to the Consolidated Financial Statements for the year ended December 31, [removed: 2022.][added: 2023.]
Noninterest income is derived from [removed: service charges on deposits,] [added: commercial banking revenue,] wealth and asset management revenue, [removed: commercial banking revenue,] [added: service charges on deposits,] card and processing revenue, [removed: leasing business revenue,] mortgage banking net revenue, [added: leasing business revenue,] other noninterest income and net securities gains or losses.
Noninterest expense includes compensation and benefits, technology and communications, net occupancy expense, equipment expense, [added: marketing expense,] leasing business expense, [removed: marketing expense,] card and processing expense and other noninterest expense.
If financial markets remain volatile, this may impact the future performance of various segments of the Bancorp’s business, [removed: including] [added: in addition to] the value of the Bancorp’s investment securities portfolio.
The Bancorp continues to closely monitor the pace of inflation and the impacts of inflation on the [removed: larger market, including labor and supply chain impacts.][added: broader market.]
For [removed: further discussion] [added: more information] on current economic conditions, refer to the Credit Risk Management subsection of the Risk Management section of MD&A.
Additionally, refer to the Interest Rate and Price Risk Management [removed: subsection] [added: and Liquidity Risk Management subsections] of the Risk Management section of MD&A for additional information about the Bancorp’s interest rate risk management [added: and liquidity risk management] activities.
[Table of [removed: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)][added: Contents](#i1f68b48eea92495388df6551a4f9ea63_52)]
Accelerated Share Repurchase [removed: Transactions][added: Transaction]
[removed: The] [added: Under this authorization, the] Bancorp entered into and settled [removed: a number of] accelerated share repurchase transactions during the years ended December 31, [removed: 2022] [added: 2023] and [removed: 2021.][added: 2022.]
As part of [removed: these transactions,] the [added: transaction, the] Bancorp entered into [added: a] forward [removed: contracts] [added: contract] in which the final number of shares delivered at settlement was based generally on a discount to [removed: the average daily volume-weighted average price of the Bancorp’s common stock during the term of these repurchase agreements.]
For [removed: further information on a subsequent event related to capital actions,] [added: more information,] refer to Note [removed: 32] [added: 15] of the Notes to Consolidated Financial Statements.
Senior Notes [removed: Offerings][added: Offering]
For more information, refer to Note [removed: 17] [added: 4] of the Notes to Consolidated Financial Statements.
[removed: During the second quarter] [added: Other consumer portfolio loans are comprised] of [removed: 2022, the Bancorp completed] [added: secured and unsecured loans originated through] the [removed: acquisition of a national] [added: Bancorp’s branch network,] point-of-sale [removed: consumer lender specializing in home improvement and] solar energy installation [added: and home improvement] loans originated through a network of contractors and [removed: installers.][added: installers, and other point-of-sale loans originated or purchased in connection with third-party companies.]
For [removed: more] [added: further] information on the [removed: acquisition,] [added: Bancorp’s adoption of ASU 2022-02,] refer to [removed: Notes 10] [added: Note 1] and [removed: 11] [added: Note 6] of the Notes to Consolidated Financial Statements.
| For the years ended December 31 ($ in millions, except per share data) | | | [removed: 2022] [added: 2023] | | | | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2020] [added: 2021] | | |
| Net interest income (U.S. GAAP) | | | $ | [removed: 5,609] [added: 5,827] | | | | | [removed: 4,770] [added: 5,609] | | | | | | [removed: 4,782] [added: 4,770] | | |
| Net interest income (FTE)*(a)(b)* | | | [removed: 5,625] [added: 5,852] | | | | | | [removed: 4,782] [added: 5,625] | | | | | | [removed: 4,795] [added: 4,782] | | |
| Noninterest income | | | [removed: 2,766] [added: 2,881] | | | | | | [removed: 3,118] [added: 2,766] | | | | | | [removed: 2,830] [added: 3,118] | | |
| Total revenue (FTE)*(a)(b)* | | | [removed: 8,391] [added: 8,733] | | | | | | [removed: 7,900] [added: 8,391] | | | | | | [removed: 7,625] [added: 7,900] | | |
| Provision for (benefit from) credit losses | | | [removed: 563] [added: 515] | | | | | | [removed: (377)] [added: 563] | | | | | | [removed: 1,097] [added: (377)] | | |
| Noninterest expense | | | [removed: 4,719] [added: 5,205] | | | | | | [removed: 4,748] [added: 4,719] | | | | | | [removed: 4,718] [added: 4,748] | | |
| Net income | | | [removed: 2,446] [added: 2,349] | | | | | | [removed: 2,770] [added: 2,446] | | | | | | [removed: 1,427] [added: 2,770] | | |
| Net income available to common shareholders | | | [removed: 2,330] [added: 2,212] | | | | | | [removed: 2,659] [added: 2,330] | | | | | | [removed: 1,323] [added: 2,659] | | |
| Earnings per share - basic | | | $ | [removed: 3.38] [added: 3.23] | | | | | [removed: 3.78] [added: 3.38] | | | | | | [removed: 1.84] [added: 3.78] | | |
| Earnings per share - diluted | | | [removed: 3.35] [added: 3.22] | | | | | | [removed: 3.73] [added: 3.35] | | | | | | [removed: 1.83] [added: 3.73] | | |
| Cash dividends declared per common share | | | [removed: 1.26] [added: 1.36] | | | | | | [removed: 1.14] [added: 1.26] | | | | | | [removed: 1.08] [added: 1.14] | | |
| Book value per share | | | [removed: 22.26] [added: 25.04] | | | | | | [removed: 29.43] [added: 22.26] | | | | | | [removed: 29.46] [added: 29.43] | | |
| Market value per share | | | [removed: 32.81] [added: 34.49] | | | | | | [removed: 43.55] [added: 32.81] | | | | | | [removed: 27.57] [added: 43.55] | | |
| Return on average assets | | | [removed: 1.18] [added: 1.13] | | % | | | | [removed: 1.34] [added: 1.18] | | | | | | [removed: 0.73] [added: 1.34] | | |
| Return on average common equity | | | [removed: 13.7] [added: 14.2] | | | | | | [removed: 12.8] [added: 13.7] | | | | | | [removed: 6.4] [added: 12.8] | | |
| Return on average tangible common equity*(b)* | | | [removed: 19.7] [added: 21.3] | | | | | | [removed: 16.6] [added: 19.7] | | | | | | [removed: 8.4] [added: 16.6] | | |
| Dividend payout | | | [removed: 37.3] [added: 42.1] | | | | | | [removed: 30.2] [added: 37.3] | | | | | | [removed: 58.7] [added: 30.2] | | |
The FTE adjustments were [removed: $16, $12] [added: $25, $16] and [removed: $13] [added: $12] for the years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020,] [added: 2021,] respectively.*
The Bancorp’s net income available to common shareholders for the year ended December 31, [removed: 2021] [added: 2023] was [removed: $2.7] [added: $2.2] billion, or [removed: $3.73] [added: $3.22] per diluted share, which was net of [removed: $111] [added: $137] million in preferred stock dividends.
Net interest income on an FTE basis (non-GAAP) was [removed: $5.6] [added: $5.9] billion for the year ended December 31, [removed: 2022,] [added: 2023,] an increase of [removed: $843] [added: $227] million compared to the prior year.
Net interest income benefited from increases in market interest rates, resulting in increases in yields on average loans and [removed: leases and] [added: leases,] average other short-term investments [added: and average taxable securities] for the year ended December 31, [removed: 2022] [added: 2023] compared to the prior year.
Net interest income also benefited from increases in average [removed: taxable securities] [added: other consumer loans] and average [removed: commercial and industrial loans] [added: taxable securities] for the year ended December 31, [removed: 2022] [added: 2023] compared to the prior year.
Economic growth was resilient in 2023 but managing inflation remained a top priority for FRB officials.
In response to inflationary pressures, FRB officials raised benchmark interest rates aggressively during 2022 and 2023 and have signaled that they will continue to monitor the cumulative economic effects of their policy actions, including tighter credit conditions for households and businesses, when determining future monetary actions.
Amidst the rapid pace of interest rate increases, several financial markets have experienced heightened volatility.
While interest rates may remain elevated for a sustained period of time, the FRB moved to a more balanced monetary policy stance in the later months of 2023 in response to easing inflationary pressures.
The bank failures that have occurred since March 2023 generated significant market volatility and increased regulatory and market focus on the liquidity, asset-liability management and unrealized securities losses of banks.
In response to these failures, the U.S. banking agencies
have proposed a number of regulatory amendments to improve the stability of U.S. banking institutions.
Among these amendments, in November 2023, the FDIC issued a final rule for a special deposit insurance assessment on banking organizations with greater than $5 billion in assets to recover the costs associated with protecting uninsured depositors following these closures.
The Bancorp’s estimate of its allocated share of the special assessment under the provisions of the final rule was $224 million, which was recognized in earnings upon issuance of the final rule in November 2023 and will be paid to the FDIC over an anticipated total of eight quarterly assessment periods beginning with the first quarter of 2024.
The estimate of the cost associated with protecting the uninsured depositors will continue to be subject to periodic adjustment until the final loss is determined upon the termination of the receiverships by the FDIC.
Proposed Updates to Regulatory Requirements for Capital and Long-Term Debt
On July 27, 2023, the U.S. banking agencies released a notice of proposed rulemaking to revise the Basel III Capital Rules, which would modify its existing risk-based capital framework for large banks and introduce a new framework that implements international capital standards.
The proposed rulemaking would increase capital requirements applicable to banking organizations with total assets of $100 billion or more, including Fifth Third, and would align the calculation of regulatory capital and the calculation of risk-weighted assets across large banking organizations.
As proposed, the rules would be effective for the Bancorp on July 1, 2025 and phased in over a three-year transition period.
The Bancorp is in the process of evaluating this proposed rulemaking and assessing its potential impact.
On August 29, 2023, the U.S. banking agencies issued a notice of proposed rulemaking to require that certain banking organizations with $100 billion or more in consolidated assets, including Fifth Third, comply with certain long-term debt requirements at the holding company and insured depository institution levels.
These proposed requirements are intended to absorb losses and recapitalize the insured depository institution in the event of the failure of a banking organization.
As proposed, the rules would be phased in over a three-year period after their effective date.
The Bancorp is in the process of evaluating this proposed rulemaking and assessing its potential impact.
In the United States, SOFR was identified as the preferred alternative rate.
As a secured borrowing rate, SOFR may not exhibit similar behavior in response to market and economic volatility as LIBOR, which was an unsecured rate.
As of December 31, 2023, substantially all contracts have transitioned to alternative reference rates.
Refer to Note 17 and Note 24 of the Notes to Consolidated Financial Statements for additional information about certain exposures which were transitioned to an alternative reference rate.
The senior notes bear interest at a rate of 6.339% per annum to, but excluding, July 27, 2028.
From, and including, July 27, 2028 until, but excluding, July 27, 2029, the senior notes will bear interest at a rate of compounded SOFR plus 2.340%.
The senior notes are redeemable in whole at par plus accrued and unpaid interest one year prior to their maturity date, or may be wholly or partially redeemed on or after 30 days prior to maturity.
Additionally, the senior notes are redeemable at the Bancorp’s option, in whole or in part, beginning 180 days after the issue date and prior to July 27, 2028, at the greater of: (a) the aggregate principal amount of the senior notes being redeemed, or (b) the discounted present value of the remaining scheduled payments of principal and interest that would be due if the senior notes being redeemed matured on July 27, 2028.
Refer to Note 32 of the Notes to Consolidated Statements for information on a subsequent event related to long-term debt.
Automobile Loan Securitization
In a securitization transaction that occurred in August of 2023, the Bancorp transferred $1.74 billion in aggregate automobile loans to a bankruptcy remote trust which subsequently issued approximately $1.58 billion of asset-backed notes, of which approximately $79 million were retained by the Bancorp, resulting in approximately $1.5 billion of outstanding notes included in long-term debt in the Consolidated Balance Sheets.
As discussed in Note 12, the bankruptcy remote trust was deemed to be a VIE and the Bancorp, as the primary beneficiary, consolidated the VIE.
The third-party holders of the asset-backed notes do not have recourse to the general assets of the Bancorp.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
the average daily volume-weighted average price of the Bancorp’s common stock during the term of the repurchase agreement.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
Net interest income was also negatively impacted by deposit balance migration into higher yielding products, resulting in a decrease in the average balances of demand deposits and an increase in the average balances of interest-bearing core deposits for the year ended December 31, 2023 compared to the prior year.
Additionally, net interest income was negatively impacted by increases in the average balances of CDs over $250,000 and long-term debt for the year ended December 31, 2023 compared to the prior year.
The provision for credit losses for the year ended December 31, 2023 was primarily driven by factors which resulted in an increase to the ACL during the year, including changes in product mix, the impacts of qualitative factors and increases in reserves for individually evaluated loans, partially offset by the impact of a decrease in the end-of-period loan and lease balances.
The provision for credit losses for the year ended December 31, 2022 also included the initial recognition of provision for credit losses on loans acquired as part of a business acquisition completed in the second quarter of 2022.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
Robust demand, labor shortages and supply chain constraints have led to persistent inflationary pressures throughout the economy.
In response to these inflationary pressures, the FRB raised benchmark interest rates and may continue to raise interest rates in response to economic conditions, particularly a continued high rate of inflation.
Amidst these uncertainties, some financial markets continued to experience volatility.
MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
During the year ended December 31, 2022, the Bancorp (including both the parent company and its banking subsidiary) issued and sold fixed-rate/floating-rate senior notes in a number of debt offerings.
These transactions included:
- A Bancorp issuance on April 25, 2022 of $1 billion of fixed-rate/floating-rate senior notes which included $400 million of notes maturing on April 25, 2028 and $600 million of notes maturing on April 25, 2033.
- A Bancorp issuance on July 28, 2022 of $1 billion of fixed-rate/floating-rate senior notes maturing on July 28, 2030.
- A Bancorp issuance on October 27, 2022 of $1 billion of fixed-rate/floating-rate senior notes maturing on October 27, 2028.
- A Bank issuance on October 27, 2022 of $1 billion of fixed-rate/floating-rate senior notes maturing on October 27, 2025.
In each of these transactions, the parent company and banking subsidiary entered into interest rate swaps designated as fair value hedges to convert the fixed-rate period of the notes to a floating rate of interest.
Business Combination
The acquisition was accounted for under the acquisition method of accounting which generally requires assets acquired and liabilities assumed to be recorded at their estimated fair values at acquisition date.
These fair value estimates are considered preliminary as of December 31, 2022 and are subject to change for up to one year after the acquisition date as additional information becomes available.
Since then, central banks around the world, including the Federal Reserve, have commissioned working groups of market participants and official sector representatives with the goal of finding suitable replacements for LIBOR.
On March 5, 2021, the FCA and ICE Benchmark Administration, Limited announced that the publication of the one-week and two-month USD LIBOR maturities and non-USD LIBOR maturities would cease immediately after December 31, 2021, with the remaining USD LIBOR maturities ceasing immediately after June 30, 2023.
In the United States, the Alternative Rates Reference Committee (the “ARRC”), a group of market participants convened in 2014 to help ensure a successful transition away from USD LIBOR, identified SOFR as its preferred alternative rate.
The composition and characteristics of SOFR are not the same as those of LIBOR, and SOFR is fundamentally different from LIBOR for two key reasons: (1) SOFR is a secured rate, while LIBOR is an unsecured rate, and (2) SOFR is an overnight rate, while LIBOR is a forward-looking rate that represents interbank funding over different maturities.
As a result, there can be no assurance that SOFR, however calculated, will perform the same way as LIBOR would have at any time, including, as a result of changes in interest and yield rates in the market, market volatility, or global or regional economic, financial, political, regulatory, judicial or other events.
On March 15, 2022, President Biden signed the Adjustable Interest Rate (LIBOR) Act (the “LIBOR Act”) into law.
The LIBOR Act offers a federal solution for transitioning legacy instruments that lack sufficient provisions addressing LIBOR’s cessation by outlining a uniform process to govern the transition from LIBOR to a replacement rate.
The LIBOR Act also establishes a safe harbor for lenders, shielding lenders from litigation as a result of their choice of a replacement rate (such as SOFR) per FRB recommendations.
On December 16, 2022, the FRB issued its final regulations which carry out the terms of the LIBOR Act.
These regulations: (i) address the applicability of the LIBOR Act to various LIBOR contracts, (ii) identify the FRB-selected benchmark replacements for various types of LIBOR contracts, (iii) include certain benchmark replacement conforming changes, (iv) address the issue of preemption and (v) provide other clarifications, definitions and information.
The regulations will become effective on February 27, 2023, which is thirty (30) days after the regulations were published in the Federal Register.
The Bancorp’s LIBOR transition plan is organized around key work streams, including continued engagement with central banks and industry working groups and regulators, active client engagement, comprehensive review of legacy documentation, internal operational and technological readiness, and risk management, among other things, to facilitate the transition to alternative reference rates.
Although the full impact of LIBOR reforms and actions remains unclear, the Bancorp has discontinued entering into new LIBOR-based contracts in accordance with regulatory guidance, except for permissible limited use, such as part of hedging and risk management programs.
During the fourth quarter of 2021, the Bancorp expanded its offering of alternative reference rate products, including SOFR.
In addition, the Bancorp is continuing its transition of existing LIBOR-based exposures to an appropriate alternative reference rate on or before June 30, 2023.
As of December 31, 2022, the Bancorp had substantial exposure to LIBOR-based products throughout several of its lines of business.
These exposures included derivative contracts with a total notional value of approximately $96 billion, loans outstanding of approximately $24 billion, preferred stock of approximately $1.4 billion and long-term debt of approximately $237 million.
The Bancorp currently estimates that approximately 8% of the existing exposures will mature before June 30, 2023.
For the contracts that will not mature prior to June 30, 2023, an additional portion of these contracts is subject to contractual terms specifying alternative reference rates (“fallback provisions”) that would become effective upon cessation of LIBOR’s publication.
Existing exposures without fallback provisions are expected to either be amended prior to June 30, 2023 to include such provisions or to transition to an alternative reference rate pursuant to the terms of the LIBOR Act and its related regulations.
For a further discussion of the various risks the Bancorp faces in connection with the replacement of LIBOR on its operations, see “Risk Factors—Market Risks—The replacement of LIBOR could adversely affect Fifth Third’s revenue or expenses and the value of those assets or obligations.” in Item 1A.
Risk Factors of this Annual Report on Form 10-K.
| | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
Provision expense increased for the year ended December 31, 2022 compared to the prior year primarily driven by factors which caused increases in the ACL during the year ended December 31, 2022 including deterioration in forecasted macroeconomic conditions and higher period-end loan and lease balances, primarily driven by commercial and industrial loan growth, originations of point-of-sale solar energy installation loans in the second half of 2022 and loans acquired in a business acquisition completed in the second quarter of 2022.
Pre-provision net revenue is net interest income plus noninterest income minus noninterest expense.
An excerpt. Shown here: 40 of 1,044 rewritten, 40 of 379 added and 40 of 333 removed. The counts are complete. For every sentence, read Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS in the FY2023 filing and the FY2022 filing.
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
1 rewritten, 0 added, 0 removed, 2 unchanged
Refer to page [removed: [19](#i48540c50bc474a4186cf9dc1957cda5d_10)] [added: [15](#i1f68b48eea92495388df6551a4f9ea63_10)] for cautionary information regarding forward-looking statements.
Item 1. BUSINESS
68 rewritten, 60 added, 38 removed, 261 unchanged
As of December 31, [removed: 2022,] [added: 2023,] Fifth Third had [removed: $207] [added: $215] billion in assets and operates [removed: 1,087] [added: 1,088] full-service Banking Centers and [removed: 2,132] [added: 2,104] Fifth Third branded ATMs in Ohio, Kentucky, Indiana, Michigan, Illinois, Florida, Tennessee, West Virginia, Georgia, North Carolina and South Carolina.
Fifth Third is among the largest money managers in the Midwest and, as of December 31, [removed: 2022,] [added: 2023,] had [removed: $510] [added: $574] billion in assets under care, of which it managed [removed: $55] [added: $59] billion for individuals, corporations and not-for-profit organizations.
Refer to Exhibit 21 filed as an attachment to this Annual Report on Form 10-K for a list of subsidiaries of the Bancorp as of February 15, [removed: 2023.][added: 2024.]
The Bancorp’s human capital [removed: programs are] [added: strategy is] designed to attract, develop and retain [removed: a workforce that reflects the communities it serves.][added: talent.]
As of December 31, [removed: 2022,] [added: 2023,] the Bancorp had [removed: 19,319] [added: 18,724] full-time equivalent employees, compared to [removed: 19,112] [added: 19,319] as of December 31, [removed: 2021.][added: 2022.]
These employees support the organization’s [removed: ambition] [added: vision] to be the One Bank people most value and trust by upholding its four Core Values: Be Respectful & Inclusive, Take Accountability, Work as One Bank and Act with Integrity.
[Table of [removed: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)][added: Contents](#i1f68b48eea92495388df6551a4f9ea63_52)]
Fifth Third believes that [removed: inclusion and diversity are] [added: an inclusive culture is] essential to living its Core Values, serving its customers, delivering financial performance and being recognized as a leader in building an engaging [removed: workplace, a strong supplier base and vibrant communities.][added: workplace.]
As of December 31, [removed: 2022,] [added: 2023,] the Bancorp’s employees were approximately [removed: 58%] [added: 57%] female and approximately [removed: 28%] [added: 29%] persons of color: [removed: 72%] [added: 71%] White, 13% Black/African American, 8% Hispanic/Latino, [removed: 5%] [added: 6%] Asian, and 2% Other.
The Bancorp has [removed: an Executive Diversity Leadership Council which continues] [added: embedded approaches that continue] to [removed: lead concentrated] [added: drive] strategies across several key workstreams that focus on employees, customers, and the community.
To support its commitment, the Bancorp has invested in the ongoing growth and expansion of its [added: nine] employee Business Resource Groups (“BRGs”).
The Bancorp’s continuous listening strategy [removed: forms the foundation] [added: is an important component] of its [removed: employee] [added: inclusive] culture.
The Bancorp’s holistic approach to collecting, measuring and responding to employee feedback enhances [removed: engagement with employees] [added: the employee experience] at critical points during [removed: their careers and during] times of change in business or work environments.
Feedback is collected through a variety of methods, including the Employee Viewpoints Survey which includes questions [removed: around] [added: related to culture,] engagement, inclusion, [removed: customer experience] [added: employee well-being, expectations] and [removed: the Bancorp’s culture.][added: intent to stay.]
[removed: Each year,] [added: In addition,] the Bancorp requires all employees and contingent workers to complete [removed: courses related to risk and] compliance [removed: on topics] [added: courses] that support strong risk management behaviors and accountability.
[removed: In addition, the] [added: The] Bancorp’s [removed: learning and] [added: learning,] development [added: and career mobility] strategy delivers personalized and accessible experiences that fuel career growth and help retain talent.
[removed: The Bancorp continues to honor] [added: Although not] a [added: nationwide requirement, Fifth Third recognizes a] footprint-wide [removed: ban on] salary [removed: history, which means that the Bancorp] [added: history ban and] does not ask for a candidate’s current salary to use as a factor in determining an employment offer.
In addition to traditional benefit offerings, the Bancorp offers a 401(k) retirement program that pays a match up to 7% of an employee’s eligible compensation, parental bonding leave, telemedicine [removed: services,] [added: services] and tools that help find the highest quality and lowest cost treatment options.
These services [removed: help] assist employees in maintaining a healthy work-life balance.
Full year [removed: 2022] turnover [removed: decreased to 21.0%] [added: significantly improved, decreasing] from [removed: 21.2%] [added: 21.0%] in [removed: 2021.][added: 2022 to 16.9% in 2023.]
These typically involve the payment of a premium over book value and current market price, and therefore, some dilution of [added: tangible] book value and net income per share may occur with any future transactions.
[removed: Among other regulatory changes, the] [added: The] EGRRCPA [removed: amends] [added: amended] various sections of Dodd-Frank, including section 165, which was revised to raise the asset thresholds for determining the application of enhanced prudential standards for BHCs.
[removed: On October 10, 2019,] [added: Subsequent to] the [added: EGRRCPA, the] FRB adopted a rule that adjusts the thresholds at which certain enhanced prudential standards (“EPS”) apply to BHCs with $100 billion or more in total consolidated assets (the “EPS Tailoring Rule”) and the FRB, the Office of the Comptroller of the Currency (the “OCC”) and FDIC adopted a rule that similarly adjusts the thresholds at which certain other capital and liquidity standards apply to BHCs and banks with $100 billion or more in total consolidated assets (the “Capital and Liquidity Tailoring Rule” and, together with the EPS Tailoring Rule, the “Tailoring Rules”).
The Tailoring Rules establish four risk-based categories of institutions, and the extent to [added: which enhanced prudential standards and certain other capital and liquidity standards apply to these BHCs and banks depends on the banking organization’s category.]
The Bancorp and the Bank are required to file various reports with and are subject to examination by various regulators, including the FRB, the [removed: OCC,] [added: OCC] and the CFPB.
This discussion is not intended to describe all laws and regulations applicable to the Bancorp, the [removed: Bank,] [added: Bank] and the Bancorp’s other subsidiaries.
[removed: The FRB] [added: U.S. banking regulators] may require a BHC to make capital injections into a troubled subsidiary bank and may charge the BHC with engaging in unsafe and unsound practices if the BHC fails to commit resources to such a subsidiary bank or if it undertakes actions that the FRB believes might jeopardize the BHC’s ability to commit resources to such subsidiary bank.
The DIF provides insurance coverage for certain deposits, up to a standard maximum deposit insurance amount of $250,000 per depositor per account ownership category [added: per bank] and is funded through assessments on insured depository institutions, based on the risk each institution poses to the DIF.
The FDIC’s amended restoration plan increases the initial base deposit insurance assessment rate schedules uniformly by 2 basis points, [removed: beginning in] [added: which began with] the first quarterly assessment period of 2023.
The FDIC, FRB and OCC have jointly issued rules for institutions that do not apply advanced approaches to regulatory capital, including the [removed: Bancorp and the Bank.]
As of December 31, [removed: 2022,] [added: 2023,] the Bancorp was permitted to use 100% of its eligible retained income for these purposes in the first quarter of [removed: 2023.][added: 2024.]
The amount of the modified CECL transition amount was then fixed as of December 31, 2021 and that amount [removed: will be] [added: is] subject to the three-year phase out.
For purposes of the FRB’s Regulation Y, including determining whether a BHC meets the requirements to be an FHC, BHCs, such as the Bancorp, must maintain [added: a Tier 1 Risk-Based Capital Ratio of 6.0% or greater and a Total Risk-Based Capital Ratio of 10.0% or greater.]
If the FRB were to apply the same or a very similar well-capitalized standard to BHCs as that applicable to the Bank, the Bancorp’s capital ratios as of December 31, [removed: 2022,] [added: 2023,] would exceed such revised well-capitalized standard.
The following table presents the minimum regulatory capital ratios, minimum ratio plus stress capital buffer, and well-capitalized minimums compared with the Bancorp’s and the Bank’s regulatory capital ratios as of December 31, [removed: 2022,] [added: 2023,] calculated using the regulatory capital methodology applicable during [removed: 2022:][added: 2023:]
| | | | Minimum Regulatory Capital Ratio | | | | | | Minimum Ratio + Stress Capital Buffer*(a)* | | | | | | Well-Capitalized Minimums*(b)* | | | | | | Actual at December 31, [removed: 2022] [added: 2023] | | |
| Fifth Third Bancorp | | | 4.50 | | % | | | | 7.00 | | | | | | N/A | | | | | | [removed: 9.28] [added: 10.29] | | |
| Fifth Third Bank, National Association | | | 4.50 | | | | | | 7.00 | | | | | | 6.50 | | | | | | [removed: 11.31] [added: 12.42] | | |
| Fifth Third Bancorp | | | 6.00 | | | | | | 8.50 | | | | | | 6.00 | | | | | | [removed: 10.53] [added: 11.59] | | |
| Fifth Third Bank, National Association | | | 6.00 | | | | | | 8.50 | | | | | | 8.00 | | | | | | [removed: 11.31] [added: 12.42] | | |
This strategy ensures that Fifth Third has the talent, capabilities, and organizational structure to support business needs now and in the future.
All employees regardless of background may join any BRG.
Each BRG focuses on three pillars: employee development, community involvement/volunteerism and business innovation.
BRGs across the footprint share best practices, embedding specific actions and activities to progress a culture of belonging and engagement.
In 2023, employees completed over 779,000 training hours.
The Bancorp is committed to providing competitive compensation programs that attract and retain top talent, while driving its business strategy and effectively managing risk.
Compensation programs are designed to pay for performance and consider applicable regulatory expectations, corporate values and behavioral expectations.
The Bancorp’s Compensation Philosophy aligns with the creation of long-term shareholder value.
In 2023, the Bancorp transitioned to a new paid time off structure that provides employees more control and flexibility to manage their time away, which includes paid time off for volunteering.
In addition, the Bancorp enhanced its wellness offerings and resources to support employees and their families.
The Bancorp continues to navigate the changing talent landscape by monitoring the external environment and adapting talent strategies to meet internal needs.
The Bancorp’s focus on the Employee Value Proposition demonstrates a continued commitment to employees by developing great leaders, evolving the employee experience, and focusing on equality, equity and inclusion.
The Bancorp’s focus on multicultural recruitment strengthens the organization by fostering an inclusive culture.
To attract the most talented employees, the Bancorp continues to enhance relationships with universities and partner organizations to attract top talent from various backgrounds including women, minorities, individuals with disabilities, veterans and LGBTQ+ individuals.
Creating and developing an inclusive workforce is important for the Bancorp’s business growth, leading to enhanced innovation while focusing on the needs of our customers.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
*19 Fifth Third Bancorp*
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
In November 2023, the FDIC issued a final rule for a special deposit insurance assessment on banking organizations with greater than $5 billion in assets to recover the costs associated with protecting uninsured depositors following the bank failures that occurred in 2023.
The estimate of the Bancorp’s special assessment under the provisions of the final rule was $224 million, which was recognized in earnings upon issuance of the final rule and will be paid to the FDIC over an anticipated total of eight quarterly assessment periods beginning with the first quarter of 2024.
On October 24, 2023, the OCC, FRB, and FDIC issued a final rule to modernize their respective CRA regulations.
The revised rules substantially alter the methodology for assessing compliance with the CRA, with material aspects taking effect January 1, 2026 and revised data reporting requirements taking effect January 1, 2027.
Among other things, the revised rules evaluate lending outside traditional assessment areas generated by the growth of non-branch delivery systems, such as online and mobile banking, apply a metrics-based benchmarking approach to assessment, and clarify eligible CRA activities.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
Bancorp and the Bank.
Refer to the Capital Management section of Management’s Discussion and Analysis of Financial Condition and Results of Operations for more information.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
*Proposed Updates to Regulatory Requirements for Capital*
On July 27, 2023, the U.S. banking agencies released a notice of proposed rulemaking to revise the Basel III Capital Rules, which would modify its existing risk-based capital framework for large banks and introduce a new framework that implements international capital standards.
The proposed rulemaking would increase capital requirements applicable to banking organizations with total assets of $100 billion or more, including Fifth Third, and would align the calculation of regulatory capital and the calculation of risk-weighted assets across large banking organizations.
As proposed, the rules would be effective for the Bancorp on July 1, 2025 and phased in over a three-year transition period.
The Bancorp is in the process of evaluating this proposed rulemaking and assessing its potential impact.
Similar to the capital conservation
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
On August 29, 2023, the U.S. banking agencies issued a notice of proposed rulemaking to require that certain banking organizations with $100 billion or more in consolidated assets, including Fifth Third, comply with certain long-term debt requirements at the holding company and insured depository institution levels.
These proposed requirements are intended to absorb losses and recapitalize the insured depository institution in the event of the failure of a banking organization.
As proposed, the rules would be phased in over a three-year period after their effective date.
The Bancorp is in the process of evaluating this proposed rulemaking and assessing its potential impact.
These laws obligate depository
The Bancorp has continued to focus on accelerating racial equality, equity and inclusion as a key priority.
These groups: African American, Asian & Pacific Islander, Individuals with Disabilities, Latino, LGBTQ+, Military, Women’s, Young Professionals, and Sustainability support the Bancorp’s three BRG Pillars; to drive business innovation, encourage community volunteerism, and provide an environment that supports employee development, engagement and networking.
In 2022, Fifth Third launched a new Sustainability BRG.
The group focuses on social, environmental and related matters which include, but are not limited to, community engagement initiatives, philanthropy, environmental programs and corporate governance practices.
The Bancorp continued to drive meaningful change in our inclusion and diversity efforts by progressing towards the Six Bold Goals it plans to achieve by 2025:
- Complete Unconscious Bias Awareness training for 100% of employees
- Ensure the diversity of the Bancorp’s workforce matches the markets it serves
- Grow leadership positions at each management level for women and persons of color
- Create a work environment where there is no disparity in race or gender
- Advance the Bancorp as a leader in diversity and inclusion
- Achieve and sustain a 10% supplier diversity spend
Progressing on these goals, the Bancorp has seen an increase in diversity of its workforce in seven of the nine states in its branch network footprint that include 250 or more employees and continues to be recognized in various nationwide rankings for advancing as a leader in inclusion and diversity.
The Bancorp has also continued to progress towards its goal of achieving and sustaining a 10% supplier diversity spend during the year ended December 31, 2022.
Employees completed over 775,000 training hours during 2022, including content covering unconscious bias.
The Bancorp is committed to providing competitive compensation programs that attract and retain top talent to drive its business strategy, effectively manage risk within incentive programs designed to pay for performance, consider applicable regulatory expectations with attention to corporate values and behavioral expectations, and align with the creation of long-term shareholder value.
In 2022, the Bancorp raised its minimum wage to $20 per hour and concurrently provided a wage adjustment for its first four job levels.
These changes resulted in a compensation increase for more than 40% of the Bancorp’s employees.
In 2022, the Bancorp conducted a Total Rewards Survey to assess which components of its compensation and benefit programs were most important to employees.
In response to feedback obtained in this survey, the Bancorp made enhancements to its benefits packages, effective
in 2023.
These included minimizing benefit cost increases on its medical plans, transitioning to a new paid time off structure that provides employees more control and flexibility to manage their time away and updating its short-term disability program to enhance the value it provides to employees.
In 2022, the Bancorp continued to face a rapidly changing work environment and workforce.
The Bancorp responded proactively by reinforcing its employee value proposition which centers around inclusion and diversity, employee health and wellness and career development.
Through strategic actions and decisions as well as its human capital policies, programs and practices, the Bancorp helped support a culture of belonging and performance where employees feel valued and motivated to succeed.
Fifth Third executed several retention strategies in 2022 to address trends in employee attrition including a focus on employee development and career progression, workplace flexibility and continued employee listening strategies.
The Bancorp’s multicultural recruitment strategy strengthens the organization by developing an employee base that reflects the communities it serves while also enhancing the lives of tomorrow’s leaders.
The Bancorp has strong partnerships with diversity-focused affinity groups, both with universities and partner organizations, that drive engagement with a diverse candidate population which includes women, minorities, LGBTQ+ communities, individuals with disabilities and veterans.
On May 24, 2018, the EGRRCPA was signed into law.
which enhanced prudential standards and certain other capital and liquidity standards apply to these BHCs and banks depends on the banking organization’s category.
On May 5, 2022, the OCC, FRB, and FDIC issued a notice of proposed rulemaking to provide for a coordinated approach to modernize their respective CRA regulations, such that all banks will be subject to the same set of CRA rules.
No final rule has been issued, but the rulemaking may affect the Bank’s CRA compliance obligations in the future.
This definition applies with respect to all of the Bancorp’s capital requirements.
a Tier 1 Risk-Based Capital Ratio of 6.0% or greater and a Total Risk-Based Capital Ratio of 10.0% or greater.
billion or more in total consolidated assets and was effective on October 1, 2020.
There have been a number of significant
For a registrant with a fiscal year ending on December 31, such as the Bancorp, the pay ratio was first required as part of its executive compensation disclosure in its annual proxy statement or Form 10-K filed starting in 2018.
plans to a firm’s size, complexity, and risk profile.
*Derivatives*
An excerpt. Shown here: 40 of 68 rewritten, 40 of 60 added and all 38 removed. The counts are complete. For every sentence, read Item 1. BUSINESS in the FY2023 filing and the FY2022 filing.
Cover and table of contents
38 rewritten, 11 added, 7 removed, 68 unchanged
[Table of [removed: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)][added: Contents](#i1f68b48eea92495388df6551a4f9ea63_52)]
For the fiscal year ended December 31, [removed: 2022][added: 2023]
[removed: ][added: ]
There were [removed: 678,585,140] [added: 681,221,886] shares of the Bancorp’s Common Stock, without par value, outstanding as of January 31, [removed: 2023.][added: 2024.]
The Aggregate Market Value of the Voting Stock held by non-affiliates of the Bancorp was [removed: $20,129,206,051] [added: $15,509,992,776] as of June 30, [removed: 2022.][added: 2023.]
[removed: *17] [added: *13] Fifth Third Bancorp*
Sections of the Bancorp’s Proxy Statement for the [removed: 2023] [added: 2024] Annual Meeting of Shareholders are incorporated by reference into Part III of this report.
Only those sections of this [removed: 2022] [added: 2023] Annual Report to Shareholders that are specified in this Cross Reference Index constitute part of the registrant’s Form 10-K for the year ended December 31, [removed: 2022.][added: 2023.]
No other information contained in this [removed: 2022] [added: 2023] Annual Report to Shareholders shall be deemed to constitute any part of this Form 10-K nor shall any such information be incorporated into the Form 10-K and shall not be deemed “filed” as part of the registrant’s Form 10-K.
| Item 1. | | | [removed: [Business](#i48540c50bc474a4186cf9dc1957cda5d_16)] [added: [Business](#i1f68b48eea92495388df6551a4f9ea63_16)] | | | [removed: 20] [added: [16](#i1f68b48eea92495388df6551a4f9ea63_16)] | | |
| | | | [Average Balance [removed: Sheets](#i48540c50bc474a4186cf9dc1957cda5d_73)] [added: Sheets](#i8947474c25204b0bbd84cf5ac022d3f2_0-0-1-12-665080)] | | | [removed: 66] [added: [62](#i8947474c25204b0bbd84cf5ac022d3f2_0-0-1-12-665080)] | | |
| | | | [Analysis of Net Interest Income and Net Interest Income [removed: Changes](#i48540c50bc474a4186cf9dc1957cda5d_73)] [added: Changes](#i1f68b48eea92495388df6551a4f9ea63_79)] | | | [removed: 65] [added: [61](#i1f68b48eea92495388df6551a4f9ea63_79)] | | |
| | | | [Risk Elements of Loan and Lease [removed: Portfolio](#i48540c50bc474a4186cf9dc1957cda5d_133)] [added: Portfolio](#i1f68b48eea92495388df6551a4f9ea63_136)] | | | [removed: 89] [added: [83](#i9be786e94af3459fb1982e0cd95e16a8_23475)] | | |
| | | | [Return on Equity and [removed: Assets](#i48540c50bc474a4186cf9dc1957cda5d_58)] [added: Assets](#ic72d4672d50e4f1980a0c0ec1e5cdc13_0-0-1-6-667308)] | | | [removed: 57] [added: [52](#ic72d4672d50e4f1980a0c0ec1e5cdc13_0-0-1-6-667308)] | | |
| Item 1A. | | | [Risk [removed: Factors](#i48540c50bc474a4186cf9dc1957cda5d_19)] [added: Factors](#i1f68b48eea92495388df6551a4f9ea63_19)] | | | [removed: 30] [added: [27](#i1f68b48eea92495388df6551a4f9ea63_19)] | | |
| Item 1B. | | | [Unresolved Staff [removed: Comments](#i48540c50bc474a4186cf9dc1957cda5d_22)] [added: Comments](#i1f68b48eea92495388df6551a4f9ea63_28)] | | | [removed: 47] [added: [42](#i1f68b48eea92495388df6551a4f9ea63_28)] | | |
| Item 2. | | | [removed: [Properties](#i48540c50bc474a4186cf9dc1957cda5d_25)] [added: [Properties](#i1f68b48eea92495388df6551a4f9ea63_31)] | | | [removed: 47] [added: [43](#i1f68b48eea92495388df6551a4f9ea63_31)] | | |
| Item 3. | | | [Legal [removed: Proceedings](#i48540c50bc474a4186cf9dc1957cda5d_28)] [added: Proceedings](#i1f68b48eea92495388df6551a4f9ea63_34)] | | | [removed: 47] [added: [43](#i1f68b48eea92495388df6551a4f9ea63_34)] | | |
| Item 4. | | | [Mine Safety [removed: Disclosures](#i48540c50bc474a4186cf9dc1957cda5d_31)] [added: Disclosures](#i1f68b48eea92495388df6551a4f9ea63_37)] | | | [removed: 47] [added: [43](#i1f68b48eea92495388df6551a4f9ea63_37)] | | |
| | | | [Information about our Executive [removed: Officers](#i48540c50bc474a4186cf9dc1957cda5d_34)] [added: Officers](#i1f68b48eea92495388df6551a4f9ea63_40)] | | | [removed: 48] [added: [44](#i1f68b48eea92495388df6551a4f9ea63_40)] | | |
| Item 5. | | | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities](#i48540c50bc474a4186cf9dc1957cda5d_40)] [added: Securities](#i1f68b48eea92495388df6551a4f9ea63_46)] | | | [removed: 50] [added: [46](#i1f68b48eea92495388df6551a4f9ea63_46)] | | |
| Item 7. | | | [Management’s Discussion and Analysis of Financial Condition and Results of [removed: Operations](#i48540c50bc474a4186cf9dc1957cda5d_55)] [added: Operations](#i1f68b48eea92495388df6551a4f9ea63_61)] | | | [removed: 54] [added: [50](#i1f68b48eea92495388df6551a4f9ea63_61)] | | |
| Item 7A. | | | [Quantitative and Qualitative Disclosures About Market [removed: Risk](#i48540c50bc474a4186cf9dc1957cda5d_175)] [added: Risk](#i1f68b48eea92495388df6551a4f9ea63_172)] | | | [removed: 117] [added: [109](#i1f68b48eea92495388df6551a4f9ea63_172)] | | |
| Item 8. | | | [Financial Statements and Supplementary [removed: Data](#i48540c50bc474a4186cf9dc1957cda5d_175)] [added: Data](#i1f68b48eea92495388df6551a4f9ea63_172)] | | | [removed: 117] [added: [109](#i1f68b48eea92495388df6551a4f9ea63_172)] | | |
| Item 9. | | | [Changes in and Disagreements with Accountants on Accounting and Financial [removed: Disclosure](#i48540c50bc474a4186cf9dc1957cda5d_301)] [added: Disclosure](#i1f68b48eea92495388df6551a4f9ea63_298)] | | | [removed: 215] [added: [211](#i1f68b48eea92495388df6551a4f9ea63_298)] | | |
| Item 9A. | | | [Controls and [removed: Procedures](#i48540c50bc474a4186cf9dc1957cda5d_304)] [added: Procedures](#i1f68b48eea92495388df6551a4f9ea63_301)] | | | [removed: 215] [added: [211](#i1f68b48eea92495388df6551a4f9ea63_301)] | | |
| Item 9B. | | | [Other [removed: Information](#i48540c50bc474a4186cf9dc1957cda5d_310)] [added: Information](#i1f68b48eea92495388df6551a4f9ea63_307)] | | | [removed: 217] [added: [213](#i1f68b48eea92495388df6551a4f9ea63_307)] | | |
| Item 9C. | | | [Disclosure Regarding Foreign Jurisdictions that Prevent [removed: Inspection](#i48540c50bc474a4186cf9dc1957cda5d_313)] [added: Inspection](#i1f68b48eea92495388df6551a4f9ea63_310)] | | | [removed: 217] [added: [213](#i1f68b48eea92495388df6551a4f9ea63_310)] | | |
| Item 10. | | | [Directors, Executive Officers and Corporate [removed: Governance](#i48540c50bc474a4186cf9dc1957cda5d_319)] [added: Governance](#i1f68b48eea92495388df6551a4f9ea63_316)] | | | [removed: 217] [added: [213](#i1f68b48eea92495388df6551a4f9ea63_316)] | | |
| Item 11. | | | [Executive [removed: Compensation](#i48540c50bc474a4186cf9dc1957cda5d_322)] [added: Compensation](#i1f68b48eea92495388df6551a4f9ea63_319)] | | | [removed: 217] [added: [213](#i1f68b48eea92495388df6551a4f9ea63_319)] | | |
| Item 12. | | | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder [removed: Matters](#i48540c50bc474a4186cf9dc1957cda5d_325)] [added: Matters](#i1f68b48eea92495388df6551a4f9ea63_322)] | | | [removed: 217] [added: [213](#i1f68b48eea92495388df6551a4f9ea63_322)] | | |
| Item 13. | | | [Certain Relationships and Related Transactions, and Director [removed: Independence](#i48540c50bc474a4186cf9dc1957cda5d_328)] [added: Independence](#i1f68b48eea92495388df6551a4f9ea63_325)] | | | [removed: 217] [added: [214](#i1f68b48eea92495388df6551a4f9ea63_325)] | | |
| Item 14. | | | [Principal Accounting Fees and [removed: Services](#i48540c50bc474a4186cf9dc1957cda5d_331)] [added: Services](#i1f68b48eea92495388df6551a4f9ea63_328)] | | | [removed: 217] [added: [214](#i1f68b48eea92495388df6551a4f9ea63_328)] | | |
| Item 15. | | | [Exhibits, Financial Statement [removed: Schedules](#i48540c50bc474a4186cf9dc1957cda5d_337)] [added: Schedules](#i1f68b48eea92495388df6551a4f9ea63_334)] | | | [removed: 218] [added: [215](#i1f68b48eea92495388df6551a4f9ea63_334)] | | |
| Item 16. | | | [Form 10–K [removed: Summary](#i48540c50bc474a4186cf9dc1957cda5d_340)] [added: Summary](#i1f68b48eea92495388df6551a4f9ea63_337)] | | | [removed: 222] [added: [219](#i1f68b48eea92495388df6551a4f9ea63_337)] | | |
[removed: *18] [added: *14] Fifth Third Bancorp*
Factors that might cause such a difference include, but are not limited to: (1) [removed: effects of the global COVID-19 pandemic; (2)] deteriorating credit quality; [removed: (3)] [added: (2)] loan concentration by location or industry of borrowers or collateral; [removed: (4)] [added: (3)] problems encountered by other financial institutions; [removed: (5)] [added: (4)] inadequate sources of funding or liquidity; [removed: (6)] [added: (5)] unfavorable actions of rating agencies; [removed: (7)] [added: (6)] inability to maintain or grow deposits; [removed: (8)] [added: (7)] limitations on the ability to receive dividends from subsidiaries; [removed: (9)] [added: (8)] cyber-security risks; [removed: (10)] [added: (9)] Fifth Third’s ability to secure confidential information and deliver products and services through the use of computer systems and telecommunications networks; [removed: (11)] [added: (10)] failures by third-party service providers; [removed: (12)] [added: (11)] inability to manage strategic initiatives and/or organizational changes; [removed: (13)] [added: (12)] inability to implement technology system enhancements; [removed: (14)] [added: (13)] failure of internal controls and other risk management [removed: systems; (15)] [added: programs; (14)] losses related to fraud, theft, misappropriation or violence; [removed: (16)] [added: (15)] inability to attract and retain skilled personnel; [removed: (17)] [added: (16)] adverse impacts of government regulation; [removed: (18)] [added: (17)] governmental or regulatory changes or other actions; [removed: (19)] [added: (18)] failures to meet applicable capital requirements; [removed: (20)] [added: (19)] regulatory objections to Fifth Third’s capital plan; [removed: (21)] [added: (20)] regulation of Fifth Third’s derivatives activities; [removed: (22)] [added: (21)] deposit insurance premiums; [removed: (23)] [added: (22)] assessments for the orderly liquidation fund; [removed: (24) replacement of LIBOR; (25)] [added: (23)] weakness in the national or local economies; [removed: (26)] [added: (24)] global political and economic uncertainty or negative actions; [removed: (27)] [added: (25)] changes in interest rates and the effects of inflation; [removed: (28)] [added: (26)] changes and trends in capital markets; [removed: (29)] [added: (27)] fluctuation of Fifth Third’s stock price; [removed: (30)] [added: (28)] volatility in mortgage banking revenue; [removed: (31)] [added: (29)] litigation, investigations, and enforcement proceedings by governmental authorities; [removed: (32)] [added: (30)] breaches of contractual covenants, representations and warranties; [removed: (33)] [added: (31)] competition and changes in the financial services industry; [removed: (34)] [added: (32) potential impacts of the adoption of real-time payment networks; (33)] changing retail distribution strategies, customer preferences and behavior; [removed: (35)] [added: (34)] difficulties in identifying, acquiring or integrating suitable strategic partnerships, investments or acquisitions; [removed: (36)] [added: (35)] potential dilution from future acquisitions; [removed: (37)] [added: (36)] loss of income and/or difficulties encountered in the sale and separation of businesses, investments or other assets; [removed: (38)] [added: (37)] results of investments or acquired entities; [removed: (39)] [added: (38)] changes in accounting standards or interpretation or declines in the value of Fifth Third’s goodwill or other intangible assets; [removed: (40)] [added: (39)] inaccuracies or other failures from the use of models; [removed: (41)] [added: (40)] effects of critical accounting policies and judgments or the use of inaccurate estimates; [removed: (42)] [added: (41)] weather-related events, other natural disasters, or health emergencies (including pandemics); [removed: (43)] [added: (42)] the impact of reputational risk created by these or other developments on such matters as business generation and retention, funding and liquidity; [removed: (44)] [added: (43)] changes in law or requirements imposed by Fifth Third’s regulators impacting our capital actions, including dividend payments and stock repurchases; and [removed: (45)] [added: (44)] Fifth Third’s ability to meet its environmental and/or social targets, goals and commitments.
[removed: *19] [added: *15] Fifth Third Bancorp*
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
| | | | [Employees](#i1f68b48eea92495388df6551a4f9ea63_16) | | | [16](#iccba0c9bf94c49ffa5a7c9a2cd90b823_141713), [67](#i15312f3c74d04e959cfccc1f737ca3ef_12467) | | |
| | | | [Segment Information](#i1f68b48eea92495388df6551a4f9ea63_94) | | | [69](#i1f68b48eea92495388df6551a4f9ea63_94), [207](#i1f68b48eea92495388df6551a4f9ea63_292) | | |
| | | | [Investment Securities Portfolio](#i1f68b48eea92495388df6551a4f9ea63_121) | | | [76](#i1f68b48eea92495388df6551a4f9ea63_121), [134](#i1f68b48eea92495388df6551a4f9ea63_208) | | |
| | | | [Loan and Lease Portfolio](#i1f68b48eea92495388df6551a4f9ea63_118) | | | [75](#i1f68b48eea92495388df6551a4f9ea63_118), [137](#i1f68b48eea92495388df6551a4f9ea63_211) | | |
| | | | [Deposits](#i1f68b48eea92495388df6551a4f9ea63_127) | | | [78](#i1f68b48eea92495388df6551a4f9ea63_127) | | |
| | | | [Short-term Borrowings](#i1f68b48eea92495388df6551a4f9ea63_130) | | | [80](#i1f68b48eea92495388df6551a4f9ea63_130), [169](#i1f68b48eea92495388df6551a4f9ea63_244) | | |
| Item 1C. | | | [Cybersecurity](#i1f68b48eea92495388df6551a4f9ea63_2413) | | | [42](#i1f68b48eea92495388df6551a4f9ea63_2413) | | |
| SIGNATURES | | | | | | [220](#i1f68b48eea92495388df6551a4f9ea63_340) | | |
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
| | | | [Employees](#i48540c50bc474a4186cf9dc1957cda5d_16) | | | 20, 70 | | |
| | | | [Segment Information](#i48540c50bc474a4186cf9dc1957cda5d_88) | | | 72, 211 | | |
| | | | [Investment Securities Portfolio](#i48540c50bc474a4186cf9dc1957cda5d_115) | | | 82, 140 | | |
| | | | [Loan and Lease Portfolio](#i48540c50bc474a4186cf9dc1957cda5d_112) | | | 81, 143 | | |
| | | | [Deposits](#i48540c50bc474a4186cf9dc1957cda5d_121) | | | 84 | | |
| | | | [Short-term Borrowings](#i48540c50bc474a4186cf9dc1957cda5d_127) | | | 86, 172 | | |
| SIGNATURES | | | | | | 223 | | |
Item 1C. CYBERSECURITY
0 rewritten, 47 added, 0 removed, 0 unchanged
New section this year
The Bancorp recognizes the importance of maintaining a cybersecurity risk management system designed to reduce the risks that cybersecurity threats pose to financial institutions.
As such, the Bancorp has adopted proactive and defensive safeguards intended to better protect the Bancorp’s information assets and supporting infrastructures from technology-related attacks.
The Bancorp’s Board of Directors and management oversee its information security and cybersecurity risk management programs.
As further discussed below, the Bancorp has established various programs, policies and procedures which are designed to proactively protect information assets.
However, not all incidents can be prevented.
As a result, the Bancorp has also established various policies and procedures governing how to respond to security incidents, with the objective of minimizing any potential impacts.
As of December 31, 2023, the Bancorp is not aware of any cybersecurity incidents that have materially affected or are reasonably likely to materially affect Fifth Third, including its business strategies, results of operations or financial condition.
*Risk Assessment and Management*
The Bancorp maintains a variety of programs and policies to support the management of cybersecurity risk within the organization with a focus on prevention, detection and recovery processes.
These programs and policies leverage frameworks and controls from the National Institute of Standards and Technology as well as various other regulatory requirements and industry-specific standards.
The Bancorp also participates in the federally recognized Financial Services Information Sharing and Analysis Center and requires its employees and contractors to complete various education and training programs related to information security.
The Bancorp’s Information Technology (IT) and Information Security (IS) teams have the primary responsibility for establishing appropriate policies and procedures that are responsive to cybersecurity threats and other information security risks.
The Bancorp’s Information Technology and Cybersecurity Risk Management (IT CSRM) team, as part of the Bancorp’s Risk Management division, provides independent risk management oversight to those IT and IS teams.
In addition to the Board oversight discussed below, the Bancorp’s Internal Audit function independently oversees, reviews and validates these activities and reports to the Board of Directors on the effectiveness of governance, risk management and internal controls.
The Bancorp has established an Enterprise Risk Management Framework which informs the Bancorp’s risk management programs.
As part of this framework, the IT CSRM team maintains the Bancorp’s IT CSRM Program, which is designed to identify, assess, manage, monitor, and report cybersecurity risks as part of the Bancorp’s independent risk management function.
The IT CSRM team is responsible for defining the risk management practices set forth in the IT CSRM Program.
Refer to the Risk Management – Overview section of Item 7 (Management’s Discussion and Analysis of Financial Condition and Results of Operations) of this Annual Report for additional information on the Bancorp’s Enterprise Risk Management Framework and related risk management processes.
In light of the complexity and evolving nature of the cybersecurity landscape, the Bancorp periodically re-assesses the maturity of its cybersecurity programs, policies and procedures, including in some instances by engaging the assistance of external experts.
The Bancorp also conducts exercises to test its incident response plans and threat assessments, some of which also involve assistance from external consultants.
The Bancorp also maintains a Third Party Risk Management Program to perform similar functions related to risks associated with the Bancorp’s relationships with third parties.
This assists the Bancorp in its management of its relationships with third parties, which includes considerations for identifying, analyzing and monitoring the cybersecurity risks that third parties may present to Fifth Third.
The Bancorp also maintains a third-party incident response program to govern its response in the event of third-party cybersecurity events.
*Board of Directors Oversight*
The Technology Committee of the Bancorp’s Board of Directors takes primary responsibility for overseeing the Bancorp’s information security programs at the Board level.
The Technology Committee’s primary purpose is to assist the Board of Directors in its oversight of plans and operations related to information technology, cybersecurity, data privacy and third-party technology strategy.
The Bancorp’s Risk and Compliance Committee of the Board of Directors oversees the Bancorp’s Enterprise Risk Management Framework and policies, including oversight of risks related to information security.
The Risk and Compliance Committee receives periodic reports from the Technology Committee and these committees meet jointly at least once per year to discuss the Company’s programs and risks.
The full Board of Directors receives reports from the Technology Committee and the Risk and Compliance Committee about the Bancorp’s cybersecurity programs as a result of the above-described oversight.
In the event of a material cybersecurity incident, the Bancorp’s incident response procedures include notifications to the Technology Committee, Risk and Compliance Committee and full Board of Directors, when appropriate and necessary.
*42 Fifth Third Bancorp*
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
*Management Oversight*
The Bancorp’s Information Security Governance Committee (ISGC) is a management committee that reviews and discusses critical information security risks that impact the Bancorp, identifies solutions to address these risks and has oversight of the Bancorp’s information technology and information security policies.
The ISGC provides cybersecurity reports periodically to the Risk and Compliance Committee and is comprised of the Bancorp’s senior information security, information technology and enterprise risk management leaders, including the Chief Information Security Officer (CISO), Chief Information Officer, Chief Technology Officer, Chief Data Officer and Chief Operational Risk Officer.
The Bancorp’s CISO is responsible for information security policies and the coordination of information security efforts across the organization.
The CISO has over 35 years of diverse experience in information technology management and cybersecurity leadership at Fifth Third and at other large, complex organizations.
This prior experience includes leadership of functions for cybersecurity threat management, intelligence, risk mitigation and incident response.
The CISO has a Bachelor of Science degree in Computer and Information Science and is a certified Six Sigma Black Belt.
The Bancorp’s CISO reports to the Chief Information Officer.
An excerpt. Shown here: all 0 rewritten, 40 of 47 added and all 0 removed. The counts are complete. For every sentence, read Item 1C. CYBERSECURITY in the FY2023 filing.
Item 2. PROPERTIES
2 rewritten, 0 added, 0 removed, 6 unchanged
At December 31, [removed: 2022,] [added: 2023,] the Bancorp, through its banking and non-banking subsidiaries, operated [removed: 1,087] [added: 1,088] banking centers, of which [removed: 744] [added: 727] were owned, [removed: 203] [added: 192] were leased and [removed: 140 for which the buildings are] [added: 169 were in] owned [added: buildings] but [removed: the land is leased.][added: on leased land.]
The banking centers are located in the states of Ohio, [removed: Kentucky, Indiana,] [added: Florida,] Michigan, Illinois, [removed: Florida,] [added: Indiana, North Carolina, Kentucky,] Tennessee, [removed: West Virginia,] Georgia, [removed: North] [added: South] Carolina and [removed: South Carolina.][added: West Virginia.]
Item 4. MINE SAFETY DISCLOSURES
16 rewritten, 18 added, 24 removed, 41 unchanged
[removed: *47] [added: *43] Fifth Third Bancorp*
[Table of [removed: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)][added: Contents](#i1f68b48eea92495388df6551a4f9ea63_52)]
The names, ages and positions of the Executive Officers of the Bancorp as of February [removed: 24, 2023] [added: 27, 2024] are listed below along with their business experience during the past five years:
[added: Executive Vice] President and Chief [removed: Executive] [added: Operating] Officer since [removed: July 2022.][added: January 2024.]
Mr. Spence has been [added: Chairman since January 2024, Chief Executive Officer since July 2022 and] President since October 2020.
He also previously served as a senior partner in the Financial Services practice at Oliver [removed: Wyman since 2006,] [added: Wyman,] a global strategy and risk management consulting [removed: firm.][added: firm, from 2006 to 2015.]
Previously, Mr. Hazel was the Assistant Bancorp Controller [removed: since] [added: from] 2006 [added: to 2010] and was the Controller of Nonbank entities [removed: since 2003.][added: from 2003 to 2006.]
Executive Vice President and Chief Financial Officer since [removed: November 2020.][added: January 2024.]
Previously, Mr. Leonard was Chief [added: Financial Officer from November 2020 to December 2023, Chief] Risk Officer from February 2020 to November 2020, Treasurer of the Bancorp from October 2013 to January 2020, Senior Vice President from October 2013 to September 2015, the Director of Business Planning and Analysis from 2006 to 2013 and the Chief Financial Officer of the Commercial Banking Division from 2001 to 2006.
Executive Vice [removed: President and] [added: President,] Chief [removed: Credit] [added: Legal] Officer [removed: since November 2020.][added: and Corporate Secretary.]
Mr. [removed: Stein] [added: Preston] has been an Executive Vice President of the Bancorp since [removed: April 2016.][added: October 2022.]
[removed: *48] [added: *44] Fifth Third Bancorp*
She also served as Senior Vice President, Chief Digital [removed: Officer,] [added: Officer] and Head of Omnichannel Banking Experiences, Design, and Innovation from May 2016 through November 2020.
[added: Ms. Zaunbrecher has been] Executive Vice President and Chief Legal Officer [removed: of the Bancorp] since May 2018.
[removed: Previously,] [added: Prior to Fifth Third,] Ms. Zaunbrecher was a partner at the law firm Dinsmore and Shohl LLP, where she practiced for 28 years and served as the Chair of the Corporate Department and a member of the firm’s board of directors and executive committee.
[removed: *49] [added: *45] Fifth Third Bancorp*
Spence, 45.
Chairman, Chief Executive Officer and President.
Garrett, 65.
Gibson, 52.
Hazel, 58.
Lavender, 62.
Leonard, 54.
Pinckney, 60.
Bryan D.
Preston, 47.
Previously, Mr. Preston served as the Treasurer of the Bancorp from February 2020 to January 2024, Consumer Line of Business Chief Financial Officer from September 2017 to February 2020, Assistant Treasurer from March 2014 to September 2017 and in various other roles in finance and accounting within Fifth Third from 2008 to 2014.
Schramm, 51.
Shaffer, 54.
Stevens, 49.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
Zaunbrecher, 64.
Ms. Zaunbrecher has been Corporate Secretary since March 2023 and was previously Corporate Secretary from May 2018 to November 2020.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
Spence, 44.
Greg D.
Carmichael, 61.
Executive Chairman of the Bancorp since July 2022.
Mr. Carmichael has been Chairman of the Board since February 2018.
Previously, Mr. Carmichael was Chief Executive Officer from November 2015 to July 2022.
He was also President of the Bancorp from September 2012 to October 2020, Chief Operating Officer of the Bancorp from June 2006 to August 2015, Executive Vice President of the Bancorp from June 2006 to September 2012 and Chief Information Officer of the Bancorp from June 2003 to June 2006.
Garrett, 64.
Gibson, 50.
Howard Hammond, 57.
Executive Vice President and Head of Consumer Bank since February 2021.
Previously, he was Senior Vice President and Head of Retail Banking and Retail Brokerage from April 2020 through February 2021, Head of Retail and Brokerage Distribution from June 2019 through April 2020, and Head Managing Director of Fifth Third Securities from March 2006 through June 2019.
Hazel, 57.
Lavender, 61.
Leonard, 53.
Pinckney, 59.
Schramm, 50.
Shaffer, 53.
Richard L.
Stein, 53.
Previously, Mr. Stein was Chief Credit Officer from March 2018 through November 2020, Head
of the Commercial Bank from March 2016 through March 2018 and Senior Vice President and Chief Credit Officer from November 2014 through March 2016.
Stevens, 48.
Zaunbrecher, 63.
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
61 rewritten, 46 added, 42 removed, 26 unchanged
Additionally, as of December 31, [removed: 2022,] [added: 2023,] the Bancorp had [removed: 34,165] [added: 32,995] common shareholders of record.
| Period | | | Total Number of Shares Purchased*(a)* | | | | | | Average Price Paid Per Share | | | | | | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | | | | | | Maximum Number of Shares that May Yet be Purchased Under the Plans or [removed: Programs] [added: Programs*(b)*] | | |
[removed: *(a)Includes 106,433 shares] [added: *(a)Shares] repurchased during the [removed: fourth quarter of 2022] [added: periods presented were] in connection with various employee compensation [removed: plans of the Bancorp.][added: plans.]
[removed: *50] [added: *46] Fifth Third Bancorp*
[Table of [removed: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)][added: Contents](#i1f68b48eea92495388df6551a4f9ea63_52)]
The graphs below summarize the cumulative return experienced by the Bancorp’s shareholders over the five and ten year periods ended December 31, [removed: 2022,] [added: 2023,] respectively, compared to the S&P 500 Stock, the S&P Banks and the KBW Banks indices.
[removed: 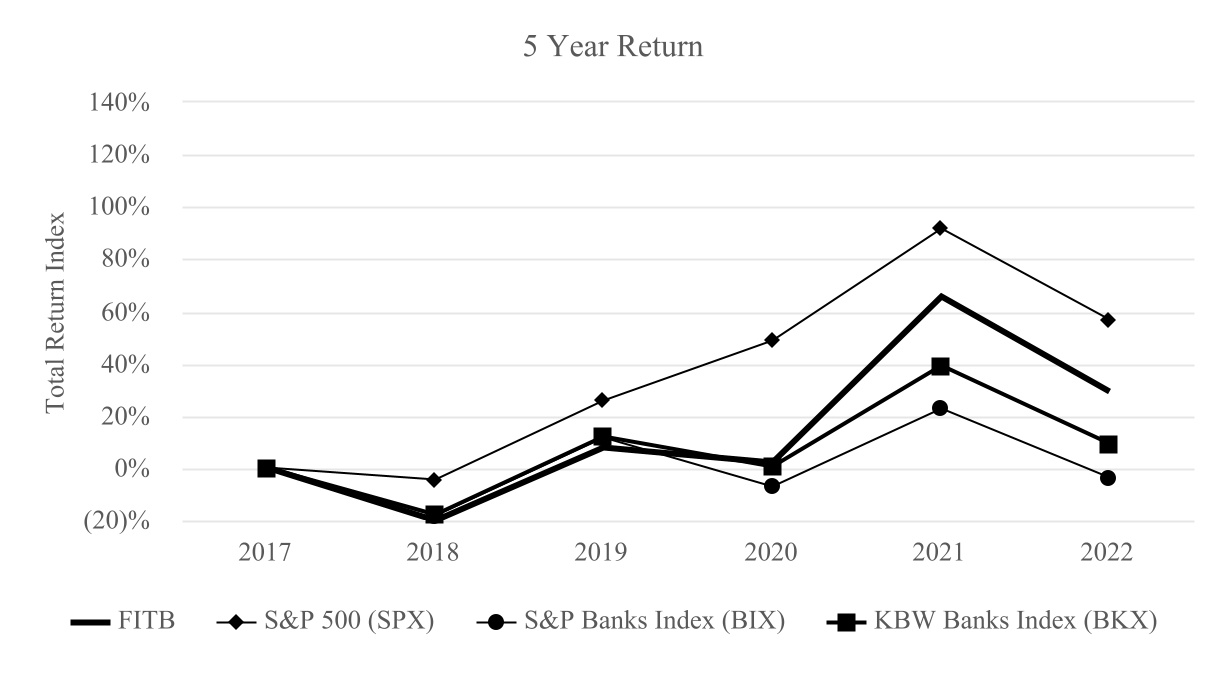][added: ]
[removed: 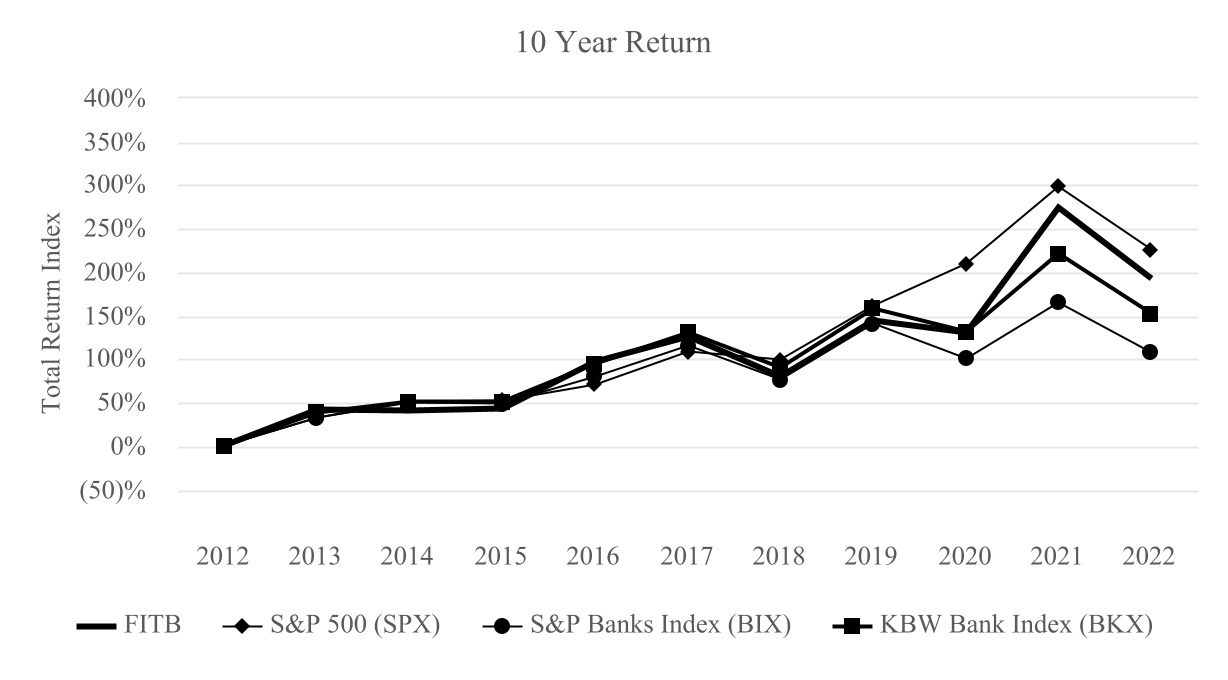][added: 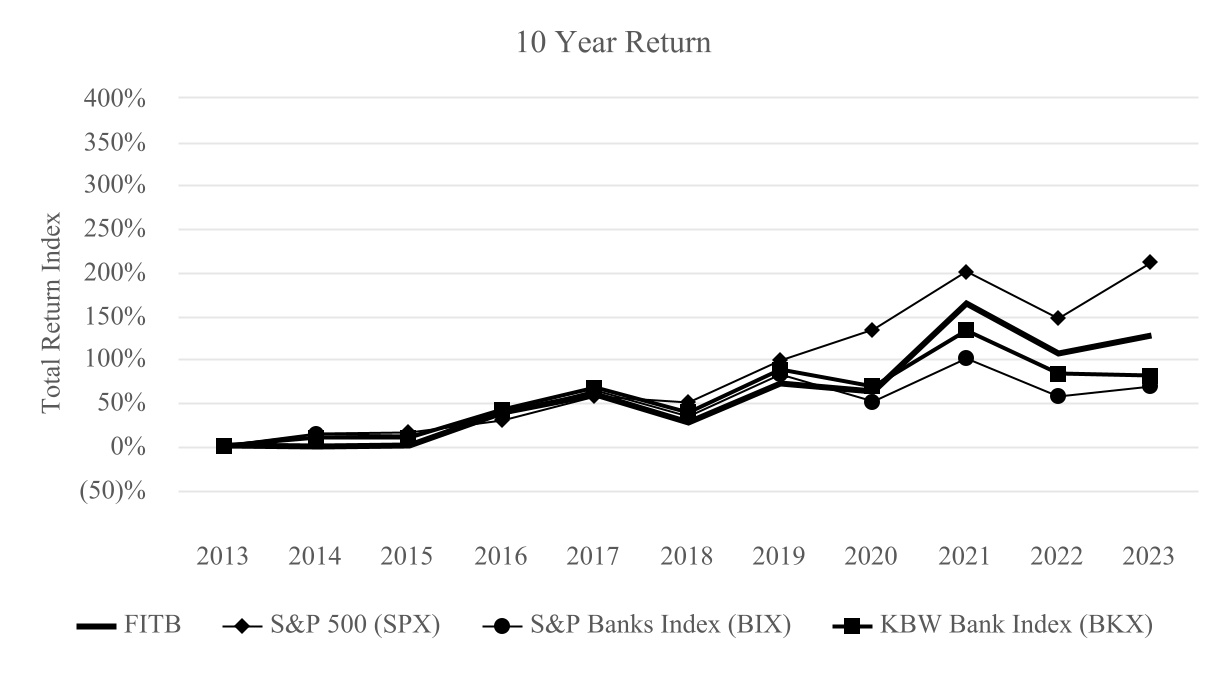]
[removed: *51] [added: *47] Fifth Third Bancorp*
[removed: ][added: ]
[removed: 2022] [added: 2023] ANNUAL REPORT
| [Glossary of Abbreviations and [removed: Acronyms](#i48540c50bc474a4186cf9dc1957cda5d_49)] [added: Acronyms](#i1f68b48eea92495388df6551a4f9ea63_58)] | | | | | | | | | [removed: [53](#i48540c50bc474a4186cf9dc1957cda5d_49)] [added: [49](#i1f68b48eea92495388df6551a4f9ea63_58)] | | |
| [Management’s Discussion and Analysis of Financial Condition and Results of [removed: Operations](#i48540c50bc474a4186cf9dc1957cda5d_55)] [added: Operations](#i1f68b48eea92495388df6551a4f9ea63_61)] | | | | | | | | | | | |
| [Non-GAAP Financial [removed: Measures](#i48540c50bc474a4186cf9dc1957cda5d_61)] [added: Measures](#i1f68b48eea92495388df6551a4f9ea63_67)] | | | | | | | | | [removed: [59](#i48540c50bc474a4186cf9dc1957cda5d_61)] [added: [54](#i1f68b48eea92495388df6551a4f9ea63_67)] | | |
| [Recent Accounting [removed: Standards](#i48540c50bc474a4186cf9dc1957cda5d_64)] [added: Standards](#i1f68b48eea92495388df6551a4f9ea63_70)] | | | | | | | | | [removed: [61](#i48540c50bc474a4186cf9dc1957cda5d_64)] [added: [56](#i1f68b48eea92495388df6551a4f9ea63_70)] | | |
| [Critical Accounting [removed: Policies](#i48540c50bc474a4186cf9dc1957cda5d_67)] [added: Policies](#i1f68b48eea92495388df6551a4f9ea63_73)] | | | | | | | | | [removed: [61](#i48540c50bc474a4186cf9dc1957cda5d_67)] [added: [56](#i1f68b48eea92495388df6551a4f9ea63_73)] | | |
| [Statements of Income [removed: Analysis](#i48540c50bc474a4186cf9dc1957cda5d_70)] [added: Analysis](#i1f68b48eea92495388df6551a4f9ea63_76)] | | | | | | | | | [removed: [65](#i48540c50bc474a4186cf9dc1957cda5d_70)] [added: [61](#i1f68b48eea92495388df6551a4f9ea63_76)] | | |
| [Business Segment [removed: Review](#i48540c50bc474a4186cf9dc1957cda5d_88)] [added: Review](#i1f68b48eea92495388df6551a4f9ea63_94)] | | | | | | | | | [removed: [72](#i48540c50bc474a4186cf9dc1957cda5d_88)] [added: [69](#i1f68b48eea92495388df6551a4f9ea63_94)] | | |
| [Balance Sheet [removed: Analysis](#i48540c50bc474a4186cf9dc1957cda5d_109)] [added: Analysis](#i1f68b48eea92495388df6551a4f9ea63_115)] | | | | | | | | | [removed: [81](#i48540c50bc474a4186cf9dc1957cda5d_109)] [added: [75](#i1f68b48eea92495388df6551a4f9ea63_115)] | | |
| [Risk Management - [removed: Overview](#i48540c50bc474a4186cf9dc1957cda5d_130)] [added: Overview](#i1f68b48eea92495388df6551a4f9ea63_133)] | | | | | | | | | [removed: [88](#i48540c50bc474a4186cf9dc1957cda5d_130)] [added: [82](#i1f68b48eea92495388df6551a4f9ea63_133)] | | |
| [Credit Risk [removed: Management](#i48540c50bc474a4186cf9dc1957cda5d_133)] [added: Management](#i1f68b48eea92495388df6551a4f9ea63_136)] | | | | | | | | | [removed: [89](#i48540c50bc474a4186cf9dc1957cda5d_133)] [added: [83](#i1f68b48eea92495388df6551a4f9ea63_136)] | | |
| [Interest Rate and Price Risk [removed: Management](#i48540c50bc474a4186cf9dc1957cda5d_154)] [added: Management](#i1f68b48eea92495388df6551a4f9ea63_157)] | | | | | | | | | [removed: [106](#i48540c50bc474a4186cf9dc1957cda5d_154)] [added: [98](#i1f68b48eea92495388df6551a4f9ea63_157)] | | |
| [Liquidity Risk [removed: Management](#i48540c50bc474a4186cf9dc1957cda5d_160)] [added: Management](#i1f68b48eea92495388df6551a4f9ea63_160)] | | | | | | | | | [removed: [112](#i48540c50bc474a4186cf9dc1957cda5d_160)] [added: [104](#i1f68b48eea92495388df6551a4f9ea63_160)] | | |
| [Operational Risk [removed: Management](#i48540c50bc474a4186cf9dc1957cda5d_163)] [added: Management](#i1f68b48eea92495388df6551a4f9ea63_163)] | | | | | | | | | [removed: [114](#i48540c50bc474a4186cf9dc1957cda5d_163)] [added: [106](#i1f68b48eea92495388df6551a4f9ea63_163)] | | |
| [Legal and Regulatory Compliance Risk [removed: Management](#i48540c50bc474a4186cf9dc1957cda5d_166)] [added: Management](#i1f68b48eea92495388df6551a4f9ea63_166)] | | | | | | | | | [removed: [115](#i48540c50bc474a4186cf9dc1957cda5d_166)] [added: [107](#i1f68b48eea92495388df6551a4f9ea63_166)] | | |
| [Capital [removed: Management](#i48540c50bc474a4186cf9dc1957cda5d_169)] [added: Management](#i1f68b48eea92495388df6551a4f9ea63_169)] | | | | | | | | | [removed: [116](#i48540c50bc474a4186cf9dc1957cda5d_169)] [added: [108](#i1f68b48eea92495388df6551a4f9ea63_169)] | | |
| [Report of Independent Registered Public Accounting [removed: Firm](#i48540c50bc474a4186cf9dc1957cda5d_178)] [added: Firm](#i1f68b48eea92495388df6551a4f9ea63_175)] | | | | | | | | | [removed: [118](#i48540c50bc474a4186cf9dc1957cda5d_178)] [added: [110](#i1f68b48eea92495388df6551a4f9ea63_175)] | | |
| [Consolidated Statements of [removed: Income](#i48540c50bc474a4186cf9dc1957cda5d_184)] [added: Comprehensive Income](#i1f68b48eea92495388df6551a4f9ea63_184)] | | | | | | | | | [removed: [121](#i48540c50bc474a4186cf9dc1957cda5d_184)] [added: [114](#i1f68b48eea92495388df6551a4f9ea63_184)] | | |
| [Consolidated Statements of Changes in [removed: Equity](#i48540c50bc474a4186cf9dc1957cda5d_190)] [added: Equity](#i1f68b48eea92495388df6551a4f9ea63_187)] | | | | | | | | | [removed: [123](#i48540c50bc474a4186cf9dc1957cda5d_190)] [added: [115](#i1f68b48eea92495388df6551a4f9ea63_187)] | | |
| [Consolidated Statements of Cash [removed: Flows](#i48540c50bc474a4186cf9dc1957cda5d_196)] [added: Flows](#i1f68b48eea92495388df6551a4f9ea63_193)] | | | | | | | | | [removed: [125](#i48540c50bc474a4186cf9dc1957cda5d_196)] [added: [117](#i1f68b48eea92495388df6551a4f9ea63_193)] | | |
| [Summary of Significant Accounting and Reporting [removed: Policies](#i48540c50bc474a4186cf9dc1957cda5d_202)] [added: Policies](#i1f68b48eea92495388df6551a4f9ea63_199)] | | | [removed: [126](#i48540c50bc474a4186cf9dc1957cda5d_202)] [added: [118](#i1f68b48eea92495388df6551a4f9ea63_199)] | | | [Long-Term [removed: Debt](#i48540c50bc474a4186cf9dc1957cda5d_250)] [added: Debt](#i1f68b48eea92495388df6551a4f9ea63_247)] | | | [removed: [173](#i48540c50bc474a4186cf9dc1957cda5d_250)] [added: [170](#i1f68b48eea92495388df6551a4f9ea63_247)] | | |
| [Supplemental Cash Flow [removed: Information](#i48540c50bc474a4186cf9dc1957cda5d_205)] [added: Information](#i1f68b48eea92495388df6551a4f9ea63_202)] | | | [removed: [139](#i48540c50bc474a4186cf9dc1957cda5d_205)] [added: [133](#i1f68b48eea92495388df6551a4f9ea63_202)] | | | [Commitments, Contingent Liabilities and [removed: Guarantees](#i48540c50bc474a4186cf9dc1957cda5d_253)] [added: Guarantees](#i1f68b48eea92495388df6551a4f9ea63_250)] | | | [removed: [177](#i48540c50bc474a4186cf9dc1957cda5d_253)] [added: [174](#i1f68b48eea92495388df6551a4f9ea63_250)] | | |
| [Restrictions [removed: on](#i48540c50bc474a4186cf9dc1957cda5d_208) [](#i48540c50bc474a4186cf9dc1957cda5d_208)[Dividends] [added: on Dividends] and Capital [removed: Actions](#i48540c50bc474a4186cf9dc1957cda5d_208)] [added: Actions](#i1f68b48eea92495388df6551a4f9ea63_205)] | | | [removed: [139](#i48540c50bc474a4186cf9dc1957cda5d_208)] [added: [133](#i1f68b48eea92495388df6551a4f9ea63_205)] | | | [Legal and Regulatory [removed: Proceedings](#i48540c50bc474a4186cf9dc1957cda5d_256)] [added: Proceedings](#i1f68b48eea92495388df6551a4f9ea63_253)] | | | [removed: [181](#i48540c50bc474a4186cf9dc1957cda5d_256)] [added: [178](#i1f68b48eea92495388df6551a4f9ea63_253)] | | |
| [Credit Quality and the Allowance for Loan and Lease [removed: Losses](#i48540c50bc474a4186cf9dc1957cda5d_217)] [added: Losses](#i1f68b48eea92495388df6551a4f9ea63_214)] | | | [removed: [145](#i48540c50bc474a4186cf9dc1957cda5d_217)] [added: [139](#i1f68b48eea92495388df6551a4f9ea63_214)] | | | [Retirement and Benefit [removed: Plans](#i48540c50bc474a4186cf9dc1957cda5d_265)] [added: Plans](#i1f68b48eea92495388df6551a4f9ea63_262)] | | | [removed: [187](#i48540c50bc474a4186cf9dc1957cda5d_265)] [added: [183](#i1f68b48eea92495388df6551a4f9ea63_262)] | | |
| [Bank Premises and [removed: Equipment](#i48540c50bc474a4186cf9dc1957cda5d_220)] [added: Equipment](#i1f68b48eea92495388df6551a4f9ea63_217)] | | | [removed: [155](#i48540c50bc474a4186cf9dc1957cda5d_220)] [added: [152](#i1f68b48eea92495388df6551a4f9ea63_217)] | | | [Accumulated Other Comprehensive [removed: Income](#i48540c50bc474a4186cf9dc1957cda5d_268)] [added: Income](#i1f68b48eea92495388df6551a4f9ea63_265)] | | | [removed: [190](#i48540c50bc474a4186cf9dc1957cda5d_268)] [added: [186](#i1f68b48eea92495388df6551a4f9ea63_265)] | | |
| [Operating Lease [removed: Equipment](#i48540c50bc474a4186cf9dc1957cda5d_223)] [added: Equipment](#i1f68b48eea92495388df6551a4f9ea63_220)] | | | [removed: [156](#i48540c50bc474a4186cf9dc1957cda5d_223)] [added: [153](#i1f68b48eea92495388df6551a4f9ea63_220)] | | | [Common, Preferred and Treasury [removed: Stock](#i48540c50bc474a4186cf9dc1957cda5d_271)] [added: Stock](#i1f68b48eea92495388df6551a4f9ea63_268)] | | | [removed: [192](#i48540c50bc474a4186cf9dc1957cda5d_271)] [added: [188](#i1f68b48eea92495388df6551a4f9ea63_268)] | | |
| [Sales of Receivables and Servicing [removed: Rights](#i48540c50bc474a4186cf9dc1957cda5d_238)] [added: Rights](#i1f68b48eea92495388df6551a4f9ea63_235)] | | | [removed: [163](#i48540c50bc474a4186cf9dc1957cda5d_238)] [added: [160](#i1f68b48eea92495388df6551a4f9ea63_235)] | | | [Regulatory Capital Requirements and Capital [removed: Ratios](#i48540c50bc474a4186cf9dc1957cda5d_289)] [added: Ratios](#i1f68b48eea92495388df6551a4f9ea63_286)] | | | [removed: [208](#i48540c50bc474a4186cf9dc1957cda5d_289)] [added: [204](#i1f68b48eea92495388df6551a4f9ea63_286)] | | |
| [Management’s Assessment as to the Effectiveness of Internal Control over Financial [removed: Reporting](#i48540c50bc474a4186cf9dc1957cda5d_304)] [added: Reporting](#i1f68b48eea92495388df6551a4f9ea63_301)] | | | [removed: [215](#i48540c50bc474a4186cf9dc1957cda5d_304)] [added: [211](#i1f68b48eea92495388df6551a4f9ea63_301)] | | | | | | | | |
| [Report of Independent Registered Public Accounting [removed: Firm](#i48540c50bc474a4186cf9dc1957cda5d_307)] [added: Firm](#i1f68b48eea92495388df6551a4f9ea63_304)] | | | [removed: [216](#i48540c50bc474a4186cf9dc1957cda5d_307)] [added: [212](#i1f68b48eea92495388df6551a4f9ea63_304)] | | | | | | | | |
| [Consolidated Ten Year [removed: Comparison](#i48540c50bc474a4186cf9dc1957cda5d_346)] [added: Comparison](#i1f68b48eea92495388df6551a4f9ea63_343)] | | | [removed: [224](#i48540c50bc474a4186cf9dc1957cda5d_346)] [added: [221](#i1f68b48eea92495388df6551a4f9ea63_343)] | | | | | | | | |
| October 1 - October 31, 2023 | | | 75,992 | | | | | | $ | 24.48 | | | | | — | | | | | | 32,115,811 | | |
| November 1 - November 30, 2023 | | | 17,203 | | | | | | 25.78 | | | | | | — | | | | | | 32,115,811 | | |
| December 1 - December 31, 2023 | | | 37,496 | | | | | | 33.77 | | | | | | — | | | | | | 32,115,811 | | |
| Total | | | 130,691 | | | | | | $ | 27.32 | | | | | — | | | | | | 32,115,811 | | |
*(b)On June 18, 2019, the Bancorp announced that its Board of Directors had authorized management to purchase 100 million shares of the Bancorp*’*s common stock through the open market or in any private party transactions.
This authorization did not include specific targets or an expiration date.*
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
| [Overview](#i1f68b48eea92495388df6551a4f9ea63_64) | | | | | | | | | [50](#i1f68b48eea92495388df6551a4f9ea63_64) | | |
| [Consolidated Balance Sheets](#i1f68b48eea92495388df6551a4f9ea63_178) | | | | | | | | | [112](#i1f68b48eea92495388df6551a4f9ea63_178) | | |
| [Consolidated Statements of Income](#i1f68b48eea92495388df6551a4f9ea63_181) | | | | | | | | | [113](#i1f68b48eea92495388df6551a4f9ea63_181) | | |
| [Investment Securities](#i1f68b48eea92495388df6551a4f9ea63_208) | | | [134](#i1f68b48eea92495388df6551a4f9ea63_208) | | | [Related Party Transactions](#i1f68b48eea92495388df6551a4f9ea63_256) | | | [180](#i1f68b48eea92495388df6551a4f9ea63_256) | | |
| [Loans and Leases](#i1f68b48eea92495388df6551a4f9ea63_211) | | | [137](#i1f68b48eea92495388df6551a4f9ea63_211) | | | [Income Taxes](#i1f68b48eea92495388df6551a4f9ea63_259) | | | [181](#i1f68b48eea92495388df6551a4f9ea63_259) | | |
| [Lease Obligations – Lessee](#i1f68b48eea92495388df6551a4f9ea63_223) | | | [153](#i1f68b48eea92495388df6551a4f9ea63_223) | | | [Stock-Based Compensation](#i1f68b48eea92495388df6551a4f9ea63_271) | | | [190](#i1f68b48eea92495388df6551a4f9ea63_271) | | |
| [Goodwill](#i1f68b48eea92495388df6551a4f9ea63_226) | | | [155](#i1f68b48eea92495388df6551a4f9ea63_226) | | | [Other Noninterest Income and Other Noninterest Expense](#i1f68b48eea92495388df6551a4f9ea63_277) | | | [193](#i1f68b48eea92495388df6551a4f9ea63_277) | | |
| [Intangible Assets](#i1f68b48eea92495388df6551a4f9ea63_229) | | | [156](#i1f68b48eea92495388df6551a4f9ea63_229) | | | [Earnings Per Share](#i1f68b48eea92495388df6551a4f9ea63_280) | | | [194](#i1f68b48eea92495388df6551a4f9ea63_280) | | |
| [Variable Interest Entities](#i1f68b48eea92495388df6551a4f9ea63_232) | | | [157](#i1f68b48eea92495388df6551a4f9ea63_232) | | | [Fair Value Measurements](#i1f68b48eea92495388df6551a4f9ea63_283) | | | [195](#i1f68b48eea92495388df6551a4f9ea63_283) | | |
| [Derivative Financial Instruments](#i1f68b48eea92495388df6551a4f9ea63_238) | | | [162](#i1f68b48eea92495388df6551a4f9ea63_238) | | | [Parent Company Financial Statements](#i1f68b48eea92495388df6551a4f9ea63_289) | | | [205](#i1f68b48eea92495388df6551a4f9ea63_289) | | |
| [Other Assets](#i1f68b48eea92495388df6551a4f9ea63_241) | | | [168](#i1f68b48eea92495388df6551a4f9ea63_241) | | | [Business Segments](#i1f68b48eea92495388df6551a4f9ea63_292) | | | [207](#i1f68b48eea92495388df6551a4f9ea63_292) | | |
| [Short-Term Borrowings](#i1f68b48eea92495388df6551a4f9ea63_244) | | | [169](#i1f68b48eea92495388df6551a4f9ea63_244) | | | [Subsequent Event](#i1f68b48eea92495388df6551a4f9ea63_295) | | | [210](#i1f68b48eea92495388df6551a4f9ea63_295) | | |
| [Directors and Officers](#i1f68b48eea92495388df6551a4f9ea63_346) | | | [222](#i1f68b48eea92495388df6551a4f9ea63_346) | | | | | | | | |
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
| ACL: Allowance for Credit Losses | | | GSE: United States Government Sponsored Enterprise | | |
| AFS: Available-For-Sale | | | HTM: Held-To-Maturity | | |
| ALCO: Asset Liability Management Committee | | | IPO: Initial Public Offering | | |
| AOCI: Accumulated Other Comprehensive Income (Loss) | | | IRLC: Interest Rate Lock Commitment | | |
| ARM: Adjustable Rate Mortgage | | | LCR: Liquidity Coverage Ratio | | |
| ATM: Automated Teller Machine | | | LLC: Limited Liability Company | | |
| BHC: Bank Holding Company | | | LTV: Loan-to-Value Ratio | | |
| BOLI: Bank Owned Life Insurance | | | MD&A: Management’s Discussion and Analysis of Financial | | |
| bps: Basis Points | | | Condition and Results of Operations | | |
| CD: Certificate of Deposit | | | N/A: Not Applicable | | |
| CECL: Current Expected Credit Loss | | | OAS: Option-Adjusted Spread | | |
| CET1: Common Equity Tier 1 | | | OCC: Office of the Comptroller of the Currency | | |
| CME: Chicago Mercantile Exchange | | | OREO: Other Real Estate Owned | | |
| C&I: Commercial and Industrial | | | PPP: Paycheck Protection Program | | |
| DCF: Discounted Cash Flow | | | PSA: Performance Share Award | | |
| DTCC: Depository Trust & Clearing Corporation | | | RCC: Risk and Compliance Committee | | |
| DTI: Debt-to-Income Ratio | | | ROU: Right-of-Use | | |
| ERMC: Enterprise Risk Management Committee | | | RSU: Restricted Stock Unit | | |
| FASB: Financial Accounting Standards Board | | | SBA: Small Business Administration | | |
| October 1 - October 31, 2022 | | | 73,176 | | | | | | $ | 33.08 | | | | | — | | | | | | 40,785,269 | | |
| November 1 - November 30, 2022 | | | 23,625 | | | | | | 34.93 | | | | | | — | | | | | | 40,785,269 | | |
| December 1 - December 31, 2022 | | | 3,089,094 | | | | | | 32.47 | | | | | | 3,079,462 | | | | | | 37,705,807 | | |
| Total | | | 3,185,895 | | | | | | $ | 32.51 | | | | | 3,079,462 | | | | | | 37,705,807 | | |
| [Overview](#i48540c50bc474a4186cf9dc1957cda5d_58) | | | | | | | | | [54](#i48540c50bc474a4186cf9dc1957cda5d_58) | | |
| [Consolidated Balance Sheets](#i48540c50bc474a4186cf9dc1957cda5d_181) | | | | | | | | | [120](#i48540c50bc474a4186cf9dc1957cda5d_181) | | |
| [Consolidated Statements of Comprehensive Income](#i48540c50bc474a4186cf9dc1957cda5d_187) | | | | | | | | | [122](#i48540c50bc474a4186cf9dc1957cda5d_187) | | |
| [Investment Securities](#i48540c50bc474a4186cf9dc1957cda5d_211) | | | [140](#i48540c50bc474a4186cf9dc1957cda5d_211) | | | [Related Party Transactions](#i48540c50bc474a4186cf9dc1957cda5d_259) | | | [183](#i48540c50bc474a4186cf9dc1957cda5d_259) | | |
| [Loans and Leases](#i48540c50bc474a4186cf9dc1957cda5d_214) | | | [143](#i48540c50bc474a4186cf9dc1957cda5d_214) | | | [Income Taxes](#i48540c50bc474a4186cf9dc1957cda5d_262) | | | [185](#i48540c50bc474a4186cf9dc1957cda5d_262) | | |
| [Lease Obligations – Lessee](#i48540c50bc474a4186cf9dc1957cda5d_226) | | | [156](#i48540c50bc474a4186cf9dc1957cda5d_226) | | | [Stock-Based Compensation](#i48540c50bc474a4186cf9dc1957cda5d_274) | | | [194](#i48540c50bc474a4186cf9dc1957cda5d_274) | | |
| [Goodwill](#i48540c50bc474a4186cf9dc1957cda5d_229) | | | [158](#i48540c50bc474a4186cf9dc1957cda5d_229) | | | [Other Noninterest Income and Other Noninterest Expense](#i48540c50bc474a4186cf9dc1957cda5d_280) | | | [197](#i48540c50bc474a4186cf9dc1957cda5d_280) | | |
| [Intangible Assets](#i48540c50bc474a4186cf9dc1957cda5d_232) | | | [159](#i48540c50bc474a4186cf9dc1957cda5d_232) | | | [Earnings Per Share](#i48540c50bc474a4186cf9dc1957cda5d_283) | | | [198](#i48540c50bc474a4186cf9dc1957cda5d_283) | | |
| [Variable Interest Entities](#i48540c50bc474a4186cf9dc1957cda5d_235) | | | [160](#i48540c50bc474a4186cf9dc1957cda5d_235) | | | [Fair Value Measurements](#i48540c50bc474a4186cf9dc1957cda5d_286) | | | [199](#i48540c50bc474a4186cf9dc1957cda5d_286) | | |
| [Derivative Financial Instruments](#i48540c50bc474a4186cf9dc1957cda5d_241) | | | [165](#i48540c50bc474a4186cf9dc1957cda5d_241) | | | [Parent Company Financial Statements](#i48540c50bc474a4186cf9dc1957cda5d_292) | | | [209](#i48540c50bc474a4186cf9dc1957cda5d_292) | | |
| [Other Assets](#i48540c50bc474a4186cf9dc1957cda5d_244) | | | [171](#i48540c50bc474a4186cf9dc1957cda5d_244) | | | [Business Segments](#i48540c50bc474a4186cf9dc1957cda5d_295) | | | [211](#i48540c50bc474a4186cf9dc1957cda5d_295) | | |
| [Short-Term Borrowings](#i48540c50bc474a4186cf9dc1957cda5d_247) | | | [172](#i48540c50bc474a4186cf9dc1957cda5d_247) | | | [Subsequent Event](#i48540c50bc474a4186cf9dc1957cda5d_298) | | | [214](#i48540c50bc474a4186cf9dc1957cda5d_298) | | |
| [Directors and Officers](#i48540c50bc474a4186cf9dc1957cda5d_349) | | | [225](#i48540c50bc474a4186cf9dc1957cda5d_349) | | | | | | | | |
| | | | | | |
| ACL: Allowance for Credit Losses | | | HTM: Held-To-Maturity | | |
| AFS: Available-For-Sale | | | IPO: Initial Public Offering | | |
| ALCO: Asset Liability Management Committee | | | IRC: Internal Revenue Code | | |
| ASC: Accounting Standards Codification | | | LLC: Limited Liability Company | | |
| ASU: Accounting Standards Update | | | LTV: Loan-to-Value Ratio | | |
| ATM: Automated Teller Machine | | | MD&A: Management’s Discussion and Analysis of Financial | | |
| BHC: Bank Holding Company | | | Condition and Results of Operations | | |
| BOLI: Bank Owned Life Insurance | | | MSR: Mortgage Servicing Right | | |
| bps: Basis Points | | | N/A: Not Applicable | | |
| CD: Certificate of Deposit | | | NII: Net Interest Income | | |
| CECL: Current Expected Credit Loss | | | OCC: Office of the Comptroller of the Currency | | |
| CET1: Common Equity Tier 1 | | | OCI: Other Comprehensive Income (Loss) | | |
| C&I: Commercial and Industrial | | | PCD: Purchased Credit Deteriorated | | |
| DCF: Discounted Cash Flow | | | PPP: Paycheck Protection Program | | |
| DTCC: Depository Trust & Clearing Corporation | | | PSA: Performance Share Award | | |
| DTI: Debt-to-Income Ratio | | | RCC: Risk and Compliance Committee | | |
| ERM: Enterprise Risk Management | | | ROU: Right-of-Use | | |
| FASB: Financial Accounting Standards Board | | | SAR: Stock Appreciation Right | | |
| FDIC: Federal Deposit Insurance Corporation | | | SBA: Small Business Administration | | |
| FINRA: Financial Industry Regulatory Authority | | | TILA: Truth in Lending Act | | |
| FNMA: Federal National Mortgage Association | | | TRA: Tax Receivable Agreement | | |
| FOMC: Federal Open Market Committee | | | TruPS: Trust Preferred Securities | | |
An excerpt. Shown here: 40 of 61 rewritten, 40 of 46 added and 40 of 42 removed. The counts are complete. For every sentence, read Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES in the FY2023 filing and the FY2022 filing.
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
1,446 rewritten, 624 added, 289 removed, 2,178 unchanged
[Table of [removed: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)][added: Contents](#i1f68b48eea92495388df6551a4f9ea63_52)]
We have audited the accompanying consolidated balance sheets of Fifth Third Bancorp and subsidiaries (the “Bancorp”) as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] the related consolidated statements of income, comprehensive income, changes in equity, and cash flows for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] and the related notes (collectively referred to as the “financial statements”).
In our opinion, the financial statements present fairly, in all material respects, the financial position of the Bancorp as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] in conformity with accounting principles generally accepted in the United States of America.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Bancorp’s internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in Internal Control—Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission and our report dated February [removed: 24, 2023] [added: 27, 2024] expressed an unqualified opinion on the Bancorp’s internal control over financial reporting.
Allowance for Loan and Lease Losses (“ALLL”) — Qualitative Factors [removed: —] [added: -] Commercial [removed: Loans—Refer] [added: Loans — Refer] to Note 1 and Note 6 of the Notes to Consolidated Financial Statements
Qualitative factors are used to capture characteristics in the portfolio that impact expected credit losses but [removed: that] are not fully captured within the Bancorp’s expected credit loss models.
At December 31, [removed: 2022,] [added: 2023,] the key qualitative factors included adjustments to the expected credit losses on the commercial loan portfolio associated with the current economic environment.
The ALLL for the commercial portfolio segment was $1.1 billion at December 31, [removed: 2022,] [added: 2023,] which includes adjustments for the qualitative factors noted above.
[removed: February 24, 2023][added: | | | | 2023 | | | | | | | | | | | |]
| As of December 31 ($ in millions, except share data) | | | [removed: 2022] [added: 2023] | | | [removed: 2021] [added: 2022] | | |
| Cash and due from banks | | | [removed: $] [added: $] | [removed: 3,466] [added: 3,466] | | [removed: 2,994] [added: 3,466] | | | [added: — | | | — | | | 3,466 | | |]
| Other short-term [removed: investments*(a)*] [added: investments] | | | [removed: 8,351] [added: 8,351] | | | [removed: 34,572] [added: 8,351] | | | [added: — | | | — | | | 8,351 | | |]
| Available-for-sale debt and other securities*(b)* | | | [removed: 51,503] [added: 50,419] | | | [removed: 38,110] [added: 51,503] | | |
| Held-to-maturity securities*(c)* | | | [removed: 5] [added: 2] | | | [removed: 8] [added: 5] | | |
| Trading debt securities | | | [removed: 414] [added: 899] | | | [removed: 512] [added: 414] | | |
| Equity securities | | | [removed: 317] [added: 613] | | | [removed: 376] [added: 317] | | |
| Loans and leases held for sale*(d)* | | | [removed: 1,007] [added: 378] | | | [removed: 4,415] [added: 1,007] | | |
| Portfolio loans and leases*(a)(e)* | | | [removed: 121,480] [added: 117,234] | | | [removed: 112,050] [added: 121,480] | | |
| Allowance for loan and lease losses*(a)* | | | [removed: (2,194)] [added: (2,322)] | | | [removed: (1,892)] [added: (2,194)] | | |
| Portfolio loans and leases, net | | | [removed: 119,286] [added: 114,912] | | | [removed: 110,158] [added: 119,286] | | |
| Bank premises and equipment*(f)* | | | [removed: 2,187] [added: 2,349] | | | [removed: 2,120] [added: 2,187] | | |
| Operating lease equipment | | | [removed: 627] [added: 459] | | | [removed: 616] [added: 627] | | |
| Goodwill | | | [removed: 4,915] [added: 4,919] | | | [removed: 4,514] [added: 4,915] | | |
| Intangible assets | | | [removed: 169] [added: 125] | | | [removed: 156] [added: 169] | | |
| Servicing rights | | | [removed: 1,746] [added: —] | | | [removed: 1,121] [added: —] | | | [added: 1,746 | | | 1,746 | | |]
| Other assets*(a)* | | | [removed: 13,459] [added: 12,538] | | | [removed: 11,444] [added: 13,459] | | |
| Total Assets | | | $ | [removed: 207,452] [added: 214,574] | | [removed: 211,116] [added: 207,452] | | |
| Noninterest-bearing deposits | | | $ | [removed: 53,125] [added: 43,146] | | [removed: 65,088] [added: 53,125] | | |
| Interest-bearing deposits | | | [removed: 110,565] [added: 125,766] | | | [removed: 104,236] [added: 110,565] | | |
| Total deposits | | | [removed: 163,690] [added: 168,912] | | | [removed: 169,324] [added: 163,690] | | |
| Federal funds purchased | | | [removed: 180] [added: 180] | | | [removed: 281] [added: 180] | | | [added: — | | | — | | | 180 | | |]
| Other short-term borrowings | | | [removed: 4,838] [added: 2,861] | | | [removed: 980] [added: 4,838] | | |
| Accrued taxes, interest and expenses | | | [removed: 1,822] [added: 2,195] | | | [removed: 2,233] [added: 1,822] | | |
| Other liabilities*(a)* | | | [removed: 5,881] [added: 4,861] | | | [removed: 4,267] [added: 5,881] | | |
| Long-term debt*(a)* | | | [removed: 13,714] [added: 16,380] | | | [removed: 11,821] [added: 13,714] | | |
| Total Liabilities | | | $ | [removed: 190,125] [added: 195,402] | | [removed: 188,906] [added: 190,125] | | |
| Capital surplus | | | [removed: 3,684] [added: 3,757] | | | [removed: 3,624] [added: 3,684] | | |
| Retained earnings | | | [removed: 21,689] [added: 22,997] | | | [removed: 20,236] [added: 21,689] | | |
| Accumulated other comprehensive [removed: (loss) income] [added: loss] | | | [removed: (5,110)] [added: (4,487)] | | | [removed: 1,207] [added: (5,110)] | | |
| Treasury stock*(g)* | | | [removed: (7,103)] [added: (7,262)] | | | [removed: (7,024)] [added: (7,103)] | | |
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
*114 Fifth Third Bancorp*
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
| Balance at December 31, 2022 | | | $ | 2,051 | | 2,116 | | | 3,684 | | | 21,689 | | | (5,110) | | | (7,103) | | | 17,327 | | |
*115 Fifth Third Bancorp*
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
| Balance at January 1, 2023 | | | $ | 2,051 | | 2,116 | | | 3,684 | | | 21,726 | | | (5,110) | | | (7,103) | | | 17,364 | | |
| Shares acquired for treasury | | | | | | | | | | | | | | | | | | (201) | | | (201) | | |
| Balance at December 31, 2023 | | | $ | 2,051 | | 2,116 | | | 3,757 | | | 22,997 | | | (4,487) | | | (7,262) | | | 19,172 | | |
*(b)Related to the adoption of ASU 2022-02 as of January 1, 2023.
*116 Fifth Third Bancorp*
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
Updates to Significant Accounting and Reporting Policies
In conjunction with the adoption of ASU 2022-02 on January 1, 2023, the Bancorp has updated its accounting and reporting policies for nonaccrual loans and leases, restructured loans and leases and the ALLL as described below.
The accounting and reporting policies for these sections for periods prior to January 1, 2023 are provided in the Significant Accounting and Reporting Policies Applicable Prior to January 1, 2023 section below.
Refer to the Accounting and Reporting Developments section for additional information.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
Debt securities classified as available-for-sale may be transferred to the held-to-maturity classification if the Bancorp determines that it has the positive intent and ability to hold the securities until their maturity.
Upon transfer to held-to-maturity, the transferred securities are reported at amortized cost plus or minus the pre-tax amount of the remaining unrealized gains or losses reported in AOCI at the transfer date.
The resulting premium or discount is amortized into income over the remaining life of the securities as an adjustment of yield.
Any unrealized gains or losses that exist on the date of transfer continue to be reported as a component of AOCI and are amortized into income over the remaining life of the securities as an adjustment to yield, offsetting the amortization of the premium or discount that was recognized at the transfer date.
Any allowance for credit losses that was previously recorded when the securities were classified as available-for-sale is reversed into earnings on the date of transfer.
After the transfer to held-to-maturity, the securities would be re-assessed for any necessary allowance for credit losses, as previously discussed.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
The Bancorp places loans and leases on nonaccrual status when full repayment of principal and interest is not expected, unless the loan or lease is well secured and in the process of collection.
Commercial loans where the principal or interest has been in default for a period of 90 days or more are generally maintained on nonaccrual status unless the loan is fully or partially guaranteed by a government agency or otherwise considered to be well secured and in the process of collection.
- Credit card loans that have been modified for a borrower experiencing financial difficulty are placed on nonaccrual status at the time of the modification.
Subsequent to the modification, accounts are placed on nonaccrual status when required payments become past due 90 days or more in accordance with the modified terms.
- Loans discharged in a Chapter 7 bankruptcy and not reaffirmed by the borrower are placed on nonaccrual status and considered collateral-dependent loans at the time of discharge, regardless of the borrower’s payment history or capacity to repay in the future.
- Consumer loans subject to a bankruptcy proceeding are placed on nonaccrual status when principal or interest becomes past due 60 days or more.
Nonaccrual loans that have been modified for a borrower experiencing financial difficulty may not be returned to accrual status unless such loans have sustained repayment performance of six months or more and are reasonably assured of repayment in accordance with the modified terms.
Loans discharged in a Chapter 7 bankruptcy and not reaffirmed by the borrower may be returned to accrual status twelve months or more after discharge provided there is a sustained payment history after bankruptcy and collectability is reasonably assured for all remaining contractual payments.
Except for loans discharged in a Chapter 7 bankruptcy that are not reaffirmed by the borrower, accruing residential mortgage loans, home equity loans and lines of credit, indirect secured consumer loans and other consumer loans modified for borrowers experiencing financial difficulty are maintained on accrual status, provided there is reasonable assurance of repayment and of performance according to the modified terms based upon a current, well-documented credit evaluation.
Modifications of commercial loans and credit card loans for borrowers experiencing financial difficulty that do not have a sustained payment history of six months or more in accordance with their modified terms remain on nonaccrual status until a six-month payment history is sustained.
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
principal.
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Balance at December 31, 2019 | | | $ | 2,051 | | 1,770 | | | 3,599 | | | 18,315 | | | 1,192 | | | (5,724) | | | 21,203 | | |
| Balance at January 1, 2020 | | | $ | 2,051 | | 1,770 | | | 3,599 | | | 17,843 | | | 1,192 | | | (5,724) | | | 20,731 | | |
| Issuance of preferred stock | | | | | | 346 | | | | | | | | | | | | | | | 346 | | |
| Other | | | | | | | | | | | | (2) | | | | | | 2 | | | — | | |
| Balance at December 31, 2021 | | | $ | 2,051 | | 2,116 | | | 3,624 | | | 20,236 | | | 1,207 | | | (7,024) | | | 22,210 | | |
| Issuance of preferred stock | | | — | | | — | | | 346 | | |
| Other | | | (85) | | | (99) | | | (47) | | |
previously accrued and unpaid interest is reversed against income.
TDRs include concessions granted under reorganization, arrangement or other provisions of the Federal Bankruptcy Act.
Upon modification of a loan, the Bancorp measures the expected credit loss as either the difference between the amortized cost of the loan and the fair value of collateral less cost to sell or the difference between the estimated future cash flows expected to be collected on the modified loan, discounted at the original effective yield of the loan, and the carrying value of the loan.
as geopolitical events, natural disasters and their effects on regional borrowers, and changes in product structures.
typically satisfied over time while performance obligations for transaction-based fees are typically satisfied at a point in time.
Standard Adopted in 2022
*ASU 2020-06 – Debt-Debt with Conversion and Other Options (Subtopic 470-20) and Derivatives and Hedging – Contracts in Entity’s Own Equity (Subtopic 815-40): Accounting for Convertible Instruments and Contracts in an Equity’s Own Equity*
In August 2020, the FASB issued ASU 2020-06, which simplified the accounting for certain financial instruments with characteristics of liabilities and equity, including convertible instruments and contracts on an entity’s own equity.
The Bancorp will be subject to the amended disclosure requirements beginning with the filing of its Quarterly Report on Form 10-Q for the first quarter of 2023.
The amendments in the ASU apply only to contracts, hedging relationships and other transactions that reference LIBOR or another reference rate expected to be discontinued because of reference rate reform.
In January 2021, the FASB issued ASU 2021-01, which clarified that the optional expedients and exceptions in Topic 848 for contract modifications and hedge accounting also apply to derivatives that are affected by the discounting transition.
The expedients and exceptions provided by the amendments did not apply to contract modifications made and hedging relationships entered into or evaluated after December 31, 2022, except for hedging relationships existing as of December 31, 2022 for which an entity had elected certain optional expedients and that are retained through the end of the hedging relationship.
Subsequently, in December 2022, the FASB issued ASU 2022-06 which deferred the sunset date of Topic 848 from December 31, 2022 to December 31, 2024, after which entities will no longer be permitted to apply the relief in Topic 848.
| | | | 2021 | | | | | | | | | | | |
The Bancorp did not consider these losses to be credit-related.
| Total | | | $ | 57,530 | | | | | 51,503 | | | | | | 5 | | | | | | 5 | | |
| 2021 | | | | | | | | | | | | | | | | | | | | |
| Total | | | $ | 7,743 | | (106) | | | 952 | | | (38) | | | 8,695 | | | (144) | | |
*(a)Includes $94 million and $1.3 billion as of December 31, 2022 and 2021, respectively, related to the SBA’s Paycheck Protection Program.*
| Net premium on acquired leases | | | — | | | 1 | | |
| 2023 | | | $ | 188 | | 502 | | |
| 2024 | | | 148 | | | 440 | | |
| Impact of adoption of ASU 2016-13(a) | | | 160 | | | 196 | | | 408 | | | (121) | | | 643 | | |
| Losses charged off*(b)* | | | (282) | | | (9) | | | (320) | | | — | | | (611) | | |
| Balance, end of period | | | $ | 1,456 | | 294 | | | 703 | | | — | | | 2,453 | | |
*(a)Includes $31, $2 and $1 in Commercial, Residential Mortgage and Consumer, respectively, related to the initial recognition of an ALLL on PCD loans.*
| Collectively evaluated | | | 1,025 | | | 189 | | | 514 | | | 1,728 | | |
| Total ALLL | | | $ | 1,102 | | 235 | | | 555 | | | 1,892 | | |
| Individually evaluated | | | $ | 579 | | 460 | | | 313 | | | 1,352 | | |
| Collectively evaluated | | | 69,689 | | | 15,783 | | | 25,072 | | | 110,544 | | |
| Pass | | | $ | 4,266 | | 2,291 | | | 1,198 | | | 552 | | | 356 | | | 752 | | | 39,486 | | | — | | | 48,901 | | |
| Substandard | | | 19 | | | 52 | | | 36 | | | 69 | | | 52 | | | 115 | | | 1,623 | | | — | | | 1,966 | | |
An excerpt. Shown here: 40 of 1,446 rewritten, 40 of 624 added and 40 of 289 removed. The counts are complete. For every sentence, read Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA in the FY2023 filing and the FY2022 filing.
Item 9A. CONTROLS AND PROCEDURES
13 rewritten, 5 added, 4 removed, 27 unchanged
The Bancorp’s management assessed the effectiveness of the Bancorp’s internal control over financial reporting as of December 31, [removed: 2022.][added: 2023.]
Management’s assessment is based on the criteria established in the *Internal Control — Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission and was designed to provide reasonable assurance that the Bancorp maintained effective internal control over financial reporting as of December 31, [removed: 2022.][added: 2023.]
Based on this assessment, management believes that the Bancorp maintained effective internal control over financial reporting as of December 31, [removed: 2022.][added: 2023.]
The Bancorp’s independent registered public accounting firm, that audited the Bancorp’s consolidated financial statements included in this annual report, has issued an audit report on our internal control over financial reporting as of December 31, [removed: 2022.][added: 2023.]
This report appears on page [removed: [216](#i48540c50bc474a4186cf9dc1957cda5d_307)] [added: [212](#i1f68b48eea92495388df6551a4f9ea63_304)] of the annual report.
| [removed: President and] [added: Chairman,] Chief Executive Officer [added: and President] | | | | | | Executive Vice President and Chief Financial Officer | | |
[removed: *215] [added: *211] Fifth Third Bancorp*
[Table of [removed: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)][added: Contents](#i1f68b48eea92495388df6551a4f9ea63_52)]
To the shareholders and [added: the] Board of Directors of Fifth Third Bancorp:
We have audited the internal control over financial reporting of Fifth Third Bancorp and subsidiaries (the “Bancorp”) as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in *Internal Control — Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the Bancorp maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in *Internal Control — Integrated Framework (2013)* issued by COSO.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated financial statements as of and for the year ended December 31, [removed: 2022,] [added: 2023,] of the Bancorp and our report dated February [removed: 24, 2023] [added: 27, 2024] expressed an unqualified opinion on those consolidated financial statements.
[removed: *216] [added: *212] Fifth Third Bancorp*
| /s/ Timothy N. Spence | | | | | | /s/ Bryan D. Preston | | |
| Timothy N. Spence | | | | | | Bryan D. Preston | | |
| February 27, 2024 | | | | | | February 27, 2024 | | |
February 27, 2024
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
| /s/ Timothy N. Spence | | | | | | /s/ James C. Leonard | | |
| Timothy N. Spence | | | | | | James C. Leonard | | |
| February 24, 2023 | | | | | | February 24, 2023 | | |
February 24, 2023
Item 9B. OTHER INFORMATION
0 rewritten, 15 added, 1 removed, 0 unchanged
Effective February 27, 2024, the Bancorp’s Board of Directors approved executive retention grant awards under the Bancorp’s 2021 Incentive Compensation Plan to certain of the Bancorp’s named executive officers, which awards were issued in part to promote continuity in key leadership roles and recognize new or expanded roles and responsibilities, where applicable.
The Board granted these awards in the form of RSUs that will vest three years from the date of grant conditioned on the recipient’s continued employment and satisfactory performance of duties.
In the event the recipient’s employment is terminated due to death or disability, any unvested RSUs will become immediately vested.
In the event the recipient’s employment is terminated for any other reason, the unvested RSUs will be forfeited.
In addition, if the Bancorp’s return on average tangible common equity for the fiscal year ending immediately prior to a vesting date (i.e., 2024, 2025 and 2026) does not meet or exceed 2%, one-third of the RSUs may be forfeited at the discretion of the Human Capital and Compensation Committee of the Bancorp’s Board of Directors.
Furthermore, as a condition to receiving the award, if the recipient is asked to assume a different role within the Bancorp before the RSUs vest, the recipient is required to accept such a role and fully cooperate with any transition of required duties, as needed.
Kevin P.
Lavender, the Bancorp’s Executive Vice President and Head of Commercial Bank, James C.
Leonard, the Bancorp’s Executive Vice President and Chief Operating Officer, Jude A.
Schramm, the Bancorp’s Executive Vice President and Chief Information Officer, and Robert P.
Shaffer, the Bancorp’s Executive Vice President and Chief Risk Officer, will each receive a grant of RSUs in the amount of $2,000,000, based on the closing price of the Bancorp’s common stock on February 27, 2024.
Adoption or Termination of Insider Trading Arrangements
On December 14, 2023, Jude A.
Schramm, Executive Vice President and Chief Information Officer of the Bancorp, adopted a trading arrangement for the sale of shares of stock (a “Rule 10b5-1 Trading Plan”) that is intended to satisfy the affirmative defense conditions of Exchange Act Rule 10b5-1(c).
Mr. Schramm’s Rule 10b5-1 Trading Plan, which shall terminate on December 31, 2024, provides for the sale of up to 10,000 shares of common stock pursuant to the terms of the Rule 10b5-1 Trading Plan.
None.
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
3 rewritten, 1 added, 0 removed, 3 unchanged
The information required by this item concerning Directors and the nomination process is incorporated herein by reference under the caption “Election of Directors” of the Bancorp’s Proxy Statement for the [removed: 2023] [added: 2024] Annual Meeting of Shareholders.
The information required by this item concerning the Audit Committee and Code of Business Conduct and Ethics is incorporated herein by reference under the captions “Corporate Governance” and “Board of Directors, [removed: Its] Committees, Meetings, and Functions” of the Bancorp’s Proxy Statement for the [removed: 2023] [added: 2024] Annual Meeting of Shareholders.
The information required by this item concerning Delinquent Section 16(a) Reports is incorporated herein by reference under the caption “Delinquent Section 16(a) Reports” of the Bancorp’s Proxy Statement for the [removed: 2023] [added: 2024] Annual Meeting of Shareholders.
The Bancorp has adopted an Enterprise Insider Trading and Ethical Investing Policy that applies to all of its directors and employees.
Item 11. EXECUTIVE COMPENSATION
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this item is incorporated herein by reference under the captions “Compensation Discussion and Analysis,” “Compensation of Named Executive Officers,” “Board of Directors Compensation,” “CEO Pay Ratio,” “Human Capital and Compensation Committee Report” and “Compensation Committee Interlocks and Insider Participation” of the Bancorp’s Proxy Statement for the [removed: 2023] [added: 2024] Annual Meeting of Shareholders.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
1 rewritten, 2 added, 0 removed, 1 unchanged
Security ownership information of certain beneficial owners and management is incorporated herein by reference under the captions “Certain Beneficial Owners,” “Election of Directors,” “Compensation Discussion and Analysis,” “Board of Directors Compensation,” and “Compensation of Named Executive Officers” of the Bancorp’s Proxy Statement for the [removed: 2023] [added: 2024] Annual Meeting of Shareholders.
*213 Fifth Third Bancorp*
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this item is incorporated herein by reference under the captions “Certain Transactions”, “Election of Directors”, “Corporate Governance” and “Board of Directors, [removed: Its] Committees, Meetings, and Functions” of the Bancorp’s Proxy Statement for the [removed: 2023] [added: 2024] Annual Meeting of Shareholders.
Item 14. PRINCIPAL ACCOUNTING FEES AND SERVICES
3 rewritten, 0 added, 0 removed, 2 unchanged
The information required by this item is incorporated herein by reference under the caption “Principal Independent External Audit Firm Fees” of the Bancorp’s Proxy Statement for the [removed: 2023] [added: 2024] Annual Meeting of Shareholders.
[removed: *217] [added: *214] Fifth Third Bancorp*
[Table of [removed: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)][added: Contents](#i1f68b48eea92495388df6551a4f9ea63_52)]
Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES
87 rewritten, 14 added, 4 removed, 75 unchanged
| [Fifth Third Bancorp and Subsidiaries Consolidated Financial [removed: Statements](#i48540c50bc474a4186cf9dc1957cda5d_181)] [added: Statements](#i1f68b48eea92495388df6551a4f9ea63_178)] | | | [removed: [120](#i48540c50bc474a4186cf9dc1957cda5d_181)] [added: [112](#i1f68b48eea92495388df6551a4f9ea63_178)] | | |
| [Notes to Consolidated Financial [removed: Statements](#i48540c50bc474a4186cf9dc1957cda5d_199)] [added: Statements](#i1f68b48eea92495388df6551a4f9ea63_196)] | | | [removed: [126](#i48540c50bc474a4186cf9dc1957cda5d_199)] [added: [118](#i1f68b48eea92495388df6551a4f9ea63_196)] | | |
| 3.2 | | | [removed: [Regulations] [added: [Code] of [added: Regulations of] Fifth Third Bancorp, as Amended as [removed: of](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm) [April 12](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)[, 202](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)[2](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)[.] [added: of December 12, 2023.] Incorporated by reference to Exhibit 3.2 to the [removed: Registrant’s](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm) [Quarte](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)[rly](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm) [Report] [added: Registrant’s Current Report] on [removed: Form](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm) [10-Q](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm) [filed] [added: Form 8-K filed] with the SEC on [removed: M](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)[ay](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm) [](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)[9](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)[, 202](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)[2](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)[.](https://www.sec.gov/Archives/edgar/data/35527/000003552722000182/a10qfitb-33122xexx32.htm)] [added: December 1](https://www.sec.gov/Archives/edgar/data/35527/000003552723000268/a20231212amendedcodeofre.htm)[8](https://www.sec.gov/Archives/edgar/data/35527/000003552723000268/a20231212amendedcodeofre.htm)[, 2023.](https://www.sec.gov/Archives/edgar/data/35527/000003552723000268/a20231212amendedcodeofre.htm)] | | |
| 4.12 | | | [Form of Certificate Representing the 6.625% Fixed-to-Floating Rate Non-Cumulative Perpetual Preferred Stock, Series I, of Fifth Third Bancorp. [removed: Incorporated](https://www.sec.gov/Archives/edgar/data/35527/000119312513465956/d640696dex42.htm) [](https://www.sec.gov/Archives/edgar/data/35527/000119312513465956/d640696dex42.htm)[by] [added: Incorporated by] reference to Exhibit 4.2 of the Registrant’s Current Report on Form 8-K filed with the SEC on December 9, 2013.](https://www.sec.gov/Archives/edgar/data/35527/000119312513465956/d640696dex42.htm) | | |
[Table of [removed: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)][added: Contents](#i1f68b48eea92495388df6551a4f9ea63_52)]
| 4.34 | | | [Form of [removed: 1.625%] [added: 2.550%] Senior Notes due [removed: 2023.] [added: 2027.] Incorporated by reference to Exhibit [removed: 4.2] [added: 4.3] to the Registrant’s Current Report on Form 8-K filed with the SEC on May 5, [removed: 2020.](https://www.sec.gov/Archives/edgar/data/35527/000119312520133774/d849424dex42.htm)] [added: 2020.](https://www.sec.gov/Archives/edgar/data/35527/000119312520133774/d849424dex43.htm)] | | |
| [removed: 4.35] [added: 4.42] | | | [Form of [removed: 2.550%] [added: 4.337% Fixed Rate/Floating Rate] Senior Notes due [removed: 2027.] [added: 2033.] Incorporated by reference to Exhibit 4.3 to the Registrant’s Current Report on Form 8-K filed with the SEC on [removed: May 5, 2020.](https://www.sec.gov/Archives/edgar/data/35527/000119312520133774/d849424dex43.htm)] [added: April 25, 2022.](https://www.sec.gov/Archives/edgar/data/35527/000119312522117623/d303267dex43.htm)] | | |
| [removed: 4.36] [added: 4.35] | | | [Form of Certificate Representing the 4.500% Fixed-Rate Reset Non-Cumulative Perpetual Preferred Stock, Series L, of Fifth Third Bancorp. Incorporated by reference to Exhibit 4.2 of the Registrant’s Current Report on Form 8-K filed with the SEC on July 30, 2020.](https://www.sec.gov/Archives/edgar/data/35527/000119312520204323/d935766dex42.htm) | | |
| [removed: 4.37] [added: 4.36] | | | [Deposit Agreement dated July 30, 2020, between Fifth Third Bancorp, as issuer, American Stock Transfer & Trust Company, LLC, as depositary, transfer agent and registrar, and the holders from time to time of depositary receipts issued. Incorporated by reference to Exhibit 4.3 to the Registrant’s Current Report on Form 8-K filed with the SEC on July 30, 2020.](https://www.sec.gov/Archives/edgar/data/35527/000119312520204323/d935766dex43.htm) | | |
| [removed: 4.38] [added: 4.37] | | | [Form of Depositary Receipt for the 4.500% Fixed-Rate Reset Non-Cumulative Perpetual Preferred Stock, Series L, of Fifth Third Bancorp. Incorporated by reference to Exhibit A of Exhibit 4.3 to the Registrant’s Current Report on Form 8-K filed with the SEC on July 30, 2020.](https://www.sec.gov/Archives/edgar/data/35527/000119312520204323/d935766dex43.htm) | | |
| [removed: 4.39] [added: 4.38] | | | [Eleventh Supplemental Indenture dated as of November 1, 2021 between Fifth Third Bancorp and Wilmington Trust Company, as Trustee, to the Indenture for Senior Debt Securities dated as of April 30, 2008 between Fifth Third Bancorp and the Trustee. Incorporated by reference to Exhibit 4.1 to the Registrant’s Current Report on Form 8-K filed with the SEC on November 1, 2021.](https://www.sec.gov/Archives/edgar/data/0000035527/000119312521315460/d251543dex41.htm) | | |
| [removed: 4.40] [added: 4.39] | | | [Form of 1.707% Fixed Rate/Floating Rate Senior Notes due 2027. Incorporated by reference to Exhibit 4.2 to the Registrant’s Current Report on Form 8-K filed with the SEC on November 1, 2021.](https://www.sec.gov/Archives/edgar/data/0000035527/000119312521315460/d251543dex42.htm) | | |
| [removed: 4.41] [added: 4.40] | | | [Twelfth Supplemental Indenture dated as of April 25, 2022 between Fifth Third Bancorp and Wilmington Trust Company, as Trustee, to the Indenture for Senior Debt Securities dated as of April 30, 2008 between Fifth Third Bancorp and the Trustee. Incorporated by reference to Exhibit 4.1 to the Registrant’s Current Report on Form 8-K filed with the SEC on April 25, 2022.](https://www.sec.gov/Archives/edgar/data/35527/000119312522117623/d303267dex41.htm) | | |
| [removed: 4.42] [added: 4.41] | | | [Form of 4.055% Fixed Rate/Floating Rate Senior Notes due 2028. Incorporated by reference to Exhibit 4.2 to the Registrant’s Current Report on Form 8-K filed with the SEC on April 25, 2022.](https://www.sec.gov/Archives/edgar/data/35527/000119312522117623/d303267dex42.htm) | | |
| [removed: 4.43] [added: 4.46] | | | [Form of [removed: 4.337%] [added: 6.361%] Fixed Rate/Floating Rate Senior Notes due [removed: 2033.] [added: 2028.] Incorporated by reference to Exhibit [removed: 4.3] [added: 4.2] to the Registrant’s Current Report on Form 8-K filed with the SEC on [removed: April 25, 2022.](https://www.sec.gov/Archives/edgar/data/35527/000119312522117623/d303267dex43.htm)] [added: October 27, 2022.](https://www.sec.gov/Archives/edgar/data/35527/000119312522271002/d354612dex42.htm)] | | |
| [removed: 4.44] [added: 4.43] | | | [Thirteenth Supplemental Indenture dated as of July 28, 2022 between Fifth Third Bancorp and Wilmington Trust Company, as Trustee, to the Indenture for Senior Debt Securities dated as of April 30, 2008 between Fifth Third Bancorp and the Trustee, as amended by Article 4 of the Twelfth Supplemental Indenture dated April 25, 2022 between Fifth Third Bancorp and the Trustee. Incorporated by reference to Exhibit 4.1 to the Registrant’s Current Report on Form 8-K filed with the SEC on July 28, 2022.](https://www.sec.gov/Archives/edgar/data/35527/000119312522204836/d387881dex41.htm) | | |
| [removed: 4.45] [added: 4.44] | | | [Form of 4.772% Fixed Rate/Floating Rate Senior Notes due 2030. Incorporated by reference to Exhibit 4.2 to the Registrant’s Current Report on Form 8-K filed with the SEC on July 28, 2022](https://www.sec.gov/Archives/edgar/data/35527/000119312522204836/d387881dex42.htm). | | |
| [removed: 4.46] [added: 4.45] | | | [Fourteenth Supplemental Indenture dated as of October 27, 2022 between Fifth Third Bancorp and Wilmington Trust Company, as Trustee, to the Indenture for Senior Debt Securities dated as of April 30, 2008 between Fifth Third Bancorp and the Trustee, as amended by Article 4 of the Twelfth Supplemental Indenture dated April 25, 2022 between Fifth Third Bancorp and the Trustee. Incorporated by reference to Exhibit 4.1 to the Registrant’s Current Report on Form 8-K filed with the SEC on October 27, 2022.](https://www.sec.gov/Archives/edgar/data/35527/000119312522271002/d354612dex41.htm) | | |
| [removed: 4.47] [added: 4.48] | | | [Form of [removed: 6.361%] [added: 6.339%] Fixed Rate/Floating Rate Senior Notes due [removed: 2028.] [added: 2029.] Incorporated by reference to Exhibit 4.2 [removed: to] [added: of] the Registrant’s Current Report on Form 8-K filed [removed: with the SEC] on [removed: October] [added: July] 27, [removed: 2022.](https://www.sec.gov/Archives/edgar/data/35527/000119312522271002/d354612dex42.htm)] [added: 2023.](https://www.sec.gov/Archives/edgar/data/35527/000119312523196135/d485744dex42.htm)] | | |
| [removed: 4.48] [added: 4.49] | | | Certain instruments defining the rights of holders of long-term debt securities of the Registrant and its subsidiaries are omitted pursuant to Item 601(b)(4)(iii) of Regulation S-K. The Registrant hereby undertakes to furnish to the SEC, upon request, copies of any such instruments. | | |
| [removed: 4.49] [added: 4.50] | | | [Description of Registrant’s Securities. Incorporated by reference to Exhibit 4.44 to the Registrant’s Annual Report on Form 10-K filed with the SEC on February 25, 2022.](https://www.sec.gov/Archives/edgar/data/35527/000003552722000119/fitb-12312020xexx444.htm) | | |
[removed: *219] [added: *215] Fifth Third Bancorp*
| [removed: 10.12] [added: 10.13] | | | [First Amendment to the Fifth Third Bancorp [removed: 2008] [added: 2011] Incentive Compensation Plan. Incorporated by reference to Exhibit [removed: 10.22] [added: 10.24] to the Registrant’s Annual Report on Form 10-K for the fiscal year ended December 31, [removed: 2018.](https://www.sec.gov/Archives/edgar/data/35527/000119312519059441/d680668dex1022.htm)*] [added: 2018.](https://www.sec.gov/Archives/edgar/data/35527/000119312519059441/d680668dex1024.htm)*] | | |
| [removed: 10.13] [added: 10.12] | | | [Fifth Third Bancorp 2011 Incentive Compensation Plan. Incorporated by reference to Annex 1 to the Registrant’s Proxy Statement dated March 10, 2011.](https://www.sec.gov/Archives/edgar/data/35527/000119312511061745/ddef14a.htm)* | | |
| [removed: 10.14] [added: 10.15] | | | [First Amendment to the Fifth Third Bancorp [removed: 2011] [added: 2014] Incentive Compensation Plan. Incorporated by reference to Exhibit [removed: 10.24] [added: 10.26] to the Registrant’s Annual Report on Form 10-K for the fiscal year ended December 31, [removed: 2018.](https://www.sec.gov/Archives/edgar/data/35527/000119312519059441/d680668dex1024.htm)*] [added: 2018.](https://www.sec.gov/Archives/edgar/data/35527/000119312519059441/d680668dex1026.htm)*] | | |
| [removed: 10.15] [added: 10.14] | | | [Fifth Third Bancorp 2014 Incentive Compensation Plan. Incorporated by reference to Annex A to the Registrant’s Proxy Statement dated March 6, 2014.](https://www.sec.gov/Archives/edgar/data/35527/000119312514086549/d644349ddef14a.htm#toc644349_39)* | | |
| [removed: 10.16] [added: 10.17] | | | [First Amendment to the Fifth Third Bancorp [removed: 2014] [added: 2017] Incentive Compensation Plan. Incorporated by reference to Exhibit [removed: 10.26] [added: 10.28] to the Registrant’s Annual Report on Form 10-K for the fiscal year ended December 31, [removed: 2018.](https://www.sec.gov/Archives/edgar/data/35527/000119312519059441/d680668dex1026.htm)*] [added: 2018.](https://www.sec.gov/Archives/edgar/data/35527/000119312519059441/d680668dex1028.htm)*] | | |
| [removed: 10.17] [added: 10.16] | | | [Fifth Third Bancorp 2017 Incentive Compensation Plan. Incorporated by reference to Annex A to the Registrant’s Proxy Statement dated March 9, 2017.](https://www.sec.gov/Archives/edgar/data/35527/000119312517075735/d271686ddef14a.htm#toc271686_222)* | | |
| [removed: 10.18] [added: 10.26] | | | [First Amendment to the Fifth Third Bancorp [removed: 2017 Incentive Compensation] [added: Executive Change in Control Severance] Plan. Incorporated by reference to Exhibit [removed: 10.28] [added: 10.40] to the Registrant’s Annual Report on Form 10-K for the fiscal year ended December 31, [removed: 2018.](https://www.sec.gov/Archives/edgar/data/35527/000119312519059441/d680668dex1028.htm)*] [added: 2018.](https://www.sec.gov/Archives/edgar/data/35527/000119312519059441/d680668dex1040.htm)*] | | |
| [removed: 10.19] [added: 10.18] | | | [Fifth Third Bancorp 2019 Incentive Compensation Plan. Incorporated by reference to Exhibit 4.3 to the Registrant’s Form S-8 Registration Statement filed on April 16, 2019 (Registration Statement No. 333-230900).](https://www.sec.gov/Archives/edgar/data/35527/000095010319004841/dp105168_ex0403.htm)* | | |
| [removed: 10.20] [added: 10.19] | | | [Fifth Third Bancorp 2021 Incentive Compensation Plan. Incorporated by reference to Annex A to the Registrant’s Proxy Statement filed on March 2, 2021.](https://www.sec.gov/Archives/edgar/data/35527/000119312521065580/d58594ddef14a.htm)* | | |
| [removed: 10.21] [added: 10.20] | | | [Amended and Restated Fifth Third Bancorp 1993 Stock Purchase Plan. Incorporated by reference to Exhibit 10.8 to the Registrant’s Annual Report on Form 10-K for the fiscal year ended December 31, 2011.](https://www.sec.gov/Archives/edgar/data/35527/000119312512089474/d305243dex108.htm)* | | |
| [removed: 10.22] [added: 10.21] | | | [Fifth Third Bancorp Non-qualified Deferred Compensation Plan (as amended and restated effective as of September 1, 2020). Incorporated by reference to Exhibit 10.1 to the Registrant’s Quarterly Report on Form 10-Q for the fiscal quarter ended September 30, 2020.](https://www.sec.gov/Archives/edgar/data/35527/000003552720000107/fitb-09302020xexx101.htm)* | | |
| [removed: 10.23] [added: 10.22] | | | [Fifth Third Bancorp Stock Option Gain Deferral Plan. Incorporated by reference to Annex 5 to the Registrant’s Proxy Statement dated February 9, 2001.](https://www.sec.gov/Archives/edgar/data/35527/000095015201000623/l86077bdef14a.txt)* | | |
| [removed: 10.24] [added: 10.23] | | | [Amendment No. 1 to Fifth Third Bancorp Stock Option Gain Deferral Plan. Incorporated by reference to Exhibit 10.1 to the Registrant’s Current Report on Form 8-K filed with the SEC on May 26, 2005.](https://www.sec.gov/Archives/edgar/data/35527/000119312505115691/dex101.htm)* | | |
| [removed: 10.25] [added: 10.24] | | | [Amended and Restated First National Bankshares of Florida, Inc. 2003 Incentive Plan. Incorporated by reference to Exhibit 10.10 to First National Bankshares of Florida, Inc.’s Annual Report on Form 10-K for the fiscal year ended December 31, 2003.](https://www.sec.gov/Archives/edgar/data/1267969/000095012804000268/j0545201exv10w10.txt)* | | |
| [removed: 10.26] [added: 10.25] | | | [Fifth Third Bancorp Executive Change in Control Severance Plan, effective January 1, 2015. Incorporated by reference to Exhibit 10.1 to Registrant’s Current Report on Form 8-K filed with the SEC on November 21, 2014.](https://www.sec.gov/Archives/edgar/data/35527/000119312514421952/d825343dex101.htm)* | | |
| 10.27 | | | [removed: [First] [added: [Second] Amendment to the Fifth Third Bancorp Executive Change in Control Severance Plan. Incorporated by reference to Exhibit [removed: 10.40 to] [added: 99.2 of] the Registrant’s [removed: Annual] [added: Current] Report on Form [removed: 10-K for the fiscal year ended December 31, 2018.](https://www.sec.gov/Archives/edgar/data/35527/000119312519059441/d680668dex1040.htm)*] [added: 8-K filed on February 23, 2021.](https://www.sec.gov/Archives/edgar/data/0000035527/000119312521052436/d147275dex992.htm)[*](https://www.sec.gov/Archives/edgar/data/0000035527/000119312521052436/d147275dex992.htm)] | | |
| 10.28 | | | [removed: [Second Amendment to the Fifth] [added: [Fifth] Third [removed: Bancorp] [added: Bank, National Association] Executive [removed: Change in Control] Severance [added: Benefits] Plan. Incorporated by reference to Exhibit [removed: 99.2] [added: 99.1] of the Registrant’s Current Report on Form 8-K filed on February 23, [removed: 2021.](https://www.sec.gov/Archives/edgar/data/0000035527/000119312521052436/d147275dex992.htm)[*](https://www.sec.gov/Archives/edgar/data/0000035527/000119312521052436/d147275dex992.htm)] [added: 2021.](https://www.sec.gov/Archives/edgar/data/0000035527/000119312521052436/d147275dex991.htm)[*](https://www.sec.gov/Archives/edgar/data/0000035527/000119312521052436/d147275dex991.htm)] | | |
| [removed: 10.30] [added: 10.29] | | | [Stock Appreciation Right Award Agreement. Incorporated by reference to Exhibit 10.2 of the Registrant’s Quarterly Report on Form 10-Q for the fiscal quarter ended June 30, 2013.](https://www.sec.gov/Archives/edgar/data/35527/000119312513324416/d568419dex102.htm)* | | |
| [Public Accounting Firm](#i1f68b48eea92495388df6551a4f9ea63_175) | | | [110](#i1f68b48eea92495388df6551a4f9ea63_175), [212](#i1f68b48eea92495388df6551a4f9ea63_304) | | |
| 4.47 | | | [Fifteenth Supplemental Indenture dated as of July 27, 2023 between Fifth Third Bancorp and Wilmington Trust Company, as Trustee, to the Indenture for Senior Debt Securities dated as of April 30, 2008 between Fifth Third Bancorp and the Trustee, as amended by Article 4 of the Twelfth Supplemental Indenture dated April 25, 2022 between Fifth Third Bancorp and the Trustee. Incorporated by reference to Exhibit 4.1 of the Registrant’s Current Report on Form 8-K filed on July 27, 2023.](https://www.sec.gov/Archives/edgar/data/35527/000119312523196135/d485744dex41.htm) | | |
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
| 10.65 | | | [2022 Long-Term Incentive Compensation Program Overview February 2023 Grants. Incorporated by reference to Exhibit 10.66 to the Registrant’s Annual Report on Form 10-K for the fiscal year ended December 31, 2022.*](https://www.sec.gov/Archives/edgar/data/35527/000003552723000122/fitb-12312022xexx1066.htm) | | |
| 10.66 | | | [2023 Performance Share Award Agreement. Incorporated by reference to Exhibit 10.67 to the Registrant’s Annual Report on Form 10-K for the fiscal year ended December 31, 2022.*](https://www.sec.gov/Archives/edgar/data/35527/000003552723000122/fitb-12312022xexx1067.htm) | | |
| 10.67 | | | [2023 Restricted Stock Unit Agreement (for Executive Officers). Incorporated by reference to Exhibit 10.68 to the Registrant’s Annual Report on Form 10-K for the fiscal year ended December 31, 2022.*](https://www.sec.gov/Archives/edgar/data/35527/000003552723000122/fitb-12312022xexx1068.htm) | | |
| 10.68 | | | [2023 Stock Appreciation Right Award Agreement (for Executive Officers). Incorporated by reference to Exhibit 10.69 to the Registrant’s Annual Report on Form 10-K for the fiscal year ended December 31, 2022.*](https://www.sec.gov/Archives/edgar/data/35527/000003552723000122/fitb-12312022xexx1069.htm) | | |
| 10.69 | | | [2023 Restricted Stock Unit Grant Agreement (for Directors). Incorporated by reference to Exhibit 10.1 to the Registrant’s Quarterly Report on Form 10-Q for the fiscal quarter ended June 30, 2023.*](https://www.sec.gov/Archives/edgar/data/35527/000003552723000214/a10qfitb-63023xexx101.htm) | | |
| 10.76 | | | [Form of 2024 Restricted Stock Unit Retention Agreement.](https://www.sec.gov/Archives/edgar/data/35527/000003552724000088/fitb-123123xexx1076.htm) | | |
| 10.77 | | | [Form of 2024 Restricted Stock Unit Retention Agreement subject to additional covenant.](https://www.sec.gov/Archives/edgar/data/35527/000003552724000088/fitb-123123xexx1077.htm) | | |
| 19 | | | [Enterprise Insider Trading and Ethical Investing Policy.](https://www.sec.gov/Archives/edgar/data/35527/000003552724000088/fitb-123123xexx19.htm) | | |
| 97 | | | [Compensation Clawback and Disclosure Policy.](https://www.sec.gov/Archives/edgar/data/35527/000003552724000088/fitb-123123xexx97.htm) | | |
| [Public Accounting Firm](#i48540c50bc474a4186cf9dc1957cda5d_178) | | | [118](#i48540c50bc474a4186cf9dc1957cda5d_178), [216](#i48540c50bc474a4186cf9dc1957cda5d_307) | | |
| 10.29 | | | [Fifth Third Bank, National Association Executive Severance Benefits Plan. Incorporated by reference to Exhibit 99.1 of the Registrant’s Current Report on Form 8-K filed on February 23, 2021.](https://www.sec.gov/Archives/edgar/data/0000035527/000119312521052436/d147275dex991.htm)[*](https://www.sec.gov/Archives/edgar/data/0000035527/000119312521052436/d147275dex991.htm) | | |
| 10.72 | | | [Supplemental Confirmation dated December 6, 2022, to Master Confirmation dated July 29, 2015, for accelerated share repurchase transaction between Fifth Third Bancorp and Morgan Stanley & Co. LLC.*](https://www.sec.gov/Archives/edgar/data/35527/000003552723000122/fitb-12312022xexx1072.htm) | | |
| 10.73 | | | [Supplemental Confirmation dated January 20, 2023, to Master Confirmation dated July 29, 2015, for accelerated share repurchase transaction between Fifth Third Bancorp and Morgan Stanley & Co. LLC.*](https://www.sec.gov/Archives/edgar/data/35527/000003552723000122/fitb-12312022xexx1073.htm) | | |
An excerpt. Shown here: 40 of 87 rewritten, all 14 added and all 4 removed. The counts are complete. For every sentence, read Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES in the FY2023 filing and the FY2022 filing.
Item 16. FORM 10–K SUMMARY
14 rewritten, 42 added, 31 removed, 164 unchanged
[Table of [removed: Contents](#i48540c50bc474a4186cf9dc1957cda5d_46)][added: Contents](#i1f68b48eea92495388df6551a4f9ea63_52)]
*Pursuant to requirements of the Securities Exchange Act of 1934, this report has been signed on February [removed: 24, 2023] [added: 27, 2024] by the following persons on behalf of the Registrant and in the capacities indicated.*
| Executive Vice President and [removed: CFO] [added: Chief Financial Officer] | | |
| [removed: Executive] Chairman | | |
[removed: *223] [added: *219] Fifth Third Bancorp*
| [removed: 2022] [added: 2022] | | | [removed: $] [added: 120,561] | [removed: 120,561] | | [removed: 12,419] [added: 12,419] | | | [removed: 53,346] [added: 53,346] | | | [removed: 186,326] [added: 186,326] | | | [removed: 3,093] [added: 3,093] | | | [removed: 19,490] [added: 19,490] | | | [removed: 206,929] [added: 206,929] | | |
| AVERAGE DEPOSITS AND [added: AVERAGE] SHORT-TERM BORROWINGS FOR THE YEARS ENDED DECEMBER 31 ($ IN MILLIONS) | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| [removed: 2022] [added: 2022] | | | [removed: $] [added: 60,185] | [removed: 60,185] | | [removed: 45,835] [added: 45,835] | | | [removed: 23,445] [added: 23,445] | | | [removed: 29,326] [added: 29,326] | | | [removed: 4,030] [added: 4,030] | | | [removed: 170] [added: 170] | | | [removed: 162,991] [added: 162,991] | | | [removed: 4,925] [added: 4,925] | | | [removed: 167,916] [added: 167,916] | | |
| [removed: 2022] [added: 2022] | | | [removed: $] [added: 6,587] | [removed: 6,587] | | [removed: 978] [added: 978] | | | [removed: 2,766] [added: 2,766] | | | [removed: 4,719] [added: 4,719] | | | [removed: 2,330] [added: 2,330] | | | [removed: 3.38] [added: 3.38] | | | [removed: 3.35] [added: 3.35] | | | [removed: 1.26] [added: 1.26] | | |
| [removed: 2022] [added: 2022] | | | [removed: 683,385,880] [added: 683,385,880] | | | [removed: $] [added: 2,051] | [removed: 2,051] | | [removed: 2,116] [added: 2,116] | | | [removed: 3,684] [added: 3,684] | | | [removed: 21,689] [added: 21,689] | | | [removed: (5,110)] [added: (5,110)] | | | [removed: (7,103)] [added: (7,103)] | | | [removed: 17,327] [added: 17,327] | | | [removed: 22.26] [added: 22.26] | | | [removed: 2,194] [added: 2,194] | | |
[removed: *224] [added: *220] Fifth Third Bancorp*
| [removed: Greg D. Carmichael] [added: Timothy N. Spence *Chairman* *Fifth Third Bancorp* Nicholas K. Akins, Lead Director *Retired Chairman & Chief Executive Officer* *American Electric Power Company* B. Evan Bayh, III *Senior Advisor* *Apollo Global Management* Jorge L. Benitez *Retired Chief Executive Officer* *North America of Accenture plc* Katherine B. Blackburn *Executive Vice President* *Cincinnati Bengals, Inc.* Emerson L. Brumback *Retired President & Chief Operating Officer* *M&T Bank* Linda W. Clement-Holmes *Retired Chief Information Officer* *The Procter & Gamble Company* C. Bryan Daniels *Founding Partner* *Prairie Capital* Laurent Desmangles *Retired Senior Partner & Managing Director* *Boston Consulting* Mitchell S. Feiger *Retired Chief Executive Officer and President* *MB Financial, Inc.* Thomas H. Harvey *Chief Executive Officer* *Energy Innovation: Policy and Technology, LLC* Gary R. Heminger *Retired Chief Executive Officer & Chairman* *Marathon Petroleum Corporation* Eileen A. Mallesch *Retired Chief Financial Officer* *Nationwide Property & Casualty Segment, Nationwide Mutual Insurance Company* Michael B. McCallister *Retired Chairman & Chief Executive Officer* *Humana, Inc.* Kathleen A. Rogers *Retired Executive Vice President* *U.S. Bancorp* Marsha C. Williams *Retired Chief Financial Officer* *Orbitz Worldwide, Inc*] | | | | | | Timothy N. Spence [added: *Chairman, Chief Executive Officer and President* Kristine R. Garrett *Executive Vice President,* *Group Regional President &* *Head of Wealth & Asset Management* Kala J. Gibson *Executive Vice President &* *Chief Corporate Responsibility Officer* Mark D. Hazel *Executive Vice President &* *Controller* Kevin P. Lavender *Executive Vice President &* *Head of Commercial Bank* James C. Leonard *Executive Vice President &* *Chief Operating Officer* Nancy C. Pinckney *Executive Vice President &* *Chief Human Resource Officer* Bryan D. Preston *Executive Vice President &* *Chief Financial Officer* Jude A. Schramm *Executive Vice President &* *Chief Information Officer* Robert P. Shaffer *Executive Vice President &* *Chief Risk Officer* Melissa S. Stevens *Executive Vice President &* *Chief Marketing Officer* Susan B. Zaunbrecher *Executive Vice President &* *Chief Legal Officer*] | | | | | | Michael Ash David Briggs Timothy Elsbrock Lee Fite David Girodat [added: Stephanie Green] Kimberly Halbauer Mark Heckler Francie Henry Randy Koporc Tom Partridge Cary Putrino [removed: Jim Weiss] Thomas G. Welch, Jr. Joseph Yurosek FIFTH THIRD BANCORP BOARD COMMITTEES Audit Committee Eileen A. Mallesch, Chair [added: Jorge L. Benitez] Katherine B. Blackburn [added: Linda W. Clement-Holmes C. Bryan Daniels] Thomas H. Harvey [removed: Jewell D. Hoover Michael B. McCallister] [added: Gary R. Heminger Kathleen A. Rogers] Finance Committee Gary R. Heminger, Chair Nicholas K. Akins Jorge L. Benitez Emerson L. Brumback Thomas H. Harvey Eileen A. Mallesch Michael B. McCallister [removed: Marsha C. Williams] Human Capital and Compensation Committee Michael B. McCallister, Chair Nicholas K. Akins [added: Jorge L. Benitez] Emerson L. Brumback [added: Linda W. Clement-Holmes] Gary R. Heminger [removed: Eileen] [added: Kathleen] A. [removed: Mallesch Marsha C. Williams] [added: Rogers] Nominating and Corporate Governance Committee Thomas H. Harvey, Chair Nicholas K. Akins B. Evan Bayh, III Jorge L. Benitez Katherine B. Blackburn [added: Laurent Desmangles] Marsha C. Williams Risk and Compliance Committee Emerson L. Brumback, Chair [removed: Linda W. Clement-Holmes] [added: Nicholas K. Akins] C. Bryan Daniels [removed: Gary R. Heminger Jewell D. Hoover] [added: Laurent Desmangles Mitchell S. Feiger] Eileen A. Mallesch [added: Michael B. McCallister Kathleen A. Rogers Marsha C. Williams] Technology Committee Jorge L. Benitez, Chair B. Evan Bayh, III Linda W. Clement-Holmes C. Bryan Daniels [added: Laurent Desmangles Mitchell S. Feiger] Thomas H. Harvey | | |
| [removed: *Executive Chairman* | | | | | | *President &] [added: Chairman,] Chief Executive [removed: Officer* | | | | | |] [added: Officer and President] | | |
[removed: | *Fifth] [added: *221 Fifth] Third Bancorp* [removed: | | | | | | | | | | | | | | |]
| February 27, 2024 | | |
| Chairman, Chief Executive Officer and President | | |
| /s/ Bryan D. Preston | | |
| Bryan D. Preston | | |
| /s/ Laurent Desmangles | | |
| Laurent Desmangles | | |
| /s/ Kathleen A. Rogers | | |
| Kathleen A. Rogers | | |
| | | |
| | | |
| | | |
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
| 2023 | | | $ | 122,282 | | 11,934 | | | 57,527 | | | 191,743 | | | 2,772 | | | 16,169 | | | 208,426 | | |
| 2023 | | | $ | 46,195 | | 52,378 | | | 20,872 | | | 30,943 | | | 13,630 | | | 158 | | | 164,176 | | | 5,351 | | | 169,527 | | |
| 2023 | | | $ | 9,760 | | 3,933 | | | 2,881 | | | 5,205 | | | 2,212 | | | 3.23 | | | 3.22 | | | 1.36 | | |
| 2023 | | | 681,124,810 | | | $ | 2,051 | | 2,116 | | | 3,757 | | | 22,997 | | | (4,487) | | | (7,262) | | | 19,172 | | | 25.04 | | | 2,322 | | |
[Table of Contents](#i1f68b48eea92495388df6551a4f9ea63_52)
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
| President and CEO | | |
| February 24, 2023 | | |
| /s/ James C. Leonard | | |
| James C. Leonard | | |
| /s/ Greg D. Carmichael | | |
| Greg D. Carmichael | | |
| /s/ Jewell D. Hoover | | |
| Jewell D. Hoover | | |
| 2013 | | | 89,093 | | | 2,417 | | | 16,444 | | | 107,954 | | | 2,482 | | | 15,025 | | | 123,704 | | |
| 2013 | | | 29,925 | | | 23,582 | | | 18,440 | | | 9,467 | | | 10,099 | | | 1,518 | | | 93,031 | | | 3,527 | | | 96,558 | | |
| 2013 | | | 3,973 | | | 412 | | | 3,227 | | | 3,978 | | | 1,799 | | | 2.05 | | | 2.02 | | | 0.47 | | |
| 2013 | | | 855,305,745 | | | 2,051 | | | 1,034 | | | 2,561 | | | 10,156 | | | 82 | | | (1,295) | | | 14,589 | | | 15.85 | | | 1,582 | | |
| | | | | | | Greg D.Carmichael | | | | | | | | |
| Nicholas K. Akins, Lead Director | | | | | | *Executive Chairman* | | | | | | | | |
| *Executive Chair* | | | | | | | | | | | | | | |
| *American Electric Power Company* | | | | | | Kristine R. Garrett *Executive Vice President,* *Group Regional President &* *Head of Wealth & Asset Management* | | | | | | | | |
| B. Evan Bayh, III *Senior Advisor* *Apollo Global Management* | | | | | | | | | | | | | | |
| Jorge L. Benitez *Retired Chief Executive Officer* *North America of Accenture plc* | | | | | | Kala J. Gibson *Executive Vice President &* *Chief Corporate Responsibility Officer* | | | | | | | | |
| Katherine B. Blackburn *Executive Vice President* *Cincinnati Bengals, Inc.* | | | | | | Howard Hammond *Executive Vice President &* *Head of Consumer Bank* | | | | | | | | |
| Emerson L. Brumback *Retired President & Chief Operating Officer* *M&T Bank* | | | | | | Mark D. Hazel *Executive Vice President &* *Controller* | | | | | | | | |
| Linda W. Clement-Holmes *Retired Chief Information Officer* *The Procter & Gamble Company* | | | | | | Kevin P. Lavender *Executive Vice President &* *Head of Commercial Bank* | | | | | | | | |
| C. Bryan Daniels *Founding Partner* *Prairie Capital* | | | | | | James C. Leonard *Executive Vice President &* *Chief Financial Officer* | | | | | | | | |
| Mitchell S. Feiger *Retired CEO and President* *MB Financial, Inc.* | | | | | | Nancy C. Pinckney *Executive Vice President &* *Chief Human Resource Officer* | | | | | | | | |
| Thomas H. Harvey *Chief Executive Officer* *Energy Innovation: Policy and Technology, LLC* | | | | | | Jude A. Schramm *Executive Vice President &* *Chief Information Officer* | | | | | | | | |
| Gary R. Heminger *Retired Chief Executive Officer & Chairman* *Marathon Petroleum Corporation* | | | | | | Robert P. Shaffer *Executive Vice President &* *Chief Risk Officer* | | | | | | | | |
| Jewell D. Hoover *Retired Senior Official* *Comptroller of the Currency* | | | | | | Richard L. Stein *Executive Vice President &* *Chief Credit Officer* | | | | | | | | |
| Eileen A. Mallesch *Retired Chief Financial Officer* *Nationwide Property & Casualty Segment, Nationwide Mutual Insurance Company* | | | | | | Melissa S. Stevens *Executive Vice President &* *Chief Marketing Officer* | | | | | | | | |
| Michael B. McCallister *Retired Chairman & Chief Executive Officer* *Humana, Inc.* | | | | | | Susan B. Zaunbrecher *Executive Vice President &* *Chief Legal Officer* | | | | | | | | |
| Timothy N. Spence *President & Chief Executive Officer* *Fifth Third Bancorp* | | | | | | | | | | | | | | |
| Marsha C. Williams *Retired Chief Financial Officer* *Orbitz Worldwide, Inc* | | | | | | | | | | | | | | |
*225 Fifth Third Bancorp*
An excerpt. Shown here: all 14 rewritten, 40 of 42 added and all 31 removed. The counts are complete. For every sentence, read Item 16. FORM 10–K SUMMARY in the FY2023 filing and the FY2022 filing.