 filings.tools
Federal Realty Investment Trust (FRT) 10-K risk factor changes: FY2019 vs FY2018
The 2019-12-31 10-K against the 2018-12-31 one, compared heading by heading and sentence by sentence. One of these filings carries no fiscal year tag, so its year is the calendar year of the period end.
Item 1A60 rewritten67 added10 removed374 unchanged
All filing items1,174 rewritten725 added489 removed1,770 unchanged
Summary
counted, not written
- Item 1A headings could not be compared: only 0 carried over between the two years, which usually means one filing was read wrongly, so none is reported as new or removed.
- Sentence by sentence, 725 added, 489 removed, 1,174 rewritten and 1,770 unchanged across 18 items that differ.
Sentences by item
22 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2019; struck-through words were in FY2018. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. RISK FACTORS
60 rewritten, 67 added, 10 removed, 374 unchanged
[removed: Revenue] [added: Revenue] from our properties may be reduced or limited if the retail operations of our tenants are not [removed: successful.][added: successful.]
Any reduction in our tenants' abilities to pay base rent, percentage rent, or other charges on a timely basis, including the [added: closing of stores prior to the end of the lease term or the] filing by any of our tenants for bankruptcy protection, will adversely affect our financial condition and results of operations.
[removed: Our] [added: Our] net income depends on the success and continued presence of our “anchor” [removed: tenants.][added: tenants.]
As of December 31, [removed: 2018,] [added: 2019,] our anchor tenant space is [removed: 97.6%] [added: 97.5%] leased and [removed: 96.9%] [added: 95.9%] occupied.
[removed: We] [added: We] may be unable to collect balances due from tenants that file for bankruptcy [removed: protection.][added: protection.]
[removed: We] [added: We] may experience difficulty or delay in renewing leases or re-leasing [removed: space.][added: space.]
[removed: The] [added: The] amount of debt we have and the restrictions imposed by that debt could adversely affect our business and financial [removed: condition.][added: condition.]
Of that outstanding debt, approximately [removed: $475.3] [added: $547.2] million was secured by all or a portion of 13 of our real estate [removed: projects and approximately $71.5 million represented capital lease obligations on four of our properties.][added: projects.]
[removed: We] [added: We] are obligated to comply with financial and other covenants pursuant to our debt obligations that could restrict our operating activities, and the failure to comply with such covenants could result in defaults that accelerate payment under our debt [removed: agreements.][added: agreements.]
Our revolving credit [removed: facility, term loan] [added: facility] and certain series of notes include financial covenants that may limit our operating activities in the future.
As of December 31, [removed: 2018,] [added: 2019,] we were in compliance with all of our default related financial covenants.
Many of our debt arrangements, including our public [removed: notes, term loan] [added: notes] and our revolving credit facility, are cross-defaulted, which means that the lenders under those debt arrangements can put us in default and require immediate repayment of their debt if we breach and fail to cure a default under certain of our other debt obligations.
[removed: Adverse] [added: Adverse] changes in our credit rating could affect our borrowing capacity and borrowing [removed: terms][added: terms.]
[removed: Our] [added: Our] development activities have inherent [removed: risks.][added: risks.]
During [removed: 2018,] [added: 2019,] construction [removed: continued] [added: was substantially completed] on the development of Phase II at both Assembly Row and Pike & Rose, with portions of both projects opening during [removed: 2018.][added: 2018 and 2019.]
Additionally, we [removed: commenced] [added: continued] construction on Phase III at both projects, and [removed: we continued] our on-going redevelopment efforts at Santana Row.
| • | delivery of residential product [removed: (both rental units and for sale condominium units)] into uncertain residential environments may result in lower rents or [removed: sale prices than underwritten or] longer time periods to reach economic stabilization; |
[removed: Redevelopments] [added: Redevelopments] and acquisitions may fail to perform as [removed: expected.][added: expected.]
| • | our estimate of the costs to improve, reposition or redevelop a property may prove to be too low, or the time we estimate to complete the improvement, repositioning or redevelopment may be too short. As a result, the property may fail to achieve the returns we have projected, either temporarily or for a longer [removed: time;] [added: period;] |
[removed: Our] [added: Our] ability to grow will be limited if we cannot obtain additional [removed: capital.][added: capital.]
[removed: Rising] [added: Rising] interest rates could adversely affect our cash flow and the market price of our outstanding debt and preferred [removed: shares.][added: shares.]
Of our [removed: approximately $3.2] [added: $3.4] billion of debt outstanding as of December 31, [removed: 2018,] [added: 2019,] approximately [removed: $275.0] [added: $56.5] million bears interest at a variable rate of LIBOR plus [removed: 90.0] [added: 195.0] basis [removed: points.][added: points and is effectively fixed through two interest rate swap agreements.]
We also have [removed: an $800.0 million] [added: a $1.0 billion] revolving credit facility, on which no balance was outstanding at December 31, [removed: 2018,] [added: 2019,] that bears interest at LIBOR plus [removed: 82.5] [added: 77.5] basis points.
We may enter into [added: additional] hedging arrangements or other transactions for all or a portion of our variable rate debt to limit our exposure to rising interest rates.
[removed: The] [added: The] market value of our debt and equity securities is subject to various factors that may cause significant fluctuations or [removed: volatility.][added: volatility.]
| • | changes in our [removed: debt] [added: credit] or analyst ratings; |
[removed: Loss] [added: Loss] of our key management could adversely affect performance and the value of our common [removed: shares.][added: shares.]
[removed: Our] [added: Our] performance and value are subject to general risks associated with the real estate [removed: industry.][added: industry.]
Our economic performance and the value of our real estate assets, [removed: and,] [added: and] consequently, the value of our investments, are subject to the risk that if our properties do not generate revenues sufficient to meet our operating expenses, including debt service and capital expenditures, our cash flow and ability to pay distributions to our shareholders will be adversely affected.
[removed: Many] [added: Many] real estate costs are fixed, even if income from our properties [removed: decreases.][added: decreases.]
[removed: Competition] [added: Competition] may limit our ability to purchase new properties and generate sufficient income from [removed: tenants.][added: tenants.]
[removed: We] [added: We] may be unable to sell properties when appropriate because real estate investments are [removed: illiquid.][added: illiquid.]
[removed: Our] [added: Our] insurance coverage on our properties may be [removed: inadequate.][added: inadequate.]
[added: In addition, insurance companies may no] longer offer coverage against certain types of losses, such as losses due to terrorist acts and toxic mold, or, if offered, the expense of obtaining these types of insurance may not be justified.
[removed: If] any of our properties were to experience a catastrophic loss, it could seriously disrupt our operations, delay revenue and result in large expenses to repair or rebuild the property.
[removed: We] [added: We] may have limited flexibility in dealing with our jointly owned [removed: investments.][added: investments.]
As of December 31, [removed: 2018,] [added: 2019,] we held [removed: 17] [added: 16] predominantly retail real estate projects jointly with other persons in addition to properties owned in a “downREIT” structure.
Although as of December 31, [removed: 2018,] [added: 2019,] we held the controlling interests in all of our existing co-investments (except the hotel investments discussed above and the investment in the La Alameda shopping center acquired in 2017), we generally must obtain the consent of the co-investor or meet defined criteria to sell or to finance these properties.
[removed: Environmental] [added: Environmental] laws and regulations could reduce the value or profitability of our [removed: properties.][added: properties.]
If a lease does not require compliance or if a tenant fails to or cannot comply, we could be [removed: forced to pay these costs.]
Risk Factors Related to our Real Estate Investments and Operations
A shift in retail shopping from brick and mortar stores to online shopping may have an adverse impact on our cash flow, financial condition and results of operations.
Many retailers operating brick and mortar stores have made online sales a vital piece of their business.
The shift to online shopping may cause declines in brick and mortar sales generated by certain of our tenants and may cause certain of our tenants to reduce the size or number of their retail locations in the future.
This risk is partially mitigated by our strategy of maintaining a diverse portfolio of retail properties.
The trend of retailers utilizing brick and mortar locations for ‘showroom’ and on-line sales distribution purposes (particularly at shopping centers in densely populated areas like ours) may further mitigate this risk.
However, there can be no assurance that our shopping centers will not be further impacted by the shift to online shopping.
As a result, our cash flow, financial condition, and results of operations could be adversely affected.
We have properties that are geographically concentrated, and adverse economic or real estate market declines in these areas could have a material adverse effect on us.
As of December 31, 2019, our tenants operated in 12 states and the District of Columbia.
Any adverse situation that disproportionately affects the the markets where our properties are concentrated may have a magnified adverse effect on our portfolio.
Refer to “Properties” (Item 2 of this Annual Report on Form 10-K) for additional discussion of the geographic concentration.
Real estate markets are subject to economic downturns, as they have been in the past, and we cannot predict how economic conditions will impact this market in both the short and long term.
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
Declines in the economy or a decline in the real estate market in these states could hurt our financial performance and the value of our properties.
Factors that may negatively affect economic conditions in these states include:
| • | business layoffs or downsizing; |
| • | industry slowdowns; |
| • | relocations of businesses; |
| • | changing demographics; |
| • | increased telecommuting and use of alternative work places; |
| • | infrastructure quality; |
| • | any oversupply of, or reduced demand for, real estate; |
| • | concessions or reduced rental rates under new leases for properties where tenants defaulted; and |
| • | increased operating costs including insurance premiums and real estate taxes. |
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
Additionally, we own an interest in the joint ventures that own the hotel components of Pike & Rose and Assembly Row.
If
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
Risk Factors Related to our Funding Strategies and Capital Structure
As of December 31, 2019, all of our $3.4 billion of debt outstanding has a fixed rate or is fixed via interest rate swap agreements.
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
The phase-out of LIBOR could affect interest rates under our variable rate debt and interest rate swap arrangements.
LIBOR is used as a reference rate for our revolving credit facility, certain mortgage payables, and in our interest rate swap arrangements.
On July 27, 2017, the United Kingdom's Financial Conduct Authority announced it intends to stop compelling banks to submit rates for the calculation of LIBOR after 2021.
It is unclear if LIBOR will cease to exist at that time, if a new method of calculating LIBOR will be established, or if an alternative reference rate will be established.
The Federal Reserve Board and the Federal Reserve Bank of New York organized the Alternative Reference Rates Committee which identified the
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
Secured Overnight Financing Rate ("SOFR") as its preferred alternative to U.S. dollar LIBOR in derivatives and other financial contracts.
As of December 31, 2018, we had approximately $3.2 billion of debt outstanding.
As of December 31, 2018, 91.5% of our debt is fixed rate, which includes all of our property secured debt, our unsecured senior notes, and our capital lease obligations.
| • | failure or inability to obtain public funding from governmental agencies to fund infrastructure projects, including public funding in connection with our development at Assembly Row; |
In addition, insurance companies may no
Additionally, we have entered into joint venture agreements related to the hotel component of Phase II of our Pike & Rose and Assembly Row development projects.
| • | we could be subject to the federal alternative minimum tax for our taxable years ending on or prior to December 31, 2017; |
Our Board of Trustees may amend or revise our operating policies without shareholder approval.
Our investment, financing and borrowing policies and policies with respect to all other activities, such as growth, debt, capitalization and operations, are determined by the Board of Trustees.
The Board of Trustees may amend or revise these policies at any time and from time to time at its discretion.
These could include attempts to gain unauthorized access to our data and computer systems.
An excerpt. Shown here: 40 of 60 rewritten, 40 of 67 added and all 10 removed. The counts are complete. For every sentence, read Item 1A. RISK FACTORS in the FY2019 filing and the FY2018 filing.
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
205 rewritten, 167 added, 222 removed, 289 unchanged
[removed: Forward-Looking Statements][added: Forward-Looking Statements]
[removed: Overview][added: Overview]
As of December 31, [removed: 2018,] [added: 2019,] we owned or had a majority interest in community and neighborhood shopping centers and mixed-use properties which are operated as 104 predominantly retail real estate projects comprising approximately [removed: 24.1] [added: 23.7] million square feet.
In total, the real estate projects were [removed: 94.6%] [added: 94.2%] leased and [removed: 93.6%] [added: 92.5%] occupied at December 31, [removed: 2018.][added: 2019.]
We have paid quarterly dividends to our shareholders continuously since our founding in 1962 and have increased our dividends per common share for [removed: 51] [added: 52] consecutive years.
[removed: Critical] [added: Critical] Accounting [removed: Policies][added: Policies]
[removed: A discussion of possible risks which may] affect these estimates is included in “Item 1A.
[removed: Revenue] [added: *Revenue] Recognition and Accounts [removed: Receivable][added: Receivable*]
Our leases with [added: our] tenants are classified as operating leases.
[removed: Base rents] [added: Lease payments] are recognized on a straight-line basis from when the tenant controls the space through the term of the related [removed: lease, net of valuation adjustments, based on management’s assessment of credit, collection and other business risk.][added: lease.]
[removed: Percentage rents, which represent additional rents based upon the level of sales achieved by certain tenants,] [added: Variable lease payments relating to percentage rent] are recognized at the end of the lease year or earlier if we have determined the required sales level is [removed: achieved and the percentage rents are collectible.][added: achieved.]
For example, in the event [added: that] our [removed: estimates] [added: collectability determinations] were not accurate and we were required to [removed: increase our allowance by] [added: write off additional receivables equaling] 1% of rental income, our [removed: bad debt expense would have increased] [added: rental income] and [removed: our] net income would [removed: have decreased] [added: decrease] by [removed: $9.0] [added: $9.3] million.
[removed: Real Estate][added: *Real Estate*]
Certain events, such as unforeseen competition or changes in customer shopping habits, could substantially alter our assumptions regarding our ability to realize the expected return on investment in the property and therefore reduce the [removed: economic life of the asset and affect the amount of depreciation expense to be charged against both the current and future revenues.]
Certain external and internal costs directly related to the development, redevelopment and leasing of real estate, including pre-construction costs, real estate taxes, insurance, [added: and] construction costs and salaries and related costs of personnel directly involved, are capitalized.
We capitalized external and internal costs related to both development and redevelopment activities of [removed: $274] [added: $352] million and [removed: $8] [added: $9] million, respectively, for [removed: 2018] [added: 2019] and [removed: $410] [added: $274] million and $8 million, respectively, for [removed: 2017.][added: 2018.]
We capitalized external and internal costs related to other property improvements of [removed: $62] [added: $80] million and $3 million, respectively, for [removed: 2018] [added: 2019] and [removed: $74] [added: $62] million and $3 million, respectively, for [removed: 2017.][added: 2018.]
We capitalized external and internal costs related to leasing activities of [removed: $20] [added: $24] million and [removed: $6] [added: $2] million, respectively, for [removed: 2018] [added: 2019] and [removed: $11] [added: $20] million and $6 million, respectively, for [removed: 2017.][added: 2018.]
The amount of capitalized internal costs for salaries and related benefits for development and redevelopment activities, other property improvements, and leasing activities were [added: $8 million, $3 million, and $2 million, respectively, for 2019 and] $7 million, $3 million, and $6 million, [added: respectively,] for [removed: both 2018 and 2017.][added: 2018.]
Total capitalized costs were [removed: $373] [added: $471] million [added: for 2019] and [removed: $512] [added: $373] million for [removed: 2018 and 2017,] [added: 2018,] respectively.
[removed: Real] [added: *Real] Estate [removed: Acquisitions][added: Acquisitions*]
We consider qualitative and quantitative factors in evaluating the likelihood of a tenant exercising a below market renewal option and [added: include such renewal options in the calculation of in-place lease value when we consider these to be bargain renewal options.]
[removed: Long-Lived] [added: *Long-Lived] Assets and [removed: Impairment][added: Impairment*]
[removed: Contingencies][added: *Contingencies*]
[removed: Self-Insurance][added: *Self-Insurance*]
[removed: Recently] [added: Recently] Adopted and Recently Issued Accounting [removed: Pronouncements][added: Pronouncements]
During the year ended December 31, [removed: 2018,] [added: 2019,] we closed on the sale of [removed: 176] [added: 43] condominium units at our Assembly Row and Pike & Rose properties [removed: (combined) and] [added: (combined),] received proceeds net of closing costs of [removed: $133.5] [added: $20.1] million, [removed: For the year ended December 31, 2018, we] [added: and] recognized a gain of [removed: $7.2] [added: $2.6] million, net of [removed: $1.6 million of] income taxes.
The cost basis for [added: the] remaining condominium units [removed: that are ready for their intended use] as of December 31, [removed: 2018] [added: 2019] is [removed: $16.6] [added: $1.7] million, and is included in "assets held for sale" on our consolidated balance sheets.
[removed: 2018 and 2019 Significant] [added: 2019 Significant] Debt and Equity [removed: Transactions][added: Transactions]
[removed: On May 7, 2018, we replaced our existing] [added: We have an] at-the-market (“ATM”) equity program [removed: with a new ATM program] in which we may from time to time offer and sell common shares having an aggregate offering price of up to $400.0 million.
[removed: For the three months ended December 31, 2018, we sold 374,725 common shares at a weighted average] price per share of [removed: $131.36] [added: $134.71] for net cash proceeds of [removed: $48.7] [added: $142.7] million and paid [removed: $0.5] [added: $1.2] million in commissions and [removed: less than $0.1] [added: $0.2] million in additional offering expenses related to the sales of these common shares.
As of December 31, [removed: 2018,] [added: 2019,] we had the capacity to issue up to [removed: $272.4] [added: $128.3] million in common shares under our ATM equity program.
[removed: Outlook][added: Outlook]
We continue to see [added: relatively] strong levels of interest from prospective tenants for our retail spaces; however, the time it takes to complete new lease deals is longer, as tenants have become more selective and more deliberate in their decision-making [added: process.]
Additionally, we have seen an overall decrease in the number of tenants available to fill anchor spaces, and have seen an uptick in the number of retail tenants [removed: closing early] [added: vacating prior to the end of their lease term] and/or filing for bankruptcy.
At December 31, [removed: 2018,] [added: 2019,] no single tenant accounted for more than [removed: 2.7%] [added: 2.6%] of annualized base rent.
We currently have redevelopment projects underway with a projected cost of approximately [removed: $210] [added: $315] million that we expect to stabilize in the next several years.
We continue our ongoing redevelopment efforts at Santana Row and are under construction on an eight story 301,000 square foot office building which will include an additional [removed: 18,000] [added: 20,000] square feet of retail space and 1,300 parking spaces.
The building is expected to cost between [removed: $205] [added: $210 million] and [removed: $215] [added: $220] million, to be delivered in [removed: 2019,] [added: 2020,] and the office portion is 100% [removed: pre-leased.][added: leased.]
[removed: Construction continues on] Phase II of Assembly Row [removed: which] includes approximately 161,000 square feet of retail space, 447 residential units, and a 158 room boutique hotel (owned and operated by a joint venture in which we are a partner).
This section generally discusses 2019 and 2018 items and year-to-year comparisons between 2019 and 2018.
Discussions of 2017 items and year-to-year comparisons between 2018 and 2017 that are not included in this Form 10-K can be found in “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in Part II, Item 7 of our Annual Report on Form 10-K for the fiscal year ended December 31, 2018 filed with the Securities and Exchange Commission on February 13, 2019.
A discussion of possible risks which may
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
Policy beginning January 1, 2019, with our adoption of Accounting Standards Codification (ASC) 842, "Leases"
When collection of substantially all lease payments during the lease term is considered probable, the lease qualifies for accrual accounting.
When collection of substantially all lease payments during the lease term is not considered probable, total lease revenue is limited to the lesser of revenue recognized under accrual accounting or cash received.
Determining the probability of collection of substantially all lease payments during lease term requires judgment.
This determination is impacted by numerous factors including our assessment of the tenant’s credit worthiness, economic conditions, our historical experience with the tenant and tenants operating in the same industry, and the length of the lease term.
If leases currently classified as probable are subsequently reclassified as not probable, any outstanding lease receivables (including straight-line rent receivables) would be written-off with a corresponding decrease in rental income.
Policy prior to January 1, 2019
Prior to January 1, 2019, management estimates of collectability were considered when reserving for billed and accrued lease receivables and straight-line rent receivables.
Full and partial reserves were recorded when determined to be appropriate with a corresponding charge to bad debt expense.
The primary impact of the adoption of ASC 842, “Leases,” on our recognition of lease revenue relates to the upfront and ongoing assessment of the collectability of substantially all lease payments required by the new standard.
*Other revenue recognition policies*
When we enter into a transaction to sell a property or a portion of a property, we evaluate the recognition of the sale under ASC 610-20, "Other Income - Gains and Losses from the Derecognition of Nonfinancial Assets." In accordance with ASC 610-20, we apply the guidance in ASC 606, "Revenue from Contracts with Customers," to determine whether and when control transfers and how to measure the associated gain or loss.
We determine the transaction price based on the consideration we expect to receive.
Variable consideration is included in the transaction price to the extent it is probable that a significant reversal of a gain recognized will not occur.
We analyze the risk of a significant gain reversal and if necessary limit the amount of variable consideration recognized in order to mitigate this risk.
The estimation of variable consideration requires us to make assumptions and apply significant judgment.
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
economic life of the asset and affect the amount of depreciation expense to be charged against both the current and future revenues.
*Variable Interest Entities (VIEs) and Consolidation*
We have 18 entities that meet the criteria of a VIE and are consolidated.
Net real estate assets related to VIEs included in our consolidated balance were approximately $1.5 billion for both December 31, 2019 and 2018, and mortgage payables related to VIEs included in our consolidated balance sheets were approximately $469.2 million and $444.4 million, as of December 31, 2019 and 2018, respectively.
In addition, we hold equity method investments in two hotel joint ventures and one shopping center which are considered variable interests in a VIE.
VIEs are required to be consolidated by their primary beneficiary.
The primary beneficiary of a VIE has both the power to direct the activities that most significantly impact economic performance of the VIE and the obligation to absorb losses or the right to receive benefits that could be significant to the VIE.
The
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
determination of the power to direct the activities that most significantly impact economic performance requires judgment and is impacted by numerous factors including the purpose of the VIE, contractual rights and obligations of variable interest holders, and mechanisms for the resolution of disputes among the variable interest holders.
2019 Property Acquisitions
| Date Acquired | | Property | | City/State | | Gross Leasable Area (GLA) | | Purchase Price | | | |
| | | | | | | (in square feet) | | (in millions) | | | |
| February 8, 2019 | | Fairfax Junction | | Fairfax, Virginia | | 75,000 | | $ | 22.5 | | |
| September 13, 2019 | | San Antonio Center | | Mountain View, California | | 6,000 | | $ | 6.5 | | |
| November 15, 2019 | | Georgetowne Shopping Center | | Brooklyn, New York | | 147,000 | | $ | 83.7 | | |
| Various 2019 | | Hoboken (37 mixed-use buildings) | | Hoboken, New Jersey | | 158,000 | | $ | 189.2 | | (1) |
(1) These acquisitions were completed through a newly formed joint venture, for which we own a 90% interest.
This property includes 123 residential units in addition to the GLA in the table above.
Substantially all such leases contain fixed escalations which occur at specified times during the term of the lease.
Current accounts receivable from tenants primarily relate to contractual minimum rent and percentage rent as well as real estate tax and other cost reimbursements.
Accounts receivable from straight-line rent is typically longer term in nature and relates to the cumulative amount by which straight-line rental income recorded to date exceeds cash rents billed to date under the contractual lease agreement.
We make estimates of the collectability of our current accounts receivable and straight-line rents receivable which requires significant judgment by management.
The collectability of receivables is affected by numerous factors including current economic conditions, bankruptcies, and the ability of the tenant to perform under the terms of their lease agreement.
While we make estimates of potentially uncollectible amounts and provide an allowance for them through bad debt expense, actual collectability could differ from those estimates which could affect our net income.
With respect to the allowance for current uncollectible tenant receivables, we assess the collectability of outstanding receivables by evaluating such factors as nature and age of the receivable, past history and current financial condition of the specific tenant including our assessment of the tenant’s ability to meet its contractual lease obligations, and the status of any pending disputes or lease negotiations with the tenant.
At December 31, 2018 and 2017, our allowance for doubtful accounts was $12.7 million and $11.8 million, respectively.
Historically, we have recognized bad debt expense between 0.3% and 1.3% of rental income and it was 0.5% in 2018.
A change in the estimate of collectability of a receivable would result in a change to our allowance for doubtful accounts and correspondingly bad debt expense and net income.
Due to the nature of the accounts receivable from straight-line rents, the collection period of these amounts typically extends beyond one year.
Our experience relative to unbilled straight-line rents is that a portion of the amounts otherwise recognizable as revenue is never billed to or collected from tenants due to early lease terminations, lease modifications, bankruptcies and other factors.
Accordingly, the extended collection period for straight-line rents along with our evaluation of tenant credit risk may result in the nonrecognition of a portion of straight-line rental income until the collection of such income is reasonably assured.
If our evaluation of tenant credit risk changes indicating more straight-line revenue is reasonably collectible than previously estimated and realized, the additional straight-line rental income is recognized as revenue.
If our evaluation of tenant credit risk changes indicating a portion of realized straight-line rental income is no longer collectible, a reserve and bad debt expense is recorded.
At December 31, 2018 and 2017, accounts receivable includes approximately $97.4 million and $93.1 million, respectively, related to straight-line rents.
Correspondingly, these estimates of collectability have a direct impact on our net income.
We completed construction on 221 condominium units at our Assembly Row and Pike & Rose properties.
Beginning on January 1, 2018, with the adoption of ASU 2014-09, "Revenue from Contracts with Customers," (see "Recent Accounting Pronouncements" for discussion of change in timing of revenue recognition), gains or losses on the sale of these condominium units are recognized as the condominium units are legally sold.
However, in 2017, we accounted for contracted condominium sales under the percentage-of completion method, based on an evaluation of the criteria specified in ASC Topic 360-20, “Property, Plant and Equipment – Real Estate Sales,” including: the legal commitment of the purchaser in the real estate contract, whether the construction of the project was beyond a preliminary phase, whether sufficient units had been contracted to ensure the project would not revert to a rental project, the ability to reasonably estimate the aggregate project sale proceeds and aggregate project costs, and the determination that the buyer had made an adequate initial and continuing cash investment under the contract.
When the percentage-of-completion criteria had not been met, no profit was recognized.
The application of these criteria can be complex and required us to make assumptions.
When applicable, as lessee, we classify our leases of land and building as operating or capital leases.
We are required to use judgment and make estimates in determining the lease term, the estimated economic life of the property and the interest rate to be used in determining whether or not the lease meets the qualification of a capital lease and is recorded as an asset.
include such renewal options in the calculation of in-place lease value when we consider these to be bargain renewal options.
2018 Property Acquisitions and Dispositions
On June 15, 2018, we formed a new joint venture to develop Jordan Downs Plaza which, when completed, will be an approximately 113,000 square foot grocery anchored shopping center located in Los Angeles County, California.
We initially invested $34.4 million as a result of a pre-funding requirement for equity to be advanced prior to the start of construction.
We own approximately 91% of the venture, and control the 9.4 acre land parcel on which the shopping center will be constructed under a long-term ground lease that expires June 15, 2093 (including two 10-year option periods which may be exercised at our option).
The Jordan Downs Plaza development is expected to generate income tax credits under the New Market Tax Credit Program ("NMTC") which was provided for in the Community Renewal Tax Relief Act of 2000 ("the Act") and is intended to induce investment in underserved areas of the United States.
The Act permits taxpayers to claim credits against their Federal income taxes for qualified investments.
A third party bank contributed $13.9 million to the development, and is entitled to the related tax credit benefits, but they do not have an interest in the underlying economics of the property.
The transaction also includes a put/call provision whereby we may be obligated or entitled to purchase the third party bank’s interest.
We believe the put will be exercised at its $1,000 strike price.
Based on our assessment of control, we concluded that the project and certain
other transaction related entities should be consolidated.
The $13.9 million in proceeds received in exchange for the transfer of the tax credits has been deferred and will be recognized when the tax benefits are delivered to the third party bank without risk of recapture.
Direct and incremental costs of $1.6 million incurred in structuring the NMTC transaction have also been deferred.
The Trust anticipates recognizing the net cash received as revenue upon completion of the seven-year NMTC compliance period.
Cash in escrow at December 31, 2018 of $32.2 million reflects cash that will ultimately be used for the development of the shopping center, and is included in "prepaid expenses and other assets" on our consolidated balance sheet.
An excerpt. Shown here: 40 of 205 rewritten, 40 of 167 added and 40 of 222 removed. The counts are complete. For every sentence, read Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS in the FY2019 filing and the FY2018 filing.
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
9 rewritten, 1 added, 3 removed, 15 unchanged
[removed: Interest] [added: Interest] Rate [removed: Risk][added: Risk]
[removed: Fixed] [added: *Fixed] Interest Rate [removed: Debt][added: Debt*]
The majority of our outstanding debt obligations (maturing at various times through 2046 or, with respect to [removed: capital] [added: finance] lease obligations through 2106) have fixed interest rates which limit the risk of fluctuating interest rates.
If market interest rates used to calculate the fair value on our fixed-rate debt instruments at December 31, [removed: 2018] [added: 2019] had been 1.0% higher, the fair value of those debt instruments on that date would have decreased by approximately [removed: $203.8] [added: $250.5] million.
If market interest rates used to calculate the fair value on our fixed-rate debt instruments at December 31, [removed: 2018] [added: 2019] had been 1.0% lower, the fair value of those debt instruments on that date would have increased by approximately [removed: $234.2] [added: $288.1] million.
[removed: Variable] [added: *Variable] Interest Rate [removed: Debt][added: Debt*]
At December 31, [removed: 2018,] [added: 2019,] we had [removed: $275.0 million of] [added: no] variable rate debt outstanding.
[removed: ITEM] [added: ITEM] 8.
FINANCIAL STATEMENTS AND SUPPLEMENTARY [removed: DATA][added: DATA]
At December 31, 2019, we had $3.4 billion of fixed-rate debt outstanding, including $56.5 million in mortgage payables that are effectively fixed by two interest rate swap agreements.
At December 31, 2018, we had $2.9 billion of fixed-rate debt outstanding; we also had capital lease obligations of $71.5 million.
Based upon this amount of variable rate debt and the specific terms, if market interest rates increased 1.0%, our annual interest expense would increase by approximately $2.8 million with a corresponding decrease in our net income and cash flows for the year.
Conversely, if market rates decreased 1.0%, our annual interest expense would decrease by approximately $2.8 million with a corresponding increase in our net income and cash flows for the year.
Item 1. BUSINESS
20 rewritten, 8 added, 1 removed, 190 unchanged
[removed: References] [added: *References] to “we,” “us,” “our” or the “Trust” refer to Federal Realty Investment Trust and our business and operations conducted through our directly or indirectly owned [removed: subsidiaries.][added: subsidiaries.*]
[removed: General][added: General]
As of December 31, [removed: 2018,] [added: 2019,] we owned or had a majority interest in community and neighborhood shopping centers and mixed-use properties which are operated as 104 predominantly retail real estate projects comprising approximately [removed: 24.1] [added: 23.7] million square [removed: feet.]
In total, the real estate projects were [removed: 94.6%] [added: 94.2%] leased and [removed: 93.6%] [added: 92.5%] occupied at December 31, [removed: 2018.][added: 2019.]
We have paid quarterly dividends to our shareholders continuously since our founding in 1962 and have increased our dividends per common share for [removed: 51] [added: 52] consecutive years.
Our website address is [removed: www.federalrealty.com.][added: *www.federalrealty.com*.]
[removed: Business] [added: Business] Objectives and [removed: Strategies][added: Strategies]
[removed: Operating Strategies][added: *Operating Strategies*]
[removed: Investing Strategies][added: *Investing Strategies*]
[removed: Investment Criteria][added: *Investment Criteria*]
[removed: Financing Strategies][added: *Financing Strategies*]
[removed: Employees][added: Employees]
At February [removed: 8, 2019,] [added: 5, 2020,] we had [removed: 298] [added: 308] full-time employees and 5 part-time employees.
[removed: Tax Status][added: Tax Status]
[removed: Under the Code, REITs are] subject to numerous organizational and operational requirements, including the requirement to generally distribute at least 90% of taxable income each year.
[removed: Governmental] [added: Governmental] Regulations Affecting Our [removed: Properties][added: Properties]
[removed: Competition][added: Competition]
[removed: Available Information][added: Available Information]
Copies of our Annual Report on Form 10-K, Quarterly Reports on Form 10-Q, Current Reports on Form 8-K, and amendments to those reports filed or furnished pursuant to Section 13(a) or 15(d) of the Securities Exchange Act of 1934 (the “Exchange Act”) are available free of charge through the Investors section of our website at [removed: www.federalrealty.com] [added: *www.federalrealty.com*] as soon as reasonably practicable after we electronically file the material with, or furnish the material to, the Securities and Exchange Commission, or the SEC.
Amendments to the Code of Ethics or Code of Business Conduct or waivers that apply to any of our executive officers or our senior financial officers will be disclosed in [removed: that] [added: the Corporate Governance] section of our website as well.
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
feet.
Our revenue is primarily generated from lease agreements with tenants.
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
Under the Code, REITs are
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
You may obtain a printed copy of any of the foregoing materials from us by writing to us at Investor Relations, Federal Realty Investment Trust, 1626 East Jefferson Street, Rockville, Maryland 20852.
Item 3. LEGAL PROCEEDINGS
0 rewritten, 4 added, 4 removed, 0 unchanged
We are involved from time-to-time in various legal and regulatory proceedings that arise in the ordinary course of our business, including, but not limited to, commercial disputes, environmental matters, and litigation in connection with transactions such as acquisitions and divestitures.
We believe that our current proceedings will not have a material adverse effect on our financial condition, liquidity or results of operations.
See Note 7 to the Consolidated Financial Statements for further discussions.
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
In November 2016, we were included as a defendant in a class action lawsuit, in the circuit court for Montgomery County, Maryland, related to predatory towing by a third party company we had retained to provide towing services at several of our properties in Montgomery County, Maryland.
Given the costs and risks of continuing litigation on this matter, we elected to participate in a settlement for which our share was approximately $0.4 million, and was reimbursed by insurance.
The settlement did not cover liability for certain tows that were included in the lawsuit that the defendant class believes cannot be pursued because of the statute of limitations.
Accordingly, we do not believe we should have any additional liability for these remaining tows; however, if we are unsuccessful in dismissing these tows from the litigation, our liability would be less than $0.1 million.
Cover and table of contents
59 rewritten, 42 added, 7 removed, 35 unchanged
[removed: UNITED STATES][added: UNITED STATES]
[removed: SECURITIES] [added: SECURITIES] AND EXCHANGE [removed: COMMISSION][added: COMMISSION]
[removed: WASHINGTON,] [added: WASHINGTON,] D.C. [removed: 20549][added: 20549]
[removed: | FORM 10-K |][added: FORM 10-K]
| [removed: ý] [added: ☒] | [removed: ANNUAL] [added: ANNUAL] REPORT PURSUANT TO THE SECTION 13 OR 15(D) OF THE SECURITIES EXCHANGE ACT OF [removed: 1934] [added: 1934] |
[removed: For] [added: For] the fiscal year [removed: ended December] [added: ended December] 31, [removed: 2018][added: 2019]
| [removed: ¨] [added: ☐] | [removed: TRANSITION] [added: TRANSITION] REPORT PURSUANT TO SECTION 13 OR 15(D) OF THE SECURITIES EXCHANGE ACT OF [removed: 1934] [added: 1934] |
[removed: For] [added: For] the transition period from [removed: to][added: to]
[removed: Commission] [added: Commission] file [removed: number: 1-07533][added: number: 1-07533]
[removed: FEDERAL] [added: FEDERAL] REALTY INVESTMENT [removed: TRUST][added: TRUST]
[removed: (Exact] [added: (Exact] Name of Registrant as Specified in its Declaration of [removed: Trust)][added: Trust)]
| [removed: Maryland] [added: Maryland] | | [removed: 52-0782497] [added: 52-0782497] |
| [removed: (State] [added: (State] of [removed: Organization)] [added: Organization)] | | [removed: (IRS] [added: (IRS] Employer Identification [removed: No.)] [added: No.)] |
[removed: | 1626] [added: 1626] East Jefferson [removed: Street, Rockville, Maryland | | 20852 |][added: Street, Rockville, Maryland 20852]
[removed: | (Address] [added: (Address] of Principal Executive Offices) [removed: | |] (Zip [removed: Code) |][added: Code)]
[removed: (301) 998-8100][added: (301) 998-8100]
[removed: (Registrant’s] [added: (Registrant’s] Telephone Number, Including Area [removed: Code)][added: Code)]
| [removed: Title] [added: Title] of Each [removed: Class] [added: Class] | [added: Trading Symbol] | [removed: Name] [added: Name] of Each Exchange On Which [removed: Registered] [added: Registered] |
| [removed: Common Shares of Beneficial Interest,] $.01 par value per share, with associated Common Share Purchase Rights | | [removed: New York Stock Exchange] |
| [removed: Depositary Shares, each representing 1/1000] of [removed: a share of] 5.00% Series C Cumulative Redeemable Preferred Stock, $.01 par value per share | | [removed: New York Stock Exchange] |
[removed: ý] [added: ☒] Yes [removed: ¨] [added: ☐] No
[removed: ¨] [added: ☐] Yes [removed: ý] [added: ☒] No
Indicate by check mark whether the [removed: Registrant] [added: registrant] has submitted electronically every Interactive Data File required to be submitted [removed: and posted] pursuant to Rule 405 of Regulation S-T [added: (§ 232.405 of this chapter)] during the preceding 12 months (or for such shorter period that the registrant was required to submit such files).
Indicate by check mark whether the [removed: Registrant] [added: registrant] is a large accelerated filer, an accelerated filer, a non-accelerated [removed: filer or] [added: filer,] a smaller reporting [added: company, or an emerging growth] company.
See definitions of “large accelerated filer,” “accelerated [removed: filer” and] [added: filer,”] “smaller reporting [removed: company”] [added: company,” and "emerging growth company"] in Rule 12b-2 of the Exchange [removed: Act.][added: Act:]
| Large [removed: Accelerated Filer] [added: accelerated filer] | [removed: ý] [added: ☒] | Accelerated [removed: Filer] [added: filer] | [removed: ¨] [added: ☐] |
| [removed: Non-Accelerated Filer] [added: Non-accelerated filer] | [removed: o] [added: ☐] | Smaller reporting company | [removed: ¨] [added: ☐] |
| | | Emerging growth company | [removed: ¨] [added: ☐] |
| If an emerging growth company, indicate by checkmark if the registrant has elected not use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. | | | [removed: ¨] [added: ☐] |
Indicate by check mark whether the [removed: Registrant] [added: registrant] is a shell company (as defined in Rule 12b-2 of the [removed: Exchange] Act).
The aggregate market value of the [removed: Registrant's] [added: registrant's] common shares held by non-affiliates of the [removed: Registrant,] [added: registrant,] based upon the closing sales price of the [removed: Registrant's] [added: registrant's] common shares on June 30, [removed: 2018] [added: 2019] was [removed: $9.3] [added: $9.7] billion.
The number of [removed: Registrant’s] [added: registrant’s] common shares outstanding on February [removed: 8, 2019] [added: 5, 2020] was [removed: 74,365,801.][added: 75,651,842.]
[removed: ANNUAL] [added: ANNUAL] REPORT ON FORM [removed: 10-K][added: 10-K]
[removed: FISCAL] [added: FISCAL] YEAR [removed: ENDED DECEMBER] [added: ENDED DECEMBER] 31, [removed: 2018][added: 2019]
[removed: DOCUMENTS] [added: DOCUMENTS] INCORPORATED BY [removed: REFERENCE][added: REFERENCE]
Portions of the Registrant’s Proxy Statement to be filed with the Securities and Exchange Commission for the Registrant’s [removed: 2018] [added: 2019] annual meeting of shareholders to be held in May [removed: 2019] [added: 2020] will be incorporated by reference into Part III hereof.
[removed: TABLE] [added: TABLE] OF [removed: CONTENTS][added: CONTENTS]
| Item 1. | Business | [removed: [3](#sE155B96CAACB5666BCD5C89ECCA52EC1)] [added: [3](#sF12C3EB19DAB5EDBA812507EFCB2972F)] |
| Item 1A. | Risk Factors | [removed: [7](#s271F7F516F44525389925AA298DD2DB5)] [added: [8](#s0BAEA5BAC8B35FCDA99C601C80DC55FE)] |
| Item 1B. | Unresolved Staff Comments | [removed: [16](#s72D35EFB0822576BA4E24D9ECBA9C7A5)] [added: [17](#sC0D1D597565F5FB9BBF5600C3CF79E76)] |
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
OR
| Common Shares of Beneficial Interest | FRT | New York Stock Exchange |
| Depositary Shares, each representing 1/1000 of a share | FRT-C | New York Stock Exchange |
☒ Yes ☐ No
☒ Yes ☐ No
☐ Yes ☒ No
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
FEDERAL REALTY INVESTMENT TRUST
| SIGNATURES | | [56](#s4CC61E15E51058AE804A9EC1C65BA32E) |
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
Forward-Looking Statements
Certain statements included in this Annual Report on Form 10-K are forward-looking statements.
Those statements include statements regarding the intent, belief or current expectations of Federal Realty Investment Trust (“we” “our” or “us”) and members of our management team, as well as the assumptions on which such statements are based, and generally are identified by the use of words such as “may,” “will,” “seeks,” “anticipates,” “believes,” “estimates,” “expects,” “plans,” “intends,” “should” or similar expressions.
Actual results may differ materially from those contemplated by such forward-looking statements.
Further, forward-looking statements speak only as of the date they are made, and we undertake no obligation to update or revise forward-looking statements to reflect changed assumptions, the occurrence of unanticipated events or changes to future operating results over time, unless required by law.
The following are some of the risks and uncertainties, although not all risks and uncertainties, that could cause our actual results to differ materially from those presented in our forward-looking statements:
| | |
| --- | --- |
| • | risks that our tenants will not pay rent, may vacate early or may file for bankruptcy or that we may be unable to renew leases or re-let space at favorable rents as leases expire; |
| | |
| --- | --- |
| • | risks that we may not be able to proceed with or obtain necessary approvals for any redevelopment or renovation project, and that completion of anticipated or ongoing property redevelopment or renovation projects that we do pursue may cost more, take more time to complete or fail to perform as expected; |
| | |
| --- | --- |
| • | risk that we are investing a significant amount in ground-up development projects that may be dependent on third parties to deliver critical aspects of certain projects, requires spending a substantial amount upfront in infrastructure, and assumes receipt of public funding which has been committed but not entirely funded; |
| | |
| --- | --- |
| • | risks normally associated with the real estate industry, including risks that occupancy levels at our properties and the amount of rent that we receive from our properties may be lower than expected, that new acquisitions may fail to perform as expected, that competition for acquisitions could result in increased prices for acquisitions, that costs associated with the periodic maintenance and repair or renovation of space, insurance and other operations may increase, that environmental issues may develop at our properties and result in unanticipated costs, and, because real estate is illiquid, that we may not be able to sell properties when appropriate; |
| | |
| --- | --- |
| • | risks that our growth will be limited if we cannot obtain additional capital; |
| | |
| --- | --- |
| • | risks associated with general economic conditions, including local economic conditions in our geographic markets; |
| | |
| --- | --- |
| • | financing on terms which are acceptable to us, our ability to meet existing financial covenants and the limitations imposed on our operations by those covenants, and the possibility of increases in interest rates that would result in increased interest expense; and |
| | |
| --- | --- |
10-K 1 frt-1231201810k.htm 10-K
| |
| --- |
OR
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K is not contained herein, and will not be contained, to the best of Registrant's knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K.
(Check one):
| SIGNATURES | | [57](#s89DC85D4265C5DE2A4BE6257FCBE153B) |
An excerpt. Shown here: 40 of 59 rewritten, 40 of 42 added and all 7 removed. The counts are complete. For every sentence, read Cover and table of contents in the FY2019 filing and the FY2018 filing.
Item 1B. UNRESOLVED STAFF COMMENTS
0 rewritten, 1 added, 0 removed, 1 unchanged
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
Item 2. PROPERTIES
160 rewritten, 49 added, 26 removed, 81 unchanged
[removed: General][added: General]
As of December 31, [removed: 2018,] [added: 2019,] we owned or had a majority ownership interest in community and neighborhood shopping centers and mixed-used properties which are operated as 104 predominantly retail real estate projects comprising approximately [removed: 24.1] [added: 23.7] million square feet.
No single commercial or residential property accounted for over 10% of our [removed: 2018] [added: 2019] total revenue.
[removed: Tenant Diversification][added: Tenant Diversification]
As of December 31, [removed: 2018,] [added: 2019,] we had approximately 3,000 commercial leases and [removed: 2,600] [added: 2,700] residential leases, with tenants ranging from sole proprietors to major national and international retailers.
No one tenant or affiliated group of tenants accounted for more than [removed: 2.7%] [added: 2.6%] of our annualized base rent as of December 31, [removed: 2018.][added: 2019.]
[removed: Geographic Diversification][added: Geographic Diversification]
The following table shows the number of projects, the gross leasable area (“GLA”) of commercial space and the percentage of total portfolio gross leasable area of commercial space in each state as of December 31, [removed: 2018.][added: 2019.]
| [removed: State] [added: State] | | [removed: Number of Projects] [added: Number of Projects] | | | [removed: Gross Leasable Area] [added: Gross Leasable Area] | | | [removed: Percentage of Gross Leasable Area] [added: Percentage of Gross Leasable Area] | |
| | | [removed: (In] [added: (In] square [removed: feet)] [added: feet)] | | | | | | | |
| New Jersey | | [removed: 6] [added: 7] | | | [removed: 1,726,000] [added: 1,887,000] | | | [removed: 7.2] [added: 8.0] | % |
| New York | | [removed: 6] [added: 7] | | | [removed: 1,246,000] [added: 1,366,000] | | | [removed: 5.2] [added: 5.8] | % |
| Illinois | | 4 | | | 797,000 | | | [removed: 3.3] [added: 3.4] | % |
| District of Columbia | | 2 | | | [removed: 169,000] [added: 170,000] | | | 0.7 | % |
| North Carolina | | 1 | | | [removed: 159,000] [added: 158,000] | | | 0.7 | % |
| [removed: Total] [added: Total] | | [removed: 104] [added: 104] | | | [removed: 24,127,000] [added: 23,676,000] | | | [removed: 100.0] [added: 100.0] | [removed: %] [added: %] |
[removed: Leases,] [added: Leases,] Lease Terms and Lease [removed: Expirations][added: Expirations]
[added: Many of our leases contain tenant options that enable the tenant to extend the term of the lease at expiration at] pre-established rental rates that often include fixed rent increases, consumer price index adjustments or other market rate adjustments from the prior base rent.
Leases on residential units are generally for a period of one year or less and, in [removed: 2018,] [added: 2019,] represented approximately [removed: 8.5%] [added: 9.1%] of total rental income.
The following table sets forth the schedule of lease expirations for our commercial leases in place as of December 31, [removed: 2018] [added: 2019] for each of the 10 years beginning with [removed: 2019] [added: 2020] and after [removed: 2028] [added: 2029] in the aggregate assuming that none of the tenants exercise future renewal options.
Annualized base rents reflect in-place contractual rents as of December 31, [removed: 2018.][added: 2019.]
| [removed: Year] [added: Year] of Lease [removed: Expiration] [added: Expiration] | | [removed: Leased Square Footage Expiring] [added: Leased Square Footage Expiring] | | | [removed: Percentage of Leased Square Footage Expiring] [added: Percentage of Leased Square Footage Expiring] | | | [removed: Annualized Base Rent Represented by Expiring Leases] [added: Annualized Base Rent Represented by Expiring Leases] | | | | [removed: Percentage] [added: Percentage] of Annualized Base Rent Represented by Expiring [removed: Leases] [added: Leases] | |
During 2018, we signed leases for a total of 1,972,000 square feet of retail space including 1,874,000 square feet of comparable space leases (leases for which there was a prior tenant) at an average rental increase of 12% on a cash [removed: basis and 23% on a straight-line] basis.
New leases for comparable spaces were signed for 796,000 square feet at an average rental increase of 25% on a cash [removed: basis and 38% on a straight-line] basis.
Renewals for comparable spaces were signed for 1,078,000 square feet at an average rental increase of 4% on a cash [removed: basis and 13% on a straight-line] basis.
During [removed: 2017,] [added: 2019,] we signed leases for a total of [removed: 1,793,000] [added: 1,675,000] square feet of retail space including [removed: 1,622,000] [added: 1,557,000] square feet of comparable space leases (leases for which there was a prior tenant) at an average rental increase of [removed: 13%] [added: 8%] on a cash [removed: basis and 26% on a straight-line] basis.
New leases for comparable spaces were signed for [removed: 773,000] [added: 793,000] square feet at an average rental increase of [removed: 19%] [added: 11%] on a cash [removed: basis and 32% on a straight-line] basis.
Renewals for comparable spaces were signed for [removed: 848,000] [added: 763,000] square feet at an average rental increase of [removed: 9%] [added: 4%] on a cash [removed: basis and 21% on a straight-line] basis.
Tenant improvements and incentives for comparable spaces were [removed: $36.00] [added: $42.60] per square foot, of which, [removed: $62.11] [added: $81.24] per square foot was for new leases and [removed: $12.18] [added: $2.43 per square foot] was for [removed: renewal leases] [added: renewals] in [removed: 2017.][added: 2019.]
The leases signed in [removed: 2018] [added: 2019] generally become effective over the following two years though some may not become effective until [removed: 2021] [added: 2022] and beyond.
Historically, we have executed comparable space leases for [removed: 1.2] [added: 1.3] to [removed: 1.7] [added: 1.9] million square feet of retail space each year and expect the volume for [removed: 2019] [added: 2020] will be in line with our historical averages with overall positive increases in rental income.
[removed: Retail] [added: Retail] and Residential [removed: Properties][added: Properties]
The following table sets forth information concerning all real estate projects in which we owned an equity interest, had a leasehold interest, or otherwise controlled and are consolidated as of December 31, [removed: 2018.][added: 2019.]
| [removed: Property,] [added: Property,] City, State, Zip [removed: Code] [added: Code] | | [removed: Year Completed] [added: Year Completed] | | [removed: Year Acquired] [added: Year Acquired] | | [removed: Square] [added: Square] Feet(1) /Apartment [removed: Units] [added: Units] | | [removed: Average] [added: Average] Base Rent Per Square [removed: Foot(2)] [added: Foot(2)] | | [removed: Percentage Leased(3)] [added: Percentage Leased(3)] | | [removed: Principal Tenant(s)] [added: Principal Tenant(s)] |
| [removed: California] [added: California] | | | | | | | | | | | | |
| Azalea South Gate, CA 90280(5)(9) | | 2014 | | 2017 | | 223,000 | | [removed: $27.95] [added: $29.03] | | [removed: 100%] [added: 100 %] | | Marshalls Ross Dress for Less Ulta [removed: CVS] [added: Michaels] |
| Bell Gardens Bell Gardens, CA 90201(4)(5)(9) | | 1990, 2003, 2006 | | 2017/2018 | | 330,000 | | [removed: $22.02] [added: $22.24] | | [removed: 93%] [added: 92 %] | | Food4Less Marshalls Ross Dress for Less Bob's Discount Furniture |
| Colorado Blvd Pasadena, CA 91103(4) | | 1905-1988 | | 1996/1998 | | [removed: 62,000] [added: 61,000] | | [removed: $46.85] [added: $47.20] | | [removed: 100%] [added: 100 %] | | Pottery Barn Banana Republic [added: True Food Kitchen] |
| | | | | | [removed: 12] [added: 9] Units | | N/A | | [removed: 100%] [added: 67 %] | | | |
| Crow Canyon Commons San Ramon, CA 94583 | | 1980, 1998, 2006 | | 2005/2007 | | 241,000 | | [removed: $28.48] [added: $29.59] | | [removed: 97%] [added: 88 %] | | Sprouts [removed: Rite Aid] Total Wine & More [added: Rite Aid] |
| California | | 20 | | | 5,119,000 | | | 21.6 | % |
| Maryland | | 20 | | | 4,349,000 | | | 18.4 | % |
| Virginia | | 17 | | | 3,685,000 | | | 15.5 | % |
| Pennsylvania(1) | | 10 | | | 2,247,000 | | | 9.5 | % |
| Massachusetts | | 8 | | | 1,978,000 | | | 8.3 | % |
| Florida | | 4 | | | 1,309,000 | | | 5.5 | % |
| Connecticut | | 3 | | | 394,000 | | | 1.7 | % |
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
| 2020 | | 1,786,000 | | | 8 | % | | $ | 50,041,000 | | | 8 | % |
| 2021 | | 2,469,000 | | | 11 | % | | 72,709,000 | | | | 11 | % |
| 2022 | | 2,943,000 | | | 14 | % | | 77,883,000 | | | | 12 | % |
| 2023 | | 2,453,000 | | | 11 | % | | 74,976,000 | | | | 12 | % |
| 2024 | | 3,301,000 | | | 15 | % | | 85,620,000 | | | | 14 | % |
| 2025 | | 2,026,000 | | | 9 | % | | 58,415,000 | | | | 9 | % |
| 2026 | | 1,067,000 | | | 5 | % | | 34,694,000 | | | | 5 | % |
| 2027 | | 1,299,000 | | | 6 | % | | 50,746,000 | | | | 8 | % |
| 2028 | | 1,188,000 | | | 6 | % | | 38,455,000 | | | | 6 | % |
| 2029 | | 1,322,000 | | | 6 | % | | 41,396,000 | | | | 7 | % |
| Thereafter | | 2,025,000 | | | 9 | % | | 50,644,000 | | | | 8 | % |
| Total | | 21,879,000 | | | 100 | % | | $ | 635,579,000 | | | 100 | % |
Tenant improvements and incentives include the total
dollars committed for the improvement (fit out) of a space as it relates to a specific lease and, except for redevelopments, may
also include base building costs (i.e. expansion, escalators or new entrances) which are required to make the space leasable.
Incentives include amounts paid to tenants as inducement to sign a lease that do not represent building improvements.
Costs
related to redevelopments require judgment by management in determining what reflects base building costs and thus, is not
included in the "tenant improvements and incentives" amount.
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
| | | | | | 12 Units | | N/A | | 100 % | | | |
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
| Property, City, State, Zip Code | | Year Completed | | Year Acquired | | Square Feet(1) /Apartment Units | | Average Base Rent Per Square Foot(2) | | Percentage Leased(3) | | Principal Tenant(s) |
| | | | | 2 Units | | N/A | | 100 % | | | | |
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
| Property, City, State, Zip Code | | Year Completed | | Year Acquired | | Square Feet(1) /Apartment Units | | Average Base Rent Per Square Foot(2) | | Percentage Leased(3) | | Principal Tenant(s) |
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
| Property, City, State, Zip Code | | Year Completed | | Year Acquired | | Square Feet(1) /Apartment Units | | Average Base Rent Per Square Foot(2) | | Percentage Leased(3) | | Principal Tenant(s) |
| | | | | | 7 Units | | N/A | | 100 % | | | |
| Hoboken Hoboken, NJ 07030(5)(9)(13) | | 1887-2006 | | 2019 | | 158,000 | | $54.99 | | 95 % | | CVS New York Sports Club Sephora Multiple Restaurants |
| | | | | | 123 Units | | N/A | | 97 % | | | |
| California | | 22 | | | 5,471,000 | | | 22.7 | % |
| Maryland | | 21 | | | 4,610,000 | | | 19.1 | % |
| Virginia | | 16 | | | 3,651,000 | | | 15.1 | % |
| Pennsylvania(1) | | 10 | | | 2,321,000 | | | 9.6 | % |
| Massachusetts | | 8 | | | 2,053,000 | | | 8.5 | % |
| Florida | | 4 | | | 1,310,000 | | | 5.4 | % |
| Connecticut | | 3 | | | 397,000 | | | 1.6 | % |
Many of our leases contain tenant options that enable the tenant to extend the term of the lease at expiration at
| 2019 | | 1,693,000 | | | 8 | % | | $ | 44,352,000 | | | 7 | % |
| 2020 | | 2,223,000 | | | 10 | % | | 59,515,000 | | | | 9 | % |
| 2021 | | 2,557,000 | | | 11 | % | | 76,611,000 | | | | 12 | % |
| 2022 | | 3,036,000 | | | 14 | % | | 78,507,000 | | | | 13 | % |
| 2023 | | 2,620,000 | | | 12 | % | | 75,880,000 | | | | 12 | % |
| 2024 | | 2,895,000 | | | 13 | % | | 69,640,000 | | | | 11 | % |
| 2025 | | 1,417,000 | | | 6 | % | | 41,728,000 | | | | 7 | % |
| 2026 | | 942,000 | | | 4 | % | | 31,996,000 | | | | 5 | % |
| 2027 | | 1,234,000 | | | 5 | % | | 49,308,000 | | | | 8 | % |
| 2028 | | 1,132,000 | | | 5 | % | | 36,245,000 | | | | 6 | % |
| Thereafter | | 2,761,000 | | | 12 | % | | 61,278,000 | | | | 10 | % |
| Total | | 22,510,000 | | | 100 | % | | $ | 625,060,000 | | | 100 | % |
| Hermosa Avenue Hermosa Beach, CA 90254 | | 1922 | | 1997 | | 23,000 | | $49.82 | | 81% | | |
| Plaza Pacoima Pacoima, CA 91331(5) | | 2010 | | 2017 | | 204,000 | | $14.36 | | 100% | | Costco Best Buy |
| | | | | 6 Units | | N/A | | 67% | | | | |
| Free State Shopping Center Bowie, MD 20715 | | 1970 | | 2007 | | 264,000 | | $19.38 | | 97% | | Giant Food TJ Maxx Ross Dress For Less Office Depot |
| | | | | | 7 Units | | N/A | | 100% | | | |
| | | | | | 9 Units | | N/A | | 67% | | | |
An excerpt. Shown here: 40 of 160 rewritten, 40 of 49 added and all 26 removed. The counts are complete. For every sentence, read Item 2. PROPERTIES in the FY2019 filing and the FY2018 filing.
Item 4. MINE SAFETY DISCLOSURES
1 rewritten, 1 added, 0 removed, 1 unchanged
[removed: PART II][added: PART II]
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
Item 5. MARKET FOR OUR COMMON EQUITY AND RELATED SHAREHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
18 rewritten, 11 added, 7 removed, 31 unchanged
| | [removed: Price] [added: Price] Per [removed: Share] [added: Share] | | | | | | | | [removed: Dividends Declared Per Share] [added: Dividends Declared Per Share] | | |
| [removed: High] [added: High] | | | | [removed: Low] [added: Low] | | | | | | | |
| [removed: 2018] [added: 2018] | | | | | | | | | | | |
On February [removed: 8, 2019,] [added: 5, 2020,] there were [removed: 2,492] [added: 2,378] holders of record of our common shares.
We have paid quarterly dividends to our shareholders continuously since our founding in 1962 and have increased our regular annual dividend rate for [removed: 51] [added: 52] consecutive years.
Our total annual dividends paid per common share for [removed: 2018] [added: 2019] and [removed: 2017] [added: 2018] were [removed: $4.02] [added: $4.11] per share and [removed: $3.94] [added: $4.02] per share, respectively.
No assurances can be given regarding what portion, if any, of distributions in [removed: 2019] [added: 2020] or subsequent years will constitute a return of capital for federal income tax purposes.
| | [removed: Year Ended December 31,] [added: Year Ended December 31,] | | | | | | |
| Ordinary dividend | $ | [removed: 3.859] [added: 4.110] | | | $ | [removed: 3.940] [added: 3.859] | |
| Ordinary dividend eligible for 15% rate | [removed: 0.161] [added: —] | | | | [removed: —] [added: 0.161] | | |
[removed: Total] [added: Total] Stockholder Return [removed: Performance][added: Performance]
The following performance graph compares the cumulative total shareholder return on Federal Realty's common shares with the S&P 500 Index and the index of equity real estate investment trusts prepared by the National Association of Real Estate Investment Trusts ("NAREIT") for the five fiscal years commencing December 31, [removed: 2013,] [added: 2014,] and ending December 31, [removed: 2018,] [added: 2019,] assuming an investment of $100 and the reinvestment of all dividends into additional common shares during the holding period.
[removed: 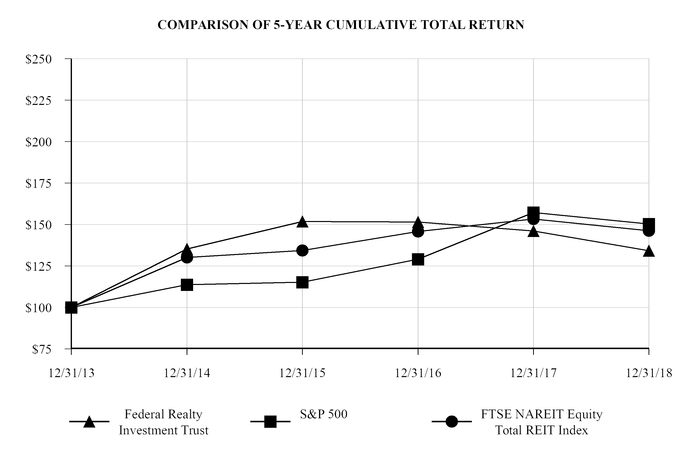][added: 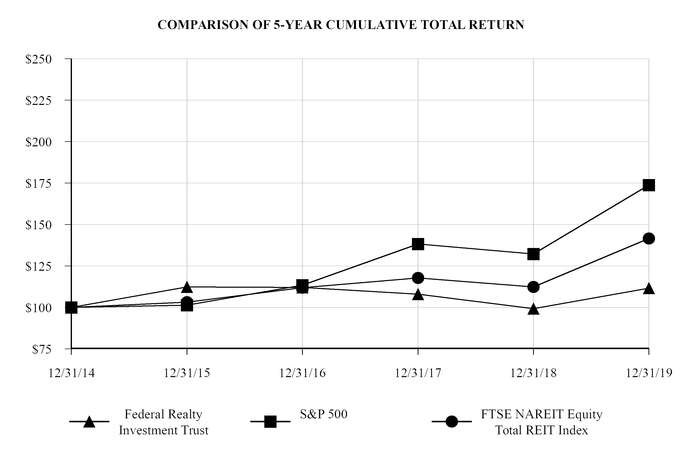]
[removed: Recent] [added: Recent] Sales of Unregistered [removed: Shares][added: Shares]
During the three months ended December 31, [removed: 2018,] [added: 2019,] we issued [removed: 864] [added: 17,035] common shares in connection with the redemption of operating partnership units.
Any other equity securities sold by us during [removed: 2018] [added: 2019] that were not registered have been previously reported in a Quarterly Report on Form 10-Q.
[removed: Purchases] [added: Purchases] of Equity Securities by the Issuer and Affiliated [removed: Purchasers][added: Purchasers]
During [removed: 2018, 46,391] [added: 2019, 10,501] restricted common shares were forfeited by former employees.
| 2019 | | | | | | | | | | | |
| Fourth quarter | $ | 141.35 | | | $ | 126.69 | | | $ | 1.050 | |
| Third quarter | $ | 137.14 | | | $ | 126.11 | | | $ | 1.050 | |
| Second quarter | $ | 139.03 | | | $ | 126.29 | | | $ | 1.020 | |
| First quarter | $ | 139.29 | | | $ | 115.09 | | | $ | 1.020 | |
| 2019 | | | | 2018 | | | |
| | $ | 4.110 | | | $ | 4.020 | |
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
Such shares of common stock were issued in reliance on Section 4(a)(2) of the Securities Act.
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
| 2017 | | | | | | | | | | | |
| Fourth quarter | $ | 134.52 | | | $ | 119.37 | | | $ | 1.000 | |
| Third quarter | $ | 135.59 | | | $ | 122.60 | | | $ | 1.000 | |
| Second quarter | $ | 138.12 | | | $ | 120.50 | | | $ | 0.980 | |
| First quarter | $ | 145.80 | | | $ | 126.02 | | | $ | 0.980 | |
| 2018 | | | | 2017 | | | |
| | $ | 4.020 | | | $ | 3.940 | |
Item 6. SELECTED FINANCIAL DATA
54 rewritten, 13 added, 4 removed, 38 unchanged
| | [removed: Year] [added: Year] Ended December [removed: 31,] [added: 31,] | | | | | | | | | | | | | | | | | | | | | | | |
| [removed: 2018] [added: 2019] | | | | | [removed: 2017] [added: 2018] | | | | | [removed: 2016] [added: 2017] | | | | | [removed: 2015] [added: 2016] | | | | | [removed: 2014] [added: 2015] | | | | |
| [removed: (In] [added: (In] thousands, except per share data and [removed: ratios)] [added: ratios)] | | | | | | | | | | | | | | | | | | | | | | | | |
| [removed: Operating Data:] [added: Operating Data:] | | | | | | | | | | | | | | | | | | | | | | | | |
| Property operating income(1) | $ | [removed: 627,566] [added: 637,030] | | | | $ | [removed: 584,619] [added: 627,566] | | | | $ | [removed: 547,979] [added: 584,619] | | | | $ | [removed: 510,595] [added: 547,979] | | | | $ | [removed: 474,167] [added: 510,595] | | |
| Gain on sale of real estate and change in control of interests, net | $ | [removed: 11,915] [added: 116,393] | | | | $ | [removed: 77,922] [added: 11,915] | | | | $ | [removed: 32,458] [added: 77,922] | | | | $ | [removed: 28,330] [added: 32,458] | | | | $ | [removed: 4,401] [added: 28,330] | | |
| Net income | $ | [removed: 249,026] [added: 360,542] | | | | $ | [removed: 297,870] [added: 249,026] | | | | $ | [removed: 258,883] [added: 297,870] | | | | $ | [removed: 218,424] [added: 258,883] | | | | $ | [removed: 172,289] [added: 218,424] | | |
| Net income available for common shareholders | $ | [removed: 233,865] [added: 345,824] | | | | $ | [removed: 287,456] [added: 233,865] | | | | $ | [removed: 249,369] [added: 287,456] | | | | $ | [removed: 209,678] [added: 249,369] | | | | $ | [removed: 163,994] [added: 209,678] | | |
| Net cash provided by operating activities | $ | [removed: 516,688] [added: 461,919] | | | | $ | [removed: 458,828] [added: 516,688] | | | | $ | [removed: 427,672] [added: 458,828] | | | | $ | [removed: 371,808] [added: 427,672] | | | | $ | [removed: 349,415] [added: 371,808] | | |
| Net cash used in investing activities | $ | [removed: (192,247] [added: (316,532] | ) | | | $ | [removed: (837,922] [added: (192,247] | ) | | | $ | [removed: (590,221] [added: (837,922] | ) | | | $ | [removed: (355,353] [added: (590,221] | ) | | | $ | [removed: (410,225] [added: (355,353] | ) | |
| Net cash (used in) provided by financing activities | $ | [removed: (241,309] [added: (100,105] | ) | | | $ | [removed: 369,445] [added: (241,309] | [added: )] | | | $ | [removed: 168,838] [added: 369,445] | | | | $ | [removed: (42,188] [added: 168,838] | [removed: )] | | | $ | [removed: 5,699] [added: (42,188] | [added: )] | |
| Net income available to common shareholders | $ | [removed: 3.18] [added: 4.61] | | | | $ | [removed: 3.97] [added: 3.18] | | | | $ | [removed: 3.51] [added: 3.97] | | | | $ | [removed: 3.04] [added: 3.51] | | | | $ | [removed: 2.42] [added: 3.04] | | |
| Weighted average number of common shares, basic | [removed: 73,274] [added: 74,766] | | | | | [removed: 72,117] [added: 73,274] | | | | | [removed: 70,877] [added: 72,117] | | | | | [removed: 68,797] [added: 70,877] | | | | | [removed: 67,322] [added: 68,797] | | | |
| Net income available to common shareholders | $ | [removed: 3.18] [added: 4.61] | | | | $ | [removed: 3.97] [added: 3.18] | | | | $ | [removed: 3.50] [added: 3.97] | | | | $ | [removed: 3.03] [added: 3.50] | | | | $ | [removed: 2.41] [added: 3.03] | | |
| Weighted average number of common shares, diluted | [removed: 73,302] [added: 74,766] | | | | | [removed: 72,233] [added: 73,302] | | | | | [removed: 71,049] [added: 72,233] | | | | | [removed: 68,981] [added: 71,049] | | | | | [removed: 67,492] [added: 68,981] | | | |
| Dividends declared per common share | $ | [removed: 4.04] [added: 4.14] | | | | $ | [removed: 3.96] [added: 4.04] | | | | $ | [removed: 3.84] [added: 3.96] | | | | $ | [removed: 3.62] [added: 3.84] | | | | $ | [removed: 3.30] [added: 3.62] | | |
| [removed: Other Data:] [added: Other Data:] | | | | | | | | | | | | | | | | | | | | | | | | |
| Funds from operations available to common shareholders(2) | $ | [removed: 461,777] [added: 465,819] | | | | $ | [removed: 419,977] [added: 461,777] | | | | $ | [removed: 406,359] [added: 419,977] | | | | $ | [removed: 352,857] [added: 406,359] | | | | $ | [removed: 327,597] [added: 352,857] | | |
| EBITDAre(3) | $ | [removed: 595,558] [added: 599,567] | | | | $ | [removed: 549,107] [added: 595,558] | | | | $ | [removed: 515,151] [added: 549,107] | | | | $ | [removed: 478,734] [added: 515,151] | | | | $ | [removed: 445,888] [added: 478,734] | | |
| Ratio of EBITDAre to combined fixed charges and preferred share dividends(3)(4) | 4.2x | | | | | [removed: 3.9x] [added: 4.2x] | | | | | [removed: 4.5x] [added: 3.9x] | | | | | [removed: 3.6x] [added: 4.5x] | | | | | [removed: 3.5x] [added: 3.6x] | | | |
| | [removed: As] [added: As] of December [removed: 31,] [added: 31,] | | | | | | | | | | | | | | | | | | |
| [removed: 2018] [added: 2019] | | | | [removed: 2017] [added: 2018] | | | | [removed: 2016] [added: 2017] | | | | [removed: 2015] [added: 2016] | | | | [removed: 2014] [added: 2015] | | | |
| [removed: (In thousands)] [added: (In thousands)] | | | | | | | | | | | | | | | | | | | |
| [removed: Balance] [added: Balance] Sheet [removed: Data:] [added: Data:] | | | | | | | | | | | | | | | | | | | |
| Real estate, at cost | $ | [removed: 7,819,472] [added: 8,298,132] | | | $ | [removed: 7,635,061] [added: 7,819,472] | | | $ | [removed: 6,759,073] [added: 7,635,061] | | | $ | [removed: 6,064,406] [added: 6,759,073] | | | $ | [removed: 5,608,998] [added: 6,064,406] | |
| Total assets | $ | [removed: 6,289,644] [added: 6,794,992] | | | $ | [removed: 6,275,755] [added: 6,289,644] | | | $ | [removed: 5,423,279] [added: 6,275,755] | | | $ | [removed: 4,896,559] [added: 5,423,279] | | | $ | [removed: 4,534,237] [added: 4,896,559] | |
| Total debt | $ | [removed: 3,229,204] [added: 3,356,594] | | | $ | [removed: 3,284,766] [added: 3,229,204] | | | $ | [removed: 2,798,452] [added: 3,284,766] | | | $ | [removed: 2,627,216] [added: 2,798,452] | | | $ | [removed: 2,397,043] [added: 2,627,216] | |
| Total shareholders’ equity | $ | [removed: 2,467,330] [added: 2,636,132] | | | $ | [removed: 2,391,514] [added: 2,467,330] | | | $ | [removed: 2,075,835] [added: 2,391,514] | | | $ | [removed: 1,781,931] [added: 2,075,835] | | | $ | [removed: 1,692,556] [added: 1,781,931] | |
| Number of common shares outstanding | [removed: 74,250] [added: 75,541] | | | | [removed: 73,091] [added: 74,250] | | | | [removed: 71,996] [added: 73,091] | | | | [removed: 69,493] [added: 71,996] | | | | [removed: 68,606] [added: 69,493] | | |
| (1) | Property operating income is a non-GAAP measure that consists of rental [removed: income, other property] income and mortgage interest income, less rental expenses and real estate taxes. This measure is used internally to evaluate the performance of property operations and we consider it to be a significant measure. Property operating income should not be considered an alternative measure of operating results or cash flow from operations as determined in accordance with GAAP. |
| | [removed: 2018] [added: 2019] | | | | [removed: 2017] [added: 2018] | | | | [removed: 2016] [added: 2017] | | | | [removed: 2015] [added: 2016] | | | | [removed: 2014] [added: 2015] | | |
| | [removed: (In thousands)] [added: (In thousands)] | | | | | | | | | | | | | | | | | | |
| General and administrative | [removed: 33,600] [added: 42,754] | | | | [removed: 36,281] [added: 33,600] | | | | [removed: 33,399] [added: 36,281] | | | | [removed: 35,645] [added: 33,399] | | | | [removed: 32,316] [added: 35,645] | | |
| Depreciation and amortization | [removed: 244,245] [added: 239,758] | | | | [removed: 216,050] [added: 244,245] | | | | [removed: 193,585] [added: 216,050] | | | | [removed: 174,796] [added: 193,585] | | | | [removed: 170,814] [added: 174,796] | | |
| Property operating income | $ | [removed: 627,566] [added: 637,030] | | | $ | [removed: 584,619] [added: 627,566] | | | $ | [removed: 547,979] [added: 584,619] | | | $ | [removed: 510,595] [added: 547,979] | | | $ | [removed: 474,167] [added: 510,595] | |
| (2) | Funds from operations ("FFO") is a supplemental non-GAAP financial measure of real estate companies’ operating performances. The National Association of Real Estate Investment Trusts (“NAREIT”) defines FFO as follows: net income, computed in accordance with GAAP, plus real estate related depreciation and [removed: amortization and excluding extraordinary items and] [added: amortization,] gains [added: and losses] on the sale of real [added: estate, and impairment write-downs of depreciable real] estate. We compute FFO in accordance with the NAREIT definition, and we have historically reported our FFO available for common shareholders in addition to our net income. |
| Net income | $ | [removed: 249,026] [added: 360,542] | | | $ | [removed: 297,870] [added: 249,026] | | | $ | [removed: 258,883] [added: 297,870] | | | $ | [removed: 218,424] [added: 258,883] | | | $ | [removed: 172,289] [added: 218,424] | |
| Net income attributable to noncontrolling interests | [removed: (7,119] [added: (6,676] | | ) | | [removed: (7,956] [added: (7,119] | | ) | | [removed: (8,973] [added: (7,956] | | ) | | [removed: (8,205] [added: (8,973] | | ) | | [removed: (7,754] [added: (8,205] | | ) |
| Gain on sale of real estate and change in control of interests, net | [removed: (11,915] [added: (116,393] | | ) | | [removed: (77,632] [added: (11,915] | | ) | | [removed: (31,133] [added: (77,632] | | ) | | [removed: (28,330] [added: (31,133] | | ) | | [removed: (4,401] [added: (28,330] | | ) |
| Depreciation and amortization of real estate assets | [removed: 213,098] [added: 215,139] | | | | [removed: 188,719] [added: 213,098] | | | | [removed: 169,198] [added: 188,719] | | | | [removed: 154,232] [added: 169,198] | | | | [removed: 154,060] [added: 154,232] | | |
| Rental income | $ | 932,738 | | | | $ | 912,287 | | | | $ | 854,286 | | | | $ | 797,598 | | | | $ | 739,622 | | |
| Operating income | $ | 470,911 | | | | $ | 361,636 | | | | $ | 410,210 | | | | $ | 353,453 | | | | $ | 328,484 | | |
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
| Operating income | $ | 470,911 | | | $ | 361,636 | | | $ | 410,210 | | | $ | 353,453 | | | $ | 328,484 | |
| Gain on sale of real estate and change in control of interests, net | (116,393 | | ) | | (11,915 | | ) | | (77,922 | | ) | | (32,458 | | ) | | (28,330 | | ) |
| | 2019 | | | | 2018 | | | | 2017 | | | | 2016 | | | | 2015 | | |
| | (In thousands) | | | | | | | | | | | | | | | | | | |
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
| | 2019 | | | | 2018 | | | | 2017 | | | | 2016 | | | | 2015 | | |
| | (In thousands) | | | | | | | | | | | | | | | | | | |
| Net income | $ | 360,542 | | | $ | 249,026 | | | $ | 297,870 | | | $ | 258,883 | | | $ | 218,424 | |
| Depreciation and amortization | 239,758 | | | | 244,245 | | | | 216,050 | | | | 193,585 | | | | 174,796 | | |
Excluding the $11.9 million charge related to the buyout of the Kmart lease at Assembly Square Marketplace, our ratio of EBITDAre to combined fixed charges and preferred share dividends remains 4.2x in 2019.
| Rental income | $ | 895,698 | | | | $ | 841,461 | | | | $ | 786,583 | | | | $ | 727,812 | | | | $ | 666,322 | | |
| Operating income | $ | 349,721 | | | | $ | 332,288 | | | | $ | 320,995 | | | | $ | 300,154 | | | | $ | 271,037 | | |
| Income from continuing operations | $ | 237,111 | | | | $ | 219,948 | | | | $ | 226,425 | | | | $ | 190,094 | | | | $ | 167,888 | | |
| Operating income | $ | 349,721 | | | $ | 332,288 | | | $ | 320,995 | | | $ | 300,154 | | | $ | 271,037 | |
An excerpt. Shown here: 40 of 54 rewritten, all 13 added and all 4 removed. The counts are complete. For every sentence, read Item 6. SELECTED FINANCIAL DATA in the FY2019 filing and the FY2018 filing.
Item 9A. CONTROLS AND PROCEDURES
11 rewritten, 2 added, 0 removed, 14 unchanged
[removed: Management's] [added: Management's] Evaluation of Disclosure Controls and [removed: Procedures][added: Procedures]
The Trust maintains disclosure controls and procedures (as defined in Rule 13a-15(e) and 15d-15(e) under the Securities Exchange Act of 1934, as amended (the "Exchange Act")) that are designed to provide reasonable assurance that information required to be disclosed in the reports that we file or submit under the Exchange Act is recorded, processed, summarized and reported within the time periods specified in the SEC's rules and forms, and that such information is accumulated and communicated to the Trust’s [removed: management, including its Chief Executive Officer and Chief Financial Officer, as appropriate to allow timely decisions regarding required disclosures.]
Our management, with the participation of the Trust’s Chief Executive Officer and Chief Financial Officer, evaluated the effectiveness of the design and operation of the Trust’s disclosure controls and procedures as of December 31, [removed: 2018.][added: 2019.]
Based on that evaluation, the Trust’s Chief Executive Officer and Chief Financial Officer concluded that, as of December 31, [removed: 2018,] [added: 2019,] the Trust’s disclosure controls and procedures were effective at a reasonable assurance level.
[removed: Internal] [added: Internal] Control over Financial [removed: Reporting][added: Reporting]
We assessed the effectiveness of the Trust’s internal control over financial reporting as of December 31, [removed: 2018.][added: 2019.]
In making this assessment, we used the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission (COSO) in [removed: Internal] [added: *Internal] Control-Integrated Framework [removed: (2013).][added: (2013)*.]
Based on that assessment and criteria, management concluded that the Trust's internal control over financial reporting was effective as of December 31, [removed: 2018.][added: 2019.]
Grant Thornton LLP, the independent registered public accounting firm that audited the Trust's consolidated financial statements included in this Annual Report on Form 10-K, has issued an attestation report on the Trust's internal control over financial reporting, which appears on page [removed: [F-2](#sB2F6F2038BD0548E9EB6DE3A73F2AF4C)] [added: [F-2](#sA4DFFD65DFD75480BF95E190AC194530)] of this Annual Report on Form 10-K.
[removed: Changes] [added: Changes] in Internal Control Over Financial [removed: Reporting][added: Reporting]
There was no change in our internal control over financial reporting during our fourth fiscal quarter of [removed: 2018] [added: 2019] that materially affected, or is reasonably likely to materially affect, our internal control over financial reporting.
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
management, including its Chief Executive Officer and Chief Financial Officer, as appropriate to allow timely decisions regarding required disclosures.
Item 9B. OTHER INFORMATION
2 rewritten, 2 added, 1 removed, 0 unchanged
[removed: PART III][added: PART III]
Certain information required in Part III is omitted from this Report but is incorporated herein by reference from our Proxy Statement for the [removed: 2019] [added: 2020] Annual Meeting of Shareholders (as amended or supplemented, the “Proxy Statement”).
None.
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
Not applicable.
Item 10. TRUSTEES, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
1 rewritten, 0 added, 0 removed, 2 unchanged
The Code of Ethics is available in the Corporate Governance section of the Investors section of our website at [removed: www.federalrealty.com.][added: *www.federalrealty.com*.]
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
1 rewritten, 0 added, 0 removed, 1 unchanged
[removed: PART IV][added: PART IV]
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
16 rewritten, 14 added, 0 removed, 111 unchanged
| [removed: (a)(1)] [added: (a)(1)] Financial [removed: Statements] [added: Statements] |
| Our consolidated financial statements and notes thereto, together with Reports of Independent Registered Public Accounting Firm are included as a separate section of this Annual Report on Form 10-K commencing on page [removed: [F-1](#s6945CFF0F87B5D2ABCE136DD0F92C971).] [added: [F-1](#sE0E8CFE64F465F7F837120AFED32E9BD).] |
| [removed: (2)] [added: (2)] Financial Statement [removed: Schedules] [added: Schedules] |
| Our financial statement schedules are included in a separate section of this Annual Report on Form 10-K commencing on page [removed: [F-32](#s461C81A100555F5A854A17BCEC5AD4FA).] [added: [F-31](#sA6178D231C1F55EBA312EA83F5567869).] |
| [removed: (3) Exhibits] [added: (3) Exhibits] |
[removed: EXHIBIT INDEX][added: EXHIBIT INDEX]
| [removed: Exhibit No.] [added: Exhibit No.] | | [removed: Description] [added: Description] |
| 3.2 | | Amended and Restated Bylaws of Federal Realty Investment Trust dated February 12, 2003, as amended October 29, 2003, May 5, 2004, February 17, 2006, May 6, 2009, [removed: and] November 2, [removed: 2016] [added: 2016, and February 5, 2019] (previously [removed: files a] [added: filed as] [Exhibit 3.2](http://www.sec.gov/Archives/edgar/data/34903/000003490317000008/frt-12312016xex32.htm) to the [removed: Trust's Annual] [added: Trust’s Quarterly] Report on Form [removed: 10-K] [added: 10-Q] for the [removed: year] [added: quarter] ended [removed: December] [added: March] 31, [removed: 2016] [added: 2019] (File No. 1-07533) and incorporated herein by reference) |
| 4.4 | | Indenture dated September 1, 1998 related to the Trust’s [removed: 5.90% Notes due 2020;] 3.00% Notes due 2022; 2.75% Notes due 2023; 3.95% Notes due 2024; 4.50% Notes due 2044; 2.55% Notes due 2021; 3.625% Notes due 2046; 3.25% Notes due [removed: 2027] [added: 2027; 3.20% Notes due 2029] (previously filed as [Exhibit 4(a)](http://www.sec.gov/Archives/edgar/data/34903/0000950109-98-004542.txt) to the Trust’s Registration Statement on Form S-3 (File No. 333-63619) filed on September 17, 1998 and incorporated herein by reference) |
| 21.1 | | [Subsidiaries of Federal Realty Investment Trust (filed [removed: herewith)](https://www.sec.gov/Archives/edgar/data/34903/000003490319000013/frt-12312018xex211.htm)] [added: herewith)](https://www.sec.gov/Archives/edgar/data/34903/000003490320000008/frt-12312019xex211.htm)] |
| 23.1 | | [Consent of Grant Thornton LLP (filed [removed: herewith)](https://www.sec.gov/Archives/edgar/data/34903/000003490319000013/frt-12312018xex231.htm)] [added: herewith)](https://www.sec.gov/Archives/edgar/data/34903/000003490320000008/frt-12312019xex231.htm)] |
| 31.1 | | [Rule 13a-14(a) Certification of Chief Executive Officer (filed [removed: herewith)](https://www.sec.gov/Archives/edgar/data/34903/000003490319000013/frt-12312018xex311.htm)] [added: herewith)](https://www.sec.gov/Archives/edgar/data/34903/000003490320000008/frt-12312019xex311.htm)] |
| 31.2 | | [Rule 13a-14(a) Certification of Chief Financial Officer (filed [removed: herewith)](https://www.sec.gov/Archives/edgar/data/34903/000003490319000013/frt-12312018xex312.htm)] [added: herewith)](https://www.sec.gov/Archives/edgar/data/34903/000003490320000008/frt-12312019xex312.htm)] |
| 32.1 | | [Section 1350 Certification of Chief Executive Officer (filed [removed: herewith)](https://www.sec.gov/Archives/edgar/data/34903/000003490319000013/frt-12312018xex321.htm)] [added: herewith)](https://www.sec.gov/Archives/edgar/data/34903/000003490320000008/frt-12312019xex321.htm)] |
| 32.2 | | [Section 1350 Certification of Chief Financial Officer (filed [removed: herewith)](https://www.sec.gov/Archives/edgar/data/34903/000003490319000013/frt-12312018xex322.htm)] [added: herewith)](https://www.sec.gov/Archives/edgar/data/34903/000003490320000008/frt-12312019xex322.htm)] |
| 101 | | [removed: [The] [added: The] following materials from Federal Realty Investment Trust’s Annual Report on Form 10-K for the year ended December 31, [removed: 2018,] [added: 2019,] formatted in XBRL (Extensible Business Reporting Language): (1) the Consolidated Balance Sheets, (2) the Consolidated Statements of Comprehensive Income, (3) the Consolidated Statement of Shareholders’ Equity, (4) the Consolidated Statements of Cash Flows, and (5) Notes to Consolidated Financial Statements that have been detail [removed: tagged.](https://www.sec.gov/Archives/edgar/data/34903/000003490319000013/frt-20181231.xml)] [added: tagged.] |
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
| 4.8 | | [Description of Securities (filed herewith)](https://www.sec.gov/Archives/edgar/data/34903/000003490320000008/frt-12312019xex48.htm) |
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
| Exhibit No. | | Description |
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
| Exhibit No. | | Description |
| 10.36 | | Amended and Restated Credit Agreement, dated as of July 25, 2019, by and among Federal Realty Investment Trust, each of the Lenders party thereto, and PNC Bank, National Association, as Administrative Agent (previously filed as [Exhibit 10.1](http://www.sec.gov/Archives/edgar/data/34903/000003490314000032/frt-08282014ex101.htm) to the Trust's Current Report on Form 8-K (File No. 1-07533), filed on July 29, 2019 and incorporated herin by reference) |
| | | |
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
| | | |
| --- | --- | --- |
| | | |
| | | |
| 104 | | Cover Page Interactive Data File (formatted in Inline XBRL and contained in Exhibit 101) |
Item 16. FORM 10-K SUMMARY
20 rewritten, 3 added, 4 removed, 23 unchanged
[removed: SIGNATURES][added: SIGNATURES]
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, as amended, the Registrant has duly caused this Report to be signed on its behalf by the undersigned thereunto duly authorized this February [removed: 13, 2019.][added: 10, 2020.]
| | [removed: Donald] [added: Donald] C. [removed: Wood President,] [added: Wood President,] Chief Executive Officer and [removed: Trustee] [added: Trustee] |
| [removed: Signature] [added: Signature] | | [removed: Title] [added: Title] | | [removed: Date] [added: Date] |
| /S/ DONALD C. WOOD | | President, Chief Executive Officer and | | February [removed: 13, 2019] [added: 10, 2020] |
| [removed: Donald] [added: Donald] C. [removed: Wood] [added: Wood] | | Trustee (Principal Executive Officer) | | |
| /S/ DANIEL GUGLIELMONE | | Executive Vice President-Chief Financial | | February [removed: 13, 2019] [added: 10, 2020] |
| [removed: Daniel Guglielmone] [added: Daniel Guglielmone] | | Officer and Treasurer (Principal | | |
| /S/ JOSEPH S. VASSALLUZZO | | Non-Executive Chairman | | February [removed: 13, 2019] [added: 10, 2020] |
| [removed: Joseph] [added: Joseph] S. [removed: Vassalluzzo] [added: Vassalluzzo] | | | | |
| /S/ JON E. BORTZ | | Trustee | | February [removed: 13, 2019] [added: 10, 2020] |
| [removed: Jon] [added: Jon] E. [removed: Bortz] [added: Bortz] | | | | |
| /S/ DAVID W. FAEDER | | Trustee | | February [removed: 13, 2019] [added: 10, 2020] |
| [removed: David] [added: David] W. [removed: Faeder] [added: Faeder] | | | | |
| /S/ ELIZABETH I. HOLLAND | | Trustee | | February [removed: 13, 2019] [added: 10, 2020] |
| [removed: Elizabeth] [added: Elizabeth] I. [removed: Holland] [added: Holland] | | | | |
| /S/ MARK S. ORDAN | | Trustee | | February [removed: 13, 2019] [added: 10, 2020] |
| [removed: Mark] [added: Mark] S. [removed: Ordan] [added: Ordan] | | | | |
| /S/ GAIL P. STEINEL | | Trustee | | February [removed: 13, 2019] [added: 10, 2020] |
| [removed: Gail] [added: Gail] P. [removed: Steinel] [added: Steinel] | | | | |
None.
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
Not applicable.
| | | | | |
| /S/ WARREN M. THOMPSON | | Trustee | | February 13, 2019 |
| Warren M. Thompson | | | | |
Item 8. and Item 15(a)(1) and (2)
537 rewritten, 340 added, 200 removed, 560 unchanged
[removed: Index] [added: Index] to Consolidated Financial Statements and [removed: Schedules][added: Schedules]
| [removed: Consolidated] [added: *Consolidated] Financial [removed: Statements] [added: Statements*] | Page No. |
[removed: | Report] [added: Report] of Independent Registered Public Accounting [removed: Firm | [F-2](#sB2F6F2038BD0548E9EB6DE3A73F2AF4C) |][added: Firm]
[removed: | Report] [added: Report] of Independent Registered Public Accounting [removed: Firm | [F-3](#s983525F2BB6058D695A96D47B260A614) |][added: Firm]
[removed: | Consolidated] [added: Consolidated] Balance [removed: Sheets | [F-4](#s81E59DC779D659AB979E8EB75BD63280) |][added: Sheets]
[removed: | Consolidated] [added: Consolidated] Statements of Comprehensive [removed: Income | [F-5](#s3AF6F66FBEE35282A4529BFCC4AD6BA5) |][added: Income]
[removed: | Consolidated] [added: Consolidated] Statement of Shareholders’ [removed: Equity | [F-6](#sE9FCFBA2EE2053F0A5D90E833CDC6711) |][added: Equity]
[removed: | Consolidated] [added: Consolidated] Statements of Cash [removed: Flows | [F-7](#s9E6AD32F049D56099CB735855DF15A49) |][added: Flows]
[removed: | Notes] [added: Notes] to Consolidated Financial [removed: Statements | [F-8](#s55184684EDCB539AA22B2E24752679CC) |][added: Statements]
| [removed: Financial] [added: *Financial] Statement [removed: Schedules] [added: Schedules*] | |
| Schedule III—Summary of Real Estate and Accumulated Depreciation | [removed: [F-32](#s461C81A100555F5A854A17BCEC5AD4FA)] [added: [F-31](#sA6178D231C1F55EBA312EA83F5567869)] |
| Schedule IV—Mortgage Loans on Real Estate | [removed: [F-40](#s4BA4E8E8B99E5680898BEE99C1144A49)] [added: [F-39](#s81645FFA87B150E0B0FDD51682B72558)] |
[added: |] Report of Independent Registered Public Accounting Firm [added: | [F-2](#sA4DFFD65DFD75480BF95E190AC194530) |]
[removed: Federal] [added: Federal] Realty Investment [removed: Trust][added: Trust]
[removed: Opinion] [added: Opinion] on internal control over financial [removed: reporting][added: reporting]
We have audited the internal control over financial reporting of Federal Realty Investment Trust (a Maryland real estate investment trust) and Subsidiaries (collectively, the "Trust") as of December 31, [removed: 2018,] [added: 2019,] based on criteria established in the 2013 [removed: Internal] [added: *Internal] Control—Integrated [removed: Framework] [added: Framework*] issued by the Committee of Sponsoring Organizations of the Treadway Commission ("COSO").
In our opinion, the Trust maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2018,] [added: 2019,] based on criteria established in the 2013 [removed: Internal] [added: *Internal] Control-Integrated [removed: Framework] [added: Framework*] issued by COSO.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (“PCAOB”), the consolidated financial statements of the Trust as of and for the year ended December 31, [removed: 2018,] [added: 2019,] and our report dated February [removed: 13, 2019] [added: 10, 2020] expressed an unqualified opinion on those financial statements.
[removed: Basis] [added: Basis] for [removed: opinion][added: opinion]
[removed: Definition] [added: Definition] and limitations of internal control over financial [removed: reporting][added: reporting]
[removed: Opinion] [added: Opinion] on the financial [removed: statements][added: statements]
We have audited the accompanying consolidated balance sheets of Federal Realty Investment Trust (a Maryland real estate investment trust) and Subsidiaries (collectively, the "Trust") as of December 31, [removed: 2018 and 2017,] [added: 2019] and [added: 2018,] the related consolidated statements of comprehensive income, changes in shareholders’ equity, and cash flows for each of the three years in the period ended December 31, [removed: 2018,] [added: 2019,] and the related notes and [added: financial statement] schedules [added: included under Item 15(a)] (collectively referred to as the “financial statements”).
In our opinion, the financial statements present fairly, in all material respects, the financial position of the Trust as of December 31, [removed: 2018] [added: 2019] and [removed: 2017,] [added: 2018,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2018,] [added: 2019,] in conformity with accounting principles generally accepted in the United States of America.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (“PCAOB”), the Trust’s internal control over financial reporting as of December 31, [removed: 2018,] [added: 2019,] based on criteria established in the 2013 [removed: Internal] [added: *Internal] Control-Integrated [removed: Framework] [added: Framework*] issued by the Committee of Sponsoring Organizations of the Treadway Commission (“COSO”), and our report dated February [removed: 13, 2019] [added: 10, 2020] expressed an unqualified opinion.
[added: |] Consolidated Balance Sheets [added: | [F-5](#sE31CE239DC0F5869AF00DAB51A2E7CCA) |]
| | [removed: December 31,] [added: December 31,] | | | | | | |
| | [removed: 2018] [added: 2019] | | | | [removed: 2017] [added: 2018] | | | [added: | 2017 | | |]
| | [removed: (In] [added: (In] thousands, except share and per share [removed: data)] [added: data)] | | | | | | |
| Operating (including [removed: $1,701,804] [added: $1,676,866] and [removed: $1,639,486] [added: $1,701,804] of consolidated variable interest entities, respectively) | $ | [removed: 7,307,622] [added: 7,535,983] | | | $ | [removed: 6,950,188] [added: 7,307,622] | |
| Construction-in-progress (including [removed: $51,313] [added: $102,583] and [removed: $43,393] [added: $51,313] of consolidated variable interest entities, respectively) | [removed: 495,274] [added: 760,420] | | | | [removed: 684,873] [added: 495,274] | | |
| Assets held for sale | [removed: 16,576] [added: 1,729] | | | | [removed: —] [added: 16,576] | | |
| Less accumulated depreciation and amortization (including [removed: $292,374] [added: $296,165] and [removed: $247,410] [added: $292,374] of consolidated variable interest entities, respectively) | [removed: (2,059,143] [added: (2,215,413] | | ) | | [removed: (1,876,544] [added: (2,059,143] | | ) |
| Net real estate | [removed: 5,760,329] [added: 6,082,719] | | | | [removed: 5,758,517] [added: 5,760,329] | | |
[removed: | Cash] [added: Cash] and [removed: cash equivalents | 64,087 | | | | 15,188 | | |][added: Cash Equivalents]
| Accounts and notes receivable | [removed: 142,237] [added: 152,572] | | | | [removed: 209,877] [added: 142,237] | | |
| Investment in [removed: real estate] partnerships | [removed: 26,859] [added: 28,604] | | | | [removed: 23,941] [added: 26,859] | | |
| Prepaid expenses and other assets | [removed: 265,703] [added: 227,060] | | | | [removed: 237,803] [added: 265,703] | | |
| TOTAL ASSETS | $ | [removed: 6,289,644] [added: 6,794,992] | | | $ | [removed: 6,275,755] [added: 6,289,644] | |
| Mortgages [removed: payable] [added: payable, net] (including [removed: $444,388] [added: $469,184] and [removed: $460,372] [added: $444,388] of consolidated variable interest entities, respectively) | $ | [removed: 474,379] [added: 545,679] | | | $ | [removed: 491,505] [added: 474,379] | |
| Capital lease obligations | [removed: 71,519] [added: —] | | | | [removed: 71,556] [added: 71,519] | | |
| Report of Independent Registered Public Accounting Firm | [F-3](#sFDD3637EB9F75319A76C5CF5A323794F) |
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
February 10, 2020
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
Change in accounting principle
As dicussed in Note 2 to the consolidated financial statements, the Trust has changed its method of accounting for leases in 2019 due to the adoption of Accounting Standards Codification (ASC) Topic 842, Leases.
Basis for opinion
Critical audit matters
The critical audit matters communicated below are matters arising from the current period audit of the financial statements that were communicated or required to be communicated to the audit committee and that: (1) relate to accounts or disclosures that are material to the financial statements and (2) involved our especially challenging, subjective, or complex judgments.
The communication of critical audit matters does not alter in any way our opinion on the financial statements, taken as a whole, and we are not, by communicating the critical audit matters below, providing separate opinions on the critical audit matters or on the accounts or disclosures to which they relate.
*Adoption of ASC 842 (Lessee) - Refer to Note 2 to the Financial Statements*
The Trust adopted ASC Topic 842, Leases (ASC 842) as of January 1, 2019, which, from a lessee perspective, resulted in the recognition of a right-of-use asset (“ROU asset”) and a lease liability for operating leases (other than leases that meet the definition of a short-term lease).
The liability is equal to the present value of future lease payments and the asset is based on the liability, subject to certain adjustments, including initial direct costs.
We identified the adoption of ASC 842, from a lessee perspective, as a critical audit matter because it is a substantial change in accounting for leases and as such requires significant auditor judgment in obtaining sufficient appropriate audit evidence
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
related to management’s determination of the lease liability and ROU asset and their selection of a discount rate to be applied to future lease payments.
Our audit procedures related to the adoption of ASC 842 included the following:
| • | We assessed the design and tested the operating effectiveness of internal controls relating to the initial adoption of ASC 842. |
| • | We verified the completeness of the population of leases that management evaluated as part of the initial adoption and ongoing accounting for leases in future periods. |
| • | We inspected a sample of lease contracts, compared the relevant inputs in management’s calculation to underlying lease documents, and recalculated the related ROU asset and lease liability. |
| • | We utilized a specialist to evaluate the discount rate used in the initial measurement of the lease liability upon adoption, including the appropriateness of the methodology employed to determine the discount rate and the final conclusion reached. |
| • | We tested the completeness and accuracy of the cumulative catch up adjustment recognized upon adoption. |
| • | We evaluated the new accounting policy for leases where the Trust is the lessee. |
*Adoption of ASC 842 (Lessor) - Refer to Note 2 to the Financial Statements*
The Trust adopted ASC 842 as of January 1, 2019, which, from a lessor perspective, resulted in a change to the Trust’s revenue recognition policy for revenue earned under operating leases with their tenants.
We identified the adoption of ASC 842, from a lessor perspective, as a critical audit matter because significant auditor judgment was required in evaluating whether management had appropriately interpreted and implemented this new accounting standard for leases that were in place on the adoption date and for new leases entered into subsequent to the adoption date.
Our audit procedures related to the adoption of ASC 842 included the following:
| • | We assessed the design and tested the operating effectiveness of internal controls relating to the initial adoption of ASC 842. |
| • | We evaluated the transition method implemented for leases that were in place at the adoption date and the new accounting policy for revenue earned under operating leases with their tenants. We utilized specialists in these evaluations. |
| • | We tested the completeness and accuracy of the cumulative catch up adjustment recognized upon adoption. |
February 10, 2020
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
| | 2019 | | | | 2018 | | |
| | 8,298,132 | | | | 7,819,472 | | |
| Operating lease right of use assets | 93,774 | | | | — | | |
| Finance lease right of use assets | 52,402 | | | | — | | |
| Operating lease liabilities | 73,628 | | | | — | | |
| Finance lease liabilities | 72,062 | | | | — | | |
[Table of Contents](#sE0E8CFE64F465F7F837120AFED32E9BD)
Federal Realty Investment Trust
February 13, 2019
| | 7,819,472 | | | | 7,635,061 | | |
| Rental income | $ | 895,698 | | | $ | 841,461 | | | $ | 786,583 | |
| Other property income | 16,589 | | | | 12,825 | | | | 11,015 | | |
| OPERATING INCOME | 349,721 | | | | 332,288 | | | | 320,995 | | |
| INCOME FROM CONTINUING OPERATIONS | 237,111 | | | | 219,948 | | | | 226,425 | | |
| BALANCE AT DECEMBER 31, 2015 | 399,896 | | | $ | 9,997 | | | 69,493,392 | | | $ | 696 | | | $ | 2,381,867 | | | $ | (724,701 | ) | | $ | (4,110 | ) | | $ | 118,182 | | | 1,781,931 | | |
| Net income, excluding $2,713 attributable to redeemable noncontrolling interests | — | | | — | | | | — | | | — | | | | — | | | | 249,910 | | | | — | | | | 6,260 | | | | 256,170 | | |
| Common shares issued | — | | | — | | | | 2,156,671 | | | 21 | | | | 324,170 | | | | — | | | | — | | | | — | | | | 324,191 | | |
| Exercise of stock options | — | | | — | | | | 55,365 | | | 1 | | | | 4,541 | | | | — | | | | — | | | | — | | | | 4,542 | | |
| Conversion and redemption of OP units | — | | | — | | | | 170,608 | | | 2 | | | | 18,677 | | | | — | | | | — | | | | (18,679 | | ) | | — | | |
Substantially all such leases contain fixed escalations which occur at specified times during the term of the lease.
We make estimates of the collectability of our accounts receivable related to minimum rents, straight-line rents, expense reimbursements and other revenue.
Accounts receivable is carried net of this allowance for doubtful accounts.
Our determination as to the collectability of accounts receivable and correspondingly, the adequacy of this allowance, is based primarily upon evaluations of individual receivables, current economic conditions, historical experience and other relevant factors.
The allowance for doubtful accounts is increased or decreased through bad debt expense.
Accounts receivable are written-off when they are deemed to be uncollectible and we are no longer actively pursuing collection.
At December 31, 2018 and 2017, our allowance for doubtful accounts was $12.7 million and $11.8 million, respectively.
In some cases, primarily relating to straight-line rents, the collection of accounts receivable extends beyond one year.
Our experience relative to unbilled straight-line rents is that a portion of the amounts otherwise recognizable as revenue is never billed to or collected from tenants due to early lease terminations, lease modifications, bankruptcies and other factors.
Accordingly, the extended collection period for straight-line rents along with our evaluation of tenant credit risk may result in
the nonrecognition of a portion of straight-line rental income until the collection of such income is reasonably assured.
If our evaluation of tenant credit risk changes indicating more straight-line revenue is reasonably collectible than previously estimated and realized, the additional straight-line rental income is recognized as revenue.
If our evaluation of tenant credit risk changes indicating a portion of realized straight-line rental income is no longer collectible, a reserve and bad debt expense is recorded.
At December 31, 2018 and 2017, accounts receivable include approximately $97.4 million and $93.1 million, respectively, related to straight-line rents.
use at which time the project is placed in service and depreciation commences.
Prior to November 1, 2018, we were party to two interest rate swap agreements that effectively fixed the rate on the term loan at 2.62%.
estate investment and the appropriate accounting thereon.
On January 12, 2017, we exercised our purchase option on non-controlling interests in San Antonio Center for $2.6 million of cash and 44,195 of downREIT operating partnership units.
| | | | | | | |
| --- | --- | --- | --- | --- | --- | --- |
| Revenue from Contracts with Customers (Topic 606) and related updates: ASU 2014-09, May 2014, Revenue from Contracts with Customers ASU 2015-14, August 2015, Revenue from Contracts with Customers: Deferral of the Effective Date ASU 2016-08, March 2016, Revenue from Contracts with Customers: Principal versus Agent Considerations ASU 2016-10, April 2016, Revenue from Contracts with Customers: Identifying Performance Obligations and Licensing ASU 2016-12, May 2016, Revenue from Contracts with Customers: Narrow-Scope Improvements and Practical Expedients ASU 2016-20, December 2016, Revenue from Contracts with Customers: Technical Corrections and Improvements | | In May 2014, the the FASB issued ASU 2014-09, "Revenue from Contracts with Customers." ASU 2014-09 as amended and interpreted by ASU 2015-14, ASU 2016-08, ASU 2016-10, ASU 2016-12, and ASU 2016-20, supersedes nearly all existing revenue recognition guidance under GAAP and replaces it with a core revenue recognition principle, that an entity will recognize revenue when it transfers control of promised goods or services to customers in an amount that reflects the consideration to which the entity expects to be entitled in exchange for those goods or services, and creates a five-step model for revenue recognition in accordance with this principle. ASU 2014-09 also requires new disclosures in both interim and annual reporting periods. The guidance in ASU 2014-09 does not apply to contracts within the scope of ASC 840, Leases. ASU 2016-08 clarifies how to identify the unit of accounting for the principal versus agent evaluation, how to apply the control principle to certain types of arrangements, such as service transactions, and reframed the indicators in the guidance to focus on evidence that an entity is acting as a principal rather than as an agent. ASU 2016-10 clarifies the existing guidance on identifying performance obligations and licensing implementation. ASU 2016-12 adds practical expedients related to the transition for contract modifications and further defines a completed contract, clarifies the objective of the collectability assessment and how revenue is recognized if collectability is not probable, and when non-cash considerations should be measured. ASU 2016-20 corrects or improves guidance in thirteen narrowly focused aspects of the guidance. The standard allows for either "full retrospective" adoption, meaning the standard is applied to all of the periods presented, or "modified retrospective" adoption, meaning the cumulative impact of applying the standard is recognized in accumulated dividends in excess of net income on the date of application. | | January 2018 | | We implemented the new revenue recognition guidance retrospectively with the cumulative effect recognized in accumulated dividends in excess of net income at the date of initial application. The primary impact relates to condominium sales. Most of our revenue is accounted for under the leasing standard, and therefore is not subject to this standard. In 2017, gains on contracted condominium sales were recognized using the percentage-of-completion method, with the gain recognized once certain criteria were met in advance of legal closing. Under the new guidance, condominium sale gains are recognized as the condominium units are legally sold, which is typically upon closing. $5.4 million of condominium gains (net of $1.4 million of income taxes) recorded under the percentage-of-completion method in 2017 were reversed through opening accumulated dividends in excess of net income. If we had used the percentage-of-completion method during 2018, we would have recorded $0.7 million of condominium gains (net of $0.2 million of income taxes) in 2018. With the exception of condominium sales, the adoption of the standard did not have a significant impact on our consolidated financial statements, with an additional cumulative effect of $0.6 million reflected in opening accumulated dividends in excess of net income. |
| ASU 2016-15, August 2016, Statement of Cash Flows (Topic 230): Classification of Certain Cash Receipts and Cash Payments | | This ASU provides classification guidance for eight specific topics including debt extinguishment costs, contingent consideration payments made after a business combination, and distributions received from equity method investees. | | January 2018 | | This standard did not have an impact on our consolidated financial statements. |
| ASU 2016-18, November 2016, Statement of Cash Flows (Topic 203) - Restricted Cash | | This ASU requires that the statement of cash flows explain the change during the period in the total of cash, cash equivalents, and amounts generally described as restricted cash or cash equivalents. Amounts generally described as restricted cash and equivalents should be included with cash and cash equivalents when reconciling the beginning and end of period total amounts on the statement of cash flows. | | January 2018 | | Prior to the adoption of this standard, "net cash provided by operating activities" was $423.7 million and $369.0 million for the years ended December 31, 2017 and 2016, respectively, and "net cash used in investing activities" was $590.2 million and $353.8 million for the years ended December 31, 2017 and 2016, respectively. After the adoption, "net cash provided by operating activities" was $458.8 million and $427.7 million for the years ended December 31, 2017 and 2016, respectively, and "net cash used in investing activities" was $837.9 million and $590.2, for the years ended December 31, 2017 and 2016, respectively. The reclassification is reflected in "increase in cash, cash equivalents, and restricted cash" in the Consolidated Statements of Cash Flows. See additional disclosures in "Consolidated Statement of Cash Flows - Supplemental Disclosures." |
| ASU 2017-05, February 2017, Other Income - Gains and Losses from the Recognition of Nonfinancial Assets (Subtopic 610-20): Clarifying the Scope of Asset Derecognition Guidance and Accounting for Partial Sales of Nonfinancial Assets | | This ASU clarifies that ASC 610-20 applies to all nonfinancial assets (including real estate) for which the counterparty is not a customer and also clarifies that all businesses are derecognized using the deconsolidation guidance. Additionally, it defines an insubstance nonfinancial asset as a financial asset that is promised to a counterparty in a contract in which substantially all of the fair value of the assets promised in the contract is concentrated in nonfinancial assets, which excludes cash or cash equivalents and liabilities. Under the current guidance, a partial sale is recognized and carryover basis is used for the retained interest, however, the new guidance eliminates the use of carryover basis and generally requires a full gain to be recognized for prospective disposals of nonfinancial assets. | | January 2018 | | The new guidance is expected to impact the gain recognized when a real estate asset is sold to a non-customer and a noncontrolling interest is retained. The adoption of this standard did not have a significant impact on our consolidated financial statements. |
| ASU 2017-09, May 2017, Compensation-Stock Compensation (Topic 718): Scope of Modification Accoutning | | The ASU clarifies when changes to the terms or conditions of a share-based payment award must be accounted for as modifications. Under the new guidance, an entity will not apply modification accounting if the awards' fair value, vesting conditions, and the classification of the award as equity or a liability are the same immediately before and after the change. The new guidance is applied prospectively to awards granted or modified after the adoption date. | | January 2018 | | The adoption of this standard did not have a significant impact on our consolidated financial statements, as there have been no modifications to awards for the year ending December 31, 2018. |
| Not Yet Adopted: | | | | | | |
A summary of our real estate investments and related encumbrances is as follows:
| | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
An excerpt. Shown here: 40 of 537 rewritten, 40 of 340 added and 40 of 200 removed. The counts are complete. For every sentence, read Item 8. and Item 15(a)(1) and (2) in the FY2019 filing and the FY2018 filing.