 filings.tools
Hartford Insurance Group 10-K 2016-12-31
Filed 2017-02-24. 12 sections, 1096K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 hig1231201610-kdocument.htm 10-K
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
(Mark One)
| þ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the fiscal year ended December 31, 2016
or
| o | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the transition period from to
Commission file number 001-13958
THE HARTFORD FINANCIAL SERVICES GROUP, INC.
(Exact name of registrant as specified in its charter)
| Delaware | 13-3317783 | |
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) |
One Hartford Plaza, Hartford, Connecticut 06155
(Address of principal executive offices) (Zip Code)
(860) 547-5000
(Registrant’s telephone number, including area code)
SECURITIES REGISTERED PURSUANT TO SECTION 12 (b) OF THE ACT
(ALL OF WHICH ARE LISTED ON THE NEW YORK STOCK EXCHANGE INC.):
Common Stock, par value $0.01 per share
Warrants (expiring June 26, 2019)
6.10% Notes due October 1, 2041
7.875% Fixed-to-Floating Rate Junior Subordinated Debentures due 2042
SECURITIES REGISTERED PURSUANT TO SECTION 12 (g) OF THE ACT:
None
| Indicate by check mark: | Yes | No | |
| • | if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. | þ | |
| • | if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Exchange Act. | þ | |
| • | whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. | þ | |
| • | whether the registrant has submitted electronically and posted on its corporate Web site, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files). | þ | |
| • | if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K is not contained herein, and will not be contained, to the best of registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. | þ | |
| • | whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, or a smaller reporting company. See definitions of “large accelerated filer,” “accelerated filer” and “smaller reporting company” in Rule 12b-2 of the Exchange Act. | ||
| Large accelerated filer þ Accelerated filer o Non-accelerated filer o Smaller reporting company o | |||
| • | whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act.) | þ |
The aggregate market value of the shares of Common Stock held by non-affiliates of the registrant as of June 30, 2016 was approximately $17 billion, based on the closing price of $44.38 per share of the Common Stock on the New York Stock Exchange on June 30, 2016.
As of February 22, 2017, there were outstanding 370,189,269 shares of Common Stock, $0.01 par value per share, of the registrant.
Documents Incorporated by Reference
Portions of the registrant’s definitive proxy statement for its 2017 annual meeting of shareholders are incorporated by reference in Part III of this Form 10-K.
THE HARTFORD FINANCIAL SERVICES GROUP, INC.
ANNUAL REPORT ON FORM 10-K
FOR THE FISCAL YEAR ENDED DECEMBER 31, 2016
TABLE OF CONTENTS
[a] The information required by this item is set forth in the Enterprise Risk Management section of Item 7, Management's Discussion and Analysis of Financial Condition and Results of Operations and is incorporated herein by reference.
[b] See Index to Consolidated Financial Statements and Schedules elsewhere herein.
[c] The information called for by Item 11 will be set forth in the Proxy Statement under the subcaptions "Compensation Discussion and Analysis", "Executive Compensation", "Director Compensation", "Report of the Compensation and Management Development Committee", and "Compensation and Management Development Committee Interlocks and Insider Participation" and is incorporated herein by reference.
[d] Any information called for by Item 13 will be set forth in the Proxy Statement under the caption and subcaption "Board and Governance Matters" and "Director Independence" and is incorporated herein by reference.
[e] The information called for by Item 14 will be set forth in the Proxy Statement under the caption "Audit Matters" and is incorporated herein by reference.
Forward-Looking Statements
Certain of the statements contained herein are forward-looking statements made pursuant to the safe harbor provisions of the Private Securities Litigation Reform Act of 1995. Forward-looking statements can be identified by words such as “anticipates,” “intends,” “plans,” “seeks,” “believes,” “estimates,” “expects,” “projects,” and similar references to future periods.
Forward-looking statements are based on management's current expectations and assumptions regarding future economic, competitive, legislative and other developments and their potential effect upon The Hartford Financial Services Group, Inc. and its subsidiaries (collectively, the “Company” or “The Hartford”). Because forward-looking statements relate to the future, they are subject to inherent uncertainties, risks and changes in circumstances that are difficult to predict. Actual results could differ materially from expectations, depending on the evolution of various factors, including the risks and uncertainties identified below, as well as factors described in such forward-looking statements or in Part I, Item 1A. Risk Factors, in Part II, Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations, and those identified from time to time in our other filings with the Securities and Exchange Commission.
| • | Risks Relating to Economic, Political and Global Market Conditions: |
| ◦ | challenges related to the Company’s current operating environment, including global political, economic and market conditions, and the effect of financial market disruptions, economic downturns or other potentially adverse macroeconomic developments on the demand for our products, returns in our investment portfolios and the hedging costs associated with our run-off annuity block; |
| ◦ | financial risk related to the continued reinvestment of our investment portfolios and performance of our hedge program for our run-off annuity block; |
| ◦ | market risks associated with our business, including changes in credit spreads, equity prices, interest rates, inflation rate, market volatility and foreign exchange rates; |
| ◦ | the impact on our investment portfolio if our investment portfolio is concentrated in any particular segment of the economy; |
| • | Insurance Industry and Product-Related Risks: |
| ◦ | the possibility of unfavorable loss development, including with respect to long-tailed exposures; |
| ◦ | the possibility of a pandemic, earthquake, or other natural or man-made disaster that may adversely affect our businesses; |
| ◦ | weather and other natural physical events, including the severity and frequency of storms, hail, winter storms, hurricanes and tropical storms, as well as climate change and its potential impact on weather patterns; |
| ◦ | the possible occurrence of terrorist attacks and the Company’s inability to contain its exposure as a result of, among other factors, the inability to exclude coverage for terrorist attacks from workers' compensation policies and limitations on reinsurance coverage from the federal government under applicable laws; |
| ◦ | the Company’s ability to effectively price its property and casualty policies, including its ability to obtain regulatory consents to pricing actions or to non-renewal or withdrawal of certain product lines; |
| ◦ | actions by competitors that may be larger or have greater financial resources than we do; |
| ◦ | technological changes, such as usage-based methods of determining premiums, advancements in automotive safety features, the development of autonomous vehicles, and platforms that facilitate ride sharing, which may alter demand for the Company's products, impact the frequency or severity of losses, and/or impact the way the Company markets, distributes and underwrites its products; |
| ◦ | the Company's ability to market, distribute and provide insurance products and investment advisory services through current and future distribution channels and advisory firms; |
| ◦ | the uncertain effects of emerging claim and coverage issues; |
| ◦ | volatility in our statutory and United States ("U.S.") Generally Accepted Accounting Principles ("GAAP") earnings and potential material changes to our results resulting from our risk management program to emphasize protection of economic value; |
| • | Financial Strength, Credit and Counterparty Risks: |
| ◦ | risks to our business, financial position, prospects and results associated with negative rating actions or downgrades in the Company’s financial strength and credit ratings or negative rating actions or downgrades relating to our investments; |
| ◦ | the impact on our statutory capital of various factors, including many that are outside the Company’s control, which can in turn affect our credit and financial strength ratings, cost of capital, regulatory compliance and other aspects of our business and results; |
| ◦ | losses due to nonperformance or defaults by others, including sourcing partners, derivative counterparties and other third parties; |
| ◦ | the potential for losses due to our reinsurers' unwillingness or inability to meet their obligations under reinsurance contracts and the availability, pricing and adequacy of reinsurance to protect the Company against losses; |
| ◦ | regulatory limitations on the ability of the Company and certain of its subsidiaries to declare and pay dividends; |
| • | Risks Relating to Estimates, Assumptions and Valuations: |
| ◦ | risk associated with the use of analytical models in making decisions in key areas such as underwriting, capital management, hedging, reserving, and catastrophe risk management; |
| ◦ | the potential for differing interpretations of the methodologies, estimations and assumptions that underlie the Company’s fair value estimates for its investments and the evaluation of other-than-temporary impairments on available-for-sale securities; |
| ◦ | the potential for further acceleration of deferred policy acquisition cost amortization and an increase in reserve for certain guaranteed benefits in our variable annuities; |
| ◦ | the potential for further impairments of our goodwill or the potential for changes in valuation allowances against deferred tax assets; |
| ◦ | the significant uncertainties that limit our ability to estimate the ultimate reserves necessary for asbestos and environmental claims; |
| • | Strategic and Operational Risks: |
| ◦ | risks associated with the run-off of our Talcott Resolution business; |
| ◦ | the Company’s ability to maintain the availability of its systems and safeguard the security of its data in the event of a disaster, cyber or other information security incident or other unanticipated event; |
| ◦ | the risks, challenges and uncertainties associated with our capital management plan, expense reduction initiatives and other actions, which may include acquisitions, divestitures or restructurings; |
| ◦ | the potential for difficulties arising from outsourcing and similar third-party relationships; |
| ◦ | the Company’s ability to protect its intellectual property and defend against claims of infringement; |
| • | Regulatory and Legal Risks: |
| ◦ | the cost and other potential effects of increased regulatory and legislative developments, including those that could adversely impact the demand for the Company’s products, operating costs and required capital levels; |
| ◦ | unfavorable judicial or legislative developments; |
| ◦ | the impact of changes in federal or state tax laws; |
| ◦ | regulatory requirements that could delay, deter or prevent a takeover attempt that shareholders might consider in their best interests; and |
| ◦ | the impact of potential changes in accounting principles and related financial reporting requirements. |
Any forward-looking statement made by the Company in this document speaks only as of the date of the filing of this Form 10-K. Factors or events that could cause the Company’s actual results to differ may emerge from time to time, and it is not possible for the Company to predict all of them. The Company undertakes no obligation to publicly update any forward-looking statement, whether as a result of new information, future developments or otherwise.
Part I - Item 1. Business
Item 1. BUSINESS
(Dollar amounts in millions, except for per share data, unless otherwise stated)
GENERAL
The Hartford Financial Services Group, Inc. (together with its subsidiaries, “The Hartford”, the “Company”, “we”, or “our”) is a holding company for a group of subsidiaries that provide property and casualty insurance, group benefits and mutual funds to individual and business customers in the United States and continues to administer life insurance and annuity products previously sold. The Hartford is headquartered in Connecticut and its oldest subsidiary, Hartford Fire Insurance Company, dates to 1810. At December 31, 2016, total assets and total stockholders’ equity of The Hartford were $223 billion and $16.9 billion, respectively.
ORGANIZATION
The Hartford strives to maintain and enhance its position as a market leader within the financial services industry. The Company sells diverse and innovative products through multiple distribution channels to individuals and businesses and is considered a leading property and casualty insurer. The Company endeavors to expand its insurance product offerings and distribution and capitalize on the strength of the Company's brand. The Hartford Stag logo is one of the most recognized symbols in the financial services industry. The Company is also working to increase efficiencies through investments in technology.
As a holding company, The Hartford is separate and distinct from its subsidiaries and has no significant business operations of its own. The Company relies on the dividends from its insurance companies and other subsidiaries as the principal source of cash flow to meet its obligations, pay dividends and repurchase common stock. Information regarding the cash flow and liquidity needs of The Hartford Financial Services Group, Inc. may be found in Part II, Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations (“MD&A”) — Capital Resources and Liquidity.
REPORTING SEGMENTS
The Hartford conducts business principally in six reporting segments including Commercial Lines, Personal Lines, Property & Casualty ("P&C") Other Operations, Group Benefits, Mutual Funds and Talcott Resolution, as well as a Corporate category. The Hartford includes in its Corporate category the Company’s capital raising activities (including debt financing and related interest expense), purchase accounting adjustments related to goodwill and other expenses not allocated to the reporting segments.
2016 Revenues of $18,300 [1] by Segment
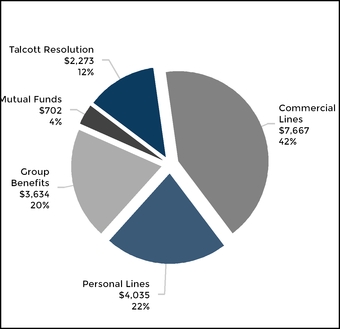
[1] Includes Revenue of $57 for P&C Other Operations and ($68) for Corporate.
The following discussion describes the principal products and services, marketing and distribution, and competition of The Hartford's reporting segments. For further discussion of the reporting segments, including financial disclosures of revenues by product line, net income (loss), and assets for each reporting segment, see Note 4 - Segment Information of Notes to Consolidated Financial Statements.
Part I - Item 1. Business
| COMMERCIAL LINES |
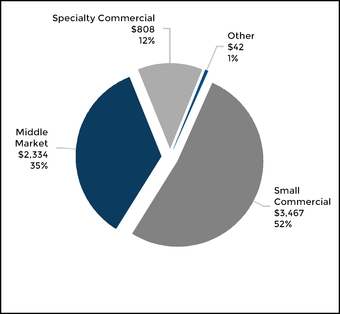
2016 Earned Premiums of $6,651 by Line of Business
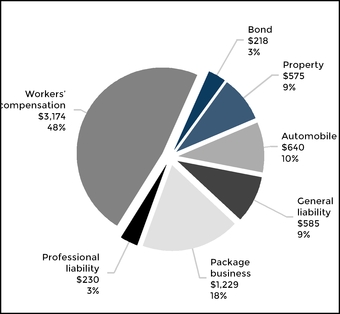
2016 Earned Premiums of $6,651 by Product
Principal Products and Services
| Automobile | Covers damage to a business's fleet of vehicles due to collision or other perils (auto physical damage). In addition to first party auto physical damage, commercial auto covers liability for bodily injuries and property damage suffered by third parties and losses caused by uninsured or under-insured motorists. |
| Property | Covers the building a business owns or leases as well as its personal property, including tools and equipment, inventory, and furniture. A commercial property insurance policy covers losses resulting from fire, wind, hail, earthquake, theft and other covered perils, including coverage for assets such as accounts receivable and valuable papers and records. Commercial property may include specialized equipment insurance, which provides coverage for loss or damage resulting from the mechanical breakdown of boilers and machinery, and ocean and inland marine insurance, which provides coverage for goods in transit and unique, one-of-a-kind exposures. |
| General Liability | Covers a business in the event it is sued for causing harm to a person and/or damage to property. General liability insurance covers third-party claims arising from accidents occurring on the insured’s premises or arising out of their operations. General liability insurance may also cover losses arising from product liability and provide replacement of lost income due to an event that interrupts business operations. |
| Package Business | Covers both property and general liability damages. |
| Workers' Compensation | Covers employers for losses incurred due to employees sustaining an injury, illness or disability in connection with their work. Benefits paid under workers’ compensation policies may include reimbursement of medical care costs, replacement income, compensation for permanent injuries and benefits to survivors. Workers’ compensation is provided under both guaranteed cost policies (coverage for a fixed premium) and loss sensitive policies where premiums are adjustable based on the loss experience of the employer. |
| Professional Liability | Covers liability arising from directors and officers acting in their official capacity and liability for errors and omissions committed by professionals and others. Coverage may also provide employment practices insurance relating to allegations of wrongful termination and discrimination. |
| Bond | Encompasses fidelity and surety insurance, including commercial surety, contract surety and fidelity bonds. Commercial surety includes bonds that insure non-performance by contractors, license and permit bonds to help meet government-mandated requirements and probate and judicial bonds for fiduciaries and civil court proceedings. Contract surety bonds may include payment and performance bonds for contractors. Fidelity bonds may include ERISA bonds related to the handling of retirement plan assets and bonds protecting against employee theft or fraud. |
Through its three lines of business of small commercial, middle market and specialty, commercial lines principally provides workers’ compensation, property, auto and general liability insurance products to businesses, primarily throughout the
United States. In addition, the specialty line of business provides professional liability, bond, inland marine and livestock insurance. The majority of Commercial Lines written premium is generated by small commercial and middle market, which provide coverage
Item 1. Business
options and customized pricing based on the policyholder’s individual risk characteristics. Within small commercial, both property and general liability coverages are offered under a single package policy, marketed under the Spectrum name. Specialty provides a variety of customized insurance products and services.
Small commercial provides coverages for small businesses, which the Company considers to be businesses with an annual payroll under $12, revenues under $25 and property values less than $20 per location. Through Maxum Specialty Insurance Group ("Maxum") small commercial also provides excess and surplus lines coverage to small businesses including umbrella, general liability, property and other coverages. Middle market provides insurance coverages to medium-sized businesses, which are companies whose payroll, revenue and property values exceed the small business definition. The Company has a small amount of property and casualty business written internationally. For U.S. exporters and other U.S. companies with international exposures, the Company covers property, marine and liability risks outside the U.S. as the assuming reinsurer under a reinsurance agreement with a third party.
In addition to offering standard commercial lines products, middle market includes program business which provides tailored programs, primarily to customers with common risk characteristics. Within specialty, a significant portion of the business is written through large deductible programs for national accounts. Other programs written within specialty are retrospectively-rated where the premiums are adjustable based on loss experience. Also within specialty, the Company writes captive programs business, which provides tailored programs to those seeking a loss sensitive solution where premiums are adjustable based on loss experience.
Marketing and Distribution
Commercial Lines provides insurance products and services through the Company’s regional offices, branches and sales and policyholder service centers throughout the United States. The products are marketed and distributed nationally using independent agents, brokers and wholesalers. The independent agent and broker distribution channel is consolidating and this trend is expected to continue. This will likely result in a larger proportion of written premium being concentrated among fewer agents and brokers. In addition, the Company offers insurance products to customers of payroll service providers through its relationships with major national payroll companies and to members of affinity organizations.
Competition
Small Commercial
In small commercial, The Hartford competes against large national carriers, as well as regional carriers in certain territories. Competitors include stock companies, mutual companies and other underwriting organizations. The small commercial market remains highly competitive as carriers seek to differentiate themselves through product expansion, price reduction, enhanced service and leading technology. Larger carriers such as The Hartford have improved their pricing sophistication and ease of doing business with agents and customers through the use of technology, analytics and other capabilities that improve the process of evaluating a risk, quoting new business and servicing customers. The Company is also adding to its digital capabilities on-line and through mobile devices as customers and distributors
demand more access and convenience, and expanding product and underwriting capabilities to accommodate both larger accounts and a broader risk appetite.
The small commercial market has also experienced low written premium growth rates in the current economic conditions, though the Company's written premium growth rate has been higher than the industry. This has put pressure on underwriting margins as competitors seek new business by increasing their underwriting appetite, and deepening their relationships with distribution partners. Also, carriers serving middle market-sized accounts are more aggressively competing for small commercial accounts, which are generally less price-sensitive. Some carriers, including start-up and non-traditional carriers, are looking to expand sales of business insurance products to small commercial market insureds through on-line and direct-to-consumer marketing.
Middle Market
Middle market business is considered “high touch” and involves individual underwriting and pricing decisions. The pricing of Middle market accounts is prone to significant volatility over time due to changes in individual account characteristics and exposure, as well as legislative and macro-economic forces. National and regional carriers participate in the middle market insurance sector, resulting in a competitive environment where pricing and policy terms are critical to securing new business and retaining existing accounts. Within this competitive environment, The Hartford is working to deepen its product and underwriting capabilities, and leverage its sales and underwriting talent with tools it has introduced in recent years. Through advanced training and data analytics, the Company’s field underwriters are working to improve risk selection and pricing decisions. In product development and related areas, such as claims and risk engineering, the Company is extending its capabilities in industry verticals, such as energy, construction, auto parts manufacturing, food processing and hospitality. Through a partnership with AXA Corporate Solutions, the Company offers business insurance coverages to exporters and other U.S. companies with a physical presence overseas. The Company has also added new middle market underwriters in the Midwest and Western U.S. to deepen relationships with its distribution partners.
Specialty Commercial
Specialty commercial competes on an account- by-account basis due to the complex nature of each transaction. Competition in this market includes stock companies, mutual companies, alternative risk sharing groups and other underwriting organizations.
For specialty casualty businesses, pricing competition continues to be significant, particularly for the larger individual accounts. As a means to mitigate the cost of insurance on larger accounts, more insureds may opt for the loss-sensitive products offered in our national accounts segment, including retrospectively rated contracts, in lieu of guaranteed cost policies. Under a retrospectively-rated contract, the ultimate premium collected from the insured is adjusted based on how incurred losses for the policy year develop over time, subject to a minimum and maximum premium. Within national accounts, the Company is implementing a phased roll out of a new risk management platform, allowing customers better access to claims data and other information needed by corporate risk managers. This
Part I - Item 1. Business
investment will allow the Company to work more closely with customers to improve long-term account performance.
In the bond business, favorable underwriting results in recent years has led to increased competition for market share, setting the stage for potential written price decreases. Public construction project work has slowed, resulting in only modest growth for our contract surety business.
In professional liability, large and medium-sized businesses are in differing competitive environments. Large public director & officers coverage, specifically excess layers, is under significant competitive price pressure. The middle market private management liability segment is in a more stable competitive and pricing environment.
| PERSONAL LINES |
2016 Earned Premiums of $3,898 by Line of Business
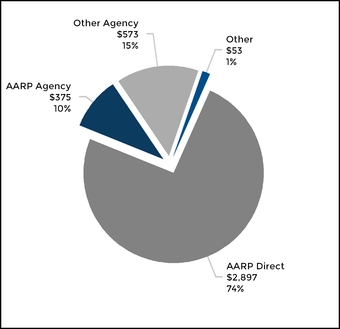
2016 Earned Premiums of $3,898 by Product
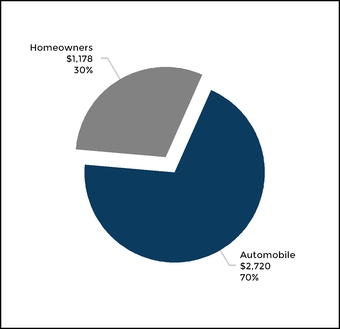
Principal Products and Services
| Automobile | Covers damage to an individual insured’s own vehicle due to collision or other perils and is referred to as auto physical damage. In addition to first party auto physical damage, automobile insurance covers liability for bodily injuries and property damage suffered by third parties and losses caused by uninsured or underinsured motorists. Also, under no-fault laws, policies written in some states provide first party personal injury protection. Some of the Company’s personal auto insurance policies also offer personal umbrella liability coverage for an additional premium. |
| Homeowners | Insures against losses to residences and contents from fire, wind and other perils. Homeowners insurance includes owned dwellings, rental properties and coverage for tenants. The policies may provide other coverages, including loss related to recreation vehicles or watercraft, identity theft and personal items such as jewelry. |
Personal Lines provides automobile, homeowners and personal umbrella coverages to individuals across the United States, including a program designed exclusively for members of AARP (“AARP Program”). The Hartford's auto and homeowners products provide coverage options and pricing tailored to a customer's individual risk. The Hartford has individual customer relationships with AARP Program policyholders and, as a group, they represent a significant portion of the total Personal Lines' business. Business sold to AARP members, either direct or through independent agents, amounted to earned premiums of $3.3 billion, $3.2 billion and $3.0 billion in 2016, 2015 and 2014, respectively.
During 2016, Personal Lines continued to refine its auto and home product offerings, i.e., its Open Road Auto and
Home Advantage products. Overall rate levels, price segmentation, rating factors and underwriting procedures were examined and updated to reflect the company’s actual experience with these products. In addition, Personal Lines also continued working with carrier partners to provide risk protection options for AARP members with needs beyond the company’s current product offering.
Marketing and Distribution
Personal Lines reaches diverse customers through multiple distribution channels, including direct-to-consumer and independent agents. In direct-to-consumer, Personal Lines markets its products through a mix of media, including direct mail,
Part I - Item 1. Business
digital marketing, television as well as digital and print advertising. Through the agency channel, Personal Lines provides products and services to customers through a network of independent agents in the standard personal lines market, primarily serving mature, preferred consumers. These independent agents are not employees of the Company.
Personal Lines has made significant investments in offering direct and agency-based customers the opportunity to interact with the company online, including via mobile devices. In addition, its technology platform for telephone sales centers enables sales representatives to provide an enhanced experience for direct-to-consumer customers, positioning The Company's to offer unique capabilities to AARP’s member base.
Most of Personal Lines' sales are associated with its exclusive licensing arrangement with AARP, with the current agreement in place through January 1, 2023, to market automobile, homeowners and personal umbrella coverages to AARP's approximately 38 million members, primarily direct but also through independent agents. This agreement provides Personal Lines with an important competitive advantage given the expected growth of the population of those over age 50 and the strength of the AARP brand. The Company has expanded its relationship with AARP to enable its members who are small business owners to purchase the Company's industry-leading small business products offered by Commercial Lines.
In addition to selling to AARP members, Personal Lines offers its automobile and homeowners products to non-AARP customers, primarily through the independent agent channel within select underwriting markets where we believe we have a competitive advantage. Personal Lines will leverage its agency channel to target AARP members and other customer segments that value the advice of an independent agent and recognize the differentiated experience The Company provides. In particular, the Company has taken action to distinguish its brand and improve profitability in the independent agent channel with fewer and more highly partnered agents.
Competition
The personal lines automobile and homeowners insurance
markets are highly competitive. Personal lines insurance is written by insurance companies of varying sizes that compete principally on the basis of price, product, service, including claims handling, the insurer's ratings and brand recognition. Companies with strong ratings, recognized brands, direct sales capability and economies of scale will have a competitive advantage. In recent years, insurers have increased their advertising in the direct-to-consumer market, in an effort to gain new business and retain profitable business. The growth of direct-to-consumer sales continues to outpace sales in the agency distribution channel.
Insurers that distribute products principally through agency channels compete by offering commissions and additional incentives to attract new business. To distinguish themselves in the marketplace, top tier insurers are offering online and self service capabilities that make it easier for agents and consumers to do business with the insurer. A large majority of agents have been using “comparative rater” tools that allow the agent to compare premium quotes among several insurance companies. The use of comparative rater tools increases price competition. Insurers that are able to capitalize on their brand and reputation, differentiate their products and deliver strong customer service are more likely to be successful in this market.
The use of data mining and predictive modeling is used by more and more carriers to target the most profitable business, and carriers have further segmented their pricing plans to expand market share in what they believe to be the most profitable segments. The Company is investing in capabilities to better utilize data and analytics, and thereby, refine and manage underwriting and pricing.
Also, new auto technology advancements, including lane departure warnings, backup cameras, automatic braking and active collision alerts, are being deployed rapidly and are expected to improve driver safety and reduce the likelihood of vehicle collisions. However, these features include expensive parts, potentially increasing average claim severity.
| PROPERTY & CASUALTY OTHER OPERATIONS |
Property & Casualty Other Operations includes certain property and casualty operations, managed by the Company, that have discontinued writing new business and includes substantially all of the Company's asbestos and environmental("A&E") exposures.
For a discussion of coverages provided under policies written with exposure to A&E, assumed reinsurance and all other non-A&E, see Part II, Item 7, MD&A - Critical Accounting Estimates, Property & Casualty Insurance Product Reserves.
Part I - Item 1. Business
| GROUP BENEFITS |
2016 Premiums and Fee Income of $3,223
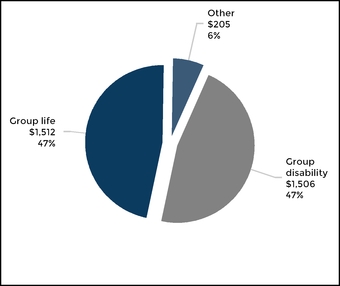
Principal Products and Services
| Group Life | Typically is term life insurance provided in the form of yearly renewable term life insurance. Other life coverages in this category include accidental death and dismemberment and travel accident insurance. |
| Group Disability | Typically comprised of both short-term and long-term disability coverage that pays a percentage of an employee’s salary for a period of time if they are ill or injured and cannot perform the duties of their job. Short-term and long-term disability policies have elimination periods that must be satisfied prior to benefit payments. In addition to premiums, administrative service fees are paid by employers for leave management and the administration of underwriting, enrollment and claims processing for employer self-funded plans. |
| Other Products | Includes other group coverages such as retiree health insurance, critical illness, accident and blanket coverages. |
Group Insurance typically covers an entire group of people under a single contract, most typically the employees of a single employer or members of an association.
Group Benefits provides group life, disability and other group coverages to members of employer groups, associations and affinity groups through direct insurance policies and provides reinsurance to other insurance companies. In addition to employer paid coverages, Group Benefits offers voluntary product coverages which are offered through employee payroll deductions. Group Benefits also offers disability underwriting, administration, and claims processing to self-funded employer plans. In addition, Group Benefits offers a single-company leave management solution, The Hartford Productivity Advantage, which integrates work absence data from the insurer’s short-term and long-term group disability and workers’ compensation insurance with its leave management administration services.
Group Benefits generally offers term insurance policies, allowing for the adjustment of rates or policy terms in order to minimize the adverse effect of market trends, loss costs, declining interest rates and other factors. Policies are typically sold with one, two or three-year rate guarantees depending upon the product and market segment.
Marketing and Distribution
The Group Benefits distribution network is managed through a regional sales office system to distribute its group insurance products and services through a variety of distribution outlets including brokers, consultants, third-party administrators and trade associations. Additionally, Group Benefits has relationships with several private exchanges which offer its products to employer groups.
Competition
Group Benefits competes with numerous insurance companies and financial intermediaries marketing insurance products. In order to differentiate itself, Group Benefits uses its risk management expertise and economies of scale to derive a competitive advantage. Competitive factors include the extent of products offered, price, the quality of customer and claims handling services, and the Company's relationship with third-party distributors and private exchanges. Active price competition continues in the marketplace, resulting in multi-year rate guarantees being offered to customers. Top tier insurers in the marketplace also offer on-line and self service capabilities to third party distributors and consumers. The relatively large size and underwriting capacity of the Group Benefits business
Part I - Item 1. Business
provides a competitive advantage over smaller companies. Additionally, as employers continue to focus on reducing the cost of employee benefits, the shift to offering voluntary products paid for by employees will become greater. Competitive factors affecting the sale of voluntary products include the breadth of products, product education, enrollment capabilities and overall customer service.
The Company is striving to expand its employer group product offerings, including the voluntary product suite, such as coverages
for short term absences from work, critical illness and accident coverages. The Company's enhanced enrollment and marketing tools, such as My Tomorrow©, are providing additional opportunities to educate individual participants about supplementary benefits and deepen their knowledge about product selection.
| MUTUAL FUNDS |
Mutual Fund Segment AUM as of December 31, 2016 [1]
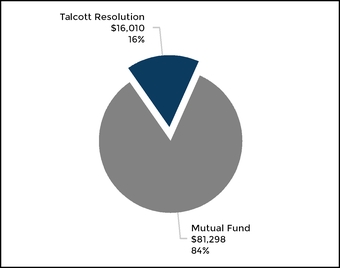
[1] Includes Mutual Fund Segment AUM for ETPs of $209.
Mutual Fund AUM as of December 31, 2016
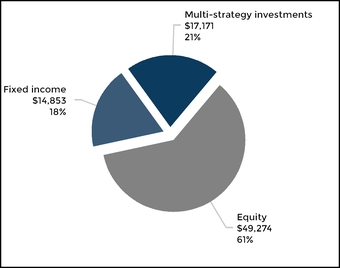
Principal Products and Services
| Mutual Fund | Includes over 75 actively managed open-ended mutual funds across a variety of asset classes including domestic and international equity, fixed income, and multi-strategy investments, principally subadvised by two unaffiliated institutional asset management firms that have comprehensive global investment capabilities. |
| ETP | Includes a suite of exchange-traded products ("ETP") traded on the New York Stock Exchange that track indices using both active and passive investment techniques, commonly referred to as strategic beta. These investments strive to improve performance relative to traditional capitalization-weighted indices. |
| Talcott Resolution | Includes mutual fund assets held in separate accounts supporting legacy run-off Talcott Resolution variable insurance contracts. |
Mutual Funds segment provides investment management, administration, product distribution and related services to investors through a diverse set of investment products in domestic and international markets. Our comprehensive range of products and services assist clients in achieving their desired investment objectives. Our products are separated into three distinct categories referred to as Mutual Fund, ETP and Talcott Resolution.
Marketing and Distribution
Our mutual funds and ETPs are sold through national and regional broker-dealer organizations, independent financial advisers, defined contribution plans, financial consultants, bank trust groups and registered investment advisers. Our distribution team is organized to sell in North America. Talcott Resolution
represents variable insurance contracts from the legacy run-off Talcott Resolution variable insurance business and are not actively distributed.
Competition
The investment management industry is mature and highly competitive. Firms are differentiated by investment performance, range of products offered, brand recognition, financial strength, proprietary distribution channels, quality of service and level of fees charged relative to quality of investment products. The Mutual Funds segment competes with a large number of asset management firms and other financial institutions and differentiates itself through superior fund performance, product breadth, strong distribution and competitive fees.
Part I - Item 1. Business
| TALCOTT RESOLUTION |
2016 Revenues of $2,273
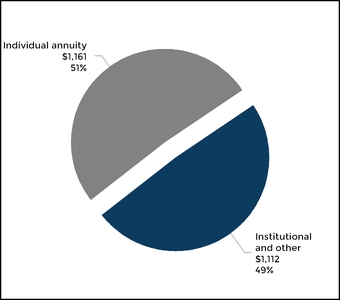
Talcott Resolution Account Values as of December 31, 2016 (in billions)

Principal Products and Services
| Individual Variable Annuities | Represents variable insurance contracts entered into between the Company and an individual policyholder. Products provide a current or future income stream based on the value of the individual's contract at annuitization, and can include a variety of guaranteed minimum death and withdrawal benefits. |
| Individual Fixed and Payout Annuities | Fixed Annuities represent fixed insurance contracts entered into between the Company and an individual policyholder. Products guarantee a minimum rate of interest and fixed amount of periodic payments. Payout Annuities represent single premium immediate payouts, deferred and matured annuity contracts. |
| Institutional Annuities | These are principally in the form of structured settlements, terminal funding agreements and guaranteed investment products. Structured settlements are contracts that provide periodic payments to claimants in settlement of a claim, a portion of which is related to the Company’s settlement of its own property and casualty insurance claims. Terminal funding agreements are single premium group annuities, most typically purchased by companies to fund pension plan liabilities. Guaranteed investment products are contracts that guarantee the owner repayment of principal plus a fixed or floating interest rate for a predetermined period of time. |
| Private Placement Life Insurance ("PPLI") | Represents variable life insurance policies that have a cash value which appreciates based on investment performance of funds held and includes individual high net worth and Corporate Owned Life Insurance (COLI). |
| Retirement Plans and Individual Life | Represents Retirement Plans and Individual Life contracts that have been reinsured to Massachusetts Mutual Life Insurance Company ("Mass Mutual") and The Prudential Insurance Company of America ("Prudential"), a subsidiary of Prudential Financial, Inc., respectively. Account values associated with these businesses no longer generate asset-based fee income due to the sales of these businesses through reinsurance. |
Talcott Resolution is comprised of the run-off of the Company's U.S. individual and institutional annuity and PPLI businesses.
The U.S. individual annuity business in run-off includes both variable and fixed annuities with many contracts in an asset accumulation phase before the contract reaches the payout or annuitization phase. Most of the Company’s variable annuity contracts sold to individuals provide a guaranteed minimum death benefit (GMDB) during the accumulation period that is generally equal to the greater of (a) the contract value at death or (b) premium payments less any prior withdrawals and may include adjustments that increase the benefit, such as for maximum anniversary value (MAV). In addition, some of the variable annuity contracts provide a guaranteed minimum withdrawal benefit (GMWB) whereby if the account value is reduced to a specified
level through a combination of market declines and withdrawals, the contract holder is entitled to a guaranteed remaining balance (GRB), which is generally equal to premiums less withdrawals. Many policyholders with a GMDB also have a GMWB. Policyholders that have a product that offers both guarantees can only receive the GMDB or GMWB, but not both.
The Talcott Resolution business segment also includes the Retirement Plans and Individual Life businesses sold in 2013 through reinsurance agreements with the respective buyers as well as the 2014 sale of Hartford Life Insurance KK, a Japanese company ("HLIKK"). For further discussion of the HLIKK transaction, see Note 2 - Business Acquisitions, Dispositions and Discontinued Operations of Notes to Consolidated Financial Statements.
Part I - Item 1. Business
| CORPORATE |
The Company includes in the Corporate category the Company's capital raising activities (including debt financing and related interest expense), purchase accounting adjustments related to
goodwill and other expenses not allocated to the reporting segments.
RESERVES
Total Reserves as of December 31, 2016
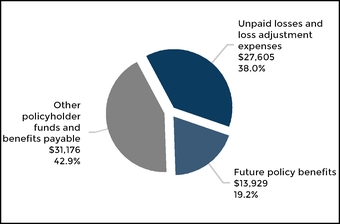
Unpaid Losses and Loss Adjustment Expenses $27,605 as of December 31, 2016
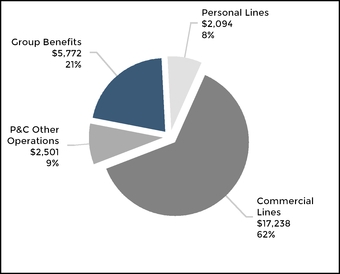
The reserves for losses and loss adjustment expenses include a liability for unpaid losses, including those that have been incurred but not yet reported, as well as estimates of all expenses associated with processing and settling these insurance claims, including reserves related to both Property & Casualty and Group Benefits.
Further discussion of The Hartford’s property and casualty insurance product reserves, including asbestos and environmental claims reserves, may be found in Part II, Item 7, MD&A — Critical Accounting Estimates — Property and Casualty Insurance Product Reserves, Net of Reinsurance. Additional discussion may be found in the Company’s accounting policies for
insurance product reserves within Note 1 - Basis of Presentation and Significant Accounting Policies of Notes to Consolidated Financial Statements.
Reserves for Future Policy Benefits
$13,929 as of December 31, 2016
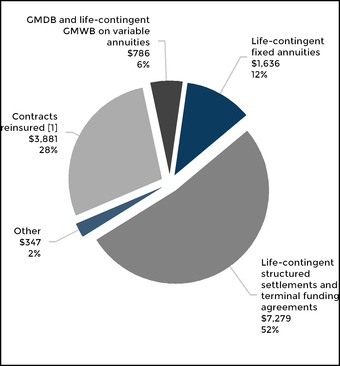
[1]Represent reserves for the individual life and retirement plans businesses that are fully reinsured and have an offsetting reinsurance recoverable.
Reserves for future policy benefits represent life-contingent reserves for which the company is subject to insurance and investment risk.
Part I - Item 1. Business
Other Policyholder Funds and Benefits Payable $31,176 as of December 31, 2016

[1]Represent reserves for individual life and retirement plans businesses that are fully reinsured and have an offsetting reinsurance recoverable.
Other policyholder funds and benefits payable represent deposits from policyholders where the company does not have insurance risk but is subject to investment risk.
UNDERWRITING FOR P&C AND GROUP BENEFITS
The Company underwrites the risks it insures in order to manage exposure to loss through favorable risk selection and diversification. Risk modeling is used to manage, within specified limits, the aggregate exposure taken in each line of business and across the Company. For property and casualty business, aggregate exposure limits are set by geographic zone and peril. Products are priced according to the risk characteristics of the insured’s exposures. Rates charged for Personal Lines products are filed with the states in which we write business. Rates for Commercial Lines products are also filed with the states but the premium charged may be modified based on the insured’s relative risk profile and workers’ compensation policies may be subject to modification based on prior loss experience. Pricing for Group Benefits products, including long-term disability and life insurance, is also based on an underwriting of the risks and a projection of estimated losses, including consideration of investment income.
Pricing adequacy depends on a number of factors, including the ability to obtain regulatory approval for rate changes, proper evaluation of underwriting risks, the ability to project future loss cost frequency and severity based on historical loss experience
adjusted for known trends, the Company’s response to rate actions taken by competitors, its expense levels and expectations about regulatory and legal developments. The Company seeks to price its insurance policies such that insurance premiums and future net investment income earned on premiums received will cover underwriting expenses and the ultimate cost of paying claims reported on the policies and provide for a profit margin.
Geographic Distribution of Earned Premium (% of total)
| Location | Commercial Lines | Personal Lines | Group Benefits | Total | |||||
| California | 8 | % | 3 | % | 2 | % | 13 | % | |
| Texas | 4 | % | 2 | % | 1 | % | 7 | % | |
| New York | 5 | % | 2 | % | 1 | % | 8 | % | |
| Florida | 2 | % | 2 | % | 1 | % | 5 | % | |
| All other [1] | 29 | % | 19 | % | 18 | % | 66 | % | |
| Total | 48 | % | 28 | % | 23 | % | 100 | % | [2] |
| [1] | No other single state or country accounted for 5% or more of the Company's consolidated earned premium written in 2016. |
| [2] | The total includes Talcott Resolution which makes up the other 1% of the total earned premium. |
CLAIMS ADMINISTRATION FOR P&C AND GROUP BENEFITS
Claims administration includes the functions associated with the receipt of initial loss notices, claims adjudication and estimates, legal representation for insureds where appropriate, establishment of case reserves, payment of losses and notification to reinsurers. These activities are performed by approximately 5,700 claim professionals located in 47 states, organized to meet the specific claim service needs for our various product offerings. Our combined Workers’ Compensation and Group Benefits units enable us to leverage synergies for improved outcomes and to accelerate continuous improvements.
Claim payments for benefit, loss and loss adjustment expenses are the largest expenditure for the Company.
REINSURANCE
For discussion of reinsurance, see Part II, Item 7, MD&A — Enterprise Risk Management and Note 8 - Reinsurance of Notes to Consolidated Financial Statements.
INVESTMENT OPERATIONS
Hartford Investment Management Company (“HIMCO”) is an SEC registered investment advisor and manages the Company's investment operations. HIMCO provides customized investment strategies, primarily for The Hartford's general account, as well as for The Hartford's pension plan, certain investment options in
Part I - Item 1. Business
Hartford Life Insurance Company's corporate owned life insurance products, a variable insurance trust and institutional clients.
As of December 31, 2016 and 2015, the fair value of HIMCO’s total assets under management was approximately $98.3 billion and $102.9 billion, respectively, of which $2.2 billion and $5.4 billion, respectively, were held in HIMCO managed third party accounts.
General Account Investment Management
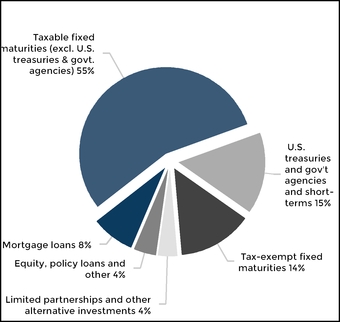
HIMCO manages the Company's portfolios to maximize economic value, and generate the returns necessary to support the Hartford’s various product obligations, within internally established objectives, guidelines and risk tolerances. The portfolio objectives and guidelines are developed based upon the asset/liability profile, including duration, convexity and other characteristics within specified risk tolerances. The risk tolerances considered include, but are not limited to, asset sector, credit issuer allocation limits, and maximum portfolio limits for below investment grade holdings. The Company attempts to minimize adverse impacts to the portfolio and the Company’s results of operations from changes in economic conditions through asset diversification, asset allocation limits, asset/liability duration matching and the use of derivatives. For further discussion of HIMCO’s portfolio management approach, see Part II, Item 7, MD&A — Enterprise Risk Management.
Investments as of December 31, 2016
ENTERPRISE RISK MANAGEMENT
The Company has insurance, operational and financial risks. For discussion on how The Hartford manages these risks, see Part II, Item 7, MD&A - Enterprise Risk Management.
REGULATION
State Insurance Laws
State insurance laws are intended to supervise and regulate insurers with the goal of protecting policyholders and ensuring the solvency of the insurers. As such, the insurance laws and regulations grant broad authority to state insurance departments (the “Departments”) to oversee and regulate the business of insurance. The Departments monitor the financial stability of an insurer by requiring insurers to maintain certain solvency standards and minimum capital and surplus requirements; invested asset requirements; state deposits of securities; guaranty fund premiums; restrictions on the size of risks which may be insured under a single policy; and adequate reserves and other necessary provisions for unearned premiums, unpaid losses and loss adjustment expenses and other liabilities, both reported and unreported. In addition, the Departments perform periodic market and financial examinations of insurers and require insurers to file annual and other reports on the financial condition of the companies. Policyholder protection is also regulated by the Departments through licensing of insurers, agents and brokers and others; approval of premium rates and policy forms; claims administration requirements; and maintenance of minimum rates for accumulation of surrender values.
Many states also have laws regulating insurance holding company systems. These laws require insurance companies, which are formed and chartered in the state (referred to as “domestic insurers”), to register with the state department of insurance (referred to as their “domestic state or regulator”) and file information concerning the operations of companies within the holding company system that may materially affect the operations, management or financial condition of the insurers within the system. Insurance holding company regulations principally relate to (i) state insurance approval of the acquisition of domestic insurers, (ii) prior review or approval of certain transactions between the domestic insurer and its affiliates, and (iii) regulation of dividends made by the domestic insurer. All transactions within a holding company system affecting domestic insurers must be determined to be fair and equitable.
The National Association of Insurance Commissioners (“NAIC”), the organization that works to promote standardization of best practices and assists state insurance regulatory authorities and insurers, conducted the “Solvency Modernization Initiative,” (the “Solvency Initiative” ). The effort focused on reviewing the U.S. financial regulatory system and financial regulation affecting insurance companies including: (1) capital requirements; (2) corporate governance and risk management; (3) group supervision; (4) statutory accounting and financial reporting; and (5) reinsurance. As a result of the Solvency Initiative, among other items, the NAIC adopted the Corporate Governance Annual Disclosure Model Act , which was enacted by the Company’s lead domestic state of Connecticut. The model law requires insurers to make an annual confidential filing regarding their corporate governance policies commencing in 2016. In addition, the NAIC adopted the Risk Management and Own Risk and Solvency Assessment Model Act (“ORSA”), which also has been adopted by Connecticut. ORSA requires insurers to maintain a risk management framework and conduct an internal risk and solvency assessment of the insurer’s material risks in normal and stressed environments. Many state insurance holding company laws, including Connecticut, have also been amended to require
Part I - Item 1. Business
insurers to file an annual confidential enterprise risk report with their lead domestic regulator, disclosing material risks within the entire holding company system that could pose an enterprise risk to the insurer.
Federal and State Securities and Financial Regulation Laws
Certain of the Company’s life insurance subsidiaries sold variable life insurance, variable annuity, and some fixed guaranteed products that are “securities” registered with the SEC under the Securities Act of 1933, as amended. Some of the products have separate accounts that are registered as investment companies under the Investment Company Act of 1940, as amended (the “1940 Act”), and/or are regulated by state law. Separate account investment products are also subject to state insurance regulation. Moreover, each registered separate account is divided into sub-accounts, each of which invests in an underlying mutual fund that is also registered as an investment company under the 1940 Act.
In addition, other subsidiaries of the Company sold and distributed the Company’s variable insurance products and retail mutual funds as broker-dealers and are subject to regulation promulgated and enforced by the Financial Industry Regulatory Authority (“FINRA”), the SEC and/or, in some instances, state securities administrators. Other subsidiaries operate as investment advisers registered with the SEC under the Investment Advisers’ Act of 1940, as amended, and are registered as investment advisers under certain state laws, as applicable. Because federal and state laws and regulations are primarily intended to protect investors in securities markets, they generally grant regulators broad rulemaking and enforcement authority. Some of these regulations include, among other things, regulations impacting sales methods, trading practices, suitability of investments, use and safekeeping of customers’ funds, corporate governance, capital, record keeping, and reporting requirements.
The Hartford operates in limited foreign jurisdictions. The extent of financial services regulation on business outside the United States varies significantly among the countries in which The Hartford operates. Some countries have minimal regulatory requirements, while others regulate financial services providers extensively. Foreign financial services providers in certain countries are faced with greater restrictions than domestic competitors domiciled in that particular jurisdiction.
Failure to comply with federal and state laws and regulations may result in fines, the issuance of cease-and-desist orders or suspension, termination or limitation of the activities of our operations and/or our employees.
INTELLECTUAL PROPERTY
We rely on a combination of contractual rights and copyright, trademark, patent and trade secret laws to establish and protect our intellectual property.
We have a trademark portfolio that we consider important in the marketing of our products and services, including, among others, the trademarks of The Hartford name, the Stag Logo and the
combination of these two trademarks. The duration of trademark registrations may be renewed indefinitely subject to country-specific use and registration requirements. We regard our trademarks as highly valuable assets in marketing our products and services and vigorously seek to protect them against infringement. In addition, we own a number of patents and patent applications relating to on-line quoting, insurance related processing, insurance telematics, proprietary interface platforms, and other matters, some of which may be important to our business operations. Patents are of varying duration depending on filing date, and will typically expire at the end of their natural term.
EMPLOYEES
The Hartford has approximately 16,900 employees as of December 31, 2016.
AVAILABLE INFORMATION
The Company’s Internet address is www.thehartford.com. Our annual report on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, and amendments to those reports are available, without charge, on the investor relations section of our website, https://ir.thehartford.com, as soon as reasonably practicable after they are filed electronically with the SEC. Reports filed with the SEC may be viewed at www.sec.gov or obtained at the SEC’s Public Reference Room at 100 F Street, N.E., Washington D.C. Information regarding the operation of the Public Reference Room may be obtained by calling the SEC at 1-800-SEC-0330. References in this report to our website address are provided only as a convenience and do not constitute, and should not be viewed as, an incorporation by reference of the information contained on, or available through, the website. Therefore, such information should not be considered part of this report.
Part I - Item 1A. Risk Factors
Item 1A. RISK FACTORS
In deciding whether to invest in The Hartford, you should carefully consider the following risks, any of which could have a material adverse effect on our business, financial condition, results of operation or liquidity and could also impact the trading price of our securities. These risks are not exclusive, and additional risks to which we are subject include, but are not limited to, the factors mentioned under “Forward-Looking Statements” above and the risks of our businesses described elsewhere in this Annual Report on Form 10-K.
The following risk factors have been organized by category for ease of use, however many of the risks may have impacts in more than one category. The occurrence of certain of them may, in turn, cause the emergence or exacerbate the effect of others. Such a combination could materially increase the severity of the impact of these risks on our business, results of operations, financial condition or liquidity.
Risks Relating to Economic, Political and Global Market Conditions
Unfavorable economic, political and global market conditions may adversely impact our business and results of operations.
The Company’s investment portfolio and insurance liabilities are sensitive to changes in economic, political and global capital market conditions, such as the effect of a weak economy and changes in credit spreads, equity prices, interest rates and inflation. Weak economic conditions, such as high unemployment, low labor force participation, lower family income, a weak real estate market, lower business investment and lower consumer spending may adversely affect the demand for insurance and financial products and lower the Company’s profitability in some cases. In addition, the Company’s investment portfolio includes limited partnerships and other alternative investments for which changes in value are reported in earnings. These investments may be adversely impacted by political turmoil and economic volatility, including real estate market deterioration, which could impact our net investment returns and result in an adverse impact on operating results.
Below are several key factors impacted by changes in economic, political, and global market conditions and their potential effect on the Company’s business and results of operation:
| • | Credit Spread Risk- Credit spread exposure is reflected in the market prices of fixed income instruments where lower rated securities generally trade at a higher credit spread. If issuer credit spreads increase or widen, the market value of our investment portfolio may decline. If the credit spread widening is significant and occurs over an extended period of time, the Company may recognize other-than-temporary impairments, resulting in decreased earnings. If credit spreads tighten, significantly, the Company’s net investment |
income associated with new purchases of fixed maturities may be reduced. In addition, the value of credit derivatives under which the Company assumes exposure or purchases protection are impacted by changes in credit spreads, with losses occurring when credit spreads widen for assumed exposure or, when credit spreads tighten if credit protection has been purchased.
Our statutory surplus is also affected by widening credit spreads as a result of the accounting for the assets and liabilities on our fixed market value adjusted (“MVA”) annuities. Statutory separate account assets supporting the fixed MVA annuities are recorded at fair value. In determining the statutory reserve for the fixed MVA annuity payments we owe contract-holders, we are required to use current crediting rates. In many capital market scenarios, current crediting rates are highly correlated with market rates implicit in the fair value of statutory separate account assets. As a result, the change in the statutory reserve from period to period will likely substantially offset the change in the fair value of the statutory separate account assets. However, in periods of volatile credit markets, actual credit spreads on investment assets may increase sharply for certain sub-sectors of the overall credit market, resulting in statutory separate account asset market value losses. As actual credit spreads are not fully reflected in current crediting rates, the calculation of statutory reserves may not substantially offset the change in fair value of the statutory separate account assets, resulting in reductions in statutory surplus. This may result in the need to devote significant additional capital to support the fixed MVA product.
| • | Equity Markets Risk - A decline in equity markets may result in lower earnings from our Mutual Funds and Talcott Resolution operations where fee income is earned based upon the fair value of the assets under management. A decline in equity markets may also decrease the value of equity securities and limited partnerships and other alternative investments held in the Company’s general account portfolio, thereby negatively impacting our financial condition or reported earnings. In addition, certain of our annuity products have guaranteed minimum death benefits ("GMDB") or guaranteed minimum withdrawal benefits ("GMWB") that increase when equity markets decline requiring us to hold more statutory capital. While our hedging assets seek to reduce the net economic sensitivity of our potential obligations from guaranteed benefits to market fluctuations, because of the accounting asymmetries between our hedging targets and statutory and GAAP accounting principles for our guaranteed benefits, rising equity markets and/or rising interest rates may result in statutory or GAAP losses. The need to use additional capital to support these guaranteed benefits may adversely affect our ability to use funds for other purposes such as to support our other businesses, repay debt or repurchase shares. |
| • | Interest Rate Risk - Global economic conditions may result in the persistence of a low interest rate environment which would continue to pressure our net investment income and could result in lower margins and lower estimated gross profits on certain products. |
Part I - Item 1A. Risk Factors
New and renewal business for our property and casualty and group benefits products is priced based on prevailing interest rates. As interest rates decline, in order to achieve the same economic return, we would have to increase product prices to offset the lower anticipated investment income earned on invested premiums. Conversely, as interest rates rise, pricing targets will tend to decrease to reflect higher anticipated investment income. Our ability to effectively react to such changes in interest rates may affect our competitiveness in the marketplace, and in turn, could reduce written premium and earnings.
In addition, due to the long-term nature of the liabilities within our Group Benefits and Talcott Resolution operations, such as structured settlements, long-term disability and guaranteed benefits on variable annuities, declines in interest rates over an extended period of time would result in our having to reinvest at lower yields, increased hedging costs, reduced spreads on our annuity products and greater capital volatility. On the other hand, a rise in interest rates, in the absence of other countervailing changes, would reduce the market value of our investment portfolio and, if long-term interest rates were to rise dramatically, certain products within our Talcott Resolution segment might be exposed to disintermediation risk. Disintermediation risk refers to the risk that our policyholders may surrender their contracts in a rising interest rate environment, requiring us to liquidate assets in an unrealized loss position. A decline in market value of invested assets due to an increase in interest rates could also limit our ability to realize tax benefits from previously recognized capital losses.
| • | Inflation Risk - Inflation is a risk to our property and casualty and group benefits businesses because, in many cases, claims are paid out many years after a policy is written and premium is collected for the risk. Accordingly, a greater than expected increase in inflation related to the cost of medical services and repairs over the claim settlement period can result in higher claim costs than what was estimated at the time the policy was written. Inflation can also affect consumer spending and business investment which can reduce the demand for our products and services. |
Concentration of our investment portfolio increases the potential for significant losses.
The concentration of our investment portfolios in any particular industry, collateral type, group of related industries or geographic sector could have an adverse effect on our investment portfolios and consequently on our business, financial condition, results of operations, and liquidity. Events or developments that have a negative impact on any particular industry, collateral type, group of related industries or geographic region may have a greater adverse effect on our investment portfolio to the extent that the portfolio is concentrated rather than diversified.
Further, if issuers of securities or loans we hold are acquired, merge or otherwise consolidate with other issuers of securities or loans held by the Company, our investment portfolio’s credit concentration risk to issuers could increase for a period of time, until the Company is able to sell securities to get back in compliance with the established investment credit policies.
Insurance Industry and Product Related Risks
Unfavorable loss development may adversely affect our business, financial condition, results of operations and liquidity.
We establish property and casualty loss reserves to cover our estimated liability for the payment of all unpaid losses and loss expenses incurred with respect to premiums earned on our policies. Loss reserves are estimates of what we expect the ultimate settlement and administration of claims will cost, less what has been paid to date. These estimates are based upon actuarial projections and on our assessment of currently available data, as well as estimates of claims severity and frequency, legal theories of liability and other factors.
Loss reserve estimates are refined periodically as experience develops and claims are reported and settled, potentially resulting in increases to our reserves. Increases in reserves would be recognized as an expense during the periods in which these determinations are made, thereby adversely affecting our results of operations for those periods. In addition, since reserve estimates of aggregate loss costs for prior years are used in pricing our insurance products, inaccurate reserves can lead to our products not being priced adequately to cover actual losses and related loss expenses in order to generate a profit.
We continue to receive asbestos and environmental ("A&E")claims, the vast majority of which relate to policies written before 1986. Estimating the ultimate gross reserves needed for unpaid losses and related expenses for asbestos and environmental claims is particularly difficult for insurers and reinsurers. The actuarial tools and other techniques used to estimate the ultimate cost of more traditional insurance exposures tend to be less precise when used to estimate reserves for some A&E exposures.
Moreover, the assumptions used to estimate gross reserves for A&E claims, such as claim frequency over time, average severity, and how various policy provisions will be interpreted, are subject to significant uncertainty. It is also not possible to predict changes in the legal and legislative environment and their effect on the future development of A&E claims. These factors, among others, make the variability of gross reserves estimates for these longer-tailed exposures significantly greater than for other more traditional exposures.
Effective December 31, 2016, the Company entered into an agreement with National Indemnity Company (“NICO”), a subsidiary of Berkshire Hathaway Inc. (“Berkshire”) whereby the Company is reinsured for subsequent adverse development on substantially all of its net A&E reserves up to an aggregate net limit of $1.5 billion. The adverse development cover excludes risk of adverse development on net asbestos and environmental reserves held by the Company's U.K. Property and Casualty run-off subsidiaries which have been accounted for as liabilities held for sale in the consolidated balance sheets as of December 31, 2016. We remain directly liable to claimants and if the reinsurer does not fulfill its obligations under the agreement or if future adverse development exceeds the $1.5 billion aggregate limit, we may need to increase our recorded net reserves which could have a material adverse effect on our financial condition, results of
Item 1A. Risk Factors
operations and liquidity. For additional information related to risks associated with the adverse development cover, see Part II, Item 7, MD&A - Critical Accounting Estimates - Property & Casualty Other Operations - Adverse Development Cover.
We are vulnerable to losses from catastrophes, both natural and man-made.
Our insurance operations expose us to claims arising out of catastrophes. Catastrophes can be caused by various unpredictable natural events, including, among others, earthquakes, hurricanes, hailstorms, severe winter weather, wind storms, fires, tornadoes, and pandemics. Catastrophes can also be man-made, such as terrorist attacks, cyber-attacks, explosions or infrastructure failures.
The geographic distribution of our business subjects us to catastrophe exposure for events occurring in a number of areas, including, but not limited to: hurricanes in Florida, the Gulf Coast, the Northeast and the Atlantic coast regions of the United States; tornadoes and hail in the Midwest and Southeast; earthquakes in California and the New Madrid (Midwest) region of the United States; and the spread of disease. Any increases in the values and concentrations of insured employees and property in these areas would increase the severity of catastrophic events in the future. In addition, over time, climate change may increase the severity of certain natural catastrophe events. Potential examples include, but are not limited to:
| • | an increase in the frequency or severity of wind and thunderstorm and tornado/hailstorm events due to increased convection in the atmosphere, |
| • | more frequent brush fires in certain geographies due to prolonged periods of drought, |
| • | higher incidence of deluge flooding, and |
| • | the potential for an increase in severity of the largest hurricane events due to higher sea surface temperatures. |
Our businesses also have exposure to global or nationally occurring pandemics caused by highly infectious and potentially fatal diseases spread through human, animal or plant populations.
In the event of one or more catastrophes, policyholders may be unable to meet their obligations to pay premiums on our insurance policies. Further, our liquidity could be constrained by a catastrophe, or multiple catastrophes, which could result in extraordinary losses. In addition, in part because accounting rules do not permit insurers to reserve for such catastrophic events until they occur, claims from catastrophic events could have a material adverse effect on our business, financial condition, results of operations or liquidity. The amount we charge for catastrophe exposure may be inadequate if the frequency or severity of catastrophe losses changes over time or if the models we use to estimate the exposure prove inadequate. In addition, regulators or legislators could limit our ability to charge adequate pricing for catastrophe exposures or shift more responsibility for covering risk.
Terrorism is an example of a significant man-made caused potential catastrophe. Private sector catastrophe reinsurance is limited and generally unavailable for terrorism losses caused by attacks with nuclear, biological, chemical or radiological weapons. Reinsurance coverage from the federal government under the Terrorism Risk Insurance Program Reauthorization Act of 2015
(“TRIPRA”) is also limited and only applies for certified acts of terrorism that exceed a certain threshold of industry losses. Accordingly, the effects of a terrorist attack in the geographic areas we serve may result in claims and related losses for which we do not have adequate reinsurance. Further, the continued threat of terrorism and the occurrence of terrorist attacks, as well as heightened security measures and military action in response to these threats and attacks or other geopolitical or military crises, may cause significant volatility in global financial markets, disruptions to commerce and reduced economic activity. These consequences could have an adverse effect on the value of the assets in our investment portfolio as well as those in our separate accounts. Terrorist attacks also could disrupt our operation centers. For a further discussion of TRIPRA, see Part II, Item 7, MD&A - Enterprise Risk Management - Insurance Risk Management, Reinsurance as a Risk Management Strategy.
As a result, it is possible that any, or a combination of all, of these factors related to a catastrophe, or multiple catastrophes, whether natural or man-made, can have a material adverse effect on our business, financial condition, results of operations or liquidity.
Pricing for our products is subject to our ability to adequately assess risks, estimate losses and comply with state insurance regulations.
We seek to price our property and casualty and group benefits insurance policies such that insurance premiums and future net investment income earned on premiums received will provide for an acceptable profit in excess of underwriting expenses and the cost of paying claims. Pricing adequacy depends on a number of factors, including proper evaluation of underwriting risks, the ability to project future claim costs, our expense levels, net investment income realized, our response to rate actions taken by competitors, legal and regulatory developments, and the ability to obtain regulatory approval for rate changes.
State insurance departments regulate many of the premium rates we charge and also propose rate changes for the benefit of the property and casualty consumer at the expense of the insurer, which may not allow us to reach targeted levels of profitability. In addition to regulating rates, certain states have enacted laws that require a property and casualty insurer to participate in assigned risk plans, reinsurance facilities, joint underwriting associations and other residual market plans. State regulators also require that an insurer offer property and casualty coverage to all consumers and often restrict an insurer's ability to charge the price it might otherwise charge or restrict an insurer's ability to offer or enforce specific policy deductibles. In these markets, we may be compelled to underwrite significant amounts of business at lower than desired rates or accept additional risk not contemplated in our existing rates, participate in the operating losses of residual market plans or pay assessments to fund operating deficits of state-sponsored funds, possibly leading to lower returns on equity. The laws and regulations of many states also limit an insurer's ability to withdraw from one or more lines of insurance in the state, except pursuant to a plan that is approved by the state's insurance department. Additionally, certain states require insurers to participate in guaranty funds for impaired or insolvent insurance companies. These funds periodically assess losses against all insurance companies doing business in the state. Any of these factors could have a material
Part I - Item 1A. Risk Factors
adverse effect on our business, financial condition, results of operations or liquidity.
Additionally, the property and casualty and group benefits insurance markets have been historically cyclical, experiencing periods characterized by relatively high levels of price competition, less restrictive underwriting standards, more expansive coverage offerings, multi-year rate guarantees and declining premium rates, followed by periods of relatively low levels of competition, more selective underwriting standards, more coverage restrictions and increasing premium rates. In all of our property and casualty and group benefits insurance product lines and states, there is a risk that the premium we charge may ultimately prove to be inadequate as reported losses emerge. In addition, there is a risk that regulatory constraints, price competition or incorrect pricing assumptions could prevent us from achieving targeted returns. Inadequate pricing could have a material adverse effect on our results of operations and financial condition.
Competitive activity, use of data analytics, or technological changes may adversely affect our market share, demand for our products, or our financial results.
The industries in which we operate are highly competitive. Our principal competitors are other property and casualty insurers, group benefits providers and providers of mutual funds and exchange-traded products. Competitors may expand their risk appetites in products and services where The Hartford currently enjoys a competitive advantage. Larger competitors with more capital and new entrants to the market could result in increased pricing pressures on a number of our products and services and may harm our ability to maintain or increase our profitability. For example, larger competitors, including those formed through consolidation, may have lower operating costs and an ability to absorb greater risk while maintaining their financial strength ratings, thereby allowing them to price their products more competitively. In addition, a number of insurers are making use of "big data" analytics to, among other things, improve pricing accuracy, be more targeted in marketing, strengthen customer relationships and provide more customized loss prevention services. If they are able to use big data more effectively than we are, it may give them a competitive advantage. Because of the highly competitive nature of the industries we compete in, there can be no assurance that we will continue to compete effectively with our industry rivals, or that competitive pressure will not have a material adverse effect on our business and results of operations.
Our business could also be affected by technological changes, including further advancements in automotive safety features, the development of autonomous or “self-driving” vehicles, and platforms that facilitate ride sharing. These technologies could impact the frequency or severity of losses, disrupt the demand for certain of our products, or reduce the size of the automobile insurance market as a whole. In addition, the risks we insure are affected by the increased use of technology in homes and businesses, including technology used in heating, ventilation and air conditioning systems and the introduction of more automated loss control measures. While there is substantial uncertainty about the timing, penetration and reliability of such technologies, any such impacts could have a material adverse effect on our business and results of operations.
We may experience difficulty in marketing and providing insurance products and investment advisory services through distribution channels and advisory firms.
We distribute our insurance products, mutual funds and ETPs through a variety of distribution channels, including brokers, independent agents, broker-dealers, banks, affinity partners, our own internal sales force and other third-party organizations. In some areas of our business, we generate a significant portion of our business through third-party arrangements. For example, we market personal lines products in large part through an exclusive licensing arrangement with AARP that continues through January 1, 2023. Our ability to distribute products through AARP may be adversely impacted by membership levels and the pace of membership growth. While we periodically seek to renew or extend third party arrangements, there can be no assurance that our relationship with these third parties will continue. An interruption in our relationship with certain of these third parties could materially affect our ability to market our products and could have a material adverse effect on our business, financial condition, results of operations and liquidity.
Unexpected and unintended claim and coverage issues under our insurance contracts may adversely impact our financial performance.
Changes in industry practices and in legal, judicial, social and other environmental conditions may require us to pay claims we did not intend to cover when we wrote the policies. These issues may either extend coverage beyond our underwriting intent or increase the frequency or severity of claims. In some instances, these changes may not become apparent until some time after we have issued insurance contracts that are affected by the changes. As a result, the full extent of liability under our insurance contracts may not be known for many years after a contract is issued, and this liability may have a material adverse effect on our business, financial condition, results of operations and liquidity at the time it becomes known.
Our program to manage interest rate and equity risk related to our variable annuity guaranteed benefits may be ineffective which could result in statutory and GAAP volatility in our earnings and potentially material charges to net income.
Some of the in-force business within our Talcott Resolution operations, especially variable annuities, offer guaranteed benefits, including GMDBs and GMWBs. These GMDBs and GMWBs expose the Company to interest rate risk and significant equity risk. A decline in equity markets would not only result in lower fee income, but would also increase our exposure to liability for benefit claims. We use reinsurance and benefit designs, such as caps, to mitigate the exposure associated with GMDB. We also use reinsurance in combination with product management actions, such as rider fee increases, investment restrictions and buyout offers, as well as derivative instruments to attempt to minimize the claim exposure and to reduce the volatility of net income associated with the GMWB liability. We remain liable for the guaranteed benefits in the event that
Part I - Item 1A. Risk Factors
reinsurers or derivative counterparties are unable or unwilling to pay, which could result in a need for additional capital to support in-force business.
From time to time, we may adjust our risk management program based on contracts in force, market conditions, or other factors. While we believe that these actions improve the efficiency of our risk management related to these benefits, changes to the risk management program may result in greater statutory and GAAP earnings volatility and, based upon the types of hedging instruments used, can result in potentially material charges to net income (loss) in periods of rising equity market pricing levels, higher interest rates and declines in volatility. We are also subject to the risk that these management actions prove ineffective or that unanticipated policyholder behavior, combined with adverse market events, produces economic losses beyond the scope of the risk management techniques employed, which individually or collectively may have a material adverse effect on our business, financial condition, results of operations and liquidity.
Financial Strength, Credit and Counterparty Risks
Downgrades in our financial strength or credit ratings may make our products less attractive, increase our cost of capital and inhibit our ability to refinance our debt.
Financial strength and credit ratings are important in establishing the competitive position of insurance companies. Rating agencies assign ratings based upon several factors. While most of the factors relate to the rated company, others relate to the views of the rating agency (including its assessment of the strategic importance of the rated company to the insurance group), general economic conditions, and circumstances outside the rated company's control. In addition, rating agencies may employ different models and formulas to assess the financial strength of a rated company, and from time to time rating agencies have altered these models. Changes to the models or factors used by the rating agencies to assign ratings could adversely impact a rating agency's judgment of its internal rating and the publicly issued rating it assigns us.
Our financial strength ratings, which are intended to measure our ability to meet policyholder obligations, are an important factor affecting public confidence in most of our products and, as a result, our competitiveness. A downgrade or a potential downgrade in the rating of our financial strength or of one of our principal insurance subsidiaries could affect our competitive position and reduce future sales of our products.
Our credit ratings also affect our cost of capital. A downgrade or a potential downgrade of our credit ratings could make it more difficult or costly to refinance maturing debt obligations, to support business growth at our insurance subsidiaries and to maintain or improve the financial strength ratings of our principal insurance subsidiaries. Downgrades could begin to trigger potentially material collateral calls on certain of our derivative instruments and enable counterparties to terminate derivative relationships, both of which could limit our ability to purchase
additional derivative instruments. These events could materially adversely affect our business, financial condition, results of operations and liquidity. For a further discussion of potential impacts of ratings downgrades on derivative instruments, including potential collateral calls, see Part II, Item 7, MD&A - Capital Resources and Liquidity - Derivative Commitments.
The amount of statutory capital that we must hold to maintain our financial strength and credit ratings and meet other requirements can vary significantly from time to time and is sensitive to a number of factors outside of our control.
We conduct the vast majority of our business through licensed insurance company subsidiaries. Statutory accounting standards and statutory capital and reserve requirements for these entities are prescribed by the applicable insurance regulators and the National Association of Insurance Commissioners (“NAIC”). The minimum capital we must hold is based on risk-based capital (“RBC”) formulas for both life and property and casualty companies. The RBC formula for life companies establishes capital requirements relating to insurance, business, asset and interest rate risks, including equity, interest rate and expense recovery risks associated with variable annuities and group annuities that contain death benefits or certain withdrawal benefits. The RBC formula for property and casualty companies sets required statutory surplus levels based on underwriting, asset, credit and off-balance sheet risks.
In any particular year, statutory surplus amounts and RBC ratios may increase or decrease depending on a variety of factors, including
| • | the amount of statutory income or losses generated by our insurance subsidiaries, |
| • | the amount of additional capital our insurance subsidiaries must hold to support business growth, |
| • | the amount of dividends or distributions taken out of our insurance subsidiaries, |
| • | changes in equity market levels, |
| • | the value of certain fixed-income and equity securities in our investment portfolio, |
| • | the value of certain derivative instruments, |
| • | changes in interest rates, |
| • | admissibility of deferred tax assets, and |
| • | changes to the NAIC RBC formulas. |
Most of these factors are outside of the Company's control. The Company's financial strength and credit ratings are significantly influenced by the statutory surplus amounts and RBC ratios of our insurance company subsidiaries. In addition, rating agencies may implement changes to their internal models that have the effect of increasing the amount of statutory capital we must hold in order to maintain our current ratings. Also, in extreme scenarios of equity market declines and other capital market volatility, the amount of additional statutory reserves that we are required to hold for our variable annuity guarantees increases at a greater than linear rate. This reduces the statutory surplus used
Part I - Item 1A. Risk Factors
in calculating our RBC ratios. When equity markets increase, surplus levels and RBC ratios would generally be expected to increase. However, as a result of a number of factors and market conditions, including the level of hedging costs and other risk transfer activities, statutory reserve requirements for death and withdrawal benefit guarantees and increases in RBC requirements, surplus and RBC ratios may not increase when equity markets increase. Due to these factors, projecting statutory capital and the related RBC ratios is complex. If our statutory capital resources are insufficient to maintain a particular rating by one or more rating agencies, we may seek to raise capital through public or private equity or debt financing. If we were not to raise additional capital, either at our discretion or because we were unable to do so, our financial strength and credit ratings might be downgraded by one or more rating agencies.
Losses due to nonperformance or defaults by counterparties can have a material adverse effect on the value of our investments, reduce our profitability or sources of liquidity.
We have credit risk with counterparties on investments, derivatives, premiums receivable and reinsurance recoverables. Among others, our counterparties include issuers of fixed maturity and equity securities we hold, borrowers of mortgage loans we hold, customers, trading counterparties, counterparties under swaps and other derivative contracts, reinsurers, clearing agents, exchanges, clearing houses and other financial intermediaries and guarantors. These counterparties may default on their obligations to us due to bankruptcy, insolvency, lack of liquidity, adverse economic conditions, operational failure, fraud, government intervention and other reasons. Defaults by these counterparties on their obligations to us could have a material adverse effect on the value of our investments, business, financial condition, results of operations and liquidity. Additionally, if the underlying assets supporting the structured securities we invest in default on their payment obligations, our securities will incur losses.
The availability of reinsurance and our ability to recover under reinsurance contracts may not be sufficient to protect us against losses.
As an insurer, we frequently use reinsurance to reduce the effect of losses that may arise from, among other things, catastrophes and other risks that can cause unfavorable results of operations, GMDBs and GMWBs under variable annuity contracts, and to effect the sale of a line of business to an independent company. Under these reinsurance arrangements, other insurers assume a portion of our losses and related expenses; however, we remain liable as the direct insurer on all risks reinsured. Consequently, ceded reinsurance arrangements do not eliminate our obligation to pay claims, and we are subject to our reinsurers' credit risk with respect to our ability to recover amounts due from them. The inability or unwillingness of any reinsurer to meet its financial obligations to us, including the impact of any insolvency or rehabilitation proceedings involving a reinsurer that could affect the Company's access to collateral held in trust, could have a material adverse effect on our financial condition, results of operations and liquidity. This risk may be magnified by a concentration of reinsurance-related credit risk resulting from the sale of the Company’s Individual Life and Retirement
Products businesses. Further details of such concentration can be found in Part II, Item 7, MD&A - Enterprise Risk Management - Reinsurance as a Risk Management Strategy.
In addition, should the availability and cost of reinsurance change materially, we may have to pay higher reinsurance costs, accept an increase in our net liability exposure, reduce the amount of business we write, or access to the extent possible other alternatives to reinsurance, such as use of the capital markets. Further, due to the inherent uncertainties as to collection and the length of time before reinsurance recoverables will be due, it is possible that future adjustments to the Company’s reinsurance recoverables, net of the allowance, could be required, which could have a material adverse effect on the Company’s consolidated results of operations or cash flows in a particular quarterly or annual period.
Our ability to declare and pay dividends is subject to limitations.
The payment of future dividends on our capital stock is subject to the discretion of our board of directors, which considers, among other factors, our operating results, overall financial condition, credit-risk considerations and capital requirements, as well as general business and market conditions. Our board of directors may only declare such dividends out of funds legally available for such payments. Moreover, our common stockholders are subject to the prior dividend rights of any holders of depositary shares representing such preferred stock then outstanding. The terms of our outstanding junior subordinated debt securities prohibit us from declaring or paying any dividends or distributions on our capital stock or purchasing, acquiring, or making a liquidation payment on such stock, if we have given notice of our election to defer interest payments and the related deferral period has not yet commenced or a deferral period is continuing.
Moreover, as a holding company that is separate and distinct from our insurance subsidiaries, we have no significant business operations of our own. Therefore, we rely on dividends from our insurance company subsidiaries and other subsidiaries as the principal source of cash flow to meet our obligations. Subsidiary dividends fund payments on our debt securities and the payment of dividends to shareholders on our capital stock. Connecticut state laws and certain other jurisdictions in which we operate limit the payment of dividends and require notice to and approval by the state insurance commissioner for the declaration or payment of dividends above certain levels. Dividends paid from our insurance subsidiaries are further dependent on their cash requirements. In addition, in the event of liquidation or reorganization of a subsidiary, prior claims of a subsidiary’s creditors may take precedence over the holding company’s right to a dividend or distribution from the subsidiary except to the extent that the holding company may be a creditor of that subsidiary. For further discussion on dividends from insurance subsidiaries, see Part II, Item 7, MD&A - Capital Resources & Liquidity.
Part I - Item 1A. Risk Factors
Risks Relating to Estimates, Assumptions and Valuations
Actual results could materially differ from the analytical models we use to assist our decision making in key areas such as underwriting, capital, hedging, reserving, and catastrophe risks.
We use models to help make decisions related to, among other things, underwriting, pricing, capital allocation, reserving, investments, hedging, reinsurance, and catastrophe risk. Both proprietary and third party models we use incorporate numerous assumptions and forecasts about the future level and variability of interest rates, capital requirements, loss frequency and severity, currency exchange rates, policyholder behavior, equity markets and inflation, among others. The models are subject to the inherent limitations of any statistical analysis as the historical internal and industry data and assumptions used in the models may not be indicative of what will happen in the future. Consequently, actual results may differ materially from our modeled results. The profitability and financial condition of the Company substantially depends on the extent to which our actual experience is consistent with assumptions we use in our models and ultimate model outputs. If, based upon these models or other factors, we misprice our products or our estimates of the risks we are exposed to prove to be materially inaccurate, our business, financial condition, results of operations or liquidity may be adversely affected.
The valuation of our securities and investments and the determination of allowances and impairments are highly subjective and based on methodologies, estimations and assumptions that are subject to differing interpretations and market conditions.
Estimated fair values of the Company’s investments are based on available market information and judgments about financial instruments, including estimates of the timing and amounts of expected future cash flows and the credit standing of the issuer or counterparty. During periods of market disruption, it may be difficult to value certain of our securities if trading becomes less frequent and/or market data becomes less observable. There may be certain asset classes that were in active markets with significant observable data that become illiquid due to the financial environment. In addition, there may be certain securities whose fair value is based on one or more unobservable inputs, even during normal market conditions. As a result, the determination of the fair values of these securities may include inputs and assumptions that require more estimation and management judgment and the use of complex valuation methodologies. These fair values may differ materially from the value at which the investments may be ultimately sold. Further, rapidly changing or unprecedented credit and equity market conditions could materially impact the valuation of securities and the period-to-period changes in value could vary significantly.
Decreases in value could have a material adverse effect on our business, results of operations, financial condition and liquidity.
Similarly, management’s decision on whether to record an other-than-temporary impairment or write down is subject to significant judgments and assumptions regarding changes in general economic conditions, the issuer's financial condition or future recovery prospects, estimated future cash flows, the effects of changes in interest rates or credit spreads, the expected recovery period and the accuracy of third party information used in internal assessments. As a result, management’s evaluations and assessments are highly judgmental and its projections of future cash flows over the life of certain securities may ultimately prove incorrect as facts and circumstances change.
If assumptions used in estimating future gross profits differ from actual experience, we may be required to accelerate the amortization of DAC and increase reserves for GMDB and GMWB on variable annuities, which could adversely affect our results of operation.
The Company has deferred acquisition costs associated with the prior sales of its variable annuity products. Deferred acquisition costs for the variable annuity products are amortized over the expected life of the contracts. The remaining deferred but not yet amortized cost is referred to as the Deferred Acquisition Cost ("DAC") asset. We amortize these costs based on the ratio of actual gross profits in the period to the present value of current and future estimated gross profits (“EGPs”). The Company evaluates the EGPs compared to the DAC asset to determine if an impairment exists. The Company also establishes reserves for GMDB and the life contingent portion of GMWB using components of EGPs. The projection of EGPs, or components of EGPs, requires the use of certain assumptions that may not prove accurate, including those related to changes in the separate account fund returns, full or partial surrender rates, mortality, withdrawal benefit utilization, withdrawal rates, annuitization and hedging costs.
In addition, if our assumptions about policyholder behavior (e.g., full or partial surrenders, benefit utilization and annuitization) and costs related to mitigating risks, including hedging costs, prove to be inaccurate or if significant or sustained equity market declines occur, we could be required to accelerate the amortization of DAC related to variable annuity contracts, and increase reserves for GMDB and life-contingent GMWB which would result in a charge to net income.
If our businesses do not perform well, we may be required to establish a valuation allowance against the deferred income tax asset or to recognize an impairment of our goodwill.
Our income tax expense includes deferred income taxes arising from temporary differences between the financial reporting and tax bases of assets and liabilities and carry-forwards for foreign tax credits, capital losses, net operating losses and alternative minimum tax credits. Deferred tax assets are assessed periodically by management to determine if it is more likely than not that the deferred income tax assets will be realized. Factors in management's determination include the performance of the
Part I - Item 1A. Risk Factors
business, including the ability to generate, from a variety of sources and tax planning strategies, sufficient future taxable income and capital gains before net operating loss and capital loss carry-forwards expire. If based on available information, it is more likely than not that we are unable to recognize a full tax benefit on deferred tax assets, then a valuation allowance will be established with a corresponding charge to net income (loss). Charges to increase our valuation allowance could have a material adverse effect on our results of operations and financial condition.
Goodwill represents the excess of the amounts we paid to acquire subsidiaries and other businesses over the fair value of their net assets at the date of acquisition. We test goodwill at least annually for impairment. Impairment testing is performed based upon estimates of the fair value of the “reporting unit” to which the goodwill relates. The reporting unit is the operating segment or a business one level below an operating segment if discrete financial information is prepared and regularly reviewed by management at that level. The fair value of the reporting unit could decrease if new business, customer retention, profitability or other drivers of performance differ from expectations. If it is determined that the goodwill has been impaired, the Company must write down the goodwill by the amount of the impairment, with a corresponding charge to net income (loss). These write downs could have a material adverse effect on our results of operations or financial condition.
Strategic and Operational Risks
As our Talcott Resolution business continues to run-off, the Company is exposed to a number of risks related to the run-off business that could adversely affect our financial condition and results of operations.
Despite being in run-off, Talcott Resolution represents a meaningful share of the Company’s earnings. Talcott Resolution’s revenues and earnings have been and will continue declining as variable and fixed annuity policies lapse. While the Company has been reducing expenses associated with the Talcott Resolution business as the revenues from that business decline, going forward it may become more difficult to reduce expenses, particularly corporate and other enterprise shared services costs, and this could adversely affect the Company’s results of operations. In addition, as Talcott Resolution's earnings decline, there will be less retained earnings in the Company’s Talcott Resolution insurance subsidiaries available to fund capital management actions.
Further, while the Company continues to actively consider alternatives for reducing the size and risk of the annuity book of business, opportunities to do so may be limited and any initiatives pursued may not achieve the anticipated benefits and may negatively impact our statutory capital, net income, core earnings or shareholders’ equity. The Company could pursue transactions or other strategic options to reduce the size and risk of Talcott Resolution's annuity book of business which could result in a significant loss to the Company.
Our businesses may suffer and we may incur substantial costs if we are unable to access our systems and safeguard the security of our data in the event of a disaster, cyber breach or other information security incident.
We use technology to process, store, retrieve, evaluate and utilize customer and company data and information. Our information technology and telecommunications systems, in turn, interface with and rely upon third-party systems. We and our third party vendors must be able to access our systems to provide insurance quotes, process premium payments, make changes to existing policies, file and pay claims, administer variable annuity products and mutual funds, provide customer support, manage our investment portfolios and hedge programs, report on financial results and perform other necessary business functions.
Systems failures or outages could compromise our ability to perform these business functions in a timely manner, which could harm our ability to conduct business and hurt our relationships with our business partners and customers. In the event of a disaster such as a natural catastrophe, a pandemic, an industrial accident, a cyber attack, a blackout, a terrorist attack (including conventional, nuclear, biological, chemical or radiological) or war, systems upon which we rely may be inaccessible to our employees, customers or business partners for an extended period of time. Even if our employees and business partners are able to report to work, they may be unable to perform their duties for an extended period of time if our data or systems used to conduct our business are disabled or destroyed.
Our systems have been, and will likely continue to be, subject to viruses or other malicious codes, unauthorized access, cyber-attacks or other computer related penetrations. The frequency and sophistication of such threats continue to increase as well. While, to date, The Hartford is not aware of having experienced a material breach of our cyber security systems, administrative and technical controls as well as other preventive actions may be insufficient to prevent physical and electronic break-ins, denial of service, cyber-attacks or other security breaches to our systems or those of third parties with whom we do business. Such an event could compromise our confidential information as well as that of our clients and third parties, impede or interrupt our business operations and result in other negative consequences, including remediation costs, loss of revenue, additional regulatory scrutiny and litigation and reputational damage. In addition, we routinely transmit, to third parties personal, confidential and proprietary information, which may be related to employees and customers, by email and other electronic means, along with receiving and storing such information on our systems. Although we attempt to keep such information confidential, we may be unable to secure the information in all events, especially with clients, vendors, service providers, counterparties and other third parties who may not have appropriate controls to protect confidential information.
Furthermore, certain of our businesses must comply with regulations to control the privacy of customer, employee and third party data. A misuse or mishandling of confidential or proprietary information could result in legal liability, regulatory action and reputational harm.
Third parties, including third party administrators, are also subject to cyber-breaches of confidential information, along with the other risks outlined above, any one of which may result in our
Part I - Item 1A. Risk Factors
incurring substantial costs and other negative consequences, including a material adverse effect on our business, reputation, financial condition, results of operations and liquidity. While we maintain cyber liability insurance that provides both third party liability and first party insurance coverages, our insurance may not be sufficient to protect against all loss.
Performance problems due to outsourcing and other third-party relationships may compromise our ability to conduct business.
We outsource certain business and administrative functions and rely on third-party vendors to perform certain functions or provide certain services on our behalf and have a significant number of information technology and business processes outsourced with a single vendor. If we are unable to reach agreement in the negotiation of agreements or renewals with certain third-party providers, or if such third-party providers experience disruptions or do not perform as anticipated, we may we may be unable to meet our obligations to customers and claimants, incur higher costs and lose business which may have a material adverse effect on our business and results of operations. For other risks associated with our outsourcing of certain functions, see the immediately preceding risk factor.
Our ability to execute on our capital management plan, expense reduction initiatives and other actions, which may include acquisitions, divestitures or restructurings, is subject to material challenges, uncertainties and risks.
The ability to execute on our capital management plan remains subject to material challenges, uncertainties and risks. We may not achieve all of the benefits we expect to derive from our plan to repurchase our equity and reduce our debt. Our capital management plan is subject to execution risks, including, among others, risks related to market fluctuations, investor interest and potential legal constraints that could delay execution at an otherwise optimal time. There can be no assurance that we will in fact complete our capital management plan over the planned time frame or at all. Initiatives to reduce expenses so that our ongoing businesses remain or become cost efficient may not be successful and we may not be able to reduce corporate and shared services expenses in the manner and on the schedule we currently anticipate. We may take further actions beyond the capital management plan, which may include acquisitions, divestitures or restructurings, that may involve additional uncertainties and risks that negatively impact our business, financial condition, results of operations and liquidity.
We may not be able to protect our intellectual property and may be subject to infringement claims.
We rely on a combination of contractual rights and copyright, trademark, patent and trade secret laws to establish and protect our intellectual property. Although we use a broad range of measures to protect our intellectual property rights, third parties may infringe or misappropriate our intellectual property. We may have to litigate to enforce and protect our intellectual property and to determine its scope, validity or enforceability, which could divert significant resources and may not prove successful.
Litigation to enforce our intellectual property rights may not be successful and cost a lot of money. The inability to secure or enforce the protection of our intellectual property assets could harm our reputation and have a material adverse effect on our business and our ability to compete. We also may be subject to costly litigation in the event that another party alleges our operations or activities infringe upon their intellectual property rights, including patent rights, or violate license usage rights. Any such intellectual property claims and any resulting litigation could result in significant expense and liability for damages, and in some circumstances we could be enjoined from providing certain products or services to our customers, or utilizing and benefiting from certain patent, copyrights, trademarks, trade secrets or licenses, or alternatively could be required to enter into costly licensing arrangements with third parties, all of which could have a material adverse effect on our business, results of operations and financial condition.
Regulatory and Legal Risks
Regulatory and legislative developments could have a material adverse impact on our business, financial condition, results of operations and liquidity.
In the U.S., regulatory initiatives and legislative developments may significantly affect our operations and prospects in ways that we cannot predict.
For example, potential repeal and replacement of the Affordable Care Act and modification of the Dodd-Frank Act could have unanticipated consequences for the Company and its businesses. With respect to the potential repeal and replacement of the Affordable Care Act, see Part II, Item 7, MD&A - Capital Resources and Liquidity - Contingencies - Regulatory and Legal Developments.
The Dodd-Frank Act was enacted on July 21, 2010, mandating changes to the regulation of the financial services industry that could adversely affect our financial condition and results of operations. The Dodd-Frank Act requires central clearing of certain derivatives transactions and greater margin requirements for those transactions, which increases the costs of our hedging program. In addition, the proprietary trading and market making limitation of the Volcker Rule could adversely affect the pricing and liquidity of our investment securities and limitations of banking entity involvement in and ownership of certain asset-backed securities transactions could adversely affect the market for insurance-linked securities, including catastrophe bonds. It is unclear whether and to what extent Congress will make changes to the Dodd-Frank Act, and how those changes might impact the Company, its business, financial conditions, results of operations and liquidity.
We are subject to extensive laws and regulations that are complex, subject to change and often conflicting in their approach or intended outcomes. Compliance with these laws and regulations can increase cost, affect our strategy, and constrain our ability to adequately price our products.
Our insurance subsidiaries are regulated by the insurance departments of the states in which they are domiciled, licensed or
Part I - Item 1A. Risk Factors
authorized to conduct business. State regulations generally seek to protect the interests of policyholders rather than an insurer or the insurer’s shareholders and other investors. U.S. state laws grant insurance regulatory authorities broad administrative powers with respect to, among other things, licensing and authorizing lines of business, approving policy forms and premium rates, setting statutory capital and reserve requirements, limiting the types and amounts of certain investments and restricting underwriting practices. State insurance departments also set constraints on domestic insurer transactions with affiliates and dividends and, in many cases, must approve affiliate transactions and extraordinary dividends as well as strategic transactions such as acquisitions and divestitures.
In addition, future regulatory initiatives could be adopted at the federal or state level that could impact the profitability of our businesses. For example, the NAIC and state insurance regulators are continually reexamining existing laws and regulations, specifically focusing on modifications to statutory accounting principles, interpretations of existing laws and the development of new laws and regulations. The NAIC continues to enhance the U.S. system of insurance solvency regulation, with a particular focus on group supervision, risk-based capital, accounting and financial reporting, enterprise risk management and reinsurance. Any proposed or future legislation or NAIC initiatives, if adopted, may be more restrictive on our ability to conduct business than current regulatory requirements or may result in higher costs or increased statutory capital and reserve requirements. In addition, the Federal Reserve Board and the International Association of Insurance Supervisors ("IAIS") each have initiatives underway to develop insurance group capital standards. While the Company would not currently be subject to either of these capital standard regimes, it is possible that in the future standards similar to what is being contemplated by the Federal Reserve Board or the IAIS could apply to the Company. The NAIC is in the process of developing a U.S. group capital calculation that will employ a methodology based on aggregated risk-based capital.
Further, a particular regulator or enforcement authority may interpret a legal, accounting, or reserving issue differently than we have, exposing us to different or additional regulatory risks. The application of these regulations and guidelines by insurers involves interpretations and judgments that may be challenged by state insurance departments. The result of those potential challenges could require us to increase levels of statutory capital and reserves or incur higher operating and/or tax costs.
In addition, our asset management businesses are also subject to extensive regulation in the various jurisdictions where they operate.. These laws and regulations are primarily intended to protect investors in the securities markets or investment advisory clients and generally grant supervisory authorities broad administrative powers. Compliance with these laws and regulations is costly, time consuming and personnel intensive, and may have an adverse effect on our business, financial condition, results of operations and liquidity.
Our insurance business is sensitive to significant changes in the legal environment that could adversely affect The Hartford’s results of operations or financial condition or harm its businesses.
Like any major P&C insurance company, litigation is a routine part of The Hartford’s business - both in defending and indemnifying our insureds and in litigating insurance coverage disputes. The Hartford accounts for such activity by establishing unpaid loss and loss adjustment expense reserves. Significant changes in the legal environment could cause our ultimate liabilities to change from our current expectations. Such changes could be judicial in nature, like trends in the size of jury awards, developments in the law relating to tort liability or the liability of insurers, and rulings concerning the scope of insurance coverage or the amount or types of damages covered by insurance. Legislative developments, like changes in federal or state laws relating to the liability of policyholders or insurers, could have a similar effect. It is impossible to forecast such changes reliably, much less to predict how they might affect our loss reserves or how those changes might adversely affect our ability to price our insurance products appropriately. Thus, significant judicial or legislative developments could adversely affect The Hartford’s business, financial condition, results of operations and liquidity.
Changes in federal or state tax laws could adversely affect our business, financial condition, results of operations and liquidity.
Changes in federal or state tax laws and tax rates could have a material adverse effect on our profitability and financial condition, and could result in our incurring materially higher corporate taxes. Higher tax rates may cause the small businesses we insure to hire fewer workers and decrease investment in their businesses, including purchasing fewer vehicles, property and equipment, which could adversely affect our ability to sell our products and services to these customers. If tax rates decline, our deferred tax asset would be reduced, resulting in a charge against earnings. In addition, a reduction in tax rates or change in laws could adversely affect the Company’s ability to realize the benefits of its net operating loss carryovers and alternative minimum tax credits. In addition, a reduction in tax rates could increase the level of statutory reserves the Company must hold which could adversely affect statutory surplus.
In addition, the Company’s tax return reflects certain items such as tax-exempt bond interest, dividends received deductions, tax credits, and insurance reserve deductions. There is an increasing risk that, in the context of deficit reduction or overall tax reform, federal and/or state tax legislation could modify or eliminate these items, impacting the Company, its investments, investment strategies, and/or its policyholders. In the context of deficit reduction or overall tax reform, federal and/or state tax legislation could modify or eliminate provisions of current tax law that are beneficial to the Company, including tax-exempt bond interest, dividends received deduction, tax credits, and insurance reserve deductions, or could impose new taxes such as on goods or services purchased overseas.
Moreover, many of the life and annuity products that the Company previously sold benefit from one or more forms of tax-favored status under current federal and state income tax
Part I - Item 1A. Risk Factors
regimes. For example, the Company previously sold annuity contracts that allowed policyholders to defer the recognition of taxable income earned within the contract. Because the Company no longer sells these products, changes in the future taxation of life insurance and/or annuity contracts will not adversely impact future sales. If, however, the tax treatment of earnings accrued inside an annuity contract changed prospectively, and the tax favored status of existing contracts were grandfathered, holders of existing contracts would be less likely to surrender, which would make running off our existing life and annuity business more difficult.
Regulatory requirements could delay, deter or prevent a takeover attempt that shareholders might consider in their best interests.
Before a person can acquire control of a U.S. insurance company, prior written approval must be obtained from the insurance commissioner of the state where the domestic insurer is domiciled. Prior to granting approval of an application to acquire control of a domestic insurer, the state insurance commissioner will consider such factors as the financial strength of the applicant, the acquirer's plans for the future operations of the domestic insurer, and any such additional information as the insurance commissioner may deem necessary or appropriate for the protection of policyholders or in the public interest. Generally, state statutes provide that control over a domestic insurer is presumed to exist if any person, directly or indirectly, owns, controls, holds with the power to vote, or holds proxies representing 10 percent or more of the voting securities of the domestic insurer or its parent company. Because a person acquiring 10 percent or more of our common stock would indirectly control the same percentage of the stock of our U.S. insurance subsidiaries, the insurance change of control laws of various U.S. jurisdictions would likely apply to such a transaction. Other laws or required approvals pertaining to one or more of our
existing subsidiaries, or a future subsidiary, may contain similar or additional restrictions on the acquisition of control of the Company. These laws may discourage potential acquisition proposals and may delay, deter, or prevent a change of control, including transactions that our Board of Directors and some or all of our shareholders might consider to be desirable.
Changes in accounting principles and financial reporting requirements could adversely affect our results of operations or financial condition.
As an SEC registrant, we are currently required to prepare our financial statements in accordance with U.S. GAAP, as promulgated by the Financial Accounting Standards Board ("FASB"). Accordingly, we are required to adopt new guidance or interpretations which may have a material effect on our results of operations and financial condition that is either unexpected or has a greater impact than expected. For a description of changes in accounting standards that are currently pending and, if known, our estimates of their expected impact, see Note 1 of the consolidated financial statements.
The FASB is working on several projects that could result in significant changes in GAAP, including how we account for our long-duration insurance contracts, which primarily relate to our life and annuity products. In particular, liabilities for life-contingent fixed annuities would be discounted using current high-quality fixed-income instrument yields rather than using historical yields, likely resulting in greater volatility in other comprehensive income. As a result, the adoption of these future accounting standards relating to insurance contracts could have a material adverse effect on our financial condition.
Item 2. PROPERTIES
As of December 31, 2016, The Hartford owned building space of approximately 1.8 million square feet which comprised its Hartford, Connecticut location and other properties within the greater Hartford, Connecticut area. In addition, as of December 31, 2016, The Hartford leased approximately 1.6 million square feet, throughout the United States of America, and
approximately 34 thousand square feet, in other countries. All of the properties owned or leased are used by one or more of all six reporting segments, depending on the location. For more information on reporting segments, see Part I, Item 1, Business — Reporting Segments. The Company believes its properties and facilities are suitable and adequate for current operations.
Item 3. LEGAL PROCEEDINGS
LITIGATION
The Hartford is involved in claims litigation arising in the ordinary course of business, both as a liability insurer defending or providing indemnity for third-party claims brought against insureds and as an insurer defending coverage claims brought against it. The Hartford accounts for such activity through the establishment of unpaid loss and loss adjustment expense reserves. Subject to the uncertainties related to The Hartford's asbestos and environmental claims discussed in Note 14 - Commitment and Contingencies of the Notes to Consolidated Financial Statements, management expects that the ultimate liability, if any, with respect to such ordinary-course claims litigation, after consideration of provisions made for potential
losses and costs of defense, will not be material to the consolidated financial condition, results of operations or cash flows of The Hartford.
The Hartford is also involved in other kinds of legal actions, some of which assert claims for substantial amounts. These actions include, among others, and in addition to the matters in the following description, putative state and federal class actions seeking certification of a state or national class. Such putative class actions have alleged, for example, underpayment of claims or improper underwriting practices in connection with various kinds of insurance policies, such as personal and commercial automobile, property, disability, life and inland marine. The Hartford also is involved in individual actions in which punitive damages are sought, such as claims alleging bad faith in the
Item 3. Legal Proceedings
handling of insurance claims or other allegedly unfair improper business practices. Like many other insurers, The Hartford also has been joined in actions by asbestos plaintiffs asserting, among other things, that insurers had a duty to protect the public from the dangers of asbestos and that insurers committed unfair trade practices by asserting defenses on behalf of their policyholders in the underlying asbestos cases. Management expects that the ultimate liability, if any, with respect to such lawsuits, after consideration of provisions made for estimated losses, will not be material to the consolidated financial condition of The Hartford. Nonetheless, given the large or indeterminate amounts sought in certain of these actions, and the inherent unpredictability of litigation, the outcome in certain matters could, from time to time, have a material adverse effect on the Company's results of operations or cash flows in particular quarterly or annual periods.
In addition to the inherent difficulty of predicting litigation outcomes, the Mutual Funds Litigation identified below purports to seek substantial damages for unsubstantiated conduct spanning a multi-year period based on novel applications of complex legal theories. The alleged damages are not quantified or factually supported in the complaint, and, in any event, the Company's experience shows that demands for damages often bear little relation to a reasonable estimate of potential loss. The application of the legal standard identified by the court for assessing the potentially available damages, as described below, is inherently unpredictable, and no legal precedent has been identified that would aid in determining a reasonable estimate of potential loss. Accordingly, management cannot reasonably estimate the possible loss or range of loss, if any.
Mutual Funds Litigation
In February 2011, a derivative action was brought on behalf of six Hartford retail mutual funds in the United States District Court for the District of New Jersey, alleging that Hartford Investment Financial Services, LLC (“HIFSCO”), an indirect subsidiary of the Company, received excessive advisory and distribution fees in violation of its statutory fiduciary duty under Section 36(b) of the
Investment Company Act of 1940. HIFSCO moved to dismiss and, in September 2011, the motion was granted in part and denied in part, with leave to amend the complaint. In November 2011, plaintiffs filed an amended complaint on behalf of The Hartford Global Health Fund, The Hartford Conservative Allocation Fund, The Hartford Growth Opportunities Fund, The Hartford Inflation Plus Fund, The Hartford Advisors Fund, and The Hartford Capital Appreciation Fund. Plaintiffs seek to rescind the investment management agreements and distribution plans between HIFSCO and these funds and to recover the total fees charged thereunder or, in the alternative, to recover any improper compensation HIFSCO received, in addition to lost earnings. HIFSCO filed a partial motion to dismiss the amended complaint and, in December 2012, the court dismissed without prejudice the claims regarding distribution fees and denied the motion with respect to the advisory fees claims. In March 2014, the plaintiffs filed a new complaint that, among other things, added as new plaintiffs The Hartford Floating Rate Fund and The Hartford Small Company Fund and named as a defendant Hartford Funds Management Company, LLC (“HFMC”), an indirect subsidiary of the Company which assumed the role as advisor to the funds as of January 2013. In June 2015, HFMC and HIFSCO moved for summary judgment, and plaintiffs crossed-moved for partial summary judgment with respect to The Hartford Capital Appreciation Fund. In March 2016, the court, in large part, denied summary judgment for all parties. The court granted judgment for HFMC and HIFSCO with respect to all claims made by The Hartford Small Company Fund and certain claims made by The Hartford Floating Rate Fund. The court further ruled that the appropriate measure of damages on the surviving claims is the difference, if any, between the actual advisory fees paid through trial and those that could have been paid under the applicable legal standard. A bench trial on the issue of liability was held in November 2016, and a decision is expected in 2017.
Item 5. MARKET FOR THE HARTFORD’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
The Hartford’s common stock is traded on the New York Stock Exchange (“NYSE”) under the trading symbol “HIG”.
Item 5. Market for the Hartford's Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
High and Low Closing Prices and Quarterly Dividends Declared per Share for the Common Stock of The Hartford
| 1st Qtr. | 2nd Qtr. | 3rd Qtr. | 4th Qtr. | |||||||||
| 2016 | ||||||||||||
| Common Stock Price | ||||||||||||
| High | $ | 46.31 | $ | 46.80 | $ | 44.77 | $ | 48.58 | ||||
| Low | $ | 37.63 | $ | 40.98 | $ | 39.85 | $ | 42.50 | ||||
| Dividends Declared | $ | 0.21 | $ | 0.21 | $ | 0.21 | $ | 0.23 | ||||
| 2015 | ||||||||||||
| Common Stock Price | ||||||||||||
| High | $ | 43.10 | $ | 42.86 | $ | 49.53 | $ | 49.24 | ||||
| Low | $ | 38.90 | $ | 40.77 | $ | 43.03 | $ | 42.11 | ||||
| Dividends Declared | $ | 0.18 | $ | 0.18 | $ | 0.21 | $ | 0.21 |
On February 23, 2017, The Hartford’s Board of Directors declared a quarterly dividend of $0.23 per common share payable on April 3, 2017 to common shareholders of record as of March 6, 2017. As of February 22, 2017, the Company had approximately 12,692 registered holders of record of the Company's common stock. A substantially greater number of holders of our common stock are “street name” holders or beneficial holders, whose shares are held of record by banks, brokers and other financial institutions. The closing price of The Hartford’s common stock on the NYSE on February 22, 2017 was $48.69.
On June 14, 2016, the Company’s Chief Executive Officer certified to the NYSE that he is not aware of any violation by the Company of NYSE corporate governance listing standards, as
required by Section 303A.12(a) of the NYSE’s Listed Company Manual.
There are also various legal and regulatory limitations governing the extent to which The Hartford’s insurance subsidiaries may extend credit, pay dividends or otherwise provide funds to The Hartford Financial Services Group, Inc. as discussed in the Liquidity Requirements and Sources o f Capital section of Part II, Item 7, MD&A — Capital Resources and Liquidity.
For information related to securities authorized for issuance under equity compensation plans, see Part III, Item 12, Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
Repurchases of Common Stock by the Issuer for the Three Months Ended December 31, 2016
| Period | Total Number of Shares Purchased | Average Price Paid per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | Approximate Dollar Value of Shares that May Yet Be Purchased Under the Plans or Programs [1] | |||||
| (in millions) | |||||||||
| October 1, 2016 – October 31, 2016 | 2,300,136 | $ | 43.41 | 2,300,136 | $ | 1,480 | |||
| November 1, 2016 – November 30, 2016 | 2,155,600 | $ | 46.26 | 2,155,600 | $ | 1,380 | |||
| December 1, 2016 – December 31, 2016 | 1,674,947 | $ | 47.98 | 1,674,947 | $ | 1,300 | |||
| Total | 6,130,683 | $ | 45.66 | 6,130,683 |
| [1] | In October 2016, the Board of Directors authorized a new equity repurchase plan for $1.3 billion for the period commencing October 31, 2016 through December 31, 2017. The Company’s repurchase authorization permits purchases of common stock, as well as warrants or other derivative securities. Repurchases may be made in the open market, through derivative, accelerated share repurchase and other privately negotiated transactions, and through plans designed to comply with Rule 10b5-1(c) under the Securities Exchange Act of 1934, as amended. The timing of any future repurchases will be dependent upon several factors, including the market price of the Company’s securities, the Company’s capital position, consideration of the effect of any repurchases on the Company’s financial strength or credit ratings, and other corporate considerations. The repurchase program may be modified, extended or terminated by the Board of Directors at any time. |
Part II - Item 5. Market for the Hartford's Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
Total Return to Shareholders
The following tables present The Hartford’s annual return percentage and five-year total return on its common stock including reinvestment of dividends in comparison to the S&P 500 and the S&P Insurance Composite Index.
| Annual Return Percentage | ||||||||||
| For the years ended | ||||||||||
| Company/Index | 2012 | 2013 | 2014 | 2015 | 2016 | |||||
| The Hartford Financial Services Group, Inc. | 41.01 | % | 64.12 | % | 17.13 | % | 6.12 | % | 11.76 | % |
| S&P 500 Index | 16.00 | % | 32.39 | % | 13.69 | % | 1.38 | % | 11.96 | % |
| S&P Insurance Composite Index | 19.09 | % | 46.71 | % | 8.29 | % | 2.33 | % | 17.58 | % |
| Cumulative Five-Year Total Return | |||||||||||||
| Base | |||||||||||||
| Period | For the years ended | ||||||||||||
| Company/Index | 2011 | 2012 | 2013 | 2014 | 2015 | 2016 | |||||||
| The Hartford Financial Services Group, Inc. | $ | 100 | 141.01 | 231.43 | 271.08 | 287.67 | 321.50 | ||||||
| S&P 500 Index | $ | 100 | 116.00 | 153.57 | 174.60 | 177.01 | 198.18 | ||||||
| S&P Insurance Composite Index | $ | 100 | 119.09 | 174.72 | 189.20 | 193.60 | 227.64 |

Part II - Item 6. Selected Financial Data
Item 6. SELECTED FINANCIAL DATA
The following table sets forth the Company's selected consolidated financial data at the dates and for the periods indicated below. The selected financial data should be read in conjunction with Management’s Discussion and Analysis of
Financial Condition and Results of Operations ("MD&A") presented in Item 7 and the Company's Consolidated Financial Statements and the related Notes beginning on page F-1.
| in millions, except per share data | 2016 | 2015 | 2014 | 2013 | 2012 | ||||||||||
| Income Statement Data | |||||||||||||||
| Total revenues | $ | 18,300 | $ | 18,377 | $ | 18,614 | $ | 20,673 | $ | 22,086 | |||||
| Income (loss) from continuing operations before income taxes | $ | 804 | $ | 1,978 | $ | 1,699 | $ | 1,471 | $ | (89 | ) | ||||
| Income from continuing operations, net of tax | $ | 896 | $ | 1,673 | $ | 1,349 | $ | 1,225 | $ | 220 | |||||
| Income (loss) from discontinued operations, net of tax | $ | — | $ | 9 | $ | (551 | ) | $ | (1,049 | ) | $ | (258 | ) | ||
| Net income (loss) | $ | 896 | $ | 1,682 | $ | 798 | $ | 176 | $ | (38 | ) | ||||
| Balance Sheet Data | |||||||||||||||
| Total assets | $ | 223,432 | $ | 228,348 | $ | 245,013 | $ | 277,884 | $ | 298,513 | |||||
| Short-term debt | $ | 416 | $ | 275 | $ | 456 | $ | 438 | $ | 320 | |||||
| Total debt (including capital lease obligations) | $ | 5,052 | $ | 5,359 | $ | 6,109 | $ | 6,544 | $ | 7,126 | |||||
| Preferred stock | $ | — | $ | — | $ | — | $ | — | $ | 556 | |||||
| Total stockholders’ equity | $ | 16,903 | $ | 17,642 | $ | 18,720 | $ | 18,905 | $ | 22,447 | |||||
| Net income (loss) per common share | |||||||||||||||
| Basic | $ | 2.31 | $ | 4.05 | $ | 1.81 | $ | 0.37 | $ | (0.18 | ) | ||||
| Diluted | $ | 2.27 | $ | 3.96 | $ | 1.73 | $ | 0.36 | $ | (0.17 | ) | ||||
| Cash dividends declared per common share | $ | 0.86 | $ | 0.78 | $ | 0.66 | $ | 0.50 | $ | 0.40 |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
(Dollar amounts in millions, except for per share data, unless otherwise stated)
The Hartford provides projections and other forward-looking information in the following discussions, which contain many forward-looking statements, particularly relating to the Company’s future financial performance. These forward-looking statements are estimates based on information currently available to the Company, are made pursuant to the safe harbor provisions of the Private Securities Litigation Reform Act of 1995 and are subject to the cautionary statements set forth on pages 4 and 5 of this Form 10-K. Actual results are likely to differ, and in the past have differed, materially from those forecast by the Company, depending on the outcome of various factors, including, but not limited to, those set forth in each following discussion and in Part I, Item 1A, Risk Factors, and those identified from time to time in our other filings with the Securities and Exchange Commission. The Hartford undertakes no obligation to publicly update any forward-looking statements, whether as a result of new information, future developments or otherwise.
On July 29, 2016, the Company completed the acquisition of Maxum Specialty Insurance Group and Lattice Strategies LLC. Maxum's revenue and earnings since the acquisition date are included in the operating results of the Company's Commercial Lines reporting segment. Lattice's revenue and earnings since the acquisition date are included in the operating results of the Company's Mutual Funds reporting segment.
On July 26, 2016, the Company announced it had entered into an agreement to sell its U.K. property and casualty run-off subsidiaries. The operating results of the Company's U.K. property and casualty run-off subsidiaries are included in the P&C Other Operations reporting segment. For discussion of these transactions, see Note 2 - Business Acquisitions, Dispositions and Discontinued Operations of Notes to Consolidated Financial Statements.
On June 30, 2014, the Company completed the sale of all of the issued and outstanding equity of Hartford Life Insurance KK, a Japanese company.
The Hartford defines increases or decreases greater than or equal to 200% as “NM” or not meaningful.
Index
| Description | Page |
| Key Performance Measures and Ratios | 33 |
| The Hartford's Operations | 36 |
| Consolidated Results of Operations | 40 |
| Investment Results | 42 |
| Critical Accounting Estimates | 44 |
| Commercial Lines | 67 |
| Personal Lines | 71 |
| Property & Casualty Other Operations | 75 |
| Group Benefits | 76 |
| Mutual Funds | 79 |
| Talcott Resolution | 81 |
| Corporate | 84 |
| Enterprise Risk Management | 85 |
| Capital Resources and Liquidity | 104 |
| Impact of New Accounting Standards | 113 |
KEY PERFORMANCE MEASURES AND RATIOS
The Company considers the measures and ratios in the following discussion to be key performance indicators for its businesses. Management believes that these ratios and measures are useful in understanding the underlying trends in The Hartford’s businesses. However, these key performance indicators should only be used in conjunction with, and not in lieu of, the results presented in the segment discussions that follow in this MD&A. These ratios and measures may not be comparable to other performance measures used by the Company’s competitors.
Definitions of Non-GAAP and Other Measures and Ratios
Account Value- includes policyholders’ balances for investment and insurance contracts and reserves for certain future policy benefits for insurance contracts. Account value is a measure used by the Company because a significant portion of the Company’s fee income is based upon the level of account value. These revenues increase or decrease with a rise or fall in assets under management whether caused by changes in the market or through net flows.
Assets Under Management (“AUM”)- include account values, mutual fund and ETP assets. AUM is a measure used by the Company because a significant portion of the
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Company’s revenues are based upon asset values. These revenues increase or decrease with a rise or fall in AUM whether caused by changes in the market or through net flows.
Book Value per Diluted Share- a U.S. GAAP financial measure that represents a per share assessment of the value of a company's equity. It is calculated by dividing (a) common stockholders' equity by (b) common shares outstanding and dilutive potential common shares. The Company provides book value per diluted share to enable investors to assess the value of the C
Showing the first 8K of 264K characters. Open the full section
Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
establishing, maintaining and communicating the framework, principles and guidelines of the Company's operational risk management program. Operational risk mitigation strategies include the following:
| • | Establishing policies and monitoring risk tolerances and exceptions; |
| • | Conducting business risk assessments and implementing action plans where necessary; |
| • | Validating existing crisis management protocols; |
| • | Identifying and monitoring emerging risks; and |
| • | Purchasing insurance coverage. |
Financial Risk
Financial risks include direct and indirect risks to the Company's financial objectives coming from events that impact market conditions or prices. Some events may cause correlated movement in multiple risk factors. The primary sources of financial risks are the Company's general account assets and the liabilities and the guarantees which the company has written over various liability products, particularly its fixed and variable annuity guarantees. Consistent with its risk appetite, the Company establishes financial risk limits to control potential loss on a U.S. GAAP, statutory, and economic basis. Exposures are actively monitored, and mitigated where appropriate. The Company uses various risk management strategies, including reinsurance and over-the-counter and exchange traded derivatives with counterparties meeting the appropriate regulatory and due diligence requirements. Derivatives are utilized to achieve one of four Company-approved objectives: hedging risk arising from interest rate, equity market, commodity market, credit spread and issuer default, price or currency exchange rate risk or volatility; managing liquidity; controlling transaction costs; or entering into synthetic replication transactions. Derivative activities are monitored and evaluated by the Company’s compliance and risk management teams and reviewed by senior management.
The Company identifies different categories of financial risk, including liquidity, credit, interest rate, equity and foreign currency exchange, as described below.
Liquidity Risk
Liquidity risk is the risk to current or prospective earnings or capital arising from the Company's inability or perceived inability to meet its contractual funding obligations as they come due.
Sources of Liquidity Risk Sources of liquidity risk include funding risk, company-specific liquidity risk and market liquidity risk resulting from differences in the amount and timing of sources and uses of cash as well as company-specific and general market conditions. Stressed market conditions may impact the ability to sell assets or otherwise transact business and may result in a significant loss in value.
Impact Inadequate capital resources and liquidity could negatively affect the Company’s overall financial strength and its ability to generate cash flows from its businesses, borrow funds at competitive rates, and raise new capital to meet operating and growth needs.
Management The Company has defined ongoing monitoring and reporting requirements to assess liquidity across the enterprise under both current and stressed market conditions. The Company measures and manages liquidity risk exposures and funding needs within prescribed limits across legal entities, taking into account legal, regulatory and operational limitations to the transferability of liquidity. The Company also monitors internal and external conditions, and identifies material risk changes and emerging risks that may impact liquidity. The Company's CFO has primary responsibility for liquidity risk.
For further discussion on liquidity see the section on Capital Resources and Liquidity.
Credit Risk
Credit risk is the risk to earnings or capital due to uncertainty of an obligor’s or counterparty’s ability or willingness to meet its obligations in accordance with contractually agreed upon terms. Credit risk is comprised of three major factors: the risk of change in credit quality, or credit migration risk; the risk of default; and the risk of a change in value due to changes in credit spread.
Sources of Credit Risk The majority of the Company’s credit risk is concentrated in its investment holdings, but it is also present in the Company’s reinsurance and insurance portfolios.
Impact A decline in creditworthiness is typically associated with an increase in an investment’s credit spread, potentially resulting in an increase in other-than-temporary impairments and an increased probability of a realized loss upon sale. Premiums receivable and reinsurance recoverables are also subject to credit risk based on the counterparty’s unwillingness or inability to pay.
Management The objective of the Company’s enterprise credit risk management strategy is to identify, quantify, and manage credit risk on an aggregate portfolio basis and to limit potential losses in accordance with an established credit risk management policy. The Company primarily manages its credit risk by holding a diversified mix of investment grade issuers and counterparties across its investment, reinsurance, and insurance portfolios. Potential losses are also limited within portfolios by diversifying across geographic regions, asset types, and sectors.
The Company manages credit risk on an on-going basis through the use of various processes and analyses. Both the investment and reinsurance areas have formulated procedures for counterparty approvals and authorizations, which establish minimum levels of creditworthiness and financial stability. Credits considered for investment are subjected to underwriting reviews. Within the investment portfolio, private securities are subject to committee review for approval. Mitigation strategies vary across the three sources of credit risk, but may include:
| • | Investing in a portfolio of high-quality and diverse securities; |
| • | Selling investments subject to credit risk; |
| • | Hedging through use of single name or basket credit default swaps; |
| • | Clearing transactions through central clearing houses that require daily variation margin; |
| • | Entering into contracts only with strong creditworthy institutions |
| • | Requiring collateral; and |
| • | Non-renewing policies/contracts or reinsurance treaties. |
The Company has developed credit exposure thresholds which are based upon counterparty ratings. Aggregate counterparty credit quality and exposure are monitored on a daily basis utilizing an enterprise-wide credit exposure information system that contains data on issuers, ratings, exposures, and credit limits. Exposures are tracked on a current and potential basis and aggregated by ultimate parent of the counterparty across investments, reinsurance receivables, insurance products with credit risk, and derivatives.
As of December 31, 2016, the Company had no investment exposure to any credit concentration risk of a single issuer or counterparty greater than 10% of the Company's stockholders' equity, other than the U.S. government and certain U.S. government securities. For further discussion of concentration of credit risk in the investment portfolio, see the Concentration of Credit Risk section in Note 6 - Investments of Notes to Consolidated Financial Statements.
Assets and Liabilities Subject to Credit Risk
Investments Essentially all of the Company's invested assets are subject to credit risk. Credit related impairments on investments were $43 and $29, in 2016 and 2015, respectively. (See the Enterprise Risk Management section of the MD&A under “Other-Than-Temporary Impairments.”)
Reinsurance recoverables Reinsurance recoverables, net of an allowance for uncollectible reinsurance, were $23,311 and $23,189, as of December 31, 2016 and 2015,
Showing the first 8K of 149K characters. Open the full section
Item 9A. Controls and Procedures
Report of Independent Registered Public Accounting Firm
To the Board of Directors and Stockholders of
The Hartford Financial Services Group, Inc.
Hartford, Connecticut
We have audited the internal control over financial reporting of The Hartford Financial Services Group, Inc. and its subsidiaries (collectively, the "Company") as of December 31, 2016, based on the criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission. The Company's management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting, included in the accompanying Item 9A. Controls and Procedures. Our responsibility is to express an opinion on the Company's internal control over financial reporting based on our audit.
We conducted our audit in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
A company's internal control over financial reporting is a process designed by, or under the supervision of, the company's principal executive and principal financial officers, or persons performing similar functions, and effected by the company's board of directors, management, and other personnel to provide reasonable assurance regarding the reliability of financial reporting and the preparation of consolidated financial statements for external purposes in accordance with generally accepted accounting principles. A company's internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of consolidated financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company's assets that could have a material effect on the consolidated financial statements.
Because of the inherent limitations of internal control over financial reporting, including the possibility of collusion or improper management override of controls, material misstatements due to error or fraud may not be prevented or detected on a timely basis. Also, projections of any evaluation of the effectiveness of the internal control over financial reporting to future periods are subject to the risk that the controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
In our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2016, based on the criteria established in Internal Control-Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), the consolidated financial statements and financial statement schedules as of and for the year ended December 31, 2016 of the Company and our report, dated February 24, 2017, expressed an unqualified opinion on those consolidated financial statements and financial statement schedules.
/s/ DELOITTE & TOUCHE LLP
Hartford, Connecticut
February 24, 2017
Part III - Item 10. Directors, and Executive Officers and Corporate Governance of the Hartford
Item 10. DIRECTORS, AND EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE OF THE HARTFORD
Certain of the information called for by Item 10 will be set forth in the definitive proxy statement for the 2017 annual meeting of shareholders (the “Proxy Statement”) to be filed by The Hartford with the Securities and Exchange Commission within 120 days after the end of the fiscal year covered by this Form 10-K under the captions and subcaptions “Board and Governance Matters”, “Director Nominees" and "Section (16)(a) Beneficial Ownership Reporting Compliance" and is incorporated herein by reference.
The Company has adopted a Code of Ethics and Business Conduct, which is applicable to all employees of the Company, including the principal executive officer, the principal financial officer and the principal accounting officer. The Code of Ethics and Business Conduct is available on the investor relations section of the Company’s website at: http://ir.thehartford.com.
Any waiver of, or material amendment to, the Code of Ethics and Business Conduct will be posted promptly to our web site in accordance with applicable NYSE and SEC rules.
Executive Officers of The Hartford
Information about the executive officers of The Hartford who are also nominees for election as directors will be set forth in The Hartford’s Proxy Statement. Set forth below is information about the other executive officers of the Company as of February 15, 2017:
| Name | Age | Position with The Hartford and Business Experience For the Past Five Years |
| Beth A. Bombara | 49 | Executive Vice President and Chief Financial Officer (July 2014-present); President of Talcott Resolution (July 2012-July 2014); Senior Vice President and Controller (June 2007-July 2012) |
| William A. Bloom | 53 | Executive Vice President of Operations and Technology (August 2014 - present); President of Global Client Services, EXL (July 2010-July 2014) |
| Kathy Bromage | 59 | Chief Marketing and Communications Officer (June 2015-present); Senior Vice President of Strategy and Marketing, Small Commercial and Senior Vice President of Brand Marketing (July 2012-June 2015); Senior Vice President, eBusiness (October 2010-June 2012) |
| James E. Davey | 52 | Executive Vice President and President of The Hartford Mutual Funds (2010-present) |
| Doug Elliot | 56 | President (July 2014-present); Executive Vice President and President of Commercial Lines (April 2011-July 2014); President and Chief Executive Officer, HSB Group (July 2007-March 2011) |
| Martha Gervasi | 55 | Executive Vice President, Human Resources (May 2012-present); Senior Vice President, Human Resources (November 2010-May 2012) |
| Brion Johnson | 57 | President of Talcott Resolution (July 2014-present); Executive Vice President, Chief Investment Officer (May 2012-Present); Chief Financial Officer, Hartford Investment Management Company [1] (October 2011-May 2012) |
| Scott R. Lewis | 54 | Senior Vice President and Controller (May 2013-present); Senior Vice President and Chief Financial Officer, Personal Lines (2009-May 2013) |
| David C. Robinson | 51 | Executive Vice President and General Counsel (June 2015-present); Senior Vice President and Director of Commercial Markets Law (August 2014-May 2015); Senior Vice President and Head of Enterprise Transformation, Strategy and Corporate Development (April 2012-August 2014); Senior Vice President and Director of Corporate Law (September 2010-April 2012) |
| Robert Rupp | 64 | Executive Vice President and Chief Risk Officer (October 2011-present); Executive Vice President, Head of Enterprise-Wide Market Risk, BONY Mellon (September 2008-October 2011) |
| John Wilcox | 51 | Chief Strategy and Ventures Officer (September 2016-present); President and Chief Operating Officer, Risk Strategies Company (June 2012-September 2016); Senior Vice President of Strategic Planning, The Hartford (January 2011-June 2012) |
| [1] | Denotes a subsidiary of The Hartford. |
Part III - Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
Certain of the information called for by Item 12 will be set forth in the Proxy Statement under the caption “Information on Stock Ownership” and is incorporated herein by reference.
Equity Compensation Plan Information
The following table provides information as of December 31, 2016 about the securities authorized for issuance under the Company’s equity compensation plans. The Company maintains The Hartford 2005 Incentive Stock Plan (the “2005 Stock Plan”), The Hartford 2010 Incentive Stock Plan (the “2010 Stock Plan”), The Hartford 2014 Incentive Stock Plan (the "2014 Stock Plan") (collectively the "Stock Plans") and The Hartford Employee Stock Purchase Plan (the “ESPP”). On May 21, 2014, the shareholders of
the Company approved the 2014 Stock Plan, which superseded the earlier plans. Pursuant to the provisions of the 2014 Stock Plan, no additional shares may be issued from the 2010 Stock Plan. To the extent that any awards under the 2005 Stock Plan and the 2010 Stock Plan are forfeited, terminated, surrendered, exchanged, expire unexercised or are settled in cash in lieu of stock (including to effect tax withholding) or for the issuance of a lesser number of shares than the number of shares subject to the award, the shares subject to such awards (or the relevant portion thereof) shall be available for award under the 2014 Stock Plan and such shares shall be added to the total number of shares available under the 2014 Stock Plan. For a description of the 2014 Stock Plan and the ESPP, see Note 19 - Stock Compensation Plans of Notes to Consolidated Financial Statements.
| (a) | (b) | (c) | |||||
| Number of Securities to be Issued Upon Exercise of Outstanding Options, Warrants and Rights [1] | Weighted-average Exercise Price of Outstanding Options, Warrants and Rights [2] | Number of Securities Remaining Available for Future Issuance Under Equity Compensation Plans (Excluding Securities Reflected in Column (a)) [3] | |||||
| Equity compensation plans approved by stockholders | 10,452,528 | $ | 34.31 | 13,257,665 | |||
| Equity compensation plans not approved by stockholders | — | — | — | ||||
| Total | 10,452,528 | $ | 34.31 | 13,257,665 |
| [1] | The amount shown in this column includes 4,598,463 outstanding options awarded under the 2005 Stock Plan and the 2010 Stock Plan. The amount shown in this column includes 4,912,781 outstanding restricted stock units and 941,284 outstanding performance shares at 100% of target (which excludes 236,892 shares that vested on December 31, 2016, related to the 2014-2016 performance period) as of December 31, 2016 under the 2010 Stock Plan and the 2014 Stock Plan. The maximum number of performance shares that could be awarded is 1,882,568 (200% of target) if the Company achieved the highest performance level. Under the 2010 and 2014 Stock Plans, no more than 500,000 shares in the aggregate can be earned by an individual employee with respect to restricted stock unit and performance share awards made in a single calendar year. As a result, the number of shares ultimately distributed to an employee with respect to awards made in the same year will be reduced, if necessary, so that the number does not exceed this limit. |
| [2] | The weighted-average exercise price reflects outstanding options and does not reflect outstanding restricted stock units or performance shares because they do not have exercise prices. |
| [3] | Of these shares, 4,722,165 remain available for purchase under the ESPP as of December 31, 2016. 8,535,500 shares remain available for issuance as options, restricted stock units, restricted stock awards or performance shares under the 2014 Stock Plan as of December 31, 2016. |
Part IV. Item 15. Exhibits, Financial Statement Schedules
Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES
| (a) | Documents filed as a part of this report: |
| (1) | Consolidated Financial Statements. See Index to Consolidated Financial Statements and Schedules elsewhere herein. |
| (2) | Consolidated Financial Statement Schedules. See Index to Consolidated Financial Statement and Schedules elsewhere herein. |
| (3) | Exhibits. See Exhibit Index elsewhere herein. |
Part IV. Item 15. Exhibits, Financial Statement Schedules
THE HARTFORD FINANCIAL SERVICES GROUP, INC.
INDEX TO CONSOLIDATED FINANCIAL STATEMENTS AND SCHEDULES
F-1
Item 15. Exhibits, Financial Statement Schedules
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
To the Board of Directors and Stockholders of
The Hartford Financial Services Group, Inc.
Hartford, Connecticut
We have audited the accompanying consolidated balance sheets of The Hartford Financial Services Group, Inc. and its subsidiaries (collectively, the “Company”) as of December 31, 2016 and 2015, and the related consolidated statements of operations, comprehensive income, changes in stockholders’ equity, and cash flows for each of the three years in the period ended December 31, 2016. Our audits also included the consolidated financial statement schedules listed in the Index at Item 15. These consolidated financial statements and financial statement schedules are the responsibility of the Company's management. Our responsibility is to express an opinion on these consolidated financial statements and financial statement schedules based on our audits.
We conducted our audits in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement. An audit includes examining, on a test basis, evidence supporting the amounts and disclosures in the consolidated financial statements. An audit also includes assessing the accounting principles used and significant estimates made by management, as well as evaluating the overall consolidated financial statement presentation. We believe that our audits provide a reasonable basis for our opinion.
In our opinion, such consolidated financial statements present fairly, in all material respects, the financial position of The Hartford Financial Services Group, Inc. and its subsidiaries as of December 31, 2016 and 2015, and the results of their operations and their cash flows for each of the three years in the period ended December 31, 2016, in conformity with accounting principles generally accepted in the United States of America. Also, in our opinion, such consolidated financial statement schedules, when considered in relation to the basic consolidated financial statements taken as a whole, present fairly, in all material respects, the information set forth therein.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), the Company's internal control over financial reporting as of December 31, 2016, based on the criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission and our report dated February 24, 2017 expressed an unqualified opinion on the Company's internal control over financial reporting.
/s/ DELOITTE & TOUCHE LLP
Hartford, Connecticut
February 24, 2017
F-2
THE HARTFORD FINANCIAL SERVICES GROUP, INC.
Consolidated Statements of Operations
| For the years ended December 31, | |||||||||
| (In millions, except for per share data) | 2016 | 2015 | 2014 | ||||||
| Revenues | |||||||||
| Earned premiums | $ | 13,811 | $ | 13,577 | $ | 13,336 | |||
| Fee income | 1,710 | 1,839 | 1,996 | ||||||
| Net investment income | 2,961 | 3,030 | 3,154 | ||||||
| Net realized capital gains (losses): | |||||||||
| Total other-than-temporary impairment (“OTTI”) losses | (64 | ) | (108 | ) | (64 | ) | |||
| OTTI losses recognized in other comprehensive income (loss) (“OCI”) | 8 | 6 | 5 | ||||||
| Net OTTI losses recognized in earnings | (56 | ) | (102 | ) | (59 | ) | |||
| Other net realized capital gains (losses) | (212 | ) | (54 | ) | 75 | ||||
| Total net realized capital gains (losses) | (268 | ) | (156 | ) | 16 | ||||
| Other revenues | 86 | 87 | 112 | ||||||
| Total revenues | 18,300 | 18,377 | 18,614 | ||||||
| Benefits, losses and expenses | |||||||||
| Benefits, losses and loss adjustment expenses | 11,351 | 10,775 | 10,805 | ||||||
| Amortization of deferred policy acquisition costs ("DAC") | 1,523 | 1,502 | 1,729 | ||||||
| Insurance operating costs and other expenses | 3,633 | 3,772 | 4,028 | ||||||
| Loss on extinguishment of debt | — | 21 | — | ||||||
| Loss (gain) on reinsurance transactions | 650 | (28 | ) | (23 | ) | ||||
| Interest expense | 339 | 357 | 376 | ||||||
| Total benefits, losses and expenses | 17,496 | 16,399 | 16,915 | ||||||
| Income from continuing operations before income taxes | 804 | 1,978 | 1,699 | ||||||
| Income tax expense (benefit) | (92 | ) | 305 | 350 | |||||
| Income from continuing operations, net of tax | 896 | 1,673 | 1,349 | ||||||
| Income (loss) from discontinued operations, net of tax | — | 9 | (551 | ) | |||||
| Net income | $ | 896 | $ | 1,682 | $ | 798 | |||
| Income from continuing operations, net of tax, per common share | |||||||||
| Basic | $ | 2.31 | $ | 4.03 | $ | 3.05 | |||
| Diluted | $ | 2.27 | $ | 3.93 | $ | 2.93 | |||
| Net income per common share | |||||||||
| Basic | $ | 2.31 | $ | 4.05 | $ | 1.81 | |||
| Diluted | $ | 2.27 | $ | 3.96 | $ | 1.73 | |||
| Cash dividends declared per common share | $ | 0.86 | $ | 0.78 | $ | 0.66 |
See Notes to Consolidated Financial Statements.
F-3
THE HARTFORD FINANCIAL SERVICES GROUP, INC.
Consolidated Statements of Comprehensive Income (Loss)
| For the years ended December 31, | |||||||||
| (In millions) | 2016 | 2015 | 2014 | ||||||
| Net income | $ | 896 | $ | 1,682 | $ | 798 | |||
| Other comprehensive income (loss): | |||||||||
| Changes in net unrealized gain on securities | (3 | ) | (1,091 | ) | 1,383 | ||||
| Changes in OTTI losses recognized in other comprehensive income | 4 | (2 | ) | 7 | |||||
| Changes in net gain on cash flow hedging instruments | (54 | ) | (20 | ) | 42 | ||||
| Changes in foreign currency translation adjustments | 61 | (47 | ) | (99 | ) | ||||
| Changes in pension and other postretirement plan adjustments | (16 | ) | (97 | ) | (326 | ) | |||
| OCI, net of tax | (8 | ) | (1,257 | ) | 1,007 | ||||
| Comprehensive income | $ | 888 | $ | 425 | $ | 1,805 |
See Notes to Consolidated Financial Statements.
F-4
THE HARTFORD FINANCIAL SERVICES GROUP, INC.
Consolidated Balance Sheets
| As of December 31, | ||||||
| (In millions, except for share and per share data) | 2016 | 2015 | ||||
| Assets | ||||||
| Investments: | ||||||
| Fixed maturities, available-for-sale, at fair value (amortized cost of $53,805 and $56,965) | $ | 56,003 | $ | 59,196 | ||
| Fixed maturities, at fair value using the fair value option (includes variable interest entity assets of $0 and $150) | 293 | 503 | ||||
| Equity securities, available-for-sale, at fair value (cost of $1,020 and $1,135) (includes equity securities, at fair value using the fair value option, of $0 and $282, and variable interest entity assets of $0 and $1) | 1,097 | 1,121 | ||||
| Mortgage loans (net of allowances for loan losses of $19 and $23) | 5,697 | 5,624 | ||||
| Policy loans, at outstanding balance | 1,444 | 1,447 | ||||
| Limited partnerships and other alternative investments (includes variable interest entity assets of $0 and $2) | 2,456 | 2,874 | ||||
| Other inves |
Showing the first 8K of 518K characters. Open the full section