 filings.tools
Item 6. SELECTED FINANCIAL DATA
264K characters. Original on sec.gov · Markdown
Item 6. SELECTED FINANCIAL DATA
The following table sets forth the Company's selected consolidated financial data at the dates and for the periods indicated below. The selected financial data should be read in conjunction with Management’s Discussion and Analysis of
Financial Condition and Results of Operations ("MD&A") presented in Item 7 and the Company's Consolidated Financial Statements and the related Notes beginning on page F-1.
| in millions, except per share data | 2016 | 2015 | 2014 | 2013 | 2012 | ||||||||||
| Income Statement Data | |||||||||||||||
| Total revenues | $ | 18,300 | $ | 18,377 | $ | 18,614 | $ | 20,673 | $ | 22,086 | |||||
| Income (loss) from continuing operations before income taxes | $ | 804 | $ | 1,978 | $ | 1,699 | $ | 1,471 | $ | (89 | ) | ||||
| Income from continuing operations, net of tax | $ | 896 | $ | 1,673 | $ | 1,349 | $ | 1,225 | $ | 220 | |||||
| Income (loss) from discontinued operations, net of tax | $ | — | $ | 9 | $ | (551 | ) | $ | (1,049 | ) | $ | (258 | ) | ||
| Net income (loss) | $ | 896 | $ | 1,682 | $ | 798 | $ | 176 | $ | (38 | ) | ||||
| Balance Sheet Data | |||||||||||||||
| Total assets | $ | 223,432 | $ | 228,348 | $ | 245,013 | $ | 277,884 | $ | 298,513 | |||||
| Short-term debt | $ | 416 | $ | 275 | $ | 456 | $ | 438 | $ | 320 | |||||
| Total debt (including capital lease obligations) | $ | 5,052 | $ | 5,359 | $ | 6,109 | $ | 6,544 | $ | 7,126 | |||||
| Preferred stock | $ | — | $ | — | $ | — | $ | — | $ | 556 | |||||
| Total stockholders’ equity | $ | 16,903 | $ | 17,642 | $ | 18,720 | $ | 18,905 | $ | 22,447 | |||||
| Net income (loss) per common share | |||||||||||||||
| Basic | $ | 2.31 | $ | 4.05 | $ | 1.81 | $ | 0.37 | $ | (0.18 | ) | ||||
| Diluted | $ | 2.27 | $ | 3.96 | $ | 1.73 | $ | 0.36 | $ | (0.17 | ) | ||||
| Cash dividends declared per common share | $ | 0.86 | $ | 0.78 | $ | 0.66 | $ | 0.50 | $ | 0.40 |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
(Dollar amounts in millions, except for per share data, unless otherwise stated)
The Hartford provides projections and other forward-looking information in the following discussions, which contain many forward-looking statements, particularly relating to the Company’s future financial performance. These forward-looking statements are estimates based on information currently available to the Company, are made pursuant to the safe harbor provisions of the Private Securities Litigation Reform Act of 1995 and are subject to the cautionary statements set forth on pages 4 and 5 of this Form 10-K. Actual results are likely to differ, and in the past have differed, materially from those forecast by the Company, depending on the outcome of various factors, including, but not limited to, those set forth in each following discussion and in Part I, Item 1A, Risk Factors, and those identified from time to time in our other filings with the Securities and Exchange Commission. The Hartford undertakes no obligation to publicly update any forward-looking statements, whether as a result of new information, future developments or otherwise.
On July 29, 2016, the Company completed the acquisition of Maxum Specialty Insurance Group and Lattice Strategies LLC. Maxum's revenue and earnings since the acquisition date are included in the operating results of the Company's Commercial Lines reporting segment. Lattice's revenue and earnings since the acquisition date are included in the operating results of the Company's Mutual Funds reporting segment.
On July 26, 2016, the Company announced it had entered into an agreement to sell its U.K. property and casualty run-off subsidiaries. The operating results of the Company's U.K. property and casualty run-off subsidiaries are included in the P&C Other Operations reporting segment. For discussion of these transactions, see Note 2 - Business Acquisitions, Dispositions and Discontinued Operations of Notes to Consolidated Financial Statements.
On June 30, 2014, the Company completed the sale of all of the issued and outstanding equity of Hartford Life Insurance KK, a Japanese company.
The Hartford defines increases or decreases greater than or equal to 200% as “NM” or not meaningful.
Index
| Description | Page |
| Key Performance Measures and Ratios | 33 |
| The Hartford's Operations | 36 |
| Consolidated Results of Operations | 40 |
| Investment Results | 42 |
| Critical Accounting Estimates | 44 |
| Commercial Lines | 67 |
| Personal Lines | 71 |
| Property & Casualty Other Operations | 75 |
| Group Benefits | 76 |
| Mutual Funds | 79 |
| Talcott Resolution | 81 |
| Corporate | 84 |
| Enterprise Risk Management | 85 |
| Capital Resources and Liquidity | 104 |
| Impact of New Accounting Standards | 113 |
KEY PERFORMANCE MEASURES AND RATIOS
The Company considers the measures and ratios in the following discussion to be key performance indicators for its businesses. Management believes that these ratios and measures are useful in understanding the underlying trends in The Hartford’s businesses. However, these key performance indicators should only be used in conjunction with, and not in lieu of, the results presented in the segment discussions that follow in this MD&A. These ratios and measures may not be comparable to other performance measures used by the Company’s competitors.
Definitions of Non-GAAP and Other Measures and Ratios
Account Value- includes policyholders’ balances for investment and insurance contracts and reserves for certain future policy benefits for insurance contracts. Account value is a measure used by the Company because a significant portion of the Company’s fee income is based upon the level of account value. These revenues increase or decrease with a rise or fall in assets under management whether caused by changes in the market or through net flows.
Assets Under Management (“AUM”)- include account values, mutual fund and ETP assets. AUM is a measure used by the Company because a significant portion of the
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Company’s revenues are based upon asset values. These revenues increase or decrease with a rise or fall in AUM whether caused by changes in the market or through net flows.
Book Value per Diluted Share- a U.S. GAAP financial measure that represents a per share assessment of the value of a company's equity. It is calculated by dividing (a) common stockholders' equity by (b) common shares outstanding and dilutive potential common shares. The Company provides book value per diluted share to enable investors to assess the value of the Company’s equity.
Catastrophe Ratio- (a component of the loss and loss adjustment expense ratio) represents the ratio of catastrophe losses incurred in the current calendar year (net of reinsurance) to earned premiums and includes catastrophe losses incurred for both the current and prior accident years. A catastrophe is an event that causes $25 or more in industry insured property losses and affects a significant number of property and casualty policyholders and insurers. The catastrophe ratio includes the effect of catastrophe losses, but does not include the effect of reinstatement premiums.
Combined Ratio- the sum of the loss and loss adjustment expense ratio, the expense ratio and the policyholder dividend ratio. This ratio is a relative measurement that describes the related cost of losses and expenses for every $100 of earned premiums. A combined ratio below 100 demonstrates underwriting profit; a combined ratio above 100 demonstrates underwriting losses.
Core Earnings- a non-GAAP measure, is an important measure of the Company’s operating performance. The Company
believes that core earnings provides investors with a valuable measure of the underlying performance of the Company’s businesses because it reveals trends in our insurance and financial services businesses that may be obscured by including the net effect of certain realized capital gains and losses, certain restructuring and other costs, pension settlements, loss on extinguishment of debt, reinsurance gains and losses from disposal of businesses, income tax benefit from reduction in deferred income tax valuation allowance, discontinued operations, and the impact of Unlocks to DAC, sales inducement assets ("SIA"), and death and other insurance benefit reserve balances. Some realized capital gains and losses are primarily driven by investment decisions and external economic developments, the nature and timing of which are unrelated to the insurance and underwriting aspects of our business. Accordingly, core earnings excludes the effect of all realized gains and losses (net of tax and the effects of DAC) that tend to be highly variable from period to period based on capital market conditions. The Company believes, however, that some realized capital gains and losses are integrally related to our insurance operations, so core earnings includes net realized gains and losses such as net periodic settlements on credit derivatives. These net realized gains and losses are directly related to an offsetting item included in the income statement such as net investment income. Net income (loss) is the most directly comparable U.S. GAAP measure. Core earnings should not be considered as a substitute for net income (loss) and does not reflect the overall profitability of the Company’s business. Therefore, the Company believes that it is useful for investors to evaluate both net income (loss) and core earnings when reviewing the Company’s performance.
Reconciliation of Net Income to Core Earnings
| For the years ended December 31, | |||||||||
| 2016 | 2015 | 2014 | |||||||
| Net income | $ | 896 | $ | 1,682 | $ | 798 | |||
| Less: Unlock benefit (charge), before tax | (2 | ) | 80 | (95 | ) | ||||
| Less: Net realized capital losses including DAC, excluded from core earnings, before tax | (256 | ) | (175 | ) | (29 | ) | |||
| Less: Restructuring and other costs, before tax | — | (20 | ) | (76 | ) | ||||
| Less: Loss on extinguishment of debt, before tax | — | (21 | ) | — | |||||
| Less: (Loss) gain on reinsurance transactions, before tax | (650 | ) | 28 | 23 | |||||
| Less: Pension settlement, before tax | — | — | (128 | ) | |||||
| Less: Income tax benefit [1] | 469 | 131 | 106 | ||||||
| Less: Income (loss) from discontinued operations, after-tax | — | 9 | (551 | ) | |||||
| Core earnings | $ | 1,335 | $ | 1,650 | $ | 1,548 |
[1] Includes income tax benefit on items not included in core earnings and other federal income tax benefits and charges.
Core Earnings Margin- a non-GAAP financial measure that the Company uses to evaluate, and believes is an important measure of, the Group Benefits segment’s operating performance. Core earnings margin is calculated by dividing core earnings by revenues excluding buyouts and realized gains (losses). Net income margin is the most directly comparable U.S. GAAP measure. The Company believes that core earnings margin provides investors with a valuable measure of the performance of Group Benefits because it reveals trends in the business that may be obscured by the effect of buyouts and realized gains (losses).
Core earnings margin should not be considered as a substitute for net income margin and does not reflect the overall profitability of Group Benefits. Therefore, the Company believes it is important for investors to evaluate both core earnings margin and net income margin when reviewing performance. A reconciliation of net income margin to core earnings margin for the years ended December 31, 2016, 2015 and 2014 is set forth in the Results of Operations section within MD&A - Group Benefits.
Expense Ratio- for the underwriting segments of Commercial Lines and Personal Lines is the ratio of underwriting
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
expenses to earned premiums. Underwriting expenses include the amortization of deferred policy acquisition costs and insurance operating costs and expenses, including certain centralized services and bad debt expense. Deferred policy acquisition costs include commissions, taxes, licenses and fees and other underwriting expenses and are amortized over the policy term.
The expense ratio for Group Benefits is expressed as the ratio of insurance operating costs and other expenses and amortization of deferred policy acquisition costs, to premiums and other considerations, excluding buyout premiums.
Fee Income- largely driven from amounts earned as a result of contractually defined percentages of assets under management, including account value of annuities and other products. These fees are generally earned on a daily basis. Therefore, the growth in assets under management either through positive net flows or net sales, or favorable market performance will have a favorable impact on fee income. Conversely, either negative net flows or net sales, or unfavorable market performance will reduce fee income.
Full Surrender Rates- an internal measure of contract surrenders calculated using annualized full surrenders divided by a two-point average of annuity account values. The full surrender rate represents full contract liquidation and excludes partial withdrawals.
Loss and Loss Adjustment Expense Ratio- a measure of the cost of claims incurred in the calendar year divided by earned premium and includes losses incurred for both the current and prior accident years, as well as the costs of mortality and morbidity and other contractholder benefits to policyholders. Among other factors, the loss and loss adjustment expense ratio needed for the Company to achieve its targeted return on equity fluctuates from year to year based on changes in the expected investment yield over the claim settlement period, the timing of expected claim settlements and the targeted returns set by management based on the competitive environment.
The loss and loss adjustment expense ratio is affected by claim frequency and claim severity, particularly for shorter-tail property lines of business, where the emergence of claim frequency and severity is credible and likely indicative of ultimate losses. Claim frequency represents the percentage change in the average number of reported claims per unit of exposure in the current accident year compared to that of the previous accident year. Claim severity represents the percentage change in the estimated average cost per claim in the current accident year compared to that of the previous accident year. As one of the factors used to determine pricing, the Company’s practice is to first make an overall assumption about claim frequency and severity for a given line of business and then, as part of the ratemaking process, adjust the assumption as appropriate for the particular state, product or coverage.
Loss and Loss Adjustment Expense Ratio before Catastrophes and Prior Accident Year Development- a measure of the cost of non-catastrophe claims incurred in the current accident year divided by earned premiums. Management believes that the current accident year loss and loss adjustment expense ratio before catastrophes is a performance measure that is useful to investors as it removes the
impact of volatile and unpredictable catastrophe losses and prior accident year development.
Loss Ratio, excluding Buyouts- utilized for the Group Benefits segment and is expressed as a ratio of benefits, losses and loss adjustment expenses to premiums and other considerations, excluding buyout premiums. Since Group Benefits occasionally buys a block of claims for a stated premium amount, the Company excludes this buyout from the loss ratio used for evaluating the underwriting results of the business as buyouts may distort the loss ratio. Buyout premiums represent takeover of open claim liabilities and other non-recurring premium amounts.
Mutual Fund and Exchange-Traded Product Assets- owned by the shareholders of those products and not by the Company and therefore are not reflected in the Company’s consolidated financial statements. Mutual fund and ETP assets are a measure used by the Company primarily because a significant portion of the Company’s revenues are based upon asset values. These revenues increase or decrease with a rise or fall in AUM whether caused by changes in the market or through net flows.
New Business Written Premium- represents the amount of premiums charged for policies issued to customers who were not insured with the Company in the previous policy term. New business written premium plus renewal policy written premium equals total written premium.
Policies in Force- represent the number of policies with coverage in effect as of the end of the period. The number of policies in force is a growth measure used for Personal Lines and standard commercial lines within Commercial Lines and is affected by both new business growth and policy count retention.
Policy Count Retention- represents the ratio of the number of policies renewed during the period divided by the number of policies available to renew. The number of policies available to renew represents the number of policies, net of any cancellations, written in the previous policy term. Policy count retention is affected by a number of factors, including the percentage of renewal policy quotes accepted and decisions by the Company to non-renew policies because of specific policy underwriting concerns or because of a decision to reduce premium writings in certain classes of business or states. Policy count retention is also affected by advertising and rate actions taken by competitors.
Policyholder Dividend Ratio- the ratio of policyholder dividends to earned premium.
Prior Accident Year Loss and Loss Adjustment Expense Ratio- represents the increase (decrease) in the estimated cost of settling catastrophe and non-catastrophe claims incurred in prior accident years as recorded in the current calendar year divided by earned premiums.
Reinstatement Premiums- represents additional ceded premium paid for the reinstatement of the amount of reinsurance coverage that was reduced as a result of a reinsurance loss payment.
Renewal Earned Price Increase (Decrease)- Written premiums are earned over the policy term, which is six
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
months for certain Personal Lines auto business and twelve months for substantially all of the remainder of the Company’s Property and Casualty business. Since the Company earns premiums over the six to twelve month term of the policies, renewal earned price increases (decreases) lag renewal written price increases (decreases) by six to twelve months.
Renewal Written Price Increase (Decrease)-represents the combined effect of rate changes, amount of insurance and individual risk pricing decisions per unit of exposure since the prior year. The rate component represents the change in rate filings during the period and the amount of insurance represents the change in the value of the rating base, such as model year/vehicle symbol for auto, building replacement costs for property and wage inflation for workers’ compensation. A number of factors affect renewal written price increases (decreases) including expected loss costs as projected by the Company’s pricing actuaries, rate filings approved by state regulators, risk selection decisions made by the Company’s underwriters and marketplace competition. Renewal written price changes reflect the property and casualty insurance market cycle. Prices tend to increase for a particular line of business when insurance carriers have incurred significant losses in that line of business in the recent past or the industry as a whole commits less of its capital to writing exposures in that line of business. Prices tend to decrease when recent loss experience has been favorable or when competition among insurance carriers increases. Renewal written price statistics are subject to change from period to period, based on a number of factors, including changes in actuarial estimates and the effect of subsequent cancellations and non-renewals on rate achieved, and modifications made to better reflect ultimate pricing achieved.
Return on Assets (“ROA”), Core Earnings- a non-GAAP financial measure that the Company uses to evaluate, and believes is an important measure of, certain of the segment’s operating performance. ROA is the most directly comparable U.S. GAAP measure. The Company believes that ROA, core earnings, provides investors with a valuable measure of the performance of certain of the Company’s on-going businesses because it reveals trends in our businesses that may be obscured by the effect of realized gains (losses). ROA, core earnings, should not be considered as a substitute for ROA and does not reflect the overall profitability of our businesses. Therefore, the Company believes it is important for investors to evaluate both ROA, core earnings, and ROA when reviewing the Company’s performance. ROA, core earnings is calculated by dividing core earnings by a daily average AUM. A reconciliation of ROA to ROA, core earnings for the years ended December 31, 2016, 2015 and 2014, is set forth in the Results of Operations section within MD&A - Mutual Funds.
Underlying Combined Ratio- a non-GAAP financial measure, represents the combined ratio before catastrophes and prior accident year development. Combined ratio is the most directly comparable U.S. GAAP measure. The Company believes the underlying combined ratio is an important measure of the trend in profitability since it removes the impact of volatile and unpredictable catastrophe losses and prior accident year loss and loss adjustment expense reserve development. A reconciliation of combined ratio to underlying combined ratio for the years ended December 31, 2016, 2015 and 2014 is set forth in the Results of Operations section within MD&A - Commercial Lines and Personal Lines.
Underwriting Gain (Loss)- The Company's management evaluates profitability of the P&C businesses primarily on the basis of underwriting gain (loss). Underwriting gain (loss) is a before-tax measure that represents earned premiums less incurred losses, loss adjustment expenses and underwriting expenses. Underwriting gain (loss) is influenced significantly by earned premium growth and the adequacy of the Company's pricing. Underwriting profitability over time is also greatly influenced by the Company's pricing and underwriting discipline, which seeks to manage exposure to loss through favorable risk selection and diversification, its management of claims, its use of reinsurance and its ability to manage its expense ratio, which it accomplishes through economies of scale and its management of acquisition costs and other underwriting expenses. Net income (loss) is the most directly comparable GAAP measure. The Company believes that underwriting gain (loss) provides investors with a valuable measure of before-tax profitability derived from underwriting activities, which are managed separately from the Company's investing activities. A reconciliation of underwriting gain (loss) to net income (loss) for Commercial Lines, Personal Lines and Property & Casualty Other Operations is set forth in segment sections of MD&A.
Written and Earned Premiums- Written premium is a statutory accounting financial measure which represents the amount of premiums charged for policies issued, net of reinsurance, during a fiscal period. Earned premium is a U.S. GAAP and statutory measure. Premiums are considered earned and are included in the financial results on a pro rata basis over the policy period. Management believes that written premium is a performance measure that is useful to investors as it reflects current trends in the Company’s sale of property and casualty insurance products. Written and earned premium are recorded net of ceded reinsurance premium.
Traditional life insurance type products, such as those sold by Group Benefits, collect premiums from policyholders in exchange for financial protection for the policyholder from a specified insurable loss, such as death or disability. These premiums together with net investment income earned from the overall investment strategy are used to pay the contractual obligations under these insurance contracts. Two major factors, new sales and persistency, impact premium growth. Sales can increase or decrease in a given year based on a number of factors, including but not limited to, customer demand for the Company’s product offerings, pricing competition, distribution channels and the Company’s reputation and ratings. Persistency refers to the percentage of policies remaining in-force from year-to-year.
THE HARTFORD'S OPERATIONS
Overview
The Hartford conducts business principally in six reporting segments including Commercial Lines, Personal Lines, Property & Casualty Other Operations, Group Benefits, Mutual Funds and Talcott Resolution, as well as a Corporate category. The Hartford includes in its Corporate category the Company’s capital raising activities (including debt financing and related interest expense, purchase accounting adjustments related to goodwill and other expenses not allocated to the reporting segments).
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
The Company derives its revenues principally from: (a) premiums earned for insurance coverage provided to insureds; (b) fee income, including asset management fees, on separate account, mutual fund and ETP assets, mortality and expense fees, as well as cost of insurance charges; (c) net investment income; (d) fees earned for services provided to third parties; and (e) net realized capital gains and losses. Premiums charged for insurance coverage are earned principally on a pro rata basis over the terms of the related policies in-force. Asset management fees and mortality and expense fees are primarily generated from separate account assets and assets under management. Cost of insurance charges are assessed on the net amount at risk for investment-oriented life insurance products.
The profitability of the Company's property and casualty insurance businesses over time is greatly influenced by the Company’s underwriting discipline, which seeks to manage exposure to loss through favorable risk selection and diversification, its management of claims, its use of reinsurance, the size of its in force block, actual mortality and morbidity experience, and its ability to manage its expense ratio which it accomplishes through economies of scale and its management of acquisition costs and other underwriting expenses. Pricing adequacy depends on a number of factors, including the ability to obtain regulatory approval for rate changes, proper evaluation of underwriting risks, the ability to project future loss cost frequency and severity based on historical loss experience adjusted for known trends, the Company’s response to rate actions taken by competitors, its expense levels and expectations about regulatory and legal developments. The Company seeks to price its insurance policies such that insurance premiums and future net investment income earned on premiums received will cover underwriting expenses and the ultimate cost of paying claims reported on the policies and provide for a profit margin. For many of its insurance products, the Company is required to obtain approval for its premium rates from state insurance departments.
The financial results in the Company’s mutual fund, ETP and variable annuity businesses depend largely on the amount of the contract holder or shareholder account value or assets under management on which it earns fees and the level of fees charged. Changes in account value or assets under management are driven by two main factors: net flows, and the market return of the
funds, which is heavily influenced by the return realized in the equity markets. Net flows are comprised of deposits less withdrawals and surrenders, redemptions, death benefits, policy charges and annuitizations of investment type contracts, such as variable annuity contracts. In the mutual fund and ETP businesses, net flows are known as net sales. Net sales are comprised of new sales less redemptions by mutual fund and ETP shareholders. The Company uses the average daily value of the S&P 500 Index as an indicator for evaluating market returns of the underlying account portfolios for the variable annuity business. Financial results of variable products are highly correlated to the growth in account values or assets under management since these products generally earn fee income on a daily basis. Equity market movements could also result in benefits for or charges against deferred acquisition costs.
The profitability of fixed annuities and other “spread-based” products depends largely on the Company’s ability to earn target spreads between earned investment rates on its general account assets and interest credited to policyholders.
The investment return, or yield, on invested assets is an important element of the Company’s earnings since insurance products are priced with the assumption that premiums received can be invested for a period of time before benefits, loss and loss adjustment expenses are paid. Due to the need to maintain sufficient liquidity to satisfy claim obligations, the majority of the Company’s invested assets have been held in available-for-sale securities, including, among other asset classes, equities, corporate bonds, municipal bonds, government debt, short-term debt, mortgage-backed securities and asset-backed securities and collateralized debt obligations.
The primary investment objective for the Company is to maximize economic value, consistent with acceptable risk parameters, including the management of credit risk and interest rate sensitivity of invested assets, while generating sufficient after-tax income to meet policyholder and corporate obligations. Investment strategies are developed based on a variety of factors including business needs, regulatory requirements and tax considerations.
For further information on the Company's reporting segments, refer to Part I, Item 1, Business — Reporting Segments.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Financial Highlights
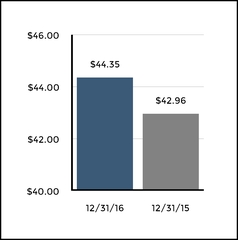
| Net Income | Net Income per Diluted Share | Book Value per Diluted Share |
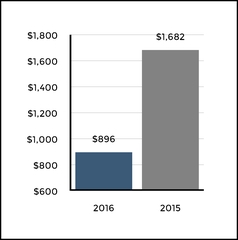

Net income was $896, or $2.31 per basic share and $2.27 per diluted share, down from prior year net income of $1,682, or $4.05 per basic share and $3.96 per diluted share, mostly due to a $423 after-tax loss on a reinsurance transaction covering asbestos and environmental exposures and higher current and prior accident year Personal Lines auto loss costs.
Common share repurchases during 2016 totaled $1,330, or 30.8 million shares and $334 of dividends were paid to shareholders.
Book value per diluted common share increased to $44.35 from $42.96 as of December 31, 2015 as a result of a 7% decrease in common shares outstanding and dilutive potential common shares, partially offset by a 4% decrease in stockholders' equity resulting from share repurchases and common stockholder dividends in excess of net income during 2016.
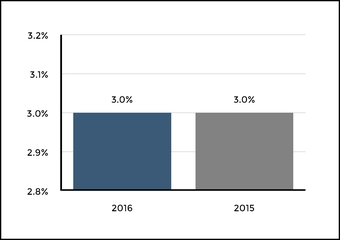
| Net Investment Income | Investment Yield After-tax |
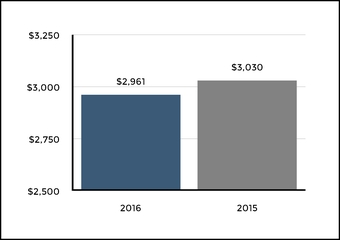
Net investment income decreased 2% to $2,961 compared with the prior year primarily due to lower make-whole payments on fixed maturities and prepayment penalties on mortgage loans, as well as lower asset levels and reinvesting at lower interest rates.
Net realized capital losses increased by $112 compared with the prior year primarily due to increased macro hedge losses on the variable annuity hedge program and a change from net gains to net losses on non-qualifying derivatives, partially offset by an increase in net realized gains on sale of corporate securities, U.S. Treasury securities, municipal bonds and equity securities.
Annualized investment yield, after-tax of 3.0%, was consistent with the prior year.
Net unrealized gains, after-tax, in the investment portfolio decreased by $3 compared with the prior year due primarily to tighter credit spreads, partially offset by higher interest rates and a decline in assets.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
| Written Premiums | Combined Ratio |

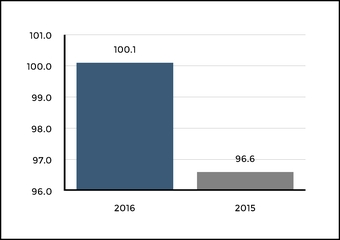
Written premiums decreased slightly over the prior year for Property & Casualty, comprised of 2% growth in Commercial Lines and a 2% decrease in Personal Lines.
Combined ratio increased to 100.1 from 96.6 in the prior year for Property & Casualty, with deterioration principally in Personal Lines.
Catastrophe losses of $416, before tax, increased from catastrophe losses of $332, before tax, in the prior year, largely due to higher losses from wind and hail events.
Prior accident year development was unfavorable by $457, before tax, driven primarily by increases in asbestos and environmental reserves and Personal Lines auto liability reserves compared with unfavorable prior year development of $250, before tax, in the prior year driven primarily by asbestos and environmental reserves.
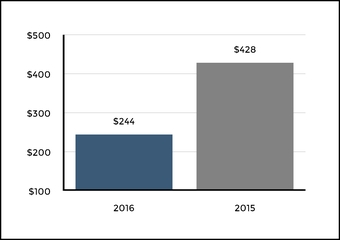
| Group Benefits Core Earnings Margin [1] | Talcott Resolution After-Tax Income From Continuing Operations |

| [1] | A reconciliation of the net income margin to core earnings margin is set forth in the Results of Operations section within MD&A - Group Benefits. |
Core earnings margin increased to 5.7% from 5.6% in the prior year for Group Benefits, primarily due to higher earned premium and fee income, partially offset by higher group life loss severity.
After-tax income from continuing operations was $244 for Talcott Resolution, compared with $428 in the prior year primarily due to lower tax benefits recognized in 2016, a write-off of DAC associated with fixed annuities, lower net investment income and a reinsurance gain on disposition in 2015.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
CONSOLIDATED RESULTS OF OPERATIONS
The Consolidated Results of Operations should be read in conjunction with the Company's Consolidated Financial Statements and the related Notes beginning on page F-1 as well as with the segment operating results sections of MD&A.
| 2016 | 2015 | 2014 | Increase (Decrease) From 2015 to 2016 | Increase (Decrease) From 2014 to 2015 | |||||||
| Earned premiums | $ | 13,811 | $ | 13,577 | $ | 13,336 | $234 | $241 | |||
| Fee income | 1,710 | 1,839 | 1,996 | (129) | (157) | ||||||
| Net investment income | 2,961 | 3,030 | 3,154 | (69) | (124) | ||||||
| Net realized capital gains (losses) | (268 | ) | (156 | ) | 16 | (112) | (172) | ||||
| Other revenues | 86 | 87 | 112 | (1) | (25) | ||||||
| Total revenues | 18,300 | 18,377 | 18,614 | (77) | (237) | ||||||
| Benefits, losses and loss adjustment expenses | 11,351 | 10,775 | 10,805 | 576 | (30) | ||||||
| Amortization of deferred policy acquisition costs | 1,523 | 1,502 | 1,729 | 21 | (227) | ||||||
| Insurance operating costs and other expenses | 3,633 | 3,772 | 4,028 | (139) | (256) | ||||||
| Loss on extinguishment of debt | — | 21 | — | (21) | 21 | ||||||
| Loss (gain) on reinsurance transactions | 650 | (28 | ) | (23 | ) | 678 | (5) | ||||
| Interest expense | 339 | 357 | 376 | (18) | (19) | ||||||
| Total benefits, losses and expenses | 17,496 | 16,399 | 16,915 | 1,097 | (516) | ||||||
| Income from continuing operations before income taxes | 804 | 1,978 | 1,699 | (1,174) | 279 | ||||||
| Income tax expense (benefit) | (92 | ) | 305 | 350 | (397) | (45) | |||||
| Income from continuing operations, net of tax | 896 | 1,673 | 1,349 | (777) | 324 | ||||||
| Income (loss) from discontinued operations, net of tax | — | 9 | (551 | ) | (9) | 560 | |||||
| Net income | $ | 896 | $ | 1,682 | $ | 798 | $(786) | $884 |
Year ended December 31, 2016 compared to the year ended December 31, 2015
Net income decreased primarily due to a loss on a reinsurance transaction covering the Company's asbestos and environmental exposure, lower net investment income and fee income, an increase in Property & Casualty and Group Benefits incurred losses and higher net realized capital losses, partially offset by higher earned premiums and lower insurance operating costs and other expenses.
Earned premiums increased 2% or $234, before tax, reflecting growth of 2% in Commercial Lines, 1% in Personal Lines and 3% in Group Benefits. For a discussion of the Company's operating results by segment, see MD&A - Results of Operations by segment.
Fee income decreased primarily due to the continued run-off of the Talcott Resolution variable annuity block.
Net investment income decreased primarily due to lower make-whole payments on fixed maturities and prepayment penalties on mortgage loans, as well as lower asset levels and reinvesting at lower interest rates. For further discussion of investment results, see the Net Investment Income (Loss) section within MD&A - Investment Results.
Net realized capital losses increased primarily due to losses associated with the pending sale of the Company's U.K.
property and casualty run-off subsidiaries and an increase in losses from the variable annuity hedge program, partially offset by higher net gains on sales of securities and lower impairment losses. Also contributing to the increase in net realized capital losses was a $96 write-down of an investment in solar energy partnerships that generated tax credits and other tax benefits of $113 in 2016. For further discussion of investment results, see the Net Realized Capital Gains (Losses) section within MD&A - Investment Results, .
Benefits, losses and loss adjustment expenses increased in both Property & Casualty and Group Benefits with the increase in Group Benefits due to the effect of growth in earned premium and higher group life loss severity. The net increase in incurred losses for Property & Casualty was due to:
| • | Losses and loss adjustment expenses before catastrophes and prior accident year development in Property & Casualty increased $259, before tax, primarily resulting from higher personal and commercial auto loss costs and the effect of earned premium growth in Small Commercial and Personal Lines, partially offset by lower workers' compensation loss costs. |
| • | Current accident year catastrophe losses of $416, before tax, in 2016, compared to $332, before tax, in 2015. Catastrophe losses in 2016 were primarily due to multiple wind and hail events across various U.S. geographic regions, concentrated |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
in Texas and the central and southern plains and, to a lesser extent, winter storms and Hurricane Matthew. Catastrophe losses in 2015 were primarily due to multiple winter storms and wind and hail events across various U.S. geographic regions as well as tornadoes and wildfires. For additional information, see MD&A - Critical Accounting Estimates, Property & Casualty Insurance Product Reserves.
| • | Unfavorable prior accident year reserve development in Property & Casualty of $457, before tax, in 2016, compared to unfavorable reserve development of $250, before tax, in 2015. |
| ▪ | Prior accident year reserve development in 2016 was primarily due to a $268 increase in asbestos and environmental reserves and a $160 increase in personal auto liability reserves. An increase in asbestos reserves of $197 primarily related to greater than expected mesothelioma claim filings for a small percentage of defendants in specific, adverse jurisdictions. As a result, aggregate indemnity and defense costs have not declined as expected. Environmental reserves increased $71 in 2016 primarily due to deterioration associated with the tendering of new sites for policy coverage, increased defense costs stemming from individual bodily injury liability suits, and increased clean-up costs associated with waterways. Reserves were increased in Personal Lines auto liability for accident years 2014 and 2015, primarily due to higher than expected emerged auto liability frequency and severity. |
| ▪ | Prior accident year reserve development in 2015 was primarily due to an increase in asbestos reserves of $146 and environmental reserves of $52. For additional information, see MD&A - Critical Accounting Estimates, Reserve Roll-forwards and Development. |
Loss on extinguishment of debt decreased due to the redemption of $296 of aggregate principal amount outstanding of 4.0% senior notes in 2015. There were no early debt extinguishments in 2016.
Loss on reinsurance transaction in 2016 represents paid premium for an asbestos and environmental adverse development cover (“ADC”) reinsurance agreement with National Indemnity Company (“NICO”), a subsidiary of Berkshire Hathaway Inc. (“Berkshire”), to reduce uncertainty about potential adverse development. For more information on this transaction, see MD&A -Critical Accounting Estimates, Annual Reserve Reviews.
Income tax benefit of $92 in 2016 compared to income tax expense of $305 in 2015, primarily due to a decrease in taxable income and the effect of $113 of federal tax credits and other tax benefits associated with investments in solar energy partnerships, partially offset by a decrease in benefits from the dividends received deduction.
Differences between the Company's effective income tax rate and the U.S. statutory rate of 35% are due primarily to tax exempt interest earned on invested assets, the dividends received deduction, changes in the valuation allowance recorded on capital loss carryovers and federal tax credits associated with investments in solar energy partnerships. For further discussion
of income taxes, see Note 16 - Income Taxes of Notes to Consolidated Financial Statements.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Earned premiums increased 2% or $241, before tax, in 2015, compared to 2014, reflecting growth of 4% in Commercial Lines and 2% in Personal Lines.
Fee income decreased $157, before tax, primarily due to the continued run-off of the Talcott Resolution annuity business.
Net investment income decreased to $3,030, before tax, in 2015 from $3,154, before tax, in 2014, primarily due to lower income from limited partnerships and other alternative investments and the continued decline in Talcott Resolution assets under management.
Net realized capital losses of $156, before tax, in 2015, compared to net realized capital gains of $16, before tax, in 2014, largely driven by results of the variable annuity hedge program.
Benefits, losses and loss adjustment expenses included unfavorable prior accident year reserve development in Property & Casualty of $250, before tax, in 2015, compared to unfavorable reserve development of $228, before tax, in 2014. Prior accident year reserve development in 2015 was primarily due to an increase in reserves for asbestos and environmental claims, in part, due to a small percentage of direct accounts having experienced greater than expected claim filings, including mesothelioma claims. Prior accident year reserve development in 2014 was primarily due to an increase in reserves for asbestos and environmental claims, primarily due to a higher than previously estimated number of mesothelioma claim filings and an increase in costs associated with asbestos litigation.
Amortization of deferred policy acquisition costs decreased $227, before tax, driven, in part, by a favorable unlock in Talcott Resolution in 2015, compared to an unfavorable unlock in 2014.
Insurance operating costs and other expenses included a pension settlement charge of $128, before tax, in 2014, related to voluntary lump-sum settlements with vested participants in the Company's defined benefit pension plan who had separated from service, but who had not yet commenced annuity benefits.
Loss on extinguishment of debt increased $21, before tax, in 2015 related to the redemption of $296 aggregate principal amount of outstanding 4.0% senior notes. The resulting loss on extinguishment of debt consists of a make-whole premium.
Income tax expense decreased by $45 in 2015 from $350 in 2014, primarily due to a federal income tax benefit of $36, related to the release of reserves due to the resolution of uncertain tax positions and a benefit of $94 from the partial reduction of the deferred tax valuation allowance on the capital loss carryover due to taxable gains on the termination of certain derivatives, partially offset by the effect of higher income from continuing operations, before tax.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Income (loss) from discontinued operations decreased $560, net of tax, in 2015 compared to 2014 primarily
due to the realized capital loss of $659 on the sale of the Japan variable annuity business in 2014.
INVESTMENT RESULTS
| December 31, 2016 | December 31, 2015 | |||||||||
| Amount | Percent | Amount | Percent | |||||||
| Fixed maturities, available-for-sale ("AFS"), at fair value | $ | 56,003 | 79.3 | % | $ | 59,196 | 81.2 | % | ||
| Fixed maturities, at fair value using the fair value option ("FVO") | 293 | 0.4 | % | 503 | 0.7 | % | ||||
| Equity securities, AFS, at fair value [1] | 1,097 | 1.6 | % | 1,121 | 1.5 | % | ||||
| Mortgage loans | 5,697 | 8.1 | % | 5,624 | 7.7 | % | ||||
| Policy loans, at outstanding balance | 1,444 | 1.9 | % | 1,447 | 2.0 | % | ||||
| Limited partnerships and other alternative investments | 2,456 | 3.5 | % | 2,874 | 4.0 | % | ||||
| Other investments [2] | 403 | 0.6 | % | 310 | 0.4 | % | ||||
| Short-term investments | 3,244 | 4.6 | % | 1,843 | 2.5 | % | ||||
| Total investments | $ | 70,637 | 100 | % | $ | 72,918 | 100 | % |
| [1] | Includes equity securities at fair value using the FVO of $282 as of December 31, 2015. The Company did not hold any equity securities, FVO as of December 31, 2016. |
| [2] | Primarily relates to derivative instruments. |
Year ended December 31, 2016 compared to the year ended December 31, 2015
Total investments decreased since December 31, 2015, primarily due to a decrease in fixed maturities, AFS and limited partnerships and other alternative investments, partially offset by an increase in short-term investments.
Fixed maturities, AFS decreased due to the continued run-off of Talcott Resolution and the transfer of investments to assets held for sale related to the U.K. property and casualty run-off subsidiaries, as well as a decline in valuations as a result of a rise in interest rates, which more than offset the effect of
tightening credit spreads. For further discussion on the disposition, see Note 2- Business Acquisitions and Dispositions of Notes to Consolidated Financial Statements.
Limited partnerships and other alternative investments decreased primarily due to redemptions in hedge fund investments which were reinvested into other asset classes.
Short-term investments increased primarily due to holding more short-term investments until those investments are reinvested into longer duration asset classes.
Net Investment Income (Loss)
| For the years ended December 31, | |||||||||||||||
| 2016 | 2015 | 2014 | |||||||||||||
| (Before tax) | Amount | Yield [1] | Amount | Yield [1] | Amount | Yield [1] | |||||||||
| Fixed maturities [2] | $ | 2,379 | 4.2 | % | $ | 2,409 | 4.2 | % | $ | 2,420 | 4.2 | % | |||
| Equity securities | 31 | 3.4 | % | 25 | 2.4 | % | 38 | 4.8 | % | ||||||
| Mortgage loans | 252 | 4.5 | % | 267 | 4.7 | % | 265 | 4.7 | % | ||||||
| Policy loans | 83 | 5.8 | % | 82 | 5.7 | % | 80 | 5.6 | % | ||||||
| Limited partnerships and other alternative investments | 214 | 8.5 | % | 227 | 8.0 | % | 294 | 10.4 | % | ||||||
| Other [3] | 115 | 138 | 179 | ||||||||||||
| Investment expense | (113 | ) | (118 | ) | (122 | ) | |||||||||
| Total net investment income | $ | 2,961 | 4.3 | % | $ | 3,030 | 4.3 | % | $ | 3,154 | 4.4 | % | |||
| Total net investment income excluding limited partnerships and other alternative investments | $ | 2,747 | 4.1 | % | $ | 2,803 | 4.1 | % | $ | 2,860 | 4.1 | % |
| [1] | Yields calculated using annualized net investment income divided by the monthly average invested assets at cost, amortized cost, or adjusted carrying value, as applicable, excluding repurchase agreement and securities lending collateral , if any, and derivatives book value. |
| [2] | Includes net investment income on short-term investments. |
| [3] | Primarily includes income from derivatives that qualify for hedge accounting and hedge fixed maturities. |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Year ended December 31, 2016 compared to the year ended December 31, 2015
Total net investment income decreased primarily due to lower make-whole payments on fixed maturities and prepayment penalties on mortgage loans, as well as lower asset levels and reinvesting at lower interest rates.
Annualized net investment income yield excluding limited partnerships and other alternative investments, was 4.1% in 2016, consistent with 2015. Excluding make-whole payments on fixed maturities, income received from previously impaired securities, and prepayment penalties on mortgage loans, the annualized investment income yield, excluding limited partnerships and other alternative investments, was 4.0% in 2016 and 2015.
New money yield excluding certain U.S. Treasury securities and cash equivalent securities, for the year ended December 31, 2016, was approximately 3.5% which was below the average yield of sales and maturities of 4.0% for the same period. For the year ended December 31, 2016, the new money yield of 3.5% increased slightly from 3.4% in 2015, largely due to an increase in interest rates.
While interest rates have risen recently, we expect the annualized net investment income yield in 2017, excluding limited partnerships and other alternative investments, to be slightly below the portfolio yield earned in 2016. This assumes the Company earns less income in 2017 from make-whole payments on fixed maturities and prepayment penalties on mortgage loans than it did in 2016 and that reinvestment rates continue to be below the average yield of sales and maturities. The estimated impact on net investment income is subject to change as the composition of the portfolio changes through portfolio management and trading activities and changes in market conditions.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Total net investment income decreased primarily due to a decrease in income from limited partnerships and other alternative investments, the impact of reinvesting at lower interest rates and a decrease in invested asset levels, partially offset by make-whole payments on fixed maturities, higher income received from previously impaired securities, and prepayment penalties on mortgage loans.
Net Realized Capital Gains (Losses)
| For the years ended December 31, | |||||||||
| (Before tax) | 2016 | 2015 | 2014 | ||||||
| Gross gains on sales | $ | 441 | $ | 460 | $ | 527 | |||
| Gross losses on sales | (253 | ) | (405 | ) | (250 | ) | |||
| Net other-than-temporary impairment ("OTTI") losses recognized in earnings [1] | (56 | ) | (102 | ) | (59 | ) | |||
| Valuation allowances on mortgage loans [2] | — | (5 | ) | (4 | ) | ||||
| Results of variable annuity hedge program | |||||||||
| GMWB derivatives, net | (38 | ) | (87 | ) | 5 | ||||
| Macro hedge program | (163 | ) | (46 | ) | (11 | ) | |||
| Total results of variable annuity hedge program | (201 | ) | (133 | ) | (6 | ) | |||
| Transactional foreign currency revaluation | (148 | ) | (4 | ) | 124 | ||||
| Non-qualifying foreign currency derivatives | 140 | (3 | ) | (142 | ) | ||||
| Other, net [3] | (191 | ) | 36 | (174 | ) | ||||
| Net realized capital gains (losses) | $ | (268 | ) | $ | (156 | ) | $ | 16 |
| [1] | See Other-Than-Temporary Impairments within the Investment Portfolio Risks and Risk Management section of the MD&A. |
| [2] | See Valuation Allowances on Mortgage Loans within the Investment Portfolio Risks and Risk Management section of the MD&A. |
| [3] | Primarily consists of changes in value of non-qualifying derivatives, including credit derivatives, interest rate derivatives used to manage duration, and embedded derivatives associated with modified coinsurance reinsurance contracts. Also included for the year ended December 31, 2016, is a loss related to the write-down of investments in solar energy partnerships, which generated tax benefits, and a loss related to the sale of the Company's U.K. property and casualty run-off subsidiaries. |
Year ended December 31, 2016
Gross gains and losses on sales were primarily a result of duration, liquidity and credit management within corporate, U.S. treasury, tax exempt municipal and equity securities.
Variable annuity hedge program losses included losses on the combined GMWB derivatives, net, which include the GMWB product, reinsurance, and hedging derivatives, primarily driven by losses of $53 due to liability/model assumption updates, $22 due to the effect of increases in equity markets and losses of $12 resulting from regression updates and
other changes, partially offset by gains of $40 resulting from policyholder behavior and $29 related to an outperformance of the underlying actively managed funds compared to their respective indices. The macro hedge program loss was primarily due to a loss of $96 due to an increase in equity markets and a loss of $58 driven by time decay on options.
Other, net loss included losses of $96 related to the write-down of investments in solar energy partnerships that generated solar tax credits and losses of $81 associated with the Company's U.K. property and casualty run-off subsidiaries currently held for sale. For further information related to the investment in solar energy partnerships and resulting solar tax credits, refer to Note
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
16 - Income Taxes of Notes to Consolidated Financial Statements. In addition, there were losses of $28 related to equity derivatives which were hedging against a decline in the equity market in the investment portfolio.
Year ended December 31, 2015
Gross gains and losses on sales were primarily a result of duration, liquidity and credit management, as well as tactical changes to the portfolio as a result of changing market conditions. This included sales to reduce exposure to energy, emerging markets and below investment grade corporate securities as well as sales within corporate, U.S. treasury and equity securities.
Variable annuity hedge program losses included losses on the combined GMWB derivatives, net, primarily driven by losses of $42 due to liability/model assumption updates and losses of $18 resulting from an underperformance of the underlying actively managed funds compared to their respective indices. The macro hedge program loss was primarily due to a loss of $44 driven by time decay on options.
Other, net gain was primarily related to gains of $46 related to modified coinsurance reinsurance contracts, primarily driven by widening credit spreads and an increase in interest rates. These gains were partially offset by losses of $14 on credit derivatives driven by widening credit spreads and losses of $12 on interest rate derivatives due to an increase in interest rates.
Year ended December 31, 2014
Gross gains and losses on sales were primarily a result of duration, liquidity and credit management as well as tactical changes to the portfolio as a result of changing market conditions. The sales were primarily within commercial mortgage-backed securities ("CMBS"), residential mortgage-backed securities ("RMBS"), and municipal securities as well as sales of corporate and foreign government and government agency securities which primarily resulted from a reduction in our exposure to the emerging market and energy sectors.
Variable annuity hedge program losses included losses on the macro hedge program primarily due to a loss of $25 driven by an improvement in domestic equity markets, partially offset by a gain of $17 related to a decrease in interest rates. These losses were partially offset by gains on the combined GMWB derivatives, net, primarily driven by gains of $25 on liability/model assumption updates and gains of $15 due to increased volatility, partially offset by a loss of $26 resulting from policyholder behavior primarily related to increased surrenders.
Other, net loss was primarily related to a loss of $172 on interest rate derivatives used to manage the risk of a rise in interest rates and manage duration, driven by a decline in U.S. interest rates.
CRITICAL ACCOUNTING ESTIMATES
The preparation of financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities and disclosure of contingent assets and liabilities at the date of the
financial statements and the reported amounts of revenues and expenses during the reporting period. Actual results could differ, and in the past have differed, from those estimates.
The Company has identified the following estimates as critical in that they involve a higher degree of judgment and are subject to a significant degree of variability:
| • | property and casualty insurance product reserves, net of reinsurance; |
| • | group benefit long-term disability reserves, net of reinsurance; |
| • | estimated gross profits used in the valuation and amortization of assets and liabilities associated with variable annuity and other universal life-type contracts; |
| • | living benefits required to be fair valued (in other policyholder funds and benefits payable); |
| • | evaluation of goodwill for impairment; |
| • | valuation of investments and derivative instruments including evaluation of other-than-temporary impairments on available-for-sale securities and valuation allowances on mortgage loans; |
| • | valuation allowance on deferred tax assets; and |
| • | contingencies relating to corporate litigation and regulatory matters. |
Certain of these estimates are particularly sensitive to market conditions, and deterioration and/or volatility in the worldwide debt or equity markets could have a material impact on the Consolidated Financial Statements. In developing these estimates management makes subjective and complex judgments that are inherently uncertain and subject to material change as facts and circumstances develop. Although variability is inherent in these estimates, management believes the amounts provided are appropriate based upon the facts available upon compilation of the financial statements.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Property & Casualty Insurance Product Reserves
P&C Loss and Loss Adjustment Expense Reserves, Net of Reinsurance, by Segment as of December 31, 2016

Loss and LAE Reserves, Net of Reinsurance as of December 31, 2016
| Commercial Lines | Personal Lines | Property & Casualty Other Operations | Total Property & Casualty Insurance | % Total Reserves-net | |||||||||
| Workers’ compensation | $ | 9,189 | $ | — | $ | — | $ | 9,189 | 48.2% | ||||
| General liability | 2,113 | — | — | 2,113 | 11.1% | ||||||||
| Package business [1] | 1,399 | — | — | 1,399 | 7.3% | ||||||||
| Commercial property | 195 | — | — | 195 | 1.0% | ||||||||
| Auto liability | 880 | 1,675 | — | 2,555 | 13.4% | ||||||||
| Auto physical damage | 9 | 36 | — | 45 | 0.2% | ||||||||
| Professional liability | 589 | — | — | 589 | 3.1% | ||||||||
| Bond | 225 | — | — | 225 | 1.2% | ||||||||
| Homeowners | — | 341 | — | 341 | 1.8% | ||||||||
| A&E [3] | 126 | 13 | 1,516 | 1,655 | 8.7% | ||||||||
| Assumed reinsurance | — | — | 129 | 129 | 1% | ||||||||
| All other [2] | 188 | 4 | 430 | 622 | 3.3% | ||||||||
| Total reserves-net | 14,913 | 2,069 | 2,075 | 19,057 | 100.0% | ||||||||
| Reinsurance and other recoverables | 2,325 | 25 | 426 | 2,776 | |||||||||
| Total reserves-gross | $ | 17,238 | $ | 2,094 | $ | 2,501 | $ | 21,833 |
| [1] | Commercial Lines policy packages that include property and general liability coverages are generally referred to as the package line of business. |
| [2] | Property & Casualty Other Operations excludes net reserves to be transferred to the buyer in connection with the pending sale of the Company's U.K. property and casualty run-off subsidiaries. |
| [3] | Commercial Lines and Personal Lines include a total of $114 of post-1985 asbestos and environmental reserves that had been previously classified within general liability and homeowners. |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
For descriptions of the coverages provided under the lines of business shown above, see Part I - Item1, Business.
Overview of Reserving for Property and Casualty Insurance Claims
It typically takes many months or years to pay claims incurred under a property and casualty insurance product; accordingly, the Company must establish reserves at the time the loss is incurred. Most of the Company’s policies provide for occurrence-based coverage where the loss is incurred when a claim event happens like an auto accident, house or building fire or injury to an employee under a workers’ compensation policy. Some of the Company's policies, mostly for directors and officers insurance and errors and omissions insurance, are claims-made policies where the loss is incurred in the period the claim event is reported to the Company even if the loss event itself occurred in an earlier period.
Loss and loss adjustment expense reserves provide for the estimated ultimate costs of paying claims under insurance policies written by the Company, less amounts paid to date. These reserves include estimates for both claims that have been reported and those that have not yet been reported, and include estimates of all expenses associated with processing and settling these claims. Incurred but not reported (“IBNR”) reserves represent the difference between the estimated ultimate cost of all claims and the actual loss and loss adjustment expenses reported to the Company by claimants (“reported losses”). Reported losses represent cumulative loss and loss adjustment expenses paid plus case reserves for outstanding reported claims. Company actuaries evaluate the total reserves (IBNR and case reserves) on an accident year basis. An accident year is the calendar year in which a loss is incurred, or, in the case of claims-made policies, the calendar year in which a loss is reported.
Factors that Change Reserve Estimates- Reserve estimates can change over time because of unexpected changes in the external environment. Inflation in medical care, hospital care, auto parts, wages and home and building repair would cause claims to settle for more than they are initially reserved. Changes in the economy can cause an increase or decrease in the number of reported claims (claim frequency). For example, an improving economy could result in more automobile miles driven and a higher number of auto reported claims while a contracting economy can sometimes lead to an increase in workers’ compensation reported claims. An increase in the number or percentage of claims litigated can increase the average settlement amount per claim (claim severity). Changes in the judicial environment can affect interpretations of damages and how policy coverage applies which could increase or decrease claim severity. Over time, judges or juries in certain jurisdictions may be more inclined to determine liability and award damages. New legislation can also change how damages are defined resulting in greater frequency or severity. In addition, new types of injuries may arise from exposures not contemplated when the policies were written. Past examples include pharmaceutical products, silica, lead paint, molestation or abuse and construction defects.
Reserve estimates can also change over time because of changes in internal Company operations. A delay or acceleration in handling claims may signal a need to increase or reduce reserves from what was initially estimated. New lines of business may have loss development patterns that are not well established. Changes
in the geographic mix of business, changes in the mix of business by industry and changes in the mix of business by policy limit or deductible can increase the risk that losses will ultimately develop differently than the loss development patterns assumed in our reserving. In addition, changes in the quality of risk selection in underwriting and changes in interpretations of policy language could increase or decrease ultimate losses from what was assumed in establishing the reserves.
In the case of assumed reinsurance, all of the above risks apply. The Company assumes insurance risk from certain pools and associations and, prior to 2004, assumed property and casualty risks from other insurance companies. Changes in the case reserving and reporting patterns of insurance companies ceding to The Hartford can create additional uncertainty in estimating the reserves. Due to the inherent complexity of the assumptions used, final claim settlements may vary significantly from the present estimates of direct and assumed reserves, particularly when those settlements may not occur until well into the future.
Reinsurance Recoverables- Through both facultative and treaty reinsurance agreements, the Company cedes a share of the risks it has underwritten to other insurance companies. The Company records reinsurance recoverables for loss and loss adjustment expenses ceded to its reinsurers representing the anticipated recovery from reinsurers of unpaid claims, including IBNR.
The Company estimates the portion of losses and loss adjustment expenses to be ceded based on the terms of any applicable facultative and treaty reinsurance, including an estimate of how IBNR for losses will ultimately be ceded.
The Company provides an allowance for uncollectible reinsurance, reflecting management’s best estimate of reinsurance cessions that may be uncollectible in the future due to reinsurers’ unwillingness or inability to pay. The estimated allowance considers the credit quality of the Company's reinsurers, recent outcomes in arbitration and litigation in disputes between reinsurers and cedants and recent communication activity between reinsurers and cedants that may signal how the Company’s own reinsurance claims may settle. Where its reinsurance contracts permit, the Company secures funding of future claim obligations with various forms of collateral, including irrevocable letters of credit, secured trusts, funds held accounts and group-wide offsets. The allowance for uncollectible reinsurance was $165 as of December 31, 2016, comprised of $29 related to Commercial Lines and $136 related to Property & Casualty Other Operations.
The Company’s estimate of reinsurance recoverables, net of an allowance for uncollectible reinsurance, is subject to similar risks and uncertainties as the estimate of the gross reserve for unpaid losses and loss adjustment expenses for direct and assumed exposures.
Review of Reserve Adequacy- The Hartford regularly reviews the appropriateness of reserve levels at the line of business or more detailed level, taking into consideration the variety of trends that impact the ultimate settlement of claims. For Property & Casualty Other Operations, asbestos and environmental (“A&E”) reserves are reviewed by type of event rather than by line of business.
Reserve adjustments, which may be material, are reflected in the operating results of the period in which the adjustment is
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
determined to be necessary. In the judgment of management, information currently available has been properly considered in establishing the reserves for unpaid losses and loss adjustment expenses and in recording the reinsurance recoverables for ceded unpaid losses.
Reserving Methodology
For a discussion of how A&E reserves are set, see MD&A - P&C Insurance Product Reserves, Reserving for Asbestos and Environmental Claims within Property & Casualty Other Operations. The following is a discussion of the reserving methods used for the Company's property and casualty lines of business other than asbestos and environmental.
How Reserves Are Set- Reserves are set by line of business within the operating segments. A single line of business may be written in more than one segment. Case reserves are established by a claims handler on each individual claim and are adjusted as new information becomes known during the course of handling the claim. Lines of business for which reported losses emerge over a long period of time are referred to as long-tail lines of business. Lines of business for which reported losses emerge more quickly are referred to as short-tail lines of business. The Company’s shortest-tail lines of business are homeowners, commercial property and auto physical damage. The longest tail lines of business include workers’ compensation, general liability, professional liability and assumed reinsurance. For short-tail lines of business, emergence of paid loss and case reserves is credible and likely indicative of ultimate losses. For long-tail lines of business, emergence of paid losses and case reserves is less credible in the early periods after a given accident year and, accordingly, may not be indicative of ultimate losses.
Use of Actuarial Methods and Judgments- The Company’s reserving actuaries regularly review reserves for both current and prior accident years using the most current claim data. A variety of actuarial methods and judgments are used for most lines of business to arrive at selections of estimated ultimate losses and loss adjustment expenses. These selections incorporate input, as appropriate, from claims personnel, pricing actuaries and operating management about reported loss cost trends and other factors that could affect the reserve estimates. Most reserves are reviewed fully each quarter, including loss and loss adjustment expense reserves for homeowners, commercial property, auto physical damage, auto liability, package business, workers’ compensation, most general liability and professional liability. Other reserves are reviewed semi-annually (twice per year) or annually. These primarily include reserves for losses incurred in accident years older than twelve years for Personal Lines and older than twenty years for Commercial Lines, as well as reserves for bond, assumed reinsurance, latent exposures, such as construction defects, and unallocated loss adjustment expense. For reserves that are reviewed semi-annually or annually, management monitors the emergence of paid and reported losses in the intervening quarters and, if necessary, performs a reserve review to determine whether the reserve estimate should change.
An expected loss ratio is used in initially recording the reserves for both short-tail and long-tail lines of business. This expected loss ratio is determined by starting with the average loss ratio of recent prior accident years and adjusting that ratio for the effect
of expected changes to earned pricing, loss frequency and severity, mix of business, ceded reinsurance and other factors. For short-tail lines, IBNR for the current accident year is initially recorded as the product of the expected loss ratio for the period, earned premium for the period and the proportion of losses expected to be reported in future calendar periods for the current accident period. For long-tailed lines, IBNR reserves for the current accident year are initially recorded as the product of the expected loss ratio for the period and the earned premium for the period, less reported losses for the period.
As losses emerge or develop in periods subsequent to a given accident year, reserving actuaries use other methods to estimate ultimate unpaid losses in addition to the expected loss ratio method. These primarily include paid and reported loss development methods, frequency / severity techniques and the Bornhuetter-Ferguson method (a combination of the expected loss ratio and paid development or reported development method). Within any one line of business, the methods that are given more influence vary based primarily on the maturity of the accident year, the mix of business and the particular internal and external influences impacting the claims experience or the methods. The output of the reserve reviews are reserve estimates that are referred to herein as the “actuarial indication”.
Reserve Discounting- Most of the Company’s property and casualty insurance product reserves are not discounted. However, the Company has discounted liabilities funded through structured settlements and has discounted certain reserves for indemnity payments due to permanently disabled claimants under workers’ compensation policies. For further discussion of these discounted liabilities, see Note 1 - Basis of Presentation and Significant Accounting Policies of Notes to Consolidated Financial Statements.
Differences Between GAAP and Statutory Basis Reserves- As of December 31, 2016 and 2015, U.S. property and casualty insurance product reserves for losses and loss adjustment expenses, net of reinsurance recoverables, reported under U.S. GAAP were approximately equal to net reserves reported on a statutory basis. Under U.S. GAAP, liabilities for unpaid losses for permanently disabled workers’ compensation claimants are discounted at rates that are no higher than risk-free interest rates in effect at the time the claims are incurred and which can vary from the statutory discount rates set by regulators. In addition, a portion of the U.S. GAAP provision for uncollectible reinsurance is not recognized under statutory accounting. These differences are offset by the reclassification of reserves associated with the pending sale of HFPI to liabilities held for sale under U.S. GAAP that remain in carried reserves under statutory accounting.
Reserving Methods by Line of Business- Apart from A&E which is discussed in the following section on Property & Casualty Other Operations, below is a general discussion of which reserving methods are preferred by line of business. Because the actuarial estimates are generated at a much finer level of detail than line of business (e.g., by distribution channel, coverage, accident period), other methods than those described for the line of business may also be employed for a coverage and accident year within a line of business. Also, as circumstances change, the methods that are given more influence will change.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Preferred Reserving Methods by Line of Business
| Commercial property, homeowners and auto physical damage | These short-tailed lines are fast-developing and paid and reported development techniques are used as these methods use historical data to develop paid and reported loss development patterns, which are then applied to cumulative paid and reported losses by accident period to estimate ultimate losses. In addition to paid and reported development methods, for the most immature accident months, the Company uses frequency and severity techniques and the initial expected loss ratio. The advantage of frequency / severity techniques is that frequency estimates are generally easier to predict and external information can be used to supplement internal data in estimating average severity. |
| Personal auto liability | For auto liability, and bodily injury in particular, the Company performs a greater number of techniques than it does for commercial property, homeowners and auto physical damage. In addition to traditional paid and reported development methods, the Company relies on frequency/severity techniques and Berquist-Sherman techniques. Because the paid development technique is affected by changes in claim closure patterns and the reported development method is affected by changes in case reserving practices, the Company uses Berquist-Sherman techniques which adjust these patterns to reflect current settlement rates and case reserving practices. The Company generally uses the reported development method for older accident years and a combination of reported development, frequency/severity and Berquist-Sherman methods for more recent accident years. For older accident periods, reported losses are a good indicator of ultimate losses given the high percentage of ultimate losses reported to date. For more recent periods, the frequency/severity techniques are not affected as much by changes in case reserve practices and changing disposal rates and the Berquist-Sherman techniques specifically adjust for these changes. |
| Auto liability for commercial lines and short-tailed general liability | For older, more mature accident years, the Company primarily uses reported development techniques. For more recent accident years, the Company typically prefers frequency / severity techniques. These techniques separately analyze losses above and below a capping level (average severity) as larger claims typically behave differently than smaller claims. |
| Professional liability | Reported and paid loss development patterns for this line tend to be volatile. Therefore, the Company typically relies on frequency and severity techniques. |
| Long-tailed general liability, bond and large deductible workers’ compensation | For these long-tailed lines of business, the Company generally relies on the expected loss ratio and reported development techniques. The Company generally weights these techniques together, relying more heavily on the expected loss ratio method at early ages of development and more on the reported development method as an accident year matures. |
| Workers’ compensation | Workers’ compensation is the Company’s single largest reserve line of business and a wide range of methods are used. Methods include paid and reported development techniques, the expected loss ratio and Bornhuetter-Ferguson methods, and an in-depth analysis on the largest states. In recent years, we have seen an acceleration of paid losses relative to historical patterns and have adjusted our expected loss development patterns accordingly. This acceleration has largely been due to two factors. First, in more recent accident years, we have seen a higher concentration of first dollar workers' compensation business and less excess of loss business resulting in fewer longer-tailed, excess workers' compensation claims. Second, over the past couple of years, the Company has seen an increase in lump sum settlements to claimants across multiple accident years. Adjusting for the effect of an acceleration in payments compared to historical patterns, paid loss development techniques are generally preferred for the workers' compensation line, particularly for more mature accident years. For less mature accident years, the Company places greater reliance on the expected loss ratio and reported development methods, open claim approaches, and state-by-state analysis. |
| Assumed reinsurance and all other | For these lines, the Company tends to rely mostly on reported development techniques. In assumed reinsurance, assumptions are influenced by information gained from claim and underwriting audits. |
| Allocated loss adjustment expenses (ALAE) | For some lines of business (e.g., professional liability and assumed reinsurance), ALAE and losses are analyzed together. For most lines of business, however, ALAE is analyzed separately, using paid development techniques and a ratio of paid ALAE to paid loss is applied to loss reserves to estimate unpaid ALAE. |
| Unallocated loss adjustment expenses (ULAE) | ULAE is analyzed separately from loss and ALAE. For most lines of business, incurred ULAE costs to be paid in the future are projected based on an expected claim handling cost per claim year, the anticipated claim closure pattern and the ratio of paid ULAE to paid loss is applied to estimated unpaid losses. |
In the final step of the reserve review process, senior reserving actuaries and senior management apply their judgment to determine the appropriate level of reserves considering the actuarial indications and other factors not contemplated in the actuarial indications. Those factors include, but are not limited to, the assessed reliability of key loss trends and assumptions used in the current actuarial indications, the maturity of the accident year, pertinent trends observed over the recent past, the level of volatility within a particular line of business, and the improvement or deterioration of actuarial indications in the current period as compared to the prior periods. The Company also considers the magnitude of the difference between the actuarial indication and the recorded reserves.
Based on the results of the quarterly reserve review process, the Company determines the appropriate reserve adjustments, if any,
to record. In general, adjustments are made more quickly to more mature accident years and less volatile lines of business. Such adjustments of reserves are referred to as “prior accident year development”. Increases in previous estimates of ultimate loss costs are referred to as either an increase in prior accident year reserves or as unfavorable reserve development. Decreases in previous estimates of ultimate loss costs are referred to as either a decrease in prior accident year reserves or as favorable reserve development. Reserve development can influence the comparability of year over year underwriting results.
Total recorded net reserves, excluding asbestos and environmental, were 4.2% higher than the actuarial indication of the reserves as of December 31, 2016.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
For a discussion of changes to reserve estimates recorded in 2016, see the Reserve Development section below.
Current Trends Contributing to Reserve Uncertainty
The Hartford is a multi-line company in the property and casualty insurance business. The Hartford is therefore subject to reserve uncertainty stemming from changes in loss trends and other conditions which could become material at any point in time. As market conditions and loss trends develop, management must assess whether those conditions constitute a long-term trend that should result in a reserving action (i.e., increasing or decreasing the reserve).
Difficult to Estimate Tort Exposures- Within Commercial Lines and Property & Casualty Other Operations, the Company has exposure to bodily injury claims as a result of long-term or continuous exposure to harmful products or substances. Examples include, but are not limited to, pharmaceutical products, silica, talcum powder, head injuries and lead paint. The Company also has exposure to claims from construction defects, where property damage or bodily injury from negligent construction is alleged. In addition, the Company has exposure to claims asserted against religious institutions and other organizations relating to molestation or abuse. Such exposures may involve potentially long latency periods and may implicate coverage in multiple policy periods. These factors make reserves for such claims more uncertain than other bodily injury or property damage claims. With regard to these exposures, the Company monitors trends in litigation, the external environment, the similarities to other mass torts and the potential impact on the Company’s reserves.
Standard Commercial Lines- In standard commercial lines, workers’ compensation is the Company’s single biggest line of business and the line of business with the longest pattern of loss emergence. To the extent that patterns in the frequency of settlement payments deviate from historical patterns, loss reserve estimates would be less reliable. Medical costs make up more than 50% of workers’ compensation payments. As such, reserve estimates for workers’ compensation are particularly sensitive to changes in medical inflation, the changing use of medical care procedures and changes in state legislative and regulatory environments. In addition, a deteriorating economic environment can reduce the ability of an injured worker to return to work and lengthen the time a worker receives disability benefits.
Specialty Lines- In specialty lines, many lines of insurance are “long-tail”, including large deductible workers’ compensation insurance; as such, reserve estimates for these lines are more difficult to determine than reserve estimates for shorter-tail lines of insurance. Reserves for large deductible workers’ compensation insurance require estimating losses attributable to the deductible amount that will be paid by the insured; if such losses are not paid by the insured due to financial difficulties, the Company is contractually liable. Uncertainty in estimated claim severity causes reserve variability for commercial auto losses including reserve variability due to changes in internal claim handling and case reserving practices as well as due to changes in the external environment. Another example of reserve variability is with directors’ and officers’ insurance where uncertainty regarding the number and severity of class action suits can result
in reserve volatility. Additionally, the Company’s exposure to losses under directors’ and officers’ insurance policies is primarily in excess layers, making estimates of loss more complex.
Personal Lines- In Personal Lines, while claims emerge over relatively shorter periods, estimates can still vary due to a number of factors, including uncertain estimates of frequency and severity trends. Severity trends are affected by changes in internal claim handling and case reserving practices as well as by changes in the external environment. Changes in claim practices increase the uncertainty in the interpretation of case reserve data, which increases the uncertainty in recorded reserve levels. Severity trends have increased in recent accident years causing additional uncertainty about the reliability of past patterns. In addition, the introduction of new products and class plans has led to a different mix of business by type of insured than the Company experienced in the past. Such changes in mix increase the uncertainty of the reserve projections, since historical data and reporting patterns may not be applicable to the new business.
Impact of Key Assumptions on Reserves
As stated above, the Company’s practice is to estimate reserves using a variety of methods, assumptions and data elements within its reserve estimation process for reserves other than asbestos and environmental. The Company does not consistently use statistical loss distributions or confidence levels around its reserve estimate and, as a result, does not disclose reserve ranges.
Across most lines of business, the most important reserve assumptions are future loss development factors applied to paid or reported losses to date. The trend in loss cost frequency and severity is also a key assumption, particularly in the most recent accident years, where loss development factors are less credible.
The following discussion discloses possible variation from current estimates of loss reserves due to a change in certain key indicators of potential losses. For auto liability lines in both Personal Lines and Commercial Lines, the key indicator is the annual loss cost trend, particularly the severity trend component of loss costs. For workers’ compensation and general liability, loss development patterns are a key indicator, particularly for more mature accident years. For workers’ compensation, paid loss development patterns have been impacted by medical cost inflation and other changes in loss cost trends. For general liability, loss development patterns have been impacted by, among other things, emergence of new types of claims (e.g., construction defect claims) and a shift in the mixture between smaller, more routine claims and larger, more complex claims.
Each of the impacts described below is estimated individually, without consideration for any correlation among key indicators or among lines of business. Therefore, it would be inappropriate to take each of the amounts described below and add them together in an attempt to estimate volatility for the Company’s reserves in total. For any one reserving line of business, the estimated variation in reserves due to changes in key indicators is a reasonable estimate of possible variation that may occur in the future, likely over a period of several calendar years. The variation discussed is not meant to be a worst-case scenario, and, therefore, it is possible that future variation may be more than the amounts discussed below.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
| Possible Change in Key Indicator | Reserves, Net of Reinsurance December 31, 2016 | Estimated Range of Variation in Reserves | |
| Personal Auto Liability | +/- 2.5 points to the annual assumed change in loss cost severity for the two most recent accident years | $1.7 billion | +/- $90 |
| Commercial Auto Liability | +/- 2.5 points to the annual assumed change in loss cost severity for the two most recent accident years | $0.9 billion | +/- $20 |
| Workers' Compensation | 2% change in paid loss development patterns | $9.2 billion | +/- $400 |
| General Liability | 10% change in reported loss development patterns | $2.1 billion | +/- $200 |
Reserving for Asbestos and Environmental Claims
How A&E Reserves are Set- The process for establishing reserves for asbestos and environmental claims first involves estimating the required reserves gross of ceded reinsurance and then estimating reinsurance recoverables. In establishing reserves for gross asbestos claims, the Company evaluates its insureds’ estimated liabilities for such claims by examining exposures for individual insureds and assessing how coverage applies. The Company considers a variety of factors, including the jurisdictions where underlying claims have been brought, past, pending and anticipated future claim activity, disease mix, past settlement values of similar claims, dismissal rates, allocated loss adjustment expense, and potential bankruptcy impact.
Similarly, the Company reviews exposures to establish gross environmental reserves. The Company considers several factors in estimating environmental liabilities, including historical values of similar claims, the number of sites involved, the insureds’ alleged activities at each site, the alleged environmental damage, the respective shares of liability of potentially responsible parties, the appropriateness and cost of remediation, the nature of governmental enforcement activities and potential bankruptcy impact.
After evaluating its insureds’ probable liabilities for asbestos and/or environmental claims, the Company evaluates the insurance coverage in place for such claims. The Company considers its insureds’ total available insurance coverage, including the coverage issued by the Company. The Company also considers relevant judicial interpretations of policy language and applicable coverage defenses or determinations, if any.
The estimated liabilities of insureds and the Company’s exposure to the insureds depends heavily on an analysis of the relevant
legal issues and litigation environment. This analysis is conducted by the Company’s lawyers and is subject to applicable privileges.
For both asbestos and environmental reserves, the Company also analyzes its historical paid and reported losses and expenses year by year, to assess any emerging trends, fluctuations or characteristics suggested by the aggregate paid and reported activity. The historical losses and expenses are analyzed on both a direct basis and net of reinsurance.
Once the gross ultimate exposure for indemnity and allocated loss adjustment expense is determined for its insureds by each policy year, the Company calculates its ceded reinsurance projection based on any applicable facultative and treaty reinsurance and the Company’s experience with reinsurance collections. See the section that follows entitled Adverse Development Cover that discusses the impact the reinsurance agreement with NICO may have on future adverse development of asbestos and environmental reserves, if any.
Uncertainties Regarding Adequacy of A&E Reserves- A number of factors affect the variability of estimates for gross asbestos and environmental reserves including assumptions with respect to the frequency of claims, the average severity of those claims settled with payment, the dismissal rate of claims with no payment, resolution of coverage disputes with our policyholders and the expense to indemnity ratio. Reserve estimates for gross asbestos and environmental reserves are subject to greater variability than reserve estimates for more traditional exposures.
The process of estimating asbestos and environmental reserves remains subject to a wide variety of uncertainties, which are detailed in Note 14 - Commitments and Contingencies of Notes to Consolidated Financial Statements. The Company believes that its current asbestos and environmental reserves are appropriate. While future developments could cause the Company to change its estimates of its gross asbestos and environmental reserves, the adverse development cover with NICO will likely lessen the effect that these changes would have on the Company's consolidated operating results and liquidity. Consistent with past practice, the Company will continue to monitor its reserves in Property & Casualty Other Operations regularly, including its annual reviews of asbestos liabilities, reinsurance recoverables, the allowance for uncollectible reinsurance, and environmental liabilities. Where future developments indicate, we will make appropriate adjustments to the reserves at that time. In 2017, the Company will complete the comprehensive annual review of asbestos and environmental reserves during the fourth quarter.
Total P&C Insurance Product Reserves Development
In the opinion of management, based upon the known facts and current law, the reserves recorded for the Company’s property and casualty insurance products at December 31, 2016 represent the Company’s best estimate of its ultimate liability for losses and loss adjustment expenses related to losses covered by policies written by the Company. However, because of the significant uncertainties surrounding reserves. it is possible that management’s estimate of the ultimate liabilities for these claims may change in the future and that the required adjustment to currently recorded reserves could be material to the Company’s results of operations and liquidity.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Roll-forward of Property and Casualty Insurance Product Liabilities for Unpaid Losses and LAE for the Year Ended December 31, 2016
| Commercial Lines | Personal Lines | Property & Casualty Other Operations | Total Property & Casualty Insurance | |||||||||
| Beginning liabilities for unpaid losses and loss adjustment expenses, gross | $ | 16,559 | $ | 1,845 | $ | 3,421 | $ | 21,825 | ||||
| Reinsurance and other recoverables | 2,293 | 19 | 570 | 2,882 | ||||||||
| Beginning liabilities for unpaid losses and loss adjustment expenses, net | 14,266 | 1,826 | 2,851 | 18,943 | ||||||||
| Add: Maxum acquisition [4] | 122 | — | — | 122 | ||||||||
| Provision for unpaid losses and loss adjustment expenses | ||||||||||||
| Current accident year before catastrophes | 3,766 | 2,808 | — | 6,574 | ||||||||
| Current accident year catastrophes | 200 | 216 | — | 416 | ||||||||
| Prior accident year development | 28 | 151 | 278 | 457 | ||||||||
| Total provision for unpaid losses and loss adjustment expenses | 3,994 | 3,175 | 278 | 7,447 | ||||||||
| Less: payments | 3,469 | 2,932 | 567 | 6,968 | ||||||||
| Less: net reserves transferred to liabilities held for sale [3] | — | — | 487 | 487 | ||||||||
| Ending liabilities for unpaid losses and loss adjustment expenses, net | 14,913 | 2,069 | 2,075 | 19,057 | ||||||||
| Reinsurance and other recoverables | 2,325 | 25 | 426 | 2,776 | ||||||||
| Ending liabilities for unpaid losses and loss adjustment expenses, gross | $ | 17,238 | $ | 2,094 | $ | 2,501 | $ | 21,833 | ||||
| Earned premiums | $ | 6,651 | $ | 3,898 | ||||||||
| Loss and loss expense paid ratio [1] | 52.2 | 75.2 | ||||||||||
| Loss and loss expense incurred ratio | 60.1 | 81.5 | ||||||||||
| Prior accident year development (pts) [2] | 0.4 | 3.9 |
| [1] | The “loss and loss expense paid ratio” represents the ratio of paid losses and loss adjustment expenses to earned premiums. |
| [2] | “Prior accident year development (pts)” represents the ratio of prior accident year development to earned premiums. |
| [3] | Represents liabilities to be transferred to the buyer in connection with the pending sale of the Company's U.K. property and casualty run-off subsidiaries. |
| [4] | Represents Maxum reserves, net of reinsurance as of the acquisition date. |
2016 Catastrophe Losses
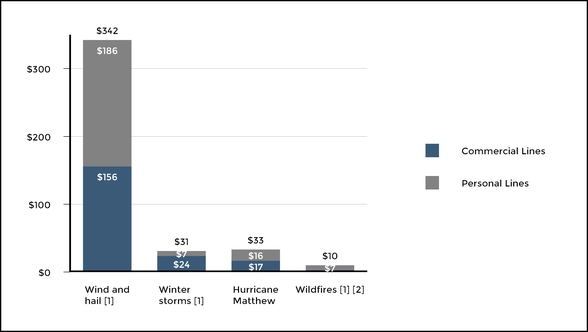
[1] These amounts represent an aggregation of multiple catastrophes.
[2] Includes Commercial Lines of $3.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Prior Accident Year Development Recorded in 2016
| Commercial Lines | Personal Lines | Property & Casualty Other Operations | Total Property & Casualty Insurance | |||||||||
| Workers’ compensation | $ | (119 | ) | $ | — | $ | — | $ | (119 | ) | ||
| Workers’ compensation discount accretion | 28 | — | — | 28 | ||||||||
| General liability | 65 | — | — | 65 | ||||||||
| Package business | 65 | — | — | 65 | ||||||||
| Commercial property | 1 | — | — | 1 | ||||||||
| Auto liability | 57 | 160 | — | 217 | ||||||||
| Professional liability | (37 | ) | — | — | (37 | ) | ||||||
| Bond | (8 | ) | — | — | (8 | ) | ||||||
| Homeowners | — | (10 | ) | — | (10 | ) | ||||||
| Net asbestos reserves | — | — | 197 | 197 | ||||||||
| Net environmental reserves | — | — | 71 | 71 | ||||||||
| Catastrophes | (4 | ) | (3 | ) | — | (7 | ) | |||||
| Uncollectible reinsurance | (30 | ) | — | — | (30 | ) | ||||||
| Other reserve re-estimates, net | 10 | 4 | 10 | 24 | ||||||||
| Total prior accident year development | $ | 28 | $ | 151 | $ | 278 | $ | 457 |
During 2016, the Company’s re-estimates of prior accident year reserves included the following significant reserve changes:
Workers’ compensation reserves consider favorable emergence on reported losses for recent accident years as well as a partially offsetting adverse impact related to two recent Florida Supreme Court rulings that have increased the Company’s exposure to workers’ compensation claims in that state. The favorable emergence has been driven by lower frequency and, to a lesser extent, lower medical severity and management has placed additional weight on this favorable experience as it becomes more credible.
General liability reserves increased for accident years 2012 - 2015 primarily due to higher severity losses incurred on a class of business that insures service and maintenance contractors and increased for accident years 2008 and 2010 primarily due to indemnity losses and legal costs associated with a litigated claim.
Small commercial package business reserves increased due to higher than expected severity on liability claims, principally for accident years 2013 - 2015. Severity for these accident years has developed unfavorably and management has placed more weight on emerged experience.
Auto liability reserves increased due to increases in both commercial lines auto and personal lines auto. Commercial auto
liability reserves increased, predominately for the 2015 accident year, primarily due to increased frequency of large claims. Personal auto liability reserves increased, primarily related to increased bodily injury frequency and severity for the 2015 accident year, including for uninsured and under-insured motorist claims, and increased bodily injury severity for the 2014 accident year. Increases in auto liability loss costs were across both the direct and agency distribution channels.
Professional liability reserves decreased for claims made years 2008 - 2013, primarily for large accounts, including on non-securities class action cases. Claim costs have emerged favorably as these years have matured and management has placed more weight on the emerged experience.
Asbestos and environmental reserves were increased during the period as a result of the second quarter 2016 comprehensive annual review.
Uncollectible reinsurance reserves decreased as a result of giving greater weight to favorable collectability experience in recent calendar periods in estimating future collections.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Roll-forward of Property and Casualty Insurance Product Liabilities for Unpaid Losses and LAE for the Year Ended December 31, 2015
| Commercial Lines | Personal Lines | Property & Casualty Other Operations | Total Property & Casualty Insurance | |||||||||
| Beginning liabilities for unpaid losses and loss adjustment expenses, gross | $ | 16,465 | $ | 1,874 | $ | 3,467 | $ | 21,806 | ||||
| Reinsurance and other recoverables | 2,459 | 18 | 564 | 3,041 | ||||||||
| Beginning liabilities for unpaid losses and loss adjustment expenses, net | 14,006 | 1,856 | 2,903 | 18,765 | ||||||||
| Provision for unpaid losses and loss adjustment expenses | ||||||||||||
| Current accident year before catastrophes | 3,712 | 2,578 | 25 | 6,315 | ||||||||
| Current accident year catastrophes [3] | 121 | 211 | — | 332 | ||||||||
| Prior accident year development | 53 | (21 | ) | 218 | 250 | |||||||
| Total provision for unpaid losses and loss adjustment expenses | 3,886 | 2,768 | 243 | 6,897 | ||||||||
| Less: payments | 3,626 | 2,798 | 295 | 6,719 | ||||||||
| Ending liabilities for unpaid losses and loss adjustment expenses, net | 14,266 | 1,826 | 2,851 | 18,943 | ||||||||
| Reinsurance and other recoverables | 2,293 | 19 | 570 | 2,882 | ||||||||
| Ending liabilities for unpaid losses and loss adjustment expenses, gross | $ | 16,559 | $ | 1,845 | $ | 3,421 | $ | 21,825 | ||||
| Earned premiums | $ | 6,511 | $ | 3,873 | ||||||||
| Loss and loss expense paid ratio [1] | 55.7 | 72.2 | ||||||||||
| Loss and loss expense incurred ratio | 59.7 | 71.5 | ||||||||||
| Prior accident year development (pts) [2] | 0.8 | (0.5 | ) |
| [1] | The “loss and loss expense paid ratio” represents the ratio of paid losses and loss adjustment expenses to earned premiums. |
| [2] | “Prior accident year development (pts)” represents the ratio of prior accident year development to earned premiums. |
| [3] | Contributing to the current accident year catastrophes losses were the following events: |
2015 Catastrophe Losses
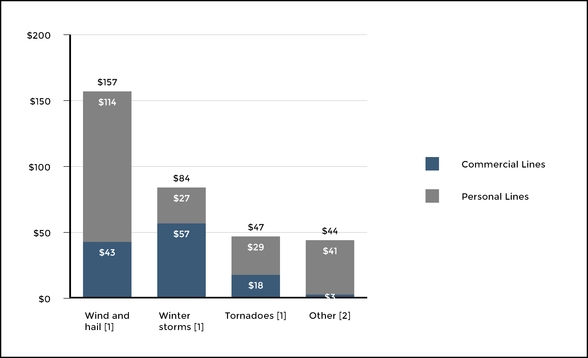
| [1] | These amounts represent an aggregation of multiple catastrophes. |
| [2] | Consists primarily of wildfires. |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Prior Accident Year Development Recorded in 2015
| Commercial Lines | Personal Lines | Property & Casualty Other Operations | Total Property & Casualty Insurance | |||||||||
| Workers’ compensation | $ | (37 | ) | $ | — | $ | — | $ | (37 | ) | ||
| Workers’ compensation discount accretion | 29 | — | — | 29 | ||||||||
| General liability | 8 | — | — | 8 | ||||||||
| Package business | 28 | — | — | 28 | ||||||||
| Commercial property | (6 | ) | — | — | (6 | ) | ||||||
| Auto liability | 62 | (8 | ) | — | 54 | |||||||
| Professional liability | (36 | ) | — | — | (36 | ) | ||||||
| Bond | (2 | ) | — | — | (2 | ) | ||||||
| Homeowners | — | 9 | — | 9 | ||||||||
| Net asbestos reserves | — | — | 146 | 146 | ||||||||
| Net environmental reserves | — | — | 55 | 55 | ||||||||
| Catastrophes | — | (18 | ) | — | (18 | ) | ||||||
| Other reserve re-estimates, net | 7 | (4 | ) | 17 | 20 | |||||||
| Total prior accident year development | $ | 53 | $ | (21 | ) | $ | 218 | $ | 250 |
During 2015, the Company’s re-estimates of prior accident year reserves included the following significant reserve changes:
Workers' compensation reserves decreased due to an improvement in claim closure rates resulting in a decrease in outstanding claims for permanently disabled claimants. In addition, accident years 2013 and 2014 continue to exhibit favorable frequency and medical severity trends; management has been placing additional weight on this favorable experience as it becomes more credible.
Small Commercial package business reserves increased due to higher than expected severity on liability claims,
impacting recent accident years.
Commercial auto liability reserves increased due to increased severity of large claims predominantly for accident years 2010 to 2013.
Professional liability reserves decreased for claims made years 2009 through 2012 primarily for large accounts.
Claim costs have emerged favorably as these years have matured and management has placed more weight on the emerged experience.
Asbestos and environmental reserves were increased during the period as a result of the 2015 comprehensive annual review.
Catastrophe reserves decreased primarily for accident year 2014 as fourth quarter 2014 catastrophes have developed favorably.
Other reserve re-estimates, net, decreased due to decreased contract surety reserves across several accident years and decreased commercial surety reserves for accident years 2012 through 2014 as a result of lower emerged losses. These reserve decreases were offset by an increase in commercial surety reserves related to accident years 2007 and prior, as the number of new claims reported has outpaced expectations.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Roll-forward of Property and Casualty Insurance Product Liabilities for Unpaid Losses and LAE for the Year Ended December 31, 2014
| Commercial Lines | Personal Lines | Property & Casualty Other Operations | Total Property & Casualty Insurance | |||||||||
| Beginning liabilities for unpaid losses and loss adjustment expenses, gross | $ | 16,293 | $ | 1,864 | $ | 3,547 | $ | 21,704 | ||||
| Reinsurance and other recoverables | 2,442 | 13 | 573 | 3,028 | ||||||||
| Beginning liabilities for unpaid losses and loss adjustment expenses, net | 13,851 | 1,851 | 2,974 | 18,676 | ||||||||
| Provision for unpaid losses and loss adjustment expenses | ||||||||||||
| Current accident year before catastrophes | 3,733 | 2,498 | — | 6,231 | ||||||||
| Current accident year catastrophes [3] | 109 | 232 | — | 341 | ||||||||
| Prior accident year development | 13 | (46 | ) | 261 | 228 | |||||||
| Total provision for unpaid losses and loss adjustment expenses | 3,855 | 2,684 | 261 | 6,800 | ||||||||
| Less: payments | 3,665 | 2,679 | 367 | 6,711 | ||||||||
| Ending liabilities for unpaid losses and loss adjustment expenses, net | 14,041 | 1,856 | 2,868 | 18,765 | ||||||||
| Reinsurance and other recoverables | 2,464 | 18 | 559 | 3,041 | ||||||||
| Ending liabilities for unpaid losses and loss adjustment expenses, gross | $ | 16,505 | $ | 1,874 | $ | 3,427 | $ | 21,806 | ||||
| Earned premiums | $ | 6,289 | $ | 3,806 | ||||||||
| Loss and loss expense paid ratio [1] | 58.3 | 70.4 | ||||||||||
| Loss and loss expense incurred ratio | 61.3 | 70.5 | ||||||||||
| Prior accident year development (pts) [2] | 0.2 | (1.2 | ) |
| [1] | The “loss and loss expense paid ratio” represents the ratio of paid losses and loss adjustment expenses to earned premiums. |
| [2] | “Prior accident year development (pts)” represents the ratio of prior accident year development to earned premiums. |
| [3] | Contributing to the current accident year catastrophes losses were the following events: |
2014 Catastrophe Losses
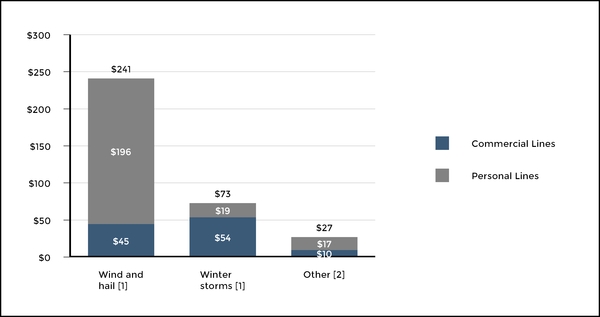
[1] These amounts represent an aggregation of multiple catastrophes.
[2] Includes tornadoes, earthquakes and flooding.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Prior Accident Year Development Recorded in 2014
| Commercial Lines | Personal Lines | Property & Casualty Other Operations | Total Property & Casualty Insurance | |||||||||
| Workers’ compensation | $ | (7 | ) | $ | — | $ | — | $ | (7 | ) | ||
| Workers’ compensation discount accretion | 30 | — | — | 30 | ||||||||
| General liability | (25 | ) | — | — | (25 | ) | ||||||
| Package business | 3 | — | — | 3 | ||||||||
| Commercial property | 2 | — | — | 2 | ||||||||
| Auto liability | 23 | 2 | — | 25 | ||||||||
| Professional liability | (17 | ) | — | — | (17 | ) | ||||||
| Bond | 8 | — | — | 8 | ||||||||
| Homeowners | — | (7 | ) | — | (7 | ) | ||||||
| Net asbestos reserves | — | — | 212 | 212 | ||||||||
| Net environmental reserves | — | — | 30 | 30 | ||||||||
| Catastrophes | (14 | ) | (31 | ) | — | (45 | ) | |||||
| Other reserve re-estimates, net | 10 | (10 | ) | 19 | 19 | |||||||
| Total prior accident year development | $ | 13 | $ | (46 | ) | $ | 261 | $ | 228 |
During 2014, the Company’s re-estimates of prior accident years reserves included the following significant reserve changes:
Workers' compensation reserves decreased for recent accident years due to improved frequency and lower estimated claim handling costs.
General liability reserves decreased due to lower frequency in late emerging claims.
Commercial auto liability reserves increased due to an increased frequency of severe claims spread across several accident years.
Professional liability reserves decreased for accident years 2013, 2012 and 2010 due to lower frequency of reported claims.
Bond reserves emerged favorably for accident years 2008 to 2013, offset by adverse emergence on reserves for accident years 2007 and prior.
Homeowners reserves emerged favorably for accident year 2013, primarily related to favorable development on fire and water related claims.
Asbestos and environmental reserves were increased during the period as a result of the 2014 comprehensive annual review.
Catastrophe reserves decreased primarily for accident year 2013, as fourth quarter 2013 catastrophes have developed favorably.
Property & Casualty Other Operations
Net reserves and reserve activity in Property & Casualty Other Operations are categorized and reported as Asbestos, Environmental, and “All other”. The “All other” category of reserves covers a wide range of insurance and assumed
reinsurance coverages, including, but not limited to, potential liability for construction defects, lead paint, silica, pharmaceutical products, molestation and other long-tail liabilities. In addition to various insurance and assumed reinsurance exposures, "All other" includes unallocated loss adjustment expense reserves. "All other" also includes the Company’s allowance for uncollectible reinsurance. When the Company commutes a ceded reinsurance contract or settles a ceded reinsurance dispute, net reserves for the related cause of loss (including asbestos, environmental or all other) are increased for the portion of the allowance for uncollectible reinsurance attributable to that commutation or settlement.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
P&C Other Operations
Total Reserves, Net of Reinsurance [1]
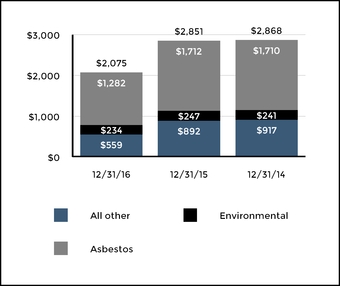
| [1] | 2016 excludes net reserves of $487 to be transferred to the buyer in connection with the pending sale of the Company's U.K. property and casualty run-off subsidiaries. These net reserves are included in liabilities held for sale as of December 31, 2016 of which $246 was for asbestos and environmental. |
Asbestos and Environmental Reserves
Reserves for asbestos and environmental are primarily within P&C Other Operations with less significant amounts of asbestos and environmental reserves included within Commercial Lines and Personal Lines reporting segments (collectively "Ongoing Operations"). The following tables include all asbestos and environmental reserves, including reserves in P&C Other Operations and Ongoing Operations.
Asbestos and Environmental Net Reserves
| Asbestos | Environmental | |||||
| 2016 | ||||||
| Property and Casualty Other Operations | $ | 1,282 | $ | 234 | ||
| Commercial Lines and Personal Lines | 81 | 58 | ||||
| Ending liability — net | $ | 1,363 | $ | 292 | ||
| 2015 | ||||||
| Property and Casualty Other Operations | $ | 1,712 | $ | 247 | ||
| Commercial Lines and Personal Lines | 91 | 71 | ||||
| Ending liability — net | $ | 1,803 | $ | 318 | ||
| 2014 | ||||||
| Property and Casualty Other Operations | $ | 1,710 | $ | 241 | ||
| Commercial Lines and Personal Lines | 101 | 75 | ||||
| Ending liability — net | $ | 1,811 | $ | 316 |
Property & Casualty Reserves
Asbestos and Environmental Summary as of December 31, 2016
| Asbestos | Environmental | Total A&E | ||||||||
| Gross | ||||||||||
| Direct | $ | 1,554 | $ | 313 | $ | 1,867 | ||||
| Assumed Reinsurance | 177 | 7 | 184 | |||||||
| London Market | 293 | 47 | 340 | |||||||
| Total | 2,024 | 367 | 2,391 | |||||||
| Ceded | (456 | ) | (34 | ) | (490 | ) | ||||
| Net reserves transferred to liabilities held for sale | (205 | ) | (41 | ) | (246 | ) | ||||
| Net | $ | 1,363 | $ | 292 | $ | 1,655 |
Roll-Forward of Asbestos and Environmental Losses and LAE
| Asbestos | Environmental | |||||
| 2016 | ||||||
| Beginning liability — net | $ | 1,803 | $ | 318 | ||
| Losses and loss adjustment expenses incurred | 197 | 71 | ||||
| Losses and loss adjustment expenses paid [1] | (462 | ) | (56 | ) | ||
| Reclassification of allowance for uncollectible insurance [3] | 30 | — | ||||
| Net reserves transferred to liabilities held for sale [2] | (205 | ) | (41 | ) | ||
| Ending liability — net | $ | 1,363 | $ | 292 | ||
| 2015 | ||||||
| Beginning liability — net | $ | 1,811 | $ | 316 | ||
| Losses and loss adjustment expenses incurred | 157 | 57 | ||||
| Losses and loss adjustment expenses paid | (165 | ) | (55 | ) | ||
| Ending liability — net | $ | 1,803 | $ | 318 | ||
| 2014 | ||||||
| Beginning liability — net | $ | 1,825 | $ | 354 | ||
| Losses and loss adjustment expenses incurred | 215 | 30 | ||||
| Losses and loss adjustment expenses paid | (229 | ) | (68 | ) | ||
| Ending liability — net | $ | 1,811 | $ | 316 |
| [1] | Included $289 related to the settlement in 2016 of PPG Industries ("PPG") asbestos liabilities, net of reinsurance billed to third-party reinsurers. |
| [2] | Liabilities to be transferred to the buyer in connection with the pending sale of the Company's U.K. property and casualty run-off subsidiaries are classified as held for sale in the Company's Consolidated Balance Sheets. |
| [3] | Related to the reclassification of an allowance for uncollectible reinsurance from the "All Other" category of P&C Other Operations reserves. |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Net Survival Ratio
Net survival ratio is the quotient of the net carried reserves divided by average annual payments net of reinsurance and is an indication of the number of years that net carried reserves would last (i.e. survive) if future annual net payments were consistent with the calculated historical average.
The net survival ratios shown below are calculated for the one and three year periods ended December 31, 2016 and are calculated excluding the effect of net carried reserves for asbestos and environmental related to the pending sale of the Company's U.K. Property & Casualty runoff subsidiaries as those carried reserves are included in liabilities held for sale in the consolidated balance sheet as of December 31, 2016. See section that follows entitled Adverse Development Cover which could materially affect the survival ratio of net reserves given that adverse development of asbestos and environmental reserves, if any, subsequent to December 31, 2016 will be ceded to NICO up to the reinsurance limit. For asbestos, the table also presents the net survival ratios excluding the effect of the PPG settlement in 2016. See section that follows entitled Major Categories of Asbestos Accounts for discussion of the PPG settlement.
Net Survival Ratios
| Asbestos | Environmental | |
| One year net survival ratio | 3.0 | 5.4 |
| Three year net survival ratio | 5.0 | 5.5 |
| One year net survival ratio - excluding PPG settlement | 8.3 | 5.4 |
| Three year net survival ratio - excluding PPG settlement | 7.6 | 5.5 |
The Company classifies its asbestos and environmental reserves into three categories: Direct, Assumed Reinsurance and London Market.
| • | Direct Insurance- includes primary and excess coverage. Of the three categories of claims, direct policies tend to have the greatest factual development from which to estimate the Company’s exposures. |
| • | Assumed Reinsurance- includes both “treaty” reinsurance (covering broad categories of claims or blocks of business) and “facultative” reinsurance (covering specific risks or individual policies of primary or excess insurance companies). Assumed Reinsurance exposures are less predictable than direct insurance exposures because the Company does not generally receive notice of a reinsurance claim until the underlying direct insurance claim is mature. This causes a delay in the receipt of information at the reinsurer level and adds to the uncertainty of estimating related reserves. |
| • | London Market- includes the business written by one or more of the Company’s subsidiaries in the United Kingdom, which are no longer active in the insurance or reinsurance business. Such business includes both direct insurance and assumed reinsurance. London Market exposures are the most uncertain of the three categories of claims. As a participant in the London Market (comprised of both Lloyd’s of London and London Market companies), certain subsidiaries of the Company wrote business on a subscription basis, with those subsidiaries’ involvement |
being limited to a relatively small percentage of a total contract placement. Claims are reported, via a broker, to the “lead” underwriter and, once agreed to, are presented to the following markets for concurrence. This reporting and claim agreement process makes estimating liabilities for this business the most uncertain of the three categories of claims.
Asbestos and Environmental
Paid and Incurred Losses and LAE Development
| Asbestos | Environmental | |||||||||||
| Paid Losses & LAE | Incurred Losses & LAE | Paid Losses & LAE | Incurred Losses & LAE | |||||||||
| 2016 | ||||||||||||
| Gross | ||||||||||||
| Direct | $ | 464 | $ | 257 | $ | 52 | $ | 77 | ||||
| Assumed Reinsurance | 55 | — | 4 | — | ||||||||
| London Market | 16 | — | 5 | — | ||||||||
| Total | 535 | 257 | 61 | 77 | ||||||||
| Ceded | (73 | ) | (60 | ) | (5 | ) | (6 | ) | ||||
| Net | $ | 462 | $ | 197 | $ | 56 | $ | 71 | ||||
| 2015 | ||||||||||||
| Gross | ||||||||||||
| Direct | $ | 156 | $ | 190 | $ | 47 | $ | 68 | ||||
| Assumed Reinsurance | 57 | (1 | ) | 5 | (4 | ) | ||||||
| London Market | 17 | 62 | 16 | 18 | ||||||||
| Total | 230 | 251 | 68 | 82 | ||||||||
| Ceded | (65 | ) | (94 | ) | (13 | ) | (25 | ) | ||||
| Net | $ | 165 | $ | 157 | $ | 55 | $ | 57 | ||||
| 2014 | ||||||||||||
| Gross | ||||||||||||
| Direct | $ | 214 | $ | 206 | $ | 65 | $ | 23 | ||||
| Assumed Reinsurance | 72 | 70 | 12 | — | ||||||||
| London Market | 17 | 28 | 6 | 7 | ||||||||
| Total | 303 | 304 | 83 | 30 | ||||||||
| Ceded | (74 | ) | (89 | ) | (15 | ) | — | |||||
| Net | $ | 229 | $ | 215 | $ | 68 | $ | 30 |
Annual Reserve Reviews
Review of Asbestos Reserves
Beginning in 2017, the Company expects to perform its regular comprehensive annual review of asbestos reserves in the fourth quarter. As part of this evaluation in the second quarter of 2016, the Company reviewed all of its open direct domestic insurance accounts exposed to asbestos liability, as well as assumed reinsurance accounts.
During the 2016 second quarter review, a substantial majority of the Company’s direct accounts trended as expected, and the
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Company observed no material changes in the underlying legal environment. However, mesothelioma claims filings have not declined as expected for a small subset of peripheral defendants with a high concentration of asbestos filings in specific, adverse jurisdictions. As a result, aggregate indemnity and defense costs did not decline as expected. While the mesothelioma and adverse jurisdiction claim trends observed in the 2016 comprehensive annual review were similar to the 2015 comprehensive annual review, most of the defendants that had reserve increases in the 2016 review did not have a material impact in the 2015 review. Based on this evaluation, the Company increased its net asbestos reserves for prior year development by $197 in second quarter 2016.
During the 2015 comprehensive annual review, the Company found a substantial majority of direct accounts trended as expected, and the Company saw no material changes in the underlying legal environment during the past year. However, a small percentage of the Company’s direct accounts experienced greater than expected claim filings, including mesothelioma claims. This was driven by a subset of peripheral defendants with a high concentration of filings in specific, adverse jurisdictions. As a result, the aggregate indemnity and defense costs did not decline as expected. To a lesser degree, the Company also saw unfavorable development on certain assumed reinsurance accounts, driven by various account-specific factors, including filing activity experienced by the direct accounts. Based on this evaluation, the Company increased its net asbestos reserves for prior year development by $146 in second quarter 2015.
During the 2014 comprehensive annual review, the Company found estimates for certain direct accounts increased, principally due to a higher than previously estimated number of mesothelioma claim filings and an increase in costs associated with asbestos litigation. The Company also experienced unfavorable development on certain of its assumed reinsurance accounts driven by a variety of account-specific factors, including those experienced by the direct policyholders. Based on this evaluation, the Company increased its net asbestos reserves for prior year development by $212 in second quarter 2014.
Review of Environmental Reserves
Beginning in 2017, the Company expects to perform its regular comprehensive annual review of environmental reserves in the fourth quarter. As part of its evaluation in the second quarter of 2016, the Company reviewed all of its open direct domestic insurance accounts exposed to environmental liability, as well as assumed reinsurance accounts and its London Market exposures for both direct and assumed reinsurance. During 2016, a substantial majority of the Company's direct environmental accounts trended as expected. However, a small percentage of the Company's direct accounts exhibited deterioration associated with the tendering of new sites for coverage, increased defense costs stemming from individual bodily injury liability suits, and increased clean-up costs associated with waterways. During 2015, a substantial majority of the Company's environmental exposures trended as expected, however the Company found loss and expense estimates for certain individual account exposures increased based upon an increase in clean-up costs, including at a handful of Superfund sites. In addition, new claim severity deteriorated, although frequency continued to decline as expected. During 2014, the Company found estimates for certain individual account exposures increased based upon unfavorable litigation results and increased clean-up and expense costs. The
net effect of these account-specific changes as well as quarterly actuarial evaluations of new account emergence and historical loss and expense paid experience resulted in increases of $71, $57 and $30 in net environmental reserves for prior years development in 2016, 2015 and 2014, respectively.
Major Categories of Asbestos Accounts
As noted above, the Company divides its gross asbestos and environmental exposures into Direct, Assumed Reinsurance and London Market.
Direct asbestos exposures include Major Asbestos Defendants, Non-Major Accounts, and Unallocated Direct Accounts.
| • | Major Asbestos Defendants- represent the “Top 70” accounts in Tillinghast's published Tiers 1 and 2 and Wellington accounts. Major Asbestos Defendants have the fewest number of asbestos accounts and include reserves related to PPG Industries, Inc. (“PPG”). In May 2016, the Company pre-paid its funding obligation in the amount of $315 as permitted under the settlement agreement, arising from participation in a 2002 settlement of asbestos liabilities of PPG. The Company's funding obligation approximated the amount reserved for this exposure. Major Asbestos Defendants gross asbestos reserves account for approximately 3% of the Company's total Direct gross asbestos reserves as of June 30, 2016. Major Asbestos Defendants gross asbestos reserves accounted for approximately 25% of the Company's total Direct gross asbestos reserves as of June 30, 2015 when reserves for this category included the reserves for PPG. |
| • | Non-Major Accounts- are all other open direct asbestos accounts and largely represent smaller and more peripheral defendants. These exposures represented 1,088 accounts and contain approximately 58% of The Company's Direct gross asbestos reserves as of June 30, 2016. These accounts had represented 1,132 exposures and approximately 46% of the Company's total Direct gross asbestos reserves as of June 30, 2015. |
| • | Unallocated Direct Accounts- includes an estimate of the reserves necessary for asbestos claims related to direct insureds that have not previously tendered asbestos claims to the Company and exposures related to liability claims that may not be subject to an aggregate limit under the applicable policies. |
Adverse Development Cover
Effective December 31, 2016, the Company entered into an asbestos and environmental adverse development cover (“ADC”) reinsurance agreement with National Indemnity Company (“NICO”), a subsidiary of Berkshire Hathaway Inc. (“Berkshire”), to reduce uncertainty about potential adverse development. Under the ADC, the Company paid a reinsurance premium of $650 for NICO to assume adverse net loss and allocated loss adjustment expense reserve development up to $1.5 billion above the Company’s existing net asbestos and environmental (“A&E”) reserves as of December 31, 2016 of approximately $1.7 billion. The $650 reinsurance premium was placed into a collateral trust account as security for NICO’s claim payment obligations to the Company. The Company has retained the risk of collection on amounts due from other third-party reinsurers and continues to be responsible for claims handling and other administrative services, subject to certain conditions. The ADC covers
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
substantially all the Company’s A&E reserve development up to the reinsurance limit. The ADC excludes risk of adverse development on net asbestos and environmental reserves held by the Company’s U.K. Property and Casualty run-off subsidiaries which have been accounted for as liabilities held for sale in the consolidated balance sheets as of December 31, 2016.
The ADC has been accounted for as retroactive reinsurance and the Company reported the $650 cost as a loss on reinsurance transaction in 2016 in the consolidated statement of operations. Under retroactive reinsurance accounting, net adverse asbestos and environmental reserve development after December 31, 2016, if any, will result in an offsetting reinsurance recoverable up to the $1.5 billion limit. Cumulative ceded losses up to the $650 reinsurance premium paid would be recognized as a dollar-for-dollar offset to direct losses incurred. Cumulative ceded losses exceeding the $650 reinsurance premium paid would result in a deferred gain. The deferred gain would be recognized over the claim settlement period in the proportion of the amount of cumulative ceded losses collected from the reinsurer to the estimated ultimate reinsurance recoveries. Consequently, until periods when the deferred gain is recognized as a benefit to earnings, cumulative adverse development of asbestos and environmental claims after December 31, 2016 in excess of $650 may result in significant charges against earnings.
Review of "All Other" Reserves in Property & Casualty Other Operations
In the fourth quarters of 2016, 2015 and 2014, the Company completed evaluations of certain of its non-asbestos and non-environmental reserves in Property & Casualty Other Operations, including its assumed reinsurance liabilities. In 2016, the Company reclassified a $30 allowance for uncollectible reinsurance to net asbestos reserves. In 2015 and 2014, the Company's prior year development was driven by unfavorable frequency of international workers' compensation claims, which resulted in overall adverse development of $29 and $19, respectively.
The Company provides an allowance for uncollectible reinsurance, reflecting management’s best estimate of reinsurance cessions that may be uncollectible in the future due to reinsurers’ unwillingness or inability to pay. During the second quarters of 2016, 2015 and 2014, the Company completed its annual evaluations of the collectability of the reinsurance recoverables and the adequacy of the allowance for uncollectible reinsurance associated with older, long-term casualty liabilities reported in Property & Casualty Other Operations. In conducting these evaluations, the Company used its most recent detailed evaluations of ceded liabilities reported in the segment. The
Company analyzed the overall credit quality of the Company’s reinsurers, recent trends in arbitration and litigation outcomes in disputes between cedants and reinsurers and recent developments in commutation activity between reinsurers and cedants. The evaluations in the second quarters of 2016, 2015, and 2014 resulted in no material adjustments to the Property & Casualty Other Operations' overall ceded reinsurance reserves, including the allowance for uncollectible reinsurance. As of December 31, 2016 , 2015, and 2014 the allowance for uncollectible reinsurance for Property & Casualty Other Operations totaled $136 (excluding the allowance on U.K. ceded recoverable held for sale),$220, and $225, respectively. Due to the inherent uncertainties as to collection and the length of time before reinsurance recoverables become due, particularly for older, long-term casualty liabilities, it is possible that future adjustments to the Company’s reinsurance recoverables, net of the allowance, could be required. Beginning in 2017, the Company expects to perform its regular annual comprehensive review of Property & Casualty Other Operations reinsurance recoverables in the fourth quarter.
Impact of Re-estimates on Property and Casualty Insurance Product Reserves
Estimating property and casualty insurance product reserves uses a variety of methods, assumptions and data elements. Ultimate losses may vary materially from the current estimates. Many factors can contribute to these variations and the need to change the previous estimate of required reserve levels. Prior accident year reserve development is generally due to the emergence of additional facts that were not known or anticipated at the time of the prior reserve estimate and/or due to changes in interpretations of information and trends.
The table below shows the range of annual reserve re-estimates experienced by The Hartford over the past ten years. The amount of prior accident year development (as shown in the reserve roll-forward) for a given calendar year is expressed as a percent of the beginning calendar year reserves, net of reinsurance. The ranges presented are significantly influenced by the facts and circumstances of each particular year and by the fact that only the last ten years are included in the range. Accordingly, these percentages are not intended to be a prediction of the range of possible future variability. For further discussion of the potential for variability in recorded loss reserves, see Preferred Reserving Methods by Line of Business - Impact of Changes in Key Assumptions on Reserve Volatility section.
Range of Prior Accident Year Unfavorable (Favorable) Development for the Ten Years Ended December 31, 2016
| Commercial Lines | Personal Lines | Property & Casualty Other Operations | Total Property & Casualty [1] | |
| Annual range of prior accident year unfavorable (favorable) development for the ten years ended December 31, 2016 | (3.1)% - 1.0% | (6.9)% - 8.3% | 1.9% - 9.8% | (1.2)% - 2.4% |
| [1] | Excluding the reserve increases for asbestos and environmental reserves, over the past ten years reserve re-estimates for total property and casualty insurance ranged from (2.5)% to 1.0%. |
The potential variability of the Company’s property and casualty insurance product reserves would normally be expected to vary
by segment and the types of loss exposures insured by those segments. Illustrative factors influencing the potential reserve
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
variability for each of the segments are discussed under Critical Accounting Estimates for Property & Casualty Insurance Product Reserves and Asbestos and Environmental Reserves. See the section entitled Property & Casualty Other Operations, Annual Reserve Reviews about the impact that the ADC retroactive reinsurance agreement with NICO may have on net reserve changes of asbestos and environmental reserves going forward.
The following table summarizes the effect of reserve re-estimates, net of reinsurance, on calendar year operations for the
ten-year period ended December 31, 2016. The total of each column details the amount of reserve re-estimates made in the indicated calendar year and shows the accident years to which the re-estimates are applicable. The amounts in the total column on the far right represent the cumulative reserve re-estimates during the ten year period ended December 31, 2016 for the indicated accident year in each row.
Effect of Net Reserve Re-estimates on Calendar Year Operations
| Calendar Year | |||||||||||||||||||||||||||||||||
| 2007 | 2008 | 2009 | 2010 | 2011 | 2012 | 2013 | 2014 | 2015 | 2016 | Total | |||||||||||||||||||||||
| By Accident Year | |||||||||||||||||||||||||||||||||
| 2006 & Prior | $ | 48 | $ | (177 | ) | $ | (34 | ) | $ | (2 | ) | $ | 237 | $ | (3 | ) | $ | 76 | $ | 348 | $ | 275 | $ | 279 | $ | 1,047 | |||||||
| 2007 | (49 | ) | (113 | ) | (156 | ) | (71 | ) | (15 | ) | (67 | ) | 10 | 9 | 17 | (435 | ) | ||||||||||||||||
| 2008 | (39 | ) | 1 | (31 | ) | (1 | ) | (37 | ) | (13 | ) | 43 | (5 | ) | (82 | ) | |||||||||||||||||
| 2009 | (39 | ) | (13 | ) | (24 | ) | (8 | ) | 7 | 7 | 10 | (60 | ) | ||||||||||||||||||||
| 2010 | 245 | 3 | 61 | (22 | ) | 16 | 15 | 318 | |||||||||||||||||||||||||
| 2011 | 36 | 148 | (4 | ) | 12 | (6 | ) | 186 | |||||||||||||||||||||||||
| 2012 | 19 | — | (55 | ) | (35 | ) | (71 | ) | |||||||||||||||||||||||||
| 2013 | (98 | ) | (43 | ) | (29 | ) | (170 | ) | |||||||||||||||||||||||||
| 2014 | (14 | ) | 20 | 6 | |||||||||||||||||||||||||||||
| 2015 | 191 | 191 | |||||||||||||||||||||||||||||||
| Increase (decrease) in net reserves | $ | 48 | $ | (226 | ) | $ | (186 | ) | $ | (196 | ) | $ | 367 | $ | (4 | ) | $ | 192 | $ | 228 | $ | 250 | $ | 457 | $ | 930 |
Accident years 2006 and Prior
The net reserve re-estimates for accident years 2006 and prior are driven mostly by increased reserves for asbestos and environmental reserves, and also for increased estimates on assumed casualty reinsurance, workers’ compensation and general liability claims.
Accident years 2007 through 2009
Estimates of ultimate losses have emerged favorably for accident years 2007 through 2009 with much of the favorable re-estimates for 2007 accident year on workers’ compensation claims, driven, in part, by state regulatory reforms in California and Florida, underwriting actions, and expense reduction initiatives that had a greater impact in controlling costs than originally estimated. Also contributing to the favorable development were reserve decreases on short-tail lines of business, where results emerge quickly.
In addition, reserves for professional liability claims for the 2007 accident year were reduced due to a lower estimate of claim severity on both directors’ and officers’ insurance claims and errors and omissions insurance claims. Reserves for Personal Lines auto liability claims were decreased largely due to an improvement in emerged claim severity for the 2007accident year.
Unfavorable reserve re-estimates for accident year 2008 are related to elevated workers' compensation loss emergence and an increase in general liability reserves.
Accident years 2010 and 2011
Unfavorable reserve re-estimates on accident year 2010 and 2011 were primarily related to workers' compensation and commercial auto liability. Workers' compensation loss cost trends
were higher than initially expected as an increase in frequency outpaced a moderation of severity trends. Unfavorable commercial auto liability reserve re-estimates were driven by higher frequency of large loss bodily injury claims.
Accident years 2012 and 2013
Reserves were decreased for accident year 2012 due to favorable frequency and medical severity trends for workers'
compensation, favorable professional liability claim emergence, and lower frequency of late emerging general liability claims, partially offset by increased reserves in commercial auto liability due to increased severity of large claims.
Reserves were decreased for accident year 2013 due to lower estimated medical severity and claim handling costs for workers' compensation, lower frequency of reported claims for professional liability and favorable emergence of losses for property lines of business, including for catastrophes. Favorable development for accident year 2013 was partially offset by unfavorable reserve re-estimates in commercial auto liability driven by increased severity of large claims.
Accident years 2014 and 2015
Reserves were decreased for the 2014 accident year largely due to favorable frequency and medical severity trends for workers' compensation and favorable development of fourth quarter catastrophes, partially offset by increased severity of liability claims on package business and unfavorable frequency and severity trends for personal and commercial auto liability.
Reserves were increased for the 2015 accident year largely due to unfavorable frequency and severity trends for personal and commercial auto liability and to a lesser extent increased severity of liability claims on package business, partially offset by
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
favorable frequency and medical severity trends for workers' compensation.
Group Benefit Long-term Disability ("LTD") Reserves, Net of Reinsurance
The Company establishes reserves for group life and accident & health contracts, including long-term disability coverage, for both outstanding reported claims and claims related to insured events that the Company estimates have been incurred but have not yet been reported. These reserve estimates can change over time based on facts and interpretations of circumstances, and consideration of various internal factors including The Hartford’s experience with similar cases, claim payment patterns, loss control programs and mix of business. In addition, the reserve estimates are influenced by various external factors including court decisions and economic conditions. The effects of inflation are implicitly considered in the reserving process. Long-tail claim liabilities are discounted because the payment pattern and the ultimate costs are reasonably fixed and determinable on an individual claim basis. The majority of Group Benefits’ reserves are for LTD claimants who are known to be disabled and are currently receiving benefits. The Company held $4,687 and $4,765 of LTD unpaid losses and loss adjustment expenses, net of reinsurance, as of December 31, 2016 and 2015, respectively.
Reserving Methodology
How Reserves are Set - A Disabled Life Reserve (DLR) is calculated for each LTD claim. The DLR for each claim is the expected present value of all future benefit payments starting with the known monthly gross benefit which is reduced for estimates of the expected claim recovery due to return to work or claimant death, offsets from other income including offsets from Social Security benefits, and discounting where the discount rate is tied to expected investment yield at the time the claim is incurred. Estimated future benefit payments represent the monthly income benefit that is paid until recovery, death or expiration of benefits. Claim recoveries are estimated based on claim characteristics such as age and diagnosis and represent an estimate of benefits that will terminate, generally as a result of the claimant returning to work or being deemed able to return to work. For claims recently closed due to recovery, a portion of the DLR is retained for the possibility that the claim reopens upon further evidence of disability. In addition, a reserve for estimated unpaid claim expenses is included in the DLR.
The DLR also includes a liability for potential payments to pending claimants who have not yet been approved for LTD either because they have not yet satisfied the waiting (or elimination) period or because the approval or denial decision has not yet been made. In these cases, the present value of future benefits is reduced for the likelihood of recovery before benefit onset or claim denial based on Company experience. For claims recently closed due to denial, a portion of the DLR is retained for the possibility that the claim is later approved upon further evidence of disability.
Estimates for incurred but not reported (IBNR) claims are made by applying completion factors to the dollar amount of claims reported. Completion factors are derived from standard actuarial techniques using triangles that display historical claim count
emergence by incurral year. These estimates are reviewed for reasonableness and are adjusted for current trends and other factors expected to cause a change in claim emergence. The reserves include an estimate of unpaid claim expenses, including a provision for the cost of initial set-up of the claim once reported.
For all products, including LTD, there is a period generally ranging from two to twelve months, depending on the product, where emerged claims for an incurral year are not yet credible enough to be a basis for estimating reserves. In these cases, the ultimate loss is estimated using earned premium multiplied by an expected loss ratio based on pricing assumptions of claim incidence, claim severity, and earned pricing.
Current Trends Contributing to Reserve Uncertainty
In group insurance, Long-Term Disability (LTD) has the longest pattern of loss emergence and the highest reserve amount. One significant risk to the reserve would be a slowdown in recoveries. In particular, the economic environment can affect the ability of an injured worker to return-to-work and the length of time a worker receives disability benefits. Another significant risk is a change in benefit offsets. Often the Company pays a reduced benefit due to offsets from other income sources such as pensions or Social Security Disability Insurance (SSDI). Possible changes to the frequency, timing, or amount of offsets, such as a change in SSDI approval standards or benefit offerings, create a risk that the amount to settle open claims will exceed initial estimates. Since the monthly income benefit for a claimant is established based on the individual’s salary at the time of disability and the level of coverages and benefits provided, inflation is not considered a significant risk to the reserve estimate. Few of the Company’s LTD policies provide for cost of living adjustments to the monthly income benefit.
Impact of Key Assumptions on Reserves
The key assumptions affecting our group life and accident & health reserves include:
Discount Rate - The discount rate is the interest rate at which expected future claim cash flows are discounted to determine the present value. A higher selected discount rate results in a lower reserve. If the discount rate is higher than our future investment returns, our invested assets will not earn enough investment income to cover the discount accretion on our claim reserves which would negatively affect our profit. For each incurral year, the discount rates are estimated based on investment yields expected to be earned net of investment expenses. The incurral year is the year in which the claim is incurred and the estimated settlement pattern is determined. Once established, discount rates for each incurral year are unchanged. The weighted average discount rate on LTD reserves was 4.3% and 4.4% in 2016 and 2015, respectively. Had the discount rate for each incurral year been 10 basis points lower at the time they were established, our Group Benefits unpaid loss and loss adjustment expense reserves would be higher by $22, pretax, as of December 31, 2016.
Claim Termination Rates (inclusive of mortality, recoveries, and expiration of benefits) - Claim termination rates are an estimate of the rate at which claimants will cease receiving benefits during a
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
given calendar year. Terminations result from a number of factors, including death, recoveries and expiration of benefits. The probability that benefits will terminate in each future month for each claim is estimated using a predictive model that uses past Company experience, contract provisions, job characteristics and other claimant-specific characteristics such as diagnosis, time since disability began, and age. Actual claim termination experience will vary from period to period. Over the past 10 years, claim termination rates for a single incurral year have generally increased and have ranged from 4% below to 8% above current assumptions over that time period. For a single recent incurral year (such as 2016), a one percent decrease in our assumption for LTD claim termination rates would increase our reserves by $4. For all incurral years combined, as of December 31, 2016, a one percent decrease in our assumption for our LTD claim termination rates would increase our Group Benefits unpaid losses and loss adjustment expense reserves by $17.
Estimated Gross Profits
Estimated gross profits (“EGPs”) are used in the valuation and amortization of assets, including DAC and SIA. Portions of EGPs are also used in the valuation of reserves for death and other insurance benefit features on variable annuity and other universal life type contracts.
Talcott Resolution Significant EGP-based Balances
| As of December 31, | ||||||
| 2016 | 2015 | |||||
| DAC [1] | $ | 1,066 | $ | 1,180 | ||
| SIA | $ | 53 | $ | 56 | ||
| Death and Other Insurance Benefit Reserves, net of reinsurance [2] | $ | 354 | $ | 340 |
| [1] | For additional information on DAC, see Note 9 - Deferred Policy Acquisition Costs of Notes to Consolidated Financial Statements. |
| [2] | For additional information on death and other insurance benefit reserves, see Note 12 - Reserve for Future Policy Benefits and Separate Account Liabilities of Notes to Consolidated Financial Statements. |
Talcott Resolution Benefit (Charge) to Income, Net of Tax, as a Result of Unlock
| For the years ended December 31, | |||||||||
| 2016 | 2015 | 2014 | |||||||
| DAC | $ | (21 | ) | $ | 69 | $ | (136 | ) | |
| SIA | 5 | (17 | ) | (35 | ) | ||||
| Unearned Revenue Reserve ("URR") | — | — | 42 | ||||||
| Death and Other Insurance Benefit Reserves | 14 | 28 | 34 | ||||||
| Total (before tax) | (2 | ) | 80 | (95 | ) | ||||
| Income tax effect | (1 | ) | 28 | (33 | ) | ||||
| Total (after-tax) | $ | (1 | ) | $ | 52 | $ | (62 | ) |
The Unlock charge, after-tax, for the year ended December 31, 2016 was primarily due to the reduction of the fixed annuity DAC balance to zero, updates to the macro hedging program cost to reflect 2016 activity, and the effect of assumption updates for
variable annuities, including to mortality, largely offset by separate account returns being above our aggregated estimated returns during the period, largely due to an increase in equity markets, as well as the effect of reducing the assumption about expected futures lapses of variable annuities.
The Unlock benefit, after-tax, for the year ended December 31, 2015 was primarily due to assumption changes related to benefit utilization and lower assumed lapse rates, partially offset by a lower assumed general account spread and higher assumed withdrawal rates.
The Unlock charge for the year ended December 31, 2014 was primarily due to lower future estimated gross profits on the fixed annuity block driven by the continued low interest rate environment as well as higher variable annuity unit costs due to higher than expected surrenders, partially offset by actual separate account returns being above our aggregated estimated returns during the period.
Use of Estimated Gross Profits in Amortization and Reserving
For most annuity contracts, the Company estimates gross profits over 20 years as EGPs emerging subsequent to that time frame are immaterial. Products sold in a particular year are aggregated into cohorts. Future gross profits for each cohort are projected over the estimated lives of the underlying contracts, based on future account value projections for variable annuity products. The projection of future account values requires the use of certain assumptions including: separate account returns; separate account fund mix; fees assessed against the contract holder’s account balance; surrender and lapse rates; interest margin; mortality; and the extent and duration of hedging activities and hedging costs. Changes in these assumptions and changes to other policyholder behavior assumptions such as resets, partial surrenders, reaction to price increases, and asset allocations cause EGPs to fluctuate, which impacts earnings.
The Company determines EGPs from a single deterministic reversion to mean (“RTM”) separate account return projection which is an estimation technique commonly used by insurance entities to project future separate account returns. Through this estimation technique, the Company’s DAC model is adjusted to reflect actual account values at the end of each quarter. Through consideration of recent market returns, the Company will unlock, or adjust, projected returns over a future period so that the account value returns to the long-term expected rate of return, providing that those projected returns do not exceed certain caps.
Annual Unlock of Assumptions
In the fourth quarter of 2016, the Company completed a comprehensive policyholder behavior assumption study which resulted in a non-market related after-tax charge of $20 and incorporated the results of that study into its projection of future gross profits. Additionally, throughout the year, the Company evaluates various aspects of policyholder behavior and will revise its policyholder assumptions if credible emerging data indicates that changes are warranted. The Company will continue to evaluate its assumptions related to policyholder behavior as initiatives to reduce the size of the annuity business are implemented by management. Upon completion of an annual assumption study or evaluation of credible new information, the Company will revise its assumptions to reflect its current best estimate. These assumption revisions will change the projected
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
account values and the related EGPs in the DAC and SIA amortization models, as well as the death and other insurance benefit reserving model.
All assumption changes that affect the estimate of future EGPs including the update of current account values, the use of the RTM estimation technique and policyholder behavior assumptions are considered an Unlock in the period of revision. An Unlock adjusts DAC, SIA, and death and other insurance benefit reserve balances in the Consolidated Balance Sheets with an offsetting benefit or charge in the Consolidated Statements of Operations in the period of the revision. An Unlock that results in an after-tax benefit generally occurs as a result of actual experience or future expectations of product profitability being favorable compared to previous estimates. An Unlock that results in an after-tax charge generally occurs as a result of actual experience or future expectations of product profitability being unfavorable compared to previous estimates.
EGPs are also used to determine the expected excess benefits and assessments included in the measurement of death and other insurance benefit reserves. These excess benefits and assessments are derived from a range of stochastic scenarios that have been calibrated to the Company’s RTM separate account returns. The determination of death and other insurance benefit reserves is also impacted by discount rates, lapses, volatilities, mortality assumptions and benefit utilization, including assumptions around annuitization rates.
Market Unlocks
In addition to updating assumptions in the fourth quarter of each year, an Unlock revises EGPs, on a quarterly basis, to reflect the Company’s current best estimate assumptions and market updates of policyholder account value. The Unlock for future separate account returns is determined each quarter. Under RTM, the expected long-term weighted average rate of return is 8.3%. The annual return assumed over the next five years of approximately 1.5% was calculated based on the return needed over that period to produce an 8.3% return since March of 2009, the date the Company adopted the RTM estimation technique to project future separate account returns. Based on the expected trend of policy lapses and annuitizations, the Company expects approximately 50% of its block of variable annuities to run-off in the next 5 years.
Aggregate Recoverability
After each quarterly Unlock, the Company also tests the aggregate recoverability of DAC by comparing the DAC balance to the present value of future EGPs. The margin between the DAC balance and the present value of future EGPs for variable annuities was 41% as of December 31, 2016. If the margin between the DAC asset and the present value of future EGPs is exhausted, then further reductions in EGPs would cause portions of DAC to be unrecoverable and the DAC asset would be written down to equal future EGPs.
Living Benefits Required to be Fair Valued
Fair values for GMWBs, classified as embedded derivatives and included in other policyholder funds and benefits payable, are calculated using the income approach based upon internally developed models, because active, observable markets do not exist for those items. The fair value of these GMWBs and the
related reinsurance and customized freestanding derivatives are calculated as an aggregation of the following components: Best Estimate Claim Payments; Credit Standing Adjustment; and Margins. The resulting aggregation is reconciled or calibrated, if necessary, to market information that is available to the Company, but may not be observable by other market participants, including reinsurance discussions and transactions. The Company believes the aggregation of these components, as calibrated to market information, results in an amount that the Company would be required to transfer to or receive from market participants in an active liquid market, if one existed, for those market participants to assume the risks associated with the guaranteed minimum benefits and the related reinsurance and customized derivatives. The fair value is likely to materially diverge from the ultimate settlement of the liability as the Company believes settlement will be based on our best estimate assumptions rather than those best estimate assumptions plus risk margins. In the absence of any transfer of the guaranteed benefit liability to a third party, the release of risk margins is likely to be reflected as realized gains in future periods’ net income.
A multidisciplinary group of finance, actuarial and risk management professionals reviews and approves changes to the Company's valuation model as well as associated controls.
For further discussion on the impact of fair value changes from living benefits see Note 5 - Fair Value Measurements of Notes to Consolidated Financial Statements, and for a discussion on the sensitivities of certain living benefits due to capital market factors see Part II, Item 7, MD&A — Variable Product Guarantee Risks and Risk Management.
Evaluation of Goodwill for Impairment
Goodwill balances are reviewed for impairment at least annually or more frequently if events occur or circumstances change that would indicate that a triggering event for a potential impairment has occurred. The goodwill impairment test follows a two-step process. In the first step, the fair value of a reporting unit is compared to its carrying value. If the carrying value of a reporting unit exceeds its fair value, the second step of the impairment test is performed for purposes of measuring the impairment. In the second step, the fair value of the reporting unit is allocated to all of the assets and liabilities of the reporting unit to determine an implied goodwill value. If the carrying amount of the reporting unit’s goodwill exceeds the implied goodwill value, an impairment loss is recognized in an amount equal to that excess, not to exceed the goodwill carrying value.
The estimated fair value of each reporting unit incorporates multiple inputs into discounted cash flow calculations including assumptions that market participants would make in valuing the reporting unit. Assumptions include levels of economic capital, future business growth, earnings projections, assets under management for Mutual Funds, and the weighted average cost of capital used for purposes of discounting. Decreases in business growth, decreases in earnings projections and increases in the weighted average cost of capital will all cause a reporting unit’s fair value to decrease, increasing the possibility of impairment.
A reporting unit is defined as an operating segment or one level below an operating segment. The Company’s reporting units, for which goodwill has been allocated include Small Commercial
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
within the Commercial Lines segment, Group Benefits, Personal Lines and Mutual Funds.
The carrying value of goodwill is $567 as of December 31, 2016 and is comprised of $38 for Small Commercial, $272 for Mutual Funds, $138 for Group Benefits and $119 for Personal Lines.
The annual goodwill assessment for the Small Commercial, Mutual Funds, Group Benefits and Personal Lines reporting units was completed as of October 31, 2016, and resulted in no write-downs of goodwill for the year ended December 31, 2016. All reporting units passed the first step of the annual impairment test with a significant margin. For information regarding the 2015 and 2014 impairment tests see Note 10 -Goodwill of Notes to Consolidated Financial Statements.
Valuation of Investments and Derivative Instruments
Fixed Maturities, Equity Securities, Short-term Investments and Free-standing Derivatives
The Company generally determines fair values using valuation techniques that use prices, rates, and other relevant information evident from market transactions involving identical or similar instruments. Valuation techniques also include, where appropriate, estimates of future cash flows that are converted into a single discounted amount using current market expectations. The Company uses a "waterfall" approach comprised of the following pricing sources which are listed in priority order: quoted prices, prices from third-party pricing services, internal matrix pricing, and independent broker quotes. The fair value of free-standing derivative instruments are determined primarily using a discounted cash flow model or option model technique and incorporate counterparty credit risk. In some cases, quoted market prices for exchange-traded transactions and transactions cleared through central clearing houses ("OTC-cleared") may be used and in other cases independent broker quotes may be used. For further discussion, see the Fixed Maturities, Equity Securities, Short-term Investments and Free-standing Derivatives section in Note 5 of Notes to Consolidated Financial Statements. For further discussion on the GMWB customized derivative valuation methodology, see the GMWB Embedded, Customized and Reinsurance Derivatives section in Note 5 of Notes to Consolidated Financial Statements.
Limited Partnerships and Other Alternative Investments
The portion of limited partnerships and other alternative investments recorded at fair value represents hedge funds for which investment company accounting has been applied to a wholly-owned fund of funds measured at fair value. During 2016, the Company liquidated this wholly-owned hedge fund of funds. Fair value was determined for these funds using the fund’s NAV, as a practical expedient. For further discussion of fair value measurement, see Note 5 of Notes to Consolidated Financial Statements. The remaining limited partnerships and other alternative investments are accounted for under the equity method of accounting. For further discussion of the accounting
policy, see the Investments - Overview section of Note 1 of Notes to the Consolidated Financial Statements.
Evaluation of OTTI on Available-for-sale Securities and Valuation Allowances on Mortgage Loans
Each quarter, a committee of investment and accounting professionals evaluates investments to determine if an other-than-temporary impairment (“impairment”) is present for AFS securities or a valuation allowance is required for mortgage loans. This evaluation is a quantitative and qualitative process, which is subject to risks and uncertainties. For further discussion of the accounting policies, see the Significant Investment Accounting Policies Section in Note 1 - Basis of Presentation and Significant Accounting Policies of Notes to Consolidated Financial Statements. For a discussion of impairments recorded, see the Other-than-temporary Impairments within the Investment Portfolio Risks and Risk Management section of the MD&A.
Valuation Allowance on Deferred Tax Assets
Deferred tax assets represent the tax benefit of future deductible temporary differences and tax carryforwards. Deferred tax assets are measured using the enacted tax rates expected to be in effect when such benefits are realized if there is no change in tax law. Under U.S. GAAP, we test the value of deferred tax assets for impairment on a quarterly basis at the entity level within each tax jurisdiction, consistent with our filed tax returns. Deferred tax assets are reduced by a valuation allowance if, based on the weight of available evidence, it is more likely than not that some portion, or all, of the deferred tax assets will not be realized. The determination of the valuation allowance for our deferred tax assets requires management to make certain judgments and assumptions. In evaluating the ability to recover deferred tax assets, we have considered all available evidence as of December 31, 2016, including past operating results, forecasted earnings, future taxable income, and prudent and feasible tax planning strategies. In the event we determine it is more likely than not that we will not be able to realize all or part of our deferred tax assets in the future, an increase to the valuation allowance would be charged to earnings in the period such determination is made. Likewise, if it is later determined that it is more likely than not that those deferred tax assets would be realized, the previously provided valuation allowance would be reversed. Our judgments and assumptions are subject to change given the inherent uncertainty in predicting future performance and specific industry and investment market conditions.
As of December 31, 2016, the Company had no valuation allowance. As of December 31, 2015, the Company had a deferred tax asset valuation allowance $79 relating primarily to U.S. capital loss carryovers. The reduction in the valuation allowance in 2016 stems primarily from taxable gains on the termination of derivatives during the period. The Company had no capital loss carryovers as of December 31, 2016.
In assessing the need for a valuation allowance, management considered future taxable temporary difference reversals, future taxable income exclusive of reversing temporary differences and carryovers, taxable income in open carry back years and other tax planning strategies. From time to time, tax planning strategies could include holding a portion of debt securities with market
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
value losses until recovery, altering the level of tax exempt securities held, making investments which have specific tax characteristics, and business considerations such as asset-liability matching. Management views such tax planning strategies as prudent and feasible and would implement them, if necessary, to realize the deferred tax assets.
Contingencies Relating to Corporate Litigation and Regulatory Matters
Management evaluates each contingent matter separately. A loss is recorded if probable and reasonably estimable. Management establishes reserves for these contingencies at its “best estimate,” or, if no one number within the range of possible losses is more probable than any other, the Company records an estimated reserve at the low end of the range of losses.
The Company has a quarterly monitoring process involving legal and accounting professionals. Legal personnel first identify
outstanding corporate litigation and regulatory matters posing a reasonable possibility of loss. These matters are then jointly reviewed by accounting and legal personnel to evaluate the facts and changes since the last review in order to determine if a provision for loss should be recorded or adjusted, the amount that should be recorded, and the appropriate disclosure. The outcomes of certain contingencies currently being evaluated by the Company, which relate to corporate litigation and regulatory matters, are inherently difficult to predict, and the reserves that have been established for the estimated settlement amounts are subject to significant changes. Management expects that the ultimate liability, if any, with respect to such lawsuits, after consideration of provisions made for estimated losses, will not be material to the consolidated financial condition of the Company. In view of the uncertainties regarding the outcome of these matters, as well as the tax-deductibility of payments, it is possible that the ultimate cost to the Company of these matters could exceed the reserve by an amount that would have a material adverse effect on the Company’s consolidated results of operations and liquidity in a particular quarterly or annual period.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
SEGMENT OPERATING SUMMARIES
| COMMERCIAL LINES |
Results of Operations
Underwriting Summary
| 2016 | 2015 | 2014 | |||||||
| Written premiums | $ | 6,732 | $ | 6,625 | $ | 6,381 | |||
| Change in unearned premium reserve | 81 | 114 | 92 | ||||||
| Earned premiums | 6,651 | 6,511 | 6,289 | ||||||
| Losses and loss adjustment expenses | |||||||||
| Current accident year before catastrophes | 3,766 | 3,712 | 3,733 | ||||||
| Current accident year catastrophes [1] | 200 | 121 | 109 | ||||||
| Prior accident year development [1] | 28 | 53 | 13 | ||||||
| Total losses and loss adjustment expenses | 3,994 | 3,886 | 3,855 | ||||||
| Amortization of deferred policy acquisition costs | 973 | 951 | 919 | ||||||
| Underwriting expenses | 1,191 | 1,178 | 1,086 | ||||||
| Dividends to policyholders | 15 | 17 | 15 | ||||||
| Underwriting gain | 478 | 479 | 414 | ||||||
| Net servicing income [2] | 22 | 20 | 23 | ||||||
| Net investment income [3] | 917 | 910 | 958 | ||||||
| Net realized capital gains (losses) [3] | 13 | (6 | ) | (30 | ) | ||||
| Other income (expenses) | (1 | ) | 2 | (3 | ) | ||||
| Income from continuing operations before income taxes | 1,429 | 1,405 | 1,362 | ||||||
| Income tax expense [4] | 422 | 409 | 385 | ||||||
| Income from continuing operations, net of tax | 1,007 | 996 | 977 | ||||||
| Income from discontinued operations, net of tax | — | 7 | 6 | ||||||
| Net income | $ | 1,007 | $ | 1,003 | $ | 983 |
| [1] | For discussion of current accident year catastrophes and prior accident year development, see MD&A - Critical Accounting Estimates, Total Property and Casualty Insurance Product Reserves Development. |
| [2] | Includes servicing revenues of $86, $87, and $113 for the years ended December 31, 2016, December 31, 2015, and December 31, 2014 respectively. |
| [3] | For discussion of consolidated investment results, see MD&A - Investment Results, Net Investment Income (Loss) and Net Realized Capital Gains (Losses). |
| [4] | For discussion of income taxes, see Note 16 - Income Taxes of Notes to Consolidated Financial Statements. |
Premium Measures [1]
| 2016 | 2015 | 2014 | |||||||
| New business premium | $ | 1,140 | $ | 1,121 | $ | 1,088 | |||
| Standard commercial lines policy count retention | 84 | % | 84 | % | 84 | % | |||
| Standard commercial lines renewal written pricing increase | 2 | % | 2 | % | 5 | % | |||
| Standard commercial lines renewal earned pricing increase | 2 | % | 4 | % | 7 | % | |||
| Standard commercial lines policies in-force as of end of period (in thousands) | 1,346 | 1,325 | 1,277 |
| [1] | Standard commercial lines consists of small commercial and middle market. Standard commercial premium measures exclude middle market programs and livestock lines of business. |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Underwriting Ratios
| 2016 | 2015 | 2014 | ||||
| Loss and loss adjustment expense ratio | ||||||
| Current accident year before catastrophes | 56.6 | 57.0 | 59.4 | |||
| Current accident year catastrophes | 3.0 | 1.9 | 1.7 | |||
| Prior accident year development | 0.4 | 0.8 | 0.2 | |||
| Total loss and loss adjustment expense ratio | 60.1 | 59.7 | 61.3 | |||
| Expense ratio | 32.5 | 32.7 | 31.9 | |||
| Policyholder dividend ratio | 0.2 | 0.3 | 0.2 | |||
| Combined ratio | 92.8 | 92.6 | 93.4 | |||
| Current accident year catastrophes and prior year development | 3.4 | 2.7 | 1.9 | |||
| Underlying combined ratio | 89.4 | 90.0 | 91.5 |
2017 Outlook
Based on an expectation that the economy will continue to grow slowly in 2017, the Company expects low single-digit written premiums growth in Commercial Lines in 2017, almost entirely driven by Small Commercial. Written premiums for Middle Market and Specialty Commercial are expected to remain relatively flat compared to 2016 as growth in new business is expected to be offset by a decline in renewal premium. In Small Commercial, the Company expects written premium growth through expanded product offerings, enhanced automation and deeper relationships with distribution partners as well as by taking advantage of new opportunities for growth from the acquisition of Maxum.
Pricing varies significantly by product line with moderate rate decreases possible in property, general liability and workers’ compensation with further rate increases expected in commercial auto. Market conditions could be influenced by interest rates. If interest rates rise significantly, it could put downward pressure on the premium rates we and other insurers charge for our insurance coverages, particularly for longer-tailed commercial lines products.
The Company expects the Commercial Lines combined ratio will be between approximately 92.5 and 94.5 for 2017, compared to 92.8 in 2016, as increases in average claim severity are expected to outpace the effect of overall modest earned pricing increases and a modest reduction in loss cost frequency. Current accident year catastrophes are assumed to be 2.3 points of the combined ratio in 2017 compared to 3.0 points in 2016.
Net Income
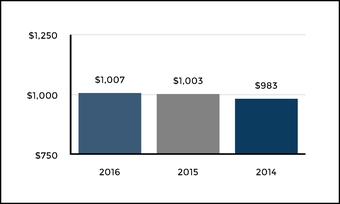
Year ended December 31, 2016 compared to the year ended December 31, 2015
Net income increased in 2016 primarily due to a shift to net realized capital gains in the current year from net realized capital losses in the prior year and higher net investment income.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Net income increased in 2015 primarily due to a higher underwriting gain and lower realized capital losses, partially offset by lower net investment income.
Underwriting Gain

Year ended December 31, 2016 compared to the year ended December 31, 2015
Underwriting gain decreased slightly driven by higher losses and loss adjustment expenses and higher underwriting expenses, partially offset by earned premium growth.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Underwriting gain increased driven by a lower current accident year loss and loss adjustment expense ratio before catastrophes, partially offset by higher underwriting expenses and unfavorable prior accident year development. Underwriting expenses in 2014 included a reduction of $49, before tax, in the
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Company's estimated liability for NY State Workers' Compensation Board assessments.
Earned Premiums
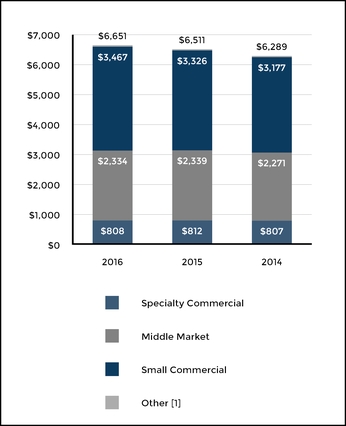
[1] Other of $42, $34, and $34 for 2016, 2015, and 2014, respectively, is included in the total.
Year ended December 31, 2016 compared to the year ended December 31, 2015
Earned premiums increased in 2016 reflecting written premium growth over the preceding twelve months.
Written premiums increased in 2016 due to growth in Small Commercial. Renewal written pricing increases and policy retention for standard commercial lines were both unchanged in 2016 compared to 2015.
| • | Small Commercial increased primarily due to workers’ compensation driven by higher new business, renewal and audit premium, and Spectrum package business driven by higher renewal premium, as well as the acquisition of Maxum. |
| • | The decrease in Middle Market was driven primarily by lower new business, renewal and endorsement premium in workers’ compensation, and lower new business and renewal premium in general liability and specialty programs, partially offset by higher new business and renewal premium in construction. |
| • | Specialty Commercial decreased primarily as a result of lower retrospective premium on loss sensitive business in national accounts. |
| • | Renewal written pricing increases averaged 2% in standard commercial, which included 3% for Small Commercial and 1% for Middle Market. |
Year ended December 31, 2015 compared to the year ended December 31, 2014
Earned premiums increased in 2015 reflecting written premium growth over the preceding twelve months.
Written premiums increased in 2015 in Small Commercial, Middle Market and Specialty Commercial lines.
| • | Small Commercial increased primarily in workers’ compensation driven by higher new, renewal and audit premium, as well as in Spectrum package business driven by higher new and renewal premium. |
| • | The increase in Middle Market was driven primarily by higher new, renewal and audit premium in construction as well as higher new and renewal premium in marine. |
| • | Specialty Commercial increased primarily as a result of higher retrospective premium on loss sensitive business in national accounts. |
Loss and LAE Ratio before Catastrophes and Prior Accident Year Development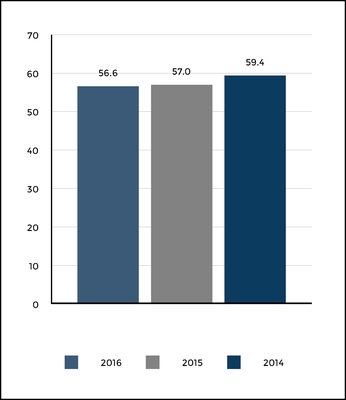
Year ended December 31, 2016 compared to the year ended December 31, 2015
Loss and LAE ratio before catastrophes and prior accident year development decreased in 2016, as compared to the prior year period, primarily due to a lower loss and loss adjustment expense ratio in workers' compensation, driven by favorable frequency, partially offset by a
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
higher loss and loss adjustment expense ratio in commercial auto, driven by elevated frequency and severity.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Loss and LAE ratio before catastrophes and prior accident year development decreased in 2015, as compared to the prior year period, primarily driven by lower loss and loss adjustment expense ratios in workers' compensation, general liability and financial products, as well as lower non-catastrophe property losses. The decrease in workers compensation was due to earned pricing increases and declining frequency, partially offset by modestly higher severity.
Catastrophes and Prior Accident Year Development
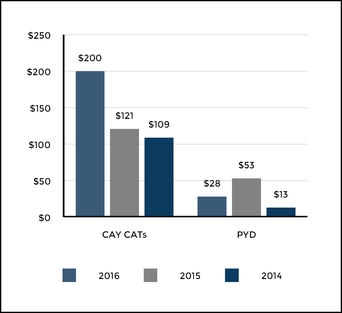
Year ended December 31, 2016 compared to the year ended December 31, 2015
Current accident year catastrophe losses totaled $200, before tax, in 2016, compared to $121, before tax, in 2015. Catastrophe losses for both years were primarily due to wind and hail events and winter storms across various U.S. geographic regions.
Prior accident year development of $28, before tax, was unfavorable in 2016, compared to unfavorable prior accident year development of $53, before tax, in 2015. Net reserve increases in 2016 were primarily related to package business, general liability and commercial auto liability, largely offset by a decrease in reserves for workers’ compensation, professional liability and uncollectible reinsurance.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Current accident year catastrophe losses totaled $121, before tax, in 2015, compared to $109, before tax, in 2014. Catastrophe losses for both years were primarily due to winter storms and wind and hail events across various U.S. geographic regions.
Prior accident year development of $53, before tax, in 2015 was unfavorable, compared to unfavorable prior accident year development of$13, before tax, in 2014. Net reserve increases in 2015 were primarily related to commercial auto liability and package business, as well as workers' compensation discount accretion, partially offset by a decrease in reserves for workers’ compensation and professional liability.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
| PERSONAL LINES |
Results of Operations
Underwriting Summary
| 2016 | 2015 | 2014 | |||||||
| Written premiums | $ | 3,837 | $ | 3,918 | $ | 3,861 | |||
| Change in unearned premium reserve | (61 | ) | 45 | 55 | |||||
| Earned premiums | 3,898 | 3,873 | 3,806 | ||||||
| Losses and loss adjustment expenses | |||||||||
| Current accident year before catastrophes | 2,808 | 2,578 | 2,498 | ||||||
| Current accident year catastrophes [1] | 216 | 211 | 232 | ||||||
| Prior accident year development [1] | 151 | (21 | ) | (46 | ) | ||||
| Total losses and loss adjustment expenses | 3,175 | 2,768 | 2,684 | ||||||
| Amortization of DAC | 348 | 359 | 348 | ||||||
| Underwriting expenses | 564 | 628 | 604 | ||||||
| Underwriting gain (loss) | (189 | ) | 118 | 170 | |||||
| Net servicing income | — | 4 | 3 | ||||||
| Net investment income [2] | 135 | 128 | 129 | ||||||
| Net realized capital gains (losses) [2] | 2 | 4 | (5 | ) | |||||
| Other income [3] | — | 15 | 2 | ||||||
| Income (loss) before income taxes | (52 | ) | 269 | 299 | |||||
| Income tax expense (benefit) [4] | (30 | ) | 82 | 92 | |||||
| Net income (loss) | $ | (22 | ) | $ | 187 | $ | 207 |
| [1] | For discussion of current accident year catastrophes and prior accident year development, see MD&A - Critical Accounting Estimates, Total Property and Casualty Insurance Product Reserves Development. |
| [2] | For discussion of consolidated investment results, see MD&A - Investment Results, Net Investment Income (Loss) and Net Realized Capital Gains (Losses). |
| [3] | Includes a benefit of $17, before tax, for the year ended December 31, 2015, from the resolution of litigation. |
| [4] | For discussion of income taxes, see Note 16 - Income Taxes of Notes to Consolidated Financial Statements. |
Written and Earned Premiums
| Written Premiums | 2016 | 2015 | 2014 | ||||||
| Product Line | |||||||||
| Automobile | $ | 2,694 | $ | 2,721 | $ | 2,659 | |||
| Homeowners | 1,143 | 1,197 | 1,202 | ||||||
| Total | $ | 3,837 | $ | 3,918 | $ | 3,861 | |||
| Earned Premiums | |||||||||
| Product Line | |||||||||
| Automobile | $ | 2,720 | $ | 2,671 | $ | 2,613 | |||
| Homeowners | 1,178 | 1,202 | 1,193 | ||||||
| Total | $ | 3,898 | $ | 3,873 | $ | 3,806 |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Premium Measures
| 2016 | 2015 | 2014 | |||||||
| Policies in-force end of period (in thousands) | |||||||||
| Automobile | 1,965 | 2,062 | 2,049 | ||||||
| Homeowners | 1,176 | 1,272 | 1,309 | ||||||
| New business written premium | |||||||||
| Automobile | $ | 311 | $ | 422 | $ | 415 | |||
| Homeowners | $ | 74 | $ | 110 | $ | 130 | |||
| Policy count retention | |||||||||
| Automobile | 84 | % | 84 | % | 85 | % | |||
| Homeowners | 84 | % | 85 | % | 86 | % | |||
| Renewal written pricing increase | |||||||||
| Automobile | 7 | % | 6 | % | 5 | % | |||
| Homeowners | 10 | % | 8 | % | 8 | % | |||
| Renewal earned pricing increase | |||||||||
| Automobile | 7 | % | 6 | % | 5 | % | |||
| Homeowners | 9 | % | 8 | % | 8 | % |
Underwriting Ratios
| 2016 | 2015 | 2014 | ||||
| Loss and loss adjustment expense ratio | ||||||
| Current accident year before catastrophes | 72.0 | 66.6 | 65.6 | |||
| Current accident year catastrophes | 5.5 | 5.4 | 6.1 | |||
| Prior accident year development | 3.9 | (0.5 | ) | (1.2 | ) | |
| Total loss and loss adjustment expense ratio | 81.5 | 71.5 | 70.5 | |||
| Expense ratio | 23.4 | 25.5 | 25.0 | |||
| Combined ratio | 104.8 | 97.0 | 95.5 | |||
| Current accident year catastrophes and prior year development | 9.4 | 4.9 | 4.9 | |||
| Underlying combined ratio | 95.4 | 92.0 | 90.6 |
Product Combined Ratios
| 2016 | 2015 | 2014 | ||||
| Automobile | ||||||
| Combined ratio | 111.6 | 99.4 | 98.4 | |||
| Underlying combined ratio | 103.9 | 99.0 | 97.1 | |||
| Homeowners | ||||||
| Combined ratio | 89.3 | 92.1 | 90.0 | |||
| Underlying combined ratio | 75.9 | 76.8 | 76.4 |
2017 Outlook
In 2017, the Company expects premium rates for auto and home across the industry will continue to rise, as the industry continues to respond to the emergence of higher loss cost trends. Automobile loss cost frequency and severity have increased due, in part, to an increase in miles driven and more expensive bodily injury and repair costs. Accordingly, the Company expects written pricing increases to be at or near double-digits in 2017 for both automobile and homeowners. The Company has been executing multiple profitability improvement initiatives in personal automobile, including actions on pricing, underwriting
and agency management and these will continue in 2017. Due to those actions, the Company expects a mid-single digit decline in Personal Lines written premiums in 2017, with a modest decrease in AARP Direct and a more significant decrease in the Agency channel.
The Company expects the combined ratio for Personal Lines will be between approximately 99.0 and 101.0 for 2017 compared to 104.8 in 2016 primarily due to an improvement in auto as 2016 included 3.9 points of adverse reserve development and the Company expects earned pricing increases and the effect of other profitability improvement initiatives in 2017 will outpace an expected increase in loss cost severity. Current accident year
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
catastrophes are assumed to be 5.8 points of the combined ratio in 2017 compared to 5.5 points in 2016. While management actions are expected to improve the combined ratio for auto in 2017, that expectation is subject to uncertainty given that severity trends had not yet moderated through year end 2016. For homeowners, the combined ratio is expected to increase in 2017 largely given that catastrophe losses and prior accident year development were favorable in 2016. The underlying combined ratio for homeowners is expected to remain relatively flat in 2017, driven by earned pricing increases, partially offset by increased average claim severity.
Net Income (Loss)
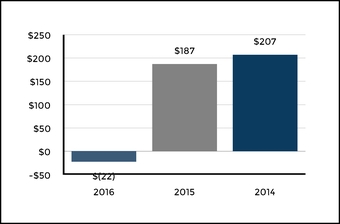
Year ended December 31, 2016 compared to the year ended December 31, 2015
Net loss in 2016 compared to net income in 2015 primarily due to a change from underwriting gain to underwriting loss.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Net income decreased in 2015 primarily due to a lower underwriting gain.
Underwriting Gain (Loss)
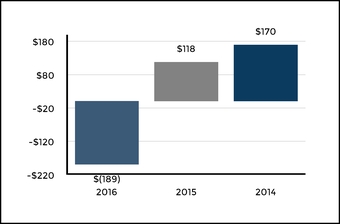
Year ended December 31, 2016 compared to the year ended December 31, 2015
Underwriting loss in 2016 compared to an underwriting gain in 2015 primarily due to an increase in auto liability loss costs, with higher current accident year loss and loss adjustment expenses and more unfavorable prior accident year reserve development, principally related to the 2015 accident year. The increase in auto loss costs was partially offset by lower direct marketing expenses.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Underwriting gain decreased driven by a deterioration in the current accident year loss and loss adjustment ratio before catastrophes and lower favorable prior accident year development, partially offset by a decrease in current accident year catastrophes.
Earned Premiums
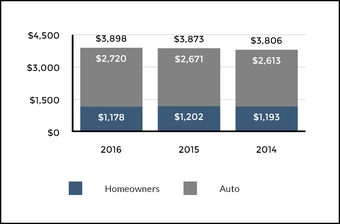
Year ended December 31, 2016 compared to the year ended December 31, 2015
Earned premiums increased in 2016 reflecting written premium growth in 2015 over the prior six to twelve months.
Written premiums decreased in 2016 primarily due a decline in new business in both auto and homeowners, partially offset by higher premium retention in auto, driven by higher written pricing increases.
Renewal written pricing increased in both auto and home as the Company increased rates to improve profitability.
Policy count retention for homeowners was lower in 2015 driven in part by renewal written pricing increases.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Earned and written premiums increased in 2015 primarily due to renewal written and earned pricing increases.
Policy count retention for both auto and homeowners was lower in 2015 driven in part by renewal written pricing increases and planned underwriting initiatives.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Loss and Loss Adjustment Expense Ratio before Catastrophes and Prior Accident Year Development
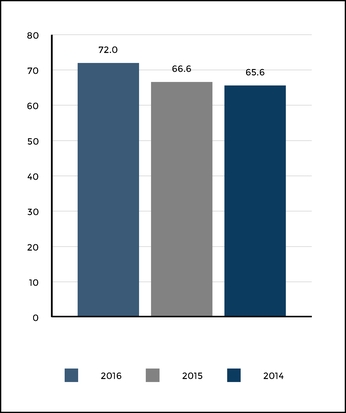
Year ended December 31, 2016 compared to the year ended December 31, 2015
Loss and loss adjustment expense ratio before catastrophes and prior accident year development increased primarily as a result of higher auto liability frequency and severity, partially offset by the effect of increases in earned pricing.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Loss and loss adjustment expense ratio before catastrophes and prior accident year development increased primarily due to increases in auto liability and auto physical damage loss costs, as well as higher homeowners water and fire-related claims, partially offset by lower homeowners weather-related claims.
Catastrophes and Prior Accident Year Development
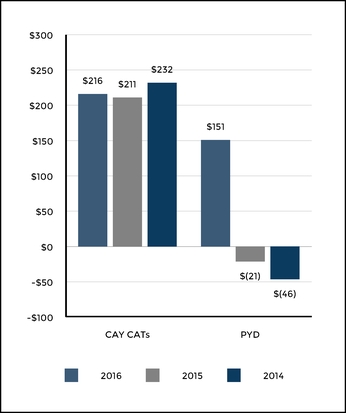
Year ended December 31, 2016 compared to the year ended December 31, 2015
Current accident year catastrophe losses of $216, before tax, in 2016, increased compared to $211, before tax, in 2015. Catastrophe losses in 2016 were primarily due to multiple wind and hail events across various U.S. geographic regions, concentrated in the Midwest and central plains. Catastrophe losses in 2015 were primarily due to wildfires in California and multiple events (wind and hail primarily) across various U.S. geographic regions.
Prior accident year development of $151, before tax, was unfavorable in 2016, compared to favorable prior accident year development of $21, before tax, in 2015. Net reserves increased for 2016 primarily due to increased bodily injury frequency and severity for the 2015 accident year and increased bodily injury severity for the 2014 accident year. Net reserves decreased for 2015 primarily due to accident year 2014 catastrophes.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Current accident year catastrophe losses of $211, before tax, in 2015 were favorable compared to $232, before tax, in 2014. Catastrophe losses in 2015 were primarily due to wildfires in California and multiple events (wind and hail primarily) across
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
various U.S. geographic regions. Catastrophe losses in 2014 were primarily due to multiple thunderstorm and winter storm events across various U.S. geographic regions.
Prior accident year development of $21, before tax, was favorable in 2015, compared to favorable prior accident year development of $46, before tax, in 2014. Net reserves decreased
for 2015 primarily due to accident year 2014 catastrophes. Net reserves decreased for 2014 primarily due to prior accident year catastrophes, as well as prior accident year homeowners and extra contractual liability reserves.
| PROPERTY & CASUALTY OTHER OPERATIONS |
Results of Operations
Underwriting Summary
| 2016 | 2015 | 2014 | |||||||
| Written premiums | $ | (1 | ) | $ | 35 | $ | 2 | ||
| Change in unearned premium reserve | (1 | ) | 3 | 1 | |||||
| Earned premiums | — | 32 | 1 | ||||||
| Losses and loss adjustment expenses | |||||||||
| Current accident year | — | 25 | — | ||||||
| Prior accident year development [1] | 278 | 218 | 261 | ||||||
| Total losses and loss adjustment expenses | 278 | 243 | 261 | ||||||
| Underwriting expenses | 19 | 32 | 37 | ||||||
| Underwriting loss | (297 | ) | (243 | ) | (297 | ) | |||
| Net investment income [2] | 127 | 133 | 129 | ||||||
| Net realized capital gains (losses) [2] | (70 | ) | 3 | 3 | |||||
| Loss on reinsurance transaction | 650 | — | — | ||||||
| Other income | 6 | 7 | 6 | ||||||
| Loss before income taxes | (884 | ) | (100 | ) | (159 | ) | |||
| Income tax benefit [3] | (355 | ) | (47 | ) | (51 | ) | |||
| Net loss | $ | (529 | ) | $ | (53 | ) | $ | (108 | ) |
[1] For discussion of prior accident year development, see MD&A - Critical Accounting Estimates, Reserve Roll-forwards and Development.
[2] For discussion of consolidated investment results, see MD&A - Investment Results, Net Investment Income (Loss) and Net Realized Capital Gains (Losses).
[3] For discussion of income taxes, see Note 16 - Income Taxes of Notes to Consolidated Financial Statements.
Net Loss

Year ended December 31, 2016 compared to the year ended December 31, 2015
Net loss increased in 2016 primarily due to a $423 after-tax loss on the reinsurance transaction that cedes adverse development on asbestos and environmental reserves and higher unfavorable net asbestos and environmental prior accident year development associated with the Company's comprehensive annual review. Net realized capital losses before tax in 2016 included an $81 estimated capital loss on the pending sale of the Company's U.K. property and casualty run-off subsidiaries. Net of tax benefits, the pending sale resulted in an estimated after-tax loss of $5.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Net loss decreased in 2015 primarily due to lower unfavorable net asbestos and environmental prior accident year development associated with the Company's comprehensive annual review.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Written premiums of $31 in 2015, recognized in connection with the assumption of previously reinsured business, were partially offset by current accident year losses of $25 upon consolidation of certain P&C run-off entities in the United Kingdom.
Pre-tax Charge for Asbestos and Environmental Reserve Increases

Year ended December 31, 2016 compared to the year ended December 31, 2015
Asbestos Reserves increased by $197 in 2016 arising from the second quarter reserve study which found that mesothelioma claims filings have not declined as expected in specific, adverse jurisdictions. As a result, aggregate indemnity and defense costs have not declined as expected resulting in unfavorable net asbestos reserve development.
Environmental Reserves increased by $71 in 2016 primarily due to deterioration associated with the tendering of new sites for policy coverage, increased defense costs stemming from individual bodily injury liability suits, and increased clean-up costs associated with waterways.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Asbestos Reserves increased by $146 in 2015 primarily due to greater than expected asbestos claim filings, including mesothelioma claims, from a small percentage of the Company's direct accounts.
Environmental Reserves increased by $52 in 2015 primarily due to an increase in estimated environmental cleanup costs, including at certain Superfund sites.
| GROUP BENEFITS |
Results of Operations
Operating Summary
| 2016 | 2015 | 2014 | |||||||
| Premiums and other considerations [1] | $ | 3,223 | $ | 3,136 | $ | 3,095 | |||
| Net investment income [2] | 366 | 371 | 374 | ||||||
| Net realized capital gains (losses) [2] | 45 | (11 | ) | 15 | |||||
| Total revenues | 3,634 | 3,496 | 3,484 | ||||||
| Benefits, losses and loss adjustment expenses | 2,514 | 2,427 | 2,362 | ||||||
| Amortization of deferred policy acquisition costs | 31 | 31 | 32 | ||||||
| Insurance operating costs and other expenses | 776 | 788 | 836 | ||||||
| Total benefits, losses and expenses | 3,321 | 3,246 | 3,230 | ||||||
| Income before income taxes | 313 | 250 | 254 | ||||||
| Income tax expense [3] | 83 | 63 | 63 | ||||||
| Net income [1] | $ | 230 | $ | 187 | $ | 191 |
| [1] | Group Benefits has a block of Association - Financial Institution business that is subject to a profit sharing arrangement with third parties which was terminated on December 31,2014. The Association - Financial Institutions business represented $72 of premiums and other considerations, and $1 of net income in 2014. |
| [2] | For discussion of consolidated investment results, see MD&A - Investment Results, Investment Income (Loss) and Net Realized Capital Gains (Losses). |
| [3] | For discussion of income taxes, see Note 16 - Income Taxes of Notes to the Consolidated Financial Statements. |
Premiums and Other Considerations
| 2016 | 2015 | 2014 | |||||||
| Fully insured — ongoing premiums | $ | 3,142 | $ | 3,068 | $ | 3,014 | |||
| Buyout premiums | 6 | 1 | 20 | ||||||
| Fee income | 75 | 67 | 61 | ||||||
| Total premiums and other considerations | $ | 3,223 | $ | 3,136 | $ | 3,095 | |||
| Fully insured ongoing sales, excluding buyouts | $ | 450 | $ | 467 | $ | 326 |
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Ratios, Excluding Buyouts
| 2016 | 2015 | 2014 | ||||
| Group disability loss ratio | 81.4 | % | 81.6 | % | 83.5 | % |
| Group life loss ratio | 75.7 | % | 74.7 | % | 70.5 | % |
| Total loss ratio | 78.0 | % | 77.4 | % | 76.2 | % |
| Expense ratio | 25.1 | % | 26.1 | % | 28.2 | % |
| Selected ratios excluding Association - Financial Institutions | ||||||
| Group life loss ratio, excluding Association - Financial Institutions | 75.7 | % | 74.7 | % | 72.8 | % |
| Total loss ratio, excluding Association - Financial Institutions | 78.0 | % | 77.4 | % | 77.4 | % |
| Expense ratio, excluding Association - Financial Institutions | 25.1 | % | 26.1 | % | 27.2 | % |
Margin
| 2016 | 2015 | 2014 | ||||
| Net income margin | 6.3 | % | 5.4 | % | 5.5 | % |
| Effect of net realized gains/(losses), net of tax on after-tax margin | 0.6 | % | (0.2 | )% | 0.3 | % |
| Core earnings margin | 5.7 | % | 5.6 | % | 5.2 | % |
2017 Outlook
Fully insured ongoing premiums in Group Benefits are expected to increase modestly in 2017 due primarily to continued strong book persistency and pricing increases. Core earnings in 2017 may be negatively impacted by approximately a $10 to $15 after-tax charge due to state guaranty fund assessments related to the likely liquidation of a carrier in the life and health industry. Excluding the potential impact from these state guaranty fund assessments, the Company expects Group Benefits core earnings in 2017 will be relatively flat with 2016 as the effect of slightly higher expenses and lower net investment income will be largely offset by expected modest improvement in the Group Benefits loss ratio driven by improved pricing and improved severity.
Net Income
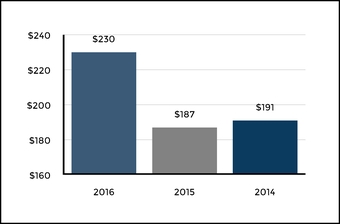
Year ended December 31, 2016 compared to the year ended December 31, 2015
Net income increased in 2016 primarily due to higher net realized capital gains, higher premiums and other considerations and lower insurance operating costs and other expenses, partially offset by higher benefits, losses and loss adjustment expenses.
Insurance operating costs and other expenses decreased 2% due primarily to decreased administrative expenses.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Net income decreased in 2015 primarily due to higher benefits, losses and loss adjustment expenses, higher net realized capital losses and lower net investment income partially offset by higher premiums and other considerations and lower insurance operating costs and other expenses.
Insurance operating costs and other expenses decreased in 2015, compared to the prior year period, due primarily to lower profit sharing expense related to the Association - Financial Institutions block of business.
Fully Insured Ongoing Premiums
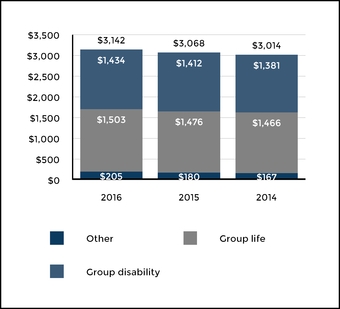
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Year ended December 31, 2016 compared to the year ended December 31, 2015
Fully insured ongoing premiums increased 2% due to strong persistency and pricing increases.
Fully insured ongoing sales, excluding buyouts decreased 4% in 2016, reflecting lower disability sales.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Fully insured ongoing premiums increased in 2015 due primarily to increased sales and improved persistency and pricing, partially offset by management actions related to the Association - Financial Institutions block of business. Excluding the Association - Financial Institutions block of business, fully insured ongoing premiums increased 4% in 2015.
Fully insured ongoing sales, excluding buyouts increased 43% in 2015, as compared to prior year period, primarily due to an increase in large case accounts.
Ratios
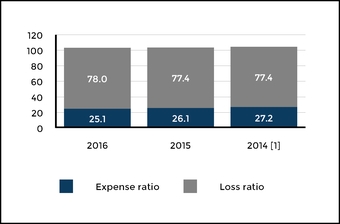
[1] Excludes Association - Financial Institutions.
Year ended December 31, 2016 compared to the year ended December 31, 2015
Total loss ratio increased 0.6 points in 2016 to 78.0% due to a higher group life loss ratio. The group life loss ratio increased 1.0 point due to higher severity in 2016. Included in the life loss ratio were favorable changes in reserve estimates of 1.3 points in 2016. The group disability loss ratio decreased 0.2 points primarily driven by increased pricing and improved incidence trends, partially offset by an increase in long-term disability claim severity. Included in the disability loss ratio were favorable changes in long-term disability reserve estimates of 0.4 points compared to 1.2 points in the prior year.
Expense ratio improved 1.0 points in 2016, reflecting premium growth and lower insurance operating costs and other expenses.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Total loss ratio increased by 1.2 points in 2015 due to a higher group life loss ratio and the impact of Association - Financial Institutions business in 2014, partially offset by a lower disability loss ratio. Excluding the Association - Financial Institutions block of business, the total loss ratio was flat to prior year. Excluding the Association - Financial Institutions block of business, the life loss ratio increased 1.9 points due to favorable changes in reserve assumptions in 2014 and less favorable severity in the current year. The disability loss ratio improved 1.9 points due to changes in long-term disability reserve assumptions for claim recoveries which favorably impacted the disability loss ratio by 1.2 points, as well as improved incidence and pricing partially offset by unfavorable long-term disability claim severity.
Expense ratio improved 2.1 points in 2015 primarily due to lower profit sharing expense related to the Association - Financial Institutions block of business. Excluding the Association - Financial Institutions block of business, the expense ratio improved 1.1 points reflecting premium growth and lower expenses.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
| MUTUAL FUNDS |
Results of Operations
Operating Summary
| 2016 | 2015 | 2014 | |||||||
| Fee income and other revenue | $ | 701 | $ | 723 | $ | 723 | |||
| Net investment income | 1 | 1 | — | ||||||
| Total revenues | 702 | 724 | 723 | ||||||
| Amortization of DAC | 24 | 22 | 28 | ||||||
| Operating costs and other expenses | 557 | 568 | 559 | ||||||
| Total benefits, losses and expenses | 581 | 590 | 587 | ||||||
| Income before income taxes | 121 | 134 | 136 | ||||||
| Income tax expense | 43 | 48 | 49 | ||||||
| Net income | $ | 78 | $ | 86 | $ | 87 | |||
| Daily Average Total Mutual Funds segment AUM | $ | 92,042 | $ | 94,687 | $ | 96,566 | |||
| Return on Assets ("ROA") [1] | 8.5 | 9.1 | 9.5 | ||||||
| Effect of restructuring, net of tax | — | — | (0.4 | ) | |||||
| ROA, core earnings [1] | 8.5 | 9.1 | 9.1 |
| [1] | Represents annualized earnings divided by a daily average of assets under management, as measured in basis points. |
Mutual Funds Segment AUM
| 2016 | 2015 | 2014 | |||||||
| Mutual Fund AUM - beginning of period | $ | 74,413 | $ | 73,035 | $ | 70,918 | |||
| Sales | 19,135 | 17,527 | 15,249 | ||||||
| Redemptions [1] | (20,055 | ) | (16,036 | ) | (16,636 | ) | |||
| Net flows | (920 | ) | 1,491 | (1,387 | ) | ||||
| Change in market value and other [2] | 7,805 | (113 | ) | 3,504 | |||||
| Mutual Fund AUM - end of period | 81,298 | 74,413 | 73,035 | ||||||
| Exchange-Traded Products AUM [3] | 209 | ||||||||
| Mutual Funds segment AUM before Talcott Resolution | 81,507 | 74,413 | 73,035 | ||||||
| Talcott Resolution AUM [4] | 16,010 | 17,549 | 20,584 | ||||||
| Total Mutual Funds segment AUM | $ | 97,517 | $ | 91,962 | $ | 93,619 |
| [1] | The year ended December 31, 2014 includes a planned asset transfer of $0.7 billion to the HIMCO Variable Insurance Trust (“HVIT”) which supports legacy retirement mutual funds and run-off mutual funds (see footnote [4]). HVIT's invested assets are managed by Hartford Investment Management Company, a wholly-owned subsidiary of the Company. |
| [2] | Other includes AUM from adoption of ten U.S. mutual funds with aggregate AUM of approximately $3.0 billion (as of October 2016) from Schroder Investment Management North America Inc. |
| [3] | Includes AUM of approximately $200 acquired upon acquisition in July 2016 of Lattice Strategies, LLC and subsequent net flows and change in market value. |
| [4] | Talcott Resolution AUM consist of Company-sponsored mutual fund assets held in separate accounts supporting variable insurance and investment products. |
Mutual Fund AUM by Asset Class
| 2016 | 2015 | 2014 | |||||||
| Equity | $ | 49,274 | $ | 47,369 | $ | 45,221 | |||
| Fixed Income | 14,853 | 12,625 | 14,046 | ||||||
| Multi-Strategy Investments | 17,171 | 14,419 | 13,768 | ||||||
| Mutual Fund AUM | $ | 81,298 | $ | 74,413 | $ | 73,035 |
2017 Outlook
Leveraging capabilities from acquiring Lattice Strategies in July 2016 and adopting ten U.S. Schroders funds in October 2016, the Company expects to increase sales in 2017 from a diversified lineup of mutual funds and ETP. Assets under management will
grow in 2017 provided the Company experiences continued strong fund performance, market appreciation and positive net flows. Assuming normal market conditions, the Company expects earnings growth in 2017, driven by improved earnings in the Mutual Fund business, partially offset by the run-off of the Talcott Resolution assets supporting the Company's legacy variable
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
insurance products. Part of the expected earnings growth in 2017 comes from the fact that 2016 earnings included approximately $3 of after-tax transaction costs associated with the Lattice Strategies acquisition and adoption of Schroders funds.
Net Income
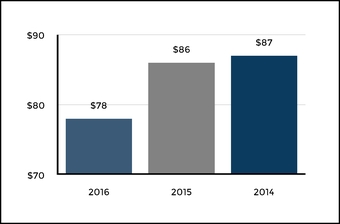
Year ended December 31, 2016 compared to the year ended December 31, 2015
Net income decreased in 2016, compared to the prior year period, primarily due to lower investment management fees as a result of lower daily average AUM combined with transaction costs of approximately $3 associated with the acquisition of Lattice Strategies, LLC and the adoption of ten Schroders funds during 2016. Daily average AUM decreased primarily due to market volatility early in the year and the continued run-off of Talcott Resolution assets.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Net income decreased in 2015, compared to the prior year period, primarily due to a combination of lower average AUM and higher spending on marketing initiatives and the effect of a one-time state tax benefit in 2014.
Total Mutual Funds Segment AUM
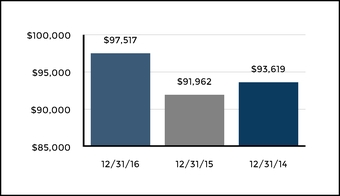
Year ended December 31, 2016 compared to the year ended December 31, 2015
Total Mutual Funds segment AUM increased in 2016 primarily due to market appreciation and the adoption of 10 Schroders funds partially offset by net outflows and the continued run-off of Talcott Resolution AUM.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Total Mutual Funds segment AUM declined in 2015 reflecting market depreciation and the continued run-off of Talcott Resolution AUM. Mutual fund AUM increased by 2% reflecting higher sales and stable redemptions.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
| TALCOTT RESOLUTION |
Results of Operations
Operating Summary
| 2016 | 2015 | 2014 | |||||||
| Earned premiums | $ | 114 | $ | 92 | $ | 206 | |||
| Fee income and other | 930 | 1,041 | 1,201 | ||||||
| Net investment income [1] | 1,384 | 1,470 | 1,542 | ||||||
| Net realized capital (losses) gains [1] | (155 | ) | (161 | ) | 26 | ||||
| Total revenues | 2,273 | 2,442 | 2,975 | ||||||
| Benefits, losses and loss adjustment expenses | 1,390 | 1,451 | 1,643 | ||||||
| Amortization of DAC | 147 | 139 | 402 | ||||||
| Insurance operating costs and other expenses | 438 | 469 | 567 | ||||||
| Reinsurance gain on disposition | — | (28 | ) | (23 | ) | ||||
| Total benefits, losses and expenses | 1,975 | 2,031 | 2,589 | ||||||
| Income from continuing operations, before income taxes | 298 | 411 | 386 | ||||||
| Income tax expense (benefit) | 54 | (17 | ) | 16 | |||||
| Income from continuing operations | 244 | 428 | 370 | ||||||
| Income (loss) from discontinued operations, net of tax [2] | — | 2 | (557 | ) | |||||
| Net income (loss) | $ | 244 | $ | 430 | $ | (187 | ) | ||
| AUM (end of period) | |||||||||
| Variable annuity account value | $ | 40,698 | $ | 44,245 | $ | 52,861 | |||
| Fixed and payout annuities | 7,673 | 8,109 | 8,748 | ||||||
| Institutional annuity account value | 15,169 | 15,077 | 15,636 | ||||||
| Other account value [3] | 86,488 | 88,151 | 91,163 | ||||||
| Total account value | $ | 150,028 | $ | 155,582 | $ | 168,408 | |||
| Variable Annuity Account Value [4] | |||||||||
| Account value, beginning of period | $ | 44,245 | $ | 52,861 | $ | 61,812 | |||
| Net outflows | (5,788 | ) | (7,938 | ) | (11,726 | ) | |||
| Change in market value and other | 2,241 | (678 | ) | 2,775 | |||||
| Account value, end of period | $ | 40,698 | $ | 44,245 | $ | 52,861 |
| [1] | For discussion of consolidated investment results, see MD&A - Investment Results, Net Investment Income (Loss) and Net Realized Capital Gains (Losses). |
| [2] | Represents the loss from operations and sale of HLIKK in 2014. For additional information, see Note 2 Business Acquisitions, Dispositions and Discontinued Operations of Notes to Consolidated Financial Statements. |
| [3] | Other account value includes $31.0 billion, $14.6 billion, and $40.8 billion as of December 31, 2016, and $33.2 billion, $14.6 billion, $40.3 billion as of December 31, 2015, and $36.5 billion, $14.9 billion, and $39.8 billion as of December 31, 2014, for the Retirement Plans, Individual Life, and Private Placement Life Insurance businesses; respectively. Account values associated with the Retirement Plans, and Individual Life businesses no longer generate asset-based fee income due to the sales of these businesses through reinsurance. |
| [4] | Excludes account value related to the HLIKK business sold on June 30, 2014. |
2017 Outlook
The principal goal for Talcott Resolution is to efficiently manage the run-off of the annuity and private placement life insurance business while honoring the Company's obligations to its contract holders. As a result, the Company expects account values, and consequently earnings, to decline due to surrenders, policyholder initiatives or transactions with third parties, that will reduce the size of this legacy book of business. Risk-reducing transactions may also cause a reduction in statutory capital and shareholders’ equity. Excluding the effect of favorable limited partnership returns and tax benefits recognized in 2016 that are not assumed
to recur in 2017, core earnings are expected to be about $300 in 2017, reflecting the continued runoff of the Company's annuity book though subject to change depending on market conditions and management initiatives. A key driver to the decline in earnings will be the pace at which customers surrender their contracts. In 2016, the Company experienced a 7.1% variable annuity full surrender rates driven by market appreciation and continued aging of the block and management expects variable annuity surrender rates to remain relatively stable in 2017. Contract counts decreased 10% for variable annuities in 2016 and a similar decline is expected in 2017.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Net Income (Loss)
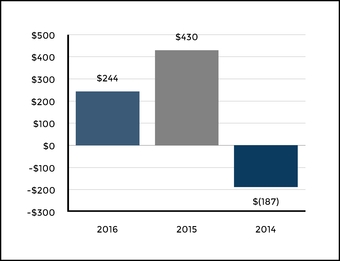
Year ended December 31, 2016 compared to the year ended December 31, 2015
Net income for 2016 decreased primarily due to lower tax benefits recognized in 2016, a write-off of DAC associated with fixed annuities, lower investment income and a reinsurance gain on disposition in 2015. Net realized capital losses were down slightly as an increase in losses on the variable annuity hedge program and a loss on the modified coinsurance reinsurance contract related to the Individual Life business were largely offset by an increase in net gains from sales of investments and lower impairment losses. In addition, the continued run-off of the variable and fixed annuity block resulted in lower fee income, partially offset by lower amortization of DAC and lower insurance operating costs and other expenses.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Net income increased primarily due to lower DAC amortization driven by a favorable unlock in 2015 versus an unfavorable unlock in 2014, lower insurance operating costs and other expenses, and lower benefits and losses due to the continued run-off of the variable annuity block, partially offset by lower fee income due to the continued run-off of the variable annuity block, lower net investment income due to a decrease in income from limited partnerships and alternative investments and realized capital losses related to the variable annuity hedge program. In addition, 2014 included a loss from discontinued operations due to the sale of HLIKK.
Total Account Value
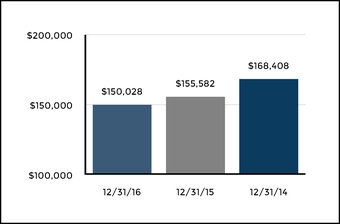
Year ended December 31, 2016 compared to the year ended December 31, 2015
Account values for Talcott Resolution decreased to approximately $150 billion for 2016 primarily due to net outflows in variable annuity account value, partially offset by market appreciation.
Variable annuity net outflows were approximately $5.8 billion due to the continued run-off of the business.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Account values for Talcott Resolution decreased to approximately $156 billion for 2015 primarily due to a reduction in Retirement Plans' account value and net outflows and market value depreciation in variable annuity account value.
Variable annuity net outflows decreased by approximately $3.8 billion due to lower outflows from in-force management initiatives.
Variable Annuity Annualized Full Surrender Rate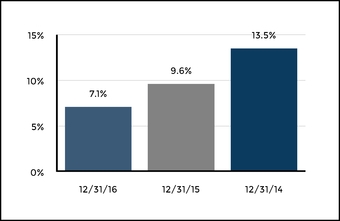
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Year ended December 31, 2016 compared to the year ended December 31, 2015
Variable annuity annualized full surrender rate declined to 7.1%. This decrease was primarily due to no in-force management initiatives in 2016 as well as the continued aging of the block, and is consistent with variable annuity industry trends.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Variable annuity annualized full surrender rate for the year ended December 31, 2015 declined to 9.6% compared to 13.5% for the year ended December 31, 2014. This decline was primarily due to lower surrenders from in-force management initiatives as well as in-force management initiatives in prior years which accelerated surrenders resulting in lower surrender rates post initiatives.
Contract Counts (in thousands)
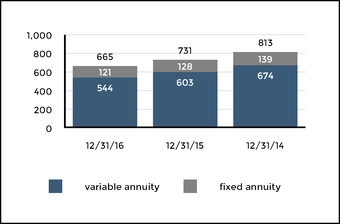
Year ended December 31, 2016 compared to the year ended December 31, 2015
Contract counts decreased 10% and 5% for variable annuity and fixed annuity, respectively, during 2016 primarily due to the continued run-off of the blocks.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Contract counts decreased 11% for variable annuities during 2015 primarily due to in-force management initiatives and the continued aging of the block.
Income Taxes
The effective tax rates in 2016, 2015 and 2014 differ from the U.S. Federal statutory rate of 35% primarily due to permanent differences related to investments in separate account dividends received deduction ("DRD"). The income tax provision for the year ended December 31, 2015 included a $36 net reduction in the provision for income taxes primarily related to the release of reserves due to the resolution of uncertain tax positions. For further discussion of income taxes, see Note 16 - Income Taxes of Notes to Consolidated Financial Statements.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
| CORPORATE |
Results of Operations
Operating Summary
| 2016 | 2015 | 2014 | |||||||
| Fee income [1] | $ | 4 | $ | 8 | $ | 10 | |||
| Net investment income | 31 | 17 | 22 | ||||||
| Net realized capital gains (losses) | (103 | ) | 15 | 7 | |||||
| Total revenues | (68 | ) | 40 | 39 | |||||
| Insurance operating costs and other expenses [1] | 14 | 53 | 114 | ||||||
| Pension Settlement | — | — | 128 | ||||||
| Loss on extinguishment of debt [2] | — | 21 | — | ||||||
| Interest expense [2] | 339 | 357 | 376 | ||||||
| Total benefits, losses and expenses | 353 | 431 | 618 | ||||||
| Loss before income taxes | (421 | ) | (391 | ) | (579 | ) | |||
| Income tax benefit [3] | (309 | ) | (233 | ) | (204 | ) | |||
| Net loss | $ | (112 | ) | $ | (158 | ) | $ | (375 | ) |
| [1] | Fee income includes the income associated with the sales of non-proprietary insurance products in the Company’s broker-dealer subsidiaries that has an offsetting commission expense in insurance operating costs and other expenses. |
| [2] | For discussion of debt, see Note 13 - Debt of Notes to Consolidated Financial Statements. |
| [3] | For discussion of income taxes, see Note 16 - Income Taxes of Notes to Consolidated Financial Statements. |
Net Loss

Year ended December 31, 2016 compared to the year ended December 31, 2015
Net loss decreased in 2016 primarily due to a decrease in insurance operating costs and other expenses, an increase in net investment income and lower interest expense. The income tax benefit in 2016 included a federal income tax benefit of $113 associated with the investments in solar energy partnerships offset by realized capital losses of $96, before tax, associated with the write-down of investments in solar energy partnerships.
Insurance operating costs and other expenses decreased in 2016 largely due a reduction in restructuring costs.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Net loss decreased in 2015 primarily due to an increase in income tax benefit of $94 from the partial reduction of the deferred tax valuation allowance on capital loss carryovers established when the HLIKK annuity business was sold. The reduction in valuation allowance stems primarily from taxable gains on sales of investments during the period. The net loss also decreased due to lower insurance operating costs and interest expense as well as the effect of a pension settlement charge in 2014, partially offset by a loss on extinguishment of debt in second quarter 2015.
Insurance operating costs and other expenses decreased for 2015 largely due to a reduction in restructuring costs. In 2014, insurance operating costs and expenses included a benefit of $10, before tax, for recoveries for past legal expenses associated with closed litigation.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Interest Expense
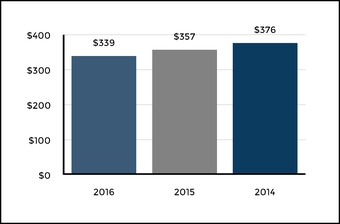
Year ended December 31, 2016 compared to the year ended December 31, 2015
Interest expense decreased in 2016 primarily due to a decrease in outstanding debt from debt maturities and the paydown of senior notes. In 2016, $275 of senior notes matured.
Year ended December 31, 2015 compared to the year ended December 31, 2014
Interest expense declined in 2015 due to a decrease in outstanding debt from debt maturities and the paydown of senior notes. In 2015, $456 of the Company's senior notes matured and $317 of senior notes were redeemed for cash.
ENTERPRISE RISK MANAGEMENT
The Company’s Board of Directors has ultimate responsibility for risk oversight, as described more fully in our Proxy Statement, while management is tasked with the day-to-day management of the Company’s risks.
The Company manages and monitors risk through risk policies, controls and limits. At the senior management level, an Enterprise Risk and Capital Committee (“ERCC”) oversees the risk profile and risk management practices of the Company. As illustrated below, a number of functional committees sit underneath the ERCC, providing oversight of specific risk areas and recommending risk mitigation strategies to the ERCC.
| ERCC Members |
| CEO (Chair) |
| President |
| Chief Financial Officer |
| Chief Investment Officer |
| Chief Risk Officer |
| General Counsel |
| Others as deemed necessary by the Committee Chair |
| ERCC | |||||||||||||||||||
| Asset Liability Committee | Underwriting Risk Committee | Emerging Risk Steering Committee | Operational Risk Committee | Catastrophe Risk Committee | Economic Capital Executive Committee | Model Oversight Committee |
The Company's enterprise risk management ("ERM") function supports the ERCC and functional committees, and is tasked with, among other things:
| • | risk identification and assessment; |
| • | the development of risk appetites, tolerances, and limits; |
| • | risk monitoring; and |
| • | internal and external risk reporting. |
The Company categorizes its main risks as insurance risk, operational risk and financial risk, each of which is described in more detail below.
Insurance Risk
Insurance risk is the risk of losses of both a catastrophic and non-catastrophic nature on the P&C and life products the Company has sold . Catastrophe insurance risk is the exposure arising from both natural (e.g., weather, earthquakes, wildfires, pandemics) and man-made catastrophes (e.g., terrorism, cyber-attacks) that create a concentration or aggregation of loss across the Company's insurance or asset portfolios.
Sources of Insurance Risk Non-catastrophe insurance risks exist within each of the Company's divisions except Mutual Funds and include:
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
| • | Property- Risk of loss to personal or commercial property from automobile related accidents, weather, explosions, smoke, shaking, fire, theft, vandalism, inadequate installation, faulty equipment, collisions and falling objects, and/or machinery mechanical breakdown resulting in physical damage and other covered perils. |
| • | Liability- Risk of loss from automobile related accidents, uninsured and underinsured drivers, lawsuits from accidents, defective products, breach of warranty, negligent acts by professional practitioners, environmental claims, latent exposures, fraud, coercion, forgery, failure to fulfill obligations per contract surety, liability from errors and omissions, derivative lawsuits, and other securities actions and covered perils. |
| • | Mortality- Risk of loss from unexpected trends in insured deaths impacting timing of payouts from life insurance or annuity products, personal or commercial automobile related accidents, and death of employees or executives during the course of employment, while on disability, or while collecting workers compensation benefits. |
| • | Morbidity- Risk of loss to an insured from illness incurred during the course of employment or illness from other covered perils. |
| • | Disability- Risk of loss incurred from personal or commercial automobile related losses, accidents arising outside of the workplace, injuries or accidents incurred during the course of employment, or from equipment, with each loss resulting in short term or long-term disability payments. |
| • | Longevity- Risk of loss from increased life expectancy trends among policyholders receiving long-term benefit payments or annuity payouts. |
Catastrophe risk primarily arises in the group life, group disability, property, and workers' compensation product lines.
Impact Non-catastrophe insurance risk can arise from unexpected loss experience, underpriced business and/or underestimation of loss reserves and can have significant effects on the Company’s earnings. Catastrophe insurance risk can arise from various unpredictable events and can have significant effects on the Company's earnings and may result in losses that could constrain its liquidity.
Management The Company's policies and procedures for managing these risks include disciplined underwriting protocols, exposure controls, sophisticated risk-based pricing, risk modeling, risk transfer, and capital management strategies. The Company has established underwriting guidelines for both individual risks, including individual policy limits, and risks in the aggregate, including aggregate exposure limits by geographic zone and peril. The Company uses both internal and third-party models to estimate the potential loss resulting from various catastrophe events and the potential financial impact those events would have on the Company's financial position and results of operations across its businesses.
Among specific risk tolerances set by the Company, risk limits are set for natural catastrophes, terrorism risk and pandemic risk.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
| Risk | Definition | Details and Company Limits | |
| Natural catastrophe | Exposure arising from natural phenomena (e.g., weather, earthquakes, wildfires, etc.) that create a concentration or aggregation of loss across the Company's insurance or asset portfolios. | The Company generally limits its estimated pre-tax loss as a result of natural catastrophes for property & casualty exposures from a single 250-year event to less than 30% of statutory surplus of the property and casualty insurance subsidiaries prior to reinsurance and to less than 15% of statutory surplus of the property and casualty insurance subsidiaries after reinsurance. From time to time the estimated loss to natural catastrophes from a single 250-year event prior to reinsurance may fluctuate above or below these limits due to changes in modeled loss estimates, exposures or statutory surplus. | |
| - The estimated 250 year pre-tax probable maximum loss from earthquake events is estimated to be $930 before reinsurance and $533 net of reinsurance. [1] | |||
| - The estimated 250 year pre-tax probable maximum losses from hurricane events are estimated to be $1.6 billion before reinsurance and $836 net of reinsurance. [1] | |||
| Terrorism | The risk of losses from terrorist attacks, including losses caused by single-site and multi-site conventional attacks, as well as the potential for attacks using nuclear, biological, chemical or radiological weapons (“NBCR”). | Enterprise limits for terrorism apply to aggregations of risk across property-casualty, group benefits and specific asset portfolios and are defined based on a deterministic, single-site conventional terrorism attack scenario. The Company manages its potential estimated loss from a conventional terrorism loss scenario, up to $1.7 billion net of reinsurance and $2.0 billion gross of reinsurance, before coverage under the Terrorism Risk Insurance Program established under “TRIPRA”. In addition, the Company monitors exposures monthly and employs both internally developed and vendor-licensed loss modeling tools as part of its risk management discipline. Our modeled exposures to conventional terrorist attacks around landmark locations may fluctuate above and below our stated limits. | |
| Pandemic | The exposure to loss arising from widespread influenza or other pathogens or bacterial infections that create an aggregation of loss across the Company's insurance or asset portfolios. | The Company generally limits its estimated pre-tax loss from a single 250 year pandemic event to less than 15% of statutory surplus of the property and casualty and group benefits insurance subsidiaries. In evaluating these scenarios, the Company assesses the impact on group life policies, short-term and long-term disability, property & casualty claims, and losses in the investment portfolio associated with market declines in the event of a widespread pandemic. While ERM has a process to track and manage these limits, from time to time, the estimated loss for pandemics may fluctuate above or below these limits due to changes in modeled loss estimates, exposures, or statutory surplus. |
| [1] | The loss estimates represent total property losses for hurricane events and property and workers compensation losses for earthquake events resulting from a single event. The estimates provided are based on 250-year return period loss estimates that have a 0.4% likelihood of being exceeded in any single year. The net loss estimates provided assume that the Company is able to recover all losses ceded to reinsurers under its reinsurance programs. The Company also manages natural catastrophe risk for group life and group disability, which in combination with property and workers compensation loss estimates are subject to separate enterprise risk management net aggregate loss limits as a percent of enterprise surplus. |
Reinsurance as a Risk Management Strategy
In addition to the policies and procedures outlined above, the Company uses reinsurance to transfer certain risks to reinsurance companies based on specific geographic or risk concentrations. A variety of traditional reinsurance products are used as part of the Company's risk management strategy, including excess of loss occurrence-based products that reinsure property and workers compensation exposures, and individual risk or quota share arrangements, that reinsure losses from specific classes or lines of business. The Company has no significant finite risk contracts in place and the statutory surplus benefit from all such prior year contracts is immaterial.
Facultative reinsurance is used by the Company to manage policy-specific risk exposures based on established underwriting guidelines. The Hartford also participates in governmentally administered reinsurance facilities such as the Florida Hurricane Catastrophe Fund (“FHCF”), the Terrorism Risk Insurance Program established under “TRIPRA” and other reinsurance programs relating to particular risks or specific lines of business.
Reinsurance for Catastrophes- The Company has several catastrophe reinsurance programs, including reinsurance treaties that cover property and workers’ compensation losses aggregating from single catastrophe events.
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Primary Catastrophe Treaty Reinsurance Coverages as of January 1, 2017
| Effective for the period | % of layer(s) reinsurance | Per occurrence limit | Retention | |||||||||
| Property losses arising from a single catastrophe event [1] [2] | 1/1/2017 to 1/1/2018 | 88% | $ | 800 | $ | 350 | ||||||
| Property catastrophe losses from a Personal Lines Florida hurricane | 6/1/2016 to 6/1/2017 | 90% | $ | 109 | [3] | $ | 34 | |||||
| Workers compensation losses arising from a single catastrophe event [4] | 1/1/2017 to 12/31/2017 | 80% | $ | 350 | $ | 100 |
| [1] | Certain aspects of our principal catastrophe treaty have terms that extend beyond the traditional one year term. While overall treaty is placed at 88%, each layer's placement varies slightly. |
| [2] | $50 of the property occurrence treaty can alternatively be used as part of the Property Aggregate treaty referenced below. |
| [3] | The per occurrence limit on the FHCF treaty is $109 for the 6/1/2016 to 6/1/2017 treaty year based on the Company's election to purchase the required coverage from FHCF. Coverage is based on the best available information from FHCF, which was updated in January 2017. |
| [4] | In addition to the limit shown, the workers compensation reinsurance includes a non-catastrophe, industrial accident layer, providing coverage for 80% of a$30 per event limit in excess of a $20 retention. |
In addition to the property catastrophe reinsurance coverage described in the above table, the Company has other catastrophe and working layer treaties and facultative reinsurance agreements that cover property catastrophe losses on an aggregate excess of loss and on a per risk basis. The principal property catastrophe reinsurance program and certain other reinsurance programs include a provision to reinstate limits in the event that a catastrophe loss exhausts limits on one or more layers under the treaties. In addition, covering the period from January 1, 2017 to December 31, 2017, the Company has a Property Aggregate treaty in place which provides one limit of $200 of aggregate qualifying property catastrophe losses in excess of a net retention of $850.
Reinsurance for Terrorism- For the risk of terrorism, private sector catastrophe reinsurance capacity is generally limited and largely unavailable for terrorism losses caused by NBCR attacks. As such, the Company's principal reinsurance protection against large-scale terrorist attacks is the coverage currently provided through TRIPRA to the end of 2020.
TRIPRA provides a backstop for insurance-related losses resulting from any “act of terrorism”, which is certified by the Secretary of the Treasury, in consultation with the Secretary of Homeland Security and the Attorney General, for losses that exceed a threshold of industry losses of $100 in 2015, with the threshold increasing to $200 by 2020. Under the program, in any one calendar year, the federal government would pay a percentage of losses incurred from a certified act of terrorism after an insurer's losses exceed 20% of the Company's eligible direct commercial earned premiums of the prior calendar year up to a combined annual aggregate limit for the federal government and all insurers of $100 billion. The percentage of losses paid by the federal government is 83% in 2017, decreasing by 1 point annually to 80% in the year 2020. The Company's estimated deductible under the program is $1.2 billion for 2017. If an act of terrorism or acts of terrorism result in covered losses exceeding the $100 billion annual industry aggregate limit, a future Congress would be responsible for determining how additional losses in excess of $100 billion will be paid.
Reinsurance Recoverables
Property and casualty insurance product reinsurance recoverables represent loss and loss
adjustment expense recoverables from a number of entities, including reinsurers and pools.
Property & Casualty Reinsurance Recoverables [2]
| As of December 31, | ||||||
| 2016 | 2015 | |||||
| Paid loss and loss adjustment expenses | $ | 89 | $ | 119 | ||
| Unpaid loss and loss adjustment expenses | 2,449 | 2,662 | ||||
| Gross reinsurance recoverables [1] | 2,538 | 2,781 | ||||
| Less: Allowance for uncollectible reinsurance | (165 | ) | (266 | ) | ||
| Net reinsurance recoverables [2] | $ | 2,373 | $ | 2,515 |
| [1] | Excludes reinsurance recoverables of $178 to be transferred to the buyer in connection with the pending sale of the Company's U.K. property and casualty run-off subsidiaries. |
| [2] | Included reinsurance recoverables of $113 resulting from the acquisition of Maxum in July 2016. |
As shown in the following table, a portion of the total gross reinsurance recoverables relates to the Company’s mandatory participation in various involuntary assigned risk pools and the value of annuity contracts held under structured settlement agreements. Reinsurance recoverables due from mandatory pools are backed by the financial strength of the property and casualty insurance industry. Annuities purchased from third-party life insurers under structured settlements are recognized as reinsurance recoverables in cases where the Company has not obtained a release from the claimant. Of the remaining gross reinsurance recoverables, the portion of recoverables due from companies rated by A.M. Best is as follows:
Part II - Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
Distribution of Gross Reinsurance Recoverables
| As of December 31, | ||||||||||
| 2016 | 2015 | |||||||||
| Gross reinsurance recoverables | $ | 2,538 | $ | 2,781 | ||||||
| Less: mandatory (assigned risk) pools and structured settlements | (528 | ) | (551 | ) | ||||||
| Gross reinsurance recoverables excluding mandatory pools and structured settlements | $ | 2,010 | $ | 2,230 | ||||||
| % of Total | % of Total | |||||||||
| Rated A- (Excellent) or better by A.M. Best [1] | $ | 1,470 | 73.1 | % | $ | 1,474 | 66.1 | % | ||
| Other rated by A.M. Best | 1 | 0.1 | % | 4 | 0.2 | % | ||||
| Total rated companies | 1,471 | 73.2 | % | 1,478 | 66.3 | % | ||||
| Voluntary pools | 79 | 3.9 | % | 82 | 3.7 | % | ||||
| Captives | 336 | 16.7 | % | 387 | 17.3 | % | ||||
| Other not rated companies | 124 | 6.2 | % | 283 | 12.7 | % | ||||
| Total | $ | 2,010 | 100.0 | % | $ | 2,230 | 100.0 | % |
| [1] | Based on A.M. Best ratings as of December 31, 2016 and 2015, respectively. |
To manage reinsurer credit risk, a reinsurance security review committee evaluates the credit standing, financial performance, management and operational quality of each potential reinsurer. In placing reinsurance, the Company considers the nature of the risk reinsured, including the expected liability payout duration, and establishes limits tiered by reinsurer credit rating.
Where its contracts permit, the Company secures future claim obligations with various forms of collateral, including irrevocable letters of credit, secured trusts, funds held accounts and group wide offsets. As part of its reinsurance recoverable review, the Company analyzes recent developments in commutation activity between reinsurers and cedants, recent trends in arbitration and litigation outcomes in disputes between cedants and reinsurers and the overall credit quality of the Company’s reinsurers. As indicated in the above table, 73.1% of the gross reinsurance recoverables due from reinsurers rated by A.M. Best were rated A- (excellent) or better as of December 31, 2016.
Annually, the Company completes evaluations of the reinsurance recoverable asset associated with older, long-term casualty liabilities reported in the Property & Casualty Other Operations reporting segment, and the allowance for uncollectible reinsurance reported in the Commercial Lines reporting segment. For a discussion regarding the results of these evaluations, see MD&A - Critical Accounting Estimates, Property and Casualty Insurance Product Reserves, Net of Reinsurance.
Group benefits and life insurance product reinsurance recoverables
represent reserve for future policy benefits and unpaid loss and loss adjustment expenses and other policyholder funds and benefits payable that are recoverable from a number of reinsurers.
Group Benefits and Life Insurance Reinsurance Recoverables
| As of December 31, | ||||||
| 2016 | 2015 | |||||
| Future policy benefits and unpaid loss and loss adjustment expenses and other policyholder funds and benefits payable | 20,938 | $ | 20,674 | |||
| Gross reinsurance recoverables | $ | 20,938 | $ | 20,674 | ||
| Less: Allowance for uncollectible reinsurance [1] | — | — | ||||
| Net reinsurance recoverables | $ | 20,938 | $ | 20,674 |
| [1] | No allowance for uncollectible reinsurance is required as of December 31, 2016 and December 31, 2015. |
As of December 31, 2016, the Company has reinsurance recoverables from MassMutual and Prudential of $8.6 billion and $11.1 billion, respectively. As of December 31, 2015 the Company had reinsurance recoverables from MassMutual and Prudential of $8.6 billion and $10.8 billion, respectively. The Company's obligations to its direct policyholders that have been reinsured to Mass Mutual and Prudential are secured by invested assets held in trust. Net of invested assets held in trust, as of December 31, 2016, the Company has no reinsurance-related concentrations of credit risk greater than 10% of the Company’s Consolidated Stockholders’ Equity.
Guaranty Funds and Other Insurance-related Assessments
As part of its risk management strategy, the Company regularly monitors the financial strength of other insurers and, in particular, activity by insurance regulators and various state guaranty associations relating to troubled insurers. In all states, insurers licensed to transact certain classes of insurance are required to become members of a guaranty fund.
Operational Risk
Operational risk is the risk of loss resulting from inadequate or failed internal processes and systems, human error, or from external events.
Sources of Operational Risk Operational risk is inherent in the Company's business and functional areas. Operational risks include legal; cyber and information security; models; third party vendors; technology; operations; business continuity; disaster recovery; external fraud; and compliance.
Impact Operational risk can result in financial loss, disruption of our business, regulatory actions or damage to our reputation.
Management Responsibility for day-to-day management of operational risk lies within each business unit and functional area. ERM provides an enterprise-wide view of the Company's operational risk on an aggregate basis. ERM is responsible for
Previous: Item 5. Market for the Hartford's Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities · Next: Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations