 filings.tools
Henry Schein 10-K 2022-12-31
Filed 2023-02-21. 23 sections, 472K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington,
D.C.
20549
FORM
10-K
(Mark One)
☒
ANNUAL REPORT PURSUANT TO
SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
For the fiscal year ended
December 31, 2022
☐
TRANSITION REPORT PURSUANT TO
SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF
1934
For the transition period from ____________ to ____________
Commission file number
0-27078
HENRY SCHEIN, INC.
(Exact name of registrant as specified in its charter)
Delaware
11-3136595
(State or other jurisdiction of
(I.R.S. Employer Identification No.)
incorporation or organization)
135 Duryea Road
Melville
,
New York
(Address of principal executive offices)
11747
(Zip Code)
(
)
843-5500
(Registrant’s telephone number, including area code)
Securities registered pursuant to Section 12(b)
of the Act:
Title of each class
Trading Symbol(s)
Name of each exchange on which registered
Common Stock, par value $.01 per share
HSIC
The Nasdaq Global Select Market
Securities registered pursuant to Section
12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act.
YES
:
☒
NO:
☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act.
YES:
☐
NO
:
☒
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934
during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing
requirements for the past 90 days.
YES
:
☒
NO:
☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of
Regulation S-T during the preceding 12 months (or for such shorter period that the registrant was required to submit such files).
YES
:
☒
NO:
☐
Indicate by check mark whether the registrant is a
large accelerated filer, an
accelerated filer, a non-accelerated filer,
a smaller reporting company,
or an
emerging
growth
company.
See
the
definitions
of
“large
accelerated
filer,”
“accelerated
filer,”
“smaller
reporting
company,”
and
“emerging
growth
company” in Rule 12b-2 of the Exchange Act.
Large accelerated filer
:
☒
Accelerated filer:
☐
Non-accelerated filer:
☐
Smaller reporting company:
☐
Emerging
growth company:
☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any
new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act.
☐
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal
control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared
or issued its audit report. YES:
☒
NO:
☐
If securities are registered pursuant to
Section 12(b) of the Act, indicate by
check mark whether the financial statements of
the registrant included in the
filing reflect the correction of an error to previously issued financial statements.
☐
Indicate
by
check
mark
whether
any
of
those
error
corrections
are
restatements
that
required
a
recovery
analysis
of
incentive-based
compensation
received by any of the registrant’s executive officers during the relevant recovery period pursuant to §240.10D-1(b).
☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act).
YES:
☐
NO:
☒
The aggregate market value of the registrant’s voting stock held by non-affiliates of the registrant, computed by reference to the closing sales price as
quoted on the Nasdaq Global Select Market on June 25, 2022, was approximately $
10,463,590,000
.
As of February 7, 2023, there were
131,283,515
shares of registrant’s Common Stock, par value $.01 per share, outstanding.
Documents Incorporated by Reference:
Portions of the Registrant’s definitive proxy statement to be filed pursuant to Regulation 14A not later than 120 days after the end of the fiscal year
(December 31, 2022) are incorporated by reference in Part III hereof.
TABLE OF CONTENTS
Page
Number
Market for Registrant's Common Equity, Related Stockholder Matters
and Issuer Purchases of Equity Securities
Management's Discussion and Analysis of Financial Condition
Quantitative and Qualitative Disclosures About Market Risk
Financial Statements and Supplementary Data
Changes in and Disagreements with Accountants on Accounting
Disclosure Regarding Foreign Jurisdictions that Prevent Inspection
Directors, Executive Officers and Corporate Governance
Security Ownership of Certain Beneficial Owners and Management
and Related Stockholder Matters
Certain Relationships and Related Transactions, and Director Independence
Principal Accounting Fees and Services
Exhibits and Financial Statement Schedules
PART
I
Item 1. Business
Business
General
Henry Schein, Inc. is a solutions company for health care professionals powered
by a network of people and
technology.
We believe we are the world’s largest
provider of health care products and services primarily to
office-
based dental and medical practitioners, as well as alternate sites of care.
Our philosophy is grounded in our
commitment to help customers operate a more efficient and successful business so
the practitioner can provide
better clinical care.
With more than 90 years of experience distributing health care products, we have built a vast set of small,
mid-sized
and large customers in the dental and medical markets, serving more than one million
customers worldwide across
dental practices, laboratories,
physician practices, and ambulatory surgery centers, as well as government,
institutional health care clinics and other alternate care clinics.
We are headquartered in Melville, New York
and employ more than 22,000 people.
Approximately 50% of our
workforce is based in the United States and approximately 50% is based
outside of the United States.
We have
operations or affiliates in 32 countries and territories.
Our broad global footprint has evolved over time through our
organic success as well as through contribution from strategic acquisitions.
We offer
a comprehensive selection of more than 300,000 branded products
and Henry Schein corporate brand
products through our distribution centers.
Our infrastructure, including over 3.8 million square
feet of space in 29
strategically located distribution and 19 manufacturing facilities around
the world, enables us to historically provide
rapid and accurate order fulfillment, better serve our customers and increase
our operating efficiency.
This
infrastructure, together with broad product and service offerings at competitive prices,
and a strong commitment to
customer service, enables us to be a single source of supply for our customers’
needs.
We conduct our business through two reportable segments: (i) health care distribution and (ii) technology and
value-added services.
These segments offer different products and services to the same customer base.
Our dental
businesses serve office-based dental practitioners, dental laboratories, schools, government
and other
institutions.
Our medical businesses serve physician offices, urgent care centers, ambulatory care sites,
emergency
medical technicians, dialysis centers, home health, federal and state governments
and large enterprises, such as
group practices
and integrated delivery networks, among other providers across a
wide range of specialties.
The health care distribution reportable segment, combining our global dental
and medical businesses, distributes
consumable products, small equipment, laboratory products, large equipment, equipment
repair services, branded
and generic pharmaceuticals, vaccines, surgical products, dental specialty products
(including implant, orthodontic
and endodontic products), diagnostic tests, infection-control products, personal
protective equipment products
(“PPE”) and vitamins.
While our primary go-to-market strategy is in our capacity
as a distributor, we also market
and sell under our own corporate brand portfolio of cost-effective, high-quality consumable
merchandise products,
and manufacture certain dental specialty products in the areas of oral
surgery, implants, orthodontics and
endodontics.
The technology and value-added services reportable segment provides
software, technology and other value-added
services to health care practitioners.
Henry Schein One, the largest contributor of sales to this category, offers
dental practice management solutions for dental and medical practitioners.
In addition, we offer dentists and
physicians a broad suite of electronic health records, patient communication
services including electronic marketing
and web-site design, analytics and patient demand generation.
Finally, our value-added practice solutions include
practice consultancy, education, integrated revenue cycle management and the facilitation of financial service
offerings (on a non-recourse basis) to help dentists and physicians operate and
expand their business operations.
We believe our hands-on consultative approach to provide solutions to support practice decision-making is a key
differentiator for our business.
Recent Developments
See “Management’s Discussion and Analysis of Financial Condition and Results of Operations – Recent
Developments” herein for a discussion related to the COVID-19
pandemic and recent corporate transactions.
Industry
The global health care distribution industry, as it relates to office-based health care practitioners, is fragmented and
diverse.
The industry ranges from sole practitioners working out of
relatively small offices to mid-sized and large
group practices ranging in size from a few practitioners to several
hundred practices owned or operated by dental
support organizations (DSOs), medical group purchasing organizations (GPOs), hospital systems
or integrated
delivery networks (IDNs).
Due in part to the limited capacity of office-based health care practitioners
to store and manage large quantities of
supplies in their offices, the distribution of health care supplies and small equipment
to office-based health care
practitioners has been characterized by frequent, small quantity orders,
and a need for rapid, reliable and
substantially complete order fulfillment.
The purchasing decisions within an office-based health care practice
are
typically made by the practitioner, hygienist or office manager.
Supplies and small equipment are generally
purchased from more than one distributor, with one generally serving as the primary supplier.
The health care distribution industry continues to experience growth due
to demand driven by the aging population,
increased health care awareness and the importance of preventative care,
an increasing understanding of the
connection between good oral health and overall health, improved access
to care globally, the proliferation of
medical technology and testing, new pharmacology treatments and
expanded third-party insurance coverage,
partially offset by the effects of unemployment on insurance coverage and technological
improvements, including
the advancement of software and services, prosthetic solutions and
telemedicine.
In addition, the non-acute market
continues to benefit from the shift of procedures and diagnostic
testing from acute care settings to alternate-care
sites, particularly physicians’ offices and ambulatory surgery centers.
We believe that consolidation within the industry will continue to result in a number of distributors, particularly
those with limited financial, operating and marketing resources, seeking
to combine with larger companies that can
provide growth
opportunities.
This consolidation also may continue to result in distributors seeking
to acquire
companies that can enhance their current product and service offerings or provide
opportunities to serve a broader
customer base.
In addition, customer consolidation will likely lead to multiple locations
under common management and the
movement of more procedures from the hospital setting to the physician
or alternate care setting as the health care
industry is increasingly focused on efficiency and cost containment.
This trend has benefited distributors capable
of providing a broad array of products and services at low prices.
It also has accelerated the growth of health
maintenance organizations (“HMOs”), group practices, other managed care accounts
and collective buying groups,
which, in addition to their emphasis on obtaining products at competitive
prices, tend to favor distributors capable
of providing specialized management information support.
We believe that the trend towards cost containment ha
Showing the first 8K of 102K characters. Open the full section
Item 1A. Risk Factors
Our business operations could be affected by factors that are not presently known
to us or that we currently
consider not to be material to our operations, so you should not consider
the risks disclosed in this section to
necessarily represent a complete statement of all risks and uncertainties.
The Company believes that the following
risks could have a material adverse impact on our business, reputation, financial
results, financial condition and/or
the trading price of our common stock.
The order in which these factors appear does not necessarily reflect
their
relative importance or priority.
COMPANY RISKS
Our business, results of operations, cash flows, financial condition and
liquidity may be negatively impacted by
the effects of disease outbreaks, epidemics, pandemics, or similar wide-spread public health
concerns and other
natural disasters
.
The COVID-19 pandemic and the responses of governments
to it had, and may again have, a
material adverse effect on our business, results of operations and cash flows and may result
in a material
adverse effect on our financial condition and liquidity.
Our business, results of operations, cash flows, financial condition and
liquidity may be negatively impacted by the
effects of disease outbreaks, epidemics, pandemics, similar wide-spread public health concerns
and other natural
disasters. The COVID-19 pandemic has had, and continues to have, an
unprecedented impact on society, worldwide
economic activity, and the health care sector (particularly, the dental market). As a global healthcare solutions
company, the COVID-19 pandemic and the governmental responses to it had, and may again have, a material
adverse effect on our business, results of operations and cash flows and may result
in a material adverse effect on
our financial condition and liquidity. Even after the COVID-19 pandemic has begun to subside, we may again
experience material adverse impacts to our business, results of operations
and cash flows as a result of, among other
things, its global economic impact, including any recession that
may occur in the future, or a prolonged period of
economic slowdown or the reluctance of patients to return for elective dental
or medical care. The impacts and
potential impacts from the COVID-19 pandemic include, but are not
limited to:
Significant volatility in supply, demand and selling prices for personal protective equipment (PPE), COVID-19
tests and other COVID-19 related products.
Available supply,
customer demand and selling prices for PPE,
COVID-19 tests and other COVID-19 related products
fluctuated in fiscal 2022 and we expect such volatility to
continue for the duration of the COVID-19 pandemic. This has resulted
in inventory reserves, fluctuating margins
and increased revenue related to such products.
The volatility in sales of COVID-19 test kits has moderated,
albeit
at a significantly lower level of sales compared with 2021, resulting in
us recording an inventory obsolescence
reserve of $17 million for COVID-19 test kits during the year
ended December 31, 2022 and we expect further
declines in sales volumes.
Our estimates for supply, demand and selling prices are inherently uncertain and if
supply, demand, selling prices or other market dynamics significantly fluctuate in the future beyond our current
assumptions, additional inventory reserves may be required, margins may be reduced and/or
revenue may decline
for such products, each which could materially adversely impact our business,
results of operations and cash flows.
Additionally, governmental policies designed to reduce the transmission of COVID-19 and variants thereof could
once again lead to the closure of dental offices or deferral of elective procedures and
wellness exams by medical
and dental patients. Such previous closures and restrictions impacted our
customers’ spending with us and had, and
if reinstated may again have, a material adverse effect on our business, results of operations
and cash flows.
Although we believe that most practices currently are able to access
adequate supply, we still may be unable to
supply our customers with the specific brand and/or quantity of certain PPE products,
COVID-19 tests and other
COVID-19 related products they demand, which may lead to our
customers seeking alternative sources of supply.
Healthcare professionals’ inability to obtain a sufficient quantity and/or brand of certain PPE, COVID-19
tests and
other COVID-19 related products would adversely impact our business,
results of operations and cash flows, and
could materially adversely affect our financial condition and liquidity;
Reduction in Peoples’ Ability and Willingness to be in Public.
Restrictions recommended by several public health
organizations, and implemented, from time to time, by federal, state and local governments,
to slow and limit the
transmission of COVID-19 and variants thereof has caused and may in
the future cause some people to be less
willing to go to elective medical and dental appointments, which could
again materially adversely affect demand
for our products.
A lengthened period of materially suppressed demand could again cause
material adverse impacts
on our business, results of operations and cash flows and could materially
adversely affect our financial condition
and liquidity;
Negative impact on our workforce and impact of adapted business practices.
The spread of COVID-19 and
variants thereof caused us to modify our business practices (including
employee travel, employee work locations,
and physical participation in meetings, events and conferences), and
we may take further actions as may be required
by government authorities or our customers or that we determine are in the
best interests of our employees. As the
COVID-19 pandemic continues to unfold, we continue to evaluate
appropriate actions for our business. At the onset
of the COVID-19 pandemic, many of our office-based workers shifted abruptly to
working remotely. As the
COVID-19 pandemic has evolved, we have modified our work
arrangements to implement more flexible working
arrangements for our office-based workers, including permanent work from home,
hybrid and office-based
arrangements. Implementing these modified business practices
to include remote work arrangements could have a
negative impact on employee morale, strain our business continuity plans,
introduce operational risk (including but
not limited to cybersecurity risks), and impair our ability
to efficiently operate our business;
Significant changes in political conditions.
Significant changes in political conditions in markets in which
we
purchase and distribute our products have occurred and are expected to
continue at least during the pendency of the
pandemic, including quarantines, governmental or regulatory actions, closures
or other restrictions that limit or
close our operating facilities, restrict our employees’ ability to
travel or perform necessary business functions, or
otherwise constrain the operations of our business partners, suppliers or
customers, which may materially adversely
affect our business, results of operations, cash flows, financial condition
and liquidity;
Volatility
in the financial markets.
Volatility
in the financial markets may materially adversely affect the
availability and cost of credit to us;
The impact of the COVID-19 pandemic may also exacerbate other risks discussed
below, any of which could have
a material adverse effect on us.
We are dependent upon third parties for the manufacture and supply of a significant volume of our products.
We obtain a significant volume of the products we distribute from third parties, with whom we generally do not
have long-term contracts.
While there is typically more than one source of supply, some key suppliers, in the
aggregate, supply a significant portion
Showing the first 8K of 73K characters. Open the full section
Item 1B. Unresolved Staff Comments
Unresolved Staff Comments
We have no unresolved comments from the staff of the SEC that were issued 180 days or more preceding the end of
our 2022 fiscal year.
Item 2. Properties
Within our health care distribution segment (for properties with more than 100,000 square feet) we lease
and/or
own approximately 5.8 million square feet of properties, consisting of distribution,
office, showroom,
manufacturing and sales space, in locations including the United States, Australia,
Austria, Belgium, Brazil,
Canada, Chile, China, the Czech Republic, France, Germany, Hong Kong SAR, Ireland, Israel, Italy, Japan,
Liechtenstein, Luxembourg, Malaysia, Mexico, the Netherlands, New Zealand, Poland,
Portugal, Singapore, South
Africa, Spain, Sweden, Switzerland, Thailand,
United Arab Emirates and the United Kingdom.
Lease expirations
range from 2023 to 2041.
We believe that our properties are in good condition, are well maintained and are suitable and adequate to carry on
our business.
We have additional operating capacity at certain distribution center facilities.
Item 3. Legal Proceedings
Legal Proceedings
For a discussion of Legal Proceedings, see
Note 15 – Commitments and Contingencies
of the Notes to the
Consolidated Financial Statements included under Item 8.
Item 4. Mine Safety Disclosures
Mine Safety Disclosures
Not applicable.
PART
II
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of
Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of
Equity Securities
Our common stock is traded on the Nasdaq Global Select Market tier of
the Nasdaq Stock Market, or Nasdaq,
under the symbol HSIC.
On February 7, 2023, there were approximately 88,000 holders of record of
our common stock and the last reported
sales price was $87.14.
A substantially greater number of holders of our common
stock are “street name” or
beneficial holders, whose shares are held by banks, brokers and other financial
institutions.
Purchases of Equity Securities by the Issuer
Our share repurchase program, announced on March 3, 2003, originally
allowed us to repurchase up to two million
shares pre-stock splits (eight million shares post-stock splits) of our common
stock, which represented
approximately 2.3% of the shares outstanding at the commencement
of the program.
Subsequent additional
increases totaling $4.5 billion, authorized by our Board of Directors,
to the repurchase program provide for a total
of $4.6 billion (including $400 million authorized on August 17, 2022) of shares
of our common stock to be
repurchased under this program.
As of December 31, 2022,
we had repurchased approximately $4.5 billion of common stock (87,180,669
shares)
under these initiatives, with $115 million available for future common stock share repurchases.
On February 8, 2023, our Board of Directors authorized the repurchase
of up to an additional $400 million in shares
of our common stock.
The following table summarizes repurchases of our common stock
under our stock repurchase program during the
fiscal quarter ended December 31, 2022:
Total Number
Maximum Number
Total
of Shares
of Shares
Number
Average
Purchased as Part
that May Yet
of Shares
Price Paid
of Our Publicly
Be Purchased Under
Fiscal Month
Purchased (1)
Per Share
Announced Program
Our Program (2)
9/25/2022 through 10/29/2022
-
-
-
5,703,693
10/30/2022 through 11/26/2022
1,249,083
$
76.29
1,249,083
3,741,485
11/27/2022 through 12/31/2022
2,333,467
81.30
2,333,467
1,439,841
3,582,550
3,582,550
(1)
All repurchases were executed in the open market under our existing publicly announced authorized program.
(2)
The maximum number of shares that may yet be purchased under this program is determined at the end of each month based on the
closing price of our common stock at that time.
This table excludes shares withheld from employees to satisfy minimum tax
withholding requirements for equity-based transactions.
Dividend Policy
We have not declared any cash or stock dividends on our common stock during fiscal years 2022 or 2021.
We
currently do not anticipate declaring any cash or stock dividends on our common
stock in the foreseeable future.
We intend to retain earnings to finance the expansion of our business and for general corporate purposes, including
our share repurchase program.
Any declaration of dividends will be at the discretion of our Board of
Directors and
will depend upon the earnings, financial condition, capital requirements,
level of indebtedness, contractual
restrictions with respect to payment of dividends and other factors.


$50
$100
$150
$200
$250
$300
December
2017
December
2018
December
2019
December
2020
December
2021
December
2022
Henry Schein, Inc.
Dow Jones US Health Care Index
NASDAQ Composite Index
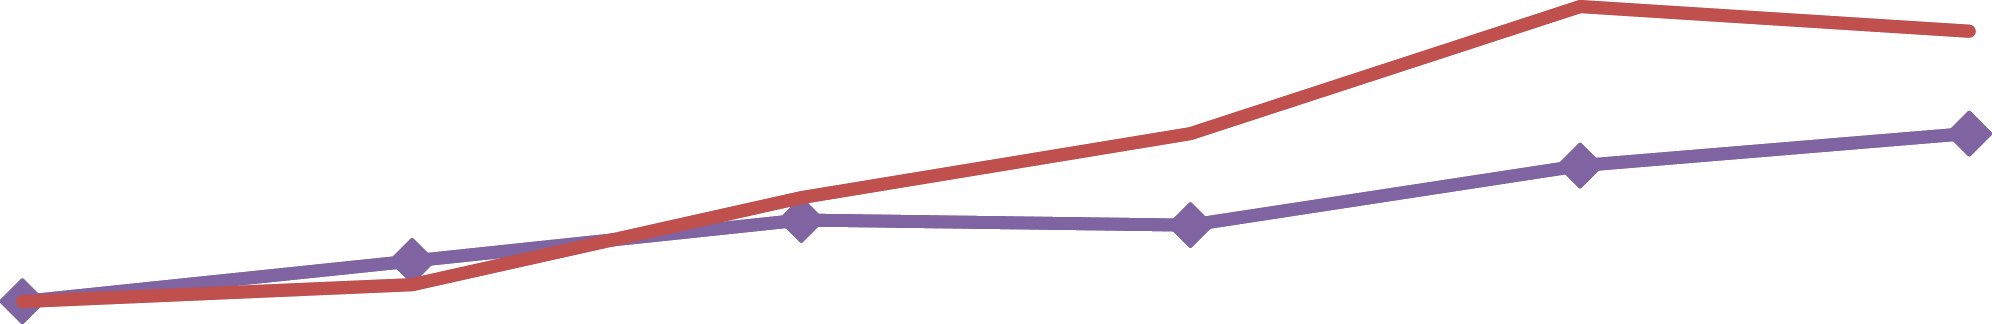
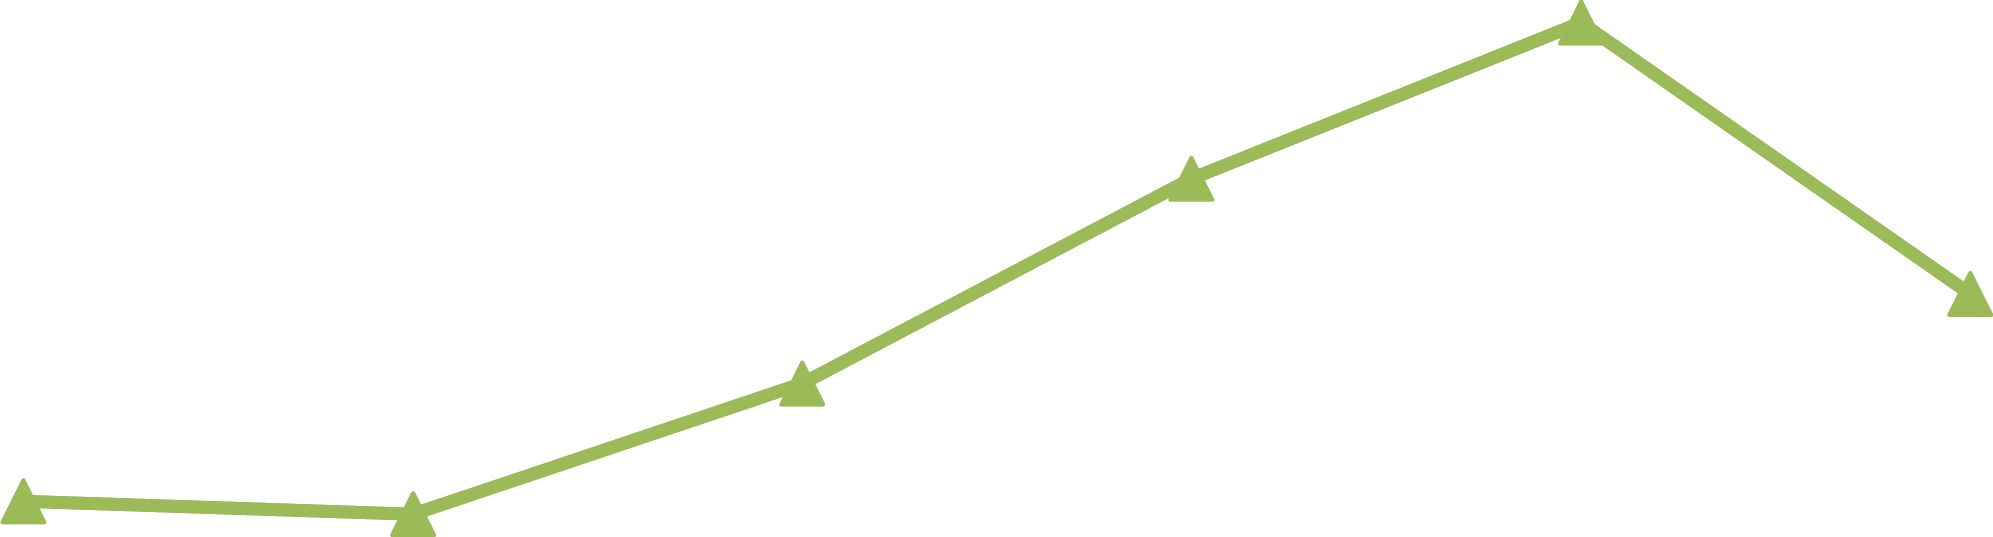
Stock Performance Graph
The graph below compares the cumulative total stockholder return
on $100 invested, assuming the reinvestment of
all dividends, on December 30, 2017, the last trading day before the
beginning of our 2018 fiscal year, through the
end of our 2022 fiscal year with the cumulative total return on $100
invested for the same period in the Dow Jones
U.S. Health Care Index and the Nasdaq Stock Market Composite Index.
COMPARISON OF 5-YEAR CUMULATIVE TOTAL
RETURN
ASSUMES $100 INVESTED ON DECEMBER 30, 2017
ASSUMES DIVIDENDS REINVESTED
December 30,
December 29,
December 28,
December 26,
December 25,
December 31,
2017
2018
2019
2020
2021
2022
Henry Schein, Inc.
$
100.00
$
111.49
$
122.98
$
121.58
$
138.37
$
147.48
Dow Jones U.S. Health
Care Index
100.00
104.72
129.31
147.48
183.33
176.40
NASDAQ Stock Market
Composite Index
100.00
96.41
133.30
191.21
235.27
158.65
Item 6. [Reserved]
[Reserved]
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of
Management’s Discussion and Analysis of Financial Condition and Results of
Operations
Cautionary Note Regarding Forward-Looking Statements
In accordance with the “Safe Harbor” provisions of the Private Securities
Litigation Reform Act of 1995, we
provide the following cautionary remarks regarding important factors
that, among others, could cause future results
to differ materially from the forward-looking statements, expectations and assumptions
expressed or implied
herein.
All forward-looking statements made by us are subject to
risks and uncertainties and are not guarantees of
future performance.
These forward-looking statements involve known and unknown
risks, uncertainties and other
factors that may cause our actual results, performance and achievements
or industry results to be materially
different from any future results, performance or achievements expressed or implied by such forward-looking
statements.
These statements are generally identified by the use of such
terms as “may,” “could,” “expect,”
“intend,” “believe,” “plan,” “estimate,” “forecast,” “project,” “anticipate,”
“to be,” “to make” or other comparable
terms.
Factors that could cause or contribute to such differences include, but are not limited
to, those discussed in
this Annual Report on Form 10-K, and in particular the risks discussed under
the caption “Risk Factors” in Item 1A
of this report and those that may be discussed in other documents we
file with the Securities and Exchange
Commission (SEC).
Forward looking statements include the overall impact of the Novel Coronavirus
Disease 2019
(COVID-19) on us, our results of operations, liquidity and financial condition
(including any estimates of the
impact on these items), the rate and consistency with which dental
and other practices resume or maintain normal
operations in the United States and internationally, expectations regarding personal protective equipment (“PPE”)
products and COVID-19 related product sales and inventory levels, whether
additional resurgences or variants of
the virus will adversely impact the resumption of normal operations, whether
supply chain disruptions will
adversely impact our business, the impact of integration and restructuring
programs as well as of any future
acquisitions, general economic conditions including exchange rates,
inflation and recession, and more generally
current expectations regarding performance in current and future periods.
Forward looking statements also include
the (i) our ability to have continued access to a variety of COVID-19
test types, expectations regarding COVID-19
test sales, demand and inventory levels, as well as the efficacy or relative efficacy of the test
results given that the
test efficacy has not been, or will not have been, independently verified under
normal FDA procedures and (ii)
potential for us to distribute the COVID-19 vaccines and ancillary supplies.
Risk factors and uncertainties that could cause actual results to differ materially from
current and historical results
include, but are not limited to: risks associated with COVID-19
and any variants thereof, as well as other disease
outbreaks, epidemics, pandemics, or similar wide-spread public health concerns
and other natural disasters; our
dependence on third parties for the manufacture and supply of our products;
our ability to develop or acquire and
maintain and protect new products (particularly technology products) and
technologies that achieve market
acceptance with acceptable margins; transitional challenges associated with acquisitions,
dispositions and joint
ventures, including the failure to achieve anticipated synergies/benefits; legal, regulatory, compliance,
cybersecurity, financial and tax risks associated with acquisitions, dispositions and joint ventures; certain provisions
in our governing documents that may discourage third-party acquisitions
of us; adverse changes in supplier rebates
or other purchasing incentives; risks related to the sale of corporate brand
products; effects of a highly competitive
(including, without limitation, competition from third-party online commerce
sites) and consolidating market; the
repeal or judicial prohibition on implementation of the Affordable Care Act; changes in the health
care industry;
risks from expansion of customer purchasing power and multi-tiered
costing structures; increases in shipping costs
for our products or other service issues with our third-party shippers; general
global and domestic macro-economic
and political conditions, including inflation, deflation, recession, fluctuations
in energy pricing and the value of the
U.S. dollar as compared to foreign currencies, and changes to other economic
indicators, international trade
agreements, potential trade barriers and terrorism; failure to comply with existing
and future regulatory
requirements; risks associated with the EU Medical Device Regulation; failure
to comply with laws and regulations
relating to health care fraud or other laws and regulations; failure to comply with
laws and regulations relating to
the collection, storage and processing of sensitive personal information
or standards in electronic health records or
transmissions; changes in tax legislation; risks related to product liability, intellectual property and other claims;
litigation risks;
new or unanticipated litigation developments and the status of litigation
matters; risks associated
with customs policies or legislative import restrictions; cyberattacks
or other privacy or data security breaches; risks
associated with our global operations; our dependence on our senior management,
employee hiring and retention,
and our relationships with customers, suppliers and manufacturers;
and disruptions in financial markets.
The order
in which these factors appear should not be construed to indicate their
relative importance or priority.
We caution that these factors may not be exhaustive and that many of these factors are beyond our ability to control
or predict.
Accordingly, any forward-looking statements contained herein should not be relied upon as a prediction
of actual results.
We undertake no duty and have no obligation to update forward-looking statements except as
required by law.
Where You
Can Find Important Information
We may disclose important information through one or more of the following channels: SEC filings, public
conference calls and webcasts, press releases, the investor relations
page of our website (www.henryschein.com)
and the social media channels identified on the Newsroom page of our website.
Recent Developments
The COVID-19 pandemic negatively impacted the global economy, disrupted global supply chains and created
significant volatility and disruption of global financial markets in
2020 and 2021.
The impact of COVID-19 had a
material adverse effect on our business, results of operations and cash flows in 2020.
During the year ended
December 25, 2021, patient traffic levels returned to levels approaching pre-pandemic
levels.
Demand for dental
products and certain medical products throughout 2021 was driven
by sales of PPE and COVID-19 test kits.
During the year ended December 31, 2022 we experienced a decrease
in the sales volume of PPE and COVID-19
test kits.
The volatility in sales of COVID-19 test kits has moderated, albeit at a significantly
lower level of sales
compared with 2021, resulting in us recording an inventory obsolescence
reserve of $17 million for COVID-19 test
kits during the year ended December 31, 2022.
While the U.S. economy has recently experienced inflationary
pressures and strengthening of the U.S dollar, their
impacts have not been material to our results of operations in the
fourth quarter or full year ended December 31,
2022, and we currently expect moderating of inflation and foreign currency
fluctuations.
Though inflation impacts
both our revenues and costs, the depth and breadth of our product portfolio
often allows us to offer lower-cost
national brand solutions or corporate brand alternatives to our more
price-sensitive customers who are unable to
absorb price increases, thus positioning us to protect our gross profit.
Our consolidated financial statements reflect estimates and assumptions
made by us that affect, among other things,
our goodwill, long-lived asset and definite-lived intangible asset valuation;
inventory valuation; equity investment
valuation; assessment of the annual effective tax rate; valuation of deferred income
taxes and income tax
contingencies; the allowance for doubtful accounts; hedging activity; supplier
rebates; measurement of
compensation cost for certain share-based performance awards and cash
bonus plans; and pension plan
assumptions.
Due to the significant uncertainty surrounding the future impact
of COVID-19, our judgments
regarding estimates and impairments could change in the future.
There is an ongoing risk that the COVID-19
pandemic may again have a material adverse effect on our business, results of operations
and cash flows and may
result in a material adverse effect on our financial condition and liquidity.
However, the extent of the potential
impact cannot be reasonably estimated at this time.
Executive-Level Overview
Henry Schein, Inc. is a solutions company for health care professionals powered
by a network of people and
technology.
We believe we are the world’s
largest provider of health care products and services primarily to office-
based dental and medical practitioners, as well as alternate sites of care.
We
serve more than one million customers
worldwide including dental practitioners, laboratories, physician practices, and
ambulatory surgery centers, as well
as government, institutional health care clinics and other alternate care clinics.
We
believe that we have a strong
brand identity due to our more than 90 years of experience distributing health
care products.
We are headquartered in Melville, New York,
employ approximately 22,000 people (of which approximately
10,700 are based outside of the United States) and have operations or
affiliates in 32 countries and territories.
Our
broad global footprint has evolved over time through our organic success as well as
through contribution from
strategic acquisitions.
We
have established strategically located distribution centers around
the world to enable us to better serve our
customers and increase our operating efficiency.
This infrastructure, together with broad product and service
offerings at competitive prices, and a strong commitment to customer service, enables
us to be a single source of
supply for our customers’ needs.
While our primary go-to-market strategy is in our capacity as a distributor, we also market and sell under
our own
corporate brand portfolio of cost-effective, high-quality consumable merchandise products,
and manufacture certain
dental specialty products in the areas of implants, orthodontics and endodontics.
We
have achieved scale in these
global businesses primarily through acquisitions as manufacturers of these
products typically do not utilize a
distribution channel to serve customers.
We
conduct our business through two reportable segments: (i) health
care distribution and (ii) technology and
value-added services.
These segments offer different products and services to the same customer base.
Our global
dental businesses serve office-based dental practitioners, dental laboratories, schools, government
and other
institutions.
Our medical businesses serve physician offices, urgent care centers, ambulatory care sites, emergency
medical technicians, dialysis centers, home health, federal and state governments
and large enterprises, such as
group practices and integrated delivery networks, among other providers
across a wide range of specialties.
The health care distribution reportable segment, combining our global dental and
medical operating segments,
distributes consumable products, small equipment, laboratory products, large equipment, equipment
repair services,
branded and generic pharmaceuticals, vaccines, surgical products, dental specialty
products (including implant,
orthodontic and endodontic products), diagnostic tests, infection-control products,
PPE products and vitamins.
Our global technology and value-added services business provides software, technology
and other value-added
services to health care practitioners.
Our technology business offerings include practice management software
systems for dental and medical practitioners.
Our value-added practice solutions include practice consultancy,
education, revenue cycle management and financial services on a non-recourse
basis, e-services, practice
technology, network and hardware services, as well as consulting, and continuing education services for
practitioners.
A key element to grow closer to our customers is our One Schein initiative, which
is a unified go-to-market
approach that enables practitioners to work synergistically with our supply chain,
equipment sales and service and
other value-added services, allowing our customers to leverage the
combined value that we offer through a single
program.
Specifically, One Schein provides customers with streamlined access to our comprehensive offering of
national brand products, our corporate brand products and proprietary specialty
products and solutions (including
implant, orthodontic and endodontic products).
In addition, customers have access to a wide range of services,
including software and other value-added services.
Industry Overview
In recent years, the health care industry has increasingly focused on cost containment.
This trend has benefited
distributors capable of providing a broad array of products and services at low
prices.
It also has accelerated the
growth of HMOs, group practices, other managed care accounts and collective buying
groups, which, in addition to
their emphasis on obtaining products at competitive prices, tend to favor distributors
capable of providing
specialized management information support.
We
believe that the trend towards cost containment has the potential
to favorably affect demand for technology solutions, including software, which can
enhance the efficiency and
facilitation of practice management.
Our operating results in recent years have been significantly affected by strategies
and transactions that we
undertook to expand our business, domestically and internationally, in part to address significant changes in the
health care industry, including consolidation of health care distribution companies, health care reform, trends
toward managed care, cuts in Medicare and collective purchasing arrangements.
Our current and future results have been and could be impacted by the COVID-19
pandemic, the current economic
environment and continued economic and public health uncertainty.
Since the onset of the COVID-19 pandemic in
early 2020, we have been carefully monitoring its impact on our global
operations and have taken appropriate steps
to minimize the risk to our employees.
We
have seen and expect to continue to see changes in demand trends
for
some of our products and services, supply chain challenges and labor
challenges, as rates of infection fluctuate, new
strains or variants of COVID-19 emerge and spread, governments adapt their approaches
to combatting the virus,
and local conditions change across geographies.
As a result, we expect to see continued volatility.
Industry Consolidation
The health care products distribution industry, as it relates to office-based health care practitioners, is fragmented
and diverse.
The industry ranges from sole practitioners working out of
relatively small offices to group practices
or service organizations ranging in size from a few practitioners to a large number of practitioners who have
combined or otherwise associated their practices.
Due in part to the inability of office-based health care practitioners to store and manage
large quantities of supplies
in their offices, the distribution of health care supplies and small equipment to office-based health
care practitioners
has been characterized by frequent, small quantity orders, and a need for rapid,
reliable and substantially complete
order fulfillment.
The purchasing decisions within an office-based health care practice are typically
made by the
practitioner or an administrative assistant.
Supplies and small equipment are generally purchased from more
than
one distributor, with one generally serving as the primary supplier.
The trend of consolidation extends to our customer base.
Health care practitioners are increasingly seeking to
partner, affiliate or combine with larger entities such as hospitals, health systems, group practices or physician
hospital organizations.
In many cases, purchasing decisions for consolidated groups
are made at a centralized or
professional staff level; however, orders are delivered to the practitioners’ offices.
We
believe that consolidation within the industry will continue to
result in a number of distributors, particularly
those with limited financial, operating and marketing resources, seeking to
combine with larger companies that can
provide growth opportunities.
This consolidation also may continue to result in distributors seeking
to acquire
companies that can enhance their current product and service offerings or provide
opportunities to serve a broader
customer base.
Our approach to acquisitions and joint ventures has been to expand our role as
a provider of products and services
to the health care industry.
This trend has resulted in our expansion into service areas that complement
our existing
operations and provide opportunities for us to develop synergies with, and thus strengthen, the acquired
businesses.
As industry
consolidation continues, we believe that we are positioned to capitalize
on this trend, as we believe we
have the ability to support increased sales through our existing infrastructure, although
there can be no assurances
that we will be able to successfully accomplish this.
We
also have invested in expanding our sales/marketing
infrastructure to include a focus on building relationships with decision
makers who do not reside in the office-
based practitioner setting.
As the health care industry continues to change, we continually evaluate possible
candidates for joint venture or
acquisition and intend to continue to seek opportunities to expand our
role as a provider of products and services to
the health care industry.
There can be no assurance that we will be able to successfully pursue
any such
opportunity or consummate any such transaction, if pursued.
If additional transactions are entered into or
consummated, we would incur merger and/or acquisition-related costs, and there
can be no assurance that the
integration efforts associated with any such transaction would be successful.
Aging Population and Other Market Influences
The health care products distribution industry continues to experience growth
due to the aging population,
increased health care awareness, the proliferation of medical technology
and testing, new pharmacology treatments,
and expanded third-party insurance coverage, partially offset by the effects of unemployment on insurance
coverage.
In addition, the physician market continues to benefit from
the shift of procedures and diagnostic testing
from acute care settings to alternate-care sites, particularly physicians’
offices.
According to the U.S. Census Bureau’s International Database, between 2022 and 2032, the 45 and older
population is expected to grow by approximately 11%.
Between 2022 and 2042, this age group is expected to grow
by approximately 21%.
This compares with expected total U.S. population growth
rates of approximately 6%
between 2022 and 2032 and approximately 12% between 2022 and 2042.
According to the U.S. Census Bureau’s International Database, in 2022 there are approximately seven million
Americans aged 85 years or older, the segment of the population most in need of long-term care
and elder-care
services.
By the year 2050, that number is projected to nearly triple to approximately
19 million.
The population
aged 65 to 84 years is projected to increase by approximately 27% during
the same period.
As a result of these market dynamics, annual expenditures for health care services
continue to increase in the
United States.
We believe that demand for our products and services will grow while continuing to be impacted by
current and future operating, economic, and industry conditions.
The Centers for Medicare and Medicaid Services,
or CMS, published “National Health Expenditure Data” indicating
that total national health care spending reached
approximately $4.3 trillion in 2021, or 18.3% of the nation’s gross domestic product, the benchmark
measure for
annual production of goods and services in the United States.
Health care spending is projected to reach
approximately $6.2 trillion in 2028, or 19.7% of the nation’s projected gross domestic product.
Government
Our businesses are generally subject to numerous laws and regulations that could
impact our financial performance,
and failure to comply with such laws or regulations could have a
material adverse effect on our business.
See “
Item 1. Business – Governmental Regulations
” for a discussion of laws, regulations and governmental activity
that may affect our results of operations and financial condition.
Results of Operations
Refer to Item 7: Management’s Discussion and Analysis of Financial Condition and Results of Operations in
our 2021 Annual Report on Form 10-K for management’s discussion and analysis of financial condition and results
of operations for the fiscal year 2021 compared to fiscal year 2020.
The following tables summarize the significant components of our operating
results and cash flows from continuing
operations:
Years
Ended
December 31,
December 25,
December 26,
2022
2021
2020
Operating results:
Net sales
$
12,647
$
12,401
$
10,119
Cost of sales
8,816
8,727
7,303
Gross profit
3,831
3,674
2,816
Operating expenses:
Selling, general and administrative
2,771
2,634
2,086
Depreciation and amortization
Restructuring and integration costs
Operating income
$
$
$
Other expense, net
$
(26)
$
(21)
$
(35)
Gain on sale of equity investments, net of tax
-
Net income from continuing operations
Income from discontinued operations, net of tax
-
-
Net income attributable to Henry Schein, Inc.
Years
Ended
December 31,
December 25,
December 26,
2022
2021
2020
Cash flows:
Net cash provided by operating activities from continuing operations
$
$
$
Net cash used in investing activities from continuing operations
(276)
(677)
(115)
Net cash used in financing activities from continuing operations
(315)
(333)
(182)
Plans of Restructuring and Integration Costs
On August 1, 2022, we committed to a restructuring plan focused on
funding the priorities of the strategic plan and
streamlining operations and other initiatives to increase efficiency.
We expect this initiative to extend through
We are currently unable in good faith to make a determination of an estimate of the amount or range of
amounts expected to be incurred in connection with these activities, both with
respect to each major type of cost
associated therewith and with respect to the total cost, or an estimate of the
amount or range of amounts that will
result in future cash expenditures.
During the year ended December 31, 2022, we recorded restructuring charges of $128
million primarily related to
severance and employee-related costs, accelerated amortization of right-of-use
lease assets, impairment of other
long-lived assets and lease exit costs.
During the three months ended December 31, 2022, in connection with our restructuring
plan, we vacated one of
the buildings at our corporate headquarters in Melville NY, which resulted in an accelerated amortization of right-
of-use lease asset of $34 million.
We also initiated the disposal of a non-profitable US business and recorded
related costs of $49 million which primarily consisted of impairment of
intangible assets and goodwill, inventory
impairment, and severance and employee-related costs.
These expenses are included in the $128 million of
restructuring charges discussed above.
The disposal is expected to be completed in the first quarter of 2023.
On August 26, 2022, we acquired Midway Dental Supply.
In connection with this acquisition, during the year
ended December 31, 2022, we recorded integration costs of $3 million related
to one-time employee and other
costs, as well as restructuring charges of $9 million, which are included in the
$128 million of restructuring charges
discussed above.
On November 20, 2019, we committed to a contemplated restructuring
initiative intended to mitigate stranded costs
associated with the spin-off of our animal health business and to rationalize operations
and provide expense
efficiencies.
These activities were originally expected to be completed by
the end of 2020 but we extended them to
the end of 2021 in light of the changes to the business environment brought
on by the COVID-19 pandemic.
The
restructuring activities under this prior initiative were completed
in 2021.
2022 Compared to 2021
Net Sales
Net sales were as follows:
% of
% of
Increase / (Decrease)
2022
Total
2021
Total
$
%
Health care distribution
(1)
Dental
$
7,473
59.1
%
$
7,544
60.8
%
$
(71)
(0.9)
%
Medical
4,451
35.2
4,210
34.0
5.7
Total health care distribution
11,924
94.3
11,754
94.8
1.4
Technology and value-added services
(2)
5.7
5.2
11.8
Total
$
12,647
100.0
$
12,401
100.0
$
2.0
The components of our sales growth were as follows:
Local Currency Growth
Total Sales
Growth
Foreign
Exchange
Impact
Total Local
Currency
Growth
Acquisition
Growth
Extra Week
Impact
Local Internal
Growth
Health care distribution
(1)
Dental Merchandise
(2.6)
%
(3.5)
%
0.9
%
1.3
%
1.0
%
(1.4)
%
Dental Equipment
4.7
(4.6)
9.3
0.6
2.3
6.4
Total Dental
(0.9)
(3.7)
2.8
1.2
1.2
0.4
Medical
5.7
(0.3)
6.0
2.4
1.5
2.1
Total Health Care Distribution
1.4
(2.5)
3.9
1.6
1.3
1.0
Technology and value-added services
(2)
11.8
(1.5)
13.3
5.4
0.8
7.1
Total
2.0
(2.4)
4.4
1.8
1.3
1.3
Note: Percentages for Net Sales; Gross Profit; Selling, General and Administrative; Other Expense, Net; and Income Taxes are based on
actual values and may not recalculate due to rounding.
(1)
Consists of consumable products, small equipment, laboratory products, large equipment, equipment repair services, branded and
generic pharmaceuticals, vaccines, surgical products, dental specialty products (including implant, orthodontic and endodontic
products), diagnostic tests, infection-control products, PPE products and vitamins.
(2)
Consists of practice management software and other value-added products, which are distributed primarily to health care providers,
practice consultancy, education, revenue cycle management and financial services on a non-recourse basis, e-services, continuing
education services for practitioners, consulting and other services.
Global Sales
Global net sales for the year ended December 31, 2022 increased 2.0% based
upon the components presented in the
table above.
We estimate that sales for the year ended
December 31, 2022 of PPE products and COVID-19 test kits
were approximately $1,245 million, an estimated decrease of 34.7% versus the prior
year.
Excluding PPE products
and COVID-19 test kits,
the estimated increase in internally generated local currency sales was 6.7%.
Dental
Dental net sales for the year ended December 31, 2022 decreased 0.9% based
upon the components presented in the
table above.
Our sales growth in local currency for dental merchandise decreased
primarily due to a decrease in
PPE product sales.
We estimate that global dental sales for the year ended December 31, 2022 of PPE products
were approximately $447 million, an estimated decrease of 32.5% versus the prior
year.
Excluding PPE products,
the estimated increase in internally generated local currency dental sales
was 3.8%.
Dental equipment sales in local
currency increased in both our North American and international markets,
primarily due to increased demand.
Medical
Medical net sales for the year ended December 31, 2022 increased 5.7% based
upon the components presented in
the table above.
Globally, we estimate our medical business recorded sales of approximately $798 million of
sales
of PPE products
and COVID-19 test kits for the year ended December 31, 2022, an estimated
decrease of
approximately 27.4% compared to the prior year.
Excluding PPE products and COVID-19 test kits, the estimated
increase in internally generated local currency medical sales was
2.1%.
Te
chnology and value-added services
Technology and value-added services net sales for the year ended December 31, 2022 increased 11.8% based upon
the components presented in the table above.
During the year ended December 31, 2022, the trend for transactional
software sales improved as we increased the number of users, generating demand
for our sales cycle management
solutions, and also from cloud-based solutions that drive practice efficiency and patient engagement.
Gross Profit
Gross profit and gross margin percentages by segment and in total were as follows:
Gross
Gross
Increase
2022
Margin %
2021
Margin %
$
%
Health care distribution
$
3,357
28.2
%
$
3,239
27.6
%
$
3.6
%
Technology and value-added services
65.5
67.2
9.0
Total
$
3,831
30.3
$
3,674
29.6
$
4.3
As a result of different practices of categorizing costs associated with distribution networks
throughout our
industry, our gross margins may not necessarily be comparable to other distribution companies.
Additionally, we
realize substantially higher gross margin percentages in our technology and value-added services
segment than in
our health care distribution segment.
These higher gross margins result from being both the developer and seller of
software products and services, as well as certain financial services.
The software industry typically realizes higher
gross margins to recover investments in research and development.
Within our health care distribution segment, gross profit margins may vary from one period to the next.
Changes in
the mix of products sold as well as changes in our customer mix have
been the most significant drivers affecting
our gross profit margin.
For example, sales of our corporate brand products achieve
gross profit margins that are
higher than average total gross profit margins of all products.
With respect to customer mix, sales to our large-
group customers are typically completed at lower gross margins due to the higher
volumes sold as opposed to the
gross margin on sales to office-based practitioners, who normally purchase lower volumes.
Health care distribution gross profit increased primarily due to the increase
in net sales discussed above.
The
overall increase in our health care distribution gross profit was attributable to
$67 million of gross profit from
acquisitions and gross margin expansion, mainly as a result of increased sales
mix of higher-margin products.
Technology and value-added services gross profit increased as a result of an increase in gross profit from internally
generated sales and gross profit from acquisitions, partially offset by a decrease in
gross margin rates.
Gross
margin rates decreased primarily due to lower gross margins of recently acquired companies in
the business
services sector and our continued investment in product development and customer
service.
Operating Expenses
Operating expenses (consisting of selling, general and administrative
expenses; depreciation and amortization,
restructuring and integration costs) by segment and in total were as follows:
% of
% of
Respective
Respective
Increase
2022
Net Sales
2021
Net Sales
$
%
Health care distribution
$
2,738
23.0
%
$
2,512
21.4
%
$
9.0
%
Technology and value-added services
47.8
48.0
11.4
Total
$
3,084
24.4
$
2,822
22.8
$
9.3
The net increase in operating expenses is attributable to the
following:
Change in
Restructuring and
Integration Costs
Increase in
Operating Costs
Acquisitions
Total
Health care distribution
$
$
$
$
Technology and value-added services
Total
$
$
$
$
The increase in restructuring and integration costs is attributable to our disposal
of an unprofitable business,
acceleration of amortization of right-of-use lease assets related
to the exit from one of the properties at our
corporate headquarters, severance costs, and other costs relating to
the exit of some facilities.
The increase in
operating costs includes a $20 million intangible assets impairment charge within
our health care distribution
segment, and increases in payroll and payroll related costs and travel and convention
expenses in both of our
reportable segments.
While the U.S. economy has recently experienced inflationary
pressures and strengthening of
the U.S dollar, their impacts have not been material to our results of operations.
Other Expense, Net
Other expense, net was as follows:
Variance
2022
2021
$
%
Interest income
$
$
$
158.9
%
Interest expense
(44)
(28)
(16)
(59.1)
Other, net
-
n/a
Other expense, net
$
(26)
$
(21)
$
(5)
(26.0)
Interest income increased primarily due to increased interest rates.
Interest expense increased primarily due to
increased borrowings and increased interest rates.
Income Taxes
For the year ended December 31, 2022, our effective tax rate was 23.5% compared to 23.8%
for the prior year
period.
In 2022, the difference between our effective tax rate and the federal statutory tax rate primarily
relates to
state and foreign income taxes and interest expense.
In 2021, the difference between our effective tax rate and the
federal statutory tax rate was primarily due to state and foreign income
taxes and interest expense.
Gain on Sale of Equity Investment
In the third quarter of 2021, we received contingent proceeds of $10 million
from the 2019 sale of Hu-Friedy
resulting in the recognition of an additional after-tax gain of $7
million.
No further proceeds are expected from this
sale.
Liquidity and Capital Resources
Our principal capital requirements have included funding of acquisitions, purchases
of additional noncontrolling
interests, repayments of debt principal, the funding of working capital needs,
purchases of fixed assets and
repurchases of common stock.
Working capital requirements generally result from increased sales, special
inventory forward buy-in opportunities and payment terms for receivables
and payables.
Historically, sales have
tended to be stronger during the second half of the year and special inventory
forward buy-in opportunities have
been most prevalent just before the end of the year, and have caused our working capital requirements
to be higher
from the end of the third quarter to the end of the first quarter of
the following year.
We finance our business primarily through cash generated from our operations, revolving credit facilities and debt
placements.
Please see
for further information.
Our ability to generate sufficient cash flows from
operations is dependent on the continued demand of our customers for our
products and services, and access to
products and services from our suppliers.
Our business requires a substantial investment in working capital, which
is susceptible to fluctuations during the
year as a result of inventory purchase patterns and seasonal demands.
Inventory purchase activity is a function of
sales activity, special inventory forward buy-in opportunities and our desired level of inventory.
We anticipate
future increases in our working capital requirements.
We finance our business to provide adequate funding for at least 12 months.
Funding requirements are based on
forecasted profitability and working capital needs, which, on occasion, may
change.
Consequently, we may change
our funding structure to reflect any new requirements.
We believe that our cash and cash equivalents, our ability to access private debt markets and public equity markets,
and our available funds under existing credit facilities provide us with
sufficient liquidity to meet our currently
foreseeable short-term and long-term capital needs.
Net cash provided by operating activities was $602 million for the
year ended December 31, 2022, compared to net
cash from continuing operations provided by operating activities of $710 million
for the prior year.
The net change
of $108 million was primarily due to unfavorable net cash used by our working
capital accounts, net of
acquisitions, driven by an impact of timing of payments which
resulted in an increase in other current assets and
relative decreases in accounts payable and accrued expenses, partially offset by the
relative year over year impact
of inventory increases (2021 increase was more significant than the
2022 increase).
Net cash used in investing activities was $276 million for the year
ended December 31, 2022, compared to $677
million for the prior year.
The net change of $401 million was primarily attributable to decreased payments
for
equity investments and business acquisitions.
Net cash used in financing activities was $315 million for the year
ended December 31, 2022, compared to net cash
used in financing activities of $333 million for the prior year.
The net change of $18 million was primarily due to
increased net borrowings from debt, partially offset by increased repurchases of common
stock.
The following table summarizes selected measures of liquidity and capital
resources:
December 31,
December 25,
2022
2021
Cash and cash equivalents
$
$
Working
capital
(1)
1,764
1,537
Debt:
Bank credit lines
$
$
Current maturities of long-term debt
Long-term debt
1,040
Total debt
$
1,149
$
Leases:
Current operating lease liabilities
$
$
Non-current operating lease liabilities
(1)
Includes $327 million and $138 million of certain accounts receivable which serve as security for U.S. trade accounts receivable
securitization at December 31, 2022 and December 25, 2021, respectively.
Our cash and cash equivalents consist of bank balances and investments
in money market funds representing
overnight investments with a high degree of liquidity.
Accounts receivable days sales outstanding and inventory turns
Our accounts receivable days sales outstanding from operations
increased to 41.9 days as of December 31, 2022
from 41.8 days as of December 25, 2021.
During the years ended December 31, 2022 and December
25, 2021, we
wrote off approximately $10 million and $8 million, respectively, of fully reserved accounts receivable against our
trade receivable reserve.
Our inventory turns from operations was 4.7 as of December
31, 2022 and 5.2 as of
December 25, 2021.
Our working capital accounts may be impacted by current and
future economic conditions.
Contractual obligations
The following table summarizes our contractual obligations related
to fixed and variable rate long-term debt and
finance lease obligations, including interest (assuming a weighted
average interest rate of 4.3%), as well as
inventory purchase commitments and operating lease obligations
as of December 31, 2022:
Payments due by period
< 1 year
2 - 3 years
4 - 5 years
> 5 years
Total
Contractual obligations:
Long-term debt, including interest
$
$
$
$
$
1,221
Inventory purchase commitments
-
Operating lease obligations
Transition tax obligations
-
-
Finance lease obligations, including interest
Total
$
$
$
$
$
1,676
For information relating to our debt please see
.
Leases
We have operating and finance leases for corporate offices, office space, distribution and other facilities, vehicles
and certain equipment.
Our leases have remaining terms of less than one year to approximately
19 years, some of
which may include options to extend the leases for up to 15 years.
As of December 31, 2022, our right-of-use
assets related to operating leases were $284 million and our current and non-current
operating lease liabilities were
$73 million and $275 million, respectively.
Please see
for further information.
Stock Repurchases
On March 8, 2021, we announced the reinstatement of our share repurchase
program, which had been temporarily
suspended in April of 2020.
From March 3, 2003 through December 31, 2022, we repurchased $4.5
billion, or 87,180,669 shares, under our
common stock repurchase programs, with $115 million available as of December 31, 2022 for future
common stock
share repurchases.
On February 8, 2023, our Board of Directors authorized the repurchase
of up to an additional $400 million in shares
of our common stock.
Redeemable Noncontrolling Interests
Some minority stockholders in certain of our consolidated subsidiaries have
the right, at certain times, to require us
to acquire their ownership interest in those entities.
Accounting Standards Codification (“ASC”) Topic 480-10 is
applicable for noncontrolling interests where we are or may be required
to purchase all or a portion of the
outstanding interest in a consolidated subsidiary from the noncontrolling
interest holder under the terms of a put
option contained in contractual agreements.
As of December 31, 2022 and December 25, 2021, our balance
for
redeemable noncontrolling interests was $576 million and $613 million, respectively.
Please see
Redeemable Noncontrolling Interests
for further information.
Unrecognized tax benefits
As more fully disclosed in
of “Notes to Consolidated Financial Statements,” we cannot
reasonably estimate the timing of future cash flows related to the unrecognized
tax benefits, including accrued
interest, of $94 million as of December 31, 2022.
Critical Accounting Policies and Estimates
Our accounting policies are more fully described in
Note 1 – Basis of Presentation and Significant Accounting
of the consolidated financial statements.
The preparation of consolidated financial statements requires us
to make estimates and judgments that affect the reported amounts of assets, liabilities, revenues
and expenses and
related disclosures of contingent assets and liabilities.
We base our estimates on historical data, when available,
experience, industry and market trends, and on various other assumptions
that are believed to be reasonable under
the circumstances, the combined results of which form the basis for
making judgments about the carrying values of
assets and liabilities that are not readily apparent from other sources.
We believe that the estimates, judgments and
assumptions upon which we rely are reasonable based upon information
available to us at the time that these
estimates, judgments and assumptions are made.
However, by their nature, estimates are subject to various
assumptions and uncertainties.
Therefore, reported results may differ from estimates and any such differences may
be material to our consolidated financial statements.
We believe that the following critical accounting estimates, which have been discussed with the Audit Committee
of our Board of Directors, affect the significant estimates and judgments used in
the preparation of our financial
statements:
Inventories and Reserves
Inventories consist primarily of finished goods and are valued at
the lower of cost or net realizable value.
Cost is
determined by the first-in, first-out method for merchandise or actual cost
for large equipment and high tech
equipment.
In estimating carrying value of inventory, we consider many factors including the condition and
salability of the inventory by reviewing on-hand quantities, historical sales,
forecasted sales and market and
economic trends.
Certain of our products, specifically PPE and COVID-19 test kits, have experienced
changes in
net realizable value, due to volatility of pricing and changes in demand
for these products.
Business Combinations
The estimated fair value of acquired identifiable intangible assets (trademarks
and trade names, customer
relationships and lists, non-compete agreements and product development)
is based on critical estimates, judgments
and assumptions derived from: analysis of market conditions; discount
rates; projected cash flows; customer
retention rates; and estimated useful lives.
Please see
Note 4 – Business Acquisitions and Divestitures
for further
discussion of our acquisitions.
Goodwill
Goodwill is subject to impairment analysis at least once annually as of
the first day of our fourth quarter, or if an
event occurs or circumstances change that would more likely than
not reduce the fair value of a reporting unit
below its carrying value.
Such impairment analyses for goodwill require a comparison of
the fair value to the
carrying value of reporting units.
We regard our reporting units to be our operating segments: global dental,
global
medical, and technology and value-added services.
Goodwill is allocated to such reporting units, for the purposes
of preparing our impairment analyses, based on a specific identification
basis.
Application of the goodwill impairment test requires judgment, including
the identification of reporting units,
assignment of assets and liabilities that are considered shared services
to the reporting units, and ultimately the
determination of the fair value of each reporting unit.
The fair value of each reporting unit is calculated by
applying the discounted cash flow methodology and confirming with
a market approach.
There are inherent
uncertainties, however, related to fair value models, the inputs and our judgments in applying them
to this analysis.
The most significant inputs include estimation of detailed future cash flows based
on budget expectations, and
determination of comparable companies to develop a weighted average
cost of capital for each reporting unit.
On an annual basis, we prepare annual and
medium-term financial projections.
These projections are based on
input from our leadership and are presented annually to our Board of Directors.
Influences on this year's forecasted
financial information and the fair value model include: the impact of planned
strategic initiatives, the continued
integration of recent acquisitions and overall market conditions.
The estimates used to calculate the fair value of a
reporting unit change from year to year based on operating results,
market conditions, and other factors.
Our third-party valuation specialists provide inputs into our determination
of the discount rate.
The rate is
dependent on a number of underlying assumptions, including the risk-free rate,
tax rate, equity risk premium, debt
to equity ratio
and pre-tax cost of debt.
Long-term growth rates are applied to our estimation of future cash flows.
The long-term growth rates are tied to
growth rates we expect to achieve beyond the years for which we have
forecasted operating results.
We also
consider external benchmarks, and other data points which we believe are
applicable to our industry and the
composition of our global operations.
Based on our quantitative assessment for the year ended December 31, 2022,
we recorded a $20 million impairment
of goodwill relating to the disposal of an unprofitable business whose
estimated fair value was lower than its
carrying value.
As part of our analysis for the rest of the goodwill balance,
we performed a sensitivity analysis on
the discount rate and long-term growth rate assumptions.
The sensitivities did not result in any additional
impairment charges.
Definite-Lived Intangible Assets
Annually, definite-lived intangible assets such as non-compete agreements, trademarks, trade names, customer
relationships and lists, and product development are reviewed for impairment
indicators.
If any impairment
indicators exist, quantitative testing is performed on the asset.
The quantitative impairment model is a two-step test under which we
first calculate the recoverability of the
carrying value by comparing the undiscounted, probability-weighted value
of the projected cash flows associated
with the asset or asset group, including its estimated residual value, to
the carrying amount.
If the cash flows
associated with the asset or asset group are less than the carrying value,
we would perform a fair value assessment
of the asset, or asset group.
If the carrying amount is found to be greater than the fair value, we record an
impairment loss for the excess of book value over the fair value.
In addition, in all cases of an impairment review,
we re-evaluate the remaining useful lives of the assets and modify them,
as appropriate.
Although we believe our
judgments, estimates and/or assumptions used in estimating cash flows
and determining fair value are reasonable,
making material changes to such judgments, estimates and/or assumptions
could materially affect such impairment
analyses and our financial results.
During the years ended December 31, 2022, December 25, 2021
and December 26, 2020, we recorded total
impairment charges on intangible assets of approximately $49 million ($34 million
related to impairment of
customer lists and relationships attributable to customer attrition rates being higher
than expected in certain
businesses and $15 million due to the disposal of an unprofitable
business), $1 million and $20 million,
respectively.
For the year ended December 31, 2022 impairment charges were recorded
within our health care
distribution segment.
For the years ended December 25, 2021 and December 26,
2020, impairment charges were
recorded within our health care distribution and technology and value-added services
segments.
Income Tax
When determining if the realization of the deferred tax asset is likely by assessing
the need for a valuation
allowance, estimates and judgement are required.
We
consider all available evidence, both positive and negative,
including estimated future taxable earnings, ongoing planning strategies,
future reversals of existing temporary
differences and historical operating results.
Additionally, changes to tax laws and statutory tax rates can have an
impact on our determination.
Our intention is to evaluate the realizability of our deferred tax assets quarterly.
ASC Topic 740 prescribes the accounting for uncertainty in income taxes recognized in the financial statements in
accordance with other provisions contained within this guidance.
This topic prescribes a recognition threshold and
a measurement attribute for the financial statement recognition and measurement
of tax positions taken or expected
to be taken in a tax return.
For those benefits to be recognized, a tax position must be more likely
than not to be
sustained upon examination by the taxing authorities.
The amount recognized is measured as the largest amount of
benefit that has a greater than 50% likely of being realized upon ultimate
audit settlement.
In the normal course of
business, our tax returns are subject to examination by various taxing
authorities.
Such examinations may result in
future tax and interest assessments by these taxing authorities for uncertain
tax positions taken in respect of certain
tax matters.
Please see
for further discussion.
The FASB Staff Q&A, Topic
740 No. 5, Accounting for Global Intangible Low-Taxed Income (“GILTI”), states
that an entity can make an accounting policy election to either recognize deferred
taxes for temporary differences
expected to reverse as GILTI in future years or provide for the tax expense related to GILTI in the year the tax is
incurred.
We elected to recognize the tax on GILTI
as a period expense in the period the tax is incurred.
Accounting Standards Update
For a discussion of accounting standards updates that have been adopted
or will be adopted in the future, please see
Note 1 – Basis of Presentation and Significant Accounting Policies
included under Item 8.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
Quantitative and Qualitative Disclosures About Market Risk
We are exposed to market risks as well as changes in foreign currency exchange rates as measured against the U.S.
dollar and each other, and changes to the credit markets.
We attempt to minimize these risks by primarily using
foreign currency forward contracts and by maintaining counter-party credit limits.
These hedging activities provide
only limited protection against currency exchange and credit risks.
Factors that could influence the effectiveness of
our hedging programs include currency markets and availability of hedging
instruments and liquidity of the credit
markets.
All foreign currency forward contracts that we enter into are components
of hedging programs and are
entered into for the sole purpose of hedging an existing or anticipated
currency exposure.
We do not enter into such
contracts for speculative purposes and we manage our credit risks by diversifying
our investments, maintaining a
strong balance sheet and having multiple sources of capital.
Foreign Currency Agreements
The value of certain foreign currencies as compared to the U.S. dollar
and the value of certain underlying functional
currencies of the Company, including its foreign subsidiaries, may affect our financial results.
Fluctuations in
exchange rates may positively or negatively affect our revenues, gross margins, operating expenses
and retained
earnings, all of which are
expressed in U.S. dollars.
Where we deem it prudent, we engage in hedging programs
using primarily foreign currency forward contracts aimed at limiting
the impact of foreign currency exchange rate
fluctuations on earnings.
We purchase short-term (i.e., generally 18 months or less) foreign currency forward
contracts to protect against currency exchange risks associated with intercompany
loans due from our international
subsidiaries and the payment of merchandise purchases to foreign
suppliers.
We do not hedge the translation of
foreign currency profits into U.S. dollars, as we regard this as an accounting
exposure, not an economic
exposure.
A hypothetical 5% change in the average value of the U.S. dollar
in 2022 compared to foreign currencies
would have changed our 2022 reported Net income attributable to Henry
Schein, Inc. by approximately $7 million.
As of December 31, 2022, we had forward foreign currency exchange
agreements, which expire through November
16, 2023, with a fair value of $23 million as determined by quoted market
prices.
Included in the forward foreign
currency exchange agreements, Henry Schein, Inc. had net investment
designated EUR/USD forward contracts
with notional values of approximately €200 million, with a reported fair value
of these contracts of $20 million.
A
5% increase in the value of the Euro to the USD from December 31, 2022,
with all other variables held constant,
would have had an unfavorable effect on the fair value of these forward contracts
by decreasing the value of these
instruments by $10 million.
Total
Return Swaps
On March 20, 2020, we entered into a total return swap for the purpose
of economically hedging our unfunded non-
qualified supplemental retirement plan (“SERP”) and our deferred compensation
plan (“DCP”).
This swap will
offset changes in our SERP and DCP liabilities.
At the inception, the notional value of the investments in these
plans was $43 million.
At December 31, 2022, the notional value of the investments
in these plans was $78
million.
At December 31, 2022, the financing blended rate for
this swap was based on LIBOR of 4.03% plus
0.55%, for a combined rate of 4.58%.
For the years ended December 31, 2022 ended and December
25, 2021, we
have recorded a gain/(loss), within the selling, general and administrative
line item in our consolidated statement of
income, of approximately $(17) million and $12 million, respectively, net of transaction costs, related to this
undesignated swap.
This swap is expected to be renewed on an annual basis after its current
expiration date of
March 31, 2023, and is expected to result in a neutral impact to our results
of operations.
Short-Term Investments
We limit our credit risk with respect to our cash equivalents, short-term investments and derivative instruments, by
monitoring the credit worthiness of the financial institutions who are
the counterparties to such financial
instruments.
As a risk management policy, we limit the amount of credit exposure by diversifying and utilizing
numerous investment grade counterparties.
Variable
Interest Rate Debt
As of December 31, 2022, we had variable interest rate exposure for certain
of our revolving credit facilities and
our U.S. trade accounts receivable securitization.
Our revolving credit facility which we entered into on August 20, 2021
and expires on August 20, 2026, has an
interest rate that is based on the U.S. Dollar LIBOR plus a spread based on
our leverage ratio at the end of each
financial reporting quarter.
As of December 31, 2022, there was $0 million outstanding under this
revolving credit
facility.
During the year ended December 31, 2022, we had no borrowings under
this revolving credit facility.
Our U.S trade accounts receivable securitization, which we entered
into on April 17, 2013 and expires on
December 15, 2025, has an interest rate that is based upon the asset-backed
commercial paper rate.
As of
December 31, 2022, the commercial paper rate was 4.58% plus 0.75%,
for a combined rate of 5.33%.
At
December 31, 2022 the outstanding balance was $330 million under
this securitization facility.
During the year
ended December 31, 2022, the average outstanding balance under this securitization
facility was approximately
$166 million.
Based upon our average outstanding balance for this securitization
facility, for each hypothetical
increase of 25 basis points, our interest expense thereunder would have
increased by $0.4 million.
Item 8. Financial Statements and Supplementary Data
INDEX TO FINANCIAL STATEMENTS
HENRY SCHEIN, INC.
Page
Number
Report of Independent Registered Public Accounting Firm (
BDO USA, LLP; New York,
NY; PCAOB
ID#
)
Consolidated Financial Statements
Balance Sheets as of December 31, 2022 and December 25, 2021
Statements of Income for the years ended December 31, 2022,
December 25, 2021 and December 26, 2020
Statements of Comprehensive Income for the years ended December 31, 2022,
December 25, 2021 and December 26, 2020
Statements of Changes in Stockholders’ Equity for the years ended
December 31, 2022, December 25, 2021 and December 26, 2020
Statements of Cash Flows for the years ended December 31, 2022,
December 25, 2021 and December 26, 2020
Notes to Consolidated Financial Statements
Note 1 – Basis of Presentation and Significant Accounting Policies
Note 2 – Net Sales from Contracts with Customers
Note 3 – Segment and Geographic Data
Note 4 – Business Acquisitions and Divestiture
Note 5 – Property and Equipment, Net
Note 7 – Goodwill and Other Intangibles, Net
Note 8 – Investments and Other
Note 9 – Fair Value Measurements
Note 10 – Concentrations of Risk
Note 11 – Derivatives and Hedging Activities
Note 14 – Plans of Restructuring and Integration Costs
Note 15 – Commitments and Contingencies
Note 16 – Stock-Based Compensation
Note 17 – Employee Benefit Plans
Note 18 – Redeemable Noncontrolling Interests
Note 19 – Comprehensive Income
Note 20 – Discontinued Operations
Note 22 – Supplemental Cash Flow Information
Note 23 – Related Party Transactions
All other schedules are omitted because the required information is either
inapplicable or is included in the consolidated
financial statements or the notes thereto.
Report Of Independent Registered Public Accounting Firm
Shareholders and Board of Directors
Henry Schein, Inc.
Melville, NY
Opinion on the Consolidated Financial Statements
We
have
audited
the
accompanying
consolidated
balance
sheets
of
Henry
Schein,
Inc.
(the
“Company”)
as
of
December 31, 2022 and December 25, 2021, the related consolidated statements of income, comprehensive income,
stockholders’ equity,
and cash
flows for
each of
the three
years in
the
period ended
December 31,
2022, and
the
related notes
(collectively referred to
as the
“consolidated financial statements”).
In our
opinion, the
consolidated
financial statements
present fairly,
in all
material respects, the
financial position of
the Company
at December
31,
2022 and
December 25, 2021,
and the
results of its
operations and its
cash flows for
each of
the three
years in the
period ended December 31,
2022, in conformity with
accounting principles generally accepted in
the United States
of America.
We
also
have
audited,
in
accordance
with
the
standards
of
the
Public
Company
Accounting
Oversight
Board
(United
States)
(“PCAOB”),
the
Company's
internal
control
over
financial
reporting
as
of
December
31,
2022,
based
on
criteria
established
in
Internal
Control
–
Integrated
Framework
(2013)
issued
by
the
Committee
of
Sponsoring
Organizations
of
the
Treadway
Commission
(“COSO”)
and
our
report
dated
February
21,
2023,
expressed an unqualified opinion thereon.
Basis for Opinion
These consolidated financial statements are
the responsibility of the
Company’s management. Our
responsibility is
to
express
an
opinion
on
the
Company’s
consolidated
financial
statements
based
on
our
audits.
We
are
a
public
accounting
firm
registered
with
the
PCAOB
and
are
required
to
be
independent
with
respect
to
the
Company
in
accordance
with
the
U.S.
federal
securities
laws
and
the
applicable
rules
and
regulations
of
the
Securities
and
Exchange Commission and the PCAOB.
We
conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and
perform
the
audit
to
obtain
reasonable
assurance
about
whether
the
consolidated
financial
statements
are
free
of
material misstatement, whether due to error or fraud.
Our audits included performing procedures to assess the risks
of
material
misstatement
of
the
consolidated
financial
statements,
whether
due
to
error
or
fraud,
and
performing
procedures that respond to those risks.
Such procedures included examining, on a test basis, evidence regarding the
amounts
and
disclosures
in
the
consolidated
financial
statements.
Our
audits
also
included
evaluating
the
accounting
principles
used
and
significant
estimates
made
by
management,
as
well
as
evaluating
the
overall
presentation of the consolidated financial
statements.
We
believe that our audits provide
a reasonable basis for our
opinion.
Critical Audit Matter
The critical audit matter communicated below is a matter arising from the
current period audit of the consolidated
financial statements that was communicated or required to be communicated
to the audit committee and that: (1)
relates to accounts or disclosures that are material to the consolidated
financial statements and (2) involved our
especially challenging, subjective,
or complex judgments. The communication of the critical
audit matter does not
alter in any way our opinion on the consolidated financial statements, taken
as a whole, and we are not, by
communicating the critical audit matter below, providing a separate opinion on the critical audit matter or on the
accounts or disclosures to which it relates.
Revenue growth rates utilized in
the determination of the fair
value of acquired customer relationships
for a
certain acquisition
As described in
Note 4 of
the consolidated financial
statements, the Company
acquired several companies in
the
current year.
As a
result of
the acquisitions,
management was
required to
determine estimated
fair values
of the
assets
acquired
and
liabilities
assumed,
including
certain
identifiable
intangible
assets.
In
some
instances,
management
utilized
third-party
valuation
specialists
to
assist
in
the
preparation
of
the
valuation
of
certain
identifiable intangible assets.
Management exercised judgment to
develop and select
revenue growth rates
in the
measurement of the fair value of the customer relationships.
We
identified
the
revenue
growth
rates
utilized
in
the
determination
of
the
fair
value
of
acquired
customer
relationships
for
a
certain
acquisition,
as
a
critical
audit
matter.
The
principal
considerations
for
our
determination included the
subjectivity and judgment
required to determine
the revenue growth
rates used
in the
fair
value
measurement
of
acquired
customer
relationships
for
a
certain
acquisition.
Auditing
these
revenue
growth rates involved especially subjective auditor judgment due to
the nature and extent of audit effort required.
The primary procedures we performed to address this critical audit matter
included:
●
Evaluating the reasonableness of the revenue growth rates by i)
reviewing the historical performance
of the acquired company using its audited financial statements and
(ii) assessing revenue projections
against industry metrics and peer-group companies.
/s/
BDO USA, LLP
We have served as the Company's auditor since 1984.
New York, NY
February 21, 2023
HENRY SCHEIN, INC.
CONSOLIDATED BALANCE SHEETS
(in millions, excep
Showing the first 8K of 160K characters. Open the full section
Item 9. Changes in and Disagreements with Accountants on Accounting and
Changes in and Disagreements with Accountants on Accounting and
Financial Disclosure
None.
Item 9A. Controls and Procedures
Controls and Procedures
Evaluation of Disclosure Controls and Procedures
Under the supervision and with the participation of management, including
our principal executive officer and
principal financial officer, we evaluated the effectiveness of the design and operation of our disclosure controls and
procedures as of the end of the period covered by this annual report as
such term is defined in Rules 13a-15(e) and
15d-15(e) promulgated under the Securities Exchange Act of 1934,
as amended (the “Exchange Act”).
Based on
this evaluation, our management, including our principal executive officer and principal
financial officer,
concluded that our disclosure controls and procedures were effective as of December 31,
2022, to ensure that all
material information required to be disclosed by us in reports that we file
or submit under the Exchange Act is
accumulated and communicated to them as appropriate to allow timely
decisions regarding required disclosure and
that all such information is recorded, processed, summarized and reported
within the time periods specified in the
SEC’s rules and forms.
Changes in Internal Control over Financial Reporting
The combination of acquisitions, continued acquisition integrations and systems
implementation activity
undertaken during the quarter ended December 31, 2022 and carried over from
prior quarters when considered in
the aggregate, does not represent a material change in our internal control over
financial reporting.
Management’s
Report on Internal Control over Financial Reporting
Our management is responsible for establishing and maintaining adequate
internal control over financial reporting,
as such term is defined in Exchange Act Rule 13a-15(f).
Our internal control system is designed to provide
reasonable assurance to our management and Board of Directors regarding the preparation
and fair presentation of
published financial statements.
Under the supervision and with the participation of our
management, including our
principal executive officer and principal financial officer, we conducted an evaluation of the effectiveness of our
internal control over financial reporting based on the framework
in Internal Control-Integrated Framework (2013),
updated and reissued by the Committee of Sponsoring Organizations, or the COSO
Framework.
Based on our
evaluation under the COSO Framework, our management concluded that our
internal control over financial
reporting was effective at a reasonable assurance level as of December 31, 2022.
The effectiveness of our internal control over financial reporting as of December
31, 2022, has been independently
audited by BDO USA, LLP, an independent registered public accounting firm, and their attestation is included
herein.
Limitations of the Effectiveness of Internal Control
A control system, no matter how well conceived and operated, can provide
only reasonable, not absolute, assurance
that the objectives of the internal control system are met.
Because of the inherent limitations of any internal control
system, no evaluation of controls can provide absolute assurance that all control
issues, if any, within a company
have been detected.
Report Of Independent Registered Public Accounting Firm
Shareholders and Board of Directors
Henry Schein, Inc.
Melville, NY
Opinion on Internal Control over Financial Reporting
We
have audited Henry
Schein, Inc.’s
(the “Company’s”)
internal control over
financial reporting as
of December
31, 2022, based on criteria established in Internal Control
– Integrated Framework (2013) (the “COSO criteria”). In
our opinion, the
Company maintained, in all
material respects, effective
internal control over
financial reporting as
of December 31, 2022, based on the COSO criteria.
We
have
also
audited,
in
accordance
with
the
standards
of
the
Public
Company
Accounting
Oversight
Board
(United
States)
(“PCAOB”),
the
consolidated
balance
sheets
of
the
Company
as
of
December
31,
2022
and
December
25,
2021, the
related
consolidated statements
of
income, comprehensive
income, stockholders’
equity,
and cash
flows for
each of
the three
years in
the period
ended December
31, 2022,
and the
related notes
and our
report dated February 21, 2023
expressed as an unqualified opinion thereon.
Basis for Opinion
The Company’s
management is
responsible for
maintaining effective
internal control
over financial
reporting and
for
its
assessment
of
the
effectiveness
of
internal
control
over
financial
reporting,
included
in
the
accompanying
“Item 9A, Management’s
Report on Internal
Control over Financial Reporting”. Our
responsibility is to
express an
opinion on the
Company’s internal
control over financial
reporting based on
our audit. We
are a public
accounting
firm
registered
with
the
PCAOB and
are
required
to
be
independent
with
respect
to
the
Company in
accordance
with
U.S.
federal
securities
laws
and
the
applicable
rules
and
regulations
of
the
Securities
and
Exchange
Commission and the PCAOB.
We conducted our audit of internal control over financial reporting in accordance with the standards of the PCAOB.
Those standards require
that we plan
and perform the
audit to
obtain reasonable assurance
about whether effective
internal
control
over
financial
reporting
was
maintained
in
all
material
respects.
Our
audit
included
obtaining
an
understanding
of
internal
control
over
financial
reporting,
assessing
the
risk
that
a
material
weakness
exists,
and
testing and
evaluating the
design and
operating effectiveness
of internal
control based
on assessed
risk. Our
audit
also included
performing such
other procedures
as we
considered necessary
in the
circumstances. We
believe that
our audit provides a reasonable basis for our opinion.
Definition and Limitations of Internal Control over Financial Reporting
A
company’s
internal
control
over
financial
reporting
is
a
process
designed
to
provide
reasonable
assurance
regarding the
reliability of
financial reporting
and the
preparation of
financial statements
for external
purposes in
accordance
with
generally
accepted
accounting
principles.
A
company’s
internal
control
over
financial
reporting
includes
those
policies
and
procedures
that
(1)
pertain
to
the
maintenance
of
records
that,
in
reasonable
detail,
accurately and
fairly reflect
the transactions
and dispositions
of the
assets of
the company;
(2) provide
reasonable
assurance
that
transactions
are
recorded
as
necessary
to
permit
preparation
of
financial
statements
in
accordance
with generally
accepted accounting
principles, and
that receipts
and expenditures
of the
company are
being made
only
in
accordance with
authorizations of
management and
directors of
the
company; and
(3) provide
reasonable
assurance
regarding
prevention
or
timely
detection
of
unauthorized
acquisition,
use,
or
disposition
of
the
company’s assets that could have a material effect on the financial statements.
Because
of
its
inherent
limitations,
internal
control
over
financial
reporting
may
not
prevent
or
detect
misstatements.
Also,
projections
of
any
evaluation
of
effectiveness
to
future
periods
are
subject
to
the
risk
that
controls
may
become
inadequate
because
of
changes
in
conditions,
or
that
the
degree
of
compliance
with
the
policies or procedures may deteriorate.
/s/ BDO USA, LLP
New York
,
NY
February 21, 2023
Item 9B. Other Information
Other Information
Not applicable.
Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections
Disclosure Regarding Foreign Jurisdictions that Prevent Inspections
Not applicable.
PART
III
Item 10. Directors, Executive Officers and Corporate Governance
Directors, Executive Officers and Corporate Governance
Information required by this item regarding our directors and executive
officers and our corporate governance is
hereby incorporated by reference to the Section entitled “Election of Directors,”
with respect to directors, and the
first paragraph of the Section entitled “Corporate Governance - Board
of Directors Meetings and Committees -
Audit Committee,” with respect to corporate governance, in each case
in our definitive 2023 Proxy Statement to be
filed pursuant to Regulation 14A and to the Section entitled “Information
about our Executive Officers” in Part I of
this report, with respect to executive officers.
There have been no changes to the procedures by which stockholders
may recommend nominees to our Board of
Directors since our last disclosure of such procedures, which appeared
in our definitive 2022 Proxy Statement filed
pursuant to Regulation 14A on April 6, 2022.
Information required by this item concerning compliance with Section
16(a) of the Securities Exchange Act of
1934 is hereby incorporated by reference to the Section entitled “Delinquent
Section 16(a) Reports” in our
definitive 2023 Proxy Statement to be filed pursuant to Regulation 14A,
to the extent responsive disclosure is
required.
We have adopted a Code of Ethics that applies to our Chief Executive Officer, Chief Financial Officer, Chief
Accounting Officer and Controller.
We make available free of charge through our Internet website,
under the “About Henry Schein--Corporate Governance
Highlights” caption, our Code of
Ethics.
We intend to disclose on our Web
site any amendment to, or waiver of, a provision of the Code
of Ethics.
Item 11. Executive Compensation
Executive Compensation
The information required by this item is hereby incorporated by reference
to the Sections
entitled “Compensation
Discussion and Analysis,” “Compensation Committee Report” (which
information shall be deemed furnished in
this Annual Report on Form 10-K), “Executive and Director Compensation” and
“Compensation Committee
Interlocks and Insider Participation” in our definitive 2023 Proxy
Statement to be filed pursuant to Regulation 14A.
Item 12. Security Ownership of Certain Beneficial Owners and Management
Security Ownership of Certain Beneficial Owners and Management
and Related Stockholder
Matters
We maintain several stock incentive plans for the benefit of certain officers, directors and employees.
All active
plans have been approved by our stockholders.
Descriptions of these plans appear in the notes to our consolidated
financial statements.
The following table summarizes information relating to these plans as of December
31, 2022:
Number of Common
Shares to be Issued Upon
Weighted-
Average
Number of Common
Exercise of Outstanding
Exercise Price of
Shares Available
for
Plan Category
Options and Rights
Outstanding Options
Future Issuances
Plans Approved by Stockholders
-
$
-
8,227,096
Plans Not Approved by Stockholders
-
-
-
Total
-
$
-
8,227,096
The other information required by this item is hereby incorporated by
reference to the Section entitled “Security
Ownership of Certain Beneficial Owners and Management” in our definitive
2023 Proxy Statement to be filed
pursuant to Regulation 14A.
Item 13. Certain Relationships and Related Transactions, and Director Independence
Certain Relationships and Related Transactions, and Director Independence
The information required by this item is hereby incorporated by reference
to the Section entitled “Certain
Relationships and Related Transactions” and “Corporate Governance – Board of Directors Meetings and
Committees – Independent Directors” in our definitive 2023 Proxy Statement
to be filed pursuant to Regulation
14A.
Item 14. Principal Accounting Fees and Services
Principal Accounting Fees and Services
The information required by this item is hereby incorporated by reference
to the Section entitled “Independent
Registered Public Accounting Firm Fees and Pre-Approval Policies and
Procedures” in our definitive 2023 Proxy
Statement to be filed pursuant to Regulation 14A.
PART
IV
Item 15. Exhibits, Financial Statement Schedules
Exhibits, Financial Statement Schedules
(a)
List of Documents Filed as a Part of This Report:
Financial Statements:
Our Consolidated Financial Statements filed as a part of this report
are listed on the index on
Page 60.
Index to Exhibits:
See exhibits listed under Item 15(b) below.
(b) Exhibits
Contribution and Distribution Agreement, dated as of April 20, 2018, by and
among us, HS Spinco, Inc., Direct Vet Marketing, Inc. and Shareholder
Representative Services LLC. (Incorporated by reference to Exhibit 2.1 to our
Current Report on Form 8-K filed on April 23, 2018 (film no. 18767875).)*
Agreement and Plan of Merger, dated as of April 20, 2018, by and among us, HS
Spinco, Inc, HS Merger Sub, Inc., Direct Vet Marketing, Inc. and Shareholder
Representative Services LLC. (Incorporated by reference to Exhibit 2.2 to our
Current Report on Form 8-K filed on April 23, 2018 (film no. 18767875).)*
Letter Agreement, Amendment No. 1 to Contribution and Distribution Agreement
and Amendment No. 1 to Agreement and Plan of Merger, dated as of September
14, 2018, by and among us, HS Spinco, Inc., HS Merger Sub, Inc., Direct Vet
Marketing, Inc. and Shareholder Representative Services LLC.( Incorporated by
reference to Exhibit 2.3 to our Annual Report on Form 10-K for the fiscal year
ended December 29, 2018 filed on February 20, 2019.)
Letter Agreement and Amendment No. 2 to Contribution and Distribution
Agreement, dated as of November 30, 2018, by and among us, HS Spinco, Inc.,
Direct Vet Marketing, Inc. and Shareholder Representative Services LLC.
(Incorporated by reference to Exhibit 2.4 to our Annual Report on Form 10-K for
the fiscal year ended December 29, 2018 filed on February 20, 2019.)
Letter Agreement and Amendment No. 3 to Contribution and Distribution
Agreement and Amendment No. 2 to Agreement and Plan of Merger, dated as of
December 25, 2018, by and among us, HS Spinco, Inc., HS Merger Sub, Inc.,
Direct Vet Marketing, Inc. and Shareholder Representative Services
LLC.(Incorporated by reference to Exhibit 2.5 to our Annual Report on Form 10-K
for the fiscal year ended December 29, 2018 filed on February 20, 2019.)
Letter Agreement and Amendment No. 4 to Contribution and Distribution
Agreement, dated as of January 15, 2019, by and among us, HS Spinco, Inc., Direct
Vet Marketing, Inc. and Shareholder Representative Services LLC.(Incorporated
by reference to Exhibit 2.6 to our Annual Report on Form 10-K for the fiscal year
ended December 29, 2018 filed on February 20, 2019.)
Second Amended and Restated Certificate of Incorporation of Henry Schein, Inc.
(Incorporated by reference to Exhibit 3.1 to our Current Report on Form 8-K filed
Third Amended and Restated By-Laws of the Company, effective May 13, 2021.
(Incorporated by reference to Exhibit 3.1 to our Current Report on Form 8-K filed
Third Amended and Restated Multicurrency Master Note Purchase Agreement,
dated as of October 20, 2021, by and among us, Metropolitan Life Insurance
Company, MetLife Investment Management, LLC and each MetLife affiliate
which becomes party thereto. (Incorporated by reference to Exhibit 4.4 to our
Current Report on Form 8-K filed on October 21, 2021.)
Third Amended and Restated Master Note Facility, dated as of October 20, 2021,
by and among us, NYL Investors LLC and each New York Life affiliate which
becomes party thereto. (Incorporated by reference to Exhibit 4.3 to our Current
Report on Form 8-K filed on October 21, 2021.)
Third Amended and Restated Multicurrency Private Shelf Agreement, dated as of
October 20, 2021, by and among us, PGIM, Inc. and each Prudential affiliate which
becomes party thereto. (Incorporated by reference to Exhibit 4.2 to our Current
Report on Form 8-K filed on October 21, 2021.)
Multicurrency Private Shelf Agreement, dated as of October 20, 2021, by and
among us, AIG Asset Management (U.S.), LLC and each AIG affiliate which
becomes party thereto. (Incorporated by reference to Exhibit 4.1 to our Current
Report on Form 8-K filed on October 21, 2021.)
Description of Securities. (Incorporated by reference to Exhibit 4.5 to our Annual
Report on Form 10-K for the fiscal year ended December 25, 2021 filed on
Henry Schein, Inc. 2013 Stock Incentive Plan, as amended and restated effective as
of May 14, 2013. (Incorporated by reference to Exhibit 10.2 to our Current Report
on Form 8-K filed on May 16, 2013.)**
Form of 2019 Restricted Stock Unit Agreement for performance-based restricted
stock unit awards pursuant to the Henry Schein, Inc. 2013 Stock Incentive Plan (as
amended and restated effective as of May 14, 2013). (Incorporated by reference to
Exhibit 10.2 to our Quarterly Report on Form 10-Q for the fiscal quarter ended
March 30, 2019 filed on May 7, 2019.)**
Form of 2019 Restricted Stock Unit Agreement for time-based restricted stock unit
awards pursuant to the Henry Schein, Inc. 2013 Stock Incentive Plan (as amended
and restated effective as of May 14, 2013). (Incorporated by reference to Exhibit
10.1 to our Quarterly Report on Form 10-Q for the fiscal quarter ended March 30,
Henry Schein, Inc. 2020 Stock Incentive Plan, as amended and restated effective as
of May 21, 2020. (Incorporated by reference to Exhibit 10.1 to our Current Report
on Form 8-K filed on May 26, 2020.)**
Form of 2021 Stock Option Agreement pursuant to the Henry Schein, Inc. 2020
Stock Incentive Plan (as amended and restated effective as of May 21, 2020).
(Incorporated by reference to Exhibit 10.1 to our Current Report on Form 8-K filed
Form of 2021 Special Pandemic Recognition Award Restricted Stock Unit
Agreement for time-based restricted stock unit awards pursuant to the Henry
Schein, Inc. 2020 Stock Incentive Plan (as amended and restated effective as of
May 21, 2020). (Incorporated by reference to Exhibit 10.2 to our Quarterly Report
on Form 10-Q for the fiscal quarter ended March 27, 2021 filed on May 4,
Form of 2022 Restricted Stock Unit Agreement for time-based restricted stock unit
awards pursuant to the Henry Schein, Inc. 2020 Stock Incentive Plan (as amended
and restated effective as of May 21, 2020). (Incorporated by reference to Exhibit
10.1 to our Quarterly Report on Form 10-Q for the fiscal quarter ended March 26,
Form of 2022 Restricted Stock Unit Agreement for performance-based restricted
stock unit awards pursuant to the Henry Schein, Inc. 2020 Stock Incentive Plan (as
amended and restated effective as of May 21, 2020). (Incorporated by reference to
Exhibit 10.2 to our Quarterly Report on Form 10-Q for the fiscal quarter ended
March 26, 2022 filed on May 3, 2022.)**
Henry Schein, Inc. 2015 Non-Employee Director Stock Incentive Plan.
(Incorporated by reference to Exhibit 10.1 to our Quarterly Report on Form 10-Q
for the fiscal quarter ended June 27, 2015 filed on July 29, 2015.)**
Form of 2018 Restricted Stock Unit Agreement for time-based restricted stock unit
awards pursuant to the Henry Schein, Inc. 2015 Non-Employee Director Stock
Incentive Plan (as amended and restated effective as of June 22, 2015).
(Incorporated by reference to Exhibit 10.6 to our Quarterly Report on Form 10-Q
for the fiscal quarter ended March 31, 2018 filed on May 8, 2018.)**
Henry Schein, Inc. Supplemental Executive Retirement Plan, amended and restated
effective as of January 1, 2014. (Incorporated by reference to Exhibit 10.1 to our
Quarterly Report on Form 10-Q for the fiscal quarter ended September 28, 2013
Amendment Number One to the Henry Schein, Inc. Supplemental Executive
Retirement Plan, amended and restated effective as of January 1, 2014.
(Incorporated by reference to Exhibit 10.18 to our Annual Report on Form 10-K for
the fiscal year ended December 28, 2020 filed on February 20, 2020.)**
Amendment Number Two to the Henry Schein, Inc. Supplemental Executive
Retirement Plan, amended and restated effective as of January 1, 2014.
(Incorporated by reference to Exhibit 10.3 to our Quarterly Report on Form 10-Q
for the fiscal quarter ended March 28, 2020 filed on May 5, 2020.)**
Amendment Number Three to the Henry Schein, Inc. Supplemental Executive
Retirement Plan, amended and restated effective as of January 1, 2014.
(Incorporated by reference to Exhibit 10.2 to our Quarterly Report on Form 10-Q
for the fiscal quarter ended September 26, 2020 filed on November 2, 2020.)**
Henry Schein, Inc. 2004 Employee Stock Purchase Plan, effective as of May 25,
2004. (Incorporated by reference to Exhibit D to our definitive 2004 Proxy
Statement on Schedule 14A, filed on April 27, 2004.)**
Henry Schein, Inc. Non-Employee Director Deferred Compensation Plan, amended
and restated effective as of January 1, 2005. (Incorporated by reference to Exhibit
10.11 to our Annual Report on Form 10-K for the fiscal year ended December 27,
2008 filed on February 24, 2009.)**
Henry Schein, Inc. Deferred Compensation Plan. (Incorporated by reference to
Exhibit 10.23 to our Annual Report on Form 10-K for the fiscal year ended
December 25, 2010 filed on February 22, 2011.)**
Amendment to the Henry Schein, Inc. Deferred Compensation Plan. (Incorporated
by reference to Exhibit 10.26 to our Annual Report on Form 10-K for the fiscal
year ended December 31, 2011 filed on February 15, 2012.)**
Amendment Number Two to the Henry Schein, Inc. Deferred Compensation
Plan. (Incorporated by reference to Exhibit 10.20 to our Annual Report on Form
10-K for the fiscal year ended December 28, 2013 filed on February 11, 2014.)**
Amendment Number Three to the Henry Schein, Inc. Deferred Compensation Plan.
(Incorporated by reference to Exhibit 10.21 to our Annual Report on Form 10-K for
the fiscal year ended December 28, 2013 filed on February 11, 2014.)**
Amendment Number Four to the Henry Schein, Inc. Deferred Compensation Plan.
(Incorporated by reference to Exhibit 10.46 to our Annual Report on Form 10-K for
the fiscal year ended December 31, 2016 filed on February 21, 2017.)**
Amendment Number Five to the Henry Schein, Inc. Deferred Compensation Plan.
(Incorporated by reference to Exhibit 10.32 to our Annual Report on Form 10-K for
the fiscal year ended December 28, 2020 filed on February 20, 2020.)**
Amendment Number Six to the Henry Schein, Inc. Deferred Compensation Plan.
(Incorporated by reference to Exhibit 10.4 to our Quarterly Report on Form 10-Q
for the fiscal quarter ended March 28, 2020 filed on May 5, 2020.)**
Henry Schein Management Team Performance Incentive Plan and Plan Summary,
effective as of January 1, 2014. (Incorporated by reference to Exhibit 10.7 to our
Quarterly Report on Form 10-Q for the fiscal quarter ended March 29, 2014 filed
Form of Performance-Based RSU Award Agreement for Stanley M. Bergman
Pursuant to the Henry Schein, Inc. 2013 Stock Incentive Plan (as Amended and
Restated as of May 14, 2013). (Incorporated by reference to Exhibit 10.2 to our
Current Report on Form 8-K filed on August 9, 2019.)**
Amended and Restated Employment Agreement dated as of November 28, 2022,
by and between Henry Schein, Inc. and Stanley M. Bergman. (Incorporated by
reference to Exhibit 10.1 to our Current Report on Form 8-K filed on November
Letter Agreement dated November 11, 2021 between Henry Schein, Inc. and Brad
Agreement dated November 11, 2021 between Henry Schein, Inc. and Brad
Special Incentive Plan dated May 24, 2021 between Henry Schein, Inc. and Brad
Form of Amended and Restated Change in Control Agreement dated December 12,
2008 between us and certain executive officers who are a party thereto (James
Breslawski, Michael S. Ettinger, Mark Mlotek and Steven Paladino, respectively).
(Incorporated by reference to Exhibit 10.15 to our Annual Report on Form 10-K for
the fiscal year ended December 27, 2008 filed on February 24, 2009.)**
Form of Amendment to Amended and Restated Change in Control Agreement
effective January 1, 2012 between us and certain executive officers who are a party
thereto (James Breslawski, Michael S. Ettinger, Mark Mlotek and Steven Paladino,
respectively). (Incorporated by reference to Exhibit 10.1 to our Current Report on
Form 8-K filed on January 20, 2012.)**
Form of Change in Control Agreement between us and certain executive officers
who are a party thereto (Walter Siegel). (Incorporated by reference to Exhibit 10.3
to our Quarterly Report on Form 10-Q for the fiscal quarter ended March 30, 2019
**
Henry Schein, Inc. Executive Change in Control Plan, effective as of May 2, 2022
between us and certain executive officers who are a party thereto (Ronald N. South,
Brad Connett, David Brous, and Lorelei McGlynn). (Incorporated by reference to
Exhibit 10.3 to our Quarterly Report on Form 10-Q for the fiscal quarter ended
March 26, 2022 filed on May 3, 2022.)**
Form of Indemnification Agreement between us and certain directors and executive
officers who are a party thereto (Mohamed Ali, Deborah Derby, Joseph L. Herring,
Kurt P. Kuehn, Philip A. Laskawy, Anne H. Margulies, Steven Paladino, Carol
Raphael, Scott P. Serota, Bradley T. Sheares, Ph.D., Reed V. Tuckson, M.D.,
FACP, Stanley M. Bergman, James P. Breslawski, David Brous, Brad Connett,
Michael S. Ettinger, Lorelei McGlynn, Mark E. Mlotek, Walter Siegel and Ronald
N. South, respectively). (Incorporated by reference to Exhibit 10.1 to our Quarterly
Report on Form 10-Q for the fiscal quarter ended September 26, 2015 filed on
Amended and Restated Revolving Credit Agreement, dated as of August 20, 2021,
among us, the several lenders parties thereto, and JPMorgan Chase Bank, N.A., as
administrative agent. (Incorporated by reference to Exhibit 10.1 to our Current
Report on Form 8-K filed on August 23, 2021.)
Receivables Purchase Agreement, dated as of April 17, 2013, by and among us, as
servicer, HSFR, Inc., as seller, The Bank of Tokyo -Mitsubishi UFJ, Ltd., as agent
and the various purchaser groups from time to time party thereto. (Incorporated by
reference to Exhibit 10.1 to our Current Report on Form 8-K filed on April 19,
Amendment No. 1 dated as of September 22, 2014 to the Receivables Purchase
Agreement, dated as of April 17, 2013, by and among us, as servicer, HSFR, Inc.,
as seller, The Bank of Tokyo -Mitsubishi UFJ, LTD., New York Branch, as agent
and the various purchaser groups from time to time party thereto. (Incorporated by
reference to Exhibit 10.2 to our Current Report on Form 8-K filed on September
Amendment No. 2 dated as of April 17, 2015 to Receivables Purchase Agreement,
dated as of April 17, 2013, by and among us, as performance guarantor, HSFR,
Inc., as seller, The Bank of Tokyo -Mitsubishi UFJ, Ltd., New York Branch, as
agent and the various purchaser groups party thereto. (Incorporated by reference to
Exhibit 10.1 to our Quarterly Report on Form 10-Q for the fiscal quarter ended
June 25, 2016 filed on August 4, 2016.)
Amendment No. 3 dated as of June 1, 2016 to Receivables Purchase Agreement,
dated as of April 17, 2013, by and among us, as performance guarantor, HSFR,
Inc., as seller, The Bank of Tokyo -Mitsubishi UFJ, Ltd., New York Branch, as
agent and the various purchaser groups party thereto. (Incorporated by reference to
Exhibit 10.2 to our Quarterly Report on Form 10-Q for the fiscal quarter ended
June 25, 2016 filed on August 4, 2016.)
Amendment No. 4 dated as of July 6, 2017 to Receivables Purchase Agreement,
dated as of April 17, 2013, by and among us, as performance guarantor, HSFR,
Inc., as seller, The Bank of Tokyo -Mitsubishi UFJ, Ltd., New York Branch, as
agent and the various purchaser groups party thereto. (Incorporated by reference to
Exhibit 10.1 to our Quarterly Report on Form 10-Q for the fiscal quarter ended
September 30, 2017 filed on November 6, 2017.)
Amendment No. 5 dated as of May 13, 2019 to Receivables Purchase Agreement,
dated as of April 17, 2013, by and among us, as performance guarantor, HSFR,
Inc., as seller, The Bank of Tokyo -Mitsubishi UFJ, Ltd., New York Branch, as
agent and the various purchaser groups party thereto. (Incorporated by reference to
Exhibit 10.1 to our Quarterly Report on Form 10-Q for the fiscal quarter ended
June 29, 2019 filed on August 6, 2019.)
Limited Waiver dated as of May 22, 2020 to Receivables Purchase Agreement,
dated as of April 17, 2013, by and among us, as servicer, HSFR, Inc., as seller,
lender, as agent and the various purchaser groups from time to time party thereto,
as amended. (Incorporated by reference to Exhibit 10.7 to our Quarterly Report on
Form 10-Q for the fiscal quarter ended June 27, 2020 filed on August 4, 2020.)
Amendment No. 6 dated as of June 22, 2020 to the Receivables Purchase
Agreement, dated as of April 17, 2013, by and among us, as servicer, HSFR, Inc.,
as seller, lender, as agent and the various purchaser groups from time to time party
thereto. (Incorporated by reference to Exhibit 10.1 to our Current Report on Form
Amendment No. 7 dated as of October 20, 2021 to Receivables Purchase
Agreement, dated as of April 17, 2013, by and among us, as servicer, HSFR, Inc.,
as seller, lender, as agent and the various purchaser groups from time to time party
thereto. (Incorporated by reference to Exhibit 10.1 to our Current Report on Form
8-K filed on October 21, 2021.)
Amendment No. 8 dated as of December 15, 2022 to Receivables Purchase
Agreement, dated as of April 17, 2013, by and among us, as servicer, HSFR, Inc.,
as seller, lender, as agent and the various purchaser groups from time to time party
Omnibus Amendment No. 1, dated July 22, 2013, to Receivables Purchase
Agreement dated as of April 17, 2013, by and among us, as servicer, HSFR, Inc., as
seller, The Bank of Tokyo -Mitsubishi UFJ, Ltd., as agent, and the various
purchaser groups from time to time party thereto and Receivables Sales Agreement,
dated as of April 17, 2013, by and among us, certain of our wholly-owned
subsidiaries and HSFR, Inc., as buyer. (Incorporated by reference to Exhibit 10.5
to our Quarterly Report on Form 10-Q for the fiscal quarter ended June 29, 2013
Omnibus Amendment No. 2, dated April 21, 2014, to Receivables Purchase
Agreement dated as of April 17, 2013, as amended, by and among us, as servicer,
HSFR, Inc., as seller, The Bank of Tokyo -Mitsubishi UFJ, Ltd., as agent, and the
various purchaser groups from time to time party thereto and Receivables Sales
Agreement, dated as of April 17, 2013, by and among us, certain of our wholly-
owned subsidiaries and HSFR, Inc., as buyer. (Incorporated by reference to Exhibit
10.8 to our Quarterly Report on Form 10-Q for the fiscal quarter ended March 29,
Receivables Sale Agreement, dated as of April 17, 2013, by and among us, certain
of our wholly-owned subsidiaries and HSFR, Inc., as buyer. (Incorporated by
reference to Exhibit 10.2 to our Current Report on Form 8-K filed on April 19,
Certification of our Chief Executive Officer pursuant to Section 302 of the
Certification of our Chief Financial Officer pursuant to Section 302 of the
Certification of our Chief Executive Officer and Chief Financial Officer pursuant
to Section 906 of the Sarbanes-Oxley Act of 2002.+
101.INS
Inline XBRL Instance Document - the instance document does not
appear in the Interactive Data File because its XBRL tags are embedded
within the Inline XBRL document.+
101.SCH
Inline XBRL Taxonomy Extension Schema Document+
101.CAL
Inline XBRL Taxonomy Extension Calculation Linkbase Document+
101.DEF
Inline XBRL Taxonomy Extension Definition Linkbase Document+
101.LAB
Inline XBRL Taxonomy Extension Label Linkbase Document+
101.PRE
Inline XBRL Taxonomy Extension Presentation Linkbase Document+
The cover page of Henry Schein, Inc.’s Annual Report on Form 10-K
for the year ended December 31, 2022, formatted in Inline XBRL
(included within Exhibit 101 attachments).+
Filed or furnished herewith.
- Schedules and exhibits have been omitted pursuant to Item 601(b)(2) of Regulation S-K. The Company
hereby agrees to furnish supplementally a copy of any of the omitted schedules and exhibits upon request
by the U.S. Securities and Exchange Commission.
**
Indicates management contract or compensatory plan or agreement.
Certain identified information has been excluded from the exhibit because it is both not material and is
the type that the registrant treats as private or confidential.
Item 16. Form 10-K Summary
Form 10-K Summary
None.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange
Act of 1934, the Registrant has duly
caused this report to be signed on its behalf by the undersigned,
thereunto duly authorized.
Henry Schein, Inc.
By: /s/ STANLEY M. BERGMAN
Stanley M. Bergman
Chairman and Chief Executive Officer
February 21, 2023
Pursuant to the requirements of the Securities Exchange Act of 1934, this
report has been signed below by the
following persons on behalf of the Registrant and in the capacities and on
the dates indicated.
Signature
Capacity
Date
/s/ STANLEY M. BERGMAN
Chairman, Chief Executive Officer
February 21, 2023
Stanley M. Bergman
and Director (principal executive officer)
/s/ RONALD N. SOUTH
Senior Vice President, Chief
Financial Officer
February 21, 2023
Ronald N. South
(principal financial and accounting officer)
/s/ JAMES P.
BRESLAWSKI
Vice Chairman, President
and Director
February 21, 2023
James P.
Breslawski
/s/ MARK E. MLOTEK
Director
February 21, 2023
Mark E. Mlotek
/s/ MOHAMAD ALI
Director
February 21, 2023
Mohamad Ali
/s/ DEBORAH DERBY
Director
February 21, 2023
Deborah Derby
/s/ JOSEPH L. HERRING
Director
February 21, 2023
Joseph L. Herring
/s/ KURT P.
KUEHN
Director
February 21, 2023
Kurt P.
Kuehn
/s/ PHILIP A. LASKAWY
Director
February 21, 2023
Philip A. Laskawy
/s/ ANNE H. MARGULIES
Director
February 21, 2023
Anne H. Margulies
/s/ STEVEN PALADINO
Director
February 21, 2023
Steven Paladino
/s/ CAROL RAPHAEL
Director
February 21, 2023
Carol Raphael
/s/ SCOTT SEROTA
Director
February 21, 2023
Scott Serota
/s/ BRADLEY T. SHEARES,
PH. D.
Director
February 21, 2023
Bradley T.
Sheares, Ph. D.
/s/ REED V.
TUCKSON, M.D., FACP
Director
February 21, 2023
Reed V.
Tuckson, M.D., FACP