 filings.tools
Ingersoll Rand 10-K 2017-12-31
Filed 2018-02-16. 22 sections, 656K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 form10k.htm 10-K
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
|---|
For the fiscal year ended December 31, 2017
Or
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
|---|
For the transition period from to
Commission File Number: 001-38095
Gardner Denver Holdings, Inc.
(Exact Name of Registrant as Specified in Its Charter)
| Delaware | 46-2393770 | |
|---|---|---|
| (State or Other Jurisdiction of Incorporation or Organization) | (I.R.S. Employer Identification No.) |
222 East Erie Street, Suite 500
Milwaukee, Wisconsin 53202
(Address of Principal Executive Offices) (Zip Code)
(414) 212-4700
(Registrant’s Telephone Number, Including Area Code)
Securities Registered Pursuant to Section 12(b) of the Act:
| Title of Each Class | Name of Each Exchange on Which Registered | |
|---|---|---|
| Common Stock, $0.01 Par Value | New York Stock Exchange |
Securities Registered Pursuant to Section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☐ No ☒
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐ No ☒
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐
Indicate by check mark whether the registrant has submitted electronically and posted on its corporate website, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files). Yes ☒ No ☐
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K (§229.405 of this chapter) is not contained herein, and will not be contained, to the best of registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. ☒
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | ☐ | Accelerated filer | ☐ |
|---|---|---|---|
| Non-accelerated filer | ☒ (Do not check if a smaller reporting company) | Smaller reporting company | ☐ |
| Emerging growth company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes ☐ No ☒
The aggregate market value of the registrant’s common stock held by non-affiliates of the registrant on June 30, 2017 was approximately $1,026.4 million based on the closing price of such Common Stock on the New York Stock Exchange on such date.
The registrant had outstanding 196,315,518 shares of Common Stock, par value $0.01 per share, as of January 31, 2018.
DOCUMENTS INCORPORATED BY REFERENCE
Portions of the Proxy Statement for the registrant’s 2018 Annual Meeting of Shareholders are incorporated by reference in Part III of this report.
Table of Contents
PART I
SPECIAL NOTE REGARDING FORWARD-LOOKING STATEMENTS
In addition to historical information, this Annual Report on Form 10-K (this “Form 10-K”) may contain “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended (the “Securities Act”), and Section 21E of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), which are subject to the “safe harbor” created by those sections. All statements, other than statements of historical facts included in this Form 10-Q, including statements concerning our plans, objectives, goals, beliefs, business strategies, future events, business conditions, results of operations, financial position, business outlook, business trends and other information, may be forward-looking statements. Words such as “estimates,” “expects,” “contemplates,” “will,” “anticipates,” “projects,” “plans,” “intends,” “believes,” “forecasts,” “may,” “should,” and variations of such words or similar expressions are intended to identify forward-looking statements. The forward-looking statements are not historical facts, and are based upon our current expectations, beliefs, estimates and projections, and various assumptions, many of which, by their nature, are inherently uncertain and beyond our control. Our expectations, beliefs, estimates and projections are expressed in good faith and we believe there is a reasonable basis for them. However, there can be no assurance that management’s expectations, beliefs, estimates, and projections will result or be achieved and actual results may vary materially from what is expressed in or indicated by the forward-looking statements.
There are a number of risks, uncertainties, and other important factors, many of which are beyond our control, that could cause our actual results to differ materially from the forward-looking statements contained in this Form 10-K. Such risks, uncertainties and other important factors include, among others, the risks, uncertainties and factors set forth under “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and elsewhere in this Form 10-K. Moreover, we operate in an evolving environment. New risk factors and uncertainties may emerge from time to time, and it is not possible for management to predict all risk factors and uncertainties. See “Item 1A. Risk Factors” for more information.
Item 1. BUSINESS
| --- | --- |
Gardner Denver Holdings, Inc. is an affiliate of Kohlberg Kravis and Roberts & Co. L.P. (“KKR” or “Sponsor”) and a holding company whose operating subsidiary is Gardner Denver, Inc. (“GDI”). The holding company and its consolidated subsidiary, GDI, are collectively referred to in this Annual Report as “we,” “us,” “our,” “ourselves,” “Company,” or “Gardner Denver.”
Service marks, trademarks and trade names, and related designs or logotypes owned by Gardner Denver or its subsidiaries are shown in italics.
Our Company
We are a leading global provider of mission-critical flow control and compression equipment and associated aftermarket parts, consumables and services, which we sell across multiple attractive end-markets within the industrial, energy and medical industries. We manufacture one of the broadest and most complete ranges of compressor, pump, vacuum and blower products in our markets, which, combined with our global geographic footprint and application expertise, allows us to provide differentiated product and service offerings to our customers. Our products are sold under a collection of premier, market-leading brands, including Gardner Denver, CompAir, Nash, Emco Wheaton, Robuschi, Elmo Rietschle and Thomas, which we believe are globally recognized in their respective end-markets and known for product quality, reliability, efficiency and superior customer service. These attributes, along with over 155 years of engineering heritage, generate strong brand loyalty for our products and foster long-standing customer relationships, which we believe have resulted in leading market positions within each of our operating segments. We have sales in more than 175 countries and our diverse customer base utilizes our products across a wide array of end-markets that have favorable near- and long-term growth prospects, including industrial manufacturing, energy (with particular exposure to the North American upstream land-based market), transportation, medical and laboratory sciences, food and beverage packaging and chemical processing.
Our products and services are critical to the processes and systems in which they are utilized, which are often complex and function in harsh conditions where the cost of failure or downtime is high. However, our products typically represent only a small portion of the costs of the overall systems or functions that they support. As a result, our customers place a high value on our application expertise, product reliability and the responsiveness of our service. To support our customers and market presence, we maintain significant global scale with 38 key manufacturing facilities, more than 30 complementary service and repair centers across six continents and approximately 6,400 employees worldwide as of December 31, 2017.
The process-critical nature of our product applications, coupled with the standard wear and tear replacement cycles associated with the usage of our products, generates opportunities to support customers with our broad portfolio of aftermarket parts, consumables and services. Customers place a high value on minimizing any time their operations are offline. As a result, the availability of replacement parts, consumables and our repair and support services are key components of our value proposition. Our large installed base of products provides a recurring revenue stream through our aftermarket parts, consumables and services offerings. As a result, our aftermarket revenue is significant, representing 41% of total Company revenue and approximately 45% of our combined Industrials and Energy segments’ revenue in 2017.
We were acquired by an affiliate of KKR on July 30, 2013 (the “KKR Transaction”) and have undergone a significant transformation since that date. From 2014 to 2016, our transformation significantly improved our underlying operating performance. Our senior leadership team, led by our CEO Vicente Reynal, has been reconstituted and expanded, which we believe brought together deep expertise from leading global industrial organizations. In addition, 45% of our top 100 business managers, including the senior management team, have joined since the KKR Transaction, which we believe added significant new levels of talent to our leadership team. As part of our transformation, we also reorganized our Company into three business segments because of the sales drivers and market characteristics of each. Together, our Industrials, Energy and Medical segments create a diverse portfolio with exposure to highly attractive end-markets, significant aftermarket revenues, upside from an upstream energy recovery and positive secular trends across all segments.
Our Segments
Our business is comprised of three strategic segments.
Industrials
We design, manufacture, market and service a broad range of air compression, vacuum and blower products, including associated aftermarket parts, consumables and services, across a wide array of technologies and applications for use in diverse end-markets. Compressors are used to increase the pressure of air or gas, vacuum products are used to remove air or gas in order to reduce the pressure below atmospheric levels, and blower products are used to produce a high volume of air or gas at low pressure. Almost every manufacturing and industrial facility, and many service and process industry applications, use air compression, vacuum and blower products in a variety of process-critical applications such as the operation of industrial air tools, vacuum packaging of food products and aeration of waste water, among others.
We offer one of the broadest portfolios of compression, vacuum and blower technology in our markets which we believe, alongside our geographic footprint, allows us to provide differentiated service to our customers globally and maintain leading positions in many of our end-markets. Our compression products cover the full range of technologies, including rotary screw, reciprocating piston, scroll, rotary vane and centrifugal compressors. Our vacuum products and blowers also cover the full technology spectrum; vacuum technologies include side channel, liquid ring, claw vacuum, screw and rotary vane vacuum pumps among others, while blower technologies include rotary lobe blowers, screw, claw and vane, turbo, side channel and radial blowers. We believe our ability to support custom industrial application needs from nearly full vacuum to approximately 7,000 pounds per square inch (psi) pressure levels makes us a partner of choice for many of our long-standing customers. The breadth and depth of our product offering creates incremental business opportunities by allowing us to cross-sell our full product portfolio and uniquely address customers’ needs in one complete solution.
We sell our industrial products through an integrated network of direct sales representatives and independent distributors, which is strategically tailored to meet the dynamics of each target geography or end-market. Our large installed base also provides for a significant stream of recurring aftermarket revenue. For example, on average, the useful life of a compressor is between 10 and 12 years. However, a customer typically services the compressor at regular intervals, starting within the first two years of purchase and continuing throughout the life of the product. The cumulative aftermarket revenue generated by a compressor over the product’s life cycle will typically exceed its original cost.
Industrial air compressors represent the largest market in which we compete in our Industrials segment and is a product category for which we believe there is significant potential to drive increased sales of our aftermarket parts, consumables and services. We use our direct salesforce and strong distributor relationships, the majority of which are exclusive to our business for the products that we sell through them, to sell our broad portfolio of aftermarket parts, consumables and services. Within our Industrials segment, we primarily sell through the Gardner Denver, CompAir, Elmo Rietschle and Robuschi brands, as well as other leading brand names.
Energy
We design, manufacture, market and service a diverse range of positive displacement pumps, liquid ring vacuum pumps, compressors and integrated systems, engineered fluid loading and transfer equipment and associated aftermarket parts, consumables and services. The highly engineered products offered by our Energy segment serve customers across upstream, midstream and downstream energy markets, as well as petrochemical processing, transportation and general industrial sectors. We are one of the largest suppliers of equipment and associated aftermarket parts, consumables and services for the energy market applications that we serve.
Our positive displacement pumps are fit-for-purpose to meet the demands and challenges of modern unconventional drilling and hydraulic fracturing activity, particularly in the major basins and shale plays in the North American land market. Our positive displacement pump offering includes mission-critical oil and gas drilling pumps, frac pumps and well servicing pumps, in addition to sales of associated consumables used in the operation of our pumps and aftermarket parts, consumables and services. The products we sell into upstream energy applications are highly aftermarket-intensive, and so we support these products in the field with one of the industry’s most comprehensive service networks, which encompasses locations across all major basins and shale plays in the North American land market. This North American land-based service network is critical to serving our customers and, by supporting them in the field, to generating demand for new original equipment sales. For example, fluid ends are key aftermarket parts used in hydraulic fracturing operations that represent approximately 30% of the original cost of the pump and need to be replaced approximately four times per year on each operating pump (depending on the basin and operating nature of the hydraulic fracturing fleet). Other aftermarket parts, such as plungers, and consumables, such as valves, seats and packing, are replaced on even shorter time frames, creating aftermarket opportunities which in aggregate are often multiples of the cost of the original pump.
Our liquid ring vacuum pumps and compressors are highly engineered products specifically designed for continuous duty in harsh environments to serve a wide range of applications, including oil and gas refining and processing, mining, chemical processing, petrochemical and industrial applications. Our liquid ring technology utilizes a service liquid to evacuate or compress gas by forming a rotating ring of liquid that acts like a piston to deliver an uninterrupted flow of gas without pulsation. In addition, our engineered fluid loading and transfer equipment and systems ensure the safe and efficient transportation and transfer of petroleum products as well as certain other liquid commodity products to serve a wide range of industries. Similar to our positive displacement pumps business, we complement these products with a broad array of aftermarket parts, service and repair capabilities by leveraging our global network of manufacturing and service locations to meet the diverse needs of our customers. Within our Energy segment, we primarily sell through the Gardner Denver, Nash and Emco Wheaton brands, as well as other leading brand names.
Medical
We design, manufacture and market a broad range of highly specialized gas, liquid and precision syringe pumps and compressors that are specified by medical and laboratory equipment suppliers and integrated into their final equipment for use in applications, such as oxygen therapy, blood dialysis, patient monitoring, laboratory sterilization and wound treatment, among others. We offer a comprehensive product portfolio across a breadth of technologies to address the medical and laboratory sciences pump and fluid handling industry, as well as a range of end-use vacuum products for laboratory science applications, and we recently expanded into liquid pumps and automated liquid handling components and systems. Our product performance, quality and long-term reliability are often mission-critical in healthcare applications. We are one of the largest product suppliers in the medical markets we serve and have long-standing customer relationships with industry-leading medical and laboratory equipment providers. Additionally, many of our Medical segment gas and liquid pumps are also used in other technology applications beyond the medical and laboratory sciences. Within our Medical segment, we primarily sell through the Thomas brand, as well as other leading brand names.
For financial information about our segments and our geographic areas, see Note 20, “Segment Information” in the audited consolidated financial statements included elsewhere in this annual report on Form 10-K.
Our Industries and Products
We operate in the global markets for flow control and air compression products for the industrial, energy and medical industries. Our highly engineered products and proprietary technologies are focused on serving specialized applications within these attractive and growing industries.
Industrials
Our Industrials segment designs, manufactures, markets and services a broad range of air compression, vacuum and blower products across a wide array of technologies. Compression, vacuum and blower products are used in a wide spectrum of applications in nearly all manufacturing and industrial facilities and many service and process industries in a variety of end-markets, including infrastructure, construction, transportation, food and beverage packaging and chemical processing.
Compression Products
Sales to industrial end-markets include industrial air compression products, as well as associated aftermarket parts, consumables and services. Industrial air compressors compress air to create pressure to power machinery, industrial tools, material handling systems and automated equipment. Compressed air is also used in applications as diversified as snow making and fish farming, on high-speed trains and in hospitals. Compressors can be either stationary or portable, depending on the requirements of the application or customer. Because compressed air is utilized as a core component in manufacturing operations in nearly every manufacturing plant, it is often referred to as the “fourth utility” (in addition to electricity, gas and water). The global industrial air compressor market is an estimated $13.2 billion industry, and according to Frost & Sullivan, we currently maintain a top three position in this market.
We focus on five basic types of air compression technologies: rotary screw, reciprocating piston, scroll, rotary vane and centrifugal compressors. Rotary screw compressors are a newer technology than reciprocating compressors and exhibit better suitability for continuous processes due to a more compact size, less maintenance and better noise profile. We believe our reciprocating piston compressors provide one of the broadest ranges of pressures in the market and are supported by increasing demand across wide-ranging attractive end-markets. Scroll compressors are most commonly seen where less oil-free air is needed, and is most commonly used in medical and food applications where the need for pure, clean and precise air is of great importance. Rotary vane compressors feature high efficiency, compact compression technology and can be found throughout all sectors of industry, including automotive, food and beverage, energy and manufacturing with specialist solutions within transit, gas and snow making. Centrifugal compressors are most effective when in applications that demand larger quantities of oil-free air and are utilized across a wide range of industries.
Vacuum Products
Industrial vacuum products are integral to manufacturing processes in applications for packaging, pneumatic conveying, drying, holding / lifting, distillation, evacuation, forming / pressing, removal and coating. Within each of these processes are a multitude of sub-applications. As an example of one such end-process, within packaging, a vacuum will be used on blister packaging, foil handling, labeling, carton erection, stacking and palletizing (placing, stacking or transporting goods on pallets), as well as central vacuum supply for entire packaging departments. Management believes that we hold a leading position in our addressable portion of the global vacuum products market.
We focus on five basic types of vacuum technologies: side channel, liquid ring, claw vacuum, screw and rotary vane vacuum pumps. Side channel vacuum pumps are used for conveying gases and gas-air mixtures in a variety of applications, including laser printers, packaging, soil treatment, textiles and food and beverage products. Liquid ring vacuum pumps are used for extreme conditions, which prevail in humid and wet processes across ceramics, environmental, medical and plastics applications. Claw vacuum pumps efficiently and economically generate contact-free vacuum for chemical, environmental and packaging applications. Screw vacuum pumps are a dry running technology used to reduce the carbon footprint and life cycle costs in drying and packaging applications. Rotary vane vacuum pumps are used for vacuum and combined pressure and vacuum applications in the environmental, woodworking, packaging and food and beverage end-markets.
Blower Products
Blower products are used for conveying high volumes of air and gas at various flow rates and at low pressures, and are utilized in a broad range of industrial and environmental applications, including waste water aeration, biogas upgrading and conveying, pneumatic transport and dehydrating applications for food and beverage, cement, pharmaceutical, petrochemical and mobile industrial applications. We also design, manufacture, market and service frac sand blowers within our Industrials segment. In many cases, blowers are a core component for the operation of the entire end-users’ systems. Management believes that we hold a leading position in our addressable portion of the global blower products market.
We focus on several key technologies within blower products: rotary lobe, screw, claw and vane, turbo, side channel and radial blowers. Rotary lobe blowers, screw blowers and claw and vane blowers are positive displacement technologies that have the ability to consistently move the same volume of gas or air and vary the volume flow according to the speed of the machine itself enabling it to adapt the flow condition in a flexible manner despite pressure in the system. Turbo blowers and side channel and radial blowers are dynamic technologies that have the ability to accelerate gas or air through an impeller and transform their kinetic energy at the discharge with some limitation on flexibility.
Energy
Our Energy segment designs, manufactures, markets and services a diverse range of positive displacement pumps, liquid ring vacuum pumps, compressors and integrated systems, engineered fluid loading and transfer equipment and associated aftermarket parts, consumables and services for a number of attractive, growing market sectors with energy exposure, spanning upstream, midstream, downstream and petrochemical applications. The high cost of failure in these applications makes quality and reliability key purchase criteria for end-users and drives demand for our highly engineered and differentiated products.
Upstream
Through the manufacture and aftermarket service of pumps and manufacture of associated aftermarket parts and consumables used in drilling, hydraulic fracturing and well servicing applications, our Energy segment is well-positioned to capitalize on an upstream recovery, particularly in the North American land-based market, where our customers include market-leading hydraulic fracturing (also known as pressure pumping) and contract drilling service companies, as well as certain other types of well service companies. Sales to upstream energy end-markets consist of positive displacement pumps and associated aftermarket parts, most notably fluid ends, as well as consumables and services.
| · | Positive displacement pumps in the upstream energy end-market primarily move fluid to assist in drilling, hydraulic fracturing and well servicing applications. The majority of positive displacement pumps we sell are frac pumps, which experience significant service intensity during use in the field and, as such, typically have useful life spans of approximately four to six years before needing to be replaced. During that useful life, such pumps will need to receive intermittent repairs as well as major overhauls. In addition, we also sell positive displacement pumps that are used in drilling and well servicing applications. Spears & Associates, Inc. estimates that we have the second largest market share in the global frac pump market based on installed base, and management estimates that we have the largest market share based on new unit sales from 2014 to 2017. |
|---|
| · | Fluid ends are a key component of positive displacement pumps that generate the pumping action, along with other parts, such as plungers, and consumables, such as valves, seats and packing, which pressurizes the fluid, in the case of drilling or well servicing applications, or fluid and proppant mixture, in the case of hydraulic fracturing, and propels such fluid or mixture out of the pump and into a series of flow lines that distribute the fluid or mixture into the well. Fluid ends are incorporated in original equipment pumps, and due to the highly corrosive nature of the fluids and the abrasive nature of the proppants used in hydraulic fracturing operations, need to be frequently replaced. Specifically, fluid ends used in hydraulic fracturing operations represent approximately 30% of the original cost of the pump and need to be replaced approximately four times per year on each operating pump, depending on the basin and the operating nature of the hydraulic fracturing fleet. As such, fluid ends, other aftermarket parts and consumables represent a significant source of aftermarket product sales. |
|---|
The level of profitability at which new wells can be drilled is a primary driver of drilling and completions activities, including hydraulic fracturing. Thus, demand for our Energy and Industrials products exposed to the upstream energy industry is driven by the prices of crude oil and natural gas, and the intensity and activity levels of drilling and hydraulic fracturing. Importantly, according to Oil & Gas Financial Journal, the threshold oil price at which wells are profitable to drill has significantly decreased by an average across all U.S. shale plays of 47% from 2014 to 2016. As a result of this improvement in well profitability and the crude oil price improvement since the low points observed during the first half of 2016, an increased number of drilling rigs have reentered the market. However, it is important to note that while the crude oil price level has a meaningful impact on the level of activity in our upstream energy applications, the growth in demand for our products into such applications is significantly heightened by numerous other market dynamics and drivers (detailed below). We believe that these additional market dynamics result in our exposure to the upstream energy industry being among the most attractive in the present environment.
We believe we are exposed to some of the highest growth market drivers in the context of an upstream energy recovery. Secular industry trends are driving increased demand for and utilization of newer, fit-for-purpose equipment with innovations that increase productivity and are increasing the frequency of replacement, refurbishment and upgrade cycles of pumping equipment and associated consumable products used in drilling and hydraulic fracturing activity. The number of wells drilled is growing at a faster rate than active rig count with each active rig drilling more unconventional wells per unit of time than previously experienced. Further, each unconventional well, on average, is being drilled with longer laterals and more hydraulic fracturing stages per well. Moreover, this quickly growing demand for hydraulic fracturing horsepower, in conjunction with the usage of more volume of abrasive proppant per well, is resulting in accelerated wear and tear on frac pumps and associated aftermarket parts and consumables. As a result, there are multiple drivers of growth in frac pumps and associated aftermarket parts, including fluid ends, consumables and services that are incremental to active rig count, creating a growth profile that is leveraged to, but meaningfully accelerated relative to, the active rig count.
Midstream and Downstream
Sales to midstream and downstream energy end-markets consist of liquid ring vacuum pumps and compressors and integrated systems, engineered fluid loading and transfer equipment and associated aftermarket parts and services. According to Petrochemical Update, North American downstream industry capital expenditures are expected to reach $17.3 billion in 2018, with the maintenance capital expenditure portion for U.S. refineries estimated to increase 39% in 2018 to a total of $1.3 billion. These large investments in midstream and downstream energy end-markets are expected to drive sales of our equipment and future sales in aftermarket parts and services as these facilities age. Further, deferred maintenance of downstream energy infrastructure is expected to drive increased future sales in our replacement products and aftermarket parts and services. Our downstream energy business contributes a larger share of revenue and profitability than our midstream energy business.
We focus on two basic types of midstream and downstream energy equipment: fluid transfer equipment and liquid ring vacuum pumps and compressors, which are employed in the midstream and downstream markets, respectively.
| · | Fluid transfer equipment, including fluid loading systems, tank truck and fleet fueling products and couplers: Fluid loading systems are used in the transfer and loading of hydrocarbons and certain other liquid commodity products in marine and land applications. Tank truck and fleet fueling products allow for safe transfer of liquid products without spillage or contamination while safeguarding the operator and the environment. Operators use Dry-Break® technology couplers and adapters to provide a secure connection for the transfer of liquid products without spillage or contamination while safeguarding the operator and the environment. |
|---|
| · | Liquid ring vacuum pumps and compressors: Liquid ring vacuum pumps and compressors are designed for continuous duty in harsh environments, including vapor and flare gas recovery equipment (which recovers and compresses certain polluting gases to transmit them for further processing), primarily in downstream applications. The liquid ring technology utilizes a service liquid, typically water, oil or fuel, to evacuate or compress gas by forming a rotating ring of liquid that follows the contour of the body of the pump or compressor and acts like a piston to deliver an uninterrupted flow of gas without pulsation. |
|---|
Petrochemical
Our Energy segment is positioned to capitalize on the large and growing petrochemical industry. Sales to petrochemical end-markets consist of vacuum and compression process systems, both of which are used in harsh, continuous-duty applications. According to the American Chemistry Council, U.S. chemical industry capital spending reached $31.9 billion in 2016 and is expected to grow at a 6.2% CAGR from 2017 to 2019. Further, the American Chemistry Council forecasts the annual U.S. capital spending by the chemical industry to reach $48 billion by 2022, more than double the level of spending in 2010.
Demand for our petrochemical industry products correlates with growth in the development of new petrochemical plants as well as activity levels therein, which drive demand for aftermarket parts and services on our market-leading installed base of equipment. Attractive secular trends in the petrochemical market provide additional sources of growth. Advancements in the development of unconventional natural gas resources in North America over the past decade have resulted in the abundant availability of locally-sourced natural gas as feedstock for petrochemical plants in North America, supporting long-term growth. In addition, new petrochemical plants are becoming larger, driving increased demand for more equipment within larger systems.
Medical
The Medical segment designs, manufactures and markets a broad range of flow control products for the durable medical equipment, laboratory vacuum and automated liquid handling end-markets. Key technologies include gas, liquid and precision syringe pumps and automated liquid handling systems.
Based on internal estimates, the durable medical equipment pump market represents approximately a $1.2 billion opportunity globally and can be divided into two primary sub-markets: gas pumps and liquid pumps. In both markets, energy efficiency, ultra-low vibration, reduced noise levels and compactness as compared to flow rate are key application considerations. Customers are mainly medium and large durable medical equipment manufacturers who integrate our products into their devices for a wide range of applications, such as aspirators, blood analyzers, blood pressure monitors, compression therapy, dental carts, dialysis machines, gas monitors and ventilators. Gas pumps transfer and compress gases and generate vacuum to enable precise flow conditions. We estimate the size of the global gas pump market to be approximately $700 million. Building on our strength in gas pump applications, we recently expanded into the liquid pump and automated liquid handling markets to gain share in sizable markets that were previously unaddressed by us. We estimate the liquid pump market to be a $450 million market globally. Our liquid pump products are primarily used to meter and transfer both neutral and chemically aggressive fluids. We view this space as an attractive adjacency to our existing strategy and one in which we are able to capture share in line with current operations in the gas pump market, building momentum and scale for our Medical business. We believe both gas and liquid pump markets present attractive long-term growth profiles based on strong secular trends.
Our products are also used in the laboratory vacuum equipment space which includes end-use chemically resistant devices used in research and commercial laboratories which is a highly attractive niche market. In addition, we recently expanded into the automated liquid handling end-market, which includes syringe pumps, systems and accessories that are integrated into large scale automated liquid handling systems primarily for clinical, pharmaceutical and environmental analyses.
Customers in the durable medical pump end-market and the automated liquid handling end-market develop and manufacture equipment used in a highly regulated environment requiring highly specialized technologies. As a result, relationships with customers are built based on a supplier’s long-term reputation and expertise and deep involvement throughout a product’s evolution, from concept to long-term commercialization. Customers value suppliers that can provide global research and development, regulatory and manufacturing support, as well as sales footprint and expertise to foster close relationships with key decision makers at their company. Combined with the long product life cycle in the regulated medical device space, these factors create a strong, recurring base of business. As a leading pump manufacturer in these markets, we have established a history of innovation that enables us to work closely with our customers to create highly customized flow control solutions for their unique applications. These products are mission-critical in the ultimate device in which they are deployed and remain a key component over the entire life cycle of the end products. The regulated market structure and nature of long-tenured customer relationships enables pump manufacturers to have a highly visible, recurring revenue stream from key customers.
Competition
Industrials
The industrial end-markets we serve are competitive, with an increasing focus on product quality, performance, energy efficiency, customer service and local presence. Although there are several large manufacturers of compression, vacuum and blower products, the marketplace for these products remains highly fragmented due to the wide variety of product technologies, applications and selling channels. Our principal competitors in sales of compression, vacuum and blower products in our Industrials segment include Atlas Copco AB, Ingersoll-Rand PLC, Colfax Corp., Flowserve Corporation, IDEX Corporation, Accudyne and Kaeser Compressors, Inc.
Energy
Across our product lines exposed to the energy industry, the competitive landscape is specific to the end-markets served. Our principal competitor for drilling pumps is National Oilwell Varco Inc., and for frac pumps is The Weir Group plc. Within upstream energy, we additionally compete with certain smaller, regional manufacturers of pumps and aftermarket parts, although these are not direct competitors for most of our products. Our principal competitors in sales of fluid transfer equipment include Dover Corporation, SVT GmbH and TechnipFMC plc. Our principal competitors in the sale of liquid ring pumps and compressors are Flowserve Corporation and Busch-Holding GmbH.
Medical
Competition in the medical pump market is primarily based on product quality and performance, as most products must be qualified by the customer for a particular use. Further, there is an increasing demand for more efficient healthcare solutions, which is driving the adoption of premium and high performance systems. Our primary competitors in medical pumps include IDEX Corporation, Watson-Marlow, Inc., KNF Neuberger, Inc. and Thermo Fisher Scientific, as well as other regional and local manufacturers.
Customers and Customer Service
We consider superior customer service to be one of our primary pillars of future success and view it as being built upon a foundation of critical application expertise, an industry leading range of compressor, pump, vacuum and blower products, a global manufacturing and sales presence and a long-standing reputation for quality and reliability. Intense customer focus is at the center of our vision of becoming the industry’s first choice for innovative and application-critical flow control and compression equipment, services and solutions. We strive to collaborate with our customers and become an essential part of their engineering process by drawing on our deep industry and application engineering experience to develop best-in-class products that are critical to the processes and systems in which they operate.
We have established strong and long-standing customer relationships with numerous industry leaders. We sell our products directly to end-use customers and to certain OEMs, and indirectly through independent distributors and sales representatives. Our Energy and Medical products are primarily sold directly to end-use customers and OEMs, while approximately 50% of our Industrials sales in 2017 were fulfilled through independent distributors and sales representatives.
We use a direct sales force to serve end-use customers and OEMs because these customers typically require higher levels of technical assistance, more coordinated shipment scheduling and more complex product service than customers that purchase through distributors. We have distribution centers and warehouses that stock parts, accessories and certain products to provide adequate and timely availability. In addition, we provide direct aftermarket support through our service and remanufacturing facilities in the United States, Germany, Finland, France, Spain, the United Kingdom, China and Australia.
In addition to our direct sales force, we are also committed to developing and supporting our global network of over 1,000 distributors and representatives who we believe provide us with a competitive advantage in the markets and industries we serve. These distributors maintain an inventory of complete units and parts and provide aftermarket services to end-users. While most distributors provide a broad range of products from different suppliers, we view our distributors as exclusive at the product category level (e.g. compressor, vacuum and blower). For example, a distributor may exclusively carry our compressor technologies, and also source additional components of the broader industrial system in which those products operate from other suppliers. Our service personnel and product engineers provide the distributors’ service representatives with technical assistance and field training, particularly with respect to installation and repair of equipment. We also provide our distributors with sales and product literature, advertising and sales promotions, order-entry and tracking systems and an annual restocking program. Furthermore, we participate in major trade shows and directly market our offerings to generate sales leads and support the distributors’ sales personnel.
Our customer base is diverse, and we did not have any customers that individually provided more than 4% of 2017 consolidated revenues.
Research and Development
Our R&D expenditures focus on developing new products and new product applications to, among other things, enhance and expand existing product capabilities and performance, improve efficiency, reduce size, weight and noise levels, increase application flexibility and maintain compliance with changing regulatory requirements.
For the years ended December 31, 2017, 2016 and 2015, we spent approximately $26 million, $22 million, and $26 million, respectively, on research activities relating to the development of new products and new product applications. All such expenditures were funded by us and were expensed as incurred.
Patents, Trademarks, and Other Intellectual Property
We rely on a combination of intellectual property rights, including patents, trademarks, copyrights, trade secrets and contractual provisions to protect our intellectual property. While in the aggregate our more than 570 patents and our trademarks are of considerable importance to the manufacture and marketing of many of our products, we believe that the success of our business depends more on the technical competence, creativity and marketing abilities of our employees than on any individual patent or trademark, and therefore we do not consider any single patent or trademark, group of patents or trademarks, copyright or trade secret to be material to our business as a whole, except for the Gardner Denver trademark. We have registered our trademarks in the countries we deem necessary or in our best interest. We also rely upon trade secret protection for our confidential and proprietary information and techniques, and we routinely enter into confidentiality agreements with our employees as well as our suppliers and other third parties receiving such information.
Pursuant to trademark license agreements, Cooper Industries has exclusive rights to use the Gardner Denver trademark for certain power tools and their components, meaning that we are prevented from using our mark in connection with those products.
Raw Materials and Suppliers
We purchase a wide variety of raw materials to manufacture our products. Our most significant commodity exposures are to cast iron, aluminum and steel. Additionally, we purchase a large number of motors and, therefore, are also exposed to changes in the price of copper, which is a primary component of motors. Most of our raw materials are generally available from a number of suppliers. We have a limited number of long-term contracts with some suppliers of key components, but we believe that our sources of raw materials and components are reliable and adequate for our needs. We use single sources of supply for certain castings, motors and other select engineered components. A disruption in deliveries from a given supplier could therefore have an adverse effect on our ability to meet commitments to our customers. Nevertheless, we believe that we have appropriately balanced this risk against the cost of maintaining a greater number of suppliers. Moreover, we have sought, and will continue to seek, cost reductions in purchases of materials and supplies by consolidating purchases and pursuing alternate sources of supply.
Employees
As of December 31, 2017, we had approximately 6,400 employees of which approximately 2,050 are located in the United States. Of those employees located outside of the United States, a significant portion are represented by works councils and labor unions, and of those employees located in the United States, approximately 200 are represented by labor unions. We believe that our current relations with employees are satisfactory.
Environmental Matters
We are subject to numerous federal, state, local and foreign laws and regulations relating to the storage, handling, emission and disposal of materials and discharge of materials into the environment. We believe that our existing environmental control procedures are adequate and we have no current plans for substantial capital expenditures in this area. We have an environmental policy that confirms our commitment to a clean environment and compliance with environmental laws. We have an active environmental management program aimed at complying with existing environmental regulations and reducing the generation of pollutants in the manufacturing processes. We are also subject to laws concerning the cleanup of hazardous substances and wastes, such as the U.S. federal “Superfund” and similar state laws that impose liability for cleanup of certain waste sites and for related natural resource damages. We have been identified as a potentially responsible party with respect to several sites designated for cleanup under the “Superfund” or similar state laws. See “Part I, Item 3., Legal Proceedings—Environmental Liabilities.”
Corporate History
Gardner Denver Holdings, Inc. was incorporated in Delaware on March 1, 2013. Through our predecessors, Gardner Denver was founded in Quincy, Illinois in 1859. From August 1943 until the KKR Acquisition we operated as a public company. In July 2013 we were acquired by affiliates of KKR in the KKR Acquisition. We completed our initial public offering in May 2017 and our common stock is listed on the New York Stock Exchange under the symbol “GDI”. Our principal executive offices are located at 222 East Erie Street, Suite 500, Milwaukee, Wisconsin 53202.
Where You Can Find More Information
We file annual, quarterly and current reports, proxy statements and other information with the Securities and Exchange Commission (“SEC”). Our SEC filings are available to the public over the internet at the SEC’s website at http://www.sec.gov. Our SEC filings are also available on our website at http://www.gardnerdenver.com as soon as reasonably practicable after they are filed with or furnished to the SEC. You may also read and copy any filed document at the SEC’s public reference room in Washington, D.C. at 100 F Street, N.E., Washington, D.C. 20549. Please call the SEC at 1-800-SEC-0330 for further information about public reference rooms.
We maintain an internet site at http://www.gardnerdenver.com. From time to time, we may use our website as a distribution channel of material company information. Financial and other important information regarding us is routinely accessible through and posted on our website at www.investors.gardnerdenver.com. In addition, you may automatically receive email alerts and other information about us when you enroll your email address by visiting the Email Alerts section at www.investors.gardnerdenver.com. Our website and the information contained on or connected to that site are not incorporated into this Annual Report on Form 10-K.
Item 1A. RISK FACTORS
| --- | --- |
The following risk factors as well as the other information included in this Form 10-K, including “Selected Historical Consolidated Financial Data,” “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and our consolidated financial statements and related notes thereto should be carefully considered. Any of the following risks could materially and adversely affect our business, financial condition or results of operations. The selected risks described below, however, are not the only risks facing us. Additional risks and uncertainties not currently known to us or those we currently view to be immaterial may also materially and adversely affect our business, financial condition or results of operations.
Risks Related to Our Business
We have exposure to the risks associated with instability in the global economy and financial markets, which may negatively impact our revenues, liquidity, suppliers and customers.
Our financial performance depends, in large part, on conditions in the markets we serve and on the general condition of the global economy, which impacts these markets. Any sustained weakness in demand for our products and services resulting from a contraction or uncertainty in the global economy could adversely impact our revenues and profitability.
In addition, we believe that many of our suppliers and customers access global credit markets to provide liquidity, and in some cases, utilize external financing to purchase products or finance operations. If our customers are unable to access credit markets or lack liquidity, it may impact customer demand for our products and services.
Furthermore, our products are sold in many industries, some of which are cyclical and may experience periodic contractions. For example, weakness in upstream energy activity in North America significantly impacted our business in 2015 and 2016. Cyclical weakness in the industries that we serve could adversely affect demand for our products and affect our profitability and financial performance.
More than half of our sales and operations are in non-U.S. jurisdictions and we are subject to the economic, political, regulatory and other risks of international operations.
For the year ended December 31, 2017, approximately 56% of our revenues were from customers in countries outside of the United States. We have manufacturing facilities in Germany, the United Kingdom, China, Finland, Italy, India and other countries. We intend to continue to expand our international operations to the extent that suitable opportunities become available. Non-U.S. operations and United States export sales could be adversely affected as a result of: political or economic instability in certain countries; differences in foreign laws, including increased difficulties in protecting intellectual property and uncertainty in enforcement of contract rights; credit risks; currency fluctuations, in particular, changes in currency exchange rates between the U.S. dollar, Euro, British Pound and the Chinese Renminbi; exchange controls; changes in tariff restrictions; significant changes in import/export trade restrictions; royalty and tax increases; nationalization of private enterprises; civil unrest and protests, strikes, acts of terrorism, war or other armed conflict; shipping products during times of crisis or war; and other factors inherent in foreign operations.
In addition, our expansion into new countries may require significant resources and the efforts and attention of our management and other personnel, which will divert resources from our existing business operations. As we expand our business globally, our success will depend, in large part, on our ability to anticipate and effectively manage these risks associated with our international operations.
Our revenues and operating results, especially in the Energy segment, depend on the level of activity in the energy industry, which is significantly affected by volatile oil and gas prices.
Demand for certain products of our Energy segment, particularly in the upstream energy market, depends on the level of activity in oil and gas exploration, development and production, and is primarily tied to the number of working and available drilling rigs, number of wells those rigs drill annually, the amount of hydraulic fracturing horsepower required on average to fracture each well and, ultimately, oil and natural gas prices overall. The energy market is volatile as the worldwide demand for oil and natural gas fluctuates. Generally, when worldwide demand or our customers’ expectations of future prices for these commodities are depressed, the demand for our products used in drilling and recovery applications is reduced. Other factors, including availability of quality drilling prospects, exploration success, relative production costs and political and regulatory environments are also expected to affect the demand for our products. Worldwide military, political and economic events have in the past contributed to oil and gas price volatility and are likely to do so in the future. Accordingly, our operating results for any particular period are not necessarily indicative of the operating results for any future period as the markets for our products have historically experienced volatility. In particular, orders in the Energy segment have historically corresponded to demand for oil and gas and petrochemical products and have been influenced by prices and inventory levels for oil and natural gas, rig count, number of wells those rigs drill annually, the amount of hydraulic fracturing horsepower required on average to fracture each well and other economic factors which we cannot reasonably predict. The Energy segment generated approximately 43% of our consolidated revenues for the year ended December 31, 2017.
Our results of operations are subject to exchange rate and other currency risks. A significant movement in exchange rates could adversely impact our results of operations and cash flows.
We conduct our business in many different currencies. A significant portion of our revenue, approximately 52% for the year ended December 31, 2017, is denominated in currencies other than the U.S. dollar. Accordingly, currency exchange rates, and in particular unfavorable movement in the exchange rates between U.S. dollars and Euros, British Pounds and Chinese Renminbi, affect our operating results. The effects of exchange rate fluctuations on our future operating results are unpredictable because of the number of currencies in which we do business and the potential volatility of exchange rates. We are also subject to the risks of currency controls and devaluations. Although historically not significant, if currency controls were enacted in countries where the Company generates significant cash balances, these controls may limit our ability to convert currencies into U.S. dollars or other currencies, as needed, or to pay dividends or make other payments from funds held by subsidiaries in the countries imposing such controls, which could adversely affect our liquidity. Currency devaluations could also negatively affect our operating margins and cash flows.
Potential governmental regulations restricting the use, and increased public attention to and litigation regarding the impacts, of hydraulic fracturing or other processes on which it relies could reduce demand for our products.
Oil and natural gas extracted from unconventional sources, such as shale, tight sands and coal bed methane, frequently requires hydraulic fracturing. Recent initiatives to study, regulate or otherwise restrict hydraulic fracturing and processes on which it relies, such as water disposal, as well as litigation over hydraulic fracturing impacts, could adversely affect some of our customers and their demand for our products, which could have a material adverse effect on our business, results of operations and financial condition.
For example, although hydraulic fracturing currently is generally exempt from regulation under the U.S. Safe Drinking Water Act’s (“SDWA”) Underground Injection Control program and is typically regulated by state oil and natural gas commissions or similar agencies, several federal agencies have asserted regulatory authority over certain aspects of the process. These include, among others, a number of regulations issued and other steps taken by the U.S. Environmental Protection Agency (“EPA”) over the last five years, including its New Source Performance Standards issued in 2012, its June 2016 rules establishing new emissions standards for methane and additional standards for volatile organic compounds from certain new, modified and reconstructed equipment and processes in the oil and natural gas source category and its June 2016 rule prohibiting the discharge of wastewater from onshore unconventional oil and natural gas extraction facilities to publicly owned wastewater treatment plants; and the federal Bureau of Land Management (“BLM”) rule in March 2015 that established new or more stringent standards relating to hydraulic fracturing on federal and American Indian lands (which was the subject of litigation and which the BLM rescinded in December 2017). While the newly appointed EPA administrator and the Trump administration more generally have indicated their interest in scaling back or rescinding regulations that inhibit the development of the U.S. oil and gas industry, it is difficult to predict the extent to which such policies will be implemented or the outcome of any litigation challenging such implementation, such as the suit the State of California’s attorney general filed in January 2018 challenging the BLM’s rescission of its March 2015 rule referred to above.
Moreover, some states and local governments have adopted, and other governmental entities are considering adopting, regulations that could impose more stringent requirements on hydraulic fracturing operations. For example, Texas, Colorado and North Dakota among others have adopted regulations that impose new or more stringent permitting, disclosure, disposal and well construction requirements on hydraulic fracturing operations. States could also elect to prohibit high volume hydraulic fracturing altogether, following the approach taken by the State of New York in 2015. Local land use restrictions, such as city ordinances, may restrict drilling in general and hydraulic fracturing in particular. Some state and federal regulatory agencies have also recently focused on a connection between the operation of injection wells used for oil and natural gas waste disposal and seismic activity. Similar concerns have been raised that hydraulic fracturing may also contribute to seismic activity. In March 2016, the United States Geological Survey identified six states with the most significant hazards from induced seismicity, including Oklahoma, Kansas, Texas, Colorado, New Mexico and Arkansas. In light of these concerns, some state regulatory agencies have modified their regulations or issued orders to address induced seismicity. For example, in December 2016, the Oklahoma Corporation Commission’s Oil and Gas Conservation Division (the “OCC Division”) and the Oklahoma Geologic Survey released well completion seismicity guidance, which requires operators to take certain prescriptive actions, including mitigation, following anomalous seismic activity within 1.25 miles of hydraulic fracturing operations; and in February 2017, the OCC Division issued an order limiting future increases in the volume of oil and natural gas wastewater injected into the ground in an effort to reduce earthquakes in the state. Ongoing lawsuits have also alleged that disposal well operations have caused damage to neighboring properties or otherwise violated state and federal rules regulating waste disposal. Increased regulation and attention given to induced seismicity could lead to greater opposition to, and litigation concerning, oil and natural gas activities utilizing hydraulic fracturing or injection wells for waste disposal. The adoption of more stringent regulations regarding hydraulic fracturing and the outcome of litigation over hydraulic fracturing could adversely affect some of our customers and their demand for our products, which could have a material adverse effect on our business, results of operations and financial condition.
We face competition in the markets we serve, which could materially and adversely affect our operating results.
We actively compete with many companies producing similar products. Depending on the particular product and application, we experience competition based on a number of factors, including price, quality, performance and availability. We compete against many companies, including divisions of larger companies with greater financial resources than we possess. As a result, these competitors may be both domestically and internationally better able to withstand a change in conditions within the markets in which we compete and throughout the global economy as a whole.
In addition, our ability to compete effectively depends on how successfully we anticipate and respond to various competitive factors, including new competitors entering our markets, new products and services that may be introduced by competitors, changes in customer preferences, pricing pressures and new government regulations. If we are unable to anticipate our competitors’ development of new products and services, identify customer needs and preferences on a timely basis, or successfully introduce new products and services or modify existing products and service offerings in response to such competitive factors, we could lose customers to competitors. If we cannot compete successfully, our sales and operating results could be materially and adversely affected.
Large or rapid increases in the cost of raw materials and component parts, substantial decreases in their availability or our dependence on particular suppliers of raw materials and component parts could materially and adversely affect our operating results.
Our primary raw materials, directly and indirectly, are cast iron, aluminum and steel. We also purchase a large number of motors and, therefore, also have exposure to changes in the price of copper, which is a primary component of motors. We have long-term contracts with only a few suppliers of key components. Consequently, we are vulnerable to fluctuations in prices and availability of such raw materials. Factors such as supply and demand, freight costs and transportation availability, inventory levels of brokers and dealers, the level of imports and general economic conditions may affect the price and availability of raw materials. In addition, we use single sources of supply for certain iron castings, motors and other select engineered components that are critical in the manufacturing of our products. From time to time in recent years, we have experienced disruptions to our supply deliveries for raw materials and component parts and may experience further supply disruptions. Any such disruption could have a material adverse effect on our ability to timely meet our commitments to customers and, therefore, our operating results.
Our operating results could be adversely affected by a loss or reduction of business with key customers or consolidation or the vertical integration of our customer base.
We derive revenue from certain key customers, in particular with respect to our oilfield service products and services. The loss or reduction of significant contracts with any of these key customers could result in a material decrease of our future profitability and cash flows. In addition, the consolidation or vertical integration of key customers may result in the loss of certain customer contracts or impact demand or competition for our products. Any changes in such customers’ purchasing practices, or decline in such customers’ financial condition, may have a material adverse impact on our business, results of operations and financial condition. Some of our customers are significantly larger than we are, have greater financial and other resources and also have the ability to purchase products from our competitors. As a result of their size and position in the marketplace, some of our customers have significant purchasing leverage and could cause us to materially reduce the price of our products, which could have a material adverse effect on our revenue and profitability. In addition, in the petroleum product market, lost sales may be difficult to replace due to the relative concentration of the customer base. We are unable to predict what effect consolidation in our customers’ industries may have on prices, capital spending by customers, selling strategies, competitive position, our ability to retain customers or our ability to negotiate favorable agreements with customers.
The loss of, or disruption in, our distribution network could have a negative impact on our abilities to ship products, meet customer demand and otherwise operate our business.
We sell a significant portion of our products through independent distributors and sales representatives. We rely in large part on the orderly operation of this distribution network, which depends on adherence to shipping schedules and effective management. We conduct all of our shipping through independent third parties. Although we believe that our receiving, shipping and distribution process is efficient and well-positioned to support our operations and strategic plans, we cannot provide assurance that we have anticipated all issues or that events beyond our control, such as natural disasters or other catastrophic events, labor disagreements, acquisition of distributors by a competitor, consolidation within our distributor network or shipping problems, will not disrupt our distribution network. If complications arise within a segment of our distribution network, the remaining network may not be able to support the resulting additional distribution demands. Any of these disruptions or complications could negatively impact our revenues and costs.
Our ongoing and expected restructuring plans and other cost savings initiatives may not be as effective as we anticipate, and we may fail to realize the cost savings and increased efficiencies that we expect to result from these actions. Our operating results could be negatively affected by our inability to effectively implement such restructuring plans and other cost savings initiatives.
We continually seek ways to simplify or improve processes, eliminate excess capacity and reduce costs in all areas of our operations, which from time to time includes restructuring activities. We have implemented significant restructuring activities across our global manufacturing, sales and distribution footprint, which include workforce reductions and facility consolidations. From 2015 to 2017, we incurred restructuring charges of approximately $42.9 million across our segments in connection with these initiatives. Costs of future initiatives may be material and the savings associated with them are subject to a variety of risks, including our inability to effectively eliminate duplicative back office overhead and overlapping sales personnel, rationalize manufacturing capacity, synchronize information technology systems, consolidate warehousing and distribution facilities and shift production to more economical facilities. As a result, the contemplated costs to effect these initiatives may materially exceed estimates. The initiatives we are contemplating may require consultation with various employees, labor representatives or regulators, and such consultations may influence the timing, costs and extent of expected savings and may result in the loss of skilled employees in connection with the initiatives.
Although we have considered the impact of local regulations, negotiations with employee representatives and the related costs associated with our restructuring activities, factors beyond the control of management may affect the timing of these projects and therefore affect when savings will be achieved under the plans. There can be no assurance that we will be able to successfully implement these cost savings initiatives in the time frames contemplated (or at all) or that we will realize the projected benefits of these and other restructuring and cost savings initiatives. If we are unable to implement our cost savings initiatives, our business may be adversely affected. Moreover, our continued implementation of cost savings initiatives may have a material adverse effect on our business, results of operations and financial condition.
In addition, as we consolidate facilities and relocate manufacturing processes to lower-cost regions, our success will depend on our ability to continue to meet customer demand and maintain a high level of quality throughout the transition. Failure to adequately meet customer demand or maintain a high level or quality could have a material adverse effect on our business, results of operations and financial condition.
Our success depends on our executive management and other key personnel.
Our future success depends to a significant degree on the skills, experience and efforts of our executive management and other key personnel, many of whom have joined the Company since the KKR Transaction, and their ability to provide us with uninterrupted leadership and direction. The failure to retain our executive officers and other key personnel or a failure to provide adequate succession plans could have an adverse impact. The availability of highly qualified talent is limited, and the competition for talent is robust. However, we provide long-term equity incentives and certain other benefits for our executive officers which provide incentives for them to make a long-term commitment to us. Our future success will also depend on our ability to have adequate succession plans in place and to attract, retain and develop qualified personnel. A failure to efficiently replace executive management members and other key personnel and to attract, retain and develop new qualified personnel could have an adverse effect on our operations and implementation of our strategic plan.
Credit and counterparty risks could harm our business.
The financial condition of our customers could affect our ability to market our products or collect receivables. In addition, financial difficulties faced by our customers as a result of an adverse economic event or other market factors may lead to cancellation or delay of orders. Our customers may suffer financial difficulties that make them unable to pay for a product or solution when payments become due, or they may decide not to pay us, either as a matter of corporate decision-making or in response to changes in local laws and regulations. Although historically not material, we cannot be certain that, in the future, expenses or losses for uncollectible amounts will not have a material adverse effect on our revenues, earnings and cash flows.
If we are unable to develop new products and technologies, our competitive position may be impaired, which could materially and adversely affect our sales and market share.
The markets in which we operate are characterized by changing technologies and introductions of new products and services. Our ability to develop new products based on technological innovation can affect our competitive position and often requires the investment of significant resources. Difficulties or delays in research, development or production of new products and technologies, or failure to gain market acceptance of new products and technologies, may significantly reduce future revenues and materially and adversely affect our competitive position. We cannot assure you that we will have sufficient resources to continue to make the investment required to maintain or increase our market share or that our investments will be successful. If we do not compete successfully, our business, financial condition, results of operations and cash flows could be materially adversely affected.
Cost overruns, delays, penalties or liquidated damages could negatively impact our results, particularly with respect to fixed-price contracts for custom engineered products.
A portion of our revenues and earnings is generated through fixed-price contracts for custom engineered products. Certain of these contracts provide for penalties or liquidated damages for failure to timely perform our obligations under the contract, or require that we, at our expense, correct and remedy to the satisfaction of the other party certain defects. Because substantially all of our custom engineered product contracts are at a fixed price, we face the risk that cost overruns, delays, penalties or liquidated damages may exceed, erode or eliminate our expected profit margin, or cause us to record a loss on our projects.
The risk of non-compliance with U.S. and foreign laws and regulations applicable to our international operations could have a significant impact on our results of operations, financial condition or strategic objectives.
Our global operations subject us to regulation by U.S. federal and state laws and multiple foreign laws, regulations and policies, which could result in conflicting legal requirements. These laws and regulations are complex, change frequently, have become more stringent over time and increase our cost of doing business. These laws and regulations include import and export control, environmental, health and safety regulations, data privacy requirements, international labor laws and work councils and anti-corruption and bribery laws such as the U.S. Foreign Corrupt Practices Act, the U.K. Bribery Act, the U.N. Convention Against Bribery and local laws prohibiting corrupt payments to government officials.
We are subject to the risk that we, our employees, our affiliated entities, contractors, agents or their respective officers, directors, employees and agents may take actions determined to be in violation of any of these laws, for which we might be held responsible, particularly as we expand our operations geographically through organic growth and acquisitions. An actual or alleged violation could result in substantial fines, sanctions, civil or criminal penalties, debarment from government contracts, curtailment of operations in certain jurisdictions, competitive or reputational harm, litigation or regulatory action and other consequences that might adversely affect our results of operations, financial condition or strategic objectives.
U.S. Federal income tax reform could adversely affect us.
On December 22, 2017, the U.S. government enacted comprehensive tax legislation commonly referred to as the Tax Cuts and Jobs Act (“Tax Act”). The Tax Act makes broad and complex changes to the U.S. tax code that will affect 2017, including, but not limited to, (1) requiring a one-time transition tax on certain unrepatriated earnings of foreign subsidiaries that is payable over eight years and (2) bonus depreciation that will allow for full expensing of qualified property.
The Tax Act also establishes new tax laws that will affect 2018, including, but not limited to, (1) reduction of the U.S. federal corporate tax rate; (2) elimination of the corporate alternative minimum tax (“AMT”); (3) the creation of the base erosion anti-abuse tax (“BEAT”), a new minimum tax; (4) a general elimination of U.S. federal income taxes on dividends from foreign subsidiaries; (5) a new provision designed to tax global intangible low-taxed income (“GILTI”), which allows for the possibility of using foreign tax credits (“FTC”) and a deduction of up to 50% to offset the income tax liability (subject to some limitations); (6) a new limitation on deductible interest expense; (7) the repeal of the domestic production activity deduction; (8) limitations on the deductibility of certain executive compensation; (9) limitations on the use of FTCs to reduce the U.S. income tax liability; and (10) limitations on net operating losses (“NOL”) generated after December 31, 2017, to 80% of taxable income.
The SEC staff issued Staff Accounting Bulletin No. 118 (“SAB 118”), which provides guidance on accounting for the tax effects of the Tax Act. SAB 118 provides a measurement period that should not extend beyond one year from the Tax Act enactment date for companies to complete the accounting under ASC 740. In accordance with SAB 118, a company must reflect the income tax effects of those aspects of the Act for which the accounting under ASC 740 is complete. To the extent that a company’s accounting for certain income tax effects of the Tax Act is incomplete but it is able to determine a reasonable estimate, it must record a provisional estimate in the financial statements. If a company cannot determine a provisional estimate to be included in the financial statements, it should continue to apply ASC 740 on the basis of the provisions of the tax laws that were in effect immediately before the enactment of the Tax Act.
In connection with our initial analysis of the impact of the Tax Act, we have recorded a discrete net tax benefit of $95.3 million in the period ending December 31, 2017. This net expense benefit primarily consists of (1) a net expense benefit for the corporate rate reduction of $89.6 million, (2) a net expense for the transition tax of $63.3 million and (3) a corresponding reduction of the repatriation liability under ASC 740-30 (formerly Accounting Principles Board 23) of $69.0 million.
For various reasons we have not completed our accounting for the income tax effects of certain elements of the Tax Act. If we were able to make reasonable estimates of the effects of elements for which our analysis is not yet complete, we recorded provisional adjustments, as described above. If we were not yet able to make reasonable estimates of the impact of certain elements, we have not recorded any adjustments related to those elements and have continued accounting for them in accordance with ASC 740 on the basis of the tax laws in effect before the Tax Act. As we complete our accounting of the income tax effects of the Tax Act, we anticipate that we may record additional charges or benefits at such time as prescribed by ASC 740 and SAB 118, and as further information becomes available regarding the Tax Act, we may make further adjustments to the provisions that have been recorded in our financial statements. We also continue to examine the impact this tax reform legislation may have on our business.
The future impacts of the Tax Act on holders of our common shares are uncertain and could in certain instances be adverse. We urge our stockholders to consult with their legal and tax advisors with respect to any such legislation and the potential tax consequences of investing in our common stock.
A significant portion of our assets consists of goodwill and other intangible assets, the value of which may be reduced if we determine that those assets are impaired.
As a result of the KKR Transaction, we applied the acquisition method of accounting and established a new basis of accounting on July 30, 2013. Goodwill is recorded as the difference, if any, between the aggregate consideration paid for an acquisition and the fair value of the tangible and identifiable intangible assets acquired, liabilities assumed and any non-controlling interest. Intangible assets, including goodwill, are assigned to our reporting units based upon their fair value at the time of acquisition. In accordance with GAAP, goodwill and indefinite-lived intangible assets are evaluated for impairment annually, or more frequently if circumstances indicate impairment may have occurred. In 2017, we recorded an impairment charge related to other intangible assets of $1.6 million primarily within the Industrials segment. In 2016, we recorded an impairment charge related to other intangible assets of $25.3 million primarily within the Industrials segment. In 2015, we recorded a goodwill impairment charge of $343.3 million within the Energy segment and recorded impairment charges related to other intangible assets of $78.1 million within our Industrials, Energy and Medical segments. As of December 31, 2017, the net carrying value of goodwill and other intangible assets, net represented $2,658.8 million, or 58%, of our total assets. A future impairment, if any, could have a material adverse effect to our consolidated financial position or results of operations. See Note 8 “Goodwill and Other Intangible Assets” to our audited consolidated financial statements for additional information related to impairment testing for goodwill and other intangible assets and the associated charges taken.
Our business could suffer if we experience employee work stoppages, union and work council campaigns or other labor difficulties.
As of December 31, 2017, we had approximately 6,400 employees of which approximately 2,050 were located in the United States. Of those employees located outside of the United States, a significant portion are represented by works councils and labor unions, and of those employees located in the United States, approximately 200 are represented by labor unions. Although we believe that our relations with employees are satisfactory and have not experienced any material work stoppages, work stoppages have occurred, and may in the future occur, and we may not be successful in negotiating new collective bargaining agreements. In addition, negotiations with our union employees may (1) result in significant increases in our cost of labor, (2) divert management’s attention away from operating our business or (3) break down and result in the disruption of our operations. The occurrence of any of the preceding conditions could impair our ability to manufacture our products and result in increased costs and/or decreased operating results.
We are a defendant in certain asbestos and silica-related personal injury lawsuits, which could adversely affect our financial condition.
We have been named as a defendant in many asbestos and silica-related personal injury lawsuits. The plaintiffs in these suits allege exposure to asbestos or silica from multiple sources, and typically we are one of approximately 25 or more named defendants. We believe that, given our financial reserves and anticipated insurance recoveries, the pending and potential future lawsuits are not likely to have a material adverse effect on our consolidated financial position, results of operations or liquidity. However, future developments, including, without limitation, potential insolvencies of insurance companies or other defendants, an adverse determination in the Adams County Case (discussed below), or other inability to collect from our historical insurers or indemnitors, could cause a different outcome. In addition, even if any damages payable by us in any individual lawsuit are not material, the aggregate damages and related defense costs could be material and could materially adversely affect our financial condition if we were to receive an adverse judgment in a number of these lawsuits. Accordingly, the resolution of pending or future lawsuits may have a material adverse effect on our consolidated financial position, results of operations or liquidity. See “Business—Legal Proceedings—Asbestos and Silica-Related Litigation.”
Acquisitions and integrating such acquisitions create certain risks and may affect our operating results.
We have acquired businesses in the past and may continue to acquire businesses or assets in the future. The acquisition and integration of businesses or assets involves a number of risks. The core risks are valuation (negotiating a fair price for the business), integration (managing the process of integrating the acquired company’s people, products, technology and other assets to extract the value and synergies projected to be realized in connection with the acquisition), regulation (obtaining necessary regulatory or other government approvals that may be necessary to complete acquisitions) and diligence (identifying undisclosed or unknown liabilities or restrictions that will be assumed in the acquisition).
In addition, acquisitions outside of the United States often involve additional or increased risks including, for example:
| · | managing geographically separated organizations, systems and facilities; |
|---|
| · | integrating personnel with diverse business backgrounds and organizational cultures; |
|---|
| · | complying with non-U.S. regulatory requirements; |
|---|
| · | fluctuations in currency exchange rates; |
|---|
| · | enforcement of intellectual property rights in some non-U.S. countries; |
|---|
| · | difficulty entering new non-U.S. markets due to, among other things, consumer acceptance and business knowledge of these new markets; and |
|---|
| · | general economic and political conditions. |
|---|
The process of integrating operations could cause an interruption of, or loss of momentum in, the activities of one or more of our combined businesses and the possible loss of key personnel. The diversion of management’s attention and any delays or difficulties encountered in connection with acquisitions and the integration of an acquired company’s operations could have an adverse effect on our business, results of operations, financial condition or prospects.
A natural disaster, catastrophe or other event could result in severe property damage, which could adversely affect our operations.
Some of our operations involve risks of, among other things, property damage, which could curtail our operations. For example, disruptions in operations or damage to a manufacturing plant could reduce our ability to produce products and satisfy customer demand. If one of more of our manufacturing facilities are damaged by severe weather or any other disaster, accident, catastrophe or event, our operations could be significantly interrupted. Similar interruptions could result from damage to production or other facilities that provide supplies or other raw materials to our plants or other stoppages arising from factors beyond our control. These interruptions might involve significant damage to, among other things, property, and repairs might take from a week or less for a minor incident to many months for a major interruption.
Information systems failure may disrupt our business and result in financial loss and liability to our customers.
Our business is highly dependent on financial, accounting and other data-processing systems and other communications and information systems, including our enterprise resource planning tools. We process a large number of transactions on a daily basis and rely upon the proper functioning of computer systems. If any of these systems fail, whether caused by fire, other natural disaster, power or telecommunications failure, acts of cyber terrorism or war or otherwise, or they do not function correctly, we could suffer financial loss, business disruption, liability to our customers, regulatory intervention or damage to our reputation. If our systems are unable to accommodate an increasing volume of transactions, our ability to grow could be limited. Although we have backup systems, procedures and capabilities in place, they may also fail or be inadequate. Further, to the extent that we may have customer information in our databases, any unauthorized disclosure of, or access to, such information could result in claims under data protection laws and regulations. If any of these risks materialize, our reputation and our ability to conduct our business may be materially adversely affected.
The nature of our products creates the possibility of significant product liability and warranty claims, which could harm our business.
Customers use some of our products in potentially hazardous applications that can cause injury or loss of life and damage to property, equipment or the environment. In addition, our products are integral to the production process for some end-users and any failure of our products could result in a suspension of operations. Although we maintain quality controls and procedures, we cannot be certain that our products will be completely free from defects. We maintain amounts and types of insurance coverage that we believe are currently adequate and consistent with normal industry practice for a company of our relative size, and we limit our liability by contract wherever possible. However, we cannot guarantee that insurance will be available or adequate to cover all liabilities incurred. We also may not be able to maintain insurance in the future at levels we believe are necessary and at rates we consider reasonable. We may be named as a defendant in product liability or other lawsuits asserting potentially large claims if an accident occurs at a location where our equipment and services have been or are being used.
Environmental compliance costs and liabilities could adversely affect our financial condition.
Our operations and properties are subject to increasingly stringent domestic and foreign laws and regulations relating to environmental protection, including laws and regulations governing air emissions, water discharges, waste management and workplace safety. Under such laws and regulations, we can be subject to substantial fines and sanctions for violations and be required to install costly pollution control equipment or put into effect operational changes to limit pollution emissions or decrease the likelihood of accidental hazardous substance releases.
We use and generate hazardous substances and waste in our manufacturing operations. In addition, many of our current and former properties are, or have been, used for industrial purposes. We have been identified as a potentially responsible party with respect to several sites designated for cleanup under U.S. federal “Superfund” or similar state laws that may impose joint and several liability for cleanup of certain waste sites and for related natural resource damages. An accrued liability on our balance sheet reflects costs that are probable and estimable for our projected financial obligations relating to these matters. If we have underestimated our remaining financial obligations, we may face greater exposure that could have an adverse effect on our financial condition, results of operations or liquidity.
We have experienced, and expect to continue to experience, operating costs to comply with environmental laws and regulations. In addition, new laws and regulations, stricter enforcement of existing laws and regulations, the discovery of previously unknown contamination or the imposition of new cleanup requirements could require us to incur costs or become the basis for new or increased liabilities that could have a material adverse effect on our business, financial condition, results of operations or liquidity.
Third parties may infringe upon our intellectual property or may claim we have infringed their intellectual property, and we may expend significant resources enforcing or defending our rights or suffer competitive injury.
Our success depends in part on the creation, maintenance and protection of our proprietary technology and intellectual property rights. We rely on a combination of patents, trademarks, trade secrets, copyrights, confidentiality provisions, contractual restrictions and licensing arrangements to establish and protect our proprietary rights. Our nondisclosure agreements and confidentiality agreements may not effectively prevent disclosure of our proprietary information, technologies and processes, and may not provide an adequate remedy in the event of breach of such agreements or unauthorized disclosure of such information, and if a competitor lawfully obtains or independently develops our trade secrets, we would have no right to prevent such competitor from using such technology or information to compete with us, either of which could harm our competitive position. Our applications for patent and trademark protection may not be granted, or the claims or scope of such issued patents or registered trademarks may not be sufficiently broad to protect our products. In addition, effective patent, copyright, trademark and trade secret protection may be unavailable or limited for some of our trademarks and patents in some foreign countries. We may be required to spend significant resources to monitor and police our intellectual property rights, and we cannot guarantee that such efforts will be successful in preventing infringement or misappropriation. If we fail to successfully enforce these intellectual property rights, our competitive position could suffer, which could harm our operating results.
Although we make a significant effort to avoid infringing known proprietary rights of third parties, the steps we take to prevent misappropriation, infringement or other violation of the intellectual property of others may not be successful and from time to time we may receive notice that a third party believes that our products may be infringing certain patents, trademarks or other proprietary rights of such third party. Responding to and defending such claims, regardless of their merit, can be costly and time-consuming, can divert management’s attention and other resources, and we may not prevail. Depending on the resolution of such claims, we may be barred from using a specific technology or other rights, may be required to redesign or re-engineer a product which may require significant resources, may be required to enter into licensing arrangements from the third party claiming infringement (which may not be available on commercially reasonable terms, or at all), or may become liable for significant damages.
If any of the foregoing occurs, our ability to compete could be affected or our business, financial condition and results of operations may be materially adversely affected.
We face risks associated with our pension and other postretirement benefit obligations.
We have both funded and unfunded pension and other postretirement benefit plans worldwide. As of December 31, 2017, our projected benefit obligations under our pension and other postretirement benefit plans exceeded the fair value of plan assets by an aggregate of approximately $97.2 million (“unfunded status”), compared to $124.4 million as of December 31, 2016. Estimates for the amount and timing of the future funding obligations of these benefit plans are based on various assumptions. These assumptions include discount rates, rates of compensation increases, expected long-term rates of return on plan assets and expected healthcare cost trend rates. If our assumptions prove incorrect, our funding obligations may increase, which may have a material adverse effect on our financial results.
We have invested the plan assets of our funded benefit plans in various equity and debt securities. A deterioration in the value of plan assets could cause the unfunded status of these benefit plans to increase, thereby increasing our obligation to make additional contributions to these plans. An obligation to make contributions to our benefit plans could reduce the cash available for working capital and other corporate uses, and may have an adverse impact on our operations, financial condition and liquidity.
Risks Related to Our Indebtedness
Our substantial indebtedness could have important adverse consequences and adversely affect our financial condition.
We have a significant amount of indebtedness. As of December 31, 2017, we had total indebtedness of $2,040.2 million, and we had availability under the Revolving Credit Facility and the Receivables Financing Agreement of $352.6 million and $66.8 million, respectively. Our high level of debt could have important consequences, including: making it more difficult for us to satisfy our obligations with respect to our debt; limiting our ability to obtain additional financing to fund future working capital, capital expenditures, investments or acquisitions, or other general corporate requirements; requiring a substantial portion of our cash flows to be dedicated to debt service payments instead of other purposes, thereby reducing the amount of cash flows available for working capital, capital expenditures, investments or acquisitions and other general corporate purposes; increasing our vulnerability to adverse changes in general economic, industry and competitive conditions; exposing us to the risk of increased interest rates as certain of our borrowings, including borrowings under the Senior Secured Credit Facilities, are at variable rates of interest; limiting our flexibility in planning for and reacting to changes in the industries in which we compete; placing us at a disadvantage compared to other, less leveraged competitors; increasing our cost of borrowing; and hampering our ability to execute on our growth strategy. For a complete description of the Company’s credit facilities and definitions of capitalized terms used in this section, see Note 10 “Debt” to our audited consolidated financial statements included elsewhere in this Form 10-K.
We may not be able to generate sufficient cash to service all of our indebtedness, and may be forced to take other actions to satisfy our obligations under our indebtedness, which may not be successful.
Our ability to make scheduled payments on, or refinance, our debt obligations depends on our financial condition and operating performance, which are subject to prevailing economic, industry and competitive conditions and to certain financial, business, legislative, regulatory and other factors beyond our control (as well as and including those factors discussed under “Risks Related to Our Business” above). We may be unable to maintain a level of cash flow from operating activities sufficient to permit us to pay the principal, premium, if any, and interest on our indebtedness.
If our cash flow and capital resources are insufficient to fund our debt service obligations, we could face substantial liquidity problems and could be forced to reduce or delay investments and capital expenditures or to dispose of material assets or operations, seek additional debt or equity capital, or restructure or refinance our indebtedness. We may not be able to implement any such alternative measures on commercially reasonable terms or at all and, even if successful, those alternative actions may not allow us to meet our scheduled debt service obligations.
If we cannot make scheduled payments on our debt, we will be in default and the lenders under the Revolving Credit Facility could terminate their commitments to loan money, and our secured lenders (including the lenders under the Senior Secured Credit Facilities) could foreclose against the assets securing their borrowings and we could be forced into bankruptcy or liquidation.
Despite our level of indebtedness, we and our subsidiaries may still be able to incur substantially more debt, including off-balance sheet financing, contractual obligations and general and commercial liabilities. This could further exacerbate the risks to our financial condition described above.
We and our subsidiaries may be able to incur significant additional indebtedness in the future, including off-balance sheet financings, contractual obligations and general and commercial liabilities. Although the credit agreement governing the Senior Secured Credit Facilities contains restrictions on the incurrence of additional indebtedness, these restrictions are subject to a number of qualifications and exceptions, and the additional indebtedness incurred in compliance with these restrictions could be substantial. In addition, we can increase the borrowing availability under the Senior Secured Credit Facilities by up to $250 million in the form of additional commitments under the Revolving Credit Facility and/or incremental term loans plus an additional amount so long as we do not exceed a specified senior secured leverage ratio. We also can incur additional secured indebtedness under the Term Loan Facilities if certain specified conditions are met under the credit agreement governing the Term Loan Facilities. If new debt is added to our current debt levels, the related risks that we now face could intensify. For a complete description of the Company’s credit facilities and definitions of capitalized terms used in this section, see Note 10 “Debt” to our audited consolidated financial statements included elsewhere in this Form 10-K.
The terms of the credit agreement governing the Senior Secured Credit Facilities may restrict our current and future operations, particularly our ability to respond to changes or to take certain actions.
The credit agreement governing the Senior Secured Credit Facilities contains a number of restrictive covenants that impose significant operating and financial restrictions on us and may limit our ability to engage in acts that may be in our best interest, including restrictions on our ability to: incur additional indebtedness and guarantee indebtedness; pay dividends, make other distributions in respect of, or repurchase or redeem capital stock; prepay, redeem or repurchase certain debt; make loans, investments and other restricted payments; sell or otherwise dispose of assets; incur liens; enter into transactions with affiliates; enter into agreements restricting our subsidiaries’ ability to pay dividends; consolidate, merge or sell all or substantially all of our assets; make needed capital expenditures; make strategic acquisitions, investments or enter into joint ventures; plan for or react to market conditions or otherwise execute our business strategies; and engage in business activities, including future opportunities, that may be in our interest.
A breach of the covenants under the credit agreement governing the Senior Secured Credit Facilities could result in an event of default under the applicable indebtedness. Such a default may allow the creditors to accelerate the related debt principal and/or related interest payments and may result in the acceleration of any other debt to which a cross-acceleration or cross-default provision applies. In addition, an event of default under the credit agreement governing our Senior Secured Credit Facilities would permit the lenders under our Revolving Credit Facility to terminate all commitments to extend further credit under that facility. Furthermore, if we were unable to repay the amounts due and payable under our Senior Secured Credit Facilities, those lenders could proceed against the collateral granted to them to secure that indebtedness. In the event our lenders or noteholders accelerate the repayment of our borrowings and/or interest, we and our subsidiaries may not have sufficient assets to repay that indebtedness.
Our variable rate indebtedness subjects us to interest rate risk, which could cause our debt service obligations to increase significantly.
Borrowings under our Senior Secured Credit Facilities and our Receivables Financing Agreement are at variable rates of interest and expose us to interest rate risk. If interest rates increase, our debt service obligations on the variable rate indebtedness will increase even though the amount borrowed will remain the same, and our net income and cash flows, including cash available for servicing our indebtedness, will correspondingly decrease.
We utilize derivative financial instruments to reduce our exposure to market risks from changes in interest rates on our variable rate indebtedness and we will be exposed to risks related to counterparty credit worthiness or non-performance of these instruments.
We have entered into pay-fixed interest rate swaps instruments to limit our exposure to changes in variable interest rates. Such instruments will result in economic losses should interest rates not rise above the pay-fixed interest rate in the derivative contracts. We will be exposed to credit-related losses which could impact the results of operations in the event of fluctuations in the fair value of the interest rate swaps due to a change in the credit worthiness or non-performance by the counterparties to the interest rate swaps. See Note 16 “Hedging Activities, Derivative Instruments and Credit Risk” to our audited consolidated financial statements included elsewhere in this Form 10-K.
If the financial institutions that are part of the syndicate of our Revolving Credit Facility fail to extend credit under our facility or reduce the borrowing base under our Revolving Credit Facility, our liquidity and results of operations may be adversely affected.
We have access to capital through our Revolving Credit Facility, which is part of our Senior Secured Credit Facilities. Each financial institution which is part of the syndicate for our Revolving Credit Facility is responsible on a several, but not joint, basis for providing a portion of the loans to be made under our facility. If any participant or group of participants with a significant portion of the commitments in our Revolving Credit Facility fails to satisfy its or their respective obligations to extend credit under the facility and we are unable to find a replacement for such participant or participants on a timely basis (if at all), our liquidity may be adversely affected.
Item 1B. UNRESOLVED STAFF COMMENTS
| --- | --- |
None
Item 2. PROPERTIES
| --- | --- |
Our corporate headquarters is a leased facility located at 222 East Erie Street, Milwaukee, Wisconsin 53202. The number of significant properties used by each of our segments is summarized by segment, type and geographic location in the tables below.
| Type of Significant Property | ||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Manufacturing | Warehouse | Other | Total | |||||||||||||
| Industrials | ||||||||||||||||
| Americas | 5 | 1 | 0 | 6 | ||||||||||||
| EMEA | 9 | 1 | 15 | 25 | ||||||||||||
| APAC | 1 | 1 | 8 | 10 | ||||||||||||
| Industrials Total | 15 | 3 | 23 | 41 | ||||||||||||
| Energy | ||||||||||||||||
| Americas | 8 | 2 | 9 | 19 | ||||||||||||
| EMEA | 5 | 0 | 2 | 7 | ||||||||||||
| APAC | 2 | 0 | 2 | 4 | ||||||||||||
| Energy Total | 15 | 2 | 13 | 30 | ||||||||||||
| Medical | ||||||||||||||||
| Americas | 3 | 0 | 0 | 3 | ||||||||||||
| EMEA | 4 | 0 | 1 | 5 | ||||||||||||
| APAC | 1 | 0 | 0 | 1 | ||||||||||||
| Medical Total | 8 | 0 | 1 | 9 | ||||||||||||
| Total (All Segments) | ||||||||||||||||
| Americas | 16 | 3 | 9 | 28 | ||||||||||||
| EMEA | 18 | 1 | 18 | 37 | ||||||||||||
| APAC | 4 | 1 | 10 | 15 | ||||||||||||
| Company Total(1) | 38 | 5 | 37 | 80 |
| (1) | Two facilities are shared between our segments and each is counted once, in the Industrials segment, to avoid double counting. |
|---|
We believe that our properties, taken as a whole, are in good operating condition and are suitable for our business operations.
Item 3. LEGAL PROCEEDINGS
| --- | --- |
We are a party to various legal proceedings, lawsuits and administrative actions, which are of an ordinary or routine nature for a company of our size and in our sector. We believe that such proceedings, lawsuits, and administrative actions will not materially adversely affect our operations, financial condition, liquidity or competitive position. A more detailed discussion of certain of these proceedings, lawsuits, and administrative actions is set forth below.
Environmental Matters
We are subject to numerous federal, state, local and foreign laws and regulations relating to the storage, handling, emission and disposal of materials and discharge of materials into the environment. We believe that our existing environmental control procedures are adequate and we have no current plans for substantial capital expenditures in this area. We have an environmental policy that confirms our commitment to a clean environment and compliance with environmental laws. We have an active environmental management program aimed at complying with existing environmental regulations and reducing the generation of pollutants in the manufacturing processes. We are also subject to laws concerning the cleanup of hazardous substances and wastes, such as the U.S. federal “Superfund” and similar state laws that impose liability for cleanup of certain waste sites and for related natural resource damages. We have been identified as a potentially responsible party with respect to several sites designated for cleanup under the “Superfund” or similar state laws.
Asbestos and Silica-Related Litigation
We have been named as a defendant in many asbestos-related and silica-related personal injury lawsuits. The plaintiffs in these suits allege exposure to asbestos or silica from multiple sources and typically we are one of approximately 25 or more named defendants. Our predecessors sometimes manufactured, distributed and/or sold products allegedly at issue in these pending asbestos and silica-related lawsuits (the “Products”). However, neither we nor our predecessors ever mined, manufactured, mixed, produced or distributed asbestos fiber or silica sand, the materials that allegedly caused the injury underlying the lawsuits. Moreover, the asbestos-containing components of the Products, if any, were enclosed within the subject Products.
Although we have never mined, manufactured, mixed, produced or distributed asbestos fiber or silica, many of the companies that did engage in such activities or produced such products are no longer in operation. This has led to law firms seeking potential alternative companies to name in lawsuits where there has been an asbestos or silica related injury. However, in our opinion, based on our experience to date, the substantial majority of the plaintiffs have not suffered an injury for which we bear responsibility.
We believe that the pending and future asbestos and silica-related lawsuits are not likely to, in the aggregate, have a material adverse effect on its consolidated financial position, results of operations or liquidity, based on: our anticipated insurance and indemnification rights to address the risks of such matters; the limited potential asbestos exposure from the Products described above; our opinion, based on our experience to date, that the vast majority of plaintiffs are not impaired with a disease attributable to alleged exposure to asbestos or silica from or relating to the Products or for which we otherwise bear responsibility; various potential defenses available to us with respect to such matters; and our prior disposition of comparable matters. However, inherent uncertainties of litigation and future developments, including, without limitation, potential insolvencies of insurance companies or other defendants, an adverse determination in the Adams County Case (discussed below), or other inability to collect from our historical insurers or indemnitors, could cause a different outcome. While the outcome of legal proceedings is inherently uncertain, based on presently known facts, experience and circumstances, we believe that the amounts accrued on the Company’s balance sheet are adequate and that the liabilities arising from the asbestos and silica-related personal injury lawsuits will not have a material adverse effect on the Company’s consolidated financial position, results of operations or liquidity. We have accrued liabilities and other liabilities on our consolidated balance sheet to include a total litigation reserve of $105.6 million and $108.5 million as of December 31, 2017 and December 31, 2016 respectively, with respect to potential liability arising from our asbestos-related litigation. Asbestos-related defense costs are excluded from the asbestos claims liability and are recorded separately as an operating expense as services are incurred. We currently expect to continue to incur significant asbestos-related defense costs. In the event of unexpected future developments, it is possible that the ultimate resolution of these matters may be material to the Company’s consolidated financial position, results of operation or liquidity, and defense costs may be material. However, at this time, based on presently available information, we view this possibility as remote.
We have entered into a series of agreements with certain of the Company’s or the Company’s predecessors’ legacy insurers and certain potential indemnitors to secure insurance coverage and/or reimbursement for the costs associated with the asbestos and silica-related lawsuits filed against us. We have also pursued litigation against certain insurers or indemnitors where necessary. We have an insurance recovery receivable for probable asbestos related recoveries of approximately $100.4 million and $97.3 million, which is included on our consolidated balance sheet as of December 31, 2017 and December 31, 2016, respectively.
The largest such recent action, Gardner Denver, Inc. v. Certain Underwriters at Lloyd’s, London, et al., was filed on July 9, 2010, in the Eighth Judicial Circuit, Adams County, Illinois, as case number 10-L-48 (the “Adams County Case”). In the lawsuit, we seek, among other things, to require certain excess insurer defendants to honor their insurance policy obligations to us, including payment in whole or in part of the costs associated with the asbestos-related lawsuits filed against us. In October 2011, we reached a settlement with one of the insurer defendants, which had issued both primary and excess policies, for approximately the amount of such defendant’s policies which were subject to the lawsuit. Since then, the case has been proceeding through the discovery and motions process with the remaining insurer defendants. On January 29, 2016, we prevailed on the first phase of that discovery and motions process (“Phase I”). Specifically, the Court in the Adams County Case ruled that we have rights under all of the policies in the case, subject to their terms and conditions, even though the policies were sold to our former owners rather than to the Company itself. On June 9, 2016, the Court denied a motion by several of the insurers who sought permission to appeal the Phase I ruling now rather than waiting until the end of the whole case as is normally required. The case has now begun proceeding through the discovery and motions process regarding the remaining issues in dispute.
A majority of our expected future recoveries of the costs associated with the asbestos-related lawsuits are the subject of the Adams County Case.
The amounts we recorded for asbestos-related liabilities and insurance recoveries are based on currently available information and assumptions that we believe are reasonable based on our evaluation of relevant factors with input from a third party actuarial expert. Our actual liabilities or insurance recoveries could be higher or lower than those recorded if actual results vary significantly from the assumptions. There are a number of key variables and assumptions including the number and type of new claims to be filed each year, the resolution or outcome of these claims, the average cost of resolution of each new claim, the amount of insurance available, allocation methodologies, the contractual terms with each insurer with whom we have reached settlements, the resolution of coverage issues with other excess insurance carriers with whom we have not yet achieved settlements and the solvency risk with respect to our insurance carriers. Other factors that may affect our future liability include uncertainties surrounding the litigation process from jurisdiction to jurisdiction and from case to case, legal rulings that may be made by state and federal courts and the passage of state or federal legislation. We make the necessary adjustments for our asbestos liability and corresponding insurance recoveries on an annual basis unless facts or circumstances warrant assessment as of an interim date.
Environmental Liabilities
We have been identified as a potentially responsible party (“PRP”) with respect to several sites designated for cleanup under U.S. federal “Superfund” or similar state laws that impose liability for cleanup of certain waste sites and for related natural resource damages. Persons potentially liable for such costs and damages generally include the site owner or operator and persons that disposed or arranged for the disposal of hazardous substances found at those sites. Although these laws impose joint and several liability on PRPs, in application, the PRPs typically allocate the investigation and cleanup costs based upon the volume of waste contributed by each PRP. Based on currently available information, our Company was only a small contributor to these waste sites, and we have, or are attempting to negotiate, de minimis settlements for our cleanup. The cleanup of the remaining sites is substantially complete and our future obligations entail a share of the sites’ ongoing operating and maintenance expense. We are also addressing four on-site cleanups for which we are the primary responsible party. Three of these cleanup sites are in the operation and maintenance stage and one is in the implementation stage.
We have an accrued liability on our consolidated balance sheet of $7.5 million and $7.6 million as of December 31, 2017 and December 31, 2016, respectively, to the extent costs are known or can be reasonably estimated for our remaining financial obligations for the environmental matters discussed above and which does not anticipate that any of these matters will result in material additional costs beyond amounts accrued. Based upon consideration of currently available information, we do not anticipate any material adverse effect on our results of operations, financial condition, liquidity or competitive position as a result of compliance with federal, state, local or foreign environmental laws or regulations, or cleanup costs relating to these matters.
Item 4. MINE SAFETY DISCLOSURES
| --- | --- |
Not Applicable
PART II
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
| --- | --- |
Market Information
Our common stock, $0.01 par value per share, began trading on the New York Stock Exchange (“NYSE”) under the symbol “GDI” on May 12, 2017. Prior to that time, there was no public market for our common stock. As of January 31, 2018, there were 216 holders of record of our common stock. This stockholder figure does not include a substantially greater number of holders whose shares are held of record by banks, brokers, and other financial institutions. The following table sets forth the high and low intra-day sale prices per share for our common stock as reported on the NYSE for the periods indicated.
| Stock Price | ||||||||
|---|---|---|---|---|---|---|---|---|
| High | Low | |||||||
| Fiscal year ended December 31, 2017: | ||||||||
| Second quarter ended June 30, 2017 (beginning on May 12, 2017) | $ | 24.55 | $ | 19.91 | ||||
| Third quarter ended September 30, 2017 | $ | 27.65 | $ | 20.55 | ||||
| Fourth quarter ended December 31, 2017 | $ | 34.63 | $ | 26.10 |
Dividend Policy
We do not intend to pay cash dividends on our common stock in the foreseeable future. We may, in the future, decide to pay dividends on our common stock. Any future determination to pay dividends will be at the discretion of our board of directors and will depend on, among other things, our results of operations, cash requirements, financial condition, contractual restrictions contained in current or future financing instruments and other factors that our board of directors deem relevant. Additionally, our ability to pay dividends is limited by restrictions on the ability of our operating subsidiaries to make distributions, including restrictions under the terms of the agreements governing our debt. We did not declare or pay dividends to the holders of our common stock in the years ended December 31, 2017 and 2016.
Company Purchases
The following table contains detail related to the repurchase of our common stock based on the date of trade during the quarter ended December 31, 2017. The repurchases relate to purchases of our common stock as a result of net exercises of stock options and have been recorded as “Treasury stock at cost” in the Consolidated Balance Sheet.
| Period | Total Number of Shares Purchased(1) | Average Price Paid Per Share(2) | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | Maximum Approximate Dollar Value of Shares that May Yet Be Purchased Under the Plans or Programs | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| October 1, 2017 - October 31, 2017 | 9,469 | $ | 29.21 | - | - | |||||||||||
| November 1, 2017 - November 30, 2017 | 24,297 | $ | 27.23 | - | - | |||||||||||
| December 1, 2017 - December 31, 2017 | - | $ | - | - | - |
| (1) | Includes 9,469 and 24,297 shares for the periods from October 1, 2017 through October 31, 2017 and November 1, 2017 through November 30, 2017, respectively, repurchased in connection with net exercises of stock options. |
|---|
| (2) | The average price paid per share includes brokerage commissions. |
|---|
Item 6. SELECTED FINANCIAL DATA
| --- | --- |
Set forth below is our selected consolidated financial data as of the dates and for the periods indicated. The selected consolidated financial data as of December 31, 2017 and 2016 and for the fiscal years ended December 31, 2017, 2016, and 2015 have been derived from our audited consolidated financial statements and related notes thereto included elsewhere in this Form 10-K. The selected consolidated financial data as of December 31, 2015, December 31, 2014, and for the period from July 30, 2013 through December 31, 2013 have been derived from our consolidated financial statements and related notes thereto not included in this Form 10-K. The selected historical consolidated financial data as of July 29, 2013 and for the period from January 1, 2013 through July 29, 2013 have been derived from the consolidated financial statements and related notes thereto of Gardner Denver, Inc., our “accounting predecessor,” not included in this Form 10-K.
Selected historical consolidated financial data are presented for two periods: Predecessor and Successor, which relate to the period preceding the KKR Transaction and the period succeeding the KKR Transaction, respectively. The Company refers to the operations of our accounting predecessor and its subsidiaries for the Predecessor period and the operations of Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.) and subsidiaries for the Successor periods. The financial Successor and Predecessor financial statements are not comparable as a result of the application of acquisition accounting and changes in the Company’s capital structure resulting from the KKR Transaction.
The selected historical consolidated financial data set forth below should be read in conjunction with, and are qualified by reference to, “Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations” and our consolidated financial statements and related notes thereto included elsewhere in this Form 10-K.
| Successor | Predecessor | |||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| (in millions, except per share amounts) | Year Ended December 31, 2017 | Year Ended December 31, 2016 | Year Ended December 31, 2015 | Year Ended December 31, 2014 | July 30, 2013 – December 31, 2013 | January 1, 2013 – July 29, 2013 | ||||||||||||||||||
| Consolidated Statements of Operations: | ||||||||||||||||||||||||
| Revenues | $ | 2,375.4 | $ | 1,939.4 | $ | 2,126.9 | $ | 2,570.0 | $ | 978.4 | $ | 1,231.6 | ||||||||||||
| Cost of sales | 1,477.5 | 1,222.7 | 1,347.8 | 1,633.2 | 666.5 | 799.5 | ||||||||||||||||||
| Gross profit | 897.9 | 716.7 | 779.1 | 936.8 | 311.9 | 432.1 | ||||||||||||||||||
| Selling and administrative expenses | 446.6 | 414.3 | 427.0 | 476.0 | 193.7 | 263.8 | ||||||||||||||||||
| Amortization of intangible assets | 118.9 | 124.2 | 115.4 | 113.3 | 111.9 | 9.9 | ||||||||||||||||||
| Impairment of goodwill | - | - | 343.3 | 220.6 | - | - | ||||||||||||||||||
| Impairment of other intangible assets | 1.6 | 25.3 | 78.1 | 14.4 | - | - | ||||||||||||||||||
| Other operating expense, net | 222.1 | 48.6 | 20.7 | 64.3 | 76.9 | 46.5 | ||||||||||||||||||
| Operating income (loss) | 108.7 | 104.3 | (205.4 | ) | 48.2 | (70.6 | ) | 111.9 | ||||||||||||||||
| Interest expense | 140.7 | 170.3 | 162.9 | 164.4 | 65.4 | 6.6 | ||||||||||||||||||
| Loss on extinguishment of debt | 84.5 | - | - | - | - | - | ||||||||||||||||||
| Other income, net | (3.8 | ) | (2.8 | ) | (1.6 | ) | (3.3 | ) | (2.1 | ) | (2.0 | ) | ||||||||||||
| (Loss) income before income taxes | (112.7 | ) | (63.2 | ) | (366.7 | ) | (112.9 | ) | (133.9 | ) | 107.3 | |||||||||||||
| (Benefit) provision for income taxes | (131.2 | ) | (31.9 | ) | (14.7 | ) | 23.0 | (59.4 | ) | 35.4 | ||||||||||||||
| Net income (loss) | 18.5 | (31.3 | ) | (352.0 | ) | (135.9 | ) | (74.5 | ) | 71.9 | ||||||||||||||
| Less: Net income (loss) attributable to noncontrolling interest | 0.1 | 5.3 | (0.8 | ) | (0.9 | ) | (1.1 | ) | 0.7 | |||||||||||||||
| Net income (loss) attributable to Gardner Denver Holdings, Inc. | $ | 18.4 | $ | (36.6 | ) | $ | (351.2 | ) | $ | (135.0 | ) | $ | (73.4 | ) | $ | 71.2 | ||||||||
| Earnings (Loss) per share, basic | $ | 0.10 | $ | (0.25 | ) | $ | (2.35 | ) | $ | (0.91 | ) | |||||||||||||
| Earnings (Loss) per share, diluted | $ | 0.10 | $ | (0.25 | ) | $ | (2.35 | ) | $ | (0.91 | ) | |||||||||||||
| Weighted average shares, basic | 182.2 | 149.2 | 149.6 | 148.9 | ||||||||||||||||||||
| Weighted average shares, diluted | 188.4 | 149.2 | 149.6 | 148.9 | ||||||||||||||||||||
| Statement of Cash Flow Data: | ||||||||||||||||||||||||
| Cash flows - operating activities | $ | 200.5 | $ | 165.6 | $ | 172.1 | $ | 141.8 | $ | (15.2 | ) | $ | 77.4 | |||||||||||
| Cash flows - investing activities | (60.8 | ) | (82.1 | ) | (84.0 | ) | (155.4 | ) | (3,806.7 | ) | (15.1 | ) | ||||||||||||
| Cash flows - financing activities | (17.4 | ) | (43.0 | ) | (35.0 | ) | (3.7 | ) | 3,929.5 | (205.0 | ) | |||||||||||||
| Balance Sheet Data (at period end): | ||||||||||||||||||||||||
| Cash and cash equivalents | $ | 393.3 | $ | 255.8 | $ | 228.3 | $ | 184.2 | $ | 218.7 | $ | 107.4 | ||||||||||||
| Total assets | 4,621.2 | 4,316.0 | 4,462.0 | 5,107.1 | 5,420.7 | 2,376.4 | ||||||||||||||||||
| Total liabilities | 3,144.4 | 4,044.2 | 4,056.5 | 4,218.5 | 4,226.4 | 847.3 | ||||||||||||||||||
| Total stockholders’ equity | 1,476.8 | 271.8 | 405.5 | 888.6 | 1,194.3 | 1,529.1 | ||||||||||||||||||
| Other Financial Data (unaudited): | ||||||||||||||||||||||||
| Adjusted EBITDA(1) | $ | 561.5 | $ | 400.7 | $ | 418.9 | ||||||||||||||||||
| Adjusted net income(1) | 249.3 | 133.6 | 128.1 | |||||||||||||||||||||
| Capital expenditures | 56.8 | 74.4 | 71.0 | |||||||||||||||||||||
| Free cash flow(1) | 143.7 | 91.2 | 101.1 |
| (1) | We report our financial results in accordance with GAAP. To supplement this information, we also use the following measures in this Form 10-K: “Adjusted EBITDA,” “Adjusted Net Income” and “Free Cash Flow.” Management believes that Adjusted EBITDA and Adjusted Net Income are helpful supplemental measures to assist us and investors in evaluating our operating results as they exclude certain items whose fluctuation from period to period do not necessarily correspond to changes in the operations of our business. Adjusted EBITDA represents net income (loss) before interest, taxes, depreciation and amortization, as further adjusted to exclude certain non-cash, non-recurring and other adjustment items. We believe that the adjustments applied in presenting Adjusted EBITDA are appropriate to provide additional information to investors about certain material non-cash items and about non-recurring items that we do not expect to continue at the same level in the future. Adjusted Net Income is defined as net income (loss) including interest, depreciation and amortization of non-acquisition related intangible assets and excluding other items used to calculate Adjusted EBITDA and further adjusted for the tax effect of these exclusions. |
|---|
We use Free Cash Flow to review the liquidity of our operations. We measure Free Cash Flow as cash flows from operating activities less capital expenditures. We believe Free Cash Flow is a useful supplemental financial measure for us and investors in assessing our ability to pursue business opportunities and investments and to service our debt. Free Cash Flow is not a measure of our liquidity under GAAP and should not be considered as an alternative to cash flows from operating activities.
As a result, we and our board of directors regularly use these measures as tools in evaluating our operating and financial performance and in establishing discretionary annual compensation. Such measures are provided in addition to, and should not be considered to be a substitute for, or superior to, the comparable measure under GAAP. In addition, we believe that Adjusted EBITDA, Adjusted Net Income and Free Cash Flow are frequently used by investors, analysts and other interested parties in the evaluation of issuers, many of which also present Adjusted EBITDA, Adjusted Net Income and Free Cash Flow when reporting their results in an effort to facilitate an understanding of their operating and financial results and liquidity.
Adjusted EBITDA, Adjusted Net Income and Free Cash Flow should not be considered as alternatives to net income (loss) or other performance measures calculated in accordance with GAAP, or as alternatives to cash flow from operating activities as a measure of our liquidity. Adjusted EBITDA, Adjusted Net Income and Free Cash Flow have limitations as analytical tools, and you should not consider such measures either in isolation or as substitutes for analyzing our results as reported under GAAP.
Set forth below are the reconciliations of net income (loss) to Adjusted EBITDA and Adjusted Net Income and cash flows from operating activities to Free Cash Flow.
| Year Ended December 31, | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| (in millions) | 2017 | 2016 | 2015 | |||||||||
| Net Income (Loss) | $ | 18.5 | $ | (31.3 | ) | $ | (352.0 | ) | ||||
| Plus: | ||||||||||||
| Interest expense | 140.7 | 170.3 | 162.9 | |||||||||
| Benefit for income taxes | (131.2 | ) | (31.9 | ) | (14.7 | ) | ||||||
| Depreciation expense | 54.9 | 48.5 | 47.6 | |||||||||
| Amortization expense(a) | 118.9 | 124.2 | 115.4 | |||||||||
| Impairment of goodwill and other intangible assets(b) | 1.6 | 25.3 | 421.4 | |||||||||
| Sponsor fees and expenses(c) | 17.3 | 4.8 | 4.6 | |||||||||
| Restructuring and related business transformation costs(d) | 24.7 | 78.7 | 31.4 | |||||||||
| Acquisition related expenses and non-cash charges(e) | 4.1 | 4.3 | 4.8 | |||||||||
| Environmental remediation loss reserve(f) | 0.9 | 5.6 | - | |||||||||
| Expenses related to public stock offerings(g) | 4.1 | - | - | |||||||||
| Establish public company financial reporting compliance(h) | 8.1 | 0.2 | - | |||||||||
| Stock-based compensation(i) | 194.2 | - | - | |||||||||
| Loss on extinguishment of debt(j) | 84.5 | - | - | |||||||||
| Foreign currency transaction losses (gains), net | 9.3 | (5.9 | ) | 1.1 | ||||||||
| Other adjustments(k) | 10.9 | 7.9 | (3.6 | ) | ||||||||
| Adjusted EBITDA | $ | 561.5 | $ | 400.7 | $ | 418.9 | ||||||
| Minus: | ||||||||||||
| Interest expense | $ | 140.7 | $ | 170.3 | $ | 162.9 | ||||||
| Income tax provision, as adjusted(l) | 105.4 | 34.7 | 71.9 | |||||||||
| Depreciation expense | 54.9 | 48.5 | 47.6 | |||||||||
| Amortization of non-acquisition related intangible assets | 11.2 | 13.6 | 8.4 | |||||||||
| Adjusted Net Income | $ | 249.3 | $ | 133.6 | $ | 128.1 | ||||||
| Free Cash Flow | ||||||||||||
| Cash flows - operating activities | $ | 200.5 | $ | 165.6 | $ | 172.1 | ||||||
| Minus: | ||||||||||||
| Capital Expenditures | 56.8 | 74.4 | 71.0 | |||||||||
| Free Cash Flow | $ | 143.7 | $ | 91.2 | $ | 101.1 |
| (a) | Represents $107.7 million, $110.6 million and $107.0 million of amortization of intangible assets arising from the KKR Transaction and other acquisitions (customer relationships and trademarks) and $11.2 million, $13.6 million, and $8.4 million of amortization of non-acquisition related intangible assets, in each case for the years ended December 31, 2017, 2016 and 2015, respectively. |
|---|
| (b) | Represents non-cash charges for impairment of goodwill and other intangible assets. |
|---|
| (c) | Represents management fees and expenses paid to our Sponsor, including a monitoring agreement termination fee of $16.2 million paid in 2017 concurrent with our initial public offering on May 12, 2017. |
|---|
| (d) | Restructuring and related business transformation costs consist of the following. |
|---|
| Year Ended December 31, | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| (in millions) | 2017 | 2016 | 2015 | |||||||||
| Restructuring charges | $ | 5.3 | $ | 32.9 | $ | 4.7 | ||||||
| Severance, sign-on, relocation and executive search costs | 3.5 | 22.4 | 18.4 | |||||||||
| Facility reorganization, relocation and other costs | 5.3 | 8.7 | 1.6 | |||||||||
| Information technology infrastructure transformation | 5.2 | 2.3 | - | |||||||||
| Losses (gains) on asset and business disposals | 0.8 | 0.1 | (4.5 | ) | ||||||||
| Consultant and other advisor fees | 1.7 | 9.7 | 10.1 | |||||||||
| Other, net | 2.9 | 2.6 | 1.1 | |||||||||
| Total restructuring and related business transformation costs | $ | 24.7 | $ | 78.7 | $ | 31.4 |
| (e) | Represents costs associated with successful and/or abandoned acquisitions, including third-party expenses, post-closure integration costs and non-cash charges and credits arising from fair value purchase accounting adjustments. |
|---|
| (f) | Represents estimated environmental remediation costs and losses relating to a former production facility. |
|---|
| (g) | Represents certain expenses related to the Company’s initial public offering and subsequent secondary offerings. |
|---|
| (h) | Represents third party expenses to comply with the requirements of Sarbanes-Oxley in 2018 and the accelerated adoption of the new revenue recognition standard (ASC 606 – Revenue from Contracts with Customers) in the first quarter of 2018, one year ahead of the adoption date for a private company. These expenses were previously included in “Expenses related to the initial public offering” and prior periods have been restated to conform to current period presentation. |
|---|
| (i) | Represents stock-based compensation expense recognized for stock options outstanding ($77.6 million) and DSUs granted to employees at the date of the initial public offering ($97.4 million) under the 2013 Stock Incentive Plan, and employer taxes related to DSUs granted to employees at the date of the initial public offering ($19.2 million). |
|---|
| (j) | Represents losses on extinguishment of debt recognized on the redemption of the senior notes and a portion of the Original Dollar Term Loan Facility with proceeds from the initial public offering in May 2017 ($50.4 million) and in connection with the refinancing of the Original Dollar Term Loan Facility and the Original Euro Term Loan Facility in August 2017 ($34.1 million). |
|---|
| (k) | Includes (i) non-cash impact of net LIFO reserve adjustments, (ii) effects of amortization of prior service costs and amortization of gains in pension and other postretirement benefits (OPEB) expense, (iii) certain legal and compliance costs and (iv) other miscellaneous adjustments. Formerly included “Foreign currency transaction losses (gains), net”, the years ended December 31 2016 and 2015 have been restated to conform to the year ended December 31, 2017 presentation. |
|---|
Represents our income tax provision adjusted for the tax effect of pre-tax items excluded from Adjusted Net Income and the removal of the applicable discrete tax items. The tax effect of pre-tax items excluded from Adjusted Net Income is computed using the statutory tax rate related to the jurisdiction that was impacted by the adjustment after taking into account the impact of permanent differences and valuation allowances. Discrete tax items include changes in tax laws or rates, changes in uncertain tax positions relating to prior years and changes in valuation allowances. All impacts relating the Tax Cuts and Jobs Act of 2017 have been included as an adjustment on the ‘Tax law change” line of the table below.
The income tax provision, as adjusted for each of the periods presented below consists of the following.
| Year Ended December 31, | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| (in millions) | 2017 | 2016 | 2015 | |||||||||
| Benefit for income taxes | $ | (131.2 | ) | $ | (31.9 | ) | $ | (14.7 | ) | |||
| Tax impact of pre-tax income adjustments | 139.3 | 71.8 | 76.7 | |||||||||
| Tax law change | 95.3 | - | - | |||||||||
| Discrete tax items | 2.0 | (5.2 | ) | 9.9 | ||||||||
| Income tax provision, as adjusted | $ | 105.4 | $ | 34.7 | $ | 71.9 |
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
| --- | --- |
The following discussion contains management’s discussion and analysis of our financial condition and results of operations and should be read together with “Item 6. Selected Financial Data” and our audited consolidated financial statements and related notes thereto included elsewhere in this Form 10-K. This discussion contains forward-looking statements and involves numerous risks and uncertainties. Our actual results may differ materially from those anticipated in any forward-looking statements as a result of many factors, including those set forth under the “Special Note Regarding Forward-Looking Statements,” “Item 1A. Risk Factors” and elsewhere in this Form 10-K.
Executive Overview
Our Company
We are a leading global provider of mission-critical flow control and compression equipment and associated aftermarket parts, consumables and services, which we sell across multiple attractive end-markets within the industrial, energy and medical industries. We manufacture one of the broadest and most complete ranges of compressor, pump, vacuum and blower products in our markets, which, combined with our global geographic footprint and application expertise, allows us to provide differentiated product and service offerings to our customers. Our products are sold under a collection of premier, market-leading brands, including Gardner Denver, CompAir, Nash, Emco Wheaton, Robuschi, Elmo Rietschle and Thomas, which we believe are globally recognized in their respective end-markets and known for product quality, reliability, efficiency and superior customer service. These attributes, along with over 155 years of engineering heritage, generate strong brand loyalty for our products and foster long-standing customer relationships, which we believe have resulted in leading market positions within each of our operating segments. We have sales in more than 175 countries and our diverse customer base utilizes our products across a wide array of end-markets that have favorable near- and long-term growth prospects, including industrial manufacturing, energy (with particular exposure to the North American upstream land-based market), transportation, medical and laboratory sciences, food and beverage packaging and chemical processing.
Our products and services are critical to the processes and systems in which they are utilized, which are often complex and function in harsh conditions where the cost of failure or downtime is high. However, our products and services typically represent only a small portion of the costs of the overall systems or functions that they support. As a result, our customers place a high value on our application expertise, product reliability and the responsiveness of our service. To support our customers and market presence, we maintain significant global scale with 38 key manufacturing facilities, more than 30 complementary service and repair centers across six continents and approximately 6,400 employees worldwide as of December 31, 2017.
The process-critical nature of our product applications, coupled with the standard wear and tear replacement cycles associated with the usage of our products, generates opportunities to support customers with our broad portfolio of aftermarket parts, consumables and services. Customers place a high value on minimizing any time their operations are offline. As a result, the availability of replacement parts, consumables and our repair and support services are key components of our value proposition. Our large installed base of products provides a recurring revenue stream through our aftermarket parts, consumables and services offerings. As a result, our aftermarket revenue is significant, representing 41% of total Company revenue and approximately 45% of our combined Industrials and Energy segments’ revenue in 2017.
Our Segments
We report our results of operations through three reportable segments: Industrials, Energy and Medical.
Industrials
We design, manufacture, market and service a broad range of air compression, vacuum and blower products, including associated aftermarket parts, consumables and services, across a wide array of technologies and applications for use in diverse end-markets. Compressors are used to increase the pressure of air or gas, vacuum products are used to remove air or gas in order to reduce the pressure below atmospheric levels and blower products are used to produce a high volume of air or gas at low pressure. Almost every manufacturing and industrial facility, and many service and process industry applications, use air compression, vacuum and blower products in a variety of process-critical applications, such as the operation of power industrial air tools, vacuum packaging of food products and aeration of waste water, among others. We offer one of the broadest portfolios of compression, vacuum and blower technology in our markets, which we believe, alongside our geographic footprint, allows us to provide differentiated service to our customers globally and maintain leading positions in many of our end-markets. We sell our Industrials products through an integrated network of direct sales representatives and independent distributors, which is strategically tailored to meet the dynamics of each target geography or end-market. In 2017, the Industrials segment generated Segment Revenue of $1,130.7 million and Segment Adjusted EBITDA of $242.7 million, reflecting a Segment Adjusted EBITDA Margin of 21.5%.
Energy
We design, manufacture, market and service a diverse range of positive displacement pumps, liquid ring vacuum pumps, compressors and integrated systems, engineered fluid loading and transfer equipment and associated aftermarket parts, consumables and services. The highly engineered products offered by our Energy segment serve customers across upstream, downstream and midstream energy markets, as well as petrochemical processing, transportation and general industrial sectors. Our positive displacement pumps are fit-for-purpose to meet the demands and challenges of modern unconventional drilling and hydraulic fracturing activity, particularly in the major basins in the North American land market. The products we sell into upstream energy applications are highly aftermarket-intensive, and so we support these products in the field with one of the industry’s most comprehensive service networks, which encompasses locations across all major basins and shale plays in the North American land market. Our liquid ring vacuum pumps and compressors are highly engineered products specifically designed for continuous duty in harsh environments to serve a wide range of applications, including oil and gas refining and processing, mining, chemical processing, petrochemical and industrial applications. Finally, our engineered fluid loading and transfer equipment and systems ensure the safe and efficient transportation and transfer of petroleum products as well as certain other liquid commodity products to serve a wide range of industries. In 2017, the Energy segment generated Segment Revenue of $1,014.5 million and Segment Adjusted EBITDA of $296.1 million, reflecting a Segment Adjusted EBITDA Margin of 29.2%.
Medical
We design, manufacture and market a broad range of highly specialized gas, liquid and precision syringe pumps and compressors that are specified by medical and laboratory equipment suppliers and integrated into their final equipment for use in applications, such as oxygen therapy, blood dialysis, patient monitoring, laboratory sterilization and wound treatment, among others. We offer a comprehensive product portfolio across a breadth of pump technologies to address the medical and laboratory sciences pump and fluid handling industry, as well as a range of end-use vacuum products for laboratory science applications, and we recently expanded into liquid pumps and automated liquid handling components and systems. Our product performance, quality and long-term
Showing the first 8K of 127K characters. Open the full section
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
| --- | --- |
Interest Rate Risk
We are exposed to interest rate risk as a result of our variable-rate borrowings. We manage our exposure to interest rate risk by maintaining a mixture of fixed and variable debt, and from time to time, use pay-fixed interest rate swaps as cash flow hedges of our variable rate debt in order to adjust the relative fixed and variable portions.
As of December 31, 2017, we had variable rate debt outstanding of $893.2 million at a current weighted average interest rate of 3.9%, substantially all of which was incurred under our $2,785.0 million Senior Secured Credit Facility, under which $1,282.3 million was outstanding under the $1,285.5 million Dollar Term Loan Facility and €613.5 million was outstanding under the €615.0 million Euro Term Loan Facility.
The Dollar Term Loan Facility and the Euro Term Loan Facility bear interest primarily based on LIBOR and EURIBOR, respectively, plus a spread. However, both facilities are subject to a 0% LIBOR base rate floor, and thus the interest rate on the Dollar Term Loan Facility and the Euro Term Loan Facility will fluctuate when LIBOR or EURIBOR, respectively, exceeds that percentage. As of December 31, 2017, LIBOR was higher and EURIBOR was lower than the 0% LIBOR minimum rate.
We use interest rate swaps to offset our exposure to interest rate movements. These outstanding interest rate swaps qualify and are designated as cash flow hedges of forecasted LIBOR-based interest payments. As of December 31, 2017, we were a fixed rate payer on 12 fixed-floating interest rate swap contracts that effectively fixed the LIBOR-based index used to determine the interest rates charged on our LIBOR-based variable rate borrowings. See Note 16 “Hedging Activities, Derivative Instruments, and Credit Risk” to our audited consolidated financial statements included elsewhere in this Form 10-K.
The following table presents the impact of hypothetical changes in market interest rates across the yield curve by 100 basis points, including the effect of our interest rate swaps for the years ended December 31, 2017 and 2016 on our interest expense.
| Year Ended December 31, | ||||||||
|---|---|---|---|---|---|---|---|---|
| (in millions) | 2017 | 2016 | ||||||
| Increase (decrease) in market interest rates | ||||||||
| 100 basis points | 6.1 | $ | 4.4 | |||||
| (100) basis points(1) (2) | (1.6 | ) | - |
| (1) | A decrease in interest rates would not have impacted our interest expense in 2017 on EURIBOR debt which was lower than the 0% base rate floors under the Senior Secured Credit Facility for the entire fiscal year 2017, but would have impacted interest expense in 2017 on LIBOR debt which was higher than the 0% based rate floors under the Senior Secured Credit Facility during the second half of fiscal year 2017. |
|---|
| (2) | A decrease in interest rates would not have impacted our interest expense in 2016 because LIBOR and EURIBOR were lower than the 1.0% base rate floors, applicable in that period, under the Senior Secured Credit Facility for the entirety of 2016. |
|---|
Foreign Currency Risk
We are exposed to foreign currency risks that arise from our global business operations. Changes in foreign currency exchange rates affect the translation of local currency balances of foreign subsidiaries, transaction gains and losses associated with intercompany loans with foreign subsidiaries and transactions denominated in currencies other than a subsidiary’s functional currency. In 2017, the relative weakening of the U.S. dollar against foreign currencies had a favorable impact on our revenues and results of operations while in 2016, the relative strengthening of the U.S. dollar against foreign currencies had an unfavorable impact on our revenues and results of operations. While future changes in foreign currency exchange rates are difficult to predict, our revenues and earnings may be adversely affected if the U.S. dollar strengthens against foreign currencies.
We seek to minimize our exposure to foreign currency risks through a combination of normal operating activities, including by conducting our international business operations primarily in their functional currencies to match expenses with revenues and the use of foreign currency forward exchange contracts and net investment cross-currency interest rate swaps. In addition, to mitigate the risk arising from entering into transactions in currencies other than our functional currencies, we typically settle intercompany trading balances monthly.
The table below presents the percentage of revenues and gross profit by principal currency for the years ended December 31, 2017 and 2016.
| U.S. Dollar | Euro | British Pound | Chinese Renminbi | Other | ||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Year Ended December 31, 2017 | ||||||||||||||||||||
| Revenues | 48 | % | 30 | % | 5 | % | 5 | % | 12 | % | ||||||||||
| Gross profit | 45 | % | 34 | % | 5 | % | 6 | % | 10 | % | ||||||||||
| Year Ended December 31, 2016 | ||||||||||||||||||||
| Revenues | 39 | % | 34 | % | 6 | % | 6 | % | 15 | % | ||||||||||
| Gross profit | 36 | % | 38 | % | 7 | % | 7 | % | 12 | % |
We utilize foreign currency denominated debt obligations supplemented from time to time with cross currency interest rate swaps designated as net investment hedges to selectively hedge portions of our investment in non-U.S. subsidiaries. The currency effects of the designated debt obligations and cross currency interest rate swaps are reflected in accumulated other comprehensive income within our stockholders’ equity, where they partially offset the currency translation effects of our investments in non-U.S. subsidiaries, which in turn partially offset gains and losses recorded on our net investments globally. These currency translation effects and offsetting impacts of our derivatives for the years ended December 31, 2017 and 2016 are summarized in Note 13 “Accumulated Other Comprehensive Income (Loss)” to our audited consolidated financial statements included elsewhere in this Form 10-K.
We also enter into foreign currency forward contracts to manage the risk arising from transaction gains and losses associated with intercompany loans with foreign subsidiaries. Our foreign currency forward contracts are typically short-term and are rolled forward as necessary upon settlement. As of December 31, 2017, we were party to 12 foreign currency forward contracts, all of which are carried on our balance sheet at fair value. See Note 16 “Hedging Activities, Derivative Instruments, and Credit Risk” to our audited consolidated financial statements included elsewhere in this Form 10-K.
The table below presents, for the year ended December 31, 2017, the hypothetical effect of a 10% appreciation in the average exchange rate of the U.S. dollar relative to the principal foreign currencies in which our revenues and gross profit are denominated.
| Year Ended December 31, 2017 | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| (in millions) | Euro | British Pound | Chinese Renminbi | |||||||||
| Revenues | $ | (70.4 | ) | $ | (11.1 | ) | $ | (12.6 | ) | |||
| Gross profit | $ | (30.3 | ) | $ | (4.7 | ) | $ | (5.6 | ) |
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
| --- | --- |
GARDNER DENVER HOLDINGS, INC. AND SUBSIDIARIES
CONSOLIDATED STATEMENTS OF OPERATIONS
(Dollars in millions, except per share amounts)
| For the Years Ended December 31, | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2017 | 2016 | 2015 | ||||||||||
| Revenues | $ | 2,375.4 | $ | 1,939.4 | $ | 2,126.9 | ||||||
| Cost of sales | 1,477.5 | 1,222.7 | 1,347.8 | |||||||||
| Gross Profit | 897.9 | 716.7 | 779.1 | |||||||||
| Selling and administrative expenses | 446.6 | 414.3 | 427.0 | |||||||||
| Amortization of intangible assets | 118.9 | 124.2 | 115.4 | |||||||||
| Impairment of goodwill | - | - | 343.3 | |||||||||
| Impairment of other intangible assets | 1.6 | 25.3 | 78.1 | |||||||||
| Other operating expense, net | 222.1 | 48.6 | 20.7 | |||||||||
| Operating Income (Loss) | 108.7 | 104.3 | (205.4 | ) | ||||||||
| Interest expense | 140.7 | 170.3 | 162.9 | |||||||||
| Loss on extinguishment of debt | 84.5 | - | - | |||||||||
| Other income, net | (3.8 | ) | (2.8 | ) | (1.6 | ) | ||||||
| Loss Before Income Taxes | (112.7 | ) | (63.2 | ) | (366.7 | ) | ||||||
| Benefit for income taxes | (131.2 | ) | (31.9 | ) | (14.7 | ) | ||||||
| Net Income (Loss) | 18.5 | (31.3 | ) | (352.0 | ) | |||||||
| Less: Net income (loss) attributable to noncontrolling interests | 0.1 | 5.3 | (0.8 | ) | ||||||||
| Net Income (Loss) Attributable to Gardner Denver Holdings, Inc. | $ | 18.4 | $ | (36.6 | ) | $ | (351.2 | ) | ||||
| Basic earnings (loss) per share | $ | 0.10 | $ | (0.25 | ) | $ | (2.35 | ) | ||||
| Diluted earnings (loss) per share | $ | 0.10 | $ | (0.25 | ) | $ | (2.35 | ) |
The accompanying notes are an integral part of these consolidated financial statements.
GARDNER DENVER HOLDINGS, INC. AND SUBSIDIARIES
CONSOLIDATED STATEMENTS OF COMPREHENSIVE INCOME (LOSS)
(Dollars in millions)
| For the Years Ended December 31, | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2017 | 2016 | 2015 | ||||||||||
| Comprehensive Income (Loss) Attributable to Gardner Denver Holdings, Inc. | ||||||||||||
| Net income (loss) attributable to Gardner Denver Holdings, Inc. | $ | 18.4 | $ | (36.6 | ) | $ | (351.2 | ) | ||||
| Other comprehensive income (loss), net of tax: | ||||||||||||
| Foreign currency translation adjustments, net | 157.6 | (76.2 | ) | (136.3 | ) | |||||||
| Foreign currency (losses) gains, net | (51.6 | ) | 13.6 | 32.6 | ||||||||
| Unrecognized gains (losses) on cash flow hedges, net | 12.4 | (0.9 | ) | (15.9 | ) | |||||||
| Pension and other postretirement prior service cost and gain or loss, net | 24.2 | (13.3 | ) | (10.7 | ) | |||||||
| Other comprehensive income (loss), net of tax | 142.6 | (76.8 | ) | (130.3 | ) | |||||||
| Comprehensive income (loss) attributable to Gardner Denver Holdings, Inc. | $ | 161.0 | $ | (113.4 | ) | $ | (481.5 | ) | ||||
| Comprehensive Income (Loss) Attributable to Noncontrolling Interests | ||||||||||||
| Net income (loss) attributable to noncontrolling interests | $ | 0.1 | $ | 5.3 | $ | (0.8 | ) | |||||
| Other comprehensive income (loss), net of tax: | ||||||||||||
| Foreign currency translation adjustments, net | - | 1.4 | (2.0 | ) | ||||||||
| Other comprehensive income (loss), net of tax | - | 1.4 | (2.0 | ) | ||||||||
| Comprehensive income (loss) attributable to noncontrolling interests | $ | 0.1 | $ | 6.7 | $ | (2.8 | ) | |||||
| Total Comprehensive Income (Loss) | $ | 161.1 | $ | (106.7 | ) | $ | (484.3 | ) |
The accompanying notes are an integral part of these consolidated financial statements.
GARDNER DENVER HOLDINGS, INC. AND SUBSIDIARIES
CONSOLIDATED BALANCE SHEETS
(Dollars in millions, except share and per share amounts)
| December 31, 2017 | December 31, 2016 | |||||||
|---|---|---|---|---|---|---|---|---|
| Assets | ||||||||
| Current assets: | ||||||||
| Cash and cash equivalents | $ | 393.3 | $ | 255.8 | ||||
| Accounts receivable, net of allowance for doubtful accounts of $18.7 and $18.7, respectively | 536.3 | 441.6 | ||||||
| Inventories | 494.5 | 443.9 | ||||||
| Other current assets | 39.5 | 47.2 | ||||||
| Total current assets | 1,463.6 | 1,188.5 | ||||||
| Property, plant and equipment, net of accumulated depreciation of $203.8 and $146.1, respectively | 363.2 | 358.4 | ||||||
| Goodwill | 1,227.6 | 1,154.7 | ||||||
| Other intangible assets, net | 1,431.2 | 1,469.9 | ||||||
| Deferred tax assets | 1.0 | 1.4 | ||||||
| Other assets | 134.6 | 143.1 | ||||||
| Total assets | $ | 4,621.2 | $ | 4,316.0 | ||||
| Liabilities and Stockholders' Equity | ||||||||
| Current liabilities: | ||||||||
| Short-term borrowings and current maturities of long-term debt | $ | 20.9 | $ | 24.5 | ||||
| Accounts payable | 269.7 | 214.9 | ||||||
| Accrued liabilities | 271.2 | 258.5 | ||||||
| Total current liabilities | 561.8 | 497.9 | ||||||
| Long-term debt, less current maturities | 2,019.3 | 2,753.8 | ||||||
| Pensions and other postretirement benefits | 99.8 | 122.7 | ||||||
| Deferred income taxes | 237.5 | 487.6 | ||||||
| Other liabilities | 226.0 | 182.2 | ||||||
| Total liabilities | 3,144.4 | 4,044.2 | ||||||
| Commitments and contingencies (Note 18) | ||||||||
| Stockholders' equity: | ||||||||
| Common stock, $0.01 par value; 1,000,000,000 shares authorized; 198,377,237 and 150,552,360 shares issued at December 31, 2017 and December 31, 2016, respectively | 2.0 | 1.5 | ||||||
| Capital in excess of par value | 2,275.4 | 1,222.4 | ||||||
| Accumulated deficit | (577.8 | ) | (596.2 | ) | ||||
| Accumulated other comprehensive loss | (199.8 | ) | (342.4 | ) | ||||
| Treasury stock at cost; 2,159,266 and 1,897,454 shares at December 31, 2017 and 2016, respectively | (23.0 | ) | (19.4 | ) | ||||
| Total Gardner Denver Holdings, Inc. stockholders' equity | 1,476.8 | 265.9 | ||||||
| Noncontrolling interests | - | 5.9 | ||||||
| Total stockholders' equity | 1,476.8 | 271.8 | ||||||
| Total liabilities and stockholders' equity | $ | 4,621.2 | $ | 4,316.0 |
The accompanying notes are an integral part of these consolidated financial statements.
GARDNER DENVER HOLDINGS, INC. AND SUBSIDIARIES
CONSOLIDATED STATEMENTS OF STOCKHOLDERS’ EQUITY
(Dollars in millions)
| December 31, 2017 | December 31, 2016 | December 31, 2015 | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Number of Common Shares Issued (in millions) | ||||||||||||
| Balance at beginning of period | 150.6 | 150.3 | 149.9 | |||||||||
| Common stock issued for initial public offering | 47.5 | - | - | |||||||||
| Common stock issued to employees for deferred stock units | 0.2 | - | - | |||||||||
| Exercise of stock options | 0.1 | - | - | |||||||||
| Common stock issued |
Showing the first 8K of 214K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
| --- | --- |
None
Item 9A. CONTROLS AND PROCEDURES
| --- | --- |
Evaluation of Disclosure Controls and Procedures
Regulations under the Securities Exchange Act of 1934, as amended (the “Exchange Act”), require public companies, including us, to maintain “disclosure controls and procedures,” which are defined in Rule 13a-15(e) and Rule 15d-15(e) of the Exchange Act to mean a company’s controls and other procedures that are designed to ensure that information required to be disclosed in the reports that it files or submits under the Exchange Act is recorded, processed, summarized and reported within the time periods specified in the SEC’s rules and forms and that such information is accumulated and communicated to management, including our principal executive officer and principal financial officer, or persons performing similar functions, as appropriate to allow timely decisions regarding required or necessary disclosures. In designing and evaluating our disclosure controls and procedures, management recognizes that disclosure controls and procedures, no matter how well conceived and operated, can provide only reasonable, not absolute, assurance that the objectives of the disclosure controls and procedures are met. The design of any controls and procedures also is based on certain assumptions about the likelihood of future events, and there can be no assurance that any design will succeed in achieving its stated goals under all potential future conditions. Additionally, in designing disclosure controls and procedures, our management necessarily was required to apply its judgment in evaluating the cost-benefit relationship of possible disclosure controls and procedures. Our management, with the participation of our principal executive officer and principal financial officer, has evaluated the effectiveness of the design and operation of our disclosure controls and procedures as of the end of the period covered by this report. Based upon that evaluation and subject to the foregoing, our principal executive officer and principal financial officer concluded that, as of the end of the period covered by this report, the design and operation of our disclosure controls and procedures were effective to accomplish their objectives at a reasonable assurance level.
Management’s Report on Internal Control Over Financial Reporting
This Annual Report on Form 10-K does not include a report of management’s assessment regarding internal control over financial reporting or an attestation report of the Company’s registered public accounting firm due to a transition period established by rules of the SEC for newly public companies.
Changes in Internal Control Over Financial Reporting
Regulations under the Exchange Act require public companies, including our Company, to evaluate any change in our “internal control over financial reporting” as such term is defined in Rule 13a-15(f) and Rule 15d-15(f) of the Exchange Act. There have been no changes in the Company’s internal control over financial reporting during the Company’s most recent fiscal quarter that have materially affected, or are reasonably likely to materially affect, the Company’s internal control over financial reporting.
Item 9B. OTHER INFORMATION
| --- | --- |
Special IPO Bonuses
On February 15, 2018, we determined to award each of Vicente Reynal, our Chief Executive Officer, Philip T. Herndon, our Vice President and Chief Financial Officer, Andrew Schiesl, our Vice President, General Counsel, Chief Compliance Officer and Secretary and Neil D. Snyder, our Vice President, Strategy, Business Development and Planning, a one-time discretionary IPO bonus for his extraordinary efforts in 2017 in connection with our initial public offering. The IPO bonuses were awarded in the following amounts: Mr. Reynal - $225,000; Mr. Herndon - $125,000; Mr. Schiesl - $100,000; and Mr. Snyder - $75,000.
Executive Severance Agreements
On February 15, 2018, in connection with our annual review of our executive compensation, we approved an increase to the benefits to which each of Neil D. Snyder, our Senior Vice President, Strategy, Business Development and Planning and Enrique Miñarro Viseras, our Vice President and General Manager, Industrials Group EMEA is entitled in the event of certain qualifying terminations to align them with the severance benefits to which our other senior executive officers are entitled.
Under the terms approved by the Compensation Committee of our Board of Directors on February 15, 2018, if the Company terminates Mr. Snyder’s employment without Cause (as that term is defined below under “Part III, Item 11, Executive Compensation―Potential Payments to Named Executive Officers upon Termination of Employment or Change in Control―Severance Arrangements and Restrictive Covenants”) or if Mr. Snyder terminates his employment with us for Good Reason (as that term is defined below under “Part III, Item 11, Executive Compensation―Potential Payments to Named Executive Officers upon Termination of Employment or Change in Control―Severance Arrangements and Restrictive Covenants”), subject to Mr. Snyder’s continued compliance with the restrictive covenants in his management equity agreements and his execution of a customary waiver and release agreement, he will be entitled to receive:
| • | Continued payment over a 12-month period (the “Severance Period”) of his annual base salary earned in respect of our fiscal year preceding the fiscal year in which the termination date occurs, payable in substantially equal monthly installments over the Severance Period; and |
|---|
| • | Continued group health coverage (on the same basis as actively employed employees of the Company), subject to his electing to receive benefits under COBRA, for 12 months following the date his employment terminates (or, if earlier, through the date that he becomes employed by another employer and eligible for health insurance coverage at such employer). |
|---|
The Compensation Committee of our Board of Directors also approved on February 15, 2018 a mutual twelve-month advance notice period for a termination of employment not for cause or without good reason, during which Mr. Miñarro Viseras may be released from his work duties but will still be entitled to remuneration.
PART III.
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
| --- | --- |
Except as set forth below, the information required by this Item will be included in our definitive proxy statement for the 2018 Annual Meeting of Stockholders and is incorporated herein by reference. Gardner Denver Holdings, Inc. will file such definitive proxy statement with the SEC pursuant to Regulation 14A within 120 days of the fiscal year ended December 31, 2017.
Code of Conduct
The Company has adopted a Code of Conduct that applies to all of the Company’s employees, including the Company’s Chief Executive Officer, Chief Financial Officer, Chief Accounting Officer, Controller and other persons performing similar functions. The Code of Conduct sets forth our policies and expectations on a number of topics, including conflicts of interest, corporate opportunities, confidentiality, compliance with laws (including insider trading laws), use of our assets and business conduct and fair dealing. This Code of Conduct also satisfies the requirements for a code of ethics, as defined by Item 406 of Regulation S-K promulgated by the SEC. The Company has posted a copy of the Code of Conduct on its website at www.gardnerdenver.com under the Investors and then the Corporate Governance link. In the event that we amend or grant any waiver from a provision of the code of ethics that applies to the Chief Executive Officer, Chief Financial Officer, Chief Accounting Officer or Controller and that requires disclosure under applicable SEC or NYSE rules, we intend to disclose such amendment or waiver and the reasons therefor on our Internet site.
Item 11. EXECUTIVE COMPENSATION
| --- | --- |
Compensation Committee Report
The Compensation Committee has reviewed and discussed the following Compensation Discussion and Analysis with management. Based on its review and discussion with management, the Compensation Committee recommended to the Board of Directors that the Compensation Discussion and Analysis be included in this Annual Report on Form 10-K for the fiscal year ended December 31, 2017 and in the Company’s proxy statement on Schedule 14A for the 2018 Annual Meeting of Stockholders.
Submitted by the Compensation Committee of the Board of Directors:
| Peter Stavros, Chair | |
|---|---|
| Nickolas Vande Steeg | |
| Joshua Weisenbeck |
Compensation Discussion and Analysis
Introduction
This section describes our compensation philosophy and details the compensation programs that cover our named executive officers (“NEOs”).
Our NEOs for 2017 are:
| • | Vicente Reynal, our Chief Executive Officer; |
|---|
| • | Philip T. Herndon, our Vice President and Chief Financial Officer; and |
|---|
| • | Our three other most highly compensated executive officers who served in such capacities as of December 31, 2017, namely: |
|---|
| • | Andrew Schiesl, our Vice President, General Counsel, Chief Compliance Officer and Secretary; |
|---|
| • | Neil D. Snyder, our Senior Vice President, Strategy, Business Development and Planning; and |
|---|
| • | Enrique Miñarro Viseras, Vice President and General Manager, Industrials Segment EMEA |
|---|
Executive Compensation Objectives and Philosophy
Our executive compensation philosophy is designed to attract and retain individuals with the qualifications to meet the Company’s strategic objectives and create value for our shareholders. We believe that the best way to align our executives with our objectives and create shareholder value is to emphasize two key compensation principles: (1) significant equity participation and (2) pay-for-performance.
In February 2018, following an evaluation with the assistance of Pearl Meyer of equity-based incentives for our executive officers, the Compensation Committee adopted a new long-term equity incentive program (the “2018 LTI Program”). Under the 2018 LTI Program, our NEOs will receive annual equity awards, 50% of which will be in the form of time-vesting restricted stock and 50% of which will be in the form of time-vesting stock options. The following charts illustrate our focus on equity participation by showing that 72% of our CEO’s expected 2018 target base salary, annual incentive, and long-term equity incentive compensation mix and 49% of our other NEOs’ expected 2018 mix is based on long-term equity incentives.See “Compensation Actions Taken in 2018―Long-Term Incentive Compensation”.
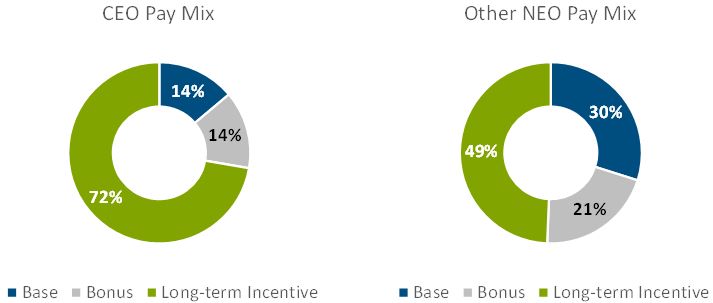
Our commitment to aligning the interests of our executives to the interests of our shareholders through equity participation is further evidenced by the fact that in 2017 we adopted what we believe is a market-leading stock ownership and retention policy for our executives and non-employee directors that combines robust stock ownership requirements with retention requirements. See “Stock Ownership and Retention Policy” below. All of our NEOs maintain a significant equity stake in the Company and currently exceed their respective ownership requirements through ownership of vested and exercisable stock options and/or direct investments in our common stock.
In addition to equity participation, we strongly believe in a pay-for-performance culture. This is evidenced by the fact that our annual cash incentive program is 100% based on the financial performance of the Company and its business units and that it accounts for 50% of the expected total cash compensation of our CEO, and on average 41% for our other NEOs, in each case when paid out at target. When paid out at the maximum payout (capped at 200% of target), this percentage increases to 67% and 58%, respectively. Also, our executives receive no payout for below threshold performance and we believe that our threshold at 95% of target is more challenging than typical market practice. See “―Executive Compensation Program Elements―Cash Bonus Opportunities―Annual Cash Bonus Opportunity”. Even more importantly, when our short-term cash incentive is combined with our long term equity incentive, it results in 84% of our CEO’s and 70% of our NEOs’ compensation being variable performance compensation.
In addition to equity compensation and our annual cash incentive opportunity, we provide NEOs a combination of the following other compensation components:
| • | Base salary - Fixed pay that is market competitive and sufficient to engage high caliber talent; |
|---|
| • | Broad-based employee benefits – Fixed pay intended to attract and retain employees while providing them with retirement and health and welfare security; and |
|---|
| • | Severance and other benefits payable upon certain terminations of employment or a change in control - Encourages the continued attention and dedication of our NEOs and provides reasonable individual security to enable our NEOs to focus on our best interests, particularly when considering strategic alternatives. |
|---|
In 2017 we did not make any equity grants to our NEOs believing that the equity grants made in prior years were sufficiently retentive and fostered the necessary level of alignment with shareholder interests. See “―Executive Compensation Program Elements―Long-Term Equity Incentive Awards”.
Strong Compensation Governance Practices and Policies
Within the context of the compensation philosophy and the Company’s business objectives, the Compensation Committee engages in an ongoing review of the Company’s executive compensation programs. In connection with this review, the Compensation Committee has adopted the following practices and policies reflecting what it believes to be a best practices approach to executive compensation.

Compensation Determination Process and Compensation Consultant Independence
Prior to our initial public offering, our Compensation Committee historically made all executive compensation decisions, including determinations as to the compensation of our NEOs. From the date of our initial public offering, the Compensation Committee has been responsible for determining the compensation of our Chief Executive Officer (“CEO”) and other executive officers and approving or recommending such compensation to the board of directors. Because of his daily involvement with the executive team, our CEO makes recommendations to the Compensation Committee regarding compensation for the executive officers other than himself. No member of management participates in discussions with the Compensation Committee regarding his or her own compensation.
In connection with our initial public offering, we engaged Pearl Meyer & Partners, LLC (“Pearl Meyer”), a compensation consulting firm, to assist us in evaluating the elements and levels of our executive compensation, including base salaries, annual cash incentive awards and equity-based incentives for our executive officers. In February 2018, the Compensation Committee determined that Pearl Meyer is independent from management and that Pearl Meyer’s work has not raised any conflicts of interest.
The Compensation Committee did not benchmark 2017 compensation against a peer group. However, over the course of the second half of 2017 and early 2018, Pearl Meyer developed a compensation peer group, conducted a competitive market assessment and developed recommendations for the 2018 LTI Program. See “Compensation Actions Taken in 2018―Long-Term Incentive Compensation.”
Executive Comp
Showing the first 8K of 105K characters. Open the full section
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
| --- | --- |
Except as set forth below, the information required by this Item will be included in our definitive proxy statement for the 2018 Annual Meeting of Stockholders and is incorporated herein by reference. Gardner Denver Holdings, Inc. will file such definitive proxy statement with the SEC pursuant to Regulation 14A within 120 days of the fiscal year ended December 31, 2017.
Equity Compensation Plan Information
The following table provides information as of December 31, 2017 about our common stock that may be issued upon the exercise of options, warrants and rights granted to employees, consultants or directors under all of our existing equity compensation plans including our 2013 Stock Incentive Plan and 2017 Omnibus Incentive Plan. All equity compensation plans are described more fully in Note 15 “Stock-Based Compensation Plans” to the Consolidated Financial Statements in Item 8 of this Annual Report on Form 10-K.
| Plan Category | Number of Securities to be issued upon Exercise of Outstanding Options, Warrants And Rights (1) | Weighted Average Exercise Price of Outstanding Options, Warrants and Rights | Number of Securities Remaining Available for Future Issuance under Equity Compensation Plans (excluding Securities reflected in the first column) (2) | ||
|---|---|---|---|---|---|
| Equity compensation plans approved by securityholders | 12,134,766 | $9.58 | 8,897,879 |
| (1) | Total includes 11,986,363 stock options and 148,403 share-settled stock appreciation rights under the Company's 2013 Stock Incentive Plan. |
|---|
| (2) | These shares are available for grant as of December 31, 2017 under the Company's 2017 Omnibus Incentive Plan. This includes 8,550,000 shares initially authorized for issuance under the Company's 2017 Omnibus Incentive Plan and shares subject to awards under the Company's 2013 Stock Incentive Plan that expired or were otherwise forfeited or terminated in accordance with their terms without the delivery of shares of the Company's common stock in settlement thereof. |
|---|
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
| --- | --- |
Except as set forth below, the information required by this item will be included in our definitive proxy statement for the 2018 Annual Meeting of Stockholders and is incorporated herein by reference. Gardner Denver Holdings, Inc. will file such definitive proxy statement with the SEC pursuant to Regulation 14A within 120 days of the fiscal year ended December 31, 2017.
Arrangements with Our Executive Officers, Directors and Advisors
We have entered into letter agreements with certain members of management, including each of our executive officers, and our directors and certain advisors, pursuant to which such individuals agreed to invest in our stock and/or through the purchase of our shares with cash. In addition, our Board of Directors granted options to purchase shares of our common stock to certain members of management and key employees, including to our executive officers. In connection with the grants of new options described above, the participating members of our management, including our executive officers, were required to enter into a Management Stockholder’s Agreement as well as a stock option agreement, as applicable.
Below is a brief summary of the principal terms of the Management Stockholder’s Agreements, the Director Stockholder’s Agreements and the Advisor Stockholder’s Agreements, which are qualified in their entirety by reference to the agreements themselves, forms of which are filed as exhibits to this Annual Report on Form 10-K.
Management, Director and Advisor Stockholder’s Agreements
The Management Stockholder’s Agreements impose significant restrictions on transfers of shares of our common stock. Generally, shares held by our management are nontransferable by any means at any time prior to the earlier of (i) the occurrence of a Change in Control (as defined in the Management Stockholder’s Agreements) or (ii) the later to occur of (a) the fifth anniversary of the execution of the applicable Management Stockholder’s Agreement or (b) the consummation of an Initial Public Offering (as defined in the Management Stockholder’s Agreements). These transfer restrictions are subject to certain exceptions, including transfers approved by our Board of Directors; transfers upon the death or Disability (as defined in the Management Stockholder’s Agreements) of the holder; transfers to immediate family members or estate planning vehicles, provided such transferees become party to the applicable Management Stockholder’s Agreement; or repurchases of such shares by the Company.
Additionally, management stockholders have limited “piggyback” registration rights with respect to certain registered offerings conducted by the Company. The maximum number of shares of common stock which a management stockholder may register is generally proportionate with the percentage of common stock being sold by certain affiliates of KKR (relative to their holdings thereof). The Management Stockholder’s Agreements also contain certain lock-up provisions in the event that any shares are offered to the public pursuant to an effective registration statement under the Securities Act.
The Director Stockholder’s Agreements and Advisor Stockholder’s Agreements are substantially similar to the Management Stockholder’s Agreements. In addition to certain exceptions to transfer restrictions related to piggyback rights available to Management Stockholders, the Director and Advisor Stockholder’s Agreements further provide that in lieu of piggyback registration rights in connection with a public offering in which such piggyback rights would otherwise be available, the Board of Directors may waive transfer restrictions with respect to the number of shares that would have been subject to such piggyback rights.
Arrangements with KKR
Stockholders Agreement
In connection with our initial public offering, we entered into a stockholders agreement with certain affiliates of KKR. This agreement grants affiliates of KKR the right to nominate to our Board of Directors a number of designees equal to: (i) at least a majority of the total number of directors comprising our Board of Directors at such time as long as affiliates of KKR beneficially own at least 50% of the shares of our common stock entitled to vote generally in the election of our directors; (ii) at least 40% of the total number of directors comprising our Board of Directors at such time as long as affiliates of KKR beneficially own at least 40% but less than 50% of the shares of our common stock entitled to vote generally in the election of our directors; (iii) at least 30% of the total number of directors comprising our Board of Directors at such time as long as affiliates of KKR beneficially own at least 30% but less than 40% of the shares of our common stock entitled to vote generally in the election of our directors; (iv) at least 20% of the total number of directors comprising our Board of Directors at such time as long as affiliates of KKR beneficially own at least 20% but less 30% of the shares of our common stock entitled to vote generally in the election of our directors; and (v) at least 10% of the total number of directors comprising our Board of Directors at such time as long as affiliates of KKR beneficially own at least 5% but less than 20% of the shares of our common stock entitled to vote generally in the election of our directors. For purposes of calculating the number of directors that affiliates of KKR are entitled to nominate pursuant to the formula outlined above, any fractional amounts would be rounded up to the nearest whole number and the calculation would be made on a pro forma basis, taking into account any increase in the size of our Board of Directors (e.g., one and one quarter (11/4) directors shall equate to two directors). In addition, in the event a vacancy on the Board of Directors is created by the death, disability, retirement or resignation of a Sponsor director designee, affiliates of KKR shall, to the fullest extent permitted by law, have the right to have the vacancy filled by a new Sponsor director-designee. In addition, the stockholders agreement grants to KKR special governance rights, for as long as KKR maintains ownership of at least 30% of our outstanding common stock, including rights of approval over certain corporate and other transactions such as mergers or other transactions involving a change in control and certain rights regarding the appointment of our chief executive officer.
Registration Rights Agreement
In connection with the KKR Transaction, certain affiliates of KKR entered into a registration rights agreement with us. In connection with the completion of our initial public offering, we and KKR entered into an amended and restated registration rights agreement. The amended and restated registration rights agreement grants such affiliates of KKR the right to cause us to register shares of our common stock held by it under the Securities Act and, if requested, to use our reasonable best efforts (if we are not eligible to use an automatic shelf registration statement at the time of filing) to maintain a shelf registration statement effective with respect to such shares. Certain affiliates of KKR are also entitled to participate on a pro rata basis in any registration of our common stock under the Securities Act that we may undertake. The amended and restated registration rights agreement also provides that we will pay certain expenses relating to such registrations and indemnify certain affiliates of KKR and members of management participating in any offering against certain liabilities, which may arise under the Securities Act, the Exchange Act, any state securities law or any rule or regulation thereunder applicable to us.
Monitoring Agreement
In connection with the KKR Transaction, we entered into a monitoring agreement with KKR pursuant to which KKR provided various management and advisory services to us and our direct and indirect divisions, subsidiaries, parent entities and controlled affiliates and received fees and reimbursements of related out-of-pocket expenses. We paid management fees of $17.3 million to KKR for the year ended December 31, 2017. In May 2017, the monitoring agreement was terminated in accordance with its terms and we paid a termination fee of approximately $16.2 million.
Indemnification Agreement
In connection with entering into the monitoring agreement, we also entered into a separate indemnification agreement with KKR and certain of its affiliates, which provides customary exculpation and indemnification provisions in favor of KKR and such affiliates in connection with the services provided to us under the monitoring, transaction fee and syndication fee agreements.
Relationship with KKR Capstone Americas LLC
We have utilized and may continue to utilize KKR Capstone Americas LLC and/or its affiliates (“KKR Capstone”), a consulting company that works exclusively with KKR’s portfolio companies, for consulting services, and have paid to KKR Capstone related fees and expenses. KKR Capstone is not a subsidiary or affiliate of KKR. KKR Capstone operates under several consulting agreements with KKR & Co. and uses the “KKR” name under license from KKR & Co.
Relationship with KKR Credit
Since 2014, investment funds or accounts managed or advised by the global credit business of KKR (“KKR Credit”) were participating lenders under our existing credit agreements and holders of notes issued by us, and as of December 31, 2017, had received in aggregate principal payments of approximately $0.5 million and interest payments of approximately $4.0 million. As of December 31, 2017, investment funds or accounts managed or advised by KKR Credit held a position in the debt of the Company.
Financing Arrangements with Related Parties
In May 2017, KKR Capital Markets LLC, an affiliate of KKR, acted as an underwriter in connection with the initial public offering of the Company’s stock and received underwriter discounts and commissions of approximately $8.9 million. In August 2017, KKR Capital Markets LLC received $1.5 million for services rendered in connection with a debt refinancing transaction. In November 2017, KKR Capital Markets LLC acted as an underwriter in connection with an offering of Company’s stock by certain selling shareholders, and earned underwriter discounts and commissions of approximately $3.5 million.
Policies and Procedures for Related Person Transactions
Our Board of Directors has adopted a written statement of policy regarding transactions with related persons, which we refer to as our “related person transaction policy.” Our related person transaction policy requires that (a) any “related person transaction” (defined as any transaction that is anticipated would be reportable by us under Item 404(a) of Regulation S-K in which we were or are to be a participant and the amount involved exceeds $120,000 and in which any related person had or will have a direct or indirect material interest) be approved or ratified by an approving body comprised of the disinterested members of our Board of Directors or any committee of the Board of Directors (provided that a majority of the members of the Board of Directors or such committee, respectively, are disinterested) and (b) any employment relationship or transaction involving an executive officer and any related compensation be approved by the Compensation Committee of the Board of Directors or recommended by the Compensation Committee to the Board of Directors for its approval. In connection with the review and approval or ratification of a related person transaction:
| · | management must disclose to the committee or disinterested directors, as applicable, the name of the related person and the basis on which the person is a related person, the material terms of the related person transaction, including the approximate dollar value of the amount involved in the transaction, and all the material facts as to the related person’s direct or indirect interest in, or relationship to, the related person transaction; |
|---|
| · | management must advise the committee or disinterested directors, as applicable, as to whether the related person transaction complies with the terms of our agreements governing our material outstanding indebtedness that limit or restrict our ability to enter into a related person transaction; |
|---|
| · | management must advise the committee or disinterested directors, as applicable, as to whether the related person transaction will be required to be disclosed in our applicable filings under the Securities Act or the Exchange Act, and related rules, and, to the extent required to be disclosed, management must ensure that the related person transaction is disclosed in accordance with such Acts and related rules; and |
|---|
| · | management must advise the committee or disinterested directors, as applicable, as to whether the related person transaction constitutes a “personal loan” for purposes of Section 402 of the Sarbanes-Oxley Act of 2002. |
|---|
In addition, the related person transaction policy provides that the committee or disinterested directors, as applicable, in connection with any approval or ratification of a related person transaction involving a non-employee director or director nominee, should consider whether such transaction would compromise the director or director nominee’s status as an “independent,” “outside,” or “non-employee” director, as applicable, under the rules and regulations of the SEC, the NYSE and the Internal Revenue Code.
Item 14. PRINCIPAL ACCOUNTING FEES AND SERVICES
| --- | --- |
Audit Fees
In connection with the audit of the 2017 financial statements, we entered into an agreement with Deloitte & Touche LLP which sets forth the terms by which Deloitte & Touche LLP would perform audit services for the Company.
The following tables sets forth the aggregate fees for professional services provided by Deloitte & Touche LLP for the audit of our financial statements for the fiscal years ended December 31, 2017 and 2016 and fees billed for other services rendered by Deloitte & Touche LLP for those periods, all of which were approved by the Audit Committee.
| For the Years Ended December 31, (in thousands) | ||||||||
|---|---|---|---|---|---|---|---|---|
| 2017 | 2016 | |||||||
| Fees: | ||||||||
| Audit fees | $ | 2,952 | $ | 3,019 | ||||
| Audit Related fees(1) | 773 | 75 | ||||||
| Tax fees(2) | 298 | 344 | ||||||
| All other fees(3) | 298 | - | ||||||
| Total | $ | 4,321 | $ | 3,438 |
| (1) | Audit related fees include fees related to the Company’s public offerings, Sarbanes-Oxley readiness and a license for an accounting research tool. |
|---|
| (2) | Tax fees include fees for income tax compliance and transfer pricing services. |
|---|
| (3) | All other fees include fees related to professional services rendered in connection with the Company’s issuance of deferred stock units during 2017. |
|---|
The Audit Committee of the Board considered whether providing the non-audit services included in this table was compatible with maintaining Deloitte & Touche LLP’s independence and concluded that it was.
Consistent with SEC policies regarding auditor independence and our Audit Committee’s charter, the Audit Committee has responsibility for engaging, setting compensation for and reviewing the performance of the independent registered public accounting firm. In exercising this responsibility, the Audit Committee has established procedures relating to the approval of all audit and non-audit services that are to be performed by our independent registered public accounting firm and pre-approves all audit and permitted non-audit services provided by any independent registered public accounting firm prior to each engagement.
PART IV
Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULE
| --- | --- |
Financial Statements, Financial Statement Schedule and Exhibits
The consolidated financial statements listed in the accompanying index to consolidated financial statements are filed as part of this Annual Report on Form 10-K.
All financial statement schedules are omitted since the required information is not present or is not present in amounts sufficient to require submission of the schedules, or because the information required is included in the consolidated financial statements and notes thereto.
The exhibits listed in the accompanying exhibit index are filed as part of this Annual Report on Form 10-K.
Index to Consolidated Financial Statements
| Consolidated Statements of Operations – For the years ended December 31, 2017, 2016 and 2015 | 53 |
|---|---|
| Consolidated Statements of Comprehensive Income (Loss) – For the years ended December 31, 2017, 2016 and 2015 | 54 |
| Consolidated Balance Sheets – As of December 31, 2017 and 2016 | 55 |
| Consolidated Statements of Stockholders’ Equity – For the years ended December 31, 2017, 2016 and 2015 | 56 |
| Consolidated Statements of Cash Flows – For the years ended December 31, 2017, 2016 and 2015 | 57 |
| Notes to Consolidated Financial Statements | 58 |
| Report of Independent Registered Public Accounting Firm | 101 |
Schedule to Consolidated Financial Statements
| Schedule I – Condensed Financial Statements Gardner Denver Holdings, Inc. (Parent Company Only) | 136 |
|---|
Exhibits
| Exhibit Number | Exhibit Description | |
|---|---|---|
| 3.1 | Second Amended and Restated Certificate of Incorporation of Gardner Denver Holdings, Inc. (incorporated by reference to Exhibit 3.1 to the Registrant’s Current Report on Form 8-K filed on May 17, 2017 (File no. 001-38095)) | |
| 3.2 | Amended and Restated Bylaws of Gardner Denver Holdings, Inc. (incorporated by reference to Exhibit 3.2 to the Registrant’s Current Report on Form 8-K filed on May 17, 2017 (File no. 001-38095)) | |
| 4.1 | Form of Common Stock Certificate (incorporated by reference to Exhibit 4.1 to Amendment No. 4 to the Registrant’s Registration Statement on Form S-1 filed on May 3, 2017 (File no. 333-216320)) | |
| 4.2 | Amended and Restated Registration Rights Agreement, dated as of May 17, 2017, by and among KKR Renaissance Aggregator L.P.; KKR Renaissance Aggregator GP LLC; Gardner Denver Holdings, Inc. and each of the other parties thereto (incorporated by reference to Exhibit 4.2 to the Registrant’s Current Report on Form 8-K filed on May 17, 2017 (File no. 001-38095)) | |
| 10.1† | 2013 Stock Incentive Plan for Key Employees of Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.) and its Subsidiaries (incorporated by reference to Exhibit 10.1 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.2 | Senior Secured Credit Agreement, dated as of July 30, 2013, among Renaissance Acquisition Corp., the foreign borrowers described therein, Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.), UBS AG, Stamford Branch, as administrative agent, and other agents and lenders party thereto (incorporated by reference to Exhibit 10.2 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.3 | Amendment No. 1 to the Senior Secured Credit Agreement, dated as of March 4, 2016, among Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.), Gardner Denver, Inc., GD German Holdings II GmbH (as successor in interest to Gardner Denver Holdings GmbH & Co. KG), GD First (UK) Limited, UBS AG, Stamford Branch, as administrative agent, and other agents and lenders party thereto (incorporated by reference to Exhibit 10.3 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.4 | Amendment No. 2 to the Credit Agreement, dated as of August 17, 2017, among Gardner Denver Holdings, Inc., Gardner Denver, Inc., GD German Holdings II GmbH, GD First (UK) Limited, UBS AG, Stamford Branch, as administrative agent, and the other parties and lenders party thereto (incorporated by reference to Exhibit 10.1 to the Registrant’s Current Report on Form 8-K filed on August 18, 2017 (File no. 001-38095)) | |
| 10.5 | Pledge Agreement, dated as of July 30, 2013, among Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.), Renaissance Acquisition Corp., the subsidiary pledgors identified therein and UBS AG, Stamford Branch, as collateral agent (incorporated by reference to Exhibit 10.4 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) |
| Exhibit Number | Exhibit Description | |
|---|---|---|
| 10.6 | Security Agreement, dated as of July 30, 2013, among Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.), Renaissance Acquisition Corp., the subsidiary grantors identified therein and UBS AG, Stamford Branch, as collateral agent (incorporated by reference to Exhibit 10.5 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.7 | Guarantee Agreement, dated as of July 30, 2013, among Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.), the subsidiary guarantors identified therein and UBS AG, Stamford Branch, as administrative agent and collateral agent (incorporated by reference to Exhibit 10.6 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.8 | Receivables Financing Agreement, dated as of May 17, 2016, by and among Gardner Denver Finance II LLC, Gardner Denver, Inc., as initial servicer, the various lenders and LC participants from time to time party thereto, PNC Bank, National Association, as LC bank and administrative agent, and PNC Capital Markets LLC, as structuring agent. (incorporated by reference to Exhibit 10.7 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.9 | Monitoring Agreement, dated as of July 30, 2013, by and between Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.) and Kohlberg Kravis Roberts & Co. L.P. (incorporated by reference to Exhibit 10.8 to Amendment No. 1 to the Registrant’s Registration Statement on Form S-1 filed on April 4, 2017 (File no. 333-216320)) | |
| 10.10 | First Amendment, dated as of June 9, 2014, to the Monitoring Agreement, dated as of July 30, 2013, by and between Garner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.) and Kohlberg Kravis Roberts & Co. L.P. (incorporated by reference to Exhibit 10.9 to Amendment No. 1 to the Registrant’s Registration Statement on Form S-1 filed on April 4, 2017 (File no. 333-216320)) | |
| 10.11 | Indemnification Agreement, dated as of July 30, 2013, by and among KKR Renaissance Aggregator L.P.; KKR Renaissance Aggregator GP LLC; Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.); Gardner Denver, Inc. and Kohlberg Kravis Roberts & Co. L.P. (incorporated by reference to Exhibit 10.10 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.12 | Transaction Fee Letter, dated as of July 30, 2013, by and between Kohlberg Kravis Roberts & Co. L.P. and Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.) (incorporated by reference to Exhibit 10.11 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.13 | Stockholders Agreement, dated as of May 17, 2017, between Gardner Denver Holdings, Inc. and KKR Renaissance Aggregator L.P. (incorporated by reference to Exhibit 4.1 to the Registrant’s Current Report on Form 8-K filed on May 17, 2017 (File no. 001-38095)) | |
| 10.14† | Form of Management Stockholder’s Agreement (incorporated by reference to Exhibit 10.13 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.15† | Form of Director Stockholder’s Agreement (incorporated by reference to Exhibit 10.14 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.16 | Form of Advisor Stockholder’s Agreement (incorporated by reference to Exhibit 10.15 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.17† | Form of Director Stock Option Agreement under the 2013 Stock Incentive Plan for Key Employees of Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.) and its Subsidiaries (incorporated by reference to Exhibit 10.16 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.18† | Form of Management Stock Option Agreement (December 2013) under the 2013 Stock Incentive Plan for Key Employees of Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.) and its Subsidiaries (incorporated by reference to Exhibit 10.17 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) |
| Exhibit Number | Exhibit Description | |
|---|---|---|
| 10.19† | Form of Management Stock Option Agreement (May 2015) under the 2013 Stock Incentive Plan for Key Employees of Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.) and its Subsidiaries (incorporated by reference to Exhibit 10.18 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.20† | Form of Management Stock Option Agreement (May 2016, 3 year vesting) under the 2013 Stock Incentive Plan for Key Employees of Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.) and its Subsidiaries (incorporated by reference to Exhibit 10.19 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.21† | Form of Management Stock Option Agreement (May 2016, 5 year vesting) under the 2013 Stock Incentive Plan for Key Employees of Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.) and its Subsidiaries (incorporated by reference to Exhibit 10.20 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.22† | Form of Management Stock Option Agreement (December 2016) under the 2013 Stock Incentive Plan for Key Employees of Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.) and its Subsidiaries (incorporated by reference to Exhibit 10.21 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.23† | Form of Amendment to Stock Option Agreement or Stock Appreciation Right Agreement under the 2013 Stock Incentive Plan for Key Employees of Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.) and its Subsidiaries (incorporated by reference to Exhibit 10.22 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.24† | Stock Option Agreement, dated as of March 7, 2014, between under the 2013 Stock Incentive Plan for Key Employees of Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.) between Gardner Denver Holdings, Inc. (formerly known as Renaissance Parent Corp.) and Andrew Schiesl (incorporated by reference to Exhibit 10.23 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.25† | Form of Sale Participation Agreement (incorporated by reference to Exhibit 10.24 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.26† | Offer Letter, dated April 17, 2015, between Vicente Reynal and Gardner Denver, Inc. (incorporated by reference to Exhibit 10.25 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.27† | Offer Letter, dated November 19, 2015, between Vicente Reynal and Gardner Denver, Inc. (incorporated by reference to Exhibit 10.26 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.28† | Offer Letter, dated November 18, 2015, between Todd Herndon and Gardner Denver, Inc. (incorporated by reference to Exhibit 10.27 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.29† | Offer Letter, dated September 2, 2016, between Todd Herndon and Gardner Denver, Inc. (incorporated by reference to Exhibit 10.28 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.32† | Offer Letter, dated November 25, 2013, between Gardner Denver, Inc. and Andy Schiesl (incorporated by reference to Exhibit 10.31 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.33† | Employment Contract, dated April 29, 2016, between Gardner Denver Deutschland GmbH and Enrique Mifiarro Viseras (incorporated by reference to Exhibit 10.32 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) |
| Exhibit Number | Exhibit Description | |
|---|---|---|
| 10.34† | Offer Letter, dated March 16, 2016, between Gardner Denver Deutschland GmbH and Enrique Mifiarro Viseras (incorporated by reference to Exhibit 10.33 to the Registrant’s Registration Statement on Form S-1 filed on February 28, 2017 (File no. 333-216320)) | |
| 10.37† | 2017 Omnibus Incentive Plan (incorporated by reference to Exhibit 10.2 to the Registrant’s Current Report on Form 8-K filed on May 17, 2017 (File no. 001-38095)) | |
| 10.38 | Monitoring Fee Termination Agreement, dated as of May 17, 2017, between Gardner Denver Holdings, Inc. Kohlberg Kravis Roberts & Co. L.P. (incorporated by reference to Exhibit 10.1 to the Registrant’s Current Report on Form 8-K filed on May 17, 2017 (File no. 001-38095)) | |
| 10.39† | Offer letter dated December 18, 2015, between Gardner Denver, Inc. and Neil Snyder. | |
| 10.40† | Gardner Denver, Inc. Supplemental Excess Defined Contribution Plan (December, 2017 Restatement) | |
| 10.41† | Form of Director Restricted Stock Grant Notice and Agreement under the Gardner Denver Holdings, Inc. 2017 Omnibus Incentive Plan | |
| 10.42† | Form of Stock Option Grant Notice and Agreement under the Gardner Denver Holdings, Inc. 2017 Omnibus Incentive Plan | |
| 21 | Subsidiaries of Gardner Denver Holdings, Inc. as of December 31, 2017 | |
| 23 | Consent of Independent Registered Public Accounting Firm | |
| 31.1 | Certification of Chief Executive Officer pursuant to Rule 13a-14(a) or 15d-14(a) | |
| 31.2 | Certification of Chief Financial Officer pursuant to Rule 13a-14(a) or 15d-14(a) | |
| 32.1 | Certification of Chief Executive Officer pursuant to 18 U.S.C. Section 1350 | |
| 32.2 | Certification of Chief Financial Officer pursuant to 18 U.S.C. Section 1350 |
† Identifies exhibits that consist of a management contract or compensatory plan or arrangement.
Item 16. FORM 10-K SUMMARY
| --- | --- |
None
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| Gardner Denver Holdings, Inc. | ||
|---|---|---|
| By: | /s/ Vicente Reynal | |
| Name: Vicente Reynal | ||
| Title: Chief Executive Officer |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below on the 16th day of February 2018 by the following persons on behalf of the registrant and in the capacities indicated.
| Signature | Capacity | |
|---|---|---|
| /s/ Vicente Reynal | Chief Executive Officer and Director | |
| Vicente Reynal | (principal executive officer) | |
| /s/ Philip T. Herndon | Vice President and Chief Financial Officer | |
| Philip T. Herndon | (principal financial officer) | |
| /s/ Mark R. Sweeney | Vice President, Chief Accounting Officer and Corporate Controller | |
| Mark R. Sweeney | (principal accounting officer) | |
| /s/ Peter Stavros | Director | |
| Peter Stavros | ||
| /s/ Brandon F. Brahm | Director | |
| Brandon F. Brahm | ||
| /s/ William P. Donnelly | Director | |
| William P. Donnelly | ||
| /s/ John Humphrey | Director | |
| John Humphrey | ||
| /s/ William E. Kassling | Director | |
| William E. Kassling | ||
| /s/ Michael V. Marn | Director | |
| Michael V. Marn | ||
| /s/ Nickolas Vande Steeg | Director | |
| Nickolas Vande Steeg | ||
| /s/ Joshua T. Weisenbeck | Director | |
| Joshua T. Weisenbeck |
SCHEDULE 1 – GARDNER DENVER HOLDINGS, INC
(PARENT COMPANY ONLY)
STATEMENTS OF OPERATIONS AND COMPREHENSIVE INCOME (LOSS)
(Dollars in millions)
| For the Years Ended December 31, | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2017 | 2016 | 2015 | ||||||||||
| Revenues | $ | - | $ | - | $ | - | ||||||
| Cost of sales | - | - | - | |||||||||
| Gross Profit | - | - | - | |||||||||
| Operating costs | 19.5 | 12.9 | 7.4 | |||||||||
| Other operating expense, net | 175.0 | - | - | |||||||||
| Operating Loss | (194.5 | ) | (12.9 | ) | (7.4 | ) | ||||||
| Interest income | 20.7 | - | - | |||||||||
| Other income, net | - | - | - | |||||||||
| Loss Before Income Taxes | (173.8 | ) | (12.9 | ) | (7.4 | ) | ||||||
| Income tax benefit | (16.1 | ) | (4.5 | ) | (2.5 | ) | ||||||
| Loss of Parent Company | (157.7 | ) | (8.4 | ) | (4.9 | ) | ||||||
| Equity in undistributed income (loss) of subsidiaries | 176.1 | (28.2 | ) | (346.3 | ) | |||||||
| Net Income (Loss) | 18.4 | (36.6 | ) | (351.2 | ) | |||||||
| Other comprehensive income (loss) | 142.6 | (76.8 | ) | (130.3 | ) | |||||||
| Comprehensive Income (Loss) | $ | 161.0 | $ | (113.4 | ) | $ | (481.5 | ) |
SCHEDULE 1 – GARDNER DENVER HOLDINGS, INC
(PARENT COMPANY ONLY)
BALANCE SHEETS
(Dollars in millions)
| As of December 31, | ||||||||
|---|---|---|---|---|---|---|---|---|
| 2017 | 2016 | |||||||
| Assets | ||||||||
| Current assets: | ||||||||
| Cash and cash equivalents | $ | 0.2 | $ | 0.3 | ||||
| Total current assets | 0.2 | 0.3 | ||||||
| Equity in net assets of subsidiaries | 605.9 | 276.9 | ||||||
| Intercompany receivables | 865.1 | - | ||||||
| Deferred tax assets | 22.2 | 7.0 | ||||||
| Total assets | $ | 1,493.4 | $ | 284.2 | ||||
| Liabilities and Stockholders' Equity | ||||||||
| Intercompany payables | $ | - | $ | 18.2 | ||||
| Other liabilities | 16.6 | 0.1 | ||||||
| Total liabilities | 16.6 | 18.3 | ||||||
| Stockholders' equity: | ||||||||
| Common stock, $0.01 par value; 1,000,000,000 shares authorized;198,377,237 and 150,552,360 shares issued at December 31, 2017 | 2.0 | 1.5 | ||||||
| Capital in excess of par value | 2,275.4 | 1,222.4 | ||||||
| Accumulated deficit | (577.8 | ) | (596.2 | ) | ||||
| Treasury stock at cost; 2,159,266 and 1,897,454 shares at | ||||||||
| December 31, 2017 and 2016, respectively | (23.0 | ) | (19.4 | ) | ||||
| Accumulated other comprehensive loss | (199.8 | ) | (342.4 | ) | ||||
| Total Gardner Denver Holdings, Inc. stockholders' equity | 1,476.8 | 265.9 | ||||||
| Total liabilities and stockholders' equity | $ | 1,493.4 | $ | 284.2 |
SCHEDULE 1 – GARDNER DENVER HOLDINGS, INC
(PARENT COMPANY ONLY)
CONDENSED STATEMENTS OF CASH FLOWS
(Dollars in millions)
| For the Years Ended December 31, | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2017 | 2016 | 2015 | ||||||||||
| Cash Flows From Operating Activities: | ||||||||||||
| Net cash provided by (used in) operating activities | $ | 9.2 | $ | 11.1 | $ | (2.0 | ) | |||||
| Cash Flows From Investing Activities: | ||||||||||||
| Advances to subsidiaries | (899.3) | - | - | |||||||||
| Net cash used in investing activities | (899.3) | - | - | |||||||||
| Cash Flows From Financing Activities: | ||||||||||||
| Purchases of treasury stock | (3.6 | ) | (14.1 | ) | (2.1 | ) | ||||||
| Proceeds from the issuance of common stock | 893.6 | 3.3 | 4.2 | |||||||||
| Net cash provided by (used in) financing activities | 890.0 | (10.9 | ) | 2.1 | ||||||||
| (Decrease) increase in cash and cash equivalents | (0.1 | ) | 0.2 | 0.0 | ||||||||
| Cash and cash equivalents, beginning of year | 0.3 | 0.1 | 0.0 | |||||||||
| Cash and cash equivalents, end of year | $ | 0.2 | $ | 0.3 | $ | 0.1 |
SCHEDULE I - GARDNER DENVER HOLDINGS, INC.
(PARENT COMPANY ONLY)
NOTES TO CONDENSED FINANCIAL STATEMENTS
- Overview and Basis of Presentation
On July 30, 2013, Gardner Denver, Inc. was acquired by an affiliate of Kohlberg Kravis Roberts & Co. L.P. (“KKR”). The acquisition (also referred to as the “Merger”) was effected by the merger of Renaissance Acquisition Corp. with and into Gardner Denver, Inc., with Gardner Denver, Inc. being the surviving corporation. As a result of the Merger, Gardner Denver, Inc. became a wholly-owned subsidiary of Gardner Denver Holdings, Inc. (formerly Renaissance Parent Corp.)
Gardner Denver Holdings, Inc. Parent Company only financial information has been derived from its consolidated financial statements and should be read in conjunction with the consolidated financial statements included in this report. The accounting policies for the registrant are the same as those described in Note 1 in the section, “Notes to the Consolidated Financial Statements”.
- Subsidiary Transactions
Investment in Subsidiaries
Gardner Denver Holdings, Inc.’s investment in subsidiaries is stated at cost plus equity in undistributed earnings of subsidiaries.
Advances to Subsidiaries
On June 30, 2017, Gardner Denver Holdings Inc, entered into an $899.3 million promissory note receivable from Gardner Denver Inc. The promissory note bears an annual interest rate of 4.5677% and payments are due on last day of December, or the first regular business day immediately following such date, commencing on December 31, 2017. The principal balance may be increased in lieu of payment of interest with the mutual agreement of both the borrower and the lender. Principal shall become due and payable in full on demand.
Dividends and Capital Distributions
There were no dividends received from subsidiaries during the years ended December 31, 2017, 2016 and 2015.
- Debt
A discussion of long-term debt, including the five-year debt maturity schedule, can be found in Note 10 in the section, “Notes to the Consolidated Financial Statements”. Gardner Denver Holdings, Inc. had no long-term debt obligations as of December 31, 2017 and 2016.
- Contingencies
For a summary of contingencies, see Note 18 in the section, “Notes to the Consolidated Financial Statements”.