 filings.tools
J.B. Hunt Transport Services (JBHT) 10-K risk factor changes: FY2022 vs FY2021
The 2022-12-31 10-K against the 2021-12-31 one, compared heading by heading and sentence by sentence.
Item 1A7 rewritten6 added0 removed100 unchanged
All filing items617 rewritten176 added137 removed985 unchanged
Summary
counted, not written
- Item 1A lists 17 risk factor headings: 0 new, 0 reworded and 17 unchanged since FY2021. 0 headings from FY2021 no longer appear.
- Sentence by sentence, 176 added, 137 removed, 617 rewritten and 985 unchanged across 18 items that differ.
New Item 1A headings (0)
No risk factor heading in this filing is absent from FY2021.
Removed Item 1A headings (0)
Every FY2021 risk factor heading is still here, word for word or reworded.
A heading is new when no FY2021 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
22 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2022; struck-through words were in FY2021. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. RISK FACTORS
7 rewritten, 6 added, 0 removed, 100 unchanged
A material change in the relationship with, the ability to utilize [removed: one] or [removed: more of these railroads or] the overall service levels provided by [added: one or more of] these railroads could have a material adverse effect on our business and operating results.
As of December 31, [removed: 2021,] [added: 2022,] we had no derivative financial instruments to reduce our exposure to fuel-price fluctuations.
If the number or severity of claims for which we are self-insured [removed: increases,] [added: continues to increase,] our operating results could be [added: further] adversely affected.
We have policies in place for [removed: 2022] [added: 2023] with substantially the same terms as our [removed: 2021] [added: 2022] policies for personal injury, property damage, workers’ compensation, and cargo loss or damage.
For the calendar year ended December 31, [removed: 2021,] [added: 2022,] our top 10 customers, based on revenue, accounted for approximately [removed: 39%] [added: 38%] of our revenue.
One customer accounted for approximately [removed: 12%] [added: 14%] of our total revenue for the year ended December 31, [removed: 2021.][added: 2022.]
An example of such legislation [added: has] recently [removed: enacted] [added: gone into effect] in [removed: California is currently under a judicial stay with respect to trucking companies while] [added: California, although] a legal challenge to the law is pending.
The transportation services provided by these railroads have been in recent years and may from time to time in the future be impacted by contractual disagreements, labor disruptions or shortages, and other rail network inefficiencies.
We regularly purchase new revenue equipment, including trucks, chassis and trailing equipment, in each of our operating segments to expand our fleets and replace aging equipment.
Since the beginning of the COVID-19 pandemic, equipment manufacturers have experienced production and delivery delays due to work stoppages, supply chain disruptions and high demand that have impacted the availability, cost and timing of our receipt of new equipment orders.
Any continued or future delays in the availability of new revenue equipment or further increases in the cost of such equipment could have a material adverse affect on our business and profitability by reducing productivity, increasing maintenance expenses and capital expenditures, and limiting our ability to expand our business.
We have experienced substantial increases in the number and severity of auto liability claims which have exceeded our insurance coverage layers, which has adversely impacted our operating results in recent periods.
We may in the future experience security breaches and other interruptions of our information technology systems despite our best efforts to prevent them.
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
109 rewritten, 42 added, 44 removed, 177 unchanged
[removed: For 2019 through 2021, we] [added: We] were [removed: self-insured for $500,000 per occurrence for personal injury and property damage and] fully insured for workers’ compensation claims for nearly all states.
We have policies in place for [removed: 2022] [added: 2023] with substantially the same terms as our [removed: 2021] [added: 2022] policies for personal injury, property damage, workers’ compensation, and cargo loss or damage.
This process involves the use of expected loss rates, loss-development factors based on our historical claims experience, [added: claim frequencies] and [added: severity, and] contractual premium adjustment factors, if applicable.
At December 31, [removed: 2021,] [added: 2022,] we had an accrual of approximately [removed: $287] [added: $427] million for estimated claims.
At December 31, [removed: 2021,] [added: 2022,] we have recorded [removed: $311] [added: $374] million of expected reimbursement for covered excess claims, other insurance deposits, and prepaid insurance premiums.
We have not identified any impairment to our assets at December 31, [removed: 2021.][added: 2022.]
See Note [removed: 7,] [added: 6,] Income Taxes, in our Consolidated Financial Statements for a discussion of our current tax contingencies.
| | | [removed: 2021] [added: 2022] | | | | [removed: 2020] [added: 2021] | | | | [removed: 2019] [added: 2020] | | | | [removed: 2021] [added: 2022] vs. [removed: 2020] [added: 2021] | | | | [removed: 2020] [added: 2021] vs. [removed: 2019] [added: 2020] | | |
| Operating revenues | | | 100.0 | % | | | 100.0 | % | | | 100.0 | % | | | [removed: 26.3] [added: 21.7] | % | | | [removed: 5.1] [added: 26.3] | % |
| Rents and purchased transportation | | | [removed: 53.0] [added: 49.9] | | | | [removed: 51.4] [added: 53.0] | | | | [removed: 49.4] [added: 51.4] | | | | [removed: 30.2] [added: 14.6] | | | | [removed: 9.4] [added: 30.2] | |
| Salaries, wages and employee benefits | | | [removed: 22.7] [added: 22.8] | | | | [removed: 24.4] [added: 22.7] | | | | [removed: 23.7] [added: 24.4] | | | | [removed: 17.6] [added: 22.1] | | | | [removed: 8.3] [added: 17.6] | |
| Depreciation and amortization | | | [removed: 4.6] [added: 4.4] | | | | [removed: 5.5] [added: 4.6] | | | | [removed: 5.4] [added: 5.5] | | | | [removed: 5.6] [added: 15.7] | | | | [removed: 5.7] [added: 5.6] | |
| Fuel and fuel taxes | | | [removed: 4.4] [added: 6.3] | | | | [removed: 3.7] [added: 4.4] | | | | [removed: 5.1] [added: 3.7] | | | | [removed: 48.4] [added: 75.6] | | | | [removed: (22.8] [added: 48.4] | [removed: )] |
| Operating supplies and expenses | | | [removed: 3.0] [added: 3.4] | | | | [removed: 3.5] [added: 3.0] | | | | [removed: 3.6] [added: 3.5] | | | | [removed: 10.5] [added: 36.1] | | | | [removed: 0.4] [added: 10.5] | |
| General and administrative expenses, net of asset dispositions | | | [removed: 1.5] [added: 1.4] | | | | [removed: 1.8] [added: 1.5] | | | | [removed: 2.1] [added: 1.8] | | | | [removed: 8.6] [added: 10.1] | | | | [removed: (6.2] [added: 8.6] | [removed: )] |
| Insurance and claims | | | [removed: 1.4] [added: 2.1] | | | | 1.4 | | | | [removed: 1.7] [added: 1.4] | | | | [removed: 22.7] [added: 92.7] | | | | [removed: (14.5] [added: 22.7] | [removed: )] |
| Operating taxes and licenses | | | 0.5 | | | | [removed: 0.6] [added: 0.5] | | | | 0.6 | | | | [removed: 9.4] [added: 14.8] | | | | [removed: (1.8] [added: 9.4] | [removed: )] |
| Communication and utilities | | | [removed: 0.3] [added: 0.2] | | | | 0.3 | | | | [removed: 0.4] [added: 0.3] | | | | [removed: 4.0] [added: 5.3] | | | | [removed: (3.7] [added: 4.0] | [removed: )] |
| Total operating expenses | | | [removed: 91.4] [added: 91.0] | | | | [removed: 92.6] [added: 91.4] | | | | [removed: 92.0] [added: 92.6] | | | | [removed: 24.6] [added: 21.2] | | | | [removed: 5.8] [added: 24.6] | |
| Operating income | | | [removed: 8.6] [added: 9.0] | | | | [removed: 7.4] [added: 8.6] | | | | [removed: 8.0] [added: 7.4] | | | | [removed: 46.6] [added: 27.4] | | | | [removed: (2.8] [added: 46.6] | [removed: )] |
| Net interest expense | | | 0.4 | | | | [removed: 0.5] [added: 0.4] | | | | [removed: 0.6] [added: 0.5] | | | | [removed: (2.8] [added: 9.7] | [removed: )] | | | [removed: (11.0] [added: (2.8] | ) |
| Earnings before income taxes | | | [removed: 8.2] [added: 8.6] | | | | [removed: 6.9] [added: 8.2] | | | | [removed: 7.4] [added: 6.9] | | | | [removed: 50.1] [added: 28.2] | | | | [removed: (2.2] [added: 50.1] | [removed: )] |
| Income taxes | | | [removed: 1.9] [added: 2.1] | | | | [removed: 1.6] [added: 1.9] | | | | [removed: 1.8] [added: 1.6] | | | | [removed: 49.4] [added: 30.6] | | | | [removed: (2.8] [added: 49.4] | [removed: )] |
| Net earnings | | | [removed: 6.3] [added: 6.5] | % | | | [removed: 5.3] [added: 6.3] | % | | | [removed: 5.6] [added: 5.3] | % | | | [removed: 50.3] [added: 27.4] | % | | | [removed: (2.0] [added: 50.3] | [removed: )%] [added: %] |
We operated five business segments during [removed: calendar year 2021.][added: 2022.]
| | | [removed: 2021] [added: 2022] | | | | [removed: 2020] [added: 2021] | | | | [removed: 2019] [added: 2020] | | |
| JBI | | $ | [removed: 5,454] [added: 7,022] | | | $ | [removed: 4,675] [added: 5,454] | | | $ | [removed: 4,745] [added: 4,675] | |
| DCS | | | [removed: 2,578] [added: 3,378] | | | | [removed: 2,196] [added: 2,578] | | | | [removed: 2,128] [added: 2,196] | |
| ICS | | | [removed: 2,538] [added: 2,386] | | | | [removed: 1,658] [added: 2,538] | | | | [removed: 1,348] [added: 1,658] | |
| FMS | | | [removed: 842] [added: 980] | | | | [removed: 689] [added: 842] | | | | [removed: 567] [added: 689] | |
| JBT | | | [removed: 796] [added: 1,082] | | | | [removed: 463] [added: 796] | | | | [removed: 389] [added: 463] | |
| Total segment revenues | | | [removed: 12,208] [added: 14,848] | | | | [removed: 9,681] [added: 12,208] | | | | [removed: 9,177] [added: 9,681] | |
| Intersegment eliminations | | | [removed: (40] [added: (34] | ) | | | [removed: (44] [added: (40] | ) | | | [removed: (12] [added: (44] | ) |
| Total | | $ | [removed: 12,168] [added: 14,814] | | | $ | [removed: 9,637] [added: 12,168] | | | $ | [removed: 9,165] [added: 9,637] | |
| JBI | | $ | [removed: 603] [added: 800] | | | $ | [removed: 428] [added: 603] | | | $ | [removed: 447] [added: 428] | |
| DCS | | | [removed: 304] [added: 345] | | | | [removed: 314] [added: 304] | | | | [removed: 278] [added: 314] | |
| ICS | | | [removed: 46] [added: 59] | | | | [removed: (45] [added: 46] | [removed: )] | | | [removed: (11] [added: (45] | ) |
| FMS | | | [removed: 28] [added: 35] | | | | [removed: (1] [added: 28] | [removed: )] | | | [removed: (9] [added: (1] | ) |
| JBT | | | [removed: 65] [added: 93] | | | | [removed: 17] [added: 65] | | | | [removed: 29] [added: 17] | |
| Total | | $ | [removed: 1,046] [added: 1,332] | | | $ | [removed: 713] [added: 1,046] | | | $ | [removed: 734] [added: 713] | |
We have umbrella policies to limit our exposure to catastrophic claim costs which may include certain coverage-layer-specific, aggregated reimbursement limits of covered excess claims.
For 2020 through 2022, we were self-insured for $500,000 per occurrence as well as subject to coverage-layer-specific, aggregated reimbursement limits of covered excess claims for personal injury and property damage.
A significant increase in the volume of claims or amount of settlements exceeding our coverage-layer specific, aggregated reimbursement limits could result in significant increase in our estimated liability for claims in future periods.
2022 Compared With 2021
Our total consolidated operating revenues increased 21.7% to $14.81 billion in 2022, compared to $12.17 billion in 2021.
This increase was primarily due to higher revenue per load and increased load volumes within JBI and JBT, increased average revenue producing trucks and fleet productivity within DCS, and increased revenue in FMS primarily driven by a business acquisition, partially offset by decreased ICS load volume.
Fuel surcharge revenues increased 94.2% to $2.43 billion in 2022, compared to $1.25 billion in 2021.
Insurance and claims expense increased 92.7% in 2022, primarily due to increased cost per claim, higher insurance policy premium expense, and the inclusion of $94.0 million of expense for additional casualty claim reserves for claims subject to insurance coverage layer specific aggregated limits in 2022.
General and administrative expenses increased 10.1% from 2021, primarily due to higher building rentals, higher software subscription expense, increased professional services expense, and higher bad debt expense, partially offset by higher net gains from sale or disposals of assets.
Net gain from sale or disposal of assets was $25.4 million in 2022, compared to a net loss from sale or disposals of assets of $5.5 million in 2021.
| | | 2022 | | | | 2021 | | | | 2020 | | |
| | | 2022 | | | | 2021 | | | | 2020 | | |
| Average trailers during the period | | | 12,798 | | | | 9,299 | | | | 7,866 | |
| Revenue per load | | $ | 2,163 | | | $ | 1,785 | | | $ | 1,138 | |
| Average length of haul | | | 520 | | | | 482 | | | | 420 | |
JBI segment revenue increased 29% to $7.02 billion in 2022, from $5.45 billion in 2021.
The increase is primarily due to increased revenue and higher net gains from the sale of equipment during the current year, partially offset by higher rail and third-party dray purchased transportation expense, higher costs to attract and retain drivers, increased non-driver salary and wages, higher equipment-related expenses, increased insurance and claims expense, and higher costs due to rail and port network inefficiencies and customer detention of equipment.
In addition, JBI incurred $33 million in expense for the segment’s portion of the additional casualty claim reserves in 2022.
The increase in productivity was primarily due to contractual index-based rate increases, partially offset by lower productivity of equipment on start-up accounts.
Higher revenues and higher net gains from the sale of equipment during 2022 were partially offset by increased driver and non-driver wages, benefits and recruiting costs, higher equipment-related expenses, higher costs related to the implementation of new long-term customer contracts, increased insurance and claims expense, and higher bad debt expense when compared to 2021.
In addition, DCS incurred $27 million in expense for the segment’s portion of the additional casualty claim reserves in 2022.
ICS segment revenue decreased 6% to $2.39 billion in 2022, from $2.54 billion in 2021.
Operating income of our ICS segment increased to $59 million in 2022, from $46 million in 2021.
The increase in operating income was primarily due to higher gross profit margins, partially offset by higher personnel costs, increased technology spending, increased insurance and claims expense, and higher bad debt expense during 2022.
In addition, ICS incurred $22 million in expense for the segment’s portion of the additional casualty claim reserves in 2022.
Gross profit margin increased to 14.7% in the current year versus 11.8% last year.
JBT segment revenue increased 36% to $1.1 billion in 2022, from $796 million in 2021.
Operating income of our JBT segment increased to $93 million in 2022, from $65 million in 2021.
The increase in operating income was driven primarily by increased load counts and revenue per load during the current year, which were partially offset by higher purchased transportation expense, higher equipment-related expenses, increased personnel costs, increased insurance and claims expense, and increased technology spending related to the continued expansion of J.B. Hunt 360box.
In addition, JBT incurred $7 million in expense for the segment’s portion of the additional casualty claim reserves in 2022.
FMS segment revenue increased 16% to $980 million in 2022 from $842 million in 2021, primarily due to the implementation of multiple new customer contracts and the acquisition of Zenith Freight Lines, LLC (Zenith) in 2022.
The increase in revenue was partially offset by the effects of internal efforts to improve revenue quality across certain accounts as well as supply-chain related constraints for goods in the primary markets served by FMS.
Operating income of our FMS segment increased to $35 million in 2022, from $28 million in 2021.
The increase in operating income was primarily due to increased revenues, partially offset by higher personnel salary, wages and benefits expense, higher equipment-related expenses, increased insurance and claims expense, increased driver recruiting costs, increased technology costs, and implementation costs related to new long-term contractual business.
In addition, FMS incurred $5 million in expense for the segment’s portion of the additional casualty claim reserves in 2022, while 2021 included an aggregated benefit of $9 million from the net settlement of claims and the reduction of a contingent liability.
In September 2022, we replaced our $750 million senior credit facility dated September 25, 2018, with a new credit facility authorizing us to borrow up to $1.5 billion through a revolving line of credit and committed term loans, which is supported by a credit agreement with a group of banks.
The revolving line of credit authorizes us to borrow up to $1.0 billion under a five-year term expiring September 2027, and allows us to request an increase in the revolving line of credit total commitment by up to $300 million and to request two one-year extensions of the maturity date.
The committed term loans authorize us to borrow up to an additional $500 million during the nine-month period beginning September 27, 2022, and if funded, will mature in September 2025.
At December 31, 2022, we had a cash balance of $51.9 million, a $317.5 million outstanding balance on the revolving line of credit at an average interest rate of 5.32% and no outstanding balance of term loans under our senior credit facility.
Our $350 million of 3.30% senior notes matured in August 2022.
We have umbrella policies to limit our exposure to catastrophic claim costs.
| Loaded miles (000) | | | 215,940 | | | | 171,141 | | | | 143,511 | |
| Nonpaid empty mile percentage | | 19.4 | | % | | | 18.8 | % | | | 18.9 | % |
| Revenue per tractor per week(2) | | $ | 4,791 | | | $ | 3,978 | | | $ | 3,917 | |
| Average tractors during the period(1) | | | 1,899 | | | | 1,837 | | | | 1,958 | |
2020 Compared With 2019
Our total consolidated operating revenues increased 5.1% to $9.64 billion in 2020, compared to $9.17 billion in 2019, primarily due to increased ICS revenue per load, the December 2019 acquisition and new contractual business onboarded throughout 2020 in FMS, and increased load volumes in JBT and DCS.
The increase in revenue was partially offset by a decrease in JBI revenue per load.
Fuel surcharge revenues decreased 27.4% to $757 million in 2020, compared to $1.04 billion in 2019.
In addition, 2020 included a $12.3 million one-time COVID-19 related bonus paid to employee drivers and other key field personnel.
General and administrative expenses decreased 6.2% from 2019, primarily due to decreased professional fees, lower advertising costs, lower driver hiring expenses and, decreased net loss from the sale or disposal of assets, partially offset by increased technology spend on the J.B. Hunt 360 platform and legacy system upgrades, higher bad debt expenses, and increased building rental expenses.
Additionally, net losses from sale or disposal of assets were $4.4 million in 2020, compared to net losses of $13.1 million in 2019.
Insurance and claims expense decreased 14.5% in 2020, primarily due to the absence of a $20 million FMS claim settlement charge and $17.4 million in reserve charges in 2019 for arbitration related legal fees, cost and interest claimed by BNSF, partially offset by an increase in insurance premiums in 2020.
JBI segment revenue decreased 1% to $4.68 billion in 2020, from $4.74 billion in 2019.
Average length of haul increased 1% in 2020 when compared to 2019.
Benefits from increased load volume in 2020 were more than offset by higher rail purchased transportation costs, COVID-19 related network inefficiencies, higher personnel costs, which included a one-time COVID-19 related bonus paid to employee drivers and other key field personnel, and higher dray costs resulting from disruptions in rail capacity and a constricted labor and truck capacity environment.
Operating income for JBI in 2019 was impacted by a $26.8 million charge to rail purchase transportation expense resulting from the issuance of a final award regarding our arbitration with BNSF and a $17.4 million charge to insurance and claims expense, for arbitration related legal fees, cost and interest claimed by BNSF.
The increase in productivity was primarily a result of better utilization of assets between customer accounts, contracted customer rate increases, and increased customer supply chain fluidity.
The increase is primarily due to increased fleet productivity, the absence of significant new customer implementation costs throughout the majority of the year, lower driver related turnover costs, and lower travel and entertainment expenses.
Operating income was partially offset by higher non-driver personnel costs, a one-time COVID-19 related bonus and higher equipment ownership costs when compared to 2019.
ICS segment revenue increased 23% to $1.66 billion in 2020, from $1.35 billion in 2019.
Overall volumes increased 2%, with truckload volumes increasing 15% when compared to 2019.
ICS segment incurred an operating loss of $45 million in 2020, compared to operating loss of $11 million in 2019.
The increase in operating loss was primarily due to lower gross profit margins and increased technology spending as the Marketplace for J.B. Hunt 360 continues to expand in functionality and capacity.
Gross profit margin decreased to 9.9% in 2020 versus 13.1% last year primarily due to a more competitive pricing environment and constricted supply dynamics compared to 2019.
FMS revenue increased 22% to $689 million in 2020 from $567 million in 2019, primarily due to two business acquisitions completed in 2019 and an increase in new customer contracts throughout 2020, partially offset by the temporary suspension of operations at various customer sites in 2020 as a result of the effects of the COVID-19 pandemic.
Stop count for 2020 increased 30%, and productivity, defined as revenue per stop, decreased 7% compared to 2019.
The reduction in productivity was primarily due to a change in the mix of service methods to a more asset-light model resulting from the 2019 business acquisitions and a shift in the mix of services provided during 2020 as customers were affected by COVID-19 within our FMS network.
FMS segment had an operating loss of $1 million in 2020 compared to an operating loss of $9 million in 2019.
The current period operating loss was primarily due to increased costs to expand and improve, through service quality performance controls, the FMS network, lost revenue resulting from the temporary suspension of operations at several customer sites in response to COVID-19, higher bad debt expense, higher personnel costs, which included a one-time COVID-19 related bonus, higher COVID-19 related operating supplies expense an increase in noncash amortization expense attributable to the 2019 business acquisitions.
FMS segment operating loss for 2019 included a $20 million insurance claim settlement charge.
JBT segment revenue increased 19% to $463 million in 2020, from $389 million in 2019.
JBT segment had operating income of $17 million in 2020 compared with $29 million in 2019.
The decrease in operating income was driven primarily by higher purchased transportation expense and higher non-driver personnel cost and technology modernization expenses for the continued expansion of J.B. Hunt 360box compared to 2019.
For our senior notes maturing in 2022, it is our intent to pay the entire outstanding balances in full, on or before the maturity dates, using our existing cash balance, senior revolving line of credit or other sources of long-term financing.
At December 31, 2021, we had a cash balance of $356 million and we had no outstanding balance on our revolving line of credit, which authorizes us to borrow up to $750 million under a senior revolving line of credit, and is supported by a credit agreement with a group of banks that expires in September 2023.
This senior credit facility allows us to request an increase in the total commitment by up to $250 million and to request a one-year extension of the maturity date.
The third is $700 million of 3.875% senior notes due March 2026, issued in March 2019.
Interest payments under this note are due semiannually in March and September of each year, beginning September 2019.
We currently have an interest rate swap agreement which effectively convert our $350 million of 3.30% fixed-rate senior notes due August 2022 to a variable rate, resulting in an interest rates of 1.51% at December 31, 2021.
An excerpt. Shown here: 40 of 109 rewritten, 40 of 42 added and 40 of 44 removed. The counts are complete. For every sentence, read Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS in the FY2022 filing and the FY2021 filing.
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
7 rewritten, 3 added, 0 removed, 10 unchanged
Our senior notes have fixed interest rates ranging from [removed: 3.30%] [added: 3.85%] to 3.875%.
Our [removed: senior] revolving line of credit has variable interest rates, which are based on [removed: the Prime Rate, the Federal Funds Rate,] [added: either SOFR] or [removed: LIBOR,] [added: a Base Rate,] depending upon the specific type of borrowing, plus [removed: any] [added: an] applicable [removed: margins.][added: margin and other fees.]
[removed: We currently have] [added: During 2022, we had] an interest rate swap agreement which effectively [removed: converts] [added: converted] our [added: then outstanding] $350 million of 3.30% fixed-rate senior notes due August 2022 to a variable rate.
The applicable interest rate under this swap agreement [removed: is] [added: was] based on LIBOR plus an established margin.
At our current level of borrowing, a one-percentage-point increase in our applicable rate would reduce annual pretax earnings by [removed: $3.5] [added: $3.2] million.
Additionally, foreign currency transaction gains and losses were not material to our results of operations for the year ended December 31, [removed: 2021.][added: 2022.]
As of December 31, [removed: 2021,] [added: 2022,] we had no derivative financial instruments to reduce our exposure to fuel-price fluctuations.
At December 31, 2022, the average interest rate under our revolving line of credit was 5.32%.
These senior notes matured in August 2022 and the related interest rate swap was terminated.
We are not currently utilizing any hedging instruments to manage our interest rate risk.
Item 1. BUSINESS
47 rewritten, 9 added, 5 removed, 110 unchanged
J.B. Hunt Transport Services, Inc. is a publicly held holding company that, [removed: together with] [added: through] our wholly owned subsidiaries, provides [removed: safe and] [added: a wide range of] reliable [removed: transportation] [added: transportation, brokerage,] and delivery services to a diverse group of customers and consumers throughout the continental United States, Canada, and Mexico.
Our service offerings include transportation of full-truckload containerized freight, which we directly transport utilizing our company-controlled revenue equipment and company [removed: drivers or] [added: drivers,] independent [removed: contractors.][added: contractors, or third-party carriers.]
In addition, we provide [added: or arrange for] local and home delivery services, generally referred to as [removed: final-mile] [added: last-mile] delivery services, to customers through a network of cross-dock and other delivery system locations throughout the continental United States.
Utilizing [removed: a network of] thousands of reliable third-party carriers, we also provide comprehensive [added: freight] transportation [added: brokerage] and logistics services.
In addition to dry-van, full-load operations, [added: we also arrange for] these unrelated outside carriers [removed: also] [added: to] provide flatbed, refrigerated, less-than-truckload (LTL), and other specialized equipment, drivers, and services.
We believe our ability to offer multiple services, utilizing our [removed: five] [added: existing lines of] business [removed: segments] and a full complement of logistics services through third parties, represents a competitive advantage.
[removed: These segments include] [added: We report our operating results for these services using five reporting segments:] Intermodal (JBI), Dedicated Contract Services® (DCS®), Integrated Capacity Solutions (ICS), Final Mile Services® (FMS) and Truckload (JBT).
Our operations [removed: continue to be] [added: have been] impacted by the COVID-19 global pandemic.
Due to the nature of our business and the large portion of our workforce consisting of drivers and other non-office personnel, fewer than 25% of our total employees [removed: have been] [added: were] able to work remotely; however, we [removed: remain] [added: remained, and continue to remain,] committed to the safety of our workforce, suppliers, and customers while continuing to meet our customers’ needs.
Our COVID-19 safety response [removed: activities at our home office campus and all other field locations throughout North America include] [added: included] requiring remote working when possible, expanded health and safety policies, facility modifications, increased security coverage, and purchase and distribution of personal protective equipment and supplies.
[removed: During 2021,] [added: In addition,] we [removed: committed to providing] [added: provided] incremental paid time off for employees to help offset any financial loss caused by their absence from work when receiving the COVID-19 vaccination.
We also [removed: continue to work] [added: worked] with local healthcare organizations to provide vaccination assistance under applicable area guidelines and procedures to employees and their family members.
We continue to review and analyze both external and internal COVID-related data, including the effects of new [removed: variants, on a daily basis.][added: variants.]
We [removed: have been] [added: are] pleased with the continued performance of our employees, particularly our drivers, who [removed: have] provided consistent service to our customers throughout the pandemic.
We are an Environmental Protection Agency (EPA) SmartWay® Transport Partner, and proud to have been awarded the EPA’s SmartWay® Excellence Award each of the [removed: last] [added: past] twelve [removed: years.][added: years it was awarded.]
Segment information is also included in Note [removed: 14] [added: 13] to our Consolidated Financial Statements.
JBI operates [removed: 104,973] [added: 115,150] pieces of company-owned trailing equipment systemwide.
We own and maintain our own chassis fleet, consisting of [removed: 85,649] [added: 95,553] units.
JBI also manages a fleet of [removed: 5,612] [added: 6,081] company-owned [removed: tractors, 582 independent contractor trucks,] [added: tractors] and [removed: 6,943] [added: 7,972] company [removed: drivers.][added: drivers and contracts 615 independent contractor trucks.]
At December 31, [removed: 2021,] [added: 2022,] the total JBI employee count was [removed: 7,940.][added: 9,229.]
Revenue for the JBI segment in [removed: 2021] [added: 2022] was [removed: $5.45] [added: $7.02] billion.
At December 31, [removed: 2021,] [added: 2022,] this segment operated [removed: 11,139] [added: 1,506] company-owned trucks, [removed: 544] [added: 303] customer-owned trucks, and [removed: 6] [added: 20] independent contractor trucks.
DCS also operates [removed: 21,069] [added: 23,354] owned pieces of trailing equipment and [removed: 7,753] [added: 4,968] customer-owned trailers.
The DCS segment employed [removed: 14,709] [added: 16,334] people, including [removed: 12,632] [added: 13,887] drivers, at December 31, [removed: 2021.][added: 2022.]
DCS revenue for [removed: 2021] [added: 2022] was [removed: $2.58] [added: $3.38] billion.
Furthermore, we offer an online multimodal marketplace via J.B. Hunt 360 that [removed: matches] [added: helps shippers and carriers match] the right load with the right carrier and the best mode.
ICS revenue for [removed: 2021] [added: 2022] was [removed: $2.54] [added: $2.39] billion.
FMS provides [removed: final-mile] [added: last-mile] delivery services to customers through a nationwide network of cross-dock and other delivery system network locations, with 98% of the continental U.S. population living within 150 miles of a network location.
FMS provides both asset and non-asset [added: (brokerage)] big and bulky delivery and installation services, as well as fulfillment and retail-pooling distributions services.
At December 31, [removed: 2021,] [added: 2022,] this segment operated [removed: 1,272] [added: 12,328] company-owned trucks, [removed: 272] [added: 570] customer-owned trucks, and [removed: 19] [added: 1] independent contractor [removed: trucks.][added: truck.]
FMS also operates [removed: 1,036] [added: 1,297] owned pieces of trailing equipment and [removed: 185] [added: 316] customer-owned trailers.
The FMS segment employed [removed: 3,161] [added: 3,768] people, including [removed: 1,697] [added: 1,926] drivers and [removed: 189] [added: 607] delivery and material assistants, at December 31, [removed: 2021.][added: 2022.]
FMS revenue for [removed: 2021] [added: 2022] was [removed: $842] [added: $980] million.
JBT also offers services [removed: though] [added: through] our J.B. Hunt 360box® program which utilizes our J.B. Hunt 360 platform to access capacity and offer efficient drop trailer solutions to our customers.
At December 31, [removed: 2021,] [added: 2022,] the JBT segment operated [removed: 734] [added: 620] company-owned tractors, [removed: 11,172] [added: 14,718] company-owned trailers, and employed [removed: 1,139] [added: 1,055] people, [removed: 733] [added: 626] of whom were drivers.
At December 31, [removed: 2021,] [added: 2022,] we had [removed: 1,501] [added: 2,098] independent contractors operating in the JBT segment.
JBT revenue for [removed: 2021] [added: 2022] was [removed: $796 million.][added: $1.08 billion.]
Despite operating over [removed: 166,000] [added: 182,000] pieces of transportation equipment, our single greatest asset and one of the factors differentiating us from our competitors is our service-oriented people.
As of December 31, [removed: 2021,] [added: 2022,] we had [removed: 33,045] [added: 37,151] employees, which consisted of [removed: 22,005] [added: 24,411] company drivers, [removed: 9,740] [added: 10,795] office personnel, [removed: 1,108] [added: 1,324] maintenance technicians, and [removed: 192] [added: 621] delivery and material assistants.
We also had arrangements with [removed: 2,108] [added: 2,734] independent contractors to transport freight in our trailing equipment.
In April 2022, we eliminated the requirement of remote working when possible, resulting in previously remote employees returning to our home office campus and all other field locations throughout North America.
At December 31, 2022, the ICS segment employed 984 people, with approximately 156,400 available third-party carriers.
In addition, our Employee Resource Groups (ERGs), Inclusion Office, and Inclusion Council work together to further our culture of inclusivity.
Our Inclusion Office is a division of our People Team where our inclusion strategy and work are centralized to enable our mission of creating an inclusive culture where all employees feel welcomed, valued, respected, safe, and heard.
Our Inclusion Council was established in 2022 and is comprised of 15 senior leaders with diverse identities from across our organization.
They are a voice for our people who share a passion for ensuring that inclusion remains a key component of creating an exceptional employee experience and drives how we do business.
In April 2022, we successfully implemented our return to office plan and began concluding our COVID-19 specific safety response activities at our home office campus and all other field locations throughout North America.
In addition, we provided incremental paid time off for employees to help offset any financial loss caused by their absence from work when receiving the COVID-19 vaccination.
We also worked with local healthcare organizations to provide vaccination assistance under applicable area guidelines and procedures to employees and their family members.
In the first quarter 2020, we began our COVID-19 response activities which have been expanded and will continue as necessary until the risks related to COVID-19 dissipate.
At December 31, 2021, the ICS segment employed 975 people, with a carrier base of approximately 136,400.
On September 9, 2021, President Biden issued an executive order that, in conjunction with guidance issued pursuant to the order, requires all employers with U.S. Government contracts to require their U.S.-based employees, contractors, or subcontractors who work on or in support of certain U.S. Government contracts, to be fully vaccinated for COVID-19 by December 8, 2021, with limited exceptions for medical and religious reasons permitted.
Various states have challenged the mandate in multiple federal district courts resulting in the enforcement of this mandate to be currently enjoined nationwide.
We are awaiting final resolution of this matter, but do not anticipate a negative impact on our operations or productivity.
An excerpt. Shown here: 40 of 47 rewritten, all 9 added and all 5 removed. The counts are complete. For every sentence, read Item 1. BUSINESS in the FY2022 filing and the FY2021 filing.
Item 3. LEGAL PROCEEDINGS
1 rewritten, 0 added, 0 removed, 4 unchanged
See Note [removed: 10,] [added: 9,] Commitments and Contingencies in our Consolidated Financial Statements for disclosures related to legal proceedings.
Cover and table of contents
8 rewritten, 5 added, 1 removed, 51 unchanged
[added: | |] ☒ [added: |] ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) [removed: OFTHE] [added: OF THE] SECURITIES EXCHANGE ACT OF 1934 [added: |]
[added: | |] ☐ [added: |] TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(D) OF THE SECURITIES EXCHANGE ACT OF 1934 FOR THE TRANSITION PERIOD FROM [removed: _______ TO _______][added: TO |]
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit [removed: and post] such files).
The aggregate market value of [removed: 83,709,217] [added: 82,346,856] shares of the registrant’s $0.01 par value common stock held by non-affiliates as of June 30, [removed: 2021,] [added: 2022,] was [removed: $13.6] [added: $13.0] billion (based upon [removed: $162.95] [added: $157.47] per share).
As of February [removed: 15, 2022,] [added: 21, 2023,] the number of outstanding shares of the registrant’s common stock was [removed: 104,850,002.][added: 103,770,366.]
Certain portions of the Notice and Proxy Statement for the Annual Meeting of Stockholders, to be held April [removed: 28, 2022,] [added: 27, 2023,] are incorporated by reference in Part III of this Form 10-K.
For The Fiscal Year Ended December 31, [removed: 2021][added: 2022]
[added: | | |] Page [added: |]
December 31, 2022
| --- | --- | --- |
If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the registrant included in the filing reflect the correction of an error to previously issued financial statements.
Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant’s executive officers during the relevant recovery period pursuant to §240.10D-1(b) .
| --- | --- | --- |
December 31, 2021
Item 6. [Reserved] 14
1 rewritten, 0 added, 0 removed, 9 unchanged
Financial Statements and Supplementary Data [removed: 26][added: 25]
Item 9C. Disclosure Regarding Foreign Jurisdictions That Prevent Inspections 26
5 rewritten, 0 added, 0 removed, 33 unchanged
Certain Relationships and Related Transactions, and Director Independence [removed: 28][added: 27]
Principal Accounting Fees and Services [removed: 28][added: 27]
Some of the factors and events that are not within our control and that could have a material impact on future operating results include the following: general economic and business conditions; potential business or operational disruptions resulting from the [removed: ongoing] effects of the novel coronavirus (COVID-19) pandemic, including any future spikes or outbreaks of the virus, as well as government actions taken in response to the pandemic; competition and competitive rate fluctuations; excess capacity in the intermodal or trucking industries; a loss of one or more major customers; cost and availability of diesel fuel; interference with or termination of our relationships with certain railroads; rail service delays; disruptions to U.S. port-of-call activity; ability to attract and retain qualified drivers, delivery personnel, independent contractors, and third-party carriers; retention of key employees; insurance costs and availability; litigation and claims expense; determination that independent contractors are employees; new or different environmental or other laws and regulations; volatile financial credit markets or interest rates; terrorist attacks or actions; acts of war; adverse weather conditions; disruption or failure of information systems; inability to keep pace with_ _technological advances affecting our information technology platforms;_ _operational disruption or adverse effects of business acquisitions; increased costs for [added: and availability of] new revenue equipment; increased tariffs assessed on or disruptions in the procurement of imported revenue equipment; decreases in the value of used equipment; and the ability of revenue equipment manufacturers to perform in accordance with agreements for guaranteed equipment trade-in values._
_You should understand that many important factors, in addition to those listed above, could impact us [added: operationally and] financially.
Some important factors that could cause our [removed: actual] [added: future] results to differ from estimates or projections contained in the forward-looking statements are described under_ “_Risk Factors_” _in Item 1A.
Item 2. PROPERTIES
6 rewritten, 0 added, 0 removed, 9 unchanged
We also own or lease [removed: 50] [added: 52] other significant facilities across the United States where we perform maintenance on our equipment, provide bulk fuel, and employ personnel to support operations.
In addition, we have [removed: 118] [added: 129] leased or owned facilities in our FMS cross-dock and other delivery system networks and multiple leased or owned remote sales offices or branches in our ICS segment.
| Maintenance and support facilities | | | [removed: 533] [added: 563] | | | | [removed: 1,132,000] [added: 935,000] | | | | 198,000 | |
| Cross-dock and delivery system facilities | | | [removed: 33] [added: 82] | | | | [removed: 3,555,000] [added: 4,567,000] | | | | [removed: 137,000] [added: 140,000] | |
| Corporate headquarters campus, Lowell, Arkansas | | | [removed: 119] [added: 130] | | | | \- | | | | [removed: 607,000] [added: 707,000] | |
| Other facilities, offices, and parking yards | | | [removed: 503] [added: 555] | | | | [removed: 418,000] [added: 995,000] | | | | [removed: 304,000] [added: 266,000] | |
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
10 rewritten, 7 added, 10 removed, 12 unchanged
Our common stock is traded on the NASDAQ Global Select Market (NASDAQ) under the symbol “JBHT.” At December 31, [removed: 2021,] [added: 2022,] we were authorized to issue up to 1 billion shares of our common stock, and 167.1 million shares were issued.
We had [removed: 105.1] [added: 103.7] million and [removed: 105.7] [added: 105.1] million shares outstanding as of December 31, [removed: 2021] [added: 2022] and [removed: 2020] [added: 2021] respectively.
On February [removed: 15, 2022,] [added: 21, 2023,] we had [removed: 971] [added: 967] stockholders of record of our common stock.
On January [removed: 20, 2022,] [added: 19, 2023,] we announced an increase in our quarterly cash dividend from [removed: $0.30 to] $0.40 [added: to $0.42] per share, which was paid February [removed: 18, 2022,] [added: 24, 2023,] to stockholders of record on February [removed: 4, 2022.][added: 10, 2023.]
[removed: The following table summarizes] [added: We made no] purchases of our common stock during the three months ended December 31, [removed: 2021:][added: 2022.]
[removed: | | (1) |] On January 22, 2020, our Board of Directors authorized the purchase of up to $500 million of our common stock. [removed: This stock repurchase program has no expiration date. |]
The following graph compares the cumulative 5-year total return of stockholders of our common stock with the cumulative total returns of the S&P 500 index and [removed: a] [added: two] customized peer [removed: group.][added: groups.]
The peer group [added: labeled “2021 Peer Group”] consists of 13 companies: C.H. Robinson Worldwide Inc., CSX Corporation, Expeditors International of Washington Inc., Hub Group Inc., Knight-Swift Transportation Holdings Inc., Norfolk Southern Corporation, Old Dominion Freight Line Inc., Republic Services Inc., Ryder System Inc., Schneider National Inc., Stericycle Inc., Waste Management Inc., and [removed: XPO Logistics] [added: XPO,] Inc. The [added: peer group labeled “2022 Peer Group” consists of 14 companies: C.H. Robinson Worldwide Inc., CSX Corporation, Expeditors International of Washington Inc., Hub Group Inc., Knight-Swift Transportation Holdings Inc., Norfolk Southern Corporation, Old Dominion Freight Line Inc., Republic Services Inc., Ryder System Inc., Schneider National Inc., Stericycle Inc., Union Pacific Corporation, Waste Management Inc., and XPO, Inc. The] graph assumes the value of the investment in our common stock, in the index, and in [added: each of] the peer [removed: group] [added: groups] (including reinvestment of dividends) was $100 on December 31, [removed: 2016] [added: 2017] and tracks it through December 31, [removed: 2021.][added: 2022.]
[removed: 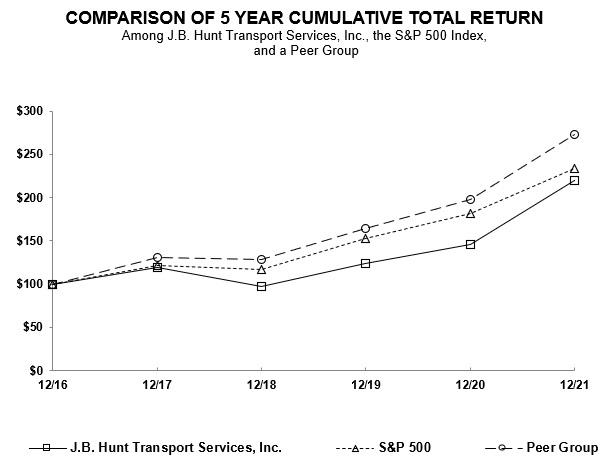][added: 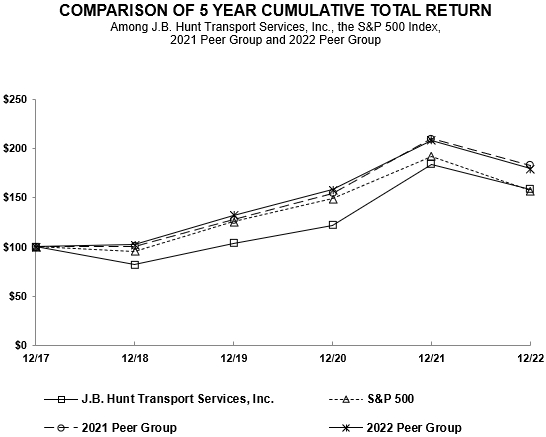]
| | | [removed: 2016 | | | |] 2017 | | | | 2018 | | | | 2019 | | | | 2020 | | | | 2021 | | | [added: | 2022 | | |]
On July 20, 2022, our Board of Directors authorized an additional purchase of up to $500 million of our common stock.
These stock repurchase programs have no expiration date.
At December 31, 2022, we had $551.1 million available under these authorized plans to purchase our common stock.
| J.B. Hunt Transport Services, Inc. | | $ | 100.00 | | | $ | 81.59 | | | $ | 103.43 | | | $ | 122.15 | | | $ | 183.99 | | | $ | 158.36 | |
| S&P 500 | | | 100.00 | | | | 95.62 | | | | 125.72 | | | | 148.85 | | | | 191.58 | | | | 156.89 | |
| 2021 Peer Group | | | 100.00 | | | | 100.83 | | | | 127.45 | | | | 154.02 | | | | 210.17 | | | | 182.35 | |
| 2022 Peer Group | | | 100.00 | | | | 102.30 | | | | 131.78 | | | | 157.84 | | | | 208.60 | | | | 179.30 | |
| Period | | Number of Common Shares Purchased | | | | Average Price Paid Per Common Share Purchased | | | | Total Number of Shares Purchased as Part of a Publicly Announced Plan (1) | | | | Maximum Dollar Amount of Shares That May Yet Be Purchased Under the Plan (in millions) (1) | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| October 1 through October 31, 2021 | | | \- | | | $ | \- | | | | \- | | | $ | 366 | |
| November 1 through November 30, 2021 | | | 75,509 | | | | 196.05 | | | | 75,509 | | | | 351 | |
| December 1 through December 31, 2021 | | | \- | | | | \- | | | | \- | | | | 351 | |
| Total | | | 75,509 | | | $ | 196.05 | | | | 75,509 | | | $ | 351 | |
| --- | --- | --- |
| J.B. Hunt Transport Services, Inc. | | $ | 100.00 | | | $ | 119.60 | | | $ | 97.58 | | | $ | 123.69 | | | $ | 146.09 | | | $ | 220.05 | |
| S&P 500 | | | 100.00 | | | | 121.83 | | | | 116.49 | | | | 153.17 | | | | 181.35 | | | | 233.41 | |
| Peer Group | | | 100.00 | | | | 130.56 | | | | 128.21 | | | | 164.52 | | | | 197.27 | | | | 272.79 | |
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
4 rewritten, 0 added, 0 removed, 7 unchanged
Consolidated Balance Sheets as of December 31, [removed: 2021] [added: 2022] and [removed: 2020][added: 2021]
Consolidated Statements of Earnings for years ended December 31, [added: 2022,] 2021, [removed: 2020,] and [removed: 2019][added: 2020]
Consolidated Statements of Stockholders’ Equity for years ended December 31, [added: 2022,] 2021, [removed: 2020,] and [removed: 2019][added: 2020]
Consolidated Statements of Cash Flows for years ended December 31, [added: 2022,] 2021, [removed: 2020,] and [removed: 2019][added: 2020]
Item 9A. CONTROLS AND PROCEDURES
3 rewritten, 0 added, 0 removed, 15 unchanged
Based upon that evaluation, our Chief Executive Officer and Chief Financial Officer concluded that our disclosure controls and procedures were effective as of December 31, [removed: 2021.][added: 2022.]
The effectiveness of internal control over financial reporting as of December 31, [removed: 2021,] [added: 2022,] has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm that also audited our Consolidated Financial Statements.
There has been no change in our internal control over financial reporting during the fourth quarter ended December 31, [removed: 2021,] [added: 2022,] that has materially affected, or is reasonably likely to materially affect, our internal control over financial reporting.
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required for Item 10 is hereby incorporated by reference from the Notice and Proxy Statement for the Annual Meeting of Stockholders to be held April [removed: 28, 2022.][added: 27, 2023.]
Item 11. EXECUTIVE COMPENSATION
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required for Item 11 is hereby incorporated by reference from the Notice and Proxy Statement for the Annual Meeting of Stockholders to be held April [removed: 28, 2022.][added: 27, 2023.]
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
3 rewritten, 0 added, 0 removed, 8 unchanged
Except as set forth below, the information required for Item 12 is hereby incorporated by reference from the Notice and Proxy Statement for the Annual Meeting of Stockholders to be held April [removed: 28, 2022.][added: 27, 2023.]
The following table summarizes, as of December 31, [removed: 2021,] [added: 2022,] information about compensation plans under which equity securities of the Company are authorized for issuance.
| Equity compensation plans approved by security holders | | | [removed: 1,664,242] [added: 1,542,366] | | | $ | [removed: \-(2)] [added: \- (2)] | | | | [removed: 4,648,867] [added: 4,233,978] | |
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required for Item 13 is hereby incorporated by reference from the Notice and Proxy Statement for the Annual Meeting of Stockholders to be held April [removed: 28, 2022.][added: 27, 2023.]
Item 14. PRINCIPAL ACCOUNTING FEES AND SERVICES
1 rewritten, 0 added, 0 removed, 1 unchanged
The information required for Item 14 is hereby incorporated by reference from the Notice and Proxy Statement for the Annual Meeting of Stockholders to be held April [removed: 28, 2022.][added: 27, 2023.]
Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES
402 rewritten, 104 added, 77 removed, 420 unchanged
[removed: | | |] The financial statements included in Item 8 above are filed as part of this annual report. [removed: |]
[removed: | | |] Schedule II – Valuation and Qualifying Accounts (in millions) [removed: |]
| December 31, 2020 | | [added: $] | 13.3 | | | [added: $] | 5.6 | | | [added: $] | (0.5 | ) | | [added: $] | 18.4 | |
| 4.1 | | [Description of Capital Stock of J.B. Hunt Transport Services, [removed: Inc.](https://www.sec.gov/Archives/edgar/data/728535/000143774922004457/ex_338296.htm)] [added: Inc.](https://www.sec.gov/Archives/edgar/data/728535/000143774923004530/ex_478219.htm)] |
| 4.4 | | [removed: [Fourth Supplemental Indenture] [added: [Base Indenture, dated as of March 1, 2019] (incorporated by reference from Exhibit [removed: 4.3] [added: 4.1] of the Company’s current report on Form 8-K, filed [removed: August 6, 2015)](http://www.sec.gov/Archives/edgar/data/728535/000143774915015006/ex4-3.htm)] [added: March 1, 2019)](http://www.sec.gov/Archives/edgar/data/728535/000143774919003755/ex_136073.htm)] |
| 4.5 | | [removed: [Base] [added: [First Supplemental] Indenture, dated as of March 1, 2019 (incorporated by reference from Exhibit [removed: 4.1] [added: 4.2] of the Company’s current report on Form 8-K, filed March 1, [removed: 2019)](http://www.sec.gov/Archives/edgar/data/728535/000143774919003755/ex_136073.htm)] [added: 2019)](http://www.sec.gov/Archives/edgar/data/728535/000143774919003755/ex_136213.htm)] |
| [removed: 4.6] [added: 10.5] | | [removed: [First Supplemental Indenture, dated as of March 1, 2019] [added: [Amended and Restated Credit Agreement and related documents] (incorporated by reference from Exhibit [removed: 4.2] [added: 10.1] of the Company’s current report on Form 8-K, filed [removed: March 1, 2019)](http://www.sec.gov/Archives/edgar/data/728535/000143774919003755/ex_136213.htm)] [added: October 3, 2022)](http://www.sec.gov/Archives/edgar/data/728535/000143774922023462/ex_427496.htm)] |
| 10.3 | | [Summary of Compensation Arrangements with Named Executive Officers for [removed: 2021] [added: 2022] (incorporated by reference from Exhibit 99.1 of the Company’s current report on Form 8-K, filed January [removed: 25, 2021)](http://www.sec.gov/Archives/edgar/data/728535/000143774921001198/ex_222086.htm)] [added: 24, 2022)](http://www.sec.gov/Archives/edgar/data/728535/000143774922001506/ex_327282.htm)] |
| 10.4 | | [Summary of Compensation Arrangements with Named Executive Officers for [removed: 2022] [added: 2023] (incorporated by reference from Exhibit 99.1 of the Company’s current report on Form 8-K, filed January 24, [removed: 2022)](http://www.sec.gov/Archives/edgar/data/728535/000143774922001506/ex_327282.htm)] [added: 2023)](http://www.sec.gov/Archives/edgar/data/728535/000143774923001645/ex_466501.htm)] |
| [removed: 10.6] [added: 3.3] | | [removed: [First Amendment] [added: [Amendment No. 1] to [removed: Credit Agreement,] [added: the Second Amended and Restated Bylaws J.B. Hunt Transport Services, Inc.,] dated [removed: as of March 1, 2019] [added: July 20, 2022] (incorporated by reference from Exhibit [removed: 10.2] [added: 3.1] of the Company’s current report on Form [removed: 8-K,] [added: 8-K] filed [removed: March 1, 2019)](http://www.sec.gov/Archives/edgar/data/728535/000143774919003755/ex_136049.htm)] [added: July 26, 2022)](http://www.sec.gov/Archives/edgar/data/728535/000143774922017755/ex_399784.htm)] |
| 21.1 | | [Subsidiaries of J.B. Hunt Transport Services, [removed: Inc.](https://www.sec.gov/Archives/edgar/data/728535/000143774922004457/ex_338297.htm)] [added: Inc.](https://www.sec.gov/Archives/edgar/data/728535/000143774923004530/ex_478220.htm)] |
| 22.1 | | [List of Guarantor Subsidiaries of J.B. Hunt Transport Services, [removed: Inc.](https://www.sec.gov/Archives/edgar/data/728535/000143774922004457/ex_338298.htm)] [added: Inc.](https://www.sec.gov/Archives/edgar/data/728535/000143774923004530/ex_478221.htm)] |
| 23.1 | | [Consent of PricewaterhouseCoopers [removed: LLP](https://www.sec.gov/Archives/edgar/data/728535/000143774922004457/ex_338299.htm)] [added: LLP](https://www.sec.gov/Archives/edgar/data/728535/000143774923004530/ex_478222.htm)] |
| 23.2 | | [Consent of [removed: Ernest] [added: Ernst] & Young [removed: LLP](https://www.sec.gov/Archives/edgar/data/728535/000143774922004457/ex_340011.htm)] [added: LLP](https://www.sec.gov/Archives/edgar/data/728535/000143774923004530/ex_478223.htm)] |
| 24.1 | | [Powers of Attorney of Members of J.B. Hunt Transport Services, Inc. Board of [removed: Directors](https://www.sec.gov/Archives/edgar/data/728535/000143774922004457/ex_339658.htm)] [added: Directors](https://www.sec.gov/Archives/edgar/data/728535/000143774923004530/ex_478224.htm)] |
| 31.1 | | [Rule 13a-14(a)/15d-14(a) [removed: Certification](https://www.sec.gov/Archives/edgar/data/728535/000143774922004457/ex_338300.htm)] [added: Certification](https://www.sec.gov/Archives/edgar/data/728535/000143774923004530/ex_478225.htm)] |
| 31.2 | | [Rule 13a-14(a)/15d-14(a) [removed: Certification](https://www.sec.gov/Archives/edgar/data/728535/000143774922004457/ex_338301.htm)] [added: Certification](https://www.sec.gov/Archives/edgar/data/728535/000143774923004530/ex_478226.htm)] |
| 32.1 | | [Section 1350 [removed: Certification](https://www.sec.gov/Archives/edgar/data/728535/000143774922004457/ex_338302.htm)] [added: Certification](https://www.sec.gov/Archives/edgar/data/728535/000143774923004530/ex_478227.htm)] |
| 104 | | Cover Page Interactive Data File [removed: (Formatted] [added: (formatted] as Inline XBRL and contained in Exhibit [removed: 101)] [added: 101).] |
Pursuant to the requirements of Sections 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned thereunto duly authorized, in the City of Lowell, Arkansas, on the [removed: 25th] [added: 24th] day of February [removed: 2022.][added: 2023.]
| [removed: By:] | [added: By:] | /s/ John N. Roberts, III | |
| | | [removed: President and] Chief Executive Officer | |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on the [removed: 25th] [added: 24th] day of February [removed: 2022,] [added: 2023,] on behalf of the registrant and in the capacities indicated.
| | /s/ John N. Roberts, III | | [removed: President and] Chief Executive Officer, [removed: Member] |
| | John N. Roberts, III | | [added: Member] of the Board of Directors |
| [removed: *By:] [added: *By] | /s/ John N. Roberts, III | | [removed: |]
| | John N. Roberts, III | | [removed: |]
| | As [removed: Attorney-In-Fact] [added: Attorney-in-Fact] Pursuant to Powers of Attorney filed herewith | | [removed: |]
| Consolidated Balance Sheets as of December 31, [removed: 2021] [added: 2022] and [removed: 2020] [added: 2021] | 37 |
| Consolidated Statements of Earnings for years ended December 31, [added: 2022,] 2021, [removed: 2020,] and [removed: 2019] [added: 2020] | 38 |
| Consolidated Statements of Stockholders’ Equity for years ended December 31, [added: 2022,] 2021, [removed: 2020,] and [removed: 2019] [added: 2020] | 39 |
| Consolidated Statements of Cash Flows for years ended December 31, [added: 2022,] 2021, [removed: 2020,] and [removed: 2019] [added: 2020] | 40 |
We assessed the effectiveness of our internal control over financial reporting as of December 31, [removed: 2021.][added: 2022.]
Based on our assessment, our management has concluded that as of December 31, [removed: 2021,] [added: 2022,] our internal control over financial reporting is effective based on those criteria.
The effectiveness of our internal control over financial reporting as of December 31, [removed: 2021,] [added: 2022,] has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm that also audited our Consolidated Financial Statements.
| [removed: President and] Chief Executive Officer | | Chief Financial Officer, | |
We have audited the accompanying consolidated balance [removed: sheet] [added: sheets] of J.B. Hunt Transport Services, Inc. and its subsidiaries (the “Company”) as of December 31, [removed: 2021] [added: 2022] and [added: 2021, and] the related consolidated statements of earnings, of stockholders' equity and of cash flows for [added: each of] the [removed: year] [added: two years in the period] ended December 31, [removed: 2021,] [added: 2022,] including the related notes and schedule of valuation and qualifying accounts for [added: each of] the [removed: year] [added: two years in the period] ended December 31, [removed: 2021] [added: 2022] appearing under Item 15(A)(2) (collectively referred to as the “consolidated financial statements”).
We also have audited the Company's internal control over financial reporting as of December 31, [removed: 2021,] [added: 2022,] based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, [added: 2022 and] 2021, and the results of its operations and its cash flows for [added: each of] the [removed: year] [added: two years in the period] ended December 31, [removed: 2021] [added: 2022] in conformity with accounting principles generally accepted in the United States of America.
Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2021,] [added: 2022,] based on criteria established in Internal Control - Integrated Framework (2013) issued by the COSO.
| December 31, 2022 | | | 16.8 | | | | 9.0 | | | | (3.5 | ) | | | 22.3 | |
| 3.4 | | [Amendment No. 2 to the Second Amended and Restated Bylaws of J.B. Hunt Transport Services, Inc. dated January 19, 2023 (incorporated by reference from Exhibit 3.1 of the Company’s current report on Form 8-K, filed January 24, 2023)](http://www.sec.gov/Archives/edgar/data/728535/000143774923001645/ex_466500.htm) |
| --- | --- | --- |
| --- | --- | --- |
February 24, 2023
| | | 2022 | | | | 2021 | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | | | |
| Comprehensive income: | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | |
| Comprehensive income: | | | | | | | | | | | | | | | | | | | | |
| Net earnings | | | \- | | | | \- | | | | 969,351 | | | | \- | | | | 969,351 | |
| Purchase of treasury shares | | | \- | | | | \- | | | | \- | | | | (300,030 | ) | | | (300,030 | ) |
| | | | | | | | | | | | | | | | | | | | | |
| Balances at December 31, 2022 | | $ | 1,671 | | | $ | 499,897 | | | $ | 6,423,730 | | | $ | (3,258,530 | ) | | $ | 3,666,768 | |
See Notes to Consolidated Financial Statements.
| Net earnings | | $ | 969,351 | | | $ | 760,806 | | | $ | 506,035 | |
| Depreciation and amortization | | | 644,520 | | | | 557,093 | | | | 527,375 | |
See Notes to Consolidated Financial Statements.
The allowance for uncollectible accounts for our trade accounts receivable was $22.3 million at December 31, 2022 and $16.8 million at December 31, 2021.
We have umbrella policies to limit our exposure to catastrophic claim costs which may include certain coverage-layer-specific, aggregated reimbursement limits of covered excess claims.
For 2020 through 2022, we were self-insured for $500,000 per occurrence as well as subject to coverage-layer-specific, aggregated reimbursement limits of covered excess claims for personal injury and property damage.
A significant increase in the volume of claims or amount of settlements exceeding our coverage-layer specific, aggregated reimbursement limits could result in significant increase in our estimated liability for claims in future periods.
| | | 2022 | | | | 2021 | | |
| Senior credit facility | | $ | 314.7 | | | $ | \- | |
On September 27, 2022, we replaced our $750 million senior credit facility dated September 25, 2018, with a new credit facility authorizing us to borrow up to $1.5 billion through a revolving line of credit and committed term loans, which is supported by a credit agreement with a group of banks.
The revolving line of credit authorizes us to borrow up to $1.0 billion under a five\-year term expiring September 2027, and allows us to request an increase in the revolving line of credit total commitment by up to $300 million and to request two one\-year extensions of the maturity date.
The committed term loans authorize us to borrow up to an additional $500 million during the nine-month period beginning September 27, 2022, and if funded, will mature in September 2025.
At December 31, 2022, we had $317.5 million outstanding on the revolving line of credit, at an average interest rate of 5.32%, and no outstanding balance of term loans under this agreement.
The first is $250 million of 3.85% senior notes due March 2024, which was issued in March 2014.
Interest payments under these notes are due semiannually in March and September of each year, beginning September 2014.
The second is $700 million of 3.875% senior notes due March 2026, issued in March 2019.
Interest payments under these notes are due semiannually in March and September of each year, beginning September 2019.
Both senior notes were issued by J.B. Hunt Transport Services, Inc., a parent-level holding company with no significant assets or operations.
Both notes are unsecured obligations and rank equally with our existing and future senior unsecured debt.
Our $350 million of 3.30% senior notes matured in August 2022.
The entire outstanding balance was paid in full at maturity.
We had no outstanding shares of preferred stock at December 31, 2022 or 2021.
On January 19, 2023, we announced an increase in our quarterly cash dividend from $0.40 to $0.42 per share, which was paid February 24, 2023, to stockholders of record on February 10, 2023.
| Granted | | | 317,751 | | | | 189.66 | |
| | | |
| | | | | | | | | | | | | | | | | |
| December 31, 2019 | | $ | 23.9 | | | $ | 2.8 | | | $ | (13.4 | ) | | $ | 13.3 | |
| 10.5 | | [Credit Agreement and related documents (incorporated by reference from Exhibit 10.1 of the Company’s current report on Form 8-K, filed September 28, 2018)](http://www.sec.gov/Archives/edgar/data/728535/000143774918017588/ex_124627.htm) |
| 16.1 | | [Letter of Ernst & Young LLP, dated June 28, 2021 (incorporated by reference from Exhibit 16.1 of the Company’s current report on Form 8-K, filed June 28, 2021)](http://www.sec.gov/Archives/edgar/data/728535/000143774921015782/ex_259944.htm) |
| --- | --- | --- | --- |
| --- | --- |
February 25, 2022
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| --- | --- | --- | --- | --- | --- | --- |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | Accumulated | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Balances at December 31, 2018 | | $ | 1,671 | | | $ | 340,457 | | | $ | 4,188,435 | | | $ | \- | | | $ | (2,429,179 | ) | | $ | 2,101,384 | |
| Net earnings | | | \- | | | | \- | | | | 516,320 | | | | | | | | \- | | | | 516,320 | |
| | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Payments on long-term debt | | | \- | | | | \- | | | | (250,000 | ) |
| Purchase of treasury stock | | | (151,720 | ) | | | (92,548 | ) | | | (275,657 | ) |
The novel coronavirus (COVID-_19_) pandemic has created and _may_ continue to create significant uncertainty in macro-economic conditions, which _may_ cause a global economic recession, business slowdowns or shutdowns, depressed demand for our transportation and logistics businesses, and adversely impact our results of operations.
We expect uncertainties around our key accounting estimates to continue to evolve depending on the duration and degree of impact associated with the COVID-_19_ pandemic.
Our estimates _may_ change, as new events occur and additional information is obtained, which are recognized or disclosed in our Consolidated Financial Statements as soon as they become known and _may_ have a material impact on our financial statements.
_41_
_42_
_43_
At inception of a derivative contract, we document relationships between derivative instruments and hedged items, as well as our risk-management objective and strategy for undertaking various derivative transactions, and assess hedge effectiveness.
_44_
We have umbrella policies to limit our exposure to catastrophic claim costs.
_45_
At _December 31, 2021,_ we were authorized to borrow up to $750 million under a senior revolving line of credit, which is supported by a credit agreement with a group of banks and expires in _September 2023._ This senior credit facility allows us to request an increase in the total commitment by up to $250 million and to request a one\-year extension of the maturity date.
At _December 31, 2021,_ we had no outstanding borrowings under this agreement.
The _first_ is $250 million of 3.85% senior notes due _March 2024,_ which was issued in _March 2014._ Interest payments under this note are due semiannually in _March_ and _September_ of each year, beginning _September 2014._ The _second_ is $350 million of 3.30% senior notes due _August 2022,_ issued in _August 2015._ Interest payments under this note are due semiannually in _February_ and _August_ of each year, beginning _February 2016._ The _third_ is $700 million of 3.875% senior notes due _March 2026,_ issued in _March 2019._ Interest payments under this note are due semiannually in _March_ and _September_ of each year, beginning _September 2019._ All _three_ senior notes were issued by J.B. Hunt Transport Services, Inc., a parent-level holding company with _no_ significant assets or operations.
See Note _4,_ Derivative Financial Instruments, for terms of an interest rate swap entered into on the _$350_ million of _3.30%_ senior notes due _August 2022._
| _4._ | Derivative Financial Instruments |
We periodically utilize derivative instruments for hedging and non-trading purposes to manage exposure to changes in interest rates and to maintain an appropriate mix of fixed and variable-rate debt.
_46_
We entered into a receive fixed-rate and pay variable-rate interest rate swap agreement simultaneously with the issuance of our $350 million of 3.30% senior notes due _August 2022,_ to effectively convert this fixed-rate debt to variable-rate.
The notional amount of this interest rate swap agreement equals that of the corresponding fixed-rate debt.
The applicable interest rate under this agreement is based on LIBOR plus an established margin, resulting in an interest rate of 1.51% for our $350 million of 3.30% senior notes at _December 31, 2021._ The swap expires when the corresponding senior notes are due.
An excerpt. Shown here: 40 of 402 rewritten, 40 of 104 added and 40 of 77 removed. The counts are complete. For every sentence, read Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES in the FY2022 filing and the FY2021 filing.