 filings.tools
Kimco Realty 2020 10-K Annual Report
KIM · CIK 879101 · Form 10-K · Fiscal year ended December 31, 2020 · Filed February 23, 2021
Revenue fell 8.7% to $1.06 billion. Operating margin was 31.4%, against 41.2% the year before. Net income was $1.00 billion.
22 sections, 567K characters. Original on sec.gov · ·
Risk FactorsBusinessMD&AFinancial StatementsWhat changed vs 2019
| Measure | Year ended Dec 31, 2020 | Year ended Dec 31, 2019 | Change |
|---|---|---|---|
| Revenue | $1.06B | $1.16B | -8.7% |
| Operating income | $333M | $478M | -30.4% |
| Net income | $1.00B | $411M | +144% |
| Operating cash flow | $590M | $584M | +1.1% |
| Cash and equivalents | $293M | $124M | +137% |
| Operating margin* | 31.4% | 41.2% | -9.8 pts |
From the XBRL facts tagged to this filing; both columns are as reported in this filing. * Computed by filings.tools: free cash flow is operating cash flow less capital spending; operating margin is operating income over revenue.
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
| ☑ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
|---|
For the fiscal year ended December 31, 2020
OR
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
|---|
For the transition period from __________ to __________
Commission file number 1-10899
Kimco Realty Corporation
(Exact name of registrant as specified in its charter)
| Maryland | 13-2744380 | |
|---|---|---|
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) |
500 North Broadway, Suite 201, Jericho, NY 11753
(Address of principal executive offices) (Zip Code)
(516) 869-9000
(Registrant’s telephone number, including area code)
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered |
|---|---|---|
| Common Stock, par value $.01 per share. | KIM | New York Stock Exchange |
| Depositary Shares, each representing one-thousandth of a share of 5.125% Class L Cumulative Redeemable, Preferred Stock, $1.00 par value per share. | KIMprL | New York Stock Exchange |
| Depositary Shares, each representing one-thousandth of a share of 5.250% Class M Cumulative Redeemable Preferred Stock, $1.00 par value per share. | KIMprM | New York Stock Exchange |
Securities registered pursuant to section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☑ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐ No ☑
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☑ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☑ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | ☑ | Accelerated filer | ☐ |
|---|---|---|---|
| Non-accelerated filer | ☐ | Smaller reporting company | ☐ |
| Emerging growth company | ☐ | ||
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☑
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). Yes ☐ No ☑
The aggregate market value of the voting and non-voting common equity held by non-affiliates of the registrant was approximately $5.4 billion based upon the closing price on the New York Stock Exchange for such equity on June 30, 2020.
(APPLICABLE ONLY TO CORPORATE REGISTRANTS)
Indicate the number of shares outstanding of each of the registrant's classes of common stock, as of the latest practicable date.
As of February 11, 2021, the registrant had 432,439,820 shares of common stock outstanding.
DOCUMENTS INCORPORATED BY REFERENCE
Part III incorporates certain information by reference to the Registrant's definitive proxy statement to be filed with respect to the Annual Meeting of Stockholders expected to be held on April 27, 2021.
Index to Exhibits begins on page 46.
FORWARD-LOOKING STATEMENTS
This annual report on Form 10-K (“Form 10-K”), together with other statements and information publicly disseminated by Kimco Realty Corporation (the “Company”) contains certain forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. The Company intends such forward-looking statements to be covered by the safe harbor provisions for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995 and includes this statement for purposes of complying with the safe harbor provisions. Forward-looking statements, which are based on certain assumptions and describe the Company’s future plans, strategies and expectations, are generally identifiable by use of the words “believe,” “expect,” “intend,” “anticipate,” “estimate,” “project,” “will,” “target,” “forecast” or similar expressions. You should not rely on forward-looking statements since they involve known and unknown risks, uncertainties and other factors which are, in some cases, beyond the Company’s control and could materially affect actual results, performances or achievements. Factors which may cause actual results to differ materially from current expectations include, but are not limited to, (i) general adverse economic and local real estate conditions, (ii) the inability of major tenants to continue paying their rent obligations due to bankruptcy, insolvency or a general downturn in their business, (iii) financing risks, such as the inability to obtain equity, debt or other sources of financing or refinancing on favorable terms to the Company, (iv) the Company’s ability to raise capital by selling its assets, (v) changes in governmental laws and regulations and management’s ability to estimate the impact of such changes, (vi) the level and volatility of interest rates and management’s ability to estimate the impact thereof, (vii) pandemics or other health crises, such as coronavirus disease 2019 (“COVID-19”), (viii) the availability of suitable acquisition, disposition, development and redevelopment opportunities, and risks related to acquisitions not performing in accordance with our expectations, (ix) valuation and risks related to the Company’s joint venture and preferred equity investments, (x) valuation of marketable securities and other investments including the shares of Albertsons Companies, Inc. common stock held by the Company, (xi) increases in operating costs, (xii) changes in the dividend policy for the Company’s common and preferred stock and the Company’s ability to pay dividends at current levels, (xiii) the reduction in the Company’s income in the event of multiple lease terminations by tenants or a failure by multiple tenants to occupy their premises in a shopping center, (xiv) impairment charges, (xv) unanticipated changes in the Company’s intention or ability to prepay certain debt prior to maturity and/or hold certain securities until maturity and (xvi) the risks and uncertainties identified under Item 1A, “Risk Factors” and elsewhere in this Form 10-K and in the Company’s other filings with the Securities and Exchange Commission (“SEC”). Accordingly, there is no assurance that the Company’s expectations will be realized. The Company disclaims any intention or obligation to update the forward-looking statements, whether as a result of new information, future events or otherwise. You are advised to refer to any further disclosures the Company makes or related subjects in the Company’s quarterly reports on Form 10-Q and current reports on Form 8-K that the Company files with the SEC.
PART I
Item 1. Business
Overview
Kimco Realty Corporation, a Maryland corporation, is one of North America’s largest publicly traded owners and operators of open-air, grocery-anchored shopping centers and mixed-use assets in the U.S. The terms “Kimco,” the “Company,” “we,” “our” and “us” each refer to Kimco Realty Corporation and our subsidiaries, unless the context indicates otherwise. In statements regarding qualification as a real estate investment trust (“REIT”), such terms refer solely to Kimco Realty Corporation. The Company’s mission is to create destinations for everyday living that inspire a sense of community and deliver value to our many stakeholders.
The Company began operations through its predecessor, The Kimco Corporation, which was organized in 1966 upon the contribution of several shopping center properties owned by its principal stockholders. In 1973, these principals formed the Company as a Delaware corporation, and, in 1985, the operations of The Kimco Corporation were merged into the Company. The Company completed its initial public stock offering (the “IPO”) in November 1991, and, commencing with its taxable year which began January 1, 1992, elected to qualify as a REIT in accordance with Sections 856 through 860 of the Internal Revenue Code of 1986, as amended (the “Code”). If, as the Company believes, it is organized and operates in such a manner so as to qualify and remain qualified as a REIT under the Code, the Company generally will not be subject to U.S. federal income tax, provided that distributions to its stockholders equal at least the amount of its REIT taxable income, as defined in the Code. The Company maintains certain subsidiaries that made joint elections with the Company to be treated as taxable REIT subsidiaries (“TRSs”), that permit the Company to engage through such TRSs in certain business activities that the REIT may not conduct directly. A TRS is subject to federal and state taxes on its income, and the Company includes a provision for taxes in its consolidated financial statements. In 1994, the Company reorganized as a Maryland corporation. In March 2006, the Company was added to the S&P 500 Index, an index containing the stock of 500 Large Cap companies, most of which are U.S. corporations. The Company's common stock, Class L Depositary Shares and Class M Depositary Shares are traded on the New York Stock Exchange (“NYSE”) under the trading symbols “KIM”, “KIMprL”, and “KIMprM”, respectively.
The Company is a self-administered REIT and has not engaged, nor does it expect to retain, any REIT advisors in connection with the operation of its properties. The Company’s ownership interests in real estate consist of its consolidated portfolio and portfolios where the Company owns an economic interest, such as properties in the Company’s investment real estate management programs, where the Company partners with institutional investors and also retains management.
The Company began to expand its operations through the development of real estate and the construction of shopping centers but revised its growth strategy to focus on the acquisition and redevelopment of existing shopping centers that include a grocery component. The Company also expanded internationally within Canada, Mexico, Chile, Brazil and Peru, but has since substantially liquidated its investments in Mexico and has completely exited Canada, Chile, Brazil and Peru. More recently the Company, on a selective basis, embarked on several ground-up development and re-development projects which include residential and mixed-use components.
The Company implemented its investment real estate management format through the establishment of various institutional joint venture programs, in which the Company has noncontrolling interests. The Company earns management fees, acquisition fees, disposition fees as well as promoted interests based on achieving certain performance metrics.
In addition, the Company has capitalized on its established expertise in retail real estate by establishing other ventures in which the Company owns a smaller equity interest and provides management, leasing and operational support for those properties. The Company has also provided preferred equity capital in the past to real estate entrepreneurs and, from time to time, provides real estate capital and management services to both healthy and distressed retailers. The Company has also made selective investments in secondary market opportunities where a security or other investment is, in management’s judgment, priced below the value of the underlying assets, however these investments are subject to volatility within the equity and debt markets.
As of December 31, 2020, the Company had interests in 400 shopping center properties (the “Combined Shopping Center Portfolio”), aggregating 70.1 million square feet of gross leasable area (“GLA”), located in 27 states. In addition, the Company had 122 other property interests, primarily through the Company’s preferred equity investments and other real estate investments, totaling 5.4 million square feet of GLA.
COVID-19 Pandemic
In March 2020, COVID-19 was recognized as a pandemic by the World Health Organization (“WHO”) and declared a national emergency throughout the United States. The COVID-19 pandemic has resulted in a widespread health crisis that has adversely affected businesses, economies, and financial markets worldwide and has caused significant volatility in U.S. and international debt and equity markets. The impact of COVID-19 on the retail industry for both landlords and tenants has been wide ranging, including, but not limited to, the temporary closures of many businesses, "shelter in place" orders, social distancing guidelines and other governmental, business and individual actions taken in response to the COVID-19 pandemic. There has also been reduced consumer spending due to job losses, government restrictions in response to COVID-19 and other effects attributable to COVID-19.
The Company is aware of the critical role its shopping centers play in the communities they serve, often providing access to essential goods and services such as groceries, drug stores, and medical care. The Company’s shopping centers have remained open throughout the COVID-19 pandemic to continue to provide access to these essential goods and services, and the Company has taken steps to protect the shoppers and tenants at its sites, following the guidance of the Centers for Disease Control and Prevention (“CDC”) and the WHO.
The COVID-19 pandemic has created significant economic uncertainty and volatility and has considerably impacted the Company’s stakeholders. The COVID-19 pandemic has impacted the Company’s financial condition, results of operations and cash flows since its onset. The extent to which the COVID-19 pandemic will continue to impact the Company’s financial condition, results of operations and cash flows, will depend on future developments, which continue to be highly uncertain and difficult to predict. The Company’s business, operations and financial results will depend on numerous evolving factors that the Company is not able to predict, including the duration and scope of the pandemic, governmental, business and individual actions that have been and continue to be, taken in response to the pandemic, the distribution and effectiveness of vaccines, the impact on economic activity from the pandemic and actions taken in response, the effect on the Company’s tenants and their businesses, the ability of tenants to make their rental payments, additional closures of tenants’ businesses and the impact of opening and reclosing of communities in response to COVID-19. Any of these events could materially adversely impact the Company’s business, financial condition, results of operations or stock price. The Company will continue to monitor the economic, financial, and social conditions resulting from the COVID-19 pandemic and will assess its asset portfolio for any impairment indicators. In addition, the Company will continue to monitor for any material or adverse effects resulting from the COVID-19 pandemic.
Since the outbreak of the COVID-19 pandemic, the Company’s shopping centers have remained open; however, a substantial number of tenants had or continue to have temporarily or permanently closed their businesses. Others had, or continue to have, shortened their operating hours or offered reduced services. The Company has also had a substantial number of tenants that have made late or partial rent payments, requested a deferral of rent payments, forgiveness of rent payments or defaulted on rent payments. Since the COVID-19 pandemic began, the Company has seen an increase in the number of tenants filing for bankruptcy, some of which emerged from bankruptcy prior to December 31, 2020. The Company continues to evaluate the impact bankruptcy filings have or will have on collections, vacancies and future rental income.
Business Objective and Strateg****ies
Over the past several years, the Company has transformed its portfolio, focusing on major metropolitan-area U.S. markets, predominantly on the East and West coasts and in the Sunbelt region, which are supported by strong demographics, significant projected population growth, and where the Company perceives significant barriers to entry. As a result of this transformation, the Company now owns a predominantly grocery-anchored portfolio clustered in the nation’s top markets which has positioned the Company to address many of the challenges brought upon by COVID-19. As of December 31, 2020, the Company derived 84.6% of its annualized base rent from its top major metro markets.
The Company’s focus on high-quality locations has led to significant opportunities for value creation through the reinvestment in its assets to add density, replace outdated shopping center concepts, and better meet changing consumer demands. In order to add density to existing properties, the Company has obtained multi-family entitlements for 4,984 units of which 1,266 units have been constructed as of December 31, 2020. The Company continues to place strategic emphasis on live/work/play environments and in reinvesting in its existing assets, while building shareholder value. This philosophy is exemplified by the Company’s Signature SeriesTM properties Dania Pointe, Grand Parkway Marketplace, Kentlands Market Square, Lincoln Square, Mill Station, Pentagon Centre, Suburban Square and The Boulevard.
The strength and security of the Company’s balance sheet remains central to its strategy. The Company’s strong balance sheet and liquidity position are evidenced by its investment grade unsecured debt ratings (Baa1/BBB+) by two major ratings agencies. The Company maintains one of the longest average debt maturity profiles in the REIT industry, now at 10.9 years. The Company expects to continue to take steps to reduce leverage, unencumber assets and improve its debt coverage metrics as redevelopment and development projects continue to come online and contribute additional cash flow growth.
Business Objective
The Company’s primary business objective is to be the premier owner and operators of open-air, grocery-anchored shopping centers and mixed-use assets in the U.S. The Company believes it can achieve this objective by:
| ● | increasing the value of its existing portfolio of properties and generating higher levels of portfolio growth; |
|---|
| ● | increasing cash flows for reinvestment and/or for distribution to shareholders; |
|---|
| ● | continuing growth in desirable demographic areas with successful retailers; and |
|---|
| ● | increasing capital appreciation. |
|---|
Business S__trateg__ies
The Company’s stronger transformed portfolio, over time, should enable the Company to maintain higher occupancy levels, rental rates and rental growth. With the COVID-19 pandemic affecting much of the retail sector the Company further concentrated its business objectives to three main areas as follows:

** The “PLUS” business encompasses investment opportunities with retailers who have significant real estate holdings. The Company believes it can utilize its Structured Investment Program to take advantage of opportunities resulting from market dislocation in the form of preferred equity investments and/or mezzanine financing for qualified real estate owners in need of capital.
To effectively execute these strategies the Company seeks to:
| ● | significantly increase its leasing efforts over the next several years to offset the impact of the COVID-19 pandemic; |
|---|
| ● | increase rental rates where possible through the leasing of space to new tenants; |
|---|
| ● | attract a diverse and robust tenant base across a variety of retailers at its properties, with a focus on essential tenants such as grocers and home improvement; |
|---|
| ● | renew leases with existing tenants; |
|---|
| ● | decrease vacancy levels and duration of vacancy; |
|---|
| ● | monitor operating costs and overhead; |
|---|
| ● | retail re-tenanting, renovating, expanding and redeveloping existing shopping centers to obtain the highest and best use to maximize the real estate value, which could include acquiring adjacent land parcels; |
|---|
| ● | selectively acquire established income-producing real estate properties and properties requiring significant re-tenanting and redevelopment, primarily in geographic regions in which the Company presently operates; |
|---|
| ● | continue to assess its portfolio and dispose of certain underperforming properties; |
|---|
| ● | provide unmatched tenant services deriving from decades of experience managing retail properties; |
|---|
| ● | assist small shop tenants during the COVID-19 pandemic to enable them to continue to successfully operate; and |
|---|
| ● | provide communities with a "just around the corner" destination for everyday living goods and services. |
|---|
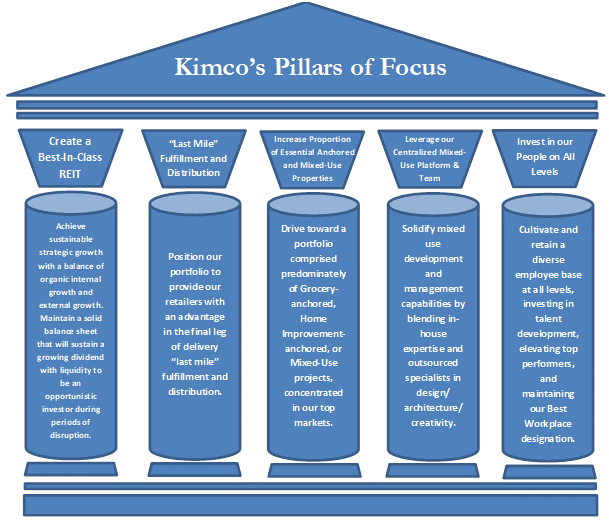
The Company has established certain areas of focus which it believes will advance the execution of its strategies over the coming years:
The Company reduces its operating and leasing risks through diversification achieved by the geographic distribution of its properties and a large tenant base. As of December 31, 2020, no single open-air shopping center accounted for more than 2.0% of the Company's annualized base rental revenues, including the proportionate share of base rental revenues from properties in which the Company has less than a 100% economic interest, or more than 2.0% of the Company’s total shopping center GLA. Furthermore, at December 31, 2020, the Company’s single largest tenant represented only 4.0%, and the Company’s five largest tenants aggregated less than 12.6%, of the Company’s annualized base rental revenues, including the proportionate share of base rental revenues from properties in which the Company has less than a 100% economic interest.
As one of the original participants in the growth of the shopping center industry and one of the nation's largest owners and operators of open-air shopping centers, the Company has established close relationships with major national and regional retailers and maintains a broad network of industry contacts. Management is associated with and/or actively participates in many shopping center and REIT industry organizations. Notwithstanding these relationships, there are numerous regional and local commercial developers, real estate companies, financial institutions and other investors who compete with the Company for the acquisition of properties and other investment opportunities and in seeking tenants who will lease space in the Company’s properties.
Human Capital Resources
The Company believes that our employees are one of our strongest resources and that a variety of perspectives and experiences found in a diverse workforce spark innovation and enrich company culture. The Company is committed to diversity and inclusion best practices in all phases of the employee life cycle, including recruitment, training and development and promotion.
The Company has been and will continue to be an equal opportunity employer committed to hiring, developing, and supporting a diverse and inclusive workplace. To ensure full implementation of this equal employment policy, we will take steps to ensure that persons are recruited, hired, assigned and promoted without regard to race, national origin, religion, age, color, sex, sexual orientation, gender identity, disability, or protected veteran status, or any other characteristic protected by local, state, or federal laws, rules, or regulations. All of our employees must adhere to a Code of Business Conduct and Ethics that sets standards for appropriate behavior and includes required internal training on preventing, identifying, reporting and stopping any type of discrimination.
In order to attract and retain high performing individuals, we are committed to partnering with our employees to provide opportunities for their professional development and promote their health and well-being. We also offer our employees a broad range of company-paid benefits, and we believe our compensation package and benefits are competitive with others in our industry. Our benefits programs include a robust offering of medical, dental, vision benefits, life, disability and other ancillary benefits requiring very low employee contributions. In addition, the Company has been recognized as a Great Place to Work® based on surveys and feedback collected from its employees.
The Company’s executive and management team promotes a true “open door” environment in which all feedback and suggestions are welcome. Whether it be through regular all employee calls, department meetings, frequent training sessions, Coffee Connections with the executive team, use of our BRAVO recognition program, awarding of iPads for Ideas, or participation in our flagship LABS (Leaders Advancing Business Strategy) program, associates are encouraged to be inquisitive and share ideas. Those ideas have resulted in a number of programs and benefit enhancements.
The Company promotes physical health, including access to a national gym membership program for associates and their family members as well as host regular wellness and nutrition seminars and health screenings. The Company also feels it is important that our associates are engaged and active in the community. At our headquarters and in each of our regions a Committee of employees host numerous volunteer and social activities that are derived from employee sentiment. Whether we’re participating in walks, runs, meal servings, food drives, toy drives, or St. Jude Ride for a Reason, the Company promotes and supports associate volunteerism with two volunteer days off per year and a company matching program that provide up to $500 per year in support of each associates charitable endeavors. In addition, each year, the Company provides $100,000 in education scholarships for children of our associates, which is managed by an independent third-party.
The Company's executive offices are located at 500 North Broadway, Suite 201, Jericho, NY 11753, a mixed-use property that is wholly owned by the Company, and its telephone number is (516) 869-9000. Nearly all operating functions, including leasing, legal, construction, data processing, maintenance, finance and accounting are administered by the Company from its executive offices in Jericho, New York and supported by the Company’s regional offices. As of December 31, 2020, a total of 484 persons were employed by the Company of which 41.5% were located in our corporate office with the remainder located in 26 offices throughout the United States. The average tenure of our employees was 10 years.
The health and safety of the Company’s employees and their families is a top priority. The Company always takes the necessary steps to protect its employees, especially during the COVID-19 pandemic where employees were empowered to work from home and care for their family members and children, whose lives have also been impacted. The Company will continue to evaluate individual situations as they arise and adjust its approach as appropriate, with the goal of enabling its employees to be as productive as possible while offering them the flexibility they need to care for themselves and their families. The following are steps that were taken by the Company in response to the COVID-19 pandemic:
| ● | Transitioned the entire workforce from full-time office to flexible work from home arrangement, which the Company successfully continued since March 2020. This included immediate and extensive technology training on virtual meetings and remote working as well as safety protocols. |
|---|
| ● | Business travel has been stopped with relatively few business-essential exceptions. |
|---|
| ● | The Company has benefited from recent investments in new technology and software over the last year, as its entire team is equipped with new laptops and cellular capability to enable them to work remotely. |
|---|
| ● | The Company’s human resources and information technology teams are available to all employees to address any needs or concerns they may have. |
|---|
| ● | Associates will be provided paid time off to care for themselves or family members diagnosed with COVID-19. |
|---|
| ● | The Company has increased communications at all levels and has initiated bi-weekly company-wide virtual meetings such that executives are accessible to answer any questions and transparently keep associates informed. |
|---|
Environment, Social and Governance (“ESG”) Programs
The Company is focused on building a thriving and viable business, one that succeeds by delivering long-term value for its stakeholders. The Company’s ESG programs are aligned with its core business strategy of creating destinations for everyday living that inspire a sense of community and deliver value to its many stakeholders.
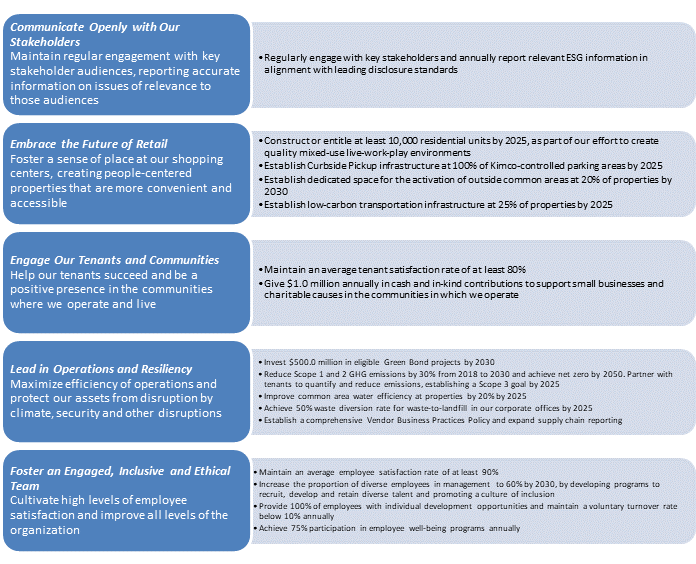
The Company has established five ESG Program Pillars and the corresponding objectives:
The Company is committed to best-in-class ESG disclosure, and has aligned its annual reporting with standards from the Global Reporting Initiative (“GRI”), Sustainability Accounting Standards Board (“SASB”) and Task Force on Climate-Related Financial Disclosures (“TCFD”). Additional ESG information of relevance to stakeholders can be found on the Company’s website in the Corporate Responsibility Report. This report, which is based on the GRI standard, summarizes the Company's environmental and social performance.
The Company recognizes that climate change is one of the most significant stakeholder issues of our times, threatening the viability of economic and environmental systems globally. As a real estate portfolio owner, the Company monitors physical and transition risks as well as opportunities posed to its business by climate change and quantifies and discloses the climate impacts of its activities. The Company’s science-based emissions reduction goals are aligned with the Paris Climate Accord and put the company on pace to achieve net zero emissions by 2050. During 2020, the Company issued $500.0 million in 2.70% notes due 2030 in its inaugural green bond offering. Net proceeds from this offering are allocated to finance or refinance, in whole or in part, recently completed, existing or future eligible green projects, in alignment with the four core components of the Green Bond Principles, 2018 as administered by the International Capital Market Association. Additionally, the Company’s $2.0 billion Credit Facility (as defined below) is a green credit facility which incorporates rate reductions associated with attainment of Scope 1 and 2 greenhouse gas emissions reductions.
The Company’s industry leading ESG initiatives led to its 2020 listing on the Dow Jones Sustainability World Index (“DJSI World Index”), where it is the only North American retail real estate owner listed. The DJSI World Index is comprised of corporate leaders in global sustainability, with companies listed on the DJSI World Index representing the top 10 percent of the largest 2,500 companies in the S&P Global Broad Market Index based on long-term economic and ESG factors. The Company has been the sole retail real estate owner listed on the Dow Jones Sustainability North America Index for the last six years, and the Company also is a constituent of the FTSE4Good Index Series, designed to measure the performance of companies demonstrating strong ESG practices.
Information About Our Executive Officers
The following table sets forth information with respect to the executive officers of the Company as of December 31, 2020:
| Name | Age | Position | Joined Kimco |
|---|---|---|---|
| Milton Cooper | 91 | Executive Chairman of the Board of Directors | Co-Founder |
| Conor C. Flynn | 40 | Chief Executive Officer | 2003 |
| Ross Cooper | 38 | President and Chief Investment Officer | 2006 |
| Glenn G. Cohen | 56 | Executive Vice President, Chief Financial Officer and Treasurer | 1995 |
| David Jamieson | 40 | Executive Vice President, Chief Operating Officer | 2007 |
Available Information
The Company’s website is located at http://www.kimcorealty.com. The information contained on our website does not constitute part of this Form 10-K. On the Company’s website you can obtain, free of charge, a copy of this Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K and amendments to those reports filed or furnished pursuant to Section 13(a) or 15(d) of the Exchange Act of 1934, as amended, as soon as reasonably practicable, after we file such material electronically with, or furnish it to, the SEC. The public may read and obtain a copy of any materials we file electronically with the SEC at http://www.sec.gov.
Item 1A. Risk Factors
We are subject to certain business and legal risks including, but not limited to, the following:
Risks Related to Our Business and Operations
Adverse global market and economic conditions may impede our ability to generate sufficient income and maintain our properties.
Our properties consist primarily of open-air shopping centers and other retail properties. Our performance, therefore, is generally linked to economic conditions in the market for retail space. The economic performance and value of our properties is subject to all of the risks associated with owning and operating real estate, including but not limited to:
| ● | changes in the national, regional and local economic climate; |
|---|
| ● | local conditions, including an oversupply of, or a reduction in demand for, space in properties like those that we own; |
|---|
| ● | trends toward smaller store sizes as retailers reduce inventory and develop new prototypes; |
|---|
| ● | increasing use by customers of e-commerce and online store sites; |
|---|
| ● | the attractiveness of our properties to tenants; |
|---|
| ● | market disruptions due to global pandemics; |
|---|
| ● | the ability of tenants to pay rent, particularly anchor tenants with leases in multiple locations; |
|---|
| ● | tenants who may declare bankruptcy and/or close stores; |
|---|
| ● | competition from other available properties to attract and retain tenants; |
|---|
| ● | changes in market rental rates; |
|---|
| ● | the need to periodically pay for costs to repair, renovate and re-let space; |
|---|
| ● | ongoing consolidation in the retail sector; |
|---|
| ● | the excess amount of retail space in a number of markets; |
|---|
| ● | changes in operating costs, including costs for maintenance, insurance and real estate taxes; |
|---|
| ● | the expenses of owning and operating properties, which are not necessarily reduced when circumstances such as market factors and competition cause a reduction in income from the properties; |
|---|
| ● | changes in laws and governmental regulations, including those governing usage, zoning, the environment and taxes; |
|---|
| ● | acts of terrorism and war and acts of God, including physical and weather-related damage to our properties; |
|---|
| ● | the continued service and availability of key personnel; and |
|---|
| ● | the risk of functional obsolescence of properties over time. |
|---|
Competition may limit our ability to purchase new properties or generate sufficient income from tenants and may decrease the occupancy and rental rates for our properties.
Numerous commercial developers and real estate companies compete with us in seeking tenants for our existing properties and properties for acquisition. Open-air lifestyle centers or other retail shopping centers with more convenient locations or better rents may attract tenants or cause them to seek more favorable lease terms at or prior to renewal. Retailers at our properties may face increasing competition from other retailers, e-commerce, outlet malls, discount shopping clubs, direct mail, telemarketing or home shopping networks, all of which could (i) reduce rents payable to us; (ii) reduce our ability to attract and retain tenants at our properties; or (iii) lead to increased vacancy rates at our properties. We may fail to anticipate the effects of changes in consumer buying practices, particularly of growing online sales and the resulting retailing practices and space needs of our tenants or a general downturn in our tenants’ businesses, which may cause tenants to close stores or default in payment of rent.
We face competition in the acquisition or development of real property from others engaged in real estate investment that could increase our costs associated with purchasing and maintaining assets. Some of these competitors may have greater financial resources than we do. This could result in competition for the acquisition of properties for tenants who lease or consider leasing space in our existing and subsequently acquired properties and for other real estate investment or development opportunities.
Our performance depends on our ability to collect rent from tenants, including anchor tenants, our tenants’ financial condition and our tenants maintaining leases for our properties.
At any time, our tenants may experience a downturn in their business that may significantly weaken their financial condition. As a result, our tenants may delay a number of lease commencements, decline to extend or renew leases upon expiration, fail to make rental payments when due, close stores or declare bankruptcy. Any of these actions could result in the termination of tenants’ leases and the loss of rental income attributable to these tenants’ leases. In the event of a default by a tenant, we may experience delays and costs in enforcing our rights as landlord under the terms of the leases.
In addition, multiple lease terminations by tenants, including anchor tenants, or a failure by multiple tenants to occupy their premises in a shopping center could result in lease terminations or significant reductions in rent by other tenants in the same shopping centers under the terms of some leases. In that event, we may be unable to re-lease the vacated space at attractive rents or at all, and our rental payments from our continuing tenants could significantly decrease. The occurrence of any of the situations described above, particularly involving a substantial tenant with leases in multiple locations, could have a material adverse effect on our financial condition, results of operations and cash flows.
A tenant that files for bankruptcy protection may not continue to pay us rent. A bankruptcy filing by, or relating to, one of our tenants or a lease guarantor would bar all efforts by us to collect pre-bankruptcy debts from the tenant or the lease guarantor, or their property, unless the bankruptcy court permits us to do so. A tenant bankruptcy could delay our efforts to collect past due balances under the relevant leases and could ultimately preclude collection of these sums. If a lease is rejected by a tenant in bankruptcy, we would have only a general unsecured claim for damages. As a result, it is likely that we would recover substantially less than the full value of any unsecured claims we hold, if at all.
Our expenses may remain constant or increase, even if income from our Combined Shopping Center Portfolio decreases, which could adversely affect our financial condition, results of operations and cash flows.
Costs associated with our business, such as common area expenses, utilities, insurance, real estate taxes, mortgage payments, and corporate expenses are relatively inflexible and generally do not decrease in the event that a property is not fully occupied, rental rates decrease, a tenant fails to pay rent or other circumstances cause our revenues to decrease. In addition, inflation could result in higher operating costs. If we are unable to lower our operating costs when revenues decline and/or are unable to pass along cost increases to our tenants, our financial condition, results of operations and cash flows could be adversely impacted.
We may be unable to sell our real estate property investments when appropriate or on terms favorable to us**.**
Real estate property investments are illiquid and generally cannot be disposed of quickly. The capitalization rates at which properties may be sold could be higher than historic rates, thereby reducing our potential proceeds from sale. In addition, the Code includes certain rest
Showing the first 8K of 61K characters. Open the full section
Item 1B. Unresolved Staff Comments
None.
Item 2. Properties
Real Estate Portfolio_._ As of December 31, 2020, the Company had interests in 400 shopping center properties aggregating 70.1 million square feet of GLA located in 27 states and Puerto Rico. In addition, the Company had 122 other property interests, primarily through the Company’s preferred equity investments and other real estate investments, totaling 5.4 million square feet of GLA. Open-air shopping centers comprise the primary focus of the Company's current portfolio. As of December 31, 2020, the Company’s Combined Shopping Center Portfolio, including noncontrolling interests, was 93.9% leased.
The Company's open-air shopping center properties, which are generally owned and operated through subsidiaries or joint ventures, had an average size of 175,302 square feet as of December 31, 2020. The Company generally retains its shopping centers for long-term investment and consequently pursues a program of regular physical maintenance together with redevelopment, major renovations and refurbishing to preserve and increase the value of its properties. This includes renovating existing facades, installing uniform signage, resurfacing parking lots and enhancing parking lot lighting. During 2020, the Company expended $175.7 million in connection with property redevelopments and $45.6 million related to improvements.
The Company's management believes its experience in the real estate industry and its relationships with numerous national and regional tenants gives it an advantage in an industry where ownership is fragmented among a large number of property owners. The Company's open-air shopping centers are usually "anchored" by a grocery store, off-price retailer, discounter or service-oriented tenant. As one of the original participants in the growth of the shopping center industry and one of the nation's largest owners and operators of shopping centers, the Company has established close relationships with a large number of major national and regional retailers. Some of the major national and regional companies that are tenants in the Company's shopping center properties include TJX Companies, The Home Depot, Ahold Delhaize, Albertsons Companies, Ross Stores, PetSmart, Whole Foods Market, Walmart, Burlington Stores and Bed Bath & Beyond.
The Company reduces its operating and leasing risks through diversification achieved by the geographic distribution of its properties and a large tenant base. As of December 31, 2020, no single open-air shopping center accounted for more than 2.0% of the Company's annualized base rental revenues, including the proportionate share of base rental revenues from properties in which the Company has less than a 100% economic interest, or more than 2.0% of the Company’s total shopping center GLA. At December 31, 2020, the Company’s five largest tenants were TJX Companies, The Home Depot, Ahold Delhaize, Albertsons Companies and Ross Stores, which represented 4.0%, 2.6%, 2.1%, 2.0% and 1.9%, respectively, of the Company’s annualized base rental revenues, including the proportionate share of base rental revenues from properties in which the Company has less than a 100% economic interest.
A substantial portion of the Company's income consists of rent received under long-term leases. Most of the leases provide for the payment of fixed-base rentals monthly in advance and for the payment by tenants of an allocable share of the real estate taxes, insurance, utilities and common area maintenance expenses incurred in operating the shopping centers (certain of the leases provide for the payment of a fixed-rate reimbursement of these such expenses). Although many of the leases require the Company to make roof and structural repairs as needed, a number of tenant leases place that responsibility on the tenant, and the Company's standard small store lease provides for reimbursements by the tenant as part of common area maintenance. Additionally, many of the leases provide for reimbursements by the tenant of capital expenditures.
Minimum base rental revenues and operating expense reimbursements accounted for 99% and other revenues, including percentage rents, accounted for 1% of the Company's total revenues from rental properties for the year ended December 31, 2020. The Company's management believes that the base rent per leased square foot for many of the Company's existing leases is generally lower than the prevailing market-rate base rents in the geographic regions where the Company operates, reflecting the potential for future growth. Additionally, a majority of the Company’s leases have provisions requiring contractual rent increases. The Company’s leases may also include escalation clauses, which provide for increases based upon changes in the consumer price index or similar inflation indices.
As of December 31, 2020, the Company’s consolidated operating portfolio, comprised of 311 shopping center properties aggregating 51.0 million square feet of GLA, was 93.9% leased. The consolidated operating portfolio consists entirely of properties located in the U.S., inclusive of Puerto Rico For the period January 1, 2020 to December 31, 2020, the Company increased the average base rent per leased square foot, which includes the impact of tenant concessions, in its consolidated portfolio of open-air shopping centers from $17.96 to $18.16, an increase of $0.20. This increase primarily consists of (i) an $0.18 increase relating to rent step-ups within the portfolio and new leases signed net of leases vacated and (ii) a $0.02 increase relating to dispositions.
The Company has a total of 5,277 leases in the consolidated operating portfolio. The following table sets forth the aggregate lease expirations for each of the next ten years, assuming no renewal options are exercised. For purposes of the table, the Total Annual Base Rent Expiring represents annualized rental revenue, excluding the impact of straight-line rent, for each lease that expires during the respective year. Amounts in thousands, except for number of leases data:
| Year Ending December 31, | Number of Leases Expiring | Square Feet Expiring | Total Annual Base Rent Expiring | % of Gross Annual Rent | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| (1) | 170 | 489 | $ | 10,931 | 1.3 | % | |||||||||||
| 2021 | 612 | 3,930 | $ | 64,045 | 7.9 | % | |||||||||||
| 2022 | 814 | 5,684 | $ | 98,680 | 12.2 | % | |||||||||||
| 2023 | 737 | 5,770 | $ | 98,264 | 12.1 | % | |||||||||||
| 2024 | 660 | 5,094 | $ | 93,610 | 11.6 | % | |||||||||||
| 2025 | 612 | 5,245 | $ | 92,695 | 11.4 | % | |||||||||||
| 2026 | 400 | 5,311 | $ | 76,080 | 9.4 | % | |||||||||||
| 2027 | 255 | 3,269 | $ | 51,477 | 6.4 | % | |||||||||||
| 2028 | 314 | 3,398 | $ | 61,161 | 7.6 | % | |||||||||||
| 2029 | 247 | 2,601 | $ | 45,274 | 5.6 | % | |||||||||||
| 2030 | 204 | 1,704 | $ | 32,698 | 4.0 | % |
| (1) | Leases currently under a month to month lease or in process of renewal. |
|---|
During 2020, the Company executed 761 leases totaling over 5.3 million square feet in the Company’s consolidated operating portfolio comprised of 204 new leases and 557 renewals and options. The leasing costs associated with these new leases are estimated to aggregate $39.1 million or $31.11 per square foot. These costs include $30.4 million of tenant improvements and $8.7 million of external leasing commissions. The average rent per square foot for (i) new leases was $19.10 and (ii) renewals and options was $18.33. The Company will seek to obtain rents that are higher than amounts within its expiring leases, however, there are many variables and uncertainties which can significantly affect the leasing market at any time; as such, the Company cannot guarantee that future leases will continue to be signed for rents that are equal to or higher than current amounts.
Ground-Leased Properties. The Company has interests in 30 consolidated shopping center properties that are subject to long-term ground leases where a third-party owns and has leased the underlying land to the Company to construct and/or operate a shopping center. The Company pays rent for the use of the land and generally is responsible for all costs and expenses associated with the building and improvements. At the end of these long-term leases, unless extended, the land together with all improvements reverts to the landowner.
More specific information with respect to each of the Company's property interests is set forth in Exhibit 99.1, which is incorporated herein by reference.
Item 3. Legal Proceedings
The Company is not presently involved in any litigation nor, to its knowledge, is any litigation threatened against the Company or its subsidiaries that, in management's opinion, would result in any material effect on the Company's ownership, management or operation of its properties taken as a whole, or which is not covered by the Company's liability insurance.
Item 4. Mine Safety Disclosures
Not applicable.
PART II
Item 5. Market for the Registrant's Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
Market Information: The Company’s common stock is traded on the NYSE under the trading symbol "KIM".
Holders: The number of holders of record of the Company's common stock, par value $0.01 per share, was 1,944 as of February 1, 2021.
Dividends: Since the IPO, the Company has paid regular quarterly cash dividends to its stockholders. While the Company intends to continue paying regular quarterly cash dividends, future dividend declarations will be paid at the discretion of the Board of Directors and will depend on the actual cash flows of the Company, its financial condition, capital requirements, the annual distribution requirements under the REIT provisions of the Code and such other factors as the Board of Directors deems relevant. The Company’s Board of Directors will continue to evaluate the Company’s dividend policy on a quarterly basis as they monitor sources of capital and evaluate operating fundamentals. The Company is required by the Code to distribute at least 90% of its REIT taxable income. The actual cash flow available to pay dividends will be affected by a number of factors, including the revenues received from operating properties, the operating expenses of the Company, the interest expense on its borrowings, the ability of lessees to meet their obligations to the Company, the ability to refinance near-term debt maturities and any unanticipated capital expenditures.
| **Year **Ended December 31, | ||||||||
|---|---|---|---|---|---|---|---|---|
| 2020**** | 2019**** | |||||||
| Dividend paid per share | $ | 0.82 | $ | 1.12 | ||||
| Ordinary income | 38 | % | 70 | % | ||||
| Capital gains | 61 | % | 21 | % | ||||
| Return of capital | 1 | % | 9 | % |
In addition to common stock offerings, the Company has capitalized on the growth in its business through the issuance of unsecured fixed and floating-rate medium-term notes, underwritten bonds, unsecured bank debt, mortgage debt and construction loans, convertible preferred stock and perpetual preferred stock. Borrowings under the Company's Credit Facility have also been an interim source of funds to both finance the purchase of properties and other investments and meet any short-term working capital requirements. The various instruments governing the Company's issuance of its unsecured public debt, bank debt, mortgage debt and preferred stock impose certain restrictions on the Company regarding dividends, voting, liquidation and other preferential rights available to the holders of such instruments. See "Management's Discussion and Analysis of Financial Condition and Results of Operations" and Footnotes 13, 14 and 17 of the Notes to Consolidated Financial Statements included in this Form 10-K.
The Company does not believe that the preferential rights available to the holders of its Class L Preferred Stock and Class M Preferred Stock, the financial covenants contained in its public bond indentures, as amended, or the credit agreement for its Credit Facility will have an adverse impact on the Company's ability to pay dividends in the normal course to its common stockholders or to distribute amounts necessary to maintain its qualification as a REIT.
The Company maintains a dividend reinvestment and direct stock purchase plan (the "Plan") pursuant to which common and preferred stockholders and other interested investors may elect to automatically reinvest their dividends to purchase shares of the Company’s common stock or, through optional cash payments, purchase shares of the Company’s common stock. The Company may, from time-to-time, either (i) purchase shares of its common stock in the open market or (ii) issue new shares of its common stock for the purpose of fulfilling its obligations under the Plan.
Recent Sales of Unregistered Securities: None.
Issuer Purchases of Equity Securities: During the year ended December 31, 2020, the Company repurchased 294,346 shares for an aggregate purchase price of $5.4 million (weighted average price of $18.27 per share) in connection with common shares surrendered or deemed surrendered to the Company to satisfy statutory minimum tax withholding obligations in connection with the vesting of restricted stock awards under the Company’s equity-based compensation plans. In addition, during February 2020, the Company extended its share repurchase program for a term of two years, which will expire in February 2022, pursuant to which the Company may repurchase shares of its common stock, par value $0.01 per share, with an aggregate gross purchase price of up to $300.0 million. The Company did not make any repurchases under this common share repurchase program during 2020. As of December 31, 2020, the Company had $224.9 million available under this common share repurchase program.
| Period | Total Number of Shares Purchased | Average Price Paid per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | Approximate Dollar Value of Shares that May Yet Be Purchased Under the Plans or Programs (in millions) | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| January 1, 2020 – January 31, 2020 | 30,631 | $ | 20.63 | - | $ | 224.9 | ||||||||||
| February 1, 2020 – February 29, 2020 | 238,412 | 18.82 | - | 224.9 | ||||||||||||
| March 1, 2020 – March 31, 2020 | 1,665 | 17.76 | - | 224.9 | ||||||||||||
| April 1, 2020 – April 30, 2020 | - | - | - | 224.9 | ||||||||||||
| May 1, 2020 – May 31, 2020 | 17,157 | 8.76 | - | 224.9 | ||||||||||||
| June 1, 2020 – June 30, 2020 | 1,020 | 12.72 | - | 224.9 | ||||||||||||
| July 1, 2020 – July 31, 2020 | - | - | - | 224.9 | ||||||||||||
| August 1, 2020 – August 31, 2020 | - | - | - | 224.9 | ||||||||||||
| September 1, 2020 – September 30, 2020 | - | - | - | 224.9 | ||||||||||||
| October 1, 2020 – October 31, 2020 | 3,155 | 11.49 | - | 224.9 | ||||||||||||
| November 1, 2020 – November 30, 2020 | 2,306 | 12.80 | - | 224.9 | ||||||||||||
| December 1, 2020 – December 31, 2020 | - | - | - | 224.9 | ||||||||||||
| Total | 294,346 | $ | 18.27 | - |
Total Stockholder Return Performance: The following performance chart compares, over the five years ended December 31, 2020, the cumulative total stockholder return on the Company’s common stock with the cumulative total return of the S&P 500 Index and the cumulative total return of the NAREIT Equity REITs Index (the “NAREIT Equity REITs”) prepared and published by the National Association of Real Estate Investment Trusts (“NAREIT”). The NAREIT Equity REITs Index is a free-float adjusted, market capitalization-weighted index of U.S. equity REITs. Constituents of the index include all tax-qualified REITs with more than 50% of total assets in qualifying real estate assets other than mortgages secured by real property.
Stockholder return performance, presented annually for the five years ended December 31, 2020, is not necessarily indicative of future results. All stockholder return performance assumes the reinvestment of dividends. The information in this paragraph and the following performance chart are deemed to be furnished, not filed.

| Comparison of 5 year cumulative total return data points | ||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Dec-15 | Dec-16 | Dec-17 | Dec-18 | Dec-19**** | ****Dec-20 | |||||||||||||||||||
| Kimco Realty Corporation | $ | 100 | $ | 99 | $ | 75 | $ | 65 | $ | 98 | $ | 75 | ||||||||||||
| S&P 500 | $ | 100 | $ | 112 | $ | 136 | $ | 130 | $ | 171 | $ | 203 | ||||||||||||
| NAREIT Equity REITs | $ | 100 | $ | 109 | $ | 114 | $ | 109 | $ | 137 | $ | 126 |
Item 6. Selected Financial Data
The following table sets forth selected, historical, consolidated financial data for the Company and should be read in conjunction with the Consolidated Financial Statements of the Company and Notes thereto and "Management’s Discussion and Analysis of Financial Condition and Results of Operations" included in this Form 10-K.
The Company believes that the book value of its real estate assets, which reflects the historical costs of such real estate assets less accumulated depreciation, is not indicative of the current market value of its properties. Historical operating results are not necessarily indicative of future operating performance.
| **Year **Ended December 31, | ||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2020 | 2019 | 2018 | 2017 | 2016**** | ||||||||||||||||
| (in thousands, except per share data) | ||||||||||||||||||||
| Operating Data: | ||||||||||||||||||||
| Revenues from rental properties, net | $ | 1,044,888 | $ | 1,142,334 | $ | 1,149,603 | $ | 1,183,785 | $ | 1,152,401 | ||||||||||
| Impairment charges (1) | $ | (6,624 | ) | $ | (48,743 | ) | $ | (79,207 | ) | $ | (67,331 | ) | $ | (93,266 | ) | |||||
| Depreciation and amortization | $ | (288,955 | ) | $ | (277,879 | ) | $ | (310,380 | ) | $ | (360,811 | ) | $ | (355,320 | ) | |||||
| Gain on sale of properties/change in control of interests (1) | $ | 6,484 | $ | 79,218 | $ | 229,840 | $ | 93,538 | $ | 92,823 | ||||||||||
| Gain/(loss) on marketable securities, net (1) (2) | $ | 594,753 | $ | 829 | $ | (3,487 | ) | $ | - | $ | - | |||||||||
| Interest expense | $ | (186,904 | ) | $ | (177,395 | ) | $ | (183,339 | ) | $ | (191,956 | ) | $ | (192,549 | ) | |||||
| Early extinguishment of debt charges | $ | (7,538 | ) | $ | - | $ | (12,762 | ) | $ | (1,753 | ) | $ | (45,674 | ) | ||||||
| (Provision)/benefit for income taxes, net | $ | (978 | ) | $ | 3,317 | $ | (1,600 | ) | $ | 880 | $ | (78,583 | ) | |||||||
| Net income | $ | 1,002,877 | $ | 413,561 | $ | 498,463 | $ | 439,671 | $ | 386,138 | ||||||||||
| Net income attributable to the Company | $ | 1,000,833 | $ | 410,605 | $ | 497,795 | $ | 426,075 | $ | 378,850 | ||||||||||
| Net income available to the Company’s common shareholders | $ | 975,417 | $ | 339,988 | $ | 439,604 | $ | 372,461 | $ | 332,630 | ||||||||||
| Earnings per common share: | ||||||||||||||||||||
| Net income available to the Company’s common shareholders: | ||||||||||||||||||||
| Basic | $ | 2.26 | $ | 0.80 | $ | 1.02 | $ | 0.87 | $ | 0.79 | ||||||||||
| Diluted | $ | 2.25 | $ | 0.80 | $ | 1.02 | $ | 0.87 | $ | 0.79 | ||||||||||
| Weighted average shares of common stock: | ||||||||||||||||||||
| Basic | 429,950 | 420,370 | 420,641 | 423,614 | 418,402 | |||||||||||||||
| Diluted | 431,633 | 421,799 | 421,379 | 424,019 | 419,709 | |||||||||||||||
| Cash dividends declared per common share | $ | 0.540 | $ | 1.120 | $ | 1.120 | $ | 1.090 | $ | 1.035 | ||||||||||
| Cash flow provided by operations | $ | 589,913 | $ | 583,628 | $ | 637,936 | $ | 614,181 | $ | 592,096 | ||||||||||
| Cash flow (used for)/provided by investing activities | $ | (33,273 | ) | $ | (120,421 | ) | $ | 253,645 | $ | (294,280 | ) | $ | 165,383 | |||||||
| Cash flow used for financing activities | $ | (387,399 | ) | $ | (482,841 | ) | $ | (986,513 | ) | $ | (223,874 | ) | $ | (804,527 | ) |
| December 31, | ||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2020 | 2019 | 2018 | 2017 | 2016**** | ||||||||||||||||
| (in thousands) | ||||||||||||||||||||
| Balance Sheet Data: | ||||||||||||||||||||
| Real estate, before accumulated depreciation | $ | 12,068,827 | $ | 11,929,276 | $ | 11,877,190 | $ | 12,653,446 | $ | 12,008,075 | ||||||||||
| Total assets | $ | 11,614,498 | $ | 10,997,867 | $ | 10,999,100 | $ | 11,763,726 | $ | 11,230,600 | ||||||||||
| Total debt | $ | 5,355,480 | $ | 5,315,767 | $ | 4,873,872 | $ | 5,478,927 | $ | 5,066,368 | ||||||||||
| Total stockholders' equity | $ | 5,608,044 | $ | 4,864,892 | $ | 5,333,804 | $ | 5,394,244 | $ | 5,256,139 |
| (1) | Amounts exclude noncontrolling interests. |
|---|
| (2) | On January 1, 2018, the Company adopted ASU 2016-01, Financial Instruments—Overall (Subtopic 825-10): Recognition and Measurement of Financial Assets and Financial Liabilities (“ASU 2016-01”). In accordance with the adoption of ASU 2016-01, the Company recognizes changes in the fair value of equity investments with readily determinable fair values in net income. Previously, changes in fair value of the Company’s available-for-sale marketable securities were recognized in accumulated other comprehensive income. |
|---|
Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
The following discussion should be read in conjunction with the Consolidated Financial Statements and Notes thereto included in this Form 10-K. Historical results and percentage relationships set forth in the Consolidated Statements of Income contained in the Consolidated Financial Statements, including trends, should not be taken as indicative of future operations.
Critical Accounting Policies
The Consolidated Financial Statements of the Company include the accounts of the Company, its wholly owned subsidiaries and all entities in which the Company has a controlling interest, including where the Company has been determined to be a primary beneficiary of a variable interest entity in accordance with the consolidation guidance of the FASB Accounting Standards Codification. The Company applies these provisions to each of its joint venture investments to determine whether the cost, equity or consolidation method of accounting is appropriate. The Company evaluates performance on a property specific or transactional basis and does not distinguish its principal business or group its operations on a geographical basis for purposes of measuring performance. Accordingly, the Company believes it has a single reportable segment for disclosure purposes in accordance with accounting principles generally accepted in the United States of America (“GAAP”). The preparation of financial statements in conformity with GAAP requires management to make estimates and assumptions in certain circumstances that affect amounts reported in the accompanying Consolidated Financial Statements and related notes. In preparing these financial statements, management has made its best estimates and assumptions that affect the reported amounts of assets and liabilities. These estimates are based on, but not limited to, historical results, industry standards and current economic conditions, giving due consideration to materiality. The most significant assumptions and estimates relate to revenue recognition and the recoverability of trade accounts receivable, depreciable lives, valuation of real estate and intangible assets and liabilities, valuation of joint venture investments and other investments, and realizability of deferred tax assets and uncertain tax positions. Application of these assumptions requires the exercise of judgment as to future uncertainties, and, as a result, actual results could materially differ from these estimates.
The Company is required to make subjective assessments as to whether there are impairments in the value of its real estate properties, investments in joint ventures and other investments. The Company’s reported net earnings are directly affected by management’s estimate of impairments.
Revenue Recognition and Recoverability of Trade Accounts Receivable
Revenues from rental properties, net are comprised of minimum base rent, percentage rent, lease termination fee income, amortization of above-market and below-market rent adjustments and straight-line rent adjustments. Upon the adoption of ASU 2016-02, Leases (Topic 842) (“ASU 2016-02”), the Company elected the lessor practical expedient to combine the lease and non-lease components, determined the lease component was the predominant component and as a result, accounted for the combined components under Topic 842. Non-lease components include reimbursements paid to the Company from tenants for common area maintenance costs and other operating expenses. The combined components are included in Revenues from rental properties, net on the Company’s Consolidated Statements of Income.
Base rental revenues from rental properties are recognized on a straight-line basis over the terms of the related leases. Certain of these leases also provide for percentage rents based upon the level of sales achieved by the lessee. These percentage rents are recognized once the required sales level is achieved. Rental income may also include payments received in connection with lease termination agreements. Lease termination fee income is recognized when the lessee provides consideration in order to terminate an existing lease agreement and has vacated the leased space. If the lessee continues to occupy the leased space for a period of time after the lease termination is agreed upon, the termination fee is accounted for as a lease modification based on the modified lease term. Upon acquisition of real estate operating properties, the Company estimates the fair value of identified intangible assets and liabilities (including above-market and below-market leases, where applicable). The capitalized above-market or below-market intangible asset or liability is amortized to rental income over the estimated remaining term of the respective leases, which includes the expected renewal option period for below-market leases.
Also included in Revenues from rental properties, net are ancillary income and tax increment financing (“TIF”) income. Ancillary income is derived through various agreements relating to parking lots, clothing bins, temporary storage, vending machines, ATMs, trash bins and trash collections, seasonal leases, etc. The majority of the revenue derived from these sources is through lease agreements/arrangements and is recognized in accordance with the lease terms described in the lease. The Company has TIF agreements with certain municipalities and receives payments in accordance with the agreements. TIF reimbursement income is recognized on a cash-basis when received.
Trade accounts receivable
The Company reviews its trade accounts receivable, including its straight-line rent receivable, related to base rents, straight-line rent, expense reimbursements and other revenues for collectability. When evaluating the probability of the collection of the lessee’s total accounts receivable, including the corresponding straight-line rent receivable balance on a lease-by-lease basis, the Company considered the effects COVID-19 has had on its tenants, including the corresponding straight-line rent receivable. The Company’s analysis of its accounts receivable included (i) customer credit worthiness, (ii) assessment of risk associated with the tenant, and (iii) current economic trends. In addition, tenants in bankruptcy are analyzed and considerations are made in connection with the expected recovery of pre-petition and post-petition bankruptcy claims. Effective January 1, 2019, in accordance with the adoption of Topic 842, the Company includes provision for doubtful accounts in Revenues from rental properties, net. If a lessee’s accounts receivable balance is considered uncollectible, the Company will write-off the receivable balances associated with the lease and will only recognize lease income on a cash basis. In addition to the lease-specific collectability assessment performed under Topic 842, the analysis also recognizes a general reserve, as a reduction to Revenues from rental properties, for its portfolio of operating lease receivables which are not expected to be fully collectible based on the Company’s historical and current collection experience and the potential for settlement of arrears. Although the Company estimates uncollectible receivables and provides for them through charges against revenues from rental properties, actual results may differ from those estimates. If the Company subsequently determines that it is probable it will collect the remaining lessee’s lease payments under the lease term, the Company will then reinstate the straight-line balance and the lease income will then be limited to the lesser of (i) the straight-line rental income or (ii) the lease payments that have been collected from the lessee.
Real Estate
Depreciable Lives
The Company’s investments in real estate properties are stated at cost, less accumulated depreciation and amortization. Expenditures for maintenance and repairs are charged to operations as incurred. Significant renovations and replacements, which improv
Showing the first 8K of 97K characters. Open the full section
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
The Company’s primary market risk exposure is interest rate risk. The Company periodically evaluates its exposure to short-term interest rates and will, from time-to-time, enter into interest rate protection agreements which mitigate, but do not eliminate, the effect of changes in interest rates on its floating-rate debt. The Company has not entered, and does not plan to enter, into any derivative financial instruments for trading or speculative purposes. The following table presents the Company’s aggregate fixed rate and variable rate debt obligations outstanding, including fair market value adjustments and unamortized deferred financing costs, as of December 31, 2020, with corresponding weighted-average interest rates sorted by maturity date. The table does not include extension options where available (amounts in millions).
| 2021**** | 2022**** | 2023**** | 2024**** | 2025**** | Thereafter | Total | Fair Value | |||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Secured Debt | ||||||||||||||||||||||||||||||||
| Fixed Rate | $ | 139.4 | $ | 147.1 | $ | 12.0 | $ | 8.3 | $ | - | $ | 4.5 | $ | 311.3 | $ | 312.9 | ||||||||||||||||
| Average Interest Rate | 5.39 | % | 4.05 | % | 3.23 | % | 6.73 | % | - | 7.08 | % | 4.73 | % | |||||||||||||||||||
| Unsecured Debt | ||||||||||||||||||||||||||||||||
| Fixed Rate | $ | - | $ | 498.0 | $ | 348.8 | $ | 397.8 | $ | 497.4 | $ | 3,302.2 | $ | 5,044.2 | $ | 5,487.0 | ||||||||||||||||
| Average Interest Rate | - | 3.40 | % | 3.13 | % | 2.7 | % | 3.3 | % | 3.42 | % | 3.3 | % |
Item 8. Financial Statements and Supplementary Data
The response to this Item 8 is included in our audited Consolidated Financial Statements and Notes to Consolidated Financial Statements, which are contained in Part IV, Item 15 of this Form 10-K.
Item 9. Changes in and Disagreements With Accountants on Accounting and Financial Disclosure
None.
Item 9A. Controls and Procedures
Evaluation of Disclosure Controls and Procedures
The Company’s management, with the participation of the Company’s Chief Executive Officer and Chief Financial Officer, has evaluated the effectiveness of the Company’s disclosure controls and procedures (as such term is defined in Rules 13a-15(e) and 15d-15(e) under the Securities Exchange Act of 1934, as amended (the "Exchange Act")) as of the end of the period covered by this report. Based on such evaluation, the Company’s Chief Executive Officer and Chief Financial Officer have concluded that the Company’s disclosure controls and procedures are effective as of December 31, 2020.
Changes in Internal Control O__ver Financial Reporting
There have not been any changes in the Company’s internal control over financial reporting (as such term is defined in Rules 13a-15(f) and 15d-15(f) under the Exchange Act) during the fourth fiscal quarter ended December 31, 2020, that have materially affected, or are reasonably likely to materially affect, the Company’s internal control over financial reporting.
Management’s Report on Internal Control Over Financial Reporting
Our management is responsible for establishing and maintaining adequate internal control over financial reporting, as such term is defined in Exchange Act Rule 13a-15(f) and 15d-15(f). Under the supervision and with the participation of our management, including our Chief Executive Officer and Chief Financial Officer, we conducted an evaluation of the effectiveness of our internal control over financial reporting based on the framework in the I__nternal Control - Integrated Framework (2013_)_ issued by the Committee of Sponsoring Organizations of the Treadway Commission. Based on our evaluation under the framework in Internal Control - Integrated Framework (2013), our management concluded that our internal control over financial reporting was effective as of December 31, 2020.
The effectiveness of our internal control over financial reporting as of December 31, 2020, has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in their report which appears under Item 8.
Item 9B. Other Information
None.
PART III
Item 10. Directors, Executive Officers and Corporate Governance
The information required by this item is incorporated by reference to “Proposal 1—Election of Directors,” “Corporate Governance,” “Committees of the Board of Directors,” “Executive Officers” and “Other Matters” in our definitive proxy statement to be filed with respect to the Annual Meeting of Stockholders expected to be held on April 27, 2021 (“Proxy Statement”).
We have adopted a Code of Business Conduct and Ethics (the “Code of Ethics”). The Code of Ethics is available at the Investors/Governance/Governance Documents section of our website at www.kimcorealty.com. A copy of the Code of Ethics is available in print, free of charge, to stockholders upon request to us at the address set forth in Item 1 of this Annual Report on Form 10-K under the section “Business - Overview.” We intend to satisfy the disclosure requirements under the Securities and Exchange Act of 1934, as amended, regarding an amendment to or waiver from a provision of our Code of Ethics by posting such information on our website.
Item 11. Executive Compensation
The information required by this item is incorporated by reference to “Compensation Discussion and Analysis,” “Executive Compensation Committee Report,” “Compensation Tables,” “Compensation of Directors” and “Other Matters” in our Proxy Statement.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
The information required by this item is incorporated by reference to “Security Ownership of Certain Beneficial Owners and Management” and “Compensation Tables” in our Proxy Statement.
Item 13. Certain Relationships and Related Transactions, and Director Independence
The information required by this item is incorporated by reference to “Certain Relationships and Related Transactions” and “Corporate Governance” in our Proxy Statement.
Item 14. Principal Accountant Fees and Services
The information required by this item is incorporated by reference to “Independent Registered Public Accountants” in our Proxy Statement.
PART IV
Item 15. Exhibits and Financial Statement Schedules
Item 16. Form 10-K Summary
None.
- Filed herewith
** Furnished herewith
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| KIMCO REALTY CORPORATION | |||
|---|---|---|---|
| By: | /s/ Conor C. Flynn | ||
| Conor C. Flynn | |||
| Chief Executive Officer |
Dated: February 23, 2021
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities and on the dates indicated.
| Signature | Title | Date | |
|---|---|---|---|
| /s/ Milton Cooper | Executive Chairman of the Board of Directors | February 23, 2021 | |
| Milton Cooper | |||
| /s/ Conor C. Flynn | Chief Executive Officer and Director | February 23, 2021 | |
| Conor C. Flynn | |||
| /s/ Frank Lourenso | Director | February 23, 2021 | |
| Frank Lourenso | |||
| /s/ Richard Saltzman | Director | February 23, 2021 | |
| Richard Saltzman | |||
| /s/ Philip Coviello | Director | February 23, 2021 | |
| Philip Coviello | |||
| /s/ Colombe Nicholas | Director | February 23, 2021 | |
| Colombe Nicholas | |||
| /s/ Mary Hogan Preusse | Director | February 23, 2021 | |
| Mary Hogan Preusse | |||
| /s/ Valerie Richardson | Director | February 23, 2021 | |
| Valerie Richardson | |||
| /s/ Henry Moniz | Director | February 23, 2021 | |
| Henry Moniz | |||
| /s/ Glenn G. Cohen | Executive Vice President - | February 23, 2021 | |
| Glenn G. Cohen | Chief Financial Officer and Treasurer | ||
| /s/ Paul Westbrook | Vice President - | February 23, 2021 | |
| Paul Westbrook | Chief Accounting Officer |
ANNUAL REPORT ON FORM 10-K
Item 8. , ITEM 15 (a) (1) and (2)
INDEX TO FINANCIAL STATEMENTS
AND
FINANCIAL STATEMENT SCHEDULES
Report of Independent Registered Public Accounting Firm
To the Board of Directors and Stockholders
of Kimco Realty Corporation:
Opinions on the Financial Statements and Internal Control over Financial Reporting
We have audited the consolidated financial statements, including the related notes, as listed in the index appearing under Item 15(a)(1), and the financial statement schedules listed in the index appearing under Item 15(a)(2), of Kimco Realty Corporation and its subsidiaries (the “Company”) (collectively referred to as the “consolidated financial statements”). We also have audited the Company's internal control over financial reporting as of December 31, 2020, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, 2020 and 2019, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2020 in conformity with accounting principles generally accepted in the United States of America. Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2020, based on criteria established in Internal Control - Integrated Framework (2013) issued by the COSO.
Basis for Opinions
The Company's management is responsible for these consolidated financial statements, for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting, included in Management’s Report on Internal Control Over Financial Reporting appearing under Item 9A. Our responsibility is to express opinions on the Company’s consolidated financial statements and on the Company's internal control over financial reporting based on our audits. We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) (PCAOB) and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audits to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement, whether due to error or fraud, and whether effective internal control over financial reporting was maintained in all material respects.
Our audits of the consolidated financial statements included performing procedures to assess the risks of material misstatement of the consolidated financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the consolidated financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the consolidated financial statements. Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audits also included performing such other procedures as we considered necessary in the circumstances. We believe that our audits provide a reasonable basis for our opinions.
Definition and Limitations of Internal Control over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (i) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (ii) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (iii) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Critical Audit Matters
The critical audit matters communicated below are matters arising from the current period audit of the consolidated financial statements that were communicated or required to be communicated to the audit committee and that (i) relate to accounts or disclosures that are material to the consolidated financial statements and (ii) involved our especially challenging, subjective, or complex judgments. The communication of critical audit matters does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit matters below, providing separate opinions on the critical audit matters or on the accounts or disclosures to which they relate.
Analysis of Real Estate Properties for Indicators of Impairment
As described in Notes 1 and 6 to the consolidated financial statements, the net carrying value of the Company’s real estate, net was $
Showing the first 8K of 327K characters. Open the full section