 filings.tools
Lennar (LEN) 10-K risk factor changes: FY2022 vs FY2021
The 2022-11-30 10-K against the 2021-11-30 one, compared heading by heading and sentence by sentence.
Item 1A58 rewritten29 added25 removed214 unchanged
All filing items983 rewritten493 added338 removed2,103 unchanged
Summary
counted, not written
- Item 1A lists 44 risk factor headings: 1 new, 9 reworded and 34 unchanged since FY2021. 1 heading from FY2021 no longer appears.
- Sentence by sentence, 493 added, 338 removed, 983 rewritten and 2,103 unchanged across 18 items that differ.
New Item 1A headings (1)
- Supply shortages and inflation could adversely affect our profitability.
Removed Item 1A headings (1)
- Supply shortages and continuing cost increases could adversely affect our operations.
Reworded Item 1A headings (9)
- Negative publicity could
[removed: negatively impact][added: hurt] our reputation, which could cause our revenues or results of operations to decline. - A [added: continuing] downturn in the homebuilding market could adversely affect our operations.
[removed: An][added: Further] increase in mortgage interest rates could reduce potential buyers’ ability or desire to obtain financing with which to buy homes.- Our results of operations and financial condition may be adversely affected by public health issues,
[removed: including the COVID-19 pandemic,]and resulting governmental actions. - Homebuilding, mortgage lending and
[removed: multifamily][added: home] rentals are very competitive industries, and competitive conditions could adversely affect our business or financial results. - Increased interest rates
[removed: would][added: could] increase the cost of the homes we build. - Our access to capital and our ability to obtain additional financing could be affected
[removed: by any][added: if there was a] downgrade of our credit ratings. [removed: An announced spin off][added: Our planned spin-off] of some of our businesses may not achieve its goals.- We have substantial investments in real estate related [added: funds and] businesses in which we are a minority investor.
A heading is new when no FY2021 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
23 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2022; struck-through words were in FY2021. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors.
58 rewritten, 29 added, 25 removed, 214 unchanged
These [removed: factors, in particular consumer confidence,] [added: factors] can be significantly adversely affected by a variety of factors beyond our control.
Negative publicity could [removed: negatively impact] [added: hurt] our reputation, which could cause our revenues or results of operations to decline.
[removed: increased dramatically] [added: These statements, even if totally untrue, can spread rapidly] through the use of electronic communication, including social media outlets, websites and other digital platforms.
[removed: An announced spin off] [added: Our planned spin-off] of some of our businesses may not achieve its goals.
We [removed: have announced our intention to transfer] [added: are in the process of transferring] some of our [removed: non-core] [added: non-homebuilding] businesses into a newly formed [removed: company and] [added: company, Quarterra Group, Inc., and, subject] to [added: market conditions, we intend to] distribute [removed: at least most of] the stock of [removed: that company] [added: Quarterra] to our stockholders.
Our hope is that doing that will result in the combined market value of our stock and [removed: the] [added: Quarterra's] stock [removed: of the new company] exceeding what the market value of our stock would be if we continued to conduct the businesses that we will transfer to [removed: the new company.][added: Quarterra.]
Among other things, making [removed: the new company] [added: Quarterra] a self-standing entity will lose some synergies [added: from which] the businesses it will own currently [removed: benefit from.][added: benefit.]
Therefore, it is possible that after the separation, the combined market value of our stock and [removed: the] [added: Quarterra's] stock [removed: of the new company] will be less, not more, than what the market value of our stock would be if we did not [removed: move some of our non-core businesses into a new company][added: spin off Quarterra.]
Principal among our current strategies is continuing to reduce [removed: our] [added: the] inventory of land we own (i.e., to become a land lighter [removed: company).][added: company), and to control a greater portion of the land we expect to use through options or other contractual arrangements.]
We cannot provide [removed: any] assurance that this strategy, or other strategies we will follow, will increase our value.
A [added: continuing] downturn in the homebuilding market could adversely affect our operations.
Supply shortages and [removed: continuing cost increases] [added: inflation] could adversely affect our [removed: operations.][added: profitability.]
[removed: An] [added: Further] increase in mortgage interest rates could reduce potential buyers’ ability or desire to obtain financing with which to buy homes.
If market conditions were to deteriorate significantly in the future, we could again be required to make significant write-downs of the carrying value of our land inventory and [added: incur] costs relating to [added: decisions not to exercise] land purchase options.
Our results of operations and financial condition may be adversely affected by public health issues, [removed: including the COVID-19 pandemic,] and resulting governmental actions.
With the exception of a period in March and April of 2020, the COVID-19 pandemic and its effects on the economy [removed: has] [added: did] not adversely [removed: affected] [added: affect] our home sales.
If [removed: COVID-19 continues to cause, or another] [added: a] contagious disease [removed: causes,] [added: causes] significant negative impacts to economic conditions or consumer confidence, our results of operations, financial condition and cash flows could be materially adversely impacted.
Homebuilding, mortgage lending and [removed: multifamily] [added: home] rentals are very competitive industries, and competitive conditions could adversely affect our business or financial results.
Our multifamily rental business competes with other [removed: multifamily apartment] developers and operators [added: of multifamily apartment communities] at locations across the U.S. where we have investments in multifamily rental properties.
We also compete in securing partners, equity capital and debt financing, and we compete for tenants with the large supply of already existing or newly built rental apartments, as well as with sellers [added: and renters] of [added: single family] homes.
These competitive conditions could negatively impact the ability of the [added: funds and] ventures [removed: in which] we [removed: are participating] [added: manage] to find renters for the apartments they are building or the prices for which those apartments can be rented.
Also, the coverage offered and the availability of general liability insurance for construction defects [removed: are] [added: is] currently limited and policies that can be obtained often include exclusions based upon past losses those insurers suffered as a result of use of defective [removed: products] [added: materials] in homes we and many other homebuilders built.
If the rate at which we sell and deliver homes slows, or if we delay the opening of new home communities, we may incur [removed: additional] [added: increased] pre-construction costs and it may take longer for us to recover our costs.
Increased interest rates [removed: would] [added: could] increase the cost of the homes we build.
At November 30, [removed: 2021,] [added: 2022,] we had a [removed: $2.5] [added: $2.6] billion revolving credit facility with a group of banks [added: (the "Credit Facility"), which had an accordion feature that could increase it to $3 billion.]
We also had warehouse borrowing facilities [removed: totaling $2.3] [added: totaling$2.85] billion to support our [added: residential and commercial] mortgage lending activities.
At November 30, [removed: 2021,] [added: 2022,] we had no borrowings under the Credit Facility.
[removed: However, if in the future we have a need for significant borrowings under the Credit Facility and] interest rates [added: continue to] increase, that would increase the cost of the homes we build, which either would make those homes more expensive for homebuyers, which is likely to reduce demand, or would lower our operating margins, or both.
If there is a [added: further] downturn in the housing market, or if mortgage financing becomes less available than it currently is, more homebuyers may cancel their agreements of sale with us, which would have an adverse effect on our business and results of operations.
If we were to lose members of our senior management, we might not be [added: able to find appropriate replacements on a timely basis and our operations could be negatively affected.]
Also, the loss of a significant number of [added: key] operating employees and our inability to hire qualified replacements could have a material adverse effect on our business.
[removed: There is a substantial possibility that substituting an alternate source of liquidity would] increase mortgage interest rates, which would increase the buyers' effective costs of paying for the homes we sell, and therefore could reduce demand for our homes and adversely affect our results of operations.
Approximately [removed: 97%] [added: 99%] of the residential mortgage loans made by our Financial Services segment in [removed: 2021] [added: 2022] were made to buyers of homes we built.
Therefore, a decrease in the demand for our homes [added: or an increase in cash used by home buyers] would adversely affect the revenues of this aspect of our business.
In addition, our Financial Services residential mortgage companies [removed: have warehouse facilities to finance their mortgage lending activities] and our LMF Commercial [added: mortgage] lending group [removed: has] [added: have] warehouse facilities to finance [removed: its] [added: their] mortgage [removed: origination activities.][added: lending.]
As of November 30, [removed: 2021,] [added: 2022,] we had outstanding senior notes which we had sold into the capital markets over a number of years totaling [removed: $4.2] [added: $3.6] billion.
We reduced our outstanding senior notes during fiscal [removed: 2021] [added: 2022] by [removed: $1.2 billion,] [added: $575 million,] but we still have a significant amount outstanding.
- [removed: we] [added: We] may have to pay higher interest rates upon refinancing indebtedness [removed: if] [added: as a result of the increase in] interest [removed: rates rise,] [added: rates,] thereby reducing our earnings and cash flows;
- [removed: \[we] [added: We] may have a competitive disadvantage relative to other companies in our [removed: industry] [added: industry, if any,] that are less [removed: leveraged\];] [added: leveraged;] and
Our access to capital and our ability to obtain additional financing could be affected [removed: by any] [added: if there was a] downgrade of our credit ratings.
Currently, potential purchasers of our homes are being affected by inflation and increased interest rates, both of which increase what homebuyers have to pay for new homes.
We could be subject to knowingly false statements made for the purpose of impairing our reputation.
During fiscal 2022, the housing market weakened in response to the Federal Reserve’s aggressive increase in interest rates in an effort to curtail inflation.
A number of our markets experienced significant market softening that required us to make substantial price reductions.
It is possible that a continued downturn could result in a further decline in demand for new homes with resulting write downs in the carrying value of our land inventory and write offs of costs of land purchase options we decide not to exercise.
In an inflationary environment, we may be precluded from raising home prices enough to keep up with the rate of inflation, which could reduce our profit margins.
Moreover, in an inflationary environment, our cost of capital, labor and materials can increase and the purchasing power of our cash resources can decline, which can have an adverse impact on our business or financial results.
During fiscal 2022, we experienced increased costs of materials and labor caused both by supply shortages and inflation.
We were able to maintain satisfactory margins by applying stringent cost controls and by raising prices.
However, declining demand for new homes as the year progressed is requiring us to reduce, rather than increase, prices.
On the other hand, it is beginning to relieve supply shortages.
We are taking steps that we expect will enable us to maintain acceptable operating margins despite the inability to raise prices.
However it is possible that those steps will not be successful, and that the combination of inflation and reduced demand for new homes will adversely affect our profitability
Housing has been considerably impacted by the more than doubling of mortgage interest rates in 2022, and the Federal Reserve Board has said it intends to continue to increase its benchmark interest rate in 2023.
However, this may not be the case with any future public health issues.
The extent to which public health issues impact our results will depend on future developments, which cannot be predicted.
Single Family Home Rentals.
In each region where our funds offer single family homes for rent, there will be competition for residents with other owners of residential real estate (whether for-rent or for-sale).
In addition, in seeking investors to acquire interests in funds we form, we will be competing with a wide variety of investment opportunities, related both to real estate and to a variety of other investment products.
Also, in seeking to acquire single family homes that our funds can hold as rental properties, our funds will be competing with other persons who plan to hold them as rental properties as well as persons who might want to purchase those homes to live in them.
In 2022, the Federal Reserve steadily raised benchmark interest rates and said it intends to continue doing so in 2023.
However, if in the future we have a need for significant borrowings under the Credit Facility and
With the weakening of the housing market, we have experienced an increase in cancellation rates.
There is a substantial possibility that substituting an alternate source of liquidity would
If any of those joint ventures are unable to do this, we could be required to provide at
certain areas in which we operate.
*Risk Related to Planned Spin-Off*
Further, there has been a significant increase in work from remote locations since the start of the COVID-19 pandemic.
However, a variety of factors can change seasonal patterns.
Furthermore, the speed at which negative publicity is disseminated has
We saw the homebuilding industry stall from mid-March through April of 2020 as a result of the COVID-19 pandemic.
However, after that, demand for new homes grew steadily through the remainder of 2020 and throughout 2021.
While the homebuilding industry only paused for a relatively brief period in 2020, a prior economic downturn in 2007-2010 severely affected for more than two years both the number of homes we could sell and the prices for which we could sell them.
That required us to write down the carrying value of our land inventory and write off costs of land purchase options.
It is possible that another downturn resulting from a health pandemic or other factors would result in a decline in demand for new homes for a significant period which would negatively impact our business, results of operations and financial condition.
During fiscal 2021, we experienced a significantly stressed supply of both labor and materials, and we expect this to continue well into fiscal 2022.
The time it takes to build a home has increased as a result of supply issues, which has led to delayed home deliveries.
In addition, the costs of construction materials and other components of homes, lumber in particular, and the costs of labor have been rising.
We have been actively managing our sales pace so we do not sell homes until construction is ready to start, in order to avoid the possibility of costs increasing after we have committed to the prices at which we will sell homes.
While we will continue to focus on cost controls, we may not be able to maintain our current level of direct construction costs as a percentage of average sales price.
We continue to operate in a labor constrained market and we cannot predict future inflationary pressures or increases in tariffs on imported building materials.
Any inability to pass on future increased costs to homebuyers would put downward pressure on our operating margins in 2022 and subsequent years.
Mortgage rates are very low as compared to most historical periods.
However, they could increase in the future, particularly if the Federal Reserve Board raises its benchmark rate.
However, this may not continue to be the case.
The extent to which COVID-19 impacts our results will depend on future developments, which cannot be predicted, including new information which may emerge concerning the continuing severity of COVID-19, whether there are additional outbreaks of COVID-19 or other contagious diseases, and the actions taken to contain them or their impact.
(the "Credit Facility") maturing in 2024.
It has a $300 million accordion feature, subject to additional commitments, thus the maximum borrowings could be $2.8 billion.
able to find appropriate replacements on a timely basis and our operations could be negatively affected.
In
Further, there has been a surge in widespread cyber-attacks during the COVID-19 pandemic.
The increase in the frequency and scope of cyber-attacks during the pandemic exacerbates data security risks.
However, a variety of factors, such as the shutdown of large portions of our national economy in the second quarter of 2020 as a result of the COVID-19 pandemic, can change seasonal patterns.
factors, including, among others, seasonal home buying patterns, the timing of home closings and land sales and weather-related problems.
An excerpt. Shown here: 40 of 58 rewritten, all 29 added and all 25 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors. in the FY2022 filing and the FY2021 filing.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
216 rewritten, 187 added, 120 removed, 363 unchanged
The following discussion and analysis of our financial condition and results of operations should be read in conjunction with [removed: "Selected Financial Data" and] our audited consolidated financial statements and accompanying notes included elsewhere in this Report.
We expect our [removed: deliveries] [added: new orders] for the first quarter of [removed: 2022 will] [added: 2023 to] be [removed: approximately 12,500] [added: in the range of 12,000 to 13,500 homes, and we anticipate our first quarter deliveries to be in the range of 12,000 to 13,500] homes.
Our net earnings attributable to Lennar were [removed: $4.4] [added: $4.6] billion, or [removed: $14.27] [added: $15.72] per diluted share [removed: ($14.28] [added: ($15.74] per basic share) in [removed: 2021] [added: 2022] and [removed: $2.5] [added: $4.4] billion, or [removed: $7.85] [added: $14.27] per diluted share [removed: ($7.88] [added: ($14.28] per basic share) in [removed: 2020.][added: 2021.]
| Equity in earnings (loss) from unconsolidated entities, Multifamily other gain and Lennar Other other income (expense), [removed: net] [added: net, and other gain (loss) (1)] | | | (14,205) | | | | | | — | | | | | | 9,031 | | | | | | [removed: 61,957] [added: 231,731] | | | | | | — | | | | | | [removed: 56,783] [added: 226,557] | | |
| | | | Year ended November 30, [removed: 2020] [added: 2022] | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Costs of homes sold | | | [removed: 16,092,069] [added: 23,025,467] | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | [removed: 16,092,069] [added: 23,025,467] | | |
| Costs of land sold | | | [removed: 172,480] [added: 171,589] | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | [removed: 172,480] [added: 171,589] | | |
| Selling, general and administrative | | | [removed: 1,697,095] [added: 1,964,243] | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | [removed: 1,697,095] [added: 1,964,243] | | |
| Equity in earnings (loss) from unconsolidated entities, Multifamily other gain and Lennar Other other income (expense), [removed: net] [added: net, and other gain (loss)] | | | [removed: (836)] [added: (17,235)] | | | | | | — | | | | | | [removed: 21,934] [added: 52,821] | | | | | | [removed: (44,669)] [added: (91,689)] | | | | | | — | | | | | | [removed: (23,571)] [added: (56,103)] | | |
| Homebuilding other [removed: expense,] [added: income,] net | | | [removed: (29,749)] [added: 4,516] | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | [removed: (29,749)] [added: 4,516] | | |
| Corporate general and administrative expenses | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | [removed: 333,446] [added: 414,498] | | | | | | [removed: 333,446] [added: 414,498] | | |
| Charitable foundation contribution | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | [removed: 24,972] [added: 66,399] | | | | | | [removed: 24,972] [added: 66,399] | | |
[removed: 2021] [added: 2022] versus [removed: 2020][added: 2021]
Revenues from home sales increased [removed: 22%] [added: 25%] in the year ended November 30, [removed: 2021] [added: 2022] to [removed: $25.3] [added: $31.8] billion from [removed: $20.8] [added: $25.3] billion in the year ended November 30, [removed: 2020.][added: 2021.]
Revenues were higher primarily due to [removed: a 13%] [added: an 11%] increase in the number of home deliveries and [removed: an 8%] [added: a 13%] increase in the average sales price.
New home deliveries increased to [removed: 59,825] [added: 66,399] homes in the year ended November 30, [removed: 2021] [added: 2022] from [removed: 52,925] [added: 59,825] homes in the year ended November 30, [removed: 2020 as a result of an increase in home deliveries in all our homebuilding segments.][added: 2021.]
The average sales price of homes delivered was [removed: $424,000] [added: $480,000] in the year ended November 30, [removed: 2021,] [added: 2022,] compared to [removed: $395,000] [added: $424,000] in the year ended November 30, [removed: 2020 as a result of price appreciation in all of our homebuilding segments as a result of the current market conditions.][added: 2021.]
Gross margins on home sales were [removed: $6.8] [added: $8.8] billion, or [removed: 26.8%,] [added: 27.5% (27.7% pre-impairment),] in the year ended November 30, [removed: 2021,] [added: 2022,] compared to [removed: $4.7] [added: $6.8] billion, or [removed: 22.8%,] [added: 26.8%,] in the year ended November 30, [removed: 2020.][added: 2021.]
Selling, general and administrative expenses were [removed: $1.8] [added: $2.0] billion in the year ended November 30, [removed: 2021,] [added: 2022,] compared to [removed: $1.7] [added: $1.8] billion in the year ended November 30, [removed: 2020.][added: 2021.]
As a percentage of revenues from home sales, selling, general and administrative expenses improved to [removed: 7.1%] [added: 6.2%] in the year ended November 30, [removed: 2021,] [added: 2022,] from [removed: 8.1%] [added: 7.1%] in the year ended November 30, [removed: 2020, primarily] [added: 2021,] due to a decrease in broker [removed: commissions] [added: commissions, an increase in leverage,] and benefits of [removed: the Company's] [added: our] technology efforts.
[removed: Excluding this fiscal 2020 gain, the improvement] [added: The decrease] in operating earnings [removed: during the year ended November 30, 2021] was primarily due to [removed: an increase in volume and margin in our title businesses, partially offset by] lower mortgage net margins driven by a more competitive mortgage [removed: market.][added: market, partially offset by an increase in rate lock volume.]
Operating earnings for [removed: our] [added: the] Multifamily segment were [removed: $21.5] [added: $66.8] million in the year ended November 30, [removed: 2021,] [added: 2022,] compared to [removed: $22.7] [added: $21.5] million in the year ended November 30, [removed: 2020.][added: 2021.]
Operating [removed: earnings] [added: loss] for [removed: our] [added: the] Lennar Other segment [removed: were $733.0] [added: was $735.6] million in the year ended November 30, [removed: 2021,] [added: 2022,] compared to [removed: an] operating [removed: loss] [added: earnings] of [removed: $10.3] [added: $733.0] million in the year ended November 30, [removed: 2020.][added: 2021.]
The operating earnings for the year ended November 30, 2021 were primarily due to [removed: mark to market gains] [added: positive mark-to-market adjustments] on our [removed: strategic] [added: publicly traded] technology investments [removed: that went public during the year] and the [added: gain on the] sale of [added: the] our solar business.
For [added: both] the years ended November 30, [removed: 2021] [added: 2022] and [removed: 2020,] [added: 2021,] we had a tax provision of $1.4 [removed: billion and $656.2 million, respectively,] [added: billion,] which resulted in an overall effective income tax rate of [removed: 23.5%] [added: 22.8%] and [removed: 21.0%,] [added: 23.5%,] respectively.
At November 30, [removed: 2021,] [added: 2022,] our [removed: homebuilding] [added: Homebuilding] operating segments and Homebuilding Other consisted of homebuilding divisions located in:
East: [added: Alabama,] Florida, New Jersey, Pennsylvania and South Carolina
| Other [removed: (2)] [added: (3)] | | | 18,419 | | | | | | 39,116 | | | | | | (112.4) | | % | | | | (61,321) | | | | | | 1,435 | | | | | | 13,678 | | | | | | (21,487) | | | | | | 695 | | | | | | (67,000) | | |
| [removed: Totals] | | | $ | 25,348,105 | | | | | 18,562,213 | | | | | | 26.8 | | % | | | | $ | 4,989,195 | | | | | 24,282 | | | | | | 29,224 | | | | | | (14,205) | | | | | | 3,266 | | | | | | 5,031,762 | | |
| | | | Year Ended November 30, [removed: 2020] [added: 2022] | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| (Dollars in thousands) | | | Sales of Homes Revenues | | | | | | Costs of Sales of Homes | | | | | | Gross Margin % | | | | | | Net Margins on Sales of Homes (1) | | | | | | Gross [removed: Margins (Loss)] [added: Loss] on Sales of [removed: Land] [added: Land (2)] | | | | | | Other Revenues | | | | | | Equity in Earnings (Loss) from Unconsolidated Entities | | | | | | Other Income (Expense), net | | | | | | Operating Earnings (Loss) | | |
[removed: (2)Negative] [added: (3)Negative] gross and net margins were due to period costs in Urban divisions that impact costs of homes sold without sufficient sales of homes revenues to offset those costs.
| | | | [removed: Years Ended November 30,] | | | | | | [added: Years Ended November 30,] | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| East | | | [removed: 18,879] [added: 21,214] | | | | | | [removed: 16,976] [added: 18,879] | | | | | | | | | | | | $ | [removed: 6,846,153] [added: 9,268,940] | | | | | [removed: 5,725,481] [added: 6,846,153] | | | | | | | | | | | | $ | [removed: 363,000] [added: 437,000] | | | | | [removed: 337,000] [added: 363,000] | | | | | | | | |
| Central | | | [removed: 12,138] [added: 13,152] | | | | | | [removed: 10,684] [added: 12,138] | | | | | | | | | | | | [removed: 4,807,195] [added: 5,830,587] | | | | | | [removed: 4,084,514] [added: 4,807,195] | | | | | | | | | | | | [removed: 396,000] [added: 443,000] | | | | | | [removed: 382,000] [added: 396,000] | | | | | | | | |
| Texas | | | [removed: 10,939] [added: 12,993] | | | | | | [removed: 9,425] [added: 10,939] | | | | | | | | | | | | [removed: 3,204,609] [added: 4,212,223] | | | | | | [removed: 2,640,762] [added: 3,204,609] | | | | | | | | | | | | [removed: 293,000] [added: 324,000] | | | | | | [removed: 280,000] [added: 293,000] | | | | | | | | |
| West | | | [removed: 17,850] [added: 19,015] | | | | | | [removed: 15,814] [added: 17,850] | | | | | | | | | | | | [removed: 10,503,304] [added: 12,513,277] | | | | | | [removed: 8,400,943] [added: 10,503,304] | | | | | | | | | | | | [removed: 588,000] [added: 658,000] | | | | | | [removed: 531,000] [added: 588,000] | | | | | | | | |
| Other | | | [removed: 19] [added: 25] | | | | | | [removed: 26] [added: 19] | | | | | | | | | | | | [removed: 18,419] [added: 21,386] | | | | | | [removed: 24,522] [added: 18,419] | | | | | | | | | | | | [removed: 969,000] [added: 855,000] | | | | | | [removed: 943,000] [added: 969,000] | | | | | | | | |
| Total | | | [removed: 59,825] [added: 66,399] | | | | | | [removed: 52,925] [added: 59,825] | | | | | | | | | | | | $ | [removed: 25,379,680] [added: 31,846,413] | | | | | [removed: 20,876,222] [added: 25,379,680] | | | | | | | | | | | | $ | [removed: 424,000] [added: 480,000] | | | | | [removed: 394,000] [added: 424,000] | | | | | | | | |
Of the total homes delivered listed above, [removed: 95] [added: 174] homes with a dollar value of [removed: $31.6] [added: $67.5] million and an average sales price of [removed: $332,000] [added: $388,000] represent home deliveries from unconsolidated entities for the year ended November 30, [removed: 2021,] [added: 2022,] compared to [removed: 112] [added: 95] home deliveries with a dollar value of [removed: $36.1] [added: $31.6] million and an average sales price of [removed: $322,000] [added: $332,000] for the year ended November 30, [removed: 2020.][added: 2021.]
We had strong 2022 results, particularly in view of the difficult home sale market in the second half of the year.
Market conditions continued to deteriorate in the fourth quarter as the now well-documented interest rate driven sales slowdown and pricing correction intersected with the still stressed supply chain, high labor and material costs and elongated cycle times (i.e., the time it takes to build a home).
Sales and sales prices are down across both the new and existing home markets.
We believe that production of single family and multifamily dwellings nationally will be down between a quarter to a third in 2023.
In addition, the supply of existing homes for sale has come down as homeowners hold on to extremely low mortgage rates.
This, combined with the housing production shortfall over the past decade, leaves the industry in the middle of what we believe should be a fairly short duration market correction and, unlike previous market corrections, there currently is no inventory overhang to resolve.
Against this backdrop, we have developed a strategy that we believe should enable us to maintain sales pace and increase market share despite the difficult market:
- We have adjusted prices in various communities to levels that are intended to enable us to maintain reasonable volume.
The result is that margin, as opposed to volume, becomes the shock absorber.
- We are working with our trade partners to right size our cost structure to current market conditions.
Although our trade partners are still completing homes that were started in the first half of 2022, the amount of new work they are receiving is down substantially.
We are offering a steady flow of starts in exchange for price reductions.
- We are being extremely selective on new land acquisitions and new communities.
We have re-reviewed and re-underwritten land purchases in our pipeline and are not going forward with land purchases that do not meet our standards under current market conditions.
- We will continue to improve our cost of doing business by focusing on and reducing SG&A expenses.
Over the past several years, we have seen quarter over quarter improvement in our SG&A expenses as a percentage of home sale revenues achieving record lows.
However, as average sales prices come down, the percentages will not hold without additional cost cuts.
Further, we know that in more difficult times there will be upward pressure on some of our sales and marketing costs in order to drive new sales.
- We will maintain tight control of our inventory under construction.
We will pace home starts to meet expected sales volume.
Nonetheless, inventory dollars related to inventory under construction has grown through the year because of expanded cycle times due to the supply chain disruption.
We expect to bring down our cycle time during the next few quarters.
This will free up a significant amount of cash that currently is tied up in the increased inventory dollars related to homes under construction.
We will continue to focus on our cash flow and bottom line to protect and enhance our already strong balance sheet.
While we continue to have many strong markets, in our more challenging areas we have had to adjust base sales prices, offer mortgage buy down programs and increase sales incentives to maintain or regain sales momentum.
Our cancellation rate increased significantly during our third quarter and into the beginning of our fourth quarter.
However, our cancellation rate peaked in October and declined significantly in November.
Our construction playbook has three primary areas of focus: lowering construction costs, reducing cycle time, and achieving even flow production.
We expect what has been a steady increase in construction costs over the last few years due to supply shortages will reverse over the course of fiscal 2023, as many homebuilders reduce or totally curtail new starts.
Similarly, we expect cycle times, which increased significantly due to shortages of materials and labor, to start to return to normal as the number of homes being built falls as a result of market conditions.
During the fourth quarter of 2022, the average cycle time was the same as in the third quarter despite the continuing effect of supply chain disruptions and two hurricanes that delayed production in Florida and parts of the Carolinas.
Even flow production is a core focus for us and is a pillar for being the builder of choice for the trades as it maximizes efficiencies for them.
By maintaining our starts pace at a time when many homebuilders are reducing or stopping construction starts, we have been able to obtain cost reductions from our trade partners and increase our market share in many markets.
We continue to strategically acquire land, primarily through options.
Our continued focus on our land-light strategy resulted in ending fiscal 2022 with a percentage of homesites controlled rather than owned of 63%, up from 59% last year.
Our
years’ supply of owned home sites decreased to 2.5 years as compared to 3.0 years at the end of the prior year.
From a leverage perspective, we continue to benefit from our paydown of senior notes and strong generation of earnings which brought our homebuilding debt to total capital down to 14.4% at year-end, our lowest ever, and an improvement from 18.3% at the end of the prior year.
While we did repurchase some stock in the fourth quarter, given the current market conditions and as a matter of careful capital allocation, we decided to go slow.
We expect to continue to look at repurchasing stock in the future as opportunities present themselves.
While supply chain challenges continued to dominate both the homebuilding and the broader economic narrative in 2021, we were extremely pleased with our performance this year.
The demand for housing continues to be strong, while the supply of new and existing homes continues to be constrained.
New home construction cannot ramp up quickly enough to fill the void of the underproduction of homes for the past decade, and short supply is likely to remain for some time to come.
Even though home prices have moved much higher, overall affordability remains strong as interest rates are still very attractive.
Personal savings for deposits are strong and wages seem to be rising faster than monthly payments.
However, those higher wages are starting to be reflected in government numbers and, unfortunately, in inflation as well.
Millennials are moving out of their parents’ homes and forming families, while large numbers of apartment dwellers are seeking first-time single-family homes.
First-time homes are selling at higher prices, and appreciated equity is enabling first-time move-ups.
The iBuyer and single-family for rent participants are providing additional liquidity to the marketplace for homes, as they evolve and provide ever more frictionless transactions.
While the housing market remains very strong in all of our major markets, our ability to actually execute and deliver results has been tested by the supply chain challenges for both land and construction, the workforce that is short in numbers while driven to produce more, and the never-ending competition for scarce entitled land assets.
The supply chain issues will continue into the first quarter of 2022 and beyond.
But we expect that as we enter the second half of the year, we will be less affected by supply chain disruptions, in part because of the greater number of homes we are starting, the lessons learned and incorporated in our Builder of Choice relationships with suppliers and trades, and the simplicity embedded in our Everything's Included® home offerings.
We remain focused on orderly, targeted growth, with our sales pace tightly matched with the numbers of homes we can build, which enables price appreciation to offset future cost escalations and therefore maximize margins.
Although there have been some headwinds throughout the year, fiscal 2021 was an extraordinary year for our company.
We established an operating plan that included cash flow generation and debt reduction in order to improve returns on capital and equity.
We expect our first quarter community count to be about 5% lower than year-end 2021 because of the shortages both of land and construction materials.
However, we expect community count to start to increase in the second quarter, and we expect to end 2022 with a low double-digit increase in community count year-over-year.
We expect our gross margin to be about 26.75%, which reflects the impact of peak lumber prices from last year and less field expense leverage.
We have remained focused on our optioned versus owned land strategy.
We ended the year with a 3.0 years supply of land owned, compared to a 3.5 years supply of land owned at the same time last year, and our homesites controlled percentage increased to 59% from 39% in the prior year.
Among other things, this has enabled us to reduce debt, such that our homebuilding debt-to-total capital ratio improved to 18.3% at year end, from 24.9% in the prior year.
We have articulated a drive and desire to have a strong focus on new technology-driven efficiencies in our core business.
We invested in numerous new technologies, while eight prior investments were either sold or went public, which resulted in significant profits for the Company in 2021.
Perhaps more importantly, we have invested in companies that have enabled improvement in our core business, while we have benefited both through the investments and through incorporation in our core.
We are working to address the issues in supply chain, labor shortages, and production, using innovative technology in innovative ways.
We have continued to work on the structural components and organization of our proposed spin-off company as we focus on the strategy of becoming a pure-play homebuilding company.
We have sufficient excess capacity and balance sheet to be able to spin off our well-established ancillary businesses, and we expect to complete a tax-free spin-off by the second or third quarter of 2022.
To that end, in November 2021, we took our first significant step to complete the spin-off by formally filing a request for a private letter ruling from the Internal Revenue Service confirming that the spin-off would not result in taxation either to us or to our stockholders.
We have concluded that the spin company will be an asset-light asset management business that will have a limited balance sheet.
Three core verticals have been identified for the spin, and they are multifamily, single-family for rent, and land strategies.
Each of these verticals already has raised third-party capital, and we are active asset managers.
We believe we have never been better positioned financially, organizationally and technologically to thrive and grow in this evolving high demand housing market.
While difficulties in the supply chain present challenges for Lennar and the industry, the housing market remains strong, and supply of new and existing homes is very limited.
We remain focused on an
orderly, targeted growth strategy, with our sales pace tightly matched with our pace of production.
We focus on gross margin by selling in step with production, while controlling costs, and reducing our SG&A, and therefore driving our net margin.
As we look to 2022, we see continued strength in the market and double-digit growth for Lennar.
| Lennar Other realized and unrealized gains | | | — | | | | | | — | | | | | | — | | | | | | 680,576 | | | | | | — | | | | | | 680,576 | | |
| Sales of homes | | | $ | 20,840,159 | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | 20,840,159 | | |
| Sales of land | | | 123,365 | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | 123,365 | | |
An excerpt. Shown here: 40 of 216 rewritten, 40 of 187 added and 40 of 120 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations. in the FY2022 filing and the FY2021 filing.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk.
9 rewritten, 11 added, 4 removed, 50 unchanged
The table below provides information at November 30, [removed: 2021] [added: 2022] about our significant instruments that are sensitive to changes in interest rates.
For loans held-for-investment, net and investments held-to-maturity, senior notes and other debts payable and notes and other debts payable, the table presents principal cash flows and related weighted average effective interest rates by expected maturity dates and estimated fair values at November 30, [removed: 2021.][added: 2022.]
Weighted average variable interest rates are based on the variable interest rates at November 30, [removed: 2021.][added: 2022.]
| (Dollars in millions) | | | [removed: 2022] [added: 2023] | | | | | | [removed: 2023] [added: 2024] | | | | | | [removed: 2024] [added: 2025] | | | | | | [removed: 2025] [added: 2026] | | | | | | [removed: 2026] [added: 2027] | | | | | | Thereafter | | | | | | Total | | | | | | [removed: 2021] [added: 2022] | | |
| Fixed rate | | | $ | 1.0 | | | | | [removed: 1.1] [added: 1.0] | | | | | | [removed: 1.1] [added: 1.0] | | | | | | 1.1 | | | | | | [removed: 1.2] [added: 1.1] | | | | | | [removed: 31.6] [added: 32.7] | | | | | | [removed: 37.1] [added: 37.9] | | | | | | [removed: 37.1] [added: 37.9] | | |
| Average interest rate | | | [removed: 3.7] [added: 3.6] | | % | | | | [removed: 3.7] [added: 3.6] | | % | | | | [removed: 3.7] [added: 3.6] | | % | | | | [removed: 3.7] [added: 3.6] | | % | | | | [removed: 3.7] [added: 3.6] | | % | | | | 3.6 | | % | | | | 3.6 | | % | | | | — | | |
| Variable rate | | | $ | [removed: —] [added: 7.3] | | | | | [removed: 7.3] [added: —] | | | | | | — | | | | | | — | | | | | | — | | | | | | [removed: 0.2] [added: 0.5] | | | | | | [removed: 7.5] [added: 7.8] | | | | | | [removed: 7.5] [added: 7.8] | | |
| Average interest rate | | | [removed: —] [added: 3.9] | | [added: %] | | | | [removed: 4.9] [added: 5.0] | | % | | | | [removed: —] [added: 4.7] | | [added: %] | | | | [removed: —] [added: 5.2] | | [added: %] | | | | [removed: —] [added: 4.8] | | [added: %] | | | | [removed: 3.1] [added: 6.2] | | % | | | | [removed: 4.8] [added: 4.9] | | % | | | | — | | |
| Fixed rate | | | $ | [removed: —] [added: 13.5] | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | [removed: 147.5] [added: —] | | | | | | [removed: 147.5] [added: 13.5] | | | | | | [removed: 148.3] [added: 13.5] | | |
November 30, 2022
| Average interest rate | | | 8.6 | | % | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | 2.8 | | % | | | | 8.3 | | % | | | | — | | |
| Fixed rate | | | $ | 223.1 | | | | | 1,537.4 | | | | | | 566.1 | | | | | | 404.5 | | | | | | 1,265.3 | | | | | | 42.4 | | | | | | 4,038.8 | | | | | | 3,993.2 | | |
| Fixed rate | | | $ | — | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | 133.3 | | | | | | 133.3 | | | | | | 134.0 | | |
| Variable rate | | | $ | 2,001.8 | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | 2,001.8 | | | | | | 2,001.8 | | |
| Average interest rate | | | 5.8 | | % | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | 5.8 | | % | | | | — | | |
| Multifamily: | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Notes and other debts payable: | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Average interest rate | | | 0.0 | | % | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | 0.0 | | % | | | | — | | |
| Variable rate | | | $ | — | | | | | 3.2 | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | 3.2 | | | | | | 3.2 | | |
| Average interest rate | | | — | | | | | | 3.6 | | % | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | 3.6 | | % | | | | — | | |
November 30, 2021
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Fixed rate | | | $ | 718.3 | | | | | 104.4 | | | | | | 1,530.0 | | | | | | 591.4 | | | | | | 402.8 | | | | | | 1,294.6 | | | | | | 4,641.5 | | | | | | 5,046.7 | | |
| Average interest rate | | | 4.4 | | % | | | | 4.2 | | % | | | | 5.0 | | % | | | | 4.8 | | % | | | | 5.2 | | % | | | | 4.9 | | % | | | | 4.8 | | % | | | | — | | |
Item 1. Business
68 rewritten, 45 added, 29 removed, 200 unchanged
We are the [added: second] largest homebuilder in the United States by [added: deliveries, revenues and] net earnings, an originator of residential and commercial mortgage loans, a provider of title insurance and closing services and a developer of multifamily rental properties.
In addition, we are a sponsor and manager of funds [added: and joint ventures] engaged in development and ownership of multifamily rental properties and a sponsor and manager of a fund engaged in ownership of single family rental properties.
Our homebuilding operations are the most substantial part of our business, generating [removed: $25.5] [added: $32] billion in revenues, or approximately [removed: 94%] [added: 95%] of consolidated revenues, in fiscal [removed: 2021.][added: 2022.]
As of November 30, [removed: 2021,] [added: 2022,] our reportable [removed: homebuilding] [added: Homebuilding] segments and [removed: Homebuilding] [added: all] Other [removed: had] [added: Homebuilding operations not required to be reported separately have] divisions located in:
East: [added: Alabama,] Florida, New Jersey, Pennsylvania and South Carolina
We are focused on increasing efficiencies in our building process and reducing selling, general and administrative expenses by using [removed: technology, deferring home sale price commitments until construction costs are finalized to protect against cost escalations] [added: technology] and [removed: using] innovative strategies to reduce customer acquisition costs.
[removed: This] [added: That] will [removed: continue our migration toward being] [added: make us] more of a pure homebuilding and financial services company.
In addition, we are continuing our [removed: pivot] [added: transition] to a land light operating model by increasing the percentage of land [removed: controlled] [added: we control] through options or agreements [removed: versus owned land and controlling the timing of land purchases,] [added: but do not own,] which [removed: reduce] [added: reduces] our [removed: years] [added: years’] supply of owned homesites.
New home deliveries, including deliveries from unconsolidated entities, were [removed: 59,825] [added: 66,399] in fiscal [removed: 2021,] [added: 2022,] compared to [removed: 52,925] [added: 59,825] in fiscal [removed: 2020] [added: 2021] and [removed: 51,491] [added: 52,925] in fiscal [removed: 2019.][added: 2020.]
For fiscal [removed: 2021,] [added: 2022,] the average sales price, excluding deliveries from unconsolidated entities, was [removed: $424,000,] [added: $480,000,] compared to [removed: $395,000] [added: $424,000] in fiscal [removed: 2020] [added: 2021] and [removed: $400,000] [added: $395,000] in fiscal [removed: 2019.][added: 2020.]
- *Strong Operating Margins -* [removed: We believe our] [added: Our] purchasing leverage combined with our focus on reducing selling, general and administrative costs by using technology and innovative strategies and reducing interest expense through paydowns of debt [removed: position] [added: has enabled] us [removed: for strong] [added: to achieve historically high gross profit and] operating margins.
- *Technology Focused* \- We partner with and/or invest in technology companies that are looking to improve the homebuilding and financial services industries to increase [removed: efficiencies] [added: efficiencies, reduce customer acquisition costs] and create a better customer experience.
- *Land light strategy* \- We are focused on reducing our [removed: years] [added: years'] supply of owned homesites and increasing the percentage of land we control through options or agreements, including agreements with strategic land [removed: funds, versus owned land.][added: funds and joint ventures, rather than ownership.]
We generally [removed: acquire] [added: acquire, or obtain options to acquire,] land for development and for the construction of homes that we sell to homebuyers.
- Acquiring land in conjunction with [removed: Multifamily.][added: our Multifamily business.]
[removed: We are in] [added: For] the [removed: process of further] [added: last several years, we have been] reducing our reliance on land we own and increasing our access to land through options and joint ventures.
At November 30, [removed: 2021, 59%] [added: 2022, 63%] of our total homesites were controlled through options and joint ventures compared to [removed: 39%] [added: 59%] at November 30, [removed: 2020.][added: 2021.]
For additional information about our investments in [removed: and relationships with unconsolidated entities,] [added: strategic technology investments,] see [removed: Management’s] [added: Management's] Discussion and Analysis of Financial Condition and Results of Operations in Item 7 of this Report.
At November 30, [removed: 2021,] [added: 2022,] we were actively building and marketing homes in [removed: 1,263] [added: 1,208] communities, including [removed: four] [added: eight] communities being constructed by unconsolidated entities.
This was [removed: an increase] [added: a decrease] from the [removed: 1,177] [added: 1,263] communities, including four communities being constructed by unconsolidated entities, in which we were actively building and marketing homes at November 30, [removed: 2020.][added: 2021.]
[removed: Even though our community count increased in 2021, the] [added: The] number of homes we built [added: in 2022] was limited by shortages of both construction materials and skilled labor.
Arrangements with our subcontractors generally provide that our subcontractors will complete specified work in accordance with price and time schedules and in compliance with applicable building codes and [added: laws.]
Although we, like homebuilders throughout the country, have encountered shortages of materials and skilled labor during [removed: 2021,] [added: 2022,] we believe that because of our size and our builder of choice program, where we work with our trade partners to drive [removed: efficiencies, we believe] [added: efficiencies for them,] we have been less affected by these shortages than many of our competitors.
We finance construction and land development activities primarily with cash generated from operations and historically from proceeds of [added: unsecured] corporate debt.
However, we also continue to advertise through more traditional media on a limited basis, including newspapers, [removed: radio advertisements and] other local and regional [removed: publications] [added: publications, radio] and on billboards where appropriate.
We strive to create a quality [removed: home buying] [added: homebuying] experience for our customers through the participation of sales associates, on-site construction supervisors and customer care associates, all working in a team effort, as well as use of technology to simplify the homebuying and financing process.
The backlog dollar value including unconsolidated entities at November 30, [removed: 2021] [added: 2022] was [removed: $11.4] [added: $8.7] billion, compared to [removed: $7.8] [added: $11.4] billion at November 30, [removed: 2020.][added: 2021.]
We expect that a [removed: substantial] [added: significant] portion of all homes currently in backlog will be delivered in fiscal year [removed: 2022.][added: 2023.]
During fiscal [removed: year] [added: years 2022 and] 2021, because of the concern about increasing labor and material [removed: costs,] [added: costs and shortages,] we, in many instances, deferred entering into contracts to sell homes and committing to the sales price until the costs of the homes were determined, which usually was shortly before construction began.
As of November 30, [removed: 2021] [added: 2022] and [removed: 2020,] [added: 2021,] we had equity investments in [removed: 41] [added: 48] and [removed: 38] [added: 41] active homebuilding and land unconsolidated entities, respectively, in which we were participating, and our maximum recourse debt exposure related to Homebuilding unconsolidated joint ventures was [removed: $5.3] [added: $9.1] million and [removed: $4.9] [added: $5.3] million, respectively.
[removed: FivePoint Holdings] [added: Five Point Holdings,] LLC
We own an indirect approximately 40% interest in [removed: FivePoint Holdings] [added: Five Point Holdings,] LLC, which is a publicly traded developer of three large master planned mixed-use developments in California (Newhall Ranch, Great Park Neighborhoods, and San Francisco Shipyard/Candlestick Point).
[removed: However,] [added: We have no active role] in [added: the management of FivePoint, except that since] August [removed: 2021,] [added: 2021] our Executive Chairman [removed: became] [added: has been] the non-employee Executive Chairman of the Board of Directors (but not the chief executive officer) of FivePoint.
As of November 30, [removed: 2021,] [added: 2022,] the carrying amount of our investment in FivePoint was [removed: $381.6] [added: $382.9] million.
In fiscal year [removed: 2021,] [added: 2022,] our financial services subsidiaries provided loans to [removed: 75%] [added: 72%] of our homebuyers who obtained mortgage financing in areas where we offered services.
During fiscal year [removed: 2021,] [added: 2022,] we originated approximately [removed: 38,100] [added: 37,700] residential mortgage loans totaling [removed: $13.2] [added: $14.4] billion, compared to [removed: 40,000] [added: 38,100] residential mortgage loans totaling [removed: $12.9] [added: $13.2] billion during fiscal year [removed: 2020.][added: 2021.]
We finance our mortgage loan activities with borrowings under our financial services warehouse facilities or [added: funds] from our operating [removed: funds.][added: activities.]
[removed: At November 30, 2021, Financial Services had four warehouse residential facilities maturing at] various dates through fiscal [removed: 2022] [added: 2023] with a total maximum borrowing capacity of $2.3 billion including an uncommitted amount of [removed: $1.1 billion.][added: $600 million.]
If they are not renewed or replaced, we would have to find other sources of funding [added: for] our mortgage originations, which might include our own funds.
This new technology has also enabled us to increase the number of digital closings, with digital document signing [removed: and] [added: and,] where [removed: possible] [added: legally permitted,] digital notarization.
Our construction playbook has three primary areas of focus: lowering construction costs, reducing cycle time and achieving even flow production.
We have aimed to maintain strong operating margins by deferring home sale price commitments until construction costs are finalized to protect against cost escalations.
Subject to market conditions, we intend to spin off our Multifamily and single family home for rent asset management businesses, together with some investment assets, by transferring them to a newly formed subsidiary, Quarterra Group, Inc. ("Quarterra"), and distributing the stock of that subsidiary to our stockholders.
Also, weaknesses in some markets in the second half of 2022 led us to decrease starts to match sales pace so that we would not have a build up of inventory.
We ended the year with about 900 completed unsold homes.
During the second half of fiscal 2022, significant increases in interest rates made our homes less affordable to many prospective buyers and led us to reduce prices or increase sales incentives in a number of our communities.
We experienced a cancellation rate of 17% in 2022 and 10% in 2021, but in the third and fourth quarters of fiscal 2022, our cancellation rate increased to 21% and 26% respectively.
During fiscal year 2022, we also locked interest rates on approximately 41,100 residential mortgage loans totaling $15.7 billion, compared to 37,900 residential mortgage loans totaling $13.3 billion during fiscal year 2021.
At November 30, 2022, Financial Services had four warehouse residential facilities maturing at
This is discussed in greater detail in Management’s Discussion and Analysis of Financial Condition and Results of Operations in Item 7 of this Report.
- Sonder, a company that manages short-term rentals, such as rental hotels;
Our Multifamily business has been engaged in the development of multifamily communities since 2011.
Initially, the Multifamily business almost exclusively participated in shorter-duration joint ventures that built multifamily communities with the intention of selling them soon after they were built, and in most cases after they were substantially occupied.
However, the Multifamily business now manages, and owns interests in, longer-duration funds that build multifamily communities with the intention of retaining them as rental income-generating assets.
At November 30, 2022, Multifamily had interests in, and was managing, four funds and 19 joint ventures.
From inception through November 30, 2022, the Multifamily business has capitalized and developed 116 multifamily residential communities with approximately 34,900 rental units across 20 states throughout the United States.
The communities
developed by the Multifamily business include a diversified mix of conventional garden, mid-rise and high-rise multifamily properties in urban and suburban locations near major employment centers.
Most communities offer residents a mix of studio, one, two, and three-bedroom homes.
Multifamily has co-investments in all the funds and ventures it manages, and receives returns on these investments.
In addition, it has carried interests in the funds or ventures it manages, and receives distributions with regard to those carried interests.
Multifamily is expected to be one of the businesses included in our proposed spin-off.
Single Family Home Rentals
In December 2020, Lennar formed the Upward America Venture, LLC (“Upward America”), which (a) acquires communities of single family rental properties (including townhomes, duplexes and condominium buildings developed or acquired for rental purposes), and (b) leases and manages homes in those communities.
Lennar subsidiaries are the manager and the general partner of Upward America.
As of November 30, 2022, institutional investors had committed $1.6 billion to Upward America, part of which was used to reduce an initial commitment Lennar had made from $225 million to $125 million.
Proceeds of commitments by other investors may be used to redeem more of Lennar’s ownership, but Lennar has agreed not to reduce its ownership below $50 million.
As owner of the general partner of Upward America, Lennar has the right to receive, in addition to distributions regarding its own commitments, distributions based on the amounts by which returns to limited partners exceed specified amounts (i.e., carried interests).
As the manager of Upward America, we receive management and acquisition fees.
Lennar subsidiaries may also receive fees for property management, leasing, construction management and other services that they render through subcontractors.
At November 30, 2022, Upward America had purchased 4,129 homes in 103 communities across 19 metropolitan statistical areas for a total purchase price of $1.1 billion (an average price of $259,000 per home), of which 2,352 of the homes owned by Upward America had been leased to occupants.
The Limited Partnership Agreement of Upward America gives Upward America the right to purchase from Lennar for their appraised value all homes or communities that are purpose built for single family home rental.
Upward America also is free to purchase homes from homebuilders other than Lennar or to purchase previously occupied homes.
Initially all the homes purchased by Upward America were purchased from Lennar, but subsequently, Upward America began purchasing homes from multiple homebuilders.
At November 30, 2022, approximately 6% of the homes owned by Upward America were built by homebuilders other than Lennar.
The single family rental business is expected to be one of the businesses included in our proposed spin-off.
In each region where we develop and operate multifamily properties, there is competition for residents with other owners of residential real estate (whether for-rent or for-sale).
In addition, when capital raising, we compete with a wide variety of other investment opportunities that are being marketed by other firms, related both to real estate and to a variety of other investment products.
We also compete for developable land with other developers of real estate for a variety of uses.
In each region where our funds offer single family homes for rent, there will be competition for residents with other owners of residential real estate (whether for-rent or for-sale).
In fiscal 2020, as the coronavirus ("COVID-19") pandemic caused the shutdown of large portions of our national economy, we accelerated the use of various technology initiatives that made our home sale process safer, including selling homes virtually or through self-guided tours and digital closings.
As a robust housing market took shape in the second half of 2020 and throughout 2021, technology initiatives helped us meet strong housing demand and reduce our marketing and other selling costs.
We also continue to focus on divesting non-core assets through a planned spin-off to our stockholders of our Multifamily and single-family home rental platforms and some investment assets.
laws.
We experienced a cancellation rate of 10% in 2021 and 15% in 2020.
Single Family Rental Operations
In the first quarter of 2021, the Company formed the Upward America Venture (“Upward America”), and is managing and participating in Upward America.
Upward America is an investment fund that acquires new single-family homes in high growth markets across the United States and rents them to the people who will live in them.
Upward America has raised equity commitments totaling $1.25 billion primarily from institutional investors, including $125 million committed by Lennar.
By leveraging these equity investments, Upward America will be positioned to acquire over $4.0 billion of new single-family homes and townhomes from Lennar and potentially other homebuilders.
During the year ended November 30, 2021, Lennar delivered 1,457 homes to Upward America.
Subsequent to November 30, 2021, the equity commitments were increased to $1.6 billion.
Until recently, we had no role in the management of FivePoint, except that our Executive Chairman was a member of its Board.
We have been actively involved, primarily through unconsolidated entities, in the development, construction and property management of multifamily rental properties.
Our Multifamily segment focuses on developing a geographically diversified portfolio of institutional quality multifamily rental properties in select U.S. markets.
Our Multifamily segment is one of the largest developers of apartment communities across the country.
At November 30, 2021, it had interests in 66 communities with development costs of approximately $7.9 billion, of which 43 communities were completed and operating, six communities were partially completed and leasing and 17 communities were under construction.
Our Multifamily segment had equity investments in 17 and 22 unconsolidated entities (including the Multifamily Ventures, described below) as of November 30, 2021 and 2020, respectively.
Originally, our Multifamily segment focused on building multifamily properties and selling them shortly after they were completed.
However, more recently we have focused on creating, participating in and managing ventures that build multifamily properties with the intention of retaining them after they are completed.
Our current ventures, Lennar Multifamily Venture Fund I LP ("LMV I") and Lennar Multifamily Venture Fund II LP ("LMV II"), are both long-term multifamily development investment vehicles involved in the development, construction and property management of class-A multifamily rental properties.
Competition is based
Our multifamily operations and the funds they manage compete with other multifamily apartment developers and operators, including REITs, across the United States.
In addition, our multifamily operations compete with a variety of investment vehicles in securing capital, partners and equity, and compete in securing tenants with the large supply of already existing rental apartments, as well as with sellers of homes.
Principal competitive factors include location, rental price and quality, and management of the apartment buildings.
Our single family home rental fund competes with other single family home rental developers and operators, including REITs, across the United States.
In addition, our single family home rental operations compete with a variety of investment vehicles in securing capital, partners and equity, and compete in securing tenants with the large supply of already existing single family rental homes as well as with sellers of homes.
Principal competitive factors include location, rental price and quality, and management of the homes.
Our worker safety metrics are measured and reviewed by our Board of Directors so we can ensure that we are successfully managing and improving our safety program.
An excerpt. Shown here: 40 of 68 rewritten, 40 of 45 added and all 29 removed. The counts are complete. For every sentence, read Item 1. Business in the FY2022 filing and the FY2021 filing.
Item 3. Legal Proceedings.
1 rewritten, 0 added, 1 removed, 10 unchanged
The costs incurred by us in construction defect lawsuits may be offset by warranty reserves, our third-party insurers, [added: subcontractor insurers or indemnity contributions from subcontractors.]
subcontractor insurers or indemnity contributions from subcontractors.
Cover and table of contents
29 rewritten, 2 added, 2 removed, 62 unchanged
For the fiscal year ended November 30, [removed: 2021][added: 2022]
[removed: ][added: ]
The aggregate market value of the registrant’s Class A and Class B common stock held by non-affiliates of the registrant [removed: (269,686,027] [added: (249,714,031] shares of Class A common stock and [removed: 15,620,380] [added: 14,423,071] shares of Class B common stock) as of May 31, [removed: 2021,] [added: 2022,] based on the closing sale price per share as reported by the New York Stock Exchange on such date, was [removed: $27,924,845,491.][added: $21,008,348,667.]
As of December 31, [removed: 2021,] [added: 2022,] the registrant had outstanding [removed: 261,373,994] [added: 253,539,060] shares of Class A common stock and [removed: 37,505,788] [added: 36,161,355] shares of Class B common stock.
| III | | | Definitive Proxy Statement to be filed pursuant to Regulation 14A on or before March 30, [removed: 2022.] [added: 2023.] | | |
| For the fiscal year ended November 30, [removed: 2021] [added: 2022] | | | | | | | | | | | | | | |
| Item 1. | | | | | | [removed: [Business](#if8875ebc30f5446fa24ed9be199539fa_13)] [added: [Business](#i7229c560662948e4bff883c99b924dfb_13)] | | | | | | [removed: [1](#if8875ebc30f5446fa24ed9be199539fa_13)] [added: [1](#i7229c560662948e4bff883c99b924dfb_13)] | | |
| Item 1A. | | | | | | [Risk [removed: Factors](#if8875ebc30f5446fa24ed9be199539fa_19)] [added: Factors](#i7229c560662948e4bff883c99b924dfb_22)] | | | | | | [removed: [9](#if8875ebc30f5446fa24ed9be199539fa_19)] [added: [10](#i7229c560662948e4bff883c99b924dfb_22)] | | |
| Item 1B. | | | | | | [Unresolved Staff [removed: Comments](#if8875ebc30f5446fa24ed9be199539fa_22)] [added: Comments](#i7229c560662948e4bff883c99b924dfb_25)] | | | | | | [removed: [19](#if8875ebc30f5446fa24ed9be199539fa_22)] [added: [19](#i7229c560662948e4bff883c99b924dfb_25)] | | |
| Item 2. | | | | | | [removed: [Properties](#if8875ebc30f5446fa24ed9be199539fa_25)] [added: [Properties](#i7229c560662948e4bff883c99b924dfb_28)] | | | | | | [removed: [19](#if8875ebc30f5446fa24ed9be199539fa_25)] [added: [20](#i7229c560662948e4bff883c99b924dfb_28)] | | |
| Item 3. | | | | | | [Legal [removed: Proceedings](#if8875ebc30f5446fa24ed9be199539fa_28)] [added: Proceedings](#i7229c560662948e4bff883c99b924dfb_31)] | | | | | | [removed: [19](#if8875ebc30f5446fa24ed9be199539fa_28)] [added: [20](#i7229c560662948e4bff883c99b924dfb_31)] | | |
| Item 4. | | | | | | [Mine Safety [removed: Disclosures](#if8875ebc30f5446fa24ed9be199539fa_31)] [added: Disclosures](#i7229c560662948e4bff883c99b924dfb_34)] | | | | | | [removed: [20](#if8875ebc30f5446fa24ed9be199539fa_31)] [added: [20](#i7229c560662948e4bff883c99b924dfb_34)] | | |
| Item 5. | | | | | | [Market for Registrant's Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities](#if8875ebc30f5446fa24ed9be199539fa_37)] [added: Securities](#i7229c560662948e4bff883c99b924dfb_40)] | | | | | | [removed: [20](#if8875ebc30f5446fa24ed9be199539fa_37)] [added: [20](#i7229c560662948e4bff883c99b924dfb_40)] | | |
| Item 6. | | | | | | [removed: [Reserved](#if8875ebc30f5446fa24ed9be199539fa_40)] [added: [Reserved](#i7229c560662948e4bff883c99b924dfb_43)] | | | | | | [removed: [21](#if8875ebc30f5446fa24ed9be199539fa_40)] [added: [22](#i7229c560662948e4bff883c99b924dfb_43)] | | |
| Item 7. | | | | | | [Management's Discussion and Analysis of Financial Condition and Results of [removed: Operations](#if8875ebc30f5446fa24ed9be199539fa_43)] [added: Operations](#i7229c560662948e4bff883c99b924dfb_46)] | | | | | | [removed: [22](#if8875ebc30f5446fa24ed9be199539fa_43)] [added: [22](#i7229c560662948e4bff883c99b924dfb_46)] | | |
| Item 7A. | | | | | | [Quantitative and Qualitative Disclosures About Market [removed: Risk](#if8875ebc30f5446fa24ed9be199539fa_121)] [added: Risk](#i7229c560662948e4bff883c99b924dfb_109)] | | | | | | [removed: [40](#if8875ebc30f5446fa24ed9be199539fa_121)] [added: [41](#i7229c560662948e4bff883c99b924dfb_109)] | | |
| Item 8. | | | | | | [Financial Statements and Supplementary [removed: Data](#if8875ebc30f5446fa24ed9be199539fa_124)] [added: Data](#i7229c560662948e4bff883c99b924dfb_112)] | | | | | | [removed: [42](#if8875ebc30f5446fa24ed9be199539fa_124)] [added: [43](#i7229c560662948e4bff883c99b924dfb_112)] | | |
| Item 9. | | | | | | [Changes in and Disagreements with Accountants on Accounting and Financial [removed: Disclosure](#if8875ebc30f5446fa24ed9be199539fa_232)] [added: Disclosure](#i7229c560662948e4bff883c99b924dfb_211)] | | | | | | [removed: [78](#if8875ebc30f5446fa24ed9be199539fa_232)] [added: [79](#i7229c560662948e4bff883c99b924dfb_211)] | | |
| Item 9A. | | | | | | [Controls and [removed: Procedures](#if8875ebc30f5446fa24ed9be199539fa_235)] [added: Procedures](#i7229c560662948e4bff883c99b924dfb_214)] | | | | | | [removed: [79](#if8875ebc30f5446fa24ed9be199539fa_235)] [added: [80](#i7229c560662948e4bff883c99b924dfb_214)] | | |
| Item 9B. | | | | | | [Other [removed: Information](#if8875ebc30f5446fa24ed9be199539fa_241)] [added: Information](#i7229c560662948e4bff883c99b924dfb_220)] | | | | | | [removed: [81](#if8875ebc30f5446fa24ed9be199539fa_241)] [added: [82](#i7229c560662948e4bff883c99b924dfb_220)] | | |
| Item 9C. | | | | | | [Disclosure Regarding Foreign Jurisdictions that Prevent [removed: Inspections](#if8875ebc30f5446fa24ed9be199539fa_2384)] [added: Inspections](#i7229c560662948e4bff883c99b924dfb_223)] | | | | | | [removed: [81](#if8875ebc30f5446fa24ed9be199539fa_2384)] [added: [82](#i7229c560662948e4bff883c99b924dfb_223)] | | |
| Item 10. | | | | | | [Directors, Executive Officers and Corporate [removed: Governance](#if8875ebc30f5446fa24ed9be199539fa_247)] [added: Governance](#i7229c560662948e4bff883c99b924dfb_229)] | | | | | | [removed: [81](#if8875ebc30f5446fa24ed9be199539fa_247)] [added: [82](#i7229c560662948e4bff883c99b924dfb_229)] | | |
| Item 11. | | | | | | [Executive [removed: Compensation](#if8875ebc30f5446fa24ed9be199539fa_250)] [added: Compensation](#i7229c560662948e4bff883c99b924dfb_232)] | | | | | | [removed: [81](#if8875ebc30f5446fa24ed9be199539fa_250)] [added: [82](#i7229c560662948e4bff883c99b924dfb_232)] | | |
| Item 12. | | | | | | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder [removed: Matters](#if8875ebc30f5446fa24ed9be199539fa_253)] [added: Matters](#i7229c560662948e4bff883c99b924dfb_235)] | | | | | | [removed: [81](#if8875ebc30f5446fa24ed9be199539fa_253)] [added: [82](#i7229c560662948e4bff883c99b924dfb_235)] | | |
| Item 13. | | | | | | [Certain Relationships and Related Transactions, and Director [removed: Independence](#if8875ebc30f5446fa24ed9be199539fa_256)] [added: Independence](#i7229c560662948e4bff883c99b924dfb_238)] | | | | | | [removed: [81](#if8875ebc30f5446fa24ed9be199539fa_256)] [added: [82](#i7229c560662948e4bff883c99b924dfb_238)] | | |
| Item 14. | | | | | | [Principal [removed: Accounting] [added: Accountant] Fees and [removed: Services](#if8875ebc30f5446fa24ed9be199539fa_259)] [added: Services](#i7229c560662948e4bff883c99b924dfb_241)] | | | | | | [removed: [81](#if8875ebc30f5446fa24ed9be199539fa_259)] [added: [82](#i7229c560662948e4bff883c99b924dfb_241)] | | |
| Item 15. | | | | | | [Exhibit and Financial Statement [removed: Schedules](#if8875ebc30f5446fa24ed9be199539fa_265)] [added: Schedules](#i7229c560662948e4bff883c99b924dfb_247)] | | | | | | [removed: [82](#if8875ebc30f5446fa24ed9be199539fa_265)] [added: [83](#i7229c560662948e4bff883c99b924dfb_247)] | | |
| Item 16. | | | | | | [Form 10-K [removed: Summary](#if8875ebc30f5446fa24ed9be199539fa_271)] [added: Summary](#i7229c560662948e4bff883c99b924dfb_253)] | | | | | | [removed: [84](#if8875ebc30f5446fa24ed9be199539fa_271)] [added: [85](#i7229c560662948e4bff883c99b924dfb_253)] | | |
| Financial Statement Schedule | | | | | | | | | | | | [removed: [87](#if8875ebc30f5446fa24ed9be199539fa_280)] [added: [88](#i7229c560662948e4bff883c99b924dfb_259)] | | |
5505 Blue Lagoon Drive, Miami, Florida 33126
| Signatures | | | | | | | | | | | | [86](#i7229c560662948e4bff883c99b924dfb_256) | | |
700 Northwest 107th Avenue, Miami, Florida 33172
| Signatures | | | | | | | | | | | | [85](#if8875ebc30f5446fa24ed9be199539fa_274) | | |
Item 1B. Unresolved Staff Comments.
8 rewritten, 0 added, 0 removed, 24 unchanged
The following individuals are our executive officers as of January [removed: 28, 2022:][added: 26, 2023:]
| Stuart Miller | | | Executive Chairman | | | [removed: 64] [added: 65] | | |
| Rick Beckwitt | | | Co-Chief Executive Officer and Co-President | | | [removed: 62] [added: 63] | | |
| Jonathan M. Jaffe | | | Co-Chief Executive Officer and Co-President | | | [removed: 62] [added: 63] | | |
| Diane J. Bessette | | | Vice President, Chief Financial Officer and Treasurer | | | [removed: 61] [added: 62] | | |
| Mark Sustana | | | Vice President, General Counsel and Secretary | | | [removed: 60] [added: 61] | | |
| David M. Collins | | | Vice President and Controller | | | [removed: 52] [added: 53] | | |
| Jeff J. McCall | | | Executive Vice President | | | [removed: 50] [added: 51] | | |
Item 2. Properties.
1 rewritten, 0 added, 0 removed, 4 unchanged
We lease and maintain our executive offices in an office [removed: complex] [added: building] in Miami, Florida.
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
13 rewritten, 4 added, 6 removed, 10 unchanged
As of December 31, [removed: 2021,] [added: 2022,] the last reported sale price of our Class A and Class B common stock on the NYSE was [removed: $116.16] [added: $90.50] and [removed: $95.62,] [added: $74.78,] respectively.
As of December 31, [removed: 2021,] [added: 2022,] there were approximately [removed: 1,629] [added: 1,567] and [removed: 844] [added: 828] holders of record of our Class A and Class B common stock, respectively.
On January 12, [removed: 2022,] [added: 2023,] our Board of Directors [removed: increased the annual dividend rate to $1.50 per share, resulting in] [added: declared] a quarterly cash dividend of $0.375 per share on both our Class A and Class B common stock.
The dividend is payable on February 10, [removed: 2022] [added: 2023] to holders of record at the close of business on January 27, [removed: 2022.][added: 2023.]
The following table provides information about our repurchases of common stock during the three months ended November 30, [removed: 2021:][added: 2022:]
(2)In [removed: January] [added: October] 2021, [removed: our] [added: the] Board of Directors authorized [removed: a stock repurchase program, which replaced a January 2019] [added: an increase to our] stock repurchase [removed: program, under which we were authorized] [added: program] to [removed: purchase] [added: enable us to repurchase] up to the lesser of [added: an additional] $1.0 billion in value, excluding commission, or 25 million in shares, of our outstanding Class A or Class B common stock.
The repurchase [removed: authority had] [added: authorization has] no expiration date.
[removed: In October 2021, the] [added: As a result of prior authorizations being almost exhausted, in March 2022, our] Board of Directors [removed: authorized] [added: approved] an [removed: increase to the stock repurchase program to enable] [added: additional authorization for] us to repurchase up to the lesser of [removed: an additional $1.0] [added: $2.0] billion in value, [removed: excluding commission,] or [removed: 25] [added: 30] million [added: in] shares, of our outstanding Class A or Class B common stock.
The graph assumes $100 invested on November 30, [removed: 2016] [added: 2017] in our Class A common stock, the Dow Jones U.S. Home Construction Index and the Dow Jones U.S. Total Market Index, and the reinvestment of all dividends.
[removed: ][added: 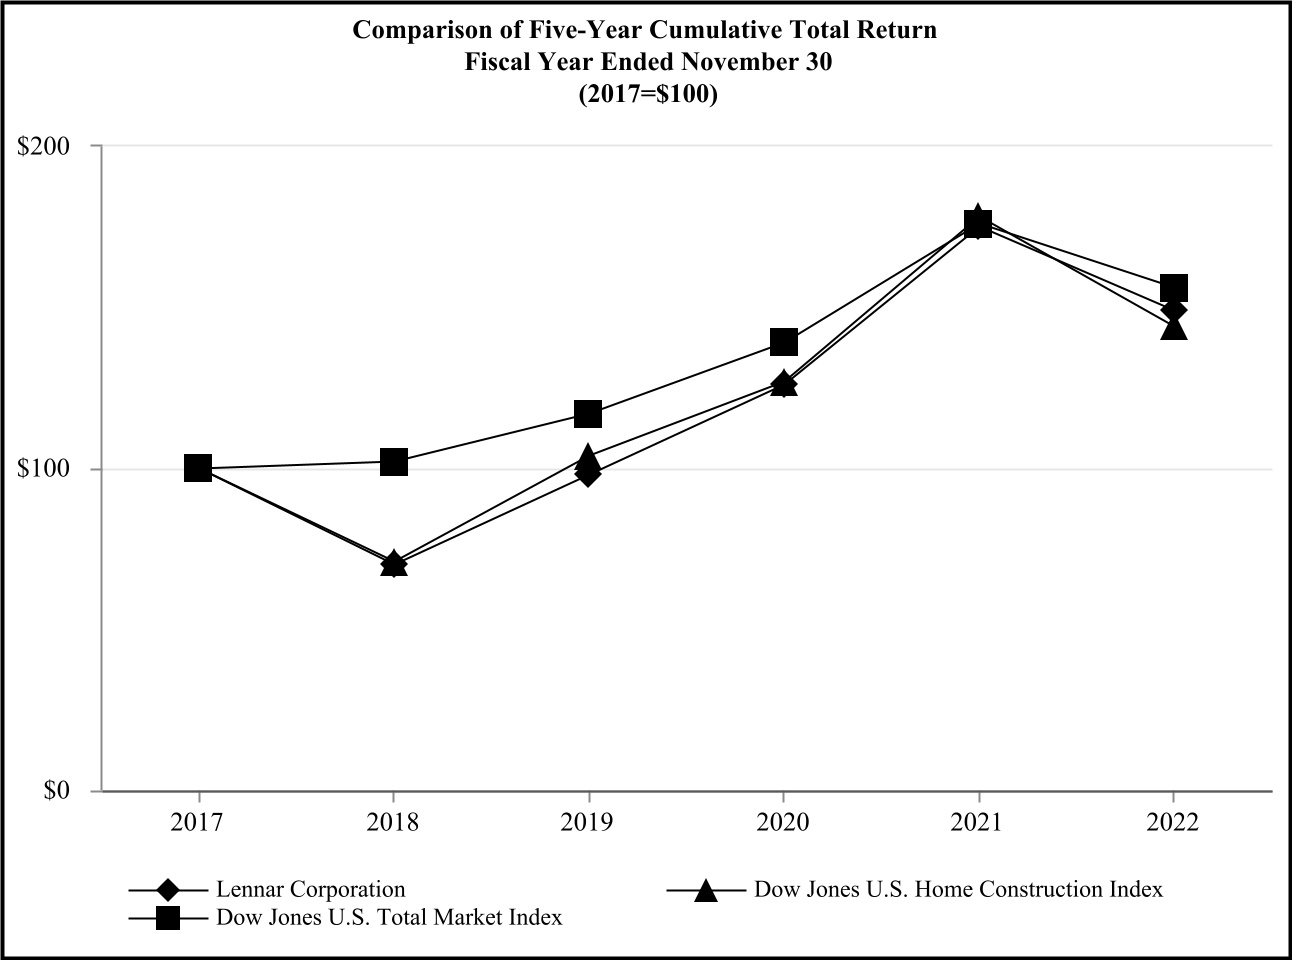]
| | | | [removed: 2016] [added: 2017] | | | | | | [removed: 2017] [added: 2018] | | | | | | [removed: 2018] [added: 2019] | | | | | | [removed: 2019] [added: 2020] | | | | | | [removed: 2020] [added: 2021] | | | | | | [removed: 2021] [added: 2022] | | |
| Dow Jones U.S. Home Construction Index | | | $ | 100 | | | | | [removed: 179] [added: 71] | | | | | | [removed: 127] [added: 104] | | | | | | [removed: 186] [added: 127] | | | | | | [removed: 227] [added: 178] | | | | | | [removed: 318] [added: 144] | | |
| Dow Jones U.S. Total Market Index | | | $ | 100 | | | | | 102 | | | | | | [removed: 107] [added: 117] | | | | | | [removed: 124] [added: 139] | | | | | | [removed: 147] [added: 176] | | | | | | [removed: 186] [added: 156] | | |
| September 1 to September 30, 2022 | | | 205,107 | | | | | | $ | 75.06 | | | | | 205,000 | | | | | | 26,999,347 | | |
| October 1 to October 31, 2022 | | | 1,295,000 | | | | | | $ | 75.94 | | | | | 1,295,000 | | | | | | 25,704,347 | | |
| November 1 to November 30, 2022 | | | 100,748 | | | | | | $ | 67.97 | | | | | 100,000 | | | | | | 25,604,347 | | |
| Lennar Corporation | | | $ | 100 | | | | | 70 | | | | | | 98 | | | | | | 126 | | | | | | 175 | | | | | | 149 | | |
| September 1 to September 30, 2021 | | | 1,245,420 | | | | | | $ | 98.61 | | | | | 1,245,000 | | | | | | 19,745,000 | | |
| October 1 to October 31, 2021 | | | 7,466,076 | | | | | | $ | 96.56 | | | | | 7,466,076 | | | | | | 22,697,884 | | |
| November 1 to November 30, 2021 | | | 1,289,481 | | | | | | $ | 103.74 | | | | | 1,288,924 | | | | | | 21,408,960 | | |
The repurchase authority has no expiration date.
Shortly after the new authorization, the January 2021 stock repurchase program was completed as we had purchased the $1.0 billion in value authorized under that stock repurchase program.
| Lennar Corporation | | | $ | 100 | | | | | 148 | | | | | | 103 | | | | | | 144 | | | | | | 183 | | | | | | 256 | | |
Item 8. Financial Statements and Supplementary Data.
519 rewritten, 198 added, 146 removed, 996 unchanged
We have audited the accompanying consolidated balance sheets of Lennar Corporation and subsidiaries (the "Company") as of November 30, [removed: 2021] [added: 2022] and [removed: 2020,] [added: 2021,] the related consolidated statements of operations and comprehensive income (loss), stockholders' equity, and cash flows, for each of the three years in the period ended November 30, [removed: 2021,] [added: 2022,] and the related notes and the financial statement schedule listed in the Index at Item 15 (collectively referred to as the "consolidated financial statements").
In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company as of November 30, [removed: 2021] [added: 2022] and [removed: 2020,] [added: 2021,] and the results of its operations and its cash flows for each of the three years in the period ended November 30, [removed: 2021,] [added: 2022,] in conformity with accounting principles generally accepted in the United States of America.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company's internal control over financial reporting as of November 30, [removed: 2021,] [added: 2022,] based on criteria established in *Internal Control - Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission and our report dated January [removed: 28, 2022,] [added: 26, 2023,] expressed an unqualified opinion on the Company's internal control over financial reporting.
Those standards require that we plan and perform the [removed: audits] [added: audit] to obtain reasonable assurance about whether the financial statements are free of material misstatement, whether due to error or fraud.
As of November 30, [removed: 2021,] [added: 2022,] the carrying value of the Company’s consolidated VIE’s assets and non-recourse liabilities was [removed: $875.9] [added: $880.2] million and [removed: $61.9] [added: $107.3] million, respectively.
Additionally, as of November 30, [removed: 2021,] [added: 2022,] the carrying value of the Company’s investments in VIEs that are unconsolidated was [removed: $686.7 million.][added: $1.2 billion.]
We identified the consolidation and primary beneficiary assessment upon formation and the occurrence of reconsideration events of [removed: certain] [added: some] of the Company’s VIEs as a critical audit matter given the significant judgment required by management.
Our audit procedures related to the accounting determination for [removed: unconsolidated] [added: all] joint ventures included the following, among others:
- We tested the [added: design and operating] effectiveness of the investment consolidation controls over the initial accounting assessment of joint ventures and the continuous reassessment for reconsideration events, as required by the accounting framework.
- We selected a sample of unconsolidated [added: and consolidated] joint ventures and evaluated the appropriateness of the Company’s accounting conclusions upon formation and reconsideration events by:
◦Reading the joint venture agreements and other related documents and evaluating the structure and terms of the agreement [added: as well as any reconsideration events which took place during the year] to determine if the joint venture should be classified as a VIE.
November 30, [removed: 2021] [added: 2022] and [removed: 2020][added: 2021]
| | | | [removed: 2021 (1)] [added: 2022] | | | | | | [removed: 2020 (1)] [added: 2021] | | | [added: | | | 2020 | | |]
| Cash and cash equivalents | | | $ | [removed: 2,735,213] [added: 4,616,124] | | | | | [removed: 2,703,986] [added: 2,735,213] | | |
| [removed: Restricted] [added: Homebuilding restricted] cash | | | [removed: 21,927] [added: 23,046] | | | | | | [added: 21,927 | | | | | |] 15,211 | | |
| Receivables, net | | | [removed: 490,278] [added: 673,980] | | | | | | [removed: 298,671] [added: 490,278] | | |
| Finished homes and construction in progress | | | [removed: 10,446,139] [added: 11,718,507] | | | | | | [removed: 8,593,399] [added: 10,446,139] | | |
| Land and land under development | | | [removed: 7,108,142] [added: 7,382,273] | | | | | | [removed: 7,495,262] [added: 7,108,142] | | |
| Consolidated inventory not owned | | | [removed: 1,161,023] [added: 2,331,231] | | | | | | [removed: 836,567] [added: 1,161,023] | | |
| Total inventories | | | [removed: 18,715,304] [added: 21,432,011] | | | | | | [removed: 16,925,228] [added: 18,715,304] | | |
| Investments in unconsolidated entities | | | [removed: 972,084] [added: 1,173,164] | | | | | | [removed: 953,177] [added: 972,084] | | |
| Other assets | | | [removed: 1,090,654] [added: 1,323,478] | | | | | | [removed: 1,190,793] [added: 1,090,654] | | |
| Financial Services | | | [removed: 2,964,367] [added: 3,254,257] | | | | | | [removed: 2,708,118] [added: 2,964,367] | | |
| Multifamily | | | [removed: 1,311,747] [added: 1,257,337] | | | | | | [removed: 1,175,908] [added: 1,311,747] | | |
| Lennar Other | | | [removed: 1,463,845] [added: 788,539] | | | | | | [removed: 521,726] [added: 1,463,845] | | |
| Total assets | | | $ | [removed: 33,207,778] [added: 37,984,295] | | | | | [removed: 29,935,177] [added: 33,207,778] | | |
As of November 30, [removed: 2020,] [added: 2022,] total assets include [removed: $1.1] [added: $1.4] billion related to consolidated VIEs of which [removed: $32.1] [added: $56.9] million is included in Homebuilding cash and cash equivalents, [removed: $0.1] [added: $0.3] million in Homebuilding receivables, net, [removed: $14.2] [added: $29.4] million in Homebuilding finished homes and construction in progress, [removed: $486.8] [added: $736.5] million in Homebuilding land and land under development, [removed: $426.3] [added: $533.8] million in Homebuilding consolidated inventory not owned, [removed: $1.6] [added: $1.0] million in Homebuilding investments in unconsolidated entities, [removed: $120.6] [added: $23.0] million in Homebuilding other [added: assets, $33.2 million in Multifamily] assets and [removed: $39.9] [added: $9.0] million in [removed: Multifamily] [added: Lennar Other] assets.
| | | | [removed: 2021 (2)] [added: 2022] | | | | | | [removed: 2020 (2)] [added: 2021] | | | [added: | | | 2020 | | |]
| Accounts payable | | | $ | [removed: 1,321,247] [added: 1,616,128] | | | | | [removed: 1,037,338] [added: 1,321,247] | | |
| Liabilities related to consolidated inventory not owned | | | [removed: 976,602] [added: 1,967,551] | | | | | | [removed: 706,691] [added: 976,602] | | |
| Senior notes and other debts payable, net | | | [removed: 4,652,338] [added: 4,047,294] | | | | | | [removed: 5,955,758] [added: 4,652,338] | | |
| Other liabilities | | | [removed: 2,920,055] [added: 3,347,673] | | | | | | [removed: 2,225,864] [added: 2,920,055] | | |
| Financial Services | | | [removed: 1,906,343] [added: 2,353,904] | | | | | | [removed: 1,644,248] [added: 1,906,343] | | |
| Multifamily | | | [removed: 288,930] [added: 313,484] | | | | | | [removed: 252,911] [added: 288,930] | | |
| Lennar Other | | | [removed: 145,981] [added: 97,894] | | | | | | [removed: 12,966] [added: 145,981] | | |
| Total liabilities | | | [removed: 12,211,496] [added: 13,743,928] | | | | | | [removed: 11,835,776] [added: 12,211,496] | | |
| Class A common stock of $0.10 par value per share; Authorized: [removed: 2021] [added: 2022] and [removed: 2020] [added: 2021] - 400,000,000 shares; Issued: [removed: 2021] [added: 2022] - [removed: 300,500,075] [added: 256,084,147] shares; [removed: 2020] [added: 2021] - [removed: 298,942,836] [added: 300,500,075] shares | | | [removed: 30,050] [added: 25,608] | | | | | | [removed: 29,894] [added: 30,050] | | |
| Class B common stock of $0.10 par value per share; Authorized: [removed: 2021] [added: 2022] and [removed: 2020] [added: 2021] - 90,000,000 shares, Issued: [removed: 2021] [added: 2022] - [removed: 39,443,168] [added: 36,601,215] shares; [removed: 2020] [added: 2021] - 39,443,168 shares | | | [removed: 3,944] [added: 3,660] | | | | | | 3,944 | | |
| Additional paid-in capital | | | [removed: 8,807,891] [added: 5,417,796] | | | | | | [removed: 8,676,056] [added: 8,807,891] | | |
| Retained earnings | | | [removed: 14,685,329] [added: 18,861,417] | | | | | | [removed: 10,564,994] [added: 14,685,329] | | |
◦For all JVs, evaluated whether any reconsideration events during the year took place that would cause deconsolidation, and if so, verified that deconsolidation occurred properly.
January 26, 2023
| | | | 2022 (1) | | | | | | 2021 (1) | | |
| | | | 32,684,162 | | | | | | 27,467,819 | | |
| | | | 2022 (2) | | | | | | 2021 (2) | | |
| | | | 10,978,646 | | | | | | 9,870,242 | | |
| Lennar Other unrealized gain (loss) from technology investments | | | (655,094) | | | | | | 510,802 | | | | | | — | | |
Years Ended November 30, 2022, 2021 and 2020
| Retirement of treasury stock | | | (4,667) | | | | | | — | | | | | | — | | |
| Retirement of treasury stock | | | (284) | | | | | | — | | | | | | — | | |
| Retirement of treasury stock | | | (3,533,425) | | | | | | — | | | | | | — | | |
| Premium paid for purchase of noncontrolling interests | | | (37,342) | | | | | | — | | | | | | — | | |
| Retirement of treasury stock | | | 3,538,376 | | | | | | — | | | | | | — | | |
Years Ended November 30, 2022, 2021 and 2020
Years Ended November 30, 2022, 2021 and 2020
| Receipts related to noncontrolling interests | | | 41,816 | | | | | | 69,675 | | | | | | 176,617 | | |
| Payments related to noncontrolling interests | | | (91,329) | | | | | | (24,605) | | | | | | (42,349) | | |
| Inventories | | | (101,946) | | | | | | — | | | | | | 95,476 | | |
In order to promote sales of the homes, the Company may offer sales incentives to homebuyers.
The types of incentives vary on a community-by-community basis and home-by-home basis.
They include primarily price discounts on individual homes and financing incentives, all of which are reflected as a reduction of home sales revenues.
For the years ended November 30, 2022, 2021 and 2020, sales incentives offered to homebuyers averaged $17,300 per home, or 3.5% as a percentage of home sales revenues, $9,000 per home, or 2.1% as a percentage of home sales revenues and $19,800 per home, or 4.8% as a percentage of home sales revenues, respectively.
| | | | 676,159 | | | | | | 492,809 | | |
absorption pace realized in its most recent quarters and the sales prices included in the Company's current backlog for such communities.
| 2022 | | | 15 | | | | | | 9 | | | | | | $ | 105,042 | | | | | $ | 33,563 | | | | | | | | | | |
| | | | Years Ended November 30, | | | | | | | | | | | | | | | | | | | | |
| | | | 2022 | | | | | | | | | | | | 2021 | | | | | | | | |
(1)Represents the projected average selling price on future deliveries for communities in which the Company recorded impairments on during the years ended November 30, 2022 and 2021.
As of November 30, 2022, the Company had $2.0 billion of nonrefundable option deposits and pre-acquisition costs related to certain of these homesites, which were included in inventories in the accompanying consolidated balance sheet.
During the year ended November 30, 2022, the Company wrote-off $47.9 million of deposit and pre-acquisition costs.
In the course of executing on the Company’s land light strategy, the Company may sell land to third parties (including land funds) and unconsolidated entities while maintaining an option to repurchase the land in the future.
Although, such transactions include cash consideration from the buyer and the transfer of title from the Company to the buyer, such transactions do not meet the criteria for revenue recognition under GAAP due to the Company’s option to repurchase the land from the buyer in the future.
As such, land related to such transactions remains on the Company’s accompanying consolidated balance sheet and is reclassified from land and land under development to consolidated inventory not owned.
The increase was primarily due to reclassifications from land and land under development to consolidated inventory not owned during the year ended November 30, 2022 as the Company continued to focus on increasing its controlled homesites as compared to owned homesites.
The increase was partially offset by takedowns during the year ended November 30, 2022.
Factors considered in determining whether the Company is the primary beneficiary include risk and reward sharing, experience and financial condition of other
Generally, Homebuilding and Multifamily unconsolidated entities become VIEs due to insufficient equity at risk for
the JV entity as the partner(s) continue to provide subordinated financial support in the form of capital contributions.
| (In thousands) | | | 2022 | | | | | | 2021 | | |
| | | | 581,917 | | | | | | 538,761 | | |
January 28, 2022
| | | | 27,467,819 | | | | | | 25,529,425 | | |
| | | | 9,870,242 | | | | | | 9,925,651 | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Cumulative-effect of accounting change | | | — | | | | | | — | | | | | | 9,753 | | |
| Lennar Other unrealized/realized gains | | | (680,576) | | | | | | — | | | | | | — | | |
| Receipts of principal payments on loans receivable and other | | | — | | | | | | — | | | | | | 2,382 | | |
| Issuances | | | — | | | | | | — | | | | | | 493 | | |
| Lennar Other restricted cash | | | — | | | | | | — | | | | | | 975 | | |
| Inventories | | | — | | | | | | 95,476 | | | | | | 187,506 | | |
| Receivables | | | — | | | | | | — | | | | | | 102,959 | | |
| Operating properties and equipment and other assets | | | — | | | | | | 6,870 | | | | | | 53,412 | | |
conditions and other factors considered relevant by the Company.
| | | | 492,809 | | | | | | 301,469 | | |
| 2020 | | | 10 | | | | | | 16 | | | | | | 79,734 | | | | | | 44,811 | | | | | | | | | | | |
When the Company does not intend to exercise an option, it writes off any unapplied deposit and pre-acquisition costs associated with the option contract.
| | | | 538,761 | | | | | | 589,037 | | |
| | | | $ | 339,906 | | | | | 411,518 | | |
Certain insurable risks such as construction defects, general liability, medical and workers’ compensation are self-insured by the Company up to certain limits.
Undiscounted accruals for claims under the Company’s self-insurance program are based on claims filed and estimates for claims incurred but not yet reported.
The Company’s self-insurance reserve, net of
During the years ended 2020 and 2019, the Company’s Class A and Class B common stockholders received a per share annual dividend of $0.625 and $0.16, respectively.
The repurchase authority has no expiration date.
Shortly after the new authorization, the January 2021 stock repurchase program was completed as the Company had purchased the $1 billion in value authorized under that stock repurchase program.
| Principal | | | | | | $ | 1,357,081 | | | | | $ | 8,197 | | | | | $ | 282,274 | | | | | $ | 6,155 | |
| Nonvested shares at November 30, 2020 | | | 3,546,576 | | | | | | $ | 55.01 | |
| Grants | | | 1,562,138 | | | | | | $ | 80.95 | |
| Vested | | | (1,829,016) | | | | | | $ | 57.56 | |
| Forfeited | | | (115,908) | | | | | | $ | 62.49 | |
Revenues from title policies issued by independent agents are recognized as revenue when notice of issuance is received from the agent, which is generally when cash payment is received by the Company.
contractor services which represents a performance obligation that the Company satisfies over time.
In June 2016, the FASB issued ASU 2016-13, *Financial Instruments - Credit Losses (Topic 326): Measurement of Credit Losses on Financial Instruments ("ASU 2016-13")*.
ASU 2016-13 significantly changes the impairment model for most financial assets and certain other instruments.
ASU 2016-13 requires immediate recognition of estimated credit losses expected to occur over the remaining life of many financial assets, which generally results in earlier recognition of allowances for credit losses on loans and other financial instruments.
In January 2017, the FASB issued ASU 2017-04, *Intangibles - Goodwill and Other* (Topic 350), Simplifying the Accounting for Goodwill Impairment ("ASU 2017-04").
ASU 2017-04 removes the requirement to perform a hypothetical purchase price allocation to measure goodwill impairment.
A goodwill impairment will now be the amount by which a reporting unit's carrying value exceeds its fair value, not to exceed the carrying amount of goodwill.
ASU 2017-04 was effective for the Company’s fiscal year beginning December 1, 2020.
New Accounting Pronouncements
ASU 2019- 12 will be effective for the Company’s fiscal year beginning December 1, 2022.
An excerpt. Shown here: 40 of 519 rewritten, 40 of 198 added and 40 of 146 removed. The counts are complete. For every sentence, read Item 8. Financial Statements and Supplementary Data. in the FY2022 filing and the FY2021 filing.
Item 9A. Controls and Procedures.
7 rewritten, 1 added, 1 removed, 30 unchanged
Based on their participation in that evaluation, our Co-CEOs and CFO concluded that our disclosure controls and procedures were effective as of November 30, [removed: 2021] [added: 2022] to ensure that information required to be disclosed in our reports filed or submitted under the Securities Exchange Act of 1934, as amended, is recorded, processed, summarized and reported within the time periods specified in the Securities and Exchange Commission’s rules and forms, and to ensure that information required to be disclosed in our reports filed or furnished under the Securities Exchange Act of 1934, as amended, is accumulated and communicated to our management, including both of our Co-CEOs and CFO, as appropriate to allow timely decisions regarding required disclosures.
Both of our Co-CEOs and CFO also participated in an evaluation by our management of any changes in our internal control over financial reporting that occurred during the quarter ended November 30, [removed: 2021.][added: 2022.]
Based on our evaluation under the framework in *Internal Control—Integrated Framework* (2013)*,* our management concluded that our internal control over financial reporting was effective as of November 30, [removed: 2021.][added: 2022.]
The effectiveness of our internal control over financial reporting as of November 30, [removed: 2021] [added: 2022] has been audited by Deloitte & Touche LLP, an independent registered public accounting firm, as stated in their attestation report which is included herein.
We have audited the internal control over financial reporting of Lennar Corporation and subsidiaries (the “Company”) as of November 30, [removed: 2021,] [added: 2022,] based on criteria established in *Internal Control - Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of November 30, [removed: 2021,] [added: 2022,] based on criteria established in *Internal Control - Integrated Framework (2013)* issued by COSO.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated financial statements as of and for the year ended November 30, [removed: 2021,] [added: 2022,] of the Company and our report dated January [removed: 28, 2022] [added: 26, 2023] expressed an unqualified opinion on those financial statements.
| January 26, 2023 | | |
| January 28, 2022 | | |
Item 10. Directors, Executive Officers and Corporate Governance.
1 rewritten, 0 added, 0 removed, 3 unchanged
The other information called for by this item is incorporated by reference to our definitive proxy statement, which will be filed with the Securities and Exchange Commission not later than March 30, [removed: 2022] [added: 2023] (120 days after the end of our fiscal year).
Item 11. Executive Compensation.
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this item is incorporated by reference to our definitive proxy statement, which will be filed with the Securities and Exchange Commission not later than March 30, [removed: 2022] [added: 2023] (120 days after the end of our fiscal year).
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
4 rewritten, 0 added, 0 removed, 5 unchanged
The information required by this item is incorporated by reference to our definitive proxy statement, which will be filed with the Securities and Exchange Commission not later than March 30, [removed: 2022] [added: 2023] (120 days after the end of our fiscal year), except for the information required by Item 201(d) of Regulation S-K, which is provided below.
The following table summarizes our equity compensation plans as of November 30, [removed: 2021:][added: 2022:]
| Equity compensation plans approved by stockholders | | | 162,338 | | | | | | $ | 100.00 | | | | | [removed: 5,600,008] [added: 13,438,078] | | |
| Total | | | 162,338 | | | | | | $ | 100.00 | | | | | [removed: 5,600,008] [added: 13,438,078] | | |
Item 13. Certain Relationships and Related Transactions, and Director Independence.
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this item is incorporated by reference to our definitive proxy statement, which will be filed with the Securities and Exchange Commission not later than March 30, [removed: 2022] [added: 2023] (120 days after the end of our fiscal year).
Item 14. Principal Accountant Fees and Services.
1 rewritten, 0 added, 0 removed, 1 unchanged
The information required by this item is incorporated by reference to our definitive proxy statement, which will be filed with the Securities and Exchange Commission not later than March 30, [removed: 2022] [added: 2023] (120 days after the end of our fiscal year).
Item 15. Exhibit and Financial Statement Schedules.
34 rewritten, 5 added, 1 removed, 60 unchanged
| [Report of Independent Registered Public Accounting [removed: Firm](#if8875ebc30f5446fa24ed9be199539fa_127)] [added: Firm](#i7229c560662948e4bff883c99b924dfb_115) (PCAOB ID No. 34)] | | | [removed: [42](#if8875ebc30f5446fa24ed9be199539fa_127)] [added: [43](#i7229c560662948e4bff883c99b924dfb_115)] | | |
| [Consolidated Balance Sheets as of November 30, [removed: 2021] [added: 2022] and [removed: 2020](#if8875ebc30f5446fa24ed9be199539fa_130)] [added: 2021](#i7229c560662948e4bff883c99b924dfb_118)] | | | [removed: [44](#if8875ebc30f5446fa24ed9be199539fa_130)] [added: [45](#i7229c560662948e4bff883c99b924dfb_118)] | | |
| [Consolidated Statements of Operations and Comprehensive Income (Loss) for the Years Ended November 30, [removed: 2021, 2020] [added: 2022, 2021] and [removed: 2019](#if8875ebc30f5446fa24ed9be199539fa_136)] [added: 2020](#i7229c560662948e4bff883c99b924dfb_124)] | | | [removed: [46](#if8875ebc30f5446fa24ed9be199539fa_136)] [added: [47](#i7229c560662948e4bff883c99b924dfb_124)] | | |
| [Consolidated Statements of Equity for the Years Ended November 30, [removed: 2021, 2020] [added: 2022, 2021] and [removed: 2019](#if8875ebc30f5446fa24ed9be199539fa_139)] [added: 2020](#i7229c560662948e4bff883c99b924dfb_127)] | | | [removed: [47](#if8875ebc30f5446fa24ed9be199539fa_139)] [added: [48](#i7229c560662948e4bff883c99b924dfb_127)] | | |
| [Consolidated Statements of Cash Flows for the Years Ended November 30, [removed: 2021, 2020] [added: 2022, 2021] and [removed: 2019](#if8875ebc30f5446fa24ed9be199539fa_142)] [added: 2020](#i7229c560662948e4bff883c99b924dfb_130)] | | | [removed: [48](#if8875ebc30f5446fa24ed9be199539fa_142)] [added: [49](#i7229c560662948e4bff883c99b924dfb_130)] | | |
| [Notes to Consolidated Financial [removed: Statements](#if8875ebc30f5446fa24ed9be199539fa_145)] [added: Statements](#i7229c560662948e4bff883c99b924dfb_133)] | | | [removed: [49](#if8875ebc30f5446fa24ed9be199539fa_145)] [added: [50](#i7229c560662948e4bff883c99b924dfb_133)] | | |
| [Schedule II—Valuation and Qualifying [removed: Accounts](#if8875ebc30f5446fa24ed9be199539fa_280)] [added: Accounts](#i7229c560662948e4bff883c99b924dfb_259)] | | | [removed: [87](#if8875ebc30f5446fa24ed9be199539fa_280)] [added: [88](#i7229c560662948e4bff883c99b924dfb_259)] | | |
| 3.2 | | | [Bylaws of the Company, as amended effective [removed: June 26, 2019] [added: September 28, 2022] - Incorporated by reference to Exhibit 3.1 of the Company’s Current Report on Form 8-K, dated [removed: June 26, 2019.](http://www.sec.gov/Archives/edgar/data/920760/000119312519187474/d60950dex31.htm)] [added: September 28, 2022.](https://www.sec.gov/Archives/edgar/data/920760/000119312522255625/d343785dex31.htm)] | | |
| 4.3 | | | [removed: [Indenture,] [added: [Tenth Supplemental Indenture,] dated [removed: October 23, 2012, between] [added: as of April 28, 2015, among] Lennar [added: Corporation, each of the guarantors identified therein] and The Bank of New York [removed: Mellon Trust Company, N.A.,] [added: Mellon,] as [removed: trustee (relating to Lennar’s] [added: trustee, including the form of] 4.750% Senior Notes due [removed: 2022)] [added: 2025] - Incorporated by reference to Exhibit [removed: 4.12] [added: 4.14] of the [removed: Company's Annual] [added: Company’s Current] Report on Form [removed: 10-K, for the fiscal year ended November 30, 2012.](http://www.sec.gov/Archives/edgar/data/920760/000144530513000116/len-20121130x10kxexh412.htm)] [added: 8-K, dated April 28, 2015.](http://www.sec.gov/Archives/edgar/data/920760/000119312515156659/d916893dex414.htm)] | | |
| 4.4 | | | [removed: [Tenth] [added: [Eleventh] Supplemental Indenture, dated as of [removed: April 28,] [added: November 5,] 2015, among Lennar Corporation, each of the guarantors identified therein and The Bank of New York Mellon, as trustee, including the form of [removed: 4.750%] [added: 4.875%] Senior Notes due [removed: 2025] [added: 2023] - Incorporated by reference to Exhibit [removed: 4.14] [added: 4.15] of the Company’s Current Report on Form 8-K, dated [removed: April 29, 2015.](http://www.sec.gov/Archives/edgar/data/920760/000119312515156659/d916893dex414.htm)] [added: November 5, 2015.](http://www.sec.gov/Archives/edgar/data/920760/000119312515370236/d63693dex415.htm)] | | |
| 4.5 | | | [removed: [Eleventh] [added: [Fourteenth] Supplemental Indenture, dated as of [removed: November 5, 2015,] [added: April 28, 2017,] among Lennar Corporation, each of the guarantors identified therein and The Bank of New York Mellon, as trustee, including the form of [removed: 4.875%] [added: 4.50%] Senior Notes due [removed: 2023] [added: 2024] - Incorporated by reference to Exhibit [removed: 4.15] [added: 4.18] of the Company’s Current Report on Form 8-K, dated [removed: November 6, 2015.](http://www.sec.gov/Archives/edgar/data/920760/000119312515370236/d63693dex415.htm)] [added: April 28, 2017.](http://www.sec.gov/Archives/edgar/data/920760/000119312517148377/d385723dex418.htm)] | | |
| 4.6 | | | [removed: [Fourteenth Supplemental Indenture,] [added: [Indenture,] dated as of [removed: April 28,] [added: November 29,] 2017, among Lennar Corporation, each of the guarantors identified therein and The Bank of New York Mellon, as trustee, including the form of [removed: 4.50%] [added: 2.95%] Senior Notes due [removed: 2024 -] [added: 2020 and the form of 4.75% Senior Notes due 2027-] Incorporated by reference to Exhibit [removed: 4.18] [added: 4.1] of the Company’s Current Report on Form 8-K, dated [removed: April 28, 2017.](http://www.sec.gov/Archives/edgar/data/920760/000119312517148377/d385723dex418.htm)] [added: November 29, 2017.](http://www.sec.gov/Archives/edgar/data/920760/000119312517357394/d438218dex41.htm)] | | |
| 4.7 | | | [Indenture, dated as of [removed: November 29, 2017,] [added: February 20, 2018,] among Lennar Corporation, each of the guarantors identified therein and The Bank of New York Mellon, as trustee, [removed: including] [added: governing] the [removed: form of 2.95%] [added: 5.875%] Senior Notes due [removed: 2020 and] [added: November 15, 2024 (including] the [removed: form] [added: forms] of [removed: 4.75%] [added: 5.875%] Senior Notes due [removed: 2027-] [added: November 15, 2024) -] Incorporated by reference to Exhibit [removed: 4.1] [added: 4.6] of the Company’s Current Report on Form 8-K, dated [removed: November 29, 2017.](http://www.sec.gov/Archives/edgar/data/920760/000119312517357394/d438218dex41.htm)] [added: February 16, 2018.](http://www.sec.gov/Archives/edgar/data/920760/000119312518050568/d513500dex46.htm)] | | |
| 4.8 | | | [Indenture, dated as of February 20, 2018, among Lennar Corporation, each of the guarantors identified therein and The Bank of New York Mellon, as trustee, governing the [removed: 5.875%] [added: 5.25%] Senior Notes due [removed: November 15, 2024] [added: June 1, 2026] (including the forms of [removed: 5.875%] [added: 5.25%] Senior Notes due [removed: November 15, 2024)] [added: June 1, 2026)] - Incorporated by reference to Exhibit [removed: 4.6] [added: 4.7] of the Company’s Current Report on Form 8-K, dated February 16, [removed: 2018.](http://www.sec.gov/Archives/edgar/data/920760/000119312518050568/d513500dex46.htm)] [added: 2018.](http://www.sec.gov/Archives/edgar/data/920760/000119312518050568/d513500dex47.htm)] | | |
| 4.9 | | | [Indenture, dated as of February 20, 2018, among Lennar Corporation, each of the guarantors identified therein and The Bank of New York Mellon, as trustee, governing the [removed: 5.25%] [added: 5.00%] Senior Notes due June [removed: 1, 2026] [added: 15, 2027] (including the forms of [removed: 5.25%] [added: 5.00%] Senior Notes due June [removed: 1, 2026)] [added: 15, 2027)] - Incorporated by reference to Exhibit [removed: 4.7] [added: 4.8] of the Company’s Current Report on Form 8-K, dated February 16, [removed: 2018.](http://www.sec.gov/Archives/edgar/data/920760/000119312518050568/d513500dex47.htm)] [added: 2018.](http://www.sec.gov/Archives/edgar/data/920760/000119312518050568/d513500dex48.htm)] | | |
| 10.1* | | | [Lennar Corporation 2016 Equity Incentive Plan [added: (Amended and Restated Effective January 12, 2022)] - Incorporated by reference to Exhibit A [removed: of] [added: to] the [removed: Company’s] [added: Registrant’s] Definitive Proxy Statement on Schedule 14A, filed with the Commission on March [removed: 2, 2016.](http://www.sec.gov/Archives/edgar/data/920760/000119312516489179/d26986ddef14a.htm)] [added: 1, 2022.](https://www.sec.gov/Archives/edgar/data/920760/000119312522059659/d188597ddef14a.htm#toc188597_33exa)] | | |
| 10.2* | | | [Lennar Corporation 2016 Incentive Compensation Plan, as Amended and Restated effective January 12, [removed: 2022– Filed herewith.](https://www.sec.gov/Archives/edgar/data/920760/000162828022001450/len-20211130x10kxexh102.htm)] [added: 2022 - Incorporated by reference to Exhibit 10.2 of the Company’s Annual Report on Form 10-K for the fiscal year ended November 30, 2021.](https://www.sec.gov/Archives/edgar/data/920760/000162828022001450/len-20211130x10kxexh102.htm)] | | |
| 10.3 | | | [removed: [Seventh] [added: [Eighth] Amended and Restated Credit Agreement, dated as of [removed: April 11, 2019,] [added: May 23, 2022,] among Lennar Corporation, as borrower, JPMorgan Chase Bank, N.A., as issuing lender and administrative agent, the several lenders from time to time parties thereto, and the other parties and agents thereto - Incorporated by reference to Exhibit 10.1 of the Company’s Current Report on Form 8-K, dated [removed: April 11, 2019.](http://www.sec.gov/Archives/edgar/data/920760/000119312519105301/d718526dex101.htm)] [added: May 23, 2022.](https://www.sec.gov/Archives/edgar/data/920760/000119312522161051/d332951dex101.htm)] | | |
| 10.4 | | | [removed: [Seventh] [added: [Eighth] Amended and Restated Guarantee Agreement, dated as of [removed: April 11, 2019,] [added: May 23, 2022,] among certain of Lennar Corporation’s subsidiaries in favor of guaranteed parties referred to therein - Incorporated by reference to Exhibit 10.2 of the Company’s Current Report on Form 8-K, dated [removed: April 11, 2019.](http://www.sec.gov/Archives/edgar/data/920760/000119312519105301/d718526dex102.htm)] [added: May 23, 2022.](https://www.sec.gov/Archives/edgar/data/920760/000119312522161051/d332951dex102.htm)] | | |
| 10.5 | | | [Form of Aircraft Time Sharing Agreement, dated February 12, 2015, between U.S. Home Corporation and Lessee [removed: -Incorporated] [added: - Incorporated] by reference to Exhibit 10.19 of the Company’s Current Report on Form 8-K, dated February [removed: 19,] [added: 12,] 2015.](http://www.sec.gov/Archives/edgar/data/920760/000119312515054307/d875705dex1019.htm) | | |
| 10.6* | | | [Form of [removed: 2019] [added: 2020] Award Agreement under the Company’s 2016 Equity Incentive Plan for Mr. Miller, Mr. [removed: Beckwitt] [added: Beckwitt, Mr. Jaffe, Ms. Bessette] and Mr. [removed: Jaffe] [added: McCall] - Incorporated by reference to Exhibit 10.2 of the Company’s Current Report on Form 8-K, dated [removed: June 25, 2019.](http://www.sec.gov/Archives/edgar/data/920760/000119312519186216/d748760dex102.htm)] [added: February 28, 2020.](https://www.sec.gov/Archives/edgar/data/920760/000119312520060518/d895314dex102.htm)] | | |
| [removed: 10.7*] [added: 10.9*] | | | [removed: [2020] [added: [2022] Award Agreements under the Company’s 2016 Incentive Compensation [removed: Plan] [added: Plan, as amended,] for Mr. Miller, Mr. Beckwitt, Mr. Jaffe, Ms. [removed: Bessette and] [added: Bessette,] Mr. McCall [added: and Mr. Sustana] - Incorporated by reference to Exhibit 10.1 of the Company’s Current Report on Form 8-K, dated February 28, [removed: 2020.](https://www.sec.gov/Archives/edgar/data/920760/000119312520060518/d895314dex101.htm)] [added: 2022.](https://www.sec.gov/Archives/edgar/data/920760/000119312522066148/d320216dex101.htm)] | | |
| 10.8* | | | [Form of [removed: 2020] [added: 2021] Award Agreement under the Company’s 2016 Equity Incentive Plan for Mr. Miller, Mr. Beckwitt, Mr. Jaffe, Ms. Bessette and Mr. McCall - Incorporated by reference to Exhibit 10.2 of the Company’s Current Report on Form 8-K, dated February [removed: 28, 2020.](https://www.sec.gov/Archives/edgar/data/920760/000119312520060518/d895314dex102.htm)] [added: 26, 2021.](https://www.sec.gov/Archives/edgar/data/920760/000119312521067743/d14705dex102.htm)] | | |
| [removed: 10.9] [added: 10.7] | | | [Master Agreement, dated October 8, 2020, between AG Essential Housing Company 1, L.P. and Essential Housing Financing, [removed: LLC](https://www.sec.gov/Archives/edgar/data/0000920760/000162828021000722/len-20201130x10kxexh1012.htm) [-](https://www.sec.gov/Archives/edgar/data/0000920760/000162828021000722/len-20201130x10kxexh1012.htm) [Incorporated] [added: LLC - Incorporated] by reference to Exhibit 10.12 of the Company's Annual Report on Form 10-K for the fiscal year ended November 30, [removed: 2020](https://www.sec.gov/Archives/edgar/data/0000920760/000162828021000722/len-20201130x10kxexh1012.htm)] [added: 2020.](https://www.sec.gov/Archives/edgar/data/0000920760/000162828021000722/len-20201130x10kxexh1012.htm)] | | |
| 10.10* | | | [removed: [2021] [added: [Form of 2022] Award [removed: Agreements] [added: Agreement] under the Company’s 2016 [added: Equity] Incentive [removed: Compensation] Plan for Mr. Miller, Mr. Beckwitt, Mr. Jaffe, Ms. [removed: Bessette, Mr. McCall] [added: Bessette] and Mr. [removed: Sustana] [added: McCall] - Incorporated by reference to Exhibit [removed: 10.1] [added: 10.2] of the Company’s Current Report on Form 8-K, dated February [removed: 26, 2021.](https://www.sec.gov/Archives/edgar/data/920760/000119312521067743/d14705dex101.htm)] [added: 28, 2022.](https://www.sec.gov/Archives/edgar/data/920760/000119312522066148/d320216dex102.htm)] | | |
| 10.11* | | | [removed: [Form of 2021] [added: [Amended and Restated 2022] Award [removed: Agreement] [added: Agreements] under the [removed: Company’s 2016 Equity] Incentive Plan for Mr. Miller, Mr. [removed: Beckwitt, Mr. Jaffe, Ms. Bessette] [added: Beckwitt] and Mr. [removed: McCall] [added: Jaffe] - Incorporated by reference to Exhibit 10.1 of the Company’s Current Report on Form 8-K, dated [removed: February 26, 2021.](https://www.sec.gov/Archives/edgar/data/920760/000119312521067743/d14705dex102.htm)] [added: November 17, 2022.](https://www.sec.gov/Archives/edgar/data/920760/000119312522290031/d386121dex101.htm)] | | |
| 21 | | | [List of [removed: subsidiaries.](https://www.sec.gov/Archives/edgar/data/920760/000162828022001450/len-20211130x10kxexh21.htm)] [added: subsidiaries.](https://www.sec.gov/Archives/edgar/data/920760/000162828023001606/len-20221130x10kxexh21.htm)] | | |
| 23 | | | [Consent of Independent Registered Public Accounting [removed: Firm.](https://www.sec.gov/Archives/edgar/data/920760/000162828022001450/len-20211130x10kxexh23.htm)] [added: Firm.](https://www.sec.gov/Archives/edgar/data/920760/000162828023001606/len-20221130x10kxexh23.htm)] | | |
| 31.1 | | | [Rule 13a-14a/15d-14(a) Certification of Rick [removed: Beckwitt.](https://www.sec.gov/Archives/edgar/data/920760/000162828022001450/len-20211130x10kxexh311.htm)] [added: Beckwitt.](https://www.sec.gov/Archives/edgar/data/920760/000162828023001606/len-20221130x10kxexh311.htm)] | | |
| 31.2 | | | [Rule 13a-14a/15d-14(a) Certification of Jonathan M. [removed: Jaffe.](https://www.sec.gov/Archives/edgar/data/920760/000162828022001450/len-20211130x10kxexh312.htm)] [added: Jaffe.](https://www.sec.gov/Archives/edgar/data/920760/000162828023001606/len-20221130x10kxexh312.htm)] | | |
| 31.3 | | | [Rule 13a-14a/15d-14(a) Certification of Diane [removed: Bessette.](https://www.sec.gov/Archives/edgar/data/920760/000162828022001450/len-20211130x10kxexh313.htm)] [added: Bessette.](https://www.sec.gov/Archives/edgar/data/920760/000162828023001606/len-20221130x10kxexh313.htm)] | | |
| 32 | | | [Section 1350 Certifications of Rick Beckwitt, Jonathan M. Jaffe and Diane [removed: Bessette.](https://www.sec.gov/Archives/edgar/data/920760/000162828022001450/len-20211130x10kxexh32.htm)] [added: Bessette.](https://www.sec.gov/Archives/edgar/data/920760/000162828023001606/len-20221130x10kxexh32.htm)] | | |
| 101 | | | The following financial statements from Lennar Corporation Annual Report on Form 10-K for the year ended November 30, [removed: 2021,] [added: 2022,] filed on January [removed: 28, 2022,] [added: 26, 2023,] formatted in iXBRL (Inline Extensible Business Reporting Language); (i) Consolidated Balance Sheets, (ii) Consolidated Statements of Operations and Comprehensive Income (Loss), (iii) Consolidated Statements of Equity (iv) Consolidated Statements of Cash Flows and (v) the Notes to Consolidated Financial Statements. | | |
| 104* | | | The cover page from Lennar Corporation's fiscal year Report on Form 10-K for the year ended November 30, [removed: 2021] [added: 2022] was formatted in iXBRL. | | |
| 10.12* | | | [Form of the Amended and Restated 2022 Award Agreement under the Equity Plan for Mr. Miller, Mr. Beckwitt and Mr. Jaffe - Incorporated by reference to Exhibit 10.2 of the Company’s Current Report on Form 8-K, dated November 17, 2022.](https://www.sec.gov/Archives/edgar/data/920760/000119312522290031/d386121dex102.htm) | | |
| 10.13* | | | [Form of the 2022 Award Agreement for Performance Shares granted under the Equity Plan for Mr. Miller, Mr. Beckwitt and Mr. Jaffe - Incorporated by reference to Exhibit 10.3 of the Company’s Current Report on Form 8-K, dated November 17, 2022.](https://www.sec.gov/Archives/edgar/data/920760/000119312522290031/d386121dex103.htm) | | |
| 22.1 | | | [List of guarantor subsidiaries.](https://www.sec.gov/Archives/edgar/data/920760/000162828023001606/len-20221130x10kxexh221.htm) | | |
| | | | | | |
| | | | | | |
| 4.10 | | | [Indenture, dated as of February 20, 2018, among Lennar Corporation, each of the guarantors identified therein and The Bank of New York Mellon, as trustee, governing the 5.00% Senior Notes due June 15, 2027 (including the forms of 5.00% Senior Notes due June 15, 2027) - Incorporated by reference to Exhibit 4.8 of the Company’s Current Report on Form 8-K, dated February 16, 2018.](http://www.sec.gov/Archives/edgar/data/920760/000119312518050568/d513500dex48.htm) | | |
Item 16. Form 10-K Summary
12 rewritten, 11 added, 3 removed, 65 unchanged
| | | | Date: | | | January [removed: 28, 2022] [added: 26, 2023] | | |
| Co-Chief Executive Officer, Co-President and Director | | | Date: | | | January [removed: 28, 2022] [added: 26, 2023] | | |
| Vice President, Chief Financial Officer and Treasurer | | | Date: | | | January [removed: 28, 2022] [added: 26, 2023] | | |
| Vice President and Controller | | | Date: | | | January [removed: 28, 2022] [added: 26, 2023] | | |
Years Ended November 30, [removed: 2021, 2020] [added: 2022, 2021] and [removed: 2019][added: 2020]
| [removed: Allowances] [added: Allowance] for credit losses [removed: and] [added: against] notes and other receivables | | | $ | 2,394 | | | | | 79 | | | | | | 59 | | | | | | (1) | | | | | | 2,531 | | |
| Allowance for loan losses [removed: and] [added: against] loans receivable | | | $ | 4,012 | | | | | — | | | | | | (31) | | | | | | (1,890) | | | | | | 2,091 | | |
| [removed: Allowances] [added: Allowance] for credit losses [removed: and] [added: against] notes and other receivables | | | $ | 3,379 | | | | | 661 | | | | | | (568) | | | | | | (1,078) | | | | | | 2,394 | | |
| Allowance for loan losses [removed: and] [added: against] loans receivable | | | $ | 4,122 | | | | | 795 | | | | | | 17 | | | | | | (922) | | | | | | 4,012 | | |
| Year ended November 30, [removed: 2019] [added: 2022] | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Allowance for loan losses [removed: and] [added: against] loans receivable | | | $ | [removed: 6,154] [added: 2,091] | | | | | [removed: 485] [added: 9,127] | | | | | | — | | | | | | [removed: (2,517)] [added: (88)] | | | | | | [removed: 4,122] [added: 11,130] | | |
| Allowance against net deferred tax assets | | | $ | [removed: 7,219] [added: 2,693] | | | | | [removed: —] [added: 784] | | | | | | — | | | | | | [removed: (2,878)] [added: (574)] | | | | | | [removed: 4,341] [added: 2,903] | | |
| | | | Date: | | | January 26, 2023 | | |
| Co-Chief Executive Officer, Co-President and Director | | | Date: | | | January 26, 2023 | | |
| | | | Date: | | | January 26, 2023 | | |
| | | | Date: | | | January 26, 2023 | | |
| | | | Date: | | | January 26, 2023 | | |
| | | | Date: | | | January 26, 2023 | | |
| | | | Date: | | | January 26, 2023 | | |
| | | | Date: | | | January 26, 2023 | | |
| | | | Date: | | | January 26, 2023 | | |
| | | | Date: | | | January 26, 2023 | | |
| Allowance for credit losses against notes and other receivables | | | $ | 2,531 | | | | | 145 | | | | | | (497) | | | | | | — | | | | | | 2,179 | | |
| | | | | | | | | |
| Steven L. Gerard | | | /S/ STEVEN L. GERARD | | | | | |
| Allowances for credit losses and notes and other receivables | | | $ | 2,793 | | | | | 1,404 | | | | | | (344) | | | | | | (474) | | | | | | 3,379 | | |