 filings.tools
Lockheed Martin 10-K 2016-12-31
Filed 2017-02-09. 22 sections, 544K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 d290249d10k.htm FORM 10-K
Table of Contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
Form 10-K
ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF
THE SECURITIES EXCHANGE ACT OF 1934
For the fiscal year ended December 31, 2016
Commission file number 1-11437
LOCKHEED MARTIN CORPORATION
(Exact name of registrant as specified in its charter)
| Maryland | 52-1893632 | |||
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) |
6801 Rockledge Drive, Bethesda, Maryland 20817-1877 (301/897-6000)
(Address and telephone number of principal executive offices)
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Name of each exchange on which registered | |||
| Common Stock, $1 par value | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☒ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐ No ☒
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐
Indicate by check mark whether the registrant has submitted electronically and posted on its corporate Web site, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files). Yes ☒ No ☐
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K (§229.405 of this chapter) is not contained herein, and will not be contained, to the best of registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, or a smaller reporting company. See the definitions of “large accelerated filer,” “accelerated filer” and “smaller reporting company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer ☒ | Accelerated filer ☐ | Non-accelerated filer ☐ | Smaller reporting company ☐ |
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes ☐ No ☒
The aggregate market value of voting and non-voting common stock held by non-affiliates of the registrant computed by reference to the last sales price of such stock, as of the last business day of the registrant’s most recently completed second fiscal quarter, which was June 24, 2016, was approximately $72.1 billion.
There were 290,315,668 shares of our common stock, $1 par value per share, outstanding as of January 27, 2017.
DOCUMENTS INCORPORATED BY REFERENCE
Portions of Lockheed Martin Corporation’s 2017 Definitive Proxy Statement are incorporated by reference into Part III of this Form 10-K.
Table of Contents
Lockheed Martin Corporation
Form 10-K
For the Year Ended December 31, 2016
Table of Contents
Table of Contents
PART I
Item 1. Business.
| --- | --- |
General
We are a global security and aerospace company principally engaged in the research, design, development, manufacture, integration and sustainment of advanced technology systems, products and services. We also provide a broad range of management, engineering, technical, scientific, logistics, system integration and cybersecurity services. We serve both U.S. and international customers with products and services that have defense, civil and commercial applications, with our principal customers being agencies of the U.S. Government. In 2016, 71% of our $47.2 billion in net sales were from the U.S. Government, either as a prime contractor or as a subcontractor (including 59% from the Department of Defense (DoD)), 27% were from international customers (including foreign military sales (FMS) contracted through the U.S. Government) and 2% were from U.S. commercial and other customers. Our main areas of focus are in defense, space, intelligence, and homeland security.
We operate in an environment characterized by increasing complexity in global security and continuing economic pressures in the U.S. and globally. A significant component of our strategy in this environment is to focus on program execution, improving the quality and predictability of the delivery of our products and services, and placing security capability quickly into the hands of our U.S. and international customers at affordable prices. Recognizing that our customers are resource constrained, we are endeavoring to develop and extend our portfolio domestically in a disciplined manner with a focus on adjacent markets close to our core capabilities, as well as growing our international sales. We continue to focus on affordability initiatives. We also expect to continue to invest in technologies to fulfill new mission requirements for our customers and invest in our people so that we have the technical skills necessary to succeed without limiting our ability to return cash to our investors in the form of dividends and share repurchases.
We operate in four business segments: Aeronautics, Missiles and Fire Control (MFC), Rotary and Mission Systems (RMS) and Space Systems. We organize our business segments based on the nature of the products and services offered.
Recent Developments
Divestiture of the Information Systems & Global Solutions Business
On August 16, 2016, we completed the divestiture of our Information Systems & Global Solutions (IS&GS) business, which merged with a subsidiary of Leidos Holdings, Inc. (Leidos), in a Reverse Morris Trust transaction. This transaction represents the culmination of the strategic review of our government information technology (IT) business and our technical services business performed in 2015 to explore whether the IS&GS business could achieve greater growth and create more value for customers and stockholders outside of Lockheed Martin. The IS&GS business generated annual net sales of $5.6 billion in 2015 and $3.4 billion in 2016 through the August 16, 2016 divestiture date. As part of the transaction, we also completed an exchange offer that resulted in a reduction of our common stock outstanding by approximately 9.4 million shares (approximately 3%). Based on an opinion of outside tax counsel, subject to customary qualifications and based on factual representations, both the exchange offer and merger will qualify as tax-free transactions to us and our stockholders, except to the extent that cash was paid to our stockholders in lieu of fractional shares. Additionally, we received a one-time special cash payment of $1.8 billion in connection with the divestiture of the IS&GS business. The operating results of the IS&GS business have been classified as discontinued operations for all periods presented. See “Note 3 – Acquisitions and Divestitures” included in our Notes to Consolidated Financial Statements for additional information about the divestiture of the IS&GS business.
AWE Management Limited
On August 24, 2016, our ownership interest in the AWE Management Limited (AWE) venture increased from 33% to 51% in exchange for our assuming a more significant role in managing the operations of the venture. AWE operates the United Kingdom’s nuclear deterrent program and generated net sales of about $1.5 billion and net earnings of about $85 million in 2015. As a result of the increase in ownership interest, we now hold a 51% controlling interest in AWE. Accordingly, we are required to consolidate AWE. AWE continues to be aligned under our Space Systems business segment. Prior to August 24, 2016, we accounted for our investment in AWE using the equity method of accounting. See “Note 3 –Acquisitions and Divestitures” included in our Notes to Consolidated Financial Statements for additional information about the consolidation of AWE.
Table of Contents
Aeronautics
In 2016, our Aeronautics business segment generated net sales of $17.8 billion, which represented 38% of our total consolidated net sales. Aeronautics’ customers include the military services and various other government agencies of the U.S. and other countries. In 2016, U.S. Government customers accounted for 66% and international customers accounted for 34% of Aeronautics’ net sales. Net sales from Aeronautics’ combat aircraft products and services represented 28% of our total consolidated net sales in both 2016 and 2015, and 26% in 2014.
Aeronautics is engaged in the research, design, development, manufacture, integration, sustainment, support and upgrade of advanced military aircraft, including combat and air mobility aircraft, unmanned air vehicles and related technologies. Aeronautics’ major programs include:
| • | F-35 Lightning II Joint Strike Fighter – international multi-role, multi-variant, fifth generation stealth fighter; |
|---|
| • | C-130 Hercules – international tactical airlifter; |
|---|
| • | F-16 Fighting Falcon – low-cost, combat-proven, international multi-role fighter; |
|---|
| • | F-22 Raptor – air dominance and multi-mission fifth generation stealth fighter; and |
|---|
| • | C-5M Super Galaxy – strategic airlifter. |
|---|
The F-35 program is our largest program, generating 23% of our total consolidated net sales, as well as 62% of Aeronautics’ net sales in 2016. The F-35 program consists of development contracts, multiple production contracts, and sustainment activities. The development contracts are being performed concurrently with the production contracts. Concurrent performance of development and production contracts is used for complex programs to test aircraft, shorten the time to field systems and achieve overall cost savings. We expect the System Development and Demonstration portion of the development contracts will be substantially complete in 2017, with less significant efforts continuing into 2019. Production of the aircraft is expected to continue for many years given the U.S. Government’s current inventory objective of 2,443 aircraft for the Air Force, Marine Corps and Navy; commitments from our eight international partners and three international customers; as well as expressions of interest from other countries. During 2016, we delivered 46 aircraft to our U.S. and international partners, resulting in total deliveries of 200 production aircraft as of December 31, 2016. We have 173 production aircraft in backlog as of December 31, 2016, including orders from our international partners. On November 2, 2016, the U.S. Government unilaterally definitized Low Rate Initial Production (LRIP) 9, which covers 57 aircraft. For additional information on the F-35 program, including a discussion of the unilateral contract action, see “Status of the F-35 Program” in Management’s Discussion and Analysis of Financial Condition and Results of Operations.
Aeronautics produces and provides support and sustainment services for the C-130J Super Hercules, as well as upgrades and support services for the legacy C-130 Hercules worldwide fleet. We delivered 24 C-130J aircraft in 2016, including five to international customers. We have 88 aircraft in our backlog as of December 31, 2016 with advanced funding from customers for additional C-130J aircraft not currently in backlog. Our C-130J backlog extends into 2020.
Aeronautics currently produces F-16 aircraft for international customers with deliveries of new aircraft planned through 2017. Aeronautics also provides service-life extension, modernization and other upgrade programs for our customers’ F-16 aircraft. We delivered 12 F-16 aircraft in 2016. As of December 31, 2016, we have eight F-16 aircraft in backlog with all deliveries expected in 2017. Although existing production contracts provide for deliveries of F-16 aircraft through late 2017, we continue to seek international opportunities to deliver additional aircraft beyond 2017. Aeronautics also provides service-life extension, modernization and other upgrade programs for our customers’ F-16 aircraft, with existing contracts continuing for several years.
While production and deliveries of F-22 aircraft were completed in 2012, Aeronautics continues to provide modernization and sustainment activities for the U.S. Air Force’s F-22 aircraft fleet. The modernization program comprises upgrading existing systems requirements, developing new systems requirements, adding capabilities and enhancing the performance of the weapon systems. The sustainment program consists of sustaining the weapon systems of the F-22 fleet, providing training systems, customer support, integrated support planning, supply chain management, aircraft modifications and heavy maintenance, systems engineering and support products.
Aeronautics provides sustainment services for the existing U.S. Air Force C-5 Galaxy fleet and modernization activities to convert 52 C-5 Galaxy aircraft to the C-5M Super Galaxy configuration. These modernization activities include the installation of new engines, landing gear and systems and other improvements that enable a shorter takeoff, a higher climb rate, an increased cargo load and longer flight range. As of December 31, 2016, we had delivered 41 C-5M aircraft under these modernization activities, including nine C-5M aircraft delivered in 2016. As of December 31, 2016, we have 11 C-5 aircraft in backlog with backlog extending into 2018.
Table of Contents
In addition to the above aircraft programs, Aeronautics is involved in advanced development programs incorporating innovative design and rapid prototype applications. Our Advanced Development Programs (ADP) organization, also known as Skunk Works®, is focused on future systems, including unmanned aerial systems and next generation capabilities for advanced strike, intelligence, surveillance, reconnaissance, situational awareness and air mobility. We continue to explore technology advancement and insertion in our existing aircraft. We also are involved in numerous network-enabled activities that allow separate systems to work together to increase effectiveness and we continue to invest in new technologies to maintain and enhance competitiveness in military aircraft design, development and production.
Missiles and Fire Control
In 2016, our MFC business segment generated net sales of $6.6 billion, which represented 14% of our total consolidated net sales. MFC’s customers include the military services, principally the U.S. Army, and various government agencies of the U.S. and other countries, as well as commercial and other customers. In 2016, U.S. Government customers accounted for 61%, international customers accounted for 37% and U.S. commercial and other customers accounted for 2% of MFC’s net sales.
MFC provides air and missile defense systems; tactical missiles and air-to-ground precision strike weapon systems; logistics; fire control systems; mission operations support, readiness, engineering support and integration services; manned and unmanned ground vehicles; and energy management solutions. MFC’s major programs include:
| • | The Patriot Advanced Capability-3 (PAC-3) and Terminal High Altitude Area Defense (THAAD) air and missile defense programs. PAC-3 is an advanced defensive missile for the U.S. Army and international customers designed to intercept and eliminate incoming airborne threats using kinetic energy. THAAD is a transportable defensive missile system for the U.S. Government and international customers designed to engage targets both within and outside of the Earth’s atmosphere. |
|---|
| • | The Multiple Launch Rocket System (MLRS), Hellfire, Joint Air-to-Surface Standoff Missile (JASSM) and Javelin tactical missile programs. MLRS is a highly mobile, automatic system that fires surface-to-surface rockets and missiles from the M270 and High Mobility Artillery Rocket System platforms produced for the U.S. Army and international customers. Hellfire is an air-to-ground missile used on rotary and fixed-wing aircraft, which is produced for the U.S. Army, Navy, Marine Corps and international customers. JASSM is an air-to-ground missile launched from fixed-wing aircraft, which is produced for the U.S. Air Force and international customers. Javelin is a shoulder-fired anti-armor rocket system, which is produced for the U.S. Army, Marine Corps and international customers. |
|---|
| • | The Apache, Sniper® and Low Altitude Navigation and Targeting Infrared for Night (LANTIRN®) fire control systems programs. The Apache fire control system provides weapons targeting capability for the Apache helicopter for the U.S. Army and international customers. Sniper is a targeting system for several fixed-wing aircraft and LANTIRN is a combined navigation and targeting system for several fixed-wing aircraft. Both Sniper and LANTIRN are produced for the U.S. Air Force and international customers. |
|---|
| • | The Special Operations Forces Contractor Logistics Support Services (SOF CLSS) program provides logistics support services to the special operations forces of the U.S. military. In 2016 we submitted a bid for the Special Operations Forces Global Logistics Support Services (SOF GLSS) contract, which is a competitive follow-on contract to SOF CLSS. We anticipate an award decision on the follow-on contract in mid-2017. |
|---|
Rotary and Mission Systems
In 2016, our RMS business segment, previously known as Mission Systems and Training (MST), generated net sales of $13.5 billion, which represented 28% of our total consolidated net sales. RMS’ customers include the military services, principally the U.S. Army and Navy, and various government agencies of the U.S. and other countries, as well as commercial and other customers. In 2016, U.S. Government customers accounted for 68%, international customers accounted for 28% and U.S. commercial and other customers accounted for 4% of RMS’ net sales.
RMS provides design, manufacture, service and support for a variety of military and commercial helicopters; ship and submarine mission and combat systems; mission systems and sensors for rotary and fixed-wing aircraft; sea and land-based missile defense systems; radar systems; the Littoral Combat Ship (LCS); simulation and training services; and unmanned systems and technologies. In addition, RMS supports the needs of government customers in cybersecurity and delivers communications and command and control capabilities through complex mission solutions for defense applications.
On November 6, 2015, we acquired Sikorsky Aircraft Corporation (Sikorsky) and aligned it under our RMS business segment. Sikorsky is one of the world’s largest helicopter companies and designs, manufactures, services and supports military and commercial helicopters. Additionally, Sikorsky offers full-spectrum aftermarket service and support solutions to commercial and military customers worldwide.
Table of Contents
RMS’ major programs include:
| • | The Black Hawk and Seahawk helicopters manufactured for U.S. and foreign governments. |
|---|
| • | The Aegis Combat System serves as a fleet ballistic missile defense system for the U.S. Navy and international customers and is also a sea and land-based element of the U.S. missile defense system. |
|---|
| • | The LCS, a surface combatant ship for the U.S. Navy designed to operate in shallow waters and the open ocean. |
|---|
| • | The Advanced Hawkeye Radar System, an airborne early warning radar, which RMS provides for the E2-C/E2-D aircraft produced for the U.S. Navy and international customers. |
|---|
| • | The Space Fence system, an advanced ground-based radar system for the U.S. Air Force designed to enhance the way objects in space are tracked and increase the ability to prevent collisions between such objects. |
|---|
| • | The CH-53K development helicopter delivering the next generation heavy lift helicopter for the U.S. Marine Corps. |
|---|
| • | The VH-92A helicopter manufactured for the U.S. Marine One transport mission. |
|---|
| • | The TPQ-53 Radar System, a sensor that quickly locates and neutralizes mortar and rocket threats, produced for the U.S. Army and international customers. |
|---|
Space Systems
In 2016, our Space Systems business segment generated net sales of $9.4 billion, which represented 20% of our total consolidated net sales. Space Systems’ customers include various U.S. government agencies and commercial customers. In 2016, U.S. Government customers accounted for 91%, international customers accounted for 5% and U.S. commercial and other customers accounted for 4% of Space Systems’ net sales. Net sales from Space Systems’ satellite products and services represented 13%, 15% and 16% of our total consolidated net sales in 2016, 2015 and 2014.
Space Systems is engaged in the research and development, design, engineering and production of satellites, strategic and defensive missile systems and space transportation systems. Space Systems provides network-enabled situational awareness and integrates complex space and ground global systems to help our customers gather, analyze and securely distribute critical intelligence data. Space Systems is also responsible for various classified systems and services in support of vital national security systems. Space Systems’ other major programs include:
| • | The Trident II D5 Fleet Ballistic Missile, a program with the U.S. Navy for the only submarine-launched intercontinental ballistic missile currently in production in the U.S. |
|---|
| • | The Orion Multi-Purpose Crew Vehicle (Orion), a spacecraft for the National Aeronautics and Space Administration (NASA) utilizing new technology for human exploration missions beyond low earth orbit. |
|---|
| • | The Space Based Infrared System (SBIRS), which provides the U.S. Air Force with enhanced worldwide missile launch detection and tracking capabilities. |
|---|
| • | The Advanced Extremely High Frequency (AEHF) system, the next generation of highly secure communications satellites for the U.S. Air Force. |
|---|
| • | AWE venture, which operates the United Kingdom’s nuclear deterrent program. |
|---|
| • | Global Positioning System (GPS) III, a program to modernize the GPS satellite system for the U.S. Air Force. |
|---|
| • | The Geostationary Operational Environmental Satellite R-Series (GOES-R), which is the National Oceanic and Atmospheric Association’s next generation of meteorological satellites. |
|---|
| • | The Mobile User Objective System (MUOS), a next-generation narrow-band satellite communication system for the U.S. Navy. |
|---|
On August 24, 2016, we obtained a controlling interest in the AWE venture, and as a result, we are required to consolidate AWE. Previously, we accounted for our investment in AWE using the equity method of accounting. See “Note 3 – Acquisitions and Divestitures” included in our Notes to Consolidated Financial Statements for additional information about the consolidation of AWE. Operating profit for our Space Systems business segment also includes our share of earnings for our 50% ownership interest in United Launch Alliance (ULA).
Financial and Other Business Segment Information
For additional information regarding our business segments, including comparative segment net sales, operating profit and related financial information for 2016, 2015, and 2014, see “Business Segment Results of Operations” in Management’s Discussion and Analysis of Financial Condition and Results of Operations and “Note 5 – Information on Business Segments” included in our Notes to Consolidated Financial Statements.
Table of Contents
Competition
Our broad portfolio of products and services competes both domestically and internationally against products and services of other large aerospace and defense companies, as well as numerous smaller competitors. We often form teams with our competitors in efforts to provide our customers with the best mix of capabilities to address specific requirements. In some areas of our business, customer requirements are changing to encourage expanded competition and increasingly what would have previously been competed as a single large procurement is being broken into multiple smaller procurements. Principal factors of competition include the value of our products and services to the customer; technical and management capability; the ability to develop and implement complex, integrated system architectures; total cost of ownership; our demonstrated ability to execute and perform against contract requirements; and our ability to provide timely solutions. Technological advances in such areas as: additive manufacturing, cloud computing, advanced materials, autonomy, robotics, and big data and new business models such as commercial access to space are enabling new factors of competition for both traditional and non-traditional competitors.
The competition for international sales is generally subject to U.S. Government stipulations (e.g., export restrictions, market access, technology transfer, industrial cooperation and contracting practices). We may compete against U.S. and non-U.S. companies (or teams) for contract awards by international governments. International competitions also may be subject to different laws or contracting practices of international governments that may affect how we structure our bid for the procurement. In many international procurements, the purchasing government’s relationship with the U.S. and its industrial cooperation programs are also important factors in determining the outcome of a competition. It is common for international customers to require contractors to comply with their industrial cooperation regulations, sometimes referred to as offset requirements, and we have entered into foreign offset agreements as part of securing some international business. For more information concerning offset agreements, see “Contractual Commitments and Off-Balance Sheet Arrangements” in Management’s Discussion and Analysis of Financial Condition and Results of Operations.
Patents
We routinely apply for and own a substantial number of U.S. and international patents related to the products and services we provide. In addition to owning a large portfolio of intellectual property, we also license intellectual property to and from third parties. The U.S. Government has licenses in our patents that are developed in performance of government contracts and it may use or authorize others to use the inventions covered by these patents for government purposes. Unpatented research, development and engineering skills also make an important contribution to our business. Although our intellectual property rights in the aggregate are important to the operation of our business, we do not believe that any existing patent, license or other intellectual property right is of such importance that its loss or termination would have a material adverse effect on our business taken as a whole.
Raw Materials and Seasonality
Some of our products require relatively scarce raw materials. Historically, we have been successful in obtaining the raw materials and other supplies needed in our manufacturing processes. We seek to manage raw materials supply risk through long-term contracts and by maintaining an acceptable level of the key materials in inventories.
Aluminum and titanium are important raw materials used in certain of our Aeronautics and Space Systems programs. Long-term agreements have helped enable a continued supply of aluminum and titanium. Carbon fiber is an important ingredient in composite materials used in our Aeronautics programs, such as the F-35 aircraft. We have been advised by some suppliers that pricing and the timing of availability of materials in some commodities markets can fluctuate widely. These fluctuations may negatively affect the price and availability of certain materials. While we do not anticipate material problems regarding the supply of our raw materials and believe that we have taken appropriate measures to mitigate these variations, if key materials become unavailable or if pricing fluctuates widely in the future, it could result in delay of one or more of our programs, increased costs or reduced operating profits.
No material portion of our business is considered to be seasonal. Various factors can affect the distribution of our sales between accounting periods, including the timing of government awards, the availability of government funding, product deliveries and customer acceptance.
Government Contracts and Regulations
Our business is heavily regulated. We contract with numerous U.S. Government agencies and entities, principally all branches of the U.S. military and NASA. We also contract with similar government authorities in other countries and they
Table of Contents
regulate our international efforts. Additionally, our commercial aircraft products are required to comply with U.S. and international regulations governing production and quality systems, airworthiness and installation approvals, repair procedures and continuing operational safety.
We must comply with, and are affected by, laws and regulations relating to the formation, administration and performance of U.S. Government and other governments’ contracts. These laws and regulations, among other things:
| • | require certification and disclosure of all cost or pricing data in connection with certain types of contract negotiations; |
|---|
| • | impose specific and unique cost accounting practices that may differ from U.S. generally accepted accounting principles; |
|---|
| • | impose acquisition regulations, which may change or be replaced over time, that define allowable and unallowable costs, the allocability of costs, and otherwise govern our right to reimbursement under certain U.S. Government and foreign contracts; |
|---|
| • | require specific security controls to protect U.S. Government controlled unclassified information and restrict the use and dissemination of information classified for national security purposes and the export of certain products, services and technical data; and |
|---|
| • | require the review and approval of contractor business systems, defined in the regulations as: (i) Accounting System; (ii) Estimating System; (iii) Earned Value Management System, for managing cost and schedule performance on certain complex programs; (iv) Purchasing System; (v) Material Management and Accounting System, for planning, controlling and accounting for the acquisition, use, issuing and disposition of material; and (vi) Property Management System. |
|---|
The U.S. Government and other governments may terminate any of our government contracts and subcontracts either at its convenience or for default based on our performance. If a contract is terminated for convenience, we generally are protected by provisions covering reimbursement for costs incurred on the contract and profit on those costs. If a contract is terminated for default, we generally are entitled to payments for our work that has been accepted by the U.S. Government or other governments; however, the U.S. Government and other governments could make claims to reduce the contract value or recover its procurement costs and could assess other special penalties. For more information regarding the U.S. Government’s and other governments’ right to terminate our contracts, see Item 1A – Risk Factors. For more information regarding government contracting laws and regulations, see Item 1A – Risk Factors as well as “Critical Accounting Policies – Contract Accounting / Sales Recognition” in Management’s Discussion and Analysis of Financial Condition and Results of Operations. For more information on the risks of doing work internationally, see Item 1A – Risk Factors. Additionally, the U.S. Government may also enter into unilateral contract actions, which they recently did on the F-35 program. This can affect our ability to negotiate mutually agreeable contract terms.
A portion of our business is classified by the U.S. Government and cannot be specifically described. The operating results of these classified contracts are included in our consolidated financial statements. The business risks associated with classified contracts historically have not differed materially from those of our other U.S. Government contracts. Our internal controls addressing the financial reporting of classified contracts are consistent with our internal controls for our non-classified contracts.
Our operations are subject to and affected by various federal, state, local and foreign environmental protection laws and regulations regarding the discharge of materials into the environment or otherwise regulating the protection of the environment. While the extent of our financial exposure cannot in all cases be reasonably estimated, the costs of environmental compliance have not had, and we do not expect that these costs will have, a material adverse effect on our earnings, financial position and cash flow, primarily because most of our environmental costs are allowable in establishing the price of our products and services under our contracts with the U.S. Government. For information regarding these matters, including current estimates of the amounts that we believe are required for remediation or cleanup to the extent that they are probable and estimable, see “Critical Accounting Policies – Environmental Matters” in Management’s Discussion and Analysis of Financial Condition and Results of Operations and “Note 14 – Legal Proceedings, Commitments and Contingencies” included in our Notes to Consolidated Financial Statements. See also the discussion of environmental matters within Item 1A – Risk Factors.
Backlog
At December 31, 2016, our backlog was $96.2 billion compared with $94.8 billion at December 31, 2015. Backlog at December 31, 2015 excludes $4.8 billion related to the IS&GS business, which we divested in 2016. Backlog is converted into sales in future periods as work is performed or deliveries are made. Approximately $34 billion, or 35%, of our backlog at December 31, 2016 is expected to be converted into sales in 2017.
Table of Contents
Our backlog includes both funded (firm orders for our products and services for which funding has been both authorized and appropriated by the customer) and unfunded (firm orders for which funding has not been appropriated) amounts. We do not include unexercised options or potential orders under indefinite-delivery, indefinite-quantity agreements in our backlog. If any of our contracts with firm orders were to be terminated, our backlog would be reduced by the expected value of the unfilled orders of such contracts. Funded backlog was $66.0 billion at December 31, 2016, as compared to $67.6 billion at December 31, 2015. Funded backlog at December 31, 2015 excludes $3.1 billion related to the IS&GS business, which we divested in 2016. For backlog related to each of our business segments, see “Business Segment Results of Operations” in Management’s Discussion and Analysis of Financial Condition and Results of Operations.
Research and Development
We conduct research and development (R&D) activities under customer-sponsored contracts and with our own independent R&D funds. Our independent R&D costs include basic research, applied research, development, systems and other concept formulation studies. Generally, these costs are allocated among all contracts and programs in progress under U.S. Government contractual arrangements. Costs we incur under customer-sponsored R&D programs pursuant to contracts are included in net sales and cost of sales. Under certain arrangements in which a customer shares in product development costs, our portion of the unreimbursed costs is expensed as incurred in cost of sales. Independent R&D costs charged to cost of sales were $988 million in 2016, $817 million in 2015, and $733 million in 2014. See “Research and development and similar costs” in “Note 1 – Significant Accounting Policies” included in our Notes to Consolidated Financial Statements.
Employees
At December 31, 2016, we had approximately 97,000 employees, about 92% of whom were located in the U.S. Approximately 21% of our employees are covered by collective bargaining agreements with various unions. A number of our existing collective bargaining agreements expire in any given year. Historically, we have been successful in negotiating renewals to expiring agreements without any material disruption of operating activities. Management considers employee relations to be good.
Available Information
We are a Maryland corporation formed in 1995 by combining the businesses of Lockheed Corporation and Martin Marietta Corporation. Our principal executive offices are located at 6801 Rockledge Drive, Bethesda, Maryland 20817. Our telephone number is (301) 897-6000 and our website home page is at www.lockheedmartin.com. We make our website content available for information purposes only. It should not be relied upon for investment purposes, nor is it incorporated by reference into this Annual Report on Form 10-K (Form 10-K).
Throughout this Form 10-K, we incorporate by reference information from parts of other documents filed with the U.S. Securities and Exchange Commission (SEC). The SEC allows us to disclose important information by referring to it in this manner.
Our annual reports on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, proxy statements for our annual stockholders’ meetings and amendments to those reports are available free of charge on our website, www.lockheedmartin.com/investor, as soon as reasonably practical after we electronically file the material with, or furnish it to, the SEC. In addition, copies of our annual report will be made available, free of charge, upon written request. The SEC also maintains a website at www.sec.gov that contains reports, proxy statements and other information regarding SEC registrants, including Lockheed Martin Corporation.
Forward-Looking Statements
This Form 10-K contains statements that, to the extent they are not recitations of historical fact, constitute forward-looking statements within the meaning of the federal securities laws and are based on our current expectations and assumptions. The words “believe,” “estimate,” “anticipate,” “project,” “intend,” “expect,” “plan,” “outlook,” “scheduled,” “forecast” and similar expressions are intended to identify forward-looking statements. These statements are not guarantees of future performance and are subject to risks and uncertainties.
Statements and assumptions with respect to future sales, income and cash flows, program performance, the outcome of litigation, anticipated pension cost and funding, environmental remediation cost estimates, planned acquisitions or dispositions of assets, or the anticipated consequences are examples of forward-looking statements. Numerous factors, including the risk factors described in the following section, could affect our forward-looking statements and actual performance.
Table of Contents
Our actual financial results likely will be different from those projected due to the inherent nature of projections. Given these uncertainties, forward-looking statements should not be relied on in making investment decisions. The forward-looking statements contained in this Form 10-K speak only as of the date of its filing. Except where required by applicable law, we expressly disclaim a duty to provide updates to forward-looking statements after the date of this Form 10-K to reflect subsequent events, changed circumstances, changes in expectations, or the estimates and assumptions associated with them. The forward-looking statements in this Form 10-K are intended to be subject to the safe harbor protection provided by the federal securities laws.
Item 1A. Risk Factors.
| --- | --- |
An investment in our common stock or debt securities involves risks and uncertainties. We seek to identify, manage and mitigate risks to our business, but risk and uncertainty cannot be eliminated or necessarily predicted. The outcome of one or more of these risks could have a material effect on our operating results, financial position, or cash flows. You should carefully consider the following factors, in addition to the other information contained in this Annual Report on Form 10-K, before deciding to purchase our common stock or debt securities.
We depend heavily on contracts with the U.S. Government for a substantial portion of our business.
We derived 71% of our total net sales from the U.S. Government in 2016, including 59% from the Department of Defense (DoD). We expect to continue to derive most of our sales from work performed under U.S. Government contracts. Those contracts are conditioned upon the continuing availability of Congressional appropriations. Congress usually appropriates funds on a fiscal-year basis even though contract performance may extend over many years. Consequently, contracts are often partially funded initially and additional funds are committed only as Congress makes further appropriations. If we incur costs in excess of funds obligated on a contract, we may be at risk for reimbursement of those costs unless and until additional funds are obligated to the contract.
As discussed within the “Industry Considerations” in Management’s Discussion and Analysis of Financial Condition and Results of Operations, the U.S. Government continues to face significant deficit reduction pressures and it is likely that discretionary spending by the U.S. Government will remain constrained for a number of years. Under such conditions, large or complex programs, which consist of multiple contracts and phases, are potentially subject to increased scrutiny.
There is also uncertainty regarding actions that may be taken by the new Presidential Administration in light of recent criticisms of the F-35 program and other large defense programs. President Trump has publicly expressed concerns over past cost overruns and delays in the program as well as overall program cost and has publicly requested that a competitor price out an alternative. Defense Secretary Mattis recently ordered a review of the program, including a comparison review of the F-35C carrier variant with a fourth generation alternative. Our Chairman, President and Chief Executive Officer has had discussions with President Trump on the importance of the F-35 program and our commitment to cut costs. However, we may continue to face pressure to reduce costs from the new Presidential Administration relating to the F-35 program and ongoing contract negotiations.
The F-35 is our largest program and represented 23% of our total net sales in 2016 and is expected to represent a higher percentage of our sales in future years. A decision to cut spending or reduce planned orders would have an adverse impact on our results of operations. Given the size and complexity of the F-35 program, we anticipate that there will be continual reviews related to aircraft performance, program schedule, cost, and requirements as part of the DoD, Congressional, and international partners’ oversight and budgeting processes. Current program challenges include, but are not limited to, supplier and partner performance, software development, level of cost associated with life cycle operations and sustainment and warranties, successfully negotiating and receiving funding for production contracts on a timely basis, executing future flight tests and findings resulting from testing and operating the aircraft. Additionally, the U.S. Government may also enter into unilateral contract actions, which they recently did on the F-35 program. This unilateral contract action obligates us to perform under terms and conditions imposed by the U.S. Government. Unilateral contract actions could negatively affect profit and cash flows, and establish a precedent for future contracts.
Based upon our diverse range of defense, homeland security and information technology products and services, we believe that this makes it less likely that cuts in any specific contract or program will have a long-term effect on our business. However, termination of multiple or large programs or contracts could adversely affect our business and future financial performance. Potential changes in funding priorities may afford new or additional opportunities for our businesses in terms of existing, follow-on or replacement programs. While we would expect to compete and be well positioned as the incumbent on existing programs, we may not be successful or the replacement programs may be funded at lower levels.
Table of Contents
We are subject to a number of procurement laws and regulations. Our business and our reputation could be adversely affected if we fail to comply with these laws.
We must comply with and are affected by laws and regulations relating to the award, administration and performance of U.S. Government contracts. Government contract laws and regulations affect how we do business with our customers and impose certain risks and costs on our business. A violation of specific laws and regulations, by us, our employees, others working on our behalf, a supplier or a venture partner, could harm our reputation and result in the imposition of fines and penalties, the termination of our contracts, suspension or debarment from bidding on or being awarded contracts, loss of our ability to export products or services and civil or criminal investigations or proceedings.
In some instances, these laws and regulations impose terms or rights that are different from those typically found in commercial transactions. For example, the U.S. Government may terminate any of our government contracts and subcontracts either at its convenience or for default based on our performance. Upon termination for convenience of a fixed-price type contract, we normally are entitled to receive the purchase price for delivered items, reimbursement for allowable costs for work-in-process and an allowance for profit on the contract or adjustment for loss if completion of performance would have resulted in a loss.
Upon termination for convenience of a cost-reimbursable contract, we normally are entitled to reimbursement of allowable costs plus a portion of the fee. Allowable costs would include our cost to terminate agreements with our suppliers and subcontractors. The amount of the fee recovered, if any, is related to the portion of the work accomplished prior to termination and is determined by negotiation. We attempt to ensure that adequate funds are available by notifying the customer when its estimated costs, including those associated with a possible termination for convenience, approach levels specified as being allotted to its programs. As funds are typically appropriated on a fiscal-year basis and as the costs of a termination for convenience may exceed the costs of continuing a program in a given fiscal year, occasionally programs do not have sufficient funds appropriated to cover the termination costs were the government to terminate them for convenience. Under such circumstances, the U.S. Government could assert that it is not required to appropriate additional funding.
A termination arising out of our default may expose us to liability and have a material adverse effect on our ability to compete for future contracts and orders. In addition, on those contracts for which we are teamed with others and are not the prime contractor, the U.S. Government could terminate a prime contract under which we are a subcontractor, notwithstanding the quality of our services as a subcontractor. In the case of termination for default, the U.S. Government could make claims to reduce the contract value or recover its procurement costs and could assess other special penalties. However, under such circumstances we have rights and remedial actions under laws and the Federal Acquisition Regulation (FAR).
In addition, certain of our U.S. Government contracts span one or more base years and multiple option years. The U.S. Government generally has the right not to exercise option periods and may not exercise an option period for various reasons. However, the U.S. Government may exercise option periods, even for contracts for which it is expected that our costs may exceed the contract price or ceiling.
U.S. Government agencies, including the Defense Contract Audit Agency, the Defense Contract Management Agency and various agency Inspectors General, routinely audit and investigate government contractors. These agencies review a contractor’s performance under its contracts, its cost structure, its business systems and compliance with applicable laws, regulations and standards. The U.S. Government has the ability to decrease or withhold certain payments when it deems systems subject to its review to be inadequate. Additionally, any costs found to be misclassified may be subject to repayment. We have unaudited and/or unsettled incurred cost claims related to past years, which places risk on our ability to issue final billings on contracts for which authorized and appropriated funds may be expiring.
If an audit or investigation uncovers improper or illegal activities, we may be subject to civil or criminal penalties and administrative sanctions, including reductions of the value of contracts, contract modifications or terminations, forfeiture of profits, suspension of payments, penalties, fines and suspension, or prohibition from doing business with the U.S. Government. In addition, we could suffer serious reputational harm if allegations of impropriety were made against us. Similar government oversight exists in most other countries where we conduct business.
Our profitability and cash flow may vary based on the mix of our contracts and programs, our performance, our ability to control costs and evolving U.S. Government procurement policies.
Our profitability and cash flow may vary materially depending on the types of government contracts undertaken, the nature of products produced or services performed under those contracts, the costs incurred in performing the work, the achievement of other performance objectives and the stage of performance at which the right to receive fees is determined, particularly under award and incentive-fee contracts.
Table of Contents
Our backlog includes a variety of contract types that are intended to address changing risk and reward profiles as a program matures. Contract types include cost-reimbursable, fixed-price incentive-fee, fixed-price and time-and-materials contracts. Contracts for development programs with complex design and technical challenges are typically cost-reimbursable. Under cost-reimbursable contracts, we are reimbursed for allowable costs and paid a fee, which may be fixed or performance-based. In these cases, the associated financial risks primarily relate to a reduction in fees and the program could be cancelled if cost, schedule or technical performance issues arise.
Other contracts in backlog are for the transition from development to production (e.g., LRIP contracts), which includes the challenge of starting and stabilizing a manufacturing production and test line while the final design is being validated. These generally are cost-reimbursable or fixed-price incentive-fee contracts. Under a fixed-price incentive-fee contract, the allowable costs incurred are eligible for reimbursement but are subject to a cost-share arrangement, which affects profitability. Generally, if our costs exceed the contract target cost or are not allowable under the applicable regulations, we may not be able to obtain reimbursement for all costs and may have our fees reduced or eliminated.
There are also contracts for production, as well as operations and maintenance of the delivered products, that have the challenge of achieving a stable production and delivery rate, while maintaining operability of the product after delivery. These contracts are mainly fixed-price, although some operations and maintenance contracts are time-and-materials type. Under fixed-price contracts, we receive a fixed price regardless of the actual costs we incur. We have to absorb any costs in excess of the fixed price. Under time-and-materials contracts, we are paid for labor at negotiated hourly billing rates and for certain expenses.
The failure to perform to customer expectations and contract requirements may result in reduced fees or losses and affect our financial performance in that period. Under each type of contract, if we are unable to control costs, our operating results could be adversely affected, particularly if we are unable to justify an increase in contract value to our customers. Cost overruns or the failure to perform on existing programs also may adversely affect our ability to retain existing programs and win future contract awards.
The U.S. Government is currently pursuing and implementing policies that could negatively impact our profitability. Changes in procurement policy favoring more incentive-based fee arrangements, different award fee criteria or government contract negotiation offers based upon the customer’s view of what our costs should be (as compared to our actual costs) may affect the predictability of our profit rates. The U.S. Government’s unilateral contract action definitizing the LRIP 9 F-35 contract reflected differing U.S. Government and Lockheed Martin views as to costs, entitlement to performance-based payments and profitability and could negatively impact the profitability and cash flows of LRIP 9, LRIP 10 (which remains an undefinitized contract) and future production contracts. Our customers are subject to pressures that may result in a change in contract types referenced above earlier in a program’s maturity than is traditional. An example of this is the use of fixed-price incentive-fee contracts for recent LRIP contracts on the F-35 program while the development contract is being performed concurrently. Our customers also may pursue non-traditional contract provisions in negotiation of contracts. For example, changes resulting from the F-35 development contract may need to be implemented on the production contracts (including the LRIP contracts), a concept referred to as concurrency, which may require us to pay for a portion of the concurrency costs. An example of customer budget pressures includes the U.S. Government requiring that bid and proposal costs be included in general and administrative costs, rather than charged directly to contracts in certain circumstances.
Other policies could negatively impact our working capital and cash flow. For example, the government has expressed a preference for requiring progress payments rather than performance based payments on new fixed-price contracts, which if implemented, delays our ability to recover a significant amount of costs incurred on a contract and thus affects the timing of our cash flows.
Increased competition and bid protests in a budget-constrained environment may make it more difficult to maintain our financial performance and customer relationships.
We are experiencing increased competition while, at the same time, our customers are facing budget constraints, trying to do more with less by cutting costs, identifying more affordable solutions, performing certain work internally rather than hiring a contractor, and reducing product development cycles. It is critical we maintain strong customer relationships and seek to understand the priorities of their requirements in this price competitive environment.
In international sales, we face substantial competition from both U.S. manufacturers and international manufacturers whose governments sometimes provide research and development assistance, marketing subsidies and other assistance for their products. Additionally, our competitors are also focusing on increasing their international sales to partially mitigate the
Table of Contents
effect of reduced U.S. Government budgets. To remain competitive, we consistently must maintain strong customer relationships and provide superior performance, advanced technology solutions and service at an affordable cost and with the agility that our customers require to satisfy their mission objectives.
A substantial portion of our business is awarded through competitive bidding. The U.S. Government increasingly has relied upon competitive contract award types, including indefinite-delivery, indefinite-quantity and other multi-award contracts, which have the potential to create pricing pressure and increase our cost by requiring that we submit multiple bids and proposals. In addition, multi-award contracts require that we make sustained efforts to obtain task orders under the contract. The competitive bidding process entails substantial costs and managerial time to prepare bids and proposals for contracts that may not be awarded to us or may be split among competitors. Additionally, the former IS&GS programs we moved to RMS and Space Systems in the fourth quarter of 2015 and retained could experience increased pricing pressures which could have a negative impact on our ability to win future follow-on contracts. Following award, we may encounter significant expenses, delays, contract modifications or bid protests from unsuccessful bidders on new program awards. Unsuccessful bidders are more frequently protesting in the hope of being awarded a subcontract for a portion of the work in return for withdrawing the protest. Bid protests could result in significant expenses to us, contract modifications or even loss of the contract award. Even where a bid protest does not result in the loss of a contract award, the resolution can extend the time until the contract activity can begin and, as a result, delay our recognizing sales. We also may not be successful in our efforts to protest or challenge any bids for contracts that were not awarded to us and we could incur significant time and expense in such efforts.
We are the prime contractor on most of our contracts and if our subcontractors, suppliers or teaming agreement or venture partners fail to perform their obligations, our performance and our ability to win future business could be harmed.
For most of our contracts we rely on other companies to provide materials, major components and products, and to perform a portion of the services that we provide to our customers. Such arrangements may involve subcontracts, teaming arrangements, ventures or supply agreements with other companies upon which we rely (contracting parties). There is a risk that we may have disputes with our contracting parties, including disputes regarding the quality and timeliness of work performed, the workshare provided to that party, customer concerns about the other party’s performance, our failure to extend existing task orders or issue new task orders, or our hiring the personnel of a subcontractor, teammate or venture partner or vice versa. In addition, changes in the economic environment, including defense budgets and constraints on available financing, may adversely affect the financial stability of our contracting parties and their ability to meet their performance requirements or to provide needed supplies on a timely basis as might their inability to perform profitably in the current highly competitive and budget constrained environment. A failure, for whatever reason, by one or more of our contracting parties to provide the agreed-upon supplies or perform the agreed-upon services on a timely basis, according to specifications, or at all may affect our ability to perform our obligations and require that we transition the work to other companies. Contracting party performance deficiencies may result in additional costs or delays in product deliveries and affect our operating results and could result in a customer terminating our contract for default or convenience. A default termination could expose us to liability and affect our ability to compete for future contracts and orders. Additionally, our efforts to increase the efficiency of our operations and improve the affordability of our products and services could negatively impact our ability to attract and retain suppliers.
International sales may pose different risks.
In 2016, 27% of our total net sales were from international customers. We have a strategy to grow international sales over the next several years, inclusive of sales of F-35 aircraft to our international partners and other countries. International sales are subject to numerous political and economic factors, regulatory requirements, significant competition, taxation, and other risks associated with doing business in foreign countries. Our exposure to such risks increased as a result of our acquisition of Sikorsky and our increased ownership interest in AWE and may further increase if our international sales grow as we anticipate.
Our international business is conducted through foreign military sales (FMS) contracted through the U.S. Government or by direct commercial sales (DCS) with international customers. In 2016, approximately 66% of our sales to international customers were FMS and about 34% were DCS. These transaction types differ as FMS transactions represent sales by the U.S. Government to international governments and our contract with the U.S. Government is subject to FAR. By contrast, DCS transactions represent sales directly to another international government or commercial customer. All sales to international customers are subject to U.S. and foreign laws and regulations, including, without limitation, regulations relating to anti-corruption, import-export control, technology transfer restrictions, taxation, repatriation of earnings, exchange
Table of Contents
controls, the Foreign Corrupt Practices Act and other anti-corruption laws, and the anti-boycott provisions of the U.S. Export Administration Act. While we have stringent policies in place to comply with such laws and regulations, failure by us, our employees or others working on our behalf to comply with these laws and regulations could result in administrative, civil, or criminal liabilities, including suspension, debarment from bidding for or performing government contracts, or suspension of our export privileges, which could have a material adverse effect on us. We frequently team with international subcontractors and suppliers who are also exposed to similar risks.
While international sales, whether contracted as FMS or DCS, present risks that are different and potentially greater than those encountered in our U.S. business, DCS with international customers may impose even greater risks. DCS transactions involve commercial relationships with parties with whom we have less familiarity and where there may be significant cultural differences. Additionally, international procurement rules and regulations, contract laws and regulations, and contractual terms differ from those in the U.S. and are less familiar to us. International regulations may be interpreted by foreign courts less bound by precedent and with more discretion; these interpretations frequently have terms less favorable to us than the FAR. Export and import, tax and currency risk also may be increased for DCS with international customers. While these risks are potentially greater than those encountered in our U.S. business, we seek to price our products and services commensurate with the risk profile on DCS with international customers.
Our international business is highly sensitive to changes in regulations, political environments or security risks that may affect our ability to conduct business outside of the U.S., including those regarding investment, procurement, taxation and repatriation of earnings. Our international business also may be impacted by changes in foreign national priorities, foreign government budgets, global economic conditions, and fluctuations in foreign currency exchange rates. Sales of military products are also affected by defense budgets and U.S. foreign policy. Additionally, the timing of orders from our international customers can be less predictable than for our U.S. customers and may lead to fluctuations in the amount reported each year for our international sales.
In conjunction with defense procurements, some international customers require contractors to comply with industrial cooperation regulations, including entering into industrial cooperation agreements, sometimes referred to as offset agreements. Offset agreements may require in-country purchases, technology transfers, local manufacturing support, investments in foreign joint ventures and financial support projects as an incentive or as a condition to a contract award. In some countries, these offset agreements may require the establishment of a venture with a local company, which must control the venture. The costs to satisfy our offset obligations are included in the estimates of our total costs to complete the contract and may impact our profitability and cash flows. The ability to recover investments that we make is generally dependent upon the successful operation of ventures that we do not control and may involve products and services that are dissimilar to our business activities. In these and other situations, we could be liable for violations of law for actions taken by these entities such as laws related to anti-corruption, import and export, taxation, and anti-boycott restrictions. Offset agreements generally extend over several years and may provide for penalties in the event we fail to perform in accordance with the offset requirements which are typically subjective and can be outside our control.
Our business could be negatively affected by cyber or other security threats or other disruptions.
We routinely experience various cybersecurity threats, threats to our information technology infrastructure, unauthorized attempts to gain access to our company sensitive information, denial-of-service attacks, threats to the security of our facilities and employees, and threats from terrorist acts, as do our customers, suppliers, subcontractors and venture partners. We may experience similar security threats at customer sites that we operate and manage.
The threats we face vary from attacks common to most industries to more advanced and persistent, highly organized adversaries who target us because we protect national security information. If we are unable to protect sensitive information, our customers or governmental authorities could question the adequacy of our threat mitigation and detection processes and procedures. Due to the evolving nature of these security threats, the impact of any future incident cannot be predicted.
Although we work cooperatively with our customers, suppliers, subcontractors, venture partners and acquisitions to seek to minimize the impact of cyber threats, other security threats, or business disruptions, we must rely on the safeguards put in place by these entities, which may affect the security of our information. These entities have varying levels of cybersecurity expertise and safeguards, and their relationships with government contractors, such as Lockheed Martin, may increase the likelihood that they are targeted by the same cyber threats we face.
The costs related to cyber or other security threats or disruptions may not be fully insured or indemnified by other means. Additionally, some cyber technologies we develop under contract for our customers, particularly those related to
Table of Contents
homeland security, may raise potential liabilities related to intellectual property and civil liberties, including privacy concerns, which may not be fully insured or indemnified by other means. Occurrence of any of these events could adversely affect our internal operations, the services we provide to our customers, our future financial results, our reputation, or our stock price. Additionally, such events could result in the loss of competitive advantages derived from our research and development efforts or other intellectual property; early obsolescence of our products and services; or contractual penalties.
If we fail to manage acquisitions, divestitures, equity investments and other transactions successfully or if acquired entities or equity investments fail to perform as expected, our financial results, business and future prospects could be harmed.
In pursuing our business strategy, we routinely conduct discussions, evaluate companies, and enter into agreements regarding possible acquisitions, divestitures, ventures and equity investments. We seek to identify acquisition or investment opportunities that will expand or complement our existing products and services or customer base, at attractive valuations. We often compete with others for the same opportunities. To be successful, we must conduct due diligence to identify valuation issues and potential loss contingencies; negotiate transaction terms; complete and close complex transactions; integrate acquired companies and employees; and realize anticipated operating synergies efficiently and effectively. Acquisition, divestiture, venture and investment transactions often require substantial management resources and have the potential to divert our attention from our existing business. Unidentified or identified but un-indemnified pre-closing liabilities could affect our future financial results, particularly successor liability under procurement laws and regulations such as the False Claims Act or Truth in Negotiations Act, anti-corruption, tax, import-export and technology transfer laws which provide for civil and criminal penalties and the potential for debarment. We also may incur unanticipated costs or expenses, including post-closing asset impairment charges, expenses associated with eliminating duplicate facilities, employee retention, transaction-related or other litigation, and other liabilities. Any of the foregoing could adversely affect our business and results of operations.
Ventures, or noncontrolling equity investments, operate under shared control with other parties. Under the equity method of accounting for nonconsolidated ventures and investments, we recognize our share of the operating profit of these ventures in our results of operations. Our operating results may be affected by the performance of businesses over which we do not exercise control, which includes the inability to influence strategic decisions that may adversely affect our business, financial condition and results of operations. Our joint ventures face many of the same risks and uncertainties as we do. The most significant impact of our equity investments is in our Space Systems business segment where approximately 25% of its 2016 operating profit was derived from its share of earnings from equity method investees, particularly that in United Launch Alliance (ULA). Approximately 3% and 7% of our Aeronautics and RMS business segments’ operating profit was derived from their shares of earnings from equity method investees, including their share in Advanced Military Maintenance, Repair and Overhaul Center LLC venture (AMMROC).
The acquired Sikorsky business may underperform relative to our expectations, the transaction may cause our financial results to differ from our expectations or the expectations of the investment community and we may not be able to achieve anticipated cost savings or other anticipated synergies.
On November 6, 2015, we completed the acquisition of Sikorsky. We believe that we will benefit from the integration of our products and technologies with those of the Sikorsky business and realize synergies and potential for long-term growth, as well as expanded capabilities and customer relationships as a result of the acquisition. However, we may not be able to capture anticipated synergies, tax benefits, cost savings, and business opportunities in the time frame anticipated, or at all. Changes to the Federal statutory tax rate could have an impact on the tax benefits we expect in connection with the acquisition. Due to the recent acquisition and valuation, the carrying value and fair value of our Sikorsky reporting unit are currently closely aligned. Therefore, any business deterioration, contract cancelations or terminations, or market pressures could cause our sales, earnings and cash flows to decline below current projections and could cause goodwill to be impaired. Additionally, Sikorsky may not perform as expected, or demand for its products may be adversely affected by global economic conditions, including oil and gas trends that are outside of their control.
If we fail to maintain an effective system of internal controls over financial reporting there is a reasonable possibility that a material misstatement of our annual or interim financial statements will not be prevented or detected on a timely basis.
Effective internal controls are necessary for us to provide reliable and accurate financial statements and to effectively prevent fraud. As further described, in Part II Item 9A “Controls and Procedures” management has concluded that, because of a material weakness in internal controls within Sikorsky’s processes (specifically, Sikorsky did not adequately identify,
Table of Contents
design and implement appropriate process-level controls for its processes and appropriate information technology controls for its information technology systems), which we acquired on November 6, 2015 and which operates as a business unit of our RMS business segment, our disclosure controls and procedures were not effective as of December 31, 2016. We have and we will continue to enhance our controls at our Sikorsky business unit and we expect that the remediation of this material weakness will be completed prior to the end of fiscal year 2017. However, we cannot be certain that these measures will be successful or that we will be able to prevent future significant deficiencies or material weaknesses. Material inaccuracies in our financial statements would impair their value to management and our Board of Directors in making decisions as to the operation of our business, could impair our reputation and cause investors to lose confidence in our reported financial information, which could have a negative effect on investor confidence in our financial statements, the trading price of our stock and our access to capital.
The divestiture of our Information Systems & Global Solutions business may not achieve the intended benefits and may expose us to potential risks and liabilities.
We completed the divestiture of our IS&GS business on August 16, 2016, which merged with a subsidiary of Leidos Holdings Inc. (Leidos), in a Reverse Morris Trust transaction. As part of the transaction, we also completed an exchange offer that resulted in a reduction of our outstanding common stock. We undertook the divestiture because we believed that this business could achieve greater growth and create more value for customers and stockholders outside of Lockheed Martin and that we could benefit from greater strategic focus of our resources and management efforts. We may not benefit as expected from the increased focus on our core business, strategic programs and objectives made possible by the split-off or from the reduced exposure to a shorter product cycle services business. Additionally, the value of the transaction may also be reduced by potential liabilities related to post-closing adjustments and indemnities, which could adversely affect our results of operations.
If the divestiture of our Information Systems & Global Solutions business or certain internal transactions undertaken in anticipation of the divestiture are determined to be taxable in whole or in part, we and our stockholders may incur significant tax liabilities.
In connection with the divestiture of our IS&GS business, we obtained opinions of outside tax counsel that the merger and exchange offer will qualify as tax-free transactions to us and our stockholders, except to the extent that cash was paid to Lockheed Martin stockholders in lieu of fractional shares. We have not sought or obtained a ruling from the Internal Revenue Service (IRS) on each of the tax consequences of the transaction. An opinion of counsel is not binding on the IRS or the courts, which may disagree with the opinion. In addition, the tax opinions are subject to customary qualifications and based on factual representations. Even if the merger and exchange offer otherwise qualified as tax-free transactions, they may become taxable to us if certain events occur that affect either Lockheed Martin or Leidos. While Leidos has agreed not to take certain actions that could cause the transactions not to qualify as tax-free transactions and is generally obligated to indemnify us against any tax consequences if it breaches this agreement, the potential tax liabilities could have a material adverse effect on us if we were not entitled to indemnification or if the indemnification obligations were not fulfilled. If the merger or exchange offer were determined to be taxable, we could be subject to a substantial tax liability, and each U.S. holder of our common stock who participated in the exchange offer could be treated as exchanging the Lockheed Martin shares surrendered for Abacus shares in a taxable transaction.
There can be no assurance that we will continue to increase our dividend or to repurchase shares of our common stock at current levels.
The payment of cash dividends and share repurchases is subject to limitations under applicable law and the discretion of our Board of Directors and is determined in light of then current conditions, including earnings, other operating results and capital requirements. Decreases in asset values or increases in liabilities, including liabilities associated with benefit plans and assets and liabilities associated with taxes, can reduce stockholders’ equity. A deficit in stockholders’ equity could limit our ability to pay dividends and make share repurchases under Maryland Law in the future. In addition, the timing and amount of share repurchases under board approved share repurchase plans is within the discretion of management and will depend on many factors, including results of operations, capital requirements as well as applicable law.
Our business involves significant risks and uncertainties that may not be covered by indemnity or insurance.
A significant portion of our business relates to designing, developing and manufacturing advanced defense and technology products and systems. New technologies may be untested or unproven. Failure of some of these products and services could result in extensive loss of life or property damage. Accordingly, we also may incur liabilities that are unique to our products and services, including combat and air mobility aircraft, missile and space systems, command and control
Table of Contents
systems, cybersecurity, homeland security and training programs. In some but not all circumstances, we may be entitled to certain legal protections or indemnifications from our customers, either through U.S. Government indemnifications under Public Law 85-804 or the Price-Anderson Act, qualification of our products and services by the Department of Homeland Security under the SAFETY Act provisions of the Homeland Security Act of 2002, contractual provisions or otherwise. We endeavor to obtain insurance coverage from established insurance carriers to cover these risks and liabilities. The amount of insurance coverage that we maintain may not be adequate to cover all claims or liabilities. Existing coverage may be cancelled while we remain exposed to the risk, and it is not possible to obtain insurance to protect against all operational risks and liabilities. For example, we are limited in the amount of insurance we can obtain to cover certain natural hazards, such as earthquakes. We have significant operations in geographic areas prone to this risk, such as Sunnyvale, California. Even if insurance coverage is available, we may not be able to obtain it at a price or on terms acceptable to us. Additionally, disputes with insurance carriers over coverage terms or the insolvency of one or more of our insurance carriers may significantly affect the amount or timing of our cash flows.
Substantial costs resulting from an accident; failure of or defect in our products or services; natural catastrophe or other incident; or liability arising from our products and services in excess of any legal protection, indemnity, and our insurance coverage (or for which indemnity or insurance is not available or not obtained) could adversely impact our financial condition, cash flows, or operating results. Any accident, failure of, or defect in our products or services, even if fully indemnified or insured, could negatively affect our reputation among our customers and the public and make it more difficult for us to compete effectively. It also could affect the cost and availability of adequate insurance in the future.
Pension funding and costs are dependent on several economic assumptions which if changed may cause our future earnings and cash flow to fluctuate significantly as well as affect the affordability of our products and services.
Many of our employees are covered by defined benefit pension plans, and we provide certain health care and life insurance benefits to eligible retirees. The impact of these plans on our U.S. generally accepted accounting principles (GAAP) earnings may be volatile in that the amount of expense we record for our postretirement benefit plans may materially change from year to year because those calculations are sensitive to funding levels as well as changes in several key economic assumptions, including interest rates, rates of return on plan assets, and other actuarial assumptions including participant longevity (also known as mortality), employee turnover, as well as the timing of cash funding. Changes in these factors, including actual returns on plan assets, may also affect our plan funding, cash flow and stockholders’ equity. In addition, the funding of our plans and recovery of costs on our contracts, as described below, also may be subject to changes caused by legislative or regulatory actions. We have taken certain actions over the last few years to mitigate the impact the plans may have on our cash flows and earnings, including amendments made in June 2014 to a significant portion of our qualified and nonqualified defined benefit pension plans for non-union employees to freeze future retirement benefits. However, the impact of these actions on our cash flow and earnings may be less than anticipated or may be offset by other factors such as changes in actuarial assumptions and plan asset investment returns.
With regard to cash flow, we have made substantial cash contributions to our plans as required by the Employee Retirement Income Security Act of 1974 (ERISA), as amended by the Pension Protection Act of 2006 (PPA). We generally are able to recover these contributions related to our plans as allowable costs on our U.S. Government contracts, including FMS, but there is a lag between when we contribute cash to our plans under pension funding rules and recover it under U.S. Government Cost Accounting Standards (CAS). Effective February 2012, the CAS rules were revised to harmonize the measurement and period assignment of the pension cost allocable to government contracts with the PPA (CAS Harmonization). In 2013, the cost impact of CAS Harmonization started being phased in with the goal of better aligning the CAS pension cost and ERISA funding requirements being fully achieved in 2017. The enactment of the Highway and Transportation Funding Act of 2014 and Bipartisan Budget Act of 2015 increased the interest rate assumption used to determine our CAS pension costs, which has the effect of lowering the recovery of pension contributions during the affected periods as it decreases our CAS pension costs.
For more information on how these factors could impact earnings, financial position, cash flow and stockholders’ equity, see “Critical Accounting Policies – Postretirement Benefit Plans” in Management’s Discussion and Analysis of Financial Conditions and Results of Operations and “Note 11 – Postretirement Plans” included in our Notes to Consolidated Financial Statements.
Environmental costs could affect our future earnings as well as the affordability of our products and services.
Our operations are subject to and affected by a variety of federal, state, local and foreign environmental protection laws and regulations. We are involved in environmental remediation at some of our facilities, some of our former facilities, and at
Table of Contents
third-party-owned sites where we have been designated a potentially responsible party. In addition, we could be affected by future regulations imposed or claims asserted in response to concerns over climate change, other aspects of the environment or natural resources. We have an ongoing comprehensive sustainability program to reduce the effects of our operations on the environment.
We manage and have managed various U.S. Government-owned facilities, and portions of U.S. Government-owned facilities, on behalf of the U.S. Government. At such facilities, environmental compliance and remediation costs historically have been the responsibility of the U.S. Government. We have relied, and continue to rely with respect to past practices, upon U.S. Government funding to pay such costs, notwithstanding efforts by some U.S. Government representatives to limit this responsibility. Although the U.S. Government remains responsible for capital and operating costs associated with environmental compliance, responsibility for fines and penalties associated with environmental noncompliance typically is borne by either the U.S. Government or the contractor, depending on the contract and the relevant facts. Some environmental laws include criminal provisions. An environmental law conviction could affect our ability to be awarded future, or perform existing, U.S. Government contracts.
We have incurred and will continue to incur liabilities under various federal, state, local and foreign statutes for environmental protection and remediation. The extent of our financial exposure cannot in all cases be reasonably estimated at this time. Among the variables management must assess in evaluating costs associated with these cases and remediation sites generally are the status of site assessment, extent of the contamination, impacts on natural resources, changing cost estimates, evolution of technologies used to remediate the site, continually evolving governmental environmental standards and cost allowability issues, including varying efforts by the U.S. Government to limit allowability of our costs in resolving liability at third party-owned sites. For information regarding these matters, including current estimates of the amounts that we believe are required for remediation or cleanup to the extent probable and estimable, see “Critical Accounting Policies –Environmental Matters” in Management’s Discussion and Analysis of Financial Condition and Results of Operations and “Note 14 – Legal Proceedings, Commitments and Contingencies” of our consolidated financial statements.
We are involved in a number of legal proceedings. We cannot predict the outcome of litigation and other contingencies with certainty.
Our business may be adversely affected by the outcome of legal proceedings and other contingencies that cannot be predicted with certainty. As required by GAAP, we estimate loss contingencies and establish reserves based on our assessment of contingencies where liability is deemed probable and reasonably estimable in light of the facts and circumstances known to us at a particular point in time. Subsequent developments in legal proceedings may affect our assessment and estimates of the loss contingency recorded as a liability or as a reserve against assets in our financial statements. For a description of our current legal proceedings, see Item 3 – Legal Proceedings and “Note 14 – Legal Proceedings, Commitments and Contingencies” included in our Notes to Consolidated Financial Statements.
Our success depends, in part, on our ability to develop new products and technologies and maintain a qualified workforce.
Many of the products and services we provide are highly engineered and involve sophisticated technologies, with related complex manufacturing and system integration processes. Our customers’ requirements change and evolve regularly. Accordingly, our future performance depends, in part, on our ability to identify emerging technological trends, develop and manufacture innovative products and service and bring those offerings to market quickly at cost-effective prices.
Additionally, due to the specialized nature of our business, our future performance is highly dependent upon our ability to maintain a workforce with the requisite skills in multiple areas including: engineering, science, manufacturing, information technology, cybersecurity, business development and strategy and management. Our operating performance is also dependent upon personnel who hold security clearances and receive substantial training in order to work on certain programs or tasks. Additionally, as we expand our operations internationally, it is increasingly important to hire and retain personnel with relevant experience in local laws, regulations, customs, traditions and business practices.
We face a number of challenges that may affect personnel retention such as our endeavors to increase the efficiency of our operations and improve the affordability of our products and services such as workforce reductions and consolidating and relocating certain operations. Additionally as our workforce ages, our demographic continues to shift toward a higher proportion of employees nearing retirement. In June 2014, we amended certain of our defined benefit pension plans for non-union employees to freeze future retirement benefits, which may encourage retirement-eligible personnel to elect to retire earlier than anticipated. The freeze takes place in two stages and will be completed January 1, 2020.
Table of Contents
To the extent that we lose experienced personnel, it is critical that we develop other employees, hire new qualified personnel, and successfully manage the transfer of critical knowledge. Competition for personnel is intense, and we may not be successful in hiring or retaining personnel with the requisite skills or clearances. We increasingly compete with commercial technology companies outside of the aerospace and defense industry for qualified technical, cyber and scientific positions as the number of qualified domestic engineers is decreasing and the number of cyber professionals is not keeping up with demand. To the extent that these companies grow at a faster rate or face fewer cost and product pricing constraints, they may be able to offer more attractive compensation and other benefits to candidates or our existing employees. To the extent that the demand for skilled personnel exceeds supply, we could experience higher labor, recruiting or training costs in order to attract and retain such employees; we could experience difficulty in performing our contracts if we were unable to do so. We also must manage leadership development and succession planning throughout our business. While we have processes in place for management transition and the transfer of knowledge, the loss of key personnel, coupled with an inability to adequately train other personnel, hire new personnel or transfer knowledge, could significantly impact our ability to perform under our contracts.
Approximately 21% of our employees are covered by collective bargaining agreements with various unions. Historically, where employees are covered by collective bargaining agreements with various unions, we have been successful in negotiating renewals to expiring agreements without any material disruption of operating activities. This does not assure, however, that we will be successful in our efforts to negotiate renewals of our existing collective bargaining agreements in the future. If we encounter difficulties with renegotiations or renewals of collective bargaining arrangements or are unsuccessful in those efforts, we could incur additional costs and experience work stoppages. Union actions at suppliers can also affect us. Any delays or work stoppages could adversely affect our ability to perform under our contracts, which could negatively impact our results of operations, cash flows, and financial condition.
Our estimates and projections may prove to be inaccurate.
The accounting for some of our most significant activities is based on judgments and estimates, which are complex and subject to many variables. For example, accounting for sales using the percentage-of-completion method requires that we assess risks and make assumptions regarding schedule, cost, technical and performance issues for each of our thousands of contracts, many of which are long-term in nature. Additionally, we initially allocate the purchase price of acquired businesses based on a preliminary assessment of the fair value of identifiable assets acquired and liabilities assumed. For significant acquisitions we may use a one-year measurement period to analyze and assess a number of factors used in establishing the asset and liability fair values as of the acquisition date and could result in adjustments to asset and liability balances. Another example is the $10.8 billion of goodwill assets recorded on our consolidated balance sheet as of December 31, 2016 from previous acquisitions, which represents approximately 23% of our total assets. These goodwill assets are subject to annual impairment testing and more frequent testing upon the occurrence of certain events or significant changes in circumstances that indicate goodwill may be impaired. If we experience changes or factors arise that negatively affect the expected cash flows of a reporting unit, we may be required to write off all or a portion of the reporting unit’s related goodwill assets.
Future changes in U.S. or foreign tax laws, including those with retroactive effect, and audits by tax authorities could result in unanticipated increases in our tax expense and affect profitability and cash flows. For example, recent proposals to lower the U.S. corporate income tax rate would require us to reduce our net deferred tax assets upon enactment of new tax legislation, with a corresponding material, one-time, non-cash increase in income tax expense, but our income tax expense and payments would be materially reduced in subsequent years. Our net deferred tax assets as of December 31, 2016 and 2015 were $6.6 billion and $6.1 billion, based on a 35% Federal statutory income tax rate, and primarily relate to our postretirement benefit plans. If legislation reducing the Federal statutory income tax rate to 15% had been enacted at December 31, 2016, our net deferred tax assets would have been reduced by $3.8 billion and we would have recorded a corresponding one-time, non-cash increase in income tax expense of $3.8 billion. This additional expense would be less if the legislation phased in the tax rate reduction or if the final rate was higher than 15%. The amount of net deferred tax assets will change periodically based on several factors, including the measurement of our postretirement benefit plan obligations and actual cash contributions to our postretirement benefit plans.
Actual financial results could differ from our judgments and estimates. See “Critical Accounting Policies” in Management’s Discussion and Analysis of Financial Condition and Results of Operations and “Note 1 – Significant Accounting Policies” included in our Notes to Consolidated Financial Statements for a complete discussion of our significant accounting policies and use of estimates.
Item 1B. Unresolved Staff Comments.
Item 2. Properties.
| --- | --- |
At December 31, 2016, we owned or leased building space (including offices, manufacturing plants, warehouses, service centers, laboratories and other facilities) at approximately 400 locations primarily in the U.S. Additionally, we manage or occupy various Government-owned facilities under lease and other arrangements.
At December 31, 2016, we had significant operations in the following locations:
| • | Aeronautics – Palmdale, California; Marietta, Georgia; Greenville, South Carolina; and Fort Worth, Texas. |
|---|
| • | Missiles and Fire Control – Camden, Arkansas; Lexington, Kentucky; Ocala and Orlando, Florida; and Grand Prairie, Texas. |
|---|
| • | Rotary and Mission Systems – Colorado Springs, Colorado; Stratford, Connecticut; Orlando, Florida; Moorestown/Mt. Laurel, New Jersey; Owego and Syracuse, New York; Akron, Ohio; Manassas, Virginia; and Mielec, Poland. |
|---|
| • | Space Systems – Sunnyvale, California; Denver, Colorado; Albuquerque, New Mexico; Valley Forge, Pennsylvania; and Reading, England. |
|---|
| • | Corporate activities – Bethesda, Maryland. |
|---|
In connection with the increase in ownership interest of AWE Management Limited, we assumed 5.8 million square feet of Government-owned floor space. As a result of our divestiture of the IS&GS business, we reduced our owned and leased floor space by 3.4 million square feet.
The following is a summary of our square feet of floor space by business segment at December 31, 2016 (in millions):
| Owned | Leased | Government- Owned | Total | |||||
| Aeronautics | 5.8 | 2.4 | 14.5 | 22.7 | ||||
| Missiles and Fire Control | 6.2 | 2.9 | 1.8 | 10.9 | ||||
| Rotary and Mission Systems | 11.2 | 7.6 | 0.4 | 19.2 | ||||
| Space Systems | 8.4 | 2.4 | 13.6 | 24.4 | ||||
| Corporate activities | 2.7 | 1.0 | — | 3.7 | ||||
| Total | 34.3 | 16.3 | 30.3 | 80.9 |
We believe our facilities are in good condition and adequate for their current use. We may improve, replace or reduce facilities as considered appropriate to meet the needs of our operations.
Item 3. Legal Proceedings.
| --- | --- |
We are a party to or have property subject to litigation and other proceedings that arise in the ordinary course of our business, including matters arising under provisions relating to the protection of the environment, and are subject to contingencies related to certain businesses we previously owned. These types of matters could result in fines, penalties, compensatory or treble damages or non-monetary sanctions or relief. We believe the probability is remote that the outcome of these matters will have a material adverse effect on the Corporation as a whole, notwithstanding that the unfavorable resolution of any matter may have a material effect on our net earnings in any particular interim reporting period. We cannot predict the outcome of legal or other proceedings with certainty. These matters include the proceedings summarized in “Note 14 – Legal Proceedings, Commitments and Contingencies” included in our Notes to Consolidated Financial Statements.
We are subject to federal, state, local and foreign requirements for protection of the environment, including those for discharge of hazardous materials and remediation of contaminated sites. As a result, we are a party to or have property subject to various lawsuits or proceedings involving environmental protection matters. Due in part to their complexity and pervasiveness, such requirements have resulted in us being involved with related legal proceedings, claims and remediation obligations. The extent of our financial exposure cannot in all cases be reasonably estimated at this time. For information regarding these matters, including current estimates of the amounts that we believe are required for remediation or clean-up to the extent estimable, see “Critical Accounting Policies – Environmental Matters” in Management’s Discussion and Analysis of Financial Condition and Results of Operations and “Note 14 – Legal Proceedings, Commitments and Contingencies” included in our Notes to Consolidated Financial Statements.
As a U.S. Government contractor, we are subject to various audits and investigations by the U.S. Government to determine whether our operations are being conducted in accordance with applicable regulatory requirements. U.S.
Table of Contents
Government investigations of us, whether relating to government contracts or conducted for other reasons, could result in administrative, civil, or criminal liabilities, including repayments, fines or penalties being imposed upon us, suspension, proposed debarment, debarment from eligibility for future U.S. Government contracting, or suspension of export privileges. Suspension or debarment could have a material adverse effect on us because of our dependence on contracts with the U.S. Government. U.S. Government investigations often take years to complete and many result in no adverse action against us. We also provide products and services to customers outside of the U.S., which are subject to U.S. and foreign laws and regulations and foreign procurement policies and practices. Our compliance with local regulations or applicable U.S. Government regulations also may be audited or investigated.
Item 4. Mine Safety Disclosures.
| --- | --- |
Not applicable.
Table of Contents
| ITEM 4(a). | Executive Officers of the Registrant. |
|---|
Our executive officers as of February 9, 2017 are listed below, with their ages on that date, positions and offices currently held, and principal occupation and business experience during at least the last five years. There were no family relationships among any of our executive officers and directors. All officers serve at the discretion of the Board of Directors.
Richard F. Ambrose (age 58), Executive Vice President – Space Systems
Mr. Ambrose has served as Executive Vice President of Space Systems since April 2013. He previously served as Vice President and Deputy, Space Systems from July 2012 to March 2013; and President, Information Systems & Global Solutions – Security from January 2011 to June 2012.
Dale P. Bennett (age 60), Executive Vice President – Rotary and Mission Systems
Mr. Bennett has served as Executive Vice President of Rotary and Mission Systems since December 2012. He previously served as President, Mission Systems & Sensors from August 2011 to December 2012.
Orlando P. Carvalho (age 58), Executive Vice President – Aeronautics
Mr. Carvalho has served as Executive Vice President of Aeronautics since March 2013. He previously served as Executive Vice President and General Manager, F-35 Program from March 2012 to March 2013; Vice President and Deputy, F-35 Program from August 2011 to March 2012.
Brian P. Colan (age 56), Vice President, Controller, and Chief Accounting Officer
Mr. Colan has served as Vice President, Controller, and Chief Accounting Officer since August 2014. He previously served as Vice President and Controller, Missiles and Fire Control from January 2013 to August 2014; and Vice President and Controller, Electronic Systems from October 2011 to January 2013.
Richard H. Edwards (age 60), Executive Vice President – Missiles and Fire Control
Mr. Edwards has served as Executive Vice President of Missiles and Fire Control since December 2012. He previously served as Executive Vice President, Program and Technology Integration, Missiles and Fire Control from June 2012 to December 2012; and Vice President, Tactical Missiles and Combat Maneuver Systems from July 2005 to June 2012.
Marillyn A. Hewson (age 63), Chairman, President and Chief Executive Officer
Ms. Hewson has served as Chairman, President and Chief Executive Officer of Lockheed Martin since January 2014. Having served over 30 years at Lockheed Martin in roles of increasing responsibility, she held the positions of Chief Executive Officer and President from January 2013 to December 2013; President and Chief Operating Officer from November 2012 to December 2012; and Executive Vice President – Electronic Systems from January 2010 to November 2012.
Maryanne R. Lavan (age 57), Senior Vice President, General Counsel and Corporate Secretary
Ms. Lavan has served as Senior Vice President and General Counsel since June 2010 and Corporate Secretary since September 2010.
John W. Mollard (age 59), Vice President and Treasurer
Mr. Mollard has served as Vice President and Treasurer since April 2016. He previously served as Vice President, Corporate Financial Planning and Analysis from 2003 to April 2016.
Bruce L. Tanner (age 57), Executive Vice President and Chief Financial Officer
Mr. Tanner has served as Executive Vice President and Chief Financial Officer since September 2007.
Table of Contents
PART II
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
| --- | --- |
At January 27, 2017, we had 28,697 holders of record of our common stock, par value $1 per share. Our common stock is traded on the New York Stock Exchange (NYSE) under the symbol LMT. Information concerning the high and low reported sales prices of Lockheed Martin common stock and dividends paid during the past two years is as follows:
Common Stock – Dividends Paid Per Share and Market Prices
| Dividends Paid Per Share | Stock Prices (High-Low) | |||||||||||||||
| Quarter | 2016 | 2015 | 2016 | 2015 | ||||||||||||
| First | $1.65 | $1.50 | $223.19 - $200.47 | $ | 207.06 - $186.01 | |||||||||||
| Second | 1.65 | 1.50 | 245.37 - 218.34 | 206.19 - 185.65 | ||||||||||||
| Third | 1.65 | 1.50 | 266.93 - 235.28 | 213.34 - 181.91 | ||||||||||||
| Fourth | 1.82 | 1.65 | 269.90 - 228.50 | 227.91 - 199.01 | ||||||||||||
| Year | $6.77 | $6.15 | $269.90 - $200.47 | $ | 227.91 - $181.91 |
Stockholder Return Performance Graph
The following graph compares the total return on a cumulative basis of $100 invested in Lockheed Martin common stock on December 31, 2011 to the Standard and Poor’s (S&P) 500 Index and the S&P Aerospace & Defense (S&P Aero) Index.
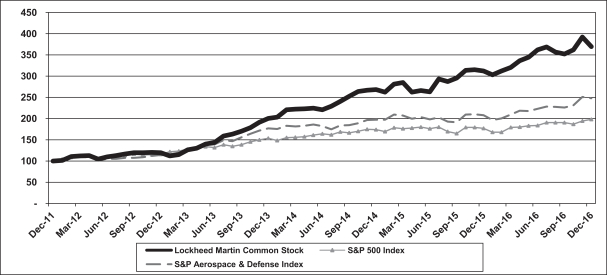
The S&P Aero Index comprises Arconic Inc., General Dynamics Corporation, L3 Technologies, Inc., Lockheed Martin Corporation, Northrop Grumman Corporation, Raytheon Company, Rockwell Collins, Inc., Textron Inc., The Boeing Company, Transdigm Group Inc., and United Technologies Corporation. The stockholder return performance indicated on the graph is not a guarantee of future performance.
This graph is not deemed to be “filed” with the U.S. Securities and Exchange Commission or subject to the liabilities of Section 18 of the Securities Exchange Act of 1934 (the Exchange Act), and should not be deemed to be incorporated by reference into any of our prior or subsequent filings under the Securities Act of 1933 or the Exchange Act.
Table of Contents
Purchases of Equity Securities
The following table provides information about our repurchases of our common stock registered pursuant to Section 12 of the Exchange Act during the quarter ended December 31, 2016.
| Period (a) | Total Number of Shares Purchased | Average Price Paid Per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs (b) | Amount Available for Future Share Repurchases Under the Plans or Programs (b) | ||||||
| (in millions) | ||||||||||
| September 26, 2016 – October 30, 2016 | 1,294,018 | $235.56 | 1,293,734 | $4,015 | ||||||
| October 31, 2016 – November 27, 2016 | 712,100 | $254.42 | 711,974 | $3,834 | ||||||
| November 28, 2016 – December 31, 2016 | 1,281,651 | $259.81 | 1,270,668 | $3,504 | ||||||
| Total | 3,287,769(c) | $249.09 | 3,276,376 |
| (a) | We close our books and records on the last Sunday of each month to align our financial closing with our business processes, except for the month of December, as our fiscal year ends on December 31. As a result, our fiscal months often differ from the calendar months. For example, September 26, 2016 was the first day of our October 2016 fiscal month. |
|---|
| (b) | In October 2010, our Board of Directors approved a share repurchase program pursuant to which we are authorized to repurchase our common stock in privately negotiated transactions or in the open market at prices per share not exceeding the then-current market prices. On September 22, 2016, our Board of Directors authorized a $2.0 billion increase to the program. Under the program, management has discretion to determine the dollar amount of shares to be repurchased and the timing of any repurchases in compliance with applicable law and regulation. This includes purchases pursuant to Rule 10b5-1 plans. The program does not have an expiration date. |
|---|
| (c) | During the quarter ended December 31, 2016, the total number of shares purchased included 11,393 shares that were transferred to us by employees in satisfaction of minimum tax withholding obligations associated with the vesting of restricted stock units. These purchases were made pursuant to a separate authorization by our Board of Directors and are not included within the program. |
|---|
Table of Contents
Item 6. Selected Financial Data.
| --- | --- |
The operating results of the IS&GS business have been classified as discontinued operations for all periods presented and the assets and liabilities of the IS&GS business have been classified as assets and liabilities of discontinued operations for all periods presented. However, the cash flows generated by the IS&GS business have not been reclassified in our cash flow information as we retained the cash as part of the divestiture of the IS&GS business. See “Note 3 – Acquisitions and Divestitures” included in our Notes to Consolidated Financial Statements for additional information about the divestiture of the IS&GS business.
| (In millions, except per share data) | 2016 | 2015 | 2014 | 2013 | 2012 | |||||||||||||||
| Operating results | ||||||||||||||||||||
| Net sales | $ | 47,248 | $ | 40,536 | $ | 39,946 | $ | 39,243 | $ | 40,573 | ||||||||||
| Operating profit (a)(b) | 5,549 | 4,712 | 5,012 | 4,066 | 3,748 | |||||||||||||||
| Net earnings from continuing operations (a)(b) | 3,753 | 3,126 | 3,253 | 2,701 | 2,297 | |||||||||||||||
| Net earnings from discontinued operations (c) | 1,549 | 479 | 361 | 280 | 448 | |||||||||||||||
| Net earnings (b) | 5,302 | 3,605 | 3,614 | 2,981 | 2,745 | |||||||||||||||
| Earnings from continuing operations per common share | ||||||||||||||||||||
| Basic (a)(b) | 12.54 | 10.07 | 10.27 | 8.42 | 7.10 | |||||||||||||||
| Diluted (a)(b) | 12.38 | 9.93 | 10.09 | 8.27 | 6.99 | |||||||||||||||
| Earnings from discontinued operations per common share | ||||||||||||||||||||
| Basic | 5.17 | 1.55 | 1.14 | 0.87 | 1.38 | |||||||||||||||
| Diluted | 5.11 | 1.53 | 1.12 | 0.86 | 1.36 | |||||||||||||||
| Earnings per common share | ||||||||||||||||||||
| Basic (b) | 17.71 | 11.62 | 11.41 | 9.29 | 8.48 | |||||||||||||||
| Diluted (b) | 17.49 | 11.46 | 11.21 | 9.13 | 8.36 | |||||||||||||||
| Cash dividends declared per common share | $ | 6.77 | $ | 6.15 | $ | 5.49 | $ | 4.78 | $ | 4.15 | ||||||||||
| Balance sheet (d) | ||||||||||||||||||||
| Cash, cash equivalents and short-term investments (b) | $ | 1,837 | $ | 1,090 | $ | 1,446 | $ | 2,617 | $ | 1,898 | ||||||||||
| Total current assets (e) | 15,108 | 14,573 | 10,684 | 12,081 | 12,401 | |||||||||||||||
| Goodwill (f) | 10,764 | 10,695 | 7,964 | 7,698 | 7,697 | |||||||||||||||
| Total assets (b)(e)(f) | 47,806 | 49,304 | 37,190 | 36,352 | 38,890 | |||||||||||||||
| Total current liabilities (e) | 12,542 | 13,918 | 10,954 | 10,983 | 11,993 | |||||||||||||||
| Total debt, net (g) | 14,282 | 15,261 | 6,142 | 6,127 | 6,280 | |||||||||||||||
| Total liabilities (b)(e)(g) | 46,200 | 46,207 | 33,790 | 31,434 | 38,851 | |||||||||||||||
| Total equity (b) | 1,606 | 3,097 | 3,400 | 4,918 | 39 | |||||||||||||||
| Common shares in stockholders’ equity at year-end | 289 | 303 | 314 | 319 | 321 | |||||||||||||||
| Cash flow information | ||||||||||||||||||||
| Net cash provided by operating activities (b)(h) | $ | 5,189 | $ | 5,101 | $ | 3,866 | $ | 4,546 | $ | 1,561 | ||||||||||
| Net cash used for investing activities (i) | (985 | ) | (9,734 | ) | (1,723 | ) | (1,121 | ) | (1,177) | |||||||||||
| Net cash provided by (used for) financing activities (j) | (3,457 | ) | 4,277 | (3,314 | ) | (2,706 | ) | (2,068) | ||||||||||||
| Backlog (k) | $ | 96,200 | $ | 94,800 | $ | 74,500 | $ | 76,300 | $ | 75,600 |
| (a) | Our operating profit and net earnings from continuing operations and earnings per share from continuing operations were affected by severance charges of $80 million ($52 million or $0.17 per share, after tax) in 2016; severance charges of $82 million ($53 million or $0.17 per share, after tax) in 2015; severance charges of $156 million ($101 million or $0.31 per share, after tax) in 2013. See “Note 15 – Restructuring Charges” included in our Notes to Consolidated Financial Statements for a discussion of 2016 and 2015 restructuring charges. |
|---|
| (b) | The impact of our postretirement benefit plans can cause our operating profit, net earnings, cash flows and certain amounts recorded on our consolidated balance sheets to fluctuate. Accordingly, our earnings were affected by a FAS/CAS pension adjustment of $902 million, $400 million and $317 million in 2016, 2015 and 2014 and $(500) million and $(832) million in 2013 and 2012. We made $23 million in 2016 and $5 million in 2015 of pension contributions (for our newly established Sikorsky plan), $2.0 billion in 2014, $2.25 billion in 2013 and $3.6 billion in 2012 (for our legacy plans), and these contributions caused fluctuations in our operating cash flows and cash balance between each of those years. Fluctuations in our total assets, total liabilities and stockholders’ equity between years 2012 to 2014 primarily were due to the annual measurement of the funded status of our postretirement benefit plans. See “Critical Accounting Policies – Postretirement Benefit Plans” in Management’s Discussion and Analysis of Financial Condition and Results of Operations for more information. |
|---|
| (c) | Our net earnings from discontinued operations includes a $1.2 billion net gain in 2016 related to the divesture of our IS&GS business. |
|---|
Table of Contents
| (d) | Certain prior period amounts have been reclassified to conform to current year presentation. |
|---|
| (e) | Included in total current assets are assets of discontinued operations of $1.0 billion in 2015, $900 million in 2014, $1.0 billion in 2013, and $1.1 billion in 2012. Included in total current liabilities are liabilities of discontinued operations of $900 million in each of the years 2015, 2014 and 2013 and $1.0 billion in 2012. Included in total assets are assets of discontinued operations of $4.1 billion in 2015, $4.2 billion in 2014, $3.9 billion in 2013, and $4.0 billion in 2012. Included in total liabilities are liabilities of discontinued operations of $1.2 billion in 2015, $1.2 billion in 2014, $1.2 billion in 2013, and $1.3 billion in 2012. |
|---|
| (f) | The increase in our goodwill and total assets from 2014 to 2015 was primarily attributable to the Sikorsky acquisition, which resulted in an increase in goodwill and total assets as of December 31, 2015 of $2.8 billion and $11.7 billion, respectively. |
|---|
| (g) | The increase in our total debt and total liabilities from 2014 to 2015 was primarily a result of the debt incurred to fund the Sikorsky acquisition, as well as the issuance of debt in February of 2015 for general corporate purposes (see “Note 3 – Acquisitions and Divestitures” and “Note 10 – Debt” included in our Notes to Consolidated Financial Statements). |
|---|
| (h) | The fluctuations in our net cash provided by operating activities between years 2012 to 2016 were due to changes in pension contributions, working capital and tax payments made. See “Liquidity and Cash Flows” in Management’s Discussion and Analysis of Financial Condition and Results of Operations for more information. |
|---|
| (i) | The increase in our cash used for investing activities in 2015 was attributable to acquisitions of businesses, including the $9.0 billion acquisition of Sikorsky in 2015, net of cash acquired (see “Note 3 – Acquisitions and Divestitures” included in our Notes to Consolidated Financial Statements). |
|---|
| (j) | The increase in our cash provided by financing activities in 2015 was primarily a result of the debt incurred to fund the Sikorsky acquisition (see “Note 10 – Debt” included in our Notes to Consolidated Financial Statements). The increase in our cash used for financing activities in 2014 was due to decreased proceeds from stock option exercises; higher dividends paid and increased payments for repurchases of common stock. See “Liquidity and Cash Flows” in Management’s Discussion and Analysis of Financial Condition and Results of Operations for more information. |
|---|
| (k) | Backlog at December 31, 2016 and 2015 includes approximately $14.7 billion and approximately $15.6 billion related to Sikorsky and excludes backlog at December 31, 2015, 2014, 2013 and 2012 of $4.8 billion, $6.0 billion, $6.3 billion and $6.7 billion related to our IS&GS business, which we divested in 2016. |
|---|
Table of Contents
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
| --- | --- |
Business Overview
We are a global security and aerospace company principally engaged in the research, design, development, manufacture, integration and sustainment of advanced technology systems, products and services. We also provide a broad range of management, engineering, technical, scientific, logistics, system integration and cybersecurity services. We serve both U.S. and international customers with products and services that have defense, civil and commercial applications, with our principal customers being agencies of the U.S. Government. In 2016, 71% of our $47.2 billion in net sales were from the U.S. Government, either as a prime contractor or as a subcontractor (including 59% from the Department of Defense (DoD)), 27% were from international customers (including foreign military sales (FMS) contracted through the U.S. Government) and 2% were from U.S. commercial and other customers. Our main areas of focus are in defense, space, intelligence, homeland security and information technology, including cybersecurity.
We operate in four business segments: Aeronautics, Missiles and Fire Control (MFC), Rotary and Mission Systems (RMS) and Space Systems. We organize our business segments based on the nature of products and services offered.
We operate in an environment characterized by both increasing complexity in global security and continuing economic pressures in the U.S. and globally. A significant component of our strategy in this environment is to focus on program execution, improving the quality and predictability of the delivery of our products and services and placing security capability quickly into the hands of our U.S. and international customers at affordable prices. Recognizing that our customers are resource constrained, we are endeavoring to develop and extend our portfolio domestically in a disciplined manner with a focus on adjacent markets close to our core capabilities, as well as growing our international sales. We continue to focus on affordability initiatives. We also expect to continue to invest in technologies to fulfill new mission requirements for our customers and invest in our people so that we have the technical skills necessary to succeed without limiting our ability to return substantially all of our free cash flow1 to our investors in the form of dividends and share repurchases.
We expect 2017 net sales will increase in the mid-single digit range from 2016 levels. The projected growth is driven by increased production and sustainment volume on the F-35 program at Aeronautics as well as increased volume at MFC and RMS, partially offset by decreased volume at Space Systems. Operating profit margin is expected to decline from 2016 levels primarily driven by higher volume on the F-35 program, which is dilutive to our overall profit margin, contract mix at MFC, lower AWE Management Limited (AWE) earnings as a result of the non-cash gain recognized in 2016 related the consolidation of AWE, amortization of AWE intangible assets in 2017 and lower equity earnings at Space Systems. Accordingly, we expect 2017 segment operating profit margin will decline from our 2016 margin to just above 10%. Our outlook for 2017 assumes the U.S. Government continues to support and fund our key programs, consistent with the government fiscal year (GFY) 2017 budget. Changes in circumstances may require us to revise our assumptions, which could materially change our current estimate of 2017 net sales and operating profit margin. For additional information related to trends in net sales and operating profit at our business segments, see the “Business Segment Results of Operations” discussion below.
We expect the 2017 FAS/CAS pension adjustment to be approximately $880 million, which incorporates a year end 2016 discount rate of 4.125%, a 25 basis point decrease from the end of 2015; an actual investment return during 2016 of approximately 5.0%; a 50 basis point reduction in our long-term rate of return assumption from 8.00% to 7.50%; and the revised longevity assumptions released on October 20, 2016 by the Society of Actuaries. We do not expect to make contributions to our legacy qualified defined benefit pension plans in 2017.
Portfolio Shaping Activities
We continuously strive to strengthen our portfolio of products and services to meet the current and future needs of our customers. We accomplish this in part by our independent research and development activities and through acquisition, divestiture and internal realignment activities.
We selectively pursue the acquisition of businesses and investments at attractive valuations that will expand or complement our current portfolio and allow access to new customers or technologies. We also may explore the divestiture of businesses that no longer meet our needs or strategy or that could perform better outside of our organization. In pursuing our business strategy, we routinely conduct discussions, evaluate targets and enter into agreements regarding possible acquisitions, divestitures, ventures and equity investments.
1 We define free cash flow as cash from operations as determined under U.S. generally accepted accounting principles (GAAP), less capital expenditures as presented on our consolidated statements of cash flows.
Table of Contents
Business Developments
Acquisition of Sikorsky Aircraft Corporation
On November 6, 2015, pursuant to a Stock Purchase Agreement, dated as of July 19, 2015 by and between us and United Technologies Corporation (UTC) and certain wholly-owned subsidiaries of UTC, we completed the acquisition of Sikorsky Aircraft Corporation (Sikorsky) for $9.0 billion, net of cash acquired. Sikorsky, a global company primarily engaged in the design, manufacture, service and support of military and commercial helicopters, has become a wholly-owned subsidiary of ours, aligned under the RMS business segment. We funded the acquisition with new debt issuances, commercial paper and cash on hand. We and UTC made a joint election under Section 338(h)(10) of the Internal Revenue Code, which treats the transaction as an asset purchase for tax purposes. Calculated using the Federal Statutory income tax rate, this election generates a cash tax benefit with an estimated net present value at the date of acquisition of $1.9 billion for us and our stockholders. The 2015 financial results of the acquired Sikorsky business have been included in our consolidated results of operations from the November 6, 2015 acquisition date through December 31, 2015. Accordingly, the consolidated financial results for the year ended December 31, 2015 do not reflect a full year of Sikorsky’s operations. See “Capital Structure, Resources and Other” included within “Liquidity and Cash Flows” discussion below and “Note 10 – Debt” included in our Notes to Consolidated Financial Statements for a discussion of the debt we incurred in connection with the Sikorsky acquisition.
Divestiture of the Information Systems & Global Solutions Business
On August 16, 2016, we completed the previously announced divestiture of the IS&GS business, which merged with a subsidiary of Leidos, in a Reverse Morris Trust transaction (the “Transaction”). The Transaction was completed in a multi-step process pursuant to which we initially contributed the IS&GS business to Abacus Innovations Corporation (Abacus), a wholly-owned subsidiary of Lockheed Martin created to facilitate the Transaction, and the common stock of Abacus was distributed to participating Lockheed Martin stockholders through an exchange offer. Under the terms of the exchange offer, Lockheed Martin stockholders had the option to exchange shares of Lockheed Martin common stock for shares of Abacus common stock. At the conclusion of the exchange offer, all shares of Abacus common stock were exchanged for 9,369,694 shares of Lockheed Martin common stock held by Lockheed Martin stockholders that elected to p
Showing the first 8K of 165K characters. Open the full section
Item 7A. Quantitative and Qualitative Disclosures About Market Risk.
| --- | --- |
We maintain active relationships with a broad and diverse group of U.S. and international financial institutions. We believe that they provide us with sufficient access to the general and trade credit we require to conduct our business. We continue to closely monitor the financial market environment and actively manage counterparty exposure to minimize the potential impact from adverse developments with any single credit provider while ensuring availability of, and access to, sufficient credit resources.
Our main exposure to market risk relates to interest rates, foreign currency exchange rates and market prices on certain equity securities. Our financial instruments that are subject to interest rate risk principally include fixed-rate long-term debt. The estimated fair value of our outstanding debt was $16.2 billion at December 31, 2016 and the outstanding principal amount was $15.3 billion, excluding unamortized discounts and issuance costs of $1.0 billion. A 10% change in the level of interest rates would not have a material impact on the fair value of our outstanding debt at December 31, 2016.
We use derivative instruments principally to reduce our exposure to market risks from changes in foreign currency exchange rates and interest rates. We do not enter into or hold derivative instruments for speculative trading purposes. We transact business globally and are subject to risks associated with changing foreign currency exchange rates. We enter into foreign currency hedges such as forward and option contracts that change in value as foreign currency exchange rates change. Our most significant foreign currency exposures relate to the British Pound Sterling, the Euro, the Canadian dollar and the Australian dollar. These contracts hedge forecasted foreign currency transactions in order to mitigate fluctuations in our earnings and cash flows associated with changes in foreign currency exchange rates. We designate foreign currency hedges as cash flow hedges. We also are exposed to the impact of interest rate changes primarily through our borrowing activities. For fixed rate borrowings, we may use variable interest rate swaps, effectively converting fixed rate borrowings to variable rate borrowings indexed to LIBOR in order to reduce the amount of interest paid. These swaps are designated as fair value hedges. For variable rate borrowings, we may use fixed interest rate swaps, effectively converting variable rate borrowings to fixed rate borrowings in order to mitigate the impact of interest rate changes on earnings. These swaps are designated as cash flow hedges. We also may enter into derivative instruments that are not designated as hedges and do not qualify for hedge accounting, which are intended to mitigate certain economic exposures.
The classification of gains and losses resulting from changes in the fair values of derivatives is dependent on our intended use of the derivative and its resulting designation. Adjustments to reflect changes in fair values of derivatives attributable to the effective portion of hedges are either reflected in earnings and largely offset by corresponding adjustments to the hedged items or reflected net of income taxes in accumulated other comprehensive loss until the hedged transaction is recognized in earnings. Changes in the fair value of the derivatives that are attributable to the ineffective portion of the hedges, or of derivatives that are not considered to be highly effective hedges, if any, are immediately recognized in earnings. The aggregate notional amount of our outstanding interest rate swaps at December 31, 2016 and 2015 was $1.2 billion and $1.5 billion. The aggregate notional amount of our outstanding foreign currency hedges at December 31, 2016 and 2015 was $4.0 billion and $4.1 billion. At December 31, 2016 and 2015, the net fair value of our derivative instruments was not material (see “Note 16 – Fair Value Measurements”) included in our Notes to Consolidated Financial Statements). A 10% appreciation or devaluation of the hedged currency as compared to the level of foreign exchange rates for currencies under contract at December 31, 2016 would not have a material impact on the aggregate net fair value of such contracts or our consolidated financial statements.
We evaluate the credit quality of potential counterparties to derivative transactions and only enter into agreements with those deemed to have acceptable credit risk at the time the agreements are executed. Our foreign currency exchange hedge portfolio is diversified across several banks. We periodically monitor changes to counterparty credit quality as well as our concentration of credit exposure to individual counterparties. We do not hold or issue derivative financial instruments for trading or speculative purposes.
Table of Contents
We maintain a separate trust that includes investments to fund certain of our non-qualified deferred compensation plans. As of December 31, 2016, investments in the trust totaled $1.2 billion and are reflected at fair value on our consolidated balance sheet in other noncurrent assets. The trust holds investments in marketable equity securities and fixed-income securities that are exposed to price changes and changes in interest rates. A portion of the liabilities associated with the deferred compensation plans supported by the trust is also impacted by changes in the market price of our common stock and certain market indices. Changes in the value of the liabilities have the effect of partially offsetting the impact of changes in the value of the trust. Both the change in the fair value of the trust and the change in the value of the liabilities are recognized on our consolidated statements of earnings in other unallocated, net and were not material for the year ended December 31, 2016.
Table of Contents
Item 8. Financial Statements and Supplementary Data.
| --- | --- |
Report of Ernst & Young LLP,
Independent Registered Public Accounting Firm,
on the Audited Consolidated Financial Statements
Board of Directors and Stockholders
Lockheed Martin Corporation
We have audited the accompanying consolidated balance sheets of Lockheed Martin Corporation as of December 31, 2016 and 2015, and the related consolidated statements of earnings, comprehensive income, equity, and cash flows for each of the three years in the period ended December 31, 2016. These financial statements are the responsibility of the Corporation’s management. Our responsibility is to express an opinion on these financial statements based on our audits.
We conducted our audits in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement. An audit includes examining, on a test basis, evidence supporting the amounts and disclosures in the financial statements. An audit also includes assessing the accounting principles used and significant estimates made by management, as well as evaluating the overall financial statement presentation. We believe that our audits provide a reasonable basis for our opinion.
In our opinion, the financial statements referred to above present fairly, in all material respects, the consolidated financial position of Lockheed Martin Corporation at December 31, 2016 and 2015, and the consolidated results of its operations and its cash flows for each of the three years in the period ended December 31, 2016, in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), Lockheed Martin Corporation’s internal control over financial reporting as of December 31, 2016, based on criteria established in Internal Control – Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework), and our report dated February 9, 2017 expressed an adverse opinion thereon.
/s/ Ernst & Young LLP
McLean, Virginia
February 9, 2017
Table of Contents
Lockheed Martin Corporation
Consolidated Statements of Earnings
(in millions, except per share data)
| Years Ended December 31, | ||||||||||||
| 2016 | 2015 | 2014 | ||||||||||
| Net sales | ||||||||||||
| Products | $ | 40,365 | $ | 34,868 | $ | 34,984 | ||||||
| Services | 6,883 | 5,668 | 4,962 | |||||||||
| Total net sales | 47,248 | 40,536 | 39,946 | |||||||||
| Cost of sales | ||||||||||||
| Products | (36,616 | ) | (31,091 | ) | (30,983) | |||||||
| Services | (6,040 | ) | (4,824 | ) | (4,184) | |||||||
| Severance charges | (80 | ) | (82 | ) | — | |||||||
| Other unallocated, net | 550 | (47 | ) | (96) | ||||||||
| Total cost of sales | (42,186 | ) | (36,044 | ) | (35,263) | |||||||
| Gross profit | 5,062 | 4,492 | 4,683 | |||||||||
| Other income, net | 487 | 220 | 329 | |||||||||
| Operating profit | 5,549 | 4,712 | 5,012 | |||||||||
| Interest expense | (663 | ) | (443 | ) | (340) | |||||||
| Other non-operating income, net | — | 30 | 5 | |||||||||
| Earnings from continuing operations before income taxes | 4,886 | 4,299 | 4,677 | |||||||||
| Income tax expense | (1,133 | ) | (1,173 | ) | (1,424) | |||||||
| Net earnings from continuing operations | 3,753 | 3,126 | 3,253 | |||||||||
| Net earnings from discontinued operations | 1,549 | 479 | 361 | |||||||||
| Net earnings | $ | 5,302 | $ | 3,605 | $ | 3,614 | ||||||
| Earnings per common share | ||||||||||||
| Basic | ||||||||||||
| Continuing operations | $ | 12.54 | $ | 10.07 | $ | 10.27 | ||||||
| Discontinued operations | 5.17 | 1.55 | 1.14 | |||||||||
| Basic earnings per common share | $ | 17.71 | $ | 11.62 | $ | 11.41 | ||||||
| Diluted | ||||||||||||
| Continuing operations | $ | 12.38 | $ | 9.93 | $ | 10.09 | ||||||
| Discontinued operations | 5.11 | 1.53 | 1.12 | |||||||||
| Diluted earnings per common share | $ | 17.49 | $ | 11.46 | $ | 11.21 |
The accompanying notes are an integral part of these consolidated financial statements.
Table of Contents
Lockheed Martin Corporation
Consolidated Statements of Comprehensive Income
(in millions)
| Years Ended December 31, | ||||||||||||
| 2016 | 2015 | 2014 | ||||||||||
| Net earnings | $ | 5,302 | $ | 3,605 | $ | 3,614 | ||||||
| Other comprehensive (loss) income, net of tax | ||||||||||||
| Postretirement benefit plans | ||||||||||||
| Net other comprehensive loss recognized during the period, net of tax benefit of $668 million in 2016, $192 million in 2015 and $1.5 billion in 2014 | (1,232 | ) | (351 | ) | (2,870) | |||||||
| Amounts reclassified from accumulated other comprehensive loss, net of tax expense of $382 million in 2016, $464 million in 2015 and $386 million in 2014 | 699 | 850 | 706 | |||||||||
| Reclassifications from divestiture of IS&GS business | (134 | ) | — | — | ||||||||
| Other, net | 9 | (73 | ) | (105) | ||||||||
| Other comprehensive (loss) income, net of tax | (658 | ) | 426 | (2,269) | ||||||||
| Comprehensive income | $ | 4,644 | $ | 4,031 | $ | 1,345 |
The accompanying notes are an integral part of these consolidated financial statements.
Table of Contents
Lockheed Martin Corporation
Consolidated Balance Sheets
(in millions, except par value)
| December 31, | ||||||||
| 2016 | 2015 | |||||||
| Assets | ||||||||
| Current assets | ||||||||
| Cash and cash equivalents | $ | 1,837 | $ | 1,090 | ||||
| Receivables, net | 8,202 | 7,254 | ||||||
| Inventories, net | 4,670 | 4,819 | ||||||
| Other current assets | 399 | 441 | ||||||
| Assets of discontinued operations | — | 969 | ||||||
| Total current assets | 15,108 | 14,573 | ||||||
| Property, plant and equipment, net | 5,549 | 5,389 | ||||||
| Goodwill | 10,764 | 10,695 | ||||||
| Intangible assets, net | 4,093 | 4,022 | ||||||
| Deferred income taxes | 6,625 | 6,068 | ||||||
| Other noncurrent assets | 5,667 | 5,396 | ||||||
| Assets of discontinued operations | — | 3,161 | ||||||
| Total assets | $ | 47,806 | $ | 49,304 | ||||
| Liabilities and equity | ||||||||
| Current liabilities |
Showing the first 8K of 212K characters. Open the full section
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure.
| --- | --- |
None.
Item 9A. Controls and Procedures.
| --- | --- |
Evaluation of Disclosure Controls and Procedures
We performed an evaluation of the effectiveness of our disclosure controls and procedures as of December 31, 2016. The evaluation was performed with the participation of senior management of each business segment and key Corporate functions, under the supervision of the Chief Executive Officer (CEO) and Chief Financial Officer (CFO). Based on this evaluation, the CEO and CFO concluded that our disclosure controls and procedures were not effective due to a material weakness in internal control over financial reporting at Sikorsky Aircraft Corporation which we acquired on November 6, 2015 and which operates as a business unit of our Rotary and Mission Systems business segment.
Notwithstanding the identified material weakness, management, including our CEO (principal executive officer) and CFO (principal financial officer), believes the consolidated financial statements included in this annual report on Form 10-K fairly represent in all material respects our financial condition, results of operations and cash flows at and for the periods presented in accordance with U.S. GAAP.
Management’s Report on Internal Control Over Financial Reporting
Our management is responsible for establishing and maintaining adequate internal control over financial reporting. Our internal control system is designed to provide reasonable assurance to our management and Board of Directors regarding the reliability of financial reporting and the preparation of consolidated financial statements for external purposes.
Our management conducted an assessment of the effectiveness of our internal control over financial reporting as of December 31, 2016. This assessment was based on the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission in Internal Control – Integrated Framework (2013 framework). Based on this assessment, management concluded that a material weakness exists in our internal control over financial reporting as of December 31, 2016. A material weakness is a deficiency, or combination of deficiencies, in internal control over financial reporting, such that there is a reasonable possibility that a material misstatement of our annual or interim financial statements could occur but will not be prevented or detected on a timely basis.
Sikorsky was acquired on November 6, 2015 and generated about 10% of our total net sales for the year ended December 31, 2016. Prior to 2016, Sikorsky was not included in assessments of the effectiveness of our internal control over financial reporting as the Securities and Exchange Commission (SEC) rules provide companies one year to assess controls at an acquired entity. Accordingly, within this period, we performed our first comprehensive assessment of the design and effectiveness of internal controls at Sikorsky and determined that Sikorsky’s internal control over financial reporting was ineffective as of December 31, 2016. Specifically, Sikorsky did not adequately identify, design and implement appropriate process-level controls for its processes and appropriate information technology controls for its information technology systems, including Sikorsky’s contract accounting / sales recognition processes, inventory accounting process and payroll process. There were no material errors in the financial results or balances identified as a result of the control deficiencies, and there was no restatement of prior period financial statements and no change in previously released financial results were required as the result of these control deficiencies.
Our independent registered public accounting firm has issued a report expressing an adverse opinion on the effectiveness of our internal control over financial reporting, which is below.
Remediation Efforts to Address Material Weakness
Management has and will continue to enhance the risk assessment process and design of internal control over financial reporting at Sikorsky. This includes initiation of compensating controls and enhanced and revised design of existing financial reporting controls, information technology applications and procedures at Sikorsky. The material weakness will not be considered remediated until the applicable remedial controls operate for a sufficient period of time and management has concluded, through testing, that these controls are operating effectively. We expect that the remediation of this material weakness will be completed prior to the end of fiscal year 2017.
Table of Contents
Changes in Internal Control Over Financial Reporting
Other than with respect to the remediation efforts described above, there were no changes in our internal control over financial reporting during the most recently completed fiscal quarter that materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
Table of Contents
Report of Ernst & Young LLP,
Independent Registered Public Accounting Firm,
Regarding Internal Control Over Financial Reporting
Board of Directors and Stockholders
Lockheed Martin Corporation
We have audited Lockheed Martin Corporation’s internal control over financial reporting as of December 31, 2016, based on criteria established in Internal Control – Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) (the COSO criteria). Lockheed Martin Corporation’s management is responsible for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting included in the accompanying Management’s Report on Internal Control Over Financial Reporting. Our responsibility is to express an opinion on the Corporation’s internal control over financial reporting based on our audit.
We conducted our audit in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
A material weakness is a deficiency, or combination of deficiencies, in internal control over financial reporting, such that there is a reasonable possibility that a material misstatement of the company’s annual or interim financial statements will not be prevented or detected on a timely basis. The following material weakness has been identified and included in management’s assessment. Management identified a material weakness in the design and operation of internal controls, including information technology controls, within Sikorsky’s processes (including the contract accounting / sales recognition processes, inventory accounting process, and payroll process). We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), the consolidated balance sheets of Lockheed Martin Corporation as of December 31, 2016 and 2015, and the related consolidated statement of earnings, comprehensive income, equity, and cash flows for each of the three years in the period ended December 31, 2016. This material weakness was considered in determining the nature, timing, and extent of audit tests applied in our audit of the 2016 financial statements, and this report does not affect our report dated February 9, 2017, which expressed an unqualified opinion on those financial statements.
In our opinion, because of the effect of the material weakness described above on the achievement of the objectives of the control criteria, Lockheed Martin Corporation has not maintained effective internal control over financial reporting as of December 31, 2016, based on the COSO criteria.
/s/ Ernst & Young LLP
McLean, Virginia
February 9, 2017
Table of Contents
Item 9B. Other Information.
| --- | --- |
None.
PART III
Item 10. Directors, Executive Officers and Corporate Governance.
| --- | --- |
The information concerning directors required by Item 401 of Regulation S-K is included under the caption “Proposal 1 – Election of Directors” in our definitive Proxy Statement to be filed pursuant to Regulation 14A (the 2017 Proxy Statement), and that information is incorporated by reference in this Form 10-K. Information concerning executive officers required by Item 401 of Regulation S-K is located under Part I, Item 4(a) of this Form 10-K. The information required by Item 405 of Regulation S-K is included under the caption “Section 16(a) Beneficial Ownership Reporting Compliance” in the 2017 Proxy Statement, and that information is incorporated by reference in this Form 10-K. The information required by Items 407(c)(3), (d)(4) and (d)(5) of Regulation S-K is included under the captions “Committees of the Board of Directors – 2016 Membership on Board Committees” and “Committees of the Board of Directors – Audit Committee Report” in the 2017 Proxy Statement, and that information is incorporated by reference in this Form 10-K.
We have had a written code of ethics in place since our formation in 1995. Setting the Standard, our Code of Ethics and Business Conduct, applies to all our employees, including our principal executive officer, principal financial officer, and principal accounting officer and controller, and to members of our Board of Directors. A copy of our Code of Ethics and Business Conduct is available on our investor relations website: www.lockheedmartin.com/investor. Printed copies of our Code of Ethics and Business Conduct may be obtained, without charge, by contacting Investor Relations, Lockheed Martin Corporation, 6801 Rockledge Drive, Bethesda, Maryland 20817. We are required to disclose any change to, or waiver from, our Code of Ethics and Business Conduct for our Chief Executive Officer and senior financial officers. We use our website to disseminate this disclosure as permitted by applicable SEC rules.
Item 11. Executive Compensation.
| --- | --- |
The information required by Item 402 of Regulation S-K is included in the text and tables under the captions “Executive Compensation” and “Director Compensation” in the 2017 Proxy Statement and that information is incorporated by reference in this Form 10-K. The information required by Item 407(e)(5) of Regulation S-K is included under the caption “Executive Compensation – Compensation Committee Report” in the 2017 Proxy Statement, and that information is furnished by incorporation by reference in this Form 10-K.
Table of Contents
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
| --- | --- |
The information required by Item 12 is included under the heading “Security Ownership of Management and Certain Beneficial Owners” in the 2017 Proxy Statement, and that information is incorporated by reference in this Form 10-K.
Equity Compensation Plan Information
The following table provides information about our equity compensation plans that authorize the issuance of shares of Lockheed Martin common stock to employees and directors. The information is provided as of December 31, 2016.
| Plan category | Number of securities to be issued upon exercise of outstanding options, warrants and rights (a) | Weighted-average exercise price of outstanding options, warrants and rights (b) | Number of securities remaining available for future issuance under equity compensation plans (excluding securities reflected in column (a)) (c) | |||||||||
| Equity compensation plans approved by security holders (1) | 5,802,673 | $85.82 | 6,216,471 | |||||||||
| Equity compensation plans not approved by security holders (2) | 1,082,347 | — | 2,481,032 | |||||||||
| Total | 6,885,020 | $85.82 | 8,697,503 |
| (1) | Column (a) includes, as of December 31, 2016: 1,747,151 shares that have been granted as Restricted Stock Units (RSUs), 936,308 shares that could be earned pursuant to grants of Performance Stock Units (PSUs) (assuming the maximum number of PSUs are earned and payable at the end of the three-year performance period) and 2,967,046 shares granted as options under the Lockheed Martin Corporation 2011 Incentive Performance Award Plan (2011 IPA Plan) or predecessor plans prior to January 1, 2013 and 23,346 shares granted as options and 128,822 stock units payable in stock or cash under the Lockheed Martin Corporation 2009 Directors Equity Plan (Directors Equity Plan) or predecessor plans for members (or former members) of the Board of Directors. Column (c) includes, as of December 31, 2016, 5,751,655 shares available for future issuance under the 2011 IPA Plan as options, stock appreciation rights (SARs), restricted stock awards (RSAs), RSUs or PSUs and 464,816 shares available for future issuance under the Directors Equity Plan as stock options and stock units. Of the 5,751,655 shares available for grant under the 2011 IPA Plan on December 31, 2016, 516,653 and 236,654 shares are issuable pursuant to grants made on January 26, 2017, of RSUs and PSUs (assuming the maximum number of PSUs are earned and payable at the end of the three-year performance period), respectively. The weighted average price does not take into account shares issued pursuant to RSUs or PSUs. |
|---|
| (2) | The shares represent annual incentive bonuses and Long-Term Incentive Performance (LTIP) payments earned and voluntarily deferred by employees. The deferred amounts are payable under the Deferred Management Incentive Compensation Plan (DMICP). Deferred amounts are credited as phantom stock units at the closing price of our stock on the date the deferral is effective. Amounts equal to our dividend are credited as stock units at the time we pay a dividend. Following termination of employment, a number of shares of stock equal to the number of stock units credited to the employee’s DMICP account are distributed to the employee. There is no discount or value transfer on the stock distributed. Distributions may be made from newly issued shares or shares purchased on the open market. Historically, all distributions have come from shares held in a separate trust and, therefore, do not further dilute our common shares outstanding. As a result, these shares also were not considered in calculating the total weighted average exercise price in the table. Because the DMICP shares are outstanding, they should be included in the denominator (and not the numerator) of a dilution calculation. |
|---|
Item 13. Certain Relationships and Related Transactions and Director Independence.
| --- | --- |
The information required by this Item 13 is included under the captions “Corporate Governance – Related Person Transaction Policy,” “Corporate Governance – Certain Relationships and Related Person Transactions of Directors, Executive Officers, and 5 Percent Stockholders,” and “Corporate Governance – Director Independence” in the 2017 Proxy Statement, and that information is incorporated by reference in this Form 10-K.
Item 14. Principal Accountant Fees and Services.
| --- | --- |
The information required by this Item 14 is included under the caption “Proposal 2 – Ratification of Appointment of Independent Auditors” in the 2017 Proxy Statement, and that information is incorporated by reference in this Form 10-K.
Table of Contents
PART IV
Item 15. Exhibits and Financial Statement Schedules.
| --- | --- |
List of financial statements filed as part of this Form 10-K
The following financial statements of Lockheed Martin Corporation and consolidated subsidiaries are included in Item 8 of this Form 10-K at the page numbers referenced below:
The report of Lockheed Martin Corporation’s independent registered public accounting firm with respect to the above-referenced financial statements and their report on internal control over financial reporting appear on pages 61 and 107 of this Form 10-K. Their consent appears as Exhibit 23 of this Form 10-K.
List of financial statement schedules filed as part of this Form 10-K
All schedules have been omitted because they are not applicable, not required or the information has been otherwise supplied in the financial statements or notes to the financial statements.
Exhibits
| 2.1 | Stock Purchase Agreement dated as of July 19, 2015 by and among United Technologies Corporation, the other Sellers identified therein and Lockheed Martin Corporation (incorporated by reference to Exhibit 2.1 to Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on July 20, 2015). The schedules and exhibits to the Stock Purchase Agreement have been omitted pursuant to Item 601(b)(2) of Regulation S-K. Lockheed Martin agrees to furnish supplementally a copy of such schedules and exhibits, or any section thereof, to the SEC upon request. | |
| 2.2 | Amendment No. 1 to Stock Purchase Agreement dated as of November 5, 2015 by and among United Technologies Corporation and certain affiliated entities identified therein and Lockheed Martin Corporation (incorporated by reference to Exhibit 2.1 to Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on November 6, 2015). The exhibits to Amendment No. 1 to Stock Purchase Agreement have been omitted pursuant to Item 601(b)(2) of Regulation S-K. Lockheed Martin agrees to furnish supplementally a copy of such exhibits, or any section thereof, to the SEC upon request. | |
| 2.3 | Agreement and Plan of Merger, dated as of January 26, 2016, among Lockheed Martin Corporation, Leidos Holdings, Inc., Abacus Innovations Corporation and Lion Merger Co. (incorporated by reference to Exhibit 2.1 to Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on January 27, 2016). The schedules and attachments to the Merger Agreement have been omitted pursuant to Item 601(b)(2) of Regulation S-K, and such schedules and attachments will be furnished to the SEC upon request. | |
| 2.4 | Amendment dated as of June 27, 2016 to Agreement and Plan of Merger, dated as of January 26, 2016, among Lockheed Martin Corporation, Leidos Holdings, Inc., Abacus Innovations Corporation and Lion Merger Co. (incorporated by reference to Exhibit 2.1 to Lockheed Martin Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 26, 2016). | |
| 2.5 | Separation Agreement, dated as of January 26, 2016, between Lockheed Martin Corporation and Abacus Innovations Corporation (incorporated by reference to Exhibit 2.2 to Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on January 27, 2016). The schedules and attachments to the Separation Agreement have been omitted pursuant to Item 601(b)(2) of Regulation S-K, and such schedules and attachments will be furnished to the SEC upon request. |
Table of Contents
| 2.6 | Amendment dated as of June 27, 2016 to Separation Agreement, dated as of January 26, 2016, between Lockheed Martin Corporation and Abacus Innovations Corporation (incorporated by reference to Exhibit 2.2 to Lockheed Martin Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 26, 2016). The schedules to the amendment have been omitted pursuant to Item 601(b)(2) of Regulation S-K, and such schedules and attachments will be furnished to the SEC upon request. | |
| 3.1 | Charter of Lockheed Martin Corporation, as amended by Articles of Amendment dated April 23, 2009 (incorporated by reference to Exhibit 3.1 to Lockheed Martin Corporation’s Annual Report on Form 10-K for the year ended December 31, 2010 (File No. 001-11437)). | |
| 3.2 | Bylaws of Lockheed Martin Corporation, as amended and restated effective September 22, 2016 (incorporated by reference to Exhibit 3.1 to Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on September 22, 2016). | |
| 4.1 | Indenture, dated May 15, 1996, among Lockheed Martin Corporation, Lockheed Martin Tactical Systems, Inc. and First Trust of Illinois, National Association as Trustee (incorporated by reference to Exhibit 4.A to Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on May 20, 1996 (File No. 001-11437)). | |
| 4.2 | Indenture, dated as of August 30, 2006, between Lockheed Martin Corporation and The Bank of New York (incorporated by reference to Exhibit 99.1 to Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on August 31, 2006 (File No. 001-11437)). | |
| 4.3 | Indenture, dated as of March 11, 2008, between Lockheed Martin Corporation and The Bank of New York (incorporated by reference to Exhibit 4.1 to Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on March 12, 2008 (File No. 001-11437)). | |
| 4.4 | Indenture, dated as of May 25, 2010, between Lockheed Martin Corporation and U.S. Bank National Association (incorporated by reference to Exhibit 99.1 to Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on May 25, 2010 (File No. 001-11437)). | |
| 4.5 | Indenture, dated as of September 6, 2011, between Lockheed Martin Corporation and U.S. Bank National Association (incorporated by reference to Exhibit 4.1 to Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on September 8, 2011 (File No. 001-11437)). | |
| 4.6 | Indenture, dated as of December 14, 2012, between Lockheed Martin Corporation and U.S. Bank National Association (incorporated by reference to Exhibit 99.1 to Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on December 17, 2012). | |
| See also Exhibits 3.1 and 3.2. | ||
| No instruments defining the rights of holders of long-term debt that is not registered are filed because the total amount of securities authorized under any such instrument does not exceed 10% of the total assets of Lockheed Martin Corporation on a consolidated basis. Lockheed Martin Corporation agrees to furnish a copy of such instruments to the SEC upon request. | ||
| 10.1 | 364-Day Credit Agreement dated as of October 9, 2015, among Lockheed Martin Corporation, the lenders listed therein, and Bank of America, N.A., as administrative agent (incorporated by reference to Exhibit 10.1 to Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on October 13, 2015). | |
| 10.2 | Five-Year Credit Agreement dated as of October 9, 2015, among Lockheed Martin Corporation, the lenders listed therein, and Bank of America, N.A., as administrative agent (incorporated by reference to Exhibit 10.2 to Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on October 13, 2015). | |
| 10.3 | Extension Agreement dated as of October 7, 2016 by and among Lockheed Martin Corporation, the lenders listed therein, and Bank of America, N.A., as administrative agent (incorporated by reference to Exhibit 10.1 to Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on October 7, 2016). | |
| 10.4 | Lockheed Martin Corporation Directors Deferred Stock Plan, as amended (incorporated by reference to Exhibit 10.4 to Lockheed Martin Corporation’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2002 (File No. 001-11437)). | |
| 10.5 | Lockheed Martin Corporation Directors Deferred Compensation Plan, as amended (incorporated by reference to Exhibit 10.2 to Lockheed Martin Corporation’s Annual Report on Form 10-K for the year ended December 31, 2008 (File No. 001-11437)). |
Table of Contents
| 10.6 | Martin Marietta Corporation Directors’ Life Insurance Program (incorporated by reference to Exhibit 10.17 to Lockheed Martin Corporation’s Registration Statement on Form S-4 (File No. 033-57645) filed with the SEC on February 9, 1995). | |
| 10.7 | Lockheed Martin Corporation Directors Equity Plan, as amended (incorporated by reference to Exhibit 10.1 to Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on November 2, 2006 (File No. 001-11437)). | |
| 10.8 | Lockheed Martin Corporation 2009 Directors Equity Plan (incorporated by reference to Appendix E to Lockheed Martin Corporation’s Definitive Proxy Statement on schedule 14A filed with the SEC on March 14, 2008 (File No. 001-11437)). | |
| 10.9 | Lockheed Martin Corporation Supplemental Savings Plan, as amended and restated effective January 1, 2015 (incorporated by reference to Exhibit 10.4 to Lockheed Martin Corporation’s Quarterly Report on Form 10-Q for the quarter ended March 29, 2015). | |
| 10.10 | Lockheed Martin Corporation Deferred Management Incentive Compensation Plan, as amended and restated effective May 16, 2016 (incorporated by reference to Exhibit 10.1 to Lockheed Martin Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 26, 2016). | |
| 10.11 | Lockheed Martin Corporation Amended and Restated 2006 Management Incentive Compensation Plan (Performance Based), amended and restated effective January 1, 2016 (incorporated by reference to Exhibit 10.1 to Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on February 2, 2016). | |
| 10.12 | Lockheed Martin Corporation Amended and Restated 2003 Incentive Performance Award Plan (incorporated by reference to Exhibit 10.17 to Lockheed Martin Corporation’s Annual Report on Form 10-K for the year ended December 31, 2008 (File No. 001-11437)). | |
| 10.13 | Forms of Stock Option Award Agreements under the Lockheed Martin Corporation 2003 Incentive Performance Award Plan (incorporated by reference to Exhibit 10.39 to Lockheed Martin Corporation’s Annual Report on Form 10-K for the year ended December 31, 2007 (File No. 001-11437)). | |
| 10.14 | Forms of Stock Option Award Agreements under the Lockheed Martin Corporation 2003 Incentive Performance Award Plan (incorporated by reference to Exhibit 10.32 to Lockheed Martin Corporation’s Annual Report on Form 10-K for the year ended December 31, 2008 (File No. 001-11437)). | |
| 10.15 | Forms of Stock Option Award Agreements under the Lockheed Martin Corporation 2003 Incentive Performance Award Plan (incorporated by reference to Exhibit 10.33 to Lockheed Martin Corporation’s Annual Report on Form 10-K for the year ended December 31, 2009 (File No. 001-11437)). | |
| 10.16 | Form of Stock Option Award Agreement under the Lockheed Martin Corporation 2003 Incentive Performance Award Plan (incorporated by reference to Exhibit 99.3 of Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on February 3, 2011 (File No. 001-11437)). | |
| 10.17 | Form of Indemnification Agreement (incorporated by reference to Exhibit 10.34 to Lockheed Martin Corporation’s Annual Report on Form 10-K for the year ended December 31, 2009 (File No. 001-11437)). | |
| 10.18 | Lockheed Martin Corporation 2011 Incentive Performance Award Plan, as amended June 23, 2016 effective as of January 1, 2017 (incorporated by reference to Exhibit 10.2 to Lockheed Martin Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 26, 2016). | |
| 10.19 | Forms of Stock Option Award Agreements under the Lockheed Martin Corporation 2011 Incentive Performance Award Plan (incorporated by reference to Exhibit 10.39 of Lockheed Martin Corporation’s Annual Report on Form 10-K for the year ended December 31, 2011 (File No. 001-11437)). | |
| 10.20 | Form of Restricted Stock Unit Award Agreement, Form of Long-Term Incentive Performance Award Agreement (2014-2016 performance period), and Form of Performance Stock Unit Award Agreement (2014-2016 performance period) under the Lockheed Martin Corporation 2011 Incentive Performance Award Plan (incorporated by reference to Exhibits 10.3, 10.4 and 10.5, respectively, to Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on January 28, 2014). | |
| 10.21 | Lockheed Martin Corporation Nonqualified Capital Accumulation Plan, as amended and restated generally effective as of December 18, 2015 (incorporated by reference to Exhibit 10.22 of Lockheed Martin Corporation’s Annual Report on Form 10-K for the year ended December 31, 2015). | |
| 10.22 | Non-Employee Director Compensation Summary (incorporated by reference to Exhibit 10.1 to Lockheed Martin Corporation’s Current Report on Form 8-K filed with the SEC on June 26, 2015). |
Table of Contents
| 10.23 | Form of Restricted Stock Unit Award Agreement, Form of Long-Term Incentive Performance Award Agreement (2015-2017 performance period), and Form of Performance Stock Unit Award Agreement (2015-2017 performance period) under the Lockheed Martin Corporation 2011 Incentive Performance Award Plan (incorporated by reference to Exhibit 10.30 to Lockheed Martin Corporation’s Annual Report on Form 10-K for the year ended December 31, 2014). | |
| 10.24 | Form of Restricted Stock Unit Award Agreement, Form of Performance Stock Unit Award Agreement (2016-2018 performance period), and Form of Long-Term Incentive Performance Award Agreement (2016-2018 performance period) under the Lockheed Martin Corporation 2011 Incentive Performance Award Plan (incorporated by reference to Exhibits 10.2, 10.3 and 10.4, respectively, to Lockheed Martin Corporation’s Current Report on Form 8-K filed on February 2, 2016). | |
| 10.25 | Lockheed Martin Corporation Consolidated Supplemental Retirement Benefit Plan. | |
| 10.26 | Lockheed Martin Corporation Executive Severance Plan, as amended and restated effective December 1, 2016. | |
| 10.27 | Amendment to Terms of Outstanding Restricted Stock Unit Awards and Performance Stock Unit Awards under the Lockheed Martin Corporation 2011 Incentive Performance Award Plan Relating to Tax Withholding. | |
| 12 | Computation of ratio of earnings to fixed charges. | |
| 21 | Subsidiaries of Lockheed Martin Corporation. | |
| 23 | Consent of Ernst & Young LLP, Independent Registered Public Accounting Firm. | |
| 24 | Powers of Attorney. | |
| 31.1 | Certification of Marillyn A. Hewson pursuant to Section 302 of the Sarbanes-Oxley Act of 2002. | |
| 31.2 | Certification of Bruce L. Tanner pursuant to Section 302 of the Sarbanes-Oxley Act of 2002. | |
| 32 | Certification of Marillyn A. Hewson and Bruce L. Tanner Pursuant to 18 U.S.C. Section 1350, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of 2002. | |
| 101.INS | XBRL Instance Document | |
| 101.SCH | XBRL Taxonomy Extension Schema Document | |
| 101.CAL | XBRL Taxonomy Extension Calculation Linkbase Document | |
| 101.DEF | XBRL Taxonomy Extension Definition Linkbase Document | |
| 101.LAB | XBRL Taxonomy Extension Label Linkbase Document | |
| 101.PRE | XBRL Taxonomy Extension Presentation Linkbase Document |
| * | Exhibits 10.4 through 10.27 constitute management contracts or compensatory plans or arrangements. |
|---|
Item 16. Form 10-K Summary.
| --- | --- |
None.
Table of Contents
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| Lockheed Martin Corporation | ||||||
| (Registrant) | ||||||
| Date: February 9, 2017 | By: | /s/ Brian P. Colan | ||||
| Brian P. Colan | ||||||
| Vice President, Controller, and Chief Accounting Officer |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities and on the dates indicated.
| Signatures | Titles | Date | ||||
| /s/ Marillyn A. Hewson Marillyn A. Hewson | Chairman, President and Chief Executive Officer (Principal Executive Officer) | February 9, 2017 | ||||
| /s/ Bruce L. Tanner Bruce L. Tanner | Executive Vice President and Chief Financial Officer (Principal Financial Officer) | February 9, 2017 | ||||
| /s/ Brian P. Colan Brian P. Colan | Vice President, Controller, and Chief Accounting Officer (Principal Accounting Officer) | February 9, 2017 | ||||
| * Daniel F. Akerson | Director | February 9, 2017 | ||||
| * Nolan D. Archibald | Director | February 9, 2017 | ||||
| * Rosalind G. Brewer | Director | February 9, 2017 | ||||
| * David B. Burritt | Director | February 9, 2017 | ||||
| * Bruce A. Carlson | Director | February 9, 2017 | ||||
| * James O. Ellis, Jr. | Director | February 9, 2017 | ||||
| * Thomas J. Falk | Director | February 9, 2017 | ||||
| * Ilene S. Gordon | Director | February 9, 2017 | ||||
| * James M. Loy | Director | February 9, 2017 | ||||
| * Joseph W. Ralston | Director | February 9, 2017 | ||||
| * Anne Stevens | Director | February 9, 2017 |
*By Maryanne R. Lavan pursuant to a Power of Attorney executed by the Directors listed above, which has been filed with this Annual Report on Form 10-K.
| Date: February 9, 2017 | By: | /s/ Maryanne R. Lavan | ||||
| Maryanne R. Lavan | ||||||
| Attorney-in-fact |