 filings.tools
Cover and table of contents
91K characters. Original on sec.gov · Markdown
Cover and table of contents
| UNITED STATES SECURITIES AND EXCHANGE COMMISSION | |||||||||||||||||
| Washington, D.C. 20549 | |||||||||||||||||
| Form | 10-K | ||||||||||||||||
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the fiscal year ended December 31, 2021
| Or | |||||
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 | ||||
| For the transition period from to |
Commission file number: 001-32877
 | ||||||||||||||||||||
| Mastercard Incorporated | ||||||||||||||||||||
| (Exact name of registrant as specified in its charter) | ||||||||||||||||||||
| Delaware | 13-4172551 | |||||||||||||||||||
| (State or other jurisdiction of incorporation or organization) | (IRS Employer Identification Number) | |||||||||||||||||||
| 2000 Purchase Street | ||||||||||||||||||||
| Purchase, | NY | 10577 | ||||||||||||||||||
| (Address of principal executive offices) | (Zip Code) |
(914) 249-2000
(Registrant’s telephone number, including area code)
| Securities registered pursuant to Section 12(b) of the Act: | ||||||||||||||
| Title of each class | Trading Symbol | Name of each exchange of which registered | ||||||||||||
| Class A Common Stock, par value $0.0001 per share | MA | New York Stock Exchange | ||||||||||||
| 1.1% Notes due 2022 | MA22 | New York Stock Exchange | ||||||||||||
| 2.1% Notes due 2027 | MA27 | New York Stock Exchange | ||||||||||||
| 2.5% Notes due 2030 | MA30 | New York Stock Exchange |
| Securities registered pursuant to Section 12(g) of the Act: | ||||||||||||||||||||
| Class B common stock, par value $0.0001 per share |
| Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. | Yes | ☒ | No | ☐ | |||||||||||||||||||
| Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. | Yes | ☐ | No | ☒ | |||||||||||||||||||
| Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. | Yes | ☒ | No | ☐ | |||||||||||||||||||
| Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). | Yes | ☒ | No | ☐ |
| Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act. (Check One): | |||||||||||||||||||||||
| Large accelerated filer | ☒ | Accelerated filer | ☐ | ||||||||||||||||||||
| Non-accelerated filer | ☐ | (do not check if a smaller reporting company) | Smaller reporting company | ☐ | |||||||||||||||||||
| Emerging growth company | ☐ | ||||||||||||||||||||||
| If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13 (a) of the Exchange Act. | ☐ | ||||||||||||||||||||||
| Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. | ☒ | ||||||||||||||||||||||
| Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). | Yes | ☐ | No | ☒ |
The aggregate market value of the registrant’s Class A common stock, par value $0.0001 per share, held by non-affiliates (using the New York Stock Exchange closing price as of June 30, 2021, the last business day of the registrant’s most recently completed second fiscal quarter) was approximately $317.9 billion. There is currently no established public trading market for the registrant’s Class B common stock, par value $0.0001 per share. As of February 8, 2022, there were 969,729,455 shares outstanding of the registrant’s Class A common stock, par value $0.0001 per share and 7,746,984 shares outstanding of the registrant’s Class B common stock, par value $0.0001 per share.
| Portions of the registrant’s definitive proxy statement for the 2022 Annual Meeting of Stockholders are incorporated by reference into Part III hereof. | ||

MASTERCARD INCORPORATED FISCAL YEAR 2021 FORM 10-K ANNUAL REPORT
TABLE OF CONTENTS
MASTERCARD 2021 FORM 10-K 3
In this Report on Form 10-K (“Report”), references to the “Company,” “Mastercard,” “we,” “us” or “our” refer to the business conducted by Mastercard Incorporated and its consolidated subsidiaries, including our operating subsidiary, Mastercard International Incorporated, and to the Mastercard brand.
Forward-Looking Statements
This Report contains forward-looking statements pursuant to the safe harbor provisions of the Private Securities Litigation Reform Act of 1995. All statements other than statements of historical facts may be forward-looking statements. When used in this Report, the words “believe”, “expect”, “could”, “may”, “would”, “will”, “trend” and similar words are intended to identify forward-looking statements. Examples of forward-looking statements include, but are not limited to, statements that relate to the Company’s future prospects, developments and business strategies.
Many factors and uncertainties relating to our operations and business environment, all of which are difficult to predict and many of which are outside of our control, influence whether any forward-looking statements can or will be achieved. Any one of those factors could cause our actual results to differ materially from those expressed or implied in writing in any forward-looking statements made by Mastercard or on its behalf, including, but not limited to, the following factors:
-
regulation directly related to the payments industry (including regulatory, legislative and litigation activity with respect to interchange rates and surcharging)
-
the impact of preferential or protective government actions
-
regulation of privacy, data, security and the digital economy
-
regulation that directly or indirectly applies to us based on our participation in the global payments industry (including anti-money laundering, counter financing of terrorism, economic sanctions and anti-corruption, account-based payments systems, and issuer practice regulation)
-
the impact of changes in tax laws, as well as regulations and interpretations of such laws or challenges to our tax positions
-
potential or incurred liability and limitations on business related to any litigation or litigation settlements
-
the impact of the global COVID-19 pandemic and measures taken in response
-
the impact of competition in the global payments industry (including disintermediation and pricing pressure)
-
the challenges relating to rapid technological developments and changes
-
the challenges relating to operating a real-time account-based payments system and to working with new customers and end users
-
the impact of information security incidents, account data breaches or service disruptions
-
issues related to our relationships with our stakeholders (including loss of substantial business from significant customers, competitor relationships with our customers, banking industry consolidation, merchants’ continued focus on acceptance costs and unique risks from our work with governments)
-
exposure to loss or illiquidity due to our role as guarantor and other contractual obligations
-
the impact of global economic, political, financial and societal events and conditions, including adverse currency fluctuations and foreign exchange controls
-
reputational impact, including impact related to brand perception and lack of visibility of our brands in products and services
-
the inability to attract, hire and retain a highly qualified and diverse workforce, or maintain our corporate culture
-
issues related to acquisition integration, strategic investments and entry into new businesses
-
issues related to our Class A common stock and corporate governance structure
Please see “Risk Factors” in Part I, Item 1A for a complete discussion of these risk factors. We caution you that the important factors referenced above may not contain all of the factors that are important to you. Our forward-looking statements speak only as of the date of this Report or as of the date they are made, and we undertake no obligation to update our forward-looking statements.
4 MASTERCARD 2021 FORM 10-K
| PART I | |||||||||||||||||
| Item 1. Business | |||||||||||||||||
| Item 1A. Risk factors | |||||||||||||||||
| Item 1B. Unresolved staff comments | |||||||||||||||||
| Item 2. Properties | |||||||||||||||||
| Item 3. Legal proceedings | |||||||||||||||||
| Item 4. Mine safety disclosures | |||||||||||||||||
| Information about our executive officers | |||||||||||||||||
PART I
ITEM 1. BUSINESS
Item 1. Business
Overview
Mastercard is a technology company in the global payments industry that connects consumers, financial institutions, merchants, governments, digital partners, businesses and other organizations worldwide, enabling them to use electronic forms of payment instead of cash and checks. We make payments easier and more efficient by providing a wide range of payment solutions and services using our family of well-known and trusted brands, including Mastercard®, Maestro® and Cirrus®. We operate a multi-rail payments network that provides choice and flexibility for consumers and merchants. Through our unique and proprietary core global payments network, we switch (authorize, clear and settle) payment transactions. We have additional payment capabilities that include automated clearing house (“ACH”) transactions (both batch and real-time account-based payments). Using these capabilities, we offer integrated payment products and services and capture new payment flows. Our value-added services include, among others, cyber and intelligence solutions to allow all parties to transact easily and with confidence, as well as other services that provide proprietary insights, drawing on our principled use of consumer and merchant data**.** Our franchise model sets the standards and ground-rules that balance value and risk across all stakeholders and allows for interoperability among them. Our payment solutions are designed to ensure safety and security for the global payments ecosystem.
For a full discussion of our business, please see page 9.
Our Performance
The following are our key financial and operational highlights for 2021, including growth rates over the prior year:
| GAAP | |||||||||||||||||||||||||||||
| Net revenue | Net income | Diluted EPS | |||||||||||||||||||||||||||
| $18.9B | $8.7B | $8.76 | |||||||||||||||||||||||||||
| up 23% | up 35% | up 38% | |||||||||||||||||||||||||||
| Non-GAAP 1 (currency-neutral) | |||||||||||||||||||||||||||||
| Net revenue | Adjusted net income | Adjusted diluted EPS | |||||||||||||||||||||||||||
| $18.9B | $8.3B | $8.40 | |||||||||||||||||||||||||||
| up 22% | up 28% | up 30% | |||||||||||||||||||||||||||
| $7.6B | $5.9B | Repurchased shares | $9.5B | ||||||||||||||||||||||||||
| in capital returnedto stockholders | $1.7B | Dividends paid | cash flowsfrom operations | ||||||||||||||||||||||||||
 | Gross dollar volume (growth on a local currency basis) |  | Cross-border volume growth (on a local currency basis) |  | Switched transactions | ||||||||||||||||||||||||
| $7.7T | up 32% | 112.1B | |||||||||||||||||||||||||||
| up 21% | up 25% | ||||||||||||||||||||||||||||
1Non-GAAP results exclude the impact of gains and losses on equity investments, Special Items and/or foreign currency. See “Management’s Discussion and Analysis of Financial Condition and Results of Operations - Financial Results Overview” in Part II, Item 7 for the reconciliation to the most direct comparable GAAP financial measures.
For a full discussion of our results of operations, including impacts of the COVID-19 pandemic, see “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in Item II, Part 7.
6 MASTERCARD 2021 FORM 10-K
PART I
ITEM 1. BUSINESS
Our Strategy
We remain committed to our strategy to grow our core payments network, diversify our customers and geographies and build new capabilities through a combination of organic and inorganic strategic initiatives. We are executing on this strategy through a focus on three key priorities:
-
expand in payments for consumers, businesses and governments
-
extend our services to enhance transactions and drive customer value
-
embrace new network opportunities to enable open banking, digital identity and other adjacent network capabilities
Each of our priorities supports and builds upon each other and are fundamentally interdependent.
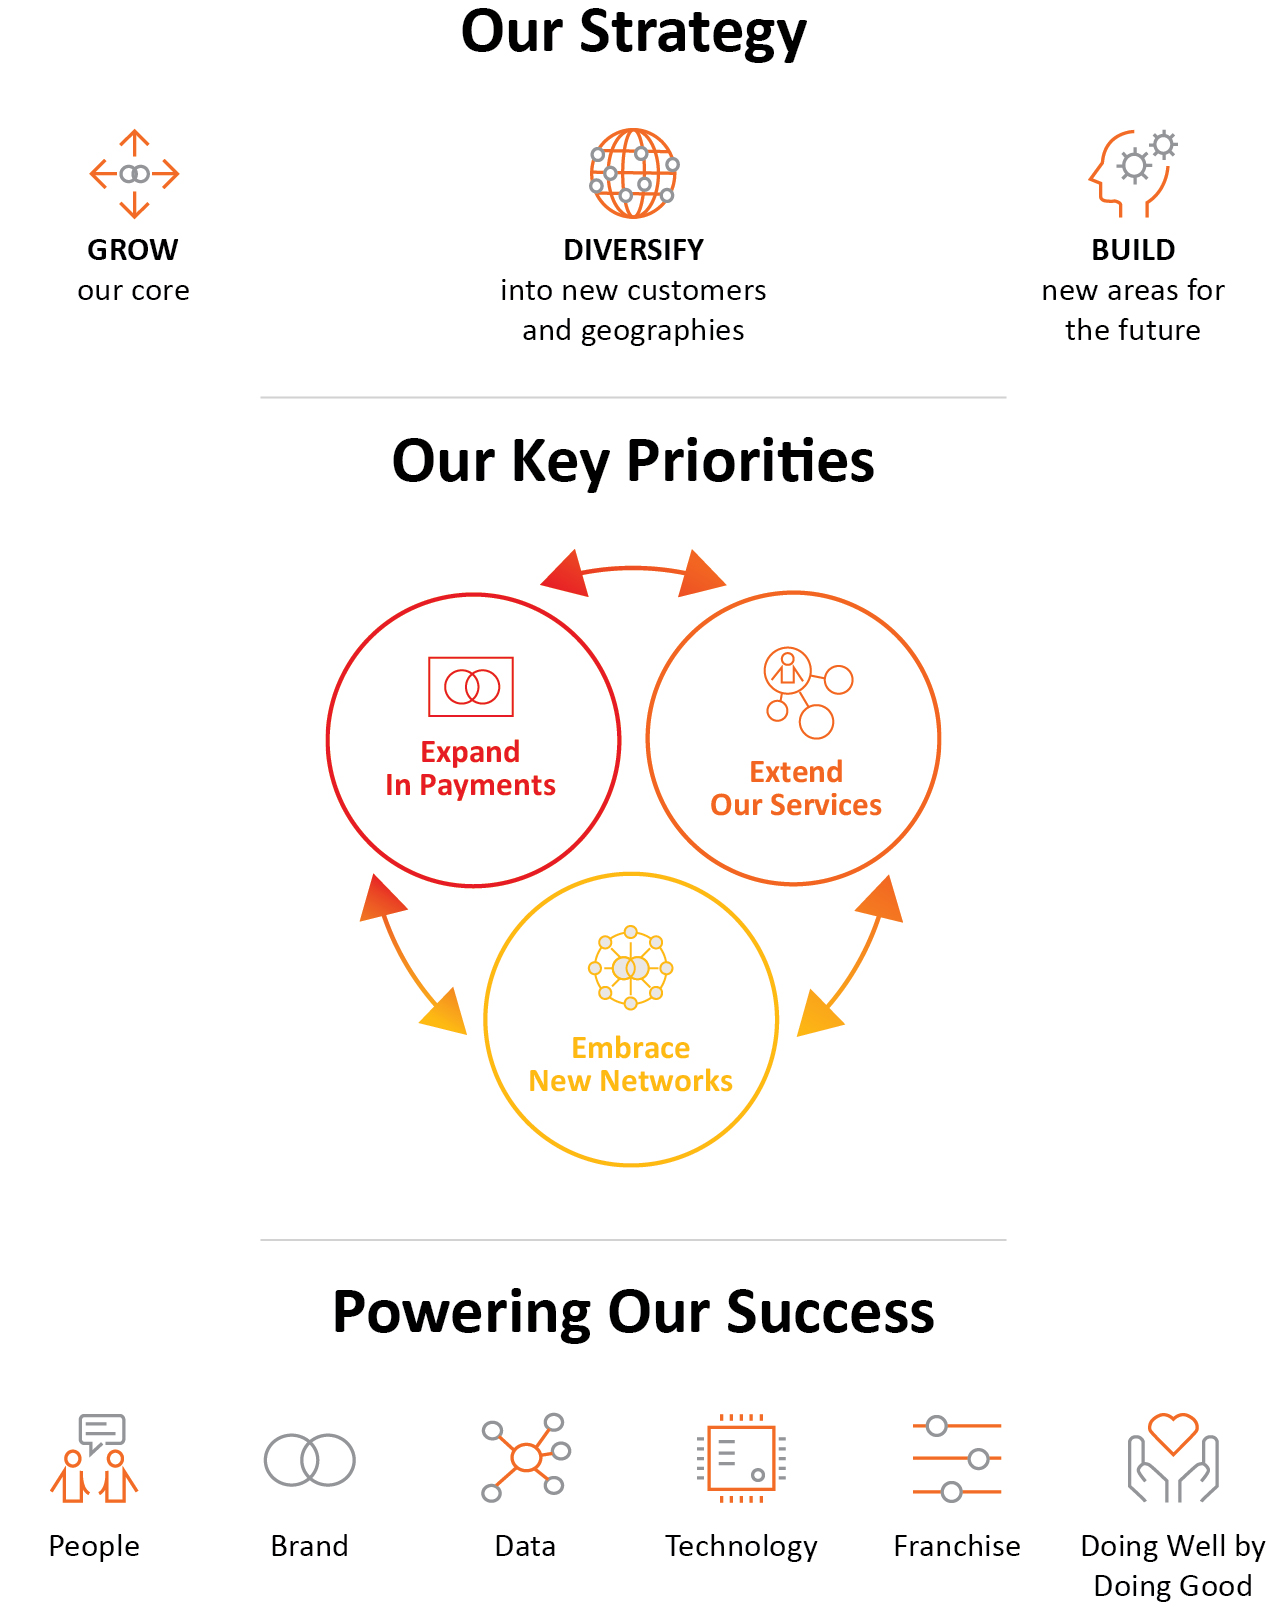
Our Key Strategic Priorities
Expand in payments. We continue to focus on expanding upon our core payments network to enable payment flows for consumers, businesses, governments and others, providing them with choice and flexibility to transact across multiple payment rails (including cards, real-time payments and account-to-account) while ensuring that all payments are done safely, securely and seamlessly. We do so by:
- Driving growth in consumer purchases** with a focus on accelerating digitization, growing acceptance and pursuing an expanded set of use cases, including through partnerships
MASTERCARD 2021 FORM 10-K 7
PART I
ITEM 1. BUSINESS
-
Capturing new payment flows** by expanding our multi-rail capabilities and applications to penetrate key flows such as disbursements and remittances (through Mastercard Send™ and Cross-Border Services), business-to-business (“B2B”) (including Mastercard Track Business Payment Service™ (“Track BPS”) and areas beyond payments such as enablement of supply chain financing) and consumer bill payments
-
Leaning into new payment innovations** such as our planned launch in 2022 of Mastercard Installments, our buy-now-pay-later solution, and developing solutions that support digital currencies and blockchain applications
Extend our services. Our services drive value for our customers and the broader payments ecosystem. We continue to do that as well as diversify our business, by extending our services, which include cyber and intelligence solutions, insights and analytics, test and learn, consulting, managed services, loyalty, processing and payment gateway solutions for e-commerce merchants. As we drive value, our services help accelerate our top-line financial performance by supporting revenue growth in our core payments network. We extend our services by:
-
Enhancing the value of payments** by making payments safe, secure, intelligent and seamless
-
Expanding services to new segments and use cases** to address the needs of a larger set of customers, including financial institutions, merchants, governments, digital players and others, while expanding our geographic reach
-
Supporting and strengthening new network capabilities,** including expanding services associated with digital identities and deploying our expertise in open banking and open data, including with improved analytics
Embrace new network opportunities. We are building and managing new adjacent network capabilities to power commerce, creating new opportunities to develop and embed services. We do so by:
-
Applying our open banking solutions** to help institutions and individuals exchange data securely and easily, by enabling the reliable access, transmission and management of consumer data (including for opening new accounts, securing loans, increasing credit scores and enabling consumer choice in money movement and personal finance management)
-
Enabling digital identity solutions***,* including device intelligence, document proofing, internet protocol (“IP”) intelligence, biometrics, transaction fraud data, location, identity attributes and payment authorization to make transactions across individual devices and accounts efficient, safe and secure
Each of our priorities supports and builds upon each other and are fundamentally interdependent:
-
Payments** provide data and distribution to drive scale and differentiation in services and enable the development and adoption of new network capabilities
-
Services** improve the security, efficiency and intelligence of payments, improve portfolio performance, differentiate our offerings and strengthen our customer relationships. They also power our open banking and digital identity platforms
-
New network opportunities** strengthen our digital payments value proposition, including improved authentication with digital identity, and new opportunities to develop and embed services in our expanding product offerings
Powering Our Success
These priorities are supported by six key drivers:
People. Our success is driven by the skills, experience, integrity and mindset of the talent we hire. We attract and retain top talent from diverse backgrounds and industries. Our people and our winning culture is based on decency, respect and inclusion where people have opportunities to perform purpose-driven work that impacts communities, customers and co-workers on a global scale. The diversity and skill sets of our people underpin everything we do.
Brand. Our brands and brand identities (including our sonic brand identity) serve as a differentiator for our business, representing our values and enabling us to accelerate growth in new areas.
Data. We use our data assets, infrastructure and platforms to create a range of products and services for our customers, while incorporating our data principles in how we design, implement and deliver those solutions. Our Privacy by Design and Data by Design processes have been developed to ensure we embed privacy, security and data controls in all of our products and services, keeping a clear focus on protecting customers’ and individuals’ data.
Technology. Our technology provides resiliency, scalability and flexibility in how we serve customers. It enables broader reach to scale digital payment services to multiple channels, including mobile devices. Our technology standards, services and governance model help us to serve as the connection that allows financial institutions, financial technology companies (fintechs) and others to interoperate and enable consumers, businesses, governments and merchants to engage through digital channels.
8 MASTERCARD 2021 FORM 10-K
PART I
ITEM 1. BUSINESS
Franchise. We manage an ecosystem of stakeholders who participate in our network. Our franchise creates and sustains a comprehensive series of value exchanges across our ecosystem. We provide a balanced ecosystem where all participants benefit from the availability, innovation and safety and security of our network and platforms. Our franchise enables the scale of our payments network and helps ensure our multiple payment capabilities operate under a single governance structure, which can be extended to new opportunities.
Doing Well by Doing Good. We apply the full breadth of our technology, insights, partnerships and people to build a more financially inclusive and sustainable digital economy, with a commitment to diversity, equity and inclusion and a focus on a sustainable future. We are committed to our core values of operating ethically, responsibly and with decency. This commitment is directly connected to our continuing success as a business. We refer you to our most recently published Sustainability Report and Proxy Statement (each located on our website) for our efforts and initiatives in the area of sustainability.
Our Business
Our Multi-Rail Network and Payment Capabilities
We enable a wide variety of payment capabilities (including integrated products and value-added service solutions) over our multi-rail network among account holders, merchants, financial institutions, businesses, governments and others, offering our customers one partner for their payment needs.
Core Network
Our core network links issuers and acquirers around the globe to facilitate the switching of transactions, permitting account holders to use a Mastercard product at tens of millions of acceptance locations worldwide. This network facilitates an efficient, safe and secure means for receiving payments, a convenient, quick and secure payment method for consumers to access their funds and a channel for businesses to receive insight through information that is derived from our network. We enable transactions for our customers through our core network in more than 150 currencies and in more than 210 countries and territories.
MASTERCARD 2021 FORM 10-K 9
PART I
ITEM 1. BUSINESS
Core Network Transactions. Our core network supports what is often referred to as a “four-party” payments network and includes the following participants: account holder (a person or entity who holds a card or uses another device enabled for payment), issuer (the account holder’s financial institution), merchant and acquirer (the merchant’s financial institution).
We do not issue cards, extend credit, determine or receive revenue from interest rates or other fees charged to account holders by issuers, or establish the rates charged by acquirers in connection with merchants’ acceptance of our products. In most cases, account holder relationships belong to, and are managed by, our customers.
The following graphic depicts a typical transaction on our core network, and our role in that transaction:
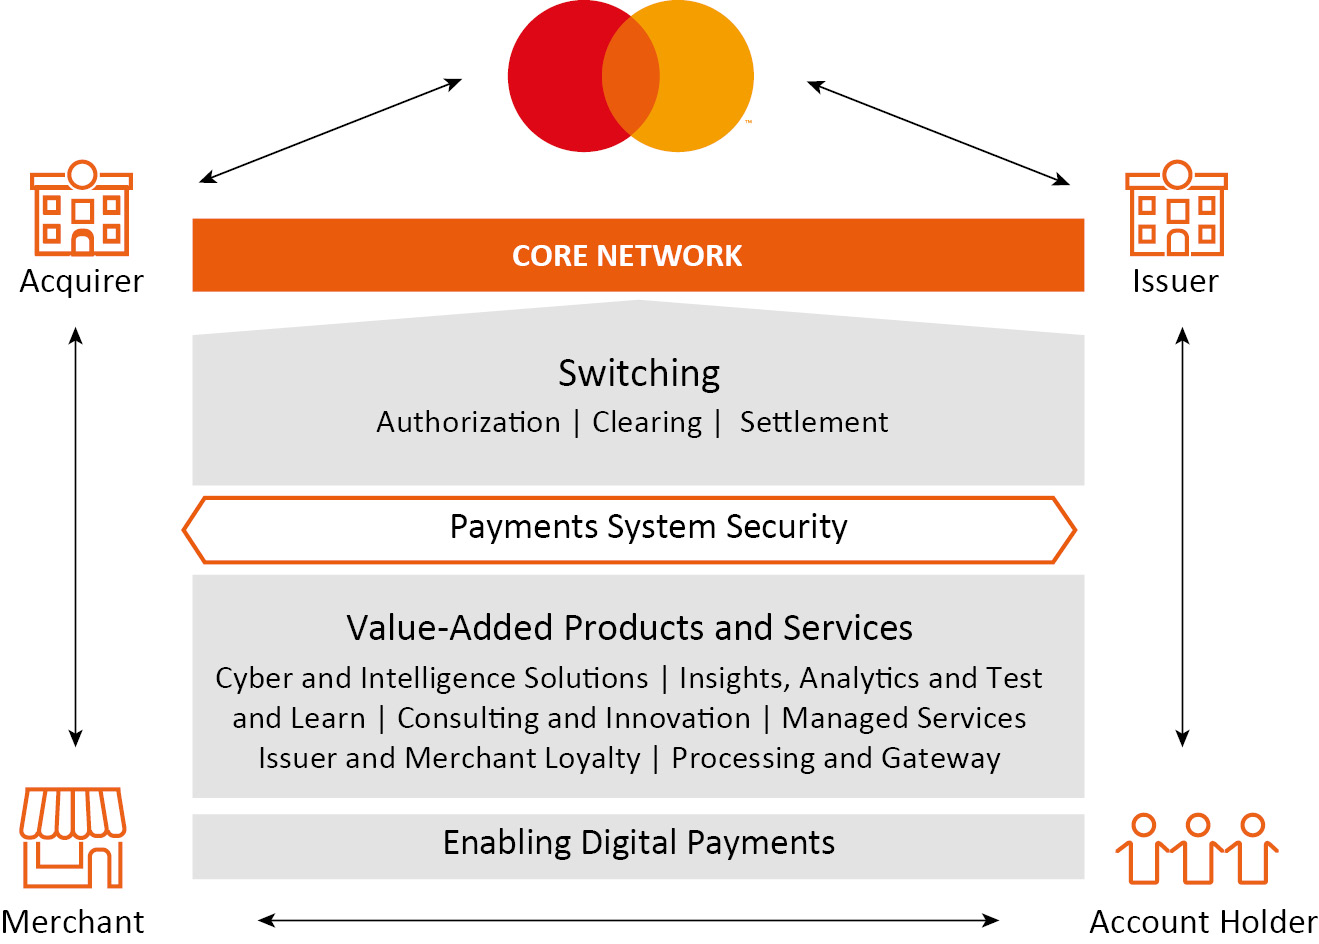
In a typical transaction, an account holder purchases goods or services from a merchant using one of our payment products. After the transaction is authorized by the issuer, the issuer pays the acquirer an amount equal to the value of the transaction, minus the interchange fee (described below) and other applicable fees, and then posts the transaction to the account holder’s account. The acquirer pays the amount of the purchase, net of a discount (referred to as the “merchant discount” rate), to the merchant.
-
Interchange Fees.** Interchange fees reflect the value merchants receive from accepting our products and play a key role in balancing the costs and benefits that consumers and merchants derive. Generally, interchange fees are collected from acquirers and paid to issuers to reimburse the issuers for a portion of the costs incurred. These costs are incurred by issuers in providing services that benefit all participants in the system, including acquirers and merchants, whose participation in the network enables increased sales to their existing and new customers, efficiencies in the delivery of existing and new products, guaranteed payments and improved experience for the customers. We (or, alternatively, financial institutions) establish “default interchange fees” that apply when there are no other established settlement terms in place between an issuer and an acquirer. We administer the collection and remittance of interchange fees through the settlement process.
-
Additional Four-Party System Fees.** The merchant discount rate is established by the acquirer to cover its costs of both participating in the four-party system and providing services to merchants. The rate takes into consideration the amount of the interchange fee which the acquirer generally pays to the issuer. Additionally, acquirers may charge merchants processing and related fees in addition to the merchant discount rate. Issuers may also charge account holders fees for the transaction, including, for example, fees for extending revolving credit.
Switched Transactions
-
Authorization, Clearing and Settlement.** Through our core network, we enable the routing of a transaction to the issuer for its approval, facilitate the exchange of financial transaction information between issuers and acquirers after a successfully conducted transaction, and settle the transaction by facilitating the exchange of funds between parties via settlement banks chosen by us and our customers.
-
Cross-Border and Domestic.** Our core network switches transactions throughout the world when the merchant country and country of issuance are different (“cross-border transactions”), providing account holders with the ability to use, and merchants
10 MASTERCARD 2021 FORM 10-K
PART I
ITEM 1. BUSINESS
to accept, our products and services across country borders. We also provide switched transaction services to customers where the merchant country and the country of issuance are the same (“domestic transactions”). We switch over 60% of all transactions for Mastercard and Maestro-branded cards, including nearly all cross-border transactions.
We guarantee the settlement of many of the transactions from issuers to acquirers to ensure the integrity of our core network. We refer to the amount of this guarantee as our settlement exposure. We do not, however, guarantee payments to merchants by their acquirers or the availability of unspent prepaid account holder account balances.
Core Network Architecture. Our core network features a globally integrated structure that provides scale for our issuers, enabling them to expand into regional and global markets. It is based largely on a distributed (peer-to-peer) architecture that enables the network to adapt to the needs of each transaction. The network accomplishes this by performing intelligent routing and applying multiple value-added services (such as fraud scoring, tokenization services, etc.) to appropriate transactions in real time. This architecture enables us to connect all parties regardless of where or how the transaction is occurring. It has 24-hour a day availability and world-class response time.
Additional Payment Capabilities
ACH Batch and Real-Time Account-Based Payments Infrastructure and Applications. We offer ACH batch and real-time account-based payments capabilities, enabling payments for ACH transactions between bank accounts in real-time. These capabilities provide consumers and businesses the ability to make instant (faster) payments while providing enhanced data and messaging capabilities. We build, implement, enhance and operate real-time clearing and settlement infrastructure, payment platforms and direct debit systems for jurisdictions globally. As of December 31, 2021, we either operated or were implementing real-time payments infrastructure in 12 of the top 50 markets as measured by GDP. We also apply our real-time payments capabilities to new payment flows, such as consumer bill payments using our real-time bill pay solutions.
Account to Account. We enable consumers, businesses, governments and merchants to send and receive money directly from account to account. We apply these capabilities to help these stakeholders with various disbursements and remittances.
We discuss below under “Our Payment Products and Applications” the ways in which we apply our real-time account-based and account to account payment capabilities to capture new payment flows.
Security and Franchise
Payments System Security. We have a multi-layered approach to protect the global payments ecosystem. As part of this approach, we have a robust program to protect our network from cyber and information security threats. Our network and platforms incorporate multiple layers of protection, providing greater resiliency and best-in-class security protection. Our programs are assessed by third parties and incorporate benchmarking and other data from peer companies and consultants. We engage in many efforts to mitigate information security challenges, including maintaining an information security program, an enterprise resilience program and insurance coverage, as well as regularly testing our systems to address potential vulnerabilities. Through the combined efforts of our Security Operations Centers, Fusion Centers and the Mastercard Intelligence Center, we work with experts across the organization (as well as through other sources such as public-private partnerships) to monitor and respond quickly to a range of cyber and physical threats.
As another feature of our multi-layered approach to protect the global payments ecosystem, we work with issuers, acquirers, merchants, governments and payments industry associations to develop and put in place technical standards (such as EMV standards for chips and smart payment cards) for safe and secure transactions and we provide solutions and products that are designed to ensure safety and security for the global payments ecosystem. We discuss specific cyber and intelligence solutions that we offer to our customers in “Our Value-Added Services”.
Our Franchise. We manage an ecosystem of stakeholders that participate in our network and payments platforms. Our franchise creates and sustains a comprehensive series of value exchanges across our ecosystem. We ensure a balanced ecosystem where all participants benefit from the availability, innovation, safety and security of our network. We achieve this through the following key activities:
-
Participant Onboarding.** We ensure the capability of new customers to use our network and define the roles and responsibilities for their operations once on the network
-
Safety and Security.** We establish the core principles, including ensuring consumer protections and integrity, so participants feel confident to transact on the network
-
Operating Standards.** We define the operational, technical and financial policies to which network participants are required to adhere
MASTERCARD 2021 FORM 10-K 11
PART I
ITEM 1. BUSINESS
-
Responsible Stewardship.** We establish performance standards to support ecosystem growth and optimization and establish proactive monitoring to ensure participant performance
-
Issue Resolution.** We operate a framework to enable the resolution of disputes for both customers and consumers
Our Payment Products and Applications
We provide a wide variety of integrated products and services that support payment products that customers can offer to consumers and merchants. These offerings facilitate transactions across our multi-rail payments network and platforms among account holders, merchants, financial institutions, digital partners, businesses, governments and other organizations in markets globally.  Core Payment Products Consumer Credit. We offer a number of products that enable issuers to provide consumers with credit, allowing them to defer payment. These programs are designed to meet the needs of our customers around the world and address standard, premium and affluent consumer segments. | How We Benefit Consumers | ||||||||||
| We enable our customers to benefit consumers by: •making electronic payments more convenient, secure and efficient •delivering better, seamless consumer experiences •providing consumers choice, empowering them to make and receive payments in the ways that best meet their daily needs •protecting consumers and all other participants in a transaction, as well as consumer data •providing loyalty rewards |
Consumer Debit. We support a range of payment products and solutions that allow our customers to provide consumers with convenient access to funds in deposit and other accounts. Our debit and deposit access programs can be used to make purchases and to obtain cash in bank branches, at ATMs and, in some cases, at the point of sale. Our branded debit programs consist of Mastercard (including standard, premium and affluent offerings), Maestro (the only PIN-based solution that operates globally) and Cirrus (our primary global cash access solution).
Prepaid. Prepaid accounts are a type of electronic payment that enables consumers to pay in advance whether or not they previously had a bank account or a credit history. These accounts can be tailored to meet specific program, customer or consumer needs, such as paying bills, sending person-to-person payments or withdrawing cash from an ATM. Our focus ranges from digital accounts (such as fintech and gig economy platforms) to business programs such as employee payroll, health savings accounts and solutions for small business owners. Our prepaid programs also offer opportunities in the private and public sectors to drive financial inclusion of previously unbanked individuals through social security payments, unemployment benefits and salary cards.
We also provide prepaid program management services, primarily outside of the United States, that provide processing and end-to-end services on behalf of issuers or distributor partners such as airlines, foreign exchange bureaus and travel agents.
Commercial Credit and Debit. We offer commercial credit and debit payment products and solutions that meet the payment needs of large corporations, midsize companies, small businesses and government entities. Our solutions streamline procurement and payment processes, manage information and expenses (such as travel and entertainment) and reduce administrative costs. Our point of sale offerings include small business (debit and credit), travel and entertainment, purchasing cards and fleet cards. Our SmartData platform provides expense management and reporting capabilities. Our virtual card offerings, supported by our Mastercard In Control™ platform, generate virtual account numbers which provide businesses with enhanced controls, more security and better data.
12 MASTERCARD 2021 FORM 10-K
PART I
ITEM 1. BUSINESS
The following chart provides gross dollar volume (“GDV”) and number of cards featuring our brands in 2021 for select programs and solutions:
| Year Ended December 31, 2021 | As of December 31, 2021 | |||||||||||||||||||||||||||||||
| GDV | Cards | |||||||||||||||||||||||||||||||
| (in billions) | Growth (Local) | % of Total GDV | (in millions) | Percentage Increase from December 31, 2020 | ||||||||||||||||||||||||||||
| Mastercard-branded Programs1,2 | ||||||||||||||||||||||||||||||||
| Consumer Credit | $ | 2,899 | 18 | % | 38 | % | 968 | 9 | % | |||||||||||||||||||||||
| Consumer Debit and Prepaid | 3,953 | 22 | % | 51 | % | 1,509 | 13 | % | ||||||||||||||||||||||||
| Commercial Credit and Debit | 867 | 25 | % | 11 | % | 111 | 11 | % |
1Excludes Maestro and Cirrus cards and volume generated by those cards.
2Prepaid includes both consumer and commercial prepaid.
 New Payment Flows
We offer platforms that apply our payment capabilities to support and capture new payment flows beyond cards.
Disbursements and Remittances. We offer applications that enable consumers, businesses, governments and merchants to send and receive money domestically and across borders with greater speed and ease.
-
Using Mastercard Send, we partner with digital messaging and payment platforms to enable consumers to send and receive money directly within applications. We partner with central banks, fintechs and financial institutions to help governments and nonprofits more efficiently enable, as applicable, distribution of social and economic assistance and business-to-consumer (“B2C”) disbursements.
-
Mastercard Cross-Border Services enables a wide range of payment flows and use cases to customers, including trade payments, remittances and disbursements. These flows are enabled via a distribution network with a single point of access that allows financial institutions, fintechs and digital partners to send and receive money globally through multiple channels, including bank accounts, mobile wallets, cards and cash payouts.
B2B Payments. We continue to focus on developing solutions to address ways that businesses move money, building on our point of sale capabilities to capture B2B payments. We offer B2B solutions globally that optimize customer choice, enabling payments through card, ACH and real-time payment rails. Mastercard Track BPS, our two-sided open-loop commercial service platform, is aimed at improving the way businesses pay and get paid by simplifying and automating payments between suppliers and buyers. It provides a single connection enabling access to multiple payment rails, providing greater control, richer data and working capital optimization capabilities to enhance B2B transactions for both buyers and suppliers. Track BPS leverages multiple payment options, including both real-time payments and batch ACH, as well as our core network.
Consumer Bill Payments.
-
We offer applications including those that make it easier for consumers and small businesses to present, view, manage and pay their bills through their online or mobile banking apps. Payments can be made in a variety of ways, using cards, real-time payments or batch ACH payments through a digital interface, providing a convenient, secure and paperless means to manage household bills in one place.
-
Our bill pay solutions, which include Bill Pay Exchange, provide an open, Application Programming Interface (“API”) based bill pay network that leverages real-time messaging to connect consumers with billers and merchants through the home banking channel. We also provide real-time bill pay solutions as well as clearing and instant payment services. Our solutions enable enhanced biller setup and expanded bill presentment. They facilitate payment choice using multiple payment rails (including real-time account-based payments) and deliver immediate payment confirmation, providing an experience that benefits consumers, financial institutions and billers.
MASTERCARD 2021 FORM 10-K 13
PART I
ITEM 1. BUSINESS
 Innovation and Technology
| Our innovation capabilities and our technology provide resiliency, scalability and flexibility in how we serve customers. They enable broader reach to scale digital payment services across multiple channels, including mobile devices. Our technology standards, services and governance model help us to serve as the connection that allows financial institutions, fintechs and technology companies to interoperate and enable consumers, businesses, governments and merchants to engage through digital channels. •Delivering better digital experiences everywhere. We are using our technologies and security protocols to develop solutions to make digital shopping and selling experiences, such as on smartphones and other connected devices, simpler, faster and safer for both consumers and merchants. We also offer products that make it easier for merchants to accept payments and expand their customer base. ◦Our contactless payment solutions help deliver a simple and intuitive way to pay, as well as health and safety benefits when consumers are looking for low-touch options | Key 2021 Developments | ||||||||||
| **•**During 2021, we announced the expansion of several programs that enabled consumers to either use their cards to purchase cryptocurrencies or to convert their cryptocurrencies back into fiat currencies at their respective financial institutions. | |||||||||||
| •During 2021, we announced Mastercard Installments, our new open loop solution to deliver buy-now-pay-later installments capabilities at scale. The solution connects lenders with merchants across our acceptance network to provide buy-now-pay-later options for consumers. The program is expected to launch in 2022. | |||||||||||
◦Our Click to Pay checkout experience is designed to provide consumers the same convenience and security in a digital environment that they have when paying in a store, make it easier for merchants to implement secure digital payments and provide issuers with improved fraud detection and prevention capability. This experience is based on the EMV Secure Remote Commerce industry standard that enables a faster, more secure checkout experience across web and mobile sites, mobile apps and connected devices
◦Our Digital First Card program enables customers to offer their cardholders a fully digital payment experience with an optional physical card, meeting cardholder expectations of immediacy, safety and convenience during card application, authentication and instant card access, securing purchases (whether contactless, in-store, in-app or via the web) and managing alerts, controls and benefits
◦Our Digital Doors program helps small businesses establish and protect an online presence, including accepting digital payments
-
Securing more transactions.** We are leveraging tokenization, biometrics and machine learning technologies in our push to secure every transaction. These efforts include driving EMV-level security and benefits through all our payment channels.
-
Simplifying access to, and integration of, our digital assets.** Our Mastercard Developer platform makes it easy for customers and partners to leverage our many digital assets and services. By providing a single access point with tools and capabilities to find what we believe are some of the best-in-class APIs across a broad range of Mastercard services, we enable easy integration of our services into new and existing solutions.
-
Identifying and experimenting with future technologies, start-ups and trends.** Through Mastercard Foundry (formerly known as Mastercard Labs), we continue to bring customers and partners access to thought leadership, innovation methodologies, new technologies and relevant early-stage fintech players.
14 MASTERCARD 2021 FORM 10-K
PART I
ITEM 1. BUSINESS
Our Value-Added Services
Our services encompass a wide-ranging portfolio of value-added and differentiating capabilities that:
-
instill trust in the ecosystem to allow parties to transact and operate with confidence
-
provide actionable insights to our customers to assist in their decision making
-
enable our customers to strengthen their engagement with their own end-users
-
enable connectivity and access for a fragmented and diverse set of parties
 Cyber and Intelligence Solutions
| As part of the security we bring to the payments ecosystem, we offer integrated products and services to prevent, detect and respond to fraud and cyber-attacks and to ensure the safety of transactions made using Mastercard products. We do this using a multi-layered safety and security strategy: •The “Prevent” layer is designed to protect against attacks on infrastructure, devices and data. We have continued to grow global usage of EMV chip and contactless security technology, helping to reduce fraud. Our solutions include SafetyNet, which protects financial institutions by helping to stop real-time attacks that are visible in the network, but not easily detected by financial institutions. •The “Identify” layer allows us to help banks and merchants verify the authenticity of consumers during the payment process using various biometric technologies, including fingerprint, face and iris scanning, and behavioral user data assessment technology to verify online purchases on mobile devices, as well as a card with biometric technology built in. | Key 2021 Developments | ||||||||||
| **•**We acquired CipherTrace, a leading digital currency intelligence platform that can map and trace blockchain-based transactions between entities, providing greater transparency and helping manage regulatory and compliance obligations. | |||||||||||
| •We became the first company to announce the retirement of legacy magnetic stripe technology enabling us to focus on technologies, such as chip and contactless, which provide increased security. |
-
The “Detect” layer spots fraudulent behavior and cyber-attacks and takes action to stop these activities once detected. Our offerings in this space include alerts when accounts are exposed to data breaches or security incidents, fraud scoring technology that scans billions of dollars of money flows each day while increasing approvals and reducing false declines, and network-level monitoring on a global scale to help detect the occurrence of widespread fraud attacks when the customer (or their processor) may be unable to detect or defend against them.
-
The “Experience” layer improves the security experience for our stakeholders in areas from the speed of transactions (enhancing approvals for online and card-on-file payments) to the ability to differentiate legitimate consumers from fraudulent ones. Our offerings in this space include solutions for consumer alerts and controls and a suite of digital token services. We also offer an e-commerce fraud and dispute management network that enables merchants to stop delivery when a fraudulent or disputed transaction is identified, and issuers to refund the cardholder to avoid the chargeback process.
-
The “Network” layer extends the services we provide to transactions in the payments ecosystem and across all of our rails, including decision intelligence and tokenization capabilities, to help secure our customers and transactions on a real-time basis.
Moreover, we use our artificial intelligence (“AI”) and data analytics, along with our cyber risk assessment capabilities, to help financial institutions, merchants, corporations and governments secure their digital assets across each of these five layers.
We have also worked with our customers to provide products to consumers globally with increased confidence through the benefit of “zero liability”, where the consumer bears no responsibility for counterfeit or lost card losses in the event of fraud.
MASTERCARD 2021 FORM 10-K 15
PART I
ITEM 1. BUSINESS


 Insights, Analytics and Test and Learn
Our capabilities incorporate payments expertise and analytical and executional skills to create end-to-end solutions which are increasingly delivered via platforms embedded in our customers’ day-to-day operations. We offer business intelligence to monitor key performance indicators (“KPIs”) and benchmark performance through self-service digital platforms, tools, and reports for financial institutions, merchants and others. We enable clients to better understand consumer behavior and improve segmentation and targeting by using our anonymized and aggregated data assets, third-party data and AI technologies. Through our Test & Learn software as a service platform, we can help our customers accurately measure the impact of their decisions and improve them by leveraging data analytics to conduct disciplined business experiments for in-market tests to drive more profitable decision making.

 Consulting and Innovation
We provide advisory services that help clients make better decisions and improve performance. By observing patterns of payments behavior based on billions of transactions switched globally, we are able to leverage anonymized and aggregated information to provide advice based on data. We also utilize our expertise, digital technology, innovation tools, methodologies and processes to collaborate with, and increasingly drive innovation at, financial institutions, merchants and governments. Through our global innovation and development arm, Mastercard Foundry, we offer “Launchpad,” a five-day app prototyping workshop, as well as other customized innovation programs such as in-lab usability testing and concept design.
 Managed Services
We deliver marketing services, digital implementation and program management with performance-based solutions at every stage of the consumer lifecycle to assist our customers in implementing actions based on insights and driving adoption and usage. These services include developing messaging, targeting key groups, launching campaigns and training staff, all of which help our customers drive engagement and portfolio profitability.

 Issuer and Merchant Loyalty
We have built a scalable rewards platform that enables issuers to provide consumers with a variety of benefits and services, such as personalized offers and rewards, access to a global airline lounge network, concierge services, insurance services, emergency card replacement, emergency cash advances and a 24-hour account holder service center. For merchants, we provide campaigns with targeted offers and rewards, management services for publishing offers, and accelerated points programs for co-brand and rewards program members. We also provide a loyalty platform that enables stronger relationships with retailers, restaurants, airlines and consumer packaged goods companies by creating experiences that drive loyalty and impactful consumer engagement.
 Processing and Gateway
We extend our processing capabilities in the payments value chain in various regions and across the globe with an expanded suite of offerings, including:
-
Issuer solutions designed to provide customers with a complete processing solution to help them create differentiated products and services and allow quick deployment of payments portfolios across banking channels
-
Payment gateways that offer a single interface to provide e-commerce merchants with the ability to process secure online and in-app payments and offer value-added solutions, including outsourced electronic payments, fraud prevention and alternative payment options
-
Mobile gateways that facilitate transaction routing and processing for mobile-initiated transactions
16 MASTERCARD 2021 FORM 10-K
PART I
ITEM 1. BUSINESS
Our Expanded Network Capabilities
 Open Banking
We offer an open banking platform that enables data providers and third parties, on a permissioned basis, to reliably access, securely transmit and confidently manage consumer data to improve the customer experience. Our platform enables consumers to have choice of financial services, providing them the ability to access, control and benefit from the use of their data, as well as an improved payment experience. Our platform is also used to serve the needs of the lending market, including through streamlining loan application processes and improving credit decisioning, thereby driving further financial inclusion. The network connections that underpin this platform leverage our data principles (including data usage guardrails, consumer protection and consent management), as well as API technology.
 Digital Identity
| We enable digital identity solutions, which provide smooth digital experiences and strengthen and secure digital payments across individuals, devices and accounts. Our digital identity capabilities focus on the identity of people, devices and transactions. They embody privacy by design principles and are consent-centric. Our solutions include device intelligence and behavioral biometrics (to determine whether the user is genuine or a fraudulent device), document proofing, IP intelligence, biometrics, transaction fraud data (from which we derive insights that can be used to significantly improve the global approval rate of transactions), location, identity attributes and payment authorization. | Key 2021 Developments | ||||||||||
| **•**We acquired Ekata, Inc., a leader in digital identity verification solutions, broadening our fraud prevention and digital identity verification programs by adding Ekata's identity verification data, machine learning technology and global experience. |
Our People
As of December 31, 2021, we employed approximately 24,000 persons globally. Our employee base is predominantly full-time and approximately 65% were employed outside of the United States in more than 80 countries around the world. We also had approximately 3,900 contractors which we used to supplement our employee base in order to meet specific needs. Our voluntary workforce turnover (rolling 12-month attrition) was 11% as of December 31, 2021. The total cost of our workforce for the year ended December 31, 2021 was $4.5 billion, which primarily consists of compensation, benefits and other personnel- and contractor-related costs.
We provide more detailed information regarding our employees, including additional workforce demographics such as gender and racial/ethnic representation, in our Sustainability Report, our Proxy Statement, our Global Inclusion Report and our U.S. Consolidated EEO-1 Report, all of which are located on our website.
We continue to support our employees during the ongoing global COVID-19 pandemic. We have extended a variety of global COVID-related employee benefits through 2022, including flexible hybrid working arrangements and additional paid time off due to illness, to get vaccinated, or to tend to childcare or eldercare-related demands. Our focus remains on the safety and well-being of our employees while maintaining health and safety protocols at each office location.
Management reviews our people strategy and culture, as well as related risks, with our Human Resources and Compensation Committee on a quarterly basis, and annually with our Board of Directors. Additionally, our Board of Directors and our Board committees are tasked with overseeing other human capital management matters on a regular basis, such as ensuring processes are in place for maintaining an ethical corporate culture, overseeing key diversity initiatives, policies and practices, and monitoring governance trends in areas such as human rights. Our ability to attract, retain and engage top talent and build a culture centered around decency, with an overall focus on diversity, equity and inclusion (“DEI”), is critical to our business strategy.
Specifically, to enable our business strategy effectively, our aim is to:
-
attract talent with the key skills needed
-
develop and retain an agile workforce that is able to compete in a fast-paced, digitally native and innovative environment and
-
build on our DEI efforts to support our employees
MASTERCARD 2021 FORM 10-K 17
PART I
ITEM 1. BUSINESS
Attract talent. Leveraging the strength of our brand, we attract talent through acquisitions, workforce planning and recruitment that incorporates a variety of sources.
Develop and retain talent. Our efforts to develop and retain our employees include:
-
An annual cycle that is focused on objective setting, performance assessment, talent evaluation, skill development, opportunities and career progression
-
Succession planning for key roles, including talent and leadership programs across various levels. These programs embed our culture principles, include diverse populations and aim to develop talent and managerial skills through personalized coaching and group executive development
-
Learning opportunities, such as Learning Academies that support our corporate business strategy and priorities and offer programs aligned to regional priorities
-
Mentorship programs that give mentees tools and resources to help build and enhance their skills, inspire personal growth, overcome dilemmas, foster inclusion and support well-being
-
A competitive compensation approach under which eligible employees across multiple job levels can receive long-term incentive equity awards
-
Holistic physical, mental, professional and other benefits to our employees and their families to provide support when and where they need it
-
Contributions to employees’ financial well-being as they plan for retirement. All employees globally are entitled to receive a matching Company contribution of $1.67 for every $1 contributed to a 401(k) or other retirement plan on the first 6% of base pay
-
Support for charitable contributions of our employees’ time and money. We support employee charitable donations with matching Company gifts of up to $15,000 per employee annually and permit full-time employees to use five paid days per year for eligible volunteer work
-
A culture of high ethical business practices and compliance standards, grounded in honesty, decency, trust and personal accountability. It is driven by “tone at the top,” reinforced with regular training, fostered in a speak-up environment, and measured by periodic employee surveys and other metrics that are designed to enable our Board of Directors to gauge the health of our culture
Diversity, equity and inclusion underpin everything we do:
-
We monitor our recruitment, development, succession and retention practices with a focus on gender, race (in the U.S.) and generational mix of our employee population
-
We have developed regional and functional action plans to identify priorities and actions that will help us make more progress for DEI, including appropriate balance and inclusion in gender and racial representation
-
We remain committed to our “In Solidarity” initiative through alignment of our DEI plans, introduction of new training programs and partnerships with historically Black colleges and universities (“HBCUs”) and other schools with diverse talent
-
We introduced a modifier to our 2021 executive compensation plan that includes quantitative goals for gender pay and other key environmental, social and governance (“ESG”) items
We expect to provide additional updates in 2022 on our diversity, equity and inclusion efforts, including the executive compensation modifier, in our upcoming Sustainability Report, Proxy Statement and Global Inclusion Report, all of which will be located on our website.
18 MASTERCARD 2021 FORM 10-K
PART I
ITEM 1. BUSINESS
Brand
Our family of well-known brands includes Mastercard, Maestro and Cirrus. We manage and promote our brands and brand identities (including our sonic brand identity) through advertising, promotions and sponsorships, as well as digital, mobile and social media initiatives, in order to increase people’s preference for our brands and usage of our products. We sponsor a variety of sporting, entertainment and charity-related marketing properties to align with consumer segments important to us and our customers. Our advertising plays an important role in building brand visibility, preference and overall usage among account holders globally. Our “Priceless®” advertising campaign, which has run in more than 50 languages and in more than 120 countries worldwide, promotes Mastercard usage benefits and acceptance, markets Mastercard payment products and solutions and provides Mastercard with a consistent, recognizable message that supports our brand around the globe.
Data
We use our data assets, infrastructure and platforms to create a range of products and services for our customers, including the majority of our value-added services, which help reduce fraud, increase security, provide actionable insights to our customers to assist in their decision making and enable our customers to increase their engagement with consumers. We do all this while incorporating our data principles in how we design, implement and deliver those solutions. Our Privacy by Design and Data by Design processes have been developed to ensure we embed privacy, security and data controls in all of our products and services, keeping a clear focus on protecting customers’ and individuals’ data. We do this in a number of ways:
-
Practicing data minimization.** We collect and retain only the data that is needed for a given product or service, and limit the amount and type of personal information shared with third parties
-
Being transparent and providing control.** We explain how we use personal information and give individuals’ access and control over how their data is used and shared
-
Working with trusted partners.** We select partners and service providers who share our principled-approach to protecting data
-
Addressing data bias.** We ensure our use of advanced analytics, including AI and Machine Learning, utilizes diverse data sets to create fair and inclusive solutions that reflect individual, group and societal interests
-
Advancing positive social impact.** We utilize our data sets to create innovative solutions to societal challenges, promoting inclusive financial, social, climate, health and education growth
Revenue Sources
We generate revenue primarily from assessing our customers based on GDV on the products that carry our brands, from the fees we charge to our customers for providing transaction processing and from other payment-related products and services. Our net revenues are classified into five categories: domestic assessments, cross-border volume fees, transaction processing, other revenues and rebates and incentives (contra-revenue).
See “Management’s Discussion and Analysis of Financial Condition and Results of Operations - Revenue” in Part II, Item 7 and Note 3, Revenue for more detail about our revenue, GDV, processed transactions and our other payment-related products and services.
Intellectual Property
We own a number of valuable trademarks that are essential to our business, including Mastercard, Maestro and Cirrus, through one or more affiliates. We also own numerous other trademarks covering various brands, programs and services offered by us to support our payment programs. Trademark and service mark registrations are generally valid indefinitely as long as they are used and/or properly maintained. Through license agreements with our customers, we authorize the use of our trademarks on a royalty-free basis in connection with our customers’ issuing and merchant acquiring businesses. In addition, we own a number of patents and patent applications relating to payment solutions, transaction processing, smart cards, contactless, mobile, biometrics, AI, security systems, blockchain and other technologies, which are important to our business operations. These patents expire at varying times depending on the jurisdiction and filing date.
MASTERCARD 2021 FORM 10-K 19
PART I
ITEM 1. BUSINESS
Competition
We face a number of competitors both within and outside of the global payments industry and compete in all categories of payment, including paper-based payments and all forms of electronic payments. Among electronic payments, we face the following competition:
-
General Purpose Payments Networks.** We compete worldwide with payments networks such as Visa, American Express, JCB, China UnionPay and Discover, among others. These competitors tend to offer a range of card-based payment products. Some competitors have more market share than we do in certain jurisdictions. Some also have different business models that may provide an advantage in pricing, regulatory compliance burdens or otherwise. Globally, financial institutions may issue both Mastercard and Visa-branded payment products, and we compete with Visa for business on the basis of individual portfolios or programs. In addition, a number of our customers issue American Express, China UnionPay and/or Discover-branded payment cards in a manner consistent with a four-party system. We continue to face intense competitive pressure on the prices we charge our issuers and acquirers, and we seek to enter into business agreements with them through which we offer incentives and other support to issue and promote our payment products.
-
Debit and Local Networks.** We compete with ATM and point of sale debit networks in various countries. In addition, in many countries outside of the United States, local debit brands serve as the main domestic brands, while our brands are used mostly to enable cross-border transactions (typically representing a small portion of overall transaction volume). Certain jurisdictions have also created domestic card schemes focused mostly on debit. In addition, several governments are promoting, or considering promoting, local networks for domestic switching. See “Risk Factors” in Part I, Item 1A for a more detailed discussion of the risks related to payments system regulation and government actions that may prevent us from competing effectively.
-
Real-time Account-based Payments Systems.** We face competition in the real-time account-based payments space from other companies that provide infrastructure, applications and services to support these payment solutions.
-
Alternative Payments Systems and New Entrants.** As the global payments industry becomes more complex, we face increasing competition from alternative payments systems and emerging payments providers. Many of these providers, who in many circumstances can also be our partners or customers, have developed payments systems focused on online activity in e-commerce and mobile channels (in some cases, expanding to other channels), and may process payments using in-house account transfers, real-time account-based payments networks or global or local networks. Examples include digital wallet providers (such as Paytm, PayPal, Alipay and Amazon), point of sale financing/buy-now-pay-later providers (such as Klarna), mobile operator services, mobile phone-based money transfer and microfinancing services (such as M-PESA) and handset manufacturers. We also compete with merchants and governments.
-
National (Government-Backed) Networks.** Governments have been increasingly creating regional payments structures, such as the newly established European Payments Initiative (“EPI”). Backed by numerous Eurozone banks and acquirers, EPI is aimed at creating a unified pan-European payments system, offering card, digital wallet and person-to-person (“P2P”) payment solutions for consumers and merchants. EPI is being positioned as an alternative to existing international payment solutions and schemes such as ours. In addition to regional networks, more than 80 national governments are exploring the use of central bank digital currencies (“CBDCs”).
-
Digital Currencies.** Stablecoins and floating cryptocurrencies may become more popular as they are increasingly viewed as providing immediacy, 24/7 accessibility, immutability and efficiency. Such currencies are starting to be accepted by person-to-merchant (“P2M”) players (such as Square). These currencies are also introducing into the payments ecosystem an emerging set of providers referred to as crypto natives, who have the ability to disrupt traditional financial markets. The increased prominence of digital currencies could compete with our products and services.
-
Value-Added Service Providers and Adjacent Network Capabilities Players.** We face competition from companies that provide alternatives to our value-added products and services, including information services and consulting firms that provide consulting services and insights to financial institutions, merchants and governments and technology companies that provide cyber and fraud solutions, as well as companies that compete against us as providers of loyalty and program management solutions. We also face competition from companies that provide alternatives to our open banking and digital identity solutions. Regulatory initiatives could also lead to increased competition in this space.
Mastercard plays a valuable role as a trusted intermediary in a complex system, creating value for individual stakeholders and the payments ecosystem overall. Our competitive advantages include our:
-
globally recognized and trusted brands
-
highly adaptable global acceptance network built over more than 50 years which can reach a variety of parties enabling payments
-
global payments network with world-class operating performance
20 MASTERCARD 2021 FORM 10-K
PART I
ITEM 1. BUSINESS
-
settlement guarantee backed by our strong credit standing
-
expertise in real-time account-based payments and open banking
-
development and adoption of innovative products and digital solutions
-
safety and security solutions offered on our network, which reduce fraud and increase security for the payments ecosystem
-
analytics insights and consulting services that help issuers and merchants optimize their payments and related businesses
-
loyalty solutions that enhance the payments value proposition for issuers and merchants
-
ability to serve a broad array of participants in global payments due to our expanded on-soil presence in individual markets and a heightened focus on working with governments
-
world class talent and culture, with a focus on inclusion and being a “force for good”
Collectively, the capabilities that we have created organically, and those that we have obtained through acquisitions, continue to enhance the total proposition we offer our customers. They enable us to partner with many participants in the broader payments ecosystem and provide choice, security and services to improve the value we provide to our customers.
Government Regulation
General. Government regulation impacts key aspects of our business. We are subject to regulations that affect the payments industry in the many countries in which our integrated products and services are used. We are committed to comply with all applicable laws and regulations and implement policies, procedures and programs designed to promote compliance. We coordinate globally while acting locally and leverage our relationships to manage the effects of regulation on us. See “Risk Factors” in Part I, Item 1A for more detail and examples of the regulation to which we are subject.
Payments Oversight and Regulation. Central banks and other regulators in several jurisdictions around the world either have, or are seeking to establish, formal oversight over the payments industry, as well as authority to regulate certain aspects of the payments systems in their countries. Such authority has resulted in regulation of various aspects of our business. In the European Union, Mastercard is subject to systemic importance regulation, which includes various requirements we must meet, including obligations related to governance and risk management. In the U.K., the Bank of England designated Vocalink, our real-time account-based payments network platform, as a “specified service provider”, and Mastercard Europe as a “recognized payment system”, which includes supervisions and examination requirements. In addition, European Union legislation requires us to separate our scheme activities (brand, products, franchise and licensing) from our switching activities and other processing in terms of how we go to market, make decisions and organize our structure. Certain of our subsidiaries are regulated as payments institutions, including as money transmitters. This regulation subjects us to licensing obligations and regulatory supervision, as well as various business conduct and risk management requirements.
Interchange Fees. Interchange fees that support the function and value of four-party payments systems like ours are being reviewed or challenged in various jurisdictions around the world via legislation to regulate interchange fees, competition-related regulatory proceedings, central bank regulation and litigation. Examples include statutes in the United States that cap debit interchange for certain regulated activities, our settlement with the European Commission resolving its investigation into our interregional interchange fees and the European Union legislation capping consumer credit and debit interchange fees on payments issued and acquired within the European Economic Area (the “EEA”). For more detail, see “Risk Factors - Other Regulation” in Part I, Item 1A and Note 21 (Legal and Regulatory Proceedings) to the consolidated financial statements included in Part II, Item 8.
Preferential or Protective Government Actions. Some governments have taken action to provide resources, preferential treatment or other protection to selected domestic payments and processing providers, as well as to create their own national providers. For example, governments in some countries mandate switching of domestic payments either entirely in that country or by only domestic companies. In China, we are currently excluded from domestic switching and are seeking market access, which is uncertain and subject to a number of factors, including receiving regulatory approval. We are in active discussions to explore different solutions. Some jurisdictions are currently considering adopting or have adopted “data localization” requirements, which mandate the collection, processing, and/or storage of data within their borders. This is the case, for instance, in India, China, Saudi Arabia and South Africa. Various forms of data localization requirements or data transfer restrictions are also under consideration in other countries and jurisdictions, including the European Union.
Anti-Money Laundering, Counter Financing of Terrorism, Economic Sanctions and Anti-Corruption. We are subject to anti-money laundering (“AML”) and counter-financing of terrorism (“CFT”) laws and regulations globally, including the U.S. Bank Secrecy Act and the USA PATRIOT Act, as well as the various economic sanctions programs, including those imposed and administered by the U.S. Office of Foreign Assets Control (“OFAC”). We have implemented a comprehensive AML/CFT program, comprised of policies, procedures and internal controls, including the designation of a compliance officer, which is designed to prevent our payments
MASTERCARD 2021 FORM 10-K 21
PART I