 filings.tools
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
66K characters. Original on sec.gov · Markdown
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
BUSINESS AND OVERVIEW
Overview
We are a worldwide operator, franchisor, and licensor of hotel, residential, and timeshare properties in 134 countries and territories under 30 brand names. Under our asset-light business model, we typically manage or franchise hotels, rather than own them. We discuss our operations in the following reportable business segments: North American Full-Service, North American Limited-Service, and Asia Pacific. Our Europe, Middle East and Africa, and Caribbean and Latin America operating segments do not individually meet the criteria for separate disclosure as reportable segments**.** In January 2020, we modified our reportable segment structure as a result of a change in the way management intends to evaluate results and allocate resources within the Company. Beginning with the first quarter of 2020, we will present the following reportable business segments: North America; Asia Pacific; and Europe, Middle East, and Africa. Our Caribbean and Latin America operating segment will be included in a combined Caribbean and Latin America and “Unallocated corporate” caption.
We earn base management fees and in many cases incentive management fees from the properties that we manage, and we earn franchise fees on the properties that others operate under franchise agreements with us. In most markets, base management and franchise fees typically consist of a percentage of property-level revenue, or certain property-level revenue in the case of franchise fees, while incentive management fees typically consist of a percentage of net house profit after a specified owner return. In our Middle East and Africa and Asia Pacific regions, incentive management fees typically consist of a percentage of gross operating profit without adjustment for a specified owner return. Net house profit is calculated as gross operating profit (also referred to as “house profit,” which we discuss under the “Performance Measures” section below) less non-controllable expenses such as property insurance, real estate taxes, and capital spending reserves.
Our emphasis on long-term management contracts and franchising tends to provide more stable earnings in periods of economic softness, while adding new hotels to our system generates growth, typically with little or no investment by the Company. This strategy has driven substantial growth while minimizing financial leverage and risk in a cyclical industry. In addition, we believe minimizing our capital investments and adopting a strategy of recycling our investments maximizes and maintains our financial flexibility.
We remain focused on doing the things that we do well; that is, selling rooms, taking care of our guests, and making sure we control costs both at company-operated properties and at the corporate level (“above-property”). We provide our guests new and memorable experiences through our portfolio of brands, innovative technology, personalized guest recognition, and access to travel experiences through our Marriott Bonvoy Tours & Activities program. Our brands remain strong due to our skilled management teams, dedicated associates, superior guest service with an emphasis on guest and associate satisfaction, significant distribution, Loyalty Program, multichannel reservation systems, and desirable property amenities. We strive to effectively leverage our size and broad distribution. We believe that our Loyalty Program generates substantial repeat business that might otherwise go to competing hotels, and we strategically market to the program’s large and growing member base to generate revenue.
We, along with owners and franchisees, continue to invest in our brands by means of new, refreshed, and reinvented properties, new room and public space designs, and enhanced amenities, technology offerings, and guest experiences. We address, through various means, hotels in our system that do not meet our standards. We continue to enhance the appeal of our proprietary, information-rich, and easy-to-use websites, and of our associated mobile applications, through functionality and service improvements.
Our profitability, as well as that of owners and franchisees, has benefited from our approach to property-level and above-property productivity. Managed properties in our system continue to maintain tight cost controls. We also control above-property costs, some of which we allocate to hotels, by remaining focused on systems, processing, and support areas.
Data Security Incident
On November 30, 2018, we announced a data security incident involving unauthorized access to the Starwood reservations database. The Starwood reservations database is no longer used for business operations.
To date, we have not seen a meaningful impact on demand as a result of the Data Security Incident.
In July 2019, the ICO issued a formal notice of intent under the U.K. Data Protection Act 2018 proposing a fine in the amount of £99 million against the Company in relation to the Data Security Incident (the “Proposed ICO Fine”). We mutually agreed with the ICO to an extension of the regulatory process until June 1, 2020 and the ICO proceeding is ongoing. In the 2019 second quarter, we recorded an accrual in the full amount of the Proposed ICO Fine for this loss contingency, and in the 2019 fourth quarter, we reduced the accrual to $65 million based on the ongoing proceeding. See Note 7 for additional information.
We are currently unable to estimate the range of total possible financial impact to the Company from the Data Security Incident in excess of the expenses already incurred. However, we do not believe this incident will impact our long-term financial health. Although our insurance program includes coverage designed to limit our exposure to losses such as those related to the Data Security Incident, that insurance may not be sufficient or available to cover all of our expenses or other losses (including fines and penalties) related to the Data Security Incident. As we expected, the cost of such insurance increased for our current policy period, and the cost of such insurance could continue to increase in future years. We expect to incur significant expenses associated with the Data Security Incident in future periods, primarily related to legal proceedings and regulatory investigations (including possible fines and penalties), increased expenses and capital investments for information technology and information security and data privacy, and increased expenses for compliance activities and to meet increased legal and regulatory requirements. See Note 7 for information related to expenses incurred in 2018 and 2019, insurance recoveries, and legal proceedings and governmental investigations related to the Data Security Incident.
Performance Measures
We believe RevPAR, which we calculate by dividing room sales for comparable properties by room nights available for the period, is a meaningful indicator of our performance because it measures the period-over-period change in room revenues for comparable properties. RevPAR may not be comparable to similarly titled measures, such as revenues, and should not be viewed as necessarily correlating with our fee revenue. We also believe occupancy and average daily rate (“ADR”), which are components of calculating RevPAR, are meaningful indicators of our performance. Occupancy, which we calculate by dividing occupied rooms by total rooms available, measures the utilization of a property’s available capacity. ADR, which we calculate by dividing property room revenue by total rooms sold, measures average room price and is useful in assessing pricing levels. Comparisons to the prior year period are on a constant U.S. dollar basis. We calculate constant dollar statistics by applying exchange rates for the current period to the prior comparable period.
We define our comparable properties as our properties that were open and operating under one of our brands since the beginning of the last full calendar year (since January 1, 2018 for the current period) and have not, in either the current or previous year: (i) undergone significant room or public space renovations or expansions, (ii) been converted between company-operated and franchised, or (iii) sustained substantial property damage or business interruption. For 2019 compared to 2018, we had 4,371 comparable North American properties and 1,232 comparable International properties. For 2018 compared to 2017, we had 4,109 comparable North American properties and 1,173 comparable International properties.
We also believe company-operated house profit margin, which is the ratio of property-level gross operating profit to total property-level revenue, is a meaningful indicator of our performance because this ratio measures our overall ability as the operator to produce property-level profits by generating sales and controlling the operating expenses over which we have the most direct control. House profit includes room, food and beverage, and other revenue and the related expenses including payroll and benefits expenses, as well as repairs and maintenance, utility, general and administrative, and sales and marketing
expenses. House profit does not include the impact of management fees, furniture, fixtures and equipment replacement reserves, insurance, taxes, or other fixed expenses.
Business Trends
Our 2019 full-year results reflected a year-over-year increase in the number of properties in our system, strong demand for our brands in many markets around the world, and generally favorable economic conditions. Comparable worldwide systemwide RevPAR for 2019 increased 1.3 percent to $117.30, ADR increased 0.8 percent on a constant dollar basis to $160.55, and occupancy increased 0.4 percentage points to 73.1 percent, compared to 2018.
In North America, RevPAR increased modestly in 2019, driven by higher ADR, partially constrained by new lodging supply in certain markets. In our Asia Pacific segment in 2019, RevPAR growth was driven by India and major urban markets in Greater China but was partially constrained by lower demand in Hong Kong. Our Europe region experienced higher demand in 2019, led by strong demand from U.S. travelers in the U.K., Italy, and Spain. In our Middle East and Africa region, RevPAR remained relatively stable in 2019 due to RevPAR growth in Africa, partially offset by ongoing geopolitical and economic instability and supply growth in the Middle East. RevPAR grew across our Caribbean and Latin America region, driven by higher ADR, partially constrained by lower demand in Mexico.
For our company-operated properties, we continue to focus on enhancing property-level house profit margins and making productivity improvements. North American company-operated house profit margins decreased by 20 basis points in 2019 compared to 2018 at comparable properties, primarily due to wage increases and modest RevPAR growth, partially offset by cost controls and synergy savings from the Starwood Combination. International company-operated house profit margins increased by 20 basis points in 2019 compared to 2018 at comparable properties, primarily due to RevPAR growth in our Asia Pacific segment and Europe region and cost controls and synergy savings from the Starwood Combination.
The Coronavirus outbreak currently is impacting our operations in China and other parts of our Asia Pacific segment by necessitating the closure of numerous hotels in mainland China and significantly reducing demand in Greater China and certain other Asia Pacific markets. We cannot presently estimate the overall operational and financial impact, which could be material to our 2020 results, and which is highly dependent on the breadth and duration of the outbreak and could be affected by other factors we are not currently able to predict.
System Growth and Pipeline
In 2019, we added 516 properties with 78,142 rooms around the world across our portfolio of brands. Approximately 44 percent of added rooms are located outside North America, and 18 percent are conversions from competitor brands. In 2019, 70 properties (11,908 rooms) exited our system.
At year-end 2019, our development pipeline grew to a record 515,000 rooms, with more than half located outside of North America. The pipeline includes hotel rooms under construction and under signed contracts, and approximately 23,000 hotel rooms approved for development but not yet under signed contracts. In 2019, we signed management and franchise agreements for 815 properties (136,000 rooms), setting company records for rooms signings in Asia Pacific, Europe, Caribbean and Latin America, and Middle East and Africa. Contracts signed in 2019 also reflected the Company’s strength in the luxury tier, with 42 properties signed across 27 countries and territories.
In 2020, we expect the number of our open hotel rooms will increase at a rate consistent with our recent experience. This growth expectation does not include any potential impact related to the Coronavirus outbreak.
Properties and Rooms
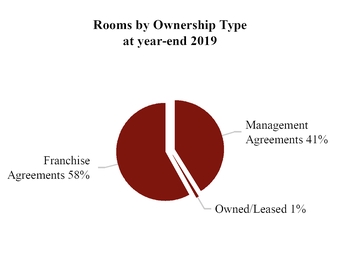
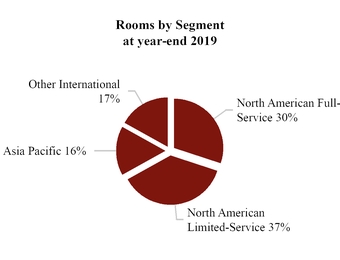
At year-end 2019, we operated, franchised, and licensed the following properties and rooms:
| Managed | Franchised/Licensed | Owned/Leased | Total | ||||||||||||||||||||
| Properties | Rooms | Properties | Rooms | Properties | Rooms | Properties | Rooms | ||||||||||||||||
| North American Full-Service | 413 | 182,691 | 738 | 210,019 | 8 | 4,833 | 1,159 | 397,543 | |||||||||||||||
| North American Limited-Service | 402 | 63,224 | 3,743 | 436,032 | 20 | 3,006 | 4,165 | 502,262 | |||||||||||||||
| Asia Pacific | 660 | 190,239 | 120 | 31,123 | 2 | 410 | 782 | 221,772 | |||||||||||||||
| Other International | 601 | 131,722 | 513 | 96,347 | 38 | 8,754 | 1,152 | 236,823 | |||||||||||||||
| Timeshare | — | — | 91 | 22,521 | — | — | 91 | 22,521 | |||||||||||||||
| Total | 2,076 | 567,876 | 5,205 | 796,042 | 68 | 17,003 | 7,349 | 1,380,921 |
Lodging Statistics
The following tables present RevPAR, occupancy, and ADR statistics for comparable properties for 2019, 2019 compared to 2018, 2018, and 2018 compared to 2017. Systemwide statistics include data from our franchised properties, in addition to our company-operated properties.
2019 Compared to 2018
| Comparable Company-Operated Properties | ||||||||||||||||||||
| RevPAR | Occupancy | Average Daily Rate | ||||||||||||||||||
| 2019 | vs. 2018 | 2019 | vs. 2018 | 2019 | vs. 2018 | |||||||||||||||
| North American Full-Service (1) | $ | 174.86 | 1.5 | % | 76.7 | % | 0.3 | % | pts. | $ | 228.12 | 1.0 | % | |||||||
| North American Limited-Service (2) | $ | 109.15 | (0.7 | )% | 73.9 | % | (1.0 | )% | pts. | $ | 147.61 | 0.6 | % | |||||||
| North American - All (3) | $ | 153.64 | 1.0 | % | 75.8 | % | (0.1 | )% | pts. | $ | 202.75 | 1.1 | % | |||||||
| Asia Pacific | $ | 102.39 | 2.2 | % | 72.4 | % | 2.1 | % | pts. | $ | 141.38 | (0.8 | )% | |||||||
| Caribbean & Latin America | $ | 132.25 | 2.3 | % | 65.1 | % | 0.7 | % | pts. | $ | 203.23 | 1.2 | % | |||||||
| Europe | $ | 149.51 | 2.8 | % | 74.7 | % | 0.9 | % | pts. | $ | 200.21 | 1.5 | % | |||||||
| Middle East & Africa | $ | 107.20 | — | % | 68.5 | % | 2.6 | % | pts. | $ | 156.43 | (3.8 | )% | |||||||
| International - All (4) | $ | 116.10 | 2.0 | % | 71.7 | % | 1.8 | % | pts. | $ | 161.91 | (0.6 | )% | |||||||
| Worldwide (5) | $ | 134.60 | 1.4 | % | 73.7 | % | 0.9 | % | pts. | $ | 182.60 | 0.2 | % |
| Comparable Systemwide Properties | ||||||||||||||||||||
| RevPAR | Occupancy | Average Daily Rate | ||||||||||||||||||
| 2019 | vs. 2018 | 2019 | vs. 2018 | 2019 | vs. 2018 | |||||||||||||||
| North American Full-Service (1) | $ | 147.53 | 2.0 | % | 74.2 | % | 0.4 | % | pts. | $ | 198.88 | 1.5 | % | |||||||
| North American Limited-Service (2) | $ | 99.67 | — | % | 73.8 | % | (0.4 | )% | pts. | $ | 135.14 | 0.5 | % | |||||||
| North American - All (3) | $ | 119.61 | 1.0 | % | 73.9 | % | (0.1 | )% | pts. | $ | 161.79 | 1.1 | % | |||||||
| Asia Pacific | $ | 103.98 | 2.4 | % | 72.3 | % | 2.1 | % | pts. | $ | 143.90 | (0.6 | )% | |||||||
| Caribbean & Latin America | $ | 102.62 | 2.1 | % | 62.7 | % | 0.1 | % | pts. | $ | 163.57 | 2.0 | % | |||||||
| Europe | $ | 130.75 | 2.7 | % | 73.3 | % | 0.8 | % | pts. | $ | 178.26 | 1.5 | % | |||||||
| Middle East & Africa | $ | 101.79 | 0.1 | % | 67.9 | % | 2.3 | % | pts. | $ | 149.88 | (3.2 | )% | |||||||
| International - All (4) | $ | 111.51 | 2.2 | % | 70.9 | % | 1.5 | % | pts. | $ | 157.31 | — | % | |||||||
| Worldwide (5) | $ | 117.30 | 1.3 | % | 73.1 | % | 0.4 | % | pts. | $ | 160.55 | 0.8 | % |
| (1) | Includes JW Marriott, The Ritz-Carlton, W Hotels, The Luxury Collection, St. Regis, EDITION, Marriott Hotels, Sheraton, Westin, Renaissance, Autograph Collection, Delta Hotels, Gaylord Hotels, and Le Méridien. Systemwide also includes Tribute Portfolio. |
| (2) | Includes Courtyard, Residence Inn, Fairfield by Marriott, SpringHill Suites, TownePlace Suites, Four Points, Aloft, Element, and AC Hotels by Marriott. Systemwide also includes Moxy. |
| (3) | Includes North American Full-Service and North American Limited-Service. |
| (4) | Includes Asia Pacific, Caribbean & Latin America, Europe, and Middle East & Africa. |
| (5) | Includes North American - All and International - All. |
2018 Compared to 2017
| Comparable Company-Operated Properties | ||||||||||||||||||||
| RevPAR | Occupancy | Average Daily Rate | ||||||||||||||||||
| 2018 | vs. 2017 | 2018 | vs. 2017 | 2018 | vs. 2017 | |||||||||||||||
| North American Full-Service (1) | $ | 169.44 | 2.2 | % | 76.1 | % | (0.1 | )% | pts. | $ | 222.60 | 2.3 | % | |||||||
| North American Limited-Service (2) | $ | 109.72 | 0.3 | % | 74.9 | % | (0.4 | )% | pts. | $ | 146.55 | 0.8 | % | |||||||
| North American - All (3) | $ | 150.42 | 1.8 | % | 75.7 | % | (0.2 | )% | pts. | $ | 198.66 | 2.0 | % | |||||||
| Asia Pacific | $ | 107.43 | 7.5 | % | 73.5 | % | 2.2 | % | pts. | $ | 146.14 | 4.2 | % | |||||||
| Caribbean & Latin America | $ | 131.52 | 8.6 | % | 64.8 | % | 0.1 | % | pts. | $ | 202.84 | 8.5 | % | |||||||
| Europe | $ | 151.86 | 4.8 | % | 74.0 | % | 0.7 | % | pts. | $ | 205.15 | 3.8 | % | |||||||
| Middle East & Africa | $ | 102.39 | (1.8 | )% | 66.4 | % | 2.4 | % | pts. | $ | 154.17 | (5.3 | )% | |||||||
| International - All (4) | $ | 118.86 | 5.2 | % | 71.6 | % | 1.7 | % | pts. | $ | 165.91 | 2.7 | % | |||||||
| Worldwide (5) | $ | 134.58 | 3.3 | % | 73.7 | % | 0.8 | % | pts. | $ | 182.67 | 2.2 | % |
| Comparable Systemwide Properties | ||||||||||||||||||||
| RevPAR | Occupancy | Average Daily Rate | ||||||||||||||||||
| 2018 | vs. 2017 | 2018 | vs. 2017 | 2018 | vs. 2017 | |||||||||||||||
| North American Full-Service (1) | $ | 143.64 | 2.1 | % | 73.8 | % | (0.1 | )% | pts. | $ | 194.59 | 2.2 | % | |||||||
| North American Limited-Service (2) | $ | 99.29 | 0.9 | % | 74.3 | % | — | % | pts. | $ | 133.61 | 1.0 | % | |||||||
| North American - All (3) | $ | 118.51 | 1.5 | % | 74.1 | % | (0.1 | )% | pts. | $ | 159.94 | 1.6 | % | |||||||
| Asia Pacific | $ | 109.14 | 7.2 | % | 73.3 | % | 2.2 | % | pts. | $ | 148.90 | 4.0 | % | |||||||
| Caribbean & Latin America | $ | 104.77 | 7.4 | % | 63.2 | % | 0.1 | % | pts. | $ | 165.71 | 7.3 | % | |||||||
| Europe | $ | 134.10 | 5.8 | % | 73.0 | % | 1.4 | % | pts. | $ | 183.74 | 3.7 | % | |||||||
| Middle East & Africa | $ | 98.38 | (1.6 | )% | 66.1 | % | 2.0 | % | pts. | $ | 148.87 | (4.6 | )% | |||||||
| International - All (4) | $ | 114.56 | 5.5 | % | 70.9 | % | 1.7 | % | pts. | $ | 161.48 | 3.0 | % | |||||||
| Worldwide (5) | $ | 117.37 | 2.6 | % | 73.2 | % | 0.4 | % | pts. | $ | 160.37 | 2.0 | % |
| (1) | Includes JW Marriott, The Ritz-Carlton, W Hotels, The Luxury Collection, St. Regis, EDITION, Marriott Hotels, Sheraton, Westin, Renaissance, Autograph Collection, Delta Hotels, Gaylord Hotels, and Le Méridien. Systemwide also includes Tribute Portfolio. |
| (2) | Includes Courtyard, Residence Inn, Fairfield by Marriott, SpringHill Suites, TownePlace Suites, Four Points, Aloft, Element, and AC Hotels by Marriott. Systemwide also includes Moxy. |
| (3) | Includes North American Full-Service and North American Limited-Service. |
| (4) | Includes Asia Pacific, Caribbean & Latin America, Europe, and Middle East & Africa. |
| (5) | Includes North American - All and International - All. |
CONSOLIDATED RESULTS
The following discussion presents an analysis of our consolidated results of operations for 2019, 2018, and 2017.
Our 2017 results were favorably impacted by the non-recurring gain on the disposition of our ownership interest in Avendra, discussed in Note 3. We committed to the owners of the hotels in our system that the benefits derived from Avendra, including any dividends or sale proceeds above our original investment, would be used for the benefit of the hotels in our system. Accordingly, in 2019 we used $118 million ($87 million after-tax) and in 2018 we used $115 million ($85 million after-tax) of the net proceeds, and we intend to use the remainder of the net proceeds, for the benefit of our system of hotels. Spending under those plans is, and will be, expensed in the “Reimbursed expenses” caption of our Income Statements, causing a reduction in our profitability in the periods it is expensed.
Fee Revenues
| ($ in millions) | 2019 | 2018 | 2017 | Change 2019 vs. 2018 | Change 2018 vs. 2017 | ||||||||||||||||||||
| Base management fees | $ | 1,180 | $ | 1,140 | $ | 1,102 | $ | 40 | 4 | % | $ | 38 | 3 | % | |||||||||||
| Franchise fees | 2,006 | 1,849 | 1,586 | 157 | 8 | % | 263 | 17 | % | ||||||||||||||||
| Incentive management fees | 637 | 649 | 607 | (12 | ) | (2 | )% | 42 | 7 | % | |||||||||||||||
| Gross fee revenues | 3,823 | 3,638 | 3,295 | 185 | 5 | % | 343 | 10 | % | ||||||||||||||||
| Contract investment amortization | (62 | ) | (58 | ) | (50 | ) | 4 | 7 | % | 8 | 16 | % | |||||||||||||
| Net fee revenues | $ | 3,761 | $ | 3,580 | $ | 3,245 | $ | 181 | 5 | % | $ | 335 | 10 | % |
2019 Compared to 2018
The $40 million increase in base management fees primarily reflected $31 million from unit growth and $15 million from RevPAR growth.
The $157 million increase in franchise fees primarily reflected $88 million from unit growth, $30 million of higher co-brand credit card fees, $23 million from AC Hotels by Marriott properties previously presented in the “Equity in earnings” caption of our Income Statements, $16 million of higher application, relicensing, and other fees, and $15 million from properties that converted from managed to franchised, partially offset by $17 million of lower residential branding fees.
In 2019 and 2018, we earned incentive management fees from 72 percent of our managed properties worldwide. We earned incentive management fees from 57 percent of managed properties in North America and 81 percent of managed properties outside North America in 2019, compared to 59 percent in North America and 82 percent outside North America in 2018. In addition, 65 percent of our total incentive management fees in 2019 came from our managed properties outside North America versus 63 percent in 2018.
2018 Compared to 2017
The $38 million increase in base management fees primarily reflected $29 million from unit growth and $28 million from RevPAR growth, partially offset by lower fees of $17 million from properties that converted from managed to franchised and $14 million from properties that were terminated.
The $263 million increase in franchise fees primarily reflected $143 million of higher branding fees, driven by $138 million of higher fees from our co-brand credit card agreements, $82 million from unit growth, $21 million from RevPAR growth, and $15 million from properties that converted from managed to franchised.
The $42 million increase in incentive management fees primarily reflected net higher profits at managed hotels and $14 million from unit growth.
In 2018, we earned incentive management fees from 72 percent of our managed properties worldwide versus 71 percent in 2017. We earned incentive management fees from 59 percent of managed properties in North America and 82 percent of managed properties outside North America in 2018, compared to 60 percent in North America and 80 percent outside North America in 2017. In addition, 63 percent of our total incentive management fees in 2018 came from our managed properties outside North America versus 62 percent in 2017.
Owned, Leased, and Other
| ($ in millions) | 2019 | 2018 | 2017 | Change 2019 vs. 2018 | Change 2018 vs. 2017 | ||||||||||||||||||||
| Owned, leased, and other revenue | $ | 1,612 | $ | 1,635 | $ | 1,752 | $ | (23 | ) | (1 | )% | $ | (117 | ) | (7 | )% | |||||||||
| Owned, leased, and other - direct expenses | 1,316 | 1,306 | 1,411 | 10 | 1 | % | (105 | ) | (7 | )% | |||||||||||||||
| $ | 296 | $ | 329 | $ | 341 | $ | (33 | ) | (10 | )% | $ | (12 | ) | (4 | )% |
2019 Compared to 2018
Owned, leased, and other revenue, net of direct expenses decreased by $33 million, primarily due to $21 million of lower termination fees and $8 million net unfavorable impact from acquisitions and dispositions.
2018 Compared to 2017
Owned, leased, and other revenue, net of direct expenses decreased by $12 million, primarily due to $81 million of lower owned and leased profits attributable to properties sold, partially offset by $51 million of higher termination fees and $17 million of net stronger results at our remaining owned and leased properties.
Cost Reimbursements
| ($ in millions) | 2019 | 2018 | 2017 | Change 2019 vs. 2018 | Change 2018 vs. 2017 | ||||||||||||||||||||
| Cost reimbursement revenue | $ | 15,599 | $ | 15,543 | $ | 15,455 | $ | 56 | — | % | $ | 88 | 1 | % | |||||||||||
| Reimbursed expenses | 16,439 | 15,778 | 15,228 | 661 | 4 | % | 550 | 4 | % | ||||||||||||||||
| $ | (840 | ) | $ | (235 | ) | $ | 227 | $ | (605 | ) | 257 | % | $ | (462 | ) | (204 | )% |
Cost reimbursement revenue, net of reimbursed expenses, varies due to timing differences between the costs we incur for centralized programs and services and the related reimbursements we receive from hotel owners and franchisees. Over the long term, our centralized programs and services are not designed to impact our economics, either positively or negatively.
2019 Compared to 2018
Cost reimbursement revenue, net of reimbursed expenses, decreased $605 million, primarily due to lower Loyalty Program revenues net of expenses.
2018 Compared to 2017
Cost reimbursement revenue, net of reimbursed expenses, decreased $462 million, primarily due to lower Loyalty Program revenues net of expenses, spending funded by the proceeds from the 2017 sale of our interest in Avendra, and higher expenses for reservations and marketing.
Other Operating Expenses
| ($ in millions) | 2019 | 2018 | 2017 | Change 2019 vs. 2018 | Change 2018 vs. 2017 | ||||||||||||||||||||
| Depreciation, amortization, and other | $ | 341 | $ | 226 | $ | 229 | $ | 115 | 51 | % | $ | (3 | ) | (1 | )% | ||||||||||
| General, administrative, and other | 938 | 927 | 921 | 11 | 1 | % | 6 | 1 | % | ||||||||||||||||
| Merger-related costs and charges | 138 | 155 | 159 | (17 | ) | (11 | )% | (4 | ) | (3 | )% |
2019 Compared to 2018
Depreciation, amortization, and other expenses increased by $115 million, primarily reflecting the $99 million asset impairment associated with the Renaissance New York Times Square Hotel lease and the $15 million impairment of the Sheraton Phoenix Downtown.
General, administrative, and other expenses increased by $11 million, primarily due to $32 million of higher administrative costs, $18 million net unfavorable impact to our legal expenses associated with litigation resolutions, and $10 million of higher bad debt reserves, partially offset by $51 million due to the company-funded supplemental retirement savings plan contributions in 2018.
Merger-related costs and charges decreased by $17 million, primarily due to $116 million of lower integration costs, partially offset by the $65 million accrual for the loss contingency related to the Proposed ICO Fine discussed in Note 7 and a $34 million impairment charge of a Legacy-Starwood office building accounted for as a finance lease.
2018 Compared to 2017
General, administrative, and other expenses increased by $6 million, primarily due to $51 million of company-funded supplemental retirement savings plan contributions in 2018 and $20 million of higher professional fees, partially offset by administrative cost savings largely due to synergies associated with the Starwood Combination. Company-funded supplemental retirement savings plan contributions represent an additional one-time contribution of up to $1,000 per eligible associate.
Merger-related costs and charges decreased by $4 million, primarily due to $23 million of lower transaction and termination costs, partially offset by $19 million of higher integration costs.
Non-Operating Income (Expense)
| ($ in millions) | 2019 | 2018 | 2017 | Change 2019 vs. 2018 | Change 2018 vs. 2017 | ||||||||||||||||||||
| Gains and other income, net | $ | 154 | $ | 194 | $ | 688 | $ | (40 | ) | (21 | )% | $ | (494 | ) | (72 | )% | |||||||||
| Interest expense | (394 | ) | (340 | ) | (288 | ) | 54 | 16 | % | 52 | 18 | % | |||||||||||||
| Interest income | 26 | 22 | 38 | 4 | 18 | % | (16 | ) | (42 | )% | |||||||||||||||
| Equity in earnings | 13 | 103 | 40 | (90 | ) | (87 | )% | 63 | 158 | % |
2019 Compared to 2018
Gains and other income, net decreased by $40 million, primarily due to the 2018 gains on our property sales ($132 million) and the 2018 gains on the sales of our interest in four equity method investments ($46 million), partially offset by the 2019 gains on our property sales ($134 million).
Interest expense increased by $54 million, primarily due to higher interest on Senior Note issuances, net of maturities.
Equity in earnings decreased by $90 million, primarily due to the 2018 gains on the sales of two properties held by equity method investees ($65 million) and lower earnings as a result of both the AC Hotels by Marriott transaction discussed in Note 3, and dispositions of other investments ($19 million).
2018 Compared to 2017
Gains and other income, net decreased by $494 million, primarily due to the 2017 gain on the disposition of our ownership interest in Avendra, net of a 2018 true-up ($653 million) and the 2017 gain on the sale of the Charlotte Marriott City Center ($24 million), partially offset by 2018 gains on our property sales ($132 million) and sales of our interest in four equity method investments ($46 million).
Interest expense increased by $52 million, primarily due to higher commercial paper interest rates and average borrowings.
Interest income decreased by $16 million, primarily due to lower outstanding loan balances.
Equity in earnings increased by $63 million, primarily due to our share of the gains on the sales of two properties held by equity method investees ($65 million).
Income Taxes
| ($ in millions) | 2019 | 2018 | 2017 | Change 2019 vs. 2018 | Change 2018 vs. 2017 | ||||||||||||||||||||
| Provision for income taxes | $ | (326 | ) | $ | (438 | ) | $ | (1,523 | ) | $ | (112 | ) | (26 | )% | $ | (1,085 | ) | (71 | )% |
2019 Compared to 2018
Provision for income taxes decreased by $112 million, primarily due to lower operating income ($101 million), the prior year tax expense for uncertain tax positions ($30 million), the current year tax benefit from the impairment charges associated with the Renaissance New York Times Square Hotel lease and Sheraton Phoenix Downtown ($29 million), the prior year state income tax expense for the future remittance of accumulated earnings of non-U.S. subsidiaries ($27 million), and higher earnings in jurisdictions with lower tax rates ($15 million). The decrease was partially offset by lower benefits resulting from finalizing prior years’ returns ($39 million), the prior year release of tax reserves ($34 million), and the prior year income tax consequences of an intercompany transaction ($18 million).
2018 Compared to 2017
Provision for income taxes decreased by $1,085 million, primarily due to the nonrecurring net tax expense in 2017 related to the 2017 Tax Act and the reduction of the U.S. federal tax rate in 2018 ($744 million), the prior year gain on the sale of our interest in Avendra ($257 million), increased earnings in jurisdictions with lower tax rates ($57 million), lower operating income ($46 million), reduction of our one-time net tax charge related to the Deemed Repatriation Transition Tax (“Transition Tax”) and the remeasurement of deferred income taxes ($41 million), the release of tax reserves due to the completion of certain examinations ($34 million), and the income tax consequences of an intercompany transaction ($18 million). The decrease was partially offset by the period’s provisional estimate of tax for Global Intangible Low-Taxed Income under the 2017 Tax Act ($34 million), tax expense incurred for uncertain tax positions relating to Legacy-Starwood operations ($30 million), an unfavorable comparison to a 2017 benefit due to tax law changes adopted in non-U.S. jurisdictions in 2017 ($18 million), the 2017 reversal of tax reserves related to interest accrued for previous periods ($15 million), net higher tax expense on dispositions ($13 million), and the 2017 release of a tax reserve due to the favorable settlement of a tax position ($12 million).
BUSINESS SEGMENTS
The following discussion presents an analysis of the results of operations of our reportable business segments at year-end 2019: North American Full-Service, North American Limited-Service, and Asia Pacific. Our Europe, Middle East and Africa, and Caribbean and Latin America operating segments do not individually meet the criteria for separate disclosure as reportable segments, and accordingly we have not included those operations in this discussion of our Business Segments. See Note 15 to our Financial Statements for other information about each segment, including revenues and a reconciliation of segment profits to net income.
North American Full-Service
| ($ in millions) | 2019 | 2018 | 2017 | Change 2019 vs. 2018 | Change 2018 vs. 2017 | ||||||||||||||||||||
| Segment revenues | $ | 13,455 | $ | 13,072 | $ | 12,909 | $ | 383 | 3 | % | $ | 163 | 1 | % | |||||||||||
| Segment profits | $ | 1,148 | $ | 1,153 | $ | 1,238 | $ | (5 | ) | — | % | $ | (85 | ) | (7 | )% |
2019 Compared to 2018
In 2019, across our North American Full-Service segment, we added 46 properties (8,746 rooms) and 13 properties (3,436 rooms) left our system.
North American Full-Service segment profits decreased by $5 million, primarily due to the following:
| • | $117 million of higher depreciation, amortization, and other expenses, primarily reflecting impairment charges of $99 million for the Renaissance New York Times Square Hotel lease and $15 million for the Sheraton Phoenix Downtown; |
| • | $14 million of lower cost reimbursement revenue, net of reimbursed expenses; |
| • | $12 million of lower owned, leased, and other revenue, net of direct expenses, primarily reflecting $8 million of lower termination fees; and |
| • | $12 million of lower equity in earnings, primarily due to a $10 million gain on an equity method investee’s sale of a property in 2018; |
partially offset by:
| • | $110 million of higher gains and other income, net, primarily reflecting a $134 million gain on the sale of two properties in 2019, partially offset by a $22 million gain on the sale of two properties in 2018; and |
| • | $47 million of higher base management and franchise fees, primarily reflecting $31 million from unit growth and $20 million from RevPAR growth. |
2018 Compared to 2017
In 2018, across our North American Full-Service segment we added 44 properties (10,454 rooms) and 20 properties (6,923 rooms) left our system.
North American Full-Service segment profits decreased by $85 million, primarily due to the following:
| • | $119 million of lower cost reimbursement revenue, net of reimbursed expenses; |
| • | $24 million of lower owned, leased, and other revenue, net of direct expenses, primarily reflecting $60 million of lower owned and leased profits attributable to properties sold, partially offset by $24 million of higher termination fees and $15 million of net stronger results at our remaining owned and leased properties; and |
| • | $1 million of lower gains and other income, net, primarily due to the 2017 gain on the sale of the Charlotte Marriott City Center of $24 million, partially offset by the 2018 gain on the sale of two properties of $22 million; |
partially offset by:
| • | $45 million of higher base management and franchise fees, primarily reflecting $23 million from unit growth and $18 million from RevPAR growth; and |
| • | $13 million of lower general, administrative, and other expenses, primarily due to administrative cost savings largely due to synergies associated with the Starwood Combination. |
North American Limited-Service
| ($ in millions) | 2019 | 2018 | 2017 | Change 2019 vs. 2018 | Change 2018 vs. 2017 | ||||||||||||||||||||
| Segment revenues | $ | 3,378 | $ | 3,217 | $ | 3,219 | $ | 161 | 5 | % | $ | (2 | ) | — | % | ||||||||||
| Segment profits | $ | 852 | $ | 786 | $ | 827 | $ | 66 | 8 | % | $ | (41 | ) | (5 | )% |
2019 Compared to 2018
In 2019, across our North American Limited-Service segment we added 288 properties (34,990 rooms) and 31 properties (3,424 rooms) left our system.
North American Limited-Service segment profits increased by $66 million, primarily due to the following:
| • | $74 million of higher base management and franchise fees, primarily reflecting $58 million from unit growth, and $18 million from AC Hotels by Marriott properties previously presented in the “Equity in earnings” caption of our Income Statements; |
partially offset by:
| • | $11 million of lower incentive management fees, primarily driven by lower fees from a few portfolios of managed hotels. |
2018 Compared to 2017
In 2018, across our North American Limited-Service segment we added 281 properties (33,418 rooms) and 38 properties (3,415 rooms) left our system.
North American Limited-Service segment profits decreased by $41 million, primarily due to the following:
| • | $100 million of lower cost reimbursement revenue, net of reimbursed expenses; |
partially offset by:
| • | $63 million of higher base management and franchise fees, primarily reflecting $56 million from unit growth. |
Asia Pacific
| ($ in millions) | 2019 | 2018 | 2017 | Change 2019 vs. 2018 | Change 2018 vs. 2017 | ||||||||||||||||||||
| Segment revenues | $ | 1,189 | $ | 1,118 | $ | 1,054 | $ | 71 | 6 | % | $ | 64 | 6 | % | |||||||||||
| Segment profits | $ | 369 | $ | 456 | $ | 361 | $ | (87 | ) | (19 | )% | $ | 95 | 26 | % |
2019 Compared to 2018
In 2019, across our Asia Pacific segment we added 78 properties (17,361 rooms) and 8 properties (2,328 rooms) left our system.
Asia Pacific segment profits decreased by $87 million, primarily due to the following changes:
| • | $69 million of lower gains and other income, net, primarily due to a $57 million gain on 2018 property sales and a $13 million gain on sale of our interest in two equity method investments in 2018; and |
| • | $9 million of lower cost reimbursement revenue, net of reimbursed expenses. |
2018 Compared to 2017
In 2018, across our Asia Pacific segment we added 82 properties (19,661 rooms) and 11 properties (3,399 rooms) left our system.
Asia Pacific segment profits increased by $95 million, primarily due to the following:
| • | $71 million of higher gains and other income, net, primarily reflecting a $57 million gain on 2018 property sales and $13 million from gains on sale of our interest in two equity method investments; |
| • | $26 million of higher base management and franchise fees, primarily reflecting $16 million from unit growth; and |
| • | $22 million of higher incentive management fees, primarily driven by net higher profits at managed hotels; |
partially offset by:
| • | $29 million of lower cost reimbursement revenue, net of reimbursed expenses. |
SHARE-BASED COMPENSATION
See Note 5 for more information.
NEW ACCOUNTING STANDARDS
See Note 2 for information on our adoption of new accounting standards.
LIQUIDITY AND CAPITAL RESOURCES
Cash Requirements and Our Credit Facility
In the 2019 second quarter, we amended and restated our multicurrency revolving credit agreement (the “Credit Facility”) to extend the maturity date of the Credit Facility and increase the aggregate amount of available borrowings to up to $4.5 billion. The available borrowings support our commercial paper program and general corporate needs. Borrowings under the Credit Facility generally bear interest at LIBOR plus a spread, based on our public debt rating. We also pay quarterly fees on the Credit Facility at a rate based on our public debt rating. While any outstanding commercial paper borrowings and/or borrowings under our Credit Facility generally have short-term maturities, we classify the outstanding borrowings as long-term based on our ability and intent to refinance the outstanding borrowings on a long-term basis. The Credit Facility expires on June 28, 2024.
The Credit Facility contains certain covenants, including a single financial covenant that limits our maximum leverage (consisting of the ratio of Adjusted Total Debt to EBITDA, each as defined in the Credit Facility) to not more than 4 to 1. The Credit Facility defines EBITDA as net income less cost reimbursement revenue, plus reimbursed expenses, plus the sum of interest expense, income taxes, depreciation, amortization, non-recurring non-cash charges, and extraordinary, non-recurring or unusual cash charges, expenses or losses up to a certain amount.
Our outstanding public debt does not contain a corresponding financial covenant or a requirement that we maintain certain financial ratios. We currently satisfy the covenants in our Credit Facility and public debt instruments, including the leverage covenant under the Credit Facility, and do not expect the covenants will restrict our ability to meet our anticipated borrowing and guarantee levels or increase those levels should we decide to do so in the future.
We believe the Credit Facility and our access to capital markets, together with cash we expect to generate from operations, remain adequate to meet our short-term and long-term liquidity requirements, finance our long-term growth plans, meet debt service, and fulfill other cash requirements.
We issue commercial paper in the U.S. We do not have purchase commitments from buyers for our commercial paper; therefore, our ability to issue commercial paper is subject to market demand. We reserve unused capacity under our Credit Facility to repay outstanding commercial paper borrowings if the commercial paper market is not available to us for any reason when outstanding borrowings mature. We do not expect that fluctuations in the demand for commercial paper will affect our liquidity, given our borrowing capacity under the Credit Facility.
At year-end 2019, our available borrowing capacity amounted to $1,522 million and reflected borrowing capacity of $1,297 million under our Credit Facility and our cash balance of $225 million. We calculated that borrowing capacity by taking $4.5 billion of effective aggregate bank commitments under our Credit Facility and subtracting $3,203 million of outstanding commercial paper (there being no outstanding letters of credit under our Credit Facility).
We monitor the status of the capital markets and regularly evaluate the effect that changes in capital market conditions may have on our ability to execute our announced growth plans and fund our liquidity needs. We expect to continue meeting part of our financing and liquidity needs primarily through commercial paper borrowings, issuances of Senior Notes, and access to long-term committed credit facilities. If conditions in the lodging industry deteriorate, or if disruptions in the capital markets take place as they did in the immediate aftermath of both the 2008 worldwide financial crisis and the events of September 11, 2001, we may be unable to place some or all of our commercial paper on a temporary or extended basis and may have to rely more on borrowings under the Credit Facility, which we believe will be adequate to fund our liquidity needs, including repayment of debt obligations, but which may carry a higher cost than commercial paper. Since we continue to have ample flexibility under the Credit Facility’s covenants, we expect that undrawn bank commitments under the Credit Facility will remain available to us even if business conditions were to deteriorate markedly.
Cash from Operations
Cash from operations for the last three fiscal years are as follows:
| ($ in millions) | 2019 | 2018 | 2017 | ||||||||
| Cash from operations | $ | 1,685 | $ | 2,357 | $ | 2,227 |
The $672 million decrease in cash from operations was primarily due to lower operating income, largely due to timing differences between the costs incurred for centralized programs and services, including our Loyalty Program, and the related reimbursements we received from hotel owners and franchisees in 2019, as well as changes in working capital.
Our ratio of current assets to current liabilities was 0.5 to 1.0 at year-end 2019 and 0.4 to 1.0 at year-end 2018. We have significant borrowing capacity under our Credit Facility should we need additional working capital.
Investing Activities Cash Flows
Capital Expenditures and Other Investments. We made capital expenditures of $653 million in 2019, $556 million in 2018, and $240 million in 2017. Capital expenditures in 2019 increased by $97 million compared to 2018, primarily reflecting the 2019 acquisitions of W New York - Union Square and Elegant and net higher spending on several owned and leased properties, partially offset by the 2018 acquisition of the Sheraton Phoenix Downtown. Capital expenditures in 2018 increased by $316 million compared to 2017, primarily reflecting the 2018 acquisition of the Sheraton Phoenix Downtown, improvements to our worldwide systems, and net higher spending on several owned properties.
We expect spending on capital expenditures and other investments will total approximately $700 million to $800 million for 2020, including contract acquisition costs, equity and other investments, loan advances, and various capital expenditures (including approximately $200 million for maintenance capital spending).
We monitor the status of the capital markets and regularly evaluate the potential impact of changes in capital market conditions on our business operations. In the Starwood Combination, we acquired various hotels and joint venture interests in various hotels, many of which we have sold or are seeking to sell. We have made, and expect to continue making selective and
opportunistic investments to add units to our lodging business, which may include property acquisitions and renovations (such as our 2018 acquisition of the Sheraton Phoenix Downtown and our 2019 acquisitions of the W New York - Union Square and Elegant), new construction, loans, guarantees, and noncontrolling equity investments. Over time, we seek to minimize capital invested in our business through asset sales subject to long-term management or franchise agreements.
Fluctuations in the values of hotel real estate generally have little impact on our overall business results because: (1) we own less than one percent of hotels that we operate or franchise; (2) management and franchise fees are generally based upon hotel revenues and profits rather than current hotel property values; and (3) our management agreements generally do not terminate upon hotel sale or foreclosure.
Dispositions. Property and asset sales generated $395 million cash proceeds in 2019 and $479 million in 2018. See Note 3 for more information on dispositions.
Loan Activity. From time to time, we make loans to owners of hotels that we operate or franchise. Loan collections, net of loan advances, amounted to $21 million in 2019, compared to net collections of $35 million in 2018. At year-end 2019, we had $126 million of senior, mezzanine, and other loans outstanding, compared to $131 million outstanding at year-end 2018.
Equity Method Investments. Cash outflows of $23 million in 2019, $72 million in 2018, and $62 million in 2017 for equity method investments primarily reflect our investments in several joint ventures.
Financing Activities Cash Flows
Debt. Debt increased by $1,593 million in 2019, to $10,940 million at year-end 2019 from $9,347 million at year-end 2018, primarily due to the issuance of our Series BB, CC and DD Notes and higher outstanding commercial paper borrowings ($951 million), partially offset by the maturity of our Series K Notes ($600 million) and Series T Notes ($181 million). See Note 9 for additional information on the debt issuances.
Our financial objectives include diversifying our financing sources, optimizing the mix and maturity of our long-term debt, and reducing our working capital. At year-end 2019, our long-term debt had a weighted average interest rate of 2.9 percent and a weighted average maturity of approximately 4.7 years. The ratio of our fixed-rate long-term debt to our total long-term debt was 0.5 to 1.0 at year-end 2019.
See the “Cash Requirements and Our Credit Facility,” caption in this “Liquidity and Capital Resources” section for more information on our Credit Facility.
Share Repurchases. We purchased 17.3 million shares of our common stock in 2019 at an average price of $130.79 per share, 21.5 million shares in 2018 at an average price of $130.67 per share, and 29.2 million shares in 2017 at an average price of $103.66 per share. At year-end 2019, 18.4 million shares remained available for repurchase under Board approved authorizations. For additional information, see “Fourth Quarter 2019 Issuer Purchases of Equity Securities” in Part II, Item 5.
Dividends. Our Board of Directors declared the following quarterly cash dividends in 2019: (1) $0.41 per share declared on February 15, 2019 and paid March 29, 2019 to shareholders of record on March 1, 2019, (2) $0.48 per share declared on May 10, 2019 and paid June 28, 2019 to shareholders of record on May 24, 2019, (3) $0.48 per share declared on August 8, 2019 and paid September 30, 2019 to shareholders of record on August 22, 2019, and (4) $0.48 per share declared on November 7, 2019 and paid December 31, 2019 to shareholders of record on November 21, 2019. Our Board of Directors declared a cash dividend of $0.48 per share on February 14, 2020, payable on March 31, 2020 to shareholders of record on February 28, 2020.
Contractual Obligations and Off-Balance Sheet Arrangements
Contractual Obligations
The following table summarizes our contractual obligations at year-end 2019:
| Payments Due by Period | |||||||||||||||||||
| ($ in millions) | Total | Less Than 1 Year | 1-3 Years | 3-5 Years | After 5 Years | ||||||||||||||
| Debt (1) | $ | 11,977 | $ | 1,228 | $ | 3,188 | $ | 4,704 | $ | 2,857 | |||||||||
| Finance lease obligations (1) | 217 | 13 | 26 | 27 | 151 | ||||||||||||||
| Operating leases where we are the primary obligor | 1,310 | 173 | 336 | 222 | 579 | ||||||||||||||
| Purchase obligations | 276 | 116 | 160 | — | — | ||||||||||||||
| Other noncurrent liabilities | 128 | — | 53 | 16 | 59 | ||||||||||||||
| Total contractual obligations | $ | 13,908 | $ | 1,530 | $ | 3,763 | $ | 4,969 | $ | 3,646 |
| (1) | Includes principal as well as interest payments. |
The preceding table does not reflect projected Transition Tax payments totaling $447 million as a result of the 2017 Tax Act at year-end 2019. In addition, the table does not reflect unrecognized tax benefits at year-end 2019 of $570 million.
In addition to the purchase obligations noted in the preceding table, in the normal course of business we enter into purchase commitments to manage the daily operating needs of the hotels that we manage. Since we are reimbursed from the cash flows of the hotels, these obligations have minimal impact on our net income and cash flow.
Other Commitments
The following table summarizes our guarantee, investment, and loan commitments at year-end 2019:
| ($ in millions) | Total Amounts Committed | Less Than 1 Year | 1-3 Years | 3-5 Years | After 5 Years | ||||||||||||||
| Guarantee commitments (expiration by period) | $ | 299 | $ | 4 | $ | 86 | $ | 63 | $ | 146 | |||||||||
| Investment and loan commitments (expected funding by period) | 55 | 34 | 17 | 2 | 2 | ||||||||||||||
| Total other commitments | $ | 354 | $ | 38 | $ | 103 | $ | 65 | $ | 148 |
In conjunction with financing obtained for specific projects or properties owned by joint ventures in which we are a party, we may provide industry standard indemnifications to the lender for loss, liability, or damage occurring as a result of our actions or the actions of the other joint venture owner.
In addition, we granted a hotel owner a one-time right to require us to purchase the leasehold interest in the land and hotel for $300 million in cash, exercisable in 2022. See Note 7 for more information.
For further information, including the nature of the commitments and their expirations, see the “Commitments” caption in Note 7.
Letters of Credit
At year-end 2019, we had $145 million of letters of credit outstanding (all outside the Credit Facility, as defined in Note 9), most of which were for our self-insurance programs. Surety bonds issued as of year-end 2019 totaled $160 million, most of which state governments requested in connection with our self-insurance programs.
RELATED PARTY TRANSACTIONS
Equity Method Investments
We have equity method investments in entities that own properties for which we provide management services and receive fees. In addition, in some cases we provide loans, preferred equity, or guarantees to these entities.
Other Related Parties
We provide management services for and receive fees from properties owned by JWM Family Enterprises, L.P., which is beneficially owned and controlled by J.W. Marriott, Jr., Deborah Marriott Harrison, and other members of the Marriott family.
For more information, including the impact to our financial statements of transactions with these related parties, see Note 16.
CRITICAL ACCOUNTING POLICIES AND ESTIMATES
Our preparation of financial statements in accordance with GAAP requires management to make estimates and assumptions that affect reported amounts and related disclosures. Management considers an accounting policy and estimate to be critical if: (1) we must make assumptions that were uncertain when the estimate was made; and (2) changes in the estimate, or selection of a different estimate methodology could have a material effect on our consolidated results of operations or financial condition. Management has discussed the development and selection of its critical accounting policies and estimates with the Audit Committee of our Board of Directors.
While we believe that our estimates, assumptions, and judgments are reasonable, they are based on information available when the estimate or assumption was made. Actual results may differ significantly. Additionally, changes in our assumptions, estimates or assessments due to unforeseen events or otherwise could have a material impact on our financial position or results of operations.
See Note 2 for further information related to our critical accounting policies and estimates, which are as follows:
Loyalty Program, including how we estimate the breakage of hotel points, credit card points, and free night certificates, the volume of points and free night certificates that will be issued under our co-brand credit card agreements, the amount of consideration to which we will be entitled under our co-brand credit card agreements, and the stand-alone selling prices of goods and services provided under our co-brand credit card agreements;
Goodwill, including how we evaluate the fair value of reporting units and when we record an impairment loss on goodwill;
Intangibles and Long-Lived Assets, including how we evaluate the fair value of intangibles and long-lived assets and when we record impairment losses on intangibles and long-lived assets;
Investments, including information on how we evaluate the fair value of investments and when we record impairment losses on investments;
Income Taxes, including information on how we determine our current year amounts payable or refundable and our estimate of deferred tax assets and liabilities; and
Business Combinations, including the assumptions that we make to estimate the fair values of assets acquired and liabilities assumed related to discount rates, royalty rates, and the amount and timing of future cash flows.
Previous: Item 6. Selected Financial Data. · Next: Item 7A. Quantitative and Qualitative Disclosures About Market Risk.