 filings.tools
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
141K characters. Original on sec.gov · Markdown
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
All statements in this section, other than statements of historical fact, are forward-looking statements that are inherently uncertain. See “Disclosures Regarding Forward-Looking Statements” and “Risk Factors” for a discussion of the factors that could cause actual results to differ materially from those projected in these statements. The following information concerning our business, results of operations and financial condition should also be read in conjunction with the information included under Item 1. Business, Item 1A. Risk Factors, Item 6. Selected Financial Data and Item 8. Financial Statements and Supplementary Data.
CORPORATE OVERVIEW
We are an independent petroleum refining and marketing, retail and midstream company. We own and operate the nation’s largest refining system through 16 refineries, located in the Gulf Coast, Mid-Continent and West Coast regions of the United States, with an aggregate crude oil refining capacity of approximately 3.0 mmbpcd. Our refineries supply refined products to resellers and consumers across the United States. We distribute refined products to our customers through transportation, storage, distribution and marketing services provided largely by our Midstream segment. We believe we are one of the largest wholesale suppliers of gasoline and distillates to resellers in the United States.
We have three strong brands: Marathon®, Speedway® and ARCO®. The branded outlets, which primarily include the Marathon brand, are established motor fuel brands across the United States available through approximately 6,800 branded outlets operated by independent entrepreneurs in 35 states, the District of Columbia and Mexico. We believe our Retail segment operates the second largest chain of company-owned and operated retail gasoline and convenience stores in the United States, with approximately 3,920 convenience stores, primarily under the Speedway brand, and 1,065 direct dealer locations, primarily under the ARCO brand, across the United States.
We primarily conduct our midstream operations through our ownership interests in MPLX and ANDX, which own and operate crude oil and light product transportation and logistics infrastructure as well as gathering, processing, and fractionation assets. As of December 31, 2018, we owned, leased or had ownership interests in approximately 16,600 miles of crude oil and refined product pipelines to deliver crude oil to our refineries and other locations and refined products to wholesale and retail market areas. We distribute our refined products through one of the largest terminal operations in the United States and one of the largest private domestic fleets of inland petroleum product barges. Our integrated midstream energy asset network links producers of natural gas and NGLs from some of the largest supply basins in the United States to domestic and international markets. Our midstream gathering and processing operations include: natural gas gathering, processing and transportation; and NGL gathering, transportation, fractionation, storage and marketing. Our assets include approximately 9.9 bcf/d of gathering capacity, 11.0 bcf/d of natural gas processing capacity and 790 mbpd of fractionation capacity as of December 31, 2018.
Our operations consist of three reportable operating segments: Refining & Marketing; Retail; and Midstream. Each of these segments is organized and managed based upon the nature of the products and services they offer. See Item 1. Business for additional information on our segments.
| • | Refining & Marketing – refines crude oil and other feedstocks at our 16 refineries in the West Coast, Gulf Coast and Mid-Continent regions of the United States, purchases refined products and ethanol for resale and distributes refined products largely through transportation, storage, distribution and marketing services provided largely by our Midstream segment. We sell refined products to wholesale marketing customers domestically and internationally, to buyers on the spot market, to our Retail business segment and to independent entrepreneurs who operate primarily Marathon® branded outlets. |
| • | Retail – sells transportation fuels and convenience products in the retail market across the United States through company-owned and operated convenience stores, primarily under the Speedway brand, and long-term fuel supply contracts with direct dealers who operate locations mainly under the ARCO brand. |
| • | Midstream – transports, stores, distributes and markets crude oil and refined products principally for the Refining & Marketing segment via refining logistics assets, pipelines, terminals, towboats and barges; gathers, processes and transports natural gas; and gathers, transports, fractionates, stores and markets NGLs. The Midstream segment primarily reflects the results of MPLX and ANDX, our sponsored master limited partnerships. |
Recent Developments
Andeavor Acquisition
On October 1, 2018, we completed the Andeavor acquisition. Under the terms of the merger agreement, Andeavor stockholders had the option to choose 1.87 shares of MPC common stock or $152.27 in cash per share of Andeavor common stock. The merger agreement included election proration provisions that resulted in approximately 22.9 million shares of Andeavor common stock being converted into cash consideration and the remaining 128.2 million shares of Andeavor common stock being converted into stock consideration. Andeavor stockholders received in the aggregate approximately 239.8 million shares of MPC common stock valued at $19.8 billion and approximately $3.5 billion in cash in connection with the Andeavor acquisition. Through the Andeavor acquisition, we acquired the general partner and 156 million common units of ANDX, which is a publicly traded MLP that was formed to own, operate, develop and acquire logistics assets.
Andeavor was a highly integrated marketing, logistics and refining company operating primarily in the Western and Mid-Continent United States. Andeavor’s operations included procuring crude oil from its source or from other third parties, transporting the crude oil to one of its 10 refineries, and producing, marketing and distributing refined products. Its marketing system included more than 3,300 stations marketed under multiple well-known fuel brands including ARCO®. Also, as noted above, we acquired the general partner and 156 million common units of ANDX, a leading growth-oriented, full service, and diversified midstream company which owns and operates networks of crude oil, refined products and natural gas pipelines, terminals with crude oil and refined products storage capacity, rail loading and offloading facilities, marine terminals including storage, bulk petroleum distribution facilities, a trucking fleet and natural gas processing and fractionation complexes.
This transaction combined two strong, complementary companies to create a leading nationwide U.S. downstream energy company. The acquisition substantially increases our geographic diversification and scale and strengthens each of our operating segments by diversifying our refining portfolio into attractive markets and increasing access to advantaged feedstocks, enhancing our midstream footprint in the Permian Basin, and creating a nationwide retail and marketing portfolio all of which is expected to substantially improve efficiencies and our ability to serve customers. We expect the combination to generate up to approximately $1.4 billion in gross run-rate synergies within the first three years, significantly enhancing our long-term cash flow generation profile.
See Item 8. Financial Statements and Supplementary Data – Note 5 for additional information on other acquisitions and investments in affiliates.
MPLX Financing Activities
In November 2018, MPLX issued $2.25 billion in aggregate principal amount of senior notes in a public offering. In December 2018, a portion of the net proceeds from the offering was used to redeem the $750 million in aggregate principal amount of senior notes due February 2023 issued by MPLX and MarkWest. The remaining net proceeds have or will be used to repay borrowings under MPLX’s revolving credit facility and intercompany loan with MPC and for general partnership purposes.
EXECUTIVE SUMMARY
Results
Select results for 2018 and 2017 are reflected in the following table. The 2018 amounts include the results of Andeavor from the October 1, 2018 acquisition date forward.
| (In millions, except per share data) | 2018 | 2017 | ||||||
| Income from operations by segment | ||||||||
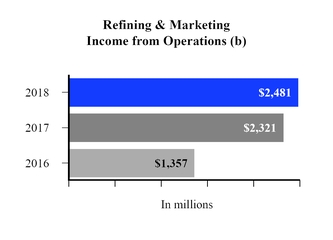
| Refining & Marketing | $ | 2,481 | $ | 2,321 | ||||
| Retail | 1,028 | 729 | ||||||
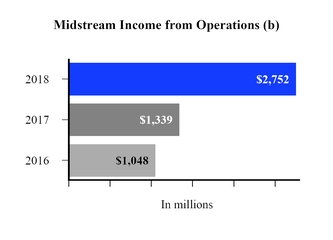
| Midstream | 2,752 | 1,339 | ||||||
| Items not allocated to segments | (690 | ) | (371 | ) | ||||
| Income from operations | $ | 5,571 | $ | 4,018 | ||||
| (Benefit) provision for income taxes | $ | 962 | $ | (460 | ) | |||
| Net income attributable to MPC | $ | 2,780 | $ | 3,432 | ||||
| Net income attributable to MPC per diluted share | $ | 5.28 | $ | 6.70 |
Net income attributable to MPC decreased $652 million, or $1.42 per diluted share, in 2018 compared to 2017. Increased income from operations was more than offset by the absence of a tax benefit of $1.5 billion resulting from the TCJA in 2017 and increased net income attributable to noncontrolling interests in 2018. Refer to the Results of Operations section for a discussion of financial results by segment for the three years ended December 31, 2018.
MPLX and ANDX
On February 1, 2018, we contributed our refining logistics assets and fuels distribution services to MPLX in exchange for $4.1 billion in cash and approximately 114 million newly issued MPLX units. Immediately following the dropdown, our IDRs were cancelled and our economic general partner interest was converted into a non-economic general partner interest, all in exchange for 275 million newly issued MPLX common units. MPLX financed the cash portion of the February 1, 2018 dropdown with its $4.1 billion 364-day term loan facility, which was entered into on January 2, 2018. On February 8, 2018, MPLX issued $5.5 billion in aggregate principal amount of senior notes in a public offering. MPLX used $4.1 billion of the net proceeds of the offering to repay the 364-day term-loan facility. The remaining proceeds were used to repay outstanding borrowings under MPLX’s revolving credit facility and intercompany loan agreement with us and for general partnership purposes.
The following table summarizes the cash distributions we received from MPLX during 2018 and 2017 and ANDX distributions received after the October 1, 2018 acquisition of Andeavor.
| (In millions) | 2018 | 2017 | ||||||
| Cash distributions received: | ||||||||
| Limited partner distributions - MPLX | $ | 1,097 | $ | 197 | ||||
| Limited partner distributions - ANDX | 146 | — | ||||||
| General partner distributions, including IDRs - MPLX | — | 301 | ||||||
| Total | $ | 1,243 | $ | 498 |
We owned approximately 505 million MPLX common units at December 31, 2018 with a market value of $15.29 billion based on the December 31, 2018 closing unit price of $30.30. On January 25, 2019, MPLX declared a quarterly cash distribution of $0.6475 per common unit, which was paid February 14, 2019. As a result, MPLX made distributions totaling $514 million to its common unitholders. MPC’s portion of this distribution was approximately $327 million.
We owned approximately 156 million ANDX common units at December 31, 2018 with a market value of $5.07 billion based on the December 31, 2018 closing unit price of $32.49. On January 25, 2019, ANDX declared a quarterly cash distribution of $1.03 per common unit, which was paid February 14, 2019. As a result, ANDX made distributions totaling $238 million to its common unitholders. MPC’s portion of this distribution was approximately $146 million.
See Item 8. Financial Statements and Supplementary Data – Note 4 for additional information on MPLX and ANDX.
Share Repurchases
During the year ended December 31, 2018, we returned $3.29 billion to our shareholders through repurchases of 47 million shares of common stock at an average price per share of $69.46. These repurchases were funded primarily by after tax proceeds from the February 1, 2018 dropdown to MPLX.
Since January 1, 2012, our board of directors has approved $18.0 billion in total share repurchase authorizations and we have repurchased a total of $13.10 billion of our common stock, leaving $4.9 billion available for repurchases as of December 31, 2018. Under these authorizations, we have acquired 293 million shares at an average cost per share of $44.60.
Liquidity
As of December 31, 2018, we had cash and cash equivalents of $1.61 billion, excluding MPLX’s and ANDX’s cash and cash equivalents of $68 million and $10 million, respectively, and no borrowings or letters of credit outstanding under our $6.0 billion bank revolving credit facilities or under our $750 million trade receivables securitization facility (“trade receivables facility”). As of December 31, 2018, eligible trade receivables supported borrowings of $750 million under the trade receivable facility. As of December 31, 2018, MPLX had approximately $2.25 billion available under its $2.25 billion revolving credit agreement and $1 billion available through its intercompany loan agreement with MPC. As of December 31, 2018, ANDX had $855 million available under its $2.10 billion revolving credit agreements and $500 million available through its intercompany loan agreement with MPC.
See Item 8. Financial Statements and Supplementary Data – Note 19 for information on our new bank revolving credit facilities.
OVERVIEW OF SEGMENTS
Refining & Marketing
Refining & Marketing segment income from operations depends largely on our Refining & Marketing margin and refinery throughputs. Our total refining capacity was 3,021 mbpcd, 1,881 mbpcd and 1,817 mbpcd as of December 31, 2018, 2017 and
2016, respectively. The increase in 2018 was primarily due to the acquisition of Andeavor on October 1, 2018, which added 10 refineries with approximately 1,117 mbpcd of total refining capacity.
Our Refining & Marketing margin is the difference between the prices of refined products sold and the costs of crude oil and other charge and blendstocks refined, including the costs to transport these inputs to our refineries and the costs of products purchased for resale. The crack spread is a measure of the difference between market prices for refined products and crude oil, commonly used by the industry as a proxy for the refining margin. Crack spreads can fluctuate significantly, particularly when prices of refined products do not move in the same relationship as the cost of crude oil. As a performance benchmark and a comparison with other industry participants, we calculate West Coast, Mid-Continent and Gulf Coast crack spreads that we believe most closely track our operations and slate of products. The following will be used for these crack-spread calculations:
| • | The West Coast crack spread uses three barrels of ANS crude producing two barrels of LA CARBOB and one barrel of LA CARB Diesel; |
| • | The Mid-Continent Crack spread uses three barrels of WTI crude producing two barrels of Chicago CBOB gasoline and one barrel of Chicago ULSD; and |
| • | The Gulf Coast Crack Spread uses three barrels of LLS crude producing two barrels of USGC CBOB gasoline and one barrel of USGC ULSD. |
Our refineries can process significant amounts of sour crude oil, which typically can be purchased at a discount to sweet crude oil. The amount of this discount, the sweet/sour differential, can vary significantly, causing our Refining & Marketing margin to differ from crack spreads based on sweet crude oil. In general, a larger sweet/sour differential will enhance our Refining & Marketing margin.
Future crude oil differentials will be dependent on a variety of market and economic factors, as well as U.S. energy policy.
The following table provides sensitivities showing an estimated change in annual net income due to potential changes in market conditions.
| (In millions, after-tax) | ||||
| Blended crack spread sensitivity(a) (per $1.00/barrel change) | $ | 900 | ||
| Sour differential sensitivity(b) (per $1.00/barrel change) | 450 | |||
| Sweet differential sensitivity(c) (per $1.00/barrel change) | 370 | |||
| Natural gas price sensitivity(d) (per $1.00/MMBtu) | 300 |
| (a) | Crack spread based on 38 percent WTI, 38 percent LLS and 24 percent ANS with Mid-Continent, Gulf Coast and West Coast product pricing, respectively and assumes all other differentials and pricing relationships remain unchanged. |
| (b) | Sour crude oil basket consists of the following crudes: ANS, ASCI, Maya and Western Canadian Select |
| (c) | Sweet crude oil basket consists of the following crudes: Bakken, Brent, LLS, WTI-Cushing and WTI-Midland |
| (d) | This is consumption based exposure for our Refining & Marketing segment and does not include the sales exposure for our Midstream segment. |
In addition to the market changes indicated by the crack spreads, the sour differential and the sweet differential, our Refining & Marketing margin is impacted by factors such as:
| • | the selling prices realized for refined products; |
| • | the types of crude oil and other charge and blendstocks processed; |
| • | our refinery yields; |
| • | the cost of products purchased for resale; |
| • | the impact of commodity derivative instruments used to hedge price risk; and |
| • | the potential impact of LCM adjustments to inventories in periods of declining prices. |
Inventories are stated at the lower of cost or market. Costs of crude oil, refinery feedstocks and refined products are stated under the LIFO inventory costing method and aggregated on a consolidated basis for purposes of assessing if the cost basis of these inventories may have to be written down to market values. At December 31, 2018, market values for refined products exceed their cost basis and, therefore, there is no LCM inventory market valuation reserve at the end of the year. Based on movements of refined product prices, future inventory valuation adjustments could have a negative effect to earnings. Such losses are subject to reversal in subsequent periods if prices recover.
Refining & Marketing segment income from operations is also affected by changes in refinery direct operating costs, which include turnaround and major maintenance, depreciation and amortization and other manufacturing expenses. Changes in
manufacturing costs are primarily driven by the cost of energy used by our refineries, including purchased natural gas, and the level of maintenance costs. Planned major maintenance activities, or turnarounds, requiring temporary shutdown of certain refinery operating units, are periodically performed at each refinery. The following table lists the refineries that had significant planned turnaround and major maintenance activities for each of the last three years and only reflects the activity for the acquired refineries after October 1, 2018.
| Year | Refinery | |
| 2018 | Canton, Detroit, Galveston Bay and Martinez | |
| 2017 | Catlettsburg, Galveston Bay and Garyville | |
| 2016 | Galveston Bay, Garyville and Robinson |
We have various long-term, fee-based commercial agreements with MPLX and ANDX. Under these agreements, MPLX and ANDX, which are reported in our Midstream segment, provide transportation, storage, distribution and marketing services to our Refining & Marketing segment. Certain of these agreements include commitments for minimum quarterly throughput and distribution volumes of crude oil and refined products and minimum storage volumes of crude oil, refined products and other products. Certain other agreements include commitments to pay for 100 percent of available capacity for certain marine transportation and refining logistics assets.
Retail
Our Retail fuel margin for gasoline and distillate, which is the price paid by consumers or direct dealers less the cost of refined products, including transportation, consumer excise taxes and bankcard processing fees (where applicable), impacts the Retail segment profitability. Gasoline and distillate prices are volatile and are impacted by changes in supply and demand in the regions where we operate. Numerous factors impact gasoline and distillate demand throughout the year, including local competition, seasonal demand fluctuations, the available wholesale supply, the level of economic activity in our marketing areas and weather conditions. According to current estimates, 2018 gasoline demand remained at 9.3 million barrels per day for the third consecutive year. Headwinds from a four-year high in average gasoline prices during 2018 offset the gasoline demand support from continuing economic growth and slowing fleet fuel efficiency gains. Meanwhile, distillate demand was up for the second consecutive year on continuing economic growth in 2018, rising 5.2 percent from 2017 to the highest level since 2007 and the third highest U.S. demand level ever. Truck tonnage posted its largest annual increase since 1998, rising 6.6 percent year over year in 2018, while port container traffic (at the 10 largest U.S. ports), grew 4.5 percent year over year in 2018 (through November). The margin on merchandise sold at our convenience stores historically has been less volatile and has contributed substantially to our Retail segment margin. Almost half of our Retail margin was derived from merchandise sales in 2018. This percentage decreased from 2017 due to the addition of long-term fuel supply contracts with direct dealers and fuel only locations as part of the Andeavor acquisition. Our Retail convenience stores offer a wide variety of merchandise, including prepared foods, beverages and non-food items.
Inventories are carried at the lower of cost or market value. Costs of refined products and merchandise are stated under the LIFO inventory costing method and aggregated on a consolidated basis for purposes of assessing if the cost basis of these inventories may have to be written down to market values. As of December 31, 2018, market values for refined products exceed their cost basis and, therefore, there is no LCM inventory market valuation reserve at the end of the year. Based on movements of refined product prices, future inventory valuation adjustments could have a negative effect to earnings. Such losses are subject to reversal in subsequent periods if prices recover.
Midstream
Our Midstream segment transports, stores, distributes and markets crude oil and refined products, principally for our Refining & Marketing segment. The profitability of our pipeline transportation operations primarily depends on tariff rates and the volumes shipped through the pipelines. The profitability of our marine operations primarily depends on the quantity and availability of our vessels and barges. The profitability of our light product terminal operations primarily depends on the throughput volumes at these terminals. The profitability of our fuels distribution services primarily depends on the sales volumes of certain refined products. The profitability of our refining logistics operations depends on the quantity and availability of our refining logistics assets. A majority of the crude oil and refined product shipments on our pipelines and marine vessels and the refined product throughput at our terminals serve our Refining & Marketing segment and our refining logistics assets and fuels distribution services are used solely by our Refining & Marketing segment. As discussed above in the Refining & Marketing section, MPLX and ANDX, which are reported in our Midstream segment, have various long-term, fee-based commercial agreements related to services provided to our Refining & Marketing segment. Under these agreements, MPLX and ANDX have received various commitments of minimum throughput, storage and distribution volumes as well as commitments to pay for all available capacity of certain assets. The volume of crude oil that we transport is directly affected by the supply of, and refiner demand for, crude oil in the markets served directly by our crude oil pipelines, terminals and marine
operations. Key factors in this supply and demand balance are the production levels of crude oil by producers in various regions or fields, the availability and cost of alternative modes of transportation, the volumes of crude oil processed at refineries and refinery and transportation system maintenance levels. The volume of refined products that we transport, store, distribute and market is directly affected by the production levels of, and user demand for, refined products in the markets served by our refined product pipelines and marine operations. In most of our markets, demand for gasoline and distillate peaks during the summer driving season, which extends from May through September of each year, and declines during the fall and winter months. As with crude oil, other transportation alternatives and system maintenance levels influence refined product movements.
NGL and natural gas prices are volatile and are impacted by changes in fundamental supply and demand, as well as market uncertainty, availability of NGL transportation and fractionation capacity and a variety of additional factors that are beyond our control. Our Midstream segment profitability is affected by prevailing commodity prices primarily as a result of processing or conditioning at our own or third‑party processing plants, purchasing and selling or gathering and transporting volumes of natural gas at index‑related prices and the cost of third‑party transportation and fractionation services. To the extent that commodity prices influence the level of natural gas drilling by our producer customers, such prices also affect profitability.
RESULTS OF OPERATIONS
The following discussion includes comments and analysis relating to our results of operations for the years ended December 31, 2018, 2017 and 2016. The 2018 amounts include the results of Andeavor from the October 1, 2018 acquisition date forward. This discussion should be read in conjunction with Item 8. Financial Statements and Supplementary Data and is intended to provide investors with a reasonable basis for assessing our historical operations, but should not serve as the only criteria for predicting our future performance.
Consolidated Results of Operations
| (In millions) | 2018 | 2017 | 2018 vs. 2017 Variance | 2016 | 2017 vs. 2016 Variance | |||||||||||||||
| Revenues and other income: | ||||||||||||||||||||
| Sales and other operating revenues(a) | $ | 95,750 | $ | 74,104 | $ | 21,646 | $ | 63,277 | $ | 10,827 | ||||||||||
| Sales to related parties | 754 | 629 | 125 | 62 | 567 | |||||||||||||||
| Income (loss) from equity method investments | 373 | 306 | 67 | (185 | ) | 491 | ||||||||||||||
| Net gain on disposal of assets | 23 | 10 | 13 | 32 | (22 | ) | ||||||||||||||
| Other income | 202 | 320 | (118 | ) | 178 | 142 | ||||||||||||||
| Total revenues and other income | 97,102 | 75,369 | 21,733 | 63,364 | 12,005 | |||||||||||||||
| Costs and expenses: | ||||||||||||||||||||
| Cost of revenues (excludes items below)(a) | 85,456 | 66,519 | 18,937 | 56,676 | 9,843 | |||||||||||||||
| Purchases from related parties | 610 | 570 | 40 | 509 | 61 | |||||||||||||||
| Inventory market valuation adjustment | — | — | — | (370 | ) | 370 | ||||||||||||||
| Impairment expense | — | — | — | 130 | (130 | ) | ||||||||||||||
| Depreciation and amortization | 2,490 | 2,114 | 376 | 2,001 | 113 | |||||||||||||||
| Selling, general and administrative expenses | 2,418 | 1,694 | 724 | 1,597 | 97 | |||||||||||||||
| Other taxes | 557 | 454 | 103 | 435 | 19 | |||||||||||||||
| Total costs and expenses | 91,531 | 71,351 | 20,180 | 60,978 | 10,373 | |||||||||||||||
| Income from operations | 5,571 | 4,018 | 1,553 | 2,386 | 1,632 | |||||||||||||||
| Net interest and other financial costs | 1,003 | 674 | 329 | 564 | 110 | |||||||||||||||
| Income before income taxes | 4,568 | 3,344 | 1,224 | 1,822 | 1,522 | |||||||||||||||
| (Benefit) provision for income taxes | 962 | (460 | ) | 1,422 | 609 | (1,069 | ) | |||||||||||||
| Net income | 3,606 | 3,804 | (198 | ) | 1,213 | 2,591 | ||||||||||||||
| Less net income (loss) attributable to: | ||||||||||||||||||||
| Redeemable noncontrolling interest | 75 | 65 | 10 | 41 | 24 | |||||||||||||||
| Noncontrolling interests | 751 | 307 | 444 | (2 | ) | 309 | ||||||||||||||
| Net income attributable to MPC | $ | 2,780 | $ | 3,432 | $ | (652 | ) | $ | 1,174 | $ | 2,258 |
| (a) | We adopted ASU 2014-09, Revenue - Revenue from Contracts with Customers (“ASC 606”) as of January 1, 2018, and elected to report certain taxes on a net basis. We adopted the standard using the modified retrospective method, and, therefore, comparative information continues to reflect certain taxes on a gross basis. See Item 8. Financial Statements and Supplementary Data - Notes 2 and 3 for further information. |
2018 Compared to 2017
Net income attributable to MPC decreased $652 million. Increased income from operations was more than offset by a tax benefit of $1.5 billion resulting from the TCJA in 2017 and increased income attributable to noncontrolling interests in 2018. See Segment Results for additional information.
Total revenues and other income increased $21.73 billion in 2018 compared to 2017 primarily due to:
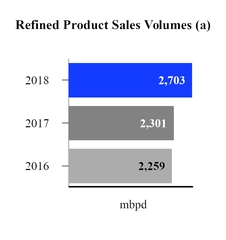
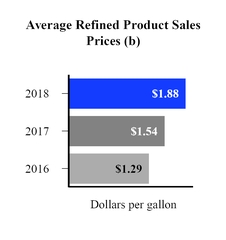
| • | increased sales and other operating revenues of $21.65 billion mainly due to an increase in our Refining & Marketing segment refined product sales volumes, which increased 402 mbpd, and higher averaged refined product sales prices, which increased $0.34 per gallon. The increase in volume is largely due to the Andeavor acquisition on October 1, 2018. These increases were partially offset by our election to present revenues net of certain taxes under ASC 606 prospectively from January 1, 2018, which resulted in a decrease in revenues of $6.66 billion for the year. See Item 8. |
Financial Statements and Supplementary Data – Notes 2 and 3 for additional information on recently adopted accounting standards;
| • | increased sales to related parties of $125 million primarily due to higher average refined product prices; |
| • | increased income from equity method investments of $67 million primarily due to an increase in income from midstream equity affiliates; and |
| • | decreased other income of $118 million primarily due to a decrease in RIN sales. |
Total costs and expenses increased $20.18 billion in 2018 compared to 2017 primarily due to:
| • | increased cost of revenues of $18.94 billion primarily due to: |
| ◦ | an increase in refined product cost of sales of $24.97 billion, primarily due to increased operations following the acquisition of Andeavor along with higher raw material costs attributable to an increase in our average crude oil costs of $13.87 per barrel; and |
| ◦ | a decrease in certain taxes of $6.66 billion as a result of our election to present revenues net of certain taxes under ASC 606 prospectively from January 1, 2018. For the year, certain taxes continue to be presented on a gross basis and are included in cost of revenues. See Item 8. Financial Statements and Supplementary Data – Notes 2 and 3 for additional information on recently adopted accounting standards; |
| • | increased depreciation and amortization of $376 million, primarily due to the depreciation of the fair value of the assets acquired in connection with the Andeavor acquisition; |
| • | increased selling, general and administrative expenses of $724 million primarily due to approximately $197 million of transaction related costs for financial advisors, employee severance and other costs associated with the Andeavor acquisition in addition to increased costs and expenses for the combined company; and |
| • | increased other taxes of $103 million primarily due to the inclusion of other taxes related to the acquired Andeavor operations. |
Net interest and other financial costs increased $329 million mainly due to increased MPLX borrowings and debt assumed in the acquisition of Andeavor. In addition, MPLX recognized $60 million of debt extinguishment costs in 2018 in connection with the redemption of its $750 million of senior notes due in 2023. We capitalized interest of $80 million in 2018 and $55 million in 2017. See Item 8. Financial Statements and Supplementary Data – Note 19 for further details.
Provision for income taxes increased $1.42 billion primarily due to the absence of a tax benefit of $1.5 billion in 2017 resulting from the TCJA and an increase in our income before income taxes, which increased $1.22 billion. The effective tax rate of 21 percent in 2018 is consistent with the U.S. statutory rate of 21 percent, as permanent benefit differences related to income attributable to noncontrolling interest were offset by state and local tax expense. In 2017, our effective tax rate was impacted by 45 percentage points as a result of the TCJA which decreased our effective tax rate from 31 percent to (14) percent. The effective tax rate, excluding the TCJA, of 31 percent in 2017 was slightly less than the U.S. statutory rate of 35 percent primarily due to certain permanent benefit differences, including differences related to net income attributable to noncontrolling interests and the domestic manufacturing deduction, partially offset by state and local tax expense. See Item 8. Financial Statements and Supplementary Data – Note 12 for further details.
Noncontrolling interests increased $454 million due to higher MPLX net income resulting primarily from the February 1, 2018 dropdown transaction, partially offset by the reduced ownership in MPLX held by noncontrolling interests following the GP/IDR Exchange. Noncontrolling ownership in MPLX decreased to 36.4 percent at December 31, 2018 from 69.6 percent at December 31, 2017. In addition, 2018 reflects $68 million of net income attributable to the noncontrolling interest in ANDX of 36.4 percent for the period from October 1, 2018 through the end of the year.
2017 Compared to 2016
Net income attributable to MPC increased $2.26 billion in 2017 compared to 2016 primarily due to a tax benefit of $1.5 billion resulting from the TCJA enacted in the fourth quarter of 2017 and an increase in our Refining & Marketing segment income from operations of $964 million. See Segment Results for additional information.
Total revenues and other income increased $12.01 billion in 2017 compared to 2016 primarily due to:
| • | increased sales and other operating revenues (including consumer excise taxes) of $10.83 billion primarily due to higher averaged refined product sales prices, which increased $0.25 per gallon, and an increase in refined product sales volumes, which increased 42 mbpd; |
| • | increased sales to related parties of $567 million mainly due to sales from our Refining & Marketing segment to PFJ Southeast, a joint venture with Pilot Flying J, which commenced in the fourth quarter of 2016; |
| • | increased income (loss) from equity method investments of $491 million primarily due to the absence of impairment charges related to equity method investments of $356 million recorded in 2016 along with increases in income from new and existing pipeline, natural gas, retail and marine affiliates; |
| • | increased other income of $142 million primarily due to increased RIN sales; and |
| • | decreased net gain on disposal of assets of $22 million primarily due to gains on the sale of certain Speedway locations in 2016. |
Total costs and expenses increased $10.37 billion in 2017 compared to 2016 primarily due to:
| • | increased cost of revenues of $9.84 billion primarily due to an increase in refined product cost of sales of $9.18 billion, primarily attributable to an increase in our average crude oil costs of $9.50 per barrel; |
| • | increased purchases from related parties of $61 million primarily due to: |
| ◦ | an increase in transportation services provided by Crowley Ocean Partners of $27 million; |
| ◦ | an increase in transportation services provided by Crowley Blue Water Partners of $23 million; and |
| ◦ | an increase in volumes purchased from LOOP of $12 million; |
| • | an inventory market valuation adjustment which decreased costs and expenses by $370 million in 2016 related to the reversal of the LCM inventory valuation reserve due to increased refined product prices; |
| • | decreased impairment expense of $130 million as the impairment expense in 2016 reflects a $130 million charge recorded by MPLX to impair a portion of the $2.21 billion of goodwill recorded in connection with the MarkWest Merger; and |
| • | increased selling, general and administrative expenses of $97 million primarily due to increases in employee-related compensation and benefit expenses, higher corporate costs and net litigation settlement expenses of $29 million. |
Net interest and other financial costs increased $110 million in 2017 compared to 2016 mainly due to the MPLX senior notes issued in February 2017 and a $45 million increase in pension settlement expenses, partially offset by decreased borrowings on the MPC term loan agreement. We capitalized interest of $55 million in 2017 and $63 million in 2016. See Item 8. Financial Statements and Supplementary Data – Note 19 for further details.
Provision for income taxes decreased $1.07 billion in 2017 compared to 2016. The TCJA was signed into law on December 22, 2017 and provided several key changes to U.S. tax law, including a federal corporate tax rate of 21 percent replacing the 2017 rate applicable to MPC of 35 percent. MPC was required to calculate the effect of the TCJA on its deferred tax balances as of the enactment date. The effect of the federal corporate income tax rate change reduced net deferred tax liabilities by $1.5 billion in 2017. This benefit was partially offset by an increase in our income before income taxes, which increased $1.52 billion in 2017 compared to 2016. The TCJA impacted our effective tax rate by 45 percentage points in 2017, decreasing our effective tax rate from 31 percent to (14) percent. The effective tax rates, excluding the TCJA in 2017, of 31 percent in 2017 and 33 percent in 2016, are slightly less than the U.S. statutory rate of 35 percent primarily due to certain permanent benefit differences, including differences related to net income attributable to noncontrolling interests and the domestic manufacturing deduction, partially offset by state and local tax expense. See Item 8. Financial Statements and Supplementary Data – Note 12 for further details.
Noncontrolling interests increased $333 million primarily due to increased MPLX net income.
Segment Results
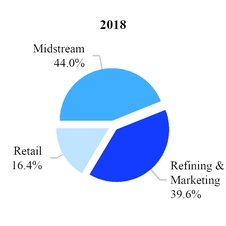
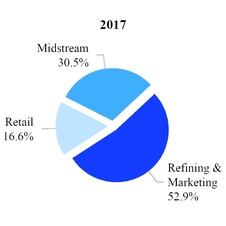
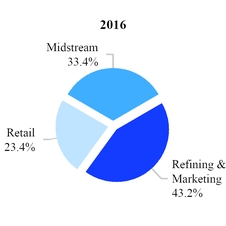
Our segment income from operations was approximately $6.26 billion, $4.39 billion and $3.14 billion for the years ended December 31, 2018, 2017 and 2016, respectively. The following shows the percentage of segment income from operations by segment for the last three years.
Refining & Marketing
| (a) | We adopted ASC 606 (Revenue from Contracts with Customers), as of January 1, 2018, and elected to report certain taxes on a net basis. We applied the standard using the modified retrospective method, and, therefore, comparative information continues to reflect certain taxes on a gross basis. |
| (b) | Results related to refining logistics and fuels distribution are presented in the Midstream segment prospectively from February 1, 2018. Prior periods are not adjusted as these entities were not considered a business prior to February 1, 2018. |
| (a) | Includes intersegment sales and sales destined for export. |
| (b) | For comparability purposes, these amounts exclude sales taxes for all periods presented. As noted above, Refining & Marketing revenues in 2018 reflect these taxes on a net basis, while 2017 and 2016 Refining & Marketing revenues continue to reflect these taxes on a gross basis. The average refined product sales prices for 2017 and 2016 included excise taxes of $0.18 per gallon before this adjustment. |
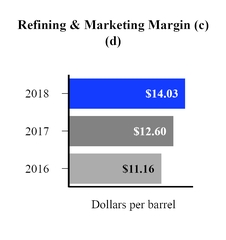
| (c) | Sales revenue less cost of refinery inputs and purchased products, divided by total refinery throughputs. Excludes LCM inventory valuation adjustments. |
| (d) | See “Non-GAAP Measures” section for reconciliation and further information regarding this non-GAAP measure. |
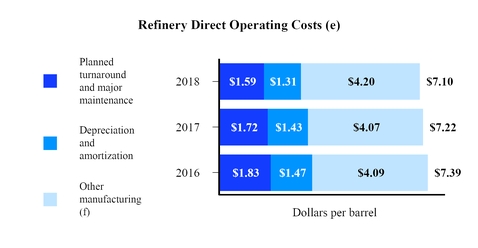
| (e) | Per barrel of total refinery throughputs. |
| (f) | Includes utilities, labor, routine maintenance and other operating costs. |
2018 Compared to 2017
The following table presents certain benchmark prices in our marketing areas and market indicators that we believe are helpful in understanding the results of our Refining & Marketing segment’s business. With the acquisition of Andeavor, we revised our market data to include a West Coast 3-2-1 crack spread. Additionally, the Chicago 6-3-2-1 crack spread was revised to reflect a Mid-Continent 3-2-1 crack spread and the Gulf coast 6-3-2-1 crack spread was also revised to reflect a 3-2-1 crack spread. See the “Overview of Segments” section for further discussion of our revised crack spreads.
| Benchmark spot prices (dollars per gallon) | 2018 | 2017 | ||||||
| Chicago CBOB unleaded regular gasoline | $ | 1.86 | $ | 1.58 | ||||
| Chicago ultra-low sulfur diesel | 2.07 | 1.64 | ||||||
| USGC CBOB unleaded regular gasoline | 1.88 | 1.60 | ||||||
| USGC ultra-low sulfur diesel | 2.05 | 1.62 | ||||||
| LA CARBOB | 2.06 | — | ||||||
| LA CARB diesel | 2.14 | — | ||||||
| Market Indicators (dollars per barrel) | ||||||||
| LLS | $ | 69.93 | $ | 54.00 | ||||
| WTI | 64.10 | 50.85 | ||||||
| ANS | 68.46 | 54.44 | ||||||
| Crack Spreads | ||||||||
| Mid-Continent WTI 3-2-1 | $ | 14.02 | $ | 12.71 | ||||
| USGC LLS 3-2-1 | 7.91 | 8.55 | ||||||
| West Coast ANS 3-2-1 | 11.66 | 14.02 | ||||||
| Blended 3-2-1(a)(b) | 10.62 | 10.22 | ||||||
| Crude Oil Differentials | ||||||||
| Sweet | $ | (3.83 | ) | $ | (1.04 | ) | ||
| Sour | (7.60 | ) | (5.02 | ) |
| (a) | Blended 3-2-1 WTI/LLS/ANS crack spread 38/38/24 percent in 2018, Blended 6-3-2-1 Chicago/USGC crack spread is 40/60 percent for the first nine months of 2018 and in 2017 and 38/62 percent in 2016. These blends are based on MPC’s refining capacity by region in each period. |
| (b) | Beginning 4Q 2018, Blended Mid-Con/USGC/West Coast crack spread is weighted 38/38/24 percent based on MPC's refining capacity by PADD. From Q1 2017 through Q3 2018, the blended spread was weighted 40/60 percent Mid-Con/USGC. |
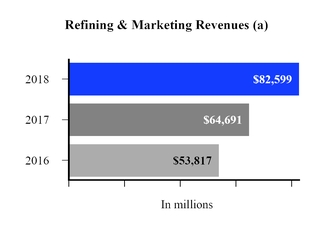
Refining & Marketing segment revenues increased $17.91 billion primarily due to higher refined product sales volumes, which increased 402 mbpd, and higher refined product sales prices, which increased $0.34 per gallon. The increase in sales volumes is largely due to the acquisition of Andeavor on October 1, 2018. These increases were partially offset by our election to present revenues net of certain taxes under ASC 606 prospectively from January 1, 2018, which resulted in a decrease in Refining & Marketing segment revenues of $4.58 billion in 2018. See Item 8. Financial Statements and Supplementary Data – Notes 2 and 3 for additional information on recently adopted accounting standards.
Refining & Marketing segment income from operations increased $160 million primarily due to higher throughputs as a result of the Andeavor acquisition as well as wider sour and sweet crude differentials. For comparison purposes, as noted in the Market Indicators table, 2017 indicators have been included which reflect the new indicators we began using subsequent to the acquisition of Andeavor. Based on this, the USGC, Mid-Continent and West Coast blended 3-2-1 crack spread was $10.62 per barrel in 2018 as compared to 10.22 per barrel in 2017. These crack spreads are net of RIN crack adjustments of $1.61 and $3.57 for 2018 and 2017, respectively.
Based on changes in the market indicators shown above and our refinery throughputs, we estimate a positive impact of $3.40 billion on Refining & Marketing segment income from operations, of which $1.81 billion and $1.59 billion are due to the effects of changes in price and volume, respectively. The market indicators use spot market values and an estimated mix of crude purchases and product sales. Differences in our results compared to these market indicators, including product price realizations, the mix of crudes purchased and their costs, the effects of LCM inventory valuation adjustments, the effects of market structure on our crude oil acquisition prices, and other items like refinery yields and other feedstock variances, had an estimated negative impact on Refining & Marketing segment income from operations of $698 million in 2018 compared to 2017. The significant elements of the negative impact were unfavorable crude acquisition costs and unfavorable product price realizations relative to the market indicators.
The cost of inventories of crude oil and refinery feedstocks, refined products and merchandise is determined primarily under the LIFO method. There were no material liquidations of LIFO inventories in 2018 and we recognized a LIFO charge of $7 million in 2017.
Refinery direct operating costs decreased $0.12 per barrel in 2018 compared to 2017. The decrease includes a $0.13 per barrel decrease in planned turnaround and major maintenance costs and a $0.12 per barrel decrease in depreciation and amortization primarily due to higher refinery throughput resulting from the addition of 10 refineries as part of the acquisition of Andeavor. Total turnaround costs increased due to costs related to these additional refineries as well as higher turnaround costs at our Detroit and Canton refineries, partially offset by lower turnaround costs at our Galveston Bay and Garyville refineries. The increase in other manufacturing costs of $0.13 per barrel is mainly due to costs associated with the acquired refineries, partially offset by an increase in throughput due to the acquisition of Andeavor. In addition, manufacturing costs and depreciation and amortization costs per barrel decreased due to the dropdown of refining and logistics assets to MPLX on February 1, 2018.
We purchase RINs to satisfy a portion of our RFS2 compliance. Our expenses associated with purchased RINs were $316 million in 2018 compared to $457 million in 2017. The decrease in 2018 was primarily due to lower weighted average RIN costs which more than offset the increase in our RINs obligation subsequent to the acquisition of Andeavor.
2017 Compared to 2016
The following table presents certain benchmark prices in our marketing areas and market indicators that we believe are helpful in understanding the results of our Refining & Marketing segment’s business.
| Benchmark spot prices (dollars per gallon) | 2017 | 2016 | ||||||
| Chicago CBOB unleaded regular gasoline | $ | 1.58 | $ | 1.33 | ||||
| Chicago ultra-low sulfur diesel | 1.64 | 1.34 | ||||||
| USGC CBOB unleaded regular gasoline | 1.60 | 1.33 | ||||||
| USGC ultra-low sulfur diesel | 1.62 | 1.32 | ||||||
| Market Indicators (dollars per barrel) | ||||||||
| LLS | $ | 54.00 | $ | 45.01 | ||||
| WTI | 50.85 | 43.47 | ||||||
| Crack Spreads | ||||||||
| Chicago LLS 6-3-2-1(a)(b) | $ | 9.77 | $ | 7.19 | ||||
| USGC LLS 6-3-2-1(a) | 9.89 | 6.80 | ||||||
| Blended 6-3-2-1(a)(c) | 9.84 | 6.96 | ||||||
| Crude Oil Differentials | ||||||||
| LLS - WTI(a) | $ | 3.15 | $ | 1.55 | ||||
| Sweet/Sour(a)(c) | 5.94 | 6.52 |
| (a) | All spreads and differentials are measured against prompt LLS. |
| (b) | Calculation utilizes USGC three percent residual fuel oil price as a proxy for Chicago three percent residual fuel oil price. |
| (c) | LLS (prompt) – [delivered cost of sour crude oil: Arab Light, Kuwait, Maya, Western Canadian Select and Mars]. |
Refining & Marketing segment revenues increased $10.87 billion in 2017 compared to 2016 primarily due to higher refined product sales prices and volumes.
Refining & Marketing segment income from operations increased $964 million in 2017 compared to 2016. Segment income in 2016 includes a $345 million non-cash benefit related to the Company’s LCM inventory reserve. Excluding the LCM inventory
benefit, the increase in segment results for 2017 primarily resulted from higher LLS crack spreads in both the U.S. Gulf Coast and Chicago markets. The LLS blended crack spread for 2017 increased to $9.84 per barrel from $6.96 per barrel in 2016. These favorable effects were partially offset by less favorable product price realizations as compared to the spot market prices used in the LLS blended crack spread.
Based on changes in the market indicators shown above and our refinery throughputs, we estimate a positive impact of $2.33 billion for 2017 compared to 2016 on Refining & Marketing segment income from operations. The market indicators use spot market values and an estimated mix of crude purchases and product sales. Differences in our results compared to these market indicators, including product price realizations, the mix of crudes purchased and their costs, the effects of LCM inventory valuation adjustments, the effects of market structure on our crude oil acquisition prices, and other items like refinery yields and other feedstock variances, had an estimated negative impact on Refining & Marketing segment income from operations of $1.35 billion in 2017 compared to 2016. The significant elements of the negative impact were unfavorable product price realizations and unfavorable crude acquisition costs relative to the market indicators.
The cost of inventories of crude oil and refinery feedstocks, refined products and merchandise is determined primarily under the LIFO method. In the second quarter of 2016, we had recognized the effects of an interim liquidation of our refined products inventories which we did not expect to reinstate by year end resulting in a pre-tax charge of approximately $54 million to income. Based on year end refined product inventories, which were higher than inventories at the beginning of the year, we had a build in refined product inventories for 2016. Therefore, we recognized the effects of this annual build in our refined products in the fourth quarter of 2016 which had the effect of reversing the second quarter charge. For the full year, we recognized a LIFO charge of $7 million in 2017 and $2 million in 2016.
Refinery direct operating costs decreased $0.17 per barrel in 2017 compared to 2016. The decrease in 2017 includes an $0.11 per barrel decrease in planned turnaround and major maintenance costs resulting from lower turnaround activity at our Garyville and Robinson refineries partially offset by higher activity at our Catlettsburg refinery.
We purchase RINs to satisfy a portion of our RFS2 compliance. Our expenses associated with purchased RINs were $457 million in 2017 and $288 million in 2016. The increase in 2017 was primarily due to higher weighted average RIN costs driven by higher market prices for purchased RINs and increases in the number of RINs purchased.
Supplemental Refining & Marketing Statistics
| 2018 | 2017 | 2016 | |||||||||
| Refining & Marketing Operating Statistics | |||||||||||
| Crude oil capacity utilization percent(a) | 96 | 97 | 95 | ||||||||
| Refinery throughputs (thousands of barrels per day): | |||||||||||
| Crude oil refined | 2,081 | 1,765 | 1,699 | ||||||||
| Other charge and blendstocks | 193 | 179 | 151 | ||||||||
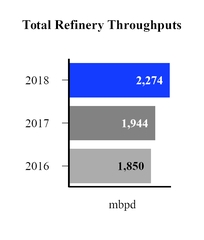
| Total | 2,274 | 1,944 | 1,850 | ||||||||
| Sour crude oil throughput percent | 52 | 59 | 60 | ||||||||
| Sweet crude oil throughput percent | 48 | 41 | 40 | ||||||||
| Refined product yields (mbpd):(b) | |||||||||||
| Gasoline | 1,107 | 932 | 900 | ||||||||
| Distillates | 773 | 641 | 617 | ||||||||
| Propane | 41 | 36 | 35 | ||||||||
| Feedstocks and petrochemicals | 288 | 277 | 241 | ||||||||
| Heavy fuel oil | 38 | 37 | 32 | ||||||||
| Asphalt | 69 | 63 | 58 | ||||||||
| Total | 2,316 | 1,986 | 1,883 | ||||||||
| Refining & Marketing Operating Statistics By Region – Gulf Coast | |||||||||||
| Refinery throughputs (mbpd):(b) | |||||||||||
| Crude oil refined | 1,135 | 1,070 | 1,039 | ||||||||
| Other charge and blendstocks | 190 | 224 | 195 | ||||||||
| Total | 1,325 | 1,294 | 1,234 | ||||||||
| Sour crude oil throughput percent | 62 | 71 | 73 | ||||||||
| Sweet crude oil throughput percent | 38 | 29 | 27 | ||||||||
| Refined product yields (mbpd):(b) | |||||||||||
| Gasoline | 574 | 546 | 514 | ||||||||
| Distillates | 432 | 405 | 399 | ||||||||
| Propane | 25 | 26 | 26 | ||||||||
| Feedstocks and petrochemicals | 291 | 311 | 286 | ||||||||
| Heavy fuel oil | 18 | 25 | 21 | ||||||||
| Asphalt | 19 | 17 | 15 | ||||||||
| Total | 1,359 | 1,330 | 1,261 | ||||||||
| Refinery direct operating costs (dollars per barrel):(c) | |||||||||||
| Planned turnaround and major maintenance | $ | 1.12 | $ | 1.75 | $ | 2.09 | |||||
| Depreciation and amortization | 1.03 | 1.12 | 1.14 | ||||||||
| Other manufacturing(d) | 3.41 | 3.74 | 3.70 | ||||||||
| Total | $ | 5.56 | $ | 6.61 | $ | 6.93 | |||||
| 2018 | 2017 | 2016 | |||||||||
| Refining & Marketing Operating Statistics By Region – Mid-Continent | |||||||||||
| Refinery throughputs (mbpd):(b) | |||||||||||
| Crude oil refined | 792 | 695 | 660 | ||||||||
| Other charge and blendstocks | 47 | 33 | 39 | ||||||||
| Total | 839 | 728 | 699 | ||||||||
| Sour crude oil throughput percent | 33 | 40 | 40 | ||||||||
| Sweet crude oil throughput percent | 67 | 60 | 60 | ||||||||
| Refined product yields (mbpd):(b) | |||||||||||
| Gasoline | 444 | 386 | 386 | ||||||||
| Distillates | 279 | 236 | 218 | ||||||||
| Propane | 14 | 11 | 11 | ||||||||
| Feedstocks and petrochemicals | 43 | 42 | 35 | ||||||||
| Heavy fuel oil | 14 | 13 | 12 | ||||||||
| Asphalt | 50 | 46 | 43 | ||||||||
| Total | 844 | 734 | 705 | ||||||||
| Refinery direct operating costs (dollars per barrel):(c) | |||||||||||
| Planned turnaround and major maintenance | $ | 1.97 | $ | 1.48 | $ | 1.15 | |||||
| Depreciation and amortization | 1.67 | 1.81 | 1.88 | ||||||||
| Other manufacturing(d) | 4.34 | 4.26 | 4.29 | ||||||||
| Total | $ | 7.98 | $ | 7.55 | $ | 7.32 | |||||
| Refining & Marketing Operating Statistics By Region – West Coast | |||||||||||
| Refinery throughputs (mbpd):(b) | |||||||||||
| Crude oil refined | 154 | — | — | ||||||||
| Other charge and blendstocks | 17 | — | — | ||||||||
| Total | 171 | — | — | ||||||||
| Sour crude oil throughput percent | 72 | — | — | ||||||||
| Sweet crude oil throughput percent | 28 | — | — | ||||||||
| Refined product yields (mbpd):(b) | |||||||||||
| Gasoline | 89 | — | — | ||||||||
| Distillates | 62 | — | — | ||||||||
| Propane | 2 | — | — | ||||||||
| Feedstocks and petrochemicals | 14 | — | — | ||||||||
| Heavy fuel oil | 7 | — | — | ||||||||
| Asphalt | — | — | — | ||||||||
| Total | 174 | — | — | ||||||||
| Refinery direct operating costs (dollars per barrel):(c) | |||||||||||
| Planned turnaround and major maintenance | $ | 2.79 | $ | — | $ | — | |||||
| Depreciation and amortization | 1.26 | — | — | ||||||||
| Other manufacturing(d) | 8.07 | — | — | ||||||||
| Total | $ | 12.12 | $ | — | $ | — |
| (a) | Based on calendar-day capacity, which is an annual average that includes down time for planned maintenance and other normal operating activities. |
| (b) | Excludes inter-refinery volumes which totaled 61 mbpd, 78 mbpd and 83 mbpd for 2018, 2017 and 2016, respectively, for all regions. |
| (c) | Per barrel of total refinery throughputs. |
| (d) | Includes utilities, labor, routine maintenance and other operating costs. |
Retail
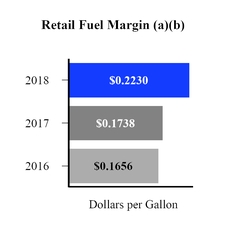
| (a) | The price paid by consumers or direct dealers less the cost of refined products, including transportation, consumer excise taxes and bankcard processing fees (where applicable), divided by gasoline and distillate sales volume. Excludes LCM inventory valuation adjustments. |
| (b) | See “Non-GAAP Measures” section for reconciliation and further information regarding this non-GAAP measure. |
| Key Financial and Operating Data | 2018 | 2017 | 2016 | |||||||||
| Average fuel sales prices (dollars per gallon) | $ | 2.71 | $ | 2.34 | $ | 2.09 | ||||||
| Merchandise sales (in millions) | $ | 5,232 | $ | 4,893 | $ | 5,007 | ||||||
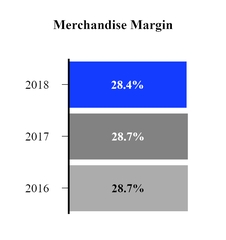
| Merchandise margin (in millions)(a)(b) | $ | 1,486 | $ | 1,402 | $ | 1,435 | ||||||
| Same store gasoline sales volume (period over period)(c) | (1.5 | )% | (1.3 | )% | (0.4 | )% | ||||||
| Same store merchandise sales (period over period)(c)(d) | 4.2 | % | 1.2 | % | 3.2 | % | ||||||
| Convenience stores at period-end | 3,923 | 2,744 | 2,733 | |||||||||
| Direct dealer locations at period-end | 1,065 | N/A | N/A |
| (a) | The price paid by the consumers less the cost of merchandise. |
| (b) | See “Non-GAAP Measures” section for reconciliation and further information regarding this non-GAAP measure. |
| (c) | Same store comparison includes only locations owned at least 13 months. |
| (d) | Excludes cigarettes. |
2018 Compared to 2017
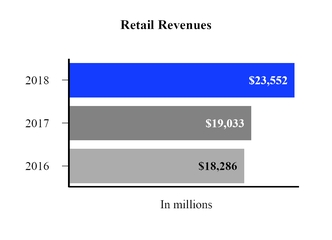
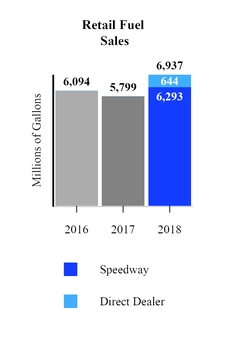
Retail segment revenues increased $4.52 billion. The majority of this increase is due to the acquisition of Andeavor on October 1, 2018, which added company-owned and operated retail locations, which are included in Speedway fuel sales, and direct dealer locations. The existing Retail business also saw a $1.18 billion increase in fuel and merchandise sales. Total fuel sales increased $5.21 billion primarily due to an increase in Speedway fuel sales volumes of 494 million gallons, the addition of direct dealer fuel sales of 644 million gallons and an increase in average gasoline and distillate selling prices of $0.37 per gallon. Merchandise sales increased $339 million. The increases in Speedway fuel sales and merchandise sales as well as the addition of sales to direct dealers were primarily due to the acquisition of Andeavor. These increases were partially offset by our election to present revenues net of certain taxes under ASC 606 prospectively from January 1, 2018, which resulted in a decrease in Retail segment revenues of $844 million in 2018. See Item 8. Financial Statements and Supplementary Data – Notes 2 and 3 for additional information on recently adopted accounting standards.
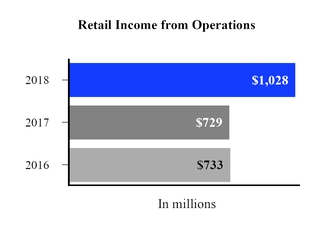
Retail segment income from operations increased $299 million primarily due to contributions from the Retail operations acquired in the Andeavor acquisition. For locations owned prior to the Andeavor acquisition, increased gasoline and distillate and merchandise margins were more than offset by increased operating expenses.
2017 Compared to 2016
Retail segment revenues increased $747 million due to an increase in fuel sales of $860 million partially offset by a decrease in merchandise sales of $114 million. Average fuel selling prices increased $0.25 per gallon which were partially offset by a decrease in sales volumes in 2017 compared to 2016. The decreases in fuel sales volumes and merchandise sales are primarily attributable to the contribution of 41 travel centers to PJF Southeast in fourth quarter of 2016.
Retail segment income from operations decreased $4 million. Segment income in 2016 includes a $25 million non-cash benefit related to the reversal of the Company’s LCM inventory reserve, which was recorded in 2015. Excluding the LCM inventory benefit recognized in 2016, the increase in segment results for 2017 was primarily due to a full year of contributions from Speedway’s travel center joint venture formed in the fourth quarter 2016 and lower operating expense, partially offset by lower merchandise margin and lower gains from asset sales.
Midstream
| (a) | We adopted ASC 606 (Revenue from Contracts with Customers), as of January 1, 2018, and elected to report certain taxes on a net basis. We applied the standard using the modified retrospective method, and, therefore, comparative information continues to reflect certain taxes on a gross basis. |
| (b) | Results related to refining logistics and fuels distribution dropdown into MPLX are presented in the Midstream segment prospectively from February 1, 2018. Prior periods are not adjusted as these entities were not considered a business prior to February 1, 2018. |
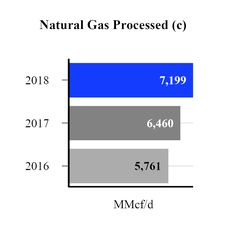
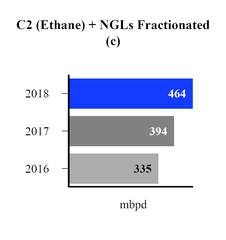
| (a) | On owned common-carrier pipelines, excluding equity method investments. |
| (b) | Includes the results of the terminal assets beginning on April 1, 2016, the date the assets became a business. |
| (c) | Includes amounts related to unconsolidated equity method investments on a 100 percent basis. |
| Benchmark Prices | 2018 | 2017 | 2016 | |||||||||
| Natural Gas NYMEX HH ($ per MMBtu) | $ | 3.07 | $ | 3.02 | $ | 2.55 | ||||||
| C2 + NGL Pricing ($ per gallon)(a) | $ | 0.78 | $ | 0.66 | $ | 0.47 |
| (a) | C2 + NGL pricing based on Mont Belvieu prices assuming an NGL barrel of approximately 35 percent ethane, 35 percent propane, six percent Iso-Butane, 12 percent normal butane and 12 percent natural gasoline. |
2018 Compared to 2017
On February 1, 2018, we completed the dropdown of our refining logistics assets and fuels distribution services to MPLX, which is reported in our Midstream segment. Refining logistics contains the integrated tank farm assets that support MPC’s refining operations. Fuels distribution is structured to provide a broad range of scheduling and marketing services as MPC’s agent. These new businesses were reported in the Midstream segment prospectively from February 1, 2018. No effect was given to prior periods as these entities were not considered businesses prior to February 1, 2018.
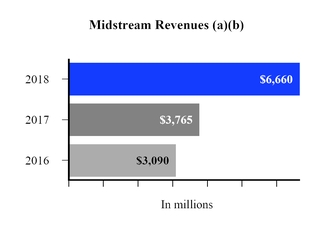
Midstream segment revenue and income from operations increased $2.90 billion and $1.41 billion, respectively. Revenue increased $1.94 billion primarily due to fees charged for fuels distribution and refining logistics services following the February 1, 2018 dropdown to MPLX in addition to services provided by ANDX following the acquisition of Andeavor on October 1, 2018. Revenues also increased by approximately $502 million due to ASC 606 gross ups. See Item 8. Financial Statements and Supplementary Data – Note 3 for additional information.
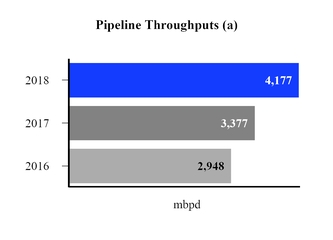
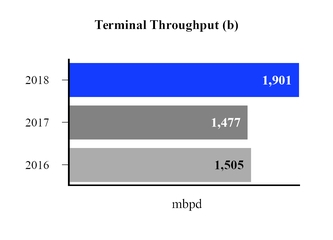
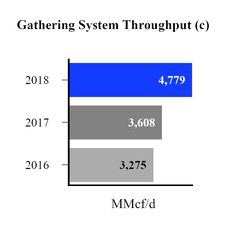
In 2018, Midstream segment income from operations includes $230 million due to contributions from ANDX and $874 million, from the refining logistics assets and fuels distribution services contributed to MPLX on February 1, 2018. Prior period Midstream segment results do not reflect the impact of these new businesses. The incremental $309 million increase in Midstream segment results in 2018, was driven by record gathered, processed and fractionated volumes and record pipeline throughput volumes for MPLX.
2017 Compared to 2016
Midstream segment revenue and income from operations increased $675 million and $291 million, respectively, primarily due to increased revenue from higher natural gas and NGL gathering, processing and fractionation volumes and changes in natural gas and NGL prices. Segment results also benefited from the first quarter 2017 acquisitions of the Ozark pipeline and our ownership interest in the Bakken Pipeline system. The comparison for 2017 and 2016 also reflects the absence of any revenues for the terminal services provided to the Refining & Marketing segment in the first quarter of 2016 versus the inclusion of revenues for these services in the first quarter of 2017. These assets were not considered a business prior to April 1, 2016, and therefore, no financial results for these assets were available from which to recast first quarter 2016 Midstream segment results.
Items not Allocated to Segments
| Key Financial Information (in millions) | 2018 | 2017 | 2016 | |||||||||
| Items not allocated to segments: | ||||||||||||
| Corporate and other unallocated items(a) | $ | (502 | ) | $ | (365 | ) | $ | (266 | ) | |||
| Transaction-related costs | (197 | ) | — | — | ||||||||
| Litigation | — | (29 | ) | — | ||||||||
| Impairment(b) | 9 | 23 | (486 | ) |
| (a) | Corporate and other unallocated items consists primarily of MPC’s corporate administrative expenses and costs related to certain non-operating assets, except for corporate overhead expenses attributable to MPLX and ANDX, which are included in the Midstream segment. Corporate overhead expenses are not allocated to the Refining & Marketing and Retail segments. |
| (b) | 2018 and 2017 includes MPC’s share of gains from the the sale of assets remaining from the canceled Sandpiper pipeline project. 2016 includes impairments of goodwill and equity method investments. See Item 8. Financial Statements and Supplementary Data – Notes16 and 17. |
2018 Compared to 2017
Corporate and other unallocated expenses increased $137 million in 2018 compared to 2017 largely due to increased costs and expenses for the combined company after the Andeavor acquisition on October 1, 2018.
Other unallocated items in 2018 include $197 million of transaction-related costs for financial advisors, employee severance and other costs associated with the Andeavor acquisition and MPC’s share of gains from the sale of assets remaining from the canceled Sandpiper pipeline project. Other unallocated items in 2017 include an $86 million litigation charge, a litigation benefit of $57 million and a benefit of $23 million related to MPC’s share of gains from the sale of assets remaining from the canceled Sandpiper pipeline project.
2017 Compared to 2016
Corporate and other unallocated expenses increased $99 million in 2017 compared to 2016 largely due to higher unallocated corporate costs and increases in employee-related expenses and corporate costs.
Other unallocated items in 2017 include an $86 million litigation charge, a litigation benefit of $57 million and a benefit of $23 million related to MPC’s share of gains from the sale of assets remaining from the canceled Sandpiper pipeline project. Other unallocated items in 2016 include impairment charges of $486 million resulting from non-cash charges of $267 million related to the indefinite deferral of the Sandpiper pipeline project, $130 million related to the goodwill recognized in connection with the MarkWest Merger and $89 million related to an MPLX equity method investment.
Non-GAAP Financial Measures
Management uses certain financial measures to evaluate our operating performance that are calculated and presented on the basis of methodologies other than in accordance with GAAP (“non-GAAP”). We believe these non-GAAP financial measures are useful to investors and analysts to assess our ongoing financial performance because, when reconciled to its most comparable GAAP financial measure, they provide improved comparability between periods through the exclusion of certain items that we believe are not indicative of our core operating performance and that may obscure our underlying business results and trends. These measures should not be considered a substitute for, or superior to, measures of financial performance prepared in accordance with GAAP, and our calculations thereof may not be comparable to similarly titled measures reported by other companies. The non-GAAP financial measures we use are as follows:
Refining & Marketing Margin
Refining margin is defined as sales revenue less the cost of refinery inputs and purchased products and excludes the LCM inventory market adjustment.
| Reconciliation of Refining & Marketing income from operations to Refining & Marketing margin (in millions) | 2018 | 2017 | 2016 | ||||||||||
| Refining & Marketing income from operations | $ | 2,481 | $ | 2,321 | $ | 1,357 | |||||||
| Plus (Less): | |||||||||||||
| Refinery direct operating costs(a) | 4,801 | 4,113 | 4,007 | ||||||||||
| Refinery depreciation and amortization | 1,089 | 1,013 | 994 | ||||||||||
| Other: | |||||||||||||
| Operating expenses(a)(b) | 3,189 | 1,425 | 1,475 | ||||||||||
| Depreciation and amortization | 85 | 69 | 69 | ||||||||||
| Inventory market valuation adjustment | — | — | (345 | ) | |||||||||
| Refining & Marketing margin(c) | $ | 11,645 | $ | 8,941 | $ | 7,557 |
| (a) | Excludes depreciation and amortization. |
| (b) | Includes fees paid to MPLX and ANDX for various midstream services. MPLX and ANDX are reported in MPC’s Midstream segment. |
| (c) | Sales revenue less cost of refinery inputs and purchased products, excluding any LCM inventory market adjustment. |
Retail Fuel Margin
Retail fuel margin is defined as the price paid by consumers or direct dealers less the cost of refined products, including transportation, consumer excise taxes and bankcard processing fees (where applicable) and excluding any LCM inventory market adjustment.
Retail Merchandise Margin
Retail merchandise margin is defined as the price paid by consumers less the cost of merchandise.
| Reconciliation of Retail income from operations to Retail total margin (in millions) | 2018 | 2017 | 2016 | ||||||||||
| Retail income from operations | $ | 1,028 | $ | 729 | $ | 733 | |||||||
| Plus (Less): | |||||||||||||
| Operating, selling, general and administrative expenses(a) | 1,796 | 1,533 | 1,555 | ||||||||||
| Depreciation and amortization(a) | 353 | 275 | 273 | ||||||||||
| Income from equity method investments | (74 | ) | (69 | ) | (5 | ) | |||||||
| Net gain on disposal of assets | (17 | ) | (14 | ) | (30 | ) | |||||||
| Other income(a) | (7 | ) | (14 | ) | (18 | ) | |||||||
| Inventory market valuation adjustment | — | — | (25 | ) | |||||||||
| Retail total margin | $ | 3,079 | $ | 2,440 | $ | 2,483 | |||||||
| Retail total margin:(a) | |||||||||||||
| Fuel margin(b) | $ | 1,547 | $ | 1,008 | $ | 1,009 | |||||||
| Merchandise margin(c) | 1,486 | 1,402 | 1,435 | ||||||||||
| Other margin | 46 | 30 | 39 | ||||||||||
| Retail total margin | $ | 3,079 | $ | 2,440 | $ | 2,483 |
| (a) | 2018 and 2017 margins and expenses do not reflect any results from the 41 travel centers contributed to PFJ Southeast, whereas they are reflected in the 2016 information. Our share of the net results from the joint venture is reflected in income from equity method investments. |
| (b) | The price paid by consumers or direct dealers less the cost of refined products, including transportation, consumer excise taxes and bankcard processing fees (where applicable) and excluding any LCM inventory market adjustment. |
| (c) | The price paid by the consumers less the cost of merchandise. |
LIQUIDITY AND CAPITAL RESOURCES
Cash Flows
Our cash and cash equivalents balance was $1.69 billion at December 31, 2018 compared to $3.01 billion at December 31, 2017. Net cash provided by (used in) operating activities, investing activities and financing activities for the past three years is presented in the following table.
| (In millions) | 2018 | 2017 | 2016 | |||||||||
| Net cash provided by (used in): | ||||||||||||
| Operating activities | $ | 6,158 | $ | 6,612 | $ | 4,017 | ||||||
| Investing activities | (7,670 | ) | (3,398 | ) | (2,967 | ) | ||||||
| Financing activities | 222 | (1,091 | ) | (1,294 | ) | |||||||
| Total | $ | (1,290 | ) | $ | 2,123 | $ | (244 | ) |
Net cash provided by operating activities decreased $454 million in 2018 compared to 2017, primarily due to an unfavorable change in working capital of $2.28 billion partially offset by an increase in operating results. Net cash provided by operating activities increased $2.60 billion in 2017 compared to 2016, primarily due to increased operating results and favorable changes in working capital of $1.74 billion compared to 2017. The above changes in working capital exclude changes in short-term debt.
For 2018, changes in working capital were a net $340 million use of cash, primarily due to the effect of decreases in energy commodity prices on working capital. Accounts payable decreased primarily due to lower crude oil payable prices. Inventories decreased primarily due to a decrease in crude and refined product inventories. Current receivables decreased primarily due to lower crude oil receivable prices. All of these effects exclude the working capital acquired in connection with the acquisition of Andeavor.
For 2017, changes in working capital were a net $1.94 billion source of cash, primarily due to the effect of increases in energy commodity prices on working capital. Accounts payable increased primarily due to higher crude oil payable volumes and prices; current receivables increased primarily due to higher crude oil and refined product receivable prices and volumes; and inventories decreased primarily due to lower crude oil inventory volumes.
For 2016, changes in working capital were a net $200 million source of cash, primarily due to the effect of increases in energy commodity prices on working capital. Accounts payable increased primarily due to higher crude oil payable prices; current
receivables increased primarily due to higher refined product and crude oil receivable prices; and inventories increased, excluding the change in the Company’s inventory valuation reserve of $370 million, primarily due to higher crude oil and refined product inventory volumes.
Cash flows used in investing activities increased $4.27 billion in 2018 compared to 2017 and increased $431 million in 2017 compared to 2016.
| • | Cash used for additions to property, plant and equipment was primarily due to spending in our Midstream segment. See discussion of capital expenditures and investments under the “Capital Spending” section. |
| • | Cash used for acquisitions of $3.82 billion in 2018 primarily includes cash paid to Andeavor stockholders of $3.5 billion in connection with the acquisition of Andeavor on October 1, 2018. |
| • | Net investments were a use of cash of $393 million in 2018 compared to $743 million in 2017 and $288 million in 2016. Investments in 2017 primarily include MPLX’s $500 million investment in a partial interest in the Bakken Pipeline system. |
| • | Cash provided by disposal of assets totaled $54 million, $79 million and $101 million in 2018, 2017 and 2016, respectively. Cash provided in 2016 was primarily due to the sale of certain Speedway locations in the normal course of business. |
The consolidated statements of cash flows exclude changes to the consolidated balance sheets that did not affect cash. A reconciliation of additions to property, plant and equipment to total capital expenditures and investments follows for each of the last three years.
| (In millions) | 2018 | 2017 | 2016 | |||||||||
| Additions to property, plant and equipment per consolidated statements of cash flows | $ | 3,578 | $ | 2,732 | $ | 2,892 | ||||||
| Asset retirement expenditures | 8 | 2 | 6 | |||||||||
| Increase (decrease) in capital accruals | 309 | 67 | (127 | ) | ||||||||
| Total capital expenditures | 3,895 | 2,801 | 2,771 | |||||||||
| Investments in equity method investees(a) | 409 | 305 | 288 | |||||||||
| Total capital expenditures and investments | $ | 4,304 | $ | 3,106 | $ | 3,059 |
| (a) | The 2016 amount excludes an adjustment of $143 million to the fair value of equity method investments acquired in connection with the MarkWest Merger. |
Financing activities were a source of cash of $222 million in 2018 and uses of cash of $1.09 billion in 2017 and $1.29 billion in 2016.
| • | Long-term debt borrowings and repayments, including debt issuance costs, were a net $5.36 billion source of cash in 2018 compared to a $2.24 billion source of cash in 2017 and a $1.42 billion use of cash in 2016. During 2018, MPLX issued $7.75 billion of senior notes, redeemed $750 million of senior notes, borrowed and repaid $4.1 billion under the MPLX term loan, and borrowed and repaid $1.41 billion and $1.92 billion, respectively, under the MPLX Credit Agreement. In addition, MPC redeemed $600 million of senior notes. During 2017, MPLX issued $2.25 billion of senior notes, borrowed $505 million under the MPLX bank revolving credit agreement, repaid the remaining $250 million under the MPLX term loan agreement and we repaid the remaining $200 million balance under the MPC term loan agreement. During 2016, MPLX used proceeds from its issuance of the MPLX Preferred Units to repay amounts outstanding under the MPLX bank revolving credit facility and MPC chose to prepay $500 million under its term loan. See Item 8. Financial Statements and Supplementary Data – Note 19 for additional information on our long-term debt. |
| • | Cash used in common stock repurchases totaled $3.29 billion in 2018, $2.37 billion in 2017, and $197 million in 2016 associated with the share repurchase plans authorized by our board of directors. See the “Capital Requirements” section for further discussion of our stock repurchases. |
| • | Cash used in dividend payments totaled $954 million in 2018, $773 million in 2017 and $719 million in 2016. The increase in 2018 was primarily due to an increase in our base dividend in addition to a net increase in the number of shares of our common stock outstanding due to issuances related to the Andeavor acquisition, partially offset by share repurchases. The increase in 2017 was due to an increase in our base dividend, partially offset by a decrease in the number of outstanding shares of our common stock as a result of share repurchases. Dividends per share were $1.84 in 2018, $1.52 in 2017 and $1.36 in 2016. |
| • | Distributions to noncontrolling interests increased $209 million in 2018 compared to 2017 and $152 million in 2017 compared to 2016, primarily due to an increase in MPLX’s distribution per common unit. In 2018, distributions to |
noncontrolling interests also included ANDX’s distribution per common unit paid in the fourth quarter subsequent to the acquisition of Andeavor on October 1, 2018.
| • | Cash proceeds from the issuance of MPLX common units were $473 million in 2017 and $776 million in 2016. Cash proceeds from the issuance of MPLX Preferred Units was $984 million in 2016. See Item 8. Financial Statements and Supplementary Data – Note 4 for further discussion of MPLX. |
| • | Cash used in financing activities in 2017 and 2016 included a portion of the payments to the seller of the Galveston Bay refinery under the contingent earnout provisions of the purchase and sale agreement. |
Derivative Instruments
See Item 7A. Quantitative and Qualitative Disclosures about Market Risk for a discussion of derivative instruments and associated market risk.
Capital Resources
Our liquidity totaled $8.3 billion at December 31, 2018 consisting of:
| December 31, 2018 | ||||||||||||
| (In millions) | Total Capacity | Outstanding Borrowings | Available Capacity | |||||||||
| Bank revolving credit facility(a) | $ | 5,000 | $ | 32 | $ | 4,968 | ||||||
| 364 day bank revolving credit facility | 1,000 | — | 1,000 | |||||||||
| Trade receivables facility | 750 | — | 750 | |||||||||
| Total | $ | 6,750 | $ | 32 | $ | 6,718 | ||||||
| Cash and cash equivalents(b) | 1,609 | |||||||||||
| Total liquidity | $ | 8,327 |
| (a) | Outstanding borrowings include $32 million in letters of credit outstanding under this facility. Excludes MPLX’s $2.25 billion bank revolving credit facility, which had no borrowings and $3 million of letters of credit outstanding as of December 31, 2018 and ANDX’s $2.10 billion bank revolving credit facilities, which had $1.25 billion outstanding as of December 31, 2018. |
| (b) | Excludes $68 million and $10 million of MPLX and ANDX cash and cash equivalents, respectively. |
Because of the alternatives available to us, including internally generated cash flow and access to capital markets, including a commercial paper program, we believe that our short-term and long-term liquidity is adequate to fund not only our current operations, but also our near-term and long-term funding requirements, including capital spending programs, the repurchase of shares of our common stock, dividend payments, defined benefit plan contributions, repayment of debt maturities and other amounts that may ultimately be paid in connection with contingencies.
On November 15, 2018, MPLX issued $2.25 billion in aggregate principal amount of senior notes in a public offering, consisting of $750 million aggregate principal amount of 4.800 percent unsecured senior notes due February 2029 and $1.5 billion aggregate principal amount of 5.500 percent unsecured senior notes due February 2049. On December 10, 2018, a portion of the net proceeds from the offering was used to redeem the $750 million in aggregate principal amount of 5.500 percent unsecured notes due February 2023 issued by MPLX and MarkWest. These notes were redeemed at 101.833 percent of the principal amount, plus the write off of unamortized deferred financing costs, resulting in a loss on extinguishment of debt of $60 million. The remaining net proceeds have or will be used to repay borrowings under MPLX’s revolving credit facility and intercompany loan agreement with MPC and for general partnership purposes.
On February 8, 2018, MPLX issued $5.5 billion in aggregate principal amount of senior notes in a public offering, consisting of $500 million aggregate principal amount of 3.375 percent unsecured senior notes due March 2023, $1.25 billion aggregate principal amount of 4.000 percent unsecured senior notes due March 2028, $1.75 billion aggregate principal amount of 4.500 percent unsecured senior notes due April 2038, $1.5 billion aggregate principal amount of 4.700 percent unsecured senior notes due April 2048, and $500 million aggregate principal amount of 4.900 percent unsecured senior notes due April 2058. On February 8, 2018, $4.1 billion of the net proceeds were used to repay the 364-day term-loan facility, which was used to finance the cash portion of the consideration for the dropdown of refining logistics assets and distribution services to MPLX. The remaining proceeds were used to repay outstanding borrowings under MPLX’s revolving credit facility and intercompany loan agreement with MPC and for general partnership purposes.
Commercial Paper – We established a commercial paper program that allows us to have a maximum of $2 billion in commercial paper outstanding, with maturities up to 397 days from the date of issuance. We do not intend to have outstanding commercial paper borrowings in excess of available capacity under our bank revolving credit facilities. At December 31, 2018, we had no amounts outstanding under the commercial paper program.
MPC Bank Revolving Credit Facilities – On August 28, 2018, in connection with the Andeavor acquisition, we entered into credit agreements with a syndicate of lenders to replace MPC’s previous five-year $2.5 billion bank revolving credit facility due in 2022 and our previous 364-day $1 billion bank revolving agreement that expired in July 2018. The new credit agreements, which became effective October 1, 2018, provide for a $5 billion five-year revolving credit facility that expires in 2023 and a $1 billion 364-day revolving credit facility that expires in 2019. The financial covenants and the interest rate terms contained in the new credit agreements are substantially the same as those contained in the previous bank revolving credit facilities. There were no borrowings and approximately $32 million of letters of credit outstanding under these facilities at December 31, 2018.
Trade receivables facility – Our trade receivables facility has a borrowing capacity of $750 million (depending on the amount of our eligible domestic trade accounts receivable) and a maturity date of July 19, 2019. As of December 31, 2018, eligible trade receivables supported borrowings of $750 million. There were no borrowings outstanding at December 31, 2018. Availability under our trade receivables facility is primarily a function of refined product selling prices.
MPLX Credit Agreement – On July 21, 2017, MPLX entered into a credit agreement with a syndicate of lenders to replace the existing $2 billion five-year bank revolving credit facility with a $2.25 billion five-year bank revolving credit facility with a maturity date of July 2022 (“MPLX credit agreement”). At December 31, 2018, MPLX had no outstanding borrowings and $3 million of letters of credit outstanding under the bank revolving credit facility, resulting in total unused loan availability of approximately $2.25 billion.
ANDX credit agreements - Through the Andeavor acquisition on October 1, 2018, we acquired the general partner and 156 million units of ANDX. ANDX is party to a $1.1 billion revolving credit agreement and a $1.0 billion dropdown credit agreement both of which expire in January 2021 (together, the “ANDX credit agreements”). As of December 31, 2018, ANDX had approximately $1.25 billion outstanding borrowings under the ANDX credit agreements, resulting in total unused loan availability of $855 million.
See Item 8. Financial Statements and Supplementary Data – Note 19 for further discussion of our debt.
The MPC credit agreements contain representations and warranties, affirmative and negative covenants and events of default that we consider usual and customary for agreements of these types. The financial covenant included in the MPC credit agreements requires us to maintain, as of the last day of each fiscal quarter, a ratio of Consolidated Net Debt to Total Capitalization (as defined in the MPC credit agreements) of no greater than 0.65 to 1.00. Other covenants restrict us and/or certain of our subsidiaries from incurring debt, creating liens on assets and entering into transactions with affiliates. As of December 31, 2018, we were in compliance with the covenants contained in the MPC credit agreements, including a ratio of Consolidated Net Debt to Total Capitalization of 0.19 to 1.00, as well as the other covenants contained in the MPC credit agreements.
The MPLX credit agreement contains certain representations and warranties, affirmative and restrictive covenants and events of default that we consider to be usual and customary for an agreement of this type. The MPLX credit agreement includes a financial covenant that requires MPLX to maintain a ratio of Consolidated Total Debt as of the end of each fiscal quarter to Consolidated EBITDA (both as defined in the MPLX credit agreement) for the prior four fiscal quarters of no greater than 5.0 to 1.0 (or 5.5 to 1.0 for up to two fiscal quarters following certain acquisitions). Consolidated EBITDA is subject to adjustments for certain acquisitions completed and capital projects undertaken during the relevant period. Other covenants restrict MPLX and/or certain of its subsidiaries from incurring debt, creating liens on assets and entering into transactions with affiliates. As of December 31, 2018, MPLX was in compliance with the covenants contained in the MPLX credit agreement, including a ratio of Consolidated Total Debt to Consolidated EBITDA of 3.80 to 1.0.
The ANDX credit agreements contain certain representations and warranties, affirmative and restrictive covenants and events of default that we consider to be usual and customary for an agreement of this type, including a financial covenant that requires ANDX to maintain a Consolidated Leverage Ratio (as defined in the ANDX credit agreements) for the prior four fiscal quarters of no greater than 5.0 to 1.0 for the prior four fiscal quarters (or 5.5 to 1.0 for up to two fiscal quarters following certain acquisitions). Consolidated EBITDA used to calculate the Consolidated Leverage Ratio is subject to adjustments for certain acquisitions completed and capital projects undertaken during the relevant period. The covenants also restrict, among other things, ANDX’s ability and/or the ability of certain of its subsidiaries to incur debt, create liens on assets and enter into transactions with affiliates. As of December 31, 2018, ANDX was in compliance with the covenants contained in the ANDX credit agreements, including a Consolidated Leverage Ratio of 3.72 to 1.0.
As disclosed in Item 8. Financial Statements and Supplementary Data – Note 3 to our audited consolidated financial statements, we expect the adoption of the lease accounting standard update to result in the recognition of a significant lease obligation. The MPC bank revolving credit facility, the MPLX credit agreement and the ANDX credit agreements contain provisions under which the effects of the new accounting standard are not recognized for purposes of financial covenant calculations.
Our intention is to maintain an investment-grade credit profile. As of February 1, 2019, the credit ratings on our, MPLX’s and ANDX’s senior unsecured debt are as follows.
| Company | Rating Agency | Rating |
| MPC | Moody’s | Baa2 (stable outlook) |
| Standard & Poor’s | BBB (stable outlook) | |
| Fitch | BBB (stable outlook) | |
| MPLX | Moody’s | Baa3 (stable outlook) |
| Standard & Poor’s | BBB (stable outlook) | |
| Fitch | BBB- (positive outlook) | |
| ANDX | Moody’s | Ba1 (review for upgrade) |
| Standard & Poor’s | BBB- (positive watch) | |
| Fitch | BBB- (stable outlook) |
The ratings reflect the respective views of the rating agencies. Although it is our intention to maintain a credit profile that supports an investment-grade rating, there is no assurance that these ratings will continue for any given period of time. The ratings may be revised or withdrawn entirely by the rating agencies if, in their respective judgments, circumstances so warrant.
None of the MPC credit agreements, the MPLX credit agreement, the ANDX credit agreements or our trade receivables facility contains credit rating triggers that would result in the acceleration of interest, principal or other payments in the event that our credit ratings are downgraded. However, any downgrades of our senior unsecured debt could increase the applicable interest rates, yields and other fees payable under such agreements. In addition, a downgrade of our senior unsecured debt rating to below investment-grade levels could, under certain circumstances, decrease the amount of trade receivables that are eligible to be sold under our trade receivables facility, impact our ability to purchase crude oil on an unsecured basis and could result in us having to post letters of credit under existing transportation services or other agreements.
Capital Requirements
For information about our capital expenditures and investments, see the “Capital Spending” section.
In 2018, we made pension contributions totaling $115 million. We have no required funding for 2019, but may make voluntary contributions at our discretion.
On January 28, 2019, we announced our board of directors approved a $0.53 per share dividend, payable March 11, 2019 to shareholders of record at the close of business on February 20, 2019.
We may, from time to time, repurchase notes in the open market, in privately-negotiated transactions or otherwise in such volumes, at such prices and upon such other terms as we deem appropriate.
Share Repurchases
Since January 1, 2012, our board of directors has approved $18.0 billion in total share repurchase authorizations and we have repurchased a total of $13.10 billion of our common stock, leaving $4.9 billion available for repurchases as of December 31, 2018. Under these authorizations, we have acquired 293 million shares at an average cost per share of $44.60. As part of our strategic actions to enhance shareholder value, for the year ended December 31, 2018, cash proceeds received from dropdowns to MPLX during the year were used in part to repurchase $3.29 billion of our common stock. The table below summarizes our total share repurchases. See Item 8. Financial Statements and Supplementary Data – Note 9 for further discussion of the share repurchase plans.
| (In millions, except per share data) | 2018 | 2017 | 2016 | ||||||||
| Number of shares repurchased | 47 | 44 | 4 | ||||||||
| Cash paid for shares repurchased | $ | 3,287 | $ | 2,372 | $ | 197 | |||||
| Average cost per share | $ | 69.46 | $ | 53.85 | $ | 41.84 |
We may utilize various methods to effect the repurchases, which could include open market repurchases, negotiated block transactions, accelerated share repurchases or open market solicitations for shares, some of which may be effected through Rule 10b5-1 plans. The timing and amount of future repurchases, if any, will depend upon several factors, including market and business conditions, and such repurchases may be discontinued at any time.
Contractual Cash Obligations
The table below provides aggregated information on our consolidated obligations to make future payments under existing contracts as of December 31, 2018. The contractual obligations detailed below do not include our contractual obligations to MPLX and ANDX under various fee-based commercial agreements as these transactions are eliminated in the consolidated financial statements.
| (In millions) | Total | 2019 | 2020-2021 | 2022-2023 | Later Years | |||||||||||||||
| Long-term debt(a) | $ | 44,673 | $ | 1,790 | $ | 4,128 | $ | 5,865 | $ | 32,890 | ||||||||||
| Capital lease obligations(b) | 897 | 65 | 127 | 148 | 557 | |||||||||||||||
| Operating lease obligations | 3,423 | 709 | 1,172 | 684 | 858 | |||||||||||||||
| Purchase obligations:(c) | ||||||||||||||||||||
| Crude oil, feedstock, refined product and renewable fuel contracts(d) | 10,306 | 8,881 | 1,115 | 196 | 114 | |||||||||||||||
| Transportation and related contracts | 2,556 | 550 | 760 | 661 | 585 | |||||||||||||||
| Contracts to acquire property, plant and equipment | 1,825 | 1,794 | 31 | — | — | |||||||||||||||
| Service, materials and other contracts(e) | 3,361 | 948 | 1,009 | 574 | 830 | |||||||||||||||
| Total purchase obligations | 18,048 | 12,173 | 2,915 | 1,431 | 1,529 | |||||||||||||||
| Other long-term liabilities reported in the consolidated balance sheet(f) | 2,734 | 297 | 587 | 531 | 1,319 | |||||||||||||||
| Total contractual cash obligations | $ | 69,775 | $ | 15,034 | $ | 8,929 | $ | 8,659 | $ | 37,153 |
| (a) | Includes interest payments of $18.42 billion for our senior notes, the MPLX senior notes and the ANDX senior notes in addition to interest on the MPLX credit agreement and ANDX credit agreements, commitment and administrative fees for our credit agreement, the MPLX credit agreement, the ANDX credit agreements and our trade receivables facility. |
| (b) | Capital lease obligations represent future minimum payments. |
| (c) | Includes both short- and long-term purchases obligations. |
| (d) | These contracts include variable price arrangements. For purposes of this disclosure we have estimated prices to be paid primarily based on futures curves for the commodities to the extent available. |
| (e) | Primarily includes contracts to purchase services such as utilities, supplies and various other maintenance and operating services. |
| (f) | Primarily includes obligations for pension and other postretirement benefits including medical and life insurance, which we have estimated through 2028. See Item 8. Financial Statements and Supplementary Data – Note 22. |
Capital Spending
The 2019 capital investment plan for MPC, MPLX and ANDX and capital expenditures and investments for each of the last three years are summarized by segment below. MPC’s capital investment plan for 2019 totals approximately $2.8 billion for capital projects and investments, excluding MPLX, ANDX, capitalized interest and acquisitions. MPC’s 2019 capital investment plan includes all of the planned capital spending for Refining & Marketing, Retail and Corporate as well as a portion of the planned capital investments in Midstream. The remainder of the planned capital spending for Midstream reflects the capital investment plans for MPLX and ANDX. We continuously evaluate our capital plan and make changes as conditions warrant.
| (In millions) | 2019 Plan | 2018 | 2017 | 2016 | ||||||||||||
| Capital expenditures and investments:(a) | ||||||||||||||||
| Refining & Marketing | $ | 1,750 | $ | 1,057 | $ | 832 | $ | 1,054 | ||||||||
| Retail | 500 | 460 | 381 | 303 | ||||||||||||
| Midstream | 3,600 | 2,630 | 1,755 | 1,558 | ||||||||||||
| Corporate and Other(b) | 60 | 157 | 138 | 144 | ||||||||||||
| Total | $ | 5,910 | $ | 4,304 | $ | 3,106 | $ | 3,059 |
| (a) | Capital expenditures include changes in capital accruals. |
| (b) | Includes capitalized interest of $80 million, $55 million and $63 million for 2018, 2017 and 2016, respectively. The 2019 capital investment plan excludes capitalized interest. |
Refining & Marketing
The Refining & Marketing segment’s forecasted 2019 capital spending and investments is approximately $1.8 billion. This amount includes approximately $1.02 billion of growth capital focused on refinery optimization, production of higher value products, increased capacity to upgrade residual fuel oil and expanded export capacity. Investing to enhance margins, we will continue our disciplined high-return investments in resid upgrading capacity and the ability to produce more diesel. We also plan to continue investing in domestic light products supply placement flexibility, as well as increasing our export capacity. Sustaining capital is approximately $730 million, which includes approximately $260 million related to regulatory spending for Tier 3 gasoline.
Major capital projects completed over the last three years have prepared us to increase our diesel production, process light crude oil, increase our export capabilities and meet the upcoming transportation fuel regulatory mandate (Tier 3 fuel standards). In addition, the STAR investment project intended to transform our Galveston Bay refinery into a world-class refining complex is progressing according to plan and is scheduled to complete in 2022.
Retail
The Retail segment’s 2019 capital forecast of approximately $500 million is focused on conversion of recently acquired locations to the Speedway brand and systems, growth in existing and new markets, dealer sites, commercial fueling/diesel expansion, food service through store remodels and high quality acquisitions.
Major capital projects over the last three years included building new store locations, remodeling and rebuilding existing locations in core markets and building out our network of commercial fueling lane locations to capitalize on diesel demand growth. We also invested in the conversion, remodel and maintenance of stores acquired in 2014.
Midstream
MPLX’s capital investment plan includes $2.2 billion of organic growth capital and approximately $200 million of maintenance capital.This growth plan includes the addition of approximately 765 million cubic feet per day of processing capacity at five gas processing plants, two in the Marcellus basin and three in the Southwest, which expands MPLX’s processing capacity in the Permian Basin and the STACK shale play of Oklahoma. The growth plan also includes the addition of approximately 100 mbpd of fractionation capacity in the Marcellus and Utica basins, continued expansion of MPLX’s marine fleet and other projects including the Permian long-haul crude oil, natural gas and NGL pipelines as well as export facility projects which will further enhance our full value chain capture.
Major capital projects over the last three years included investments for the development of natural gas and gas liquids infrastructure to support MPLX’s producer customers, primarily in the Marcellus and Utica shale regions, development of various crude oil and refined petroleum products infrastructure projects, including a build-out of Utica Shale infrastructure in connection with the Cornerstone Pipeline, a butane cavern in Robinson, Illinois, and a tank farm expansion in Texas City, Texas.
ANDX’s capital investment plan includes $600 million of organic growth capital and approximately $100 million of maintenance capital. The growth plan includes the construction of additional crude storage capacity for unloading of marine vessels, the construction of a crude gathering system to provide connectivity to multiple long-haul pipelines and a pipeline interconnect project designed to provide direct connectivity between certain MPC refineries.
The remaining Midstream segment’s forecasted 2019 capital spend, excluding MPLX and ANDX, is approximately $500 million which primarily relates to investments in equity affiliate pipelines, including our expected investments in the Gray Oak Pipeline, a new pipeline spanning from the West Texas Permian Basin to the Gulf Coast which is expected to be in service by the end of 2019.
Corporate and Other
The 2019 capital forecast includes approximately $60 million to support corporate activities. Major projects over the last three years included an expansion project for our corporate headquarters and upgrades to information technology systems.
Off-Balance Sheet Arrangements
Off-balance sheet arrangements comprise those arrangements that may potentially impact our liquidity, capital resources and results of operations, even though such arrangements are not recorded as liabilities under accounting principles generally accepted in the United States. Our off-balance sheet arrangements are limited to indemnities and guarantees that are described below. Although these arrangements serve a variety of our business purposes, we are not dependent on them to maintain our liquidity and capital resources, and we are not aware of any circumstances that are reasonably likely to cause the off-balance sheet arrangements to have a material adverse effect on liquidity and capital resources.
We have provided various guarantees related to equity method investees. In conjunction with the Spinoff, we entered into various indemnities and guarantees to Marathon Oil. These arrangements are described in Item 8. Financial Statements and Supplementary Data – Note 25.
TRANSACTIONS WITH RELATED PARTIES
We believe that transactions with related parties were conducted on terms comparable to those with unaffiliated parties. See Item 8. Financial Statements and Supplementary Data – Note 7 for discussion of activity with related parties.
ENVIRONMENTAL MATTERS AND COMPLIANCE COSTS
We have incurred and may continue to incur substantial capital, operating and maintenance, and remediation expenditures as a result of environmental laws and regulations. If these expenditures, as with all costs, are not ultimately reflected in the prices of our products and services, our operating results will be adversely affected. We believe that substantially all of our competitors must comply with similar environmental laws and regulations. However, the specific impact on each competitor may vary depending on a number of factors, including the age and location of its operating facilities, marketing areas, production processes and whether it is also engaged in the petrochemical business or the marine transportation of crude oil and refined products.
Legislation and regulations pertaining to fuel specifications, climate change and greenhouse gas emissions have the potential to materially adversely impact our business, financial condition, results of operations and cash flows, including costs of compliance and permitting delays. The extent and magnitude of these adverse impacts cannot be reliably or accurately estimated at this time because specific regulatory and legislative requirements have not been finalized and uncertainty exists with respect to the measures being considered, the costs and the time frames for compliance, and our ability to pass compliance costs on to our customers. For additional information see Item 1A. Risk Factors.
Our environmental expenditures, including non-regulatory expenditures, for each of the last three years were:
| (In millions) | 2018 | 2017 | 2016 | |||||||||
| Capital | $ | 380 | $ | 343 | $ | 302 | ||||||
| Compliance:(a) | ||||||||||||
| Operating and maintenance | 525 | 413 | 541 | |||||||||
| Remediation(b) | 52 | 36 | 40 | |||||||||
| Total | $ | 957 | $ | 792 | $ | 883 |
| (a) | Based on the American Petroleum Institute’s definition of environmental expenditures. |
| (b) | These amounts include spending charged against remediation reserves, where permissible, but exclude non-cash provisions recorded for environmental remediation. |
We accrue for environmental remediation activities when the responsibility to remediate is probable and the amount of associated costs can be reasonably estimated. As environmental remediation matters proceed toward ultimate resolution or as additional remediation obligations arise, charges in excess of those previously accrued may be required.
New or expanded environmental requirements, which could increase our environmental costs, may arise in the future. We believe we comply with all legal requirements regarding the environment, but since not all of them are fixed or presently determinable (even under existing legislation) and may be affected by future legislation or regulations, it is not possible to predict all of the ultimate costs of compliance, including remediation costs that may be incurred and penalties that may be imposed.
Our environmental capital expenditures accounted for ten percent, twelve percent and eleven percent of capital expenditures, for 2018, 2017 and 2016, respectively, excluding acquisitions. Our environmental capital expenditures are expected to approximate $420 million, or 7 percent, of total planned capital expenditures in 2019. Actual expenditures may vary as the number and scope of environmental projects are revised as a result of improved technology or changes in regulatory requirements and could increase if additional projects are identified or additional requirements are imposed. The amount of expenditures in 2019 is also dependent upon the resolution of the matters described in Item 3. Legal Proceedings, which may require us to complete additional projects and increase our actual environmental capital and operating expenditures.
For more information on environmental regulations that impact us, or could impact us, see Item 1. Business – Environmental Matters, Item 1A. Risk Factors and Item 3. Legal Proceedings.
CRITICAL ACCOUNTING ESTIMATES
The preparation of financial statements in accordance with GAAP requires us to make estimates and assumptions that affect the reported amounts of assets and liabilities and the disclosure of contingent assets and liabilities as of the date of the consolidated financial statements and the reported amounts of revenues and expenses during the respective reporting periods. Accounting estimates are considered to be critical if (1) the nature of the estimates and assumptions is material due to the levels of subjectivity and judgment necessary to account for highly uncertain matters or the susceptibility of such matters to change; and (2) the impact of the estimates and assumptions on financial condition or operating performance is material. Actual results could differ from the estimates and assumptions used.
Fair Value Estimates
Fair value is the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date. There are three approaches for measuring the fair value of assets and liabilities: the market approach, the income approach and the cost approach, each of which includes multiple valuation techniques. The market approach uses prices and other relevant information generated by market transactions involving identical or comparable assets or liabilities. The income approach uses valuation techniques to measure fair value by converting future amounts, such as cash flows or earnings, into a single present value amount using current market expectations about those future amounts. The cost approach is based on the amount that would currently be required to replace the service capacity of an asset. This is often referred to as current replacement cost. The cost approach assumes that the fair value would not exceed what it would cost a market participant to acquire or construct a substitute asset of comparable utility, adjusted for obsolescence.
The fair value accounting standards do not prescribe which valuation technique should be used when measuring fair value and does not prioritize among the techniques. These standards establish a fair value hierarchy that prioritizes the inputs used in applying the various valuation techniques. Inputs broadly refer to the assumptions that market participants use to make pricing decisions, including assumptions about risk. Level 1 inputs are given the highest priority in the fair value hierarchy while Level 3 inputs are given the lowest priority. The three levels of the fair value hierarchy are as follows:
| • | Level 1 – Observable inputs that reflect unadjusted quoted prices for identical assets or liabilities in active markets as of the measurement date. Active markets are those in which transactions for the asset or liability occur in sufficient frequency and volume to provide pricing information on an ongoing basis. |
| • | Level 2 – Observable market-based inputs or unobservable inputs that are corroborated by market data. These are inputs other than quoted prices in active markets included in Level 1, which are either directly or indirectly observable as of the measurement date. |
| • | Level 3 – Unobservable inputs that are not corroborated by market data and may be used with internally developed methodologies that result in management’s best estimate of fair value. |
Valuation techniques that maximize the use of observable inputs are favored. Assets and liabilities are classified in their entirety based on the lowest priority level of input that is significant to the fair value measurement. The assessment of the significance of a particular input to the fair value measurement requires judgment and may affect the placement of assets and liabilities within the levels of the fair value hierarchy. We use an income or market approach for recurring fair value measurements and endeavor to use the best information available. See Item 8. Financial Statements and Supplementary Data – Note 17 for disclosures regarding our fair value measurements.
Significant uses of fair value measurements include:
| • | assessment of impairment of long-lived assets; |
| • | assessment of impairment of intangible assets: |
| • | assessment of impairment of goodwill; |
| • | assessment of impairment of equity method investments; |
| • | recorded values for assets acquired and liabilities assumed in connection with acquisitions; and |
| • | recorded values of derivative instruments. |
Impairment Assessments of Long-Lived Assets, Intangible Assets, Goodwill and Equity Method Investments
Fair value calculated for the purpose of testing our long-lived assets, intangible assets, goodwill and equity method investments for impairment is estimated using the expected present value of future cash flows method and comparative market prices when appropriate. Significant judgment is involved in performing these fair value estimates since the results are based on forecasted financial information prepared using significant assumptions including:
| • | Future margins on products produced and sold. Our estimates of future product margins are based on our analysis of various supply and demand factors, which include, among other things, industry-wide capacity, our planned utilization rate, end-user demand, capital expenditures and economic conditions. Such estimates are consistent with those used in our planning and capital investment reviews. |
| • | Future volumes. Our estimates of future refinery, retail, pipeline throughput and natural gas and NGL processing volumes are based on internal forecasts prepared by our Refining & Marketing, Retail and Midstream segments operations personnel. |
| • | Discount rate commensurate with the risks involved. We apply a discount rate to our cash flows based on a variety of factors, including market and economic conditions, operational risk, regulatory risk and political risk. This discount rate is also compared to recent observable market transactions, if possible. A higher discount rate decreases the net present value of cash flows. |
| • | Future capital requirements. These are based on authorized spending and internal forecasts. |
We base our fair value estimates on projected financial information which we believe to be reasonable. However, actual results may differ materially from these projections.
The need to test for impairment can be based on several indicators, including a significant reduction in prices of or demand for products produced, a poor outlook for profitability, a significant reduction in pipeline throughput volumes, a significant reduction in natural gas or NGLs processed, a significant reduction in refining or retail fuel margins, other changes to contracts or changes in the regulatory environment.
Long-lived assets used in operations are assessed for impairment whenever changes in facts and circumstances indicate that the carrying value of the assets may not be recoverable based on the expected undiscounted future cash flow of an asset group. For purposes of impairment evaluation, long-lived assets must be grouped at the lowest level for which independent cash flows can be identified, which generally is the refinery and associated distribution system level for Refining & Marketing segment assets, company-owned convenience store locations for Retail segment assets, and the plant level or pipeline system level for Midstream segment assets. If the sum of the undiscounted estimated pretax cash flows is less than the carrying value of an asset group, fair value is calculated, and the carrying value is written down if greater than the calculated fair value.
Unlike long-lived assets, goodwill is subject to annual, or more frequent if necessary, impairment testing. At December 31, 2018, we had a total of $20.18 billion of goodwill recorded on our consolidated balance sheet, including $16.31 billion that was preliminarily recognized as a result of the Andeavor acquisition and remains subject to finalization within one year of the October 1, 2018 acquisition date.
For the reporting units included in our annual impairment testing for 2018, the analysis resulted in the fair value of the reporting units exceeding their carrying value by percentages ranging from approximately 14 percent to 4,608 percent. The reporting unit with fair value exceeding its carrying value by approximately 14 percent has goodwill of $228 million at December 31, 2018. An increase of one percentage to the discount rate used to estimate the fair value of the reporting units would not have resulted in a goodwill impairment charge as of November 30, 2018. Significant assumptions used to estimate the reporting units’ fair value included estimates of future cash flows. If estimates for future cash flows, which are impacted by commodity prices and producers’ production plans, were to decline, the overall reporting units’ fair value would decrease, resulting in potential goodwill impairment charges. Fair value determinations require considerable judgment and are sensitive to changes in underlying assumptions and factors. As a result, there can be no assurance that the estimates and assumptions made for purposes of the impairment tests will prove to be an accurate prediction of the future.
Equity method investments are assessed for impairment whenever factors indicate an other than temporary loss in value. Factors providing evidence of such a loss include the fair value of an investment that is less than its carrying value, absence of an ability to recover the carrying value or the investee’s inability to generate income sufficient to justify our carrying value. At December 31, 2018, we had $5.90 billion of investments in equity method investments recorded on our consolidated balance sheet.
An estimate of the sensitivity to net income resulting from impairment calculations is not practicable, given the numerous assumptions (e.g., pricing, volumes and discount rates) that can materially affect our estimates. That is, unfavorable adjustments to some of the above listed assumptions may be offset by favorable adjustments in other assumptions.
See Item 8. Financial Statements and Supplementary Data – Note 14 for additional information on our equity method investments. See Item 8. Financial Statements and Supplementary Data – Note 16 for additional information on our goodwill and intangibles.
Acquisitions
In accounting for business combinations, acquired assets, assumed liabilities and contingent consideration are recorded based on estimated fair values as of the date of acquisition. The excess or shortfall of the purchase price when compared to the fair value of the net tangible and identifiable intangible assets acquired, if any, is recorded as goodwill or a bargain purchase gain, respectively. A significant amount of judgment is involved in estimating the individual fair values of property, plant and equipment, intangible assets, contingent consideration and other assets and liabilities. We use all available information to make these fair value determinations and, for certain acquisitions, engage third-party consultants for valuation assistance.
The fair value of assets and liabilities, including contingent consideration, as of the acquisition date are often estimated using a combination of approaches, including the income approach, which requires us to project future cash flows and apply an appropriate discount rate; the cost approach, which requires estimates of replacement costs and depreciation and obsolescence estimates; and the market approach which uses market data and adjusts for entity-specific differences. The estimates used in determining fair values are based on assumptions believed to be reasonable but which are inherently uncertain. Accordingly, actual results may differ materially from the projected results used to determine fair value.
See Item 8. Financial Statements and Supplementary Data – Note 5 for additional information on our acquisitions. See Item 8. Financial Statements and Supplementary Data – Note 17 for additional information on fair value measurements.
Derivatives
We record all derivative instruments at fair value. Substantially all of our commodity derivatives are cleared through exchanges which provide active trading information for identical derivatives and do not require any assumptions in arriving at fair value. Fair value estimation for all our derivative instruments is discussed in Item 8. Financial Statements and Supplementary Data – Note 17. Additional information about derivatives and their valuation may be found in Item 7A. Quantitative and Qualitative Disclosures about Market Risk.
Variable Interest Entities
We evaluate all legal entities in which we hold an ownership or other pecuniary interest to determine if the entity is a VIE. Our interests in a VIE are referred to as variable interests. Variable interests can be contractual, ownership or other pecuniary interests in an entity that change with changes in the fair value of the VIE’s assets. When we conclude that we hold an interest in a VIE we must determine if we are the entity’s primary beneficiary. A primary beneficiary is deemed to have a controlling financial interest in a VIE. This controlling financial interest is evidenced by both (a) the power to direct the activities of the VIE that most significantly impact the VIE’s economic performance and (b) the obligation to absorb losses that could potentially be significant to the VIE or the right to receive benefits that could potentially be significant to the VIE. We consolidate any VIE when we determine that we are the primary beneficiary. We must disclose the nature of any interests in a VIE that is not consolidated.
Significant judgment is exercised in determining that a legal entity is a VIE and in evaluating our interest in a VIE. We use primarily a qualitative analysis to determine if an entity is a VIE. We evaluate the entity’s need for continuing financial support; the equity holder’s lack of a controlling financial interest; and/or if an equity holder’s voting interests are disproportionate to its obligation to absorb expected losses or receive residual returns. We evaluate our interests in a VIE to determine whether we are the primary beneficiary. We use a primarily qualitative analysis to determine if we are deemed to have a controlling financial interest in the VIE, either on a standalone basis or as part of a related party group. We continually monitor our interests in legal entities for changes in the design or activities of an entity and changes in our interests, including our status as the primary beneficiary to determine if the changes require us to revise our previous conclusions.
Changes in the design or nature of the activities of a VIE, or our involvement with a VIE, may require us to reconsider our conclusions on the entity’s status as a VIE and/or our status as the primary beneficiary. Such reconsideration requires significant judgment and understanding of the organization. This could result in the deconsolidation or consolidation of the affected subsidiary, which would have a significant impact on our financial statements.
Variable Interest Entities are discussed in Item 8. Financial Statements and Supplementary Data – Note 6.
Pension and Other Postretirement Benefit Obligations
Accounting for pension and other postretirement benefit obligations involves numerous assumptions, the most significant of which relate to the following:
| • | the discount rate for measuring the present value of future plan obligations; |
| • | the expected long-term return on plan assets; |
| • | the rate of future increases in compensation levels; |
| • | health care cost projections; and |
| • | the mortality table used in determining future plan obligations. |
We utilize the work of third-party actuaries to assist in the measurement of these obligations. We have selected different discount rates for our funded pension plans and our unfunded retiree health care plans due to the different projected benefit payment patterns. The selected rates are compared to various similar bond indexes for reasonableness. In determining the assumed discount rates, we use our third-party actuaries’ discount rate models. These models calculate an equivalent single discount rate for the projected benefit plan cash flows using yield curves derived from Aa or higher bond yields. The yield curves represent a series of annualized individual spot discount rates from 0.5 to 99 years. The bonds used have an average rating of Aa or higher by a recognized rating agency and generally only non-callable bonds are included. Outlier bonds that have a yield to maturity that deviate significantly from the average yield within each maturity grouping are not included. Each issue is required to have at least $250 million par value outstanding.
Of the assumptions used to measure the year-end obligations and estimated annual net periodic benefit cost, the discount rate has the most significant effect on the periodic benefit cost reported for the plans. Decreasing the discount rates of 4.21 percent for our pension plans and 4.26 percent for our other postretirement benefit plans by 0.25 percent would increase pension obligations and other postretirement benefit plan obligations by $69 million and $31 million, respectively, and would increase defined benefit pension expense and other postretirement benefit plan expense by $8 million and $1 million, respectively.
The long-term asset rate of return assumption considers the asset mix of the plans (currently targeted at approximately 42 percent equity securities and 58 percent fixed income securities for the primary funded pension plan), past performance and other factors. Certain components of the asset mix are modeled with various assumptions regarding inflation and returns. In addition, our long-term asset rate of return assumption is compared to those of other companies and to historical returns for reasonableness. We used the 6.15 percent long-term rate of return to determine our 2018 defined benefit pension expense. After evaluating activity in the capital markets, along with the current and projected plan investments, we did not change the asset rate of return for our primary plan from 6.15 percent effective for 2019. Decreasing the 6.15 percent asset rate of return assumption by 0.25 percent would increase our defined benefit pension expense by $4 million.
Compensation change assumptions are based on historical experience, anticipated future management actions and demographics of the benefit plans.
Health care cost trend assumptions are developed based on historical cost data, the near-term outlook and an assessment of likely long-term trends.
We utilized the 2018 mortality tables from the U.S. Society of Actuaries.
Item 8. Financial Statements and Supplementary Data – Note 22 includes detailed information about the assumptions used to calculate the components of our annual defined benefit pension and other postretirement plan expense, as well as the obligations and accumulated other comprehensive loss reported on the year-end balance sheets.
Contingent Liabilities
We accrue contingent liabilities for legal actions, claims, litigation, environmental remediation, tax deficiencies related to operating taxes and third-party indemnities for specified tax matters when such contingencies are both probable and estimable. We regularly assess these estimates in consultation with legal counsel to consider resolved and new matters, material developments in court proceedings or settlement discussions, new information obtained as a result of ongoing discovery and past experience in defending and settling similar matters. Actual costs can differ from estimates for many reasons. For instance, settlement costs for claims and litigation can vary from estimates based on differing interpretations of laws, opinions on degree of responsibility and assessments of the amount of damages. Similarly, liabilities for environmental remediation may vary from estimates because of changes in laws, regulations and their interpretation, additional information on the extent and nature of site contamination and improvements in technology.
We generally record losses related to these types of contingencies as cost of revenues or selling, general and administrative expenses in the consolidated statements of income, except for tax deficiencies unrelated to income taxes, which are recorded as other taxes. For additional information on contingent liabilities, see Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations – Environmental Matters and Compliance Costs.
An estimate of the sensitivity to net income if other assumptions had been used in recording these liabilities is not practical because of the number of contingencies that must be assessed, the number of underlying assumptions and the wide range of reasonably possible outcomes, in terms of both the probability of loss and the estimates of such loss.
ACCOUNTING STANDARDS NOT YET ADOPTED
As discussed in Item 8. Financial Statements and Supplementary Data – Note 3 to our audited consolidated financial statements, certain new financial accounting pronouncements will be effective for our financial statements in the future.
Previous: Item 6. SELECTED FINANCIAL DATA · Next: Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK