 filings.tools
M&T Bank (MTB) 10-K risk factor changes: FY2023 vs FY2022
The 2023-12-31 10-K against the 2022-12-31 one, compared heading by heading and sentence by sentence.
Item 1A100 rewritten34 added66 removed288 unchanged
All filing items2,049 rewritten1,836 added1,735 removed2,195 unchanged
Summary
counted, not written
- Item 1A lists 29 risk factor headings: 0 new, 5 reworded and 24 unchanged since FY2022. 3 headings from FY2022 no longer appear.
- Sentence by sentence, 1,836 added, 1,735 removed, 2,049 rewritten and 2,195 unchanged across 20 items that differ.
- New this year: Item 1C. Cybersecurity..
New Item 1A headings (0)
No risk factor heading in this filing is absent from FY2022.
Removed Item 1A headings (3)
- M&T may fail to realize the anticipated benefits of the acquisition of People’s United and integrating People’s United may be more difficult, costly or time-consuming than expected.
- M&T may be unable to retain personnel successfully.
- Litigation related to the acquisition has been filed in the past and additional litigation may be filed in the future, which could result in the payment of damages or otherwise negatively impact the business and operations of the Company.
Reworded Item 1A headings (5)
- The discontinuation of
[removed: LIBOR][added: benchmark rates] as[removed: a]permissible rate[removed: index][added: indices] in new[removed: contracts, the formal announcement of LIBOR’s cessation date,][added: contracts] and the development of[removed: SOFR and other]alternative benchmark indices to replace[removed: LIBOR][added: discontinued benchmarks] could adversely impact the Company’s business and results of operations. - The Company may be subject to more stringent capital and liquidity
[removed: requirements.][added: requirements and new requirements relating to long-term debt.] - If an orderly liquidation of a systemically important BHC or non-bank financial company were triggered, M&T could face assessments for the
[removed: Orderly Liquidation Fund (“OLF”).][added: OLF.] [removed: M&T][added: The Company] could suffer if it fails to attract and retain skilled personnel.- Pandemics,
[removed: including COVID-19,]acts of war or terrorism and other adverse external events could significantly impact the Company’s business.
A heading is new when no FY2022 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
24 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2023; struck-through words were in FY2022. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors.
100 rewritten, 34 added, 66 removed, 288 unchanged
The discontinuation of [removed: LIBOR] [added: benchmark rates] as [removed: a] permissible rate [removed: index] [added: indices] in new [removed: contracts, the formal announcement of LIBOR’s cessation date,] [added: contracts] and the development of [removed: SOFR and other] alternative benchmark indices to replace [removed: LIBOR] [added: discontinued benchmarks] could adversely impact the Company’s business and results of operations.
The Company may be subject to more stringent capital and liquidity [removed: requirements.][added: requirements and new requirements relating to long-term debt.]
If an orderly liquidation of a systemically important BHC or non-bank financial company were triggered, M&T could face assessments for the [removed: Orderly Liquidation Fund (“OLF”).][added: OLF.]
[removed: M&T] [added: The Company] could suffer if [removed: the Company] [added: it] fails to attract and retain skilled personnel.
The Company could incur higher costs, experience lower revenue, and suffer reputational damage in the event of the theft, loss or misuse of information, including due to a [removed: cyber security] [added: cybersecurity] attack.
Pandemics, [removed: including COVID-19,] acts of war or terrorism and other adverse external events could significantly impact the Company’s business.
Potential higher FDIC assessments due to the DIF falling below minimum required [removed: levels.][added: levels or special FDIC assessments relating to the failure of specific banks.]
Volatility and uncertainty related to inflation and the effects of inflation, [added: including potentially higher interest rates,] which may lead to increased costs for businesses and consumers and potentially contribute to poor business and economic conditions generally, may also enhance or contribute to some of the risks discussed herein.
Additionally, economic conditions, financial markets and inflationary pressures may be adversely affected by the impact of current or anticipated geopolitical [removed: uncertainties,] [added: uncertainties;] military conflicts, including Russia’s invasion of [removed: Ukraine,] [added: Ukraine and the attacks on Israel and conflict in the Middle East;] pandemics, including the COVID-19 [removed: pandemic,] [added: pandemic;] and global, national and local responses thereto by governmental authorities and other third parties.
The Federal Reserve raised benchmark interest rates [removed: throughout] [added: in] 2022 and [added: 2023 and] may continue to raise [added: or maintain] interest rates in response to economic conditions, particularly inflationary pressures.
Adversely affect the ability of borrowers to meet obligations under variable or adjustable-rate loans and other debt [removed: instruments,] [added: instruments (including due to an inability to refinance loans),] which, in turn, affects the Company’s loss rates on those assets.
Interest rate increases have [removed: recently] reduced the value of the Company’s investment portfolio, for example, by decreasing the estimated fair value of fixed income securities.
Furthermore, as interest rates rise, the Company’s unrealized gains on fixed income securities would ordinarily decrease and unrealized losses would ordinarily increase, which occurred in [added: both] 2022 and [added: 2023 and] could continue to occur in [removed: 2023.][added: 2024.]
[removed: Should tax laws change or the tax] authorities determine that management’s assumptions were inappropriate, the result and adjustments required could have a material effect on the Company’s results of operations.
*The discontinuation of [removed: LIBOR] [added: benchmark rates] as [removed: a] permissible rate [removed: index] [added: indices] in new [removed: contracts, the formal announcement of LIBOR’s cessation date,] [added: contracts] and the development of [removed: SOFR and other] alternative benchmark indices to replace [removed: LIBOR] [added: discontinued benchmarks] could adversely impact the Company’s business and results of operations.*
The Company’s floating-rate funding, certain hedging transactions and a significant portion of the Company’s products, such as floating-rate loans and mortgages, determine the applicable interest rate or payment amount by reference to a benchmark [removed: rate, such as the London Interbank Offered Rate (“LIBOR”),] [added: rate] or to an alternative index.
[removed: The market’s] [added: Any cessation of a benchmark rate and resulting] transition [removed: from LIBOR] to [removed: an alternative reference rate will] [added: a successor benchmark would] be complex and unpredictable, giving rise to a variety of risks, including operational risks, risks of value transfer between contract parties, the potential for customer disputes and litigation, as well as regulatory scrutiny.
Turmoil and volatility in U.S. and global financial markets can be a major contributory factor to overall weak economic conditions, leading to some of [added: the risks discussed herein, including the impaired ability of borrowers and other counterparties to meet obligations to the Company.]
Therefore, the Company is, or in the future may be, particularly vulnerable to adverse changes in economic conditions in the Northeast and Mid-Atlantic [added: regions, as well as events particularly affecting those] regions.
The trends and risks affecting borrower credit quality, particularly in the Northeast and Mid-Atlantic regions, have caused, and in the future may cause, the Company to experience impairment charges, which are reductions in the recoverable value of an [removed: asset,] [added: asset;] increased purchase demands, wherein customers make withdrawals with minimum [removed: notice,] [added: notice;] higher costs (e.g. servicing, foreclosure, property [removed: maintenance),] [added: maintenance);] additional write-downs and losses and a potential impact to [added: the ability to] engage in lending transactions based on a reduction of customer deposits, which could have a material adverse effect on the Company’s business, financial condition and results of operations.
Failure to comply with laws, regulations or policies, or to meet supervisory expectations, could result in civil or criminal penalties, including monetary penalties, the loss of FDIC insurance, the revocation of a banking [added: charter, other sanctions by regulatory agencies, and/or reputational damage, which could have a material adverse effect on the Company’s business, financial condition and results of operations.]
[removed: In this regard, government] [added: Government] authorities, including the bank regulatory agencies, can pursue aggressive enforcement actions with respect to compliance and other legal matters involving financial activities, which heightens the risks associated with actual and perceived compliance failures and may also adversely affect the Company’s ability to enter into certain transactions or engage in certain activities, or obtain necessary regulatory approvals in connection therewith.
[removed: Additionally, such activity could affect the] behaviors of third parties with which the Company deals in the ordinary course of business, such as rating agencies, insurance companies and investors.
For more information on the regulations to which the Company is subject and recent initiatives to reform financial institution regulation, see Part I, Item [removed: 1 — Business.][added: 1, "Business."]
*The Company may be subject to more stringent capital and liquidity [removed: requirements.*][added: requirements and new requirements relating to long-term debt.*]
[removed: Bank holding companies,] [added: BHCs,] including M&T, are subject to capital and liquidity requirements and standards imposed as a result of the Dodd-Frank Act (as amended by EGRRCPA) and the U.S. Basel III-based capital rules.
For additional information, see “Capital Requirements” under Part I, Item [removed: 1 — Business.][added: 1, "Business."]
For [removed: bank holding companies] [added: BHCs] designated as Category IV institutions under the Tailoring Rules, including M&T, the Federal Reserve conducts biennial supervisory stress tests required under the Dodd-Frank Act whereby the BHC’s financial position is tested under assumed severely adverse economic conditions.
The results of those stress tests are incorporated in the determination of M&T’s [removed: Stress Capital Buffer.][added: SCB.]
[removed: As a general matter,] if M&T is unable to maintain capital in excess of regulatory minimum levels inclusive of its [removed: Stress Capital Buffer,] [added: SCB,] it would be subject to limitations on its ability to make capital distributions, including paying dividends and repurchasing stock.
In June [removed: 2022,] [added: 2023,] the Federal Reserve released the results of its most recent supervisory stress tests, and based on those results, on October 1, [removed: 2022,] [added: 2023,] M&T’s [removed: stress capital buffer] [added: SCB] of [removed: 4.7%] [added: 4.0%] became effective.
The results of future supervisory stress tests [added: and the impact of proposed revisions to capital and long-term debt requirements upon the stress testing framework] are uncertain, and a more severe outcome may result in a higher [removed: Stress Capital Buffer] [added: SCB] and an increase in M&T’s effective capital requirements.
An increased [removed: Stress Capital Buffer] [added: SCB] may restrict M&T’s ability to return capital to shareholders, including through paying dividends, entering into acquisitions or repurchasing its common stock, which in turn could negatively impact market and investor perceptions of M&T.
The Federal Reserve has in the past implemented, and may in the future implement, restrictions on share repurchase programs and common stock dividends at large [removed: bank holding companies] [added: BHCs] such as M&T, including in response to adverse or uncertain economic conditions.
*If an orderly liquidation of a systemically important BHC or non-bank financial company were triggered, M&T could face assessments for the [removed: Orderly Liquidation Fund (“OLF”).*][added: OLF.*]
The Dodd-Frank Act created a mechanism, the OLF, for liquidation of systemically important [removed: bank holding companies] [added: BHCs] and non-bank financial companies.
Risk-based assessments would be first made on entities that received more in the resolution than they would have received in the liquidation to the extent of such excess, and second, if necessary, on, among others, [removed: bank holding companies] [added: BHCs] with total consolidated assets of $50 billion or more, such as M&T.
Factors that can influence the Company’s credit loss experience include: (i) the impact of residential real estate values on loans to residential real estate builders and developers and other loans secured by residential real estate; (ii) the concentrations of commercial real estate loans in the Company’s loan portfolio, including in the [added: office, retail, healthcare and multifamily sectors and in the] New York City area; (iii) the amount of commercial and industrial loans to businesses in areas of New York State outside of the New York City area and in central Pennsylvania that have historically experienced less economic growth and vitality than many other regions of the country; (iv) the repayment performance associated with first and second lien loans secured by residential real estate; and (v) the size of the Company’s portfolio of loans to individual consumers, which historically have experienced higher net charge-offs as a percentage of loans outstanding than loans to other types of borrowers.
The Company’s credit risk and the performance of its lending portfolios may be affected by concentration in an industry, [removed: geography or asset type.]
Emerging and evolving factors such as the shift to work-from-home or hybrid-work arrangements, changing consumer preferences (including for online shopping), [removed: COVID-19-related restrictions] and resulting changes in occupancy rates as a result of these and other trends can also impact such valuations over relatively short periods.
Concern regarding the ability of Congress to reach agreement on federal budgetary matters (including the debt ceiling), or total or partial governmental shutdowns, also can adversely affect the economy and increase the risk of economic instability or market volatility, which could have adverse consequences on our business, financial condition, liquidity and results of operations.
Should tax laws change or the tax
In the past, the regulators and administrators of certain benchmark rates have determined to cease publication of those rates, and they may do so again in the future with respect to other benchmark rates the Company utilizes.
Following the failures of certain banks in 2023, banking regulators have proposed changes, or indicated the potential for changes, regarding the regulation and supervision of banking organizations, in particular those, such as M&T, with $100 billion or more in assets.
The introduction of new or more stringent regulatory requirements, as well as heightened supervisory expectations, could require the Company to maintain additional capital or liquidity or incur significant expenses.
Additionally, such activity could affect the
A determination by the Federal Reserve that M&T does not meet supervisory expectations regarding capital planning or liquidity risk management could have a variety of adverse consequences, including ratings downgrades, heightened supervisory scrutiny, expenses associated with remediation activities and potentially an enforcement action.
See “Capital Requirements” and “Resolution Planning and Resolution-Related Requirements” under Part I, Item 1, "Business" for information regarding the federal banking regulators’ July 2023 proposal implementing the revisions to the Basel capital framework and August 2023 long-term debt proposal.
The long-term debt proposal, if adopted, would require M&T to maintain more long-term debt than it does currently, which may adversely affect interest expense, net interest income and net interest margin.
As a general matter,
geography or asset type.
In addition, adverse developments at other financial institutions, including failures of other financial institutions, could result in negative media coverage regarding the financial services industry, which may negatively influence the perceptions of investors, borrowers or depositors regarding the financial services industry in general, a subset of financial institutions or M&T in particular.
In addition to customer deposits, sources of liquidity include brokered deposits
Following the failures of certain large banks in 2023, banking regulators indicated they may revise the liquidity requirements applicable to large financial institutions.
alternative investments, causing the Company to lose a lower cost source of funding.
The Company could be subject to sudden withdrawals of deposits, including as a result of negative media coverage, which may be spread through social media, regarding the financial services industry generally, a subset of financial institutions or M&T specifically.
Online and mobile banking have made it easier for customers to withdraw their deposits or transfer funds to other accounts with short notice.
This may make retaining deposits during periods of stress more difficult.
In addition, depositors of certain types of deposits, such as uninsured or uncollateralized deposits, may be more likely to withdraw their deposits and do so more quickly.
Any such withdrawals could result in higher funding costs to the Company as it loses a lower cost source of funding, and significant unanticipated withdrawals could materially and adversely affect the Company’s liquidity, financial condition and results of operations.
The Company has and may continue
In recent years, federal authorities, including the bank regulators and Department of Justice, have increased their scrutiny of bank mergers and acquisitions, and there is continued uncertainty with regard to how they will evaluate bank mergers and acquisitions, including from an antitrust perspective.
Anticipated challenges in obtaining any requisite regulatory approval, or uncertainty as to the prospects for obtaining approvals, could also prevent the Company from pursuing a potential acquisition it may otherwise view as attractive.
Reputational risks.
contractual and other obligations.
For example, in 2023, a widely reported global cybersecurity incident occurred involving MOVEit, a file transfer software product owned by Progress Software Corporation that is used by thousands of public and private sector entities worldwide.
As reported, this incident resulted in the theft of sensitive data from a large number of organizations, and certain Company customer information in the possession of the Company’s external service providers was compromised in connection with it, while no information was obtained from the Company’s internal systems and these systems were not at risk from the MOVEit incident.
Further, cybersecurity and information security risks for financial institutions have generally increased because of, among other things, the growth of new technologies, the use of the Internet and telecommunications technologies (including computers, smartphones, and
The Company may not be insured against all
when it may not, or may lead the Company to misjudge the business and economic environment in which it operates.
technological advancement associated with the changes necessary to limit climate change.
For example, the Federal Reserve, the FDIC, and the OCC jointly issued interagency guidance for large financial institutions on principles for climate-related financial risk management in October 2023, the NYSDFS issued proposed guidance for New York State-regulated banking and mortgage institutions relating to the management of material financial risks from climate change in December 2022, and the SEC proposed climate-related disclosure rules in March 2022.
In addition, a number of states in which the Company operates have enacted or proposed statutes and regulations addressing climate change and sustainability issues.
Any such new or heightened requirements may result in higher regulatory, compliance, and other expenses, and may subject the Company to different and potentially conflicting requirements in the various jurisdictions in which it operates.
Risks Relating to the Acquisition of People’s United
M&T may fail to realize the anticipated benefits of the acquisition of People’s United and integrating People’s United may be more difficult, costly or time-consuming than expected.
M&T may be unable to retain personnel successfully.
Litigation related to the acquisition has been filed in the past and additional litigation may be filed in the future, which could result in the payment of damages or otherwise negatively impact the business and operations of M&T.
Risks Related to the Acquisition of People’s United
*M&T may fail to realize the anticipated benefits of the acquisition of People’s United and integrating People’s United may be more difficult, costly or time-consuming than expected.*
In connection with the acquisition of People’s United that was completed on April 1, 2022, M&T has incurred and may further incur costs as M&T continues to integrate the People’s United business.
The success of the acquisition depends, in part, on the ability to realize the anticipated cost savings from combining the businesses of M&T and People’s United.
To realize the anticipated benefits and cost savings from the acquisition, M&T must integrate and combine People’s United’s businesses in a manner that permits cost savings to be realized, without adversely affecting revenues and future growth.
If M&T is not able to successfully achieve these objectives, the anticipated benefits of the acquisition may not be realized fully or at all or may take longer to realize than expected.
In addition, the actual cost savings of the acquisition could be less than anticipated.
There can be no assurances that the expected benefits and efficiencies related to the acquisition will be realized to offset the transaction and integration costs over time.
M&T may also incur additional costs to retain legacy People’s United customers, maintain employee morale and to retain key employees.
M&T has waived certain fees following conversion of customer deposit accounts to M&T’s deposit servicing system, and similar or other costs related to integration of People's United or operations as a combined company may be incurred in the future.
It is possible that challenges related to operating as a combined company could result in the loss of key employees, the disruption of ongoing businesses or inconsistencies in standards, controls, procedures and policies that adversely affect M&T’s abilities to maintain relationships with clients, customers, depositors and employees or to achieve the anticipated benefits and cost savings of the acquisition.
An inability to realize the full extent of the anticipated benefits of the acquisition could have an adverse effect upon the revenues, levels of expenses and operating results of M&T, which may adversely affect the value of M&T’s common stock.
*M&T may be unable to retain personnel successfully.*
The success of the acquisition will depend in part on the Company’s ability to retain the talents and dedication of key employees.
It is possible that these employees, including key legacy People’s United employees, may decide not to remain with the Company.
If the Company is unable to retain key employees, including management, who are critical to the successful future operations of the combined company, the Company could face disruptions in its operations, loss of existing customers, loss of key information, expertise or know-how and unanticipated additional recruitment costs.
If key employees terminate their employment, the Company’s business activities may be adversely affected and the Company may not be able to locate or retain suitable replacements.
*Litigation related to the acquisition has been filed in the past and additional litigation may be filed in the future, which could result in the payment of damages or otherwise negatively impact the business and operations of the Company.*
Although not currently active, litigation related to the acquisition was filed against People’s United, the People’s United board of directors and M&T prior to the completion of the acquisition.
Additional litigation may be filed against M&T and the M&T board of directors in the future.
Among other remedies, litigation that was filed sought damages, and additional litigation by shareholders of M&T in the future may seek damages or other remedies.
The outcome of any litigation is uncertain.
Such lawsuits and the defense or settlement of any such lawsuits may have an adverse effect on the financial condition and results of operations of M&T.
With respect to LIBOR, the United Kingdom’s Financial Conduct Authority (“FCA”), which regulates LIBOR, and the ICE Benchmark Administration (“IBA”), the administrator of LIBOR, have announced that the publication of all tenors of USD LIBOR, which to date have been calculated and determined by the IBA based on the required submissions by independent panel banks, will cease to exist and/or cease to be “representative” after June 30, 2023.
In response and in coordination, U.S. federal bank regulators, including the Federal Reserve, required U.S. banks to cease using USD LIBOR as a reference rate in new contracts by December 31, 2021.
Concurrently, the Federal Reserve-sponsored Alternative Reference Rates Committee (“ARRC”) finalized and issued recommendations for the use of so-called “hardwired” LIBOR fallback language that, when incorporated into existing LIBOR-based loan documents, provides for, upon LIBOR’s permanent cessation (or an announcement from LIBOR’s administrator or certain governmental authorities that LIBOR is no longer representative of the underlying market), the replacement of LIBOR with the Secured Overnight Financing Rate (“SOFR”) as the benchmark index, with an appropriate spread adjustment that is representative of the historical difference between LIBOR and SOFR, which when added to SOFR would be intended to facilitate a value-neutral transition.
Subsequently, the ARRC expanded its recommendation to include CME Term SOFR, a derivative of SOFR that is currently administered and published by the CME Group Benchmark Administration Limited.
In 2021 M&T adopted hardwired fallback language modeled after the ARRC recommendations for use in all new commercial LIBOR loans, and continues to proactively seek amendments to its existing LIBOR-based commercial loan contracts to incorporate such hardwired fallback language or move to an alternative index prior to the cessation of LIBOR.
SOFR is a measure of the cost of borrowing cash overnight, collateralized by U.S. Treasury securities, and is based on directly observable U.S. Treasury-based repurchase transactions.
The fact that SOFR is a secured overnight rate and considered a “risk free” rate, while LIBOR is an unsecured term rate that factors in credit risk, means that SOFR may perform differently than LIBOR, and those differences may be material, particularly in times of economic stress, negatively impacting the Company’s profitability.
While the ARRC has maintained its recommendation that SOFR is the preferred replacement for LIBOR, some industry participants have questioned whether a “risk free” SOFR-based rate is an ideal replacement for LIBOR in the commercial lending market and suggesting that a credit-sensitive component or alternative be considered and developed.
One such credit sensitive alternative is the Bloomberg Short-Term Bank Yield Index (BSBY), which gained some modest attention and use in the commercial lending market in the latter half of 2021 (primarily in syndicated loans), but has since gained little traction.
Whether BSBY or other alternatives to SOFR develop and gain any significant market traction in the future are unknown and unpredictable at this time, and this adds further market uncertainty with respect to introducing alternative benchmark rates for new contracts.
LIBOR cessation is also impacting the derivatives market.
In October 2020, The International Swaps and Derivatives Association, Inc. (ISDA), published the IBOR Fallbacks Supplement (Supplement) and IBOR Fallbacks Protocol (Protocol).
The Supplement, which became effective on January 25, 2021, amends existing standard definitions for interest rate derivatives to incorporate robust fallbacks to the SOFR benchmark for derivatives linked to LIBOR.
An excerpt. Shown here: 40 of 100 rewritten, all 34 added and 40 of 66 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors. in the FY2023 filing and the FY2022 filing.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
640 rewritten, 845 added, 731 removed, 387 unchanged
M&T [removed: Bank Corporation (“M&T”)] is a [removed: bank holding company] [added: BHC] headquartered in Buffalo, New York with consolidated assets of [removed: $200.7] [added: $208.3] billion at December 31, [removed: 2022.][added: 2023.]
[added: M&T’s wholly owned bank subsidiaries are M&T Bank and Wilmington Trust, N.A.] Among other subsidiaries of M&T is M&T [removed: Securities, Inc.] [added: Securities] which provides institutional brokerage and securities services and had total assets of [removed: $49] [added: $56] million at December 31, [removed: 2022.][added: 2023.]
M&T Bank, with total assets of [removed: $200.3] [added: $207.8] billion at December 31, [removed: 2022,] [added: 2023,] is a New York-chartered commercial bank with [removed: 1,010] [added: 961] domestic banking offices in New York State, Maryland, New Jersey, Pennsylvania, Delaware, Connecticut, Massachusetts, Maine, Vermont, New Hampshire, Virginia, West Virginia, and the District of Columbia, and a full-service commercial banking office in Ontario, Canada.
[added: Other subsidiaries of M&T Bank include M&T Realty Capital, a multifamily commercial mortgage lender; WT Investment] Advisors, [removed: Inc.,] which serves as an investment advisor to the Wilmington Funds, a family of proprietary mutual funds, and other funds and institutional clients; and entities obtained in the People's United acquisition including LEAF Commercial Capital, Inc., M&T Capital and Leasing Corp. (formerly known as People's Capital and Leasing Corp.) and M&T Equipment Finance Corp. (formerly known as People's United Equipment Finance Corp.) that provide equipment leasing and financing services.
Wilmington Trust, N.A. is a national bank with total assets of [removed: $692] [added: $683] million at December 31, [removed: 2022.][added: 2023.]
On April 1, 2022, M&T completed the acquisition of People’s [removed: United Financial, Inc. (“People’s United”).][added: United.]
The People's United transaction [removed: has been] [added: was] accounted for using the acquisition method of accounting and, accordingly, assets acquired, liabilities assumed, and consideration exchanged were recorded at estimated fair value on the acquisition date.
M&T [removed: preliminarily] recorded assets acquired of $64.2 billion, including $35.8 billion of loans and leases and $11.6 billion of investment securities, and liabilities assumed totaling $55.5 billion, including $53.0 billion of deposits.
The acquisition of People's United formed a banking franchise with [removed: approximately] [added: over] $200 billion in assets serving communities in the Northeast and Mid-Atlantic from Maine to Virginia, including Washington D.C.
Net acquisition and integration-related expenses (included herein as merger-related expenses) associated with the People's United acquisition totaled $432 million [removed: after tax-effect,] [added: after-tax effect,] or $2.63 of diluted earnings per common share in [removed: 2022,] [added: 2022] and $34 million [removed: after tax-effect,] [added: after-tax effect,] or $0.25 of diluted earnings per common share in 2021.
The Company [removed: does] [added: did] not [removed: expect] [added: incur] any [removed: People's United] merger-related expenses [removed: to be material] during 2023.
On [removed: September 29,] [added: October 31,] 2022 M&T Bank [removed: announced it had entered into a definitive agreement to sell M&T Insurance Agency, Inc. ("MTIA"),] [added: sold MTIA,] a wholly owned insurance agency subsidiary of M&T Bank to Arthur J.
Gallagher & Co. [removed: The transaction was completed on October 31, 2022 and resulted] [added: resulting] in a pre-tax gain of $136 million.
The Company’s significant accounting policies conform with [removed: generally accepted accounting principles (“GAAP”)] [added: GAAP] and are described in note 1 of Notes to Financial Statements.
[added: Certain of the critical accounting estimates] are more dependent on such judgment and in some cases may contribute to volatility in the Company’s reported financial performance should the assumptions and estimates used change over time due to changes in circumstances.
[removed: Under that accounting guidance, the] [added: Accounting for credit losses — The] allowance for credit losses represents a valuation account that is deducted from the amortized cost basis of certain financial assets, including loans and leases, to present the net amount expected to be collected at the balance sheet date.
Such models consider historical correlations of credit losses with various macroeconomic assumptions including unemployment, [removed: gross domestic product] [added: GDP] and real estate prices.
[removed: A] discussion of facts and circumstances considered by management in determining the allowance for credit losses is included herein under the heading “Provision for Credit Losses” and in note 5 of Notes to Financial Statements.
Examples of these items include loans, deposits, borrowings, goodwill, core deposit and other intangible assets, other assets and liabilities obtained or assumed in business combinations, capitalized servicing assets, pension [removed: and other postretirement] benefit [removed: obligations, estimated residual values of property associated with leases,] [added: obligations] and certain derivative and other financial instruments.
[added: Specific assumptions and estimates] utilized by management are discussed in detail herein in [removed: management’s discussion] [added: Management's Discussion] and [removed: analysis] [added: Analysis] of [removed: financial condition] [added: Financial Condition] and [removed: results] [added: Results] of [removed: operations] [added: Operations] and in notes 1, [added: 2,] 3, [removed: 4,] 7, 8, 13, [removed: 19, 20] [added: 19] and 21 of Notes to Financial Statements.
[removed: The Company recognized a] [added: Noninterest income increased $241 million predominantly due to the] $136 million gain on [removed: the] sale of MTIA in the fourth quarter of 2022.
Merger-related expenses [removed: largely] [added: incurred in 2022 and associated with the People's United acquisition generally] consisted of professional services, temporary help fees and other costs associated with actual or planned conversions of systems and/or integration of operations and the introduction of [removed: the Company] [added: M&T] to its new customers, costs related to terminations of existing contractual arrangements to purchase various services, severance, travel costs, and, in the second quarter of 2022, an initial provision for credit losses on loans not deemed to be [removed: purchased credit deteriorated ("PCD")] [added: PCD] on the April 1, 2022 acquisition date of People's United.
[removed: GAAP also provides that an allowance] [added: Allowance] for [removed: credit losses on loans][added: Credit Losses]
There were no merger-related expenses [removed: during 2020.][added: in 2023.]
The [removed: return on] [added: ratio of] average common shareholders’ equity [added: to average total assets] was [removed: 8.67% in 2022, 11.54% in 2021] [added: 11.63%, 11.49%] and [removed: 8.72%] [added: 10.13%] in [removed: 2020.][added: 2023, 2022 and 2021, respectively.]
[removed: Dollars] [added: | (Dollars] in [removed: millions][added: millions) | | Balances | | | | Balances | | | | Balances | | |]
| [removed: 2021 to 2022] | | | | | | | | [removed: 2020 to 2021] | | | | | | [removed: | | | | | | | | | | | | | |] [added: 2022 to 2023] | | | | | | | | [added: 2021 to 2022] | | [removed: 5 Years] | | | | |
| [removed: | 15.5 | | | | — | | | | (11.8 | ) | | | — | | |] Gain (loss) on bank investment securities | | | [removed: (5.7] [added: 4] | [removed: )] | | | [removed: (21.2] [added: (6] | ) | | | [removed: (9.4] [added: (21] | ) | | | [removed: 18.0 | | | | (6.3] [added: —] | [removed: )] | | | — | | [removed: | |]
*Interest income data are on a taxable-equivalent [removed: basis.][added: basis.*]
[removed: That] [added: The] increase [removed: includes] [added: in 2022 reflected] the impact of [added: $33.7 billion in additional average earning assets predominantly resulting from the People's United transaction and] a 63 basis point [removed: (hundredths of one percent)] widening of the net interest margin to 3.39% in 2022 from 2.76% in [removed: 2021 and a growth in average earning assets to $172.8 billion in 2022 from $139.1 billion in] 2021.
Taxable-equivalent net interest income was [removed: $3.88] [added: $3.84] billion in [removed: 2020.][added: 2021.]
The [added: higher] provision for credit losses [removed: was $517 million] in 2022 [removed: reflecting] [added: as compared with 2021 reflects] the $242 million People's United-related provision for non-PCD loans [removed: acquired] [added: obtained] in the acquisition and a forecasted weakening of macroeconomic conditions as of December 31, 2022, as compared with forecasts in 2021 during which a recapture of previously recorded provisions of $75 million was recorded.
[added: The increase in other income in 2022 as compared with 2021 reflected increases related to the acquired operations associated with the People's United] acquisition (predominantly reflected in trust income, service charges on deposit accounts and other revenues from operations, including credit-related fees), higher trust income from legacy operations and the $136 million gain on sale of [removed: MTIA were most impactful to the higher levels of noninterest income in 2022.][added: MTIA.]
Other expense totaled [removed: $5.05] [added: $5.38] billion in [removed: 2022,] [added: 2023,] compared with [removed: $3.61] [added: $5.05] billion in [removed: 2021] [added: 2022] and [removed: $3.39] [added: $3.61] billion in [removed: 2020.][added: 2021.]
Included in those amounts are expenses considered [removed: by M&T] to be “nonoperating” in [removed: nature,] [added: nature] consisting of amortization of core deposit and other intangible assets [removed: of $56 million, $10 million] and [removed: $15 million in 2022, 2021 and 2020, respectively, and] merger-related [removed: expenses of $338 million and $44 million in 2022 and 2021, respectively.][added: expenses.]
No merger-related expenses were [removed: recorded] [added: incurred] in [removed: 2020.][added: 2023.*]
Exclusive of those nonoperating expenses, noninterest operating expenses [removed: totaled $4.66] [added: aggregated $5.32] billion in [removed: 2022, compared with $3.56] [added: 2023, $4.66] billion in [removed: 2021] [added: 2022] and [removed: $3.37] [added: $3.56] billion in [removed: 2020.][added: 2021.]
[removed: Acquired operations from People's United were] [added: As compared with 2021,] the predominant factor for increased noninterest [removed: operating] expenses in [removed: 2022.][added: 2022 was acquired operations from People's United and associated merger-related expenses.]
In addition to the People's United acquisition, factors contributing to the higher level of [added: noninterest] expenses included higher costs for salaries and employee benefits, outside data processing and software, equipment and net [removed: occupancy and] [added: occupancy,] professional [added: and other] services [removed: expenses,] [added: expenses] and (in the fourth quarter of 2022) a [added: $135 million] contribution to The M&T Charitable Foundation.
The [added: calculations of the] Company’s efficiency ratio, or noninterest operating expenses [removed: (as previously defined)] divided by the sum of taxable-equivalent net interest income and noninterest income (exclusive of gains and losses from bank investment securities), [removed: was 56.6% in 2022, compared with 59.0%] and [removed: 56.3%] [added: reconciliations of GAAP amounts with corresponding non-GAAP amounts are presented] in [removed: 2021 and 2020, respectively.][added: Table 3.]
On April 29, 2023 Wilmington Trust, N.A. sold its CIT business to a private equity firm, resulting in a pre-tax gain of $225 million.
Financial Reporting Matters
Included within this Management's Discussion and Analysis of Financial Condition and Results of Operations are certain financial reporting changes described in note 1 of Notes to Financial Statements that were effective in the fourth quarter of 2023 including:
Reclassification of the substantial majority of loans secured by commercial real estate that were considered owner-occupied from commercial real estate loans to commercial and industrial loans;
Presentation of "professional and other services" as an individual component of "other expense" while combining the presentation of "printing, postage and supplies" into "other costs of operations" within the Consolidated Statement of Income; and
Revisions to the Company's reportable segments to now comprise of Commercial Bank, Retail Bank and Institutional Services and Wealth Management.
Prior periods have been presented in conformity with the new classifications.
The results of the Company’s operations for the year ended December 31, 2023 continued to be impacted by multiple hikes by the FOMC of its federal funds target rate that totaled 5.25% from March of 2022 through July of 2023 in response to inflationary pressures.
The higher interest rate environment has resulted in increased yields on the Company’s earning assets, higher costs of interest-bearing liabilities and a shift in the mix of those liabilities, including from noninterest-bearing deposits to higher cost deposit products.
The provision for credit losses reflects declines in commercial real estate values and higher interest rates contributing to a deterioration in the performance of loans to commercial borrowers as well as a $2.5 billion increase in loans and leases since December 31, 2022.
In the second quarter of 2023, M&T completed the divestiture of its CIT business to a private equity firm.
The sale of that business resulted in a pre-tax gain of $225 million ($157 million after-tax effect, or $0.94 of diluted earnings per common share) in the 2023 results of operations.
In the fourth quarter of 2023, the FDIC issued a final rule on special assessment pursuant to systemic risk determination resulting from the closures of certain failed banks earlier in the year.
As a result, the Company recorded an expense of $197 million ($146 million after-tax effect, or $0.88 of diluted earnings per common share) for the special assessment in the 2023 results of operations.
A comparative summary of financial results for the Company is provided in Table 1.
SUMMARY OF FINANCIAL RESULTS
| | | | | | | | | | | | | | | Change from | | | | | | | | | | | | | | |
| (Dollars in millions, except per share) | | 2023 | | | | 2022 | | | | 2021 | | | | Amount | | | | % | | | | Amount | | | | % | | |
| Net interest income | | $ | 7,115 | | | $ | 5,822 | | | $ | 3,825 | | | $ | 1,293 | | | | 22 | % | | $ | 1,997 | | | | 52 | % |
| Taxable\-equivalent adjustment (a) | | | 54 | | | | 39 | | | | 15 | | | | 15 | | | | 40 | | | | 25 | | | | 166 | |
| Net interest income (taxable-equivalent basis) (a) | | | 7,169 | | | | 5,861 | | | | 3,840 | | | | 1,308 | | | | 22 | | | | 2,022 | | | | 53 | |
| Provision for credit losses | | | 645 | | | | 517 | | | | (75 | ) | | | 128 | | | | 25 | | | | 592 | | | | — | |
| Other income | | | 2,528 | | | | 2,357 | | | | 2,167 | | | | 172 | | | | 7 | | | | 190 | | | | 9 | |
| Other expense | | | 5,379 | | | | 5,050 | | | | 3,612 | | | | 329 | | | | 7 | | | | 1,439 | | | | 40 | |
| Net income | | | 2,741 | | | | 1,992 | | | | 1,859 | | | | 749 | | | | 38 | | | | 133 | | | | 7 | |
| Per common share data: | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Basic earnings | | | 15.85 | | | | 11.59 | | | | 13.81 | | | | 4.26 | | | | 37 | | | | (2.22 | ) | | | \-16 | |
| Diluted earnings | | | 15.79 | | | | 11.53 | | | | 13.80 | | | | 4.26 | | | | 37 | | | | (2.27 | ) | | | \-16 | |
| Performance ratios | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Return on: | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Average assets | | | 1.33 | % | | | 1.05 | % | | | 1.22 | % | | | | | | | | | | | | | | | | |
| Average common shareholders' equity | | | 11.06 | | | | 8.67 | | | | 11.54 | | | | | | | | | | | | | | | | | |
| Net interest margin | | | 3.83 | | | | 3.39 | | | | 2.76 | | | | | | | | | | | | | | | | | |
*Net interest income data are presented on a taxable-equivalent basis which is a non-GAAP measure.
The increase in net income in 2023 as compared with 2022 included one additional quarter of operations acquired from People's United.
That increase reflects a 44 basis point (hundredth of one percent) widening of the net interest margin to 3.83% in 2023 from 3.39% in 2022.
Included in the second quarter of 2022 was the $242 million provision related to loans obtained in the People's United acquisition that were considered non-PCD.
The comparatively higher provision for credit losses in the most recent year as compared with 2022 reflects declines in commercial real estate values and higher interest rates contributing to a deterioration in the performance of loans to commercial borrowers as well as commercial and industrial loan growth.
Noninterest income rose $172 million, or 7%, to $2.53 billion in 2023 as compared with $2.36 billion in 2022, reflecting the sale of the CIT business in the second quarter of 2023, the sale of MTIA in the fourth quarter of 2022 and one additional quarter of revenues in 2023 from operations acquired from People's United.
Other favorable factors contributing to the rise in noninterest income included higher mortgage banking revenues and trading account and other non-hedging derivatives gains.
The consolidated financial information presented herein reflects M&T and all of its subsidiaries, which are referred to collectively as “the Company.” M&T’s wholly owned bank subsidiaries are Manufacturers and Traders Trust Company (“M&T Bank”) and Wilmington Trust, National Association (“Wilmington Trust, N.A.”).
Other subsidiaries of M&T Bank include M&T Realty Capital Corporation, a multifamily commercial mortgage lender; Wilmington Trust Investment
On December 19, 2022 Wilmington Trust, N.A. announced it had entered into an agreement to sell its Collective Investment Trust ("CIT") business to a private equity firm.
That sale is expected to close in the first half of 2023 and result in recognition of a gain at that time.
Certain of the critical accounting estimates
Accounting for credit losses — Effective January 1, 2020 the Company adopted amended accounting guidance that impacts how the allowance for credit losses is determined.
Prior to 2020, the allowance for credit losses represented the amount that in management’s judgment reflected incurred credit losses inherent in the loan and lease portfolio as of the balance sheet date.
The estimation of the allowance for credit losses prior to 2020 did not consider reasonable and supportable forecasts that could have affected the collectability of the reported amounts.
Specific assumptions and estimates
The recognition or de-recognition in the Company’s consolidated financial statements of assets and liabilities held by so-called variable interest entities is subject to the interpretation and application of complex accounting pronouncements or interpretations that require management to estimate and assess the relative significance of the Company’s financial interests in those entities and the degree to which the Company can influence the most important activities of the entities.
Information relating to the Company’s involvement in such entities and the accounting treatment afforded each such involvement is included in note 20 of Notes to Financial Statements.
During 2022 the Federal Reserve took steps to address rising inflation, including several increases in the target Federal funds rate totaling 4.25%.
Those actions have led to an expansion of the Company's net interest margin, or taxable-equivalent net interest income expressed as a percentage of average earning assets.
A higher level of earning assets associated with the People's United acquisition and the expanded net interest margin have increased taxable-equivalent net interest income in 2022 as compared with 2021 and 2020.
The Company's estimates of expected credit losses at December 31, 2022 reflected risks including inflation, a projected rise in unemployment, reduction of economic growth projections, decreasing residential real estate values as compared with December 31, 2021 and continued concerns about commercial real estate values in the hospitality and office building sectors.
Also during the fourth quarter of 2022, the Company made a $135 million tax-deductible contribution to The M&T Charitable Foundation.
Net income recorded by the Company in 2022 was $1.99 billion or $11.53 of diluted earnings per common share, compared with $1.86 billion or $13.80 of diluted earnings per common share in 2021.
Basic earnings per common share were $11.59 in 2022 and $13.81 in 2021.
In connection with M&T’s acquisition of People’s United, the after-tax impact of merger-related expenses was $432 million ($580 million pre-tax), or $2.63 of diluted earnings per common share in 2022, compared with $34 million ($44 million pre-tax), or $0.25 of diluted earnings per common share in 2021.
GAAP requires that acquired loans be recorded at estimated fair value, which includes the use of interest rate and expected credit loss assumptions to forecast estimated cash flows.
acquired, but not classified as PCD also be recognized.
Given the requirement to recognize such losses above and beyond the impact of forecasted losses used in determining the fair value of acquired loans, M&T considers that initial provision to be a merger-related expense.
Net income in 2020 totaled $1.35 billion, while diluted and basic earnings per common share were each $9.94.
Expressed as a rate of return on average assets, net income in 2022 was 1.05%, compared with 1.22% in 2021 and 1.00% in 2020.
EARNINGS SUMMARY
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Increase (Decrease) (a) | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | Compound Growth Rate | | | | |
| Amount | | | | % | | | | Amount | | | | % | | | | | | 2022 | | | | 2021 | | | | 2020 | | | | 2019 | | | | 2018 | | | | 2017 to 2022 | | | | |
| $ | 2,332.8 | | | | 59 | | | $ | (256.5 | ) | | | (6 | ) | | Interest income (b) | | $ | 6,286.3 | | | $ | 3,953.5 | | | $ | 4,210.0 | | | $ | 4,902.4 | | | $ | 4,620.6 | | | | 8 | | % | |
| | 311.2 | | | | 273 | | | | (212.4 | ) | | | (65 | ) | | Interest expense | | | 425.2 | | | | 114.0 | | | | 326.4 | | | | 749.3 | | | | 526.4 | | | | 2 | | | |
| | 2,021.6 | | | | 53 | | | | (44.1 | ) | | | (1 | ) | | Net interest income (b) | | | 5,861.1 | | | | 3,839.5 | | | | 3,883.6 | | | | 4,153.1 | | | | 4,094.2 | | | | 9 | | | |
| | 592.0 | | | | — | | | | (875.0 | ) | | | (109 | ) | | Less: provision for credit losses | | | 517.0 | | | | (75.0 | ) | | | 800.0 | | | | 176.0 | | | | 132.0 | | | | 25 | | | |
| | 174.1 | | | | 8 | | | | 90.3 | | | | 4 | | | Other income | | | 2,362.3 | | | | 2,188.2 | | | | 2,097.9 | | | | 2,043.7 | | | | 1,862.3 | | | | 5 | | | |
| | | | | | | | | | | | | | | | | Less: | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | 741.7 | | | | 36 | | | | 95.0 | | | | 5 | | | Salaries and employee benefits | | | 2,787.4 | | | | 2,045.7 | | | | 1,950.7 | | | | 1,900.8 | | | | 1,752.3 | | | | 11 | | | |
| | 697.1 | | | | 45 | | | | 131.4 | | | | 9 | | | Other expense | | | 2,263.0 | | | | 1,565.9 | | | | 1,434.5 | | | | 1,567.9 | | | | 1,535.8 | | | | 9 | | | |
| | 180.4 | | | | 7 | | | | 683.0 | | | | 38 | | | Income before income taxes | | | 2,650.3 | | | | 2,469.9 | | | | 1,786.9 | | | | 2,570.1 | | | | 2,530.1 | | | | 2 | | | |
| | 24.4 | | | | 166 | | | | (2.6 | ) | | | (15 | ) | | Taxable\-equivalent adjustment(b) | | | 39.1 | | | | 14.7 | | | | 17.3 | | | | 22.9 | | | | 21.9 | | | | 3 | | | |
| | 23.1 | | | | 4 | | | | 180.0 | | | | 43 | | | Income taxes | | | 619.5 | | | | 596.4 | | | | 416.4 | | | | 618.1 | | | | 590.1 | | | | (8 | ) | | |
An excerpt. Shown here: 40 of 640 rewritten, 40 of 845 added and 40 of 731 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations. in the FY2023 filing and the FY2022 filing.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk.
1 rewritten, 0 added, 0 removed, 0 unchanged
Incorporated by reference to the discussion contained in Part II, Item 7, “Management’s Discussion and Analysis of Financial Condition and Results of Operations,” under the captions [removed: “Liquidity, Market Risk,] [added: "Liquidity Risk", “Market Risk] and Interest Rate Sensitivity” (including Table [removed: 20)] [added: 37)] and “Capital.”
Item 1. Business.
184 rewritten, 88 added, 175 removed, 210 unchanged
M&T [removed: Bank Corporation (“Registrant” or “M&T”)] is a New York business corporation which is registered as a [removed: financial holding company] [added: FHC] under the [removed: Bank Holding Company Act of 1956, as amended (“BHCA”)] [added: BHCA] and as a [removed: bank holding company (“BHC”)] [added: BHC] under Article III-A of the New York Banking [removed: Law (“Banking Law”).][added: Law.]
[removed: M&T and its direct and indirect subsidiaries are collectively referred to herein as the “Company.”] As of December 31, [removed: 2022,] [added: 2023,] the Company had consolidated total assets of [removed: $200.7] [added: $208.3] billion, deposits of [removed: $163.5] [added: $163.3] billion and shareholders’ equity of [removed: $25.3] [added: $27.0] billion.
The Company had [removed: 22,210] [added: 21,736] full-time and [removed: 598] [added: 487] part-time employees as of December 31, [removed: 2022.][added: 2023.]
[added: At December 31, 2023, M&T had two wholly owned bank subsidiaries: M&T Bank and Wilmington Trust, N.A.] The banks collectively offer a wide range of retail and commercial banking, trust and wealth management, and investment services to their customers.
At December 31, [removed: 2022,] [added: 2023,] M&T Bank represented over 99% of consolidated assets of the Company.
On April 1, 2022, M&T completed the acquisition of [removed: People's United Financial, Inc. (“People’s United”).][added: People’s United.]
M&T Bank is a member of the Federal Reserve System and the [removed: Federal Home Loan Bank] [added: FHLB] System, and its deposits are insured by the [removed: Federal Deposit Insurance Corporation (“FDIC”)] [added: FDIC] through its [removed: Deposit Insurance Fund (“DIF”)] [added: DIF] up to applicable limits.
As of December 31, [removed: 2022,] [added: 2023,] M&T Bank had [removed: 1,010] [added: 961] domestic banking offices located in New York State, Maryland, New Jersey, Pennsylvania, Delaware, Connecticut, Massachusetts, Maine, Vermont, New Hampshire, Virginia, West Virginia, and the District of Columbia and a full-service commercial banking office in Ontario, Canada.
As of December 31, [removed: 2022,] [added: 2023,] M&T Bank had consolidated total assets of [removed: $200.3] [added: $207.8] billion, deposits of [removed: $166.0] [added: $167.3] billion and shareholder’s equity of [removed: $24.4] [added: $25.7] billion.
Lending is largely focused on consumers residing in areas where M&T Bank maintains banking offices, and on small and medium-size businesses based in those areas, although loans are originated [added: through offices in other states and in Ontario, Canada.]
M&T Bank and certain of its subsidiaries also offer commercial mortgage loans secured by income producing properties or properties used by borrowers [removed: in a trade or business.]
Wilmington Trust, N.A., a national banking association and a member of the Federal Reserve System and the FDIC, commenced operations [removed: on] [added: in] October [removed: 2,] 1995.
The deposit liabilities of Wilmington Trust, N.A. are insured by the FDIC through [removed: the] [added: its] DIF.
As of December 31, [removed: 2022,] [added: 2023,] Wilmington Trust, N.A. had total assets of [removed: $692] [added: $683] million, deposits of [removed: $10] [added: $6] million and shareholder’s equity of [removed: $585] [added: $582] million.
M&T [removed: Securities, Inc. (“M&T Securities”)] [added: Securities] is a wholly owned subsidiary of M&T that was incorporated as a New York business corporation in November 1985.
M&T Securities is registered as a broker/dealer under the [removed: Securities] Exchange [removed: Act of 1934.][added: Act.]
As of December 31, [removed: 2022, M&T Securities] [added: 2023, WTIM] had [added: total] assets and [removed: shareholder's] [added: shareholder’s] equity of [removed: $49] [added: $5] million.
M&T Securities recorded [removed: $6] [added: $13] million of revenue [removed: during 2022.][added: in 2023.]
[removed: Wilmington Trust Investment Management, LLC (“WTIM”)] [added: WTIM] is a wholly owned subsidiary of M&T and was incorporated in December 2001 as a Georgia limited liability company.
[removed: WTIM] [added: WTAM] is a registered investment advisor under the Investment Advisors Act and provides investment management services to [removed: clients, including] certain private funds.
As of December 31, [removed: 2022, WTIM] [added: 2023, WTAM] had [added: total] assets [removed: of $7 million] and shareholder’s equity of [removed: $5] [added: $3] million.
WTIM recorded revenues of $2 million in [removed: 2022.][added: 2023.]
As of December 31, [removed: 2022,] [added: 2023,] Wilmington Trust Company had total assets of [removed: $1.2] [added: $1.1] billion and shareholder’s equity of [removed: $712] [added: $757] million.
Revenues of Wilmington Trust Company were [removed: $138] [added: $142] million in [removed: 2022.][added: 2023.]
M&T Realty [removed: Capital Corporation (“M&T Realty Capital”),] [added: Capital,] a wholly owned subsidiary of M&T Bank, was incorporated as a Maryland corporation in October 1973.
As of December 31, [removed: 2022,] [added: 2023,] M&T Realty Capital serviced or sub-serviced [removed: $26.0] [added: $28.0] billion of commercial mortgage loans for non-affiliates and had [added: total] assets of [removed: $932 million] [added: $1.2 billion] and shareholder’s equity of [removed: $179] [added: $175] million.
M&T Realty Capital recorded revenues of [removed: $155] [added: $192] million in [removed: 2022.][added: 2023.]
[removed: Wilmington Trust] [added: WT] Investment Advisors, [removed: Inc. (“WT Investment Advisors”),] a wholly owned subsidiary of M&T Bank, was incorporated as a Maryland corporation [removed: on] [added: in] June [removed: 30,] 1995.
[removed: WT Investment Advisors, a registered investment advisor under] the Investment Advisors Act, serves as an investment advisor to the Wilmington Funds, a family of proprietary mutual funds, and institutional clients.
As of December 31, [removed: 2022,] [added: 2023,] WT Investment Advisors had [added: total] assets of [removed: $64] [added: $28] million and shareholder’s equity of [removed: $52] [added: $17] million.
WT Investment Advisors recorded revenues of [removed: $42] [added: $43] million in [removed: 2022.][added: 2023.]
Wilmington Funds Management [removed: Corporation (“Wilmington Funds Management”)] is a wholly owned subsidiary of M&T that was incorporated in September 1981 as a Delaware corporation.
Wilmington Funds Management had [added: total] assets of [removed: $35] [added: $16] million and shareholder's equity of [removed: $34] [added: $15] million as of December 31, [removed: 2022.][added: 2023.]
Wilmington Funds Management recorded revenues of [removed: $24] [added: $31] million in [removed: 2022.][added: 2023.]
Following the acquisition of People’s United on April 1, 2022, M&T Bank's subsidiaries also include [removed: People's United Advisors, Inc. ("PUA"),] [added: PUA,] a Connecticut corporation formed in 2018 that provides investment advisory services and financial management and planning services.
As of December 31, [removed: 2022] [added: 2023,] PUA had [added: total] assets and shareholder's equity of [removed: $11 million and $10 million, respectively.][added: $15 million.]
Those subsidiaries are: LEAF Commercial Capital, Inc., a Delaware corporation incorporated in 2010, M&T Capital and Leasing Corp. [removed: (f/k/a] [added: (formerly known as] People’s Capital and Leasing Corp.) a Connecticut corporation formed in 1997, and M&T Equipment Finance Corp. [removed: (f/k/a] [added: (formerly known as] People’s United Equipment Finance Corp.), a Texas corporation formed in 1989.
The combined [added: total] assets and [removed: shareholders'] [added: shareholder's] equity of the three entities was [removed: $5.9] [added: $6.6] billion and [removed: $482] [added: $440] million, respectively, at December 31, [removed: 2022.][added: 2023.]
The combined revenues of the equipment leasing and financing services subsidiaries were [removed: $280] [added: $449] million [removed: in] [added: for] the [removed: nine months following their acquisition on April 1, 2022.][added: year ended December 31, 2023.]
[removed: The Registrant] [added: M&T] and its banking subsidiaries have a number of other special-purpose or inactive subsidiaries.
in a trade or business.
As of December 31, 2023, M&T Securities had total assets of $56 million and shareholder's equity of $55 million.
WTIM is a registered investment advisor under the Investment Advisors Act of 1940 and provides investment management services to wealth clients.
WTAM is a wholly owned subsidiary of M&T and was incorporated in February 2023 as a Delaware limited liability company.
WTAM recorded revenues of less than $1 million in 2023.
WTAM’s headquarters is located at 1100 North Market Street, Wilmington, Delaware 19890.
WT Investment Advisors, a registered investment advisor under
PUA recorded revenues of $6 million in 2023.
Prior period reportable segment results have been presented in conformity with the new segment reporting structure.
Such initiatives may include proposals to
substantial risk to the safety and soundness of depository institutions or the financial system generally (as solely determined by the Federal Reserve).
On July 27, 2023, the Federal Reserve, the FDIC and the OCC proposed revisions to the capital framework applicable to BHCs and their depository institution subsidiaries with $100 billion or more in assets, such as M&T.
The proposed rule would introduce a new approach for calculating risk-based
capital requirements and generally align the calculation of RWA and regulatory capital for firms in all four categories.
Category IV firms would become subject to the SLR and CCyB and would no longer be eligible to opt-out of the requirement to recognize most elements of accumulated other comprehensive income in regulatory capital.
Those firms would be required to include all accumulated other comprehensive income components in regulatory capital, except gains and losses on cash flow hedges.
Those adjustments recognized in accumulated other comprehensive income, among other items, would include unrealized losses on available-for-sale debt securities and any amounts recorded in accumulated other comprehensive income attributed to defined benefit postretirement plans.
The inclusion of accumulated other comprehensive income components in regulatory capital would be subject to a phase-in period beginning July 1, 2025 until June 30, 2028, with full inclusion of required accumulated other comprehensive income components starting July 1, 2028.
For further discussion of the proposed revisions to the capital framework, see the section captioned “Capital Requirements” included herein.
4.5% CET1 to RWA;
As a “non-advanced approaches” firm under the Capital Rules, M&T is subject to rules that provide for simplified capital requirements relating to the threshold deductions for mortgage servicing assets, deferred tax
On July 27, 2023, the Federal Reserve, the FDIC and the OCC proposed revisions to the Capital Rules to implement the Basel Committee’s 2017 standards and make other changes to the Capital Rules.
The proposal introduces revised credit risk, equity risk, operational risk, credit valuation adjustment risk and market risk requirements (together, the “Expanded Risk-Based Approach”).
The Expanded Risk-Based Approach would apply to Category I through Category IV firms and would replace the existing advanced approaches with respect to credit and operational risk.
Under the proposal, banking organizations with more than $100 billion in total consolidated assets would be required to calculate RWAs using the higher of (i) the Expanded Risk-Based Approach or (ii) the current standardized approach and revised market risk requirements.
Calculating RWAs under the Expanded Risk-Based Approach would impose additional operational costs, including the costs to collect the data elements that would be used in the calculations.
In addition, the proposal would subject Category IV firms, like M&T, to the deductions framework for mortgage servicing assets and deferred tax assets and the methodology for calculating minority interest limitations currently applicable only to Category I and Category II firms.
Category IV firms would also no longer be eligible to opt-out of including certain components of accumulated other comprehensive income in regulatory capital.
Under existing rules, a depository institution is deemed to be “well
On November 16, 2023, the FDIC finalized a rule that imposes a special assessment to recover the costs to the DIF resulting from the FDIC’s use in 2023 of the systemic risk exception to the least-cost resolution test under the FDIA in connection with the receiverships of certain failed banks.
The FDIC estimated in approving the rule that those assessed losses total approximately $16.3 billion.
The rule provides that this loss estimate will be periodically adjusted, which will affect the amount of the special assessment.
Under the rule, the assessment base is the estimated uninsured deposits that an IDI reported in its Consolidated Report of Condition and Income at December 31, 2022, excluding the first $5 billion in estimated uninsured deposits.
For a holding company that has more than one IDI subsidiary, such as M&T, the $5 billion exclusion is allocated among the company’s IDI subsidiaries in proportion to each IDI’s estimated uninsured deposits.
The special assessments will be collected at an annual rate of approximately 13.4 basis points per year (3.36 basis points per quarter) over eight quarters in 2024 and 2025, with the first assessment period beginning January 1, 2024.
Because the estimated loss pursuant to the systemic risk determination will be periodically adjusted, the FDIC retains the ability to cease collection early, extend the special assessment collection period and impose a final shortfall special assessment on a one-time basis.
The special assessments are tax deductible.
The total of the assessments for M&T is estimated at $197 million and such amount was recorded as an expense in the fourth quarter of 2023 when the final rule was enacted.
The NYSE’s listing standards pursuant to the SEC’s rule became effective October 2, 2023.
M&T’s clawback policy adopted in accordance with these listing standards is included as Exhibit 97.1 to this Annual Report on Form 10-K.
At December 31, 2022, M&T had two wholly owned bank subsidiaries: Manufacturers and Traders Trust Company (“M&T Bank”) and Wilmington Trust, National Association (“Wilmington Trust, N.A.”).
through offices in other states and in Ontario, Canada.
PUA recorded revenues of $23 million during the nine months ended December 31, 2022.
Certain strategic business units have been combined for segment information reporting purposes where the nature of the products and services, the type of customer and the distribution of those products and services are similar.
The reportable segments are Business Banking, Commercial Banking, Commercial Real Estate, Discretionary Portfolio, Residential Mortgage Banking and Retail Banking.
the banking and financial system as a whole, and generally is not intended for the protection of shareholders, investors or creditors other than insured depositors.
Other non-bank affiliates and activities, particularly insurance brokerage and agency activities, are subject to other federal and state laws and regulations as well as licensing and regulation by state insurance and bank regulatory agencies.
Although the scope of regulation and the form of supervision may vary from state to state, insurance laws generally grant broad discretion to regulatory authorities in adopting regulations and supervising regulated activities.
This supervision generally includes the licensing of insurance brokers and agents and the regulation of the handling of customer funds held in a fiduciary capacity as well as regulations requiring, among other things, maintenance of capital, record keeping, and reporting.
Its deposits are insured by the FDIC,
For example, M&T Securities is regulated by the SEC, FINRA, SIPC, and state securities regulators, and WT Investment Advisors and PUA are also subject to SEC regulation.
risk-based indicators: (i) cross-jurisdictional activity, (ii) weighted short-term wholesale funding, (iii) nonbank assets, (iv) off-balance sheet exposure, and (v) status as a U.S. global systemically important BHC (“G-SIB”).
4.5% Common Equity Tier 1 Capital (“CET1”) to RWAs;
and associated tax effects not reflected in net income and (ii) the average of net income over the preceding four quarters.
The federal bank regulators have not yet proposed rules implementing these standards.
The impact of these standards will depend on the manner in which they are implemented by the federal banking regulators.
In January 2021, the Federal Reserve issued a final rule to align its process with the categories set forth in the Tailoring Rules.
The Federal Reserve publishes the results of its supervisory stress tests by June 30 of each year.
If an institution fails to comply with such an
“Covered
of the proposed transaction are clearly outweighed by the public interest in meeting the convenience and needs of the community to be served.
The final rule requires the exchanges to propose conforming listing standards by February 26, 2023 and requires the standards to become effective no later than November 28, 2023.
Each listed issuer, which includes M&T as a listed issuer on the New York Stock Exchange, would
then be required to adopt a clawback policy within 60 days after its exchange’s listing standard has become effective.
M&T will work to implement these new requirements as the rule becomes effective.
Insolvency of an Insured Depository Institution or a Bank Holding Company
Under the orderly liquidation authority, the FDIC may be appointed as receiver for the systemically
and income information from applications.
The rule was effective April 1, 2022, with compliance required by May 1, 2022.
the Real Estate Settlement Procedures Act, the Military Lending Act, the Servicemembers Civil Relief Act, and various state law counterparts.
Community Reinvestment Act
The proposed rule would adjust CRA evaluations based on bank size and type, with many of the proposed changes applying only to banks with over $2 billion in assets and several applying only to banks with over $10 billion in assets, such as M&T.
The effects on the Company of any potential change to the CRA rules will depend on the final form of any Federal Reserve rulemaking.
Bank Secrecy Act Regulation and Anti-Money Laundering Obligations
Failure of a
Office of Foreign Assets Control Regulation
These are typically known as the “OFAC” rules based on their administration by the U.S. Treasury Department Office of Foreign Assets Control (“OFAC”).
Regulation of Insurers and Insurance Brokers
The Company’s operations in the areas of insurance agency/brokerage and reinsurance of credit life insurance are subject to regulation and supervision by various state insurance regulatory authorities.
Although the scope of regulation and form of supervision may vary from state to state, insurance laws generally grant broad discretion to regulatory authorities in adopting regulations and supervising regulated activities.
An excerpt. Shown here: 40 of 184 rewritten, 40 of 88 added and 40 of 175 removed. The counts are complete. For every sentence, read Item 1. Business. in the FY2023 filing and the FY2022 filing.
Item 3. Legal Proceedings.
1 rewritten, 0 added, 0 removed, 5 unchanged
Although not considered probable, the range of reasonably possible losses for such matters in the aggregate, beyond the existing recorded liability, was between $0 and $25 million as of December 31, [removed: 2022.][added: 2023.]
Cover and table of contents
49 rewritten, 90 added, 4 removed, 98 unchanged
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE [removed: SECURITIES EXCHANGE] [added: SECURITIES EXCHANGE] ACT OF 1934 |
For the fiscal year ended December [removed: 31, 2022][added: 31, 2023]
| [removed: ☐] [added: Exchange Act] | [removed: TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934] [added: Securities Exchange Act of 1934] |
| Common Stock, [removed: $.50] [added: $0.50] par value | MTB | New York Stock Exchange |
Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant’s executive [removed: officers] [added: officers] during the relevant recovery period pursuant to §240.10D-1(b).
Aggregate market value of the Common Stock, $0.50 par value, held by non-affiliates of the registrant, computed by reference to the closing price as of the close of business on June 30, [removed: 2022: $27,304,085,267.][added: 2023: $19,900,658,494.]
Number of shares of the Common Stock, $0.50 par value, outstanding as of the close of business on February [removed: 17, 2023: 167,792,740] [added: 16, 2024: 166,624,291] shares.
(1) Portions of the Proxy Statement for the [removed: 2023] [added: 2024] Annual Meeting of Shareholders of M&T Bank Corporation in Parts II and III.
Form 10-K for the year ended December 31, [removed: 2022][added: 2023]
| Item 1. | | [Business](#business) | | [removed: 1] [added: 3] |
| | | A. | Average balance sheets | | [removed: 63] [added: 60] |
| | | B. | Interest income/expense and resulting yield or rate on average interest-earning assets and interest‑bearing liabilities | | [removed: 63] [added: 60] |
| | | C. | Rate/volume variances | | [removed: 23] [added: 61] |
| | | A. | Maturity schedule and [removed: weighted average] [added: weighted-average] yield | | 94 |
| | | A. | Maturity schedule | | [removed: 92] [added: 95] |
| | IV. | Allowance for credit [removed: losses] [added: loss] | | | |
| | | A. | Credit ratios | | [removed: 75\-79] [added: 74\-75] |
| | | | Factors driving material changes in credit ratios or related components | | [removed: 74\-84, 135, 139\-145] [added: 73\-83, 141\-147] |
| | | B. | Allocation of the allowance for credit losses | | [removed: 84, 139] [added: 83, 141] |
| | | A. | Average balances and rates | | [removed: 63] [added: 60] |
| | | B. | Uninsured [added: deposits] and time deposits over $250,000 | | [removed: 70\-71, 95] [added: 68\-69, 93, 96] |
| Item 1B. | [Unresolved Staff Comments](#unresolved_staff_comments) | | [removed: 46] [added: 44] |
| Item 5. | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities](#market_registrants_common_equity_related) | | [removed: 51] [added: 50] |
| | | A. | Principal market | | [removed: 51] [added: 50] |
| | | B. | Approximate number of holders at year-end | | [removed: 21] [added: 50] |
| | | C. | Frequency and amount of dividends declared | | [removed: 22\-23, 109, 121] [added: 102, 111, 122] |
| | | D. | Restrictions on dividends | | [removed: 8] [added: 10] |
| | | E. | Securities authorized for issuance under equity compensation plans | | [removed: 51] [added: 50] |
| | | F. | Performance graph | | [removed: 52] [added: 51] |
| | | G. | Repurchases of common stock | | [removed: 53] [added: 52] |
| Item 6. | [Selected Financial Data](#selected_financial_data) | | [removed: 53] [added: 52] |
| Item 7. | [Management’s Discussion and Analysis of Financial Condition and Results of Operations](#mda) | | [removed: 53] [added: 52] |
| Item 7A. | [Quantitative and Qualitative Disclosures About Market Risk](#quantitative_qualitative_disclosures_mar) | | [removed: 111] [added: 113] |
| Item 8. | [Financial Statements and Supplementary Data](#financial_statements_supplementary_data) | | [removed: 111] [added: 113] |
| | | A. | [Report on Internal Control Over Financial Reporting](#report_internal_control_financial_report) | | [removed: 112] [added: 114] |
| | | B. | [Report of Independent Registered Public Accounting Firm](#report_independent_registered_public) | | [removed: 113] [added: 115] |
| | | C. | [Consolidated Balance Sheet — December 31, [removed: 2022] [added: 2023] and [removed: 2021](#consolidated_balance_sheet)] [added: 2022](#consolidated_balance_sheet)] | | [removed: 117] [added: 118] |
| | | D. | [Consolidated Statement of Income — Years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020](#consolidated_statement_income)] [added: 2021](#consolidated_statement_income)] | | [removed: 118] [added: 119] |
| | | E. | [Consolidated Statement of Comprehensive Income — Years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020](#consolidated_statement_comp_income)] [added: 2021](#consolidated_statement_comp_income)] | | [removed: 119] [added: 120] |
| | | F. | [Consolidated Statement of Cash Flows — Years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020](#consolidated_statement_cash_flows)] [added: 2021](#consolidated_statement_cash_flows)] | | [removed: 120] [added: 121] |
| Glossary of terms | | | | 1 |
| Item 1C. | [Cybersecurity](#cybersecurity) | | 44 |
| | | | |
| --- | --- | --- | --- |
| [S](#signatures)ignatures | | 199 |
Glossary of Terms
The following listing includes acronyms and terms used throughout the document.
| Term | Definition |
| AML | Anti-Money Laundering |
| AMLA | Anti-Money Laundering Act of 2020 |
| Basel III | Basel Committee's December 2010 final capital framework for strengthening international capital standards |
| Bayview Financial | Bayview Financial Holdings, L.P. together with its affiliates |
| BHC | Bank holding company |
| BHCA | Bank Holding Company Act of 1956, as amended |
| BLG | Bayview Lending Group, LLC |
| BSA | Bank Secrecy Act |
| Capital Rules | Capital adequacy standards established by the federal banking agencies |
| CCyB | Countercyclical capital buffer |
| CET1 | Common Equity Tier 1 |
| CFPB | Consumer Financial Protection Bureau |
| CISO | Chief Information Security Officer |
| CIT | Collective Investment Trust |
| Common Securities | Common securities issued in connection with the issuance of Junior Subordinated Debentures |
| Company | M&T Bank Corporation and its consolidated subsidiaries |
| COVID-19 | Coronavirus disease 2019 |
| CRA | Community Reinvestment Act of 1977 |
| DIF | Deposit Insurance Fund |
| Dodd-Frank Act | Dodd-Frank Wall Street Reform and Consumer Protection Act |
| DUS | Delegated Underwriting and Servicing |
| EGRRCPA | Economic Growth, Regulatory Relief, and Consumer Protection Act |
| FASB | Financial Accounting Standards Board |
| FDIA | Federal Deposit Insurance Act |
| FDIC | Federal Deposit Insurance Corporation |
| Federal Reserve | Board of Governors of the Federal Reserve System |
| FHC | Financial Holding Company |
| FHLB | Federal Home Loan Bank |
| FINRA | Financial Industry Regulatory Authority |
| FOMC | Federal Open Market Committee |
| FRB | Federal Reserve Bank |
| GAAP | Accounting principles generally accepted in the U.S. |
or
| | | | | | |
| --- | --- | --- | --- | --- | --- |
| [SIGNATURES](#signatures) | | 198 |
An excerpt. Shown here: 40 of 49 rewritten, 40 of 90 added and all 4 removed. The counts are complete. For every sentence, read Cover and table of contents in the FY2023 filing and the FY2022 filing.
Item 1C. Cybersecurity.
0 rewritten, 37 added, 0 removed, 0 unchanged
New section this year
The Company has established polices, processes, controls and systems designed to identify, assess, measure, manage, monitor and report risks related to cybersecurity and help prevent or limit the effect of possible cybersecurity threats and attacks.
As cybersecurity threats continue to evolve, the Company expects to continue to expend significant resources to modify or enhance its measures to detect and prevent cybersecurity attacks or to investigate and remediate any information security vulnerabilities
that become known.
The risks faced by the Company from cybersecurity threats that could materially affect the Company, including its business strategy, results of operations or financial condition, are discussed in Part I, Item 1A, “Risk Factors” as part of this Annual Report on Form 10-K.
Cybersecurity is integrated into the Company’s Risk Framework through which the Company identifies, assesses, monitors, controls, communicates and escalates risks.
The Risk Framework, which is reviewed and approved by the Risk Committee of the Board of Directors at least annually, represents the Company’s overall risk management approach, including the policies, processes, controls and systems, through which the Company seeks to manage risk, including cybersecurity risk.
It provides a common foundation for all employees and officers as well as directors to understand and communicate the types of risks that the Company faces in pursuit of its business objectives.
The Risk Framework includes oversight by management through a multi-tiered committee structure responsible for overseeing proactive risk identification, developing an aggregated view of risks, and providing a consistent governance methodology across the Company.
All such committees, including the Operational Risk Committee which has primary authority for oversight of cybersecurity, report up to the Management Risk Committee, which is chaired by the Chief Risk Officer, and serves as the executive level committee responsible for the implementation and oversight of the Risk Framework.
The Risk Framework is designed to ensure the Board of Directors and its Risk Committee, which is the primary Board committee that oversees cybersecurity, are provided the information necessary to be effective in its risk management oversight responsibilities.
The Risk Committee of the Board of Directors receives regular reports on cybersecurity from the CISO.
The CISO is responsible for the design and execution of the Security Program, which is supported by the governance structure defined within the Risk Framework.
The CISO reports as necessary to executive management, the Risk Committee of the Board and the Board of Directors on cyber and information security issues and the effectiveness of the Company’s cyber and information security program.
The Risk Committee of the Board and the Board of Directors receive the results of the Company’s annual cybersecurity risk assessment.
Aligned with leading industry standards, including the U.S. Department of Commerce’s National Institute of Standards and Technology Cybersecurity Framework, the Security Program is built upon a foundation of policies, standards and procedures, which leverage the National Institute of Standards and Technology standards, to help safeguard customer information and reduce the risk of cyber incidents and breaches.
The Security Program features layered controls of network and endpoint intrusion detection and prevention, enterprise malware protection, threat-monitoring and a Security Operations Center that provides full time support and additional operational measures to monitor and respond to data breaches and cyberattacks.
In accordance with the Gramm-Leach-Bliley Act, the Company undertakes periodic assessments to identify and assess risks to customer information and evaluate the effectiveness of security controls.
The Company engages third parties in connection with such cybersecurity preparedness efforts.
Ongoing audits, including vulnerability and penetration testing of the Company’s computing infrastructure, are performed by independent third parties and by our internal cybersecurity personnel.
The Company has also established processes to oversee and identify cybersecurity risks from third-party service providers.
Third-party service providers (including suppliers and business partners) are required to have security policies, standards and procedures that meet or exceed the information security guidelines as specified in the Security Program.
The Company has an established third-party due diligence program to ensure vendors meet the Company's expectations as agreed to in their contract.
Roles, responsibilities and expectations for service providers and other third parties are communicated and documented through contracts (and other associated agreements) and monitored through oversight as part of the Company’s Third-Party Risk Management Program.
The Company’s Cybersecurity Leadership Team includes the CISO, Mr. Timothy Byrd.
Mr. Byrd is responsible for overseeing and reporting on the development and implementation of the Company's
information security program.
Mr. Byrd has over twenty years of experience in information security for large financial institutions.
He also served as chairman for the Bank Policy Institute's Technology Policy Division Information Security Committee and as a board member of Financial Services Information Sharing and Analysis Center.
Mr. Byrd currently serves on the Advisory Council for New York University's Graduate School of Engineering, as well as the Advisory Board for University of North Carolina - Charlotte College of Computing and Informatics.
The CISO reports to the Company’s Chief Information Officer, Mr. Michael A.
Wisler, who has two decades of experience in the financial and technology industries.
Prior to joining the Company in 2018, Mr. Wisler served as Chief Technology Officer of North American Credit Cards and Chief Information Officer of Europe at Capital One Financial Corporation.
He holds a Masters of Science in Management of Information Technology from the University of Virginia.
In addition, the Cybersecurity Leadership Team includes management with expertise in vulnerability management, digital forensics, threat intelligence, software development, cybersecurity operations, and project management.
Many individuals on the Cybersecurity Leadership Team hold cybersecurity-relevant certifications.
The Company’s Information Security Awareness Program, a component of the Security Program, is designed to ensure that all employees are aware of relevant cyber-related policies, principles, standards and practices, as well as new and current regulatory requirements related to safeguarding customer and corporate information assets.
Cybersecurity awareness initiatives and resources are regularly provided to employees, including through mandatory annual cybersecurity awareness training, ongoing simulated phishing email exercises and communications from the Company's Cybersecurity Division on the Company's internal communication channels.
Item 2. Properties.
11 rewritten, 1 added, 1 removed, 10 unchanged
At December 31, [removed: 2022,] [added: 2023,] the cost of this property (including improvements subsequent to the initial construction), net of accumulated depreciation, was [removed: $25.9] [added: $36.5] million.
M&T Bank [added: also] owns and occupies [removed: an additional] [added: a] facility in Buffalo, New York (known as M&T Center) with approximately 395,000 rentable square feet of space.
At December 31, [removed: 2022,] [added: 2023,] the cost of this building (including improvements subsequent to acquisition), net of accumulated depreciation, was [removed: $11.9] [added: $12.8] million.
The total square footage of these facilities approximates 290,000 square feet and their combined cost (including improvements subsequent to acquisition), net of accumulated depreciation, was [removed: $24.6] [added: $22.5] million at December 31, [removed: 2022.][added: 2023.]
[added: At December 31, 2023, the cost of these buildings (including improvements] subsequent to acquisition), net of accumulated depreciation, was [removed: $39.1] [added: $38.0] million and [removed: $14.5] [added: $14.0] million, respectively.
M&T Bank also owns facilities in Millsboro, Delaware and Harrisburg, Pennsylvania with approximately 325,000 and [removed: 220,000] [added: 225,000] rentable square feet of space, respectively.
At December 31, [removed: 2022,] [added: 2023,] the cost of those buildings (including improvements subsequent to acquisition), net of accumulated depreciation, was [removed: $15.9] [added: $15.2] million and [removed: $8.0] [added: $9.1] million, respectively.
[removed: The] [added: In 2022, the] Company obtained facilities in connection with the People's United acquisition, including a building in Bridgeport, Connecticut, (known as Bridgeport Center) with approximately [removed: 450,000 rentable square feet of space.]
The Company [added: currently] occupies approximately [removed: 89%] [added: 92%] of that facility.
At December 31, [removed: 2022,] [added: 2023,] the cost of that building (including improvements subsequent to acquisition), net of accumulated depreciation, was [removed: $35.7] [added: $31.8] million.
Of the [removed: 1,010] [added: 961] domestic banking office locations of M&T’s subsidiary banks at December 31, [removed: 2022, 366] [added: 2023, 360] are owned and [removed: 644] [added: 601] are leased.
460,000 rentable square feet of space.
At December 31, 2022, the cost of these buildings (including improvements
Item 4. Mine Safety Disclosures.
29 rewritten, 9 added, 24 removed, 35 unchanged
Jones, age [removed: 58,] [added: 59,] is [removed: chief executive officer, chairman] [added: Chief Executive Officer, Chairman] of the [removed: board] [added: Board] and a [removed: director] [added: Director] of M&T and M&T Bank (2017).
[added: Mr. Jones had also] served as [removed: chairman] [added: Chairman] of the [removed: board] [added: Board] and a [removed: director] [added: Director] of [removed: Wilmington Trust] [added: WT] Investment Advisors, [removed: a director of M&T Insurance Agency, chief financial officer] [added: Chief Financial Officer] of M&T, M&T Bank and Wilmington Trust, N.A. and held a number of management positions within M&T Bank’s Finance Division since 1992.
[removed: Previously, he was] [added: Bible, age 62, is] a [removed: senior executive vice president, chief risk officer] [added: Senior Executive Vice President] and [removed: director] [added: Chief Financial Officer (2023)] of M&T and [removed: was a vice chairman and chief risk officer of] M&T Bank.
[removed: Mr. Gold had been] [added: Todaro, age 62, is a Senior Executive Vice President (2015) and Chief Risk Officer (2021) of M&T and M&T Bank where he is] responsible for overseeing the Company’s governance and strategy for risk [removed: management,] [added: management] as well as relationships with [removed: key] [added: the Company’s] regulators and supervisory agencies.
He is a [removed: senior executive vice president (2021)] [added: Senior Executive Vice President and Chief Financial Officer (2023)] of Wilmington Trust, N.A. and [added: a Senior Executive Vice President (2023) of] Wilmington Trust Company.
[added: Previously,] Mr. [removed: Gold had] [added: Pearson] served as [removed: chairman, president] [added: a Director of M&T, Chairman of the Board of Wilmington Trust Company] and [removed: chief executive officer] [added: Chairman] of [added: the Board of] Wilmington Trust, [removed: N.A.,] [added: N.A. He also previously served] as a [removed: senior vice president] [added: Senior Executive Vice President] of M&T [added: and M&T] Bank [removed: from 2000 to 2006] and has held a number of management positions since he began his career with M&T Bank [removed: in 1989.]
Pearson, age [removed: 61,] [added: 62,] is [removed: vice chairman] [added: Vice Chairman] (2020) of M&T and is [removed: vice chairman] [added: Vice Chairman] (2014) and a [removed: director] [added: Director] (2018) of M&T Bank.
Mr. Pearson has oversight of the Commercial [removed: Banking, Technology and] Banking [removed: Operations,] and [removed: Wealth and] [added: the] Institutional Services [added: and Wealth Management] Divisions.
He is a [removed: director] [added: Director] (2014) of Wilmington Trust, [removed: N.A. and] [added: N.A.,] a [removed: director] [added: Director] (2022) of [removed: PUA.][added: PUA and a Director (2023) of WTAM.]
Bojdak, age [removed: 67,] [added: 68,] is a [removed: senior executive vice president] [added: Senior Executive Vice President] and [removed: chief credit officer] [added: Chief Credit Officer] (2004) of M&T and M&T Bank where he is responsible for managing the overall risk involving M&T Bank’s loan portfolio, monitoring portfolio metrics and workout activities.
[removed: D'Arcy,] [added: D’Arcy,] age [removed: 49,] [added: 50,] is a [removed: senior executive vice president] [added: Senior Executive Vice President] (2022) of M&T and M&T Bank and is the head of Commercial Banking.
Previously, Mr. [removed: D'Arcy] [added: D’Arcy] served as an Area Executive, was [removed: co-head] [added: Co-Chair] of M&T Bank’s Senior Loan Committee, and supervised M&T Bank’s [removed: commercial real estate segment,] [added: Commercial Real Estate,] Capital Markets and Corporate and Institutional Banking Divisions.
King, age [removed: 53,] [added: 54,] is a [removed: senior executive vice president] [added: Senior Executive Vice President] (2010) [removed: and chief financial officer (2016)] of M&T and [removed: senior executive vice president] [added: a Senior Executive Vice President] (2009) [removed: and chief financial officer (2016)] of M&T Bank.
[added: Prior to his current role,] Mr. King [removed: has] [added: served as Chief Financial Officer of M&T and M&T Bank with the] responsibility for the [added: Company’s] overall financial management [removed: of the Company] and [removed: oversees the Finance and Treasury Divisions.][added: treasury functions.]
[removed: vice president of M&T Bank and] [added: Mr. King] has held a number of management positions within M&T Bank since 2000.
[removed: Mr. King] [added: Ms. O’Hara] is a [removed: senior executive vice president (2009)] [added: Senior Executive Vice President (2020)] and [removed: chief financial officer (2016)] [added: Chief Legal Officer (2018)] of Wilmington Trust, [removed: N.A.][added: N.A., a Senior Executive Vice President (2020) of Wilmington Trust Company, and a Senior Executive Vice President and Chief Legal Officer (2023) of WTIM.]
Meister, age [removed: 68,] [added: 69,] is a [removed: senior executive vice president] [added: Senior Executive Vice President] (2016) of M&T and M&T Bank and is responsible for overseeing the Company’s [removed: wealth management] [added: Wealth Management] business, including Wilmington Trust Wealth Management, M&T Securities and WT Investment Advisors.
Ms. Meister is a [removed: director, chair] [added: Director, Chair] of the [removed: board] [added: Board] and [removed: chief executive officer] [added: Chief Executive Officer] (2022) of [removed: PUA.][added: PUA, and a Director, Chair of the Board and Chief Executive Officer (2023) of WTAM.]
O’Hara, age [removed: 63,] [added: 64,] is a [removed: senior executive vice president] [added: Senior Executive Vice President] (2020) and [removed: chief legal officer] [added: Chief Legal Officer] (2017) of M&T and M&T Bank.
Ms. [removed: O’Hara] [added: Urban] is a [removed: senior executive vice president] [added: Senior Executive Vice President] (2020) and [removed: chief legal officer] [added: Chief Auditor] (2018) of Wilmington Trust, [removed: N.A., and senior executive vice president] [added: N.A.] and [removed: chief legal officer] [added: a Senior Executive Vice President] (2020) of Wilmington Trust Company.
She has almost [removed: 40] [added: forty] years of litigation, regulatory compliance and risk management experience, including time spent at Santander Bank, where she served as [removed: executive vice president] [added: Executive Vice President] and [removed: general counsel] [added: General Counsel] from 2015 until she joined M&T in 2017.
Julianne Urban, age [removed: 50,] [added: 51,] is a [removed: senior executive vice president] [added: Senior Executive Vice President] (2020) and [removed: chief auditor] [added: Chief Auditor] (2017) of M&T and M&T Bank.
During her tenure, she has served as [removed: audit manager] [added: Audit Manager] and [removed: audit director] [added: Audit Director] responsible for examining various business lines including Commercial Banking, [removed: Consumer] [added: Retail] Banking, [added: Institutional Services and Wealth Management,] Credit, [removed: Finance, Mortgage,] [added: Finance and Treasury,] Operations, Regulatory, [removed: Retail, Risk Management,] and [removed: Treasury.][added: Risk Management.]
[removed: Warman,] [added: Jennifer Warren,] age [removed: 57,] [added: 59,] is a [removed: senior executive vice president (2009) and treasurer (2008)] [added: Senior Executive Vice President (2022)] of M&T and M&T Bank.
[removed: Jennifer Warren,] [added: Woodrow,] age [removed: 58,] [added: 50,] is a [removed: senior executive vice president (2022)] [added: Senior Executive Vice President (2020) and Chief Administrative Officer (2023)] of M&T and M&T Bank.
Ms. Warren is responsible for managing administrative and business development functions of [removed: Institutional Client Services within] the [removed: Wealth and] Institutional Services Division.
Ms. Warren is a [removed: director] [added: Director] (2022) of Wilmington Funds Management, [added: WT Investment Advisors,] WTIM and [removed: PUA.][added: PUA, and a Director (2023) of WTAM.]
Ms. Warren previously served as head of the U.S. region and [removed: president] [added: President] and [removed: chief executive officer] [added: Chief Executive Officer] of CIBC World Markets Corp., where she worked for nearly [removed: 12] [added: twelve] years.
Ms. Woodrow is responsible for managing the Company’s Human Resources, Banking Services and Corporate Services Divisions, and leading [removed: the ESG initiative.][added: M&T's sustainability efforts.]
in 1989.
Daryl N.
Mr. Bible leads the Finance Division, which includes the Company's Treasury Division, and has responsibility for the overall financial management of the Company including oversight of SEC and regulatory reporting, acquisitions and divestitures, shareholder capital, and interest rate and liquidity risk management.
Prior to his current role, Mr. Bible was the Chief Financial Officer of Truist Financial Corporation.
Mr. Bible joined Truist Financial Corporation’s predecessor, Branch Banking and Trust Company, in 2008 after a twenty-four year career with U.S. Bancorp, during which he served ten years as Treasurer.
Kay, age 58, is a Senior Executive Vice President (2018) of M&T and M&T Bank, and is responsible for Enterprise Platforms, which includes the Customer Experience, Digital, Strategy and Transformation, and Marketing Divisions.
Mr. King has responsibility for a portfolio of businesses comprising the Retail Banking Division, including Retail, Business Banking, Residential Mortgage, Indirect and Consumer Lending activities.
He is also the head of Dealer Lending.
Ms. Woodrow previously served as Chief Human Resources Officer (2020) for M&T and M&T Bank and as the BSA/AML/OFAC Officer (2013) for M&T, M&T Bank and Wilmington Trust, N.A.
Mr. Jones had also
Richard S.
Gold, age 62, is president and chief operating officer of M&T (2017) and president, chief operating officer and a director of M&T Bank (2017).
Mr. Gold oversees the Consumer Banking, Business Banking, Legal and Human Resources Divisions.
In June 2022 Mr. Gold announced his intention to retire effective after the first quarter of 2023, and his plans to remain a director of M&T Bank.
Previously, Mr. Pearson served as a director of M&T, chairman of the board of Wilmington Trust Company and chairman of the board of Wilmington Trust, N.A. He also previously served as a senior executive vice president of M&T and M&T Bank and has held a number of management positions since he began his career with M&T Bank in 1989.
Kay, age 57, is a senior executive vice president (2018) of M&T and M&T Bank, and is responsible for all aspects of Consumer Banking, including the Mortgage, Consumer Lending and Retail businesses.
He is also responsible for Business Banking, Customer Experience, Digital, Strategy and Transformation, Marketing and Enterprise Platforms.
Prior to his current role, Mr. King was the Retail Banking executive with responsibility for overseeing Business Banking, Consumer Deposits, Consumer Lending and M&T Bank’s Marketing and Communications team.
Mr. King previously served as senior
Todaro, age 61, is a senior executive vice president (2015) and chief risk officer (2021) of M&T and M&T Bank where he is responsible for overseeing the Company’s governance and strategy for risk management as well as relationships with the Company’s regulators and supervisory agencies.
Michele D.
Trolli, age 61, is a senior executive vice president (2005) and head of corporate operations and enterprise initiatives (2018) of M&T and M&T Bank.
Previously, she was chief information officer of M&T and M&T Bank.
Ms. Trolli has led a wide range of the Company’s Banking Operations, which includes Banking Services, Corporate Services, Business Continuity and Enterprise Transformation and Change Management and overseeing the Environmental, Social and Governance ("ESG") initiative.
In December 2022 Ms. Trolli announced her plans to retire from M&T Bank effective in March of 2023.
Ms. Urban is a senior executive vice president (2020) and chief auditor (2018) of Wilmington Trust, N.A. and a senior executive vice president (2020) and chief auditor (2017) of Wilmington Trust Company.
D.
Scott N.
He is responsible for managing the Company’s Treasury Division, including asset/liability management, funding, investment and derivative portfolio management, capital markets foreign exchange trading and sales.
Mr. Warman previously served as senior vice president of M&T Bank and has held a number of management positions within M&T Bank since 1995.
He is a senior executive vice president and treasurer of Wilmington Trust, N.A. (2008) and is a senior executive vice president and treasurer of Wilmington Trust Company (2012).
Woodrow, age 49, is a senior executive vice president (2020), chief human resources officer (2020) and chief administrative officer (2023) of M&T and M&T Bank.
Ms. Woodrow previously served as the Bank Secrecy Act / Anti-Money Laundering / Office of Foreign Assets Control Officer for M&T, M&T Bank and Wilmington Trust, N.A. upon joining M&T Bank in 2013.
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
18 rewritten, 9 added, 10 removed, 25 unchanged
M&T’s common stock is traded under the symbol MTB on the [removed: New York Stock Exchange.][added: NYSE.]
See cross-reference sheet for disclosures incorporated elsewhere in this Annual Report on Form 10-K for [removed: approximate number of common shareholders at year-end,] frequency and amounts of dividends on common stock and restrictions on the payment of dividends.
During the fourth quarter of [removed: 2022,] [added: 2023,] M&T did not issue any shares of its common stock that were not registered under the Securities [removed: Act of 1933.][added: Act.]
The following table provides information as of December 31, [removed: 2022] [added: 2023] with respect to shares of common stock that may be issued under M&T’s existing equity compensation plans.
Footnote (1) to the table sets forth the total number of shares of common stock issuable upon the exercise of such assumed options and rights as of December 31, [removed: 2022,] [added: 2023,] and their weighted-average exercise price.
| Equity compensation plans [added: not] approved by security holders | | | [removed: 729,771] [added: 10,238] | | | [removed: $] | [removed: 164.12] [added: 82.31] | | | | [removed: 1,650,696] [added: —] | |
| Equity compensation plans [removed: not] approved by security holders | | | [removed: 11,725] [added: 902,570] | | | [added: $] | [removed: 80.46] [added: 162.50] | | | | [removed: —] [added: 4,218,093] | |
*As of December 31, [removed: 2022,] [added: 2023,] a total of [removed: 1,612,597] [added: 1,298,073] shares of M&T common stock were issuable upon exercise of outstanding options or rights assumed by M&T in connection with merger and acquisition transactions.
The weighted-average exercise price of those outstanding options or rights is [removed: $139.36] [added: $145.14] per common share.*
The following graph contains a comparison of the cumulative shareholder return on M&T common stock against the cumulative total returns of the KBW Nasdaq Bank Index, compiled by Keefe, Bruyette & Woods, Inc., and the S&P 500 Index, compiled by [removed: Standard & Poor’s Corporation,] [added: S&P Dow Jones Indices, LLC,] for the five-year period beginning on December 31, [removed: 2017] [added: 2018] and ending on December 31, [removed: 2022.][added: 2023.]
The KBW Nasdaq Bank Index is a modified market capitalization weighted index consisting of [removed: 25] [added: 24] banking stocks representing leading large U.S. national money centers, regional banks and thrift institutions.
[removed: ][added: 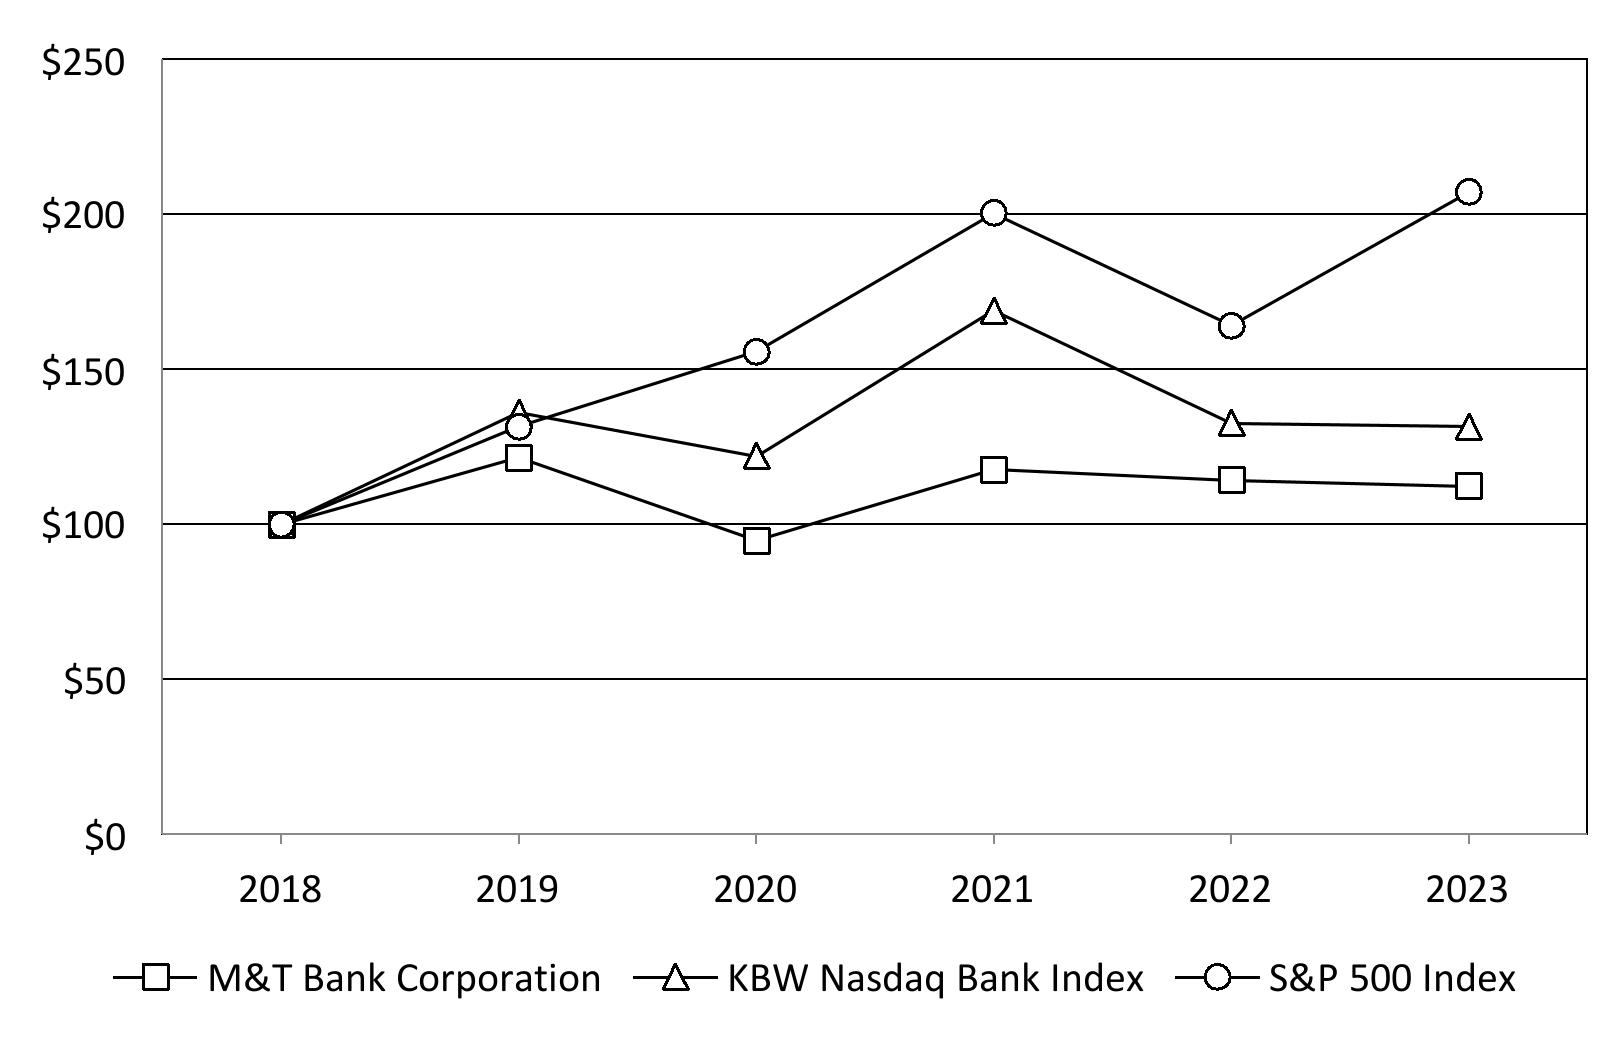]
| | [removed: 2017 | | |] 2018 | | | 2019 | | | 2020 | | | 2021 | | | 2022 | | | [added: 2023 | | |]
Assumes a $100 investment on December 31, [removed: 2017] [added: 2018] and reinvestment of all dividends.*
In accordance with and to the extent permitted by applicable law or regulation, the information set forth above under the heading “Performance Graph” shall not be incorporated by reference into any future filing under the Securities [removed: Act of 1933, as amended (the “Securities Act”),] [added: Act,] or the Exchange Act and shall not be deemed to be “soliciting material” or to be “filed” with the SEC under the Securities Act or the Exchange Act.
During the fourth quarter of [removed: 2022,] [added: 2023,] M&T purchased shares of its common stock as follows:
| Period | | [removed: (a) Total] [added: Total] Number of Shares (or Units) Purchased (1) | | | | [removed: (b) Average] [added: Average] Price Paid per Share (or Unit) | | | | [removed: (c) Total] [added: Total] Number of Shares (or Units) Purchased as Part of Publicly Announced Plans or Programs | | | | [removed: (d) Maximum] [added: Maximum] Number (or Approximate Dollar Value) of Shares (or Units) that may yet be Purchased Under the Plans or Programs (2) | | |
*In July 2022, M&T's Board of Directors authorized a program under which $3.0 billion of common shares may be repurchased with the exact number, timing, price and terms of such repurchases to be determined at the discretion of management and subject to all regulatory [removed: limitations.][added: limitations.*]
Shareholders of M&T approximated 31,325 at December 31, 2023.
| Total | | | 912,808 | | | $ | 161.60 | | | | 4,218,093 | |
| M&T Bank Corporation | | 100 | | | 122 | | | 95 | | | 118 | | | 114 | | | 112 | |
| KBW Nasdaq Bank Index | | 100 | | | 136 | | | 122 | | | 169 | | | 133 | | | 132 | |
| S&P 500 Index | | 100 | | | 132 | | | 156 | | | 200 | | | 164 | | | 207 | |
| October 1 - October 31, 2023 | | | — | | | $ | — | | | | — | | | $ | 1,200,060,000 | |
| November 1 - November 30, 2023 | | | 76 | | | | 116.41 | | | | — | | | | 1,200,060,000 | |
| December 1 - December 31, 2023 | | | 171 | | | | 137.87 | | | | — | | | | 1,200,060,000 | |
| Total | | | 247 | | | $ | 131.27 | | | | — | | | | | |
| Total | | | 741,496 | | | $ | 162.79 | | | | 1,650,696 | |
| M&T Bank Corporation | | 100 | | | 85 | | | 104 | | | 81 | | | 101 | | | 98 | |
| KBW Nasdaq Bank Index | | 100 | | | 82 | | | 112 | | | 100 | | | 139 | | | 109 | |
| S&P 500 Index | | 100 | | | 96 | | | 126 | | | 149 | | | 192 | | | 157 | |
| | | | | | | | | | | | | | | | | |
| October 1 - October 31, 2022 | | | 211,886 | | | $ | 169.42 | | | | 200,000 | | | $ | 2,366,318,142 | |
| November 1 - November 30, 2022 | | | 2,125,262 | | | | 167.80 | | | | 2,125,000 | | | | 2,009,747,682 | |
| December 1 - December 31, 2022 | | | 1,340,649 | | | | 156.55 | | | | 1,339,887 | | | | 1,800,000,226 | |
| Total | | | 3,677,797 | | | $ | 163.79 | | | | 3,664,887 | | | | | |
That authorization replaces the previous program.*
Item 8. Financial Statements and Supplementary Data.
961 rewritten, 711 added, 707 removed, 1,044 unchanged
Financial Statements and Supplementary Data consist of the financial statements as indexed and presented below and Table [removed: 22] [added: 40] “Quarterly Trends” presented in Part II, Item 7, “Management’s Discussion and Analysis of Financial Condition and Results of Operations.”
| Report on Internal Control Over Financial Reporting | [removed: 112] [added: 114] |
| Report of Independent Registered Public Accounting Firm | [removed: 113] [added: 115] |
| Consolidated Balance Sheet — December 31, [removed: 2022] [added: 2023] and [removed: 2021] [added: 2022] | [removed: 117] [added: 118] |
| Consolidated Statement of Income — Years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020] [added: 2021] | [removed: 118] [added: 119] |
| Consolidated Statement of Comprehensive Income — Years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020] [added: 2021] | [removed: 119] [added: 120] |
| Consolidated Statement of Cash Flows — Years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020] [added: 2021] | [removed: 120] [added: 121] |
| Consolidated Statement of Changes in Shareholders’ Equity — Years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020] [added: 2021] | [removed: 121] [added: 122] |
| Notes to Financial Statements | [removed: 122] [added: 123] |
Management is responsible for establishing and maintaining adequate internal control over financial reporting at [removed: M&T Bank Corporation and subsidiaries (“the Company”).][added: the Company.]
Management has assessed the effectiveness of the Company’s internal control over financial reporting as of December 31, [removed: 2022] [added: 2023] based on criteria described in “Internal Control — Integrated Framework (2013)” issued by the Committee of Sponsoring Organizations of the Treadway Commission.
Based on that assessment, management concluded that the Company maintained effective internal control over financial reporting as of December 31, [removed: 2022.][added: 2023.]
| | [removed: ] [added: ] |
| | [removed: ] [added: ] |
We have audited the accompanying consolidated balance sheet of M&T Bank Corporation and its subsidiaries (the “Company”) as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] and the related consolidated statements of income, of comprehensive income, of changes in shareholders' equity and of cash flows for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] including the related notes (collectively referred to as the “consolidated financial statements”).
We also have audited the Company's internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in *Internal Control - Integrated Framework* (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2022] [added: 2023] in conformity with accounting principles generally accepted in the United States of America.
Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in *Internal Control - Integrated Framework* (2013) issued by the COSO.
Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and [added: evaluating the design and operating effectiveness of internal control based on the assessed risk.]
Critical Audit [removed: Matters][added: Matter]
The critical audit [removed: matters] [added: matter] communicated below [removed: are matters] [added: is a matter] arising from the current period audit of the consolidated financial statements that [removed: were] [added: was] communicated or required to be communicated to the audit committee and that (i) [removed: relate] [added: relates] to accounts or disclosures that are material to the consolidated financial statements and (ii) involved our especially challenging, subjective, or complex judgments.
The communication of critical audit matters does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit [removed: matters] [added: matter] below, providing [added: a] separate [removed: opinions] [added: opinion] on the critical audit [removed: matters] [added: matter] or on the accounts or disclosures to which [removed: they relate.][added: it relates.]
The principal considerations for our determination that performing procedures relating to the [removed: fair value of acquired commercial real estate loans in the acquisition of People’s United] [added: allowance for credit losses, specifically certain adjustments to model forecasts,] is a critical audit matter are (i) the significant judgment [removed: and estimation] by management in [removed: developing the market interest rate, expected credit losses, and prepayment assumptions used in estimating the fair value of] [added: determining] the [removed: acquired commercial real estate loans,] [added: adjustments to model forecasts,] (ii) a high degree of auditor judgment, [removed: subjectivity,] [added: subjectivity] and effort in performing procedures and [added: in] evaluating [added: audit evidence related to] management’s [removed: development] [added: determination] of [removed: market interest rates, expected credit losses, and prepayment assumptions,] [added: these adjustments to model forecasts,] and (iii) the audit effort involved the use of professionals with specialized skill and knowledge.
As described in Notes 1 and 5 to the consolidated financial statements, the Company’s allowance for credit losses of [removed: $1.9] [added: $2.1] billion reflects management's expected credit losses in the loan and lease portfolio of [removed: $131.6] [added: $134.1] billion as of December 31, [removed: 2022.][added: 2023.]
[removed: ][added: ]
[removed: February 22, 2023][added: | 2023 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |]
| (Dollars in [removed: thousands,] [added: millions,] except per [removed: share)] [added: share, shares in thousands)] | | [added: 2023 | | | |] 2022 | | | | 2021 | | |
| Cash and due from banks | | $ | [removed: 1,517,244] [added: 1,731] | | | $ | [removed: 1,337,577] [added: 1,517] | |
| Interest-bearing deposits at banks | | | [removed: 24,958,719 | | | | 41,872,304] [added: 9,193] | |
| Federal funds sold | | | [removed: 3,000] [added: —] | | | | [removed: —] [added: 3] | |
| Loans and leases | | | [removed: 132,074,156] [added: 134,936] | | | | [removed: 93,136,678] [added: 132,074] | |
| Loans and leases, net of unearned discount | | | [removed: 131,564,163] [added: 134,068] | | | | [removed: 92,912,452] [added: 131,564] | |
| Allowance for credit losses | | | [removed: (1,925,331] [added: (2,129] | ) | | | [removed: (1,469,226] [added: (1,925] | ) |
| Loans and leases, net | | | [removed: 129,638,832] [added: 131,939] | | | | [removed: 91,443,226] [added: 129,639] | |
| Core deposit and other intangible assets | | | [removed: 209,374] [added: 147] | | | | [removed: 3,998] [added: 209] | |
| Accrued interest and other assets | | | [removed: 8,930,237] [added: 9,171] | | | | [removed: 7,506,573] [added: 8,930] | |
| Savings and interest-checking deposits | | | [removed: 87,911,463] [added: (87,911] | [added: )] | | | [removed: 68,603,966] [added: (87,911] | [added: )] | [added: | | — | | | | (87,911 | ) | | | — | |]
| Short-term borrowings | | | [removed: 3,554,951] [added: 292] | | | | [removed: 47,046] [added: 19] | | [added: | | — | |]
| Accrued interest and other liabilities | | | [removed: 4,377,495] [added: 4,516] | | | | [removed: 2,127,931] [added: 4,377] | |
| Preferred stock, $1.00 par, 20,000,000 shares authorized; Issued and outstanding: Liquidation preference of $1,000 per share: 350,000 shares at December 31, [removed: 2022] [added: 2023] and December 31, [removed: 2021;] [added: 2022;] Liquidation preference of $10,000 per share: 140,000 shares at December 31, [removed: 2022] [added: 2023] and [removed: 2021;] [added: December 31, 2022;] Liquidation preference of $25 per share: 10,000,000 shares at December 31, [added: 2023 and December 31,] 2022 | | | [removed: 2,010,600] [added: 2,011] | | | | [removed: 1,750,000] [added: 2,011] | |
| | Daryl N. Bible |
February 21, 2024
| (Dollars in millions, except per share) | | 2023 | | | | 2022 | | |
| Trading account | | | 106 | | | | 118 | |
| Available for sale (cost: $10,691 at December 31, 2023; $11,193 at December 31, 2022) | | | 10,440 | | | | 10,749 | |
| Held to maturity (fair value: $14,308 at December 31, 2023; $12,375 at December 31, 2022) | | | 15,330 | | | | 13,530 | |
| Equity and other securities (cost: $1,125 at December 31, 2023; $934 at December 31, 2022) | | | 1,127 | | | | 932 | |
| Total investment securities | | | 26,897 | | | | 25,211 | |
| Unearned discount | | | (868 | ) | | | (510 | ) |
| Premises and equipment | | | 1,739 | | | | 1,654 | |
| Goodwill | | | 8,465 | | | | 8,490 | |
| Total assets | | $ | 208,264 | | | $ | 200,730 | |
| Noninterest-bearing deposits | | $ | 49,294 | | | $ | 65,502 | |
| Time deposits | | | 20,759 | | | | 10,102 | |
| Total deposits | | | 163,274 | | | | 163,515 | |
| Long-term borrowings | | | 8,201 | | | | 3,965 | |
| Total liabilities | | | 181,307 | | | | 175,412 | |
| Retained earnings | | | 17,524 | | | | 15,754 | |
| Total shareholders’ equity | | | 26,957 | | | | 25,318 | |
| (Dollars in millions, except per share) | | 2023 | | | | 2022 | | | | 2021 | | |
| Fully taxable | | | 773 | | | | 448 | | | | 141 | |
| Total interest income | | | 10,224 | | | | 6,247 | | | | 3,939 | |
| Time deposits | | | 671 | | | | 24 | | | | 19 | |
| Net interest income | | | 7,115 | | | | 5,822 | | | | 3,825 | |
| Mortgage banking revenues | | | 409 | | | | 357 | | | | 571 | |
| Trust income | | | 680 | | | | 741 | | | | 645 | |
| Total other income | | | 2,528 | | | | 2,357 | | | | 2,167 | |
| Professional and other services | | | 413 | | | | 509 | | | | 379 | |
| FDIC assessments | | | 315 | | | | 90 | | | | 70 | |
| Other costs of operations | | | 527 | | | | 668 | | | | 424 | |
| Total other expense | | | 5,379 | | | | 5,050 | | | | 3,612 | |
| Income before taxes | | | 3,619 | | | | 2,612 | | | | 2,455 | |
| Income taxes | | | 878 | | | | 620 | | | | 596 | |
| Net income | | $ | 2,741 | | | $ | 1,992 | | | $ | 1,859 | |
| Basic | | $ | 2,636 | | | $ | 1,891 | | | $ | 1,777 | |
| Diluted | | | 2,636 | | | | 1,891 | | | | 1,777 | |
| Net income | $ | 2,741 | | | $ | 1,992 | | | $ | 1,859 | |
| Cash flow hedges adjustments | | 98 | | | | (315 | ) | | | (211 | ) |
| (Dollars in millions) | | 2023 | | | | 2022 | | | | 2021 | | |
| Net income | | $ | 2,741 | | | $ | 1,992 | | | $ | 1,859 | |
Management has excluded processes and controls of People’s United that have not yet been converted to M&T's systems or processes from its assessment of internal control over financial reporting for the year ended December 31, 2022.
Assets and liabilities associated with those processes and procedures as of December 31, 2022 include loans and leases of $5.8 billion, other assets of $107 million and other liabilities of $184 million.
Approximately $280 million of total revenues for the nine months ended December 31, 2022 was contributed from business activities of People's United that have not yet been converted to M&T's systems or processes.
| | Darren J. King |
*Change in Accounting Principle*
As discussed in Note 1 to the consolidated financial statements, the Company changed the manner in which it accounts for the allowance for credit losses as of January 1, 2020.
evaluating the design and operating effectiveness of internal control based on the assessed risk.
As described in Management’s Report on Internal Control over Financial Reporting, management has excluded certain elements of the internal control over financial reporting of People's United Financial, Inc. (“People’s United”) from its assessment of the Company’s internal control over financial reporting as of December 31, 2022 because it was acquired by the Company in a purchase business combination during 2022.
Subsequent to the acquisition, certain elements of People's United’s internal control over financial reporting and related processes were integrated into the Company’s existing systems and internal control over financial reporting.
Those controls that were not integrated have been excluded from management’s assessment of the effectiveness of internal control over financial reporting as of December 31, 2022.
We have also excluded these elements of the internal control over financial reporting of People's United from our audit of the Company’s internal control over financial reporting.
The excluded elements represent controls over approximately $5.9 billion of the Company's consolidated total assets of $200.7 billion, $184 million of the Company's consolidated total liabilities of $175.4 billion, and $280 million of the Company's consolidated total interest and other income of $8.6 billion.
*Acquisition of People's United Financial, Inc. - Fair Value of Acquired Commercial Real Estate Loans*
As described in Note 2 to the consolidated financial statements, on April 1, 2022, the Company completed the acquisition of People's United Financial, Inc. (“People’s United”).
The People’s United transaction has been accounted for using the acquisition method of accounting and, accordingly, assets acquired, liabilities assumed and preferred stock converted were recorded at estimated fair value on the acquisition date.
As disclosed by management, the fair value of loans acquired from People’s United totaled $35.8 billion as of April 1, 2022, of which $13.5 billion were commercial real estate loans.
The fair values of loans were generally based on a discounted cash flow methodology that considered market interest rates, expected credit losses, prepayment assumptions and other market factors for loans with similar characteristics including loan type, collateral, fixed or variable interest rate and credit risk characteristics.
Addressing the matter involved performing procedures and evaluating audit evidence in connection with forming our overall opinion on the consolidated financial statements.
These procedures included testing the effectiveness of controls relating to management’s fair value of the acquired commercial real estate loans.
These procedures also included, among others, testing the completeness and accuracy of the underlying acquired commercial real estate loan data provided by management that was used to develop the fair value of acquired commercial real estate loans, and the involvement of professionals with specialized skill and knowledge to assist in evaluating the reasonableness of management’s estimate by developing independent ranges of fair value for the acquired commercial real estate loans using independently developed market interest rates, expected credit losses, and prepayment assumptions and comparing the independent ranges to management’s estimate.
The principal considerations for our determination that performing procedures relating to the allowance for credit losses, specifically certain adjustments to model forecasts, is a critical audit matter are (i) the significant judgment by management in determining the adjustments to model forecasts, (ii) a high
degree of auditor judgment, subjectivity and effort in performing procedures and in evaluating audit evidence related to management’s determination of these adjustments to model forecasts, and (iii) the audit effort involved the use of professionals with specialized skill and knowledge.
| | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Trading account | | | 117,847 | | | | 49,745 | |
| Available for sale (cost: $11,193,152 at December 31, 2022; $3,849,347 at December 31, 2021) | | | 10,748,961 | | | | 3,955,804 | |
| Held to maturity (fair value: $12,375,420 at December 31, 2022; $2,771,290 at December 31, 2021) | | | 13,529,969 | | | | 2,734,674 | |
| Equity and other securities (cost: $933,766 at December 31, 2022; $461,516 at December 31, 2021) | | | 931,941 | | | | 465,382 | |
| Total investment securities | | | 25,210,871 | | | | 7,155,860 | |
| Unearned discount | | | (509,993 | ) | | | (224,226 | ) |
| Premises and equipment | | | 1,653,628 | | | | 1,144,765 | |
| Goodwill | | | 8,490,089 | | | | 4,593,112 | |
| Total assets | | $ | 200,729,841 | | | $ | 155,107,160 | |
| Noninterest-bearing deposits | | $ | 65,501,860 | | | $ | 60,131,480 | |
| Time deposits | | | 10,101,545 | | | | 2,807,963 | |
| Total deposits | | | 163,514,868 | | | | 131,543,409 | |
| Long-term borrowings | | | 3,964,537 | | | | 3,485,369 | |
| Total liabilities | | | 175,411,851 | | | | 137,203,755 | |
| Retained earnings | | | 15,753,978 | | | | 14,646,448 | |
| Total shareholders’ equity | | | 25,317,990 | | | | 17,903,405 | |
An excerpt. Shown here: 40 of 961 rewritten, 40 of 711 added and 40 of 707 removed. The counts are complete. For every sentence, read Item 8. Financial Statements and Supplementary Data. in the FY2023 filing and the FY2022 filing.
Item 9A. Controls and Procedures.
3 rewritten, 0 added, 3 removed, 8 unchanged
Jones, Chairman of the Board and Chief Executive Officer, and [removed: Darren J.][added: Daryl N.]
[removed: King,] [added: Bible,] Senior Executive Vice President and Chief Financial Officer, concluded that M&T’s disclosure controls and procedures were effective as of December 31, [removed: 2022.][added: 2023.]
No changes in internal control over financial reporting have been identified in connection with the evaluation of disclosure controls and procedures during the quarter ended December 31, [removed: 2022] [added: 2023] that have materially affected, or are reasonably likely to materially affect, M&T’s internal control over financial reporting.
Management has excluded processes and controls of People’s United that have not yet been converted to M&T's systems or processes from its assessment of internal control over financial reporting for the year ended December 31, 2022.
Assets and liabilities associated with those processes and procedures as of December 31, 2022 include loans and leases of $5.8 billion, other assets of $107 million and other liabilities of $184 million.
Approximately $280 million of total revenues for the nine months ended December 31, 2022 was contributed from business activities of People's United that have not yet been converted to M&T's systems or processes.
Item 9B. Other Information.
0 rewritten, 5 added, 1 removed, 0 unchanged
(a) Effective February 21, 2024, M&T’s Board of Directors approved and adopted M&T’s Amended and Restated Bylaws.
The Amended and Restated Bylaws were adopted to: (i) clarify that stockholder meetings may take place by means of remote communications, in light of updates to the New York Business Corporation Law; (ii) update M&T’s bylaws in connection with the SEC rules relating to universal proxy cards, including requiring stockholders providing notice pursuant to Rule 14a-19(b) under the Exchange Act to certify to M&T that they have complied with certain requirements under such rules no later than seven business days prior to the applicable stockholder meeting; (iii) specify that, in connection with a stockholder nomination, proposed nominees and the proposing stockholders, as applicable, must complete a questionnaire and certain representations and agreements in the form provided by M&T; (iv) require any stockholder directly or indirectly soliciting proxies from other stockholders to use a proxy card color other than white; (v) clarify the power of M&T’s Board of Directors and the person presiding at each applicable stockholder meeting to establish rules for the conduct of such meetings, including to determine and address deficient nominations or proposals; and (vi) make certain other clarifications and administrative, technical or conforming revisions.
The foregoing description of the Amended and Restated Bylaws does not purport to be complete and is qualified in its entirety by reference to the full text of the Amended and Restated Bylaws, which is filed as Exhibit 3.2 to this Annual Report and incorporated by reference herein.
(b) Certain of our officers or directors have made elections to participate in, and are participating in, our tax-qualified 401(k) plan and nonqualified deferred compensation plans, or have made, and may from time to time make, elections to reinvest dividends in M&T Bank Corporation common stock, or have shares withheld to cover withholding taxes upon the vesting of equity awards or to pay the exercise price of options, each of which may be designed to satisfy the affirmative defense conditions
of Rule 10b5-1 under the Exchange Act or may constitute non-Rule 10b5-1 trading arrangements (as defined in Item 408(c) of Regulation S-K).
None.
Item 10. Directors, Executive Officers and Corporate Governance.
5 rewritten, 0 added, 1 removed, 0 unchanged
The information required to be furnished pursuant to Items 401, 405, 406 and 407(c)(3), (d)(4) and (d)(5) of Regulation S-K will be included in M&T’s Proxy Statement for the [removed: 2023] [added: 2024] Annual Meeting of Shareholders, which will be filed with the SEC pursuant to Regulation 14A not later than 120 days after the end of [removed: 2022] [added: 2023] (the [removed: “2023] [added: “2024] Proxy Statement”).
The information concerning M&T’s directors will appear [removed: under] [added: in] the [removed: caption] [added: section] “NOMINEES FOR DIRECTOR” in the [removed: 2023] [added: 2024] Proxy Statement.
The information concerning M&T’s Code of Ethics for [removed: CEO] [added: Chief Executive Officer] and Senior Financial Officers will appear [removed: under] [added: in] the [removed: caption] [added: section] “CORPORATE GOVERNANCE OF M&T BANK CORPORATION” in the [removed: 2023][added: 2024 Proxy Statement.]
The information regarding the procedures by which shareholders can recommend director nominees as well as M&T’s Audit Committee, including “audit committee financial experts,” will also appear [removed: under] [added: in] the [removed: caption] [added: section] “CORPORATE GOVERNANCE OF M&T BANK CORPORATION.” The information concerning compliance with Section 16(a) of the Exchange Act will appear, if necessary, [removed: under] [added: in] the [removed: caption] [added: section] “STOCK OWNERSHIP INFORMATION.” Such information is incorporated herein by reference.
The information concerning M&T’s executive officers is [removed: presented under the caption] [added: provided in] “Executive Officers of the Registrant” [removed: contained] in Part I of this [removed: Annual Report on] Form 10-K.
Proxy Statement.
Item 11. Executive Compensation.
1 rewritten, 0 added, 0 removed, 1 unchanged
The information required to be furnished pursuant to Items 402 and 407(e)(4) and (e)(5) of Regulation S-K will appear [removed: under] [added: in] the [removed: captions] [added: sections] “COMPENSATION DISCUSSION AND ANALYSIS,” “EXECUTIVE COMPENSATION,” “DIRECTOR COMPENSATION,” “COMPENSATION AND HUMAN CAPITAL COMMITTEE INTERLOCKS AND INSIDER PARTICIPATION,” and “COMPENSATION AND HUMAN CAPITAL COMMITTEE REPORT” in the [removed: 2023] [added: 2024] Proxy Statement.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
2 rewritten, 0 added, 0 removed, 1 unchanged
The information required to be furnished pursuant to Item 403 of Regulation S-K will appear [removed: under] [added: in] the [removed: caption] [added: section] “STOCK OWNERSHIP INFORMATION” in the [removed: 2023] [added: 2024] Proxy Statement.
The information required to be furnished pursuant to Item 201(d) concerning equity compensation plans is [removed: presented under the caption] [added: provided in] “Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities” [removed: contained] in Part II, Item 5 of this [removed: Annual Report on] Form 10-K.
Item 13. Certain Relationships and Related Transactions, and Director Independence.
1 rewritten, 0 added, 0 removed, 1 unchanged
The information required to be furnished pursuant to Items 404 and 407(a) of Regulation S-K will appear [removed: under] [added: in] the [removed: caption] [added: sections] “TRANSACTIONS WITH [removed: DIRECTORS AND] [added: DIRECTORS,] EXECUTIVE [removed: OFFICERS”] [added: OFFICERS AND CERTAIN SHAREHOLDERS”] and “CORPORATE GOVERNANCE OF M&T BANK CORPORATION” in the [removed: 2023] [added: 2024] Proxy Statement.
Item 14. Principal Accountant Fees and Services.
1 rewritten, 0 added, 0 removed, 2 unchanged
The information required to be furnished by Item 9(e) of Schedule 14A will appear [removed: under] [added: in] the [removed: caption] [added: section] “PROPOSAL TO RATIFY THE APPOINTMENT OF PRICEWATERHOUSECOOPERS LLP AS THE INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM OF M&T BANK CORPORATION FOR THE YEAR ENDING DECEMBER 31, [removed: 2023”] [added: 2024”] in the [removed: 2023] [added: 2024] Proxy Statement.
Item 15. Exhibits and Financial Statement Schedules.
22 rewritten, 5 added, 9 removed, 25 unchanged
[added: See Part II, Item 8,] “Financial Statements and Supplementary Data.” Financial statement schedules are not required or are inapplicable, and therefore have been omitted.
| [removed: 2.1] [added: 10.18] | | [removed: [Agreement] [added: [Non-Competition] and [removed: Plan of Merger] [added: Non-Solicitation Agreement,] dated as of February 21, 2021, by and between [removed: M&T Bank Corporation, Bridge Merger Corp.] [added: John P. Barnes] and People’s United Financial, Inc. Incorporated by reference to Exhibit [removed: 2.1] [added: 10.1] of [removed: M&T Bank Corporation’s] [added: the Current Report on] Form 8-K [removed: dated February 25, 2021] [added: of M&T Bank Corporation filed on April 4, 2022.] (File No. [removed: 1-9861).](https://www.sec.gov/Archives/edgar/data/1378946/000119312521057178/d109088dex21.htm)] [added: 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000119312522094296/d349120dex101.htm)] |
| [removed: 2.2] [added: 10.19] | | [removed: [Amendment No. 1 to the Agreement] [added: [Non-Competition] and [removed: Plan of Merger,] [added: Non-Solicitation Agreement,] dated [added: as of] February 21, 2021, by and [removed: among M&T Bank Corporation, Bridge Merger Corp., a direct, wholly owned subsidiary of M&T Bank Corporation,] [added: between Kirk W. Walters] and People’s United Financial, Inc. Incorporated by reference to Exhibit [removed: 2.1] [added: 10.2] of the Current Report on Form 8-K of M&T Bank Corporation filed on [removed: February 25, 2021.] [added: April 4, 2022.] (File No. [removed: 1-9861).](https://www.sec.gov/Archives/edgar/data/1378946/000119312521057178/d109088dex21.htm)] [added: 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000119312522094296/d349120dex102.htm)] |
| [removed: 3.2] [added: 10.21] | | [removed: [Amended and Restated Bylaws of M&T] [added: [M&T] Bank [removed: Corporation,] [added: Corporation 2019 Equity Incentive Compensation Plan, as amended and restated] effective [removed: November 15, 2022.] [added: as of April 18, 2023.] Incorporated by reference to [removed: Exhibit 3.2 to] [added: Appendix B of] the [removed: Form 8-K] [added: Proxy Statement of M&T Bank Corporation] dated [removed: November 18, 2022] [added: March 7, 2023] (File No. [removed: 1-9861).](https://www.sec.gov/Archives/edgar/data/36270/000119312518124876/d575854dex32.htm)] [added: 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000119312523062138/d437251ddef14a.htm)] |
| 4.2 | | [Description of Registrant’s Securities. Filed [removed: herewith.](https://www.sec.gov/Archives/edgar/data/36270/000095017023003804/mtb-ex4_2.htm)] [added: herewith.](https://www.sec.gov/Archives/edgar/data/36270/000095017024017990/mtb-ex4_2.htm)] |
| 10.6 | | [Amendment No. 1 to M&T Bank Corporation Supplemental Retirement [added: Savings] Plan. Incorporated by reference to Exhibit 10.7 of M&T Bank Corporation’s Form 10-K for the year ended December 31, 2018 (File No. 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000156459019003467/mtb-ex107_440.htm) |
| 10.7 | | [Amendment No. 2 to M&T Bank Corporation Supplemental Retirement [added: Savings] Plan. Incorporated by reference to Exhibit 10.8 of M&T Bank Corporation’s Form 10-K for the year ended December 31, 2018 (File No. 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000156459019003467/mtb-ex108_439.htm) |
| 10.10 | | [M&T Bank Corporation Form of Performance Share Unit Award Agreement. Incorporated by reference to Exhibit 10.1 to M&T Bank Corporation’s Form 10-Q for the quarter ended March 31, [removed: 2019] [added: 2020] (File No. [removed: 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000156459019015404/mtb-ex101_267.htm)] [added: 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000156459020022168/mtb-ex101_136.htm)] |
| 10.11 | | [removed: [M&T] [added: [Amendment No. 3 to M&T] Bank Corporation [removed: Form of Performance Share Unit Award Agreement.] [added: Supplemental Pension Plan.] Incorporated by reference to Exhibit [removed: 10.1] [added: 10.2] to M&T Bank Corporation’s Form 10-Q for the quarter ended March 31, 2020 (File No. [removed: 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000156459020022168/mtb-ex101_136.htm)] [added: 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000156459020022168/mtb-ex102_138.htm)] |
| 10.12 | | [removed: [Amendment No. 3 to M&T] [added: [M&T] Bank Corporation [added: Leadership Retirement Savings Plan (f/k/a] Supplemental [removed: Pension Plan.] [added: Savings Retirement Plan), amended and restated effective as of January 1, 2020.] Incorporated by reference to Exhibit [removed: 10.2] [added: 10.3] to M&T Bank Corporation’s Form 10-Q for the quarter ended March 31, 2020 (File No. [removed: 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000156459020022168/mtb-ex102_138.htm)] [added: 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000156459020022168/mtb-ex103_137.htm)] |
| [removed: 10.13] [added: 10.14] | | [M&T Bank Corporation [removed: Leadership Retirement Savings Plan.] [added: Form of Stock Option Agreement.] Incorporated by reference to Exhibit [removed: 10.3] [added: 10.25] to M&T Bank Corporation’s Form [removed: 10-Q] [added: 10-K] for the [removed: quarter] [added: year] ended [removed: March] [added: December] 31, 2020 (File No. [removed: 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000156459020022168/mtb-ex103_137.htm)] [added: 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000156459021007188/mtb-ex1025_534.htm)] |
| [removed: 10.14] [added: 10.13] | | [M&T Bank Corporation Form of Performance-Hurdled Restricted Stock Unit Award Agreement. Incorporated by reference to Exhibit 10.24 to M&T Bank Corporation’s Form 10-K for the year ended December 31, 2020 (File No. 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000156459021007188/mtb-ex1024_535.htm) |
| [removed: 10.15] [added: 10.20] | | [M&T Bank Corporation Form of [removed: Stock Option] [added: Performance Share Unit Award] Agreement. Incorporated by reference to Exhibit [removed: 10.25] [added: 10.21] to M&T Bank Corporation’s Form 10-K for the year ended December 31, [removed: 2020] [added: 2022] (File No. [removed: 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000156459021007188/mtb-ex1025_534.htm)] [added: 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000095017023003804/mtb-ex10_21.htm)] |
| [removed: 10.16] [added: 10.15] | | [M&T Bank Corporation Form of Directors’ Restricted Stock Unit Award [removed: Agreement.] [added: Agreement (one-year vesting).] Incorporated by reference to Exhibit [removed: 10.1] [added: 10.17] to M&T Bank Corporation’s Form [removed: 10-Q] [added: 10-K] for the [removed: quarter] [added: year] ended [removed: June 30, 2021] [added: December 31, 2022] (File No. [removed: 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000156459021041556/mtb-ex101_159.htm)] [added: 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000095017023003804/mtb-ex10_17.htm)] |
| [removed: 10.17] [added: 10.23] | | [M&T Bank Corporation Form of [removed: Directors’ Restricted Stock] [added: Performance Share] Unit Award [removed: Agreement (one-year vesting).] [added: Agreement.] Filed [removed: herewith.*](https://www.sec.gov/Archives/edgar/data/36270/000095017023003804/mtb-ex10_17.htm)] [added: herewith.*](https://www.sec.gov/Archives/edgar/data/36270/000095017024017990/mtb-ex10_23.htm)] |
| [removed: 10.18] [added: 10.16] | | [M&T Bank Corporation Voluntary Deferred Compensation Plan for Directors. Incorporated by reference to Exhibit 10.28 to M&T Bank Corporation’s Form 10-K for the year ended December 31, 2021. (File No. 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000156459022005400/mtb-ex1028_927.htm) |
| 23.1 | | [Consent of PricewaterhouseCoopers LLP re: Registration Statements on Form S-3 (No. [removed: 333-259888)] [added: 333-274646)] and Form S-8 (Nos.33-32044, 333-43175, 333-16077, 333-40640, 333-84384, 333-127406, 333-150122, 333-164015, 333-163992, 333-160769, 333-159795, 333-170740, 333-189099, 333-184504, 333-189097, 333-184411, 333-231217, 333-254786, 333-264099, [removed: 333-254962] [added: 333-254962, 333-264392] and [removed: 333-264392).] [added: 333-271322).] Filed [removed: herewith.](https://www.sec.gov/Archives/edgar/data/36270/000095017023003804/mtb-ex23_1.htm)] [added: herewith.](https://www.sec.gov/Archives/edgar/data/36270/000095017024017990/mtb-ex23_1.htm)] |
| 31.1 | | [Certification of Chief Executive Officer under Section 302 of the Sarbanes-Oxley Act of 2002. Filed [removed: herewith.](https://www.sec.gov/Archives/edgar/data/36270/000095017023003804/mtb-ex31_1.htm)] [added: herewith.](https://www.sec.gov/Archives/edgar/data/36270/000095017024017990/mtb-ex31_1.htm)] |
| 31.2 | | [Certification of Chief Financial Officer under Section 302 of the Sarbanes-Oxley Act of 2002. Filed [removed: herewith.](https://www.sec.gov/Archives/edgar/data/36270/000095017023003804/mtb-ex31_2.htm)] [added: herewith.](https://www.sec.gov/Archives/edgar/data/36270/000095017024017990/mtb-ex31_2.htm)] |
| 32.1 | | [Certification of Chief Executive Officer under 18 U.S.C. §1350 pursuant to Section 906 of the Sarbanes-Oxley Act of 2002. Filed [removed: herewith.](https://www.sec.gov/Archives/edgar/data/36270/000095017023003804/mtb-ex32_1.htm)] [added: herewith.](https://www.sec.gov/Archives/edgar/data/36270/000095017024017990/mtb-ex32_1.htm)] |
| 32.2 | | [Certification of Chief Financial Officer under 18 U.S.C. §1350 pursuant to Section 906 of the Sarbanes-Oxley Act of 2002. Filed [removed: herewith.](https://www.sec.gov/Archives/edgar/data/36270/000095017023003804/mtb-ex32_2.htm)] [added: herewith.](https://www.sec.gov/Archives/edgar/data/36270/000095017024017990/mtb-ex32_2.htm)] |
| 104 | | The cover page from M&T Bank Corporation’s Annual Report on Form 10-K for the year ended December 31, [removed: 2022] [added: 2023] has been formatted in Inline XBRL. |
| 3.2 | | [Amended and Restated Bylaws of M&T Bank Corporation, effective February 21, 2024. Filed herewith.](https://www.sec.gov/Archives/edgar/data/36270/000095017024017990/mtb-ex3_2.htm) |
| 10.17 | | [M&T Bank Corporation Employee Severance Pay Plan, restated June 1, 2021 (with amended Appendix A effective March 28, 2022). Filed herewith.*](https://www.sec.gov/Archives/edgar/data/36270/000095017024017990/mtb-ex10_17.htm) |
| 10.22 | | [First Amendment, effective November 30, 2023, to the M&T Bank Corporation Leadership Retirement Savings Plan, as amended and restated effective as of January 1, 2020. Filed herewith.*](https://www.sec.gov/Archives/edgar/data/36270/000095017024017990/mtb-ex10_22.htm) |
| 97.1 | | [M&T Bank Corporation Executive Compensation Recoupment Policy. Filed herewith.](https://www.sec.gov/Archives/edgar/data/36270/000095017024017990/mtb-ex97_1.htm) |
| 101.SCH | | Inline XBRL Taxonomy Extension Schema with embedded Linkbase documents. |
See Part II, Item 8.
| 10.19 | | [Non-Competition and Non-Solicitation Agreement, dated as of February 21, 2021, by and between John P. Barnes and People’s United Financial, Inc. Incorporated by reference to Exhibit 10.1 of the Current Report on Form 8-K of M&T Bank Corporation filed on April 4, 2022. (File No. 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000119312522094296/d349120dex101.htm) |
| 10.20 | | [Non-Competition and Non-Solicitation Agreement, dated as of February 21, 2021, by and between Kirk W. Walters and People’s United Financial, Inc. Incorporated by reference to Exhibit 10.2 of the Current Report on Form 8-K of M&T Bank Corporation filed on April 4, 2022. (File No. 1-9861).*](https://www.sec.gov/Archives/edgar/data/36270/000119312522094296/d349120dex102.htm) |
| 10.21 | | [M&T Bank Corporation Form of Performance Share Unit Award Agreement. Filed herewith.*](https://www.sec.gov/Archives/edgar/data/36270/000095017023003804/mtb-ex10_21.htm) |
| 101.SCH | | Inline XBRL Taxonomy Extension Schema. Filed herewith. |
| 101.CAL | | Inline XBRL Taxonomy Extension Calculation Linkbase. Filed herewith. |
| 101.LAB | | Inline XBRL Taxonomy Extension Label Linkbase. Filed herewith. |
| 101.PRE | | Inline XBRL Taxonomy Extension Presentation Linkbase. Filed herewith. |
| 101.DEF | | Inline XBRL Taxonomy Definition Linkbase. Filed herewith. |
Item 16. Form 10-K Summary.
20 rewritten, 2 added, 3 removed, 51 unchanged
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized, on the [removed: 22nd] [added: 21st] day of February, [removed: 2023.][added: 2024.]
| /s/ René F. Jones | | Chairman of the Board and | | February [removed: 22, 2023] [added: 21, 2024] |
| /s/ [removed: Darren J. King] [added: Daryl N. Bible] | | Senior Executive Vice President and | | February [removed: 22, 2023] [added: 21, 2024] |
| [removed: Darren J. King] [added: Daryl N. Bible] | | Chief Financial Officer | | |
| /s/ [removed: Michael] [added: John] R. [removed: Spychala] [added: Taylor] | | Executive Vice President | | February [removed: 22, 2023] [added: 21, 2024] |
| /s/ John P. Barnes | | February [removed: 22, 2023] [added: 21, 2024] |
| [removed: /s/] Robert T. Brady [removed: Robert T. Brady] | | February [removed: 22, 2023] [added: 21, 2024] |
| /s/ Carlton J. Charles Carlton J. Charles | | February [removed: 22, 2023] [added: 21, 2024] |
| /s/ William F. Cruger, Jr. | | February [removed: 22, 2023] [added: 21, 2024] |
| /s/ T. Jefferson Cunningham III | | February [removed: 22, 2023] [added: 21, 2024] |
| /s/ Gary N. Geisel | | February [removed: 22, 2023] [added: 21, 2024] |
| /s/ Leslie V. Godridge | | February [removed: 22, 2023] [added: 21, 2024] |
| [added: /s/] Richard H. Ledgett, Jr. [added: Richard H. Ledgett, Jr.] | | February [removed: 22, 2023] [added: 21, 2024] |
| /s/ Melinda R. Rich Melinda R. Rich | | February [removed: 22, 2023] [added: 21, 2024] |
| /s/ Robert E. Sadler, Jr. Robert E. Sadler, Jr. | | February [removed: 22, 2023] [added: 21, 2024] |
| /s/ Denis J. Salamone Denis J. Salamone | | February [removed: 22, 2023] [added: 21, 2024] |
| /s/ John R. Scannell John R. Scannell | | February [removed: 22, 2023] [added: 21, 2024] |
| /s/ Rudina Seseri Rudina Seseri | | February [removed: 22, 2023] [added: 21, 2024] |
| /s/ Kirk W. Walters Kirk W. Walters | | February [removed: 22, 2023] [added: 21, 2024] |
| /s/ Herbert L. Washington Herbert L. Washington | | February [removed: 22, 2023] [added: 21, 2024] |
| John R. Taylor | | and Controller | | |
| | | February 21, 2024 |
| | | |
| Michael R. Spychala | | and Controller | | |
| /s/ Jane Chwick | | February 22, 2023 |