 filings.tools
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
122K characters. Original on sec.gov · Markdown
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
The following discussion and analysis of the financial condition and results of operations of Nasdaq should be read in conjunction with our consolidated financial statements and related notes included in this Form 10-K, as well as the discussion under “Item 1A. Risk Factors.” For further discussion of our business, including our growth strategy, see “Item 1. Business.”
Overview
Our Company
We are a leading provider of trading, clearing, marketplace technology, regulatory, securities listing, information and public and private company services. Our global offerings are diverse and include trading and clearing across multiple asset classes, trade management services, market data products, financial indexes, investment data and analytics, capital formation solutions, corporate solutions, and market technology products and services. Our technology powers markets across the globe, supporting equity derivative trading, clearing and settlement, cash equity trading, fixed income trading, trading surveillance and many other functions.
Strategic Direction
Under the strategic direction that we have been implementing over the past two years, we have focused on maximizing the resources, people and capital allocated to our largest growth opportunities, particularly in our Market Technology and Information Services businesses. Our investments include our organic initiatives, notably the Nasdaq Financial Framework and related initiatives to deliver our marketplace expertise to banks, brokers and market operators outside the financial industry, as well as to provide compliance capabilities to the buy-side, and our eVestment private markets solutions. It also includes the recent acquisitions of Cinnober and Quandl.
The other pillar of our strategic direction is our continued investment and commitment to sustain our marketplace core. These foundational businesses, comprising the Market Services and Corporate Services segments, have earned Nasdaq a strategic position at the center of the capital markets in the U.S. and Europe. We have been able to create strategic relationships across broker-dealers, investment professionals, corporate clients, and other global market centers, which then provides the potential to expand those relationships with our technology and analytics capabilities.
The focus for both our non-trading (which includes Market Technology, Information Services, Corporate Services and Trade Management Services) and trading (which includes all of Market Services except Trade Management Services) businesses continues to include identifying organic growth and developing adjacent opportunities to our existing businesses. In addition, our strategy includes identifying acquisitions that both complement our strengths and extend our capabilities, as well as offer opportunities for revenue and expense synergies and increased shareholder value.
Factors Affecting Our Business
In broad terms, our business performance is impacted by a number of drivers including macroeconomic events affecting the risk and return of financial assets, investor sentiment, government and private sector demands for capital, the regulatory environment for capital markets, changes in technology, and changes in investment patterns and priorities. Our future revenues and net income will continue to be influenced by a number of domestic and international economic trends including, among others:
| • | the challenges created by the automation of market data consumption, including competition and the quickly evolving nature of the market data business; |
| • | regulatory changes relating to market structure, including market data, or affecting certain types of instruments, transactions, pricing structures or capital market participants; |
| • | the demand for information about, or access to, our markets, which is dependent on the products we trade, our importance as a liquidity center, and the quality and pricing of our market data and trade management services; |
| • | the demand for ETPs licensed to Nasdaq's indexes, enhanced analytics and other financial products based on our indexes as well as changes to the underlying assets associated with existing licensed financial products; |
| • | the outlook of our technology customers for capital market activity; |
| • | technological advances and members’ and customers’ demand for speed, efficiency, and reliability; |
| • | the acceptance of cloud-based services and advanced analytics by our customers and global regulators; |
| • | trading volumes and values in equity derivatives, cash equities and FICC, which are driven primarily by overall macroeconomic conditions; |
| • | the number of companies seeking equity financing, which is affected by factors such as investor demand, the global economy, and availability of diverse sources of financing, as well as tax and regulatory policies; |
| • | the demand by companies and other organizations for the products sold by our Corporate Solutions business, which is largely driven by the overall state of the economy and the attractiveness of our offerings; |
| • | continuing pressure in transaction fee pricing due to intense competition in the U.S. and Europe; and |
| • | competition related to pricing, product features and service offerings. |
The following chart presents the current consensus forecast for gross domestic product growth:
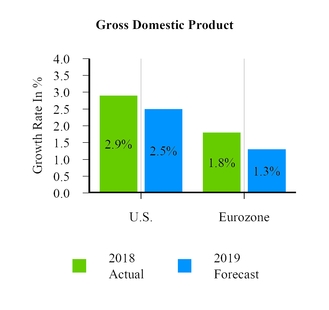
Although employment and wage data in many regions seems robust, indicating that the underlying global economy is still quite strong, leading indicators in many regions are pointing to a slowdown. Global gross domestic product growth forecasts have recently started to slow. In the last quarter of 2018, consensus 2019 growth forecasts have declined 0.1 percentage points to 2.5% for the U.S. and 0.5 percentage points to 1.3% for the Eurozone. There are a number of significant structural and political issues continuing to impact the global economy. Uncertainty surrounding the impact of China's economy, trade tariffs and Brexit contributed to an increase in market volatility in the last quarter of 2018 and continue to pose a risk to global growth.
Additional impacts on our business drivers include the international enactment and implementation of legislative and regulatory initiatives (notably MiFID II in Europe), the evolution of market participants’ trading and investment strategies, and the continued rapid progression and deployment of new technology in the financial services industry.
The business environment that we expect may influence our financial performance in 2019 may be characterized as follows:
| • | rapidly evolving technology for our businesses and their clients; |
| • | increased demand for applications using emerging technologies and sophisticated analytics by both new entrants and industry incumbents; |
| • | the expansion of the number of industries, and emergence of new industries, seeking to use advanced market technology; |
| • | intense competition among U.S. exchanges and dealer-owned systems for cash equity trading and strong competition between MTFs and exchanges in Europe for cash equity trading; and |
| • | globalization of exchanges, customers and competitors extending the competitive horizon beyond national markets. |
Business Segments
We manage, operate and provide our products and services in four business segments: Market Services, Corporate Services, Information Services and Market Technology. See Note 1, “Organization and Nature of Operations,” and Note 20, “Business Segments,” to the consolidated financial statements for further discussion of our reportable segments and geographic data, as well as how management allocates resources, assesses performance and manages these businesses as four separate segments.
Sources of Revenues and Transaction-Based Expenses
See “Revenue Recognition and Transaction-Based Expenses,” of Note 2, “Summary of Significant Accounting Policies,” to the consolidated financial statements for further discussion of our sources of revenues and transaction-based expenses.
Nasdaq’s Operating Results
Key Drivers
The following table includes key drivers for our Market Services, Corporate Services, Information Services and Market Technology segments. In evaluating the performance of our business, our senior management closely evaluates these key drivers.
| Year Ended December 31, | ||||||||||||
| 2018 | 2017 | 2016 | ||||||||||
| Market Services | ||||||||||||
| Equity Derivative Trading and Clearing | ||||||||||||
| U.S. equity options | ||||||||||||
| Total industry average daily volume (in millions) | 18.2 | 14.7 | 14.4 | |||||||||
| Nasdaq PHLX matched market share | 15.7 | % | 17.3 | % | 16.0 | % | ||||||
| The Nasdaq Options Market matched market share | 9.4 | % | 9.2 | % | 7.8 | % | ||||||
| Nasdaq BX Options matched market share | 0.4 | % | 0.7 | % | 0.8 | % | ||||||
| Nasdaq ISE Options matched market share | 8.8 | % | 9.1 | % | 5.8 | % | ||||||
| Nasdaq GEMX Options matched market share | 4.5 | % | 5.2 | % | 1.1 | % | ||||||
| Nasdaq MRX Options matched market share | 0.1 | % | 0.1 | % | 0.1 | % | ||||||
| Total matched market share executed on Nasdaq’s exchanges | 38.9 | % | 41.6 | % | 31.6 | % | ||||||
| Nasdaq Nordic and Nasdaq Baltic options and futures | ||||||||||||
| Total average daily volume of options and futures contracts(1) | 339,139 | 330,218 | 376,730 | |||||||||
| Cash Equity Trading | ||||||||||||
| Total U.S.-listed securities | ||||||||||||
| Total industry average daily share volume (in billions) | 7.32 | 6.53 | 7.35 | |||||||||
| Matched share volume (in billions) | 358.5 | 295.9 | 321.6 | |||||||||
| The Nasdaq Stock Market matched market share | 15.9 | % | 14.2 | % | 14.0 | % | ||||||
| Nasdaq BX matched market share | 2.8 | % | 3.1 | % | 2.4 | % | ||||||
| Nasdaq PSX matched market share | 0.8 | % | 0.8 | % | 1.0 | % | ||||||
| Total matched market share executed on Nasdaq’s exchanges | 19.5 | % | 18.1 | % | 17.4 | % | ||||||
| Market share reported to the FINRA/Nasdaq Trade Reporting Facility | 31.3 | % | 34.5 | % | 33.1 | % | ||||||
| Total market share(2) | 50.8 | % | 52.6 | % | 50.5 | % | ||||||
| Nasdaq Nordic and Nasdaq Baltic securities | ||||||||||||
| Average daily number of equity trades executed on Nasdaq’s exchanges | 618,579 | 552,104 | 472,428 | |||||||||
| Total average daily value of shares traded (in billions) | $ | 5.6 | $ | 5.3 | $ | 5.1 | ||||||
| Total market share executed on Nasdaq’s exchanges | 67.0 | % | 67.5 | % | 62.5 | % | ||||||
| FICC | ||||||||||||
| Fixed Income | ||||||||||||
| U.S. fixed income notional trading volume (in billions) | $ | 15,983 | $ | 17,800 | $ | 21,504 | ||||||
| Total average daily volume of Nasdaq Nordic and Nasdaq Baltic fixed income contracts | 132,475 | 116,357 | 89,252 | |||||||||
| Commodities | ||||||||||||
| Power contracts cleared (TWh)(3) | 1,067 | 1,199 | 1,658 | |||||||||
| Corporate Services | ||||||||||||
| Initial public offerings | ||||||||||||
| The Nasdaq Stock Market | 186 | 136 | 91 | |||||||||
| Exchanges that comprise Nasdaq Nordic and Nasdaq Baltic | 53 | 88 | 62 | |||||||||
| Total new listings | ||||||||||||
| The Nasdaq Stock Market(4) | 303 | 268 | 283 | |||||||||
| Exchanges that comprise Nasdaq Nordic and Nasdaq Baltic(5) | 73 | 108 | 88 | |||||||||
| Number of listed companies | ||||||||||||
| The Nasdaq Stock Market(6) | 3,058 | 2,949 | 2,897 | |||||||||
| Exchanges that comprise Nasdaq Nordic and Nasdaq Baltic(7) | 1,019 | 984 | 900 | |||||||||
| Information Services | ||||||||||||
| Number of licensed ETPs | 365 | 324 | 298 | |||||||||
| ETP assets under management tracking Nasdaq indexes (in billions) | $ | 172 | $ | 167 | $ | 124 | ||||||
| Market Technology | ||||||||||||
| Order intake (in millions)(8) | $ | 223 | $ | 249 | $ | 235 | ||||||
| Total order value (in millions)(9) | $ | 695 | $ | 717 | $ | 691 |
| (1) | Includes Finnish option contracts traded on Eurex. |
| (2) | Includes transactions executed on The Nasdaq Stock Market’s, Nasdaq BX’s and Nasdaq PSX’s systems plus trades reported through the FINRA/Nasdaq Trade Reporting Facility. |
| (3) | Transactions executed on Nasdaq Commodities or OTC and reported for clearing to Nasdaq Commodities measured by Terawatt hours (TWh). |
| (4) | New listings include IPOs, including those completed on a best efforts basis, issuers that switched from other listing venues, closed-end funds and separately listed ETPs. |
| (5) | New listings include IPOs and represent companies listed on the Nasdaq Nordic and Nasdaq Baltic exchanges and companies on the alternative markets of Nasdaq First North. |
| (6) | Number of total listings on The Nasdaq Stock Market at period end, including 392 ETPs as of December 31, 2018, 373 as of December 31, 2017 and 328 as of December 31, 2016. |
| (7) | Represents companies listed on the Nasdaq Nordic and Nasdaq Baltic exchanges and companies on the alternative markets of Nasdaq First North at period end. |
| (8) | Total contract value of orders signed during the period. |
| (9) | Represents total contract value of signed orders that are yet to be recognized as revenue. Market technology deferred revenue, as discussed in Note 8, “Deferred Revenue,” to the consolidated financial statements, represents consideration received that is yet to be recognized as revenue for these signed orders. Total order value for the years ended December 31, 2017 and 2016 was restated as a result of the adoption of Topic 606. |
Financial Summary
The following table summarizes our financial performance for the year ended December 31, 2018 when compared with the same period in 2017 and for the year ended December 31, 2017 when compared with the same period in 2016. The comparability of our results of operations between reported periods is impacted by the divestiture of the Public Relations Solutions and Digital Media Services businesses in April 2018 and the acquisition of eVestment in October 2017. See Note 3, “Acquisitions and Divestiture,” to the consolidated financial statements for further discussion of these transactions. For a detailed discussion of our results of operations, see “Segment Operating Results” below. In addition, on January 1, 2018, we adopted Topic 606 using the full retrospective method which required restatement of 2017 and 2016 financial statements.
| Year Ended December 31, | Percentage Change | |||||||||||||||||
| 2018 | 2017 | 2016 | 2018 vs. 2017 | 2017 vs. 2016 | ||||||||||||||
| (in millions, except per share amounts) | ||||||||||||||||||
| Revenues less transaction-based expenses | $ | 2,526 | $ | 2,411 | $ | 2,276 | 4.8 | % | 5.9 | % | ||||||||
| Operating expenses | 1,498 | 1,420 | 1,440 | 5.5 | % | (1.4 | )% | |||||||||||
| Operating income | 1,028 | 991 | 836 | 3.7 | % | 18.5 | % | |||||||||||
| Interest expense | (150 | ) | (143 | ) | (135 | ) | 4.9 | % | 5.9 | % | ||||||||
| Gain on sale of investment security | 118 | — | — | N/M | — | % | ||||||||||||
| Net gain on divestiture of businesses | 33 | — | — | N/M | — | % | ||||||||||||
| Asset impairment charge | — | — | (578 | ) | — | % | (100.0 | )% | ||||||||||
| Income before income taxes | 1,064 | 872 | 133 | 22.0 | % | 555.6 | % | |||||||||||
| Income tax provision | 606 | 143 | 27 | 323.8 | % | 429.6 | % | |||||||||||
| Net income attributable to Nasdaq | $ | 458 | $ | 729 | $ | 106 | (37.2 | )% | 587.7 | % | ||||||||
| Diluted earnings per share | $ | 2.73 | $ | 4.30 | $ | 0.63 | (36.5 | )% | 582.5 | % | ||||||||
| Cash dividends declared per common share | $ | 1.70 | $ | 1.46 | $ | 1.21 | 16.4 | % | 20.7 | % |
N/M - Not meaningful.
In countries with currencies other than the U.S. dollar, revenues and expenses are translated using monthly average exchange rates. Impacts on our revenues less transaction-based expenses and operating income associated with fluctuations in foreign currency are discussed in more detail under “Item 7A. Quantitative and Qualitative Disclosures about Market Risk.”
Segment Operating Results
The following table shows our revenues by segment, transaction-based expenses for our Market Services segment and total revenues less transaction-based expenses:
| Year Ended December 31, | Percentage Change | |||||||||||||||||
| 2018 | 2017 | 2016 | 2018 vs. 2017 | 2017 vs. 2016 | ||||||||||||||
| (in millions) | ||||||||||||||||||
| Market Services | $ | 2,709 | $ | 2,418 | $ | 2,255 | 12.0 | % | 7.2 | % | ||||||||
| Transaction-based expenses | (1,751 | ) | (1,537 | ) | (1,428 | ) | 13.9 | % | 7.6 | % | ||||||||
| Market Services revenues less transaction-based expenses | 958 | 881 | 827 | 8.7 | % | 6.5 | % | |||||||||||
| Corporate Services | 528 | 501 | 477 | 5.4 | % | 5.0 | % | |||||||||||
| Information Services | 714 | 588 | 540 | 21.4 | % | 8.9 | % | |||||||||||
| Market Technology | 270 | 247 | 241 | 9.3 | % | 2.5 | % | |||||||||||
| Other revenues(1) | 56 | 194 | $ | 191 | (71.1 | )% | 1.6 | % | ||||||||||
| Total revenues less transaction-based expenses | $ | 2,526 | $ | 2,411 | $ | 2,276 | 4.8 | % | 5.9 | % |
| (1) | Includes the revenues from the Public Relations Solutions and Digital Media Services businesses which were sold in April 2018. Prior to the sale date, these revenues were included in our Corporate Solutions business. See “2018 Divestiture,” of Note 3, “Acquisitions and Divestiture,” to the consolidated financial statements for further discussion. |
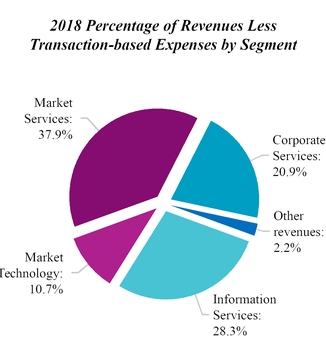
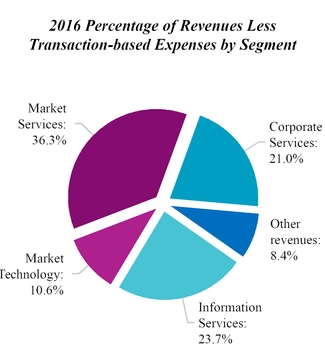
The following charts show our Market Services, Corporate Services, Information Services and Market Technology segments as a percentage of our total revenues less transaction-based expenses of $2,526 million in 2018, $2,411 million in 2017 and $2,276 million in 2016:

MARKET SERVICES
The following table shows total revenues, transaction-based expenses, and total revenues less transaction-based expenses from our Market Services segment:
| Year Ended December 31, | Percentage Change | |||||||||||||||||
| 2018 | 2017 | 2016 | 2018 vs. 2017 | 2017 vs. 2016 | ||||||||||||||
| (in millions) | ||||||||||||||||||
| Market Services Revenues: | ||||||||||||||||||
| Equity Derivative Trading and Clearing Revenues(1) | $ | 849 | $ | 752 | $ | 541 | 12.9 | % | 39.0 | % | ||||||||
| Transaction-based expenses: | ||||||||||||||||||
| Transaction rebates | (506 | ) | (450 | ) | (288 | ) | 12.4 | % | 56.3 | % | ||||||||
| Brokerage, clearance and exchange fees(1) | (44 | ) | (43 | ) | (25 | ) | 2.3 | % | 72.0 | % | ||||||||
| Equity derivative trading and clearing revenues less transaction-based expenses | 299 | 259 | 228 | 15.4 | % | 13.6 | % | |||||||||||
| Cash Equity Trading Revenues(2) | 1,476 | 1,279 | 1,349 | 15.4 | % | (5.2 | )% | |||||||||||
| Transaction-based expenses: | ||||||||||||||||||
| Transaction rebates | (830 | ) | (692 | ) | (785 | ) | 19.9 | % | (11.8 | )% | ||||||||
| Brokerage, clearance and exchange fees(2) | (361 | ) | (334 | ) | (309 | ) | 8.1 | % | 8.1 | % | ||||||||
| Cash equity trading revenues less transaction-based expenses | 285 | 253 | 255 | 12.6 | % | (0.8 | )% | |||||||||||
| FICC Revenues | 92 | 96 | 99 | (4.2 | )% | (3.0 | )% | |||||||||||
| Transaction-based expenses: | ||||||||||||||||||
| Transaction rebates | (8 | ) | (16 | ) | (19 | ) | (50.0 | )% | (15.8 | )% | ||||||||
| Brokerage, clearance and exchange fees | (2 | ) | (2 | ) | (2 | ) | — | % | — | % | ||||||||
| FICC revenues less transaction-based expenses | 82 | 78 | 78 | 5.1 | % | — | % | |||||||||||
| Trade Management Services Revenues | 292 | 291 | 266 | 0.3 | % | 9.4 | % | |||||||||||
| Total Market Services revenues less transaction-based expenses | $ | 958 | $ | 881 | $ | 827 | 8.7 | % | 6.5 | % |
| (1) | Includes Section 31 fees of $39 million in 2018, $40 million in 2017, and $24 million in 2016. Section 31 fees are recorded as equity derivative trading and clearing revenues with a corresponding amount recorded in transaction-based expenses. |
| (2) | Includes Section 31 fees of $343 million in 2018, $319 million in 2017, and $290 million in 2016. Section 31 fees are recorded as cash equity trading revenues with a corresponding amount recorded in transaction-based expenses. |
Equity Derivative Trading and Clearing Revenues
Equity derivative trading and clearing revenues and equity derivative trading and clearing revenues less transaction-based expenses increased in both 2018 compared with 2017 and 2017 compared with 2016.
The increases in 2018 were primarily due to higher U.S. industry trading volumes, partially offset by a decrease in our overall U.S. matched market share executed on Nasdaq's exchanges.
The increases in 2017 were primarily due to the inclusion of a full year of revenues from our acquisition of ISE compared with six months in 2016, higher U.S. industry trading volumes and an increase in our overall matched market share executed on Nasdaq's U.S. exchanges. Further impacting the increase in equity derivative trading revenues was higher Section 31 pass-through fee revenue.
Section 31 fees are recorded as equity derivative trading and clearing revenues with a corresponding amount recorded as transaction-based expenses. In the U.S., we are assessed these fees from the SEC and pass them through to our customers in the form of incremental fees. Pass-through fees can increase or decrease due to rate changes by the SEC, our percentage of the overall industry volumes processed on our systems, and differences in actual dollar value of shares traded. Since the amount recorded in revenues is equal to the amount recorded as transaction-based expenses, there is no impact on our revenues less transaction-based expenses. Section 31 fees decreased slightly in 2018 compared with 2017 and increased in 2017 compared with 2016. The increase in 2017 was primarily due to the inclusion of a full year of Section 31 fees from our acquisition of ISE compared with six months in 2016.
Transaction rebates, in which we credit a portion of the per share execution charge to the market participant, increased in both
2018 compared with 2017 and 2017 compared with 2016. The increase in 2018 was primarily due to higher U.S. industry trading volumes, partially offset by decrease in our overall U.S. matched market share executed on Nasdaq's exchanges. The increase in 2017 was primarily due to the inclusion of a full year of rebates associated with our acquisition of ISE compared with six months in 2016, increases in the U.S. rebate capture rate, higher U.S. industry trading volumes, and an increase in our overall U.S. matched market share.
Brokerage, clearance and exchange fees increased slightly in 2018 compared with 2017. The increase was primarily due to higher routing fees partially offset by lower Section 31 pass-through fees. The increase in 2017 compared with 2016 was primarily due to higher Section 31 pass-through fees, associated with our acquisition of ISE, as discussed above.
Cash Equity Trading Revenues
Cash equity trading revenues and cash equity trading revenues less transaction-based expenses increased in 2018 compared 2017 and decreased in 2017 compared with 2016.
The increases in 2018 were primarily due to higher U.S. and European industry trading volumes and an increase in our overall matched market share executed on Nasdaq's U.S. exchanges. Further impacting the increase in cash equity trading revenues in 2018 was an increase in Section 31 pass-through fee revenue.
Cash equity trading revenues and cash equity trading revenues less transaction-based expenses decreased in 2017 compared with 2016.
The decreases in 2017 were primarily due to:
| • | lower U.S. industry trading volumes, partially offset by; |
| • | higher European industry trading volumes; and |
| • | an increase in our overall U.S. matched market share and European market share executed on Nasdaq's exchanges. |
The decrease in cash equity trading revenues in 2017 was also partially offset by an increase in Section 31 pass-through fee revenue.
Similar to equity derivative trading and clearing, in the U.S. we record Section 31 fees as cash equity trading revenues with a corresponding amount recorded as transaction-based expenses. We are assessed these fees from the SEC and pass them through to our customers in the form of incremental fees. Since the amount recorded as revenues is equal to the amount recorded as transaction-based expenses, there is no impact on our revenues less transaction-based expenses. Section 31 fees increased in both 2018 compared with 2017 and 2017 compared with 2016. The increase in 2018 was primarily due to higher dollar value traded on Nasdaq’s exchanges, partially offset by lower average SEC fee rates. The increase in 2017 was primarily due to higher dollar value traded on Nasdaq’s exchanges and higher average SEC fee rates.
Transaction rebates increased in 2018 compared with 2017 and decreased in 2017 compared with 2016. For The Nasdaq Stock
Market, Nasdaq PSX and Nasdaq Canada, we credit a portion of the per share execution charge to the market participant that provides the liquidity, and for Nasdaq BX, we credit a portion of the per share execution charge to the market participant that takes the liquidity. The increase in 2018 was primarily due to an increase in our overall U.S. matched market share executed on Nasdaq’s exchanges and higher U.S. industry trading volumes, partially offset by a decrease in the U.S. rebate capture rate. The decrease in 2017 was primarily due to lower U.S. industry trading volumes, partially offset by an increase in our matched market share executed on Nasdaq’s exchanges.
Brokerage, clearance and exchange fees increased in both 2018 compared with 2017 and 2017 compared with 2016. The increases were primarily due to higher Section 31 pass-through fees, as discussed above.
FICC Revenues
FICC revenues decreased in 2018 compared with the same period in 2017 primarily due to a decline in revenues related to U.S. fixed income products. FICC revenues less transaction-based expenses increased in 2018 compared with 2017 primarily due to higher net revenues at NFX, partially offset by a decline in revenues related to U.S. fixed income products.
FICC revenues decreased in 2017 compared with the same period in 2016 primarily due to volume declines in European commodities products and U.S. fixed income products, partially offset by higher volumes and pricing changes at NFX. FICC revenues less transaction-based expenses were flat in 2017 compared with 2016 as declines in European commodities products and U.S. fixed income products were offset by higher volumes and pricing changes at NFX.
Trade Management Services Revenues
Trade management services revenues increased slightly in 2018 compared with 2017 primarily due to an increase in co-location revenues, partially offset by a decline in port connectivity revenues. The increase in 2017 compared with 2016 was primarily due to an increase in customer demand for third party connectivity, co-location, and test facilities and the inclusion of a full year of revenues from our acquisition of ISE compared with six months in 2016.
CORPORATE SERVICES
The following table shows revenues from our Corporate Services segment:
| Year Ended December 31, | Percentage Change | ||||||||||||||||
| 2018 | 2017 | 2016 | 2018 vs. 2017 | 2017 vs. 2016 | |||||||||||||
| (in millions) | |||||||||||||||||
| Corporate Services: | |||||||||||||||||
| Corporate Solutions | $ | 238 | $ | 234 | $ | 208 | 1.7 | % | 12.5 | % | |||||||
| Listing Services | 290 | 267 | 269 | 8.6 | % | (0.7 | )% | ||||||||||
| Total Corporate Services | $ | 528 | $ | 501 | $ | 477 | 5.4 | % | 5.0 | % |
Corporate Solutions Revenues
Corporate solutions revenues increased in both 2018 compared with 2017 and 2017 compared with 2016. The increase in 2018 was primarily due to an increase in board & leadership revenues and a favorable impact from foreign exchange of $2 million, partially offset by a decrease in our governance, risk & compliance revenues. The increase in 2017 was primarily due to the inclusion of revenues associated with the acquisition of Boardvantage. See “Acquisition of Boardvantage,” of Note 3, “Acquisitions and Divestiture,” to the consolidated financial statements for further discussion of the Boardvantage acquisition.
Listing Services Revenues
Listing services revenues increased in 2018 compared with 2017 and decreased in 2017 compared with 2016. The increase in 2018 was primarily from client adoption of our all-inclusive annual listing fee program and an increase in the number and size of IPOs, partially offset by the run-off of fees earned from U.S. listing of additional shares. The decrease in 2017 was primarily due to a decrease in U.S. listing of additional share fees as a result of our all-inclusive annual listing fee program, partially offset by an increase in European listing services revenues due to new company listings.
INFORMATION SERVICES
The following table shows revenues from our Information Services segment:
| Year Ended December 31, | Percentage Change | ||||||||||||||||
| 2018 | 2017 | 2016 | 2018 vs. 2017 | 2017 vs. 2016 | |||||||||||||
| (in millions) | |||||||||||||||||
| Information Services: | |||||||||||||||||
| Market Data | $ | 390 | $ | 369 | $ | 354 | 5.7 | % | 4.2 | % | |||||||
| Index | 206 | 171 | 149 | 20.5 | % | 14.8 | % | ||||||||||
| Investment Data & Analytics | 118 | 48 | 37 | 145.8 | % | 29.7 | % | ||||||||||
| Total Information Services | $ | 714 | $ | 588 | $ | 540 | 21.4 | % | 8.9 | % |
Market Data Revenues
Market data revenues increased in both 2018 compared with 2017 and 2017 compared with 2016. The increase in 2018 was primarily due to higher revenues from sales of data subscriptions (notably growth in the Asia Pacific region), an increase in market share in U.S. tape plans and higher revenues from under reported usage. Further impacting the increase in market data revenues was a favorable impact from foreign exchange of $4 million. The increase in 2017 was primarily due to growth in U.S. equities and European data products subscriptions.
Index Revenues
Index revenues increased in both 2018 compared with 2017 and 2017 compared with 2016. The increases in both 2018 and 2017 were primarily due to higher assets under management in ETPs linked to Nasdaq indexes and higher licensing revenues from futures trading volume related to the Nasdaq 100 Index.
Investment Data & Analytics Revenues
Investment data & analytics revenues increased in both 2018 compared with 2017 and 2017 compared with 2016. The increases in both 2018 and 2017 were primarily due to the inclusion of revenues associated with the acquisition of eVestment.
MARKET TECHNOLOGY
The following table shows revenues from our Market Technology segment:
| Year Ended December 31, | Percentage Change | ||||||||||||||||
| 2018 | 2017 | 2016 | 2018 vs. 2017 | 2017 vs. 2016 | |||||||||||||
| (in millions) | |||||||||||||||||
| Market Technology | $ | 270 | $ | 247 | $ | 241 | 9.3 | % | 2.5 | % |
Market Technology Revenues
Market technology revenues increased in both 2018 compared with 2017 and 2017 compared with 2016. The increase in 2018 was primarily due to an increase in delivery and support revenues and higher software as a service revenues, partially offset by a decrease in change request and advisory revenues and an unfavorable impact from foreign exchange of $2 million. The increase in 2017 was primarily due to higher change request revenues and an increase in revenues from software as a service.
OTHER REVENUES
Other revenues include the revenues from the Public Relations Solutions and Digital Media Services businesses which were sold in April 2018. Prior to the sale date, these revenues were included in our Corporate Solutions business. See “2018 Divestiture,” of Note 3, “Acquisitions and Divestiture,” to the consolidated financial statements for further discussion.
Expenses
Operating Expenses
The following table shows our operating expenses:
| Year Ended December 31, | Percentage Change | ||||||||||||||||
| 2018 | 2017 | 2016 | 2018 vs. 2017 | 2017 vs. 2016 | |||||||||||||
| (in millions) | |||||||||||||||||
| Compensation and benefits | $ | 712 | $ | 670 | $ | 665 | 6.3 | % | 0.8 | % | |||||||
| Professional and contract services | 144 | 153 | 153 | (5.9 | )% | — | % | ||||||||||
| Computer operations and data communications | 127 | 125 | 111 | 1.6 | % | 12.6 | % | ||||||||||
| Occupancy | 95 | 94 | 86 | 1.1 | % | 9.3 | % | ||||||||||
| General, administrative and other | 120 | 82 | 73 | 46.3 | % | 12.3 | % | ||||||||||
| Marketing and advertising | 37 | 31 | 30 | 19.4 | % | 3.3 | % | ||||||||||
| Depreciation and amortization | 210 | 188 | 170 | 11.7 | % | 10.6 | % | ||||||||||
| Regulatory | 32 | 33 | 35 | (3.0 | )% | (5.7 | )% | ||||||||||
| Merger and strategic initiatives | 21 | 44 | 76 | (52.3 | )% | (42.1 | )% | ||||||||||
| Restructuring charges | — | — | 41 | — | % | (100.0 | )% | ||||||||||
| Total operating expenses | $ | 1,498 | $ | 1,420 | $ | 1,440 | 5.5 | % | (1.4 | )% |
The increase in compensation and benefits expense in 2018 was primarily due to overall higher compensation costs resulting from our acquisition of eVestment and higher compensation expense reflecting higher performance incentives, partially offset by lower compensation costs due to the sale of the Public Relations Solutions and Digital Media Services businesses. The increase in compensation and benefits expense in 2017 was primarily due to overall higher compensation costs resulting from our 2017 and 2016 acquisitions and an unfavorable impact from foreign exchange of $2 million, partially offset by lower compensation expense reflecting lower performance incentives. Also impacting the increase in compensation expense in 2017 was accelerated expense recorded in 2016 for
equity awards previously granted due to the retirement of the company's former CEO.
Headcount decreased to 4,099 employees as of December 31, 2018 from 4,734 as of December 31, 2017 primarily due to the sale of the Public Relations Solutions and Digital Media Services businesses, partially offset by our 2018 acquisitions.
Professional and contract services expense decreased in 2018 primarily due to the sale of the Public Relations Solutions and Digital Media Services businesses, partially offset by additional expense associated with our 2017 acquisitions and litigation costs.
Computer operations and data communications expense increased in 2018 primarily due to higher market data feed costs
due to higher volumes as well as higher software maintenance costs, and additional costs associated with our 2017 acquisitions, partially offset by lower costs resulting from the sale of the Public Relations Solutions and Digital Media Services businesses. The increase in 2017 was due to higher hardware and license costs associated with our 2017 and 2016 acquisitions.
Occupancy expense increased in 2018 primarily due to additional facility and rent costs resulting from expansion of our new world headquarters, partially offset by lower costs from the sale of the Public Relations Solutions and Digital Media Services businesses. The increase in 2017 was associated with our 2017 and 2016 acquisitions.
The increase in general, administrative and other expense in 2018 was primarily due to charges associated with the clearing default and lower regulatory fine collections. See “Nasdaq Commodities Clearing Default,” of Note 15, “Clearing Operations,” for further discussion of the capital relief program and default. The increase in 2017 was primarily due to a pre-tax charge of $10 million in the second quarter of 2017 which primarily included a make-whole redemption price premium paid on the early extinguishment of previously outstanding debt and lower regulatory fine collections.
Marketing and advertising expense increased in both 2018 compared with 2017 and 2017 compared with 2016 primarily
due to an increase in advertising spend relating to our Listing Services and Information Services businesses.
Depreciation and amortization expense increased in both 2018 compared with 2017 and 2017 compared with 2016 primarily due to additional amortization expense associated with acquired intangible assets. The increase in 2018 was associated with our 2017 acquisition and in the increase in 2017 was associated with our 2017 and 2016 acquisitions. The increase in 2018 was also associated with software assets placed in service.
Merger and strategic initiatives expense decreased in both 2018 compared with 2017 and 2017 compared with 2016. We have pursued various strategic initiatives and completed a divestiture and a number of acquisitions in recent years which have resulted in expenses which would not have otherwise been incurred. These expenses generally include integration costs, as well as legal, due diligence and other third party transaction costs and will vary based on the size and frequency of the activities described above.
See Note 18, “Restructuring Charges,” to the consolidated financial statements for a discussion of our restructuring charges recorded during 2016.
Non-operating Income and Expenses
The following table shows our non-operating income and expenses:
| Year Ended December 31, | Percentage Change | ||||||||||||||||
| 2018 | 2017 | 2016 | 2018 vs. 2017 | 2017 vs. 2016 | |||||||||||||
| (in millions) | |||||||||||||||||
| Interest income | $ | 10 | $ | 7 | $ | 5 | 42.9 | % | 40.0 | % | |||||||
| Interest expense | (150 | ) | (143 | ) | (135 | ) | 4.9 | % | 5.9 | % | |||||||
| Net interest expense | (140 | ) | (136 | ) | (130 | ) | 2.9 | % | 4.6 | % | |||||||
| Gain on sale of investment security | 118 | — | — | N/M | — | % | |||||||||||
| Net gain on divestiture of businesses | 33 | — | — | N/M | — | % | |||||||||||
| Asset impairment charge | — | — | (578 | ) | — | % | (100.0 | )% | |||||||||
| Other investment income | 7 | 2 | 3 | 250.0 | % | (33.3 | )% | ||||||||||
| Net income from unconsolidated investees | 18 | 15 | 2 | 20.0 | % | 650.0 | % | ||||||||||
| Total non-operating income (expenses) | $ | 36 | $ | (119 | ) | $ | (703 | ) | (130.3 | )% | (83.1 | )% |
N/M - Not meaningful.
Interest Income
Interest income increased in both 2018 compared with 2017 and 2017 compared with 2016 primarily due to an increase in prevailing market rates.
Interest Expense
The following table shows our interest expense:
| Year Ended December 31, | Percentage Change | ||||||||||||||||
| 2018 | 2017 | 2016 | 2018 vs. 2017 | 2017 vs. 2016 | |||||||||||||
| (in millions) | |||||||||||||||||
| Interest expense on debt | $ | 140 | $ | 135 | $ | 129 | 3.7 | % | 4.7 | % | |||||||
| Accretion of debt issuance costs and debt discount | 7 | 6 | 5 | 16.7 | % | 20.0 | % | ||||||||||
| Other bank and investment-related fees | 3 | 2 | 1 | 50.0 | % | 100.0 | % | ||||||||||
| Interest expense | $ | 150 | $ | 143 | $ | 135 | 4.9 | % | 5.9 | % |
Interest expense increased in both 2018 and 2017 primarily due to higher interest rates on floating rate debt and debt issuances related to our acquisitions. See Note 9, “Debt Obligations,” to the consolidated financial statements for further discussion of our debt obligations.
Gain on Sale of Investment Security
In December 2018, we recorded a pre-tax gain of $118 million ($93 million after tax) on the sale of an investment security. See “Equity Securities,” of Note 6, “Investments,” to the consolidated financial statements for further discussion.
Net Gain on Divestiture of Businesses
In April 2018, we sold our Public Relations Solutions and Digital Media Services businesses. See “2018 Divestiture,” of Note 3, “Acquisitions and Divestiture,” to the consolidated financial statements for further discussion.
Asset Impairment Charge
The asset impairment charge in 2016 relates to a pre-tax, non-cash intangible asset impairment charge related to the full write-off of a trade name from an acquired business due to a continued decline in the operating performance of the business during 2016 and a rebranding of our fixed income business under a single brand called Nasdaq Fixed Income.
Other Investment Income
Other investment income in 2018 primarily related to dividend income received on an equity security.
Net Income from Unconsolidated Investees
Net income from unconsolidated investees in both 2018 and 2017 primarily relates to income recognized from our equity method investment in OCC. See “Equity Method Investments,” of Note 6, “Investments,” to the consolidated financial statements for further discussion of our equity method investments.
Tax Matters
The following table shows our income tax provision and effective tax rate:
| Year Ended December 31, | Percentage Change | ||||||||||||||||
| 2018 | 2017 | 2016 | 2018 vs. 2017 | 2017 vs. 2016 | |||||||||||||
| ($ in millions) | |||||||||||||||||
| Income tax provision | $ | 606 | $ | 143 | $ | 27 | 323.8 | % | 429.6 | % | |||||||
| Effective tax rate | 57.0 | % | 16.4 | % | 20.3 | % |
The majority of the increase in our effective tax rate in 2018 compared to 2017 and the decrease in our effective tax rate in 2017 compared to 2016 was the result of the final and provisional impacts from the Tax Cuts and Jobs Act which was enacted on December 22, 2017. For further discussion of the impacts of the tax act and other tax matters, see Note 17, “Income Taxes,” to the consolidated financial statements.
The effective tax rate may vary from period to period depending on, among other factors, the geographic and business mix of earnings and losses. These same and other factors, including history of pre-tax earnings and losses, are taken into account in assessing the ability to realize deferred tax assets.
Non-GAAP Financial Measures
In addition to disclosing results determined in accordance with U.S. GAAP, we also have provided non-GAAP net income attributable to Nasdaq and non-GAAP diluted earnings per share. Management uses this non-GAAP information internally, along with U.S. GAAP information, in evaluating our performance and in making financial and operational decisions. We believe our presentation of these measures provides investors with greater transparency and supplemental data relating to our financial condition and results of operations. In addition, we believe the presentation of these measures is useful to investors for period-to-period comparisons of our ongoing operating performance.
These measures are not in accordance with, or an alternative to, U.S. GAAP, and may be different from non-GAAP measures used by other companies. Investors should not rely on any single financial measure when evaluating our business. We recommend investors review the U.S. GAAP financial measures included in this Annual Report on Form 10-K, including our consolidated financial statements and the notes thereto. When viewed in conjunction with our U.S. GAAP results and the accompanying reconciliation, we believe these non-GAAP measures provide greater transparency and a more complete understanding of factors affecting our business than U.S. GAAP measures alone.
We understand that analysts and investors regularly rely on non-GAAP financial measures, such as non-GAAP net income attributable to Nasdaq and non-GAAP diluted earnings per share, to assess operating performance. We use non-GAAP net income attributable to Nasdaq and non-GAAP diluted earnings per share because they highlight trends more clearly in our business that may not otherwise be apparent when relying solely on U.S. GAAP financial measures, since these measures eliminate from our results specific financial items that have less bearing on our ongoing operating performance. Non-GAAP net income attributable to Nasdaq for the periods presented below is calculated by adjusting for the following items:
Amortization expense of acquired intangible assets: We amortize intangible assets acquired in connection with various acquisitions. Intangible asset amortization expense can vary from period to period due to episodic acquisitions completed, rather than from our ongoing business operations. As such, if intangible asset amortization is included in performance measures, it is more difficult to assess the day-to-day operating performance of the businesses, the relative operating performance of the businesses between periods, and the earnings power of Nasdaq. Performance measures excluding intangible asset amortization therefore provide investors with a more useful representation of our businesses’ ongoing activity in each period.
Merger and strategic initiatives expense: We have pursued various strategic initiatives and completed a divestiture and a number of acquisitions in recent years which have resulted in expenses which would not have otherwise been incurred. These expenses generally include integration costs, as well as legal, due diligence and other third party transaction costs. The frequency and the amount of such expenses vary significantly based on the size, timing and complexity of the transaction. Accordingly, we exclude these costs for purposes of calculating non-GAAP measures which provide a more meaningful analysis of Nasdaq’s ongoing operating performance or comparisons in Nasdaq’s performance between periods.
Clearing Default: For the year ended December 31, 2018, we recorded $31 million in expense related to the clearing default of a Nasdaq Clearing commodities member that occurred in September 2018. We recorded an $8 million loss in September 2018 relating to this default. In December 2018, we recorded a $23 million charge as a result of initiating a capital relief program. These charges are recorded in general, administrative and o
ther expense in our Consolidated Statements of Income. See “Nasdaq Commodities Clearing Default,” of Note 15, “Clearing Operations,” for further discussion of the default. We have excluded these charges as we believe they are non-recurring, as there has never been a loss due to member default in our clearinghouse, and they should be excluded when evaluating the ongoing operating performance of Nasdaq. Any expenses associated with the enhancement of processes and procedures relating to our clearing business will not be excluded from our GAAP results.
Other significant items: We have excluded certain other charges or gains, including certain tax items, that are the result of other non-comparable events to measure operating performance. We believe the exclusion of such amounts allows management and investors to better understand the ongoing financial results of Nasdaq.
For the year ended December 31, 2018, other significant items primarily included:
| • | gain on sale of investment security which represents our pre-tax gain of $118 million on the sale of our 5.0% ownership interest in LCH; |
| • | net gain on divestiture of businesses which represents our pre-tax net gain of $33 million on the sale of the Public Relations Solutions and Digital Media Services businesses; |
| • | other items: |
| ◦ | charges related to uncertain positions pertaining to sales and use tax and VAT which are recorded in general, administrative and other expense in our Consolidated Statements of Income; and |
| ◦ | certain litigation costs which are recorded in professional and contract services expense in our Consolidated Statements of Income. |
For the year ended December 31, 2017, other significant items primarily included:
| • | loss on extinguishment of debt of $10 million which is recorded in general, administrative and other expense in our Consolidated Statements of Income; and |
| • | wind down costs associated with an equity method investment that was previously written off which are recorded in net income from unconsolidated investees in our Consolidated Statements of Income. |
For the year ended December 31, 2016, other significant items primarily included:
| • | restructuring charges of $41 million which were associated with our 2015 restructuring plan; |
| • | an asset impairment charge of $578 million related to the full write-off of a trade name from an acquired business; |
| • | executive compensation of $12 million which represents accelerated expense for equity awards previously granted due to the retirement of the company’s former CEO which is recorded in compensation and benefits expense in our Consolidated Statements of Income; |
| • | a regulatory matter that resulted in a regulatory fine of $6 million received by our Nordic exchanges and clearinghouse which is recorded in regulatory expense in our Consolidated Statements of Income; |
| • | other items: |
| ◦ | the release of a sublease loss reserve due to the early exit of a facility which is recorded in occupancy expense in our Consolidated Statements of Income; and |
| ◦ | the impact of the write-off of an equity method investment, partially offset by a gain resulting from the sale of a percentage of a separate equity method investment which is recorded in net income from unconsolidated investees in our Consolidated Statements of Income. |
Significant tax items: The non-GAAP adjustment to the income tax provision included the tax impact of each non-GAAP adjustment and:
| • | for the year ended December 31, 2018, a net $7 million increase to tax expense due to a remeasurement of unrecognized tax benefits (excluding the reversal of certain Swedish tax benefits discussed below) and the impact of state tax rate changes; |
| • | for the year ended December 31, 2017, a $12 million decrease to tax expense due to a remeasurement of unrecognized tax benefits; and |
| • | for the year ended December 31, 2016, a tax expense of $27 million due to an unfavorable tax ruling received during the second quarter of 2016, the impact of which is related to prior periods. |
Additional adjustments included the following items:
| • | The impact of newly enacted U.S. tax legislation is related to the Tax Cuts and Jobs Act which was enacted on December 22, 2017. |
| ◦ | For the year ended December 31, 2018, we recorded an increase to tax expense of $290 million and a reduction to deferred tax assets related to foreign currency translation as a result of the finalization of the provisional estimate related to this act. |
| ◦ | For the year ended December 31, 2017, we recorded a decrease to tax expense of $89 million, primarily related to the remeasurement of our net U.S. deferred tax liability at the lower U.S. federal corporate income tax rate which reflected the provisional impact associated with the enactment of this act. |
| • | The reversal of certain Swedish tax benefits. See Note 17, “Income Taxes,” to the consolidated financial statements for further discussion. |
| • | Excess tax benefits related to employee share-based compensation of $9 million for the year ended December 31, 2018 and $40 million for the year ended December 31, 2017, were recorded as a result of the adoption of accounting guidance on January 1, 2017. This guidance requires all income tax effects of share-based awards to be recognized as income tax expense or benefit in the income statement when the awards vest or are settled on a prospective basis, as opposed to stockholders’ equity where it was previously recorded, and will be a recurring item going forward. This item is subject to volatility and will vary based on the timing of the vesting of employee share-based compensation arrangements and fluctuation in our stock price. |
We believe the exclusion of such amounts allows management and investors to better understand the financial results of Nasdaq.
The following table represents reconciliations between U.S. GAAP net income attributable to Nasdaq and diluted earnings per share and non-GAAP net income attributable to Nasdaq and diluted earnings per share:
| Year Ended December 31, 2018 | Year Ended December 31, 2017 | Year Ended December 31, 2016 | |||||||||||||||||||||
| Net Income | Diluted Earnings Per Share | Net Income | Diluted Earnings Per Share | Net Income | Diluted Earnings Per Share | ||||||||||||||||||
| (in millions, except share and per share amounts) | |||||||||||||||||||||||
| U.S. GAAP net income attributable to Nasdaq and diluted earnings per share | $ | 458 | $ | 2.73 | $ | 729 | $ | 4.30 | $ | 106 | $ | 0.63 | |||||||||||
| Non-GAAP adjustments: | |||||||||||||||||||||||
| Amortization expense of acquired intangible assets | 109 | 0.65 | 92 | 0.54 | 82 | 0.49 | |||||||||||||||||
| Merger and strategic initiatives expense | 21 | 0.13 | 44 | 0.26 | 76 | 0.45 | |||||||||||||||||
| Clearing default | 31 | 0.18 | — | — | — | — | |||||||||||||||||
| Gain on sale of investment security | (118 | ) | (0.69 | ) | — | — | — | — | |||||||||||||||
| Net gain on divestiture of businesses | (33 | ) | (0.20 | ) | — | — | — | — | |||||||||||||||
| Extinguishment of debt | — | — | 10 | 0.06 | — | — | |||||||||||||||||
| Restructuring charges | — | — | — | — | 41 | 0.24 | |||||||||||||||||
| Asset impairment charge | — | — | — | — | 578 | 3.42 | |||||||||||||||||
| Executive compensation | — | — | — | — | 12 | 0.07 | |||||||||||||||||
| Regulatory matter | — | — | — | — | 6 | 0.04 | |||||||||||||||||
| Other | 17 | 0.10 | 5 | 0.02 | 5 | 0.03 | |||||||||||||||||
| Adjustment to the income tax provision to reflect non-GAAP adjustments and other tax items | 4 | 0.02 | (70 | ) | (0.40 | ) | (287 | ) | (1.70 | ) | |||||||||||||
| Impact of newly enacted U.S. tax legislation | 290 | 1.73 | (89 | ) | (0.52 | ) | — | — | |||||||||||||||
| Reversal of certain Swedish tax benefits | 41 | 0.24 | — | — | — | — | |||||||||||||||||
| Excess tax benefits related to employee share-based compensation | (9 | ) | (0.05 | ) | (40 | ) | (0.24 | ) | — | — | |||||||||||||
| Total non-GAAP adjustments, net of tax | 353 | 2.11 | (48 | ) | (0.28 | ) | 513 | 3.04 | |||||||||||||||
| Non-GAAP net income attributable to Nasdaq and diluted earnings per share | $ | 811 | $ | 4.84 | $ | 681 | $ | 4.02 | $ | 619 | $ | 3.67 | |||||||||||
| Weighted-average common shares outstanding for diluted earnings per share | 167,691,299 | 169,585,031 | 168,800,997 |
Liquidity and Capital Resources
Historically, we have funded our operating activities and met our commitments through cash generated by operations, augmented by the periodic issuance of our common stock and debt. See Note 9, “Debt Obligations,” to the consolidated financial statements for further discussion. Currently, our cost and availability of funding remain healthy.
As part of the purchase price consideration of a prior acquisition, Nasdaq has contingent future obligations to issue 992,247 shares of Nasdaq common stock. See “Non-Cash Contingent Consideration,” of Note 19, “Commitments, Contingencies and Guarantees,” to the consolidated financial statements for further discussion.
In April 2017, we entered into the 2017 Credit Facility which replaced a former credit facility. We also entered into a commercial paper program which enables us to borrow efficiently at reasonable short-term interest rates and is supported by our 2017 Credit Facility. See “Commercial Paper Program,” and “2017 Credit Facility,” of Note 9, “Debt Obligations,” to the consolidated financial statements for further discussion.
As of December 31, 2018, no amounts were outstanding on the 2017 Credit Facility. The $4 million balance represents unamortized debt issuance costs. Of the $1 billion that is available for borrowing, $277 million provides liquidity support for the commercial paper program and for a letter of
credit. As such, as of December 31, 2018, the total remaining amount available under the 2017 Credit Facility was $723 million.
In the near term, we expect that our operations and the availability under our revolving credit commitment and commercial paper program will provide sufficient cash to fund our operating expenses, capital expenditures, debt repayments, any share repurchases, and any dividends.
The value of various assets and liabilities, including cash and cash equivalents, receivables, accounts payable and accrued expenses, and commercial paper can fluctuate from month to month. Working capital (calculated as current assets less current liabilities) was $(200) million as of December 31, 2018, compared with $276 million as of December 31, 2017, a decrease of $476 million. Current asset balance changes increased working capital by $860 million, with increases in default funds and margin deposits, cash and cash equivalents, financial investments, at fair value, receivables, net and restricted cash, partially offset by a decrease in other current assets. Current liability balance changes decreased working capital by $1,336 million, due to increases in default funds and margin deposits, short-term debt, other current liabilities, deferred revenue, accrued personnel costs, and accounts payable and accrued expenses, partially offset by a decrease in Section 31 fees payable to the SEC.
Principal factors that could affect the availability of our internally-generated funds include:
| • | deterioration of our revenues in any of our business segments; |
| • | changes in regulatory and working capital requirements; and |
| • | an increase in our expenses. |
Principal factors that could affect our ability to obtain cash from external sources include:
| • | operating covenants contained in our credit facilities that limit our total borrowing capacity; |
| • | increases in interest rates under our credit facilities; |
| • | credit rating downgrades, which could limit our access to additional debt; |
| • | a decrease in the market price of our common stock; and |
| • | volatility or disruption in the public debt and equity markets. |
The following sections discuss the effects of changes in our financial assets, debt obligations, clearing and broker-dealer net capital requirements, and cash flows on our liquidity and capital resources.
Financial Assets
The following table summarizes our financial assets:
| December 31, 2018 | December 31, 2017 | |||||||
| (in millions) | ||||||||
| Cash and cash equivalents | $ | 545 | $ | 377 | ||||
| Restricted cash | 41 | 22 | ||||||
| Financial investments, at fair value | 268 | 235 | ||||||
| Total financial assets | $ | 854 | $ | 634 |
Cash and Cash Equivalents and Restricted Cash
Cash and cash equivalents includes all non-restricted cash in banks and highly liquid investments with original maturities of 90 days or less at the time of purchase. The balance retained in cash and cash equivalents is a function of anticipated or possible short-term cash needs, prevailing interest rates, our investment policy, and alternative investment choices. As of December 31, 2018, our cash and cash equivalents of $545 million were primarily invested in bank deposits, money market funds and commercial paper. In the long-term, we may use both internally generated funds and external sources to satisfy our debt obligations and other long-term liabilities. Cash and cash equivalents as of December 31, 2018 increased $168 million from December 31, 2017, primarily due to:
| • | net cash provided by operating activities; |
| • | proceeds from divestiture of businesses, net; |
| • | proceeds received from the sale of an investment security, partially offset by; |
| • | repurchases of our common stock; |
| • | cash dividends paid on our common stock; |
| • | repayments made on commercial paper, net; |
| • | repayments of long-term debt; |
| • | purchases of property and equipment; |
| • | cash paid for acquisitions, net of cash and cash equivalents acquired and other investment activities; |
| • | net purchases of securities; and |
| • | net payments related to employee stock activity. |
See “Cash Flow Analysis” below for further discussion.
Restricted cash is restricted from withdrawal due to a contractual or regulatory requirements or is not available for general use. Restricted cash was $41 million as of December 31, 2018 and $22 million as of December 31, 2017, an increase of $19 million. The increase primarily relates to an increase in cash pledged as collateral and an increase in regulatory capital requirements. Restricted cash is classified as restricted cash in the Consolidated Balance Sheets.
Repatriation of Cash
Our cash and cash equivalents held outside of the U.S. in various foreign subsidiaries totaled $367 million as of December 31, 2018 and $137 million as of December 31, 2017. The remaining
balance held in the U.S. totaled $178 million as of December 31, 2018 and $240 million as of December 31, 2017.
Unremitted earnings of subsidiaries outside of the U.S. are used to finance our international operations and are considered to be indefinitely reinvested.
Share Repurchase Program
See “Share Repurchase Program,” of Note 12, “Nasdaq Stockholders’ Equity,” to the consolidated financial statements for further discussion of our share repurchase program.
Cash Dividends on Common Stock
The following table shows quarterly cash dividends paid per common share on our outstanding common stock:
| 2018 | 2017 | ||||||
| First quarter | $ | 0.38 | $ | 0.32 | |||
| Second quarter | 0.44 | 0.38 | |||||
| Third quarter | 0.44 | 0.38 | |||||
| Fourth quarter | 0.44 | 0.38 | |||||
| Total | $ | 1.70 | $ | 1.46 |
See “Cash Dividends on Common Stock,” of Note 12, “Nasdaq Stockholders’ Equity,” to the consolidated financial statements
for further discussion of the dividends.
Financial Investments, at Fair Value
Our financial investments, at fair value totaled $268 million as of December 31, 2018 and $235 million as of December 31, 2017 and are primarily comprised of trading securities, mainly highly rated European government debt securities. Of these securities, $166 million as of December 31, 2018 and $160 million as of December 31, 2017 are assets primarily utilized to meet regulatory capital requirements, mainly for our clearing operations at Nasdaq Clearing. See Note 6, “Investments,” to the consolidated financial statements for further discussion of
our trading investment securities.
Debt Obligations
The following table summarizes our debt obligations by contractual maturity:
| Maturity Date | December 31, 2018 | December 31, 2017 | ||||||||
| (in millions) | ||||||||||
| Short-term debt: | ||||||||||
| Commercial paper | Weighted-average maturity of 33 days | $ | 275 | $ | 480 | |||||
| Senior unsecured floating rate notes(1) | March 2019 | 500 | 498 | |||||||
| $400 million senior unsecured term loan facility(2) | November 2019 | 100 | 100 | |||||||
| Total short-term debt | 875 | 1,078 | ||||||||
| Long-term debt: | ||||||||||
| 5.55% senior unsecured notes | January 2020 | 599 | 599 | |||||||
| 3.875% senior unsecured notes | June 2021 | 686 | 716 | |||||||
| $1 billion revolving credit commitment | April 2022 | (4 | ) | 110 | ||||||
| 1.75% senior unsecured notes | May 2023 | 682 | 712 | |||||||
| 4.25% senior unsecured notes | June 2024 | 497 | 496 | |||||||
| 3.85% senior unsecured notes | June 2026 | 496 | 496 | |||||||
| Total long-term debt | 2,956 | 3,129 | ||||||||
| Total debt obligations | $ | 3,831 | $ | 4,207 |
| (1) | Balance was reclassified to short-term debt as of March 31, 2018. |
| (2) | Balance was reclassified to short-term debt as of December 31, 2018. |
In addition to the $1 billion revolving credit commitment, we also have other credit facilities primarily related to our Nasdaq Clearing operations in order to provide further liquidity. Other credit facilities, which are available in multiple currencies, totaled $220 million as of December 31, 2018 and $187 million as of December 31, 2017, in available liquidity, none of which was utilized.
As of December 31, 2018, we were in compliance with the covenants of all of our debt obligations.
See Note 9, “Debt Obligations,” to the consolidated financial statements for further discussion of our debt obligations.
Regulatory Capital Requirements
Clearing Operations Regulatory Capital Requirements
We are required to maintain minimum levels of regulatory capital for the clearing operations of Nasdaq Clearing. The level of regulatory capital required to be maintained is dependent upon many factors, including market conditions and creditworthiness of the counterparty. As of December 31, 2018, our required regulatory capital of $121 million is primarily comprised of highly rated European government debt securities that are included in financial investments, at fair value in the Consolidated Balance Sheets.
Broker-Dealer Net Capital Requirements
Our broker-dealer subsidiaries, Nasdaq Execution Services, Execution Access, NPM Securities, SMTX, and Nasdaq Capital Markets Advisory, are subject to regulatory requirements intended to ensure their general financial soundness and liquidity. These requirements obligate these subsidiaries to comply with minimum net capital requirements. The required minimum net capital is included in restricted cash in the Consolidated Balance Sheets. The following table summarizes the net capital requirements for our broker-dealer subsidiaries as of December 31, 2018:
| Broker-Dealer Subsidiaries | Total Net Capital | Required Minimum Net Capital | Excess Capital | |||||||||
| (in millions) | ||||||||||||
| Nasdaq Execution Services | $ | 16.3 | $ | 0.3 | $ | 16.0 | ||||||
| Execution Access | 47.1 | 0.3 | 46.8 | |||||||||
| NPM Securities | 0.6 | 0.3 | 0.3 | |||||||||
| SMTX | 4.0 | 0.3 | 3.7 | |||||||||
| Nasdaq Capital Markets Advisory | 0.5 | 0.3 | 0.2 |
Nordic and Baltic Exchange Regulatory Capital Requirements
The entities that operate trading venues in the Nordic and Baltic countries are each subject to local regulations and are required to maintain regulatory capital intended to ensure their general financial soundness and liquidity. As of December 31, 2018, our required regulatory capital of $34 million is primarily invested in European mortgage bonds that are included in financial investments, at fair value and restricted cash in the Consolidated Balance Sheets.
Other Capital Requirements
We operate several other businesses which are subject to local regulation and are required to maintain certain levels of regulatory capital. As of December 31, 2018, other required regulatory capital was $17 million and was primarily included in restricted cash and financial investments, at fair value in the
Consolidated Balance Sheets.
Cash Flow Analysis
The following table summarizes the changes in cash flows:
| Year Ended December 31, | Percentage Change | |||||||||||||||||
| 2018 | 2017 | 2016 | 2018 vs. 2017 | 2017 vs. 2016 | ||||||||||||||
| Net cash provided by (used in): | (in millions) | |||||||||||||||||
| Operating activities | $ | 1,028 | $ | 909 | $ | 776 | 13.1 | % | 17.1 | % | ||||||||
| Investing activities | 196 | (890 | ) | (1,657 | ) | (122.0 | )% | (46.3 | )% | |||||||||
| Financing activities | (1,027 | ) | (53 | ) | 948 | 1,837.7 | % | (105.6 | )% | |||||||||
| Effect of exchange rate changes on cash and cash equivalents and restricted cash | (10 | ) | 15 | (6 | ) | (166.7 | )% | (350.0 | )% | |||||||||
| Net increase in cash and cash equivalents and restricted cash | 187 | (19 | ) | 61 | (1,084.2 | )% | (131.1 | )% | ||||||||||
| Cash and cash equivalents and restricted cash at beginning of period | 399 | 418 | 357 | (4.5 | )% | 17.1 | % | |||||||||||
| Cash and cash equivalents and restricted cash at end of period | $ | 586 | $ | 399 | $ | 418 | 46.9 | % | (4.5 | )% |
Net Cash Provided by Operating Activities
Net cash provided by operating activities increased $119 million in 2018 compared with 2017 and increased $133 million in 2017 compared with 2016. The increase in 2018 was primarily due to higher operating income due to growth in our equity derivative trading and clearing, cash equity trading, market data, index and listing services businesses, and growth related to a full year of eVestment activity, these increases were partially offset by an increase in estimated tax payments, a payment to increase the funded status of our U.S. defined-benefit pension plans and higher Section 31 fee payments. The increase in 2017 was primarily due to higher net income, mainly due to the inclusion of a full year of cash flows from our 2016 acquisitions, partially offset by higher compensation payments driven by our 2016 acquisitions.
Net Cash Provided by (Used in) Investing Activities
Net cash provided by investing activities increased $1,086 million in 2018 compared with 2017. The increase was primarily due to a decrease in cash flows used for acquisitions of businesses, net of cash and cash equivalents acquired, an increase in proceeds from divestiture of businesses, net and an increase in proceeds from the sale of an investment security.
Net cash used in investing activities decreased $767 million in 2017 compared with 2016. The decrease was primarily due to a decrease in cash flows used for acquisitions of businesses, net of cash and cash equivalents acquired.
Net Cash Provided by (Used in) Financing Activities
Net cash used in financing activities increased $974 million in 2018 compared with 2017. The increase was primarily due to an increase in repayments of commercial paper, a decrease in proceeds from long-term debt issuances, and an increase in repurchases of common stock and dividends paid, partially offset by a decrease in repayments of long-term debt.
Net cash used in financing activities increased $1,001 million in 2018 compared with 2017. The increase was primarily due to a decrease in proceeds from long-term debt issuances and an increase in repurchases of common stock and dividends paid, partially offset by an increase in proceeds from commercial paper and a decrease in repayments of long-term debt.
See Note 3, “Acquisitions and Divestiture,” to the consolidated financial statements for further discussion of our divestiture and acquisitions.
See “Equity Securities,” of Note 6, “Investments,” to the consolidated financial statements for further discussion of the sale of an investment security and consideration received under a market technology agreement.
See Note 9, “Debt Obligations,” to the consolidated financial statements for further discussion of our debt obligations.
See “Share Repurchase Program,” and “Cash Dividends on Common Stock,” of Note 12, “Nasdaq Stockholders’ Equity,” to the consolidated financial statements for further discussion of our share repurchase program and cash dividends paid on our common stock.
Contractual Obligations and Contingent Commitments
Nasdaq has contractual obligations to make future payments under debt obligations by contract maturity, minimum rental commitments under non-cancelable operating leases, net and other obligations. The following table shows these contractual obligations as of December 31, 2018:
| Payments Due by Period | ||||||||||||||||||||
| Contractual Obligations | Total | Less than 1 year | 1-3 years | 3-5 years | More than 5 years | |||||||||||||||
| (in millions) | ||||||||||||||||||||
| Debt obligations by contract maturity(1) | $ | 4,311 | $ | 996 | $ | 1,463 | $ | 793 | $ | 1,059 | ||||||||||
| Minimum rental commitments under non-cancelable operating leases, net(2) | 637 | 75 | 131 | 86 | 345 | |||||||||||||||
| Purchase obligations(3) | 21 | 11 | 10 | — | — | |||||||||||||||
| Other obligations(4) | 12 | 12 | — | — | — | |||||||||||||||
| Total | $ | 4,981 | $ | 1,094 | $ | 1,604 | $ | 879 | $ | 1,404 |
| (1) | Our debt obligations include both principal and interest obligations. As of December 31, 2018, an interest rate of 4.04% was used to compute the amount of the contractual obligations for interest on the 2016 Credit Facility, 3.72% was used to compute the amount of the contractual obligations for interest on the 2017 Credit Facility and 3.21% was used to compute the amount of the contractual obligations for interest on the 2019 Notes. All other debt obligations were primarily calculated on a 360-day basis at the contractual fixed rate multiplied by the aggregate principal amount as of December 31, 2018. See Note 9, “Debt Obligations,” to the consolidated financial statements for further discussion. |
| (2) | We lease some of our office space under non-cancelable operating leases with third parties and sublease office space to third parties. Some of our leases contain renewal options and escalation clauses based on increases in property taxes and building operating costs. |
| (3) | Purchase obligations primarily represent minimum outstanding obligations due under software license agreements. |
| (4) | Other obligations primarily consist of potential future escrow agreement payments related to prior acquisitions. |
Acquisition of Cinnober
For further discussion of our acquisition of Cinnober, see “Acquisition of Cinnober,” of Note 3, “Acquisitions and Divestiture,” to the consolidated financial statements.
Other Commitment
We have a 40.0% ownership in OCC. Under the OCC's capital plan, the OCC shareholders have committed to contribute up to $200 million in equity capital if certain capital thresholds are breached, including up to $80 million to be contributed by Nasdaq. See “Equity Method Investments,” of Note 6, “Investments,” to the consolidated financial statements for further discussion of our equity method investment in OCC.
Offer for Oslo Børs VPS
For further discussion of our offer for Oslo Børs VPS, see “Offer for Oslo Børs VPS,” of Note 21, “Subsequent Events,” to the consolidated financial statements.
Non-Cash Contingent Consideration
See “Non-Cash Contingent Consideration,” of Note 19, “Commitments, Contingencies and Guarantees,” to the consolidated financial statements for further discussion.
Off-Balance Sheet Arrangements
For discussion of off-balance sheet arrangements see:
| • | Note 15, “Clearing Operations,” to the consolidated financial statements for further discussion of our non-cash default fund contributions and margin deposits received for clearing operations; and |
| • | Note 19, “Commitments, Contingencies and Guarantees,” to the consolidated financial statements for further discussion of: |
| • | Guarantees issued and credit facilities available; |
| • | Lease commitments; |
| • | Other guarantees; |
| • | Non-cash contingent consideration; |
| • | Escrow agreements; |
| • | Routing brokerage activities; |
| • | Acquisition of Cinnober; |
| • | Other commitment; |
| • | Offer for Oslo Børs VPS; |
| • | Legal and regulatory matters; and |
| • | Tax audits. |
Quantitative and Qualitative Disclosures About Market Risk
Market risk represents the potential for losses that may result from changes in the market value of a financial instrument due to changes in market conditions. As a result of our operating, investing and financing activities, we are exposed to market risks such as interest rate risk and foreign currency exchange rate risk. We are also exposed to credit risk as a result of our normal business activities.
We have implemented policies and procedures to measure, manage, monitor and report risk exposures, which are reviewed regularly by management and the board of directors. We identify risk exposures and monitor and manage such risks on a daily basis.
We perform sensitivity analyses to determine the effects of market risk exposures. We may use derivative instruments solely to hedge financial risks related to our financial positions or risks that are incurred during the normal course of business. We do not use derivative instruments for speculative purposes.
Interest Rate Risk
We are subject to the risk of fluctuating interest rates in the normal course of business. Our exposure to market risk for changes in interest rates relates primarily to our financial investments and debt obligations which are discussed below.
Financial Investments
As of December 31, 2018, our investment portfolio was primarily comprised of trading securities, mainly highly rated European government debt securities, which pay a fixed rate of interest. These securities are subject to interest rate risk and will decrease in value if market interest rates increase. If market interest rates were to increase immediately and uniformly by 100 basis points from levels as of December 31, 2018, the fair value of this portfolio would have declined by $4 million.
Debt Obligations
As of December 31, 2018, substantially all of our debt obligations are fixed-rate obligations. While changes in interest rates will have no impact on the interest we pay on fixed-rate obligations, we are exposed to changes in interest rates as a result of the issuance of our 2019 Notes, borrowings under our 2017 Credit Facility and 2016 Credit Facility, and amounts outstanding from the sale of commercial paper under our commercial paper program, all of which have variable interest rates. As of December 31, 2018, we had principal amounts outstanding of $500 million on the 2019 Notes, $100 million under the 2016 Credit Facility, and $276 million of commercial paper. A hypothetical 100 basis points increase in interest rates on our outstanding 2019 Notes, the 2016 Credit Facility and our outstanding commercial paper would increase annual interest expense by approximately $9 million based on borrowings as of December 31, 2018.
Foreign Currency Exchange Rate Risk
As a leading global exchange group, we are subject to foreign currency transaction risk. Our primary exposure to foreign currency denominated revenues less transaction-based expenses and operating income for the years ended December 31, 2018 and 2017 are presented in the following table:
| Euro | Swedish Krona | Other Foreign Currencies | U.S. Dollar | Total | ||||||||||||||||
| (in millions, except currency rate) | ||||||||||||||||||||
| Year Ended December 31, 2018 | ||||||||||||||||||||
| Average foreign currency rate to the U.S. dollar | 1.1800 | 0.1150 | # | N/A | N/A | |||||||||||||||
| Percentage of revenues less transaction-based expenses | 8.9 | % | 7.3 | % | 5.2 | % | 78.6 | % | 100.0 | % | ||||||||||
| Percentage of operating income | 11.3 | % | 0.1 | % | (7.0 | )% | 95.6 | % | 100.0 | % | ||||||||||
| Impact of a 10% adverse currency fluctuation on revenues less transaction-based expenses | $ | (23 | ) | $ | (18 | ) | $ | (13 | ) | $ | — | $ | (54 | ) | ||||||
| Impact of a 10% adverse currency fluctuation on operating income | $ | (12 | ) | $ | — | $ | (7 | ) | $ | — | $ | (19 | ) | |||||||
| Euro | Swedish Krona | Other Foreign Currencies | U.S. Dollar | Total | ||||||||||||||||
| (in millions, except currency rate) | ||||||||||||||||||||
| Year Ended December 31, 2017 | ||||||||||||||||||||
| Average foreign currency rate to the U.S. dollar | 1.1273 | 0.1170 | # | N/A | N/A | |||||||||||||||
| Percentage of revenues less transaction-based expenses | 9.7 | % | 8.2 | % | 6.0 | % | 76.1 | % | 100.0 | % | ||||||||||
| Percentage of operating income | 15.4 | % | 2.5 | % | (4.9 | )% | 87.0 | % | 100.0 | % | ||||||||||
| Impact of a 10% adverse currency fluctuation on revenues less transaction-based expenses | $ | (24 | ) | $ | (20 | ) | $ | (14 | ) | $ | — | $ | (58 | ) | ||||||
| Impact of a 10% adverse currency fluctuation on operating income | $ | (15 | ) | $ | (2 | ) | $ | (5 | ) | $ | — | $ | (22 | ) |
| # | Represents multiple foreign currency rates. |
| N/A | Not applicable. |
Our investments in foreign subsidiaries are exposed to volatility in currency exchange rates through translation of the foreign subsidiaries’ net assets or equity to U.S. dollars. Substantially all of our foreign subsidiaries operate in functional currencies other than the U.S. dollar. Fluctuations in currency exchange rates may create volatility in our results of operations as we are required to translate the balance sheets and operational results of these foreign currency denominated subsidiaries into U.S. dollars for consolidated reporting. The translation of foreign subsidiaries’ non-U.S. dollar balance sheets into U.S. dollars for consolidated reporting results in a cumulative translation adjustment which is recorded in accumulated other comprehensive loss within stockholders’ equity in the Consolidated Balance Sheets.
Our primary exposure to net assets in foreign currencies as of December 31, 2018 is presented in the following table:
| Net Assets | Impact of a 10% Adverse Currency Fluctuation | |||||||
| (in millions) | ||||||||
| Swedish Krona(1) | $ | 3,477 | $ | (348 | ) | |||
| Norwegian Krone | 176 | (18 | ) | |||||
| Canadian Dollar | 120 | (12 | ) | |||||
| British Pound | 145 | (14 | ) | |||||
| Euro | 89 | (9 | ) | |||||
| Australian Dollar | 107 | (11 | ) |
| (1) | Includes goodwill of $2,466 million and intangible assets, net of $580 million. |
Credit Risk
Credit risk is the potential loss due to the default or deterioration in credit quality of customers or counterparties. We are exposed to credit risk from third parties, including customers, counterparties and clearing agents. These parties may default on their obligations to us due to bankruptcy, lack of liquidity, operational failure or other reasons. We limit our exposure to credit risk by evaluating the counterparties with which we make investments and execute agreements. The financial investment portfolio objective is to invest in securities to preserve principal while maximizing yields, without significantly increasing risk. Credit risk associated with investments is minimized substantially by ensuring that these financial assets are placed with governments which have investment grade ratings, well-capitalized financial institutions and other creditworthy counterparties.
Our subsidiary, Nasdaq Execution Services, may be exposed to credit risk, due to the default of trading counterparties, in connection with the routing services it provides for our trading customers. System trades in cash equities routed to other market centers for members of our cash equity exchanges are routed by Nasdaq Execution Services for clearing to the NSCC. In this function, Nasdaq Execution Services is to be neutral by the end of the trading day, but may be exposed to intraday risk if a trade extends beyond the trading day and into the next day, thereby leaving Nasdaq Execution Services susceptible to counterparty risk in the period between accepting the trade and routing it to the clearinghouse. In this interim period, Nasdaq Execution Services is not novating like a clearing broker but instead is subject to the short-term risk of counterparty failure before the clearinghouse enters the transaction. Once the clearinghouse officially accepts the trade for novation, Nasdaq Execution Services is legally removed from trade execution risk. However, Nasdaq has membership obligations to NSCC independent of Nasdaq Execution Services’ arrangements.
Pursuant to the rules of the NSCC and Nasdaq Execution Services’ clearing agreement, Nasdaq Execution Services is liable for any losses incurred due to a counterparty or a clearing agent’s failure to satisfy its contractual obligations, either by making payment or delivering securities. Adverse movements in the prices of securities that are subject to these transactions can increase our credit risk. However, we believe that the risk of material loss is limited, as Nasdaq Execution Services’ customers are not permitted to trade on margin and NSCC rules limit counterparty risk on self-cleared transactions by establishing credit limits and capital deposit requirements for all brokers that clear with NSCC. Historically, Nasdaq Execution Services has never incurred a liability due to a customer’s failure to satisfy its contractual obligations as counterparty to a system trade. Credit difficulties or insolvency, or the perceived possibility of credit difficulties or insolvency, of one or more larger or visible market participants could also result in market-wide credit difficulties or other market disruptions.
Execution Access is an introducing broker which operates the trading platform for our Fixed Income business to trade in U.S. Treasury securities. Execution Access has a clearing
arrangement with Industrial and Commercial Bank of China Financial Services LLC, or ICBC. As of December 31, 2018, we have contributed $15 million of clearing deposits to ICBC in connection with this clearing arrangement. These deposits are recorded in other current assets in our Consolidated Balance Sheets. Some of the trading activity in Execution Access is cleared by ICBC through the Fixed Income Clearing Corporation, with ICBC acting as agent. Execution Access assumes the counterparty risk of clients that do not clear through the Fixed Income Clearing Corporation. Counterparty risk of clients exists for Execution Access between the trade date and settlement date of the individual transactions, which is at least one business day (or more, if specified by the U.S. Treasury issuance calendar). Counterparties that do not clear through the Fixed Income Clearing Corporation are subject to a credit due diligence process and may be required to post collateral, provide principal letters, or provide other forms of credit enhancement to Execution Access for the purpose of mitigating counterparty risk. Daily position trading limits are also enforced for such counterparties.
We have credit risk related to transaction and subscription-based revenues that are billed to customers on a monthly or quarterly basis, in arrears. Our potential exposure to credit losses on these transactions is represented by the receivable balances in our Consolidated Balance Sheets. We review and evaluate changes in the status of our counterparties’ creditworthiness. Credit losses such as those described above could adversely affect our consolidated financial position and results of operations.
We also are exposed to credit risk through our clearing operations with Nasdaq Clearing. See Note 15, “Clearing Operations,” to the consolidated financial statements for further discussion. Our clearinghouse holds material amounts of clearing member cash deposits which are held or invested primarily to provide security of capital while minimizing credit, market and liquidity risks. While we seek to achieve a reasonable rate of return, we are primarily concerned with preservation of capital and managing the risks associated with these deposits. As the clearinghouse may pass on interest revenues (minus costs) to the members, this could include negative or reduced yield due to market conditions. The following is a summary of the risks associated with these deposits and how these risks are mitigated.
| • | Credit Risk. When the clearinghouse has the ability to hold cash collateral at a central bank, the clearinghouse utilizes its access to the central bank system to minimize credit risk exposures. When funds are not held at a central bank, we seek to substantially mitigate credit risk by ensuring that investments are primarily placed in highly rated government and supranational debt instruments. |
| • | Liquidity Risk. Liquidity risk is the risk a clearinghouse may not be able to meet its payment obligations in the right currency, in the right place and the right time. To mitigate this risk, the clearinghouse monitors liquidity requirements closely and maintains funds and assets in a manner which minimizes the risk of loss or delay in the access by the clearinghouse to such funds and assets. For example, |
holding funds with a central bank where possible or investing in highly liquid government or supranational debt instruments serves to reduce liquidity risks.
| • | Interest Rate Risk. Interest rate risk is the risk that interest rates rise causing the value of purchased securities to decline. If we were required to sell securities prior to maturity, and interest rates had risen, the sale of the securities might be made at a loss relative to the latest market price. Our clearinghouse seeks to manage this risk by making short term investments of members' cash deposits. In addition, the clearinghouse investment guidelines allow for direct purchases or repurchase agreements of high quality sovereign debt (for example, European government and U.S. Treasury securities), central bank certificates and supranational debt instruments with short dated maturities. |
| • | Security Issuer Risk. Security issuer risk is the risk that an issuer of a security defaults on its payment when the security matures. This risk is mitigated by limiting allowable investments and collateral under reverse repurchase agreements to high quality sovereign, government agency or supranational debt instruments. |
Critical Accounting Policies and Estimates
The preparation of financial statements and related disclosures in conformity with U.S. GAAP requires management to make judgments, assumptions, and estimates that affect the amounts reported in the consolidated financial statements and accompanying notes. Note 2, “Summary of Significant Accounting Policies,” to the consolidated financial statements describes the significant accounting policies and methods used in the preparation of the consolidated financial statements. The accounting policies described below are significantly affected by critical accounting estimates. Such accounting policies require significant judgments, assumptions, and estimates used in the preparation of the consolidated financial statements, and actual results could differ materially from the amounts reported based on these policies.
Revenue Recognition
Corporate Services Revenues
Listing Services Revenues
Listing services revenues primarily include annual renewal fees and initial listing fees. Annual renewal fees do not require any judgments or assumptions by management as these amounts are recognized ratably over the following 12-month period. However, the initial listing fee is allocated to multiple performance obligations including initial and subsequent listing services and corporate solutions services (when a company qualifies to receive these services under the applicable Nasdaq rule), as well as a customer's material right to renew the option to list on our exchanges.
In performing this allocation, the standalone selling price of the performance obligations is based on the initial and annual listing fees and the standalone selling price of the corporate solutions services is based on its market value. All listing fees are billed
upfront and the identified performance obligations are satisfied over time since the customer receives and consumes the benefit as Nasdaq provides the listing service. The amount of revenue related to the corporate solutions services performance obligation is recognized ratably over a two-year period, which is based on contract terms, with the remaining revenue recognized ratably over six years which is based on our historical listing experience and projected future listing duration.
Market Technology Revenues
We enter into long-term contracts with customers to develop customized technology solutions, license the right to use software and provide support and other services to our customers which results in these contracts containing multiple performance obligations. We allocate the contract transaction price to each performance obligation using our best estimate of the standalone selling price of each distinct good or service in the contract. In instances where standalone selling price is not directly observable, such as when we do not sell the product or service separately, we determine the standalone selling price predominately through an expected cost plus a margin approach.
We generally recognize revenue over time as our customers simultaneously receive and consume the benefits provided by our performance because our customer controls the asset for which we are creating, our performance does not create an asset with alternative use, and we have a right to payment for performance completed to date. For these services, we recognize revenue over time using costs incurred to date relative to total estimated costs at completion to measure progress toward satisfying our performance obligation. Incurred costs represent work performed, which corresponds with, and thereby depicts, the transfer of control to the customer.
Accounting for our long-term contracts requires judgment relative to assessing risks and their impact on the estimate of revenues and costs. Our estimates are impacted by factors such as the potential for schedule and technical issues, productivity, and the complexity of work performed. When adjustments in estimated total contract costs are required, any changes in the estimated revenues from prior estimates are recognized in the current period for the effect of such change. If estimates of total costs to be incurred on a contract exceed estimates of total revenues, a provision for the entire estimated loss on the contract is recorded in the period in which the loss is determined.
For further discussion related to recognition of these fees, see “Revenue From Contracts with Customers - Listing Services,” and “Revenue From Contracts with Customers - Market Technology,” of Note 2, “Summary of Significant Accounting Policies,” to the consolidated financial statements for further discussion.
Goodwill and Related Impairment
Goodwill represents the excess of purchase price over the value assigned to the net assets, including identifiable intangible assets, of a business acquired. Goodwill is allocated to our reporting units based on the assignment of the fair values of
each reporting unit of the acquired company. We test goodwill for impairment at the reporting unit level annually, or in interim periods if certain events occur indicating that the carrying amount may be impaired, such as changes in the business climate, poor indicators of operating performance or the sale or disposition of a significant portion of a reporting unit. For purposes of performing our goodwill impairment test, our five reporting units are the Market Services segment, the two businesses comprising the Corporate Services segment: Corporate Solutions and Listing Services, the Information Services segment, and the Market Technology segment. We test for impairment during the fourth quarter of our fiscal year using an October 1 measurement date. When testing goodwill for impairment, we have the option of first performing a qualitative assessment to determine whether it is more likely than not that the fair value of a reporting unit is less than its carrying amount as the basis to determine if it is necessary to perform a quantitative goodwill impairment test. In performing a qualitative assessment, we consider the extent to which unfavorable events or circumstances identified, such as changes in economic conditions, industry and market conditions or company specific events, could affect the comparison of the reporting unit’s fair value with its carrying amount. If we choose not to complete a qualitative assessment for a given reporting unit, or if the initial assessment indicates that it is more likely than not that the carrying amount of a reporting unit exceeds its estimated fair value, a quantitative test is required.
When assessing goodwill for impairment, our decision to perform a qualitative impairment assessment for a reporting unit in a given year is influenced by a number of factors, including but not limited to, the size of the reporting unit’s goodwill, the significance of the excess of the reporting unit’s estimated fair value over its carrying amount at the last quantitative assessment date, and the amount of time in between quantitative fair value assessments.
The quantitative goodwill impairment test consists of two steps performed at the reporting unit level.
| • | The first step compares the estimated fair value of each reporting unit to its corresponding carrying amount, including goodwill. The fair value of each reporting unit is estimated using a combination of discounted cash flow valuation, which incorporates assumptions regarding future growth rates, terminal values, and discount rates, as well as guideline public company valuations, incorporating relevant trading multiples of comparable companies and other factors. The estimates and assumptions used consider historical performance and are consistent with the assumptions used in determining future profit plans for each reporting unit, which are approved by our board of directors. If the reporting unit’s estimated fair value exceeds its estimated carrying amount, goodwill is not impaired. |
| • | If the first step results in the carrying amount exceeding the fair value of the reporting unit, then a second step must be completed in order to determine the amount of goodwill impairment that should be recorded, if any. In the second |
step, the implied fair value of the reporting unit’s goodwill is determined by allocating the reporting unit’s fair value to all of its assets and liabilities other than goodwill in a manner similar to a purchase price allocation. The implied fair value of the goodwill that results from the application of this second step is then compared to the carrying amount of the goodwill and an impairment charge is recorded for any difference.
The following table presents the balances of goodwill for our reportable segments at the time of our 2018 annual impairment test:
| October 1, 2018 | |||
| (in millions) | |||
| Market Services | $ | 3,435 | |
| Corporate Services | 503 | ||
| Information Services | 2,283 | ||
| Market Technology | 148 | ||
| $ | 6,369 |
In 2018, we performed a qualitative goodwill impairment test for all reporting units, as the excesses of their fair values over their respective carrying amounts at the time of the quantitative test in 2017 were significant. In conducting the qualitative assessment, we evaluated the performance of each of these reporting units since the last quantitative test, as well as future financial projections to determine if there were any changes in the key inputs used to determine the fair values of each reporting unit. We also considered the qualitative factors in FASB ASC Topic 350, “Intangibles–Goodwill and Other,” as well as other relevant events and circumstances. Based on the results of the qualitative assessment for each reporting unit, we concluded based on a predominance of positive indicators and the weight of such indicators that the fair values of our reporting units are more likely than not greater than their respective carrying amounts and as a result, quantitative analyses were not needed. No goodwill impairment was recorded in 2018, 2017 and 2016.
Although we believe our estimates of fair value are reasonable, the determination of certain valuation inputs is subject to management’s judgment. Changes in these inputs could materially affect the results of our impairment review. If our forecasts of cash flows or other key inputs are negatively revised in the future, the estimated fair value of each reporting unit would be adversely impacted, potentially leading to an impairment in the future that could materially affect our operating results.
Subsequent to our annual impairment test, no indications of impairment were identified.
Indefinite-Lived Intangible Assets and Related Impairment
Intangible assets deemed to have indefinite useful lives, primarily exchange and clearing registrations, are not amortized but instead are tested for impairment at least annually and more frequently whenever events or changes in circumstances indicate that the fair value of the asset may be less than its carrying amount. Similar to goodwill impairment testing, we
test for impairment of indefinite-lived intangible assets during the fourth quarter of our fiscal year using an October 1 measurement date and may first perform a qualitative assessment, considering similar factors as discussed above in the goodwill impairment discussion, to determine if it is more likely than not that the fair value of the indefinite-lived intangible asset is less than its carrying amount. If we elect to perform or are required to perform a quantitative assessment, the test consists of a comparison of the fair value of the indefinite-lived intangible asset to its carrying amount as of the impairment testing date. If the carrying amount of the indefinite-lived intangible asset exceeds its fair value, an impairment charge is recorded for the difference. The fair value of indefinite-lived intangible assets is primarily determined on the basis of estimated discounted value, using the Greenfield Approach for exchange and clearing registrations and licenses and the relief from royalty approach or excess earnings approach for trade names, both of which incorporate assumptions regarding future revenue projections and discount rates. During our annual indefinite-lived intangible asset impairment test during the fourth quarter of 2018, we performed a qualitative test as the excess fair value of each individual indefinite-lived intangible asset over its respective carrying amount at the time of the quantitative test in 2017 was significant. Based on the results of the qualitative assessment, we concluded based on a predominance of positive indicators and the weight of such indicators that the fair values of our indefinite-lived intangible assets are more likely than not greater than their respective carrying amounts and as a result, quantitative analyses were not needed. There were no indefinite-lived intangible asset impairment charges in 2018 and 2017. Subsequent to our annual indefinite-lived impairment test, no indications of impairment were identified.
In 2016, we recorded a pre-tax, non-cash indefinite-lived intangible asset impairment charge of $578 million to write off the full value of a trade name from an acquired business due to a continued decline in the operating performance of the business during 2016 and a rebranding of our fixed income business under a single brand called Nasdaq Fixed Income. This charge is recorded in asset impairment charge in the Consolidated Statements of Income for 2016. There were no other impairments of indefinite-lived intangible assets for the year ended December 31, 2016.
Other Long-Lived Assets and Related Impairment
We review our other long-lived assets, such as finite-lived intangible assets, equity method investments and equity securities, as well as property and equipment for potential impairment when there is evidence that events or changes in circumstances indicate that the carrying amount of an asset may not be recoverable. The carrying amount of an asset is not recoverable if it exceeds the sum of the undiscounted cash flows expected to result from the use and eventual disposition of the asset. Fair value of finite-lived intangible assets and property and equipment is based on various valuation techniques. We evaluate our equity method investments and equity securities for other-than-temporary declines in value by considering a variety of factors such as the earnings capacity of the investment
and the fair value of the investment compared to its carrying amount. In addition, for investments where the market value is readily determinable, we consider the underlying stock price as an additional factor. Any required impairment loss is measured as the amount by which the carrying amount of the asset exceeds its fair value and is recorded as a reduction in the carrying amount of the related asset and a charge to operating results.
In 2016, we recorded a pre-tax, non-cash impairment charge of $7 million to write off the full value of an equity method investment since the fair value of the investment was less than the carrying value and management considered the decline in value to be other-than-temporary. This charge is partially offset by a gain resulting from the sale of a percentage of a separate equity method investment and is recorded in net income from unconsolidated investees in the Consolidated Statements of Income for 2016. No other impairments of equity method investments or equity securities were recorded in 2018, 2017 or 2016.
We recorded pre-tax, non-cash property and equipment asset impairment charges of $9 million in 2017 and $8 million in 2016. The impairment charge in 2017 primarily related to the write-off of capitalized software and hardware equipment associated with our 2017 and 2016 acquisitions and is included in merger and strategic initiatives expense in the Consolidated Statements of Income for 2017. The asset impairment charge in 2016 primarily related to fixed assets and capitalized software that were retired and is included in restructuring charges in the Consolidated Statements of Income for 2016. There were no other impairments of property and equipment recorded in 2018, 2017 or 2016.
Income Taxes
Estimates and judgments are required in the calculation of certain tax liabilities and in the determination of the recoverability of certain deferred tax assets, which arise from net operating loss carryforwards, tax credit carryforwards and temporary differences between the tax and financial statement recognition of revenue and expense. Our deferred tax assets are reduced by a valuation allowance if it is more likely than not that some portion or all of the recorded deferred tax assets will not be realized in future periods. Management is required to determine whether a tax position is more likely than not to be sustained upon examination, including resolution of any related appeals or litigation processes, based on the technical merits of the position. Once it is determined that a position meets the recognition thresholds, the position is measured to determine the amount of benefit to be recognized in the consolidated financial statements.
In assessing the need for a valuation allowance, we consider all available evidence including past operating results, the existence of cumulative losses in the most recent fiscal years, estimates of future taxable income and the feasibility of tax planning strategies. In the event that we change our determination as to the amount of deferred tax assets that can be realized, we will adjust our valuation allowance with a corresponding impact to the provision for income taxes in the period in which such determination is made.
In addition, the calculation of our tax liabilities involves uncertainties in the application of tax regulations in the U.S. and other tax jurisdictions. We recognize potential liabilities for anticipated tax audit issues in such jurisdictions based on our estimate of whether, and the extent to which, additional taxes and interest may be due. While we believe that our tax liabilities reflect the probable outcome of identified tax uncertainties, it is reasonably possible that the ultimate resolution of any tax matter may be greater or less than the amount accrued. If events occur and the payment of these amounts ultimately proves unnecessary, the reversal of the liabilities would result in tax benefits being recognized in the period when we determine the liabilities are no longer necessary. If our estimate of tax liabilities proves to be less than the ultimate assessment, a further charge to expense would result.
The Tax Cuts and Jobs Act was enacted on December 22, 2017. This act contained several key provisions, including a reduction of the U.S. corporate income tax rate from 35% to 21%. It also imposed a transition tax on unremitted aggregate accumulated earnings of non-U.S. subsidiaries, which did not impact us and the act also created a new requirement to provide U.S. tax on foreign earnings, global intangible low-taxed income, or GILTI, which was immaterial for 2018. In December 2017, the SEC staff issued Staff Accounting Bulletin No. 118, “Income Tax Accounting Implications of the Tax Cuts and Jobs Act,” or SAB 118, which allowed us to record provisional amounts during a measurement period not to extend beyond one year of the enactment date. During the fourth quarter of 2018, we finalized the effects of the new legislation. For further discussion of the impact of the Tax Cuts and Jobs Act on our financial statements, see “Tax Cuts and Jobs Act,” of Note 17, “Income Taxes,” to the consolidated financial statements.
Recent Accounting Pronouncements
See “Recent Accounting Pronouncements,” of Note 2, “Summary of Significant Accounting Policies,” to the consolidated financial statements for further discussion of recently adopted and recently issued accounting pronouncements that are applicable to Nasdaq.
Previous: Item 6. Selected Financial Data. · Next: Item 7A. Quantitative and Qualitative Disclosures About Market Risk