 filings.tools
NVR (NVR) 10-K risk factor changes: FY2012 vs FY2011
The 2012-12-31 10-K against the 2011-12-31 one, compared heading by heading and sentence by sentence. One of these filings carries no fiscal year tag, so its year is the calendar year of the period end.
Item 1A16 rewritten10 added9 removed114 unchanged
All filing items801 rewritten374 added239 removed1,633 unchanged
Summary
counted, not written
- Item 1A lists 15 risk factor headings: 2 new, 0 reworded and 13 unchanged since FY2011. 1 heading from FY2011 no longer appears.
- Sentence by sentence, 374 added, 239 removed, 801 rewritten and 1,633 unchanged across 18 items that differ.
New Item 1A headings (2)
- The homebuilding industry experienced a significant downturn over the past several years, which could continue to adversely affect our business and our results of operations.
- Our current indebtedness may impact our future operations.
Removed Item 1A headings (1)
- The homebuilding industry continues to experience a significant downturn. The continuation of this slowdown could adversely affect our business and our results of operations.
A heading is new when no FY2011 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
21 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2012; struck-through words were in FY2011. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors.
16 rewritten, 10 added, 9 removed, 114 unchanged
[removed: The] [added: Over the past several years, the] homebuilding industry [removed: has continued to experience] [added: experienced] a significant downturn as a result of low consumer confidence driven by an economic recession, high unemployment levels, affordability issues and uncertainty as to the stability of home prices.
As a result, we [removed: have] experienced reduced demand for new homes.
[removed: A continued] [added: The] downturn [added: experienced] in the homebuilding industry could have a material adverse effect on our sales either through fewer gross sales and/or higher cancellation rates, which could have a material adverse effect on our profitability, stock performance, ability to service our debt obligations and future cash flows.
We sell all of the loans we originate into the secondary mortgage market generally within 30 [removed: to 60] days from origination.
This may result in [removed: a loss] [added: losses] which could have a material adverse effect on our profitability, stock performance, ability to service our debt obligations and future cash flows.
Our mortgage banking business sells all of the loans it originates into the secondary market usually within 30 [removed: to 60] days from the date of closing, and has up to approximately $25 million available in a repurchase agreement to fund mortgage closings.
In the event that [removed: other] disruptions to the secondary markets similar to [removed: this and to] those which occurred during 2007 and 2008 continue to tighten or eliminate the available liquidity within the secondary markets for mortgage loans, or the underwriting requirements by our secondary market investors continue to become more stringent, our ability to sell future mortgages could decline and we could be required, among other things, to fund our commitments to our buyers with our own financial resources, which is limited, or require our home buyers to find another source of financing.
In particular, approximately [removed: 35%] [added: 38%] of our home settlements during [removed: 2011] [added: 2012] occurred in the Washington, D.C. and Baltimore, MD metropolitan areas, which accounted for approximately [removed: 46%] [added: 47%] of our homebuilding revenues in [removed: 2011.][added: 2012.]
If we require working capital greater than that provided by our operations, we may be required to [removed: seek to] obtain alternative financing.
If we are required to seek financing to fund our working capital requirements, continued volatility in these markets [added: similar to that experienced in the past several years] may restrict our flexibility to access financing.
We are subject to various local, state and federal statutes, ordinances, rules and regulations concerning zoning, building design, construction and similar matters, including local regulations that impose restrictive zoning and density requirements in order to limit the number of homes that can eventually be built [removed: within the boundaries of a particular area.]
In addition, we have from time to time been subject to, and may also be subject in the future to, periodic delays in our homebuilding projects due to building moratoriums in the areas in which we [added: operate.]
[removed: Because these provisions are to be implemented through future rulemaking, the] [added: The] ultimate impact of such provisions on lending institutions, including our mortgage banking subsidiary, will depend on [removed: how] the [removed: implementing rules are written.][added: banking industry’s implementation of these new standards.]
We are an approved seller/servicer of FNMA mortgage loans and an approved [removed: lender/seller] [added: seller/issuer] of GNMA, FHLMC, VA and FHA mortgage loans, and are subject to all of those agencies’ rules and regulations.
The homebuilding business has from time to time experienced building material and labor shortages, [added: including shortages in insulation, drywall, certain carpentry work and concrete, as well as fluctuating lumber prices and supply.]
In addition, [removed: high employment levels and] strong construction market conditions could restrict the labor force available to our subcontractors and us in one or more of our markets.
The homebuilding industry experienced a significant downturn over the past several years, which could continue to adversely affect our business and our results of operations.
During 2012, we began to see signs of strengthening within the homebuilding industry with increasing sales and stabilization of selling prices in many markets.
However, the housing market continues to face challenges from a tight mortgage lending environment and consumer confidence issues due to sustained high levels of unemployment.
Our current indebtedness may impact our future operations.
Our existing indebtedness contains restrictive covenants and any future indebtedness may also contain covenants.
These covenants include, or could include, restrictions on our ability to create, incur, assume or guarantee secured debt, enter into sale and leaseback transactions and conditions related to mergers and/or the sale of assets.
Substantial losses by us or other action or inaction by us or our subsidiaries could result in the violation of one or more of these covenants, which could result in decreased liquidity or a default on our current or future indebtedness, thereby having a material adverse effect on our sales, profitability, stock performance, ability to service our debt obligations and future cash flows.
within the boundaries of a particular area.
The Consumer Financial Protection Bureau issued rules governing multiple issues in January 2013, including “Ability to Repay” underwriting provisions, appraisal standards, servicing and escrow rules, and loan officer compensation requirements.
Additional rulemaking is expected within the next couple of months.
The homebuilding industry continues to experience a significant downturn.
The continuation of this slowdown could adversely affect our business and our results of operations.
Additionally, the tightening credit markets have made it more difficult for customers to obtain financing to purchase homes.
These ongoing market factors have also resulted in pricing pressures and in turn gross profit margin pressure in all of our markets.
In October 2011, Bank of America discontinued their correspondent lending program.
As a result, this reduced the number of investors available in our loan sale distribution channels, increasing the loan volume of the remaining correspondent investors and in turn lengthening the time period it takes for us to sell loans and increasing our inventory of mortgages held for sale at December 31, 2011.
In addition, the credit and capital markets are experiencing significant volatility that is difficult to predict.
operate.
including shortages in insulation, drywall, certain carpentry work and concrete, as well as fluctuating lumber prices and supply.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
224 rewritten, 141 added, 95 removed, 398 unchanged
[removed: | |] (dollars in thousands, except per share data) [removed: |]
Results of Operations for the Years Ended December 31, [removed: 2011, 2010] [added: 2012, 2011] and [removed: 2009][added: 2010]
| _Mid Atlantic:_ | | Maryland, Virginia, West [removed: Virginia and] [added: Virginia,] Delaware [added: and Washington, D.C.] |
However, [removed: economic conditions and] [added: during] the [removed: continued downturn] [added: past several years, the impact] of [added: economic conditions on] the homebuilding industry [removed: have exerted pressure on] [added: has negatively impacted] our developers’ ability to obtain acquisition and development financing or to raise equity investments to finance land development activity, potentially constraining our supply of finished lots.
Once we acquire control of any raw ground, we determine whether to sell the raw parcel to a developer and enter into a fixed price purchase agreement with the developer to purchase the finished lots, or whether [removed: to] [added: we will] hire a developer to develop the land on our behalf.
As of December 31, [removed: 2011,] [added: 2012,] we controlled approximately [removed: 48,200] [added: 53,200] lots under purchase agreements with deposits in cash and letters of credit totaling approximately [removed: $202,300] [added: $256,600] and [removed: $3,200,] [added: $3,300,] respectively.
Additionally, we controlled approximately [removed: 6,700] [added: 7,400] lots through joint venture limited liability corporations with an aggregate investment of approximately [removed: $89,500.][added: $82,900.]
Of the lots controlled by the joint ventures, approximately [removed: 2,700] [added: 2,800] were not under contract at December 31, [removed: 2011.][added: 2012.]
Included in the number of controlled lots are approximately [removed: 10,600] [added: 10,200] lots for which we have recorded a contract land deposit impairment reserve of approximately [removed: $70,300] [added: $65,000] as of December 31, [removed: 2011.][added: 2012.]
See Note 3 [added: and Note 4] to the consolidated financial statements included herein for additional information regarding contract land [removed: deposits.][added: deposits and land under development, respectively.]
Further, as of December 31, [removed: 2011,] [added: 2012,] we had approximately [removed: $78,000] [added: $68,300] in land under development, that once fully developed will result in approximately [removed: 800 lots.][added: 700 lots for use in our homebuilding operations.]
As a [removed: result,] [added: result of the favorable market conditions in 2012,] our new orders, net of cancellations (“new orders”), for [removed: 2011 were down 2%] [added: 2012 increased 18%] from the prior year while our average new order selling price of [removed: $304.1 remained flat year over] [added: $328.8 was 8% higher than the prior] year.
Gross profit margins in 2011 [removed: within our homebuilding business] were negatively impacted by pricing pressure and increased construction and sales incentive [removed: costs year over year, declining to 17.1% from 18.2%] [added: costs, driven by challenging market conditions] in [removed: 2010.][added: 2011.]
[removed: We believe that significant] [added: Significant] economic uncertainties remain which could result in [removed: continued] sales, pricing and gross [added: profit] margin pressure over the next several quarters.
[removed: Because these provisions are to be implemented through future rulemaking, the] [added: The] ultimate impact of such provisions on lending institutions, including our mortgage banking subsidiary, will depend on [removed: how] the [removed: implementing rules are written.][added: banking industry’s implementation of these new standards.]
Despite these ongoing economic uncertainties, we believe that we are well positioned to [removed: withstand this market uncertainty and] take advantage of opportunities that may arise due to the strength of our balance [removed: sheet and liquidity.][added: sheet.]
| | | [removed: 2011] [added: 2012] | | | | [removed: 2010] [added: 2011] | | | | [removed: 2009] [added: 2010] | | |
| Revenues | | $ | [removed: 2,611,195] [added: 3,121,244] | | | $ | [removed: 2,980,758] [added: 2,611,195] | | | $ | [removed: 2,683,467] [added: 2,980,758] | |
| Cost of sales | | $ | [removed: 2,165,625] [added: 2,575,639] | | | $ | [removed: 2,438,292] [added: 2,165,625] | | | $ | [removed: 2,185,733] [added: 2,438,292] | |
| Gross profit margin percentage | | | [removed: 17.1] [added: 17.5] | % | | | [removed: 18.2] [added: 17.1] | % | | | [removed: 18.5] [added: 18.2] | % |
| Selling, general and administrative expenses | | $ | [removed: 264,266] [added: 301,184] | | | $ | [removed: 257,394] [added: 264,266] | | | $ | [removed: 233,152] [added: 257,394] | |
| Settlements (units) | | | [removed: 8,487] [added: 9,843] | | | | [removed: 10,030] [added: 8,487] | | | | [removed: 9,042] [added: 10,030] | |
| Average settlement price | | $ | [removed: 307.5] [added: 317.1] | | | $ | [removed: 297.1] [added: 307.5] | | | $ | [removed: 296.4] [added: 297.1] | |
| New orders (units) | | | [removed: 9,247] [added: 10,954] | | | | [removed: 9,415] [added: 9,247] | | | | [removed: 9,409] [added: 9,415] | |
| Average new order price | | $ | [removed: 304.1] [added: 328.8] | | | $ | [removed: 304.0] [added: 304.1] | | | $ | [removed: 292.7] [added: 304.0] | |
| Backlog (units) | | | [removed: 3,676] [added: 4,979] | | | | [removed: 2,916] [added: 3,676] | | | | [removed: 3,531] [added: 2,916] | |
| Average backlog price | | $ | [removed: 315.8] [added: 346.2] | | | $ | [removed: 328.6] [added: 315.8] | | | $ | [removed: 304.9] [added: 328.6] | |
| New order cancellation rate | | | [removed: 14] [added: 14.5] | % | | | [removed: 14] [added: 13.6] | % | | | [removed: 14] [added: 13.8] | % |
Average settlement prices in [removed: the current year] [added: 2011] were favorably impacted by an 8% higher average price of homes in the beginning backlog entering 2011 compared to the same period in 2010.
New orders in 2011 decreased 2% when compared to [removed: the prior year,] [added: 2010,] while the average sales price of new orders remained flat year over year.
[removed: As discussed in the _Overview_ section above,] [added: During 2011,] we [removed: continue] [added: continued] to face selling pressure in most of our markets due to continuing economic uncertainty, driven by low consumer confidence and high unemployment rates.
The increase in the average [added: selling] price [removed: of new orders year over year, was] [added: is] attributable to a product mix shift away from our attached products to our detached [removed: product] [added: products] which generally sell at higher price points.
[removed: As discussed in] [added: Despite this gross profit margin improvement year over year,] the [removed: _Overview_ section above,] [added: South East segment’s] gross profit [removed: margins in 2011] [added: margins, similar to our other segments,] were negatively impacted by pricing pressure and increased construction and sales incentive [removed: costs.][added: costs year over year.]
The increase in backlog units was primarily attributable to the decreased settlement activity in [removed: 2011 as discussed above.][added: 2011.]
Expressed as the total of all cancellations during the period as a percentage of gross sales during the period, our cancellation rate was [removed: approximately 14%] [added: 14.5%, 13.6% and 13.8%] in each of [removed: 2011, 2010] [added: 2012, 2011] and [removed: 2009.][added: 2010, respectively.]
[removed: Of a reporting quarter’s opening backlog, 6% during] [added: During each of 2012,] 2011 and 2010, [removed: and 7% during 2009,] [added: approximately 6%] of [removed: that] [added: a reporting quarter’s] opening backlog [removed: balance] cancelled during the fiscal quarter.
For presentation purposes below, the contract land deposit reserve at December 31, [removed: 2011, 2010] [added: 2012, 2011] and [removed: 2009,] [added: 2010,] respectively, has been allocated to the reportable segments to show contract land deposits on a net basis.
The net contract land deposit balances below also includes approximately [removed: $3,200, $6,600] [added: $3,300, $3,200] and [removed: $4,900] [added: $6,600] at December 31, [removed: 2011, 2010] [added: 2012, 2011] and [removed: 2009,] [added: 2010,] respectively, of letters of credit issued as deposits in lieu of cash.
| Mid Atlantic | | $ | [removed: 1,582,826] [added: 1,877,905] | | | $ | [removed: 1,780,521] [added: 1,582,826] | | | $ | [removed: 1,661,244] [added: 1,780,521] | |
| North East | | | [removed: 221,146] [added: 278,715] | | | | [removed: 287,561] [added: 221,146] | | | | [removed: 254,654] [added: 287,561] | |
Throughout 2012, the homebuilding market continued to experience a stabilization in prices and improving sales trends for new homes, after several years of declining home prices and sales.
These favorable market conditions are driven by improved affordability levels resulting from historically low mortgage interest rates and rising costs in the rental market.
In addition, certain markets have been favorably impacted by lower inventory levels.
Despite these improvements, the housing market continues to face challenges from a tight mortgage lending environment, consumer confidence issues due to sustained high levels of unemployment and uncertainty as to the long-term sustainability of the economic recovery, which to this point has been uneven.
Consolidated revenues totaled $3,184,650 for 2012, an increase of 20% from $2,659,149 in 2011.
Net income for 2012 increased 40% from the prior year to $180,588.
Diluted earnings per share in 2012 was $35.12, an increase of 53% from the prior year.
On December 31, 2012, we completed the acquisition of substantially all of the assets and assumed certain liabilities of Heartland Homes, Inc., the second largest homebuilder in the Pittsburgh, PA market.
The acquisition added approximately 200 units and $81,600 to our backlog balance at the end of 2012.
The acquisition did not impact our sales or settlements for 2012.
Heartland Homes settled approximately 400 homes during 2012.
Although there were signs in 2012 that the housing market has begun to recover, we believe that continued growth in sales and prices will be reliant on a sustained overall economic recovery and higher consumer confidence levels.
The Consumer Financial Protection Bureau issued rules governing multiple issues in January 2013, including “Ability to Repay” underwriting provisions, appraisal standards, servicing and escrow rules, and loan officer compensation requirements.
Additional rulemaking is expected within the next couple of months.
Homebuilding revenues for 2012 increased 20% from 2011, as a result of a 16% increase in the number of homes settled and a 3% increase in the average settlement price year over year.
The increase in the number of homes settled was attributable to an 18% increase in new orders during the first half of 2012 compared to the same period in 2011, coupled with a 26% higher beginning backlog unit balance entering 2012 as compared to 2011.
These increases were offset partially by a lower backlog turnover rate in 2012 compared to 2011.
Average settlement prices in the current year were favorably impacted primarily by a 7% higher average sales price of new orders during the first six months of 2012 as compared to the same period in 2011, offset partially by a 4% lower average price of homes in backlog entering 2012 compared to the average price of homes in backlog entering 2011.
New orders and the average sales price of new orders in 2012 increased 18% and 8%, respectively, when compared to 2011.
New orders and the average new order selling prices were higher year over year in each of our market segments.
The increase in new orders was driven by a 5% increase in the number of active communities year over year and by improved absorption rates in many of our markets.
As discussed in the _Overview_ section above, we believe this increase as well as the increase in the average new order selling prices is attributable to lower housing inventory, improved affordability and a stabilization of housing prices in certain of our markets.
Gross profit margins in 2012 increased to 17.5% from 17.1% in 2011.
Margins were favorably impacted in 2012 by a $2,000 recovery of contract land deposits previously determined to be uncollectible compared to an $11,200 contract land deposit impairment charge in 2011.
In addition, the aforementioned increased settlement volume and higher average settlement prices in 2012 allowed us to better leverage certain operating costs.
However, this favorable impact was offset by higher construction, lumber and certain other commodity costs year over year.
SG&A expenses in 2012 increased approximately $36,900, or 14%, compared to 2011, but as a percentage of revenue decreased to 9.7% in 2012 from 10.1% in the prior year.
The increase in SG&A expense was attributable to an increase of approximately $19,700 in management incentive costs driven by our improved financial results.
In addition, personnel costs and sales and marketing costs, were approximately $9,400 and $6,400 higher, respectively, in the current year due primarily to the 5% increase in the number of active communities year over year.
SG&A expenses decreased as a percentage of revenue due to the aforementioned 20% increase in revenues year over year.
Backlog units and dollars increased approximately 35% to 4,979 and 49% to $1,723,914, respectively, as of December 31, 2012, compared to 3,676 and $1,160,879 as of December 31, 2011.
The increase in backlog units was primarily attributable to new orders being approximately 800 units higher for the six month period ended December 31, 2012 compared to the same period in 2011, coupled with a slower backlog turnover rate in 2012.
In addition, as mentioned in the _Overview_ section above, the December 31, 2012 acquisition of Heartland Homes added approximately 200 units and $81,600 to our current year-end backlog.
The increase in backlog dollars is attributable to the increase in units and to a 9% higher average selling price for new orders for the six month period ended December 31, 2012.
| | | 2012 | | | | | | | | 2011 | | | | | | | | 2010 | | | | | | |
| | | 2012 | | | | | | | | 2011 | | | | | | | | 2010 | | | | | | |
| | | 2012 | | | | 2011 | | | | 2010 | | |
| | | 2012 | | | | 2011 | | | | 2010 | | |
| | | 2012 | | | | 2011 | | | | 2010 | | |
| | | 2012 | | | | 2011 | | | | 2010 | | |
The homebuilding environment remained challenging throughout 2011 as it continued to be impacted by the economic downturn and uncertainty that has been experienced over the past several years.
The sluggish economy and high unemployment rates continue to weigh on consumer confidence and in turn, suppress housing demand.
In addition, new home sales and selling prices continue to be pressured by market uncertainty surrounding home prices and by a more restrictive mortgage lending environment.
Consolidated revenues totaled $2,659,149 for 2011, a decrease of 13% from $3,041,892 in 2010.
Net income declined 37% to $129,420 in 2011 from the prior year and diluted earnings per share declined 31% to $23.01 year over year.
Further, our expectation of continued sales and pricing pressures has been factored into the impairment analysis of our homebuilding inventory, land under development and contract land deposits.
We assess our land under development, including land under development held in joint ventures, and contract land deposits each quarter for impairment on a community-by-community basis by considering, among other items, overall market and economic conditions, and analyzing, as applicable, current sales absorption levels and recent sales’ gross profit.
At this time, we do not believe that any of the land under development is impaired, and we consider the allowance for losses on contract land deposits reflected on the December 31, 2011 balance sheet to be adequate.
Further, we believe that our homebuilding inventory is stated at the lower of cost or market.
However, there can be no assurance that we will not incur impairment charges in the future due to unanticipated adverse changes in the economy or other events adversely affecting specific markets or the homebuilding industry.
| | | | | | | | | | | | | |
Homebuilding revenues for 2010 increased 11% from 2009, as a result of an 11%, increase in the number of homes settled.
The increase in the number of homes settled was primarily attributable to the impact of the
federal homebuyer tax credit which resulted in strong first quarter sales and increased settlements through the second quarter of 2010 as compared to the same period in 2009.
In addition, the increase in settlements was also favorably impacted by a 12% higher beginning backlog unit balance entering 2010 compared to the same period in 2009.
We expect to face continued sales and pricing pressure over the next several quarters until we see economic stability and improved consumer confidence levels.
New orders in 2010 remained flat with 2009 new orders, while the average sales price of new orders increased 4% year over year.
New orders remained flat despite a strong first quarter in 2010, driven we believe by the federal homebuyer tax credit, and increased sales in the Indianapolis, IN, Orlando, FL and Raleigh, NC markets, each of which began operations in the second half of 2009.
From the first quarter of 2010, we experienced a consistent decline in the number of new orders across all of our markets in each of the second, third and fourth quarters of 2010 compared to the respective periods in 2009.
We expect to experience gross profit margin pressure over at least the next several quarters due to significant market uncertainties as discussed in the _Overview_ section above.
Gross profit margins in 2010 declined slightly to 18.2% from 18.5% in 2009.
Gross profit margins in 2010 were negatively impacted by a contract land deposit impairment charge of approximately $4,300, or 14 basis points, while 2009 gross profit margins were favorably impacted by the recovery of approximately $6,500, or 24 basis points, of contract land deposits previously determined to be uncollectible.
SG&A expenses in 2010 increased approximately $24,200 compared to 2009, but remained flat as a percentage of revenue year over year.
The increase in SG&A expenses was attributable to an approximate $13,500 increase in stock-based compensation costs in 2010 compared to the same period in 2009, due to the grant of non-qualified stock options and restricted share units under the 2010 Equity Incentive Plan, offset partially by a reversal of approximately $6,600 in stock-based compensation expense previously recorded to
SG&A expense as we adjusted our stock option forfeiture estimates to our actual forfeiture experience.
SG&A expense was also higher due to an approximate $5,600 increase in management incentive costs as 2009 incentive plans were limited to payouts of 50% of incentive earned, while no similar restrictions were imposed on 2010 incentive compensation.
In addition, SG&A expenses were impacted by an approximate $7,600 increase in selling and marketing costs year over year due primarily to an approximate $5,700 increase in advertising and model home costs attributable in part to an increase in the average number of active communities to 371 communities in 2010 from 355 communities in 2009.
Backlog units and dollars decreased approximately 17% to 2,916 and 11% to $958,287, respectively, as of December 31, 2010 compared to 3,531 and $1,076,437 as of December 31, 2009.
The decrease in backlog units was primarily attributable to the increased settlement activity in 2010 as discussed above.
Backlog dollars were negatively impacted by the decrease in backlog units.
| | | | | | | | | | | | | | | | | | | | | | | | | |
_2010 versus 2009_
Revenues increased approximately $119,300, or 7%, in 2010 from 2009 on a 7% increase in the number of units settled.
The increase in units settled was attributable to the impact of the federal homebuyer tax credit which we believe resulted in higher first quarter sales and increased settlements through the second quarter of 2010 as compared to the same period in 2009.
In addition, 2010 settlements were also favorably impacted by a 5% higher beginning backlog unit balance entering 2010 as compared to 2009.
The segment’s gross profit margin percentage increased to 19.0% in 2010 from 18.5% in 2009.
Segment profit and gross profit margins were favorably impacted by lower contract land deposit impairment charges in 2010 of $9,150, or 51 basis points, compared to $18,425, or 111 basis points in 2009.
Revenues increased approximately $32,900, or 13%, in 2010 from 2009.
The increase in units settled was primarily attributable to the impact of the federal homebuyer tax credit which we believe resulted in higher first quarter sales and increased settlements through the second quarter of 2010 as compared to the same period in 2009.
The increase in the average settlement price resulted from a product mix shift away from our attached products to our detached product, which generally sells at higher price points.
An excerpt. Shown here: 40 of 224 rewritten, 40 of 141 added and 40 of 95 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations. in the FY2012 filing and the FY2011 filing.
Item 7A. Quantitative and Qualitative Disclosure About Market Risk.
21 rewritten, 11 added, 3 removed, 19 unchanged
Our market risk arises from interest rate risk inherent in our financial [removed: instruments.][added: instruments and debt obligations.]
Advances under the Repurchase Agreement carry a Pricing Rate based on the LIBOR Rate plus the LIBOR Margin, or the Default Pricing Rate, as determined under the Repurchase Agreement, provided that the Pricing Rate shall not be less than [removed: 3.75%.][added: 3.10%.]
At December 31, [removed: 2011] [added: 2012] there was no debt outstanding under the Repurchase Agreement.
The following table represents the contractual balances of our on-balance sheet financial instruments at the expected maturity dates, as well as the fair values of those on-balance sheet financial instruments at December 31, [removed: 2011.][added: 2012.]
Consequently, advances outstanding under the Repurchase Agreement [removed: are] [added: would] also [added: be] assumed to mature in the first year.
[removed: | | | | | | |] Maturities (000’s) [removed: | | | | | | | | | | | | | | | | | | | | | | |]
| | | [removed: 2012] [added: 2013] | | | | [removed: 2013] [added: 2014] | | | | [removed: 2014] [added: 2015] | | | | [removed: 2015] [added: 2016] | | | | [added: 2017 | | | |] Thereafter | | | | Total | | | | Fair Value | | |
| Mortgage banking segment | | | | | | | | | | | | | | | | | | | | | | | | | | | | | [added: | | | |]
| _Interest rate sensitive assets:_ | | | | | | | | | | | | | | | | | | | | | | | | | | | | | [added: | | | |]
| Mortgage loans held for sale | | $ | [removed: 250,826] [added: 190,826] | | | | — | | | | — | | | | — | | | | — | | | [added: | — | | |] $ | [removed: 250,826] [added: 190,826] | | | $ | [removed: 252,352] [added: 188,929] | |
| Average interest rate | | | 4.0 | % | | | [removed: —] [added: 4.0] | [added: %] | | | [removed: —] [added: 4.0] | [added: %] | | | [removed: —] [added: 4.0] | [added: %] | | | [removed: —] [added: 4.0] | [added: %] | | | 4.0 | % | | | [added: 4.0] | [added: %] | [added: | | | |]
| _Interest rate sensitive liabilities:_ | | | | | | | | | | | | | | | | | | | | | | | | | | | | | [added: | | | |]
| Variable rate repurchase agreement | | | — | | | | — | | | | — | | | | — | | | | — | | | | — | | | | — | | [added: | | — | |]
| Average interest rate | | | — | | | | — | | | | — | | | | — | | | | — | | | | — | | | | [added: —] | | [added: | | | |]
| _Other:_ | | | | | | | | | | | | | | | | | | | | | | | | | | | | | [added: | | | |]
| Forward trades of mortgage-backed securities (a) | | $ | [removed: (2,430] [added: 490] | [removed: )] | | | — | | | | — | | | | — | | | | — | | | [added: | — | | |] $ | [removed: (2,430] [added: 490] | [removed: )] | | $ | [removed: (2,430] [added: 490] | [removed: )] |
| Forward loan commitments (a) | | $ | [removed: 833] [added: (1,094] | [added: )] | | | — | | | | — | | | | — | | | | — | | | [added: | — | | |] $ | [removed: 833] [added: (1,094] | [added: )] | | $ | [removed: 833] [added: (1,094] | [added: )] |
| Homebuilding segment | | | | | | | | | | | | | | | | | | | | | | | | | | | | | [added: | | | |]
| Interest-bearing deposits | | $ | [removed: 442,693] [added: 1,082,848] | | | | — | | | | — | | | | — | | | | — | | | [added: | — | | |] $ | [removed: 442,693] [added: 1,082,848] | | | $ | [removed: 442,693] [added: 1,082,848] | |
| Average interest rate | | | [removed: 0.3] [added: 3.3] | % | | | — | | | | — | | | | — | | | | — | | | | [removed: 0.3] [added: —] | [added: | | | 3.3 |] % | | | | |
| Average interest rate | | | [removed: 13.2] [added: 0.2] | % | | | [removed: 13.3] [added: —] | [removed: %] | | | [removed: 13.9] [added: —] | [removed: %] | | | [added: —] | | | | [added: —] | | | | [removed: 13.3] [added: —] | [added: | | | 0.2 |] % | | | | |
Our homebuilding segment is exposed to interest rate risk as it relates to its debt obligations.
In September 2012, we issued $600,000 of 3.95% Senior Notes due 2022 (the “Notes”).
The Notes mature on September 15, 2022 and bear interest at 3.95%, payable semi-annually in arrears on March 15 and September 15, commencing on March 15, 2013.
Changes to interest rates generally affect the fair value of fixed-rate debt instruments, but not earnings or cash flows.
We generally have no obligation to prepay the Notes prior to maturity, and thus interest rate fluctuations should not have a significant impact on our fixed-rate debt.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| _Interest rate sensitive assets:_ | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| _Interest rate sensitive liabilities:_ | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Fixed rate obligations (b) | | $ | 642 | | | $ | 115 | | | $ | — | | | $ | — | | | $ | — | | | $ | 600,000 | | | $ | 600,757 | | | $ | 618,757 | |
| (b) | The $600,000 maturing thereafter relates to the 3.95% Senior Notes due 2022. |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Fixed rate obligations , including interest | | $ | 609 | | | $ | 644 | | | $ | 725 | | | $ | — | | | $ | — | | | $ | 1,978 | | | $ | 1,978 | |
Item 1. Business.
33 rewritten, 10 added, 8 removed, 92 unchanged
NVR, Inc. (“NVR”) was formed in 1980 as NVHomes, Inc. Our primary business is the construction and sale of single-family detached homes, townhomes and condominium [removed: buildings.][added: buildings, all of which are primarily constructed on a pre-sold basis.]
While we operate in multiple locations in fifteen [removed: states,] [added: states and Washington, D.C.,] primarily in the eastern part of the United States, approximately [removed: 35%] [added: 38%] of our home settlements in [removed: 2011] [added: 2012] occurred in the Washington, D.C. and Baltimore, MD metropolitan areas, which accounted for approximately [removed: 46%] [added: 47%] of our [removed: 2011] [added: 2012] homebuilding revenues.
Our homebuilding operations include the construction and sale of single-family detached homes, townhomes and condominium buildings under four trade names: Ryan Homes, NVHomes, Fox Ridge Homes [removed: and Rymarc Homes.][added: and, as of January 1, 2013, Heartland Homes, which we acquired on December 31, 2012.]
The Ryan [removed: Homes,] [added: Homes and] Fox Ridge [removed: Homes, and Rymarc] Homes products are marketed primarily to first-time [removed: homeowners] and first-time move-up buyers.
[removed: The] Ryan Homes [removed: product is currently sold] [added: operates] in [removed: twenty-five] [added: twenty-seven] metropolitan areas located in Maryland, Virginia, [added: Washington, D.C.,] West Virginia, Pennsylvania, New York, North Carolina, South Carolina, [added: Florida,] Ohio, New Jersey, Delaware, [removed: Kentucky,] Indiana, [removed: Illinois] [added: Illinois, Kentucky] and [removed: Florida.][added: Tennessee.]
The Fox Ridge Homes product is sold solely in the Nashville, TN metropolitan [removed: area and the Rymarc Homes product is sold solely in the Columbia, SC metropolitan] area.
The NVHomes product is [removed: marketed primarily to move-up and upscale buyers and is] sold in [added: Delaware and] the Washington, D.C., Baltimore, [removed: MD,] [added: MD and] Philadelphia, PA [removed: and the Maryland Eastern Shore] metropolitan areas.
[removed: In] [added: During] 2011, our average price [removed: of a settled unit] was approximately $307,500.
However, [removed: current economic conditions and] [added: during] the [removed: continued downturn] [added: past several years, the impact] of [added: economic conditions on] the homebuilding industry [removed: have exerted pressure on] [added: has negatively impacted] our developers’ ability to obtain acquisition and development financing or to raise equity investments to finance land development activity, potentially constraining our supply of finished lots.
[removed: This pressure has necessitated that in certain specific strategic circumstances we deviate from our historical lot] acquisition strategy and engage in joint venture arrangements with land developers or directly acquire raw ground already zoned for its intended use for development.
[added: Once we acquire control of any raw ground, we determine] whether to sell the raw parcel to a developer and enter into a fixed price purchase agreement with the developer to purchase the finished lots, or whether to hire a developer to develop the land on our behalf.
As of December 31, [removed: 2011,] [added: 2012,] we controlled approximately [removed: 48,200] [added: 53,200] lots under purchase agreements with deposits in cash and letters of credit totaling approximately [removed: $202.3] [added: $256.6] million and [removed: $3.2] [added: $3.3] million, respectively.
Included in the number of controlled lots are approximately [removed: 10,600] [added: 10,200] lots for which we have recorded a contract land deposit impairment reserve of approximately [removed: $70.3] [added: $65.0] million as of December 31, [removed: 2011.][added: 2012.]
In addition, we had an aggregate investment totaling approximately [removed: $89.5] [added: $82.9] million in four separate joint venture limited liability corporations (“JVs”), expected to produce approximately [removed: 6,700] [added: 7,400] lots.
Of the lots controlled by the JVs, approximately [removed: 2,700] [added: 2,800] were not under contract [added: with us] at December 31, [removed: 2011.][added: 2012.]
Further, as of December 31, [removed: 2011,] [added: 2012,] we directly owned three separate raw parcels of land, zoned for their intended use, with a current cost basis, including development costs, of approximately [removed: $78.0] [added: $68.3] million that we intend to develop into approximately [removed: 800] [added: 700] finished lots for use in our homebuilding operations.
Our homes combine traditional, [removed: colonial, or] [added: transitional,] cottage [added: or urban] exterior designs with contemporary interior designs and amenities, generally include two to four bedrooms and range from approximately [removed: 1,000] [added: 1,400] to 7,300 square feet.
During [removed: 2011,] [added: 2012,] the prices at which we settled homes ranged from approximately [removed: $103,000] [added: $100,000] to [removed: $2.3] [added: $2.1] million and averaged approximately [removed: $307,500.][added: $317,100.]
[removed: During 2010,] [added: In 2012,] our average price [added: of a settled unit] was approximately [removed: $297,100.][added: $317,100.]
| [added: | |] _Mid Atlantic:_ | | Maryland, Virginia, West [removed: Virginia and] [added: Virginia,] Delaware [added: and Washington, D.C.] |
| [added: | |] _North East:_ | | New Jersey and eastern Pennsylvania |
| [added: | |] _Mid East:_ | | Kentucky, New York, Ohio, western Pennsylvania, Indiana and Illinois |
| [added: | |] _South East:_ | | North Carolina, South Carolina, Florida and Tennessee |
Backlog totaled [removed: 3,676] [added: 4,979] units and approximately [removed: $1.2] [added: $1.7] billion at December 31, [removed: 2011] [added: 2012] compared to backlog of [removed: 2,916] [added: 3,676] units and approximately [removed: $1.0] [added: $1.2] billion at December 31, [removed: 2010.][added: 2011.]
Expressed as the total of all cancellations during the period as a percentage of gross sales during the period, our cancellation rate was approximately [added: 15% in 2012 and] 14% in [removed: each of 2011, 2010] [added: both 2011] and [removed: 2009.][added: 2010.]
[removed: Of a reporting quarter’s opening backlog, 6% during] [added: During each of 2012,] 2011 and 2010, [removed: and 7% during 2009,] [added: approximately 6%] of [removed: that] [added: a quarter’s] opening backlog balance cancelled during the fiscal quarter.
In [removed: 2011,] [added: 2012,] NVRM closed approximately [removed: 7,000] [added: 8,000] loans with an aggregate principal amount of approximately [removed: $1.9] [added: $2.2] billion as compared to approximately [removed: 8,600] [added: 7,000] loans with an aggregate principal amount of approximately [removed: $2.2] [added: $1.9] billion in [removed: 2010.][added: 2011.]
NVRM sells all of the mortgage loans it closes to investors in the secondary markets on a servicing released basis, typically within 30 [removed: to 60] days from the loan closing.
NVRM is an approved seller/servicer for FNMA mortgage loans and an approved [removed: lender/seller] [added: seller/issuer] of GNMA, FHLMC, VA and FHA mortgage loans.
NVRM is an approved seller/servicer of FNMA mortgage loans and an approved [removed: lender/seller] [added: seller/issuer] of GNMA, FHLMC, VA and FHA mortgage loans, and is subject to all of those agencies’ rules and regulations.
NVRM’s mortgage loans in process that have not closed (“Pipeline”) at December 31, [removed: 2011] [added: 2012] and [removed: 2010,] [added: 2011,] had an aggregate principal balance of approximately [removed: $790 million] [added: $1.1 billion] and [removed: $670] [added: $790] million, respectively.
NVRM’s cancellation rate was approximately [removed: 29%] [added: 36%] in [removed: 2011.][added: 2012.]
During [removed: 2010] [added: both 2011] and [removed: 2009,] [added: 2010,] NVRM’s loan cancellation rates were approximately [removed: 29% and 35%, respectively.][added: 29%.]
See Item 7 herein for additional discussion of the Heartland Homes acquisition.
The NVHomes and Heartland Homes products are marketed primarily to move-up and up-scale buyers.
The Heartland Homes product is sold in the Pittsburgh, PA metropolitan area.
This pressure has necessitated that in certain specific strategic circumstances we deviate from our historical lot
During the current year, the homebuilding market continued to experience a stabilization in prices and improving sales trends.
These favorable market conditions are driven by improved housing affordability levels resulting from historically low mortgage interest rates and rising costs in the rental market.
Despite these improvements, the homebuilding environment continues to face challenges from a tight mortgage lending environment, consumer confidence issues due to sustained high levels of unemployment and uncertainties as to the sustainability of the economic recovery.
| | | | | |
| --- | --- | --- | --- | --- |
At December 31, 2012, we employed 3,291 full-time persons.
Once we acquire control of any raw ground, we determine
The homebuilding environment remains challenging as it continues to be impacted by the economic downturn and uncertainty that has existed in the U.S. throughout the past six years.
The sluggish economy and high unemployment rates continue to weigh on consumer confidence and in turn, suppress housing demand, despite what have been historically low mortgage rates in 2011.
New home sales also continue to be adversely impacted by a highly restrictive mortgage lending environment that has made it more difficult for our customers to obtain mortgage financing.
We expect to continue to see market volatility, pricing pressure and reduced demand for new homes until there is economic stability and improved consumer confidence.
| | | |
| --- | --- | --- |
At December 31, 2011, we employed 2,765 full-time persons, of whom 1,077 were officers and management personnel, 182 were technical and construction personnel, 619 were sales personnel, 477 were administrative personnel and 410 were engaged in various other service and labor activities.
Item 3. Legal Proceedings.
5 rewritten, 5 added, 1 removed, 22 unchanged
However, while a number of individuals have filed consents to join and assert federal claims in the New York action, none of the groups of employees that the lawsuits purport to represent have been certified as a [removed: class.][added: class, and we have filed a motion to decertify the federal collective action claim and dismiss the individuals who filed consents from the case.]
[removed: The three courts to most recently consider] [added: Courts that have considered] similar claims against other homebuilders have acknowledged the DOL’s position that sales and marketing representatives were properly classified as exempt from overtime wages and the only court to have directly addressed the exempt status of such employees concluded that the DOL’s position was valid.
[removed: A meeting] [added: Meetings] took place in [removed: late] January 2012 [added: and August 2012] with representatives from both the EPA and DOJ.
In August 2011, the Wage and Hour Division of the [removed: U.S. Department of Labor (“DOL”)] [added: DOL] notified us that it was initiating an investigation to determine our compliance with the Fair Standards Labor Act (“FSLA”).
We have cooperated with this information [removed: request,] [added: request and] have either provided or made available the information that the DOL has [removed: requested and expect to continue to cooperate with the DOL’s investigation.][added: requested.]
The DOL has investigated our headquarters, two manufacturing facilities and certain of our operating divisions.
The DOL has communicated that it has not found any violations at any of these operations.
The DOL appears to have completed its investigation, although, in accordance with DOL practice, we have not been formally notified of such.
Thus, we cannot predict whether the DOL will investigate our other operations.
Further, it is important to understand that under the law, the DOL can investigate our other operations or even operations that it has previously audited, either on its own initiative or in response to an employee complaint.
At this time, we cannot predict the outcome of this investigation, nor can we reasonably estimate the potential costs that may be associated with its eventual resolution.
Cover and table of contents
32 rewritten, 8 added, 3 removed, 50 unchanged
For the fiscal year ended December 31, [removed: 2011][added: 2012]
Registrant’s telephone number, including area [removed: code: (703) 956-4000][added: code:]
Securities registered pursuant to Section 12(g) of the [removed: Act: None][added: Act:]
The aggregate market value of the voting stock held by non-affiliates of NVR, Inc. on June 30, [removed: 2011,] [added: 2012,] the last business day of NVR, Inc.’s most recently completed second fiscal quarter, was approximately [removed: $3,840,650,000.][added: $4,130,615,000.]
As of February [removed: 17, 2012] [added: 14, 2013] there were [removed: 5,058,781] [added: 4,996,234] total shares of common stock outstanding.
Portions of the Proxy Statement of NVR, Inc. to be filed with the Securities and Exchange Commission pursuant to Regulation 14A of the Securities Exchange Act of 1934 on or prior to April 30, [removed: 2012] [added: 2013] are incorporated by reference into Part III of this report.
| | | | | Page | [removed: | |]
| PART I | | | | | [removed: | |]
| Item 1. | | [removed: [Business](#tx250145_1) |] [added: [Business](#tx446058_1)] | | 2 | [removed: |]
| Item 1A. | | [Risk [removed: Factors](#tx250145_2) |] [added: Factors](#tx446058_2)] | | 6 | [removed: |]
| Item 1B. | | [Unresolved Staff [removed: Comments](#tx250145_3) |] [added: Comments](#tx446058_3)] | | 11 | [removed: |]
| Item 2. | | [removed: [Properties](#tx250145_4) |] [added: [Properties](#tx446058_4)] | | 11 | [removed: |]
| Item 3. | | [Legal [removed: Proceedings](#tx250145_5) |] [added: Proceedings](#tx446058_5)] | | 12 | [removed: |]
| Item 4. | | [Mine Safety [removed: Disclosures](#tx250145_6) |] [added: Disclosures](#tx446058_6)] | | 13 | [removed: |]
| | | [Executive Officers of the [removed: Registrant](#tx250145_7) |] [added: Registrant](#tx446058_7)] | | 13 | [removed: |]
| PART II | | | | | [removed: | |]
| Item 5. | | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities](#tx250145_8) |] [added: Securities](#tx446058_8)] | | 13 | [removed: |]
| Item 6. | | [Selected Financial [removed: Data](#tx250145_9) |] [added: Data](#tx446058_9)] | | 15 | [removed: |]
| Item 7. | | [Management’s Discussion and Analysis of Financial Condition and Results of [removed: Operations](#tx250145_10) |] [added: Operations](#tx446058_10)] | | 16 | [removed: |]
| Item 7A. | | [Quantitative and Qualitative Disclosure About Market [removed: Risk](#tx250145_11) | |] [added: Risk](#tx446058_11)] | [removed: 37] | [added: 38] |
| Item 8. | | [Financial Statements and Supplementary [removed: Data](#tx250145_12) | |] [added: Data](#tx446058_12)] | [removed: 40] | [added: 41] |
| Item 9. | | [Changes in and Disagreements with Accountants on Accounting and Financial [removed: Disclosure](#tx250145_13) | |] [added: Disclosure](#tx446058_13)] | [removed: 40] | [added: 41] |
| Item 9A. | | [Controls and [removed: Procedures](#tx250145_14) | |] [added: Procedures](#tx446058_14)] | [removed: 40] | [added: 41] |
| Item 9B. | | [Other [removed: Information](#tx250145_15) | |] [added: Information](#tx446058_15)] | [removed: 40] | [added: 41] |
| PART III | | | | | [removed: | |]
| Item 10. | | [Directors, Executive Officers, and Corporate [removed: Governance](#tx250145_16) | |] [added: Governance](#tx446058_16)] | [removed: 41] | [added: 42] |
| Item 11. | | [Executive [removed: Compensation](#tx250145_17) | |] [added: Compensation](#tx446058_17)] | [removed: 41] | [added: 42] |
| Item 12. | | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder [removed: Matters](#tx250145_18) | |] [added: Matters](#tx446058_18)] | [removed: 41] | [added: 42] |
| Item 13. | | [Certain Relationships and Related Transactions, and Director [removed: Independence](#tx250145_19) | |] [added: Independence](#tx446058_19)] | [removed: 42] | [added: 43] |
| Item 14. | | [Principal Accountant Fees and [removed: Services](#tx250145_20) | |] [added: Services](#tx446058_20)] | [removed: 42] | [added: 43] |
| PART IV | | | | | [removed: | |]
| Item 15. | | [Exhibits and Financial Statement [removed: Schedules](#tx250145_21) | |] [added: Schedules](#tx446058_21)] | [removed: 42] | [added: 43] |
10-K 1 d446058d10k.htm FORM 10-K
(703) 956-4000
None
| | | | | |
| --- | --- | --- | --- | --- |
| | | | | |
| | | | | |
| | | | | |
10-K 1 d250145d10k.htm 10-K
| | | | | | | |
| --- | --- | --- | --- | --- | --- | --- |
Item 2. Properties.
2 rewritten, 1 added, 3 removed, 8 unchanged
[removed: The Dayton] [added: We own a manufacturing] facility [added: in Dayton, Ohio which] contains approximately 100,000 square feet of manufacturing space.
We also, in connection with both our homebuilding and mortgage banking businesses, lease office space in multiple locations for homebuilding divisional offices and mortgage banking and title services branches under leases expiring at various times through [removed: 2019,] [added: 2020,] none of which are individually material to our business.
Our current plant utilization has remained flat with the prior year at 31% of total capacity.
| --- | --- |
In March 2011, we purchased a manufacturing facility in Dayton, Ohio and began production in June 2011.
Due to the economic downturn and the related decline in our homebuilding activity, our current plant utilization has dropped to approximately 31% of total capacity.
Item 4. Mine Safety Disclosures.
7 rewritten, 11 added, 2 removed, 14 unchanged
| Paul C. Saville | | [removed: 56] [added: 57] | | President and Chief Executive Officer of NVR |
| Robert [removed: A. Goethe] [added: W. Henley] | | [removed: 57] [added: 46] | | President of NVRM |
| Dennis M. Seremet | | [removed: 57] [added: 58] | | Senior Vice President, Chief Financial Officer and Treasurer of NVR |
| [removed: Robert W. Henley] [added: Eugene J. Bredow] | | [removed: 45] [added: 43] | | Vice President and Controller of NVR |
[removed: Goethe_] [added: Henley_] was named President of NVRM effective [removed: January 25, 2010.][added: October 1, 2012.]
[removed: Henley_] [added: Bredow_] was named Vice President and Controller of NVR effective [removed: July] [added: June] 1, [removed: 2005.][added: 2012.]
From May 2000 to June 30, 2005, Mr. Henley was [removed: the] Assistant Controller.
| Daniel D. Malzahn | | 43 | | Vice President, Chief Financial Officer and Treasurer of NVR |
Mr. Seremet is retiring from NVR effective February 19, 2013 and will be succeeded by Daniel D.
Malzahn.
Mr. Henley had been serving as interim acting President of NVRM since June 1, 2012.
Prior to June 1, 2012, Mr. Henley served as Vice President and Controller of NVR since July 1, 2005.
_Eugene J.
Prior to June 1, 2012, Mr. Bredow was the Vice President of Internal Audit and Corporate Governance since January 2008 and Director of Internal Audit and Corporate Governance from August 2004 to January 2008.
_Daniel D.
Malzahn_ has been named Vice President, Chief Financial Officer and Treasurer of NVR effective February 20, 2013 to succeed Mr. Seremet.
Prior to February 20, 2013, Mr. Malzahn was Vice President of Planning and Investor Relations since February 1, 2004.
From January 2000 to January 31, 2004, Mr. Malzahn was Manager of Business Planning.
_Robert A.
From 2008 until January, 2010, Mr. Goethe served as a Senior Principal of Mortgage Connect Corp. From 2006 to 2008, Mr. Goethe served as the Senior Executive Vice President of Regions Mortgage Corporation, and from 1996 until 2006, he served as the Chief Executive Officer of Regions Financial Corporation.
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
8 rewritten, 10 added, 15 removed, 22 unchanged
The following table sets forth the high and low prices per share for our common stock for each fiscal quarter during the years ended December 31, [removed: 2011] [added: 2012] and [removed: 2010:][added: 2011:]
As of the close of business on February [removed: 17, 2012,] [added: 14, 2013,] there were [removed: 351] [added: 341] shareholders of record.
We have never paid a cash dividend on our shares of common stock and have no current [removed: intentions] [added: intention] to do so in the future.
We had two repurchase authorizations outstanding during the quarter ended December 31, [removed: 2011.][added: 2012.]
On [removed: July 28,] [added: December 14,] 2011 [removed: (“July] [added: (“2011] Authorization”) and [removed: on] December [removed: 14, 2011 (“December] [added: 18, 2012 (“2012] Authorization”), we publicly announced the Board of Directors’ approval for us to repurchase up to an aggregate of $300 million per authorization, of our common stock in one or more open market and/or privately negotiated transactions.
The following table provides information regarding common stock repurchases for the quarter ended December 31, [removed: 2011:][added: 2012:]
The following chart graphs our performance in the form of cumulative total return to holders of our Common Stock since December 31, [removed: 2006] [added: 2007] in comparison to the Dow/Home Construction Index and the Dow Jones Industrial Index for that same period, assuming that $100 was invested in NVR stock and the indices on December 31, [removed: 2006.][added: 2007.]
[removed: 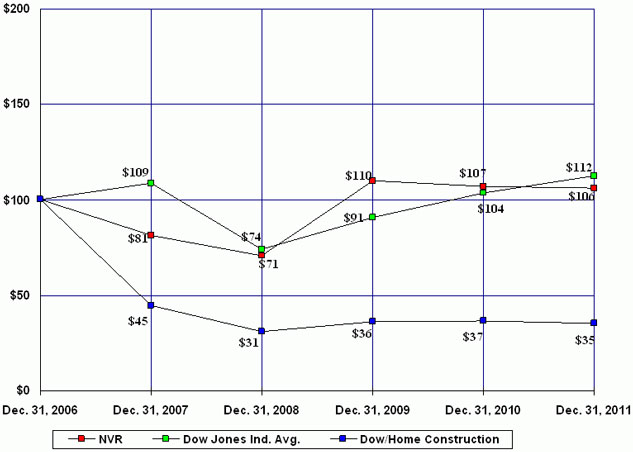][added: ]
| _2012_ | | | | | | | | |
| Fourth Quarter | | $ | 966.93 | | | $ | 830.00 | |
| Third Quarter | | $ | 879.99 | | | $ | 721.56 | |
| Second Quarter | | $ | 855.00 | | | $ | 711.75 | |
| First Quarter | | $ | 759.13 | | | $ | 667.98 | |
| Period | | Total Number of Shares Purchased | | | | Average Price Paid per Share | | | | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | | | | Maximum Number (or Approximate Dollar Value) of Shares that May Yet Be Purchased Under the Plans or Programs | | |
| October 1 – 31, 2012 | | | — | | | $ | — | | | | — | | | $ | 99,770,000 | |
| November 1 – 30, 2012 | | | 8,500 | | | $ | 841.53 | | | | 8,500 | | | $ | 92,617,000 | |
| December 1 – 31, 2012 | | | — | | | $ | — | | | | — | | | $ | 392,617,000 | |
| Total | | | 8,500 | | | $ | 841.53 | | | | 8,500 | | | | | |
| _2010_ | | | | | | | | |
| Fourth Quarter | | $ | 699.28 | | | $ | 611.50 | |
| Third Quarter | | $ | 680.05 | | | $ | 595.00 | |
| Second Quarter | | $ | 769.50 | | | $ | 627.43 | |
| First Quarter | | $ | 759.27 | | | $ | 655.00 | |
| | | | | | | | | | | | | | | Maximum Number (or | | |
| | | | | | | | | | | Total Number of | | | | Approximate Dollar | | |
| | | | | | | | | | | Shares Purchased | | | | Value) of Shares that | | |
| | | Total Number | | | | Average | | | | as Part of Publicly | | | | May Yet Be | | |
| | | of Shares | | | | Price Paid | | | | Announced Plans | | | | Purchased Under the | | |
| Period | | Purchased | | | | per Share | | | | or Programs | | | | Plans or Programs | | |
| October 1 - 31, 2011 | | | 38,323 | | | $ | 591.65 | | | | 38,323 | | | $ | 19,897,000 | |
| November 1 - 30, 2011 | | | — | | | $ | — | | | | — | | | $ | 19,897,000 | |
| December 1 - 31, 2011 | | | — | | | $ | — | | | | — | | | $ | 319,897,000 | |
| Total | | | 38,323 | | | $ | 591.65 | | | | 38,323 | | | | | |
Item 6. Selected Financial Data.
16 rewritten, 1 added, 1 removed, 18 unchanged
[removed: | |] (dollars in thousands, except per share amounts) [removed: |]
| | | [removed: 2011] [added: 2012] | | | | [removed: 2010] [added: 2011] | | | | [removed: 2009] [added: 2010] | | | | [removed: 2008] [added: 2009] | | | | [removed: 2007] [added: 2008] | | |
| Revenues | | $ | [removed: 2,611,195] [added: 3,121,244] | | | $ | [removed: 2,980,758] [added: 2,611,195] | | | $ | [removed: 2,683,467] [added: 2,980,758] | | | $ | [removed: 3,638,702] [added: 2,683,467] | | | $ | [removed: 5,048,187] [added: 3,638,702] | |
| Gross profit | | | [removed: 445,570] [added: 545,605] | | | | [removed: 542,466] [added: 445,570] | | | | [removed: 497,734] [added: 542,466] | | | | [removed: 457,692] [added: 497,734] | | | | [removed: 821,128] [added: 457,692] | |
| _Mortgage Banking [removed: data_ _:_] [added: data:_] | | | | | | | | | | | | | | | | | | | | |
| Mortgage banking fees | | | [removed: 47,954] [added: 63,406] | | | | [removed: 61,134] [added: 47,954] | | | | [removed: 60,381] [added: 61,134] | | | | [removed: 54,337] [added: 60,381] | | | | [removed: 81,155] [added: 54,337] | |
| Interest income | | | [removed: 5,702] [added: 4,504] | | | | [removed: 5,411] [added: 5,702] | | | | [removed: 2,979] [added: 5,411] | | | | [removed: 3,955] [added: 2,979] | | | | [removed: 4,900] [added: 3,955] | |
| Interest expense | | | [removed: 875] [added: 546] | | | | [removed: 1,126] [added: 875] | | | | [removed: 1,184] [added: 1,126] | | | | [removed: 754] [added: 1,184] | | | | [removed: 681] [added: 754] | |
| Income from continuing operations | | $ | [removed: 129,420] [added: 180,588] | | | $ | [removed: 206,005] [added: 129,420] | | | $ | [removed: 192,180] [added: 206,005] | | | $ | [removed: 100,892] [added: 192,180] | | | $ | [removed: 333,955] [added: 100,892] | |
| Income from continuing operations per diluted share (1) | | $ | [removed: 23.01] [added: 35.12] | | | $ | [removed: 33.42] [added: 23.01] | | | $ | [removed: 31.26] [added: 33.42] | | | $ | [removed: 17.04] [added: 31.26] | | | $ | [removed: 54.14] [added: 17.04] | |
| Homebuilding inventory | | $ | [removed: 533,150] [added: 678,131] | | | $ | [removed: 431,329] [added: 533,150] | | | $ | [removed: 418,718] [added: 431,329] | | | $ | [removed: 400,570] [added: 418,718] | | | $ | [removed: 688,854] [added: 400,570] | |
| Contract land deposits, net | | | [removed: 131,930] [added: 191,538] | | | | [removed: 100,786] [added: 131,930] | | | | [removed: 49,906] [added: 100,786] | | | | [removed: 29,073] [added: 49,906] | | | | [removed: 188,528] [added: 29,073] | |
| Total assets | | | [removed: 1,779,485] [added: 2,604,842] | | | | [removed: 2,260,061] [added: 1,779,485] | | | | [removed: 2,395,770] [added: 2,260,061] | | | | [removed: 2,103,236] [added: 2,395,770] | | | | [removed: 2,194,416] [added: 2,103,236] | |
| Notes and loans payable | | | [removed: 1,613] [added: 599,745] | | | | [removed: 92,089] [added: 1,613] | | | | [removed: 147,880] [added: 92,089] | | | | [removed: 210,389] [added: 147,880] | | | | [removed: 286,283] [added: 210,389] | |
| Shareholders’ equity | | | [removed: 1,374,799] [added: 1,480,477] | | | | [removed: 1,740,374] [added: 1,374,799] | | | | [removed: 1,757,262] [added: 1,740,374] | | | | [removed: 1,373,789] [added: 1,757,262] | | | | [removed: 1,129,375] [added: 1,373,789] | |
| (1) | For the years ended December 31, [added: 2012,] 2011, 2010, [removed: 2009, 2008] [added: 2009] and [removed: 2007,] [added: 2008,] income from continuing operations per diluted share was computed based on [added: 5,141,529;] 5,623,817; 6,164,617; [removed: 6,148,769; 5,920,285] [added: 6,148,769] and [removed: 6,167,795] [added: 5,920,285] shares, respectively, which represents the weighted average number of shares and share equivalents outstanding for each year. |
| | | 2012 | | | | 2011 | | | | 2010 | | | | 2009 | | | | 2008 | | |
| --- | --- |
Item 9A. Controls and Procedures.
4 rewritten, 0 added, 0 removed, 6 unchanged
Based on that evaluation, the principal executive officer and principal financial officer concluded that the design and operation of these disclosure controls and procedures as of December 31, [removed: 2011] [added: 2012] were effective to provide reasonable assurance that information required to be disclosed in our reports under the Securities [removed: and] Exchange Act of 1934 is recorded, processed, summarized and reported within the time periods specified in the Securities and Exchange Commission’s rules and forms and that such information is accumulated and communicated to our management, including our principal executive officer and principal financial officer, as appropriate, to allow timely decisions regarding required disclosure.
Our management is responsible for establishing and maintaining adequate internal control over financial reporting, as such term is defined in Rule 13a-15(f) under the Securities [removed: and] Exchange Act of 1934.
Based on our evaluation under the framework in _Internal Control – Integrated Framework_, our management concluded that our internal control over financial reporting was effective as of December 31, [removed: 2011.][added: 2012.]
Our internal control over financial reporting as of December 31, [removed: 2011] [added: 2012] has been audited by KPMG LLP, an independent registered public accounting firm, as stated in their attestation report which is included herein.
Item 9B. Other Information.
0 rewritten, 17 added, 1 removed, 3 unchanged
Daniel D.
Malzahn has been named as the Vice President, Chief Financial Officer and Treasurer of NVR, Inc. effective February 20, 2013, replacing Dennis M.
Seremet upon Mr. Seremet’s retirement from NVR on February 19, 2013.
Mr. Seremet’s intention to retire was disclosed on a Form 8-K, filed with the Securities and Exchange Commission on May 10, 2012 which is incorporated herein by reference.
Mr. Malzahn, age 43, started his career at KPMG LLP after graduating from James Madison University in 1992.
He joined NVR in 1994 and served as an Internal Auditor until 1995, a Financial Analyst from 1995 until 2000, the Manager of Business Planning from 2000 until 2004 and NVR’s Vice President of Planning and Investor Relations from February 1, 2004 until February 2013.
On February 19, 2013, the Company entered into an employment agreement with Mr. Malzahn for a term ending on January 1, 2016.
Pursuant to the agreement, Mr. Malzahn is entitled to a minimum base salary of $350,000.
A copy of Mr. Malzahn’s employment agreement is attached as Exhibit 10.8 to this Form 10-K, and is incorporated herein by reference.
Mr. Malzahn will participate in the 2013 Named Executive Officer Annual Incentive Compensation Plan as described in Exhibit 10.24, attached to this Form 10-K and incorporated herein by reference.
His maximum potential payout under the 2013 Named Executive Officer Annual Incentive Compensation Plan is equal to 100% of his base salary.
Mr. Malzahn will also receive a grant of 14,000 non-qualified fixed-priced stock options from the NVR, Inc. 2010 Equity Incentive Plan, which was filed as Exhibit 10.1 to NVR’s Form S-8 (No. 333-166512) filed on May 4, 2010 and is incorporated herein by reference.
The equity grant to Mr. Malzahn will be issued pursuant to the Form of Non-Qualified Stock Option Agreement filed as Exhibit 10.1 to NVR’s Form 8-K filed on May 6, 2010 and incorporated herein by reference.
NVR’s employment agreements with Mssrs.
Bredow and Henley were amended on February 19, 2013 to increase the payments due them upon retirement, termination without cause or voluntary termination within one year after a change in control from 50% of annual base salary to 100% of annual base salary.
The amendments to the employment agreements for Mssrs.
Bredow and Henley are attached to this Form 10-K as Exhibits 10.7 and 10.5, respectively, and are incorporated herein by reference.
None.
Item 10. Directors, Executive Officers, and Corporate Governance.
1 rewritten, 0 added, 0 removed, 2 unchanged
Item 10 is hereby incorporated by reference to our Proxy Statement expected to be filed with the Securities and Exchange Commission on or prior to April 30, [removed: 2012.][added: 2013.]
Item 11. Executive Compensation.
1 rewritten, 0 added, 0 removed, 1 unchanged
Item 11 is hereby incorporated by reference to our Proxy Statement expected to be filed with the Securities and Exchange Commission on or prior to April 30, [removed: 2012.][added: 2013.]
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
7 rewritten, 1 added, 2 removed, 10 unchanged
Security ownership of certain beneficial owners and management is hereby incorporated by reference to our Proxy Statement expected to be filed with the Securities and Exchange Commission on or prior to April 30, [removed: 2012.][added: 2013.]
The table below sets forth information as of the end of our [removed: 2011] [added: 2012] fiscal year for (i) all equity compensation plans approved by our shareholders and (ii) all equity compensation plans not approved by our shareholders:
| [removed: Plan category] [added: Plan category] | | [removed: Number] [added: Number] of securities to be issued upon exercise of outstanding options, warrants and [removed: rights] [added: rights] | | | | [removed: Weighted-average] [added: Weighted-average] exercise price of outstanding options, warrants and [removed: rights] [added: rights] | | | | [removed: Number] [added: Number] of securities remaining available for future issuance under equity compensation plans (excluding securities reflected in the first [removed: column)] [added: column)] | | |
| Equity compensation plans [added: not] approved by security holders [removed: (1)] | | | [removed: 552,138] [added: 233,213] | | | $ | [removed: 476.97] [added: 622.77] | | | | [removed: 239,646] [added: —] | |
| Equity compensation plans [removed: not] approved by security holders [added: (1)] | | | [removed: 340,047] [added: 488,484] | | | $ | [removed: 585.93] [added: 591.92] | | | | [removed: —] [added: 172,107] | |
| (1) | This category includes the restricted share units (“RSUs”) authorized by the 2010 Equity Incentive Plan, which was approved by our shareholders at the May 4, 2010 Annual Meeting. At December 31, [removed: 2011,] [added: 2012,] there are [removed: 154,483] [added: 82,619] RSUs outstanding, issued at a $0 exercise price. Of the total [removed: 239,646] [added: 172,107] shares remaining available for future issuance, up to [removed: 85,517] [added: 83,967] may be issued as RSUs. The weighted-average exercise price of outstanding options under security holder approved plans excluding outstanding RSUs was [removed: $662.26.] [added: $712.41.] |
Equity compensation plans approved by our shareholders include the NVR, Inc. Management Long-Term Stock Option Plan; the NVR, Inc. 1998 Management Long-Term Stock Option Plan; the 1998 Directors’ [added: Long-Term Stock Option Plan; and the 2010 Equity Incentive Plan.]
| Total | | | 721,697 | | | $ | 601.89 | | | | 172,107 | |
| Total | | | 892,185 | | | $ | 518.50 | | | | 239,646 | |
Long-Term Stock Option Plan; and the 2010 Equity Incentive Plan.
Item 13. Certain Relationships and Related Transactions, and Director Independence.
1 rewritten, 0 added, 0 removed, 1 unchanged
Item 13 is hereby incorporated by reference to our Proxy Statement expected to be filed with the Securities and Exchange Commission on or prior to April 30, [removed: 2012.][added: 2013.]
Item 14. Principal Accountant Fees and Services.
1 rewritten, 0 added, 0 removed, 2 unchanged
Item 14 is hereby incorporated by reference to our Proxy Statement expected to be filed with the Securities and Exchange Commission on or prior to April 30, [removed: 2012.][added: 2013.]
Item 15. Exhibits and Financial Statement Schedules.
422 rewritten, 148 added, 96 removed, 845 unchanged
_NVR, [removed: Inc.-Consolidated] [added: Inc.—Consolidated] Financial Statements_
| [removed: _Exhibit Number_] [added: _Exhibit_ _Number_] | | _Description_ |
| 10.3* | | Employment Agreement between NVR, Inc. and Robert [removed: A. Goethe] [added: W. Henley] dated December 21, 2010. Filed as Exhibit [removed: 10.3] [added: 10.4] to NVR’s Form 8-K filed on December 21, 2010 and incorporated herein by reference. |
| 10.4* | | [added: Amendment No. 1 to the] Employment Agreement between NVR, Inc. and Robert W. Henley dated December 21, 2010. Filed as Exhibit [removed: 10.4] [added: 10.1] to NVR’s Form 8-K filed on [removed: December 21, 2010] [added: May 31, 2012] and incorporated herein by reference. |
| [removed: 10.5*] [added: 10.9*] | | Profit Sharing Plan of NVR, Inc. and Affiliated Companies. Filed as Exhibit 4.1 to NVR’s Registration Statement on Form S-8 (No. 333-29241) filed June 13, 1997 and incorporated herein by reference. |
| [removed: 10.6*] [added: 10.10*] | | Employee Stock Ownership Plan of NVR, Inc. Incorporated by reference to NVR’s Annual Report on Form 10-K/A for the year ended December 31, 1994. |
| [removed: 10.7*] [added: 10.11*] | | NVR, Inc. 1998 Management Long-Term Stock Option Plan. Filed as Exhibit 4 to NVR’s Registration Statement on Form S-8 (No. 333-79951) filed June 4, 1999 and incorporated herein by reference. |
| [removed: 10.8*] [added: 10.12*] | | NVR, Inc. 1998 Directors’ Long-Term Stock Option Plan. Filed as Exhibit 4 to NVR’s Registration Statement on Form S-8 (No. 333-79949) filed June 4, 1999 and incorporated herein by reference. |
| [removed: 10.09*] [added: 10.13*] | | NVR, Inc. Management Long-Term Stock Option Plan. Filed as Exhibit 99.3 to NVR’s Registration Statement on Form S-8 (No. 333-04975) filed May 31, 1996 and incorporated herein by reference. |
| [removed: 10.10*] [added: 10.14*] | | NVR, Inc. 2000 Broadly-Based Stock Option Plan. Filed as Exhibit 99.1 to NVR’s Registration Statement on Form S-8 (No. 333-56732) filed March 8, 2001 and incorporated herein by reference. |
| [removed: 10.11*] [added: 10.15*] | | NVR, Inc. Nonqualified Deferred Compensation Plan. Filed as Exhibit 10.1 to NVR’s Form 8-K filed on December 16, 2005 and incorporated herein by reference. |
| [removed: 10.12*] [added: 10.16*] | | Description of the Board of Directors’ compensation arrangement. Filed as Exhibit 10.27 to NVR’s Annual Report on Form 10-K for the period ended December 31, 2004 and incorporated herein by reference. |
| [removed: 10.13*] [added: 10.17*] | | The NVR, Inc. 2010 Equity Incentive Plan. Filed as exhibit 10.1 to NVR’s Form S-8 (No. 333-166512) filed on May 4, 2010 and incorporated herein by reference. |
| [removed: 10.14*] [added: 10.18*] | | The Form of Non-Qualified Stock Option Agreement (Management grants) under the NVR, Inc. 2010 Equity [removed: incentive] [added: Incentive] Plan. Filed as exhibit 10.1 to NVR’s Form 8-K filed on May 6, 2010 and incorporated herein by reference. |
| [removed: 10.15*] [added: 10.19*] | | The Form of Non-Qualified Stock Option Agreement (Director grants) under the NVR, Inc. 2010 Equity [removed: incentive] [added: Incentive] Plan. Filed as exhibit 10.2 to NVR’s Form 8-K filed on May 6, 2010 and incorporated herein by reference. |
| [removed: 10.16*] [added: 10.20*] | | The Form of Restricted Share Units Agreement (Management grants) under the NVR, Inc. 2010 Equity [removed: incentive] [added: Incentive] Plan. Filed as exhibit 10.3 to NVR’s Form 8-K filed on May 6, 2010 and incorporated herein by reference. |
| [removed: 10.17*] [added: 10.21*] | | The Form of Restricted Share Units Agreement (Director grants) under the NVR, Inc. 2010 Equity [removed: incentive] [added: Incentive] Plan. Filed as exhibit 10.4 to NVR’s Form 8-K filed on May 6, 2010 and incorporated herein by reference. |
| [removed: 10.18*] [added: 10.22*] | | The Form of Non-Qualified Stock Option Agreement under the NVR, Inc. 2000 Broadly Based Stock Option Plan. Filed as Exhibit 10.1 to NVR’s Form 8-K filed January 3, 2008 and incorporated herein by reference. |
| [removed: 10.19*] [added: 10.23*] | | The Form of Non-Qualified Stock Option Agreement under the 1998 Directors’ [removed: Long- Term] [added: Long-Term] Stock Option Plan. Filed as Exhibit 10.34 to NVR’s Annual Report on Form 10-K for the period ended December 31, 2007 and incorporated herein by reference. |
| [removed: 10.20*] [added: 10.24*] | | Summary of [removed: 2012] [added: 2013] Named Executive Officer annual incentive compensation plan. Filed herewith. |
| NVR, Inc. | | | [removed: | |]
| [removed: | |] By: | | /s/ Paul C. Saville |
| | | [removed: | |] Paul C. Saville |
| | | [removed: | |] _President and Chief Executive Officer_ |
| /s/ Dwight C. Schar [added: Dwight C. Schar] | | Chairman | | February [removed: 22, 2012] [added: 19, 2013] |
| /s/ C. E. Andrews [added: C. E. Andrews] | | Director | | February [removed: 22, 2012] [added: 19, 2013] |
| /s/ Robert C. Butler [added: Robert C. Butler] | | Director | | February [removed: 22, 2012] [added: 19, 2013] |
| /s/ Timothy M. Donahue [added: Timothy M. Donahue] | | Director | | February [removed: 22, 2012] [added: 19, 2013] |
| /s/ Thomas D. Eckert [added: Thomas D. Eckert] | | Director | | February [removed: 22, 2012] [added: 19, 2013] |
| /s/ Alfred E. Festa [added: Alfred E. Festa] | | Director | | February [removed: 22, 2012] [added: 19, 2013] |
| /s/ Manuel H. Johnson [added: Manuel H. Johnson] | | Director | | February [removed: 22, 2012] [added: 19, 2013] |
| /s/ William A. Moran [added: William A. Moran] | | Director | | February [removed: 22, 2012] [added: 19, 2013] |
| /s/ David A. Preiser [added: David A. Preiser] | | Director | | February [removed: 22, 2012] [added: 19, 2013] |
| /s/ W. Grady Rosier [added: W. Grady Rosier] | | Director | | February [removed: 22, 2012] [added: 19, 2013] |
| /s/ John M. Toups [added: John M. Toups] | | Director | | February [removed: 22, 2012] [added: 19, 2013] |
| /s/ Paul W. Whetsell [added: Paul W. Whetsell] | | Director | | February [removed: 22, 2012] [added: 19, 2013] |
| /s/ Paul C. Saville [added: Paul C. Saville] | | Principal Executive Officer | | February [removed: 22, 2012] [added: 19, 2013] |
| /s/ Dennis M. Seremet [added: Dennis M. Seremet] | | Principal Financial Officer | | February [removed: 22, 2012] [added: 19, 2013] |
| /s/ [removed: Robert W. Henley] [added: Eugene J. Bredow Eugene J. Bredow] | | Principal Accounting Officer | | February [removed: 22, 2012] [added: 19, 2013] |
We have audited the accompanying consolidated balance sheets of NVR, Inc. and subsidiaries as of December 31, [removed: 2011] [added: 2012] and [removed: 2010,] [added: 2011,] and the related consolidated statements of income, shareholders’ equity and cash flows for each of the years in the three-year period ended December 31, [removed: 2011.][added: 2012.]
| 4.3 | | Fifth Supplement Indenture dated September 10, 2012 among NVR, Inc. and U.S. Bank Trust National Association. Filed as Exhibit 4.1 to NVR’s Form 8-K filed on September 10, 2012 and incorporated herein by reference. |
| 4.4 | | Form of Global Note filed as Exhibit 4.2 to NVR’s Form 8-K filed on September 10, 2012 and incorporated herein by reference. |
| 10.5* | | Amendment No. 2 to the Employment Agreement between NVR, Inc. and Robert W. Henley dated December 21, 2010. Filed herewith. |
| 10.6* | | Employment Agreement between NVR, Inc. and Eugene J. Bredow dated May 31, 2012. Filed as Exhibit 10.2 to NVR’s Form 8-K filed on May 31, 2012 and incorporated herein by reference. |
| 10.7* | | Amendment No. 1 to the Employment Agreement between NVR, Inc. and Eugene J. Bredow dated May 31, 2012. Filed herewith. |
| 10.8* | | Employment Agreement between NVR, Inc. and Daniel D. Malzahn dated February 19, 2013. Filed herewith. |
| | | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | | |
| /s/ Melquiades R. Martinez Melquiades R. Martinez | | Director | | February 19, 2013 |
February 19, 2013
February 19, 2013
| | | 2012 | | | | 2011 | | |
| | | | 678,131 | | | | 533,150 | |
| Goodwill | | | 441 | | | | — | |
| Finite-lived intangible assets | | | 8,778 | | | | — | |
| | | | 2,382,270 | | | | 1,501,318 | |
| | | | 222,572 | | | | 278,167 | |
| Total assets | | $ | 2,604,842 | | | $ | 1,779,485 | |
| | | 2012 | | | | 2011 | | |
| Accrued expenses and other liabilities | | | 234,804 | | | | 185,423 | |
| Senior notes | | | 598,988 | | | | — | |
| | | | 1,103,679 | | | | 378,291 | |
| | | | 20,686 | | | | 26,395 | |
| Tax benefit from equity benefit plan activity | | | — | | | | 63,558 | | | | — | | | | — | | | | — | | | | — | | | | 63,558 | |
| Tax benefit from equity benefit plan activity | | | — | | | | 22,835 | | | | — | | | | — | | | | — | | | | — | | | | 22,835 | |
| Purchase of common stock for treasury | | | — | | | | — | | | | — | | | | (227,281 | ) | | | — | | | | — | | | | (227,281 | ) |
| Tax benefit from equity benefit plan activity | | | — | | | | 14,319 | | | | — | | | | — | | | | — | | | | — | | | | 14,319 | |
| _Balance, December 31, 2012_ | | $ | 206 | | | $ | 1,169,699 | | | $ | 4,339,080 | | | $ | (4,028,508 | ) | | $ | (25,331 | ) | | $ | 25,331 | | | $ | 1,480,477 | |
| Acquisition, net of cash acquired | | | (14,257 | ) | | | — | | | | — | |
| Repayments on loans assumed in acquisition | | | (21,910 | ) | | | — | | | | — | |
| Proceeds from issuance of Senior Notes due 2022 | | | 598,962 | | | | — | | | | — | |
| Debt issuance costs for Senior Notes due 2022 | | | (5,096 | ) | | | — | | | | — | |
| Increase in assets in connection with acquisition | | $ | 55,759 | | | $ | — | | | $ | — | |
| Increase in liabilities in connection with acquisition | | $ | 41,502 | | | $ | — | | | $ | — | |
Certain prior year amounts in the consolidated financial statements have been reclassified to conform to 2012 presentation.
| --- | --- | --- | --- | --- |
| Dwight C. Schar | | | | |
| C. E. Andrews | | | | |
| Robert C. Butler | | | | |
| Timothy M. Donahue | | | | |
| Thomas D. Eckert | | | | |
| Alfred E. Festa | | | | |
| Manuel H. Johnson | | | | |
| William A. Moran | | | | |
| David A. Preiser | | | | |
| W. Grady Rosier | | | | |
| John M. Toups | | | | |
| Paul W. Whetsell | | | | |
| Paul C. Saville | | | | |
| Dennis M. Seremet | | | | |
| Robert W. Henley | | | | |
February 22, 2012
| | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | 533,150 | | | | 431,329 | |
| | | | 1,501,318 | | | | 2,056,273 | |
| | | | 278,167 | | | | 203,788 | |
| | | | | | | |
| Accrued expenses and other liabilities | | | 183,810 | | | | 237,052 | |
| Other term debt | | | 1,613 | | | | 1,751 | |
| | | | 378,291 | | | | 416,178 | |
| Note payable | | | — | | | | 90,338 | |
| | | | 26,395 | | | | 103,509 | |
| | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| _Balance, December 31, 2008_ | | $ | 206 | | | $ | 722,265 | | | $ | 3,630,887 | | | $ | (2,979,569 | ) | | $ | (74,978 | ) | | $ | 74,978 | | | $ | 1,373,789 | |
| Tax benefit from stock options exercised and deferred compensation distributions | | | — | | | | 66,448 | | | | — | | | | — | | | | — | | | | — | | | | 66,448 | |
| Tax benefit from stock options exercised and deferred compensation distributions | | | — | | | | 63,558 | | | | — | | | | — | | | | — | | | | — | | | | 63,558 | |
| Tax benefit from stock options exercised and deferred compensation distributions | | | — | | | | 22,835 | | | | — | | | | — | | | | — | | | | — | | | | 22,835 | |
| Change in net consolidated variable interest entities | | $ | — | | | $ | — | | | $ | (976 | ) |
deposits when it is determined that it is probable that recovery of the deposit is impaired.
| Marketable securities | | | — | | | | — | | | | 219,535 | |
| Consolidated Assets | | $ | 1,779,485 | | | $ | 2,260,061 | | | $ | 2,395,770 | |
During the second quarter of 2011, NVR invested $61,250 for a fifty percent (50%) interest in a joint venture entered into with Morgan Stanley Real Estate Investing, which holds the other fifty percent interest.
An excerpt. Shown here: 40 of 422 rewritten, 40 of 148 added and 40 of 96 removed. The counts are complete. For every sentence, read Item 15. Exhibits and Financial Statement Schedules. in the FY2012 filing and the FY2011 filing.