 filings.tools
NVR (NVR) 10-K risk factor changes: FY2015 vs FY2014
The 2015-12-31 10-K against the 2014-12-31 one, compared heading by heading and sentence by sentence. One of these filings carries no fiscal year tag, so its year is the calendar year of the period end.
Item 1A32 rewritten12 added20 removed99 unchanged
All filing items867 rewritten287 added313 removed1,328 unchanged
Summary
counted, not written
- Item 1A headings could not be compared: only 0 carried over between the two years, which usually means one filing was read wrongly, so none is reported as new or removed.
- Sentence by sentence, 287 added, 313 removed, 867 rewritten and 1,328 unchanged across 18 items that differ.
Sentences by item
21 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2015; struck-through words were in FY2014. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors.
32 rewritten, 12 added, 20 removed, 99 unchanged
Read the full itemFY2015 item · filed February 17, 2016FY2014 item · filed February 19, 2015
| [added: |] ● | the availability of mortgage financing; |
| [added: |] ● | actual and expected direction of interest rates, which affect our costs, the availability of construction financing, and long-term financing for potential purchasers of homes; |
| [added: |] ● | the availability of adequate land in desirable locations on favorable terms; |
| [added: |] ● | unexpected changes in customer preferences; and |
| [added: |] ● | changes in the national economy and in the local economies of the markets in which we have operations. |
[removed: Although housing industry conditions are improving, a deterioration] [added: An economic downturn or decline] in [removed: industry] [added: economic] conditions could adversely affect our business and our results of operations.
If the [removed: improvements in the homebuilding industry do not continue or the] [added: housing] industry suffers [removed: another] [added: a] downturn, our sales may [removed: decrease,] [added: decline] which could have a material adverse effect on our profitability, stock performance, ability to service our debt obligations and future cash flows.
We must, in the ordinary course of our business, continuously seek and make acquisitions of lots for expansion into new markets as well as for replacement and expansion within our current markets, which is generally accomplished by us entering fixed price purchase agreements and paying forfeitable deposits under the purchase [removed: agreement] [added: agreements] to developers for the contractual right to acquire the lots.
In the event of adverse changes in economic or market conditions, we may cease further building activities in [added: certain] communities or restructure existing purchase agreements, resulting in forfeiture of some or all of any remaining land contract deposit paid to the developer.
[removed: Either action may result in a loss which] [added: Any resulting losses] could have a material adverse effect on our profitability, stock performance, ability to service our debt obligations and future cash flows.
[removed: This] [added: The forfeiture of land contract deposits or inventory impairments] may result in [removed: losses which] [added: a loss that] could have a material adverse effect on our profitability, stock performance, ability to service our debt obligations and future cash flows.
Our mortgage banking operations may be responsible for losses associated with mortgage loans originated and sold to investors in the event of errors or omissions relating to certain representations and warranties that the loans sold meet certain requirements, including representations as to underwriting standards, the type of collateral, the existence of primary mortgage insurance, and the [added: validity of certain borrower representations in connection with the loan.]
The resolution of claims related to alleged breaches of these representations and warranties and repurchase claims could have a material adverse effect on our financial condition, cash flows and results of operations and could [added: result in losses that] exceed existing estimates and accruals.
Our mortgage banking business sells all of the loans it originates into the secondary market [removed: usually] [added: usually,] within 30 days from the date of closing, and has up to approximately [removed: $25] [added: $150] million available [removed: in] [added: under] a repurchase agreement to fund mortgage closings.
In particular, during [removed: 2014,] [added: 2015,] approximately [removed: 26%] [added: 25%] and 11% of our home settlements occurred in the Washington, D.C. and Baltimore, MD metropolitan areas, respectively, which accounted for approximately [removed: 33%] [added: 31%] and 13%, respectively, of our [removed: 2014] [added: 2015] homebuilding revenues.
The results of our homebuilding operations [removed: are dependent] [added: depend] upon our continuing ability to control an adequate number of homebuilding lots in desirable locations.
If we require working capital greater than [removed: that provided by] our [removed: operations,] [added: operations provide,] we may be required to obtain alternative [removed: financing.][added: financing, which might not be available on terms that are favorable or acceptable.]
[removed: No assurance can be given that additional] [added: Additional or replacement] financing [removed: will] [added: might not] be available on terms that are favorable or acceptable.
If we are required to seek financing to fund our working capital requirements, volatility in [removed: those] [added: credit or capital] markets may restrict our flexibility to access financing.
If we are at any time unsuccessful in obtaining sufficient capital to fund our planned homebuilding expenditures, we may experience a substantial delay in the [removed: completion of homes then under construction, or we may be unable to control or purchase finished building lots.]
Our mortgage banking operations [removed: are dependent] [added: depend] in part on the availability, cost and other terms of mortgage financing facilities, and may be adversely affected by any shortage or increased cost of such financing.
The cost of these assessments is subject to substantial change and [removed: can] [added: could] cause increases in the construction cost of our homes, which, in turn, could reduce our profitability.
[removed: The tighter] [added: Tighter] underwriting requirements and fee restrictions and [added: the] increasingly complex regulatory environment [removed: under these standards] may negatively impact our mortgage loan origination business in the form of lower demand, decreased revenue and increased operating costs.
| [added: |] ● | for suitable and desirable lots at acceptable prices; |
| [added: |] ● | from selling incentives offered by competing builders within and across developments; and |
| [added: |] ● | from the existing home resale market. |
[removed: There can] [added: We might not] be [removed: no assurance that we will] [added: able to] continue to compete successfully in our homebuilding or mortgage banking operations.
Despite our quality control efforts, we may discover that our subcontractors [removed: were engaging] [added: have engaged] in improper construction practices.
The cost of insuring against construction defect and product liability [removed: related] claims, as well as the claims themselves, can be high.
As described in, but not limited to, [removed: Part I,] Item 3, “Legal Proceedings” of this Form 10-K, we are currently subject to certain legal proceedings.
[removed: We cannot assure you that these] [added: These] or other litigation or legal proceedings [removed: will not] [added: could] materially affect our ability to conduct our business in the manner that we expect or otherwise adversely affect us should an unfavorable ruling occur.
Our failure to maintain the security of the data [removed: which] we are required to protect, including via the penetration of our network security and the misappropriation of confidential and personal information, could result in business disruption, damage to our reputation, financial obligations to third parties, fines, penalties, regulatory proceedings and private litigation with potentially large costs, and also in deterioration in customers’ confidence in us and other competitive disadvantages, and thus could have a material adverse effect on our sales, profitability, stock performance, ability to service our debt obligations and future cash flows.
| --- | --- | --- |
| --- | --- | --- |
| --- | --- | --- |
| --- | --- | --- |
| --- | --- | --- |
Demand for new homes is sensitive to economic changes driven by conditions such as employment levels, job growth, consumer confidence and interest rates.
See “Management’s Discussion and Analysis of Financial Condition and Results of Operations – Liquidity and Capital Resources” in Item 7 of this Form 10-K for more information about the repurchase agreement.
We may also have significant impairments of land under development.
completion of homes then under construction, or we may be unable to control or purchase finished building lots.
| --- | --- | --- |
| --- | --- | --- |
| --- | --- | --- |
| --- | --- |
| --- | --- |
| --- | --- |
| --- | --- |
| --- | --- |
| --- | --- |
The homebuilding industry experienced a significant downturn from 2006 through 2011.
During 2006 through 2011, the homebuilding industry experienced a significant downturn as a result of low consumer confidence driven by an economic recession, high unemployment levels, affordability issues and uncertainty as to the stability of home prices.
As a result, we experienced reduced demand for new homes.
Since 2011, we have experienced strengthening within the homebuilding industry with increasing sales.
However, the housing market continues to face challenges from a tight mortgage lending environment and consumer confidence issues.
validity of certain borrower representations in connection with the loan.
No assurance can be given that any additional or replacement financing will be available on terms that are favorable or acceptable.
In addition, the Dodd-Frank Wall Street Reform and Consumer Protection Act, enacted on July 21, 2010, contains numerous provisions affecting residential mortgages and mortgage lending practices.
The CFPB issued rules governing multiple issues in January 2013, including “Ability to Repay” underwriting provisions, definition and parameters of “Qualified Mortgages” and the establishment of certain protections from liability under “Ability to Repay” provisions for “Qualified Mortgages”.
The CFPB’s rulemaking also included limitations on certain fees and loan officer compensation requirements.
These rules were effective January 2014.
In addition, the new requirements integrating disclosures under the Truth In Lending Act and the Real Estate Settlement Protection Act become effective August 1, 2015.
| --- | --- |
| --- | --- |
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
260 rewritten, 104 added, 110 removed, 335 unchanged
Read the full itemFY2015 item · filed February 17, 2016FY2014 item · filed February 19, 2015
[added: | |] (dollars in thousands, except per share data) [added: |]
Results of Operations for the Years Ended December 31, [removed: 2014, 2013] [added: 2015, 2014] and [removed: 2012][added: 2013]
Instead, we [added: typically] have acquired finished lots at market prices from various third party land developers pursuant to fixed price purchase agreements.
[removed: As a result, in] [added: In] certain specific strategic circumstances we deviate from our historical lot acquisition strategy and engage in joint venture arrangements with land developers or directly acquire raw ground already zoned for its intended use for development.
As of December 31, [removed: 2014,] [added: 2015,] we controlled approximately [removed: 62,800] [added: 68,800] lots under purchase agreements with deposits in cash and letters of credit totaling approximately [removed: $348,400] [added: $373,300] and [removed: $1,700,] [added: $3,000,] respectively.
Included in the number of controlled lots are approximately [removed: 7,800] [added: 6,100] lots for which we have recorded a contract land deposit impairment reserve of approximately [removed: $56,100] [added: $42,200] as of December 31, [removed: 2014.][added: 2015.]
See Notes 3, 4 and 5 to the consolidated financial statements included herein for additional information regarding fixed price purchase agreements, [removed: joint ventures] [added: JVs] and land under development, respectively.
[removed: Additionally,] [added: In addition,] we have certain properties under contract with land owners that are expected to yield approximately [removed: 5,700] [added: 8,800] lots, which are not included in our number of total lots [removed: controlled.][added: controlled above.]
These properties are controlled with [added: cash] deposits and letters of credit totaling approximately [removed: $2,300] [added: $12,200] and [removed: $3,000,] [added: $350,] respectively, as of December 31, [removed: 2014,] [added: 2015,] of which approximately [removed: $2,600] [added: $8,700] is refundable if we do not perform under the contract.
[removed: There has also been] [added: However, new home prices continued to be constrained by] an increase in the number of new home communities in many markets.
The housing market also continues to face challenges from [added: tight] mortgage underwriting standards.
[removed: Our new] [added: New] orders, net of cancellations (“New Orders”) [removed: for 2014] [added: during 2015] increased [removed: 5%] [added: 14%] from [removed: 2013] [added: 2014] while our average [removed: new order] [added: New Order] sales price increased [removed: 4%] [added: 1%] to [removed: $373.7] [added: $378.7] in [removed: 2014.][added: 2015.]
[removed: Consolidated] [added: Our consolidated] revenues for the year ended December 31, [removed: 2014] [added: 2015] totaled [removed: $4,375,059,] [added: $5,159,008,] an increase of [removed: 6%] [added: 16%] from [removed: $4,134,481] [added: $4,444,568] in [removed: 2013.][added: 2014.]
[removed: Our gross] [added: Gross] profit margin [removed: within our homebuilding business] [added: percentage in 2014] increased to 18.4% [removed: in 2014] compared to 17.2% in 2013.
We believe that a continuation of the housing market recovery [removed: which began in 2012] is dependent upon a sustained overall economic recovery, driven by continued improvement in job [removed: growth] and [removed: consumer confidence levels as well as improvement in] wage growth and household formation.
[removed: Due to the strength of our balance sheet, we] [added: We] believe that we are well positioned to take advantage of opportunities that may arise from future economic and homebuilding market [removed: volatility.][added: volatility due to the strength of our balance sheet.]
| | | [removed: 2014] [added: 2015] | | | | [removed: 2013] [added: 2014] | | | | [removed: 2012] [added: 2013] | | |
| Revenues | | $ | [removed: 4,375,059] [added: 5,065,200] | | | $ | [removed: 4,134,481] [added: 4,375,059] | | | $ | [removed: 3,121,244] [added: 4,134,481] | |
| Cost of sales | | $ | [removed: 3,568,586] [added: 4,118,782] | | | $ | [removed: 3,424,204] [added: 3,568,586] | | | $ | [removed: 2,575,639] [added: 3,424,204] | |
| Gross profit margin percentage | | | [removed: 18.4] [added: 18.7] | % | | | [removed: 17.2] [added: 18.4] | % | | | [removed: 17.5] [added: 17.2] | % |
| Selling, general and administrative expenses | | $ | [removed: 358,851] [added: 371,127] | | | $ | [removed: 313,029] [added: 358,851] | | | $ | [removed: 301,184] [added: 313,029] | |
| Settlements (units) | | | [removed: 11,859] [added: 13,326] | | | | [removed: 11,834] [added: 11,859] | | | | [removed: 9,843] [added: 11,834] | |
| Average settlement price | | $ | [removed: 368.5] [added: 379.9] | | | $ | [removed: 349.1] [added: 368.5] | | | $ | [removed: 317.1] [added: 349.1] | |
| New orders (units) | | | [removed: 12,389] [added: 14,080] | | | | [removed: 11,800] [added: 12,389] | | | | [removed: 10,954] [added: 11,800] | |
| Average new order price | | $ | [removed: 373.7] [added: 378.7] | | | $ | [removed: 360.4] [added: 373.7] | | | $ | [removed: 328.8] [added: 360.4] | |
| Backlog (units) | | | [removed: 5,475] [added: 6,229] | | | | [removed: 4,945] [added: 5,475] | | | | [removed: 4,979] [added: 4,945] | |
| Average backlog price | | $ | [removed: 384.6] [added: 381.3] | | | $ | [removed: 373.2] [added: 384.6] | | | $ | [removed: 346.2] [added: 373.2] | |
| New order cancellation rate | | | [removed: 14.6] [added: 14.5] | % | | | [removed: 14.9] [added: 14.6] | % | | | [removed: 14.5] [added: 14.9] | % |
The higher average price of homes in backlog entering 2014 was attributable to [removed: the aforementioned] [added: favorable market conditions in 2013, leading to] increasing prices [removed: in 2013.][added: during that year.]
Homebuilding revenues [removed: in 2013] increased [removed: 32% from 2012,] [added: 16% in 2015 compared 2014,] as a result of a [removed: 20%] [added: 12%] increase in the number of [removed: homes] [added: units] settled and a [removed: 10%] [added: 3%] increase in the average settlement price year over year.
The increase in [removed: the number of homes] [added: units] settled was [removed: primarily] attributable to a [removed: 35%] [added: 19%] higher [removed: beginning] backlog unit balance entering [removed: 2013] [added: 2015] compared to [removed: 2012,] [added: the backlog unit balance entering 2014,] offset partially by a [removed: lower] [added: slower] backlog turnover rate [removed: in 2013 compared to 2012.][added: year over year.]
[removed: Average] [added: In addition, the unit and average] settlement [removed: prices in 2013] [added: price increases] were favorably impacted [removed: primarily] by a [removed: 10% higher average price of homes in backlog entering 2013 compared to the average price of homes] [added: 15% increase] in [removed: backlog entering 2012] [added: New Orders] and a [removed: 10% higher] [added: 2% increase in the] average sales price of New [removed: Orders] [added: Orders, respectively,] for the first six months of [removed: 2013] [added: 2015] compared to [removed: 2012.][added: the same period in 2014.]
The number of New Orders and the average sales price of New Orders increased 5% and 4%, respectively, [removed: during] [added: in] 2014 [removed: when] compared to 2013.
The number of New Orders and the average sales price of New Orders [removed: in 2013] increased [removed: 8%] [added: 14%] and [removed: 10%,] [added: 1%,] respectively, [removed: when] [added: in 2015] compared to [removed: 2012.][added: 2014.]
[removed: New Orders] [added: Units settled] and the average [removed: sales price] [added: settlement prices] were higher [removed: year over year] in each of our market [removed: segments.][added: segments year over year.]
[removed: As noted in the Overview section above, gross profit] margins in 2013 were negatively impacted by two service related accruals which reduced the 2013 gross profit margin by 76 basis points.
We expect continued gross margin pressure over the next several quarters due to weakness in sales [removed: prices.][added: pricing.]
Equity-based compensation expense increased primarily due to the [removed: granting] [added: grant] of non-qualified stock options (“Options”) under the 2014 Equity Incentive Plan (the “2014 Plan”) following shareholder approval of the 2014 Plan in May 2014 and restricted share [removed: unit] [added: units] (“RSUs”) [removed: grants] in the second quarter of 2013.
Sales and marketing expenses increased due primarily to an increase in model home expenditures attributable to the 8% increase in the number of active [removed: communities.][added: communities year over year.]
[removed: Backlog dollars were higher] [added: The increase in backlog units was] primarily [removed: due] [added: attributable] to a [removed: 10%] [added: 13%] increase in [removed: the average price of] New Orders for the [removed: six-month] [added: six month] period ended December 31, [removed: 2013] [added: 2015] compared to the same period in [removed: 2012.][added: 2014.]
We generally do not engage in land development (see discussion below of our limited land development activities).
In addition, we controlled approximately 8,000 lots through six JVs with an aggregate investment of approximately $60,500.
Of the lots controlled by the JVs, approximately 3,300 were not under contract with us at December 31, 2015.
Further, as of December 31, 2015, we directly owned four separate raw parcels of land, zoned for their intended use, with a current cost basis, including development costs, of approximately $60,600 that we intend to develop into approximately 980 finished lots.
We have additional funding commitments under a joint development agreement related to our land under development of approximately $19,200, a portion of which we expect will be offset by development credits of approximately $9,600.
We also had a $2,200 obligation under a letter of credit related to one of our land parcels.
In February 2016, we acquired an additional raw parcel of land at a cost of approximately $150,000 which is expected to produce approximately 1,000 lots, of which approximately 160 lots are under contract with unrelated parties.
Of the $12,200 in cash deposits, $5,000 relates to the raw parcel of land acquired in February 2016 discussed above.
New home demand continued to improve throughout 2015.
Our net income for 2015 was $382,927, or $89.99 per diluted share, increases of 36% and 42% compared to 2014 net income and diluted earnings per share, respectively.
Diluted earnings per share was favorably impacted by our ongoing share repurchase program.
Our homebuilding gross profit margin percentage increased to18.7% in 2015 from 18.4% in 2014.
Our backlog of homes sold but not yet settled with the customer as of December 31, 2015 increased on a unit basis by 14% to 6,229 units and increased on a dollar basis by 13% to $2,375,182 when compared to December 31, 2014.
We expect to continue to face gross profit margin and pricing pressures due to higher land and construction costs, as well as increased competition associated with the increase in the
number of new home communities in our markets.
| Financial data: | | | | | | | | | | | | |
| Operating data: | | | | | | | | | | | | |
The increases in the number of units settled and the average settlement price were attributable to an 11% higher backlog unit balance entering 2015 and a 3% higher average price of homes in backlog entering 2015 compared to backlog entering 2014.
Gross profit margin percentage in 2015 increased to 18.7% from 18.4% in 2014.
Gross profit margin was favorably impacted in 2015 by an approximate $11,100, or 22 basis points of revenue, recovery of contract land deposits previously determined to be unrecoverable.
Excluding the contract land deposit impairment recovery, gross profit margin was flat year over year as higher revenues were offset by higher lot and construction costs year over year.
Gross profit
SG&A expenses in 2015 increased approximately $12,300, or 3%, compared to 2014.
SG&A expenses increased primarily due to an approximate $14,900 increase in management incentive compensation attributable to the improved operating results in 2015.
SG&A expenses decreased as a percentage of revenue to 7.3% in 2015 from 8.2% in 2014 due to improved leveraging of SG&A expenses.
Backlog units and dollars increased approximately 14% to 6,229 units and 13% to $2,375,182, respectively, as of December 31, 2015 compared to 5,475 units and $2,105,635, respectively, as of December 31, 2014.
Backlog dollars were favorably impacted by the increase in backlog units.
deposits in lieu of cash.
| | | 2015 | | | | 2014 | | |
| | | 2015 | | | | 2014 | | |
| --- | --- | --- |
| | | 2015 | | | | 2014 | | |
| | | 2015 | | | | 2014 | | |
| | | 2015 | | | | 2014 | | |
2015 versus 2014
The Mid Atlantic segment had an approximate $50,900, or 19%, increase in segment profit in 2015 compared to 2014, driven by an increase in revenues of approximately $405,700, or 16%, year over year.
The number of units settled and the average settlement price were favorably impacted by a 9% higher backlog unit balance and a 3% higher average price of homes in backlog, respectively, entering 2015 compared to 2014.
The Mid Atlantic segment’s gross profit margin percentage decreased to 18.6% in 2015 from 19.1% in 2014, due primarily to higher lot and construction costs year over year.
New Orders increased despite a 5% decrease in the average number of active communities year over year, due to higher sales absorption year over year.
Community sales absorption was impacted by improved market conditions in 2015 compared to 2014.
| --- | --- |
Historically, we generally have not engaged in land development to obtain finished lots for use in our homebuilding operations.
In addition, we controlled approximately 5,500 lots through joint venture limited liability corporations with an aggregate investment of approximately $82,000.
Further, as of December 31, 2014, we had approximately $33,700 in land under development, that once fully developed will result in approximately 480 lots for use in our homebuilding operations.
Of the total finished lots expected to be developed, 94 lots are under contract to be sold to an unrelated party under lot purchase agreements.
The housing market recovery continues to be uneven.
During 2014, the housing market experienced some weakness as existing home inventory increased and affordability decreased following increasing prices during 2013.
These factors have resulted in weakness in housing prices in 2014.
Gross profit in 2013 was negatively impacted by two previously disclosed service related accruals totaling approximately $31,600, a 76 basis point reduction to gross profit in 2013.
Net income for 2014 increased 6% from 2013 to $281,630.
Diluted earnings per share in 2014 was $63.50, an increase of 16% from 2013.
Diluted earnings per share was favorably impacted by our ongoing share repurchase program, under which we repurchased 507,648 shares of our stock at an aggregate purchase price of $567,544 during 2014.
We expect to face a challenging market in 2015, as a result of the weakness in new home sales prices and increased competition associated with an expected increase in new home communities in our markets.
The higher beginning backlog balance and average sales prices were driven by the favorable market conditions experienced in the second half of 2012.
The increase in New Orders was driven by a 12% increase in the number of active communities year over year, offset partially by a lower absorption rate in 2013.
In addition, our December 2012 acquisition of Heartland Homes added 355 New Orders in 2013.
The increase in active communities and pricing in 2013 was attributable to the favorable market conditions through the first half of 2013.
Gross profit margins in 2014 increased to 18.4% compared to 17.2% in 2013.
Gross profit margins in 2013 decreased to 17.2% from 17.5% in 2012.
Gross profit margins were negatively impacted in 2013 by two service related accruals totaling approximately $31,600 (see Note 13 in the accompanying consolidated financial statements for additional discussion of service accruals).
Excluding these charges, gross profit margin was 17.9% in 2013, an increase of 46 basis points from the prior year.
Gross profit margins were favorably impacted by higher settlement volume in 2013 allowing us to better
leverage our operating costs, partially offset by higher construction costs, including lumber and certain other commodity costs, year over year.
SG&A expenses in 2013 increased approximately $11,800, or 4%, compared to 2012, but as a percentage of revenue decreased to 7.6% in 2013 from 9.7% in 2012.
The increase in SG&A expenses was attributable to increases of approximately $20,300 in personnel costs in 2013 due to an increase in headcount year over year.
In addition, sales and marketing expenses were approximately $14,400 higher in 2013 due to the increase in the number of active communities.
These cost increases were partially offset by an approximate $28,700 reduction in equity-based compensation expense in 2013 compared to 2012.
Equity-based compensation expense was favorably impacted as a result of the restricted share units (“RSUs”) issued in 2010 becoming fully vested as of December 31, 2012 and the reversal of approximately $7,100 in equity-based compensation expense previously recorded to SG&A expense as we adjusted our stock option forfeiture rates based on our actual forfeiture experience.
These reductions were offset partially by equity-based compensation expense incurred in 2013 related to RSUs issued in May 2013.
The decrease in SG&A costs as a percentage of revenue was driven by the 32% increase in revenue in 2013, allowing us to better leverage our overhead costs.
Backlog units decreased approximately 1% to 4,945 as of December 31, 2013 compared to 4,979 as of December 31, 2012, while backlog dollars increased approximately 7% to $1,845,600 from $1,723,914 as of December 31, 2013 and December 31, 2012, respectively.
that it is probable that recovery of the deposit is impaired.
| --- | --- |
| (2) | The year over year increases in unsold inventory are primarily due to the transfer of costs attributable to completed lots from our land under development to unsold inventory. |
| --- | --- |
| | | 2014 | | | | 2013 | | | | 2012 | | |
2013 versus 2012
The increase in units settled was attributable to a 36% higher backlog unit balance entering 2013 compared to the backlog unit balance entering 2012, offset partially by a lower backlog turnover rate year over year.
Gross profit margins in 2013 were negatively impacted by a previously disclosed service related accrual of approximately $15,600, or 64 basis points of revenue.
Excluding this charge, gross profit margin increased 119 basis points to 19.6% in 2013 due to increased settlement volume, which allowed us to better leverage certain operating costs.
An excerpt. Shown here: 40 of 260 rewritten, 40 of 104 added and 40 of 110 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations. in the FY2015 filing and the FY2014 filing.
Item 7A. Quantitative and Qualitative Disclosure About Market Risk.
12 rewritten, 2 added, 1 removed, 36 unchanged
Read the full itemFY2015 item · filed February 17, 2016FY2014 item · filed February 19, 2015
NVRM has available a mortgage Repurchase Agreement, which [removed: provides] [added: as of December 31, 2015 provided] for loan repurchases up to $25,000, subject to certain sub limits.
Advances under the Repurchase Agreement carry a Pricing Rate based on the LIBOR Rate plus the LIBOR Margin, as determined under the Repurchase Agreement, provided that the Pricing Rate shall not be less than [removed: 2.825%.][added: 2.70%.]
At December 31, [removed: 2014,] [added: 2015,] there was no debt outstanding under the Repurchase Agreement.
The following table represents the contractual balances of our on-balance sheet financial instruments at the expected maturity dates, as well as the fair values of those on-balance sheet financial instruments at December 31, [removed: 2014.][added: 2015.]
| | | [removed: 2015 | | | |] 2016 | | | | 2017 | | | | 2018 | | | | 2019 | | | | [added: 2020 | | | |] Thereafter | | | | Total | | | | Value | | |
| Mortgage loans held for sale | | $ | [removed: 203,305] [added: 319,212] | | | | — | | | | — | | | | — | | | | — | | | | — | | | $ | [removed: 203,305] [added: 319,212] | | | $ | [removed: 205,664] [added: 319,553] | |
| Average interest rate | | | [removed: 3.8] [added: 4.0] | % | | | — | | | | — | | | | — | | | | — | | | | — | | | | [removed: 3.8] [added: 4.0] | % | | | | |
| Forward trades of mortgage-backed securities (a) | | $ | [removed: (909)] [added: 3,804] | | | | — | | | | — | | | | — | | | | — | | | | — | | | $ | [removed: (909)] [added: 3,804] | | | $ | [removed: (909)] [added: 3,804] | |
| Forward loan commitments (a) | | $ | [removed: 2,374] [added: 3,187] | | | | — | | | | — | | | | — | | | | — | | | | — | | | $ | [removed: 2,374] [added: 3,187] | | | $ | [removed: 2,374] [added: 3,187] | |
| Interest-bearing deposits | | $ | [removed: 474,205] [added: 347,538] | | | | — | | | | — | | | | — | | | | — | | | | — | | | $ | [removed: 474,205] [added: 347,538] | | | $ | [removed: 474,205] [added: 347,538] | |
| Average interest rate | | | [removed: 0.3] [added: 0.4] | % | | | — | | | | — | | | | — | | | | — | | | | — | | | | [removed: 0.3] [added: 0.4] | % | | | | |
| Fixed rate obligations (b) | | $ | — | | | | — | | | | — | | | | — | | | | — | | | $ | 600,00 | 0 | | $ | 600,000 | | | $ | [removed: 622,800] [added: 606,000] | |
On January 18, 2016, the Repurchase Agreement was amended (“Amended Repurchase Agreement”) to increase the borrowing capacity to $150,000 with an incremental commitment pursuant to which NVRM may from time to time request increases in the total commitment available under the agreement by up to $50,000 in the aggregate.
Other terms of the Amended Repurchase Agreement are materially consistent with the Repurchase Agreement.
The table does not include the debt of our consolidated joint venture as it is non-recourse to us.
Item 1. Business.
34 rewritten, 7 added, 11 removed, 106 unchanged
Read the full itemFY2015 item · filed February 17, 2016FY2014 item · filed February 19, 2015
During [removed: 2014,] [added: 2015,] approximately [removed: 26%] [added: 25%] and 11% of our home settlements occurred in the Washington, D.C. and Baltimore, MD metropolitan areas, respectively, which accounted for approximately [removed: 33%] [added: 31%] and 13%, respectively, of our [removed: 2014] [added: 2015] homebuilding revenues.
Ryan Homes operates in [removed: twenty-seven] [added: twenty-eight] metropolitan areas located in Maryland, Virginia, Washington, D.C., West Virginia, Pennsylvania, New York, North Carolina, South Carolina, Florida, Ohio, New Jersey, Delaware, Indiana, Illinois and Tennessee.
[removed: In] [added: During] 2014, our average price [removed: of a settled unit] was approximately $368,500.
[removed: Historically, we] [added: We] generally [removed: have] [added: do] not [removed: engaged] [added: engage] in land development (see discussion below on our limited land development activities).
As of December 31, [removed: 2014,] [added: 2015,] we controlled approximately [removed: 62,800] [added: 68,800] lots under purchase agreements with deposits in cash and letters of credit totaling approximately [removed: $348.4] [added: $373.3] million and [removed: $1.7] [added: $3.0] million, respectively.
Included in the number of controlled lots are approximately [removed: 7,800] [added: 6,100] lots for which we have recorded a contract land deposit impairment reserve of approximately [removed: $56.1] [added: $42.2] million as of December 31, [removed: 2014.][added: 2015.]
Of the lots controlled by the JVs, approximately 3,300 were not under contract with us at December 31, [removed: 2014.][added: 2015.]
Further, as of December 31, [removed: 2014,] [added: 2015,] we directly owned four separate raw parcels of land, zoned for their intended use, with a current cost basis, including development costs, of approximately [removed: $33.7] [added: $60.6] million [added: that we intend to develop into approximately 980 finished lots.]
See Notes 3, 4 and 5 to the consolidated financial statements included herein for additional information regarding fixed [removed: price purchase agreements, JVs and land under development, respectively.]
[removed: Additionally,] [added: In addition to the lots] we [added: currently control as discussed above, we] have certain properties under contract with land owners that are expected to yield approximately [removed: 5,700 lots, which are not included in our number of total lots controlled.][added: 8,800 lots.]
These properties are controlled with deposits and letters of credit totaling approximately [removed: $2.3] [added: $12.2] million and [removed: $3.0 million, respectively] [added: $350,000, respectively,] as of December 31, [removed: 2014,] [added: 2015,] of which approximately [removed: $2.6] [added: $8.7] million is refundable if we do not perform under the contract.
[removed: There has also been] [added: However, new home prices continued to be constrained due to] an increase in the number of new home communities in many markets.
[removed: In addition, the] [added: The] housing market [added: also] continues to face challenges from [removed: tightened] [added: tight] mortgage underwriting standards.
We believe that a continuation of the housing market recovery [removed: which began in 2012] is dependent upon a sustained overall economic recovery, driven by continued improvement in job [removed: growth] and [removed: consumer confidence levels as well as improvement in] wage growth and household formation.
Our homes combine traditional, transitional, cottage or urban exterior designs with contemporary interior designs and amenities, generally include two to four bedrooms and range from approximately [removed: 800] [added: 1,000] to [removed: 7,300] [added: 7,000] square feet.
During [removed: 2014,] [added: 2015,] the prices at which we settled homes ranged from approximately [removed: $120,000] [added: $136,000] to [removed: $1.5] [added: $1.9] million and averaged approximately [removed: $368,500.][added: $379,900.]
| Mid Atlantic: | [added: |] Maryland, Virginia, West Virginia, Delaware and Washington, D.C. |
| North East: | [added: |] New Jersey and [removed: eastern] [added: Eastern] Pennsylvania |
| Mid East: | [added: |] New York, Ohio, [removed: western] [added: Western] Pennsylvania, Indiana and Illinois |
| South East: | [added: |] North Carolina, South Carolina, Tennessee and Florida |
Backlog totaled [removed: 5,475] [added: 6,229] units and approximately [removed: $2.1] [added: $2.4] billion at December 31, [removed: 2014] [added: 2015] compared to backlog of [removed: 4,945] [added: 5,475] units and approximately [removed: $1.8] [added: $2.1] billion at December 31, [removed: 2013.][added: 2014.]
Expressed as the total of all cancellations during the period as a percentage of gross sales during the period, our cancellation rate was approximately 15% in each of [removed: 2014, 2013] [added: 2015, 2014] and [removed: 2012.][added: 2013.]
Additionally, during each of [removed: 2014, 2013] [added: 2015, 2014] and [removed: 2012,] [added: 2013,] approximately 6% of a reporting quarter’s opening backlog balance cancelled during the fiscal quarter.
We can provide no assurance that our historical cancellation rates are indicative of the actual cancellation [added: rate that may occur in future periods.]
Other than those units that are cancelled, we expect to settle substantially all of our December 31, [removed: 2014] [added: 2015] backlog during [removed: 2015.][added: 2016.]
Other factors that affect the housing industry and the demand for new homes [removed: include] [added: include:] the availability and the cost of land, labor and materials; changes in consumer preferences; demographic trends; and the availability of mortgage finance programs.
See “Risk Factors” in Item 1A of this Form [removed: 10-K.][added: 10-K for additional information regarding these risks.]
In [removed: 2014,] [added: 2015,] NVRM closed approximately [removed: 9,100] [added: 10,900] loans with an aggregate principal amount of approximately [removed: $2.8] [added: $3.5] billion as compared to approximately [removed: 8,600] [added: 9,100] loans with an aggregate principal amount of approximately [removed: $2.5] [added: $2.8] billion in [removed: 2013.][added: 2014.]
NVRM’s mortgage loans in process that had not closed at December 31, [removed: 2014] [added: 2015] and [removed: 2013] [added: 2014] had an aggregate principal balance of approximately [removed: $1.4] [added: $1.6] billion and [removed: $1.1] [added: $1.4] billion, respectively.
NVRM’s cancellation rate was approximately [removed: 31%, 35%] [added: 29%, 31%] and [removed: 36%] [added: 35%] in [removed: 2014, 2013] [added: 2015, 2014] and [removed: 2012,] [added: 2013,] respectively.
At December 31, [removed: 2014,] [added: 2015,] we employed [removed: 3,942] [added: approximately 4,300] full-time persons.
All of the documents we file with the SEC may also be read and copied at the SEC’s public reference room located at 100 F Street, NE, Washington, [removed: DC] [added: D.C.] 20549.
Some of the statements in this Form 10-K, as well as statements made by us in periodic press releases or other public communications, constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995, Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as [removed: amended (the “Exchange Act”).][added: amended.]
Such risk factors include, but are not limited to the following: general economic and business conditions (on both a national and regional level); interest rate changes; access to suitable financing by NVR and NVR’s customers; increased regulation in the mortgage banking industry; the ability of our mortgage banking subsidiary to sell loans it originates into the secondary market; competition; the [added: availability and cost of land and other raw materials used by NVR in its homebuilding operations; shortages of labor; weather related slow-downs; building moratoriums; governmental regulation; fluctuation and volatility of stock and other financial markets; mortgage financing availability; and other factors over which NVR has little or no control.]
In 2015, our average price of a settled unit was approximately $379,900.
In addition, we controlled approximately 8,000 lots through six JVs with an aggregate investment of approximately $60.5 million.
price purchase agreements, JVs and land under development, respectively.
In February 2016, we acquired one of these properties at a cost of approximately $150 million which is expected to produce approximately 1,000 lots, of which approximately 160 lots are under contract with unrelated parties.
New home demand continued to improve throughout 2015.
| --- | --- | --- |
See “Risk Factors” in Item 1A in this Form 10-K for additional information about factors that could increase our cancellation rate.
| --- | --- |
In addition, we had an aggregate investment totaling approximately $82.0 million in five separate joint venture limited liability corporations (“JVs”), expected to produce approximately 8,800 lots.
that we intend to develop into approximately 480 finished lots for use in our homebuilding operations.
Of the total finished lots expected to be developed, 94 lots are under contract to be sold to an unrelated party under lot purchase agreements.
The housing market recovery continues to be uneven.
During 2014, the housing market experienced some weakness as existing home inventory increased and affordability decreased following increasing prices during 2013.
These factors have resulted in weakness in housing prices in 2014.
During 2013, our average price was approximately $349,100.
rate that may occur in future periods.
See “Risk Factors” in Item 1A in this Form 10-K.
availability and cost of land and other raw materials used by NVR in its homebuilding operations; shortages of labor; weather related slow-downs; building moratoriums; governmental regulation; fluctuation and volatility of stock and other financial markets; mortgage financing availability; and other factors over which NVR has little or no control.
Item 3. Legal Proceedings.
1 rewritten, 2 added, 13 removed, 9 unchanged
Read the full itemFY2015 item · filed February 17, 2016FY2014 item · filed February 19, 2015
We have continued discussions with the EPA and [removed: DOJ.][added: DOJ and are presently engaged in settlement discussions with them.]
Any settlement is expected to include injunctive relief and payment of a civil penalty.
Although there can be no assurance that a settlement will be reached, we recorded a liability and corresponding expense associated with an estimated civil penalty amount on the accompanying consolidated financial statements in 2015.
In October 2004, Patrick Tracy, whom we had employed as a Sales and Marketing Representative (“SMR”), filed a lawsuit against us in the U.S. District Court for the Western District of New York alleging that we had misclassified him and other SMRs as outside sales personnel exempt from certain state and federal wage laws, including overtime pay requirements.
Mr. Tracy’s attorneys subsequently filed several other lawsuits in various courts asserting substantially similar claims on behalf of various classes or groups of SMRs.
None of those courts have held that the claims are appropriate for class, collective, or other group treatment, and the Western District of New York ruled in April 2013 that the claims in Mr. Tracy’s case could not proceed on such a basis.
The Western District of New York reached the same conclusion in July 2014 regarding a separate case that Mr. Tracy’s attorneys brought on behalf of other SMRs.
In October 2013, Mr. Tracy’s individual claims were tried by a jury, which returned a unanimous verdict in our favor and found that we had properly classified Mr. Tracy as an exempt outside sales person.
The plaintiff has sought review in the U.S. Court of Appeals for the Second Circuit, in which he challenges the legal standard that the trial court applied in crafting its jury instructions regarding the outside sales exemption, in addition to rulings that the trial court made at earlier stages of the case.
That appeal is fully briefed, and the parties are awaiting a ruling or an oral argument date.
The remainder of the cases noted above are in various stages of pre-trial proceedings, many of them stayed or administratively closed pending a final disposition of the Tracy action.
We believe that our compensation practices in regard to SMRs are entirely lawful and have vigorously defended all claims challenging those practices.
In light of the points noted above, we have not recorded any associated liabilities on the accompanying condensed consolidated balance sheets in conjunction with any of those claims.
It is as yet unclear what next steps the DOJ will take in the matter.
We intend to continue cooperating with any future EPA and/or DOJ inquiries.
At this time, we cannot predict the outcome of this inquiry, nor can we reasonably estimate the potential costs that may be associated with its eventual resolution.
Cover and table of contents
32 rewritten, 4 added, 2 removed, 43 unchanged
Read the full itemFY2015 item · filed February 17, 2016FY2014 item · filed February 19, 2015
10-K 1 [removed: nvr-10k_20141231.htm] [added: nvr-10k_20151231.htm] 10-K
Washington, [removed: DC] [added: D.C.] 20549
For the fiscal year ended December 31, [removed: 2014][added: 2015]
The aggregate market value of the voting stock held by non-affiliates of NVR, Inc. on June 30, [removed: 2014,] [added: 2015,] the last business day of NVR, Inc.’s most recently completed second fiscal quarter, was approximately [removed: $4,572,320,000.][added: $5,130,019,000.]
As of February [removed: 17, 2015] [added: 12, 2016] there were [removed: 4,048,671] [added: 3,881,141] total shares of common stock outstanding.
Portions of the Proxy Statement of NVR, Inc. to be filed with the Securities and Exchange Commission pursuant to Regulation 14A of the Securities Exchange Act of 1934 on or prior to April 30, [removed: 2015] [added: 2016] are incorporated by reference into Part III of this report.
| | | | | Page | | [removed: | | | |]
| PART I | | | | | | [removed: | | | |]
| Item 1. | | [Business](#Business) | | [removed: | 2 | | |] [added: 1] | |
| Item 1A. | | [Risk Factors](#Risk_Factors) | | [removed: | 6 | | |] [added: 5] | |
| Item 1B. | | [Unresolved Staff Comments](#Item_1B_Unresolved_Staff_Comments) | | [removed: | 10 | | |] [added: 9] | |
| Item 2. | | [Properties](#Properties) | | [removed: | 10 | | |] [added: 9] | |
| Item 3. | | [Legal Proceedings](#Legal_Proceedings) | | [removed: | 11 | | |] [added: 9] | |
| Item 4. | | [Mine Safety Disclosures](#Mine_Safety_Disclosures) | | [removed: | 11 | | |] [added: 9] | |
| | | [Executive Officers of the Registrant](#Executive_Officers_of_the_Registrant) | | [removed: | 11 | | |] [added: 10] | |
| PART II | | | | | | [removed: | | | |]
| Item 5. | | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities](#Item_5) | | [removed: | 12 | | |] [added: 11] | |
| Item 6. | | [Selected Financial Data](#Selected_Financial_Data) | | [removed: | 14 | | |] [added: 13] | |
| Item 7. | | [Management’s Discussion and Analysis of Financial Condition and Results of Operations](#Managements_Discussion_and_Analysis) | | [removed: | 14 | | |] [added: 13] | |
| Item 7A. | | [Quantitative and Qualitative Disclosure About Market Risk](#Quantitative_and_Qualitative_Disclosure) | | [removed: | 32 | | |] [added: 31] | |
| Item 8. | | [Financial Statements and Supplementary Data](#Financial_Statements_and_Supplementary) | | [removed: | 34 | | |] [added: 32] | |
| Item 9. | | [Changes in and Disagreements with Accountants on Accounting and Financial Disclosure](#Changes_in_and_Disagreement) | | [removed: | 34 | | |] [added: 32] | |
| Item 9A. | | [Controls and Procedures](#Controls_and_Procedures) | | [removed: | 34 | | |] [added: 32] | |
| Item 9B. | | [Other Information](#Other_Information) | | [removed: | 34 | | |] [added: 32] | |
| PART III | | | | | | [removed: | | | |]
| Item 10. | | [Directors, Executive Officers, and Corporate Governance](#Directors_Executive) | | [removed: | 34 | | |] [added: 32] | |
| Item 11. | | [Executive Compensation](#Executive_Compensation) | | [removed: | 34 | | |] [added: 32] | |
| Item 12. | | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters](#Security_Ownership) | | [removed: | 34 | | |] [added: 33] | |
| Item 13. | | [Certain Relationships and Related Transactions, and Director Independence](#Certain_Relationships) | | [removed: | 35 | | |] [added: 33] | |
| Item 14. | | [Principal Accountant Fees and Services](#Principal_Accountant) | | [removed: | 35 | | |] [added: 33] | |
| PART IV | | | | | | [removed: | | | |]
| Item 15. | | [Exhibits and Financial Statement Schedules](#Exhibits_and_Financial) | | [removed: | 35 | | |] [added: 34] | |
NVR, Inc.
Form 10-K
TABLE OF CONTENTS
| --- | --- | --- | --- | --- | --- |
INDEX
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
Item 2. Properties.
2 rewritten, 0 added, 0 removed, 9 unchanged
Read the full itemFY2015 item · filed February 17, 2016FY2014 item · filed February 19, 2015
Our plant utilization was [added: 40% and] 35% of total capacity in [removed: both 2014] [added: 2015] and [removed: 2013.][added: 2014, respectively.]
In connection with both our homebuilding and mortgage banking businesses, we also lease office space in multiple locations for homebuilding divisional offices and mortgage banking and title services branches under leases expiring at various times through [removed: 2023,] [added: 2025,] none of which are individually material to our business.
Item 4. Mine Safety Disclosures.
4 rewritten, 6 added, 0 removed, 22 unchanged
Read the full itemFY2015 item · filed February 17, 2016FY2014 item · filed February 19, 2015
| Paul C. Saville | | | [removed: 59] [added: 60] | | | President and Chief Executive Officer of NVR |
| Daniel D. Malzahn | | | [removed: 45] [added: 46] | | | Vice President, Chief Financial Officer and Treasurer of NVR |
| Robert W. Henley | | | [removed: 48] [added: 49] | | | President of NVRM |
| Eugene J. Bredow | | | [removed: 45] [added: 46] | | | Vice President and Controller of NVR |
| Jeffrey D. Martchek | | | 50 | | | President of Homebuilding Operations of NVR |
Jeffrey D.
Martchek was named President of Homebuilding Operations of NVR effective January 1, 2016.
Prior to January 1, 2016, Mr. Martchek was Area President for the Maryland and Virginia homebuilding operations since February 2011.
Mr. Martchek was Area President of NVR’s Mid East homebuilding operations from October 2008 until January 2011.
Mr. Martchek has been employed by NVR since 1988.
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
9 rewritten, 13 added, 15 removed, 16 unchanged
Read the full itemFY2015 item · filed February 17, 2016FY2014 item · filed February 19, 2015
Our shares of common stock are listed and principally traded on the New York Stock Exchange under the ticker symbol “NVR.” The following table sets forth the high and low prices per share for our common stock for each fiscal quarter during the years ended December 31, [removed: 2014] [added: 2015] and [removed: 2013:][added: 2014:]
As of the close of business on February [removed: 17, 2015,] [added: 12, 2016,] there were [removed: 303] [added: 287] shareholders of record.
We had two [removed: stock] [added: share] repurchase authorizations outstanding during the quarter ended December 31, [removed: 2014.][added: 2015.]
On [removed: December 17, 2013] [added: February 18, 2015] and [removed: July 31, 2014,] [added: November 4, 2015,] we publicly announced the Board of Directors’ approval for us to repurchase [removed: up to an aggregate of $300 million per authorization of] our [added: outstanding] common stock in one or more open market and/or privately negotiated [removed: transactions.][added: transactions, up to an aggregate of $300 million per authorization.]
The repurchase authorizations do not have [removed: an] expiration [removed: date.][added: dates.]
The following table provides information regarding common stock repurchases during the quarter ended December 31, [removed: 2014:][added: 2015:]
The following chart graphs our performance in the form of cumulative total return to holders of our common stock since December 31, [removed: 2009] [added: 2010] in comparison to the Dow Jones US Home Construction [added: Index, the S&P 500] Index and the Dow Jones US Industrial Average Index for that same period, assuming that $100 was invested in NVR stock and the indices on December 31, [removed: 2009.][added: 2010.]
[removed: ][added: 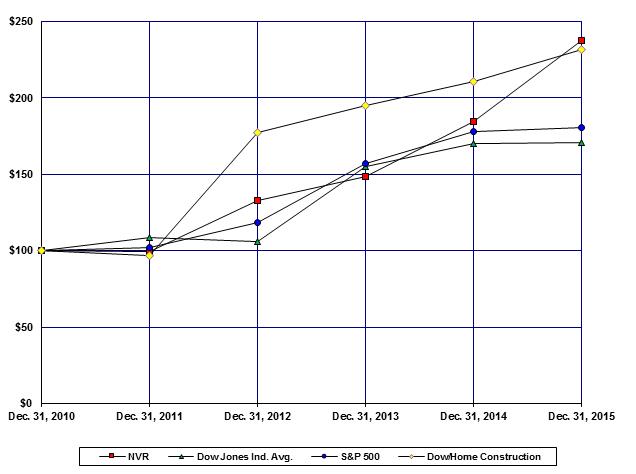]
| Comparison of 5 Year Cumulative Total Return | | [removed: 2009 | | | |] 2010 | | | | 2011 | | | | 2012 | | | | 2013 | | | | 2014 | | | [added: | 2015 | | |]
| 2015 | | | | | | | | |
| Fourth Quarter | | $ | 1,721.95 | | | $ | 1,500.23 | |
| Third Quarter | | $ | 1,610.00 | | | $ | 1,317.23 | |
| Second Quarter | | $ | 1,387.40 | | | $ | 1,292.11 | |
| First Quarter | | $ | 1,377.76 | | | $ | 1,187.84 | |
| October 1 - 31, 2015 | | | 74,393 | | | $ | 1,548.99 | | | | 74,393 | | | $ | 91,900,607 | |
| November 1 - 30, 2015 | | | 17,827 | | | $ | 1,630.34 | | | | 17,827 | | | $ | 362,836,550 | |
| December 1 - 31, 2015 | | | 14,339 | | | $ | 1,647.45 | | | | 14,339 | | | $ | 339,213,700 | |
| Total | | | 106,559 | | | $ | 1,575.85 | | | | 106,559 | | | | | |
| NVR, Inc. | | $ | 100 | | | $ | 99 | | | $ | 133 | | | $ | 148 | | | $ | 185 | | | $ | 238 | |
| Dow Jones US Industrial Average | | $ | 100 | | | $ | 108 | | | $ | 106 | | | $ | 155 | | | $ | 170 | | | $ | 171 | |
| S&P 500 | | $ | 100 | | | $ | 102 | | | $ | 118 | | | $ | 157 | | | $ | 178 | | | $ | 181 | |
| Dow Jones US Home Construction | | $ | 100 | | | $ | 97 | | | $ | 177 | | | $ | 195 | | | $ | 211 | | | $ | 232 | |
| 2013 | | | | | | | | |
| Fourth Quarter | | $ | 1,042.55 | | | $ | 883.96 | |
| Third Quarter | | $ | 967.00 | | | $ | 830.00 | |
| Second Quarter | | $ | 1,084.00 | | | $ | 885.43 | |
| First Quarter | | $ | 1,100.00 | | | $ | 920.00 | |
| October 1 - 31, 2014 | | | 76,663 | | | $ | 1,127.91 | | | | 76,663 | | | $ | 242,220,702 | |
| November 1 - 30, 2014 | | | — | | | $ | — | | | | — | | | $ | 242,220,702 | |
| December 1 - 31, 2014 | | | 59,258 | | | $ | 1,208.95 | | | | 59,258 | | | $ | 170,580,957 | |
| Total | | | 135,921 | | | $ | 1,163.24 | | | | 135,921 | | | | | |
The October 2014 repurchase activity included 25,332 shares purchased under the December 17, 2013 authorization, which fully utilized that authorization.
The remaining 51,331 shares were purchased under the July 31, 2014 authorization.
On February 18, 2015, the Board of Directors approved a repurchase authorization providing us authorization to repurchase up to an aggregate of $300 million of our common stock in one or more open market and/or privately negotiated transactions.
| NVR, Inc. | | $ | 100 | | | $ | 97 | | | $ | 97 | | | $ | 129 | | | $ | 144 | | | $ | 179 | |
| Dow Jones US Industrial Average | | $ | 100 | | | $ | 114 | | | $ | 124 | | | $ | 121 | | | $ | 177 | | | $ | 194 | |
| Dow Jones US Home Construction | | $ | 100 | | | $ | 101 | | | $ | 98 | | | $ | 179 | | | $ | 197 | | | $ | 213 | |
Item 6. Selected Financial Data.
18 rewritten, 1 added, 0 removed, 18 unchanged
Read the full itemFY2015 item · filed February 17, 2016FY2014 item · filed February 19, 2015
[added: | |] (in thousands, except per share amounts) [added: |]
| | | [removed: 2014] [added: 2015] | | | | [removed: 2013] [added: 2014] | | | | [removed: 2012] [added: 2013] | | | | [removed: 2011] [added: 2012] | | | | [removed: 2010] [added: 2011] | | |
| Revenues | | $ | [removed: 4,375,059] [added: 5,065,200] | | | $ | [removed: 4,134,481] [added: 4,375,059] | | | $ | [removed: 3,121,244] [added: 4,134,481] | | | $ | [removed: 2,611,195] [added: 3,121,244] | | | $ | [removed: 2,980,758] [added: 2,611,195] | |
| Gross profit | | | [removed: 806,473] [added: 946,418] | | | | [removed: 710,277] [added: 806,473] | | | | [removed: 545,605] [added: 710,277] | | | | [removed: 445,570] [added: 545,605] | | | | [removed: 542,466] [added: 445,570] | |
| Mortgage banking fees | | | [removed: 69,509] [added: 93,808] | | | | [removed: 76,786] [added: 69,509] | | | | [removed: 63,406] [added: 76,786] | | | | [removed: 47,954] [added: 63,406] | | | | [removed: 61,134] [added: 47,954] | |
| Interest income | | | [removed: 4,940] [added: 6,485] | | | | [removed: 4,983] [added: 4,940] | | | | [removed: 4,504] [added: 4,983] | | | | [removed: 5,702] [added: 4,504] | | | | [removed: 5,411] [added: 5,702] | |
| Interest expense | | | [removed: 549] [added: 641] | | | | [removed: 545] [added: 549] | | | | [removed: 546] [added: 545] | | | | [removed: 875] [added: 546] | | | | [removed: 1,126] [added: 875] | |
| Net [removed: Income] [added: income] | | | [removed: 281,630] [added: 382,927] | | | | [removed: 266,477] [added: 281,630] | | | | [removed: 180,588] [added: 266,477] | | | | [removed: 129,420] [added: 180,588] | | | | [removed: 206,005] [added: 129,420] | |
| Basic | | $ | [removed: 65.83] [added: 95.21] | | | $ | [removed: 56.25] [added: 65.83] | | | $ | [removed: 36.04] [added: 56.25] | | | $ | [removed: 23.66] [added: 36.04] | | | $ | [removed: 34.96] [added: 23.66] | |
| Diluted | | $ | [removed: 63.50] [added: 89.99] | | | $ | [removed: 54.81] [added: 63.50] | | | $ | [removed: 35.12] [added: 54.81] | | | $ | [removed: 23.01] [added: 35.12] | | | $ | [removed: 33.42] [added: 23.01] | |
| Basic | | | [removed: 4,278] [added: 4,022] | | | | [removed: 4,737] [added: 4,278] | | | | [removed: 5,011] [added: 4,737] | | | | [removed: 5,469] [added: 5,011] | | | | [removed: 5,893] [added: 5,469] | |
| Diluted | | | [removed: 4,435] [added: 4,255] | | | | [removed: 4,862] [added: 4,435] | | | | [removed: 5,142] [added: 4,862] | | | | [removed: 5,624] [added: 5,142] | | | | [removed: 6,165] [added: 5,624] | |
| | | [removed: 2014] [added: 2015] | | | | [removed: 2013] [added: 2014] | | | | [removed: 2012] [added: 2013] | | | | [removed: 2011] [added: 2012] | | | | [removed: 2010] [added: 2011] | | |
| Homebuilding inventory | | $ | [removed: 869,486] [added: 1,006,526] | | | $ | [removed: 738,565] [added: 869,486] | | | $ | [removed: 678,131] [added: 738,565] | | | $ | [removed: 533,150] [added: 678,131] | | | $ | [removed: 431,329] [added: 533,150] | |
| Contract land deposits, net | | | [removed: 294,676] [added: 343,295] | | | | [removed: 236,885] [added: 294,676] | | | | [removed: 191,538] [added: 236,885] | | | | [removed: 131,930] [added: 191,538] | | | | [removed: 100,786] [added: 131,930] | |
| Total assets | | | [removed: 2,351,335] [added: 2,515,131] | | | | [removed: 2,486,148] [added: 2,351,335] | | | | [removed: 2,604,842] [added: 2,486,148] | | | | [removed: 1,779,485] [added: 2,604,842] | | | | [removed: 2,260,061] [added: 1,779,485] | |
| Notes and loans payable (1) | | | [removed: 599,166] [added: 599,260] | | | | [removed: 599,190] [added: 599,166] | | | | [removed: 599,745] [added: 599,190] | | | | [removed: 1,613] [added: 599,745] | | | | [removed: 92,089] [added: 1,613] | |
| Shareholders’ equity | | | [removed: 1,124,255] [added: 1,239,165] | | | | [removed: 1,261,352] [added: 1,124,255] | | | | [removed: 1,480,477] [added: 1,261,352] | | | | [removed: 1,374,799] [added: 1,480,477] | | | | [removed: 1,740,374] [added: 1,374,799] | |
| --- | --- |
Item 9A. Controls and Procedures.
4 rewritten, 0 added, 0 removed, 6 unchanged
Read the full itemFY2015 item · filed February 17, 2016FY2014 item · filed February 19, 2015
Based on that evaluation, the principal executive officer and principal financial officer concluded that the design and operation of these disclosure controls and procedures as of December 31, [removed: 2014] [added: 2015] were effective to provide reasonable assurance that information required to be disclosed in our reports under the Exchange Act, processed, summarized and reported within the time periods specified in the Securities and Exchange Commission’s rules and forms and that such information is accumulated and communicated to our management, including our principal executive officer and principal financial officer, as appropriate, to allow timely decisions regarding required disclosure.
Based on our evaluation under the framework in Internal Control – Integrated Framework (2013), our management concluded that our internal control over financial reporting was effective as of December 31, [removed: 2014.][added: 2015.]
There have been no changes in our internal [removed: controls] [added: control] over financial reporting identified in connection with the evaluation referred to above that have materially affected, or are reasonably likely to materially affect, our internal [removed: controls] [added: control] over financial reporting.
Our internal control over financial reporting as of December 31, [removed: 2014] [added: 2015] has been audited by KPMG LLP, an independent registered public accounting firm, as stated in their attestation report which is included herein.
Item 9B. Other Information.
0 rewritten, 1 added, 1 removed, 2 unchanged
Read the full itemFY2015 item · filed February 17, 2016FY2014 item · filed February 19, 2015
None.
None
Item 10. Directors, Executive Officers, and Corporate Governance.
1 rewritten, 0 added, 0 removed, 2 unchanged
Read the full itemFY2015 item · filed February 17, 2016FY2014 item · filed February 19, 2015
Item 10 is incorporated herein by reference to our Proxy Statement expected to be filed with the Securities and Exchange Commission on or prior to April 30, [removed: 2015.][added: 2016.]
Item 11. Executive Compensation.
1 rewritten, 0 added, 0 removed, 1 unchanged
Read the full itemFY2015 item · filed February 17, 2016FY2014 item · filed February 19, 2015
Item 11 is incorporated herein by reference to our Proxy Statement expected to be filed with the Securities and Exchange Commission on or prior to April 30, [removed: 2015.][added: 2016.]
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
6 rewritten, 1 added, 1 removed, 7 unchanged
Read the full itemFY2015 item · filed February 17, 2016FY2014 item · filed February 19, 2015
Item 12 is incorporated herein by reference to our Proxy Statement expected to be filed with the Securities and Exchange Commission on or prior to April 30, [removed: 2015.][added: 2016.]
The table below sets forth information as of [removed: the end of our 2014 fiscal year] [added: December 31, 2015] for (i) all equity compensation plans approved by our shareholders and (ii) all equity compensation plans not approved by our shareholders:
| Equity compensation plans [added: not] approved by security holders [removed: (1)] | | | [removed: 1,086,851] [added: 125,516] | | | $ | [removed: 945.26] [added: 678.79] | | | | [removed: 362,123] [added: —] | |
| Equity compensation plans [removed: not] approved by security holders [added: (1)] | | | [removed: 169,658] [added: 1,020,789] | | | $ | [removed: 651.15] [added: 988.60] | | | | [removed: —] [added: 340,658] | |
| (1) | This category includes the RSUs authorized [removed: by] [added: to be issued under] the 2010 Equity Incentive Plan, which was approved by our shareholders at [removed: the] [added: our] May 4, 2010 Annual Meeting. At December 31, [removed: 2014,] [added: 2015,] there are [removed: 55,494] [added: 50,724] RSUs outstanding, issued at a $0 exercise price. Of the total [removed: 362,123] [added: 340,658] shares remaining available for future [removed: issuance,] [added: issuance under the shareholder approved plans,] up to [removed: 33,106] [added: 35,691] may be issued as RSUs. The weighted-average exercise price of outstanding options under security holder approved [removed: plans] [added: plans,] excluding outstanding [removed: RSUs] [added: RSUs,] was [removed: $996.12.] [added: $1,040.30.] |
Equity compensation plans approved by our shareholders [removed: include] [added: include:] the NVR, Inc. 1998 Management Long-Term Stock Option Plan; the 1998 Directors’ Long-Term Stock Option Plan; the 2010 Equity Incentive Plan; and the 2014 Equity Incentive Plan.
| Total | | | 1,146,305 | | | $ | 954.68 | | | | 340,658 | |
| Total | | | 1,256,509 | | | $ | 905.54 | | | | 362,123 | |
Item 13. Certain Relationships and Related Transactions, and Director Independence.
1 rewritten, 0 added, 0 removed, 1 unchanged
Read the full itemFY2015 item · filed February 17, 2016FY2014 item · filed February 19, 2015
Item 13 is incorporated herein by reference to our Proxy Statement expected to be filed with the Securities and Exchange Commission on or prior to April 30, [removed: 2015.][added: 2016.]
Item 14. Principal Accountant Fees and Services.
1 rewritten, 0 added, 0 removed, 2 unchanged
Read the full itemFY2015 item · filed February 17, 2016FY2014 item · filed February 19, 2015
Item 14 is incorporated herein by reference to our Proxy Statement expected to be filed with the Securities and Exchange Commission on or prior to April 30, [removed: 2015.][added: 2016.]
Item 15. Exhibits and Financial Statement Schedules.
449 rewritten, 134 added, 139 removed, 608 unchanged
Read the full itemFY2015 item · filed February 17, 2016FY2014 item · filed February 19, 2015
[removed: Notes] [added: See notes] to [removed: Consolidated Financial Statements][added: consolidated financial statements.]
| [removed: 3.2] [added: 10.12*] | | [removed: Bylaws, as amended,] [added: Description] of [removed: NVR, Inc.] [added: the Board of Directors’ compensation arrangement.] Filed as Exhibit [removed: 3.2] [added: 10.27] to NVR’s Annual Report on Form 10-K for the year ended December 31, [removed: 2010] [added: 2004] and incorporated herein by reference. |
| 4.3 | | Fifth Supplemental Indenture dated September 10, 2012 among NVR, Inc. and U.S. Bank Trust National Association. Filed as Exhibit 4.1 to NVR’s [added: Current Report on] Form 8-K filed on September 10, 2012 and incorporated herein by reference. |
| 4.4 | | Form of Global Note. Filed as Exhibit 4.2 to NVR’s [added: Current Report on] Form 8-K filed on September 10, 2012 and incorporated herein by reference. |
| 10.1* | | [added: Amended and Restated] Employment Agreement between NVR, Inc. and Paul C. Saville dated [removed: December 21, 2010.] [added: November 4, 2015.] Filed as Exhibit 10.1 to NVR’s [added: Quarterly Report on] Form [removed: 8-K] [added: 10-Q] filed on [removed: December 21, 2010] [added: November 6, 2015] and incorporated herein by reference. |
| [removed: 10.2*] [added: 10.3*] | | [added: Amended and Restated] Employment Agreement between NVR, Inc. and Robert W. Henley dated [removed: December 21, 2010.] [added: November 4, 2015.] Filed as Exhibit [removed: 10.4] [added: 10.3] to NVR’s [added: Quarterly Report on] Form [removed: 8-K] [added: 10-Q] filed on [removed: December 21, 2010] [added: November 6, 2015] and incorporated herein by reference. |
| 10.4* | | [removed: Amendment No. 2 to the] [added: Amended and Restated] Employment Agreement between NVR, Inc. and [removed: Robert W. Henley] [added: Eugene J. Bredow] dated [removed: December 21, 2010.] [added: November 4, 2015.] Filed as Exhibit [removed: 10.5] [added: 10.4] to NVR’s [added: Quarterly Report on] Form [removed: 10-K] [added: 10-Q] filed on [removed: February 19, 2013] [added: November 6, 2015] and incorporated herein by reference. |
| [removed: 10.5*] [added: 10.2*] | | [added: Amended and Restated] Employment Agreement between NVR, Inc. and [removed: Eugene J. Bredow] [added: Daniel D. Malzahn] dated [removed: May 31, 2012.] [added: November 4, 2015.] Filed as Exhibit 10.2 to NVR’s [added: Quarterly Report on] Form [removed: 8-K] [added: 10-Q] filed on [removed: May 31, 2012] [added: November 6, 2015] and incorporated herein by reference. |
| [removed: 10.8*] [added: 10.6*] | | Profit Sharing Plan of NVR, Inc. and Affiliated Companies. Filed as Exhibit 4.1 to NVR’s Registration Statement on Form S-8 (No. 333-29241) filed on June 13, 1997 and incorporated herein by reference. |
| [removed: 10.9*] [added: 10.7*] | | Employee Stock Ownership Plan of NVR, Inc. Incorporated herein by reference to NVR’s Annual Report on Form 10-K/A for the year ended December 31, 1994. |
| [removed: 10.10*] [added: 10.8*] | | NVR, Inc. 1998 Management Long-Term Stock Option Plan. Filed as Exhibit 4 to NVR’s Registration Statement on Form S-8 (No. 333-79951) filed on June 4, 1999 and incorporated herein by reference. |
| [removed: 10.11*] [added: 10.9*] | | NVR, Inc. 1998 Directors’ Long-Term Stock Option Plan. Filed as Exhibit 4 to NVR’s Registration Statement on Form S-8 (No. 333-79949) filed on June 4, 1999 and incorporated herein by reference. |
| [removed: 10.12*] [added: 10.10*] | | NVR, Inc. 2000 Broadly-Based Stock Option Plan. Filed as Exhibit 99.1 to NVR’s Registration Statement on Form S-8 (No. 333-56732) filed on March 8, 2001 and incorporated herein by reference. |
| [removed: 10.13*] [added: 10.11*] | | [added: Amended and Restated] NVR, Inc. Nonqualified Deferred Compensation Plan. Filed as Exhibit [removed: 10.1] [added: 10.5] to NVR’s [added: Quarterly Report on] Form [removed: 8-K] [added: 10-Q] filed on [removed: December 16, 2005] [added: November 6, 2015] and incorporated herein by reference. |
| [removed: 10.14*] [added: 10.24*] | | [removed: Description] [added: The Form] of [added: Non-Qualified Stock Option Agreement under] the [removed: Board of] [added: 1998] Directors’ [removed: compensation arrangement.] [added: Long-Term Stock Option Plan.] Filed as Exhibit [removed: 10.27] [added: 10.34] to NVR’s Annual Report on Form 10-K for the year ended December 31, [removed: 2004] [added: 2007] and incorporated herein by reference. |
| [removed: 10.15*] [added: 10.13*] | | NVR, Inc. 2014 Equity Incentive Plan. Filed as Exhibit 10.1 to NVR’s [added: Registration Statement on] Form S-8 (No. 333-195756) filed on May 7, 2014 and incorporated herein by reference. |
| [removed: 10.16*] [added: 10.14*] | | The Form of Non-Qualified Stock Option Agreement (Management time-based grants) under the NVR, Inc. 2014 Equity Incentive Plan. Filed as Exhibit 10.1 to NVR’s [added: Current Report on] Form 8-K filed on May 7, 2014 and incorporated herein by reference. |
| [removed: 10.17*] [added: 10.15*] | | The Form of Non-Qualified Stock Option Agreement (Director time-based grants) under the NVR, Inc. 2014 Equity Incentive Plan. Filed as Exhibit 10.2 to NVR’s [added: Current Report on] Form 8-K filed on May 7, 2014 and incorporated herein by reference. |
| [removed: 10.18*] [added: 10.16*] | | The Form of Non-Qualified Stock Option Agreement (Management performance-based grants) under the NVR, Inc. 2014 Equity Incentive Plan. Filed as Exhibit 10.3 to NVR’s [added: Current Report on] Form 8-K filed on May 7, 2014 and incorporated herein by reference. |
| [removed: 10.19*] [added: 10.17*] | | The Form of Non-Qualified Stock Option Agreement (Director performance-based grants) under the NVR, Inc. 2014 Equity Incentive Plan. Filed as Exhibit 10.4 to NVR’s [added: Current Report on] Form 8-K filed on May 7, 2014 and incorporated herein by reference. |
| [removed: 10.20*] [added: 10.18*] | | NVR, Inc. 2010 Equity Incentive Plan. Filed as Exhibit 10.1 to NVR’s [added: Registration Statement on] Form S-8 (No. 333-166512) filed on May 4, 2010 and incorporated herein by reference. |
| [removed: 10.21*] [added: 10.19*] | | The Form of Non-Qualified Stock Option Agreement (Management grants) under the NVR, Inc. 2010 Equity Incentive Plan. Filed as Exhibit 10.1 to NVR’s [added: Quarterly Report on] Form 10-Q filed on July 30, 2013 and incorporated herein by reference. |
| [removed: 10.22*] [added: 10.20*] | | The Form of Non-Qualified Stock Option Agreement (Director grants) under the NVR, Inc. 2010 Equity Incentive Plan. Filed as Exhibit 10.2 to NVR’s [added: Current Report on] Form 8-K filed on May 6, 2010 and incorporated herein by reference. |
| [removed: 10.23*] [added: 10.21*] | | The Form of Restricted Share Units Agreement (Management grants) under the NVR, Inc. 2010 Equity Incentive Plan. Filed as Exhibit 10.2 to NVR’s [added: Quarterly Report on] Form 10-Q filed on July 30, 2013 and incorporated herein by reference. |
| [removed: 10.24*] [added: 10.22*] | | The Form of Restricted Share Units Agreement (Director grants) under the NVR, Inc. 2010 Equity Incentive Plan. Filed as Exhibit 10.4 to NVR’s [added: Current Report on] Form 8-K filed on May 6, 2010 and incorporated herein by reference. |
| [removed: 10.25*] [added: 10.23*] | | The Form of Non-Qualified Stock Option Agreement under the NVR, Inc. 2000 [removed: Broadly Based] [added: Broadly-Based] Stock Option Plan. Filed as Exhibit 10.1 to NVR’s [added: Current Report on] Form 8-K filed on January 3, 2008 and incorporated herein by reference. |
| [removed: 10.27*] [added: 10.33*] | | Summary of [removed: 2015] [added: 2016] Named Executive Officer annual incentive compensation plan. Filed herewith. |
| [removed: *] | [added: | *] Exhibit is a management contract or compensatory plan or arrangement. |
| /s/ Dwight C. Schar | | Chairman | | February [removed: 19, 2015] [added: 17, 2016] |
| /s/ C. E. Andrews | | Director | | February [removed: 19, 2015] [added: 17, 2016] |
| /s/ Timothy M. Donahue | | Director | | February [removed: 19, 2015] [added: 17, 2016] |
| /s/ Thomas D. Eckert | | Director | | February [removed: 19, 2015] [added: 17, 2016] |
| /s/ Alfred E. Festa | | Director | | February [removed: 19, 2015] [added: 17, 2016] |
| /s/ Ed Grier | | Director | | February [removed: 19, 2015] [added: 17, 2016] |
| /s/ Manuel H. Johnson | | Director | | February [removed: 19, 2015] [added: 17, 2016] |
| /s/ Mel Martinez | | Director | | February [removed: 19, 2015] [added: 17, 2016] |
| /s/ William A. Moran | | Director | | February [removed: 19, 2015] [added: 17, 2016] |
| /s/ David A. Preiser | | Director | | February [removed: 19, 2015] [added: 17, 2016] |
| /s/ W. Grady Rosier | | Director | | February [removed: 19, 2015] [added: 17, 2016] |
| /s/ Paul W. Whetsell | | Director | | February [removed: 19, 2015] [added: 17, 2016] |
| 3.2 | | Bylaws, as amended, of NVR, Inc. Filed as Exhibit 3.1 to NVR’s Quarterly Report on Form 10-Q filed on November 6, 2015 and incorporated herein by reference |
| 10.5* | | Employment Agreement between NVR, Inc. and Jeffrey D. Martchek dated January 1, 2016. Filed herewith. |
| 10.25 | | Amended and Restated Master Repurchase Agreement dated as of August 2, 2011, between NVR Mortgage Finance, Inc. and U.S. Bank National Association. Filed as Exhibit 10.1 to NVR’s Current Report on Form 8-K filed on January 21, 2016 and incorporated herein by reference. |
| 10.26 | | First Amendment to Amended and Restated Master Repurchase Agreement dated as of August 1, 2012, between NVR Mortgage Finance, Inc. and U.S. Bank National Association. Filed as Exhibit 10.2 to NVR’s Current Report on Form 8-K filed on January 21, 2016 and incorporated herein by reference. |
| 10.27 | | Second Amendment to Amended and Restated Master Repurchase Agreement dated as of November 13, 2012, between NVR Mortgage Finance, Inc. and U.S. Bank National Association. Filed as Exhibit 10.3 to NVR’s Current Report on Form 8-K filed on January 21, 2016 and incorporated herein by reference. |
| 10.28 | | Third Amendment to Amended and Restated Master Repurchase Agreement dated as of November 29, 2012, between NVR Mortgage Finance, Inc. and U.S. Bank National Association. Filed as Exhibit 10.4 to NVR’s Current Report on Form 8-K filed on January 21, 2016 and incorporated herein by reference. |
| 10.29 | | Fourth Amendment to Amended and Restated Master Repurchase Agreement dated as of July 31, 2013, between NVR Mortgage Finance, Inc. and U.S. Bank National Association. Filed as Exhibit 10.5 to NVR’s Current Report on Form 8-K filed on January 21, 2016 and incorporated herein by reference. |
| 10.30 | | Fifth Amendment to Amended and Restated Master Repurchase Agreement dated as of July 30, 2014, between NVR Mortgage Finance, Inc. and U.S. Bank National Association. Filed as Exhibit 10.6 to NVR’s Current Report on Form 8-K filed on January 21, 2016 and incorporated herein by reference. |
| 10.31 | | Sixth Amendment to Amended and Restated Master Repurchase Agreement dated as of July 29, 2015, between NVR Mortgage Finance, Inc. and U.S. Bank National Association. Filed as Exhibit 10.7 to NVR’s Current Report on Form 8-K filed on January 21, 2016 and incorporated herein by reference. |
| 10.32 | | Seventh Amendment to Amended and Restated Master Repurchase Agreement dated as of January 18, 2016, between NVR Mortgage Finance, Inc. and U.S. Bank National Association. Filed as Exhibit 10.8 to NVR’s Current Report on Form 8-K filed on January 21, 2016 and incorporated herein by reference. |
| | | |
February 17, 2016
February 17, 2016
| | | | 1,006,526 | | | | 869,486 | |
| | | | 2,135,581 | | | | 2,088,019 | |
| | | | 379,550 | | | | 263,316 | |
| | | | 1,243,675 | | | | 1,201,283 | |
| | | | 32,291 | | | | 25,797 | |
| Net income | | | — | | | | — | | | | 382,927 | | | | — | | | | — | | | | — | | | | 382,927 | |
| Balance, December 31, 2015 | | $ | 206 | | | $ | 1,447,795 | | | $ | 5,270,114 | | | $ | (5,478,950 | ) | | $ | (17,333 | ) | | $ | 17,333 | | | $ | 1,239,165 | |
conducted each quarter.
tax benefits that would be credited or charged to additional paid-in-capital assuming exercise of the stock option or vesting of the restricted share unit.
In July 2015, the FASB delayed the standard’s effective date for one year.
Early adoption is permitted for the annual period beginning January 1, 2017.
In February 2015, FASB issued ASU 2015-02, Consolidation (Topic 810) – Amendments to the Consolidation Analysis.
The standard changes the manner in which reporting entities evaluate consolidation requirements of certain legal entities.
The standard is effective for the Company as of January 1, 2016.
The Company does not believe that the adoption of this standard will have a material effect on its consolidated financial statements and related disclosures.
In April 2015, FASB issued ASU 2015-03, Interest – Imputation of Interest (Subtopic 835-30) – Simplifying the Presentation of Debt Issuance Costs.
The standard requires that debt issuance costs related to a recognized debt liability be presented on the balance sheet as a direct deduction from the debt liability, rather than as an asset.
The standard is effective for the Company for the first annual period beginning after December 15, 2015, and must be applied retrospectively to all prior periods presented in the financial statements.
The Company does not believe that the adoption of this standard will have a material effect on its consolidated financial statements and related disclosures.
In April 2015, FASB issued ASU 2015-05, Intangibles – Goodwill and Other – Internal-Use Software (Subtopic 350-40).
The standard adds guidance to Subtopic 350-40 to help entities evaluate the accounting for fees paid by a customer in a cloud computing arrangement.
The standard provides a basis for evaluating whether a cloud computing arrangement includes a software license or whether the arrangement should be accounted for as a service contract.
The standard is effective for the Company as of January 1, 2016.
The Company does not believe that the adoption of this standard will have a material effect on its consolidated financial statements and related disclosures.
In July 2015, FASB issued ASU 2015-11, Inventory (Topic 330): Simplifying the Measurement of Inventory.
The standard simplifies the subsequent measurement of inventory by requiring inventory to be measured at the lower of cost or net realizable value.
The amendments in the standard do not apply to inventory that is measured using last-in, first-out (LIFO) or the retail inventory
| --- | --- |
| --- | --- |
| --- | --- |
| 10.3* | | Amendment No. 1 to the Employment Agreement between NVR, Inc. and Robert W. Henley dated December 21, 2010. Filed as Exhibit 10.1 to NVR’s Form 8-K filed on May 31, 2012 and incorporated herein by reference. |
| 10.6* | | Amendment No. 1 to the Employment Agreement between NVR, Inc. and Eugene J. Bredow dated May 31, 2012. Filed as Exhibit 10.7 to NVR’s Form 10-K filed on February 19, 2013 and incorporated herein by reference. |
| 10.7* | | Employment Agreement between NVR, Inc. and Daniel D. Malzahn dated February 19, 2013. Filed as Exhibit 10.8 to NVR’s Form 10-K filed on February 19, 2013 and incorporated herein by reference. |
| 10.26* | | The Form of Non-Qualified Stock Option Agreement under the 1998 Directors’ Long-Term Stock Option Plan. Filed as Exhibit 10.34 to NVR’s Annual Report on Form 10-K for the year ended December 31, 2007 and incorporated herein by reference. |
| --- | --- |
| /s/ Robert C. Butler | | Director | | February 19, 2015 |
| Robert C. Butler | | | | |
February 19, 2015
February 19, 2015
NVR, Inc.
| --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | |
| Homebuilding: | | | | | | | | |
| | | | 869,486 | | | | 738,565 | |
| | | | 2,088,019 | | | | 2,225,380 | |
| | | | 263,316 | | | | 260,768 | |
| | | | 1,201,283 | | | | 1,203,022 | |
| | | | 25,797 | | | | 21,774 | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Balance, December 31, 2011 | | $ | 206 | | | $ | 1,072,779 | | | $ | 4,158,492 | | | $ | (3,856,678 | ) | | $ | (25,581 | ) | | $ | 25,581 | | | $ | 1,374,799 | |
| Net income | | | — | | | | — | | | | 180,588 | | | | — | | | | — | | | | — | | | | 180,588 | |
| Deferred compensation activity | | | — | | | | — | | | | — | | | | — | | | | 250 | | | | (250 | ) | | | — | |
See notes to consolidated financial statements
| Acquisition, net of cash acquired | | | — | | | | — | | | | (14,257 | ) |
| Repayments on loans assumed in acquisition | | | — | | | | — | | | | (21,910 | ) |
| Proceeds from issuance of Senior Notes due 2022 | | | — | | | | — | | | | 598,962 | |
| Debt issuance costs for Senior Notes due 2022 | | | — | | | | — | | | | (5,096 | ) |
| Supplemental disclosures of non-cash activities: | | | | | | | | | | | | |
| Increase in assets in connection with acquisition | | $ | — | | | $ | — | | | $ | 55,759 | |
| Increase in liabilities in connection with acquisition | | $ | — | | | $ | — | | | $ | 41,502 | |
(dollars and shares in thousands, except per share data)
| --- | --- |
Reclassifications
Certain prior year amounts in the consolidated financial statements have been reclassified to conform to the 2014 presentation.
Reclassifications did not impact net income, total assets or total liabilities, or statement of cash flow classifications.
Amortization of capital lease assets is included in depreciation expense.
related appeals or litigation processes, based on the technical merits.
An excerpt. Shown here: 40 of 449 rewritten, 40 of 134 added and 40 of 139 removed. The counts are complete. For every sentence, read Item 15. Exhibits and Financial Statement Schedules. in the FY2015 filing and the FY2014 filing.