 filings.tools
NVR (NVR) 10-K risk factor changes: FY2016 vs FY2015
The 2016-12-31 10-K against the 2015-12-31 one, compared heading by heading and sentence by sentence. One of these filings carries no fiscal year tag, so its year is the calendar year of the period end.
Item 1A16 rewritten0 added1 removed126 unchanged
All filing items852 rewritten324 added220 removed1,339 unchanged
Summary
counted, not written
- Item 1A headings could not be compared: only 0 carried over between the two years, which usually means one filing was read wrongly, so none is reported as new or removed.
- Sentence by sentence, 324 added, 220 removed, 852 rewritten and 1,339 unchanged across 17 items that differ.
Sentences by item
21 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2016; struck-through words were in FY2015. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors.
16 rewritten, 0 added, 1 removed, 126 unchanged
| | [removed: ●] [added: •] | actual and expected direction of interest rates, which affect our costs, the availability of construction financing, and long-term financing for potential purchasers of homes; |
| | [removed: ●] [added: •] | the availability of mortgage financing; |
| | [removed: ●] [added: •] | the availability of adequate land in desirable locations on favorable terms; |
| | [removed: ●] [added: •] | unexpected changes in customer preferences; and |
| | [removed: ●] [added: •] | changes in the national economy and in the local economies of the markets in which we [removed: have operations.] [added: operate.] |
In particular, during [removed: 2015,] [added: 2016,] approximately [removed: 25%] [added: 23%] and 11% of our home settlements occurred in the Washington, D.C. and Baltimore, MD metropolitan areas, respectively, which accounted for approximately [removed: 31%] [added: 30%] and 13%, respectively, of our [removed: 2015] [added: 2016] homebuilding revenues.
Our mortgage banking business sells all of the loans it originates into the secondary [removed: market usually,] [added: market, usually] within 30 days from the date of closing, and has up to [removed: approximately] $150 million available under a repurchase agreement to fund mortgage closings.
We [removed: must, in the ordinary course of our business,] [added: must] continuously seek and make acquisitions of lots for expansion into new markets as well as for replacement and expansion within our current markets, which [removed: is] [added: we] generally [removed: accomplished] [added: accomplish] by [removed: us] entering [removed: fixed price purchase agreements] [added: into Lot Purchase Agreements] and paying forfeitable deposits under the [removed: purchase agreements] [added: Lot Purchase Agreements] to developers for the contractual right to acquire the lots.
In the event of adverse changes in economic or market conditions, we may cease further building activities in certain communities or restructure existing [removed: purchase agreements,] [added: Lot Purchase Agreements,] resulting in forfeiture of some or all of any remaining land contract deposit paid to the developer.
We sell all of the loans we originate into the secondary mortgage market generally within 30 days from [removed: origination.][added: the date of closing.]
If we require working capital greater than [added: that provided by] our operations [removed: provide,] [added: and our credit facility,] we may be required to [removed: obtain] [added: seek to increase the amount available under the facility or seek] alternative financing, which might not be available on terms that are favorable or acceptable.
If we are at any time unsuccessful in obtaining sufficient capital to fund our planned homebuilding expenditures, we may experience a substantial delay in the [added: completion of homes then under construction, or we may be unable to control or purchase finished building lots.]
| | [removed: ●] [added: •] | for suitable and desirable lots at acceptable prices; |
| | [removed: ●] [added: •] | from selling incentives offered by competing builders within and across developments; and |
| | [removed: ●] [added: •] | from the existing home resale market. |
The homebuilding business has from time to time experienced building material and labor shortages, including [removed: shortages in insulation, drywall, certain carpentry work and concrete, as well as] fluctuating lumber prices and supply.
completion of homes then under construction, or we may be unable to control or purchase finished building lots.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
259 rewritten, 128 added, 88 removed, 320 unchanged
Results of Operations for the Years Ended December 31, [removed: 2015, 2014] [added: 2016, 2015] and [removed: 2013][added: 2014]
| South East: | | North Carolina, South Carolina, [removed: Tennessee and] Florida [added: and Tennessee] |
We generally do not engage in land development (see discussion below of our [removed: limited] land development activities).
Instead, we typically [removed: have acquired] [added: acquire] finished lots at market prices from various third party land developers pursuant to [removed: fixed price purchase agreements.][added: Lot Purchase Agreements.]
These [removed: purchase agreements] [added: Lot Purchase Agreements] require deposits, typically ranging up to 10% of the aggregate purchase price of the finished lots, in the form of cash or letters of credit that may be forfeited if we fail to perform under the [removed: purchase agreement.][added: Lot Purchase Agreement.]
In certain specific strategic [removed: circumstances] [added: circumstances,] we deviate from our historical lot acquisition strategy and engage in joint venture arrangements with land developers or directly acquire raw ground already zoned for its intended use for development.
Once we acquire control of [removed: any] raw ground, we determine whether to sell the raw parcel to a developer and enter into a [removed: fixed price purchase agreement] [added: Lot Purchase Agreement] with the developer to purchase the finished [removed: lots,] [added: lots] or to hire a developer to develop the land on our behalf.
We expect, however, to continue to acquire substantially all of our finished lot inventory using [removed: fixed price purchase agreements] [added: Lot Purchase Agreements] with forfeitable deposits.
[removed: As of December 31, 2015, we] [added: We] controlled approximately [removed: 68,800] [added: 73,200] lots under [removed: purchase agreements] [added: Lot Purchase Agreements] with [added: third parties through] deposits in cash and letters of credit totaling approximately [removed: $373,300] [added: $396,200] and [removed: $3,000,] [added: $2,400,] respectively.
Included in the number of controlled lots are approximately [removed: 6,100] [added: 4,000] lots for which we have recorded a contract land deposit impairment reserve of approximately [removed: $42,200] [added: $31,300] as of December 31, [removed: 2015.][added: 2016.]
Of the lots [removed: controlled] [added: to be produced] by the JVs, approximately [removed: 3,300] [added: 4,200 lots] were [removed: not] [added: controlled by us and approximately 3,200 lots were either] under contract with [removed: us at December 31, 2015.][added: unrelated parties or currently not under contract.]
[removed: Further, as of December 31, 2015, we] [added: We] directly owned four separate raw [removed: parcels of land,] [added: land parcels,] zoned for their intended use, with a current cost basis, including development costs, of approximately [removed: $60,600] [added: $47,000] that we intend to develop into approximately [removed: 980] [added: 600] finished lots.
We [removed: have] [added: had] additional funding commitments [added: of approximately $12,000] under a joint development agreement related to [removed: our land under development of approximately $19,200,] [added: one parcel,] a portion of which we expect will be offset by development credits of approximately [removed: $9,600.][added: $7,100.]
See Notes 3, 4 and 5 to the consolidated financial statements included herein for additional information regarding [removed: fixed price purchase agreements,] [added: Lot Purchase Agreements,] JVs and land under development, respectively.
In addition to the lots we currently control as discussed above, we have certain properties under contract with land owners that are expected to yield approximately [removed: 8,800] [added: 9,600] lots.
These properties are controlled with cash deposits [removed: and letters of credit] totaling approximately [removed: $12,200 and $350, respectively,] [added: $14,900] as of December 31, [removed: 2015,] [added: 2016,] of which approximately [removed: $8,700] [added: $1,400] is refundable if we do not perform under the contract.
However, new home prices continued to be constrained [removed: by an increase in] [added: due to] the [removed: number of new home communities in many markets.][added: competitive market environment.]
Our consolidated revenues for the year ended December 31, [removed: 2015] [added: 2016] totaled [removed: $5,159,008,] [added: $5,822,544,] an increase of [removed: 16%] [added: 13%] from [removed: $4,444,568] [added: $5,159,008] in [removed: 2014.][added: 2015.]
Our net income for [removed: 2015] [added: 2016] was [removed: $382,927,] [added: $425,262,] or [removed: $89.99] [added: $103.61] per diluted share, increases of [removed: 36%] [added: 11%] and [removed: 42%] [added: 15%] compared to [removed: 2014] [added: 2015] net income and diluted earnings per share, respectively.
Our homebuilding gross profit margin percentage [removed: increased to18.7%] [added: decreased to 17.5%] in [removed: 2015] [added: 2016] from [removed: 18.4%] [added: 18.7%] in [removed: 2014.][added: 2015.]
New orders, net of cancellations (“New Orders”) during [removed: 2015] [added: 2016] increased [removed: 14%] [added: 11%] from [removed: 2014] [added: 2015] while our average New Order sales price increased [removed: 1%] [added: 2%] to [removed: $378.7] [added: $386.4] in [removed: 2015.][added: 2016.]
Our backlog of homes sold but not yet settled with the customer as of December 31, [removed: 2015] [added: 2016] increased on a unit basis by [removed: 14%] [added: 11%] to [removed: 6,229] [added: 6,884] units and increased on a dollar basis by [removed: 13%] [added: 14%] to [removed: $2,375,182] [added: $2,704,277] when compared to December 31, [removed: 2014.][added: 2015.]
We expect to continue to face gross profit margin and pricing pressures due to higher land and construction costs, as well as increased competition associated with the increase in the [added: number of new home communities in our markets.]
| | | [removed: 2015] [added: 2016] | | | | [removed: 2014] [added: 2015] | | | | [removed: 2013] [added: 2014] | | |
| Revenues | | $ | [removed: 5,065,200] [added: 5,709,223] | | | $ | [removed: 4,375,059] [added: 5,065,200] | | | $ | [removed: 4,134,481] [added: 4,375,059] | |
| Cost of sales | | $ | [removed: 4,118,782] [added: 4,707,861] | | | $ | [removed: 3,568,586] [added: 4,118,782] | | | $ | [removed: 3,424,204] [added: 3,568,586] | |
| Gross profit margin percentage | | | [removed: 18.7] [added: 17.5] | % | | | [removed: 18.4] [added: 18.7] | % | | | [removed: 17.2] [added: 18.4] | % |
| Selling, general and administrative expenses | | $ | [removed: 371,127] [added: 382,459] | | | $ | [removed: 358,851] [added: 371,127] | | | $ | [removed: 313,029] [added: 358,851] | |
| Settlements (units) | | | [removed: 13,326] [added: 14,928] | | | | [removed: 11,859] [added: 13,326] | | | | [removed: 11,834] [added: 11,859] | |
| Average settlement price | | $ | [removed: 379.9] [added: 381.2] | | | $ | [removed: 368.5] [added: 379.9] | | | $ | [removed: 349.1] [added: 368.5] | |
| New orders (units) | | | [removed: 14,080] [added: 15,583] | | | | [removed: 12,389] [added: 14,080] | | | | [removed: 11,800] [added: 12,389] | |
| Average new order price | | $ | [removed: 378.7] [added: 386.4] | | | $ | [removed: 373.7] [added: 378.7] | | | $ | [removed: 360.4] [added: 373.7] | |
| Backlog (units) | | | [removed: 6,229] [added: 6,884] | | | | [removed: 5,475] [added: 6,229] | | | | [removed: 4,945] [added: 5,475] | |
| Average backlog price | | $ | [removed: 381.3] [added: 392.8] | | | $ | [removed: 384.6] [added: 381.3] | | | $ | [removed: 373.2] [added: 384.6] | |
| New order cancellation rate | | | [removed: 14.5] [added: 15.5] | % | | | [removed: 14.6] [added: 14.5] | % | | | [removed: 14.9] [added: 14.6] | % |
Consolidated Homebuilding [removed: Revenues]
Homebuilding revenues increased [removed: 6%] [added: 13%] in [removed: 2014] [added: 2016] compared to [removed: 2013] [added: 2015,] primarily as a result of a [removed: 6%] [added: 12%] increase in the [removed: average settlement price, while the] number of units settled [removed: was flat] year over year.
The increase in [removed: the] [added: units settled and] average settlement price was primarily attributable to [removed: the average price of homes] [added: a 4% increase] in [removed: backlog being approximately 8% higher entering 2014 compared to 2013] [added: both segment New Orders] and [removed: a 5% higher] average sales price of New Orders for the first six months of [removed: 2014] [added: 2016] compared to the same period in [removed: 2013.][added: 2015.]
New Orders increased in 2015 despite a 3% decrease in the average number of active communities year over year, due to more favorable market conditions in 2015, which led to [added: a] higher sales absorption [added: rate] in each of our market segments.
The number of New Orders and the average sales price of New Orders increased [removed: 5%] [added: 11%] and [removed: 4%,] [added: 2%,] respectively, in [removed: 2014] [added: 2016] compared to [removed: 2013.][added: 2015.]
As of December 31, 2016, we controlled lots as described below.
Lot Purchase Agreements
Joint Venture Limited Liability Corporations (“JVs”)
We had an aggregate investment totaling approximately $49,400 in six JVs, expected to produce approximately 7,400 lots.
Raw Land Purchase Agreements
The housing market in 2016 continued the trend experienced in 2015 of steady new home demand.
The housing market also faces challenges from tight mortgage underwriting standards as well as from higher mortgage interest rates, which towards the end of 2016 began to move up from historical lows.
2016 versus 2015
In addition, the number of units settled was favorably impacted by a 10% increase in New Orders for the first six months of 2016 compared to the same period in 2015.
New Orders and the average sales price of New Orders increased in each of our market segments due to more favorable
market conditions in 2016 compared to 2015, which led to a higher sales absorption rate year over year.
Gross profit margin percentage in 2016 decreased to 17.5% from 18.7% in 2015, due to higher construction and selling related costs year over year.
SG&A expenses in 2016 increased approximately $11,300, or 3% compared to 2015, but as a percentage of revenue decreased to 6.7% from 7.3% year over year.
Backlog represents homes sold but not yet settled with the customer.
Backlog units and dollars were 6,884 units and $2,704,277, respectively, as of December 31, 2016 compared to 6,229 units and $2,375,182, respectively, as of December 31, 2015.
providing the desired rate of return after covering our cost of capital.
| | | 2016 | | | | 2015 | | | | 2014 | | |
| | | 2016 | | | | 2015 | | | | 2014 | | |
| | | 2016 | | | | | | | | 2015 | | | | | | | | 2014 | | | | | | |
| | | 2016 | | | | | | | | 2015 | | | | | | | | 2014 | | | | | | |
| | | 2016 | | | | | | | | 2015 | | | | | | | | 2014 | | | | | | |
| | | 2016 | | | | 2015 | | | | 2014 | | |
| | | 2016 | | | | 2015 | | | | 2014 | | |
| | | 2016 | | | | 2015 | | |
| | | 2016 | | | | 2015 | | |
| | | 2016 | | | | 2015 | | | | 2014 | | |
| | | 2016 | | | | 2015 | | |
| | | 2016 | | | | 2015 | | |
| | | 2016 | | | | 2015 | | |
| | | 2016 | | | | 2015 | | | | 2014 | | |
2016 versus 2015
The Mid Atlantic segment had an approximate $21,700, or 7%, decrease in segment profit in 2016 compared to 2015, despite an increase in segment revenues of approximately $297,000, or 10%, year over year.
Segment revenues increased due primarily to a 9% increase in the number of units settled in 2016 compared to 2015.
In addition, units settled in 2016 were favorably impacted by an 11% increase in New Orders for the first six months of 2016 compared to the same period in 2015.
The Mid Atlantic segment’s gross profit margin percentage decreased to 16.9% in 2016 from 18.6% in 2015.
Segment profit and gross profit margin were negatively impacted primarily by higher construction and selling related costs.
New Orders increased due to favorable market conditions in 2016 compared to 2015, which led to a higher sales absorption rate year over year.
2016 versus 2015
The North East segment had an approximate $16,000, or 42%, decrease in segment profit in 2016 compared to 2015, despite an increase in segment revenues of approximately $30,200, or 7%, year over year.
Segment profit and gross profit margin were negatively impacted primarily by higher construction costs, service costs and contract land deposit impairments year over year.
| --- | --- |
In addition, we controlled approximately 8,000 lots through six JVs with an aggregate investment of approximately $60,500.
We also had a $2,200 obligation under a letter of credit related to one of our land parcels.
In February 2016, we acquired an additional raw parcel of land at a cost of approximately $150,000 which is expected to produce approximately 1,000 lots, of which approximately 160 lots are under contract with unrelated parties.
Of the $12,200 in cash deposits, $5,000 relates to the raw parcel of land acquired in February 2016 discussed above.
New home demand continued to improve throughout 2015.
The housing market also continues to face challenges from tight mortgage underwriting standards.
number of new home communities in our markets.
The higher average price of homes in backlog entering 2014 was attributable to favorable market conditions in 2013, leading to increasing prices during that year.
Consolidated Homebuilding New Orders
Average sales prices were higher in each of our market segments year over year as a result of favorable market conditions in 2013, which led to higher prices entering 2014.
Gross profit margin percentage in 2014 increased to 18.4% compared to 17.2% in 2013.
Gross profit margins were favorably impacted by our average settlement prices increasing at a higher rate than material and lot costs year over year, as well as by a relative shift in settlements to our Mid-Atlantic and North East segments which have higher average gross profit margins.
Gross profit
margins in 2013 were negatively impacted by two service related accruals which reduced the 2013 gross profit margin by 76 basis points.
Consolidated Homebuilding Selling, General and Administrative (“SG&A”)
SG&A expenses in 2014 increased approximately $45,800, or 15%, compared to 2013 and increased as a percentage of revenue to 8.2% from 7.6% year over year.
The increase in SG&A expenses was attributable to an approximate $26,000 increase in equity-based compensation expense and an approximate $14,100 increase in sales and marketing expenses in 2014.
Equity-based compensation expense increased primarily due to the grant of non-qualified stock options (“Options”) under the 2014 Equity Incentive Plan (the “2014 Plan”) following shareholder approval of the 2014 Plan in May 2014 and restricted share units (“RSUs”) in the second quarter of 2013.
In addition, in 2013 we recorded a reversal of approximately $7,100 in equity-based compensation expense as a result of an adjustment to our stock option forfeiture rates based on our actual forfeiture experience.
Consolidated Homebuilding Backlog
Backlog units and dollars increased approximately 11% to 5,475 units and 14% to $2,105,635, respectively, as of December 31, 2014 compared to 4,945 units and $1,845,600, respectively, as of December 31, 2013.
We evaluate our entire net contract land deposit portfolio for impairment each quarter.
For additional information regarding our contract land deposit impairment analysis, see the “Critical Accounting Policies” section within this “Management Discussion and Analysis of Financial Condition and Results of Operations”.
deposits in lieu of cash.
The Mid Atlantic segment had an approximate $4,400, or 2%, decrease in segment profit in 2014 compared to 2013.
Segment profit was negatively impacted by higher SG&A expense attributable to an 11% increase in the average number of active communities year over year and an increase in the corporate capital allocation due primarily to higher inventory levels.
Segment revenues increased approximately $177,700, or 7%, year over year due primarily to a 6% increase in the average settlement price in 2014 compared to 2013.
The average settlement price was favorably impacted by a 7% higher average price of homes in backlog entering 2014 compared to the same period in 2013.
The Mid Atlantic segment’s gross profit margin percentage was flat year over year; however, the gross profit margin in 2013 was negatively impacted by a service related accrual which reduced 2013 gross profit margin by 64 basis points.
Excluding this charge, gross profit margin decreased 49 basis points to 19.1% in 2014.
The decrease in gross profit margin was attributable to an increase in certain material costs.
The increase in the average sales price of New Orders was attributable to the favorable market conditions in 2013, which led to higher average sales prices entering 2014.
Segment profit in 2013 was negatively impacted by a charge of approximately $12,700 related to a service related accrual.
Excluding that charge in 2013, segment profit increased approximately $6,400, or 24%, year over year.
The increase in the average settlement price was driven by a 5% higher average price of homes in backlog entering 2014 compared to the same period in 2013 and a shift in settlements to higher priced markets.
Excluding the previously discussed service accrual which reduced gross profit margin in 2013 by 382 basis points, gross profit margin increased 109 basis points year over year.
Gross profit margin was favorably impacted by a shift in settlements to higher priced markets with higher gross margins and by increased settlement volume, which allowed us to better leverage certain operating costs in 2014.
The increase in New Orders was driven by an 11% increase in the average number of active communities.
The Mid East segment had an approximate $8,000, or 14%, decrease in segment profit in 2014 compared to 2013.
An excerpt. Shown here: 40 of 259 rewritten, 40 of 128 added and 40 of 88 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations. in the FY2016 filing and the FY2015 filing.
Item 7A. Quantitative and Qualitative Disclosure About Market Risk.
13 rewritten, 7 added, 3 removed, 34 unchanged
The Repurchase Agreement is used to fund NVRM’s [removed: mortgage origination activities.]
Advances under the Repurchase Agreement carry a Pricing Rate based on the LIBOR Rate plus the LIBOR Margin, as determined under the Repurchase Agreement, provided that the Pricing Rate shall not be less than [removed: 2.70%.][added: 2.25%.]
[removed: On January 18, 2016, the Repurchase Agreement was amended (“Amended] [added: NVRM has available a mortgage] Repurchase [removed: Agreement”) to increase the borrowing capacity] [added: Agreement, which as of December 31, 2016 provided for loan repurchases up] to $150,000 with an incremental commitment pursuant to which NVRM may from time to time request increases in the total commitment available under the agreement by up to $50,000 in the aggregate.
At December 31, [removed: 2015,] [added: 2016,] there was no debt outstanding under the Repurchase Agreement.
The following table represents the contractual balances of our on-balance sheet financial instruments at the expected maturity dates, as well as the fair values of those on-balance sheet financial instruments at December 31, [removed: 2015.][added: 2016.]
| | | [removed: 2016 | | | |] 2017 | | | | 2018 | | | | 2019 | | | | 2020 | | | | [added: 2021 | | | |] Thereafter | | | | Total | | | | Value | | |
| Mortgage loans held for sale | | $ | [removed: 319,212] [added: 357,912] | | | | — | | | | — | | | | — | | | | — | | | | — | | | $ | [removed: 319,212] [added: 357,912] | | | $ | [removed: 319,553] [added: 351,958] | |
| Average interest rate | | | [removed: 4.0] [added: 3.9] | % | | | — | | | | — | | | | — | | | | — | | | | — | | | | [removed: 4.0] [added: 3.9] | % | | | | |
| Forward trades of mortgage-backed securities (a) | | $ | [removed: 3,804] [added: 8,064] | | | | — | | | | — | | | | — | | | | — | | | | — | | | $ | [removed: 3,804] [added: 8,064] | | | $ | [removed: 3,804] [added: 8,064] | |
| Forward loan commitments (a) | | $ | [removed: 3,187] [added: 2,076] | | | | — | | | | — | | | | — | | | | — | | | | — | | | $ | [removed: 3,187] [added: 2,076] | | | $ | [removed: 3,187] [added: 2,076] | |
| Interest-bearing deposits | | $ | [removed: 347,538] [added: 326,873] | | | | — | | | | — | | | | — | | | | — | | | | — | | | $ | [removed: 347,538] [added: 326,873] | | | $ | [removed: 347,538] [added: 326,873] | |
| Average interest rate | | | [removed: 0.4] [added: 0.5] | % | | | — | | | | — | | | | — | | | | — | | | | — | | | | [removed: 0.4] [added: 0.5] | % | | | | |
| Fixed rate obligations (b) | | $ | — | | | | — | | | | — | | | | — | | | | — | | | $ | 600,00 | 0 | | $ | 600,000 | | | $ | [removed: 606,000] [added: 612,000] | |
(dollars in thousands)
In July 2016, we entered into a Credit Agreement which provides for aggregate revolving loan commitments of $200,000.
Under the Credit Agreement, we may request increases of up to $300,000 to the Facility in the form of revolving loan commitments or term loans to the extent that new or existing lenders agree to provide additional revolving loan or term loan commitments.
The Credit Agreement provides for a $100,000 sublimit for the issuance of letters of credit of which there was approximately $8,300 outstanding at December 31, 2016, and a $25,000 sublimit for a swing line commitment.
Borrowings under the Credit Agreement generally bear interest for Base Rate Loans at a Base Rate equal to the highest of (i) a Federal Funds Rate plus one-half of one percent, (ii) Bank of America’s publicly announced “prime rate,” and (iii) the Eurodollar Rate plus one percent, plus the Applicable Rate which is based on our debt rating, or for Eurodollar Rate Loans, at the Eurodollar Rate equal to LIBOR plus the Applicable Rate.
At December 31, 2016, there was no debt outstanding under the Facility.
mortgage origination activities.
NVRM has available a mortgage Repurchase Agreement, which as of December 31, 2015 provided for loan repurchases up to $25,000, subject to certain sub limits.
Other terms of the Amended Repurchase Agreement are materially consistent with the Repurchase Agreement.
Consequently, advances outstanding under the Repurchase Agreement would also be assumed to mature in the first year.
Item 1. Business.
31 rewritten, 4 added, 15 removed, 101 unchanged
During [removed: 2015,] [added: 2016,] approximately [removed: 25%] [added: 23%] and 11% of our home settlements occurred in the Washington, D.C. and Baltimore, MD metropolitan areas, respectively, which accounted for approximately [removed: 31%] [added: 30%] and 13%, respectively, of our [removed: 2015] [added: 2016] homebuilding revenues.
Our homebuilding operations include the construction and sale of single-family detached homes, townhomes and condominium buildings under [removed: four] [added: three] trade names: Ryan Homes, [removed: NVHomes, Fox Ridge Homes] [added: NVHomes] and Heartland Homes.
[removed: The] [added: Our] Ryan Homes [removed: and Fox Ridge Homes products are] [added: product is] marketed primarily to first-time and first-time move-up buyers.
Ryan Homes operates in [removed: twenty-eight] [added: twenty-nine] metropolitan areas located in Maryland, Virginia, Washington, D.C., West Virginia, Pennsylvania, New York, North Carolina, South Carolina, Florida, Ohio, New Jersey, Delaware, Indiana, Illinois and Tennessee.
[removed: The] [added: Our] NVHomes and Heartland Homes products are marketed primarily to move-up and [removed: up-scale] [added: upscale] buyers.
[removed: In] [added: During] 2015, our average price of [removed: a] [added: homes] settled [removed: unit] was approximately $379,900.
We generally do not engage in land development (see discussion below [removed: on] [added: of] our [removed: limited] land development activities).
Instead, we typically acquire finished building lots at market prices from various [removed: development entities under] [added: third party land developers pursuant to] fixed price [added: finished lot] purchase agreements [removed: (“purchase agreements”)] [added: (“Lot Purchase Agreements”)] that require deposits that may be forfeited if we fail to perform under the [removed: purchase agreements.][added: Lot Purchase Agreements.]
The deposits required under the [removed: purchase agreements] [added: Lot Purchase Agreements] are in the form of cash or letters of credit in varying amounts and represent a percentage, typically ranging up to 10%, of the aggregate purchase price of the finished lots.
We may, at our option, choose for any reason and at any time not to perform under these [removed: purchase agreements] [added: Lot Purchase Agreements] by delivering notice of our intent not to acquire the finished lots under contract.
Our sole legal obligation and economic loss for failure to perform under these [removed: purchase agreements] [added: Lot Purchase Agreements] is limited to the amount of the deposit pursuant to the liquidated damage provision contained within the [removed: purchase agreements.][added: Lot Purchase Agreements.]
We do not have any financial guarantees or completion obligations and we typically do not guarantee lot purchases on a specific performance basis under these [removed: purchase agreements.][added: Lot Purchase Agreements.]
None of the creditors of any of the development entities with which we have entered these [removed: purchase agreements] [added: Lot Purchase Agreements] have recourse to our general credit.
Once we acquire control of [removed: any] raw ground, we determine whether to sell the raw parcel to a developer and enter into a [removed: purchase agreement] [added: Lot Purchase Agreement] with the developer to purchase the finished [removed: lots,] [added: lots] or [removed: whether to] hire a developer to develop the land on our behalf.
We expect, however, to continue to acquire substantially all of our finished lot inventory using [removed: purchase agreements] [added: Lot Purchase Agreements] with forfeitable deposits.
[removed: See] [added: In addition, see] Notes 3, 4 and 5 [removed: to] [added: in] the [added: accompanying] consolidated financial statements included herein for additional information regarding [removed: fixed][added: Lot Purchase Agreements, JVs and land under development, respectively.]
However, new home prices continued to be constrained due to [removed: an increase in] the [removed: number of new home communities in many markets.][added: competitive market environment.]
The housing market also continues to face challenges from tight mortgage underwriting [removed: standards.][added: standards as well as from higher mortgage interest rates, which towards the end of 2016 began to move up from historical lows.]
Our homes combine traditional, transitional, cottage or urban exterior designs with contemporary interior designs and amenities, generally include two to four bedrooms and range from approximately 1,000 to [removed: 7,000] [added: 9,000 finished] square feet.
During [removed: 2015,] [added: 2016,] the prices at which we settled homes ranged from approximately [removed: $136,000] [added: $140,000] to [removed: $1.9] [added: $1.8] million and averaged approximately [removed: $379,900.][added: $381,200.]
| South East: | | North Carolina, South Carolina, [removed: Tennessee and] Florida [added: and Tennessee] |
Backlog totaled [removed: 6,229] [added: 6,884] units and approximately [removed: $2.4] [added: $2.7] billion at December 31, [removed: 2015] [added: 2016] compared to backlog of [removed: 5,475] [added: 6,229] units and approximately [removed: $2.1] [added: $2.4] billion at December 31, [removed: 2014.][added: 2015.]
Expressed as the total of all cancellations during the period as a percentage of gross sales during the period, our cancellation rate was approximately [added: 16% in 2016 and] 15% in [removed: each of 2015, 2014] [added: both 2015] and [removed: 2013.][added: 2014.]
Additionally, during each of [removed: 2015, 2014] [added: 2016, 2015] and [removed: 2013,] [added: 2014,] approximately 6% of a reporting quarter’s opening backlog balance cancelled during the [removed: fiscal] quarter.
Other than those units that are cancelled, we expect to settle substantially all of our December 31, [removed: 2015] [added: 2016] backlog during [removed: 2016.][added: 2017.]
In [removed: 2015,] [added: 2016,] NVRM closed approximately [removed: 10,900] [added: 12,300] loans with an aggregate principal amount of approximately [removed: $3.5] [added: $4.0] billion as compared to approximately [removed: 9,100] [added: 10,900] loans with an aggregate principal amount of approximately [removed: $2.8] [added: $3.5] billion in [removed: 2014.][added: 2015.]
NVRM’s mortgage loans in process that had not closed at December 31, [removed: 2015] [added: 2016] and [removed: 2014] [added: 2015] had an aggregate principal balance of approximately [removed: $1.6] [added: $1.8] billion and [removed: $1.4] [added: $1.6] billion, respectively.
NVRM’s cancellation rate was approximately [removed: 29%, 31%] [added: 34%, 29%] and [removed: 35%] [added: 31%] in [removed: 2015, 2014] [added: 2016, 2015] and [removed: 2013,] [added: 2014,] respectively.
At December 31, [removed: 2015,] [added: 2016,] we employed approximately [removed: 4,300] [added: 4,900] full-time persons.
Our website also includes a corporate governance section which contains our Corporate Governance Guidelines (which includes our Directors’ Independence Standards), Code of Ethics, Charters for the Audit, Compensation, Corporate [removed: Governance, Nominating] [added: Governance] and [removed: Qualified Legal Compliance] [added: Nominating] Committees of our Board of Directors, Policies and Procedures for the Consideration of Board of Director Candidates, and Policies and Procedures Regarding Communications with the NVR, Inc. Board of Directors, the Independent Lead Director and the Non-Management Directors as a Group.
[removed: Forward looking] [added: Forward-looking] statements contained in this document include those regarding market trends, NVR’s financial position, business strategy, the outcome of pending litigation, investigations or similar contingencies, projected plans and objectives of management for future operations.
In 2016, our average price of a settled unit was approximately $381,200.
See “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in Item 7 of this Form 10-K for additional discussion of lots controlled.
The housing market in 2016 continued the trend experienced in 2015 of steady new home demand.
NVRM is subject to the rules and regulations of FNMA, GNMA, FHLMC, VA and FHA.
Fox Ridge Homes operates in the Nashville, TN metropolitan area.
As of December 31, 2015, we controlled approximately 68,800 lots under purchase agreements with deposits in cash and letters of credit totaling approximately $373.3 million and $3.0 million, respectively.
Included in the number of controlled lots are approximately 6,100 lots for which we have recorded a contract land deposit impairment reserve of approximately $42.2 million as of December 31, 2015.
In addition, we controlled approximately 8,000 lots through six JVs with an aggregate investment of approximately $60.5 million.
Of the lots controlled by the JVs, approximately 3,300 were not under contract with us at December 31, 2015.
Further, as of December 31, 2015, we directly owned four separate raw parcels of land, zoned for their intended use, with a current cost basis, including development costs, of approximately $60.6 million that we intend to develop into approximately 980 finished lots.
price purchase agreements, JVs and land under development, respectively.
In addition to the lots we currently control as discussed above, we have certain properties under contract with land owners that are expected to yield approximately 8,800 lots.
Some of these properties may require rezoning or other approvals to achieve the expected yield.
These properties are controlled with deposits and letters of credit totaling approximately $12.2 million and $350,000, respectively, as of December 31, 2015, of which approximately $8.7 million is refundable if we do not perform under the contract.
We generally expect to assign the raw land contracts to a land developer and simultaneously enter into a lot purchase agreement with the assignee if the project is determined to be feasible.
In February 2016, we acquired one of these properties at a cost of approximately $150 million which is expected to produce approximately 1,000 lots, of which approximately 160 lots are under contract with unrelated parties.
New home demand continued to improve throughout 2015.
During 2014, our average price was approximately $368,500.
NVRM is an approved seller/servicer of FNMA mortgage loans and an approved seller/issuer of GNMA, FHLMC, VA and FHA mortgage loans, and is subject to all of those agencies’ rules and regulations.
Item 3. Legal Proceedings.
4 rewritten, 0 added, 0 removed, 8 unchanged
Although there can be no assurance that a settlement will be reached, [added: in 2015] we recorded a liability and corresponding expense associated with an estimated civil penalty [removed: amount on the accompanying consolidated financial statements in 2015.][added: amount.]
We are also involved in various other litigation [added: matters] arising in the ordinary course of business.
In the opinion of management, and based on advice of legal counsel, [removed: this litigation is] [added: these matters are] not expected to have a material adverse effect on our financial position, results of operations or cash flows.
Legal costs incurred in connection with outstanding litigation [added: matters] are expensed as incurred.
Cover and table of contents
27 rewritten, 3 added, 0 removed, 49 unchanged
10-K 1 [removed: nvr-10k_20151231.htm 10-K][added: nvr-10k_20161231.htm NVR-10K-20161231-FY]
| [removed: x] [added: ☒] | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the fiscal year ended December 31, [removed: 2015][added: 2016]
| [removed: ¨] [added: ☐] | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
Yes [removed: x] [added: ☒] No [removed: ¨][added: ☐]
Yes [removed: ¨] [added: ☐] No [removed: x][added: ☒]
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K (§229.405) is not contained herein, and will not be contained, to the best of registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. [removed: x]
| Large accelerated filer | | [removed: x] [added: ☒] | | Accelerated filer | | [removed: ¨] [added: ☐] |
| Non-accelerated filer | | [removed: ¨] [added: ☐] (Do not check if a Smaller Reporting Company) | | Smaller Reporting Company | | [removed: ¨] [added: ☐] |
The aggregate market value of the voting stock held by non-affiliates of NVR, Inc. on June 30, [removed: 2015,] [added: 2016,] the last business day of NVR, Inc.’s most recently completed second fiscal quarter, was approximately [removed: $5,130,019,000.][added: $6,489,296,000.]
As of February [removed: 12, 2016] [added: 10, 2017] there were [removed: 3,881,141] [added: 3,704,206] total shares of common stock outstanding.
Portions of the Proxy Statement of NVR, Inc. to be filed with the Securities and Exchange Commission pursuant to Regulation 14A of the Securities Exchange Act of 1934 on or prior to April 30, [removed: 2016] [added: 2017] are incorporated by reference into Part III of this report.
| Item 1A. | | [Risk Factors](#Risk_Factors) | | [removed: 5] [added: 4] | |
| Item 1B. | | [Unresolved Staff Comments](#Item_1B_Unresolved_Staff_Comments) | | [removed: 9] [added: 8] | |
| Item 2. | | [Properties](#Properties) | | [removed: 9] [added: 8] | |
| | | [Executive Officers of the Registrant](#Executive_Officers_of_the_Registrant) | | [removed: 10] [added: 9] | |
| Item 7. | | [Management’s Discussion and Analysis of Financial Condition and Results of Operations](#Managements_Discussion_and_Analysis) | | [removed: 13] [added: 14] | |
| Item 8. | | [Financial Statements and Supplementary Data](#Financial_Statements_and_Supplementary) | | [removed: 32] [added: 33] | |
| Item 9. | | [Changes in and Disagreements with Accountants on Accounting and Financial Disclosure](#Changes_in_and_Disagreement) | | [removed: 32] [added: 33] | |
| Item 9A. | | [Controls and Procedures](#Controls_and_Procedures) | | [removed: 32] [added: 33] | |
| Item 9B. | | [Other Information](#Other_Information) | | [removed: 32] [added: 33] | |
| Item 10. | | [Directors, Executive Officers, and Corporate Governance](#Directors_Executive) | | [removed: 32] [added: 33] | |
| Item 11. | | [Executive Compensation](#Executive_Compensation) | | [removed: 32] [added: 33] | |
| Item 12. | | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters](#Security_Ownership) | | [removed: 33] [added: 34] | |
| Item 13. | | [Certain Relationships and Related Transactions, and Director Independence](#Certain_Relationships) | | [removed: 33] [added: 34] | |
| Item 14. | | [Principal Accountant Fees and Services](#Principal_Accountant) | | [removed: 33] [added: 34] | |
| Item 15. | | [Exhibits and Financial Statement Schedules](#Exhibits_and_Financial) | | [removed: 34] [added: 35] | |
Yes ☒ No ☐
Yes ☒ No ☐
Yes ☐ No ☒
Item 2. Properties.
1 rewritten, 0 added, 0 removed, 10 unchanged
Our plant utilization was [removed: 40%] [added: 43%] and [removed: 35%] [added: 40%] of total capacity in [removed: 2015] [added: 2016] and [removed: 2014,] [added: 2015,] respectively.
Item 4. Mine Safety Disclosures.
12 rewritten, 1 added, 0 removed, 20 unchanged
| Paul C. Saville | | | [removed: 60] [added: 61] | | | President and Chief Executive Officer of NVR |
| Daniel D. Malzahn | | | [removed: 46] [added: 47] | | | [added: Senior] Vice President, Chief Financial Officer and Treasurer of NVR |
| Robert W. Henley | | | [removed: 49] [added: 50] | | | President of NVRM |
| Eugene J. Bredow | | | [removed: 46] [added: 47] | | | Vice [removed: President] [added: President, Chief Accounting Officer] and Controller of NVR |
| Jeffrey D. Martchek | | | [removed: 50] [added: 51] | | | President of Homebuilding Operations of NVR |
Malzahn was named [added: Senior] Vice [removed: President,] [added: President in February 2016, and continues to serve as] Chief Financial Officer and Treasurer of [removed: NVR effective] [added: NVR, roles he has occupied since] February 20, 2013.
[removed: Prior to] [added: From] February [added: 1, 2004 through February] 20, 2013, Mr. Malzahn was Vice President of Planning and Investor Relations of [removed: NVR since February 1, 2004.][added: NVR.]
Mr. Henley [removed: had been serving] [added: served] as interim acting President of NVRM [removed: since] [added: from] June 1, [added: 2012 until October 1,] 2012.
[removed: Prior to] [added: From July 1, 2005 through] June 1, 2012, Mr. Henley served as Vice President and Controller of [removed: NVR since July 1, 2005.][added: NVR.]
Bredow was named [added: Chief Accounting Officer in February 2016, and continues to serve as] Vice President and Controller of [removed: NVR effective] [added: NVR, roles he has occupied since] June 1, 2012.
[removed: Prior to] [added: From January 2008 through] June 1, 2012, Mr. Bredow was the Vice President of Internal Audit and Corporate Governance of [removed: NVR since January 2008.][added: NVR.]
[removed: Prior to] [added: From February 2011 through] January 1, 2016, Mr. Martchek was Area President for the Maryland and Virginia homebuilding [removed: operations since February 2011.][added: operations.]
| | | | | | | |
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
8 rewritten, 15 added, 14 removed, 16 unchanged
Our shares of common stock are listed and principally traded on the New York Stock Exchange under the ticker symbol “NVR.” The following table sets forth the high and low prices per share for our common stock for each [removed: fiscal] quarter during the years ended December 31, [removed: 2015] [added: 2016] and [removed: 2014:][added: 2015:]
As of the close of business on February [removed: 12, 2016,] [added: 10, 2017,] there were [removed: 287] [added: 278] shareholders of record.
We had two share repurchase authorizations outstanding during the quarter ended December 31, [removed: 2015.][added: 2016.]
On [removed: February 18,] [added: November 4,] 2015 and November [removed: 4, 2015,] [added: 2, 2016,] we publicly announced the Board of Directors’ approval for us to repurchase our outstanding common stock in one or more open market and/or privately negotiated transactions, up to an aggregate of $300 million per authorization.
The following table provides information regarding common stock repurchases during the quarter ended December 31, [removed: 2015:][added: 2016:]
The following [removed: chart graphs our performance in] [added: graph compares] the [removed: form of] cumulative total return to holders of our common stock since December 31, [removed: 2010 in comparison to] [added: 2011 with] the Dow Jones US Home Construction [removed: Index, the S&P 500] Index and the [removed: Dow Jones US Industrial Average] [added: S&P 500] Index for that same period, assuming that $100 was invested in NVR stock and the indices on December 31, [removed: 2010.][added: 2011.]
[removed: 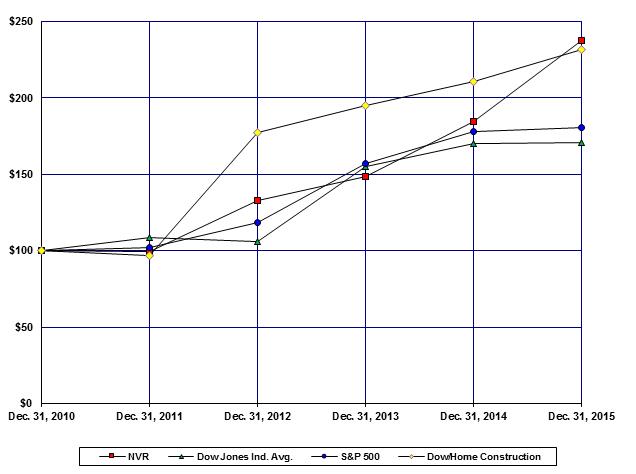][added: ]
| Comparison of 5 Year Cumulative Total Return | | [removed: 2010 | | | |] 2011 | | | | 2012 | | | | 2013 | | | | 2014 | | | | 2015 | | | [added: | 2016 | | |]
| 2016 | | | | | | | | |
| Fourth Quarter | | $ | 1,695.41 | | | $ | 1,478.04 | |
| Third Quarter | | $ | 1,845.37 | | | $ | 1,633.00 | |
| Second Quarter | | $ | 1,801.94 | | | $ | 1,606.75 | |
| First Quarter | | $ | 1,820.00 | | | $ | 1,462.02 | |
| October 1 - 31, 2016 | | | 26,284 | | | $ | 1,608.69 | | | | 26,284 | | | $ | 5,187 | |
| November 1 - 30, 2016 (1) | | | 29,930 | | | $ | 1,565.04 | | | | 29,930 | | | $ | 258,344 | |
| December 1 - 31, 2016 | | | 45,768 | | | $ | 1,627.41 | | | | 45,768 | | | $ | 183,861 | |
| Total | | | 101,982 | | | $ | 1,604.28 | | | | 101,982 | | | | | |
| | (1) | 3,405 outstanding shares were repurchased under the November 4, 2015 share repurchase authorization, which fully utilized the authorization. The remaining 26,525 outstanding shares were repurchased under the November 2, 2016 share repurchase authorization. |
| --- | --- | --- |
On February 15, 2017, the Board of Directors approved a repurchase authorization providing us authorization to repurchase up to an aggregate of $300 million of our common stock in one or more open market and/or privately negotiated transactions.
| NVR, Inc. | | $ | 100 | | | $ | 134 | | | $ | 150 | | | $ | 186 | | | $ | 240 | | | $ | 243 | |
| S&P 500 | | $ | 100 | | | $ | 116 | | | $ | 154 | | | $ | 175 | | | $ | 177 | | | $ | 198 | |
| Dow Jones US Home Construction | | $ | 100 | | | $ | 183 | | | $ | 202 | | | $ | 218 | | | $ | 240 | | | $ | 224 | |
| 2014 | | | | | | | | |
| Fourth Quarter | | $ | 1,284.50 | | | $ | 1,050.95 | |
| Third Quarter | | $ | 1,200.00 | | | $ | 1,040.83 | |
| Second Quarter | | $ | 1,173.78 | | | $ | 1,027.00 | |
| First Quarter | | $ | 1,220.95 | | | $ | 991.05 | |
| October 1 - 31, 2015 | | | 74,393 | | | $ | 1,548.99 | | | | 74,393 | | | $ | 91,900,607 | |
| November 1 - 30, 2015 | | | 17,827 | | | $ | 1,630.34 | | | | 17,827 | | | $ | 362,836,550 | |
| December 1 - 31, 2015 | | | 14,339 | | | $ | 1,647.45 | | | | 14,339 | | | $ | 339,213,700 | |
| Total | | | 106,559 | | | $ | 1,575.85 | | | | 106,559 | | | | | |
COMPARISON OF CUMULATIVE TOTAL EQUITYHOLDER RETURN ON EQUITY
| NVR, Inc. | | $ | 100 | | | $ | 99 | | | $ | 133 | | | $ | 148 | | | $ | 185 | | | $ | 238 | |
| Dow Jones US Industrial Average | | $ | 100 | | | $ | 108 | | | $ | 106 | | | $ | 155 | | | $ | 170 | | | $ | 171 | |
| S&P 500 | | $ | 100 | | | $ | 102 | | | $ | 118 | | | $ | 157 | | | $ | 178 | | | $ | 181 | |
| Dow Jones US Home Construction | | $ | 100 | | | $ | 97 | | | $ | 177 | | | $ | 195 | | | $ | 211 | | | $ | 232 | |
Item 6. Selected Financial Data.
15 rewritten, 5 added, 2 removed, 19 unchanged
| | | [removed: 2015] [added: 2016] | | | | [removed: 2014] [added: 2015] | | | | [removed: 2013] [added: 2014] | | | | [removed: 2012] [added: 2013] | | | | [removed: 2011] [added: 2012] | | |
| Revenues | | $ | [removed: 5,065,200] [added: 5,709,223] | | | $ | [removed: 4,375,059] [added: 5,065,200] | | | $ | [removed: 4,134,481] [added: 4,375,059] | | | $ | [removed: 3,121,244] [added: 4,134,481] | | | $ | [removed: 2,611,195] [added: 3,121,244] | |
| Gross profit | | | [removed: 946,418] [added: 1,001,362] | | | | [removed: 806,473] [added: 946,418] | | | | [removed: 710,277] [added: 806,473] | | | | [removed: 545,605] [added: 710,277] | | | | [removed: 445,570] [added: 545,605] | |
| Mortgage banking fees | | | [removed: 93,808] [added: 113,321] | | | | [removed: 69,509] [added: 93,808] | | | | [removed: 76,786] [added: 69,509] | | | | [removed: 63,406] [added: 76,786] | | | | [removed: 47,954] [added: 63,406] | |
| Interest income | | | [removed: 6,485] [added: 7,569] | | | | [removed: 4,940] [added: 6,485] | | | | [removed: 4,983] [added: 4,940] | | | | [removed: 4,504] [added: 4,983] | | | | [removed: 5,702] [added: 4,504] | |
| Interest expense | | | [removed: 641] [added: 1,086] | | | | [removed: 549] [added: 641] | | | | [removed: 545] [added: 549] | | | | [removed: 546] [added: 545] | | | | [removed: 875] [added: 546] | |
| Net income | | | [removed: 382,927] [added: 425,262] | | | | [removed: 281,630] [added: 382,927] | | | | [removed: 266,477] [added: 281,630] | | | | [removed: 180,588] [added: 266,477] | | | | [removed: 129,420] [added: 180,588] | |
| Basic | | $ | [removed: 95.21] [added: 110.53] | | | $ | [removed: 65.83] [added: 95.21] | | | $ | [removed: 56.25] [added: 65.83] | | | $ | [removed: 36.04] [added: 56.25] | | | $ | [removed: 23.66] [added: 36.04] | |
| Diluted | | $ | [removed: 89.99] [added: 103.61] | | | $ | [removed: 63.50] [added: 89.99] | | | $ | [removed: 54.81] [added: 63.50] | | | $ | [removed: 35.12] [added: 54.81] | | | $ | [removed: 23.01] [added: 35.12] | |
| Basic | | | [removed: 4,022] [added: 3,847] | | | | [removed: 4,278] [added: 4,022] | | | | [removed: 4,737] [added: 4,278] | | | | [removed: 5,011] [added: 4,737] | | | | [removed: 5,469] [added: 5,011] | |
| Diluted | | | [removed: 4,255] [added: 4,104] | | | | [removed: 4,435] [added: 4,255] | | | | [removed: 4,862] [added: 4,435] | | | | [removed: 5,142] [added: 4,862] | | | | [removed: 5,624] [added: 5,142] | |
| Homebuilding inventory | | $ | [removed: 1,006,526] [added: 1,092,100] | | | $ | [removed: 869,486] [added: 1,006,526] | | | $ | [removed: 738,565] [added: 869,486] | | | $ | [removed: 678,131] [added: 738,565] | | | $ | [removed: 533,150] [added: 678,131] | |
| Contract land deposits, net | | | [removed: 343,295] [added: 379,844] | | | | [removed: 294,676] [added: 343,295] | | | | [removed: 236,885] [added: 294,676] | | | | [removed: 191,538] [added: 236,885] | | | | [removed: 131,930] [added: 191,538] | |
| Shareholders’ equity | | | [removed: 1,239,165] [added: 1,304,441] | | | | [removed: 1,124,255] [added: 1,239,165] | | | | [removed: 1,261,352] [added: 1,124,255] | | | | [removed: 1,480,477] [added: 1,261,352] | | | | [removed: 1,374,799] [added: 1,480,477] | |
| [removed: (1)] [added: (2)] | Balance does not include non-recourse debt related to the consolidated variable interest entity. |
| | | 2016 | | | | 2015 | | | | 2014 | | | | 2013 | | | | 2012 | | |
| Total assets (1) | | | 2,643,943 | | | | 2,511,718 | | | | 2,347,413 | | | | 2,481,718 | | | | 2,599,903 | |
| Notes and loans payable (1) (2) | | | 596,455 | | | | 595,847 | | | | 595,244 | | | | 594,760 | | | | 594,806 | |
| (1) | In 2016, we adopted Accounting Standards Update (“ASU”) 2015-03, Interest – Imputation of Interest, which requires that debt issuance costs be presented on the balance sheet as a direct deduction from the carrying amount of the related debt liability. The balances as of December 31, 2016 reflect the amounts shown on the accompanying consolidated balance sheets following the adoption of the standard. For comparative purposes, the balances as of December 31, 2015, 2014, 2013 and 2012 have been adjusted and present the Notes net of unamortized debt issuance costs of $3,413, $3,922, $4,430 and $4,939, respectively. |
| --- | --- |
| Total assets | | | 2,515,131 | | | | 2,351,335 | | | | 2,486,148 | | | | 2,604,842 | | | | 1,779,485 | |
| Notes and loans payable (1) | | | 599,260 | | | | 599,166 | | | | 599,190 | | | | 599,745 | | | | 1,613 | |
Item 9A. Controls and Procedures.
3 rewritten, 0 added, 0 removed, 7 unchanged
Based on that evaluation, the principal executive officer and principal financial officer concluded that the design and operation of these disclosure controls and procedures as of December 31, [removed: 2015] [added: 2016] were effective to provide reasonable assurance that information required to be disclosed in our reports under the Exchange Act, processed, summarized and reported within the time periods specified in the Securities and Exchange Commission’s rules and forms and that such information is accumulated and communicated to our management, including our principal executive officer and principal financial officer, as appropriate, to allow timely decisions regarding required disclosure.
Based on our evaluation under the framework in Internal Control – Integrated Framework (2013), our management concluded that our internal control over financial reporting was effective as of December 31, [removed: 2015.][added: 2016.]
Our internal control over financial reporting as of December 31, [removed: 2015] [added: 2016] has been audited by KPMG LLP, an independent registered public accounting firm, as stated in their attestation report which is included herein.
Item 10. Directors, Executive Officers, and Corporate Governance.
1 rewritten, 0 added, 0 removed, 2 unchanged
Item 10 is incorporated herein by reference to our Proxy Statement expected to be filed with the Securities and Exchange Commission on or prior to April 30, [removed: 2016.][added: 2017.]
Item 11. Executive Compensation.
1 rewritten, 0 added, 0 removed, 1 unchanged
Item 11 is incorporated herein by reference to our Proxy Statement expected to be filed with the Securities and Exchange Commission on or prior to April 30, [removed: 2016.][added: 2017.]
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
7 rewritten, 1 added, 1 removed, 6 unchanged
Item 12 is incorporated herein by reference to our Proxy Statement expected to be filed with the Securities and Exchange Commission on or prior to April 30, [removed: 2016.][added: 2017.]
The table below sets forth information as of December 31, [removed: 2015] [added: 2016] for (i) all equity compensation plans approved by our shareholders and (ii) all equity compensation plans not approved by our shareholders:
| Equity compensation plans [added: not] approved by security holders [removed: (1)] | | | [removed: 1,020,789] [added: 117,968] | | | $ | [removed: 988.60] [added: 683.04] | | | | [removed: 340,658] [added: —] | |
| Equity compensation plans [removed: not] approved by security holders [added: (1)] | | | [removed: 125,516] [added: 974,221] | | | $ | [removed: 678.79] [added: 1,075.45] | | | | [removed: —] [added: 312,471] | |
| (1) | This category includes the [removed: RSUs] [added: restricted share units (“RSUs”)] authorized to be issued under the 2010 Equity Incentive Plan, which was approved by our shareholders at our May 4, 2010 Annual Meeting. At December 31, [removed: 2015,] [added: 2016,] there are [removed: 50,724] [added: 15,951] RSUs outstanding, issued at a $0 exercise price. Of the total [removed: 340,658] [added: 312,471] shares remaining available for future issuance under the shareholder approved plans, up to [removed: 35,691] [added: 37,774] may be issued as RSUs. The weighted-average exercise price of outstanding options under security holder approved plans, excluding outstanding RSUs, was [removed: $1,040.30.] [added: $1,093.35.] |
Equity compensation plans approved by our shareholders include: the [removed: NVR, Inc.] 1998 Management Long-Term Stock Option [removed: Plan;] [added: Plan,] the 1998 Directors’ Long-Term Stock Option [removed: Plan;] [added: Plan,] the 2010 Equity Incentive [removed: Plan;] [added: Plan,] and the 2014 Equity Incentive Plan.
The only equity compensation plan that was not approved by our shareholders is the [removed: NVR, Inc.] 2000 Broadly-Based Stock Option Plan.
| Total | | | 1,092,189 | | | $ | 1,033.07 | | | | 312,471 | |
| Total | | | 1,146,305 | | | $ | 954.68 | | | | 340,658 | |
Item 13. Certain Relationships and Related Transactions, and Director Independence.
1 rewritten, 0 added, 0 removed, 1 unchanged
Item 13 is incorporated herein by reference to our Proxy Statement expected to be filed with the Securities and Exchange Commission on or prior to April 30, [removed: 2016.][added: 2017.]
Item 14. Principal Accountant Fees and Services.
1 rewritten, 0 added, 0 removed, 2 unchanged
Item 14 is incorporated herein by reference to our Proxy Statement expected to be filed with the Securities and Exchange Commission on or prior to April 30, [removed: 2016.][added: 2017.]
Item 15. Exhibits and Financial Statement Schedules.
452 rewritten, 160 added, 96 removed, 608 unchanged
| Exhibit Number | | [added: Exhibit] Description | [added: | Form | | File Number | | Exhibit Number | | Filing Date |]
| 4.1 | | Indenture dated as of April 14, 1998 between NVR, Inc., as issuer and the Bank of New York as trustee. [removed: Filed as Exhibit 4.3 to NVR’s Current Report on Form] [added: | |] 8-K [removed: filed on April 23, 1998 and incorporated herein by reference.] | [added: | | | 4.3 | | 4/23/1998 |]
| 4.2 | | Form of Note (included in [removed: Indenture filed as Exhibit 4.1).] [added: Indenture).] | [added: | 8-K | | | | 4.5 | | 4/23/1998 |]
| 4.3 | | Fifth Supplemental Indenture dated September 10, 2012 among NVR, Inc. and U.S. Bank Trust National Association. [removed: Filed as Exhibit 4.1 to NVR’s Current Report on Form] [added: | |] 8-K [removed: filed on September 10, 2012 and incorporated herein by reference.] | [added: | | | 4.1 | | 9/10/2012 |]
| 10.1* | | Amended and Restated Employment Agreement between NVR, Inc. and Paul C. Saville dated November 4, 2015. [removed: Filed as Exhibit 10.1 to NVR’s Quarterly Report on Form] [added: | |] 10-Q [removed: filed on November 6, 2015 and incorporated herein by reference.] | [added: | | | 10.1 | | 11/6/2015 |]
| 10.2* | | Amended and Restated Employment Agreement between NVR, Inc. and Daniel D. Malzahn dated November 4, 2015. [removed: Filed as Exhibit 10.2 to NVR’s Quarterly Report on Form] [added: | |] 10-Q [removed: filed on November 6, 2015 and incorporated herein by reference.] | [added: | | | 10.2 | | 11/6/2015 |]
| 10.3* | | Amended and Restated Employment Agreement between NVR, Inc. and Robert W. Henley dated November 4, 2015. [removed: Filed as Exhibit 10.3 to NVR’s Quarterly Report on Form] [added: | |] 10-Q [removed: filed on November 6, 2015 and incorporated herein by reference.] | [added: | | | 10.3 | | 11/6/2015 |]
| 10.4* | | Amended and Restated Employment Agreement between NVR, Inc. and Eugene J. Bredow dated November 4, 2015. [removed: Filed as Exhibit 10.4 to NVR’s Quarterly Report on Form] [added: | |] 10-Q [removed: filed on November 6, 2015 and incorporated herein by reference.] | [added: | | | 10.4 | | 11/6/2015 |]
| 10.5* | | Employment Agreement between NVR, Inc. and Jeffrey D. Martchek dated January 1, 2016. [removed: Filed herewith.] | [added: | 10-K | | | | 10.5 | | 2/17/2016 |]
| 10.6* | | Profit Sharing Plan of NVR, Inc. and Affiliated Companies. [removed: Filed as Exhibit 4.1 to NVR’s Registration Statement on Form] [added: | |] S-8 [removed: (No. 333-29241) filed on June 13, 1997 and incorporated herein by reference.] | [added: | 333-29241 | | 4.1 | | 6/13/1997 |]
| 10.8* | | NVR, Inc. 1998 Management Long-Term Stock Option Plan. [removed: Filed as Exhibit 4 to NVR’s Registration Statement on Form] [added: | |] S-8 [removed: (No. 333-79951) filed on June 4, 1999 and incorporated herein by reference.] | [added: | 333-79951 | | 4 | | 6/4/1999 |]
| 10.9* | | NVR, Inc. 1998 Directors’ Long-Term Stock Option Plan. [removed: Filed as Exhibit 4 to NVR’s Registration Statement on Form] [added: | |] S-8 [removed: (No. 333-79949) filed on June 4, 1999 and incorporated herein by reference.] | [added: | 333-79949 | | 4 | | 6/4/1999 |]
| 10.10* | | NVR, Inc. 2000 Broadly-Based Stock Option Plan. [removed: Filed as Exhibit 99.1 to NVR’s Registration Statement on Form] [added: | |] S-8 [removed: (No. 333-56732) filed on March 8, 2001 and incorporated herein by reference.] | [added: | 333-56732 | | 99.1 | | 3/8/2001 |]
| 10.11* | | Amended and Restated NVR, Inc. Nonqualified Deferred Compensation Plan. [removed: Filed as Exhibit 10.5 to NVR’s Quarterly Report on Form] [added: | |] 10-Q [removed: filed on November 6, 2015 and incorporated herein by reference.] | [added: | | | 10.5 | | 11/6/2015 |]
| 10.13* | | NVR, Inc. 2014 Equity Incentive Plan. [removed: Filed as Exhibit 10.1 to NVR’s Registration Statement on Form] [added: | |] S-8 [removed: (No. 333-195756) filed on May 7, 2014 and incorporated herein by reference.] | [added: | 333-195756 | | 10.1 | | 5/7/2014 |]
| 10.14* | | The Form of Non-Qualified Stock Option Agreement (Management time-based grants) under the NVR, Inc. 2014 Equity Incentive Plan. [removed: Filed as Exhibit 10.1 to NVR’s Current Report on Form] [added: | |] 8-K [removed: filed on May 7, 2014 and incorporated herein by reference.] | [added: | | | 10.1 | | 5/7/2014 |]
| 10.15* | | The Form of Non-Qualified Stock Option Agreement (Director time-based grants) under the NVR, Inc. 2014 Equity Incentive Plan. [removed: Filed as Exhibit 10.2 to NVR’s Current Report on Form] [added: | |] 8-K [removed: filed on May 7, 2014 and incorporated herein by reference.] | [added: | | | 10.2 | | 5/7/2014 |]
| 10.16* | | The Form of Non-Qualified Stock Option Agreement (Management performance-based grants) under the NVR, Inc. 2014 Equity Incentive Plan. [removed: Filed as Exhibit 10.3 to NVR’s Current Report on Form] [added: | |] 8-K [removed: filed on May 7, 2014 and incorporated herein by reference.] | [added: | | | 10.3 | | 5/7/2014 |]
| 10.17* | | The Form of Non-Qualified Stock Option Agreement (Director performance-based grants) under the NVR, Inc. 2014 Equity Incentive Plan. [removed: Filed as Exhibit 10.4 to NVR’s Current Report on Form] [added: | |] 8-K [removed: filed on May 7, 2014 and incorporated herein by reference.] | [added: | | | 10.4 | | 5/7/2014 |]
| 10.18* | | NVR, Inc. 2010 Equity Incentive Plan. [removed: Filed as Exhibit 10.1 to NVR’s Registration Statement on Form] [added: | |] S-8 [removed: (No. 333-166512) filed on May 4, 2010 and incorporated herein by reference.] | [added: | 333-166512 | | 10.1 | | 5/4/2010 |]
| 10.19* | | The Form of Non-Qualified Stock Option Agreement (Management grants) under the NVR, Inc. 2010 Equity Incentive Plan. [removed: Filed as Exhibit 10.1 to NVR’s Quarterly Report on Form] [added: | |] 10-Q [removed: filed on July 30, 2013 and incorporated herein by reference.] | [added: | | | 10.1 | | 7/30/2013 |]
| 10.20* | | The Form of Non-Qualified Stock Option Agreement (Director grants) under the NVR, Inc. 2010 Equity Incentive Plan. [removed: Filed as Exhibit 10.2 to NVR’s Current Report on Form] [added: | |] 8-K [removed: filed on May 6, 2010 and incorporated herein by reference.] | [added: | | | 10.2 | | 5/6/2010 |]
| 10.21* | | The Form of Restricted Share Units Agreement (Management grants) under the NVR, Inc. 2010 Equity Incentive Plan. [removed: Filed as Exhibit 10.2 to NVR’s Quarterly Report on Form] [added: | |] 10-Q [removed: filed on July 30, 2013 and incorporated herein by reference.] | [added: | | | 10.2 | | 7/30/2013 |]
| 10.22* | | The Form of Restricted Share Units Agreement (Director grants) under the NVR, Inc. 2010 Equity Incentive Plan. [removed: Filed as Exhibit 10.4 to NVR’s Current Report on Form] [added: | |] 8-K [removed: filed on May 6, 2010 and incorporated herein by reference.] | [added: | | | 10.4 | | 5/6/2010 |]
| 10.23* | | The Form of Non-Qualified Stock Option Agreement under the NVR, Inc. 2000 Broadly-Based Stock Option Plan. [removed: Filed as Exhibit 10.1 to NVR’s Current Report on Form] [added: | |] 8-K [removed: filed on January 3, 2008 and incorporated herein by reference.] | [added: | | | 10.1 | | 1/3/2008 |]
| 10.24* | | The Form of Non-Qualified Stock Option Agreement under the 1998 Directors’ Long-Term Stock Option Plan. [removed: Filed as Exhibit 10.34 to NVR’s Annual Report on Form] [added: | |] 10-K [removed: for the year ended December 31, 2007 and incorporated herein by reference.] | [added: | | | 10.34 | | 2/22/2008 |]
| 10.25 | | Amended and Restated Master Repurchase Agreement dated as of August 2, 2011, between NVR Mortgage Finance, Inc. and U.S. Bank National Association. [removed: Filed as Exhibit 10.1 to NVR’s Current Report on Form] [added: | |] 8-K [removed: filed on January 21, 2016 and incorporated herein by reference.] | [added: | | | 10.1 | | 1/21/2016 |]
| 10.26 | | First Amendment to Amended and Restated Master Repurchase Agreement dated as of August 1, 2012, between NVR Mortgage Finance, Inc. and U.S. Bank National Association. [removed: Filed as Exhibit 10.2 to NVR’s Current Report on Form] [added: | |] 8-K [removed: filed on January 21, 2016 and incorporated herein by reference.] | [added: | | | 10.2 | | 1/21/2016 |]
| 10.27 | | Second Amendment to Amended and Restated Master Repurchase Agreement dated as of November 13, 2012, between NVR Mortgage Finance, Inc. and U.S. Bank National Association. [removed: Filed as Exhibit 10.3 to NVR’s Current Report on Form] [added: | |] 8-K [removed: filed on January 21, 2016 and incorporated herein by reference.] | [added: | | | 10.3 | | 1/21/2016 |]
| 10.28 | | Third Amendment to Amended and Restated Master Repurchase Agreement dated as of November 29, 2012, between NVR Mortgage Finance, Inc. and U.S. Bank National Association. [removed: Filed as Exhibit 10.4 to NVR’s Current Report on Form] [added: | |] 8-K [removed: filed on January 21, 2016 and incorporated herein by reference.] | [added: | | | 10.4 | | 1/21/2016 |]
| 10.29 | | Fourth Amendment to Amended and Restated Master Repurchase Agreement dated as of July 31, 2013, between NVR Mortgage Finance, Inc. and U.S. Bank National Association. [removed: Filed as Exhibit 10.5 to NVR’s Current Report on Form] [added: | |] 8-K [removed: filed on January 21, 2016 and incorporated herein by reference.] | [added: | | | 10.5 | | 1/21/2016 |]
| 10.30 | | Fifth Amendment to Amended and Restated Master Repurchase Agreement dated as of July 30, 2014, between NVR Mortgage Finance, Inc. and U.S. Bank National Association. [removed: Filed as Exhibit 10.6 to NVR’s Current Report on Form] [added: | |] 8-K [removed: filed on January 21, 2016 and incorporated herein by reference.] | [added: | | | 10.6 | | 1/21/2016 |]
| 10.31 | | Sixth Amendment to Amended and Restated Master Repurchase Agreement dated as of July 29, 2015, between NVR Mortgage Finance, Inc. and U.S. Bank National Association. [removed: Filed as Exhibit 10.7 to NVR’s Current Report on Form] [added: | |] 8-K [removed: filed on January 21, 2016 and incorporated herein by reference.] | [added: | | | 10.7 | | 1/21/2016 |]
| 10.32 | | Seventh Amendment to Amended and Restated Master Repurchase Agreement dated as of January 18, 2016, between NVR Mortgage Finance, Inc. and U.S. Bank National Association. [removed: Filed as Exhibit 10.8 to NVR’s Current Report on Form] [added: | |] 8-K [removed: filed on January 21, 2016 and incorporated herein by reference.] | [added: | | | 10.8 | | 1/21/2016 |]
| [removed: 10.33*] [added: 10.35*] | | Summary of [removed: 2016] [added: 2017] Named Executive Officer annual incentive compensation plan. Filed herewith. | [added: | | | | | | | |]
| 21 | | NVR, Inc. Subsidiaries. Filed herewith. | [added: | | | | | | | |]
| 23 | | Consent of KPMG LLP (Independent Registered Public Accounting Firm). Filed herewith. | [added: | | | | | | | |]
| 31.1 | | Certification of NVR’s Chief Executive Officer pursuant to Rule 13a-14(a). Filed herewith. | [added: | | | | | | | |]
| 31.2 | | Certification of NVR’s Chief Financial Officer pursuant to Rule 13a-14(a). Filed herewith. | [added: | | | | | | | |]
| 32 | | Certification of NVR’s Chief Executive Officer and Chief Financial Officer pursuant to 18 U.S.C. Section 1350, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of 2002. Filed herewith. | [added: | | | | | | | |]
| | | | | Incorporated by Reference | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| 3.1 | | Restated Articles of Incorporation of NVR, Inc. | | 10-K | | | | 3.1 | | 2/25/2011 |
| 3.2 | | Bylaws, as amended, of NVR, Inc. | | 8-K | | | | 3.1 | | 3/17/2016 |
| 4.4 | | Form of Global Note. | | 8-K | | | | 4.2 | | 9/10/2012 |
| 10.7* | | Employee Stock Ownership Plan of NVR, Inc. | | 10-K/A | | | | | | 12/31/1994 |
| 10.12* | | Description of the Board of Directors’ compensation arrangement. | | 10-K | | | | 10.27 | | 2/28/2005 |
| | | | | Incorporated by Reference | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Exhibit Number | | Exhibit Description | | Form | | File Number | | Exhibit Number | | Filing Date |
| | | | | Incorporated by Reference | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Exhibit Number | | Exhibit Description | | Form | | File Number | | Exhibit Number | | Filing Date |
| 10.33 | | Eighth Amendment to Amended and Restated Master Repurchase Agreement dated as of July 27, 2016, between NVR Mortgage Finance, Inc. and U.S. Bank National Association. | | 10-Q | | | | 10.2 | | 7/28/2016 |
| 10.34 | | Credit Agreement dated as of July 15, 2016 among NVR, Inc. and the lenders party hereto, Bank of America, N.A., as Administrative Agent, Swing Line Lender and L/C Issuer, and Merrill Lynch, Pierce, Fenner & Smith Incorporated as Sole Lead Arranger and Sole Book Runner. | | 8-K | | | | 10.1 | | 7/18/2016 |
| 10.36* | | First Amendment to NVR, Inc. Nonqualified Deferred Compensation Plan. Filed herewith. | | | | | | | | |
| | | | | | | | | | | |
| /s/ Susan W. Ross | | Director | | February 15, 2017 |
| Susan W. Ross | | | | |
February 15, 2017
February 15, 2017
| | | | 1,092,100 | | | | 1,006,526 | |
| Other assets | | | 87,159 | | | | 96,136 | |
| | | | 2,233,346 | | | | 2,132,168 | |
| Restricted cash | | | 1,857 | | | | 2,038 | |
| Other assets | | | 24,875 | | | | 18,495 | |
| | | | 410,597 | | | | 379,550 | |
| Total assets | | $ | 2,643,943 | | | $ | 2,511,718 | |
| Senior notes | | | 596,455 | | | | 595,847 | |
| | | | 1,307,103 | | | | 1,240,262 | |
| Total liabilities | | | 1,339,502 | | | | 1,272,553 | |
| Total liabilities and shareholders' equity | | $ | 2,643,943 | | | $ | 2,511,718 | |
| Net income | | | — | | | | — | | | | 425,262 | | | | — | | | | — | | | | — | | | | 425,262 | |
| Balance, December 31, 2016 | | $ | 206 | | | $ | 1,515,828 | | | $ | 5,695,376 | | | $ | (5,906,969 | ) | | $ | (17,375 | ) | | $ | 17,375 | | | $ | 1,304,441 | |
| Net income | | $ | 425,262 | | | $ | 382,927 | | | $ | 281,630 | |
| | | 2016 | | | | 2015 | | | | 2014 | | |
The Company calculates the
Reclassifications
Certain prior period amounts have been reclassified to conform to 2016 presentation.
On January 1, 2016, the Company adopted the standard which on a retrospective basis resulted in the reclassification of the unamortized debt issuance costs related to the Company’s 3.95% Senior Notes due 2022 from the homebuilding “Other assets” line item to the homebuilding “Senior notes” line item in the accompanying condensed consolidated balance sheets.
| --- | --- |
| --- | --- | --- |
| 3.1 | | Restated Articles of Incorporation of NVR, Inc. Filed as Exhibit 3.1 to NVR’s Annual Report on Form 10-K for the year ended December 31, 2010 and incorporated herein by reference. |
| 3.2 | | Bylaws, as amended, of NVR, Inc. Filed as Exhibit 3.1 to NVR’s Quarterly Report on Form 10-Q filed on November 6, 2015 and incorporated herein by reference |
| 4.4 | | Form of Global Note. Filed as Exhibit 4.2 to NVR’s Current Report on Form 8-K filed on September 10, 2012 and incorporated herein by reference. |
| 10.7* | | Employee Stock Ownership Plan of NVR, Inc. Incorporated herein by reference to NVR’s Annual Report on Form 10-K/A for the year ended December 31, 1994. |
| 10.12* | | Description of the Board of Directors’ compensation arrangement. Filed as Exhibit 10.27 to NVR’s Annual Report on Form 10-K for the year ended December 31, 2004 and incorporated herein by reference. |
| | | |
February 17, 2016
| | | | 1,006,526 | | | | 869,486 | |
| Other assets | | | 122,989 | | | | 137,091 | |
| | | | 2,135,581 | | | | 2,088,019 | |
| | | | 379,550 | | | | 263,316 | |
| Total assets | | $ | 2,515,131 | | | $ | 2,351,335 | |
| Senior notes | | | 599,260 | | | | 599,166 | |
| | | | 1,243,675 | | | | 1,201,283 | |
| | | | 32,291 | | | | 25,797 | |
| Total liabilities | | | 1,275,966 | | | | 1,227,080 | |
| Total liabilities and shareholders' equity | | $ | 2,515,131 | | | $ | 2,351,335 | |
| Balance, December 31, 2012 | | $ | 206 | | | $ | 1,169,699 | | | $ | 4,339,080 | | | $ | (4,028,508 | ) | | $ | (25,331 | ) | | $ | 25,331 | | | $ | 1,480,477 | |
| Net income | | | — | | | | — | | | | 266,477 | | | | — | | | | — | | | | — | | | | 266,477 | |
| Repayments under non-recourse debt related to consolidated variable interest entity | | | (64 | ) | | | (3,301 | ) | | | (4,314 | ) |
| Borrowings under non-recourse debt related to consolidated variable interest entity | | | — | | | | — | | | | 3,105 | |
Restricted cash is recorded in “Other assets” in the homebuilding section of the accompanying consolidated balance sheets.
The mortgage banking segment’s restricted cash is recorded in “Other assets” in the mortgage banking section of the accompanying consolidated balance sheets.
conducted each quarter.
tax benefits that would be credited or charged to additional paid-in-capital assuming exercise of the stock option or vesting of the restricted share unit.
In August 2014, FASB issued ASU 2014-15, Presentation of Financial Statements – Going Concern (Subtopic 205-40): Disclosure of Uncertainties about an Entity’s Ability to Continue as a Going Concern.
The standard requires an entity’s management to evaluate at each annual and interim reporting period whether there are conditions or events that raise substantial doubt about the entity’s ability to continue as a going concern within one year after the date the financial statements are issued and to provide related footnote disclosures.
The standard is effective for the first annual period ending after December 15, 2016, and interim periods thereafter.
The standard is effective for the Company for the first annual period beginning after December 15, 2015, and must be applied retrospectively to all prior periods presented in the financial statements.
Early adoption is permitted.
In April 2015, FASB issued ASU 2015-05, Intangibles – Goodwill and Other – Internal-Use Software (Subtopic 350-40).
The standard adds guidance to Subtopic 350-40 to help entities evaluate the accounting for fees paid by a customer in a cloud computing arrangement.
The standard provides a basis for evaluating whether a cloud computing arrangement includes a software license or whether the arrangement should be accounted for as a service contract.
method.
The standard is effective for the Company for the first annual period beginning after December 15, 2016.
Fox Ridge Homes operates in the Nashville, TN metropolitan area.
| Reconciling items sub-total | | | 619,352 | | | | 736,326 | |
| Consolidated assets | | $ | 2,515,131 | | | $ | 2,351,335 | |
An excerpt. Shown here: 40 of 452 rewritten, 40 of 160 added and 40 of 96 removed. The counts are complete. For every sentence, read Item 15. Exhibits and Financial Statement Schedules. in the FY2016 filing and the FY2015 filing.