 filings.tools
ONEOK 10-K 2019-12-31
Filed 2020-02-25. 18 sections, 541K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 10-K
☒ ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
For the fiscal year ended December 31, 2019.
OR
☐ TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
For the transition period from __________ to __________.
Commission file number 001-13643
ONEOK, Inc.
(Exact name of registrant as specified in its charter)
| Oklahoma | 73-1520922 |
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) |
| 100 West Fifth Street, | Tulsa, | OK | 74103 | ||
| (Address of principal executive offices) | (Zip Code) |
Registrant’s telephone number, including area code (918) 588-7000
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered |
| Common stock, par value of $0.01 | OKE | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☒ No ☐.
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐ No ☒.
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports) and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☒ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, smaller reporting company or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company” and “emerging growth company” in Rule 12b-2 of the Exchange Act. (Check one)
Large accelerated filer ☒ Accelerated filer ☐ Non-accelerated filer ☐ Smaller reporting company ☐
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). Yes ☐ No ☒.
Aggregate market value of registrant’s common stock held by non-affiliates based on the closing trade price on June 28, 2019, was $28.1 billion.
On February 18, 2020, the Company had 413,319,000 shares of common stock outstanding.
DOCUMENTS INCORPORATED BY REFERENCE:
Portions of the definitive proxy statement to be delivered to shareholders in connection with the Annual Meeting of Shareholders to be held May 20, 2020, are incorporated by reference in Part III.
ONEOK, Inc.
2019 ANNUAL REPORT
As used in this Annual Report, references to “we,” “our,” or “us” refer to ONEOK, Inc., an Oklahoma corporation, and its predecessors and subsidiaries unless the context indicates otherwise.
GLOSSARY
The abbreviations, acronyms and industry terminology used in this Annual Report are defined as follows:
| $1.5 Billion Term Loan Agreement | The senior unsecured delayed-draw three-year $1.5 billion term loan agreement dated November 19, 2018 |
| $2.5 Billion Credit Agreement | ONEOK’s $2.5 billion revolving credit agreement, as amended |
| AFUDC | Allowance for funds used during construction |
| Annual Report | Annual Report on Form 10-K for the year ended December 31, 2019 |
| ASU | Accounting Standards Update |
| Bbl | Barrels, 1 barrel is equivalent to 42 United States gallons |
| BBtu/d | Billion British thermal units per day |
| Bcf | Billion cubic feet |
| Bcf/d | Billion cubic feet per day |
| Btu | British thermal unit |
| CFTC | U.S. Commodity Futures Trading Commission |
| Clean Air Act | Federal Clean Air Act, as amended |
| Clean Water Act | Federal Water Pollution Control Act Amendments of 1972, as amended |
| DJ | Denver-Julesburg |
| DOT | United States Department of Transportation |
| EBITDA | Earnings before interest expense, income taxes, depreciation and amortization |
| EPA | United States Environmental Protection Agency |
| Exchange Act | Securities Exchange Act of 1934, as amended |
| FERC | Federal Energy Regulatory Commission |
| Foundation | ONEOK Foundation, Inc. |
| GAAP | Accounting principles generally accepted in the United States of America |
| GHG | Greenhouse gas |
| Intermediate Partnership | ONEOK Partners Intermediate Limited Partnership, a wholly owned subsidiary of ONEOK Partners, L.P. |
| KCC | Kansas Corporation Commission |
| LIBOR | London Interbank Offered Rate |
| MBbl/d | Thousand barrels per day |
| MDth/d | Thousand dekatherms per day |
| Merger Transaction | The transaction, effective June 30, 2017, in which ONEOK acquired all of ONEOK Partners’ outstanding common units not already directly or indirectly owned by ONEOK |
| MMBbl | Million barrels |
| MMBbl/d | Million barrels per day |
| MMBtu | Million British thermal units |
| MMcf/d | Million cubic feet per day |
| Moody’s | Moody’s Investors Service, Inc. |
| Natural Gas Act | Natural Gas Act of 1938, as amended |
| Natural Gas Policy Act | Natural Gas Policy Act of 1978, as amended |
| NGL(s) | Natural gas liquid(s) |
| NGL products | Marketable natural gas liquid purity products, such as ethane, ethane/propane mix, propane, iso-butane, normal butane and natural gasoline |
| Northern Border Pipeline | Northern Border Pipeline Company, a 50% owned joint venture |
| NYMEX | New York Mercantile Exchange |
| NYSE | New York Stock Exchange |
| OCC | Oklahoma Corporation Commission |
| ONEOK | ONEOK, Inc. |
| ONEOK Partners | ONEOK Partners, L.P. |
| ONEOK Partners Term Loan Agreement | The senior unsecured three-year $1.0 billion term loan agreement dated January 8, 2016, as amended |
| OPIS | Oil Price Information Service |
| Overland Pass Pipeline | Overland Pass Pipeline Company, LLC, a 50% owned joint venture |
| PHMSA | United States Department of Transportation Pipeline and Hazardous Materials Safety Administration |
| POP | Percent of Proceeds |
| Quarterly Report(s) | Quarterly Report(s) on Form 10-Q |
| Roadrunner | Roadrunner Gas Transmission, LLC, a 50% owned joint venture |
| RRC | Railroad Commission of Texas |
| S&P | S&P Global Ratings |
| SCOOP | South Central Oklahoma Oil Province, an area in the Anadarko Basin in Oklahoma |
| SEC | Securities and Exchange Commission |
| Securities Act | Securities Act of 1933, as amended |
| Series E Preferred Stock | Series E Non-Voting, Perpetual Preferred Stock, par value $0.01 per share |
| STACK | Sooner Trend Anadarko Canadian Kingfisher, an area in the Anadarko Basin in Oklahoma |
| Tax Cuts and Jobs Act | H.R. 1, the tax reform bill, signed into law on December 22, 2017 |
| Topic 606 | Accounting Standards Update 2014-09, “Revenue from Contracts with Customers” |
| West Texas LPG | West Texas LPG pipeline and Mesquite pipeline |
| WTI | West Texas Intermediate |
| WTLPG | West Texas LPG Pipeline Limited Partnership |
| XBRL | eXtensible Business Reporting Language |
The statements in this Annual Report that are not historical information, including statements concerning plans and objectives of management for future operations, economic performance or related assumptions, are forward-looking statements. Forward-looking statements may include words such as “anticipate,” “believe,” “continue,” “could,” “estimate,” “expect,” “forecast,” “goal,” “guidance,” “intend,” “may,” “might,” “outlook,” “plan,” “potential,” “project,” “scheduled,” “should,” “will,” “would” and other words and terms of similar meaning. Although we believe that our expectations regarding future events are based on reasonable assumptions, we can give no assurance that such expectations or assumptions will be achieved. Important factors that could cause actual results to differ materially from those in the forward-looking statements are described under Part I, Item 1A, Risk Factors, and Part II, Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations and “Forward-Looking Statements,” in this Annual Report.
PART I
Item 1. BUSINESS
GENERAL
We are incorporated under the laws of the state of Oklahoma, and our common stock is listed on the NYSE under the trading symbol “OKE.” We are a leading midstream service provider and own one of the nation’s premier NGL systems, connecting NGL supply in the Rocky Mountain, Permian and Mid-Continent regions with key market centers and an extensive network of natural gas gathering, processing, storage and transportation assets. We apply our core capabilities of gathering, processing, fractionating, transporting, storing and marketing natural gas and NGLs through vertical integration across the midstream value chain to provide our customers with premium services while generating consistent and sustainable earnings growth.
Midstream Value Chain
| Legend | 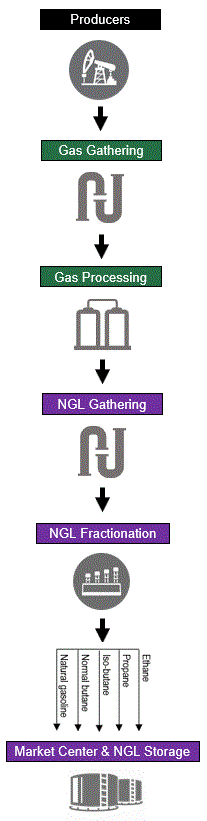 | ||||
| We are connected to supply in natural gas and NGL producing basins and have significant basin diversification, including the Williston, Permian, Powder River and DJ Basins and the STACK and SCOOP areas. In our Natural Gas Gathering and Processing segment, we have more than 3 million dedicated acres in the Williston Basin and approximately 300,000 dedicated acres in the STACK and SCOOP areas. In our Natural Gas Liquids segment, we are the largest NGL takeaway provider in the Williston Basin; Oklahoma, including the STACK and SCOOP areas; Kansas; and the Texas Panhandle. We also have a significant presence in the Permian Basin. | |||||
| Natural Gas Gathering & Processing | |||||
| Natural Gas Liquids | |||||
| Natural Gas Pipelines | |||||
| Raw natural gas is typically gathered at the wellhead, compressed and transported through pipelines to our processing facilities. Most raw natural gas produced at the wellhead contains a mixture of NGL components, such as ethane, propane, iso-butane, normal butane and natural gasoline, which remain in a mixed unfractionated form. | |||||
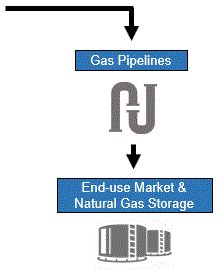
| Once processed, residue natural gas is recompressed and delivered to intrastate and interstate natural gas pipelines. | |||||
| Gathered wellhead natural gas is directed to our processing plants to remove NGLs, resulting in residue natural gas (primarily methane). | |||||
 | |||||
| NGLs extracted at processing plants, both third-party and our own, are then gathered by our NGL gathering pipelines. | |||||
| Gathered NGLs are directed to our downstream fractionators in the Mid-Continent region and Mont Belvieu, Texas, to be separated into purity products. | |||||
| Residue natural gas is transported to storage facilities and end-users, such as large industrial customers, natural gas and electric utilities serving commercial and residential consumers, and international markets through liquefied natural gas exports. | |||||
| Purity products are stored or distributed to our customers, such as petrochemical companies, propane distributors, heating fuel users, ethanol producers, refineries and exporters. | |||||
EXECUTIVE SUMMARY
Business Update and Market Conditions - We operate primarily fee-based businesses in each of our three reportable segments, and our consolidated earnings were approximately 90% fee-based in 2019. Volumes increased across our system in our Natural Gas Gathering and Processing and Natural Gas Liquids segments in 2019, compared with 2018, as a result of our completed capital-growth projects, continued drilling and producer improvements in production due to enhanced completion techniques, offset partially by natural production declines. Since the beginning of 2018, we have completed several capital-growth projects that include NGL pipelines, NGL fractionators, natural gas processing plants and related natural gas and NGL infrastructure, and expect capital expenditures to decrease in 2020 and 2021, compared with 2019. Our NGL projects in the Gulf Coast allow flexibility to add NGL fractionators, NGL storage and, potentially, new export facilities in the future. We expect these projects to meet the needs of producers, natural gas processors and the petrochemical industry that require additional midstream infrastructure to accommodate increasing supply and demand.
We experienced fluctuating NGL location price differentials due to increased supply, increased demand in the Mid-Continent region, infrastructure constraints and slower demand growth in the Gulf Coast due primarily to delays in the startup of petrochemical facilities and constrained NGL export facilities. The Conway-to-Mont Belvieu OPIS price differential for ethane in ethane/propane mix averaged $0.07 per gallon in 2019, compared with $0.15 per gallon in 2018, which resulted in lower earnings from our optimization and marketing activities in our Natural Gas Liquids segment. We expect narrower NGL location price differentials in 2020.
Rocky Mountain Region - We expect to benefit from increased production in this region, which includes the Williston, Powder River and DJ Basins. In our Natural Gas Gathering and Processing segment, gathered and processed volumes increased in 2019, compared with 2018, due primarily to our capital-growth projects, new well connections and increased producer productivity. Our Demicks Lake I natural gas processing plant was placed in service in October 2019, and we expect it to reach its 200 MMcf/d capacity in the first quarter 2020 due to natural gas flaring by producers on our more than 3 million dedicated acres in the Williston Basin. In addition, we completed construction of our Demicks Lake II natural gas processing plant in January 2020. With continued volume growth expected, we are in the process of expanding our Bear Creek plant by 200 MMcf/d, which is expected to be completed in first quarter 2021, and recently announced plans to construct our Demicks Lake III natural gas processing plant, with capacity of 200 MMcf/d and expected completion in the third quarter 2021. Upon completion of these projects, our total processing capacity will be approximately 1.9 Bcf/d in the Williston Basin and is expected to help producers meet North Dakota’s natural gas capture targets and add incremental NGLs to our NGL gathering system.
In our Natural Gas Liquids segment, we announced the completion of our Elk Creek pipeline in December 2019. We are the largest NGL takeaway provider and expect our NGL pipelines to transport more than 240 MBbl/d of NGLs out of this region by the end of the first quarter 2020 due to a combination of growth in volumes from our new and existing processing plants, third-party processing plants and volumes previously transported by rail. In addition, we recently announced an expansion of our Elk Creek pipeline to 400 MBbl/d by adding additional pump stations. The project is expected to be fully completed in the third quarter 2021, with a portion of this incremental capacity available as early as first quarter 2021. In April 2019,
Showing the first 8K of 66K characters. Open the full section
Item 1A. RISK FACTORS
Our investors should consider the following risks that could affect us and our business. Although we have tried to identify key factors, our investors need to be aware that other risks may prove to be important in the future. New risks may emerge at any time, and we cannot predict such risks or estimate the extent to which they may affect our financial performance. Investors should consider carefully the following discussion of risks and the other information included or incorporated by reference in this Annual Report, including “Forward-Looking Statements,” which are included in Part II, Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations.
If the level of drilling in the regions in which we operate declines substantially near our assets, our volumes and revenues could decline.
Our gathering and transportation pipeline systems are dependent upon production from natural gas and crude oil wells, which naturally declines over time. As a result, our cash flows associated with these wells will also decline over time. In order to maintain or increase throughput levels on our gathering and transportation pipeline systems and the asset utilization rates at our processing and fractionation facilities, we must continually obtain new supplies. Our ability to maintain or expand our businesses depends largely on the level of drilling and production by third parties in the regions in which we operate. Our natural gas and NGL supply volumes may be impacted if producers curtail or redirect drilling and production activities. Drilling and production are impacted by factors beyond our control, including:
| • | demand and prices for natural gas, NGLs and crude oil; |
| • | producers’ access to capital; |
| • | producers’ finding and development costs of reserves; |
| • | producers’ ability to obtain necessary permits, drilling rights and surface access in a timely manner and on reasonable terms; |
| • | natural gas field characteristics and production performance; and |
| • | capacity constraints on natural gas, crude oil and NGL infrastructure from the producing areas and our facilities. |
Commodity prices have experienced significant volatility. Drilling and production activity levels may vary across our geographic areas; however, a prolonged period of low commodity prices may reduce drilling and production activities across all areas. If we are not able to obtain new supplies to replace the natural decline in volumes from existing wells or because of competition, throughput on our gathering and transportation pipeline systems and the utilization rates of our processing and fractionation facilities would decline, which could affect adversely our business, results of operations, financial position and cash flows, and our ability to pay cash dividends.
Continued development of supply sources outside of our operating regions could impact demand for our services.
Natural gas production areas outside of our operating regions may compete with natural gas originating in production areas connected to our systems. For example, increased production in the Marcellus Shale may cause natural gas and NGLs in supply areas connected to our systems to be diverted to markets other than our traditional market areas and may affect capacity utilization adversely on our pipeline systems and our ability to renew or replace existing contracts. In our Natural Gas Gathering and Processing segment, the development of reserves could move drilling rigs from our current service areas to other areas, which may reduce demand for our services. In our Natural Gas Pipelines segment, the displacement of natural gas originating in supply areas connected to our pipeline systems by supply sources that are closer to the end-use markets could reduce demand for our services. Either of these possibilities could result in lower revenues, which could affect adversely our business, results of operations, financial position and cash flows.
Our operations are subject to operational hazards and unforeseen interruptions, which could affect adversely our business and for which we may not be adequately insured.
Our operations are subject to all of the risks and hazards typically associated with the operation of natural gas and NGL gathering, transportation and distribution pipelines, storage facilities and processing and fractionation facilities, which include, but are not limited to, leaks, pipeline ruptures, the breakdown or failure of equipment or processes and the performance of facilities below expected levels of capacity and efficiency. Other operational hazards and unforeseen interruptions include adverse weather conditions, accidents, explosions, fires, the collision of equipment with our pipeline facilities (for example, this may occur if a third party were to perform excavation or construction work near our facilities) and catastrophic events such as tornados, hurricanes, earthquakes, floods, and other similar events beyond our control. Also, the United States government warned that energy assets, specifically the nation’s pipeline infrastructure, may be targets of terrorist attacks. An act of terrorism could target our facilities, those of our suppliers or customers or those of other pipelines. A casualty occurrence may result in injury or loss of life, extensive property damage or environmental damage. Liabilities incurred and interruptions to the operations of our pipeline or other facilities caused by such an event could reduce our revenues and increase expenses, thereby impairing our ability to meet our obligations. Insurance proceeds may not be adequate to cover all liabilities or expenses incurred or revenues lost, and we are not fully insured against all risks inherent to our business.
As a result of market conditions, premiums and deductibles for certain insurance policies can increase substantially, and, in some instances, certain insurance may become unavailable or available only for reduced amounts of coverage. Consequently, we may not be able to renew existing insurance policies or purchase other desirable insurance on commercially reasonable terms, if at all. If we were to incur a significant liability for which we were not fully insured, it could affect adversely our business, results of operations, financial position and cash flows. Further, the proceeds of any such insurance may not be paid in a timely manner and may be insufficient if such an event were to occur.
Our operating results may be affected adversely by unfavorable economic and market conditions.
An adverse change in economic conditions worldwide or in the economic regions in which we operate could negatively affect the crude oil and natural gas industry, as well as in the specific segments and markets in which we operate, resulting in reduced demand and increased price competition for our services and products. Our operating results in one or more geographic regions may also be affected by uncertain or changing economic conditions within that region. Volatility in commodity prices may have an impact on many of our suppliers and customers, which, in turn, could have a negative impact on their ability to meet their obligations to us. Periods of severe volatility in equity and credit markets may disrupt our access to such markets, make it difficult to obtain financing necessary to expand facilities or acquire assets, increase financing costs and result in the imposition of restrictive financial covenants. If adverse global or regional economic and market conditions remain uncertain or persist, spread or deteriorate further, we may experience material impacts on our business, results of operations, financial position, cash flows and liquidity.
**Increased regulation of exploration and production activities, including hydraulic f
Showing the first 8K of 62K characters. Open the full section
Item 1B. UNRESOLVED STAFF COMMENTS
Not applicable.
Item 2. PROPERTIES
A description of our properties is included in Item 1, Business.
Item 3. LEGAL PROCEEDINGS
Information about our legal proceedings is included in Note N of the Notes to Consolidated Financial Statements in this Annual Report.
Item 4. MINE SAFETY DISCLOSURES
Not applicable.
PART II
| ITEM 5. | MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES |
Our common stock is listed on the NYSE under the trading symbol “OKE.” The corporate name ONEOK is used in newspaper stock listings.
At February 18, 2020, there were 14,001 holders of record of our 413,319,000 outstanding shares of common stock.
For information regarding our Employee Stock Award Program and other equity compensation plans see Note J of the Notes to Consolidated Financial Statements and “Equity Compensation Plan Information” included in Part III, Item 12, Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters, in this Annual Report.
PERFORMANCE GRAPH
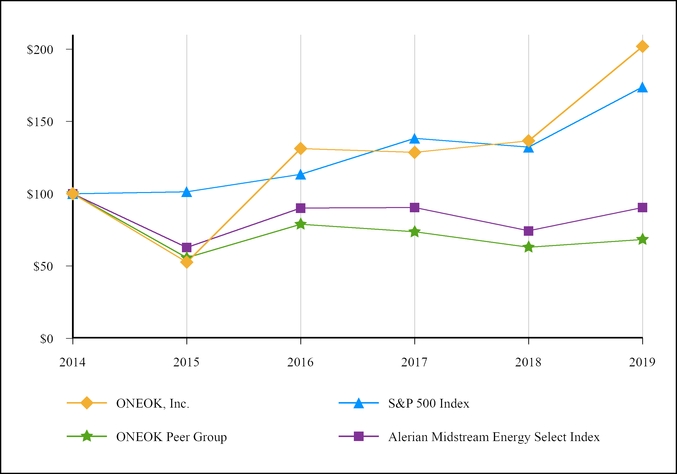
The following performance graph compares the performance of our common stock with the S&P 500 Index, the Alerian Midstream Energy Select Index and a ONEOK Peer Group during the period beginning on December 31, 2014, and ending on December 31, 2019.
The graph assumes a $100 investment in our common stock and in each of the indices at the beginning of the period and a reinvestment of dividends paid on such investments throughout the period.
Value of $100 Investment, Assuming Reinvestment of Distributions/Dividends,
at December 31, 2014**, and at the End of Every Year Through December 31,** 2019**.**
| Cumulative Total Return | ||||||||||||||||||||
| Years Ended December 31, | ||||||||||||||||||||
| 2015 | 2016 | 2017 | 2018 | 2019 | ||||||||||||||||
| ONEOK, Inc. | $ | 52.64 | $ | 131.26 | $ | 128.53 | $ | 136.60 | $ | 201.86 | ||||||||||
| S&P 500 Index | $ | 101.37 | $ | 113.49 | $ | 138.26 | $ | 132.19 | $ | 173.80 | ||||||||||
| ONEOK Peer Group (a) | $ | 55.66 | $ | 78.90 | $ | 73.65 | $ | 63.01 | $ | 68.41 | ||||||||||
| Alerian Midstream Energy Select Index (b) | $ | 62.86 | $ | 90.08 | $ | 90.52 | $ | 74.34 | $ | 90.52 |
(a) - The ONEOK Peer Group is composed of the following companies: DCP Midstream, LP; Enable Midstream Partners, LP; Energy Transfer LP.; EnLink Midstream, LLC; Enterprise Products Partners L.P.; Kinder Morgan, Inc.; Magellan Midstream Partners, L.P.; MPLX LP; NuStar Energy L.P.; Plains All American Pipeline, L.P.; Targa Resources Corp.; and The Williams Companies, Inc.
(b) - The Alerian Midstream Energy Select Index measures the composite performance of approximately 35 North American energy infrastructure companies who are engaged in midstream activities involving energy commodities.
Item 6. SELECTED FINANCIAL DATA
The following table sets forth our selected financial data for the periods indicated:
| Years Ended December 31, | ||||||||||||||||||||
| 2019 | 2018 | 2017 | 2016 | 2015 | ||||||||||||||||
| (Millions of dollars, except per share data) | ||||||||||||||||||||
| Revenues | $ | 10,164.4 | $ | 12,593.2 | $ | 12,173.9 | $ | 8,920.9 | $ | 7,763.2 | ||||||||||
| Net income | $ | 1,278.6 | $ | 1,155.0 | $ | 593.5 | $ | 743.5 | $ | 379.2 | ||||||||||
| Total assets | $ | 21,812.1 | $ | 18,231.7 | $ | 16,845.9 | $ | 16,138.8 | $ | 15,446.1 | ||||||||||
| Long-term debt, including current maturities | $ | 12,487.4 | $ | 9,381.0 | $ | 8,524.3 | $ | 8,330.6 | $ | 8,434.2 | ||||||||||
| Earnings per share - total | ||||||||||||||||||||
| Basic | $ | 3.09 | $ | 2.80 | $ | 1.30 | $ | 1.67 | $ | 1.17 | ||||||||||
| Diluted | $ | 3.07 | $ | 2.78 | $ | 1.29 | $ | 1.66 | $ | 1.16 | ||||||||||
| Dividends declared per share of common stock | $ | 3.53 | $ | 3.245 | $ | 2.72 | $ | 2.46 | $ | 2.43 |
Changes in commodity prices and sales volumes affect both revenue and cost of sales and fuel, and, therefore, the changes in revenue in the above table are largely offset in cost of sales and fuel.
In 2019, we completed underwritten public offerings of $1.25 billion and $2.0 billion senior unsecured notes in March and August, respectively, primarily to fund our capital-growth projects.
Upon adoption of Topic 606 in January 2018, we determined that certain Natural Gas Gathering and Processing segment POP with fee contracts and Natural Gas Liquids segment exchange services contracts that include the purchase of commodities are supplier contracts. Contractual fees in these identified contracts are recorded as a reduction of the commodity purchase price in cost of sales and fuel. In 2017 and prior periods, these fees were recorded as services revenue.
In the fourth quarter 2017, we recorded a one-time noncash charge to net income through income tax expense of $141.3 million, related to the revaluation of our deferred tax balances and a valuation allowance on certain state net operating loss and tax credit carryforwards resulting from the enactment of the Tax Cuts and Jobs Act. For more information, see Note L in the Notes to the Consolidated Financial Statements in this Annual Report.
Also in 2017, we incurred a $20.0 million noncash expense related to our Series E Preferred Stock contribution to the Foundation and operating costs related to the Merger Transaction of $30.0 million.
We recorded noncash impairment charges of $20.2 million and $264.3 million in 2017 and 2015, respectively.
| ITEM 7. | MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS |
The following discussion and analysis should be read in conjunction with Part I, Item 1, Business, our audited Consolidated Financial Statements and the Notes to Consolidated Financial Statements in this Annual Report.
RECENT DEVELOPMENTS
Please refer to the “Financial Results and Operating Information” and “Liquidity and Capital Resources” sections of Management’s Discussion and Analysis of Financial Condition and Results of Operations in this Annual Report for additional information.
Market Conditions - Volumes increased across our system in our Natural Gas Gathering and Processing and Natural Gas Liquids segments in 2019, compared with 2018, which resulted in higher fee-based earnings, primarily as a result of our completed capital-growth projects, continued drilling and producer improvements in production due to enhanced completion techniques, offset partially by natural production declines.
We experienced fluctuating NGL location price differentials due to increased supply, increased demand in the Mid-Continent region, infrastructure constraints and slower demand growth in the Gulf Coast due primarily to delays in the startup of petrochemical facilities and constrained NGL export facilities. The Conway-to-Mont Belvieu OPIS price differential for ethane in ethane/propane mix averaged $0.07 per gallon in 2019, compared with $0.15 per gallon in 2018, which resulted in lower
earnings from our optimization and marketing activities in our Natural Gas Liquids segment. We expect narrower NGL location price differentials in 2020.
Ethane Opportunity - Ethane volumes under long-term contracts delivered to our NGL system averaged 385 MBbl/d in 2019, compared with 380 MBbl/d in 2018, and have generally been increasing since 2017, primarily as a result of NGL demand increasing from exports and petrochemical companies completing ethylene production projects and plant expansions. Our NGL capital-growth projects are expected to help alleviate system constraints, enabling additional NGLs, including ethane, to reach the Mont Belvieu, Texas, market center.
Northern Border Pipeline, which provides key natural gas takeaway capacity out of the Williston Basin, recently notified shippers that it plans to place restrictions on the Btu content of the residue natural gas it receives in order to meet downstream pipeline specifications. When these restrictions take effect, natural gas processors in the Williston Basin may recover incremental ethane into the NGL stream in order to lower the Btu content of the residue natural gas delivered to Northern Border Pipeline. As a result, ethane deliveries to our NGL system may increase.
Growth Projects - Our announced large capital-growth projects that have recently been completed or are currently under construction are outlined in the tables below:
| Project | Scope | Approximate Costs (a) | Expected Completion |
| Natural Gas Gathering and Processing | (In millions) | ||
| Demicks Lake I plant and related infrastructure | 200 MMcf/d processing plant and related gathering infrastructure in the core of the Williston Basin | $400 | Completed October 2019 |
| Supported by acreage dedications with long-term primarily fee-based contracts | |||
| Demicks Lake II plant and related infrastructure | 200 MMcf/d processing plant and related gathering infrastructure in the core of the Williston Basin | $410 | Completed January 2020 |
| Supported by acreage dedications with long-term primarily fee-based contracts | |||
| Bear Creek plant expansion and related infrastructure | 200 MMcf/d processing plant expansion and related gathering infrastructure in the Williston Basin | $405 | First Quarter 2021 |
| Supported by acreage dedications with long-term primarily fee-based contracts | |||
| Demicks Lake III plant and related infrastructure | 200 MMcf/d processing plant and related gathering infrastructure in the core of the Williston Basin | $305 | Third Quarter 2021 |
| Supported by acreage dedications with primarily fee-based contracts | |||
| (a) - Excludes capitalized interest/AFUDC. |
| Project | Scope | Approximate Costs (a) | Expected Completion |
| Natural Gas Liquids | |||
| Elk Creek pipeline and related infrastructure | 900-mile NGL pipeline from the Williston Basin to the Mid-Continent region, with capacity of up to 240 MBbl/d, and related infrastructure | $1,400 | Completed December 2019 (b) |
| A |
Showing the first 8K of 87K characters. Open the full section
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
Our exposure to market risk discussed below includes forward-looking statements and represents an estimate of possible changes in future earnings that could occur assuming hypothetical future movements in interest rates or commodity prices. Our views on market risk are not necessarily indicative of actual results that may occur and do not represent the maximum possible gains and losses that may occur since actual gains and losses will differ from those estimated based on actual fluctuations in interest rates or commodity prices and the timing of transactions.
We are exposed to market risk due to commodity price and interest-rate volatility. Market risk is the risk of loss arising from adverse changes in market rates and prices. We may use financial instruments, including forward sales, swaps, options and futures, to manage the risks of certain identifiable or anticipated transactions and achieve more predictable cash flows. Our risk-management function follows established policies and procedures to monitor our natural gas, condensate and NGL
marketing activities and interest rates to ensure our hedging activities mitigate market risks. We do not use financial instruments for trading purposes.
See Note A of the Notes to Consolidated Financial Statements in this Annual Report for discussion on our accounting policies for our derivative instruments and the impact on our Consolidated Financial Statements.
COMMODITY PRICE RISK
As part of our hedging strategy, we use commodity derivative financial instruments and physical-forward contracts described in Note C of the Notes to Consolidated Financial Statements in this Annual Report to reduce the impact of near-term price fluctuations of natural gas, NGLs and condensate.
Although our businesses are primarily fee-based, in our Natural Gas Gathering and Processing segment, we are exposed to commodity price risk as a result of retaining a portion of the commodity sales proceeds associated with our POP with fee contracts. Under certain POP with fee contracts, our contractual fees and POP percentage may increase or decrease if production volumes, delivery pressures or commodity prices change relative to specified thresholds. We are exposed to basis risk between the various production and market locations where we buy and sell commodities.
The following tables set forth hedging information for our Natural Gas Gathering and Processing segment’s forecasted equity volumes for the periods indicated:
| Year Ending December 31, 2020 | ||||||||||
| Volumes Hedged | Average Price | Percentage Hedged | ||||||||
| NGLs - excluding ethane (MBbl/d) - Conway/Mont Belvieu | 10.3 | $ | 0.55 | / gallon | 63% | |||||
| Condensate (MBbl/d) - WTI-NYMEX | 3.0 | $ | 54.08 | / Bbl | 62% | |||||
| Natural gas (BBtu/d) - NYMEX and basis | 125.0 | $ | 2.39 | / MMBtu | 76% |
| Year Ending December 31, 2021 | ||||||||||
| Volumes Hedged | Average Price | Percentage Hedged | ||||||||
| Natural gas (BBtu/d) - NYMEX and basis | 36.4 | $ | 2.43 | / MMBtu | 19% |
Our Natural Gas Gathering and Processing segment’s commodity price sensitivity is estimated as a hypothetical change in the price of NGLs, crude oil and natural gas at December 31, 2019. Condensate sales are typically based on the price of crude oil. Assuming normal operating conditions, we estimate the following for our forecasted equity volumes:
| • | a $0.01 per gallon change in the composite price of NGLs, excluding ethane, would change adjusted EBITDA for the years ending December 31, 2020 and 2021, by $2.5 million and $3.0 million, respectively; |
| • | a $1.00 per barrel change in the price of crude oil would change adjusted EBITDA for the years ending December 31, 2020 and 2021, by $1.5 million and $1.8 million, respectively; and |
| • | a $0.10 per MMBtu change in the price of residue natural gas would change adjusted EBITDA for the years ending December 31, 2020 and 2021, by $6.1 million and $7.1 million, respectively. |
These estimates do not include any effects of hedging or effects on demand for our services or natural gas processing plant operations that might be caused by, or arise in conjunction with, commodity price fluctuations. For example, a change in the gross processing spread may cause a change in the amount of ethane extracted from the natural gas stream, impacting gathering and processing financial results for certain contracts.
INTEREST-RATE RISK
We are exposed to interest-rate risk through borrowings under our $2.5 Billion Credit Agreement, $1.5 Billion Term Loan Agreement, commercial paper program and long-term debt issuances. Future increases in LIBOR or the established replacement rate, commercial paper rates or bond rates could expose us to increased interest costs on future borrowings. We manage interest-rate risk through the use of fixed-rate debt, floating-rate debt and interest-rate swaps. Interest-rate swaps are agreements to exchange interest payments at some future point based on specified notional amounts. In 2019, we entered into $625 million of forward-starting interest-rate swaps to hedge the variability of interest payments on a portion of our forecasted debt issuances that may result from changes in the benchmark interest rate before the debt is issued. We also settled $1.8
billion of our forward-starting interest-rate swaps related to our underwritten public offering of $1.25 billion senior unsecured notes in March 2019 and $2.0 billion senior unsecured notes in August 2019.
At December 31, 2019 and 2018, we had forward-starting interest-rate swaps with notional amounts totaling $1.8 billion and $3.0 billion, respectively, to hedge the variability of interest payments on a portion of our forecasted debt issuances. At December 31, 2019 and 2018, we had interest-rate swaps with notional amounts totaling $1.3 billion to hedge the variability of our LIBOR-based interest payments. All of our interest-rate swaps are designated as cash flow hedges. At December 31, 2019, we had derivative assets of $0.6 million and derivative liabilities of $201.9 million related to these interest-rate swaps. At December 31, 2018, we had derivative assets of $19.0 million and derivative liabilities of $99.3 million related to these interest-rate swaps.
See Note C of the Notes to Consolidated Financial Statements in this Annual Report for more information on our hedging activities.
COUNTERPARTY CREDIT RISK
We assess the creditworthiness of our counterparties on an ongoing basis and require security, including prepayments and other forms of collateral, when appropriate. Certain of our counterparties may be impacted by a relatively low commodity price environment and could experience financial problems, which could result in nonpayment and/or nonperformance, which could impact adversely our results of operations.
Customer concentration - In 2019, no single customer represented more than 10% of our consolidated revenues.
Natural Gas Gathering and Processing - Our Natural Gas Gathering and Processing segment derives services revenue primarily from major and independent crude oil and natural gas producers, which include both large integrated and independent exploration and production companies. In this segment, our downstream commodity sales customers are primarily utilities, large industrial companies, marketing companies and our NGL affiliate. We are not typically exposed to material credit risk with producers under POP with fee contracts as we sell the commodities and remit a portion of the sales proceeds back to the producer less our contractual fees. In 2019 and 2018, approximately 90% and 95%, respectively, of the downstream commodity sales in our Natural Gas Gathering and Processing segment were made to investment-grade customers, as rated by S&P, Moody’s or our comparable internal ratings, or were secured by letters of credit or other collateral.
Natural Gas Liquids - Our Natural Gas Liquids segment’s counterparties are primarily NGL and natural gas gathering and processing companies; major and independent crude oil and natural gas production companies; utilities; large industrial companies; natural gasoline distributors; propane distributors; municipalities; and petrochemical, refining and marketing companies. We charge fees to NGL and natural gas gathering and processing counterparties and NGL pipeline transportation customers. We are not typically exposed to material credit risk on the majority of our exchange services fees, as we purchase NGLs from our gathering and processing counterparties and deduct our fee from the amounts we remit. We also earn sales revenue on the downstream sales of NGL products. In 2019 and 2018, approximately 80% of this segment’s commodity sales were made to investment-grade customers, as rated by S&P, Moody’s or our comparable internal ratings, or were secured by letters of credit or other collateral. In addition, the majority of our Natural Gas Liquids segment’s pipeline tariffs provide us the ability to require security from shippers.
Natural Gas Pipelines - Our Natural Gas Pipelines segment’s customers are primarily local natural gas distribution companies, electric-generation facilities, large industrial companies, municipalities, producers, processors and marketing companies. In 2019 and 2018, approximately 85% of our revenues in this segment were from investment-grade customers, as rated by S&P, Moody’s or our comparable internal ratings, or were secured by letters of credit or other collateral. In addition, the majority of our Natural Gas Pipelines segment’s pipeline tariffs provide us the ability to require security from shippers.
This page intentionally left blank.
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
Report of Independent Registered Public Accounting Firm
To the Board of Directors and Shareholders of ONEOK, Inc.:
Opinions on the Financial Statements and Internal Control over Financial Reporting
We have audited the accompanying consolidated balance sheets of ONEOK, Inc. and its subsidiaries (the “Company”) as of December 31, 2019 and 2018, and the related consolidated statements of income, of comprehensive income, of changes in equity and of cash flows for each of the three years in the period ended December 31, 2019, including the related notes (collectively referred to as the “consolidated financial statements”). We also have audited the Company’s internal control over financial reporting as of December 31, 2019, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, 2019 and 2018, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2019 in conformity with accounting principles generally accepted in the United States of America. Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2019, based on criteria established in Internal Control - Integrated Framework (2013) issued by the COSO.
Change in Accounting Principle
As discussed in Notes A and P to the consolidated financial statements, the Company changed the manner in which it accounts for revenue from contracts with customers in 2018.
Basis for Opinions
The Company’s management is responsible for these consolidated financial statements, for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting, included in Management’s Report on Internal Control over Financial Reporting appearing under Item 9A. Our responsibility is to express opinions on the Company’s consolidated financial statements and on the Company’s internal control over financial reporting based on our audits. We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) (PCAOB) and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audits to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement, whether due to error or fraud, and whether effective internal control over financial reporting was maintained in all material respects.
Our audits of the consolidated financial statements included performing procedures to assess the risks of material misstatement of the consolidated financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the consolidated financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the consolidated financial statements. Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audits also included performing such other procedures as we considered necessary in the circumstances. We believe that our audits provide a reasonable basis for our opinions.
Definition and Limitations of Internal Control over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (i) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (ii) provide reasonable assurance that transactions are recorded as necessary to
permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (iii) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Critical Audit Matters
The critical audit matter communicated below is a matter arising from the current period audit of the consolidated financial statements that was communicated or required to be communicated to the audit committee and that (i) relates to accounts or disclosures that are material to the consolidated financial statements and (ii) involved our especially challenging, subjective, or complex judgments. The communication of critical audit matters does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit matter below, providing a separate opinion on the critical audit matter or on the accounts or disclosures to which it relates.
Valuation of Level 3 Commodity Derivative Assets and Liabilities
As described in Notes A, B and C to the consolidated financial statements, the Company’s level 3 commodity derivative assets and liabilities total $55.6 million and $24.8 million, respectively, as of December 31, 2019. As disclosed by management, commodity price risk includes basis risk, which is the difference in price between various locations where commodities are purchased and sold. Management records all derivative instruments at fair value, except for normal purchases and normal sales transactions that are expected to result in physical delivery. Many of the contracts in its derivative portfolio are executed in liquid markets where price transparency exists. Fair value measurements classified as Level 3 are comprised predominantly of exchange-cleared and over-the-counter derivatives to hedge NGL price risk and natural gas basis risk between various transaction locations and the NYMEX Henry Hub. These measurements are based on inputs that may include one or more unobservable inputs, including internally developed commodity price curves, that incorporate market data from broker quotes and third-party pricing services. The commodity derivatives are generally valued using forward quotes provided by third-party pricing services that are validated with other market data.
The principal considerations for our determination that performing procedures relating to the valuation of level 3 commodity derivative assets and liabilities is a critical audit matter are there was significant estimation by manage
Showing the first 8K of 253K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND
FINANCIAL DISCLOSURE
None.
Item 9A. CONTROLS AND PROCEDURES
Evaluation of Disclosure Controls and Procedures
Our Chief Executive Officer (Principal Executive Officer) and Chief Financial Officer (Principal Financial Officer) have concluded that our disclosure controls and procedures were effective as of the end of the period covered by this report based on the evaluation of the controls and procedures required by Rules 13a-15(e) and 15d-15(e) of the Exchange Act.
Management’s Report on Internal Control Over Financial Reporting
Our management is responsible for establishing and maintaining adequate internal control over financial reporting, as such term is defined in Exchange Act Rule 13a-15(f). Under the supervision and with the participation of our management, including our Principal Executive Officer and Principal Financial Officer, we evaluated the effectiveness of our internal control over financial reporting based on the framework in Internal Control-Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission. Because of inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate. Based on our evaluation under that framework, our management concluded that our internal control over financial reporting was effective as of December 31, 2019.
The effectiveness of our internal control over financial reporting as of December 31, 2019, has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in their report which is included herein (Item 8).
Changes in Internal Control Over Financial Reporting
There have been no changes in our internal control over financial reporting during the quarter ended December 31, 2019, that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
Item 9B. OTHER INFORMATION
Not applicable.
PART III
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
Directors of the Registrant
Information concerning our directors is set forth in our 2020 definitive Proxy Statement and is incorporated herein by this reference.
Executive Officers of the Registrant
Information concerning our executive officers is included in Part I, Item 1, Business, of this Annual Report.
Compliance with Section 16(a) of the Exchange Act
Information on compliance with Section 16(a) of the Exchange Act is set forth in our 2020 definitive Proxy Statement and is incorporated herein by this reference.
Code of Ethics
Information concerning the code of ethics, or code of business conduct, is set forth in our 2020 definitive Proxy Statement and is incorporated herein by this reference.
Nominating Committee Procedures
Information concerning the Nominating Committee procedures is set forth in our 2020 definitive Proxy Statement and is incorporated herein by this reference.
Audit Committee
Information concerning the Audit Committee is set forth in our 2020 definitive Proxy Statement and is incorporated herein by this reference.
Audit Committee Financial Experts
Information concerning the Audit Committee Financial Experts is set forth in our 2020 definitive Proxy Statement and is incorporated herein by this reference.
Item 11. EXECUTIVE COMPENSATION
Information on executive compensation is set forth in our 2020 definitive Proxy Statement and is incorporated herein by this reference.
| ITEM 12. | SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS |
Security Ownership of Certain Beneficial Owners
Information concerning the ownership of certain beneficial owners is set forth in our 2020 definitive Proxy Statement and is incorporated herein by this reference.
Security Ownership of Management
Information on security ownership of directors and officers is set forth in our 2020 definitive Proxy Statement and is incorporated herein by this reference.
Equity Compensation Plan Information
The following table sets forth certain information concerning our equity compensation plans as of December 31, 2019:
| Number of Securities to be Issued Upon Exercise of Outstanding Options, Warrants and Rights | Weighted-Average Exercise Price of Outstanding Options, Warrants and Rights | Number of Securities Remaining Available For Future Issuance Under Equity Compensation Plans (Excluding Securities in Column (a)) | |||||||||||
| Plan Category | (a) | (b) (3) | (c) | ||||||||||
| Equity compensation plans approved by security holders (1) | 2,076,295 | $ | 64.33 | 8,960,329 | |||||||||
| Equity compensation plans not approved by security holders (2) | 350,029 | $ | 75.67 | — | |||||||||
| Total | 2,426,324 | $ | 65.96 | 8,960,329 |
(1) - Includes shares granted under our Employee Stock Purchase Plan and Employee Stock Award Program and restricted stock incentive unit awards and performance unit awards granted under our former Long-Term Incentive Plan, our former Equity Compensation Plan and our Equity Incentive Plan. For a brief description of the material features of these plans, see Note J of the Notes to Consolidated Financial Statements in this Annual Report. Column (a) includes shares based on 100% of the performance units vesting at the end of the three-year performance period. Column (c) includes 1,211,710, 133,075 and 7,615,544 shares available for future issuance under our Employee Stock Purchase Plan, Employee Stock Award Program and Equity Incentive Plan, respectively.
(2) - Includes our NQDC Plan, Deferred Compensation Plan for Non-Employee Directors and our former Stock Compensation Plan for Non-Employee Directors. For a brief description of the material features of these plans, see Note J of the Notes to Consolidated Financial Statements in this Annual Report.
(3) - Compensation deferred into our common stock under our former Equity Compensation Plan and our Deferred Compensation Plan for Non-Employee Directors is distributed to participants at fair market value on the date of distribution. The price used for these plans to calculate the weighted-average exercise price in the table is $75.67, which represents the 2019 year-end closing price of our common stock on the NYSE.
| ITEM 13. | CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE |
Information on certain relationships and related transactions and director independence is set forth in our 2020 definitive Proxy Statement and is incorporated herein by this reference.
Item 14. PRINCIPAL ACCOUNTING FEES AND SERVICES
Information concerning the principal accountant’s fees and services is set forth in our 2020 definitive Proxy Statement and is incorporated herein by this reference.
PART IV
Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES
| (1) Financial Statements | Page No. | ||
| (a) | Report of Independent Registered Public Accounting Firm | 54-55 | |
| (b) | Consolidated Statements of Income for the years ended December 31, 2019, 2018 and 2017 | 56 | |
| (c) | Consolidated Statements of Comprehensive Income for the years ended December 31, 2019, 2018 and 2017 | 57 | |
| (d) | Consolidated Balance Sheets as of December 31, 2019 and 2018 | 58-59 | |
| (e) | Consolidated Statements of Cash Flows for the years ended December 31, 2019, 2018 and 2017 | 61 | |
| (f) | Consolidated Statements of Changes in Equity for the years ended December 31, 2019, 2018 and 2017 | 62-63 | |
| (g) | Notes to Consolidated Financial Statements | 64-111 | |
| (2) Financial Statements Schedules | |||
| All schedules have been omitted because of the absence of conditions under which they are required. |
Attached as Exhibit 101 to this Annual Report are the following XBRL-related documents: (i) Document and Entity Information; (ii) Consolidated Statements of Income for the years ended December 31, 2019, 2018 and 2017; (iii) Consolidated Statements of Comprehensive Income for the years ended December 31, 2019, 2018 and 2017; (iv) Consolidated Balance Sheets at December 31, 2019 and 2018; (v) Consolidated Statements of Cash Flows for the years ended December 31, 2019, 2018 and 2017; (vi) Consolidated Statements of Changes in Equity for the years ended December 31, 2019, 2018 and 2017; and (vii) Notes to Consolidated Financial Statements.
Item 16. FORM 10-K SUMMARY
None.
Signatures
Pursuant to the requirements of Section 13 or 15(d) of the Exchange Act, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| ONEOK, Inc. | ||
| Registrant | ||
| Date: February 25, 2020 | By: | /s/ Walter S. Hulse III |
| Walter S. Hulse III | ||
| Chief Financial Officer, Treasurer and | ||
| Executive Vice President, Strategic Planning | ||
| and Corporate Affairs | ||
| (Principal Financial Officer) |
Pursuant to the requirements of the Exchange Act, this report has been signed below by the following persons on behalf of the registrant and in the capacities indicated on this 25th day of February 2020.
| /s/ John W. Gibson | /s/ Terry K. Spencer | ||
| John W. Gibson | Terry K. Spencer | ||
| Chairman of the Board | President, Chief Executive Officer and | ||
| Director | |||
| /s/ Walter S. Hulse III | /s/ Mary M. Spears | ||
| Walter S. Hulse III | Mary M. Spears | ||
| Chief Financial Officer, Treasurer and | Vice President and | ||
| Executive Vice President, Strategic | Chief Accounting Officer | ||
| Planning and Corporate Affairs | |||
| /s/ Brian L. Derksen | /s/ Julie H. Edwards | ||
| Brian L. Derksen | Julie H. Edwards | ||
| Director | Director | ||
| /s/ Mark W. Helderman | /s/ Randall J. Larson | ||
| Mark W. Helderman | Randall J. Larson | ||
| Director | Director | ||
| /s/ Steven J. Malcolm | /s/ Jim W. Mogg | ||
| Steven J. Malcolm | Jim W. Mogg | ||
| Director | Director | ||
| /s/ Pattye L. Moore | /s/ Gary D. Parker | ||
| Pattye L. Moore | Gary D. Parker | ||
| Director | Director | ||
| /s/ Eduardo A. Rodriguez | |||
| Eduardo A. Rodriguez | |||
| Director | |||