 filings.tools
Regency Centers (REG) 10-K risk factor changes: FY2017 vs FY2016
The 2017-12-31 10-K against the 2016-12-31 one, compared heading by heading and sentence by sentence. One of these filings carries no fiscal year tag, so its year is the calendar year of the period end.
Item 1A136 rewritten104 added195 removed219 unchanged
All filing items1,717 rewritten1,562 added1,189 removed2,202 unchanged
Summary
counted, not written
- Item 1A headings could not be compared: only 0 carried over between the two years, which usually means one filing was read wrongly, so none is reported as new or removed.
- Sentence by sentence, 1,562 added, 1,189 removed, 1,717 rewritten and 2,202 unchanged across 18 items that differ.
- New this year: Item 5. Market for the Registrant's Common Equity, Related Stockholder Matters, and Issuer Purchases of Equity Securities; Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
Sentences by item
21 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2017; struck-through words were in FY2016. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors
136 rewritten, 104 added, 195 removed, 219 unchanged
Read the full itemFY2017 item · filed February 27, 2018FY2016 item · filed February 27, 2017
[removed: At the effective time] [added: As a result] of [removed: the merger,] [added: our merger with Equity One, Inc.,] the Gazit Parties [removed: will become] [added: became] significant stockholders of Regency Centers and may have interests that are different [removed: from, or are in addition to, Regency Centers or] [added: from] our other [removed: stockholders in the future.][added: stockholders.]
[removed: At the effective time of the merger,] Mr. Chaim Katzman and Gazit-Globe, Ltd. and certain of its affiliated entities ("the Gazit Parties") [removed: will] own [removed: approximately 13%] [added: less than 10%] of outstanding shares of our common [removed: stock, based on their ownership of approximately 34% of the Equity One common stock as of November 14, 2016.][added: stock.]
This concentration of ownership in one group of stockholders [removed: could] [added: may] potentially be disadvantageous to the interests of our other stockholders.
[removed: For example, if the Gazit Parties were to sell or otherwise transfer all or a large percentage] [added: Continued sales] of [removed: their holdings,] our [added: shares may cause volatility in our] stock [removed: price could decline,] [added: price,] and we [removed: could] [added: may] find it more expensive to raise capital, if needed, through the sale of additional equity securities.
[removed: The governance agreement also provides that in] [added: However, so long as] the [removed: event of Mr. Katzman’s death, disability, resignation or removal,] [added: Gazit Parties beneficially own 7%] or [removed: failure] [added: more] of [removed: Mr. Katzman to be re-elected,] [added: our outstanding common stock,] the Gazit Parties will have the right to designate another person to be appointed to our board of directors, which person must be reasonably acceptable to our board of directors.
Risk Factors Related to [removed: Our Industry and] Real Estate Investments [added: and Operations]
[removed: A shift in retail shopping from brick] [added: The integration of bricks] and mortar stores [removed: to] [added: and] e-commerce [added: by retailers and a continued shift in retail sales towards e-commerce] may [removed: have an adverse] [added: adversely] impact [removed: on] our revenues and cash [removed: flow.][added: flows.]
This shift [removed: could] [added: may] adversely impact our occupancy and rental rates, which would impact our revenues and cash flows.
[removed: Our] [added: Therefore, our] performance [removed: therefore is generally] [added: and operating results are directly] linked to [added: the] economic [added: and market] conditions [added: occurring] in the [removed: market for] retail [removed: space.][added: industry.]
The market for [added: leasing] retail space [removed: could] [added: in our properties may] be adversely affected by any of the following:
| • | [removed: continued] consolidation [removed: in] [added: within] the retail sector; |
| • | [removed: reduction in the demand by tenants to occupy our shopping centers as a result of] reduced consumer demand for certain retail categories; |
| • | [removed: consequences of any] armed [removed: conflict involving, or terrorist attack against,] [added: conflicts against] the United States. |
To the extent that any of these conditions [removed: occur,] [added: occur] they are likely to impact [added: the retail industry, our retail tenants, the demand and] market rents for retail space, [removed: occupancy in] the [removed: operating portfolio,] [added: occupancy levels of] our [added: properties, our] ability to sell, acquire or develop properties, [added: our operating results] and our cash available for distributions to stock and unit holders.
[removed: The economic] [added: Economic] conditions in markets [removed: in which] [added: where] our properties are concentrated [added: can] greatly influence our financial performance.
During the year ended December 31, [removed: 2016,] [added: 2017,] our properties in California, Florida, and Texas accounted for [removed: 31.0%, 12.1%,] [added: 30.1%, 17.3%,] and [removed: 10.3%,] [added: 7.8%,] respectively, of our [removed: net operating income] [added: NOI] from Consolidated Properties plus our pro-rata share from Unconsolidated [removed: Properties ("pro-rata basis").]
Our revenues and cash [removed: available to pay expenses, maintain our properties, and for distributions to stock and unit holders could] [added: flow may] be adversely affected by this geographic concentration if market conditions, such as supply of or demand for retail space, deteriorate [added: more significantly] in California, Florida, or Texas [removed: relative] [added: compared] to other geographic areas.
Anchor [removed: tenants (those] [added: Tenants ("Anchor Tenants" or "Anchors"] occupying 10,000 square feet or more) occupy large [removed: amounts of square footage,] [added: stores in our shopping centers,] pay a significant portion of the total [removed: rents] [added: rent] at a property and contribute to the success of other tenants by [removed: drawing significant numbers of customers] [added: attracting shoppers] to [removed: a] [added: the] property.
We derive significant revenues from anchor tenants such as [removed: Kroger,] Publix, [removed: and] [added: Kroger,] Albertsons/Safeway, [added: TJX Companies, and Whole Foods] who accounted for [removed: 4.7%,] 3.1%, [added: 3.1%, 2.9%, 2.4%,] and [removed: 2.7%,] [added: 2.3%,] respectively, of our total annualized base rent on a pro-rata basis, for the year ended December 31, [removed: 2016.][added: 2017.]
Our net income [removed: could] [added: and cash flow may] be adversely affected by the loss of revenues [added: and additional costs] in the event a significant [added: anchor] tenant:
| • | does not renew its leases as they expire; [removed: or] |
Some anchors have the right to vacate [added: their space] and [added: may] prevent [added: us from] re-tenanting by [removed: paying] [added: continuing to comply and pay] rent [removed: for the balance of the] [added: in accordance with their] lease [removed: term.][added: agreement.]
Vacated anchor space, including space owned by the anchor, can reduce rental revenues generated by the shopping center [added: in other spaces] because of the loss of the departed [removed: anchor tenant's] [added: anchor's] customer drawing power.
A significant percentage of our revenues are derived from smaller shop [added: space] tenants and our net income [removed: could] [added: may] be adversely impacted if our smaller shop tenants are not successful.
A significant percentage of our revenues are derived from smaller shop [added: space] tenants [removed: (those] [added: ("Shop Space Tenants"] occupying less than 10,000 square feet).
[removed: Smaller shop tenants] [added: Shop Space Tenants] may be more vulnerable to negative economic conditions as they have more limited resources than [removed: larger tenants.][added: Anchor Tenants.]
The types of [removed: smaller shop tenants] [added: Shop Space Tenants] vary from retail shops [added: and restaurants] to service providers.
If we are unable to attract the right type or mix of [removed: smaller shop tenants] [added: Shop Space Tenants] into our centers, our [removed: net income could] [added: revenues and cash flow may] be adversely impacted.
At December 31, [removed: 2016, shop space represents] [added: 2017, Shop Space Tenants represent] approximately [removed: 38%] [added: 36%] of our GLA [removed: and is] leased at average base rents of [removed: $31] [added: $32] PSF.
A one-percent decline in our shop space occupancy [removed: could] [added: may] result in a reduction to minimum rent of approximately [removed: $8.6] [added: $4.7] million.
Although minimum rent [removed: is] [added: and recoveries from tenants are] supported by long-term lease contracts, tenants who file bankruptcy have the legal right to reject any or all of their leases and close related stores.
In the event that a tenant with a significant number of leases in our shopping centers files bankruptcy and rejects its leases, we [removed: could] [added: may] experience a significant reduction in our revenues and may not be able to collect all pre-petition amounts owed by [removed: that party.][added: the bankrupt tenant.]
Our real estate assets may [added: decline in value and] be subject to impairment [removed: charges.][added: losses which may reduce our net income.]
Our [removed: long-lived assets, primarily] real estate [removed: held for investment,] [added: properties] are carried at cost unless circumstances indicate that the carrying value of [removed: the] [added: these] assets may not be recoverable.
We evaluate whether there are any indicators, including property operating performance and general market conditions, such that the value of the real estate properties (including any related [removed: amortizable] [added: tangible or] intangible assets or [removed: liabilities)] [added: liabilities and goodwill)] may not be recoverable.
These key assumptions are subjective in nature and [removed: could] [added: may] differ materially from actual results.
Changes in our disposition strategy or changes in the marketplace may alter the holding period of an asset or asset group, which may result in an impairment loss and such loss [removed: could] [added: may] be material to the Company's financial condition or operating performance.
The fair value of real estate assets is subjective and is determined through [added: the use of] comparable sales information and other market data if available, or through use of an income approach such as the direct capitalization method or the traditional discounted cash flow approach.
Changes in [removed: those] [added: these] factors [removed: could] [added: may] impact the determination of fair value.
These subjective assessments have a direct impact on our net income because recording an impairment charge results in an immediate negative adjustment to net [removed: income.][added: income, which may be material.]
Risk Factors Related to the Retail Industry
Economic and market conditions may adversely affect the retail industry and consequently reduce our revenues and cash flow, and increase our operating expenses.
Our properties are leased primarily to retail tenants from whom we derive most of our revenue in the form of minimum rent, expense recoveries and other income.
| • | changes in national, regional and local economic conditions; |
| • | deterioration in the competitiveness and creditworthiness of our retail tenants; |
| • | increased competition from the use of e-commerce by retailers and consumers as well as other concepts such as super-stores and warehouse clubs; |
| • | tenant bankruptcies and subsequent rejections of our leases; |
| • | reductions in consumer spending and retail sales; |
| • | reduced tenant demand for retail space; |
| • | oversupply of retail space; |
| • | increased operating costs; |
| • | perceptions by retailers and shoppers of the safety, convenience and attractiveness of our properties; |
| • | casualties, natural disasters and terrorist attacks; and |
The recent merger of Amazon.com with Whole Foods Market, Inc. highlights the increasing impact of e-commerce on retailers and changes in customer buying habits, including curbside pick-up of items ordered on line and home delivery of food kits, such as Blue Apron and HelloFresh.
Retailers are considering these e-commerce trends when making decisions regarding their bricks and mortar stores and how they will compete and innovate in a rapidly changing e-commerce environment.
Many retailers in our shopping centers provide services or sell goods, which have historically been less likely to be purchased online; however, the continuing increase in e-commerce sales in all retail categories may cause retailers to adjust the size or number of retail locations in the future or close stores.
Changes in shopping trends as a result of the growth in e-commerce may also impact the profitability of retailers that do not adapt to changes in market conditions.
These conditions may adversely impact our results of operations and cash flows if we are unable to meet the needs of our tenants or if our tenants encounter financial difficulties as a result of changing market conditions.
Our business is dependent on perceptions by retailers and shoppers of the safety, convenience and attractiveness of our retail properties.
We are dependent on perceptions by retailers or shoppers of the safety, convenience and attractiveness of our retail properties.
If retailers and shoppers perceive competing retail properties and other retailing options to be safer, more convenient, or of a higher quality, our revenues may be adversely affected.
Changing economic and retail market conditions in geographic areas where our properties are concentrated may reduce our revenues and cash flow.
Properties ("pro-rata basis").
| • | renews at lower rental rates and/or requires a tenant improvement allowance; or |
| • | renews, but reduces its store size, which results in down-time and additional tenant improvement costs to the landlord to release the vacated space. |
Shop Space Tenants are facing reductions in sales as a result of an increase in competition including from e-commerce retailers.
Certain Shop Space Tenants are incorporating e-commerce into their business strategies and may seek to reduce their store sizes upon lease expiration as they adjust to and implement alternative distribution channels.
Any unsecured claim we hold against a bankrupt tenant for unpaid rent might be paid only to the extent that funds are available and only in the same percentage as is paid to all other holders of unsecured claims.
As a result, it is likely that we would recover substantially less than the full value of any unsecured claims we hold.
Additionally, we may incur significant expense to recover our claim and to release the vacated space.
We are subject to numerous laws and regulations that may adversely affect our operations or expose us to liability.
Our properties are subject to numerous federal, state, and local laws and regulations, some of which may conflict with one another or be subject to varying judicial or regulatory interpretations.
These laws and regulations may include zoning laws, building codes, competition laws, rules and agreements, landlord-tenant laws, property tax regulations, changes in real estate assessments and other laws and regulations generally applicable to business operations.
Noncompliance with such laws and regulations, and any associated litigation may expose us to liability.
We face risks associated with development, redevelopment and expansion of properties.
We actively pursue opportunities for new retail development, or existing property redevelopment or expansion.
| • | a reduction in the demand for new retail space may reduce our future development activities, which in turn may reduce our net operating income; |
| • | a shift in our development and acquisition focus to mixed use properties in very dense urban locations (with or without joint venture or development partners for residential or office components), with differing tenant profiles or mixes, and/or multi-story buildings, all in select cases. |
We face risks associated with the acquisition of properties.
average household incomes and population densities.
Risks Relating to the Merger
The Merger may not be completed on the terms or timeline currently contemplated, or at all.
Although Regency Centers' stockholders and Equity One's stockholders approved the Merger in separate stockholder meetings on February 24, 2017, the completion of the merger is subject to certain conditions, including: (1) approval for listing on the NYSE of the common stock of Regency Centers to be issued in connection with the merger; (2) the registration statement for our shares being issued pursuant to the merger not being the subject of any stop order or proceeding seeking a stop order; (3) no injunction or law prohibiting the merger; (4) accuracy of each party’s representations, subject in most cases to materiality or material adverse effect qualifications; (5) material compliance with each party’s covenants; and (6) receipt by each of Equity One and Regency Centers of an opinion to the effect that the merger will qualify as a “reorganization” within the meaning of Section 368(a) of the Code and of an opinion that each of Equity One and Regency Centers qualify as a REIT under the Internal Revenue Code of 1986, as amended (the "Code").
Neither Equity One nor Regency Centers can provide assurances that the merger will be consummated on the terms or timeline currently contemplated, or at all.
The exchange ratio is fixed and will not be adjusted in the event of any change in either our or Equity One’s stock prices.
At the effective time of the Merger, each share of Equity One common stock (other than any shares owned directly by Regency Centers or Equity One and in each case not held on behalf of third parties) outstanding immediately prior to the effective time of the merger will be converted into the right to receive 0.45 of a newly issued share of our common stock, with cash paid in lieu of fractional shares.
The exchange ratio is fixed in the merger agreement and will not be adjusted for changes in the market price of either our common stock or Equity One common stock.
Changes in the price of our common stock prior to the merger will affect the market value of the merger consideration that Equity One stockholders will receive on the closing of the merger.
Stock price changes may result from a variety of factors (many of which are beyond the control of Regency Centers and Equity One), including the following factors:
| | |
| --- | --- |
| • | changes in the respective businesses, operations, assets, liabilities and prospects of either company; |
changes in market assessments of the business, operations, financial position and prospects of either company;
| | |
| --- | --- |
| • | market assessments of the likelihood that the merger will be completed; |
| | |
| --- | --- |
| • | interest rates, general market and economic conditions and other factors generally affecting the price of our common stock and Equity One common stock; |
| | |
| --- | --- |
| • | federal, state and local legislation, governmental regulation and legal developments in the businesses in which we and Equity One operate; and |
| | |
| --- | --- |
| • | other factors beyond the control of Regency Centers or Equity One, including those described under this “Risk Factors” heading. |
Our stockholders may be diluted by the merger.
The merger may dilute the ownership position of our stockholders.
Upon completion of the merger, our legacy stockholders will own approximately 62% of the issued and outstanding shares of our common stock, and legacy Equity One stockholders will own approximately 38% of the issued and outstanding shares of our common stock.
Consequently, our stockholders may have less influence over our management and policies after the effective time of the merger than they currently exercise over our management and policies.
Failure to complete the merger could adversely affect our stock price and our future business and financial results.
If the merger is not completed, our ongoing businesses may be adversely affected and we will be subject to numerous risks, including the following:
| | |
| --- | --- |
| • | upon termination of the merger agreement under specified circumstances, Equity One may be required to pay Regency Centers a termination fee of $150 million and we may be required to pay Equity One a termination fee of $240 million; |
| | |
| --- | --- |
| • | we are paying substantial costs relating to the merger, such as legal, accounting, financial advisor, filing, printing and mailing fees and integration preparation costs that have already been incurred or will continue to be incurred until the closing of the merger; |
| | |
| --- | --- |
| • | our management focusing on the merger instead of on pursuing other opportunities that could be beneficial to Regency Centers without realizing any of the benefits of having the merger completed; and |
An excerpt. Shown here: 40 of 136 rewritten, 40 of 104 added and 40 of 195 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors in the FY2017 filing and the FY2016 filing.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
234 rewritten, 258 added, 226 removed, 507 unchanged
Read the full itemFY2017 item · filed February 27, 2018FY2016 item · filed February 27, 2017
| • | We achieved pro-rata same property NOI growth, excluding termination fees, of [removed: 3.5%.] [added: 3.6%.] |
[removed: Develop new,] [added: We developed and redeveloped] high quality shopping centers [removed: and redevelop existing centers] at attractive returns on [removed: investment from a disciplined development program.][added: investment:]
| • | [added: In January 2017, we issued] $300.0 million of 4.4% [added: senior unsecured] notes due February 1, 2047, [removed: which priced at 99.110%. The Company used a portion of] the [removed: net] proceeds [added: of which were used] to redeem all of the [removed: outstanding shares of its] [added: $250.0 million] 6.625% Series 6 preferred [removed: shares on February 16, 2017] [added: stock] and [removed: intends to use] [added: reduce] the balance [removed: to fund investment activities and for general corporate purposes.] [added: of our unsecured line of credit (the "Line").] |
| | | December 31, [removed: 2016] [added: 2017] | | December 31, [removed: 2015] [added: 2016] |
| % Leased – Operating [removed: (1)] | | [removed: 96.0%] [added: 96.2%] | | [removed: 95.9%] [added: 96.0%] |
| Anchor space | | [removed: 97.8%] [added: 98.3%] | | [removed: 98.5%] [added: 97.8%] |
| Shop space | | [removed: 93.1%] [added: 92.5%] | | [removed: 91.7%] [added: 93.1%] |
The following table summarizes leasing activity, including [removed: Regency's] [added: our] pro-rata share of activity within the portfolio of our co-investment partnerships:
| | | Leasing Transactions [removed: (1)] [added: (1)(3)] | | SF (in thousands) | | Base Rent PSF (2) | | | | Tenant Improvements PSF (2) | | | | Leasing Commissions PSF (2) | | |
| Renewal | | 84 | | 1,610 | | [removed: $ |] 14.00 | | | [removed: $] | 0.50 | | | [removed: $] | 0.54 | | [added: |]
| Renewal | | 987 | | 1,502 | | [removed: $ |] 31.16 | | | [removed: $] | 1.26 | | | [removed: $] | 3.87 | | [added: |]
| Year ended December 31, [removed: 2015] [added: 2017] | | | | | | | | | | | | | | | | |
[added: |] (1) Number of leasing transactions reported at 100%; all other statistics reported at pro-rata share. [added: | | | | | | | | | | | | | | | | |]
[added: |] (2) Totals for base rent, tenant improvements, and leasing commissions reflect the weighted average PSF. [added: | | | | | | | | | | | | | | | | |]
Total average [added: pro-rata] base rent [removed: signed] on [removed: our] [added: signed] shop space leases [removed: of $30.95 increased in 2016 compared to 2015] [added: during 2017 was $31.68 PSF] and [removed: exceeds] [added: approximates] the [added: pro-rata] average annual base rent of all shop space leases due to expire during the next twelve months of [removed: $28.39 PSF by 9%.][added: $31.72 PSF.]
The following table summarizes our [removed: four] most significant tenants, based on their percentage of annualized base [removed: rent, each of which is a grocery tenant:][added: rent:]
| [removed: Grocery] Anchor | | Number of Stores [removed: (1)] | | Percentage of Company- owned GLA [removed: (2)] [added: (1)] | | Percentage of Annualized Base Rent [removed: (2)] [added: (1)] |
| Publix | | [removed: 41] [added: 69] | | [removed: 5.7%] [added: 6.2%] | | 3.1% |
| Whole Foods | | [removed: 21] [added: 27] | | [removed: 2.5%] [added: 2.2%] | | [removed: 2.5%] [added: 2.3%] |
[removed: (2)] [added: | (1)] Includes Regency's pro-rata share of Unconsolidated Properties and excludes those owned by anchors. [added: | | | | | | |]
Our management team devotes significant time to researching and monitoring [added: retail trends,] consumer preferences, customer shopping behaviors, [removed: alternative] [added: changes in] retail [removed: methods accessible via the Internet,] [added: delivery methods,] and [added: changing] demographics in order to anticipate the challenges and opportunities impacting the retail industry.
We closely monitor the operating performance and rent collections of [removed: the] tenants in our shopping [removed: centers, but also] [added: centers as well as] those retailers experiencing significant changes to their business models as a result of reduced customer traffic in their stores and increased competition from [removed: Internet] [added: e-commerce] sales.
Retailers who are unable to withstand these and other business [removed: pressures, such as operating and financing their business,] [added: pressures] may [removed: approach us to modify their lease agreement or] file [added: for] bankruptcy.
[removed: Also, as] [added: As] a result of our research and findings, we may reduce new leasing, suspend leasing, or curtail [removed: the allowance] [added: allowances] for [removed: the] construction of leasehold improvements within a certain retail category or to a specific retailer in order to reduce our risk from bankruptcies and store closings.
| (in thousands) | | [removed: 2016] [added: 2017] | | | | [removed: 2015] [added: 2016] | | | Change | |
Minimum rent [removed: increased] [added: changed] as follows:
| • | $15.3 million increase from [removed: new] acquisitions of operating properties; and |
Recoveries from tenants [removed: increased] [added: changed] as follows:
| • | $4.2 million increase from [removed: new] acquisitions of operating properties; and |
| (in thousands) | | [removed: 2016] [added: 2017] | | | | [removed: 2015] [added: 2016] | | | Change | |
Depreciation and amortization costs [removed: increased] [added: changed] as follows:
| • | $8.8 million increase from [removed: new] acquisitions of operating properties; and |
Operating and maintenance costs [removed: increased] [added: changed] as follows:
| • | $6.2 million increase from [removed: new] acquisitions of operating properties; and |
Real estate taxes [removed: increased] [added: changed] as follows:
| • | $2.8 million increase from [removed: new] acquisitions of operating properties; and |
Other operating expenses increased $6.2 million primarily due to costs incurred from 2016 acquisition activities, including costs associated with the [removed: announced pending] merger [removed: of] [added: with] Equity One, Inc.
| (in thousands) | | [removed: 2016] [added: 2017] | | | | [removed: 2015] [added: 2016] | | | Change | |
| Interest expense, net | | [removed: 90,712] [added: $] | [added: 90,712] | | | 102,622 | | | (11,910 | ) |
During 2016, we recognized $4.2 million of impairment losses on two operating properties and two land [removed: parcels.][added: parcels, all of which have since been sold.]
During the year ended 2017, we completed the merger with Equity One on March 1, 2017 and acquired 121 properties representing 16.0 million SF of GLA for $5.2 billion, further enhancing the quality of our operating portfolio of retail shopping centers.
The consolidated net assets and results of operations of Equity One are included in the consolidated financial statements from the closing date, March 1, 2017.
We had Net income attributable to common stockholders of $159.9 million, net of $80.7 million of merger costs, as compared to $143.9 million of Net income attributable to common stockholders during the year ended December 31, 2016.
We sustained superior same property NOI growth compared to the average of our shopping center peers:
| • | We executed 1,849 leasing transactions representing 6.3 million pro-rata SF of new and renewal leasing, with trailing twelve month rent spreads of 7.8% on comparable retail operating property spaces. |
| • | At December 31, 2017, our total property portfolio was 95.5% leased, while our same property portfolio was 96.3% leased. |
| • | We started five new developments representing a total investment of $197.5 million upon completion, with projected weighted average returns on investment of 7.3%. |
| • | Including these new projects, a total of 23 properties were in the process of development or redevelopment at December 31, 2017, representing a pro-rata investment upon completion of $543.8 million. |
We maintained a conservative balance sheet providing financial flexibility to cost effectively fund investment opportunities and debt maturities:
| • | On March 1, 2017 in conjunction with the merger with Equity One, we increased the commitment amount of our line to $1.0 billion. |
| • | In June 2017, we issued an additional $125.0 million of 4.4% senior unsecured notes due February 1, 2047, the proceeds of which were used to redeem the $75.0 million of 6.0% Series 7 preferred stock on August 23, 2017, and to reduce the Line balance. |
| • | Also in June 2017, the Company issued an additional $175.0 million of 3.6% senior unsecured public notes due in 2027, with proceeds used to retire $112.0 million of mortgage loans with interest rates ranging from 7.0% to 7.8% on various properties, and to reduce the Line balance. |
| • | At December 31, 2017, our annualized net debt-to-adjusted EBITDA ratio on a pro-rata basis was 5.4x. |
The decline in shop space percent leased is due to the merger with Equity One, which had lower shop space occupancy than Regency.
| New | | 39 | | 895 | | $ | 17.34 | | | $ | 9.71 | | | $ | 4.92 | |
| Renewal | | 87 | | 2,465 | | 14.47 | | | | — | | | | 0.46 | | |
| Total Anchor Leases | | 126 | | 3,360 | | $ | 15.24 | | | $ | 2.59 | | | $ | 1.65 | |
| New | | 548 | | 952 | | $ | 32.45 | | | $ | 12.06 | | | $ | 13.17 | |
| Renewal | | 1,175 | | 2,005 | | 31.31 | | | | 1.02 | | | | 2.40 | | |
| Total Shop Space Leases | | 1,723 | | 2,957 | | $ | 31.68 | | | $ | 4.57 | | | $ | 5.87 | |
| Total Leases | | 1,849 | | 6,317 | | $ | 22.93 | | | $ | 3.52 | | | $ | 3.62 | |
| (3) For the period ending December 31, 2017, amounts include leasing activity of properties acquired from Equity One beginning March 1, 2017. | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | |
| (1) Number of leasing transactions reported at 100%; all other statistics reported at pro-rata share. | | | | | | | | | | | | | | | | |
| (2) Totals for base rent, tenant improvements, and leasing commissions reflect the weighted average PSF. | | | | | | | | | | | | | | | | |
| | | December 31, 2017 | | | | |
| Kroger | | 58 | | 6.5% | | 3.1% |
| Albertsons/Safeway | | 46 | | 4.0% | | 2.9% |
| TJX Companies | | 58 | | 3.2% | | 2.4% |
A greater shift to e-commerce, large-scale retail business failures, unemployment, and tight credit markets could negatively impact consumer spending and have an adverse effect on our results of operations.
We seek to mitigate these potential impacts through tenant diversification, re-tenanting weaker tenants with stronger operators, anchoring our centers with market leading grocery stores that drive foot traffic, and maintaining a presence in affluent suburbs and dense infill trade areas.
Any unsecured claim we hold against a bankrupt tenant for unpaid rent might be paid only to the extent that funds are available and only in the same percentage as is paid to all other holders of unsecured claims.
As a result, it is likely that we would recover substantially less than the full value of any unsecured claims we hold.
Additionally, we may incur significant expense to recover our claim and to release the vacated space.
Tenants who have filed for bankruptcy and continue to occupy space in our shopping centers represent an aggregate of 0.3% of our annual base rent on a pro-rata basis.
Results from operations for the twelve months ended December 31, 2017 reflect the results of our merger with Equity One on March 1, 2017.
| Minimum rent | | $ | 728,078 | | | 444,305 | | | 283,773 | |
| Percentage rent | | 6,635 | | | | 4,128 | | | 2,507 | |
| Recoveries from tenants | | 206,675 | | | | 127,677 | | | 78,998 | |
Pending Merger with Equity One, Inc.
On November 14, 2016, Regency Centers Corporation entered into an Agreement and Plan of Merger (the “Merger Agreement”) with Equity One, Inc. (“Equity One”), pursuant to which, subject to the satisfaction or waiver of certain conditions, Equity One will merge with and into the Regency Centers Corporation, with Regency Centers Corporation being the surviving corporation (the “Merger”).
The combined company will retain the Regency name and continue to trade under the ticker symbol “REG” on the New York Stock Exchange (the “NYSE”).
On the terms and subject to the conditions set forth in the Merger Agreement, which has been unanimously approved by the boards of directors of Regency Centers Corporation and Equity One, at the effective time of the Merger (the “Effective Time”), each share of the common stock, par value $0.01 per share, of Equity One issued and outstanding immediately prior to the Effective Time (other than shares of Equity One owned directly by Equity One or the Regency Centers Corporation and in each case not held on behalf of third parties) will be converted into the right to receive 0.45 of a newly issued share of the common stock of Regency Centers Corporation.
The closing of the Merger is subject to certain conditions, including the requisite approvals from the stockholders of each of Regency Centers Corporation and Equity One (which approvals were received at special meetings of the stockholders of each company held on February 24, 2017), the receipt of certain tax opinions by Regency Centers Corporation and Equity One, and other customary closing conditions.
The Merger is expected to close on March 1, 2017.
However, the Company cannot predict with certainty when, or if, the Merger will be completed because completion of the Merger is subject to conditions beyond the control of the Company.
For more information about the Merger, the Merger Agreement and related agreements, see Note 16 of the Notes to the Consolidated Financial Statements in Item 8 herein.
During 2016, we executed on our strategic objectives to further solidify Regency’s position as a leader among shopping center REITs:
Sustain average annual 3% same property NOI growth from a high-quality, growing portfolio of thriving community and neighborhood shopping centers.
We earn revenues and generate cash flow by leasing space in our shopping centers to grocery stores, major retail anchors, restaurants, side-shop retailers, and service providers, as well as ground leasing or selling out-parcels to these same types of tenants.
We experience growth in revenues by increasing occupancy and rental rates in our existing shopping centers, by acquiring and developing new shopping centers, and by redeveloping shopping centers within our portfolio.
Noteworthy milestones and achievements during 2016 include:
| • | Pro-rata same property percent leased remained high at 96.2% at December 31, 2016. |
| • | We grew rental rates 11.3% on comparable spaces for new and renewal leases. |
| • | We acquired three operating properties for a gross purchase price of $333.8 million. |
We capitalize on our development capabilities, market presence, and anchor relationships by investing in new developments and redevelopments of existing centers.
| • | During 2016, we started $221.4 million of development and redevelopment projects, net of partner funding requirements, with a weighted average projected return of 7.8% upon completion. |
| • | At December 31, 2016, we have six ground-up developments in process, with total expected net development costs of $209.3 million, net of partner funding requirements, and have $97.7 million of net costs to complete. These developments are projected to return 7.4% on capital upon completion and are currently 78.6% leased. |
| • | We also have 15 redevelopments of existing centers in process with total expected net redevelopment costs of $88.4 million, with $59.3 million of costs to complete, and projected incremental returns ranging from 7.0% - 10.0% upon completion. |
Cost-effectively enhance our balance sheet to reduce our cost of capital, provide financial flexibility and weather economic downturns.
We fund acquisitions and development activities from various capital sources including operating cash flows, the sale of operating properties that no longer meet our investment standards, equity offerings, new debt financing, and capital from our co-investment partners.
| • | At December 31, 2016, our net debt-to-core EBITDA ratio on a pro-rata basis for the trailing twelve months was 4.4x versus 5.2x at December 31, 2015. We had $13.3 million of cash and $779.2 million available on our line of credit. |
| • | In June 2016, we settled 1.85 million of the 3.1 million shares of the forward equity offering resulting in net proceeds of $137.5 million, which were used to partially repay the line of credit balance. |
| • | In July 2016, we amended our existing Term Loan, which increased the facility size by $100.0 million to $265.0 million, extended the maturity date to January 5, 2022 and fixed the interest rate at 2.0%. |
| • | In July 2016, we issued 5.0 million shares of common stock resulting in net proceeds of $400.1 million, used to (i) repay in full our $300.0 million 5.875% Senior Unsecured Notes due June 2017 ("$300 million note"), including a make-whole payment, (ii) settle the forward interest rate swaps, and (iii) fund investment activities and general corporate purposes. |
| • | In January 2017, we completed a combined $650 million public offering of two tranches of senior unsecured notes: |
| • | $350.0 million of 3.6% notes due February 1, 2027, which priced at 99.741%. The Company intends to use the net proceeds in connection with the consummation of the previously announced pending merger with Equity One, Inc., including (i) to repay approximately $285.0 million in aggregate principal amount of debt of Equity One, and any related interest, fees and expenses and (ii) to pay transaction expenses related to the pending merger with Equity One. In the event that the merger agreement is not consummated, we will be required to redeem these notes then outstanding at a redemption price equal to 101% of the principal amount to be redeemed plus accrued and unpaid interest, if any. |
Improvements in the economy, combined with historically low levels of new supply and robust tenant demand, allow us to focus on merchandising of our centers to ensure the right mix of operators and unique retailers, which draws more retail customers to our centers.
For the purpose of the following disclosures of occupancy and leasing activity, "anchor space" is considered space greater than or equal to 10,000 SF and "shop space" is less than 10,000 SF.
| | | | | |
(1) Excludes properties in development.
The decline in anchor percent leased is due, in part, to the bankruptcy of Sports Authority and its rejection of two leases at our shopping centers.
See additional discussion below about bankruptcies.
| New | | 15 | | 295 | | $ | 13.81 | | | $ | 5.28 | | | $ | 5.14 | |
| Renewal | | 48 | | 972 | | $ | 11.96 | | | $ | 0.01 | | | $ | 1.08 | |
| Total Anchor Leases (1) | | 63 | | 1,267 | | $ | 12.39 | | | $ | 1.24 | | | $ | 2.03 | |
| New | | 445 | | 724 | | $ | 30.67 | | | $ | 10.35 | | | $ | 13.53 | |
| Renewal | | 950 | | 1,497 | | $ | 30.33 | | | $ | 0.64 | | | $ | 3.92 | |
| Total Shop Space Leases (1) | | 1,395 | | 2,221 | | $ | 30.44 | | | $ | 3.81 | | | $ | 7.06 | |
An excerpt. Shown here: 40 of 234 rewritten, 40 of 258 added and 40 of 226 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations in the FY2017 filing and the FY2016 filing.
Item 7A. Quantitative and Qualitative Disclosures about Market Risk
8 rewritten, 5 added, 2 removed, 15 unchanged
Read the full itemFY2017 item · filed February 27, 2018FY2016 item · filed February 27, 2017
| • | We have a Line commitment, as further described in Note [removed: 6] [added: 7] to the Consolidated Financial Statements, which has a variable interest rate that is based upon an annual rate of LIBOR plus [removed: 0.925% .] [added: 0.925%.] LIBOR rates charged on our Line change monthly. The spread on the Line is dependent upon maintaining specific credit ratings. If our credit ratings are downgraded, the spread on the Line would increase, resulting in higher interest costs. The interest rate spread based on our credit rating ranges from LIBOR plus 0.875% to LIBOR plus 1.550%. |
The table below presents the principal cash flows, weighted average interest rates of remaining debt, and the fair value of total debt as of December 31, [removed: 2016] [added: 2017] (dollars in thousands).
Although the average interest rate for variable rate debt is included in the table, those rates represent rates that existed as of December 31, [removed: 2016] [added: 2017] and are subject to change on a monthly basis.
Further, the table below incorporates only those exposures that exist as of December 31, [removed: 2016] [added: 2017] and does not consider exposures or positions that could arise after that date.
| | | [removed: 2017 | | | |] 2018 | | | [added: |] 2019 | | | 2020 | | | 2021 | | | [added: 2022 | | |] Thereafter | | | Total | | | Fair Value | |
| Variable rate LIBOR debt | | $ | — | | | [removed: —] [added: 68,569] | | | [removed: 15,000] [added: —] | | | [removed: —] [added: 27,750] | | | — | | | — | | | [removed: 15,000] [added: 96,319] | | | [removed: 14,970] [added: 96,371] | |
| Average interest rate for all variable rate debt (1) | | — | | % | | [removed: —] [added: 2.16] | % | | [removed: 1.41] [added: —] | % | | [removed: —] [added: 2.39] | % | | — | % | | — | % | | [added: —] | | | | |
[added: |] (1) Average interest rates at the end of each year presented. [added: | | | | | | | | | | | | | | | | | | | | | | | | | |]
In addition, the Company continually assesses the market risk for its floating rate debt and believes that a 1% increase in interest rates would decrease future earnings and cash flows by approximately $1.0 million per year based on $36.3 million of floating rate mortgage debt and $60.0 million of floating rate line of credit debt outstanding at December 31, 2017.
If the Company increases its line of credit balance in the future, additional decreases to future earnings and cash flows would occur.
| Fixed rate debt | | $ | 122,867 | | | 22,578 | | | 539,702 | | | 300,427 | | | 582,466 | | | 1,947,384 | | | 3,515,424 | | | 3,586,673 | |
| Average interest rate for all fixed rate debt (1) | | 3.89 | | % | | 3.88 | % | | 3.83 | % | | 3.70 | % | | 3.89 | % | | 3.91 | % | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | |
| Fixed rate debt | | $ | 91,618 | | | 62,186 | | | 110,205 | | | 239,047 | | | 288,970 | | | 840,066 | | | 1,632,092 | | | 1,699,730 | |
| Average interest rate for all fixed rate debt (1) | | 4.34 | | % | | 4.27 | % | | 3.99 | % | | 3.67 | % | | 3.25 | % | | 3.78 | % | | | | | | |
Item 1. Business
34 rewritten, 16 added, 82 removed, 107 unchanged
Read the full itemFY2017 item · filed February 27, 2018FY2016 item · filed February 27, 2017
Our [removed: centers] [added: properties] are [added: principally] located in [removed: the top markets of 25 states] [added: affluent] and [removed: the District] [added: infill trade areas] of [removed: Columbia,] [added: the United States,] and contain [removed: 37.8] [added: 53.9] million square feet ("SF") of gross leasable area ("GLA").
Our pro-rata [added: ownership] share of this GLA is [removed: 28.7] [added: 44.0] million square feet.
Our mission is to be the preeminent national [removed: grocery-anchored] shopping center [removed: owner] [added: owner, operator,] and [removed: developer through:][added: developer.]
Our strategy [removed: is:][added: is to:]
| • | Develop [removed: new,] and redevelop [removed: existing,] high quality shopping centers at attractive returns on [removed: investment from a disciplined development program;] [added: investment;] |
| • | Maintain [removed: our] [added: a conservative] balance sheet [removed: to provide] [added: providing] financial [removed: flexibility,] [added: flexibility] to cost effectively fund [removed: uses of capital,] [added: investment opportunities] and [added: debt maturities on a favorable basis, and] to weather economic downturns; [removed: and] |
[removed: Environmental] Sustainability
We believe [removed: being an industry leader in] sustainability is in the best interest of our tenants, investors, employees, and the communities in which we [removed: operate.][added: operate and are committed to reducing our environmental impact, including energy and water use, greenhouse gas emissions, and waste.]
We currently have a Green Star rating from the Global Real Estate Sustainability Benchmark, or GRESB, for the [removed: second consecutive year.][added: third]
We are [removed: amongst] [added: among] the largest owners of shopping centers in the nation based on revenues, number of properties, GLA, and market capitalization.
We presently maintain [removed: 18] [added: 21] market offices nationwide, including our corporate headquarters, where we conduct management, leasing, construction, and investment activities.
We have [removed: 371] [added: 446] employees [added: throughout the United States] and we believe that our relations with our employees are good.
| Martin E. Stein, Jr. | [removed: 64] [added: 65] | Chairman and Chief Executive Officer | 1993 |
| Lisa Palmer | [removed: 49] [added: 50] | President and Chief Financial Officer | 2016 (1) |
| Dan M. Chandler, III | [removed: 49] [added: 50] | Executive Vice President of [removed: Development] [added: Investments] | 2016 (2) |
| James D. Thompson | [removed: 61] [added: 62] | Executive Vice President of Operations | 2016 (3) |
[added: |] (1) Ms. Palmer assumed the responsibilities of President, effective January 1, 2016 in addition to her responsibilities as Chief Financial Officer, which she has held since January 2013. [added: Prior to that, Ms. Palmer served as Senior Vice President of Capital Markets since 2003 and has been with the Company since 1996. | | | |]
[added: |] (2) Mr. Chandler assumed the role of Executive Vice President of [removed: Development] [added: Investments] on January 1, 2016 and previously served as [removed: our] Managing Director [removed: - West] since [removed: 2009.][added: 2006. Prior to that, Mr. Chandler served in various investment officer positions since the merger with Pacific Retail Trust in 1999. | | | |]
[added: |] (3) Mr. Thompson assumed the role of Executive Vice President of Operations on January 1, 2016 and previously served as our Managing Director - East since our initial public offering in 1993. [added: Prior to that time, Mr. Thompson served as Executive Vice President of our predecessor real estate division beginning in 1981. | | | |]
We offer a dividend reinvestment plan (“DRIP”) that enables our [removed: stockholders] [added: shareholders] to reinvest dividends automatically, as well as to make voluntary cash payments toward the purchase of additional shares.
Annual Meeting [added: of Shareholders]
on Thursday, April [removed: 27, 2017.][added: 26, 2018.]
| • | Same Property information is provided for [added: retail] operating properties that were owned and operated for the entirety of both calendar year periods being compared and excludes Non-Same Properties and Properties in Development. |
| • | A Non-Same Property is a property acquired, sold, or a [removed: development completion] [added: Development Completion] during either calendar year period being compared. [removed: Corporate] [added: Non-retail properties and corporate] activities, including [removed: the] [added: activities of our] captive insurance company, are part of Non-Same Property. |
| • | Property In Development includes land or [removed: properties] [added: Retail Operating Properties] in various stages of development and redevelopment including active pre-development activities. |
| • | Development Completion is a [removed: project in] development [added: project] that is deemed complete upon the earliest of: (i) 90% of total estimated net development costs have been incurred and percent leased equals or exceeds 95%, or (ii) the project features at least two years of anchor operations, or (iii) three years have passed since the start of construction. Once deemed complete, the property is termed [removed: an] [added: a Retail] Operating Property. |
| • | Pro-Rata information includes 100% of our consolidated properties plus our [added: economic share (based on our] ownership [removed: interest] [added: interest)] in our unconsolidated real estate investment partnerships. |
The partners are entitled to profit or loss allocations and distributions of cash flows according to the operating agreements, which provide for such [removed: allocations according to their invested capital.]
| • | Other companies in our industry may calculate their pro-rata interest differently, limiting the [removed: usefulness as a comparative measure.] [added: comparability of pro-rata information.] |
| • | [removed: Core] [added: Adjusted] EBITDA is defined as earnings before interest, taxes, depreciation and amortization, real estate gains and losses, [removed: and] development and acquisition pursuit [removed: costs.] [added: costs, straight line rental income, and above and below market rent amortization.] |
| • | Fixed Charge Coverage Ratio is defined as [removed: Core] [added: Adjusted] EBITDA divided by the sum of the gross interest and scheduled mortgage principal paid to our lenders plus dividends paid to our preferred stockholders. |
| • | Net Operating Income ("NOI") is the sum of minimum rent, percentage rent and recoveries from tenants and other income, less operating and maintenance, real estate taxes, and provision for doubtful accounts. NOI excludes [removed: straight-] [added: straight-line rental income and expense, above and below market rent and ground rent amortization and other fees. The Company also provides disclosure of NOI excluding termination fees, which excludes both termination fee income and expenses.] |
| • | NAREIT Funds from Operations ("NAREIT FFO") is a commonly used measure of REIT performance, which the National Association of Real Estate Investment Trusts ("NAREIT") defines as net income, computed in accordance with GAAP, excluding gains and losses from sales of depreciable property, net of tax, excluding operating real estate impairments, plus depreciation and amortization, and after adjustments for unconsolidated partnerships and joint ventures. We compute NAREIT FFO for all periods presented in accordance with NAREIT's definition. Many companies use different depreciable lives and methods, and real estate values historically fluctuate with market conditions. Since NAREIT FFO excludes depreciation and amortization and gains and losses from depreciable property dispositions, and impairments, it provides a performance measure that, when compared year over year, reflects the impact on operations from trends in occupancy rates, rental rates, operating costs, acquisition and development activities, and financing costs. This provides a perspective of our financial performance not immediately apparent from net income determined in accordance with GAAP. Thus, NAREIT FFO is a supplemental non-GAAP financial measure of our operating performance, which does not represent cash generated from operating activities in accordance with GAAP; and, therefore, should not be considered a substitute measure of cash flows from operations. [added: The Company provides a reconciliation of Net Income (Loss) Attributable to Common Stockholders to NAREIT FFO.] |
| • | Core FFO is an additional performance measure used by Regency as the computation of NAREIT FFO includes certain [removed: non-cash and] non-comparable items that affect the Company's period-over-period performance. Core FFO excludes from NAREIT [removed: FFO, but is not limited to:] [added: FFO:] (a) transaction related [removed: gains,] income or expense; (b) impairments on land; (c) gains or losses from the early extinguishment of debt; and (d) other [removed: non-core] amounts as they occur. The Company provides a reconciliation of NAREIT FFO to Core FFO. |
Regency Centers began its operations as a publicly-traded REIT in 1993, and, as of December 31, 2017, had full or partial ownership interests in 426 retail properties primarily anchored by market leading grocery stores.
On March 1, 2017, Regency completed its merger with Equity One Inc. ("Equity One"), whereby Equity One merged with and into Regency, with Regency continuing as the surviving public company.
Under the terms of the Merger Agreement, each Equity One stockholder received 0.45 of a newly issued share of Regency common stock for each share of Equity One common stock owned immediately prior to the effective time of the merger resulting in approximately 65.5 million shares being issued to effect the merger.
As part of the merger, Regency acquired 121 properties representing 16.0 million SF of GLA, including 8 properties held through co-investment partnerships.
| • | Own and manage an unequaled portfolio of high-quality neighborhood and community shopping centers anchored by market leading grocers and located in affluent suburban and near urban trade areas in the country’s most desirable metro areas. We expect that this combination will produce highly desirable and attractive centers with best-in-class retailers. These centers should command higher rental and occupancy rates resulting in excellent prospects to grow net operating income ("NOI"); |
| • | Maintain an industry leading and disciplined development and redevelopment platform to deliver exceptional retail centers at higher returns as compared to acquisitions; |
| • | Support our business activities with a strong balance sheet; and |
| • | Engage a talented, dedicated team of employees, who are guided by Regency’s strong values and special culture, which are aligned with shareholder interests. |
Key goals to achieve our strategy are to:
| • | Sustain superior same property NOI growth compared to our shopping center peers; |
| • | Attract and motivate an exceptional team of employees who operate efficiently and are recognized as industry leaders; and |
| • | Generate reliable growth in earnings per share, funds from operations per share, and most importantly total shareholder returns that consistently rank at or near the top of shopping center REITS. |
consecutive year.
Our 2018 annual meeting of shareholders will be held at the Ponte Vedra Inn and Club, 200 Ponte Vedra Blvd., Ponte Vedra Beach, Florida, at 10:30 a.m.
| • | A Retail Operating Property is any property where the majority of the income is generated from retail uses, and is not termed a Property in Development. |
allocations according to their invested capital.
Regency Centers began its operations as a publicly-traded REIT in 1993, and, as of December 31, 2016, owns direct or partial interests in 307 shopping centers, the majority of which are grocery-anchored community and neighborhood centers.
| | |
| --- | --- |
| • | First-rate performance of our exceptionally merchandised and located national portfolio; |
| | |
| --- | --- |
| • | Value-enhancing services from an accomplished team of professionals in the business; and |
| | |
| --- | --- |
| • | Creation of superior growth in shareholder value. |
| | |
| --- | --- |
| • | Sustain average annual 3% same property NOI growth from a high-quality, growing portfolio of thriving community and neighborhood shopping centers; |
| | |
| --- | --- |
| | |
| --- | --- |
| | |
| --- | --- |
| • | Engage a talented and dedicated team with high standards of integrity that operates efficiently and is recognized as a leader in the real estate industry. |
We expect to execute our strategy as follows:
Sustain average annual 3% same property NOI growth from a high-quality, growing portfolio of thriving community and neighborhood shopping centers:
| | |
| --- | --- |
| • | Own and develop centers that are located at key corners in our nation’s most attractive metro areas; |
| | |
| --- | --- |
| • | Target trade areas characterized by their strong demographics and consumer buying power, and draw shoppers to our centers with highly productive anchor tenants; |
| | |
| --- | --- |
| • | Attract the best national, regional and local retailers and restaurants; |
| | |
| --- | --- |
| • | Pursue initiatives that reinforce the underlying quality of our portfolio and maximize long-term growth such as “Fresh Look®,” an operating philosophy that guides our merchandising and place-making programs; |
| | |
| --- | --- |
| • | Fortify future NOI growth by rigorously reviewing our portfolio to identify and sell operating properties that no longer meet our investment standards; and |
| | |
| --- | --- |
| • | Opportunistically upgrade our portfolio by acquiring high quality shopping centers with meaningful upside in NOI growth funded from the sale of operating properties that no longer meet our investment standards. |
An excerpt. Shown here: all 34 rewritten, all 16 added and 40 of 82 removed. The counts are complete. For every sentence, read Item 1. Business in the FY2017 filing and the FY2016 filing.
Item 3. Legal Proceedings
1 rewritten, 0 added, 16 removed, 1 unchanged
Read the full itemFY2017 item · filed February 27, 2018FY2016 item · filed February 27, 2017
[removed: Except for the matter noted below, we] [added: We] are not currently involved in any [removed: litigation] [added: litigation,] nor to our [removed: knowledge,] [added: knowledge] is any litigation threatened against us, the outcome of which would, in our judgment based on information currently available to us, have a material adverse effect on our financial position or results of operations.
After the announcement of the merger agreement on November 14, 2016, a putative class action was filed on behalf of a purported stockholder in the Circuit Court for Duval County, Florida, under the following caption: Robert Garfield on Behalf of Himself and All Others Similarly Situated vs. Regency Centers Corporation, Martin E.
Stein, Jr., John C.
Schweitzer, Raymond L.
Bank, Bryce Blair, C.
Ronald Blankenship, J.
Dix Druce, Jr., Mary Lou Fiala, David P.
O'Connor, and Thomas G.
Wattles, No. 16-2017-CA-000688-XXXX-MA, filed February 3, 2017.
The class action alleges, among other matters, that the definitive joint proxy statement/prospectus filed by Regency and Equity One with the Securities and Exchange Commission (the “SEC”) on January 24, 2017 (the “Joint Proxy Statement/Prospectus”) omitted certain material information in connection with the Merger.
The complainant seeks various remedies, including injunctive relief to prevent the consummation of the Merger unless certain allegedly material information is disclosed and seeking compensatory and rescissory damages in the event the Merger is consummated without such disclosures.
On February 17, 2017, the defendants entered into a stipulation of settlement with respect to the class action, pursuant to which the parties have agreed, among other things, that Regency will make certain supplemental disclosures.
The supplemental disclosures were made by Regency in the Current Report on Form 8-K filed by Regency with the SEC on February 17, 2017.
The supplemental disclosures should be read in conjunction with the Joint Proxy Statement/Prospectus, which should be read in its entirety.
Regency believes that the class action is without merit and that no supplemental disclosure is or was required to the Joint Proxy Statement/Prospectus under any applicable rule, statute, regulation or law.
However, to, among other things, eliminate the burden, inconvenience, expense, risk and disruption of further litigation, Regency has determined to provide supplemental disclosures.
Additional information regarding the stipulation of settlement may be found in the Current Report on Form 8-K as filed with the SEC on February 17, 2017.
Cover and table of contents
35 rewritten, 13 added, 23 removed, 136 unchanged
Read the full itemFY2017 item · filed February 27, 2018FY2016 item · filed February 27, 2017
For the fiscal year ended December 31, [removed: 2016][added: 2017]
| FLORIDA (REGENCY CENTERS CORPORATION) | [removed: ] [added: ] | 59-3191743 |
Regency Centers Corporation [removed: x] [added: YES o NO o] Regency Centers, L.P. [removed: x][added: YES o NO o]
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, [removed: or] a smaller reporting [added: company, or an emerging growth] company.
See the definitions of “large accelerated filer,” “accelerated [removed: filer” and] [added: filer,”] “smaller reporting [added: company,” and “emerging growth] company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | x | [removed: |] Accelerated filer | o | [added: Emerging growth company | o |]
| Non-accelerated filer | o | [removed: |] Smaller reporting company | o | [added: | |]
| Large accelerated filer | o | [removed: |] Accelerated filer | x | [added: Emerging growth company | o |]
| Non-accelerated filer | o | [removed: |] Smaller reporting company | o | [added: | |]
Regency Centers Corporation [removed: $8.2] [added: $9.3] billion Regency Centers, L.P. N/A
The number of shares outstanding of the Regency Centers Corporation’s [removed: voting] common stock was [removed: 104,704,642] [added: 170,794,466] as of February [removed: 24, 2017.][added: 23, 2018.]
Portions of Regency Centers Corporation's proxy statement in connection with its [removed: 2017] [added: 2018] Annual Meeting of Stockholders are incorporated by reference in Part III.
This report combines the annual reports on Form 10-K for the year ended December 31, [removed: 2016] [added: 2017] of Regency Centers Corporation and Regency Centers, L.P. Unless stated otherwise or the context otherwise requires, references to “Regency Centers Corporation” or the “Parent Company” mean Regency Centers Corporation and its controlled subsidiaries; and references to “Regency Centers, L.P.” or the “Operating Partnership” mean Regency Centers, L.P. and its controlled subsidiaries.
As of December 31, [removed: 2016,] [added: 2017,] the Parent Company owned [removed: all of the Preferred Units of the Operating Partnership and] approximately [removed: 99.9%] [added: 99.8%] of the Units in the Operating Partnership.
The Company believes it is important to understand the [removed: few] [added: key] differences between the Parent Company and the Operating Partnership in the context of how the Parent Company and the Operating Partnership operate as a consolidated company.
[removed: The] [added: Except for the $500 million of unsecured public and private placement debt assumed with the Equity One merger on March 1, 2017, the] Parent Company does not hold any indebtedness, but guarantees all of the unsecured [removed: public] debt of the Operating Partnership.
The Operating Partnership's capital includes general and limited common Partnership [removed: Units, and Preferred Units owned by the Parent Company.][added: Units.]
| 1A. | [Risk [removed: Factors](#s04FD03564F9EEBB9F8914EDF73CC7B08)] [added: Factors](#s036EDB2EDEBFBE08ED2DBCAA1F6F302B)] | [removed: [7](#s04FD03564F9EEBB9F8914EDF73CC7B08)] [added: [5](#s036EDB2EDEBFBE08ED2DBCAA1F6F302B)] |
| 1B. | [Unresolved Staff [removed: Comments](#s0FB56CF43BF6F9EC43CE4EDF73F7283A)] [added: Comments](#s6673A46A54533138600EBCAA1F9257B8)] | [removed: [20](#s0FB56CF43BF6F9EC43CE4EDF73F7283A)] [added: [16](#s6673A46A54533138600EBCAA1F9257B8)] |
| 3. | [Legal [removed: Proceedings](#sD1ADC410474070D5241C4EDF757DF648)] [added: Proceedings](#sEC5272291044553B0A63BCAA20890457)] | [removed: [34](#sD1ADC410474070D5241C4EDF757DF648)] [added: [34](#sEC5272291044553B0A63BCAA20890457)] |
| 4. | [Mine Safety [removed: Disclosures](#s91623B18435964CCD6B54EDF7587C6F0)] [added: Disclosures](#s621CE764313BFB87D8F9BCAA20902777)] | [removed: [34](#s91623B18435964CCD6B54EDF7587C6F0)] [added: [34](#s621CE764313BFB87D8F9BCAA20902777)] |
| 5. | [Market for the Registrant's Common Equity, Related Stockholder Matters, and Issuer Purchases of Equity [removed: Securities](#s47745F57FEEEB83A59CE4EDF759866EB)] [added: Securities](#sC90D5EC5D2C80143A11CBCAA20999729)] | [removed: [34](#s47745F57FEEEB83A59CE4EDF759866EB)] [added: [34](#sC90D5EC5D2C80143A11CBCAA20999729)] |
| 6. | [Selected Financial [removed: Data](#sF1E71B4E24736F28B0E24EDF75BFE777)] [added: Data](#sDD372570A6AAB0A5E44BBCAA20BB2B92)] | [removed: [37](#sF1E71B4E24736F28B0E24EDF75BFE777)] [added: [37](#sDD372570A6AAB0A5E44BBCAA20BB2B92)] |
| 7. | [Management's Discussion and Analysis of Financial Condition and Results of [removed: Operations](#sF3F034F8D1C90EED73244EDF760A9A2A)] [added: Operations](#sF27D718660513F60FE73BCAA20FD6264)] | [removed: [41](#sF3F034F8D1C90EED73244EDF760A9A2A)] [added: [41](#sF27D718660513F60FE73BCAA20FD6264)] |
| 7A. | [Quantitative and Qualitative Disclosures About Market [removed: Risk](#sBA306D370ADFAF6E49F34EDF780AF0C5)] [added: Risk](#s4FE9438F08F5516D026ABCAA2304C64C)] | [removed: [64](#sBA306D370ADFAF6E49F34EDF780AF0C5)] [added: [64](#s4FE9438F08F5516D026ABCAA2304C64C)] |
| 8. | [Consolidated Financial Statements and Supplementary [removed: Data](#s999E54D64E2BB8D08F5D4EDF783F9542)] [added: Data](#s113A03507F6EF1BC3612BCAA23230646)] | [removed: [66](#s999E54D64E2BB8D08F5D4EDF783F9542)] [added: [65](#s113A03507F6EF1BC3612BCAA23230646)] |
| 9. | [Changes in and Disagreements with Accountants on Accounting and Financial [removed: Disclosure](#s317B8E4125BE9768126D4EDF819B154B)] [added: Disclosure](#s1E8E52C47CB33636262EBCAA310DA59D)] | [removed: [135](#s317B8E4125BE9768126D4EDF819B154B)] [added: [139](#s1E8E52C47CB33636262EBCAA310DA59D)] |
| 9A. | [Controls and [removed: Procedures](#sF8A08D0C11074204D1BB4EDF81CDD2DA)] [added: Procedures](#sDA1E29BD802937876320BCAA3125F662)] | [removed: [135](#sF8A08D0C11074204D1BB4EDF81CDD2DA)] [added: [139](#sDA1E29BD802937876320BCAA3125F662)] |
| 9B. | [Other [removed: Information](#sD3AE3AC915A0B93BA82D4EDF81EB5D74)] [added: Information](#s566A8CDD0BABBDC0B675BCAA3156A8B0)] | [removed: [136](#sD3AE3AC915A0B93BA82D4EDF81EB5D74)] [added: [140](#s566A8CDD0BABBDC0B675BCAA3156A8B0)] |
| 10. | [Directors, Executive Officers, and Corporate [removed: Governance](#s9969A6CEDB5084AB8A1B4EDF823F16B0)] [added: Governance](#s29EC8DE8E9A0D0D4A447BCAA31ABA97A)] | [removed: [136](#s9969A6CEDB5084AB8A1B4EDF823F16B0)] [added: [140](#s29EC8DE8E9A0D0D4A447BCAA31ABA97A)] |
| 11. | [Executive [removed: Compensation](#s533C24F85B589C5C54534EDF8272282A)] [added: Compensation](#sBB48EA490B8E4B1C1814BCAA31CB36C8)] | [removed: [136](#s533C24F85B589C5C54534EDF8272282A)] [added: [140](#sBB48EA490B8E4B1C1814BCAA31CB36C8)] |
| 12. | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder [removed: Matters](#sAFC51487E07BA3C751AB4EDF8292F34E)] [added: Matters](#sED12B4723C7FB66043C7BCAA31FEEB2E)] | [removed: [137](#sAFC51487E07BA3C751AB4EDF8292F34E)] [added: [141](#sED12B4723C7FB66043C7BCAA31FEEB2E)] |
| 13. | [Certain Relationships and Related Transactions, and Director [removed: Independence](#s3A918352EFD5077678364EDF82C65332)] [added: Independence](#sA1A510A1486D161BCFC5BCAA322091B5)] | [removed: [137](#s3A918352EFD5077678364EDF82C65332)] [added: [141](#sA1A510A1486D161BCFC5BCAA322091B5)] |
| 14. | [Principal Accountant Fees and [removed: Services](#s43CE03BBC8B0E9437EAB4EDF82E56FAC)] [added: Services](#sCE3A2FD7626FC6458B9FBCAA32511948)] | [removed: [137](#s43CE03BBC8B0E9437EAB4EDF82E56FAC)] [added: [141](#sCE3A2FD7626FC6458B9FBCAA32511948)] |
| 15. | [Exhibits and Financial Statement [removed: Schedules](#s28F8CD300F747BABA0A54EDF83399FEA)] [added: Schedules](#sC55F0DED996872C19814BCAA32A52A94)] | [removed: [138](#s28F8CD300F747BABA0A54EDF83399FEA)] [added: [142](#sC55F0DED996872C19814BCAA32A52A94)] |
10-K 1 reg10-k123117.htm 10-K-123117
Regency Centers Corporation x Regency Centers, L.P x
| | | | | | |
| --- | --- | --- | --- | --- | --- |
| | | | | | |
| | | | | | |
| --- | --- | --- | --- | --- | --- |
| | | | | | |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act.
The Operating Partnership is also the co-issuer and guarantees the $500 million of debt of the Parent Company assumed in the Equity One merger.
| 1. | [Business](#sECE8D28B57953291B5E0BCAA1F3C5C86) | [1](#sECE8D28B57953291B5E0BCAA1F3C5C86) |
| 2. | [Properties](#s113B54A5A39BBDD6BE83BCAA1FC28C1A) | [17](#s113B54A5A39BBDD6BE83BCAA1FC28C1A) |
| 16. | [Signatures](#sDAFB3C2A548B53206450BCAA32C69A83) | [148](#sDAFB3C2A548B53206450BCAA32C69A83) |
10-K 1 reg10-k123116.htm 10-K
| | | |
| | | |
| 6.625% Series 6 Cumulative Redeemable Preferred Stock, $.01 par value | | New York Stock Exchange |
| 6.000% Series 7 Cumulative Redeemable Preferred Stock, $.01 par value | | New York Stock Exchange |
| | | | | |
| --- | --- | --- | --- | --- |
| | | | | |
| | | | | |
| --- | --- | --- | --- | --- |
| | | | | |
The Preferred Units owned by the Parent Company are eliminated in consolidation in the accompanying consolidated financial statements of the Parent Company and are classified as preferred units of general partner in the accompanying consolidated financial statements of the Operating Partnership.
| 1. | [Business](#sC743D77F35CECA7F5D1E4EDF73999CD3) | [1](#sC743D77F35CECA7F5D1E4EDF73999CD3) |
| 2. | [Properties](#s088157F491130714FDDD4EDF742263E2) | [21](#s088157F491130714FDDD4EDF742263E2) |
| 16. | [Signatures](#sF81E24BDD47CFFAB731D4EDF836A0C9D) | [143](#sF81E24BDD47CFFAB731D4EDF836A0C9D) |
Pending Merger with Equity One, Inc.
On November 14, 2016, Regency Centers Corporation entered into an Agreement and Plan of Merger (the “Merger Agreement”) with Equity One, Inc. (“Equity One”), pursuant to which, subject to the satisfaction or waiver of certain conditions, Equity One will merge with and into the Regency Centers Corporation, with Regency Centers Corporation being the surviving corporation (the “Merger”).
The combined company will retain the Regency name and continue to trade under the ticker symbol “REG” on the New York Stock Exchange (the “NYSE”).
On the terms and subject to the conditions set forth in the Merger Agreement, which has been unanimously approved by the boards of directors of Regency Centers Corporation and Equity One, at the effective time of the Merger (the “Effective Time”), each share of the common stock, par value $0.01 per share, of Equity One issued and outstanding immediately prior to the Effective Time (other than shares of Equity One owned directly by Equity One or the Regency Centers Corporation and in each case not held on behalf of third parties) will be converted into the right to receive 0.45 of a newly issued share of the common stock of Regency Centers Corporation.
The closing of the Merger is subject to certain conditions, including the requisite approvals from the stockholders of each of Regency Centers Corporation and Equity One (which approvals were received at special meetings of the stockholders of each company held on February 24, 2017), the receipt of certain tax opinions by Regency Centers Corporation and Equity One, and other customary closing conditions.
The Merger is expected to close on March 1, 2017.
However, the Company cannot predict with certainty when, or if, the Merger will be completed because completion of the Merger is subject to conditions beyond the control of the Company.
For more information about the Merger, the Merger Agreement and related agreements, see note 16 of the Notes to the Consolidated Financial Statements in Item 8 herein.
Item 2. Properties
353 rewritten, 206 added, 72 removed, 56 unchanged
Read the full itemFY2017 item · filed February 27, 2018FY2016 item · filed February 27, 2017
| | | December 31, [removed: 2016] [added: 2017] | | | | | | | | | | | | December 31, [removed: 2015] [added: 2016] | | | | | | | | | | |
| California | | [removed: 43] [added: 56] | | | [removed: 5,734] [added: 8,549] | | | [removed: 24.0] [added: 22.1] | % | | [removed: 97.7] [added: 96.5] | % | | [removed: 42] [added: 43] | | | [removed: 5,619] [added: 5,734] | | | [removed: 24.1] [added: 24.0] | % | | [removed: 95.6] [added: 97.7] | % |
| Florida | | [removed: 37] [added: 96] | | | [removed: 4,167] [added: 11,255] | | | [removed: 17.4] [added: 29.1] | % | | [removed: 93.6] [added: 94.7] | % | | [removed: 39] [added: 37] | | | [removed: 4,214] [added: 4,168] | | | [removed: 18.1] [added: 17.4] | % | | [removed: 94.7] [added: 93.6] | % |
| Texas | | 23 | | | [removed: 3,014] [added: 3,018] | | | [removed: 12.6] [added: 7.8] | % | | [removed: 96.0] [added: 97.4] | % | | [removed: 22] [added: 23] | | | [removed: 2,716] [added: 3,014] | | | [removed: 11.7] [added: 12.6] | % | | [removed: 97.6] [added: 96.0] | % |
| Georgia | | [removed: 15] [added: 21] | | | [removed: 1,395] [added: 2,047] | | | [removed: 5.8] [added: 5.3] | % | | [removed: 93.8] [added: 95.2] | % | | 15 | | | [removed: 1,392] [added: 1,395] | | | [removed: 6.0] [added: 5.8] | % | | [removed: 92.9] [added: 93.8] | % |
| Colorado | | 14 | | | 1,146 | | | [removed: 4.8] [added: 3.0] | % | | [removed: 93.8] [added: 97.2] | % | | [removed: 15] [added: 14] | | | [removed: 1,266] [added: 1,146] | | | [removed: 5.4] [added: 4.8] | % | | [removed: 91.3] [added: 93.8] | % |
| North Carolina | | 10 | | | 895 | | | [removed: 3.8] [added: 2.3] | % | | [removed: 96.2] [added: 97.0] | % | | 10 | | | 895 | | | 3.8 | % | | [removed: 95.8] [added: 96.2] | % |
| Ohio | | 8 | | | [removed: 1,184] [added: 1,196] | | | [removed: 4.9] [added: 3.1] | % | | [removed: 98.4] [added: 99.5] | % | | 8 | | | [removed: 1,164] [added: 1,184] | | | [removed: 5.0] [added: 4.9] | % | | [removed: 98.6] [added: 98.4] | % |
| Virginia | | [removed: 7] [added: 8] | | | [removed: 1,233] [added: 1,420] | | | [removed: 5.2] [added: 3.7] | % | | [removed: 87.5] [added: 86.3] | % | | [removed: 6] [added: 7] | | | [removed: 841] [added: 1,233] | | | [removed: 3.6] [added: 5.2] | % | | [removed: 96.2] [added: 87.5] | % |
| Oregon | | 7 | | | 741 | | | [removed: 3.1] [added: 1.9] | % | | [removed: 93.3] [added: 94.8] | % | | 7 | | | [removed: 742] [added: 741] | | | [removed: 3.2] [added: 3.1] | % | | [removed: 87.9] [added: 93.3] | % |
| Washington | | [removed: 6] [added: 7] | | | [removed: 672] [added: 825] | | | [removed: 2.8] [added: 2.1] | % | | [removed: 99.3] [added: 99.4] | % | | [removed: 5] [added: 6] | | | [removed: 606] [added: 672] | | | [removed: 2.6] [added: 2.8] | % | | [removed: 98.7] [added: 99.3] | % |
| Illinois | | [removed: 5] [added: 6] | | | [removed: 817] [added: 1,069] | | | [removed: 3.4] [added: 2.8] | % | | [removed: 98.7] [added: 88.3] | % | | 5 | | | 817 | | | [removed: 3.5] [added: 3.4] | % | | [removed: 98.2] [added: 98.7] | % |
| Missouri | | 4 | | | 408 | | | [removed: 1.7] [added: 1.1] | % | | [removed: 99.5] [added: 99.7] | % | | 4 | | | 408 | | | [removed: 1.8] [added: 1.7] | % | | [removed: 100.0] [added: 99.5] | % |
| Massachusetts | | [removed: 3] [added: 9] | | | [removed: 516] [added: 907] | | | [removed: 2.2] [added: 2.3] | % | | [removed: 95.5] [added: 99.1] | % | | 3 | | | 516 | | | 2.2 | % | | [removed: 96.1] [added: 95.5] | % |
| Tennessee | | 3 | | | 317 | | | [removed: 1.3] [added: 0.8] | % | | [removed: 96.3] [added: 97.6] | % | | 3 | | | 317 | | | [removed: 1.4] [added: 1.3] | % | | [removed: 96.1] [added: 96.3] | % |
| Connecticut | | [removed: 3] [added: 14] | | | [removed: 316] [added: 1,458] | | | [removed: 1.3] [added: 3.8] | % | | [removed: 94.7] [added: 96.9] | % | | 3 | | | [removed: 315] [added: 316] | | | [removed: 1.4] [added: 1.3] | % | | [removed: 96.3] [added: 94.7] | % |
| Pennsylvania | | 3 | | | 317 | | | [removed: 1.3] [added: 0.8] | % | | [removed: 94.7] [added: 93.2] | % | | 3 | | | [removed: 311] [added: 317] | | | 1.3 | % | | [removed: 98.4] [added: 94.7] | % |
| Indiana | | 1 | | | 254 | | | [removed: 1.1] [added: 0.7] | % | | [removed: 97.9] [added: 97.7] | % | | [removed: 3] [added: 1] | | | [removed: 281] [added: 254] | | | [removed: 1.2] [added: 1.1] | % | | [removed: 93.8] [added: 97.9] | % |
| Arizona | | [removed: 1] [added: —] | | | [removed: 36] [added: —] | | | [removed: 0.1] [added: —] | % | | [removed: 60.4] [added: —] | % | | [removed: 2] [added: 1] | | | [removed: 274] [added: 36] | | | [removed: 1.2] [added: 0.1] | % | | [removed: 92.7] [added: 60.4] | % |
| Delaware | | 1 | | | 232 | | | [removed: 1.0] [added: 0.6] | % | | [removed: 93.6] [added: 95.6] | % | | 1 | | | 232 | | | 1.0 | % | | [removed: 90.1] [added: 93.6] | % |
| Maryland | | [removed: 1] [added: 3] | | | [removed: 117] [added: 372] | | | [removed: 0.5] [added: 1.0] | % | | [removed: 97.9] [added: 86.6] | % | | 1 | | | [removed: 113] [added: 117] | | | 0.5 | % | | [removed: 96.1] [added: 97.9] | % |
| Michigan | | 1 | | | 97 | | | [removed: 0.4] [added: 0.3] | % | | [removed: 97.1] [added: 98.6] | % | | 1 | | | 97 | | | 0.4 | % | | [removed: 95.7] [added: 97.1] | % |
| New York | | [removed: 1] [added: 9] | | | [removed: 105] [added: 1,198] | | | [removed: 0.4] [added: 3.1] | % | | [removed: —%] [added: 99.0] | [added: %] | | [removed: —] [added: 1] | | | [removed: —] [added: 105] | | | [removed: —%] [added: 0.4] | [added: %] | | —% | |
| New Jersey | | 1 | | | 218 | | | [removed: 0.9] [added: 0.6] | % | | [removed: 65.9] [added: 86.7] | % | | [removed: —] [added: 1] | | | [removed: —] [added: 218] | | | [removed: —%] [added: 0.9] | [added: %] | | [removed: —%] [added: 65.9] | [added: %] |
| South Carolina | | [removed: —] [added: 1] | | | [removed: —] [added: 80] | | | [removed: —%] [added: 0.5] | [added: %] | | [removed: —%] [added: 100.0] | [added: %] | | 1 | | | [removed: 59] [added: 80] | | | [removed: 0.2] [added: 0.6] | % | | 100.0 | % |
Certain Consolidated Properties are encumbered by mortgage loans of [removed: $467.1] [added: $636.7] million, excluding debt [added: issuance costs and] premiums and discounts, as of December 31, [removed: 2016.][added: 2017.]
The weighted average annual effective rent for the consolidated portfolio of properties, net of tenant concessions, is [removed: $19.70] [added: $21.01] and [removed: $18.95] [added: $19.70] per square foot ("PSF") as of December 31, [removed: 2016] [added: 2017] and [removed: 2015,] [added: 2016,] respectively.
| | | December 31, [removed: 2016] [added: 2017] | | | | | | | | [added: | | | |] December 31, [removed: 2015] [added: 2016] | | | | | | | [added: | | | |]
| Location | | Number of Properties | | [added: |] GLA (in thousands) | | [added: |] Percent of Total GLA | | [added: |] Percent Leased | | [added: |] Number of Properties | | [added: |] GLA (in thousands) | | [added: |] Percent of Total GLA | | [added: |] Percent Leased | [added: |]
Certain Unconsolidated Properties are encumbered by mortgage loans of [removed: $1.3] [added: $1.5] billion, excluding debt [added: issuance costs and] premiums and discounts, as of December 31, [removed: 2016.][added: 2017.]
The weighted average annual effective rent for the unconsolidated portfolio of properties, net of tenant concessions, is [removed: $19.25] [added: $20.63] and [removed: $18.81] [added: $19.25] PSF as of December 31, [removed: 2016] [added: 2017] and [removed: 2015,] [added: 2016,] respectively.
The following table summarizes the largest tenants occupying our shopping centers for Consolidated Properties plus our pro-rata share of Unconsolidated Properties, as of December 31, [removed: 2016,] [added: 2017,] based upon a percentage of total annualized base rent (GLA and dollars in thousands):
| Tenant | | GLA | | Percent of Company Owned GLA | | Annualized Base Rent | | | [added: |] Percent of Annualized Base Rent | | Number of Leased Stores | [removed: | Anchor Owned Stores (1) |]
| H.E.B. | | 344 | | [removed: 1.2%] [added: 0.8%] | | 5,762 | | | [removed: 1.0%] | [removed: | 5] [added: 0.6%] | | [removed: —] [added: 5] |
| Trader Joe's | | [removed: 179] [added: 252] | | 0.6% | | [removed: 4,995 |] [added: 7,667] | | [removed: 0.9%] | | [removed: 19] [added: 0.9%] | | [removed: —] [added: 25] |
| Ross Dress For Less | | [removed: 306 |] [added: 564] | [removed: 1.1%] | [added: 1.3%] | [removed: 4,982] | [added: 8,072] | | [removed: 0.9%] | | [removed: 16] [added: 0.9%] | | [removed: —] [added: 24] |
| Wells Fargo Bank | | [removed: 85] [added: 133] | | 0.3% | | [removed: 4,416 |] [added: 6,465] | | [removed: 0.8%] | | [removed: 41] [added: 0.7%] | | [removed: —] [added: 54] |
| JPMorgan Chase Bank | | [removed: 64] [added: 109] | | 0.2% | | [removed: 3,995 |] [added: 5,855] | | [removed: 0.7%] | | [removed: 25] [added: 0.7%] | | [removed: —] [added: 36] |
| Dick's Sporting Goods | | [removed: 267] [added: 417] | | 0.9% | | [removed: 3,441 |] [added: 6,520] | | [removed: 0.6%] | | [removed: 5] [added: 0.7%] | | [removed: —] [added: 8] |
Our leases for tenant space under 10,000 square feet generally have [added: initial] terms ranging from three to seven years.
| Louisiana | | 5 | | | 753 | | | 1.9 | % | | 94.2 | % | | — | | | — | | | — | % | | — | % |
| South Carolina | | 1 | | | 51 | | | 0.1 | % | | 71.2 | % | | — | | | — | | | —% | | | —% | |
| Total | | 311 | | | 38,743 | | | 100.0 | % | | 95.5 | % | | 198 | | | 23,932 | | | 100.0 | % | | 94.8 | % |
| | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | | | | | | | |
| California | | 21 | | | 2,791 | | | 18.4 | % | | 97.0 | % | | 20 | | | 2,652 | | | 19.1 | % | | 97.5 | % |
| Virginia | | 18 | | | 2,554 | | | 16.9 | % | | 94.3 | % | | 18 | | | 2,551 | | | 18.3 | % | | 95.1 | % |
| North Carolina | | 8 | | | 1,326 | | | 8.8 | % | | 91.6 | % | | 8 | | | 1,275 | | | 9.2 | % | | 95.3 | % |
| Maryland | | 11 | | | 1,184 | | | 7.8 | % | | 95.8 | % | | 11 | | | 1,182 | | | 8.5 | % | | 96.1 | % |
| Florida | | 10 | | | 1,040 | | | 6.9 | % | | 97.4 | % | | 7 | | | 729 | | | 5.2 | % | | 98.4 | % |
| Texas | | 7 | | | 933 | | | 6.2 | % | | 97.4 | % | | 7 | | | 932 | | | 6.7 | % | | 98.4 | % |
| Colorado | | 5 | | | 836 | | | 5.5 | % | | 96.2 | % | | 5 | | | 853 | | | 6.1 | % | | 95.1 | % |
| Massachusetts | | 2 | | | 726 | | | 4.8 | % | | 95.7 | % | | — | | | — | | | — | % | | — | % |
| Minnesota | | 5 | | | 674 | | | 4.4 | % | | 98.3 | % | | 5 | | | 674 | | | 4.8 | % | | 98.6 | % |
| Illinois | | 4 | | | 671 | | | 4.4 | % | | 95.5 | % | | 4 | | | 671 | | | 4.8 | % | | 95.7 | % |
| Pennsylvania | | 6 | | | 666 | | | 4.4 | % | | 95.7 | % | | 6 | | | 664 | | | 4.8 | % | | 91.7 | % |
| Washington | | 5 | | | 621 | | | 4.1 | % | | 96.5 | % | | 5 | | | 621 | | | 4.6 | % | | 95.2 | % |
| New Jersey | | 3 | | | 287 | | | 1.9 | % | | 98.2 | % | | 2 | | | 158 | | | 1.1 | % | | 100.0 | % |
| Connecticut | | 1 | | | 186 | | | 1.2 | % | | 100.0 | % | | 1 | | | 186 | | | 1.3 | % | | 94.8 | % |
| New York | | 1 | | | 141 | | | 0.9 | % | | 100.0 | % | | 1 | | | 141 | | | 1.0 | % | | 100.0 | % |
| Indiana | | 2 | | | 139 | | | 0.9 | % | | 99.1 | % | | 2 | | | 139 | | | 1.0 | % | | 100.0 | % |
| Oregon | | 1 | | | 93 | | | 0.6 | % | | 98.4 | % | | 1 | | | 93 | | | 0.7 | % | | 94.7 | % |
| Georgia | | 1 | | | 86 | | | 0.6 | % | | 97.5 | % | | 1 | | | 86 | | | 0.6 | % | | 98.5 | % |
| Delaware | | 1 | | | 64 | | | 0.4 | % | | 90.1 | % | | 1 | | | 64 | | | 0.5 | % | | 92.6 | % |
| District of Columbia | | 2 | | | 40 | | | 0.3 | % | | 91.8 | % | | 2 | | | 40 | | | 0.3 | % | | 100.0 | % |
| Arizona | | — | | | — | | | — | % | | — | % | | 1 | | | 108 | | | 0.8 | % | | 89.7 | % |
| Total | | 115 | | | 15,138 | | | 100.0 | % | | 95.6 | % | | 109 | | | 13,899 | | | 100.0 | % | | 96.3 | % |
| | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | |
| Publix | | 2,750 | | 6.2% | | $ | 28,002 | | | 3.1% | | 69 |
| Kroger | | 2,868 | | 6.5% | | 27,560 | | | | 3.1% | | 58 |
| Albertsons/Safeway | | 1,772 | | 4.0% | | 25,465 | | | | 2.9% | | 46 |
| TJX Companies | | 1,427 | | 3.2% | | 20,958 | | | | 2.4% | | 58 |
| Whole Foods | | 970 | | 2.2% | | 20,133 | | | | 2.3% | | 27 |
| Ahold/Delhaize | | 623 | | 1.4% | | 13,509 | | | | 1.5% | | 16 |
| CVS | | 640 | | 1.5% | | 12,975 | | | | 1.5% | | 57 |
| Nordstrom | | 320 | | 0.7% | | 8,747 | | | | 1.0% | | 9 |
| L.A. Fitness Sports Club | | 445 | | 1.0% | | 8,384 | | | | 0.9% | | 12 |
| Alabama | | — | | | — | | | —% | | | —% | | | 1 | | | 85 | | | 0.4 | % | | 95.0 | % |
| Total | | 198 | | | 23,931 | | | 100.0% | | | 94.8% | | | 200 | | | 23,280 | | | 100.0% | | | 95.4% | |
| | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | |
| California | | 20 | | 2,652 | | 19.1% | | 97.5% | | 20 | | 2,652 | | 18.0% | | 98.7% |
| Virginia | | 18 | | 2,551 | | 18.3% | | 95.1% | | 19 | | 2,645 | | 17.9% | | 96.9% |
| Maryland | | 11 | | 1,182 | | 8.5% | | 96.1% | | 13 | | 1,491 | | 10.1% | | 92.5% |
| North Carolina | | 8 | | 1,275 | | 9.2% | | 95.3% | | 8 | | 1,275 | | 8.6% | | 97.6% |
| Florida | | 7 | | 729 | | 5.2% | | 98.4% | | 8 | | 682 | | 4.6% | | 97.4% |
| Texas | | 7 | | 932 | | 6.7% | | 98.4% | | 7 | | 932 | | 6.3% | | 99.3% |
| Pennsylvania | | 6 | | 664 | | 4.8% | | 91.7% | | 6 | | 664 | | 4.5% | | 88.7% |
| Colorado | | 5 | | 853 | | 6.1% | | 95.1% | | 5 | | 862 | | 5.8% | | 92.9% |
| Minnesota | | 5 | | 674 | | 4.8% | | 98.6% | | 5 | | 674 | | 4.6% | | 98.3% |
| Washington | | 5 | | 621 | | 4.6% | | 95.2% | | 5 | | 621 | | 4.2% | | 97.0% |
| Illinois | | 4 | | 671 | | 4.8% | | 95.7% | | 7 | | 944 | | 6.4% | | 94.6% |
| New Jersey | | 2 | | 158 | | 1.1% | | 100.0% | | 2 | | 158 | | 1.1% | | 95.7% |
| Indiana | | 2 | | 139 | | 1.0% | | 100.0% | | 2 | | 139 | | 0.9% | | 100.0% |
| District of Columbia | | 2 | | 40 | | 0.3% | | 100.0% | | 2 | | 40 | | 0.3% | | 100.0% |
| Connecticut | | 1 | | 186 | | 1.3% | | 94.8% | | 1 | | 186 | | 1.3% | | 98.8% |
| South Carolina | | 1 | | 80 | | 0.6% | | 100.0% | | 2 | | 162 | | 1.1% | | 100.0% |
| New York | | 1 | | 141 | | 1.0% | | 100.0% | | 1 | | 141 | | 1.0% | | 100.0% |
| Arizona | | 1 | | 108 | | 0.8% | | 89.7% | | 1 | | 108 | | 0.7% | | 87.4% |
| Oregon | | 1 | | 93 | | 0.7% | | 94.7% | | 1 | | 93 | | 0.6% | | 98.1% |
| Georgia | | 1 | | 86 | | 0.6% | | 98.5% | | 1 | | 86 | | 0.6% | | 100.0% |
| Delaware | | 1 | | 64 | | 0.5% | | 92.6% | | 1 | | 67 | | 0.5% | | 91.0% |
| Wisconsin | | — | | — | | —% | | —% | | 1 | | 133 | | 0.9% | | 92.8% |
| Total | | 109 | | 13,899 | | 100.0% | | 96.3% | | 118 | | 14,755 | | 100.0% | | 96.3% |
| | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | |
| Kroger | | 2,686 | | 9.3% | $ | 26,288 | | | 4.7% | | 54 | | 5 |
| Publix | | 1,641 | | 5.7% | | 17,617 | | | 3.1% | | 40 | | 1 |
| Albertsons/Safeway | | 1,361 | | 4.7% | | 15,178 | | | 2.7% | | 41 | | 7 |
| Whole Foods | | 713 | | 2.5% | | 13,895 | | | 2.5% | | 21 | | — |
| TJX Companies | | 807 | | 2.8% | | 10,895 | | | 1.9% | | 38 | | — |
| CVS | | 498 | | 1.7% | | 8,644 | | | 1.5% | | 45 | | — |
| PETCO | | 324 | | 1.1% | | 7,218 | | | 1.3% | | 41 | | — |
| Ahold/Delhaize | | 460 | | 1.6% | | 6,301 | | | 1.1% | | 14 | | — |
| Nordstrom Rack | | 174 | | 0.6% | | 4,937 | | | 0.9% | | 5 | | — |
An excerpt. Shown here: 40 of 353 rewritten, 40 of 206 added and 40 of 72 removed. The counts are complete. For every sentence, read Item 2. Properties in the FY2017 filing and the FY2016 filing.
Item 4. Mine Safety Disclosures
0 rewritten, 0 added, 41 removed, 2 unchanged
Read the full itemFY2017 item · filed February 27, 2018FY2016 item · filed February 27, 2017
| | |
| --- | --- |
| Item 5. | Market for the Registrant's Common Equity, Related Stockholder Matters, and Issuer Purchases of Equity Securities |
Our common stock is traded on the New York Stock Exchange under the symbol "REG." The following table sets forth the high and low sales prices and the cash dividends declared on our common stock by quarter for 2016 and 2015.
| | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | | | |
| | | 2016 | | | | | | | | | | 2015 | | | | | | | | |
| Quarter Ended | | High Price | | | | Low Price | | | Cash Dividends Declared | | | High Price | | | | Low Price | | | Cash Dividends Declared | |
| March 31 | | $ | 77.17 | | | 66.05 | | | 0.5000 | | | $ | 70.80 | | | 63.38 | | | 0.4850 | |
| June 30 | | 83.73 | | | | 72.35 | | | 0.5000 | | | 69.45 | | | | 58.81 | | | 0.4850 | |
| September 30 | | 85.35 | | | | 75.76 | | | 0.5000 | | | 64.79 | | | | 55.79 | | | 0.4850 | |
| December 31 | | 77.25 | | | | 65.16 | | | 0.5000 | | | 69.45 | | | | 61.71 | | | 0.4850 | |
We have determined that the dividends paid during 2016 and 2015 on our common stock qualify for the following tax treatment:
| | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | |
| | | Total Distribution per Share | | | | Ordinary Dividends | | | Total Capital Gain Distributions | | | Nontaxable Distributions | | | Qualified Dividends (included in Ordinary Dividends) | | Unrecapt Sec 1250 Gain | |
| 2016 | | $ | 2.0000 | | | 1.0600 | | | 0.1600 | | | 0.7800 | | | — | | 0.1600 | |
| 2015 | | 1.9400 | | | | 1.4744 | | | 0.0970 | | | 0.3686 | | | 0.0970 | | 0.0388 | |
As of February 13, 2017, there were 41,805 holders of common equity.
We intend to pay regular quarterly distributions to Regency Centers Corporation's common stockholders.
Future distributions will be declared and paid at the discretion of our Board of Directors and will depend upon cash generated by operating activities, our financial condition, capital requirements, annual dividend requirements under the REIT provisions of the Internal Revenue Code of 1986, as amended, and such other factors as our Board of Directors deems relevant.
In order to maintain Regency Centers Corporation's qualification as a REIT for federal income tax purposes, we are generally required to make annual distributions at least equal to 90% of our real estate investment trust taxable income for the taxable year.
Under certain circumstances, which we do not expect to occur, we could be required to make distributions in excess of cash available for distributions in order to meet such requirements.
We have a dividend reinvestment plan under which shareholders may elect to reinvest their dividends automatically in common stock.
Under the plan, we may elect to purchase common stock in the open market on behalf of shareholders or may issue new common stock to such stockholders.
Under the loan agreement of our line of credit, in the event of any monetary default, we may not make distributions to stockholders except to the extent necessary to maintain our REIT status.
There were no unregistered sales of equity securities, and we did not repurchase any of our equity securities during the quarter ended December 31, 2016.
The performance graph furnished below shows Regency's cumulative total stockholder return to the S&P 500 Index, the FTSE NAREIT Equity REIT Index, and the FTSE NAREIT Equity Shopping Centers index since December 31, 2010.
The stock performance graph should not be deemed filed or incorporated by reference into any other filing made by us under the Securities Act of 1933 or the Securities Exchange Act of 1934, except to the extent that we specifically incorporate the stock performance graph by reference in another filing.
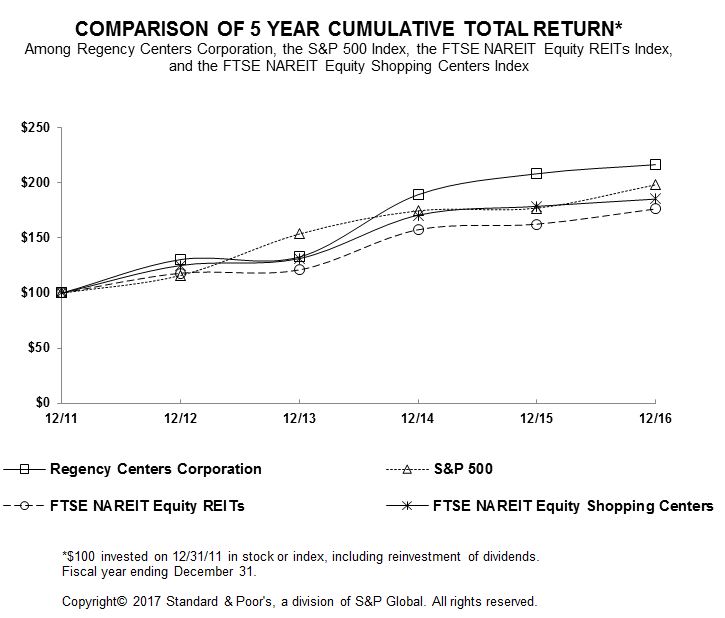
| | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | |
| | | 12/11 | | | 12/12 | | 12/13 | | 12/14 | | 12/15 | | 12/16 | |
| | | | | | | | | | | | | | | |
| Regency Centers Corporation | | $ | 100.00 | | 130.37 | | 132.73 | | 189.19 | | 208.15 | | 216.42 | |
| S&P 500 | | 100.00 | | | 116.00 | | 153.58 | | 174.60 | | 177.01 | | 198.18 | |
| FTSE NAREIT Equity REITs | | 100.00 | | | 118.06 | | 120.97 | | 157.43 | | 162.46 | | 176.30 | |
An excerpt. Shown here: all 0 rewritten, all 0 added and 40 of 41 removed. The counts are complete. For every sentence, read Item 4. Mine Safety Disclosures in the FY2017 filing and the FY2016 filing.
Item 5. Market for the Registrant's Common Equity, Related Stockholder Matters, and Issuer Purchases of Equity Securities
0 rewritten, 54 added, 0 removed, 0 unchanged
New section this year
Read the full itemFY2017 item · filed February 27, 2018
Our common stock is traded on the New York Stock Exchange under the symbol "REG." The following table sets forth the high and low sales prices and the cash dividends declared on our common stock by quarter for 2017 and 2016.
| | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | | | |
| | | 2017 | | | | | | | | | | 2016 | | | | | | | | |
| Quarter Ended | | High Price | | | | Low Price | | | Cash Dividends Declared | | | High Price | | | | Low Price | | | Cash Dividends Declared | |
| March 31 | | $ | 72.05 | | | 61.90 | | | 0.51 | | | $ | 77.17 | | | 66.05 | | | 0.50 | |
| June 30 | | 69.07 | | | | 58.63 | | | 0.53 | | | 83.73 | | | | 72.35 | | | 0.50 | |
| September 30 | | 67.67 | | | | 60.80 | | | 0.53 | | | 85.35 | | | | 75.76 | | | 0.50 | |
| December 31 | | 70.64 | | | | 61.19 | | | 0.53 | | | 77.25 | | | | 65.16 | | | 0.50 | |
We have determined that the dividends paid during 2017 and 2016 on our common stock qualify for the following tax treatment:
| | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | |
| | | Total Distribution per Share | | | | Ordinary Dividends | | | Total Capital Gain Distributions | | | Nontaxable Distributions | | | Unrecapt Sec 1250 Gain | |
| 2017 | | $ | 2.10 | | | 1.81 | | | 0.21 | | | 0.08 | | | 0.02 | |
| 2016 | | 2.00 | | | | 1.06 | | | 0.16 | | | 0.78 | | | 0.16 | |
As of February 9, 2018, there were 65,170 holders of common equity.
We intend to pay regular quarterly distributions to Regency Centers Corporation's common stockholders.
Future distributions will be declared and paid at the discretion of our Board of Directors and will depend upon cash generated by operating activities, our financial condition, capital requirements, annual dividend requirements under the REIT provisions of the Internal Revenue Code of 1986, as amended, and such other factors as our Board of Directors deems relevant.
In order to maintain Regency Centers Corporation's qualification as a REIT for federal income tax purposes, we are generally required to make annual distributions at least equal to 90% of our real estate investment trust taxable income for the taxable year.
Under certain circumstances, which we do not expect to occur, we could be required to make distributions in excess of cash available for distributions in order to meet such requirements.
We have a dividend reinvestment plan under which shareholders may elect to reinvest their dividends automatically in common stock.
Under the plan, we may elect to purchase common stock in the open market on behalf of shareholders or may issue new common stock to such stockholders.
Under the loan agreement of our line of credit, in the event of any monetary default, we may not make distributions to stockholders except to the extent necessary to maintain our REIT status.
On February 7, 2018, our board of directors (the "Board") authorized a share repurchase program for up to $250 million of shares of our common stock.
The share repurchase program authorizes us to purchase from time to time our outstanding common stock through open market purchases and/or in privately negotiated transactions.
Any shares purchased will be retired.
The program is scheduled to expire on February 6, 2020.
The timing of share purchases under this new program depends upon marketplace conditions and other factors, and the program remains subject to the discretion of the Board.
There were no unregistered sales of equity securities during the quarter ended December 31, 2017.
The following table represents information with respect to purchases by the Parent Company of its common stock
during the months in the three month period ended December 31, 2017:
| | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | |
| Period | | Total number of shares purchased (1) | | Average price paid per share | | | | Total number of shares purchased as part of publicly announced plans or programs | | Maximum number or approximate dollar value of shares that may yet be purchased under the plans or programs |
| October 1, 2017, through October 31, 2017 | | 61 | | $ | 64.31 | | | — | | — |
| November 1, 2017, through November 30, 2017 | | — | | $ | — | | | — | | — |
| December 1, 2017, through December 31, 2017 | | — | | $ | — | | | — | | — |
An excerpt. Shown here: all 0 rewritten, 40 of 54 added and all 0 removed. The counts are complete. For every sentence, read Item 5. Market for the Registrant's Common Equity, Related Stockholder Matters, and Issuer Purchases of Equity Securities in the FY2017 filing.
Item 6. Selected Financial Data
77 rewritten, 15 added, 13 removed, 22 unchanged
Read the full itemFY2017 item · filed February 27, 2018FY2016 item · filed February 27, 2017
The following table sets forth Selected Financial Data for the Company on a historical basis for the five years ended December 31, [removed: 2016] [added: 2017] (in thousands, except per share and unit data, number of properties, and ratio of earnings to fixed charges).
| | | [removed: 2016] [added: 2017] | | | [added: (1)] | [removed: 2015] [added: 2016] | | | [removed: 2014] [added: 2015] | | | [removed: 2013] [added: 2014] | | | [removed: 2012] [added: 2013] | |
| Revenues | | $ | [added: 984,326 | | |] 614,371 | | | 569,763 | | | 537,898 | | | 489,007 | | [removed: | 473,929 | |]
| Operating expenses | | [removed: 403,152] [added: 744,763] | | | [added: (2)] | [removed: 365,098] [added: 403,152] | | [added: (2)] | [removed: 353,348] [added: 365,098] | | | [removed: 324,687] [added: 353,348] | | | [removed: 307,493] [added: 324,687] | |
| Total other expense (income) | | [removed: 148,066] [added: 141,093] | | | [removed: (1)] | [removed: 110,236] [added: 148,066] | | [added: (3)] | [removed: 83,046] [added: 110,236] | | [removed: (2)] | [removed: 111,741] [added: 83,046] | | | [removed: 131,240] [added: 111,741] | |
| Income from operations before equity in income of investments in real estate partnerships [added: and income taxes] | | [removed: 63,153] [added: 98,470] | | | | [removed: 94,429] [added: 63,153] | | | [removed: 101,504] [added: 94,429] | | | [removed: 52,579] [added: 101,504] | | | [removed: 35,196] [added: 52,579] | |
| Equity in income of investments in real estate partnerships | | [removed: 56,518] [added: 43,341] | | | | [removed: 22,508] [added: 56,518] | | | [removed: 31,270] [added: 22,508] | | | [removed: 31,718] [added: 31,270] | | | [removed: 23,807] [added: 31,718] | |
| [removed: Income] [added: Deferred income] tax (benefit) [removed: expense] of taxable REIT subsidiary | | [removed: —] [added: (9,737] | | [added: )] | | — | | | [removed: (996] [added: —] | [removed: )] | | [removed: —] [added: (996] | [added: )] | | [removed: 13,224] [added: —] | |
| Income from continuing operations | | [removed: 119,671] [added: 151,548] | | | | [removed: 116,937] [added: 119,671] | | | [removed: 133,770] [added: 116,937] | | | [removed: 84,297] [added: 133,770] | | | [removed: 45,779] [added: 84,297] | |
| Income (loss) from discontinued operations [removed: (3)] [added: (4)] | | — | | | | — | | | — | | | [removed: 65,285] [added: —] | | | [removed: (21,728] [added: 65,285] | [removed: )] |
| Gain on sale of real estate, net of tax | | [removed: 47,321] [added: 27,432] | | | | [removed: 35,606] [added: 47,321] | | | [removed: 55,077] [added: 35,606] | | | [removed: 1,703] [added: 55,077] | | | [removed: 2,158] [added: 1,703] | |
| Net income | | [removed: 166,992] [added: 178,980] | | | | [removed: 152,543] [added: 166,992] | | | [removed: 188,847] [added: 152,543] | | | [removed: 151,285] [added: 188,847] | | | [removed: 26,209] [added: 151,285] | |
| Income attributable to noncontrolling interests | | [removed: (2,070] [added: (2,903] | | ) | | [removed: (2,487] [added: (2,070] | ) | | [removed: (1,457] [added: (2,487] | ) | | [removed: (1,481] [added: (1,457] | ) | | [removed: (342] [added: (1,481] | ) |
| Net income attributable to the Company | | [removed: 164,922] [added: 176,077] | | | | [removed: 150,056] [added: 164,922] | | | [removed: 187,390] [added: 150,056] | | | [removed: 149,804] [added: 187,390] | | | [removed: 25,867] [added: 149,804] | |
| Preferred stock dividends [added: and issuance costs] | | [removed: (21,062] [added: (16,128] | | ) | | (21,062 | ) | | (21,062 | ) | | (21,062 | ) | | [removed: (32,531] [added: (21,062] | ) |
| Net income [removed: (loss)] attributable to common stockholders | | $ | [added: 159,949 | | |] 143,860 | | | 128,994 | | | 166,328 | | | 128,742 | | [removed: | (6,664 | ) |]
| NAREIT FFO [removed: (4)] [added: (5)] | | [removed: 277,301] [added: 494,843] | | | | [removed: 276,515] [added: 277,301] | | | [removed: 269,149] [added: 276,515] | | | [removed: 240,621] [added: 269,149] | | | [removed: 222,100] [added: 240,621] | |
| Core FFO [removed: (4)] [added: (5)] | | [removed: 333,957] [added: 592,137] | | | | [removed: 288,872] [added: 333,957] | | | [removed: 261,506] [added: 288,872] | | | [removed: 241,619] [added: 261,506] | | | [removed: 230,937] [added: 241,619] | |
| Income per common share - diluted (note [removed: 12):] [added: 13)] | | | | | | | | | | | | | | | | |
| Continuing operations | | $ | [added: 1.00 | | |] 1.42 | | | 1.36 | | | 1.80 | | | 0.69 | | [removed: | 0.16 | |]
| Discontinued operations [removed: (3)] [added: (4)] | | — | | | | — | | | — | | | [removed: 0.71] [added: —] | | | [removed: (0.24] [added: 0.71] | [removed: )] |
| Net income attributable to common stockholders | | $ | [added: 1.00 | | |] 1.42 | | | 1.36 | | | 1.80 | | | 1.40 | | [removed: | (0.08 | ) |]
| Net cash provided by operating activities | | $ | [removed: 289,376] [added: 471,146] | | | [removed: 275,637] [added: 297,360] | | [added: (7)] | [removed: 277,742] [added: 285,543] | | [added: (7)] | [removed: 250,731] [added: 277,742] | | | [removed: 257,215] [added: 250,731] | |
| Net cash (used in) [removed: provided by] investing activities | | [removed: (409,671] [added: (1,007,980] | | ) | | [removed: (139,346] [added: (409,671] | ) | | [removed: (210,290] [added: (139,346] | ) | | [removed: (9,817] [added: (210,290] | ) | | [removed: 3,623] [added: (9,817] | [added: )] |
| Net cash provided by (used in) financing activities | | [removed: 96,695] [added: 568,948] | | | | [removed: (213,211] [added: 88,711] | [removed: )] | [added: (7)] | [removed: (34,360] [added: (223,117] | ) | [added: (7)] | [removed: (182,579] [added: (34,360] | ) | | [removed: (249,891] [added: (182,579] | ) |
| Dividends paid to common stockholders [added: and unit holders] | | [removed: 201,336] [added: 323,285] | | | | [removed: 181,691] [added: 201,336] | | | [removed: 172,900] [added: 181,691] | | | [removed: 168,095] [added: 172,900] | | | [removed: 164,747] [added: 168,095] | |
| Common dividends declared per share | | [removed: 2.00] [added: 2.10] | | | | [removed: 1.94] [added: 2.00] | | | [removed: 1.88] [added: 1.94] | | | [removed: 1.85] [added: 1.88] | | | 1.85 | |
| Common stock outstanding including exchangeable operating partnership units | | [removed: 104,651] [added: 171,715] | | | | [removed: 97,367] [added: 104,651] | | | [removed: 94,262] [added: 97,367] | | | [removed: 92,499] [added: 94,262] | | | [removed: 90,572] [added: 92,499] | |
| Ratio of earnings to fixed charges [removed: (5)] [added: (6)] | | [removed: 2.6] [added: 2.2] | | | | [removed: 2.5] [added: 2.6] | | | [removed: 2.6] [added: 2.5] | | | [removed: 1.8] [added: 2.6] | | | [removed: 1.6] [added: 1.8] | |
| Ratio of earnings to combined fixed charges and preference dividends [removed: (5)] [added: (6)] | | 2.1 | | | | 2.1 | | | [removed: 2.2] [added: 2.1] | | | [removed: 1.5] [added: 2.2] | | | [removed: 1.4] [added: 1.5] | |
| Real estate investments before accumulated depreciation | | $ | [added: 11,279,125 | | |] 5,230,198 | | | 4,852,106 | | | 4,743,053 | | | 4,385,380 | | [removed: | 4,352,839 | |]
| Total assets | | [removed: 4,488,906] [added: 11,145,717] | | | | [removed: 4,182,881] [added: 4,488,906] | | | [removed: 4,197,170] [added: 4,182,881] | | | [removed: 3,913,516] [added: 4,197,170] | | | [removed: 3,853,458] [added: 3,913,516] | |
| Total debt | | [removed: 1,642,420] [added: 3,594,977] | | | | [removed: 1,864,285] [added: 1,642,420] | | | [removed: 2,021,357] [added: 1,864,285] | | | [removed: 1,854,697] [added: 2,021,357] | | | [removed: 1,941,891] [added: 1,854,697] | |
| Total liabilities | | [removed: 1,864,404] [added: 4,412,663] | | | | [removed: 2,100,261] [added: 1,864,404] | | | [removed: 2,260,688] [added: 2,100,261] | | | [removed: 2,052,382] [added: 2,260,688] | | | [removed: 2,107,547] [added: 2,052,382] | |
| Total stockholders’ equity | | [removed: 2,591,301] [added: 6,692,052] | | | | [removed: 2,054,109] [added: 2,591,301] | | | [removed: 1,906,592] [added: 2,054,109] | | | [removed: 1,843,354] [added: 1,906,592] | | | [removed: 1,730,765] [added: 1,843,354] | |
| Total noncontrolling interests | | [removed: 33,201] [added: 41,002] | | | | [removed: 28,511] [added: 33,201] | | | [removed: 29,890] [added: 28,511] | | | [removed: 17,780] [added: 29,890] | | | [removed: 15,146] [added: 17,780] | |
[removed: (1)] [added: | (3)] During the year ended December 31, 2016, the Company recognized a $40.6 million charge to settle $220 million of forward starting interest rate swaps related to new debt previously expected to be issued in 2017. [added: As a result of its July 2016 equity offering and the early redemption of the $300 million notes in August 2016, the Company believed that the issuance of new fixed rate debt within the remaining period of the forward starting swaps was probable to no longer occur. Accordingly, the Company ceased hedge accounting and reclassified the $40.6 million paid to settle the forward starting swaps from Accumulated other comprehensive loss to earnings. | | | | | | | | | | | | | | | | |]
[added: | (3) During the year ended December 31, 2016, the Operating Partnership recognized a $40.6 million charge to settle $220 million of forward starting interest rate swaps related to new debt previously expected to be issued in 2017.] As a result of its July 2016 equity offering and the early redemption of the $300 million notes in August 2016, the [removed: Company] [added: Operating Partnership] believed that the issuance of new fixed rate debt within the remaining period of the forward starting swaps was probable to no longer occur. [added: Accordingly, the Operating Partnership ceased hedge accounting and reclassified the $40.6 million paid to settle the forward starting swaps from Accumulated other comprehensive loss to earnings. | | | | | | | | | | | | | | | | |]
[removed: (3)] [added: | (4)] On January 1, 2014, the Company prospectively adopted Financial Accounting Standards Board ("FASB") Accounting Standards Update ("ASU") No. 2014-08, Presentation of Financial Statements (Topic 205) and Property, Plant and Equipment (Topic 360): Reporting Discontinued Operations and Disclosures of Disposals of Components of an Entity, which changes the requirements for reporting discontinued operations. [added: Under the new guidance, only disposals representing a strategic shift in operations should be presented as discontinued operations. No property disposals since adoption of this ASU qualify as discontinued operations, therefore prior period amounts were not reclassified for property sales since adoption. | | | | | | | | | | | | | | | | |]
[removed: (4)] [added: | (5)] See Item 1, Defined Terms, for the definition of NAREIT FFO and Core FFO and Item 7, Supplemental Earnings Information, for a reconciliation to the nearest GAAP measure. [added: | | | | | | | | | | | | | | | | |]
| (1) 2017 reflects the results of our merger with Equity One on March 1, 2017. | | | | | | | | | | | | | | | | |
| (2) During the years ended December 31, 2017 and 2016, the Company recognized $80.7 million and $6.5 million, respectively, of merger and integration related costs within Operating expenses associated with the Equity One merger, which was effective on March 1, 2017. | | | | | | | | | | | | | | | | |
| (7) In January 2017, the Company adopted ASU 2016-09, Improvements to Share-Based Payment Accounting, resulting in the reclassification of previously reported employee tax withholdings from Net cash provided by operating activities to Net cash provided by (used in) financing activities. See note 1 for further discussion. | | | | | | | | | | | | | | | | |
(in thousands, except per share and unit data, number of properties, and ratio of earnings to fixed charges)
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | |
| (1) 2017 reflects the results of our merger with Equity One on March 1, 2017. | | | | | | | | | | | | | | | | |
| (2) During the years ended December 31, 2017 and 2016, the Operating Partnership recognized $80.7 million and $6.5 million, respectively, of merger and integration related costs within Operating expenses associated with the Equity One merger, which was effective on March 1, 2017. | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | |
| (7) In January 2017, the Company adopted ASU 2016-09, Improvements to Share-Based Payment Accounting, which resulted in the reclassification of previously reported employee tax withholdings from Net cash provided by operating activities to Net cash provided by (used in) financing activities. See note 1 for further discussion. | | | | | | | | | | | | | | | | |
Accordingly, the Company ceased hedge accounting and reclassified the $40.6 million paid to settle the forward starting swaps from Accumulated other comprehensive loss to earnings.
(2) During the year ended December 31, 2014, the Company recognized a gain on remeasurement of investment in real estate partnership of $18.3 million, which is included in Total other expense (income) and Income from operations, upon the acquisition of the remaining 50% interest in a single operating property, resulting in consolidation of the property as a business
combination.
The gain on remeasurement was calculated based on the difference between the carrying value and the fair value of the previously held equity interest.
Under the new guidance, only disposals representing a strategic shift in operations should be presented as discontinued operations.
No property disposals since adoption of this ASU qualify as discontinued operations, therefore prior period amounts were not reclassified for property sales since adoption.
(1) During the year ended December 31, 2016, the Operating Partnership recognized a $40.6 million charge to settle $220 million of forward starting interest rate swaps related to new debt previously expected to be issued in 2017.
As a result of its July 2016 equity offering and the early redemption of the $300 million notes in August 2016, the Operating Partnership believed that the issuance of new fixed rate debt within the remaining period of the forward starting swaps was probable to no longer occur.
Accordingly, the Operating Partnership ceased hedge accounting and reclassified the $40.6 million paid to settle the forward starting swaps from Accumulated other comprehensive loss to earnings.
(2) During the year ended December 31, 2014, the Operating Partnership recognized a gain on remeasurement of investment in real estate partnership of $18.3 million, which is included in Total other expense (income) and Income from operations, upon the acquisition of the remaining 50% interest in a single operating property, resulting in consolidation of the property as a business combination.
The gain on remeasurement was calculated based on the difference between the carrying value and the fair value of the previously held equity interest.
Under the new guidance, only disposals representing a strategic shift in operations should be presented as discontinued operations.
No property disposals since adoption of this ASU qualify as discontinued operations, therefore prior period amounts were not reclassified for property sales since adoption.
An excerpt. Shown here: 40 of 77 rewritten, all 15 added and all 13 removed. The counts are complete. For every sentence, read Item 6. Selected Financial Data in the FY2017 filing and the FY2016 filing.
Item 8. Consolidated Financial Statements and Supplementary Data
762 rewritten, 815 added, 491 removed, 940 unchanged
Read the full itemFY2017 item · filed February 27, 2018FY2016 item · filed February 27, 2017
| [Reports of Independent Registered Public Accounting [removed: Firm](#sA5F2140B6CFF06C2EA014EDF78590099)] [added: Firm](#s65F9CA23C2D36D2F3FB1BCAA235674EF)] | [removed: [67](#sA5F2140B6CFF06C2EA014EDF78590099)] [added: [66](#s65F9CA23C2D36D2F3FB1BCAA235674EF)] |
| [Consolidated Balance Sheets as of December 31, [removed: 2016] [added: 2017] and [removed: 2015](#s059EE8154E4D1616808E4EDF3EDCA892)] [added: 2016](#s501992A1CA9CA3B7FDBABCA9C5C4F32C)] | [removed: [71](#s059EE8154E4D1616808E4EDF3EDCA892)] [added: [70](#s501992A1CA9CA3B7FDBABCA9C5C4F32C)] |
| [Consolidated Statements of Operations for the years ended December 31, [added: 2017,] 2016, [removed: 2015,] and [removed: 2014](#sEB3ECD6989106FC411834EDF3EFBE57E)] [added: 2015](#s8960B67B39F31C2E4BE1BCA9C61A9368)] | [removed: [72](#sEB3ECD6989106FC411834EDF3EFBE57E)] [added: [71](#s8960B67B39F31C2E4BE1BCA9C61A9368)] |
| [Consolidated Statements of Comprehensive Income for the years ended December 31, [added: 2017,] 2016, [removed: 2015,] and [removed: 2014](#s24F734F59F3882A2EE674EDF3F23EB11)] [added: 2015](#s828870E12D13E45CAE34BCA9C6AF4AB1)] | [removed: [73](#s24F734F59F3882A2EE674EDF3F23EB11)] [added: [72](#s828870E12D13E45CAE34BCA9C6AF4AB1)] |
| [Consolidated Statements of Equity for the years ended December 31, [added: 2017,] 2016, [removed: 2015,] and [removed: 2014](#sA719C734F0778EE2036C4EDF3F302820)] [added: 2015](#sC00D53403EC3B8D764BFBCA9C6DBC14F)] | [removed: [74](#sA719C734F0778EE2036C4EDF3F302820)] [added: [73](#sC00D53403EC3B8D764BFBCA9C6DBC14F)] |
| [Consolidated Statements of Cash Flows for the years ended December 31, [added: 2017,] 2016, [removed: 2015,] and [removed: 2014](#s4960189B296C71EEC3174EDF40E2C2C9)] [added: 2015](#sAE86F3C32ACBF4C74F29BCA9CF0B0215)] | [removed: [76](#s4960189B296C71EEC3174EDF40E2C2C9)] [added: [75](#sAE86F3C32ACBF4C74F29BCA9CF0B0215)] |
| [Consolidated Balance Sheets as of December 31, [removed: 2016] [added: 2017] and [removed: 2015](#s059EE8154E4D1616808E4EDF3EDCA892)] [added: 2016](#s501992A1CA9CA3B7FDBABCA9C5C4F32C)] | [removed: [78](#s0CD92C7B4B6E7BE356224EDF415F5CF0)] [added: [77](#s2E2BB74A17A8E329B46BBCA9D0F6C8C6)] |
| [Consolidated Statements of Operations for the years ended December 31, [added: 2017,] 2016, [removed: 2015,] and [removed: 2014](#sEB3ECD6989106FC411834EDF3EFBE57E)] [added: 2015](#s8960B67B39F31C2E4BE1BCA9C61A9368)] | [removed: [79](#sB4B280286C65412EDB7E4EDF4197C662)] [added: [78](#s5198BABBDA733C093838BCA9D1627815)] |
| [Consolidated Statements of Comprehensive Income for the years ended December 31, [added: 2017,] 2016, [removed: 2015,] and [removed: 2014](#s6951F18F9C1D93E35AB64EDF7BD01159)] [added: 2015](#s3D4A83316D306C25E929BCAA27486A03)] | [removed: [80](#s6D896FDF477615DE6BE64EDF41E830C5)] [added: [79](#s21785D5F8E8A192A8088BCA9D20E0A3D)] |
| [Consolidated Statements of Capital for the years ended December 31, [added: 2017,] 2016, [removed: 2015,] and [removed: 2014](#s1DE4C3CC93CF2844D6BE4EDF4201A932)] [added: 2015](#sFEC14578477CEE2F4827BCA9D2445713)] | [removed: [81](#s1DE4C3CC93CF2844D6BE4EDF4201A932)] [added: [80](#sFEC14578477CEE2F4827BCA9D2445713)] |
| [Consolidated Statements of Cash Flows for the years ended December 31, [added: 2017,] 2016, [removed: 2015,] and [removed: 2014](#s4960189B296C71EEC3174EDF40E2C2C9)] [added: 2015](#sAE86F3C32ACBF4C74F29BCA9CF0B0215)] | [removed: [83](#s7FF9F0649AA03956883F4EDF4361CC5C)] [added: [82](#sFF1565499EDFF1B08ECEBCA9D47E9769)] |
| [Notes to Consolidated Financial [removed: Statements](#s6951F18F9C1D93E35AB64EDF7BD01159)] [added: Statements](#s3D4A83316D306C25E929BCAA27486A03)] | [removed: [85](#s6951F18F9C1D93E35AB64EDF7BD01159)] [added: [84](#s3D4A83316D306C25E929BCAA27486A03)] |
| [Schedule III - Consolidated Real Estate and Accumulated Depreciation - December 31, [removed: 2016](#s189F6C7F267A372090A04EDF478F8F87)] [added: 2017](#s5DA25FA9B7B2B8C005D9BCA9D94E4F3B)] | [removed: [127](#s189F6C7F267A372090A04EDF478F8F87)] [added: [128](#s5DA25FA9B7B2B8C005D9BCA9D94E4F3B)] |
[removed: The] [added: To the Stockholders and] Board of Directors [removed: and Stockholders]
We have audited the accompanying consolidated balance sheets of Regency Centers Corporation and subsidiaries [added: (the “Company”)] as of December 31, [removed: 2016 and 2015,] [added: 2017] and [added: 2016,] the related consolidated statements of operations, comprehensive income, equity, and cash flows for each of the years in the three‑year period ended December 31, [removed: 2016.][added: 2017, and the related notes and the financial statement schedule III - Real Estate and Accumulated Depreciation (collectively, the “consolidated financial statements”).]
These consolidated financial statements [removed: and financial statement schedule] are the responsibility of the Company’s management.
Our responsibility is to express an opinion on these consolidated financial statements [removed: and financial statement schedule] based on our audits.
We conducted our audits in accordance with the standards of the [removed: Public Company Accounting Oversight Board (United States).][added: PCAOB.]
Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the [added: consolidated] financial statements are free of material [removed: misstatement.][added: misstatement, whether due to error or fraud.]
[removed: An audit includes] [added: Such procedures included] examining, on a test basis, evidence [removed: supporting] [added: regarding] the amounts and disclosures in the [added: consolidated] financial statements.
[removed: An audit] [added: Our audits] also [removed: includes assessing] [added: included evaluating] the accounting principles used and significant estimates made by management, as well as evaluating the overall [added: presentation of the consolidated] financial [removed: statement presentation.][added: statements.]
In our opinion, the consolidated financial statements [removed: referred to above] present fairly, in all material respects, the financial position of [removed: Regency Centers Corporation and subsidiaries] [added: the Company] as of December 31, [removed: 2016] [added: 2017] and [removed: 2015,] [added: 2016,] and the results of [removed: their] [added: its] operations and [removed: their] [added: its] cash flows for each of the years in the three‑year period ended December 31, [removed: 2016,] [added: 2017,] in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United [removed: States), Regency Centers Corporation’s] [added: States) (“PCAOB”), the Company’s] internal control over financial reporting as of December 31, [removed: 2016,] [added: 2017,] based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway [removed: Commission (COSO),] [added: Commission,] and our report dated February 27, [removed: 2017] [added: 2018,] expressed an unqualified opinion on the effectiveness of the Company’s internal control over financial reporting.
The [added: Stockholders and] Board of Directors [removed: and Stockholders]
We have audited Regency Centers [removed: Corporation’s] [added: Corporation and subsidiaries' (the “Company”)] internal control over financial reporting as of December 31, [removed: 2016,] [added: 2017,] based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway [removed: Commission (COSO).][added: Commission.]
[removed: Regency Centers Corporation’s] [added: The Company’s] management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting, included in the accompanying Management’s Report on Internal Control over Financial Reporting.
We conducted our audit in accordance with the standards of the [removed: Public Company Accounting Oversight Board (United States).][added: PCAOB.]
Our audit [added: of internal control over financial reporting] included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk.
In our opinion, [removed: Regency Centers Corporation] [added: the Company] maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2016,] [added: 2017,] based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United [removed: States),] [added: States) (“PCAOB”),] the consolidated balance sheets of [removed: Regency Centers Corporation and subsidiaries] [added: the Company] as of December 31, [removed: 2016 and 2015,] [added: 2017] and [added: 2016,] the related consolidated statements of operations, comprehensive income, equity, and cash flows for each of the years in the three-year period ended December 31, [removed: 2016,] [added: 2017,] and [added: the related notes and financial statement schedule III - Real Estate and Accumulated Depreciation (collectively, the “consolidated financial statements”), and] our report dated February 27, [removed: 2017] [added: 2018,] expressed an unqualified opinion on those consolidated financial statements.
[removed: The] [added: To the] Partners
We have audited the accompanying consolidated balance sheets of Regency Centers, L.P. and subsidiaries [added: (the “Partnership”)] as of December 31, [removed: 2016 and 2015,] [added: 2017] and [added: 2016,] the related consolidated statements of operations, comprehensive income, capital, and cash flows for each of the years in the three‑year period ended December 31, [removed: 2016.][added: 2017, and the related notes and the financial statement schedule III - Real Estate and Accumulated Depreciation (collectively, the “consolidated financial statements”).]
These consolidated financial statements [removed: and financial statement schedule] are the responsibility of the Partnership’s management.
Our responsibility is to express an opinion on these consolidated financial statements [removed: and financial statement schedule] based on our audits.
We conducted our audits in accordance with the standards of the [removed: Public Company Accounting Oversight Board (United States).][added: PCAOB.]
Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the [added: consolidated] financial statements are free of material [removed: misstatement.][added: misstatement, whether due to error or fraud.]
[removed: An audit includes] [added: Such procedures included] examining, on a test basis, evidence [removed: supporting] [added: regarding] the amounts and disclosures in the [added: consolidated] financial statements.
[removed: An audit] [added: Our audits] also [removed: includes assessing] [added: included evaluating] the accounting principles used and significant estimates made by management, as well as evaluating the overall [added: presentation of the consolidated] financial [removed: statement presentation.][added: statements.]
In our opinion, the consolidated financial statements [removed: referred to above] present fairly, in all material respects, the financial position of [removed: Regency Centers, L.P. and subsidiaries] [added: the Partnership] as of December 31, [removed: 2016] [added: 2017] and [removed: 2015,] [added: 2016,] and the results of [removed: their] [added: its] operations and [removed: their] [added: its] cash flows for each of the years in the three‑year period ended December 31, [removed: 2016,] [added: 2017,] in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United [removed: States), Regency Centers, L.P.’s] [added: States) (“PCAOB”), the Partnership’s] internal control over financial reporting as of December 31, [removed: 2016,] [added: 2017,] based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway [removed: Commission (COSO),] [added: Commission,] and our report dated February 27, [removed: 2017] [added: 2018,] expressed an unqualified opinion on the effectiveness of the Partnership’s internal control over financial reporting.
Opinion on the Consolidated Financial Statements
Basis for Opinion
We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
Our audits included performing procedures to assess the risks of material misstatement of the consolidated financial statements, whether due to error or fraud, and performing procedures that respond to those risks.
We have served as the Company's auditor since 1993.
February 27, 2018
Opinion on Internal Control Over Financial Reporting
Basis for Opinion
We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
Definition and Limitations of Internal Control Over Financial Reporting
February 27, 2018
Opinion on the Consolidated Financial Statements
Basis for Opinion
We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Partnership in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
Our audits included performing procedures to assess the risks of material misstatement of the consolidated financial statements, whether due to error or fraud, and performing procedures that respond to those risks.
We have served as the Partnership's auditor since 1998.
February 27, 2018
Opinion on Internal Control Over Financial Reporting
Basis for Opinion
We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Partnership in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
Definition and Limitations of Internal Control Over Financial Reporting
February 27, 2018
| | | 2017 | | | | 2016 | |
| | | 10,892,821 | | | | 4,933,499 | |
| | | 9,553,050 | | | | 3,809,108 | |
| Other assets (note 1) | | 427,127 | | | | 65,667 | |
| (in thousands, except per share data) | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Net income | | — | | | — | | | — | | | — | | | — | | | 176,077 | | | 176,077 | | | 388 | | | 2,515 | | | 2,903 | | | 178,980 | |
| Other comprehensive income (loss) | | — | | | — | | | — | | | — | | | 12,057 | | | — | | | 12,057 | | | 21 | | | 168 | | | 189 | | | 12,246 | |
| REGENCY CENTERS CORPORATION Consolidated Statements of Equity | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| (in thousands, except per share data) | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Deferred compensation plan, net | | — | | | — | | | (1,245 | ) | | 1,236 | | | — | | | — | | | (9 | ) | | — | | | — | | | — | | | (9 | ) |
| Restricted stock issued, net of amortization | | — | | | 2 | | | — | | | 15,293 | | | — | | | — | | | 15,295 | | | — | | | — | | | — | | | 15,295 | |
| Restricted stock issued upon Equity One merger | | — | | | 1 | | | — | | | 7,950 | | | — | | | — | | | 7,951 | | | — | | | — | | | — | | | 7,951 | |
| Redemption of preferred stock | | (325,000 | ) | | — | | | — | | | 11,099 | | | — | | | (11,099 | ) | | (325,000 | ) | | — | | | — | | | — | | | (325,000 | ) |
| Reallocation of limited partners' interest | | — | | | — | | | — | | | (72 | ) | | — | | | — | | | (72 | ) | | — | | | 72 | | | 72 | | | — | |
| Distributions to partners | | — | | | — | | | — | | | — | | | — | | | — | | | — | | | — | | | (8,206 | ) | | (8,206 | ) | | (8,206 | ) |
| Common stock/unit ($2.10 per share) | | — | | | — | | | — | | | — | | | — | | | (323,860 | ) | | (323,860 | ) | | (635 | ) | | — | | | (635 | ) | | (324,495 | ) |
| Balance at December 31, 2017 | $ | — | | | 1,714 | | | (18,307 | ) | | 7,873,104 | | | (6,289 | ) | | (1,158,170 | ) | | 6,692,052 | | | 10,907 | | | 30,095 | | | 41,002 | | | 6,733,054 | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
In connection with our audits of the consolidated financial statements, we also have audited the financial statement schedule III.
Also in our opinion, the related financial statement schedule, when considered in relation to the basic consolidated financial statements taken as a whole, present fairly, in all material respects, the information set forth therein.
February 27, 2017
February 27, 2017
| --- | --- | --- | --- | --- | --- | --- | --- |
| | | 3,809,108 | | | | 3,502,113 | |
| Gain on remeasurement of investment in real estate partnership | | — | | | | — | | | (18,271 | ) |
| Less: realized gains on sale of available-for-sale securities recognized in net income | | — | | | | — | | | (7,765 | ) |
| REGENCY CENTERS CORPORATION Consolidated Statements of Equity For the years ended December 31, 2016, 2015, and 2014 (in thousands, except per share data) | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Balance at December 31, 2013 | $ | 325,000 | | | 923 | | | (16,726 | ) | | 2,426,477 | | | (17,404 | ) | | (874,916 | ) | | 1,843,354 | | | (1,426 | ) | | 19,206 | | | 17,780 | | | 1,861,134 | |
| Net income | | — | | | — | | | — | | | — | | | — | | | 187,390 | | | 187,390 | | | 319 | | | 1,138 | | | 1,457 | | | 188,847 | |
| Other comprehensive income (loss) | | — | | | — | | | — | | | — | | | (40,344 | ) | | — | | | (40,344 | ) | | (70 | ) | | (201 | ) | | (271 | ) | | (40,615 | ) |
| Distributions to partners | | — | | | — | | | — | | | (1,404 | ) | | — | | | — | | | (1,404 | ) | | — | | | (4,543 | ) | | (4,543 | ) | | (5,947 | ) |
| Common stock/unit ($1.88 per share) | | — | | | — | | | — | | | — | | | — | | | (173,784 | ) | | (173,784 | ) | | (300 | ) | | — | | | (300 | ) | | (174,084 | ) |
| REGENCY CENTERS CORPORATION Consolidated Statements of Equity For the years ended December 31, 2016, 2015, and 2014 (in thousands, except per share data) | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Gain on remeasurement of investment in real estate partnership | | — | | | | — | | | (18,271 | ) |
| Accounts receivable, net | | (9,565 | | ) | | (11,965 | ) | | (6,225 | ) |
| Net cash provided by operating activities | | 289,376 | | | | 275,637 | | | 277,742 | |
| Common stock issued for partnership units exchanged | | $ | — | | | — | | | 137 | |
| Initial fair value of non-controlling interest recorded at acquisition | | $ | — | | | — | | | 15,385 | |
Consolidated Balance Sheets
| | | 3,809,108 | | | | 3,502,113 | |
| Other assets | | 37,079 | | | | 26,935 | |
Consolidated Statements of Operations
| Gain on remeasurement of investment in real estate partnership | | — | | | | — | | | (18,271 | ) |
| Effective portion of change in fair value of derivative instruments | | (10,332 | | ) | | (10,089 | ) | | (49,968 | ) |
| Less: realized gains on sale of available-for-sale securities recognized in net income | | — | | | | — | | | (7,765 | ) |
| Balance at December 31, 2013 | $ | 1,860,758 | | | (1,426 | ) | | (17,404 | ) | | 1,841,928 | | | 19,206 | | | 1,861,134 | |
| Net income | | 187,390 | | | 319 | | | — | | | 187,709 | | | 1,138 | | | 188,847 | |
| Other comprehensive income (loss) | | — | | | (70 | ) | | (40,344 | ) | | (40,414 | ) | | (201 | ) | | (40,615 | ) |
| Distributions to partners | | (175,188 | ) | | (300 | ) | | — | | | (175,488 | ) | | (4,543 | ) | | (180,031 | ) |
| Common units exchanged for common stock of the Parent Company | | 137 | | | (137 | ) | | — | | | — | | | — | | | — | |
| Redemption of preferred units | | — | | | — | | | — | | | — | | | — | | | — | |
| Gain on remeasurement of investment in real estate partnership | | — | | | | — | | | (18,271 | ) |
| Accounts receivable, net | | (9,565 | | ) | | (11,965 | ) | | (6,225 | ) |
| Net cash provided by operating activities | | 289,376 | | | | 275,637 | | | 277,742 | |
An excerpt. Shown here: 40 of 762 rewritten, 40 of 815 added and 40 of 491 removed. The counts are complete. For every sentence, read Item 8. Consolidated Financial Statements and Supplementary Data in the FY2017 filing and the FY2016 filing.
Item 9A. Controls and Procedures
5 rewritten, 1 added, 0 removed, 27 unchanged
Read the full itemFY2017 item · filed February 27, 2018FY2016 item · filed February 27, 2017
Based on its evaluation under the framework in Internal Control - Integrated Framework (2013), the Parent Company's management concluded that its internal control over financial reporting was effective as of December 31, [removed: 2016.][added: 2017.]
[removed: There] [added: Other than the integration of Equity One's operations into our control structure, there] have been no changes in the Parent Company's internal controls over financial reporting identified in connection with this evaluation that occurred during the fourth quarter of [removed: 2016] [added: 2017] and that have materially affected, or are reasonably likely to materially affect, its internal controls over financial reporting.
[removed: These disclosure controls and procedures include controls and procedures designed to ensure that information required to be disclosed by the Operating] Partnership in the reports it files or submits is accumulated and communicated to management, including the chief executive officer and chief financial officer of its general partner, as appropriate, to allow timely decisions regarding required disclosure.
Based on its evaluation under the framework in Internal Control - Integrated Framework (2013), the Operating Partnership's management concluded that its internal control over financial reporting was effective as of December 31, [removed: 2016.][added: 2017.]
[removed: There] [added: Other than the integration of Equity One's operations into our control structure, there] have been no changes in the Operating Partnership's internal controls over financial reporting identified in connection with this evaluation that occurred during the fourth quarter of [removed: 2016] [added: 2017] and that have materially affected, or are reasonably likely to materially affect, its internal controls over financial reporting.
These disclosure controls and procedures include controls and procedures designed to ensure that information required to be disclosed by the Operating
Item 10. Directors, Executive Officers, and Corporate Governance
3 rewritten, 0 added, 0 removed, 3 unchanged
Read the full itemFY2017 item · filed February 27, 2018FY2016 item · filed February 27, 2017
Information concerning our directors, executive officers, and corporate governance is incorporated herein by reference to our definitive proxy statement to be filed with the Securities and Exchange Commission within 120 days after the end of the fiscal year covered by this Form 10-K with respect to the [removed: 2017] [added: 2018] Annual Meeting of Stockholders.
We have [removed: adopted] a code of ethics applicable to our Board of Directors, principal executive officers, principal financial officer, principal accounting officer and persons performing similar functions.
We [removed: intend to] [added: will] post a notice of any waiver from, or amendment to, any provision of our code of ethics on our web site.
Item 11. Executive Compensation
1 rewritten, 0 added, 16 removed, 0 unchanged
Read the full itemFY2017 item · filed February 27, 2018FY2016 item · filed February 27, 2017
Incorporated herein by reference to our definitive proxy statement to be filed with the Securities and Exchange Commission within 120 days after the end of the fiscal year covered by this Form 10-K with respect to the [removed: 2017] [added: 2018] Annual Meeting of Stockholders.
| | |
| --- | --- |
| Item 12. | Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters |
Equity Compensation Plan Information
| | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | |
| | | (a) | | | (b) | | | | (c) | |
| Plan Category | | Number of securities to be issued upon exercise of outstanding options, warrants and rights (1) | | | Weighted-average exercise price of outstanding options, warrants and rights(2) | | | | Number of securities remaining available for future issuance under equity compensation plans (excluding securities reflected in column a) (3) | |
| Equity compensation plans approved by security holders | | 8,740 | | | $ | 88.45 | | | 1,787,149 | |
| Equity compensation plans not approved by security holders | | N/A | | | N/A | | | | N/A | |
| Total | | 8,740 | | | $ | 88.45 | | | 1,787,149 | |
(1) This column does not include 561,261 shares that may be issued pursuant to unvested restricted stock and performance share awards.
(2) The weighted average exercise price excludes stock rights awards, which we sometimes refer to as unvested restricted stock.
(3) The Regency Centers Corporation 2011 Omnibus Incentive Plan, (“Omnibus Plan”), as approved by stockholders at our 2011 annual meeting, provides that an aggregate maximum of 4.1 million shares of our common stock are reserved for issuance under the Omnibus Plan.
Information about security ownership is incorporated herein by reference to our definitive proxy statement to be filed with the Securities and Exchange Commission within 120 days after the end of the fiscal year covered by this Form 10-K with respect to the 2017 Annual Meeting of Stockholders.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
0 rewritten, 14 added, 0 removed, 0 unchanged
New section this year
Read the full itemFY2017 item · filed February 27, 2018
Equity Compensation Plan Information
| | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | |
| | | (a) | | | (b) | | | | (c) | |
| Plan Category | | Number of securities to be issued upon exercise of outstanding options, warrants and rights (1) | | | Weighted-average exercise price of outstanding options, warrants and rights(2) | | | | Number of securities remaining available for future issuance under equity compensation plans (excluding securities reflected in column a) (3) | |
| Equity compensation plans approved by security holders | | — | | | $ | — | | | 1,502,643 | |
| Equity compensation plans not approved by security holders | | N/A | | | N/A | | | | N/A | |
| Total | | — | | | $ | — | | | 1,502,643 | |
| | | | | | | | | | | |
| (1) This column does not include 570,077 shares that may be issued pursuant to unvested restricted stock and performance share awards. | | | | | | | | | | |
| (2) The weighted average exercise price excludes stock rights awards, which we sometimes refer to as unvested restricted stock. | | | | | | | | | | |
| (3) The Regency Centers Corporation 2011 Omnibus Incentive Plan, (“Omnibus Plan”), as approved by stockholders at our 2011 annual meeting, provides that an aggregate maximum of 4.1 million shares of our common stock are reserved for issuance under the Omnibus Plan. | | | | | | | | | | |
Information about security ownership is incorporated herein by reference to our definitive proxy statement to be filed with the Securities and Exchange Commission within 120 days after the end of the fiscal year covered by this Form 10-K with respect to the 2018 Annual Meeting of Stockholders.
Item 13. Certain Relationships and Related Transactions, and Director Independence
1 rewritten, 0 added, 0 removed, 0 unchanged
Read the full itemFY2017 item · filed February 27, 2018FY2016 item · filed February 27, 2017
Incorporated herein by reference to our definitive proxy statement to be filed with the Securities and Exchange Commission within 120 days after the end of the fiscal year covered by this Form 10-K with respect to the [removed: 2017] [added: 2018] Annual Meeting of Stockholders.
Item 14. Principal Accountant Fees and Services
1 rewritten, 0 added, 0 removed, 1 unchanged
Read the full itemFY2017 item · filed February 27, 2018FY2016 item · filed February 27, 2017
Incorporated herein by reference to our definitive proxy statement to be filed with the Securities and Exchange Commission within 120 days after the end of the fiscal year covered by this Form 10-K with respect to the [removed: 2017] [added: 2018] Annual Meeting of Stockholders.
Item 15. Exhibits and Financial Statement Schedules
66 rewritten, 61 added, 12 removed, 162 unchanged
Read the full itemFY2017 item · filed February 27, 2018FY2016 item · filed February 27, 2017
Regency Centers Corporation and Regency Centers, L.P. [removed: 2016] [added: 2017] financial statements and financial statement schedule, together with the reports of KPMG LLP are listed on the index immediately preceding the financial statements in Item 8, Consolidated Financial Statements and Supplemental Data.
[added: | (a) | [Form of Equity Distribution Agreement dated May 17, 2017 among Regency Centers Corporation, Regency Centers, L.P. and the parties listed below](http://www.sec.gov/Archives/edgar/data/910606/000119312517173741/d389253dex11.htm) (incorporated by reference to Exhibit 1.1 to the Company’s Form 8-K filed on May 17, 2017).] The Equity Distribution Agreements listed below are substantially identical in all material respects to the [removed: Wells] [added: Form of Equity Distribution] Agreement, except for the identities of the parties, and have not been filed as exhibits to the [removed: Company's] [added: Company’s] 1934 Act reports pursuant to Instruction 2 to [removed: Item] [added: item] 601 of Regulation S-K: [added: |]
| [removed: (i)] [added: (iii)] | Equity Distribution Agreement [added: dated May 17, 2017] among [removed: the Company,] Regency [added: Centers Corporation, Regency] Centers, L.P. and Merrill Lynch, Pierce, Fenner & Smith [removed: Incorporated dated August 10, 2012, as amended by Amendment Nos. 1, 2, and 3; and] [added: Incorporated;] |
| (ii) | Equity Distribution Agreement [added: dated May 17, 2017] among [removed: the Company,] Regency [added: Centers Corporation, Regency] Centers, L.P. and J.P. Morgan Securities [removed: LLC dated August 10, 2012, as amended by Amendment Nos. 1, 2, and 3.] [added: LLC;] |
[removed: reference to the Company’s Form 8-K filed on March 4, 2014) and Amendment No. 2] (incorporated by reference to Exhibit [removed: 1(b)] [added: 4.1] to the Company’s Form [removed: 10-Q] [added: 8-K] filed on [removed: May 7,] [added: August 18,] 2015).
| [removed: (i)] [added: (vi)] | Equity Distribution Agreement [added: dated May 17, 2017] among [removed: the Company,] Regency [added: Centers Corporation, Regency] Centers, L.P. and RBC Capital Markets, [removed: LLC dated August 6, 2013 as amended by Amendment No. 1 dated March 4, 2014 and Amendment No. 2 dated February 24, 2015.] [added: LLC;] |
| (a) | [removed: Restated] [added: [Restated] Articles of Incorporation of Regency Centers [removed: Corporation (incorporated] [added: Corporation](http://www.sec.gov/Archives/edgar/data/910606/000091060617000019/ex-3a063017.htm) (amendment is incorporated] by reference to Exhibit [removed: 3.1] [added: 3.A] to the [removed: Company's] [added: Company’s] Form [removed: 8-K] [added: 10-Q] filed on [removed: June 5, 2013).] [added: August 8, 2017).] |
| (b) | [removed: Amended] [added: [Amended] and Restated Bylaws of Regency Centers [removed: Corporation (incorporated] [added: Corporation](http://www.sec.gov/Archives/edgar/data/910606/000091060617000019/ex-3b063017.htm) (amendment is incorporated] by reference to Exhibit [removed: 3.1] [added: 3.B] to the [removed: Company's] [added: Company’s] Form [removed: 8-K] [added: 10-Q] filed on [removed: April 21, 2016).] [added: August 8, 2017).] |
| (c) | [removed: Fourth] [added: [Fifth] Amended and Restated [removed: Certificate] [added: Agreement] of Limited Partnership of Regency Centers, [removed: L.P.] [added: L.P.](http://www.sec.gov/Archives/edgar/data/910606/000091060614000004/ex-3dlpagreementrclp.htm),] (incorporated by reference to Exhibit [removed: 3(a)] [added: 3(d)] to [removed: Regency Centers, L.P.'s] [added: the Company's] Form 10-K filed on [removed: March 17, 2009).] [added: February 19, 2014).] |
| (b) | [removed: Indenture] [added: [Indenture] dated December 5, 2001 between Regency Centers, L.P., the guarantors named therein and First Union National Bank, as [removed: trustee] [added: trustee](http://www.sec.gov/Archives/edgar/data/1066247/000089706901500635/dkm94a.txt)] (incorporated by reference to Exhibit 4.4 to Regency Centers, L.P.'s Form 8-K filed on December 10, 2001). |
| (i) | [removed: First] [added: [First] Supplemental Indenture dated as of June 5, 2007 among Regency Centers, L.P., the Company as guarantor and U.S. Bank National Association, as successor to Wachovia Bank, National Association (formerly known as First Union National Bank), as [removed: trustee] [added: trustee](http://www.sec.gov/Archives/edgar/data/1066247/000089706907001350/dkm1220b.htm)] (incorporated by reference to Exhibit 4.1 to Regency Centers, L.P.'s Form 8-K filed on June 5, 2007). |
| (ii) | [removed: Second] [added: [Second] Supplemental Indenture dated as of June 2, 2010 to the Indenture dated as of December 5, 2001 between Regency Centers, L.P., Regency Centers Corporation, as guarantor, and U.S. Bank National Association, as successor to Wachovia Bank, National Association (formerly known as First Union National Bank), as [removed: Trustee incorporated] [added: Trustee](http://www.sec.gov/Archives/edgar/data/1066247/000119312510132000/dex41.htm) (incorporated] by reference to Exhibit 4.1 to the Company’s Form 8-K filed on June 3, 2010). |
| (iii) | [removed: Third] [added: [Third] Supplemental Indenture dated as of August 17, 2015 to the Indenture dated as of December 5, 2001 among Regency Centers, L.P., Regency Centers Corporation, as guarantor, and U.S. Bank, National Association, as [removed: trustee (incorporated by reference to Exhibit 4.1 to the Company’s Form 8-K filed on August 18, 2015).] [added: trustee](http://www.sec.gov/Archives/edgar/data/910606/000119312515294166/d26820dex41.htm)] |
| (iv) | [removed: Fourth] [added: [Fourth] Supplemental Indenture dated as of January 26, 2017 among Regency Centers, L.P., Regency Centers Corporation, as guarantor, and U.S. Bank National Association, as [removed: trustee] [added: trustee](http://www.sec.gov/Archives/edgar/data/910606/000119312517019774/d312562dex41.htm)] (incorporated by reference to Exhibit 4.1 to the Company's Form 8-K filed on January 26, 2016). |
| [removed: ~(i)] [added: ~(a)] | [removed: Form] [added: [Form] of Stock Rights Award [removed: Agreement pursuant to the Company's Long Term Omnibus Plan] [added: Agreement](http://www.sec.gov/Archives/edgar/data/910606/000119312506049806/dex10b.htm)] (incorporated by reference to Exhibit 10(b) to the Company's Form 10-K filed on March 10, 2006). |
| [removed: ~(ii)] [added: ~(b)] | [removed: Form] [added: [Form] of 409A Amendment to Stock Rights Award [removed: Agreement] [added: Agreement](http://www.sec.gov/Archives/edgar/data/910606/000119312509056701/dex10bi.htm)] (incorporated by reference to Exhibit 10(b)(i) to the Company's Form 10-K filed on March on 17, 2009). |
| [removed: ~(iii)] [added: ~(c)] | [removed: Form] [added: [Form] of Nonqualified Stock Option [removed: Agreement pursuant to the Company's Long Term Omnibus Plan] [added: Agreement](http://www.sec.gov/Archives/edgar/data/910606/000119312506049806/dex10c.htm)] (incorporated by reference to Exhibit 10(c) to the Company's Form 10-K filed on March 10, 2006). |
| [removed: ~(iv)] [added: ~(d)] | [removed: Form] [added: [Form] of 409A Amendment to Stock Option [removed: Agreement] [added: Agreement](http://www.sec.gov/Archives/edgar/data/910606/000119312509056701/dex10ci.htm)] (incorporated by reference to Exhibit 10(c)(i) to the Company's Form 10-K filed on March 17, 2009). |
| [removed: ~(v)] [added: ~(e)] | [removed: Amended] [added: [Amended] and Restated Deferred Compensation Plan dated May 6, [removed: 2003] [added: 2003](http://www.sec.gov/Archives/edgar/data/910606/000089706904000579/dkm115f.txt)] (incorporated by reference to Exhibit 10(k) to the Company's Form 10-K filed on March 12, 2004). |
| [removed: ~(vi)] [added: ~(f)] | [removed: Regency] [added: [Regency] Centers Corporation 2005 Deferred Compensation [removed: Plan] [added: Plan](http://www.sec.gov/Archives/edgar/data/910606/000089706904002175/dkm452a.txt)] (incorporated by reference to Exhibit 10(s) to the Company's Form 8-K filed on December 21, 2004). |
| [removed: ~(vii)] [added: ~(g)] | [removed: First] [added: [First] Amendment to Regency Centers Corporation 2005 Deferred Compensation Plan dated December [removed: 2005] [added: 2005](http://www.sec.gov/Archives/edgar/data/910606/000119312506049806/dex10qi.htm)] (incorporated by reference to Exhibit 10(q)(i) to the Company's Form 10-K filed on March 10, 2006). |
| [removed: ~(viii)] [added: ~(h)] | [removed: Second] [added: [Second] Amendment to the Regency Centers Corporation Amended and Restated Deferred Compensation [removed: Plan] [added: Plan](http://www.sec.gov/Archives/edgar/data/910606/000091060611000012/a10-02.htm)] (incorporated by reference to Exhibit 10.2 to the Company's Form 8-K filed on June [removed: 13,] [added: 14,] 2011). |
| [removed: ~(ix)] [added: ~(i)] | [removed: Third] [added: [Third] Amendment to the Regency Centers Corporation 2005 Deferred Compensation [removed: Plan] [added: Plan](http://www.sec.gov/Archives/edgar/data/910606/000091060611000012/a10-01.htm)] (incorporated by reference to Exhibit 10.1 to the Company's Form 8-K filed on June [removed: 13,] [added: 14,] 2011). |
| [removed: ~(b)] [added: ~(j)] | [removed: Regency] [added: [Regency] Centers Corporation 2011 Omnibus [removed: Plan] [added: Plan](http://www.sec.gov/Archives/edgar/data/910606/000119312511076088/ddef14a.htm)] (incorporated by reference to Annex A to the Company's 2011 Annual Meeting Proxy Statement filed on March 24, 2011). |
| [removed: ~(c)] [added: ~(k)] | Form of Director/Officer Indemnification Agreement (filed as an Exhibit to Pre-effective Amendment No. 2 to the Company's registration statement on Form S-11 filed on October 5, 1993 (33-67258), and incorporated by reference). |
| [removed: ~(d)] [added: ~(l)] | [removed: Form of Amended] [added: [Amended] and Restated Severance and Change of Control Agreement dated as of [removed: July 15, 2015] [added: April 27, 2017,] by and between the Company and Martin E. Stein, [removed: Jr.] [added: Jr.](http://www.sec.gov/Archives/edgar/data/910606/000091060617000012/ex101severencecicagreement.htm)] (incorporated by reference to Exhibit 10.1 of the Company's Form [removed: 8-K] [added: 10-Q] filed on [removed: July 20, 2015).] [added: May 10, 2017).] |
| [removed: ~(e)] [added: ~(m)] | [removed: Form] [added: [Form] of Amended and Restated Severance and Change of Control Agreement dated as of July 15, 2015 by and between the Company and Lisa [removed: Palmer] [added: Palmer](http://www.sec.gov/Archives/edgar/data/910606/000119312515256579/d45987dex103.htm)] (incorporated by reference to Exhibit 10.3 of the Company's Form 8-K filed on July 20, 2015). |
| [removed: ~(f)] [added: ~(n)] | [removed: Form] [added: [Form] of Amended and Restated Severance and Change of Control Agreement dated as of July 15, 2015 by and between the Company and Dan M. Chandler, [removed: III] [added: III](http://www.sec.gov/Archives/edgar/data/910606/000119312515256579/d45987dex104.htm)] (incorporated by reference to Exhibit 10.4 of the Company's Form 8-K filed on July 20, 2015). |
| [removed: ~(g)] [added: ~(o)] | [removed: Form] [added: [Form] of Amended and Restated Severance and Change of Control Agreement dated as of July 15, 2015 by and between the Company and James D. [removed: Thompson] [added: Thompson](http://www.sec.gov/Archives/edgar/data/910606/000119312515256579/d45987dex106.htm)] (incorporated by reference to Exhibit 10.6 of the Company's Form 8-K filed on July 20, 2015). |
| [removed: (h)] [added: (p)] | [removed: Third] [added: [Third] Amended and Restated Credit Agreement dated as of September 7, 2011 by and among Regency Centers, , L.P., the Company, each of the financial institutions party thereto, and Wells Fargo Bank, National [removed: Association] [added: Association](http://www.sec.gov/Archives/edgar/data/910606/000091060611000022/ex101093011.htm)] (incorporated by reference to Exhibit 10.1 to the Company's Form 10-Q filed on November 8, 2011). |
| (i) | [removed: First] [added: [First] Amendment to Third Amended and Restated Credit Agreement dated September 13, [removed: 2012] [added: 2012](http://www.sec.gov/Archives/edgar/data/910606/000091060612000030/ex-101093012.htm)] (incorporated by reference to Exhibit 10.1 to the Company's Form 10-Q filed on November 9, 2012). |
| (ii) | [removed: Second] [added: [Second] Amendment to Third Amended and Restated Credit Agreement dated June 27, [removed: 2014] [added: 2014](http://www.sec.gov/Archives/edgar/data/910606/000091060614000029/ex-101revolvingloanx2ndame.htm)] (incorporated by reference to Exhibit 10.1 to the Company's Form 10-Q filed on August 8, 2014). |
| (iii) | [removed: Third] [added: [Third] Amendment to Third Amended and Restated Credit Agreement dated May 13, [removed: 2015] [added: 2015](http://www.sec.gov/Archives/edgar/data/910606/000091060615000024/exhibit101thirdamendmentcr.htm)] (incorporated by reference to Exhibit 10.1 to the Company’s Form 8-K filed on May 18, 2015). |
| [removed: (i)] [added: (q)] | [removed: Term] [added: [Term] Loan Agreement dated as of November 17, 2011 by and among Regency Centers, L.P., the Company, each of the financial institutions party thereto and Wells Fargo Securities, [removed: LLC] [added: LLC](http://www.sec.gov/Archives/edgar/data/910606/000091060612000004/ex-101123111.htm)] (incorporated by reference to Exhibit 10.1 to the Company's Form 10-K filed on February 29, 2012). |
| (i) | [removed: First] [added: [First] Amendment to Term Loan Agreement dated as of June 19, [removed: 2012] [added: 2012](http://www.sec.gov/Archives/edgar/data/910606/000091060613000009/ex-10hi123112.htm)] (incorporated by reference to Exhibit 10(h)(i) to the Company's Form 10-K filed on March 1, 2013). |
| (ii) | [removed: Second] [added: [Second] Amendment to Term Loan Agreement dated as of December 19, [removed: 2012] [added: 2012](http://www.sec.gov/Archives/edgar/data/910606/000091060613000009/ex-10hii123112.htm)] (incorporated by reference to Exhibit 10(h)(ii) to the Company's Form 10-K filed on March 1, 2013). |
| (iii) | [removed: Third] [added: [Third] Amendment to Term Loan Agreement dated as of June 27, [removed: 2014] [added: 2014](http://www.sec.gov/Archives/edgar/data/910606/000091060614000029/ex-102thirdamendmenttoterm.htm)] (incorporated by reference to Exhibit 10.2 to the Company's Form 10-Q filed on August 8, 2014). |
| (iv) | [removed: Fourth] [added: [Fourth] Amendment to Term Loan Agreement dated as of May 13, [removed: 2015] [added: 2015](http://www.sec.gov/Archives/edgar/data/910606/000091060616000047/ex-10jivtermloan4thamend12.htm)] (incorporated by reference to Exhibit 10(j)(iv) to the Company's Form 10-K filed on February 18, 2016). |
| (v) | [removed: Fifth] [added: [Fifth] Amendment to Term Loan Agreement dated as of July 7, [removed: 2016] [added: 2016](http://www.sec.gov/Archives/edgar/data/910606/000119312516643500/d382983dex101.htm)] (incorporated by reference to exhibit 10.1 to the Company's Form 8-K filed on July 7, 2016). |
| [removed: (j)] [added: (r)] | [removed: Second] [added: [Second] Amended and Restated Limited Liability Company Agreement of Macquarie CountryWide-Regency II, LLC dated as of July 31, 2009 by and among Global Retail Investors, LLC, Regency Centers, L.P. and Macquarie CountryWide (US) No. 2 [removed: LLC] [added: LLC](http://www.sec.gov/Archives/edgar/data/910606/000119312509227616/dex101.htm)] (incorporated by reference to Exhibit 10.1 to the Company's Form 10-Q filed on November 6, 2009). |
| (i) | Equity Distribution Agreement dated May 17, 2017 among Regency Centers Corporation, Regency Centers, L.P. and Wells Fargo Securities, LLC; |
| (iv) | Equity Distribution Agreement dated May 17, 2017 among Regency Centers Corporation, Regency Centers, L.P. and BB&T Capital Markets, a division of BB&T Securities, LLC; |
| (v) | Equity Distribution Agreement dated May 17, 2017 among Regency Centers Corporation, Regency Centers, L.P. and BTIG, LLC; |
| (vii) | Equity Distribution Agreement dated May 17, 2017 among Regency Centers Corporation, Regency Centers, L.P. and SunTrust Robinson Humphrey, Inc.; and |
| (viii) | Equity Distribution Agreement dated May 17, 2017 among Regency Centers Corporation, Regency Centers, L.P. and Mizuho Securities USA LLC. |
| (b) | [Forward Master Confirmation, dated May 17, 2017, by and between Regency Centers Corporation and Wells Fargo Bank, National Association](http://www.sec.gov/Archives/edgar/data/910606/000119312517173741/d389253dex12.htm) (incorporated by reference to Exhibit 1.2 to the Company’s Form 8-K filed on May 17, 2017). |
| (d) | [Forward Master Confirmation, dated May 17, 2017, by and between Regency Centers Corporation and Bank of America, N.A.](http://www.sec.gov/Archives/edgar/data/910606/000119312517173741/d389253dex14.htm) (incorporated by reference to Exhibit 1.4 to the Company’s Form 8-K filed on May 17, 2017) |
| (e) | [Forward Master Confirmation, dated May 17, 2017, by and between Regency Centers Corporation and Royal Bank of Canada](http://www.sec.gov/Archives/edgar/data/910606/000119312517173741/d389253dex15.htm) (incorporated by reference to Exhibit 1.5 to the Company’s Form 8-K filed on May 17, 2017). |
| (c) | [Indenture dated September 9, 1998 between the Company, as successor-by-merger to IRT Property Company, and SunTrust Bank, as trustee](http://www.sec.gov/Archives/edgar/data/311099/0000950144-98-010736.txt) (incorporated by reference to Exhibit 4.2 of Form 8-K filed by IRT Property Company on September 15, 1998) |
| (i) | [Supplemental Indenture No. 1, dated September 9, 1998, between the Company, as successor-by-merger to IRT Property Company, and SunTrust Bank, as Trustee](http://www.sec.gov/Archives/edgar/data/311099/0000950144-98-010736.txt) (incorporated by reference to Exhibit 4.3 of Form 8-K filed by IRT Property Company on September 15, 1998) |
| (ii) | [Supplemental Indenture No. 2, dated November 1, 1999, between the Company, as successor-by-merger to IRT Property Company, and SunTrust Bank, as Trustee](http://www.sec.gov/Archives/edgar/data/311099/000095014499012961/0000950144-99-012961.txt) (incorporated by reference to Exhibit 4.5 of Form 8-K filed by IRT Property Company on November 12, 1999) |
| (iii) | [Supplemental Indenture No. 3, dated February 12, 2003, between the Company and SunTrust Bank, as Trustee](http://www.sec.gov/Archives/edgar/data/1042810/000104281003000025/exh4_2.txt) (incorporated by reference to Exhibit 4.2 of Form 8-K filed by Equity One, Inc. on February 20, 2003) |
| (iv) | [Supplemental Indenture No. 5, dated April 23, 2004, between the Company and SunTrust Bank, as Trustee](http://www.sec.gov/Archives/edgar/data/1042810/000104281004000071/exh4_1.txt) (incorporated by reference to Exhibit 4.1 of Form 10-Q filed by Equity One, Inc. on May 10, 2004) |
| (v) | [Supplemental Indenture No. 6, dated May 20, 2005, between the Company and SunTrust Bank, as Trustee](http://www.sec.gov/Archives/edgar/data/1042810/000104281005000072/exh4_2.htm) (incorporated by reference to Exhibit 4.2 of Form 10-Q filed by Equity One, Inc. on August 5, 2005) |
| (vi) | [Supplemental Indenture No. 8, dated December 30, 2005, between the Company and SunTrust Bank, as Trustee](http://www.sec.gov/Archives/edgar/data/1042810/000114036106003367/ex4_17.htm) (incorporated by reference to Exhibit 4.17 of Form 10-K filed by Equity One, Inc. on March 3, 2006) |
| (vii) | [Supplemental Indenture No. 13, dated as of October 25, 2012, between the Company and U.S. Bank National Association, as Trustee](http://www.sec.gov/Archives/edgar/data/1042810/000119312512435547/d430150dex41.htm) (incorporated by reference to Exhibit 4.1 of Form 8-K filed by Equity One, Inc. on October 25, 2012) |
| (d) | [Supplemental Indenture No. 14, dated as of March 1, 2017, among Equity One, Inc., Regency Centers Corporation, Regency Centers, L.P., and U.S. Bank National Association](http://www.sec.gov/Archives/edgar/data/910606/000119312517065897/d325889dex41.htm) (incorporated by reference to Exhibit 4.1 to the Company’s Form 8-K filed on March 1, 2017). |
| (e) | [Supplemental Indenture No. 15, dated as of July 26, 2017, among Regency Centers Corporation, Regency Centers, L.P., and U.S. Bank National Association](http://www.sec.gov/Archives/edgar/data/910606/000119312517237509/d424730dex101.htm) (incorporated by reference to Exhibit 10.1 to the Company’s Form 8-K filed on July 27, 2017). |
| (f) | [Assumption Agreement, dated as of March 1, 2017, by Regency Centers Corporation](http://www.sec.gov/Archives/edgar/data/910606/000119312517065897/d325889dex42.htm) (incorporated by reference to Exhibit 4.2 to the Company’s Form 8-K filed on March 1, 2017) |
| | |
| --- | --- |
| | |
| --- | --- |
| | |
| --- | --- |
| | |
| --- | --- |
| (iv) | [Fourth Amendment to Third Amended and Restated Credit Agreement dated June 15, 2016](http://www.sec.gov/Archives/edgar/data/910606/000091060616000073/ex-101lineofcredit4thamend.htm) (incorporated by reference to Exhibit 10.1 to the Company’s Form 10-Q filed on August 5, 2016). |
| | |
| --- | --- |
| (v) | [Fifth Amendment to Third Amended and Restated Credit Agreement, dated as of March 2, 2017, by and among Regency Centers, L.P., as borrower, Regency Centers Corporation, as guarantor, Wells Fargo Bank, National Association, as administrative agent, and certain lenders party thereto](http://www.sec.gov/Archives/edgar/data/910606/000119312517067828/d323515dex42.htm) (incorporated by reference to Exhibit 4.2 to the Company’s Form 8-K filed on March 2, 2017). |
| | |
| --- | --- |
| | |
| --- | --- |
| | |
| --- | --- |
| | |
| --- | --- |
| | |
| (a) | Equity Distribution Agreement (the “Wells Agreement”) among the Company, Regency Centers, L.P. and Wells Fargo Securities, LLC dated August 10, 2012 (incorporated by reference to Exhibit 1.1 to the Company's report on Form 8-K filed on August 10, 2012), as amended by Amendment No. 1 dated August 6, 2013 (incorporated by reference to Exhibit 1.2 to the Company’s report on Form 8-K filed on August 6, 2013), Amendment No. 2 dated March 4, 2014 (incorporated by reference to Exhibit 1.1 to the Company’s report on Form 8-K filed on March 4, 2014) and Amendment No. 3 dated February 24, 2015 (incorporated by reference to Exhibit 1(a) to the Company’s Form 10-Q filed on May 7, 2015). |
| (b) | Equity Distribution Agreement (the “Jefferies Agreement”) among the Company, Regency Centers, L.P. and Jefferies LLC dated August 6, 2013 (incorporated by reference to Exhibit 1.1 to the Company's report on Form 8-K filed on August 6, 2013), as amended by Amendment No. 1 dated March 4, 2014 (incorporated by |
The Equity Distribution Agreements listed below is substantially identical in all material respects to the Jefferies Agreement except for the identities of the parties, and has not been filed as an exhibit to the Company's 1934 Act reports pursuant to Instruction 2 to Item 601 of Regulation S-K:
2.
Plan of Acquisition, Reorganization, Arrangement, Liquidation or Succession
| (a) | Agreement and Plan of Merger, dated as of November 14, 2016, by and between Regency and Equity One (incorporated by reference to Exhibit 2.1 to the Company’s Form 8-K filed on November 15, 2016) (Schedules and exhibits omitted pursuant to Item 601(b)(2) of Regulation S-K. The Company agrees to supplementally furnish to the Securities and Exchange Commission upon request any omitted schedule or exhibit to the Merger Agreement.) |
| (d) | Fifth Amended and Restated Agreement of Limited Partnership of Regency Centers, L.P., (incorporated by reference to Exhibit 3(d) to the Company's Form 10-K filed on February 19, 2014). |
| ~(a) | Regency Centers Corporation Long Term Omnibus Plan (incorporated by reference to Exhibit 10.9 to the Company's Form 10-Q filed on May 8, 2008). |
| (l) | Voting Agreement, dated as of November 14, 2016, by and among Regency and the Gazelle Stockholders (incorporated by reference to Exhibit 10.1 to the Company’s Form 8-K filed on November 15, 2016). |
| (m) | Governance Agreement, dated as of November 14, 2016, by and among Regency and the Gazelle Stockholders (incorporated by reference to Exhibit 10.2 to the Company’s Form 8-K filed on November 15, 2016). |
| February 27, 2017 | REGENCY CENTERS, L.P. | |
| February 27, 2017 | | /s/ J. Dix Druce J. Dix Druce, Director |
An excerpt. Shown here: 40 of 66 rewritten, 40 of 61 added and all 12 removed. The counts are complete. For every sentence, read Item 15. Exhibits and Financial Statement Schedules in the FY2017 filing and the FY2016 filing.