 filings.tools
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
99K characters. Original on sec.gov · Markdown
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
INTRODUCTION
We have elected to omit discussion on the earliest of the three years covered by the consolidated financial statement presented. Refer to Item 7. “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and “Financial Liquidity and Capital Resources” located in our Form 10-K for the fiscal year ended February 28, 2019, filed on April 23, 2019, for reference to discussion of the fiscal year ended February 28, 2018, the earliest of the three fiscal years presented. This MD&A, which should be read in conjunction with our Financial Statements, provides additional information on our businesses, current developments, financial condition, cash flows, and results of operations. It is organized as follows:
| • | Overview. This section provides a general description of our business, which we believe is important in understanding the results of our operations, financial condition, and potential future trends. |
| • | Strategy*.* This section provides a description of our strategy and a discussion of recent developments, significant investments, acquisitions, and divestitures. |
| • | Results of operations. This section provides an analysis of our results of operations presented on a business segment basis. In addition, a brief description of significant transactions and other items that affect the comparability of the results is provided. |
| • | Financial liquidity and capital resources. This section provides an analysis of our cash flows, outstanding debt, and commitments. Included in the analysis of outstanding debt is a discussion of the amount of financial capacity available to fund our ongoing operations and future commitments, as well as a discussion of other financing arrangements. |
| • | Critical accounting estimates and policies. This section identifies those accounting policies that are considered important to our results of operations and financial condition, require significant judgment and involve significant management estimates. Our significant accounting policies, including those considered to be critical accounting policies, are summarized in Note 1 of the Notes to the Financial Statements. |
OVERVIEW
We are an international beverage alcohol company with a broad portfolio of consumer-preferred high-end imported beer brands, and higher-end wine and spirits brands. Many of our products are recognized as leaders in their respective categories. We are one of the leading U.S. growth drivers at retail among beverage alcohol suppliers. In the U.S. market, we are the third-largest beer company and a leading higher-end wine company.
Through February 28, 2019, our internal management financial reporting consisted of two business divisions: (i) Beer and (ii) Wine and Spirits. Beginning March 1, 2019, as a result of our November 2018 Canopy Investment and a change in our CODM on March 1, 2019, we have changed our internal management financial reporting to consist of three business divisions: (i) Beer, (ii) Wine and Spirits, and (iii) Canopy. Consequently, beginning with the first quarter of fiscal 2020, we report our operating results in four segments: (i) Beer, (ii) Wine and Spirits, (iii) Corporate Operations and Other, and (iv) Canopy. Our Canopy Equity Method Investment makes up the Canopy segment.
In the Beer segment, our portfolio consists of high-end imported and craft beer and alternative beverage alcohol brands. We have an exclusive perpetual brand license to import, market, and sell our
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 31 |
| PART II | ITEM 7. MD&A | Table of Contents |
Mexican beer portfolio in the U.S. In the Wine and Spirits segment, our portfolio includes higher-margin, higher-growth wine brands complemented by certain higher-end spirits brands. Amounts included in the Corporate Operations and Other segment consist of costs of executive management, corporate development, corporate finance, corporate growth and strategy, human resources, internal audit, investor relations, legal, public relations, and information technology, as well as our investments made through our corporate venture capital function. All costs included in the Corporate Operations and Other segment are general costs that are applicable to the consolidated group and are therefore not allocated to the other reportable segments. All costs reported within the Corporate Operations and Other segment are not included in our CODM’s evaluation of the operating income (loss) performance of the other reportable segments. The new business segments reflect how our operations are managed, how resources are allocated, how operating performance is evaluated by senior management, and the structure of our internal financial reporting.
STRATEGY
Our overall strategy is to drive industry-leading growth, build unrivaled shareholder value, and shape the future of our industry by building brands that people love. We believe sharing a toast, unwinding after a day, celebrating milestones, and helping people connect, is Worth Reaching For. We position our portfolio to benefit from the consumer-led trend towards premiumization, which we believe will continue to result in faster growth rates in the higher-end of the beer, wine, and spirits categories. We focus on developing our expertise in consumer insights and category management, as well as our strong distributor network, which provides an effective route-to-market. Additionally, we leverage our scale across the total beverage alcohol market and our level of diversification hedges our portfolio risk. In addition to growing our existing business, we focus on targeted acquisitions of, and investments in, businesses that are higher-margin, higher-growth, consumer-led, have a low integration risk, and/or fill a gap in our portfolio. We also strive to identify, meet, and stay ahead of evolving consumer trends and market dynamics (see “Investments, Acquisitions, and Divestitures – Canopy Investments” below).
We strive to strengthen our portfolio of higher-end beer, wine, and spirits brands and differentiate ourselves through:
| • | leveraging our leading position in total beverage alcohol and our scale with wholesalers and retailers to expand distribution of our product portfolio; |
| • | strengthening relationships with wholesalers and retailers by providing consumer and beverage alcohol insights; |
| • | investing in brand building and innovation activities; |
| • | positioning ourselves for success with consumer-led products that identify, meet, and stay ahead of evolving consumer trends and market dynamics; |
| • | realizing operating efficiencies through expanding and enhancing production capabilities and maximizing asset utilization; and |
| • | developing employees to enhance performance in the marketplace. |
Our business strategy for the Beer segment focuses on leading the high-end segment of the U.S. beer market and includes continued focus on growing our beer portfolio in the U.S. through expanding distribution for key brands, as well as new product development and innovation within the existing portfolio of brands, and continued expansion, construction, and optimization activities for our Mexico beer operations. Additionally, in an effort to more fully compete in growing sectors of the high-end segment of the U.S. beer market, we have leveraged our innovation capabilities to introduce new brands that align with consumer trends. We continue to refine our options to optimize the value of our Beer segment and drive increased focus on our high-performing import portfolio and upcoming new product introductions. See “Recent Developments - Ballast Point Transaction” below.
In connection with our business strategy for the Beer segment, we have more than tripled the production capacity of our brewery located in Nava, Coahuila, Mexico since its June 2013 acquisition.
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 32 |
| PART II | ITEM 7. MD&A | Table of Contents |
Additionally, we are continuing to invest to expand our brewery operations in Obregon, Sonora, Mexico, where expansion is expected to be completed by the end of Fiscal 2021, although containment actions associated with COVID-19 may alter that timeline. See “Capital Expenditures” below for discussion of a recent public consultation on construction of a new brewery in Mexicali, Baja California, Mexico. Expansion, construction, and optimization efforts continue under our previously-announced Mexico Beer Expansion Projects (as defined below in “Capital Expenditures”) to align with our anticipated future growth expectations (see “Capital Expenditures” below).
Our business strategy for the Wine and Spirits segment is to build an industry-leading portfolio of higher-end wine and spirits brands. We are investing to meet the evolving needs of consumers; building brands through consumer insights, sensory expertise, and innovation; and refreshing existing brands, as we continue to focus on moving our branded wine and spirits portfolio towards a higher-margin, higher-growth portfolio of brands. We dedicate a large share of our sales and marketing resources to well-known wine and spirits brands sold in the U.S., which comprise the U.S. Power Brands as they represent a majority of our U.S. wine and spirits revenue and profitability, and generally hold strong positions in their respective price categories. We focus our innovation and investment dollars on those brands within our portfolio which position us to benefit from the consumer-led trend towards premiumization. Additionally, in connection with the New Wine and Spirits Transactions, Other Wine and Spirits Transactions, and the Black Velvet Divestiture, we expect to optimize the value of our wine and spirits portfolio by driving increased focus on our higher-end Power Brands to accelerate growth and improve overall operating margins. In markets where it is feasible, we entered into contractual arrangements to consolidate our U.S. distribution network in order to obtain dedicated distributor selling resources which focus on our U.S. wine and spirits portfolio to drive organic growth. This consolidated U.S. distribution network currently represents about 70% of our branded wine and spirits volume in the U.S. Throughout the terms of these contracts, we generally expect shipments on an annual basis to these distributors to essentially equal the distributors’ shipments to retailers.
Marketing, sales, and distribution of our products are managed on a geographic basis in order to fully leverage leading market positions. In addition, market dynamics and consumer trends vary across each of our markets. Within our primary market in the U.S., we offer a range of beverage alcohol products across the imported beer, craft beer, branded wine, and spirits categories, with generally separate distribution networks utilized for (i) our beer portfolio and (ii) our wine and spirits portfolio. The environment for our products is competitive in each of our markets.
We complemented our total beverage alcohol strategy in an adjacent category by making investments in Canopy, a world-leading, diversified cannabis company. These investments are consistent with our long-term strategy to identify, meet, and stay ahead of evolving consumer trends and market dynamics, and they represent a significant expansion of our strategic relationship to position Canopy as a global leader in cannabis production, branding, intellectual property, and retailing.
We remain committed to our long-term financial model of: growing sales, expanding margins, and increasing cash flow in order to achieve earnings per share growth, maintain our targeted leverage ratio, and deliver returns to shareholders through the payment of quarterly cash dividends and periodic share repurchases.
Recent Developments
COVID-19
We have an existing Crisis Management Committee that has been closely monitoring the impact of the novel strain of a virus, COVID-19, on our Company and our workforce since January 2020. In March 2020, the World Health Organization (“WHO”) recognized COVID-19 as a pandemic. COVID-19 has severely restricted the level of economic activity around the world. In response to COVID-19, the governments of many countries, states, cities, and other geographic regions have taken preventative or protective actions, such as imposing restrictions on travel and business operations and advising or requiring individuals to
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 33 |
| PART II | ITEM 7. MD&A | Table of Contents |
limit or forgo their time outside of their homes. Temporary closures of businesses have been ordered and numerous other businesses have temporarily closed voluntarily. Further, individuals' ability to travel has been curtailed through mandated travel restrictions and may be further limited through additional voluntary or mandated closures of travel-related businesses. In most of our locations, the beverage alcohol industry has been classified as an essential business and as such we are still able to produce and sell our products. COVID-19 has affected us primarily in the reduction of depletion volume on our products in the on-premise business due to shelter in place mandates and bar and restaurant closures. The on-premise business has historically been about 10% to 15% of our depletion volume for beer, wine, and spirits.
Currently, our major breweries, wineries, and bottling facilities are still operating but, in some instances, at lower production levels than planned. We have closed all hospitality, tasting rooms, retail, restaurants, and other non-essential public facilities. However, our supply chains and distribution channels have not been materially impacted and we have adequate supply of products to meet forecasted demand. The March 2020 closure of the U.S. and Mexico border to non-essential travel does not impact the movement of commercial products including the products we manufacture in Mexico and import to the U.S.
We have implemented various measures to reduce the spread of the virus including working from home, restricting visitors to our production locations, splitting our production workforces, reducing the on-site production workforce levels, screening workers before they enter facilities, implementing social distancing, and encouraging employees to adhere to prevention measures recommended by the Center for Disease Control (“CDC”) and the WHO. Since our non-production workforce is able to work remotely using various technology tools, we are able to maintain our operations and internal controls over financial reporting and disclosures.
At this time, we are not able to estimate the long-term impact of COVID-19 on our business, financial condition, results of operations, and/or cash flow. We believe we have sufficient liquidity available from operating cash flow, cash on hand, and availability under our $2.0 billion revolving credit facility. We expect to have continued access to capital markets and to continue to return value to shareholders.
New Wine and Spirits Transactions
In April 2019, we entered into a definitive agreement with E. & J. Gallo Winery (“Gallo”) to sell a portion of our wine and spirits business, including approximately 30 lower-margin, lower-growth wine and spirits brands, wineries, vineyards, offices, and facilities.
In December 2019, we agreed to revise and supersede the Wine and Spirits Transaction. The revisions to the transaction address competitive concerns raised by the FTC specifically related to the sparkling wine, brandy, dessert wine, and concentrate categories. As a result, the brands Cook’s California Champagne, J. Roget American Champagne, Paul Masson Grande Amber Brandy, and our concentrate business will be excluded from the transaction with Gallo resulting in an adjusted transaction price of approximately $843 million, with the potential to earn an incremental $250 million of contingent consideration if certain brand performance provisions are met over a two-year period after closing. The Revised Wine and Spirits Transaction is expected to close around the end of first quarter of fiscal 2021, and is subject to required regulatory clearances and governmental review and approval. Additionally, in a separate, but related, transaction we agreed that upon execution and delivery of a definitive agreement for the Revised Wine and Spirits Transaction, we would enter into an agreement to sell the New Zealand-based Nobilo Wine brand and certain related assets for $130 million to Gallo. The Nobilo Wine Transaction is expected to close by the end of second quarter of fiscal 2021 and is subject to FTC and New Zealand regulatory review and approval. Completion of the Nobilo Transaction is also conditioned on completion of the Revised Wine and Spirits Transaction. We expect to use the net cash proceeds from the New Wine and Spirits Transactions primarily to reduce outstanding borrowings. The New Wine and Spirits Transactions are consistent with our strategic focus on higher-margin, higher-growth brands.
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 34 |
| PART II | ITEM 7. MD&A | Table of Contents |
We have communicated our intent to retain the brands Cook’s California Champagne and J. Roget American Champagne contemplated under the Wine and Spirits Transaction and the FTC is currently reviewing our business plans to support these brands in the future.
Other Wine and Spirits Transactions
We are pursuing other opportunities to divest the Paul Masson Grande Amber Brandy brand and concentrate business excluded from the Revised Wine and Spirits Transaction to companies with more aligned business strategies.
In connection with the New Wine and Spirits Transactions and the Other Wine and Spirits Transactions, we have wine and spirits net assets of $1,072.4 million that have met the held for sale criteria as of February 29, 2020.
Selected financial information included in our results of operations for the portion of the business that we expect will no longer be part of our consolidated results after the closing of the New Wine and Spirits Transactions and Other Wine and Spirits Transactions is as follows:
| Net Sales | Gross Profit | Marketing (1) | |||||||||
| (in millions) | |||||||||||
| Fiscal 2020 | |||||||||||
| Wine and Spirits segment results | $ | 875 | $ | 336 | $ | 18 |
| (1) | This expense is included in selling, general, and administrative expenses within our consolidated results of operations. |
For additional information regarding the New Wine and Spirits Transactions and the Other Wine and Spirits Transactions, refer to Note 2 of the Notes to the Financial Statements.
Ballast Point Transaction
In March 2020, we sold the Ballast Point craft beer business, including a number of its associated production facilities and brewpubs. This divestiture is consistent with our strategic focus on our high-performing import portfolio and upcoming new product introductions. For additional information regarding the Ballast Point Transaction, refer to Note 2 of the Notes to the Financial Statements.
Primarily in connection with the Ballast Point Transaction, we have beer net assets of $45.3 million that met the held for sale criteria as of February 29, 2020.
Canopy production optimization
In March 2020, Canopy announced its plans to close two Canadian greenhouse facilities as part of its efforts to align supply and demand while improving production efficiencies over time. In April 2020, Canopy announced its plans to close an additional Canadian greenhouse facility, exit its operations in Africa, and reduce Latin America and United States cultivation activities. Canopy expects to record an estimated pre-tax loss of approximately C$700 million to C$800 million in their fourth quarter fiscal 2020 results from the facilities closures as well as other changes related to its organizational and strategic review. We will record our proportional share of Canopy’s estimated pre-tax loss of approximately C$245 million to C$280 million, in our first quarter fiscal 2021 results.
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 35 |
| PART II | ITEM 7. MD&A | Table of Contents |
Investments, Acquisitions, and Divestitures
Canopy Segment
Canopy Investments
Our investments in Canopy, and the method of accounting for these investments, consist of the following:
| Date of Investment | Investment Acquired | Purchase Price | Method of Accounting | |||||
| (in millions) | ||||||||
| Nov 2017 | Common shares | $ | 130.1 | Fair value / equity method (1) | ||||
| Nov 2017 | Warrants | 61.2 | Fair value | |||||
| $ | 191.3 | |||||||
| June 2018 | Convertible debt securities | $ | 150.5 | Fair value | ||||
| Nov 2018 | Common shares | $ | 2,740.3 | Equity method | ||||
| Nov 2018 | Warrants (3) | 1,146.8 | Fair value | |||||
| $ | 3,887.1 | (2) |
We recognized an unrealized net gain (loss) from the changes in fair value of these investments accounted for at fair value in income (loss) from unconsolidated investments, as follows:
| Date of Investment | Investment | Fiscal 2020 | Fiscal 2019 | |||||||
| (in millions) | ||||||||||
| Nov 2017 | Common shares (1) | $ | — | $ | 292.5 | |||||
| Nov 2017 | Warrants | (543.7 | ) | 465.5 | ||||||
| June 2018 | Convertible debt securities | (94.6 | ) | 55.5 | ||||||
| Nov 2018 | Warrants (3) | (1,488.1 | ) | 1,157.7 | ||||||
| $ | (2,126.4 | ) | $ | 1,971.2 |
| (1) | Accounted for at fair value from the date of investment in November 2017 through October 31, 2018. Accounted for under the equity method from November 1, 2018 (see Note 10 of the Notes to the Financial Statements). |
| (2) | Includes $17.2 million of direct acquisition costs capitalized under the equity method cost accumulation model. Excludes $7.3 million of direct acquisition costs associated with the investment in warrants which are expensed as incurred in selling, general, and administrative expenses. |
| (3) | In June 2019, the Canopy Shareholders approved the modification of the terms of the November 2018 Canopy Warrants. For additional information refer to Note 10 of the Notes to the Financial Statements. Fiscal 2020 includes a $1,176.0 million unrealized gain resulting from the June 2019 Warrant Modification. |
We expect the value of the Canopy investments accounted for at fair value to be volatile in future periods. We evaluated the Canopy investments as of February 29, 2020, and determined that there was not an other-than-temporary-impairment. Additionally, since November 1, 2018, we recognize equity in earnings (losses) and related activities for our Canopy Equity Method Investment on a two-month lag. Accordingly, we recognized our share of Canopy’s earnings (losses) from January through December 2019, in our Fiscal 2020 results. We recognized our share of Canopy’s losses from November and December 2018, in our Fiscal 2019 results. We expect Canopy’s earnings to be volatile in future periods.
As of February 29, 2020, the conversion of Canopy equity securities held by its employees and/or held by other third parties, excluding our November 2017 Canopy Warrants, New November 2018 Canopy Warrants, Canopy Debt Securities, and the Acreage Call Option, would not have a significant effect on our share of Canopy’s reported earnings or losses. Additionally, under an amended and restated investor
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 36 |
| PART II | ITEM 7. MD&A | Table of Contents |
rights agreement, we have the option to purchase additional common shares of Canopy at the then-current price of the underlying equity security to allow us to maintain our relative ownership interest. If we exercised all of our outstanding November 2017 Canopy Warrants and New November 2018 Canopy Warrants, it could have a significant effect on our share of Canopy’s reported earnings or losses and our ownership interest in Canopy would be expected to increase to greater than 50 percent. In connection with the Acreage Transaction, Canopy has the Acreage Call Option, which would require the issuance of Canopy shares. If Canopy exercised the Acreage Call Option it could have a significant effect on our share of Canopy’s reported earnings or losses and our ownership interest in Canopy would decrease and no longer be expected to be greater than 50 percent.
As previously noted, these investments are consistent with our long-term strategy to identify, meet, and stay ahead of evolving consumer trends and market dynamics, and they represent a significant expansion of our strategic relationship to position Canopy as a global leader in cannabis production, branding, intellectual property, and retailing.
Beer Segment
Four Corners acquisition
In July 2018, we acquired Four Corners, which primarily included the acquisition of operations, goodwill, property, plant, and equipment, and trademarks. This acquisition included a portfolio of high-quality, dynamic, and bicultural, Texas-based craft beers which further strengthened our position in the high-end segment of the U.S. beer market. The results of operations of Four Corners are reported in the Beer segment and have been included in our consolidated results of operations from the date of acquisition.
Wine and Spirits Segment
Black Velvet Divestiture
On November 1, 2019, we sold the Black Velvet Canadian Whisky business and the brand’s associated production facility, along with a subset of Canadian whisky brands produced at that facility, and related inventory at a transaction value of $266.3 million. Accordingly, our consolidated results of operations include the results of operations of our Canadian whisky business through the date of divestiture. We received cash proceeds of $269.7 million, subject to estimated working capital adjustments. This divestiture is consistent with our strategic focus on higher-margin, higher-growth brands. We recognized a net gain of $74.1 million on the sale of the business for the year ended February 29, 2020.
Nelson’s Green Brier acquisition
In May 2019, we increased our ownership interest in Nelson’s Green Brier to 75%, resulting in consolidation of the business and recognition of a 25% noncontrolling interest. This acquisition included a portfolio of award-winning, Tennessee-based craft bourbon and whiskey products. The preliminary fair value of the business combination was allocated primarily to goodwill, trademarks, inventory, and property, plant, and equipment. The results of operations of Nelson’s Green Brier are reported in the Wine and Spirits segment and have been included in our consolidated results of operations from the date of acquisition.
Sale of Accolade Wine Investment
In May 2018, we completed the sale of our remaining interest in our previously-owned Australian and European business for A$149.1 million, or $113.6 million. We received cash proceeds, net of direct costs to sell, of $111.7 million. This interest consisted of an investment accounted for under the cost method and AFS debt securities. We recognized net gains of $0.4 million and $99.8 million in connection with this transaction for the years ended February 29, 2020, and February 28, 2019, respectively. These net gains are included in income from unconsolidated investments.
For additional information on these recent developments, investments, acquisitions, and divestitures refer to Notes 2, 7, and 10 of the Notes to the Financial Statements.
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 37 |
| PART II | ITEM 7. MD&A | Table of Contents |
RESULTS OF OPERATIONS
FINANCIAL HIGHLIGHTS
References to organic throughout the following discussion exclude the impact of divested brand activity in connection with the Black Velvet Divestiture (wine and spirits), as appropriate.
Financial Highlights for Fiscal 2020:
| • | Our results of operations were negatively impacted by (i) an unrealized net loss from the changes in fair value of our investments in Canopy, (ii) equity in losses from Canopy’s results of operations and related activities, and (iii) an impairment of long-lived assets held for sale primarily in connection with the New Wine and Spirits Transactions, partially offset by (i) an unrealized gain resulting from the June 2019 modification of the terms of the November 2018 Canopy Warrants and (ii) the continued improvements within the Beer segment. |
| • | Net sales increased 3% primarily due to an increase in Beer net sales driven predominantly by volume growth and a favorable impact from pricing within our Mexican beer portfolio, partially offset by a decrease in Wine and Spirits net sales led by branded volume decline largely from brands to be divested. |
| • | Operating income (loss) decreased 11% largely due to an impairment of long-lived assets held for sale primarily in connection with the New Wine and Spirits Transactions and restructuring and other strategic business development costs incurred in connection with ongoing efforts to gain efficiencies and reduce our cost structure primarily within the Wine and Spirits segment, partially offset by the net sales volume growth and favorable impact from pricing within our Mexican beer portfolio and a net gain related to the Black Velvet Divestiture. |
| • | Net income (loss) attributable to CBI and diluted net income (loss) per common share attributable to CBI decreased significantly primarily due to an unrealized net loss on our investments in Canopy for Fiscal 2020, as compared with an unrealized net gain from the changes in fair value on our investments for Fiscal 2019, partially offset by a net income tax benefit recognized as a result of tax reform enacted in Switzerland. |
COMPARABLE ADJUSTMENTS
Management excludes items that affect comparability from its evaluation of the results of each operating segment as these Comparable Adjustments are not reflective of core operations of the segments. Segment operating performance and segment management compensation are evaluated based on core segment operating income (loss). As such, the performance measures for incentive compensation purposes for segment management do not include the impact of these Comparable Adjustments.
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 38 |
| PART II | ITEM 7. MD&A | Table of Contents |
As more fully described herein and in the related Notes to the Financial Statements, the Comparable Adjustments that impacted comparability in our segment results for each period are as follows:
| Fiscal 2020 | Fiscal 2019 | ||||||
| (in millions) | |||||||
| Cost of product sold | |||||||
| Strategic business development costs | $ | (124.5 | ) | $ | (6.0 | ) | |
| Net gain (loss) on undesignated commodity derivative contracts | (49.0 | ) | 1.8 | ||||
| Accelerated depreciation | (7.6 | ) | (8.9 | ) | |||
| Flow through of inventory step-up | (1.5 | ) | (4.9 | ) | |||
| Settlements of undesignated commodity derivative contracts | 11.7 | (8.6 | ) | ||||
| Recovery of (loss on) inventory write-down | 8.6 | (3.3 | ) | ||||
| Total cost of product sold | (162.3 | ) | (29.9 | ) | |||
| Selling, general, and administrative expenses | |||||||
| Restructuring and other strategic business development costs | (25.3 | ) | (17.1 | ) | |||
| Impairment of intangible assets | (11.0 | ) | (108.0 | ) | |||
| Transaction, integration, and other acquisition-related costs | (9.2 | ) | (10.2 | ) | |||
| Net gain (loss) on foreign currency derivative contracts associated with acquisition of investment | — | (32.6 | ) | ||||
| Deferred compensation | — | (16.3 | ) | ||||
| Other gains (losses) | 5.5 | 10.1 | |||||
| Total selling, general, and administrative expenses | (40.0 | ) | (174.1 | ) | |||
| Impairment of assets held for sale | (449.7 | ) | — | ||||
| Gain (loss) on sale of business | 74.1 | — | |||||
| Comparable Adjustments, Operating income (loss) | $ | (577.9 | ) | $ | (204.0 | ) | |
| Income (loss) from unconsolidated investments | $ | (2,480.1 | ) | $ | 2,084.9 |
Cost of Product Sold
Strategic Business Development Costs
We recognized costs primarily in connection with losses on write-downs of excess inventory, bulk wine sales, and contract terminations resulting from our ongoing efforts to optimize our portfolio, gain efficiencies, and reduce our cost structure within the Wine and Spirits segment.
Undesignated Commodity Derivative Contracts
Net gain (loss) on undesignated commodity derivative contracts represents a net gain (loss) from the changes in fair value of undesignated commodity derivative contracts. The net gain (loss) is reported outside of segment operating results until such time that the underlying exposure is recognized in the segment operating results. At settlement, the net gain (loss) from the changes in fair value of the undesignated commodity derivative contracts is reported in the appropriate operating segment, allowing the results of our operating segments to reflect the economic effects of the commodity derivative contracts without the resulting unrealized mark to fair value volatility.
Accelerated Depreciation
We recognized accelerated depreciation for certain assets primarily in connection with our current multi-year implementation of a new ERP system which is intended to replace our existing operating and financial systems.
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 39 |
| PART II | ITEM 7. MD&A | Table of Contents |
I**nventory Step-Up
In connection with acquisitions, the allocation of purchase price in excess of book value for certain inventories on hand at the date of acquisition is referred to as inventory step-up. Inventory step-up represents an assumed manufacturing profit attributable to the acquired business prior to acquisition.
Recovery of (Loss on) Inventory Write-Down
We recognized a reimbursement from our insurance carriers for losses recognized on the write-down of certain bulk wine inventory as a result of smoke damage sustained during the Fall 2017 California wildfires (Fiscal 2020). We recognized a loss on the write-down of certain bulk wine inventory as a result of smoke damage sustained during the Fall 2017 California wildfires (Fiscal 2019). For additional information, refer to Note 17 of the Notes to the Financial Statements.
Selling, General, and Administrative Expenses
Restructuring and Other Strategic Business Development Costs
We recognized costs primarily in connection with (i) costs from our ongoing efforts to gain efficiencies and reduce our cost structure in connection with a program intended to optimize the Wine and Spirits segment (Fiscal 2020) and (ii) costs recognized in connection with the development of a program specifically intended to identify opportunities for further streamlining of processes and improving capabilities, linking strategy with execution, prioritizing resources, and enabling a new ERP system.
Impairment of Intangible Assets
We recognized trademark impairment losses related to our Beer segment’s Ballast Point craft beer trademark asset. For additional information, refer to Note 7 of the Notes to the Financial Statements.
Transaction, Integration, and Other Acquisition-Related Costs
We recognized transaction, integration, and other acquisition-related costs in connection with our acquisitions, divestitures, and investments.
Net Gain (Loss) on Foreign Currency Derivative Contracts Associated with Acquisition of Investment
We recognized a net loss in connection with the settlement of foreign currency option contracts entered into to fix the U.S. dollar cost of the November 2018 Canopy Transaction.
Deferred Compensation
We recognized an adjustment related to prior periods to correct for previously unrecognized deferred compensation costs associated with certain employment agreements.
Other Gains (Losses)
We recognized other gains (losses) primarily in connection with (i) a gain on the remeasurement of our previously held equity interest in Nelson’s Green Brier to the acquisition-date fair value (Fiscal 2020), (ii) an increase in estimated fair value of a contingent liability associated with a prior period acquisition (Fiscal 2020), (iii) recognition of previously deferred gain upon release of a related guarantee (Fiscal 2020), and (iv) a gain primarily in connection with the sale of certain non-core assets (Fiscal 2019).
Impairment of Assets Held for Sale
We recognized an impairment of long-lived assets held for sale in connection with the New Wine and Spirits Transactions, Other Wine and Spirits Transactions, and the Ballast Point Transaction.
Gain (Loss) on Sale of Business
We recognized a net gain on sale of the Black Velvet Canadian Whisky business.
Income (Loss) from Unconsolidated Investments
We recognized an unrealized gain (loss) primarily from (i) the changes in fair value of our securities measured at fair value, (ii) the increase in fair value resulting from the June 2019 modification
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 40 |
| PART II | ITEM 7. MD&A | Table of Contents |
of the terms of the November 2018 Canopy Warrants (Fiscal 2020), (iii) equity in earnings (losses) from Canopy’s results of operations and related activities, and (iv) a net gain in connection with the sale of our Accolade Wine Investment (Fiscal 2019). For additional information, refer to Notes 7, 10, and 23 of the Notes to the Financial Statements.
Net Sales
| Fiscal 2020 | Fiscal 2019 | Dollar Change | Percent Change | |||||||||||
| (in millions) | ||||||||||||||
| Beer | $ | 5,615.9 | $ | 5,202.1 | $ | 413.8 | 8 | % | ||||||
| Wine and Spirits: | ||||||||||||||
| Wine | 2,367.5 | 2,532.5 | (165.0 | ) | (7 | %) | ||||||||
| Spirits | 360.1 | 381.4 | (21.3 | ) | (6 | %) | ||||||||
| Total Wine and Spirits | 2,727.6 | 2,913.9 | (186.3 | ) | (6 | %) | ||||||||
| Canopy | 290.2 | 48.6 | 241.6 | NM | ||||||||||
| Consolidation and Eliminations | (290.2 | ) | (48.6 | ) | (241.6 | ) | NM | |||||||
| Consolidated net sales | $ | 8,343.5 | $ | 8,116.0 | $ | 227.5 | 3 | % | ||||||
| NM = Not Meaningful |
| Beer Segment | Fiscal 2020 | Fiscal 2019 | Dollar Change | Percent Change | ||||||||||
| (in millions, branded product, 24-pack, 12-ounce case equivalents) | ||||||||||||||
| Net sales | $ | 5,615.9 | $ | 5,202.1 | $ | 413.8 | 8 | % | ||||||
| Shipment volume | 311.9 | 294.1 | 6.1 | % | ||||||||||
| Depletion volume (1) | 7.5 | % |
| (1) | Depletions represent distributor shipments of our respective branded products to retail customers, based on third-party data. |
 | The increase in Beer net sales is primarily due to $330.9 million of volume growth within our Mexican beer portfolio, which benefited from continued consumer demand, increased marketing spend, and new product introductions; and a $118.4 million favorable impact from pricing in select markets within our Mexican beer portfolio. The increase was partially offset by a decline of $25.2 million in craft beer net sales. The shipment volume timing benefit that occurred at the end of Fiscal 2019 reversed in Fiscal 2020. |
| Wine and Spirits Segment | Fiscal 2020 | Fiscal 2019 | Dollar Change | Percent Change | ||||||||||
| (in millions, branded product, 9-liter case equivalents) | ||||||||||||||
| Net sales | $ | 2,727.6 | $ | 2,913.9 | $ | (186.3 | ) | (6 | %) | |||||
| Shipment volume | ||||||||||||||
| Total | 53.6 | 58.5 | (8.4 | %) | ||||||||||
| Organic (2) | 53.6 | 57.8 | (7.3 | %) | ||||||||||
| U.S. Domestic | 49.5 | 54.4 | (9.0 | %) | ||||||||||
| Organic U.S. Domestic (2) | 49.5 | 53.7 | (7.8 | %) | ||||||||||
| U.S. Domestic Power Brands | 23.0 | 23.4 | (1.7 | %) | ||||||||||
| Depletion volume (1) | ||||||||||||||
| U.S. Domestic (2) | (5.2 | %) | ||||||||||||
| U.S. Domestic Power Brands | 1.9 | % |
| (2) | Includes an adjustment to remove volume associated with the Black Velvet Divestiture for the period November 1, 2018, through February 28, 2019. |
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 41 |
| PART II | ITEM 7. MD&A | Table of Contents |
 | The decrease in Wine and Spirits net sales is primarily due to (i) $193.0 million decline in branded wine and spirits volume and (ii) $26.0 million decrease in net sales from the Black Velvet Divestiture, partially offset by (i) $20.0 million of favorable product mix shift and (ii) $7.7 million favorable impact from pricing. The Wine and Spirits Fiscal 2020 results have been negatively impacted by transition activities with distributors who are repositioning for ownership of brands upon closing the New Wine and Spirits Transactions and the Black Velvet Divestiture. |
 | Canopy Segment Our ownership interest in Canopy allows us to exercise significant influence, but not control, and, therefore, we account for our investment in Canopy under the equity method. Amounts included for the Canopy segment represent 100% of Canopy’s reported results on a two-month lag, prepared in accordance with U.S. GAAP, and converted from Canadian dollars to U.S. dollars. Although we own less than 100% of the outstanding shares of Canopy, 100% of the Canopy results are included and subsequently eliminated in order to reconcile to our consolidated financial statements. Canopy segment amounts reflect twelve months of activity for Fiscal 2020 as compared with two months of activity for Fiscal 2019, due to the timing of the November 2018 Canopy Investment. See “Income (Loss) from Unconsolidated Investments” below for a discussion of Canopy’s net sales, gross profit (loss), selling, general, and administrative expenses, and operating income (loss). |
Gross Profit
| Fiscal 2020 | Fiscal 2019 | Dollar Change | Percent Change | |||||||||||
| (in millions) | ||||||||||||||
| Beer | $ | 3,125.2 | $ | 2,830.7 | $ | 294.5 | 10 | % | ||||||
| Wine and Spirits | 1,189.0 | 1,279.5 | (90.5 | ) | (7 | %) | ||||||||
| Canopy | 45.4 | 11.2 | 34.2 | NM | ||||||||||
| Consolidation and Eliminations | (45.4 | ) | (11.2 | ) | (34.2 | ) | NM | |||||||
| Comparable Adjustments | (162.3 | ) | (29.9 | ) | (132.4 | ) | NM | |||||||
| Consolidated gross profit | $ | 4,151.9 | $ | 4,080.3 | $ | 71.6 | 2 | % |
| The increase in Beer is primarily due to $183.4 million of volume growth, $118.4 million of favorable impact from pricing, and $17.5 million of lower cost of product sold for our Mexican beer business, partially offset by a decline of $14.0 million in our craft beer portfolio. The lower cost of product sold is largely due to foreign currency transactional benefits of $24.2 million and decreased operational costs of $3.9 million, partially offset by increased warehousing and transportation costs of $10.6 million. |
| The decrease in Wine and Spirits is largely due to (i) $83.1 million of decline in branded wine and spirits volume, (ii) $27.2 million higher cost of product sold, and (iii) $12.3 million decrease in gross profit from the Black Velvet Divestiture, partially offset by $27.3 million of favorable product mix shift. The higher cost of product sold is largely attributable to higher grape raw material and processing costs as well as increased transportation costs. |
Gross profit as a percent of net sales decreased to 49.8% for Fiscal 2020 compared with 50.3% for Fiscal 2019. This was largely due to an unfavorable change of 155 basis points in Comparable Adjustments and higher cost of product sold within the Wine and Spirits segment, which resulted in approximately 30 basis points of rate decline, partially offset by rate growth from (i) the favorable impact from Beer pricing in select markets, which contributed approximately 70 basis points, (ii) favorable impact from Wine and Spirits product mix shift, which resulted in 20 basis points, (iii) lower cost of product sold within the Beer segment, which resulted in 20 basis points of rate growth, and (iv) favorable volume growth from Beer which resulted in approximately 20 basis points.
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 42 |
| PART II | ITEM 7. MD&A | Table of Contents |
Selling, General, and Administrative Expenses
| Fiscal 2020 | Fiscal 2019 | Dollar Change | Percent Change | |||||||||||
| (in millions) | ||||||||||||||
| Beer | $ | 877.3 | $ | 787.8 | $ | 89.5 | 11 | % | ||||||
| Wine and Spirits | 480.6 | 508.3 | (27.7 | ) | (5 | %) | ||||||||
| Corporate Operations and Other | 223.9 | 197.9 | 26.0 | 13 | % | |||||||||
| Canopy | 731.2 | 93.9 | 637.3 | NM | ||||||||||
| Consolidation and Eliminations | (731.2 | ) | (93.9 | ) | (637.3 | ) | NM | |||||||
| Comparable Adjustments | 40.0 | 174.1 | (134.1 | ) | (77 | %) | ||||||||
| Consolidated selling, general, and administrative expenses | $ | 1,621.8 | $ | 1,668.1 | $ | (46.3 | ) | (3 | %) |
| The increase in Beer is primarily due to an increase of $76.0 million in marketing spend and $13.7 million in general and administrative expenses. The increase in marketing spend is due to planned investment to support the growth of our Mexican beer portfolio, including support of the new product introductions. The increase in general and administrative expenses is largely driven by increased headcount supporting the growth of the business, partially offset by favorable foreign currency transaction gains. |
| The decrease in Wine and Spirits is largely due to a decrease of $19.4 million in general and administrative expenses. The decrease in general and administrative expenses is driven by certain cost saving initiatives including decreased compensation and benefits. |
 | The increase in Corporate Operations and Other is due to an increase of approximately $17 million in insurance related costs, $13 million in compensation and benefits, and higher information technology costs supporting the implementation of our new ERP system, partially offset by a reduction in consulting costs. |
Selling, general, and administrative expenses as a percent of net sales decreased to 19.4% for Fiscal 2020 as compared with 20.6% for Fiscal 2019. The decrease is driven largely by (i) a favorable change of 170 basis points in Comparable Adjustments. The rate decline was offset by an increase in Corporate Operations and Other and Beer selling, general, and administrative expenses, which resulted in approximately 30 basis points and 10 basis points of rate growth, respectively.
Operating Income (Loss)
| Fiscal 2020 | Fiscal 2019 | Dollar Change | Percent Change | |||||||||||
| (in millions) | ||||||||||||||
| Beer | $ | 2,247.9 | $ | 2,042.9 | $ | 205.0 | 10 | % | ||||||
| Wine and Spirits | 708.4 | 771.2 | (62.8 | ) | (8 | %) | ||||||||
| Corporate Operations and Other | (223.9 | ) | (197.9 | ) | (26.0 | ) | (13 | %) | ||||||
| Canopy | (685.8 | ) | (82.7 | ) | (603.1 | ) | NM | |||||||
| Consolidation and Eliminations | 685.8 | 82.7 | 603.1 | NM | ||||||||||
| Comparable Adjustments | (577.9 | ) | (204.0 | ) | (373.9 | ) | NM | |||||||
| Consolidated operating income | $ | 2,154.5 | $ | 2,412.2 | $ | (257.7 | ) | (11 | %) |
| The increase in Beer is primarily attributable to the strong volume growth and favorable pricing impact, partially offset by the planned increase in marketing spend combined with the decline in craft beer. |
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 43 |
| PART II | ITEM 7. MD&A | Table of Contents |
| The decrease in Wine and Spirits was driven largely by the decline in branded wine and spirits volume, higher cost of product sold, and the impact from the Black Velvet Divestiture partially offset by the favorable impact of product mix shift, lower general and administrative expenses, and the favorable impact from pricing. |
| As previously discussed, the Corporate Operations and Other increase in operating loss is due to increased insurance, compensation and benefits, and information technology costs, partially offset by a reduction in consulting costs. |
Income (Loss) From Unconsolidated Investments
General
Income (loss) from unconsolidated investments decreased to $(2,668.6) million for Fiscal 2020 from $2,101.6 million for Fiscal 2019, a decrease of $4,770.2 million. This decrease is driven largely by an unrealized net loss of $2,126.4 million for Fiscal 2020, which consists of an unrealized net loss from the changes in fair value of our securities measured at fair value of $3,302.4 million, partially offset by an unrealized gain of $1,176.0 million from the June 2019 modification of the terms of the November 2018 Canopy Warrants, as compared with an unrealized net gain of $1,971.2 million recognized for Fiscal 2019. Fiscal 2020 was also negatively impacted by $575.9 million of equity in losses from Canopy’s results of operations, and related activities, while Fiscal 2019 benefited from a net gain in connection with the sale of our Accolade Wine Investment of $99.8 million.
| Canopy Segment Canopy’s Fiscal 2020 net sales; gross profit (loss); selling, general, and administrative expenses; and operating income (loss) are not comparable against Fiscal 2019 due the timing of the November 2018 Canopy Investment and recognizing equity in earnings (losses) and related activities on a two-month lag. We have recognized twelve months of activity for Fiscal 2020 as compared with two months of activity for Fiscal 2019. |
Interest Expense
Interest expense increased to $428.7 million for Fiscal 2020 from $367.1 million for Fiscal 2019, an increase of $61.6 million, or 17%. This increase is predominantly due to higher average borrowings of approximately $1.7 billion primarily attributable to the November 2018 Canopy Transaction.
(Provision For) Benefit From Income Taxes
Our effective tax rate for Fiscal 2020 was 102.3% of tax benefit as compared with 16.5% of tax expense for Fiscal 2019. The change in effective tax rate was driven primarily by the recognition of a $547.4 million net income tax benefit resulting from the remeasurement of our deferred tax assets for Fiscal 2020 in connection with the September 2019 enactment of tax reform in Switzerland. The Fiscal 2020 rate also benefited from (i) a higher effective rate of tax benefit from our foreign businesses including the tax benefits recorded on the net unrealized loss from the changes in fair value of our investments in Canopy and the tax benefits recorded on the Canopy equity in losses and related activities and (ii) recognition of net income tax benefits from stock-based compensation award activity.
For additional information, refer to Note 14 of the Notes to the Financial Statements.
We expect our reported effective tax rate for the next fiscal year to be in the range of 17% to 19%. This includes an estimated impact for (i) benefits related to the recognition of the income tax effect of stock-based compensation awards in the income statement when the awards vest or are settled and (ii) lower effective tax rates applicable to our foreign businesses. This range does not reflect (i) any potential impacts from COVID-19, (ii) any future changes in the fair value of our Canopy investments measured at fair value and any future equity in earnings (losses) and related activities from the Canopy Equity Method Investment, and (iii) any additional gain (loss) recognized in connection with the New Wine and Spirits Transactions, Other Wine and Spirits Transactions, and the Ballast Point Transaction since these estimates are not currently available.
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 44 |
| PART II | ITEM 7. MD&A | Table of Contents |
Net Income (Loss) Attributable to CBI
Net income (loss) attributable to CBI decreased to $(11.8) million for Fiscal 2020 from $3,435.9 million for Fiscal 2019. This decrease of $3,447.7 million is largely attributable to the significant decrease in income (loss) from unconsolidated investments discussed above, an impairment of long-lived assets held for sale as well as the decline in operating performance from Wine and Spirits. These decreases were partially offset by solid operating performance from Beer contributing an additional $205.0 million of operating income.
FINANCIAL LIQUIDITY AND CAPITAL RESOURCES
General
Our ability to consistently generate cash flow from operating activities is one of our most significant financial strengths. Our strong cash flows enable us to invest in our people and our brands, make appropriate capital investments, provide a quarterly cash dividend program, and from time-to-time, repurchase shares of our common stock and make strategic investments and acquisitions that we believe will enhance shareholder value. Our primary source of liquidity has been cash flow from operating activities. Our principal use of cash in our operating activities is for purchasing and carrying inventories and carrying seasonal accounts receivable. Historically, we have used cash flow from operating activities to repay our short-term borrowings and fund capital expenditures. Additionally, we have a commercial paper program which we use to fund our short-term borrowing requirements and to maintain our access to the capital markets. We will continue to use our short-term borrowings, including our commercial paper program, to support our working capital requirements and capital expenditures. COVID-19 has negatively impacted the global economy and financial markets which could interfere with our ability to access sources of liquidity at favorable rates and generate operating cash flows. We are currently evaluating recent COVID-19 related legislation and governmental initiatives and expect to take advantage of opportunities to temporarily defer some payments including certain excise and payroll taxes.
We have maintained adequate liquidity to meet working capital requirements, fund capital expenditures, and repay scheduled principal and interest payments on debt. Absent deterioration of market conditions, we believe that cash flows from operating activities and financing activities, primarily short-term borrowings, will provide adequate resources to satisfy our working capital, scheduled principal and interest payments on debt, anticipated dividend payments, periodic share repurchases, and anticipated capital expenditure requirements for both our short-term and long-term capital needs.
We have plans to sell a portion of our U.S. wine and spirits business. We expect to use the net cash proceeds from closing these transactions primarily to reduce outstanding borrowings.
The November 2017 Canopy Warrants with an exercise price of C$12.98 per warrant share will expire on May 1, 2020. We will evaluate exercise of the warrants immediately prior to expiration. If a decision is made to exercise the November 2017 Canopy Warrants, we expect to fund the C$245 million transaction with cash from operations.
Cash Flows
| Fiscal 2020 | Fiscal 2019 | Dollar Change | |||||||||
| (in millions) | |||||||||||
| Net cash provided by (used in): | |||||||||||
| Operating activities | $ | 2,551.1 | $ | 2,246.3 | $ | 304.8 | |||||
| Investing activities | (531.0 | ) | (4,831.8 | ) | 4,300.8 | ||||||
| Financing activities | (2,031.4 | ) | 2,593.3 | (4,624.7 | ) | ||||||
| Effect of exchange rate changes on cash and cash equivalents | (0.9 | ) | (4.5 | ) | 3.6 | ||||||
| Net increase (decrease) in cash and cash equivalents | $ | (12.2 | ) | $ | 3.3 | $ | (15.5 | ) |
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 45 |
| PART II | ITEM 7. MD&A | Table of Contents |
Operating Activities
The increase in net cash provided by operating activities for Fiscal 2020 is largely due to strong cash flow from the Beer segment driven primarily by the segment’s solid operating results, combined with the timing of collections for recoverable value-added taxes. Net cash provided by operating activities also benefited from lower income tax payments largely due to a change in estimated taxable income and the receipt of a higher federal tax refund for Fiscal 2020 as compared with Fiscal 2019. The increase in net cash provided by operating activities was partially offset by higher cash outflows from accounts payable primarily attributable to the timing of payments for the Wine and Spirits segment.
Investing Activities
Net cash used in investing activities for Fiscal 2020 decreased primarily due to the $3,869.9 million November 2018 Canopy Transaction, proceeds of $269.7 million from the November 2019 Black Velvet Divestiture, and lower Fiscal 2020 capital expenditures of $159.8 million. The decrease in net cash used in investing activities was partially offset by proceeds received in Fiscal 2019 of $110.2 million from the May 2018 sale of our Accolade Wine Investment.
Business acquisitions, divestitures, and investments consist primarily of the following:
| Acquisitions | Divestitures | Investments | |||
| Fiscal 2020 | |||||
| ● Nelson’s Green Brier | ● Black Velvet Canadian Whisky | ||||
| Fiscal 2019 | |||||
| ● Four Corners | ● Accolade Wine Investment | ● November 2018 Canopy Investment |
Financing Activities
The increase in net cash provided by (used in) financing activities consists of:
| Fiscal 2020 | Fiscal 2019 | Dollar Change | |||||||||
| (in millions) | |||||||||||
| Net proceeds from (payments of) debt, current and long-term, and related activities | $ | (1,464.8 | ) | $ | 3,605.7 | $ | (5,070.5 | ) | |||
| Dividends paid | (569.2 | ) | (557.7 | ) | (11.5 | ) | |||||
| Purchases of treasury stock | (50.0 | ) | (504.3 | ) | 454.3 | ||||||
| Net cash provided by stock-based compensation activities | 63.9 | 49.6 | 14.3 | ||||||||
| Payment of contingent consideration | (11.3 | ) | — | (11.3 | ) | ||||||
| Net cash provided by (used in) financing activities | $ | (2,031.4 | ) | $ | 2,593.3 | $ | (4,624.7 | ) |
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 46 |
| PART II | ITEM 7. MD&A | Table of Contents |
Debt
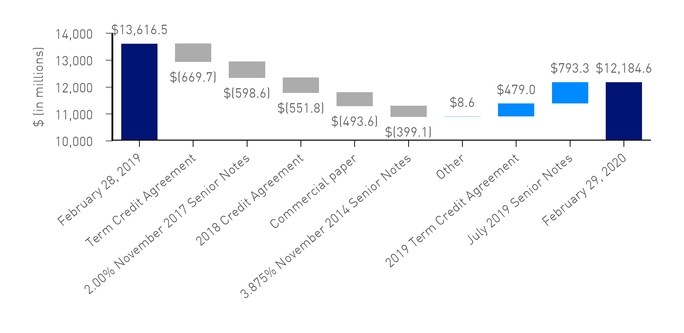
Total debt outstanding as of February 29, 2020, amounted to $12,184.6 million, a decrease of $1,431.9 million from February 28, 2019. The decrease consisted of:
Bank Facilities
In June 2019, we entered into the 2019 Term Credit Agreement which resulted in the creation of a $491.3 million five-year term loan facility. We utilized the proceeds from the borrowings under the 2019 Term Credit Agreement to repay in full the U.S. Term A-1 Facility under the 2018 Credit Agreement.
In March 2020, we entered into the 2020 Restatement Agreement that amended and restated the 2018 Credit Agreement. The 2020 Restatement Agreement resulted in (i) the removal of the subsidiary guarantees and termination of the guarantee agreement, (ii) the inclusion of the parent guaranty provisions in connection with the termination of the guarantee agreement, (iii) the removal of certain provisions pertaining to term loans since no term loans are outstanding, and (iv) the revision of the LIBOR successor rate provisions to permit the use of rates based on the SOFR administered by the Federal Reserve Bank of New York.
In March 2020, we entered into the Term Loan Restatement Agreement and the 2020 Term Loan Restatement Agreement, that amended and restated the Term Credit Agreement and the 2019 Term Credit Agreement, respectively. The Term Loan Restatement Agreement and the 2020 Term Loan Restatement Agreement each resulted in (i) the removal of the subsidiary guarantees and termination of the respective guarantee agreements and (ii) the revision of the LIBOR successor rate provisions in each to permit the use of rates based on SOFR.
Senior Notes
In July 2019, we issued the July 2019 Senior Notes. Proceeds from this offering, net of discount and debt issuance costs, of $793.0 million were used for the repayment of our 3.875% November 2014 Senior Notes and a portion of the outstanding obligations under the Five-Year Term Facility under our Term Credit Agreement.
General
The majority of our outstanding borrowings as of February 29, 2020, consisted of fixed-rate senior unsecured notes, with maturities ranging from calendar 2020 to calendar 2048, and variable-rate senior unsecured term loan facilities under our Term Credit Agreement and 2019 Term Credit Agreement, with maturities ranging from calendar 2021 to calendar 2024.
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 47 |
| PART II | ITEM 7. MD&A | Table of Contents |

Additionally, we have a commercial paper program which provides for the issuance of up to an aggregate principal amount of $2.0 billion of commercial paper. Our commercial paper program is backed by unused commitments under our revolving credit facility under our 2018 Credit Agreement. Accordingly, outstanding borrowings under our commercial paper program reduce the amount available under our revolving credit facility under our 2018 Credit Agreement.
We do not have purchase commitments from buyers for our commercial paper and, therefore, our ability to issue commercial paper is subject to market demand. If the commercial paper market is not available to us for any reason when outstanding commercial paper borrowings mature, we will utilize unused commitments under our revolving credit facility under our 2018 Credit Agreement to repay commercial paper borrowings. We do not expect that fluctuations in demand for commercial paper will affect our liquidity given our borrowing capacity available under our revolving credit facility under our 2018 Credit Agreement.
We had the following borrowing capacity available under our 2018 Credit Agreement:
| Remaining Borrowing Capacity | |||||||
| February 29, 2020 | April 15, 2020 | ||||||
| (in millions) | |||||||
| Revolving Credit Facility (1) | $ | 1,749.2 | $ | 1,988.2 |
| (1) | Net of outstanding revolving credit facility borrowings and outstanding letters of credit under our 2018 Credit Agreement and outstanding borrowings under our commercial paper program. |
The financial institutions participating in our 2018 Credit Agreement have complied with prior funding requests and we believe such financial institutions will comply with any future funding requests. However, there can be no assurances that any particular financial institution will continue to do so.
We and our subsidiaries are subject to covenants that are contained in the 2018 Credit Agreement, including those restricting the incurrence of additional indebtedness (including guarantees of indebtedness) by subsidiaries, additional liens, mergers and consolidations, transactions with affiliates, and sale and leaseback transactions, in each case subject to numerous conditions, exceptions, and thresholds. The financial covenants are limited to a minimum interest coverage ratio and a maximum net
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 48 |
| PART II | ITEM 7. MD&A | Table of Contents |
leverage ratio, both as defined in the 2018 Credit Agreement. As of February 29, 2020, under the 2018 Credit Agreement, the minimum interest coverage ratio was 2.5x and the maximum net leverage ratio was 5.0x.
The representations, warranties, covenants, and events of default set forth in our Term Credit Agreement and our 2019 Term Credit Agreement are substantially similar to those set forth in our 2018 Credit Agreement.
Our indentures relating to our outstanding senior notes contain certain covenants, including, but not limited to: (i) a limitation on liens on certain assets, (ii) a limitation on certain sale and leaseback transactions, and (iii) restrictions on mergers, consolidations, and the transfer of all or substantially all of our assets to another person. Upon the March 2020 removal of all of the subsidiary guarantors from our 2018 Credit Agreement, the subsidiary guarantors were automatically released from the indentures relating to our outstanding senior notes.
As of February 29, 2020, we were in compliance with our covenants under the 2018 Credit Agreement, Term Credit Agreement, 2019 Term Credit Agreement, and our indentures, and have met all debt payment obligations.
For a complete discussion and presentation of all borrowings and available sources of borrowing, refer to Note 13 of the Notes to the Financial Statements.
Common Stock Dividends
On April 2, 2020, our Board of Directors declared a quarterly cash dividend of $0.75 per share of Class A Common Stock, $0.68 per share of Class B Convertible Common Stock, and $0.68 per share of Class 1 Common Stock payable on May 19, 2020, to stockholders of record of each class on May 5, 2020. We expect to return approximately $565 million to stockholders in Fiscal 2021 through cash dividends.
We currently expect to continue to pay a regular quarterly cash dividend to stockholders of our common stock in the future, but such payments are subject to approval of our Board of Directors and are dependent upon our financial condition, results of operations, capital requirements, and other factors, including those set forth under Item 1A “Risk Factors” of this Annual Report on Form 10-K.
Share Repurchase Program
Our Board of Directors have authorized the repurchase of up to $3.0 billion of our Class A Common Stock and Class B Convertible Common Stock under the 2018 Authorization. Shares repurchased under this authorization have become treasury shares.
As of February 29, 2020, total shares repurchased under this authorization are as follows:
| Class A Common Shares | |||||||||
| Repurchase Authorization | Dollar Value of Shares Repurchased | Number of Shares Repurchased | |||||||
| (in millions, except share data) | |||||||||
| 2018 Authorization | $ | 3,000.0 | $ | 1,045.9 | 4,897,605 |
Share repurchases under the 2018 Authorization may be accomplished at management’s discretion from time to time based on market conditions, our cash and debt position, and other factors as determined by management. Shares may be repurchased through open market or privately negotiated transactions. We may fund future share repurchases with cash generated from operations and/or proceeds from borrowings. Any repurchased shares will become treasury shares.
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 49 |
| PART II | ITEM 7. MD&A | Table of Contents |
We currently expect to continue to repurchase shares in the future, but such repurchases are dependent upon our financial condition, results of operations, capital requirements, and other factors, including those set forth under Item 1A “Risk Factors” of this Annual Report on Form 10-K.
For additional information, refer to Note 18 of the Notes to the Financial Statements.
Contractual Obligations and Commitments
The following table sets forth information about our contractual obligations outstanding at February 29, 2020. It brings together data for easy reference from our balance sheet and Notes to the Financial Statements. For a detailed discussion of the items noted in the following table, refer to Notes 12, 13, 14, 15, and 17 of the Notes to the Financial Statements.
| Payments Due By Period | |||||||||||||||||||
| Total | Less than 1 year | 1-3 years | 3-5 years | After 5 years | |||||||||||||||
| (in millions) | |||||||||||||||||||
| Short-term borrowings | $ | 238.9 | $ | 238.9 | $ | — | $ | — | $ | — | |||||||||
| Long-term debt (excluding unamortized debt issuance costs and unamortized discounts) | 12,021.8 | 736.2 | 3,511.1 | 2,174.5 | 5,600.0 | ||||||||||||||
| Interest payments on long-term debt (1) | 3,770.6 | 426.0 | 732.4 | 515.4 | 2,096.8 | ||||||||||||||
| Operating leases | 686.8 | 94.1 | 150.7 | 112.3 | 329.7 | ||||||||||||||
| Other long-term liabilities (2) | 302.9 | 97.7 | 94.0 | 78.6 | 32.6 | ||||||||||||||
| Purchase obligations (3) | 6,024.7 | 1,413.7 | 2,266.4 | 1,166.7 | 1,177.9 | ||||||||||||||
| Total contractual obligations | $ | 23,045.7 | $ | 3,006.6 | $ | 6,754.6 | $ | 4,047.5 | $ | 9,237.0 |
| (1) | Interest rates on long-term debt obligations range from 2.3% to 5.3% as of February 29, 2020. Interest payments on long-term debt do not include interest related to finance lease obligations, which represent approximately 0.2% of our total long-term debt, as amounts are not material. |
| (2) | Includes $45.8 million associated with expected payments for unrecognized tax benefit liabilities as of February 29, 2020, $0.5 million of which is expected to be paid in the less than one year period. The payments are reflected in the period in which we believe they will ultimately be settled based on our experience in these matters. Other long-term liabilities do not include payments for unrecognized tax benefit liabilities of $203.6 million due to the uncertainty of the timing of future cash flows associated with these unrecognized tax benefit liabilities. In addition, other long-term liabilities do not include expected payments for interest and penalties associated with unrecognized tax benefit liabilities as amounts are not material. For a detailed discussion of these items, refer to Note 14 of the Notes to the Financial Statements. |
| (3) | Consists primarily of $4,789.5 million for contracts to purchase certain raw materials and supplies over the next eighteen fiscal years and approximately $115 million for contracts to purchase equipment and services related to the construction of the Mexicali Brewery. For further information about these purchase obligations, and others, refer to “Capital Expenditures” below and Note 17 of the Notes to the Financial Statements. |
Off-Balance Sheet Arrangements
We do not have any off-balance sheet arrangements that either have, or are reasonably likely to have, a current or future effect on our financial condition, changes in financial condition, revenues or expenses, results of operations, liquidity, capital expenditures, or capital resources that is material to investors.
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 50 |
| PART II | ITEM 7. MD&A | Table of Contents |
Capital Expenditures
During Fiscal 2020, we incurred $726.5 million for capital expenditures, including $571.7 million for the Beer segment primarily for (i) our Obregon Brewery optimization and expansion, (ii) our Nava Brewery and glass production plant expansions, and (iii) our Mexicali Brewery construction (collectively, the “Mexico Beer Expansion Projects”). Management reviews the capital expenditure program periodically and modifies it as required to meet current business needs. We do not believe it is prudent at this time to provide capital expenditure guidance for Fiscal 2021 as we are not able to estimate the long-term impact of COVID-19, including the demand for our products and the impact on the timeframes for completion of our Mexico Beer Expansion Projects.
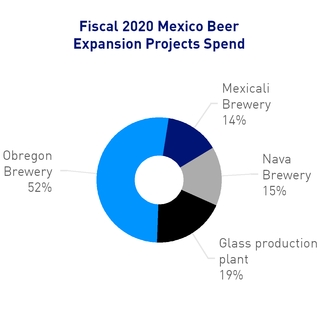
In fiscal 2017, we began construction of the Mexicali Brewery. In March 2020, a public consultation on the construction of our Mexicali Brewery was held. We have initiated early stage discussions with government officials in Mexico regarding next steps for our brewery construction project and options elsewhere in the country following the result of the public consultation. These discussions have been positive and we will continue working with government officials to mutually agree upon a path forward. In the medium-term, we have ample capacity, based on current growth forecasts and production capabilities at the Nava and Obregon breweries, to meet consumer needs. As of February 29, 2020, we recognized approximately $700 million of capital expenditures for construction in progress related to the Mexicali Brewery.
Effects of Inflation and Changing Prices
Our results of operations and financial condition have not been significantly affected by inflation and changing prices. We intend to pass along rising costs through increased selling prices, subject to normal competitive conditions. There can be no assurances, however, that we will be able to pass along rising costs through increased selling prices. In addition, we continue to identify on-going cost savings initiatives.
Critical Accounting Estimates and Policies
Our significant accounting policies are more fully described in Note 1 of the Notes to the Financial Statements. However, certain of our accounting policies are particularly important to the portrayal of our financial position and results of operations and require the application of significant judgment by management; as a result, they are subject to an inherent degree of uncertainty. In applying those policies, management uses its judgment to determine the appropriate assumptions to be used in the determination of certain estimates. Those estimates are based on our historical experience, our observance of trends in the industry, information provided by our customers and information available from other outside sources, as appropriate. On an ongoing basis, we review our estimates to ensure that they appropriately reflect changes in our business. Our critical accounting estimates include:
| • | Fair value of financial instruments. Certain inputs and assumptions to models used to determine fair value measurements require judgment, considering factors specific to the asset or liability. The use of certain inputs may include information derived through extrapolation or interpolation which involves management assumptions as well as valuation |
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 51 |
| PART II | ITEM 7. MD&A | Table of Contents |
techniques. The fair values of our financial instruments that require the application of significant judgment by management are as follows:
Canopy investments
Equity securities, Warrants - estimated using the Black-Scholes option-pricing model (Level 2 fair value measurement) and Monte Carlo simulations (Level 2 fair value measurement). These valuation models use various market-based inputs, including stock price, remaining contractual term, expected volatility, risk-free interest rate, and expected dividend yield, as applicable. Management applies significant judgment in its determination of expected volatility. We consider both historical and implied volatility levels of the underlying equity security and apply limited consideration of historical peer group volatility levels.
Debt securities, Convertible - estimated using a binomial lattice option-pricing model (Level 2 fair value measurement), which includes an estimate of the credit spread based on the implied spread as of the issuance date of the notes. This valuation model uses various market-based inputs, including stock price, remaining term, expected volatility, risk-free interest rate, and expected dividend yield, as applicable.
Management’s estimate of fair value requires significant management judgment and is subject to a high degree of variability based upon market conditions, the availability of specific information and management’s assumptions.
| • | Goodwill and other intangible assets. We account for goodwill and other intangible assets by classifying intangible assets into three categories: (i) intangible assets with definite lives subject to amortization, (ii) intangible assets with indefinite lives not subject to amortization, and (iii) goodwill. For intangible assets with definite lives, impairment testing is required if conditions exist that indicate the carrying value may not be recoverable. For intangible assets with indefinite lives and for goodwill, impairment testing is required at least annually or more frequently if events or circumstances indicate that these assets might be impaired. We perform annual impairment tests and re-evaluate the useful lives of other intangible assets with indefinite lives at the annual impairment test measurement date of January 1 or when circumstances arise that indicate a possible impairment or change in useful life might exist. |
The guidance for goodwill impairment testing allows an entity to assess qualitative factors to determine whether the existence of events or circumstances leads to a determination that it is more likely than not that the estimated fair value of a reporting unit is less than its carrying amount or to proceed directly to performing a quantitative impairment test. Under the quantitative assessment, the estimated fair value of each reporting unit is compared to its carrying value, including goodwill. The estimate of fair value of the reporting unit is generally calculated based on an income approach using the discounted cash flow method. If the estimated fair value of the reporting unit is less than the carrying value of the reporting unit, a goodwill impairment will be recognized. The amount of impairment charge for goodwill is equal to the excess of the carrying value of the goodwill over the implied fair value of the goodwill. Our reporting units with goodwill include the Beer segment and the Wine and Spirits segment. In estimating the fair value of the reporting units, management must make assumptions and projections regarding such items as future cash flows, future revenues, future earnings, and other factors. The assumptions used in the estimate of fair value are based on historical trends and the projections and assumptions that are used in current strategic operating plans. These assumptions reflect management’s estimates of future economic and competitive conditions and are, therefore, subject to change as a result of changing market conditions. If these estimates or their related assumptions change in the future, we may be required to recognize an impairment loss for these assets. The recognition of any resulting impairment loss could have a material adverse impact on our financial statements.
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 52 |
| PART II | ITEM 7. MD&A | Table of Contents |
In the fourth quarter of fiscal 2020, we performed our annual goodwill impairment analysis using the quantitative assessment. No indication of impairment was noted for any of our reporting units, as the estimated fair value of each of our reporting units with goodwill exceeded their carrying value. Based on this analysis, the reporting unit with the lowest amount of estimated fair value in excess of its carrying value was the Wine and Spirits reporting unit with approximately 107% excess fair value. For Fiscal 2019 and Fiscal 2018, as a result of our annual goodwill impairment analyses, we concluded that there were no indications of impairment for either of our reporting units.
The most significant assumptions used in the discounted cash flow calculation to determine the estimated fair value of our reporting units in connection with the impairment testing are: (i) the discount rate, (ii) the expected long-term growth rate, and (iii) the annual cash flow projections. As of January 1, 2020, if we used a discount rate that was 50 basis points higher or used an expected long-term growth rate that was 50 basis points lower or used annual cash flow projections that were 100 basis points lower in our impairment testing of goodwill, then the changes individually would not have resulted in the carrying value of the respective reporting unit’s net assets, including its goodwill, exceeding its estimated fair value, which would indicate the potential for impairment and the requirement to measure the amount of impairment, if any.
Our other intangible assets consist primarily of customer relationships and trademarks obtained through business acquisitions. Customer relationships are amortized over their estimated useful lives. The trademarks that were determined to have indefinite useful lives are not amortized. The guidance for indefinite lived intangible asset impairment testing allows an entity to assess qualitative factors to determine whether the existence of events or circumstances indicates that it is more likely than not that the indefinite lived intangible asset is impaired or to proceed directly to performing the quantitative impairment test. Under the quantitative assessment, our trademarks are evaluated for impairment by comparing the carrying value of the trademarks to their estimated fair value. The estimated fair value of trademarks is calculated based on an income approach using the relief from royalty method. The estimate of fair value is then compared to the carrying value of each trademark. If the estimated fair value is less than the carrying value of the trademark, then an impairment charge is recognized to reduce the carrying value of the trademark to its estimated fair value. In estimating the fair value of the trademarks, management must make assumptions and projections regarding future cash flows based upon future revenues and other factors. The assumptions used in the estimate of fair value are consistent with historical trends and the projections and assumptions that are used in current strategic operating plans. These assumptions reflect management’s estimates of future economic and competitive conditions and are, therefore, subject to change as a result of changing market conditions. If these estimates or their related assumptions change in the future, we may be required to recognize an impairment loss for these assets. The recognition of any resulting impairment loss could have a material adverse impact on our financial statements.
During the second quarter of fiscal 2020, certain continuing negative trends within our Beer segment’s Ballast Point craft beer portfolio, including increased rate of revenue decline and increased competition, indicated that it was more likely than not that the fair value of our indefinite-lived intangible asset associated with the Ballast Point craft beer trademarks might be below its carrying value. Accordingly, we performed a quantitative assessment for impairment. As a result of this assessment, the Ballast Point craft beer trademark asset recognized an impairment loss of $11.0 million. For the fourth quarter of fiscal 2019, the Beer segment’s Ballast Point business recognized a trademark impairment loss of $108.0 million in connection with certain continuing negative trends within its craft beer portfolio and a change in strategy for this portfolio focused on improving profitability by rationalizing the number of product offerings while targeting distribution growth in select strategic markets. In the first
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 53 |
| PART II | ITEM 7. MD&A | Table of Contents |
quarter of fiscal 2018, the Beer segment’s Ballast Point business recognized a trademark impairment loss of $86.8 million in connection with certain negative trends within its craft beer portfolio.
The most significant assumptions used in the relief from royalty method to determine the estimated fair value of intangible assets with indefinite lives in connection with impairment testing are: (i) the estimated royalty rate, (ii) the discount rate, (iii) the expected long-term growth rate, and (iv) the annual revenue projections. As of January 1, 2020, if we used a royalty rate that was 50 basis points lower or used a discount rate that was 50 basis points higher or used an expected long-term growth rate that was 50 basis points lower or used annual revenue projections that were 100 basis points lower in our impairment testing of intangible assets with indefinite lives, then each change individually would not have resulted in any unit of accounting’s carrying value exceeding its estimated fair value.
The guidance for divestitures requires that when some, but not all of a reporting unit is disposed of, some of the goodwill of the reporting unit should be allocated to the portion of the reporting unit being disposed of, if that portion constitutes a business. The allocation of goodwill shall be based on the relative fair values of the portion of the reporting unit being disposed of and the portion of the reporting unit remaining. This approach requires a determination of the fair value of both the business being disposed and the businesses retained within the reporting unit.
Our estimate of fair value for the New Wine and Spirits Transactions was determined based on the expected proceeds from the transactions. The components being sold are a part of the Wine and Spirits segment and were included in our wine and spirits reporting unit. Accordingly, goodwill was allocated to the New Wine and Spirits Transactions assets held for sale based on the relative fair value of the businesses being sold compared to the relative fair value of the reporting unit. Goodwill not allocated to assets held for sale remains in the wine and spirits reporting unit.
| • | Accounting for income taxes. We estimate our deferred tax assets and liabilities, income taxes payable, provision for income taxes, and unrecognized tax benefit liabilities based upon various factors including, but not limited to, historical pretax operating income, future estimates of pretax operating income, differences between book and tax treatment of various items of income and expense, interpretation of tax laws, and tax planning strategies. We are subject to income taxes in Canada, Mexico, Switzerland, the U.S., and other jurisdictions. We are regularly audited by federal, state, and foreign tax authorities, but a number of years may elapse before an uncertain tax position, is audited and finally resolved. |
We believe that all tax positions are fully supported. However, we recognize tax assets and liabilities in accordance with the FASB guidance for income tax accounting. Accordingly, we recognize a tax benefit from an uncertain tax position when it is more likely than not that the position will be sustained upon examination. We measure and recognize the tax benefit from such a position based on the largest benefit that has a greater than 50% likelihood of being realized upon ultimate settlement. Due to the complexity of some of these uncertainties, the ultimate resolution may result in a payment that is materially different from our current estimate of the unrecognized tax benefit liabilities. In addition, changes in existing tax laws or rates could significantly change our current estimate of our unrecognized tax benefit liabilities. These differences will be reflected as increases or decreases to income tax expense in the period in which they are determined. Changes in current estimates, if significant, could have a material adverse impact on our financial statements.
We recognize our deferred tax assets and liabilities based upon the expected future tax outcome of amounts recognized in our results of operations. If necessary, we recognize a valuation allowance on deferred tax assets when it is more likely than not that they will not be
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 54 |
| PART II | ITEM 7. MD&A | Table of Contents |
realized. We evaluate our ability to realize the tax benefits associated with deferred tax assets by assessing the adequacy of future expected taxable income, historical, and projected operating results, and the availability of prudent and feasible tax planning strategies. The realization of deferred tax assets is evaluated by jurisdiction and the realizability of these assets can vary based on the character of the tax attribute and the carryforward periods specific to each jurisdiction. We believe it is more likely than not that the results of future operations will generate sufficient taxable income to realize our existing deferred tax assets, net of valuation allowances. Changes in the realizability of our deferred tax assets will be reflected in our effective tax rate in the period in which they are determined.
ACCOUNTING GUIDANCE
Accounting guidance adopted for Fiscal 2020 did not have a material impact on our consolidated financial statements. For additional information on recently adopted accounting guidance refer to Note 1 in the Notes to the Financial Statements.
| Constellation Brands, Inc. FY 2020 Form 10-K | #WORTHREACHINGFOR I 55 |
| PART II | ITEM 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES | Table of Contents |
Previous: Item 6. SELECTED FINANCIAL DATA · Next: Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK